


Abstract
This study examines whether inward foreign direct investment (FDI) has ultimately supported or hindered sustainable economic growth in Türkiye by analyzing the impact of FDI stocks on output per worker within an endogenous-growth framework. Using annual data for 1970–2024 and an ARDL approach, the study estimates the short- and long-run effects of FDI stock, distinguishes these effects from those of domestic capital stock, and assesses whether they remain stable across different sub-periods. The results show that FDI stock has a robustly negative impact in the long run, and this adverse long-run effect persists when the sample is split into pre- and post-2001 crisis subsamples, while domestic capital does not emerge as a significant driver of growth. Human capital—measured by years of schooling—also displays a negative long-run association with output per worker, whereas institutional quality has a strong positive effect. The study contributes to the Turkish FDI–growth literature by providing, to the best of available knowledge, the first time-series evidence that focuses on FDI stocks and jointly models foreign and domestic capital stocks, and by documenting a long-run-negative effect of FDI stock that is robust over time. The findings imply that policy in Türkiye should shift from maximizing the volume of FDI toward improving its sectoral structure and governance, upgrading education quality and retaining high-skilled workers, and implementing concrete rule-of-law reforms.
1. Introduction
FDI is widely recognized as an important driver of sustainable economic growth in developing countries, as it helps to ease development bottlenecks such as the savings–investment gap [1] and institutional quality deficits [2]. In this context, many developing economies implement various policies to attract FDI inflows. In this vein, FDI is frequently considered a key channel for enhancing sustainable economic growth, particularly in developing economies facing chronic savings deficits Foreign direct investment (FDI) refers to an investment in which an investor from one country acquires at least 10 per cent of the voting rights in an enterprise located in another country, with the intention of establishing a lasting interest and exerting significant influence over its management. FDI also serves as the backbone of multinational enterprises (MNEs), enabling them to establish and maintain control over operations across multiple countries.
Sustainable economic growth refers to an economy’s ability to achieve and maintain a higher steady-state growth path through persistent improvements in productivity, technology, and institutional quality—without generating structural imbalances or eroding its domestic productive base. Unlike standard long-run growth, which primarily emphasizes steady-state output expansion driven by capital accumulation and exogenous technological progress (as in neoclassical models), sustainable growth focuses on endogenous mechanisms—knowledge spill-overs, human capital deepening, and institutional capacity—that enable continuous productivity gains and macroeconomic stability. Empirically, this concept is proxied by real GDP per worker, capturing the labour productivity improvements that are central to enduring growth dynamics in both neoclassical and endogenous frameworks [3,4,5].
For this reason, there is considerable attention on the relationship between FDI and economic growth empirically, and this is particularly stimulated by the emergence of endogenous growth models pioneered by Romer (1986) [4]. In neoclassical growth models, capital is subject to diminishing marginal returns, so that steady state growth is limited to advances in labour or technology. Consequently, the impact of FDI in these models is confined to technological improvements. However, endogenous growth theories take a broader view of capital, including human capital, which does not exhibit diminishing returns [4]. This broader view significantly alters the potential impact of FDI on steady-state economic growth. Endogenous growth theories suggest that FDI not only expands the domestic capital stock [6,7] but also generates Marshallian-type externalities [8]. In particular, FDI has an important role in generating knowledge and technology spill-overs that enhance labour and management skills and strengthen organizational capacity [7,9,10,11,12]. Thus, these mechanisms enable the economy to achieve and maintain steady-state economic growth. In this context, FDI is regarded as a key driver of sustainable economic growth, mainly by fostering innovation, accelerating technological progress, and strengthening the productive structure of the host country.
The channels of FDI effects on economic growth have been widely discussed in the theoretical and empirical literature. One of the most important channels is the ability of the host country to acquire intangible and non-tradable assets [13]. This, in turn, leads to increasing returns [5]. Additionally, FDI, especially in the form of multinational enterprises (MNEs), creates backward linkages [14]. While MNEs can increase government tax revenues, they can also help create local firms that supply inputs to these MNEs. Amighini et al. (2017) [15] highlight that MNEs could also signal to domestic firms to invest in sectors where profitable opportunities are emerging. Moreover, in emerging economies where there is a shortage of skilled labour, FDI through MNEs could improve the quality of labour [16] and boost total factor productivity [17,18]. In addition, FDI can provide a stable source of financing for these emerging economies, which are often struggling with balance of payments problems [19].
In the case of Türkiye, FDI is often considered a pivotal driver of economic growth. Between 1970 and 2001, Türkiye attracted only $14 billion in cumulative FDI inflows. However, following the 2001 financial crisis, the government implemented comprehensive structural reforms aimed at stabilizing the economy and improving the investment climate. These reforms, combined with legislative changes, tax incentives, privatization programs, and Türkiye’s candidacy for European Union (EU) membership, created a more favourable environment for foreign capital. As a result, FDI inflows increased substantially, reaching a peak of $22 billion in 2007—equivalent to 3.3% of GDP. However, the 2008 global financial crisis interrupted this momentum. Although FDI inflows recovered somewhat after 2010, they never returned to pre-crisis levels. Since 2018, Türkiye has experienced a further decline in foreign investment, with average annual FDI inflows of approximately $11 billion, representing only 0.9% of GDP.
Given these pronounced fluctuations and the structural shifts in FDI patterns, Türkiye provides an important case for examining the dynamic relationship between FDI and sustainable economic growth. Furthermore, the endogenous growth framework offers a particularly suitable lens for analyzing the role of FDI in Türkiye’s sustainable growth. Türkiye has long been characterized by a persistent savings deficit, recurrent external imbalances, and structural shortcomings in human capital and institutional quality, all of which limit the effectiveness of pure capital accumulation as a driver of long-run sustainable growth. From this perspective, FDI is not only an additional source of physical capital but also a potential vehicle for knowledge spill-overs, technology transfer, and managerial and organizational upgrading, which are central channels in the endogenous growth framework [17,18].
The aim of this study is to examine the effects of FDI on sustainable economic growth in Türkiye over the period 1970–2024, by developing an endogenous growth model that incorporates FDI stocks. Specifically, this study addresses the following research question: What is the long-run impact of FDI stock on real GDP per worker in Türkiye, after controlling for domestic capital accumulation, human capital, and institutional quality? Unlike many previous studies, which predominantly rely on FDI flows, this study employs FDI stocks. The use of FDI stock rather than flow is more appropriate for capturing the long-term impact of FDI on growth, since stocks reflect the cumulative level of foreign capital embedded in the economy and provide a more accurate measure of its enduring influence [6,7,12]. Moreover, by separating domestic from foreign capital, the model provides an empirical framework that makes it possible to quantify and compare the distinct contributions of domestic capital accumulation and FDI stocks to economic growth. Given that the time series data used in this study are non-stationary, the Autoregressive Distributed Lag (ARDL) methodology is employed. This approach is particularly advantageous as it allows for the modelling of both short-run dynamics and long-run equilibrium relationships.
The remainder of this study is structured as follows. The next section reviews the theoretical and empirical literature relevant to the relationship between FDI and economic growth. Section 3 develops the theoretical framework of the study. Section 4 presents the empirical model, data, and results of the empirical analysis. In Section 5, the empirical results are discussed in light of the existing literature. Finally, Section 6 concludes by summarizing the key findings and outlining their policy implications.
2. Theoretical and Empirical Literature
The empirical literature on the FDI–growth nexus is extensive; however, it has not been able to provide conclusive results. Iamsiraroj and Ulubaşoğlu (2015) [19] reviewed the literature concerning the relationship between FDI and economic growth, analyzing 108 empirical studies to conduct a meta-regression analysis (Bruno and Cipollina conducted a meta-regression analysis and offer more updated data [20]. For bibliometric analysis, see Pintilie, Cicea, and Marinescu [21], and for empirical analysis, see Kostoulis (2023) [22]). They concluded that 43% of the studies found a positive and significant relationship, and 17% of the studies found a negative and significant relationship, while 40% of the studies could not find a significant effect.
De Gregorio (1992) [23], Blömström et al. (1994) [24], Balasubramanyam et al. (1996) [25], and Basu et al. (2003) [26] are some of the leading studies that find a positive relationship between FDI and growth. However, several studies find a positive relationship conditioned on the absorptive capacity or initial characteristics of the host country [6]. As mentioned above, FDI leads to technological spill-overs, but to benefit from these technological advances, the labour force should be equipped with the basic skills needed to produce [6]. Thus, the quality of the labour force is important for technological catching-up [25,27]. An educated workforce leads to reduced costs and increased efficiency as it can adopt the new technology faster [28]. On the contrary, Benetrix et al. (2023) claim that the effect of human capital, as indicated by education, is negative after the sample periods that cover the post-1990s [29]. The authors suggest that this is due to the Global Value Chain (GVC) revolution, which Baldwin (2006) calls the ‘second unbundling’ [30]. GVCs outsource production to low-education, low-wage countries, and through backward linkages, they could trigger domestic investment and growth.
Financial development is also vital in determining the impact of FDI on economic growth [27,31,32,33,34,35]. In countries with low levels of financial development, domestic firms may not benefit from backward linkages as they often lack the financial resources to establish firms that supply inputs to newly established foreign firms [30]. Balasubramanyam et al. (1996) [25] and Akinlo (2004) [7] stress the importance of trade openness in the relationship between FDI and economic growth. In a similar vein, Durham (2004) [36], Jude and Leviegue (2014) [37], and Yimer (2023) [12] emphasize the crucial role of institutional quality in their models and conclude that it is a key determinant in the relationship between FDI and economic growth. Melnyk et al. (2014) [38] argue that a favourable business climate and positive institutional changes are also significant contributors. Moreover, Çiftçi and Çiftçi (2021) find positive growth effects of FDI in countries characterized by regulatory efficiency and free markets [39].
There is a substantial body of research indicating a negative impact of FDI on growth, such as Carkovic and Levine (2005) [40], Akinlo (2004) [7], and Shittu et al. (2022) [41]. These studies mainly argue that FDI can lead to the crowding out of domestic firms [42]. Moreover, if MNEs acquire significant market power, this could reduce domestic investment, an issue highlighted by Markusen and Venables (1998) [43]. Particularly in emerging economies, as discussed by Easterly (1993) [44] and Iwasaki and Tokunaga (2014) [45], MNEs often benefit from tax incentives that may disincentivise domestic firms. Ramirez (2000) [46] and Akinlo [7] also highlight the important role of capital outflows, including remittances and investment income. According to Fry (1999), this can lead to balance of payments problems [47]. Furthermore, MNEs may use host country financial markets for financing, which may lead to higher interest rates and distortions in domestic investment. Moreover, Findley (1978) argues that FDI inflows could induce Dutch disease, causing real appreciation that undermines domestic competitiveness [48].
Akinlo (2004) finds a negative relationship between FDI and economic growth in Nigeria from 1970 to 2001, attributing this to the specific sectors targeted by FDI [7]. Since FDI in Nigeria is mainly focused on oil production, the expected spill-over effects do not materialize. Similarly, Vu and Noy (2009) report a negative impact of FDI on growth within the oil sector, highlighting the critical role of the target sector in determining the impact of FDI on growth [49]. The prevailing argument is that FDI in manufacturing is likely to lead to technology spill-overs and backward linkages [50,51]. Aykut and Sayek (2008) suggest that while FDI has a positive effect in the manufacturing sector, its impact remains negative in the primary sector [52]. In addition, Haini and Tan (2022) [53] and Ullah et al. (2023) [54] find a positive relationship between FDI and growth in other sectors, but also stress that the contribution of FDI to growth is most significant in the manufacturing sector. Marasco et al. (2024) also find a positive impact of FDI on growth in high technology sectors, which they attribute to the spill-over effects generated by FDI [55].
The methodologies used may be one possible reason for the divergent results in the literature on the impact of FDI on economic growth. Studies such as De Mello (1999) [6], Zhang and Song (2001) [56], Carkovic and Levine (2005) [40], Akadiri and Ajmi (2020) [57], Osei and Kim (2023) [35], Yimer (2023) [12] and Marasco et al. (2024) [55] have used panel data methodologies. However, these approaches often struggle to fully integrate country-specific characteristics and tend to ignore parameter heterogeneity, which is significant according to Herzer and Klasen (2008) [42]. In contrast, another strand of the literature focuses on country-specific studies that use a variety of time series methodologies. Notable studies in this category include Kokko (1994) [58], Blomström et al. (1996) [24], Akinlo (2004) [7], Cioabanu (2015) [59] and Rakhsit (2021) [60], Gupta et al. (2022) [61], Drob et al. (2026) [62]. A summary of the results of selected empirical studies is presented in Table 1.
Table 1.
Summary of the Selective Empirical Literature.
Given Türkiye’s status as a significant host of FDI and its concurrent deficit in domestic investment, it represents an essential case study for exploring the role of FDI as a catalyst for sustainable economic growth. However, the existing literature on Türkiye’s experience with FDI is somewhat limited and exhibits several methodological characteristics that may explain the inconsistent findings (Table 1). Türkiye-specific studies [18,72,73,74,77,78,79,80] employ FDI flows rather than stocks. Flow indicators capture only annual net inflows and do not reflect the cumulative stock of foreign capital embedded in the economy [12]. This may overstate short-term effects while underrepresenting long-run structural impacts. Several studies are characterized by limited sample periods or constrained treatment of non-stationarity. For instance, Bildirici et al. (2010) [72] analyze 16 years (1992–2008) using monthly data with industrial production as a proxy for output, which may not fully capture steady-state growth dynamics. Demirsel et al. (2014) [77] cover 2002–2014 with quarterly data, a relatively short period for identifying long-run equilibrium relationships. Studies do not separate domestic from foreign capital, which limits the ability to identify their heterogeneous impacts [6].
Furthermore, comprehensive control for human capital and institutional quality is generally absent. Critically, none of the Türkiye-specific studies account for structural breaks associated with major crises (1994 currency crisis, 2001 financial crisis, 2009 global crisis), which may affect the reliability of estimates. No Türkiye-specific study examines FDI at the industry level, despite well-documented sectoral heterogeneity in FDI effects internationally [49,52]. This gap reflects a broader data availability constraint that extends beyond Türkiye. While cross-country panel studies have examined sectoral FDI flows [54,55] single-country time-series studies employing sectoral FDI stocks are virtually non-existent in the literature, primarily due to the lack of consistent, disaggregated time-series data on sectoral FDI inflows over extended periods.
Thus, this study contributes to the developing literature on Türkiye by addressing the first three limitations: employing FDI stocks (rather than flows), separating domestic and foreign capital to identify heterogeneous effects, and controlling for human capital, institutional quality, and structural breaks. However, due to the aforementioned data constraints, sectoral disaggregation remains beyond the scope of this study.
3. Theoretical Model: An Endogenous Framework for Sustainable Economic Growth
This study follows an endogenous growth framework to examine the effects of FDI on sustainable economic growth in Türkiye. In this framework, long-run sustainable growth is determined not only by capital accumulation but also by knowledge spillovers and technology transfers that are generated within the economy. FDI is incorporated into the model as both a source of physical capital and a channel for technological diffusion, aligning with the endogenous growth theory that emphasizes internal mechanisms in sustaining economic development.
The endogenous growth model is specified as Equation (1) following Akinlo (2004) [7] and Yimer (2023) [12].
In this model, A denotes factors affecting productivity in the economy, such as institutional factors. Y denotes real GDP and Kd denotes real domestic capital stock. Capital accumulation remains a central determinant of output growth in neoclassical and endogenous growth frameworks [3,4]. L stands for labour input and H refers to the level of human capital. Higher levels of human capital enhance productivity and foster innovation, which in turn promote long-term economic growth [81,82]. μ denotes the externality generated by the stock of FDI, while α and β represent the respective shares of labor and domestic capital. α and β are assumed to be smaller than 1, indicating diminishing returns to capital.
The externality that is generated by the stock of FDI, μ, can be formulated following Yimer (2023) [12] as follows,
Kf is the foreign capital stock, namely FDI stock. As FDI has a sustaining effect on growth, the FDI stock is more accurate to measure the effect of FDI on GDP [6,12,17,83]. is the marginal elasticity of substitution and is the intertemporal elasticity of substitution between and . As noted by Akinlo (2004) [7], assuming implies that the stock of FDI exerts a positive externality on GDP. Likewise, indicates the presence of intertemporal complementarity between FDI and domestic capital. Conversely, if , it suggests that FDI displaces domestic investment and consequently hampers economic growth in the host country.
In this study, sustainable economic growth is proxied by real GDP per worker. In long-run growth models, including those of Solow (1956) [3], Mankiw, Romer, and Weil (1992) [5], and Barro and Sala-i-Martin (1992) [84], the production function is typically specified in terms of output per worker. This formulation provides a convenient basis for examining how capital accumulation, human capital, and institutional factors are related to economic growth. In Equation (3), the production function is reformulated on a per-worker basis:
Substituting Equation (4) into Equation (3) allows Equation (5) to be reformulated as
By grouping similar terms, Equation (7) takes the following form;
To derive a dynamic production function, Equation (8) is transformed using natural logarithms, resulting in a standard growth accounting equation [7,12]. The log-transformed version of Equation (8) is presented as follows:
4. Empirical Methodology and Results
Accordingly, the equation to be estimated is specified as follows:
In this specification, represents real GDP per worker, obtained and calculated from the World Development Indicators (WDI). The variable captures institutional and political factors influencing economic growth, proxied by the “liberal democracy” index from the V-Dem dataset. Stronger legal institutions and enforcement mechanisms are widely recognized as crucial drivers of sustained economic performance, as they reduce transaction costs, protect property rights, and encourage investment [85,86]. Human capital, denoted by , is measured using a human capital index for Türkiye constructed in line with the methodology of Hall and Jones (1999) [87], as detailed in Appendix A. This index captures the effects of years of schooling and returns to education, respectively. This method is common in the literature to capture the effects of human capital on growth [88]. Domestic capital stock per worker, is the domestic portion of capital; first, domestic investment is calculated by subtracting the foreign capital inflows from gross capital formation, and then, the domestic capital is calculated using the Perpetual Inventory Method (PIM) [83]. Finally, fdistock denotes the stock of foreign direct investment and is constructed using the PIM based on foreign direct investment inflows. Gross capital formation and FDI data are obtained from the WDI database. The assumptions and procedures described in Appendix B. FDI stocks can stimulate economic growth by transferring technology, enhancing managerial skills, and integrating domestic firms into global value chains [10,32]. The empirical analysis employs annual data covering the period from 1970 to 2024, based on data availability. All econometric analyses were conducted using EViews 13.
Equation (10) is estimated using the Autoregressive Distributed Lag (ARDL) approach to investigate both the short-run and long-run effects of FDI stock on economic growth in Türkiye. The ARDL method has become a widely employed methodology for exploring dynamic relationships among time-series variables. Its main advantage is the flexibility to include variables that are integrated of order zero, I(0), or order one, I(1), without requiring pre-testing for a common integration order [89]. By incorporating appropriate lags of the dependent and independent variables, the model can capture both immediate adjustments and long-run equilibrium relationships [90]. Furthermore, the ARDL approach produces robust and consistent estimates even when the sample size is relatively small, which makes it particularly suitable for this study, given the annual dataset covering the period 1970–2024 [91].
Rewriting Equation (10) within the ARDL specification yields the following functional form,
In Equation (11), Δ denotes the first-difference operator; , , , , represent the short-run coefficients, , , , , while correspond to the long-run coefficients, , and are the dummy variables included to capture the effects of crisis, is the error term. These dummies correspond to the 1994 currency crisis, the 2001 financial crisis and the 2009 global financial crisis respectively. The short-run dynamics and the associated error correction term are obtained through the following ARDL specification:
4.1. Unit Root Test Results
Given the specification of the ARDL model in Equation (12), it is essential to ensure that none of the variables are integrated of order two, as the validity of the bounds testing procedure relies on this condition. While the ARDL framework accommodates both I(0) and I(1) variables, Ouattara (2004) [92] emphasizes that the inclusion of I(2) variables makes the critical bounds values invalid. To verify the integration properties of the series, Augmented Dickey–Fuller (ADF), Phillips–Perron (PP) and Kwiatkowski-Phillips-Schmidt-Shin (KPSS) unit root tests are conducted. As summarized in Table 2, the results provide a comprehensive view of the integration orders. The ADF-PP-KPSS tests generally suggest that the variables are non-stationary in their levels but become stationary after the first difference, indicating that they are integrated of order one, I(1). However, the KPSS test results offer a more nuanced perspective; while most series remain I(1), certain variables (specifically lA) exhibit I(0) tendencies at the level form. As Table 2 indicates that none of the variables are integrated of order two (For convenience, variables in logarithmic form are denoted with an ‘l’ prefix (e.g., ly = log(y))).
Table 2.
Unit Root Test Results.
In addition, given the long sample period and the presence of multiple economic and institutional shocks in Türkiye, conventional unit root tests such as ADF may suffer from loss of power and size distortions when structural breaks are ignored. To address this issue and to avoid spurious non-stationarity, the Lee–Strazicich Lagrange Multiplier (LM) unit root test is employed [95]. The Lee–Strazicich test is implemented using the crash model that permits shifts in intercept, capturing permanent structural changes rather than transitory shocks. This feature is particularly important for macroeconomic time series characterized by major crises, policy regime changes, and external shocks (Given the economic history of Türkiye, major shocks—such as the 1980 liberalization reforms, the 1994 and 2001 financial crises—typically cause abrupt level shifts (intercept) rather than fundamental changes in the long-run growth rate (slope)).
The results in Table 3 indicate that while all variables appear non-stationary in levels according to the ADF-PP-KPSS tests and become stationary after first differencing. ly, lh, and lfdistock variables are stationary around their respective structural breaks. Both lkd and lA are found to be integrated of order one [I(1)], becoming stationary after differencing. As there is a mixed integration order [I(0) and I(1)] with no variable being I(2), the ARDL bounds testing approach is the most appropriate methodology for this study.
Table 3.
Lee–Strazicich LM Unit Root Test Results (Crash Model, Model A).
These results also justify including D1994, D2001, and D2009 dummy variables in the ARDL model to account for structural changes in Türkiye’s macroeconomic environment. These dummies were treated as fixed regressors in the ARDL framework to preserve the degrees of freedom while ensuring the stability of the estimated coefficients.
4.2. ARDL Long- and Short-Run Estimates
The optimal lag length (p) is selected based on the Akaike Information Criterion (AIC) and the Schwarz Information Criterion (SIC). The information criteria indicate that the appropriate lag structure for the model is ARDL (1,1,2,0,2). After determining the optimal lag structure, the presence of a long-run equilibrium relationship among the variables is examined using the ARDL bounds testing procedure proposed by Pesaran et al. (2001) [89]. Given the systematic trends observed in the variables, the ARDL model includes an unrestricted constant and linear trend to adequately capture long-run dynamics. The results of the bounds test are reported in Table 4.
Table 4.
Bounds Test Results for ARDL (1,1,2,0,2) Model.
The bounds test results in Table 4 indicate a calculated F-statistic of 10.33 for the ARDL (1,1,2,0,2) model and clearly reject the null hypothesis of no co-integration (H0: β6 = β7 = β8 = β9 = β10 = 0), providing strong statistical evidence of a long-run equilibrium relationship among the variables in the model. The result confirms that the variables move together in the long run. This finding justifies proceeding with the estimation of both short-run and long-run coefficients within the ARDL framework.
The long-run estimation results (Panel A) indicate that the rule of law (lA) variable has a positive and statistically significant effect on GDP per worker. That means improvements in institutional quality enhance the efficiency of economic activity and support higher output levels per worker. In contrast, the human capital variable (lH) exhibits a statistically significant and negative coefficient. This counterintuitive finding may reflect structural issues in Türkiye’s education system: while the average years of schooling have increased, the quality of education and the alignment of skills with labour market needs remain persistent challenges [96]. As a result, the accumulation of formal education does not necessarily translate into productivity gains.
Domestic capital per worker (lkd) has found to be insignificant. The insignificance of domestic capital stock per worker suggests that capital accumulation alone is insufficient to enhance output per worker. Conversely, the FDI stock variable (lfdisstock) has a highly significant but negative coefficient in the long run. This finding is consistent with the earlier empirical evidence in the literature, such as Akinlo (2004) [7], Carkovic and Levine (2005) [40], Herzer and Klasen (2008) [42], Shittu et al. (2022) [41], and Yimer (2023) [12].
Short-run estimates (Panel B) in Table 5 reveal that institutional quality (lA) has a statistically significant and positive short-run effect on output per worker, suggesting that short-term improvements in institutional quality are positively associated with output per worker. Short-run estimates point to statistically significant but temporally differentiated effects of human capital. The contemporaneous coefficient (Δ lH) is negative, whereas the lagged change (ΔlH (−1)) is positive and significant, reflecting short-run adjustment processes.
Table 5.
Estimated Long-Run and Short-Run Results-ARDL Model.
While FDI stock ( lfdistock) has a negative sign; FDI stock variable with lag ( lfdistock (−1) has a positive and significant effect. The impact effect of changes in FDI stock is negative, whereas the one-period lag enters the model with a positive and statistically significant sign. This pattern is indicative of short-run adjustment dynamics, implying that the effect of changes in FDI stock on real GDP per worker is subject to transitional frictions. This pattern is consistent with a transmission mechanism in which FDI generates short-run demand and capital-formation gains, especially through greenfield projects, but may produce negative cumulative effects in the long run when inflows are dominated by service-sector and in the form of mergers and acquisitions, technology spill-overs to domestic firms are limited, and domestic enterprises are gradually crowded out of key markets.
The short-run results reveal that the structural break dummies (DUM1994, DUM2001, DUM2009) enter the model with statistically significant coefficients, pointing to the presence of temporary regime shifts affecting real GDP per worker. The negative coefficients reflect the adverse short-run effects of major crisis episodes on output. The error correction term (ECM) is negative and highly significant, indicating a rapid adjustment toward the long-run equilibrium. The statistical significance of the deterministic components confirms the relevance of controlling for underlying time trends in the model specification.
As shown in Table 5, Panel C, the diagnostic test results for the ARDL (1,1,2,0,2) model indicate no evidence of serial correlation (p = 0.89), heteroskedasticity (p = 0.13), or model misspecification (p = 0.67) at the 5% significance level. Moreover, the Jarque–Bera normality test (p = 0.44) confirms that the residuals are normally distributed. These results demonstrate that the ARDL model is econometrically robust and appropriately specified. Therefore, coefficient estimates can be considered statistically reliable.
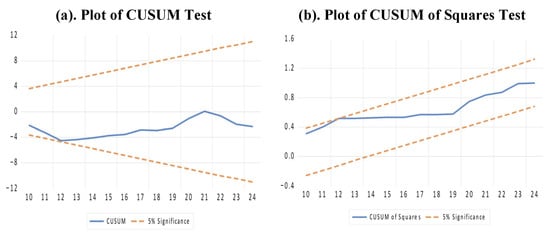
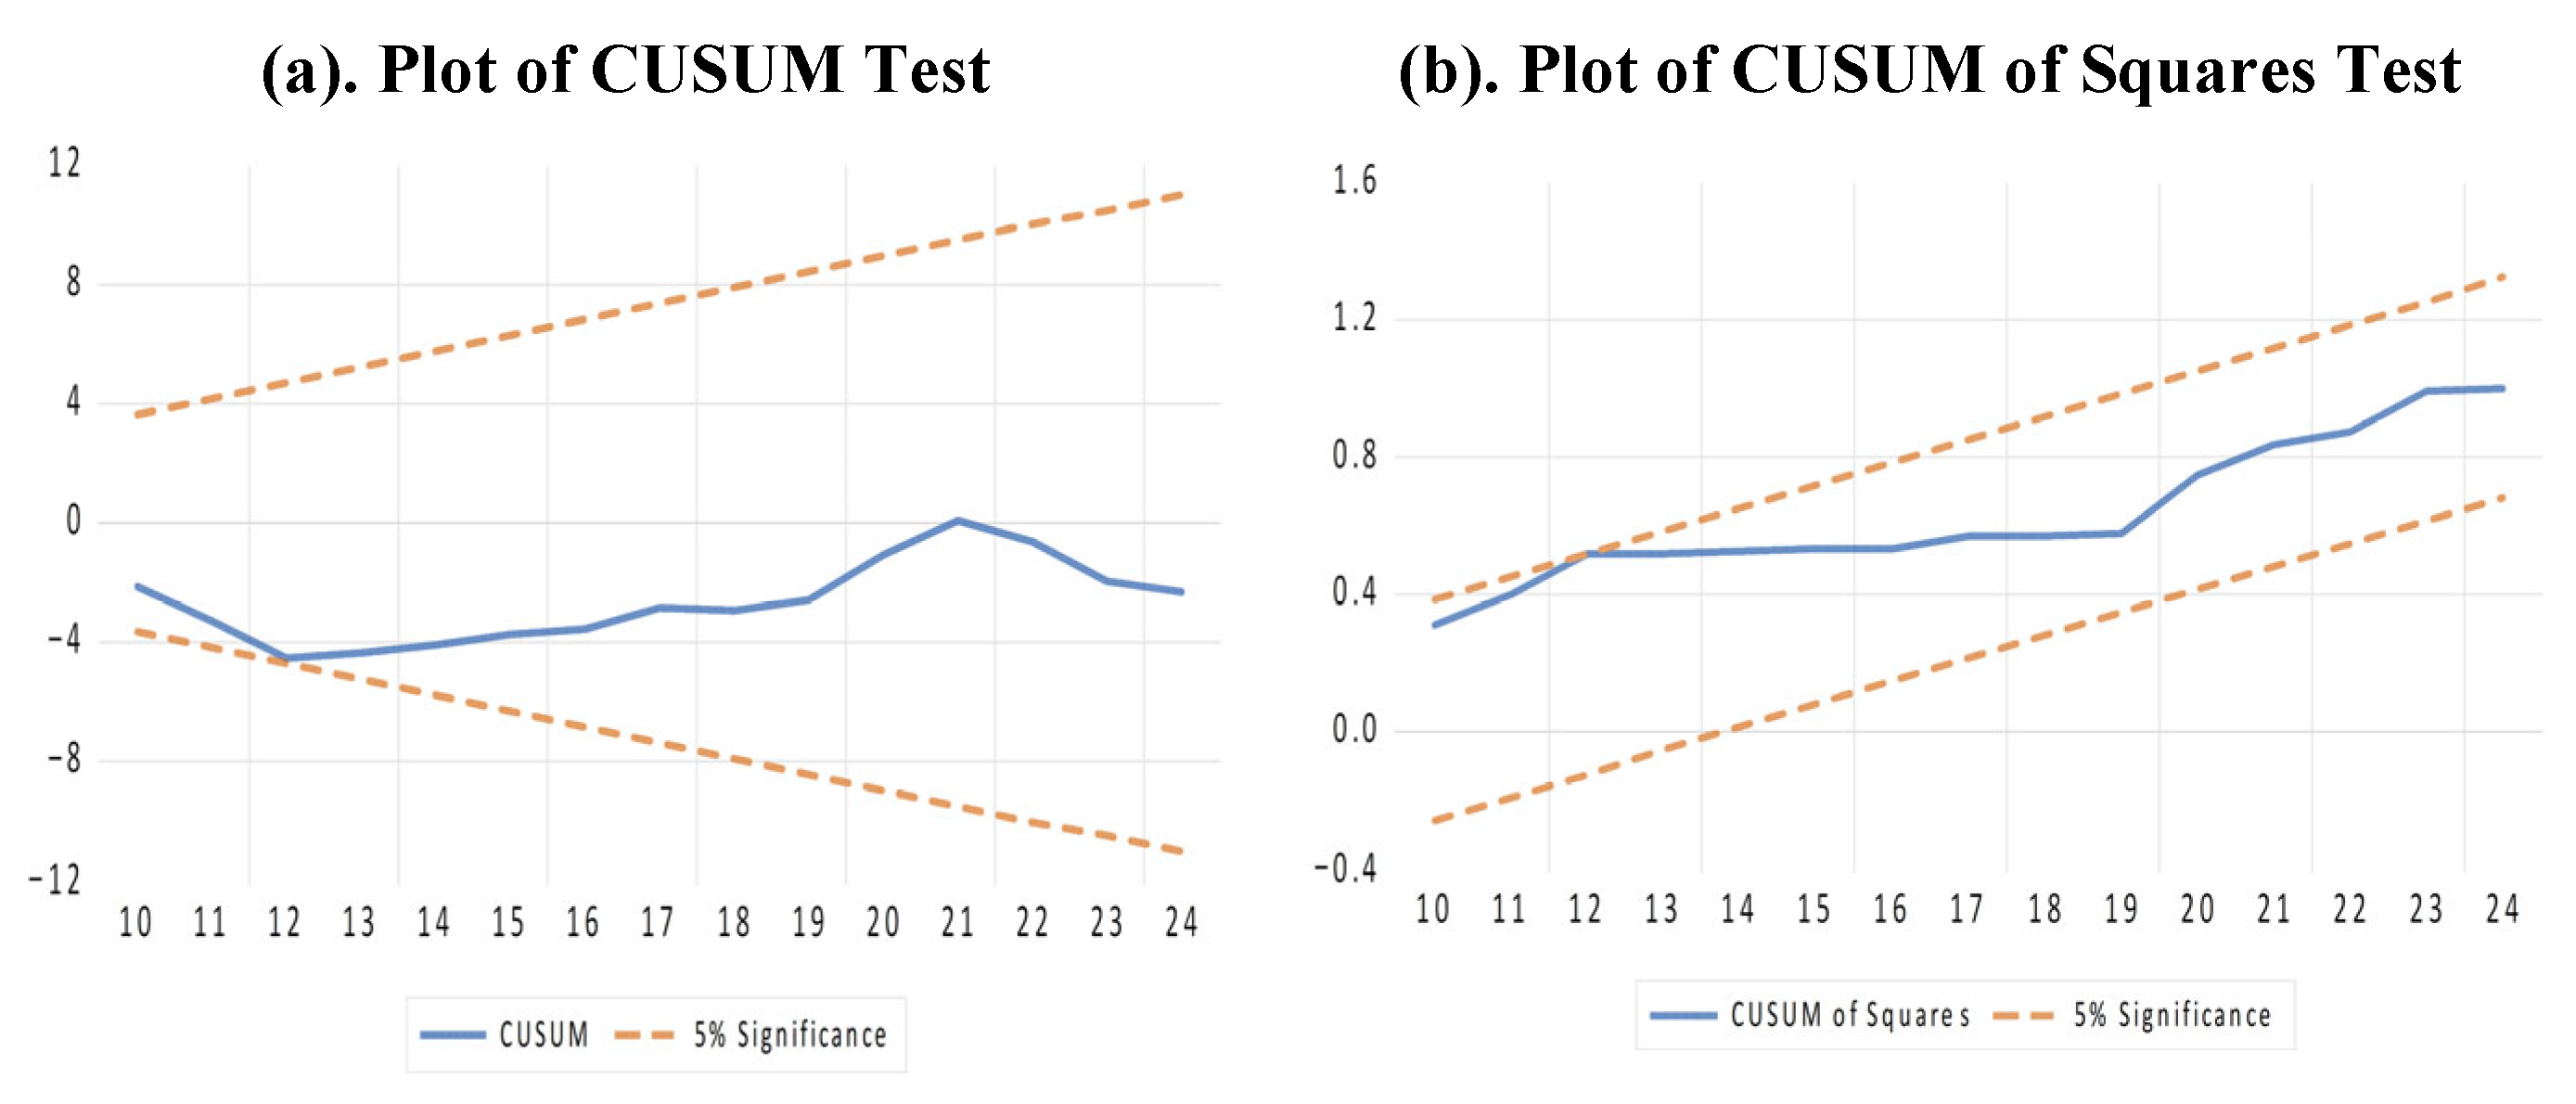
The stability of the ARDL (1,1,2,0,2) model was further assessed using the CUSUM and CUSUM of Squares tests. As shown in Figure 1, both statistics remain within the 5% significance bounds throughout the sample period, indicating that the estimated parameters are structurally stable. This suggests that there are no significant parameter shifts or changes in error variance over time. The stability of the model supports the reliability of the estimated short-run and long-run results.
Figure 1.
CUSUM and CUSUM of Squares Test Results.
4.3. Robustness: Time-Period Heterogeneity
This subsection examines whether the main findings are robust to alternative sample periods and, in particular, whether the long-run effect of FDI on output differs across distinct phases of Türkiye’s recent macroeconomic history. To this end, the baseline ARDL model is re-estimated for two subsamples that roughly correspond to the pre- and post-2001 crisis eras of FDI in Türkiye. The first covers 1970–2001, when FDI inflows were relatively modest and structural reforms were gradual, while the second spans 2002–2024, a period marked by post-crisis stabilization, financial liberalization, large-scale privatization, and EU-related institutional changes. Table 6 reports the resulting subsample ARDL estimates of the long-run coefficients.
Table 6.
Subsample ARDL estimates: long-run coefficients.
The subsample ARDL estimates in Table 6 suggest that the negative long-run association between FDI stock and output per worker is not confined to a specific period. In the 1970–2001 subsample, the long-run coefficient on FDI stock is negative and statistically significant. A similar, but smaller, negative and significant coefficient is obtained for the 2002–2024 subsample, despite the sharp increase in FDI inflows and the post-crisis reform environment. In both subsamples, the error-correction term is negative and highly significant, confirming a stable long-run relationship, while the bounds F-statistics exceed the upper critical values reported by Narayan (2004) [91], which reinforces the robustness of the cointegration evidence across time.
Standard diagnostic checks for the ARDL specifications do not reveal serious econometric problems in either subsample. In particular, Breusch–Godfrey LM tests fail to reject the null of no serial correlation, White-type tests indicate no problematic heteroskedasticity, and Ramsey RESET tests do not suggest functional form misspecification.
As a further extension, the baseline ARDL model is augmented with interaction terms between FDI stock and institutional quality and between FDI stock and human capital. The long-run coefficient on FDI stock remains negative and statistically significant, while the interaction terms are small and insignificant, indicating no clear evidence that institutional quality or human capital mitigates the adverse long-run growth effect of FDI in the Turkish case.
5. Discussion
The study robustly finds that FDI stock exerts a negative impact on GDP per worker. This result is in line with recent evidence for fragile and developing economies, including Akinlo (2004) [7], Carkovic and Levine (2005) [40], Shittu et al. (2022) [41], Ofori and Asangu (2024) [70], and Yimer (2023) [12]. The negative relationship between FDI and economic growth in Türkiye may be explained by several channels. Foreign firms can crowd out domestic producers when preferential tax treatment and other incentives weaken the competitiveness of local enterprises [97], while large capital inflows may appreciate the domestic currency and generate Dutch-disease-type effects that undermine tradable-sector production [48,68]. A more plausible explanation, however, relates to the sectoral composition of FDI stock. The literature emphasizes that FDI in manufacturing tends to generate positive spill-overs, whereas FDI concentrated in primary or non-tradable activities often has weak or even adverse growth effects [49,50,52,55,68]. In Türkiye, descriptive evidence shows that the composition of inward FDI has shifted away from industry towards services: in 2000, industry accounted for around 62% of the FDI stock and services for about 37%, whereas by 2024 these shares had moved to roughly 45% and 54%, respectively, with inflows increasingly concentrated in sectors such as banking, telecommunications, retail trade and real estate rather than export-oriented, technology-intensive manufacturing.
The dynamic estimates further clarify why FDI can appear growth-enhancing in the short run but harmful in the long run [98,99]. In the short run, FDI stock exerts a modest positive effect on output, as greenfield projects expand production capacity, stimulate construction and equipment demand, and temporarily raise employment and aggregate demand, while mergers and acquisitions can also generate short-lived expansionary effects through balance-sheet improvements, restructuring expenditures, and improved expectations. Over longer horizons, however, the dominance of non-tradeable service sectors weakens technology-transfer and spill-over channels. The technological gap between foreign affiliates and domestic firms, shallow backward and forward linkages, and the privileged access of foreign firms to credit, skills, and policy incentives can crowd out domestic enterprises, reducing domestic investment and innovation capacity [97]. Taken together, these mechanisms provide a coherent explanation for why FDI yields transitory gains but a negative long-run impact on output per worker in the Turkish case.
The empirical analysis also reveals a robust and statistically significant negative relationship between human capital and economic growth across model specifications, which is consistent with Shittu et al. (2022) [41] for MENA economies. This finding can be traced to both measurement and structural factors. The human-capital index follows the standard Hall and Jones (1999) [87] approach based on years of schooling, capturing the quantity of education rather than its quality; as Hanushek and Woessmann (2008) [100] stress, it is cognitive skills that drive growth, not schooling. In Türkiye, successive PISA rounds have documented relatively low and often stagnating performance in core competencies, so rising enrolment has not translated into sufficient gains in learning outcomes, and the labour force has expanded in numbers without a commensurate improvement in productivity-enhancing skills. The negative association is further compounded by the “brain drain” phenomenon: the emigration of high-skilled professionals to advanced economies deprives the domestic market of some of its most productive agents, thereby lowering total factor productivity and undermining long-run, sustainable growth prospects [101,102]. Recent evidence indicates that Türkiye has experienced a sizeable outflow of highly educated workers [103] while Mike et al. (2025) [104] show that brain drain significantly reduces innovation and weakens long-run sustainable growth in the Turkish context. In contrast, the results for institutional quality are positive and significant, with the democracy proxy displaying a robust association with economic performance, consistent with Acemoglu et al. (2019) [105] and the institutionalist hypotheses of North and Rodrik et al. (2004) [106]. Domestic capital, by contrast, is not statistically significant, suggesting that physical capital accumulation alone has not been the primary engine of growth over the sample period and that capital deepening without complementary institutional and structural improvements is insufficient to sustain long-term economic expansion.
Several limitations should be acknowledged, which also suggest avenues for future research. Future work could combine macro time-series evidence with sectoral or firm-level data, construct quality-adjusted human-capital indicators that explicitly account for skilled emigration.
6. Conclusions and Policy Implications
FDI is widely regarded as an important driver of sustainable economic growth, particularly in countries with a savings deficit. The FDI–growth nexus has been examined extensively in both theoretical and empirical work, yet the evidence for Türkiye remains mixed and inconclusive despite decades of FDI-promotion policies. This study contributes to the literature by analyzing the effect of FDI stocks on output per worker within an endogenous-growth framework. Focusing on stocks rather than flows provides a more suitable basis for assessing growth effects, because stocks reflect the cumulative accumulation of foreign capital and thus capture the medium- to long-run influence of foreign ownership.
The econometric results indicate that FDI stock has a negative impact on output in the long run. The finding is consistent with earlier evidence of weak or negative long-run FDI effects in developing and fragile economies [7,11,40,42,98]. A plausible explanation is that FDI concentrated in primary or non-tradable, low-productivity activities generates limited spill-overs [49,50,51,52,68], whereas FDI in technology-intensive manufacturing is more likely to foster growth. Because of data constraints, however, the present analysis cannot explicitly distinguish sectors and therefore treats FDI in aggregate form.
The behaviour of the control variables reveals additional structural features of the Turkish growth process. The statistical insignificance of domestic capital suggests that physical investment, in its current allocation, has not been a decisive engine of sustainable growth, implying that higher investment ratios alone are insufficient without improvements in efficiency and sectoral orientation. Human capital shows a negative long-run association with output per worker, which most plausibly reflects the quantitative expansion but limited quality of education—as well as the loss of skills through brain drain—rather than an intrinsically growth-reducing role of schooling. Against this background, the strong and robust positive effect of institutional quality stands out: the results indicate that, in the current Turkish context, “getting the institutions right” is more important for sustainable growth than expanding either domestic or foreign capital in isolation.
These findings carry clear policy implications. In the short term, FDI policy should shift from volume-based targets toward improving the composition and governance of foreign investment, prioritizing projects that create new productive capacity, are embedded in export-oriented and technology-intensive manufacturing, and include credible commitments to technology transfer and worker training, rather than non-tradable, merger-and-acquisition-type deals in services that mainly reallocate existing assets and weaken spill-over channels. In the long term, the persistent negative association between FDI stock and output per worker, together with the strong positive effect of institutional quality, underscores the central importance of strengthening the rule of law, property-rights protection, and broader democratic governance within a transparent, stable, and corruption-resistant policy framework. These institutional reforms, combined with efforts to improve the quality and labour-market relevance of education, are crucial to achieve sustainable growth.
Funding
This research received no external funding.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The data presented in this study are openly available in World Bank at https://databank.worldbank.org/source/world-development-indicators, accessed on 4 November 2025.
Conflicts of Interest
The author declares no conflicts of interest.
Abbreviations
The following abbreviations are used in this manuscript:
| ARDL | Auto Regressive Distributed Lag |
| CCR | Canonical Cointegrating Regression |
| DOLS | Dynamic Ordinary Least Squares |
| EU | European Union |
| FDI | Foreign Direct Investment |
| FMOLS | Fully Modified Ordinary Least Squares |
| GCF | Gross Capital Formation |
| GDP | Gross Domestic Product |
| GVC | Global Value Chain |
| PIM | Perpetual Inventory Method |
| WDI | World Development Indicators |
Appendix A
The human capital index used in this study follows the methodology of Hall and Jones (1999) [87] and Bakış and Acar (2021) [107]. It is constructed by combining data on average years of schooling with the corresponding returns to education. This index captures the effect of education as a function of average years of schooling.
with
where Ht denotes the human capital index and Et corresponds to the average years of schooling, obtained from TurkStat.
Appendix B
In this study, the domestic capital stock and FDI Stock were calculated using the Perpetual Inventory Method (PIM). To isolate domestic investment from total gross capital formation (GCF), annual FDI inflows were subtracted from GCF, yielding the series for domestic investment. The PIM was then applied as follows:
where denotes the domestic capital stock at time t, is the depreciation rate and represents domestic investment, calculated as gross capital formation minus FDI inflows.
The initial capital stock was estimated using the standard formula:
where is domestic investment in the base year, is the long-run average growth rate of domestic investment, and is the depreciation rate. In this study, was set at 4.64%, calculated as the average growth rate of investment between 1970 and 2024, while was fixed at 6% following Bakış and Acar (2021) [107].
Gross capital formation data were obtained from the World Development Indicators (WDI) and TurkStat, while FDI inflows were sourced from WDI. The resulting domestic capital stock series was expressed in per-worker terms by dividing by the labor force, which was also taken from WDI and TurkStat.
References
- Harrison, M.J. Can Corrupt Countries Attract Foreign Direct Investment? A Comparison of FDI Inflows Between Corrupt and Non-Corrupt Countries. Int. Bus. Econ. Res. J. 2003, 2. [Google Scholar] [CrossRef] [Scilit]
- Hyun, H.J. Quality of institutions and foreign direct investment in developing countries: Causality tests for cross-country panels. J. Bus. Econ. Manag. 2006, 7, 103–110. [Google Scholar] [CrossRef] [Scilit]
- Solow, R.M. A contribution to the theory of economic growth. Q. J. Econ. 1956, 70, 65–94. [Google Scholar] [CrossRef] [Scilit]
- Romer, P.M. Increasing returns and long-run growth. J. Political Econ. 1986, 94, 1002–1037. [Google Scholar] [CrossRef] [Scilit]
- Mankiw, N.G.; Romer, D.; Weil, D.N. A contribution to the empirics of economic growth. Q. J. Econ. 1992, 107, 407–437. [Google Scholar] [CrossRef] [Scilit]
- De Mello, L.R., Jr. Foreign direct investment in developing countries and growth: A selective survey. J. Dev. Stud. 1997, 34, 1–34. [Google Scholar] [CrossRef] [Scilit]
- Akinlo, A.E. Foreign direct investment and growth in Nigeria: An empirical investigation. J. Policy Model. 2004, 26, 627–639. [Google Scholar] [CrossRef] [Scilit]
- Iamsiraroj, S. The foreign direct investment–economic growth nexus. Int. Rev. Econ. Financ. 2016, 42, 116–133. [Google Scholar] [CrossRef] [Scilit]
- Dunning, J.H. The determinants of international production. Oxf. Econ. Pap. 1973, 25, 289–336. [Google Scholar] [CrossRef] [Scilit]
- Borensztein, E.; de Gregorio, J.; Lee, J.W. How does foreign direct investment affect economic growth? J. Int. Econ. 1998, 45, 115–135. [Google Scholar] [CrossRef] [Scilit]
- Javorcik, B.S. Does foreign direct investment increase the productivity of domestic firms? In search of spillovers through backward linkages. Am. Econ. Rev. 2004, 94, 605–627. [Google Scholar] [CrossRef] [Scilit]
- Yimer, A. The effects of FDI on economic growth in Africa. J. Int. Trade Econ. Dev. 2023, 32, 2–36. [Google Scholar] [CrossRef] [Scilit]
- Dunning, J.H. Explaining the international direct investment position of countries: Towards a dynamic or developmental approach. Weltwirtschaftliches Arch. 1981, 117, 30–64. [Google Scholar] [CrossRef] [Scilit]
- Görg, H.; Greenaway, D. Foreign Direct Investment and Intra-Industry Spillovers: A Review of the Literature; University of Nottingham: Nottingham, UK, 2001. [Google Scholar]
- Amighini, A.A.; McMillan, M.S.; Sanfilippo, M. FDI and Capital Formation in Developing Economies: New Evidence from Industry-Level Data (No. w23049); National Bureau of Economic Research: Cambridge, MA, USA, 2017. [Google Scholar]
- Simionescu, M.; Naroş, M.S. The role of foreign direct investment in human capital formation for a competitive labour market. Manag. Res. Pract. 2019, 11, 5–14. [Google Scholar]
- Ramirez, M.D. Is foreign direct investment beneficial for Mexico? An empirical analysis, 1960–2001. World Dev. 2006, 34, 802–817. [Google Scholar] [CrossRef] [Scilit]
- Arısoy, İ. The impact of foreign direct investment on total factor productivity economic growth in Türkiye. J. Dev. Areas 2012, 46, 17–29. [Google Scholar] [CrossRef] [Scilit]
- Iamsiraroj, S.; Ulubaşoğlu, M.A. Foreign direct investment and economic growth: A real relationship or wishful thinking? Econ. Model. 2015, 51, 200–213. [Google Scholar] [CrossRef] [Scilit]
- Bruno, R.L.; Cipollina, M. A meta-analysis of the indirect impact of foreign direct investment in old and new EU member states: Understanding productivity spillovers. World Econ. 2018, 41, 1342–1377. [Google Scholar] [CrossRef] [Scilit]
- Pintilie, N.; Cicea, C.; Marinescu, C. A bibliometric study of environmental protection and economic development: Revealing links and dynamics. In Proceedings of the 14th International Management Conference: Managing Sustainable Organizations, Bucharest, Romania, 5–6 November 2020; Faculty of Management, Bucharest University of Economic Studies; Management Academic Society in Romania (SAMRO): Bucharest, Romania, 2020; pp. 335–345. [Google Scholar]
- Kostoulis, D. Foreign Direct Investment and Growth: A Literature Review from 1990 To Date. Eur. J. Econ. Financ. Res. 2023, 7, 68–84. [Google Scholar] [CrossRef] [Scilit]
- de Gregorio, J. Economic growth in latin america. J. Dev. Econ. 1992, 39, 59–84. [Google Scholar] [CrossRef] [Scilit]
- Blomström, M.; Kokko, A.; Zejan, M. Host country competition, labor skills, and technology transfer by multinationals. Rev. World Econ. 1994, 130, 521–533. [Google Scholar] [CrossRef] [Scilit]
- Balasubramanyam, V.N.; Salisu, M.; Sapsford, D. Foreign direct investment and growth in EP and IS countries. Econ. J. 1996, 106, 92–105. [Google Scholar] [CrossRef] [Scilit]
- Basu, P.; Chakraborty, C.; Reagle, D. Liberalization, FDI, and growth in developing countries: A panel cointegration approach. Econ. Inq. 2003, 41, 510–516. [Google Scholar] [CrossRef] [Scilit]
- Baharumshah, A.Z.; Almasaied, S.W. Foreign direct investment and economic growth in Malaysia: Interactions with human capital and financial deepening. Emerg. Mark. Financ. Trade 2009, 45, 90–102. [Google Scholar] [CrossRef] [Scilit]
- Jude, C. Does FDI crowd out domestic investment in transition countries? Econ. Transit. Institutional Change 2019, 27, 163–200. [Google Scholar]
- Bénétrix, A.; Pallan, H.M.; Panizza, U. The Elusive Link Between FDI and Economic Growth; The World Bank: Washington, DC, USA, 2023. [Google Scholar]
- Baldwin, R.E. Globalisation: The Great Unbundling (s); Economic Council of Finland: Helsinki, Finland, 2006. [Google Scholar]
- Hermes, N.; Lensink, R. Foreign direct investment, financial development and economic growth. J. Dev. Stud. 2003, 40, 142–163. [Google Scholar] [CrossRef] [Scilit]
- Alfaro, L.; Chanda, A.; Kalemli-Ozcan, S.; Sayek, S. FDI and economic growth: The role of local financial markets. J. Int. Econ. 2004, 64, 89–112. [Google Scholar] [CrossRef] [Scilit]
- Azman-Saini, W.N.W.; Law, S.H. FDI and economic growth: New evidence on the role of financial markets. Econ. Lett. 2010, 107, 211–213. [Google Scholar] [CrossRef] [Scilit]
- Alfaro, L.; Chanda, A.; Kalemli-Ozcan, S.; Sayek, S. Does foreign direct investment promote growth? Exploring the role of financial markets on linkages. J. Dev. Econ. 2010, 91, 242–256. [Google Scholar] [CrossRef] [Scilit]
- Osei, M.J.; Kim, J. Foreign direct investment and economic growth: Is more financial development better? Econ. Model. 2020, 93, 154–161. [Google Scholar] [CrossRef] [Scilit]
- Durham, J.B. Absorptive capacity and the effects of foreign direct investment and equity foreign portfolio investment on economic growth. Eur. Econ. Rev. 2004, 48, 285–306. [Google Scholar] [CrossRef] [Scilit]
- Jude, C.; Levieuge, G. Growth effect of foreign direct investment in developing economies: The role of institutional quality. World Econ. 2017, 40, 715–742. [Google Scholar] [CrossRef] [Scilit]
- Melnyk, L.; Kubatko, O.; Pysarenko, S. The impact of foreign direct investment on economic growth: Case of post communism transition economies. Probl. Perspect. Manag. 2014, 12, 17–24. [Google Scholar]
- Ciftci, C.; Durusu-Ciftci, D. Economic freedom, foreign direct investment, and economic growth: The role of sub-components of freedom. J. Int. Trade Econ. Dev. 2022, 31, 233–254. [Google Scholar] [CrossRef] [Scilit]
- Carkovic, M.; Levine, R. Does foreign direct investment accelerate economic growth. Does Foreign Direct Invest. Promot. Dev. 2005, 195, 220. [Google Scholar] [CrossRef] [Scilit]
- Shittu, W.O.; Musibau, H.O.; Jimoh, S.O. The complementary roles of human capital and institutional quality on natural resource-FDI—Economic growth Nexus in the MENA region. Environ. Dev. Sustain. 2022, 24, 7936–7957. [Google Scholar] [CrossRef] [Scilit]
- Herzer, D.; Klasen, S. In search of FDI-led growth in developing countries: The way forward. Econ. Model. 2008, 25, 793–810. [Google Scholar] [CrossRef] [Scilit]
- Markusen, J.R.; Venables, A.J. Multinational firms and the new trade theory. J. Int. Econ. 1998, 46, 183–203. [Google Scholar] [CrossRef] [Scilit]
- Easterly, W. How much do distortions affect growth? J. Monet. Econ. 1993, 32, 187–212. [Google Scholar] [CrossRef] [Scilit]
- Iwasaki, I.; Tokunaga, M. Macroeconomic impacts of FDI in transition economies: A meta-analysis. World Dev. 2014, 61, 53–69. [Google Scholar] [CrossRef] [Scilit]
- Ramirez, M. Foreign direct investment in Mexico: A cointegration analysis. J. Dev. Stud. 2000, 37, 138–162. [Google Scholar] [CrossRef] [Scilit]
- Fry, M.J. Financing economic reform: Mobilising domestic resources and attracting the right kind of external resources. In Growth and Competition in the New Global Economy; OECD Publishing: Paris, France, 1999; p. 59. [Google Scholar]
- Findlay, R. Relative backwardness, direct foreign investment, and the transfer of technology: A simple dynamic model. Q. J. Econ. 1978, 92, 1–16. [Google Scholar] [CrossRef] [Scilit]
- Vu, T.B.; Noy, I. Sectoral analysis of foreign direct investment and growth in the developed countries. J. Int. Financ. Mark. Inst. Money 2009, 19, 402–413. [Google Scholar] [CrossRef] [Scilit]
- Chakraborty, D.; Nagarajan, S.; Aggarwal, P.; Gupta, V.K.; Tomar, R.K.; Garg, R.N.; Sahoo, R.N.; Sarkar, A.; Chopra, U.K.; Sarma, K.S.S.; et al. Effect of mulching on soil and plant water status, and the growth and yield of wheat (Triticum aestivum L.) in a semi-arid environment. Agric. Water Manag. 2008, 95, 1323–1334. [Google Scholar] [CrossRef] [Scilit]
- Wang, M. Manufacturing FDI and economic growth: Evidence from Asian economies. Appl. Econ. 2009, 41, 991–1002. [Google Scholar] [CrossRef] [Scilit]
- Aykut, D.; Sayek, S. The role of the sectoral composition of foreign direct investment on growth. Do Multinatl. Feed Local Dev. Growth 2007, 22, 35–62. [Google Scholar]
- Haini, H.; Tan, P. Re-examining the impact of sectoral-and industrial-level FDI on growth: Does institutional quality, education levels and trade openness matter? Aust. Econ. Pap. 2022, 61, 410–435. [Google Scholar]
- Ullah, S.; Luo, R.; Ali, K.; Irfan, M. How does the sectoral composition of FDI induce economic growth in developing countries? The key role of business regulations. Econ. Res.-Ekon. Istraživanja 2023, 36, 2129406. [Google Scholar] [CrossRef] [Scilit]
- Marasco, A.; Khalid, A.M.; Tariq, F. Does technology shape the relationship between FDI and growth? A panel data analysis. Appl. Econ. 2024, 56, 2544–2567. [Google Scholar] [CrossRef] [Scilit]
- Zhang, K.H.; Song, S. Promoting exports: The role of inward FDI in China. China Econ. Rev. 2001, 11, 385–396. [Google Scholar] [CrossRef] [Scilit]
- Akadiri, S.S.; Ajmi, A.N. Causality relationship between energy consumption, economic growth, FDI, and globalization in SSA countries: A symbolic transfer entropy analysis. Environ. Sci. Pollut. Res. 2020, 27, 44623–44628. [Google Scholar] [CrossRef] [Scilit]
- Kokko, A.O. Foreign Direct Investment, Host Country Characteristics, and Spillovers; Economic Research Institute, Stockholm School of Economics: Stockholm, Sweden, 1994. [Google Scholar]
- Ciobanu, M. Foreign direct investments and processing industry competitiveness in the Republic of Moldova. Meridian Ing. 2015, 50–57. Available online: https://ibn.idsi.md/sites/default/files/imag_file/50_57_Foreign%20direct%20investments%20and%20processing%20industry%20competitiveness%20in%20the%20Republic%20of%20Moldova.pdf (accessed on 3 March 2026).
- Rakshit, B. Dynamics between trade openness, FDI and economic growth: Evidence from an emerging economy. J. Int. Trade Law Policy 2022, 21, 16–41. [Google Scholar] [CrossRef] [Scilit]
- Gupta, S.; Yadav, S.S.; Jain, P.K. Absorptive capacities, FDI and economic growth in a developing economy: A study in the Indian context. J. Adv. Manag. Res. 2022, 19, 741–759. [Google Scholar] [CrossRef] [Scilit]
- Drob, C.; Plescau, I.; Zichil, V. Foreign Direct Investments and Economic Growth in Romania: A Time-Series Approach for Sustainable Development. Sustainability 2025, 18, 343. [Google Scholar] [CrossRef] [Scilit]
- Bengoa, M.; Sanchez-Robles, B. Foreign direct investment, economic freedom and growth: New evidence from Latin America. Eur. J. Political Econ. 2003, 19, 529–545. [Google Scholar] [CrossRef] [Scilit]
- Iqbal Chaudhry, N.; Mehmood, A.; Saqib Mehmood, M. Empirical relationship between foreign direct investment and economic growth: An ARDL co-integration approach for China. China Financ. Rev. Int. 2013, 3, 26–41. [Google Scholar]
- Chowdhury, R.A.; Abdullah, M.N.; Tooheen, R.B. FDI-based business: The case of Bangladesh. World 2017, 7, 1–8. [Google Scholar]
- Raza, S.A.; Shah, N.; Arif, I. Relationship between FDI and economic growth in the presence of good governance system: Evidence from OECD Countries. Glob. Bus. Rev. 2021, 22, 1471–1489. [Google Scholar] [CrossRef] [Scilit]
- Emako, E.; Nuru, S.; Menza, M. Determinants of foreign direct investments inflows into developing countries. Transnatl. Corp. Rev. 2023, 15, 72–85. [Google Scholar] [CrossRef] [Scilit]
- Bergougui, B.; Murshed, S.M. Spillover effects of FDI inflows on output growth: An analysis of aggregate and disaggregated FDI inflows of 13 MENA economies. Aust. Econ. Pap. 2023, 62, 668–692. [Google Scholar] [CrossRef] [Scilit]
- Majumder, T.; Roy, S.S. FDI and growth: A re-look at evidence on developing economies. Arthaniti J. Econ. Theory Pract. 2023. [Google Scholar] [CrossRef] [Scilit]
- Ofori, I.K.; Asongu, S.A. Repackaging FDI for inclusive growth: Nullifying effects and policy-relevant thresholds of governance. Transnatl. Corp. Rev. 2024, 16, 200056. [Google Scholar] [CrossRef] [Scilit]
- Elimam, H.; Alattas, H. Foreign direct investment: A strategic approach towards sustainable economic growth in Saudi Arabia. Cogent Econ. Financ. 2025, 13, 2492203. [Google Scholar] [CrossRef] [Scilit]
- Bildirici, M.; Aykaç-Alp, E.; Kayıkçı, F. Effects of Foreign Direct Investment on Growth in Türkiye. In Proceedings of the International Conference on Eurasian Economies, Istanbul, Istanbul, 4–5 November 2010; pp. 4–5. [Google Scholar]
- Ilgun, E.; Karl-Josef, K.O.C.H.; Orhan, M. How Do Foreign Direct Investment And Growth Interact In Türkiye? Eurasian J. Bus. Econ. 2010, 3, 41–55. [Google Scholar]
- Ekinci, A. Doğrudan yabancı yatırımların ekonomik büyüme ve istihdama etkisi: Türkiye uygulaması (1980–2010). Eskişehir Osman. Üniversitesi İİBF Derg. 2011, 6, 71–96. [Google Scholar]
- Aga, A.A.K. The impact of foreign direct investment on economic growth: A case study of Türkiye 1980–2012. Int. J. Econ. Financ. 2014, 6, 71–84. [Google Scholar]
- Cambazoglu, B.; Simay Karaalp, H. Does foreign direct investment affect economic growth? The case of Türkiye. Int. J. Soc. Econ. 2014, 41, 434–449. [Google Scholar] [CrossRef] [Scilit]
- Demirsel, M.T.; Adem, Ö.; Mucuk, M. The effect of foreign direct investment on economic growth: The case of Türkiye. In Proceedings of International Academic Conferences (No. 0702081); International Institute of Social and Economic Sciences: Prague, Czech Republic, 2014. [Google Scholar]
- Gokmen, O. The relationship between foreign direct investment and economic growth: A case of Türkiye. arXiv 2021, arXiv:2106.08144. [Google Scholar] [CrossRef] [Scilit]
- Kurul, Z. Türkiye’de doğrudan yabancı yatırım girişleri ve yurtiçi yatırım ilişkisi: Doğrusal olmayan ARDL yaklaşımı. Sosyoekonomi 2021, 29, 271–292. [Google Scholar] [CrossRef] [Scilit]
- Saglam, B.B.; Yalta, A.Y. Dynamic linkages among foreign direct investment, public investment and private investment: Evidence from Türkiye. Appl. Econom. Int. Dev. 2011, 11, 71–82. [Google Scholar]
- Lucas, R.E., Jr. On the mechanics of economic development. J. Monet. Econ. 1988, 22, 3–42. [Google Scholar]
- Barro, R.J. Human capital and growth. Am. Econ. Rev. 2001, 91, 12–17. [Google Scholar] [CrossRef] [Scilit]
- Neuhaus, M. The Impact of FDI on Economic Growth: An Analysis for the Transition Countries of Central and Eastern Europe; Physica-Verlag HD: Heidelberg, Germany, 2006. [Google Scholar]
- Barro, R.J.; Sala-i-Martin, X. Convergence. J. Political Econ. 1992, 100, 223–251. [Google Scholar] [CrossRef] [Scilit]
- Acemoglu, D.; Johnson, S.; Robinson, J.A. Institutions as a fundamental cause of long-run growth. Handb. Econ. Growth 2005, 1, 385–472. [Google Scholar]
- North, D.C. Institutions, Institutional Change and Economic Performance; Cambridge University: Cambridge, UK, 1990. [Google Scholar]
- Hall, R.E.; Jones, C.I. Why do some countries produce so much more output per worker than others? Q. J. Econ. 1999, 114, 83–116. [Google Scholar] [CrossRef] [Scilit]
- Barro, R.J.; Lee, J.W. A new data set of educational attainment in the world, 1950–2010. J. Dev. Econ. 2013, 104, 184–198. [Google Scholar] [CrossRef] [Scilit]
- Pesaran, M.H.; Shin, Y.; Smith, R.J. Bounds testing approaches to the analysis of level relationships. J. Appl. Econom. 2001, 16, 289–326. [Google Scholar] [CrossRef] [Scilit]
- Pesaran, M.H.; Shin, Y. An autoregressive distributed lag modelling approach to cointegration analysis. In Econometrics and Economic Theory in the 20th Century: The Ragnar Frisch Centennial Symposium; Strom, S., Ed.; Cambridge University Press: Cambridge, UK, 1999; Chapter 11. [Google Scholar]
- Narayan, P.K. The saving and investment nexus for China: Evidence from cointegration tests. Appl. Econ. 2005, 37, 1979–1990. [Google Scholar] [CrossRef] [Scilit]
- Ouattara, B. Modelling the Long Run Determinants of Private Investment in Senegal (No. 04/05); Credit Research Paper; University of Nottingham: Nottingham, UK, 2004. [Google Scholar]
- MacKinnon, J.G. Numerical distribution functions for unit root and cointegration tests. J. Appl. Econom. 1996, 11, 601–618. [Google Scholar] [CrossRef] [Scilit]
- Kwiatkowski, D.; Phillips, P.C.; Schmidt, P.; Shin, Y. Testin. the null hypothesis of stationarity against the alternative of a unit root: How sure are we that economic time series have a unit root? J. Econom. 1992, 54, 159–178. [Google Scholar] [CrossRef] [Scilit]
- Lee, J.; Strazicich, M.C. Minimum Lagrange Multiplier unit root test with two structural breaks. Rev. Econ. Stat. 2003, 85, 1082–1089. [Google Scholar] [CrossRef] [Scilit]
- Easterly, W.; Kremer, M.; Pritchett, L.; Summers, L.H. Good policy or good luck? J. Monet. Econ. 1993, 32, 459–483. [Google Scholar] [CrossRef] [Scilit]
- Singer, H.W. The Distribution of Gains Between Investing and Borrowing Countries. In American Economic Review, Papers and Proceedings; American Economic Association: Nashville, TN, USA, 1950. [Google Scholar]
- Mišun, J.; Tomšík, V. Foreig direct investment in central europe-does it crowd in domestic investment? Prague Econ. Pap. 2002, 11, 57–66. [Google Scholar] [CrossRef] [Scilit]
- Herzer, D. Outward FDI and economic growth. J. Econ. Stud. 2010, 37, 476–494. [Google Scholar] [CrossRef] [Scilit]
- Hanushek, E.A.; Woessmann, L. Schooling, Cognitive Skills, and the Latin American Growth Puzzle (No. w15066); National Bureau of Economic Research: Cambridge, MA, USA, 2009. [Google Scholar]
- Yu, W. Brain drain and economic growth: Evidence of productivity growth from brain circulation. Eur. J. Gov. Econ. (EJGE) 2021, 10, 128–145. [Google Scholar] [CrossRef] [Scilit]
- Docquier, F.; Rapoport, H. Globalization, brain drain, and development. J. Econ. Lit. 2012, 50, 681–730. [Google Scholar] [CrossRef] [Scilit]
- Topal, F.; Hopyar, Z. On Causes and Costs of Brain Drain. In The Economics of Migration of Highly Skilled Workers from Türkiye: The New Age of Colonialism; Springer Nature Switzerland: Cham, Switzerland, 2026; pp. 29–60. [Google Scholar]
- Mike, F.; Akyıldız, İ.E.; Doğanlar, M.; Kızılkaya, O. The innovation exodus: How Türkiye’s brain drain challenges technological progress. Econ. Innov. New Technol. 2025, 1–19. [Google Scholar] [CrossRef] [Scilit]
- Acemoglu, D.; Naidu, S.; Restrepo, P.; Robinson, J.A. Democracy does cause growth. J. Political Econ. 2019, 127, 47–100. [Google Scholar] [CrossRef] [Scilit]
- Rodrik, D.; Subramanian, A.; Trebbi, F. Institutions rule: The primacy of institutions over geography and integration in economic development. J. Econ. Growth 2004, 9, 131–165. [Google Scholar] [CrossRef] [Scilit]
- Bakış, O.; Acar, U. Türkiye ekonomisinde toplam faktör verimliliği: 1980–2019. J. Res. Econ. 2021, 5, 1–27. [Google Scholar] [CrossRef] [Scilit]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the author. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.