


Abstract
The rapid diffusion of electric vehicles (EVs) is weakening the conventional fuel tax base, creating new challenges for transport-energy taxation. Although South Korea does not currently tax EV charging electricity, such taxation is becoming increasingly relevant as EV adoption expands. This study examines consumer preferences for EV fuel-tax design by focusing on revenue recycling and tax salience, operationalized as the visibility of tax information on EV charging receipts. Using stated-preference data from a discrete choice experiment with South Korean adults aged 20–59, we estimate a mixed-mixed multinomial logit model capturing both discrete preference segments and continuous within-segment heterogeneity. A post-estimation multinomial logit analysis of individual-level salience coefficients identifies characteristics associated with relatively strong positive or negative preferences for tax salience. The results reveal two distinct segments. The majority shows positive preferences for tax salience and the revenue-use outcomes, whereas the minority is highly cost-sensitive and favors direct EV performance improvements. Stronger preferences for tax salience are associated with greater knowledge of the tax system, while negative preferences are associated with lower education and not currently driving. The results therefore represent conditional preferences among alternative EV fuel-tax designs, rather than acceptance of an EV fuel tax relative to no tax. The study provides policy-relevant insights into consumer preferences for EV fuel-tax design during the electric mobility transition.
1. Introduction
The rapid proliferation of electric vehicles (EVs) represents one of the most transformative shifts in transportation policy of the past decade. In Korea, EV registrations have grown exponentially, driven by generous government subsidies, expanding charging infrastructure, and growing environmental awareness among consumers. While this transition advances decarbonization goals, it simultaneously erodes the conventional fuel tax base, which has long served as a cornerstone of public revenue used to fund road infrastructure, environmental programs, and social services. Vehicle electrification is being promoted across both developed and developing economies not only in response to energy, climate, and environmental concerns, but also as part of broader industrial and trade strategies aimed at strengthening national positions in the global automotive value chain [1]. The fiscal consequences of electrification therefore arise alongside industrial commitments that shape how governments design and adjust vehicle-related taxation.
As EVs become mainstream, governments worldwide face the pressing challenge of reforming fuel taxation to ensure fiscal sustainability without alienating the public. At the same time, transport-tax reforms need to restore declining revenue without substantially weakening the cost advantages that have supported EV adoption. Several governments have already begun to act on this tension. New Zealand ended its long-standing exemption of light electric vehicles from distance-based road user charges in April 2024, once such vehicles reached about two percent of the light fleet [2]. Iceland introduced a per-kilometer charge for electric, hydrogen, and plug-in hybrid vehicles in 2024 as the first stage of replacing fuel excise duties, extending the same charge to petrol and diesel vehicles thereafter [3]. Several US states, including Iowa, Kentucky, and Montana, have instead adopted per-kilowatt-hour taxes on electricity dispensed at public charging stations, at rates between 2.6 and 3.0 US cents per kWh [4]. Balancing revenue adequacy with the affordability implications of EV taxation has therefore emerged as an important policy issue in the transition toward electric mobility [5,6,7].
The Korean case reflects this broader policy tension. Fuel taxes have historically been used to generate revenue for public infrastructure and to internalize the external costs of fossil fuel consumption, including air pollution, congestion, and greenhouse gas emissions [8]. In Korea, the conventional fuel tax system is centered on petroleum-based transport fuels, particularly gasoline and diesel, under the Act on Transportation, Energy and Environment Tax. The tax is intended to secure resources for transport infrastructure and public transportation, energy and resource projects, and environmental conservation and improvement [9]. Korea’s fuel tax rates are among the highest in the OECD, and the statutory connection between the tax and transportation, energy, and environmental expenditures provides a visible link between taxation and public investment [9,10]. The fuel tax system is generally designed to be responsive to economic pressures, and temporary reductions in fuel-tax rates have been repeatedly extended in response to changing energy-price conditions, including an extension through February 2026 [11].
Despite this flexibility, the rapid adoption of electric vehicles and the associated decline in gasoline and diesel consumption are eroding the traditional fuel tax base, raising concerns about the sustainability of revenues for infrastructure and environmental objectives. In Korea, electricity used for EV charging is subject to general electricity charges and broad electricity-related levies, including value-added tax and the Electric Power Industry Basis Fund surcharge, but no dedicated EV fuel tax or transport-energy tax equivalent to gasoline and diesel fuel taxation is currently imposed on EV charging. According to the Ministry of Land, Infrastructure and Transport, cumulative EV registrations reached 684,000 vehicles by the end of 2024, up from approximately 390,000 at the end of 2022, while the overall share of clean vehicles in new registrations exceeded 40 percent for the first time [12]. Concurrently, conventional internal combustion engine vehicle registrations declined for the second consecutive year in 2024, signaling a structural shift in the fleet composition. In 2023, spending on electric- and hydrogen-vehicle programs accounted for 25.3 percent of the Ministry of Environment’s total budget of 9.8 billion USD (12.9 trillion won), predominantly for purchase subsidies and charging infrastructure installation [13]. The transition signifies a structural fiscal challenge that policymakers may need to address through reforms to transport-energy taxation and revenue recycling strategies [5,6,14,15]. The introduction of a dedicated EV fuel tax, as one possible response to this challenge, would therefore need to balance fiscal objectives with the way consumers evaluate the costs and benefits of the proposed tax design.
Public resistance to new or increased taxes is well documented. High-profile episodes of tax-driven social unrest such as the Gilets Jaunes movement in France triggered by fuel tax hikes in 2018 underscore the political risks of poorly designed or poorly communicated tax policies. Research has consistently demonstrated that consumer acceptance of environmental taxes depends not only on their absolute level, but on how the revenue is used and communicated [16,17]. When consumers understand and trust how tax revenue is recycled, their willingness to accept the tax increases substantially. Along with good communication, another important lever for improving tax acceptance is revenue recycling, which channels tax proceeds to specific, visible, and valued public purposes. Previous studies show that assigning revenues for environmental investments, public transportation improvements, or household rebates significantly increases public support for carbon and fuel taxes [18,19]. Equally important is the concept of tax salience, or the degree to which tax-related information is made visible and accessible to consumers at the point of transaction. Prior research demonstrates that greater visibility of tax information can materially affect consumer responses to taxation [20].
Three related gaps in the existing literature motivate this study. Substantively, previous studies of fuel and carbon taxation have shown that the use of tax revenue, particularly through earmarking and revenue recycling, can influence public support [16,18,19], while a separate body of the literature on tax salience has shown that the visibility of taxes can affect consumer responses [20]. Studies of emerging EV taxation have meanwhile focused primarily on the fiscal consequences of electrification, including the use of mileage-based taxation and other mechanisms to replace declining conventional fuel-tax revenues [5,6,14,15,21,22,23]. However, it remains unclear how consumers value tax salience relative to the specific outcomes financed by an EV tax. Empirically, these dimensions have not been jointly evaluated within the same EV fuel-tax choice design, making it difficult to quantify the trade-offs consumers make between tax salience and alternative uses of the resulting revenue.
Methodologically, consumers are not homogeneous in how they evaluate EV fuel taxation, and their preferences toward these policy attributes may exhibit both discrete and continuous heterogeneity. Consumers may differ qualitatively in the types of tax packages they prefer, while also differing in the strength of those preferences within each group. To account for both sources of heterogeneity, this study applies a mixed-mixed multinomial logit model, which accommodates discrete preference segments while simultaneously allowing continuous preference variation within each segment.
This study examines consumer preferences for the design of a prospective EV fuel tax in South Korea. The first focus of this study is tax salience, operationalized in the choice experiment as whether individual tax items and amounts are displayed on the EV charging receipts. Specifically, the experiment examines how respondents value the disclosure of individual tax items and amounts on EV charging receipts when choosing among alternative EV fuel-tax designs. Since all alternatives involve a positive EV fuel tax, the analysis does not identify whether respondents would accept an EV fuel tax relative to no tax. Rather, it identifies conditional preferences among alternative EV fuel-tax packages and the marginal valuation of their attributes. The second focus is consumer preferences regarding alternative revenue-recycling attributes, which include improved accessibility to charging infrastructure, CO2 emissions reduction, extended maximum driving distance, and reduced commuting time. The analysis uses stated-preference data collected in April 2017 from a stratified sample of South Korean adults aged 20 to 59. Since the survey was conducted during an early stage of EV diffusion in Korea and before the introduction of a dedicated EV fuel tax, the resulting estimates should be interpreted as ex ante preferences for hypothetical tax designs rather than as evidence of the preferences of current EV owners or experienced EV users.
In the first stage, this study estimates a mixed-mixed multinomial logit (MM-MNL) model to identify the consumer segments and to capture the within-segment heterogeneity of attribute valuations. The MM-MNL model is suitable for this analysis because it nests both the standard mixed logit and the latent class models as special cases, and it lets the data determine how much of the preference heterogeneity is discrete across segments and how much is continuous within each segment. In the second stage, the posterior individual-level coefficients for tax salience recovered from the MM-MNL model are used to classify respondents according to the direction and strength of their salience preferences. A multinomial logit (MNL) model is then estimated to examine which observable respondent characteristics are associated with stronger or weaker preferences for tax salience.
By jointly examining tax salience and alternative revenue-use outcomes, this study provides evidence for how consumers trade off different components of a prospective EV fuel-tax package. It also contributes methodologically by showing how discrete preference segments and continuous within-segment heterogeneity can coexist in evaluations of an emerging transport-tax instrument. Given the timing of the survey, the empirical estimates are best interpreted as an early-transition benchmark rather than as direct evidence on the preferences of current Korean EV users.
2. Literature Review
2.1. Fuel Taxation, Revenue Adequacy, and the Rise of Electric Vehicles
Fuel taxes play an important role in transportation fiscal policy across OECD countries. The revenues from fuel taxes support road infrastructure maintenance, environmental programs, and broader public services. In Korea, fuel taxes are levied under the Act on Transportation, Energy and Environment Tax, and they are among the highest in the OECD when measured as a share of the retail fuel price [10]. The tax is intended to secure resources for transport infrastructure and public transportation, energy and resource projects, and environmental conservation and improvement [9]. This statutory purpose creates a direct institutional link between fuel taxation and the public expenditures it is intended to support.
The accelerating adoption of EVs, however, poses a structural challenge to fuel tax revenues. Because EVs consume electricity rather than gasoline or diesel, they do not pay conventional fuel excise taxes tied to transport fuel consumption, even though they continue to use road infrastructure. In Korea, no dedicated EV fuel tax has yet been implemented, but policy discussions have increasingly raised the possibility of transport-electricity taxation, mileage-based road user charges, or broader transport-energy tax reform as EV adoption expands. Studies from the United States and Europe project significant revenue shortfalls as the EV market share grows [24]. Korea faces a similar long-term fiscal challenge as the share of EVs in the vehicle fleet increases. Cumulative EV registrations reached 684,000 vehicles at the end of 2024, up from only 130,000 in 2020 [12]. Clean vehicles, including EVs, hydrogen vehicles, and hybrids, accounted for over 40 percent of new vehicle registrations in 2024, while the cumulative stock of conventional internal combustion engine vehicles declined for the second consecutive year. Transportation, energy and environmental tax receipts fell to approximately 11.2 trillion won in 2022, the lowest level in a decade [25].
Governments have begun exploring various mechanisms to extend tax obligations to EV users. These mechanisms include mileage-based road-user charges, taxes linked to electricity used for vehicle charging, and EV-specific road or registration charges. The academic literature has paid particular attention to mileage-based road-user charges as a potential substitute for declining fuel-tax revenues [21,22,23]. Several jurisdictions have also moved from policy discussion to implementation. New Zealand extended its road-user charging system to light electric vehicles from April 2024 [2], while the United Kingdom has announced a mileage-based EV Excise Duty (eVED) to take effect from April 2028 [26]. These examples illustrate that governments are beginning to incorporate EVs into transport-tax systems, although the tax base and administrative design differ across jurisdictions. An electricity-based EV fuel tax levied at the point of charging represents one possible approach within this broader set of reforms. Its evaluation, however, involves not only the additional cost imposed on EV use, but also how consumers value the visibility of the tax and the outcomes associated with the use of its revenues. Prior research on environmental taxation suggests that revenue use and the communication of tax information can materially shape consumer responses to tax policy [16,17,18,19]. These considerations motivate the joint examination of tax salience and revenue-recycling outcomes in the present study.
2.2. Tax Salience and Consumer Responses
Tax salience refers to the degree to which tax information is visible, comprehensible, and cognitively accessible to consumers at the point of transaction. In the present study, this concept is operationalized through the visible disclosure of tax information on EV charging receipts. Research in behavioral economics has demonstrated that consumers do not respond uniformly to taxes regardless of their structure. Rather, the framing and visibility of tax information significantly shape behavioral and attitudinal responses. Chetty, Looney, and Kroft conducted influential field experiments in grocery stores and showed that when taxes were incorporated into displayed prices, demand for taxed goods fell measurably compared to conditions where taxes were added only at the register [20]. Their findings demonstrate that consumers can underreact to taxes when those taxes are not fully salient, and that making tax-inclusive prices more visible can alter consumer behavior.
The salience framework has been examined in transportation and vehicle markets. Finkelstein showed that the adoption of electronic toll collection reduced drivers’ awareness of toll payments and made driving less responsive to toll levels. In the longer run, toll rates were estimated to be substantially higher under electronic collection, illustrating how lower tax salience can affect both consumer responses and policy outcomes [27]. In the vehicle market, Grigolon, Reynaert, and Verboven documented modest consumer undervaluation of future fuel costs and found that fuel taxes can be more effective than vehicle product taxes in reducing fuel use, in part because they more directly target high-mileage consumers [28]. Huse and Koptyug further showed that consumers undervalue both fuel costs and vehicle taxes, but that undervaluation is substantially greater for less salient vehicle taxes. Their results identify differences in salience as an important explanation for variation in consumer responses to these policy instruments [29].
In the Korean context, the salience of fuel taxation is particularly relevant because fuel taxes constitute a substantial and recurrent component of retail fuel prices, yet the extent to which consumers value transparent tax information remains underexplored. The behavioral literature establishes that the visibility and comprehensibility of tax information shape consumer responses [20,27], but it does not imply that greater salience is uniformly preferred or produces the same response across consumers. Goldin shows theoretically that the welfare implications of tax salience involve trade-offs between behavioral responses and consumer attention [30]. Taubinsky and Rees-Jones provide empirical evidence of substantial individual heterogeneity in responses to non-salient taxes, showing that consumers differ considerably in the extent to which they underreact to tax information [31]. These findings suggest that heterogeneity in preferences and responses to tax salience is itself an important dimension of tax-policy design.
In the EV charging context, itemized tax information on charging receipts provides a natural way to operationalize tax salience. Displaying individual tax items and amounts can make the tax component of the charging cost more visible to consumers, while withholding this information represents a less salient presentation. Whether consumers value such visibility, however, remains an empirical question. Moreover, the evidence that consumers differ substantially in their responses to tax salience [27,29,31] suggests that an average effect may conceal important differences across and within consumer segments. This study therefore operationalizes Tax Salience as a binary attribute indicating whether individual tax items and amounts are displayed on the charging receipt and estimates the value respondents place on this attribute while allowing for both between-segment and within-segment preference heterogeneity. The resulting coefficient should be interpreted as a preference for tax salience as a feature of the hypothetical tax package, rather than as the causal effect of salience on tax acceptance or actual behavior.
2.3. Revenue Recycling and Public Support for Environmental Taxes
The way in which environmental tax revenues are recycled is widely recognized as an important determinant of public support for environmental taxation. Revenue recycling refers to the reallocation of tax proceeds to specific public uses through infrastructure investment, environmental programs, household rebates, or reductions in other distortionary taxes. The theoretical case for revenue recycling is rooted in the double-dividend hypothesis, which holds that environmental taxes can simultaneously reduce pollution and generate economic efficiency gains if revenues are used to reduce pre-existing tax distortions such as labor taxes [8,32]. Empirical research also shows that the use of tax revenues can substantially influence public support for environmental taxes. Kallbekken, Kroll, and Cherry demonstrated in laboratory experiments that tax aversion is substantially reduced when participants are informed that revenues will be recycled to public goods rather than disappearing into a general budget [18]. Baranzini and Carattini found in Swiss survey data that earmarking carbon tax revenues for environmental purposes or household compensation significantly boosted acceptance, while hypothecation to general government purposes did not [16]. Similarly, Kotchen, Turk, and Leiserowitz found that many Americans who opposed a carbon tax shifted to conditional support when revenues were directed toward clean energy investment or household dividends [19].
In the EV policy context, revenue recycling can produce benefits through different policy channels. Revenues from an EV fuel tax could support expanded public charging infrastructure, renewable electricity, or other programs associated with CO2 reduction, battery R&D, and vehicle-efficiency technologies that may contribute to improvements in EV driving range, and transportation infrastructure or traffic-management measures that may contribute to shorter commute times [33,34]. Some of these uses of revenue, such as investment in public charging infrastructure, involve a relatively direct link between government expenditure and the benefit experienced by EV users, while other outcomes may arise through longer technological or infrastructural pathways. Accordingly, the attributes used in the present study represent stylized benefit outcomes associated with alternative uses of EV fuel-tax revenue rather than mechanically guaranteed or immediately realizable effects of tax expenditure. Respondents may consequently have evaluated not only the type of benefit represented by each attribute, but also the perceived credibility and attainability of the stated outcome. This distinction should be considered when interpreting differences in the estimated valuations of the revenue-recycling attributes. The choice experiment incorporates these outcomes alongside Tax Salience to examine how respondents trade off the visibility of the tax burden against different private and broader policy benefits associated with the use of tax revenues.
2.4. Consumer Heterogeneity and Tax Preferences
A robust finding in the tax acceptance literature is that consumer preferences are heterogeneous. The same tax policy generates widely varying responses depending on individual characteristics, values, and circumstances. Income is among the most well-documented determinants. Since fuel and energy taxes tend to be regressive and consume a larger share of income for lower-income households, lower-income individuals may be more sensitive to the burden imposed by such taxes, particularly when revenue-recycling mechanisms do not include compensatory transfers [35,36]. Higher-income households may, by contrast, place relatively greater weight on environmental or other non-cost attributes of tax policy. Political ideology and environmental attitudes also play important roles in tax acceptance. Consumers with stronger environmental concern, pro-climate values, or greater confidence in public institutions tend to support environmental taxes more readily, as they view such taxes as appropriate policy tools rather than fiscal impositions [17,37,38]. Trust in government is a particularly critical factor because support for taxation may depend partly on whether consumers believe that revenues will be used effectively and for their stated purposes [39]. Conversely, concerns about the use or allocation of public revenues can weaken support even when the environmental objective of the tax is accepted.
Heterogeneity may not only arise from socioeconomic characteristics, but also from differences in respondents’ policy knowledge, trust, environmental orientation, mobility patterns, and intertemporal outlook. These characteristics may influence both of the attributes that consumers emphasize when evaluating a tax package and the strength of those preferences. For example, consumers who place greater weight on immediate private costs may evaluate an increase in charging cost differently from those who place greater weight on benefits generated using tax revenues. Likewise, preferences for Tax Salience may vary according to the extent to which respondents value visible information about the tax burden. Importantly, such heterogeneity need not be purely between groups. Even among respondents with broadly similar preference patterns, the intensity of preferences for Tax Salience, revenue-use outcomes, and charging cost may vary substantially. These considerations motivate a modeling framework that can identify qualitatively different preference segments while simultaneously allowing continuous variation in attribute valuations within each segment.
2.5. Modelling Heterogeneous Preferences in Discrete Choice Experiments
Discrete choice experiments (DCEs) are widely used to elicit preferences in environmental and tax policy contexts where market data are limited or unavailable [40,41]. Because preferences toward policy attributes may vary substantially across individuals, different choice models have been developed to capture preference heterogeneity. Mixed logit models allow preferences to vary continuously across respondents [42,43], while latent class models identify discrete groups with distinct preference structures [44]. The MM-MNL model combines these two approaches by allowing both discrete preference differences across classes and continuous preference variation within each class [45,46,47,48,49]. This makes it suitable for the present study, where respondents may differ both in the types of EV fuel-tax packages they prefer and in the strength of those preferences.
Prior stated-preference research in environmental and transportation policy has examined carbon-tax revenue recycling [19], mileage-based and road-user taxation [21,22,23], and consumer valuations of EV and vehicle-related attributes [50,51,52,53]. However, limited research has jointly examined Tax Salience and multiple revenue-use outcomes within the same EV fuel-tax choice experiment. The present study addresses this gap by applying the MM-MNL model to estimate both between-segment and within-segment heterogeneity in these preferences. The analysis is further extended through a post-estimation MNL model that examines which observable respondent characteristics are associated with relatively stronger or weaker preferences for Tax Salience.
3. Materials and Methods
3.1. Research Framework
This study consists of two stages of analysis. In the first stage, a mixed-mixed multinomial logit (MM-MNL) model is estimated using the stated-preference choice data. The objective of the first stage is to identify consumer segments that have different preferences toward revenue recycling schemes and to capture the heterogeneity within each segment. In the second stage, a multinomial logit (MNL) model is used to conduct a post-estimation analysis. The objective of the second stage is to take a closer look at how observable respondent characteristics relate to preferences for tax salience.
The first stage aims to achieve two goals. First, it aims to identify the latent consumer segments that have qualitatively different evaluations of revenue recycling schemes using stated-preference choice data. Second, it aims to derive the heterogeneity of attribute valuations within each segment. The MM-MNL model is suitable for this analysis because it nests the mixed logit and the latent class models as special cases. If the within-class covariance shrinks to zero, the MM-MNL model becomes equivalent to a standard LC model. If the class weights concentrate on a single class, it becomes equivalent to a MIXL model with a multivariate-normal mixing distribution. By using the MM-MNL model, this study lets the data determine how much of the preference heterogeneity is discrete across segments and how much is continuous within segments, rather than relying on an a priori modeling assumption. Prior to the MM-MNL estimation, the number of discrete preference classes was first determined using a conventional latent class (LC) model. The selected number of classes was then retained in the MM-MNL model, which additionally allows for continuous preference heterogeneity within each class. Based on the selected model, class-specific coefficients, relative importance shares, characteristics associated with class membership, and marginal willingness to pay (MWTP) are estimated (This sequential approach is consistent with previous random-parameter latent class applications, which build on a fixed-parameter LC structure and subsequently introduce continuous preference heterogeneity within the identified classes. Bujosa et al. [45] used the same two-class structure for their LC and LC-RPL specifications, while Greene and Hensher [54] characterize the random-parameter latent class model as a natural extension of the fixed-parameter LC model).
The second stage focuses on the salience of the per-kWh fuel tax, which is the single attribute of greatest interest to the policy argument of this study. Based on the posterior individual-level salience coefficients recovered from the MM-MNL model, respondents are sorted into different salience preference groups. By examining how preferences for tax salience vary across respondents, this study examines which observable characteristics are associated with relatively stronger or weaker preferences for making the per-kWh tax burden visible at the point of charging. A multinomial logit model is then estimated to relate group membership to observable respondent characteristics, and three nested specifications are reported to examine how the associations change as additional characteristics are introduced. Model (1) includes the posterior individual-level estimates of the remaining preference coefficients. Model (2) adds socio-demographic characteristics, and Model (3) further adds attitudinal and policy-knowledge variables. The two stages of analysis are complementary. The first stage establishes the overall structure of respondent preferences over the components of a revenue recycling package. The second stage focuses on preferences for Tax Salience. Together, the two stages characterize the broader structure of preferences across respondents and the observable characteristics associated with variation in preferences for Tax Salience.
Two features of the elicitation define what the estimates identify. First, every alternative within a choice task is an EV fuel tax scenario and the charging cost attribute takes only positive increases. The model therefore recovers preferences among alternative tax designs conditional on a tax being introduced, and the estimates should not be read as evidence on whether respondents would accept an EV fuel tax rather than no tax. Second, the Tax Salience attribute varies whether individual tax items appear on the charging receipt. The associated coefficient identifies the value respondents place on disclosure as a described feature of a tax package. It does not measure the causal effect of making a tax salient on behavior or on acceptance, which would require variation in actual tax visibility rather than in a stated policy attribute. Interpretation throughout Section 4 and Section 5 is bounded accordingly.
Generative artificial intelligence was not used in the study design, data collection, data analysis, or interpretation of the results. It was used only after the analysis was complete, to format the manuscript to the journal template and to check grammar and language. All content was reviewed and verified by the authors, who take full responsibility for the work.
3.2. Data Description
The data used in this study were collected through an online stated-preference survey administered by a professional survey company, Gallup Korea. The target population consisted of South Korean adults aged 20 to 59. Age was the only eligibility criterion applied at recruitment; driver’s license holding, vehicle ownership, and vehicle fuel type were recorded as respondent characteristics rather than used as screening criteria. The recruited sample was therefore intended to cover South Korean adults aged 20 to 59 rather than current drivers or vehicle owners alone. To apply the proportionate stratified sampling method, we first divided the total potential respondents into different exclusive subpopulations, where each respondent was randomly selected. The total population first excluded anyone outside of the 20–59 age range, which denoted the economically active population, then they were categorized into subpopulations based on gender, age, income, and region. Respondents from each subpopulation were then chosen according to the demographics of the South Korean population [55]. A total of 809 respondents completed the survey in April 2017, and all 809 respondents constitute the analytical sample. No respondents were excluded from an initially larger completed sample. Compared with the national population, the analytical sample was broadly comparable by gender but showed some differences in age and regional composition [56]. In particular, respondents in their fifties were under-represented, accounting for 18.7% of the analytical sample compared with 27.1% of the national population aged 20 to 59, while the capital area was somewhat over-represented (57.5% versus 49.6%). These differences should be considered when generalizing the estimates. Table 1 compares the demographic distribution of the analytical sample with the national population by gender, age, and region. Table 2 summarizes respondents’ socioeconomic, residential, and mobility-related characteristics.
Table 1.
Sample Distribution by Gender, Age, and Region.
Table 2.
Socioeconomic, Residential, and Mobility Characteristics of Respondents.
Within the analytical sample, 748 respondents (92.5%) held a driver’s license and 61 (7.5%) did not. Among the holders, 672 reported that they currently drive, while 76 reported that they do not currently drive. Of the 735 respondents whose household owned a vehicle, only 2 reported an electric vehicle and 23 a hybrid as the household’s main vehicle, which is consistent with the negligible EV penetration in Korea at the time of the survey. The estimates reported below therefore describe how South Korean adults aged 20 to 59 in the analytical sample evaluated the design of a prospective EV fuel tax, rather than how experienced EV drivers evaluate a tax they already pay. Since an EV fuel tax would also apply to future adopters beyond current EV owners, preferences elicited before ownership is established can provide ex ante evidence for policy design, but they should not be interpreted as the preferences of the current EV-driving population.
Table 3 presents the descriptive statistics for respondents’ policy knowledge, policy orientation, and attitudinal variables. Policy knowledge was assessed through questions regarding the tax system, energy policy, and EV policy. To capture general attitudes and perceptions, variables such as trust in government, interest in environmental issues, a careful consumer orientation, and the perceived importance of the future were each evaluated on a five-point Likert scale ranging from “strongly disagree” to “strongly agree”.
Table 3.
Descriptive statistics of perception and attitudinal variables.
The DCE was designed to elicit consumer preferences toward an EV fuel tax under alternative revenue recycling schemes. The six attributes were selected to represent the tax burden and Tax Salience of the proposed EV fuel tax, as well as different potential outcomes associated with the use of tax revenues. The first attribute is the Increase in Charging Cost, which is expressed in KRW per kWh and serves as the monetary attribute for the MWTP calculations in Section 4.1 [50,51,52]. The second attribute is Tax Salience, which is a binary attribute that indicates whether individual tax items and amounts are displayed on the charging receipt [20,53]. The third attribute is the Station Availability, which is expressed as a percentage change in the density of charging stations within the respondent’s region [57,58]. The fourth attribute is the CO2 Reduction, which is expressed in CO2 Emissions in grams per kilometer of vehicle use [50,59,60]. The fifth attribute is the EV Range Extension, which is expressed as a percentage change in the range of the representative EV [50,61]. The sixth attribute is the Commute Time Savings, which is expressed as a percentage change in the average commute [62,63,64]. As shown in Table 4, the attributes and their levels were specified with reference to the prevailing Korean EV market conditions and the relevant policy context at the time of the survey (The upper levels of EV Range Extension and Commute Time Savings were designed to represent a broad range of hypothetical policy outcomes for preference elicitation and should not be interpreted as engineering or fiscal forecasts of the benefits achievable from a specific amount of EV fuel-tax revenue).
Table 4.
EV Fuel Tax Policy Attributes and Levels.
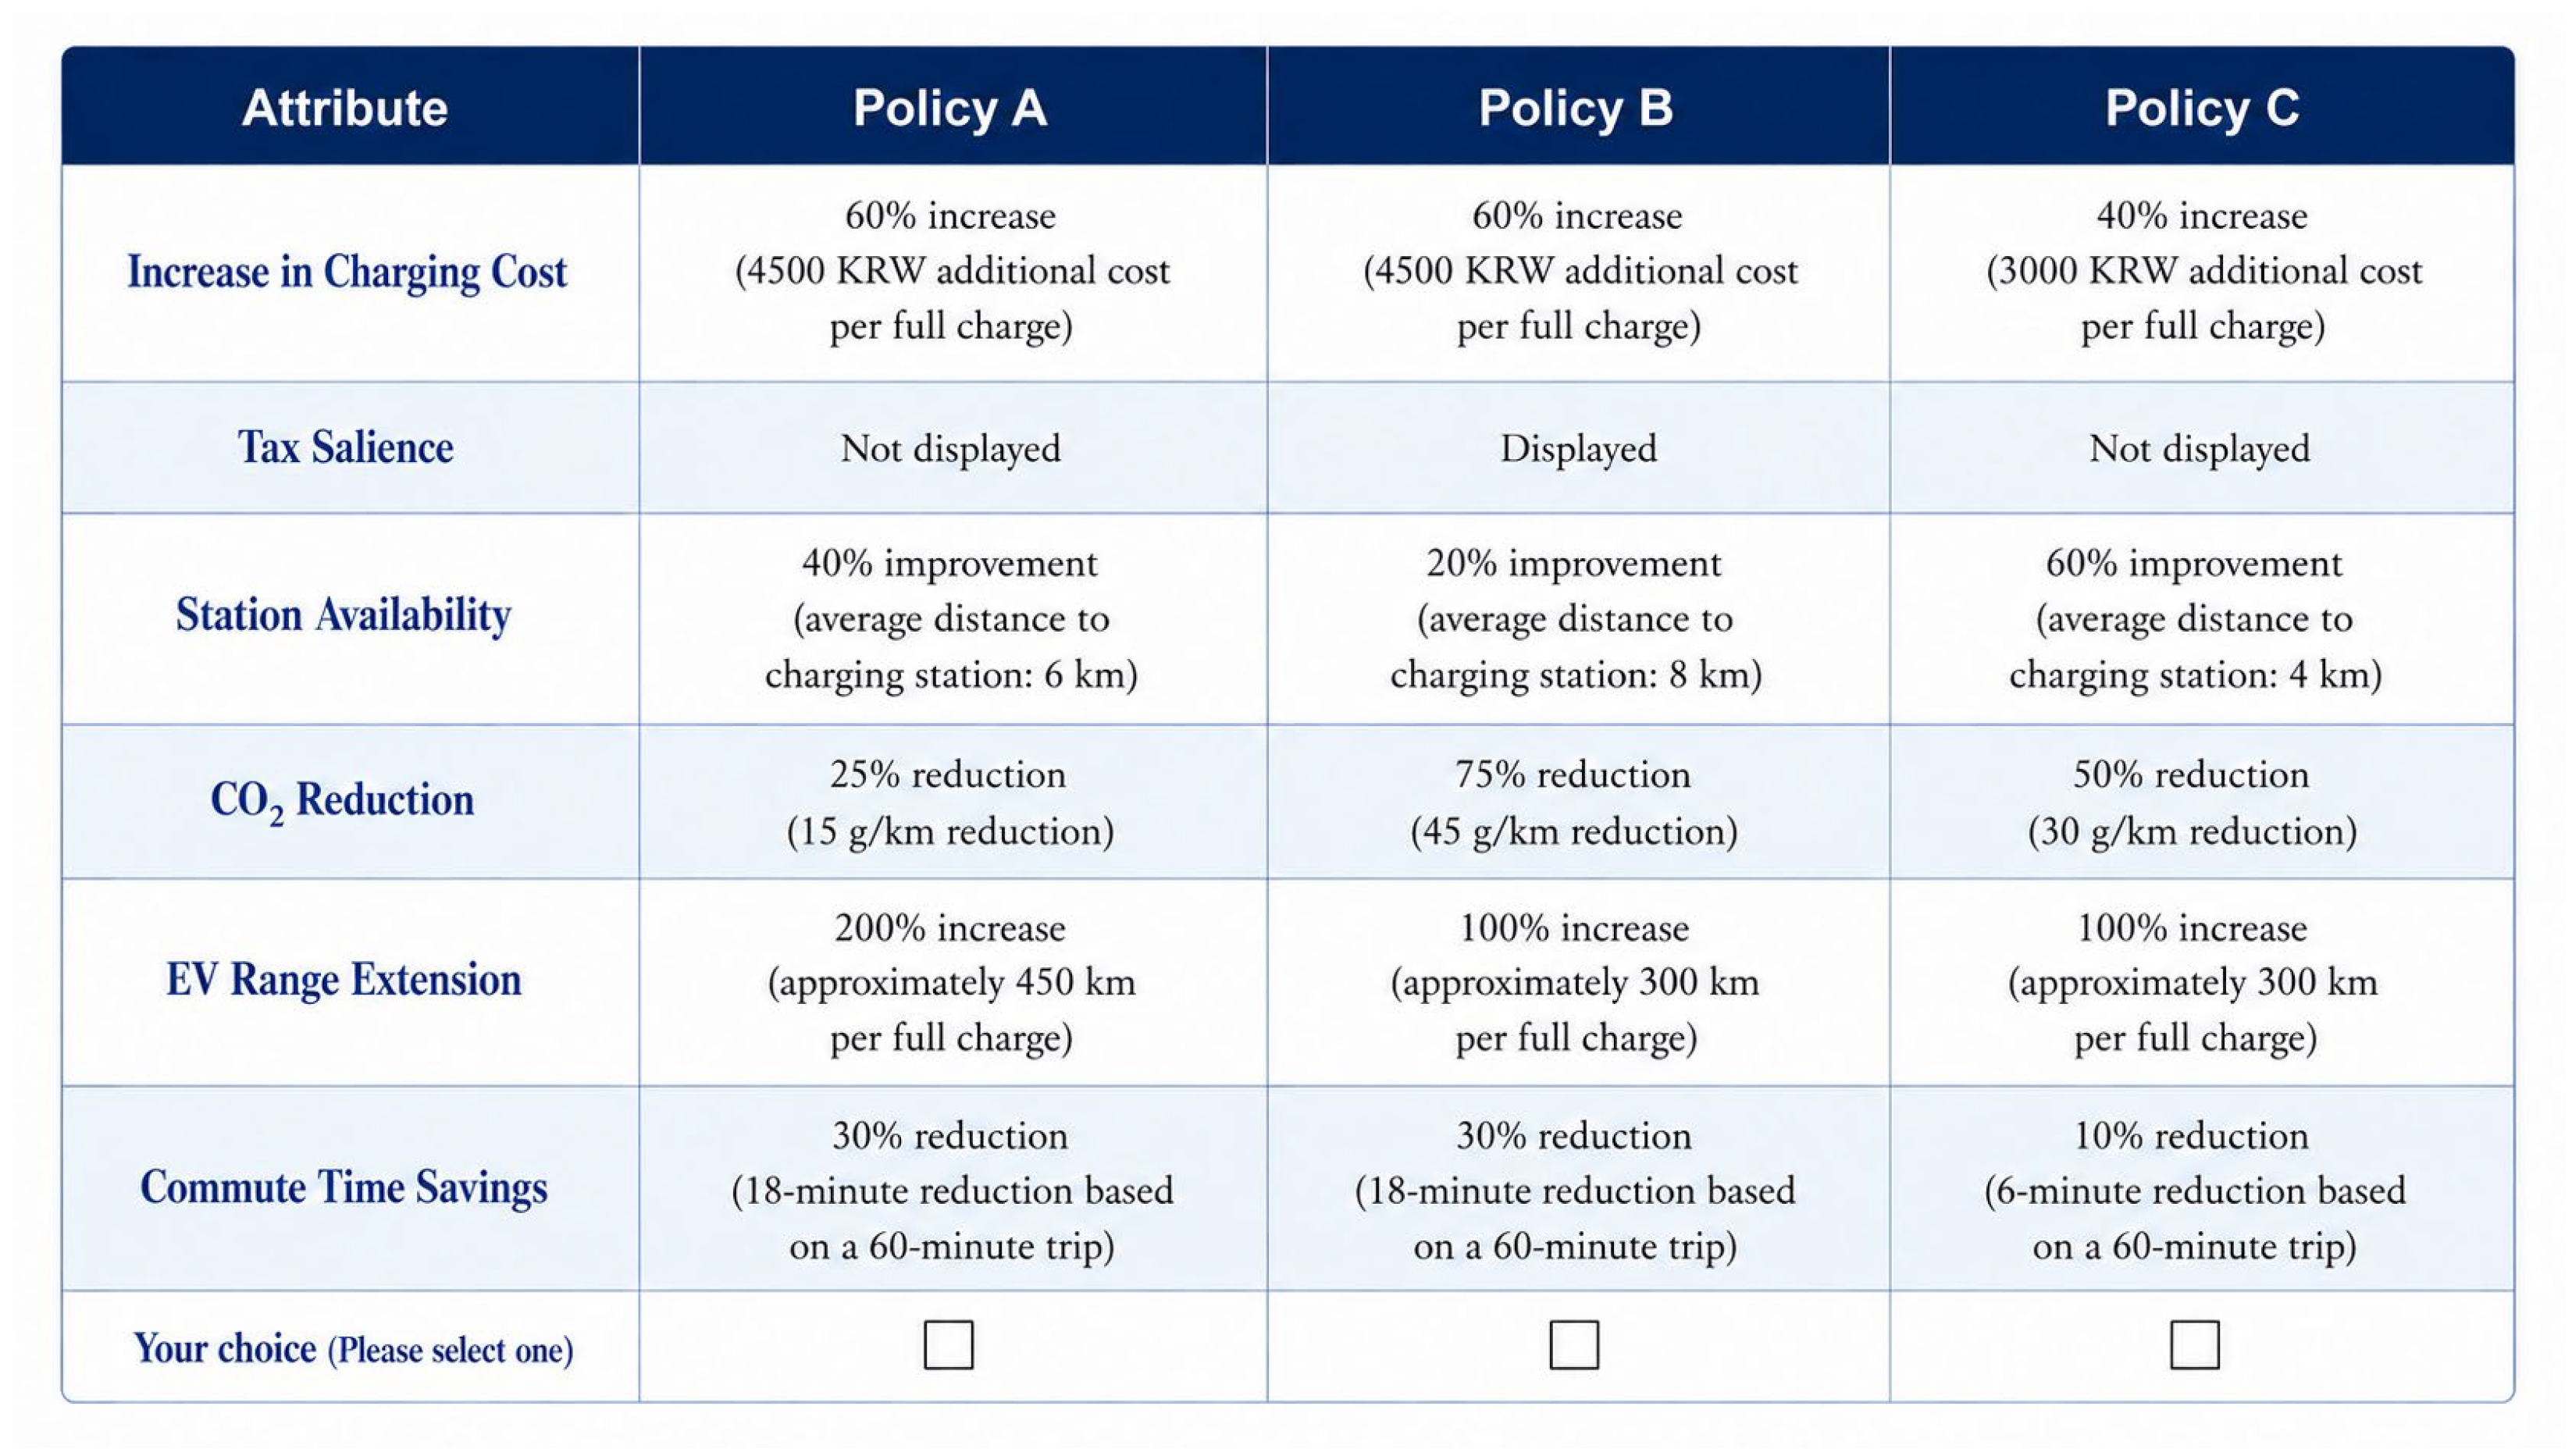
Among the 486 possible policy profiles, 18 profiles were derived using an orthogonal fractional factorial design generated using the Orthoplan procedure in SPSS (version 18). No parameter priors or blocking were used in constructing the design, and the order of the six choice sets was fixed across respondents. No separate pilot test was conducted prior to the main survey. The 18 profiles were then arranged into six choice sets, with three hypothetical policy alternatives in each set. Each of the 809 respondents completed all six choice sets, resulting in 4854 choice situations for estimation. An example of the choice task presented to respondents is provided in Figure A1 in Appendix A. Respondents were asked to rank the three alternatives in order of preference, and the first-ranked alternative was treated as the observed choice in the analysis. For the present study, the no-choice option was not considered in the choice model, as the analysis focused on preferences among alternative EV fuel-tax designs rather than on whether the tax should be introduced.
3.3. Model Specification
In this section, the MM-MNL model used in the first stage and the standard MNL model used in the second stage are explained.
3.3.1. Stage 1 Model: Mixed-Mixed Multinomial Logit Model
The MM-MNL model extends the standard MIXL model by specifying the mixing distribution of the random coefficients as a mixture of multivariate normals rather than a single multivariate normal. With this specification, the MM-MNL model captures within-class continuous heterogeneity and between-class discrete heterogeneity simultaneously, and it nests both the MIXL and LC models as special cases. The utility function of the MM-MNL model is denoted by Equation (1). Conditional on the membership of class s, the utility that respondent n obtains from choosing alternative j on choice occasion t is expressed as follows:
denotes the vector of attributes of alternative , is a vector of class-specific taste parameters, and is an error term that is assumed to follow an i.i.d. Type-I extreme value distribution. The within-class taste vector follows a multivariate normal distribution with mean and a diagonal covariance matrix . The mixing weight denotes the probability that respondent belongs to class , satisfying and for all . The indices are defined as for classes, for respondents, for alternatives, and for choice occasions. The class weight can also be modeled as a logit function of respondent characteristics so that observable variables can influence segment assignment.
Two limiting cases clarify the role of the MM-MNL specification. If converges to zero for all classes except one, Equation (1) reduces to a MIXL model with a multivariate-normal mixing distribution. If shrinks to zero for every class , Equation (1) reduces to a standard LC model with homogeneous within-class preferences.
The unconditional probability that respondent makes a particular sequence of observed choices is denoted by Equation (2):
is the density of the multivariate normal distribution . The parameters are estimated by maximizing the simulated log-likelihood, where the inner integral is approximated using Halton draws. All LC and MM-MNL models were estimated in R (version 4.3.2) using the ‘gmnl’ package. In the final MM-MNL specification, all six attribute coefficients were specified as normally distributed random parameters with a diagonal within-class covariance matrix, with off-diagonal covariances fixed at zero (The diagonal covariance restriction was adopted for model parsimony and numerical stability. This represents a modelling simplification because within-class correlations among random coefficients are not estimated). The simulated likelihood was approximated using 500 Halton draws with a random seed of 123. The default BFGS optimization routine was used with a relative convergence tolerance of approximately .
After estimation, the posterior class-membership probabilities and the posterior individual-level coefficient vectors are recovered using Bayes’ rule [67]. The posterior salience coefficients are used to define the salience preference groups for the second-stage analysis. MWTP for attribute is calculated as , where is the Charging Cost coefficient. The relative importance (RI) of each attribute within a class was calculated based on its part-worth, defined as the absolute value of the class-specific coefficient multiplied by the range between its maximum and minimum attribute levels. The RI of attribute was then calculated as its part-worth relative to the sum of the part-worths of all attributes:
3.3.2. Stage 2 Model: Multinomial Logit Model
In the second stage, this study uses a standard MNL model to relate the salience preference group membership to observable respondent characteristics. As explained in Section 3.1, respondents are sorted into three different mutually exclusive groups based on their posterior salience coefficients, with the moderately positive group serving as the reference category. Under the standard random utility framework with i.i.d. Type-I extreme value errors, the probability that respondent n belongs to group m is given by Equation (4) [41]:
where is a vector of respondent characteristics and is the corresponding coefficient vector for group m. The coefficient vector of the reference group is normalized to zero for identification, and the model is estimated by the maximum likelihood method. Three nested specifications are estimated and reported in Section 4.2.
4. Results and Discussion
4.1. Estimation Results of Mixed-Mixed Multinomial Logit Model
Prior to estimating the MM-MNL model, the number of discrete preference classes was determined using conventional LC specifications. Table 5 reports the information criteria for specifications with one to six classes. In the baseline class enumeration, BIC and CAIC were minimized at the two-class specification. To assess the sensitivity of class enumeration to initialization, the two- to six-class specifications were additionally re-estimated using 30 alternative sets of starting values. As reported in Appendix B, the two-class specification had the lowest mean BIC and CAIC and was also the most frequently selected specification according to both BIC and CAIC. Considering these results together with model parsimony and interpretability, the two-class structure was retained for the subsequent MM-MNL estimation.
Table 5.
Information criteria by number of classes.
Table 6 displays the class-specific coefficient estimates and the relative importance (RI) of each attribute for the two-class MM-MNL model. The result shows a substantial qualitative difference between the two classes in their evaluation of the attributes included in the EV fuel-tax packages.
Table 6.
Estimation results for the mixed-mixed multinomial logit model.
Based on Table 6, the two classes differ markedly in their evaluations of the attributes included in the EV fuel-tax packages. Class 2 accounts for most respondents (73.67%) and is characterized by positive and statistically significant coefficients for all non-cost attributes, including Tax Salience, Station Availability, CO2 Reduction, EV Range Extension, and Commute Time Savings. We therefore refer to Class 2 as the broadly responsive segment. The positive coefficients indicate that, conditional on choosing among the hypothetical tax packages, respondents in this segment place positive value on each of these attributes. The Charging Cost coefficient is negative as expected (−0.565, p < 0.01), indicating that higher charging costs reduce utility. Among the non-cost attributes, EV Range Extension has the largest relative importance share (27.10%), followed by Tax Salience (14.07%), Commute Time Savings (12.18%), Station Availability (11.15%), and CO2 Reduction (7.41%).
Class 1 accounts for 26.33% of respondents and displays a more concentrated preference structure. The Charging Cost coefficient is large and negative and has the highest relative importance share (42.43%), while EV Range Extension (23.01%) and Tax Salience (18.74%) are the two most important non-cost attributes. Station Availability, CO2 Reduction, and Commute Time Savings have negative and statistically significant coefficients. We therefore refer to Class 1 as the cost- and range-focused segment. Within the stated choice design, this segment places positive value on Tax Salience and EV Range Extension while responding negatively to the other revenue-use outcomes. These coefficients should be interpreted as preferences for the specific benefit outcomes presented as potential uses of EV fuel-tax revenues rather than as preferences for abstract revenue-recycling categories. The estimates do not establish why respondents evaluate the broader revenue-use outcomes negatively; factors such as the type, credibility, or perceived attainability of the stated outcomes cannot be separately identified from the present experiment. The relatively large hypothetical levels used for some outcomes, particularly EV Range Extension and Commute Time Savings, may also have affected how credible or attainable respondents perceived these outcomes to be. This possibility should be considered when interpreting the negative coefficients observed for some revenue-use outcomes in Class 1.
Table 7 reports the observable characteristics associated with class membership relative to Class 1. Respondents are more likely to belong to the broadly responsive Class 2 if they are female, belong to the Metropolitan Cities category, report higher knowledge of the tax system, greater trust in government, stronger careful-consumer orientation, and greater importance of the future. The education coefficient is negative and marginally significant (−0.167, p < 0.10), indicating that respondents with higher education are somewhat more likely to belong to the cost- and range-focused Class 1. Age, income, driving status, knowledge of energy policy, environmental interest, and knowledge of EV policy are not statistically significant predictors of class membership in this specification. These results identify associations between observable respondent characteristics and class membership; they should not be interpreted as causal determinants of the underlying preferences.
Table 7.
Class membership coefficient estimates.
Taken together, Table 6 and Table 7 show two related but distinct patterns. Class 1 assigns negative utility to Station Availability, CO2 Reduction, and Commute Time Savings within the stated EV fuel-tax packages, while greater trust in government is associated with a higher probability of belonging to Class 2. These findings should not, however, be interpreted as evidence of a single underlying mechanism. The experiment did not directly measure respondents’ perceived credibility of each revenue-use outcome or experimentally vary confidence in the government’s delivery. We therefore cannot distinguish whether the negative Class 1 coefficients reflect lower intrinsic valuation of the stated outcomes, lower confidence that the outcomes would be delivered as described, or other unobserved considerations. In particular, the estimates should not be interpreted as evidence that Class 1 respondents are generally opposed to public-good spending.
Figure 1 displays the posterior individual-level distributions of the six attribute coefficients estimated from the MM-MNL model and illustrates how the two latent segments identified in Table 6 are reflected in the individual-level preference distributions. The first pattern is visible in the distributions for Station Availability (Figure 1b), Commute Time Savings (Figure 1e), and EV Range Extension (Figure 1d), which show relatively distinct modes associated with the two classes. For Station Availability and Commute Time Savings, the mode associated with Class 2 is located at a small positive value, whereas the mode associated with Class 1 is in the negative range. The two classes therefore differ not only in the magnitude but also in the direction of their preferences for these attributes. For EV Range Extension, both modes are positive, but the Class 1 distribution is centered at substantially larger positive values than the Class 2 distribution. These patterns illustrate the between-class differences in preference structure reported in Table 6. A second pattern is visible in the distributions for Tax Salience (Figure 1a), CO2 Reduction (Figure 1c), and Charging Cost (Figure 1f), which show substantial continuous variation rather than two clearly separated modes. For Tax Salience, the distribution is concentrated on the positive side but also extends into the negative range, while the long right tail indicates that some respondents have substantially stronger positive preferences. The CO2 Reduction distribution similarly spans both positive and negative values, indicating considerable variation in respondents’ valuations of this attribute. The Charging Cost distribution is concentrated in the negative range but also shows substantial dispersion. Together, these distributions illustrate that respondents within the same broad preference structure may still differ considerably in the intensity of their attribute valuations, consistent with the within-class heterogeneity captured by the MM-MNL model.
Figure 1.
Distribution of individual beta. (a) Tax Salience. (b) Station Availability. (c) CO2 Reduction. (d) EV Range Extension. (e) Commute Time Savings. (f) Charging Cost. Note: The red lines indicate kernel density estimates.
Table 8 presents the median MWTP estimates and their 90% bootstrap confidence intervals for the two-class MM-MNL model. For Tax Salience, Class 1 shows a higher median MWTP of 59.669 KRW/kWh than Class 2, at 32.988 KRW/kWh. Although both classes show positive MWTP for Tax Salience, Class 1 places relatively greater value on Tax Salience, whereas Class 2 shows positive valuations across a broader range of revenue-recycling attributes. Because MWTP estimates may be sensitive to the sign and near-zero values of the Charging Cost coefficient, additional robustness analyses were conducted by restricting the denominator to negative cost coefficients and by trimming coefficients closest to zero. As reported in Appendix C, the magnitudes of the Class 2 MWTP estimates increase under these restrictions, while the signs and overall qualitative preference patterns remain unchanged.
Table 8.
MWTP results for the mixed-mixed multinomial logit model.
4.2. Post-Estimation Analysis of Heterogeneity in Tax Salience Preferences
By using the posterior individual-level Tax Salience coefficients from the MM-MNL model, this study sorts respondents into three Tax Salience preference groups for the post-estimation analysis. Group 1 consists of respondents with negative posterior salience coefficients. Group 2 consists of respondents in the top quintile of the positive distribution. To assess sensitivity to this classification rule, Model (3) was re-estimated using alternative definitions of the high-salience group, corresponding to the top 10%, 15%, 25%, and 30% of the positive posterior Tax Salience coefficient distribution, while holding the definition of the negative-salience group constant. Several associations vary across classification thresholds, whereas the positive association with knowledge of the tax system remains relatively consistent across most specifications. The detailed profile of the high-salience group should therefore be interpreted with caution. The results are reported in Appendix D. The remaining respondents form the reference group. To examine how the associations change as additional respondent characteristics are introduced, three nested specifications of the MNL model are estimated. Model (1) controls only for the individual-level posterior estimates of the remaining preference coefficients. Model (2) adds demographic characteristics. Model (3) further adds attitudinal and policy-knowledge variables. The posterior preference coefficients are included to control for individual heterogeneity in preferences for the other policy attributes. Because these coefficients are estimated quantities from the first-stage MM-MNL model and first-stage estimation uncertainty is not fully propagated into the second-stage standard errors, the significance results should be interpreted as suggestive conditional associations rather than definitive inference. The estimation results are reported in Table 9.
Table 9.
Multinomial logit model estimates of group membership in the salience preference distribution.
Table 9 displays the MNL estimates of group membership in the salience preference distribution. The discussion focuses on the most complete specification, Model (3), which includes the posterior preference coefficients together with socio-demographic, attitudinal, and policy-knowledge variables. For Group 2, the high-salience group, Model (3) shows that respondents are more likely to belong to this group if they belong to the metropolitan cities category, have higher knowledge of the tax system, report higher trust in government, and place greater importance on the future. At the same time, the coefficient for self-reported knowledge of energy policy is negative and significant, and the income coefficient is negative and marginally significant. These results describe observable characteristics associated with relatively stronger preferences for Tax Salience, but they do not establish the behavioral mechanisms underlying those preferences. In particular, the positive association with tax-system knowledge and the negative association with energy-policy knowledge should not be interpreted as evidence that limited policy knowledge causes respondents to seek additional tax information. Likewise, the marginal association with income does not establish that lower-income respondents prefer salience because of greater charging-cost sensitivity. The estimated relationships are therefore interpreted as associations rather than causal explanations of salience preferences. For Group 1, which is the negative-salience group, the result shows that respondents are more likely to belong to this group if they have lower education levels (−0.885, p < 0.05) and do not currently drive (−0.991, p < 0.05). These estimates indicate that lower education and not currently driving are associated with a greater likelihood of having a negative Tax Salience coefficient relative to the reference group. The analysis does not, however, identify why these respondents value disclosure negatively. Explanations such as lower familiarity with tax information or perceiving disclosure as an unwanted reminder of additional cost remain possible interpretations rather than mechanisms directly measured by the study.
Taken together, the post-estimation results indicate that preferences for Tax Salience are heterogeneous across respondents. However, the present experiment varies only whether individual tax items and amounts are displayed on the charging receipt; it does not vary the communication channel, message source, educational format, or degree of information detail. The results therefore identify heterogeneity in the valuation of Tax Salience but do not establish the effectiveness of alternative disclosure or communication approaches. Any differentiated disclosure format or communication strategy suggested by these patterns should be treated as a testable hypothesis for future research rather than as a policy recommendation. Future studies could examine whether respondents with stronger or negative Tax Salience preferences respond differently to alternative presentation formats or levels of information detail.
5. Conclusions
The MM-MNL analysis identifies two distinct preference segments in the evaluation of prospective EV fuel-tax packages. Class 2, representing 73.67% of respondents, shows positive preferences for all non-cost attributes and is therefore described as the broadly responsive segment. Class 1, representing 26.33%, places greater importance on Charging Cost and EV Range Extension, while also showing a positive preference for Tax Salience, and is described as the cost- and range-focused segment. Median MWTP for Tax Salience is positive in both classes, indicating that visible disclosure of individual tax items and amounts is valued across both preference structures. Because all choice alternatives involve a positive EV fuel tax, these results should be interpreted as conditional preferences among alternative tax designs rather than as evidence of tax acceptance relative to no tax.
The post-estimation analysis further shows that stronger preferences for Tax Salience are associated with greater knowledge of the tax system, while lower education and not currently driving are associated with negative Tax Salience preferences. Some characteristics of the high-salience group are sensitive to the classification threshold and should therefore be interpreted with caution. These relationships describe observable associations rather than the behavioral mechanisms underlying them. The observed differences between the two segments provide hypotheses for future policy experiments rather than direct communication prescriptions. For the cost- and range-focused segment, future studies could test whether Tax Salience is evaluated differently when disclosure is paired with relatively direct EV-related outcomes, such as EV Range Extension. For the broadly responsive segment, future studies could examine whether Tax Salience is evaluated differently when combined with a wider range of infrastructure, environmental, and transportation outcomes. These propositions should be evaluated experimentally before any differentiated disclosure or communication strategy is considered as a policy recommendation.
Several limitations should be considered. The data were collected in April 2017 during an early stage of EV diffusion in Korea and before the introduction of a dedicated EV fuel tax. The estimates therefore provide ex ante, early-transition evidence rather than preferences of current EV users. As with other stated-preference studies involving hypothetical policies, the estimates may also be subject to hypothetical bias. No separate pilot test of the DCE was conducted before the main survey. In addition, some attribute levels, particularly the upper levels of EV Range Extension and Commute Time Savings, represented relatively large, stylized outcomes. These design features may have affected respondents’ perceptions of the credibility or attainability of the stated outcomes and should therefore be considered when interpreting the corresponding preference estimates. Future studies could distinguish these explanations more directly by measuring respondents’ perceived credibility of the stated revenue-use outcomes or experimentally varying the credibility of their delivery. In addition, the analytical sample consisted of 809 South Korean adults aged 20–59 and was not restricted to licensed drivers or EV owners; only two vehicle-owning households reported an EV as their main vehicle. Some differences in age and regional composition also limit population-level generalization. In particular, the over-representation of the capital area in the analytical sample may have affected the estimated class proportions and could potentially contribute to a higher estimated share of Class 2 than in the target population. However, the present class-membership specification does not separately identify a capital-area effect, so the direction and magnitude of this potential compositional influence cannot be determined directly.
Future research using more recent samples with greater EV ownership and direct charging experience should examine whether the two-class preference structure and the valuation of Tax Salience remain stable as electric mobility becomes more widespread. A further limitation is that the second-stage analysis is conditional on the individual-level posterior coefficients estimated from the first-stage MM-MNL model and therefore does not fully propagate first-stage estimation uncertainty. The post-estimation results should accordingly be interpreted as conditional associations. Within these limitations, the study provides an early benchmark for understanding heterogeneity in preferences for Tax Salience and alternative revenue-use outcomes and demonstrates the value of jointly considering between-segment and within-segment preference variation in EV tax design.
Author Contributions
Conceptualization, S.Y.P. and H.M.; methodology, S.Y.P. and H.M.; validation, Y.B. and N.C.; formal analysis, S.Y.P. and H.M.; investigation, S.Y.P. and H.M.; data curation, S.Y.P. and H.M.; writing—original draft preparation, S.Y.P.; writing—review and editing, S.Y.P., Y.B., N.C. and H.M.; supervision, Y.B. and N.C. All authors have read and agreed to the published version of the manuscript.
Funding
This work was supported by the National Research Foundation of Korea (NRF) with a grant funded by the South Korean government (MSIT) (No. RS-2023-00242528; RS-2025-16071586). This work was supported by the Global Joint Research Program funded by Pukyong National University (202506780001).
Institutional Review Board Statement
Ethical review and approval were waived for this study because the study met the criteria for exemption from Institutional Review Board (IRB) review under Article 9-2 of the Standard Operating Procedures of the IRB at Pukyong National University. Although the study involved human participants, it was conducted anonymously, and no personally identifiable information was collected or recorded from the participants.
Informed Consent Statement
Informed consent was obtained from all subjects involved in the study.
Data Availability Statement
Available from the authors upon request. The data are not publicly available because participants did not provide consent for public sharing of the study data.
Acknowledgments
During the preparation of this manuscript, the authors used generative artificial intelligence to format the manuscript according to the journal template and to check grammar and language. The authors have reviewed and edited the output and take full responsibility for the content of this publication.
Conflicts of Interest
The authors declare no conflicts of interest.
Abbreviations
The following abbreviations are used in this manuscript:
| CO2 | Carbon dioxide |
| DCE | Discrete choice experiment |
| EV | Electric vehicle |
| ICE | Internal combustion engine |
| LC | Latent class |
| MIXL | Mixed logit |
| MM-MNL | Mixed-mixed multinomial logit |
| MNL | Multinomial logit |
| MWTP | Marginal willingness to pay |
| OECD | Organisation for Economic Co-operation and Development |
| RI | Relative importance |
Appendix A
Figure A1 shows an example of the discrete choice task presented to respondents, in which three hypothetical EV fuel-tax policies were compared based on six attributes.
Figure A1.
Example of the Discrete Choice Task.
Appendix B
To assess the sensitivity of class enumeration to initial values, each latent class specification was re-estimated using 30 alternative sets of starting values. For each specification, the estimates obtained from the baseline model were used as reference starting values, and alternative starting values were generated by adding normally distributed random perturbations with mean zero and a standard deviation of 0.2 to each parameter. Thirty reproducible perturbation sets were generated using different random seeds. Table A1 summarizes the resulting information criteria and the frequency with which each number of classes was selected. Although the results showed some sensitivity to initialization, the two-class specification had the lowest mean BIC and CAIC and was also the most frequently selected specification, according to both criteria. Accordingly, the multi-start exercise should be interpreted as a robustness assessment of the class-enumeration results rather than as a guarantee that the global maximum was identified for every specification.
Table A1.
Robustness of Latent Class Enumeration across Alternative Starting Values.
Appendix C
To assess the robustness of the MWTP estimates to the sign and magnitude of the charging-cost coefficient, additional sensitivity analyses were conducted using the posterior individual-level coefficients. First, MWTP was recalculated using only respondents with negative posterior charging-cost coefficients, thereby excluding observations with economically inconsistent positive cost coefficients. Second, to examine whether coefficients close to zero disproportionately affect the MWTP ratios, additional specifications excluded 5% and 10% of respondents with the smallest absolute charging-cost coefficients among those with negative cost coefficients. Table A2 compares the median MWTP estimates across these specifications.
Table A2.
Sensitivity of Median MWTP Estimates to the Sign and Magnitude of the Charging-Cost Coefficient.
The results indicate that the Class 1 MWTP estimates are highly stable across the alternative specifications. All respondents assigned to Class 1 have negative posterior charging-cost coefficients, and excluding coefficients closest to zero produces only minor changes in the median MWTP estimates. For Class 2, restricting the analysis to respondents with negative charging-cost coefficients increases the magnitude of the MWTP estimates, indicating some sensitivity to the sign of the cost coefficient. However, further trimming of near-zero coefficients does not alter the signs or the overall qualitative pattern of the estimates. These results suggest that, although the magnitudes of the Class 2 MWTP estimates are sensitive to the treatment of the charging-cost coefficient, the substantive preference patterns are generally robust.
Appendix D
Appendix D presents a sensitivity analysis of the second-stage MNL results using alternative definitions of the high-salience group. In addition to the baseline definition based on the top 20% of the positive posterior Tax Salience coefficient distribution, the model was re-estimated using thresholds of 10%, 15%, 25%, and 30%, while the definition of the negative-salience group was held constant.
Table A3.
Sensitivity of the Second-Stage MNL Results to Alternative High-Salience Thresholds.
The results indicate that the characteristics associated with the negative-salience group are highly stable across alternative thresholds, particularly the negative associations with education and current driving status. For the high-salience group, higher knowledge of the tax system shows a relatively consistent positive association across most specifications, whereas several other characteristics, including membership in the metropolitan cities category and trust in government, are more sensitive to the choice of threshold. Overall, the sensitivity analysis suggests that some of the main second-stage patterns are robust to alternative classification rules, while others should be interpreted with greater caution.
References
- Dua, R. China’s Vehicle Trade-In Subsidy: Impact, Cost-Effectiveness, and Barriers to Electric Vehicle Purchase. Energy Sustain. Dev. 2026, 93, 102021. [Google Scholar] [CrossRef] [Scilit]
- Ministry of Transport. Road User Charges System. Available online: https://www.transport.govt.nz/area-of-interest/revenue/road-user-charges-system (accessed on 30 August 2026).
- European Alternative Fuels Observatory. Iceland: Incentives and Legislation. Available online: https://alternative-fuels-observatory.ec.europa.eu/transport-mode/road/iceland/incentives-legislations (accessed on 30 August 2026).
- Tax Foundation. Electric Vehicles: EV Taxes by State. Available online: https://taxfoundation.org/data/all/state/electric-vehicle-ev-taxes/ (accessed on 30 August 2026).
- Noll, B.; Schmidt, T.S.; Egli, F. Managing trade-offs between electric vehicle taxation and adoption. Cell Rep. Sustain. 2024, 1, 100130. [Google Scholar] [CrossRef] [Scilit]
- Santos, G.; Cornford, C.A. Road transport electrification and motoring taxation in the UK. Energy Rep. 2024, 11, 4326–4337. [Google Scholar] [CrossRef] [Scilit]
- Dua, R.; Almutairi, S.; Bansal, P. Emerging Energy Economics and Policy Research Priorities for Enabling the Electric Vehicle Sector. Energy Rep. 2024, 12, 1836–1847. [Google Scholar] [CrossRef] [Scilit]
- Parry, I.W.H.; Bento, A. Revenue recycling and the welfare effects of road pricing. Scand. J. Econ. 2001, 103, 645–671. [Google Scholar] [CrossRef] [Scilit]
- Government of the Republic of Korea. Transportation, Energy and Environment Tax Act. National Law Information Center. 2026. Available online: https://www.law.go.kr/LSW/lsInfoP.do?lsiSeq=276071&viewCls=lsRvsDocInfoR (accessed on 20 June 2026). (In Korean)
- OECD. Taxing Energy Use 2024: Tax Rates on Energy Use; OECD Publishing: Paris, France, 2024. [Google Scholar] [CrossRef]
- Ministry of Economy and Finance. Flexible Tax Rate Operation Plan for the First Half of 2026; Government of the Republic of Korea: Sejong, Republic of Korea, 2025. Available online: https://mofe.go.kr/nw/nes/detailNesDtaView.do?menuNo=4010100&searchBbsId1=MOSFBBS_000000000028&searchNttId1=MOSF_000000000076275 (accessed on 6 September 2026). (In Korean)
- Ministry of Land, Infrastructure and Transport. 2024 Vehicle Registration Status; Government of the Republic of Korea: Sejong, Republic of Korea, 2025. Available online: https://stat.molit.go.kr/portal/board/statPublicDetail.do?hNum=196 (accessed on 6 September 2026). (In Korean)
- Kim, H. Directions for Improving Eco-Friendly Vehicle Adoption Policies; KDI Focus 2024, 135; Korea Development Institute: Sejong, Republic of Korea, 2024. Available online: https://www.kdi.re.kr/research/focusView?pub_no=18382 (accessed on 6 September 2026). (In Korean)
- Rajagopal, D. Implications of the energy transition for government revenues, energy imports and employment: The case of electric vehicles in India. Energy Policy 2023, 175, 113466. [Google Scholar] [CrossRef] [Scilit]
- Bonilla, D.; Soberon, H.A.; Galarza, O.U. Electric vehicle deployment and fossil fuel tax revenue in Mexico to 2050. Energy Policy 2022, 171, 113276. [Google Scholar] [CrossRef] [Scilit]
- Baranzini, A.; Carattini, S. Effectiveness, earmarking and labeling: Testing the acceptability of carbon taxes with survey data. Environ. Econ. Policy Stud. 2017, 19, 197–227. [Google Scholar] [CrossRef] [Scilit]
- Maestre-Andrés, S.; Drews, S.; van den Bergh, J. Perceived fairness and public acceptability of carbon pricing: A review of the literature. Clim. Policy 2019, 19, 1186–1204. [Google Scholar] [CrossRef] [Scilit]
- Kallbekken, S.; Kroll, S.; Cherry, T.L. Do you not like Pigou, or do you not understand him? Tax aversion and revenue recycling in the lab. J. Environ. Econ. Manag. 2011, 62, 53–64. [Google Scholar] [CrossRef] [Scilit]
- Kotchen, M.J.; Turk, Z.M.; Leiserowitz, A.A. Public willingness to pay for a U.S. carbon tax and preferences for spending the revenue. Environ. Res. Lett. 2017, 12, 094012. [Google Scholar] [CrossRef] [Scilit]
- Chetty, R.; Looney, A.; Kroft, K. Salience and taxation: Theory and evidence. Am. Econ. Rev. 2009, 99, 1145–1177. [Google Scholar] [CrossRef] [Scilit]
- Duncan, D.; Graham, J. Road user fees instead of fuel taxes: The quest for political acceptability. Public Adm. Rev. 2013, 73, 415–426. [Google Scholar] [CrossRef] [Scilit]
- Levis, A.; Lichtin, F.; Bernauer, T. Compensating losses in fossil fuel tax revenues: First evidence of public support for a BEV mileage tax. Transp. Policy 2025, 171, 359–369. [Google Scholar] [CrossRef] [Scilit]
- Davis, L.W.; Sallee, J.M. Should electric vehicle drivers pay a mileage tax? Environ. Energy Policy Econ. 2020, 1, 65–94. [Google Scholar] [CrossRef] [Scilit]
- Dumortier, J.; Zhang, F.; Marron, J. State and federal fuel taxes: The road ahead for U.S. infrastructure funding. Transp. Policy 2017, 53, 39–49. [Google Scholar] [CrossRef] [Scilit]
- National Tax Service. National Tax Statistical Yearbook 2023; National Tax Service: Sejong, Republic of Korea, 2023. Available online: https://www.nts.go.kr (accessed on 7 July 2025).
- HM Treasury. The Introduction of Electric Vehicle Excise Duty (eVED): Consultation Response; UK Government: London, UK, 2026. Available online: https://assets.publishing.service.gov.uk/media/6a5117eda4890e65cce64d2f/eVED_Government_Consultation_Response.pdf (accessed on 30 August 2026).
- Finkelstein, A. E-ZTax: Tax salience and tax rates. Q. J. Econ. 2009, 124, 969–1010. [Google Scholar] [CrossRef] [Scilit]
- Grigolon, L.; Reynaert, M.; Verboven, F. Consumer valuation of fuel costs and tax policy: Evidence from the European car market. Am. Econ. J. Econ. Policy 2018, 10, 193–225. [Google Scholar] [CrossRef] [Scilit]
- Huse, C.; Koptyug, N. Salience and policy instruments: Evidence from the auto market. J. Assoc. Environ. Resour. Econ. 2022, 9, 345–382. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Goldin, J. Optimal tax salience. J. Public Econ. 2015, 131, 115–123. [Google Scholar] [CrossRef] [Scilit]
- Taubinsky, D.; Rees-Jones, A. Attention variation and welfare: Theory and evidence from a tax salience experiment. Rev. Econ. Stud. 2018, 85, 2462–2496. [Google Scholar] [CrossRef] [Scilit]
- Schöb, R. The Double Dividend Hypothesis of Environmental Taxes: A Survey; FEEM Working Paper No. 60.2003; Fondazione Eni Enrico Mattei: Milan, Italy, 2003. [Google Scholar] [CrossRef] [Scilit]
- Woerner, A.; Imai, T.; Pace, D.D.; Schmidt, K.M. How to increase public support for carbon pricing with revenue recycling. Nat. Sustain. 2024, 7, 1633–1641. [Google Scholar] [CrossRef] [Scilit]
- Mohammadzadeh Valencia, F.; Mohren, C.; Ramakrishnan, A.; Merchert, M.; Minx, J.C.; Steckel, J.C. Public support for carbon pricing policies and revenue recycling options: A systematic review and meta-analysis of the survey literature. npj Clim. Action 2024, 3, 74. [Google Scholar] [CrossRef] [Scilit]
- Hsu, S.L.; Walters, J.; Purgas, A. Pollution tax heuristics: An empirical study of willingness to pay higher gasoline taxes. Energy Policy 2008, 36, 3612–3619. [Google Scholar] [CrossRef] [Scilit]
- Hammerle, M.; Best, R.; Crosby, P. Public acceptance of carbon taxes in Australia. Energy Econ. 2021, 101, 105420. [Google Scholar] [CrossRef] [Scilit]
- Sommer, S.; Mattauch, L.; Pahle, M. Supporting carbon taxes: The role of fairness. Ecol. Econ. 2022, 195, 107359. [Google Scholar] [CrossRef] [Scilit]
- Maestre-Andrés, S.; Drews, S.; Savin, I.; van den Bergh, J. Carbon tax acceptability with information provision and mixed revenue uses. Nat. Commun. 2021, 12, 7017. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Kirchler, E.; Hoelzl, E.; Wahl, I. Enforced versus voluntary tax compliance: The “slippery slope” framework. J. Econ. Psychol. 2008, 29, 210–225. [Google Scholar] [CrossRef] [Scilit]
- McFadden, D. Economic choices. Am. Econ. Rev. 2001, 91, 351–378. [Google Scholar] [CrossRef] [Scilit]
- Train, K.E. Discrete Choice Methods with Simulation, 2nd ed.; Cambridge University Press: Cambridge, UK, 2009. [Google Scholar] [CrossRef] [Scilit]
- McFadden, D.; Train, K. Mixed MNL models for discrete response. J. Appl. Econom. 2000, 15, 447–470. [Google Scholar] [CrossRef]
- Allenby, G.M.; Arora, N.; Ginter, J.L. On the heterogeneity of demand. J. Mark. Res. 1998, 35, 384–389. [Google Scholar] [CrossRef] [Scilit]
- Greene, W.H.; Hensher, D.A. A latent class model for discrete choice analysis: Contrasts with mixed logit. Transp. Res. Part B Methodol. 2003, 37, 681–698. [Google Scholar] [CrossRef] [Scilit]
- Bujosa, A.; Riera, A.; Hicks, R.L. Combining discrete and continuous representations of preference heterogeneity: A latent class approach. Environ. Resour. Econ. 2010, 47, 477–493. [Google Scholar] [CrossRef] [Scilit]
- Burda, M.; Harding, M.; Hausman, J. A Bayesian mixed logit–probit model for multinomial choice. J. Econom. 2008, 147, 232–246. [Google Scholar] [CrossRef] [Scilit]
- Train, K. EM algorithms for nonparametric estimation of mixing distributions. J. Choice Model. 2008, 1, 40–69. [Google Scholar] [CrossRef] [Scilit]
- Bajari, P.; Fox, J.T.; Ryan, S.P. Linear regression estimation of discrete choice models with nonparametric distributions of random coefficients. Am. Econ. Rev. 2007, 97, 459–463. [Google Scholar] [CrossRef] [Scilit]
- Keane, M.; Wasi, N. Comparing alternative models of heterogeneity in consumer choice behavior. J. Appl. Econom. 2013, 28, 1018–1045. [Google Scholar] [CrossRef] [Scilit]
- Hidrue, M.K.; Parsons, G.R.; Kempton, W.; Gardner, M.P. Willingness to pay for electric vehicles and their attributes. Resour. Energy Econ. 2011, 33, 686–705. [Google Scholar] [CrossRef] [Scilit]
- Hackbarth, A.; Madlener, R. Willingness-to-pay for alternative fuel vehicle characteristics: A stated choice study for Germany. Transp. Res. Part A Policy Pract. 2016, 85, 89–111. [Google Scholar] [CrossRef] [Scilit]
- Lashari, Z.A.; Ko, J.; Jung, S.; Choi, S. Choices of potential car buyers regarding alternative fuel vehicles in South Korea: A discrete choice modeling approach. Sustainability 2022, 14, 5360. [Google Scholar] [CrossRef] [Scilit]
- Brückmann, G.; Bernauer, T. An experimental analysis of consumer preferences towards public charging infrastructure. Transp. Res. Part D Transp. Environ. 2023, 116, 103626. [Google Scholar] [CrossRef] [Scilit]
- Greene, W.H.; Hensher, D.A. Revealing additional dimensions of preference heterogeneity in a latent class mixed multinomial logit model. Appl. Econ. 2013, 45, 1897–1902. [Google Scholar] [CrossRef] [Scilit]
- Kim, H.Y.; Kim, S.K.; Kang, D.M.; Hwang, Y.S.; Oh, J.E. The relationships between sixteen perfluorinated compound concentrations in blood serum and food, and other parameters, in the general population of South Korea with proportionate stratified sampling method. Sci. Total Environ. 2014, 470–471, 1390–1400. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Statistics Korea. Projected Population by Gender and Age; Korean Statistical Information Service (KOSIS): Daejeon, Republic of Korea, 2018. Available online: https://kosis.kr (accessed on 13 June 2025).
- Wolff, S.; Madlener, R. Charged Up? Preferences for Electric Vehicle Charging and Implications for Charging Infrastructure Planning; FCN Working Paper No. 17/2019; E.ON Energy Research Center, RWTH Aachen University: Aachen, Germany, 2019. [Google Scholar] [CrossRef] [Scilit]
- Globisch, J.; Dütschke, E.; Wietschel, M. Adoption of electric vehicles in commercial fleets: Why do car pool managers campaign for BEV procurement? Transp. Res. Part D Transp. Environ. 2018, 64, 122–133. [Google Scholar] [CrossRef] [Scilit]
- Achtnicht, M. German car buyers’ willingness to pay to reduce CO2 emissions. Clim. Change 2012, 113, 679–697. [Google Scholar] [CrossRef] [Scilit]
- Rizki, M.; Syahputri, J.; Belgiawan, P.F.; Irawan, M.Z. Electrifying tourist mobility in Bali, Indonesia: Setting the target and estimating the CO2 reduction based on stated choice experiment. Sustainability 2021, 13, 11656. [Google Scholar] [CrossRef] [Scilit]
- Dimitropoulos, A.; Rietveld, P.; van Ommeren, J.N. Consumer valuation of changes in driving range: A meta-analysis. Transp. Res. Part A Policy Pract. 2013, 55, 27–45. [Google Scholar] [CrossRef] [Scilit]
- Small, K.A. Valuation of travel time. Econ. Transp. 2012, 1, 2–14. [Google Scholar] [CrossRef] [Scilit]
- Brownstone, D.; Small, K.A. Valuing time and reliability: Assessing the evidence from road pricing demonstrations. Transp. Res. Part A Policy Pract. 2005, 39, 279–293. [Google Scholar] [CrossRef] [Scilit]
- Poudel, N.; Singleton, P.A. Willingness to pay for changes in travel time and work time: A stated choice experiment of US commuters. Res. Transp. Econ. 2024, 103, 101381. [Google Scholar] [CrossRef] [Scilit]
- Kim, H.; Kim, D.W.; Kim, M.K. Economics of charging infrastructure for electric vehicles in Korea. Energy Policy 2022, 164, 112875. [Google Scholar] [CrossRef] [Scilit]
- Ministry of Land, Infrastructure and Transport. Certified Driving Range of Registered Electric Vehicle Models; Government of the Republic of Korea: Sejong, Republic of Korea, 2017. Available online: https://www.molit.go.kr (accessed on 12 August 2025). (In Korean)
- Rossi, P.E.; Allenby, G.M. Bayesian statistics and marketing. Mark. Sci. 2003, 22, 304–328. [Google Scholar] [CrossRef] [Scilit]
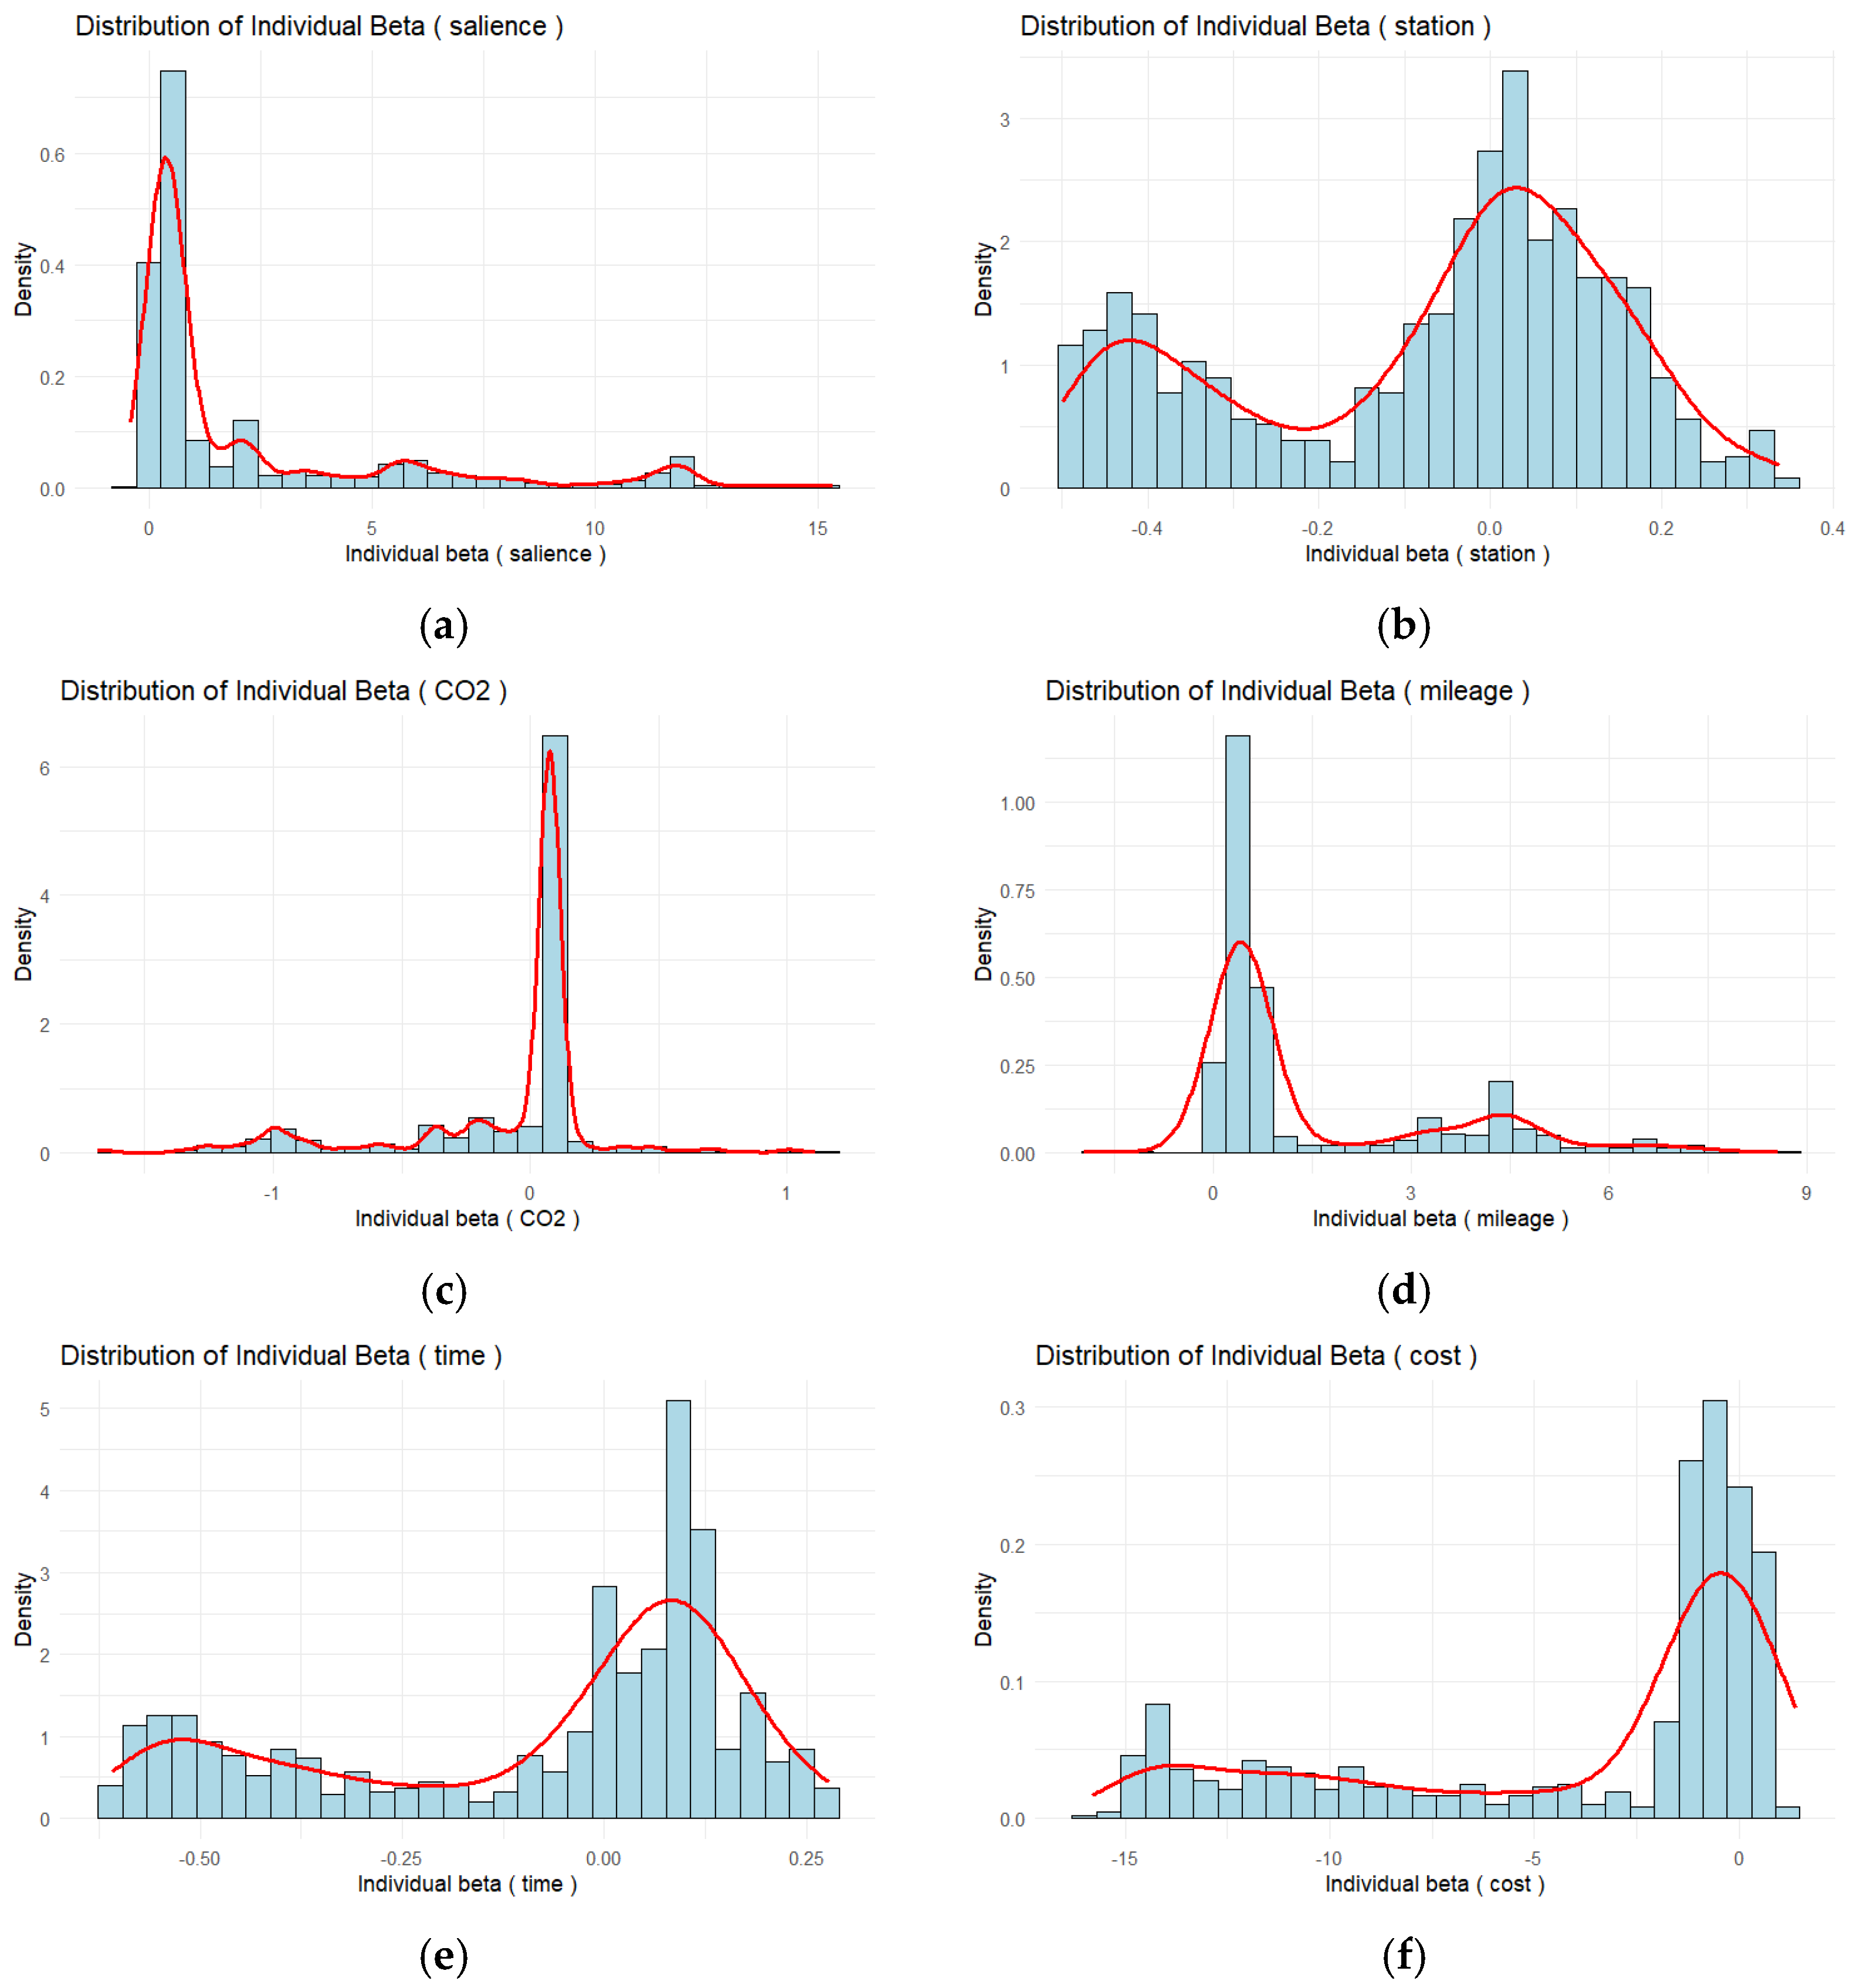

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.