


Abstract
Under geopolitical conflicts, the deployment of emergency green energy in energy-import-dependent countries is constrained by limited upfront capital and uncertainty regarding the conflict duration. This study evaluates financial leasing as a policy instrument by combining a benchmark decision model under conventional procurement with a tripartite evolutionary game involving the energy demand side, financial leasing companies, and the government. The results show that conventional procurement creates an underinvestment-idle-capacity dilemma governed by the critical conflict-persistence probability. Financial leasing alleviates financial constraints and redistributes the risks associated with demand uncertainty, producing market-driven and policy-guided stable equilibria. A global grid search shows that the policy-guided basin expands as the conflict-persistence probability increases. However, government subsidies have an inverted-U-shaped effect because their effectiveness is jointly constrained by the demand-side participation condition and the government’s net-benefit condition. The numerical example shows that combining financial leasing with government subsidies reduces the critical conflict-persistence probability for adopting financial leasing from 0.286 to 0.127, a decrease of approximately 56%, and substantially relaxes the feasible upper bound of the risk-sharing coefficient. These findings provide a theoretical basis for the use of financial leasing as a policy instrument to enhance energy security in energy-import-dependent countries and for the design of complementary incentive mechanisms.
1. Introduction
Against the backdrop of frequent geopolitical conflicts, the Strait of Hormuz serves as a vital shipping route for global oil and natural gas transportation. If passage through the Strait were blocked, energy-import-dependent countries would face a higher risk of supply disruptions, and energy supply-chain resilience would be severely compromised [1]. In response to uncertainties in fossil fuel supplies, innovations in renewable energy, energy storage, and clean technologies have gradually become key policy directions for reducing energy dependence, advancing the decarbonization transition, and enhancing energy security [2]. Countries such as the United Kingdom are promoting the development of renewable energy through policies supporting offshore wind power. Relevant studies indicate that such policies not only contribute to the decarbonization of the energy system but also enhance energy security by reducing reliance on energy imports [3]. European countries are also placing increasing emphasis on enhancing the resilience of their energy systems through the development of renewable energy, diversification of the energy mix, and energy security governance [4]. Multiple policies have reduced dependence on Russian natural gas, and countries are actively building emergency green-energy infrastructure [5]. Furthermore, the renewable-energy transition not only alters the energy supply structure but also reshapes interdependence and geopolitical relations among countries [6,7]. At the same time, the coordinated application of wind, solar, and storage systems can mitigate inherent energy fluctuations, thereby enhancing the flexibility and resilience of the energy system [8,9]. Consequently, designing effective financial policy instruments to promote emergency green-energy development has become a critical issue for energy-import-dependent countries seeking to ensure energy security.
However, the development and management of emergency green energy face dual challenges. First, capital availability and financing costs can affect investment in the energy transition. Financial constraints may alter the scale and implementation pathway of energy projects [10]. The financial viability of renewable-energy projects is also shaped by their financing structures, risk-allocation arrangements, and broader institutional environments [11]. Second, demand is uncertain because the duration and impact of geopolitical conflicts are difficult to predict. This may lead to underinvestment or overinvestment in energy-reserve development [12]. Therefore, selecting an effective approach to systematically address the challenges facing the development of emergency green energy holds significant theoretical and practical importance.
Financial leasing enables project developers to acquire the equipment they need without paying the full cost upfront, thereby reducing the financial burden of green-energy projects. Existing research shows that, under severe financial constraints, leasing can serve as an important alternative to debt financing for firms [13]. Unlike conventional equipment purchase methods, financial leasing offers the following advantages. First, financial leasing can alleviate financial constraints. By acquiring green-energy equipment through leasing and making installment payments, the demand side can reduce upfront financial pressure, rapidly expand green-energy capacity, and meet emergency needs [14]. Second, financial leasing helps mitigate the risks associated with demand uncertainty. Acquiring green-energy equipment through leasing facilitates risk sharing, thereby enhancing the flexibility and responsiveness of the supply chain and increasing the willingness to build emergency green-energy supply chains [15].
However, the effectiveness of financial leasing in improving emergency supply adequacy as one operational dimension of emergency green-energy supply-chain resilience depends on the coordinated decisions of multiple actors. On the one hand, the energy demand side needs to compare the expected costs of conventional procurement versus financial leasing under different conflict scenarios; on the other hand, financial leasing companies need to balance lease revenue, equipment residual value, operating costs, and the risk of equipment idling. At the same time, the government must weigh improvements in energy security and emergency supply adequacy against the fiscal cost of subsidies. Thus, the diffusion of financial leasing in emergency green-energy supply chains is essentially a process in which the energy demand side, financial leasing companies, and the government continuously adjust their strategies and seek stable equilibria. Consequently, it is necessary to construct a comprehensive analytical framework that simultaneously captures investment decisions, changes in emergency supply adequacy, and the evolution of strategies among multiple actors.
To address these issues, this study first develops an emergency green-energy investment decision model under conventional procurement, derives the critical conflict-persistence probability at which the demand side shifts from small-scale to large-scale investment, and reveals the underinvestment–idle-capacity dilemma inherent in the conventional procurement model. Second, it constructs a tripartite evolutionary game involving the energy demand side, financial leasing companies, and the government. Through payoff matrices, replicator dynamics, and stability analysis of the Jacobian matrix, the study identifies the conditions under which financial leasing leads to market-driven and policy-guided equilibria. Finally, numerical simulations and a global grid search over initial conditions are conducted to examine how key contractual and policy parameters affect the system’s evolutionary outcomes.
Accordingly, this study addresses the following three research questions:
(1) What dilemmas and critical conditions characterize the demand side’s emergency green-energy investment decisions under conventional procurement?
(2) How do initial participation conditions and key contractual and policy parameters affect the evolutionary outcomes of the tripartite system?
(3) Under what contractual and policy conditions can the financial leasing model be successfully implemented and sustained?
The main contributions of this study are as follows: First, it links three mechanisms that are usually examined separately: upfront financing constraints on emergency capacity deployment, uncertainty over conflict duration that creates a trade-off between shortage and idle-capacity losses, and a leasing-based allocation of idle-capacity risk. This integrated structure yields explicit conflict-persistence thresholds for financial-leasing adoption and a feasible risk-sharing boundary. Second, it integrates demand-side adoption, leasing-company service provision, and government incentives in a tripartite evolutionary game, thereby distinguishing market-driven and policy-guided cooperative equilibria. Third, it combines analytical threshold derivation with a global grid search over initial conditions and robustness analyses to quantify the basin of attraction of the policy-guided equilibrium and identify the dual boundary and inverted-U-shaped effect of demand-side subsidies.
2. Literature Review
This section reviews three closely related strands of research: emergency energy supply-chain resilience and geopolitical energy security, renewable-energy financing and financial leasing, and evolutionary game applications in supply chains and energy systems. The purpose is to establish the theoretical basis of the study while clarifying how the proposed mechanism differs from adjacent financing, servitization, and emergency supply-chain models.
Supply-chain resilience generally refers to the capacity to withstand disruption, maintain essential functions, and recover or adapt after shocks [16]. Energy supply-chain resilience extends this logic to the continuity and restoration of energy provision under severe disturbances [17]. Prior studies have developed the concept from theoretical and quantitative perspectives, emphasizing recovery, survivability, network structure, and the ability to maintain core functions during disruption [18,19,20,21,22,23]. Together, this literature provides the resilience foundation for analyzing emergency energy supply, but it does not by itself explain how capital-constrained demand-side actors finance rapid capacity deployment when the duration of a geopolitical shock is uncertain.
Research on energy geopolitics further shows that the Russia–Ukraine conflict and related supply disruptions have intensified concern over energy-security dependence, diversification, and the pace of the low-carbon transition [24,25,26]. Renewable-energy development may also reshape conventional patterns of energy dependence and geopolitical interaction [27], while the European Union has adjusted its decarbonization and energy-security policies under geopolitical pressure [28]. These studies mainly emphasize national strategies, policy responses, and system-level transition. Comparatively less attention has been paid to the micro-level financing decisions of demand-side actors that must balance emergency shortages against the risk of post-conflict idle capacity.
A second strand examines financing and contractual arrangements for renewable-energy investment. Public policy, project-finance structures, credit conditions, and alternative financing channels materially affect renewable-energy investment [29,30,31,32]. Financial leasing can also alleviate funding pressure and support renewable-energy investment [14]. Related research on Energy Storage as a Service examines asset pricing, sizing, and capacity allocation under service contracts [33,34], while operations-finance studies show that supplier financing and trade credit can alter ordering decisions and supply-chain stability [35,36]. This literature demonstrates that financing and servitization can reshape capital constraints and risk allocation, but it generally does not address temporary conflict-induced emergency demand together with the possibility that newly deployed capacity becomes idle when the disruption ends.
A third strand applies evolutionary game theory to supply-chain and energy-system coordination. Building on the theoretical foundations of evolutionary games [37], prior studies have examined green supply-chain diffusion, green investment under subsidies, emergency equipment introduction and overcapacity risk sharing, energy-storage coordination, government regulation, and multi-actor energy-market participation [38,39,40,41,42,43,44,45]. In particular, emergency supply-chain research shows that equipment-introduction and overcapacity risks can be analyzed through repeated strategic adjustment [15]. These studies support the use of evolutionary games for boundedly rational multi-actor interaction, but they have not integrated emergency green-energy financing through leasing with conflict-duration uncertainty and government incentive design.
The related literature therefore provides important building blocks, but the central mechanisms are usually examined separately. Conventional renewable-energy financing studies emphasize capital availability and financing structure [14,29,30,31,32]; energy-as-a-service studies emphasize asset pricing and service allocation [33,34]; operations-finance studies emphasize financing-induced changes in supply-chain decisions [35,36]; and emergency supply-chain models emphasize equipment introduction and overcapacity risk under disruption [15]. The contribution of this study does not derive from any of these elements individually. Rather, it links an upfront financing constraint on emergency green-energy deployment with conflict-duration uncertainty, post-conflict idle-capacity risk sharing, and government incentives. This integrated structure yields explicit conflict-persistence thresholds for leasing adoption, a feasible risk-sharing boundary, and distinct market-driven and policy-guided cooperative equilibria.
Accordingly, this study develops an analytical framework comprising a benchmark conventional-procurement decision model and a tripartite evolutionary game among the energy demand side, financial leasing companies, and the government. Critical-probability derivation, stability analysis, numerical simulation, a global grid search over initial conditions, continuous-capacity robustness analysis, joint parameter uncertainty analysis, and numerical convergence tests are used to identify the conditions under which financial leasing can improve emergency supply adequacy and support one operational dimension of emergency green-energy supply-chain resilience.
3. Tripartite Evolutionary Game Model of Financial Leasing
3.1. Benchmark Decision Model Under Conventional Procurement
Geopolitical conflict may obstruct critical energy corridors and expose conventional fossil-fuel supply chains, particularly those for oil and natural gas, to disruption risk. To compensate for the resulting shortfall in conventional energy supply, the demand side must decide, once conflict erupts, whether to expand emergency green-energy capacity based on wind-power, photovoltaic, and energy-storage technologies. However, green-energy equipment requires substantial upfront investment and is highly asset-specific, while the duration of conflict-induced disruption to energy corridors is highly uncertain. Under conventional procurement, the demand side therefore faces a dilemma between insufficient supply under small-scale investment and idle capacity under large-scale investment, which may weaken its willingness to expand investment to offset conventional-energy shortages. Accordingly, this study treats the demand side as the decision maker and develops an emergency green-energy investment model to assess whether conventional procurement can respond effectively to geopolitical conflict.
To distinguish economic preference from financing feasibility, the benchmark model first compares the two representative investment scales while temporarily abstracting from a binding budget constraint. The numerical values used later have different interpretations. Let denote the demand side’s one-off disposable internal funds. Under conventional procurement, the demand side must finance the full capital expenditure upfront, so the maximum feasible capacity is determined by . With the benchmark values USD 7.452 million and USD 0.0931 million per standardized unit, this financing ceiling is exactly 80 units when calculated from the unrounded converted values. By contrast, the 120-unit capacity under financial leasing is a benchmark scenario selected after the upfront financing constraint is relaxed to cover the normalized emergency demand of 100 units and retain a safety margin; it is not an endogenously optimized capacity. Section 4.5 therefore relaxes the discrete 80/120 specification and examines whether the main financing mechanism persists when deployment capacity is continuously selected.
The investment decision model is based on the following assumptions.
Assumption 1.
The demand side chooses between small-scale investment and large-scale investment , with . Here, denotes the scale of emergency energy demand during a prolonged geopolitical conflict; cannot fully meet this demand, whereas can broadly satisfy it. For analytical simplicity, is assumed to be broadly aligned with the emergency energy demand under prolonged conflict, such that is close to or equal to . If slightly exceeds , the excess is treated as an emergency safety margin under prolonged conflict and is not counted as idle capacity in that state. Potential idle capacity following a short-term end to the conflict is treated separately in Assumption 5. In this assumption, , , and are quantitative capacity variables measured in standardized emergency green-energy equipment-package units (hereafter, standardized units); they represent deployment quantities rather than monetary resources. Monetary requirements are introduced separately through the unit construction cost and the resulting total capital expenditure.
Assumption 2.
Geopolitical conflict has two possible states. In the first state, the conflict persists and the energy corridor remains disrupted, with probability . In the second state, the conflict ends in the short term and the energy corridor gradually reopens, with probability .
Assumption 3.
Let denote the construction cost per unit of green-energy capacity. The construction costs associated with small-scale and large-scale investment are and , respectively. Because , it follows that . The unit of is USD per standardized unit. Accordingly, multiplying the unit cost by the corresponding quantitative capacity level yields the total monetary construction expenditure, measured in USD.
Assumption 4.
Under prolonged conflict, the unit shortage loss caused by insufficient energy capacity is . If the conflict ends in the short term, the unit idle-capacity loss caused by excess energy capacity is . The parameters , , and are all positive. Both and are measured in USD per standardized unit. The strict positivity restrictions on , , and reflect their economic meanings as a construction cost, a shortage loss, and an idle-capacity loss, respectively, and exclude degenerate zero-cost or zero-loss cases.
Assumption 5.
To avoid asymmetry in the payoff specification, small-scale investment is assumed not to generate additional idle-capacity losses. Green-energy capacity is developed on an ongoing basis, and the component continues to serve as self-consumed baseload capacity after a short-term end to the conflict and is therefore not treated as idle capacity. Only the portion of large-scale investment above this self-consumed baseload, , may become idle after the conflict ends. Accordingly, the idle-capacity loss under large-scale investment is calculated on the basis of .
The demand side in this study refers to large energy-consuming enterprises, industrial parks, and similar entities that deploy integrated wind–solar–storage systems for self-generation and self-consumption in order to maintain a stable energy supply. All newly deployed emergency green energy is used for the demand side’s own emergency supply and is not sold in the electricity market; the associated benefit is represented by avoided shortage losses , and the analysis therefore adopts a cost-minimization framework. The effects of energy shortages on downstream industries and the public are captured by the social risk cost and incremental policy-synergy benefit parameters in the government’s payoff function in Section 3.2.
Under the small-scale investment strategy , if the conflict ends in the short term, the demand side incurs only the construction cost of small-scale green-energy capacity, . If the conflict persists, , and small-scale investment cannot fully satisfy emergency energy demand; the demand side therefore incurs both the construction cost and the shortage loss, . The expected cost of the small-scale investment strategy is therefore , which can be simplified as follows:
Under the large-scale investment strategy , if the conflict persists, , and large-scale investment can broadly meet emergency energy demand; the demand side therefore incurs only the construction cost, . If the conflict ends in the short term, the portion of large-scale investment above the baseload absorption level, , becomes idle, and the demand side incurs both the construction cost and idle-capacity loss, . The expected cost of the large-scale investment strategy is therefore , which can be simplified as follows:
The demand side compares the expected costs of small-scale and large-scale investment. When the two expected costs are equal, the demand side is indifferent between the two strategies. Setting , that is, , and rearranging yields . The critical conflict-persistence probability at which the demand side switches from small-scale to large-scale investment is therefore given by: Here, denotes the exogenous actual probability that the conflict persists, whereas denotes the endogenous critical value of that probability obtained by equating the expected costs of the two investment strategies.
In Equation (3), the numerator represents the additional fixed construction cost and potential idle-capacity loss associated with large-scale rather than small-scale investment. The denominator is the sum of the marginal loss differences between the two investment strategies across the two conflict states. Specifically, is the shortage loss that large-scale investment avoids when the conflict persists, whereas is the additional idle-capacity loss that large-scale investment may generate if the conflict ends in the short term.
When the actual conflict-persistence probability satisfies , the expected cost of large-scale investment is lower than that of small-scale investment, and the demand side tends to build emergency green-energy capacity on a large scale. When , the expected cost of small-scale investment is lower, and the demand side tends to adopt a conservative investment strategy. The critical probability must also lie within the valid interval .
Because , , and , and because the denominator satisfies , it follows that . The condition is equivalent to . Thus, large-scale investment is economically rational only when its additional fixed construction cost is smaller than the shortage loss it can avoid under prolonged conflict. If , even a prolonged geopolitical conflict does not generate sufficient avoided shortage losses to cover the additional construction cost of large-scale investment. The demand side will then prefer small-scale investment throughout the valid probability range , resulting in insufficient emergency green-energy capacity.
To further examine how financial constraints and idle-capacity risk affect the demand side’s investment decision, comparative statics are performed for the critical probability . Let , , and . The critical probability can then be written as: Here, continues to denote the demand side’s one-off disposable internal funds defined earlier; the incremental construction cost is denoted separately from to avoid ambiguity. denotes the shortage-loss exposure associated with the unmet capacity under small-scale investment, and denotes the incremental capacity between the two investment scales.
First, consider the effect of the additional construction cost on the critical probability: The left-hand side of Equation (5) is the partial derivative of the critical probability with respect to the incremental construction cost; it measures the marginal change in caused by a change in that cost while the other variables are held constant.
The result shows that a higher incremental construction cost of large-scale investment relative to small-scale investment raises the critical probability and reduces the demand side’s willingness to invest on a large scale. Under conventional procurement, a high one-off construction cost therefore raises the decision threshold for expanding emergency green-energy capacity and exacerbates underinvestment.
Second, consider the effect of the unit shortage loss on the critical probability: The left-hand side of Equation (6) is the partial derivative of the critical probability with respect to the unit shortage loss and measures the corresponding marginal sensitivity of .
A higher unit shortage loss lowers the critical probability and makes large-scale investment more likely. Thus, the more severe the energy-shortage losses caused by geopolitical conflict, the stronger the incentive for the demand side to expand green-energy capacity in advance and reduce the consequences of supply disruption.
Finally, consider the effect of the unit idle-capacity loss on the critical probability: The left-hand side of Equation (7) is the partial derivative of the critical probability with respect to the unit idle-capacity loss and measures the corresponding marginal sensitivity of .
Because , the sign of depends on , or equivalently on . When , . In this case, a higher unit idle-capacity loss raises the critical probability and strengthens the demand side’s preference for avoiding large-scale investment. When , . However, under this condition, the additional construction cost of large-scale investment already exceeds the shortage loss it can avoid, and , which means that large-scale investment is never the demand side’s superior strategy within the valid probability range . Accordingly, although the unit idle-capacity loss affects the numerical value of , it does not alter the basic conclusion that the demand side tends to choose small-scale investment.
It is therefore incorrect to conclude unconditionally that a higher idle-capacity loss must increase the critical probability . More precisely, within the parameter range in which large-scale investment is economically rational, namely , an increase in raises and reinforces the demand side’s conservative investment tendency. When large-scale investment is not economically rational in the first place, the demand side continues to prefer small-scale investment throughout the valid probability range, and underinvestment under the conventional procurement model becomes even more pronounced.
In summary, large-scale investment has a lower expected cost when the actual conflict-persistence probability exceeds the critical probability; otherwise, small-scale investment is preferable. The demand side is therefore willing to deploy wind–solar–storage systems on a large scale when conflict is likely to persist, but the probability itself is highly uncertain. The benchmark model also reveals the fragility of conventional procurement: investment decisions depend heavily on a critical threshold that is raised by high incremental construction costs and idle-capacity losses. When incremental construction costs are high, financing constraints are binding, and idle-capacity losses are substantial, the demand side may still favor conservative small-scale investment even under relatively high conflict risk, thereby restricting emergency green-energy deployment. Lowering this decision threshold requires an institutional arrangement that spreads upfront investment costs and reallocates idle-capacity risk. The following sections introduce financial leasing into this benchmark setting and characterize the evolution of strategies among the energy demand side, financial leasing companies, and the government.
3.2. Description of the Tripartite Game and Model Assumptions
The tripartite evolutionary game comprises three players: the energy demand side, financial leasing companies, and the government. The energy demand side chooses between conventional procurement and financial leasing according to its emergency energy-security needs; leasing companies, as providers of capital and equipment, choose whether to offer financial leasing services; and the government, which is responsible for policy guidance and system coordination, chooses whether to provide incentives. The model examines, from a dynamic tripartite-game perspective, how financial leasing can improve emergency supply adequacy and thereby support one operational dimension of emergency green-energy supply-chain resilience. The capacity and cost specifications for the demand side build on the benchmark model in Section 3.1. That model identifies the economically preferred capacity scale by comparing expected costs while temporarily abstracting from a binding budget constraint. The tripartite model then introduces financing feasibility: conventional procurement requires full upfront payment and, under the numerical calibration, limits the feasible deployment scale to , whereas installment rental payments under financial leasing relax the capital constraint and make feasible. The remaining assumptions are stated below.
Let denote the strategy set of the energy demand side:
Here, denotes conventional procurement and denotes financial leasing.
Let denote the strategy set of the financial leasing company:
Here, denotes the provision of financial leasing services and denotes non-provision.
Let denote the government’s strategy set:
Here, denotes the provision of incentive policies and denotes non-provision.
The model is based on the following assumptions.
Assumption 6.
If the energy demand side chooses financial leasing but the leasing company does not provide the service, the leasing transaction cannot be completed and the demand side reverts to conventional procurement.
Assumption 7.
If the leasing company chooses to provide services while the demand side chooses conventional procurement, the leasing company incurs a market-entry, service-preparation, or equipment-prepositioning cost denoted by .
Assumption 8.
Capacity scale and capital cost follow the definitions in the benchmark model in Section 3.1. Financing constraints determine the feasible capacity set under each financing mode, while the actual deployment scale is determined by emergency demand and the required safety margin. As defined in Section 3.1, denotes the demand side’s one-off disposable internal funds. Conventional procurement requires the demand side to advance the full equipment capital expenditure, , so that the maximum feasible scale is , with equality when the budget is fully used. In the numerical example in Section 4, and ; using the unrounded converted values, this gives ; thus, the capital constraint directly produces underinvestment. Under financial leasing, the demand side advances only a down-payment share with , subject to , which substantially relaxes the financing constraint and permits a feasible deployment scale based on emergency demand. The numerical setting is retained only as a benchmark scenario after the financing constraint is relaxed; it covers the emergency demand with a safety margin and should not be interpreted as the unique or endogenously optimal leasing capacity. Its financing feasibility requires only , while down-payment ratios of 10–30% used as the reference range in this study are well below this upper bound. The down-payment constitutes the first rental payment, is already included in and , and is not counted again as a separate demand-side cost. Because , participation in financial leasing is sufficient to cover emergency demand under prolonged conflict, and the demand side no longer incurs shortage losses. Capital expenditure is measured uniformly as ; hence, capital expenditure under conventional procurement is , whereas the leasing company’s equipment investment is . The leasing company does not purchase all equipment solely with its own funds; it borrows from banks at the financing rate and leases the assets to the demand side at the leasing rate , where , and the difference constitutes its interest spread. The full lease term applies when the conflict persists, whereas the early-termination term applies when the conflict ends in the short term. Accordingly, the contractual rents paid by the demand side, under prolonged conflict and when the conflict ends in the short term, are calculated on the principal at the leasing rate and include emergency-dispatch services and a risk premium, as calibrated in the Supplementary Materials. The corresponding bank financing costs incurred by the leasing company are denoted by and and are included in its net payoff together with equipment capital expenditure and operating cost .
Assumption 9.
Government intervention includes a rental or interest subsidy for the energy demand side and a subsidy or risk compensation for the financial leasing company, and it entails a policy implementation and regulatory cost . The parameter subsidizes the leasing company’s service capacity, equipment prepositioning, or risk-bearing activities and is therefore received whenever the company provides services and the government adopts the incentive strategy.
Assumption 10.
is defined as the incremental policy-synergy benefit generated by government intervention relative to spontaneous market diffusion. It includes the additional benefits arising from standardization, platform coordination, credit enhancement, and large-scale promotion by the government. The basic energy-security benefit generated by successful financial leasing arises under both market-driven and policy-guided implementation and therefore cancels out in the payoff difference between the government’s incentive and non-incentive strategies and does not enter the government replicator dynamic. Accordingly, represents only the incremental component attributable to government intervention. By definition, is a positive benefit parameter; a negative sign appearing before in the local-stability eigenvalue does not mean that itself is a cost.
Government inaction may also entail accountability or opportunity costs when a crisis is not effectively coordinated; these costs may be written as , where . This term is set to zero in the model, which is a conservative simplification. If were included, the government’s incentive condition would be relaxed from to , which would make the condition for the policy-guided equilibrium easier to satisfy. The current results therefore provide a lower bound on the government’s willingness to offer incentives.
Assumption 11.
The government’s social risk cost after the successful implementation of financial leasing is simplified as . This assumption does not imply that shortage and idle-capacity risks disappear entirely in practice. Rather, lease-term adjustment, renewal, subleasing, residual-value disposal, and government supervision are assumed to absorb the principal risks within the market and substantially reduce their social spillovers. Thus, is a simplifying specification introduced to highlight the reduction in emergency shortage-related social risk and the improvement in supply adequacy, rather than to represent a comprehensive improvement in supply-chain resilience.
Assumption 12.
If the conflict ends in the short term, the redundant leased capacity becomes idle. The resulting idle-capacity loss () is shared between the demand side and the leasing company according to the risk-sharing coefficient , with the demand side bearing a share and the leasing company bearing a share .
Two methodological points should also be noted. First, the replicator dynamics in this study should be interpreted as a reduced-form bounded-rationality adjustment process rather than as literal biological imitation. For the demand-side population, actors may update their financing choices by observing the relative costs of conventional procurement and financial leasing, the realized consequences of supply shortages and idle capacity, and the adoption experience of comparable firms or industrial parks. Financial leasing companies may adjust whether to provide services in response to observed leasing demand, realized transaction profitability, residual-value recovery, and the service decisions of competing providers. For the government, the replicator dynamic represents the gradual adjustment of policy orientation according to observed market participation, fiscal costs, and incremental policy benefits; alternatively, the government variable may be interpreted as the proportion of regional governments adopting the incentive policy. Under these interpretations, the strategy proportions describe aggregate adaptive tendencies across heterogeneous institutional actors, and the replicator equations provide a parsimonious representation of repeated payoff-based adjustment rather than an empirically estimated behavioral law for each individual actor. Second, when the financial leasing company does not provide services, the two demand-side strategies yield identical payoffs and the corresponding replicator dynamic degenerates, producing zero eigenvalues at some boundary equilibria. This property arises from the payoff specification that the demand side reverts to conventional procurement when the leasing transaction fails and is therefore a consequence of the modeling assumptions. Such equilibria are treated as neutrally stable boundary equilibria rather than locally asymptotically stable equilibria in the subsequent stability analysis.
3.3. Construction of the Payoff Matrix
To maintain consistency between the payoff matrix and the direction of the replicator dynamics, all payoffs are expressed as benefits, with cost items entering the payoff functions as negative values.
Under conventional procurement, the expected cost of the energy demand side is:
Under financial leasing, the expected cost of the energy demand side is:
Because , financial leasing generates no additional shortage loss under prolonged conflict.
When a leasing transaction is completed, the expected net payoff of the financial leasing company is:
Here, denotes the net residual value obtained when the leasing company recovers and disposes of the equipment after a short-term end to the conflict. It incorporates equipment depreciation and disposal costs but excludes the idle-capacity loss borne by the leasing company; the term is therefore included separately as its risk-bearing cost to avoid double counting. The parameter denotes the net residual value of the equipment after prolonged conflict. In addition, and denote the bank financing costs incurred when the leasing company borrows an amount equal to the equipment principal at the financing rate under prolonged conflict and when the conflict ends in the short term, respectively, and these costs enter its net payoff separately.
Under conventional procurement or unsuccessful financial leasing, the government’s social risk cost is:
When financial leasing is successfully implemented, green-energy capacity can effectively cover emergency demand, while idle-capacity risk can be partly absorbed within the market through lease-term adjustment, renewal, subleasing, and residual-value disposal. The government’s social risk cost is therefore simplified to the baseline social risk cost:
This specification does not imply that shortage and idle-capacity risks vanish in practice; rather, it indicates that financial leasing can substantially reduce their social spillovers. The simplification is adopted to highlight the improvement that financial leasing introduces into the government’s social-risk function while preserving the tractability and interpretability of the tripartite evolutionary game.
The combined payoff matrix for the energy demand side, the financial leasing company, and the government is shown in Table 1. For notational simplicity, the government’s payoff in the table is written as:
Table 1.
Payoff matrix of the tripartite game.
In the strategy combination , the energy demand side intends to use financial leasing but the leasing company does not provide the service; the demand side therefore reverts to conventional procurement and receives payoff . In the combination , the leasing company has established service capacity but the demand side does not adopt financial leasing, so the leasing company incurs the service-preparation cost .
3.4. Replicator Dynamics
Let denote the proportion of demand-side actors adopting the financial leasing strategy , and let denote the proportion adopting conventional procurement . Let denote the proportion of financial leasing companies providing leasing services , and let denote the proportion not providing services . Let denote the proportion of governments adopting the incentive strategy , and let denote the proportion adopting the non-incentive strategy .
3.4.1. Replicator Dynamic of the Energy Demand Side
The expected payoff to the energy demand side from choosing financial leasing is:
The expected payoff to the energy demand side from choosing conventional procurement is:
The average expected payoff of the energy demand-side population is:
The replicator dynamic of the energy demand side is therefore:
Define as the energy demand side’s payoff advantage of financial leasing over conventional procurement:
Then:
When , financial leasing offers a cost-saving advantage over conventional procurement, and the proportion of demand-side actors adopting financial leasing increases.
3.4.2. Replicator Dynamic of Financial Leasing Companies
The expected payoff to a financial leasing company from providing leasing services is:
After simplification:
The expected payoff to a financial leasing company from not providing services is:
The average expected payoff of the population of financial leasing companies is:
The replicator dynamic of financial leasing companies is therefore:
Define as the financial leasing company’s payoff advantage of providing financial leasing services over non-provision:
Then:
When , providing financial leasing services yields a higher payoff than not providing them, and the proportion of companies offering such services increases.
3.4.3. Replicator Dynamic of the Government
The expected payoff to the government from providing incentive policies is:
Here, .
The expected payoff to the government from not providing incentive policies is:
The average expected payoff of the population of governments is:
The government’s replicator dynamic is therefore:
Define as the government’s payoff advantage of adopting the incentive strategy over the non-incentive strategy:
Then:
When , adopting the incentive strategy yields a higher payoff to the government than adopting the non-incentive strategy, and the proportion of governments adopting incentive policies increases.
3.4.4. System of Tripartite Replicator Dynamics
Combining the three equations yields the following system of replicator dynamics for the energy demand side, financial leasing companies, and the government:
3.5. System Equilibria and Local Stability
Setting:
The system has the following eight pure-strategy boundary equilibria:
The equilibrium represents a state in which the energy demand side adopts financial leasing, the leasing company provides services, and the government provides no incentive. The equilibrium represents a state in which the energy demand side adopts financial leasing, the leasing company provides services, and the government provides incentives. Because the central concern is whether financial leasing can generate stable cooperation, the analysis focuses primarily on the stability conditions of and .
The Jacobian matrix of the system is:
In addition to the eight pure-strategy boundary equilibria, the tripartite replicator system may admit an interior mixed-strategy equilibrium under particular parameter combinations. An interior equilibrium must satisfy:
That is:
The existence of an interior equilibrium depends closely on the parameter combination and generally represents a critical state in which each of the three populations maintains an interior strategy proportion. Because this study focuses on whether financial leasing can produce a stable cooperative state with clear institutional meaning and practical applicability, the analysis concentrates on pure-strategy equilibria, particularly the market-driven equilibrium and the policy-guided equilibrium .
A further point concerns the factor in the demand-side replicator dynamic. When the service-provision proportion reaches one, that is, , the corresponding boundary plane also contains a mixed-strategy equilibrium. Setting and yields , where and . Under the numerical parameters in Section 4 at , . Substitution into the Jacobian matrix gives eigenvalues of approximately 236.4, −236.4, and −634, so is a saddle point whose stable manifold forms an important local separating structure on the boundary of the basin of attraction of the policy-guided equilibrium . Moreover, when , the demand-side strategy cannot be implemented in practice and its replicator dynamic degenerates; the plane therefore contains two neutrally stable boundary equilibrium lines, and , with , rather than only the corresponding pure-strategy vertices. The value is precisely the critical initial proportion of government incentives required for sustained diffusion of the demand-side strategy, which explains why entry into tripartite coordination in the interval depends strongly on the initial policy proportion, as illustrated in Section 4.4. Substituting the pure-strategy equilibria into the Jacobian matrix yields Table 2.
Table 2.
Eigenvalues at the pure-strategy equilibria.
Table 2 shows that and have zero eigenvalues and are therefore neutrally stable boundary equilibria rather than locally asymptotically stable equilibria. The equilibria , , and each contain a positive eigenvalue and do not satisfy the local asymptotic stability conditions. The principal equilibria capable of supporting stable cooperation are and .
The sign of in the government-direction eigenvalue at the policy-guided boundary equilibrium also requires clarification. The government replicator dynamic multiplies the government payoff advantage by the standard boundary factor for the incentive-strategy proportion. At the boundary where the incentive-strategy proportion equals one, linearization reverses the sign of that payoff advantage. Because the payoff advantage is the incremental policy-synergy benefit net of the two subsidies and the policy-implementation cost, the relevant eigenvalue is the negative of that bracketed payoff advantage. Thus, the leading negative sign on is generated by boundary linearization and does not redefine as a negative benefit. The separate government-inaction term introduced in Assumption 10 represents an optional accountability or opportunity cost and is set to zero in the benchmark model.
Proposition 1.
If:
then is a locally asymptotically stable equilibrium.
Under these conditions, financial leasing has a cost advantage over conventional procurement, so the energy demand side tends to adopt financial leasing. The leasing company’s rental-business revenue is sufficient to cover its costs, so it chooses to provide leasing services. However, the incremental policy-synergy benefit from government intervention is insufficient to cover subsidies and policy-implementation costs, so the government’s stable strategy is not to provide incentives. This equilibrium indicates that the financial leasing market can operate stably through market mechanisms alone.
Proof.
According to Table 2, the three eigenvalues at are , , and . When the conditions of the proposition hold, all three eigenvalues are negative. By Lyapunov’s indirect method, is therefore a locally asymptotically stable equilibrium. Under the numerical parameters in Section 4, the condition corresponds to a conflict-persistence probability . This completes the proof. □
Proposition 2.
If , then is a locally asymptotically stable equilibrium.
Under these conditions, government subsidies and policy support make financial leasing attractive to the energy demand side, while the leasing company also earns a positive payoff. The incremental policy-synergy benefit generated by government intervention exceeds the combined subsidy and policy-implementation costs, so the government’s stable strategy is to provide incentives. This equilibrium indicates that financial leasing can form a stable cooperative configuration among the demand side, leasing companies, and the government under policy incentives.
Proof.
Similarly, when the conditions of the proposition hold, the eigenvalues , , and at are all negative; therefore, is a locally asymptotically stable equilibrium. This completes the proof. □
3.6. Comparative Statics of Key Parameters
Before presenting the model implications, this section analytically examines how key contractual and policy parameters affect each player’s payoff advantage and provides a theoretical basis for the numerical sensitivity analysis in Section 4.
3.6.1. Effect of the Risk-Sharing Coefficient
The risk-sharing coefficient is the proportion of idle-capacity loss borne by the demand side when the conflict ends in the short term. From the financial leasing cost function:
It follows that:
A higher increases the idle-capacity loss borne by the demand side and weakens the attractiveness of financial leasing to that side.
From the leasing company’s net payoff:
It follows that:
A higher reduces the idle-capacity loss borne by the leasing company and increases its payoff.
The risk-sharing coefficient therefore affects the demand side and the leasing company in opposite directions. In practice, should not be set too high, because this would discourage the demand side from adopting financial leasing; nor should it be set too low, because this would weaken the leasing company’s incentive to supply services. A balanced allocation of risk is therefore essential for cooperation between the two actors. Under the numerical parameters in Section 4 at , the demand-side participation constraint implies feasible upper bounds of approximately 0.063 without the demand-side subsidy and 0.688 with the demand-side subsidy. Under the spread-based pricing structure, the leasing company remains profitable over the benchmark range of conflict-persistence probabilities, so its break-even lower bound is not binding.
3.6.2. Effect of the Unit Shortage Loss
The unit shortage loss primarily affects shortage risk under conventional procurement. From the conventional-procurement cost function:
Therefore:
A higher increases the shortage loss under conventional procurement and strengthens the relative advantage of financial leasing. Accordingly, the more severe the consequences of energy shortages, the more likely the demand side is to use financial leasing to deploy sufficient green-energy capacity.
3.6.3. Effect of the Full Rental Payment
The full rental payment affects the demand side and the financial leasing company in opposite directions. For the demand side:
A higher raises the cost of financial leasing and reduces the demand side’s willingness to adopt it.
For the financial leasing company:
A higher increases rental income and strengthens the company’s incentive to provide services.
The parameter is therefore a key contractual variable balancing demand-side acceptance and leasing-company profitability. An excessively high discourages demand-side participation, whereas an excessively low may weaken the leasing company’s supply incentive. A reasonable rental interval must satisfy both of the following conditions:
And
3.6.4. Effects of Government Subsidies and , and the Incremental Policy-Synergy Benefit
The subsidy to the demand side directly increases its payoff advantage from adopting financial leasing:
The subsidy to the financial leasing company directly increases its payoff advantage from providing leasing services:
However, subsidies also increase the government’s fiscal burden. The government’s payoff advantage is:
Although and encourage participation by the demand side and the leasing company, excessive subsidies reduce the government’s net payoff from adopting the incentive strategy. Government subsidies should therefore be designed to move the system into a stable cooperative state rather than to maximize the subsidy amount itself.
The incremental policy-synergy benefit has a positive effect on the government’s willingness to provide incentives:
The greater the incremental policy-synergy benefit generated by standardization, platform coordination, credit enhancement, and large-scale promotion, the stronger the government’s incentive to intervene. This result reflects the public-safety attributes of emergency green-energy supply-chain projects and supports the government’s policy-guidance role through subsidies, guarantees, and interest subsidies.
3.6.5. Effect of the Leasing Company’s Service-Preparation Cost
The service-preparation cost primarily affects the leasing company’s willingness to supply services before market demand is fully established. From the leasing company’s payoff advantage , it follows that:
When , all demand-side actors adopt financial leasing, and the service-preparation cost no longer affects the leasing company’s marginal strategic choice. When , however, a higher reduces the payoff advantage from providing services, making the leasing company more likely to withdraw because of insufficient market demand and high upfront preparation costs. The leasing company is willing to provide services only if , that is, . When , this condition can be rearranged as . Thus, when the proportion of demand-side actors adopting financial leasing is low, a high service-preparation cost substantially narrows the leasing company’s participation space. Reducing or offsetting it through the government subsidy can therefore expand the basin of attraction of the policy-guided equilibrium . This also explains why the early diffusion of financial leasing requires both an initial market-participation base and an initial policy push.
In summary, stable diffusion of financial leasing requires financial leasing to be payoff-preferred by the demand side and service provision to be payoff-preferred by the leasing company, while the sign of the government’s payoff advantage from adopting the incentive strategy determines whether the stable cooperative equilibrium is market-driven or policy-guided. The system therefore admits two stable equilibria, a market-driven equilibrium and a policy-guided equilibrium . Section 4 provides numerical verification of these conditions, quantifies the basins of attraction, and reports the thresholds of the key parameters.
4. Numerical Simulation Analysis
Numerical simulations are used to visualize and further examine the theoretical model developed above. First, a calibrated numerical example consistent with an emergency green-energy supply-chain setting is specified, and the analytical conditions derived in Section 3 are verified. Second, the dynamic evolution of the strategies adopted by the energy demand side, financial leasing companies, and the government is simulated to test the stability of the evolutionary outcomes. Third, sensitivity analyses are conducted for the key parameters. Finally, a global grid search, a continuous-capacity robustness analysis, a joint parameter uncertainty analysis, and numerical convergence tests are conducted to quantify the basin of attraction, calculate key parameter thresholds, and examine whether the main conclusions remain robust to alternative capacity choices, simultaneous variation in multiple scenario parameters, and alternative numerical settings.
4.1. Parameterization of the Numerical Example
The numerical example considers a geopolitical conflict that disrupts energy-import corridors and requires the demand side to deploy emergency wind-power, photovoltaic, and energy-storage equipment rapidly. The parameters are calibrated using publicly available cost ranges and scenario-based assumptions. Table 3 reports the core parameters: equipment costs are benchmarked against publicly available cost levels for wind-power and energy-storage projects in China [46,47]; shortage losses are based on published studies of outage costs and scenario assumptions for critical energy users [48,49,50]; and lease and subsidy parameters are informed by financial leasing price ranges and regional support policies for new energy storage [51,52,53], as detailed in the Supplementary Materials. These values are intended to test the theoretical mechanisms and threshold relationships rather than to estimate any single real project precisely. Importantly, the standardized unit used in this study represents a stylized emergency green-energy equipment-package unit rather than a fixed MW measure of firm or reliable power output. The 0.1 MW nominal-power value used in the Supplementary Materials serves only as an illustrative benchmark for order-of-magnitude cost and shortage-loss conversions and should not be interpreted as a fixed engineering equivalence. The effects of these parameter choices are further examined through the sensitivity analysis in Section 4.3, the threshold calculations in Section 4.4, and the joint parameter uncertainty analysis in Section 4.6.
Table 3.
Core parameters of the numerical example.
For international comparability, all monetary values in the numerical example are presented in U.S. dollars (USD). Values originally denominated in Chinese yuan (CNY) are converted using a fixed presentation exchange rate of USD 1 = CNY 6.71. Converted values are rounded for presentation, whereas all analytical ratios, thresholds, and model calculations use the unrounded proportional conversion; therefore, the dimensionless probabilities, strategy proportions, and equilibrium conditions are unchanged.
It should be noted that is not merely an interim rental payment. Rather, it is the comprehensive leasing charge paid by the demand side when the conflict ends in the short term and includes the basic rent, equipment-occupation charge, emergency-dispatch service fee, and risk premium. Accordingly, may exceed the capital expenditure under conventional procurement.
The baseline social risk cost represents the residual crisis-related social burden that remains even after the incremental shortage-loss and idle-capacity components are separated from the government’s payoff. Economically, it captures background energy-security exposure and unavoidable social or industrial disruption associated with a geopolitical energy-supply shock that is common to the compared government states. It excludes the incremental shortage and idle-capacity losses already represented elsewhere in the social-risk function and is also distinct from , the policy implementation and regulatory cost incurred when the government adopts the incentive strategy. The benchmark value of USD 1.490 million is therefore a scenario-based normalization used to anchor the absolute level of the government’s payoff rather than an empirical estimate for a specific government or project. Because enters the relevant government payoff states symmetrically and cancels in the incentive-versus-non-incentive payoff difference, its exact magnitude does not affect the government’s replicator dynamic, the direction of strategy evolution, or the equilibrium conditions.
According to the tripartite evolutionary game in Section 3, the cost of conventional procurement is:
Substituting the parameters in Table 3 gives:
After simplification:
The cost of financial leasing is:
Substituting the parameters gives:
After simplification:
The cost advantage of financial leasing over conventional procurement for the demand side is therefore:
Without the demand-side subsidy, the critical conflict-persistence probability for the demand side to adopt financial leasing is:
When the government provides the demand-side subsidy = USD 1.4903 million and adopts the incentive strategy, that is, , the cost advantage of financial leasing becomes:
The corresponding critical probability is:
The demand-side subsidy therefore substantially lowers the adoption threshold for financial leasing. It enables the demand side to adopt financial leasing even when the conflict-persistence probability is relatively low.
The expected net payoff of the financial leasing company when the transaction is completed is:
Substituting the parameters gives:
After simplification:
Because holds for all , the financial leasing company has an economic incentive to provide services whenever the demand side generates actual leasing demand.
The government’s payoff advantage from providing incentives under tripartite coordination is:
Thus, when both the demand side and the leasing company participate actively, government intervention generates a positive incremental net benefit.
The improvement in emergency supply capacity attributable to financial leasing can also be measured directly from the deployment scale. Under the capital constraint, conventional procurement deploys only , leaving a capacity shortfall of under prolonged conflict, equivalent to approximately 20% of emergency demand. Financial leasing increases the deployment scale to and eliminates the shortfall. Define the Emergency Supply Adequacy Ratio as . Under prolonged conflict, the ratio is for conventional procurement and for financial leasing. Financial leasing therefore increases emergency green-energy deployment by , or 50%, and raises the Emergency Supply Adequacy Ratio from 80% to 100%. If the conflict-persistence probability is also considered, the expected capacity shortfall under conventional procurement is , whereas it is zero under financial leasing. At the benchmark value , the expected Emergency Supply Adequacy Ratio rises from 0.96 to 1.00, providing direct capacity-based evidence that financial leasing strengthens energy security. Because this indicator captures only static capacity adequacy under prolonged conflict and does not include recovery or adaptation, it is termed the Emergency Supply Adequacy Ratio rather than a comprehensive supply-chain resilience index. Accordingly, the reported 80% and 100% adequacy ratios should be interpreted as normalized capacity-adequacy measures within the stylized model rather than as engineering estimates of firm renewable-energy output or comprehensive physical-system resilience. In this study, emergency supply adequacy is therefore treated as one operational dimension of energy supply-chain resilience rather than as a comprehensive resilience measure.
The following sections focus on the dynamic evolution of the three strategies, sensitivity to key parameters, a global grid search over initial conditions and basin-of-attraction analysis, and parameter thresholds.
4.2. Simulation of the Tripartite Evolutionary Game
4.2.1. Simulation Objective
Based on the tripartite evolutionary game in Section 3, this subsection simulates the dynamic evolution of the strategy proportions of the energy demand side, financial leasing companies, and the government. The purpose is to examine whether financial leasing evolves into a stable cooperative outcome under different conflict-persistence probabilities and levels of policy support. The tripartite system of replicator dynamics is given in Section 3.4.4 and is not repeated here.
Here, is the proportion of demand-side actors adopting financial leasing, is the proportion of financial leasing companies providing services, and is the proportion of governments providing incentives.
4.2.2. Evolutionary Outcomes Under Different Conflict-Persistence Probabilities
To examine the effect of the conflict-persistence probability on system evolution, the following values are considered:
These values represent low, medium, and high risks of conflict persistence, respectively. To ensure reproducibility, the three scenarios for the conflict-persistence probability in Figure 1 use the same initial strategy proportions:
Figure 1.
Dynamic evolution of the three strategy proportions under different conflict-persistence probabilities.
The initial condition represents a relatively high willingness to participate on the part of the energy demand side, financial leasing companies, and the government at the early stage of financial leasing diffusion and is used to compare the direction of strategy evolution under different conflict-persistence probabilities.
The evolutionary incentives in the three scenarios can be determined directly from the analytical conditions. When , even with the demand-side subsidy, the demand-side payoff advantage is ; financial leasing has no cost advantage, and continues to decline. When , , so diffusion of the demand-side strategy requires . A sustained increase in government incentives further requires , which in turn requires a relatively strong initial participation base among the demand side and leasing companies. When , , financial leasing already has a clear cost advantage without subsidies, and ; the payoff basis for full tripartite coordination is therefore satisfied.
Figure 1 illustrates clear differences in strategy evolution across the three scenarios. When , the demand-side proportion declines first and approaches zero before ; the leasing-company proportion remains temporarily high because of existing demand but collapses around ; and the proportion of governments providing incentives declines simultaneously. The system thus exhibits a chain reaction of demand withdrawal, service contraction, and incentive failure. When , all three proportions converge to 1; and converge first by , while converges more slowly, indicating that diffusion of government incentives depends on the prior accumulation of participation by the demand side and leasing companies. When , all three proportions rapidly converge to 1 by , substantially faster than in the medium-risk scenario. Comparison across the three panels confirms that a higher conflict-persistence probability accelerates the diffusion of financial leasing and reduces its dependence on initial policy support, consistent with the analytical conditions above.
4.2.3. Evolutionary Trajectories Under Different Initial Conditions
To further test the local stability of the policy-guided equilibrium, four sets of initial strategy proportions are selected from the basin of attraction of , , , and . At the benchmark , all four initial conditions satisfy the demand-side diffusion requirement and provide the market-participation base required for government incentives to continue increasing.
The evolutionary trajectories under the four initial conditions are shown in Figure 2. The simulation results show that the three strategy proportions increase gradually under all four initial conditions and ultimately converge to , thereby confirming the stability conditions in Proposition 2.
Figure 2.
Evolutionary trajectories of the three strategies under different initial conditions. Note: To display trajectories within the basin of attraction of the policy-guided equilibrium more clearly, the axes in Figure 2 are locally rescaled.
It should be emphasized that, if , , or is too low initially, the system may fail to enter the basin of attraction of and thus fail to achieve tripartite coordination. At the early stage of financial leasing diffusion, the government therefore needs not only to provide subsidies or risk compensation but also to increase the initial willingness of the demand side and leasing companies to participate through policy communication, demonstration projects, credit guarantees, and trading-platform development. These measures can help the system move beyond a low-cooperation state and enter a stable coordination region. Section 4.4 systematically quantifies the failure trajectories under low initial participation and the corresponding basin of attraction.
As shown in Figure 2, all four trajectories converge to , but their paths and convergence times differ markedly. The initial condition with the highest overall participation, , follows the most direct path and converges fastest. By contrast, the condition with the lowest initial proportion of governments providing incentives, , follows a pronounced detour: demand and service participation advance while remains relatively low, and accelerates only after a sufficient participation base has formed, producing the longest convergence time. This ordering is consistent with the structural dependence of on in the government replicator dynamic: the diffusion of government incentives requires a sufficient market-participation base, while demand-side adoption may also depend on initial policy support. The two mechanisms therefore reinforce each other during the early stage of diffusion.
4.3. Sensitivity Analysis of Key Parameters
Building on the comparative statics in Section 3.6, this subsection uses numerical simulations to quantify how the key parameters affect the demand-side payoff advantage , the leasing-company payoff advantage and net payoff , and the government’s incentive payoff advantage , as defined in Section 3. The parameters examined are the risk-sharing coefficient , the unit shortage loss , the full rental payment , the government subsidies and , the incremental policy-synergy benefit , and the leasing company’s service-preparation cost .
To ensure reproducibility, the sensitivity analysis uses the following medium conflict-persistence probability as the benchmark:
and the following neighborhood of the tripartite coordinated state:
These values are held fixed in the sensitivity analysis. In Figure 3, all parameters other than the parameter under examination remain at the benchmark values reported in Table 3. Figure 3a–c examine how contractual and market parameters affect the demand-side payoff advantage and the leasing company’s net payoff . Figure 3d examines the effects of the demand-side subsidy on and ; Figure 3e examines the effects of the leasing-company subsidy on and ; and Figure 3f examines the effect of the incremental policy-synergy benefit on .
Figure 3.
Sensitivity of the demand-side payoff advantage, the leasing company’s net payoff, and the government’s incentive payoff advantage to key parameters. The asterisks (*) indicate the zero-crossing thresholds of the corresponding payoff measures.
The numerical results in Figure 3 are fully consistent with the directions predicted by the comparative statics in Section 3.6. In Figure 3a, decreases linearly with , whereas increases linearly with , confirming that the risk-sharing arrangement affects the demand side and the leasing company in opposite directions. equals zero at approximately , while remains positive for all because the spread structure keeps the leasing company profitable at the benchmark conflict-persistence probability. In Figure 3b, increases linearly with and crosses zero at approximately . In Figure 3c, decreases with and crosses zero at approximately . In Figure 3d, the demand-side subsidy improves , which equals zero at approximately USD 0.805 million, but weakens , which equals zero at approximately USD 1.937 million, directly illustrating the dual boundary of the demand-side subsidy. In Figure 3e, increases but reduces , which equals zero at approximately . In Figure 3f, increases linearly with , and the zero-crossing corresponds to the critical condition in Proposition 2. These zero-crossings corroborate the quantitative thresholds reported in Section 4.4.2.
The sensitivity analysis in Figure 3 is conducted in a neighborhood of the tripartite coordinated state , where . Under this condition, the marginal effect of the service-preparation cost on is eliminated. A separate sensitivity curve for is therefore not plotted; its effect on the market-participation base before the system enters the basin of attraction of is discussed analytically in Section 3.6.5.
4.4. Global Grid Search over Initial Conditions and Numerical Analysis of the Basin of Attraction
4.4.1. Global Grid Search and Quantification of the Basin of Attraction
Figure 2 examined convergence primarily under relatively high initial participation. To systematically evaluate the basin of attraction of the policy-guided equilibrium , a uniform grid is constructed over the initial strategy space , using the center of each grid cell and yielding 8000 initial points. The tripartite replicator system is integrated numerically using a fourth-order Runge–Kutta method with a step size of 0.05 and an integration horizon of 200. Payoffs are normalized by a common scale, which only rescales time and does not affect the direction of evolution or the classification of the basin of attraction. An initial point is classified as converging to if the terminal state satisfies , , and . Otherwise, it is classified as a low-leasing-adoption boundary state characterized by , , and stagnation of . The grid, integration horizon, and terminal thresholds are held constant across all parameter settings to ensure comparability of the basin shares. Figure 4a shows trajectories from 34 initial points at , including 28 uniformly sampled random points with seed 42 and six representative points. Green trajectories converge to , whereas red trajectories converge to low-leasing-adoption states, revealing a clear separation between basins of attraction. A numerical convergence assessment of the grid density, integration step, integration horizon, and terminal classification threshold is reported in Section 4.7.
Figure 4.
Global grid search over initial conditions and quantification of the basin of attraction of The blue lines with circular markers in panels (b) and (c) represent the simulated basin share of under varying conflict-persistence probabilities and demand-side subsidies, respectively.
Figure 4b reports the share of the initial strategy space occupied by the basin of attraction of as the conflict-persistence probability varies. Analytically, when , where 0.127 is the critical probability under the demand-side subsidy, the demand-side strategy cannot diffuse persistently and the basin share approaches zero. The basin expands as rises, with its share increasing further once exceeds the unsubsidized critical probability . The numerical results are consistent with this prediction: the basin share is approximately 23.2% at , approximately 64% near , approximately 77% at , approximately 87% at , and 96.3% at , approaching approximately 98% as tends to 1. The underlying mechanism is that, once , financial leasing has a cost advantage even when the proportion of governments providing incentives is low. The diffusion of the demand-side strategy therefore becomes less dependent on initial policy support. However, because the incremental net benefit of government intervention remains positive under the benchmark parameters, the system may still converge to the policy-guided equilibrium rather than the market-driven equilibrium.
Figure 4c further examines how the demand-side subsidy affects the basin share at . The demand-side subsidy exhibits a clear dual boundary. When , the demand-side participation condition cannot be satisfied and the basin share is zero. When , the incremental net benefit of government intervention becomes negative, causing to lose stability and the basin to disappear again. Within the effective interval of USD 0.805–1.937 million, the basin share follows an inverted-U-shaped pattern as the demand-side subsidy increases and reaches a peak of approximately 23.5% when is approximately USD 1.341 million before declining rapidly and approaching zero near both boundaries in the numerical scan. Both insufficient and excessive demand-side subsidies can therefore undermine tripartite coordination. The objective of subsidy design should be to move the system into the cooperative basin of attraction rather than simply to increase the subsidy level.
4.4.2. Quantitative Thresholds of Key Parameters
Using the analytical expressions in Section 4.1, the quantitative thresholds of the key contractual and policy parameters can be calculated for the benchmark case , with all other parameters set to the values in Table 3. All thresholds are calculated from the complete expressions for and at . Specifically, , so that in units of USD million. The thresholds reported in the table are critical boundaries under strict inequalities. The results are summarized in Table 4, and the corresponding critical-value curves are shown in Figure 5.
Table 4.
Quantitative thresholds of key parameters (benchmark case: ).
Figure 5.
Critical-value curves of the key parameters (). The asterisks (*) denote the critical parameter values at which the corresponding payoff advantage equals zero.
Table 4 and Figure 5 show that these thresholds have direct implications for contract design and policy formulation. First, the feasible upper bound of the risk-sharing coefficient increases from approximately 0.06 to approximately 0.69 when the demand-side subsidy is introduced. This substantial relaxation of the demand-side participation constraint creates greater bargaining space for allocating risk between the leasing actors. Under spread-based pricing, the leasing company’s break-even lower bound is not binding at the benchmark conflict-persistence probability because remains positive; the feasible interval is therefore determined mainly by the upper bound imposed by the demand-side participation condition. Second, the upper bound on the full rental payment increases from USD 11.624 million to USD 19.076 million with the demand-side subsidy, indicating that part of the demand-side subsidy may be converted into pricing space for the leasing company. Policy design should therefore prevent excessively high rents from absorbing the demand-side subsidy benefit. Third, the demand-side subsidy has an effective interval of USD 0.805–1.937 million, within which the basin share follows an inverted-U-shaped pattern as the demand-side subsidy increases. This result is consistent with the stability condition in Proposition 2 and provides a quantitative basis for designing moderate and targeted incentive policies.
4.5. Robustness Check with Continuous Capacity Choice
The benchmark analysis adopts discrete capacity levels to obtain transparent analytical thresholds. However, the comparison between 80 units under conventional procurement and 120 units under financial leasing may raise the concern that the capacity advantage of financial leasing is partly driven by the predetermined scenario. To address this concern, this subsection relaxes the discrete-capacity assumption and allows the demand side to select emergency green-energy capacity continuously under the financing constraints of the two financing modes.
Let denote the continuously selected emergency green-energy capacity and let denote the baseload capacity that can continue to be absorbed after a short-term end to the conflict. Under conventional procurement, the expected cost of the demand side is:
subject to:
The optimal capacity under conventional procurement is therefore:
The first term represents capacity investment cost, the second represents the expected shortage loss when deployed capacity is below emergency demand, and the third represents the expected idle-capacity loss when capacity exceeds the baseload absorption level. Under the benchmark parameters, USD 7.452 million and USD 0.0931 million per standardized unit. Using the unrounded converted values:
Thus, even when capacity is continuously selected, conventional procurement cannot finance more than 80 standardized units under the benchmark capital constraint.
Under financial leasing, the upfront financing requirement is reduced to a fraction of the equipment investment and the demand side bears only a share of the idle-capacity loss. To isolate the capacity-feasibility mechanism from the contractual cash flows analyzed in the tripartite game, the auxiliary optimization retains as the underlying equipment resource cost, while financing feasibility is represented by the relaxed upfront constraint . The auxiliary resource-cost function is therefore specified as:
subject to:
Similarly, the optimal capacity under financial leasing is:
For the robustness calculation, and , consistent with the benchmark emergency-demand and baseload-absorption settings. The reference range for the down-payment ratio under financial leasing is . Accordingly, the financing ceiling under financial leasing ranges from approximately 266.7 to 800 standardized units, which is above the emergency demand of 100 units throughout the reference range. To make the robustness test conservative, the maximum leasing capacity is capped at the actual emergency demand , thereby removing the 20-unit safety margin contained in the original 120-unit benchmark scenario.
Using the remaining benchmark parameters in Table 3, the optimal capacities under the three representative conflict-persistence probabilities used in Figure 1 are reported in Table 5.
Table 5.
Continuous-capacity robustness results.
The continuous-capacity results confirm that the main capacity conclusion does not depend on fixing deployment at 80 and 120 units. When the conflict-persistence probability is low (), neither financing mode supports additional emergency deployment in the auxiliary optimization. When the conflict-persistence probability increases to or , conventional procurement reaches its financing-constrained ceiling of 80 units and therefore leaves a 20-unit emergency-capacity shortfall, whereas financial leasing reaches the full 100-unit emergency-demand level. Importantly, this result is obtained after eliminating the original 20-unit safety margin under financial leasing. The capacity advantage of financial leasing therefore arises from the relaxation of the upfront financing constraint rather than from the exogenous 80/120 capacity specification.
This continuous-capacity analysis is intended as a robustness check of the financing-induced capacity mechanism and does not replace the full contractual payoff model developed in Section 3.2, Section 3.3, Section 3.4, Section 3.5 and Section 3.6. In particular, the critical conflict-persistence probabilities for adopting financial leasing reported in Section 4.1 continue to be derived from the complete payoff comparison incorporating rental payments, residual values, financing costs, risk sharing, and government subsidies.
4.6. Joint Parameter Uncertainty Analysis
The preceding sensitivity analysis varies individual parameters while holding the remaining parameters at their benchmark values. However, several capacity, contractual, and policy parameters in the numerical example are scenario-based rather than estimated from a single empirical project. Simultaneous variation in these parameters may therefore affect the quantitative thresholds reported above. To examine whether the main conclusions remain robust under joint parameter uncertainty, this subsection conducts a Latin hypercube sampling (LHS) analysis in which the principal scenario parameters are varied simultaneously.
A total of joint parameter combinations are generated using Latin hypercube sampling. For scenario parameters without project-level empirical probability distributions, triangular distributions centered on the benchmark values are adopted. The benchmark value is treated as the most likely value, while the lower and upper bounds represent deliberately broad scenario ranges rather than estimated statistical confidence intervals. Most monetary scenario parameters are varied within ±30% of their benchmark values. A wider range of 50–150% of the benchmark value is adopted for the unit shortage loss , reflecting the greater uncertainty associated with the calibration of shortage losses. The parameter ranges and distributions are reported in Table 6.
Table 6.
Parameter ranges for the joint parameter uncertainty analysis.
The sampling procedure preserves the structural relationships required by the model. In particular, , , , and are maintained. Samples violating these restrictions are redrawn. The variation in should be interpreted as uncertainty in the financing-constrained feasible capacity associated with the underlying capital constraint, rather than as an arbitrarily imposed investment scale. Accordingly, is not treated as an independent uncertainty parameter. For each sampled value of , the corresponding one-off internal-fund ceiling is implicitly adjusted according to , with the unit construction cost held at its benchmark value. Thus, the conventional-procurement financing constraint remains binding for every sampled combination. All other parameters not included in the joint sampling are held at their benchmark values in Table 3.
For each sampled parameter combination, four outcomes are evaluated: (i) the critical conflict-persistence probability for demand-side adoption of financial leasing without the demand-side subsidy; (ii) the corresponding critical probability with the demand-side subsidy; (iii) the maximum risk-sharing coefficient consistent with demand-side participation under the subsidized case; and (iv) whether the conditions for the policy-guided cooperative equilibrium are simultaneously satisfied. These quantities are calculated directly from the analytical expressions developed in Section 3 and Section 4.1, without rerunning the global initial-condition grid search for each sample.
Without the demand-side subsidy, the critical conflict-persistence probability for demand-side adoption is:
With the demand-side subsidy , the corresponding critical probability is:
The critical-probability interpretation applies when the denominator in Equations (41) and (42) is positive, so that the relative advantage of financial leasing increases with the conflict-persistence probability. Samples that do not generate a unique economically admissible threshold within are retained for feasibility classification but are reported separately from the percentile statistics of the interior thresholds.
At the benchmark conflict-persistence probability , the maximum risk-sharing coefficient consistent with demand-side participation under the subsidized case is:
If , the entire economically admissible interval satisfies the demand-side participation condition. If , no positive risk-sharing interval satisfies the participation condition under that sampled parameter combination.
To evaluate the robustness of policy-guided cooperation at , three local conditions are checked simultaneously: , , and . Define the indicator:
The share of samples for which measures the proportion of sampled parameter combinations for which all three local conditions supporting the policy-guided cooperative equilibrium are simultaneously satisfied.
Although is included in the joint sampling for completeness, it does not affect the four threshold and local-stability outcomes reported here. As shown analytically in Section 3.6.5, enters the leasing-company replicator dynamic when demand-side adoption is below one but drops out of the local stability condition at the policy-guided equilibrium; because the global diffusion process is not rerun for each sampled combination, its variation does not affect the reported joint-uncertainty results.
The joint uncertainty results show that the exact adoption thresholds vary across scenario combinations, but the directional effect of demand-side support remains robust. Among samples generating economically admissible interior thresholds, the median critical conflict-persistence probability without the demand-side subsidy is 0.279 (5th–95th percentile: 0.095–0.664), close to the benchmark value of 0.286. With the demand-side subsidy, the median threshold decreases to 0.150 (5th–95th percentile: 0.023–0.421), compared with the benchmark value of 0.127. Among samples for which both thresholds are interior, the subsidized threshold is lower than the unsubsidized threshold in 100% of cases, consistent with the analytical structure of Equations (41) and (42). These benchmark and percentile results are summarized in Table 7.
Table 7.
Joint parameter uncertainty results for key thresholds.
The threshold classification further clarifies the non-interior cases. Without the demand-side subsidy, 92.80% of samples generate an interior threshold, 1.08% yield a threshold below zero, 4.08% yield a threshold above one, and 2.04% have a non-positive denominator for which the standard monotonic threshold interpretation does not apply. With the demand-side subsidy, 79.00% of samples generate an interior threshold, 18.04% yield a threshold below zero, 0.92% yield a threshold above one, and 2.04% have a non-positive denominator for which the standard monotonic threshold interpretation does not apply. A threshold below zero indicates that financial leasing is already attractive to the demand side throughout the feasible range of the conflict-persistence probability. At , the share of sampled parameter combinations supporting demand-side adoption rises from 26.6% without the subsidy to 72.1% with the subsidy, and all three conditions for the policy-guided cooperative equilibrium are simultaneously satisfied in 55.2% of the sampled combinations.
Figure 6 compares the distributions of the interior critical conflict-persistence probabilities. The subsidized distribution of economically admissible interior thresholds shifts downward relative to the unsubsidized distribution, while the benchmark values lie close to the central parts of their respective distributions. The dispersion across samples confirms that the numerical thresholds are scenario-dependent, but the reduction in the demand-side adoption threshold under policy-supported financial leasing persists under simultaneous variation in multiple parameters.
Figure 6.
Critical conflict-persistence thresholds under joint parameter uncertainty. Note: The black diamonds indicate the benchmark values, and the horizontal lines within the boxes indicate the medians. The boxplots are based on samples generating economically admissible interior thresholds . Parameter combinations producing thresholds below zero, above one, or a non-positive threshold denominator are classified separately in the text.
The joint analysis also shows that the risk-sharing boundary is quantitatively uncertain. The raw value is non-positive in 7.88% of samples, implying that no positive risk-sharing interval satisfies demand-side participation under those combinations. An interior upper bound exists in 62.20% of samples; within this subset, the median is 0.559, with a 5th–95th percentile range of 0.087–0.951. In the remaining 29.92% of samples, is at least one, so the full economically admissible range satisfies the demand-side participation condition. These results indicate that the benchmark thresholds should be interpreted as scenario-specific reference values rather than point predictions for a particular project, while the main mechanism by which targeted policy support relaxes demand-side participation constraints remains robust.
Because the unit shortage loss has greater calibration uncertainty than most contract and policy parameters, an additional targeted robustness check is conducted to make its quantitative influence transparent. Consistent with the probabilistic specification in Table 6, is varied from USD 0.373 million/unit to USD 1.118 million/unit, with USD 0.745 million/unit as the benchmark. Using the illustrative 216,000 kWh unserved-energy basis in Section S2.2 of the Supplementary Materials, these values correspond to approximately USD 1.725, 3.450, and 5.175/kWh, respectively. All other parameters are held at their benchmark values. The resulting key thresholds are reported in Table 8.
Table 8.
Robustness of key thresholds to alternative unit shortage-loss calibrations.
The targeted calibration shows that the exact thresholds are sensitive to the assumed shortage-loss magnitude, as expected from the comparative statics in Section 3.6.2. Under the low-loss scenario ( = USD 0.373 million/unit), = 1.385 > 1, so unsubsidized financial leasing is not cost-preferred within the feasible range of the conflict-persistence probability, whereas the demand-side subsidy lowers the threshold to = 0.615. At the benchmark = USD 0.745 million/unit, the thresholds are 0.286 and 0.127. Under the high-loss scenario ( = USD 1.118 million/unit), the thresholds fall further to 0.159 and 0.071, while = 1.313 > 1, implying that the full risk-sharing interval is feasible from the demand-side participation perspective. Thus, although the numerical threshold values depend materially on , the directional mechanism remains unchanged: higher shortage losses reduce the adoption threshold for financial leasing, and the demand-side subsidy further reduces the threshold in all three scenarios.
4.7. Numerical Convergence Check
Because the basin shares reported in Section 4.4 are obtained using a finite initial-condition grid and numerical integration, additional convergence tests are conducted to examine whether the results are sensitive to the numerical settings. The benchmark calculation uses a 20 × 20 × 20 grid of initial conditions, a fourth-order Runge–Kutta integration step of 0.05, an integration horizon of 200, and a terminal classification threshold of 0.95. Holding the economic parameters fixed in the benchmark case , the basin calculation is repeated using denser 303 and 403 grids, a smaller integration step of 0.025, a longer integration horizon of 400, and alternative terminal thresholds of 0.90 and 0.99. An initial condition is classified as converging to the policy-guided equilibrium when all three terminal strategy proportions exceed the specified terminal threshold.
As shown in Table 9, the estimated basin share is highly stable across the alternative numerical specifications. Increasing the grid density from 203 to 303 and 403 changes the basin share only from 23.20% to 23.25% and 23.27%, respectively, with a maximum deviation of less than 0.07 percentage points from the baseline estimate. Halving the RK4 step size from 0.05 to 0.025, doubling the integration horizon from 200 to 400, and changing the terminal classification threshold from the baseline value of 0.95 to 0.90 and 0.99 leave the estimated basin share unchanged at 23.20%. These results indicate that the approximately 23.2% basin share reported in Section 4.4 is numerically stable and is not materially driven by the baseline grid density, integration step, horizon, or terminal classification rule.
Table 9.
Numerical convergence of the basin-of-attraction calculation.
5. Conclusions
This study develops a benchmark conventional-procurement decision model and a tripartite evolutionary game to examine how financial leasing affects emergency green-energy deployment under geopolitical conflict. The analysis focuses on financing feasibility, conflict-duration uncertainty, risk sharing, and government incentives, while interpreting emergency supply adequacy as one operational dimension rather than a comprehensive measure of energy-system resilience.
The main theoretical contribution is to connect three mechanisms that are usually analyzed separately: a binding upfront capital constraint on emergency capacity, the shortage-versus-idle-capacity trade-off created by uncertain conflict duration, and a leasing-based allocation of financing and idle-capacity risk coordinated with government incentives. This structure generates explicit adoption thresholds and risk-sharing boundaries and distinguishes market-driven from policy-guided cooperative equilibria.
The main quantitative findings are as follows.
(1) The conventional-procurement benchmark exhibits an underinvestment–idle-capacity dilemma. Under the numerical calibration, the demand side’s USD 7.452 million internal-fund constraint and unit construction cost of USD 0.0931 million per standardized unit limit conventional deployment to 80 standardized units against 100 units of emergency demand. The continuous-capacity robustness analysis confirms that, in the medium- and high-risk scenarios, conventional procurement remains financing-constrained at 80 units, whereas financial leasing reaches the full normalized emergency-demand level of 100 units even after the original 20-unit leasing safety margin is removed.
(2) Financial leasing and targeted demand-side support materially lower the adoption barrier. The critical conflict-persistence probability for demand-side adoption decreases from 0.286 without the subsidy to 0.127 with the subsidy, a reduction of approximately 56%. At the benchmark conflict-persistence probability, the subsidy raises the feasible upper bound of the risk-sharing coefficient from approximately 0.063 to 0.688 and the maximum acceptable full rental payment from USD 11.624 million to USD 19.076 million. The effective demand-side subsidy interval is USD 0.805–1.937 million; within this interval, the policy-guided basin exhibits an inverted-U pattern and peaks at approximately 23.5% when the subsidy is about USD 1.341 million.
(3) The tripartite system admits both market-driven and policy-guided cooperative equilibria. At the benchmark value p = 0.20, the policy-guided equilibrium occupies approximately 23.2% of the initial-strategy space, showing that favorable payoff conditions alone do not guarantee coordination when initial participation is weak. Numerical convergence tests confirm that this estimate is stable: refining the initial-condition grid from 203 to 403 changes the basin share only from 23.20% to 23.27%, while a smaller RK4 step, a longer integration horizon, and terminal thresholds of 0.90 and 0.99 leave the estimate unchanged at 23.20%.
(4) The exact numerical thresholds are scenario-dependent, but the principal directional mechanisms are robust. In the 5000-run Latin hypercube analysis, the share of sampled parameter combinations supporting demand-side adoption at p = 0.20 rises from 26.6% without the demand-side subsidy to 72.1% with it, while all three local conditions for the policy-guided equilibrium are simultaneously satisfied in 55.2% of samples. Among economically admissible interior thresholds, the median adoption threshold falls from 0.279 to 0.150 under the subsidy. A targeted shortage-loss calibration over USD 0.373–1.118 million per unit likewise preserves the directional result that higher shortage losses reduce the leasing-adoption threshold and that demand-side support lowers it further.
These findings imply differentiated actions for the three actors. Demand-side firms should compare procurement and leasing using conflict-persistence risk, shortage losses, and contractual risk sharing rather than relying only on upfront price. Leasing companies should use flexible lease duration, risk-sharing arrangements, and residual-value management to preserve participation incentives. Governments should target the early coordination barrier through moderate subsidies, credit enhancement, demonstration projects, and platform development, while avoiding subsidy levels that make the incremental net benefit of government intervention negative.
This study also has limitations. First, the numerical parameters are primarily scenario-calibrated rather than estimated from a single project. Regarding the benchmark decision model, the two-state conflict representation and stylized capacity-cost structure abstract from continuous changes in conflict intensity and project-specific dispatch decisions; although the continuous-capacity robustness analysis relaxes the original discrete-capacity assumption, it does not replace a full engineering dispatch model. Regarding the tripartite evolutionary game, the replicator dynamics represent an aggregate payoff-based adjustment process under bounded rationality and do not explicitly estimate actor-specific learning speeds, within-population behavioral heterogeneity, institutional delays, or one-off strategic bargaining. The model also considers a standardized leasing arrangement, while the normalized capacity representation abstracts from hourly wind and solar generation, storage duration, capacity credit, load variation, and detailed dispatch. It therefore does not quantify recovery speed, adaptive reconfiguration, redundancy, or long-term system restoration. Future research can estimate the model using project and leasing-contract data, compare alternative leasing structures, represent conflict intensity dynamically, incorporate heterogeneous adjustment processes, and map the normalized capacity variables to physically validated wind–solar–storage configurations.
Supplementary Materials
The following supporting information can be downloaded at: https://www.mdpi.com/article/10.3390/en19184346/s1, Supplementary File S1: Calibration Basis and Data Sources for Numerical Parameters (Sections S1–S3, Tables S1 and S2, and Equations (S1)–(S3)).
Author Contributions
Conceptualization, H.C.; methodology, H.C.; software, Y.L.; validation, Y.L.; formal analysis, H.C.; investigation, Z.W.; resources, Z.W.; data curation, Z.W.; writing—original draft preparation, J.H.; writing—review and editing, Z.W.; visualization, Y.L.; supervision, Z.W.; project administration, Z.W.; funding acquisition, J.H. All authors have read and agreed to the published version of the manuscript.
Funding
This research was funded by the Hunan Provincial Social Science Foundation Youth Project (Grant No. 25YBQ174).
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The original contributions presented in this study are included in the article; further inquiries may be directed to the corresponding author.
Conflicts of Interest
The authors declare no conflicts of interest.
References
- Shepard, J.U.; Pratson, L.F. Maritime piracy in the Strait of Hormuz and implications of energy export security. Energy Policy 2020, 140, 111379. [Google Scholar] [CrossRef] [Scilit]
- Colombo, E. The Fifth Freedom: Shaping EU innovation policy for renewable energy storage and decarbonization. Energies 2025, 18, 3570. [Google Scholar] [CrossRef] [Scilit]
- Ghorbani Pashakolaie, V.; Cotton, M.; Jansen, M. The co-benefits of offshore wind under the UK Renewable Obligation scheme: Integrating sustainability in energy policy evaluation. Energy Policy 2024, 192, 114259. [Google Scholar] [CrossRef] [Scilit]
- Ivashko, O.; Simakhova, A.; Soliakov, V.; Choroszczak, J. Clustering EU member states by energy security level using Kohonen maps. Energies 2025, 18, 4750. [Google Scholar] [CrossRef] [Scilit]
- Ah-Voun, D.; Chyong, C.K.; Li, C. Europe’s energy security: From Russian dependence to renewable reliance. Energy Policy 2024, 184, 113856. [Google Scholar] [CrossRef] [Scilit]
- Overland, I. The geopolitics of renewable energy: Debunking four emerging myths. Energy Res. Soc. Sci. 2019, 49, 36–40. [Google Scholar] [CrossRef] [Scilit]
- Scholten, D.; Bazilian, M.; Overland, I.; Westphal, K. The geopolitics of renewables: New board, new game. Energy Policy 2020, 138, 111059. [Google Scholar] [CrossRef] [Scilit]
- Jurasz, J.; Canales, F.A.; Kies, A.; Guezgouz, M.; Beluco, A. A review on the complementarity of renewable energy sources: Concept, metrics, application and future research directions. Sol. Energy 2020, 195, 703–724. [Google Scholar] [CrossRef] [Scilit]
- Tan, K.M.; Babu, T.S.; Ramachandaramurthy, V.K.; Kasinathan, P.; Solanki, S.G.; Raveendran, S.K. Empowering smart grid: A comprehensive review of energy storage technology and application with renewable energy integration. J. Energy Storage 2021, 39, 102591. [Google Scholar] [CrossRef] [Scilit]
- Ekholm, T.; Ghoddusi, H.; Krey, V.; Riahi, K. The effect of financial constraints on energy-climate scenarios. Energy Policy 2013, 59, 562–572. [Google Scholar] [CrossRef] [Scilit]
- Benavides-Franco, J.; Gómez, J.M.; Pérez-Uribe, M.A. Determinants of project finance success for renewable energy. Renew. Energy 2023, 211, 188–201. [Google Scholar] [CrossRef] [Scilit]
- Wang, J.; Dong, X.; Zhang, L. A multi-cycle rotation strategy for relief supplies considering demand uncertainty. Comput. Ind. Eng. 2026, 213, 111778. [Google Scholar] [CrossRef] [Scilit]
- Lin, J.-R.; Wang, C.-J.; Chou, D.-W.; Chueh, F.-C. Financial constraint and the choice between leasing and debt. Int. Rev. Econ. Financ. 2013, 27, 171–182. [Google Scholar] [CrossRef] [Scilit]
- Xie, Y.; Lin, B. Financial leasing and China’s renewable energy firms’ investment behavior: In the context of government subsidy reduction. Renew. Sustain. Energy Rev. 2025, 214, 115547. [Google Scholar] [CrossRef] [Scilit]
- Chen, H.; Wang, Z.; Yu, X. Sustainability strategies of equipment introduction and overcapacity risk sharing in mask emergency supply chains during pandemics. Sustainability 2021, 13, 10355. [Google Scholar] [CrossRef] [Scilit]
- Kamalahmadi, M.; Parast, M.M. A review of the literature on the principles of enterprise and supply chain resilience: Major findings and directions for future research. Int. J. Prod. Econ. 2016, 171, 116–133. [Google Scholar] [CrossRef] [Scilit]
- Emenike, S.N.; Falcone, G. A review on energy supply chain resilience through optimization. Renew. Sustain. Energy Rev. 2020, 134, 110088. [Google Scholar] [CrossRef] [Scilit]
- Tukamuhabwa, B.R.; Stevenson, M.; Busby, J.; Zorzini, M. Supply chain resilience: Definition, review and theoretical foundations for further study. Int. J. Prod. Res. 2015, 53, 5592–5623. [Google Scholar] [CrossRef] [Scilit]
- Hosseini, S.; Ivanov, D.; Dolgui, A. Review of quantitative methods for supply chain resilience analysis. Transp. Res. Part E Logist. Transp. Rev. 2019, 125, 285–307. [Google Scholar] [CrossRef] [Scilit]
- Ivanov, D.; Dolgui, A. Viability of intertwined supply networks: Extending the supply chain resilience angles towards survivability. Int. J. Prod. Res. 2020, 58, 2904–2915. [Google Scholar] [CrossRef] [Scilit]
- Linkov, I.; Bridges, T.; Creutzig, F.; Decker, J.; Fox-Lent, C.; Kröger, W.; Lambert, J.H.; Levermann, A.; Montreuil, B.; Nathwani, J.; et al. Changing the resilience paradigm. Nat. Clim. Chang. 2014, 4, 407–409. [Google Scholar] [CrossRef] [Scilit]
- Panteli, M.; Mancarella, P. The grid: Stronger, bigger, smarter? Presenting a conceptual framework of power system resilience. IEEE Power Energy Mag. 2015, 13, 58–66. [Google Scholar] [CrossRef] [Scilit]
- Ma, C.; Zhang, L.; You, L.; Tian, W. A review of supply chain resilience: A network modeling perspective. Appl. Sci. 2025, 15, 265. [Google Scholar] [CrossRef] [Scilit]
- Kuzemko, C.; Blondeel, M.; Dupont, C.; Brisbois, M.C. Russia’s war on Ukraine, European energy policy responses and implications for sustainable transformations. Energy Res. Soc. Sci. 2022, 93, 102842. [Google Scholar] [CrossRef] [Scilit]
- Mišík, M. The EU needs to improve its external energy security. Energy Policy 2022, 165, 112930. [Google Scholar] [CrossRef] [Scilit]
- Osička, J.; Černoch, F. European energy politics after Ukraine: The road ahead. Energy Res. Soc. Sci. 2022, 91, 102757. [Google Scholar] [CrossRef] [Scilit]
- Vakulchuk, R.; Overland, I.; Scholten, D. Renewable energy and geopolitics: A review. Renew. Sustain. Energy Rev. 2020, 122, 109547. [Google Scholar] [CrossRef] [Scilit]
- Proedrou, F. EU decarbonization under geopolitical pressure: Changing paradigms and implications for energy and climate policy. Sustainability 2023, 15, 5083. [Google Scholar] [CrossRef] [Scilit]
- Polzin, F.; Migendt, M.; Täube, F.A.; von Flotow, P. Public policy influence on renewable energy investments: A panel data study across OECD countries. Energy Policy 2015, 80, 98–111. [Google Scholar] [CrossRef] [Scilit]
- Steffen, B. The importance of project finance for renewable energy projects. Energy Econ. 2018, 69, 280–294. [Google Scholar] [CrossRef] [Scilit]
- Chang, K.; Zeng, Y.; Wang, W.; Wu, X. The effects of credit policy and financial constraints on tangible and research and development investment: Firm-level evidence from China’s renewable energy industry. Energy Policy 2019, 130, 438–447. [Google Scholar] [CrossRef] [Scilit]
- Vásquez-Ordóñez, L.R.; Lassala, C.; Ulrich, K.; Ribeiro-Navarrete, S. Efficiency factors in the financing of renewable energy projects through crowdlending. J. Bus. Res. 2023, 155, 113389. [Google Scholar] [CrossRef] [Scilit]
- Arteaga, J.; Zareipour, H.; Amjady, N. Energy storage as a service: Optimal pricing for transmission congestion relief. IEEE Open Access J. Power Energy 2020, 7, 514–523. [Google Scholar] [CrossRef] [Scilit]
- Arteaga, J.; Zareipour, H.; Amjady, N. Energy storage as a service: Optimal sizing for transmission congestion relief. Appl. Energy 2021, 298, 117095. [Google Scholar] [CrossRef] [Scilit]
- Kouvelis, P.; Zhao, W. Financing the newsvendor: Supplier vs. bank, and the structure of optimal trade credit contracts. Oper. Res. 2012, 60, 566–580. [Google Scholar] [CrossRef] [Scilit]
- Ersahin, N.; Giannetti, M.; Huang, R. Trade credit and the stability of supply chains. J. Financ. Econ. 2024, 155, 103830. [Google Scholar] [CrossRef] [Scilit]
- Maynard Smith, J. Evolution and the Theory of Games; Cambridge University Press: Cambridge, UK, 1982. [Google Scholar]
- Tian, Y.; Govindan, K.; Zhu, Q. A system dynamics model based on evolutionary game theory for green supply chain management diffusion among Chinese manufacturers. J. Clean. Prod. 2014, 80, 96–105. [Google Scholar] [CrossRef] [Scilit]
- Sun, H.; Wan, Y.; Zhang, L.; Zhou, Z. Evolutionary game of the green investment in a two-echelon supply chain under a government subsidy mechanism. J. Clean. Prod. 2019, 235, 1315–1326. [Google Scholar] [CrossRef] [Scilit]
- Wang, K.; Cheng, L.; Yin, M.; Zhang, K.; Wang, R.; Zhang, M.; Sun, R. Evolutionary game theory in energy storage systems: A systematic review of collaborative decision-making, operational strategies, and coordination mechanisms for renewable energy integration. Sustainability 2025, 17, 7400. [Google Scholar] [CrossRef] [Scilit]
- Fu, H.; Wu, X.; Zhang, Y.; Yan, W. Evolutionary game strategy for distributed energy sharing in industrial parks under government carbon regulation. Energies 2026, 19, 1764. [Google Scholar] [CrossRef] [Scilit]
- Cui, K.; Chi, M.; Zhao, Y.; Liu, Z. Evolutionary game-based regulatory strategy optimization for information transmission prices in integrated energy systems. Energies 2025, 18, 1452. [Google Scholar] [CrossRef] [Scilit]
- Yang, Y.; Yu, X.; Wang, B. Evolutionary game analysis of multi-agent synergistic incentives driving green energy market expansion. Sustainability 2025, 17, 7002. [Google Scholar] [CrossRef] [Scilit]
- Chen, Y.; Mei, S.; Zhou, F.; Low, S.H.; Wei, W.; Liu, F. An energy sharing game with generalized demand bidding: Model and properties. IEEE Trans. Smart Grid 2020, 11, 2055–2066. [Google Scholar] [CrossRef] [Scilit]
- Chen, Y.; Zhao, C.; Low, S.H.; Mei, S. Approaching prosumer social optimum via energy sharing with proof of convergence. IEEE Trans. Smart Grid 2021, 12, 2484–2495. [Google Scholar] [CrossRef] [Scilit]
- China Renewable Energy Engineering Institute; Renewable Energy Quota Station. China Renewable Energy Engineering Cost Management Report 2025; China Water & Power Press: Beijing, China, 2026; ISBN 978-7-5226-4537-7. (In Chinese) [Google Scholar]
- China Energy Storage Alliance. 2025 Energy Storage Bidding Price Analysis—CNESA Year-End Review. 8 January 2026. Available online: https://www.cnesa.org/information/detail/?column_id=2&id=7750 (accessed on 10 July 2026). (In Chinese)
- National Bureau of Statistics of China. Statistical Communiqué of the People’s Republic of China on the 2024 National Economic and Social Development. 28 February 2025. Available online: https://www.stats.gov.cn/sj/zxfb/202502/t20250228_1958817.html (accessed on 10 July 2026). (In Chinese)
- National Energy Administration. Total Electricity Consumption in 2024 Increased by 6.8% Year-on-Year. 20 January 2025. Available online: https://www.nea.gov.cn/20250120/4f7f249bac714e7693adecac996d742f/c.html (accessed on 10 July 2026). (In Chinese)
- Zheng, X.; Ding, J.; Shang, C.; Lei, Q.; Wang, X. An assessment method of grid outage cost considering multifactorial influences. Eng. J. Wuhan Univ. 2016, 49, 83–87. (In Chinese) [Google Scholar] [CrossRef]
- Energy Bureau of Inner Mongolia Autonomous Region. Notice on Accelerating the Construction of New Energy Storage. 12 March 2025. Available online: https://www.cnesa.org/information/detail/?column_id=3&id=6923 (accessed on 10 July 2026). (In Chinese)
- National Energy Administration. China New Energy Storage Development Report 2025; National Energy Administration: Beijing, China, 2025. Available online: https://www.nea.gov.cn/20250731/1d40d09f75714280a9218d5bea178fbd/202507311d40d09f75714280a9218d5bea178fbd_453d9a0609da1d4456a8b12d843bd256cf.pdf (accessed on 10 July 2026). (In Chinese)
- National Energy Administration. China Electricity Market Development Report 2025; National Energy Administration: Beijing, China, 2026. Available online: https://www.nea.gov.cn/20260609/2d1bf220b5a642e2b1199a015bd6cf13/202606092d1bf220b5a642e2b1199a015bd6cf13_073fd3822bbbd048df9c5e8a6d3befc423.pdf (accessed on 10 July 2026). (In Chinese)
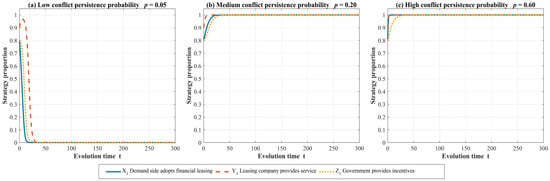
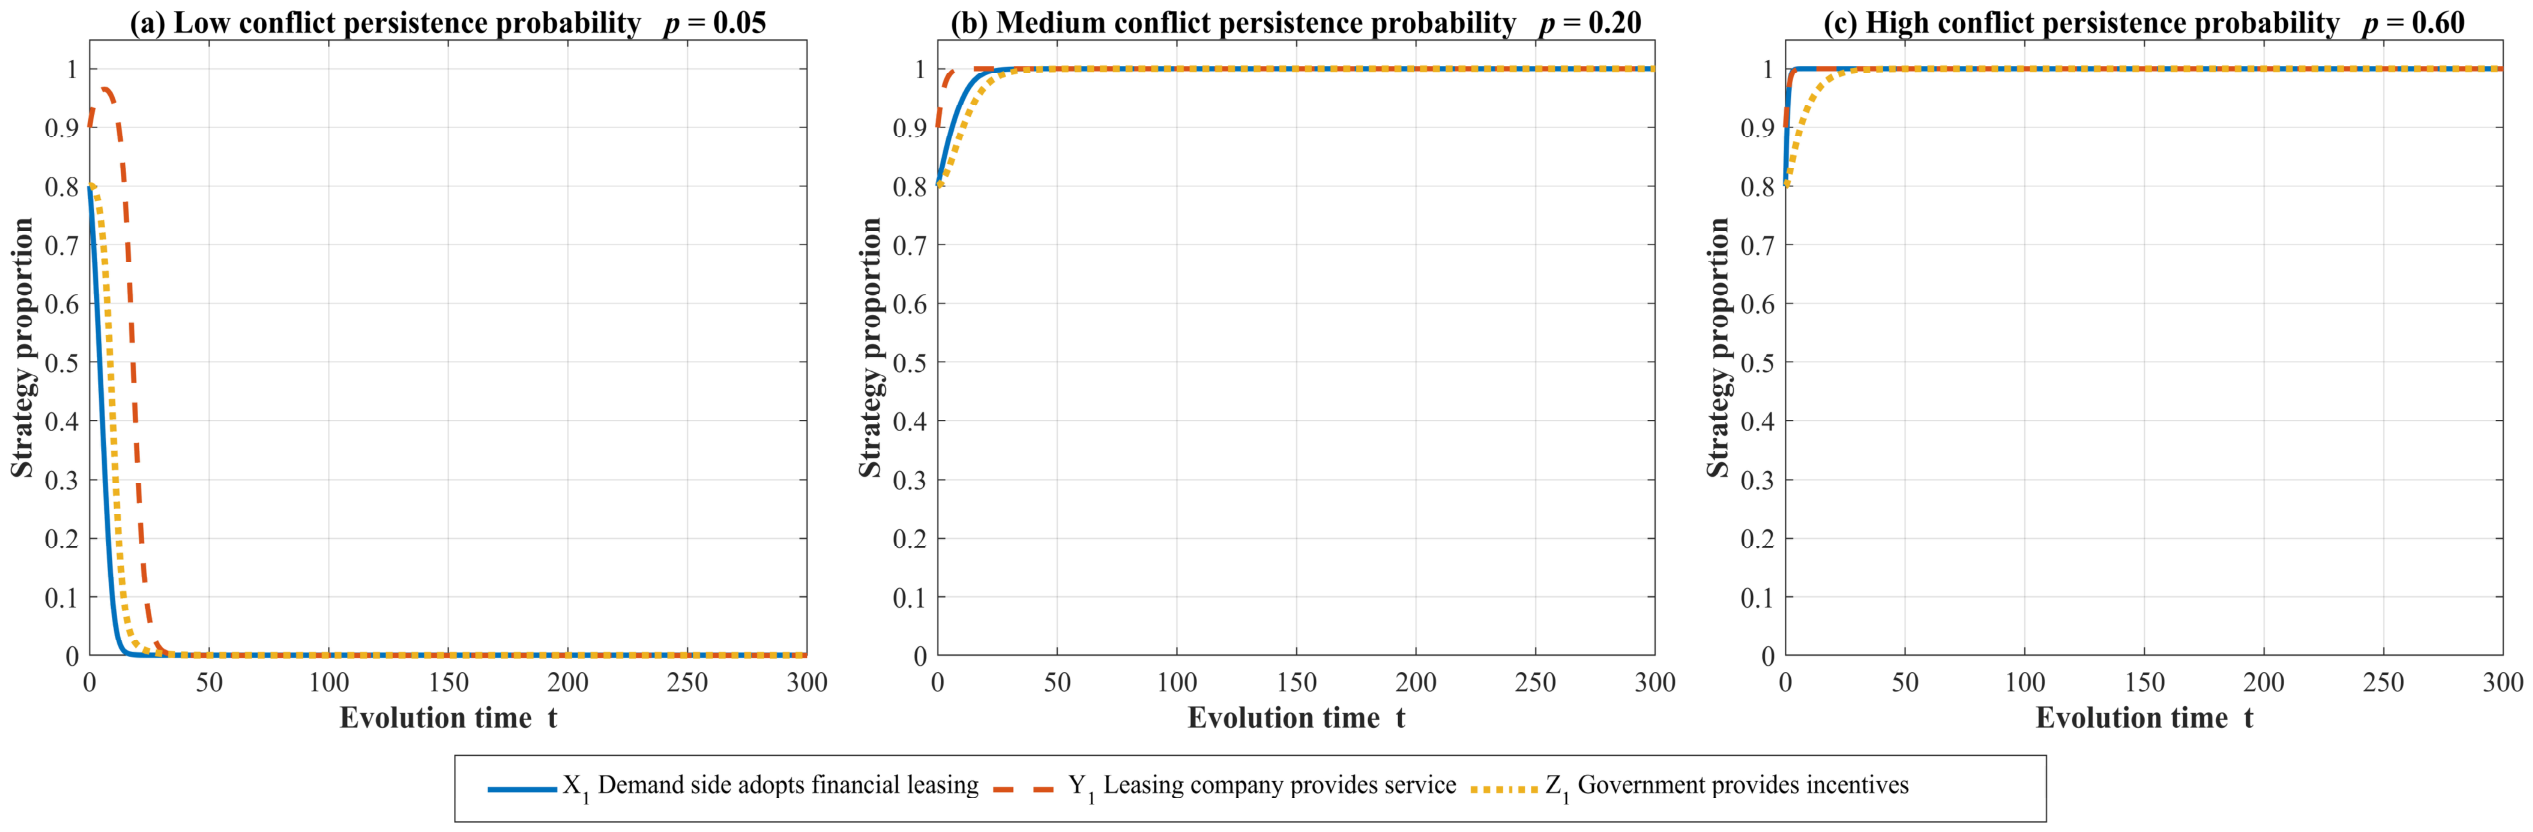
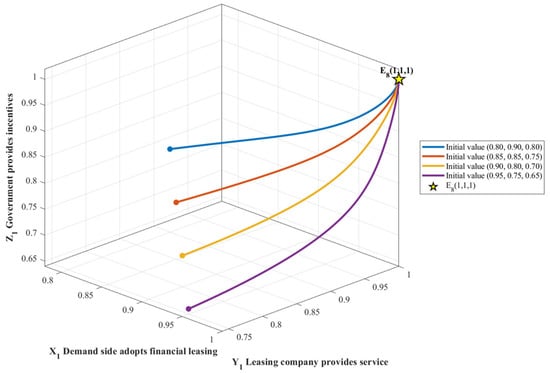
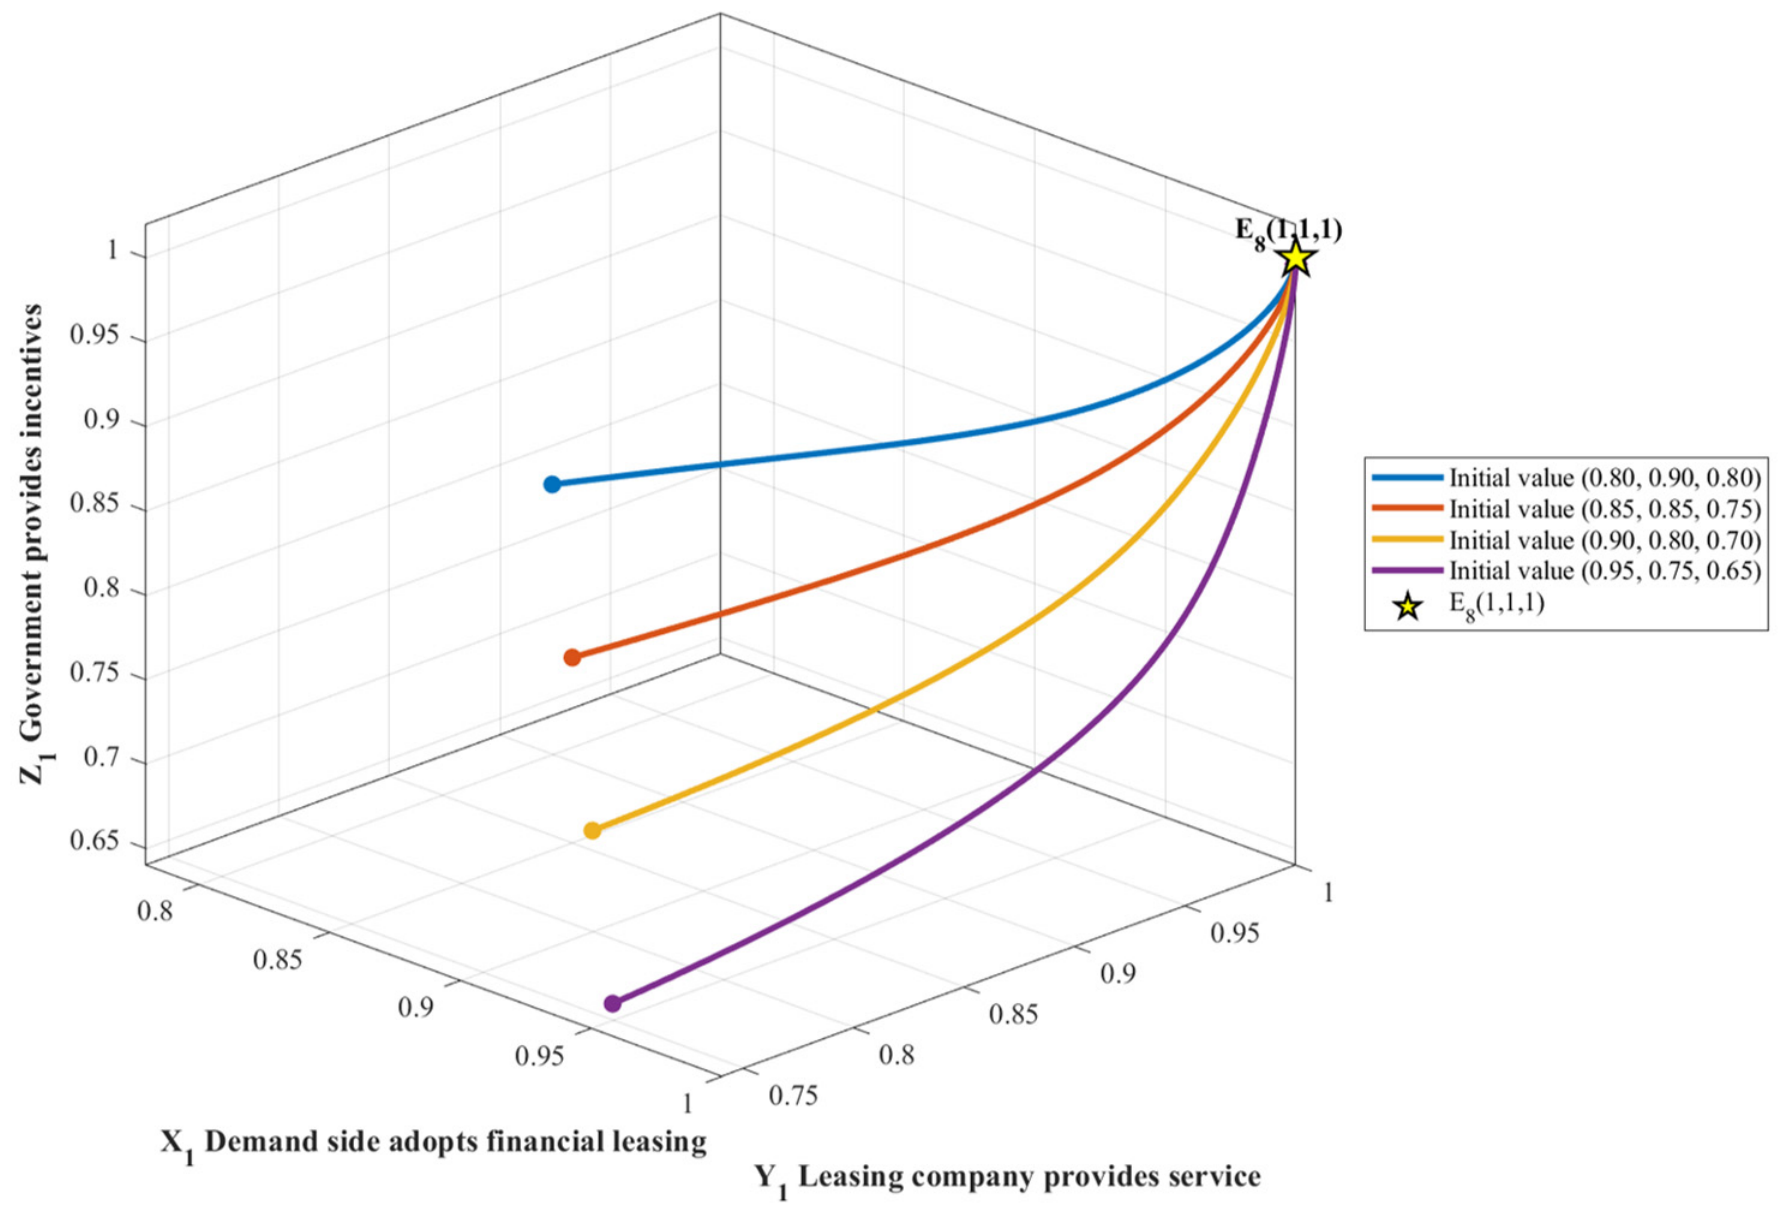
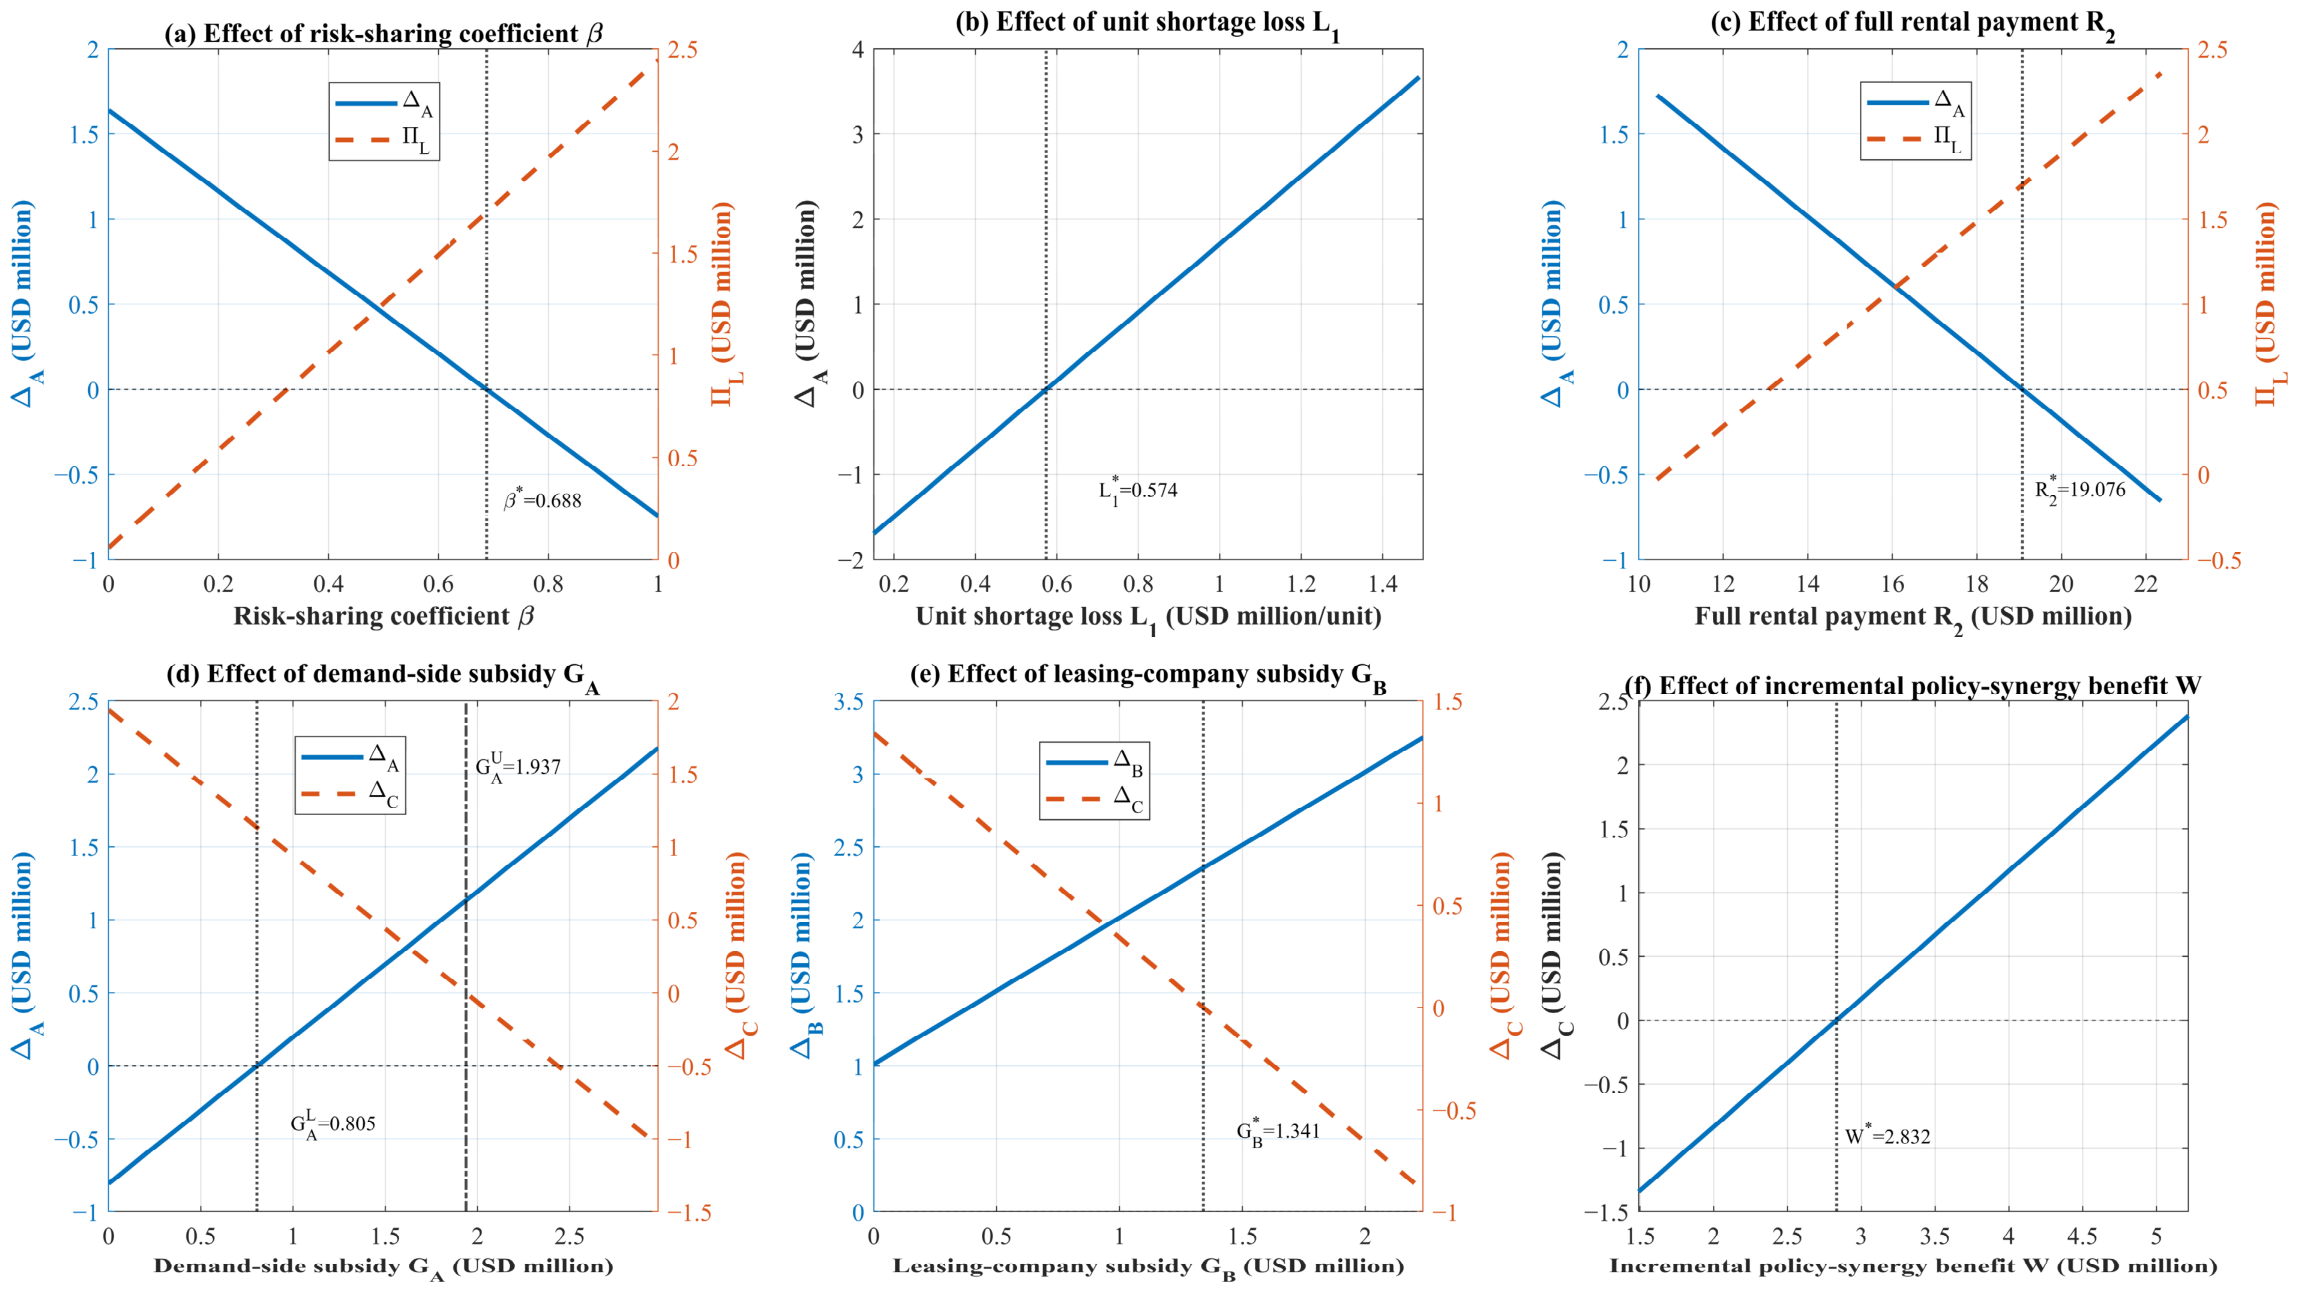
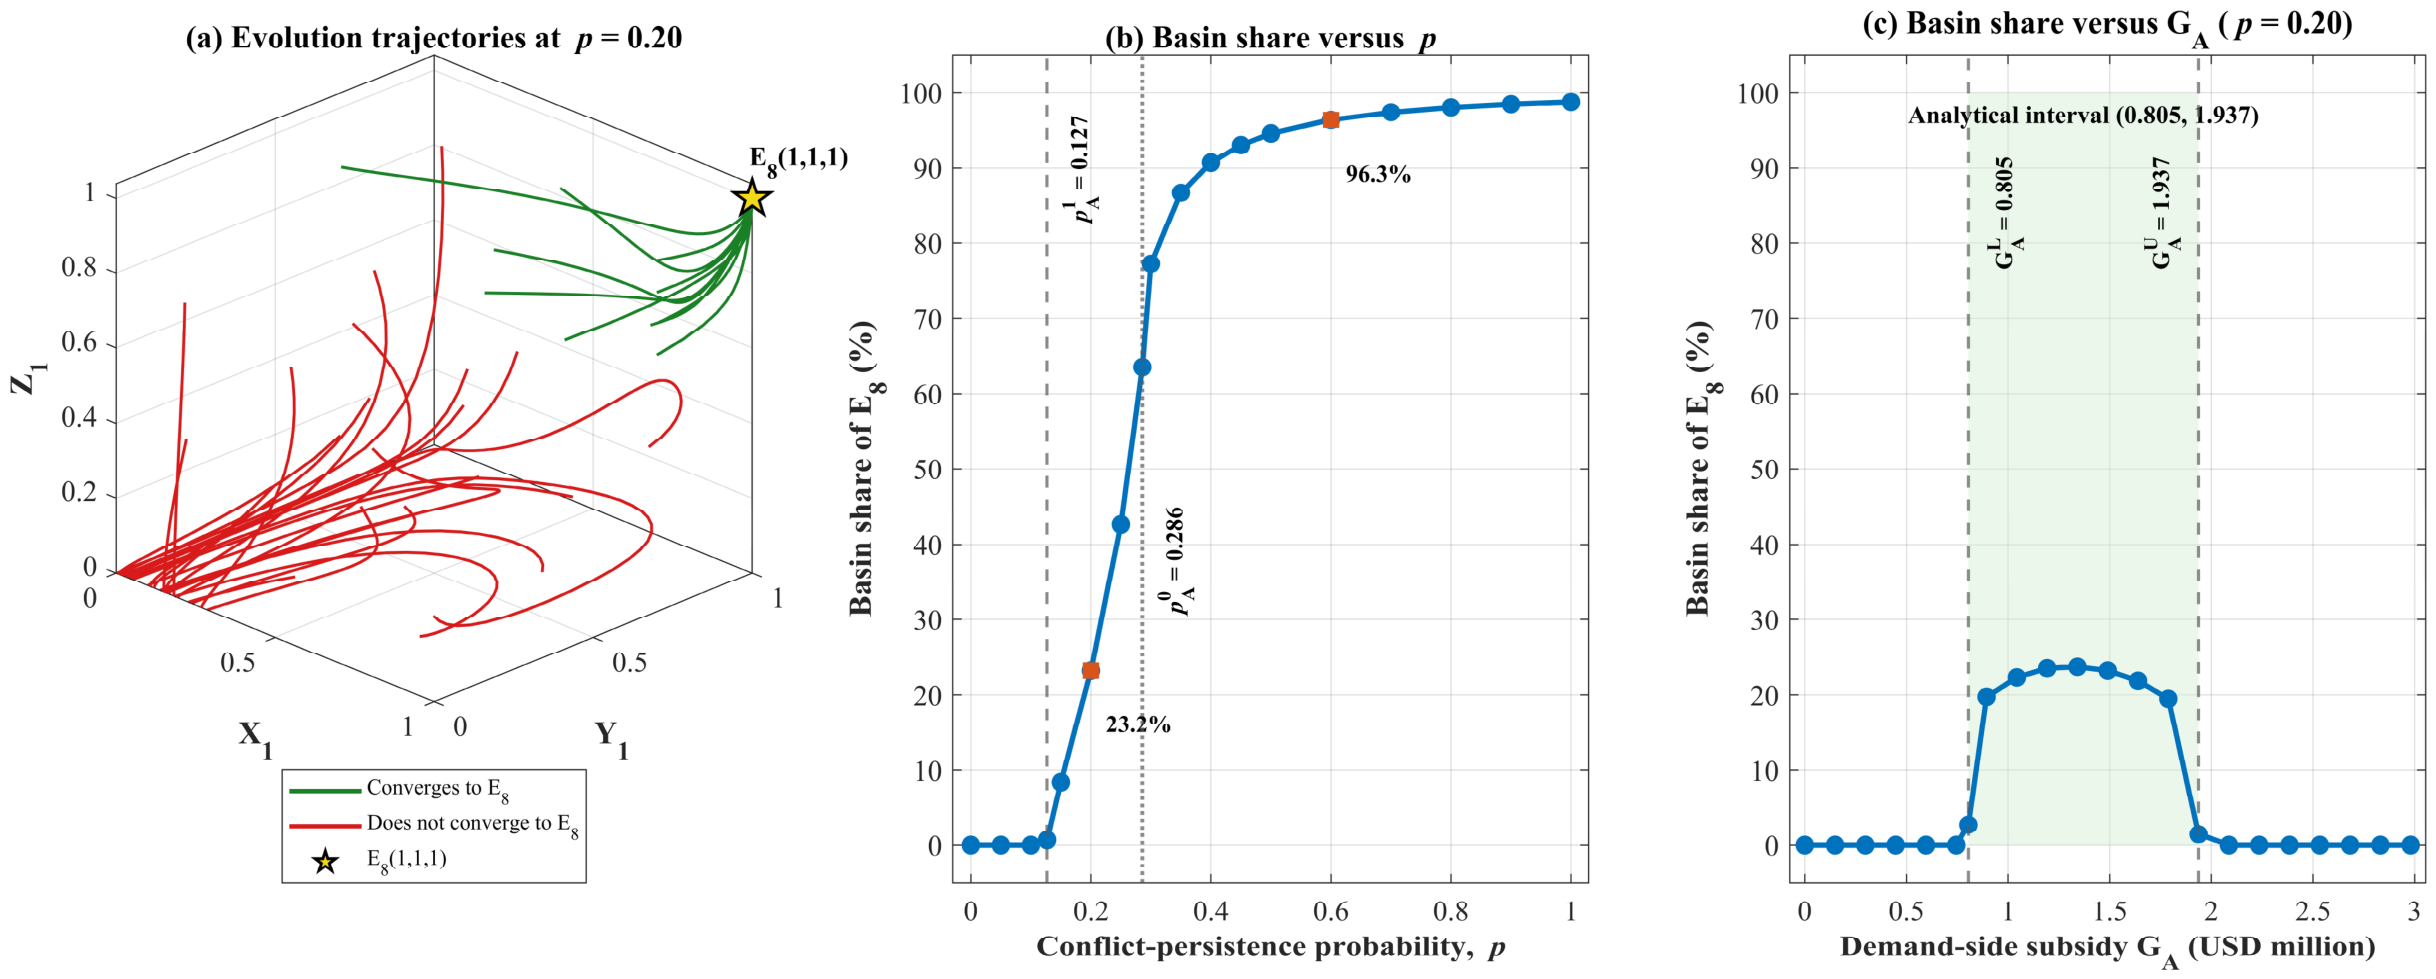
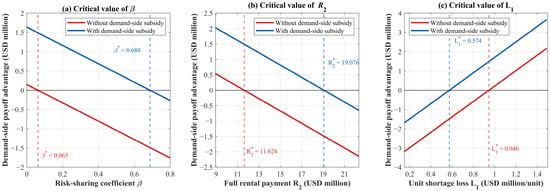
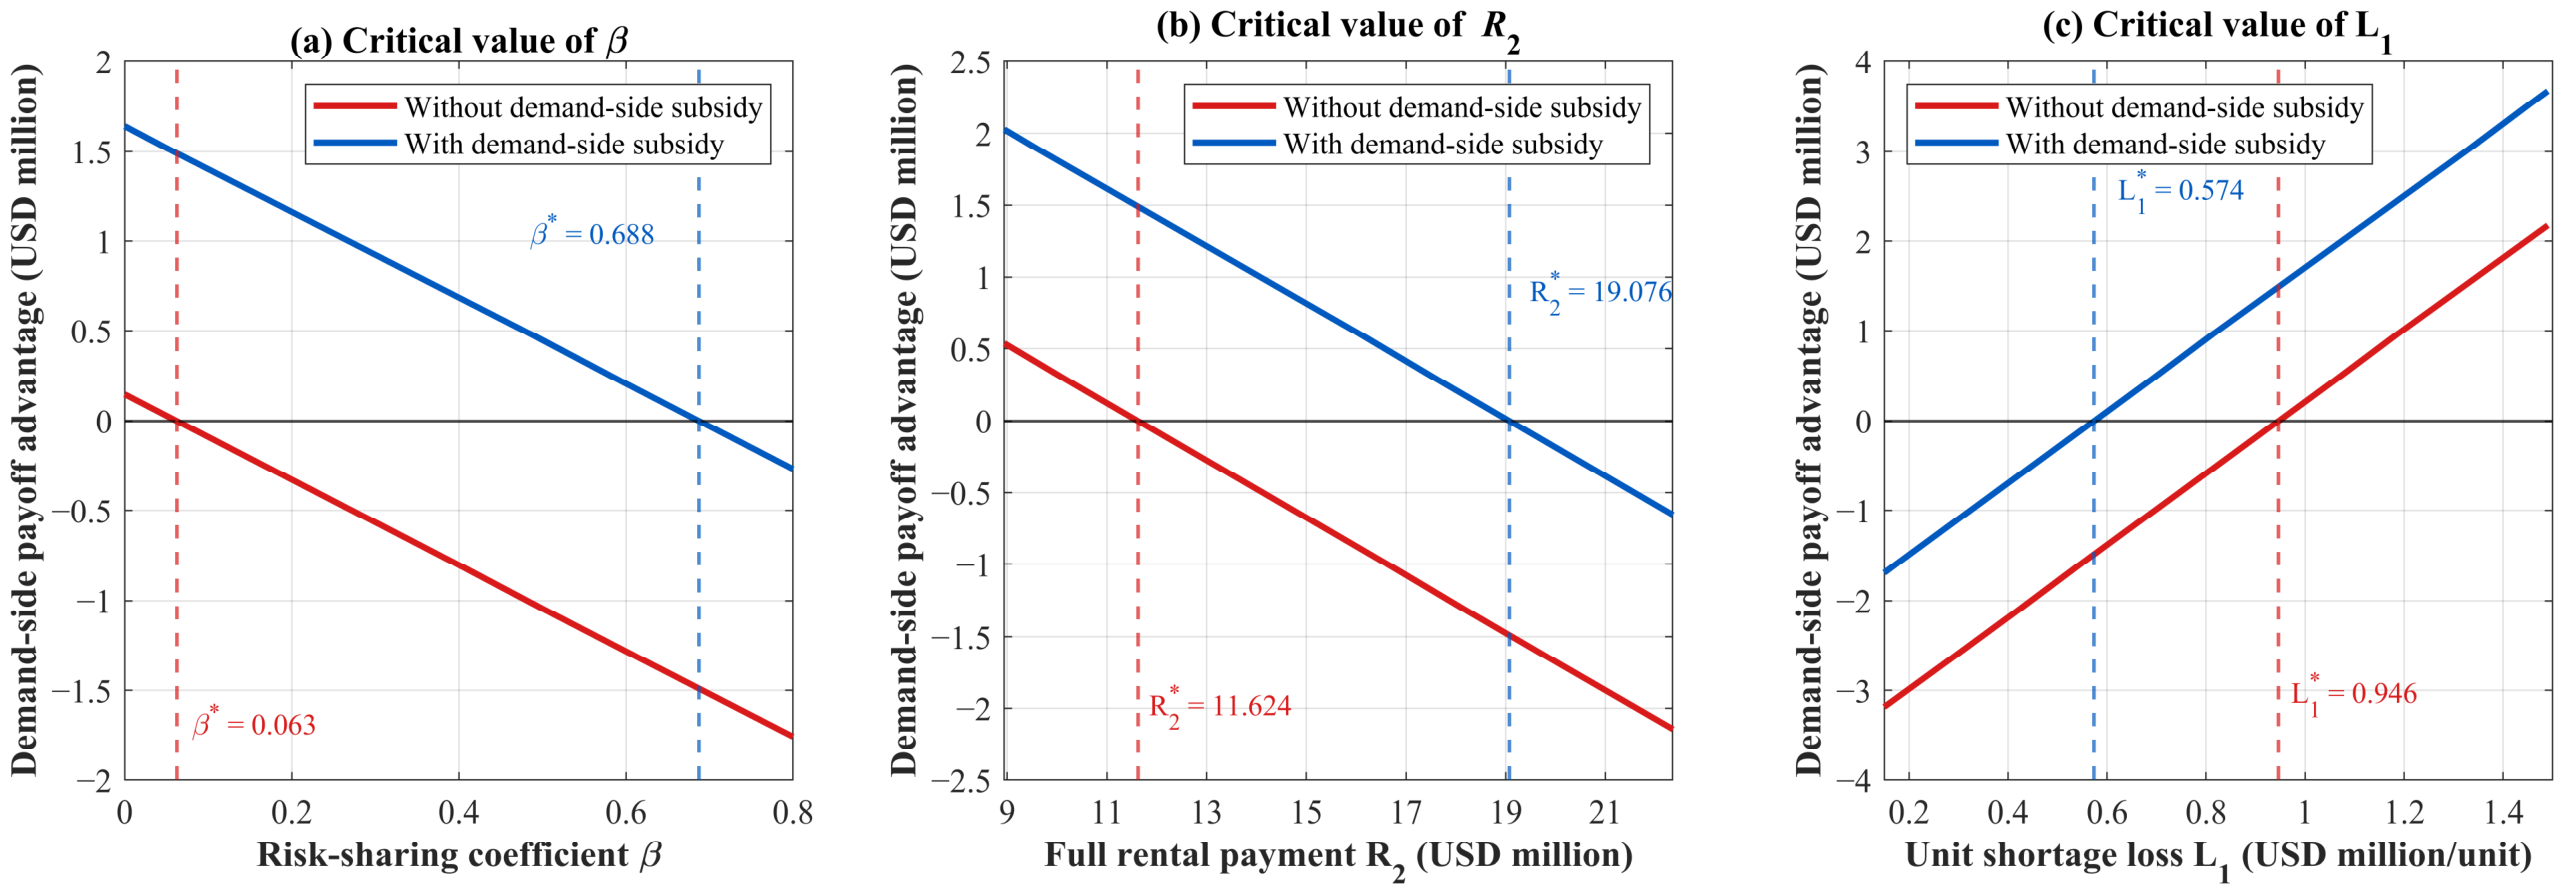
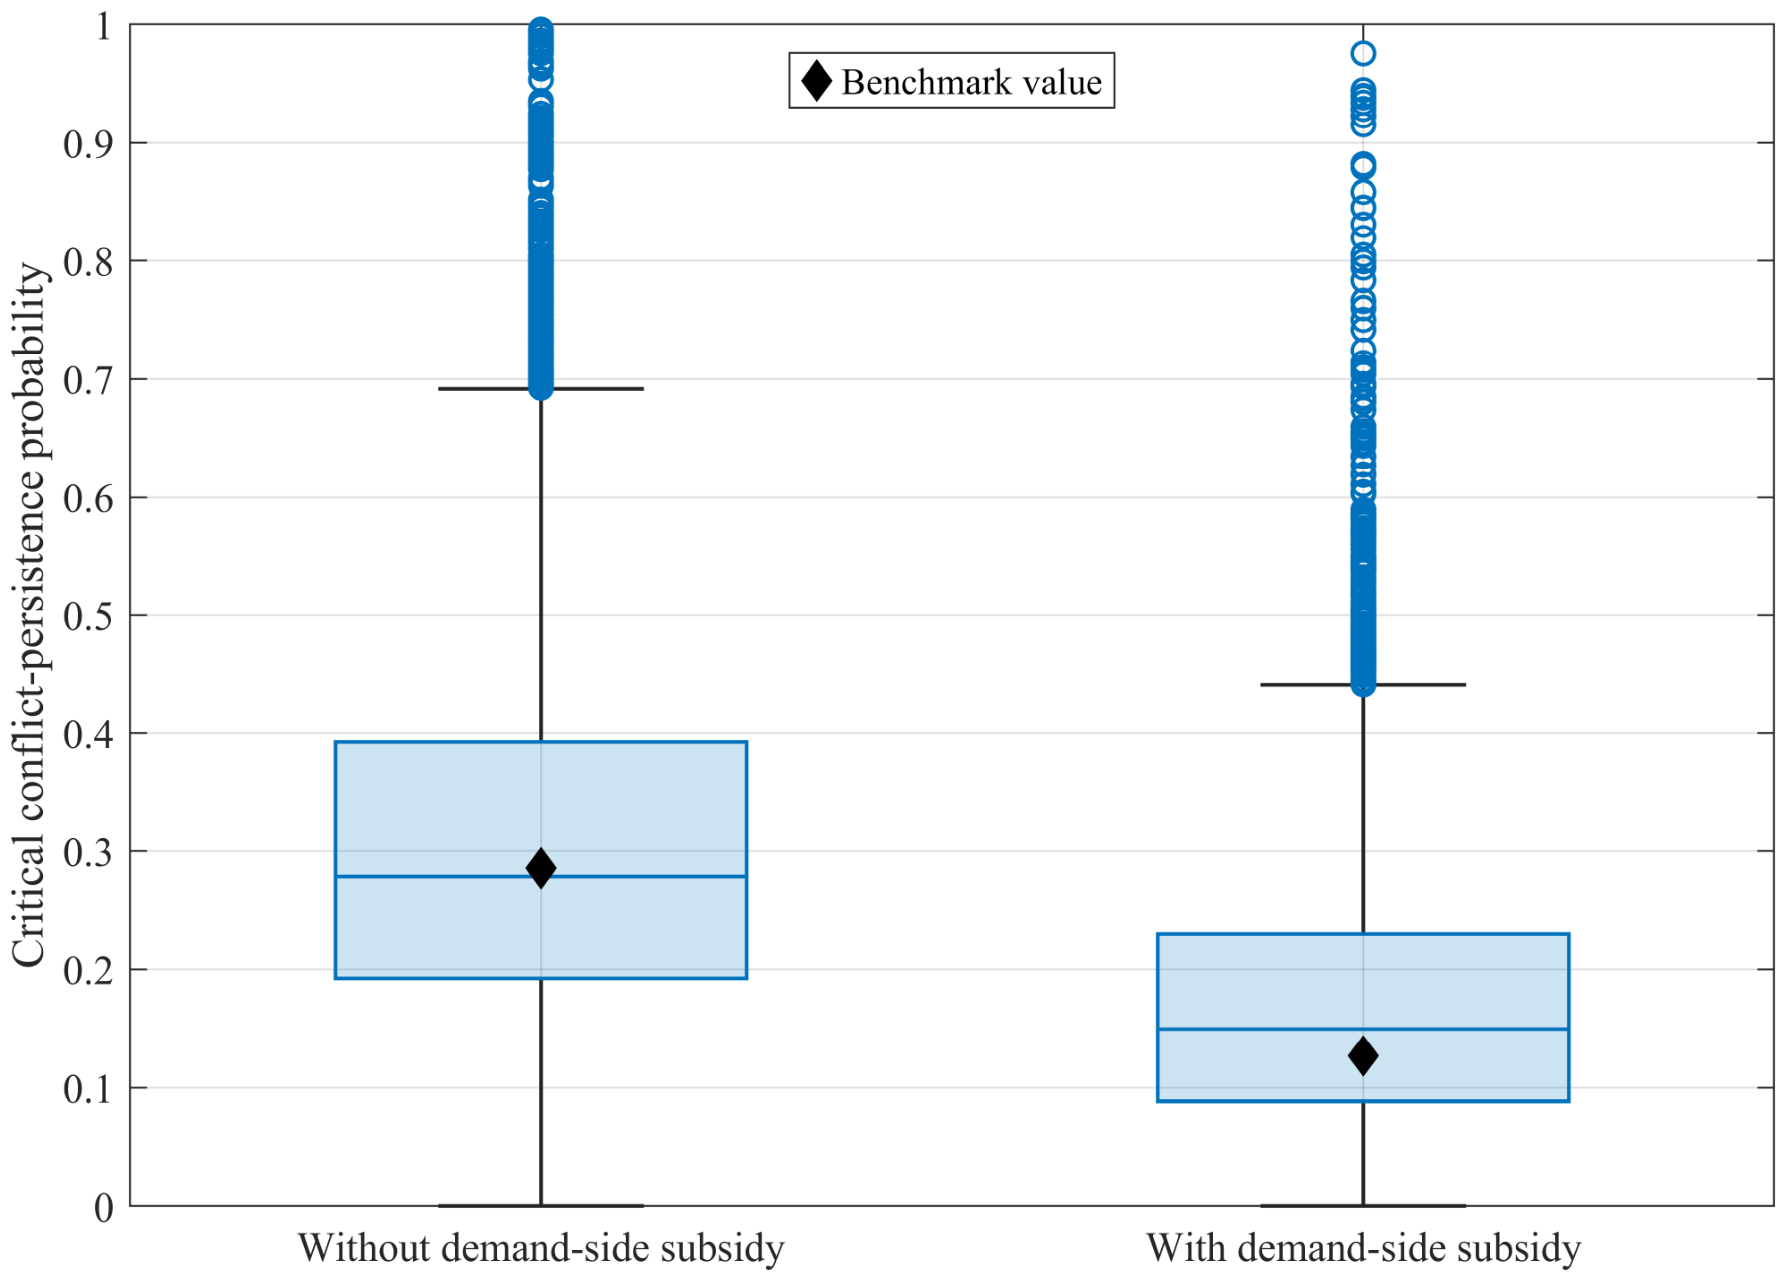

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.