


Abstract
I give for the first time explicit formulas for the coefficients needed for the fourth-order Edgeworth expansions of a multivariate standard estimate. I call these the Edgeworth coefficients. They are Bell polynomials in the cumulant coefficients. Standard estimates include most estimates of interest, including smooth functions of sample means and other empirical estimates. I also give applications to ellipsoidal and hyperrectangular sets.
Keywords:
Edgeworth expansions; standard estimates; multivariate Edgeworth coefficients; ellipsoidal and hyperrectangular sets MSC:
62E20; 62F12
1. Introduction and Summary
Suppose that is a standard estimate, as defined in Section 2, of an unknown parameter of a statistical model, based on a sample of size n. For example, may be a smooth function of a sample mean, or a smooth functional of an empirical distribution. A smooth function of a standard estimate is also a standard estimate: see [1]. Section 2 summarises the multivariate Edgeworth expansions of Withers and Nadarajah (2010) [2] for the distribution and density of in powers of about the multivariate normal in terms of the Edgeworth coefficients, the -coefficients of (18). For , these are needed for the st term of the multivariate Edgeworth expansions. They are Bell polynomials in the cumulant coefficients of (9). They are given for by (19) and for by (19)–(21) in terms of the symmetrizing operator and explicitly in Appendix A. Section 3 derives expansions on ellipsoidal and hyperrectangular sets.
When , Section 4 simplifies these Edgeworth coefficients using an alternative notation. Examples include the distribution and density of a sample mean and of bivariate entangled gamma random variables.
Section 5 and Section 6 give conclusions and discussion and suggest some future directions. Appendix B explicitly gives the bivariate Hermite polynomials needed for bivariate Edgeworth expansions to . The results of [3,4] could be considered heuristic. However, Section 5 of [5] showed that the Cornish–Fisher expansions (4) are valid under the usual conditions for validity of multivariate Edgeworth expansions. Their Section 5 appears to show that this is also true for the multivariate case. See also [6]. Appendix C gives for the first time a theorem for the validity of the Edgeworth expansions given here. Appendix D gives some corrigenda to the references. When q = 1, see also [7].
Univariate estimates. Suppose that is a standard estimate of with respect to n, (typically the sample size). That is, is non-lattice, as , and its rth cumulant can be expanded as
where the cumulant coefficients may depend on n but are bounded as , and is bounded away from 0. Here and below, ≈ indicates an asymptotic expansion that need not converge. Thus, (1) holds in the sense that
where means that is bounded in n. Ref. [4] replaced the artificial assumptions of [3,8] by (1) and gave the distribution, density and quantiles of
as asymptotic expansions in powers of :
where is the probability that A is true,
is a unit normal random variable with even moments , and and are polynomials in u and also in the standardized cumulant coefficients . For example,
where is the kth Hermite polynomial. By [9], for ,
(A2) gives for . Since is even/odd for r odd/even,
From (4), it follows that
Note 1.
Edgeworth’s expansion [11] was for , the mean of n independent identically distributed random variables on R from a distribution with rth cumulant . Thus, (1) holds with and . An explicit formula for its general term was given in [12].
For examples of the many applications of Cornish–Fisher expansions and the extensions of [13], see [14,15,16]. Applications in finance include [17,18]. For an application to Rayleigh fading amplitudes, see [19]. Ref. [20] used them for GPS accuracy. Refs. [21,22,23] successfully used them for system reliability, even though binomial random variables fall on a lattice. Ref. [24] used them for cosmology. Ref. [25] used them for optimal electric power flow.
Now suppose that is another standard estimate of w with the same asymptotic variance . Denote its standardized cumulant coefficients by . Suppose that
Then, one can expand about rather than . The above expressions for become
Therefore, if, for example, we choose so that , then
and the number of terms in the analogues of are greatly reduced. The disadvantage is that is more complicated than . See [19]. For expansions about a matching Student’s, gamma, or F distribution, see [14,15,26].
Regularity conditions. The expansions of [27] and subsequent extensions by [1,3,4] all build on the fact that for a density on R with finite cumulants, is a density with the same cumulants except that its rth cumulant has increased by A, and similarly for a density on . For a sample mean, many authors have given precise conditions for the Edgeworth expansions. See, for example, p. 229 of [28] and (19.17), (20.48), (23.3) of [29]. The latter gives corrections for a lattice sample mean. Ref. [30] and its references also give conditions for their validity.
2. Multivariate Edgeworth Expansions
Suppose that is a standard estimate of with respect to n. That is, is non-lattice, as , and for , the rth order cumulants of can be expanded as
and the cumulant coefficients may depend on n but are bounded as . Thus, the bar replaces each by k. The use of is reserved for this purpose. For example, and I use this bar notation repeatedly to avoid double subscripts . Therefore, I use I, not i, for below.
the multivariate normal on , with density and distribution
V may depend on n, but I assume that is bounded away from 0.
where here and below, I use the tensor summation convention of implicitly summing each over its range . For example,
Ordinary Bell polynomials. For a sequence from R, the partial ordinary Bell polynomial is defined by the identity
where for They are tabled on p. 309 of [31]. (The partial exponential Bell polynomials are not used in this paper.) The complete ordinary Bell polynomial, , is defined in terms of S of (14) by
where the rth Edgeworth coefficient, , is a function of . One could use unsymmetrized . For example, by (17), needs the cross term in . Thus, we could use in . But as (68) below illustrates, there is a big advantage in making symmetric in using the operator that symmetrizes over . Therefore, the that we need for are
These formulas are mostly new. The terms involving are given explicitly for the first time in Appendix A. By [2], the distribution and density of of (10) can be expanded as
is the multivariate Hermite polynomial. By [9], for ,
for of (12). These give and , and so of (22) to . For , for needed for when , see Appendix B. is just with replaced by of (26). For example,
I call the partial moments of
By (22), the Edgeworth expansions to for the distribution and density of of (10) about those of are given by
for and of (25). Each has terms, but many are duplicates, as I make symmetric in . Let us call (22) the basic Edgeworth expansions. Typically, is a one-to-one function of w. In this case, an alternative is to use the zero-mean Edgeworth expansions, that is, the expansions for
by (9) with . That is,
and is the zero-mean Edgeworth coefficient, that is, with These are mostly simpler. By (19)–(21),
The simplest example is when sampling from a distribution where is a known distribution with mean ; then, the cumulant coefficients do not depend on w apart from the mean.
For the location-scale model when sampling from a distribution , where is a known distribution with finite moments, mean and covariance , if depends on w, then so do the cumulant coefficients. To make an inference on w, one needs to consider the Studentised statistic. For this and more general models, see [32,33].
Returning to the expansion for the density of , the density of relative to its asymptotic value is
and of (24). Thus, is a simple measure of the inaccuracy of the Central Limit Theorem (CLT) approximation.
Example 1.
If the distribution of is symmetric about w, then, for r odd, , and by (20), . Thus,
since In this case, is a measure of the inaccuracy of the CLT approximation. Also,
Example 2.
Note 2.
For , the univariate Hermite polynomial of (6), and , I define the jth marginal Hermite polynomial as
Ref. [34] gave explicit expressions for a multivariate version of the Cornish–Fisher expansion when . Ref. [35] showed how to extend (4) to the multivariate case by replacing (8) by
It would be very useful to obtain these multivariate explicitly. How does one extend the univariate formula for in terms of ?
Note 3.
Standard estimates have a natural extension to Type b estimates. These are estimates for which the cumulant expansion (9) is replaced by
Examples are one-sided confidence interval limits. These have the form
where is a standard estimate and are smooth functions. See [2] for more details.
3. Secondary or Derived Expansions
Let V have the Hermitian form , where .
As in (25)–(27), I use tensor summation and the bar notation, and
From the second Edgeworth expansion in (22), it follows that for ,
As is a linear combination of , we can write in terms of
This gives and of (45). Therefore, it gives to . For a sample mean, , and for the needed for are given by Example 2.
If , then for r odd, so that
I now consider three such C’s.
Example 3.
where now, for and so that are independent. Set
Ellipsoidal C. Take for some .
(We might choose u such that or .) of (51) is given by
Similarly, unless k is even and , where are even integers and is a string of j’s of length k.
- For of (56), set
Similarly, using to mean a sum over distinct ,
of (52) is now given by (58), (60) and (61). Note that
We can write in terms of
For of (10), set
where is an estimate (empirical, semi-parametric, or parametric depending on the model used). Therefore,
the quantile of . It is often true that
(An exact confidence region for w is only possible if is normal: see 5.3.2 of [36].) , where , and is a gamma random variable with mean γ. Thus, if ,
with probability , and typically,
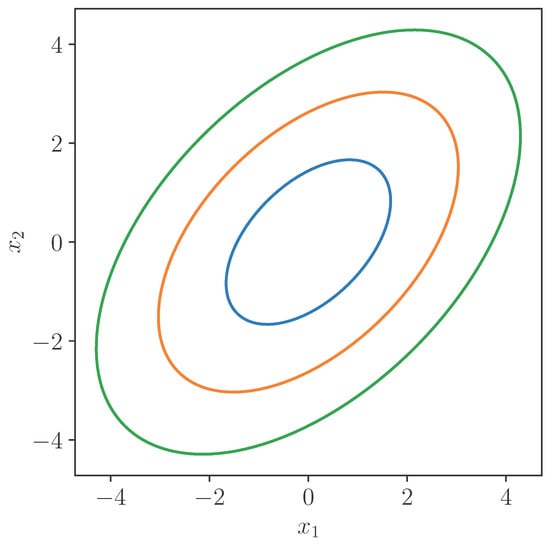
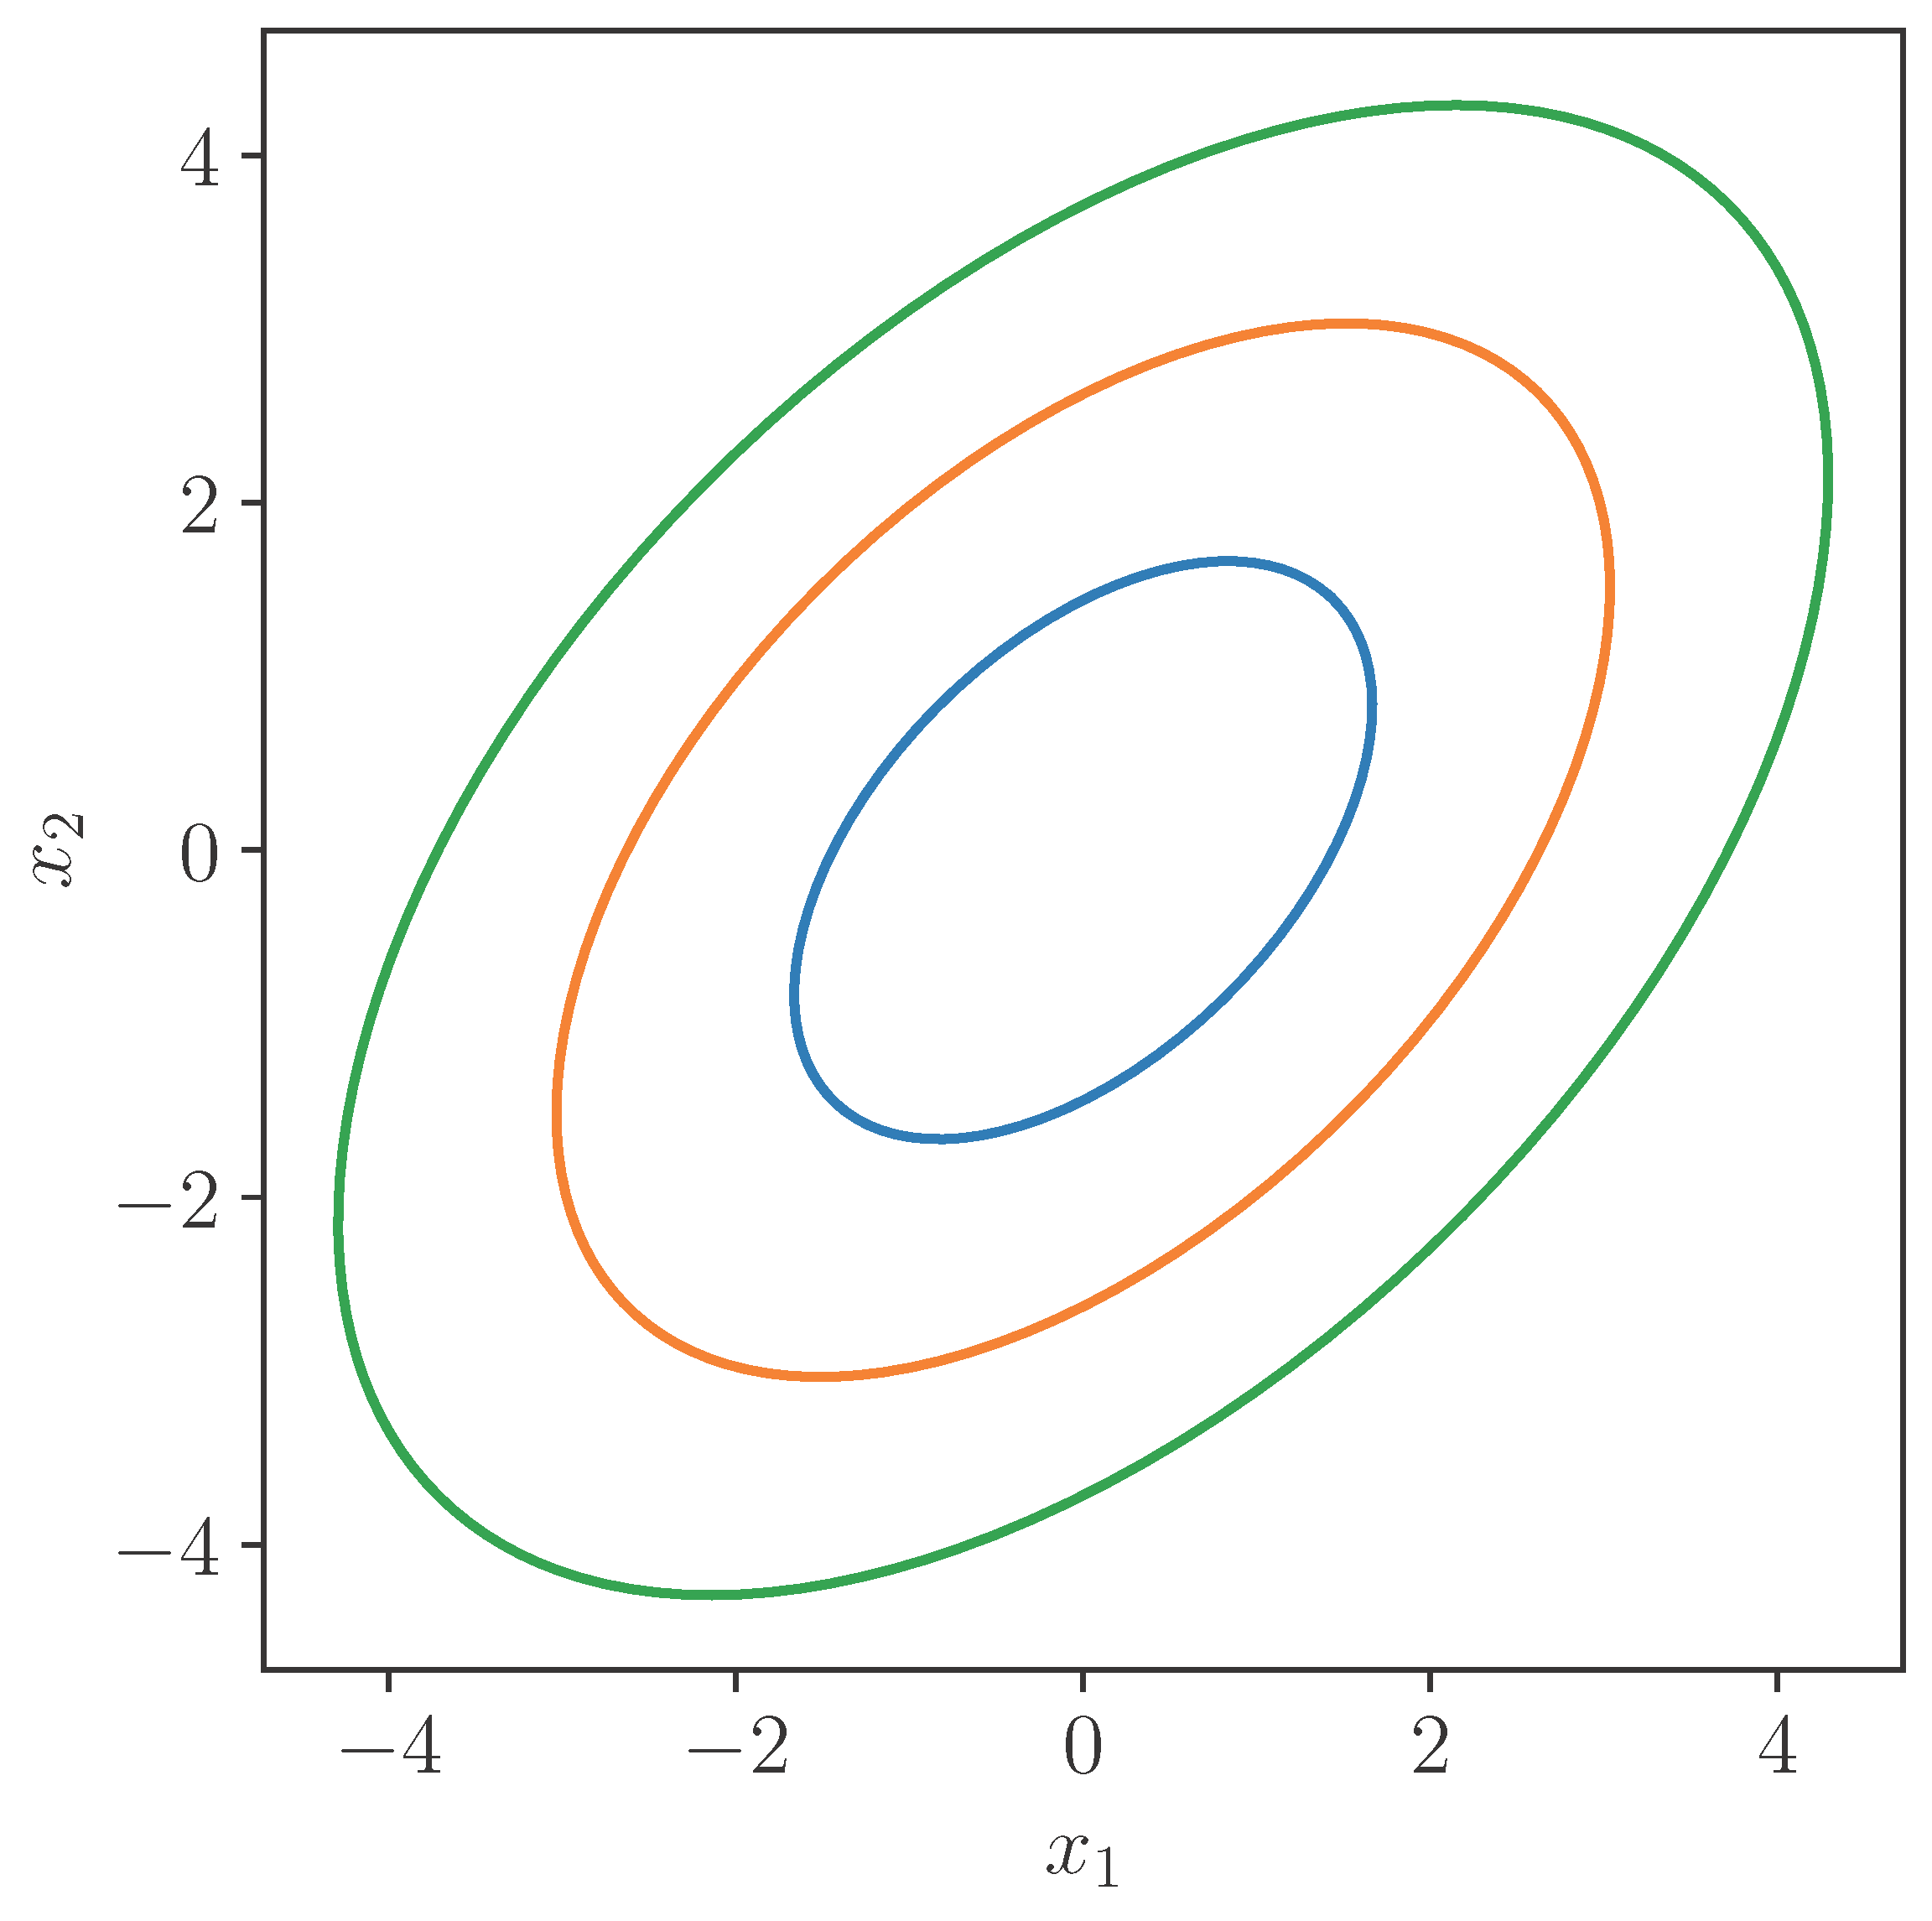
By way of illustration, Figure 1 plots the elliptical contours when , for when
Therefore, the asymptotic correlation of and is 1/2.
Figure 1.
when for the inner ellipse, , the outer ellipse, courtesy of Dr Paul Teal.
One can do similarly for , using and two-dimensional slices of these ellipsoids. For related references on confidence regions, see [10].
The R functions. Ifthen for , and
is given in Example 4 using a recurrence formula. (A simpler way is to just use (7).)
Now take .
Then,
To obtain a recurrence formula for , set
This recurrence formula for of (63) gives
Therefore, we need . By Example 4,
Transforming to
where is the confluent or degenerate hypergeometric function: see Section 9.21 of [37] and p. 504 of [38].
By Theorem 2.2 of [10], for
Its extension to is given in Section 3 of [10] for parametric and non-parametric models.
Example 4.
Take .
- Thus, . For and ,
Example 5.
Take . Thus, . This choice gives a set of q simultaneous intervals. For and
Thus, for k odd. ( is no longer zero.) But each of those non-zero terms requires q numerical integrations. Consider the case .
For more on these types of expansions and their inverses, see [13] and their simplifications given in Sections 4 and 5 of [16]. However, in these papers, the need to express results in terms of did not arise. See also [39]. For the case of a sample mean with estimated covariance, it is possible to avoid the use of ; see [40].
4. The Distribution of Xn = n1/2() for q = 2
As above, we set . Taking , we switch notation to
Thus, and are given by (42) with and 2:
and so on. The and needed here are given in Appendix B. Let us write the cumulant expansion (9) as
Thus The density of , , is given by (22) and (25) in terms of and of (25). As is symmetric,
for of (19)–(21). Therefore, is just with 1 and 2 reversed.
Then, is given for by (34)–(36) in terms of
The needed in (68) for are as follows, in terms of of (67):
Equations (22) and (25) now give the density of to .
The distribution of is given by (22) and (26) in terms of . is just the above with replaced by of (71). That is,
Equations (22) and (26) now give to for . For example, for and , the values of are given in Example A1.
By (45), is given to by , of (45) and (52). These are given by replacing above by of (48) and the of (49).
By Section 3, for and , is given by
These expressions can be read off those for in Appendix B. If , then for odd. For Examples 3 and 4, and of (48) is given by (58) in terms of . For , this is given by (70).
Example 6.
For a specific case of a bivariate sample mean, consider the following.
Example 7.
An
entangled gamma
model. Let be independent gamma random variables with means . For , set , and let be the mean of a random sample of size n distributed as . Thus, and , where are independent gamma random variables with means . The rth order cumulants of X are and otherwise, . For example, , and
Thus, Set Then, V has correlation . This ranges from 0 at to 1 at Thus, and are positively entangled. (For a negatively entangled example, replace by : the correlation is then . An extension to is ) For set
By Example 6, for are given by the equations following (69) in terms of
Now, consider the
entangled exponential
case . Thus, V and are given by (62),
For and , the values of are given in Example A1, and by symmetry, can be replaced by 2 in (69) and the other equations for .
Thus, if , then so that our measure of the inaccuracy of the CLT is for and
If , then , and our measure of the inaccuracy of the CLT is for , and for .
Example 8.
As in Example 1, suppose that the distribution of is symmetric about w. By (40),
and needed for (41) is with replaced by of (71). Now, suppose that , where and are independent copies of a random vector Then, the cumulants of of odd order are zero, and the cumulants of even order are twice those of
Consider the case , the bivariate entangled gamma of Example 7. Thus, , the odd cumulants of are zero, and the odd are zero. Denote of Example 4 as . Then,
By Example 2, , where
Now, consider the exponential case . Thus,
Thus, for Here, I used the values of given in the example of [41].
5. Conclusions
Most estimates of interest are standard estimates, including functions of sample moments, like the sample correlation, and any smooth multivariate function of Fisher’s k-statistics; see [5] for these. In Section 2, I gave the density and distribution of to , for any standard estimate, in terms of functions of the cumulants coefficients of (9), the coefficients of (18)–(21). Section 3 gave explicit detail when using the alternative notation . Section 3 gave as examples Edgeworth expansions for the probability of lying in an ellipsoidal or hyperrectangular set.
6. Discussion
A good approximation for the distribution of an estimate is vital for accurate inference. It enables one to explore the distribution’s dependence on underlying parameters. Equation (22) gives expansions in powers of , for the distribution and density of a multivariate standard estimate, in terms of the Edgeworth coefficients of (18). As noted at the end of Sections 1 and 5 of [35], the Cornish–Fisher expansions (4) are valid under the usual conditions for validity of the Edgeworth expansion (2), and their Section 5 appears to show that this is also true for the multivariate case. Appendix C shows for the first time how to find the extended Edgeworth expansions of (22) on a rigorous basis. Examples of standard estimates are moment estimates and maximum likelihood estimates. The underlying cumulant coefficients will be functions of the parameters of the model on which is based. For a k-statistic or a polynomial in k-statistics, the cumulant coefficients are polynomials in the cumulants of the sample.
The analytic results given here avoid the need for simulation, jack-knife or bootstrap methods while providing greater accuracy than them. Ref. [42] used the Edgeworth expansion to show that the bootstrap gives accuracy to . Ref. [43] said that “2nd order correctness usually cannot be bettered”. But this is not true using these analytic results. Simulation, while popular, can at best shine a light on behaviour when there is only a small number of parameters.
Estimates based on a sample of independent but not identically distributed random vectors, are also generally standard estimates. For example, for a univariate sample mean , where has an rth cumulant , , where is the average rth cumulant. For some examples, see [2,44,45,46]. The latter is for a function of a weighted mean of complex random matrices. It gives an application in electrical engineering of channel capacity for multiple arrays.
Estimates based on a stationary sample can also be standard estimates. See [47].
For conditions for the validity of multivariate Edgeworth expansions, see [30] and its references.
Refs. [3,8] did not deal with the question of when these expansions diverged. I showed how to confront this in the numerical examples in Example 7 and [4].
Lastly, I discuss numerical computation. I have used [41] for the numerical calculations in Example 7. One could also download R-4.4.1 for Windows and google the routines needed. dmvnorm computes the density function of the multivariate normal specified by the mean and co-variance matrix. Use mvtnorm for the multivariate normal. See also qmvnorm for quantiles. rmvnorm generates multivariate normal variables. Googling “bivariate hermite polynomials r” gives https://cran.r-project.org/web/packages/calculus/vignettes/hermite.html (accessed on 25 June 2025). One can then use install.packages(“calculus”). However, I have not used this route.
Some future directions.
- Ref. [13] showed how to generalise the expansions of Cornish and Fisher about to expansions about an arbitrary continuous distribution. Their results are cumbersome as they involve partition theory. In [16], I overcame this using Bell polynomials. It would be straightforward to apply these to expansions about in Example 3 to obtain the percentiles of and . However, in the latter case, we first need to derive the cumulant coefficients of from those of . This can be done by applying [1].
- It would very useful to obtain the multivariate of (44) explicitly.
- The multivariate expansions considered here have been about the multivariate normal. However, as noted at the end of Section 1, expansions about other distributions can greatly reduce the number of terms in each and by matching bias and/or skewness. While this was derived for by Withers and [10,14,15] about Student’s distribution, the F-distribution and the gamma distribution, to date, this has yet to be derived for multivariate expansions about, for example, a multivariate gamma distribution.
- The results given here are the first step for constructing confidence intervals and confidence regions. To do this one estimates the cumulant coefficients. See [32,33,48] for the case .
- The results here can be extended to tilted (saddle-point) expansions by applying the results of [2]. These are very useful where convergence fails, that is, where the CLT cannot be improved upon, typically due to being in a tail. The tilted version of the multivariate distribution and density of a standard estimate are given by Corollaries 3 and 4 there. Tilting was first used in statistics by [27]. He gave an approximation to the density of a sample mean. See also [49]. Ref. [7] gave a univariate extension to where was the sum of N independent and identically distributed observations, and N was Poisson. The extension of the present results from to would be useful for both univariate and multivariate observations. For a review of references on tilting, see [2].
- Ref. [41] wrote a python program to obtain both analytic and numerical values of multivariate normal moments and multivariate Hermite polynomials when . It would be useful to have these extended to and 4. (The alternative notation for and when or 4 is straightforward.)
- The end of Appendix C suggests a way of giving more theorems for Edgeworth expansions.
Funding
This research received no external funding.
Data Availability Statement
The original contributions presented in this study are included in the article. Further inquiries can be directed to the author.
Conflicts of Interest
Author Christopher Stroude Withers was employed by the company Industrial Research Ltd. before retiring. The author declares that the research was conducted in the absence of any commercial or financial relationships that could be construed as a potential conflict of interest.
Appendix A. The Edgeworth Coefficients Needed for (18)
Appendix B. μab and Hab of (66) for a + b ≤ 9
Here, we give the bivariate normal moments of (65) and the bivariate Hermite polynomials of (66) for . These are needed for the Edgeworth expansions to . The first nine univariate Hermite polynomials are
These are needed for of (2), (3), that is, for the univariate Edgeworth expansions to . See [5].
Let be a q-variate normal random variable with mean , positive-definite covariance V, with density and distribution of (11). Set as in (12), so that Y has odd moments of zero and even moments
where sums over the m permutations of giving distinct terms. For example,
Ref. [41] wrote a python program to obtain the bivariate moments using (A3). Let be the multivariate Hermite polynomial is defined by (27) and (28). For is given by (12)–(33). In these expressions, can be replaced by any integer in . For example,
Now, consider the bivariate case, , and denote the moments of Y by
Two special cases are
The needed here are those up to order
For example, to derive from of (A3), replace by 1 and by 2. can be read off using symmetry. For example, . Formulas for the general were given by [50,51]. By (66),
This is the formula used in [41] to obtain bivariate Hermite polynomials. is said to be of order . Most of those of order up to are needed to expand the density of to , but not those of order 8 (nor those of order 6 if the distribution of is symmetric about w). But we include them here for completeness. We can write in terms of of (A6) and :
These are actually simpler formulas than their univariate forms because of the use of . The other up to order nine are
The method of the proof is illustrated as follows for :
Now, expand the second term to get
Similarly, for , expand
The above formulas for can be called their short form as each uses . The explicit form when of (A8) is substituted can be called its long form. My short forms for were checked against the long forms given by [41]. Here is a selection of his results for comparison.
For example the short and long forms for have 5 and 10 terms, and those for have 8 and 13 terms.
Example A1.
These results were computed by [41], using (A7), and are used in Example 7. Note how for these examples, when the elements of x and V are integers, is an integer .
Appendix C. Regularity Conditions for the Edgeworth Expansions of (22)
Here, I build on (20.53) of [29]. By (20.50), this holds for all q (their k) not just for . Unlike theirs, my version is explicit.
Theorem A1.
Let be independent identically distributed (i.i.d.) random vectors in with means zero, covariance V, and distribution function . Set . Assume that for some integer , and that Cramer’s condition holds,
and is of (38) with of Example 2 and the cumulants of
Corollary A1.
Let be i.i.d. random vectors in with mean , distribution function with mean 0, covariance with minimum evalue bounded away from 0, and Fourier transform satisfying
Suppose also that for some integer . Then,
for of Theorem C.1 and replaced by , the cumulants of up to order s.
If all cumulants are finite, then we can represent as , by requiring that their cumulants be the same, that is, by choosing
However if we only require cumulants up to order s to match, then we can apply the corollary to obtain
Corollary A2.
Let be i.i.d. random vectors in chosen so that (A12) holds for cumulants up to order s. Suppose that the regularity conditions of Corollary A1 hold.Then for ,
for of Corollary A1 with , where
where is truncated by dropping terms.
The reason (A16) drops the , is that for ,
We skip further details of the proof.
Expanding about w, as and , we obtain
One could also treat the density expansion of (22) similarly, by building on their (19.17). And for corrections for a lattice sample mean, one could build on their (23.3).
Appendix D. Some Corrigenda to the References
For typos and corrections for [2,4,15,16,19,32], see p. 23–25 of [1].
Typos and corrections for [33]:
p. 4231, seventh and eighth lines from the bottom: replace “” by “”.
p. 4233, line 13: replace “” by “”.
p. 4233, at the end of the seventh to last line, replace by
p. 4236, second to last line: “1982a” should read “1983b”; in the last line, “Example 3.3” should read “Example 3.4”.
p. 4241, in the last equation, replace by .
p. 4250: in the first equation in Example 3.5, “” should read “”.
p. 4253: in the first equation, “” should read “”; in the fourth equation, , not . in the seventh to last line, (2.1) should be (4.1); in the sixth to last line, “, which Section 4”, (2.1) should read “, which by Section 4”.
p. 4254, line 1: replace by .
Typos in [14]: p. 217, line 7: replace stem by step. p. 220: replace the first two words “That is,” by “Suppose now that”. p. 220: after “replace” in line 6, insert “ by ,”. p. 226: replace lines 5–7, “Suppose that … This is”, as follows: “Suppose that for in and satisfies where as This is”. p. 226: replace on the LHS of fourth displayed equation by . p. 226: replace on RHS of sixth displayed equation by . p. 227: replace r in (7.5) and the following equation by . p. 227: replace “variance” in (7.6) by “covariance”.
Typos and corrections to [10]: p. 4369, lines 8–11 should read:
where is the dual Hermite polynomial; see [9].
p. 4370: in Theorem 2.2, where
p. 4379: Replace the third line after (A.3) by In the second equation after (A.3), replace by . For example, The next equation should read where is the complete exponential Bell polynomial. Thus, for , where is the partial exponential Bell polynomial tabled on pp. 307–308 of [31] for .
References
- Withers, C.S. 5th-Order multivariate Edgeworth expansions for parametric estimates. Mathematics 2024, 12, 905. [Google Scholar] [CrossRef] [Scilit]
- Withers, C.S.; Nadarajah, S. Tilted Edgeworth expansions for asymptotically normal vectors. Ann. Inst. Stat. Math. 2010, 62, 1113–1142. [Google Scholar] [CrossRef] [Scilit]
- Cornish, E.A.; Fisher, R.A. Moments and Cumulants in the Specification of Distributions. Rev. l’Inst. Int. Statist. 1937, 5, 307–322. [Google Scholar]
- Withers, C.S. Asymptotic expansions for distributions and quantiles with power series cumulants. J. R. Statist. Soc. B 1984, 46, 389–396, Erratum in J. R. Statist. Soc. B 1986, 48, 256. [Google Scholar]
- Stuart, A.; Ord, K. Kendall’s Advanced Theory of Statistics, 2, 5th ed.; Griffin: London, UK, 1991. [Google Scholar]
- Kolassa, J.E. Series Approximation Methods in Statistics; Springer: Berlin/Heidelberg, Germany, 1997. [Google Scholar]
- Jensen, J.L. Uniform saddlepoint approximations. Adv. Appl. Prob. 1988, 20, 622–634. [Google Scholar]
- Fisher, R.A.; Cornish, E.A. The percentile points of distributions having known cumulants. Technometrics 1960, 2, 209–225. [Google Scholar] [CrossRef] [Scilit]
- Withers, C.S. A simple expression for the multivariate Hermite polynomials. Stat. Prob. Lett. 2000, 47, 165–169. [Google Scholar]
- Withers, C.S.; Nadarajah, S.N. Improved confidence regions based on Edgeworth expansions. Comput. Stat. Data Anal. 2012, 56, 4366–4380. [Google Scholar] [CrossRef] [Scilit]
- Edgeworth, F.Y. The law of error. Proc. Camb. Philos. Soc. 1905, 20, 36–65. [Google Scholar]
- Withers, C.S.; Nadarajah, S.N. Charlier and Edgeworth expansions via Bell polynomials. Probab. Math. Stat. 2009, 29, 271–280. [Google Scholar]
- Hill, G.W.; Davis, A.W. Generalised asymptotic expansions of Cornish-Fisher type. Ann. Math. Statist. 1968, 39, 1264–1273. [Google Scholar]
- Withers, C.S.; Nadarajah, S. Generalized Cornish-Fisher expansions. Bull. Braz. Math. Soc. New Ser. 2011, 42, 213–242. [Google Scholar] [CrossRef] [Scilit]
- Withers, C.S.; Nadarajah, S. Expansions about the gamma for the distribution and quantiles of a standard estimate. Methodol. Comput. Appl. Prob. 2014, 16, 693–713. [Google Scholar] [CrossRef] [Scilit]
- Withers, C.S.; Nadarajah, S. Edgeworth-Cornish-Fisher-Hill-Davis expansions for normal and non-normal limits via Bell polynomials. Stochastics Int. J. Probab. Stoch. Processes 2015, 87, 794–805. [Google Scholar] [CrossRef] [Scilit]
- Simonato, J.G. The performance of Johnson distributions for computing value at risk and expected shortfall. J. Deriv. 2011, 19, 7–24. [Google Scholar] [CrossRef] [Scilit]
- Zhang, L.; Mykl, P.A.; Ait-Sahalia, Y. Edgeworth expansions for realised volatility and related estimators. J. Econom. 2011, 160, 190–203. [Google Scholar]
- Withers, C.S.; Nadarajah, S.N. Moment generating functions for Rayleigh Random Variables. Wirel. Pers. Commun. 2008, 46, 463–468. [Google Scholar]
- Song, T.; Wang, S.; An, W. GPS positioning accuracy estimation using Cornish-Fisher expansions. In Proceedings of the 2009 WRI International Conference on Communications and Mobile Computing, Kunming, China, 6–8 January 2009; pp. 152–155. [Google Scholar]
- Abdel-Wahed, A.R.; Winterbottom, A. Approximating posterior distributions of system reliability. Statistician 1983, 32, 224–228. [Google Scholar]
- Winterbottom, A. Asymptotic expansions to improve large sample confidence intervals for system reliability. Biometrika 1980, 67, 351–357. [Google Scholar] [CrossRef] [Scilit]
- Winterbottom, A. The interval estimation of system reliability component test data. Oper. Res. 1984, 32, 628–640. [Google Scholar] [CrossRef] [Scilit]
- Sellentin, E.; Jaffe, A.H.; Heavens, A.F. On the use of the Edgeworth expansion in cosmology I: How to foresee and evade its pitfalls. arXiv 2017, arXiv:1709.03452. [Google Scholar] [CrossRef] [Scilit]
- Perninge, M. Stochastic Optimal Power Flow by Multivariate Edgeworth Expansions; Electric Power Systems Research; Elsevier: Amsterdam, The Netherlands, 2014. [Google Scholar]
- Withers, C.S.; Nadarajah, S.N. Cornish-Fisher expansions about the F-distribution. Appl. Math. Comput. 2012, 218, 7947–7957. [Google Scholar] [CrossRef] [Scilit]
- Daniels, H.E. Saddlepoint approximations in statistics. Ann. Math. Statist. 1954, 25, 631–650. [Google Scholar]
- Cramer, H. Mathematical Methods of Statistics; Princeton University Press: Princeton, NJ, USA, 1946. [Google Scholar]
- Bhattacharya, R.N.; Rao Ranga, R. Normal Approximation and Asymptotic Expansions; Wiley: New York, NY, USA, 1976. [Google Scholar]
- Skovgaard, I.M. On multivariate Edgeworth expansions. Int. Statist. Rev. 1986, 54, 169–186. [Google Scholar]
- Comtet, L. Advanced Combinatorics; Reidel: Dordrecht, The Netherlands, 1974. [Google Scholar]
- Withers, C.S. Nonparametric confidence intervals for functions of several distributions. Ann. Inst. Statist. Math. 1988, 40, 727–746. [Google Scholar]
- Withers, C.S. Accurate confidence intervals when nuisance parameters are present. Comm. Statist.-Theory Methods 1989, 18, 4229–4259. [Google Scholar]
- Takeuchi, K. A multivariate generalization of Cornish-Fisher expansion and its applications. Keizaigaku Ronshu 1978, 44, 1–12. (In Japanese) [Google Scholar]
- Takemura, A.; Takeuchi, K. Some results on univariate and multivariate Cornish-Fisher expansions: Algebraic properties and validity. Sankhya Ser. A 1988, 50, 111–136. [Google Scholar]
- Anderson, T.W. An Introduction to Multivariate Analysis; John Wiley: New York, NY, USA, 1958. [Google Scholar]
- Gradshteyn, I.S.; Ryzhik, I.M. Tables of Integrals, Series and Products, 6th ed.; Academic Press: New York, NY, USA, 2000; (The Generalized Hypergeometric Function Is Defined in Section 9.14.). [Google Scholar]
- Abramowitz, M.; Stegun, I.A. Handbook of Mathematical Functions; Applied Mathematics Series 55; U.S. Department of Commerce; National Bureau of Standards: Gaithersburg, MD, USA, 1964. [Google Scholar]
- Bentkus, V.; Gtze, F.; van Zwet, W.R. An Edgeworth expansion for symmetric statistics. Ann. Stat. 1997, 25, 851–896. [Google Scholar] [CrossRef] [Scilit]
- Xu, J.; Gupta, A.K. Improved confidence regions for a mean vector under general conditions. Comput. Stat. Data Anal. 2006, 51, 1051–1062. [Google Scholar]
- Teal, P. A code to calculate bivariate Hermite polynomials. Its input is V11,V12,V22 and y1,y2, not V11,V12,V22 and x1,x2. 2024. Available online: https://github.com/paultnz/bihermite/blob/main/bihermite.py (accessed on 26 June 2025).
- Hall, P. The Bootstrap and Edgeworth Expansion; Springer: New York, NY, USA, 1992. [Google Scholar]
- Hall, P. Rejoinder: Theoretical Comparison of Bootstrap Confidence Intervals. Ann. Stat. 1988, 16, 981–985. [Google Scholar] [CrossRef] [Scilit]
- Skovgaard, I.M. Edgeworth expansions of the distributions of maximum likelihood estimators in the general (non i.i.d.) case. Scand. J. Statist. 1981, 8, 227–236. [Google Scholar]
- Skovgaard, I.M. Transformation of an Edgeworth expansion by a sequence of smooth functions. Scand. J. Statist. 1981, 8, 207–217. [Google Scholar]
- Withers, C.S.; Nadarajah, S. The distribution and percentiles of channel capacity for multiple arrays. Sadhana SADH Indian Acad. Sci. 2020, 45, 155. [Google Scholar] [CrossRef] [Scilit]
- Withers, C.S. Edgeworth-Cornish-Fisher expansion for the mean when sampling from a stationary process. Axioms 2025, 14, 406. [Google Scholar] [CrossRef] [Scilit]
- Withers, C.S. Expansions for the distribution and quantiles of a regular functional of the empirical distribution with applications to nonparametric confidence intervals. Annals Statist. 1983, 11, 577–587. [Google Scholar]
- Field, C.A.; Hampel, F.R. Small sample asymptotic distributions of M-estimators of location. Biometrika 1982, 69, 29–46. [Google Scholar]
- Isserlis, L. On a formula for the product-moment coefficient of any order of a normal frequency distribution in any number of variables. Biometrika 1918, 12, 134–139. [Google Scholar] [PubMed]
- Withers, C.S. New methods for multivariate normal moments. Stats 2025, 8, 46. [Google Scholar] [CrossRef] [Scilit]
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2025 by the author. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).