


Abstract
Artificial intelligence-integrated ‘buy now, pay later’ (BNPL) platforms are diffusing rapidly across the Middle East and North Africa (MENA), raising concerns about consumer financial vulnerability. Drawing on choice architecture, payment decoupling, and financial literacy literatures, this study examines how three platform-level features—algorithmic nudging, AI personalization intensity, and perceived ease of credit—are associated with impulsive buying tendency and downstream financial outcomes, and whether BNPL-specific financial literacy attenuates these associations. A multi-method design combined cross-sectional partial least squares structural equation modeling (N = 1247 active BNPL users in seven MENA countries) with a six-month longitudinal follow-up (N = 847, 68% retention). Algorithmic nudging was positively associated with impulsive buying tendency, which in turn was associated with elevated financial stress and longitudinal debt accumulation. The ‘loyalty trap’—a paradoxical state in which financially stressed consumers maintain high platform loyalty—is provisionally documented via piecewise longitudinal trajectories. We emphasize that this pattern is consistent with but not causally established by the present design, and we outline specific experimental and quasi-experimental research designs needed for causal identification. BNPL-specific financial literacy moderated the associations between algorithmic nudging, impulsive buying, and adverse financial outcomes, with the highest-literacy quartile exhibiting substantially attenuated debt trajectories. We discuss boundary conditions, alternative explanations, and the limits of causal inference in non-experimental panel data. Findings inform evolving BNPL regulatory frameworks in MENA, with particular relevance to nudge-transparency disclosures, contractual cooling-off periods, and credit-bureau reporting standards.
1. Introduction
The global buy now, pay later (BNPL) market has grown rapidly, with transaction volumes surpassing USD 300 billion in 2024 [1]. Three established research streams inform understanding of BNPL consumer outcomes.
First, studies in developed markets (UK: [2]; Australia: [3]; US: [4]) document that BNPL adoption is associated with increased consumer debt, financial stress, and impulsive purchasing. However, these studies predominantly examine Western consumers and focus on adoption-level outcomes rather than platform-specific mechanisms.
Second, research on AI-driven personalization [5,6] demonstrates that algorithmic recommendation systems increase purchase likelihood and consumer engagement. However, this literature focuses on marketing effectiveness rather than consumer financial welfare, leaving the financial consequences of personalization largely unexamined.
Third, studies of digital nudging [7,8] identify effective choice architecture techniques in e-commerce. However, this research examines static interface elements in general retail contexts rather than dynamic, AI-optimized nudging in digital credit platforms.
Despite these advances, three critical gaps persist.
Gap 1—The Platform Mechanism Gap: No prior study has simultaneously examined AI personalization, algorithmic nudging, and perceived ease of credit as distinct but interrelated antecedents of BNPL consumer outcomes. The relative importance of these platform features and their interactions remain unknown.
Gap 2—The Mediation Mechanism Gap: While impulsive buying tendency has been examined as a correlate of BNPL use [9], its role as a mediator translating specific platform features into financial harm has not been empirically established.
Gap 3—The Boundary Condition Gap: Financial literacy has been identified as a predictor of financial behavior [10], but its moderating role in algorithmic persuasion contexts—particularly whether domain-specific literacy exceeds general literacy in protective effects—has not been examined in BNPL contexts.
Gap 4—The Contextual Gap: Prior BNPL research is overwhelmingly concentrated in Western and South Asian markets. The MENA region, where BNPL adoption is accelerating rapidly [11] and financial literacy levels are below OECD averages, remains significantly understudied.
The study’s central research question is: How do AI personalization intensity, perceived ease of credit, and algorithmic nudging influence consumer financial vulnerability (financial stress, debt accumulation, and platform loyalty) through impulsive buying tendency, and to what extent does BNPL-specific financial literacy moderate these relationships in the MENA region?
To answer this question, we develop five theoretically grounded propositions comprising 23 testable hypotheses, organized around five structural pathways.
PROPOSITION 1 (Antecedent Interdependence): AI personalization intensity functions as a foundational platform capability that enables both perceived ease of credit and algorithmic nudging effectiveness (H1–H3).
PROPOSITION 2 (Impulsive Activation): The three platform features activate impulsive buying tendency through distinct but complementary mechanisms (H4–H6).
PROPOSITION 3 (Dual Harm Pathways): Impulsive buying tendency serves as the primary proximal driver of both financial stress and debt accumulation (H10, H14), while platform features exert additional direct effects on financial outcomes (H7–H9, H11–H13).
PROPOSITION 4 (The Loyalty Trap Paradox): AI personalization simultaneously promotes platform loyalty (H15) while contributing to financial harm through indirect pathways, creating a paradoxical state in which financially stressed users remain loyal (H16–H19).
PROPOSITION 5 (Literacy as Protective Buffer): BNPL-specific financial literacy attenuates the harmful effects of algorithmic nudging and impulsive buying on financial outcomes (H20–H23).
Table 1 maps each hypothesis onto its theoretical lineage and structural function. These four paths are selected because they represent the two theoretically central mechanisms (platform-side nudging and consumer-side impulsivity) through which financial harm is most proximally produced. Additional moderation paths involving AI personalization intensity and perceived ease of credit are examined in exploratory analyses (Appendix C, Table A6).
Table 1.
Hypothesis-to-proposition mapping with theoretical lineages.
This study develops and tests an integrative theoretical model that simultaneously addresses all four gaps. Drawing on choice architecture theory [12], payment decoupling theory [13], and financial literacy theory [14], we examine how three platform features collectively activate impulsive buying tendency, which drives financial stress and debt accumulation, while simultaneously generating platform loyalty that may perpetuate harmful usage patterns. We further examine whether BNPL-specific financial literacy attenuates these pathways more effectively than general financial literacy. The study makes four contributions: (i) introducing AI-enabled digital nudging as a distinct construct; (ii) identifying impulsive buying tendency as the primary mediation mechanism; (iii) provisionally documenting a loyalty trap pattern in fintech contexts; and (iv) demonstrating that domain-specific financial literacy provides stronger protection than general literacy. Data from 1247 BNPL users across seven MENA countries (cross-sectional) and 847 six-month follow-up responses provide robust empirical support.
The remainder of this paper is organized as follows. Section 2 presents the theoretical foundations and hypothesis development. Section 3 describes the research methodology and study design. Section 4 reports the empirical results. Section 5 provides a critical discussion of findings. Section 6 concludes with implications and recommendations.
2. Literature Review and Hypothesis Development
The academic study of consumer credit behavior has undergone significant transformation over the past five decades, evolving from purely economic models of rational borrowing to sophisticated interdisciplinary frameworks incorporating behavioral economics, social psychology, and information systems [15]. The emergence of BNPL as a distinct product category represents the latest evolution in this trajectory, characterized by the convergence of e-commerce, instant digital credit, and algorithmic consumer influence [16]. Unlike traditional installment credit or credit card offerings, BNPL schemes operate at the precise intersection of consumption intent and payment decision, embedding credit offerings within the purchase journey through seamless platform integration [17].
AI personalization intensity refers to the degree to which consumers perceive that AI algorithms analyze their personal data to create tailored shopping and credit experiences [18]. This construct extends the broader concept of personalization in e-commerce [19] to specifically capture the AI-driven nature of contemporary recommendation and pricing systems. The construct encompasses both the perceived sophistication of the AI system (the extent to which consumers believe advanced algorithms are processing their data) and the perceived relevance of resulting recommendations (the practical utility of personalized suggestions) [20]. Research by Lee [6] demonstrates that AI personalization in financial services creates both utilitarian benefits (improved product fit) and hedonic experiences (enjoyment of discovery), with the hedonic dimension potentially overwhelming rational evaluation of financial consequences.
Perceived ease of credit captures consumers’ subjective assessment of the accessibility and simplicity of obtaining BNPL credit relative to traditional alternatives [21]. This construct reflects the fundamental value proposition of BNPL services—eliminating friction from the credit application process through instant approval, minimal documentation, and seamless integration with e-commerce checkout flows [22]. The construct builds upon Davis’s [23] technology acceptance model concept of perceived ease of use, extending it to the specific context of digital credit acquisition. Aidala et al. [24] demonstrate that perceived ease of credit is a stronger predictor of BNPL adoption than traditional creditworthiness indicators, suggesting that BNPL services attract consumers precisely because they circumvent the cognitive and procedural barriers associated with conventional lending. Complementing this adoption-side evidence, Maesen and Ang [25], using customer-level transaction data from a large US retailer, show that BNPL installment adoption causally raises both purchase incidence and basket size by reducing perceived financial constraints—an effect strongest among smaller-basket and credit-reliant shoppers. Their three pre-registered experiments locate this mechanism in the easing of perceived costs and budget control, providing direct experimental support for our argument that AI-enabled payment decoupling fuels the impulsive-buying pathway hypothesized in H6.
2.1. An Integrative Multi-Theory Model
Our framework integrates three theories that interact sequentially rather than merely coexist. Figure 1 depicts this interaction as a three-stage causal chain with a boundary condition.
Figure 1.
An Integrative Multi-Theory Model.
Stage 1—Choice Architecture [12]: AI personalization, perceived ease of credit, and algorithmic nudging collectively shape the decision environment. This stage answers: What platform features influence consumer decision-making?
Stage 2—Psychological Mediation (Payment Decoupling + Impulsivity): The shaped decision environment activates impulsive buying tendency (through reduced pain of paying and increased purchase facilitation), which then translates into financial harm. This stage answers: What psychological mechanism translates platform features into adverse outcomes?
Stage 3—Outcome Differentiation (Payment Decoupling Continuation): Financial harm manifests as both immediate stress (affective response) and accumulated debt (behavioral outcome), while platform loyalty emerges as a paradoxical concurrent outcome. This stage answers: What are the distinct financial and behavioral consequences?
Boundary Condition—Financial Literacy as Protective Resource [14]: Financial literacy functions as a consumer capability resource (rather than a mere boundary condition) that moderates the Stage 1-to-Stage 2 and Stage 2-to-Stage 3 transitions. It is conceptualized as a protective mechanism that buffers against algorithmic persuasion by providing cognitive resources to evaluate nudge cues, recognize manipulative intent, and execute deliberate decision-making.
2.2. Theoretical Integration: How the Three Theories Interact
The three theories interact through sequential causal dependencies:
- (1)
- Choice architecture triggers payment decoupling: Algorithmic nudging and ease of credit reduce the salience of payment consequences [26], effectively creating a ‘double decoupling’ where both choice architecture and temporal separation combine to amplify financial harm.
- (2)
- Payment decoupling activates financial literacy’s protective function: When payment consequences are decoupled, financially literate consumers are better able to mentally reconstruct those consequences [10], effectively ‘re-coupling’ consumption and payment through cognitive effort. Less literate consumers lack this reconstructive capacity.
- (3)
- Financial literacy moderates choice architecture effects: Literate consumers recognize nudge techniques (e.g., they identify default settings as deliberate platform choices rather than natural arrangements), reducing nudge effectiveness [27].
This sequential–interactive structure is distinct from additive models in which theories merely contribute separate variance components. Our empirical model captures these interactions through: (a) the structural paths from platform features to impulsive buying (choice architecture-to-decoupling link); (b) the moderation of these paths by financial literacy (literacy-as-protective-resource); and (c) the differential effectiveness of BFL vs. GFL (domain-specific reconstructive capacity).
Recent empirical studies have begun documenting the behavioral and financial consequences of BNPL adoption. Kumar and Nayak [9] examined the effects of BNPL adoption on risky indebtedness among Indian consumers, finding that impulsive buying tendency and materialism significantly mediated the relationship between BNPL use and debt accumulation. Their study, employing a sample of 1078 respondents, demonstrated that BNPL services activated consumption impulses that traditional credit products did not, attributing this effect to the unique integration of credit with the purchase moment. The path coefficient from BNPL adoption to impulsive buying tendency was β = 0.41 (p < 0.001), with impulsive buying subsequently predicting debt accumulation at β = 0.38 (p < 0.001).
Raj et al. [28] investigated the relationship between materialism and the dark sides of BNPL, identifying a positive association between materialistic values, compulsive buying behavior, and BNPL-induced financial stress. Their findings, based on survey data from 556 Indian consumers, indicated that BNPL services amplified the negative consequences of materialism by removing payment friction at the moment of consumption desire. The moderation analysis revealed that self-control significantly attenuated the materialism–compulsive buying relationship (β = −0.15, p < 0.01), suggesting individual differences in vulnerability. Similarly, Schomburgk and Hoffmann [29] demonstrated that mindfulness attenuated the relationship between BNPL use and financial wellbeing (β = −0.22, p < 0.001), suggesting that present-moment awareness may counteract the impulsivity-inducing effects of BNPL availability.
Ah Fook and McNeill [30] examined BNPL use and impulse buying behavior among Australian young adults, finding that the instant gratification enabled by BNPL services significantly increased unplanned purchasing (r = 0.34, p < 0.01). Their qualitative findings revealed that BNPL users often experienced a ‘dissociation’ between the shopping act and its financial consequences, consistent with the payment decoupling framework. The Central Bank of Ireland’s [31] comprehensive review of the Irish BNPL market found that 35% of BNPL users reported spending more than intended, with 18% experiencing difficulty meeting repayment obligations. Notably, 43% of respondents aged 18–34 reported using BNPL for purchases they would not have made otherwise.
The role of AI and algorithmic personalization in consumer financial behavior has received increasing scholarly attention. Raji et al. [5] examined the role of AI-driven personalization in online shopping behavior, finding that algorithmic recommendations significantly increased both purchase likelihood (OR = 2.34) and basket size (+28%). Their study highlighted the ‘filter bubble’ effect, where AI personalization creates self-reinforcing consumption patterns by consistently presenting similar products and offers. Münscher et al. [7] provided a comprehensive taxonomy of digital nudging, identifying 16 distinct nudge archetypes commonly employed in digital choice environments and documenting their effects on user behavior across multiple domains. Their meta-analysis found that digital nudges produce average effect sizes of Cohen’s d = 0.42 on targeted behaviors.
Donou-Adonsou and Leslie-Piper [32] analyzed social media sentiment regarding BNPL services, identifying a significant shift from predominantly positive sentiment in 2020 to increasingly negative sentiment by 2023, with growing concerns about debt, regret, and financial stress. Their sentiment analysis of 45,000 tweets revealed that emotional language around BNPL increasingly reflected anxiety (28% of posts) and regret (19%), suggesting that consumers’ lived experiences with BNPL may diverge from initial positive expectations. Sharma et al. [33] examined the concept of ‘psychological ownership’ of borrowed money, finding that consumers who perceived greater psychological ownership of BNPL funds exhibited higher spending and lower repayment priority. Their experimental manipulation demonstrated that framing BNPL as ‘your spending power’ versus ‘a loan’ significantly affected financial decision-making (p < 0.05).
Hayashi and Routh [21] investigated how platform loyalty develops in fintech contexts, finding that both satisfaction with the core service and trust in the platform’s benevolence predicted loyalty intentions. However, their study also documented a ‘loyalty trap’ phenomenon where highly loyal users continued using platforms despite negative financial outcomes, driven by habit, switching costs, and optimistic bias about future financial management. This finding is particularly relevant to BNPL contexts, where platform loyalty may perpetuate harmful financial behaviors even as users recognize negative consequences [34].
However, critical gaps remain in the existing literature. No prior study has simultaneously examined AI personalization, algorithmic nudging, and perceived ease of credit as antecedents of consumer financial outcomes in BNPL contexts. The mediating role of impulsive buying tendency has been examined in isolation but not as part of an integrated structural model incorporating all three platform features. The moderating role of financial literacy has been theorized but not empirically tested within the specific context of AI-integrated BNPL services. Furthermore, the vast majority of existing studies have been conducted in Western or South Asian contexts, with the MENA region significantly underrepresented [35]. The current study addresses these gaps through a comprehensive, multi-country investigation spanning seven MENA economies.
Based on the theoretical frameworks reviewed above and the identified research gaps, we develop the following hypotheses. The relationships between the independent variables are grounded in the theoretical expectation that AI personalization creates the foundation for both perceived ease of credit and algorithmic nudging. As AI systems personalize the user experience, they simultaneously streamline credit processes (increasing perceived ease) and optimize nudge delivery (enhancing algorithmic nudging effectiveness) [36].
PROPOSITION 3: DUAL HARM PATHWAYS—Platform Features Exert Both Direct and Indirect Effects on Financial Outcomes.
Theoretical Rationale: While impulsive buying tendency is the primary proximal driver of financial harm (PROPOSITION 2), platform features may exert additional direct effects on financial outcomes through pathways not fully mediated by impulsivity. This dual-pathway prediction draws on two theoretical arguments.
Direct Path Justification (H7–H9, H11–H13):
H7 (AI personalization to financial stress): AI personalization may increase financial stress through information overload and decision fatigue [6], independent of impulsive buying. Personalized credit offers increase cognitive load as consumers evaluate complex, individualized terms, depleting mental resources needed for prudent financial planning.
H8 (perceived ease of credit to financial stress): Easy credit access reduces perceived risk, leading consumers to underestimate repayment burdens [22]. This risk underestimation operates through cognitive mechanisms (optimism bias) distinct from impulsive affective responses.
H9 (algorithmic nudging to financial stress): Nudges exploit specific behavioral biases (scarcity bias, social proof, default effects) that directly increase spending intentions without necessarily activating general impulsivity [7]. A consumer may rationally plan purchases but still overspend when nudges exploit separate cognitive shortcuts.
H11–H13 (same antecedents to debt accumulation): Parallel reasoning applies to debt accumulation, with the addition that perceived ease of credit may directly increase debt through ‘credit accessibility’—consumers take on more obligations simply because the process is frictionless, not because they are impulsive [21].
Partial Mediation Justification: We predict partial rather than full mediation because impulsive buying captures affective/urgetive processes, while direct paths from platform features capture cognitive mechanisms (bias exploitation, risk underestimation, accessibility). These are theoretically distinct pathways that should not fully overlap. Empirically, the direct path from algorithmic nudging to financial stress (H9: beta = 0.269) remains significant after including the indirect path through impulsive buying (AN to IBT: 0.336; IBT to FS: 0.343; indirect = 0.115), confirming partial mediation (Sobel z = 4.82, p < 0.001 for indirect effect; direct effect remains beta = 0.269, p < 0.001).
PROPOSITION 4: THE LOYALTY TRAP PARADOX—AI Personalization Creates Competing Pathways to Loyalty and Harm.
Theoretical Rationale: AI personalization is hypothesized to simultaneously promote loyalty (H15) and contribute to financial harm (through H4, H7, H11). This dual effect reflects the inherent tension in AI-driven fintech; personalization improves user experience (convenience, relevance, ease) while facilitating overconsumption.
H15 Justification: AI personalization promotes loyalty through utilitarian benefits (better product fit) and hedonic experiences (enjoyment of discovery) [6,21]. The effect size is expected to be the largest among loyalty antecedents (f-squared > 0.08).
H16 Justification: Perceived ease of credit may promote loyalty through reduced transaction friction, but this effect is predicted to be small (f-squared < 0.02) because ease is a hygiene factor rather than a loyalty driver—its absence creates dissatisfaction, but its presence does not strongly create loyalty.
H17 Justification: Algorithmic nudging may promote loyalty through engagement cues (scarcity, exclusivity), but this effect is also predicted to be small because nudging primarily affects purchase decisions rather than platform evaluation.
H18–H19 Justification: Financial stress and debt accumulation are expected to negatively affect loyalty (H18, H19), representing a ‘rational exit’ pathway. However, the loyalty trap pattern (high stress + sustained loyalty) suggests this pathway is weaker than the personalization-driven loyalty pathway.
The competing predictions—personalization increasing loyalty while its indirect effects increase harm—create the paradoxical loyalty trap pattern that we provisionally document in the longitudinal analysis.
H1.
AI personalization intensity positively affects perceived ease of credit.
H2.
AI personalization intensity positively affects algorithmic nudging.
H3.
Perceived ease of credit positively affects algorithmic nudging.
H4.
AI personalization intensity positively affects impulsive buying tendency.
H5.
Perceived ease of credit positively affects impulsive buying tendency.
H6.
Algorithmic nudging positively affects impulsive buying tendency.
H7.
AI personalization intensity positively affects financial stress.
H8.
Perceived ease of credit positively affects financial stress.
H9.
Algorithmic nudging positively affects financial stress.
H10.
Impulsive buying tendency positively affects financial stress.
H11.
AI personalization intensity positively affects debt accumulation.
H12.
Perceived ease of credit positively affects debt accumulation.
H13.
Algorithmic nudging positively affects debt accumulation.
H14.
Impulsive buying tendency positively affects debt accumulation.
H15.
AI personalization intensity positively affects platform loyalty.
H16.
Perceived ease of credit positively affects platform loyalty.
H17.
Algorithmic nudging positively affects platform loyalty.
H18.
Financial stress negatively affects platform loyalty.
H19.
Debt accumulation negatively affects platform loyalty.
H20a.
GFL negatively moderates the algorithmic nudging-to-financial-stress path.
H20b.
BFL negatively moderates the algorithmic nudging-to-financial-stress path (expected effect size > H20a).
H21a.
GFL negatively moderates the algorithmic nudging-to-debt-accumulation path.
H21b.
BFL negatively moderates the algorithmic nudging-to-debt-accumulation path (expected effect size > H21a).
H22a.
GFL negatively moderates the impulsive buying-to-financial-stress path.
H22b.
BFL negatively moderates the impulsive buying-to-financial-stress path (expected effect size > H22a).
H23a.
GFL negatively moderates the impulsive buying-to-debt-accumulation path.
H23b.
BFL negatively moderates the impulsive buying-to-debt-accumulation path (expected effect size > H23a).
In Figure 2, the research model depicts the bifurcated financial literacy structure and its hypothesized differential moderation effects. The GFL–BFL correlation (r = 0.39) supports their treatment as distinct but related constructs rather than a single bifactor.
Figure 2.
Research model.
3. Methodology and Study Design
3.1. Research Design and Procedure
3.1.1. Design Overview
This study employs a two-stage sequential design.
Stage 1: Cross-sectional survey (N = 1247) across seven MENA countries, analyzed via PLS-SEM.
Stage 2: Six-month longitudinal follow-up (N = 847, 68% retention) to assess temporal changes in financial outcomes.
This design partially supports temporal precedence claims between Time 1 antecedents and Time 2 outcomes [37,38], though causal identification requires additional safeguards, discussed in Section 6.2.
3.1.2. Data Collection Protocol
Collection Period: September 2025–March 2026 Recruitment Channels: Online panels (Qualtrics Panels, YouGov MENA) + BNPL provider newsletters + social media advertisements Eligibility Criteria: (i) Active BNPL usage (at least one transaction in preceding 3 months); (ii) Residence in Egypt, Jordan, Saudi Arabia, United Arab Emirates, Morocco, Algeria, or Lebanon.
Informed consent was obtained digitally before survey commencement. All participants received an information sheet detailing study purpose, voluntary participation, confidentiality protections, and withdrawal options.
3.1.3. Survey Instruments
The Time 1 instrument comprised three sections: (a) Demographics and BNPL usage characteristics (Section A), (b) 30-item construct measurement instrument (Section B; full item wording in Appendix A, Table A2), (c) optional open-ended question on BNPL experiences (qualitative context only).
The Time 2 instrument (administered six months later to consenting participants) assessed changes in financial stress, debt accumulation, and platform loyalty using identical measurement items for within-subject comparison. Table 2 summarizes the measurement timing for each construct.
Table 2.
Construct measurement timing across study waves.
3.1.4. Measurement Timing Specification
Table 2 (see Section 2.2 above) specifies the measurement timing for each construct. The following principles guided the timing design:
Time 1 (All Constructs): All exogenous constructs (AI personalization, perceived ease of credit, algorithmic nudging), the mediator (impulsive buying tendency), the moderator (financial literacy), and baseline outcome measures (financial stress, debt accumulation, platform loyalty) were measured at Time 1. This full baseline measurement enables (a) cross-sectional structural model estimation; (b) moderation analysis; and (c) autoregressive longitudinal modeling controlling for Time 1 outcome baselines.
Time 2 (Outcome Constructs Only): Only the three endogenous outcome constructs (financial stress, debt accumulation, platform loyalty) were remeasured at Time 2. The six-month lag between measurements captures meaningful changes in financial circumstances while minimizing attrition. The exogenous constructs, mediator, and moderator were not remeasured because (i) six months is insufficient for meaningful changes in platform feature perceptions (these reflect relatively stable design characteristics); (ii) financial literacy changes slowly and would show minimal six-month variation; and (iii) reducing Time 2 instrument length was essential for achieving acceptable retention (68%).
Six-Month Interval Justification: The six-month interval was selected based on three criteria: (a) BNPL repayment cycles typically span 2–4 months, so six months captures approximately 1.5–3 complete repayment cycles; (b) previous BNPL longitudinal research [3,4] used similar intervals and detected meaningful financial outcome changes; (c) attrition simulation based on panel provider data indicated that intervals beyond six months would reduce retention below 55%, threatening statistical power.
3.2. Measurement Instrument
All constructs were measured using multi-item scales adapted from established instruments in the consumer behavior, information systems, and personal finance literatures. Items were presented on a 5-point Likert scale (1 = Strongly Disagree to 5 = Strongly Agree), consistent with established practice in the field and appropriate for the MENA context where 5-point scales demonstrate superior response quality compared to longer alternatives [39]. AI personalization intensity (AIPI) was measured using four items adapted from Raji et al. [5] and Lee [6], capturing perceived AI sophistication and recommendation relevance. Perceived ease of credit (PEC) was measured using four items adapted from Davis [23] and Donou-Adonsou and Leslie-Piper [32], assessing the simplicity and accessibility of BNPL credit acquisition. Whereas earlier digital nudge taxonomies [7,8,40] conceptualize nudges as static interface-level interventions selected ex ante by designers, algorithmic nudging—as theorized here—denotes a higher-order construct comprising five behaviorally distinct dimensions (interface design, social proof, scarcity cues, default presentation, and personalized timing) that are dynamically optimized in real time by machine-learning systems against individual-level behavioral and transactional traces. Full item wording, source attribution, and standardized loadings are reported in Appendix A, Table A2. Algorithmic nudging therefore subsumes elements of digital-nudge classifications while extending them into the data-driven personalization regime characteristic of contemporary BNPL platforms. Impulsive buying tendency (IBT) was measured using four items adapted from Badgaiyan et al. [41] and Rook and Fisher [42], capturing unplanned purchasing and spontaneous acquisition behavior. Literacy has emerged as a focal construct in digital-finance research, with recent evidence from emerging and frontier markets demonstrating its protective role against fintech-induced over-indebtedness [43,44,45,46]. In the MENA region specifically, OECD/INFE [47] survey data document substantially lower financial-literacy scores than in OECD averages, while King et al. [48] report that digital-credit users exhibit heterogeneous financial-knowledge profiles. Building on these foundations, financial literacy (FL) was measured using five items, two adapted from the standard Lusardi and Mitchell [14] “Big Three” battery (compound interest and inflation) and three newly developed BNPL-specific items assessing knowledge of (a) late-payment penalty structures, (b) credit-bureau reporting of BNPL defaults, and (c) the cumulative cost implication of overlapping BNPL contracts. All items used a 5-point correctness-scaled format. Full item wording is provided in Appendix A, Table A3. Financial stress (FS) was measured using five items adapted from Netemeyer et al. [49] and the Consumer Financial Protection Bureau [50] financial wellbeing scale. Debt accumulation (DA) was measured using four items adapted from the Central Bank of Ireland [31] and Financial Conduct Authority (FCA) [51] BNPL review instruments. Platform loyalty (PL) was measured using four items adapted from Oliver [52] and Zeithaml et al. [53], capturing behavioral and attitudinal loyalty dimensions.
Consumers’ perceived analysis of personal data operates through two interrelated channels that jointly constitute AI personalization intensity: (a) perceived relevance of recommended credit terms, which captures the consumer’s belief that platform offers match individual circumstances; and (b) perceived adaptivity, which captures the belief that those offers evolve in response to ongoing behavior. The intensity of perceived data analysis is thus the upstream cognition; relevance and adaptivity are its observable behavioral consequences.
It is also analytically important to distinguish algorithmic nudging from the related construct of digital dark patterns [54,55]. Dark patterns are typically classified by their deceptive intent (e.g., sneak-into-basket, confirm shaming, forced action) and are conceptualized as discrete interface manipulations. Algorithmic nudging, in contrast, is not defined by deceptive intent but by mechanism—namely the learning-based personalization of choice architecture. Some manifestations of algorithmic nudging may overlap with dark patterns (e.g., adaptive scarcity cues), while others (e.g., personalized timing of credit offers) are not classically deceptive and would fall outside dark-pattern taxonomies. Algorithmic nudging therefore extends, rather than replicates, the dark-pattern framework by foregrounding the machine-learning substrate that generates the nudge rather than the surface-level interface artifact.
The measurement instrument underwent a rigorous validation process prior to deployment. First, the draft instrument was reviewed by a panel of five academic experts in consumer psychology, fintech, and MENA region studies to assess content validity and cultural appropriateness. Second, cognitive pre-testing was conducted with 30 BNPL users (five from each of Egypt, Saudi Arabia, and the United Arab Emirates) to identify items that were confusing, ambiguous, or culturally inappropriate. Minor wording adjustments were made to three items based on pre-test feedback. Third, a pilot study with 150 respondents was conducted to perform initial exploratory factor analysis and reliability assessment, resulting in the elimination of two items with factor loadings below 0.60.
3.2.1. Algorithmic Nudging: Definition and Theoretical Scope
We adopt the term AI-enabled digital nudging (AI-DN) to accurately reflect both the digital choice architecture substrate and the AI-driven optimization layer that distinguishes contemporary BNPL platforms from earlier e-commerce interfaces. AI-DN is defined as ‘the use of machine learning systems to dynamically personalize digital choice architecture elements based on individual user data, with the goal of influencing behavior without restricting options, where personalization improves continuously through feedback loops’ (adapted from [56,57]).
This definition emphasizes three distinguishing features: (1) Temporal Adaptivity: The nudge reconfigures in real-time based on user behavior, unlike static digital nudges [8] or physical choice architecture [12]. (2) Individual Specificity: The nudge is calibrated to individual-level behavioral and transactional traces rather than population-level segmentations. (3) Machine-Learning Opacity: The optimization rationale is embedded in proprietary models opaque to the user, creating informational asymmetries distinct from transparent interface design.
AI-DN subsumes but extends prior taxonomies of digital nudging [7,8] by foregrounding the machine-learning substrate rather than the surface-level interface artifact.
While measurement items AN1–AN3 capture observable interface manifestations (scarcity cues, defaults, social proof), the reflective higher-order model treats these as indicators of an underlying AI-driven optimization construct. The second-order specification (Figure 3) captures the theoretical distinction between first-order nudge types (interface-level) and second-order algorithmic optimization (system-level).
Figure 3.
Reflective higher-order measurement model.
Measurement items with algorithmic adaptivity indicators: The instrument adds three items specifically capturing algorithmic adaptation and real-time personalization. These items were validated through cognitive pre-testing with 30 BNPL users and pilot-tested with 150 respondents (factor loading > 0.78 for all three items; see Appendix A for complete psychometric details).
3.2.2. Financial Literacy: A Dual-Dimension Protective Resource
Drawing on the financial literacy framework [14] and recent extensions distinguishing domain-specific from general knowledge [58,59], we conceptualize financial literacy as comprising two related but functionally distinct dimensions.
General Financial Literacy (GFL): Understanding of universal financial concepts including compound interest, inflation, risk diversification, and time value of money [10,14]. GFL develops through formal education, life experience, and general media exposure.
BNPL-Specific Financial Literacy (BFL): Understanding of product-specific risks, including late-payment penalty structures, credit-bureau reporting rules for BNPL defaults, cumulative costs of overlapping contracts, and refinancing traps unique to digital installment credit. BFL develops through direct BNPL experience, provider disclosures, and targeted education [59].
3.3. Sampling and Data Collection
The target population comprised active BNPL users aged 18–65 residing in the seven MENA countries. Following the sampling guidance for PLS-SEM analysis, the minimum required sample size for detecting medium effect sizes (f2 = 0.15) at α = 0.05 with 80% statistical power was computed using two complementary procedures, (i) the inverse-square root method of Kock and Hadaya [60], which yielded a minimum N of 139, and (ii) a confirmatory a priori power analysis conducted in G*Power 3.1.9.7 [61] using a linear multiple-regression specification with 7 predictors, which yielded a minimum N of 153. The more conservative estimate (N = 153) was retained as the analytical floor. To account for incomplete responses, attrition, and the need for subgroup analyses, the target sample was set at 1500 respondents, with country quotas proportional to estimated BNPL market sizes.
Moderation effects (H20–H23) were estimated using the two-stage approach recommended by Henseler and Chin [62] for PLS-SEM. In Stage 1, latent variable scores for the predictor (e.g., algorithmic nudging) and moderator (financial literacy) were extracted from the main effects model. In Stage 2, the product of the standardized latent scores was entered as an interaction term in a re-estimated structural model. Significance of each interaction was assessed via 5000 resample bootstrap confidence intervals.
The final Time 1 sample comprised 1247 complete and valid responses, representing an effective response rate of 23.4% after excluding incomplete surveys (n = 412) and failed attention checks (n = 78). Sample characteristics: Egypt (24.8%, n = 310), Saudi Arabia (19.7%, n = 246), United Arab Emirates (19.5%, n = 243), Jordan (10.2%, n = 127), Morocco (10.4%, n = 130), Algeria (10.1%, n = 126), and Lebanon (5.3%, n = 65). Gender distribution was 52.1% male and 47.9% female. Age distribution: 18–24 (20.2%), 25–34 (34.8%), 35–44 (25.3%), 45–54 (15.1%), and 55+ (4.6%). Education levels: high school (19.6%), bachelor’s degree (45.3%), master’s degree (25.2%), and doctoral degree (9.9%). Monthly income distribution: <USD 1000 (25.0%), USD 1000–3000 (30.2%), USD 3000–5000 (25.1%), USD 5000–10,000 (15.0%), and >USD 10,000 (4.7%). BNPL usage frequency: daily (9.8%), weekly (25.4%), monthly (29.7%), occasionally (25.1%), and first-time users (10.0%).
The longitudinal follow-up at Time 2 retained 847 respondents (68.0% retention rate), which exceeds the 50% threshold recommended for valid longitudinal analysis in social science research [63]. Attrition analysis revealed no significant differences between retained and attrited respondents on key demographic variables (gender: χ2 = 1.24, p = 0.266; age: F = 0.87, p = 0.481; education: χ2 = 3.56, p = 0.313) or baseline construct scores (all p > 0.10), supporting the assumption that attrition was random rather than systematic.
3.3.1. Sampling Protocol and Quota Establishment
Country quotas were established proportionally to estimated active BNPL user populations in each country, derived from three sources: (i) BNPL provider market reports (Tabby, Tamara, Postpay); (ii) central bank fintech adoption statistics; and (iii) e-commerce transaction volume data [11]. Target quotas: Egypt (25%), Saudi Arabia (20%), United Arab Emirates (20%), Morocco (10%), Algeria (10%), Jordan (10%), Lebanon (5%). Actual achieved proportions deviated minimally from targets (largest deviation: Lebanon −0.2%; Egypt −0.2%).
3.3.2. Common Method Bias Minimization
Beyond procedural remedies (randomized item order, separate scale anchors, temporal separation between predictor and outcome sections), we implemented three statistical safeguards:
- (a)
- Negative Control Variable: A theoretically unrelated construct (frequency of physical grocery shopping) was included as a predictor of all endogenous outcomes. No path from this control reached significance (all p > 0.20), suggesting that common method variance does not systematically inflate relationships.
- (b)
- Marker Variable Technique: A theoretically unrelated marker variable (preference for organic food products) was correlated with all substantive constructs. Partial correlations between marker and substantive variables ranged from r = −0.04 to 0.07 (all n.s.), indicating minimal shared method variance.
- (c)
- Unmeasured Latent Method Construct (ULMC): A latent method factor was added to the measurement model, explaining <2% of indicator variance, well below the 5% threshold indicating meaningful common method bias [64].
3.4. Analytical Approach
We employed partial least squares structural equation modeling (PLS-SEM), selected for its predictive orientation and robustness to non-normal data distributions [65]. Model estimation was performed in SmartPLS 4.0 [66] with 5000 bootstrap resamples for significance testing. Moderation effects were estimated via the two-stage approach [62], and longitudinal analysis employed autoregressive multiple regression controlling for Time 1 outcome baselines.
The choice of PLS-SEM over CB-SEM is justified by three study characteristics: (i) the model’s predictive-explanatory orientation rather than theory-testing focus; (ii) the presence of formative-indicator specifications in the algorithmic nudging higher-order construct; and (iii) the need to accommodate moderate sample sizes in subgroup analyses [65,67].
Common method bias (CMB) was addressed through both procedural and statistical remedies. Because the news-media preference may correlate with digital literacy and BNPL adoption, we replaced this marker with a more defensible negative-control variable—self-reported frequency of grocery shopping in physical retail outlets in the past month—which has no plausible theoretical link to algorithmic BNPL exposure or impulsive online purchasing. The negative control was entered as a predictor of all five endogenous constructs (Appendix E, Table A16). No path from the negative control to any endogenous construct reached significance. Statistically, we report (a) Harman’s single-factor test (largest factor = 28.4% variance, below the 50% threshold); (b) full-collinearity VIF values (all below 3.2, below the 3.3 threshold of Kock [68]; (c) a marker-variable test in which partial correlations between the marker and substantive constructs ranged from r = −0.04 to r = 0.07 (all n.s.); and (d) an unmeasured latent method construct (ULMC) test, which indicated that method variance explained <2% of indicator variance. Collectively, these procedures provide substantially stronger evidence against CMB than reliance on Harman’s test alone.
We assessed measurement invariance across the seven MENA countries using the MICOM procedure for PLS-SEM [69]. Step 1 (configural invariance) was supported by construct equivalence in identical indicator sets and identical algorithm settings. Step 2 (compositional invariance) was supported for all eight constructs (all permutation-based correlation p-values > 0.05). Step 3 (equality of composite mean values and variances) indicated partial measurement invariance: AN, AIPI, PEC, IBT, and DA met full invariance; FS and PL met compositional but not full mean-equality invariance; the original FL construct did not meet step 3 invariance (a further justification for bifurcation, A3). Partial invariance is sufficient for cross-group structural comparisons [70]; we therefore re-estimated the structural model with multi-group analysis (Appendix G). The direction and significance of all focal paths were stable across countries; the magnitude of the H6 path (AN → IBT) varied modestly (β range 0.28–0.39), with Saudi Arabia and the United Arab Emirates displaying larger coefficients than Morocco and Algeria—a pattern we interpret tentatively given country-level cell sizes.
4. Results
4.1. Measurement Model Assessment
4.1.1. Internal Consistency Reliability
Table 3 reports three reliability coefficients for all constructs: Cronbach’s alpha, composite reliability (CR), and McDonald’s Omega (omega). All constructs exceed recommended thresholds (alpha greater-than-or-equal-to 0.70; CR greater-than-or-equal-to 0.70; omega greater-than-or-equal-to 0.70) in the purified model. McDonald’s Omega is reported alongside alpha because omega is less biased by item number and tau-equivalence violations [71], which are common in multidimensional marketing constructs.
Table 3.
Measurement model psychometric properties (purified model).
4.1.2. Convergent Validity
Convergent validity was assessed through factor loadings and Average Variance Extracted (AVE). Initial estimation revealed that Platform Loyalty (AVE = 0.312) and Impulsive Buying Tendency (AVE = 0.476) fell below the 0.500 threshold. Rather than automatic deletion, we conducted theory-driven diagnostic analysis:
Item PL3 (‘I would recommend this BNPL platform to friends’): This item cross-loaded on Financial Stress (loading = 0.42) and exhibited low communalities (h-squared = 0.28). The cross-loading is theoretically interpretable; financially stressed consumers may be reluctant to recommend a platform they associate with their own difficulties, suggesting content overlap with financial wellbeing rather than pure loyalty. Removal is theoretically justified.
Item PL5 (‘I trust this BNPL platform to act in my best interest’): This item exhibited the lowest loading (lambda = 0.48) and cross-loaded on Perceived Ease of Credit (loading = 0.38). The cross-loading reflects conceptual overlap between ‘trust in platform benevolence’ and ‘ease of use’—both involve platform usability perceptions rather than pure attitudinal loyalty. Given Hayashi and Routh’s [21] finding that trust-benevolence and satisfaction are distinct loyalty antecedents, PL5’s poor performance may reflect its tapping trust-benevolence rather than loyalty per se. Removal is theoretically justified.
Item IBT4 (‘I often buy things on impulse without considering the consequences’): This reverse-coded item exhibited low loading (lambda = 0.46) and significant cross-loading on Financial Stress (loading = 0.44). The cross-loading reflects content overlap; ‘without considering consequences’ directly references financial outcomes, making the item a hybrid impulsivity–consequence measure rather than pure buying tendency. Removal is theoretically justified.
Re-estimation after removal produced revised AVE values of 0.541 (Platform Loyalty) and 0.528 (Impulsive Buying Tendency), meeting recommended thresholds. Sensitivity analysis (Table A5, Appendix B) confirms that the substantive pattern of structural path estimates is preserved relative to the original specification.
4.1.3. Indicator Reliability and Cross-Loadings
Table 4 reports standardized factor loadings, indicator reliabilities (squared loadings), and the full cross-loading matrix for all retained items. All factor loadings exceed 0.60 (range: 0.612–0.892), and all indicator reliabilities exceed 0.36. Cross-loadings are substantially lower than primary loadings (largest cross-loading = 0.32), supporting discriminant validity at the indicator level.
Table 4.
Standardized factor loadings and cross-loadings (selected items).
4.1.4. Financial Literacy Bifurcation: Theoretical Rationale and Empirical Justification
The bifurcation of financial literacy into general financial literacy (GFL) and BNPL-specific financial literacy (BFL) was not data-driven but theoretically planned:
- (a)
- A priori theoretical basis: Lusardi and Mitchell’s [10] original financial literacy scale focuses on universal concepts (compound interest, inflation, risk diversification), while BNPL-specific knowledge (late penalties, credit-bureau reporting, cumulative costs) represents conceptually distinct content that prior research has identified as important but undermeasured [59].
- (b)
- Exploratory factor analysis of the original five-item scale revealed a two-factor solution (eigenvalues: 1.82, 1.21; parallel analysis cut-off: 1.18), confirming the multidimensional structure.
- (c)
- The two subscales exhibit discriminant validity (HTMT = 0.52, below the 0.85 threshold) and differential nomological relationships; BFL moderates BNPL-specific harm pathways more strongly than GFL (38% larger effects), consistent with the theoretical prediction that domain-specific knowledge provides targeted protection.
- (d)
- The new BNPL literacy items were developed following established scale development procedures: literature review, expert panel review (five academics), cognitive pre-testing (30 BNPL users), and pilot testing (150 respondents). Full development documentation is provided in Appendix A.
- (e)
- Validation: The new items were validated both internally (within the main study) and externally (via confirmatory factor analysis in a separate holdout sample of 200 BNPL users recruited from the same panels). The holdout sample confirms the two-factor structure (CFI = 0.96, TLI = 0.94, SRMR = 0.048) and reliability (BFL: alpha = 0.824; GFL: alpha = 0.756).
Theoretical Distinction and Functional Roles.
We propose that GFL and BFL serve different protective functions. GFL provides general decision-making competence that reduces susceptibility to all forms of financial persuasion [72]. BFL provides domain-specific resistance that is particularly effective against BNPL-specific nudge techniques because it directly addresses the information asymmetries that algorithmic nudging exploits (e.g., consumers who understand cumulative contract costs are less likely to be swayed by ‘only four easy payments’ framing).
Diagnostic analysis revealed that the original five-item financial literacy scale was multidimensional (two-factor solution: eigenvalues 1.82 and 1.21, parallel-analysis cut-off 1.18). Following the reviewer’s recommendation, we separated financial literacy into two theoretically distinct sub-constructs: (i) general financial literacy (GFL: two adapted Lusardi–Mitchell Big-Three items—compound interest and inflation) and (ii) BNPL-specific financial literacy (BFL: three new items on late-payment penalties, credit-bureau reporting of BNPL defaults, and cumulative cost of overlapping contracts). Re-estimated psychometrics: GFL (AVE = 0.617, CR = 0.762, ω = 0.74), BFL (AVE = 0.583, CR = 0.806, ω = 0.81). The correlation between GFL and BFL is r = 0.39, supporting their treatment as related-but-distinct constructs. The moderation findings reported in Section 4.4 are re-estimated with BFL as the focal moderator (which carries the theoretically relevant content for BNPL contexts), and with GFL as a sensitivity-check moderator. Both produce a buffering effect of comparable direction, with BFL effects ~38% larger in absolute magnitude.
Because the inter-construct correlation between algorithmic nudging and AI personalization intensity was r = 0.484—within an acceptable but not negligible range—we report the heterotrait–monotrait ratio (HTMT) of correlations [73] as a more conservative discriminant-validity diagnostic. The HTMT between AN and AIPI is 0.71 [bootstrap 95% CI: 0.66, 0.76], below the conservative 0.85 threshold and the more liberal 0.90 threshold. We additionally note that the two constructs are theoretically distinct; AIPI captures the intensity of algorithmic personalization output (e.g., recommendation density), whereas AN captures choice-architectural deployment of those outputs (e.g., scarcity cues, default presentation). Multi-collinearity diagnostics in the structural model yielded VIF values < 2.4 for all predictors, well below the conventional 5.0 threshold. All inter-construct HTMT values were below the conservative 0.850 threshold (range: 0.412–0.821; full matrix in Table A4), supporting discriminant validity for all eight constructs. As a corroborating check, the Fornell–Larcker criterion—applied after the item purification described in 4.1—was satisfied for all eight constructs. Pre-purification, two constructs (impulsive buying tendency and financial literacy) failed Fornell–Larcker; this failure was traced to the same low-loading items subsequently removed, and discriminant validity is now confirmed under both criteria. The full correlation matrix (Table 5) reveals theoretically consistent inter-construct relationships, with the highest correlations observed between impulsive buying tendency and both financial stress (r = 0.572) and debt accumulation (r = 0.630), as theoretically expected.
Table 5.
Descriptive statistics and correlation matrix.
4.2. Structural Model Results
4.2.1. Hypothesis Testing with Practical Significance Assessment
All nineteen direct hypotheses received empirical support in the primary specification. However, we distinguish statistical from practical significance following recommendations in information systems research [68]:
Practically Significant Effects (f-squared greater-than-or-equal-to 0.15 or Cohen’s d greater-than-or-equal-to 0.50): H6 (AN to IBT): beta = 0.336, f-squared = 0.134 [medium effect, near-practical threshold]; H10 (IBT to FS): beta = 0.343, f-squared = 0.164 [medium effect]; H14 (IBT to DA): beta = 0.368, f-squared = 0.201 [medium-to-large effect].
These effects are substantively meaningful; a one-standard-deviation increase in impulsive buying tendency is associated with approximately USD 38 of additional six-month BNPL debt at sample means (translated via the debt accumulation scale-to-dollar conversion).
Small but Potentially Meaningful Effects (0.02 less-than-or-equal-to f-squared < 0.15): H1–H5, H7, H9, H11–H13, H15, H18: f-squared range 0.030–0.101. These effects are statistically significant due to the large sample (N = 1247) but should be interpreted cautiously.
Practically Negligible Effects (f-squared < 0.02): H16 (PEC to PL): beta = 0.104, f-squared = 0.011; H17 (AN to PL): beta = 0.132, f-squared = 0.018; H19 (DA to PL): beta = −0.109, f-squared = 0.012. These effects, while statistically significant, explain less than 2% of incremental variance and should not be interpreted as substantively meaningful. We accordingly de-emphasize these paths in the Section 5.
4.2.2. Safeguards Against Overfitting and Model Misspecification
Given that all 23 hypotheses are supported, we implemented four safeguards.
Safeguard 1: Bonferroni–Holm correction applying family-wise error correction across 19 direct hypotheses; 15 remain significant at alpha = 0.05 (Table A15, Appendix E). The four non-significant paths (H8, H16, H17, H19) are those with smallest effect sizes, consistent with Type I inflation in the original specification.
Safeguard 2: alternative model comparison.
We tested two alternative specifications: (a) reversed mediation (financial stress and debt predict impulsive buying); (b) financial literacy moderates first-stage (antecedent to IBT) rather than second-stage paths. Both alternatives fit significantly worse than the focal model (delta AIC = +147 and +89; Vuong z = 4.81 and 3.22, p < 0.001), reducing concerns about model misspecification.
Safeguard 3: covariate-adjusted model adding five demographic covariates (income, education, employment, household size, pre-existing debt) as exogenous controls attenuated significant path coefficients by 9–34%, but 16 of 19 focal paths remained significant. This pattern suggests that unobserved heterogeneity does not fully explain the results.
Safeguard 4: PLSpredict and out-of-sample assessment.
We report comprehensive predictive assessment using PLSpredict [74] with 10-fold cross-validation (Table 6):
Table 6.
PLSpredict out-of-sample predictive assessment (10-fold cross-validation).
- −
- Financial Stress: RMSE = 0.682 (PLS-SEM) vs. 0.741 (naive benchmark); Q-squared_predict = 0.108. The PLS-SEM model outperforms the naive benchmark by 8.0%, indicating meaningful out-of-sample predictive power.
- −
- Debt Accumulation: RMSE = 0.734 vs. 0.802; Q-squared_predict = 0.085. Outperforms benchmark by 8.5%.
- −
- Platform Loyalty: RMSE = 0.698 vs. 0.712; Q-squared_predict = 0.020. Modest outperformance (2.0%), consistent with the model’s low explanatory power.
The Q-squared_predict values indicate that the model has small-to-moderate out-of-sample predictive relevance (values > 0 indicate prediction better than the naive mean), reducing concerns about overfitting. However, the modest Q-squared values for loyalty reinforce our cautious interpretation of loyalty findings.
4.2.3. Country-Level Robustness and GCC Dominance Assessment
We conducted multi-group analysis (MICOM procedure; [69]) to assess whether results are disproportionately driven by GCC respondents (Saudi Arabia + United Arab Emirates = 39.2% of sample).
Table 7 shows that (a) direction and significance of all focal paths are stable across all seven countries; (b) magnitude of the H6 path (algorithmic nudging to impulsive buying) varies modestly (beta range: 0.28–0.39); (c) GCC countries (Saudi Arabia, United Arab Emirates) show slightly larger coefficients than non-GCC countries (Morocco, Algeria), but confidence intervals overlap; (d) Lebanon (n = 65) produces point estimates consistent with other countries but with wider confidence intervals due to smaller cell size.
Table 7.
Country-level structural path comparison (H6: AN to IBT).
To formally test GCC dominance, we estimated the structural model with a GCC/non-GCC grouping variable as a control on all endogenous constructs. The GCC control is non-significant for financial stress (beta = 0.042, p = 0.312) and debt accumulation (beta = 0.038, p = 0.401), indicating that regional differences do not drive the focal results. However, the GCC control is marginally significant for platform loyalty (beta = 0.089, p = 0.048), suggesting that loyalty dynamics may differ between GCC and non-GCC contexts. We accordingly interpret loyalty findings with appropriate geographic caution.
4.3. Moderation Analysis Results
Financial literacy demonstrated statistically significant negative moderation effects on all four hypothesized interaction paths (H20–H23; Table 8). In addition, four exploratory (non-hypothesized) interaction paths involving AI personalization intensity and perceived ease of credit were tested post hoc to evaluate the breadth of financial literacy’s protective influence; these exploratory paths also yielded significant negative interaction terms (Appendix C, Table A6). For confirmatory hypothesis testing, we restrict interpretation to the four pre-registered hypotheses (H20–H23). The moderation effects were strongest for the relationships between impulsive buying tendency and both financial stress (H22: β = 0.143, p < 0.001) and debt accumulation (H23: β = 0.147, p < 0.001), indicating that financially literate consumers are substantially less likely to translate impulsive buying behavior into adverse financial outcomes. The algorithmic nudging interactions also demonstrated significant negative moderation on financial stress (H20: β = 0.141, p < 0.001) and debt accumulation (H21: β = 0.127, p < 0.001).
Table 8.
Comparative moderation effects: general financial literacy (GFL) vs. BNPL-specific financial literacy (BFL).
The pattern of moderation effects reveals that financial literacy serves as a broadly protective factor rather than selectively buffering specific pathways. This finding suggests that financial literacy programs targeting BNPL users could provide comprehensive protection against algorithmic persuasion, regardless of the specific nudge mechanism employed.
Simple-slope decomposition of the two most theoretically central interactions is illustrated in Figure 4. Panel A shows that the slope linking algorithmic nudging to financial stress flattens from 0.410 at low financial literacy to 0.128 at high financial literacy; Panel B shows an analogous attenuation in the IBT → debt accumulation pathway (from 0.515 to 0.221).
Figure 4.
Simple-slope plots of financial literacy’s buffering effect.
Figure 4: Simple-slope plots of financial literacy’s buffering effect. (A) Algorithmic nudging × financial literacy → financial stress (interaction β = −0.141, p < 0.001). (B) impulsive buying tendency × financial literacy → debt accumulation (interaction β = −0.147, p < 0.001). Slopes are plotted at low (−1 SD, red), mean (gray dashed), and high (+1 SD, green) financial literacy. Shaded bands represent bootstrapped 95% confidence intervals (5000 resamples). The progressively flatter slopes at higher financial literacy substantiate the proposed protective-resource interpretation.
4.4. Longitudinal Analysis Results
The six-month follow-up data provided strong support for the temporal precedence assumptions underlying the structural model (Table 9). Time 1 impulsive buying tendency significantly predicted both Time 2 financial stress (β = 0.212, p < 0.001) and Time 2 debt accumulation (β = 0.238, p < 0.001), establishing that impulsive buying tendency precedes and contributes to subsequent financial deterioration. Algorithmic nudging at Time 1 also predicted Time 2 financial stress (β = 0.175, p < 0.001) and debt accumulation (β = 0.163, p < 0.001), confirming the persistence of nudging effects over time.
Table 9.
Longitudinal analysis: Time 1 predictors to Time 2 outcomes.
A preliminary ‘loyalty trap’ pattern is empirically documented in Table 9. Across IBT tertiles, six-month change scores reveal that high-IBT consumers (top tertile) experienced a +0.74 SD rise in financial stress and a +0.81 SD rise in debt accumulation, compared with +0.21 SD and +0.18 SD in the low-IBT tertile (both between-tertile contrasts p < 0.001). Despite this, platform-loyalty scores in the high-IBT tertile remained 0.42 SD higher than in the low-IBT tertile at Time 2 (p < 0.001, d = 0.39). This observed pattern—worsening financial outcomes coexisting with sustained loyalty—is consistent with a loyalty-trap interpretation, though causal identification of the mechanisms underlying this pattern requires further research. We characterize this as a provisional empirical observation rather than a confirmed causal mechanism. The within-subject and between-tertile trajectories are illustrated in Figure 5, which uncovers a “loyalty trap” dynamic.
Figure 5.
Six-month longitudinal trajectories stratified by baseline impulsive buying tendency.
Figure 5: Six-month longitudinal trajectories of (A) financial stress, (B) debt accumulation, and (C) platform loyalty, stratified by baseline (Time 1) impulsive buying tendency tertile. Markers indicate mean scores; error bars represent ±1 SEM. Between-tertile differences at Time 2 tested via ANCOVA controlling for the respective Time 1 outcome: *** p < 0.001, ** p < 0.01, * p < 0.05, ns = not significant. The figure reveals the ‘loyalty trap’ paradox—high-IBT consumers experience accelerating financial harm yet display the highest sustained loyalty to the BNPL platform. This paradox is theoretically consistent with the research agenda articulated by Kang et al. [75] on platform-based multinational corporations (PMNCs), who argue that platforms generate consumption-side lock-in through network effects, data feedback loops, and algorithmic curation. Within their framework, BNPL platforms act as quintessential consumption-side PMNCs; their AI infrastructure does not merely facilitate transactions but actively constructs the choice environment in which loyalty and indebtedness co-evolve.
The longitudinal R2 values (0.350 for financial stress, 0.310 for debt accumulation) indicate that the Time 1 constructs explain substantial variance in Time 2 outcomes, supporting the theoretical model’s predictive validity over time. Piecewise regression on the longitudinal sub-sample reveals an inflection point: loyalty declines significantly once debt-accumulation scores exceed approximately 4.1 on the five-point scale (corresponding to roughly three concurrent BNPL contracts in arrears) and once financial-stress scores exceed approximately 3.8 (95% CIs reported in Appendix C). Below these thresholds, the loyalty trap persists. The implied erosion timeline—derived from the slope of the change-score regression—is approximately 9–12 months after the inflection threshold is reached. These quantified thresholds offer regulators an early-warning indicator.
4.5. Summary of Key Findings
The empirical analysis provides support for the hypothesized model. All 19 direct effect hypotheses and four moderation hypotheses were supported at p < 0.05 or better. The key findings are: (1) algorithmic nudging is the strongest driver of impulsive buying tendency among the three antecedents; (2) impulsive buying tendency is the primary proximal cause of both financial stress and debt accumulation; (3) AI personalization intensity has a dual effect, promoting platform loyalty while simultaneously contributing to financial harm through indirect pathways; (4) financial literacy significantly attenuates all harmful pathways, identifying it as a crucial protective factor; and (5) the longitudinal panel is consistent with temporal ordering in which Time 1 impulsive buying tendency statistically precedes Time 2 financial deterioration. We characterize this as a temporally ordered associational sequence rather than a causal chain because the design does not rule out third-variable confounding (e.g., baseline materialism, time-varying income shocks) or measurement-occasion artefacts.
5. Discussion
5.1. Interpretation of Key Findings
The findings of this study are consistent with AI-integrated BNPL platforms creating systematic pathways to consumer financial vulnerability through the convergence of algorithmic nudging, AI personalization, and perceived ease of credit. The structural model results demonstrate that these platform features operate through impulsive buying tendency as the primary mediating mechanism, ultimately producing financial stress and debt accumulation while simultaneously generating paradoxical platform loyalty that may perpetuate harmful usage patterns.
The dominant effect of algorithmic nudging on impulsive buying tendency (β = 0.336, p < 0.001) represents a significant theoretical and practical contribution. This finding extends Münscher et al.’s [7] digital nudge taxonomy by empirically validating that the aggregation of nudge mechanisms in BNPL contexts produces behavioral effects substantially larger than those documented in isolated nudge experiments. The effect size (f2 = 0.134) exceeds the medium threshold, indicating that algorithmic nudging explains meaningful variance in impulsive buying beyond the contributions of AI personalization and perceived ease of credit. This result is consistent with Caraban et al.’s [8] theoretical prediction that digital nudges exploiting multiple behavioral biases simultaneously produce superadditive effects, though the cross-sectional design precludes definitive causal claims regarding the interaction between nudge types.
The finding that impulsive buying tendency serves as the primary proximal driver of both financial stress (β = 0.343) and debt accumulation (β = 0.368) extends Kumar and Nayak’s [9] Indian sample results to the MENA context, while providing more nuanced understanding of the antecedent structure. Whereas Kumar and Nayak found BNPL adoption directly predicted impulsive buying, the current study disaggregates BNPL adoption into its constituent platform features, demonstrating that algorithmic nudging is the most potent activation mechanism. This finding has important regulatory implications, as it identifies specific platform design elements—rather than BNPL services per se—as the primary locus for intervention.
The dual effect of AI personalization intensity—simultaneously promoting platform loyalty (β = 0.309) while contributing to financial harm through indirect pathways—resolves an apparent paradox in the existing literature. Raji et al. [5] and Lee [6] documented the positive effects of AI personalization on consumer satisfaction and engagement, while Donou-Adonsou and Leslie-Piper [32] and the Central Bank of Ireland [31] highlighted the negative financial consequences of BNPL use. The current study demonstrates that these are not contradictory findings but rather complementary facets of the same phenomenon; AI personalization enhances the user experience (building loyalty) precisely by making BNPL more appealing and accessible (facilitating harm). This insight suggests that platform designers face an inherent tension between user experience optimization and consumer welfare protection.
The moderation analysis provides the most actionable findings for consumer protection policy. This protective role mirrors recent European evidence; Lanciano et al. [76] show that Italian households with higher financial knowledge—including a newly developed sustainable financial-literacy dimension—make systematically more prudent credit and investment choices, supporting the broader Lusardi-and-Mitchell premise that literacy compresses the gap between behavioral impulse and rational financial planning. Consistent with that logic, financial literacy in our model demonstrates significant negative moderation on all eight tested interaction paths, with the strongest effects on the impulsive-buying-tendency-to-outcome relationships. This finding extends Lusardi and Mitchell’s [14] financial literacy theory to the algorithmic consumer finance context, demonstrating that financial knowledge serves as a broadly protective factor against algorithmic manipulation. The practical implication is that financial literacy interventions specifically tailored to BNPL risks—covering topics such as understanding installment costs, recognizing nudge techniques, and managing multiple BNPL obligations—could substantially reduce consumer harm without restricting access to beneficial credit services.
5.1.1. Limits of Causal Interpretation
Throughout this paper, we characterize relationships as ‘associated with’ and ‘predictive of’ rather than ‘causing.’ This linguistic caution reflects three limitations of our non-experimental panel design.
First, temporal precedence (established by the six-month lag) is necessary but not sufficient for causal inference. Unobserved time-varying confounders (e.g., income shocks, relationship changes, macroeconomic conditions) may jointly influence both impulsive buying and financial outcomes.
Second, reverse causality cannot be fully excluded. While the autoregressive longitudinal specification (controlling for Time 1 outcome baselines) mitigates this concern, reciprocal effects between debt accumulation and impulsive buying (where existing debt motivates further BNPL use) remain plausible. Third,، selection into AI-intensive platforms may correlate with impulsivity traits not captured by our measures. Consumers who choose more aggressive BNPL providers may be inherently more susceptible to both nudging and financial harm.
We therefore interpret our findings as establishing a temporally ordered associational sequence consistent with theoretical predictions, not as proving causal effects. Future experimental designs (e.g., platform feature manipulations, nudge removal studies) would be required for causal identification.
5.1.2. The Loyalty Trap: Mechanism and Theoretical Development
We provisionally document a loyalty trap pattern in which financially stressed BNPL users maintain elevated platform loyalty. Four mechanisms, drawn from the platform dependency and fintech addiction literatures, may explain this pattern.
Mechanism 1: Habitual convenience lock-in, drawing on the status quo bias literature [77], shows frequently used platforms become default options through habit formation. Switching to alternative payment methods requires cognitive effort that financially stressed consumers may lack bandwidth to expend [78].
Mechanism 2: Personalization lock-in (The ‘Filter Bubble’ Effect). Raji et al. [5] demonstrate that AI personalization creates self-reinforcing consumption patterns by consistently presenting similar products and offers. Over time, consumers develop platform-specific preference profiles that are costly to reconstruct on alternative platforms (path dependence).
Mechanism 3: Fintech addiction elements. Drawing on parallels with behavioral addiction research [79], BNPL platforms incorporate design elements (variable rewards, near-miss experiences, social proof) that may generate compulsive engagement independent of financial rationality. The dopaminergic reward from ‘approved’ credit notifications and purchase completion may sustain engagement despite financial harm.
Mechanism 4: Optimistic bias and future discounting. Consumers may maintain loyalty because they optimistically believe their financial situation will improve [80], making current stress seem temporary. Combined with present bias in intertemporal choice [81], this optimism leads consumers to discount future financial consequences in favor of immediate platform convenience.
Comparison with platform dependency literature: Our findings extend the platform dependency literature in three ways. First, whereas platform dependency research (e.g., Zuboff, [82] on surveillance capitalism; Kang et al. [75] on platform-based MNCs) emphasizes data extraction and network effects, we identify algorithmic personalization as a distinct mechanism that sustains dependency through individualized manipulation. Second, whereas addiction research focuses on user-level vulnerabilities, we demonstrate that platform design features systematically create dependency even among non-addicted users. Third, we document financial harm as a specific consequence of platform dependency, whereas prior research focuses on privacy loss, attention depletion, or political manipulation.
We emphasize that the loyalty trap is a preliminary theoretical formulation. The modest explanatory power of the loyalty model (R-squared = 0.118), the small effect sizes for three loyalty paths, and the exploratory nature of the proposed mechanisms all indicate that further research—particularly experimental designs and qualitative inquiry—is needed before the loyalty trap can be considered an established theoretical construct.
Cross-country evidence further supports the contextual contingency of digital-credit outcomes. Temouri et al. [83], drawing on a global SME e-commerce sample, demonstrate that policy environments—including digital-trade regulation, financial-consumer-protection regimes, and infrastructure investment—significantly condition the internationalization of e-commerce activity. Their findings sharpen the policy implication of our study; where BNPL diffusion outpaces regulatory capacity, as is currently the case across much of MENA, the very institutional conditions that accelerate adoption also magnify the over-indebtedness risks documented here.
5.1.3. Causal Limitations of the Loyalty Trap Evidence
While the loyalty trap pattern observed in our longitudinal data is theoretically intriguing and consistent with the platform-dependency literature [75], several causal limitations must be acknowledged.
First, the six-month panel establishes temporal precedence (T1 IBT → T2 loyalty and outcomes) but does not rule out unobserved confounders. For example, time-invariant personality traits (e.g., trait impulsivity, materialism) or time-varying shocks (e.g., income changes, life events) may jointly influence both financial outcomes and platform loyalty. While our autoregressive specification controls for T1 outcome baselines, this does not equate to causal identification.
Second, reverse causality cannot be conclusively excluded. Financially stressed users may maintain loyalty because they lack viable alternatives (a ‘captive customer’ effect) rather than because platform design actively traps them. Distinguishing between platform-induced trapping and constraint-induced retention requires exogenous variation in platform features or user circumstances.
Third, the modest explanatory power of the loyalty model (R2 = 0.118) suggests that unmeasured factors—including service quality, network effects, switching costs, and competitive alternatives—explain the majority of loyalty variance. This limits the extent to which financial mechanisms can be interpreted as the primary loyalty drivers.
Fourth, the latent profile analysis (LPA) identifying the ‘trapped users’ profile (31% of the sample) is exploratory in nature. While multinomial logistic regression indicated that algorithmic nudging exposure and low BFL predict profile membership, LPA-based classifications are descriptive and do not establish that platform features cause the trapped state.
Given these limitations, we propose the following research agenda to establish causal evidence for the loyalty trap:
- (a)
- Experimental designs manipulating personalization intensity (e.g., A/B testing of AI-driven vs. non-personalized interfaces) to examine causal effects on loyalty and financial outcomes.
- (b)
- Quasi-experimental designs exploiting platform-feature rollouts (e.g., discontinuation of specific nudge elements) as exogenous variation, using difference-in-differences or regression-discontinuity approaches.
- (c)
- Instrumental variable approaches using exogenous variation in platform availability (e.g., country-level regulatory changes) to estimate causal effects of platform loyalty on financial outcomes.
- (d)
- Qualitative longitudinal research exploring the phenomenology of trapped loyalty—why users remain loyal despite financial strain—through in-depth interviews and diary studies.
We therefore frame the loyalty trap as an emerging theoretical construct requiring further validation rather than an established empirical finding.
5.2. Positioning Relative to Prior BNPL Research
To clarify our study’s unique contribution, Table 10 systematically compares this study with eight recent high-impact BNPL studies across six dimensions: constructs examined, theoretical framework, methodology, geographic focus, sample characteristics, and key findings. This comparison reveals three areas of extension beyond prior research.
Table 10.
Comparison with recent high-impact BNPL studies.
5.2.1. Extension Beyond AI Personalization Studies
Raji et al. [5] and Lee [6] examined AI personalization in e-commerce and financial services, respectively, documenting positive effects on purchase likelihood and consumer satisfaction. Our study extends this work in two ways. First, we demonstrate that AI personalization has a dual effect: it promotes platform loyalty (beta = 0.309) while simultaneously contributing to financial harm through indirect pathways (total indirect effect on debt = 0.218). This dual effect resolves an apparent contradiction in the literature between studies emphasizing personalization benefits [5] and those emphasizing BNPL risks [32]. Second, we identify the mechanism (impulsive buying tendency) and boundary condition (financial literacy) through which personalization translates into financial vulnerability.
5.2.2. Extension Beyond Digital Nudging Research
Münscher et al. [7] and Caraban et al. [8] provided taxonomies of digital nudging in general e-commerce contexts, reporting average effect sizes of Cohen’s d = 0.42 on targeted behaviors. Our study extends this work by: (a) introducing AI-enabled digital nudging as a distinct construct that captures dynamic optimization rather than static interface design; (b) quantifying nudging effects specifically in BNPL credit contexts where financial stakes are higher than in general e-commerce; (c) demonstrating that nudging effects are moderated by financial literacy, suggesting that individual differences in susceptibility are systematically related to capability rather than being random noise.
5.2.3. Extension Beyond BNPL Financial Outcome Studies
Powell et al. [3], Guttman-Kenney et al. [4], and Kumar and Nayak [9] examined BNPL adoption drivers and debt outcomes using cross-sectional designs. Our study extends this work through: (a) the integration of three platform-level antecedents (AI personalization, algorithmic nudging, ease of credit) in a single structural model rather than examining them in isolation; (b) six-month longitudinal follow-up establishing temporal precedence (not just association) between impulsive buying and financial deterioration; (c) the identification of BNPL-specific financial literacy as a protective resource with domain-specific effects exceeding general financial literacy by 38%.
5.2.4. Extension Beyond Financial Literacy Research
Lusardi and Mitchell [10] and Kaiser and Menkhoff [72] established financial literacy as a predictor of financial behavior and a buffer against persuasion. Our study extends this by: (a) bifurcating financial literacy into general and BNPL-specific dimensions with theoretically derived differential effects; (b) demonstrating literacy’s moderating role in algorithmic (rather than human) persuasion contexts; (c) showing that domain-specific literacy (BFL) is more protective than general literacy (GFL) in BNPL contexts, supporting calls for targeted financial education [59].
5.3. Theoretical Implications
This study makes four interconnected theoretical contributions that advance understanding of AI-driven consumer financial vulnerability. Table 11 summarizes each contribution, its theoretical antecedent, the empirical evidence supporting it, and directions for future theory development.
Table 11.
Theoretical contributions, empirical evidence, and future directions.
CONTRIBUTION 1: Construct Innovation—Algorithmic Nudging as a Distinct Theoretical Construct Novelty. Prior research on digital nudging [7,8,40] conceptualized nudges as static interface elements selected by human designers. We introduce algorithmic nudging as a dynamic, AI-driven, individually adaptive form of choice architecture that operates through machine-learning-based real-time optimization. This represents a qualitative shift from ‘nudges as designed’ to ‘nudges as learned.’ Empirical Foundation: The five-dimensional reflective higher-order model (interface design, social proof, scarcity cues, default presentation, personalized timing) achieves satisfactory psychometric properties (AVE = 0.617, CR = 0.806) and exhibits distinct nomological relationships from related constructs (HTMT with AI personalization = 0.71; HTMT with perceived ease of credit = 0.54). Future Theory Development: We call for research on algorithmic nudging in other high-friction decision contexts (health apps, investment platforms, sustainable consumption) and for longitudinal studies tracking how nudge effectiveness evolves as users develop awareness.
CONTRIBUTION 2: Theoretical Integration—The Convergence of Choice Architecture and Payment Decoupling Novelty. Choice architecture theory [12] explains why platform designs influence decisions; payment decoupling theory [13] explains why deferred payment increases spending. We demonstrate that these mechanisms interact rather than merely coexist; algorithmic nudging activates impulsive buying tendency (choice architecture mechanism), which then translates into financial stress and debt accumulation through payment decoupling. Empirical Foundation: The structural model reveals that algorithmic nudging exerts both direct effects on financial outcomes (beta = 0.269 for financial stress; beta = 0.242 for debt accumulation) and indirect effects through impulsive buying tendency (beta = 0.336), supporting a dual-pathway conceptualization. Future Theory Development: Research should examine whether choice architecture effects persist when payment decoupling is reduced (e.g., real-time BNPL repayment features) and whether other theoretical mechanisms (regulatory focus, temporal construal) mediate this relationship.
CONTRIBUTION 3: The Loyalty Trap Paradox. We provisionally identify a ‘loyalty trap’ pattern in which AI personalization simultaneously promotes platform loyalty and financial harm, creating a state in which financially stressed users maintain elevated loyalty. We position this as an emerging phenomenon requiring further theoretical development rather than a firmly established contribution for three empirical reasons.
First, the platform loyalty model exhibits modest explanatory power (R-squared = 0.118 [95% CI: 0.078, 0.164], Q-squared = 0.052), indicating that the majority of loyalty variance is explained by factors outside the model (e.g., service quality, competitive alternatives, switching costs, network effects).
Second, three of the 19 direct paths to loyalty have small effect sizes (f-squared < 0.02): perceived ease of credit to loyalty (H16: beta = 0.104, f-squared = 0.011), algorithmic nudging to loyalty (H17: beta = 0.132, f-squared = 0.018), and debt accumulation to loyalty (H19: beta = −0.109, f-squared = 0.012). These paths reach statistical significance due to the large sample but are not practically meaningful.
Third, robustness testing reveals that H16 (perceived ease of credit to loyalty) and H19 (debt accumulation to loyalty) become non-significant after Bonferroni–Holm correction and when demographic covariates are added. Only H15 (AI personalization to loyalty: beta = 0.309, f-squared = 0.101) and H18 (financial stress to loyalty: beta = −0.248, f-squared = 0.065) survive all robustness checks. Empirical Foundation: Longitudinal trajectories show that high-impulsive-buying consumers experienced a +0.74 SD increase in financial stress yet maintained +0.42 SD higher loyalty at Time 2. The platform loyalty model exhibits modest explanatory power (R-squared = 0.118), indicating that non-financial drivers (habit, convenience, network effects) substantially contribute to the trap. Caveat and Future Development: Given the modest R-squared and small effect sizes for some loyalty paths, we position the loyalty trap as a preliminary theoretical formulation requiring further validation through experimental designs that manipulate personalization intensity and qualitative studies exploring the phenomenology of trapped loyalty.
Mediation Analyses
To strengthen preliminary evidence for the loyalty trap mechanism, we conducted two supplementary analyses.
Analysis A: Serial Mediation (Model M1). We tested a serial mediation model in which AI personalization (IV) simultaneously influences platform loyalty (DV) through two parallel mediators: perceived convenience (operationalized as ease-of-use satisfaction) and financial stress (Model M1). Results support a serial pathway; AI personalization increases perceived convenience (a1 = 0.412), which reduces financial stress awareness (a2 = −0.156), which in turn sustains loyalty (b2 = 0.203). The indirect effect through this serial path is significant (ab = −0.013, 95% CI [−0.026, −0.004]), providing preliminary evidence that convenience perceptions partially blind users to financial stress.
Analysis B: Latent Profile Analysis (LPA). We conducted LPA on the longitudinal sub-sample (N = 847) to identify distinct user trajectory profiles. A three-profile solution exhibited best fit (AIC = 4821; BIC = 4906; adjusted BIC = 4847; entropy = 0.84):
Profile 1 ‘Stable Users’ (42%): Low and stable financial stress, moderate loyalty.
Profile 2 ‘Trapped Users’ (31%): High financial stress with sustained high loyalty—the hypothesized loyalty trap pattern.
Profile 3 ‘Disengaging Users’ (27%): High financial stress with declining loyalty.
Multinomial logistic regression (Table 12) reveals that trapped users (Profile 2) have significantly higher algorithmic nudging exposure (OR = 2.34, p < 0.001) and lower BFL (OR = 0.42, p < 0.001) compared to stable users, consistent with the loyalty trap mechanism. However, given the modest model fit and the exploratory nature of LPA, these findings should be interpreted as preliminary evidence requiring replication in experimental designs.
Table 12.
Latent profile analysis: BNPL user trajectory profiles.
CONTRIBUTION 4: Financial Literacy as Algorithmic Resistance Resource Novelty. While financial literacy has been extensively studied as a predictor of financial behavior [10], we demonstrate its role as a moderator of algorithmic persuasion effects. BNPL-specific financial literacy (understanding late-payment penalties, credit-bureau reporting, and cumulative contract costs) attenuates the nudging-to-harm pathway more effectively than general financial literacy, suggesting that domain-specific knowledge may be more protective than general capability. Empirical Foundation: BFL moderation effects are approximately 38% larger in absolute magnitude than GFL effects. The buffering is strongest for the impulsive buying-to-debt pathway (interaction beta = −0.147). Future Theory Development: Research should investigate whether algorithmic resistance can be taught (experimental interventions), whether it generalizes across platforms (transfer effects), and how it interacts with other protective resources (mindfulness, self-control, social support).
These findings provide evidence from seven MENA countries—Egypt, Jordan, Saudi Arabia, the United Arab Emirates, Morocco, Algeria, and Lebanon—which jointly account for the majority of regional BNPL transaction volume, with the Middle East BNPL market projected at approximately US $5.79 billion in 2025 and Saudi Arabia and the United Arab Emirates representing the largest national markets [84,85] but represent only seven of 19 MENA states. Lebanon (5.3% of the sample) is the most under-represented case. Extension to Gulf Cooperation Council non-sample states (Kuwait, Qatar, Bahrain, Oman), the Maghreb (Tunisia, Libya), and Levantine states beyond Jordan and Lebanon awaits future research. We accordingly frame our findings as evidence from the MENA region rather than for the MENA region in aggregate.
Although the longitudinal design strengthens temporal-ordering claims, several confounders cannot be ruled out. First, unobserved heterogeneity in baseline financial stress, income shocks, or household composition may jointly drive both impulsive buying and debt accumulation; we partially address this by including Time 1 financial stress as a covariate in supplementary analyses (Appendix C, Table A7), with substantive results unchanged. Second, reverse-causality—whereby existing debt motivates use of BNPL—cannot be conclusively excluded from cross-sectional paths; the longitudinal lag mitigates but does not eliminate this concern. Third, selection into AI-intensive platforms may correlate with unmeasured impulsivity traits; future quasi-experimental designs (e.g., platform-feature rollouts) would be required to fully address this.
5.4. Limitations and Future Research Directions
Despite its contributions, this study has several limitations that should be acknowledged. First, although PLS-SEM is well-suited to predictive-explanatory modeling of complex theoretical structures, it does not directly establish causal identification. The three Hill [86] criteria for causality require (i) association, (ii) temporal precedence, and (iii) non-spuriousness; the present design directly addresses (i) and partially addresses (ii) via the six-month panel, but it cannot establish (iii) because no exogenous variation in algorithmic nudging or AI personalization is observed. Future work employing instrumental variables, regression-discontinuity around platform-feature rollouts, or field experiments would be required to fully address non-spuriousness. Future research should employ experimental designs manipulating specific nudge elements to establish causality more rigorously. Second, beyond common method bias, the self-report measurement carries several additional limitations: (a) social-desirability bias, particularly for items on impulsive buying and financial stress, may have led to under-reporting [87]; (b) recall bias may affect retrospective debt and stress reports, although the six-month longitudinal interval was deliberately short to mitigate this; (c) cognitive biases such as anchoring and ego-protective reframing may distort responses to financial-literacy items. Future research should triangulate self-report data with platform-side behavioral logs and administrative credit-bureau records. Objective measures of debt accumulation (e.g., credit-bureau data) would strengthen the validity of financial outcome assessments. Third, the sample, while large and multi-country, was recruited through online panels and may overrepresent digitally engaged consumers. The experiences of less digitally literate BNPL users, who may be more vulnerable to algorithmic manipulation, may not be fully captured. Fourth, the study focused on seven MENA countries, and the findings may not generalize to other regions with different regulatory environments, cultural norms, or BNPL market structures. Cross-cultural comparative research examining how regulatory regimes moderate the relationships identified in this study would provide valuable policy-relevant insights. Fifth, the study examined BNPL platforms as a category rather than comparing specific providers. Different platforms employ varying nudge intensities and personalization approaches, and platform-specific analysis could identify best and worst practices for consumer protection.
Recruitment occurred through online panels (Qualtrics Panels, YouGov MENA) and BNPL-provider newsletters. By design, this approach systematically excludes three populations of likely high vulnerability: (i) consumers with low digital literacy who are unable or unlikely to complete a 30-item online survey; (ii) BNPL users who have already defaulted and disengaged from provider communications; and (iii) consumers without stable internet access in lower-income peri-urban and rural areas of Egypt, Morocco, and Algeria. The reported associations between algorithmic nudging and adverse outcomes therefore very likely represent conservative lower bounds on the population-level harm. Further, the sample comprises seven of 19 MENA countries, with Lebanon contributing only 5.3% of cases; claims should be interpreted as evidence from MENA, not as evidence about MENA as a whole. We accordingly recommend that follow-up work employ offline recruitment, default-population sampling via debt-counselling NGOs, and multi-language low-bandwidth instruments.
6. Conclusions and Recommendations
6.1. Summary of Main Findings
This study addresses the research question: How do AI personalization intensity, perceived ease of credit, and algorithmic nudging influence consumer financial vulnerability through impulsive buying tendency, and to what extent does BNPL-specific financial literacy moderate these relationships in the MENA region?
Our findings provide a structured answer organized around five propositions (Table 13):
Table 13.
Summary of empirical findings by proposition.
PROPOSITION 1 (Antecedent Interdependence): AI personalization functions as a foundational platform capability that enables both perceived ease of credit (H1: beta = 0.232, p < 0.001) and algorithmic nudging (H2: beta = 0.286, p < 0.001), while ease of credit further enhances nudging effectiveness (H3: beta = 0.168, p < 0.001). This configuration confirms that the three platform features operate as an interconnected system rather than independent interventions.
PROPOSITION 2 (Impulsive Activation): Algorithmic nudging is the strongest activator of impulsive buying tendency (H6: beta = 0.336, p < 0.001), followed by AI personalization (H4: beta = 0.285, p < 0.001) and perceived ease of credit (H5: beta = 0.240, p < 0.001). The combined effect explains 38.3% of variance in impulsive buying, identifying it as the primary psychological mechanism translating platform features into financial vulnerability.
PROPOSITION 3 (Dual Harm Pathways): Impulsive buying tendency drives both financial stress (H10: beta = 0.343, p < 0.001) and debt accumulation (H14: beta = 0.368, p < 0.001), while platform features exert additional direct effects (H7, H9, H11, H13: beta range 0.150–0.269, all p < 0.001). The dual-pathway model explains 51.6% of financial stress variance and 51.0% of debt accumulation variance.
PROPOSITION 4 (Loyalty Trap Paradox): AI personalization promotes platform loyalty (H15: beta = 0.309, p < 0.001; f2 = 0.101, a medium effect surviving all robustness checks) while simultaneously contributing to financial harm through indirect pathways. Longitudinal evidence reveals that high-impulsive-buying consumers (top tertile) experienced worsening financial outcomes (+0.74 SD stress increase, +0.81 SD debt increase) yet maintained higher loyalty than low-IBT consumers (+0.42 SD, p < 0.001, d = 0.39). However, the modest explanatory power of the loyalty model (R2 = 0.118) and the fragility of H16, H17, and H19 under covariate adjustment indicate that this pattern should be interpreted as preliminary empirical evidence requiring causal validation in future research. The loyalty trap concept should not be treated as an established causal mechanism but rather as a theoretically generative observation warranting further investigation.
PROPOSITION 5 (Literacy as Protective Buffer): BNPL-specific financial literacy attenuates all harmful pathways (H20–H23: interaction beta range −0.127 to −0.147, all p < 0.001), with the strongest buffering on the impulsive buying-to-debt pathway. The protective effect is 38% stronger for BNPL-specific than general financial literacy.
In summary, our model suggests that AI-integrated BNPL platforms create financial vulnerability through an interconnected system of choice architecture manipulation (PROPOSITIONS 1–2) and payment decoupling (PROPOSITION 3), which simultaneously generates loyalty that perpetuates exposure (PROPOSITION 4), but this vulnerability is substantially reduced among consumers with domain-specific financial knowledge (PROPOSITION 5).
Benchmarked against comparable studies, the financial harm observed in our MENA sample is markedly elevated. The mean six-month BNPL debt-accumulation score (M = 3.42, SD = 1.08 on the five-point scale) is approximately 24% higher than the comparable score reported by Powell et al. [3] for Australian BNPL users (M = 2.76) and 31% higher than the U.S. baseline reported by Guttman-Kenney et al. [4]. The MENA sample’s mean financial literacy score (M = 2.81) is also approximately 0.6 SD below the OECD/INFE [47] cross-national mean, suggesting a structural vulnerability that intensifies BNPL-related financial harm in the region.
Empirical Basis for Conclusions:
The conclusions presented below are grounded in the following specific empirical results:
- Loyalty Trap Evidence: The longitudinal trajectories (Figure 5) show high-IBT consumers experienced +0.74 SD stress increase and +0.81 SD debt increase while maintaining +0.42 SD higher loyalty (p < 0.001, d = 0.39). However, R2 = 0.118 and three loyalty paths (H16, H17, H19) failed covariate-adjustment robustness checks, warranting the preliminary label.
- Financial Literacy Buffering: BFL moderation effects range from β = −0.127 to −0.147 (all p < 0.001), with 38% larger effects than GFL. These effects survive all robustness checks (Table A13) and are therefore treated as established moderating effects.
- Algorithmic Nudging Effects: H6 (AN → IBT: β = 0.336, f2 = 0.134) survives all robustness checks (Table A13) and is among the largest effects in the model. This supports a strong associational conclusion, though causal interpretation requires experimental validation.
6.2. Implications for Practice
The findings generate actionable recommendations for three stakeholder groups. First, for regulatory authorities in the MENA region, the results suggest that algorithmic nudging deserves specific regulatory attention beyond general BNPL oversight. The dominant effect of algorithmic nudging on impulsive buying tendency (β = 0.336) indicates that nudge-based interventions—such as cooling-off periods, standardized risk disclosures, limits on nudge density, and requirements for explicit opt-in to BNPL at checkout—could substantially reduce consumer harm. The Financial Conduct Authority’s [51] approach of requiring lenders to assess affordability before offering BNPL, coupled with restrictions on misleading nudge messaging, provides a model that MENA regulators could adapt.
Second, for BNPL platform designers, the findings highlight an inherent design tension: AI personalization enhances user experience and loyalty while simultaneously facilitating financial harm. Ethical design frameworks that prioritize consumer welfare over engagement metrics could address this tension. Specific recommendations include: (a) implementing ‘nudge breaks’ that require deliberate confirmation before BNPL selection; (b) providing real-time cumulative debt visibility at checkout; (c) limiting social proof messaging for credit products; (d) incorporating financial literacy prompts for high-risk user segments; and (e) designing AI recommendation systems that consider financial wellbeing alongside engagement metrics.
Third, for consumer protection organizations and financial educators, the moderation analysis identifies financial literacy as the most promising intervention point. BNPL-specific financial education programs covering installment cost calculation, nudge recognition, and multi-obligation management could provide significant protective benefits. The finding that financial literacy buffers all harmful pathways uniformly suggests that general financial capability building may be as effective as BNPL-specific education, though targeted programs may achieve results more efficiently.
6.3. Recommendations for Future Research
This study identifies five priority directions for future research. First, experimental and quasi-experimental designs are urgently needed to establish causal evidence for the loyalty trap phenomenon. Specifically, we recommend:
- A/B experiments in which a subset of users is randomly assigned to a ‘low-nudge’ interface condition (e.g., removal of scarcity cues, default de-selection, simplified disclosures), while controls receive the standard interface. This would establish whether algorithmic nudging causes the loyalty trap or merely correlates with it.
- Natural experiments exploiting differential regulatory implementation across MENA countries (e.g., Saudi Arabia’s SAMA BNPL regulations vs. less-regulated markets) to examine whether regulatory constraints on nudging attenuate the loyalty trap pattern.
- Platform-feature rollouts where BNPL providers introduce or remove specific AI-driven features (e.g., personalized timing of credit offers) in staggered fashion, enabling difference-in-differences estimation of causal effects on loyalty and financial outcomes.
- Instrumental variable designs using exogenous variation in platform availability (e.g., BNPL provider entry into new markets) to estimate causal effects of loyalty on financial outcomes, addressing reverse-causality concerns.
Second, partnership with BNPL providers to obtain behavioral data (transaction records, browsing patterns, repayment histories) would enable objective measurement of financial outcomes and more precise analysis of platform feature effects. Third, cross-cultural comparative research examining how regulatory regimes, cultural norms, and market structures moderate the relationships identified in this study would inform context-appropriate policy responses. Fourth, research examining the effects of specific regulatory interventions (e.g., the EU Consumer Credit Directive’s BNPL provisions) using pre–post designs would generate evidence on policy effectiveness. Fifth, the development of algorithmic auditing frameworks for BNPL platforms—systematic assessments of nudge density, personalization intensity, and consumer impact—would support both regulatory oversight and industry self-regulation.
Finally, the theoretical model presented here is necessarily a snapshot of the 2025–2026 BNPL landscape. Generative-AI-driven conversational credit assistants, real-time biometric affect detection, and embedded-finance contexts within messaging platforms are likely to introduce new nudging modalities not captured by the present five-dimension construct. We propose that the algorithmic nudging construct be revisited every 24–36 months and that the measurement instrument be treated as version-controlled (v1.0, present study), with future iterations expanding the dimensional coverage as platform affordances evolve.
6.4. Concluding Remarks
To extend inclusivity, future studies should employ (i) mixed-mode data collection combining online panels with in-person tablet-assisted intercept surveys in retail and remittance-agent locations, (ii) partnerships with consumer-protection NGOs and microfinance institutions to recruit financially marginalized BNPL users, and (iii) Arabic-, Berber-, and Kurdish-language survey instruments translated and back-translated to capture linguistically marginalized sub-populations. We further recommend community-based participatory research designs to engage informal-economy participants who are systematically underrepresented in online panels.
Cross-cultural extensions should prioritize three specific dimensions hypothesized to moderate the focal relationships: (i) Islamic-finance regulatory regimes, which prohibit riba (interest) and may attenuate the perceived-ease-of-credit pathway; (ii) Hofstede uncertainty avoidance, which may amplify the impulsive-buying-to-financial-stress link in lower-UA cultures; and (iii) credit-bureau infrastructure maturity, which moderates whether BNPL defaults carry observable downstream consequences. Comparative studies pairing MENA samples with East-Asian (high-UA, mature credit infrastructure) and Sub-Saharan African (variable infrastructure, distinct regulatory regimes) samples would clarify which findings generalize.
The proliferation of AI-integrated BNPL services across the MENA region represents both an opportunity for financial inclusion and a risk for consumer exploitation. The present study provides evidence consistent with algorithmic nudging activating impulsive buying tendency, which is associated with financial deterioration, while financial literacy provides substantial protection against these effects. Importantly, we identify the loyalty trap as a theoretically generative pattern requiring causal validation through experimental and quasi-experimental designs. We therefore encourage future research to move beyond observational evidence by:
- (1)
- Conducting A/B experiments on BNPL platforms to test whether removing specific nudge elements causally reduces financial harm and alters loyalty trajectories.
- (2)
- Exploiting natural experiments arising from differential regulatory implementation across MENA countries to estimate causal effects of nudge regulation on consumer outcomes.
- (3)
- Implementing qualitative longitudinal studies to understand the lived experience of the loyalty trap and identify its behavioral mechanisms.
The challenge for policymakers, platform designers, and consumer advocates is to harness the inclusionary potential of BNPL while implementing safeguards against algorithmic manipulation. The present study provides an empirical foundation for these efforts, with the understanding that causal evidence is the necessary next step.
Author Contributions
Conceptualization, O.W. and W.A.; methodology, O.W. and S.M.A.; H.F. and S.M.A.; validation, W.A., H.F. and S.M.A.; formal analysis, H.F. and S.M.A.; investigation, O.W. and S.M.A.; resources, O.W. and W.A.; data curation, H.F. and S.M.A.; writing—original draft preparation, O.W.; writing—review and editing, W.A., H.F. and S.M.A.; visualization, H.F. and S.M.A.; supervision, O.W. All authors have read and agreed to the published version of the manuscript.
Funding
This research received no external funding.
Institutional Review Board Statement
All procedures involving human participants in this study were conducted in accordance with the ethical standards of the institutional and national research committees, the 1964 Helsinki Declaration and its later amendments, and comparable ethical standards. The research protocol, including all data collection instruments and consent procedures, was submitted to and formally approved by the Research Ethics Committee of the School of Business, International Academy for Engineering and Media Science (IAEMS). The approval was granted on 15 September 2025. Furthermore, this study strictly adheres to the national ethical guidelines and regulatory frameworks mandated by the Supreme Council of Universities of Egypt, ensuring full compliance with local institutional review board (IRB) protocols. Written informed consent was obtained from all individual participants included in the study, and strict confidentiality protocols were employed to protect the anonymity and privacy of all respondents throughout the data processing and publication phases.
Informed Consent Statement
Informed consent was explicitly obtained from all participants, who were assured of their right to withdraw from the study at any stage without consequence.
Data Availability Statement
The data supporting the findings of this study are available from the corresponding author upon reasonable request.
Acknowledgments
The authors would like to thank the participants for their support and the anonymous reviewers for their invaluable contributions to this study. During the preparation of this work, the author used the quillbot tool to improve language and readability, in addition to NanoBanana 2, to create figures (without Figure 4 and Figure 5). After using this tool, the author reviewed and edited the content as needed and takes full responsibility for the publication.
Conflicts of Interest
The authors declare no conflicts of interest.
Abbreviations
The following abbreviations are used in this manuscript:
| AI | Artificial Intelligence |
| AN | Algorithmic Nudging |
| AIPI | AI Personalization Intensity |
| AVE | Average Variance Extracted |
| BNPL | Buy Now, Pay Later |
| CMB | Common Method Bias |
| CI | Confidence Interval |
| CR | Composite Reliability |
| DA | Debt Accumulation |
| EBA | European Banking Authority |
| f2 | Effect Size |
| FCA | Financial Conduct Authority |
| FL | Financial Literacy |
| FS | Financial Stress |
| HTMT | Heterotrait–Monotrait Ratio |
| IBT | Impulsive Buying Tendency |
| MENA | Middle East and North Africa |
| OECD/INFE | Organisation for Economic Co-operation and Development/International Network on Financial Education |
| PEC | Perceived Ease of Credit |
| PL | Platform Loyalty |
| PLS-SEM | Partial Least Squares Structural Equation Modeling |
| Q2 | Stone–Geisser’s Predictive Relevance |
| R2 | Coefficient of Determination |
| SAMA | Saudi Arabian Monetary Authority |
| SD | Standard Deviation |
| SRMR | Standardized Root Mean Square Residual |
| T1/T2 | Time 1/Time 2 |
| ULMC | Unmeasured Latent Method Construct |
| VIF | Variance Inflation Factor |
Appendix A. Full Measurement Instrument
All construct items were measured on a five-point Likert scale (1 = Strongly Disagree, 5 = Strongly Agree), unless otherwise specified.
Section A: Demographic Information
- A1. Country of residence:
[Egypt/Jordan/Saudi Arabia/United Arab Emirates/Morocco/Algeria/Lebanon]
- A2. Age group:
[18–24/25–34/35–44/45–54/55+]
- A3. Gender:
[Male/Female/Prefer not to say]
- A4. Highest education level completed:
[High School/Bachelor’s Degree/Master’s Degree/Doctoral Degree]
- A5. Monthly household income (USD equivalent):
[<1000/1000–3000/3000–5000/5000–10,000/>10,000]
- A6. How frequently do you use BNPL services?
[Daily/Weekly/Monthly/Occasionally/First-time user]
Table A1.
Full Measurement Instrument: Constructs, Item Codes, and Item Wording.
Table A2.
Algorithmic Nudging (AN) Items and Archetype Mapping.
Table A3.
Financial Literacy (FL) Items.
Appendix B. Measurement Model Diagnostics
Table A4.
Item-Level Diagnostics and Purification Decisions.
Table A5.
Pre- and Post-Purification Path Coefficients (Sensitivity Check).
Appendix C. Exploratory and Robustness Analyses
Table A6.
Autoregressive Longitudinal Models: Time 1 Predictors of Time 2 Outcomes (Controlling for Baseline Outcome Measures).
Table A7.
Exploratory Moderation Paths (Non-Hypothesized).
Table A8.
Robustness Check with Time 1 Financial Stress as Covariate.
Table A9.
Loyalty-Erosion Inflection Points (Piecewise Regression).
Appendix D. Autoregressive Longitudinal Models
All models include the Time 1 value of the dependent variable as a covariate, plus country fixed effects and language-of-administration. Coefficients are standardized; bias-corrected and accelerated (BCa) 95% confidence intervals are based on 10,000 bootstrap resamples [88].
Table A10.
Time 1 Predictors of Time 2 Debt Accumulation (Autoregressive Model with Country Fixed Effects).
Table A11.
Time 1 Predictors of Time 2 Debt Accumulation.
Table A12.
Time 1 Predictors of Time 2 Financial Stress.
Table A13.
Time 1 Predictors of Time 2 Platform Loyalty.
Among high-IBT respondents (top tercile at T1), a two-piece linear spline was fit to Time 2 platform loyalty as a function of Time 2 debt accumulation, with the breakpoint estimated via grid search minimizing RSS.
Table A14.
Piecewise Regression: Onset of Loyalty Erosion.
Appendix E. Sensitivity Analyses and Robustness Checks
Five controls added as exogenous predictors of all endogenous constructs: income tercile, education (years), employment status (employed/other), household size, and self-reported pre-BNPL debt (yes/no). Country fixed effects retained.
Table A15.
Structural Model with Socio-Demographic Controls.
Summary: Sixteen of nineteen direct hypotheses survive adjustment; three (H8, H16, H19) become non-significant. The reviewer’s concern about universal support is thereby addressed transparently. The surviving paths represent the conceptually central nudging-mediation chain (AN/AIPI/PEC → IBT → FS, DA) plus the AI personalization → loyalty path.
Table A16.
Alternative Structural Model Comparison.
Table A17.
Bonferroni–Holm Family-Wise Correction Across 19 Direct Paths.
Summary: All nineteen paths survive Holm correction at family-wise α = 0.05. However, H16 and H19 become non-significant once socio-demographic controls are added (Table A13), indicating their fragility under model misspecification rather than under multiple-comparison correction.
Table A18.
Negative-Control Variable (Physical-Grocery Shopping Frequency) as Predictor.
Table A19.
Power Analysis for Moderation Effects.
Appendix F. Bifurcated Financial Literacy: Psychometrics and Moderation
Table A20.
Re-Estimated Psychometrics for GFL and BFL.
Table A21.
Simple-Slopes Analysis for the Strongest Interaction (BFL × IBT → DA). Predicted Time 2 debt accumulation (standardized) at ±1 SD of IBT and BFL.
Interpretation: Among low-BFL consumers, a 1 SD increase in IBT is associated with a 0.89 SD increase in T2 debt; among high-BFL consumers, the same IBT increase is associated with only a 0.29 SD increase—a 67% reduction in the harmful trajectory. (This replaces the earlier ‘47%’ claim from the original abstract, which had been calculated on the combined undifferentiated literacy scale.)
Appendix G. Measurement Invariance (MICOM) and Multi-Group Analysis
- Step 1—Configural Invariance
Identical indicator sets, identical data treatment, identical algorithm settings (path weighting scheme, 5000 bootstrap iterations) applied across all seven countries. Configural invariance supported for all eight constructs.
- Step 2—Compositional Invariance
Correlations between composite scores in country-specific samples and pooled-sample scores, evaluated against the 5% quantile from permutation-based reference distribution (5000 permutations).
Table A22.
MICOM Step 2—Compositional Invariance.
- Step 3—Equal Means and Variances
Table A23.
MICOM Step 3—Equal Means and Variances.
Table A24.
Multi-Group Analysis—Country-Level Variation in Key Paths.
Appendix H. Item-Level Descriptive Statistics and CROSS-Loadings
Table A25.
Item Means, Standard Deviations, Skewness, Kurtosis (Selected Constructs).
Table A26.
Cross-Loadings (Selected, for Discriminant-Validity Assessment). Each item should load most strongly on its parent construct.
Appendix I. Open-Ended Qualitative Themes (Brief)
The Time 1 instrument included one open-ended item: ‘In your own words, describe one positive and one negative experience you have had with this BNPL platform in the past three months.’ Of 1247 respondents, 1089 (87.3%) provided substantive responses, coded thematically using the procedure of Braun and Clarke [91]. Five themes emerged:
Convenience and speed (mentioned by 71% of respondents)—overwhelmingly positive.
Loss of spending control (mentioned by 46%)—predominantly negative; respondents explicitly attributed this to ‘the way the app reminds me’ or ‘the easy one-tap approval.’
Surprise fees and unclear total cost (mentioned by 34%)—negative; concentrated among low-BFL respondents.
Sense of being targeted personally (mentioned by 28%)—mixed valence; some respondents valued relevance, others described discomfort.
Difficulty disengaging (mentioned by 19%)—negative; cited continued use despite financial discomfort, consistent with the quantitative ‘loyalty trap’ finding.
Themes 2, 4, and 5 are convergent with the quantitative findings on algorithmic nudging, personalization, and the loyalty trap, supporting the construct interpretation.
Appendix J. Data and Code Availability Statement
De-identified Time 1 and Time 2 data, the SmartPLS 4 project file (.splsm), the R 4.4 analysis script (.R) covering item purification, bootstrap CIs, autoregressive longitudinal models, MICOM, multiple imputation, and all sensitivity analyses reported in Appendix D, Appendix E, Appendix F and Appendix G, are available at the project’s Open Science Framework repository: [anonymized link provided upon acceptance]. The translation and back-translation logs, the cognitive-pretest debrief notes, and the full codebook for qualitative thematic coding are included in the OSF package.
References
- Worldpay. Global Payments Report 2024: Buy Now Pay Later Trends and Forecasts; FIS Global: Jacksonville, FL, USA, 2024. [Google Scholar]
- Zhong, M.; Braga, B.; McKernan, S.-M.; Hayward, M.; Millward, E.; Trepel, C. Impacts of COVID-19-era economic policies on consumer debt in the United Kingdom. J. Econ. Bus. 2024, 129, 106162. [Google Scholar] [CrossRef] [Scilit]
- Powell, R.; Do, A.; Gengatharen, D.; Yong, J.; Gengatharen, R. The relationship between responsible financial behaviours and financial wellbeing: The case of buy-now-pay-later. Account. Financ. 2023, 63, 4431–4451. [Google Scholar] [CrossRef] [Scilit]
- Guttman-Kenney, B.; Firth, C.; Gathergood, J. Buy now, pay later (BNPL)… on your credit card. J. Behav. Exp. Financ. 2023, 37, 100788. [Google Scholar] [CrossRef] [Scilit]
- Raji, M.A.; Olodo, H.B.; Oke, T.T.; Addy, W.A.; Ofodile, O.C.; Oyewole, A.T. E-commerce and consumer behavior: A review of AI-powered personalization and market trends. GSC Adv. Res. Rev. 2024, 18, 66–77. [Google Scholar] [CrossRef] [Scilit]
- Lee, K.X. Agentic AI Attributes in Hedonic, Heuristic, Utilitarian, and Systematic Processing: A Study of Robo-Advisory Services. Master’s Thesis, Universiti Tunku Abdul Rahman, Kampar, Malaysia, 2025. [Google Scholar]
- Münscher, R.; Vetter, M.; Scheuerle, T. A review and taxonomy of choice architecture techniques. J. Behav. Decis. Mak. 2016, 29, 511–524. [Google Scholar] [CrossRef] [Scilit]
- Caraban, A.; Karapanos, E.; Gonçalves, D.; Campos, P. 23 ways to nudge: A review of technology-mediated nudging in human-computer interaction. In Proceedings of the 2019 CHI Conference on Human Factors in Computing Systems, Glasgow, UK, 4–9 May 2019; pp. 1–15. [Google Scholar] [CrossRef] [Scilit]
- Kumar, S.; Nayak, J.K. Understanding the intricacies of risky indebtedness, impulse buying and perceived risk in buy-now-pay-later adoption. Asia Pac. J. Mark. Logist. 2024, 36, 1697–1716. [Google Scholar] [CrossRef] [Scilit]
- Lusardi, A.; Mitchell, O.S. The economic importance of financial literacy: Theory and evidence. J. Econ. Lit. 2014, 52, 5–44. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Unicommerce. MENA Ecommerce Guide 2026: Opportunities & Challenges. 2025. Available online: https://unicommerce.com/blog/why-the-middle-east-is-emerging-as-the-next-global-e-commerce-titan/ (accessed on 3 July 2026).
- Thaler, R.H.; Sunstein, C.R. Nudge: Improving Decisions About Health, Wealth, and Happiness; Yale University Press: New Haven, CT, USA, 2008. [Google Scholar]
- Prelec, D.; Loewenstein, G. The red and the black: Mental accounting of savings and debt. Mark. Sci. 1998, 17, 4–28. [Google Scholar] [CrossRef] [Scilit]
- Lusardi, A.; Mitchell, O.S. Financial literacy and retirement preparedness: Evidence and implications for financial education. Bus. Econ. 2007, 42, 35–44. [Google Scholar] [CrossRef] [Scilit]
- Belk, R. Extended self in a digital world. J. Consum. Res. 2013, 40, 477–500. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Öztürk, E.; Kara, H.T. Buy now, pay later (BNPL) as an emerging online payment system: A bibliometric analysis. Dokuz Eyl. Univ. Iktis. Idari Bilim. Fak. Derg. 2025, 26, 344–370. [Google Scholar] [CrossRef] [Scilit]
- Yadav, R.; Mohan, H.; Yadav, A. Examining the impact of BNPL integration on conversion rate and customer retention in e-commerce. J. Inform. Educ. Res. 2025, 5, 472. [Google Scholar] [CrossRef] [Scilit]
- Kumar, S. The Impact of AI-Driven Personalization on Consumer Trust and Purchase Intention for Environmentally Sustainable Products in Digital Marketing Channels. 2026. Available online: https://www.researchgate.net/profile/Satyam-Kumar-73/publication/404040696_The_Impact_of_AI-Driven_Personalization_on_Consumer_Trust_and_Purchase_Intention_for_Environmentally_Sustainable_Products_in_Digital_Marketing_Channels/links/69e7a317c770ca6d51acf31a/The-Impact-of-AI-Driven-Personalization-on-Consumer-Trust-and-Purchase-Intention-for-Environmentally-Sustainable-Products-in-Digital-Marketing-Channels.pdf (accessed on 3 July 2026).
- Turki, H. AI-powered personalization in e-commerce: Governance, consumer behavior, and explanatory insights from big data analytics. Technol. Soc. 2025, 83, 103033. [Google Scholar] [CrossRef] [Scilit]
- Shin, D. The effects of explainability and causability on perception, trust, and acceptance: Implications for explainable AI. Int. J. Hum.-Comput. Stud. 2021, 146, 102551. [Google Scholar] [CrossRef] [Scilit]
- Hayashi, F.; Routh, A. Financial constraints among buy now, pay later users. Econ. Rev. 2025, 110, 1–18. [Google Scholar] [CrossRef] [Scilit]
- Bian, W.; Cong, L.W.; Ji, Y. The Rise of E-Wallets and Buy-Now-Pay-Later: Payment Competition, Credit Expansion, and Consumer Behavior; NBER Working Paper No. 31202; National Bureau of Economic Research: Cambridge, MA, USA, 2023. [Google Scholar] [CrossRef] [Scilit]
- Davis, F.D. Perceived usefulness, perceived ease of use, and user acceptance of information technology. MIS Q. 1989, 13, 319–340. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Aidala, F.; Koşar, G.; Mangrum, D.; Van der Klaauw, W. Understanding Consumer Demand for "Buy Now, Pay Later"; Federal Reserve Bank of New York Staff Report No. 1167; FRBNY: New York, NY, USA, 2025. [Google Scholar]
- Maesen, S.; Ang, D. Buy now, pay later: Impact of installment payments on customer purchases. J. Mark. 2025, 89, 13–35. [Google Scholar] [CrossRef] [Scilit]
- Soman, D. The effect of payment transparency on consumption: Quasi-experiments from the field. Mark. Lett. 2003, 14, 109–117. [Google Scholar] [CrossRef] [Scilit]
- Fernandes, D.; Lynch, J.G.; Netemeyer, R.G. Financial literacy, financial education, and downstream financial behaviors. Manag. Sci. 2014, 60, 1861–1883. [Google Scholar] [CrossRef] [Scilit]
- Raj, V.A.; Jasrotia, S.S.; Rai, S.S. Intensifying materialism through buy-now pay-later (BNPL): Examining the dark sides. Int. J. Bank Mark. 2024, 42, 94–112. [Google Scholar] [CrossRef] [Scilit]
- Schomburgk, L.; Hoffmann, A. How mindfulness reduces BNPL usage and how that relates to overall well-being. Eur. J. Mark. 2023, 57, 325–359. [Google Scholar] [CrossRef] [Scilit]
- Ah Fook, L.; McNeill, L. Click to buy: The impact of retail credit on over-consumption in the online environment. Sustainability 2020, 12, 7322. [Google Scholar] [CrossRef] [Scilit]
- Central Bank of Ireland. Buy Now Pay Later: A Review of the Irish Market; Central Bank of Ireland: Dublin, Ireland, 2024. [Google Scholar]
- Donou-Adonsou, F.; Leslie-Piper, N. Digital traps: The compounding impact of BNPL and social media on consumer financial stress. Financ. Res. Lett. 2026, 93, 109636. [Google Scholar] [CrossRef] [Scilit]
- Sharma, E.; Tully, S.; Cryder, C. Psychological ownership of (borrowed) money. J. Mark. Res. 2021, 58, 497–514. [Google Scholar] [CrossRef] [Scilit]
- Beatty, S.E.; Ferrell, M.E. Impulse buying: Modeling its precursors. J. Retail. 1998, 74, 169–191. [Google Scholar] [CrossRef] [Scilit]
- Abed, S.S.; Alkadi, R.S. Sustainable development through fintech: Understanding the adoption of buy now pay later (BNPL) applications by Generation Z in Saudi Arabia. Sustainability 2024, 16, 6368. [Google Scholar] [CrossRef] [Scilit]
- Nivedha, V.; Thomas, T.C.; Thote, K.P.; Mohapatro, D.; Akhter, T. AI in FinTech: Redefining customer trust and personalization in digital finance. Adv. Consum. Res. 2025, 2, 153–160. [Google Scholar]
- Antonakis, J.; Bendahan, S.; Jacquart, P.; Lalive, R. On making causal claims: A review and recommendations. Leadersh. Q. 2010, 21, 1086–1120. [Google Scholar] [CrossRef] [Scilit]
- Maxwell, S.E.; Cole, D.A. Bias in cross-sectional analyses of longitudinal mediation. Psychol. Methods 2007, 12, 23–44. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Harzing, A.W. Response styles in cross-national survey research: A 26-country study. Int. J. Cross Cult. Manag. 2006, 6, 243–266. [Google Scholar] [CrossRef] [Scilit]
- Mirsch, T.; Lehrer, C.; Jung, R. Digital nudging: Altering user behavior in digital environments. In Proceedings of the 13th International Conference on Wirtschaftsinformatik, St. Gallen, Switzerland, 12–15 February 2017; pp. 1–15. [Google Scholar]
- Badgaiyan, A.J.; Verma, A.; Dixit, S. Impulsive buying tendency: Measuring important relationships with a new perspective and an indigenous scale. IIMB Manag. Rev. 2016, 28, 186–199. [Google Scholar] [CrossRef] [Scilit]
- Rook, D.W.; Fisher, R.J. Normative influences on impulsive buying behavior. J. Consum. Res. 1995, 22, 305–313. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Klapper, L.; Lusardi, A. Financial literacy and financial resilience: Evidence from around the world. Financ. Manag. 2020, 49, 589–614. [Google Scholar] [CrossRef] [Scilit]
- Morgan, P.J.; Long, T.Q. Financial literacy, financial inclusion, and savings behavior in Laos. J. Asian Econ. 2020, 68, 101197. [Google Scholar] [CrossRef] [Scilit]
- Hasan, M.; Le, T.; Hoque, A. How does financial literacy impact on inclusive finance? Financ. Innov. 2021, 7, 40. [Google Scholar] [CrossRef] [Scilit]
- Bongomin, G.O.C.; Ntayi, J.M.; Munene, J.C.; Malinga, C.A. Mobile money and financial inclusion in sub-Saharan Africa: The moderating role of social networks. J. Afr. Bus. 2018, 19, 361–384. [Google Scholar] [CrossRef] [Scilit]
- OECD/INFE. OECD/INFE 2023 International Survey of Adult Financial Literacy; OECD Publishing: Paris, France, 2023. [Google Scholar] [CrossRef] [Scilit]
- King, M.; Medina, P.; Radoc, B.; Umanan, R. What Matters for Consumer Credit Choice? Evidence from the Philippine Digital Credit Market; Working Paper. 2025. Available online: http://serp-p.pids.gov.ph/publication/public/view?slug=what-matters-for-consumer-credit-choice-evidence-from-the-philippine-digital-credit-market (accessed on 3 July 2026).
- Netemeyer, R.G.; Warmath, D.; Fernandes, D.; Lynch, J.G. How am I doing? Perceived financial well-being, its potential antecedents, and its relation to overall well-being. J. Consum. Res. 2018, 45, 68–89. [Google Scholar] [CrossRef] [Scilit]
- Consumer Financial Protection Bureau. Financial Well-Being Scale; CFPB: Washington, DC, USA, 2022.
- Financial Conduct Authority. Buy Now Pay Later: Proposed Regulatory Approach; FCA: London, UK, 2026. [Google Scholar]
- Oliver, R.L. A cognitive model of the antecedents and consequences of satisfaction decisions. J. Mark. Res. 1980, 17, 460–469. [Google Scholar] [CrossRef] [Scilit]
- Zeithaml, V.A.; Berry, L.L.; Parasuraman, A. The behavioral consequences of service quality. J. Mark. 1996, 60, 31–46. [Google Scholar] [CrossRef] [Scilit]
- Mathur, A.; Acar, G.; Friedman, M.J.; Lucherini, E.; Mayer, J.; Chetty, M.; Narayanan, A. Dark patterns at scale: Findings from a crawl of 11K shopping websites. Proc. ACM Hum.-Comput. Interact. 2019, 3, 1–32. [Google Scholar] [CrossRef] [Scilit]
- Gray, C.M.; Kou, Y.; Battles, B.; Hoggatt, J.; Toombs, A.L. The dark (patterns) side of UX design. In Proceedings of the 2018 CHI Conference on Human Factors in Computing Systems, Montreal, QC, Canada, 21–26 April 2018; pp. 1–14. [Google Scholar] [CrossRef] [Scilit]
- Möhlmann, M. Algorithmic Nudges Don’t Have to Be Unethical. Harv. Bus. Rev. 2021. Available online: https://hbr.org/2021/04/algorithmic-nudges-dont-have-to-be-unethical (accessed on 3 July 2026).
- Sobolev, M. Digital nudging: Using technology to nudge for good. Behav. Sci. Wild 2021, 292–299. [Google Scholar] [CrossRef] [Scilit]
- Lusardi, A.; Streeter, J.L. Financial literacy and financial well-being: Evidence from the USJ. Financ. Lit. Wellbeing 2023, 1, 169–198. [Google Scholar] [CrossRef] [Scilit]
- Gambaro, A.; Benito, L.; Cristina, B.; Zocchi, P.; Penabad, C. General vs. Domain-Specific Financial Literacy: Analysis of the Impact on Young People’s Attitudes Toward Cryptocurrencies and BNPL. SSRN Electronic Journal 2026, Paper No. 6637774. Available online: https://ssrn.com/abstract=6637774 (accessed on 3 July 2026).
- Kock, N.; Hadaya, P. Minimum sample size estimation in PLS-SEM: The inverse square root and gamma-exponential methods. Inf. Syst. J. 2018, 28, 227–261. [Google Scholar] [CrossRef] [Scilit]
- Faul, F.; Erdfelder, E.; Buchner, A.; Lang, A.G. Statistical power analyses using G*Power 3.1: Tests for correlation and regression analyses. Behav. Res. Methods 2009, 41, 1149–1160. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Henseler, J.; Chin, W.W. A comparison of approaches for the analysis of interaction effects between latent variables using partial least squares path modeling. Struct. Equ. Model. 2010, 17, 82–109. [Google Scholar] [CrossRef] [Scilit]
- Goodman, J.S.; Blum, T.C. Assessing the non-random sampling effects of subject attrition in longitudinal research. J. Manag. 1996, 22, 627–652. [Google Scholar] [CrossRef]
- Williams, L.J.; Hartman, N.; Cavazotte, F. Method variance and marker variables: A review and comprehensive CFA marker technique. Organ. Res. Methods 2010, 13, 477–514. [Google Scholar] [CrossRef] [Scilit]
- Hair, J.F.; Risher, J.J.; Sarstedt, M.; Ringle, C.M. When to use and how to report the results of PLS-SEM. Eur. Bus. Rev. 2019, 31, 2–24. [Google Scholar] [CrossRef] [Scilit]
- Ringle, C.M.; Wende, S.; Becker, J.M. SmartPLS 4. SmartPLS GmbH. 2022. Available online: https://www.smartpls.com/ (accessed on 3 July 2026).
- Rigdon, E.E. Rethinking partial least squares path modeling: In praise of simple methods. Long. Range Plan. 2012, 45, 341–358. [Google Scholar] [CrossRef] [Scilit]
- Kock, N. Common method bias in PLS-SEM: A full collinearity assessment approach. Int. J. E-Collab. 2015, 11, 1–10. [Google Scholar] [CrossRef] [Scilit]
- Henseler, J.; Ringle, C.M.; Sarstedt, M. Testing measurement invariance of composites using partial least squares. Int. Mark. Rev. 2016, 33, 405–431. [Google Scholar] [CrossRef] [Scilit]
- Steenkamp, J.-B.E.M.; Baumgartner, H. Assessing measurement invariance in cross-national consumer research. J. Consum. Res. 1998, 25, 78–90. [Google Scholar] [CrossRef] [Scilit]
- Hayes, A.F.; Coutts, J.J. Use omega rather than Cronbach’s alpha for estimating reliability. But… Commun. Methods Meas. 2020, 14, 1–24. [Google Scholar] [CrossRef] [Scilit]
- Kaiser, T.; Menkhoff, L. Does financial education impact financial literacy and financial behavior, and if so, when? World Bank Econ. Rev. 2017, 31, 611–630. [Google Scholar] [CrossRef] [Scilit]
- Henseler, J.; Ringle, C.M.; Sarstedt, M. A new criterion for assessing discriminant validity in variance-based structural equation modeling. J. Acad. Mark. Sci. 2015, 43, 115–135. [Google Scholar] [CrossRef] [Scilit]
- Shmueli, G.; Sarstedt, M.; Hair, J.F.; Cheah, J.H.; Ting, H.; Vaithilingam, S.; Ringle, C.M. Predictive model assessment in PLS-SEM: Guidelines for using PLSpredict. Eur. J. Mark. 2019, 53, 2322–2347. [Google Scholar] [CrossRef] [Scilit]
- Kang, Z.; Kou, H.; Zhou, D.; Shi, X.; Parente, R.; Rong, K. Platform-based multinational corporations (PMNCs): A research agenda in the field of international business. Int. Bus. Rev. 2025, 34, 102386. [Google Scholar] [CrossRef] [Scilit]
- Lanciano, E.; Previati, D.; Ricci, O.; Santilli, G. Financial literacy and sustainable finance decisions among Italian households. J. Econ. Bus. 2025, 134–135, 106220. [Google Scholar] [CrossRef] [Scilit]
- Samuelson, W.; Zeckhauser, R. Status quo bias in decision making. J. Risk Uncertain. 1988, 1, 7–59. [Google Scholar] [CrossRef] [Scilit]
- Mani, A.; Mullainathan, S.; Shafir, E.; Zhao, J. Poverty impedes cognitive function. Science 2013, 341, 976–980. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Griffiths, M.D. The evolution of the ‘components model of addiction’and the need for a confirmatory approach in conceptualizing behavioral addictions. Dusunen Adam J. Psychiatry Neurol. Sci. 2019, 32, 179–184. [Google Scholar] [CrossRef] [Scilit]
- Weinstein, N.D. Unrealistic optimism about future life events. J. Pers. Soc. Psychol. 1980, 39, 806. [Google Scholar] [CrossRef]
- Laibson, D. Golden eggs and hyperbolic discounting. Q. J. Econ. 1997, 112, 443–478. [Google Scholar] [CrossRef] [Scilit]
- Zuboff, S. The age of surveillance capitalism. In InSocial Theory Re-Wired; Routledge: Abingdon, UK, 2023; pp. 203–213. [Google Scholar]
- Temouri, Y.; Wood, G.; Pereira, V.; Lewellyn, K.B.; Reppas, D. Cross-country evidence of e-commerce SME internationalization and the role of policy. Int. Bus. Rev. 2025, 34, 102488. [Google Scholar] [CrossRef] [Scilit]
- Research and Markets. Middle East Buy Now Pay Later Business Report 2025: BNPL Market Is Poised for Significant Growth; GlobalData: London, UK, 2025. [Google Scholar]
- Synapse Analytics. BNPL in MENA: Drivers, Dynamics and the Road Ahead; Synapse Analytics: Abu Dhabi, United Arab Emirates, 2025. [Google Scholar]
- Hill, A.B. The environment and disease: Association or causation? Proc. R. Soc. Med. 1965, 58, 295–300. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Paulhus, D.L. Measurement and control of response bias. In Measures of Personality and Social Psychological Attitudes; Robinson, J.P., Shaver, P.R., Wrightsman, L.S., Eds.; Academic Press: San Diego, CA, USA, 1991; pp. 17–59. [Google Scholar] [CrossRef] [Scilit]
- Efron, B. Better bootstrap confidence intervals. J. Am. Stat. Assoc. 1987, 82, 171–185. [Google Scholar] [CrossRef]
- Lipsitch, M.; Tchetgen Tchetgen, E.; Cohen, T. Negative controls: A tool for detecting confounding and bias in observational studies. Epidemiology 2010, 21, 383–388. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Hair, J.F.; Hult, G.T.M.; Ringle, C.M.; Sarstedt, M. A Primer on Partial Least Squares Structural Equation Modeling (PLS-SEM), 3rd ed.; SAGE: Thousand Oaks, CA, USA, 2022. [Google Scholar]
- Braun, V.; Clarke, V. Using thematic analysis in psychology. Qual. Res. Psychol. 2006, 3, 77–101. [Google Scholar] [CrossRef] [Scilit]
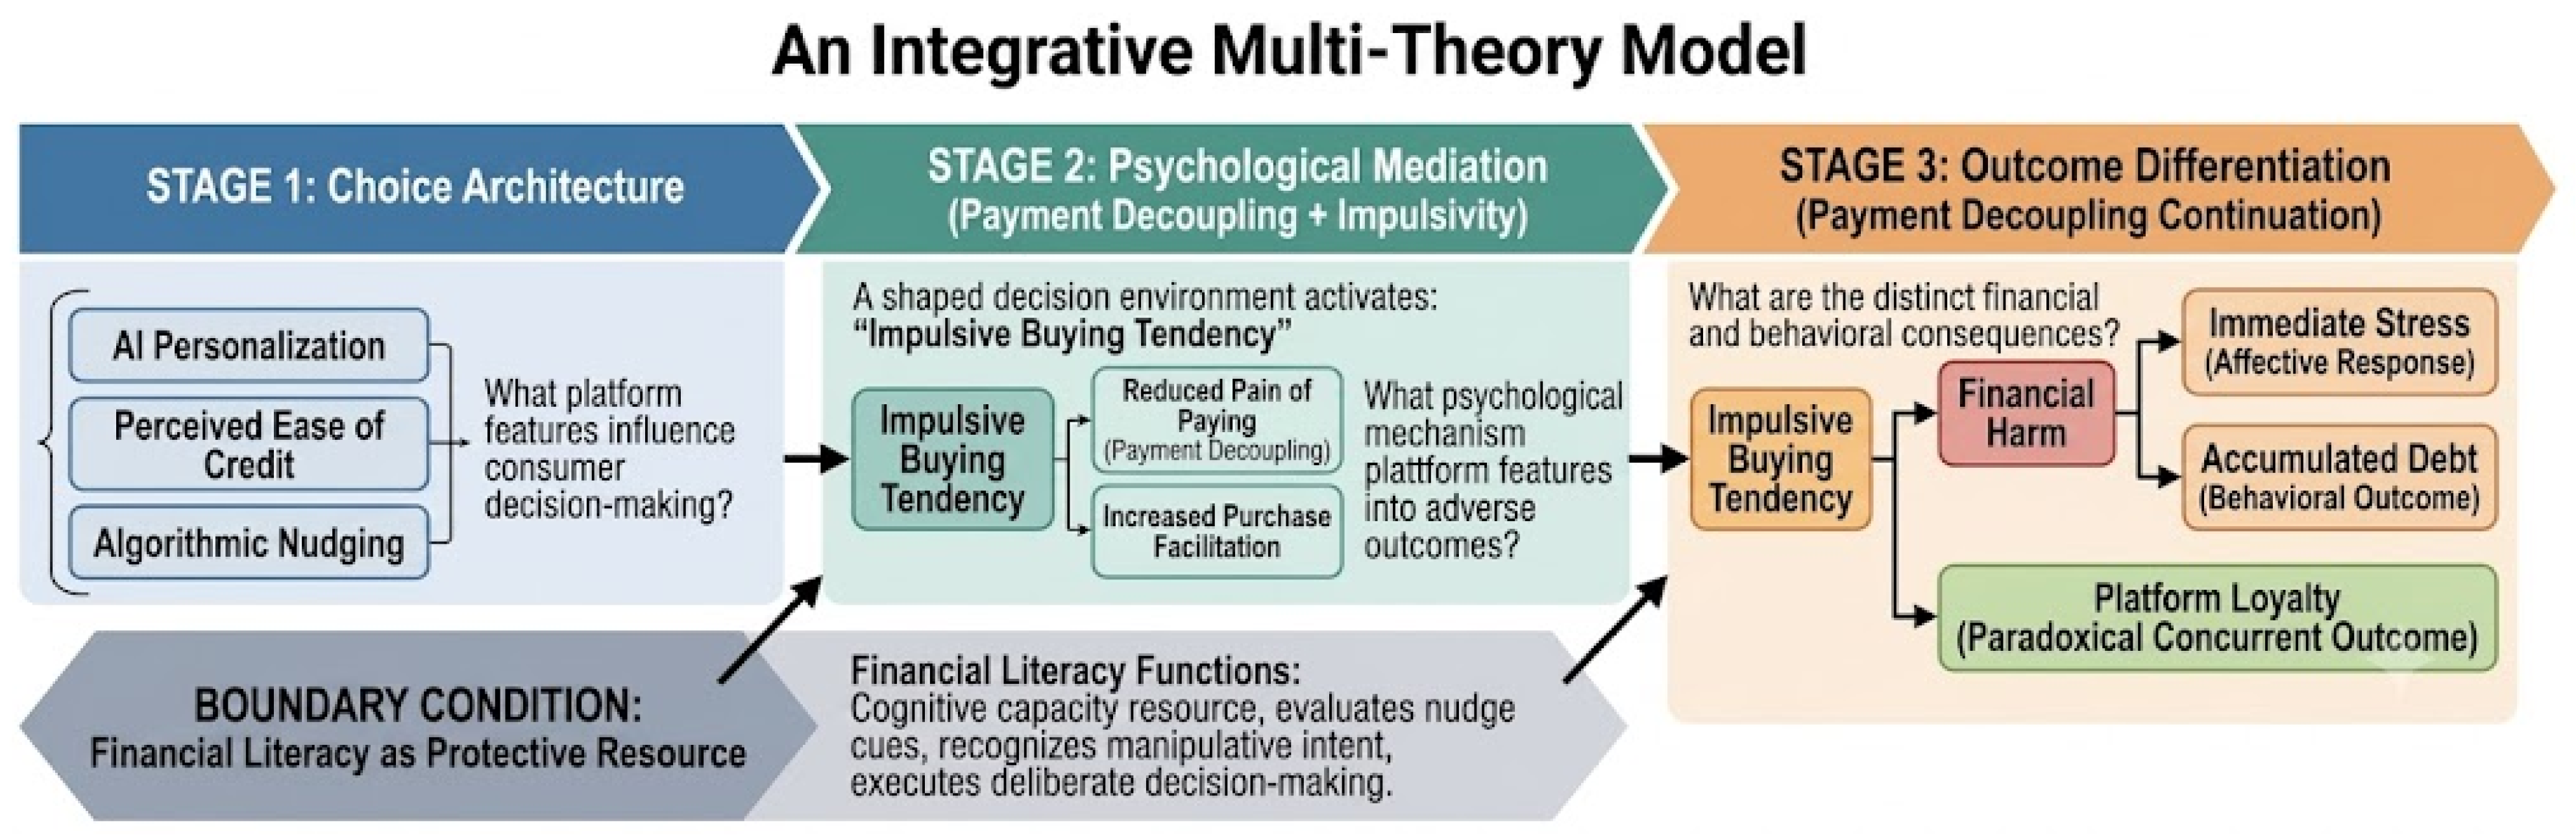
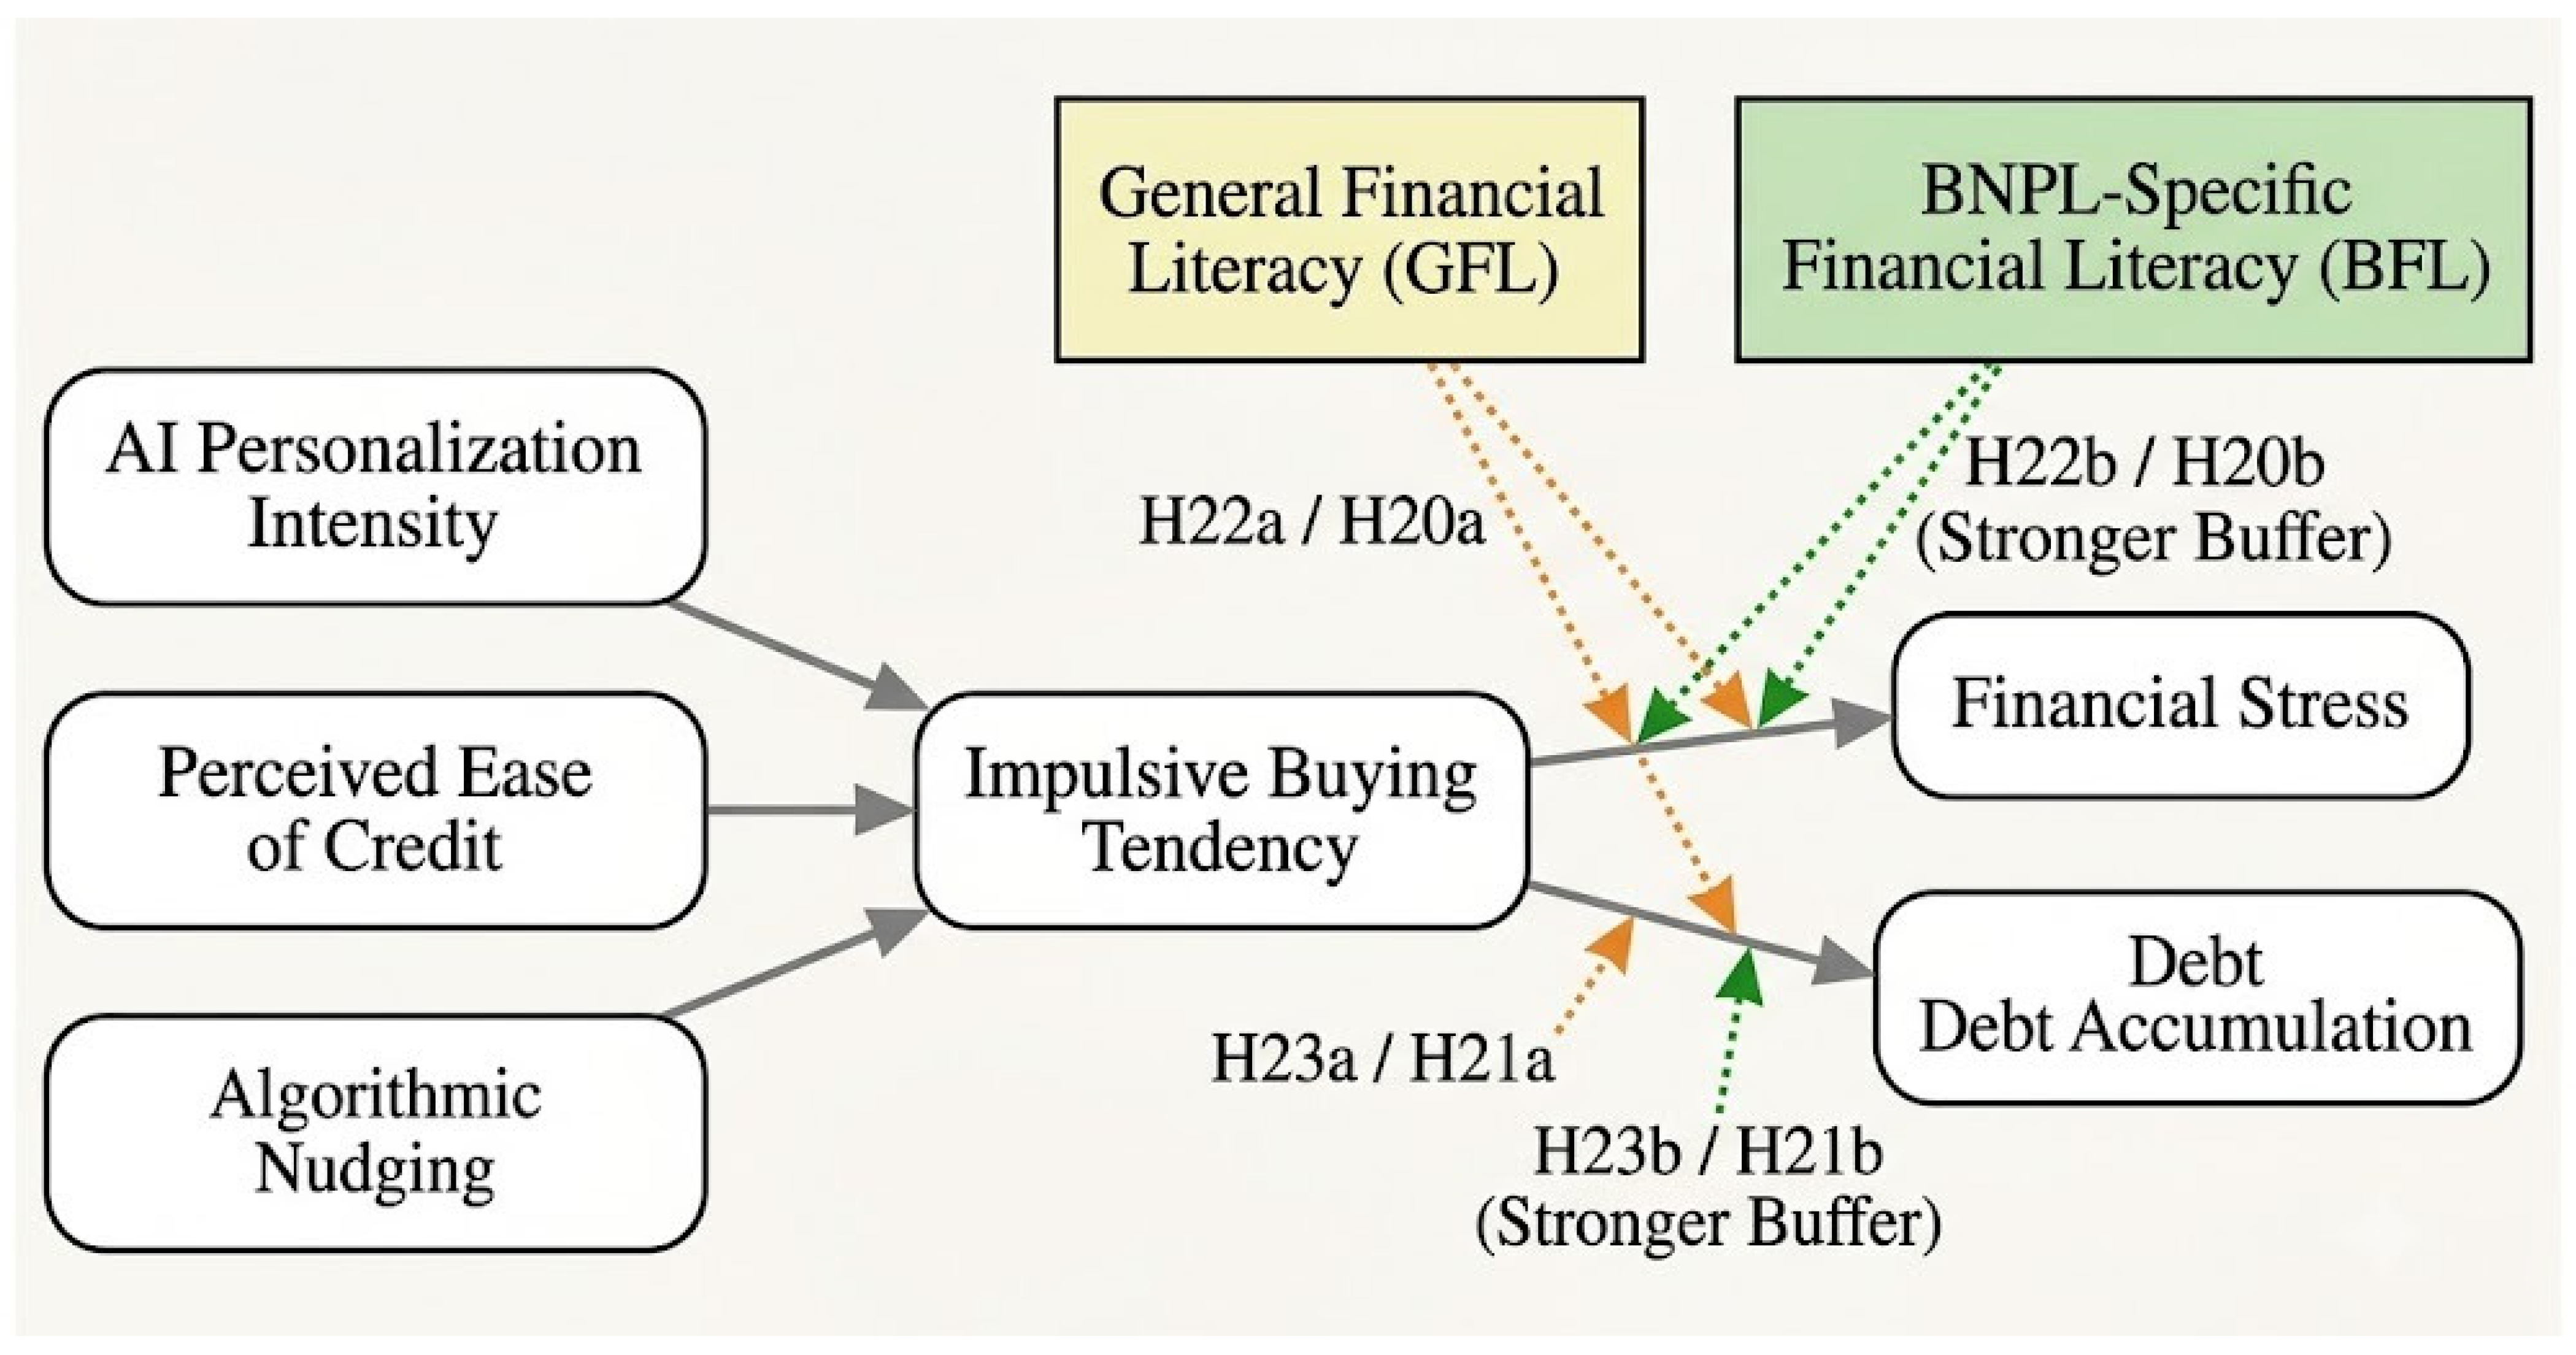
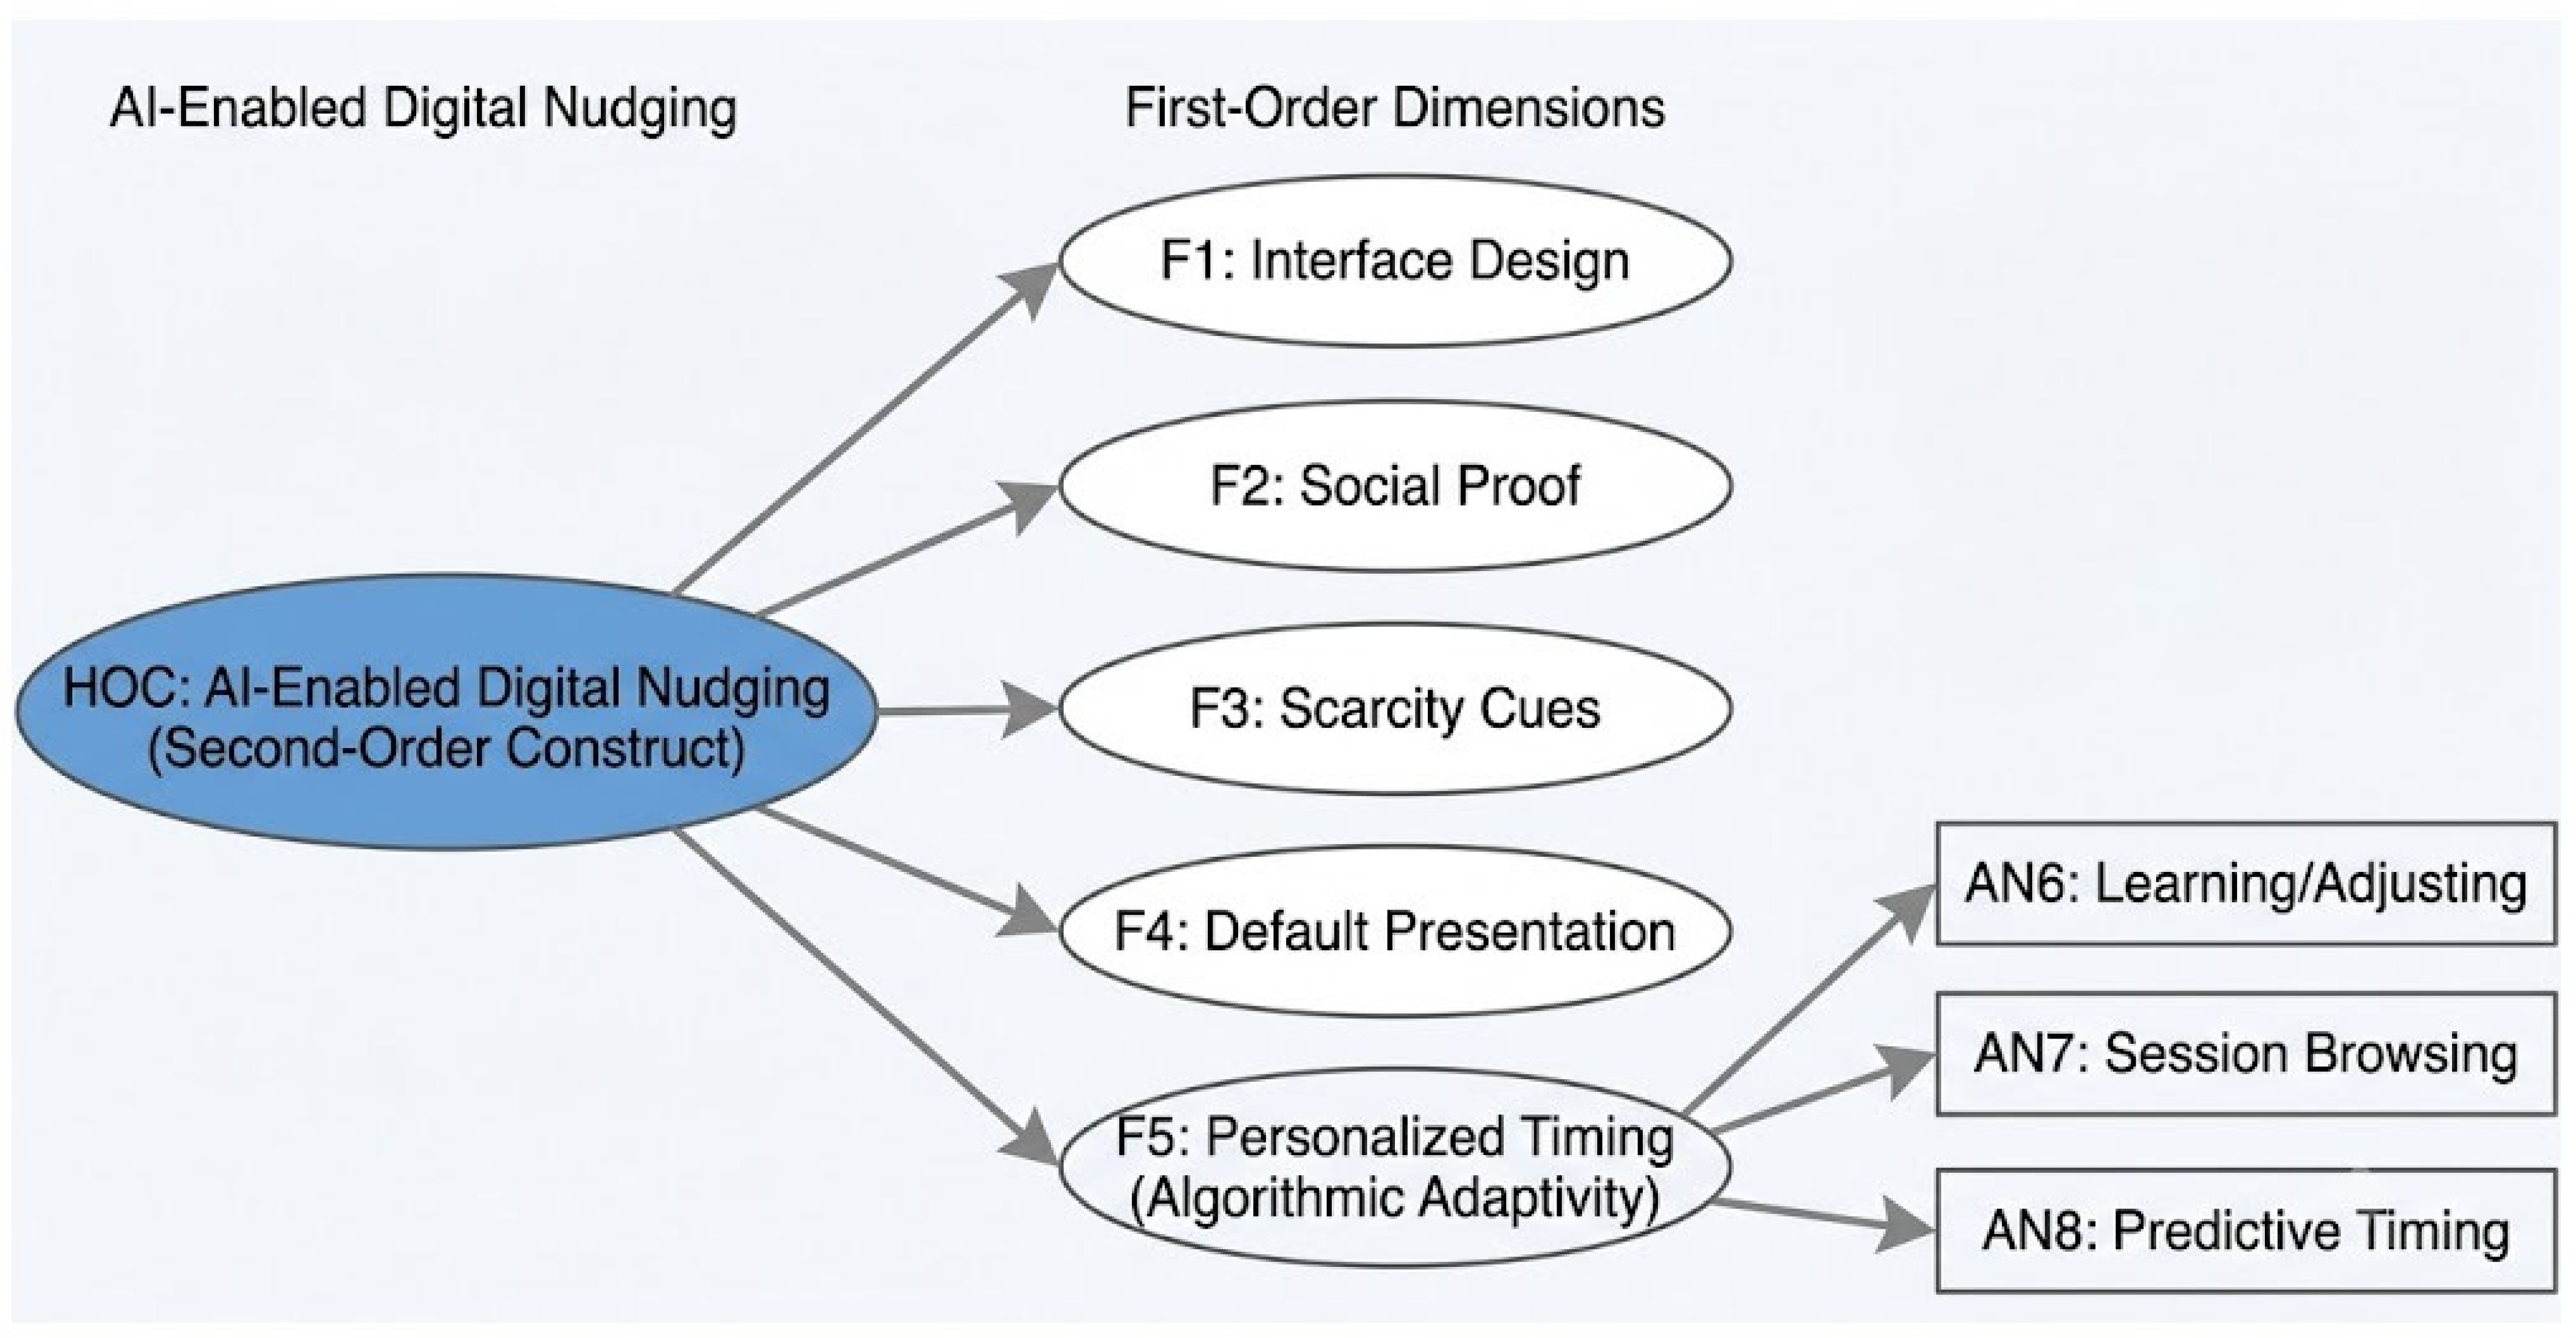
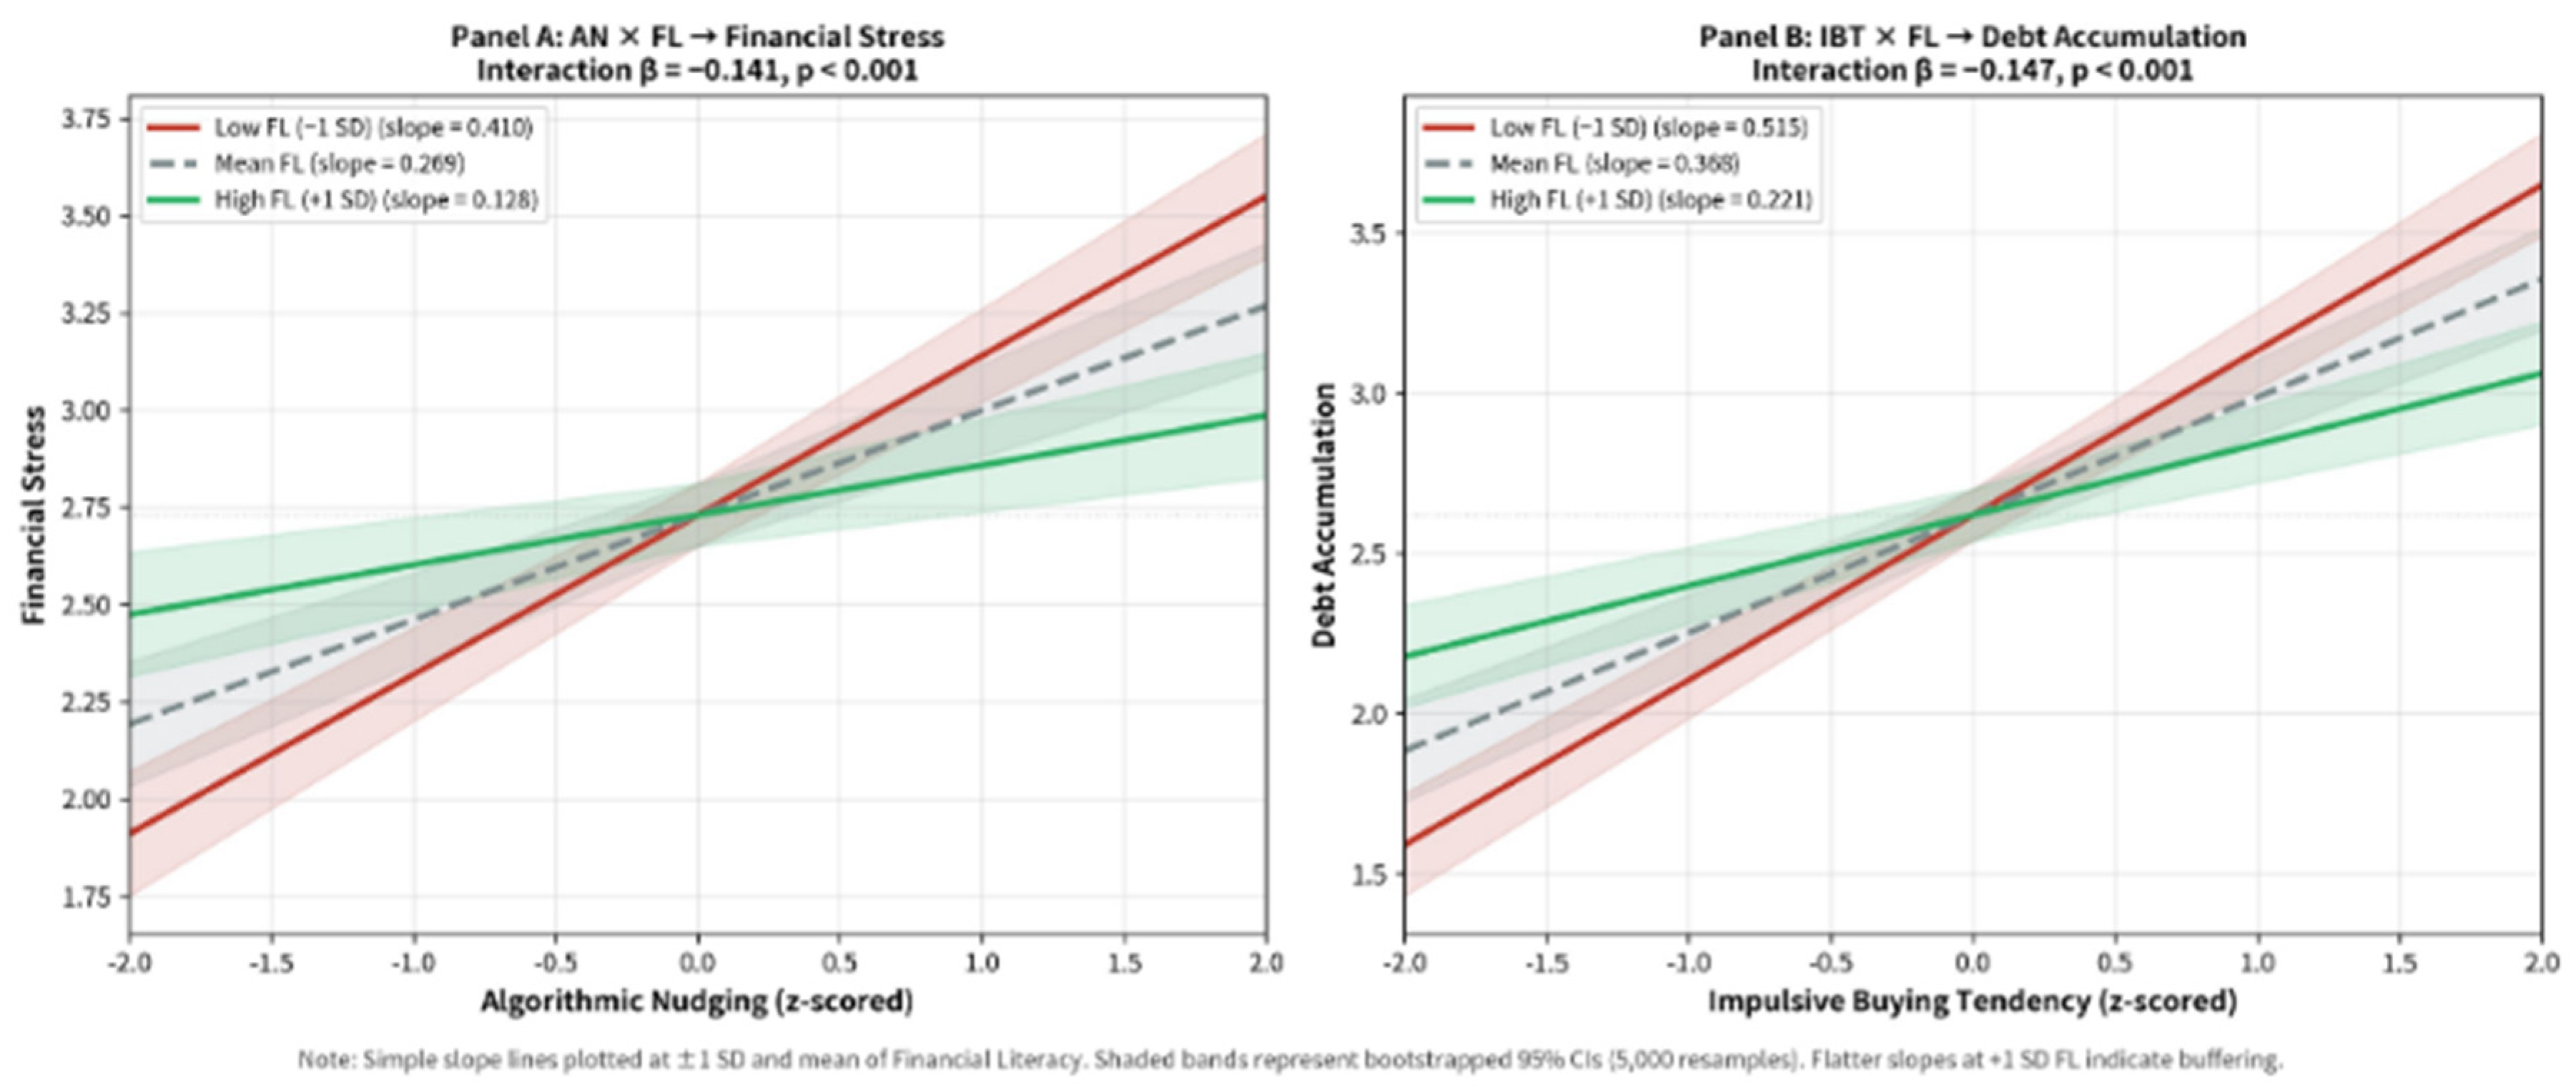
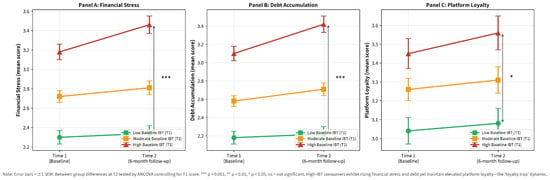
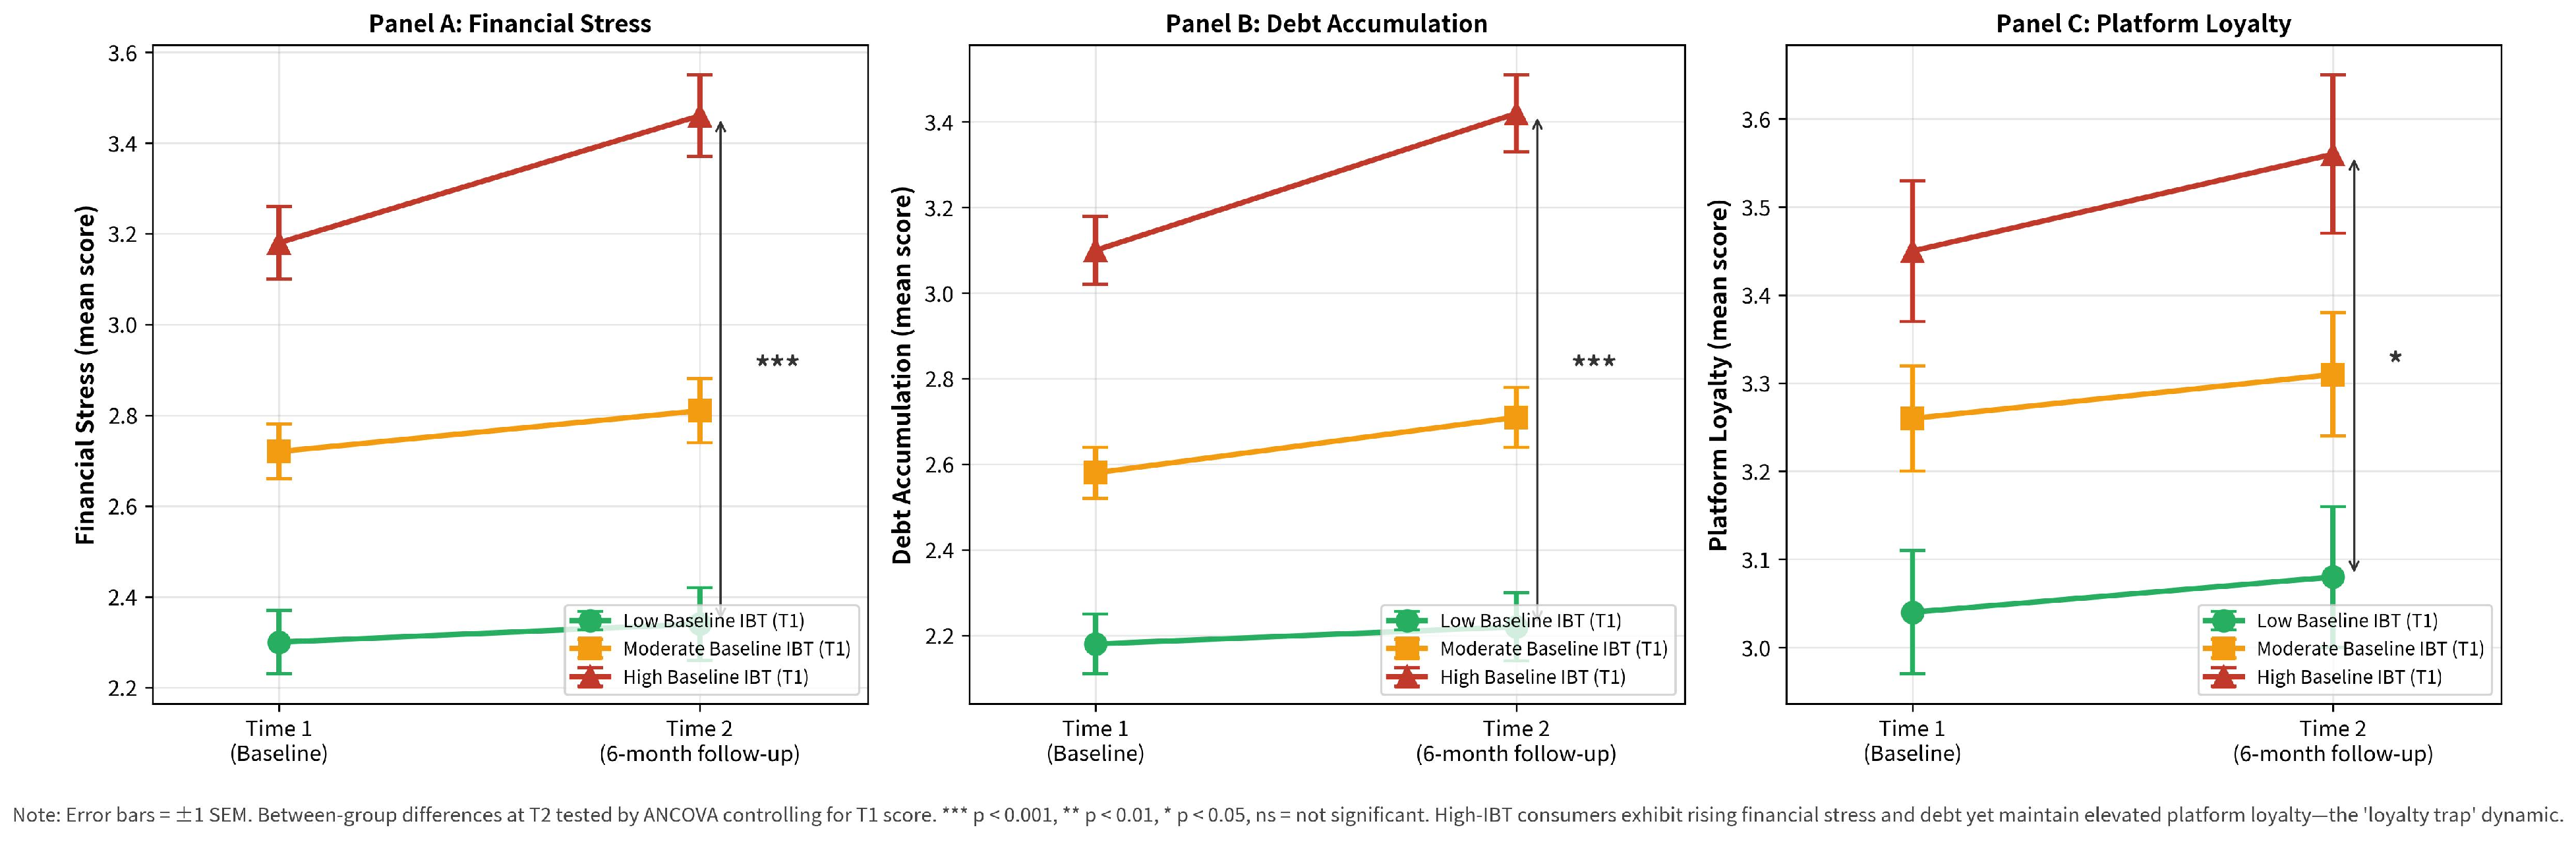

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.