


Abstract
This article proposes a novel approach for dealing with the time-fractional Navier–Stokes equations via the natural generalized Laplace transform decomposition method (NGLTDM). This hybrid method utilizes both the natural generalized Laplace transform (NGLT) and a decomposition method. The method is correct because the series solutions become more accurate when more terms are added. We establish precise theorems that verify the existence of solutions and the convergence of the series. The analysis shows that the suggested method is more general than the Homotopy Perturbation Method (HPM) and the Adomian Decomposition Method (ADM). Also, this approach can be applied to handle difficult fluid dynamics problems governed by the Navier–Stokes equations. This study enhances analytical methodologies for fractional-order flow models.
Keywords:
natural generalized-Laplace transform; inverse natural generalized-Laplace transform; generalized-Laplace transform; fractional Navier–Stokes equation; decomposition methods MSC:
35A22; 44A30
1. Introduction
The time-fractional Navier–Stokes equations are a big step forward in fluid dynamics, especially when it comes to modeling flow processes that are complicated and have memory effects and interactions that are not local. The were developed by adding fractional derivatives in time to the normal Navier–Stokes equations (NSE).
Researchers first developed the (NSE) in [1]. They are partial differential equations that explain how fluids that stay together move. It is very important to know that the Navier–Stokes equation is a basic tool for describing many physical phenomena in the field of fluid dynamics. These include fluid flow through pipes and atmospheric currents [2,3]. The Navier-Stokes equation (NSE) is a very useful tool for finding how viscous fluids and solid objects interact. It is the best tool in the fields of thermohydraulics, meteorology, petroleum engineering, plasma physics, and technology, as noted in [4]. Different researchers have employed various methodologies to obtain the solution to the NSE. For instance, the authors in [5] addressed the time-fractional Navier–Stokes equations utilizing an innovative analytical and approximate approach. In [6], the researchers solved the time-fractional NSE system using the hybrid method called the Laplace–Adomian decomposition method.
The Adomian decomposition transform method and the q-homotopy analysis transform method were used in [7] to get numerical results for the multi-dimensional NSE. The homotopy perturbation method, a new recursive transform method that uses natural transformation, was used to find the solution to the multi-dimensional NSE in [8]. In [9], the authors examine the solution of the multi-dimensional fractional NSE employing the Sumudu transform in conjunction with the Caputo fractional derivative.
The authors in [10] utilize the variational iteration transform method to deal with solutions of the fractional-order NSE. The generalized Laplace transform was first examined in [11], and further characteristics of this transformation were acquired in [12]; a Laplace-type integral transform associated with Adomian’s was utilized to derive the solution of nonlinear evolution equations featuring non-integer derivatives in [13]. In [14], the authors examined the solution of the fractional-order Kaup–Kupershmidt (KK) equation by employing the natural decomposition method, utilizing two distinct fractional derivatives: the Atangana–Baleanu derivative in Caputo form (ABC) and the Caputo–Fabrizio (CF) derivative.
The double generalized Laplace transform with the decomposition method was applied to gain the solution of nonlinear sine-Gordon and coupled sine-Gordon equations [15]; later the same technique was extended to solve a time-fractional partial differential equation [16]. In [17], the authors introduced the natural generalized Laplace transform decomposition method (NGLTDM) for obtaining analytical solutions to time-fractional linear and nonlinear dispersive dKdV-type equations. The author in [18] employed the natural generalized Laplace transform decomposition method (NGLTDM) to obtain the solution of the singular one-dimensional Boussinesq equation. Based on the aforementioned research, this article utilizes the new natural generalized Laplace transform (NGLT) and the double natural generalized Laplace transform (DNGLT) together with the decomposition method to investigate the solution of the time-fractional Navier–Stokes equation.
Observation: The abbreviations used in this study are as follows:
- (1)
- (GLT) as a replacement for ”Generalized Laplace Transform”.
- (2)
- (NT) as a replacement for ” Natural transform”.
- (3)
- (NGLT) as a replacement for ” natural generalized Laplace transform”.
- (4)
- (INGLT) as a replacement for ” inverse natural generalized Laplace transform”.
- (5)
- (NGLTDM) as a replacement for ” natural generalized Laplace transform decomposition method”.
- (6)
- (DNGLTDM) as a replacement for ” double natural generalized Laplace transform decomposition method”.
2. Important Ideas
This unit covers the most important definitions and properties of fractional calculus, as well as the single and DNGLT theory, which will be used throughout the article:
Definition 1
([11]). Let be integrable, for . The generalized integral transform of the function is denoted by
for, and .
Definition 2.
The Caputo time-fractional derivative operator of order is determined by
For additional details, refer to [19].
The NGLT is defined as follows.
Definition 3
([18]). Let and be functions of the definition of the (NGLT) of the functions and ; are granted by
and the DNGLT is defined by
where and indicate (NGLT) and (DNGLT) respectively and the symbols and s denote transforms of the variable and σ respectively.
Therefore, the inverse (NGLT) and (DNGLT) can be written, respectively, as
and
where the symbols and represent the inverse (NGLT) and (DNGLT) respectively.
Based on the definition of the natural generalized Laplace transform, we can derive the following transformation:
- 1.
- Setting , , we obtain the double Sumudu transform:
- 2.
- Setting , and , we obtain the double Laplace transform:
- 3.
- Setting , , and , we obtain the Laplace–Yang transform:
From the above remark, we conceded that the natural generalized Laplace transform is more general than other transformations.
The NGLT and DNGLT of the function and are proposed by and so, the NGLT and DNGLT of the partial derivatives and are presented by
and and are provided by
For further details, the reader is referred to [17]. The example below provides valuable support for the present analysis.
Example 1.
The NGLT of the function is given by
and
The following theorem is used to handle the singularities.
Theorem 1.
The NGLT of the fractional partial derivatives is denoted by
Proof.
By utilizing the definition of NGLT, we have
By utilizing the derivatives with respect to for Equation (9), we get
you can find the derivative inside the brackets like this:
By putting the right-hand-side of Equation (11) into Equation (10), we get
By arranging Equation (12), we have
The first integral on the right side of Equation (13) is the NGLT of the function and the second integral is the NGLT of
By manipulating Equation (14) and using Equation (5), we will obtain the proof for Equation (7) as follows
To establish Equation (9), we can use the derivatives concerning , so we have
Hence, Equation (15) becomes
Therefore
The proof is complete. □
3. Convergence Analysis and NGLTDM
This section of the article describes the foundational principles of the natural generalized Laplace transform decomposition method (NGLTDM), which is used to solve time-fractional partial differential equations.
Let us examine the following linear one-dimensional time-fractional partial differential equation along with its initial conditions condition:
and
Here denotes the Caputo fractional operator, L the linear differential operator, H the general nonlinear differential operator, and the external source term. To study the solution of Equation (17), we proceed through the following analytical steps:
- Step 1:
- Applying the (NGLT) yields the following form of Equation (17).
- Step 2:
- Employing Equation (5), we get
- Step 3:
- Multiplying Equation (20) by , one can get
- Step 4:
- Applying the inverse natural generalized Laplace transform to Equation (21)
- Step 5:
- For the linear component, the following formulation is employed:
For the nonlinear component, the formulation is expressed as follows:
where is given by
Putting Equations (23) and (24) into Equation (22), is granted by
where
Theorem 2 (Uniqueness Theorem).
Equation (17) has a unique solution, as long as , where
Proof.
Assume that is the Banach space of all continuous functions defined on the and the norm , then define in order that
Presume that and and additionally let
and
where are the Lipschitz constants with and are two various solutions of Equation (17). Hence
where
Therefore, the above inequality becomes
So, according to the Banach fixed-point theorem for contractions in [20], there is a unique solution to Equation (17). Since (), it follows that is a contraction mapping. So, the proof is complete. □
Theorem 3 (Convergence Theorem).
Proof.
To show that is a Cauchy sequence in let denote the partial sum sequence corresponding to Equation (23). Assume that
Given a partial sum sequence and , where and utilizing the triangle inequality, it follows that
from we notice that ; thus
and since is bounded, hence at . Hence, the sequence is a Cauchy sequence
Consequently, the sequence in the Banach space is . It follows that the series solution of Equation (23) converges, which completes the proof of the theorem. □
4. Analysis of the Natural Generalized Laplace Transform Decomposition Method (NGLTDM)
In this part of the paper, the NGLTDM is a mix of analytical methods that works well and is strong enough to solve fractional NSE.
In order to demonstrate the essential strategy of the NGLTDM, we consider the following time-fractional NSE
under the initial condition
where is the fractional Caputo derivative, , and the right-hand-side function is the source term. To utilize the NGLTDM, the following steps are required:
- Step 1:
- We multiply first Equation (29) by and obtain
- Step 2:
- Applying the NGLT on both sides of Equation (2), we have
- Step 3:
- Step 4:
- By employing the inverse NGLT for Equation (33), we get
5. Analysis of the Method of Double Natural Generalized Laplace Transform Decomposition Method (DNGLTDM)
The DNGLTDM is a powerful and adaptable approach for solving a wide range of fractional partial differential equations (FPDEs). It makes hard problems easier and offers exact series solutions for difficult cases. We discuss the following (2 + 1)-dimensional time-fractional NSE.
given the initial condition
where is the fractional Caputo derivative, k is defined as the kinematic viscosity of the flow. denotes dynamic viscosity and is density; and To get a solution for Equation (39), the following next steps are necessary.
- 1.
- By applying DNGLT for Equation (39), one can get
- 2.
- 3.
- 4.
- The DNGLTDM solution and are offered by the following infinite seriesTherefore, the nonlinear terms and are fixed by
- 5.
We derive a recurrence relation for the above equations by employing decomposition methods; we get
and the remainder of the components and are confirmed by
and
where indicates the DNGLT with respect to , and IDNGLT is denoted by with respect to . We indicated that ITGLT with respect to and s exist for Equations (47)–(49).
The few terms of the Adomian polynomials and are defined
Example 2.
Consider the following homogeneous NSE, with the condition given by
initial condition
The fractional derivative model is used to introduce the time derivative term; Equation (54) can be written in the form of
where By multiplying the above equation with , we have
by applying Equation (31) and Theorem 1, we get
By using the natural transform for the initial condition and substituting it in Equation (58), we obtain
By taking the integral for both sides of Equation (59) from 0 to u with respect to u and dividing the results, we obtain
Now the inverse natural generalized Laplace transform of Equation (60) is given by
We assume an infinite series solution of the unknown function is given by
Substituting Equation (62) into Equation (61), we get:
The zeroth component is suggested by the Adomian method and always contains the initial condition and the source term, both of which are assumed to be known. Accordingly, we put
The remaining components , are given by using the relation
by substituting into Equation (64), we get
Similarly, at
At we have
Thus, the solution for Equation (54) can be expressed as
The non-homogeneous time-fractional NSE.
The initial condition
Applying the natural generalized Laplace transform on both sides of Equation (65), and natural transform to the initial condition in Equation (66), we have
Using the formula for the geometric series, the terms and can be written in the form of
Operating with the natural generalized Laplace transform inverse on both sides of Equation (67) gives
If we use the method above, we can assume that the solution is an infinite series of the form Equation (35), so we have
The first several terms of the NGLTDM series are expressed by:
and
Hence, at we get
Following the same procedure
and
Therefore, the series solution is obtained as
When in Equation (4), the exact solution for the time-fractional Navier–Stokes equation takes the form
Table 1 presents the numerical error analysis at and . It is observed that the approximate solution is in excellent agreement with the exact solution. The absolute error remains extremely small across all time levels, confirming the high accuracy of the method. The very small values of the and error norms further validate the efficiency and stability of the proposed numerical scheme.
Table 1.
Numerical error analysis at , .
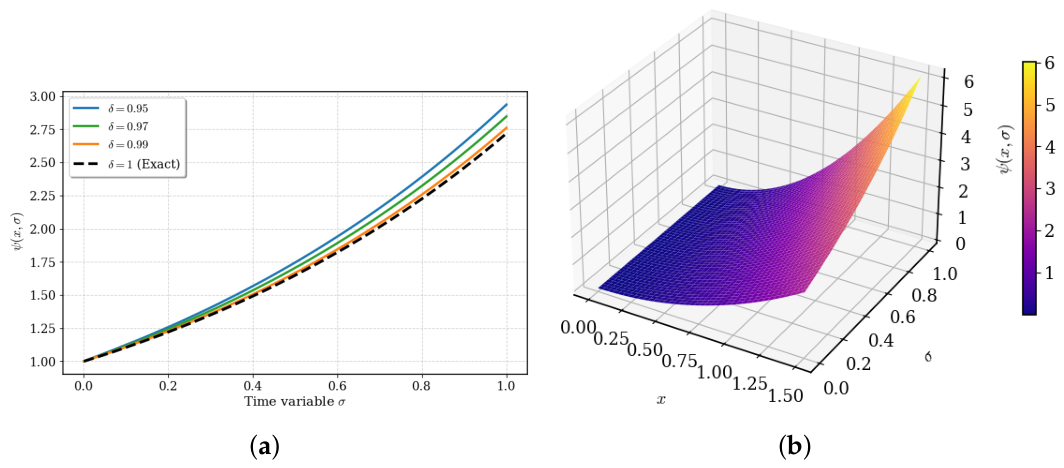
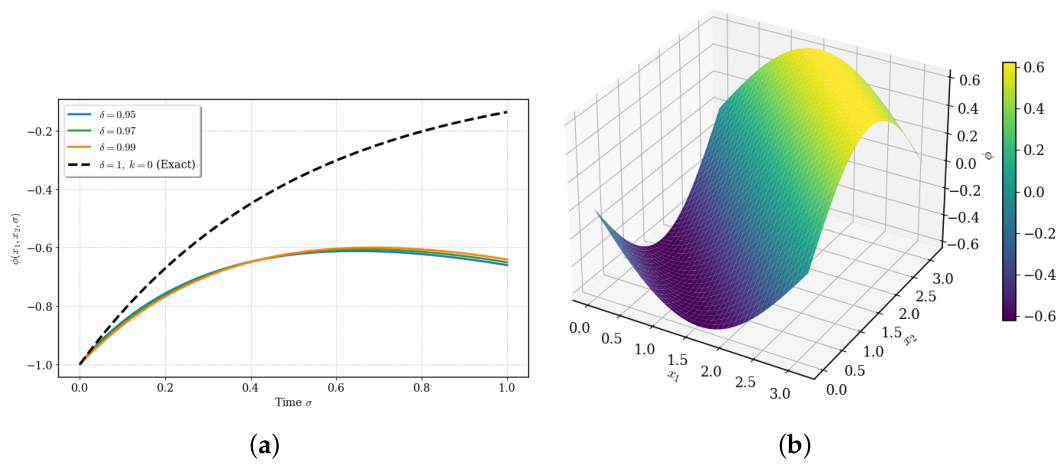
Figure 1a presents a comparison between the exact solution and the obtained numerical solutions of Equation (4) at . By taking , we obtain the exact solution, while for different values of such as , we get the approximate fractional solutions.
Figure 1.
(a) Exact vs. numerical solutions. (b) 3D surface plot of exact .
Figure 1b shows the three-dimensional surface plot of , illustrating the combined effects of the spatial variable x and the time variable on the evolution of the solution.
Example 3.
Let us consider the time-fractional, two-dimensional NSE:
under the condition
By invoking the DNGLT on both sides of Equation (70), we have
From the differentiation property of the natural transform, it follows that
By substituting the initial condition and arranging Equation (71), we have
After substituting the initial condition and rearranging Equation (72), we derive
The zeroth components and proposed by the Adomian method always include the initial condition and the source term, both of which are presumed to be known, so we set
The remaining components , are given by using the relation
and
The first several terms of the Adomian polynomials and are
By putting into Equations (74) and (75), we get
and
Similarly, at
and
In the same way, at we have
And by the same way
In a similar manner, we have
The solution to Equation (70) is given by
Hence, at and the exact solution of the classical Navier–Stokes equation is given by
Table 2 illustrates the comparison between the exact solution and the series approximation at and . It is observed that the approximate solution deviates significantly from the exact solution, as indicated by the relatively large absolute errors. Furthermore, the error norm and error norm are and , respectively.
Table 2.
Numerical error analysis at , .
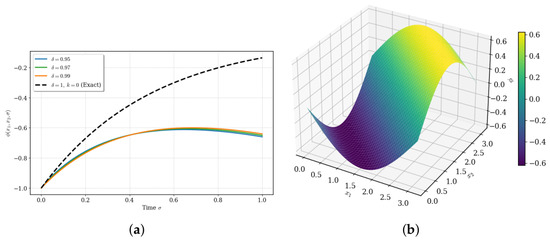
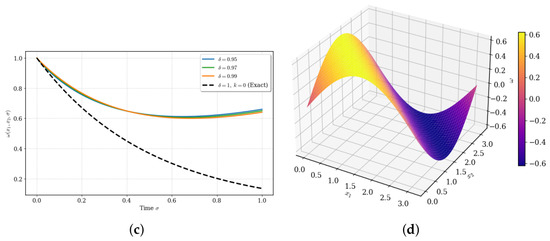
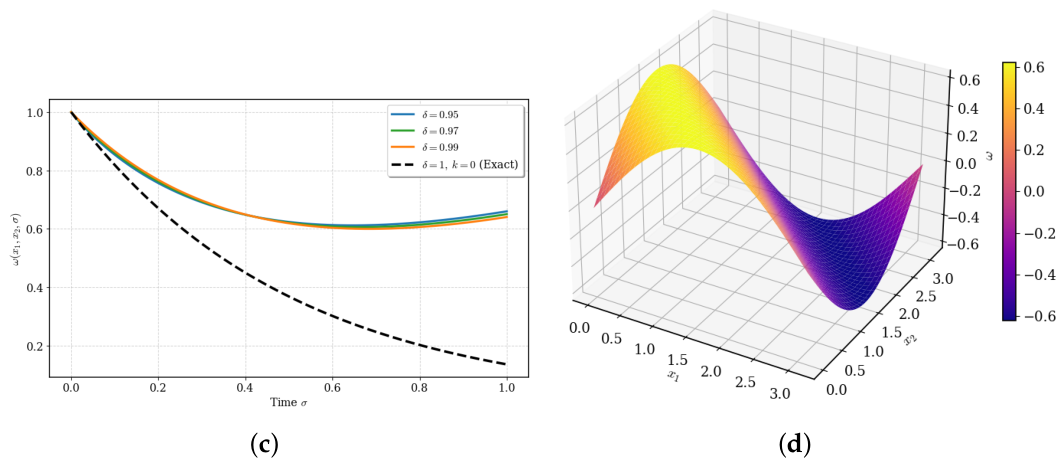
Figure 2a,b present a comparison between the exact solutions and the obtained numerical solutions of and at . By taking , we obtain the exact solutions, while for different values of , we get the approximate solutions.
Figure 2.
Comparison of the functions and in 2D and 3D views. (a) at . (b) 3D surface of . (c) 2D comparison of and . (d) 3D surface of .
Figure 2c,d show the three-dimensional plots of the functions and at , illustrating the combined effects of the spatial variables and on the evolution of the solutions in three dimensions.
6. Conclusions
This article employs the NGLTDM and DNGLTDM techniques for the time-fractional Navier–Stokes system of partial differential equations. These techniques facilitate the resolution of Caputo fractional-order differential equations and yield accurate solutions via iterative processes. We use Theorem 1 to deal with the singularities, Theorem 2 to make sure there is only one solution, and Theorem 3 to look into how solutions converge. Consequently, NGLTDM and DNGLTDM are instrumental in deriving both exact and numerical solutions to fractional NSE.
Funding
The authors would like to extend their sincere appreciation to the Ongoing Research Funding program (ORF-2026-948), King Saud University, Riyadh, SaudiArabia.
Data Availability Statement
The original contributions presented in this study are included in the article. Further inquiries can be directed to the corresponding author.
Conflicts of Interest
The author declares no conflicts of interest.
References
- Poincare, H. Memoires et observations. Sur l’equilibre d’une masse fluide animee d’un mouvement de rotation. Bull. Astron. Ser. I 1885, 2, 109–118. [Google Scholar]
- Wang, Y.; Zhao, Z.; Li, C.; Chen, Y.Q. Adomian’s method applied to Navier-Stokes equation with a fractional order. In Proceedings of the ASME 2009 IDETC/CIE, San Diego, CA, USA, 30 August–2 September 2009; pp. 1047–1054. [Google Scholar]
- Bazhlekova, E.; Jin, B.; Lazarov, R.; Zhou, Z. An analysis of the Rayleigh-Stokes problem for a generalized second-grade fluid. Numer. Math. 2015, 131, 1–31. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Zhou, Y.; Peng, L. Weak solutions of the time-fractional Navier-Stokes equations and optimal control. Comput. Math. Appl. 2017, 73, 1016–1027. [Google Scholar] [CrossRef] [Scilit]
- Kumar, S.; Kumar, D.; Abbasbandy, S.; Rashidi, M. Analytical solution of fractional Navier-Stokes equation by using modified Laplace decomposition method. Ain Shams Eng. J. 2014, 5, 569–574. [Google Scholar] [CrossRef] [Scilit]
- Mahmood, S.; Shah, R.; khan, H.; Arif, M. Laplace Adomian Decomposition Method for Multi Dimensional Time Fractional Model of Navier-Stokes Equation. Symmetry 2019, 11, 149. [Google Scholar] [CrossRef] [Scilit]
- Mukhtar, S.; Shah, R.; Noor, S. The Numerical Investigation of a Fractional-Order Multi-Dimensional Model of Navier–Stokes Equation via Novel Techniques. Symmetry 2022, 14, 1102. [Google Scholar] [CrossRef] [Scilit]
- Singh, M.; Hussein, A.; Tamsir, M.; Ahmadini, A.A.H. An analytical approach of multi-dimensional Navier-Stokes equation in the framework of natural transform. AIMS Math. 2024, 9, 8776–8802. [Google Scholar] [CrossRef] [Scilit]
- Albalawi, K.S.; Mishra, M.N.; Goswami, P. Analysis of the Multi-Dimensional Navier–Stokes equation by Caputo Fractional Operator. Fractal Fract. 2022, 6, 743. [Google Scholar] [CrossRef] [Scilit]
- Chu, Y.M.; Ali Shah, N.; Agarwal, P.; Dong Chung, J. Analysis of fractional multi-dimensional Navier–Stokes equation. Adv. Differ. Equ. 2021, 2021, 91. [Google Scholar] [CrossRef] [Scilit]
- Kim, H. The intrinsic structure and properties of Laplace-typed integral transforms. Math. Probl. Eng. 2017, 2017, 1762729. [Google Scholar] [CrossRef] [Scilit]
- Supaknaree, S.; Nonlapon, K.; Kim, H. Further properties of Laplace-type integral transform. Dyn. Sys. Appl. 2019, 28, 195–215. [Google Scholar] [CrossRef]
- Nuruddeen, R.I.; Akbar, Y.; Kim, H. On the application of G integral transform to nonlinear dynamical models with non-integer order derivatives. AIMS Math. 2022, 7, 17859–17878. [Google Scholar] [CrossRef] [Scilit]
- Shah, N.A.; Hamed, Y.S.; Abualnaja, K.M.; Chung, J.-D.; Shah, R.; Khan, A. A Comparative Analysis of Fractional-Order Kaup–Kupershmidt Equation within Different Operators. Symmetry 2022, 14, 986. [Google Scholar] [CrossRef] [Scilit]
- Eltayeb, H.; Mesloub, S. The New G-Double-Laplace Transforms and One-Dimensional Coupled Sine-Gordon Equations. Axioms 2024, 13, 385. [Google Scholar] [CrossRef] [Scilit]
- Eltayeb, H. Analytic Solution of the Time-Fractional Partial Differential Equation Using a Multi-G-Laplace Transform Method. Fractal Fract. 2024, 8, 435. [Google Scholar] [CrossRef] [Scilit]
- Eltayeb, H.; Aldossari, S.; Mesloub, S. A Note on Solutions of Fractional Third-Order Dispersive Partial Differential Equations Using the Natural Generalized Laplace Transform Decomposition Method. Fractal Fract. 2025, 9, 770. [Google Scholar] [CrossRef] [Scilit]
- Eltayeb, H. Application of Natural Generalized-Laplace Transform and Its Properties. Mathematics 2025, 13, 3194. [Google Scholar] [CrossRef] [Scilit]
- Bayrak, M.; Demir, A. A new approach for space-time fractional partial differential equations by residual power series method. Appl. Math. Comput. 2018, 336, 215–230. [Google Scholar] [CrossRef] [Scilit]
- He, J.H.; Elagan, S.K.; Li, Z.B. Geometrical explanation of the fractional complex transform and derivative chain rule for fractional calculus. Phys. Lett. A 2012, 376, 257–259. [Google Scholar] [CrossRef] [Scilit]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the author. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.