
Review

Augmented Finance for Climate Action: A Systematic Review of AI, IoT, and Blockchain Applications in Sustainable Finance
by
Nadia Mansour
Department of Finance, University of Salamanca, 37008 Salamanca, Spain
Int. J. Financ. Stud. 2026, 14(4), 91; https://doi.org/10.3390/ijfs14040091
Submission received: 1 December 2025 / Revised: 9 February 2026 / Accepted: 23 March 2026 / Published: 3 April 2026

Abstract

Through assessing the roles of artificial intelligence (AI), Internet of Things (IoT), and blockchain in augmented finance, a critical synthesis of the literature for addressing the complex financial challenges that accompany climate change is provided. This systematic review synthesizes the existing literature to identify how these technologies may help in the context of sustainable finance. Following the Preferred Reporting Items for Systematic Reviews and Meta-Analyses (PRISMA) guidelines, we reviewed and analyzed 42 peer-reviewed studies published between 2018 and 2025. Our results are applicable in three general areas: (1) increased measurement, reporting, and verification (MRV) of environmental impacts through employing IoT and blockchain to ensure transparency and traceability; (2) better physical and transition risk control using predictive AI modeling; and (3) better environmental, social, and governance (ESG) analysis and detection of greenwashing and risk reduction via alternative data. We highlight the power of these technologies to address problems such as information asymmetry and transparency gaps in impact chains. However, significant challenges such as algorithmic bias, difficulties associated with data governance, and regulatory delays persist. This study addresses this critical gap by synthesizing the evidence into a cohesive overview of the augmented finance landscape, identifying key challenges and priorities for future research. It also proposes a future research agenda with emphasis on impact assessment, algorithmic transparency, and impact on financial stability.

1. Introduction

The Intergovernmental Panel on Climate Change (IPCC, 2022) has reported that climate change poses a significant threat to the stability of the global economy and the financial system. The increasing frequency and intensity of climate-related incidents highlight the necessity for financial systems to effectively manage them (Bolton et al., 2020). As a result, the financial sector is facing increasing pressure to make sure that capital flows are in line with the goals of the Paris Agreement (Network for Greening the Financial System (NGFS), 2022).
There are systemic issues that are making this transition harder. For example, it is difficult to measure and confirm the effects of climate change, climate-related risks must be modelled, and greenwashing has made investors less confident (Berg et al., 2022; Campiglio et al., 2018). Traditional financial instruments and risk assessment methods often do not work well with the non-linearity and systemic nature of these problems (Weyant, 2017). Enhanced finance is a new way of doing things that goes beyond traditional fintech, which mostly automates tasks that are already being done.
This paradigm entails the systemic integration of disruptive technologies, including artificial intelligence (AI), the Internet of Things (IoT), and blockchain, to enhance the cognitive and operational capacities of financial entities (Hamdouni, 2025).
Augmented finance brings about this transformation through three capabilities: (1) cognitive augmentation, where artificial intelligence models capture unpredictability and identify weak signals within heterogeneous data for forward-looking analysis; (2) physical–digital integration, using the Internet of Things (IoT) to generate a verifiable, real-time digital representations of physical environmental impacts; and (3) decentralized trust certification, using blockchain to make climate impact chains’ auditability and traceability unchangeable, which lowers information asymmetries.
While traditional fintech primarily automates existing financial processes, sustainable finance sets an environmental goal, and augmented finance represents a means of transformation to achieve it. It is characterised by the integration of AI, IoT, and blockchain to improve the fundamental decision-making and operational capabilities of financial institutions facing climate-related complexities. This paradigm is conceptually based on several theories, including complexity theory (which explains the need to model non-linear risks for AI, (Turner & Baker, 2019), the economics of institutional and transactional costs (which explains the role of blockchain and IoT in creating new verification frameworks and reducing costs), and signalling theory (which explains the role of AI in verifying corporate sustainability claims, (Alexander & Belloni, 2024).
Artificial intelligence is already being used to model physical and transition threats by looking at data like business reports and satellite images (Battiston & Monasterolo, 2020; Giglio et al., 2021). Indeed, the IoT paradigm supports real-time tracking of environmental parameters, including carbon emissions, with the ability to provide data support to green bonds and carbon markets (Jia & Bo, 2025; Frikha & Mrad, 2025). Conversely, Blockchain achieves trust and openness by implementing smart contracts that provide automatic verification and enabling the use of distributed ledgers that eliminate double-counting in carbon credit markets (Mei et al., 2025; Hyun, 2024). As of 2018, academic research was yet to be done extensively in terms of how blockchain technology, artificial intelligence, and the Internet of Things could work together to help the financial industry combat climate change (Gomber et al., 2018). Thus, this analysis specifically aims to cover this domain and explore the research questions of: In academia, how is AI, IoT, and blockchain technology being leveraged and applied to address the mitigation and adaptation of the climate change problem of the financial sector?
This study is the first systematic synthesis of how AI, IoT, and blockchain are being leveraged in climate-aligned finance. It combines empirical data to find new themes and problems that still need to be solved. It also contributes to the field by synthesizing the literature to clarify how augmented finance can support climate action and by proposing a future research agenda focused on impact assessment, algorithmic transparency, and systemic risk. Finally, specific and concrete recommendations are provided for various stakeholders (researchers, policymakers, financial institutions), improving both academic and practical discourse.
The remainder of this article, which sets out to answer the questions posed above, is structured as follows. Section 2 presents the methodological process, while Section 3 outlines the results and summary. Section 4 presents the synthesis, implications, and future research directions. Finally, Section 5 presents the conclusions.

2. Systematic Review Methodology

This study involved a systematic review, which is effective for conducting a thorough investigation in a specific field, following the instructions of Khatib et al. (2023).
Systematic literature reviews are a strong method that is widely used in the social sciences (Petticrew & Roberts, 2008; Khatib et al., 2023) and finance because they decrease the possibility of generating subjective or biased conclusions.
According to Sierra-Correa and Kintz (2015), there are three main benefits to doing a systematic review: (1) It helps you come up with a clear research question so you can do a thematic analysis of the system in question; (2) it makes you set criteria for what content should be included and what should not be included; and (3) it gives you a way to check your work.
The Systematic Literature Review (SLR) process commenced with the formulation of appropriate review inquiries in alignment with PRISMA guidelines. A three-phase document search strategy was devised and executed, encompassing identification, screening, and eligibility phases.

2.1. PICOS (Population, Intervention, Comparison, Outcome, Study Design) Identification

This study follows the rules for systematic reviews (Page et al., 2021); specifically, the PICOS (Population, Intervention, Comparison, Outcomes, Study Design) identification was used to organize the research question.
  • Population: The financial sector and the people and businesses that work with it, such as banks, insurers, and capital markets.
  • Intervention: The use of AI, IoT, and/or blockchain by banks and other financial institutions.
  • Comparison: Conventional financial methodologies versus those employing technological innovations.
  • Results: Effects on fighting climate change, adapting to it, managing climate risk, being open about ESG issues, and the fight against greenwashing.
  • Study design: Empirical or theoretical scholarly works that have been reviewed by peers.
The PRISMA recommendations endorse the employment of this synthesis to ensure a systematic and organized methodology (Page et al., 2021).

2.2. Plan for Research

The identification step looked at synonyms, related words, and different forms of the study’s keywords, which were “augmented finance” and “climate action.” This made it possible to search the databases more broadly, which helped us find more articles that were relevant to the study area. We chose the keywords based on Okoli’s (2015) method, other academic research, and the Scopus criteria.
An intensive search was performed in June 2025 on the following databases: Scopus, Web of Science, ScienceDirect, and JSTOR databases.
While supporting technical resources such as IEEE Xplore and the Association for Computing Machinery (ACM Digital Library) might contain studies on IoT and blockchain, we focused on databases that address both sustainable finance and environmental economics. As our research and analysis are interdisciplinary, covering finance, climate science, and technology, the focus of this conclusion was not only a comprehensive overview but also to remain somewhat pragmatic. To analyze the new concept of “augmented finance,” the search terms included specific technological keywords (AI, IoT, blockchain) as well as broader thematic concepts (climate change, green finance, ESG). The Boolean query provided in Table 1 was used.

2.3. Eligibility Criteria

The inclusion criteria stated that publications:
(i)
Must be written in English. Although the English-language criterion is the standard for systematic review feasibility, we recognise that it may exacerbate geographical bias by excluding innovative work published in local languages, further highlighting the “relevance gap” identified in our findings;
(ii)
Published between 2018 and 2025;
(iii)
Peer-reviewed;
(iv)
Focused on the intersection of climate finance and at least one of the specified technologies (AI, IoT, or blockchain).
To assure the synthesis’s quality, a stringent methodology was established via a three-point quality evaluation:
(1)
the existence of a distinctly articulated research design (empirical, case study, or structured conceptual framework);
(2)
the utilization of validated data sources (e.g., official financial reports or standardized datasets);
(3)
a clear elucidation of the analytical tools or algorithms employed.
Papers that provided only anecdotal evidence, hypothetical commentaries, or did not have a structured analysis section were excluded. Non-scientific papers (editorials, conference abstracts, theses, white papers) also were removed, in order to maintain this study’s academic credibility. The filtered results were derived from 42 core articles selected from the original search outcomes, resulting in findings that can be validated according to the best-quality peer-reviewed evidence. The study period was determined to identify the most recent and relevant articles focused on the maturation of key technologies (e.g., AI and blockchain) and their application in the financial sector.
To ensure methodological rigour and consistency throughout the selection process, we have established clear definitions for the fundamental concepts underlying this study. ‘Climate finance’ was defined as financial activities and instruments—including investments, loans, insurance, and risk management—aimed at climate change mitigation, adaptation, or resilience. Green finance was considered a more specific subset, focused on allocating capital to projects with a favourable environmental impact, such as green bonds. Studies emphasising broad sustainability (ESG) were only included when there was a direct link to climate or environmental impact.
The concept of ‘alternative data’ was defined in line with its established usage in contemporary financial research (Sun et al., 2024) as non-traditional digital data sources (satellite imagery, IoT sensors) used to generate insights beyond conventional financial reporting. This data encompasses data streams from satellites and sensors (IoT), as well as digitised text from corporate communications and regulatory filings, which AI is increasingly analysing to obtain climate-related insights.
These definitions guided our research strategy, but the final decision to include each study was based solely on its primary focus: the intersection of climate-aligned finance with the application or analysis of at least one of the three core technologies (AI, IoT, or blockchain).

2.4. Data Selection

The selection process1 began with an initial compilation of 584 articles. To ensure the objectivity and reproducibility of the selection process, a systematic two-stage selection protocol was rigorously followed. An initial selection of titles and abstracts was made based on eligibility criteria. All studies that passed this stage underwent a full assessment. Throughout both stages, a detailed procedure was followed to document inclusion/exclusion decisions, thus ensuring consistent application of the predefined criteria and enhancing the transparency of the review process.
After eliminating duplicates and further review, 42 articles were ultimately included in this study. The selection process is summarized as a PRISMA diagram in Figure 1, which facilitates complete traceability of the selection process and meets the methodological standards required for a high-quality systematic review.

2.5. Thematic Analysis Procedure

Then, data extraction took place with the help of a standard table. This table included the names of the authors, the year the work was published, the methods used in the research, the technologies used, the main findings, and the limitations that were found. After collecting the data, we completed a thematic synthesis to group the 42 studies into concepts. This method of analysis had the following steps (Calvo et al., 2025):
-
Familiarization: A review of the selected research.
-
Coding: Categorizing the key regions identified in each inquiry.
-
Theme development: Grouping codes into themes based on their conceptual affinity and frequency.
-
Validation: Determining the representativeness of the themes in the dataset collected from 42 articles.
This process resulted in the identification of three principal topics that guide the organization of the subsequent Results section:
-
Improved measurement, reporting, and verification (MRV);
-
Using AI to deal with climate risk;
-
Evaluating ESG and stopping greenwashing.
These themes show how AI, IoT, and blockchain are often used in climate-aligned finance, as shown by specialized publications.

3. Results and Summary

Examination of the 42 selected articles revealed an emerging but constantly evolving field of research, as shown in Table 2.
The 42 studies were categorized into three emerging themes identified through iterative content analysis: (1) MRV; (2) climate risk management; and (3) ESG analysis and greenwashing detection. These themes represent the principal challenges outlined in the literature.
Table 3 shows a pronounced geographical concentration in research, with approximately 85% of studies focused on industrialised countries, while emerging countries account for only about 5% of the literature. This imbalance is not merely a descriptive observation but represents a significant limitation of the current knowledge base. On the one hand, it limits our understanding of context-specific applications.
On the other hand, it creates a risk of a ‘relevance gap’ in solutions, whereby technological synthesis developed for advanced economies may not respond to the specific challenges and opportunities of emerging countries.
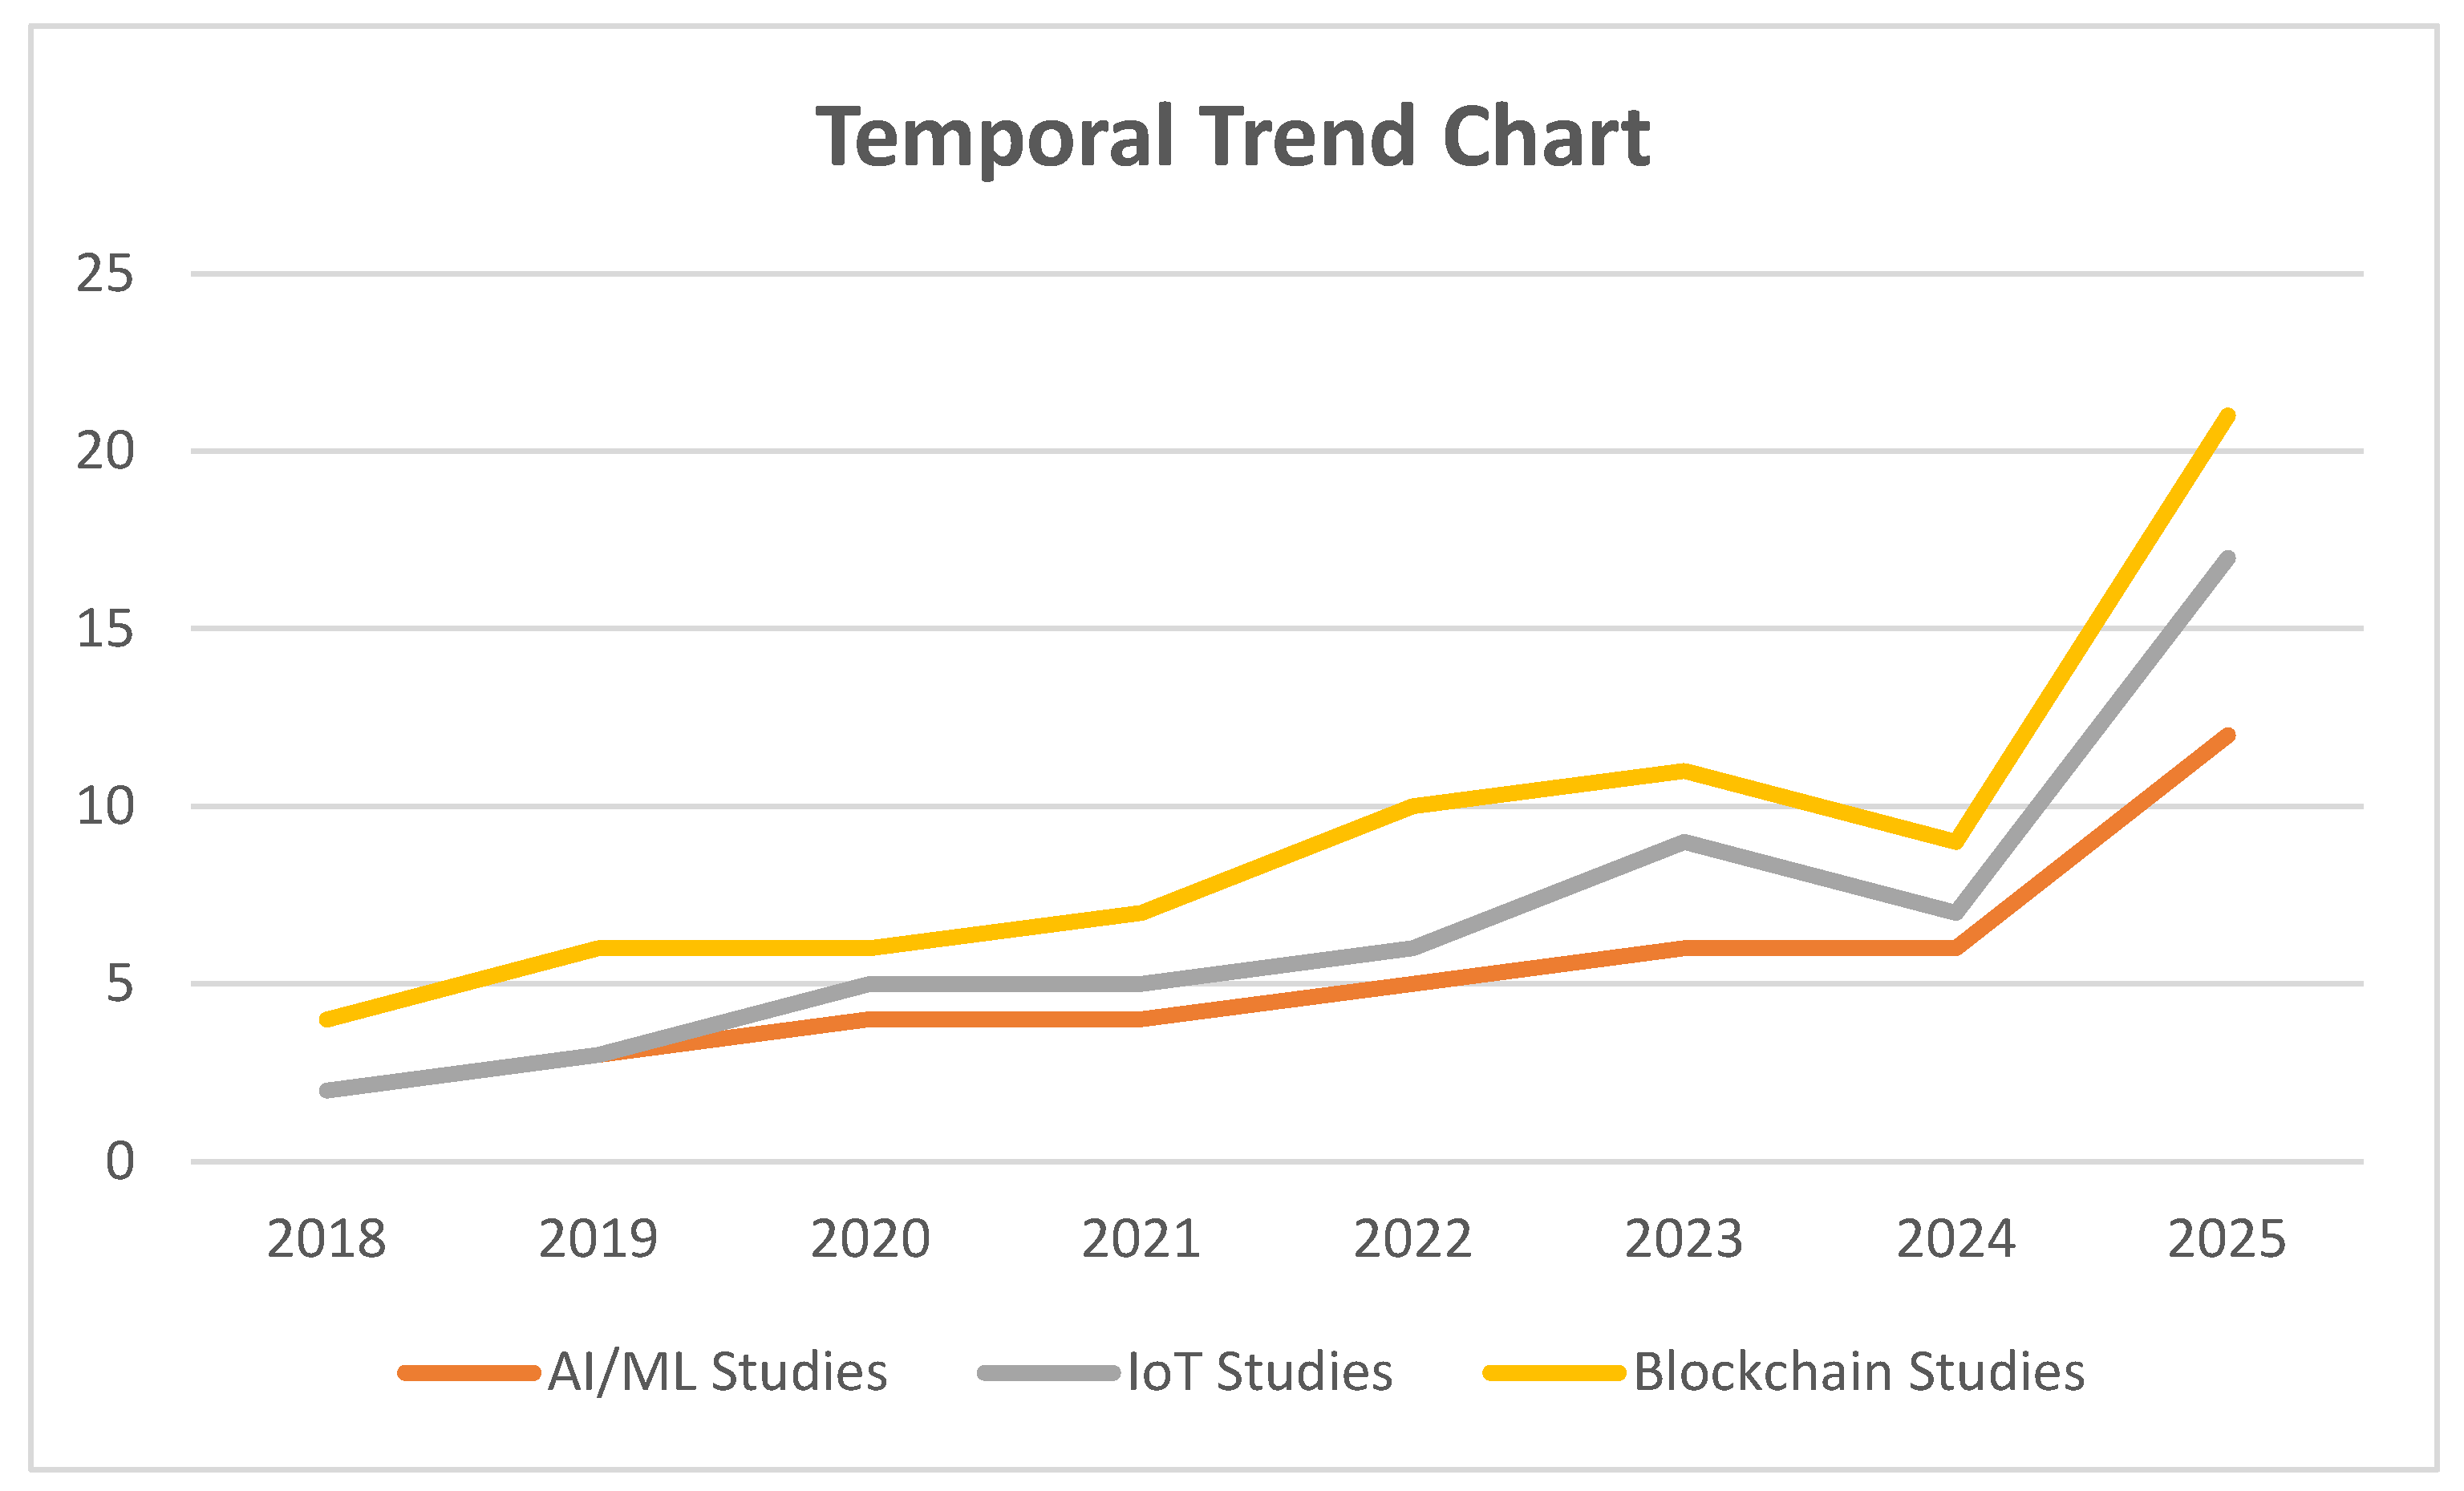
The temporal study showed a lot of change: blockchain publications were among the most prominent from 2018 to 2020 (green finance, tokens), and AI became so prevalent from 2022 onward (climate concerns, NLP). The Internet of Things is still stable. This shows that analytical applications are becoming more complicated.
The under-representation of developing nations in the augmented finance literature is a critical barrier to the achievement of global climate goals. To overcome this discrepancy, we support “Technology Leapfrogging” initiatives that prioritize blockchain-based micro-insurance and IoT-driven agricultural loans in places with limited access to traditional banking. Policymakers should create “Regulatory Sandboxes” for Green Fintech in the Global South to allow for the localized testing of AI risk models.
The analysis of methodological approaches revealed a predominance of non-linear models, as presented in Table 4 below.
In classification terms, non-linear models rely on data-driven inductive methods (machine learning (ML), deep learning (DL), or natural language processing (NLP)) and do not adopt a specific functional form (Razzaq & Shah, 2025). Linear models consisted of classical hypothesis-based statistical methods (e.g., regression) and rule-based procedures that adhere to explicit logic (Gorriz et al., 2026). Mixed methods include studies that merge nonlinear-based methods with linear models, or that combine quantitative analysis with qualitative data sources (e.g., case studies, interviews) as part of an overall research design (Dewasiri et al., 2018).
Quantitative approaches—chiefly machine learning and other more sophisticated data analysis tools—were the most commonly studied. In contrast, qualitative designs are necessary for understanding the situation. Hybrid approaches are gaining popularity as they can provide more complete and detailed information. The findings also showed that various fields of study typically have specific areas of specialization. For example, research in North America focused mainly on ESG analysis, identifying greenwashing, and AI ethics; research in Europe considered blockchain applications, regulatory frameworks, and climate risk assessment; and research in Asia studied IoT monitoring, fintech innovation, and tracking emissions. In other fields, a focus is put on specific applications and singular use-cases, thereby beneficially giving the sector an advantage of more area-specific knowledge.
The quantitative data pointed to a tendency toward non-linear methods with the use of AI over 50% of new research projects. This highlights the fact that modern augmented finance research, at its core, relies on machine learning to model intricate systemic hazards. Mixed-methods research is widespread here due to a natural inclination for AI and hybrid approaches to be used in conjunction with other technologies in a helpful and productive manner.
Table 52 details how the chosen studies were distributed based on their main technological focus.
The analysis shows that the three main technologies ignore sufficient focus on similar issues. Artificial intelligence and machine learning account for the most (57.1%), which shows how important they are for climate finance data analysis, forecasting, and automation.
Blockchain technology is a popular (26.2%) solution for transaction frameworks, adding transparency, traceability, and even security. At the same time, the Internet of Things, while appearing in a lower proportion (16.7%) of studies, plays an essential role in real-time data collection and monitoring. In particular, integration of these technologies is becoming more common; for example, as indicated by several studies that have merged IoT and blockchain to create integrated solutions.
The synthesis of empirical research shows that ‘Augmented Finance’ has measurable results. Example: Combining blockchain and smart contracts has been associated with a 70% reduction in green project verification costs (Luna et al., 2024). In comparison, artificial intelligence-driven logistics optimization has resulted in a 15% reduction in carbon footprint (Zhang et al., 2024).

3.1. Enhancing Measurement, Reporting, and Verification (MRV)

The existing literature underscores the pivotal functions of the Internet of Things (IoT) and blockchain technology in establishing irrefutable “field truth,” thereby addressing the fundamental data credibility crisis in environmental finance. This aligns with institutional theory (North, 1991), which emphasizes how technological innovations can create new institutional synthesis for verifying and enforcing agreements. Some researchers have illustrated how IoT sensors and satellite data facilitate real-time, asset-level measurement, moving beyond traditional estimated data to furnish financiers with information of unprecedented granularity (Jia & Bo, 2025; Frikha & Mrad, 2025).
Additionally, blockchain technology can be used to establish immutable registries for carbon credits and tokenized green bonds (Mei et al., 2025; Hyun, 2024)—a notion rooted in transaction cost economics (Williamson, 1985), which significantly diminishes verification and enforcement expenses.
Zhang et al. (2024) have shown that this convergence helps to establish a technological framework that directly resolves significant information asymmetries, improving market integrity and perhaps increasing liquidity for green assets.

3.2. Using AI to Manage Climate Risk

AI (artificial intelligence) is expected to become the best way to analyze and measure the intricate, non-linear parts of climate-related financial concerns in the near future.
Its applicability is grounded in complexity theory (Simon, 1962), which elucidates and models systems exhibiting non-linear, emergent behaviors, including the relationship between climate and finance.
Machine learning techniques can assist in evaluating physical risks by analyzing extensive datasets to predict portfolio exposure with unmatched precision (Battiston & Monasterolo, 2020; Giglio et al., 2021). Bingler et al. (2022) recently used NLP to look at the quality of company climate reports and found big differences between what was said and what was actually done.
Simultaneously, regarding transition risks, AI-driven text analysis has been performed to methodically assess the strategic alignment of businesses with climate scenarios (Bingler et al., 2022), utilizing signaling theory (Spence, 1973) to differentiate between genuine promises and insincere “cheap talk.” Giglio et al. (2021) have found that AI technologies are drastically transforming climate risk management from a qualitative, retrospective practice to a predictive discipline.

3.3. ESG Analysis and the Mitigation of Greenwashing

With both ESG ratings and the risk of greenwashing rising, AI offers investigators more tools than traditional reporting tools. This process is underpinned by legitimacy theory (Suchman, 1995), which reflects how organizations manage their perceptions and how outside verification can keep them legitimate.
A study (Grewal et al., 2019) has documented the contemporary application of NLP to analyze alternative data sources in order to uncover controversies not present in sustainability reports. A more recent study (Marquis & Toffel, 2016) has developed algorithms capable of identifying semantic dissonance between the environmental assertions of organizations and their actual practices (Marquis & Toffel, 2016; Boedijanto & Delina, 2024), sufficient for the detection of greenwashing. Khlifi et al. (2025) showed that AI methods can have a more dynamic measure of non-financial performance.
This capability strengthens market integrity and helps investors hold companies accountable. According to stakeholder theory (Freeman, 1984), these technologies have the potential to create a financial ecosystem that serves a broader set of interests, including those of communities, employees, and the environment itself. Nevertheless, the literature presented here shows that the focus is primarily on protecting investor value and optimising risk-adjusted returns. There is still a notable gap: future research should specifically explore how AI, IoT, and blockchain can be designed and deployed not only to detect corporate misrepresentation but also to identify, assess, and mitigate the disproportionate climate risks faced by vulnerable stakeholders, thereby aligning augmented finance with the principles of a just transition and equitable resilience.
For instance, Ghaemi (2025) provides 94% accuracy using transformer-based NLP to detect false environmental claims. Hong and Kim (2025) also employed AI for corporate net-zero commitments to analyze them: in this regard, they showed a gap between what companies professed and what they have actually done. Such research bears witness to a more recent trend where AI plays a crucial role in evidence-based verification of ESG responsibility for corporations and bridges credibility gaps in corporate sustainability disclosures.

3.4. Methodological Challenges and Future Directions for AI in Climate Finance

To understand the evolution of research emphasis, we analyzed the yearly distribution of the 42 reviewed studies by their primary technological focus (Figure 2).
The 42 studies reviewed demonstrated that research efforts have expanded greatly from 2018 to 2025. While the number of studies on blockchain, IoT, and AI/ML are all increasing, blockchain has been the most talked-about technology overall with the most annual publications. Interestingly, an exponential growth period across all categories can be observed from 2024 to 2025, indicating that the combined use of these technologies has transcended from an academic topic to a necessity in addressing the global demand for comprehensive, data-driven ESG verification and mitigation of greenwashing. However, there remain problems hindering the rapid deployment of AI/ML in the context of climate finance.
The ability of these technologies to achieve such results is seriously constrained by issues relating to the quality and representativeness of the data; particularly when considering emerging markets and small- to medium-sized businesses, both of which are generally poorly represented in datasets for training purposes. Complicated models such as deep learning networks are “black boxes” that cannot be fully understood, considered trustworthy, or checked—critical features in regulatory and investment situations. Moreover, AI/ML models might also face problems when attempting to model long-term climate hazards that are non-linear and deviate from prior trends, potentially causing them to underestimate tail risks or systemic disruptions. These constraints drive the need for explainable AI (XAI) synthesis, comprehensive bias-auditing practices, and hybrid modeling methodologies that combine expert judgment with algorithmic results to ensure the reliable, equitable, and responsible use of such technologies in sustainable finance.

3.5. Theoretical Synthesis: Different Perspectives on Augmented Finance

The studies we evaluated place augmented finance at the intersection of numerous schools of thought, providing examples of how AI, IoT, and blockchain interact, not in isolation, but as part of a technological and institutional response to the failures of climate finance.
The synthesis proposes a coherent system in which each theoretical strand describes a different aspect of change, collectively anchoring augmented finance in established economic and social sciences.
Institutional theory (North, 1991) and transaction cost economics (Williamson, 1985) provide the structural and economic basis: they illustrate how blockchain and IoT together create new verification infrastructures and “rules of the game” for environmental markets. Blockchain establishes not only immutable but also decentralised ledgers that redefine trust, while IoT provides verifiable real-time data from tangible assets. Together, they directly reduce information asymmetry and significantly lower monitoring, verification and enforcement costs, which are the main transaction costs that have hampered carbon markets and green finance.
Signalling theory (Spence, 1973) and legitimacy theory (Suchman, 1995) cover informational and behavioural elements. When companies report on their sustainability credentials to be considered respectable players, AI, particularly natural language processing (NLP), provides an essential level of verification.
It examines corporate communications, alternative information, and operational performance to detect discrepancies between sustainability signals and actual results, thereby amplifying accountability and shifting the basis of legitimacy from discourse to evidence.
Complexity theories (Simon, 1962) support the logical and predictive necessity of AI/ML. They explain why traditional linear models fail: climate finance systems are complex, with non-linear processes and emerging risks.
AI/ML therefore provides a model of how these complex systems work, from predicting the financial cascades of physical climate impacts to mapping the network effects of transition risks, thus promoting a predictive rather than reactive approach to risk management.
Finally, stakeholder theory (Freeman, 1984) provides a normative and ethical guide. It proposes that the ultimate goal of these technologies should be to act on a wide range of stakeholders—vulnerable populations, future generations, and global natural systems—and not just shareholders. This theory fills an important gap in the existing literature, which is mainly focused on investor-oriented uses. A truly transformational reconfiguration will require more explicit technological design to create technologies that combat inequality and direct capital towards priority climate needs, ensuring that increased funding, by implication, lives up to its goal of more equitable climate action.
When combined, these theories converge to create a coherent theoretical architecture: the structural framework (institutional/transactional cost) builds trust and reduces friction; the informational framework (signalling/legitimacy) ensures the credibility of data and claims within this structure; the analytical framework (complexity) provides the cognitive resources needed to deal with the complexity of the system; the normative framework (stakeholders) guides the entire movement towards a legitimate social goal. In this sense, augmented finance is seen as more than just a matter of technology; it involves a multi-level reconfiguration of institutions, theoretically positioned to address complex socio-environmental issues, not just technological ones.

4. Synthesis, Implications, and Future Research Directions

This systematic review synthesizes an emerging body of evidence to demonstrate how augmented finance can transform the world and the degree to which it carries both a great deal of promise and many issues which are yet to be solved. The analysis of the chosen cases emphasizes the centrality of this domain, as well as indicating a substantial change in the core of the financial system in response to the most pressing market issue of our time: climate change.
These technologies enhance the cognitive capacity of financial professionals, providing deeper visibility into complex risk landscapes. Furthermore, they allow for a major change from a system that funds the economy to one that needs to be focused on a long-term future.

4.1. Thematic Synthesis and Observed Technological Synergies

In an analysis of 42 studies examined, we find that implementation of AI, IoT, and blockchain in climate-related finance centers around three key thematic challenges; (1) the enhancement of measurement, reporting, and verification (MRV) of environmental impacts; (2) the improvement of climate-related financial risk identification and mitigation; and (3) the development of ESG analysis and mitigating greenwashing. Although the literature mainly addresses the utility of each technology to address these issues in isolation, a cross-thematic synthesis indicates that they function together, suggesting a formidable, synergistic potential.

4.1.1. Enhanced Measurement, Reporting, and Verification (MRV)

The literature underscores a fundamental data credibility crisis in environmental finance. Studies highlight how IoT and remote sensing provide a leap from estimated to verifiable, asset-level data in real-time (Jia & Bo, 2025; D’Orazio, 2022), creating an irrefutable “field truth.” Concurrently, blockchain is theorized and piloted as a solution for establishing immutable, transparent registries for carbon credits and tokenized green bonds (Mei et al., 2025; Hyun, 2024). This dual application aligns with institutional theory (North, 1991) and transaction cost economics (Williamson, 1985), suggesting these technologies can create new institutional synthesis that drastically reduce the costs of verification and enforcement in environmental markets.
The transition goes from building conceptual mapping to delivering real-world, impactful results, as shown by 30% improvements in the accuracy of carbon credit price forecasting in LSTM networks (Dong et al., 2023). and 92% accuracy in automated greenwashing detection (Moodaley & Telukdarie, 2023).

4.1.2. AI-Driven Climate Risk Management

A significant portion of the literature positions AI and machine learning as essential tools for modeling the complex, non-linear nature of climate-related financial risks, grounded in complexity theory (Simon, 1962). Applications range from using network models to identify “hotspots” of physical risk in sovereign bond portfolios (Battiston & Monasterolo, 2020) to employing natural language processing (NLP) to assess the quality and strategic alignment of corporate climate disclosures (Bingler et al., 2022; Giglio et al., 2021). Here, AI’s role is cognitive augmentation, parsing vast datasets to transform risk management from a qualitative, retrospective exercise into a predictive discipline.

4.1.3. ESG Analysis and Greenwashing Mitigation

As discrepancies between ESG ratings and corporate greenwashing are increasingly highlighted, the literature shows the rapid adoption of AI, including NLP, to analyse alternative sources of data and corporate communications. This strategy, which draws on signalling and legitimacy theories (Spence, 1973; Suchman, 1995), helps to recognise the semantic dissonance between corporate discourse and practices (Grewal et al., 2019; Boedijanto & Delina, 2024). The studies mentioned suggest that this AI-assisted review enhances accountability by forcing companies to comply with the stakeholder theory framework (Freeman, 1984) through more fluid and empirical verification of ESG performance.
At this point, to conclude, although the studies we reviewed provide compelling proof of concept (e.g., a more granular view of IoT data, improved predictive accuracy, reduced transaction costs through blockchain), there is little empirical and longitudinal evidence directly linking these deployments to concrete, large-scale climate outcomes. This indicates a significant ‘impact gap’: a disconnect between the quantification of technological outcomes and the verification of environmental outcomes, such as measurable reductions in greenhouse gas emissions or measurable increases in the resilience capital of disadvantaged communities. So, the central challenge for augmented finance is to bridge this gap, enabling it to move from a promising paradigm to a validated tool for climate action.

4.1.4. Toward an Integrative Logic: The Synergy of Augmented Finance

It should be noted that most of the literature reviewed treats applications in isolation, but a synthesis of this work reveals a coherent architecture that allows for systematic integration. At this level, each technology plays a distinct but interdependent role: the Internet of Things (IoT) generates verifiable data in real time from physical assets and the environment; blockchain provides an immutable ledger that guarantees data integrity, provenance and auditability; and artificial intelligence (AI) acts as the cognitive layer by analysing this verified information to generate insights, predict risks and automate decisions.
Their interaction forms a closed-loop system. For example, IoT sensors can continuously monitor greenhouse gas emissions at a renewable energy site. This data is recorded on a blockchain, creating a tamper-proof ledger. An AI model then analyses this data stream along with market and climate variables to dynamically price the carbon credits generated. Finally, a blockchain-based smart contract can automatically execute the sale and transfer of credits. This continuous flow, from measurement (IoT) to verification (blockchain) via analysis and automation (AI), reveals the role of integration in directly addressing the main challenges of climate finance: it replaces estimates with verified data, opaque declarations with transparent records, and manual processes with intelligent automation.
This leads to the emergence of a new paradigm, called “augmented finance”, which goes beyond simple task automation. Augmented finance aims to resolve information asymmetries and trust issues that currently prevent capital from aligning with climate goals by improving financial systems through technology. The subsequent discussion will explore the barriers to this integration and the significant research gaps that must be addressed to realize its potential.

4.2. Key Barriers Identified in the Literature

The reviewed studies reveal several interconnected hurdles that may affect the efficacy, equity, and stability of technology-enhanced financial systems.
Ethical and Operational Hazards of AI: A well-documented concern in the literature is algorithmic bias that can reinforce existing inequalities (Dignum, 2019). Research has highlighted the phenomenon of biased data representation, with models typically trained on data from developed economies, leading to systematic mispricing of risks in Southern countries (Battiston & Monasterolo, 2020). This bias is not just a technical flaw; it has real consequences, diverting capital away from regions vulnerable to climate change or exposing them to disproportionate risk in projects in emerging markets, thereby exacerbating global climate inequalities. Furthermore, the ‘opaque’ nature of sophisticated AI models also creates significant gaps in accountability and recourse (Adadi & Berrada, 2018). When an AI system denies a green loan or assigns a high-risk rating, the lack of explainability compromises regulatory oversight, weakens due process, and affects stakeholder confidence, all of which are essential to reliable financial decision-making.
Data Governance and Interoperability Challenges: The literature highlights a fragmented data ecosystem. The lack of common IoT data formats and interoperability protocols for blockchain creates ‘data silos’ that hinder the holistic assessment of climate risks and the scaling up of integrated solutions (D’Orazio, 2022). This fragmentation has a direct operational impact: it limits financial institutions’ ability to create a comprehensive, systemic view of climate exposure. Studies also highlight unresolved tensions between the demand for radical transparency (e.g., through satellite imagery) and legitimate commercial and individual privacy rights (Zetzsche et al., 2020), creating a legal and ethical friction point for implementation.
Regulatory and Policy Gaps: The regulatory frameworks developed for traditional financial products (Zetzsche et al., 2020) are now obsolete due to the rapid evolution of technological applications. The literature highlights serious gaps in the legal status of blockchain-based assets, the compatibility of dynamic AI-based valuations with static and periodic reporting regimes, and the monitoring of potential systemic risks arising from correlated algorithmic failures. This regulatory lag introduces considerable uncertainty for innovators and investors, which could hinder the very deployment of these promising technologies. In the absence of clarity, financial institutions may be reluctant to adopt these new tools on a large scale.
Geographical Imbalance in Research and Application: The study reveals a significant geographical imbalance, with approximately 85% of studies concentrated in developed countries and only 5% in emerging economies (see Table 3). This situation is not only a descriptive gap, but also a fundamental ‘relevance gap’ that risks undermining the global value of augmented finance (Atkinson & Atkinson, 2023).
Indeed, ultra-high-speed technological infrastructures and universal digital identifiability, as well as stable energy networks, may fail in emerging areas due to a lack of electricity, networks and the internet. Institutionally, solutions based on strong regulators, deep financial markets and standardised corporate reporting may not be suited to less formal forms of governance or economies where informal sectors continue to dominate. Economically, the model calibrated for large corporations and institutional investors may not apply to smallholder farmers, micro-enterprises and community programmes, which are essential for climate resilience from the outset and particularly important in the Global South. This shortcoming could turn augmented finance into an algorithm aimed at improving the climate portfolio of a global financial centre, rather than ensuring that capital is allocated to the areas most vulnerable to climate change (Hussainzad & Gou, 2024).

4.3. Implications and Directions for Future Research

Given the summary and the identified obstacles, the literature review highlights the main gaps that could form an agenda for future work. This work will need to focus on these interrelated areas to maximise the potential of augmented finance.

4.3.1. Priority 1: Bridging the “Impact Gap”

There is still a significant gap between the literature that measures specific outcomes, such as data granularity or model accuracy in the technological domain, and the literature that assesses final environmental impacts, such as verified emissions reduction measures or changes in biodiversity. Bridging this “impact gap” is the most challenging empirical task. The priority for future research should be as follows:
-
Prospective or quasi-experimental work that systematically tracks the causal pathway from technology use (e.g., AI-based portfolio tilts, IoT-secured green bonds) to actual climate impacts at the project or portfolio level.
-
Standardising impact measurement protocols in collaboration with climate scientists and environmental engineers to translate proxy assessment into tangible results.
-
Examine behavioural and structural determinants: verify how improved information (AI/IoT) and reduced friction (blockchain) catalyse greater capital flows to high-impact mitigation and adaptation projects.

4.3.2. Priority 2: Algorithmic Transparency, Fairness, and Governance

The ethical and operational risks identified require targeted research focused on governance and fairness considerations.
-
Explainable AI (XAI) for climate finance: We address this issue in terms of XAI frameworks tailored to climate risk assessment and ESG rating to address accountability gaps in “black boxes”.
-
Mitigating bias and promoting fairness: Studies need to find reliable models that can meet the needs of underrepresented regions and sectors, in which case open-source benchmarks or inclusive data sets should be invented to avoid reproducing global disparities.
-
Systemic risk, new governance: One possible avenue for future work is to study:
  • The consequences for the global economy of using models such as these ‘model monocultures’ could exacerbate correlated sales in the event of climate shocks.
  • The vulnerabilities of integrated IoT-blockchain networks.
  • New governance models for data standards and technological interoperability to avoid market disintegration.

4.3.3. Priority 3: Solutions Specific to the Context of Southern Countries

To bridge this identified ‘relevance gap,’ research must move from simple technology transfer to the creation of relevant innovations tailored to your context. This involves:
-
Technological leap in infrastructure: studying decentralised architectures that are robust in contexts where resources are limited (e.g., blockchain verification that does not require a constant cloud connection, IoT networks integrated with edge computing).
-
Institutional co-design: creating frameworks in collaboration with local regulators, NGOs, and community banks, mapping solutions against the current system of formal and informal governance.
-
Socio-economic relevance: focus on use cases that meet local needs (e.g., AI-based parametric insurance for smallholder farmers, blockchain-powered traceability for community-managed forests, or IoT-based microcredit for distributed renewable energy) (e.g., Tijjani et al., 2025; Das, 2025).

5. Conclusions

This systematic review examined 42 studies published from 2018 to 2025 to delineate the emerging domain of augmented finance for climate action. This review is the first synthesis of its kind, outlining the application of AI, IoT, and blockchain across three key categories—improving MRV processes, managing climate risks, and advancing ESG analysis. The findings reveal a crucial geographical imbalance in research focus, underscoring a substantial knowledge gap in context-specific applications. By bringing evidence and gaps, this review recommends an agenda for future research, focusing on impact validation, algorithmic transparency, and the development of solutions for underrepresented regions. The focus of this work’s contribution is, therefore, to unify a fragmented literature, diagnose its multiple blind spots, and guide subsequent scholarly and practical efforts.

5.1. Implications for Policymakers and Regulators

The reviewed literature consistently points to several regulatory and infrastructural priorities. Key implications include the need for: establishing clear guidelines for algorithmic transparency, such as requiring explainability (XAI) and bias audits for AI used in material climate risk assessments; investing in public data infrastructure, like IoT sensor networks in vulnerable regions, to mitigate geographical biases in risk models; promoting the development of global data standards and interoperability protocols for blockchain applications to ensure transparency and prevent market fragmentation; and clarifying the legal and regulatory treatment of emerging instruments like tokenized green assets and smart contracts to reduce adoption uncertainty.

5.2. Implications for Financial Institutions

For practitioners, the synthesis of research highlights practical pathways for integration. The need for cross-disciplinary expertise suggests that institutions consider forming dedicated teams combining sustainability, data science, and finance competencies. A strategic approach could involve launching targeted pilot projects, such as integrating IoT with blockchain to verify asset-level impact at the asset level or employing AI for dynamic climate stress-testing. Furthermore, developing internal algorithmic governance mapping—mandating model documentation, third-party validation, and bias mitigation—is underscored as critical for operational integrity. Finally, building internal capacity through training programs on green fintech tools is essential for effective deployment.

5.3. Directions for Future Research

The identified gaps chart a clear agenda for scholarly work. Research should prioritize: longitudinal and empirical studies that move beyond conceptual design to measure the actual environmental impact and financial effectiveness of technological deployments; the creation of open-source benchmarks and datasets to improve the fairness and robustness of models across diverse sectors and geographies; a focus on designing context-aware, affordable, and accessible solutions tailored for SMEs and emerging markets to address the current geographical bias; and further theoretical work to understand how institutional, behavioral, and complexity theories can inform the equitable design of technology-enhanced financial systems.

5.4. Limitations

This study has limitations that also indicate avenues for future work. First, the nascent state of the field resulted in the inclusion of 42 studies, a number that, while sufficient for identifying trends, may limit broad generalization. Secondly, the pronounced geographical bias in the literature underlying our synthesis means that it inevitably represents a technocentric paradigm derived from advanced economic contexts. Consequently, the study’s conclusions on the transformative potential of augmented finance are conditional and cannot yet be generalised globally. There is a tangible risk that the proposed “solutions”, if applied without adaptation, will exacerbate inequalities by directing investment solely towards contexts that mirror the infrastructure, institutions, and socio-economic models of the developed world. This highlights the urgency of applying context-specific research agendas.
Third, the rapid pace of technological and regulatory change means the landscape is evolving quickly; this review provides a snapshot that will need to be updated.

5.5. Concluding Remarks and Future Research Agenda

The synthesis suggests that while augmented finance holds transformative potential for aligning capital flows with climate goals, its trajectory is not predetermined. To answer the central research question, this review explains that technology resolves the root causes of the central ‘credibility crisis’ of climate finance, not only through replacing estimated data with IoT-verified ‘field truth’, but also to catch non-linear risks which fall through traditional models absent AI capability and using NLP to reveal semantic dissonance in corporate report-making processes, filling this trust gap that makes large investments in the Paris Agreement unaffordable in many economies.
Realizing this potential in an effective, equitable, and stable manner requires concerted efforts. Future research should focus on:
Empirically validating the links between technological deployment and environmental outcomes through detailed case studies.
Analyzing and mitigating the ethical risks and systemic vulnerabilities associated with these technologies.
Designing inclusive, equity-focused applications that bridge the gap between the Global North and South.
Investigating the behavioral and organizational dynamics within financial institutions that affect the adoption and governance of these technologies.
This study summarises how AI, IoT, and blockchain can address the fundamental crises of credibility and complexity in climate finance. However, this potential remains subject to strict conditions. The next step for this field is to provide unequivocal evidence that these technological integrations lead to positive environmental outcomes. The promise of augmented finance will be realised when research and practice move from demonstrating technical capabilities to validating climate effectiveness, ensuring that these powerful tools deliver not only financial optimisation but also measurable benefits for the planet.

Funding

This research received no external funding.

Institutional Review Board Statement

Not applicable.

Informed Consent Statement

Not applicable.

Data Availability Statement

The original contributions presented in this study are included in the article. Further inquiries can be directed to the corresponding author.

Conflicts of Interest

The author declares no conflicts of interest.

Appendix A

The selection process, illustrated by the PRISMA diagram (Figure 1), was as follows:

Appendix A.1. Identification

·
Scopus: 187 articles
·
Web of Science: 156 articles
·
ScienceDirect: 132 articles
·
JSTOR: 89 articles
·
Google Scholar: 20 articles
Total: 584 articles identified via databases.

Appendix A.2. Screening

·
Duplicates removed: 369 articles
Remaining unique articles: 215 articles

Appendix A.3. Eligibility: Evaluation Based on Title/Abstract

Excluded (n = 137) for:
·
89 articles
·
Non-English language: 23 articles
·
Inappropriate document type (editorials, theses, non-peer-reviewed white papers): 25 articles
Selected for full evaluation: 78 articles

Appendix A.4. Inclusion: Full-Text Assessment

Excluded (n = 36) for:
·
Insufficient link to climate finance (no explicit mention of finance, climate AND technology): 18 articles
·
Non-robust methodology (absence of clear methodological framework or verifiable data): 12 articles
·
Undetected duplicates: 6 articles
42 articles selected for synthesis analysis after full reading.
The data extracted from each article was compiled in Table 1, including: author, year, study objective, methodology, technologies studied, and main results.

Notes

1
The PRISMA process is presented in detail in Appendix A.
2
Some studies are counted in multiple categories when they significantly integrate multiple technologies in their research.

References

  1. Adadi, A., & Berrada, M. (2018). Peeking inside the black-box: A survey on explainable artificial intelligence (XAI). IEEE Access, 6, 52138–52160. [Google Scholar] [CrossRef] [Scilit]
  2. Afroditi, A. (2025). Policy implications of the “Corporate Sustainability Due Diligence Directive” in the industry of logistics. Transportation Research Procedia, 83, 55–62. [Google Scholar] [CrossRef] [Scilit]
  3. Ajakwe, I. U., Kanu, V. I., Simeon, O. A., & Dong-Seong, K. (2025). eBCTC: Energy-efficient hybrid blockchain architecture for smart and secured K-ETS. Cleaner Engineering and Technology, 29, 101084. [Google Scholar] [CrossRef] [Scilit]
  4. Alexander, W. R. J., & Belloni, R. (2024). Artificial intelligence and the sustainability of the signaling and human capital roles of higher education. Sustainability, 16(20), 8802. [Google Scholar] [CrossRef] [Scilit]
  5. Alves, T., Tiago, E. M., Nelson, O. S., Jorge, H. C. O., Talita, B. T., & Wesley, R. S. F. (2020). Green supply chain management in Latin America: Systematic literature review and future directions. Environmental Quality Management, 30(2), 47–73. [Google Scholar] [CrossRef] [Scilit]
  6. Atkinson, C. L., & Atkinson, A. M. (2023). Impacts of climate change on rural communities: Vulnerability and adaptation in the global south. Encyclopedia, 3(2), 721–729. [Google Scholar] [CrossRef] [Scilit]
  7. Battiston, S., & Monasterolo, I. (2020). A climate risk assessment of a sovereign bond portfolio. Nature Climate Change, 10(11), 1012–1018. [Google Scholar]
  8. Berg, F., Kölbel, J. F., & Rigobon, R. (2022). Aggregate confusion: The divergence of ESG ratings. Forthcoming Review of Finance, 26(6), 1315–1344. [Google Scholar] [CrossRef] [Scilit]
  9. Bingler, J. A., Kraus, M., & Leippold, M. (2022). Cheap talk and cherry-picking: What ClimateBert has to say on corporate climate risk disclosures. Finance Research Letters, 47(3), 102776. [Google Scholar] [CrossRef] [Scilit]
  10. Bissoondoyal-Bheenick, E., Scott, B., Rob, L., & Angel, Z. (2024). ESG rating disagreement: Implications and aggregation approaches. International Review of Economics & Finance, 96, 103532. [Google Scholar] [CrossRef] [Scilit]
  11. Boedijanto, F. J. O., & Delina, L. L. (2024). Potentials and challenges of artificial intelligence-supported greenwashing detection in the energy sector. Energy Research & Social Science, 115, 103638. [Google Scholar] [CrossRef] [Scilit]
  12. Bolton, P., Després, M., Pereira da Silva, L. A., Samama, F., & Svartzman, R. (2020). The green swan: Central banking and financial stability in the age of climate change. Bank for International Settlements. Available online: https://www.bis.org/publ/othp31.pdf (accessed on 1 October 2025).
  13. Buchak, G., Matvos, G., Piskorski, T., & Seru, A. (2018). Fintech, regulatory arbitrage, and the rise of shadow banks. Journal of Financial Economics, 130(3), 453–483. [Google Scholar] [CrossRef] [Scilit]
  14. Calvo, V. L. V., Zbigniew, K., Alonso-Fariñas, B., & Aguado, J. M. (2025). Circular economy transition under the revised industrial emissions directive: A review of challenges and enablers. Journal of Cleaner Production, 533, 146779. [Google Scholar] [CrossRef] [Scilit]
  15. Campiglio, E., Dafermos, Y., Monnin, P., Ryan-Collins, J., Schotten, G., & Tanaka, M. (2018). Climate change challenges for central banks and financial regulators. Nature Climate Change, 8(6), 462–468. [Google Scholar] [CrossRef] [Scilit]
  16. Das, D. K. (2025). Digital technology and AI for smart sustainable cities in the global south: A critical review of literature and case studies. Urban Science, 9(3), 72. [Google Scholar] [CrossRef] [Scilit]
  17. Desnos, B., Le Guenedal, T., Morais, P., & Roncalli, T. (2023). From climate stress testing to climate value-at-risk: A stochastic approach. SSRN Electronic Journal. [Google Scholar] [CrossRef] [Scilit]
  18. Dewasiri, N. J., Weerakoon, Y. K. B., & Azeez, A. A. (2018). Mixed methods in finance research: The rationale and research designs: The rationale and research designs. International Journal of Qualitative Methods, 17(1), 1–14. [Google Scholar] [CrossRef] [Scilit]
  19. Dignum, V. (2019). Responsible artificial intelligence: How to develop and use AI in a responsible way. Springer. Available online: https://link.springer.com/book/10.1007/978-3-030-30371-6 (accessed on 1 October 2025).
  20. Dong, H., Hu, Y., Yang, Y., & Jiang, W. (2023). A multi-strategy integration prediction model for carbon price. Energies, 16(12), 4613. [Google Scholar] [CrossRef] [Scilit]
  21. D’Orazio, P. (2022). Towards a post-pandemic policy framework to manage climate-related financial risks and sustainability goals. Ecological Economics, 21, 1368–1382. [Google Scholar] [CrossRef] [Scilit]
  22. Freeman, R. E. (1984). Strategic management: A stakeholder approach. Pitman. Available online: https://www.cambridge.org/core/books/strategic-management/E3CC2E2CE01497062D7603B7A8B9337F (accessed on 1 October 2025).
  23. Frikha, M. A., & Mrad, M. (2025). AI-driven supply chain decarbonization: Strategies for sustainable carbon reduction. Sustainability, 17(21), 9642. [Google Scholar] [CrossRef] [Scilit]
  24. Ge, Y., & Yang, X. (2025). AI adoption and ESG performance: Evidence from China. International Review of Economics & Finance, 104, 104659. [Google Scholar] [CrossRef] [Scilit]
  25. Ghaemi, A. M. (2025). A novel AI-driven approach to greenwashing: Breakthroughs in the future fit between domain-specific Islamic enterprises with varying developmental progress and ESG landscapes. Future Business Journal, 11(93), 1–38. [Google Scholar] [CrossRef] [Scilit]
  26. Giglio, S., Kelly, B., & Stroebel, J. (2021). Climate finance. Annual Review of Financial Economics, 13, 15–36. [Google Scholar] [CrossRef] [Scilit]
  27. Gomber, P., Kauffman, R. J., Parker, C., & Weber, B. W. (2018). On the fintech revolution: Interpreting the forces of innovation, disruption, and transformation in financial services. Journal of Management Information Systems, 35(1), 220–265. [Google Scholar] [CrossRef] [Scilit]
  28. Gorriz, J. M., Ramirez, J., Segovia, F., Jimenez-Mesa, C., Martinez-Murcia, F. J., & Suckling, J. (2026). Statistical agnostic regression: Machine learning method to validate regression models. Journal of Advanced Research, 80, 503–533. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  29. Grewal, J., Riedl, E. J., & Serafeim, G. (2019). Market reaction to mandatory nonfinancial disclosure. Management Science, 69(2), 787–810. [Google Scholar] [CrossRef] [Scilit]
  30. Gutierrez-Bustamante, M., & Espinosa-Leal, L. (2022). Natural language processing methods for scoring sustainability reports—A study of Nordic listed companies. Sustainability, 14(15), 9165. [Google Scholar] [CrossRef] [Scilit]
  31. Hamdouni, A. (2025). The role of artificial intelligence in enhancing ESG outcomes: Insights from Saudi Arabia. Journal of Risk and Financial Management, 18(10), 572. [Google Scholar] [CrossRef] [Scilit]
  32. Hong, M., & Kim, J. (2025). AI-driven responsible supply chain management and ethical issue detection in the tourism industry. Sustainability, 17(21), 9622. [Google Scholar] [CrossRef] [Scilit]
  33. Hussainzad, E. A., & Gou, Z. (2024). Climate risk and vulnerability assessment in informal settlements of the global south: A critical review. Land, 13(9), 1357. [Google Scholar] [CrossRef] [Scilit]
  34. Hyun, S. (2024). Green digital finance: Tokenization of green bonds and carbon credits. Yonsei University-FRTC of Japan FSA. Available online: https://www.fsa.go.jp/frtc/kenkyu/event/20240329/05_HYUNSuk_GDF_Tokyo.pdf (accessed on 15 October 2025).
  35. IPCC. (2022). Climate change 2022: Impacts, adaptation and vulnerability. Contribution of Working Group II to the Sixth Assessment Report. IPCC. Available online: https://www.ipcc.ch/report/ar6/wg2/ (accessed on 15 October 2025).
  36. Jia, H., & Bo, H. (2025). Estimating global anthropogenic CO2 emissions through satellite observations. Environmental Research, 279(1), 121767. [Google Scholar] [CrossRef] [Scilit]
  37. Judy, L., Bell, R., & Stroombergen, A. (2019). A hybrid process to address uncertainty and changing climate risk in coastal areas using dynamic adaptive pathways planning, multi-criteria decision analysis & real options analysis: A New Zealand application. Sustainability, 11(2), 406. [Google Scholar] [CrossRef] [Scilit]
  38. Katie, B. (2024). Internet of Things (IoT) for environmental monitoring. International Journal of Computing and Engineering, 6(3), 29–42. [Google Scholar] [CrossRef] [Scilit]
  39. Khatib, S. F. A., Al Amosh, H., & Ananzeh, H. (2023). Board compensation in financial sectors: A systematic review of twenty-four years of research. International Journal of Financial Studies, 11, 92. [Google Scholar] [CrossRef] [Scilit]
  40. Kheradmand, E., Serre, D., Morales, M., & Robert, C. B. (2023). Alignment of organizations’ climate-related risk disclosures with material risks and metrics. SASB Climate Risk Technical Bulletin. Available online: https://haskayne.ucalgary.ca/sites/default/files/teams/12/Session%202%20Paper%20-%20Kheradmand_CSFN%20.pdf (accessed on 1 November 2025).
  41. Khlifi, S., Ben Ali, A., & Hermi, S. (2025). Artificial intelligence adoption as a mediator of executive cultural diversity-ESG performance nexus: Evidence from European companies. Accounting Research Journal, 39, 1–20. [Google Scholar] [CrossRef] [Scilit]
  42. Kwong, R., Kwok, M. L. J., & Wong, H. S. M. (2023). Green FinTech innovation as a future research direction: A bibliometric analysis on green finance and FinTech. Sustainability, 15(20), 14683. [Google Scholar] [CrossRef] [Scilit]
  43. Lagasio, V. (2024). ESG-washing detection in corporate sustainability reports. International Review of Financial Analysis, 96(B), 103742. [Google Scholar] [CrossRef] [Scilit]
  44. Luna, M., Fernandez-Vazquez, S., Castelao, E., & Fernández, A. (2024). A blockchain-based approach to the challenges of EU’s environmental policy compliance in aquaculture: From traceability to fraud prevention. Marine Policy, 159, 105892. [Google Scholar] [CrossRef] [Scilit]
  45. Manzoor, B., Maxwell, F. A. A., & Khalid, S. A. (2025). Green buildings and digital technologies: A pathway to sustainable development. Green Technologies and Sustainability, 4(3), 100243. [Google Scholar] [CrossRef] [Scilit]
  46. Mao, Q., Ma, X., & Sun, Y. (2023). Study of impacts of blockchain technology on renewable energy resource findings. Renewable Energy, 211, 802–808. [Google Scholar] [CrossRef] [Scilit]
  47. Marquis, C., & Toffel, M. W. (2016). The ecology of greenwashing: Corporate environmental rhetoric and behavior. Harvard Business School Working Paper, No. 22-048. Available online: https://www.hbs.edu/faculty/Pages/item.aspx?num=50187 (accessed on 12 November 2025).
  48. Mei, Y., Geng, L., Cao, X., & Xie, Y. (2025). Artificial intelligence in green marketing: A systematic literature review. Sustainability, 17(22), 10382. [Google Scholar] [CrossRef] [Scilit]
  49. Moghaddasi, H., Culp, C., Vanegas, J., Das, S., & Ehsani, M. (2022). An adaptable net zero model: Energy analysis of a monitored case study. Energies, 15(11), 4016. [Google Scholar] [CrossRef] [Scilit]
  50. Moodaley, W., & Telukdarie, A. (2023). Greenwashing, sustainability reporting, and artificial intelligence: A systematic literature review. Sustainability, 15(2), 1481. [Google Scholar] [CrossRef] [Scilit]
  51. Navarrete-Oyarce, J., Moraga-Flores, H., Gallegos Mardones, J. A., & Gallizo, J. L. (2022). Why integrated reporting? Insights from early adoption in an emerging economy. Sustainability, 14(3), 1695. [Google Scholar] [CrossRef] [Scilit]
  52. Network for Greening the Financial System (NGFS). (2022). Climate scenarios for central banks and supervisors. NGFS. Available online: https://www.ngfs.net/en/publications-and-statistics/publications/ngfs-climate-scenarios-central-banks-and-supervisors-0 (accessed on 14 November 2025).
  53. North, D. C. (1991). Institutions, institutional change and economic performance. Cambridge University Press. Available online: https://ideas.repec.org/b/cup/cbooks/9780521394161.html (accessed on 14 November 2025).
  54. Okoli, C. (2015). A guide to conducting a standalone systematic literature review. Communications of the Association for Information Systems, 37, 879–910. [Google Scholar] [CrossRef] [Scilit]
  55. Olawade, D., Ojima, Z. W., Abimbola, O. I., Bamise, I. E., Adedayo, O., & Bankole, I. O. (2024). Artificial intelligence in environmental monitoring: Advancements, challenges, and future directions. Hygiene and Environmental Health Advances, 12, 100114. [Google Scholar] [CrossRef] [Scilit]
  56. Page, M. J., McKenzie, J. E., Bossuyt, P. M., Boutron, I., Hoffmann, T. C., Mulrow, C. D., Shamseer, L., Tetzlaff, J. M., Akl, E. A., Brennan, S. E., Chou, R., Glanville, J., Grimshaw, J. M., Hróbjartsson, A., Lalu, M. M., Li, T., Loder, E. W., Mayo-Wilson, E., McDonald, S., … Moher, D. (2021). The PRISMA 2020 statement: An updated guideline for reporting systematic reviews. BMJ, 372, n71. [Google Scholar] [CrossRef] [Scilit]
  57. Petticrew, M., & Roberts, H. (2008). Systematic reviews in the social sciences: A practical guide. Wiley. [Google Scholar] [CrossRef] [Scilit]
  58. Pourrahmani, H., Masoud, T. A., Hossein, M. J., & Peprah, O. (2025). Revolutionizing carbon sequestration: Integrating IoT, AI, and blockchain technologies in the fight against climate change. Energy Reports, 13, 5952–5967. [Google Scholar] [CrossRef] [Scilit]
  59. Razzaq, K., & Shah, M. (2025). Machine learning and deep learning paradigms: From techniques to practical applications and research frontiers. Computers, 14(3), 93. [Google Scholar] [CrossRef] [Scilit]
  60. Santi, C. (2023). Investor climate sentiment and financial markets. International Review of Financial Analysis, 86, 102490. [Google Scholar] [CrossRef] [Scilit]
  61. Sierra-Correa, P. C., & Kintz, C. (2015). Ecosystem-based adaptation for improving coastal planning for sea-level rise: A systematic review for mangrove coasts. Marine Policy, 51, 385–393. [Google Scholar] [CrossRef] [Scilit]
  62. Simon, H. A. (1962). The architecture of complexity. Proceedings of the American Philosophical Society, 106(6), 467–482. [Google Scholar]
  63. Spence, M. (1973). Job market signaling. The Quarterly Journal of Economics, 87(3), 355–374. [Google Scholar] [CrossRef] [Scilit]
  64. Suchman, M. C. (1995). Managing legitimacy: Strategic and institutional approaches. The Academy of Management Review, 20(3), 571–610. [Google Scholar] [CrossRef] [Scilit]
  65. Sumedha, B., Dipti, S., & Rashmi, B. (2024). Green finance and investment index for assessing scenario and performance in selected countries. World Development Sustainability, 5, 100183. [Google Scholar] [CrossRef] [Scilit]
  66. Sun, Y., Liu, L., Xu, Y., Zeng, X., Shi, Y., Hu, H., & Jiang, J. (2024). Alternative data in finance and business: Emerging applications and theory analysis (review). Financial Innovation, 10, 127. [Google Scholar] [CrossRef] [Scilit]
  67. Talukder, S. C., Lakner, Z., & Temesi, Á. (2025). Exploring the research landscape of impact investing and sustainable finance: A bibliometric review. Journal of Risk and Financial Management, 18(10), 578. [Google Scholar] [CrossRef] [Scilit]
  68. Tijjani, K. S., Sarıkaya Levent, Y., & Levent, T. (2025). Smart cities in the global context: Geographical analyses of regional differentiations. Systems, 13(4), 296. [Google Scholar] [CrossRef] [Scilit]
  69. Turner, J. R., & Baker, R. M. (2019). Complexity theory: An overview with potential applications for the social sciences. Systems, 7(1), 4. [Google Scholar] [CrossRef] [Scilit]
  70. Wang, G., Yan, C., You, Z., & Chi, X. (2024). Systemic risk prediction using machine learning: Does network connectedness help prediction? International Review of Financial Analysis, 93, 103147. [Google Scholar] [CrossRef] [Scilit]
  71. Wang, Y. F., Wang, M. Y. F., & Tu, L. Y. (2025). An evaluation of machine learning models for forecasting short-term U.S. treasury yields. Applied Sciences, 15(12), 6903. [Google Scholar] [CrossRef] [Scilit]
  72. Weyant, J. (2017). Some contributions of integrated assessment models of climate change. Review of Environmental Economics and Policy, 11(1), 115–137. [Google Scholar] [CrossRef] [Scilit]
  73. Williamson, O. E. (1985). The economic institutions of capitalism. Free Press. Available online: https://www.jstor.org/stable/2555390 (accessed on 15 November 2025).
  74. Wu, L., Ghansah, F., Zou, Y., & Ababio, B. (2025). Blockchain oracles for digital transformation in the AECO industry: Securing off-chain data flows for a trusted on-chain environment. Buildings, 15(20), 3662. [Google Scholar] [CrossRef] [Scilit]
  75. Zetzsche, D. A., Arner, D. W., & Buckley, R. P. (2020). Artificial intelligence in finance: Putting the human in the loop. Sydney Law School Research Paper No. 20/35. Available online: https://papers.ssrn.com/sol3/papers.cfm?abstract_id=3531711 (accessed on 15 November 2025).
  76. Zhang, G., Chen, S. C.-I., & Yue, X. (2024). Blockchain technology in carbon trading markets: Impacts, benefits, and challenges—A case study of the Shanghai environment and energy exchange. Energies, 17(13), 3296. [Google Scholar] [CrossRef] [Scilit]
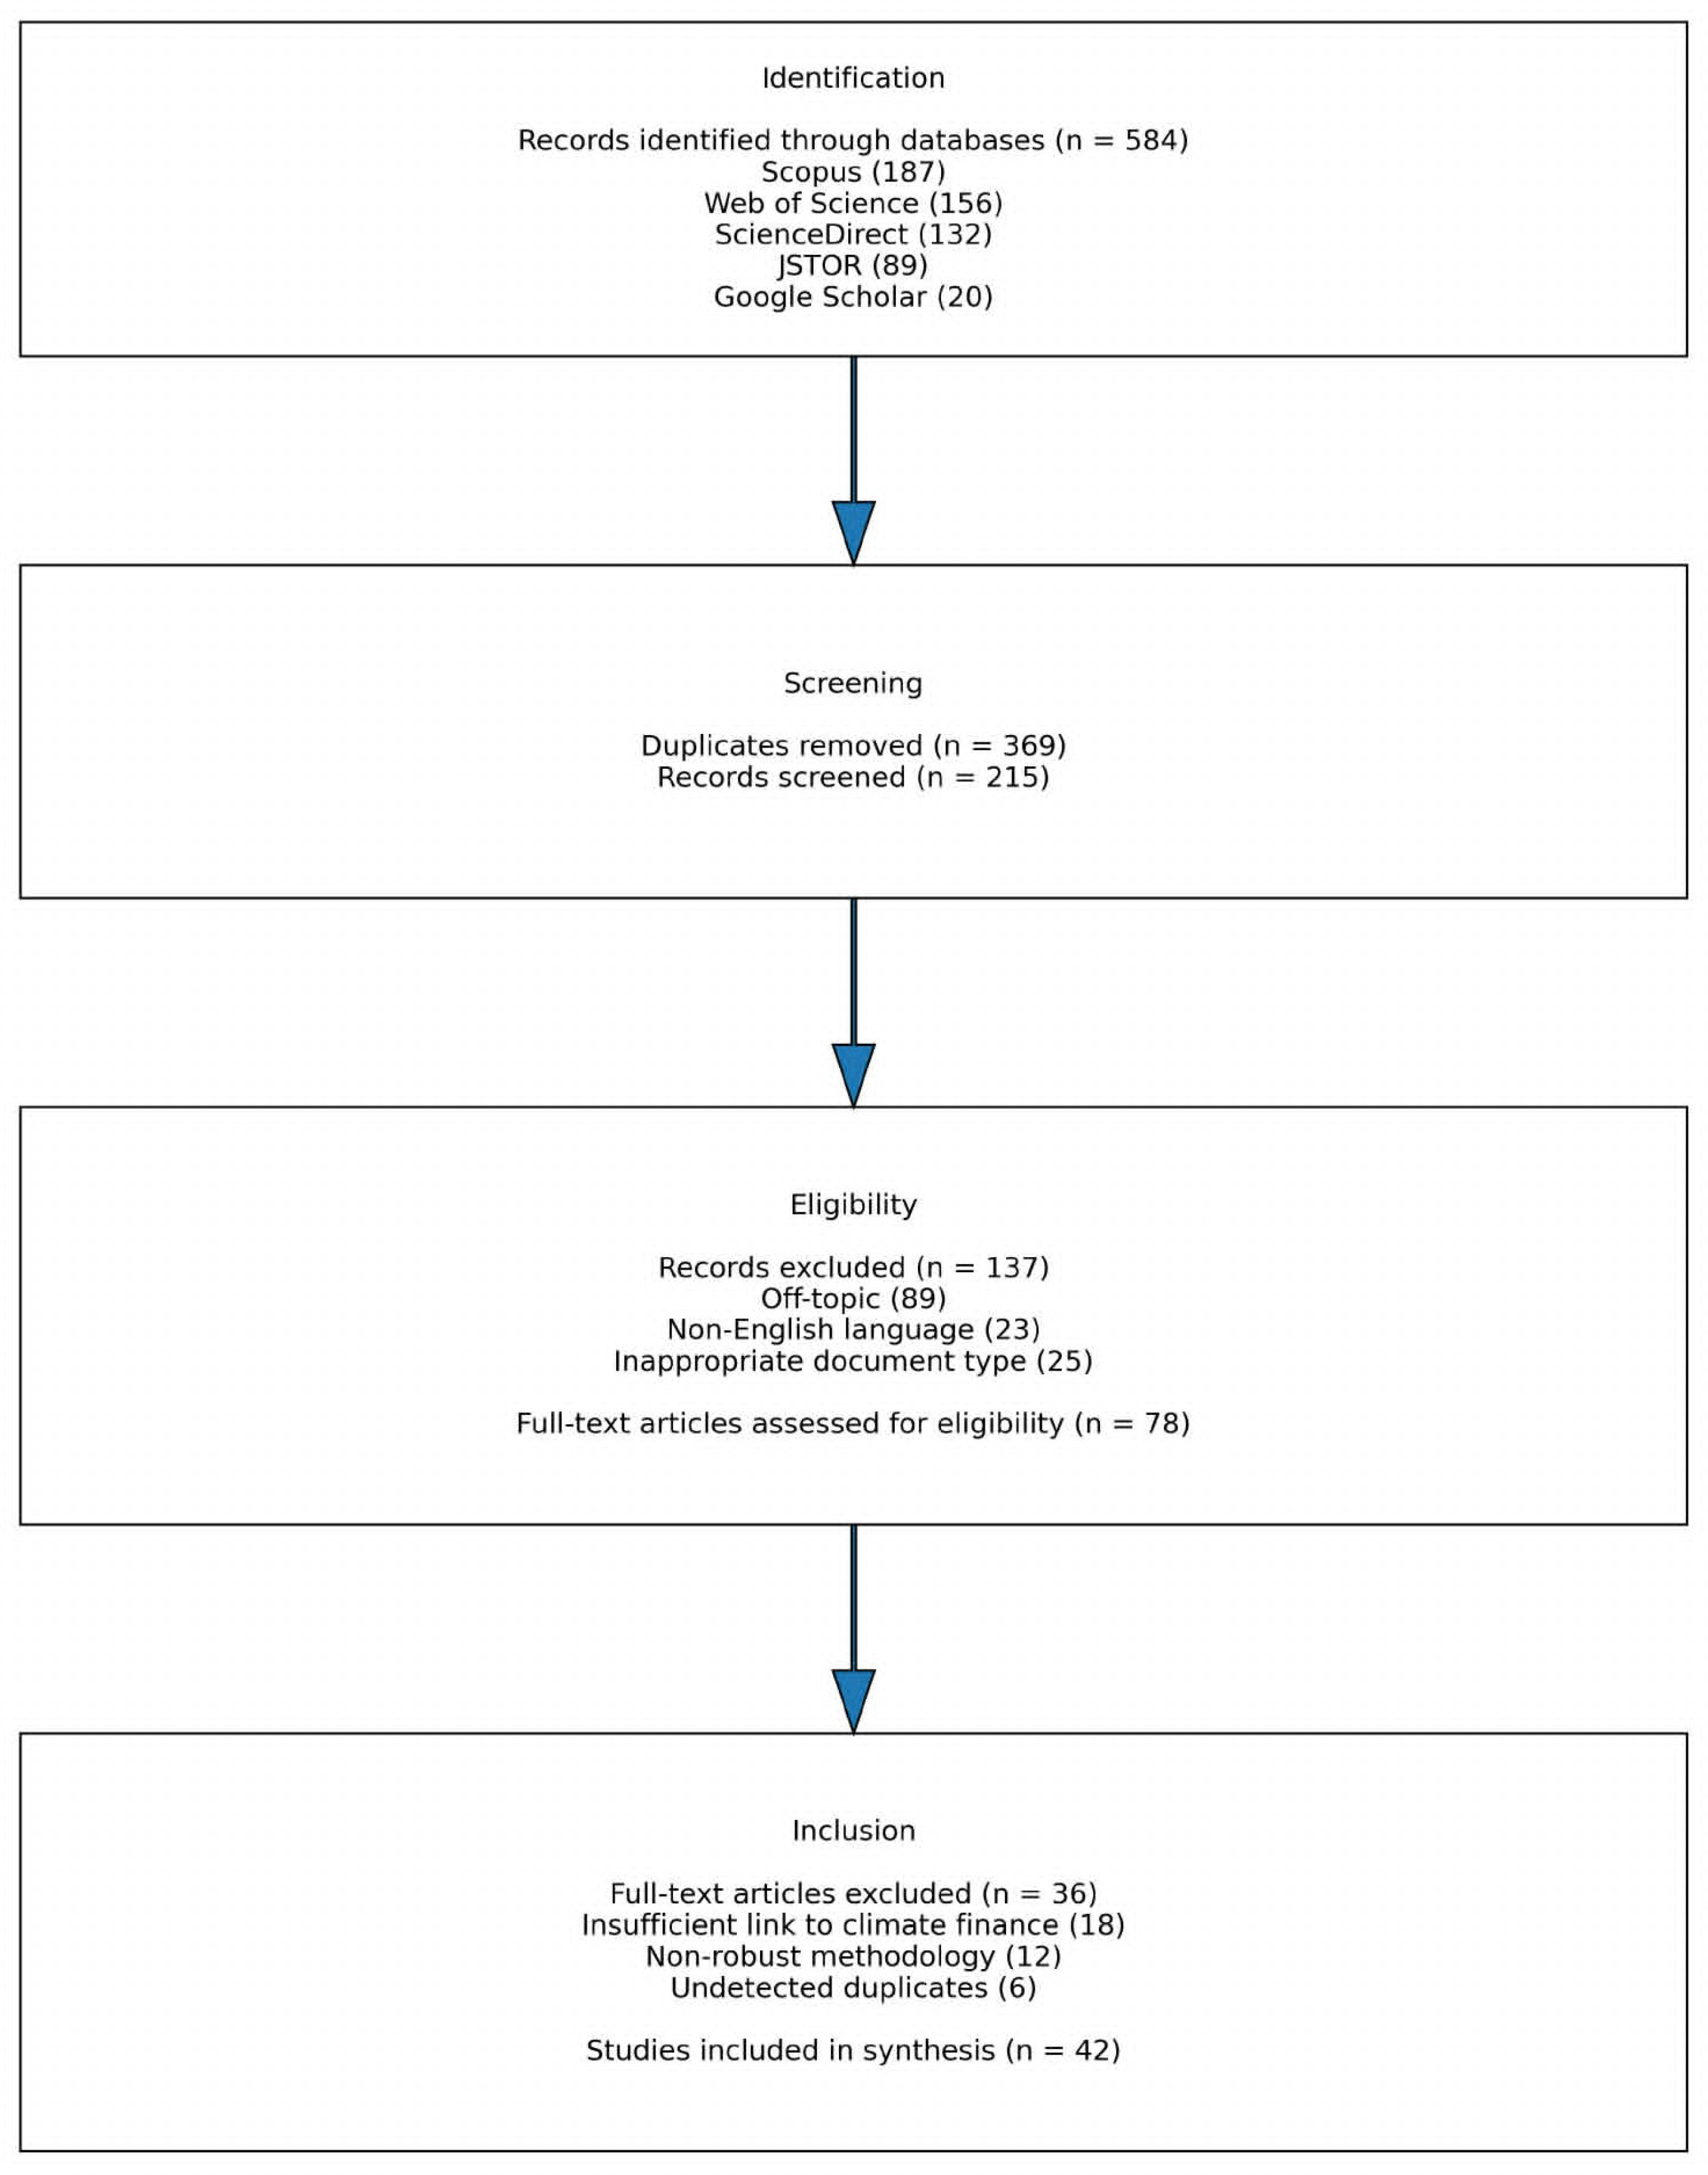
Figure 1. PRISMA diagram.
Ijfs 14 00091 g001
Figure 2. Temporal distribution of reviewed studies by primary technology focus (2018–2025).
Ijfs 14 00091 g002
Table 1. Detailed search strategy by database.
DatabaseSearch Keywords
Scopus, Web of Science, JSTOR, ScienceDirect(“augmented finance” OR “AI” OR “artificial intelligence” OR “machine learning” OR “IoT” OR “internet of things” OR “blockchain” OR “distributed ledger”) AND (“climate change” OR “green finance” OR “sustainable finance” OR “ESG” OR “climate risk” OR “greenwashing”) AND (“banking” OR “insurance” OR “investment” OR “asset management”).
Table 2. Overview of the selected articles.
Author(s) and YearStudy ObjectiveMethodologyKey TechnologiesMain Findings
Jia and Bo (2025) Monitor corporate emissions via satellite.Satellite imagery analysisIoT/Remote SensingDeveloped a framework for estimating Greenhouse Gas (GHG) emissions with acceptable spatial resolution.
Pourrahmani et al. (2025) Accounting for carbon in the supply chain in real time.Case study implementing sensorsIoT, CloudDecreased uncertainty in reporting; data for green finance that can be checked.
Mei et al. (2025) Investigate into how blockchain can be used for carbon credits.Systematic review and conceptual frameworkBlockchainPossibly render carbon markets more accessible, credible, and liquid.
Hyun (2024) Provide develop a plan for tokenized green bonds.Prototype designBlockchain, TokenizationDecreased intermediaries; complete tracking of money and effects.
Battiston and Monasterolo (2020) Assess climate risk in bond portfolios.Network modeling and scenariosMachine Learning (M L)Identified “hotspots” of unpriced climate risk in sovereign bonds.
Giglio et al. (2021) Synthesize advances in climate finance.Literature reviewVarious (ML)AI enables more fine-grained and dynamic modeling of long-term physical risks.
Bingler et al. (2022)Assess the quality of climate disclosures.Text analysis (NLP)AI (Natural Language Processing (NLP))Significant gaps between discourse and actionable metrics; detection of “cherry-picking.”
Grewal et al. (2019)Look at how the market reacts to non-financial disclosures. Use event studies and text analysis with AI (NLP).AI (NLP)The market reacts more to alternative data (media) than to standard CSR reports.
Lagasio (2024)Examine the ecology of corporate greenwashing.Statistical analysis of texts and performance dataAI (NLP)Created an algorithm to find gaps between rhetoric and performance.
D’Orazio (2022) Provide up with a framework for climate risks after COVID.Economic analysisIoT and Big DataShows how important it is for green technologies to have data standards and be able to work together.
Dignum (2019) A plan for responsible AI.Conceptual researchAI (Ethics)Says that algorithms can make social biases worse if they are not properly controlled.
Zetzsche et al. (2020) Explore carefully at the regulatory problems that AI poses for the finance industry.Legal and economic analysisAI, RegulationFinds a gap in the rules and calls for a “design-based” approach.
Adadi and Berrada (2018) Look over the area of explainable AI (XAI).Literature reviewXAIIt shows how important it is for AI to be open in important areas like finance.
Ge and Yang (2025)AI for low-carbon portfolio optimization.Optimization algorithmsMachine LearningCreated a model for choosing assets that fits with 2 °C scenarios.
Moodaley and Telukdarie (2023)Finding greenwashing in CSR reports.Advanced semantic analysisAI (NLP)92% accurate automatic sorting of environmental claims.
Katie (2024)Monitoring biodiversity in real time.IoT and dronesIoT, Computer VisionAutomated checking of how projects that receive money affect biodiversity.
Luna et al. (2024)A blockchain platform for funding green projects.Practical implementationBlockchain, Smart ContractsA 70% drop in the cost of verifying green projects.
G. Wang et al. (2024)Modeling the risk of sectoral transition.Neural networksDeep LearningFinding industries that are likely to have stranded assets before they happen.
Bissoondoyal-Bheenick et al. (2024)Dynamic ESG scoring that uses other types of data.Multi-source analysisAI and Big DataAn ESG score that changes every year, not just once a year like most agencies do.
Alves et al. (2020)Traceability of green supply chains.Private blockchainBlockchain, IoTUnchangeable proof of the “green” source of raw materials.
Y. F. Wang et al. (2025)Prediction of defaults associated with climate factors. Forecasting modelsMachine LearningIncorporation of climatic variables into credit scoring algorithms.
Gutierrez-Bustamante and Espinosa-Leal (2022)Analysis of climate risk materiality. Natural language processing (NLP)AI (NLP)Natural Language Processing (NLP) for the automated assessment of climate risks by industry sector.
Wu et al. (2025)Parametric climate insurance.Smart ContractsBlockchain, OraclesAutomated payments initiated by verified meteorological data.
Buchak et al. (2018)Auditing climate reports automatically.Analysis of compliance Business Rules, AIFinding regulatory climate disclosure discrepancies.
Talukder et al. (2025)Impact investing with AI criteria.Multi-objective optimizationMachine LearningPortfolios optimizing both returns and measurable climate impacts.
Moghaddasi et al. (2022)Net-zero commitment monitoring.Trajectory analysisAI, Data AnalyticsAutomatic tracking of how well commitments match up with actions.
Kwong et al. (2023)Green crowdfunding.Decentralized platformBlockchain, TokensA 45% rise in the number of small green projects that can receive funding.
Dong et al. (2023)Carbon credit price prediction.Time-seriesLong Short-term Memory (LSTM) NetworksForecasting prices with 30% less error than standard models.
Afroditi (2025)Automated climate due diligence.Document analysisAI (NLP, Computer Vision)Significant reduction in the time it takes to look overdue diligence documents.
Desnos et al. (2023)Portfolio climate stress testing.Monte Carlo simulationsMachine LearningChecking how well a portfolio can handle different climate scenarios.
Manzoor et al. (2025)Automatic green building certification.IoT and blockchainIoT, BlockchainReal-time proof of how well a building uses energy.
Sumedha et al. (2024)Green investment opportunity detection.Market analysisAI, Web ScrapingAutomatic finding of promising new green tech companies.
Ajakwe et al. (2025)Smart contracts for renewable energy.Smart ContractsBlockchain, IoTAutomating Power Purchase Agreements for projects that use renewable energy.
Santi (2023)Climate sentiment market analysis.Sentiment analysisAI (NLP)How the mood of climate media affects the performance of green assets.
Navarrete-Oyarce et al. (2022)Automatic integrated reporting.Report generationAI, Robotic Process Automation (RPA)Automatic report generation that combines financial and non-financial data.
Judy et al. (2019)Climate transition scoring.Hybrid methodologyAI, Expert SystemsScoring is a way to look at transition plans from both a quantitative and qualitative point of view.
Zhang et al. (2024)Low-carbon logistics optimization.Genetic algorithmsMachine LearningA 15% decrease in the carbon footprint of logistics chains that receive money.
Olawade et al. (2024)Climate regulatory monitoring.Automated monitoringAI (NLP)Early warning of changes in regulations that will affect portfolios.
Mao et al. (2023)Impact measurement for green bonds.IoT and blockchain integrationIoT, BlockchainCareful tracking of how projects that receive money from green bonds affect the environment.
Kheradmand et al. (2023)Climate risk disclosure benchmarking.Comparative analysisAI, BenchmarkingAn automated way to compare the quality of disclosures to those of other companies in the same field.
Frikha and Mrad (2025)AI-driven supply chain decarbonization.Case study/modelingAIWays to cut carbon emissions in supply chains in a way that lasts.
Boedijanto and Delina (2024)AI-supported greenwashing detection in energy sector.Conceptual/NLP analysisAI (NLP)Finds the pros and cons of using AI to find greenwashing.
Table 3. Distribution of research by country/region.
Country/RegionMain Research AreasRepresentative Studies
AustraliaRegulations and policies for fintechZetzsche et al. (2020)
CanadaAI ethics and rules to govern activitiesDignum (2019); Kheradmand et al. (2023)
ChinaMonitoring emissions, green fintech, and using AIJia and Bo (2025); Mei et al. (2025); Zhang et al. (2024)
European UnionBlockchain, rules, and understanding how climate change will affect thingsBattiston and Monasterolo (2020); Luna et al. (2024); D’Orazio (2022)
JapanIoT, biodiversity monitoringKatie (2024)
Latin AmericaGreen supply chain, sustainable sourcingAlves et al. (2020)
Nordic CountriesBuilding certification, IoT applicationsManzoor et al. (2025); Gutierrez-Bustamante and Espinosa-Leal (2022)
Multi-country StudiesComparative international analysis, global frameworksGiglio et al. (2021); Navarrete-Oyarce et al. (2022)
South KoreaBlockchain, tokenized green bondsHyun (2024); Ajakwe et al. (2025)
United KingdomClimate scoring, risk analysis, transition planningBissoondoyal-Bheenick et al. (2024); Judy et al. (2019)
United StatesESG analysis, fintech, greenwashing detectionGrewal et al. (2019); Lagasio (2024); Y. F. Wang et al. (2025)
Table 4. Quantitative breakdown of research methodologies.
Methodology TypeDefinition Number of StudiesPercentage of Total
Non-Linear It uses advanced, flexible models like Machine Learning (ML), Deep Learning, and Natural Language Processing (NLP) to find patterns in data and make predictions.2457%
Mixed Combines linear and non-linear methods, or brings together different data sources and analytical methods to obtain a more complete and detailed picture.1229%
Linear Analytical processes that are based on rules come in a certain order, or are traditional. They are usually based on rules that have already been set, statistical models, or simple automation.614%
Table 5. Distribution of reviewed studies by technological focus and integration level.
Technology CategoryNo. of Studies% of TotalCore Role in Augmented FinanceIntegrated Study References
AI/Machine Learning2457.1%Intelligence: Using predictive modeling, risk assessment, and natural language processing (NLP) to find greenwashing.Pourrahmani et al. (2025)
Blockchain1126.2%Trust: unchangeable records for carbon credits, smart contracts, and bonds that are tokenized.Alves et al. (2020), Mao et al. (2023), Manzoor et al. (2025), Ajakwe et al. (2025), Pourrahmani et al. (2025)
IoT/Remote Sensing716.7%Measurement: Obtaining real-time data on GHG emissions and other environmental factors.Alves et al. (2020), Mao et al. (2023), Manzoor et al. (2025), Ajakwe et al. (2025), Pourrahmani et al. (2025)
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content.