


Abstract
Intellectual capital comprises human, structural, and customer capital. Traditional assessment methods, such as the Value-Added Intellectual Coefficient, rely on financial reporting and do not provide a direct indicator of customer capital. This study proposes domain type (global or local) as a publicly available proxy for customer capital and examines its association with the financial performance (ROA, profit margin) of 2558 leading European IT companies by sales volume in 2023. The models include management intensity and intangible asset intensity as proxies for human and structural capital and control for listing status, company size, country and industry. Ordinary least squares models with heteroskedasticity-robust standard errors were estimated, adding controls in blocks. A global domain was weakly negatively associated with ROA, and this association was sensitive to the inclusion of size and country controls, with no association with profit margin. Management intensity was weakly positively associated with profit margin but not with ROA. Intangible asset intensity showed a stable negative association with both indicators across all specifications and robustness checks. The results indicate that intangible asset intensity is the most stable factor, while the suitability of domain type as a proxy for customer capital requires further verification using panel data.
1. Introduction
The intellectual capital of a company determines its competitive advantage (Edvinsson & Malone, 1997). Its structure is commonly divided into three elements, namely human, structural, and customer capital (Stewart, 1997). This division provides grounds for investigating the effect of each of these components on the financial performance of companies, particularly in industries with a substantial share of intangible assets, such as the IT sector.
The relationship between intellectual capital and financial performance remains an open field for scholarly debate, owing to the paradoxical results of a number of studies examining the corresponding effect of its components in IT companies. In particular, the results of the reviewed works range from positive (Duc et al., 2025; Shaneeb & Sumathy, 2021; Mata et al., 2024; N. Joshi & Aggarwal, 2024) to negative effects (Dsouza et al., 2026) and no effect at all (Singh, 2024), and even to mixed results within a single study (Bansal et al., 2025; Lehenchuk et al., 2023). Most of these studies employed the Value-Added Intellectual Coefficient (VAIC) method, which involves calculating the efficiency of intellectual capital utilisation on the basis of the value added created by a firm. This method does not account for customer capital. Improved models, in particular the Modified VAIC (MVAIC), additionally incorporate Research and Development Efficiency and Relational Capital Efficiency, thereby partially compensating for this limitation of the classical VAIC (Lehenchuk et al., 2023; Yin & Xu, 2025). This limitation is further compounded by the broader trend of economic digitalisation, which requires the modernisation of corporate accounting systems to reflect new forms of assets and business processes that emerge in the digital environment and are not always captured by traditional accounting methods (Chyzhevska et al., 2021). Because the aforementioned methods (VAIC, MVAIC) rely on financial statements and do not always capture non-financial manifestations of capital, researchers are seeking alternative, easily verifiable indicators.
For IT companies, whose operations take place predominantly in a digital environment, the website is a primary channel of interaction with customers and the market. Since the direct measurement of customer capital requires complex surveys or expert assessments, the search for publicly available proxy indicators becomes increasingly relevant. Researchers have proposed various non-traditional web proxies for assessing the non-financial aspects of a company’s activity (Yu et al., 2024; Cruciata et al., 2024). Such web proxies may include a company’s domain name and website domain. The domain name provides firm recognisability, while the domain, that is, its extension, indicates the market the company addresses. Within this study, the term “domain” is used in a narrow sense, referring to the Top-Level Domain (TLD) of the company’s website domain name, that is, the part of the URL following the final dot (for example, .com), rather than the domain name as a whole or the company’s field of activity. The domain (TLD), together with the site name chosen by its owner, forms the company’s complete domain name (Zimmerman & Abel, 1999). The full website address is denoted by the term “domain name”. A global domain does not tie a company to a particular country, whereas a country-code domain links it to a specific national market and its local web ecosystem (Sommese et al., 2024). This raises the question of whether the type of an IT company’s domain can serve as a valid proxy for customer capital, and whether this indicator is associated with the company’s financial performance. Customer capital reflects the value that arises at the interface of a firm’s interaction with its external environment, in particular with customers, partners, and the market. By its functional nature, a domain is an element of firm identification for external observers, so it structurally belongs to the customer component of intellectual capital rather than to its human or structural components. The proposed study develops this idea by applying a classification of companies’ domains into global and local as a proxy indicator of customer capital that reflects the declared market scope of a company.
Given that customer capital is only one component of intellectual capital, a comprehensive model also requires proxy indicators of human and structural capital, which within this study are represented by management intensity and intangible asset intensity. Accordingly, the aim of the study is to examine the association between domain type (global or local), as a proxy indicator of customer capital, and the financial performance (ROA, profit margin) of 2558 European IT companies that were market leaders in 2023, taking into account management intensity and intangible asset intensity and controlling for listing status, company size, country and industry.
The scientific novelty of the study lies in formalising an IT company’s domain type as a publicly available and easily verifiable proxy indicator of customer capital, integrated into a model that comprehensively covers all three components of intellectual capital.
The practical significance of the results lies in a low-cost and publicly available approach to approximating the customer component of companies’ intellectual capital, although its validity requires further verification. The findings of the study can be used by investment analysts and consulting companies in conducting due diligence, as well as by IT companies themselves for benchmarking their market positioning against competitors.
2. Literature Review
The inconsistency of results regarding the effect of intellectual capital on financial performance persists irrespective of the research context. In particular, the study by Bansal et al. (2025), conducted on a sample of 237 Indian companies from seven industries (including IT) using a modified VAIC model and dynamic panel models (GMM), demonstrated a robust positive effect of structural capital and capital utilisation efficiency on ROA, ROE, and ROCE, whereas the effect of human capital proved statistically insignificant in most model specifications. Similar heterogeneity was also observed by Nkambule et al. (2021) in a sample of American multinational software firms over the period 2012–2016, applying the Data Envelopment Analysis (DEA) method. Human capital showed a significant positive effect on company efficiency when considered separately; however, when combined with other IC components (innovation, process, and customer capital), its contribution became less significant, as the remaining elements partially absorbed this effect. Applying the classical VAIC, which does not account for customer capital, Singh (2024), using a sample of 50 leading Indian technology companies over the period 2009–2019, found no statistically significant relationship between intellectual capital and companies’ productivity, profitability, or market valuation, whereas physical and financial capital showed a significant positive effect. The application of the same VAIC to a different sample of Indian IT companies yields the opposite result. N. Joshi and Aggarwal (2024), examining, on the basis of a PLS-PM model, the 10 leading IT companies of the Nifty-IT index over the period 2011–2023, found a statistically significant positive effect of intellectual capital on financial performance, accounting for 77.2% of the variation in company indicators. An opposite picture for the IT sector is recorded by the study of Dsouza et al. (2026), based on a sample of 345 publicly listed US IT companies over the period 2011–2022 (1792 observations). VAIC and all three of its components (HCE, SCE, CEE) demonstrated a statistically significant negative effect on ROA, which the authors attribute to the inefficient use of intangible assets and high short-term expenditures on personnel and infrastructure that have not yet had time to translate into financial returns. None of the reviewed studies cover the European IT market, which in itself provides grounds for empirical testing on a European sample. Moreover, the divergence in results is partly explained by the fact that researchers apply different indicators and measurement methods to denote the same components of intellectual capital, which complicates the direct comparison of findings across studies.
The problem of finding proxy indicators for intellectual capital components is further exacerbated by the fact that non-financial disclosure is voluntary in nature and depends on management decisions. Rep et al. (2019), using a sample of Croatian high-tech companies, found an extremely low level of voluntary intellectual capital disclosure (only 19%), with this indicator depending substantially only on firm size rather than on financial performance. Similar conclusions were reached by Bhasin (2011), based on a sample of Indian IT corporations, applying a content-analysis model with a defined list of specific intellectual capital terms developed by Bontis (2003). The study established that the core components of intellectual capital, in particular relational, structural, and customer capital, are practically not reflected in companies’ reporting. The same model was applied by M. Joshi et al. (2012), who compared intellectual capital disclosure among the top 20 IT companies in India and Australia and found that a low and unsystematic level of disclosure is characteristic of companies in both countries regardless of their level of economic development.
Companies that require reporting-based proxy indicators of intellectual capital face not only the limitations of accounting standards but also the inconsistency and selectivity of voluntary disclosure, which reinforces the rationale for seeking publicly available web proxies independent of management’s reporting decisions.
In response to this problem, researchers propose various configurations of non-traditional proxy indicators. One of the earliest examples is the study by Riahi-Belkaoui (2003), who measured the intellectual capital of US multinational firms through the number of trademark applications, that is, through a publicly registered identifier rather than financial reporting data. Following similar logic, Yu et al. (2024) measure brand recognisability through the number of a company’s registered trademarks. This is an example of a non-traditional, easily verifiable proxy indicator of an intellectual capital element, in particular customer or relational capital. A similar approach is applied by Cruciata et al. (2024), who use textual analysis of companies’ web pages to construct a proxy indicator. This indicator correlates with an organisation’s actual environmental index, confirming the suitability of web signals for assessing the non-financial aspects of a company’s activity. Based on an analysis of the activities of 74 Australian public companies, the findings of Mauder (2018) demonstrate that the number of a company’s LinkedIn followers (unlike Facebook and Twitter) has a positive, statistically significant effect on stock returns, which is interpreted as a signal of the company’s social and relational capital. In other words, the number of followers on a specific social network has an effect on a company’s performance and can be used as yet another web proxy.
Empirical studies predominantly confirm the positive effect of technological capabilities on companies’ financial indicators. Oliveira et al. (2016) demonstrated that IT capabilities explain up to 48% of the variation in organisational process performance and improve companies’ profit and market share growth. Ma et al. (2021) found a significant relationship between IT capabilities and firm performance through the enhancement of knowledge management and operational processes. However, Masli et al. (2011), examining a panel of companies over the period 1988–2007, revealed more complex dynamics. Companies with superior IT capabilities achieved higher levels of return on assets (ROA) and return on sales (ROS) up to 1999, but this advantage disappeared in the post-1999 period as basic technologies became widely replicated. Only companies with the highest levels of technological excellence were able to sustain superior ROA and ROS throughout the entire period. For their part, Moro-Visconti et al. (2025) confirmed a non-linear relationship, identifying a concave relationship between digital intensity and organisational financial performance based on an analysis of profitability indicators (ROS) and cash flow measures (Free Cash Flow to Equity/Revenues, Free Cash Flow to the Firm/Revenues) of European companies, which points to the existence of an optimal point of investment in digitalisation beyond which returns diminish. Valaskova et al. (2025), using a sample of 500 Slovak enterprises, likewise record a selective nature of this relationship. The level of digitalisation is statistically significantly related to total assets, earnings after taxes, and shareholders’ funds, but not to total liabilities. The findings of the studies reviewed above demonstrate that the relationship between a company’s technological capabilities and its financial performance depends on the time horizon, the industry, and the financial indicators selected.
This reinforces the need for a framework that would explain why observable company attributes, rather than financial indicators alone, can serve as an indicator of a firm’s condition for external parties. Drawing on signalling theory, it can be assumed that certain observable company attributes are signals, that is, actions or characteristics that directly or indirectly indicate to stakeholders the intentions, motives, goals, or internal state of a firm, without requiring direct access to internal information (Zmud et al., 2010). As Connelly et al. note, an effective signal has two key characteristics, namely observability, that is, how easily external parties can notice it, and cost, which makes it difficult to falsify (Connelly et al., 2011). Wang et al. empirically confirm this relationship, showing that a higher level of information disclosure on a company’s website is positively related to financial performance, with this effect being reinforced by greater readability and a more positive tone of the text (Y. Wang et al., 2025). Mavlanova et al. distinguish signals along three dimensions (timing of purchase, cost, and ease of verification), including contact information, third-party certifications, privacy and return policies, consumer reviews, industry-specific content, payment mechanisms, and order confirmation (Mavlanova et al., 2012). Similar conclusions are reached by Sharma and Klein (2025), who analyse website features as trust signals for unfamiliar online sellers, among which authenticity attributes (professional website appearance, content quality) have the strongest effect on trust, whereas security attributes show the weakest effect according to the study’s findings. The studies reviewed above generally confirm that observable, easily verifiable company attributes can serve as a reliable indicator of a firm’s condition for external stakeholders even in the absence of direct access to internal information.
Among all elements of a company’s digital presence, the domain occupies a special place, since, unlike website content, it is a static, publicly registered, and legally fixed element. Website disclosure or text tone can change arbitrarily and frequently, whereas changing a domain entails registration and reputational costs, which makes this signal more stable and less susceptible to falsification. As Zimmerman and Abel (1999) note, an important purpose of a domain is to identify the entity to which a website belongs, which directly links the domain to the function of enabling recognition of a company specifically by its customers and other external users. This signalling function of the domain is confirmed empirically. Nagel and Sandner, on the basis of expert interviews, show that a brand’s domain extension is perceived as a signal of a company’s trustworthiness, quality, security, and authenticity (Nagel & Sandner, 2015). The signalling function of the domain manifests itself not only in a marketing context but also in a broader technological one. Taplin (2023) shows that AI-based cybersecurity systems use the sender’s domain as a verified identifier, assessing whether this domain has been encountered before and whether a confirmed business relationship with it exists. This indicates that the domain functions as a verified identifier not only for customers but also for automated trust-recognition systems, which further reinforces the argument for the robustness of this signal.
Empirical confirmation of this argument is provided by the study of Desmet et al. (2021), who developed and implemented, within the .eu domain registry, a system for predicting malicious registrations based on registrant data. The authors show that even malicious actors, when registering domains in bulk, are compelled to incur real economic costs in order to maintain the plausibility of registration data, which confirms the principle of “economic disincentivization”, since the cost and complexity of domain registration make it difficult to falsify this signal.
The study of Altındağ and Öngel (2021), based on a sample of 495 managers from Turkish IT companies, also provides empirical confirmation of the relationship between management practices, as a proxy for human capital, and performance, showing that information management practices have a direct and positive effect on both the innovative and financial performance of a firm, thereby confirming the role of managerial capability as a component of human capital in the IT sector. A similar relationship is confirmed by the study of Mata et al. (2024), based on a sample of 308 managers from Portuguese IT companies, in which a firm’s absorptive capacity, that is, its ability to accumulate and apply new knowledge, closely linked to managerial routines, mediates the effect of collaborative innovation on financial performance.
Intangible assets, as a proxy for structural capital, reflect an IT company’s capacity to create new products, technologies, and solutions, which directly affects its competitiveness and long-term financial performance. In empirical studies based on financial statements, this capacity is often captured through the share of intangible assets in total assets. Dancaková et al. (2022) defined this ratio as intangible asset intensity and examined its effect on the market value of companies. Jonek-Kowalska and Rupacz (2023) used the same ratio to identify the effects of innovative activities in Polish energy companies. Pascaru et al. (2026) applied the same ratio to 1170 listed European companies, arguing that intangible assets reflect capitalized investments in software, licenses, R&D, patents, and databases, and therefore represent the technological and innovation capacity of a firm. Dragomir (2024) likewise treated the proportion of intangible assets as a proxy for structural capital in a study of 625 European technology and healthcare companies. Accounting for this aspect in the model is important, since the effect of investment in intangible assets on company performance manifests itself with a time lag. Campbell (2012), using a sample of American companies, showed that technological investments begin to positively affect company performance already in the year of investment, although this effect reaches its maximum only after 3–4 years, while Xie et al. (2020) confirmed a similarly long-term lag in the effect of R&D investment on the value of companies in China’s technology sector. Empirical confirmation of the significance of innovation capital is provided by W.-Y. Wang and Chang (2005), who, using a sample of Taiwanese IT companies, demonstrated that innovation capital has a direct and positive effect on a company’s financial performance. A similar relationship is confirmed by Radonić et al. (2021), who examined the perceptions of 101 experts from the Serbian IT industry, finding that, among the four components of intellectual capital, innovation capital (product reputation, copyrights, product reliability) shows the strongest relationship with a company’s financial performance. The direct relationship between innovation performance and financial indicators is further confirmed by an empirical study of Turkish IT companies (Altındağ & Öngel, 2021), which demonstrated that a firm’s innovation performance has a direct and positive effect on its financial and growth performance. The studies reviewed above generally confirm that innovation activity is a significant factor in the financial performance of IT companies, although its effect may manifest itself with a certain time lag.
The effect of a company’s public status on its financial indicators remains contested. Kim et al. (2025), analysing 62,702 Japanese companies over the period 2002–2022, found that listed companies are more prone to earnings manipulation than non-listed ones, which indicates that short-term incentives outweigh the corporate governance benefits conferred by listing. At the same time, Capasso et al. (2005), applying a matched-pairs methodology to a sample of 30 pairs of European companies over the period 1999–2003, showed the opposite picture. Listed companies demonstrate faster revenue growth and use lower financial leverage, yet exhibit lower return on equity (ROE) compared with non-listed companies. A decline in profitability following a company’s transition to public status is also confirmed by the study of Pagano et al. (1998), who, unlike the cross-sectional comparisons of Kim et al. and Capasso et al., track the same panel of Italian companies before and after their Initial Public Offering (IPO), thereby recording a persistent decline in ROA after a company’s listing. A similar post-IPO decline in performance is also recorded by Mikkelson et al. (1997), using a sample of 283 American companies, although the authors attribute the main cause to company size and age rather than to earnings manipulation or changes in managerial ownership structure. The findings of these studies demonstrate the contradictory nature of listing’s effect on financial performance, since the benefits of access to capital are offset by heightened pressure on managers to deliver short-term results. Given these contradictory findings and the fact that listing status is a firm characteristic rather than a component of intellectual capital, it is included in the model as a control variable.
The literature review conducted demonstrates that traditional methods of assessing intellectual capital are based predominantly on financial reporting and do not provide a direct indicator of customer capital. Since the domain performs the function of identifying a company specifically for its customers and external users (Zimmerman & Abel, 1999), and since its type signals the market a company addresses (Connelly et al., 2011; Nagel & Sandner, 2015), it can serve as a publicly available and easily verifiable proxy indicator of customer capital. A global domain signals that a company addresses an international audience, whereas a country-code domain links it to a particular national market (Sommese et al., 2024). For IT companies, whose services can be delivered across borders, orientation towards an international market may provide access to a broader customer base and support higher profitability. Accordingly, a positive relationship is expected between a global domain and financial performance.
H1 (ROA, PM).
European IT companies with a global domain have higher financial performance indicators (ROA, PM) compared with companies with a local domain.
Although the study of Altındağ and Öngel (2021) records a positive relationship between management practices and IT firm performance, management intensity, as measured in this study, reflects not the quality of practices but the share of managerial personnel, that is, rather an additional operational burden. We therefore expect a cost-related effect rather than a positive one.
H2 (ROA, PM).
Management intensity is negatively associated with the financial performance indicators (ROA, PM) of European IT companies.
Since the effect of investment in intangible assets manifests itself with a time lag (Campbell, 2012; Xie et al., 2020), within a single year under study, we expect a rather cost-related effect of intangible asset intensity on financial indicators.
H3 (ROA, PM).
Intangible asset intensity is negatively associated with the financial performance indicators (ROA, PM) of European IT companies.
3. Materials and Methods
The study is based on cross-sectional data covering 2558 European IT companies that represent market leaders by sales volume in 2023. The empirical basis of the study comprises secondary data obtained from the international Orbis database and companies’ financial statements.
The sample covers different types of IT enterprises in accordance with the NACE Rev. 2 classification (Section J, Information and Communication): 620, Computer programming, consultancy and related activities; 631, Data processing, hosting and related activities; web portals; and 639, Other information service activities. It therefore includes leading European IT companies for which all variables required for the analysis are reported in the Orbis database. Since the availability of these data depends on national filing and disclosure requirements, the country composition of the sample reflects national disclosure practice rather than the structure of the European IT sector as a whole.
The initial extraction from the Orbis database comprised 2743 European IT companies that were leaders by sales volume in 2023. Companies with implausible or inconsistent data on employees and managers, as well as companies whose website could not be attributed to them or whose core activity lay outside the IT sector, were excluded, resulting in a final sample of 2558 companies (Table 1).
Table 1.
Sample construction.
The use of cross-sectional data for 2023 allows for an analysis of the association between the variables under study and the financial performance of IT companies without accounting for temporal dynamics, which is consistent with the aim of the study, namely to identify current relationships among the variables.
Hypotheses for ROA:
H1ROA.
European IT companies with a global domain have a higher return on assets compared with companies with a local domain.
H2ROA.
Management intensity is negatively associated with the return on assets of European IT companies.
H3ROA.
Intangible asset intensity is negatively associated with the return on assets of European IT companies.
Hypotheses for PM:
H1PM.
European IT companies with a global domain have a higher profit margin compared with companies with a local domain.
H2PM.
Management intensity is negatively associated with the profit margin of European IT companies.
H3PM.
Intangible asset intensity is negatively associated with the profit margin of European IT companies.
Model specification. Regression equation:
where DVi is the dependent variable (ROA or PM) of company i; α is the intercept; β1–β5 are the regression coefficients; Dom_type, Man_Int and Intang_Int are the explanatory variables; DList_st and l_TA are the control variables for listing status and company size; DCNTRi and DNACEi are vectors of country and industry dummy variables; β6 and β7 are the corresponding vectors of coefficients (Italy and NACE code 6201 are the reference categories); and εi is the error term.
DVi = α + β1 × Dom_typei + β2 × Man_Inti + β3 × Intang_Inti + β4 × DList_sti + β5 × l_TAi + β6 × DCNTRi + β7 × DNACEi + εi
Equation (1) represents the final specification. To assess how the coefficients of the explanatory variables change when control variables are taken into account, the models are estimated stepwise. Models 1a and 2a include the explanatory variables and listing status, Models 1b and 2b add company size, Models 1c and 2c add country fixed effects, and Models 1d and 2d add industry fixed effects and correspond to Equation (1). Models 1 and 2 refer to the dependent variables ROA and PM, respectively. All models are estimated using the OLS method with heteroskedasticity-robust standard errors.
To empirically test the formulated hypotheses, the study variables were defined, the specification of which is presented in Table 2.
Table 2.
Summary of variables used in the study.
The research approach employs proxy indicators for customer, human, and structural capital as the three components of the intellectual capital of leading European IT companies. Specifically, domain type (global or local) serves as a proxy for customer capital, management intensity serves as a proxy for human capital, and intangible asset intensity serves as a proxy for structural capital. Listing status, company size, country and industry are included as control variables to account for differences in ownership structure, scale, national environment and type of activity that may affect financial performance independently of intellectual capital components.
The choice of the three proxies is determined by the availability of comparable information for a large sample of mostly unlisted companies. Alternative measures, such as employee education and training expenditure for human capital, R&D expenditure and patent counts for structural capital, and survey-based assessments or social media indicators for customer capital (Garomssa et al., 2022; Mauder, 2018; Radonić et al., 2021), are not available in a consistent form for all companies in the sample. Management intensity and intangible asset intensity are calculated from data available in the Orbis database for all companies, and domain type is observable for every company with a website.
The authors’ approach uses the top-level domain of a company’s website as an indicator of its declared market scope. A global domain does not tie the company to a particular country, and some of these domains (.tech, .software, .digital, .io, .ai) also indicate its field of activity. A local country-code domain, in contrast, links the company to a specific national market, as websites under country-code domains reflect a local or regional web ecosystem (Sommese et al., 2024). Generic top-level domains and country-code domains that Google Search Central treats as generic were classified as global (Dom_type = 1), and all other country-code domains and the regional .eu domain were classified as local (Dom_type = 0) (adapted from Google, 2025). The full classification is presented in Table 3. Like other web-based proxies used instead of questionnaire surveys or expert assessments (Cruciata et al., 2024; Yu et al., 2024), domain names are a publicly available and directly observable indicator that allows large-scale analysis.
Table 3.
Classification of domains by type.
The emergence of new domain extensions, which formed the basis of the proposed classification, is directly linked to the launch of the New gTLD Programme by the Internet Corporation for Assigned Names and Numbers (ICANN) in 2012–2013. Prior to this, the number of generic top-level domains (gTLDs) was limited to twenty-two. The new programme allowed companies and organisations to apply for their own customised top-level domains, substantially expanding their number (Musiani, 2013).
The categorical division of domain names into top-level domains that are not tied to a specific country (for example, .com, .org) and country-code domains, control over which is exercised by the respective state (for example, .de, .pl, .fr), is well established in domain name research (Sinisalo, 2018) and underlies the distinction between the global and local categories in the proposed classification (Table 3).
The developed classification (Table 3) transforms the qualitative characteristics of domain extensions into a binary indicator of the declared market scope of a company. This approach provides the foundation for testing the hypotheses concerning the association between domain type and the financial indicators of IT companies (H1ROA and H1PM). Each company in the sample is assessed on the basis of its primary corporate domain, even if several companies of one group use the same root domain with different extensions (for example, conscia.dk, conscia.com, conscia.no).
The research methodology is based on the application of multiple linear regression using the ordinary least squares (OLS) method to examine the association of the studied variables with the ROA and PM indicators of European IT companies. Heteroskedasticity-robust standard errors (HC1) are used in all models, and standard errors clustered by country of registration with wild cluster bootstrap p-values, models with winsorized variables and Cook’s distance are used as robustness checks. An additional robustness check uses return on tangible assets (ROTA) as the dependent variable to exclude intangible assets from the denominator. Statistical analysis was performed using the Gretl software package 2025c.
4. Results
4.1. Sample
The structural distribution of the sample by type of economic activity is presented in Table 4.
Table 4.
Sample distribution by NACE activity codes (by frequency).
The structural analysis of the sample shows that the largest share is accounted for by companies in the categories “Computer programming activities” (42.1%) and “Computer consultancy activities” (23.4%), which together form over 65% of the companies in the sample.
The structure of the sample by country of origin of the companies is given in Table 5.
Table 5.
Sample distribution by country (by frequency).
The sample covers 36 European countries. Geographical analysis shows the predominance of Italy (16.2%), Germany (10.5%), Sweden (10.0%), and Spain (9.9%), which together account for 46.7% of all companies under study, indicating a high geographical concentration of the sample.
To control for country and industry effects, companies were grouped on the basis of their distribution in the sample. Countries with 50 or more companies form separate categories, namely Italy, Germany, Sweden, Spain, Poland, Belgium, Norway, Finland, Portugal, Denmark, France, Romania and Hungary. The remaining 23 countries, with fewer than 50 companies each, are grouped into the “Other” category (389 companies, 15.2% of the sample). Similarly, NACE codes accounting for more than 10% of the sample (6201, 6202 and 6209) form separate categories, while the remaining codes are grouped into the “Other” category (448 companies, 17.5% of the sample). This grouping avoids unstable coefficient estimates for categories with a small number of observations. Italy and NACE code 6201, as the largest groups, are used as the reference categories.
4.2. Descriptive Statistics
Table 6 shows the descriptive statistics of the variables used in the models (N = 2558).
Table 6.
Descriptive statistics of the variables used in the models.
Descriptive statistics show positive (right) skewness for most indicators, which is manifested in the excess of the mean values over the medians for ROA, PM, Man_Int and Intang_Int. The most pronounced skewness is observed for Intang_Int, with a large difference between the mean (11.32%) and the median (1.83%), indicating that most companies hold few intangible assets, while a small group holds a substantial share. ROA and PM range from negative to high positive values, which indicates considerable heterogeneity in the profitability of the companies. Companies with a global domain account for 50.9% of the sample. The share of listed companies is 6.8%, which indicates that the sample consists predominantly of unlisted companies. ROTA has a wider range than ROA, since excluding intangible assets reduces the denominator. No observations were excluded on this ground, as the tangible assets of all companies amount to at least 5% of total assets, and only two companies have an intangible asset intensity above 90%.
4.3. Diagnostic Tests
Before interpreting the regression results, the final specifications (Models 1d and 2d) were checked for multicollinearity, overall significance, normality of residuals, heteroskedasticity and within-country dependence of residuals.
(1) Multicollinearity. The presence of multicollinearity among the independent variables used in Model 1d and Model 2d was assessed using a correlation matrix (Figure 1).
Figure 1.
Correlation matrix of explanatory and control variables. Note: Generated using Gretl software package. Source: compiled by authors.
The correlation matrix shows the absence of multicollinearity problems between the explanatory and control variables. The highest correlation coefficient is observed between DList_st and Intang_Int (0.37), followed by l_TA with Intang_Int (0.32) and with DList_st (0.31). These values are at an acceptable level and do not exceed the critical value of 0.7. Other variables are characterized by weak correlations, which indicates that they can be jointly included in the regression models. Variance inflation factors in the final specifications range from 1.08 to 1.77, and the VIF of Dom_type with the country dummies included is 1.08. The country fixed effects explain only 4.3% of the variation in Dom_type (7.5% together with all other regressors), so most of its variation occurs within countries, as also shown by the share of global domains by country (Table 5).
(2) F-test. The F-test confirms the overall significance of the final specifications. Model 1d with the dependent variable ROA is characterized by an F-statistic of 20.18 (p < 0.001), which indicates a high overall significance of the model and rejection of the null hypothesis that all regression coefficients are zero. Model 2d with the dependent variable PM also confirms statistical significance with an F-statistic of 6.58 (p < 0.001).
(3) Checking the normality of the distribution of residuals. The diagnosis of the normality of the residuals was carried out using Q-Q plots, which are presented in Figure 2.
Figure 2.
Normality diagnostics of residuals in regression models (Q-Q plots). Note: Generated using Gretl software package. The horizontal axis shows the quantiles of the normal distribution, and the vertical axis shows the quantiles of the residuals. Source: compiled by authors.
The Q-Q plot of residuals for Model 1d (dependent variable ROA) indicates that the residuals follow the diagonal line in the central part of the distribution. Deviations are observed in both tails, indicating heavier tails than under the normal distribution, which is typical for profitability indicators with extreme values. A similar situation is observed for Model 2d (dependent variable PM), where the deviations in the tails are somewhat more pronounced. Given the large sample size (N = 2558), the coefficient estimates and significance tests in both models remain reliable according to the central limit theorem. Heteroskedasticity-robust standard errors are additionally used in all models.
(4) Heteroskedasticity. The Breusch–Pagan test confirmed the presence of heteroskedasticity in both models (LM = 458.21 for Model 1d and LM = 691.76 for Model 2d, p < 0.001 for both), which justifies the use of robust standard errors to ensure the correctness of the statistical inferences.
(5) Autocorrelation and within-country dependence. Testing for autocorrelation of residuals was not conducted, since the study is based on cross-sectional data representing different IT companies at a single point in time. Under such conditions, autocorrelation of residuals is unlikely, owing to the absence of a natural temporal ordering among observations. However, residuals of companies from the same country may be correlated, owing to the common institutional and economic environment. To account for this dependence, the models were additionally estimated with standard errors clustered by country (Section 4.5).
4.4. Regression Results
The results of the stepwise estimation for ROA are presented in Table 7.
Table 7.
Regression results for ROA with the stepwise inclusion of control variables.
Intang_Int is negatively and significantly associated with ROA at the 1% level in all four specifications, and its coefficient changes only slightly after the inclusion of control variables (from −0.212 in Model 1a to −0.181 in Model 1d). The coefficient of Dom_type is negative and significant at the 5% level in Model 1a (−1.110). After company size and country fixed effects are added, it decreases in absolute value and becomes insignificant (Models 1b and 1c), while in the final Model 1d it is significant only at the 10% level (−1.024). The association between domain type and ROA is therefore weak and partly reflects differences in company size and country composition. Man_Int is negative and significant in Models 1a and 1b, but loses significance after country and industry fixed effects are included. Listing status is not significantly associated with ROA in any specification. Company size is negatively associated with ROA at the 1% level in all models where it is included. The F-tests confirm the joint significance of country fixed effects (F = 5.18, p < 0.001) and industry fixed effects (F = 6.00, p < 0.001) in Model 1d. With the inclusion of control variables, the adjusted R2 increases from 7.8% to 11.5%.
The results for PM are presented in Table 8.
Table 8.
Regression results for PM with the stepwise inclusion of control variables.
Intang_Int is negatively and significantly associated with PM at the 1% level in all specifications, with a coefficient of about −0.19 after the inclusion of control variables. Man_Int is positively associated with PM, and its coefficient increases from 0.027 (significant at the 10% level) in Model 2a to 0.045 (significant at the 1% level) in Model 2d. Dom_type and listing status are not significantly associated with PM in any specification. Company size is positively associated with PM at the 1% level. In Model 2d, country fixed effects are jointly significant only at the 10% level (F = 1.60, p = 0.077), and industry fixed effects are jointly insignificant (F = 1.33, p = 0.264). The adjusted R2 of the final model is 6.2%.
Table 9 summarises the results of hypothesis testing based on the final Models 1d and 2d.
Table 9.
Results of hypothesis testing.
H3 is supported for both indicators of financial performance, as Intang_Int is negatively associated with ROA and PM in all specifications. H1 and H2 are rejected. For H1ROA and H2PM, the coefficients are significant but have the sign opposite to the expected one, while for H1PM and H2ROA the coefficients are insignificant.
4.5. Robustness Checks
To verify that the results do not depend on the assumption of independent residuals, the final models were re-estimated with standard errors clustered by country of registration (36 clusters), while the country fixed effects use the 14 grouped categories. Since 36 clusters is still a moderate number, wild cluster bootstrap p-values are additionally reported for the explanatory variables. The main results remain unchanged (Table 10). Intang_Int remains significant at the 1% level in both models, which is confirmed by the wild cluster bootstrap (p < 0.001). Dom_type is significant at the 5% level in the ROA model with clustered standard errors, although its wild cluster bootstrap p-value is 0.050, and it remains insignificant in the PM model. Man_Int remains significant in the PM model at the 5% level (wild cluster bootstrap p = 0.027), while DList_st remains insignificant in both models. Given the moderate number of clusters, the models with heteroskedasticity-robust standard errors are treated as the main specification.
Table 10.
Robustness checks: country-clustered standard errors, winsorized variables and an alternative dependent variable.
To address the possible mechanical link between Intang_Int and ROA, as total assets enter the denominators of both variables, the final ROA model was re-estimated with return on tangible assets (ROTA) as the dependent variable. ROTA is calculated as net income divided by total assets less intangible assets. The negative association of Intang_Int remains significant at the 1% level (−0.214), and its magnitude is close to that in the ROA model (−0.181) (Table 10). Company size remains negatively associated with ROTA at the 1% level, while Dom_type, Man_Int and listing status are insignificant.
To check whether extreme values drive the results, the final models were re-estimated with all continuous variables winsorized at the 1st and 99th percentiles. The coefficients remain close to those in the main specifications (Table 10). Intang_Int remains negative and significant at the 1% level for both ROA (−0.179) and PM (−0.183), Dom_type remains negative and significant only at the 10% level for ROA (−0.902), and Man_Int remains positive and significant for PM (0.042).
The influence of individual observations was assessed using Cook’s distance. Its maximum value is 0.033 in the ROA model and 0.025 in the PM model, far below the conventional threshold of 1, so no single observation materially affects the estimates. When observations with Cook’s distance above 4/N are excluded (141 observations in the ROA model and 145 in the PM model), the coefficients of Intang_Int (−0.153 for ROA and −0.137 for PM) and Dom_type (−0.894 for ROA) remain significant and close to the main estimates. In contrast, the positive association of Man_Int with PM disappears (0.003), and its association with ROA becomes negative and significant (−0.032). The results for management intensity are therefore sensitive to a group of influential observations and should be interpreted with caution.
5. Discussion
The results support H3 for both indicators of financial performance and do not support H1 and H2. Intangible asset intensity is the only explanatory variable whose association with ROA and PM is stable across all specifications and robustness checks, while the associations of domain type and management intensity are weak or depend on the dependent variable and the set of control variables.
Contrary to H1, a global domain is not associated with higher financial performance. For ROA, the coefficient of Dom_type is negative, significant at the 5% level only before company size and country fixed effects are added, and significant at the 10% level in the final model. Its magnitude is small. Companies with a global domain have an ROA about 1 percentage point lower than companies with a local domain, which corresponds to about 0.07 standard deviations of ROA, and the 95% confidence interval (from −2.07 to 0.02) includes values close to zero. The coefficient is significant at the 5% level with country-clustered standard errors, although its wild cluster bootstrap p-value is 0.050, and it is insignificant when ROTA is used as the dependent variable. The decrease in the coefficient after size and country controls are added indicates that the raw difference between companies with global and local domains partly reflects differences in company size and country composition. This pattern is consistent with the view that a domain functions primarily as a signal for external stakeholders (Zimmerman & Abel, 1999; Nagel & Sandner, 2015) rather than as a direct driver of operational efficiency, so a positive association with current profitability should not necessarily be expected. A country-code domain links a company to its national web ecosystem (Sommese et al., 2024), which does not by itself imply a weaker market position, since IT companies with a local domain may hold an established customer base in their home market.
The weak association of domain type with financial performance is also consistent with Y. Wang et al. (2025), who show that the effect of a company’s digital presence depends on website content characteristics such as readability and tone rather than on the mere presence of a website. Domain type captures only one dimension of a company’s digital presence. Garomssa et al. (2022), assessing relational capital through expert surveys in commercial open-source software companies, found a positive relationship between relational capital and company success. The difference from the present results suggests that the declared market scope signalled by a domain and the depth of customer relationships assessed by experts capture different aspects of customer capital.
A categorical approach to digital characteristics of companies is also applied by Moro-Visconti et al. (2025), who classify European companies by digital intensity on the basis of the share of digitalised business processes. That approach requires detailed internal data, whereas the domain classification proposed in this study relies only on publicly available information and allows large-scale analysis. The present results indicate, however, that such an easily observable proxy has limited explanatory power for financial performance, and its suitability as an indicator of customer capital requires further verification.
H2 is not supported. Management intensity is negatively associated with ROA only in the models without country and industry fixed effects, and this association becomes insignificant once these controls are included. This suggests that the initial negative association reflected differences in managerial structures across countries and types of activity. For PM, the association is positive and significant at the 1% level in the final model, which is opposite to the expected sign. The magnitude is small, as an increase in Man_Int by one standard deviation (18.5 percentage points) is associated with an increase in PM of about 0.8 percentage points (95% confidence interval for the coefficient from 0.016 to 0.074). Moreover, this association disappears when influential observations are excluded, which indicates that it is driven by a limited group of companies. Since the measure reflects the share of managerial personnel rather than the quality of management, these results cannot be directly compared with the positive effects of management practices reported by Altındağ and Öngel (2021) and Mata et al. (2024). As the difference between the coefficients for ROA and PM was not formally tested, the results for the two indicators are interpreted separately.
H3 is supported for both indicators. The coefficient of Intang_Int is negative and significant at the 1% level in all specifications, with country-clustered standard errors and when ROA is replaced with ROTA. An increase in Intang_Int by one standard deviation (18.4 percentage points) is associated with a decrease in ROA of about 3.3 percentage points and in PM of about 3.6 percentage points, which corresponds to standardised coefficients of −0.23 and −0.26, respectively. This is the largest association among the explanatory variables. Since PM is calculated relative to sales and ROTA excludes intangible assets from the denominator, the negative association cannot be attributed only to the mechanical link between intangible assets and total assets. This result is consistent with the time-lag argument underlying H3. Campbell (2012) showed that the positive effect of technological investments on company performance reaches its maximum only after three to four years, and Xie et al. (2020) recorded a similar lag for R&D investment in China’s technology sector. Cross-sectional data for a single year capture companies at different stages of this cycle, in which current costs may outweigh the returns that have not yet materialised. An alternative explanation is related to goodwill, which may be included in intangible assets and reflects acquisition premiums rather than internally created resources.
The negative association differs from the positive relationship between innovation capital and financial performance reported by W.-Y. Wang and Chang (2005) and Radonić et al. (2021) for Taiwanese and Serbian IT companies. This divergence may be explained by the measures used. Radonić et al. (2021) relied on expert perceptions of innovation capital, and W.-Y. Wang and Chang (2005) used R&D expenditure, whereas Intang_Int captures the accumulated stock of intangible assets rather than current innovation effort. The result is consistent with Dragomir (2024), who found that a higher proportion of intangible assets is negatively associated with profitability among European technology and healthcare companies. Özcan (2025), using the same ratio, found a positive effect on ROA for Turkish manufacturing firms, in which intangible assets averaged 2.9% of total assets compared with 11.32% in the present sample. This difference reflects the distinct nature of the two industries, as intangible assets play a much larger role in the IT industry than in manufacturing (W.-Y. Wang & Chang, 2005).
Among the control variables, listing status is not significantly associated with either ROA or PM, which corresponds to the contradictory evidence on the effect of listing (Capasso et al., 2005; Kim et al., 2025; Pagano et al., 1998) and to the small share of listed companies in the sample (6.8%). Company size is negatively associated with ROA and positively associated with PM, and country fixed effects are jointly significant for ROA, which confirms the importance of controlling for size and national environment when analysing the financial performance of IT companies.
The study has several limitations. First, the sample includes only European IT companies that were market leaders by sales volume, so the findings cannot be generalised to all IT companies, including small firms and companies outside Europe. Moreover, the sample is constrained by the availability of the required variables in the Orbis database, which depends on national filing and disclosure requirements. The results therefore apply primarily to companies from jurisdictions with extensive disclosure and cannot be generalised to the European IT sector as a whole. Second, the analysis is based on cross-sectional data for a single year (2023), which does not allow causal conclusions to be drawn or the lagged effects of intangible assets to be captured. Third, the domain type reflects the declared rather than the actual market scope of a company, as a global domain does not necessarily mean that a company operates in international markets. The classification is based only on the domain extension and does not take into account the language versions or content of the website. Fourth, Intang_Int is based on the total value of intangible assets, which may include goodwill, as the available data did not allow goodwill to be separated from other intangible assets. Goodwill arises from acquisitions and reflects the acquisition premium rather than the company’s own investment in software, R&D or databases. In addition, total assets enter the denominators of both Intang_Int and ROA, which may partly produce a mechanical negative association between them. However, the negative association persists when ROA is replaced with return on tangible assets and when PM, which is calculated relative to sales, is used as the dependent variable. Fifth, the study does not control for company age, as there is no unambiguous date from which to measure it. The year of foundation, the year of incorporation and, for subsidiaries of international groups, the year of registration in a particular country can differ considerably. Sixth, the explanatory power of the models is modest (adjusted R2 of 11.5% for ROA and 6.2% for PM), so most of the variation in financial performance is explained by factors not included in the models. Finally, the number of country clusters (36) is relatively small for reliable clustered standard errors. Future research could use panel data covering several years, separate goodwill from other intangible assets, include company age based on a consistently defined reference date, combine domain type with other web-based indicators of market scope (for example, website language versions) and extend the analysis to IT companies of different sizes and regions.
6. Conclusions
This study examined the association between domain type (global or local), as a proxy indicator of customer capital, and the financial performance (ROA, profit margin) of 2558 leading European IT companies by sales volume in 2023. The activities of such companies take place predominantly in a digital environment, which justifies using the website domain as a publicly available indicator of a company’s declared market scope. The models also included management intensity and intangible asset intensity as proxies for human and structural capital and controlled for listing status, company size, country and industry.
The choice of domain as a proxy indicator is based on its stability. Unlike website content, the number of social media followers or the tone of communication, which can change frequently, a change in domain entails registration and reputational costs, which makes this signal less susceptible to falsification.
The results show that the three components of intellectual capital are associated with financial performance in different ways. A global domain was weakly negatively associated with ROA, and this association was sensitive to the inclusion of company size and country controls and was not observed for profit margin. Its magnitude was small, corresponding to about 1 percentage point of ROA. Management intensity was not associated with ROA after country and industry controls were included, and it was weakly positively associated with profit margin. Intangible asset intensity showed the strongest and most stable association, as it was negatively associated with both ROA and profit margin in all specifications, with country-clustered standard errors and when return on tangible assets was used as the dependent variable. Listing status was not associated with either indicator.
The results do not confirm the suitability of domain type as a standalone proxy indicator of customer capital. The weak and unstable association with ROA and the absence of an association with profit margin indicate that domain type reflects a company’s declared market scope and, to a large extent, overlaps with company size and country of registration. At the same time, the negative association of intangible asset intensity with current profitability is consistent with the time lag between investment in intangible assets and its financial returns.
The scientific novelty of the study lies in formalising an IT company’s domain type as a publicly available and easily verifiable proxy indicator of customer capital, integrated into a model that covers all three components of intellectual capital, and in testing it with country, industry, and size controls.
The results have implications for theory, policy and practice. For value-added-based research on intellectual capital (VAIC, MVAIC), they show that components measured by publicly available indicators independent of value added are associated with profitability in different directions, and that the short-term association of capitalised intangible assets with profitability may be negative. For policymakers and standard setters, the results indicate that publicly observable signals cannot substitute for the disclosure of information on intangible resources. In practice, investment analysts and consulting companies should take into account that a high share of intangible assets may be associated with lower current profitability, while domain type can be used only for the preliminary assessment of a company’s declared market scope in combination with other indicators.
Since domain type and the financial ratios used in this study are available for companies in any country, the approach can be applied by analysts, regulators and researchers in other jurisdictions, particularly where non-financial disclosure is limited. The significance of country fixed effects indicates, however, that the national environment should be controlled for in such applications.
The conclusions are limited by the cross-sectional data and the focus on market leaders. Further research could use panel data to identify dynamic effects, separate goodwill from other intangible assets, and combine domain type with other web-based indicators of market scope.
Author Contributions
Conceptualization, T.Z. and S.L.; methodology, T.Z.; software, T.Z.; validation, T.Z. and S.L.; formal analysis, T.Z.; investigation, T.Z.; resources, T.Z. and S.L.; data curation, T.Z.; writing—original draft preparation, T.Z.; writing—review and editing, T.Z. and S.L.; visualization, T.Z.; supervision, S.L.; project administration, S.L.; funding acquisition, not applicable. All authors have read and agreed to the published version of the manuscript.
Funding
This research received no external funding.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The data supporting the results of this study are openly available in Zenodo at https://doi.org/10.5281/zenodo.23195374 (Zavalii, 2026).
Acknowledgments
During the preparation of this manuscript, the authors used Claude (Anthropic, Claude Sonnet 5) to improve the translation of the manuscript text, as well as for language editing and improving readability. All content was reviewed, edited, and approved by the authors, who take full responsibility for the content of this publication.
Conflicts of Interest
The authors declare no conflicts of interest.
Abbreviations
The following abbreviations are used in this manuscript:
| CEE | Capital Employed Efficiency |
| DEA | Data Envelopment Analysis |
| FE | Fixed Effect |
| GMM | Generalized Method of Moments |
| gTLD | Generic Top-Level Domain |
| gccTLD | Generic Country-Code Top-Level Domain |
| HCE | Human Capital Efficiency |
| HC1 | Heteroskedasticity-Robust Standard Errors |
| IC | Intellectual Capital |
| ICANN | Internet Corporation for Assigned Names and Numbers |
| IPO | Initial Public Offering |
| MVAIC | Modified Value-Added Intellectual Coefficient |
| NACE | Statistical Classification of Economic Activities in the European Union |
| OLS | Ordinary Least Squares |
| PLS-PM | Partial Least Squares Path Modeling |
| PM | Profit Margin |
| ROA | Return on Assets |
| ROCE | Return on Capital Employed |
| ROE | Return on Equity |
| ROS | Return on Sales |
| ROTA | Return on Tangible Assets |
| SCE | Structural Capital Efficiency |
| TLD | Top-Level Domain |
| VAIC | Value-Added Intellectual Coefficient |
References
- Altındağ, Ö., & Öngel, V. (2021). Information management, organizational intelligence, and innovation performance triangle: Empirical research on Turkish IT firms. SAGE Open, 11(4), 1–18. [Google Scholar] [CrossRef] [Scilit]
- Bansal, A., Singh, S., & Bansal, P. (2025). The intellectual capital-performance nexus: Analyzing financial returns through static and dynamic models. International Research Journal of Multidisciplinary Scope, 6(1), 911–926. [Google Scholar] [CrossRef] [Scilit]
- Bhasin, M. L. (2011). Disclosure of intellectual capital in annual reports: An empirical study of the Indian IT corporations. Modern Economy, 2(5), 455–467. [Google Scholar] [CrossRef]
- Bonanno, G., Ferrando, A., & Rossi, S. P. S. (2023). Do innovation and financial constraints affect the profit efficiency of European enterprises? Eurasian Business Review, 13(1), 57–86. [Google Scholar] [CrossRef] [Scilit]
- Bontis, N. (2003). Intellectual capital disclosure in Canadian corporations. Journal of Human Resource Costing and Accounting, 7(1), 9–20. [Google Scholar] [CrossRef] [Scilit]
- Campbell, M. (2012). What a difference a year makes: Time lag effect of information technology investment on firm performance. Journal of Organizational Computing and Electronic Commerce, 22(3), 237–255. [Google Scholar] [CrossRef] [Scilit]
- Capasso, A., Rossi, M., & Simonetti, B. (2005). Ownership structure heterogeneity and performance: A comparison between listed and unlisted companies [Working paper]. SSRN. [Google Scholar] [CrossRef] [Scilit]
- Chyzhevska, L., Voloschuk, L., Shatskova, L., & Sokolenko, L. (2021). Digitalization as a vector of information systems development and accounting system modernization. Studia Universitatis “Vasile Goldis” Arad. Economics Series, 31(4), 18–39. [Google Scholar] [CrossRef] [Scilit]
- Connelly, B. L., Certo, S. T., Ireland, R. D., & Reutzel, C. R. (2011). Signaling theory: A review and assessment. Journal of Management, 37(1), 39–67. [Google Scholar] [CrossRef] [Scilit]
- Cruciata, P., Pulizzotto, D., & Beaudry, C. (2024). First impressions on sustainable innovation matter, using NLP to replicate B-lab environmental index by analyzing companies’ homepages. Technological Forecasting & Social Change, 205, 123455. [Google Scholar] [CrossRef] [Scilit]
- Dancaková, D., Sopko, J., Glova, J., & Andrejovská, A. (2022). The impact of intangible assets on the market value of companies: Cross-sector evidence. Mathematics, 10(20), 3819. [Google Scholar] [CrossRef] [Scilit]
- Desmet, L., Spooren, J., Vissers, T., Janssen, P., & Joosen, W. (2021). Premadoma: An operational solution to prevent malicious domain name registrations in the .eu TLD. Digital Threats: Research and Practice, 2(1), 1–24. [Google Scholar] [CrossRef] [Scilit]
- Dragomir, V. D. (2024). The impact of intangible capital on firm profitability in the technology and healthcare sectors. International Journal of Financial Studies, 12(1), 5. [Google Scholar] [CrossRef] [Scilit]
- Dsouza, S., Kallach, L., Demiraj, R., & Zaidi, S. F. H. (2026). Unveiling the power of intellectual capital in driving financial performance: A deep dive into the IT sector. Emerging Science Journal, 10(1), 165–183. [Google Scholar] [CrossRef] [Scilit]
- Duc, K. H., Tai, D. D., & Van Hau, N. (2025). The impact of intellectual capital on financial performance in information technology and telecommunications firms. Financial and Credit Activity: Problems of Theory and Practice, 4(63), 264–278. [Google Scholar] [CrossRef] [Scilit]
- Edvinsson, L., & Malone, M. S. (1997). Intellectual capital: Realizing your company’s true value by finding its hidden brainpower. HarperBusiness. [Google Scholar]
- Garomssa, S. D., Kannan, R., Chai, I., & Riehle, D. (2022). How software quality mediates the impact of intellectual capital on commercial open-source software company success. IEEE Access, 10, 47827–47842. [Google Scholar] [CrossRef] [Scilit]
- Google. (2025). Managing multi-regional and multilingual sites. Google Search Central. Available online: https://developers.google.com/search/docs/specialty/international/managing-multi-regional-sites (accessed on 3 October 2026).
- Goto, M. (2010). Financial performance analysis of US and world telecommunications companies: Importance of Information Technology in the telecommunications industry after the AT&T breakup and the NTT divestiture. Decision Support Systems, 48(3), 447–456. [Google Scholar] [CrossRef] [Scilit]
- Jonek-Kowalska, I., & Rupacz, S. (2023). The innovative nature of selected Polish companies in the energy sector compared to the use of renewable energy sources from a financial and an investor’s perspective. Resources, 12(12), 147. [Google Scholar] [CrossRef] [Scilit]
- Joshi, M., Ubha, D. S., & Sidhu, J. (2012). Intellectual capital disclosures by Indian and Australian information technology companies: A comparative analysis. Journal of Intellectual Capital, 13(4), 582–598. [Google Scholar] [CrossRef] [Scilit]
- Joshi, N., & Aggarwal, A. (2024). Modelling the impact of intellectual capital on financial performance: A case of Indian IT companies. Intellectual Economics, 18(1), 34–58. [Google Scholar] [CrossRef] [Scilit]
- Jung, Y. L., & Yoo, H. S. (2023). Environmental, social, and governance activities and firm performance: Global evidence and the moderating effect of market competition. Corporate Social Responsibility and Environmental Management, 30(6), 2830–2839. [Google Scholar] [CrossRef] [Scilit]
- Kim, H., Yasuda, Y., & Iwata, K. (2025). Listing status, stock liquidity, and earnings management: Evidence from listed and unlisted firms in Japan [Preprint]. SSRN. [CrossRef] [Scilit]
- Koutroumpis, P., Leiponen, A., & Thomas, L. D. W. (2020). Small is big in ICT: The impact of R&D on productivity. Telecommunications Policy, 44(1), 101833. [Google Scholar] [CrossRef] [Scilit]
- Lehenchuk, S., Zeytinoglu, E., Hrabchuk, I., Zhalinska, I., & Oleksich, Z. (2023). Nexus between intellectual capital, financial performance and sustainable growth: Evidence from the Turkish ICT industry. Marketing and Management of Innovations, 14(2), 152–162. [Google Scholar] [CrossRef] [Scilit]
- Loderer, C., & Waelchli, U. (2010). Protecting minority shareholders: Listed versus unlisted firms. Financial Management, 39(1), 33–57. [Google Scholar] [CrossRef] [Scilit]
- Ma, F., Khan, F., Khan, K. U., & XiangYun, S. (2021). Investigating the impact of information technology, absorptive capacity, and dynamic capabilities on firm performance: An empirical study. SAGE Open, 11(4), 1–18. [Google Scholar] [CrossRef] [Scilit]
- Masli, A., Richardson, V. J., Sanchez, J. M., & Smith, R. E. (2011). Returns to IT excellence: Evidence from financial performance around information technology excellence awards. International Journal of Accounting Information Systems, 12(3), 189–205. [Google Scholar] [CrossRef] [Scilit]
- Mata, M. N., Martins, J. M., & Inácio, P. L. (2024). Collaborative innovation and absorptive capacity as an antecedent on IT firm financial performance. Journal of the Knowledge Economy, 15(4), 6339–6361. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Mauder, P. (2018). The impact of social media followers on corporate value: An investigation of Australian firms. The International Technology Management Review, 7(1), 1–12. [Google Scholar] [CrossRef] [Scilit]
- Mavlanova, T., Benbunan-Fich, R., & Koufaris, M. (2012). Signaling theory and information asymmetry in online commerce. Information & Management, 49(5), 240–247. [Google Scholar] [CrossRef] [Scilit]
- Mikkelson, W. H., Partch, M. M., & Shah, K. (1997). Ownership and operating performance of companies that go public. Journal of Financial Economics, 44(2), 281–307. [Google Scholar] [CrossRef] [Scilit]
- Moro-Visconti, R., Sánchez García, J., López Pascual, J., & Cruz Rambaud, S. (2025). Digitalization intensity and its impact on financial performance: The role of scalable platforms. Finance Research Letters, 74, 106772. [Google Scholar] [CrossRef] [Scilit]
- Musiani, F. (2013). New global top-level domain names: Europe, the challenger. Internet Policy Review, 2(2). [Google Scholar] [CrossRef] [Scilit][Green Version]
- Nagel, A., & Sandner, P. (2015). Evaluation of new generic top level domains from a brand and a trademark perspective. International Journal of Management and Marketing Research, 8(1), 93–112. [Google Scholar]
- Nkambule, N. A., Wang, W.-K., Ting, I. W. K., & Lu, W.-M. (2021). Intellectual capital and firm efficiency of US multinational software firms. Journal of Intellectual Capital, 23(6), 1404–1434. [Google Scholar] [CrossRef] [Scilit]
- Oliveira, D. de L., Maçada, A. C. G., & Oliveira, G. D. (2016). Business value of IT capabilities: Effects on processes and firm performance in a developing country. Review of Business Management, 18(60), 245–266. [Google Scholar] [CrossRef] [Scilit]
- Özcan, A. (2025). Navigating volatility: How to maintain strong profitability in uncertain times: Evidence from manufacturing firms. SAGE Open, 15(4). [Google Scholar] [CrossRef] [Scilit]
- Pagano, M., Panetta, F., & Zingales, L. (1998). Why do companies go public? An empirical analysis. The Journal of Finance, 53(1), 27–64. [Google Scholar] [CrossRef] [Scilit]
- Pascaru, A. G., Hategan, C.-D., & Pitorac, R.-I. (2026). Digital transformation and audit pricing: The learning curve effect. Systems, 14(5), 590. [Google Scholar] [CrossRef] [Scilit]
- Radonić, M., Milosavljević, M., & Knežević, S. (2021). Intangible assets as financial performance drivers of IT industry: Evidence from an emerging market. E&M Economics and Management, 24(2), 119–135. [Google Scholar] [CrossRef] [Scilit]
- Rep, A., Žager, K., & Oliveira, C. (2019). The role of firm characteristics in voluntary disclosure of IC information and its importance for high-tech companies. Journal of Information and Organizational Sciences, 43(2), 185–209. [Google Scholar] [CrossRef] [Scilit]
- Riahi-Belkaoui, A. (2003). Intellectual capital and firm performance of US multinational firms: A study of the resource-based and stakeholder views. Journal of Intellectual Capital, 4(2), 215–226. [Google Scholar] [CrossRef] [Scilit]
- Shaneeb, P., & Sumathy, M. (2021). Impact of intellectual capital on firm performance in Indian IT companies. Journal of Contemporary Issues in Business and Government, 27(2), 4335–4340. [Google Scholar] [CrossRef] [Scilit]
- Sharma, V. M., & Klein, A. (2025). A signaling theory-based analysis of website features, investment perception and trust propensity in initial trust formation on unfamiliar small online retailers. Journal of Marketing Theory and Practice, 33(2), 232–253. [Google Scholar] [CrossRef] [Scilit]
- Singh, R. D. (2024). The impact of intellectual capital on financial performance: An empirical investigation of Indian technology industry. Journal of Management Research and Analysis, 11(2), 123–130. [Google Scholar] [CrossRef] [Scilit]
- Sinisalo, T. J. (2018). .eu regulations under Brexit. Baltic Journal of European Studies, 8(2), 121–144. [Google Scholar] [CrossRef] [Scilit]
- Sommese, R., van Rijswijk-Deij, R., & Jonker, M. (2024). This is a local domain: On amassing country-code top-level domains from public data. ACM SIGCOMM Computer Communication Review, 54(2), 2–9. [Google Scholar] [CrossRef] [Scilit]
- Stewart, T. A. (1997). Intellectual capital: The new wealth of organizations. Currency Doubleday. [Google Scholar]
- Taplin, R. (2023). Artificial intelligence, intellectual property, cyber risk and robotics: An overview. In R. Taplin (Ed.), Artificial intelligence, intellectual property, cyber risk and robotics: A new digital age (pp. 1–17). Routledge. [Google Scholar] [CrossRef] [Scilit]
- Valaskova, K., Nagy, M., & Juracka, D. (2025). Digital transformation and financial performance: An empirical analysis of strategic alignment in the digital age. Journal of Enterprising Communities: People and Places in the Global Economy, 19(5), 1178–1205. [Google Scholar] [CrossRef] [Scilit]
- Wang, W.-Y., & Chang, C. (2005). Intellectual capital and performance in causal models: Evidence from the information technology industry in Taiwan. Journal of Intellectual Capital, 6(2), 222–236. [Google Scholar] [CrossRef] [Scilit]
- Wang, Y., Wang, T., Li, Y., & Li, J. (2025). Website disclosure and financial performance, evidence from U.S. hospitals using a textual analysis approach. International Journal of Accounting Information Systems, 56, 100741. [Google Scholar] [CrossRef] [Scilit]
- Xie, H., Yang, J., Yu, W., Yang, Y., & Wu, W. (2020). The time-lag effect of R&D investment on the value of listed companies in China: A cross-industry analysis. SAGE Open, 10(2). [Google Scholar] [CrossRef] [Scilit]
- Yin, J., & Xu, J. (2025). Intellectual capital, digital transformation and firms’ financial performance: Evidence from ecological protection and environmental governance industry in China. PLoS ONE, 20(1), e0316724. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Yu, S., Liu, Y., & Hyun, E. (2024). From technology to traffic: How website technological sophistication, brand recognition, and business model innovation drive consumer traffic in Korean e-commerce. Journal of Theoretical and Applied Electronic Commerce Research, 19(3), 2051–2069. [Google Scholar] [CrossRef] [Scilit]
- Zavalii, T. (2026). Data for article (How are intellectual capital components associated with financial performance? Evidence from European IT market leaders) (Version v2) [Data set]. Zenodo. [CrossRef]
- Zavalii, T., Zhyhlei, I., Ivashko, O., & Kornatka, A. (2025). Does size determine financial performance of advertising and marketing companies? Evidence from Western Europe on SDGs. Sustainability, 17(13), 5812. [Google Scholar] [CrossRef] [Scilit]
- Zimmerman, M., & Abel, S. M. (1999). Securing and protecting a domain name for your web site: Trademarks, trade names and domain names in cyberspace. Computer Law & Security Report, 15(6), 363–378. [Google Scholar]
- Zmud, R. W., Shaft, T., Zheng, W., & Croes, H. (2010). Systematic differences in firm’s information technology signaling: Implications for research design. Journal of the Association for Information Systems, 11(3), 149–181. [Google Scholar] [CrossRef] [Scilit]
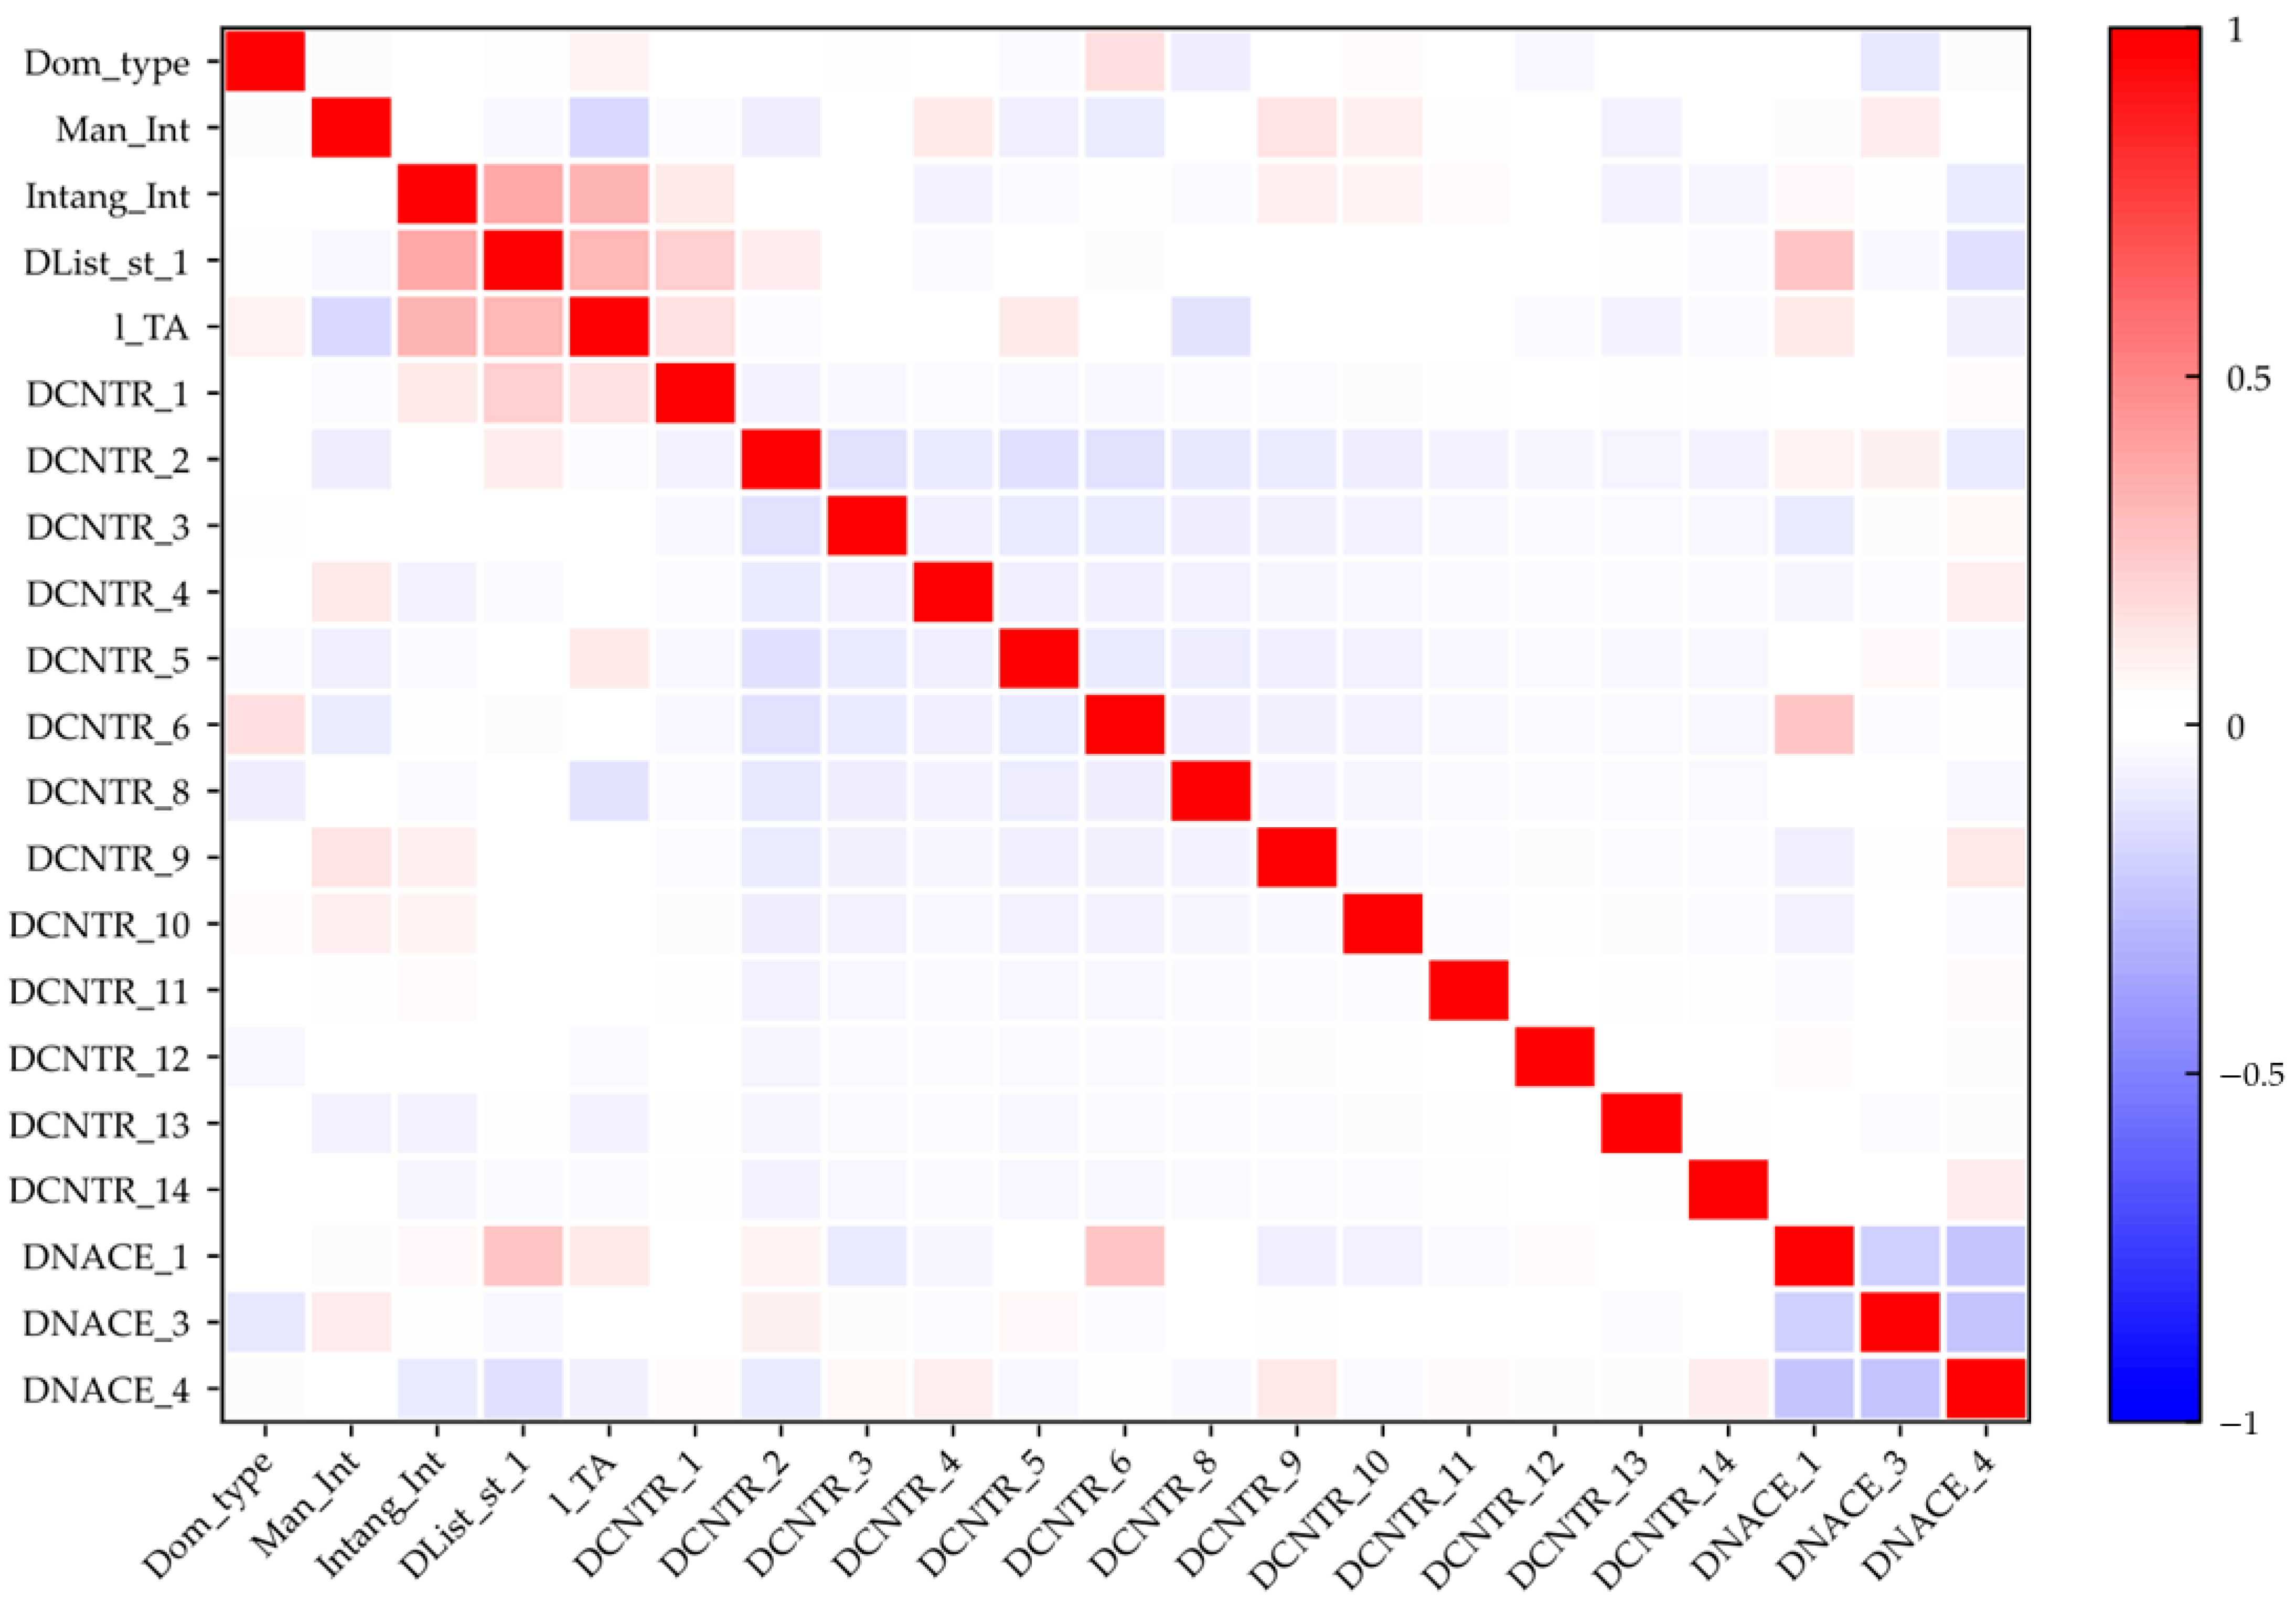
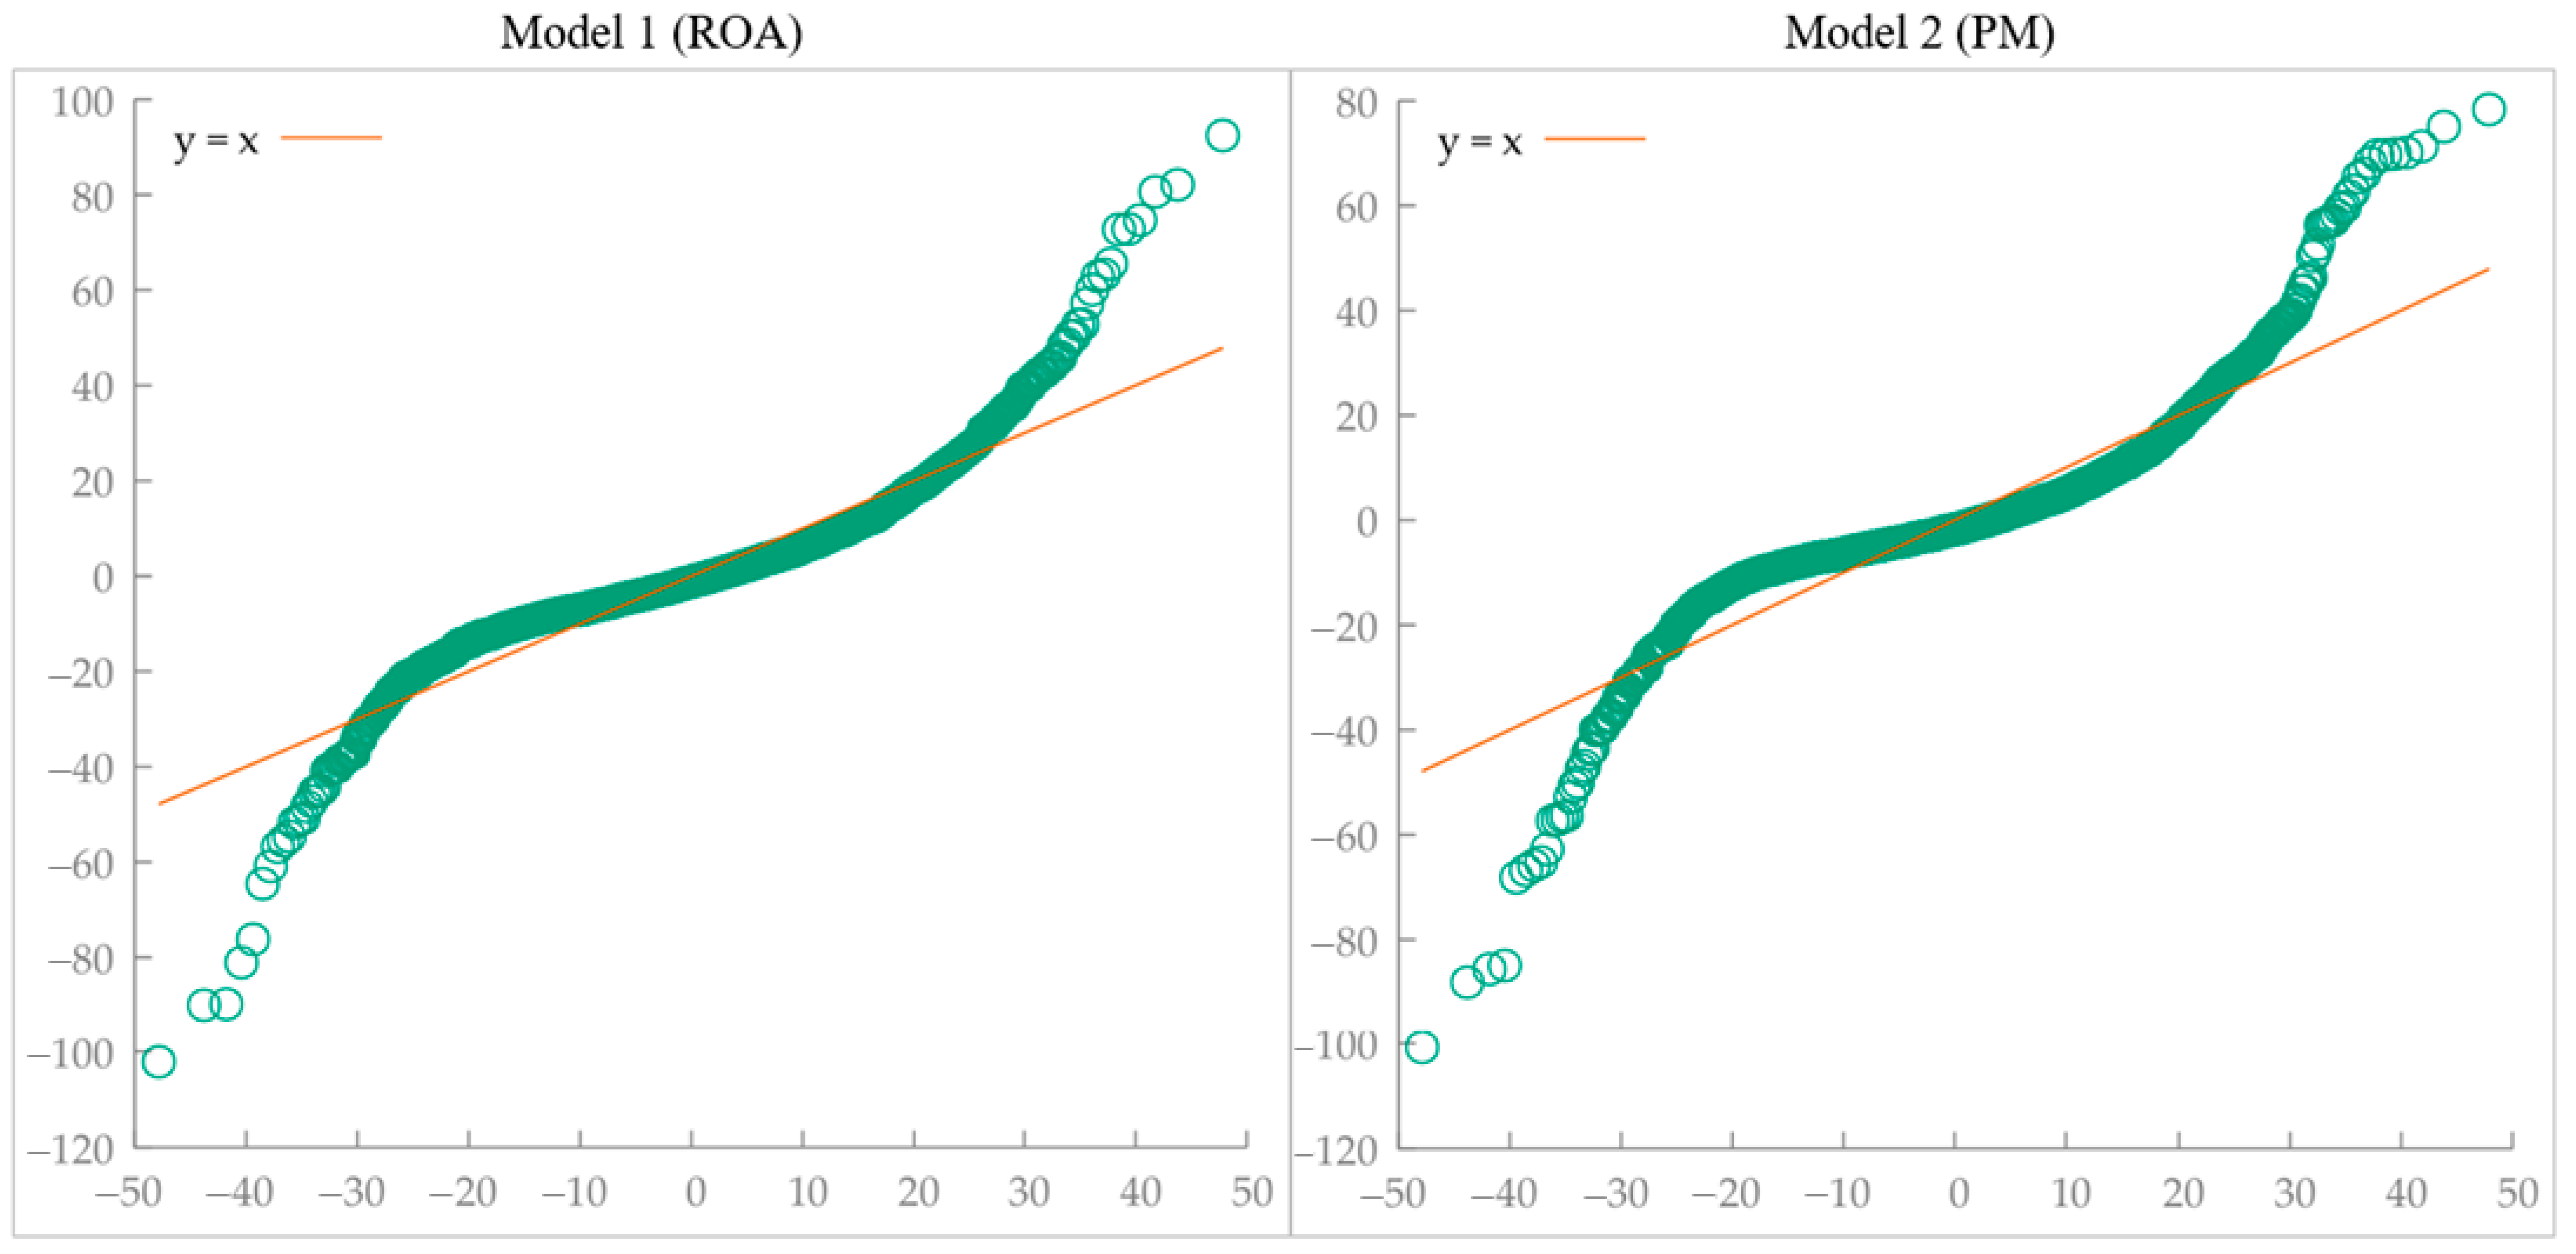

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.