


Abstract
This paper continues a series of papers by the author devoted to unsolved problems in the theory of stability and optimal control for stochastic systems. A delay differential equation with stochastic perturbations of the white noise and Poisson’s jump types is considered. In contrast with the known stability condition, in which it is assumed that stochastic perturbations fade on the infinity quickly enough, a new situation is studied, in which stochastic perturbations can either fade on the infinity slowly or not fade at all. Some unsolved problem in this connection is brought to readers’ attention. Additionally, some unsolved problems of stabilization for one stochastic delay differential equation and one stochastic difference equation are also proposed.
Keywords:
Wiener process; Poisson’s measure; asymptotic mean square stability; stability in probability; numerical simulation MSC:
34K20; 34K50; 60H10
1. Introduction
The unsolved problems proposed here continue a series of unsolved problems in stability and optimal control theory for stochastic differential and stochastic difference equations that have been presented during the recent years at some international conferences and papers (see [1,2,3,4,5,6,7,8,9,10]). All these problems still need to be solved.
Let be a complete probability space; be a nondecreasing family of sub--algebras of , i.e., for ; be the expectation with respect to the measure ; and be the space of -adapted stochastic processes , , .
Following Gikhman and Skorokhod [11,12], let us consider the stochastic delay differential equation
where , are -matrices and , are mutually independent standard Wiener processes, which are also independent of the Poisson measure ,
Auxiliary Definitions and Statements
Let be a solution to Equation (1) in the time moment t, and , , be a trajectory of the Equation (1) solution until the time moment t. Consider a functional that can be presented in the form , , and for , put
Let D be a set of functionals , for which the function defined in (2) has a continuous derivative with respect to t and two continuous derivatives with respect to x. Let ′ be the sign of transpose and and be respectively the first and the second derivatives of the function with respect to x. For the functionals from D, the generator L of Equation (1) has the form [11,12,13]
Definition 1
([13]). The zero solution to Equation (1) is called:
- -
- mean square stable if, for each , there exists such that , , provided that ;
- -
- asymptotically mean square stable if it is mean square stable, and for each initial function , the solution to Equation (1) satisfies the condition .
Theorem 1
([13]). Let there exist a functional and positive constants , and such that the following conditions hold:
Then the zero solution to Equation (1) is asymptotically mean square stable.
Some special cases of Equation (1) are considered in [14,15]. In particular, it is shown that if the zero solution of a deterministic system is asymptotically stable, then it remains asymptotically mean square stable under stochastic perturbations that fade quickly enough on the infinity.
In particular, in [15], the asymptotic mean square stability of the zero solution to Equation (1) with is proven by virtue of the general method of Lyapunov functionals construction [13,16] and the method of Linear Matrix Inequalities (LMIs) [17,18,19]. By that it is supposed that, for some positive definite matrix P, the following conditions hold:
Using (4), the Lyapunov functional is constructed in the form , where
Remark 1.
Note that, in order for the constructed Lyapunov functional (5) to satisfy the conditions of Theorem 1, the integrability condition (4) of the function must be satisfied. This condition means that stochastic perturbations fade on the infinity quickly enough. Below, another situation is studied. It is supposed that stochastic perturbations can either fade on the infinity slowly or not fade at all. By that, some unsolved problem is also proposed.
2. Equation Without Delays
Consider at first Equation (1) without delays, i.e., by the condition
Let L be the generator of Equation (1), (6). Then, via (3) for the function we have
where
Let be the norm of the matrix , i.e.,
Assume that the symmetric matrix is a negative definite matrix, i.e.,
and additionally, suppose that
Put also
Remark 2.
Theorem 2.
Proof.
Using the generator (7) and the definitions (8) and (9) for and , we have
From this and Dynkin’s formula [11]
for the function it follows that
or
Integrating this inequality and using (11), we obtain
From this and it follows that and ; i.e., the zero solution to Equation (1), (6) is asymptotically mean square stable. The proof is completed. □
Remark 3.
Note that the condition (4) of integrability of the function is not a necessary condition for the asymptotic mean square stability of the zero solution to the stochastic differential Equation (1). For instance, for a simple scalar equation of the type of (1) with constant coefficients
where and is the constant, i.e.,
the condition (12) holds, but the zero solution to Equation (13) is asymptotically mean square stable if .
3. About the Problem of Stabilization by Noise
Note that the problem of stabilization has a long history; in particular, a very popular problem of stabilization of the inverted pendulum is considered in a lot of works, for example, the well-known work of Kapitsa [20] and many others [21,22,23,24,25,26,27,28,29,30,31,32]. Below, another problem of stabilization by noise is discussed.
Consider the scalar linear Ito’s stochastic differential equation [11]
where a, b, and are constants and is the standard Wiener process.
Definition 2
3.1. Equation Without Delay
Consider now Equation (14) by the condition , i.e., without delay, as follows:
Khasminskii shows [33] that unstable by the conditions and , the zero solution to Equation (15) becomes stable by the presence of a big-enough level of noise. More exactly, by the condition
so-called “stabilization by noise” occurs and the zero solution to Equation (15) becomes stable in probability.
Really, let L be the generator [11,12,13,33] of Equation (15). Then for the Lyapunov function
we have
It is known [13,33] that if there exist a Lyapunov function with the condition , then the zero solution to Equation (15) is stable in probability.
3.2. Purely Stochastic Equation
From the condition (16), it follows, in particular, that the zero solution to the “purely stochastic” differential equation
is stable in probability for arbitrary . Moreover, the larger , the faster the trajectories of the solution to Equation (17) converge to zero.
Note that the solution to Equation (17) has the form [11]
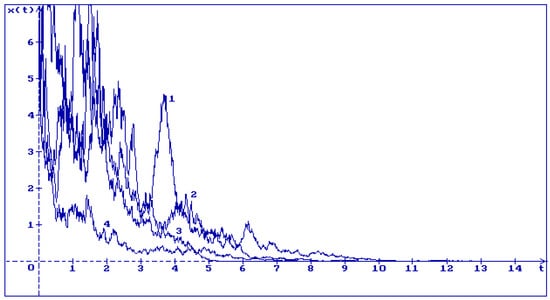
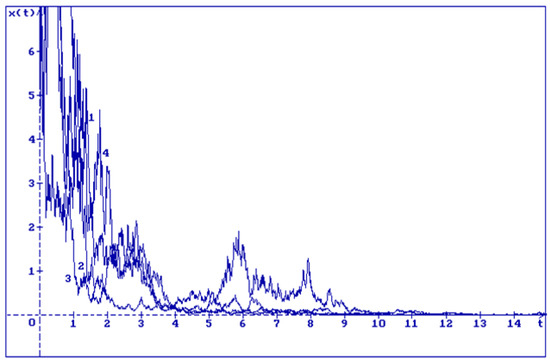
In Figure 1, one can see 4 trajectories of the solution (18) to Equation (17) for and different values of , as follows:
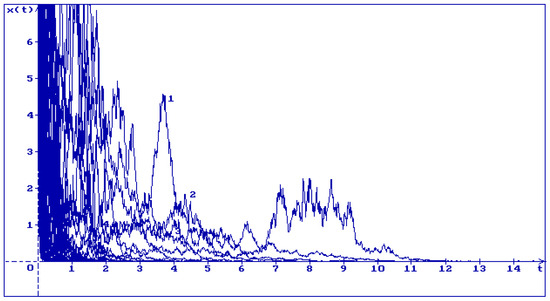
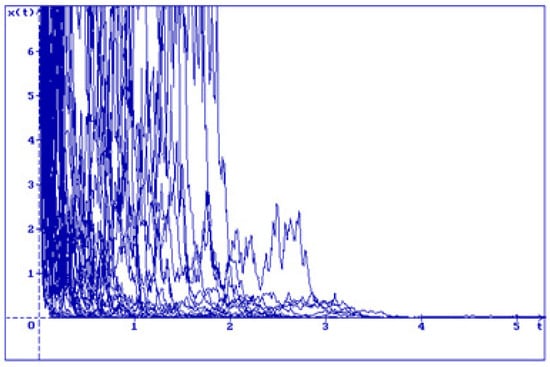
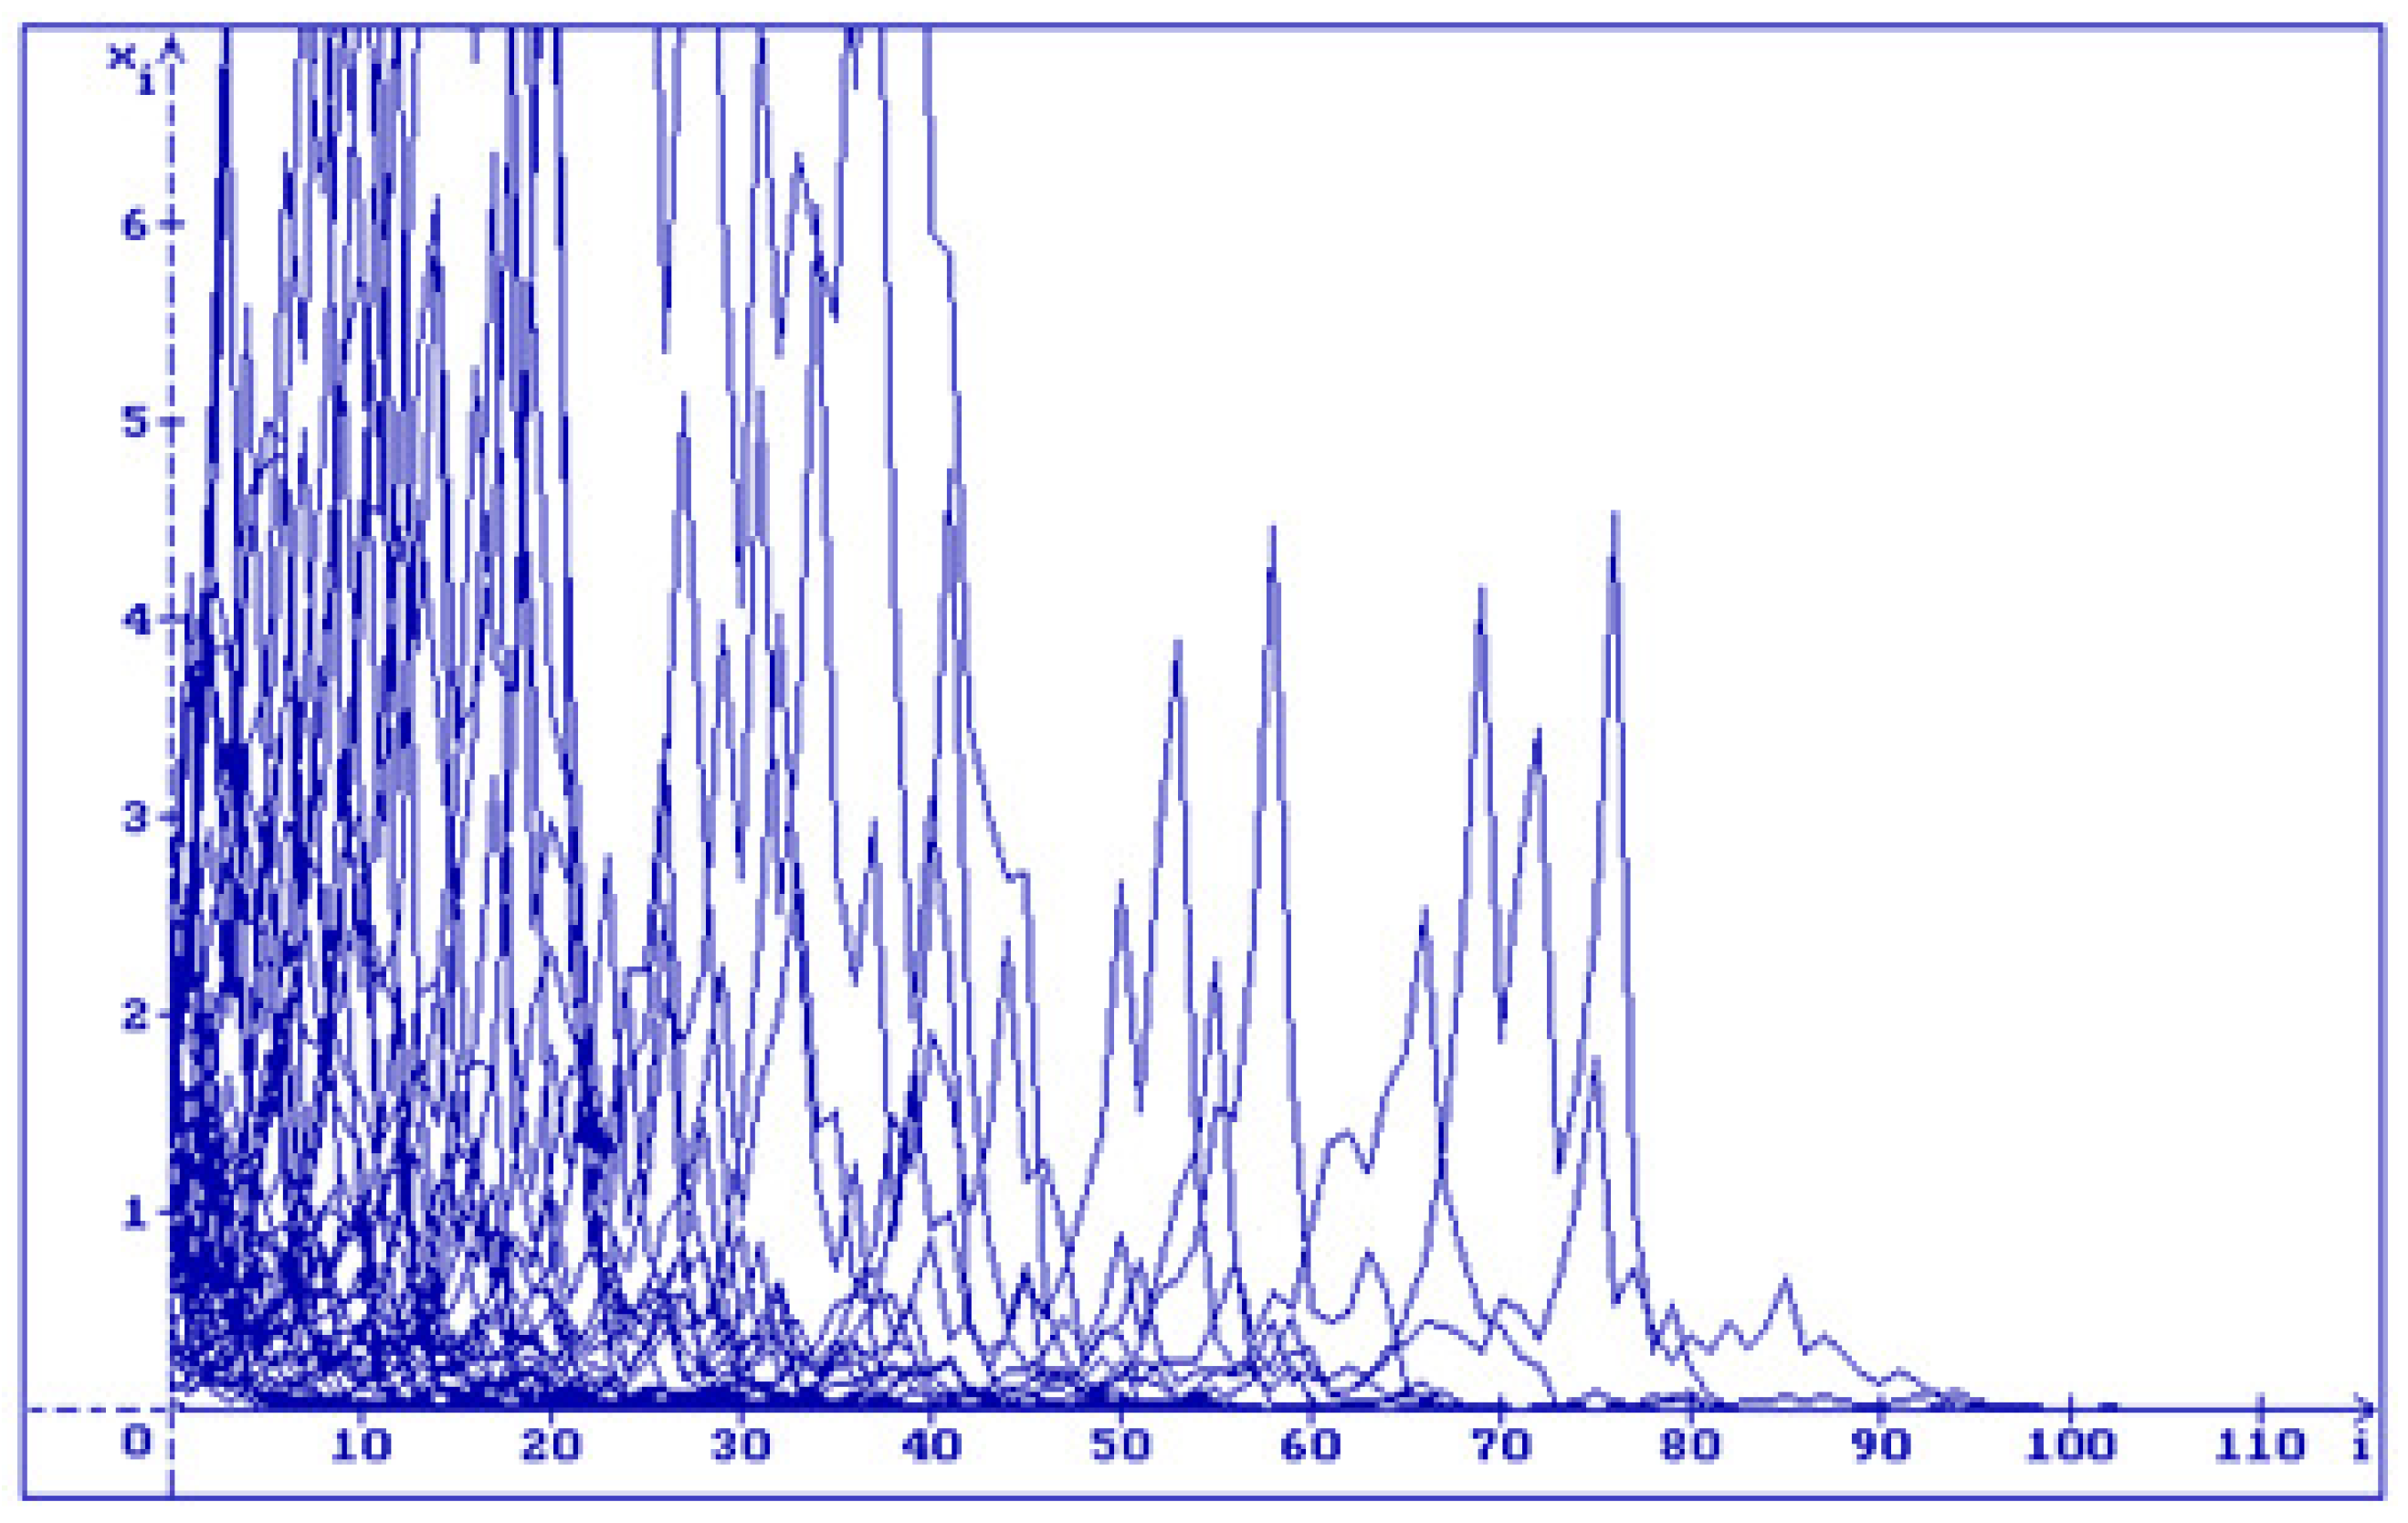
In Figure 2, one can see 50 trajectories of the solution (18) to Equation (17) for and different values of , as follows:
Figure 1.
Four trajectories of the solution to Equation (17) with and (1) , (2) , (3) , (4) .
Figure 2.
Fifty trajectories of the solution to Equation (17) with and (1) , (2) , …, (49) , (50) .
A similar situation is demonstrated by 50 trajectories with negative : in Figure 3, for
and in Figure 4, for
Figure 3.
Four trajectories of the solution to Equation (17) with and (1) , (2) , (3) , (4) .
Figure 4.
Forty-six trajectories of the solution to Equation (17) with and (5) , (6) , …(49) , (50) .
Remark 4.
Remark 5.
Note that, by the numerical simulation of the solution (18) for the simulation of trajectories of the Wiener process , the special algorithm was used, described in [13].
3.3. Stochastic Difference Equation
Consider now the scalar linear stochastic difference equation
where and are constants and , , is a sequence of mutually independent random values with the conditions
It is known [16] that by the condition
the zero solution to Equation (19) is asymptotic mean square stable.
Let us consider an analogue of the condition (16) for the linear stochastic difference Equation (19) by the condition . For this aim, let us represent the difference analogue of Equation (15) in the form (19).
Put , , , , . Then the difference analogue of Equation (15) takes the form
Note that
satisfies the conditions (20). Using (23), rewrite Equation (22) as follows:
i.e., in the form (19) with the coefficients
From (24) we have
and via (16) we obtain
i.e., the condition
In Figure 5, 50 trajectories of Equation (19) are shown for , , and different initial conditions, as follows:
By the fact that the condition (25) holds, all trajectories converge to zero.
Figure 5.
Fifty trajectories of the solution to Equation (19) with , , and different initial conditions: (1) , (2) , …, (49) , (50) .
Therefore, we obtain the following:
Hypothesis 1.
Unsolved problem. Can the above reasoning be considered as a proof of Hypothesis 1 or not? Why?
4. Conclusions
Some unsolved problems in the field of stability of differential and difference equations under stochastic perturbations are brought to the attention of potential readers. In particular, the difference in the influence of quickly or slowly fading stochastic perturbations on the stability of stochastic differential equations is discussed, as well as the possibility of stabilizing solutions of stochastic differential equations using stochastic perturbations.
The proposed paper cannot be considered a classical research paper, in which new important results are obtained. There is hope that the solution to the unsolved problems, proposed both here and in similar previously published papers of the author, will contribute to the emergence of new ideas and the further development and improvement of the theory of stability of stochastic systems.
There is also hope that some potential readers of this paper, after some time, will submit to this journal interesting solutions to the unsolved problems proposed here.
Funding
This research received no external funding.
Data Availability Statement
No new data were created or analyzed in this study. Data sharing is not applicable to this article.
Conflicts of Interest
The author declares no conflict of interest.
References
- Shaikhet, L. About some unsolved problems of stability theory for stochastic hereditary systems. In Proceedings of the Leverhulme International Network: Numerical and Analytical Solution of Stochastic Delay Differential Equations, University of Chester, Chester, UK, 31 August–3 September 2010; Abstracts. pp. 6–7. [Google Scholar]
- Shaikhet, L. Unsolved stability problem for stochastic differential equation with varying delay. In Proceedings of the Leverhulme International Network: Numerical and Analytical Solution of Stochastic Delay Differential Equations, University of Chester, Chester, UK, 5–7 September 2011; Abstracts. p. 21. [Google Scholar]
- Shaikhet, L. About an unsolved stability problem for a stochastic difference equation with continuous time. J. Differ. Equ. Appl. 2011, 17, 441–444. [Google Scholar] [CrossRef] [Scilit]
- Shaikhet, L. Two unsolved problems in the stability theory of stochastic differential equations with delay. Appl. Math. Lett. 2012, 25, 636–637. [Google Scholar] [CrossRef] [Scilit]
- Shaikhet, L. About an unsolved optimal control problem for stochastic partial differential equation. In Proceedings of the XVI International Conference “Dynamical System Modeling and Stability Investigations” (DSMSI-2013), Kiev, Ukraine, 29–31 May 2013; Abstracts. p. 344. [Google Scholar]
- Shaikhet, L. Some Unsolved Problems: Problem 1, Problem 2. In Lyapunov Functionals and Stability of Stochastic Functional Differential Equations; Springer Science & Business Media: Berlin/Heidelberg, Germany, 2013; pp. 51–52. [Google Scholar]
- Shaikhet, L. Some unsolved problems in stability and optimal control theory of stochastic systems. Mathematics 2022, 10, 474. [Google Scholar] [CrossRef] [Scilit]
- Shaikhet, L. About an unsolved problem of stabilization by noise for difference equations. Mathematics 2024, 12, 110. [Google Scholar] [CrossRef] [Scilit]
- Shaikhet, L. Unsolved problem about stability of stochastic difference equations with continuous time and distributed delay. Mod. Stochastics Theory Appl. 2024, 11, 395–402. [Google Scholar] [CrossRef] [Scilit]
- Shaikhet, L. About one unsolved problem in asymptotic p-stability of stochastic systems with delay. AIMS Math. 2024, 9, 32571–32577. [Google Scholar] [CrossRef] [Scilit]
- Gikhman, I.I.; Skorokhod, A.V. Stochastic Differential Equations; Springer: Berlin/Heidelberg, Germany, 1972. [Google Scholar]
- Gikhman, I.I.; Skorokhod, A.V. The Theory of Stochastic Processes; Springer: Berlin/Heidelberg, Germany, 1979; Volume III. [Google Scholar]
- Shaikhet, L. Lyapunov Functionals and Stability of Stochastic Functional Differential Equations; Springer Science & Business Media: Berlin/Heidelberg, Germany, 2013. [Google Scholar] [CrossRef] [Scilit]
- Shaikhet, L. About stability of delay differential equations with square integrable level of stochastic perturbations. Appl. Math. Lett. 2019, 90, 30–35. [Google Scholar] [CrossRef] [Scilit]
- Shaikhet, L. Stability of delay differential equations with fading stochastic perturbations of the type of white noise and Poisson’s jumps. Discret. Contin. Dyn. Syst. Ser. B 2020, 25, 3651–3657. [Google Scholar] [CrossRef] [Scilit]
- Shaikhet, L. Lyapunov Functionals and Stability of Stochastic Difference Equations; Springer Science & Business Media: Berlin/Heidelberg, Germany, 2011. [Google Scholar] [CrossRef] [Scilit]
- Gu, K. Discretized LMI set in the stability problem of linear time-delay systems. Int. J. Control 1997, 68, 923–934. [Google Scholar] [CrossRef] [Scilit]
- Fridman, E.; Shaikhet, L. Stabilization by using artificial delays: An LMI approach. Automatica 2017, 81, 429–437. [Google Scholar] [CrossRef] [Scilit]
- Fridman, E.; Shaikhet, L. Simple LMIs for stability of stochastic systems with delay term given by Stieltjes integral or with stabilizing delay. Syst. Control Lett. 2019, 124, 83–91. [Google Scholar] [CrossRef] [Scilit]
- Kapitza, P.L. Dynamical stability of a pendulum when its point of suspension vibrates, and pendulum with a vibrating suspension. In Collected Papers of P.L. Kapitza; ter Haar, D., Ed.; Pergamon Press: London, UK, 1965; Volume 2, pp. 714–737. [Google Scholar]
- Mitchell, R. Stability of the inverted pendulum subjected to almost periodic and stochastic base motion—An application of the method of averaging. Int. J. Nonlinear Mech. 1972, 7, 101–123. [Google Scholar] [CrossRef] [Scilit]
- Levi, M. Stability of the inverted pendulum—A topological explanation. SIAM Rev. 1988, 30, 639–644. [Google Scholar] [CrossRef] [Scilit]
- Blackburn, J.A.; Smith, H.J.T.; Gronbech-Jensen, N. Stability and Hopf bifurcations in an inverted pendulum. Am. J. Phys. 1992, 60, 903–908. [Google Scholar] [CrossRef] [Scilit]
- Levi, M.; Weckesser, W. Stabilization of the inverted linearized pendulum by high frequency vibrations. SIAM Rev. 1995, 37, 219–223. [Google Scholar] [CrossRef] [Scilit]
- Lozano, R.; Fantoni, I.; Block, D.J. Stabilization of the inverted pendulum around its homoclinic orbit. Syst. Control Lett. 2000, 40, 197–204. [Google Scholar] [CrossRef] [Scilit]
- Borne, P.; Kolmanovskii, V.; Shaikhet, L. Stabilization of inverted pendulum by control with delay. Dyn. Syst. Appl. 2000, 9, 501–514. [Google Scholar]
- Imkeller, P.; Lederer, C. Some formulas for Lyapunov exponents and rotation numbers in two dimensions and the stability of the harmonic oscillator and the inverted pendulum. Dyn. Syst. 2001, 16, 29–61. [Google Scholar] [CrossRef] [Scilit]
- Mata, G.J.; Pestana, E. Effective Hamiltonian and dynamic stability of the inverted pendulum. Eur. J. Phys. 2004, 25, 717–721. [Google Scholar] [CrossRef] [Scilit]
- Sharp, R.; Tsai, Y.-H.; Engquist, B. Multiple time scale numerical methods for the inverted pendulum problem. In Multiscale Methods in Science and Engineering; Lecture Notes Computing Science and Engineering; Springer: Berlin/Heidelberg, Germany, 2005; Volume 44, pp. 241–261. [Google Scholar]
- Ovseyevich, A.I. The stability of an inverted pendulum when there are rapid random oscillations of the suspension point. J. Appl. Math. Mech. 2006, 70, 762–768. [Google Scholar] [CrossRef] [Scilit]
- Sanz-Serna, J.M. Stabilizing with a hammer. Stoch. Dyn. 2008, 8, 47–57. [Google Scholar] [CrossRef] [Scilit]
- Shaikhet, L. About Stabilization of the Controlled Inverted Pendulum under Stochastic Perturbations of the Type of Poisson’s Jumps. Axioms 2025, 14, 29. [Google Scholar] [CrossRef] [Scilit]
- Khasminskii, R.Z. Stochastic Stability of Differential Equations; Springer: Berlin/Heidelberg, Germany, 2012. [Google Scholar]
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2025 by the author. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).