


Abstract
Although the voluntary carbon market (VCM) converts mitigation and removal outcomes into tradable credits, concerns about additionality, measurement, reporting and verification (MRV), double counting and credit quality continue to constrain credibility. The same integrity requirements can increase the data, expertise and procedural burdens faced by supply-side actors. In this study, we examine how these requirements are related to market entry and value creation. Our core empirical analysis uses a structured qualitative comparison of legal, policy and market operation documents from the European Union, Singapore and the Republic of Korea, while a supplementary SciVal landscape check provides research context. Our comparison shows that integrity rules operate both as trust conditions and as participation requirements. Entry is supported by standardization, technical assistance, burden mitigation, collective participation and VCM-specific support, while participation generates strategic and economic value only when buyer access, price discovery, contracting, risk allocation and scaling mechanisms operate. On this basis, we propose an Integrity–Entry–Value (IEV) structure as a conditional rather than linear account of VCM formation, with bounded implications for markets facing comparable institutional challenges.
1. Introduction
The voluntary carbon market (VCM) has developed as a market-based mechanism that converts greenhouse gas (GHG) mitigation and removal activities outside compliance markets into carbon credits, thereby encouraging private climate action and mitigation investment. As the market has grown, however, questions concerning the actual mitigation effects and environmental integrity of credits have persisted. A synthesis of existing empirical evidence covering 2346 carbon-crediting projects reported that only a limited share of the credits issued by the projects examined was supported by actual emission reductions [1]. It has also been noted that a substantial share of the credits used by major companies originated from projects at high risk of failing to deliver real and additional mitigation [2]. This body of work indicates that the sustainability of the VCM does not follow from growth in traded credit volume alone; rather, it depends on credible mitigation outcomes supported by additionality, appropriate quantification, measurement, reporting and verification (MRV), and transparent tracking.
Although institutions designed to strengthen environmental integrity may raise market trust, they may at the same time generate new entry costs for new firms. Unlike the market entry of ordinary products or services, the recognition of a carbon mitigation project as a source of credits requires compliance with requirements for the measurement, reporting, verification and certification of mitigation outcomes, as well as with trading rules. A meta-analytical review of forest carbon sequestration projects has shown that transaction costs arise not only from project establishment and management but also from compliance with trading requirements and MRV, pointing out that such costs may not be sufficiently accounted for in assessments of project economics [3]. Conversely, a study of 18,110 cleantech startups across 33 countries reported that market-based climate policy and technical support are positively associated with the entry of new cleantech firms and that complementary institutional environments such as financial systems strengthen this relationship [4]. Taken together, these findings suggest that the institutional arrangements of carbon markets are simultaneously the foundation of market trust and a condition that may enable or constrain firm entry.
After entry, a further question remains as to whether carbon mitigation activities can be translated into value creation for the firm. A review of 143 academic studies and 49 industry and policy sources typologizing low-carbon business models—the ways in which firms propose, create and capture value through decarbonization—noted that research integrating decarbonization and value creation in low-carbon settings remains limited [5]. While studies that link the VCM directly to entrepreneurship have begun to appear [6], this literature is not yet well developed. In addition, an analysis of actual transactions in Japan’s J-Blue Credit scheme found that project characteristics, co-benefits, purchaser characteristics and the fit between them influenced transaction outcomes [7], suggesting that economic value is not created automatically by generating credible credits, but rather that purchase demand and market relationships must be formed alongside them.
Despite this literature, an important disconnect persists across research areas. While a recent systematic review of empirical VCM research has highlighted environmental, financial and socio-economic performance and the importance of policy frameworks [8], the existing work has largely analyzed the environmental integrity of credits and projects, climate policy and firm entry, business models and value creation and project–purchaser transaction relationships separately. In particular, relatively few studies explain, from the perspective of firms and within a single structure, how the MRV, verification and certification systems that secure environmental integrity enable or constrain the market entry of new supply-side actors, and how this entry is in turn connected to value creation. This question is timely from an institutional perspective: through the Carbon Removals and Carbon Farming Certification Framework (CRCF) established by Regulation (EU) 2024/3012, the European Union is institutionalizing quality criteria and verification and certification procedures for permanent carbon removals, carbon farming and carbon storage in products. Although the CRCF is not identical to the EU-wide VCM, it is an important case representing the institutionalization of the credibility of carbon outcomes [9]. Singapore presents criteria for identifying high-quality carbon credits, independent third-party verification and the avoidance of double counting in official policy guidance, while also operating actual VCM trading infrastructure, making it a case in which environmental integrity and firm-level market access can be examined together [10]. The Republic of Korea, in turn, published the Direction for the Establishment of a Korean Voluntary Carbon Market in April 2026, covering registration, assessment and trading, demand development and support for the market entry of small- and medium-sized enterprises (SMEs) and identifying MRV support and the easing of entry barriers as key policy tasks [11]. Because market operation has not yet produced accumulated outcomes, Korea is a case in which the joint design of environmental integrity and firm entry can be examined at the stage of institutional formation.
While adjacent approaches have illuminated different parts of this problem, they do not connect them within the same analytical sequence. Credit quality and integrity research focuses on whether credits represent credible mitigation; carbon market governance research focuses on institutional rules and information asymmetries; pricing research examines the market valuation of credits; and low-carbon business model research explains how firms create and capture value [1,2,5,8,12,13]. The IEV structure neither replaces these approaches nor proposes a new credit-quality standard. Instead, it connects credit integrity, firm entry, and post-entry value creation and capture through two explicitly conditional mechanisms: entry-enabling conditions and value-conversion functions. Entry-enabling conditions determine whether supply-side actors can meet integrity requirements despite cost, information, and capability demands, whereas value-conversion functions determine whether participation can be translated into strategic opportunities and captured economic returns. The IEV framework therefore identifies two potential breakpoints—Integrity-to-Entry and Entry-to-Value—rather than treating Integrity, Entry, and Value as an additive sequence.
Accordingly, in this study, we examine how the VCM’s integrity requirements relate to market entry and value creation for supply-side actors. For conciseness, these actors are referred to as supply-side actors when the analysis concerns participation on the supply side of the market. Our core empirical analysis compares equivalent institutional functions in the EU, Singapore and Korea, while a supplementary SciVal (Elsevier, Amsterdam, The Netherlands) landscape check provides context but does not define the IEV categories or establish the research gap. Our study links environmental integrity (Integrity), market entry (Entry) and value creation and capture (Value) and identifies the conditions that connect these dimensions.
Our study addresses the following research questions:
RQ1
(Integrity). What conditions and potential burdens do integrity requirements—including additionality, MRV, verification and certification—create for supply-side actors seeking market access?
RQ2
(Entry). What institutional conditions are required to mitigate these entry requirements and potential burdens without undermining market credibility?
RQ3
(Value). Through which market functions does participation create strategic value and enable value capture for supply-side actors?
2. Materials and Methods
2.1. Research Design
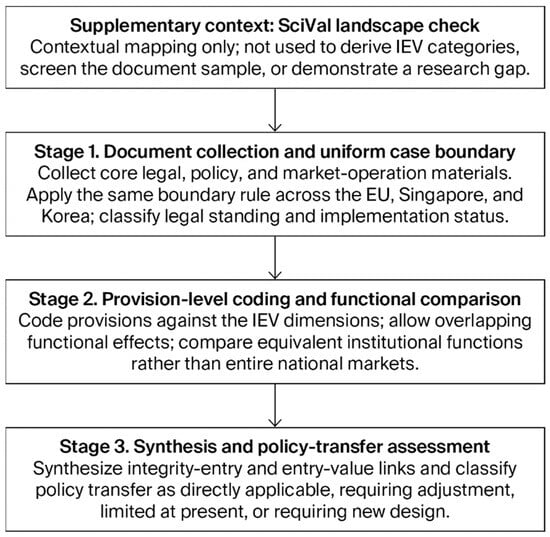
This study provides a structured, focused comparison of the EU, Singapore and Korea, examining how institutional functions connect environmental integrity, market participation and value. The document analysis follows Bowen [14], while the case comparison follows common analytical questions and functional equivalence rather than formal institutional identity [15,16]. Figure 1 summarizes the three-stage core empirical design. A SciVal landscape check is retained only as supplementary context; it is not a formal analytical stage, a screening procedure or evidence of a research gap.
Figure 1.
Three-stage core analytical design with a supplementary SciVal landscape check. Arrows indicate the sequence of the analytical workflow.
The core empirical analysis proceeded in three stages as follows: (1) collection of case materials under a common boundary rule; (2) provision-level coding and functional cross-case comparison; and (3) synthesis of the IEV relationships and policy transfer classification. This shorter sequence avoids treating the preliminary SciVal check as an empirical stage of the case analysis.
2.2. Supplementary SciVal Landscape Check
Elsevier SciVal was used only to contextualize the wider VCM research landscape [17]. The author-defined research area was constructed using the exact phrase “voluntary carbon market” and analyzed on 28 August 2026 for the 2020–2026 period, yielding 792 Scholarly Outputs, 131 Topic Clusters, and 274 Topics. The 2026 value is a partial-year result. Appendix A reports the retained search configuration and representative Topic information. Because the SciVal check was not designed as a thematic bibliometric test of every IEV concept, terms such as MRV and additionality were not treated as independent query filters, and no inference is drawn from their frequency or absence.
SciVal did not generate the Integrity, Entry and Value dimensions, screen the policy document sample or provide statistical evidence of a research gap. Rather, the three dimensions were specified deductively from the research questions and the literature. Topic and Topic Cluster outputs are reported descriptively only, keeping the role of SciVal proportionate to the evidence it provides.
2.3. Case Selection and Data Sources
The EU, Singapore and Korea were selected purposively because they represent different legal and market settings in which comparable VCM functions can be observed. One boundary rule was applied to all three cases: the core comparison includes legal, policy or market operation instruments that directly define or operate credit quality, registration and tracking, market access, trading, buyer-use or claim rules or support explicitly tied to VCM/CRCF participation. Broader economy-wide climate-finance or decarbonization programs were excluded from the core comparison unless the selected source explicitly linked them to VCM/CRCF participation. This rule prevents broad Korean support measures from being compared with a CRCF-only EU boundary or the buyer-focused Singapore Guidance. For Singapore, a function that falls outside the scope of the buyer guidance is treated as outside the selected evidence base, not as proof of market-wide absence. Functional equivalence therefore refers to the same market problem—such as additionality, MRV, verification, traceability, market access, buyer demand or value conversion—rather than identical legal form or credit type. Removal and reduction/avoidance credits are compared only at this functional level (Table 1). The cases were selected as theoretically contrasting institutional configurations rather than as matched national markets: the EU represents rule-based carbon removal certification centered on the CRCF; Singapore combines buyer-oriented guidance with an operating trading hub; and Korea represents a formation-stage policy design [9,10,11,18,19]. This contrast allows us to examine whether equivalent Integrity, Entry and Value functions can be compared across different legal forms and stages of market development, while the common functional boundary prevents institutional difference from being mistaken for non-comparability.
Table 1.
Case selection, legal status, credit scope and functional comparability.
The EU core sources are the CRCF Regulation, its delegated methodology and the CRCF Buyers Club [9,20,21]. Singapore is represented by official buyer guidance and CIX market operation materials [10,18,19], with compliance use kept analytically separate. Korea is treated as a formation-stage case using the 2026 VCM policy direction and legislative-process material [11,22]. These sources are compared within the common boundary above, while differences in document purpose and legal force are retained rather than interpreted as equivalent evidence.
2.4. Data Collection and Classification of Implementation Status
The reference date for the core case analysis was 31 August 2026. Statutes and Delegated Regulations were treated as binding legal sources; official government guidance and policy documents were treated as authoritative but non-equivalent policy sources; and official market-operator materials were treated as evidence of operational functions rather than legal requirements. Media reports, unclear web sources and general promotional materials were excluded. Appendix B lists the core sources, their evidentiary standing and their analytical use.
Each element was also classified as institutionalized, operational, planned/proposed or not identified within the selected evidence base. The phrase “not identified in the core official documents analyzed as of the reference date” denotes an evidentiary limit, not institutional absence.
2.5. Analytical Dimensions and Coding
Our analysis uses three higher-order dimensions: Integrity, Entry and Value (Table 2). Capitalized Integrity, Entry and Value refer only to the formal IEV dimensions, whereas lower-case integrity, entry and value refer to general concepts. Hyphenated modifiers are written in lower case (for example, entry-enabling and value-conversion). In this study, supply-side actors refer collectively to climate-tech firms and carbon mitigation project developers participating on the supply side of the VCM.
Table 2.
Operationalization of the Integrity–Entry–Value analytical dimensions.
Credit integrity concerns whether a credit represents a credible mitigation or removal outcome, while claim integrity concerns how buyers retire, disclose and communicate credit use [23,24]. Value creation refers to buyer utility, market access, commercialization and strategic opportunity. Value capture refers to realized economic returns through sales, pricing, contracts and repeat transactions. In this study, value-conversion functions are the market arrangements that translate participation into strategic or economic value, including buyer access, price discovery, contracting, risk allocation and repeat transactions.
Coding was primarily deductive: the IEV dimensions were specified from the research questions and the literature, while recurrent functions in official materials were added as subcodes. Effects were recorded qualitatively as integrity-enhancing, entry-enabling, entry-constraining, value-creating or value-capturing. Because the corpus is purposive and heterogeneous, code frequencies are not treated as comparative performance measures. Recurrent functions were added as subcodes only within the three predefined IEV dimensions when the documents revealed a more specific institutional function that was not adequately represented by the existing coding elements. This preserved the deductive higher-order structure while allowing document-level institutional functions to be represented more precisely.
Two researchers independently checked the coding of the core materials and resolved disagreements by consensus after re-reading the source text. Appendix C reports the visible coding output as a provision/source matrix, including representative dual-coded provisions and their connection to the results. The second-coder check covered both the IEV dimension assignment and any overlapping functional-effect labels; the consensus version is the coding reported in Appendix C.
2.6. Functional Cross-Case Comparison
Cross-case comparison used equivalent institutional functions—not whole national markets—as the unit of comparison. The functions covered quality criteria and MRV, verification and tracking, market access and support, buyer demand, trading and price discovery, contracting and value capture. The same case boundary and implementation status rules were applied throughout.
RQ1 compares integrity functions with the participation requirements they create; RQ2 compares entry-enabling responses that preserve integrity; and RQ3 compares the functions that connect participation to value creation and capture. Supply-side credit integrity is analyzed separately from demand-side claim integrity.
2.7. Structure Development and Assessment of Policy Applicability
The cross-case findings were synthesized into the IEV structure. This structure is conditional rather than linear: entry-enabling conditions connect Integrity to Entry, while value-conversion functions connect Entry to Value.
Policy applicability was assessed with reference to Dolowitz and Marsh [25]. EU and Singapore functions were classified as directly applicable principles, functions requiring institutional adjustment, functions limited at Korea’s present stage or functions requiring new design. Section 3.4 reports this classification.
The assessment considered integrity, entry burden, feasibility in Korea and connectivity with demand and value, and it does not rank source jurisdictions or treat foreign arrangements as best practice.
2.8. Analytical Rigor
Analytical rigor was supported by primary-source verification, a common case boundary, common IEV coding rules, explicit implementation status labels and source traceability. Planned functions were not interpreted as realized market outcomes.
3. Results
Results are presented according to the three research questions and the policy transfer assessment. Appendix C makes the coding output visible at the source/provision level, showing, for example, that MRV and verification can strengthen integrity while increasing capability requirements; that group participation or VCM-specific support can enable entry; and that buyer access, trading, and contracting instruments can connect Entry to Value. Because the corpus is purposive and heterogeneous, these codes are interpreted qualitatively rather than as frequency-based cross-case scores.
3.1. Integrity Requirements and Their Implications for Market Entry
A comparison of the policy and institutional materials of the EU, Singapore and Korea shows that all three cases include institutional functions related to additionality, quantification and MRV, verification and certification, permanence and registration and tracking in order to secure the environmental integrity of carbon credits. The ways in which these functions are implemented and their implementation status, however, differ. The EU institutionalizes quality criteria and certification procedures in legal and methodological terms through the CRCF [9,20], whereas Singapore relies on non-binding official guidance, together with international carbon standards and independent verification, to support the voluntary use of carbon credits by firms [10]. Korea presents quality-assessment principles such as additionality and permanence and a registration, assessment and tracking system as policy directions [11], though as of the reference date, the relevant arrangements and detailed operating systems were at the stage of formation [22]. The main comparative results are presented in Table 3.
Table 3.
Cross-case comparison of integrity components and their market-entry implications.
As Table 3 shows, the clearest difference among the three cases lies not in the principles used to secure environmental integrity but in the way these principles are institutionalized and applied to the market. The EU CRCF specifies additionality, quantification, independent verification and certification as legal and methodological requirements [9,20]; in particular, additionality requires that an activity go beyond EU and national legal obligations at the level of the individual operator and that the incentive effect of certification be necessary for the financial viability of the activity. Where activity-specific baselines are applied, a separate additionality test is required [9]. Singapore, by contrast, does not maintain a national statutory certification system applying directly to the VCM; instead, it presents criteria such as additional, real, quantified and verified, permanent, no leakage and the avoidance of double counting as non-binding official guidance for identifying high-quality credits [10]. Korea presents additionality beyond BAU and permanence as quality-assessment principles [11], though certain detailed methodologies, such as a common approach to baseline calculation, were not confirmed in the policy documents analyzed.
Quantification and MRV, together with verification and certification, emerged as the core functions for converting mitigation outcomes into information that the market can trust. In the EU, operators submit an activity plan and a monitoring plan and undergo a certification audit and re-certification by independent certification bodies [9,20]. Singapore recommends a conservative quantification of mitigation and removal volumes, together with verification by accredited independent third parties and project-level due diligence [10]. Korea presents private-sector MRV as its basic direction and plans a structure that combines the approval, certification and issuance functions of the registry body with the quality-assessment function of a separate assessment body [11]. These differences show that, while the three cases share the same integrity elements, they implement them in different ways: the EU through a statutory certification system, Singapore through guidance and international standards and Korea through a public management structure at the stage of institutional formation.
A common mechanism of market trust was also identified in the registration and tracking function. The EU provides for the issuance and use of certified units to be tracked through certification registries and, in future, the Union Registry, and for double issuance and double use to be prevented [9]. Singapore advises the use of credits registered in reputable registries and the claiming of a retired credit only once [10]. Korea plans on utilizing a structure in which the registry body manages the entire process of issuance, transfer and retirement of mitigation outcomes and reflects transaction and retirement information in the registry [11]. Traceability therefore performs a complementary function: by making ownership, transaction and retirement histories verifiable, it extends credibility beyond the generation of a credit to the mitigation outcome as used in the market.
The expanded comparison also separates leakage, double counting and claims. ICVCM defines double counting as including double issuance, double use and double claiming, and its Core Carbon Principles add program governance, tracking, transparency, robust validation/verification, no-double-counting and sustainable-development safeguards as cross-cutting quality criteria [23]. Article 6 authorization and corresponding adjustments are analytically distinct from ordinary voluntary-use claims as they apply when mitigation outcomes are authorized for international transfer/use under the Paris Agreement accounting framework, whereas Singapore’s VCM guidance explicitly treats corresponding adjustment as separate from the intrinsic quality assessment of a voluntary credit [10,26]. On the demand side, the VCMI Claims Code provides a separate claim integrity layer governing how firms disclose and communicate credit use [24].
Taken together, these results indicate that environmental integrity requirements have a dual function with respect to the market entry of supply-side actors. Additionality, quantification and MRV, independent verification and certification and traceability are market access conditions that allow mitigation outcomes to be recognized in the market and, at the same time, require the technical and procedural capacity to set baselines, collect and manage data, measure and report, undergo external verification and complete registration procedures. However, the analysis of policy and institutional documents alone does not permit the conclusion that these requirements have actually reduced firm entry rates. Rather than treating them as entry barriers in a strict sense, these results are therefore interpreted as a structure in which the trust conditions that enable market access and the entry requirements and potential entry burdens needed to satisfy them are formed simultaneously.
3.2. Institutional Conditions Mitigating Entry Requirements While Preserving Integrity
Comparison of the institutional responses of the EU, Singapore and Korea against the entry requirements and potential burdens identified in RQ1 reveals a set of institutional approaches: clarifying criteria and procedures, supporting technical and professional capacity, and easing verification, certification and early-stage funding burdens without relaxing environmental integrity standards. The scope and degree of institutionalization of these entry-enabling functions, however, differ across cases. The main comparative results are presented in Table 4.
Table 4.
Cross-case comparison of entry-enabling institutional functions.
The EU case demonstrates entry-enabling functions inside the CRCF boundary: simplified certification, group participation and advisory arrangements for smaller operators [9]. These measures reduce the burden of meeting integrity rules without lowering the rules themselves.
Singapore requires a different interpretation, as its core guidance is aimed mainly at corporate credit users. Although it clarifies credit quality criteria and due diligence [10], CIX materials show project and buyer access to market infrastructure [18,19]. The selected sources do not support a market-wide conclusion that supplier-side assistance is absent, but rather show only that such assistance is not evidenced within the defined case boundary.
Korea’s formation-stage policy explicitly includes SME MRV, mitigation consulting and plans for market-support infrastructure [11]. Broader low-carbon loans, guarantees, equipment finance or transition-finance measures are treated as contextual rather than as VCM-specific entry support unless the source directly links them to VCM participation. The same boundary rule is applied to all three cases.
Across cases, comparable entry-enabling functions are standardization, technical support, burden mitigation, collective or institutional support and—where directly linked to the VCM—finance. As their presence differs by source scope and implementation stage, the comparison does not rank jurisdictions by completeness.
3.3. Market Functions Converting Carbon Outcomes into Value Creation and Capture
Value creation and value capture are distinct: value creation occurs when credible outcomes generate buyer utility, market access, commercialization or strategic opportunity, whereas value capture occurs when participants realize economic returns through sales, pricing, contracts, risk allocation and repeat transactions. Table 5 summarizes these functions and the demand-side claim conditions that can strengthen or weaken durable demand. Accordingly, buyer access and strategic/commercial opportunity are treated as value-creation functions, whereas revenue realization, price valuation, revenue predictability/contracting, risk-adjusted value preservation and transaction-based commercial scaling are treated as value-capture functions, as they concern the appropriation, stabilization or expansion of economic returns after market access.
Table 5.
Distinguishing value creation, value capture and demand-side conditions.
The first value pathway identified in Table 5 is revenue realization. In the EU, purchase agreements are being pursued for CRCF-certified carbon removals [21], while, in Singapore, spot trading of carbon credits is operating through CIX [18,19]. In Korea, a plan to build a voluntary carbon credit trading market centered on the Korea Exchange has been set out [11], forming the pathway through which mitigation outcomes cease to be related to environmental performance alone and instead become saleable economic output.
The second value pathway is price valuation. On the CIX Exchange in Singapore, market prices and benchmarks are formed through bids, offers and actual transactions [19], and Korea plans on adopting a structure in which mitigation outcomes of similar quality are composed into product groups and prices are formed by product group [11]. By contrast, in the core official materials of the EU CRCF Buyers Club, purchase agreements for individual projects are more prominent than a public benchmark price formation function [21]. It follows that economic value is not determined by the existence of tradable mitigation outcomes alone; a separate function is required through which that value becomes visible in the market as price information.
The third value pathway is revenue predictability. The EU CRCF Buyers Club presents the use of multi-year offtake agreements for permanent carbon removals as a means of increasing the future revenue certainty of projects and supporting investment decisions [21]. In the core materials analyzed for Singapore and Korea, no corresponding long-term purchase structure was confirmed as an independent function. This indicates that one-off credit sales and predictable long-term revenue structures represent different stages of value capture.
Finally, commercial scaling was also identified as a value pathway. In the EU, the CRCF Buyers Club presents multi-year offtake agreements for permanent carbon removals as a potential route for expanding initial projects into larger-scale carbon removal businesses [21]. In Singapore, an operating global trading market can enable repeated transactions and expand the scope of sales [18,19]. Korea likewise identifies purchases of domestic mitigation outcomes by overseas buyers and broader uses of mitigation outcomes as medium- to long-term market-development tasks [11]. Because some EU and Korean functions remain at early or planned stages, they are not interpreted as realized firm-level outcomes. In the IEV operationalization, scaling is classified as value capture when it expands realized transactions, contracted demand, or revenue opportunities after entry; strategic opportunity before realized returns remains part of value creation.
Across the three cases, market entry does not by itself generate either strategic value or captured revenue. Buyer access, demand formation and commercialization create market and strategic value, while sales, price formation, contracting and repeat transactions determine how much of that value is captured. Contractual instruments such as ERPAs, forward purchases and multi-year offtakes can improve revenue visibility and project bankability by allocating future demand and price risk [21,27]. For reversal-exposed activities, collective buffers, insurance and other liability mechanisms perform a different but complementary function: they protect the credibility and deliverability of the asset and therefore preserve risk-adjusted value [9,28]. Demand-side disclosure and claim rules further affect whether buyers are willing to purchase and publicly use credits without engaging in greenwashing or double-claiming risk [10,24].
3.4. Policy Transfer Applicability to Korea
Applying the four-fold classification specified in Section 2.7 shows that policy transfer is function-specific rather than jurisdiction-wide. Table 6 classifies the functions observed in the EU and Singapore according to whether they can be used as a direct principle, require institutional adjustment, are limited within Korea’s present market formation stage or require new design. The classification is based on functional applicability, not institutional superiority.
Table 6.
Functional policy transfer assessment for the Republic of Korea.
The results therefore do not support unidirectional copying from a single source market: integrity principles are the most portable, while operational instruments such as aggregation, contracting, claim governance and reversal-risk allocation depend more heavily on legal authority, market maturity, buyer depth and project type. This finding is carried into the Discussion Section as a policy transfer boundary condition.
4. Discussion
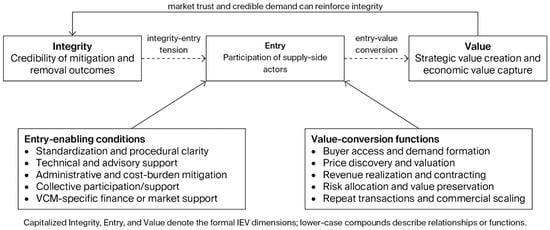
Our comparative results indicate that environmental integrity, firm market entry and value creation in the VCM are better understood not as three independent problems but as interconnected institutional and market processes that nevertheless perform distinct functions. Figure 2 summarizes this relationship as the Integrity–Entry–Value (IEV) structure derived from the comparison, and the interpretation that follows is organized around it.
Figure 2.
Conditional Integrity–Entry–Value (IEV) structure and the functions connecting its three dimensions. Dashed arrows indicate the conditional links between the IEV dimensions (integrity–entry tension and entry–value conversion); solid arrows indicate the entry-enabling conditions and value-conversion functions acting on Entry, and the feedback through which market trust and credible demand can reinforce Integrity.
The IEV structure is not a linear causal chain: credible credits do not automatically bring suppliers into the market, and participation does not automatically generate value. Entry-enabling conditions connect Integrity to Entry, while value-conversion functions—buyer access, price discovery, contracting, risk allocation, and repeat transactions—connect Entry to Value. A missing link can interrupt the sequence. The framework therefore asks three concrete questions: are outcomes credible, can supply-side actors participate and can participation generate and capture value?
These two linking mechanisms constitute the theoretical contribution of the IEV framework. Entry-enabling conditions are not a fourth domain, but rather specify the conditions under which integrity requirements become feasible for prospective suppliers. Value-conversion functions are not a second definition of Value, but rather specify the arrangements through which participation becomes buyer utility, revenue, risk-adjusted returns or scalable commercial activity. The framework therefore explains why high integrity can coexist with weak entry and why market participation can coexist with weak value capture.
4.1. Interpretation of the IEV Relationship and Implications
Whereas previous research has treated credit integrity, market governance, firm entry, pricing and business model value largely as separate analytical problems [1,2,3,4,5,6,7,8,12,13], the IEV structure connects them without claiming to replace those studies. Table 7 clarifies this incremental positioning.
Table 7.
Incremental positioning of the IEV structure relative to adjacent approaches.
The contribution of IEV is relational rather than substitutive: it does not propose a new quality standard, governance regime or pricing model, but rather identifies where the connection can fail between credible credits, supplier participation and value creation or capture.
First, integrity and participation should not be treated as a simple trade-off. Although additionality, quantification, verification and traceability can increase data, technical and procedural demands on new entrants, lowering those standards would weaken market trust. The relevant policy question is therefore how to help supply-side actors meet demanding integrity requirements through complementary institutional support [1,2,4]. The present study interprets this as institutional complementarity rather than direct causation because it does not test firm-level outcomes.
Second, market infrastructure and supplier capability are different. Although Singapore provides clear buyer-oriented quality guidance and active trading infrastructure [10,18,19], the selected evidence base does not establish the full range of supplier support policies in the wider Singaporean economy. The appropriate inference is therefore limited: trading access can be observed, while supplier support functions outside the common case boundary are not assessed. This supports treating Entry as a distinct analytical dimension without turning document-scope gaps into market-wide claims.
Third, entry, value creation and value capture are different processes. Buyer access and commercialization create strategic value, whereas sales, prices, contracts and repeat transactions determine how much value is captured. Offtake and ERPA-type contracts can reduce revenue uncertainty, while pooled buffers or insurance can preserve risk-adjusted value for reversal-exposed credits [9,21,27,28]. Claim integrity also affects demand because weak disclosure or unsupported public claims can create reputational and greenwashing risk [10,24].
This interpretation also connects with the findings of Kuwae et al. [7], who analyzed transaction data from Japan’s J-Blue Credit scheme and showed that transaction outcomes were related not only to mitigation volume itself but also to the characteristics of projects and purchasers and the fit between them, supporting the view that producing environmentally credible credits and capturing economic value from those credits are not the same process. For climate-tech firms and project developers, credit issuance should therefore be understood as one stage in the process of converting mitigation outcomes into market value rather than as the end point of a project.
Fourth, the differences among the EU, Singapore and Korea show that no single institutional model implements the IEV relationship. What matters is not replicating the arrangements of any one jurisdiction but identifying the functions those arrangements perform. In the EU, the combination of a public certification system with long-term purchase is comparatively prominent; in Singapore, international standards and actual trading and price discovery functions are prominent. Korea is attempting to build integrity management, firm support and trading and price formation functions within a single institutional framework from the earliest stage of market formation. Given these differences, late-forming markets such as Korea need to select and combine the functions required at the Integrity, Entry and Value stages in line with their own institutional environment and stage of market development, rather than transplanting the arrangements of earlier markets. This is consistent with the argument of Dolowitz and Marsh [25] that policy transfer should be a process of selection and adjustment according to policy objectives and institutional context rather than the simple replication of institutions. Table 6 reports this assessment explicitly through a four-fold transfer classification, linking the methodological commitment in Section 2.7 to the results.
The policy transfer analysis also highlights the three failure risks identified by Dolowitz and Marsh [25]. Uninformed transfer can occur when the legal force, credit scope or implementation status of a source arrangement is overlooked; incomplete transfer can occur when an integrity rule is imported without the supporting MRV, registry, finance, demand or claims infrastructure needed for it to function; and inappropriate transfer can occur when a mechanism developed for a different credit type or market stage is applied without adjustment. These risks are particularly relevant to Korea, as the source cases are functionally comparable but not institutionally identical.
Korea may, in particular, enjoy a late-mover advantage in market design, as the relevant arrangements are not yet locked in. This does not mean that its institutions lag behind those of earlier jurisdictions; rather, it can observe both the institutional strengths and the gaps of markets already formed abroad and reflect them selectively at the stage of market formation. Instead of concentrating either on strengthening integrity standards alone or, conversely, relaxing quality standards to broaden participation, it can design a structure that considers the formation of credible mitigation outcomes, the participation possibilities of new suppliers and value capture after entry together. Such an approach is significant as a Korean VCM could develop its own market design logic rather than simply following earlier markets.
The IEV structure also extends the focus of VCM research beyond credit quality or market size to the whole process through which firms and project developers generate credible mitigation outcomes and convert them into market participation and sustainable business value.
4.2. Limitations and Future Research
This study has several limitations: First, because it is a qualitative comparative policy and institutional analysis based on legal, policy and market operation materials from the EU, Singapore and Korea, it does not empirically test whether particular institutional functions actually changed firm entry rates, transaction costs, revenues or profitability. The entry-enabling conditions and value-conversion functions presented here are therefore findings about institutional functions and their relationships, as confirmed in official materials, and should not be interpreted as direct causal effects on firm performance.
Second, the cases differ in legal standing, market role and document purpose. The EU CRCF is not the entire EU VCM; Singapore’s buyer guidance is not a supplier support code or statutory certification system; and Korea remains a formation-stage market. A common boundary rule reduces, but does not eliminate, this asymmetry. Our analysis therefore avoids interpreting a function that is outside a selected document’s purpose as proof that the wider jurisdiction lacks that function. The EU and Singapore also remain the two external source cases, and no deliberately selected counterexample is included. Our findings support analytical transferability of functions, not universal generalization.
The boundary conditions of the IEV structure should therefore be explicit: it is intended primarily as a functional analytical framework for VCMs that are being formed, redesigned or connected to new suppliers and buyers and that must jointly address integrity requirements, entry capacity and value-conversion mechanisms. It should not be treated as a universal causal model for all carbon markets. Markets with materially different legal mandates, credit types, claims regimes, buyer structures or stages of maturity require re-operationalization and empirical validation before the same relationships are assumed to hold.
Third, because the proposed IEV structure was derived from policy and institutional materials, it requires validation through subsequent empirical research. Future work should analyze the relationships among Integrity, Entry and Value at the firm and project level using data on the MRV and verification costs of climate-tech firms and project developers, project registration periods, credit issuance volumes, actual transaction prices, long-term purchase agreements, revenues and business expansion. Quantitative tests of which entry-enabling conditions substantively reduce the costs or time faced by new entrants, and which value-conversion functions connect one-off credit sales to sustained business performance, would allow the explanatory power of the IEV structure to be assessed more clearly.
Finally, future research should analyze the connection between the environmental credibility of mitigation outcomes and market value in more technical terms. Approaches that link life cycle assessment (LCA) to MRV can be used to evaluate the life cycle environmental burdens and net mitigation effects of projects systematically [29]. Combining these with actual transaction prices, purchase agreements and firm performance would make it possible to analyze the conditions under which environmental integrity and economic value are formed together. This would extend the IEV structure from a comparative analysis at the policy and institutional level to an empirical analytical scheme at the firm and project level.
5. Conclusions
In this study, we examined how VCM integrity requirements relate to the participation and value creation of supply-side actors. Our core analysis compared legal, policy and market operation materials from the EU, Singapore and Korea under a common case boundary, while a supplementary SciVal landscape check provided context. The results were synthesized into an Integrity–Entry–Value (IEV) structure.
Our analysis shows that environmental integrity is not a condition opposed to firm participation but is rather a foundation that allows credible mitigation outcomes to be recognized in the market and, at the same time, a condition that requires additional capacity and procedures. In addressing these requirements, what matters is not the relaxation of integrity standards but entry-enabling conditions—standardization, technical and professional capacity support, mitigation of procedural and cost burdens, collective participation and early-stage finance—that raise participants’ ability to meet standards. Nor does the ability to participate in the market by itself secure sustained economic value: for mitigation outcomes to be linked to value creation and value capture, value-conversion functions such as revenue realization, price valuation, revenue predictability and commercial scaling need to operate separately.
The IEV structure is conditional rather than linear. While integrity rules create trust, they can also require data, expertise and procedures. Entry-enabling conditions help supply-side actors meet those requirements, while value-conversion functions determine whether participation produces strategic opportunity and economic returns. The academic contribution of this article lies in connecting these stages within one functional framework while keeping their mechanisms distinct. Its theoretical contribution lies specifically in specifying two conditional linking mechanisms rather than merely combining three research domains: entry-enabling conditions explain whether Integrity can lead to Entry, and value-conversion functions explain whether Entry can lead to Value.
In policy terms, our results suggest that a jurisdiction forming or redesigning a voluntary carbon market should not treat market credibility and broader firm participation as inherently conflicting objectives. The institutional functions observed in the EU and Singapore were not implemented in the same way: our transfer analysis shows that some principles are portable, while other instruments require adjustment or new design. The implications should therefore be read as analytically bounded and conditional rather than as a universal model for late-forming markets. They are most relevant to VCMs facing institutional challenges comparable to Korea’s formation-stage problem: simultaneously establishing credible credit and claim integrity, enabling new suppliers to meet market requirements and building demand and value-conversion functions.
Author Contributions
Conceptualization, M.-S.J. and Y.-W.H.; methodology, M.-S.J.; formal analysis, M.-S.J., H.J.R. and H.-W.L.; investigation, M.-S.J. and H.J.R.; data curation, H.J.R. and H.-W.L.; writing—original draft preparation, M.-S.J.; writing—review and editing, Y.-W.H., H.J.R. and H.-W.L.; visualization, M.-S.J.; supervision, Y.-W.H.; project administration, Y.-W.H.; funding acquisition, Y.-W.H. All authors have read and agreed to the published version of the manuscript.
Funding
This research was supported by the Knowledge-based Environmental Service Specialized Graduate School Program through the Korea Environmental Industry & Technology Institute (KEITI), funded by the Ministry of Climate, Energy and Environment (MCEE).
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The legal, policy and market operation documents analyzed in this study are publicly available and cited in the reference list. The provision/source coding output used for the qualitative synthesis is reported in Appendix C.
Conflicts of Interest
The authors declare no conflicts of interest.
Abbreviations
The following abbreviations are used in this manuscript:
| BAU | Business as usual |
| CIX | Climate Impact X |
| CRCF | Carbon Removals and Carbon Farming Certification Framework |
| IEV | Integrity–Entry–Value |
| LCA | Life cycle assessment |
| MRV | Measurement, reporting and verification |
| SME | Small- and medium-sized enterprise |
| VCM | Voluntary carbon market |
Appendix A. SciVal Search Configuration and Transparency Note
SciVal was used as a supplementary research landscape tool rather than as a systematic review or thematic bibliometric stage. The exact phrase “voluntary carbon market” was used to construct the author-defined research area, saved as “VCM—Voluntary Carbon Market”. The retained record includes the analysis date, the 2020–2026 window, aggregate counts, exploratory Topic-name terms and representative Topic labels. The check was not designed to test every IEV concept; MRV and additionality were not independent query filters, and no research gap claim is based on hit counts for individual terms. No Topic or Topic Cluster was used to derive the IEV dimensions or screen the policy document sample. Because a cluster-name export was not retained, the Appendix A reports the verified cluster count and the representative Topic labels actually inspected rather than reconstructing unverified cluster names.
Table A1.
SciVal Search Configuration and Descriptive Landscape Outputs.
Appendix B. Core Document Inventory and Evidentiary Standing
Table A2.
Core Document Inventory, Evidentiary Standing, and Analytical Use.
Appendix C. Provision/Source Coding Output and Overlapping Functional Effects
This matrix reports the visible output of the qualitative coding. It is not a frequency table. Each row records a source- or provision-level function and the functional effects used in the cross-case synthesis. Overlapping effects show where one provision serves more than one IEV role.
Table A3.
Provision/Source Coding Matrix and Overlapping IEV Functional Effects.
References
- Probst, B.S.; Toetzke, M.; Kontoleon, A.; Anadón, L.D.; Minx, J.C.; Haya, B.K.; Schneider, L.; Trotter, P.A.; West, T.A.P.; Gill-Wiehl, A.; et al. Systematic Assessment of the Achieved Emission Reductions of Carbon Crediting Projects. Nat. Commun. 2024, 15, 9562. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Trencher, G.; Nick, S.; Carlson, J.; Johnson, M. Demand for Low-Quality Offsets by Major Companies Undermines Climate Integrity of the Voluntary Carbon Market. Nat. Commun. 2024, 15, 6863. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Martins Karpavicius, L.; Elofsson, K.; Yan, S. The Determinants of Transaction Costs for Carbon Sequestration Projects: A Meta-Analytical Review. J. For. Econ. 2026. Advance online publication. [Google Scholar] [CrossRef] [Scilit]
- Khan, M.Z.; Hameed, A.; Khan, N.U.; Khan, Z.U. Beyond Compliance: The Role of Climate Policy Stringency and Financial Institutions in Cleantech Startup Entry. Bus. Strategy Environ. 2026, 1–30. [Google Scholar] [CrossRef] [Scilit]
- Sairanen, M.; Aarikka-Stenroos, L. Low-Carbon Business Models: Review and Typology. Ind. Mark. Manag. 2024, 123, 222–250. [Google Scholar] [CrossRef] [Scilit]
- Dhanda, K.K.; Malik, M. Voluntary Carbon Markets: Potential for Social Entrepreneurship? N. Engl. J. Entrep. 2025, 28, 7–24. [Google Scholar] [CrossRef] [Scilit]
- Kuwae, T.; Suzuki, Y.; Furuya, M. Empirical Analysis of Project–Purchaser Dynamics in Japan’s Blue Carbon Dioxide Removal Credit Scheme. npj Ocean Sustain. 2026, article in press. [Google Scholar] [CrossRef] [Scilit]
- Kochar, R.; Kalsie, A.; Deka, N. Voluntary Carbon Markets (VCMs) in a Nutshell: A Systematic Review Based on the Empirical Evidence from across the Globe. J. Clean. Prod. 2025, 522, 146261. [Google Scholar] [CrossRef] [Scilit]
- European Parliament and Council of the European Union. Regulation (EU) 2024/3012 of 27 November 2024 Establishing a Union Certification Framework for Permanent Carbon Removals, Carbon Farming and Carbon Storage in Products. Off. J. Eur. Union 2024, L 2024/3012. Available online: http://data.europa.eu/eli/reg/2024/3012/oj (accessed on 24 September 2026).
- National Climate Change Secretariat; Ministry of Trade and Industry; Enterprise Singapore. Guidance on Role of Carbon Credits in Corporate Decarbonisation; Government of Singapore: Singapore, 2025.
- Ministry of Planning and Budget. Direction for the Establishment of a Korean Voluntary Carbon Market; Ministry of Planning and Budget: Sejong, Republic of Korea, 2026. (In Korean)
- Battocletti, V.; Enriques, L.; Romano, A. The Voluntary Carbon Market: Market Failures and Policy Implications. Univ. Colo. Law Rev. 2024, 95, 519–573. [Google Scholar]
- Ahn, P.; Shin, D.-H. An Empirical Analysis of Global Emission Offset Price Determinants on Voluntary Carbon Market: Focusing on Demand Factors. Crisisonomy 2024, 20, 137–148. [Google Scholar] [CrossRef] [Scilit]
- Bowen, G.A. Document Analysis as a Qualitative Research Method. Qual. Res. J. 2009, 9, 27–40. [Google Scholar] [CrossRef] [Scilit]
- Yin, R.K. Case Study Research and Applications: Design and Methods, 6th ed.; SAGE: Thousand Oaks, CA, USA, 2018. [Google Scholar]
- George, A.L.; Bennett, A. Case Studies and Theory Development in the Social Sciences; MIT Press: Cambridge, MA, USA, 2005. [Google Scholar]
- Elsevier. SciVal [Database]; Author-Defined Research Area: “VCM—Voluntary Carbon Market”; Elsevier: Amsterdam, The Netherlands, 2026. [Google Scholar]
- Climate Impact X. Climate Impact X Launches Global Carbon Marketplace to Accelerate Climate Action Through Quality Carbon Credits; Press Release; Climate Impact X: Singapore, 2022. [Google Scholar]
- Climate Impact X. Climate Impact X Launches CIX Exchange to Level Up Carbon Market Transparency, Certainty and Liquidity; Press Release; Climate Impact X: Singapore, 2023. [Google Scholar]
- European Commission. Commission Delegated Regulation (EU) 2026/285 of 3 February 2026 Supplementing Regulation (EU) 2024/3012 by Establishing the Certification Methodologies for Permanent Carbon Removals Activities. Off. J. Eur. Union 2026, L 2026/285. Available online: http://data.europa.eu/eli/reg_del/2026/285/oj (accessed on 24 September 2026).
- European Commission, Directorate-General for Climate Action. EU CRCF Buyers Club; European Commission: Brussels, Belgium, 2026. [Google Scholar]
- Ministry of Planning and Budget. National Assembly Debate Held on the Direction for Enacting a Voluntary Carbon Market Act; Press Release; Ministry of Planning and Budget: Sejong, Republic of Korea, 2026. (In Korean)
- Integrity Council for the Voluntary Carbon Market (ICVCM). Core Carbon Principles, Assessment Framework and Assessment Procedure, version 3; ICVCM: London, UK, 2024; Available online: https://icvcm.org/assessment-framework/ (accessed on 24 September 2026).
- Voluntary Carbon Markets Integrity Initiative (VCMI). Claims Code of Practice, version 3.1; VCMI: Suitland, MD, USA, 2025; Available online: https://vcmintegrity.org/wp-content/uploads/2025/08/VCMI-Claims-Code_2025_Update.pdf (accessed on 24 September 2026).
- Dolowitz, D.P.; Marsh, D. Learning from Abroad: The Role of Policy Transfer in Contemporary Policy-Making. Governance 2000, 13, 5–23. [Google Scholar] [CrossRef] [Scilit]
- UNFCCC. Decision 2/CMA.3: Guidance on Cooperative Approaches Referred to in Article 6, Paragraph 2, of the Paris Agreement; United Nations Framework Convention on Climate Change: Bonn, Germany, 2021. [Google Scholar]
- Forest Carbon Partnership Facility. ERPA General Conditions and Commercial Terms; Forest Carbon Partnership Facility/World Bank: Washington, DC, USA, 2014; Available online: https://www.forestcarbonpartnership.org/erpa-general-conditions (accessed on 24 September 2026).
- Integrity Council for the Voluntary Carbon Market (ICVCM). Continuous Improvement Work Program Report on Permanence; ICVCM: London, UK, 2025; Available online: https://www.icvcm.org/ciwp-report-on-permanence/ (accessed on 24 September 2026).
- Yao, Y.; Zhang, B. Life Cycle Assessment in the Monitoring, Reporting, and Verification of Land-Based Carbon Dioxide Removal: Gaps and Opportunities. Environ. Sci. Technol. 2025, 59, 11950–11963. [Google Scholar] [CrossRef] [Scilit] [PubMed]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.