


Abstract
This study examines the impact of green finance on optimizing China’s agricultural industrial structure. It emphasizes the importance of innovative green financial services, improved efficiency, tailored regional approaches, and enhanced foresight to foster a high-level development in the agricultural sector amid China’s economic transformation. Based on the provincial panel data of 31 provinces in China from 2012 to 2021, this study empirically tests the effect mechanism of green finance on the optimization process of the agricultural industrial structure by constructing a fixed-effects model. This study finds that green finance can effectively promote the development of the optimization of the agricultural industrial structure. Under the current trend of China’s economic structural transformation and optimization, we suggest that China should innovate green financial service products, improve the efficiency of green finance, and enhance the depth of green financial services for the optimization of the agricultural industrial structure. It is required to strengthen foresight and improve relevant laws, regulations, policies, and standards. To help green finance be better promoted, a high-level development of the agricultural industrial structure is required.
1. Introduction
1.1. Background
To expedite agricultural modernization and achieve sustainable economic development while working towards China’s “carbon peak and carbon neutrality” targets, it is imperative to prioritize ecological civilization construction and the rural revitalization strategy. The optimization of the product industry’s structure, as outlined in the No. 1 Central Document, becomes crucial for future agricultural deployment [1]. The advancement of the agricultural industrial structure is a key measure for sustainable development [2].
In recent years, green finance has increasingly played a significant role in promoting the optimization of the agricultural industrial structure. Green finance involves investment and financing in projects that support environmental protection, energy efficiency, clean energy, green buildings, and other environmentally friendly practices, aiming to mitigate climate change and maximize resource conservation and efficiency [3,4,5,6,7]. The interconnection between the agricultural industrial structure and green financing has gained attention from scholars, but there remains a lack of relevant research and empirical studies, and data support needs improvement.
Therefore, a comprehensive investigation is necessary to determine how green finance can contribute to the upgrading of the agricultural industrial system. This study aims to investigate the impact of green finance on the industrial structure of the agriculture sector using a fixed-effects model and analyzing data from 31 Chinese provinces and municipalities (excluding Hong Kong, Macau, and Taiwan) from 2012 to 2021. The findings emphasize the importance of optimizing the agricultural industrial structure based on regional conditions and pursuing sustainable development, energy conservation, and emission reduction. Green finance instruments should be actively utilized to maximize this growth.
1.2. Literature Review
When examining the relationship between green finance and restructuring the agricultural industrial structure, researchers from other countries initially focused on the connection between financial development and industrial structure [8]. Financial policies have been proposed to distribute social resources across sectors, ensuring adequate funding for industrial development [9]. Green finance, as described by Muganyi et al. is a subset of financial innovation that connects the financial sector with environmental causes to protect the environment [10]. It is suggested that green finance could increase the likelihood of return on investment for environmentally friendly energy projects [11].
In the domestic literature, there has been limited research specifically on green finance and the adjustment of the agricultural industrial structure. Ma Biao et al. used a four-sector dynamic stochastic general equilibrium (DSGE) model, highlighted the role of credit support in promoting economic growth, efficiency, and adjustment in the industrial structure [12]. Financial development and industrial structure upgrading are two core areas of concern in development economics [13]. In addition, the development of green finance has a significant role in promoting the transformation and upgrading of industrial structure, which is still valid after the endogeneity test and robustness test [14,15]. Some scholars suggested that promoting green industries and coordinating economic and social development through industrial structure optimization, green low-carbon transformation, and ecological industry optimization contributed to industrial upgrading [16,17,18]. Qian et al. proposed that the reconstruction of a green industrial system, facilitated by green finance, could drive the transformation and enhancement of industrial structures [19,20,21].
Many researchers rely on models to study the relationship between agricultural industrial development and economic growth, with limited attention to the connection between green finance and the agricultural industrial structure. Qualitative methods dominate the study of green finance, underscoring the importance and validity of its growth. Extensive and systematic research on the role of enhancing the agricultural industrial structure in green finance growth is lacking. A static panel model falls short in capturing the dynamic process by which green finance influences the high-level development of the agricultural industrial structure. This study employs a dynamic panel model to empirically explore the mechanism of green finance in upgrading China’s agricultural industrial structure, considering the development of green finance and the level of industrial structure upgrading in the country. These findings contribute to the modernization of China’s agricultural industrial structure and long-term economic prosperity.
2. Theoretical Framework and Research Hypotheses
2.1. Measure the Development Level of Green Finance
Green finance supports the adoption of the concept of green sustainable growth by financial institutions [22]. The improvement and modernization of the agricultural industrial system are also supported by green funding. The academic community has not yet produced a standard measurement of the expanding level of green finance; however, because of the new emergence of green finance in China. The building of an index system is currently the main method used to evaluate the current state of green finance development. This study examined green finance from seven perspectives: green credit, green insurance, green bonds, green support, and green funds, as well as green rights and interests. It also takes into account the complexity and timing of the development of the green finance system. The advancement of the green finance system’s evaluation indicators is shown in Table 1.
Table 1.
Evaluation index system of the development of green finance.
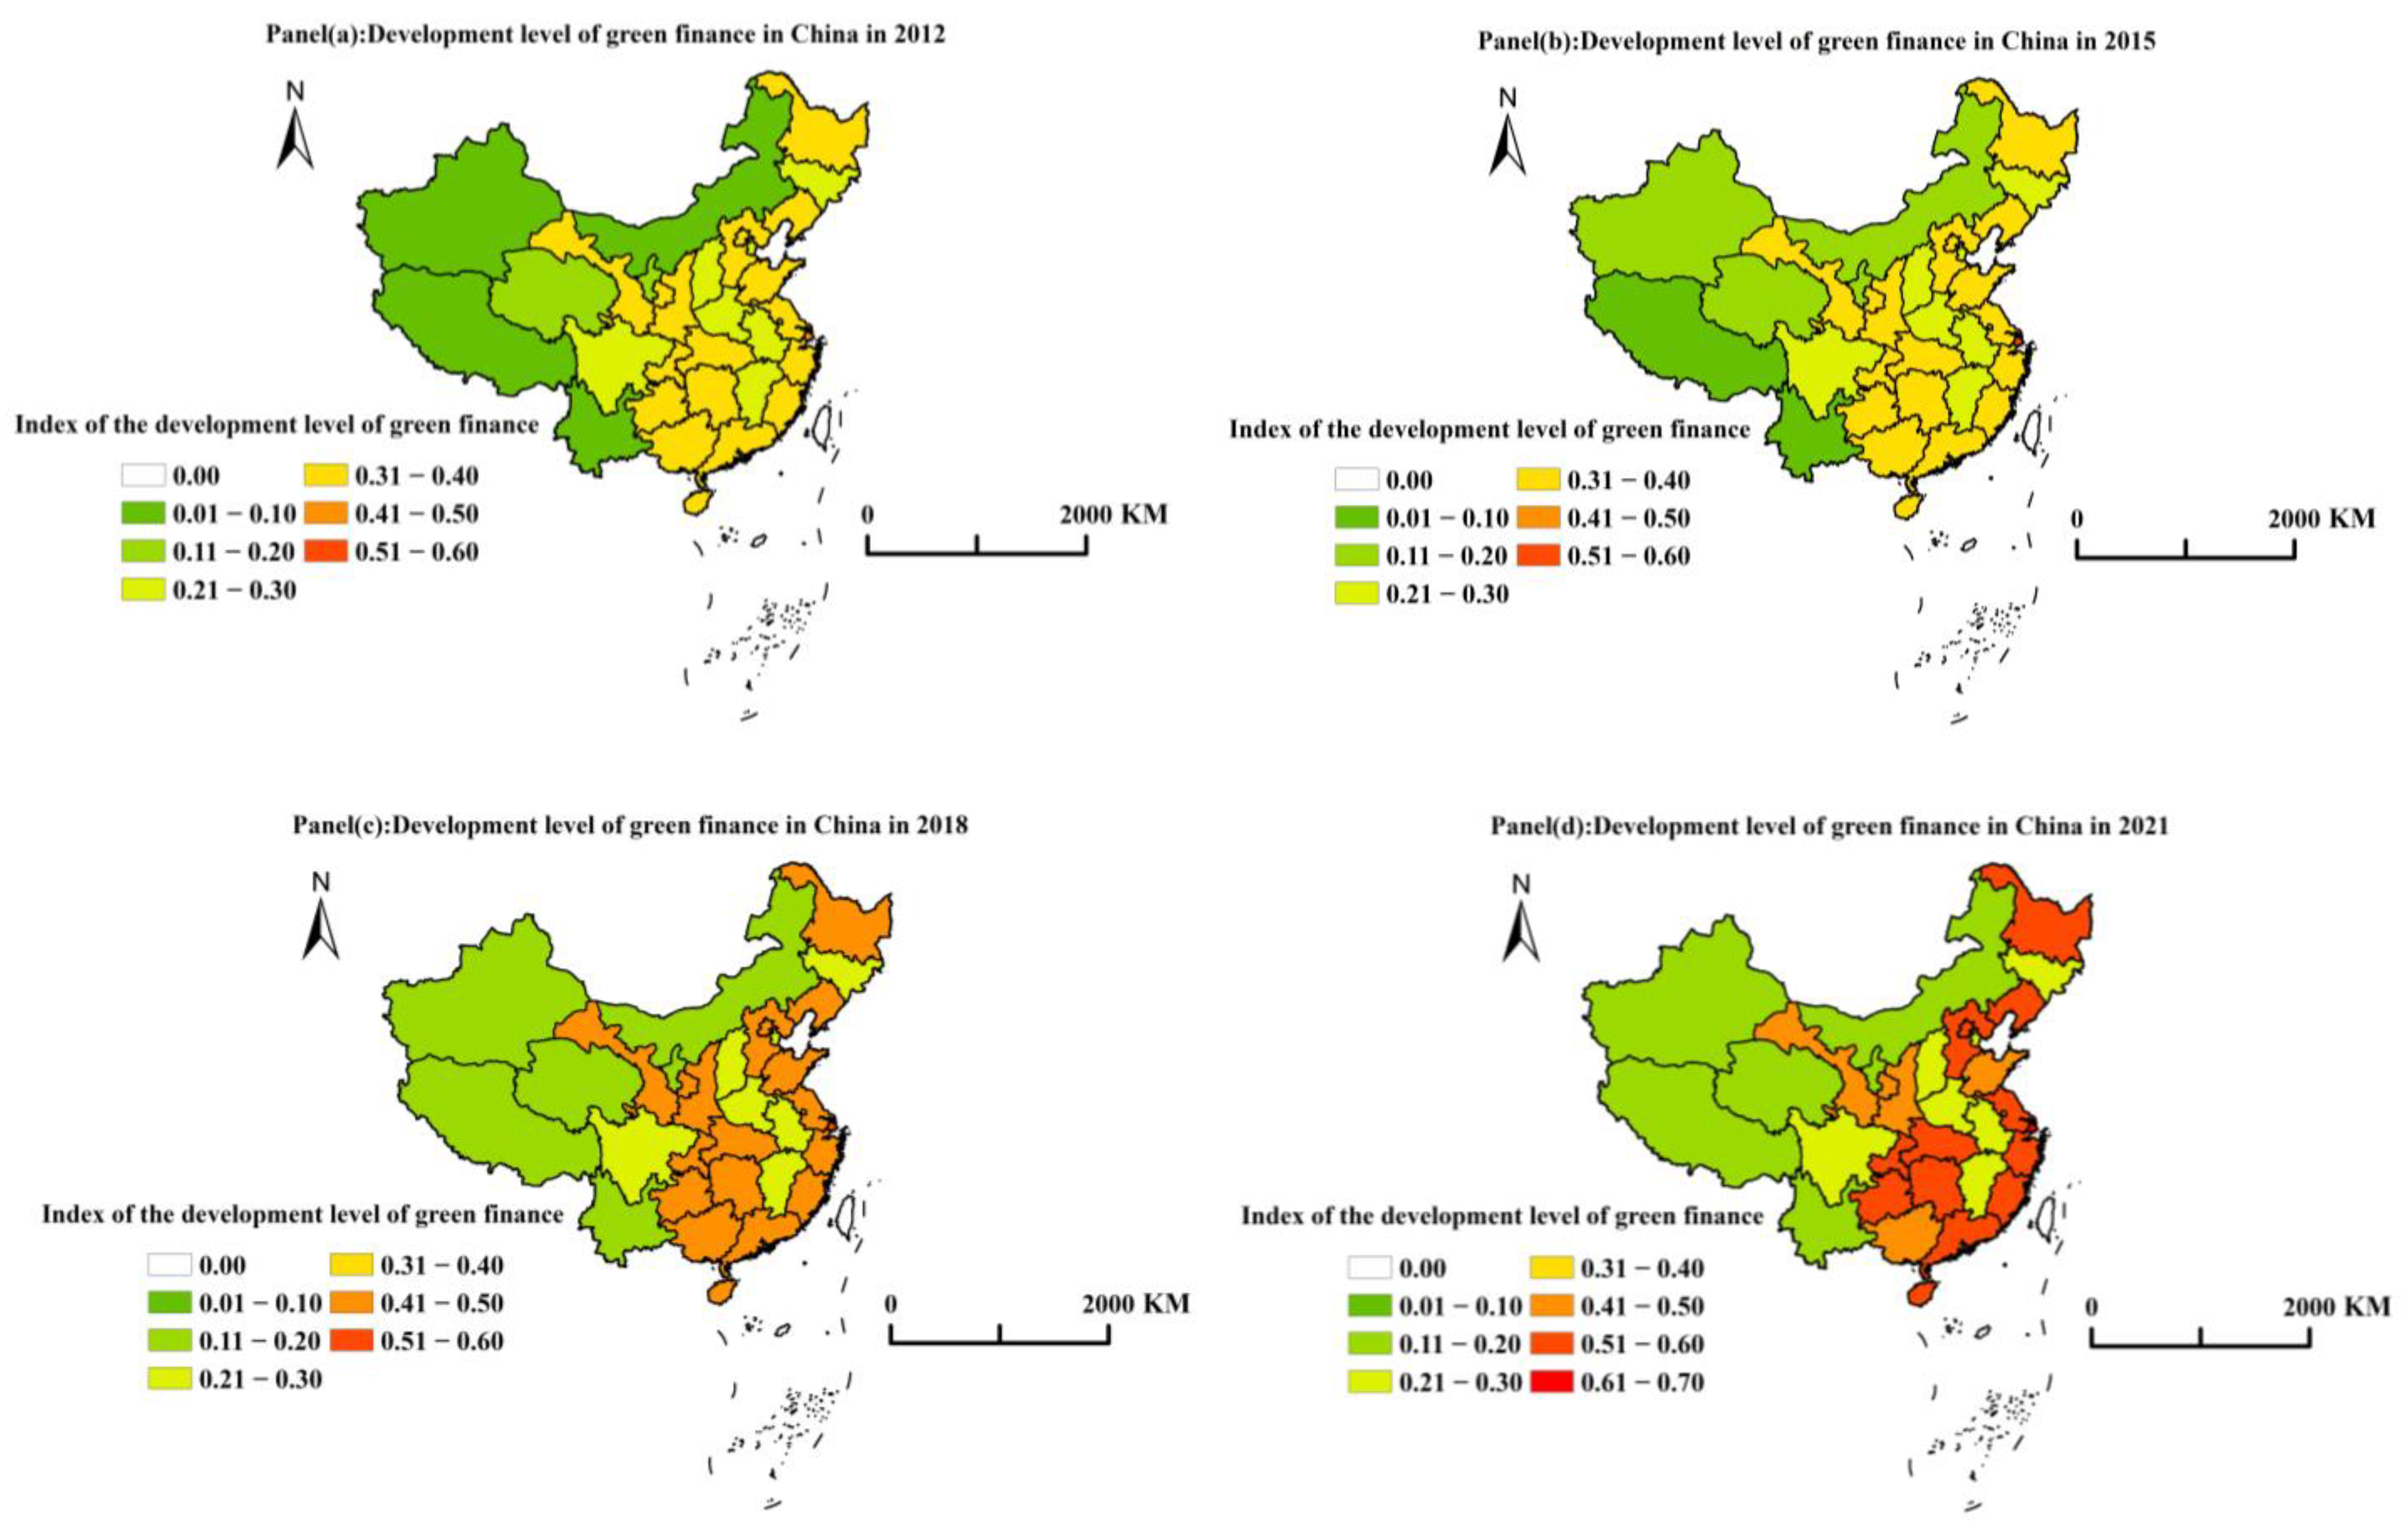
The development level of green finance in China’s provinces from 2012 to 2021 (excluding Hong Kong, Macao, and Taiwan) was quantified using the entropy value technique. To provide a comprehensive view of the changes in green finance development over the past decade, this study employed ArcGIS Pro 2.8 ((https://esribelux.com/2021/05/20/arcgis-pro-2-8/), accessed on 2 December 2022) to analyze the spatial and temporal effects. Specifically, the analysis focused on four specific years: 2012, 2015, 2018, and 2021, with a visualization created every two years. This approach allowed for a more intuitive observation of the variations in green finance development among China’s provinces and the overall changes in the development level of green finance over time (Figure 1). The decision to use a biennial representation was because yearly descriptions may not effectively capture the significant-change effects, which could hinder a comprehensive understanding of the current state of green finance development.
Figure 1.
The development level of green finance in Chinese provinces.
The legend displayed in Figure 1 represents the range of the green finance development level index, presented without specific units. Analyzing the GIS maps depicting the development of green finance over the past four years reveals a consistent improvement in the level of green finance in China. Additionally, the coastal provinces and municipalities show a higher level of green finance development compared to the inland provinces. However, due to data limitations, there are no available statistics on the development level of green finance in Hong Kong, Macao, and Taiwan.
Despite progress, the growth of green finance development has been slower when compared to the average GDP growth rate during the same period. Industries characterized by pollution, inefficient energy use, and excess capacity continue to drive economic growth, while the agricultural sector has limited impact and demand for green finance. To channel market funds effectively, Ding Pan et al. [23] emphasized the importance of targeted and controlled policies to provide greater financial support to green industries and impose higher investment costs on industries with a high resource consumption and low profitability. This accelerates the growth of the ecological industry structure. These findings underscore the need for further research on the relationship between green finance and agriculture to stimulate its demand and driving effect. Urgent discussions are necessary to expedite the healthy and sustainable growth of green financing, supporting the high-level progress of the agricultural industrial system.
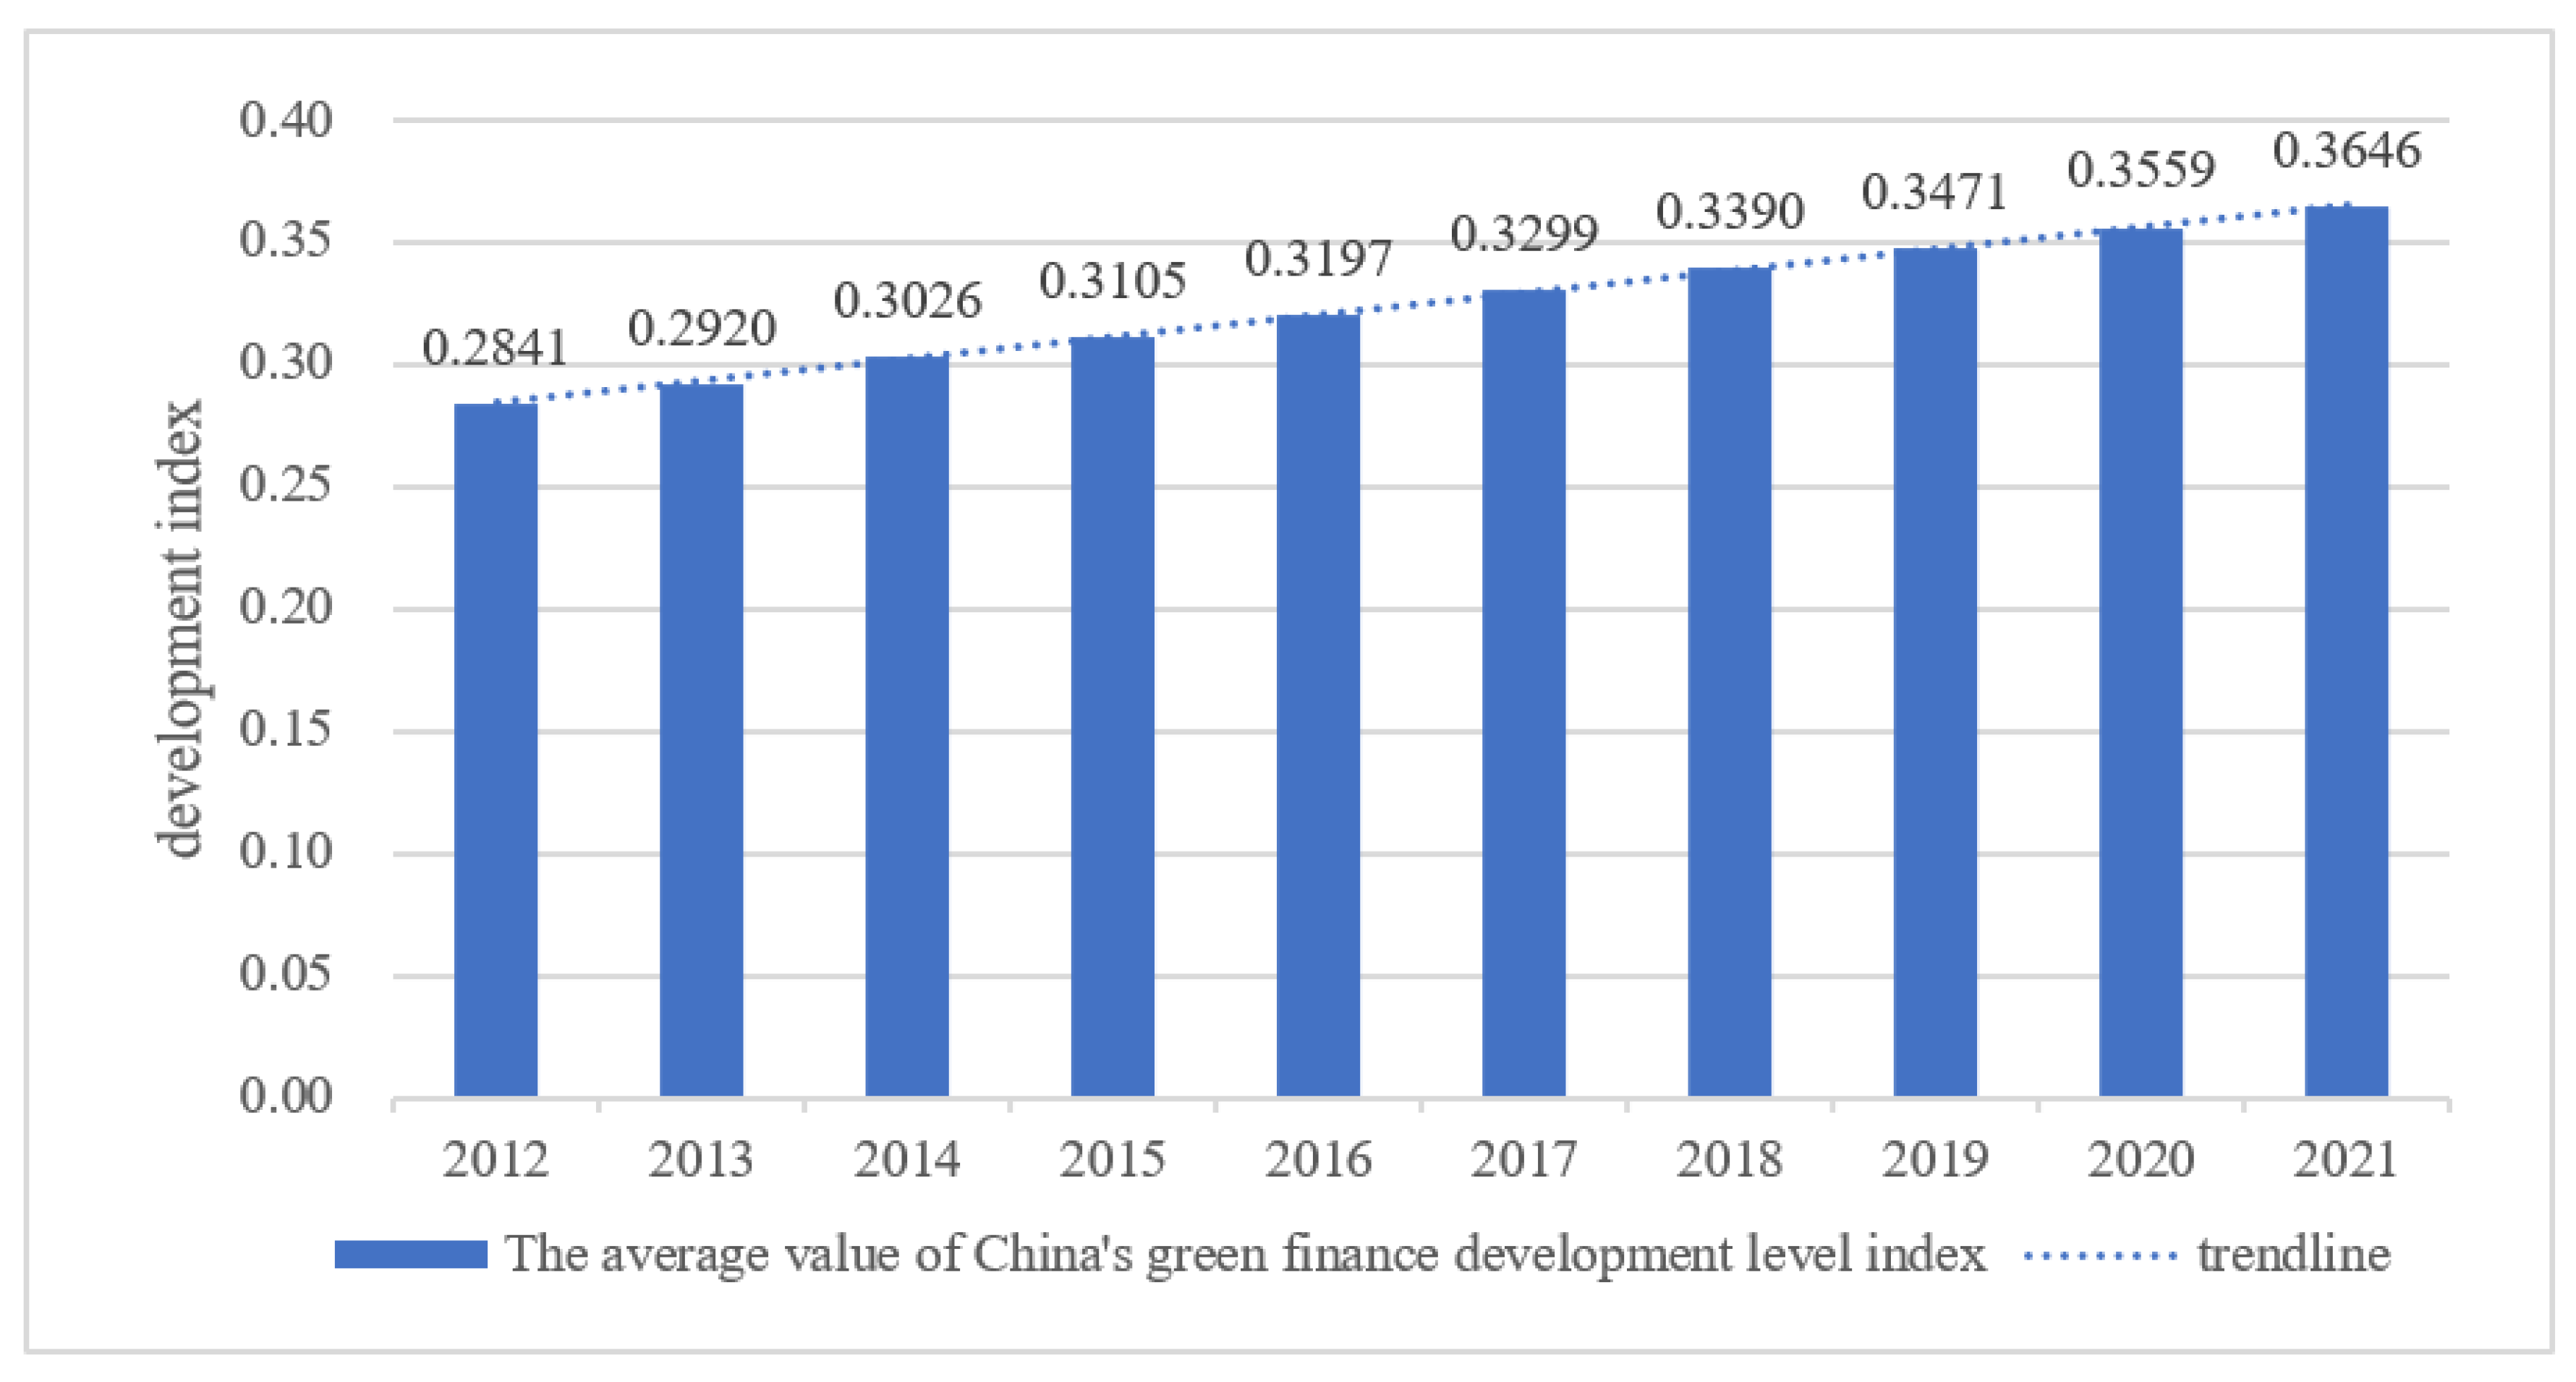
Figure 2 illustrates the fluctuations in the average value of the green finance development level index between 2012 and 2021. The index experienced an upward trajectory, rising from 0.2841 in 2012 to 0.3646 in 2021. Based on the trend line depicted in Figure 2, this study posits that green finance is expected to continue its upward trajectory in the coming years. This trend is intricately linked to China’s array of energy-saving and emission-reduction policies, which play a vital role in shaping the future of green finance.
Figure 2.
Changes in green finance development level index from 2012 to 2021.
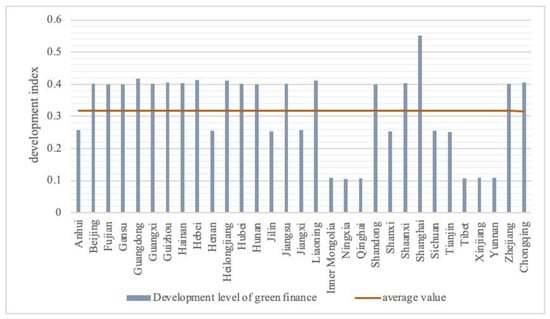
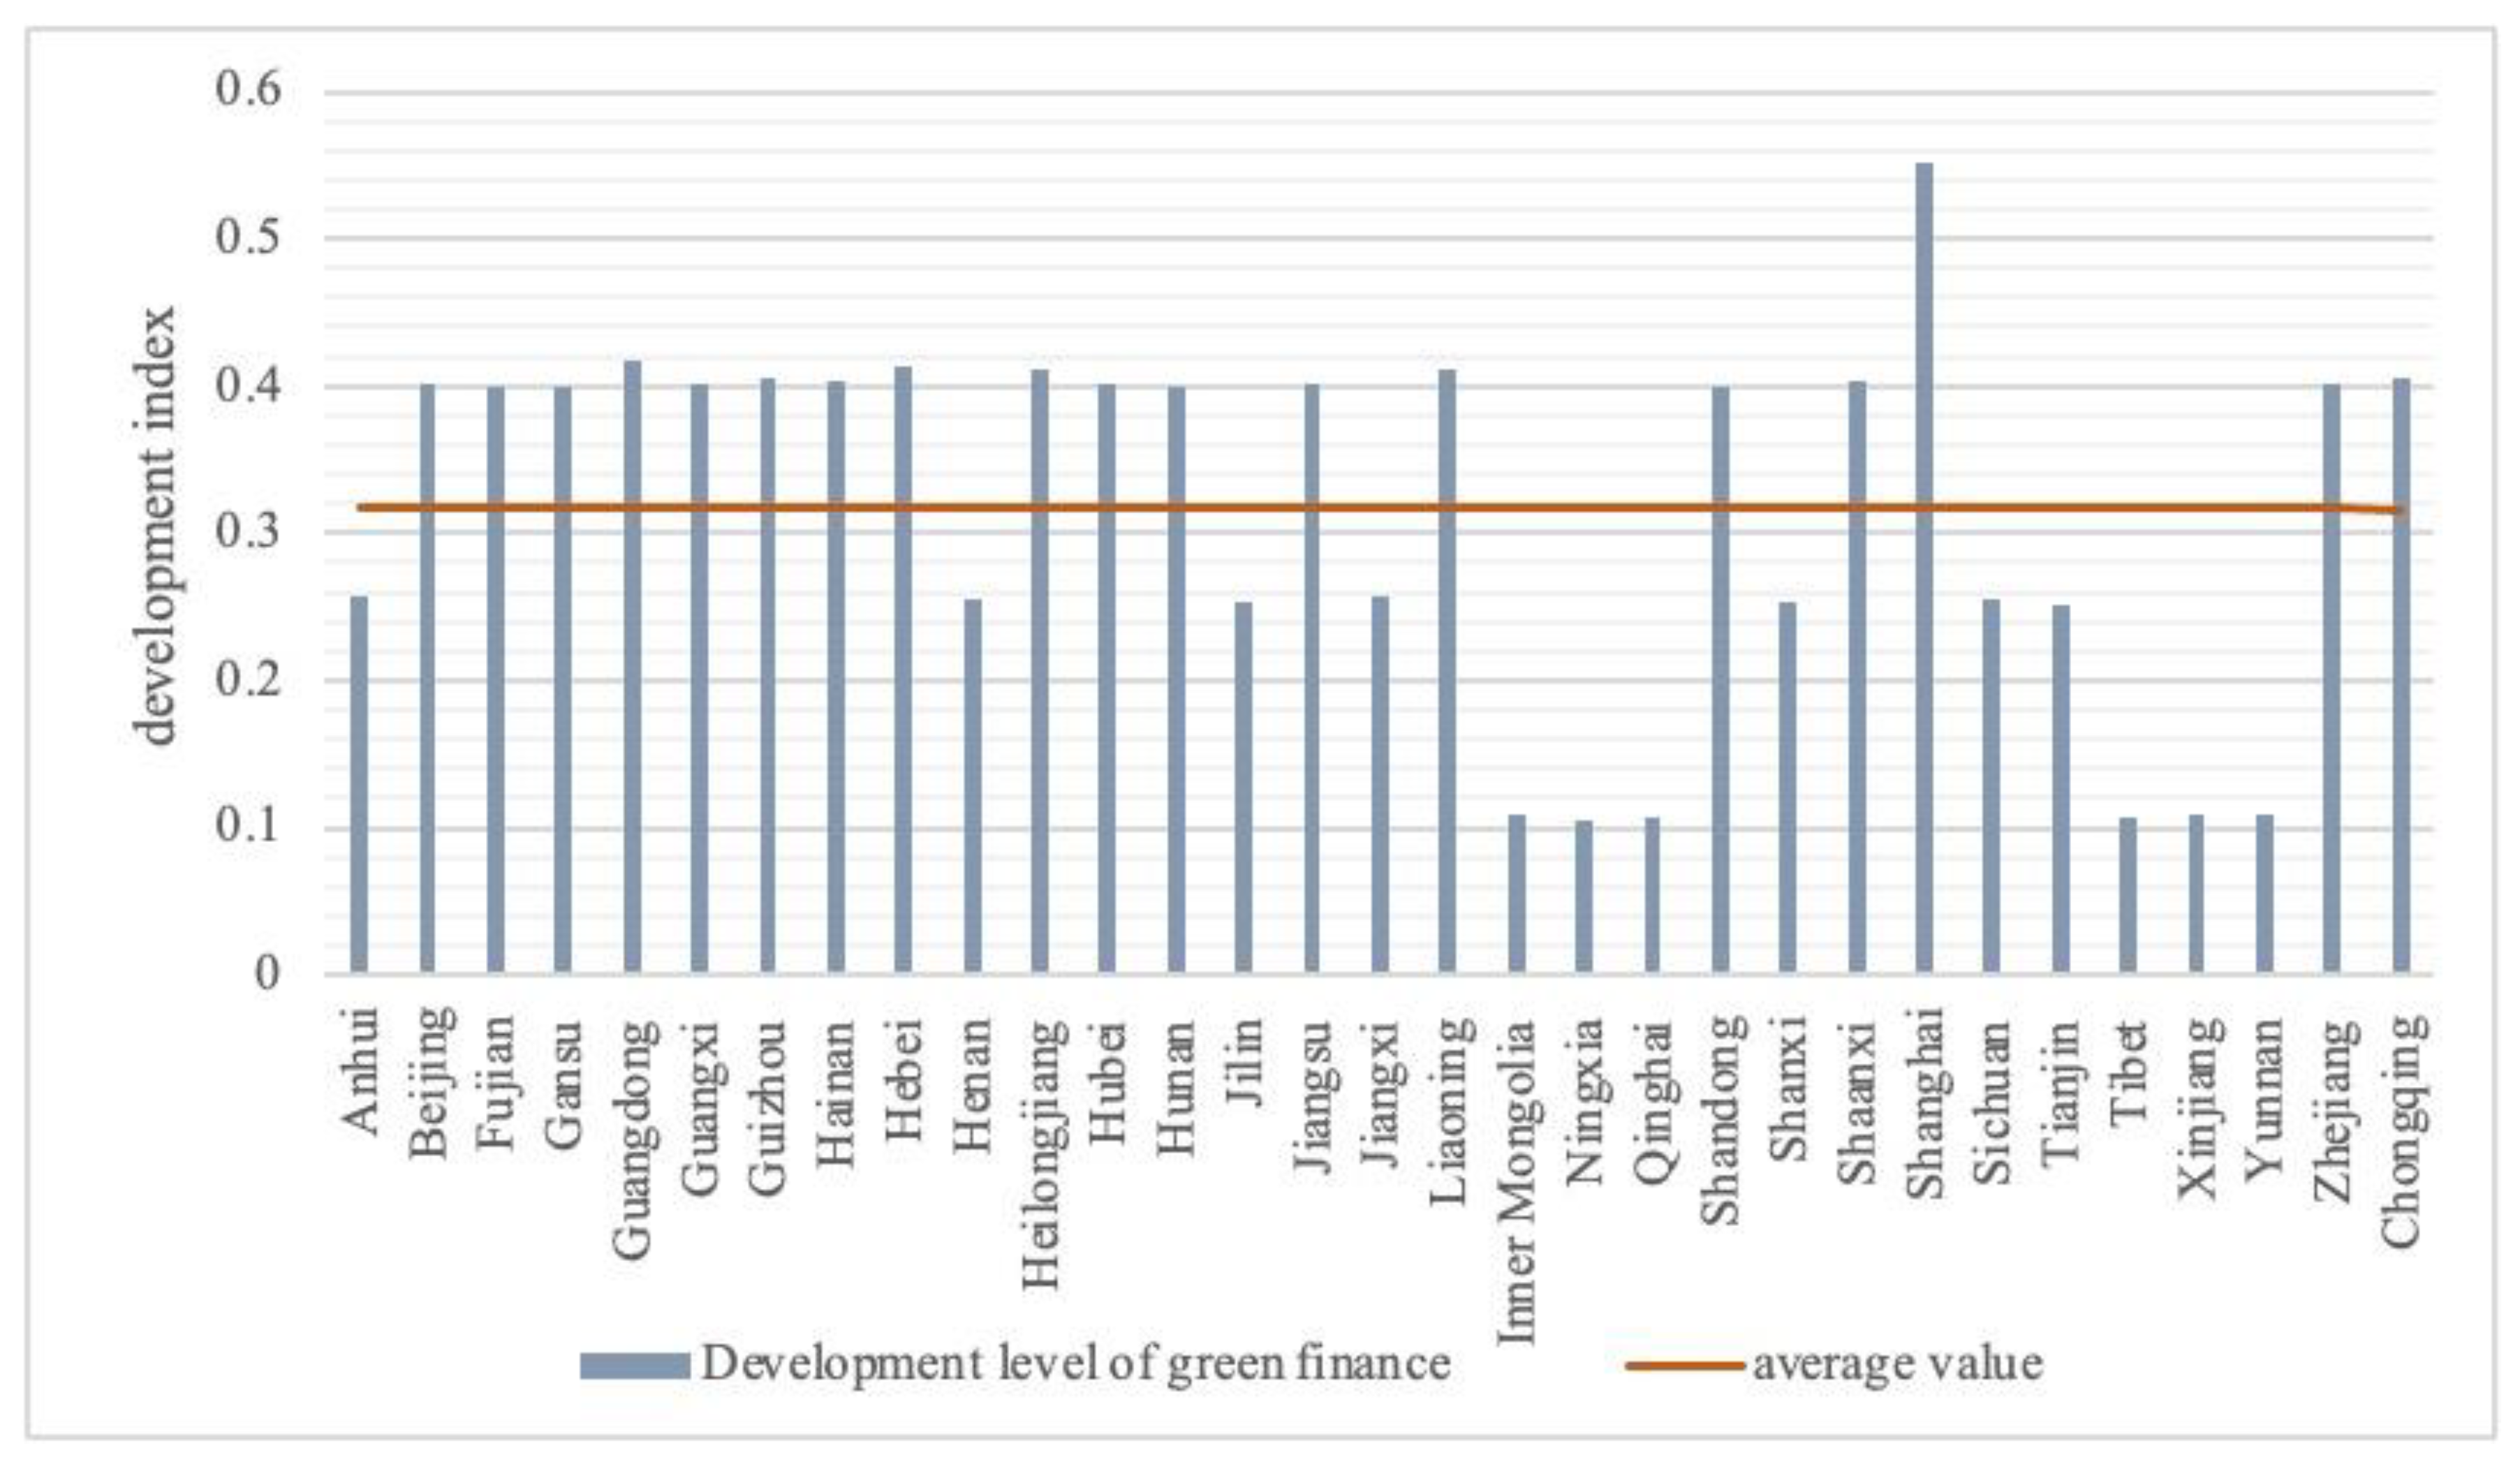
In Figure 3, the average value of the development level index of green finance from 2012 to 2021 is presented for the 31 provinces and cities in China. The report classifies the green finance development level into three distinct levels based on the province level. The first level encompasses 14 provinces and municipalities, as indicated in the figure, with a development index ranging between 0.4 and 0.5. The second level consists of four provinces, districts, and cities, with a development index ranging from 0.3 to 0.4. The third level comprises thirteen provinces, with a development index below 0.3.
Figure 3.
Development level index and the average value of green finance.
It is evident that China’s provinces and cities have considerable potential to accelerate the growth of green financing. The overall green finance development index for China has an average value of 0.3178, with 18 provinces and cities surpassing the national average. However, most provinces and cities in the country still have room for further advancement in developing their green finance systems. The integration of green finance with the optimization and upgrading of the agricultural industrial structure holds great potential for facilitating the high-level development of the agricultural industrial system. This, in turn, will support long-term growth and contribute to the aspirations of the population for an enhanced quality of life.
2.2. Assessing the Development Level of China’s Agricultural Industrial Structure Optimization
The transition from low-level to high-level capital- and technology-intensive enterprises signifies an enhanced agricultural industrial structure. Achieving this transformation necessitates the ongoing development of an industrial structure based on rationalization, innovation, and the adoption of new technologies [24]. To assess the improvement of the agricultural industrial structure, we can employ the industrial structure height index developed by Liu Wei et al. [25]. The calculation formula for this test index is as follows:
where is the specific industry analyzed, and refers to the year in which the analysis was carried out. is the proportion of industrial output value in the domestic output value in period , is the universal labor productivity formed in industry in period and is the ratio of the growth of industry to the total employment. Because statistics on agriculture are limited, provincial statistical data on rural employees in the whole industry were not available.
Hence, building upon the findings of previous scholars, this study incorporated the substitution of labor productivity across key industries within the analysis of the agricultural sector [26]. This was achieved by considering the ratio of value-added to intermediate consumption within various industries. The significance of enhancing the agricultural industrial structure becomes more pronounced as the value of the unified agricultural industrial structure (UAIS) increases, as demonstrated by previous research.
The formula for this measurement was used to determine the advanced level of the industrial structure of agriculture in different parts of China using the original data from regional statistics yearbooks from 2012 to 2021 (excluding Hong Kong, Macau, and Taiwan).
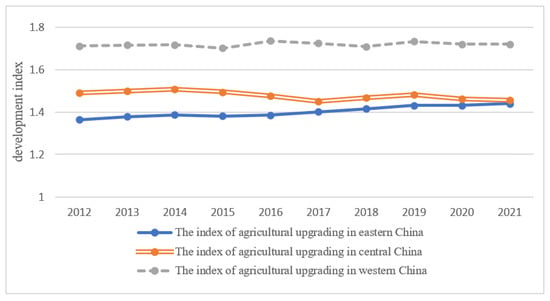
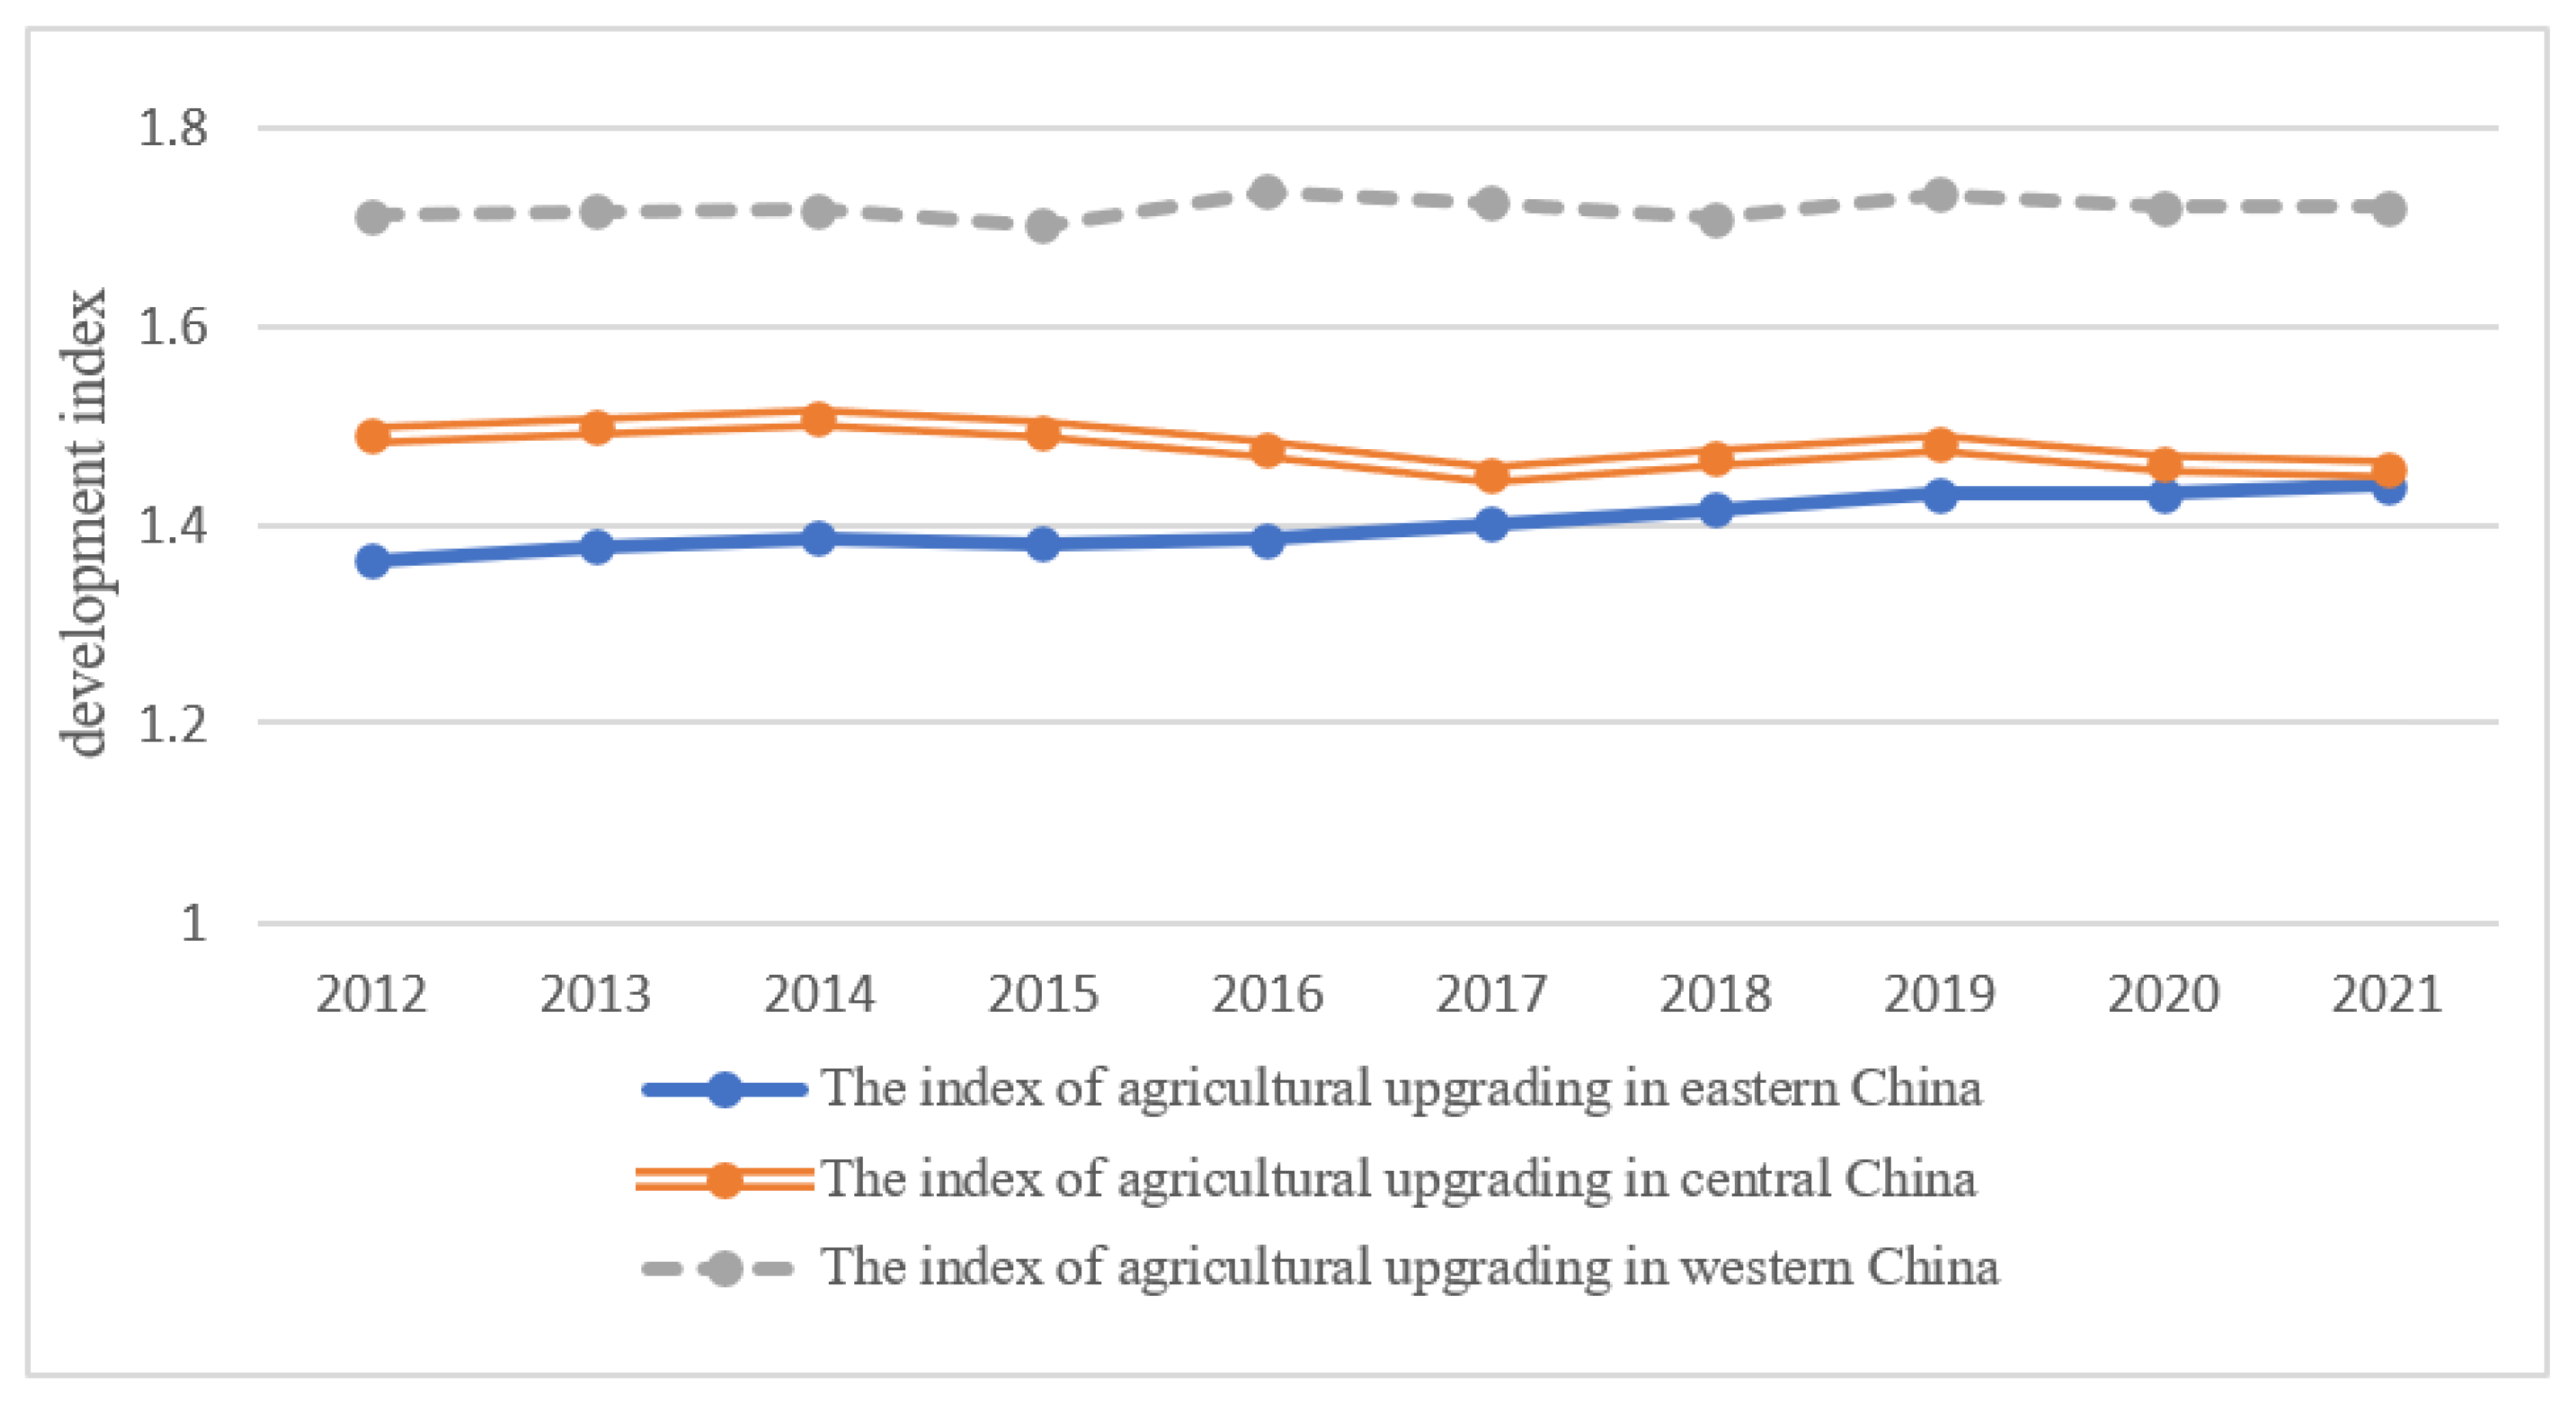
Figure 4 demonstrates the progress of the agricultural industrial structure in the eastern region, indicating a movement towards an advanced level. Initially, the trend in the central section showed a decline, followed by an upward shift. Geographical disparities are apparent in the level of agricultural industrial structure upgrading, with the western region exhibiting a stable growth at an advanced level. In contrast, the agricultural industrial system in the eastern region, despite being well-established, has been experiencing a slower growth. Factors such as inadequate power for agricultural machinery and inefficiencies in mechanized production and operation may hinder the development of a high-level agricultural industrial structure, resulting in a lower labor productivity in these regions. The significance of this study lies in the comprehensive analysis of China’s agricultural business structure, which highlights the considerable potential for optimization.
Figure 4.
The trend of the level of growth of agricultural industrial structure optimization in eastern, central, and western China from 2012 to 2021.
2.3. Research Hypotheses
Green finance serves as an indicator of the future trend and direction of financial development. The transformation of the agriculture industry, sustainable expansion of the local economy, and acceleration of social progress are all reliant on green finance. China has a wide range of green financial instruments, such as green bonds and green insurance, to facilitate the improvement and modernization of agricultural organizations [27]. The optimization and upgrading of the agricultural industry play a crucial role in adjusting the overall industrial structure. With the active expansion of green financing, green industries can flourish, enabling traditional agricultural sectors in China to become more environmentally friendly. Green finance achieves this by spreading risks in agriculture production, expanding the supply of agricultural credit, securing sufficient funds for improving the agricultural industry’s structure, and enhancing farmers’ motivation for large-scale and specialized product management. This, in turn, fosters the strengthening of internal frameworks and professional management within the agricultural business, leading to economies of scale. The availability of ample capital makes agricultural industry growth and expansion capital-intensive, achieving the goal of a modern agricultural industrial structure. Thus, a first hypothesis is proposed:
Hypothesis 1:
Green finance significantly promotes the optimization and upgrading of China’s agricultural industrial structure, effectively facilitating the high-level development of the agricultural industrial structure.
However, the application of green finance policies in China currently varies by industry and region. Existing agricultural green finance standards are not standardized, are imperfect, and lack clarity regarding their scope. Consequently, in certain regions and agricultural sectors, it is challenging to determine whether loans fall under the purview of green financial services. Moreover, regional variations in the interpretation and implementation of green finance regulations by regulators make it difficult to provide financial support for a sustainable agriculture, highlighting the need to address market failures in green financing. Furthermore, due to disparities in environmental laws and regulations, ecological conditions, and economic development objectives, the growth of green finance differs significantly across locations. This lack of consistency in circulation mechanisms and the early stage of the capital market hinder the proper allocation of necessary green financing for the advancement of the agricultural industrial structure across different sectors. Based on these observations, the following proposition is put forth:
Hypothesis 2:
Differences in the expansion of green financing across the eastern, central, and western regions of China contribute to regional disparities in promoting the upgrading of the agricultural industrial structure.
3. Materials and Methods
The definitions of variables are given in Table 2.
Table 2.
Definitions of variables.
3.1. Variable Selection and Setting
3.1.1. Explained Variables
The upgrading of the agricultural industrial structure (uais) was used in this article as an explanatory variable to investigate the impact of green funding on the enhancement of the agricultural industrial structure.
3.1.2. Core Explanatory Variables
The key explanatory variable used in the current study to investigate the effect of green financing on the upgrading of the agricultural structure was the previously computed green finance development level index. The research results, however, would be different in the high-grade development of the Chinese agricultural industrial system if green finance was the only explanatory variable. As a result, we included additional variables as control variables in the model that influenced the development of the agricultural business. To be able to determine the relationship between green finance and the optimization of the agricultural industrial structure, the influence of control factors on this optimization of the agricultural structure was removed.
3.1.3. Control Variables
To comprehensively understand the factors influencing the construction of the agricultural industry and minimize estimation errors resulting from variable limitations, we propose a control strategy for the development of a high-grade agricultural industrial structure. This strategy takes into account various elements based on existing research findings.
Firstly, the urbanization level (urb) was considered as a crucial factor. Urbanization can enhance specialization and scale within the agricultural industry but may also lead to the appropriation of agricultural resources [28]. The urbanization rate, calculated as the ratio of urban to total population in each province, was utilized to assess the level and progress of urbanization.
Secondly, the education level in rural areas was taken into account. These variables measured the number of students enrolled in higher-education institutions (including general college students) divided by the total number of rural residents in each province. Education plays a significant role in developing human capital, which refers to individuals with specific traits and abilities to efficiently utilize resources, thereby advancing the agricultural industrial structure’s development.
Thirdly, the technological mechanization level (tec) was considered. Advanced agricultural machinery and technology can enhance production efficiency, reduce labor costs, and meet the increasing demand for agricultural products. The level of mechanization was determined by the degree of agricultural mechanization, which examined the relationship between total agricultural mechanization power and the total area of grains sown in each province.
Lastly, the degree of marketization (Mopen) was included as a factor. This variable evaluated the level of agricultural marketization by comparing the proportion of funds allocated to the agriculture in the local government budget with the total budget allocation. It provided insights into the extent of local government investment in agriculture and its impact on marketization. The promotion of the green economy, international trade in green products and services, and the development of the market system driven by green financing contribute to an increased marketization [29]. Higher marketization levels correlate with more economic development, which positively influences agriculture.
By considering these additional variables, we aimed to capture a comprehensive understanding of the factors influencing the optimization and upgrading of the agricultural industrial structure. This control strategy enhanced the accuracy of our analysis and provided a more nuanced understanding of the relationship between green finance and the development of the agricultural industry.
3.2. Model Setting
To examine the influence of green financing on the agricultural industrial structure, we employed a benchmark econometric analysis model that served as the foundation for empirical research to validate the previously proposed Hypothesis 1.
The agricultural upgrading level index of provinces and municipalities directly under the central government is represented by the explained variable in the Equation (2). The core explanatory variable represents the level of development of green finance in each region, and the control variable is the previously mentioned variable. The letters stand for the regional fixed effect, for the random perturbation term, for the time fixed effect, and i and t, respectively, denote the province and time in the data.
3.3. Data Explanation
This study adhered to research standards by utilizing panel data from 31 Chinese municipalities and provinces for the period between 2012 and 2021 (excluding Hong Kong, Macao, and Taiwan). The initial data on urbanization level and rural human capital were sourced from the China Population and Employment Statistical Yearbook. The degree of agricultural mechanization data was obtained from China’s Rural Statistical Yearbook. The marketization level data were sourced from the National Bureau of Statistics and the province Bureau of Statistics. Additional data sources included the Wind database, the China Regional Economic Statistical Yearbook, and the China Financial Yearbook.
4. Results
4.1. Descriptive Statistics
To gain a comprehensive understanding of the sample distribution and identify potential outliers that may affect the regression results, it was necessary to calculate the descriptive statistics for the variables utilized in this study. This included listing the sample size, mean, variance, minimum, and maximum values separately. Analyzing these data measurements enabled us to draw relevant conclusions regarding the research findings (refer to Table 3).
Table 3.
Descriptive statistics of variables.
Table 3 presents a wide range of variable values, indicating the influence of various factors, such as the degree of agricultural mechanization and rural human capital, on the development and optimization of the agricultural industrial structure. The agricultural industry upgrading index ranged from a minimum of 0.622 to a maximum of 2.455, highlighting the variation in the level of agricultural upgrading across regions. Similarly, the maximum and minimum values of green financing were 0.578 and 0.093, respectively, highlighting the diversity in the implementation of green financing initiatives. Furthermore, significant differences were observed in other variables, underscoring the existing imbalance in the promotion of agricultural industrial structure optimization across different regions in China. These findings emphasize the importance and relevance of the subsequent research conducted in this paper.
4.2. VIF Test
If a variable can be expressed linearly by other variables, it indicates that the model has some multicollinearity problems. Since advanced green financing development and agricultural industrial structure were calculated by building an index system, more variables were adopted, and more control variables were selected. Therefore, this study needed to use the variance inflation factor to test the multicollinearity of the data (Table 4).
Table 4.
Multicollinearity test of variables.
The mean variance inflation factor of the variables was 1.22, and the variance inflation factor of the remaining variables was also significantly less than 10, with the maximum variance inflation factor of the five variables being 1.41, which is much less than 10. This demonstrated that there was no multicollinearity, and that the model could be used for a regression analysis.
4.3. Unit-Root Test
To avoid problems such as spurious regression in the model estimation, a unit-root test should be conducted on the variables before model regression on the panel data of 31 provinces and municipalities in China (except Hong Kong, Macao, and Taiwan) to ensure the stationarity of all data. The IPS test (Im–Pesaran–Shin unit-root test) method was used to conduct a unit-root test for each variable, and the test results are shown in Table 5. When the unit-root test was conducted on the original data, the level of agricultural industrial structure optimization, green finance development, urbanization rate, rural human capital, and marketization was stable, while the level of agricultural mechanization was stable only after the first-order difference. All the data were stable after the first-order difference of the variables.
Table 5.
Panel unit-root test.
4.4. Cointegration Test
The cointegration test helped us determine if there was a long-term relationship between variables. The Westerlund cointegration and Pedroni cointegration tests were also employed in this study.
H0: No cointegration in the Westerlund test. H1: Some panels are cointegrated.
The p value of the variance ratio statistics reported in Table 6 was 0.0000, and their corresponding p values were all less than 0.01. Therefore, the original hypothesis “no cointegration relationship exists” could be strongly rejected at the 1% level, and we believed that there was a cointegration relationship between variables.
Table 6.
Westerlund test.
In the Pedroni test, the hypotheses were: H0: no cointegration; H1: all panels are cointegrated. Three different test statistics are reported in Table 7, and their corresponding p-values were all less than 0.01.
Table 7.
Pedroni test.
4.5. Results of Regression
This section of the study verifies the impact of green finance on the optimization of the agricultural industrial structure through a comprehensive analysis. Several tests, including the VIF test, unit-root test, and cointegration test, were conducted on the model to examine the relationship between the variables. The results presented in Table 7, incorporating fixed region effects, indicated that the development of green finance had a significant positive influence on the improvement of the agricultural industrial structure’s optimization level.
However, it is crucial to consider potential endogeneity issues arising from the causal relationship between variables. To ensure the reliability of the results, the Hausman test was employed to compare the fixed-effects and random-effects models. The Hausman test statistics and associated p-values were utilized to determine the most suitable regression model.
The statistical indicators and p-values from the Hausman test guided the selection of the specific regression model. The null hypothesis (H0) assumes that the random-effects model is the ideal choice, regardless of the accuracy of the initial hypothesis. Conversely, if the null hypothesis is proven incorrect, the fixed-effects model is deemed more reliable. In this study, the findings of the Hausman test strongly rejected the null hypothesis at a 99% confidence level (Prob > Chi2 = 0.0000, as shown in Table 8). Hence, the fixed-effects model was chosen as the preferred regression model for the analysis. This ensured a robust and trustworthy examination of the relationship between green finance and the optimization of the agricultural industrial structure.
Table 8.
Hausman specification test.
The obtained result was highly significant at the 1% level, as confirmed by the test, thus providing evidence to support Hypothesis 1 in this study. Based on the fixed-effects model, it was observed that a 1% increase in the level of improvement in green finance corresponded to a 0.599 increase in the level of upgrading of the agricultural industrial structure (as shown in Table 9).
Table 9.
Results of baseline regression.
The control variables in this study exhibited important relationships with the optimization and upgrading of the agricultural industrial structure. Firstly, the level of rural human capital demonstrated a significant positive impact at the 1% level of significance. This suggests that an increase in rural human capital not only enhances the skills and knowledge of individuals in rural areas but also has spillover effects on technology adoption and management practices. The presence of a highly skilled rural workforce is crucial for driving innovation and facilitating the development of the agricultural industry. Moreover, the modernization and upgrading of the agricultural industrial structure heavily rely on the availability of a skilled labor force.
Secondly, the degree of marketization played a key role in promoting the development of regional industries. A higher level of marketization corresponds to increased demand for a wide range of industries and a greater flexibility in adjusting the industrial structure. However, it is important to note that during the adjustment phase, the marketization level may not effectively support the transformation and modernization of the agricultural industrial structure. This could be attributed to the unique characteristics of the agricultural sector, where market forces may not have a significant impact on agricultural sales and output due to factors such as price distortions and nonmarket influences. Additionally, the level of technological innovation in the agricultural sector is low in China compared to more advanced industrialized nations. Enhancing technological innovation is crucial for the modernization of the agricultural industrial system, and it requires increased investment in agricultural research and development, as well as the adoption of improved production techniques.
The control variables in this study, including rural human capital and marketization level, have important implications for the optimization and upgrading of the agricultural industrial structure. The findings highlight the significance of investing in human capital development, promoting marketization reforms, and fostering technological innovation to support the modernization and advancement of the agricultural sector.
4.6. Robustness Test
To ensure the robustness of the empirical findings, this study conducted two robustness tests. The first test involved Winsorizing the tail, which aimed to mitigate the potential influence of extreme values in the sample on the estimation results. Specifically, the main variables used in this analysis were subjected to a Winsorizing process of 1%, effectively reducing the impact of outliers. The second test focused on excluding municipalities directly under the Central Government. This was done to account for any potential bias resulting from specific policies that may favor these municipalities and their potential impact on the regression results. In this robustness test, the municipalities directly under the Central Government, namely Beijing, Tianjin, Shanghai, and Chongqing, were excluded from the research sample (as shown in Table 10). By conducting these robustness tests, the study aimed to enhance the reliability and validity of the empirical results, ensuring that the findings were not overly influenced by extreme values or specific policies targeting municipalities directly under the Central Government.
Table 10.
Results of the robustness test.
A fixed-effects model (FE) was employed in this study, and it demonstrated its robustness by passing the significance test at a 1% level of significance with a 99% confidence level. The adoption of an FE model confirmed that for every 1% increase, the upgrading degree of the agricultural industrial structure expanded by 0.599. These findings indicate the consistent and reliable nature of the model, demonstrating that green finance plays a supportive role in the modernization of the agricultural industrial structure throughout the entire sample period. This conclusion is in alignment with the results obtained from the standard regression analysis.
4.7. Heterogeneity Analysis
The vastness of China’s territory gives rise to significant regional disparities in various aspects such as economic status, industrial structure, and resource endowment. As a result, the effects of green financing on the advancement of the agricultural industrial structure can differ between the eastern and western regions of China. This distinction is underscored by the findings presented in Table 11, which highlight the unique dynamics and outcomes of green financing in these two regions.
Table 11.
Results of subsample regression.
A significant correlation existed between green finance and the optimization of the agricultural industrial structure in the eastern region. Green finance played a prominent role in promoting the optimization of the agricultural industrial structure at a 1% significance level. This could be attributed to the fact that the eastern region has historically prioritized resource-intensive industries as drivers of rapid economic development (as indicated in Table 11).
However, the central and western regions exhibited slower development and lower levels of green finance, resulting in a weaker driving effect on the agricultural industry and a limited impact on the optimization and upgrading of the agricultural industrial structure. Quantitatively, the influence of green finance on the optimization of the agricultural industrial structure was significantly higher in the eastern region compared to the central and western regions. This disparity may be attributed to the higher level of green finance development and availability of green financial products in the eastern region. Additionally, the higher level of marketization in eastern China facilitated a smoother connection between green finance and industrial upgrading, thereby driving the advancement of the agricultural industry. Furthermore, the overall level of financial development in the eastern region was higher, leading to greater spillover effects that promoted the upgrading of the agricultural industry.
Notable regional differences existed in the impact of green finance development on the optimization of the agricultural industrial structure in the eastern, central, and western regions of China, thus confirming Hypothesis 2.
5. Discussion
The findings presented in the previous sections provide important insights into the relationship between green finance development and the optimization of the agricultural industrial structure in China. Here, we discuss the findings and their significance in the context of sustainable development and regional disparities.
Firstly, the descriptive statistics of the variables highlighted the diverse range and distribution of the key factors influencing the agricultural industrial structure in different regions of China. The wide variation in the values of variables such as agricultural mechanization, rural human capital, and marketization level indicated the existence of an unbalanced development and the need for optimization in the agricultural sector across different regions [30,31,32]. These disparities emphasize the importance of targeted policies and interventions to promote the upgrading and modernization of the agricultural industry in specific areas [33].
Secondly, the VIF test results indicated that there was no significant multicollinearity among the selected variables in the regression model. This ensured the reliability of the regression analysis and suggested that each variable contributed independently to the explanation of the agricultural industrial structure optimization [34]. Thirdly, the unit-root tests confirmed the stationarity of the variables after the first-order difference, except for the level of agricultural mechanization. This implied that the variables were suitable for a further regression analysis, and the first-order differencing helped eliminate any spurious regression issues [35].
Next, the cointegration tests provided evidence of a long-term relationship among the variables, indicating that they moved together in the long run. This finding supports the idea that green finance development and the optimization of the agricultural industrial structure are interconnected and mutually reinforcing [36].
Moving on to the baseline regression results, a fixed-effects model was chosen based on the Hausman test, which confirmed the significant impact of green finance development on the improvement of the agricultural industrial structure. The coefficient estimate indicated that a 1% increase in green finance development led to a 0.599 increase in the upgrading level of the agricultural industrial structure. This finding supports the hypothesis that green finance plays a crucial role in promoting the optimization of the agricultural industry. Furthermore, the control variables in the regression model revealed important insights. Rural human capital positively influenced the agricultural industrial structure optimization, indicating the importance of skilled labor and knowledge transfer in driving agricultural development. Urbanization level showed a negative relationship, suggesting that the migration of rural populations to urban areas may hinder the advancement of the agricultural industrial structure. Marketization level, on the other hand, did not show a significant impact, due to the specific conditions of agricultural sales and output in China.
The robustness tests further validated the results, as they yielded consistent findings with the baseline regression. The Winsorizing test and the exclusion of municipalities directly under the Central Government support the robustness of the relationship between green finance development and the agricultural industrial structure optimization. Lastly, the heterogeneity analysis revealed regional disparities in the impact of green finance development on the agricultural industrial structure. The eastern region demonstrated a significant positive relationship, suggesting that the well-developed green finance and higher marketization level in the eastern region contributed to the effective promotion of agricultural industrial structure optimization. However, the central and western regions showed weaker effects, due to the lower development level of green finance and other factors limiting the impact on agricultural development.
Overall, these findings provide empirical evidence of the importance of green finance in driving the optimization of the agricultural industrial structure in China. They highlight the need for targeted policies and support in different regions to promote sustainable agricultural development and address regional disparities. The results underscore the role of human capital, urbanization, and marketization in shaping the agricultural sector and suggest the significance of technological innovation for the modernization of agriculture.
6. Conclusions, Limitations, Recommendations for Future Studies, and Policy Implications
6.1. Conclusions
This study utilized a fixed-effects model, a robust statistical technique that accounts for unobserved time-invariant variation among provinces. This approach enhanced the reliability and validity of the findings, providing credible information to support sustainable agricultural practices. The empirical results demonstrated that at the national level, green finance significantly promoted the optimization of the agricultural industrial structure with a 99% level of confidence. This confirmed Hypothesis 1, indicating that the development of green finance has a substantial impact on optimizing the agricultural industrial structure.
The strong support of green finance for agriculture enables the adjustment of the agricultural industrial structure by providing adequate funding. It facilitates the large-scale and professional development of agriculture, leading to the upgrading of production and operational modes. This, in turn, generates economies of scale and promotes the optimization of the agricultural industrial structure.
Furthermore, through a heterogeneity analysis, the study revealed significant regional disparities in the impact of green finance development on the optimization process of the agricultural industrial structure, confirming Hypothesis 2. The research highlighted the geographical distribution of green financing in eastern, central, and western China, emphasizing the implications for sustainable agriculture. This knowledge can inform the development of policies and programs that promote a more equitable allocation of green funds across the country, thereby fostering sustainable agriculture.
The study underscores the importance of adopting a tailored approach to promote sustainable agriculture, considering regional variations, and adapting development strategies accordingly. By recognizing and addressing the unique needs and characteristics of each region, sustainable agricultural practices can be enhanced.
6.2. Limitations of the Study and Recommendation for the Future Research
This paper has certain limitations that should be acknowledged. Firstly, while green finance was identified as a significant factor in promoting the optimization of China’s agricultural industrial structure, there may have been other influencing factors that were not thoroughly explored in this study. Future research should delve deeper into these factors to gain a comprehensive understanding of the drivers behind agricultural industrial structure optimization.
Secondly, the calculation of the agricultural industrial structure optimization index relied on approximate data due to a limited availability of agricultural statistics. Although these approximations held representative significance, obtaining more accurate and comprehensive data on the labor productivity of various rural industries would enhance the precision of the analysis.
To address these limitations and further advance our understanding of China’s agricultural industrial structure optimization, several recommendations can be made. Firstly, researchers should conduct in-depth investigations into other potential influencing factors beyond green finance, thereby contributing to a more holistic understanding of the optimization process. Comparative studies across different regions or provinces can also shed light on regional variations and verify the consistency of green finance’s influence.
Efforts should be made to improve data collection methods by collaborating with relevant agencies and employing advanced techniques to obtain more accurate and comprehensive data. Additionally, supplementing quantitative approaches with qualitative research methods, such as interviews and case studies, can provide deeper insights into stakeholders’ perspectives and motivations.
Longitudinal studies tracking the dynamics and changes in the agricultural industrial structure over time would be valuable in identifying patterns and assessing the long-term impacts of green finance initiatives. Lastly, adopting a multidisciplinary approach by collaborating with experts from diverse fields can provide a comprehensive understanding of the complex interactions involved in agricultural industrial structure optimization. Future research can overcome the limitations of this study and contribute to a more robust and nuanced understanding of China’s agricultural industrial structure optimization.
6.3. Policy Implications
To facilitate the growth of the green financing system and support the upgrading of the agricultural industrial structure, this article proposes the following policy recommendations based on the research findings:
- Enhance the development of green finance: To promote the ecological industrial structure, all regions should focus on improving the development level of green finance. This can be achieved by encouraging green credit innovation, incorporating green environmental protection concepts into credit policies, and introducing new products such as allowing low-carbon enterprises to provide intellectual property pledges. Furthermore, the promotion of green securities, green funds, and other financial products should be emphasized. The establishment of environmental and energy-saving evaluation criteria for enterprise listings and the enhancement of the green financial derivatives market and green intermediary service market are also important steps.
- Strengthen legal and institutional frameworks: To support the optimization of the agricultural industrial structure, it is crucial to improve laws, regulations, and institutional systems. Clear policies should be implemented to emphasize the importance of the agricultural industrial structure optimization and differentiate agricultural green finance from traditional finance. Providing preferential treatment to green credit in terms of policy and establishing a robust agricultural insurance system are vital. Expanding the coverage of rural social insurance and enhancing the level of security for farmers will provide essential support for the adjustment of the agricultural industrial structure.
- Develop tailored strategies: Considering the variations in the development level of green finance and the agricultural industrial structure across different regions, it is necessary to develop region-specific strategies. In the central and western regions, governments should increase their support for green finance by encouraging nonbank financial institutions to actively engage in green finance activities. Creating an attractive business environment to attract investments, strictly adhering to environmental standards, and preventing the relocation of heavily polluting industries to these regions are critical for sustainable development.
By implementing these policy recommendations, China can foster the growth of green finance and effectively support the optimization of the agricultural industrial structure. This will contribute to sustainable agricultural development and environmental protection.
Author Contributions
Conceptualization, M.Z. and M.S.; methodology, Y.L. and M.Z.; validation, E.E.; formal analysis, Y.L.; investigation, E.E. and Z.K. resources, Z.K. and E.E.; writing—original draft preparation, E.E., Z.K. and M.Z.; writing—review and editing, E.E.; supervision, M.Z. and E.E.; project administration, E.E. All authors have read and agreed to the published version of the manuscript.
Funding
The study was financially supported by the Taishan Scholar Foundation of Shandong Province, China (tsqn202103070).
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The data used to support the findings of this study are available from the corresponding author upon request.
Conflicts of Interest
The authors declare no conflict of interest.
References
- Zhao, P. Empirical analysis on the relationship between agricultural industrial structure adjustment and agricultural economic growth in Henan Province. Jiangsu Agric. Sci. 2022, 50, 243–247. [Google Scholar] [CrossRef]
- Ma, J. On building China’s green finance System. Financ. Forum 2015, 20, 18–27. [Google Scholar] [CrossRef]
- Elahi, E.; Khalid, Z.; Zhang, Z. Understanding farmers’ intention and willingness to install renewable energy technology: A solution to reduce the environmental emissions of agriculture. Appl. Energy 2022, 309, 118459. [Google Scholar] [CrossRef] [Scilit]
- Elahi, E.; Khalid, Z. Estimating smart energy inputs packages using hybrid optimisation technique to mitigate environmental emissions of commercial fish farms. Appl. Energy 2022, 326, 119602. [Google Scholar] [CrossRef] [Scilit]
- Elahi, E.; Khalid, Z.; Tauni, M.Z.; Zhang, H.; Lirong, X. Extreme weather events risk to crop-production and the adaptation of innovative management strategies to mitigate the risk: A retrospective survey of rural Punjab, Pakistan. Technovation 2022, 117, 102255. [Google Scholar] [CrossRef] [Scilit]
- Wang, F.; Cai, W.; Elahi, E. Do Green Finance and Environmental Regulation Play a Crucial Role in the Reduction of CO2 Emissions? An Empirical Analysis of 126 Chinese Cities. Sustainability 2021, 13, 13014. [Google Scholar] [CrossRef] [Scilit]
- Elahi, E.; Zhang, H.; Lirong, X.; Khalid, Z.; Xu, H. Understanding cognitive and socio-psychological factors determining farmers’ intentions to use improved grassland: Implications of land use policy for sustainable pasture production. Land Use Policy 2021, 102, 105250. [Google Scholar] [CrossRef] [Scilit]
- Anderson, J. Environmental Finance. In Handbook of Environmental and Sustainable Finance; Ramiah, V., Gregoriou, G.N., Eds.; Elsevier Inc.: Amsterdam, The Netherlands, 2016. [Google Scholar]
- Hellmann, T.; Murdock, K.; Stiglitz, J. Financial Restrain: Toward a New Paradigm. In The Role of Government in East Asia Economic Development Comparative Institutional Analysis; Oxford University Press: Oxford, UK, 1997. [Google Scholar]
- Muganyi, T.; Yan, L.; Sun, H.-P. Green finance, fintech and environmental protection: Evidence from China. Environ. Sci. Ecotechnol. 2021, 7, 100107. [Google Scholar] [CrossRef] [Scilit]
- Taghizadeh-Hesary, F.; Yoshino, N. The way to induce private participation in green finance and investment. Financ. Res. Lett. 2019, 31, 98–103. [Google Scholar] [CrossRef] [Scilit]
- Ma, B.; Lin, L.; Wu, J. Research on the relationship between production capacity, financial support and economic fluctuation in supply-side structural reform. Ind. Econ. Res. 2017, 5, 12–24. [Google Scholar] [CrossRef]
- Su, R.; Zhao, X.; Hu, X. Can inclusive finance become a new driving force to optimize and upgrade China’s industrial structure? Mechanism analysis based on Internet development. J. Technol. Econ. 2020, 39, 39–52. [Google Scholar]
- Li, Y.; Zhou, H.M. Spatial effects and heterogeneity of green finance development on industrial structure transformation and upgrading: Based on spatial Dubin Model. J. Southwest Univ. (Sci. Technol. Ed.) 2023, 45, 164–174. [Google Scholar] [CrossRef]
- Lin, X.; Xiao, Y. The measurement and mechanism of green finance promoting high-quality economic development. Contemp. Econ. Sci. 2023, 3, 1–18. [Google Scholar] [CrossRef]
- Chen, X. Financial structure, technological innovation and carbon emission: Also on the development of green finance system. Guangdong Soc. Sci. 2020, 4, 41–50. [Google Scholar]
- Chen, H.; Zheng, J. The impact of technological progress and industrial restructuring on carbon emission intensity in China. Bus. Res. 2022, 6, 1–12. [Google Scholar] [CrossRef]
- Li, S.; Liu, H.N. The impact of green finance on the development of low-carbon economy from a spatial perspective. J. North Univ. Natl. 2023, 1, 140–147. [Google Scholar] [CrossRef]
- Qian, S.; Wang, W.; Fang, H. An empirical analysis of the effect of green credit on industrial structure optimization in China. Financ. Theory Pract. 2018, 1, 7–14. [Google Scholar]
- Xie, D.; Hu, S. Green finance, industrial structure and green total factor productivity of urban industry. Ind. Int. Financ. Res. 2023, 5, 46–56. [Google Scholar] [CrossRef]
- Wu, B.; Ma, R. Impact of green finance on industrial structure upgrading: A Case study of Gansu Province. J. Lanzhou Univ. Financ. Econ. 2023, 39, 114–124. [Google Scholar]
- Gao, J.; Zhang, W. The impact of green finance on the ecological development of industrial structure in China: An empirical test based on Systematic GMM model. Econ. Rev. 2021, 2, 105–115. [Google Scholar] [CrossRef]
- Ding, P.; Jin, W.; Chen, N. Green finance development, industrial structure upgrading and sustainable economic growth. South. Financ. 2021, 2, 13–24. [Google Scholar]
- Liu, X.; Chen, C. Study on the path of transformation and upgrading of agricultural industrial structure promoted by digital technology. Adm. Reform 2022, 12, 57–65. [Google Scholar] [CrossRef]
- Liu, W.; Zhang, H.; Huang, Z. The height of industrial structure and industrialization process and regional differences in China. J. Econ. 2008, 11, 4–8. [Google Scholar]
- Fan, H.; Pan, N.; Wu, T. Carbon emission reduction effect of digital economy development: Based on 223 prefecture-level cities. J. Beijing Technol. Bus. Univ. (Soc. Sci. Ed.) 2023, 38, 25–38. [Google Scholar]
- Meng, W.; Li, S.; Liu, J.; Chen, Y. Research on the influence mechanism of digital inclusive finance promoting rural revitalization. Econ. Issues 2023, 3, 102–111. [Google Scholar] [CrossRef]
- Xiang, G.; Mao, Q. How rural urbanization affects agricultural industrial structure. J. Guangdong Univ. Financ. Econ. 2016, 31, 77–87. [Google Scholar]
- An, G.; Zi, W. Discussion on green finance promoting sustainable development of Free Trade Zone. Fisc. Res. 2020, 5, 117–129. [Google Scholar] [CrossRef]
- Du, Y.; Zhao, Z.; Liu, S.; Li, Z. The impact of agricultural labor migration on the urban–rural dual economic structure: The case of Liaoning province, China. Land 2023, 12, 622. [Google Scholar] [CrossRef] [Scilit]
- Jiang, Q.; Li, J.; Si, H.; Su, Y. The Impact of the Digital Economy on Agricultural Green Development: Evidence from China. Agriculture 2022, 12, 1107. [Google Scholar] [CrossRef] [Scilit]
- Cai, X.; Cheng, Q.; Shi, Y. The impact, mechanism and heterogeneity of digital inclusive finance on farmland transfer. Econ. Rev. 2023, 4, 118–128. [Google Scholar] [CrossRef]
- Xu, Y.; Lyu, J.; Xue, Y.; Liu, H. Does the Agricultural Productive Service Embedded Affect Farmers’ Family Economic Welfare Enhancement? An Empirical Analysis in Black Soil Region in China. Agriculture 2022, 12, 1880. [Google Scholar] [CrossRef] [Scilit]
- Lin, D.; Foster, D.P.; Ungar, L.H. VIF regression: A fast regression algorithm for large data. J. Am. Stat. Assoc. 2011, 106, 232–247. [Google Scholar] [CrossRef] [Scilit]
- Guo, L.; Zhao, S.; Song, Y.; Tang, M.; Li, H. Green finance, chemical fertilizer use and carbon emissions from agricultural production. Agriculture 2022, 12, 313. [Google Scholar] [CrossRef] [Scilit]
- Fang, Z.; Gao, X.; Sun, C. Do financial development, urbanization and trade affect environmental quality? Evidence from China. J. Clean. Prod. 2020, 259, 120892. [Google Scholar] [CrossRef] [Scilit]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2023 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).