


Abstract
Geopolitical risk (GPR) is increasingly recognized as a central concern for financial stability, yet its transmission to the financial sector remains relatively underexplored. To address this gap, a Bibliometric–Systematic Literature Review combining PRISMA-guided screening with bibliometric performance analysis and science mapping (Bibliometrix 5.4.0, VOSviewer 1.6.21) was carried out. A total of 604 journal articles were retrieved from Scopus on the broader GPR and finance literature, including a subsample of 78 documents addressing banking (67), insurance (10), and both sectors jointly (1). Results of the analysis show that scientific production accelerates sharply from 2018, with growth in the banking- and insurance-focused subsample outpacing growth in the field overall. Our co-citation analysis of cited references and authors finds that the field’s intellectual core is organized around Caldara and Iacoviello’s foundational GPR index, alongside clusters extending towards commodity and energy market applications and spillover-index methodology, with four distinct author-centered citation clusters identified; the co-authorship analysis further identified China as the dominant contributor to international research collaboration. Our analysis adds to the growing body of bibliometric reviews on GPR to provide a structured research agenda for future investigations, particularly regarding the still-limited evidence on insurance relative to banking.
1. Introduction
Recent international events, especially the Russia–Ukraine conflict and rising tensions in the Middle East, have significantly heightened concerns about global economic and financial stability. These incidents render geopolitical risk (GPR) a core element in financial models, not just a temporary issue.
Scholarly interest in GPR has increased significantly over the past decade, with a notable acceleration in scientific output after 2020. This growth correlates with both the formalization of the geopolitical risk (GPR) index developed by Caldara and Iacoviello in 2018, which was subsequently revised in 20211 to incorporate additional methodologies, and the emergence of large-scale geopolitical crises that rendered the topic unavoidable for financial researchers. The index quantifies the proportion of newspaper articles that reference geopolitical tensions using specific keywords associated with geopolitical risk (Caldara and Iacoviello 2022). The GPR index serves as a reliable proxy for assessing geopolitical risk across nations (Aysan et al. 2023). Most scholarly investigations focus on the impact of GPR on financial markets, recognizing its importance as a variable in the broader financial system. However, a handful of studies have examined the relationship between GPR and specific segments of the financial sector, particularly banking and insurance institutions. Many of these studies apply econometric models and focus on specific geographic regions (Adel and Naili 2024; Aftab and Naveed 2022; Alsadan et al. 2025; Fianto and Ibrahim 2025; Olalere and Mukuddem-Petersen 2024; Sivaprasad et al. 2025). Understanding how geopolitical risk transmits specifically to banking and insurance institutions carries substantial practical significance. Banks and insurers are not passive recipients of macro-financial shocks but function as key channels through which systemic risk propagates across the financial system. The impact of geopolitical risk events varies significantly between countries and financial intermediaries and affects their financial stability (Billio et al. 2012; Zhang et al. 2024; Behn et al. 2025; Wang et al. 2025).
The rapid expansion of this research domain complicates the identification of well-established trends and emerging gaps and, to date, a systematic bibliometric mapping of the field has yet to be fully developed. A related scientometric analysis by Aysan et al. (2023) maps the broader geopolitical risk literature; however, their study is not sector-specific. Similar gaps apply to Aiswarya and Muthumeenakshi (2024), whose PRISMA-guided review of 810 documents likewise covers the general field, without a sector-specific focus. Kumar and Singh (2025) extend this line of research by combining Scopus and Web of Science data over a 27-year period (1997–2024), addressing geopolitical risk and financial markets in broad terms, without isolating banking or insurance as a distinct object of study. Additional studies remain similarly general in scope: El Rhrib and Bennis (2025) examine the geofinance literature through a qualitative thematic synthesis of 45 studies, while Iddouch (2026) provides a narrative review of 743 articles on GPR in emerging markets; neither employs bibliometric mapping techniques nor focuses specifically on the banking and insurance sectors. Finally, Petroccione et al. (2026) examine how geopolitical risk (GPR) affects the banking sector, risk exposure, and organizational decision-making processes through a systematic review following the PRISMA protocol, which analyzes 58 articles (2000–2026) from Scopus and Google Scholar. Even this sector-specific contribution, however, does not extend to the insurance sector, which remains a further gap the present study seeks to address. The findings of the analyses presented are summarized in Table 1.
Table 1.
Comparison with Existing Bibliometric and Systematic Reviews on Geopolitical Risk.
The existing literature generally agrees that GPR weakens financial stability through several well-known transmission channels, including energy price shocks, declining credit quality, and capital flow volatility, with a significant focus on the banking sector as a key point of exposure. However, the insurance industry is relatively underexplored, with empirical results varying across contexts. To address this gap and guide future research, the present study provides a detailed bibliometric analysis of contemporary research on the GPR’s influence on the financial sector, identifying documents related to both the banking and insurance sectors, quantifying publication patterns, and mapping co-citation and co-authorship networks.
To achieve these objectives, this research seeks to address the following questions:
- RQ1:
- What emerging trends in scientific production on GPR in the financial sector are evident, and which journals and authors are most influential?
- RQ2:
- What is the intellectual and social structure of the field, as revealed by co-citation, thematic, and co-authorship analyses?
These research questions examine the intellectual and social fabric of the field through science-mapping techniques such as co-citation, co-authorship, and co-word analysis. Such methods, as highlighted by Marzi et al. (2025) and Donthu et al. (2021), are essential to uncovering hidden trends and connections within the literature, to bring to light the underlying web of academic collaboration and demonstrate how scholarship has responded to major shocks like the Russia–Ukraine conflict.
- RQ3:
- What does the existing literature reveal about banking and insurance-specific applications of GPR research, and what under-researched gaps should shape the future research agenda within this sub-field?
Methodologically, the study employs a Bibliometric–Systematic Literature Review framework (Marzi et al. 2025), utilizing data from Scopus and advanced mapping tools like Bibliometrix and VOSviewer to visualize the field’s intellectual landscape. The paper is organized as follows: Section 2 reviews the literature and theoretical concepts of geopolitical risk; Section 3 describes the methodology, including data collection and bibliometric methods; Section 4 presents the results of the entire sample; Section 5 investigates the geopolitical risk in the sub-sample of banks and insurance companies; Section 6 discusses empirical findings; and Section 7 summarizes key insights and suggests future research directions.
2. Literature Review
In recent years, geopolitical risk (GPR) has emerged as a significant systemic risk factor capable of influencing macroeconomic dynamics and threatening global financial stability (Liang et al. 2023; J. Zheng et al. 2023), as well as the stability of financial institutions (Caldara and Iacoviello 2022; Istiak and Serletis 2020). It has been defined as “the threat, realization, and escalation of adverse events associated with wars, terrorism, and any tensions among states and political actors that affect the peaceful course of international relations” (Caldara and Iacoviello 2022). The GPR captures a broad spectrum of adverse geopolitical developments, and given the complexity of this construct, its measurement requires an analytical approach beyond simply documenting conflicts. To address the lack of standardized tension-tracking metrics, Caldara and Iacoviello (2019, 2022) propose the GPR index, a news-based methodology that monitors the monthly proportion of newspaper articles covering adverse geopolitical events and threats across 10 major international newspapers. The research is organized around eight keyword categories, which the authors aggregate into two subindexes: the geopolitical threat (GPT) index, indicating tension buildup and future risk, and the geopolitical act (GPA) index, reflecting the direct occurrence of crises such as terrorist attacks or wars (Caldara and Iacoviello 2022). While alternative geopolitical risk indices have been proposed in the literature, for instance, Galimova et al. (2025) develop a geopolitical risk index specifically oriented toward international sustainable energy trade, and Bondarenko et al. (2024) construct country-specific indices based on local news sources, showing that local risk perceptions can diverge substantially from those derived from the original index’s predominantly US- and UK-based newspaper sources, the Caldara and Iacoviello (2022) GPR index remains the dominant measure employed in this research field. As Aysan et al. (2023) note, other GPR measures are not widely used in the literature since they tend to be either country-specific or not generalizable, whereas the widespread adoption of the Caldara and Iacoviello index is based on its reliability and its coverage of multiple countries.
There is a strong consensus in the literature that GPR destabilizes global financial stability. Many studies systematically examine how geopolitical tensions influence the financial system through various channels, such as energy price shocks (Nasim et al. 2023), credit quality declines (Pham et al. 2021; Phan et al. 2022; Trinh and Tran 2024), and direct disruptions in conflict zones, which cause physical damage and operational crises (Pham et al. 2021). In addition to these known pathways, a key transmission channel involves shifts in investor sentiment, which lead to delayed economic decisions. Increased GPR heightens uncertainty and often causes market panic, prompting firms and investors to postpone large expenditures, consumption, and irreversible investments (Bouri et al. 2023; Albaity et al. 2024; Cui and Maghyereh 2024a; Godil et al. 2020; Khraiche et al. 2023; Salisu et al. 2022; Shabir et al. 2023; Sheikh et al. 2024; Sohag et al. 2022; Tang et al. 2023). This decline in expected profitability can result in macroeconomic shifts like reduced employment and overall economic activity (Bouri et al. 2023; Khraiche et al. 2023; Salisu et al. 2022; Sheikh et al. 2024). Additionally, this behavior and increased risk aversion trigger a flight to capital outflows from emerging and conflict-affected regions toward more stable economies and safe assets (Będowska-Sójka et al. 2022; Cheng et al. 2022; Cui and Maghyereh 2024a; Salisu et al. 2022; Sheikh et al. 2024; Sohag et al. 2022; Tang et al. 2023; Triki and Ben Maatoug 2021; Umar et al. 2022; Yang et al. 2023; J. Zheng et al. 2023). Recent evidence suggests that ESG assets and climate-related markets could act as effective safe havens, attracting investors seeking resilience through sustainable investments during geopolitical events (Hoque et al. 2023; Tang et al. 2023; Yang et al. 2024).
Gheorghe et al. (2025) provide more detail, finding that ESG-focused ETFs tend to be more resilient during extreme geopolitical crises, partly buffering against market chaos. In contrast, AI-themed ETFs perform better in moderate-risk settings but are more susceptible to systemic shocks. Additionally, GPR contributes to global inflation by raising commodity and energy prices, which raises trade and operational costs for companies (Cui and Maghyereh 2024b; Fang and Shao 2022; Huang et al. 2021; Li et al. 2022; Nasim et al. 2023). These changes often cause currency fluctuations, with affected countries’ currencies depreciating during geopolitical shocks (Fang and Shao 2022; Sheikh et al. 2024; J. Zheng et al. 2023). Such shifts can trigger risk contagion, where geopolitical events strengthen interconnectedness in financial markets, heightening systemic risk globally (Cui and Maghyereh 2024a; Umar et al. 2022; Yang et al. 2023; J. Zheng et al. 2023), as during the Russia–Ukraine conflict or the 9/11 attacks (Tang et al. 2023; J. Zheng et al. 2023). One main transmission pathway is the oil-stock relationship: the financialization of commodities promotes risk spread through heightened precautionary and speculative demand in futures markets, especially for vital resources like crude oil (Cheng et al. 2022; Cui and Maghyereh 2024b; Huang et al. 2021; Li et al. 2022; Liu et al. 2021; D. Zheng et al. 2023). Several studies highlight a negative relationship between geopolitical events and stock performance, with varying intensity across markets and economic conditions (Balcilar et al. 2018). Specifically, while advanced economies are generally more sensitive to GPR shocks, emerging markets exhibit heterogeneous reactions (Salisu et al. 2022; NguyenHuu and Örsal 2024).
As a result, GPR greatly influences crude oil price volatility, which then spills over into equity markets, notably in energy-intensive sectors (Huang et al. 2021; Tang et al. 2023). Conversely, GPR can also act as a catalyst for the energy transition, encouraging a shift from geopolitically sensitive fossil fuels to renewable energy and green bonds as part of strategic diversification and hedging (Sohag et al. 2022; Tang et al. 2023; D. Zheng et al. 2023). In bond markets, GPR often prompts a flight to quality, with investors shifting funds from risky equities to government securities, potentially boosting bond returns during conflicts (Cheng et al. 2022; Tang et al. 2023; J. Zheng et al. 2023).
The existing literature also examines how precious metals, especially gold and silver, consistently serve as strong safe havens and hedges against GPR shocks, particularly in the short and medium term (Cheng et al. 2022; Tang et al. 2023). The dominant literature finds a significant negative link between rising GPR and stock market performance (Balcilar et al. 2018; Caldara and Iacoviello 2022; Tang et al. 2023; Zhou et al. 2020). Shocks to the GPR index generally cause declines in stock returns and yields on long-term investments (Bouri et al. 2023; Tang et al. 2023), although Balcilar et al. (2018) note that this relationship varies across markets and economic conditions. Stock returns in advanced economies are more susceptible to GPR (Salisu et al. 2022), while emerging markets show mixed responses (NguyenHuu and Örsal 2024).
Although the literature has analyzed the effects of geopolitical risk on the real economy and financial markets, relatively few studies focus on the consequences for financial intermediaries, in particular banks and insurance companies. Geopolitical events, in fact, can also affect the stability of financial institutions, amplifying risks at a systemic level. This issue has attracted increasing attention, especially since the global financial crisis, which reinforced the regulators’ focus on identifying and containing financial risks. Recent studies show that greater exposure to geopolitical risk can increase systemic risk in the banking sector, with effects that depend on the regulatory system of each country (Gabbiadini et al. 2025; Wang et al. 2025). It is generally agreed that GPR weakens bank solvency via Non-Performing Loan (NPL) buildup (Pham et al. 2021; Vu et al. 2023), prompts credit risk revaluation (Nguyen and Thuy 2023), and encourages a flight-to-headquarters in lending practices (Pham et al. 2021). Still, debates exist over how capital structures respond: some research finds a counter-cyclical increase in banks’ leverage to maintain client relationships and manage public debt (Istiak and Serletis 2020), while others report sharp credit cuts driven by elevated risk premiums (Khoo and Cheung 2021). Bettin et al. (2023) demonstrate that standard risk measures often underestimate capital shortfalls by neglecting interactions among systemic, climate, and geopolitical shocks, thereby emphasizing the need for more integrated analytical approaches. Resilience in advanced markets has its limits, as European banks near the Russia–Ukraine conflict reduced protection from robust institutions (Vu et al. 2023), although ECB oversight has somewhat alleviated liquidity stresses. Similarly, the insurance sector is also affected by geopolitical tensions that can affect both risk assessment and premium determination. However, empirical evidence remains limited. Therefore, the analysis of the effects of GPR on financial intermediaries is a particularly relevant area both to understand the direct consequences on the sector and to identify the transmission channels of shocks and how it may affect financial stability (Hemrit and Nakhli 2021).
3. Methodology
This study utilizes the Bibliometric–Systematic Literature Review (B-SLR) framework developed by Marzi et al. (2025). It combines the rigorous methodology of systematic reviews, following the PRISMA (Preferred Reporting Items for Systematic Reviews and Meta-Analyses) protocol (Page et al. 2021), with quantitative science-mapping techniques. This hybrid approach facilitates the identification, selection, and synthesis of relevant studies and explores the structure of the GPR literature within banking and insurance sectors. The B-SLR process in this paper comprises three main stages: (1) data collection and search strategy, (2) selection and screening criteria, and (3) bibliometric analysis and visualization tools.
Bibliographic data were collected from the Scopus database, chosen for its extensive multidisciplinary coverage and frequent use in bibliometric research within management and finance fields (Donthu et al. 2021). The reliability of Scopus as a data source is further evidenced by its adoption in national research assessment exercises (Baas et al. 2020), consistent with recent high-impact bibliometric reviews in finance that have made the same methodological choice (Goodell et al. 2021).
The search was performed on 5 September 2026, focusing on the Title, Abstract, and Keywords of indexed documents. The search string targeted the intersection between geopolitical risk and the financial sector, particularly banking and insurance institutions, following the structure outlined in Table 2. The first block of the query limited results to documents that explicitly address the geopolitical risk construct, using both the full term and its common acronym, “GPR”, as established by the Caldara and Iacoviello (2022) index, with its most common conceptual variants (“geopolitical uncertainty”, “geopolitical tension”, “war risk”). The second block focused on the financial sector by combining sector-specific terms (bank*, insurance, reinsurance) with broader institutional categories (financial market*, financial institution*). This ensured studies on GPR’s impact on financial intermediaries were not excluded if they did not explicitly mention “bank” or “insurance” in the title, abstract, or keywords. Four additional filters were applied in Scopus for thematic and methodological consistency: (i) subject area limited to Economics, Econometrics, and Finance (“ECON”) and Business, Management, and Accounting (“BUSI”); (ii) document type limited to journal articles (“ar”), excluding conference papers, book chapters, and reviews; (iii) language limited to English to ensure consistency in subsequent analyses; and (iv) publication stage limited to “final”, excluding articles in press with unstable bibliometric metadata. No publication-date restriction was applied to capture the full historical development of the literature up to the extraction date. The initial search returned 810 documents.
Table 2.
Search Equation.
This choice of terms reflects a deliberate scope decision. Concepts such as political risk, political instability, country risk, and sovereign risk were not included, as they denote analytically distinct constructs that are not anchored to the war-, terrorism-, and interstate-tension-based conceptualization of geopolitical risk underlying the Caldara and Iacoviello (2022) GPR index around which the literature, and the present review, are organized. By contrast, international conflict, military conflict, and conflict risk are substantively subsumed within the “war risk*” and “geopolitical tension*” terms, both of which build directly on the GPR index’s own operationalization of war and conflict-related events.
Following the PRISMA protocol (Page et al. 2021), document selection involved the stages of identification, screening and eligibility assessment, and inclusion, with titles, abstracts, and, where necessary, full texts jointly assessed by all three authors to determine relevance. The identification phase yielded a raw dataset of 810 records from the Scopus query described earlier. To corroborate the scope of our search terms, we additionally reviewed all editions of the World Economic Forum’s (WEF) Global Risks Report from 2006 to 2026, cataloguing the risk labels each edition classified under its geopolitical risk domain. Despite frequent relabeling across editions, this review identifies a stable set of principally recurring categories (interstate conflict and war, terrorism, weapons of mass destruction, and geoeconomic confrontation) consistent with the conceptualization of geopolitical risk captured by the Caldara and Iacoviello (2022) GPR index and, in turn, by our search terms. A further set of categories recurring across editions (failure of national or global governance, transnational organized crime, corruption, illicit trade, intrastate violence, and militarization of space) is not treated as a core dimension of geopolitical risk in the Caldara and Iacoviello framework or the broader empirical GPR-finance literature; these categories were not used to inform our search terms or the academic definition of GPR adopted in this study. The WEF taxonomy therefore did not generate search terms or override this academic definition, but it served only as a secondary reference checklist during the manual screening and eligibility assessment of the 810 records retrieved from the database search to confirm that a screened record’s own framing of geopolitical risk corresponded to an empirically recognized category, with the academic definition taking precedence wherever the two classifications diverged.
Since a single database was used, duplicate records were not expected. This combined screening and eligibility assessment, conducted independently by all three authors across the entire dataset, led to the exclusion of 206 records because they did not address geopolitical risk within the financial sector. Discrepancies in inclusion/exclusion decisions were resolved through discussion among the authors until consensus was reached. The final dataset, consisting of 604 articles, was used for bibliometric analysis.
Within this final dataset, a dedicated sub-sample of documents explicitly addressing banking and insurance-related applications of geopolitical risk was further identified through the same manual screening procedure. This additional screening, conducted independently by all three authors with the same consensus-based resolution of disagreements, sought to capture documents in which banking or insurance institutions constitute the primary object of empirical analysis, rather than being mentioned only incidentally. Each qualifying document was further classified as addressing banking, insurance, or both sectors jointly, based on the sector(s) constituting its primary object of empirical analysis. This process yielded a sub-sample of 78 documents: 67 addressing banking applications, 10 addressing insurance applications, and 1 addressing both sectors jointly. In line with B-SLR guidelines (Marzi et al. 2025), the number and reasons for excluded records are shown in the PRISMA flow diagram (Figure 1), ensuring transparency and reproducibility in the dataset construction.
Figure 1.
PRISMA flow diagram for sample selection. Source: Authors’ processing based on Scopus data.
The final dataset, exported from Scopus in CSV format with full bibliographic details, abstracts, and cited references, was analyzed using dedicated bibliometric software (Bibliometrix 5.4.0), reflecting the growing recognition and adoption of such tools in research (Tomaszewski 2023). Consistent with the combined use of performance analysis and science mapping tools recommended within the B-SLR framework (Marzi et al. 2025), two complementary packages were selected. First, the Bibliometrix package (Aria and Cuccurullo 2017) was selected, among the bibliometric software packages available and widely adopted in the literature (Moral-Muñoz et al. 2020), for its capacity to compute performance indicators (RQ1) and generate thematic maps (RQ2) directly within the R environment. Second, VOSviewer (van Eck and Waltman 2010) was selected for its strong network visualization capabilities (Moral-Muñoz et al. 2020) and was used to develop and visualize science maps addressing RQ2. For all VOSviewer analyses, mapping was based on full counting, with association strength used as the normalization method and a clustering resolution parameter of 1.00 (minimum cluster size = 1), applied consistently across the co-citation and co-authorship networks. This involved constructing co-citation networks of references and authors to explore the field’s intellectual foundation, creating co-authorship networks at the country level to reveal collaboration patterns, and analyzing keywords to identify the domain’s structure. These combined methods enable a triangulated analysis of research performance and themes, intellectual structure, and social collaborations within the GPR literature in the financial sector, aligning with the B-SLR framework’s multi-method approach (Marzi et al. 2025).
4. Results
Bibliometric methods are broadly classified into performance analysis and science mapping (Cobo et al. 2011; Donthu et al. 2021). While the former concerns the quantitative evaluation of research constituents (e.g., authors, journals, institutions), science mapping focuses on uncovering the structural and relational properties that connect these constituents, thereby revealing the intellectual, social, and conceptual architecture of a research field. Prior to examining this relational structure, a performance analysis was conducted to characterize the productivity and impact of the geopolitical risk literature. This analysis, performed in R using the Bibliometrix package (Aria and Cuccurullo 2017), covers the full sample of 604 documents retrieved from Scopus and addresses five main dimensions: annual scientific production, the most productive and impactful authors, the leading countries and journals, and the most cited publications. This same analysis also generated the trend topics chart used to identify the field’s main research themes.
Building on this, the present study further draws on co-citation and co-authorship analysis, as they jointly allow for a comprehensive characterization of the geopolitical risk literature along two complementary dimensions: its intellectual structure (which foundational works and authors have shaped it) and its social structure (who is producing this knowledge and through which collaborative patterns). Co-citation analysis identifies which documents, authors, or sources are frequently cited together by later publications, on the premise that works repeatedly cited alongside one another are intellectually related. Co-authorship analysis identifies which authors, institutions, or countries frequently publish together, mapping the collaborative structure underlying the field’s knowledge production (Donthu et al. 2021). Both analyses were performed using VOSviewer software (van Eck and Waltman 2010), which enables the construction and visualization of bibliometric networks based on co-citation and co-authorship data extracted from Scopus.
The distribution of publications over time shows that research on geopolitical risk was scarce before 2018, with only sporadic contributions between 2005 and 2017, rarely exceeding one or two articles per year. Scientific output appears to have accelerated from 2018 onward, with a marked increase in 2020 and a steeper growth trajectory from 2021 to 2024. The highest complete-year figure in the sample is 175 articles in 2025. The count for 2026 (206 articles, as of the data extraction date) already exceeds the 2025 figure despite covering only part of the current year.
Table 3 reports author productivity alongside citation-based impact indices. The two rankings only partially overlap. Publication volume and citation impact diverge most visibly for two authors with short publishing histories: one (Bossman A.) shows an unusually high h-index relative to career length, while another (Ahmed F.), despite an even shorter history, posts the highest m-index in the sample, reflecting a faster year-on-year citation accumulation rate over a narrower window. A third case (Teplova T.) decouples citations from both productivity and career length: despite a modest publication count, this author accumulates the highest total citation count in the dataset, traceable to a single highly influential contribution tied to a major geopolitical shock. Together, these patterns indicate that scientific influence in this field reflects the timing and thematic positioning of a contribution relative to unfolding events, not publication volume alone.
Table 3.
Author impact indices (h-index, g-index, m-index).
At the country level (Table 4), China is by far the most productive contributor, with 150 documents, more than five times the output of the second-ranked country, the United States (29 documents), followed by India (25), France (23), Tunisia and Turkey (21 each), the United Kingdom (19), Saudi Arabia (17), Portugal (16), and Greece (14). This degree of concentration is consistent with the strong presence of Chinese-affiliated researchers noted in the science mapping section.
Table 4.
Scientific production by country.
China’s key position stands out, with its link to the United Kingdom representing the network’s most prominent collaborative tie, followed by a dense fan of thinner connections linking China to Turkey, Saudi Arabia, and a broader set of Gulf, South and East Asian, and European countries.
At the journal level (Table 5), Finance Research Letters is the most prolific outlet with 45 articles, followed by Resources Policy (39) and Energy Economics (36). Together, these three journals alone account for 120 documents, confirming their role as the primary publication outlets for this literature. When journal impact is assessed using citation-based indices, Resources Policy shows the highest h-index and total citation count, closely followed by Finance Research Letters, and then Energy Economics.
Table 5.
Journal impact indices (h-index, g-index, m-index).
The most highly cited documents in the dataset retrieved through this study’s search strategy are listed in Table 6. The most-cited paper (Umar et al. 2022, Finance Research Letters) has accumulated 367 citations, followed by Balcilar et al. (2018, Economic Systems, 361 citations) and Liang et al. (2022, Technological Forecasting and Social Change, 351 citations).
Table 6.
Most globally cited documents.
In addition to the performance indicators discussed above, the Bibliometrix package was used to construct a trend topics chart (Figure 2), which plots each keyword’s period of use (horizontal bar, from first to last occurrence in the dataset) against its frequency (bubble size, minimum frequency of 8) and median year of occurrence (bubble position).
Figure 2.
Trend topics. Source: Authors’ own elaboration based on Scopus data (Bibliometrix, R).
Geopolitical risk is by far the highest-frequency term, active since around 2015 and still rising. War and monetary policy are the earliest-appearing terms, dating back to the mid-to-late 2000s, while a second group (stock returns, event study, volatility, stock market, financial stress, emerging markets, and economic policy uncertainty) emerges between roughly 2014 and 2020. The chart’s most notable feature is a large cluster of terms that all first appear within the narrow 2021–2022 window (e.g., geopolitical uncertainty, TVP-VAR, quantile regression, investor sentiment, commodity markets, Russia–Ukraine War, inflation, hedge, green bonds), pointing to a sudden expansion of specialized vocabulary coinciding with the conflict’s onset, followed by a further, more recent wave from 2023 onward (e.g., systemic risk, ESG, machine learning, financial stability). Notably, terms specifically related to the banking sector do not meet the minimum frequency threshold for inclusion in this field-wide analysis.
4.1. Co-Citation Analysis
The co-citation analysis (Figure 3), conducted on cited authors and references, allows the field’s foundational intellectual structure to be reconstructed. A thesaurus file was applied to each of the three co-citation networks before clustering to merge equivalent name and reference variants. A minimum threshold of 20 citations was applied throughout the co-citation analyses to isolate the network’s most important and consistently co-cited elements.
Figure 3.
Co-citation analysis performed on cited authors’ bibliometric map. Source: Authors’ own elaboration based on Scopus data (VOSviewer).
For the cited-authors analysis, among the 13,734 authors in the dataset, only 198 met this threshold.
For the cited-references analysis, out of 27,882 cited references, 21 met the threshold, resulting in three clusters, described in Table 7. This more granular network confirms and refines the structure emerging from the cited-authors network. Caldara and Iacoviello’s paper is unambiguously the most co-cited reference and occupies the most central position in the network, acting as a bridge between all other clusters. Around it, Cluster 1 (red) groups foundational measurement studies together with the parallel economic policy uncertainty (EPU) literature, reflecting the close conceptual proximity between the two streams. Cluster 2 (green) brings together applied papers that extend the GPR framework to specific hedging, commodity, and asset-pricing questions. Cluster 3 (blue) is distinctly methodological, comprising the core spillover-index literature.
Table 7.
Distribution of most cited references in clusters.
Taken together, these two analyses indicate that the intellectual structure of the field is organized around a single foundational reference (Caldara and Iacoviello’s GPR index), from which two parallel branches depart: one methodological, concerned with the measurement of connectedness and spillovers, and one applied, concerned with extending geopolitical risk measures to an increasingly broad set of financial assets.
4.2. Co-Authorship Analysis
Co-authorship analysis was used to examine the collaborative structure of the field at the author, country, and organizational levels. Overall, this analysis yields a meaningful structure only at the country level, while at both the author and organizational levels, the networks do not support substantive conclusions beyond confirming the field’s collaborative fragmentation. The co-authorship analysis of countries (Figure 4), by contrast, is the only one of the three co-authorship analyses to produce a dense network. With a minimum document threshold of 5, 53 countries met the selection criterion, resulting in seven clusters.
Figure 4.
Co-authorship analysis performed on the countries’ bibliometric map. Source: Authors’ own elaboration based on Scopus data (VOSviewer).
Two distinct dimensions emerge from this analysis and are kept separate throughout: productivity, measured by document count, and impact, measured by citations, which do not always align. Cluster 4 is anchored by China, both the network’s most productive country by a wide margin (170 documents) and its most central node (highest total link strength), together with the United Kingdom, New Zealand, Egypt, Qatar, Hong Kong, and Macao. This document count differs from the 150 documents reported for China in the country-level productivity analysis (Table 4): the discrepancy reflects a difference in counting method between the two software tools rather than an inconsistency in the underlying data. The Bibliometrix-based analysis in Table 4 attributes each document to the corresponding author’s country only, whereas the VOSviewer co-authorship network applies full counting, crediting every country appearing among a document’s author affiliations; consequently, internationally co-authored papers involving China contribute to its count in the co-authorship network even when China is not the corresponding-author country in the productivity analysis. Cluster 5 is anchored by France (50 documents), which records the network’s second-highest total link strength (85), together with Saudi Arabia, Pakistan, Tunisia, Romania, Kuwait, and Morocco. Cluster 2 brings together a Gulf–Southeast Asian–Pacific group led by Bangladesh, together with the United Arab Emirates, Australia, Vietnam, Indonesia, Malaysia, Japan, Taiwan, and Jordan. Cluster 1 is anchored by Turkey (45 documents), together with India, Poland, Italy, Algeria, Hungary, Spain, Oman, Belgium, and Malta; within this cluster, Algeria stands out for recording the highest average citation count per document (47.17) despite contributing only 6 documents.
This configuration indicates that, despite the weak collaborative ties observed among individual authors, the field benefits from substantial cross-country research collaboration.
4.3. Robustness Checks
Robustness checks were conducted across all bibliometric networks by testing alternative thresholds.
For co-citation analysis, thresholds of 18, 20, and 22 minimum citations were tested for cited authors and cited references. At the reference level, Caldara and Iacoviello’s (2022) “Measuring Geopolitical Risk” is the most central and most cited node across all three thresholds. At the author level, results were more threshold-sensitive, with Iacoviello M. and Yilmaz K. alternating as the most central node, though both were consistently among the top three most-cited authors.
For co-authorship analysis at the country level, thresholds of 4, 5, and 6 minimum documents were tested. China remained the network’s most central node by total link strength across all three specifications, followed consistently by France, and by the United Kingdom and the United States in close succession.
Overall, these sensitivity checks indicate that the field’s core structure, dominated by geopolitical risk as a construct, Caldara and Iacoviello’s foundational index, and China’s central position in international collaboration, is robust to threshold specification.
5. Assessing a Subsample for the Banking and Insurance Sector
This section is dedicated to a subsample of 78 documents (67 banking, 10 insurance, and 1 addressing both sectors) that underwent the same performance analysis and science mapping procedures.
Annual growth in the sub-sample increased even more steeply than the field as a whole: from an isolated contribution in 2014, output stayed minimal through 2020–2022 (no more than three documents per year), before increasing markedly to 7 documents in 2023, 9 in 2024, 24 in 2025, and 29 in the partial year 2026, demonstrating that banking and insurance have become an increasingly prominent application domain, mirroring the field-wide acceleration (Section 4.1.).
The most cited contribution in the sub-sample is “Geopolitical Risk and Bank Stability” (Phan et al. 2022, Finance Research Letters, 169 citations), followed by “The Impact of Economic Uncertainty and Geopolitical Risks on Bank Credit” (Demir and Danisman 2021, North American Journal of Economics and Finance, 103 citations) and “Geopolitical Risk and the Cost of Bank Loans” (Nguyen and Thuy 2023, Finance Research Letters, 78 citations). These contributions point to bank stability, lending behavior, and credit risk as the dominant angles through which the impact of geopolitical risk on the banking sector has been studied. Insurance-specific applications remain comparatively less developed, both in number and in citation impact.
At the journal level, Finance Research Letters is confirmed as the primary outlet for this literature (11 of the 78 documents), consistent with its central role in the field overall, followed by Economics Letters (5 documents). When journal impact is assessed, Finance Research Letters again leads with an h-index of 6 (300 citations across its 11 papers), while Economics Letters, despite a lower h-index (3), shows the highest m-index in the sub-sample (1.5), reflecting a very recent but fast-accumulating citation record.
At the country level, China (14 documents) and Saudi Arabia (6) are the most active contributors, followed by Germany and Turkey (4 each), and a broader group of European, Middle Eastern, and South Asian economies (Greece, India, Italy, the United Kingdom, and the United States, 3 each). This pattern suggests that banking and insurance sector applications of geopolitical risk research are particularly salient in economies with either systemically important banking sectors or substantial exposure to geopolitical instability.
To further probe the intellectual structure underlying banking and insurance-focused geopolitical risk research, a dedicated co-citation analysis of cited sources was conducted on the sub-sample (Figure 5).
Figure 5.
Co-citation analysis focused on the banking and insurance sectors performed on cited sources, bibliometric map. Source: Authors’ own elaboration based on Scopus data (VOSviewer).
Cluster 1 (red) is dominated by The American Economic Review (total link strength 2888, 107 citations, the most central node in the cluster), together with the Journal of Financial Stability (2696, 77), The Journal of Finance (2494, 76), the Journal of International Financial Markets, Institutions and Money (2212, 53), and the Journal of International Money and Finance (1856, 49). Cluster 2 (green) is led by the Journal of Banking and Finance (total link strength 3769, 132 citations, the second most central node overall), together with the Journal of Financial Economics (3386, 98), the International Review of Financial Analysis (2305, 62), Research in International Business and Finance (1777, 42), and Economic Modelling (1523, 48). Of these five leading sources, three (the Journal of Banking and Finance, the Journal of Financial Economics, and Economic Modelling) come from the field-wide generic Cluster 1, while the remaining two (the International Review of Financial Analysis and Research in International Business and Finance) belong to the field-wide applied-finance Cluster 2. Cluster 3 (blue) is anchored by Finance Research Letters (total link strength 4381, 170 citations, the most central node in the entire sub-sample network), together with Energy Economics (2130, 61), the International Review of Economics and Finance (1861, 49), the North American Journal of Economics and Finance (1697, 51), and the Pacific-Basin Finance Journal (1414, 37).
The thematic strategic diagram constructed on this sub-sample (Figure 6) provides the most granular evidence, across all analyses conducted in this study, of thematic clusters explicitly and exclusively dedicated to banking and insurance topics.
Figure 6.
Thematic strategic diagram (motor, basic, niche, and emerging/declining themes) focused on the banking and insurance sectors. Source: Authors’ own elaboration based on Scopus data (Bibliometrix, R).
Nine clusters emerge, distributed across all four quadrants of the diagram. The basic themes quadrant (high centrality, low density) contains two clusters: a large one built around geopolitical risk, bank stability, and financial stability, showing these constructs remain the central but still relatively undeveloped core around which the sub-field is organized, and a smaller one centered on insurance, economic growth, and the world uncertainty index: the first appearance, across the entire study, of a cluster explicitly dedicated to the sub-field’s insurance dimension within the basic themes quadrant. The motor themes quadrant (high centrality, high density) contains a single cluster centered on corporate governance, geopolitical uncertainty, and monetary policy, indicating that this specific line of inquiry has matured into the sub-field’s first genuinely well-developed and main research stream. The niche themes quadrant (high density, low centrality) remains the most populated, comprising five distinct clusters: banking vulnerability, cross-border banking flows, and financial fragmentation; banking sector, emerging economies, and financial stress; uncertainty, spillover, and contagion; climate risk; and European banks, bank lending, and credit risk. The presence of five separate niche clusters indicates that banking-specific geopolitical risk research continues to diversify into distinct conceptual sub-strands, though these remain largely disconnected both from one another and from the sub-field’s central and motor themes. Finally, the emerging or declining themes quadrant (low centrality, low density) contains a single cluster, centered on emerging markets. Taken together, this structure indicates a sub-field organized around a well-established conceptual core (geopolitical risk and bank stability) and a still-fragmented set of specialized niches, within which the insurance dimension occupies a distinct but comparatively narrow position. Banks and insurance companies are closely linked to financial markets and global economies, making them particularly vulnerable to geopolitical risk and increasing the likelihood of misallocation in their products and services. Empirical evidence confirms that increased geopolitical risk and economic policy uncertainty reduce both banking and insurance stability (Olalere and Mukuddem-Petersen 2024; Phan et al. 2022; Zhang et al. 2024). Reflecting banking’s key intermediary role and its documented vulnerability to external shocks (Demir and Danisman 2021; Nasim et al. 2023; Trinh and Tran 2024; Vu et al. 2023), this sector has attracted considerably more research attention than insurance and other financial intermediaries, despite the latter’s non-negligible exposure to systemic and geopolitical shocks (Billio et al. 2012).
The literature converges on a significant negative relationship between geopolitical risk and bank solvency, typically assessed through the Z-score, and particularly severe in emerging economies, less capitalized banking systems, and BRICS countries (Olalere and Mukuddem-Petersen 2024; Shabir et al. 2023; Trinh and Tran 2024). A 120-year historical perspective qualifies this relationship as non-linear: only major geopolitical events, such as world wars, produce substantial drops in bank capitalization, while moderate shocks have minimal impact (Behn et al. 2025). This solvency deterioration operates primarily through rising non-performing loans (NPLs): geopolitical tensions reduce borrowers’ ability and willingness to service debt, causing rapid declines in asset quality (Pham et al. 2021; Trinh and Tran 2024) that are especially acute for conflict-affected banks (Wang et al. 2025) and in war zones, where infrastructure damage and occupation destroy collateral and leave credit exposures unsecured, at times doubling NPL ratios (Bernardelli et al. 2023; Pham et al. 2019, 2021). Banks typically respond by prioritizing asset quality over loan volume (Pham et al. 2021) and by repricing risk through higher loan costs and stricter non-price conditions such as shorter maturities and higher collateral requirements (Nguyen and Thuy 2024). NPLs also function as signals for wholesale financiers, who rely on them to decide whether to extend or withdraw funding given their limited capacity for detailed monitoring; high NPL ratios accordingly raise the likelihood of funding runs, liquidity shortages, and inefficient asset liquidation, particularly for small and medium-sized banks (Nguyen and Thuy 2024).
Lending behavior itself shifts under geopolitical stress: economic policy uncertainty mainly depresses business credit, while GPR specifically reduces consumer loans and mortgages without affecting overall credit growth (Demir and Danisman 2021), and banks tend to redirect lending toward headquarters and nearby regions where monitoring costs are lower (Pham et al. 2021). In Europe, geopolitical exposure reduces overall lending mainly through declines in foreign activity, with domestic lending remaining comparatively stable, while state-owned banks exhibit more resilient lending during crises than private banks (Chiaramonte et al. 2025). Leverage responses diverge by institution type: US commercial banks tend to increase leverage after a GPR shock, reflecting ties to government debt and a desire to preserve customer relationships and fund public debt (Istiak and Serletis 2020; Trinh and Tran 2024), whereas market-based institutions tend to reduce it; asset quality can also temporarily improve in wartime contexts owing to regulatory interventions and public moratoriums (Olalere and Mukuddem-Petersen 2024; Trinh and Tran 2024).
Beyond individual-institution solvency, geopolitical risk raises system-wide risk by elevating individual bank and asset risk and by triggering the bursting of speculative bubbles (Wang et al. 2025). Country-specific evidence corroborates this channel: rising US-China tensions increase systemic risk in China’s commercial banking sector through both macro channels, such as exchange rates and expectations, and micro channels, such as corporate credit quality and loan concentration (Yuan et al. 2026), while in Europe, exposure to external geopolitical risk disproportionately raises the vulnerability of large euro-area banks through cross-border interconnection (Gabbiadini et al. 2025). The Russia–Ukraine conflict illustrates this dynamic directly, severely affecting European bank performance and valuations, raising default and liquidity risk, although proactive authority responses have partially supported liquidity positions (Vu et al. 2023). A multivariate approach combining systemic, climate, and geopolitical risk further shows that geopolitical factors play a disproportionately large role in aggregate capital shortfalls during periods of intense tension, consistent with the Caldara and Iacoviello (2022) GPR Threats index, and that conventional two-variable measures tend to underestimate these shortfalls by overlooking interactions among shocks (Bettin et al. 2023). At the market level, geopolitical shocks trigger rapid but temporary increases in bank CDS spreads and declines in stock returns (Dieckelmann et al. 2025), with effects that depend on prevailing market conditions: returns fall in bearish markets. However, they can generate positive risk premiums in bullish ones (Albaity et al. 2024), and bank stock indices show heightened sensitivity to tensions precisely when market performance is at its highest (Boungou and Urom 2025). The capacity to anticipate shocks, rather than being caught by surprise, appears conducive to profitability (Adel and Naili 2024). Geopolitical shocks also heighten interbank risk spillovers, with short-term market sensitivity increasing during periods of global uncertainty (He et al. 2025), and interact with inflation dynamics: GPR-driven inflation may initially raise interest and non-interest income but tends to erode operational efficiency and long-term stability over time (Karkowska et al. 2025).
A bank’s capacity to absorb geopolitical shocks depends heavily on its structural characteristics. Higher capitalization, diversification, and large or publicly owned status confer greater resilience, as do maturity and financial innovation more broadly (Vu et al. 2023; Yuan et al. 2026), while financial development and institutional quality support more effective risk management overall (Trinh and Tran 2024; Vu et al. 2023). Large, foreign, or listed banks tend to be more resilient than small, young, or low-capital institutions (Demir and Danisman 2021; Vu et al. 2023), and well-capitalized banks not only buffer shocks more effectively but can benefit from a “flight to safety” as investors shift toward more stable institutions during periods of uncertainty (Nguyen and Thuy 2024; Phan et al. 2022; Trinh and Tran 2024). Even where insolvency is avoided, declining capital ratios can still produce broader credit constraints (Bernardelli et al. 2023). Leadership matters as well: CEOs with stronger access to, and management of, strategic information can mitigate or even reverse the effects of geopolitical risk (Vashisht and Mundi 2025). Structural and policy factors provide further buffers: oil rents help oil-dependent economies offset geopolitical risk, to the point that risk can be positively associated with profitability in crude-dependent contexts (Alsagr and Almazor 2020), while FinTech adoption and strong capital adequacy ratios similarly help mitigate adverse effects (Yuan et al. 2026). Two additional dimensions compound bank vulnerability: the tension between geopolitical urgency and climate objectives, which points to a need for transparency reforms and dedicated geopolitical stress tests to safeguard financial sustainability (Trinh and Tran 2024), including reduced investment efficiency and higher operational costs, such as maintaining branches and data centers, caused by energy shocks (Nasim et al. 2023); and escalating cybersecurity risk, with state-sponsored hacking of banking and payment infrastructure reported to intensify during wartime (Bernardelli et al. 2023). Against this backdrop, stringent regulation and targeted monetary policy are considered essential to containing the systemic risk associated with international geopolitical tensions (Wang et al. 2025; Yuan et al. 2026).
Compared with the extensive research on banking, studies on the impact of geopolitical risk on the insurance sector remain considerably more fragmented. Evidence from BRICS countries shows that geopolitical risk significantly predicts insurance market activity, with a dual effect: geopolitical shocks influence pricing while simultaneously boosting demand for protective coverage (Lee and Lee 2020). Focusing on Property and Casualty premiums, geopolitical risk affects both their average level and their variability, suggesting that insurers revise their models upward in response to higher extreme-event risk, raising costs and potentially rendering some risks uninsurable (Aggarwal and Kalia 2022). This relationship is state-dependent: in Russia, bidirectional causality between geopolitical risk and premiums emerges mainly during bearish markets (Lee and Lee 2020), while evidence across 14 countries shows asymmetric and non-linear effects on premiums, with long-term impacts generally exceeding short-term ones (Hemrit and Nakhli 2021). In Saudi Arabia, increased geopolitical tension negatively affects insurance demand by reducing government spending and the efficiency of private-sector investment (Hemrit 2022), operating partly through stricter underwriting requirements and heightened adverse selection and moral hazard stemming from information asymmetry (Hemrit and Nakhli 2021). At the firm level, perceived geopolitical uncertainty raises the likelihood of purchasing Directors’ and Officers’ liability insurance, interpreted as a governance signal that reassures stakeholders during uncertain times; notably, political ties and state ownership increase rather than reduce this demand, as managers face heightened risk aversion under political and regulatory pressure (Li et al. 2025). Even so, investors in markets such as China continue to view life insurance as a comparatively safe asset, particularly at higher distribution quantiles, despite the long-term negative impact of geopolitical risk on premiums (Xiang et al. 2023).
Insurance companies’ relationship to geopolitical risk can be understood through two main perspectives. On one hand, the industry functions as a risk-mitigation tool: multinational firms increasingly seek specialized political risk coverage to safeguard foreign direct investment amid rising tensions, which in turn increases insurers’ own exposure to large payouts in the event of major conflicts (Bussy and Zheng 2023). On the other hand, insurers operate within strict regulatory and operational boundaries that clearly separate their activities from banking groups (Shabir et al. 2023). This separation, however, does not shield them from systemic pressures, as capital outflows from emerging economies triggered by geopolitical uncertainty can directly threaten insurer stability (Hemrit and Nakhli 2021). Responses vary by region, with some insurers reallocating assets abroad to hedge domestic risk and others raising premiums to build reserves against high-impact events (Hemrit and Nakhli 2021). Despite this body of work, a notable gap remains due to limited empirical studies directly examining how geopolitical risk affects insurer solvency or strategic asset allocation, a concern heightened by insurers’ substantial holdings of GPR-sensitive assets such as sovereign bonds and stocks (Baur and Smales 2020). A partial exception is Zhang et al. (2024), who model the joint default dependence between US insurers and banks using a time-varying asymmetric copula and find a significant negative correlation between this systemic linkage and the Caldara and Iacoviello (2022) GPR index, a counterintuitive result the authors attribute to central banks’ stabilizing interventions during geopolitical turmoil, suggesting that the relationship between geopolitical risk and insurer-bank interconnectedness is more nuanced than a simple risk-amplification channel. Beyond these systemic considerations, incorporating geopolitical risk into insurance pricing is crucial for risk management, though doing so may also constrain the availability of coverage during periods of global unrest (Hemrit and Nakhli 2021).
6. Discussion
This section revisits the study’s three research questions, considering the bibliometric evidence presented in the Sections above.
On scientific production (RQ1), the field’s growth since 2018, accelerating further after 2020, is consistent with the introduction of the Caldara and Iacoviello GPR index and with the escalation of real-world geopolitical shocks. This trajectory should not, however, be read uncritically as evidence of a maturing research field. Much of this growth appears to reflect the rapid application of an increasingly standardized methodological toolkit (the GPR index itself, combined with a small set of econometric techniques) to a widening set of events and asset classes, rather than necessarily reflecting genuine theoretical diversification. The concentration of output in three journals and one country, together with the productivity-impact divergence documented for individual authors, points to a field whose growth is currently driven more by opportunistic responsiveness to geopolitical events than by a widening research infrastructure.
The field’s intellectual structure (RQ2) presents a mixed picture. Intellectually, the field is organized around a single foundational reference, a pattern consistent with a cumulative-advantage or “Matthew effect” dynamic (Merton 1968): once a validated, cross-country index becomes available, subsequent research tends to adopt it by default. As Aysan et al. (2023) emphasize, prior to the introduction of this index, scholars relied on fragmented, localized proxies that hindered systematic cross-study comparisons. The rapid institutionalization of Caldara and Iacoviello’s index stems from its multi-country coverage and methodological reliability, a pattern confirmed across bibliometric reviews (Aiswarya and Muthumeenakshi 2024; Iddouch 2026). Consequently, while centralization around a unified framework fosters cumulative knowledge building, it also risks fostering a methodological monoculture that obscures context-specific nuances. This convergence, however, cuts both ways. On one hand, it facilitates cumulative comparability across studies; on the other, the fact that multiple independent bibliometric reviews converge on the same finding may itself be worth noting as a possible symptom of the phenomenon it describes, namely a field whose apparent consensus could be consistent with methodological lock-in around a single measure rather than necessarily reflecting substantive theoretical agreement. Whether this concentration reflects a genuinely superior measurement approach or a path-dependent default that discourages alternative conceptualizations of geopolitical risk cannot be settled by bibliometric evidence alone.
The trend topics analysis reinforces this picture of a field whose applications are more differentiated than its foundations, but the observed pattern warrants a methodological caveat. Because trend topics are selected based on a minimum frequency threshold applied across the full period, smaller but potentially meaningful themes, including banking-specific ones, may be under-represented. This is not because they are substantively marginal, but because they have not yet accumulated sufficient keyword density to surface in a field-wide analysis. Indeed, no banking-specific term meets the frequency threshold in the field-wide analysis (Figure 2), yet the dedicated sub-sample analysis (Section 5) reveals a markedly different structure, one that is more developed. This divergence should not be read solely as an artifact of aggregation and threshold choice: with only 78 of the 604 documents (12.9%) specifically addressing banking or insurance, banking-related terms are, by construction, a numerical minority within the field-wide vocabulary, and their absolute frequency is correspondingly modest. Threshold choice may still shape exactly where this minority falls relative to the cutoff, but the underlying scarcity is a substantive feature of the corpus, not simply a methodological artifact.
A further feature of the field’s evolving vocabulary is its pronounced orientation toward energy and commodity markets, evident in the persistence and recurrence of terms such as commodity markets, clean energy, and risk and volatility spillover among the trend topics identified in Figure 2. This pattern is consistent with a transmission channel documented in the literature, whereby geopolitical shocks raise energy-supply uncertainty, which propagates into commodity price volatility (Gong and Xu 2022) and, from there, into broader financial market instability through spillover dynamics (Fang and Shao 2022). It is worth asking, however, whether this prominence reflects a genuine judgment by the research community that energy markets are the primary channel through which GPR affects the financial sector, or whether it instead reflects the greater availability of high-frequency and publicly accessible energy and commodity price data relative to bank- or insurer-level microdata, which are typically harder to access. If so, the field’s thematic priorities may reflect data availability as much as genuine economic importance, a point taken up again in the discussion of RQ3 below.
Reframing the analysis specifically around banking and insurance applications (RQ3) both confirms and qualifies the qualitative imbalance between banking- and insurance-focused research already noted in the literature, whereby banking has historically attracted more scholarly attention than insurance despite the latter’s non-negligible exposure to systemic and geopolitical shocks (Billio et al. 2012). On the encouraging side, the dedicated sub-sample analysis shows that once the parent literature is filtered out, a genuinely banking-focused citation core crystallizes around the Journal of Banking and Finance, together with the Journal of Financial Economics, and the motor themes quadrant is occupied by a cluster on corporate governance and monetary policy. This structure, however, should be interpreted with caution rather than treated as settled evidence of a maturing sub-field: with only 78 documents in the sub-sample, of which 67 address banking specifically, these clustering solutions are considerably less robust than the field-wide results, and it remains to be seen whether they will hold as the literature continues to grow.
Insurance shows a more limited version of the same story: it now surfaces as a small, dedicated cluster in the basic themes quadrant yet still does not organize into an autonomous cluster in the co-citation and co-authorship networks. Rather than treating this exclusively as a research gap to be filled, it is also worth considering whether insurers’ geopolitical exposure is intrinsically harder to study empirically than banks’, given that insurance data are typically harder to access than banking data. If so, the observed imbalance may reflect a data access constraint on researchers as much as a lack of scholarly interest, a distinction with different implications for how future research might be encouraged.
Two further implications follow from this combined reading. First, the near-total absence of author- and institution-level collaboration—only partially offset by country-level ties—is not necessarily a lack in itself. However, closing the gaps identified above will require not only new empirical studies but also more structured collaborative arrangements, particularly between banking-focused and insurance-focused research communities, which at present appear to operate largely in isolation from one another. Second, the event-driven nature of the field’s growth and citation patterns, evident across the performance analysis, implies that future geopolitical shocks are likely to remain the primary catalyst for new research and raises a genuine concern about the durability of this research program.
7. Conclusions
This study addresses the absence of a systematic bibliometric mapping of the geopolitical risk (GPR) literature specifically focused on banking and insurance institutions, the financial system’s primary institutions. Adopting a Bibliometric–Systematic Literature Review framework and combining PRISMA-guided screening with performance analysis and science mapping on a sample of 604 documents, complemented by a dedicated sub-sample of 78 documents addressing banking (67), insurance (10), and both sectors jointly (1), the study provides an account of the field’s development, along with an assessment of the limits within which this account should be interpreted.
Three contributions follow, each qualified by the limits discussed above. First, the field’s rapid recent growth appears driven more by responsiveness to geopolitical events and by the availability of a standardized measurement tool than by a broadening theoretical infrastructure, a distinction that matters for assessing whether this expansion is likely to prove durable. Second, the field’s intellectual core is concentrated around a single measurement framework in a manner consistent with, but not conclusively explained by, a cumulative advantage dynamic; whether this concentration reflects genuine methodological superiority or a path-dependent default remains an open question. Third, banking-related research shows converging, if still sample-sensitive, evidence of an emerging distinct identity within the field, while insurance-related research remains comparatively underdeveloped, a gap that may reflect both limited scholarly attention and data-access constraints specific to the insurance industry.
These findings carry both theoretical and practical implications. Theoretically, the study offers scholars entering this field a structured map of its intellectual architecture to guide future contributions. Practically, the findings suggest that the academic evidence base available to inform banking-related geopolitical risk assessments is considerably more developed than that available for insurance, a gap worth bearing in mind by anyone consulting this literature for either sector.
Several limitations of this study should be acknowledged, most of which stem from choices inherent to the bibliometric method itself. First, bibliographic data were retrieved from a single database, Scopus. While this choice is consistent with established practice in bibliometric studies in management and finance (Donthu et al. 2021), it may exclude relevant work indexed exclusively in other databases. Scopus generally offers broader journal coverage than Web of Science across major disciplinary areas (Mongeon and Paul-Hus 2016); however, the same study also shows that both databases underrepresent Social Sciences journals relative to their overall share of academic publishing (21.3% coverage in Web of Science and 27.8% in Scopus, against a 36% share in the reference journal directory used for comparison), a limitation directly relevant to economics and finance research such as the present study, though shared by both major citation databases rather than specific to the choice of Scopus. Future studies could usefully cross-validate the present findings against a multi-database sample.
Second, the search was restricted to English-language journal articles.
Third, the search string, although informed by a systematic review of the World Economic Forum’s Global Risks Reports, necessarily relies on keyword matching within titles, abstracts, and keywords. Despite the thesaurus-based harmonization applied before clustering, this approach may still under- or over-include studies that discuss geopolitical risk using different terminology or address financial sector outcomes without using the specific search terms employed.
Fourth, the dataset constitutes a snapshot extracted on a single date (5 September 2026) from a field whose annual output is still growing exponentially. Both the performance indicators and, especially, the citation-based impact measures are likely to understate the eventual influence of the most recent contributions, particularly those published in 2025 and 2026.
Fifth, the dedicated subsample of banking- and insurance-focused documents (78 records) is considerably smaller than the full sample, and the resulting thematic and co-citation clusters should accordingly be interpreted as indicative rather than definitive, given the greater sensitivity of small networks to clustering resolution choices.
Building on results and the limitations discussed above, three avenues for future research appear particularly promising. First, given the pronounced imbalance documented throughout this study, future empirical work should focus specifically on the insurance sector, examining insurer solvency, underwriting behavior, and portfolio reallocation under geopolitical stress. Second, future bibliometric work could complement the present analyses with bibliographic coupling, which is better suited to detecting the field’s most recent and still emerging research fronts than the backward-looking co-citation techniques employed here. Third, replicating this analysis on a multi-database sample and at a later point in the field’s development would help determine whether the concentration patterns and thematic gaps identified here reflect a durable structural feature of the field or a transient stage in its rapid early growth.
Author Contributions
Conceptualization, E.D., G.O. and M.S.; Methodology, E.D., G.O. and M.S.; Software, M.S.; Formal analysis, E.D., G.O. and M.S.; Data curation, E.D., G.O. and M.S.; Writing—original draft, E.D., G.O. and M.S.; Writing—review & editing, E.D., G.O. and M.S.; Supervision, E.D., G.O. and M.S. All authors have read and agreed to the published version of the manuscript.
Funding
This research received no external funding.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The raw data supporting the conclusions of this article will be made available by the authors on request.
Conflicts of Interest
The authors declare no conflict of interest.
Note
| 1 | Source: https://www.matteoiacoviello.com/gpr_files/gpr_methodology.htm (accessed on 10 September 2026). |
References
- Adel, Nabil, and Maryem Naili. 2024. Geopolitical Risk and Banking Performance: Evidence from Emerging Economies. The Journal of Risk Finance 25: 646–63. [Google Scholar] [CrossRef] [Scilit]
- Aftab, Rehan, and Muhammad Naveed. 2022. Is Financial Institutions’ Stability of BRICS Block Responsive to Uncertain Dimensions? Cogent Business & Management 9: 2010484. [Google Scholar] [CrossRef] [Scilit]
- Aggarwal, Divya, and Deepali Kalia. 2022. Examining Comovement and Causality between Producer Price Index for P&C Insurance Premium and Uncertainty Indices: Wavelet and Non-Parametric Quantile Causality Approach. Research in Economics 76: 141–48. [Google Scholar] [CrossRef] [Scilit]
- Aiswarya, Selva, and Muthu Muthumeenakshi. 2024. Exploratory Bibliometric Analysis on Geopolitical Risk. International Research Journal of Multidisciplinary Scope 5: 1180–97. [Google Scholar] [CrossRef] [Scilit]
- Albaity, Mohamed, Ray Saadaoui Mallek, and Hasan Mustafa. 2024. Heterogeneity of Investor Sentiment, Geopolitical Risk and Economic Policy Uncertainty: Do Islamic Banks Differ during COVID-19 Pandemic? International Journal of Emerging Markets 19: 4094–115. [Google Scholar] [CrossRef] [Scilit]
- Alsadan, Abdullah, Hassan Alalmaee, Chokri Zehri, and Wissem Ajili Ben Youssef. 2025. Global Financial Fragmentation under Raised Geopolitical Risk. International Economics and Economic Policy 22: 44. [Google Scholar] [CrossRef] [Scilit]
- Alsagr, Naif, and Stefan F. Van Hemmen Almazor. 2020. Oil Rent, Geopolitical Risk and Banking Sector Performance. International Journal of Energy Economics and Policy 10: 305–14. [Google Scholar] [CrossRef] [Scilit]
- Aria, Massimo, and Corrado Cuccurullo. 2017. Bibliometrix: An R-Tool for Comprehensive Science Mapping Analysis. Journal of Informetrics 11: 959–75. [Google Scholar] [CrossRef] [Scilit]
- Aysan, Ahmet Faruk, Ali Yavuz Polat, Hasan Tekin, and Ahmet Semih Tunalı. 2023. The Ascent of Geopolitics: Scientometric Analysis and Ramifications of Geopolitical Risk. Defence and Peace Economics 34: 791–809. [Google Scholar] [CrossRef] [Scilit]
- Baas, Jeroen, Michiel Schotten, Andrew Plume, Grégoire Côté, and Reza Karimi. 2020. Scopus as a Curated, High-Quality Bibliometric Data Source for Academic Research in Quantitative Science Studies. Quantitative Science Studies 1: 377–86. [Google Scholar] [CrossRef] [Scilit]
- Balcilar, Mehmet, Matteo Bonato, Riza Demirer, and Rangan Gupta. 2018. Geopolitical Risks and Stock Market Dynamics of the BRICS. Economic Systems 42: 295–306. [Google Scholar] [CrossRef] [Scilit]
- Baur, Dirk G., and Lee A. Smales. 2020. Hedging Geopolitical Risk with Precious Metals. Journal of Banking & Finance 117: 105823. [Google Scholar] [CrossRef] [Scilit]
- Behn, Markus, Jan Hannes Lang, and Alessio Reghezza. 2025. 120 Years of Insight: Geopolitical Risk and Bank Solvency. Economics Letters 247: 112168. [Google Scholar] [CrossRef] [Scilit]
- Bernardelli, Michał, Zbigniew Korzeb, Paweł Niedziółka, and Krzysztof Waliszewski. 2023. Channels for the Impact of the War in Ukraine on the Commercial Banking Sector in Poland—First Results of the Study. Contemporary Economics 17: 142–73. [Google Scholar] [CrossRef] [Scilit]
- Bettin, Giulia, Gian Marco Mensi, and Maria Cristina Recchioni. 2023. Multifactor Risk Attribution Applied to Systemic, Climate and Geopolitical Tail Risks for the Eurozone Banking Sector. Risks 11: 173. [Google Scholar] [CrossRef] [Scilit]
- Będowska-Sójka, Barbara, Ender Demir, and Adam Zaremba. 2022. Hedging Geopolitical Risks with Different Asset Classes: A Focus on the Russian Invasion of Ukraine. Finance Research Letters 50: 103192. [Google Scholar] [CrossRef] [Scilit]
- Billio, Monica, Mila Getmansky, Andrew W. Lo, and Loriana Pelizzon. 2012. Econometric Measures of Connectedness and Systemic Risk in the Finance and Insurance Sectors. Journal of Financial Economics 104: 535–59. [Google Scholar] [CrossRef] [Scilit]
- Bondarenko, Yevheniia, Vivien Lewis, Matthias Rottner, and Yves Schüler. 2024. Geopolitical Risk Perceptions. Journal of International Economics 152: 104005. [Google Scholar] [CrossRef] [Scilit]
- Boungou, Whelsy, and Christian Urom. 2025. Geopolitical Tensions and Banks’ Stock Market Performance. Economics Letters 247: 112093. [Google Scholar] [CrossRef] [Scilit]
- Bouri, Elie, Rami Hammoud, and Christina Abou Kassm. 2023. The Effect of Oil Implied Volatility and Geopolitical Risk on GCC Stock Sectors under Various Market Conditions. Energy Economics 120: 106617. [Google Scholar] [CrossRef] [Scilit]
- Bussy, Adrien, and Huanhuan Zheng. 2023. Responses of FDI to Geopolitical Risks: The Role of Governance, Information, and Technology. International Business Review 32: 102136. [Google Scholar] [CrossRef] [Scilit]
- Caldara, Dario, and Matteo Iacoviello. 2019. Measuring Geopolitical Risk; working paper. Washington, DC: Board of Governors of the Federal Reserve Board.
- Caldara, Dario, and Matteo Iacoviello. 2022. Measuring Geopolitical Risk. American Economic Review 112: 1194–225. [Google Scholar] [CrossRef] [Scilit]
- Cheng, Sheng, Zongyou Zhang, and Yan Cao. 2022. Can Precious Metals Hedge Geopolitical Risk? Fresh Sight Using Wavelet Coherence Analysis. Resources Policy 79: 102972. [Google Scholar] [CrossRef] [Scilit]
- Chiaramonte, Laura, Federico Mecchia, Andrea Paltrinieri, and Stefano Piserà. 2025. Does Geopolitical Risk Affect Bank Lending Behavior? Evidence from Europe. The European Journal of Finance 31: 2089–113. [Google Scholar] [CrossRef] [Scilit]
- Cobo, Manuel J., Antonio Gabriel López-Herrera, Enrique Herrera-Viedma, and Francisco Herrera. 2011. Science Mapping Software Tools: Review, Analysis, and Cooperative Study among Tools. Journal of the American Society for Information Science and Technology 62: 1382–402. [Google Scholar] [CrossRef] [Scilit]
- Cui, Jinxin, and Aktham Maghyereh. 2024a. Higher-Order Moment Risk Spillovers across Various Financial and Commodity Markets: Insights from the Israeli–Palestinian Conflict. Finance Research Letters 59: 104832. [Google Scholar] [CrossRef] [Scilit]
- Cui, Jinxin, and Aktham Maghyereh. 2024b. Unveiling Interconnectedness: Exploring Higher-Order Moments among Energy, Precious Metals, Industrial Metals, and Agricultural Commodities in the Context of Geopolitical Risks and Systemic Stress. Journal of Commodity Markets 33: 100380. [Google Scholar] [CrossRef] [Scilit]
- Demir, Ender, and Gamze Ozturk Danisman. 2021. The Impact of Economic Uncertainty and Geopolitical Risks on Bank Credit. The North American Journal of Economics and Finance 57: 101444. [Google Scholar] [CrossRef] [Scilit]
- Dieckelmann, Daniel, Chloe Larkou, Peter McQuade, Cosimo Pancaro, and Denise Rößler. 2025. Geopolitical Risk and Euro Area Bank CDS Spreads and Stock Prices: Evidence from a New Index. Economics Letters 254: 112461. [Google Scholar] [CrossRef] [Scilit]
- Donthu, Naveen, Satish Kumar, Debmalya Mukherjee, Nitesh Pandey, and Weng Marc Lim. 2021. How to Conduct a Bibliometric Analysis: An Overview and Guidelines. Journal of Business Research 133: 285–96. [Google Scholar] [CrossRef] [Scilit]
- El Rhrib, Oumayma, and Laila Bennis. 2025. Geofinance: A Systematic Review of the Literature. International Journal of Accounting, Finance, Auditing, Management and Economics 6: 524–41. Available online: https://ijafame.org/index.php/ijafame/article/view/2017 (accessed on 10 September 2026).
- Fang, Yi, and Zhiquan Shao. 2022. The Russia-Ukraine Conflict and Volatility Risk of Commodity Markets. Finance Research Letters 50: 103264. [Google Scholar] [CrossRef] [Scilit]
- Fianto, Bayu Arie, and Mansor H. Ibrahim. 2025. Bank Lending amid Geopolitical Risk: The GCC Case. Review of Financial Economics 43: 608–28. [Google Scholar] [CrossRef] [Scilit]
- Gabbiadini, Mirko, Michele Meoli, and Silvio Vismara. 2025. Geopolitical Risk and Systemic Risk in the European Banking System. Finance Research Letters 86: 108796. [Google Scholar] [CrossRef] [Scilit]
- Galimova, Tansu, Chieh-en Chou, Dominik Keiner, and Christian Breyer. 2025. Geopolitical Risk Index for Guiding International Sustainable Energy Trade. Smart Energy 19: 100200. [Google Scholar] [CrossRef] [Scilit]
- Gheorghe, Catalin, Oana Panazan, Hind Alnafisah, and Ahmed Jeribi. 2025. ETF Resilience to Uncertainty Shocks: A Cross-Asset Nonlinear Analysis of AI and ESG Strategies. Risks 13: 161. [Google Scholar] [CrossRef] [Scilit]
- Godil, Danish Iqbal, Salman Sarwat, Arshian Sharif, and Kittisak Jermsittiparsert. 2020. How Oil Prices, Gold Prices, Uncertainty and Risk Impact Islamic and Conventional Stocks? Empirical Evidence from QARDL Technique. Resources Policy 66: 101638. [Google Scholar] [CrossRef] [Scilit]
- Gong, Xu, and Jun Xu. 2022. Geopolitical Risk and Dynamic Connectedness between Commodity Markets. Energy Economics 110: 106028. [Google Scholar] [CrossRef] [Scilit]
- Goodell, John W., Satish Kumar, Weng Marc Lim, and Debidutta Pattnaik. 2021. Artificial Intelligence and Machine Learning in Finance: Identifying Foundations, Themes, and Research Clusters from Bibliometric Analysis. Journal of Behavioral and Experimental Finance 32: 100577. [Google Scholar] [CrossRef] [Scilit]
- He, Yue, Miaomiao Tao, and Xiaohang Ren. 2025. U.S. Interbank Risk Spillover Network: Temporal Dynamics and External Shocks. Finance Research Letters 85: 107910. [Google Scholar] [CrossRef] [Scilit]
- Hemrit, Wael. 2022. Does Insurance Demand React to Economic Policy Uncertainty and Geopolitical Risk? Evidence from Saudi Arabia. The Geneva Papers on Risk and Insurance—Issues and Practice 47: 460–92. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Hemrit, Wael, and Mohamed Sahbi Nakhli. 2021. Insurance and Geopolitical Risk: Fresh Empirical Evidence. The Quarterly Review of Economics and Finance 82: 320–34. [Google Scholar] [CrossRef] [Scilit]
- Hoque, Mohammad Enamul, Low Soo-Wah, and Mabruk Billah. 2023. Time-Frequency Connectedness and Spillover among Carbon, Climate, and Energy Futures: Determinants and Portfolio Risk Management Implications. Energy Economics 127: 107034. [Google Scholar] [CrossRef] [Scilit]
- Huang, Jianbai, Qian Ding, Hongwei Zhang, Yaoqi Guo, and Muhammad Tahir Suleman. 2021. Nonlinear Dynamic Correlation between Geopolitical Risk and Oil Prices: A Study Based on High-Frequency Data. Research in International Business and Finance 56: 101370. [Google Scholar] [CrossRef] [Scilit]
- Iddouch, Karim. 2026. How Does Geopolitical Risk Shape Economic and Financial Outcomes in Emerging Markets? SSRN Electronic Journal, 1–54. [Google Scholar] [CrossRef] [Scilit]
- Istiak, Khandokar, and Apostolos Serletis. 2020. Risk, Uncertainty, and Leverage. Economic Modelling 91: 257–73. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Karkowska, Renata, Zbigniew Korzeb, and Paweł Niedziółka. 2025. Inflation’s Dual Impact on European Banks’ Profitability. Journal of Policy Modeling 47: 64–77. [Google Scholar] [CrossRef] [Scilit]
- Khoo, Joye, and Adrian (Wai Kong) Cheung. 2021. Does Geopolitical Uncertainty Affect Corporate Financing? Evidence from MIDAS Regression. Global Finance Journal 47: 100519. [Google Scholar] [CrossRef] [Scilit]
- Khraiche, Maroula, James W. Boudreau, and Md Shahedur R. Chowdhury. 2023. Geopolitical Risk and Stock Market Development. Journal of International Financial Markets, Institutions and Money 88: 101847. [Google Scholar] [CrossRef] [Scilit]
- Kumar, Kshitij, and Bateshwa Singh. 2025. Geopolitical risks and financial markets: A 27-year bibliometric study of global financial trends. International Journal of Trade and Global Markets 21: 462–84. [Google Scholar] [CrossRef] [Scilit]
- Lee, Chi-Chuan, and Chien-Chiang Lee. 2020. Insurance Activity, Real Output, and Geopolitical Risk: Fresh Evidence from BRICS. Economic Modelling 92: 207–15. [Google Scholar] [CrossRef] [Scilit]
- Li, Conggang, Yijun Liu, Rong Xu, and Xingmei Xu. 2025. Insuring Legitimacy: The Role of Uncertainty Perceptions in Shaping Corporate Insurance Demand. Economic Modelling 151: 107157. [Google Scholar] [CrossRef] [Scilit]
- Li, Sufang, Dalun Tu, Yan Zeng, Chenggang Gong, and Di Yuan. 2022. Does Geopolitical Risk Matter in Crude Oil and Stock Markets? Evidence from Disaggregated Data. Energy Economics 113: 106191. [Google Scholar] [CrossRef] [Scilit]
- Liang, Chao, Qin Luo, Yan Li, Luu Duc, and Toan Huynh. 2023. Global Financial Stress Index and Long-Term Volatility Forecast for International Stock Markets. Journal of International Financial Markets, Institutions and Money 88: 101825. [Google Scholar] [CrossRef] [Scilit]
- Liu, Yang, Liyan Han, and Yang Xu. 2021. The Impact of Geopolitical Uncertainty on Energy Volatility. International Review of Financial Analysis 75: 101743. [Google Scholar] [CrossRef] [Scilit]
- Marzi, Giacomo, Marco Balzano, Andrea Caputo, and Massimiliano M. Pellegrini. 2025. Guidelines for Bibliometric-Systematic Literature Reviews: 10 Steps to Combine Analysis, Synthesis and Theory Development. International Journal of Management Reviews 27: 81–103. [Google Scholar] [CrossRef] [Scilit]
- Merton, Robert King. 1968. The Matthew Effect in Science. Science 159: 56–63. [Google Scholar] [CrossRef] [Scilit]
- Mongeon, Philippe, and Adèle Paul-Hus. 2016. The Journal Coverage of Web of Science and Scopus: A Comparative Analysis. Scientometrics 106: 213–28. [Google Scholar] [CrossRef] [Scilit]
- Moral-Muñoz, José A., Enrique Herrera-Viedma, Antonio Santisteban-Espejo, and Manuel J. Cobo. 2020. Software Tools for Conducting Bibliometric Analysis in Science: An up-to-Date Review. El Profesional de La Información 29. [Google Scholar] [CrossRef] [Scilit]
- Nasim, Asma, Subhan Ullah, Ja Ryong Kim, and Affan Hameed. 2023. Energy Shocks and Bank Efficiency in Emerging Economies. Energy Economics 126: 107005. [Google Scholar] [CrossRef] [Scilit]
- Nguyen, Thanh Cong, and Tien Ho Thuy. 2023. Geopolitical Risk and the Cost of Bank Loans. Finance Research Letters 54: 103812. [Google Scholar] [CrossRef] [Scilit]
- Nguyen, Thanh Cong, and Tien Ho Thuy. 2024. Bank Wholesale Funding in an Era of Rising Geopolitical Risk. The World Economy 47: 4306–30. [Google Scholar] [CrossRef] [Scilit]
- NguyenHuu, Tam, and Deniz Karaman Örsal. 2024. Geopolitical Risks and Financial Stress in Emerging Economies. The World Economy 47: 217–37. [Google Scholar] [CrossRef] [Scilit]
- Olalere, Oluwaseyi Ebenezer, and Janine Mukuddem-Petersen. 2024. Geopolitical Risk, Economic Policy Uncertainty, and Bank Stability in BRICS Countries. Cogent Economics & Finance 12: 2290368. [Google Scholar] [CrossRef] [Scilit]
- Page, Matthew J., Joanne E. McKenzie, Patrick M. Bossuyt, Isabelle Boutron, Tammy C. Hoffmann, Cynthia D. Mulrow, Larissa Shamseer, Jennifer M Tetzlaff, Elie A. Akl, Sue E. Brennan, and et al. 2021. The PRISMA 2020 Statement: An Updated Guideline for Reporting Systematic Reviews. BMJ 372: n71. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Petroccione, Gerardo, Elvira Anna Graziano, Luca Salerno, and Zuzana Vincurova. 2026. Managing geopolitical risk in banking systems: An integrative framework based on a systematic and bibliometric review. Management Decision, 1–35. [Google Scholar] [CrossRef] [Scilit]
- Pham, Tho, Oleksandr Talavera, and Andriy Tsapin. 2021. Shock Contagion, Asset Quality and Lending Behaviour: The Case of War in Eastern Ukraine. Kyklos 74: 243–69. [Google Scholar] [CrossRef] [Scilit]
- Pham, Tho, Oleksandr Talavera, and Junhong Yang. 2019. Multimarket Competition and Profitability: Evidence from Ukrainian Banks. Oxford Economic Papers 72: gpz041. [Google Scholar] [CrossRef] [Scilit]
- Phan, Dinh Hoang Bach, Vuong Thao Tran, and Bernard Njindan Iyke. 2022. Geopolitical Risk and Bank Stability. Finance Research Letters 46: 102453. [Google Scholar] [CrossRef] [Scilit]
- Salisu, Afees A., Lukman Lasisi, and Jean Paul Tchankam. 2022. Historical Geopolitical Risk and the Behaviour of Stock Returns in Advanced Economies. The European Journal of Finance 28: 889–906. [Google Scholar] [CrossRef] [Scilit]
- Shabir, Mohsin, Ping Jiang, Yasir Shahab, and Peng Wang. 2023. Geopolitical, Economic Uncertainty and Bank Risk: Do CEO Power and Board Strength Matter? International Review of Financial Analysis 87: 102603. [Google Scholar] [CrossRef] [Scilit]
- Sheikh, Umaid A., Mehrad Asadi, David Roubaud, and Shawkat Hammoudeh. 2024. Global Uncertainties and Australian Financial Markets: Quantile Time-Frequency Connectedness. International Review of Financial Analysis 92: 103098. [Google Scholar] [CrossRef] [Scilit]
- Sivaprasad, Sheeja, Roberta Adami, Issam Malki, Dildora Ibragimova, and Feruza Yodgorova. 2025. Spillover Effects of Geopolitical Risk on the Banking Sectors of Post-Soviet Countries. Review of Behavioral Finance 17: 544–62. [Google Scholar] [CrossRef] [Scilit]
- Sohag, Kazi, Shawkat Hammoudeh, Ahmed H. Elsayed, Oleg Mariev, and Yulia Safonova. 2022. Do Geopolitical Events Transmit Opportunity or Threat to Green Markets? Decomposed Measures of Geopolitical Risks. Energy Economics 111: 106068. [Google Scholar] [CrossRef] [Scilit]
- Tang, Yumei, Xihui Haviour Chen, Provash Kumer Sarker, and Sarra Baroudi. 2023. Asymmetric Effects of Geopolitical Risks and Uncertainties on Green Bond Markets. Technological Forecasting and Social Change 189: 122348. [Google Scholar] [CrossRef] [Scilit]
- Tomaszewski, Robert. 2023. Visibility, Impact, and Applications of Bibliometric Software Tools through Citation Analysis. Scientometrics 128: 4007–28. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Triki, Mohamed Bilel, and Abderrazek Ben Maatoug. 2021. The GOLD Market as a Safe Haven against the Stock Market Uncertainty: Evidence from Geopolitical Risk. Resources Policy 70: 101872. [Google Scholar] [CrossRef] [Scilit]
- Trinh, Hai Hong, and Thao Phuong Tran. 2024. Global Banking Systems, Financial Stability, and Uncertainty: How Have Countries Coped with Geopolitical Risks? International Review of Economics & Finance 96: 103647. [Google Scholar] [CrossRef] [Scilit]
- Umar, Zaghum, Onur Polat, Sun-Yong Choi, and Tamara Teplova. 2022. The Impact of the Russia-Ukraine Conflict on the Connectedness of Financial Markets. Finance Research Letters 48: 102976. [Google Scholar] [CrossRef] [Scilit]
- van Eck, Nees Jan, and Ludo Waltman. 2010. Software Survey: VOSviewer, a Computer Program for Bibliometric Mapping. Scientometrics 84: 523–38. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Vashisht, Shailja, and Hardeep Singh Mundi. 2025. Do Well-Connected Bank CEOs Mitigate the Impact of Geopolitical Risk on Bank Stability? Evidence from an Emerging Market. Finance Research Letters 84: 107777. [Google Scholar] [CrossRef] [Scilit]
- Vu, Phuong Thi Thu, Nhan Huynh, Hoa Phan, and Hanh Hoang. 2023. Financial Earthquakes and Aftershocks: From Brexit to Russia-Ukraine Conflict and the Stability of European Banks. Journal of International Financial Markets, Institutions and Money 88: 101830. [Google Scholar] [CrossRef] [Scilit]
- Wang, Yu, Gaoya Song, and Yiming Lu. 2025. Geopolitical Risk, Bank Regulation, and Systemic Risk: A Cross-Country Analysis. Finance Research Letters 76: 106893. [Google Scholar] [CrossRef] [Scilit]
- Xiang, Feiyun, Tsangyao Chang, and Shi-jie Jiang. 2023. Economic and Climate Policy Uncertainty, Geopolitical Risk and Life Insurance Premiums in China: A Quantile ARDL Approach. Finance Research Letters 57: 104211. [Google Scholar] [CrossRef] [Scilit]
- Yang, Junhua, Samuel Kwaku Agyei, Ahmed Bossman, Mariya Gubareva, and Edward Marfo-Yiadom. 2024. Energy, Metals, Market Uncertainties, and ESG Stocks: Analysing Predictability and Safe Havens. The North American Journal of Economics and Finance 69: 102030. [Google Scholar] [CrossRef] [Scilit]
- Yang, Yajie, Longfeng Zhao, Yipin Zhu, Lin Chen, Gangjin Wang, and Chao Wang. 2023. Spillovers from the Russia-Ukraine Conflict. Research in International Business and Finance 66: 102006. [Google Scholar] [CrossRef] [Scilit]
- Yuan, Chen, Runqi Kang, and Lanbiao Liu. 2026. Geopolitical Tensions and Systemic Vulnerability in the Banking Sector: Evidence from China. Finance Research Letters 94: 109679. [Google Scholar] [CrossRef] [Scilit]
- Zhang, Xuan, Minjoo Kim, Cheng Yan, and Yang Zhao. 2024. Default Dependence in the Insurance and Banking Sectors: A Copula Approach. Journal of International Financial Markets, Institutions and Money 91: 101911. [Google Scholar] [CrossRef] [Scilit]
- Zheng, Deyuan, Chunguang Zhao, and Jiaying Hu. 2023. Impact of Geopolitical Risk on the Volatility of Natural Resource Commodity Futures Prices in China. Resources Policy 83: 103568. [Google Scholar] [CrossRef] [Scilit]
- Zheng, Jinlin, Baoyu Wen, Yaohui Jiang, Xiaohan Wang, and Yue Shen. 2023. Risk Spillovers across Geopolitical Risk and Global Financial Markets. Energy Economics 127: 107051. [Google Scholar] [CrossRef] [Scilit]
- Zhou, Mei-Jing, Jian-Bai Huang, and Jin-Yu Chen. 2020. The Effects of Geopolitical Risks on the Stock Dynamics of China’s Rare Metals: A TVP-VAR Analysis. Resources Policy 68: 101784. [Google Scholar] [CrossRef] [Scilit]
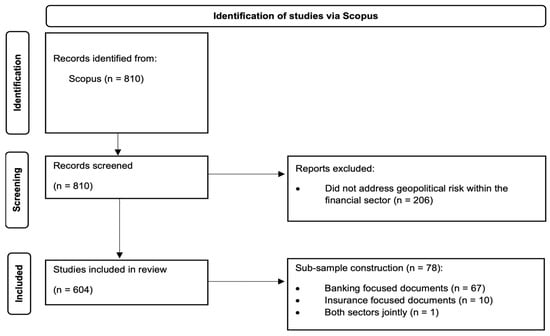
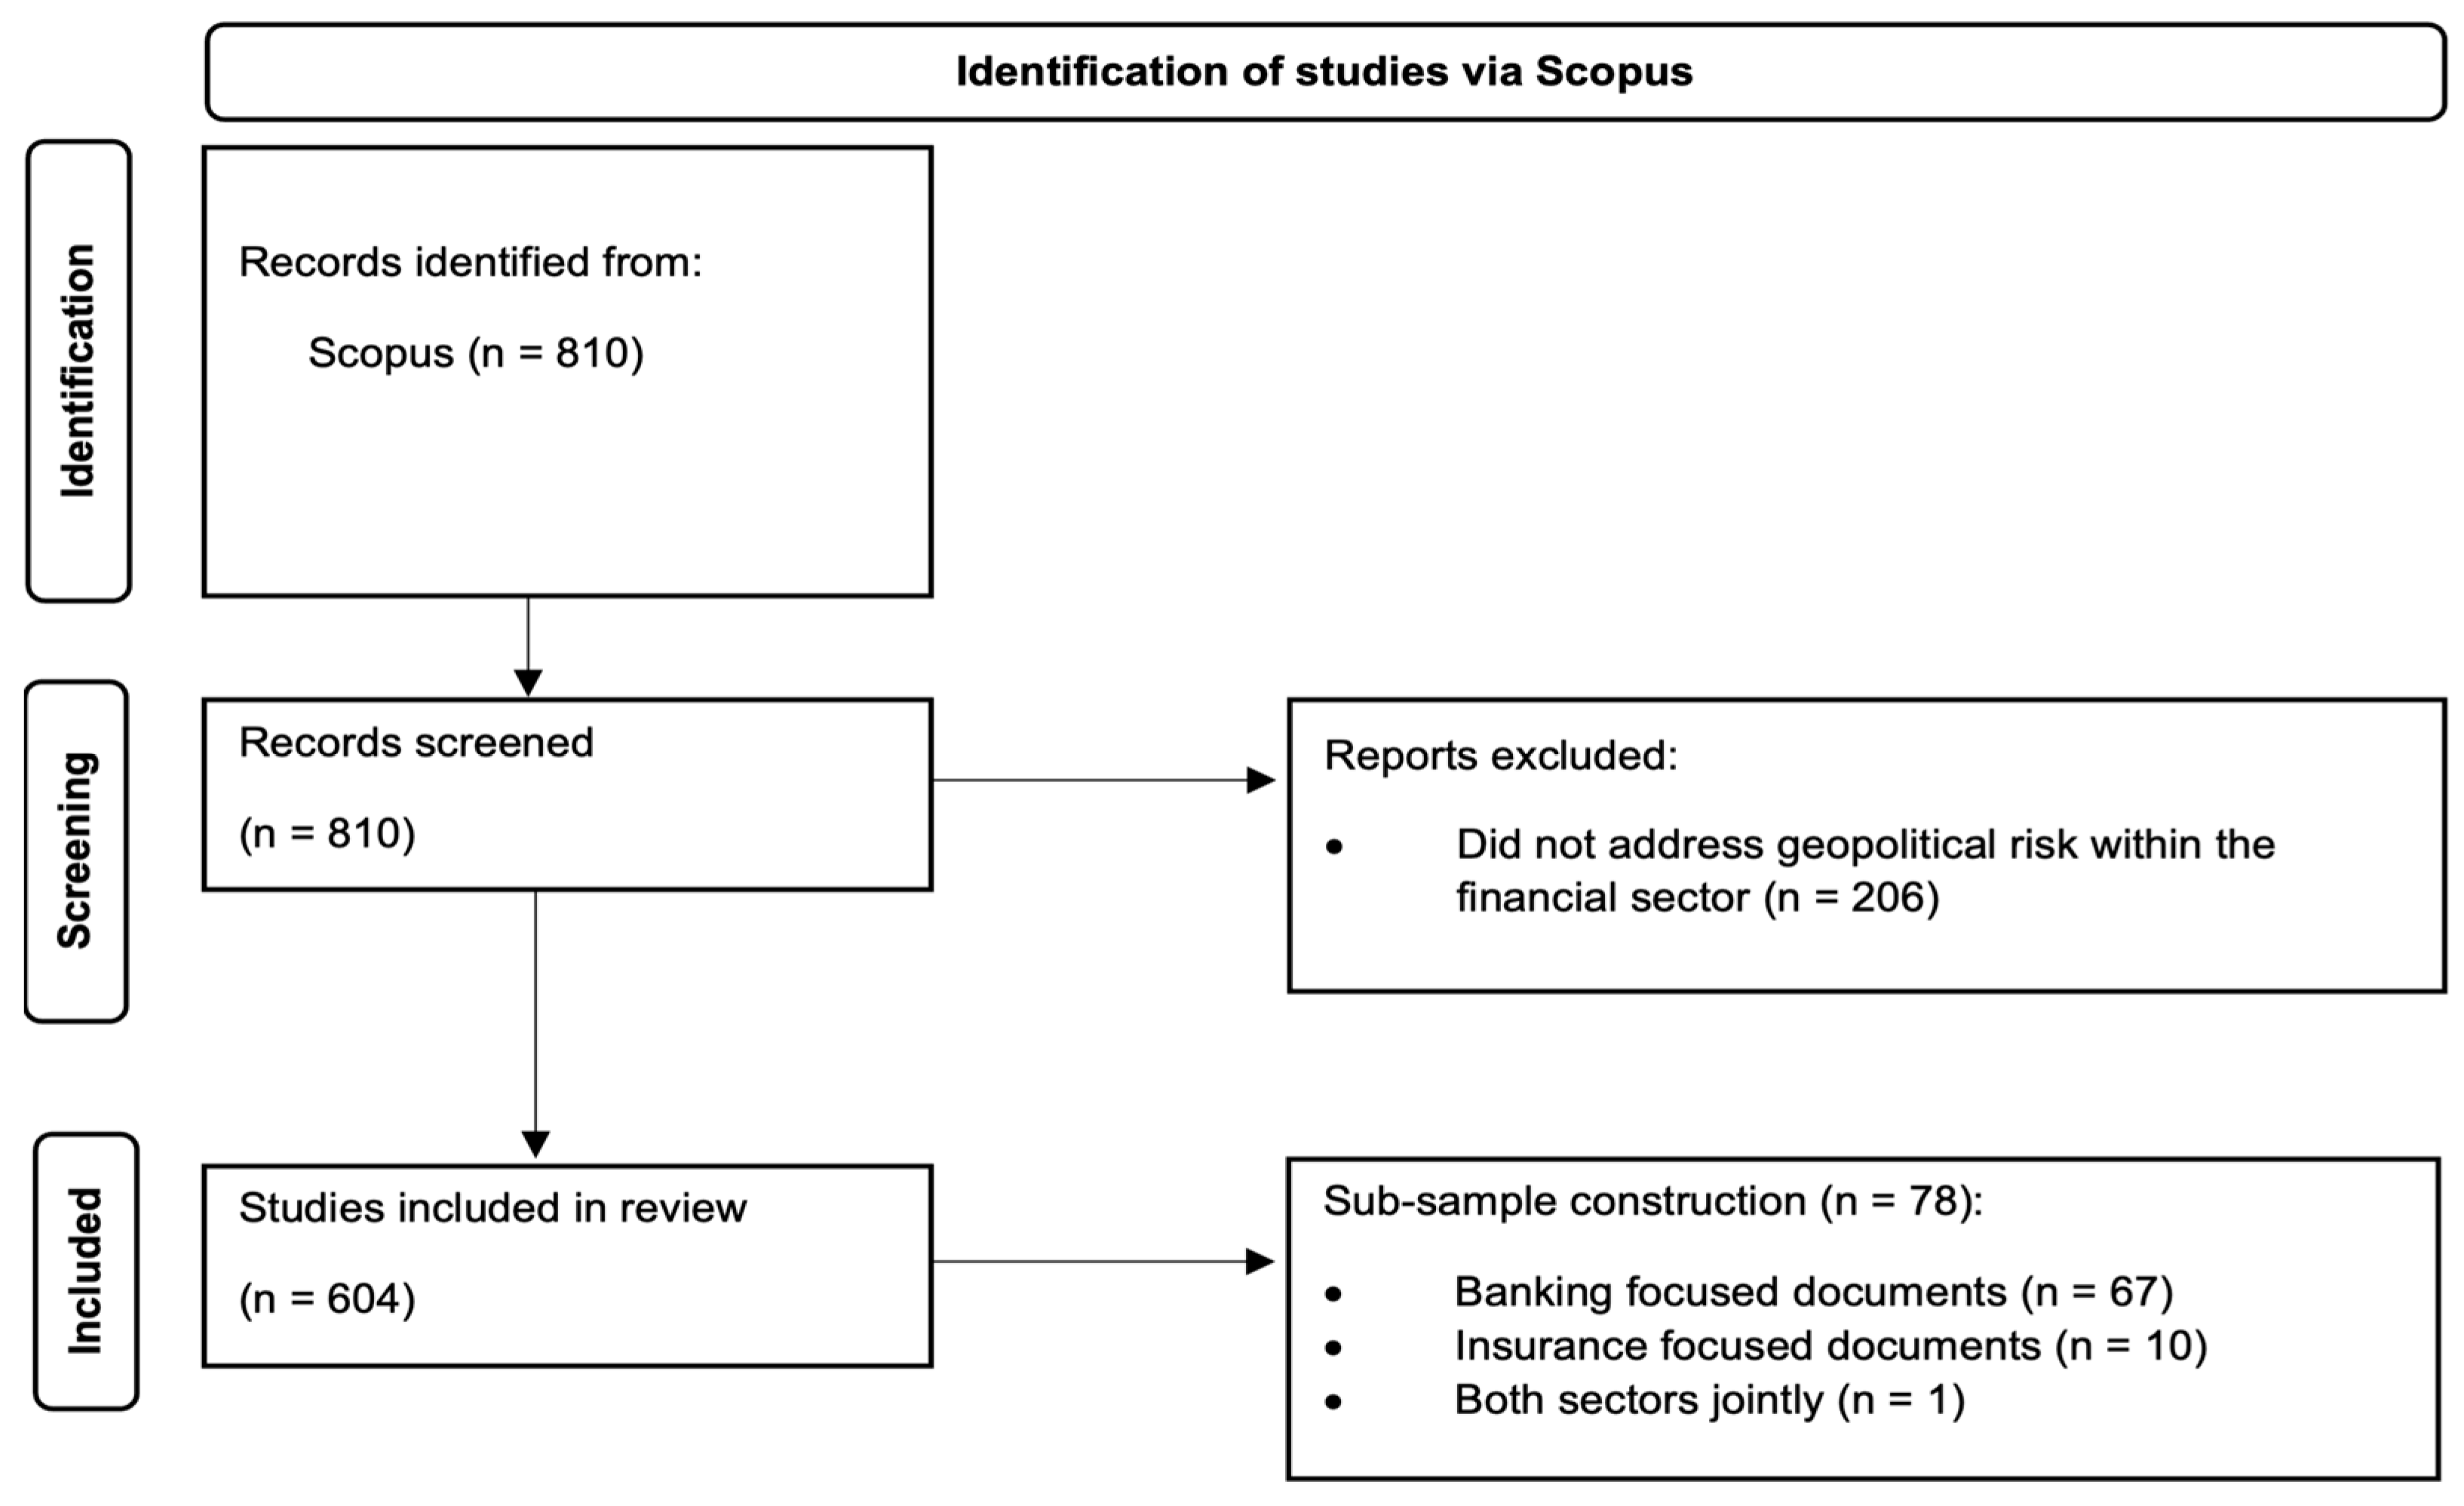
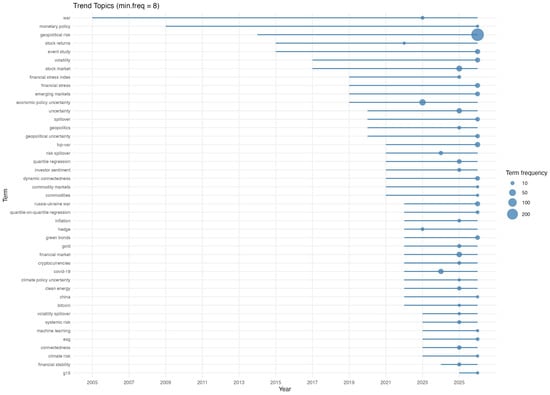
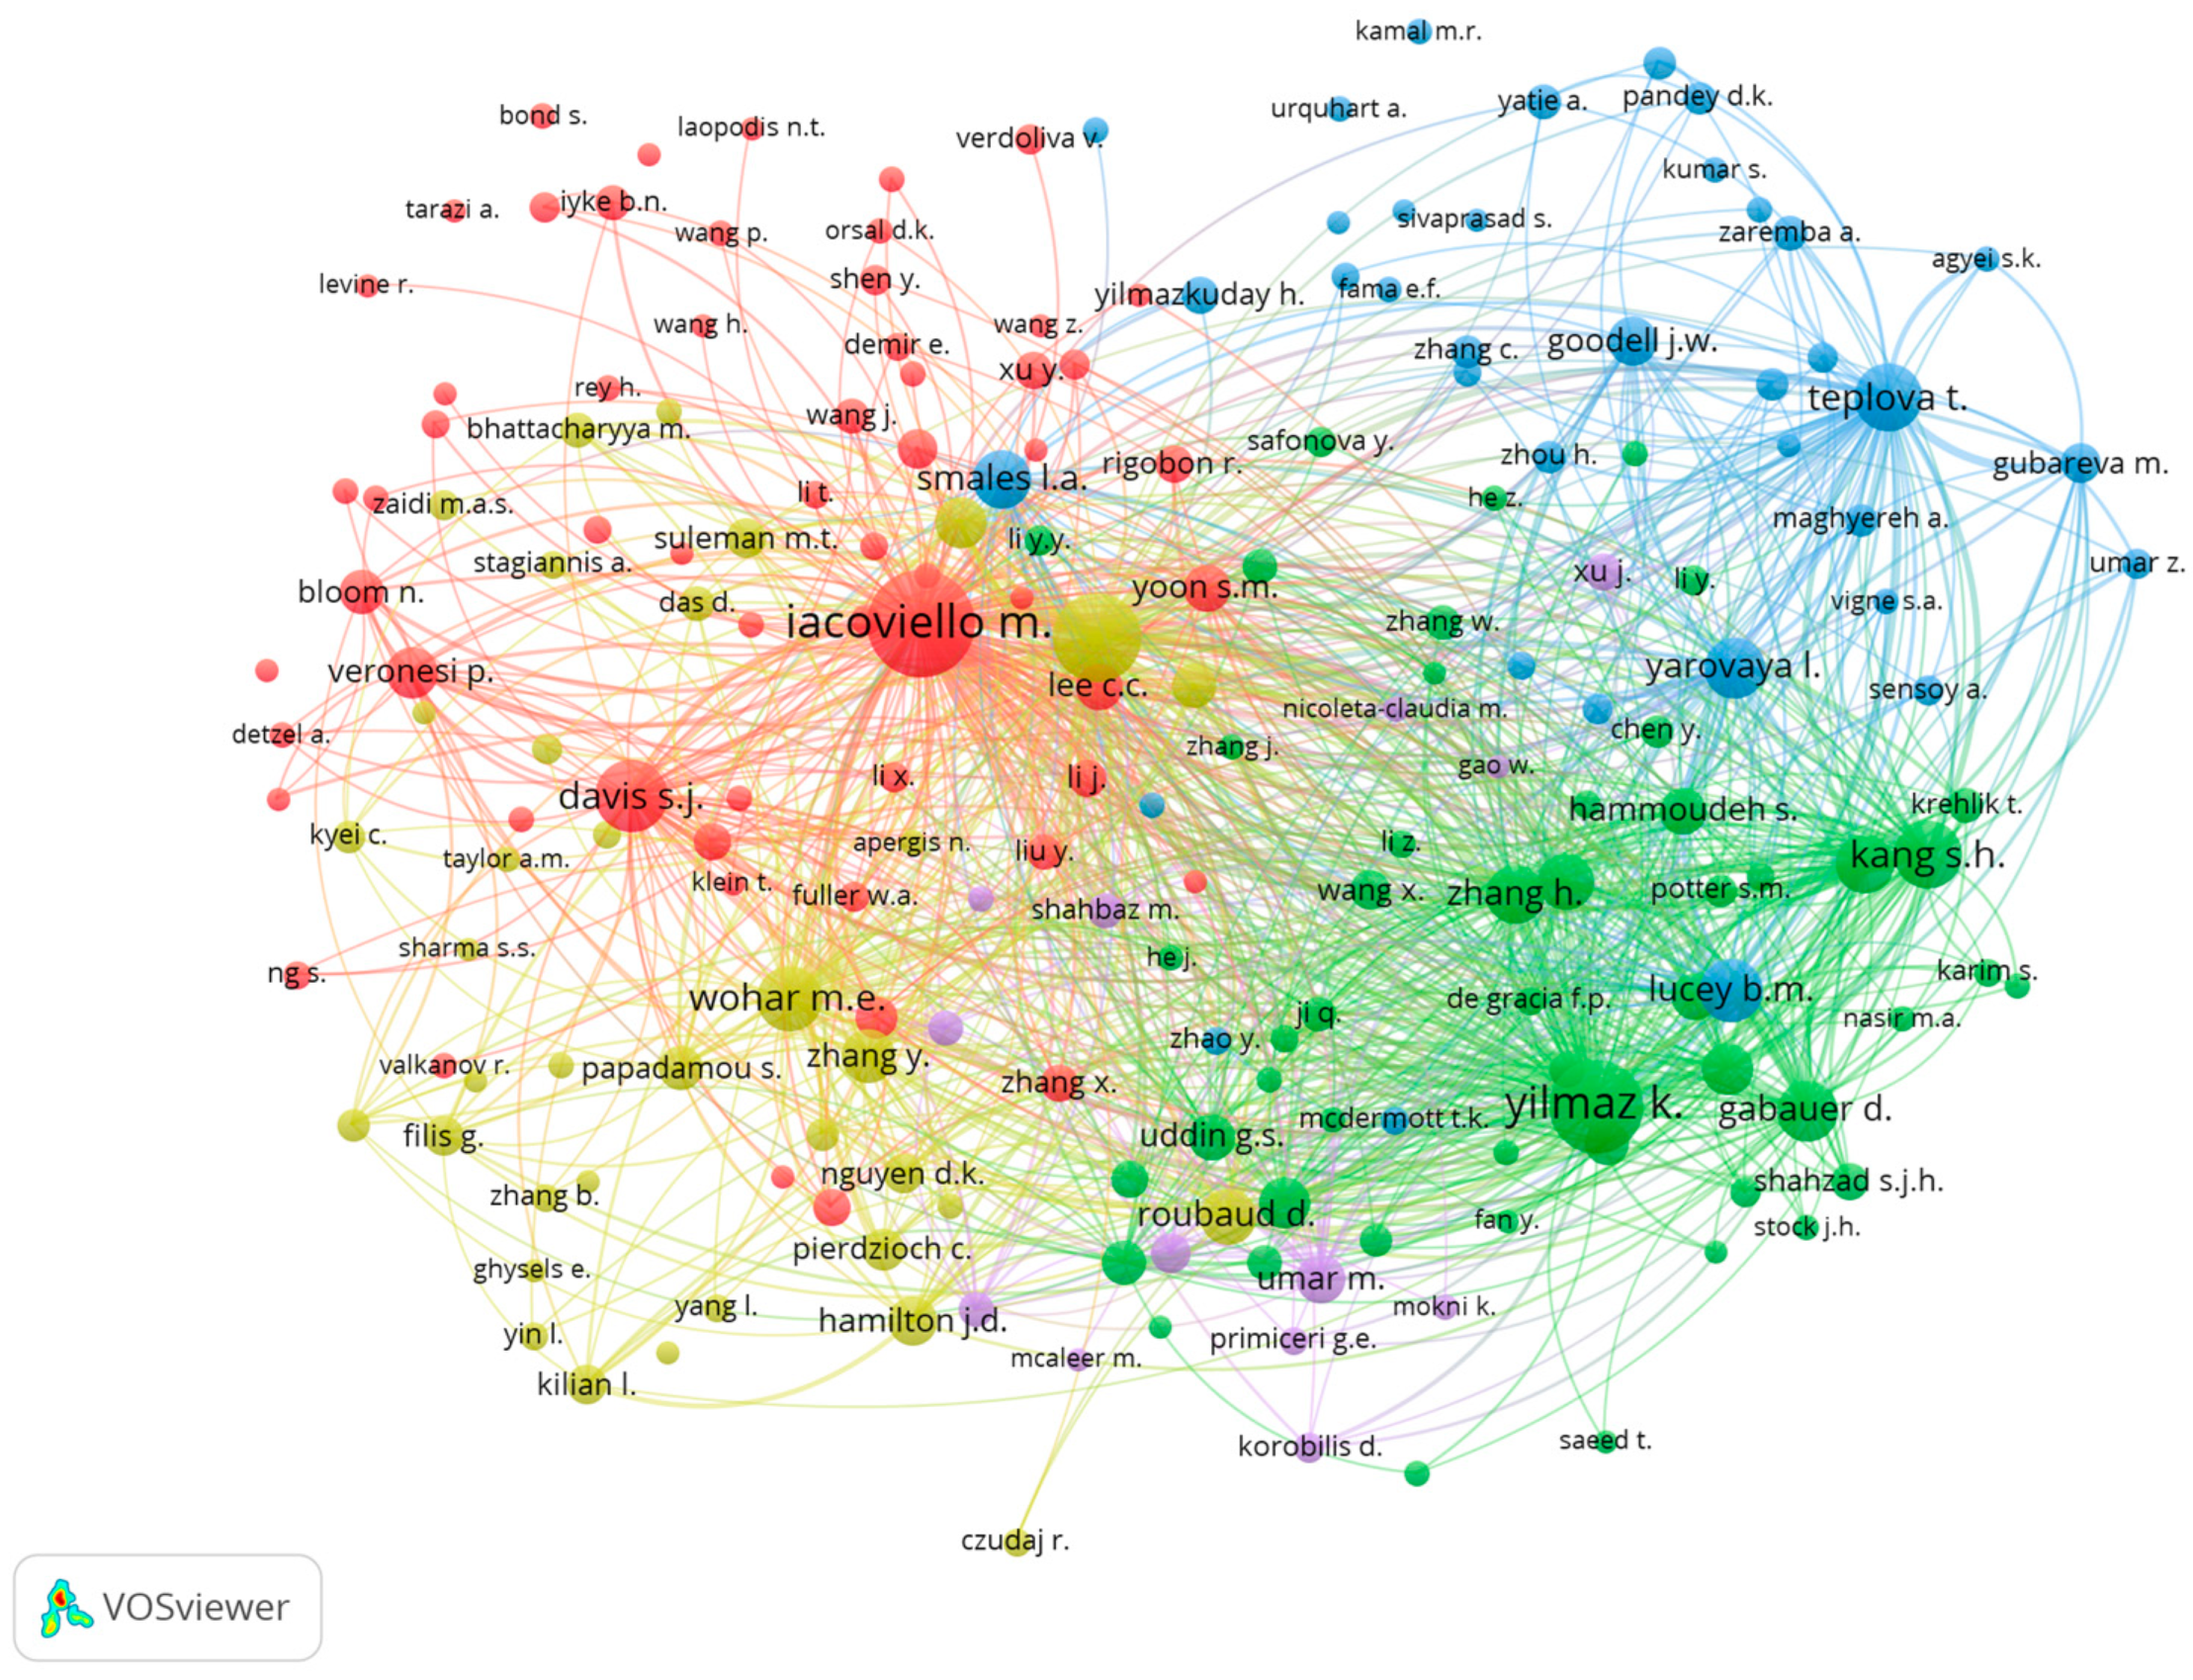
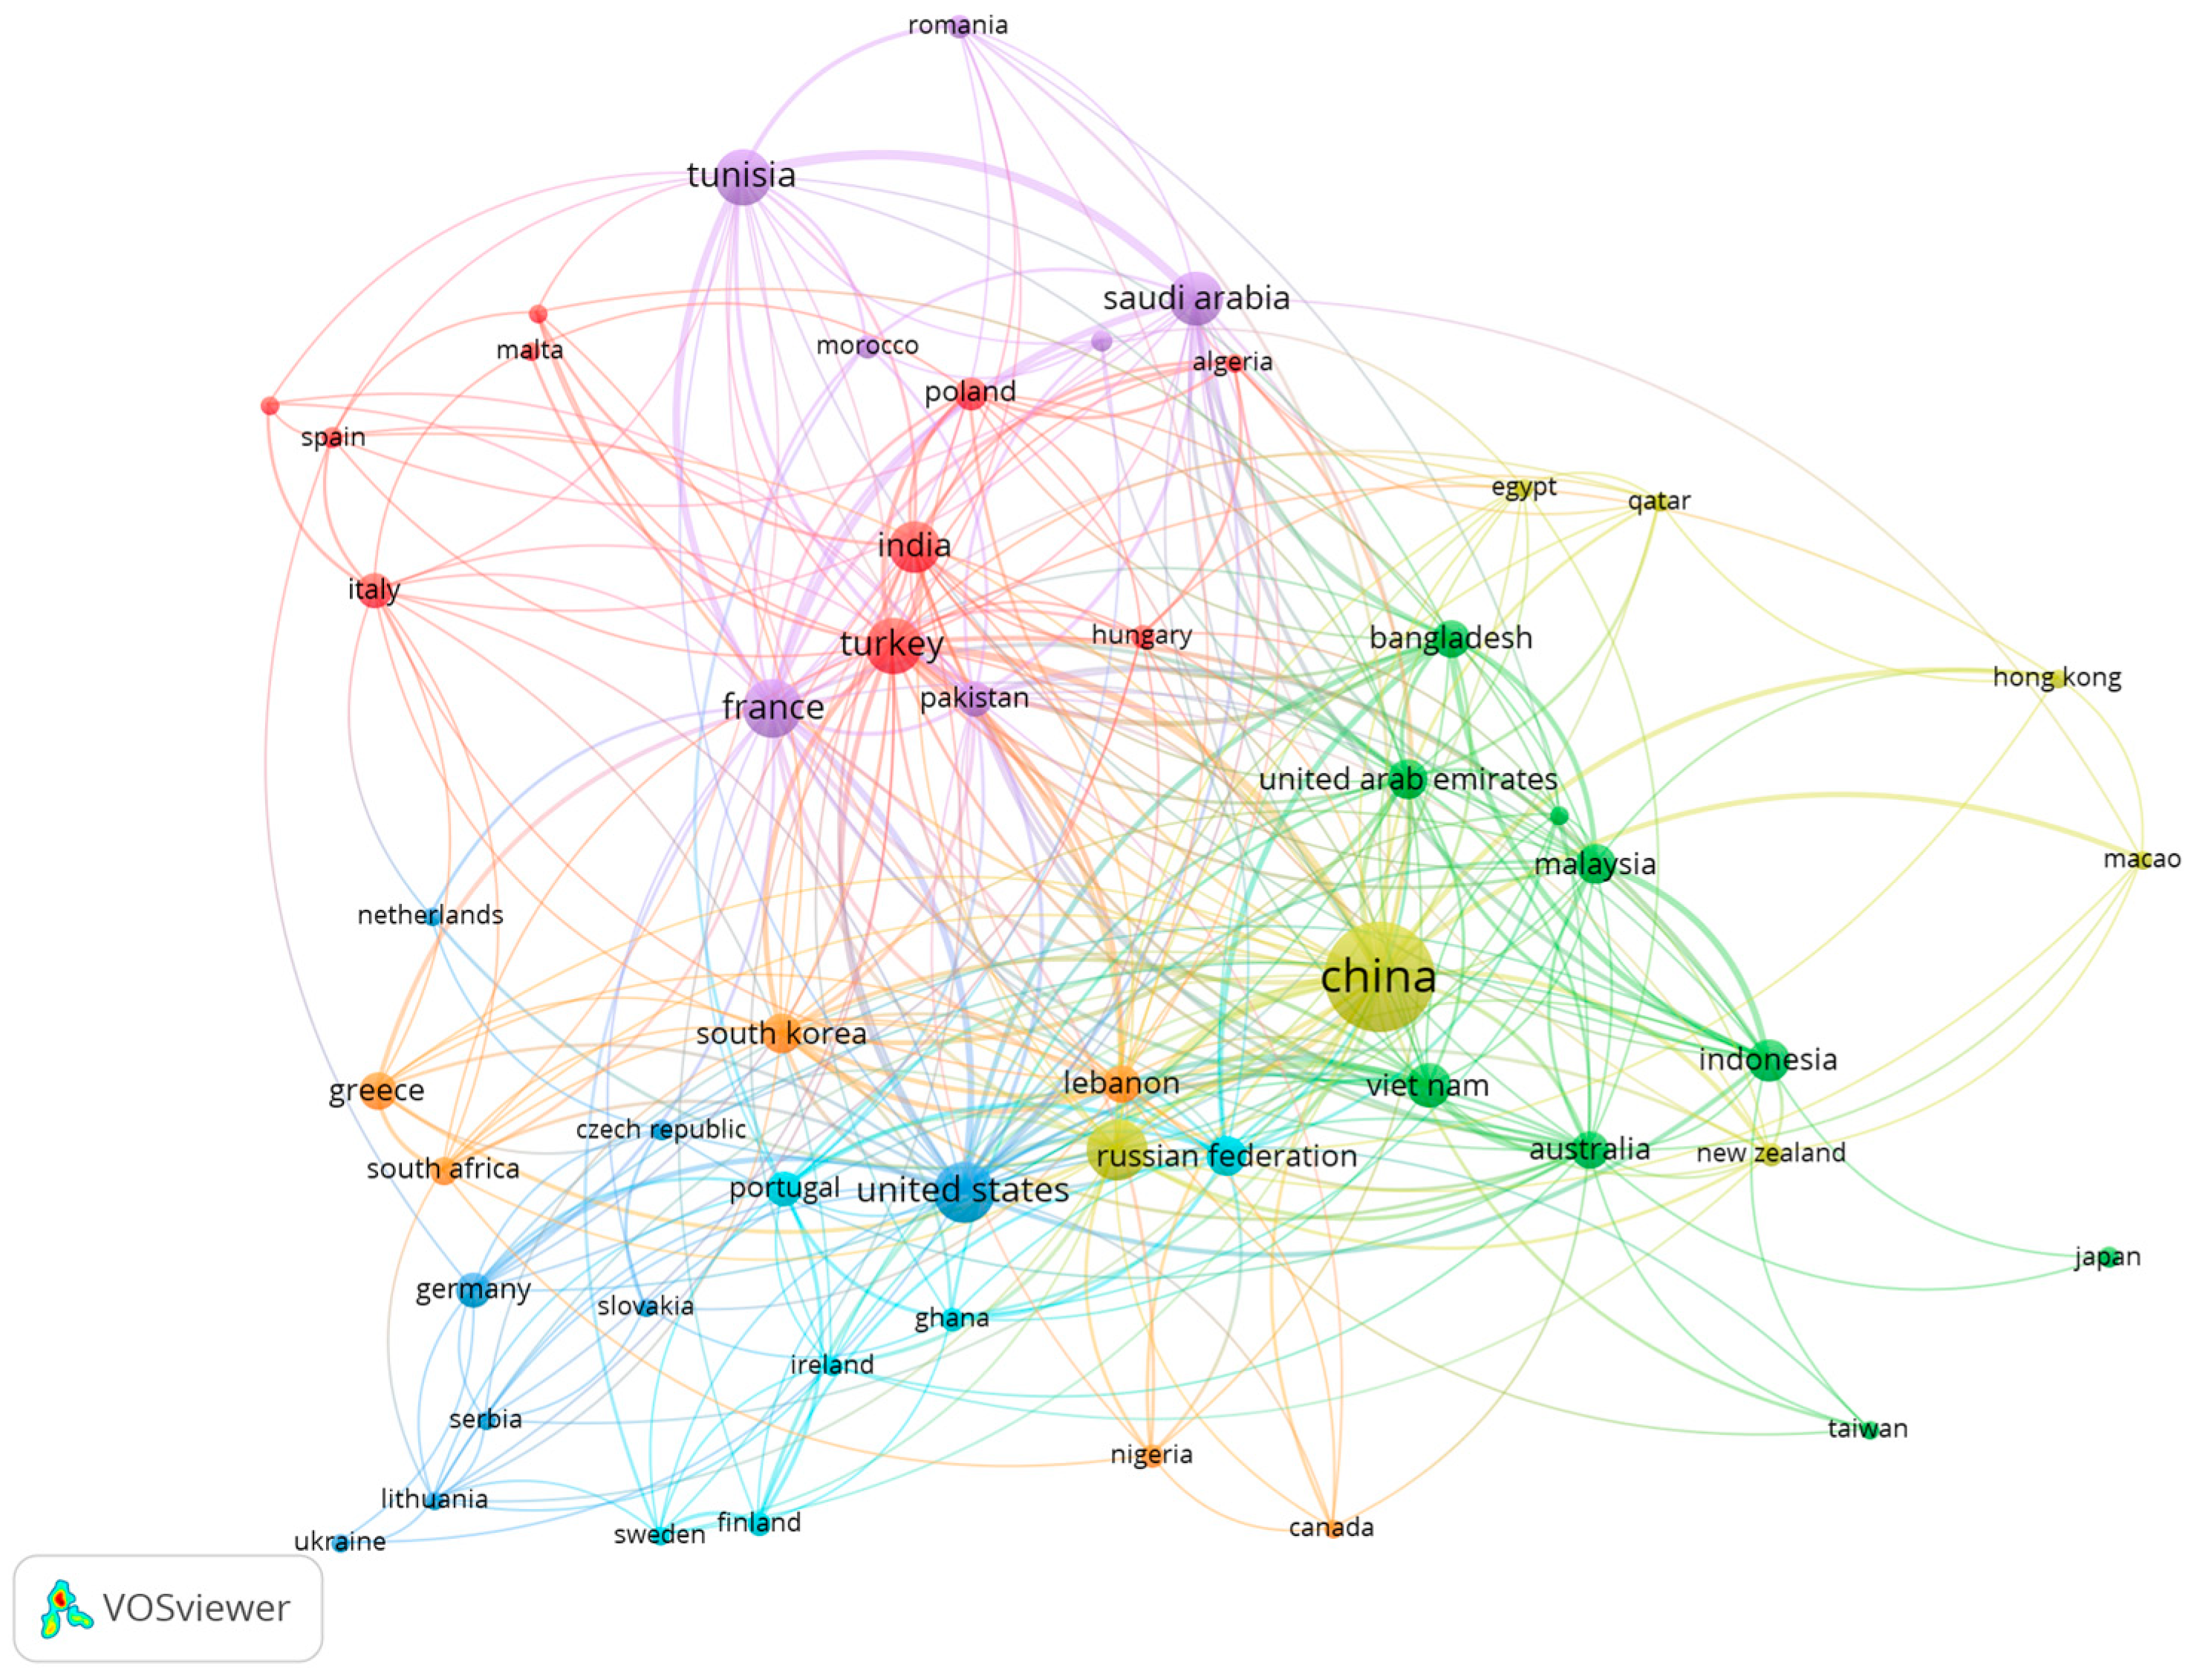
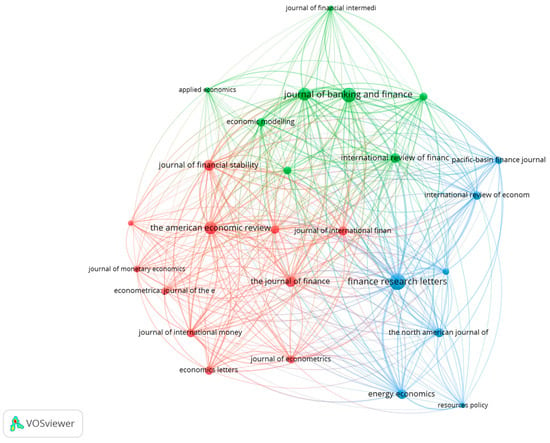
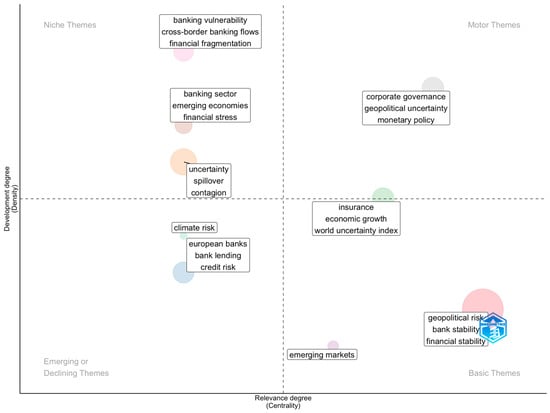

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.