


Abstract
This paper addresses the problem of parameter identification for discrete-time stochastic systems with unknown exogenous inputs. These systems form an important class of dynamic stochastic system models used to describe objects and processes under a high level of a priori uncertainty, when it is not possible to make any assumptions about the evolution of the unknown input signal or its statistical properties. The main purpose of this paper is to construct a new SVD-based modification of the existing Gillijns and De Moor filtering algorithm for linear discrete-time stochastic systems with unknown exogenous inputs. Using the theoretical results obtained, we demonstrate how this modified algorithm can be applied to solve the problem of parameter identification. The results of our numerical experiments conducted in MATLAB confirm the effectiveness of the SVD-based parameter identification method that was developed, under conditions of unknown exogenous inputs, compared to maximum likelihood parameter identification when exogenous inputs are known.
Keywords:
unknown exogenous input; simultaneous input and state estimation; SVD filter; parameter identification; instrumental identification criterion MSC:
93E12
1. Introduction
The singular value decomposition (SVD) is the most significant matrix factorization technique because it produces numerically stable factors and is always applicable to any rectangular or square matrix, including those close to singular [1]. SVD is a highly popular and powerful approach for solving real-world problems in various fields of research.
Our analysis of the specialized literature has revealed that the singular value decomposition method has been actively employed in recent years in the fields for parameter identification and discrete-time filtering in stochastic dynamical systems.
To the best of our knowledge, for linear discrete-time stochastic systems with additive Gaussian noises, for which the Kalman filter (KF) is the optimal parameter estimation method, the idea of constructing a numerically stable modification of the KF with the use of SVD factorization was first proposed in [2]. The authors named their variant of the SVD filter the V- filter. In [3], the V- filter was applied to solve the parameter identification problem for linear discrete-time stochastic systems with additive noises. A little later, another variants of the SVD filter corresponding to the conventional KF and extended KF filters were proposed in [4,5].
Furthermore, in order to eliminate some drawbacks of the previous versions of the SVD filter, an improved version of the SVD KF was proposed in [6]. It differs from other known variants is that this modification of the KF is free from the conditions of positive semi-definiteness of the state noise covariance matrix and positive definiteness of the measurement noise covariance matrix, required both in the conventional KF and in all its square-root modifications [7,8]. As shown in [6], this variant of the SVD filter showed the best results in terms of numerical stability against machine roundoff errors. Additionally, some numerically robust SVD-based Kalman filter implementations were explored in [9]. For some extensions of classical state-space models, i.e., linear time-invariant multiple-input, multiple-output systems, and linear pairwise Markov models with the related pairwise KF, the SVD-based state, and parameter estimation approach were proposed in [10].
Parameter estimation methods based on SVD factorization have also been developed for a class of nonlinear stochastic systems. SVD-based extended [11], cubature [12], and extended-cubature [13] Kalman filters were proposed for state estimation in continuous-discrete nonlinear stochastic systems. Advanced square-root cubature Kalman filters, which are based on the SVD factorization and sequential processing, were suggested in [14]. The sequential cubature KF avoids the matrix inversion operation involved in the original filters and directly propagates the square-root factor in each iteration of the filtering algorithm. The authors of [15] developed the SVD iterated extended Kalman filter to analyze event count time series, and applied it to the daily number of seizures in drug-resistant epilepsy patients’ time series. Improved SVD-Adaptive Unscented Kalman Filter algorithm with adaptive rule for the fast identification of thermal errors of machine tool spindle was proposed in [16].
For discrete-time linear stochastic systems with multiplicative and additive noises, discrete-time filtering, and parameter identification methods based on the SVD factorization were recently proposed in [17].
Currently, the SVD approach has proven its effectiveness in solving many different problems. For example, it was used to solve the problem of identifying parameters for linear discrete-time stochastic systems [18], as well as the problems of Kalman filtering for inertial measurement unit readings [19], research of MIMU/GPS integrated navigation [20], adaptive KF filtering for some engineering applications [21], and an indoor positioning and tracking based on angle-of-arrival using a dual-channel array antenna [22]. It was also used to determine attitude and angle rate of gyroless spacecraft only using a star sensor [23], estimate GARCH-in-Mean(1,1) models [10], model epileptic seizures count time series with external inputs [24], and identify parameters of convection-diffusion transport models [25].
All the above results relate to the case of stochastic systems with known exogenous (or control) inputs. However, stochastic systems with unknown exogenous inputs form an important class of dynamic stochastic systems used to model objects and processes in case of a high level of a priori uncertainty. For example, this may be the case for problems related to fault detection and isolation or estimating geophysical processes when there is no information about the input signals of the system.
One of the main challenges for such systems is the simultaneous estimation of unknown inputs and system states. The first solution in the form of an optimal recurrent filter for estimating the state vector based on the assumption that a priori information about unknown input signals is not available, was developed in [26]. Further, S. Gillijns and B. De Moor [27] developed Kalman-like methods for discrete-time filtering in stochastic systems with unknown input signals. They have proposed a recurrent filtering algorithm for the simultaneous estimation of the system state vector and unknown input signals. The estimate of the input signal is obtained from the innovation using least-squares estimation. S. Gillijns and B. De Moor have transformed the state estimation problem into a standard Kalman filtering problem for a system with correlated process and measurement noise. They proved that their approach yields the same state update as in [26,28] and the same input estimate as in [29]. The authors also showed that the optimal input estimate within the class of all linear unbiased estimates can be written in the proposed recursive form.
It is well known that for discrete-time linear stochastic systems, the Kalman-type filters can be prone to numerical instabilities due to different factors [7]. One approach to addressing this issue is to employ numerically stable filtering techniques based on different covariance or information matrices factorization methods. However, such modifications for systems with unknown input signals are largely unknown. One of the first attempts was in [30], where a square-root filtering method in the presence of unknown inputs was proposed. It should be noted that the application of the square-root method requires the strong positive definiteness of the noise covariance matrices. This limitation can be overcome by using the SVD decomposition. As far as we know, the SVD-based approach has not yet been used to construct methods for the simultaneous estimation of an unknown input signal and the state vector of discrete-time stochastic systems.
Thus, the main goal of this paper is to propose a novel SVD-based modification of the existing Gillijns and De Moor (GDM) filtering algorithm for linear discrete-time stochastic systems with unknown exogenous inputs. We also will demonstrate how this modified algorithm can be used to solve the parameter identification problem.
The paper is organized as follows. Section 2 describes the problem of simultaneous input and state estimation for linear discrete-time stochastic systems with unknown exogenous inputs, and formulates the existing solution to this problem—the GDM filtering algorithm. Section 3 contains the main result of the paper, which is a novel SVD-based modification of the GDM filtering algorithm for linear discrete-time stochastic systems with unknown exogenous inputs. Three lemmas and a theorem are proved, which state algebraic equivalence between this SVD method and the “conventional” GDM filtering algorithm. Additionally, the problem of parameter identification under conditions of unknown exogenous inputs is explored. Finally, Section 4 demonstrates how the proposed SVD-based algorithm can be applied to solve the parameter identification problem for a convection-diffusion model with unknown boundary conditions and noisy measurements. Section 5 concludes the paper.
2. Methods
2.1. The Problem of Simultaneous Input and State Estimation for Linear Discrete-Time Stochastic Systems with Unknown Exogenous Inputs
Consider the discrete-time linear time invariant (LTI) stochastic system
where is the system state vector; is an unknown exogenous input; is the measurements vector; matrices , , , ; K is the number of measurements; initial state , additive model disturbance and measurement noise are mutually independent. Covariance matrices Q and R of and are positive semi-definite.
In this paper, we consider system (1) in the case when exogenous input is completely unknown, i.e., there is no prior knowledge about the dynamics or statistic characteristics of .
In [27], the authors proposed two variants of the optimal filtering algorithm for simultaneous input and state estimation of the linear discrete-time stochastic systems. They differ in the step, which is measurement update of the state vector estimate. The first variant of the algorithm allows for computing a minimum-variance unbiased (MVU) estimate of the input vector and an unbiased estimate of the state vector . In the second version of the algorithm, due to more complex calculations, an MVU estimate of the state vector is obtained.
Before formulating the GDM filtering algorithm, we have to assume that the following sufficient condition for the existence of an unbiased state estimator is satisfied [28]:
Assumption (2) implies and .
2.2. Gillijns and De Moor Filtering Algorithm for the Discrete-Time Stochastic Systems with Unknown Exogenous Inputs
Let denote the identity matrix of size n. Then the filtering algorithm for the system (1) can be written as following Algorithm 1.
| Algorithm 1: Gillijns and De Moor algorithm (GDM). |
Initialization. , . For
do I. Time Update step. Find a priori estimation error covariance matrix and a priori estimate of the state vector as follows:
II. Input Estimation step. Find an unknown input estimate as follows: III. Measurement Update step. Using the a priori estimates , and input estimate , find a posteriori values and as follows:
End. |
3. Main Result
Consider the SVD factorization [31]. Any matrix of rank s can be represented as
where , are unitary matrices, means conjugate and transposed to , and is a real non-negative diagonal matrix. The values are singular values of the matrix . Note that if and/or , some of the zero submatrices in are absent.
Since the error covariance matrix P is symmetric positive semi-definite matrix, the spectral decomposition produces which is also a SVD factorization. In this case, the diagonal matrix contains the singular values of P. SVD decomposition is a very robust algorithm to factorize any covariance matrix especially when it becomes nearly singular [8].
In the next subsection, we present our main result—the new SVD-based filtering algorithm for discrete-time stochastic systems with unknown exogenous inputs. To the best of our knowledge, this algorithm is a firstly constructed SVD-based modification (Algorithm 2) of the GDM algorithm (Algorithm 1).
| Algorithm 2: SVD-based modification of the Gillijns and De Moor algorithm (SVD-GDM). |
Initialization. Apply the SVD factorization , , . Set , , . For
do I. Time Update step. I.1. Find a priori estimate of the state vector as follows: I.2. Build the pre-array and apply the SVD factorization in order to obtain the SVD factors as follows: II. Input Estimation step. II.1. Build the pre-arrays and apply the SVD factorization in order to obtain the SVD factors and as follows: II.2. Compute
III. Measurement Update step. III.1. Compute
III.2. Build the pre-arrays and apply the SVD factorization in order to obtain the SVD factors and as follows: III.3. Find a posteriori estimate as follows: End. |
3.1. The New SVD-Based Filtering Algorithm for Systems with Unknown Exogenous Inputs
Remark 1.
In algorithm SVD-GDM, – are left orthogonal matrices of the corresponding SVD factorizations.
Lemma 1.
Time update steps of the GDM and SVD-GDM algorithms for system (1) are algebraically equivalent.
Proof.
Lemma 2.
Input estimation steps of the GDM and SVD-GDM algorithms are algebraically equivalent.
Proof.
Lemma 3.
Measurement update steps of the GDM and SVD-GDM algorithms are algebraically equivalent.
Proof.
Theorem 1.
Algorithms GDM and SVD-GDM are algebraically equivalent.
Proof of the Theorem 1 directly follows from proofs of Lemmas 1–3.
3.2. Application of the New SVD-Based Filtering Algorithm to the Problem of Parameter Identification
In practical applications, the matrices characterizing discrete-time linear stochastic system (1) are often known up to certain parameters. Consider an important problem of parameter identification [32]. Assume that elements of system matrices F, G, Q, and R are functions of unknown system parameters vector . The last needs to be identified. For the sake of simplicity, instead of , , etc., we will write F, G, etc.
In this paper, we pose the problem of numerical identification of the system model parameter by available measurements . To solve the problem, we will use a new instrumental identification criterion which recently has been proposed in [33].
As an original identification criterion we consider the functional
where is an estimation error of the state vector , is the estimate that can be evaluated within the Algorithms 1 or 2 for a given value of . This original functional (28) is not suitable for solving the parameter identification problem due to it is not instrumental, i.e., it is not practically feasible because the estimation errors, , are not available for direct observation. In addition, the presence of unknown exogenous inputs significantly complicates the problem.
Let . Following [33], construct an observable process as
where .
Then the instrumental identification criterion will be the next:
Theorem 2
([33]). Let matrices H and B in (1) not depend on θ and , rank. Then and have one and the same minimizer and the following relation holds
where
does not depend on θ.
The proof can be found in [33].
Replacing the expectation operator in (30) by the uniform time averaging, we can write the workable identification criterion which can be calculated in practice:
For solving the problem of identifying parameters for the model (1), we use as the objective function, which minimization can be provided by various known numerical methods [34]. Thus, the estimate of the unknown parameter is calculated in the numerical identification algorithm as
To obtain the values of (32), one can use Equation (29) and Algorithms 1 or 2 for a current estimate of and given K.
4. Numerical Results and Its Discussion
4.1. Parameter Identification Problem
To show the applicability of the proposed approach, let us consider the following convection-diffusion model
or
where is the spatial coordinate; is a time variable; is the desired function, for example, the concentration of some substance in a fluid flow at a point with coordinate x at time t; v is the convection velocity; is the diffusion coefficient; (34) is the initial condition; and functions , , and coefficient determine boundary conditions (35), (36). Thus, models are considered either with boundary conditions of the first kind or with mixed boundary conditions of the first and third kind.
Consider the problem of parameter identification, which involves determining the parameters v and in Equation (33), based on noisy measurements of the function at various points along a segment under consideration, at different points in time. In this case, is a two-dimensional vector.
Following [25], let us move from the original continuous model to a discrete-time model. This model is described by a linear dynamic system in state space. Let us define a finite-difference grid in the space-time domain , where
Let us denote , , , . Replacing the partial derivatives in Equations (33)–(36) with their finite-difference approximations, for boundary conditions (35), we obtain the discrete-time linear dynamic system
and in the case of boundary conditions (36), we obtain
Both systems (37) and (38) are discrete-time, linear dynamic systems in which the boundary conditions are included in a two-dimensional input vector . The coefficients in the matrices and of both systems are given by
where , . Note that in these systems, the coefficients of matrix B, which depend on the parameter , can be included in the input vector .
4.2. Numerical Example
Now let us consider the following example
or
where , . Thus, , , , , .
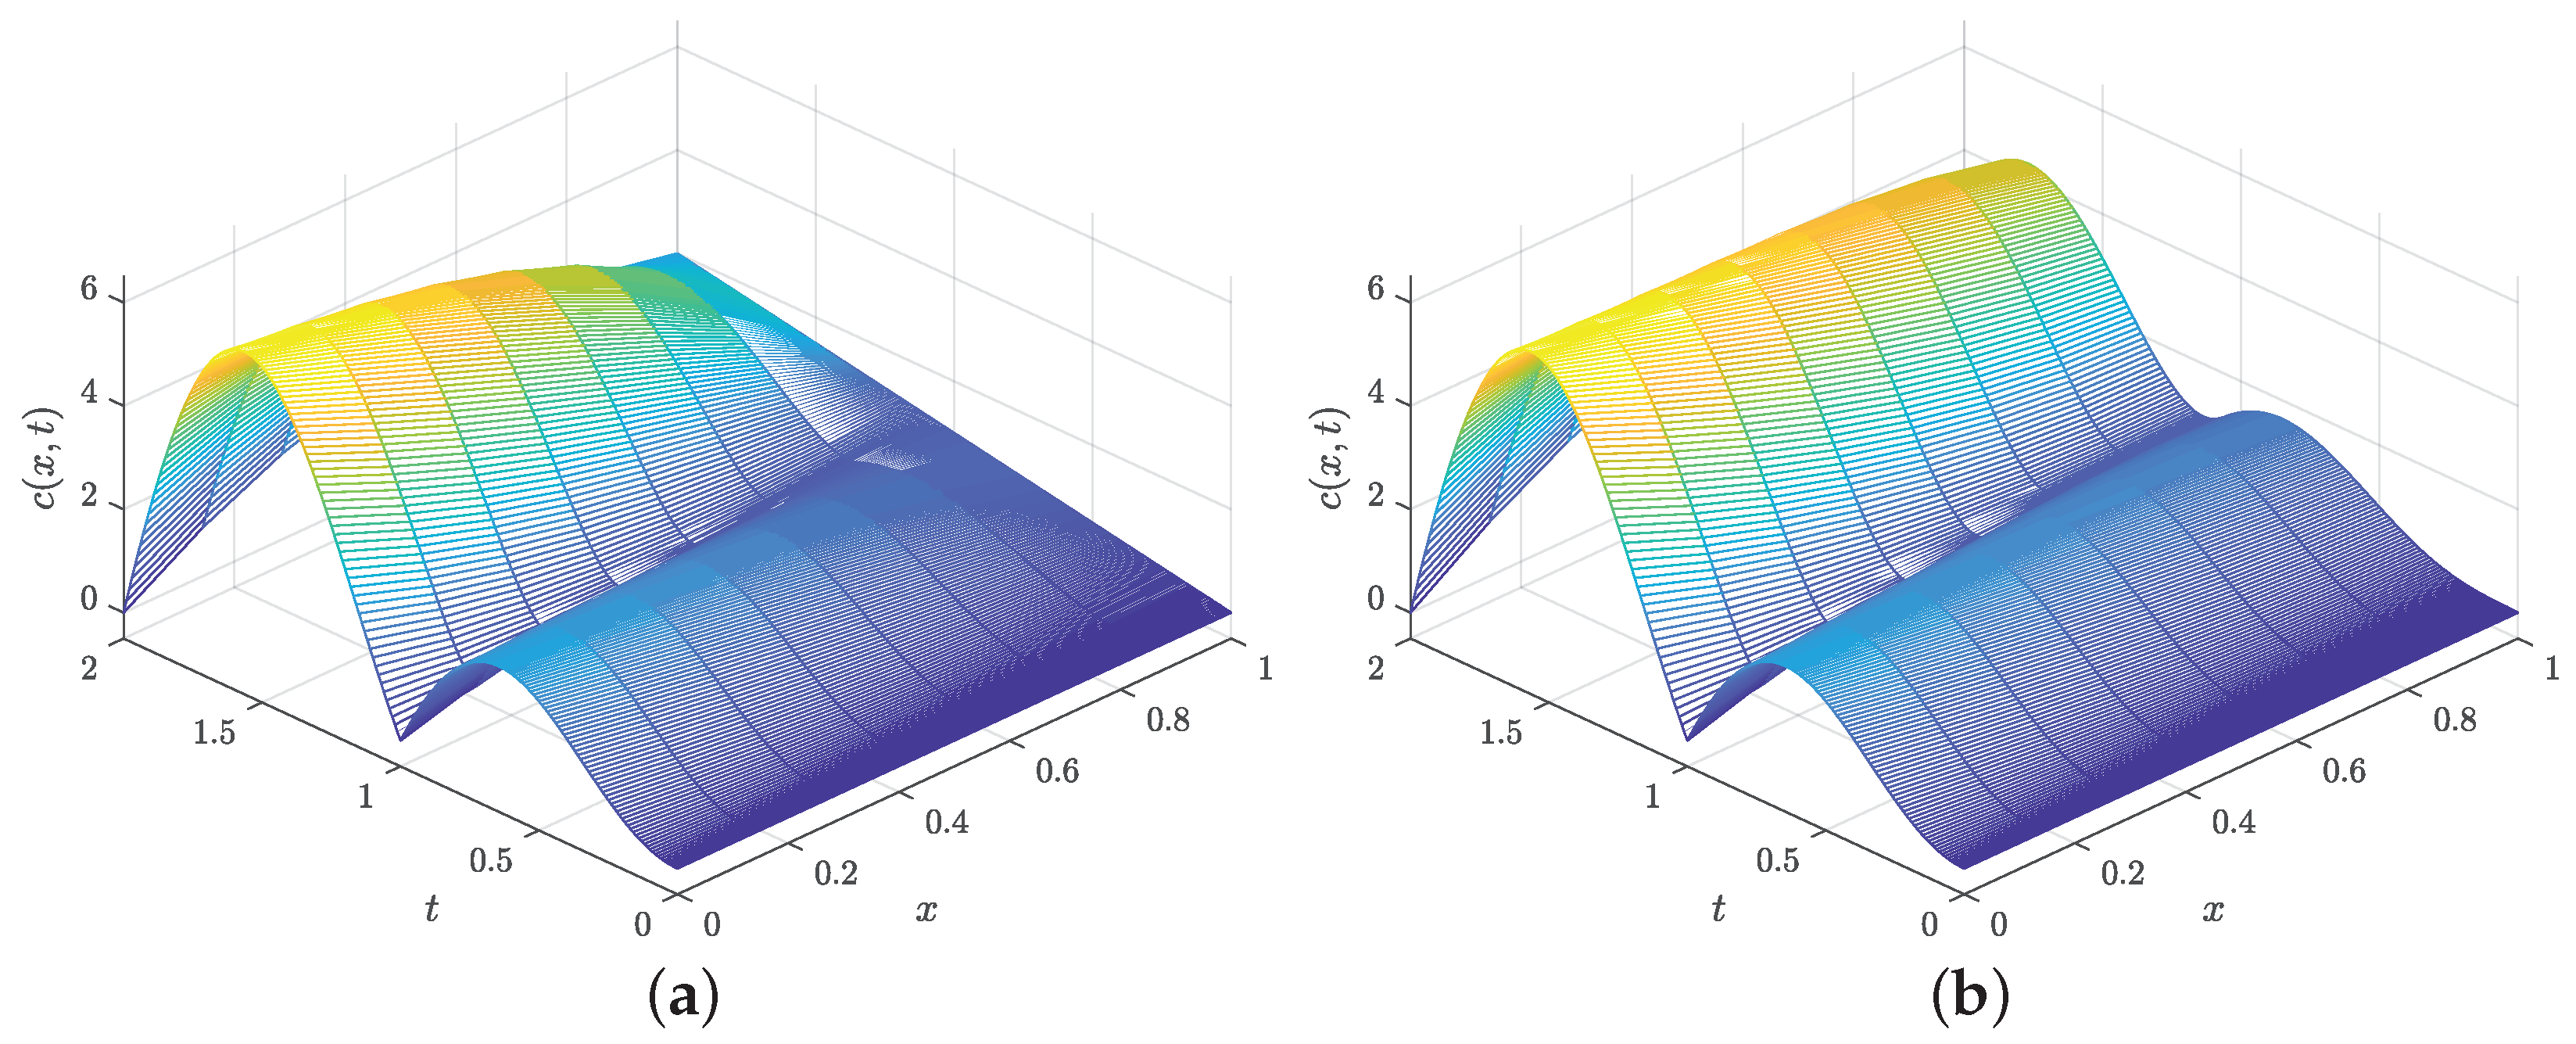
We have simulated the identification process on a grid of size (i.e., and ) using the MATLAB R2017a. Solutions of Equation (39) obtained by the finite-difference method for different boundary conditions are presented in Figure 1.
Consider the following measurement scheme
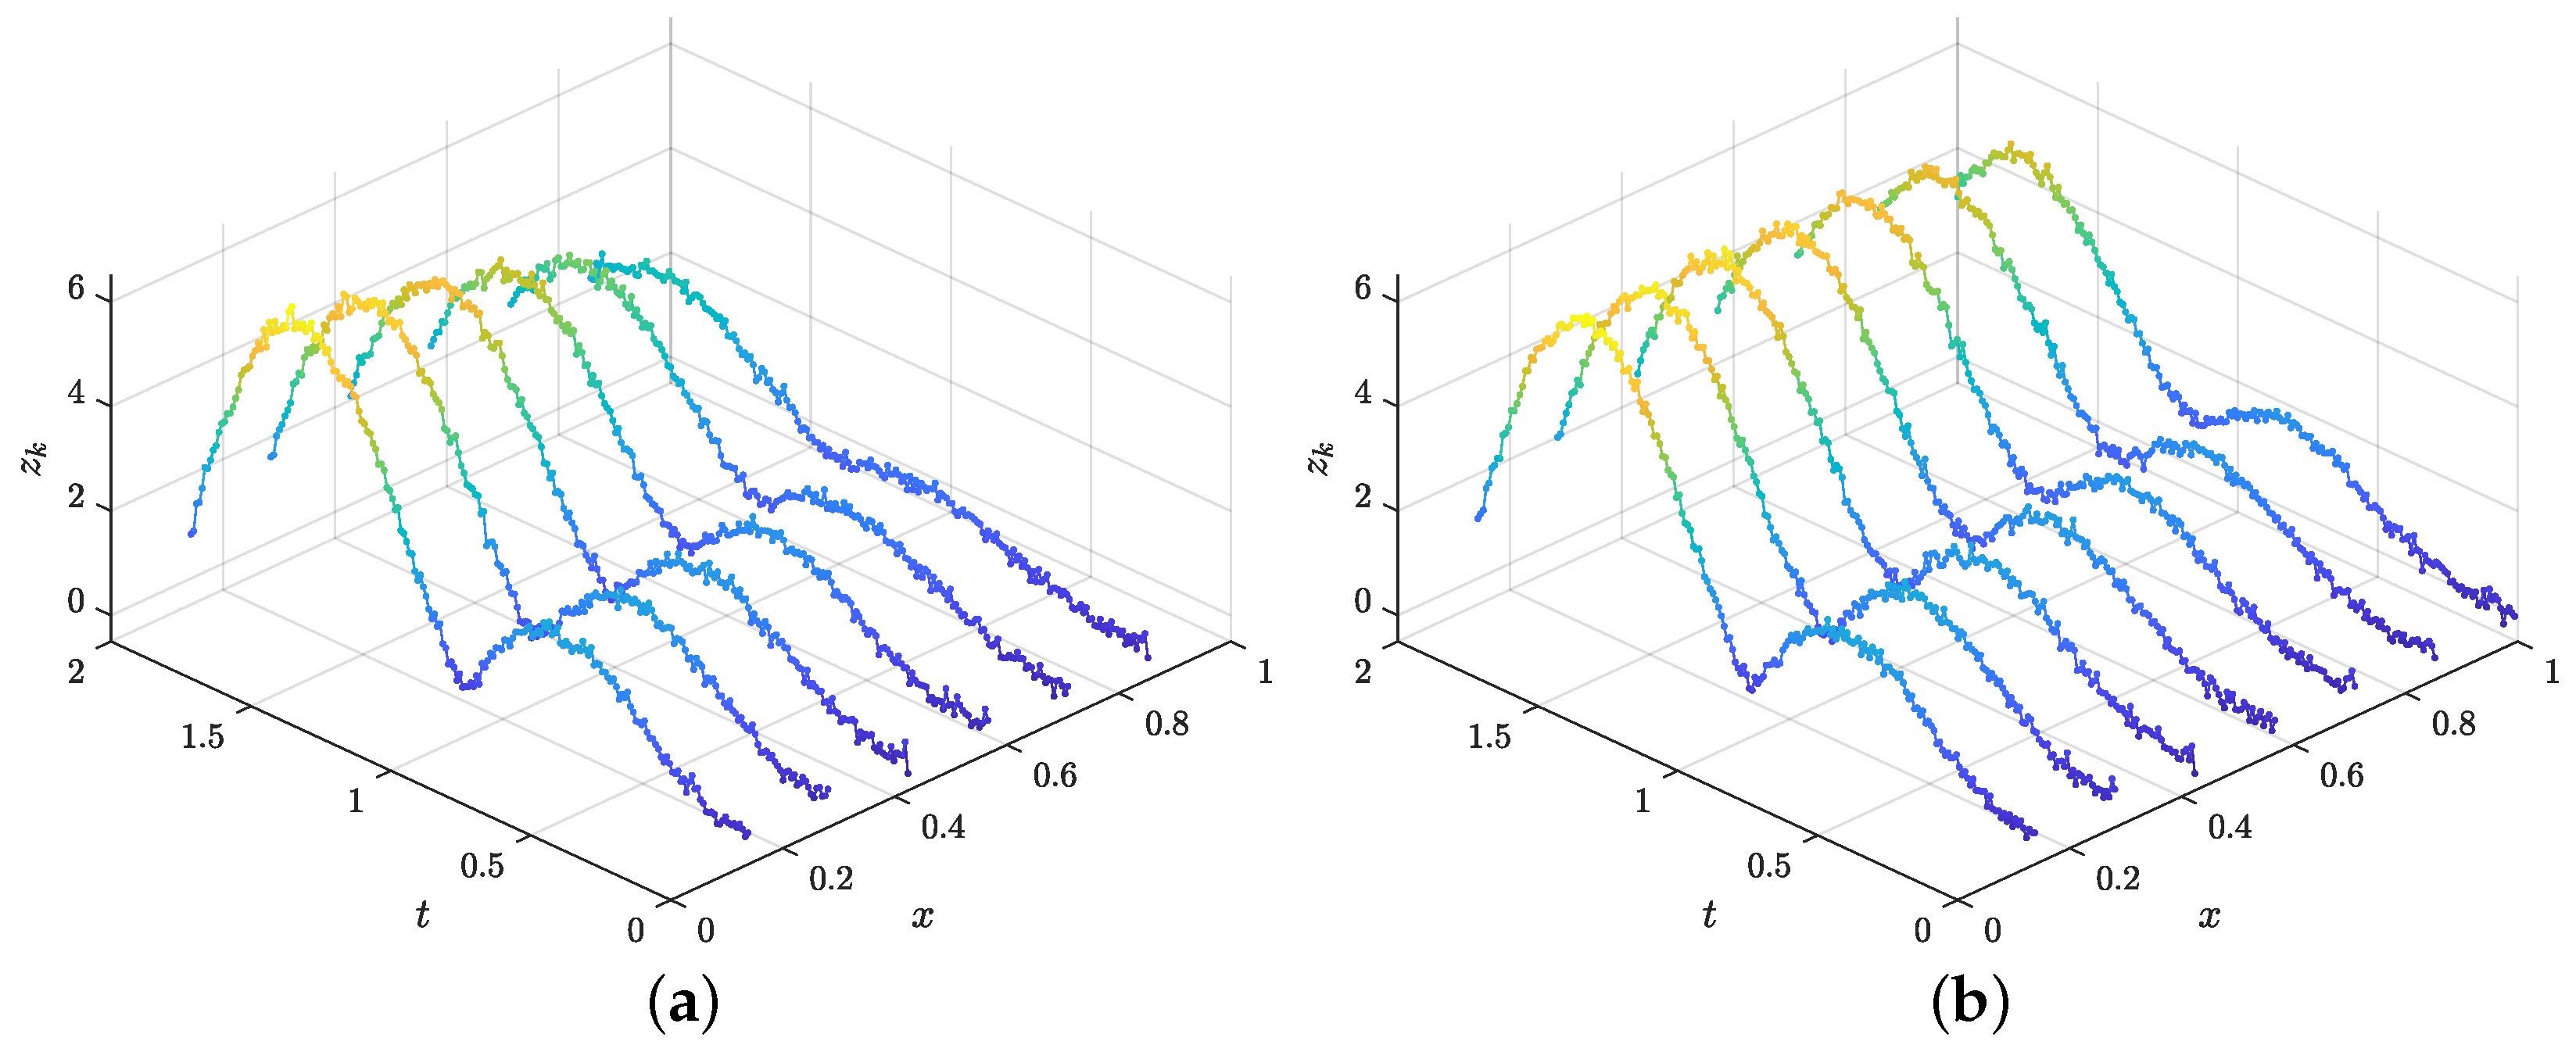
where , for boundary conditions (41) and , for boundary conditions (42). Figure 2 shows simulated measurements for both boundary conditions with .
Solving the parameter identification problem, we will apply two different numerical identification methods: the first is with known boundary conditions (41), (42), and the second with unknown boundary conditions.
The first solution is based on the approach considered in [25] where the identification criterion has the form of the negative logarithmic likelihood function with the associated conventional Kalman filter (KF) [35]. The second solution is based on the instrumental criterion and the novel SVD-GDM algorithm.
Minimization of identification criteria and was performed in the region using the function fmincon of MATLAB with the following parameters: ‘SpecifyObjectiveGradient’ = false, ‘Algorithm’ = ’sqp’, ‘MaxFunctionEvaluations’ = 100, ‘OptimalityTolerance’ = 1 × 10⁻¹⁴, ‘FunctionTolerance’ = 1 × 10⁻¹⁴, ‘StepTolerance’ = 1 × 10⁻¹⁴, ‘Display’ = ‘off’. The center of the region D was chosen as the initial point for the fmincon function. The identification results for different values of were averaged over 100 runs. The results obtained, as well as RMSE and MAPE errors, for boundary conditions (41) and (42) are presented in Table 1 and Table 2, respectively.
Table 1.
Identification results for boundary conditions (41).
Table 2.
Identification results for boundary conditions (42).
As can be seen from the results, the proposed identification criterion, , allows us to obtain estimates of unknown model parameters when the inputs are unknown. For high noise levels, the criterion outperforms the . When tends to zero, the results of both criteria first improve; however, starting at some point, the identification errors for the criterion start to increase, whereas the criterion continues to work stably, maintaining increasing accuracy. This fact can be explained by the divergence of the conventional Kalman filter with increasing measurement accuracy, and as a result incorrect calculation of values of . At the same time, the SVD-GDM algorithm does not have this drawback.
It should also be noted that, for the problem under consideration, the average times of one iteration of the SVD-GDM, GDM, and KF algorithms in MATLAB are 0.0353 s, 0.0159 s, and 0.0048 s, respectively. This means that the SVD-GDM algorithm is about 2.23 times slower than the GDM algorithm, which, in turn, is about 3.3 times slower than KF. The slower speed of the GDM algorithms compared to the KF can be explained by the fact that they need to evaluate unknown inputs, in addition to the state vector. Furthermore, the SVD-GDM algorithm involves performing several SVD decompositions during each iteration.
However, the proposed SVD-based parameter identification method for discrete-time stochastic systems with unknown exogenous inputs is not inferior in terms of quality to corresponding methods for systems with known exogenous inputs. Although unknown inputs undoubtedly add additional uncertainty to the description of a system model, our SVD-based method can be effectively used in practice.
5. Conclusions
The paper proposes an instrumental SVD-based method for identifying parameters of linear discrete-time stochastic systems with unknown exogenous inputs. We have constructed a novel SVD-based modification of the Gillijns and De Moor filtering algorithm for these systems, which allows us to calculate filter quantities using a numerically stable singular value decomposition.
Lemmas 1–3 and Theorem 1 contain the main theoretical results of the paper. We have proved the algebraic equivalence of Algorithms 1 or 2. To solve the problem of parameter identification for the class of systems considered, we have developed the SVD-based instrumental identification criterion. Numerical optimization techniques were used to find optimal values for the unknown system parameters.
After carrying out a series of numerical experiments using MATLAB, we demonstrated how the new SVD-based Algorithm 2 can be employed to solve the problem of parameter identification for a convection-diffusion model with unknown boundary conditions and noisy measurements.
The results of our numerical experiments confirm the efficiency of the SVD-based parameter identification method developed, under conditions where exogenous inputs are unknown, compared to the maximum likelihood parameter identification when exogenous inputs are known.
The shortcomings of the proposed SVD-based algorithm include the more complex programming implementation (due to the need for the SVD decomposition), as well as slower operation speed. Nevertheless, the undoubted advantages of the new algorithm include: the use of the SVD factorization for noise covariance matrices does not require its positive definiteness, compared to square root methods. The SVD-GDM algorithm is robust to machine roundoff errors due to the use of SVD at each iteration. The proposed approach allows for solving the problem of parameter identification in conditions of increased prior uncertainty, i.e., when not only the model parameters but also the input signals are not known.
Author Contributions
Conceptualization, A.T. and Y.T.; methodology, A.T. and Y.T.; software, A.T.; validation, Y.T.; formal analysis, A.T. and Y.T.; investigation, A.T. and Y.T.; resources, A.T. and Y.T.; data curation, A.T. and Y.T.; writing—original draft preparation, Y.T.; writing—review and editing, A.T. and Y.T.; visualization, A.T. and Y.T. All authors have read and agreed to the published version of the manuscript.
Funding
This work was supported by the Russian Science Foundation, grant no. 23–21–00361, https://rscf.ru/project/23-21-00361/ (accessed on 28 February 2024).
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The data presented in this study are available on request from the corresponding author.
Conflicts of Interest
The authors declare no conflicts of interest.
Abbreviations and Symbols
The following abbreviations and symbols are used in this manuscript:
| LTI | Linear Time Invariant |
| KF | Kalman filter |
| SVD | Singular Value Decomposition |
| GDM | Gillijns and De Moor algorithm |
| SVD-GDM | SVD-based GDM algorithm |
| RMSE | Root mean square error |
| MAPE | Mean absolute percentage error |
| Identity matrix of size n | |
| Left unitary matrix in SVD factorization | |
| Right unitary matrix in SVD factorization | |
| Block diagonal matrix in SVD factorization | |
| Square orthogonal matrix | |
| Square root of matrix A () | |
| Pseudo inverse matrix () | |
| Original identification criterion | |
| Instrumental identification criterion | |
| SVD-based identification criterion | |
| Negative logarithmic likelihood function |
References
- Golub, G.H.; van Loan, C.F. Matrix Computations; Johns Hopkins University Press: Baltimore, MD, USA, 1983. [Google Scholar]
- Oshman, Y.; Bar-Itzhack, I.Y. Square root filtering via covariance and information eigenfactors. Automatica 1986, 22, 599–604. [Google Scholar] [CrossRef] [Scilit]
- Oshman, Y. Maximum likelihood state and parameter estimation via derivatives of the V-Lambda filter. J. Guid. Control Dyn. 1992, 15, 717–726. [Google Scholar] [CrossRef] [Scilit]
- Wang, L.; Libert, G.; Manneback, P. Kalman filter algorithm based on Singular Value Decomposition. In Proceedings of the 31st Conference on Decision and Control, Westin La Paloma, Tucson, AZ, USA, 16–18 December 1992; pp. 1224–1229. [Google Scholar]
- Zhang, Y.; Dai, G.; Zhang, H.; Li, Q. A SVD-based extended Kalman filter and applications to aircraft flight state and parameter estimation. In Proceedings of the 1994 American Control Conference–ACC ’94, Baltimore, MD, USA, 29 June–1 July 1994; pp. 1809–1813. [Google Scholar]
- Kulikova, M.V.; Tsyganova, J.V. Improved discrete-time Kalman filtering within singular value decomposition. IET Control Theory Appl. 2017, 11, 2412–2418. [Google Scholar] [CrossRef] [Scilit]
- Grewal, M.S.; Andrews, A.P. Kalman Filtering: Theory and Practice Using MATLAB, 4th ed.; John Wiley & Sons, Inc.: New York, NY, USA, 2015. [Google Scholar]
- Vodeněarević, A. Overview of factorisation methods in Kalman filtering. B & H Electr. Eng. 2022, 14, 51–60. [Google Scholar]
- Kulikova, M.V. Numerically robust SVD-based Kalman filter implementations. In Proceedings of the 22nd International Conference on System Theory, Control and Computing (ICSTCC), Sinaia, Romania, 10–12 October 2018; pp. 170–175. [Google Scholar]
- Kulikova, M.V.; Tsyganova, J.V.; Kulikov, G.Y. SVD-based state and parameter estimation approach for generalized Kalman filtering with application to GARCH-in-Mean estimation. J. Comput. Appl. Math. 2021, 387, 112487. [Google Scholar] [CrossRef] [Scilit]
- Kulikov, G.Y.; Kulikova, M.V. SVD-based factored-form extended Kalman filters for state estimation in nonlinear continuous-discrete stochastic systems. In Proceedings of the 23rd International Conference on System Theory, Control and Computing (ICSTCC), Sinaia, Romania, 9–11 October 2019; pp. 137–142. [Google Scholar]
- Kulikova, M.V.; Kulikov, G.Y. SVD-based factored-form cubature Kalman filtering for continuous-time stochastic systems with discrete measurements. Automatica 2020, 120, 109110. [Google Scholar] [CrossRef] [Scilit]
- Kulikova, M.V.; Kulikov, G.Y. Square-root filtering via covariance SVD factors in the accurate continuous-discrete extended-cubature Kalman filter. Appl. Numer. Math. 2022, 171, 32–44. [Google Scholar] [CrossRef] [Scilit]
- Li, Z.; Zhang, J.; Wang, J.; Zhou, Q. Advanced square-root cubature Kalman filters based on singular value decomposition and sequential processing. IET Radar Sonar Navig. 2020, 14, 10–18. [Google Scholar] [CrossRef] [Scilit]
- Moontaha, S.; Arnrich, B.; Galka, A. State space modeling of event count time series. Entropy 2023, 25, 1372. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Fu, G.; Zhou, L.; Zheng, Y.; Lu, C.; Wang, X.; Xie, L. Improved unscented Kalman filter algorithm-based rapid identification of thermal errors of machine tool spindle for shortening thermal equilibrium time. Measurement 2022, 195, 111121. [Google Scholar] [CrossRef] [Scilit]
- Tsyganov, A.; Tsyganova, Y. SVD-based identification of parameters of the discrete-time stochastic systems models with multiplicative and additive noises using metaheuristic optimization. Mathematics 2023, 11, 4292. [Google Scholar] [CrossRef] [Scilit]
- Tsyganova, J.V.; Kulikova, M.V. SVD-based Kalman filter derivative computation. IEEE Trans. Autom. Control 2017, 62, 4869–4875. [Google Scholar] [CrossRef] [Scilit]
- Alessandrini, M.; Biagetti, G.; Crippa, P.; Falaschetti, L.; Manoni, L.; Turchetti, C. Singular Value Decomposition in Embedded Systems Based on ARM Cortex-M Architecture. Electronics 2021, 10, 34. [Google Scholar] [CrossRef] [Scilit]
- Zhang, F.; Shan, B.; Wang, Y.; Yang, B.; Teng, H.; Zhang, Z. Research of MIMU/GPS integrated navigation based on improved Kalman filter. In Proceedings of the 2018 Chinese Control and Decision Conference (CCDC), Shenyang, China, 9–11 June 2018; pp. 4350–4355. [Google Scholar]
- Bermúdez Ordoñez, J.C.; Arnaldo Valdés, R.M.; Gómez Comendador, V.F. Engineering Applications of Adaptive Kalman Filtering Based on Singular Value Decomposition (SVD). Appl. Sci. 2020, 10, 5168. [Google Scholar] [CrossRef] [Scilit]
- Li, C.; Zhen, J.; Chang, K.; Xu, A.; Zhu, H.; Wu, J. An indoor positioning and tracking algorithm based on angle-of-arrival using a dual-channel array antenna. Remote Sens. 2021, 13, 4301. [Google Scholar] [CrossRef] [Scilit]
- Gaoxiang, O.; Wenliang, L.; Pingke, D.; Guocan, Z. Attitude and angle rate determination of gyroless spacecraft based on SVD Kalman filter only using star sensor. In Proceedings of the 33rd Chinese Control and Decision Conference (CCDC), Kunming, China, 22–24 May 2021; pp. 5256–5260. [Google Scholar]
- Moontaha, S.; Galka, A.; Siniatchkin, M.; Scharlach, S.; von Spiczak, S.; Stephani, U.; May, T.; Meurer, T. SVD square-root iterated extended Kalman filter for modeling of epileptic seizure count time series with external inputs. In Proceedings of the 41st Annual International Conference of the IEEE Engineering in Medicine and Biology Society (EMBC), Berlin, Germany, 23–27 July 2019; pp. 616–619. [Google Scholar]
- Kuvshinova, A.N.; Andrey, V.; Tsyganov, A.V.; Tsyganova, Y.V. Mathematical modeling of parameter identification process of convection-diffusion transport models using the SVD-based Kalman filter. J. Samara State Tech. Univ. Ser. Phys. Math. Sci. 2021, 25, 716–737. [Google Scholar]
- Kitanidis, P.K. Unbiased minimum-variance linear state estimation. Automatica 1987, 23, 775–778. [Google Scholar] [CrossRef] [Scilit]
- Gillijns, S.; De Moor, B. Unbiased minimum-variance input and state estimation for linear discrete-time systems. Automatica 2007, 43, 111–116. [Google Scholar] [CrossRef] [Scilit]
- Darouach, M.; Zasadzinski, M. Unbiased minimum variance estimation for systems with unknown exogenous inputs. Automatica 1997, 33, 717–719. [Google Scholar] [CrossRef] [Scilit]
- Hsieh, C.S. Robust two-stage Kalman filters for systems with unknown inputs. IEEE Trans. Autom. Control 2000, 45, 2374–2378. [Google Scholar] [CrossRef] [Scilit]
- Gillijns, S.; Haverbeke, N.; De Moor, B. Information, covariance and square-root filtering in the presence of unknown inputs. In Proceedings of the 2007 European Control Conference (ECC), Kos, Greece, 2–5 July 2007; pp. 2213–2217. [Google Scholar]
- Björck, A. Numerical Methods in Matrix Computations; Springer International Publishing: Berlin/Heidelberg, Germany, 2015; Volume XVI, 800p. [Google Scholar]
- Ljung, L. System Identification: Theory for the User, 2nd ed.; Prentice Hall PTR: Upper Saddle River, NJ, USA, 1999. [Google Scholar]
- Tsyganova, Y.; Tsyganov, A. Parameter identification of the linear discrete-time stochastic systems with uknown exogenous inputs. Cybern. Phys. 2023, 12, 219–229. [Google Scholar] [CrossRef] [Scilit]
- Nocedal, J.; Wright, S.J. Numerical Optimization; In Springer Series in Operations Research and Financial Engineering; Springer Nature: Berlin/Heidelberg, Germany, 2006. [Google Scholar]
- Åström, K.-J. Maximum Likelihood and Prediction Error Methods. Automatica 1980, 16, 551–574. [Google Scholar] [CrossRef] [Scilit]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2024 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).