


Abstract
This study investigates the impact of FinTech on the monetary policy dynamics of the four major payment channels of banks in Nigeria, namely the automated teller machine (ATM), mobile payment (MOBPAY), web payment (WEBPAY), and Point-of-Sale (POS), from 2012 to 2025. The paper employs the Autoregressive Distributed Lag (ARDL) bounds testing approach to examine the relationships between the variables, whilst conducting a robustness check using dynamic ordinary least squares (DOLS). The study shows that POS transaction values have a positive and statistically significant impact on both the monetary policy rate (MPR) and the treasury bill rate (TBR). The findings also indicate that the savings deposit rate (SDR) increases both the MPR and the TBR, whereas the maximum lending rate (MLR) does not affect these policy rates. Mobile payments lead to significantly lower treasury bill and monetary policy rates. These findings empirically affirm that FinTech channels have expanded over the years, driven by the central bank’s cashless policy and banks’ response to the introduction of FinTech start-ups into the financial system. Thus, FinTech channels are important determinants of monetary policy transmission, justifying the need for the monetary authority to examine channel-specific sensitivities to its effectiveness in Nigeria’s fast-growing digital payment ecosystem.
1. Introduction
Technological innovations and developments, such as the Internet of Things, blockchain, big data, and, more recently, artificial intelligence, continue to shape the world of finance. Moreover, these technologies have enabled the emergence of financial technology (FinTech) to address frictions in the financial system. FinTech, therefore, refers to the combination of ‘financial’ and ‘technology’ innovations to address frictions within the financial ecosystem and unlock the potential for sustainable growth of the financial services industry (Boot et al., 2021; Gai et al., 2018). FinTech also refers to digital tools that automate processes, thereby improving efficiency and cost-effectiveness (Aloulou et al., 2024; Arner et al., 2015). The use of these technologies (digitalisation, biometrics, blockchain, automation, and identity management) has been instrumental in expanding FinTech adoption, enabling services for underserved populations in remote areas where traditional brick-and-mortar financial institutions cannot serve. Siddiqui and Rivera (2022) reaffirmed the existence of a FinTech ecosystem with active participation from relevant stakeholders, including lawmakers, financial institutions, customers, investors, and information technology companies. Moreover, this is key, especially in developing countries, as FinTech now offers opportunities across the financing and payment ecosystem, investment, and wealth creation (Elsaid, 2023). The existing literature has highlighted some of the important roles of FinTech, including efficient delivery of capital resources through its financial inclusion potential, especially to unbanked and hard-to-reach rural areas; reduced transaction costs; elimination of imperfect markets; investment in human capital; alleviation of poverty; financial system stability; sustainability; economic growth; improvement of information symmetry; reduction in risk-taking, and bank’s environmental performance (Badrous et al., 2025; Tay et al., 2022; Lagna & Ravishankar, 2022; Jonker & Kosse, 2022; Banna et al., 2022; Demir et al., 2022; Ahamed & Mallick, 2019; Allen et al., 2016).
Related studies, such as Mehrotra and Yetman (2014), examined how financial inclusion may impact monetary policy. Others, such as Attanasio et al. (2002), have examined the impact of FinTech using ATMs as a proxy for FinTech and interest rates, and report that these interactions or sensitivities enhance the financial system. Also, Kömürcüoğlu and Akyazi (2024), Hasan et al. (2024), and Mumtaz and Smith (2020) explored the impact of FinTech developments on monetary policy and sustainable finance. They found that FinTech developments reduce the effectiveness of the monetary transmission channel. Several other studies, such as Fegatelli (2022), Sakharov (2021), Nabilou (2020), and Kesavaraj et al. (2022), examined FinTech through the lens of central bank digital currency and its effects on various transmission channels. Also, several other studies focus on the monetary policy impact on money demand with inconsistent findings; studies by Ugwuanyi et al. (2022) and Wasiaturrahma et al. (2019) report that increases in FinTech lead to an increase in money demand, contradicting studies by Mlambo and Msosa (2020) and Fujiki and Tanaka (2009), which affirmed that increases in variables used as proxies for FinTech decrease money demand. Hundal and Zinakova (2021), in their study based on commercial banks in Finland, reported that FinTech impacted the behaviours of customers, the dynamics of risk management, investors and operations within the financial services industry, as well as the competitiveness and future growth of the FinTech ecosystem, with the COVID-19 pandemic having a more significant effect on the changes. Hoang and Le (2026) found that increased competitive pressure from FinTech innovations, as measured in a study of 29 commercial banks in Vietnam, negatively affected the profitability of traditional banks.
Whilst the literature on FinTech is clear about the significant roles it plays within the financial system, there are inconsistencies regarding the interactions among monetary policy, the banking system’s transmission mechanism (stakeholders/banks), and payment systems. Therefore, our study contributes to the literature by examining monetary policy and banking system transmission through FinTech channels and comparing transmission elasticities across payment system channels. This aspect of our study is very important, considering that between 2023 and 2025, Nigeria’s central bank adopted an aggressive tightening stance, with the MPR accelerating from 17.75% to 27.50%, one of the most unique trends in the world at a time when Nigeria recorded its most significant expansion in FinTech adoption and channels. However, to the best of our knowledge, no study has examined whether these tightenings influenced payment system channels such as ATMs, internet banking, mobile money payments, and POS, nor has it examined causality vis-à-vis banking system transmission through savings and lending rates. The rest of our paper is structured as follows: in Section 2, we review the existing literature. Section 3 outlines the data and research methodology, with a focus on related studies. Section 4 presents the results; Section 5 discusses the analysis; and Section 6 summarises the conclusions, limitations, and recommendations for future studies.
2. Literature Review
Three major research approaches have dominated the existing literature on FinTech: systematic and bibliometric analyses, case studies and conceptual research, and quantitative methods. Some studies explore the evolution of FinTech and the financial system to establish trends through a systematic, bibliometric approach, in which researchers construct a comprehensive bibliometric map of the FinTech and financial system landscape (Khan et al., 2026; Zakaria & Abdelhalim, 2025; Sahid et al., 2023; Garg et al., 2023; Sahabuddin et al., 2023; Tepe et al., 2021). Moreover, recent empirical research has examined how digital currencies and FinTech, in particular, affect central bank monetary regulations (Nawaz et al., 2024; Ia & Miglionico, 2019; Mills et al., 2016). From a quantitative perspective, the theme has centred on how FinTech impacts monetary and economic output (Mittal et al., 2023; Rehman et al., 2023; Kömürcüoğlu & Akyazi, 2024; Cornelli et al., 2024). There is indeed an integration gap between monetary policy transmission and FinTech expansion and adoption, with most studies examining one or the other from a financial inclusion perspective (Ozili, 2023; Lee et al., 2022; Mehrotra & Yetman, 2014). This study simultaneously investigates how central bank rate decisions, via the monetary policy rate (MPR) and the Treasury bill rate (TBR), causally influence FinTech adoption and, more generally, payment-system channels. Therefore, this study makes a very important theoretical contribution to the existing literature.
The monetary transmission mechanism theory provides a foundational pillar for answering our main research question: how do monetary policy rates influence FinTech expansion and the entire payment system? We consider this from the perspective that the traditional monetary policy transmission mechanism, which has its origins in decades of central bank management of interest rates and the nominal money stock with a price stability goal, was preceded by the evolution of FinTech. We therefore approach the theoretical lens through three major channels that remain relevant to FinTech expansion and the payment system. Under the quantity theory of money (QTM), central banks have the mandate to deploy monetary policy with greater manoeuvrability and, to do so, aim to forecast money demand more effectively (Goldfeld et al., 1973). Also, monetary policy is deployed to control the level of liquidity. When liquidity or demand for money increases, deposit money banks (DMBs) meet the demand by borrowing from the central bank at the monetary policy rate. Cash demand is determined by factors such as inflationary pressures and seasonal demand for money.
Therefore, FinTech developments, along with their various channels, affect the demand for money and the channels through which this demand is influenced (Kömürcüoğlu & Akyazi, 2024). Based on the QTM, existing studies have reported mixed findings on how changes in money demand impact FinTech. For instance, Mlambo and Msosa (2020), Wasiaturrahma et al. (2019) and Fujiki and Tanaka (2009) found that an expansion in FinTech adoption decreases demand for money. These studies are contrary to other studies that found that expansion or increases in FinTech channels adoption increase the demand for money (Ugwuanyi et al., 2022; Wasiaturrahma et al., 2019; Tehranchian et al., 2012). The monetary policy transmission mechanism in our study can operate through the bank lending channel. When a central bank raises interest rates, it automatically increases the cost of bank funding. In response to these higher MPRs, banks usually contract lending, thereby reducing their ability to create credit. However, the core of banking activities is the creation of credit; therefore, banks resort to credit rationing by increasing their lending rates. According to Winker (1999), this credit rationing, which is associated with rigidity of interest rates, is caused by ‘adverse selection’ and ‘switching costs’. As this happens, more bank borrowers, excluded by these high lending rates, are turning to FinTech alternatives, suggesting that banks have transmitted monetary policy through FinTech expansion, thereby displacing the bank credit channel. A study by Le et al. (2021) covering 80 countries from 2013 to 2017 confirmed a two-way relationship between FinTech credit and traditional banks, in which a positive or negative relationship between the two affects banking system efficiency.
Under the monetary policy transmission channel through lending rates, existing studies have relied on industrial organisation theory to postulate that an economy’s market structure determines the pass-through or stickiness of lending rates. In this instance, factors such as the level of competition within the banking system, entry barriers, sophistication of the financial system, market concentration, as well as the role of state-owned institutions are major determinants of MPR transmission through lending rates (Bendezu & Rodriguez, 2026; Van Leuvensteijn et al., 2013). In contrast, some studies on developed and emerging markets find that the influence of MPR on lending rates depends on the degree of interaction within the financial institutions’ ecosystem. Therefore, the pass-through effect of MPR on lending rates is determined by factors such as the size of the institution, the banks’ risk appetite, the banks’ funding costs, source and type, as well as the banks’ liability structures, as they affect their share of deteriorating assets (Blot & Labondance, 2021; Altavilla et al., 2018; Holton & Rodriguez d’Acri, 2015).
In the Technology Acceptance Model (TAM), for instance, monetary policy tightening is expected to increase the perceived usefulness of FinTech adoption, as FinTech reduces costs and improves efficiency. Beltrame et al. (2022), based on a study of FinTech investments on a sample of 17 banks in Italy, asserted that there is a positive relationship between banks’ investments in FinTech and their financial performance using the capital asset pricing model (CAPM), return on equity and price-to-book value as performance proxies. Wahab et al. (2025), in an expanded study covering 119 countries, examined the impact of FinTech on financial literacy and development and reported that digital payment channels had a positive and significant effect on both. However, foreign currency volatility and exposure negatively moderate this relationship, especially with respect to financial development. Mahmud et al. (2022) report that customers’ adoption of FinTech is determined by the levels of information security and government control, based on a sample of customers in Bangladesh. These findings are important as they deviate from the more common narrative of demographic variables. Ethical and privacy issues are therefore important safeguards for building trust in the adoption of FinTech channels by customers, ensuring compliance with data protection laws (Aldboush & Ferdous, 2023).
Existing studies have used the number of automated teller machines (ATMs) as a proxy for FinTech development when investigating its effect on monetary policy (Mabandla, 2026; Ugwuanyi et al., 2022; Mumtaz & Smith, 2020; Tule & Oduh, 2017). Others have used the number of points of sale (POS) devices, online/mobile digital/internet payments, central bank digital currency (CBDC), e-money, and crypto asset transactions (Ozili, 2023; Jiang et al., 2022; Saraswati et al., 2020; Mlambo & Msosa, 2020; Mumtaz & Smith, 2020). As reflected in the existing literature, studies that comprehensively investigate the relationship between money supply and demand and FinTech expansion across the entire payment system are quite limited, and we found no study specific to Nigeria in this context. In a related study by Mittal et al. (2023), based in India, the authors report a positive relationship between financial inclusion (a proxy for monetary policy effectiveness) and FinTech. Complementarily, a causality test conducted in the study indicates a bidirectional relationship between FinTech and monetary policy effectiveness. In an expanded study across 19 countries, Cornelli et al. (2024) investigated the impact of FinTech and bank credit on changes in monetary policy. Their results show that FinTech credit does not respond significantly to monetary policy shocks. A study by Al Sharif (2025) reports that FinTechs have a positive impact on banks’ financial performance, manifested through direct and indirect channels, thereby enhancing banks’ soundness in Jordan.
Using a quantitative methodology, Hasan et al. (2024), based on a study of FinTechs in Chinese provinces, employed Panel Vector Autoregression (PVAR) with interactions to examine the impact of FinTech on monetary policy and found that FinTech mitigates monetary policy transmission through regulatory arbitrage, competition, and counterfactual credit expansion. In a related study using panel data regression, Mansour (2024) examined bank profitability and reported that FinTech expansion led to a decline in bank profitability and that an accommodative monetary policy stance can mitigate this effect among Chinese banks. Wang et al. (2025) reported similar findings, namely that FinTech harms bank performance in China, using a fixed-effects panel regression model. Other studies in the Chinese context, such as Renzhi and Beirne (2025), Li et al. (2024), and J. Huang (2022), used a similar methodology. Other areas that have been empirically examined using quantitative methods include the study by Mlambo and Msosa (2020), which used the GMM panel technique to test the effect of FinTech on money demand, based on 23 years of data from five sub-Saharan African countries, including Nigeria. This study by Mlambo and Msosa (2020) used variables such as the number of ATMs and mobile subscriptions as proxies for FinTech and found that both negatively affect money demand. A similar method was used by Mumtaz and Smith (2020) on 25 developed and emerging countries. They reported that FinTech, proxied by mobile and internet technologies, and digital currencies were robust determinants of money demand. In contrast, inflation, the real interest rate, GDP, stock market indices, and the level of financial development were not determinants of FinTech expansion.
Mashamba and Gani (2023), based on a study of 56 banks across 19 Sub-Saharan African countries, found that traditional banks in Africa can resist FinTech disruptions, primarily due to the resilience of their funding structures. Also, Mashamba and Gani (2023) postulated that, despite FinTechs’ progress in credit expansion, traditional banks, through their branch networks, remain a crucial catalyst for lending growth and financial inclusion. This assertion confirms that FinTechs complement traditional banks rather than compete with them. Moreover, mobile money, as a FinTech instrument, has been reported to affect the monetary policy rate negatively, rendering monetary policy ineffective amid its expansion in Ghana (Wiafe et al., 2022). However, investments in FinTech are positively and significantly associated with economic growth, especially in high-growth economies (Alalmaee, 2026). FinTech has also been attributed to strong customer satisfaction and retention (Ajouz et al., 2025), although concerns with security as it relates to data protection, information privacy, and limited government control hinder the adoption of FinTech services (Mahmud et al., 2022).
Building on the above literature, we use bank-level data from the entire Nigerian banking sector to explore the relationships between monetary policy and the payment system through their various FinTech channels, a distinct approach from the existing empirical review.
Background of the Nigerian Banking Sector
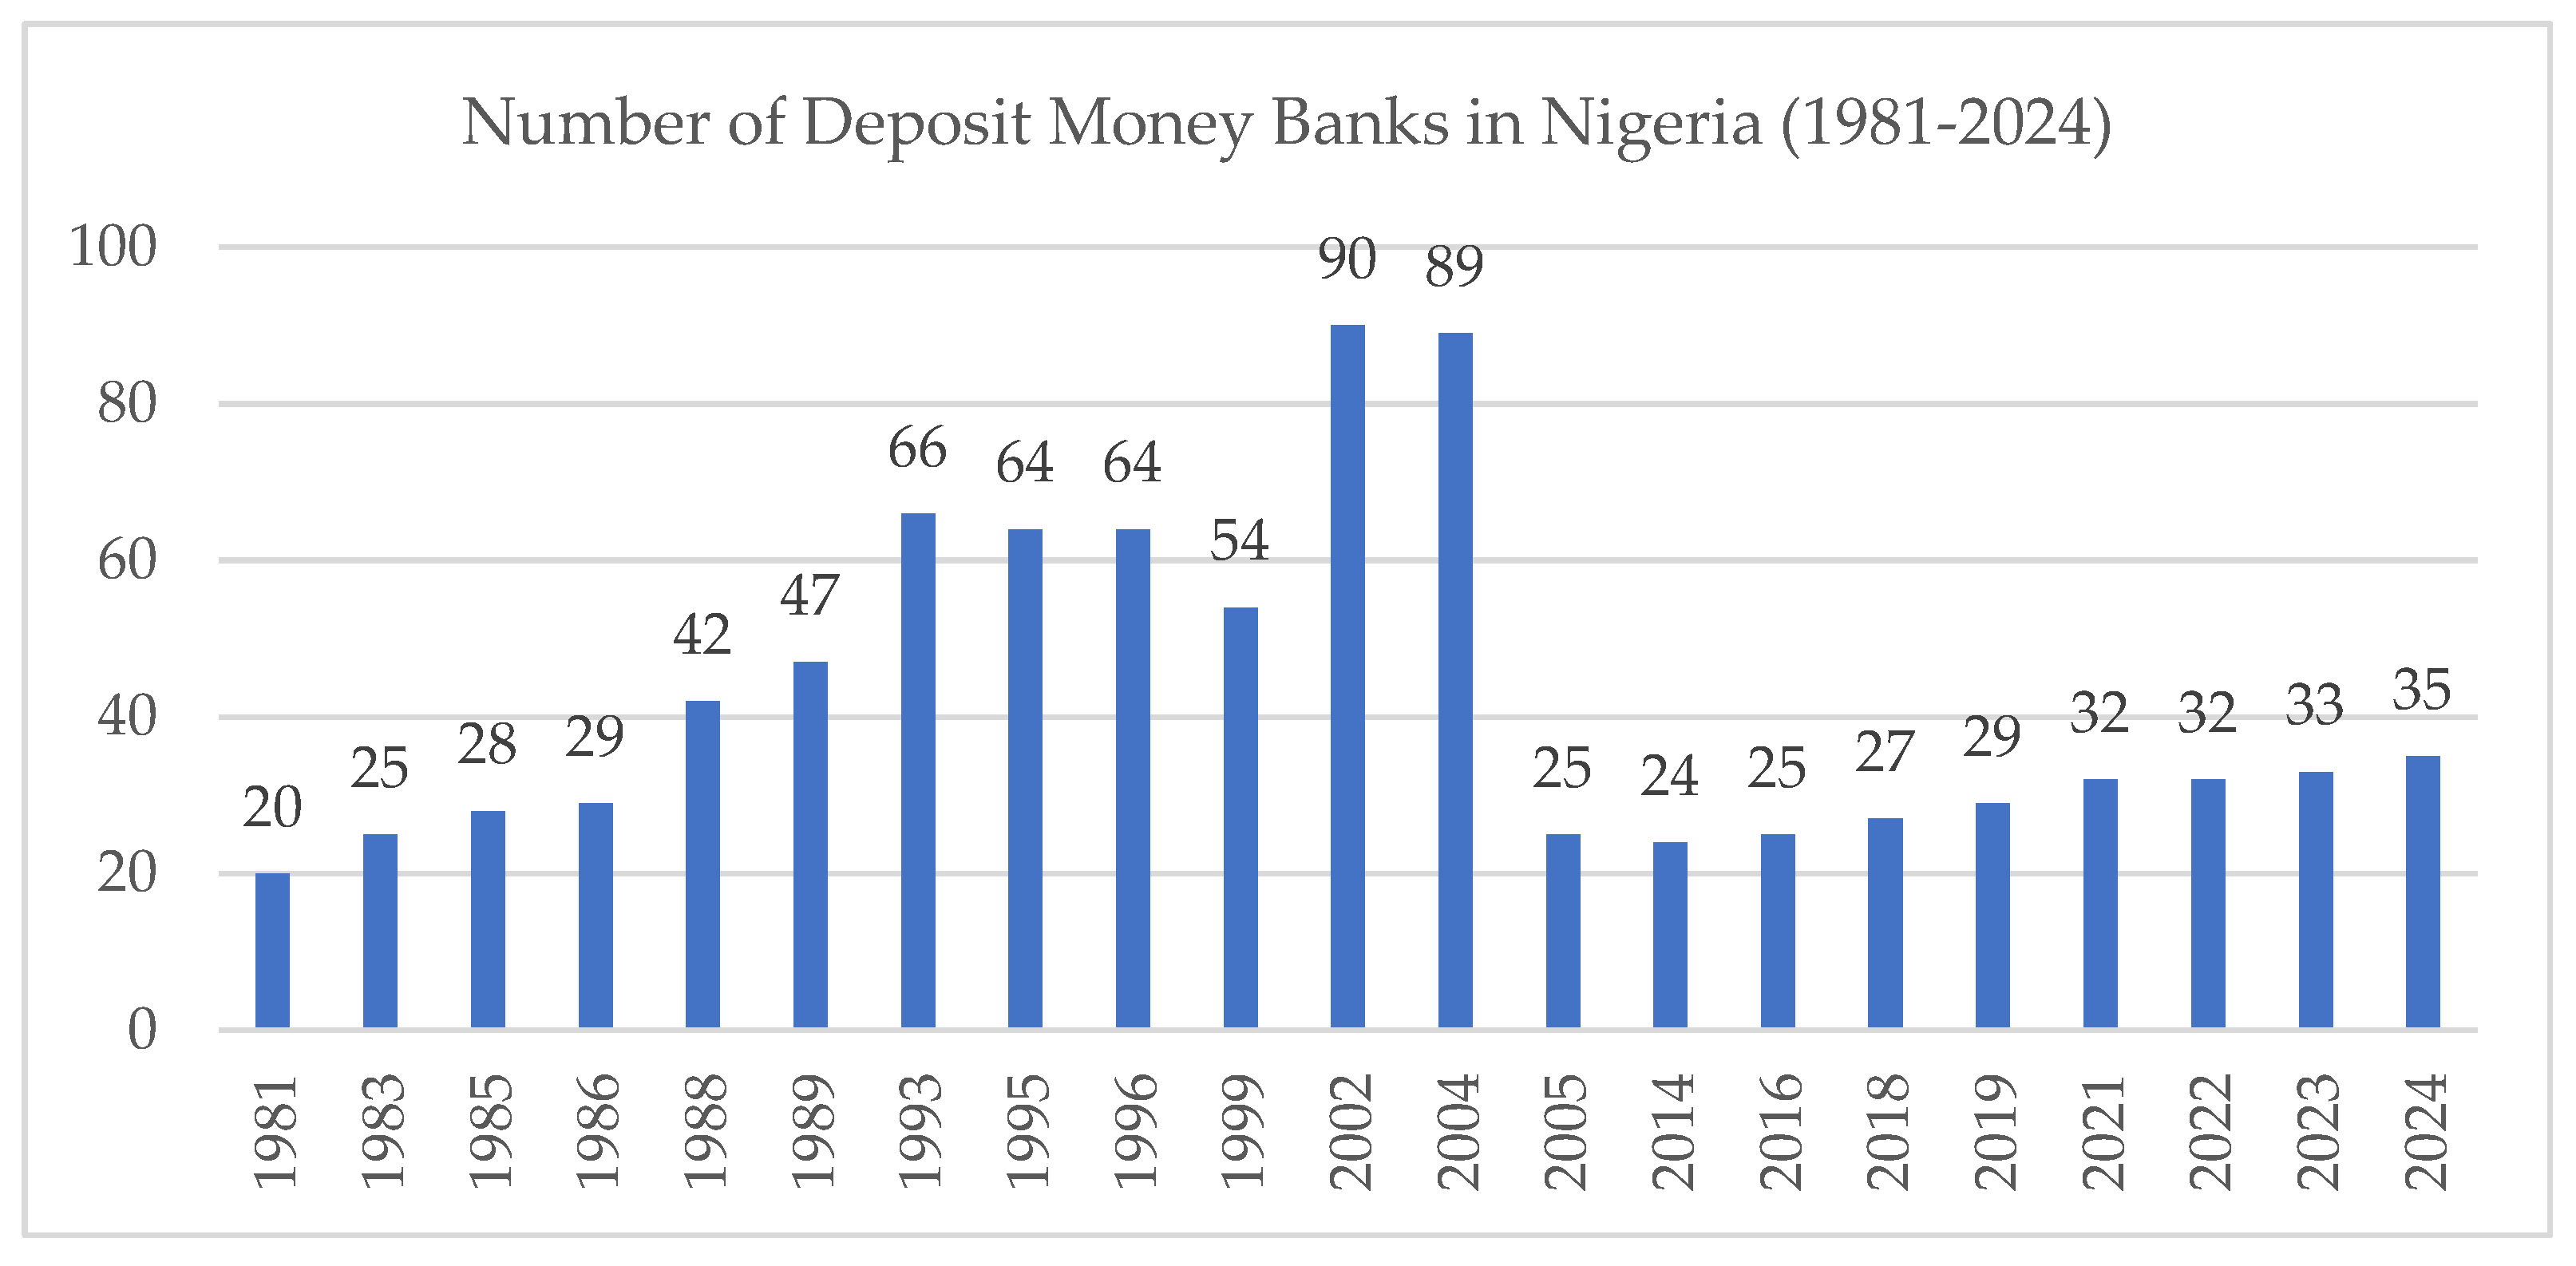
The banking sector in Nigeria is one of the most successful stories of financial services development in sub-Saharan Africa. From the formal commencement of banking operations in Lagos in 1892 by the African Banking Corporation (ABC) and the entrance of other colonial banks and indigenous/local banks from 1945, Nigeria’s commercial banking system evolved long before the arrival of the regulator—the Central Bank of Nigeria (CBN). The CBN is a relatively latecomer, entering in 1959 (Uche, 1997). From 20 deposit money banks as of 1981 to 89 banks as of 2004, before declining to 25 recapitalised banks after the 2004 recapitalisation exercise. It is important to note that the CBN recognises and distinguishes banks’ unique scope based on the classification of their operational licence, and therefore allows for varied cash reserve requirements (CRRs) and minimum capital bases. These classifications are commercial banks (with international, national, and regional authorisations), merchant banks (with national authorisation), non-interest banks (with national authorisation), and financial holding companies. The CBN generally refers to all these banks as deposit money banks (DMBs).
According to Sanusi (2010), a Central Bank of Nigeria (CBN) survey in March 2004 found that, of the 89 banks at the time, only 62 were certified as sound/satisfactory and 14 as marginally unsound. Generally, the CBN stress test confirmed that the banking sector was over-reliant on credit from the apex bank and public-sector funds, indicating that it was grossly undercapitalised, with just 10 banks accounting for over 50 per cent of the sector’s assets and liabilities. The CBN cited weak and ineffective corporate governance, poor asset quality, and inadequate/misleading reporting as major factors inhibiting the effectiveness of the banking sector to the economy, and therefore decided to embark on a regulatory-induced banking consolidation exercise with an increase in the minimum paid-up capital base to N25 billion (from a N2 billion prior capital requirement) to address inefficiencies in the banking sector (Sanusi, 2010). To meet the recapitalisation deadline, banks resorted to mergers, acquisitions, and capital raises through the stock exchange. At the end of the 2004 bank recapitalisation exercise, many banks merged; in some cases, up to six banks merged to meet the required regulatory capital (e.g., Fidelity Bank), and in others, a stronger bank acquired more than two banks (e.g., First Bank of Nigeria). The number of banks has since increased to 35 as of 2024 (see Figure 1), dominated by indigenous banks, with over 8 commercial banks with international authorisation operating within the African continent, Europe, the United Kingdom, Asia, and North America.
Figure 1.
Number of Deposit Money Banks in Nigeria, Source: CBN Statistical Bulletin (CBN, 2014, 2024).
The government organises, influences, and controls a market economy through two principal means: monetary policy and fiscal policy. Whilst the government directly controls fiscal policy through its ministerial/departmental bureaucracy, it delegates monetary policy to an ‘independent’ specialised agency, the Central Bank. In the context of this study, monetary policy is the means by which a specialised monetary authority (CBN) influences, controls, and manages the pace of economic activity through tools that affect employment, production, growth, and the general price level. Moreover, one of these tools is the interest rate or the monetary policy rate (MPR). As noted by Friedman (2000), the core objectives of central banks in this era are to maintain general price stability or control inflation while also promoting economic growth.
Based on the data used in this study, we establish four phases of the monetary policy environment, as shown in Table 1.
Table 1.
Phases of Monetary Policy Environment in Nigeria.
Also, within the payment ecosystem, the Nigerian banking sector continues to rank amongst the top global leaders in the use of FinTech channels. According to the International Finance Corporation (IFC) in its 2019 Special Report on Digital Skills in Sub-Saharan Africa (IFC, 2019), by 2030, over 230 million jobs in sub-Saharan Africa will be digital-skills-intensive, requiring the creation of almost 650 million training opportunities. The report estimates that the FinTech industry, projected to deliver significant social benefits, can transform healthcare delivery, improve insurance access, and enhance the agricultural value chain across Africa. Moreover, this development contributes to improving financial inclusion, particularly for women, who bear the brunt of financial exclusion in most developing countries.
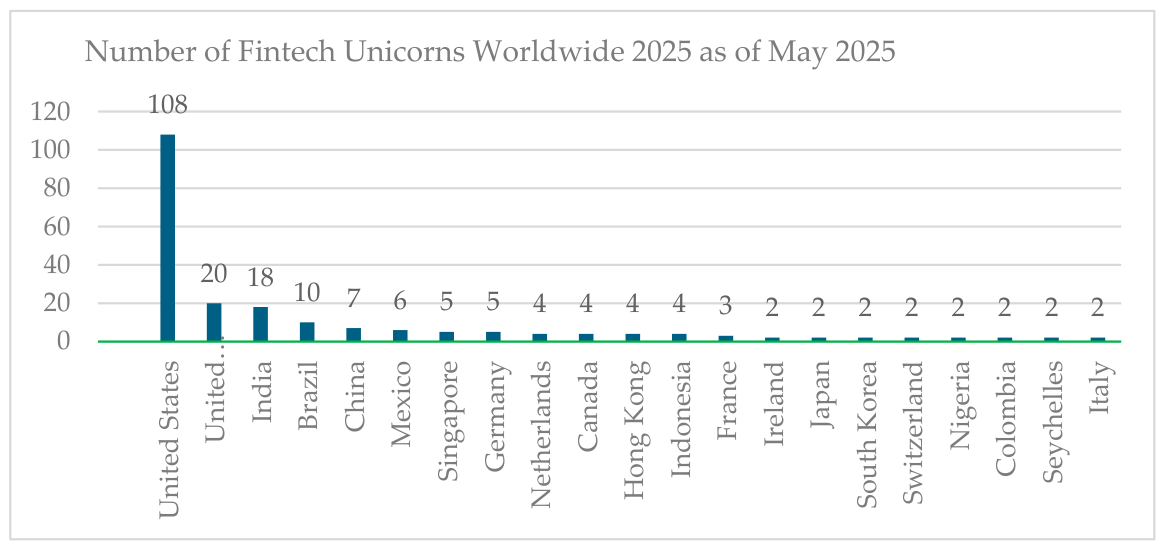
According to a CBN (2025) report on FinTech, Nigeria-based start-ups in the FinTech ecosystem raised $520 million in 2024, accounting for 37% of the total $2.2 billion raised by start-ups in Africa. The Nigerian FinTech ecosystem is indeed thriving, with two unicorns (start-ups valued at over $1 billion) as of May 2025. Developed countries such as Japan, South Korea, Switzerland, and Italy also have two unicorns, as shown in Figure 2 below.
Figure 2.
Number of FinTech Unicorns—source: CBN Insights—Statista (CBN, 2025).
The Nigeria Inter-Bank Settlement System (NIBSS), owned by all licensed deposit money banks and the CBN, operates an instant payment platform called NIP (NIBSS Instant Payment), which serves as the core interoperable infrastructure, providing all banks with access to process digital payments. The CBN also plays a vital role in regulation, and this framework influences the entire financial system, with FinTechs embedded within the banking system through a shared, robust payment system. Therefore, these regulatory oversight efforts contribute to adoption rates and the financial system’s positive trajectory. Nigeria continues to make great strides in FinTech innovation and adoption, becoming one of the earliest pioneers of digital financial infrastructure with the rollout of a real-time payment system in 2011, well ahead of many developed countries. Moreover, these achievements occurred despite macroeconomic headwinds, as the data show (ACI Worldwide, 2022), and over 25% of all electronic transactions in Nigeria were processed through real-time channels, driven by its robust payment infrastructure (CBN, 2025).
3. Research Methodology
3.1. Data Description
To investigate the impact of FinTech expansion on monetary policy through the lens of banks’ payment systems in Nigeria, this study used secondary data sourced from the apex bank, the CBN. According to CBN statistics, the final sample comprises 21 deposit money banks (DMBs) in Nigeria as of 2021, rising to 33 as of 2025. The study used monthly panel data from January 2012 to June 2025 (162 months or 13 years) for the following reasons: first, the data were complete during this period; and second, this period better captures the evolution of the payment system and the monetary policy environment than any prior period. Secondly, the start period of 2012 was intentional because the CBN began implementing the cashless policy in January 2012 in Lagos, the commercial city where all the banks’ head offices are located, and by 2013, the policy had been extended nationwide. This study used EViews 13 to process the data.
3.2. Variable Measurement
This study includes eight variables, with the Monetary Policy Rate (MPR) as the dependent variable, to assess the monetary transmission effect. The MPR is the benchmark interest rate set by the CBN, and all other interest rates and financial indices are anchored to it. The decision on the MPR is communicated in a communiqué at the end of a two-day deliberation by the CBN’s monetary policy committee (MPC), held in accordance with the MPC’s scheduled calendar for that year. The MPR unit of measurement is in percentage (%). Another important measure for assessing monetary policy transmission is the 91-day Treasury Bill Rate (TBR). The TBR is the discount rate for 91-day Treasury bills, expressed as a percentage (%), and serves as a measure of short-term liquidity and as a money market instrument that may influence the money supply. The independent variables are four major FinTech mechanisms that dominate banks’ payment systems. These are the Automated Teller Machines (ATMs), the Point of Sale (POS), the Web-Internet Pay (WEBPAY), and the Mobile Pay (MOBPAY). The unit of measurement for these FinTech variables is the monthly total absolute value of transactions executed through these channels, in millions. This measurement is more relevant to this study than transaction counts, mobile banking users, or the number of ATMs, as used in some studies (Mabandla, 2026; Antwi-Wiafe et al., 2023), because we are examining how these FinTech mechanisms are affected by monetary policy transmission through the money supply. The other two variables are the control variables—the DMBs’ Saving Deposit Rate (SDR) and the DMBs’ Maximum Lending Rate (MLR)—both measured monthly as percentages. The use of these two control variables is based on the existing literature, which suggests the MPR may influence them. These eight variables are presented in Table 2, along with their measurement and data sources.
Table 2.
Summary of variables and their measurement.
3.3. Model Specification
This research employed the Autoregressive Distributed Lag (ARDL) cointegration framework proposed by Pesaran et al. (2001), as it allows us to estimate and test the model specification regardless of whether the regressors in the MPR equation are stationary or non-stationary at levels. ARDL was considered appropriate for its ability to generate both short- and long-run estimates simultaneously. This ARDL estimation approach is important because it does not require the pre-testing often undertaken in other conventional models (Imhanzenobe, 2024). The fact that issues of endogeneity are not a major problem with the ARDL, since the model is often not associated with residual correlation (Baharumshah et al., 2009).
Therefore, the model used for empirical investigations of the relationships between the variables in this study is specified thus:
Since the variables are first-difference stationary, we can use the ARDL technique to re-specify Equation (1), which yields the following:
where ∆ denotes the difference operator, and represents the error term. While , , , , , and parameters are short-run dynamic coefficients, , …, depict the long-run coefficients for LNATM, LNMOBPAY, LNPOS, LNWEBPAY, MLR, and SDR, respectively.
4. Results
4.1. Summary Statistics
The characteristics of the dataset used in the study are reported in Table 3. The policy rate variables MPR, TBR, MLR, and SDR have smaller standard deviations because they are measured in percentages rather than transaction values such as MOBPAY, POS, WEBPAY, and ATM.
Table 3.
Descriptive Statistics.
The MPR mean is 14.71, with a median of 13.50%, ranging from a high (maximum) of 27.50% to a low (minimum) of 11.00%, indicating a sustained tightening stance. The MPR is also positively skewed at 1.95, as shown in Table 3 below, indicating that, for most of the period, the MPR was lower or moderate, with relative stability, and only started accelerating upwards in the later period, indicating a period of a high-interest-rate environment, as the MPR and TBR showed the most variability, whilst the MLR remained stable. However, at a higher level, the SDR was much lower comparatively.
The TBR showed noticeable variation, with a mean of 9.28%, a median of 10.20%, and a standard deviation of 5.04%. In contrast, the MLR showed that the maximum lending rates of banks were relatively high at around the 20.00% level, with a mean of 27.99%, a standard deviation of 2.28%; the SDR was less volatile than the MLR, with a mean of 3.36% and a standard deviation of 1.57%. The FinTech variables all have much larger and more dispersed values than the MPR variables, with WEBPAY having the highest mean of 35,725,029.80 N’Mil, followed by MOBPAY, POS and ATM at 6,267,188.53 N’Mil, 3,455,330.48 N’Mil, and 1,250,810.17 N’Mil, respectively.
In terms of absolute transaction values, our analysis of the four FinTech variables indicates that WEBPAY had the largest cumulative transaction value, accounting for 76.50% of the total FinTech value, at approximately N5787.455 trillion, for the period January 2012 to June 2025. This is followed by MOBPAY, in second, accounting for 13.42% with a transaction value of N1,015.285 trillion. This is followed by POS transactions totalling N559.764 trillion, or 7.40%, and ATM transactions totalling N202.631 trillion, or 2.68%, of the absolute transaction values during the review period.
To further explore the data gap and possible baseline-value concern regarding the number of banks, we analysed the four main FinTech variables annually, as shown in Table A1, Table A2 and Table A3 in Appendix A, and juxtaposed them with the figure on the number of banks. From the data, there are three distinct phases, as follows:
- (i)
- The Consolidation and stability phase (2004 to 2007): saw banking consolidation drive mergers and acquisitions within the sector, reducing DMBs from 89 in 2004 to 25 in 2005 and leaving the count unchanged through 2011.
- (ii)
- The Disruption and Recovery phase (2012–2016): the banking sector experienced its largest decline in 2012, when the number of DMBs fell from 24 to 21, a 12.50% decline, and the lowest number of banks since 1981. The three banks were liquidated following the CBN’s revocation of their operating licences for failing stress testing. However, there was a recovery in the licensing of new banks, with the number rising to 24 in 2013 and to 25 by 2015.
- (iii)
- The Sustained expansion and Consolidation era (2017–2025): From 2017, the banking sector experienced increasing expansion with many firms applying for banking licenses, as the number of DMBs increased to 27 in 2017, and 30 in 2020 and 33 by 2023, and as of June 2025, the end period for our research, the number of DMBs in Nigeria stood at 35.
When the above trend is analysed alongside the FinTech variables, we note that the number of DMBs grew steadily, whereas banks’ annual transaction values increased rapidly over the same period. Therefore, the expansion of MOBPAY, ATM, POS, and WEBPAY transaction value is not due to the increase or decline in the number of DMBs; rather, the expansion in the adoption and usage of FinTech variables can be attributed to the expansion of digital infrastructure by the banks, increasing trust and usage by customers, and increasing technological adoption. This is evident from the fact that bank-count measures only the number of banks, without consideration for a bank’s size, customer base, capitalisation, digital innovation, or technological deployment. Hence, the number of banks is not proportional to the volume of transactions recorded in the banking sector during the period.
4.2. Unit Root Test
It is customary to examine the time-series characteristics of the variables used in the study to ascertain whether the mean and variance of the data series are time-invariant, that is, constant over time (stationary). Thus, estimation results from non-stationary time series are subject to the spurious regression problem (Bai & Perron, 2003), making them unsuitable for policy prescriptions. The results of the Augmented Dickey–Fuller (ADF) and Phillips–Perron (PP) tests are presented in Table 4.
Table 4.
Unit Root Test.
From Table 4, the tests at the levels and trend specifications indicate that all variables are first-difference stationary.
4.3. Cointegration Test
Cointegration must be established among the series for the coefficient interpretations regarding the long-run equilibrium relationship to be valid. Otherwise, even if statistically significant, the results will be considered spurious/degenerate (Mert & Çağlar, 2020). Thus, we used the F-bounds test results for long-run forecasts, and the error-correction model was used for analysis. Table 5 shows the Bound Test results.
Table 5.
Bound Test Results.
The bound tests shown in Table 5, the F-statistic (3.92 > 3.28), and the upper critical values (I(1)) exceed the 5% significance level, hence confirming the existence of cointegration among the variables. Upon confirming the cointegrating relationship, the long-run effects of the FinTech payment system on monetary policy, estimated using the ARDL model, are reported in Table 6 below.
Table 6.
Long-Run Estimation Results.
5. Discussion
The results in 6 showed that LNPOS was the only FinTech variable of concern to exhibit a statistically significant relationship with MPR. It implies that MPR will increase by 4.562 per cent due to a percentage increase in the POS value at the 5% significance level. This positive and significant relationship between the use of POS by bank customers and MPR clearly indicates that increases in the value of POS activities may be related to either inflationary pressures or may be signalling the expansion or velocity of POS services, which in turn compels the monetary authority (CBN) to raise the MPR to target inflation and maintain price stability (Syafi’i, 2025). Our findings provide strong validation that POS and MPR are indeed positively and significantly correlated, as they are linked to currency in circulation and inflationary pressures, given the Nigerian economy’s growing retail and consumer services, especially in the informal sector. Related studies by Nathan (2023) and Ikechi et al. (2020) also confirm this positive and significant association.
LNATM is negative and insignificant in the ARDL long-run model, with a coefficient of −4.2344 and a p-value of 0.16. This insignificant relationship with the MPR is also confirmed by the DOLS results, as shown in Table 6. This result was expected, as ATM usage is typically cash-linked, and customers primarily withdraw cash from ATMs, which is not a significant determinant of long-run FinTech payment system drivers within the monetary policy transmission mechanism. Banks mainly deploy ATMs to ease traffic in banking halls while providing customers with a smart, efficient way to withdraw cash from their deposit accounts.
WEBPAY has a negative, statistically insignificant association with MPR in both the ARDL long-run model and the Treasury bills rate (TBR) equation specification. However, in the robustness check using DOLS, LNWEBPAY is positive and significant, with a coefficient of 0.6925 and a p-value of 0.02. This means that WEBPAY, or internet banking services offered by banks to their customers, has some long-run relevance with the MPR, but is not robust across all estimators. We attribute these findings to a significant change in the data point, beginning in January 2020, when the CBN began including values for WEBPAY transactions conducted through the interbank system on behalf of bank customers, as well as those conducted through banks’ web/internet banking platforms. These findings also align with the study by Z. Huang et al. (2024), which shows that digital money may indeed affect the MPR. Still, the magnitude of the impact depends on data coverage and on the determination of the FinTech mechanism’s strength vis-à-vis the banking system, whether as a substitute or a complement to banks.
For MOBPAY, the long-run results indicate that LNMOBPAY is negative and not statistically significant with respect to the MPR. In contrast, in the short run, it is positive at the 10% significance level. Moreover, in the DOLS model and the TBR equation, the coefficients on MPR and TBR are strongly negative at the 1% significance level. These findings show that as more bank customers use their mobile devices for banking, there is less pressure on monetary policy rates. The existing literature has clearly documented that FinTech mechanisms, such as mobile banking apps, enhance financial inclusion and efficiency, reduce costs, and reduce reliance on the banking system for liquidity management by reducing visits to banking halls (Ayoade & Areghan, 2025; Oyadeyi, 2023; Tonuchi et al., 2021). Also, related to the result from WEBPAY is the fact that mobile money payment (MOBPAY) does serve as a substitute for cash holdings, thus decreasing the demand for cash from the CBN and banks, thereby restraining the monetary authority from adopting hikes in the policy rates, as collaborated by related studies by Iorngurum (2019), but a contrasting study by Kulu and Bondzie (2024) and Wiafe et al. (2022) reports that increasing value of mobile money activities can weaken the effectiveness of monetary policy by creating huge liquidity that are outside the banking system, thus making it difficult for the apex bank to control system liquidity.
MLR and SDR showed negative and positive statistical relationships with MPR, respectively. This suggested that MPR would decrease by 1.34 per cent and increase by 2.06 per cent, driven by a 1 per cent decrease in MLR and an increase in SDR, respectively. The SDR is positive and statistically significant when estimated using the main ARDL model and the DOLS MPR equation as a robustness check. This clearly indicates that savings deposit rates in Nigeria move in the same direction as the MPR, suggesting that they serve as a monetary transmission mechanism. In contrast, the MLR has a negative and significant relationship with the MPR in the ARDL model, but a very weak negative relationship in the DOLS estimation results. These findings are supported by similar studies, such as those by Ishaku and Yakubu (2025) and Oyadeyi (2023). In our view, this is due to the high lending rates in the Nigerian banking sector, where deposit money banks have significant pricing power over loans with no real competitors. As a result, there is a delayed pass-through of this channel in the policy rate transmission. This result also shows that the maximum lending rate (MLR) variable does not rely solely on the policy rate, but rather primarily on current macroeconomic-induced credit risk conditions and the borrowing customer’s risk profile and cash flows.
The short-run dynamics in Table 7 revealed that ECT(−1) is negative and statistically significant at the 1% confidence level, thus confirming the existence of a long-run equilibrium relationship among the variables. The results suggest that any short-run deviations from equilibrium would be corrected at an adjustment speed of 6.63 per cent per month.
Table 7.
Short-run and Error Correction Model Results.
Furthermore, MOBPAY and SDR are positive and significant at the 10% and 1% levels, respectively, implying that MPR would increase by 0.26% and 0.56% with a 1% increase in MOBPAY and SDR, respectively. However, MLR has no significant short-run impact on MPR, except for its previous value, which shows a significant positive impact, suggesting that a 1 per cent increase in its past realisation would cause a 0.11 per cent increase in MPR. The diagnostic test results in Table 8 below showed mixed outcomes. While linearity, partial stability, and serial correlation are not issues with the model, there are issues of normality and heteroskedasticity, perhaps due to the sample size.
Table 8.
Diagnostic Test.
5.1. The 91-Day Treasury Bill Rate (TBR) Equation
Regarding the TBR model, the cointegration bounds test results are presented in Table 9. The F-statistic value of 2.6454 lies between the lower bound I(0) of 2.45 and the upper bound I(1) of 3.61. This suggests that cointegration cannot be determined using the F-statistic critical value. However, cointegration (a long-run relationship) can still be established, with the error-correction term having the expected negative sign and being statistically significant.
Table 9.
Bound Test Results.
The estimated long-run coefficient showed that POS was the only variable of concern, with a significant impact on TBR. This suggests that TBR would increase by 7.11 per cent because of a percentage increase in POS. Meanwhile, the control variables, MLR and SDR, exhibited significant negative and positive effects on TBR, indicating that TBR would decrease by 1.66 per cent and increase by 2.44 per cent with a 1 per cent increase in MLR and SDR, respectively, as shown in Table 10 below.
Table 10.
Long-Run Estimation Results.
The parameter estimates of short-run coefficients reported in Table 11 show evidence that the error correction term [ECT(−1)] is negative and statistically significant at 1%. This implies the existence of a long-run equilibrium relationship among the variables. Based on the results, any short-run deviation from equilibrium during the period under consideration would be corrected at an adjustment rate of 13.51 per cent per month. The short-run coefficients in the error-correction model indicate that MLR does not affect MPR. On the other hand, at the 5% significance level, POS and SDR would increase MPR by 1.73% and 0.81%, respectively.
Table 11.
Short-Run and Error Correction Model Results.
The diagnostic results presented in Table 12. indicate that there are no issues with serial correlation or model linearity, and partial stability is established in the CUSUM plot, with the blue line lying within the 95% confidence interval. However, the dataset used in the study exhibits normality and heteroskedasticity, with a CUSUMSQ deviation that persists for some time before returning to equilibrium.
Table 12.
Diagnostic Test of the TBR Equation.
5.2. Robustness Check—DOLS
To enhance the empirical analysis of this study, we conducted a robustness check using dynamic ordinary least squares (DOLS). The dynamic ordinary least squares (DOLS) proposed by Stock and Watson (1993, 1996) is an alternative parametric technique that uses leads and lags to address endogeneity. It is a cointegration technique applicable regardless of the orders of integration, useful for both small and large sample sizes, and robust to serial correlation. The inclusion of leads and lags in DOLS not only resolves endogeneity and serial correlation but also produces efficient estimates that eliminate feedback effects. The t-statistics generated by DOLS approximate the standard normal distribution better than those generated by OLS. While the DOLS technique was not used as the main estimation technique in this study, it is used as a robustness check for triangulation (i.e., to confirm the results of the ARDL long-run estimates), thus showing that the problems of endogeneity of model residuals and the presence of serial correlation do not significantly affect the results of the ARDL long-run models (Tan et al., 2020).
A comparison of the ARDL long-run result and the DOLS estimator for the MPR models shows largely consistent direction (sign), magnitude (coefficient) and statistical significance (p-values) for the POS FinTech variable (Table 6 and Table 13). The directions of causality are both positive; the coefficients of 4.56 and 3.82 are largely close, and the p-values are both significant at 5% for the ARDL and DOLS models, respectively. A comparison of the ARDL long-run results and the DOLS estimator for the TBR models also shows largely consistent directions (signs), magnitudes (coefficients), and statistical significance (p-values) for the POS FinTech variable (Table 10 and Table 14). The directions of causality are both positive; the coefficients of 7.11 and 6.01 are largely close, and the p-values are both significant at 5% for the ARDL and DOLS models, respectively. These consistencies provide evidence that the positive and significant relationship observed in the ARDL long-run models for both MPR and TBR is relatively robust to differences in estimator specification.
Table 13.
Effect of FinTech on Monetary Policy Rate in Nigeria.
Table 14.
Effect of TBR on FinTech and Transmission Variables.
Based on all results, we can confirm from Table 6, Table 10, Table 13 and Table 14 that POS has a consistently positive and significant long-run relationship with monetary policy, as captured by the MPR and TBR, across both estimation techniques. Meanwhile, MOBPAY and WEBPAY were significant in both estimation techniques, suggesting that their coefficients may be unreliable. ATM was not significant in any of the models, thus affirming its relative irrelevance in influencing CBN’s monetary policy decisions. Overall, the results suggest that the value of point-of-sale transactions is a major determinant of monetary policy decisions, given its strong, positive long-run correlation with the monetary policy rate and the 91-day treasury bill rate set by the Central Bank of Nigeria.
5.3. Bidirectional Relationship—Granger Causality
Pairwise Granger causality was deployed to examine the direction of causal flows between FinTech variables and monetary policy. Causality describes a situation where the previous value of a variable predicts the present or future value of another variable, upon taking into consideration the variable’s own previous value.
The results presented in Table 15 indicate evidence of six (6) bidirectional flows, with only one (1) between FinTech and monetary policy, and thirteen (13) unidirectional flows, of which five (5) address FinTech and monetary policy.
Table 15.
Granger Causality.
Evidence of bidirectional flows between POS and MPR is observed. This suggests that the past value of POS contains information for predicting MPR’s present and future, after accounting for POS’s own past realisation. Similarly, the previous value of MPR contains information useful for predicting the current and future values of POS.
Furthermore, the results showed evidence of unidirectional causality between MOBPAY and MPR, with causality flowing from MOBPAY to MPR; unidirectional causality between WEBPAY and MPR, with causality flowing from WEBPAY to MPR; unidirectional causality between MOBPAY and TBR, with causality flowing from MOBPAY to TBR; unidirectional causality between POS and TBR, with causality flowing from POS to TBR; and unidirectional causality between TBR and WEBPAY, with causality flowing from TBR to WEBPAY. (See Table A2 for the full results).
6. Conclusions
Nigeria’s digital payment ecosystem has evolved over the years to become one of Africa’s most advanced and dynamic, driven by the convergence of traditional banks, FinTechs, and finance start-up platforms, and has also witnessed increasing regulatory reform. This paper investigates how traditional banks have increasingly leveraged FinTech-enabled channels across four major payment systems (automated teller machines, web pay/internet banking, mobile pay, and point-of-sale) and the effects of these channels on monetary policy transmission mechanisms. The analysis covered the period from January 2012, when the CBN introduced the cashless policy, to June 2025, capturing important milestones, including the COVID-19 pandemic in 2020 and the naira redesign policy in 2023. The analysis used unit root tests based on the Augmented Dickey–Fuller (ADF) and Phillips–Perron (PP) statistics, indicating that all variables are I(1). Furthermore, bounds tests for the ARDL model confirmed the presence of cointegration among monetary policy dynamics (the monetary policy rate and the treasury bill rate), the FinTech payment system channels, and the control variables (the maximum lending rate and the savings deposit rate). The long-run ARDL shows that point-of-sale transaction value had a positive and statistically significant effect on both the monetary policy rate and the treasury bill rate. The Dynamic Ordinary Least Squares robustness check revealed that mobile payments are associated with significantly lower monetary policy and treasury bill rates, and that point-of-sale web payments increase the monetary policy rate. In contrast, point-of-sale increases the treasury bill rate after controlling for the maximum lending rate and the savings deposit rate.
More specifically, the results indicate that monetary policy and FinTech payment-system channels in Nigeria are cointegrated. Among the FinTech variables, point-of-sale is the most robust channel in both the ARDL and DOLS models, with a positive and significant effect on the monetary policy rate. Also, the savings deposit rate reveals a very significant traditional banking rate channel, affirming its role as a determinant of monetary policy transmission. Furthermore, automated teller machines, web pay/internet banking, and mobile pay are not significant determinants of policy rates in the baseline model. These findings have indeed contributed to the literature by affirming that FinTech, particularly the four major payment system channels used by traditional banks, does not uniformly affect monetary policy transmission, contrary to what most studies imply when they combine all FinTech channels into a single index. Lastly, the monetary authorities needs to ensure that the monetary policy rate and treasury bills rate decisions are not based solely on inflationary pressures, the money demand and supply dynamics, and the macroeconomic environment, but also consider a detailed review of the various FinTech channels, the banking system linkage of those channels, as well as the effect of changes in the data to arrive at a more effective monetary policy transmission mechanism which compliments the banking sector and still provides FinTechs start-ups with huge opportunities to deepen the payment and credit ecosystem. Our study is empirically sound in its applicability, methodology, and analysis of results. However, it is not without limitations. Having explored the impact of traditional banks’ use of FinTech channels on monetary policy, there is a need to address another gap in the literature by examining how the regulatory framework affects FinTech start-ups and banks.
Author Contributions
Conceptualisation: E.O.A. and F.O.A.; Methodology: F.O.A. and E.O.A.; Formal Analysis: E.O.A., F.O.A. and J.O.I.; Investigation: F.O.A., E.O.A. and J.O.I.; Resources: E.O.A., F.O.A. and J.O.I.; Writing—Original Draft: E.O.A.; Writing—Review and Editing: F.O.A., E.O.A. and J.O.I.; Visualisation: E.O.A. and F.O.A.; Project Administration: E.O.A., F.O.A. and J.O.I. All authors have read and agreed to the published version of the manuscript.
Funding
We received no funding for this research.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The data that support the findings of this study are available upon reasonable request.
Conflicts of Interest
Eze Okechukwu Agha was employed by the company Keystone Bank Head Office. The authors declare that the research was conducted in the absence of any commercial or financial relationships that could be construed as potential conflict of interest.
Abbreviations
The following abbreviations are used in this manuscript:
| ATM | Automated Teller Machine |
| CBN | Central Bank of Nigeria |
| DMB | Deposit Money Bank |
| FinTech | Financial Technology |
| MLR | Maximum Lending Rate |
| MOBPAY | Mobile pay |
| MPR | Monetary Policy Rate |
| POS | Point-of-Sale |
| SDR | Savings Deposit Rate |
| TBR | Treasury Bills Rate (91-day) |
| WEBPAY | Web/Internet Pay |
Appendix A
Table A1.
Annual FinTech Transactions Value and Number of DMBs.
Table A2.
Pairwise Granger Causality Test.
Table A3.
Number of Deposit Money Banks from 1981 to June 2025.
References
- ACI Worldwide. (2022). Prime time for real-time. Available online: https://www.aciworldwide.com/wp-content/uploads/2022/04/Prime-Time-for-Real-Time-Report-2022.pdf (accessed on 25 June 2026).
- Ahamed, M. M., & Mallick, S. K. (2019). Is financial inclusion good for bank stability? International evidence. Journal of Economic Behaviour & Organisation, 157, 403–427. [Google Scholar] [CrossRef] [Scilit]
- Ajouz, M., Shehadeh, M., Issa, S., & Nawawra, H. (2025). The moderating role of FinTech in the relationship between customer satisfaction and retention in the banking sector. International Journal of Financial Studies, 13(4), 226. [Google Scholar] [CrossRef] [Scilit]
- Alalmaee, H. (2026). The impact of fintech investment on economic growth. Cogent Economics & Finance, 14(1), 2614002. [Google Scholar] [CrossRef] [Scilit]
- Aldboush, H. H., & Ferdous, M. (2023). Building trust in FinTech: An analysis of ethical and privacy considerations in the intersection of big data, AI, and customer trust. International Journal of Financial Studies, 11(3), 90. [Google Scholar] [CrossRef] [Scilit]
- Allen, F., Demirguc-Kunt, A., Klapper, L., & Peria, M. S. M. (2016). The foundations of financial inclusion: Understanding ownership and use of formal accounts. Journal of Financial Intermediation, 27, 1–30. [Google Scholar] [CrossRef] [Scilit]
- Aloulou, M., Grati, R., Al-Qudah, A. A., & Al-Okaily, M. (2024). Does FinTech adoption increase the diffusion rate of digital financial inclusion? A study of the banking industry sector. Journal of Financial Reporting and Accounting, 22(2), 289–307. [Google Scholar] [CrossRef] [Scilit]
- Al Sharif, B. M. M. (2025). Digital finance strategy and bank performance in emerging markets: The role of financial soundness. Corporate & Business Strategy Review, 6(3), 401–410. [Google Scholar] [CrossRef] [Scilit]
- Altavilla, C., Boucinha, M., & Peydró, J. L. (2018). Monetary policy and bank profitability in a low-interest-rate environment. Economic Policy, 33(96), 531–586. [Google Scholar] [CrossRef] [Scilit]
- Antwi-Wiafe, K., Asante, G. N., & Takyi, P. O. (2023). Is financial technology a complement or substitute for domestic financial institutions in Ghana? Journal of Financial Economic Policy, 15(4–5), 424–443. [Google Scholar] [CrossRef] [Scilit]
- Arner, D. W., Barberis, J., & Buckley, R. P. (2015). The evolution of FinTech: A new post-crisis paradigm. Georget. J. Int. Law, 47, 1271. [Google Scholar]
- Attanasio, O. P., Guiso, L., & Jappelli, T. (2002). The demand for money, financial innovation, and the welfare cost of inflation: An analysis with household data. Journal of Political Economy, 110(2), 317–351. [Google Scholar] [CrossRef] [Scilit]
- Ayoade, O. V., & Areghan, I. (2025). Nigeria’s financial system and financial inclusion. African Journal of Accounting and Financial Research, 8(2), 55–66. [Google Scholar] [CrossRef] [Scilit]
- Badrous, Y. M. L., Tawfik, O. I., Elmaasrawy, H. E., Srour, M. I., & Sharaf, M. A. A. (2025). FinTech adoption and commercial banks’ environmental performance: Do green accounting practices matter? International Journal of Financial Studies, 13(2), 90. [Google Scholar] [CrossRef] [Scilit]
- Baharumshah, A. Z., Mohd, S. H., & Masih, A. M. M. (2009). The stability of money demand in China: Evidence from the ARDL model. Economic Systems, 33(3), 231–244. [Google Scholar] [CrossRef] [Scilit]
- Bai, J., & Perron, P. (2003). Computation and analysis of multiple structural change models. Journal of Applied Econometrics, 18(1), 1–22. [Google Scholar] [CrossRef] [Scilit]
- Banna, H., Mia, M. A., Nourani, M., & Yarovaya, L. (2022). FinTech-based financial inclusion and risk-taking of microfinance institutions (MFIs): Evidence from Sub-Saharan Africa. Finance Research Letters, 45, 102149. [Google Scholar] [CrossRef] [Scilit]
- Beltrame, F., Zorzi, G., & Grassetti, L. (2022). The effect of FinTech investments on listed banks: Evidence from an Italian sample. Risk Governance and Control: Financial Markets & Institutions, 12(2), 47–55. [Google Scholar] [CrossRef] [Scilit]
- Bendezu, L., & Rodriguez, G. (2026). Lending rate sensitivity to monetary policy: A bank-level empirical analysis. Journal of Economics, Finance and Administrative Science, 31(61), 35–55. [Google Scholar] [CrossRef] [Scilit]
- Blot, C., & Labondance, F. (2021). Beyond the interest rate pass-through: Monetary policy and banks’ interest rates during the effective lower bound. HAL Open Science. Available online: https://hal.science/hal-04221606v1 (accessed on 3 June 2026).
- Boot, A., Hoffmann, P., Laeven, L., & Ratnovski, L. (2021). FinTech: What is old, what’s new? Journal of Financial Stability, 53, 100836. [Google Scholar] [CrossRef] [Scilit]
- Central Bank of Nigeria. (2014). Statistical bulletin. Available online: https://www.cbn.gov.ng/documents/Statbulletin.html (accessed on 16 June 2026).
- Central Bank of Nigeria. (2024). Statistical bulletin. Available online: https://www.cbn.gov.ng/documents/Statbulletin.html (accessed on 17 June 2026).
- Central Bank of Nigeria. (2025). Shaping the future of FinTech in Nigeria: Innovation, inclusion and integrity. Available online: https://www.cbn.gov.ng/Out/2026/CCD/CBN_FINTECH_REPORT_.pdf (accessed on 17 June 2026).
- Cornelli, G., De Fiore, F., Gambacorta, L., & Manea, C. (2024). FinTech vs bank credit: How do they react to monetary policy? Economics Letters, 234, 111475. [Google Scholar] [CrossRef] [Scilit]
- Demir, A., Pesqué-Cela, V., Altunbas, Y., & Murinde, V. (2022). FinTech, financial inclusion and income inequality: A quantile regression approach. The European Journal of Finance, 28(1), 86–107. [Google Scholar] [CrossRef] [Scilit]
- Elsaid, H. M. (2023). A review of literature directions regarding the impact of FinTech firms on the banking industry. Qualitative Research in Financial Markets, 15(5), 693–711. [Google Scholar] [CrossRef] [Scilit]
- Fegatelli, P. (2022). A central bank digital currency in a heterogeneous monetary union: Managing the effects on the bank lending channel. Journal of Macroeconomics, 71, 103392. [Google Scholar] [CrossRef] [Scilit]
- Friedman, B. M. (2000). Monetary policy. Working Paper, No. 8057. National Bureau of Economic Research. Available online: https://www.nber.org/papers/w8057 (accessed on 7 June 2026).
- Fujiki, H., & Tanaka, M. (2009). Demand for currency, new technology and the adoption of electronic money: Evidence using individual household data. Paper No. 09-E-27. Institute for Monetary and Economic Studies, Bank of Japan. Available online: https://www.newyorkfed.org/medialibrary/media/research/conference/2010/econ/emoney_fujiki_tanaka.pdf (accessed on 9 June 2026).
- Gai, K., Qiu, M., & Sun, X. (2018). A survey on FinTech. Journal of Network and Computer Applications, 103, 262–273. [Google Scholar] [CrossRef] [Scilit]
- Garg, G., Shamshad, M., Gauhar, N., Tabash, M. I., Hamouri, B., & Daniel, L. N. (2023). A bibliometric analysis of fintech trends: An empirical investigation. International Journal of Financial Studies, 11(2), 79. [Google Scholar] [CrossRef] [Scilit]
- Goldfeld, S. M., Duesenberry, J., & Poole, W. (1973). The demand for money revisited. Brookings Papers on Economic Activity, 1973(3), 577–646. [Google Scholar] [CrossRef] [Scilit]
- Hasan, M. H., Hossain, M. Z., Hasan, L., & Dewan, M. A. (2024). FinTech and sustainable finance: How is FinTech shaping the future of sustainable finance? European Journal of Management, Economics and Business, 1(3), 100–115. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Hoang, H. T. T., & Le, C. D. H. (2026). Assessing the impact of financial technology on bank profitability: The moderating role of bank size. Risk Governance and Control: Financial Markets & Institutions, 16(2), 102–111. [Google Scholar] [CrossRef] [Scilit]
- Holton, S., & Rodriguez d’Acri, C. (2015). Jagged cliffs and stumbling blocks: Interest rate pass-through fragmentation during the euro area crisis. ECB Working Paper. No. 1850. Available online: https://hdl.handle.net/10419/154283 (accessed on 22 June 2026).
- Huang, J. (2022). Research on the impact of FinTech on China’s economic growth and tertiary industry development—Empirical analysis based on panel data. In Proceedings of the 9th international conference on management of e-commerce and e-government (pp. 103–110). Association for Computing Machinery. [Google Scholar] [CrossRef] [Scilit]
- Huang, Z., Lahreche, A., Saito, M., & Wiriadinata, U. (2024). E-money and monetary policy transmission (Working Paper, WP/24/69). International Monetary Fund. Available online: https://www.imf.org/-/media/files/publications/wp/2024/english/wpiea2024069-print-pdf.pdf (accessed on 20 June 2026).
- Hundal, S., & Zinakova, T. (2021). Financial technology in the Finnish banking sector and its impact on stakeholders in the wake of COVID-19. Risk Governance and Control: Financial Markets & Institutions, 11(1), 8–19. [Google Scholar] [CrossRef] [Scilit]
- Ia, G., & Miglionico, A. (2019). Artificial intelligence and automation in financial services: The case of the Russian banking sector. Law and Economics Yearly Review, 8(1), 125–147. [Google Scholar]
- Ikechi, K., Chinonso, E., Anthony, N., & Eze, I. (2020). The use of e-payment products and their impact on the currency in demand in Nigeria. International Journal of Innovation and Economic Development, 6(1), 31–46. [Google Scholar] [CrossRef] [Scilit]
- Imhanzenobe, J. O. (2024). IFRS adoption and performance of stock markets: A comparative analysis of frontier stock markets in Sub-Saharan Africa. Thunderbird International Business Review, 66(6), 549–565. [Google Scholar] [CrossRef] [Scilit]
- International Finance Corporation. (2019). Digital skills in Sub-Saharan Africa. Available online: https://www.ifc.org/content/dam/ifc/doc/mgrt/digital-skills-final-web-5-7-19.pdf (accessed on 17 June 2026).
- Iorngurum, T. (2019). Gauging the effects of modern payment technologies adoption on the demand for money in Nigeria. Economic Analysis, 52(2), 12–27. [Google Scholar] [CrossRef] [Scilit]
- Ishaku, R., & Yakubu, M. (2025). Monetary policy rate and market interest rates in Nigeria. In Proceedings of the international conference on business, economics & management. Diamond Scientific Publishing. [Google Scholar] [CrossRef] [Scilit]
- Jiang, S., Qiu, S., & Zhou, H. (2022). Will digital financial development affect the effectiveness of monetary policy in emerging market countries? Economic Research-Ekonomska Istraživanja, 35(1), 3437–3472. [Google Scholar] [CrossRef] [Scilit]
- Jonker, N., & Kosse, A. (2022). The interplay of financial education, financial inclusion and financial stability and the role of Big Tech. Contemporary Economic Policy, 40(4), 612–635. [Google Scholar] [CrossRef] [Scilit]
- Kesavaraj, S. V., Jakhiya, C. M., & Bhandari, C. N. (2022). A study on upcoming central bank digital currency: Opportunities, obstacles, and potential FinTech solutions using cryptography in the Indian scenario. In Proceedings of the 13th international conference on computing, communication, and networking technologies (ICCCNT) (pp. 1–10). IEEE. [Google Scholar] [CrossRef] [Scilit]
- Khan, M. A. H., Adnan, A. T. M., Sultana, R., Sultana, H., & Uddin, M. B. (2026). Mapping the evolution of FinTech and digital payments: A bibliometric analysis of the shift to a cashless economy (2015–2024). FinTech and Digital Accounting Review, 2(1), 128–154. [Google Scholar] [CrossRef] [Scilit]
- Kömürcüoğlu, Ö. F., & Akyazi, H. (2024). Novel analysis on the impact of FinTech developments on monetary policy: The case of Türkiye. Ekonomika, 103(3), 70–90. [Google Scholar] [CrossRef] [Scilit]
- Kulu, E., & Bondzie, E. A. (2024). Mobile money, credit to deposit ratio and monetary policy: Empirics from Ghana. Transnational Corporations Review, 16(3), 200060. [Google Scholar] [CrossRef] [Scilit]
- Lagna, A., & Ravishankar, M. N. (2022). Making the world a better place with FinTech research. Information Systems Journal, 32(1), 61–102. [Google Scholar] [CrossRef] [Scilit]
- Le, T. D., Ho, T. H., Nguyen, D. T., & Ngo, T. (2021). FinTech credit and bank efficiency: International evidence. International Journal of Financial Studies, 9(3), 44. [Google Scholar] [CrossRef] [Scilit]
- Lee, C. C., Wang, C. W., & Ho, S. J. (2022). Financial aid and financial inclusion: Does risk uncertainty matter? Pacific-Basin Finance Journal, 71, 101700. [Google Scholar] [CrossRef] [Scilit]
- Li, P., Liu, T., Li, J., Ling, F. K., & Li, Z. (2024). Exploring the impact of FinTech, natural resources, energy consumption, and international trade on economic growth in China: A dynamic ARDL approach. Resources Policy, 98, 105310. [Google Scholar] [CrossRef] [Scilit]
- Mabandla, N. Z. (2026). The effects of technology and liquidity on bank capital structure. International Journal of Financial Studies, 14(4), 98. [Google Scholar] [CrossRef] [Scilit]
- Mahmud, K., Joarder, M. M. A., & Muheymin-Us-Sakib, K. (2022). Adoption factors of FinTech: Evidence from an emerging economy country-wide representative sample. International Journal of Financial Studies, 11(1), 9. [Google Scholar] [CrossRef] [Scilit]
- Mansour, N. (2024). The impact of FinTech development on commercial banks’ profitability. Journal of Organisational and End User Computing (JOEUC), 36(1), 1–18. [Google Scholar] [CrossRef] [Scilit]
- Mashamba, T., & Gani, S. (2023). Fintech, bank funding, and economic growth in Sub-Saharan Africa. Cogent Economics & Finance, 11(1), 2225916. [Google Scholar] [CrossRef] [Scilit]
- Mehrotra, A. N., & Yetman, J. (2014). Financial inclusion and optimal monetary policy. Working Paper No. 476. Bank for International Settlements. Available online: https://ssrn.com/abstract=2542220 (accessed on 26 June 2026).
- Mert, M., & Çağlar, A. E. (2020). Testing pollution haven and pollution halo hypotheses for Turkey: A new perspective. Environmental Science and Pollution Research, 27(26), 32933–32943. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Mills, D. C., Wang, K., Malone, B., Ravi, A., Marquardt, J., Chen, C., Badev, A. I., Brezinski, T., Fahy, L., Liao, K., Kargenian, V., Ellithorpe, M., Ng, W., & Baird, M. (2016). Distributed ledger technology in payments, clearing, and settlement (FEDS Working Paper No. 2016-095). Board of Governors of the Federal Reserve System. [CrossRef] [Scilit]
- Mittal, R., Kathuria, T., Saini, M., Dhingra, B., & Yadav, M. (2023). Effect of financial inclusion and FinTech on the effectiveness of Indian monetary policy: An empirical investigation. International Journal of Social Economics, 50(12), 1702–1718. [Google Scholar] [CrossRef] [Scilit]
- Mlambo, C., & Msosa, S. K. (2020). The effect of financial technology on money demand: Evidence from selected African states. International Journal of Economics and Business Administration, 8(1), 366–373. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Mumtaz, M. Z., & Smith, Z. A. (2020). Empirical examination of the role of FinTech in monetary policy. Pacific Economic Review, 25(5), 620–640. [Google Scholar] [CrossRef] [Scilit]
- Nabilou, H. (2020). Testing the waters of the Rubicon: The European Central Bank and central bank digital currencies: H. Nabilou. Journal of Banking Regulation, 21(4), 299–314. [Google Scholar] [CrossRef] [Scilit]
- Nathan, O. (2023). Monetary policy transmission channels on the performance of Nigerian stock market. International Journal of Economics and Financial Management, 8(3), 140–152. [Google Scholar] [CrossRef] [Scilit]
- Nawaz, F., Aysan, A. F., Kayani, U., & Nasseredine, H. (2024). Do CBDCs promote financial inclusion and strengthen the monetary regulations? Journal of Infrastructure, Policy and Development, 8(8), 5870. [Google Scholar] [CrossRef] [Scilit]
- Oyadeyi, O. (2023). Financial development, interest rate pass-through and interest rate channel of monetary policy. Cogent Economics & Finance, 11(1), 2209952. [Google Scholar] [CrossRef] [Scilit]
- Ozili, P. K. (2023). Impact of monetary policy on financial inclusion in emerging markets. Journal of Risk and Financial Management, 16(7), 303. [Google Scholar] [CrossRef] [Scilit]
- Pesaran, M. H., Shin, Y., & Smith, R. J. (2001). Bounds testing approaches to the analysis of level relationships. Journal of Applied Econometrics, 16(3), 289–326. [Google Scholar] [CrossRef] [Scilit]
- Rehman, S. U., Khan, S. N., Subhani, W., Mehboob, I., Yaseen, M. N., & Qayoom, A. (2023). Impact of Distributed Ledger Technology (DLT) and FinTech investment on central bank policy and monetary policy effectiveness. Bulletin of Business and Economics (BBE), 12(3), 202–210. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Renzhi, N., & Beirne, J. (2025). The nexus of peer-to-peer lending and monetary policy transmission: Evidence from the People’s Republic of China. Pacific-Basin Finance Journal, 91, 102770. [Google Scholar] [CrossRef] [Scilit]
- Sahabuddin, M., Sakib, M. N., Rahman, M. M., Jibir, A., Fahlevi, M., Aljuaid, M., & Grabowska, S. (2023). The evolution of FinTech in scientific research: A bibliometric analysis. Sustainability, 15(9), 7176. [Google Scholar] [CrossRef] [Scilit]
- Sahid, A., Maleh, Y., Asemanjerdi, S. A., & Martín-Cervantes, P. A. (2023). A bibliometric analysis of the FinTech agility literature: Evolution and review. International Journal of Financial Studies, 11(4), 123. [Google Scholar] [CrossRef] [Scilit]
- Sakharov, D. M. (2021). Central bank digital currencies: Key aspects and impact on the financial system. Finance: Theory and Practice, 25(5), 133–149. [Google Scholar] [CrossRef] [Scilit]
- Sanusi, L. S. (2010). Global financial meltdown and the reforms in the Nigerian banking sector. CBN Journal of Applied Statistics, 2(1), 93–108. [Google Scholar]
- Saraswati, B. D., Maski, G., Kaluge, D., & Sakti, R. K. (2020). The effect of financial inclusion and financial technology on the effectiveness of the Indonesian monetary policy. Business: Theory and Practice, 21(1), 230–243. [Google Scholar] [CrossRef] [Scilit]
- Siddiqui, Z., & Rivera, C. A. (2022). FinTech and FinTech ecosystem: A review of literature. Risk Governance and Control: Financial Markets & Institutions, 12(1), 63–73. [Google Scholar] [CrossRef] [Scilit]
- Stock, J. H., & Watson, M. W. (1993). A simple estimator of cointegrating vectors in higher order integrated systems. Econometrica, 61(4), 783–820. [Google Scholar] [CrossRef] [Scilit]
- Stock, J. H., & Watson, M. W. (1996). Evidence on structural instability in macroeconomic time series. Journal of Business & Economic Statistics, 14(1), 11–30. [Google Scholar] [CrossRef] [Scilit]
- Syafi’i, A. (2025). Econometric analysis of inflation dynamics in digital payment ecosystems in emerging markets. Journal of Applied Econometrics, 1(1), 9–15. [Google Scholar] [CrossRef] [Scilit]
- Tan, C. T., Mohamed, A., Habibullah, M. S., & Chin, L. (2020). The impacts of monetary and fiscal policies on economic growth in Malaysia, Singapore and Thailand. South Asian Journal of Macroeconomics and Public Finance, 9(1), 114–130. [Google Scholar] [CrossRef] [Scilit]
- Tay, L. Y., Tai, H. T., & Tan, G. S. (2022). Digital financial inclusion: A gateway to sustainable development. Heliyon, 8(6), e09766. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Tehranchian, A. M., Jafari Samimi, A., & Yazdandoust, A. (2012). The impact of modern technology on demand for money in Iran. Iranian Economic Review, 16(32), 133–148. [Google Scholar] [CrossRef] [Scilit]
- Tepe, G., Geyikci, U. B., & Sancak, F. M. (2021). FinTech companies: A bibliometric analysis. International Journal of Financial Studies, 10(1), 2. [Google Scholar] [CrossRef] [Scilit]
- Tonuchi, J., Nwolisa, C., Obikaomu, P., & Alase, G. (2021). Monetary policy effectiveness and financial inclusion in Nigeria: FinTech, ‘the disrupter’ or ‘Enabler’. International Journal of Applied Economics, Finance and Accounting, 9(1), 19–27. [Google Scholar] [CrossRef] [Scilit]
- Tule, M. K., & Oduh, M. O. (2017). Financial innovations and the future of monetary policy in Nigeria. Economics of Innovation and New Technology, 26(5), 453–476. [Google Scholar] [CrossRef] [Scilit]
- Uche, C. U. (1997). Banking developments in pre-independence Nigeria: A study in regulation, control and politics. London School of Economics and Political Science (United Kingdom). [Google Scholar]
- Ugwuanyi, U., Ugwuoke, R., Onyeanu, E., Festus Eze, E., Isahaku Prince, A., Anago, J., & Ibe, G. I. (2022). Financial inclusion-economic growth nexus: Traditional finance versus digital finance in Sub-Saharan Africa. Cogent Economics & Finance, 10(1), 2133356. [Google Scholar] [CrossRef] [Scilit]
- Van Leuvensteijn, M., Sørensen, C. K., Bikker, J. A., & Van Rixtel, A. A. (2013). Impact of bank competition on the interest rate pass-through in the euro area. Applied Economics, 45(11), 1359–1380. [Google Scholar] [CrossRef] [Scilit]
- Wahab, A., Bohari, S. A., & Ling, P.-S. (2025). Bridging financial gaps: How FinTech drives global financial literacy and development under currency exposure constraints. Risk Governance and Control: Financial Markets & Institutions, 15(4), 65–75. [Google Scholar] [CrossRef] [Scilit]
- Wang, W., Xiong, D., & Li, Y. (2025). The impact of FinTech on financial institution performance and risk: An empirical analysis from China. SAGE Open, 15(2), 21582440251344376. [Google Scholar] [CrossRef] [Scilit]
- Wasiaturrahma, D., Wahyuningtyas, Y. T., & Ajija, S. R. (2019). Non-cash payment and demand for real money in Indonesia. Journal of Economics, Business, and Accountancy, Ventura (JEBAV), 22(1), 1–8. [Google Scholar] [CrossRef] [Scilit]
- Wiafe, E. A., Quaidoo, C., & Sekyi, S. (2022). Monetary policy effectiveness in the advent of mobile money activity: Empirical evidence from Ghana. Cogent Economics & Finance, 10(1), 2039343. [Google Scholar] [CrossRef] [Scilit]
- Winker, P. (1999). Sluggish adjustment of interest rates and credit rationing: An application of unit root testing and error correction modelling. Applied Economics, 31(3), 267–277. [Google Scholar] [CrossRef] [Scilit]
- Zakaria, E., & Abdelhalim, L. (2025). The rise of FinTech: Bibliometric analysis of global growth, emerging themes and the quality of scientific contributions. International Journal of Innovative Research and Scientific Studies, 8, 1408–1423. [Google Scholar] [CrossRef] [Scilit]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.