


Abstract
Armed conflict threatens financial resilience by disrupting the infrastructure, liquidity, information flows, and financial networks that support access to and use of financial services. This study examines how state-based and non-state conflict shape financial access and use across 33 Sub-Saharan African countries. We combine Global Findex 2025 data with 2024 Uppsala Conflict Data Program fatalities and GSMA mobile money regulatory indicators. Financial resilience serves as an interpretive framework rather than a directly observed outcome. The empirical outcomes measure separate dimensions of financial access and use relevant to resilience; they do not directly measure continuity, adaptation, or recovery under conflict exposure. Multilevel mixed-effects logit marginal effects show that a one-standard-deviation increase in state-based conflict intensity corresponds to reductions of 2.9 percentage points in formal financial-institution account ownership and 1.3 percentage points in any-account ownership. State-based conflict is also linked to lower borrowing, domestic remittances, and transfer receipt. Non-state conflict is associated with lower formal financial-institution account ownership, while its associations with most financial-use outcomes are imprecisely estimated; domestic remittances provide weaker evidence of a negative association at the 10 percent level. Predicted probabilities across the conflict distribution further show lower remittance and transfer participation at higher levels of state-based conflict. These findings demonstrate that financial resilience under conflict is function-specific: services requiring active transactions, liquidity, counterparties, and functioning delivery networks are more vulnerable than financial stocks and established institutional receipts. The study advances the literature by distinguishing financial access from actual use and identifying how financial vulnerability varies across conflict types, intensity levels, and financial functions. The findings underscore the need for central banks, financial institutions, and mobile money providers to assess resilience through service functionality rather than account ownership alone. Policy should prioritise payment and transfer continuity, agent liquidity, sustained credit access, network reliability, and resilient financial infrastructure in conflict-exposed economies.
1. Introduction
Armed conflict affects financial systems through destruction, displacement, uncertainty, interrupted markets, and weaker institutions (Collier, 1999; Blattman & Miguel, 2010). Banks and other providers depend on branches, communications networks, staff mobility, cash logistics, identification systems, borrower information, and enforceable repayment arrangements. Conflict raises operating and monitoring costs, weakens borrower cash flows, and increases credit risk. Households simultaneously face income losses, mobility restrictions, and greater need for emergency liquidity and transfers. Financial disruption under conflict therefore reflects linked pressures on banking stability, credit supply, payment continuity, and household financial behaviour.
These pressures are important in Sub-Saharan Africa, where conflict exposure coexists with gaps in formal financial access and uneven financial infrastructure. Mobile money and agent networks have reduced distance and transaction costs and widened access to transfers, savings, and credit (Aron, 2018; Jack & Suri, 2014; Suri & Jack, 2016; Kodom et al., 2020, 2022; Grzybowski et al., 2023). Yet digital finance also depends on connectivity, agents, liquidity, electricity, identification, and regulatory capacity. Conflict therefore tests whether financial systems preserve their core functions when both providers and users face stress.
Existing evidence leaves an important gap. Conflict studies document losses in output, capital, infrastructure, and institutional capacity (Bellows & Miguel, 2009; Blattman & Miguel, 2010), while financial-inclusion studies focus mainly on income, education, gender, technology, and institutions (Allen et al., 2014; Aron, 2018; Asongu et al., 2024). Direct evidence links insecurity to weaker branches, ATMs, credit, and composite financial inclusion (Garang, 2024; Abu et al., 2026), but three issues remain. First, aggregate inclusion measures conceal differences between account ownership and actual use. Second, state-based and non-state violence differ institutionally and may display different outcome-specific association patterns. Third, average estimates conceal how predicted financial outcomes vary across the observed distribution of conflict intensity.
This study addresses these gaps through a financial-resilience framework. Given the cross-sectional design, financial resilience is proxied by differences in access to and use of financial services associated with conflict exposure; the study does not observe continuity or recovery longitudinally. We combine individual-level Global Findex 2025 data with UCDP conflict fatalities and GSMA mobile money regulatory indicators in 33 Sub-Saharan African countries. The analysis separates formal financial-institution accounts from any account and examines borrowing, saving, pensions, domestic remittances, wages, utility payments, and transfers. It also distinguishes state-based from non-state conflict, evaluates predicted outcomes across the observed conflict-intensity distribution, and examines heterogeneity by country income classification.
The results show selective financial disruption. State-based conflict is associated with lower formal and any-account ownership and with lower borrowing, domestic remittances, and transfer receipt. Non-state conflict is associated with lower formal account ownership, while its borrowing estimate is negative but statistically insignificant. Domestic remittances show weaker evidence of a negative association at the 10 percent level. Saving, pensions, and wages show greater average continuity. Predicted probabilities further show lower remittance and transfer participation at higher observed levels of state-based conflict. These patterns indicate that conflict exposure is associated differently with financial functions according to their dependence on networks, liquidity, counterparties, and institutional infrastructure.
The paper contributes to the Special Issue’s focus on banking stability, credit risk, and financial resilience in emerging markets in three ways. First, it links household financial resilience to financial-sector stress by separating access from transaction-dependent use. Second, it shows that conflict type and intensity are important for the continuity of credit and payment functions. Third, it places these responses within national regulatory and agent-service conditions. The analysis does not estimate bank solvency or portfolio quality directly. Instead, it identifies the household-side outcomes through which conflict-related operational risk, credit rationing, liquidity constraints, and payment disruption become visible. This provides evidence relevant to regulators and financial institutions designing resilience strategies for conflict-exposed emerging markets.
This paper is structured as follows. Section 2 reviews the literature, develops the conceptual framework, and states the hypotheses. Section 3 describes the data sources, variable measurement, and empirical estimation model. Section 4 presents the results on financial access, financial use, and heterogeneity by conflict intensity and income classification. Section 5 discusses the findings. Section 6 concludes and sets out the policy implications and recommendations.
2. Literature, Conceptual Framework and Hypotheses
2.1. Conflict and Economic Disruption
Conflict affects economic activity through destruction, displacement, uncertainty, and higher transaction costs (Collier, 1999; Blattman & Miguel, 2010). These mechanisms are crucial for finance because intermediation depends on infrastructure, information, mobility, contract enforcement, and repeated interaction. Conflict also creates spillovers through trade, migration, and confidence (Ogbe et al., 2024). For financial institutions, the resulting stress appears through higher operating costs, weaker collateral and borrower cash flows, impaired monitoring, and greater default risk.
Financial institutions therefore face connected operational, liquidity, and credit-risk channels. Violence raises the cost of maintaining branches and agents, moving cash, verifying customers, and monitoring borrowers. Providers may tighten screening, reduce lending, close access points, or concentrate operations in safer areas. Evidence from South Sudan links civil war to weaker branch and ATM access and constrained credit (Garang, 2024), while African panel evidence associates insecurity with lower financial inclusion (Abu et al., 2026). Global syndicated-loan evidence similarly shows foreign banks reducing lending to conflict-affected countries (De Haas et al., 2025). These findings motivate the expectation that conflict weakens financial access and use, with state-based conflict producing broader disruption because state participation places administrative systems and public infrastructure under greater stress.
2.2. Financial Inclusion, Digital Finance and Resilience
Financial inclusion extends beyond account ownership to the effective use of financial services. This distinction is important for understanding resilience because an account may remain registered even when households are unable to borrow, save, transfer funds, receive remittances, or make payments. In Sub-Saharan Africa, constraints on infrastructure and population density have historically limited formal financial access (Allen et al., 2014). Digital finance, particularly mobile money, has reduced some of these constraints by lowering distance and transaction costs and expanding access to payments, transfers, savings, and credit (Aron, 2018; Kodom et al., 2020, 2022; Grzybowski et al., 2023). The expansion of digital finance therefore shifts the resilience question from whether households possess accounts to whether financial services continue to function when households and financial systems experience shocks.
Evidence on mobile money supports this functional perspective. Mobile money strengthens households’ capacity to respond to shocks by facilitating transfers and widening risk-sharing networks (Jack & Suri, 2014). Its longer-term expansion has also been associated with lower extreme poverty and greater household resilience (Suri & Jack, 2016), while mobile savings products influence saving and investment decisions (Batista & Vicente, 2020). These benefits, however, depend on an operational financial ecosystem. Digital transactions require connectivity, electricity, functioning agents, adequate liquidity, cash logistics, and accessible payment infrastructure. Digitalisation therefore reduces dependence on physical bank branches without eliminating infrastructure dependence. Under conflict, disruption to these supporting systems may weaken the same financial channels households rely on to manage shocks.
This dependence places institutions and financial-sector stability at the centre of financial resilience. Evidence across Sub-Saharan Africa links financial inclusion to institutional quality, infrastructure, and macroeconomic conditions (Anifowose & Chummun, 2025; Golpet et al., 2026). Meniago (2025) similarly shows that institutional conditions shape the economic gains associated with digital financial inclusion in SADC countries. At the financial-system level, Jungo et al. (2022) find that financial stability conditions the relationship between financial regulation, inclusion, and banking-sector competitiveness. This literature suggests that expanding financial access and maintaining financial access under stress are related but distinct outcomes. Regulation and institutional capacity influence whether providers, payment systems, and delivery networks continue functioning when economic or security conditions deteriorate.
The relevant institutional environment extends from formal regulation to the infrastructure through which users access financial services. Consumer protection, safeguarding arrangements, identification requirements, and agent-service conditions influence financial access and service continuity (Balasubramanian et al., 2023; Gyamerah & Tetteh, 2024). Evidence from fragile and conflict-affected settings further shows that payment resilience depends on the functioning of the entire transaction chain, including connectivity, intermediaries, payment solutions, liquidity, and user access (Malaika et al., 2025). Weakness at any point in this chain may interrupt transactions even where account ownership remains unchanged. This provides a basis for examining regulatory and agent-service conditions alongside conflict exposure rather than treating financial inclusion primarily as an individual-level outcome.
Financial inclusion contributes to resilience through the resources and opportunities users have to act on financial access. Gender and age differences in digital financial service use indicate unequal participation even where services are available (Chamboko, 2022). Analysing gender gaps through socioeconomic characteristics therefore shifts attention towards the structural conditions shaping access (Kodom et al., 2026). The relationship between digital financial inclusion and women’s economic empowerment also makes control over financial resources relevant to interpreting participation (Kodom et al., 2024). Greater use, however, does not necessarily translate into better financial health (Osarfo et al., 2025). Resilience analysis consequently requires attention to who accesses services, how those services are used and whether users secure financial benefits. Policy design also shapes incentives to use digital services. Ghana’s E-levy illustrates how transaction-related policy choices influence public responses to digital finance (Asante et al., 2024), while evidence from the eCedi pilot shows how adoption of new digital payment instruments operates within an already established mobile money ecosystem (Osafoh & Kodom, 2026). These findings reinforce the need to distinguish availability from effective use and to account for institutional and user-level conditions when assessing resilience.
Financial resilience captures this broader concern. It refers to the capacity to absorb, adapt to, and recover from financial shocks while preserving core financial functions (Liu et al., 2025; Kamble et al., 2026). Much of this literature examines household-specific, economic, or pandemic-related shocks. Armed conflict presents a different resilience problem because it simultaneously affects households and the institutions serving them. Income loss and displacement may increase households’ demand for liquidity, credit, and transfers at the same time that insecurity disrupts agents, payment networks, cash logistics, borrower monitoring, and financial infrastructure. Financial resilience under conflict therefore depends on whether specific financial functions continue operating under a joint demand-and-supply shock. This study builds on this distinction by examining whether access and different forms of financial use respond differently as state-based and non-state conflict intensify, while accounting for the regulatory and agent-service environment in which these responses occur.
2.3. Conceptual Framework and Testable Expectations
The conceptual framework treats financial resilience as a cross-sectional proxy for the capacity to maintain specific financial functions under conflict exposure. The data identify differences in access and use associated with conflict, rather than directly observing continuity or recovery over time. Conflict raises the cost of mobility, communication, liquidity management, verification, screening, monitoring, and settlement. Account ownership is largely a stock outcome and can persist without active use. Borrowing, remittances, utility payments, and transfers are flows requiring functioning providers, counterparties, payment rails, or agents at the point of use. Transaction-dependent services should therefore be more sensitive to conflict than registered account status or established institutional receipts (Dhawan et al., 2024; Malaika et al., 2025).
Saving is theoretically ambiguous. Conflict reduces income and raises emergency spending, encouraging dissaving, but insecurity can also strengthen precautionary saving among households with resources. Wages and pensions may show greater continuity where established employer or government payment arrangements remain operational. The framework therefore expects unequal effects across financial uses rather than a common decline.
Conflict type provides a second distinction. UCDP state-based conflict involves armed force in which at least one party is a state, while non-state conflict involves organised armed groups where neither party is a state. State involvement is expected to create broader financial disruption because administrative systems, transport corridors, public infrastructure, and state-linked financial arrangements face simultaneous pressure. This expectation is consistent with evidence of wider lender retrenchment when conflict affects sovereign and institutional risk (De Haas et al., 2025).
Conflict intensity provides the third dimension. In this study, intensity is based on UCDP resulting deaths for each conflict type. Fatalities are transformed as ln(1 + deaths) and standardized across the merged estimation sample. Higher values therefore represent more severe conflict, and one unit equals a one-standard-deviation increase in the log-transformed fatality measure. Predicted probabilities at the 25th, 50th, and 75th percentiles represent relatively low, median, and high intensity. This allows the analysis to test whether financial disruption changes as violence becomes more severe rather than imposing a constant interpretation across the conflict distribution.
Domestic remittances provide a useful test because conflict can increase the need for support while simultaneously disrupting sender–recipient networks, mobility, liquidity, and connectivity. Evidence from conflict settings shows both stronger support motives and constraints on transfer delivery (Ibrahim, 2025; van Asselt et al., 2025; Lindley, 2024). The net association is therefore empirical: resilience depends on whether financial networks continue to transmit support when insecurity rises.
2.4. Conceptual Model
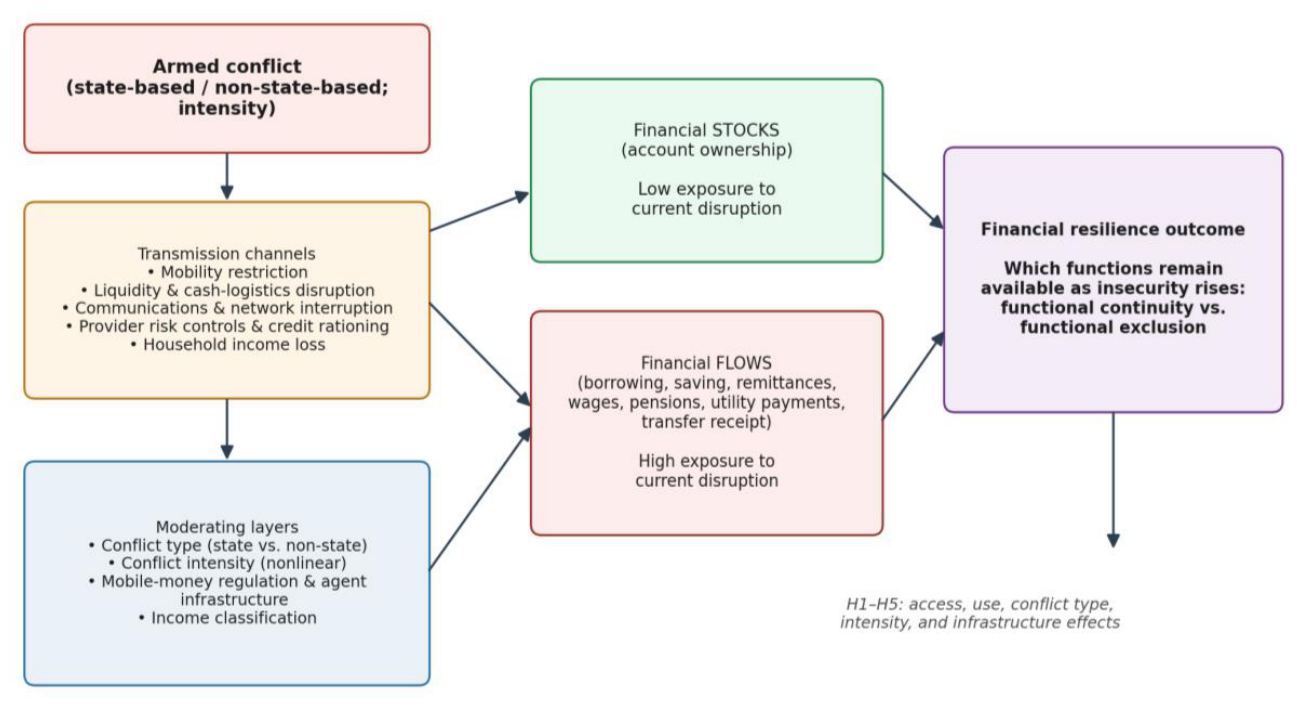
Figure 1 organizes these mechanisms. Armed conflict enters by type and intensity and operates through mobility restrictions, liquidity and cash-logistics disruption, communications failures, provider risk controls and credit rationing, and household income loss. These channels affect financial stocks, represented by account ownership, and financial flows, represented by borrowing, saving, remittances, wages, pensions, utility payments, and transfers. National regulatory conditions and income classification capture differences in institutional capacity and structural resilience.
Figure 1.
Conceptual model of financial resilience under conflict.
The framework generates six expectations. H1 predicts lower formal and any-account ownership as state-based and non-state conflict intensity rises. H2 predicts that negative conflict associations will be concentrated in transaction-dependent uses, particularly borrowing, remittances, utility payments, and transfers, while saving and selected institutional receipts will show greater continuity. H3 predicts that state-based and non-state conflict will display distinct outcome-specific patterns of association with financial access and use; because the conflict measures are estimated in separate models, H3 does not imply a formal statistical ranking of their coefficients. H4 predicts lower predicted probabilities for conflict-sensitive functions at higher observed conflict values, without interpreting differences between percentile contrasts as evidence of structural nonlinearity. H5 predicts positive associations between stronger agent-service conditions, consumer protection, flexible minimum KYC requirements, and selected financial outcomes. H6 predicts heterogeneous conflict associations across country income classifications without imposing a uniform direction. These hypotheses map to Tables 3–8.
3. Method
3.1. Data Sources
The study merges three sources (see Table 1). Individual financial outcomes and socioeconomic characteristics come from the 2025 Global Findex database (Klapper et al., 2025). The analytical sample contains 32,951 adults from 33 Sub-Saharan African countries with complete information for the main access models. Usage models contain between 31,912 and 32,951 observations because some questions apply to smaller subsamples.
Table 1.
Variable Description and Data Sources.
Conflict exposure comes from the Uppsala Conflict Data Program Georeferenced Event Dataset (UCDP GED), which records conflict events and resulting deaths and distinguishes state-based from non-state conflict (Sundberg & Melander, 2013; Pettersson et al., 2021). The study measures country-level conflict intensity using resulting deaths for each conflict type. Raw fatalities are transformed as ln(1 + deaths) to retain zero-conflict observations and reduce skewness, then standardized over the merged estimation sample. One unit therefore represents a one-standard-deviation increase in log-transformed conflict fatalities.
National institutional conditions come from the GSMA Mobile Money Regulatory Index (GSMA, 2025). The analysis includes consumer protection, safeguarding of funds, agent services, and minimum know-your-customer requirements. Each indicator ranges from 0 to 100. Higher scores represent stronger consumer protection, stronger safeguarding, better agent-service conditions, or more flexible minimum KYC rules.
3.2. Measurement of Variables
The two access outcomes are binary indicators for ownership of an account at a formal financial institution and ownership of any account. Usage outcomes are binary indicators for borrowing, saving, pension receipt, domestic remittances, wage receipt, utility payments, and transfer receipt. Conflict intensity is constructed at the country level.
Let Fck denote the number of resulting deaths associated with conflict type k in country c. The standardized conflict measure is defined as follows:
Here, r indexes the countries used to calculate the unweighted cross-country mean and sample standard deviation. Accordingly, a one-unit increase in Cck represents a one-standard-deviation increase in log-transformed fatalities across the 33 countries in the analytical sample.
For each conflict type, total resulting deaths recorded during 2024 are transformed as ln(1 + fatalities) to retain countries with zero recorded deaths and reduce the influence of extreme fatality counts. The transformed measure is then standardized across the 33 countries in the analytical sample, with each country entering the calculation once. The resulting country-level value is assigned to every Findex respondent within the relevant country. A one-unit increase therefore represents a one-standard-deviation increase in log-transformed fatalities across the sampled countries. Global Findex sampling weights enter the estimation models but do not enter the country-level standardization. The 25th, 50th, and 75th percentiles of each standardized index represent relatively low, median, and high conflict intensity within the estimation sample.
Financial resilience is not measured as a single composite variable in this study. Rather, it is operationalised as a function-specific construct reflected in the pattern of financial access and use associated with conflict exposure. The relevant functions comprise formal financial-institution account ownership, any-account ownership, borrowing, saving, pension receipt, domestic remittances, wage receipt, utility payments, and transfer receipt. These outcomes are estimated separately because aggregating them into a single index would conceal differences in the vulnerability of financial stocks, transaction-dependent services, and established institutional receipts. Accordingly, greater resilience is inferred where a specific financial function shows limited disruption across conflict exposure, while greater vulnerability is indicated by lower participation associated with higher conflict exposure. Given the cross-sectional design, this operationalisation represents a proxy for financial resilience rather than a direct longitudinal measure of continuity or recovery.
State-based and non-state conflict enter separate baseline specifications. Individual controls include sex, age, age squared, employment, household income quintile, rural residence, secondary education, tertiary education, and internet access. The fifth income quintile is the reference group, while primary education or less is the education reference category. Regulatory controls capture consumer protection, safeguarding of funds, agent services, and minimum KYC requirements. The merged sample covers 33 countries, while outcome-specific observation counts vary only where Findex questions apply to smaller subsamples.
Standardization places annual country-level fatalities on a common statistical scale, but it does not make different conflicts substantively equivalent. Conflicts with the same standardized value may differ in duration, onset and timing within 2024, geographic concentration, population exposed, displacement, infrastructure damage, and proximity to surveyed respondents. The estimates therefore compare relative annual country-level conflict intensity rather than comprehensive conflict histories or individual exposure. Financial resilience is not directly observed; the analysis examines whether specific dimensions of financial access and use differ with this annual measure of conflict exposure.
3.3. Empirical Estimation Model
The binary nature of the outcomes and the clustering of individuals within countries motivate a multilevel mixed-effects logit model. The model combines fixed covariate effects with a country random intercept that captures unobserved country-level heterogeneity. World Bank income classification enters as fixed effects because the sample contains only three income groups. The baseline specification is
where denotes financial outcome j for individual i in country c. Cck is the standardized logged conflict measure of type k, where k = S denotes state-based conflict and k = N denotes non-state-based conflict. The two conflict measures are estimated in separate models because of their high correlation. Xic is a vector of individual characteristics, Rc contains country-level mobile-money and regulatory indicators, and Dcm represents income-group fixed effects, with low-income countries as the reference category. The country random intercept, vc, is assumed to follow a normal distribution with mean zero and variance and to be independent of the observed regressors. Conditional on the covariates and the random intercept, follows a Bernoulli distribution with success probability given by the logistic cumulative distribution function.
The models are estimated by maximum likelihood using adaptive Gauss-Hermite quadrature. Global Findex sampling weights are applied at the individual level, and standard errors are clustered by country. Because the country-level conflict and regulatory variables vary across 33 countries, score-based wild cluster bootstrap tests provide an additional small-cluster inference check.
Logit coefficients express changes in log odds and do not translate directly into percentage-point changes in outcome probabilities. The paper therefore reports average marginal effects. Let denote the fitted probability of outcome j, marginal over the distribution of the country random intercept. For a continuous regressor xr, the average marginal effect is
The derivative is evaluated for each respondent using the observed values of the remaining covariates and then averaged over the outcome-specific estimation sample. For a binary covariate, the reported effect represents the average discrete change in predicted probability when the indicator changes from zero to one. Standard errors for the marginal effects are calculated using the delta method.
The first heterogeneity analysis examines predicted financial behaviour across the observed conflict distribution. After fitting Equation (2), the 25th, 50th, and 75th percentiles of the relevant standardized conflict index are calculated using one observation per country represented in the estimation sample. Adjusted predicted probabilities are then calculated at each percentile while averaging over the observed values of the remaining covariates:
Pairwise contrasts compare the adjusted predictions at the median and 25th percentile and at the 75th percentile and median. Where two percentiles have the same conflict value because several countries record zero fatalities, the associated predicted probabilities are identical and the contrast equals zero.
The second heterogeneity analysis examines whether the association between conflict and financial behaviour differs across low-income, lower-middle-income, and upper-middle-income countries. Each conflict measure is interacted with income classification in a separate pooled model:
Income-group-specific average marginal effects are calculated for borrowing, saving, domestic remittances, and receipt of transfers. A joint Wald test of H0:λjk2 = λjk3 = 0 assesses whether the association between conflict and each outcome differs across income groups. The upper-middle-income interaction for state-based conflict is unidentified because this conflict measure has no within-group variation among the upper-middle-income countries in the sample. The corresponding marginal effect is therefore left unreported, and the state-based interaction test applies only to the estimable lower-middle-income interaction. Both income-group interactions are estimable for non-state-based conflict.
4. Results
4.1. Descriptive Characteristics of the Sample
Table 2 describes a financially diverse and conflict-exposed sample. Any-account ownership is 62.2%, compared with 36.1% for formal financial-institution accounts, confirming the importance of non-bank channels. Borrowing (72.1%) and saving (63.2%) are common and domestic remittances involve 45.3% of respondents, while utility payments (19.8%), wages (15.9%), transfers (5.1%), and pensions (2.6%) are less prevalent. Conflict exposure is highly dispersed. Mean state-based fatalities are 900.6, compared with 46.3 for non-state fatalities, with maxima of 24,107 and 510, respectively. The sample is also structurally constrained: 66.7% live in rural areas and 41.6% have internet access. These patterns justify separating access from use and examining conflict type and intensity.
Table 2.
Descriptive Characteristics.
4.2. Conflict and Access to Financial Services
Table 3 presents the access associations for the two conflict types separately. A one-standard-deviation increase in state-based intensity is associated with a 2.9 percentage-point reduction in formal financial-institution account ownership (p < 0.01) and a 1.3 point reduction in any-account ownership (p < 0.05). Non-state conflict is associated with a 1.8 point reduction in formal account ownership (p < 0.01). This association is statistically significant at the 5 percent level under both conventional delta-method inference (p = 0.039) and the score-based wild cluster bootstrap (p = 0.042). Relative to the sample mean, the state-based formal-account association equals about 8%. The results indicate different outcome-specific patterns across the separate specifications. They do not establish that either conflict coefficient is statistically larger than the other because no formal equality test is conducted.
Table 3.
Access to Financial Services and Conflict Exposure in Sub-Saharan Africa.
Pre-existing inclusion inequalities remain important. Women and rural residents have lower account ownership, while employment, education, and internet access are positively associated with access. Internet access is associated with 12.9 points higher formal-account ownership and 19.8 points higher any-account ownership. Agent-service quality is also positively associated with both access measures. These results indicate that resilience reflects both conflict exposure and the resources and delivery infrastructure available to remain financially connected.
4.3. Conflict and Use of Financial Services
Table 4 and Table 5 present the associations between conflict and financial service use. In the state-based specification, a one-standard-deviation increase in intensity is associated with lower borrowing by 2.7 percentage points (p < 0.05), domestic remittances by 5.4 points (p < 0.05), and transfer receipt by 1.4 points (p < 0.05). The corresponding score-bootstrap p-values are 0.047, 0.009, and 0.020, respectively, compared with conventional p-values of 0.041, 0.016, and 0.009. Saving, pensions, and wages are statistically unchanged. In the non-state specification, domestic remittances are associated with a 3.4 point reduction (p < 0.1), while the marginal effects for the other use outcomes are imprecisely estimated. Activities such as domestic remittances, borrowing, and transfers require functioning counterparties, payment rails, liquidity, connectivity, or provider interaction at the time of use. Saving, pensions, and wages show greater average continuity. Comparisons across the two specifications are confined to direction, precision, and outcome-specific patterns and do not imply a statistically significant difference between conflict types.
Table 4.
Usage of financial services and state-based conflict in Sub-Saharan Africa.
Table 5.
Usage of financial services and non-state-based conflict in Sub-Saharan Africa.
Socioeconomic gradients remain substantial. Internet access is positively associated with every use outcome, especially remittances, saving, and utility payments. Employment predicts borrowing, saving, remittances, wages, and utilities. Lower income is strongly associated with reduced saving, remittances, wages, and utility payments. State-based conflict-related disruption therefore operates alongside digital, spatial, and resource inequalities.
4.4. Heterogeneity by Conflict Intensity
Table 6 and Table 7 show how adjusted predicted probabilities vary across selected points of the observed conflict distribution. For state-based conflict, predicted borrowing remains at 0.726 between the 25th percentile and the median before falling to 0.679 at the 75th percentile, a 4.7 percentage-point decline from the median. Predicted domestic-remittance participation falls by 1.6 percentage points from the 25th percentile to the median, from 0.441 to 0.425, and by a further 8.3 percentage points from the median to the 75th percentile, reaching 0.342. Transfer receipt falls from 0.056 at the 25th percentile to 0.052 at the median and then to 0.033 at the 75th percentile. Savings show no significant reported contrasts. These differences describe changes in predicted probabilities generated by the fitted logit model at observed conflict values. Because conflict enters the model linearly, the unequal probability contrasts across percentiles do not establish a nonlinear structural association between conflict intensity and the outcomes.
Table 6.
Pairwise Comparison of Predicted Margins for State-Based Conflict.
Table 7.
Pairwise comparison of predicted margins for non-state-based conflict.
For non-state conflict, domestic remittances decline by 5.8 percentage points between the median and the 75th percentile, at the 10 percent level, while borrowing, saving, and transfer receipt remain statistically unchanged across the reported contrasts. Taken together, Table 6 and Table 7 show different outcome-specific patterns and levels of precision across the separately estimated conflict specifications. The analysis does not test whether the state-based and non-state conflict coefficients are statistically equal, so differences in significance or magnitude are not interpreted as evidence that one conflict type has a larger association than the other.
4.5. Heterogeneity by Income Classification
Table 8 shows that conflict exposure is most consistently associated with domestic remittances and transfers. Among lower-middle-income countries, a one-standard-deviation increase in state-based conflict is associated with a 6.9 percentage-point reduction in domestic remittances and a 2.2 percentage-point reduction in received transfers. The associations differ significantly across income groups for both outcomes, with joint interaction p-values of 0.022 and 0.005, respectively.
Table 8.
Average marginal effects after income–conflict interactions.
For non-state-based conflict, domestic remittances decline by 11.4 percentage points among upper-middle-income countries, while received transfers increase by 13.5 percentage points. Received transfers also decline by 1.6 percentage points among lower-middle-income countries. Income-group differences are statistically significant for transfers (p < 0.001) and weakly significant for domestic remittances (p = 0.075).
The implication is that national income does not mechanically protect every financial function. Resilience depends on the specific infrastructure, provider networks, household resources, and institutional arrangements supporting each service. This supports function-specific rather than income-group-wide policy responses.
5. Discussion
The results support a functional view of financial resilience under conflict, while the cross-sectional design requires a precise interpretation of resilience. The study does not observe the same households or countries before and after a conflict shock and therefore does not measure continuity or recovery directly. Instead, financial resilience is proxied by differences in financial access and use associated with contemporaneous conflict exposure. Within this interpretation, conflict-related associations are concentrated in functions built on live exchange, liquidity, information, and provider interaction rather than appearing uniformly across all financial outcomes. This finding extends financial-resilience research beyond household buffers toward the functioning of financial systems under stress (Liu et al., 2025; Kamble et al., 2026) and aligns with payment-resilience research showing how failures in connectivity, intermediaries, liquidity, or user access interrupt end-to-end service in fragile settings (Malaika et al., 2025).
The access results reveal distinct outcome-specific patterns across the separately estimated conflict specifications. State-based conflict is negatively associated with both formal financial-institution and any-account ownership, whereas non-state conflict is negatively associated with formal account ownership and its any-account estimate is imprecise. These patterns are consistent with the possibility that violence involving state actors places administrative systems, transport corridors, courts, land registries, and national identification systems under stress, while some non-bank channels remain available (Xiao et al., 2025; Wang et al., 2024). This mechanism remains interpretive rather than identified by the data. Importantly, the separate models do not provide a formal test that the state-based coefficient differs from the non-state coefficient. The comparison is therefore limited to direction, precision, and the financial outcomes with which each conflict measure is associated.
The use results also show outcome-specific associations relevant to banking stability and credit risk, but they do not identify the underlying banking mechanism. Borrowing is negatively associated with state-based conflict. Conflict-related income loss, weaker collateral values, reduced information quality, monitoring difficulties, and higher operating costs provide plausible channels through which credit supply or credit demand may change. Cross-border evidence of lender retrenchment from conflict-affected economies is consistent with a supply-side channel (De Haas et al., 2025), but the present household data do not distinguish lender rationing from lower borrower demand and do not measure portfolio quality, screening behaviour, liquidity management, or asset allocation. The borrowing estimates should therefore be read as household-level associations with credit use rather than direct evidence of a particular bank response.
Domestic remittances provide clear evidence of transaction vulnerability in the state-based specification and a less precise pattern in the non-state specification. Sending and receiving money depends on an active link between sender and recipient at the moment of transfer, mediated by agents, network coverage, and cash or e-money liquidity. Predicted domestic-remittance participation falls by 1.6 percentage points from the 25th percentile to the median and by a further 8.3 percentage points from the median to the 75th percentile of state-based conflict. Because the underlying logit model includes conflict linearly, these probability changes reflect the fitted probability function and are not evidence that the structural association itself becomes nonlinear. Evidence from conflict settings documents the tension between stronger support motives and constrained delivery channels (Ibrahim, 2025; van Asselt et al., 2025; Lindley, 2024), while research on digital finance and risk sharing shows that the benefit depends on the network remaining functional (Jack & Suri, 2014; Suri & Jack, 2016).
The findings broadly support the transaction-dependence argument, although the evidence is not uniform across all transaction-dependent services. Borrowing, domestic remittances and transfer receipt show significant negative associations under state-based conflict. Utility-payment estimates are negative but imprecisely estimated, indicating that transaction dependence alone does not determine vulnerability. Saving, pensions, and wages hold up better on average, though the null estimates likely mask offsetting movements rather than an absence of financial stress. Conflict lowers income and raises emergency spending, pushing some households towards dissaving, while insecurity strengthens precautionary saving among households still holding resources to protect. Wage and pension arrangements tied to established employers or government payroll systems continue operating as long as the underlying payment channel remains intact, independent of the saving decisions households make at the same time.
Income heterogeneity shows that conflict associations do not follow development level in a mechanical way. The formal interaction tests confirm that income-group heterogeneity is outcome-specific rather than a uniform gradient in resilience. The significant differences for remittances and transfers indicate that national income classification conditions some conflict-finance relationships, but higher national income does not consistently attenuate conflict exposure across financial functions. These patterns are consistent with differences in formal credit and deposit depth, mobile money corridors, network investment, institutional capacity, and household resources across countries (Golpet et al., 2026; Grzybowski et al., 2023). Evidence from post-conflict Burundi similarly suggests that institutional capacity and delivery infrastructure shape financial participation in fragile settings (Atta-Aidoo et al., 2023). Income classification is therefore an incomplete proxy for financial-system resilience because infrastructure redundancy, digital connectivity, provider depth, and household resources differ across services and countries (Osabutey & Jackson, 2024; Nefla et al., 2026).
The regulatory coefficients offer supporting, non-causal evidence for this institutional reading. Among the regulatory indicators, agent-service conditions show the most consistent positive associations with financial access and use. Consumer protection and minimum KYC flexibility are associated with selected outcomes, while safeguarding does not display a uniformly positive pattern. The results therefore point more clearly to the operational role of agent networks than to a general positive association across all regulatory dimensions. These results do not show regulation moderating conflict effects directly; rather, they indicate that selected features of the institutional environment are associated with households’ capacity to remain financially connected once conflict exposure is held constant.
This interpretation lines up with evidence showing institutions condition the effects of digital financial inclusion (Meniago, 2025) and with evidence showing financial inclusion, institutional quality, and growth move together over the long run in Sub-Saharan Africa (Golpet et al., 2026). The pattern also accords with Jungo et al. (2022), who show financial stability shapes the relationship between regulation, inclusion, and banking competitiveness. In conflict settings, these institutional relationships turn operational: rules governing agents, customer identification, consumer protection, and safeguarding either support continuity or compound disruption in liquidity, connectivity, and provider risk management. Demographic differences in digital financial service use (Chamboko, 2022) suggest service continuity likely differs across population groups rather than moving uniformly with national averages.
Taken together, the findings contribute to emerging-market finance research by showing that conflict exposure is associated with financial functionality in an outcome-specific way, that state-based and non-state conflict display distinct patterns across separately estimated models, that predicted financial participation varies across the observed conflict distribution, and that income classification conditions selected associations. These findings complement evidence showing that digital finance supports resilience while remaining dependent on infrastructure vulnerable to conflict (Ozili, 2026; Nandnaba, 2026). They are also relevant to banking-stability debates because disruptions in payments, liquidity, and household borrowing are channels through which conflict may interact with financial intermediation. However, the study does not observe bank solvency, non-performing loans, screening decisions, fee income, liquidity management, or portfolio allocation. Such mechanisms are therefore proposed interpretations for future testing rather than empirical findings of this study.
The analysis remains associational. Conflict is measured at the country level even though violence is often geographically concentrated. Annual fatalities capture one dimension of conflict severity but do not measure duration, timing within the year, territorial reach, displacement, infrastructure destruction, network outages, or respondents’ proximity to conflict events. Similar standardized fatality values therefore do not imply equivalent conflict experiences across countries. The cross-sectional design also does not observe continuity, adaptation, or recovery over time. Financial resilience should consequently be understood as an interpretive framework for the observed access and use patterns rather than a directly measured outcome. Future research combining geocoded conflict exposure with panel data, bank or agent-network information, and quasi-experimental conflict-onset designs would strengthen causal claims. Linking household outcomes to bank-level non-performing loans, liquidity, capital, and credit allocation would test the proposed banking-stability mechanisms directly.
Robustness Analysis
We conduct several robustness checks. First, we replace the main conflict measures with fatalities per 100,000 population and a conflict-presence indicator. The population-adjusted measure equals the number of conflict-related fatalities divided by the country’s population and multiplied by 100,000. The conflict-presence indicator equals one if a country recorded at least one conflict-related death in 2024 and zero otherwise. Estimates based on fatalities per 100,000 population are broadly consistent with the main results for both state-based and non-state-based conflict (see Table A2 and Table A3). By contrast, the conflict-presence indicator produces mostly statistically insignificant estimates, partly reflecting its limited variation across countries (see Table A4 and Table A5). This pattern suggests that differences in conflict intensity are more closely associated with financial access and use than the simple occurrence of conflict.
Second, we conduct a leave-one-country-out analysis by re-estimating each model after sequentially excluding one country. The estimated average marginal effects remain broadly stable across the resulting samples, and their cross-model standard deviations are small relative to the corresponding mean absolute effects (see Table A6). No single country exclusion materially changes the main patterns. Overall, the robustness checks indicate that the findings do not depend on the use of absolute fatalities or the inclusion of a particular country.
Third, to assess whether inference was sensitive to the limited number of country clusters, we applied a score-based wild cluster bootstrap to the multilevel logit models, clustering at the country level and using Webb weights (see Table A7 and Table A8). The bootstrap procedure clustered score contributions at the country level, applied Webb weights, and used 9999 replications, following the approach proposed for maximum-likelihood models with a limited number of clusters (Roodman et al., 2019). The score-bootstrap p-values and the delta method p-values are largely similar to the robust standard errors from the multilevel logit estimations. Overall, the score-bootstrap results broadly corroborate the conventional inference based on country-clustered standard errors. Nevertheless, estimates close to conventional significance thresholds are interpreted cautiously, given the limited number of country clusters.
6. Conclusions and Policy Implications
This study examined how financial access and use are associated with armed conflict by financial service, conflict type, observed conflict intensity, and country income classification across 33 Sub-Saharan African countries. It addressed three gaps in the literature by distinguishing account ownership from actual financial use, separating state-based from non-state conflict, and examining predicted financial outcomes across the observed conflict distribution. Given the cross-sectional design, financial resilience is interpreted as a proxy based on differences in access and use associated with conflict exposure rather than directly observed continuity or recovery.
The findings provide qualified support for the study’s hypotheses. H1 receives partial support: state-based conflict is negatively associated with formal and any-account ownership, while non-state conflict is negatively associated with formal account ownership and its any-account estimate is imprecise. H2 receives partial support. Significant negative associations are concentrated in borrowing, domestic remittances, and transfer receipt under state-based conflict. Under non-state conflict, only domestic remittances show weak evidence of a negative association, while borrowing and the remaining use outcomes are imprecisely estimated. H3 is supported as an outcome-pattern hypothesis: state-based and non-state conflict display distinct patterns across financial access and use. Because the conflict measures are estimated separately, these differences are not interpreted as a statistical ranking of the two conflict types. H4 is supported for selected conflict-sensitive outcomes. Predicted borrowing, remittance participation, and transfer receipt are lower at higher observed levels of state-based conflict, while the corresponding non-state patterns are more limited. H5 receives partial support because agent-service conditions show the most consistent positive associations, while consumer protection and KYC flexibility are associated with selected outcomes. H6 is supported for selected outcomes by the formal conflict-by-income interaction tests, which show that heterogeneity does not follow a uniform development gradient.
The central conclusion is that conflict exposure is associated selectively with financial functions rather than uniformly with all dimensions of inclusion. Functions requiring live transactions, liquidity, connectivity, counterparties, and provider interaction show more consistent negative associations than some stock or institutional-receipt outcomes. These household-level patterns are relevant to financial-intermediation resilience, but they do not demonstrate changes in bank solvency, portfolio quality, credit rationing, or liquidity management. Those mechanisms remain plausible transmission channels requiring direct bank- or provider-level evidence. The main patterns remain broadly stable when conflict exposure is measured using fatalities per 100,000 population and when countries are sequentially excluded from the estimation sample, reinforcing the interpretation that conflict intensity, rather than conflict presence alone, is relevant to financial access and use.
The findings motivate several policy implications for African economies, while the cross-sectional evidence does not demonstrate the effectiveness of any specific intervention. Central banks, financial-sector regulators, and mobile money providers in conflict-exposed markets should consider monitoring functioning services alongside account registration. Indicators such as remittance completion, cash-in and cash-out availability, payment failure rates, network uptime, credit access, and geographic service continuity would provide information on functional access that account-ownership statistics alone do not capture.
The negative remittance associations motivate attention to payment and transfer continuity. Regulators, payment providers, humanitarian agencies, and government transfer programmes should assess whether transaction channels, agent liquidity, and cash-out points remain operational in conflict-exposed areas. Interoperability, contingency routing, and liquidity planning are plausible resilience measures, but the present analysis does not test their effectiveness. Their relevance follows from the dependence of remittances and payments on functioning networks, agents, and settlement channels rather than from a direct policy evaluation in this study.
The significant negative borrowing association under state-based conflict motivates closer monitoring of credit access in these settings. The corresponding non-state estimate is statistically insignificant, and neither specification distinguishes lower borrower demand from lender-side restriction. Supervisors and financial institutions should therefore track loan applications, approval rates, repayment performance, and geographic service availability where such data exist. Measures such as restructuring, guarantees, or alternative borrower information are potential responses for settings where separate evidence identifies conflict-related credit-supply constraints; they should not be read as policies demonstrated by the present household-level analysis.
Income heterogeneity argues against assuming a uniform response by country income group. The interaction results indicate that the association between conflict and selected financial functions differs across income classifications. Policy design should therefore consider the particular service at risk and the infrastructure supporting it, rather than infer resilience solely from national income classification.
The positive associations between agent-service quality, consumer protection, flexible KYC requirements, and selected financial outcomes are consistent with an institutional role in financial access and use. They do not establish that changing these regulations would causally offset conflict-related disruption. Risk-based KYC arrangements, agent-liquidity planning, communications backup, and consumer-protection procedures remain plausible components of a resilience agenda, but their effectiveness under conflict requires direct evaluation.
Financial resilience under conflict should therefore be assessed through both registered access and the financial functions households are able to use. The evidence shows selective, outcome-specific associations with contemporaneous conflict exposure, not a causal ranking of conflict types or a direct test of banking-stability mechanisms. This distinction keeps the paper’s contribution at the level supported by the data while identifying payment continuity, credit access, agent functionality, and institutional capacity as priorities for further policy testing and research.
Author Contributions
M.K.: conceptualization, methodology, literature review, writing—original draft preparation, writing—review and editing, and proofreading. D.O.: conceptualization, methodology, formal analysis, writing—original draft preparation, writing—review and editing, and proofreading. E.O.: literature review, writing—original draft, writing—review and editing, and proofreading. All authors have read and agreed to the published version of the manuscript.
Funding
This research received no external funding.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The data used in this study are publicly available from three sources. (1) Individual-level financial inclusion data were obtained from the World Bank Global Findex Database 2025, available from the World Bank Global Findex Database (https://www.worldbank.org/en/publication/globalfindex/download-data) (accessed on 15 February 2026). (2) Conflict data were obtained from the Uppsala Conflict Data Program (UCDP), available through the UCDP Download Center (https://ucdp.uu.se/downloads/?utm_source) (accessed on 15 February 2026). (3) Mobile money regulatory indicators were obtained from the GSMA Mobile Money Regulatory Index, available through the GSMA Mobile Money Regulatory Index (https://www.gsma.com/mobile-money-metrics/#regulatory-index) (accessed on 15 February 2026). The analytical dataset was constructed by merging information from these sources as described in the Methods section.
Acknowledgments
The authors acknowledge the World Bank, the Uppsala Conflict Data Program (UCDP), and GSMA for making the data used in this study publicly available.
Conflicts of Interest
Author Edwin Osafoh was employed by the Bank of Ghana. The authors declare that the research was conducted in the absence of any commercial or financial relationships that could be construed as a potential conflict of interest.
Appendix A
Table A1.
Income interaction models (coefficients).
Table A2.
Robustness to alternative measure of conflict (state-based conflict per 100,000).
Table A3.
Robustness to alternative measure of conflict (non-state-based conflict per 100,000).
Table A4.
Robustness to alternative measure of conflict (presence of state-based conflict).
Table A5.
Robustness to alternative measure of conflict (presence of non-state-based conflict).
Table A6.
Leave-one-country-out sensitivity analysis.
Table A7.
Average Marginal Effects of State-Based Conflict on Financial Access and Use: Score-Based Wild Cluster Bootstrap Inference.
Table A8.
Average Marginal Effects of Non-State Conflict on Financial Access and Use: Score-Based Wild Cluster Bootstrap Inference.
Table A9.
Income group classification.
References
- Abu, N., Sakanko, M. A., & Haron, N. F. (2026). Insecurity and financial inclusion nexus in Africa: Evidence from System-GMM approach. African Journal of Economic and Management Studies, 1–17. [Google Scholar] [CrossRef] [Scilit]
- Allen, F., Carletti, E., Cull, R., Qian, J. Q. J., Senbet, L., & Valenzuela, P. (2014). The African financial development and financial inclusion gaps. Journal of African Economies, 23(5), 614–642. [Google Scholar] [CrossRef] [Scilit]
- Anifowose, O. L., & Chummun, B. Z. (2025). A panel data analysis of determinants of financial inclusion in Sub-Saharan Africa (SSA) countries from 1999 to 2024. Journal of Risk and Financial Management, 18(5), 275. [Google Scholar] [CrossRef] [Scilit]
- Aron, J. (2018). Mobile money and the economy: A review of the evidence. The World Bank Research Observer, 33(2), 135–188. [Google Scholar] [CrossRef] [Scilit]
- Asante, K. T., Kumi, E., & Kodom, M. (2024). Post-COVID economic crisis, citizen-state relations, and the Electronic Transactions Levy (E-levy) controversy in Ghana. World Development Perspectives, 35, 100621. [Google Scholar] [CrossRef] [Scilit]
- Asongu, S. A., Agyemang-Mintah, P., Nnanna, J., & Ngoungou, Y. E. (2024). Mobile money innovations, income inequality and gender inclusion in sub-Saharan Africa. Financial Innovation, 10, 11. [Google Scholar] [CrossRef] [Scilit]
- Atta-Aidoo, J., Bizoza, S., Saleh, A. O., & Matthew, E. C. (2023). Financial inclusion choices in post-conflict and fragile states of Africa: The case of Burundi. Cogent Social Sciences, 9(1), 2216996. [Google Scholar] [CrossRef] [Scilit]
- Balasubramanian, K., Drake, D. F., & Urrea, G. (2023). The impact of poverty on base of the pyramid operations: Evidence from mobile money in Africa. Journal of Operations Management, 69(4), 616–642. [Google Scholar] [CrossRef] [Scilit]
- Batista, C., & Vicente, P. C. (2020). Improving access to savings through mobile money: Experimental evidence from African smallholder farmers. World Development, 129, 104905. [Google Scholar] [CrossRef] [Scilit]
- Bellows, J., & Miguel, E. (2009). War and local collective action in Sierra Leone. Journal of Public Economics, 93(11–12), 1144–1157. [Google Scholar] [CrossRef] [Scilit]
- Blattman, C., & Miguel, E. (2010). Civil war. Journal of Economic Literature, 48(1), 3–57. [Google Scholar] [CrossRef] [Scilit]
- Chamboko, R. (2022). On the role of gender and age in the use of digital financial services in Zimbabwe. International Journal of Financial Studies, 10(3), 82. [Google Scholar] [CrossRef] [Scilit]
- Collier, P. (1999). On the economic consequences of civil war. Oxford Economic Papers, 51(1), 168–183. [Google Scholar] [CrossRef] [Scilit]
- De Haas, R., Mamonov, M., Popov, A., & Shala, I. (2025). Violent conflict and cross-border lending (ECB working paper series No. 3073). European Central Bank. Available online: https://www.ecb.europa.eu/pub/pdf/scpwps/ecb.wp3073~85c24bca25.en.pdf?utm_source=chatgpt.com (accessed on 24 March 2026).
- Dhawan, S. M., Wilson, K., & Zademach, H.-M. (2024). From financial inclusion to financial health of refugees: Urging for a shift in perspective. Third World Quarterly, 45(5), 926–945. [Google Scholar] [CrossRef] [Scilit]
- Garang, J. A. (2024). Effects of the civil war on financial inclusion in South Sudan: Theory and evidence. African Journal of Economic and Sustainable Development, 9(3), 255–271. [Google Scholar] [CrossRef] [Scilit]
- Golpet, M. K., Makoni, P. L., & Marozva, G. (2026). A cointegrating linkage of financial inclusion, institutional quality and economic growth in Sub-Saharan African countries. International Journal of Financial Studies, 14(3), 71. [Google Scholar] [CrossRef] [Scilit]
- Grzybowski, L., Lindlacher, V., & Mothobi, O. (2023). Mobile money and financial inclusion in Sub-Saharan Africa. Information Economics and Policy, 65, 101064. [Google Scholar] [CrossRef] [Scilit]
- GSMA. (2025). Mobile money regulatory index. GSMA. [Google Scholar]
- Gyamerah, K. K., & Tetteh, F. K. (2024). Examining the impact of mobile money on financial inclusion in Sub-Saharan Africa: The role of institutions and governance. SAM Advanced Management Journal, 89(4), 315–339. [Google Scholar] [CrossRef] [Scilit]
- Ibrahim, M. A. (2025). Remittance flow determinants and the role of government policy in conflict-affected Palestinian territories. Journal of Government and Economics, 18, 100143. [Google Scholar] [CrossRef] [Scilit]
- Jack, W., & Suri, T. (2014). Risk sharing and transactions costs: Evidence from Kenya’s mobile money revolution. American Economic Review, 104(1), 183–223. [Google Scholar] [CrossRef] [Scilit]
- Jungo, J., Madaleno, M., & Botelho, A. (2022). Financial regulation, financial inclusion and competitiveness in the banking sector in SADC and SAARC countries: The moderating role of financial stability. International Journal of Financial Studies, 10(1), 22. [Google Scholar] [CrossRef] [Scilit]
- Kamble, P. A., Mehta, A., & Rani, N. (2026). Building financial resilience: A systematic literature review and future research agenda. Journal of Economic Surveys, 40(2), 954–981. [Google Scholar] [CrossRef] [Scilit]
- Klapper, L., Singer, D., Starita, L., & Norris, A. (2025). The global findex database 2025: Connectivity and financial inclusion in the digital economy. World Bank. [Google Scholar] [CrossRef] [Scilit]
- Kodom, M., Ackah, C., Steel, W. F., & Bokpin, G. A. (2020). Drivers of mobile financial inclusion in Ghana. Enterprise Development and Microfinance, 31(4), 226–253. [Google Scholar] [CrossRef] [Scilit]
- Kodom, M., Osarfo, D., & Quartey, P. (2024). Digital financial inclusion and women’s economic empowerment in Northern Ghana: The experience of rural women in the shea value chain. In I. Koomson, & R. A. Villano (Eds.), Financial inclusion and sustainable rural development (pp. 179–200). Palgrave Macmillan. [Google Scholar] [CrossRef] [Scilit]
- Kodom, M., Steel, W. F., Ackah, C., & Bokpin, G. A. (2022). Mobile money: A gateway to achieving financial inclusion in Ghana. Enterprise Development and Microfinance, 33(2), 105–123. [Google Scholar] [CrossRef] [Scilit]
- Kodom, M., Yeboah, E. A. A., & Anoku, J. K. (2026). Structural determinants of gender gaps in financial inclusion in Ghana: Evidence from Fairlie decomposition analysis. Review of Behavioral Finance, 1–20. [Google Scholar] [CrossRef] [Scilit]
- Lindley, A. (2024). Remitting through crisis: Looking beyond resilience in UK migrant and diaspora communities. Migration Studies, 12(3), mnae026. [Google Scholar] [CrossRef] [Scilit]
- Liu, Z., Chen, J.-K., & Xiao, J. J. (2025). Financial resilience: A scoping review, conceptual synthesis and theoretical framework. International Journal of Bank Marketing, 43(7), 1541–1576. [Google Scholar] [CrossRef] [Scilit]
- Malaika, M., Soderberg, G., & Zhabska, K. (2025). Payment resilience in fragile and conflict-affected states: Lessons for central bank digital currency (CBDC) (IMF fintech note no. 2025/009). International Monetary Fund. [Google Scholar] [CrossRef] [Scilit]
- Meniago, C. (2025). Digital financial inclusion and economic growth: The moderating role of institutions in SADC countries. International Journal of Financial Studies, 13(1), 4. [Google Scholar] [CrossRef] [Scilit]
- Nandnaba, A. M. (2026). From capabilities to peace: Can mobile money reduce conflicts in developing countries? Economics & Politics, 38(2), 598–618. [Google Scholar] [CrossRef] [Scilit]
- Nefla, D., Hassan, R., Jellouli, S., & Ben Thabet, S. (2026). Financial inclusion as a sustainable development imperative in Africa: Trends, gaps, and future directions. Sustainable Development, 34(3), 3053–3079. [Google Scholar] [CrossRef] [Scilit]
- Ogbe, M. A., Abdullahi, M. S., & Ding, Y. (2024). Measuring how armed conflict impacts economic growth in sub-Saharan Africa through spatial analysis. Frontiers in Political Science, 6, 1433584. [Google Scholar] [CrossRef] [Scilit]
- Osabutey, E. L. C., & Jackson, T. (2024). Mobile money and financial inclusion in Africa: Emerging themes, challenges and policy implications. Technological Forecasting and Social Change, 202, 123339. [Google Scholar] [CrossRef] [Scilit]
- Osafoh, E., & Kodom, M. (2026). Adoption of central bank digital currency in the era of mobile money in Ghana. Enterprise Development and Microfinance, 36(2), 139–158. Available online: https://www.papjournals.com/index.php/edm/article/view/44 (accessed on 24 March 2026).
- Osarfo, D., Kodom, M., Quartey, P., & Darkwah, H. A. (2025). The effect of financial services utilization on financial health: Insights from the Ghanaian experience. Social Sciences & Humanities Open, 12, 102171. [Google Scholar] [CrossRef] [Scilit]
- Ozili, P. K. (2026). War and digital financial inclusion: Role of digital financial services in war and armed conflict. Conflict Resolution Quarterly, 44(1), 31–38. [Google Scholar] [CrossRef] [Scilit]
- Pettersson, T., Davies, S., Deniz, A., Engström, G., Hawach, N., Högbladh, S., Sollenberg, M., & Öberg, M. (2021). Organized violence 1989–2020, with a special emphasis on Syria. Journal of Peace Research, 58(4), 809–825. [Google Scholar] [CrossRef] [Scilit]
- Roodman, D., MacKinnon, J. G., Nielsen, M. Ø., & Webb, M. D. (2019). Fast and wild: Bootstrap inference in Stata using boottest. The Stata Journal, 19(1), 4–60. [Google Scholar] [CrossRef] [Scilit]
- Sundberg, R., & Melander, E. (2013). Introducing the UCDP georeferenced event dataset. Journal of Peace Research, 50(4), 523–532. [Google Scholar] [CrossRef] [Scilit]
- Suri, T., & Jack, W. (2016). The long-run poverty and gender impacts of mobile money. Science, 354(6317), 1288–1292. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- van Asselt, J., Naing, P. T., Sabai, M., Minten, B., & Kham Synt, N. L. (2025). Remittances in fragile and conflict-affected settings: Insights from Myanmar. European Journal of Development Research, 37(6), 1013–1043. [Google Scholar] [CrossRef] [Scilit]
- Wang, M. G., Wong, M. C. S., Zhuang, H., & Cate, R. (2024). The impact of armed conflict on inward foreign direct investment (FDI): An analysis of conflict over government, conflict over territory, and FDI. Global Economic Review, 53(1), 25–51. [Google Scholar] [CrossRef] [Scilit]
- Xiao, H., Tang, B., & Dai, L. (2025). The effects of African civil conflicts on FDI: The moderating role of bilateral political relations. China Economic Review, 89, 102326. [Google Scholar] [CrossRef] [Scilit]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.