


Abstract
As environmental sustainability becomes an increasingly important component of corporate strategy, understanding the internal drivers of green innovation has become a critical research issue. This study examines how executive environmental cognition influences corporate green innovation. Drawing on upper echelons theory and the natural resource-based view, we distinguish between green technological innovation and green managerial innovation and propose that green investment serves as an important mechanism linking executive cognition to innovation outcomes. Using panel data from Chinese A-share manufacturing firms from 2014 to 2023 and a two-way fixed effects model, we find that executive environmental cognition significantly promotes both types of green innovation. Further analysis shows that green investment partially mediates this relationship. Moreover, environmental information disclosure quality strengthens the positive effect of executive environmental cognition on green innovation. By integrating managerial cognition, resource allocation, and information environment perspectives, this study contributes to the literature by revealing the micro-cognitive foundations of corporate green innovation and highlighting the heterogeneous mechanisms through which executive cognition translates into sustainability-oriented innovation.
1. Introduction
Although prior research has examined the role of environmental regulation and institutional pressures in driving corporate green innovation, comparatively less attention has been paid to how top executives cognitively interpret and internalize such external environmental signals in strategic decision-making. Upper echelons theory posits that organizational outcomes reflect the cognitive frames, value orientations, and attention allocation of top executives [1,2]. In the environmental domain, this study defines executive environmental cognition as the extent to which top executives recognize, interpret, prioritize, and strategically respond to environmental issues in corporate decision-making. This cognition is not formed in isolation; it is shaped by both executives’ internal values and by external institutional factors such as environmental policy, regulation, compliance requirements, and stakeholder expectations. Accordingly, executive environmental cognition reflects how managers cognitively translate environmental pressures into strategic orientation and organizational action. For example, CEO hubris is demonstrated to significantly influence environmental innovation intensity, highlighting the importance of executive cognition in shaping green strategic outcomes [3].
In the digital economy, corporate strategic decision-making increasingly depends on managerial cognition and information processing capabilities, as digital technologies expand information availability and accelerate strategic responses to environmental challenges. Recent studies on complex dynamic systems also suggest that effective forecasting and decision support increasingly rely on the integration of heterogeneous information and data-driven analytical approaches [4]. Digital transformation not only changes firms’ access to information and external financing but also amplifies the role of managerial interpretation in shaping sustainability strategies. In the digital economy, firms face faster information flows, greater visibility of environmental issues, and more immediate stakeholder scrutiny. These changes make managerial interpretation increasingly important because executives must not only access more information, but also selectively process, prioritize, and translate environmental signals into strategic innovation decisions. Consequently, executives’ environmental cognition may play a particularly important role in guiding firms’ green innovation decisions in the digital economy context. At the same time, the digital economy is not environmentally neutral; emerging digital infrastructures such as AI data centers may themselves face resource dependence and sustainability-related operational risks, which further heightens the importance of managerial environmental interpretation in strategic decision-making [5].
However, the role of executive environmental cognition in shaping corporate green innovation remains insufficiently understood.
First, green innovation is frequently treated as a single aggregated construct. More broadly, recent analytical studies indicate that heterogeneous patterns are often obscured when complex phenomena are treated as homogeneous aggregates, reinforcing the need for differentiated analytical frameworks [6]. However, prior research has distinguished between green product innovation and green process innovation, showing that different innovation types may exhibit heterogeneous performance implications [7]. Evidence from other empirical contexts likewise shows that post-shock dynamics may display substantial temporal and regional heterogeneity, further supporting the value of differentiated analytical perspectives [8]. Broader reviews of green innovation research also emphasize the conceptual diversity of green innovation and call for more differentiated analyses [9]. Building on this insight, the present study distinguishes between technological green innovation and managerial green innovation, arguing that the two dimensions differ in resource intensity and organizational embeddedness.
Second, while executive environmental cognition may shape strategic orientation, cognition alone does not automatically translate into innovation outcomes. According to the resource-based view [10] and its environmental extension—the natural resource-based view [11,12]—strategic intent must be supported by resource allocation in order to generate sustained competitive advantage. In the context of green transformation, green investment represents a tangible commitment of financial and organizational resources, serving as a potential transmission mechanism linking executive cognition to green innovation.
Moreover, the effectiveness of this translation process may depend on the firm’s information environment. Environmental innovation is characterized by long-term returns and substantial uncertainty, which makes it sensitive to information asymmetry between managers and external stakeholders. Research on nonfinancial disclosure indicates that mandatory environmental and sustainability reporting can significantly influence capital market reactions and corporate behavior [13,14]. High-quality environmental information disclosure may therefore improve the information environment surrounding firms’ environmental strategies by enhancing transparency, strengthening external monitoring, and increasing accountability for disclosed commitments. In this way, disclosure quality may not directly generate green innovation, but it can strengthen the implementation and credibility of innovation-oriented actions associated with executive environmental cognition.
To address these gaps, this study develops a differentiated mechanism framework. We propose that executive environmental cognition influences technological and managerial green innovation through distinct pathways. This differentiated perspective is also consistent with recent resilience-oriented research showing that organizational and regional responses to external shocks are often heterogeneous and shaped by underlying adaptive capacities [15]. Specifically, green investment is expected to play a stronger mediating role in technological green innovation due to its capital-intensive nature, whereas managerial green innovation may rely more directly on leadership commitment and organizational alignment. For example, in manufacturing settings, leadership commitment may support GTI by approving cleaner production equipment, energy-saving process upgrades, or low-emission production redesign, whereas it may support GMI by promoting environmental management systems, internal training, cross-departmental coordination, and sustainability-oriented performance routines. Furthermore, environmental information disclosure quality is theorized to strengthen the translation of executive cognition into both types of green innovation.
Using panel data from Chinese A-share manufacturing firms from 2014 to 2023, this study empirically examines these relationships. By distinguishing between technological and managerial green innovation and integrating resource allocation and information environment perspectives, this study provides a more nuanced understanding of how executive environmental cognition shapes heterogeneous green innovation outcomes.
This study makes three main contributions. First, it moves beyond treating green innovation as a homogeneous construct by distinguishing between green technological innovation and green managerial innovation, thereby providing a more differentiated understanding of how executive environmental cognition shapes corporate green transformation. Second, it opens the “black box” of this relationship by showing that executive environmental cognition influences different types of green innovation through distinct mechanisms and contextual conditions, especially environmental protection investment and environmental information disclosure quality. Third, by situating the analysis in the digital economy context, this study highlights that executive cognition becomes increasingly consequential when firms operate in information-rich, highly visible, and rapidly changing environments in which environmental signals must be strategically interpreted and acted upon. Rather than proposing an entirely new topic, this study seeks to refine and deepen existing research by differentiating innovation types, specifying transmission mechanisms, and clarifying the contextual relevance of the digital economy.
2. Literature Review and Hypotheses Development
2.1. Executive Environmental Cognition and Green Innovation
Green innovation has been increasingly conceptualized as a strategic response that enables firms to manage environmental constraints while sustaining competitiveness [16]. However, green innovation is internally heterogeneous and may follow distinct implementation routes with different organizational requirements [17].
From a managerial perspective, upper echelons research emphasizes that strategic choices and organizational outcomes reflect top executives’ cognitive bases, values, and attention allocation, especially when decision contexts are complex and ambiguous [2]. In complex environments, effective judgment often depends on the integration of multiple streams of information rather than isolated signals, which highlights the importance of cognitive interpretation and information-processing capability in organizational decision-making [18]. In sustainability contexts, executive-level cognitive orientations and leadership attributes have been shown to shape firms’ environmental innovation engagement [3].
Building on this logic, we define executive environmental cognition (EC) as a managerial cognitive orientation toward environmental issues, referring to the extent to which top executives identify the strategic relevance of environmental challenges, interpret environmental policy, regulatory requirements, and compliance-related signals, and incorporate such considerations into corporate priority setting and strategic decision-making [19,20]. Thus, EC should not be understood merely as executives’ technical knowledge of environmental matters. Rather, it reflects a broader interpretive and strategic awareness through which top managers cognitively internalize external environmental pressures and translate them into organizational attention, resource commitment, and environmentally oriented strategic action.
2.2. Executive Environmental Cognition and Green Technological Innovation
Green technological innovation (GTI) in this study mainly refers to technology-based innovations that reduce environmental impacts through cleaner production, process upgrading, resource conservation, and energy-efficiency improvement, rather than merely adding end-of-pipe control devices after the core production process [21,22]. In this sense, GTI is more closely associated with source-oriented and efficiency-enhancing technological change [21]. Such innovation typically requires R&D effort, technological search, and cross-functional coordination, and may involve uncertain returns and substantial organizational commitment, especially when firms attempt to redesign products, materials, or production processes in environmentally beneficial ways [23]. Although technologists and engineers play a direct role in developing and implementing such innovations, top executives remain important because they determine whether cleaner and strategically consequential technological upgrading is prioritized, funded, and sustained over time. In practical terms, this may include executive support for cleaner process redesign, waste-heat recovery systems, energy-efficient equipment replacement, or low-emission production upgrading in manufacturing operations. Executives with stronger environmental cognition are therefore more likely to view environmental challenges as opportunities for cleaner and more resource-efficient technological transformation, thereby increasing the likelihood that firms engage in substantive green technology development and generate green patent outputs [24]. Compared with GTI, the role of technical specialists is more direct in implementation, whereas the role of executives is more prominent in strategic prioritization and resource mobilization.
H1a:
Executive environmental cognition is positively associated with green technology innovation (GTI).
2.3. Executive Environmental Cognition and Green Managerial Innovation
Green managerial innovation (GMI) refers to innovative changes in managerial systems, organizational processes, coordination mechanisms, and decision rules through which environmental objectives are newly integrated into the firm’s management architecture [25]. Therefore, GMI should not be understood as a synonym for general environmental management. Rather, it emphasizes the novelty and reconfiguration of organizational arrangements that embed environmental considerations into planning, evaluation, coordination, and control processes. Compared with GTI, GMI is more strongly related to internal governance, organizational alignment, and the institutionalization of sustainability-oriented routines [26]. Because managerial innovation is closely tied to leadership values and managerial attention, executives with stronger environmental cognition are more likely to promote new sustainability-oriented systems and routines, thereby facilitating GMI as a form of organizational change [27]. For instance, such leadership commitment may be reflected in the introduction of new environmental management systems, the establishment of internal environmental responsibility structures, employee training on energy-saving and compliance practices, routine monitoring mechanisms for environmental targets, and cross-functional coordination arrangements that connect environmental goals with organizational decision-making.
H1b:
Executive environmental cognition is positively associated with green management innovation (GMI).
2.4. Green Investment as a Mediating Mechanism
While cognition shapes strategic priorities, innovation outcomes typically require tangible resource commitment. The natural resource-based view argues that proactive environmental strategies can become sources of advantage when firms build capabilities through resource allocation and organizational processes [11]. In this context, green investment (EPI) reflects firms’ allocation of capital toward environmental protection and green transformation (e.g., pollution control facilities, cleaner production equipment, environmental engineering projects) [28].
Green investment can provide the material basis for GTI by enabling technology upgrading and supporting R&D-related infrastructure [22]. It can also support GMI by financing systems, training, and process integration, which facilitate the institutionalization of environmental management routines [26].
Accordingly, executive environmental cognition is expected to increase green investment, which in turn promotes both GTI and GMI, implying an indirect (mediated) effect.
H2a:
Green investment mediates the relationship between executive environmental cognition and GTI.
H2b:
Green investment mediates the relationship between executive environmental cognition and GMI.
2.5. Environmental Information Disclosure Quality as a Moderating Factor
Even when executives possess strong environmental cognition, the implementation of green innovation may still be constrained by information asymmetry and stakeholder skepticism because external stakeholders often find it difficult to directly assess the substance and long-term credibility of firms’ environmental strategies. In this context, environmental information disclosure quality does not itself create green innovation outcomes; rather, it shapes the informational conditions under which environmental strategies are communicated, evaluated, and monitored. Higher-quality environmental disclosure can improve transparency and make firms’ environmental commitments more informative and comparable [14,29]. It may also strengthen external scrutiny and increase the reputational cost of selective disclosure or symbolic environmental claims, thereby encouraging firms to implement more substantive environmental actions rather than merely communicate environmental intentions [30,31]. Therefore, environmental information disclosure quality is expected to strengthen the positive relationship between executive environmental cognition and both GTI and GMI by improving the transparency, credibility, and accountability conditions under which environmentally oriented strategies are implemented.
Importantly, this moderating effect does not imply that disclosure quality generates environmental awareness in the absence of executive environmental cognition. Rather, it indicates that disclosure quality shapes the governance and information environment in which pre-existing executive cognition is translated into substantive innovation action.
H3a:
Environmental information disclosure quality positively moderates the relationship between executive environmental cognition and GTI by strengthening the transparency and accountability conditions under which environmentally oriented technological strategies are implemented.
H3b:
Environmental information disclosure quality positively moderates the relationship between executive environmental cognition and GMI by strengthening the transparency and accountability conditions under which environmentally oriented managerial changes are implemented.
3. Research Design
3.1. Data and Sample
This study uses panel data from Chinese A-share listed manufacturing firms from 2014 to 2023. The manufacturing sector is selected because it represents a key source of industrial emissions and plays a critical role in China’s green transformation. Following prior research on corporate green innovation, manufacturing firms provide an appropriate empirical context for examining firms’ environmental strategies and innovation activities.
The data are collected from multiple sources. Green patent data used to measure green technological innovation are obtained from the China Research Data Service Platform (CNRDS). Firm-level financial and governance data are collected from the China Stock Market and Accounting Research (CSMAR) database. Information on executive environmental cognition and green investment is manually collected from firms’ annual reports. Environmental information disclosure data are obtained from the CSMAR environmental database.
Several screening procedures are applied to construct the final sample. First, firms in the financial and insurance industries are excluded because their financial structures differ substantially from those of industrial firms. Second, observations with missing key variables are removed. Third, continuous variables are winsorized at the 1% and 99% levels to mitigate the influence of extreme values.
After these procedures, the final sample consists of 1119 manufacturing firms and 11,190 firm-year observations. The focus on Chinese A-share listed manufacturing firms provides a relatively comparable empirical setting for testing Hypothesis 1a because these firms face similar regulatory and disclosure requirements while operating in a sector with substantial environmental pressure and green transformation demands. Firm-year panel regressions are estimated within this setting, and firm size as well as industry-related heterogeneity are accounted for through control variables and fixed effects.
3.2. Variable Measurement
3.2.1. Dependent Variables
Green technological innovation (GTI): Green technological innovation reflects firms’ technological activities aimed at reducing environmental impacts and improving resource efficiency. Following prior studies on corporate green innovation, this study measures green technological innovation using the number of green patent applications filed by firms [7,32]. Specifically, the total number of green invention patents and green utility model patents is aggregated. To mitigate potential skewness in the distribution of patent counts, the natural logarithm of one plus the total number of green patent applications is used as the proxy for green technological innovation.
Green managerial innovation (GMI): Green managerial innovation in this study is measured as a composite indicator reflecting the extent to which firms adopt environmentally oriented managerial and organizational practices [25,27]. Specifically, the indicator is constructed from five items: the establishment of environmental management systems, environmental certifications, environmental education and training, internal environmental responsibility arrangements, and environmental initiatives. The values assigned to these items are summed to obtain the overall GMI score, with a higher score indicating a greater extent of managerial innovation in integrating environmental objectives into organizational processes and governance arrangements.
3.2.2. Independent Variable
Executive environmental cognition (EC): In this study, executive environmental cognition is proxied using a textual analysis approach. Prior studies have shown that textual information in corporate disclosures can capture managerial attention, issue salience, and strategic orientation [33,34]. Following this approach, this study constructs a dictionary of environmental keywords and calculates the frequency of these keywords in firms’ annual reports.
The keyword dictionary includes terms related to environmental strategy, environmental governance, environmental responsibility, environmental regulation, and sustainability. Because annual reports typically contain sections describing corporate strategy and management discussions prepared under the supervision of top executives, the frequency of environmental-related expressions in these disclosures provides an observable proxy for the extent to which environmental issues are emphasized and strategically framed in executives’ corporate discourse. Accordingly, the criteria used to characterize EC in this study are the salience, emphasis, and strategic framing of environmental issues in executive-led corporate disclosures, rather than realized environmental outcomes.
Accordingly, the EC measure used in this study should not be interpreted as a direct psychological measure of executives’ inner cognition, nor as a measure of firms’ realized environmental outcomes. Rather, it reflects the salience and strategic articulation of environmental concerns in executive-led corporate disclosures. This distinction is important because environmental outcomes such as resource efficiency, pollution prevention, waste minimization, or green product design are conceptually closer to firms’ environmental performance and green innovation results, rather than to executive cognition itself.
3.2.3. Mediating Variable
Green investment (EPI): Green investment reflects firms’ capital allocation toward environmental protection and green transformation. In line with prior studies examining corporate environmental investment, this study measures green investment as the ratio of environmental protection investment related to construction projects to total assets [35]. This measure captures firms’ financial commitment to environmental initiatives, including pollution control facilities, environmental engineering projects, and cleaner production technologies. A higher value indicates that firms allocate more resources to environmental protection activities.
3.2.4. Moderating Variable
Environmental information disclosure quality (EIDQ): Environmental information disclosure quality reflects the transparency and comprehensiveness of firms’ environmental reporting. Prior research suggests that higher-quality environmental disclosure reduces information asymmetry and enhances external monitoring by stakeholders [14,29]. Following this line of research, this study constructs an environmental disclosure index based on multiple dimensions of environmental reporting, including environmental management practices, environmental certifications, environmental performance indicators, and environmental governance disclosures. The disclosure scores are aggregated to obtain a comprehensive measure of environmental information disclosure quality. To reduce skewness in the distribution, the total disclosure score is logarithmically transformed.
The definitions and measurements of all variables used in this study are reported in Table 1.
Table 1.
Variable definitions and measurements.
3.3. Model Specification
To examine the relationship between executive environmental cognition and corporate green innovation, this study estimates the following baseline model:
where denotes corporate green innovation for firm i in year t. Following the research design, is measured separately as green technological innovation (GTI) and green managerial innovation (GMI). denotes executive environmental cognition. is a vector of firm-level and top-management-level control variables, including firm size, leverage, return on assets, ownership concentration, firm age, state ownership, top management team age, and executive compensation. and represent industry and year fixed effects, respectively, and is the error term.
These control variables are selected to account for firm characteristics and governance conditions that may independently influence green innovation. Firm size is controlled for because larger firms typically possess more financial, technological, and organizational resources to support green innovation activities. Leverage is included because firms with higher debt pressure may face tighter financial constraints in undertaking innovation with uncertain returns. Return on assets is controlled for to capture firms’ profitability and internal funding capacity. Ownership concentration may affect the efficiency of strategic decision-making and the monitoring of long-term innovation investment. Firm age is included because older firms may differ from younger firms in organizational routines, path dependence, and adaptive capacity. State ownership is controlled for because state-owned enterprises may face different institutional pressures, policy expectations, and resource access in environmental and innovation-related decisions. At the top-management level, team age and executive compensation are included because managerial demographic characteristics and incentive structures may shape strategic attention, risk preferences, and support for innovation. In addition, industry and year fixed effects are used to absorb unobservable heterogeneity across sectors and time periods.
To test the mediating role of environmental protection investment, the following models are estimated:
where denotes environmental protection investment. A significant coefficient in Equation (2) and a significant coefficient in Equation (3), together with a reduction in relative to , indicate the presence of a mediating effect. In addition, this study further employs a bootstrap test to examine the significance of the indirect effect.
To examine the moderating role of environmental information disclosure quality, the following model is estimated:
where denotes environmental information disclosure quality, and is the interaction term capturing the moderating effect of environmental disclosure quality on the relationship between executive environmental cognition and corporate green innovation.
4. Empirical Results
4.1. Descriptive Statistics
Table 2 reports the descriptive statistics of the main variables used in this study. The sample consists of 11,190 firm-year observations from Chinese A-share manufacturing firms over the period 2014–2023.
Table 2.
Descriptive statistics of variables.
With respect to the dependent variables, the mean value of green technological innovation (GTI) is 0.380, with a median of 0 and a maximum value of 3.871. This indicates that the overall level of green technological innovation among manufacturing firms remains relatively low, and a considerable proportion of firms have not yet generated green patent applications. This finding reflects the high cost and uncertainty associated with technological green innovation.
In contrast, the mean value of green managerial innovation (GMI) is 0.699, with a median of 1 and a maximum value of 5. Because GMI is constructed as a composite indicator based on five managerial practices—environmental management systems, environmental certifications, environmental education and training, internal environmental responsibility arrangements, and environmental initiatives—these statistics suggest that the typical firm has adopted only a limited subset of such practices rather than a comprehensive green management system. In other words, green managerial innovation in the sample appears to be moderate and unevenly distributed, with some firms adopting multiple environmentally oriented managerial arrangements while others have implemented few or none.
Regarding the key explanatory variable, executive environmental cognition (EC) has a mean value of 1.289 and a standard deviation of 0.905, indicating significant variation in the level of environmental attention expressed by top executives in corporate disclosures.
Among the mechanism variables, the mean value of green investment (EPI) is 0.112, with a median of 0, suggesting that many firms make limited environmental capital investment.
For the moderating variable, the mean value of environmental information disclosure quality (EIDQ) is 1.994, indicating that the overall level of environmental disclosure among manufacturing firms remains moderate but varies considerably across firms.
Overall, the distribution of the variables appears reasonable and provides sufficient variation for subsequent regression analysis.
4.2. Correlation Analysis
Table 3 presents the Pearson correlation coefficients among the main variables.
Table 3.
Correlation analysis results.
The results show that executive environmental cognition (EC) is positively correlated with both green technological innovation (GTI) and green managerial innovation (GMI), suggesting that firms with stronger environmental awareness among executives tend to exhibit higher levels of green innovation. Green investment (EPI) is also positively correlated with both GTI and GMI, providing preliminary evidence that environmental capital allocation may play an important role in promoting corporate green innovation. Furthermore, environmental information disclosure quality (EIDQ) shows significant positive correlations with both types of green innovation, indicating that firms with higher levels of environmental transparency tend to demonstrate stronger green innovation performance. Although some variables exhibit moderate pairwise correlations, the mean variance inflation factor (VIF) is only 1.65, suggesting that multicollinearity is unlikely to be a serious concern in this study.
4.3. Baseline Regression
Table 4 reports the baseline regression results examining the relationship between executive environmental cognition and corporate green innovation. In the two-way fixed effects specification, the coefficient of EC remains positive and statistically significant for both GTI and GMI, indicating that stronger executive environmental cognition is associated with higher levels of both technological and managerial green innovation. Importantly, the estimated coefficient is noticeably larger for GMI than for GTI, suggesting that executive environmental cognition is more readily translated into organizational and managerial changes than into technological innovation. This pattern is consistent with the argument that green managerial innovation depends more directly on leadership attention, organizational alignment, and managerial commitment, whereas green technological innovation additionally requires technological capabilities, longer implementation horizons, and stronger resource support. From a practical perspective, the results imply that improvements in executive environmental cognition are associated not only with symbolic environmental concern, but with observable changes in firms’ innovation orientation, especially in managerial and organizational domains.
Table 4.
Baseline regression results.
4.4. Mediation Analysis
To examine whether green investment serves as a transmission mechanism linking executive environmental cognition to corporate green innovation, this study conducts mediation analysis following the approach widely used in prior research.
Table 5 reports the results. First, the regression results show that executive environmental cognition (EC) has a significantly positive effect on green investment (EPI). This finding suggests that executives with stronger environmental awareness are more likely to allocate financial resources toward environmental protection and green transformation activities. Second, when both EC and EPI are included in the regression model, the coefficient of EPI remains positive and statistically significant for both green technological innovation (GTI) and green managerial innovation (GMI). At the same time, the coefficient of EC decreases compared with the baseline model. To provide a more rigorous test of the mediating role of environmental protection investment, this study supplements the coefficient-comparison approach with a bootstrap test based on 1000 replications. The results show that the indirect effect of executive environmental cognition on GTI through EPI is positive and statistically significant (indirect effect = 0.0028, 95% CI [0.0004, 0.0053]). Similarly, the indirect effect of executive environmental cognition on GMI through EPI is also positive and significant (indirect effect = 0.0046, 95% CI [0.0006, 0.0087]). Table 6 reports the results. Since the confidence intervals do not include zero in either case, the bootstrap results provide further support for the mediating role of environmental protection investment. At the same time, the direct effects of executive environmental cognition on both GTI and GMI remain significant after EPI is included, indicating that environmental protection investment plays a partial rather than full mediating role. These findings suggest that executive environmental cognition influences green innovation not only through direct strategic orientation, but also through firms’ resource commitment to environmental protection and green transformation. Moreover, the indirect effects are statistically significant but relatively small compared with the corresponding direct effects, suggesting that environmental protection investment is an important transmission channel, but not the dominant mechanism through which executive environmental cognition affects green innovation.
Table 5.
Mediation analysis results.
Table 6.
Bootstrap test results for the mediating effect of environmental protection investment.
These results indicate that green investment partially mediates the relationship between executive environmental cognition and corporate green innovation. In other words, executives’ environmental cognition not only directly influences firms’ innovation behavior but also indirectly promotes green innovation by increasing environmental investment.
Thus, Hypotheses 2a and 2b are supported.
4.5. Moderation Analysis
Table 7 reports the moderating effect of environmental information disclosure quality (EIDQ) on the relationship between executive environmental cognition (EC) and green innovation. The interaction term between EC and EIDQ is positive and statistically significant in both models, indicating that higher-quality environmental information disclosure strengthens the positive effect of executive environmental cognition on both green technological innovation (GTI) and green managerial innovation (GMI). Therefore, Hypotheses H3a and H3b are supported.
Table 7.
Moderation analysis results.
More importantly, the magnitude of the moderating effect differs across the two types of green innovation. The interaction coefficient is smaller in the GTI model but notably larger in the GMI model, suggesting that environmental information disclosure quality plays a stronger reinforcing role in the relationship between EC and green managerial innovation than in the relationship between EC and green technological innovation. This pattern is consistent with the theoretical argument that green managerial innovation is more directly associated with organizational arrangements, governance routines, and managerial accountability, all of which are more visible and more easily reinforced by a transparent information environment. By contrast, although disclosure quality also strengthens the EC–GTI relationship, green technological innovation remains more dependent on technological capabilities, longer development cycles, and sustained resource commitment, which makes the moderating role of disclosure quality comparatively weaker.
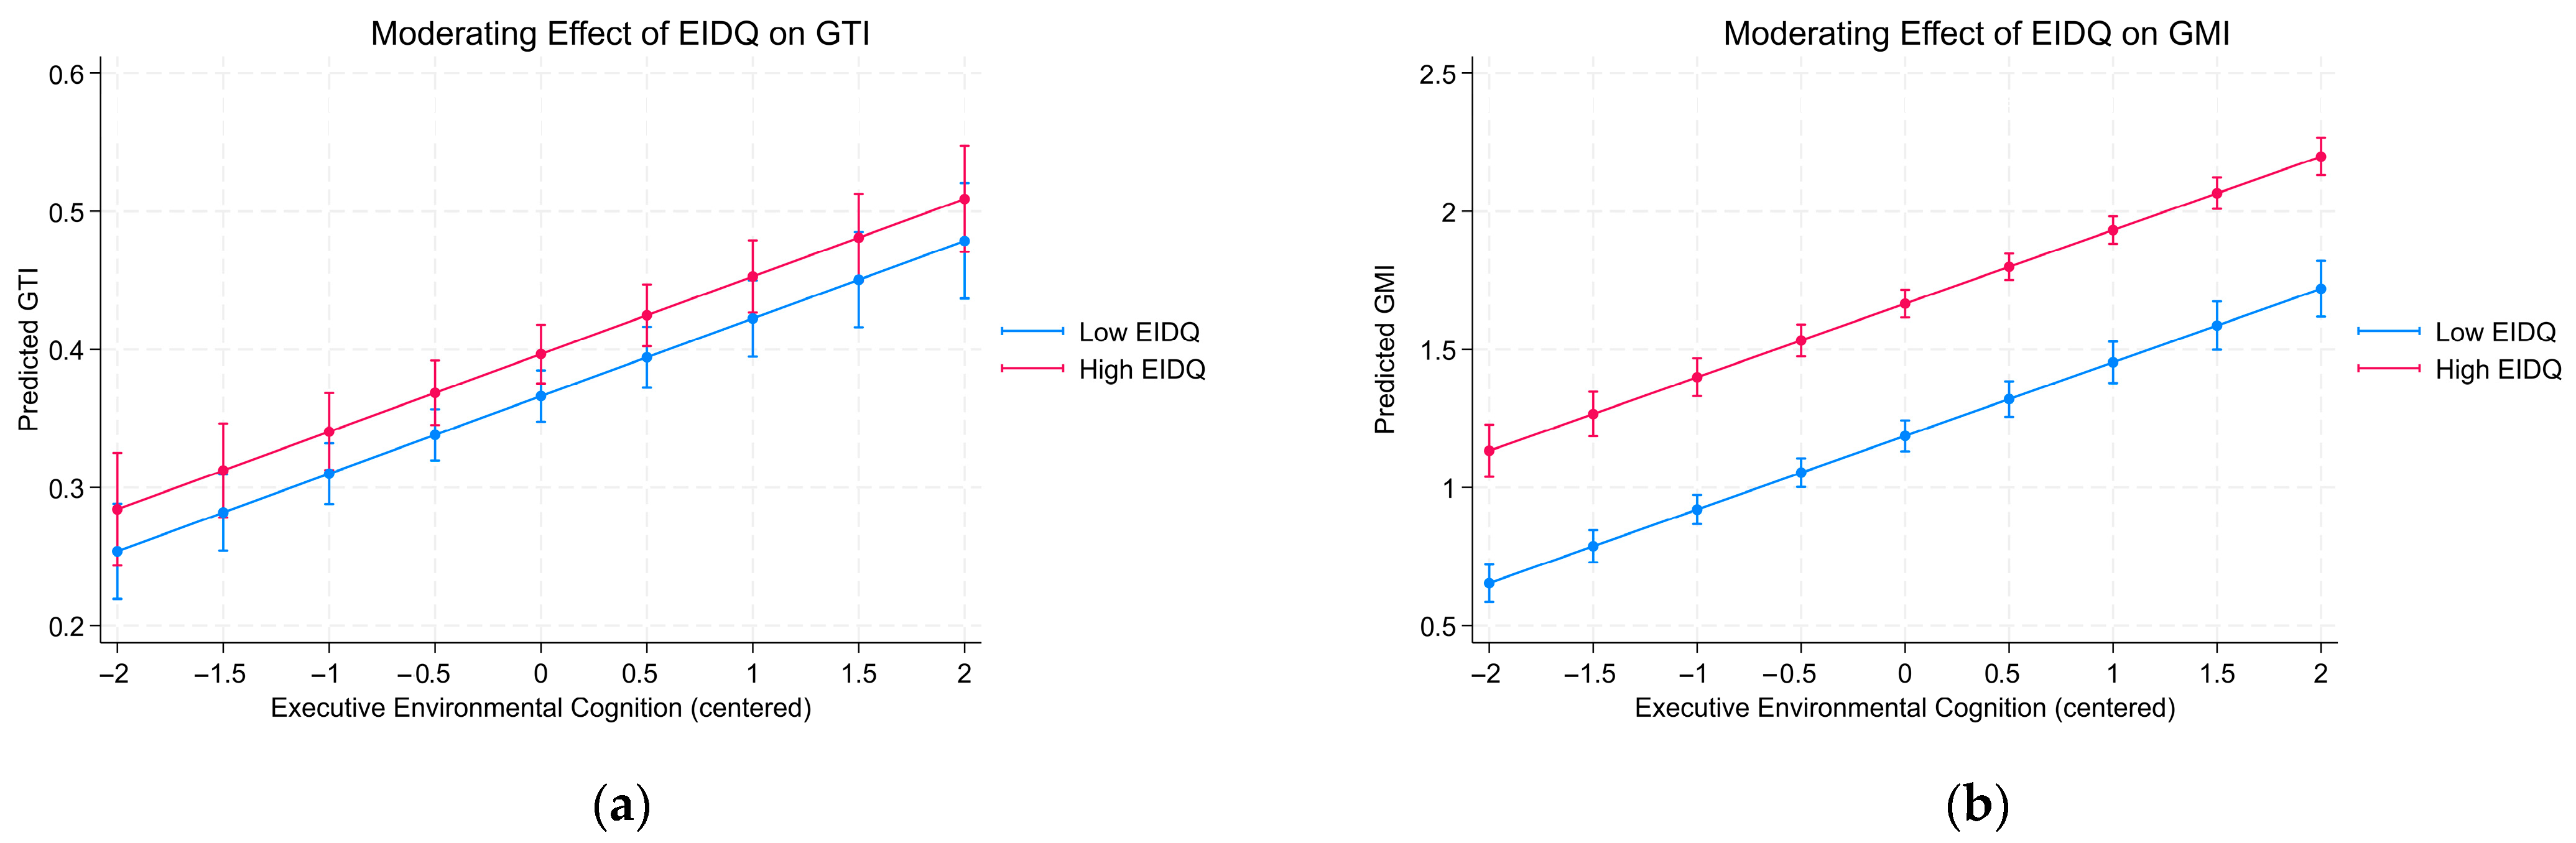
To further illustrate the moderating effect, Figure 1a,b plot the relationship between executive environmental cognition and green innovation at high and low levels of EIDQ. As shown in Figure 1a, the positive relationship between EC and GTI becomes stronger when EIDQ is high. Figure 1b shows an even more pronounced pattern for GMI, where the slope under high EIDQ is steeper and the gap between the high- and low-EIDQ groups is larger. These graphical results provide intuitive support for the regression findings and further suggest that high-quality environmental disclosure does not itself generate green innovation, but improves the transparency, monitoring, and accountability conditions under which executives’ environmental cognition is translated into substantive innovation outcomes.
Figure 1.
Moderating effect of environmental information disclosure quality on the relationship between executive environmental cognition and green innovation: (a) green technological innovation (GTI); (b) green managerial innovation (GMI).
Overall, the moderating results imply that executive environmental cognition is more likely to be converted into credible and substantive green innovation when firms operate in a higher-quality environmental information environment. In this sense, EIDQ functions as an important boundary condition that strengthens the implementation of environmentally oriented strategies, especially in the managerial and organizational domain.
Therefore, Hypotheses 3a and 3b are supported.
4.6. Robustness Checks
To ensure the robustness of the empirical results, several additional tests are conducted. Table 8 reports the results of these robustness checks.
Table 8.
Robustness checks results.
First, alternative measures of green innovation are employed. Specifically, green technological innovation is remeasured using the number of green patent grants (GTI1), and green managerial innovation is alternatively proxied by whether the firm has obtained ISO 14001 environmental management system certification (GMI1), which reflects the degree of standardization in environmental management systems, process control, and continuous improvement mechanisms. The results reported in Columns (1)–(2) remain positive and statistically significant, indicating that the main findings are not sensitive to the specific measurement of green innovation.
Second, the baseline regressions are re-estimated using firm and year fixed effects. As shown in Columns (3)–(4), the coefficient of executive environmental cognition remains significantly positive for both GTI and GMI. This suggests that the main findings are robust after controlling for time-invariant firm-level heterogeneity more stringently.
Third, to reduce the possible influence of region-specific factors associated with municipalities directly under the central government, the sample is re-estimated after excluding firms located in these municipalities. The results in Columns (5)–(6) continue to support the baseline conclusions, indicating that the main findings are not driven by this particular subgroup of firms.
Overall, the robustness checks confirm that the positive relationship between executive environmental cognition and corporate green innovation remains stable across alternative variable measurements, fixed-effects specifications, and sample restrictions.
4.7. Endogeneity Test
Although the baseline regressions include relevant control variables as well as fixed effects, potential endogeneity may still arise from omitted variables or reverse causality. In particular, executive environmental cognition, as a managerial cognition variable, may be influenced by firms’ pre-existing green innovation foundations, regional green development climates, and external regulatory environments. At the same time, firms with stronger green innovation performance may also reinforce executives’ attention to environmental issues through reputation effects and organizational learning. As a result, the explanatory variable may be correlated with the error term, which would weaken the causal interpretation of the baseline estimates. To further strengthen identification, this study employs an instrumental variable (IV) approach.
To satisfy both relevance and exogeneity conditions, and following the peer-group mean strategy commonly used in prior research, this study uses the mean value of executive environmental cognition among other firms in the same industry, province, and year as the instrumental variable for executive environmental cognition (IV1). With respect to relevance, firms operating in the same industry and province are usually exposed to similar environmental regulatory intensity, local policy orientation, and social attention. In addition, executives may be influenced by industry communication, regional demonstration effects, and social network connections. Therefore, the environmental cognition of peer firms is expected to be closely related to the focal firm’s executive environmental cognition. With respect to exogeneity, after controlling for firm characteristics and fixed effects, the instrumental variable is intended to capture the common industry–regional cognitive environment rather than firm-specific innovation shocks. Nevertheless, because the exclusion restriction cannot be directly tested in empirical research, the IV results should still be interpreted with appropriate caution.
The first-stage regression results are reported in Column (1) of Table 9. The coefficient on IV1 is 0.0916 and statistically significant at the 1% level, indicating that the instrumental variable is strongly correlated with executive environmental cognition. The first-stage F-statistic is 54.11, which is well above the rule-of-thumb threshold of 10, suggesting that weak-instrument concerns are unlikely to be severe. In addition, the Kleibergen–Paap LM statistic and Wald F statistic also support the relevance of the instrument under heteroskedasticity.
Table 9.
Instrumental variable estimation results.
Columns (2) and (3) of Table 9 report the second-stage estimation results using green technological innovation (GTI) and green managerial innovation (GMI) as the dependent variables, respectively. After accounting for endogeneity, the coefficient of executive environmental cognition remains positive and statistically significant for both GTI and GMI. Specifically, the estimated coefficient is 0.3711 for GTI and 0.6291 for GMI. These results are consistent in sign and substantive meaning with the baseline regressions, indicating that the positive relationship between executive environmental cognition and the two dimensions of green innovation remains robust under a more stringent identification strategy. Moreover, the estimated coefficient is larger for GMI than for GTI, further supporting the argument that executive environmental cognition is more readily translated into managerial and organizational forms of green innovation than into technological innovation. Overall, the instrumental variable results provide additional support for the baseline findings, although the causal interpretation remains conditional on the validity of the instrument.
5. Discussion
The findings of this study provide several important insights into the relationship between executive environmental cognition and corporate green innovation.
First, the results highlight the critical role of managerial cognition in shaping firms’ environmental strategies. Consistent with upper echelons theory, the empirical findings indicate that executives’ environmental awareness significantly promotes both green technological innovation and green managerial innovation. This suggests that executives’ interpretations of environmental issues influence firms’ strategic priorities and innovation decisions.
Second, the results reveal heterogeneous mechanisms underlying different types of green innovation. While both technological and managerial green innovation are positively influenced by executive environmental cognition, the pathways through which cognition translates into innovation may differ. Green technological innovation typically requires substantial financial investment and technological resources, whereas green managerial innovation relies more heavily on organizational routines and managerial commitment.
Third, the mediation analysis demonstrates that green investment serves as an important transmission mechanism linking executive environmental cognition and corporate green innovation. Executives with stronger environmental awareness are more likely to allocate resources toward environmental protection and sustainability-related projects, which in turn facilitate green innovation activities.
Fourth, the moderating role of environmental information disclosure quality highlights the importance of the external information environment. When firms provide higher-quality environmental disclosure, stakeholders can more effectively evaluate firms’ environmental strategies. This transparency enhances the credibility of executives’ environmental commitments and strengthens the relationship between executive environmental cognition and green innovation.
Overall, the findings suggest that corporate green innovation is shaped not only by external institutional pressures but also by internal managerial cognition and resource allocation decisions.
6. Conclusions
This study examines how executive environmental cognition influences corporate green innovation from the perspectives of resource allocation and information environment. Using panel data from Chinese A-share manufacturing firms from 2014 to 2023, the empirical results show that executive environmental cognition significantly promotes both green technological innovation and green managerial innovation.
Further analysis indicates that green investment plays a mediating role in this relationship. Executives with stronger environmental awareness tend to allocate more financial resources toward environmental protection and green transformation, which in turn facilitates corporate green innovation. In addition, environmental information disclosure quality strengthens the positive relationship between executive environmental cognition and green innovation, suggesting that a transparent information environment enhances the effectiveness of executives’ environmental strategies.
This study makes several contributions to the literature. First, it extends research on green innovation by distinguishing between technological and managerial green innovation and demonstrating that executive environmental cognition influences both dimensions. Second, it contributes to the upper echelons literature by highlighting the role of managerial environmental cognition in shaping corporate sustainability strategies. Third, by identifying green investment as a mediating mechanism and environmental disclosure quality as a moderating factor, this study provides a more comprehensive understanding of how managerial cognition translates into corporate environmental innovation.
The findings also provide several practical implications. Firms should recognize the importance of executive environmental awareness in promoting sustainability-oriented innovation. Strengthening executives’ environmental cognition and strategic commitment to sustainability may help firms develop more effective green innovation strategies. In addition, firms should improve environmental information disclosure practices to enhance transparency and strengthen stakeholder trust.
This study should be interpreted within a specific empirical and theoretical scope. Empirically, the analysis focuses on Chinese A-share listed manufacturing firms during 2014–2023, and the findings are therefore most applicable to firms operating in a highly regulated manufacturing context with relatively standardized disclosure requirements. Theoretically, the model assumes that executive environmental cognition affects green innovation through organizational decision-making and strategic prioritization, rather than through direct technical implementation. It also assumes that environmental protection investment and environmental information disclosure quality function as contextual mechanisms that shape how executive cognition is translated into substantive innovation outcomes, rather than replacing managerial cognition itself.
Several limitations should also be acknowledged. First, the measurement of executive environmental cognition relies on textual analysis of annual report disclosures and therefore captures the observable salience and strategic framing of environmental issues in executive-led corporate discourse, rather than executives’ inner cognition in a direct psychological sense. Second, although the indicators for green managerial innovation, environmental protection investment, and environmental information disclosure quality are constructed based on prior literature, they may not fully capture all dimensions of these constructs. Third, because the sample is limited to listed manufacturing firms in China, caution is needed in generalizing the findings to small firms, non-manufacturing sectors, or firms operating in other institutional environments. Future research may extend the analysis by using alternative measures, richer institutional comparisons, and broader samples to further test the robustness and boundary conditions of the proposed framework.
Author Contributions
Conceptualization, J.H.; Validation, J.H.; Investigation, Y.G.; Resources, Y.G.; Data curation, Y.G.; Writing—original draft, Y.G.; Writing—review and editing, J.H.; Supervision, J.H. All authors have read and agreed to the published version of the manuscript.
Funding
This research received no external funding.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The original contributions presented in this study are included in the article. Further inquiries can be directed to the corresponding author.
Conflicts of Interest
The authors declare no conflicts of interest.
References
- Hambrick, D.C.; Mason, P.A. Upper echelons: The organization as a reflection of its top managers. Acad. Manag. Rev. 1984, 9, 193–206. [Google Scholar] [CrossRef] [Scilit]
- Hambrick, D.C. Upper echelons theory: An update. Acad. Manag. Rev. 2007, 32, 334–343. [Google Scholar] [CrossRef] [Scilit]
- Arena, C.; Michelon, G.; Trojanowski, G. Big Egos Can Be Green: A Study of CEO Hubris and Environmental Innovation. Br. J. Manag. 2018, 29, 316–336. [Google Scholar] [CrossRef] [Scilit]
- Liu, B.; Liu, F.F.; Song, F. Coupling sPCA-Based Statistical Modeling with Deep Residual Networks Considering Thermal Effect for Deformation Forecasting in High Dams. Struct. Control. Health Monit. 2025, 2025, 6688960. [Google Scholar] [CrossRef] [Scilit]
- He, Q.; Shan, R.; Qu, C.; Tang, Y.; Zou, Y. Rare-Earth Exposure and Bottlenecks in AI Data Centers: Cost and Schedule Risk; SSRN: Rochester, NY, USA, 2026. [Google Scholar]
- Hu, Y. Customer market analysis based on interval value data dynamic clustering algorithm. In Proceedings of the 2023 International Conference on Integrated Intelligence and Communication Systems (ICIICS), Kalaburagi, India, 24–25 November 2023; IEEE Press: Piscataway, NJ, USA, 2023; pp. 1–6. [Google Scholar]
- Xie, X.M.; Huo, J.G.; Zou, H.L. Green process innovation, green product innovation, and corporate financial performance: A content analysis method. J. Bus. Res. 2019, 101, 697–706. [Google Scholar] [CrossRef] [Scilit]
- Hu, Y.; Huang, Y. Seasonality in the U.S. Housing Market: Post-Pandemic Shifts and Regional Dynamics. Real Estate 2025, 2, 22. [Google Scholar] [CrossRef] [Scilit]
- Takalo, S.K.; Tooranloo, H.S.; Shahabaldini Parizi, Z. Green innovation: A systematic literature review. J. Clean. Prod. 2021, 279, 122474. [Google Scholar] [CrossRef] [Scilit]
- Barney, J. Firm resources and sustained competitive advantage. J. Manag. 1991, 17, 99–120. [Google Scholar] [CrossRef] [Scilit]
- Hart, S.L.; Dowell, G. A Natural-Resource-Based View of the Firm: Fifteen Years After. J. Manag. 2011, 37, 1464–1479. [Google Scholar] [CrossRef] [Scilit]
- Hart, S.L. A natural-resource-based view of the firm. Acad. Manag. Rev. 1995, 20, 986–1014. [Google Scholar] [CrossRef] [Scilit]
- Grewal, J.; Riedl, E.J.; Serafeim, G. Market Reaction to Mandatory Nonfinancial Disclosure. Manag. Sci. 2019, 65, 3061–3084. [Google Scholar] [CrossRef] [Scilit]
- Christensen, H.B.; Hail, L.; Leuz, C. Mandatory CSR and sustainability reporting: Economic analysis and literature review. Rev. Account. Stud. 2021, 26, 1176–1248. [Google Scholar] [CrossRef] [Scilit]
- Shen, Q.; Liu, D.; Zou, Y. Business Resilience Index (BRI): Evaluating Economic Recovery Through Event-Study Heterogeneity; Preprint; Research Square: Durham, NC, USA, 2026. [Google Scholar] [CrossRef] [Scilit]
- Dangelico, R.; Pujari, D. Mainstreaming Green Product Innovation: Why and How Companies Integrate Environmental Sustainability. J. Bus. Ethics 2010, 95, 471–486. [Google Scholar] [CrossRef] [Scilit]
- Dangelico, R.M. Green Product Innovation: Where we are and Where we are Going. Bus. Strateg. Environ. 2016, 25, 560–576. [Google Scholar] [CrossRef] [Scilit]
- Shen, Q.; Zhang, J. MFTFormer: Meteorological-Frequency-Temporal Transformer with Block-Aligned Fusion for Traffic Flow Prediction; Research Square: Durham, NC, USA, 2026. [Google Scholar]
- Grewatsch, S.; Kleindienst, I. How organizational cognitive frames affect organizational capabilities: The context of corporate sustainability. Long Range Plan. 2018, 51, 607–624. [Google Scholar] [CrossRef] [Scilit]
- Wu, L.; Wang, C.; Ren, H.; Zhang, W. How does executive green cognition affect enterprise green technology innovation? The mediating effect of ESG performance. Heliyon 2024, 10, e34287. [Google Scholar] [CrossRef] [Scilit]
- Garcia-Quevedo, J.; Martinez-Ros, E.; Tchórzewska, K.B. End-of-pipe and cleaner production technologies. Do policy instruments and organizational capabilities matter? Evidence from Spanish firms. J. Clean. Prod. 2022, 340, 130307. [Google Scholar] [CrossRef] [Scilit]
- Ghisetti, C.; Rennings, K. Environmental innovations and profitability: How does it pay to be green? An empirical analysis on the German innovation survey. J. Clean. Prod. 2014, 75, 106–117. [Google Scholar] [CrossRef] [Scilit]
- Aragón-Correa, J.A.; Sharma, S. A contingent resource-based view of proactive corporate environmental strategy. Acad. Manag. Rev. 2003, 28, 71–88. [Google Scholar] [CrossRef] [Scilit]
- Quan, X.F.; Ke, Y.; Qian, Y.T.; Zhang, Y. CEO Foreign Experience and Green Innovation: Evidence from China. J. Bus. Ethics 2023, 182, 535–557. [Google Scholar] [CrossRef] [Scilit]
- Damanpour, F.; Aravind, D. Managerial Innovation: Conceptions, Processes, and Antecedents. Manag. Organ. Rev. 2012, 8, 423–454. [Google Scholar] [CrossRef] [Scilit]
- Testa, F.; Boiral, O.; Iraldo, F. Internalization of environmental practices and institutional complexity: Can stakeholders pressures encourage greenwashing? J. Bus. Ethics 2018, 147, 287–307. [Google Scholar] [CrossRef] [Scilit]
- Boiral, O.; Heras-Saizarbitoria, I.; Testa, F. SA8000 as CSR-washing? The role of stakeholder pressures. Corp. Soc. Responsib. Environ. Manag. 2017, 24, 57–70. [Google Scholar] [CrossRef] [Scilit]
- Flammer, C. Corporate green bonds. J. Financ. Econ. 2021, 142, 499–516. [Google Scholar] [CrossRef] [Scilit]
- Clarkson, P.M.; Li, Y.; Richardson, G.D.; Vasvari, F.P. Revisiting the relation between environmental performance and environmental disclosure: An empirical analysis. Account. Organ. Soc. 2008, 33, 303–327. [Google Scholar] [CrossRef] [Scilit]
- Hahn, R.; Reimsbach, D.; Wickert, C. Nonfinancial Reporting and Real Sustainable Change: Relationship Status-It’s Complicated. Organ. Environ. 2023, 36, 3–16. [Google Scholar] [CrossRef] [Scilit]
- Marquis, C.; Toffel, M.W.; Zhou, Y.H. Scrutiny, Norms, and Selective Disclosure: A Global Study of Greenwashing. Organ. Sci. 2016, 27, 483–504. [Google Scholar] [CrossRef] [Scilit]
- Zhang, D.Y.; Rong, Z.; Ji, Q. Green innovation and firm performance: Evidence from listed companies in China. Resour. Conserv. Recycl. 2019, 144, 48–55. [Google Scholar] [CrossRef] [Scilit]
- Cho, C.H.; Roberts, R.W.; Patten, D.M. The language of US corporate environmental disclosure. Account. Organ. Soc. 2010, 35, 431–443. [Google Scholar] [CrossRef] [Scilit]
- Li, F. The information content of forward-looking statements in corporate filings—A naïve Bayesian machine learning approach. J. Account. Res. 2010, 48, 1049–1102. [Google Scholar] [CrossRef] [Scilit]
- He, L.; Zhang, L.; Zhong, Z.; Wang, D.; Wang, F. Green credit, renewable energy investment and green economy development: Empirical analysis based on 150 listed companies of China. J. Clean. Prod. 2019, 208, 363–372. [Google Scholar] [CrossRef] [Scilit]
- ISO 14001:2015; Environmental Management Systems—Requirements with Guidance for Use. International Organization for Standardization: Geneva, Switzerland, 2015.
- ISO 9001:2015; Quality Management Systems—Requirements. International Organization for Standardization: Geneva, Switzerland, 2015.

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.