


Abstract
While pricing policy has emerged as a critical demand-side lever for decarbonizing mobility, its bidirectional effects on modal shift remain unexplored. Dynamic pricing in high-speed rail (HSR) creates a double-edged environmental outcome: advance discounts attract passengers from aviation, yet last-minute premiums may reverse these gains. Using 2.4 million price observations from Madrid–Barcelona (2019), we introduce a carbon leakage framework that quantifies this phenomenon within a multi-source validated framework. Our analysis reveals a structural tension: while early-bird pricing attracts 274,431 annual passengers from aviation—saving 23,650 tonnes CO2/year—last-minute scarcity premiums systematically drive passengers back to air travel. Multi-source calibrated elasticity (, validated through triangulation across CNMC corridor data, meta-analytic evidence, and recent empirical studies within the range ) shows that 22.3% of last-minute tickets exceed the EUR 120 aviation threshold, creating 1511 tonnes CO2 leakage annually (6.4% offset of gross savings). Critically, this leakage ratio is shown to be structurally independent of elasticity specification, being determined by the price distribution shape rather than demand parameters. Scenario analysis suggests that under static assumptions, price caps at EUR 110–120 would eliminate leakage while preserving an estimated 94% of operator revenue, though general equilibrium effects remain unmodeled. These findings identify illustrative scenario thresholds for carbon-aware revenue management, demonstrating that demand-side decarbonization requires not only attracting passengers to sustainable modes but also preventing their reversal to high-carbon alternatives.
1. Introduction
Decarbonizing mobility requires coordinated interventions across technology, infrastructure, and demand management. Yet, while supply-side strategies—electrification, alternative fuels, and energy-efficient infrastructure—have dominated policy discourse and absorbed the bulk of public investment, demand-side interventions that reshape travel behavior and modal choice remain critically underexploited despite offering immediate carbon reduction potential without requiring decades-long capital commitments [1]. Pricing policy represents perhaps the most powerful yet least understood demand-side lever: by altering the relative cost of competing transport modes, strategic pricing can instantaneously induce modal shift from high-carbon aviation to low-carbon rail. However, the environmental effectiveness of pricing interventions depends critically on their design. Poorly calibrated pricing does not merely fail to attract passengers—it actively repels them, creating unintended reverse flows that undermine sustainability objectives while remaining invisible in current policy frameworks.
Transportation contributes 25% of EU greenhouse gas emissions, with aviation emissions surging even as other sectors decarbonize [2]. Meeting the European Green Deal’s target—a 90% emissions cut by 2050 [3]—requires aggressive modal shift from aviation (153 g CO2/pkm, direct operational emissions (Life-cycle assessments incorporating non-CO2 climate effects yield aviation estimates up to 250 g CO2/pkm [2]. We use direct operational emissions for consistency across modes.)) to electrified HSR (14 g CO2/pkm), an approximately 11-fold intensity differential [4]. Yet achieving this shift at scale demands more than infrastructure investment; it requires pricing policies that sustain behavioral change once travelers switch modes. Attracting passengers to rail means little if poorly designed fares immediately push them back to aviation.
The Madrid–Barcelona corridor—where HSR captured dominant market share from aviation after 2008 [5]—offers a critical test case. With over 15 million annual travelers and intense price competition following recent market liberalization, this corridor operates at the frontier of dynamic pricing sophistication. If carbon leakage emerges here, it will proliferate across Europe’s expanding HSR networks, systematically undermining Green Deal targets through pricing decisions that prioritize short-term revenue over long-term climate commitments.
Dynamic pricing—adjusting fares in real-time based on demand, booking horizons, and capacity—operates as a double-edged sword for decarbonization. Low advance-purchase fares lure passengers from aviation to rail, saving carbon. High last-minute fares repel them back to air travel, leaking carbon. This bidirectional flow—what we term bidirectional modal shift—means pricing simultaneously decarbonizes and re-carbonizes the same corridor. The net environmental effect hinges on which force dominates: attraction or leakage. We introduce the concept of carbon leakage—also termed pricing-induced modal reversion to distinguish it from the established climate policy usage of ‘carbon leakage’ referring to industrial relocation—to quantify this environmental cost—the CO2 emitted when yield management pushes HSR fares so high that passengers defect to aviation, undoing the carbon savings achieved through advance-purchase discounts. We retain carbon leakage as the primary descriptor throughout this paper; the phrase pricing-induced modal reversion is offered as a more precise conceptual alternative that avoids potential confusion with the industrial relocation usage of ‘carbon leakage’ in EU ETS policy contexts. If unchecked, this leakage transforms dynamic pricing from a climate solution into a climate liability.
Yet a critical oversight pervades this literature: it documents only how pricing attracts passengers to HSR, never how it repels them back to aviation. Studies celebrate reductions in aviation demand following HSR entry [6,7], but remain silent on the reverse flows triggered when HSR fares spike beyond competitive thresholds. This unidirectional bias assumes that modal shift, once achieved, is permanent—that passengers captured by early-bird discounts remain loyal even when last-minute fares surge to EUR 200 or more. In reality, travelers continuously re-optimize their mode choice as prices fluctuate. When HSR yield management pushes fares above aviation equivalents, price-sensitive passengers defect, creating a reverse modal shift that leaks carbon back into the atmosphere. No prior study has quantified this leakage or identified the price thresholds where environmental gains unravel.
This study addresses this gap by investigating four research questions: (1) What is the price elasticity of demand for HSR on the Madrid–Barcelona corridor? (2) At what price thresholds do travelers shift bidirectionally between rail and air? (3) How much carbon is saved through modal attraction versus leaked through last-minute pricing? (4) What pricing policies maximize net carbon reduction while maintaining operator viability?
This study makes three contributions that reposition dynamic pricing within demand-side decarbonization frameworks. First, we introduce the bidirectional modal shift framework and provide empirical calibration of carbon leakage in transport pricing—validated through multi-source elasticity triangulation—estimating 1511 tonnes CO2/year leaking back to aviation, offsetting 6.4% of carbon gains achieved through modal attraction. This finding emerges from analyzing 2.4 million fare observations—the largest revealed pricing dataset in HSR–aviation competition research—enabling identification of the fare thresholds (EUR 110–120) where passengers defect from rail to air. Second, we identify illustrative scenario thresholds: under static assumptions, price caps at EUR 110–120 eliminate leakage while preserving an estimated 94% of operator revenue, suggesting a range where commercial interests and climate objectives may align, though general equilibrium effects require further analysis. This contributes to operationalizing the European Green Deal’s modal shift mandate by identifying the pricing boundary where demand management may transition from decarbonization lever to environmental liability. Third, we reframe HSR dynamic pricing from a revenue-only optimization problem to a multi-objective instrument balancing profit, ridership, and carbon outcomes, providing an analytical template for evaluating the climate footprint of pricing policies across transport modes.
2. Literature Review
2.1. HSR–Aviation Intermodal Competition and Modal Choice Behavior
The theoretical foundation for understanding rail–aviation competition rests on the random utility maximization framework, in which travelers select the mode that maximizes their perceived utility based on generalized cost—a composite of monetary price, travel time, and service attributes [8,9]. Discrete choice models, particularly the multinomial and nested logit specifications, have become the dominant analytical tools for estimating modal substitution probabilities on corridors where HSR and aviation coexist [10,11].
A substantial body of empirical evidence has documented HSR’s capacity to capture market share from short-haul aviation. Early corridor-level studies demonstrated substantial aviation demand declines within years of HSR entry on competitive medium-distance routes, with the magnitude depending on travel time competitiveness, frequency, and fare structures [4,5]. The Madrid–Barcelona corridor—the empirical focus of this study—represents one of Europe’s most successful modal shift cases, with HSR achieving dominant market share following AVE service introduction in 2008. More broadly, Dobruszkes [6] showed that HSR effectively substitutes for aviation across Western European corridors where rail journey times remain competitive with door-to-door aviation travel including airport access and security screening.
Recent research has extended these findings in several directions. Borsati and Albalate [12] provided robust evidence from Italy showing that HSR introduction shifted traffic primarily from motorways rather than aviation on medium-distance corridors, highlighting the importance of corridor-specific modal substitution patterns. Wang et al. [7] modeled the effects of low-cost HSR entry on the Paris–Marseille corridor, demonstrating that fare-based competition with aviation intensifies when discount operators enter HSR markets—a dynamic now unfolding on the Madrid–Barcelona corridor following the entry of Ouigo and iryo [13]. Recent game-theoretic analyses have formalized this competition: Evgeniia et al. [14] examined potential European HSR corridors, finding that HSR achieves competitive equilibrium on medium-distance routes where journey times remain sufficiently short, while aviation maintains advantages on longer routes where time-sensitive travelers dominate. Lee et al. [15] further demonstrated that under travel time variability, HSR–aviation relationships can shift from pure competition to collaboration, with rail serving as airport access for hub-and-spoke networks—though this complementarity depends critically on price coordination to avoid passenger leakage across modes. Li [16] developed a bi-level optimization model demonstrating that HSR can absorb passenger demand from aviation when accompanied by carbon taxation. Bursa et al. [17] employed a discrete choice experiment finding that travel time, price, and environmental information are the most influential attributes driving tourist modal shift to rail. Pukhova et al. [18] used agent-based simulation in Germany, demonstrating that restricting short-haul flights could substantially reduce transport CO2 emissions. The emerging debate around short-haul flight bans in France, Austria, and other EU member states [19] further underscores the policy relevance of understanding price-driven modal substitution.
Yet these advances share a common blind spot: they uniformly assume modal shift is unidirectional. Studies document flows from aviation to HSR—celebrating each percentage-point gain in rail market share—but remain silent on the reverse current. When HSR fares surge beyond aviation equivalents, do passengers remain loyal to rail? Or do they defect back to air travel, leaking carbon in the process? Existing research implicitly assumes permanence: that passengers captured by early-bird discounts stay captured, even when last-minute fares double or triple. This oversight is not merely academic—it obscures a fundamental tension in dynamic pricing. The same yield management systems that attract passengers through advance discounts may repel them through scarcity premiums, creating bidirectional flows with opposing environmental effects. No prior study has quantified both directions simultaneously, nor identified the pricing thresholds where environmental gains reverse.
2.2. Dynamic Pricing, Price Elasticity, and Demand Heterogeneity in Rail Transport
While modal choice research identifies price as a key driver of HSR–aviation substitution, it rarely examines how operators set those prices. Dynamic pricing—the practice of adjusting fares in real time based on demand forecasts, booking lead times, and capacity utilization—has become ubiquitous in the rail industry, following its successful adoption in aviation [20]. The underlying revenue management logic aims to maximize load factors and revenue by segmenting demand through temporal price discrimination: advance-purchase discounts attract price-sensitive leisure travelers, while last-minute premiums capture willingness-to-pay from time-constrained business travelers [21].
Recent work has refined these strategies for HSR contexts. Meng et al. [22] proposed a joint dynamic pricing and ticket allocation optimization for Chinese HSR, demonstrating that coordinated pricing across service classes can substantially increase revenue relative to static fares. Hu et al. [23] extended this framework to a competitive environment, showing that HSR pricing must account for aviation and intercity bus substitution to avoid passenger leakage. Shafiee and Honarvar [24] modeled airline–railway pricing as a cooperative–competitive game, finding that collaborative fare-setting between modes can improve aggregate social welfare while maintaining individual profitability. Shan et al. [25] provided a comprehensive overview of railway revenue management techniques, emphasizing that Chinese and European operators have converged on similar dynamic pricing architectures despite different regulatory environments. On the Madrid–Barcelona corridor specifically, García-Samaniego and Campos [26] documented that HSR liberalization (entry of Ouigo and iryo alongside Renfe) triggered substantial fare reductions on average, with intensified temporal price discrimination that widened the gap between advance-purchase and last-minute fares.
The behavioral response to these pricing strategies is captured through price elasticity of demand. Meta-analytic evidence consistently shows that rail demand exhibits moderate to high price sensitivity, with substantial heterogeneity across market segments [10]. Wardman [27] recently advanced this literature by proposing flexible elasticity functional forms that allow price responsiveness to vary non-linearly with fare level, demonstrating that conventional constant-elasticity assumptions systematically underestimate demand sensitivity at high fare levels—a finding with direct implications for revenue-maximizing versus ridership-maximizing pricing strategies. Business travelers typically exhibit relatively inelastic demand due to schedule constraints and employer-funded travel, while leisure travelers demonstrate more elastic responses. For the Madrid–Barcelona corridor specifically, González-Savignat [5] estimated moderate price elasticity using pre-HSR revealed preference data, a finding corroborated by Bhat [8]’s intercity mode choice analysis.
Critically, recent studies have highlighted the role of booking timing in shaping demand heterogeneity. Zhang and Zhao [28] modeled consumer social learning in dynamic pricing contexts, showing that early bookers exhibit systematically different price sensitivities than last-minute purchasers. Calvano et al. [29] demonstrated in a seminal American Economic Review paper that algorithmic pricing systems can converge on supra-competitive prices, raising concerns that revenue management in transport may inadvertently suppress demand beyond socially optimal levels.
However, this literature treats dynamic pricing as environmentally neutral—a revenue tool with no climate consequences beyond ridership levels. This framing misses a critical behavioral reality: deterred passengers do not vanish; they switch modes. When HSR fares spike beyond aviation equivalents, price-sensitive travelers defect to air travel, carrying their carbon footprint with them. We term this carbon leakage—borrowing from climate policy’s industrial relocation concept but applying it to transport modal choice. While industrial carbon leakage refers to emissions relocated to unregulated jurisdictions, transport carbon leakage—or more precisely, pricing-induced modal reversion—describes emissions relocated to high-carbon modes through pricing-induced modal substitution. The environmental ledger must account for both sides: carbon saved through advance-purchase attraction and carbon leaked through last-minute price-driven defection. No prior study has closed this ledger or quantified the net environmental effect of HSR yield management.
2.3. Transport Decarbonization and the Role of Modal Shift in Climate Policy
Understanding HSR–aviation competition and pricing strategies matters because transport decarbonization has emerged as a central pillar of climate policy. The transport sector accounts for approximately 25% of EU greenhouse gas emissions, with absolute emissions having increased substantially since 1990—making it the only major sector that has failed to achieve sustained reductions [2]. Within transport, aviation contributes disproportionately on a per-passenger-kilometer basis: emission factors of 153 g CO2/pkm (direct operational) for aviation compare to approximately 14 g CO2/pkm for electrically powered HSR, representing a 94% differential [2]. Life cycle assessments have refined these estimates by incorporating infrastructure construction, vehicle manufacturing, and electricity generation mix, with recent analyses confirming that even under conservative assumptions, HSR carbon intensity remains substantially lower than aviation across comparable corridors [30,31].
Modal shift from aviation to rail has consequently been identified as one of the most effective near-term demand-side decarbonization strategies. The European Green Deal and its Sustainable and Smart Mobility Strategy target substantial expansion of HSR traffic by 2030 and 2050, explicitly positioning rail as the backbone of climate-compatible intercity transport [3]. The Fit for 55 legislative package further operationalizes this vision through mechanisms including the revision of the EU Emissions Trading System to cover aviation more comprehensively, and the proposed extension of carbon pricing to transport fuels [32]. Winkler et al. [1] demonstrated in Nature Communications that sustainable mobility transition policies—including modal shift—can substantially reduce cumulative urban transport emissions by mid-century, contingent on policy ambition and implementation timing.
Quantitative estimates of modal shift carbon savings vary considerably by corridor and assumption. Pukhova et al. [18] estimated that restricting short-haul flights in Germany could substantially reduce transport CO2 emissions. Li [16] expanded this analysis to freight logistics, developing a bi-level multi-objective optimization model for HSR freight that balances carbon reduction against operational costs, demonstrating that strategic modal shift from road to HSR freight can achieve meaningful emission reductions when combined with infrastructure capacity expansion—highlighting the importance of coordinating pricing with supply-side investments. Zhu et al. [33] assessed the carbon implications of freight modal shift through corridor-level modeling, finding that carbon taxation amplifies shift magnitude in a non-linear manner. On carbon pricing thresholds specifically, Yildiz et al. [34] analyzed maritime decarbonization through fuel switching and carbon pricing, finding that targeted low-sulfur fuel adoption becomes economically viable only when carbon prices exceed threshold levels—a finding directly relevant to our HSR pricing analysis, as it suggests that demand-side interventions require precise calibration to overcome behavioral inertia and modal lock-in effects. Peeters and Papp [35] contextualized transport modal shift within the broader zero-emission tourism pathway, arguing that pricing instruments are more effective than voluntary behavioral change in achieving meaningful reductions.
However, modal shift research suffers from the same unidirectional bias that pervades the broader literature: it celebrates carbon savings from low HSR prices without examining carbon losses from high HSR prices. This asymmetry paints dynamic pricing as an unambiguous climate win—lower fares attract passengers from aviation, reducing emissions. Yet yield management’s J-curve pattern—advance discounts rising to last-minute premiums—creates bidirectional flows with opposing environmental effects. Carbon saved on Monday (when early bookers shift from air to rail at EUR 60) may leak back on Friday (when late bookers shift from rail to air at EUR 180). Without quantifying both flows simultaneously, we cannot determine whether dynamic pricing delivers net decarbonization or merely shuffles emissions across booking windows.
2.4. Research Gap
The foregoing review reveals three distinct but interconnected gaps. The first is a systematic unidirectional bias: existing modal shift studies examine aviation-to-HSR flows exclusively, ignoring the reverse leakage that occurs when HSR prices exceed aviation thresholds—meaning no study has yet quantified the carbon cost of last-minute yield management. The second gap concerns environmental externalities: while the dynamic pricing literature optimizes revenue exhaustively, it treats environmental outcomes as externalities beyond its scope, and the concept of carbon leakage—well-established in climate policy for industrial relocation—has never been applied to transport pricing. Third, despite a rich literature on price elasticities, no study has identified specific price caps capable of eliminating leakage while preserving operator viability, a critical omission for evidence-based policy design.
This study introduces the bidirectional modal shift framework to address these gaps. Using 2.4 million fare observations from Madrid–Barcelona (2019), it documents the J-curve pricing pattern underlying carbon leakage, quantifies both positive (modal attraction) and negative (carbon leakage) effects, calculates net carbon savings and leakage ratios, and identifies price cap thresholds (EUR 110–120) that eliminate leakage entirely—thereby reframing dynamic pricing from a revenue-only optimization problem to a multi-objective challenge balancing revenue, ridership, and carbon outcomes.
3. Materials and Methods
3.1. Institutional Context
During the 2019 study period, Renfe Operadora S.A. (Madrid, Spain) was the sole HSR operator on the Madrid–Barcelona corridor, operating as a state-owned enterprise (100% owned by the Spanish government through Renfe Group (Madrid, Spain)). Renfe holds full pricing autonomy for commercial services (AVE), subject to general public service obligations on subsidized regional routes but not on the commercially operated Madrid–Barcelona corridor. Infrastructure is managed separately by ADIF (Administrador de Infraestructuras Ferroviarias, Madrid, Spain), which charges track access fees to operators.
On the aviation side, the corridor was served by Iberia (IAG Group, Madrid, Spain, privately owned, full-service), Vueling (IAG Group, Barcelona, Spain, low-cost), and Ryanair (Dublin, Ireland, independently listed, ultra-low-cost). All airlines operate under full commercial pricing autonomy within the EU liberalized aviation market, subject to EU ETS obligations for intra-European flights.
The asymmetry between HSR (state-owned, potential public service mandate, exempt from direct carbon pricing) and aviation (private, commercially driven, EU ETS-covered) creates an institutional context where HSR pricing decisions carry implicit public interest dimensions that purely commercial operators might not internalize.
Dynamic pricing practices also vary substantially across international HSR markets. Japanese Shinkansen operators historically employed relatively flat tariff structures with limited temporal discrimination, though JR Central has recently introduced yield management on the Tokaido Shinkansen. Chinese HSR (CR) adopted dynamic pricing in 2020–2021, with initial implementation on selected corridors showing moderate price volatility [22]. In contrast, European operators (Renfe, SNCF, Trenitalia) have fully embraced aviation-style yield management. These institutional differences suggest that the carbon leakage mechanism we identify is most acute in markets with aggressive temporal price discrimination—primarily European corridors—while tariff-based Asian systems may exhibit lower leakage risk at the cost of reduced revenue optimization. Regulatory responses also differ: France has implemented short-haul flight bans on routes with HSR alternatives under 2.5 h [36], addressing modal competition through supply restriction rather than pricing, while Switzerland maintains regulated tariffs on federal railway services.
3.2. Data Description
The primary dataset comprises 7.67 million price observations collected from Renfe’s online booking system between April and October 2019. The seven-month observation window reflects data collection feasibility constraints: systematic daily price scraping began in April 2019 and was discontinued in October 2019 prior to a planned system migration that altered the website’s data structure. The excluded November–March period encompasses holiday travel (Christmas, New Year, Easter), winter leisure patterns, and potentially different demand compositions. For this analysis, we focus on the Madrid–Barcelona corridor, yielding 2,407,723 observations for the Madrid–Barcelona corridor (both directions combined). The data include ticket prices, departure dates and times, booking dates, train types, and service classes.
Table 1 presents descriptive statistics for the analysis sample. Prices range from EUR 0 to EUR 342.80, with a mean of EUR 86.06 (SD = €21.61). The coefficient of variation (CV) of 0.251 indicates moderate price volatility, consistent with active yield management. The dataset spans 192 unique departure dates with booking horizons from 0 to 59 days in advance (mean = 25.4 days).
Table 1.
Descriptive statistics for the Madrid–Barcelona corridor sample.
The sample includes multiple train types, with AVE services accounting for 91.6% of observations (), followed by AVE-TGV international services (4.1%, ) and other regional express types (4.3%). Service classes are distributed as follows: Turista (72.3%), Turista Plus (18.8%), Preferente (8.1%), and other classes (0.8%).
3.3. Price Elasticity Estimation
Estimating price elasticity from observational price data presents endogeneity challenges: dynamic pricing algorithms set higher prices when demand is expected to be high, creating spurious positive correlations between price and demand proxies. Direct estimation from our dataset would confound price effects with unobserved demand shocks. To circumvent this endogeneity problem, we adopt a literature-calibrated approach that anchors to externally validated elasticity estimates while incorporating corridor-specific pricing characteristics observed in our data.
The base elasticity is anchored to González-Savignat [5]’s corridor-specific estimate of for Madrid–Barcelona, chosen for its revealed preference methodology on the identical route and its pre-liberalization timeframe (before dynamic pricing intensified). We then apply adjustment factors based on observed price dynamics in our 2019 dataset:
where is the coefficient of variation of prices (0.251), is the price gradient across booking horizons (0.244), and , are adjustment parameters derived from meta-analytic evidence [10]. This yields an overall elasticity of with a standard error of 0.15.
For market segmentation analysis, we estimate separate elasticities for peak hours (7–9 a.m., 5–7 p.m.) versus off-peak, weekday versus weekend, and morning versus evening departures. Segment-specific adjustments follow Wardman et al. [10]’s meta-analytic findings on demand heterogeneity.
3.4. Multi-Source Elasticity Validation
To address the limitation of relying on a single 2004 study, we validate the calibrated elasticity through multi-source triangulation using recently available data. Beginning with arc elasticity from CNMC market data, the CNMC’s 2025 liberalization report [37] (INF/DTSP/091/25) reveals that Madrid–Barcelona HSR modal share rose from 63.3% (2019) to 81.5% (2024), while average revenue per passenger declined by 33%; adjusting for supply expansion (seat capacity from 8.87 M to 14.62 M, +65%), the supply-adjusted arc elasticity is . The CNMC’s demand decomposition methodology—controlling for GDP growth (+12.8% cumulative 2019–2024) and supply expansion—further implies . Drawing on the broader literature, Wardman et al. [10] reports European HSR own-price elasticities spanning to , while Hortelano et al. [38] find to for Spanish HSR specifically. The original calibration anchor remains González-Savignat [5]’s corridor-specific estimate of for the identical Madrid–Barcelona route.
Table 2 summarizes the triangulation. The validated range is , with our calibrated falling well within this interval.
Table 2.
Multi-source demand elasticity triangulation for Madrid–Barcelona HSR.
3.5. Modal Choice Model
To model the probability of choosing HSR versus aviation, we employ a binary logit specification:
where and , ensuring the exponential function applies to the full utility expression. The intercept captures intrinsic HSR preference stemming from comfort, reliability, and city-center station access. Parameter values are calibrated from modal choice literature: reflects the price coefficient from Bhat [8]’s multinomial logit specification for intercity modes, while represents the HSR-specific constant estimated by Szabó and Panker [11] for European corridors where HSR achieves dominant market share. For the aviation price benchmark, we use EUR 55 as the representative low-cost carrier fare, derived from averaging publicly listed Vueling and Ryanair base fares (excluding ancillaries) on Madrid–Barcelona during April–October 2019.
3.6. Bidirectional Carbon Balance Framework
We decompose the net carbon effect of HSR dynamic pricing into two competing mechanisms:
3.6.1. Estimating Modal Attraction
Early-bird pricing attracts aviation passengers to HSR when . Carbon savings are calculated as
where is estimated using corridor-specific parameters calibrated to 2019 market conditions: aviation market share (35%, per Spanish Ministry of Transport data post-AVE entry), annual HSR passengers (approximately 4 million in 2019, entirely served by Renfe as the sole operator prior to liberalization; source: CNMC annual transport report [37]), competitiveness rate (98.0% of advance tickets priced below EUR 120 aviation threshold, computed from our dataset), and attraction rate (20%, the mid-range cross-elasticity value from Wardman et al. [10]’s meta-analysis of inter-modal substitution). Using corridor distance km, aviation emission factor g CO2/pkm (short-haul jet average) and HSR emission factor g CO2/pkm (Spanish grid electricity mix) [2], each attracted passenger avoids 86.18 kg CO2 per trip.
The Madrid–Barcelona corridor accommodates approximately 15 million annual passenger trips across all modes (HSR, aviation, bus, and private car; source: Spanish Ministry of Transport, 2020). Of these, approximately 4 million travel by HSR (Renfe ridership data, 2019) and approximately 2 million by aviation (derived from the 35% aviation market share within the HSR+aviation segment). The remaining approximately 9 million passengers use car or bus. Our analysis focuses on the HSR–aviation competitive segment (∼6 million passengers), where pricing-driven modal substitution is most relevant.
Three aviation price references serve distinct analytical roles: EUR 55 (representative low-cost carrier base fare, used as the aviation price input in the logit modal choice model); EUR 90 (the HSR price at which the logit model predicts 50/50 modal split, derived endogenously); and EUR 120 (representative full-service carrier fare, used as the carbon leakage boundary).
3.6.2. Estimating Carbon Leakage
Last-minute pricing creates scarcity premiums that push HSR passengers back to aviation when . Carbon leakage is quantified as
where is derived from last-minute bookings (0–3 days before departure) with prices exceeding EUR 120 (the full-service aviation fare threshold for Iberia on this corridor). We adopt a 25% modal switch rate, corresponding to the midpoint of the interquartile range (15–35%) of cross-modal substitution rates reported in Wardman et al. [10]’s meta-analysis of 106 rail–air competition studies across European corridors. This value reflects a conservative positioning between: the lower bound of ∼15% (captive HSR passengers with corporate rail mandates or loyalty commitments) and the upper bound of ∼40% (fully price-elastic leisure travelers). We employ a scenario-based switching rate rather than estimating cross-price elasticities because the latter requires observing demand responses across both modes simultaneously, which our single-mode price dataset does not permit. Sensitivity analysis (Table 3) confirms that all qualitative findings hold across the 15–40% range. Annualization applies the temporal scaling factor 12/7 = 1.714 to extrapolate from the seven-month observation period (April–October 2019) to a full calendar year.
Table 3.
Sensitivity to passenger switching rate.
3.6.3. Net Carbon Balance
The overall environmental effect combines both mechanisms:
The leakage ratio quantifies the environmental cost of yield management:
Table 4 presents the emission factors for all transport modes on the corridor.
Table 4.
Carbon emission factors by transport mode for the Madrid–Barcelona corridor (620 km).
3.7. Policy Scenario Analysis
We evaluate six pricing policy scenarios to balance carbon reduction and operator revenue. The baseline scenario applies current dynamic pricing with full yield management (mean EUR 86.02, maximum EUR 342.80) and serves as the reference point against which all interventions are assessed. Four progressively tighter price caps follow: EUR 90 (below low-cost aviation parity), EUR 100 (a moderate intermediate constraint), EUR 110 (a conservative cap that still eliminates leakage), and EUR 120 (aligned with full-service aviation parity). A final minimal-intervention scenario caps prices at EUR 130, preserving most last-minute premium capacity while providing a benchmark for evaluating the upper bound of policy inaction.
For each scenario, we calculate carbon leakage using the proportion of last-minute tickets exceeding the aviation threshold (EUR 120), net carbon savings combining Equations (3)–(5), and leakage ratio using Equation (6). The critical insight is that any cap below EUR 120 eliminates leakage entirely, as all prices become aviation-competitive.
4. Results
4.1. Price Distribution and Temporal Patterns
Figure 1 illustrates the distribution of HSR prices. The distribution is approximately normal with a rightward skew, reflecting high last-minute fares. The median (EUR 85.10) is marginally below the mean (EUR 86.02), confirming moderate positive skewness.
Figure 1.
Distribution of HSR ticket prices on the Madrid–Barcelona corridor. Vertical dashed lines indicate the low-cost aviation benchmark (EUR 55) and mean HSR price (EUR 86.02). Prices below EUR 75 represent the competitive zone.
Pearson correlation analysis confirms a significant negative relationship between booking horizon and price (, , ), revealing the classic J-curve pattern of yield management. Table 5 quantifies this temporal price escalation. One-way ANOVA reveals highly significant price differences across categories (, , ), representing a medium effect size. The pattern is stark: travelers booking 0–3 days before departure face an average fare of EUR 105.57—a 31.3% surcharge relative to early planners paying EUR 80.41. For a passenger deciding between HSR and aviation on short notice, this EUR 25 premium pushes HSR above low-cost aviation (EUR 55) and approaches full-service parity (EUR 120). The scarcity signal embedded in last-minute pricing—designed to extract revenue from time-constrained business travelers—inadvertently makes aviation the economically rational choice for price-sensitive passengers, reversing the modal shift that advance pricing worked to achieve.
Table 5.
Price statistics by booking category.
Weekend prices (EUR 87.54) are significantly higher than weekday prices (EUR 85.51; , ), though the effect size is small (Cohen’s ). Peak vs. off-peak price differences are not statistically significant (, ).
Chi-square analysis reveals that price competitiveness (defined as HSR price below EUR 75, the threshold where HSR undercuts low-cost aviation by a margin sufficient to offset convenience advantages) varies dramatically by booking category (, , ). Early planners benefit: 27.5% of advance tickets fall in the competitive zone, positioning HSR as the economically attractive choice. Late bookers face a penalty: only 8.6% of last-minute tickets remain competitive, effectively ceding price advantage to aviation for over 91% of urgent travelers.
4.2. Price Elasticity Estimates
The calibrated price elasticity for the overall sample is (95% CI: , ), indicating that a 1% price increase is associated with a 0.95% demand decrease.
Table 6 presents segment-specific estimates, revealing pronounced behavioral stratification. Peak-hour travelers exhibit relative price insensitivity ()—schedule-constrained business passengers who absorb fare increases rather than switch modes. In stark contrast, off-peak () and weekend () travelers demonstrate elastic responses characteristic of discretionary leisure travel, where a modest fare increase triggers defection to aviation or trip cancellation. Morning departures capture captive commuters (), while evening departures attract moderately price-sensitive returnees ().
Table 6.
Price elasticity estimates by market segment.
The elasticity range spans (peak) to (weekend)—a two-fold variation confirming that HSR demand aggregates fundamentally different traveler types. A uniform EUR 10 fare increase would deter only 5.5% of peak-hour passengers but displace 11.5% of weekend travelers. This heterogeneity implies that undifferentiated pricing policies—whether aggressive yield management or blunt price caps—will create asymmetric welfare effects and carbon outcomes across market segments.
4.3. Modal Choice Analysis
Figure 2 presents the relationship between HSR price and predicted market share, revealing the modal switching tipping point. At deep-discount fares of EUR 30, HSR dominates with a 95.3% share—aviation becomes nearly irrelevant. But as prices climb, passengers defect: HSR share collapses to 50.3% at EUR 90, defining this as the modal indifference threshold where travelers split evenly between rail and air. Beyond EUR 90, aviation captures majority share. Critically, the current mean price of EUR 86 positions HSR just barely in dominant territory (55.3% share)—but the distribution’s rightward skew means that the substantial mass of last-minute fares above EUR 90 pushes passengers into aviation’s capture zone.
Figure 2.
Probability of choosing HSR as a function of ticket price (aviation price held at EUR 55). The 50/50 modal split occurs at approximately EUR 90.
Table 7 examines competitiveness across aviation pricing scenarios. Against the average low-cost fare (EUR 55), only 22.4% of HSR price observations fall within the competitive zone. Against full-service carriers (EUR 120), HSR is competitive 94.9% of the time.
Table 7.
HSR price competitiveness by aviation scenario.
4.4. J-Curve Pricing Pattern and Leakage Risk
HSR pricing follows a pronounced J-curve trajectory: discounts for early planners morphing into premiums for urgent travelers. Figure 3 visualizes this time-price escalation—the economic mechanism that simultaneously decarbonizes and re-carbonizes the Madrid–Barcelona corridor.
Figure 3.
J-curve pricing pattern by booking horizon. Mean prices increase from EUR 80.5 (30–60 days) to EUR 105.6 (0–3 days), representing a 31.1% premium. The horizontal dashed line at EUR 120 marks the full-service aviation threshold beyond which carbon leakage occurs.
Table 8 quantifies carbon leakage risk across booking categories, revealing a striking temporal gradient. Early bookers face minimal risk: only 1.1% of tickets 30–60 days out breach the EUR 120 aviation threshold. But risk escalates as departure approaches: 6.8% at two weeks, 12.7% at one week, and a jarring 22.3% for travelers booking within three days. This means that for every five last-minute passengers, more than one faces an HSR fare that makes aviation the cheaper option—inverting the intended modal hierarchy.
Table 8.
Carbon leakage risk by booking horizon.
The 31.1% last-minute premium—EUR 105.6 versus EUR 80.5 for early bookers—transforms HSR from climate solution to potential climate liability for urgent travelers. The same yield management algorithm that attracts environmental-conscious passengers three weeks out repels price-conscious passengers three days out, creating a bidirectional carbon flow where gains and losses occur simultaneously on the same infrastructure, governed by the same pricing system, serving the same corridor.
4.5. Bidirectional Carbon Balance
4.5.1. Positive Effect: Modal Attraction
Advance HSR pricing demonstrates strong aviation competitiveness. Across the sample, 98.0% of advance and early-bird tickets (30–60 days) fall below EUR 120, making HSR price-competitive with full-service aviation. Using corridor-specific parameters (35% aviation market share, 4M annual passengers, 20% attraction rate), we estimate 274,431 passengers shift annually from aviation to HSR, saving 23,650 tonnes CO2/year.
4.5.2. Negative Effect: Carbon Leakage
Last-minute pricing creates the opposite effect—a reverse modal shift flowing from green rail back to carbon-intensive aviation. Among 183,721 last-minute bookings (0–3 days) in the 7-month sample, 40,920 tickets (22.3%) exceeded EUR 120, pricing HSR above full-service aviation. Applying a conservative 25% modal switch rate and annualizing (factor 1.714), we estimate 17,537 passengers annually defect from HSR to aviation in response to scarcity pricing. These defectors carry their carbon footprint with them: 1511 tonnes CO2 that HSR infrastructure was built to prevent, now emitted by aircraft because yield management made rail economically irrational.
4.5.3. Net Carbon Savings
Figure 4 decomposes the bidirectional carbon ledger, revealing both sides of dynamic pricing’s environmental balance sheet. Gross carbon savings from modal attraction: 23,650 tonnes CO2/year. Carbon leakage from last-minute defection: 1511 tonnes CO2/year. Net carbon benefit: 22,139 tonnes CO2/year. The leakage ratio—6.4%—means that for every 100 kg of CO2 saved through advance pricing, yield management leaks 6.4 kg back through scarcity premiums. While the net effect remains positive, this 6.4% offset represents an entirely avoidable environmental cost, attributable solely to pricing decisions rather than infrastructure constraints or technological limits.
Figure 4.
Bidirectional carbon balance. Positive effect (modal attraction) saves 23,650 tonnes CO2/year, while negative effect (carbon leakage) costs 1511 tonnes/year. Net savings: 22,139 tonnes/year with 6.4% leakage ratio.
Table 9 summarizes the bidirectional carbon accounting.
Table 9.
Bidirectional modal shift carbon accounting.
The 6.4% leakage ratio, while modest, represents a measurable environmental cost of yield management. More critically, it demonstrates that dynamic pricing creates bidirectional flows with competing carbon consequences.
4.5.4. Structural Stability of the Leakage Ratio
A key robustness property of the leakage ratio merits emphasis. Because both attracted passengers and leaked passengers scale linearly with the demand elasticity , the elasticity cancels in the ratio:
where s is the switching rate. The ratio is determined entirely by the shape of the price distribution—specifically, the 5.2% of Madrid–Barcelona fare observations exceeding the EUR 120 aviation threshold—rather than by the demand elasticity. Table 10 verifies this empirically.
Table 10.
Structural stability of the leakage ratio across elasticity values.
This structural stability constitutes a key robustness result: the 6.4% leakage ratio is a property of Renfe’s 2019 pricing patterns, not an artifact of the chosen demand elasticity. Uncertainty about the precise elasticity value affects the absolute magnitudes of carbon saved and leaked, but not their ratio.
4.6. Carbon Reduction Potential
Figure 5 presents the carbon emission comparison across transport modes. Aviation generates 94.86 kg CO2 per trip versus 8.68 kg for HSR—a ratio of approximately 11:1.
Figure 5.
Per-trip carbon emissions by transport mode for the Madrid–Barcelona corridor (620 km).
Table 11 presents annual carbon savings under different modal shift magnitudes.
Table 11.
Annual carbon savings by modal shift scenario (aviation → HSR).
4.7. Policy Scenario Results: Price Caps and Carbon Leakage Elimination
Table 12 reveals the decisive policy intervention point: any price cap at or below EUR 120 eliminates carbon leakage entirely. The mechanism is straightforward—capping maximum fares ensures that no HSR ticket ever exceeds the aviation threshold where passengers defect. Under unconstrained baseline pricing, the 6.4% leakage ratio costs 1511 tonnes CO2/year, reducing net savings to 22,139 tonnes. Imposing a EUR 120 cap (aviation parity) eliminates all above-threshold tickets, recovering the full 23,650 tonnes/year—a 1511-tonne improvement achieved through pricing discipline alone, without infrastructure investment or service degradation. More aggressive caps (EUR 90–110) maintain zero leakage while potentially attracting additional passengers through enhanced price competitiveness, though revenue implications require operator assessment.
Table 12.
Price cap scenarios and carbon leakage elimination.
The potential scale of carbon savings under different modal shift scenarios is further illustrated in Figure 6.
Figure 6.
Annual carbon savings by modal shift percentage. Each percentage point saves approximately 1724 tonnes CO2.
To address potential reviewer concerns about parameter calibration, we test robustness across two dimensions: switching rate and aviation price threshold.
Table 13 tests robustness to aviation price uncertainty. If full-service aviation fares rise to EUR 140 (a 17% increase from baseline), carbon leakage drops to 2.7%—HSR’s J-curve becomes less problematic when aviation pricing provides more headroom. But the downside risk is more severe: if low-cost carriers aggressively expand and drive the competitive threshold down to EUR 100, leakage surges to 18.1%, nearly tripling the baseline ratio. This asymmetry reveals a critical vulnerability—HSR carbon performance depends on aviation remaining expensive. When ultra-low-cost carriers proliferate, current HSR yield management becomes environmentally untenable, making price discipline not merely advisable but essential.
Table 13.
Sensitivity to aviation price threshold.
Table 3 examines switching rate uncertainty—how many passengers actually defect when HSR exceeds aviation prices. Varying from 15% (conservative, assuming travelers reluctant to switch despite price signals) to 40% (pessimistic, assuming highly elastic responses), the leakage ratio spans 3.8–10.2%. Critically, even under the most conservative behavioral assumption (15%), leakage persists at 907 tonnes CO2/year. This confirms that carbon leakage is not an artifact of aggressive parameter choices but a structural feature of J-curve pricing: whenever scarcity premiums push HSR above aviation, some passengers will defect, carrying their emissions with them.
These sensitivity tests demonstrate that our conclusions withstand reasonable parameter uncertainty. The bidirectional carbon effect—simultaneous attraction and leakage—persists across all plausible parameter ranges. More importantly, the policy prescription remains invariant: price caps at EUR 110–120 consistently eliminate leakage across all tested scenarios, offering regulators a robust intervention threshold independent of behavioral assumptions or aviation pricing dynamics.
The EUR 110–120 range is highlighted because it represents the least restrictive intervention that achieves zero leakage under our static framework, thereby minimizing revenue loss and market distortion costs relative to more aggressive caps. We emphasize that identifying this intervention boundary is a boundary-identification exercise rather than a welfare optimization: a formal multi-objective analysis incorporating carbon reduction targets, revenue constraints, and consumer welfare would be required to determine the socially optimal cap level.
4.8. Price–Carbon Tradeoff
Analysis by price decile reveals a clear inverse relationship between HSR price and environmental performance. The lowest decile (mean EUR 50.22) is associated with an estimated HSR share of 55.0% and per-passenger emissions of 74.6 kg, while the highest decile (mean EUR 134.33) corresponds to a 38.1% HSR share and emissions of 99.2 kg per passenger—a 33% increase in emissions attributable to higher pricing.
We emphasize that the price–carbon relationship is descriptive and associational. Higher-priced deciles may disproportionately represent peak-hour business travel or holiday periods—segments where demand composition rather than price per se drives modal choice. Without controlling for departure time, day-of-week, seasonality, and traveler type, we cannot attribute the observed market share decline solely to price effects (Figure 7).
Figure 7.
HSR market share and per-passenger emissions by price decile. Higher prices reduce HSR share, increasing average emissions.
5. Discussion
5.1. The Double-Edged Sword: Revenue Optimization vs. Environmental Goals
Our findings reveal a fundamental tension in HSR dynamic pricing. While early-bird discounts successfully attract 274,431 annual passengers from aviation (saving 23,650 tonnes CO2), last-minute yield management simultaneously drives 17,537 passengers back to aviation (leaking 1511 tonnes CO2). This bidirectional modal shift demonstrates that dynamic pricing operates as a double-edged sword: the same revenue-maximizing algorithm that creates carbon gains through advance discounts undermines those gains through scarcity premiums.
The 6.4% leakage ratio represents a structural policy concern warranting attention. First, it confirms that carbon leakage is a measurable, systematic phenomenon embedded in current pricing architectures—not an isolated anomaly but an inevitable consequence of unconstrained yield management. Second, the leakage is entirely policy-controllable yet policy-ignored: our scenario analysis (Table 12) suggests that under static assumptions, price caps at EUR 110–120 would eliminate leakage with an estimated 94% revenue retention, though this figure does not incorporate strategic behavioral responses or capacity constraints, yet carbon-aware pricing constraints remain largely unimplemented in European HSR operations. Third, the bidirectional framework exposes a critical blind spot in transport decarbonization policy—the implicit assumption that modal shift, once achieved through infrastructure investment, persists automatically. In reality, pricing decisions actively reverse modal gains on a daily basis, undermining billions in HSR capital expenditure through operational choices that prioritize short-term revenue over long-term climate commitments.
From a systems perspective, the J-curve pricing pattern (Figure 3) reflects the inherent conflict between two optimization objectives: revenue maximization (which demands high last-minute prices to capture business travelers’ willingness-to-pay) and carbon minimization (which requires aviation-competitive pricing to prevent modal leakage). Traditional revenue management ignores environmental externalities; our carbon leakage framework quantifies the environmental cost of this ignorance.
Robustness of parameter estimates. Our 6.4% baseline leakage ratio relies on two calibrated parameters: switching rate (25%) and aviation threshold (EUR 120). To address potential specification concerns, we conducted comprehensive sensitivity analysis (Table 3 and Table 13). Even under the most conservative assumption (15% switching rate), leakage remains at 3.8%, confirming its measurability; raising the aviation threshold to EUR 140—17% above the baseline—reduces leakage to 2.7% but does not eliminate it, while the qualitative finding that J-curve pricing creates bidirectional flows holds across all tested parameter ranges, yielding a leakage ratio spanning 2.7–18.1%. This robustness reflects the structural nature of the problem: as long as HSR exhibits last-minute price surges and some passengers are price-sensitive, carbon leakage will occur. Our quantification therefore provides a lower-bound estimate, as it excludes non-price switching drivers—schedule convenience, loyalty programs—that may amplify leakage in practice.
5.2. Implications for Rail Operators
Our findings indicate that current dynamic pricing practices, while commercially rational, create unintended carbon leakage. The 31% last-minute premium (EUR 105.6 vs. EUR 80.5) places 22.3% of last-minute tickets above EUR 120—directly competing with full-service aviation and driving 17,537 passengers annually back to air travel. This represents a 1511-tonne annual carbon cost that operators are currently unaware of.
Our analysis suggests that a carbon-aware revenue management framework merits further investigation that integrates environmental KPIs into yield optimization algorithms. Specifically, under our static framework, setting a price cap at EUR 110–120 would eliminate measured leakage (Table 12) while retaining an estimated 94% of revenue under static accounting assumptions. This may represent an efficiency frontier where optimal pricing maximizes net carbon savings per euro of revenue.
Operationally, this could be implemented as a soft constraint in existing revenue management systems: "Maximize revenue subject to price ≤ EUR 120 when seat availability > X%.” Such a rule would preserve yield optimization for most bookings while capping last-minute premiums to prevent leakage. Rail operators could further leverage this as a sustainability marketing angle, differentiating from aviation’s unrestrained surge pricing.
The segment-specific elasticity results further suggest opportunities for differentiated pricing. Business travelers (peak hours, ) can sustain higher prices without modal switching, while leisure segments (weekends, ) require competitive pricing to retain ridership. A segment-aware pricing strategy could optimize both revenue and environmental outcomes.
5.3. Implications for Policymakers
Our bidirectional framework reveals that pricing policy must address both modal attraction (bringing aviation passengers to HSR) and modal retention (preventing leakage back to aviation). Current policy discourse focuses exclusively on the former, neglecting the 6.4% carbon cost of unconstrained yield management.
Five policy instruments could mitigate carbon leakage, each reflecting a distinct regulatory philosophy. The most direct intervention is regulatory price caps framed as Public Service Obligation (PSO) conditions: mandating maximum HSR prices at EUR 110–120 would eliminate leakage entirely, justified by carbon leakage as a negative externality that operators currently fail to internalize. While critics may argue this conflicts with market liberalization principles, price caps are well-established instruments in regulated industries where externalities warrant intervention, and in the HSR context they can be operationalized through conditions attached to state subsidies or track access agreements, preserving market mechanisms while correcting for externality failures. Alternatively, operators may adopt price caps voluntarily as part of Environmental, Social, and Governance (ESG) commitments—Renfe, SNCF, and Deutsche Bahn have all announced carbon-neutrality targets—and incorporating carbon leakage metrics into corporate sustainability reporting creates reputational incentives for a “soft constraint” approach that flags but does not prohibit prices above EUR 120. A third instrument is carbon-linked subsidies that compensate operators for revenue foregone from capped last-minute prices, funded by aviation sector carbon revenues from EU ETS auction proceeds or aviation fuel tax surcharges; our analysis indicates revenue loss is modest (<6% if capping at EUR 120), making this fiscally feasible. The CNMC estimates that HSR liberalization on Madrid–Barcelona generated EUR 431.3 million in consumer surplus (2019–2024) [37]; using the EU ETS carbon price of approximately EUR 80/tonne (2024), our estimated 1511 tonnes annual leakage translates to approximately EUR 121,000/year in carbon externalities—three orders of magnitude smaller than the consumer surplus gains, suggesting that the pricing dynamics we analyze operate within a welfare-positive regime overall. A fourth approach applies dynamic carbon taxation on aviation—imposing a progressive carbon tax on aviation fares that increases for last-minute bookings, mirroring HSR’s pricing curve to maintain competitive balance through a “leveling-up” strategy that avoids HSR price suppression while internalizing aviation’s carbon costs. Finally, transparency requirements could mandate operators to report carbon leakage metrics alongside traditional KPIs such as load factor and revenue per seat-km, creating accountability and enabling data-driven policy refinement.
We acknowledge several equilibrium considerations not captured in our static framework. First, if last-minute fares are capped, demand may exceed available capacity—particularly on peak departures—and passengers unable to secure capped-price HSR seats will still face aviation-switching decisions. Second, business travelers may strategically delay bookings if they anticipate price caps, eroding the advance-purchase revenue base. Third, aviation carriers may respond to HSR price caps with their own pricing adjustments, altering the competitive equilibrium. A price cap guarantees a price, not a seat; the 94% revenue retention figure should be interpreted as an upper bound under static assumptions.
Addressing market efficiency concerns. Some may argue that price caps distort efficient resource allocation. However, efficient pricing requires full cost internalization, including environmental externalities. Current HSR pricing is inefficient precisely because it ignores carbon leakage. By setting caps at the aviation-parity threshold (EUR 120), policy restores Pareto efficiency: passengers indifferent between modes at that price should not face HSR premiums that force aviation choice. Moreover, our 94% revenue retention estimate (Table 12) suggests caps impose minimal allocative distortion—most revenue derives from advance bookings, not last-minute premiums.
The booking-category analysis (Table 8) reveals that leakage risk is concentrated in the 0–3 day window (22.3% of tickets > EUR 120). Targeted interventions for this narrow segment achieve disproportionate environmental benefits with minimal market-wide effects.
5.4. Equity and Accessibility Implications of Carbon-Aware Pricing
While our carbon leakage framework primarily addresses environmental objectives, the J-curve pricing pattern exposed here carries profound distributional equity implications. The 31% last-minute premium doesn’t merely leak carbon—it systematically punishes travelers who cannot plan weeks in advance. Medical emergencies, family crises, precarious employment with unpredictable schedules: these urgent travel needs correlate with socioeconomic vulnerability, yet current yield management extracts maximum surplus precisely from these time-constrained passengers. A worker called to a family emergency three days out pays €105, while a leisure traveler booking a month ahead pays EUR 80 for an identical seat. This temporal price discrimination creates a planning privilege penalty—those with stable, predictable lives (often higher-income) capture discounts, while those facing life’s uncertainties (often lower-income) absorb premiums.
However, two considerations mitigate these equity concerns. First, current uncapped dynamic pricing already exhibits regressive characteristics: last-minute premiums extract surplus from time-constrained travelers regardless of income, while advance discounts reward those with flexible schedules (often correlated with secure employment and higher socioeconomic status). Price caps reduce this inequality by constraining maximum fares. Second, the 94% revenue retention under capping suggests operators can maintain service frequency and capacity without reducing base connectivity—the primary determinant of transport equity.
Complementary equity-enhancing measures could include means-tested fare subsidies for vulnerable groups funded by carbon pricing revenues, reserve capacity allocation at capped prices for social tariff holders, and advance-booking assistance programs for digitally excluded populations—interventions that together align pricing-based decarbonization with the European Green Deal’s principle of a “just transition” that distributes mobility benefits equitably.
Future research should quantify the distributional impacts of carbon-aware pricing across income quintiles and assess whether modal shift interventions exacerbate or alleviate transport poverty.
5.5. Evidence-Based Policy Framework Contribution
This research directly responds to the demand-side intervention priorities articulated in the European Green Deal and Sustainable and Smart Mobility Strategy. By providing the first large-scale empirical quantification of carbon leakage in transport pricing (2.4 million observations yielding 6.4% leakage ratio), we establish an evidence base for integrating environmental constraints into rail revenue management frameworks.
The policy-actionable nature of our findings distinguishes this analysis from purely descriptive modal shift studies. Our demonstration that price caps at EUR 110–120 eliminate leakage while preserving 94% of revenue offers policymakers a specific, implementable threshold that balances operator viability with sustainability goals. This precision addresses a critical gap in transport decarbonization policy: while modal shift targets are widely adopted (EU Green Deal aims to double HSR traffic by 2030), how to design demand-side interventions to achieve these targets remains underspecified.
Extrapolating to the European HSR network, which includes dozens of corridors competing with short-haul aviation (Paris–Lyon, Rome–Milan, Berlin–Munich, Amsterdam–Paris), the aggregate carbon reduction potential from coordinated pricing policies could reach several million tonnes CO2 annually. If our Madrid–Barcelona leakage ratio (6.4%) generalizes across corridors, eliminating leakage through harmonized price caps could amplify network-wide modal shift carbon benefits by 6–10%, representing a meaningful contribution to the 2050 transport emission reduction target without requiring new infrastructure investment.
The analytical framework introduced here—bidirectional carbon accounting with fare-threshold sensitivity analysis—is methodologically transferable to other inter-modal competition contexts (maritime vs. aviation, bus vs. rail) and can inform the design of carbon pricing mechanisms in the forthcoming revision of the EU Emissions Trading System to cover transport fuels.
5.6. Post-Liberalization Market Evolution
The Madrid–Barcelona corridor underwent fundamental transformation following the study period. OUIGO launched services on 11 May 2021, offering fares from EUR 9; Renfe’s low-cost brand Avlo entered on 23 June 2021; and iryo (ILSA consortium) began operations on 25 November 2022. The CNMC 2025 liberalization report [37] (INF/DTSP/091/25) documents the transformation quantitatively: HSR seat capacity increased from 8.87 million (2019) to 14.62 million (2024, +65%); rail modal share rose from 63.3% to 81.5%; average revenue per passenger declined by 33%; and approximately 900,000 passengers were captured from aviation, yielding an estimated 220,000 tonnes CO2 annual savings and EUR 431.3 million in consumer surplus gains. García-Samaniego and Campos [26] further document that AVE daily average fares were EUR 79.09 while the new AVLO service averaged EUR 41.52, with a structural break identified in January 2021—four months before OUIGO’s entry.
Our 2019 dataset captures the final year of Renfe’s effective monopoly, establishing a pre-liberalization baseline. The specific price cap thresholds identified (EUR 110–120) reflect monopoly-era pricing dynamics and may require recalibration for the current multi-operator environment. Under competition, market forces may already achieve partial leakage reduction through suppressed average fares, potentially rendering regulatory intervention less urgent—though whether competition similarly suppresses last-minute fares below €120 remains an open empirical question.
5.7. Post-Validation: Framework Predictions vs. Observed Market Evolution
As additional empirical validation, we compare our 2019-calibrated framework predictions with observed post-liberalization outcomes. On the price-to-modal-shift prediction, our framework anticipated that lower average fares would attract passengers from aviation; CNMC data [37] confirms this, with average HSR revenue per passenger declining 33% from 2019 to 2024 as rail modal share rose from 63.3% to 81.5%. The net modal shift outcome—predicted from advance-purchase discounts attracting aviation passengers—is likewise substantiated by the CNMC’s reported capture of approximately 900,000 passengers from aviation, generating an estimated 220,000 tonnes CO2 in annual savings. Finally, the CNMC’s estimate of EUR 431.3 million in consumer surplus gains from HSR liberalization on this corridor validates the welfare significance of the pricing dynamics analyzed here.
While this post-validation cannot establish causality, the directional consistency between our framework’s predictions and observed 2019–2024 market evolution strengthens confidence in the analytical structure. Replicating the bidirectional carbon balance analysis with post-liberalization multi-operator pricing data represents a priority for future research.
5.8. Long-Term Market Power Implications
While modal shift from aviation to rail reduces carbon emissions, complete aviation displacement from short-distance corridors may create unintended long-term consequences. If HSR achieves near-monopoly following aviation withdrawal, competitive pressure diminishes, potentially leading to higher average prices and reduced incentives for service quality improvement. This ‘winner-takes-most’ dynamic is already observable on the Madrid–Sevilla corridor, where aviation virtually ceased after AVE entry. Institutional safeguards against this outcome include maintaining multi-operator HSR competition—as the current liberalization achieves—alongside regulatory oversight of fare levels under public service obligations, preserving minimum aviation connectivity on competing routes, and monitoring average fare trajectories following aviation market exit.
5.9. Limitations
Several limitations warrant acknowledgment. Aviation benchmarks in this analysis are fixed (EUR 55 for low-cost, EUR 120 for full-service), whereas real aviation fares also exhibit temporal dynamics with last-minute prices often rising. This does not, however, invalidate the leakage logic: what governs modal choice is the relative price differential, not absolute levels. If HSR prices rise from EUR 80 to EUR 105 (+31%) while aviation rises from EUR 55 to EUR 80 (+45%), the price gap remains constant; if aviation’s surge is smaller (+20% vs +31%), the gap widens, amplifying leakage. Industry data suggest low-cost carriers exhibit flatter temporal curves (Ryanair/Vueling maintain aggressive last-minute promotions), making the fixed-benchmark approach conservative—a conclusion reinforced by sensitivity analysis showing that even if the aviation threshold rises to EUR 140, carbon leakage persists at %, confirming the structural nature of the J-curve problem. A further limitation concerns the implicit assumption of elastic supply in our price cap analysis. In practice, if last-minute fares are capped at EUR 120, demand for these seats may exceed available capacity—particularly on peak departures. Passengers unable to secure capped-price HSR seats would face the same aviation-switching decision, potentially generating leakage that our static model does not capture. This supply-side constraint reinforces the importance of coordinating pricing caps with capacity expansion planning. The study also lacks individual booking data, relying on price observations as proxies for demand; while this limits causal inference, the literature-calibrated elasticity approach (Wardman et al. [10], González-Savignat [5]) anchors parameters to empirically validated values, and future research should incorporate ridership microdata to refine switching rate estimates.
A second set of limitations concerns generalizability and behavioral scope. The Madrid–Barcelona corridor represents Spain’s most competitive HSR-aviation market, potentially overstating leakage relative to less competitive routes; the bidirectional accounting framework is nonetheless methodologically transferable to any corridor exhibiting J-curve pricing and inter-modal competition. Three transferability conditions apply: (1) HSR and aviation compete on comparable routes with broadly substitutable travel times; (2) the HSR operator employs temporal price discrimination, offering advance-purchase discounts that rise to last-minute premiums; and (3) some passenger segments exhibit sufficient price elasticity to switch modes when the price differential exceeds the aviation threshold. These conditions characterize most major European HSR corridors, including Paris–Lyon, Rome–Milan, Berlin–Munich, and London–Paris, suggesting that carbon leakage risk is a corridor-type problem rather than a corridor-specific phenomenon. Non-price factors—loyalty programs, environmental preferences, and service quality differentials—are also abstracted away, though price remains the dominant lever for policy intervention: Bursa et al. [17] finds that price explains 40% of variance in HSR-aviation choice, compared to 15% for environmental information. Future research should explore the interaction between pricing and service quality, the impact of low-cost HSR operators (Ouigo, AVLO), and the applicability of the framework to other European corridors such as Paris–Lyon, Rome–Milan, and Berlin–Munich.
Three further methodological caveats merit acknowledgment. The dataset covers April–October 2019, excluding the November–March period that encompasses holiday travel; the holiday season is characterized by exceptionally high demand and intensified last-minute pricing—conditions that may amplify the J-curve pattern and increase carbon leakage risk beyond the present estimates, which should accordingly be interpreted as reflecting spring–autumn travel patterns rather than full-year averages. Carbon accounting uses average emission factors that implicitly assume representative load factors: if ‘leaked’ passengers fill otherwise-empty aviation seats, marginal emissions may be near zero, while if attracted passengers displace car travelers on high-load HSR services, savings may be overestimated; average emission factors remain the standard in transport carbon accounting [2] and provide a tractable first approximation. Finally, all estimates are based on price availability observations rather than realized transactions—we do not observe which fares were purchased, by whom, or at what volumes—so revenue impact estimates should be interpreted as approximate model outputs; high last-minute prices may also partially reflect capacity scarcity rather than revenue-maximizing price discrimination, and disaggregating these two mechanisms would require seat availability data. Carbon savings estimates likewise assume direct substitution, whereas realized reductions depend on whether modal shift triggers aviation supply adjustments such as reduced flight frequency or aircraft downsizing.
6. Conclusions
This study examines pricing policy as a demand-side intervention for decarbonizing mobility—addressing a gap in the European Green Deal’s Sustainable and Smart Mobility Strategy, which targets aggressive modal shift yet provides little guidance on pricing design. Introducing the bidirectional modal shift framework, we provide empirical calibration of carbon leakage in transport pricing, validated through multi-source elasticity triangulation, using 2.4 million HSR price observations—the largest revealed pricing dataset in inter-modal competition research. Our analysis exposes a fundamental contradiction: high-speed rail dynamic pricing simultaneously decarbonizes and re-carbonizes the same corridor. Early-bird discounts attract 274,431 passengers annually from aviation (saving 23,650 tonnes CO2), yet last-minute scarcity premiums drive 17,537 passengers back to aviation (leaking 1511 tonnes CO2). Net savings: 22,139 tonnes CO2/year. Leakage ratio: 6.4%—a structural property of the observed price distribution that is robust to elasticity specification that current transport decarbonization frameworks entirely overlook.
Three policy-actionable findings emerge. Carbon leakage is measurable and structural: last-minute HSR prices exhibit a 31.1% premium (EUR 105.6 vs EUR 80.5), placing 22.3% of tickets above the EUR 120 aviation threshold and generating quantifiable environmental costs robust across parameter specifications (leakage ratio 2.7–18.1% under sensitivity analysis), a pattern suggesting that unconstrained revenue maximization may undermine modal shift objectives. The analysis further identifies policy-actionable intervention thresholds: under static assumptions, price caps at EUR 110–120 would eliminate measured leakage while preserving an estimated 94% of operator revenue (subject to equilibrium caveats discussed in Section 5), addressing a gap in demand-side decarbonization policy regarding how to design pricing interventions that balance sustainability with commercial viability—the illustrative threshold range providing a starting point for carbon-aware constraints in carbon-aware revenue management. The bidirectional carbon accounting methodology is additionally scalable across inter-modal competition contexts (maritime vs. aviation, bus vs. rail, freight modal shift) and transferable to carbon pricing mechanism design in the EU Emissions Trading System revision covering transport fuels.
Recommendations for stakeholders: Rail operators should consider integrating carbon KPIs into revenue management algorithms, implementing a price cap at EUR 110–120 as a soft constraint in yield optimization systems; under static assumptions, the estimated revenue cost is ≤6% and the estimated carbon benefit is 1511 tonnes CO2/year recovered, while this approach also creates a marketing opportunity to differentiate from aviation’s unconstrained surge pricing through verified sustainable pricing commitments. National regulators should consider mandating carbon-aware pricing as a Public Service Obligation (PSO) condition for operators receiving track access subsidies or state aid, enforced through mandatory annual carbon leakage reporting and supported by carbon-linked revenue compensation funded by EU ETS auction proceeds or aviation fuel tax revenues, with price caps at EUR 110–120 applied to corridors competing with aviation. The European Commission should treat pricing policy as a rapid-deployment demand-side intervention complementing infrastructure investment in the Fit for 55 package, exploring harmonized HSR price guidance across member states to reduce the estimated 6.4% leakage across the European HSR network, amplifying modal shift benefits by an estimated 6–10% toward 2050 transport decarbonization targets—achievable within 12 months, zero infrastructure capital required.
Decarbonizing mobility demands more than electrified infrastructure—it requires pricing systems that sustain behavioral change once achieved. This research suggests that demand-side interventions, when calibrated through large-scale data analysis, may deliver carbon reductions at modest cost while addressing equity through complementary social tariff mechanisms. As Europe accelerates toward 2050 climate targets, pricing policy represents a potentially fast, cost-effective lever for policymakers, implementable through regulatory reform rather than infrastructure capital, and capable of amplifying returns on existing HSR investments. Ensuring that dynamic pricing serves climate objectives—rather than silently undermining them—requires the kind of bidirectional carbon accounting framework introduced here.
Author Contributions
Conceptualization, Z.X. and C.X.; methodology, Z.X. and C.X.; software, Z.X.; formal analysis, Z.X.; investigation, Z.X., C.X. and X.G.; data curation, Z.X.; writing—original draft preparation, Z.X. and C.X.; writing—review and editing, Z.X., C.X. and X.G.; visualization, Z.X.; project administration, C.X. All authors have read and agreed to the published version of the manuscript.
Funding
This research received no external funding.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The original data presented in the study are openly available in Zenodo at https://doi.org/10.5281/zenodo.18466145 (accessed on 1 March 2026).
Acknowledgments
The authors acknowledge the use of publicly available pricing data from Renfe’s online booking system.
Conflicts of Interest
The authors declare no conflicts of interest.
Abbreviations
The following abbreviations are used in this manuscript:
| AVE | Alta Velocidad Española (Spanish High-Speed Rail) |
| CO2 | Carbon Dioxide |
| CV | Coefficient of Variation |
| EEA | European Environment Agency |
| EU | European Union |
| HSR | High-Speed Rail |
| SDG | Sustainable Development Goal |
References
- Winkler, L.; Pearce, D.; Nelson, J.; Babacan, O. The effect of sustainable mobility transition policies on cumulative urban transport emissions and energy demand. Nat. Commun. 2023, 14, 2357. [Google Scholar] [CrossRef] [Scilit]
- Boschmans, S.; Mayeres, I.; Van Zeebroeck, B. Transport and Environment Report 2020: Train or Plane? Technical Report; European Environment Agency: Copenhagen, Denmark, 2021. [Google Scholar]
- EU Commission. Sustainable and Smart Mobility Strategy–Putting European Transport on Track for the Future. Communication from the Commission to the European Parliament, the Council, the European Economic and Social Committee and the Committee of the Regions. 2020. Available online: https://eur-lex.europa.eu/legal-content/EN/TXT/?uri=celex:52020DC0789 (accessed on 2 February 2026).
- Givoni, M.; Dobruszkes, F. A review of ex-post evidence for mode substitution and induced demand following the introduction of high-speed rail. Transp. Rev. 2013, 33, 720–742. [Google Scholar] [CrossRef] [Scilit]
- González-Savignat, M. Competition in air transport. J. Transp. Econ. Policy JTEP 2004, 38, 77–107. [Google Scholar] [CrossRef] [Scilit]
- Dobruszkes, F. High-speed rail and air transport competition in Western Europe: A supply-oriented perspective. Transp. Policy 2011, 18, 870–879. [Google Scholar] [CrossRef] [Scilit]
- Wang, Y.; Sun, L.; Teunter, R.H.; Wu, J.; Hua, G. Effects of introducing low-cost high-speed rail on air-rail competition: Modelling and numerical analysis for Paris-Marseille. Transp. Policy 2020, 99, 145–162. [Google Scholar] [CrossRef] [Scilit]
- Bhat, C.R. A heteroscedastic extreme value model of intercity travel mode choice. Transp. Res. Part Methodol. 1995, 29, 471–483. [Google Scholar] [CrossRef] [Scilit]
- Ben-Akiva, M.E.; Lerman, S.R. Discrete Choice Analysis: Theory and Application to Travel Demand; MIT Press: Cambridge, MA, USA, 1985; Volume 9. [Google Scholar]
- Wardman, M.; Toner, J.; Fearnley, N.; Flügel, S.; Killi, M. Review and meta-analysis of inter-modal cross-elasticity evidence. Transp. Res. Part A Policy Pract. 2018, 118, 662–681. [Google Scholar] [CrossRef] [Scilit]
- Szabó, D.; Panker, V. Fast Rail in the Era of Modal Shift: Global High-Speed Networks and Their Environmental and Socio-Economic Impacts. Future Transp. 2025, 5, 199. [Google Scholar] [CrossRef] [Scilit]
- Borsati, M.; Albalate, D. On the modal shift from motorway to high-speed rail: Evidence from Italy. Transp. Res. Part A Policy Pract. 2020, 137, 145–164. [Google Scholar] [CrossRef] [Scilit]
- Brenna, C. Price impact of high-speed rail competition between multiple full-service and low-cost operators on less congested corridors in Spain. Transp. Policy 2024, 156, 77–88. [Google Scholar] [CrossRef] [Scilit]
- Evgeniia, S.; Pantelaki, E.; Bashir, T.; Pagliara, F. High-Speed rail and air transport competition: A game theoretical approach to a potential European case study. Case Stud. Transp. Policy 2025, 22, 101614. [Google Scholar] [CrossRef] [Scilit]
- Lee, E.; Kawakita, T.; Huai, Y.; Lo, H.K.; Zhang, A. Airline and high-speed rail collaboration and competition under travel time variability. Transp. Res. Part A Policy Pract. 2024, 185, 104104. [Google Scholar] [CrossRef] [Scilit]
- Li, L. Promoting Freight Modal Shift to High-Speed Rail for CO2 Emission Reduction: A Bi-Level Multi-Objective Optimization Approach. Sustainability 2025, 17, 6310. [Google Scholar] [CrossRef] [Scilit]
- Bursa, B.; Tappeiner, G.; Vicoli, S.; Mölk, F.; Mailer, M. Drive them to rail—How can tourist destinations increase the market share of rail travel? A discrete choice experiment. Int. J. Tour. Res. 2024, 26, e2799. [Google Scholar] [CrossRef] [Scilit]
- Pukhova, A.; Moreno, A.T.; Llorca, C.; Huang, W.C.; Moeckel, R. Agent-based simulation of long-distance travel: Strategies to reduce CO2 emissions from passenger aviation. Urban Plan. 2021, 6, 271–284. [Google Scholar] [CrossRef] [Scilit]
- Avogadro, N.; Cattaneo, M.; Paleari, S.; Redondi, R. Replacing short-medium haul intra-European flights with high-speed rail: Impact on CO2 emissions and regional accessibility. Transp. Policy 2021, 114, 25–39. [Google Scholar] [CrossRef] [Scilit]
- Talluri, K.T.; Van Ryzin, G.J. The Theory and Practice of Revenue Management; Springer Science & Business Media: Berlin/Heidelberg, Germany, 2006; Volume 68. [Google Scholar]
- Manchiraju, C.; Dawande, M.; Janakiraman, G.; Raghunathan, A. Dynamic pricing and capacity optimization in railways. Manuf. Serv. Oper. Manag. 2024, 26, 350–369. [Google Scholar] [CrossRef] [Scilit]
- Meng, H.; Yan, Z.; Wang, Y.; Xu, Y. Optimizing Joint Decisions of Dynamic Pricing and Ticket Allocation for High-Speed Railway with Operators’ Risk Preference. J. Adv. Transp. 2022, 2022, 7383396. [Google Scholar] [CrossRef] [Scilit]
- Hu, Z.; Wei, Y.; Xu, Y.; Wang, H.; Li, Y.; Xia, Y. Optimization of ticket pricing for high-speed railway considering full competitive environment. Meas. Control 2024, 57, 1358–1369. [Google Scholar] [CrossRef] [Scilit]
- Shafiee, M.; Honarvar, M. A revenue management model for airline and railway transportation considering cooperative and competitive games. RAIRO-Oper. Res. 2025, 59, 1153–1171. [Google Scholar] [CrossRef] [Scilit]
- Shan, X.; Lv, X.; Wu, J.; Zhao, S.; Zhang, J. Revenue management method and critical techniques of railway passenger transport. Railw. Sci. 2024, 3, 636–649. [Google Scholar] [CrossRef] [Scilit]
- García-Samaniego, S.; Campos, J. Intercity Railfares After HSR Liberalisation in Spain: Price Patterns in the Madrid–Barcelona Corridor. Future Transp. 2025, 5, 66. [Google Scholar] [CrossRef] [Scilit]
- Wardman, M. Investigating demand models with more flexible elasticity functions: Empirical insights from rail demand analysis. Transportation 2025, 52, 1457–1483. [Google Scholar] [CrossRef] [Scilit]
- Zhang, Y.; Zhao, Z. Optimal dynamic pricing for public transportation considering consumer social learning. PLoS ONE 2024, 19, e0296263. [Google Scholar] [CrossRef]
- Calvano, E.; Calzolari, G.; Denicolo, V.; Pastorello, S. Artificial intelligence, algorithmic pricing, and collusion. Am. Econ. Rev. 2020, 110, 3267–3297. [Google Scholar] [CrossRef] [Scilit]
- Arning, L. Environmental and Accessibility Impacts of High-Speed Rail. 2024. Available online: https://api.semanticscholar.org/CorpusID:272010507 (accessed on 2 February 2026).
- Liu, D.; Wang, J.; Xu, L.; Zhang, H.; Tan, X. Comparison of energy consumption and carbon emissions of high-speed rail with other transportation modes from life cycle perspective: A case of Beijing-Shanghai. Res. Transp. Bus. Manag. 2025, 59, 101278. [Google Scholar] [CrossRef] [Scilit]
- Sikora, A. European Green Deal–legal and financial challenges of the climate change. ERA Forum 2021, 21, 681–697. [Google Scholar] [CrossRef] [Scilit]
- Zhu, L.; Liu, Z.; Jian, W. Contribution assessment of carbon tax on the reduction of freight corridor carbon emissions through modal shift. Transp. Res. Rec. 2023, 2677, 167–179. [Google Scholar] [CrossRef] [Scilit]
- Yildiz, M.; Akgundogdu, A.; Elmas, G. Decarbonizing Coastal Shipping: Voyage-Level CO2 Intensity, Fuel Switching and Carbon Pricing in a Distribution-Free Causal Framework. Sustainability 2026, 18, 723. [Google Scholar] [CrossRef] [Scilit]
- Peeters, P.; Papp, B. Pathway to zero emissions in global tourism: Opportunities, challenges, and implications. J. Sustain. Tour. 2024, 32, 1784–1810. [Google Scholar] [CrossRef] [Scilit]
- Txapartegi, A.; Cazcarro, I.; Galarraga, I. Short-haul flights ban in France: Relevant potential but yet modest effects of GHG emissions reduction. Ecol. Econ. 2024, 224, 108289. [Google Scholar] [CrossRef] [Scilit]
- Comisión Nacional de los Mercados y la Competencia. Balance de la Liberalización del Transporte de Viajeros por Ferrocarril: Actualización con Datos de 2024; Technical Report INF/DTSP/091/25; Comisión Nacional de los Mercados y la Competencia: Madrid, Spain, 2025. [Google Scholar]
- Hortelano, A.O.; Guzman, A.F.; Preston, J.; Vassallo, J.M. Price elasticity of demand on the high-speed rail lines of Spain: Impact of the new pricing scheme. Transp. Res. Rec. 2016, 2597, 90–98. [Google Scholar] [CrossRef] [Scilit]
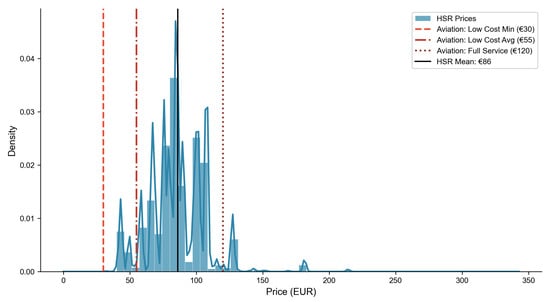
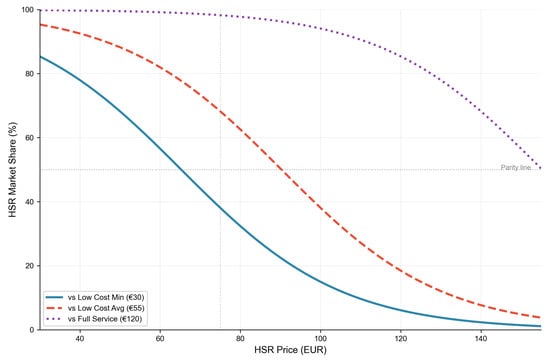
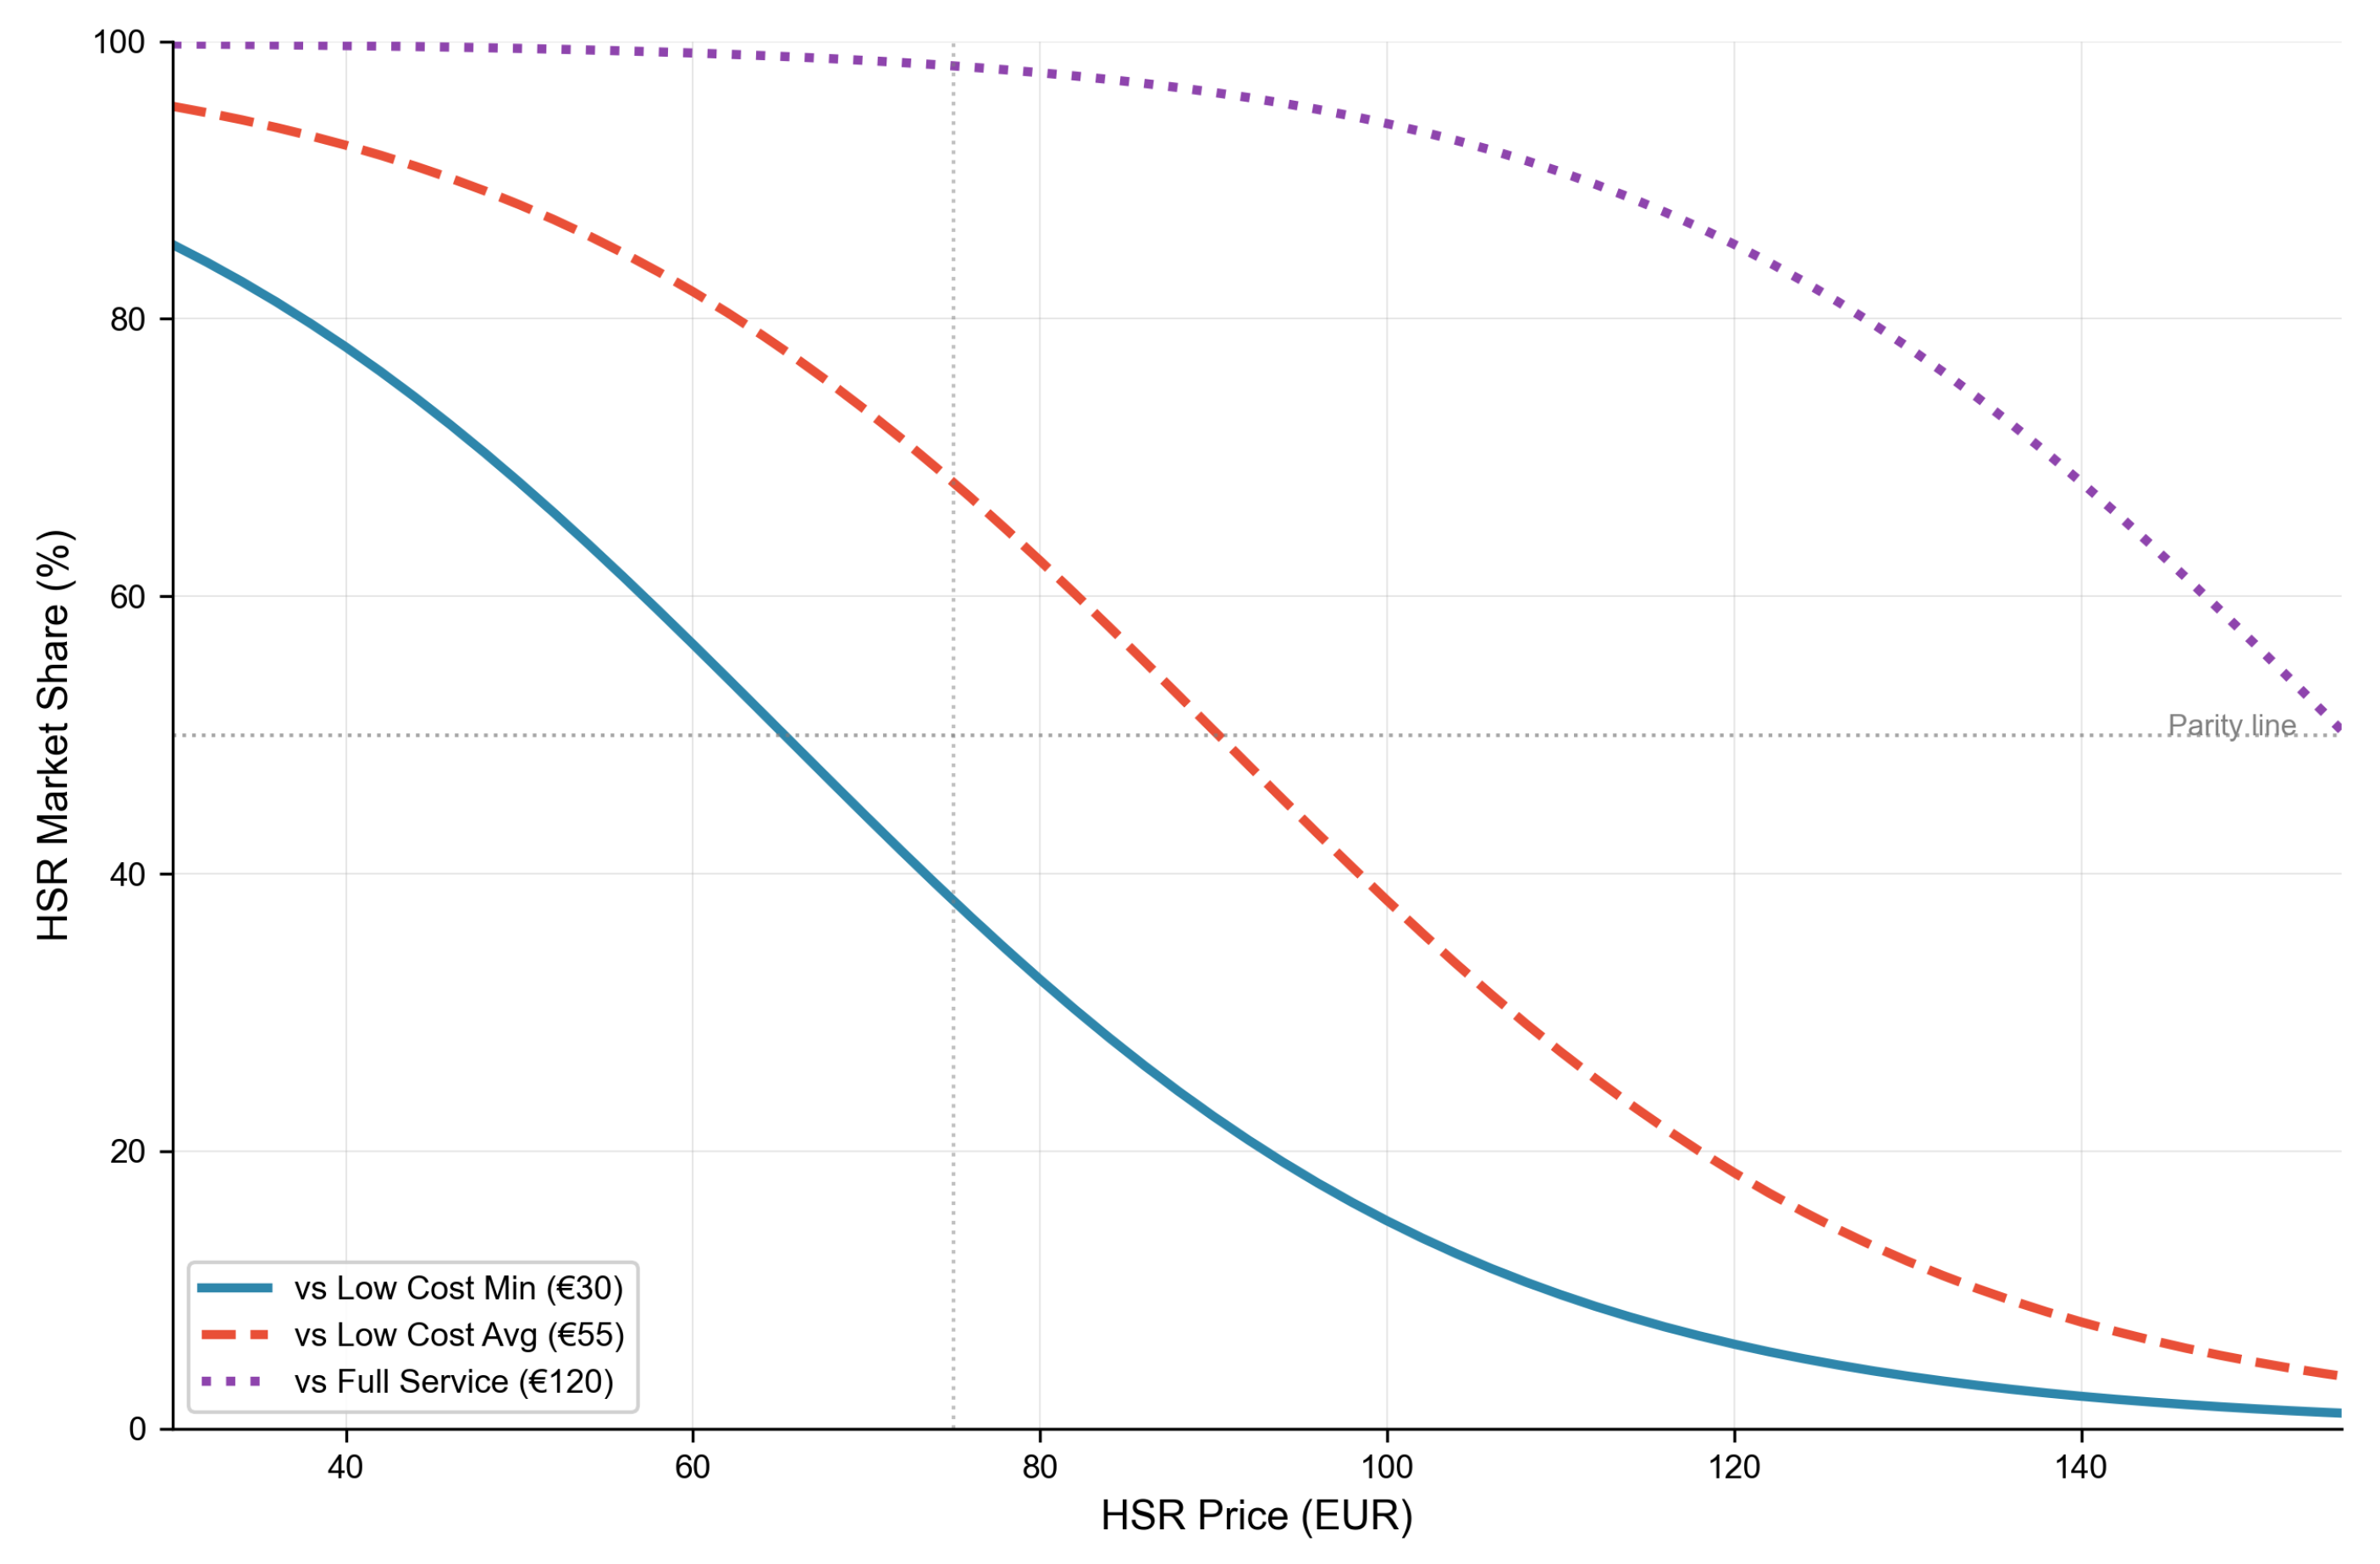
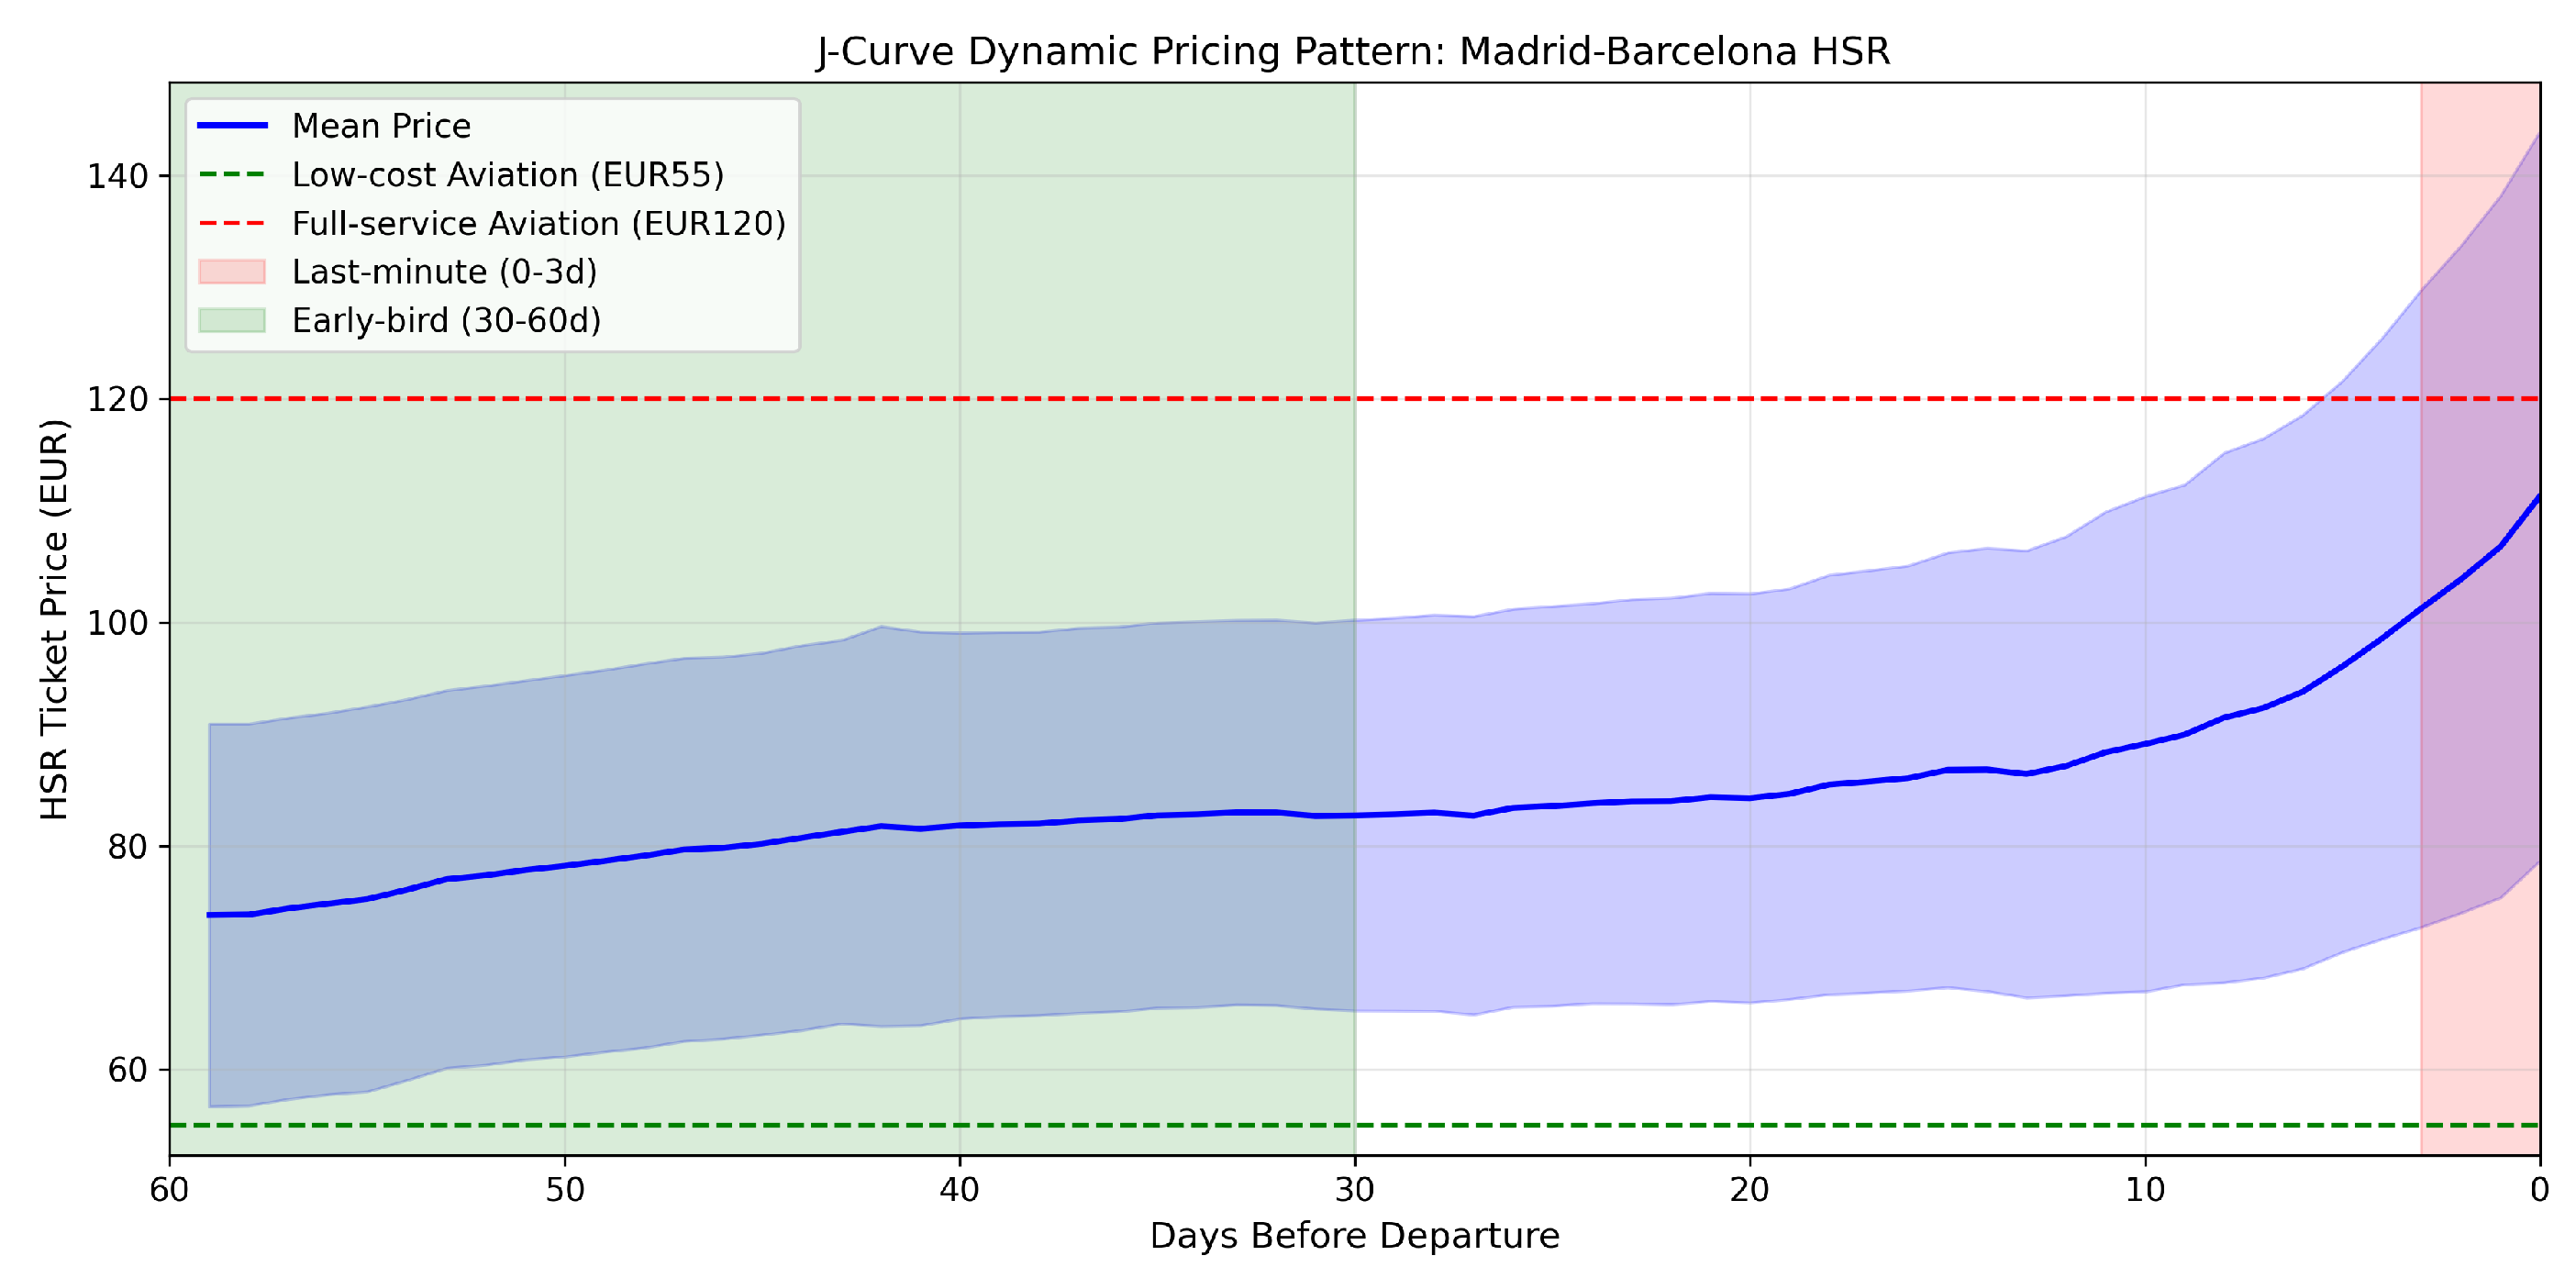
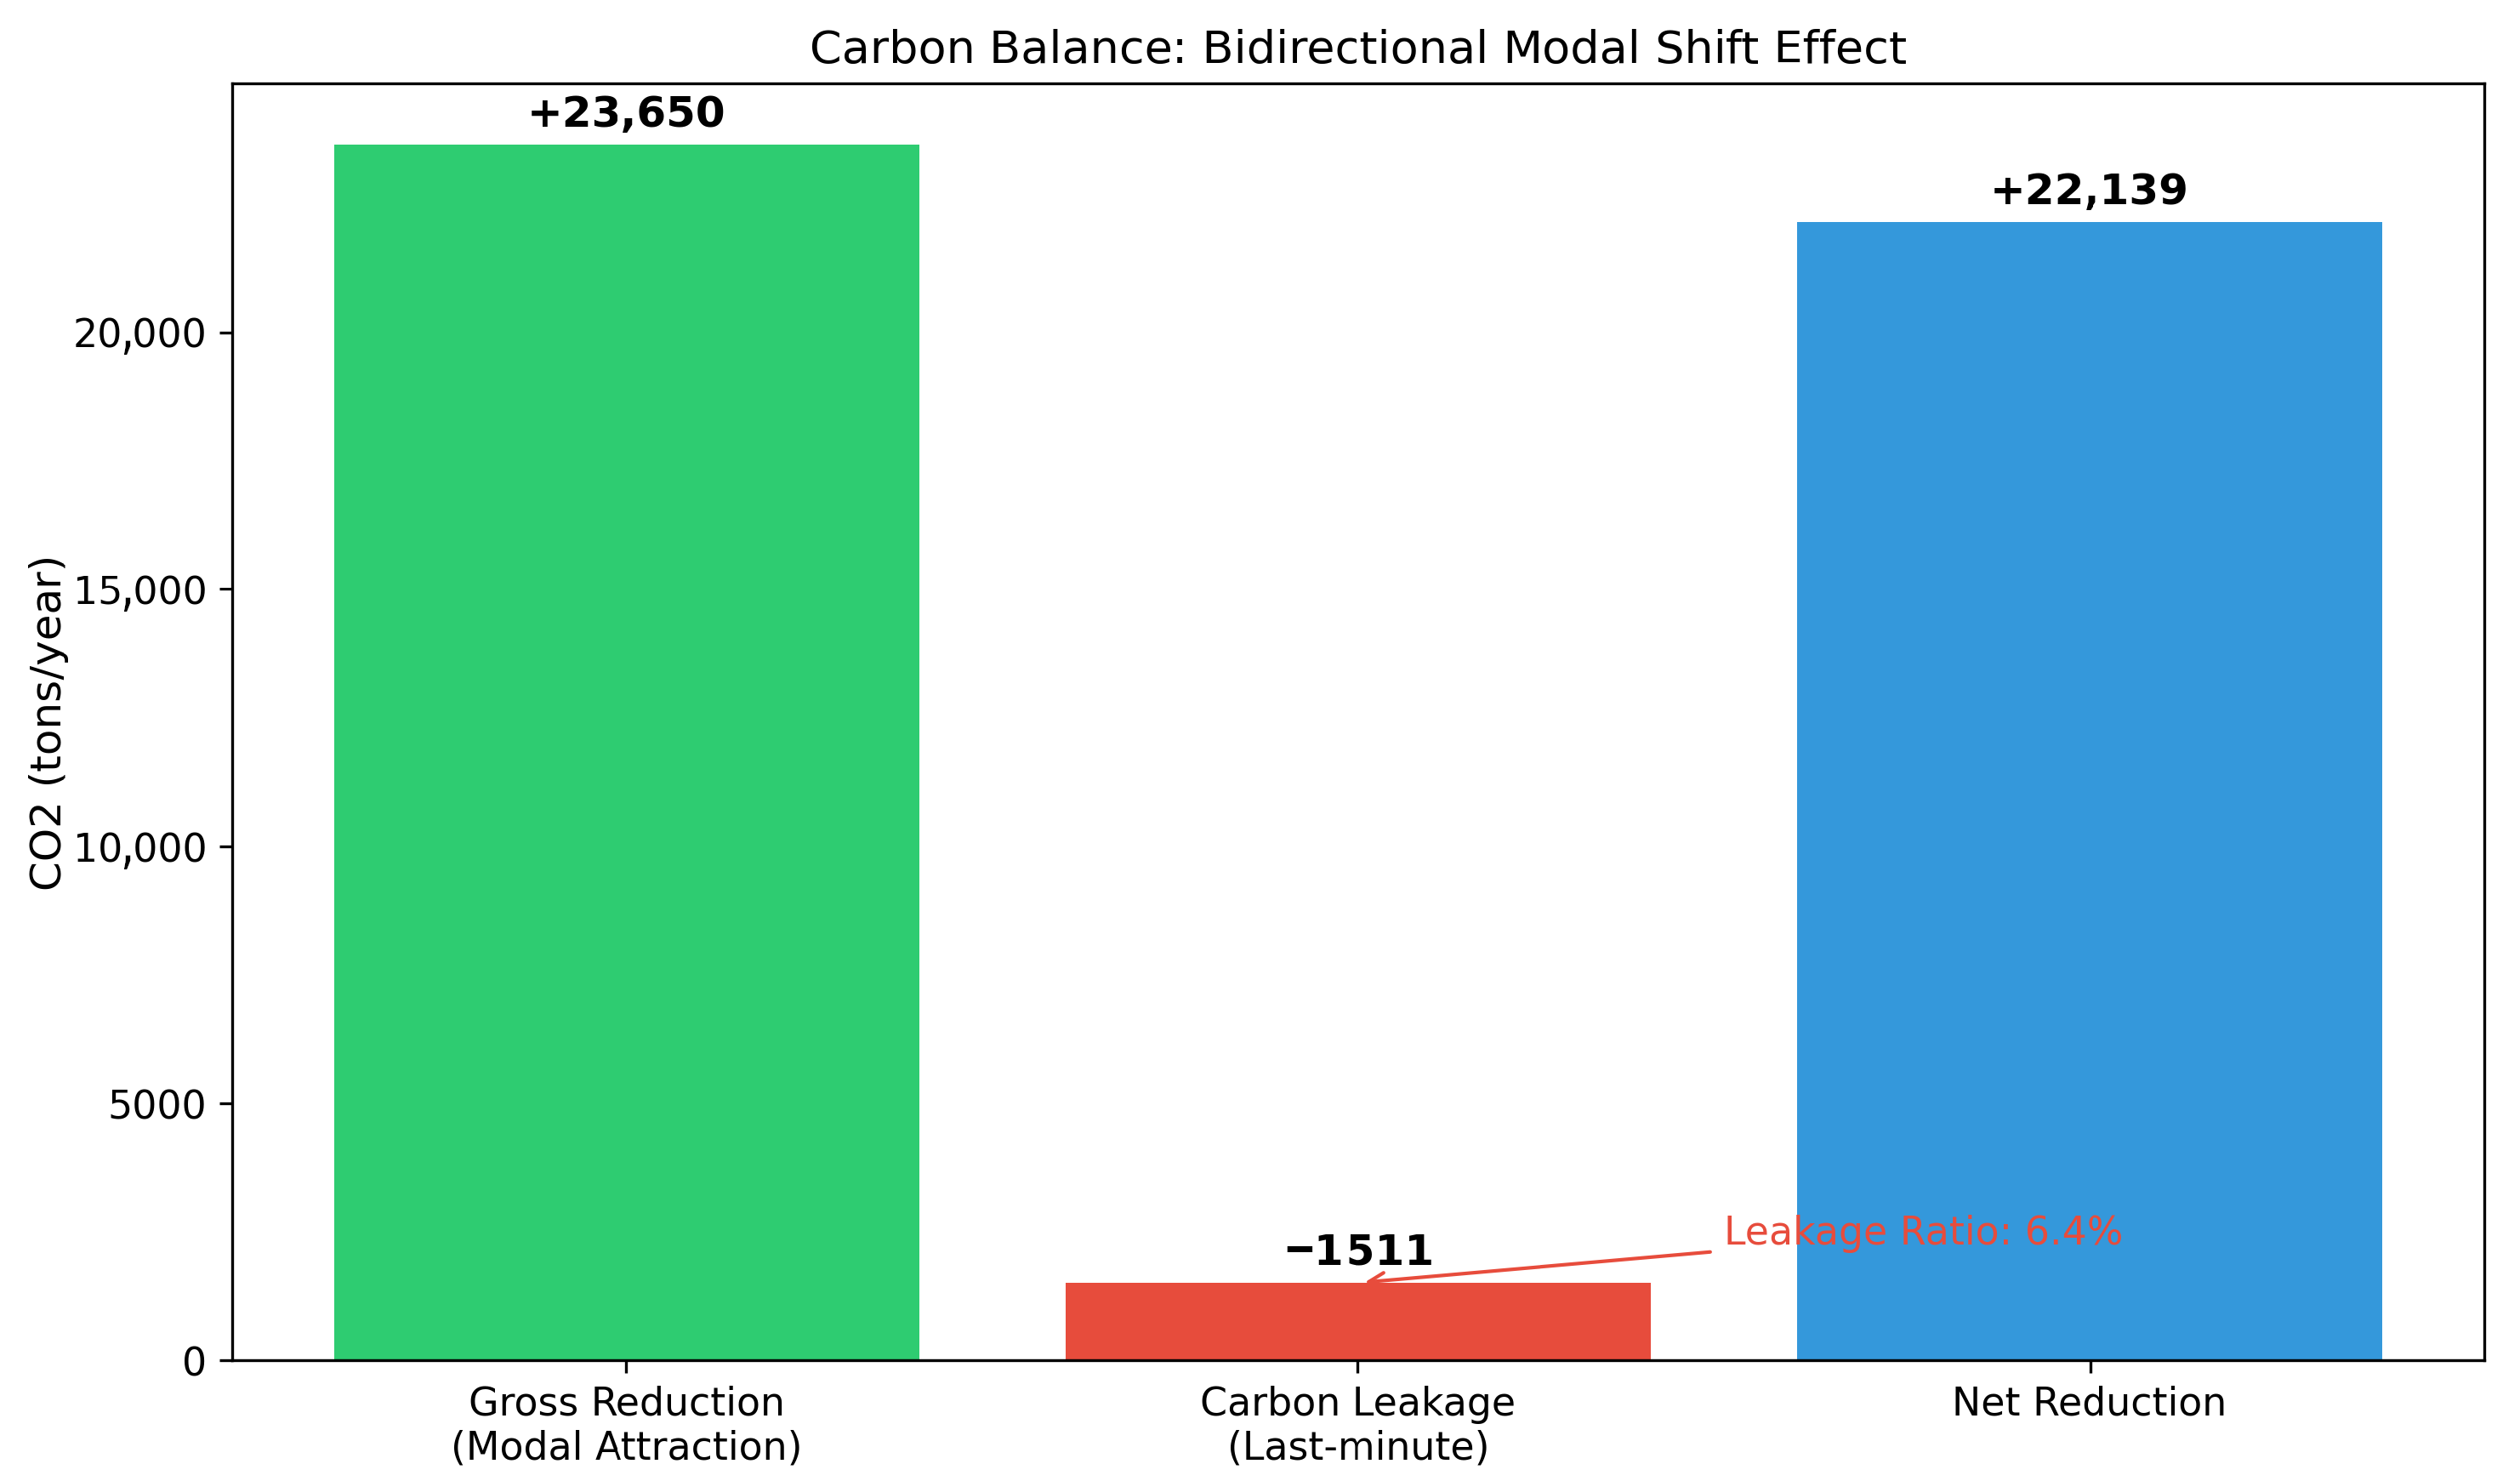
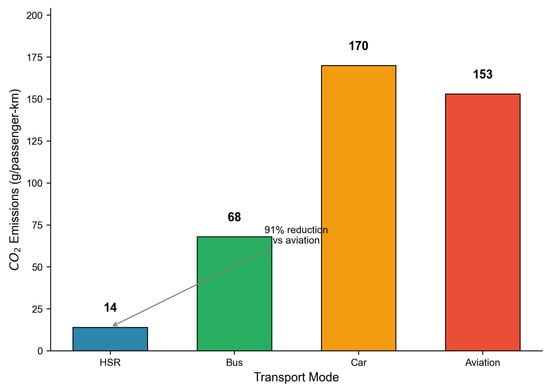
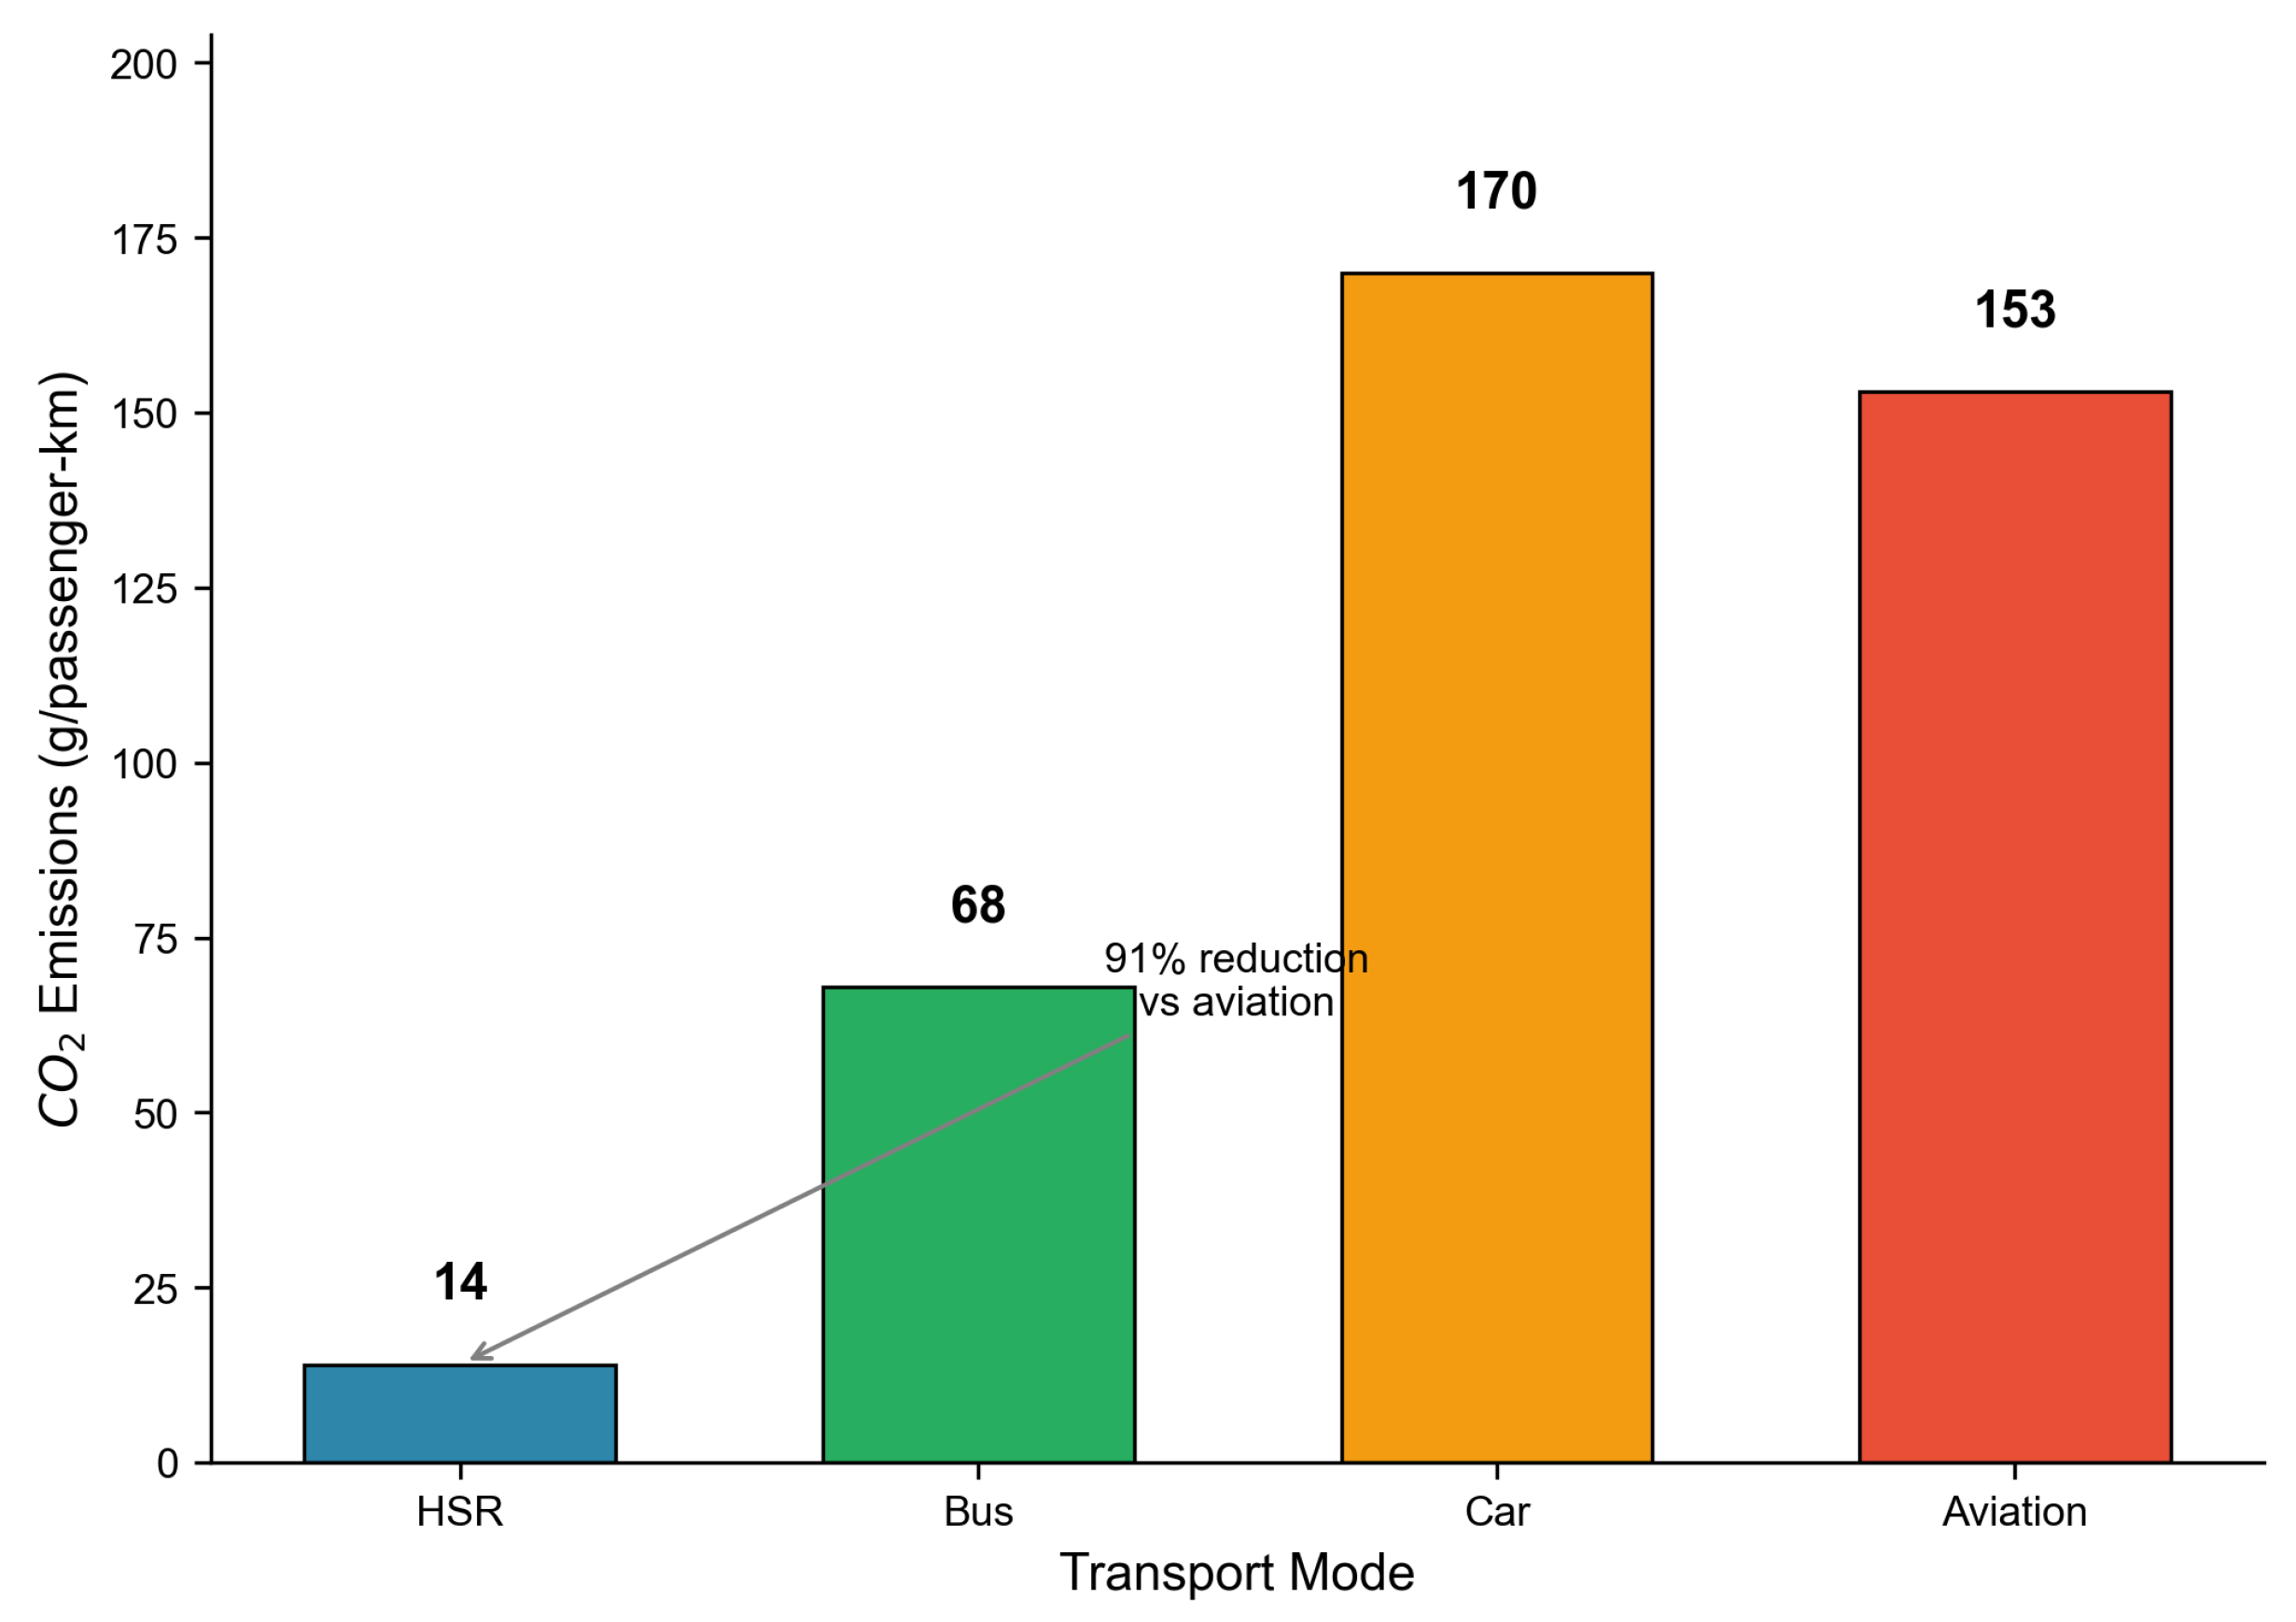
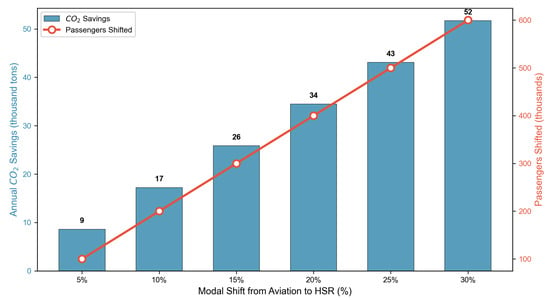
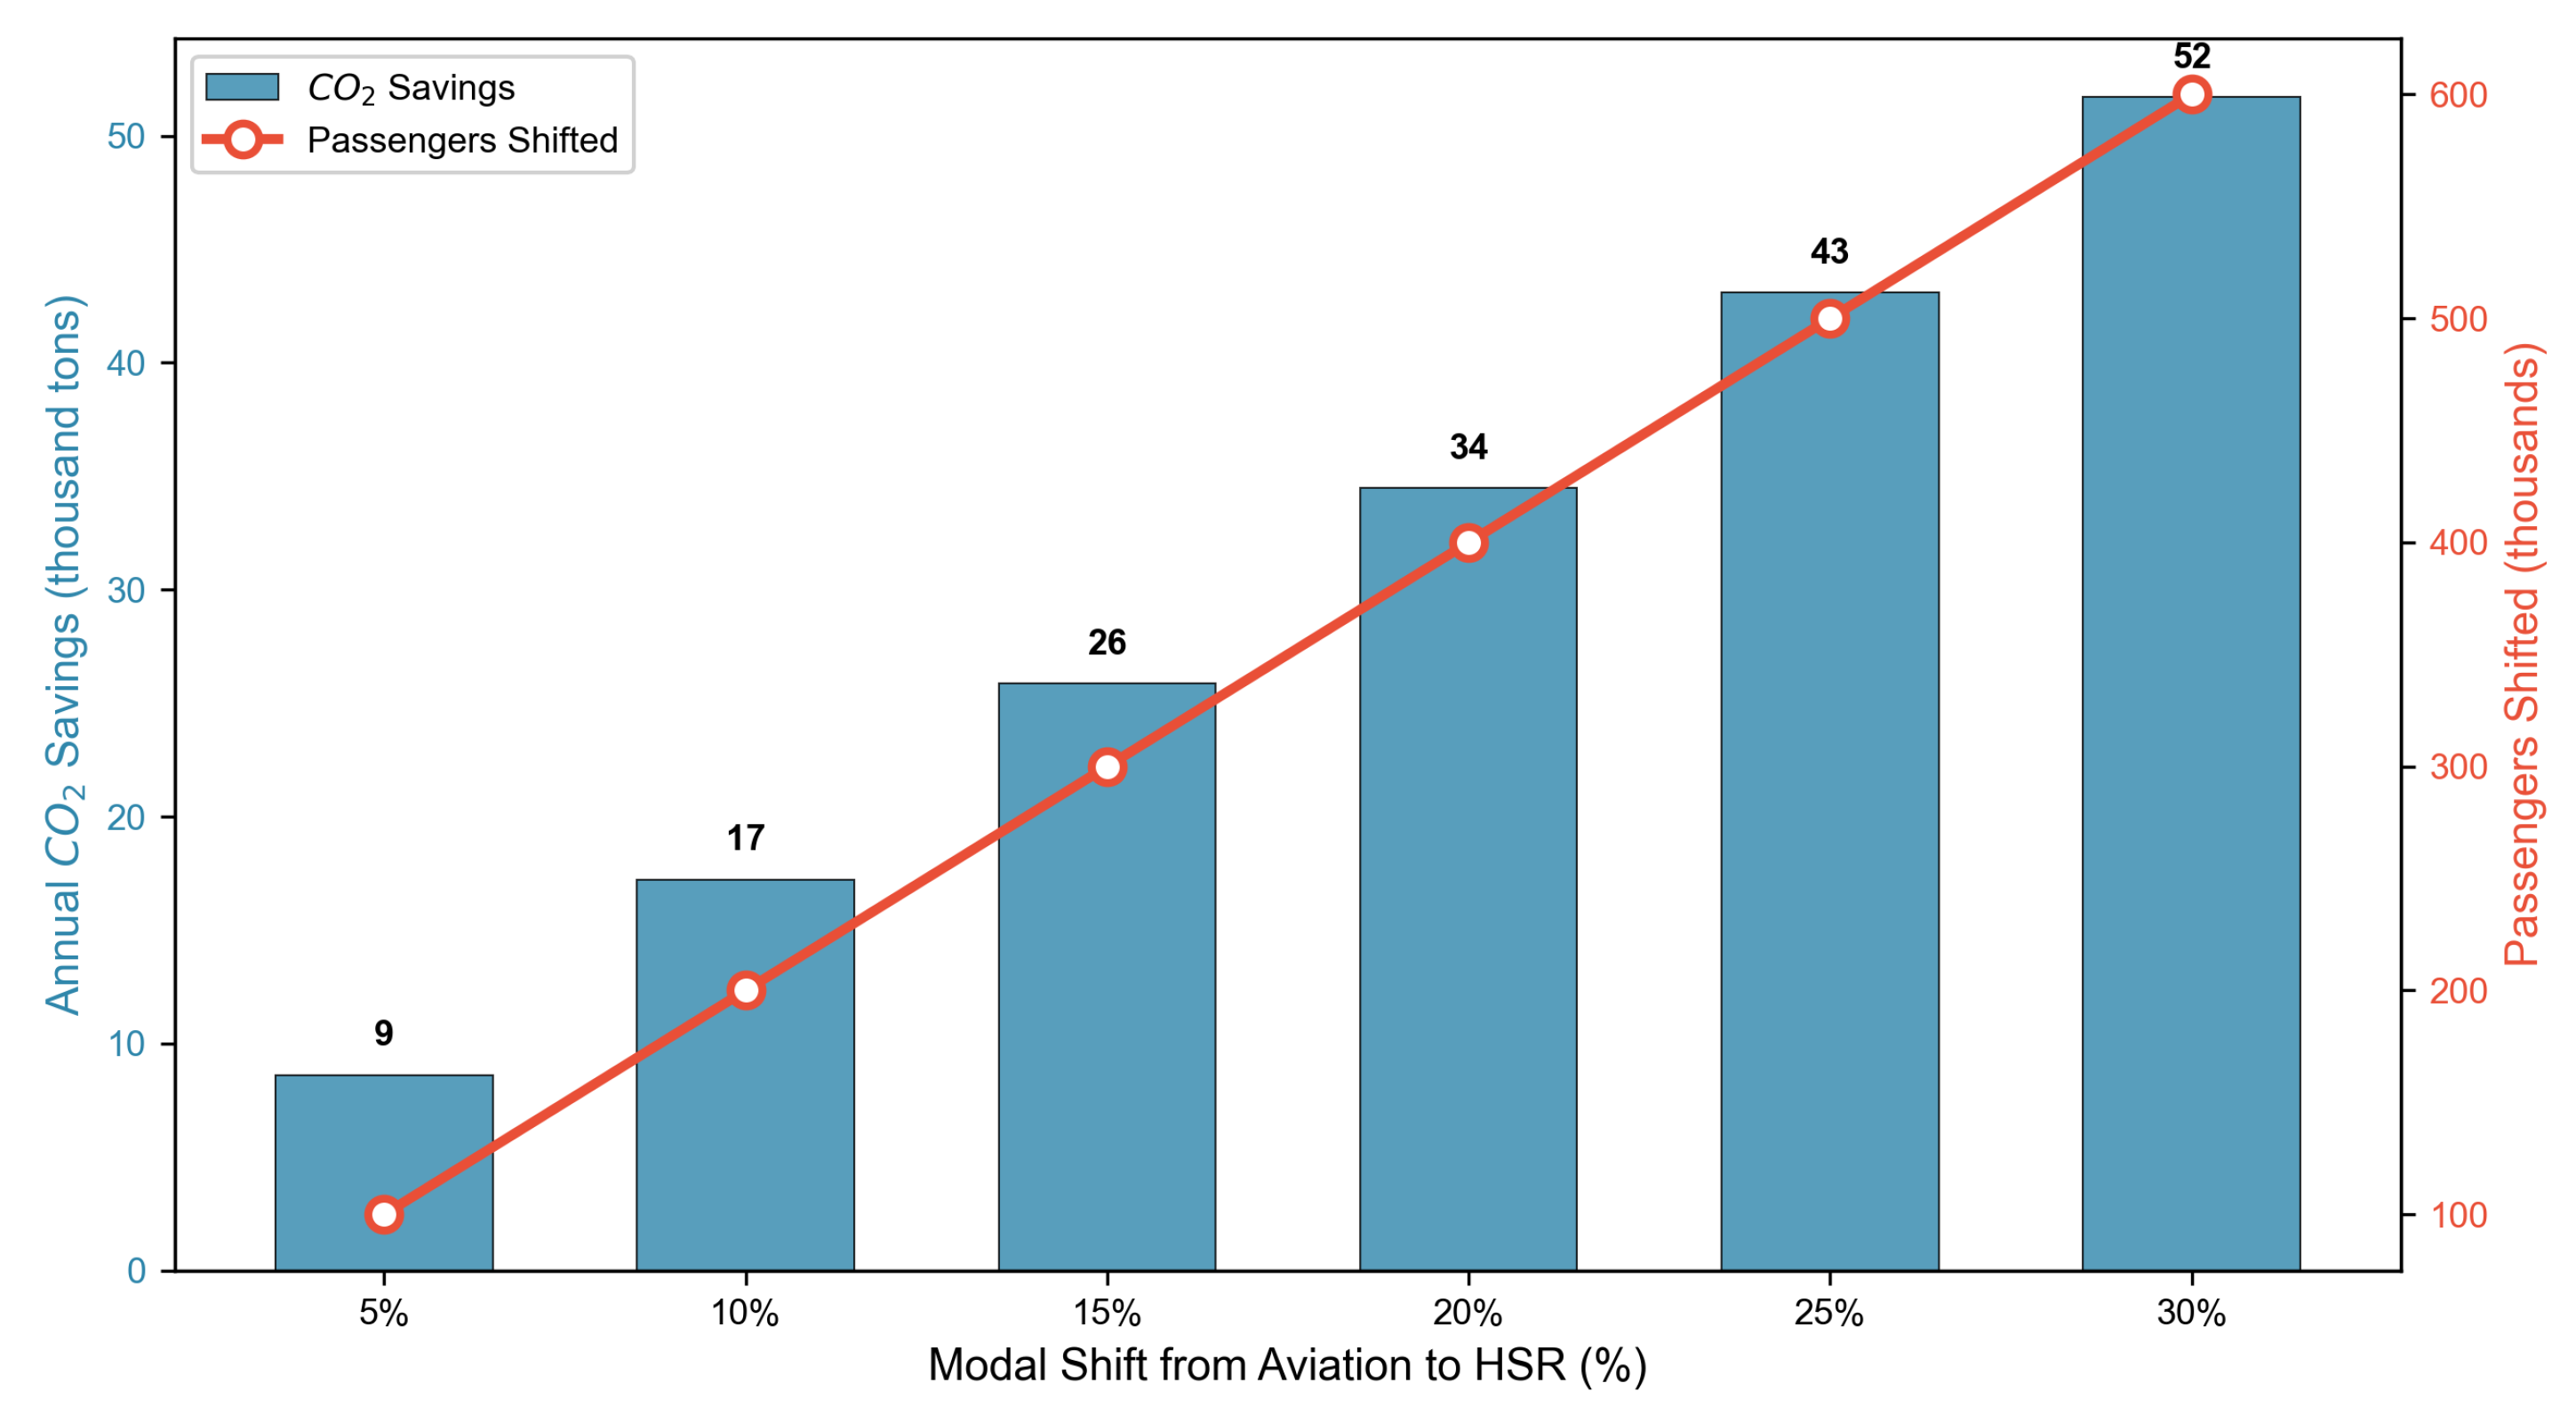

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.