


Abstract
The sustainable transition of rail transit is central to sustainable mobility under China’s dual-carbon goals, yet operating energy use and emissions keep rising as networks expand. Existing causal evidence is concentrated at the city and line levels, where rail networks abate by substituting for high-carbon travel; what operators’ own green practices deliver inside their operations remains largely unmeasured. This study provides, to our knowledge, the first firm-level assessment for the industry. Using a 2017–2025 panel of eight A-share listed rail transit operators, we apply a two-way fixed-effects difference-in-differences (DID) specification—reported as an exploratory descriptive comparison, since identification rests on a single treated firm—and simulate four pathways for 2026–2030 (business as usual, green electricity and technology, inclusion in carbon trading, and their combination), calibrated on Shentong Metro’s 2025 annual report operating data and extrapolated to the industry. Existing green practices remain marginal: the green electricity purchased by Beijing–Shanghai High-Speed Railway in 2025 covered about 1% of its estimated electricity use, and the comparison detects no statistically significant change in carbon intensity (β = 0.225, p = 0.421; wild cluster bootstrap p = 0.508) or in financial performance. In contrast to the significant network-level effects in the literature, this null shows that abatement inside the operator’s own boundary is far from exhausted. The simulations indicate that the green electricity and technology pathway cuts carbon intensity by 41.6% below the baseline by 2030, with a cumulative abatement of about 39.8 kt CO2 and a cumulative net profit gain of 9.15 million CNY over five years; the combined pathway preserves the abatement with stronger cost resilience under tightening quotas. Raising the green-electricity share of China’s urban rail transit to 40% would abate about 6.46 Mt CO2 per year. By moving measurement from the city to the firm, the study supplies reproducible tools for monitoring the sustainability performance of rail operators and evidence-based references for corporate strategy and policy design in the transport sector.
1. Introduction
The green and low-carbon transition of transport is a standing item in China’s carbon peaking deployment. Both the Action Plan for Carbon Peaking before 2030 and the Energy Conservation and Carbon Reduction Action Plan for 2024–2025 encourage the construction of photovoltaic facilities at transport hubs and along transport networks. Rail transit is known as a low-carbon mode of travel, but operations themselves consume large amounts of energy. According to the annual statistical and analytical reports on urban rail transit issued by the China Association of Metros, by the end of 2025 urban rail was in operation in 58 cities, covering 13,067.89 km of lines and carrying 33.383 billion passenger trips in the year, with total electricity consumption of 29.008 billion kWh, of which traction accounted for 52.22% [1]; these figures are record highs. On the railway side, the statistical bulletins of the National Railway Administration report 4.601 billion passenger trips and 5.277 billion tonnes of freight sent in 2025, and the comprehensive energy intensity of national railways reached 3.90 tce per million converted tonne-km [2]. Existing studies estimate that operating carbon emissions of China’s urban rail transit grew by about 217% between 2015 and 2022 [3] and that emissions of the railway operation sector rose from 57.75 million to 64.21 million tonnes between 2016 and 2021, with the share of indirect electricity-based emissions climbing to 78.8% [4]. Operating decarbonisation also ties rail transit ever more tightly to the power system and other urban infrastructure: recent work models such interdependence explicitly, from the PDE-constrained dispatch of the coupled electricity–water nexus [5] to spatio-temporal outage-risk prediction for interdependent electricity and drainage networks under rainstorm disasters [6]. Networks are still expanding, and industry energy use and emissions are unlikely to turn downward in the short run. How to cut emissions from operations is therefore a question that the rail transit industry has to answer.
A considerable body of causal evidence already exists on the environmental externalities and abatement effects of rail transit. At the facility level, opening a metro line lowers downtown particulate concentrations by roughly 4% in initially heavily polluted cities [7]. At the city level, the opening of high-speed rail [8,9], better metro network accessibility [10], the launch of urban rail transit [11] and the operation of China–Europe freight trains [12] have all been shown to reduce carbon emissions significantly. High-speed rail networks also lower residents’ exposure to pollution [13] and encourage substitution towards electric vehicles [14], which brings additional health and carbon benefits. Systematic reviews group these mechanisms into a mode-shift effect and a ridership-scale effect, and note that the net outcome depends on factors such as the generation mix of the power system [15]. On emission accounting, studies have quantified operating emissions of urban rail at the national scale [3], examined the spatiotemporal heterogeneity of railway operating emissions [4], estimated life-cycle emission intensities and carbon payback periods [16,17,18], forecasted operating emissions and evaluated abatement measures [19], characterised the operating emissions of regional high-speed railways and railway bureaus [20,21], measured the carbon emission efficiency of railway transport enterprises [22], assessed the contribution of rail transit to urban transport decarbonisation [23,24], modelled operating energy consumption [25] and decomposed the drivers of transport-sector emissions [26]. Together they describe the level, structure and determinants of emissions in the industry.
Research on mechanisms and policy offers further reference points. General-equilibrium assessments of China’s national carbon market find that an intensity-based tradable performance standard yields environmental benefits well above its costs, and that allowance auctioning would lower economy-wide costs by a further 30% [27,28]. Broadening the coverage of emissions trading improves social welfare [29], and studies of carbon pricing for railway freight show that, with well-designed allowances and carbon prices, transport firms can earn surplus revenue from their quotas [30]. Equilibrium sorting models at the city level indicate that combining congestion charging with metro expansion delivers the largest efficiency gains [31], while work on frictions in transport markets cautions that policy evaluation should not ignore the efficiency properties of the market itself [32]. At the firm level, ESG ratings significantly promote the green transition of listed companies [33], information disclosure alone produces behavioural and health benefits [34], and energy prices are the core driver of transport electrification [35]. Evidence from European railways shows that carbon emission efficiency rises with passenger efficiency, with the economy-wide share of freight turnover, and with competition in the passenger market, whereas fiercer competition in freight may induce substitution towards low-cost diesel traction and lower efficiency [36]. On pathway design, multi-scenario peaking simulations [37,38]; forecasts of peaking dates for the transport sector [39]; measurements of the abatement effects of freight restructuring [40]; pathway design for urban rail peaking [41]; coordinated pollution-and-carbon control frameworks [42]; and estimates of industry abatement costs [43], supply methods, and parameters. At the technical level, key technologies for integrating photovoltaics into AC/DC traction power supply [44], the demonstration of distributed photovoltaics on the Shanghai network [45], the technoeconomic analysis of rooftop PV at elevated stations [46], measured savings across the source-grid-load-storage-operation chain [47], network-level estimates of multi-technology savings [48] and the integrated application of new energy technologies [49] together support the feasibility of green-electricity substitution and retrofits by rail operators.
Several gaps remain. First, causal evidence is concentrated at the city and facility levels and rarely reaches the firm: how much carbon the green practices of rail operators actually abate, and whether they pay, is still an open micro question. Second, assessments of carbon markets mostly target power and other industrial sectors; how the cost and revenue structure of rail operating firms would change if they were included in emissions trading has not been quantified. Third, the effects of scaling up green electricity, photovoltaics and carbon trading at the firm level have not been examined in scenario assessments calibrated with real firm data. Each gap has a concrete consequence. Without firm-level evidence, regulators cannot tell whether the operators to whom abatement targets are assigned are actually delivering, and investors cannot price green practice. Without firm-calibrated scenarios, pathway studies stay at the level of aggregate technical potential and cannot say what a pathway implies for the cost and revenue structure of an operating firm. There is also a methodological gap in sustainable transportation research: causal studies work at the city or line level, where the operator’s own abatement actions cannot be separated from network substitution effects, while simulation studies are not anchored in the disclosed data of the firms that would carry the pathways out. A design that links firm-level causal estimation with firm-calibrated simulation is, to our knowledge, not yet available for rail transit. Listed companies are the micro actors with the most complete disclosure in the industry and are a suitable window onto its low-carbon transition. Practice has already started. Shentong Metro (600834.SH) set up its wholly owned subsidiary Shanghai Metro New Energy at the end of 2018; by the end of 2025 it had built and operated, or managed under trust, about 67.3 MWp of photovoltaic plants, the largest installed capacity in China’s rail transit sector, abating about 29,704 tonnes of CO2 in 2025 alone (according to the company’s annual and ESG reports). Beijing–Shanghai High-Speed Railway (601816.SH) signed a strategic cooperation agreement with China Power International Development in January 2022 giving priority to clean electricity; in 2025 it purchased 7339.30 MWh of green electricity and generated 16,228.90 MWh from rooftop photovoltaics at its stations (according to the company’s annual and sustainability reports). Guanghui Logistics (600603.SH) completed the electrification of the Hongnao railway in September 2024, replacing diesel locomotives with electric ones and cutting energy costs by 60–70% (according to company announcements). Under the Beijing carbon trading management measures, the Beijing carbon market already manages five urban rail operators as key emitters, and rail transit firms will soon face carbon constraints directly.
Building on a 2017–2025 panel of eight A-share listed rail transit companies, this paper combines operating data, a difference-in-differences (DID) model and scenario simulation. It first uses a two-way fixed-effects DID model to test the net impact of corporate green practices (photovoltaic and new energy operations, purchases of green electricity and green certificates) on carbon intensity and financial performance. It then takes Shentong Metro’s 2025 [50] actuals as the benchmark and simulates four pathways—business as usual, green electricity and technology, carbon trading inclusion, and their combination—over the 15th Five-Year Plan period (2026–2030) and extrapolates the results to the industry level. The paper makes three contributions. First, it moves the unit of analysis down: causal evidence on rail transit abatement has so far been city- and line-based, whereas here, DID identification is applied to the green practices of listed operators, tracing the chain from practice scale through emission intensity to financial performance. This unit shift provides the measurement basis that firm-level carbon regulation and green appraisal require and it separates the operator’s own abatement margin from the network substitution margin that city-level estimates capture. Second, it links micro evidence with forward-looking simulation: following the practice of combining econometric estimation with scenario analysis in transport policy evaluation and carbon market assessment, the scenario parameters are calibrated with real operating data. The linkage converts a backward-looking estimate into forward-looking magnitudes that a firm or a regulator can act on, and every parameter is traceable to a public source. Third, it reports a null result as it is and interprets it quantitatively; on that basis, it sizes the abatement and profit space of scaled-up pathways over 2026–2030, providing a reproducible quantitative reference for corporate low-carbon strategy and industry incentive design. A null result reported with its quantitative decomposition distinguishes ‘no effect’ from ‘no statistical power to detect an effect’, which is exactly the information needed to judge whether scaling up is worthwhile. In doing so, the paper also responds to the broader agenda of defining, quantifying and monitoring sustainability in the transport sector: it measures corporate-level sustainability performance with reproducible operating data and links that measurement to sustainability-oriented policy design for the rail industry.
2. Theoretical Analysis and Research Hypotheses
2.1. Decarbonisation Pathways for Rail Transit Operators
Rail transit in this paper covers urban rail transit and national railway operators. Low-carbon development refers to a development model that reduces carbon emissions per unit of transport work while maintaining service supply, through a cleaner energy mix, higher energy efficiency and management innovation. In the emission structure, indirect emissions from purchased electricity dominate and their share keeps rising: the indirect-emission share of the 18 railway group companies rose from 67.9% in 2016 to 81.4% in 2021 [22], some railway bureaus already reached 90.9% in 2022, and electric traction accounts for more than nine tenths of traction emissions [21]. Nearly all operating emissions of urban rail come from purchased electricity. Green-electricity substitution is therefore the most effective lever available to the industry. Tracing the source–grid–load–storage-operation chain, three firm-level pathways stand out.
The first is green-electricity substitution. Rail operators hold contiguous space resources, including depot rooftops, elevated stations and land along lines, and their power loads are stable, which favours distributed photovoltaics and green-electricity consumption. Key technologies for connecting photovoltaics to AC/DC traction supply are mature, demonstration projects on the Shanghai network have confirmed operational feasibility, and the economics of rooftop PV at elevated stations has been quantified; integrating transport and energy infrastructure has been made a national policy orientation. The second is energy-efficiency retrofits. Traction takes about half of metro energy use, and station ventilation and air conditioning another 16–30% [18,47,48]. Permanent-magnet synchronous traction, regenerative braking recovery, storage devices, smart lighting and high-efficiency air conditioning can further cut unit consumption, and the measured saving rate of permanent-magnet traction already exceeds 20% [47]. The third pathway combines efficiency improvement with market mechanisms. European experience shows that passenger efficiency, the economy-wide share of freight turnover and competition in the passenger market all raise railway carbon efficiency [36]; better transport organisation is itself an abatement measure, while purchases of green electricity and green certificates and participation in carbon trading shape low-carbon incentives from the energy mix and the cost side respectively.
2.2. Research Hypotheses
Three hypotheses follow. H1: Adopting green electricity, photovoltaics and other new energy technologies lowers the carbon intensity of listed rail transit companies and delivers low-carbon benefits. H2: Once included in the carbon market, the internalisation of carbon costs pushes firms to increase low-carbon investment and further reduce emissions. H3: Relative to business as usual, the green electricity and technology pathway and the carbon trading pathway abate more, and the combination of the two performs best. Since no listed company in the sample is yet under carbon quota management, H1 is tested directly with the DID model; H2 and H3 cannot be identified within the listed sample and are recast as scenario questions examined quantitatively in Section 5. The three hypotheses are not arbitrary: they map one-to-one onto the three firm-level pathways identified in Section 2.1. H1 concerns the green-electricity and new-energy pathway, the only one already observable in the sample, and is tested directly. H2 concerns the market-mechanism pathway, which no listed firm in the sample has yet experienced, and H3 concerns the relative performance and interaction of the two pathways; both are forward-looking and are therefore examined as scenario questions in Section 5 rather than estimated on the panel.
3. Research Design
3.1. Sample and Data
Three criteria govern sample selection: the core business must be rail transport services, the firm must be listed on A-shares with publicly available data, and the sample should cover both urban rail and railway operations. Eight firms meet them: Shentong Metro (urban rail operation plus new energy), Beijing–Shanghai High-Speed Railway (high-speed passenger transport), Daqin Railway (railway freight, mainly coal), Guangshen Railway (railway passenger and freight transport), Tielong Logistics (special container transport and logistics), Xibu Chuangye (railway freight within Ningxia), Guanghui Logistics (freight on the Hongnao railway in Xinjiang, now trading as ST Guangwu) and China Railway Special Cargo (transport of commodity cars, cold-chain and outsize cargo, listed in 2021). The sample period is 2017–2025 (Table 1). Financial data come from annual reports, operating volumes from annual reports and announcements, and industry statistics from the association reports and railway bulletins cited above. Two caveats apply. Guanghui Logistics was administratively penalised by the CSRC in October 2024 for prematurely recognising revenue in its property business, and its 2023 annual report restated the 2022 figures; this paper uses the restated data (according to the annual report and the restatement announcement). Hongnao railway volumes for 2019–2021 follow the disclosure of Guanghui Energy and those from 2023 follow Guanghui Logistics announcements; the 2022 value is not disclosed precisely and is treated as missing, with the two calibres marked line by line in the data files. For China Railway Special Cargo the main operating indicator is the number of commodity cars dispatched (8.0587 million units in 2025), which is not comparable with freight tonnage; the firm is therefore excluded from the carbon intensity calculations and included only in the financial performance models. The eight firms differ widely in scale, business mix and financial profile (Table 2). Rather than compressing this heterogeneity into a composite performance score, as multi-criteria decision methods such as TOPSIS or data envelopment analysis would do, the design keeps firm identity explicit and lets firm fixed effects absorb time-invariant performance differences, so that the estimates read as within-firm changes around well-defined events rather than as cross-firm rankings.
Table 1.
Basic information on the sample listed companies.
Table 2.
Descriptive statistics of the sample firms, 2017–2025: mean ± SD [min, max] by firm.
Operating scales differ widely across the sample. In 2025 Daqin Railway recorded a revenue of about 77.65 billion CNY and net profit attributable to shareholders of about 5.90 billion CNY, the largest in the sample; Beijing–Shanghai High-Speed Railway recorded revenue of about 43.06 billion CNY and net profit of about 13.17 billion CNY, the most profitable; Shentong Metro recorded revenue of about 596 million CNY, the smallest. Treatment status and timing are set as follows: Shentong Metro from 2020, the first full operating year of its new energy business, and Beijing–Shanghai High-Speed Railway from 2022, the year of the green-electricity cooperation; the other six firms form the control group. Both treatment dates are firm decisions rather than external policy shocks, so self-selection cannot be ruled out: the timing of green investment may correlate with unobserved business conditions. Two institutional anchors nonetheless narrow the window for discretion. Shentong Metro’s new energy subsidiary was incorporated in late 2018 under Shanghai’s distributed photovoltaic promotion programme, which makes 2020 the first full operating year rather than a discretionary pick; Beijing–Shanghai HSR’s green-electricity cooperation in 2022 followed the national green-electricity trading pilots launched in 2021. The estimates below are therefore interpreted as associations around these events rather than as the effect of an exogenous treatment (Section 6.3).
3.2. Estimation of Carbon Intensity
Listed companies do not disclose operating emissions, so emissions are estimated from operating volumes and public factors. For the railway firms, converted turnover equals (passengers sent × national average trip length + freight sent × national average haul)/106—in million converted tonne-km—and CO2 equals converted turnover × the comprehensive energy intensity of national railways × 2.66 tCO2 per tonne of standard coal, where average trip length, average haul and energy intensity are taken from the railway statistical bulletins. For Shentong Metro, CO2 equals passenger trips × the national average metro electricity use per trip × 0.5568 kgCO2/kWh—where electricity use per trip is computed from the association’s statistics on total electricity use and ridership for the year—and 0.5568 kgCO2/kWh is the 2021 national average emission factor for electricity published by the Ministry of Ecology and Environment. Carbon intensity is defined as estimated CO2 over operating revenue (tCO2 per 10,000 CNY of revenue). Three properties of this estimator matter for what follows. First, the electricity factor and the railway energy intensity are national values common to all firms in a given year; in logarithmic form, such common factors are absorbed by the year fixed effects, so switching to year-varying national factors—the Ministry of Ecology and Environment and the National Bureau of Statistics published 0.5366 kgCO2/kWh for 2022 in December 2024—changes estimated levels but not the DID coefficients. The 2021 factor is a deliberate choice rather than a data constraint: it was the latest official national average when the panel was assembled, and since the factor enters all firms identically in a given year, the choice shifts levels only. Second, applying the national average energy intensity to every railway firm introduces firm-specific level errors (a high-speed passenger line plausibly runs below the freight-heavy national average), but time-invariant level errors are absorbed by the firm fixed effects; bias would arise only if the treated firm’s measurement error trended differently around treatment, which the event study in Section 4.3 examines directly. Third, revenue is an imperfect denominator because it mixes transport and non-transport business; Section 4.2 therefore repeats the test with ln(CO2) as the outcome, which removes the denominator altogether. Estimates carry uncertainty proportional to the factor error: a ±10% error in the energy intensity factor shifts firm-level intensity by the same proportion but does not affect the sign or significance of the DID estimates. Throughout the paper, ‘authors’ estimates’ refers to values calculated from public data with the methods of this section, and ‘authors’ simulation’ refers to the scenario outputs of Section 5. What the estimator measures also delimits what the DID test can show. Estimated emissions are gross emissions implied by operating volumes at national-average intensities; they do not net out firm-specific purchases of green electricity or self-generated photovoltaic power, which current accounting rules would count as zero-emission. The DID coefficient therefore tests whether green practice has reached a scale that registers against volume-driven variation in gross emissions—not whether green electricity abates, which is an engineering identity. Firm-disclosed electricity and green-electricity figures would be needed for a direct test of the procurement margin, and Section 4.2 uses the disclosed figures of the treated firms to bound how large that margin currently is.
The main limitation is that Xibu Chuangye and Guanghui Logistics are regional short-haul freight carriers, and applying the national average haul probably overstates their turnover and emissions; a robustness regression that excludes Xibu Chuangye addresses this, and the results should be read as exploratory. The calibration is consistent with earlier studies. The 0.5568 kgCO2/kWh factor used here is the 2021 national average, close to the 2022 national factor of 0.581 kgCO2/kWh used in life-cycle studies. At the 2025 national railway energy intensity of 3.90 tce per million converted tonne-km, emissions per unit of converted turnover are about 10.4 tCO2 per million converted tonne-km, near the lower bound of the 13.59–19.1 range reported in bureau-level studies, which is what one would expect, since the national average mixes in passenger services while the bureau-level figures are dominated by coal freight. The magnitude of the level error can be bounded. Bureau-level estimates with freight-dominated profiles range from 13.59 to 19.1 tCO2 per million converted tonne-km [20,21], that is, 1.31–1.84 times the national-average value of 10.4 used here; conversely, if the true intensity of a passenger-dominated high-speed line were 60–80% of the national average (an illustrative assumption), the measured level for such a firm would be overstated by roughly 25–67%. Because these ratios are time-invariant, they shift firm intercepts, not slopes: the national energy-intensity factor itself moved by only −0.01 log points per year on average over 2021–2025—an order of magnitude below the standard error of the DID coefficient—so differential factor drift cannot account for the estimates.
3.3. Model Specification and Variables
A two-way fixed-effects DID model is specified. The specification is deliberately standard: a canonical estimator keeps the results directly comparable with the city-level DID literature cited in Section 1 and keeps the contribution of the paper in the measurement and the data rather than in estimator novelty:
where the dependent variables Y are ln(carbon intensity), ROA (net profit attributable to shareholders over total assets) and the gross margin; DIDit is the treated × post interaction; the controls X are ln(total assets), the debt-to-asset ratio, and ln(number of employees); αi and λt are firm and year fixed effects; and standard errors are clustered at the firm level (CR1). The specification follows common practice for staggered and multi-period DID in transport studies. Because Shentong Metro disclosed ridership only from 2020, it has no pre-treatment observations in the intensity model, and the carbon-intensity DID is in effect identified by Beijing–Shanghai High-Speed Railway alone (42 observations, 6 firms); the financial performance models use all eight firms (72 observations). Identification checks comprise an event study with the year before treatment as the base (parallel trends), a placebo test with 500 random permutations of treated status and timing, and a robustness regression excluding Xibu Chuangye. Because the intensity model is identified by a single treated firm whose treatment date is self-selected, the DID results are reported as an exploratory descriptive comparison rather than definitive causal estimates. Pre-treatment balance is limited. Over 2017–2021, standardised mean differences between the treated firm and the five control firms in the intensity sample are −2.64 for ln carbon intensity, +2.73 for ln total assets, −3.16 for ln staff and +1.17 for the gross margin, with ROA closer (−0.18) and the debt ratio moderate (−0.42); in the eight-firm financial sample the differences are +0.12 for ln total assets, −2.62 for ln staff, +0.62 for the debt ratio and −0.39 for ROA. Firm and year fixed effects and the control variables absorb time-invariant gaps and common shocks, but the remaining imbalance is a further reason to read the estimates descriptively. Inference is supplemented with wild cluster bootstrap p-values computed by enumerating all 2G Rademacher sign combinations of cluster weights (Section 4.2). A synthetic control design was considered and set aside: with five candidate controls that differ sharply in scale and business mix, and with the pandemic dominating pre-treatment outcomes, synthetic weights would interpolate between dissimilar firms and lend the counterfactual a false sense of precision. Reporting the imbalance explicitly and relying on fixed effects with conservative inference is the more honest presentation of what this sample can support.
Yit = αi + λt + βDIDit + γ’Xit + εit
4. Empirical Results
4.1. Descriptive Statistics
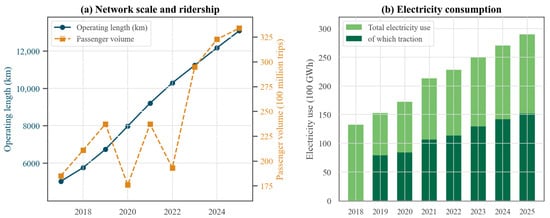
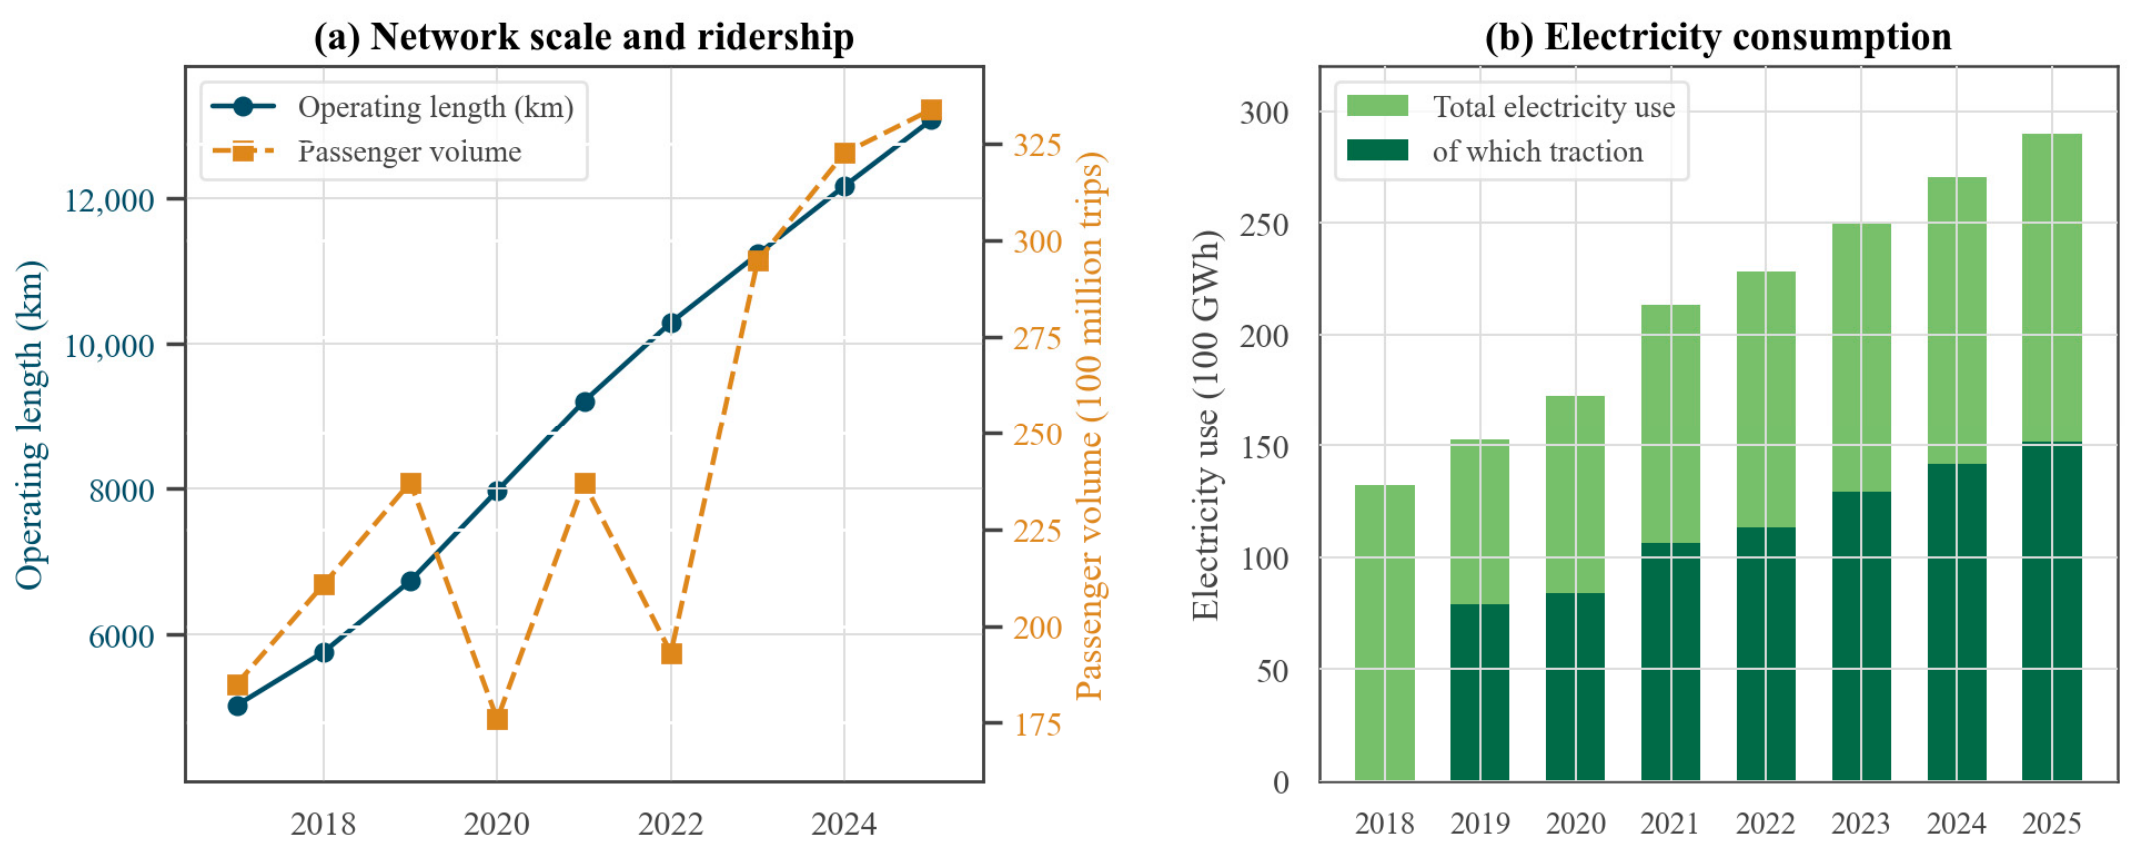
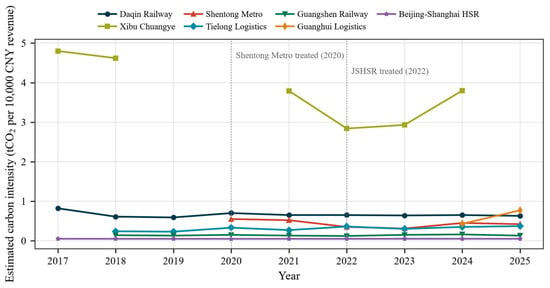
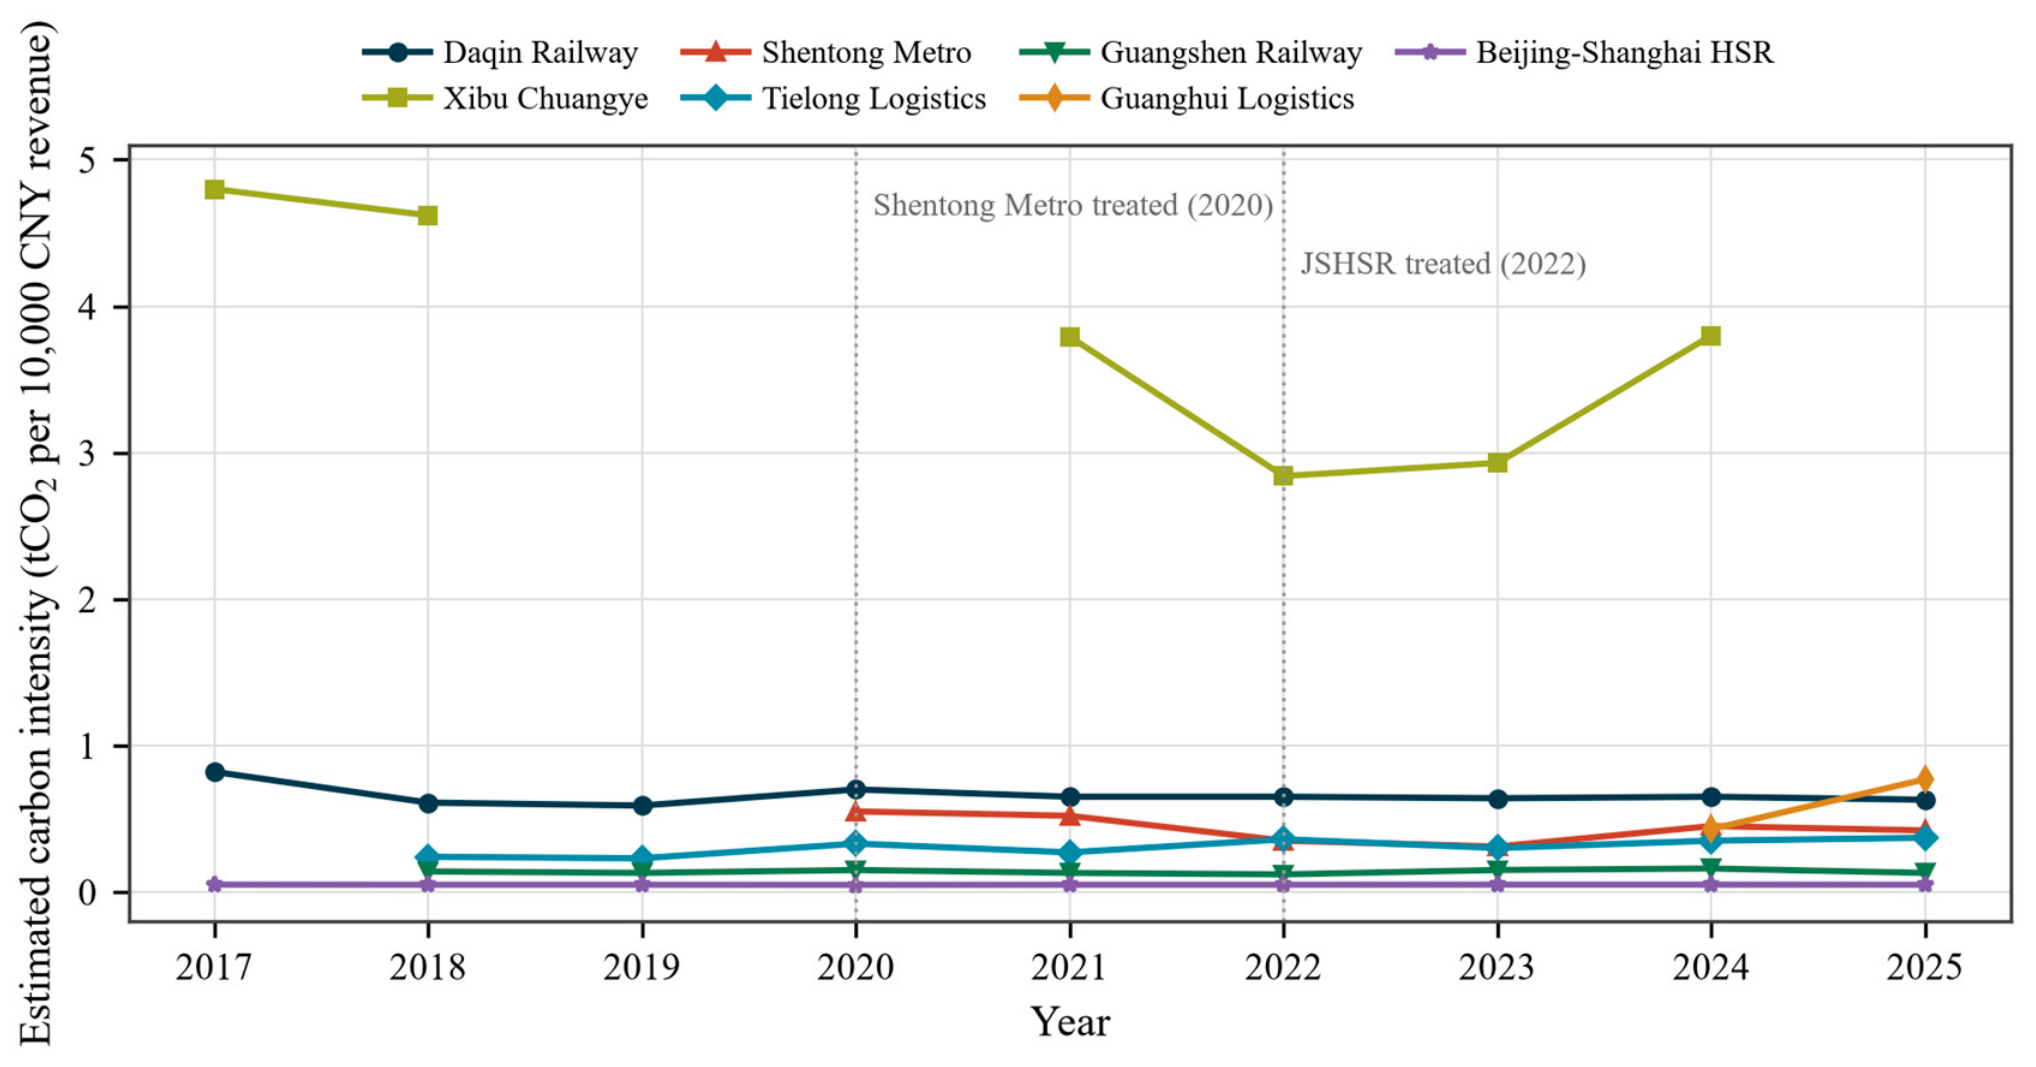
Table 2 reports sample-period means of the main indicators. Estimated carbon intensity differs sharply across firms: Beijing–Shanghai High-Speed Railway is the lowest at 0.049 tCO2 per 10,000 CNY of revenue and Xibu Chuangye the highest at 3.805, the latter reflecting the likely overstatement of turnover under a regional short-haul profile. Table 2 reports the within-firm standard deviation and range alongside the mean, which shows that the cross-firm differences dwarf within-firm variation. Figure 1 shows that national urban rail operating length and ridership nearly doubled between 2017 and 2025, with electricity use climbing in step. Figure 2 shows that firm-level intensity drifted down or stayed flat at a low level, with the centre of Shentong Metro’s intensity shifting down after 2020.
Figure 1.
Operating scale and electricity consumption of China’s urban rail transit, 2017–2025. Source: annual statistical and analytical reports on urban rail transit, China Association of Metros.
Figure 2.
Estimated carbon intensity of the sample listed rail transit companies. Carbon intensity is estimated as described in Section 3.2. Source: authors’ estimates.
4.2. Baseline Estimates
Table 3 reports the DID estimates, which, given the single treated firm, should be read as a descriptive comparison around the green-practice events. In column (1), the carbon-intensity model, the DID coefficient is 0.225 with a cluster-robust standard error of 0.279 (p = 0.421) and is statistically insignificant; excluding Xibu Chuangye in column (2) gives 0.188 (p = 0.540) and leaves the conclusion unchanged. Replacing the revenue-deflated outcome with ln(CO2), which removes the denominator and the dilution concern, gives 0.371 (p = 0.253), again insignificant. In columns (3) and (4), the effects on ROA (β = 0.006, p = 0.477) and on the gross margin (β = 0.087, p = 0.245) are insignificant as well. Because inference with six clusters is fragile, wild cluster bootstrap p-values were computed by enumerating all Rademacher sign combinations (plus-one adjusted): 0.508 in column (1), 0.758 in column (2), 0.494 for ROA and 0.269 for the gross margin. The conclusions are unchanged under small-sample-robust inference.
Table 3.
Two-way fixed-effects DID estimates.
The explanation lies in treatment intensity. Beijing–Shanghai High-Speed Railway purchased 7339.30 MWh of green electricity in 2025, only about 1% of its estimated operating electricity use (according to the annual and sustainability reports). Shentong Metro’s photovoltaic output has grown fast, but it is booked mainly as revenue of the new energy business rather than as an abatement of the operator’s own emissions. Corporate green practice is still in its infancy and too small in scale to move firm-level carbon intensity by an identifiable margin. A decomposition confirms that scale, not direction, binds. Between 2022 and 2024 the treated firm’s estimated emissions rose by ln 1.02, of which the recovery of converted turnover from the pandemic trough accounts for about ln 1.04 (101%), while the national energy-intensity factor contributes −0.01; against volume swings of this size, abatement from a green-electricity share of about 1% cannot be identified statistically. The alternative reading that green abatement was offset by volume growth therefore reinforces, rather than contradicts, the conclusion that current practice is too small to register. This null result does not contradict the significant city-level evidence on metro opening, high-speed rail opening and network expansion: those estimates capture the macro effect of rail networks substituting for high-carbon travel, whereas this paper captures the net effect of green practices inside the operator’s own operations, which are two different margins. For the purposes of this paper, the null carries information: the abatement potential of current corporate practice is far from exhausted, and that is precisely what motivates the scaled-up settings of the scenario analysis in Section 5. H1 therefore receives no empirical support at the current scale of practice. A simple bound separates treatment intensity from measurement insensitivity: if the estimator netted out green electricity, the treated firm’s measured intensity after treatment would shift by at most about 1% (about 0.01 log points, the current green-electricity share), an order of magnitude below the standard error of 0.28; the null is therefore the expected outcome at current treatment intensity under any estimator of this class, not an artefact of a particular measurement choice.
4.3. Parallel Trends and Placebo Tests
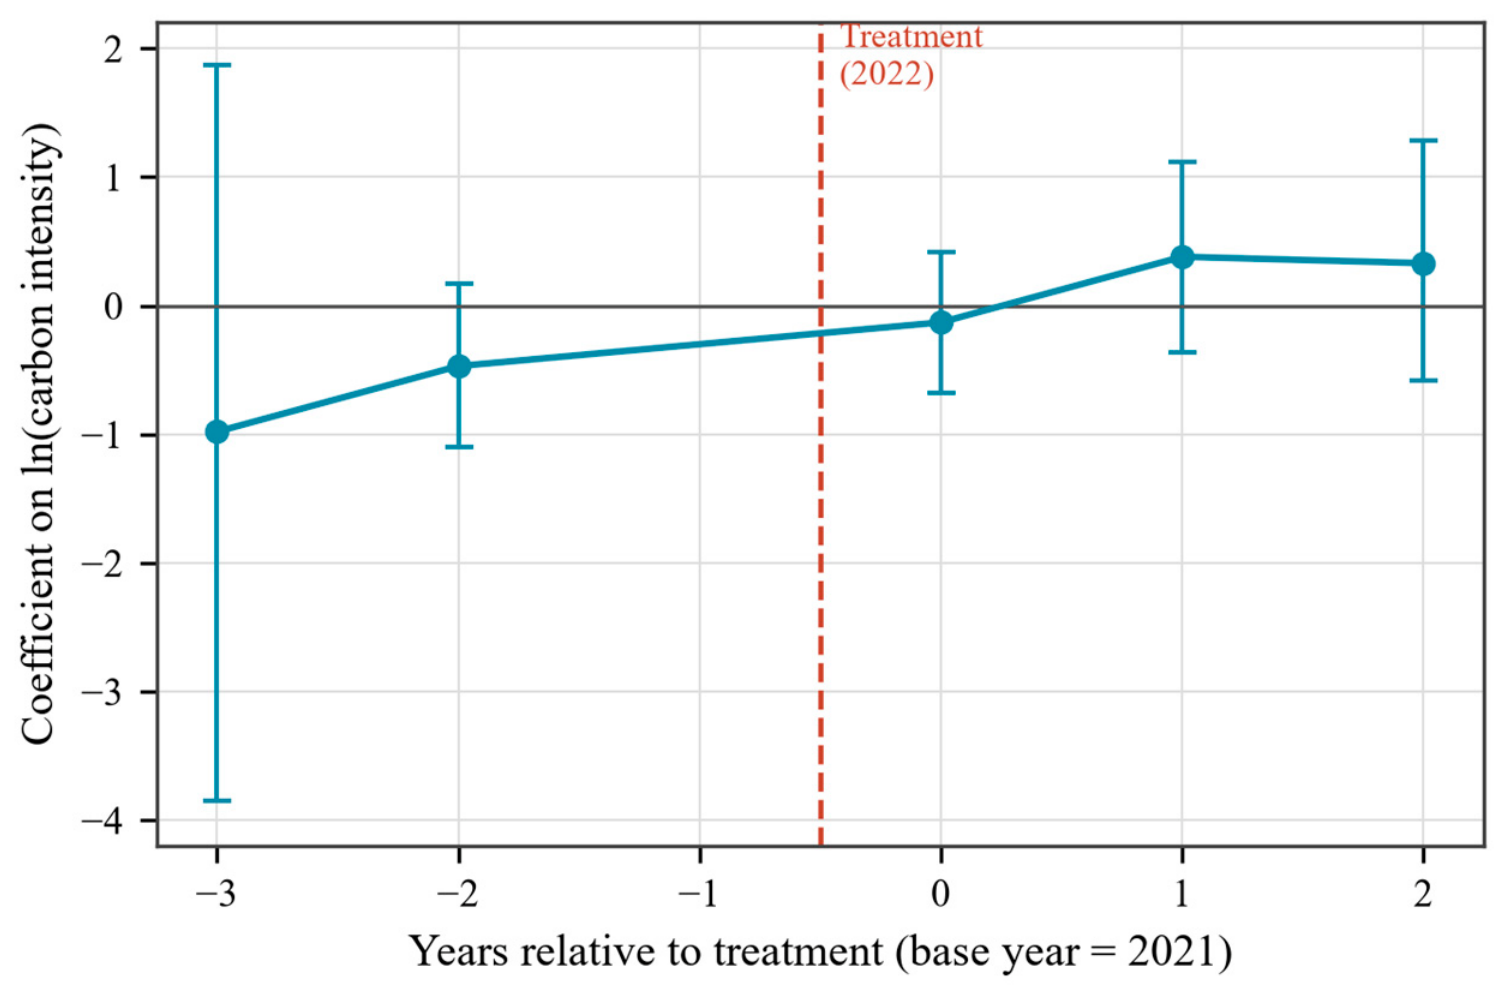
Figure 3 reports the event study with 2021, the year before treatment, as the base. The coefficient at lead 2 is insignificant, and so are the coefficients in the treatment year and afterwards, consistent with the baseline. The coefficient at lead 3 (2019) is large and carries a wide confidence interval, which reflects the disruption that the pandemic inflicted on intensity estimates through swings in ridership between 2020 and 2022; the parallel-trends assumption is supported outside that disturbed interval. In the placebo test, treated status and timing are randomly permuted 500 times. The placebo coefficients centre on zero, the true estimate (β = 0.225) lies inside the distribution, and the share of |placebo| ≥ |true| is 0.594. The baseline estimate is therefore statistically indistinguishable from random assignment under the null of no effect; the placebo exercise compares the estimate with noise under randomised assignment and cannot by itself rule out omitted variables. Given the small number of firms, the DID results should be read as exploratory, descriptive evidence (Section 6.3).
Figure 3.
Event study: change in carbon intensity around the green-electricity practice of Beijing–Shanghai HSR (base year = 2021). Source: authors’ estimates.
The central fact of this section is that existing green practices have not yet produced a statistically significant net effect on the aggregate carbon intensity or the financial performance of listed operators, and the reason is scale rather than direction. The new energy segment of Shentong Metro earned a net margin of about 42% in 2025 (net profit of 20.04 million CNY on revenue of 47.71 million CNY, according to the annual report), which shows that the photovoltaic business itself is economically sound at project level.
5. Scenario Simulation
5.1. Scenario Design and Parameters
Following the benchmark-plus-policy structure of the scenario literature, the simulation uses the actual 2025 operating and new energy data of Shentong Metro as the carrier; it is the only A-share listed company whose main business is urban rail operation and whose new energy disclosure is complete. The simulation covers 2026–2030, the 15th Five-Year Plan period. All base parameters come from public sources or are stated as assumptions (Table 4): 2025 revenue of 596.33 million CNY, net profit attributable to shareholders of 54.22 million CNY and 54.69 million passenger trips (annual report); a national average metro electricity use of 0.869 kWh per trip (association statistics for 2025); an electricity emission factor of 0.5568 kgCO2/kWh (Ministry of Ecology and Environment); an average on-line allowance price of 111 CNY/t in the Beijing carbon market in 2024 (Beijing Municipal Ecology and Environment Bureau); an average CCER price of 70.76 CNY/t in the national market in 2025 (Ministry of Ecology and Environment); an average green electricity price in Beijing of about 0.4 CNY/kWh over the past three years; a 2030 green-electricity target share of 40%; a photovoltaic yield of 1051 kWh/kWp per year and a new energy net margin of about 42% (2025 actuals); a traction share of 52.22%; and a technology saving rate of 10%. The traction share lies within the 50–53% range reported in measurement studies, and the assumed saving rate is well below the measured saving of permanent-magnet traction and similar technologies, which exceeds 20%; the parameters are thus conservative and the simulation results should be read as a lower bound on abatement. Shentong Metro is small—its 2025 revenue is about 0.8% of Daqin Railway’s and 1.4% of Beijing–Shanghai HSR’s—and is not claimed to be a statistically representative operator. It serves as the carrier because the parameters that drive the pathway mechanics are national rather than firm-specific: electricity use per trip is the national metro average, the emission factor is the national value and green-electricity accounting follows national rules. Two firm-specific features cut in known directions: its photovoltaic endowment is the largest in China’s rail transit sector, so PV-specific gains are best read as an upper bound for an average city, whereas its per-trip revenue of about 10.9 CNY includes non-fare business and exceeds the sector’s fare-only level, which makes the profit impacts conservative. Scale itself is not a parameter: the industry extrapolation in Section 5.3 multiplies national aggregates, not Shentong Metro’s own size. Every parameter is listed with its source in Table 4 so that the simulation can be reproduced exactly and so that assumptions are separated from observed inputs; Section 5.2 varies the parameters that drive the results. The 40% green-electricity target is demanding but grounded: it follows the appraisal basis applied to Beijing municipal state-owned enterprises; green-electricity trading has expanded rapidly since the national pilots of 2021; and Shentong Metro’s own photovoltaic build-out averaged about 9.6 MWp a year over 2019–2025, above the 5 MWp assumed here, so the supply trajectory of the carrier firm is consistent with the target. The simulation is a policy scenario exercise conditional on these assumptions, not a hypothesis test: it quantifies what each pathway would deliver if the assumptions hold, and the sensitivity analysis reports how the conclusions move when the key assumptions vary.
Table 4.
Base parameters of the scenario simulation and data sources.
Four scenarios are specified. S1 (business as usual) assumes no additional low-carbon action: ridership grows 5% a year, and unit electricity use and the emission factor stay constant. S2 (green electricity and technology) raises the green-electricity share year by year to 40% by 2030—with purchased green electricity counted as zero-emission under the accounting rules—adds 5 MWp of photovoltaic capacity a year, and extends traction retrofits to 50% of the network by 2030. S3 (carbon trading inclusion) puts the firm under quota management: the free allocation ratio starts at 95% and tightens by one percentage point a year, and the internalisation of carbon costs induces an additional 2% energy saving a year. S4 (synergy) combines S2 and S3. Accounting rules follow current practice: purchased green electricity is counted as zero-emission (Beijing rule since 2023); photovoltaic output is sold to the operator under the business model and enters as new energy revenue; and CCER offsets may not exceed 5% of the allowances to be surrendered (national market rule).
The accounting rules deserve explicit discussion because they shape the interpretation of the results. Zero-emission accounting of purchased green electricity is the regulatory reality under which firms report and are assessed: it is the rule in force in the Beijing market since 2023 and it is what would appear on a firm’s carbon ledger. Additionality at the system level is a separate question. Purchased green electricity redistributes existing renewable generation unless it induces new capacity, so the economy-wide abatement behind the ledger figure depends on the expansion of renewable supply; the photovoltaic component of the pathway is additional by construction, since it builds new capacity, whereas the purchased component should be read as compliance abatement whose system value grows as the green-electricity market expands. The intensity reductions reported below are therefore ledger figures under current accounting rules, which is exactly the magnitude that determines a firm’s quota position, its compliance cost and its incentive to procure green electricity.
5.2. Simulation Results
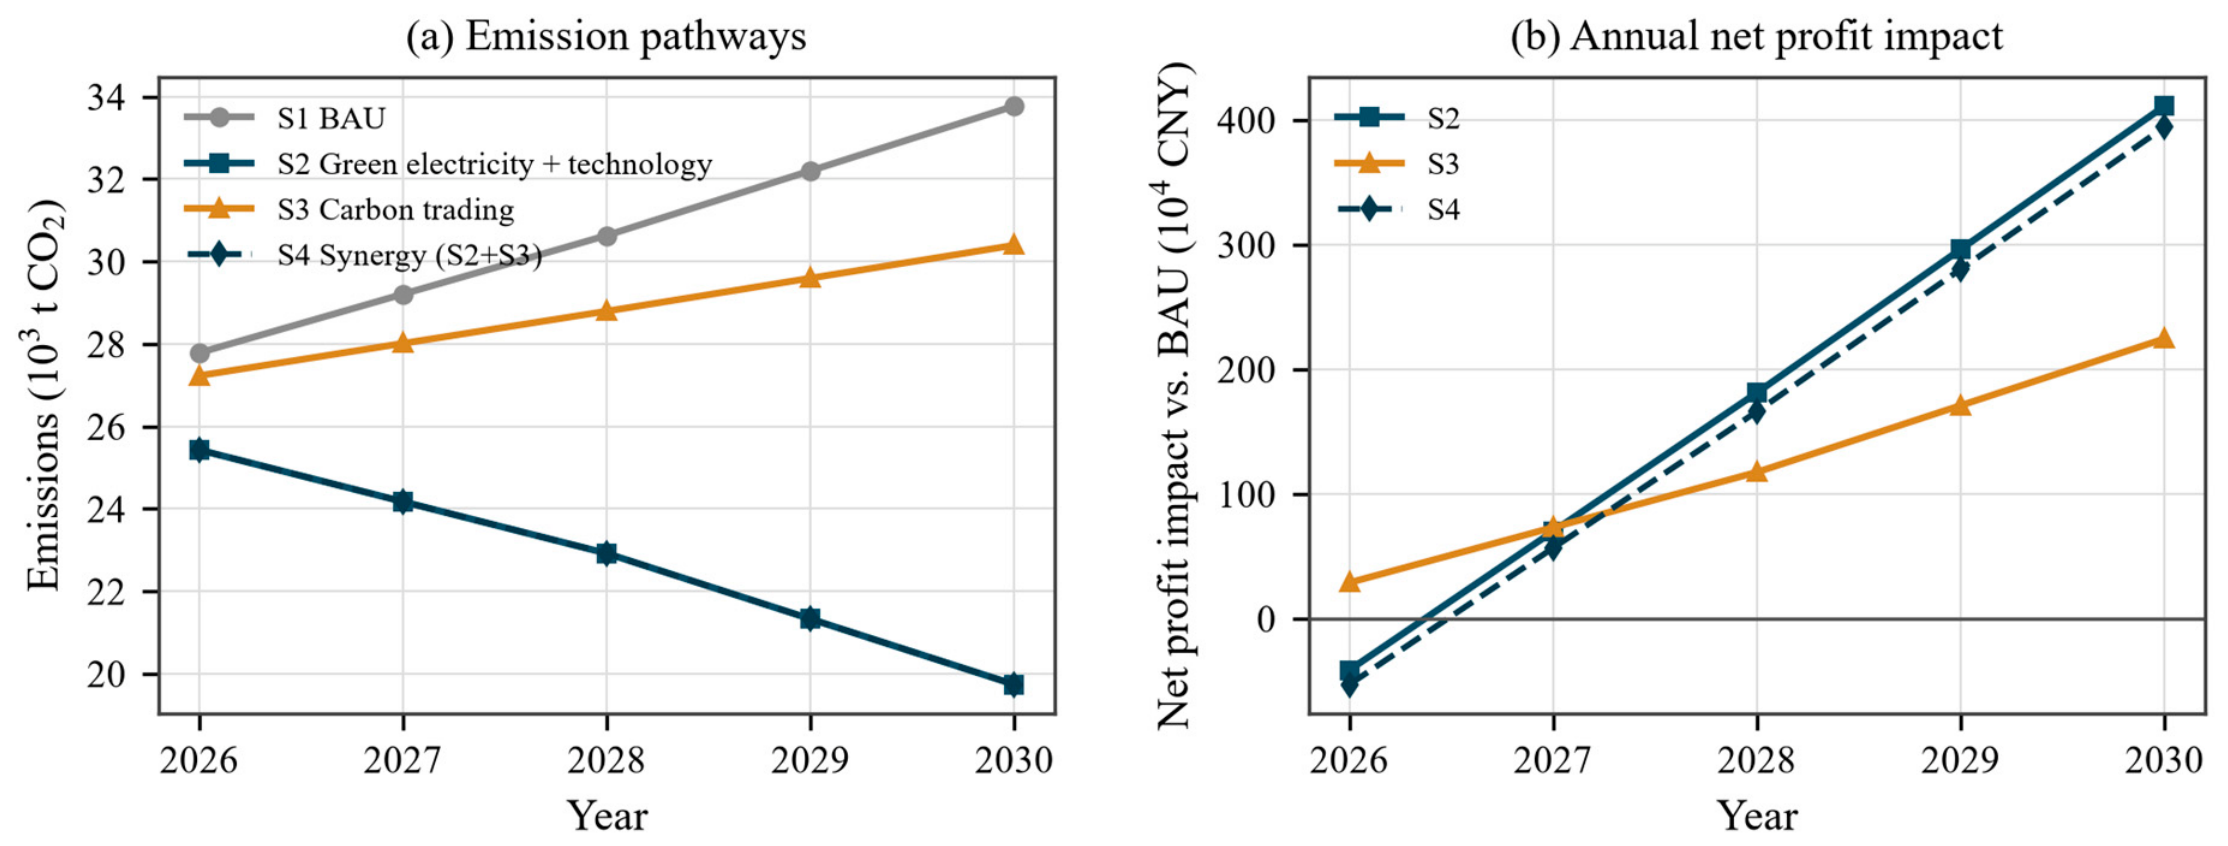
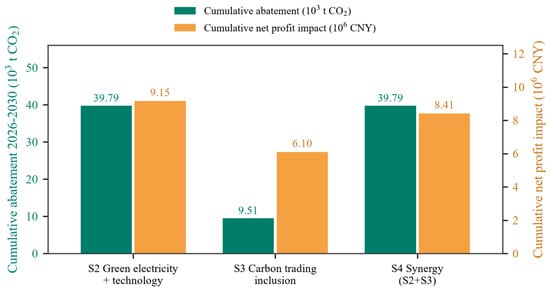
Table 5 and Figure 4 report the results. On abatement, S2 and S4 clearly outperform S3. By 2030, carbon intensity falls to 2.83 tCO2 per 10,000 passenger trips, 41.6% below the baseline, with cumulative abatement of about 39.8 thousand tonnes of CO2 over 2026–2030; S3 abates about 9.5 thousand tonnes cumulatively and lowers intensity by 10.0%. On the economic side, S2 adds about 4.11 million CNY to annual net profit by 2030 and 9.15 million CNY cumulatively over five years, as new energy revenue and electricity savings more than cover the technology outlay; S3 adds 6.10 million CNY cumulatively under the assumption that energy savings exceed carbon costs; S4 adds 8.41 million CNY, slightly less than S2 because the firm bears carbon costs, but it is more resilient if quotas tighten further or carbon prices rise (Figure 5). Sensitivity checks support these rankings.
Table 5.
Summary of simulation results for the four scenarios (2026, 2028 and 2030).
Figure 4.
Emission pathways and economic effects of the four scenarios, 2026–2030. Source: authors’ simulation.
Figure 5.
Cumulative effects of the scenarios over 2026–2030. Source: authors’ simulation.
Varying annual ridership growth between 3% and 7% (baseline 5%) leaves the 2030 intensity cut of S2 unchanged at 41.6%—the intensity ratio is scale-invariant—and moves cumulative abatement only between 37.0 and 42.7 thousand tonnes for S2 (8.9–10.2 thousand tonnes for S3) and the five-year profit gain between 8.95 and 9.36 million CNY, so the ordering S2 ≈ S4 ≫ S3 is robust to the volume assumption. The robustness is two-fold: the 2030 intensity cut is scale-invariant by construction, since ridership cancels in the ratio of intensities, and the cumulative magnitudes move by less than ±10% across the volume range, far from any sign or ranking reversal. Under the stated assumptions, inclusion in carbon trading produces additional abatement and net gains through cost internalisation, consistent with the mechanism underlying H2; the green electricity and technology pathway abates most, and the combined pathway performs best overall once policy adaptability is taken into account, consistent with H3. These are hypothetical outcomes conditional on the assumptions: the simulation shows what the mechanisms would deliver if they operate as specified, not that they do. The finding is consistent with earlier work on carbon trading in railway freight: with well-designed allowances and prices, transport firms can earn surplus revenue from quotas.
Two features of Table 5 warrant explanation. First, S4 abates exactly as much as S2. This is a deliberate, conservative modelling choice: under the zero-emission accounting rule, the emissions that carbon-cost-induced saving would remove are already zero-rated once the green-electricity share rises, and the quota gap under S4 is small (carbon costs of 17.9 × 10⁴ CNY in 2030 against 27.6 × 10⁴ under S3), so the incremental incentive to save is weak and is set to zero to avoid double counting. As a verification, an alternative variant S4b that mechanically stacks the 2% annual induced saving on top of S2 abates 46.4 kt cumulatively, 6.7 kt more than S2—about 70% of S3′s standalone abatement, the remainder being covered by the zero rating—and raises the five-year profit gain to 15.48 million CNY; the ranking S2 ≈ S4 ≫ S3 is unchanged, and the simulation equations were re-verified line by line against the published code. Second, the value of the combination lies in resilience rather than in additional abatement. The sensitivity analysis was extended beyond ridership growth to the parameters that drive the results. Carbon prices of 60–160 CNY/t move the five-year profit gain of S3 between 5.88 and 6.32 million CNY and that of S4 between 8.25 and 8.58 million CNY, without affecting abatement. Setting the green-electricity price equal to the conventional benchmark (0.4155 CNY/kWh) lowers the S2 profit gain from 9.15 to 8.11 million CNY—the 0.0155 CNY/kWh price advantage contributes only 1.04 million CNY over five years—so the profitability of S2 rests on photovoltaic net revenue and electricity savings, not on the green-electricity spread; even at 0.45 CNY/kWh the gain remains 5.80 million CNY. Doubling the pace of quota tightening to two percentage points a year reduces the gains to 5.61 (S3) and 8.05 (S4) million CNY.
Using the 2022 national emission factor (0.5366 kgCO2/kWh) or the life-cycle value (0.581) moves S2′s cumulative abatement between 38.3 and 41.5 kt. None of these variations changes signs or rankings. The assumed 2% carbon-cost-induced saving was varied as well: at 1% per year S3 abates 4.76 kt cumulatively and gains 2.51 million CNY, at 3% it abates 14.27 kt and gains 9.69 million CNY, and at 0% the pathway reduces to a pure compliance cost of −1.07 million CNY with no abatement. The outcomes of S3 are therefore transparently conditional on the induced-saving assumption, which is why they are reported as hypothetical outcomes rather than tested effects.
5.3. Industry-Level Extrapolation
Extending the S2 pathway to the industry: if the green-electricity share of national urban rail rose to 40%, the total electricity use of 29.008 billion kWh in 2025 and the 0.5568 kgCO2/kWh factor imply an annual abatement of about 6.46 million tonnes of CO2, worth about 720 million CNY a year at the Beijing carbon price of 111 CNY/t. Adding traction retrofits (a 10% saving over 50% of the network) would abate a further 0.42 million tonnes. Indirect electricity emissions account for close to four fifths of railway operating emissions, so green-electricity substitution is the most effective lever for the railway sector as well. Following the idea of coordinated pollution and carbon control, the key at the industry level is to build a mechanism that links green electricity, the carbon market and green certificates, so that abatement becomes measurable revenue for firms. The extrapolation is deliberately simple: it applies a uniform 40% share and the national average factor to all cities, although green-electricity endowments differ widely—eastern cities rely on inter-provincial green-electricity trading at a premium, whereas north-western cities can draw on local wind and solar at lower cost. The figure scales with the emission factor: at the 2022 national factor (0.5366 kgCO2/kWh) it is 6.23 Mt and at the life-cycle value (0.581) 6.74 Mt, so 6.2–6.7 Mt is the defensible range. Regional differences cut both ways: regions with coal-heavy grids gain more abatement per kWh of green electricity but face scarcer local renewable supply and higher procurement costs, whereas renewable-rich north-western regions gain less per kWh but procure at lower cost. Under the zero-emission accounting rule, the ledger abatement depends on the share achieved rather than on where the electricity is generated, so 6.46 Mt should be read as the national-average ledger estimate under uniform policy reach; what varies most by region is the cost of achieving the 40% share, not the abatement itself. Region-differentiated simulation is left to future work.
6. Conclusions and Policy Implications
6.1. Main Findings
Three findings stand out. First, the abatement delivered by existing green practices is small relative to the operating scale of listed rail companies, and the DID estimates detect no statistically significant net effect on carbon intensity (β = 0.225, p = 0.421; wild cluster bootstrap p = 0.508) or on financial performance. The result complements the significant city-level evidence on rail networks: substitution by the macro network abates visibly, while the abatement potential inside the operators’ own operations is far from realised. Second, the simulations show that the green electricity and technology pathway is the main abatement lever: by 2030 it cuts the carbon intensity of a representative metro operator by 41.6% relative to the baseline, abates about 39.8 thousand tonnes of CO2 over five years and adds about 9.15 million CNY to cumulative net profit through new energy revenue and electricity savings, so abatement and profit improvement can go together. Third, under the stated assumptions, carbon trading inclusion abates about 9.5 thousand tonnes cumulatively as carbon costs induce energy saving, and the synergy pathway preserves the same abatement while strengthening cost resilience under tightening policy. Extrapolation suggests that a 40% green-electricity share in national urban rail would abate about 6.46 million tonnes of CO2 a year, roughly a tenth of the 2021 emissions of China’s railway operation sector—a scale reference across two distinct sectors, not an addition—so the industry-level value of green-electricity substitution is substantial. This direction is consistent with bureau-level evidence that indirect emissions from electric traction and net purchased electricity dominate, which makes decarbonising the electricity supply the focus of operating abatement. Taken together, the findings show how firm-level measurement can support the monitoring of sustainability performance in rail transit and how green-electricity substitution and carbon trading can be combined into a coherent sustainable-transition pathway for the industry.
6.2. Policy Implications
The results connect directly to the Sustainable Development Goals. Scaling up green electricity and distributed photovoltaics serves SDG 7 (Affordable and Clean Energy); traction retrofits and the integration of energy and transport infrastructure serve SDG 9 (Industry, Innovation and Infrastructure); cleaner urban rail operations serve SDG 11 (Sustainable Cities and Communities); and the quantified abatement pathways and the design of carbon-market inclusion serve SDG 13 (Climate Action). The policy implications below follow this structure.
At the firm level, green electricity and distributed photovoltaics should be scaled up first. The Shentong model of photovoltaics plus metro can be replicated by making full use of depot rooftops, elevated stations and land along lines; the share of green electricity purchased should enter corporate energy strategy and performance appraisal, with long-term power purchase agreements locking in prices; and retrofits such as permanent-magnet traction and regenerative braking recovery should proceed in step, with measured savings above 20% on existing networks.
At the industry level, the green electricity, green certificate and carbon market mechanisms need to be coordinated. Metro operators could take part in green electricity trading and CCER development collectively, and the abatement from photovoltaics could be developed into tradable carbon assets. Industry associations could take the lead in drawing up accounting rules for operating emissions and green electricity consumption in urban rail, unifying calibres and lowering transaction costs. The concrete mix should differ by region. In eastern cities with mature trading markets, the priority is aggregated green-electricity purchasing and long-term power purchase agreements, because local renewable resources are limited and green power carries a premium. In central and western cities with wind and solar endowments, self-built distributed photovoltaics with storage are usually the cheaper route and can proceed before trading markets deepen. In smaller cities under fiscal pressure, efficiency retrofits with short payback periods should come first, with market-based instruments phased in as local carbon and electricity markets mature.
At the policy level, rail operating firms should be brought into the carbon market steadily, with transition arrangements. Beijing already manages five rail firms under its quota system; other cities that follow are advised to set reasonable free allocation ratios and gradual tightening schedules, so as to avoid cost shocks to firms with a public service mandate. Allowance auctioning and other cost-saving devices deserve consideration; general-equilibrium estimates suggest that auctioning can cut economy-wide costs by about 30%. The supply of green electricity trading should expand, grid connection and subsidies for distributed photovoltaics along rail lines should be eased, and abatement performance should enter green transport appraisal.
6.3. Limitations and Future Research
Several limitations remain. First, emissions are estimated from operating volumes; accuracy would improve if firms disclosed measured emissions, and passenger- and freight-specific energy intensities would remove the level errors of the national-factor method. Second, the DID evidence is weak by construction: the intensity model is identified by a single treated firm whose treatment date is self-selected, and the control firms differ in scale and business mix, so the estimates are reported as an exploratory descriptive comparison. More exogenous variation will become available as municipal carbon markets bring rail operators under quota management—Beijing has already included five—and event-study designs around those inclusion dates are a promising extension. Third, the simulation is carried by one small operator and extrapolated under uniform regional assumptions; differentiating green-electricity endowments and carbon-market coverage by region would sharpen the industry estimates. Future work could also compare listed with unlisted operators, refine the accounting of green certificate revenue, and examine carbon accounting treatment. Fourth, the emission estimator does not observe firms’ green-electricity procurement; if listed operators disclosed electricity use and green-electricity purchases in a standardised format, the procurement margin could be tested directly rather than bounded.
Author Contributions
Y.L.: Conceptualization, Methodology, Supervision, Funding acquisition, Writing—review and editing. H.W.: Conceptualisation, Data curation, Formal analysis, Methodology, Software, Visualisation, Writing—original draft. X.C.: Investigation, Resources, Validation, Writing—review and editing. Q.L.: Data curation, Investigation, Validation. All authors have read and agreed to the published version of the manuscript.
Funding
Key Project of the Beijing Social Science Fund, “Research on the Mechanism, Effects and Pathways of Coordinated Promotion of Carbon Reduction, Pollution Reduction, and Green Growth in the Capital from the Perspective of New Quality Productive Forces” (24GLA007).
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The data that support the findings of this study were derived from public sources (annual and sustainability reports of listed companies, statistical reports of the China Association of Metros and statistical bulletins of the National Railway Administration), which are publicly available. The data presented in this study are available on request from the corresponding author due to privacy restrictions. Declaration of generative AI and AI-assisted technologies in the manuscript preparation process: During the preparation of this work the author(s) used basic grammar and spelling checking tools only. No generative AI or AI-assisted technologies were used for content creation or scientific writing. After using these basic tools, the author(s) reviewed and edited the content as needed and take(s) full responsibility for the content of the published article.
Conflicts of Interest
Author Xi Chen and Qiuping Leng was employed by the company CTC Eco-Environmental Protection Technology Research Institute Co., Ltd., Beijing, China. The remaining authors declare that the research was conducted in the absence of any commercial or financial relationships that could be construed as a potential conflict of interest.
References
- China Association of Metros. Annual Statistics and Analysis Report on Urban Rail Transit (2025); China Association of Metros: Beijing, China, 2026. (In Chinese) [Google Scholar]
- National Railway Administration. Statistical Bulletin on Railway Development (2025); National Railway Administration: Beijing, China, 2026. (In Chinese) [Google Scholar]
- Pu, J.; Cai, C.; Guo, R.; Su, J.; Lin, R.; Liu, J.; Peng, K.; Huang, C.; Huang, X. Carbon emissions of urban rail transit in Chinese cities: A comprehensive analysis. Sci. Total Environ. 2024, 921, 171092. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Li, M.; Zhu, Z.; Liu, Q.; Du, P.; Xiong, X.; Sun, J.; Wang, Y. Spatiotemporal heterogeneities of carbon emissions and driving factors of railway sector in China. Environ. Eng. 2026, 44, 225–235. (In Chinese) [Google Scholar]
- Hua, Z.; Zhou, B.; Chan, K.W.; Zhang, C.; Cao, Y.; Wang, P.; Xia, M. A progressive polyhedral approximation method for nonlinear PDE-constrained electricity-water nexus dispatch. IEEE Trans. Smart Grid 2025, 16, 2703–2706. [Google Scholar] [CrossRef] [Scilit]
- Wang, Y.; Zhou, B.; Xu, Y.; Chung, C.Y.; Yang, Y.; Yuan, Z.; Hu, C. Spatio-temporal power outage risk prediction for interdependent urban electricity and drainage networks under rainstorm disasters. IEEE Trans. Smart Grid 2026, 17, 2888–2902. [Google Scholar] [CrossRef] [Scilit]
- Gendron-Carrier, N.; Gonzalez-Navarro, M.; Polloni, S.; Turner, M. Subways and urban air pollution. Am. Econ. J. Appl. Econ. 2022, 14, 164–196. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Xu, C.; Xu, Z. Mechanisms and effects of the influence of opening high-speed railway on urban carbon emission under the goal of “carbon peaking and carbon neutrality”. J. Chang. Univ. Sci. Technol. 2023, 38, 117–130. (In Chinese) [Google Scholar]
- Huang, H.; Xie, Y. Research on Carbon Emission Reduction Effect of High-Speed Rail Opening: The Constraints of both Economic and Environmental Objectives. J. Environ. Econ. 2022, 7, 97–118. (In Chinese) [Google Scholar] [CrossRef]
- Gao, Z.; Wang, Y. A Study on the Carbon Emission Reduction Effect of Subway Network Development. J. Finance Econ. 2026, 52, 64–78. (In Chinese) [Google Scholar]
- Xu, S.; Chen, Y.; Liu, M. Can urban rail transit in China reduce carbon dioxide emissions? An investigation of the resource allocation perspective. Sustainability 2025, 17, 3901. [Google Scholar] [CrossRef] [Scilit]
- Qiu, Z.; Liu, D.; Liao, Q. Can the opening of China railway express reduce urban carbon emissions? A difference-in-differences analysis in China. Front. Environ. Sci. 2023, 10, 1073208. [Google Scholar] [CrossRef] [Scilit]
- Barwick, P.J.; Donaldson, D.; Li, S.; Lin, Y.; Rao, D. Transportation Networks, Short-Term Mobility, and Pollution Exposure: Evidence from High-Speed Rail in China; NBER Working Paper No. 30462; National Bureau of Economic Research: Cambridge, MA, USA, 2022. [Google Scholar] [CrossRef] [Scilit]
- Fang, H.; Li, M.; Wang, L.; Yang, Z. High-Speed Rail and China’s Electric Vehicle Adoption Miracle; NBER Working Paper No. 33489; National Bureau of Economic Research: Cambridge, MA, USA, 2025. [Google Scholar] [CrossRef] [Scilit]
- Yuan, Z.; Yuan, X.; Yang, Y.; Chen, J.; Huang, S.; Nie, Y.; Cao, M.; Chen, L. Review on Research of Low-Carbon Effects in Urban Rail Transit. Railw. Transp. Econ. 2024, 46, 8–23, 57. (In Chinese) [Google Scholar]
- Chen, K.; Zhou, D.; Su, Y.; Duan, H.; Chen, X. Research on Carbon Emission Intensity and Reduction Potentials of Urban Rail Transit Life Cycle. Railw. Stand. Des. 2022, 66, 1–7. (In Chinese) [Google Scholar]
- Yang, Y.; Wang, X.; Yuan, Z.; Chen, J.; Na, Y. Calculation for Carbon Emission Reduction Effect of Urban Rail Transit Based on Carbon Recovery Period Theory. J. Transp. Syst. Eng. Inf. Technol. 2023, 23, 1–11. (In Chinese) [Google Scholar]
- Li, X.; Wang, L.; Luan, C.; Yu, Q.; Xie, J.; Luo, C. Whole Life-cycle Carbon Emissions Based on Actual Metro Lines. Urban Rapid Rail Transit 2024, 37, 82–87. (In Chinese) [Google Scholar]
- Li, Y.; Yang, Y.; Wen, Y.; Yu, H. Prediction of Carbon Emissions of the Urban Rail Transit System during Its Operation Period and Research on Carbon Reduction Measures. Rail Transit Equip. Technol. 2025, 33, 7–12. (In Chinese) [Google Scholar]
- Liang, Y. Study on the Characteristics of Carbon Emissions from Regional High-speed Railway Operations and Energy-Saving and Carbon Reduction Strategies. Railw. Energy Sav. Environ. Prot. Occup. Saf. Health 2025, 15, 7–14. (In Chinese) [Google Scholar]
- Ding, Z.; Zhang, H.; Cao, B.; Yin, S.; Dong, J.; Xu, L.; Yao, S. Analysis on Carbon Emission Characteristics of Railway Transport Enterprises. China Railw. 2024, 108–114. (In Chinese) [Google Scholar]
- Zhao, R.; Zhao, Y.; Xiong, X.; Tang, Y. Measurement of Carbon Emission Efficiency and Analysis of Influencing Factors in Railway Transportation Enterprise Based on SBM-Malmquist-Tobit Model. Railw. Transp. Econ. 2025, 47, 11–23. (In Chinese) [Google Scholar]
- Yue, Y.; Yang, X.; Zhou, H.; Zheng, Y.; Xiu, G. Analysis of the contribution of rail transit to carbon emission reduction of urban transportation: A case study of Shanghai. Chin. J. Environ. Eng. 2025, 19, 548–558. (In Chinese) [Google Scholar]
- Li, L.; Hu, J.; Shao, D. Effects of accelerated development of urban rail transit in Shanghai before the World Expo on greenhouse gas emission reduction. China Environ. Sci. 2012, 32, 1141–1147. (In Chinese) [Google Scholar]
- Chen, B.; Lin, Y. Construction of a prediction model for energy consumption in urban rail transit operations using a bottom-up approach. Energies 2025, 18, 888. [Google Scholar] [CrossRef] [Scilit]
- Wang, S.; Kuai, L. Driving factors and peaking path of CO2 emissions for China’s transportation sector. Resour. Sci. 2022, 44, 2415–2427. (In Chinese) [Google Scholar] [CrossRef] [Scilit]
- Goulder, L.H.; Long, X.; Lu, J.; Morgenstern, R.D. China’s unconventional nationwide CO2 emissions trading system: Cost-effectiveness and distributional impacts. J. Environ. Econ. Manag. 2022, 111, 102561. [Google Scholar] [CrossRef] [Scilit]
- Goulder, L.H.; Long, X.; Qu, C.; Zhang, D. China’s nationwide CO2 emissions trading system: A general equilibrium assessment. Am. Econ. J. Econ. Policy 2026, 18, 32–62. [Google Scholar] [CrossRef] [Scilit]
- Long, X.; Astier, N.; Zhang, D. Is broader trading welfare improving for emission trading systems? J. Environ. Econ. Manag. 2025, 130, 103110. [Google Scholar] [CrossRef] [Scilit]
- Wei, X.; Wang, H. Research on China’s railway freight pricing under a carbon emissions trading mechanism. Sustainability 2025, 17, 5265. [Google Scholar] [CrossRef] [Scilit]
- Barwick, P.J.; Li, S.; Waxman, A.; Wu, J.; Xia, T. Efficiency and equity impacts of urban transportation policies with equilibrium sorting. Am. Econ. Rev. 2024a, 114, 3161–3205. [Google Scholar] [CrossRef] [Scilit]
- Brancaccio, G.; Kalouptsidi, M.; Papageorgiou, T.; Rosaia, N. Search frictions and efficiency in decentralized transport markets. Q. J. Econ. 2023, 138, 2451–2503. [Google Scholar] [CrossRef] [Scilit]
- Hu, J.; Yu, X.; Han, Y. Can ESG Rating Promote Green Transformation of Enterprises? A Validation Based on the Time-Varying DID Model. J. Quant. Technol. Econ. 2023, 40, 90–111. (In Chinese) [Google Scholar]
- Barwick, P.J.; Li, S.; Lin, L.; Zou, E.Y. From fog to smog: The value of pollution information. Am. Econ. Rev. 2024b, 114, 1338–1381. [Google Scholar] [CrossRef] [Scilit]
- Bushnell, J.B.; Muehlegger, E.; Rapson, D.S. Energy Prices and Electric Vehicle Adoption; NBER Working Paper No. 29842; National Bureau of Economic Research: Cambridge, MA, USA, 2022. [Google Scholar] [CrossRef] [Scilit]
- Xu, Z. Study on Carbon Emission Efficiency Level and Influencing Factors of European Union Railway Industry. Railw. Econ. Res. 2025, 3, 38–49, 80. (In Chinese) [Google Scholar] [CrossRef]
- Hong, J.; Li, Y.; Cai, W. Simulating China’s carbon emission peak path under different scenarios based on RICE-LEAP model. Resour. Sci. 2021, 43, 639–651. (In Chinese) [Google Scholar]
- Huang, Y.; Guo, H.; Liao, C.; Zhao, D. Study on low-carbon development path of urban transportation sector based on LEAP model: Take Guangzhou as an example. Clim. Change Res. 2019, 15, 670–683. (In Chinese) [Google Scholar]
- Zhu, C.; Yang, S.; Liu, P.; Wang, M. Study on carbon dioxide peak of transportation industry in China. J. Transp. Syst. Eng. Inf. Technol. 2022, 22, 291–299. (In Chinese) [Google Scholar]
- Zhu, L.; Liu, Z.; Wang, R.; Xiong, Q. Measurement of carbon emission reduction effect of China’s freight transportation structure optimization. J. Transp. Syst. Eng. Inf. Technol. 2022, 22, 309–315. (In Chinese) [Google Scholar]
- Su, T.; Zheng, L.; Li, Z. Pathways to carbon peaking for urban rail transit under the new situation. China Eng. Consult. 2023, 10, 68–72. (In Chinese) [Google Scholar]
- Deng, H.; Liang, Q.; Liu, L. Review and Prospect of Co-control for Reducing Pollution and Carbon Emissions in Transportation Industry. Chin. J. Environ. Manag. 2023, 15, 23–29. (In Chinese) [Google Scholar] [CrossRef]
- Tian, J.; Tong, Q.; Liang, D. Cost assessment and potential analysis of carbon emission reduction in China’s transportation sector. J. Beijing Jiaotong Univ. 2025, 24, 86–98. (In Chinese) [Google Scholar]
- Deng, W.; Dai, C.; Chen, W. Application of PV Generation in AC/DC Traction Power Supply System and the Key Problem Analysis under the Background of Rail Transit Energy Internet. Proc. CSEE 2019, 39, 5692–5702. (In Chinese) [Google Scholar]
- Zheng, X.; Zhuang, Y.; Xu, W. The Exemplary application and prospects of Distributed PV Generation in Shanghai Metro. Green Build. 2018, 10, 17–20. (In Chinese) [Google Scholar]
- Guan, B.; Yang, H.; Zhang, T.; Liu, X.; Wang, X. Technoeconomic analysis of a rooftop PV system in an elevated metro station for cost-effective operation and clean electrification. Renew. Energy 2024, 226, 120305. [Google Scholar] [CrossRef] [Scilit]
- Tian, C.; Zhang, X. Research and application of comprehensive energy-saving in urban rail transit under the ‘double carbon’ goals. Energy Conserv. 2026, 45, 153–156. (In Chinese) [Google Scholar]
- Li, Z.; Xia, X.; Zheng, X.; Bai, Y. Study on Energy Saving and Carbon Reduction Strategies of Beijing Rail Transit Driven by Multi-Technology Synergy. Energy Conserv. Environ. Prot. 2025, 3–9. (In Chinese) [Google Scholar]
- Cui, T.; Li, L.; Li, M. Application of a New Energy Technology in the Urban Rail Transit System. Urban Rapid Rail Transit 2022, 35, 19–24. (In Chinese) [Google Scholar]
- Shanghai Shentong Metro Co., Ltd. 2025 Annual Report; Shanghai Shentong Metro Co., Ltd.: Shanghai, China, 2026. (In Chinese) [Google Scholar]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.