1. Introduction
In the aftermath of the 2008 Global Financial Crisis (GFC), the banking sector has operated within a prolonged low-interest-rate environment driven by accommodative monetary policies (
Claessens et al., 2018;
Lopez et al., 2020). This macroeconomic shift has compressed net interest margins, weakening the traditional profitability of lending based activities (
Gehrig, 2015;
Savona, 2022). As a result, banks have been pressured to reconfigure their business models by reducing reliance on interest income and expanding non interest income (NNIN) sources to remain competitive (
Alzoubi, 2025;
Nisar et al., 2018). At the same time, post crisis regulatory reforms such as Basel II and Basel III introduced stricter capital requirements aimed at absorbing economic shocks. These reforms have also unintentionally encouraged banks to shift toward fee based activities to optimize capital usage (
Aderogba et al., 2025;
Alnabulsi et al., 2023;
Birindelli et al., 2022).
Despite its strategic appeal, the transition toward diversified business models presents a persistent theoretical and empirical paradox. From a resource-based view (RBV) perspective, bank performance depends on how efficiently resources such as human capital, cash assets, and technology are transformed into productive outputs (
Akinyemi, 2025;
Arbelo et al., 2020). However, extensive empirical evidence documents a diversification discount, particularly when potential gains are offset by exposure to volatile non interest activities (
Doan et al., 2018;
Guerry & Wallmeier, 2017;
Kim et al., 2022). Early studies show that greater engagement in non interest income often increases income volatility without delivering proportional performance improvements (
Stiroh, 2004;
Stiroh & Rumble, 2006). Evidence from emerging markets reinforces this ambiguity, as revenue diversification in ASEAN banking systems does not necessarily improve financial stability (
Lestari et al., 2023).
In parallel, the relationship between financial stability and market power remains contested. Market power is widely recognized as a key determinant of competitive strength (
Fukuyama & Tan, 2022). However, the quiet life hypothesis suggests that excessive stability or dominance may weaken managerial incentives to maintain operational discipline (
Ikeda et al., 2018;
Le et al., 2024). This concern is particularly relevant given that many studies rely on narrow efficiency measures, such as cost efficiency (
P. H. Nguyen & Pham, 2020) or technical efficiency linked to default risk (
Curi et al., 2015;
Maghyereh & Awartani, 2014). Such approaches may overlook broader performance trade-offs faced by banks.
The strategic environment is further complicated by rising institutional complexity and information asymmetry, especially in settings with weaker governance structures (
Chen et al., 2025;
Leonard et al., 2013). As banks expand their product portfolios and geographic reach, they develop increasingly complex organizational structures that obscure risk exposure and elevate coordination costs (
Buch & Goldberg, 2022;
Pham & Doan, 2023). These complexities generate governance challenges and increase compliance burdens, reducing organizational flexibility and limiting banks’ ability to translate strategic initiatives into gains in market power and efficiency (
Krause et al., 2017;
Olarewaju, 2018;
Palermo et al., 2017).
In response to these constraints, banks are undergoing a rapid digital transformation. Digitalization offers a mechanism to mitigate the diversification efficiency trade-off by reducing operational costs and improving service delivery (
Beccalli, 2007;
Manta et al., 2024). At the same time, competition from financial technology (FinTech) and big technology (BigTech)firms poses significant challenges for traditional banks, particularly those constrained by legacy systems (
Karim & Lucey, 2024;
Vives, 2019). While digital technologies can strengthen efficiency and competitive positioning (
Y. Li et al., 2025;
Shanti et al., 2024), they also involve high investment costs and heightened data security risks, making their net performance effects uncertain (
Bueno et al., 2024;
Varma et al., 2022).
A critical research gap emerges from this literature. Most existing studies examine bank performance through isolated efficiency dimensions, such as cost efficiency (
P. H. Nguyen & Pham, 2020), profit efficiency (
Arbelo et al., 2020), or technical efficiency (
Curi et al., 2015). This fragmented approach fails to capture the complex trade-offs inherent in modern banking. A bank may perform well in technical efficiency while suffering from allocative inefficiency due to suboptimal capital allocation or scale inefficiency driven by excessive diversification. Moreover, limited attention has been given to the joint roles of internal digital transformation maturity and external market digitalization as conditioning factors within a multidimensional efficiency framework.
The primary objective of this study is to assess how banks navigate the dual strategic challenge of securing market power while optimizing multidimensional operational efficiency, comprising technical, scale, and allocative efficiency, within emerging and transitional economies. The analysis focuses on two distinct regions: Association of Southeast Asian Nations (ASEAN) banking systems, characterized by rapid fintech adoption and expanding digital infrastructure (
Khan et al., 2021), and the Middle East and North Africa (MENA) sector, where banking environments are shaped by commodity price volatility, geopolitical risks, and stability oriented regulatory priorities (
Aliyu et al., 2023;
Alzoubi, 2025;
Mateev et al., 2023). By applying Partial Least Squares Structural Equation Modeling and multi group analysis, this study identifies systematic cross regional differences in how banks balance diversification, stability, and digital transformation under heterogeneous institutional conditions.
This study contributes to the banking and corporate finance literature in three ways. First, it incorporates institutional complexity as a structural constraint that may weaken the translation of financial stability into market power, extending the stability competition debate. Second, it advances the digital banking literature by disentangling the dual role of digitalization, examining digital transformation maturity as an internal mediating mechanism and market digitalization level as an external moderating condition. Third, the cross regional evidence from ASEAN and MENA offers new insights into how differences in regulatory frameworks and digital readiness shape the strategic nexus between diversification, stability, and bank performance.
3. Materials and Methods
This study utilizes secondary data from conventional commercial banks operating in ASEAN and MENA countries over the period 2010–2019. The initial sample includes all conventional commercial banks with continuous financial and governance disclosures available in Bloomberg L.P. (New York, NY, USA) during the observation period. To ensure consistency and replicability, banks with incomplete data on key variables were excluded. The final sample consists of the ten largest banks by total assets in each country. The list of countries and specific sample sizes are detailed in
Table A1 in the
Appendix A.
Financial, governance, and risk-related bank-level data are primarily obtained from Bloomberg due to its standardized reporting framework and extensive coverage of cross-country banking institutions. Where necessary, Bloomberg L.P. (New York, NY, USA) data are cross-validated and complemented with publicly available information from banks’ annual reports and official stock exchange disclosures. Supplementary country-level indicators related to digital infrastructure, financial inclusion, and digital development are sourced from the World Bank (Washington, DC, USA) Digital Development database, the International Telecommunication Union (ITU, Geneva, Switzerland) ICT statistics, and the World Bank (Washington, DC, USA) Global Findex Database. All country-level indicators are harmonized at the country–year level and normalized to ensure cross-country comparability.
The observation period is deliberately chosen to exclude both the Global Financial Crisis and the COVID-19 pandemic, thereby capturing banking behavior under relatively stable regulatory and macroeconomic conditions. Focusing on large banks is consistent with prior literature emphasizing their dominant role in market competition, financial stability transmission, and digital adoption dynamics, particularly in emerging and transitional banking systems.
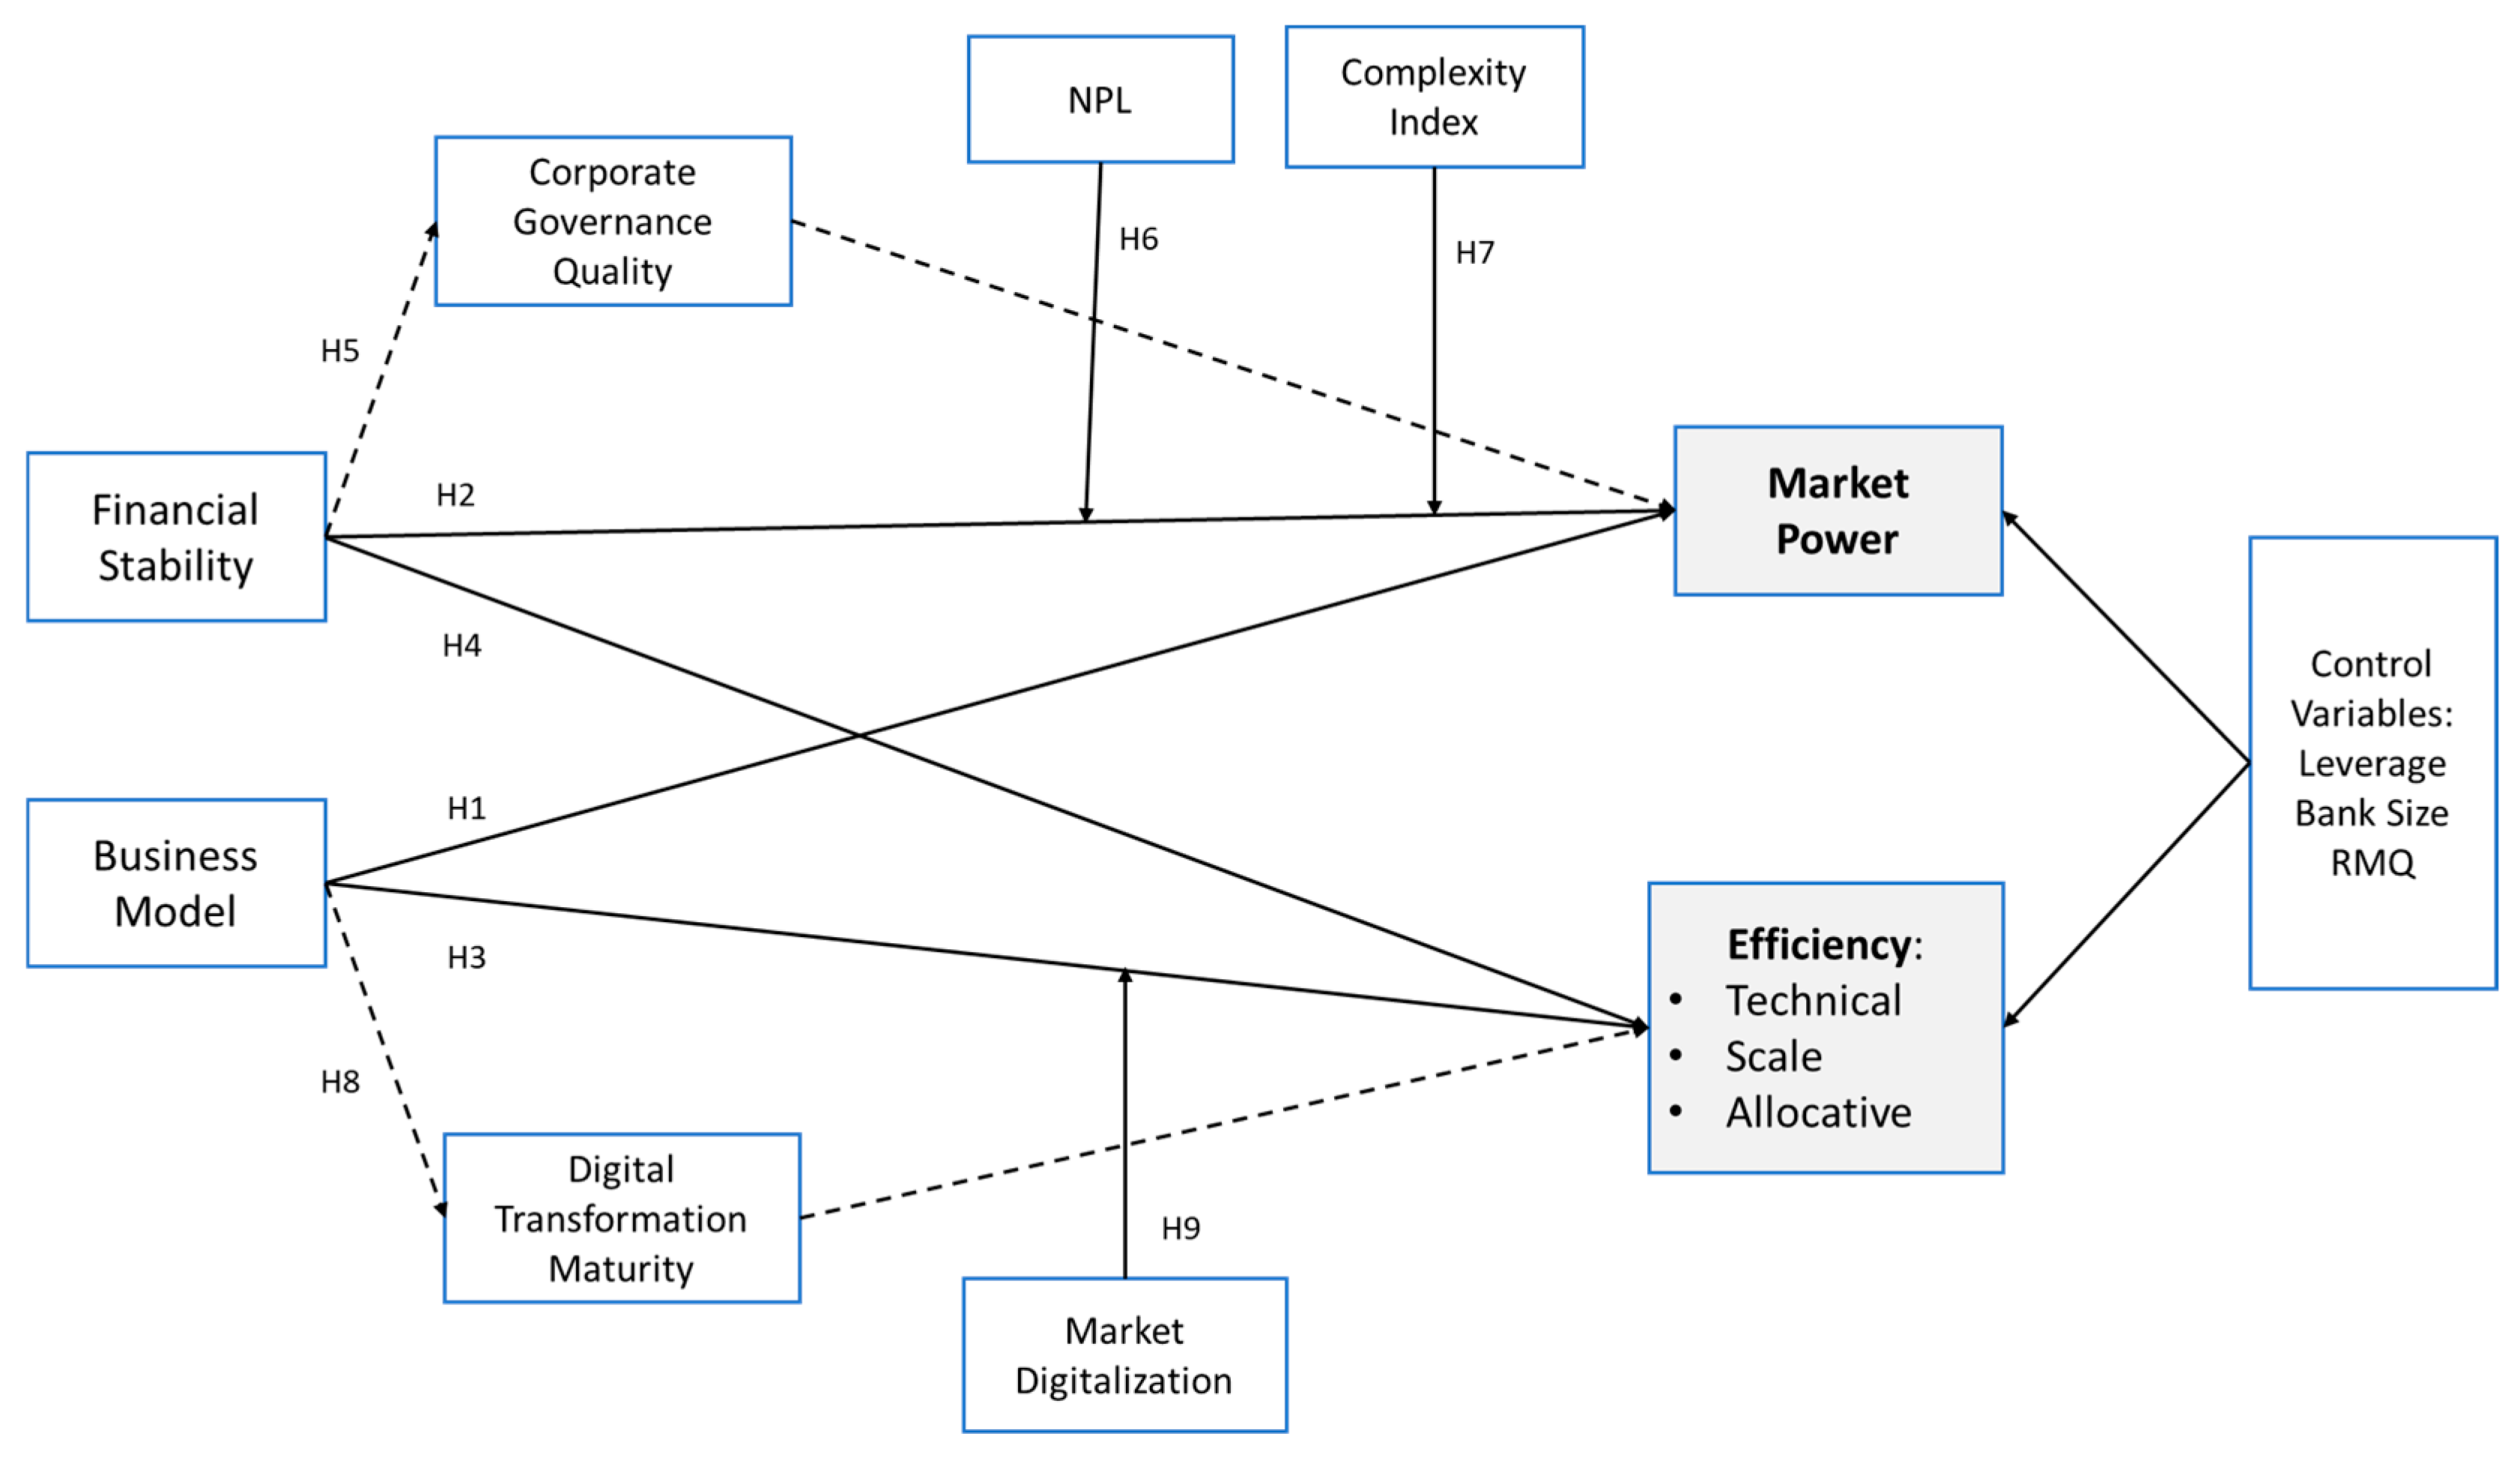
The conceptual framework illustrating the direct, mediating, and moderating relationships examined in this study is presented in
Figure 1 (Conceptual framework showing direct and moderated relationships). The framework explicitly models two distinct but interrelated performance outcomes, market power and multidimensional efficiency, allowing the analysis to capture potential trade-offs and complementarities between competitive dominance and operational performance. A detailed summary of variable measurements is reported in
Table 1.
Business model diversification is proxied by non-interest income (NNIN), which reflects banks’ reliance on non-traditional activities beyond interest-based intermediation. Consistent with the diversification literature, NNIN is measured as the ratio of non-interest operating income to total operating income, expressed as:
where
represents the aggregate share of non-interest income for bank
i in year
t. Non-interest income includes fees and commissions, trading and derivatives income, and other operating revenues. Operating income, on the other hand, comprises net interest income and non-interest income. This measure builds upon prior studies that utilize income structure to capture banks’ strategic diversification choices (
Aliyu et al., 2023).
Bank financial stability is measured using the Z-score, a widely adopted indicator of bank risk and distance-to-default in the banking and finance literature (
Banna & Alam, 2021). The Z-score explicitly compares profitability and capitalization buffers against earnings volatility and is defined as:
where
denotes return on assets,
represents the equity-to-total-assets ratio, and
is the standard deviation of ROA. Higher Z-score values indicate greater financial stability and lower risk of insolvency. Following recent empirical studies, the logarithm of the Z-score is employed to mitigate skewness in the distribution (
Banna & Alam, 2021;
Lestari et al., 2023), while risk-adjusted ROA and ROE are used as complementary stability measures.
Bank efficiency is estimated using Data Envelopment Analysis (DEA), a non-parametric frontier technique originally developed by
Charnes et al. (
1978) and widely applied in banking efficiency studies (
Alhassan & Tetteh, 2017;
Vidyarthi, 2019). DEA measures relative efficiency by maximizing the ratio of weighted outputs to weighted inputs, expressed as:
where
is the efficiency score of bank
s,
and
denote output and input quantities, and
and
are the corresponding weights. Efficiency scores range between 0 and 1. This study applies both Constant Returns to Scale (CRS) and Variable Returns to Scale (VRS) assumptions to derive technical efficiency, allocative efficiency, and scale efficiency. The VRS specification is used to capture both pure technical and allocative efficiency, reflecting the assumption that banks may not operate at optimal scale. In contrast, scale efficiency is computed as the ratio of CRS to VRS scores (
Chortareas et al., 2011;
Liu et al., 2024).
Market power is proxied by the Lerner Index, a non-structural measure of pricing power widely used in banking competition studies (
Lin et al., 2021;
Tan & Anchor, 2017). The Lerner Index is calculated as:
where
represents the ratio of total revenue to total assets for bank
s at time
t, and
denotes marginal cost. Marginal cost is estimated from a translog cost function using Stochastic Frontier Analysis (SFA), as described in
Berger et al. (
2017). Higher Lerner values indicate greater market power and weaker competitive pressure, consistent with evidence from both developed and emerging banking systems (
Das & Pati, 2025;
T. T. H. Nguyen et al., 2022;
Pak & Nurmakhanova, 2013).
Digital Transformation Maturity (DTM) is constructed as a composite index capturing banks’ digital capabilities and technology deployment. Following recent digital banking studies, DTM is defined as:
where
DI represents digital infrastructure,
OO online operations,
PI payment innovation, and
ITI IT investment intensity, each component is normalized to a 0–1 scale using publicly disclosed information. Each component is measured annually at the bank level using publicly disclosed information and normalized to a 0–1 scale to ensure cross-bank and cross-country comparability. This approach is consistent with prior efforts to operationalize digital transformation in the presence of data constraints (
Banna & Alam, 2021;
Citterio et al., 2024).
Digital infrastructure is measured using indicators of mobile and internet banking coverage, API availability, and disclosed information on data system quality obtained from Bloomberg financial analysis, annual reports, and regulatory filings. Online operations capture the degree of digital service delivery, measured by the share of transactions and customers using digital channels and the presence of automated lending systems. Payment innovation reflects the adoption of real-time payment systems, digital wallet integration, and emerging payment technologies, based on fintech databases and public disclosures. IT investment intensity is calculated as IT expenditure relative to total operating costs using annual report expense breakdowns.
Corporate Governance Quality (CGQ) is measured using a weighted composite index reflecting board effectiveness, ownership structure, disclosure quality, and executive alignment, expressed as:
where
BI denotes board independence,
OA ownership adjustment,
DQ disclosure quality, and
EA executive alignment. All governance components are derived from observable disclosures and normalized to a 0–1 scale. The index design draws on governance dimensions commonly used in banking governance research (
Bhatia, 2024;
Dedu & Chitan, 2013;
Muranda, 2006). Board independence is measured by the proportion of independent directors using predefined thresholds. Ownership adjustment is calculated as the inverse of the Herfindahl index to capture ownership concentration. Disclosure quality is assessed based on compliance with core International Corporate Governance Network (ICGN) governance principles using annual and sustainability reports. Executive alignment reflects the share of performance-based compensation in total executive remuneration.
Market Digitalization (MDL) captures the digital financial ecosystem at the country level and is measured as:
where
DI represents national digital infrastructure,
FI financial inclusion,
RR regulatory readiness, and
PS policy support, this construction aligns with ICT-based and digital inclusion indices used in cross-country studies (
Cheng et al., 2021;
Khera et al., 2022;
Vuong et al., 2025). All components are measured at the country–year level and normalized to a 0–1 scale. Digital infrastructure is proxied by internet coverage, mobile penetration, and data security indicators. Financial inclusion reflects account ownership and fintech adoption rates. Regulatory readiness captures the development of digital finance regulations and sandbox initiatives. Policy support reflects national digital finance strategies and cybersecurity frameworks, based on official government and international databases.
Organizational complexity is measured using a composite Complexity Index (CI) that integrates asset, geographic, and organizational dimensions, defined as:
where
AC denotes asset complexity,
GC geographic complexity, and
OC organizational complexity, this approach is consistent with the multidimensional view of banking complexity proposed by
Cetorelli and Goldberg (
2014) and extended by
Carmassi and Herring (
2016) and
Krause et al. (
2017). Each component is normalized to a 0–1 scale. Asset complexity is proxied by bank size quartiles and adjusted for loan portfolio diversification. Geographic complexity reflects the number of countries in which a bank operates. Organizational complexity captures the internal structural arrangement of banks, distinguishing between simple, standard, and holding-company structures.
Credit risk is proxied by the non-performing loan (NPL) ratio, which is measured as the ratio of non-performing loans to total loans. This ratio is a standard indicator of asset quality and risk-taking behavior in banking studies (
Maghyereh & Awartani, 2014). Leverage, bank size (natural logarithm of total assets), and risk management quality are included as control variables. Risk management quality (RMQ) is constructed as a composite index capturing banks’ internal risk governance effectiveness. The index aggregates risk monitoring, credit assessment, compliance, internal controls, and external audit quality using predefined weights and standardized scoring criteria based on public disclosures. Sub-components assess the quality of risk identification and reporting, credit evaluation and collection practices, regulatory compliance, internal control systems, and external audit outcomes. The composite RMQ index mitigates omitted-variable bias related to internal risk governance.
All data are analyzed using Partial Least Squares Structural Equation Modeling (SEM-PLS) with WarpPLS version 8.0. SEM-PLS is selected due to the moderate sample size, the complexity of the research model involving multiple latent constructs, mediation and moderation effects, and the absence of strict multivariate normality assumptions. Moreover, the study emphasizes prediction-oriented analysis and theory extension rather than strict model confirmation, further supporting the use of PLS-SEM over covariance-based SEM. The structural analysis is conducted using two separate models: the first specifies market power as the dependent variable, while the second focuses on multidimensional efficiency outcomes. This separation allows clearer identification of the distinct strategic mechanisms underlying competition and efficiency.
To address potential institutional heterogeneity between ASEAN and MENA banking systems, a multi-group analysis (MGA) is conducted. Configural invariance is ensured by applying identical construct definitions, indicators, and model specifications across both regional subsamples. Compositional equivalence is assessed by examining the consistency of indicator loadings, weights, and multicollinearity diagnostics across groups, following established PLS-SEM practices. The results indicate stable construct composition across regions, supporting the validity of cross-group structural comparisons. The Satterthwaite method is subsequently applied to test for statistically significant differences in path coefficients between ASEAN and MENA banks.
4. Results
4.1. Descriptive Statistics
Table 2 presents the descriptive statistics for all variables across the full sample and by regional classification (ASEAN and MENA). Overall, the statistics reveal substantial heterogeneity in bank characteristics, business models, and operational conditions across regions.
Banks in ASEAN exhibit markedly higher levels of business model diversification, as reflected in the mean non-interest income (NNIN), compared to their counterparts in the MENA region. This suggests a stronger reliance on fee-based and non-traditional income sources in ASEAN banking systems. Financial stability, measured by the Z-score, also appears considerably higher in ASEAN, indicating a greater distance to default and more resilient balance sheets relative to banks in the MENA region.
Market power, proxied by the Lerner Index, is high across both regions, with limited dispersion, suggesting relatively concentrated banking markets. However, efficiency patterns differ notably. MENA banks demonstrate higher average technical, scale, and allocative efficiency, accompanied by lower variability, implying more consistent operational performance. In contrast, ASEAN banks exhibit greater dispersion in efficiency scores, particularly in terms of technical and scale efficiency, reflecting the heterogeneous production structures and competitive environments within the region.
Risk and organizational characteristics further distinguish the regions. ASEAN banks report lower non-performing loan ratios and higher risk management quality (RMQ), while MENA banks exhibit greater institutional complexity (CI) and higher leverage. ASEAN banks are, on average, larger in size and display slightly stronger corporate governance quality (CGQ). In contrast, MENA banks show higher levels of digital transformation maturity (DTM) and market digitalization (MDL), indicating more advanced digital environments at the country level.
Taken together, these descriptive patterns underscore meaningful regional differences in stability, diversification, efficiency, governance, and digitalization, justifying the subsequent structural and multi-group analyses.
4.2. Correlation Analysis of Latent Variables
This study employs Partial Least Squares Structural Equation Modeling (PLS-SEM) to investigate the relationships between banks’ strategic characteristics, stability, market power, multidimensional efficiency, and contextual factors, evaluating the measurement model prior to structural estimation to ensure construct validity. Because all latent variables in this study are operationalized as single-item constructs based on standardized secondary financial data and composite indices, traditional internal consistency reliability tests, such as Cronbach’s alpha and composite reliability (CR), are not applicable as their values are inherently fixed at 1.000. Consequently, the measurement model evaluation focuses on discriminant validity and collinearity diagnostics to ensure construct distinctiveness and model stability, using latent variable correlation analysis to confirm that all pairwise correlations remain below the commonly accepted threshold of 0.70 (
MacKenzie et al., 2005).
Discriminant validity is assessed using latent variable correlation analysis. As reported in
Table 3 and
Table 4, all pairwise correlations among latent constructs remain below the commonly accepted threshold of 0.70, indicating satisfactory discriminant validity (
MacKenzie et al., 2005). These results confirm that the constructs capture conceptually distinct dimensions and are appropriate for subsequent structural model estimation.
4.3. Measurement Model Assessment
The adequacy of the measurement and structural models was evaluated using the PLS-SEM model fit and quality criteria provided by WarpPLS, as summarized in
Table 5. Overall, the results indicate that both Model 1 (Market Power) and Model 2 (Efficiency) meet the recommended thresholds for goodness-of-fit, multicollinearity, and predictive relevance, supporting the robustness of subsequent hypothesis testing.
In terms of global model fit, the Average Path Coefficient (APC), Average R-squared (ARS), and Average Adjusted R-squared (AARS) are all statistically significant at the 1% level in both models, indicating that the structural relationships are jointly meaningful. The Tenenhaus Goodness-of-Fit (GoF) values of 0.749 for Model 1 and 0.515 for Model 2 exceed the cut-off for a large effect size (≥0.36), suggesting strong overall explanatory power.
Multicollinearity diagnostics further confirm model adequacy. The Average Variance Inflation Factor (AVIF) and Average Full Collinearity VIF (AFVIF) values for both models are well below the conservative threshold of 3.3, indicating that multicollinearity is not a concern and that the estimated path coefficients are stable. In addition, the Sympson’s Paradox Ratio (SPR), R-squared Contribution Ratio (RSCR), and Statistical Suppression Ratio (SSR) meet or exceed their respective minimum requirements, providing further evidence of a well-specified model without pathological suppression effects.
Regarding explanatory power, the R-squared values indicate moderate explanatory strength for market power (LI) and scale efficiency (SE). In contrast, technical efficiency (TE) and allocative efficiency (AE) exhibit relatively weaker explanatory levels. A similar pattern is observed for the adjusted R-squared values, suggesting that efficiency outcomes—particularly TE and AE—are influenced by additional operational and institutional factors beyond the core variables included in the model. This finding is consistent with the notion that bank efficiency is inherently multidimensional and heterogeneous across efficiency components.
Finally, the Stone–Geisser Q2 values for all endogenous constructs are positive, confirming adequate predictive relevance for both models. Collectively, these results demonstrate that the measurement and structural specifications are statistically sound, free from critical estimation issues, and suitable for analyzing the determinants of bank market power and multidimensional efficiency.
4.4. Determinants of Bank Market Power: Structural Model Analysis
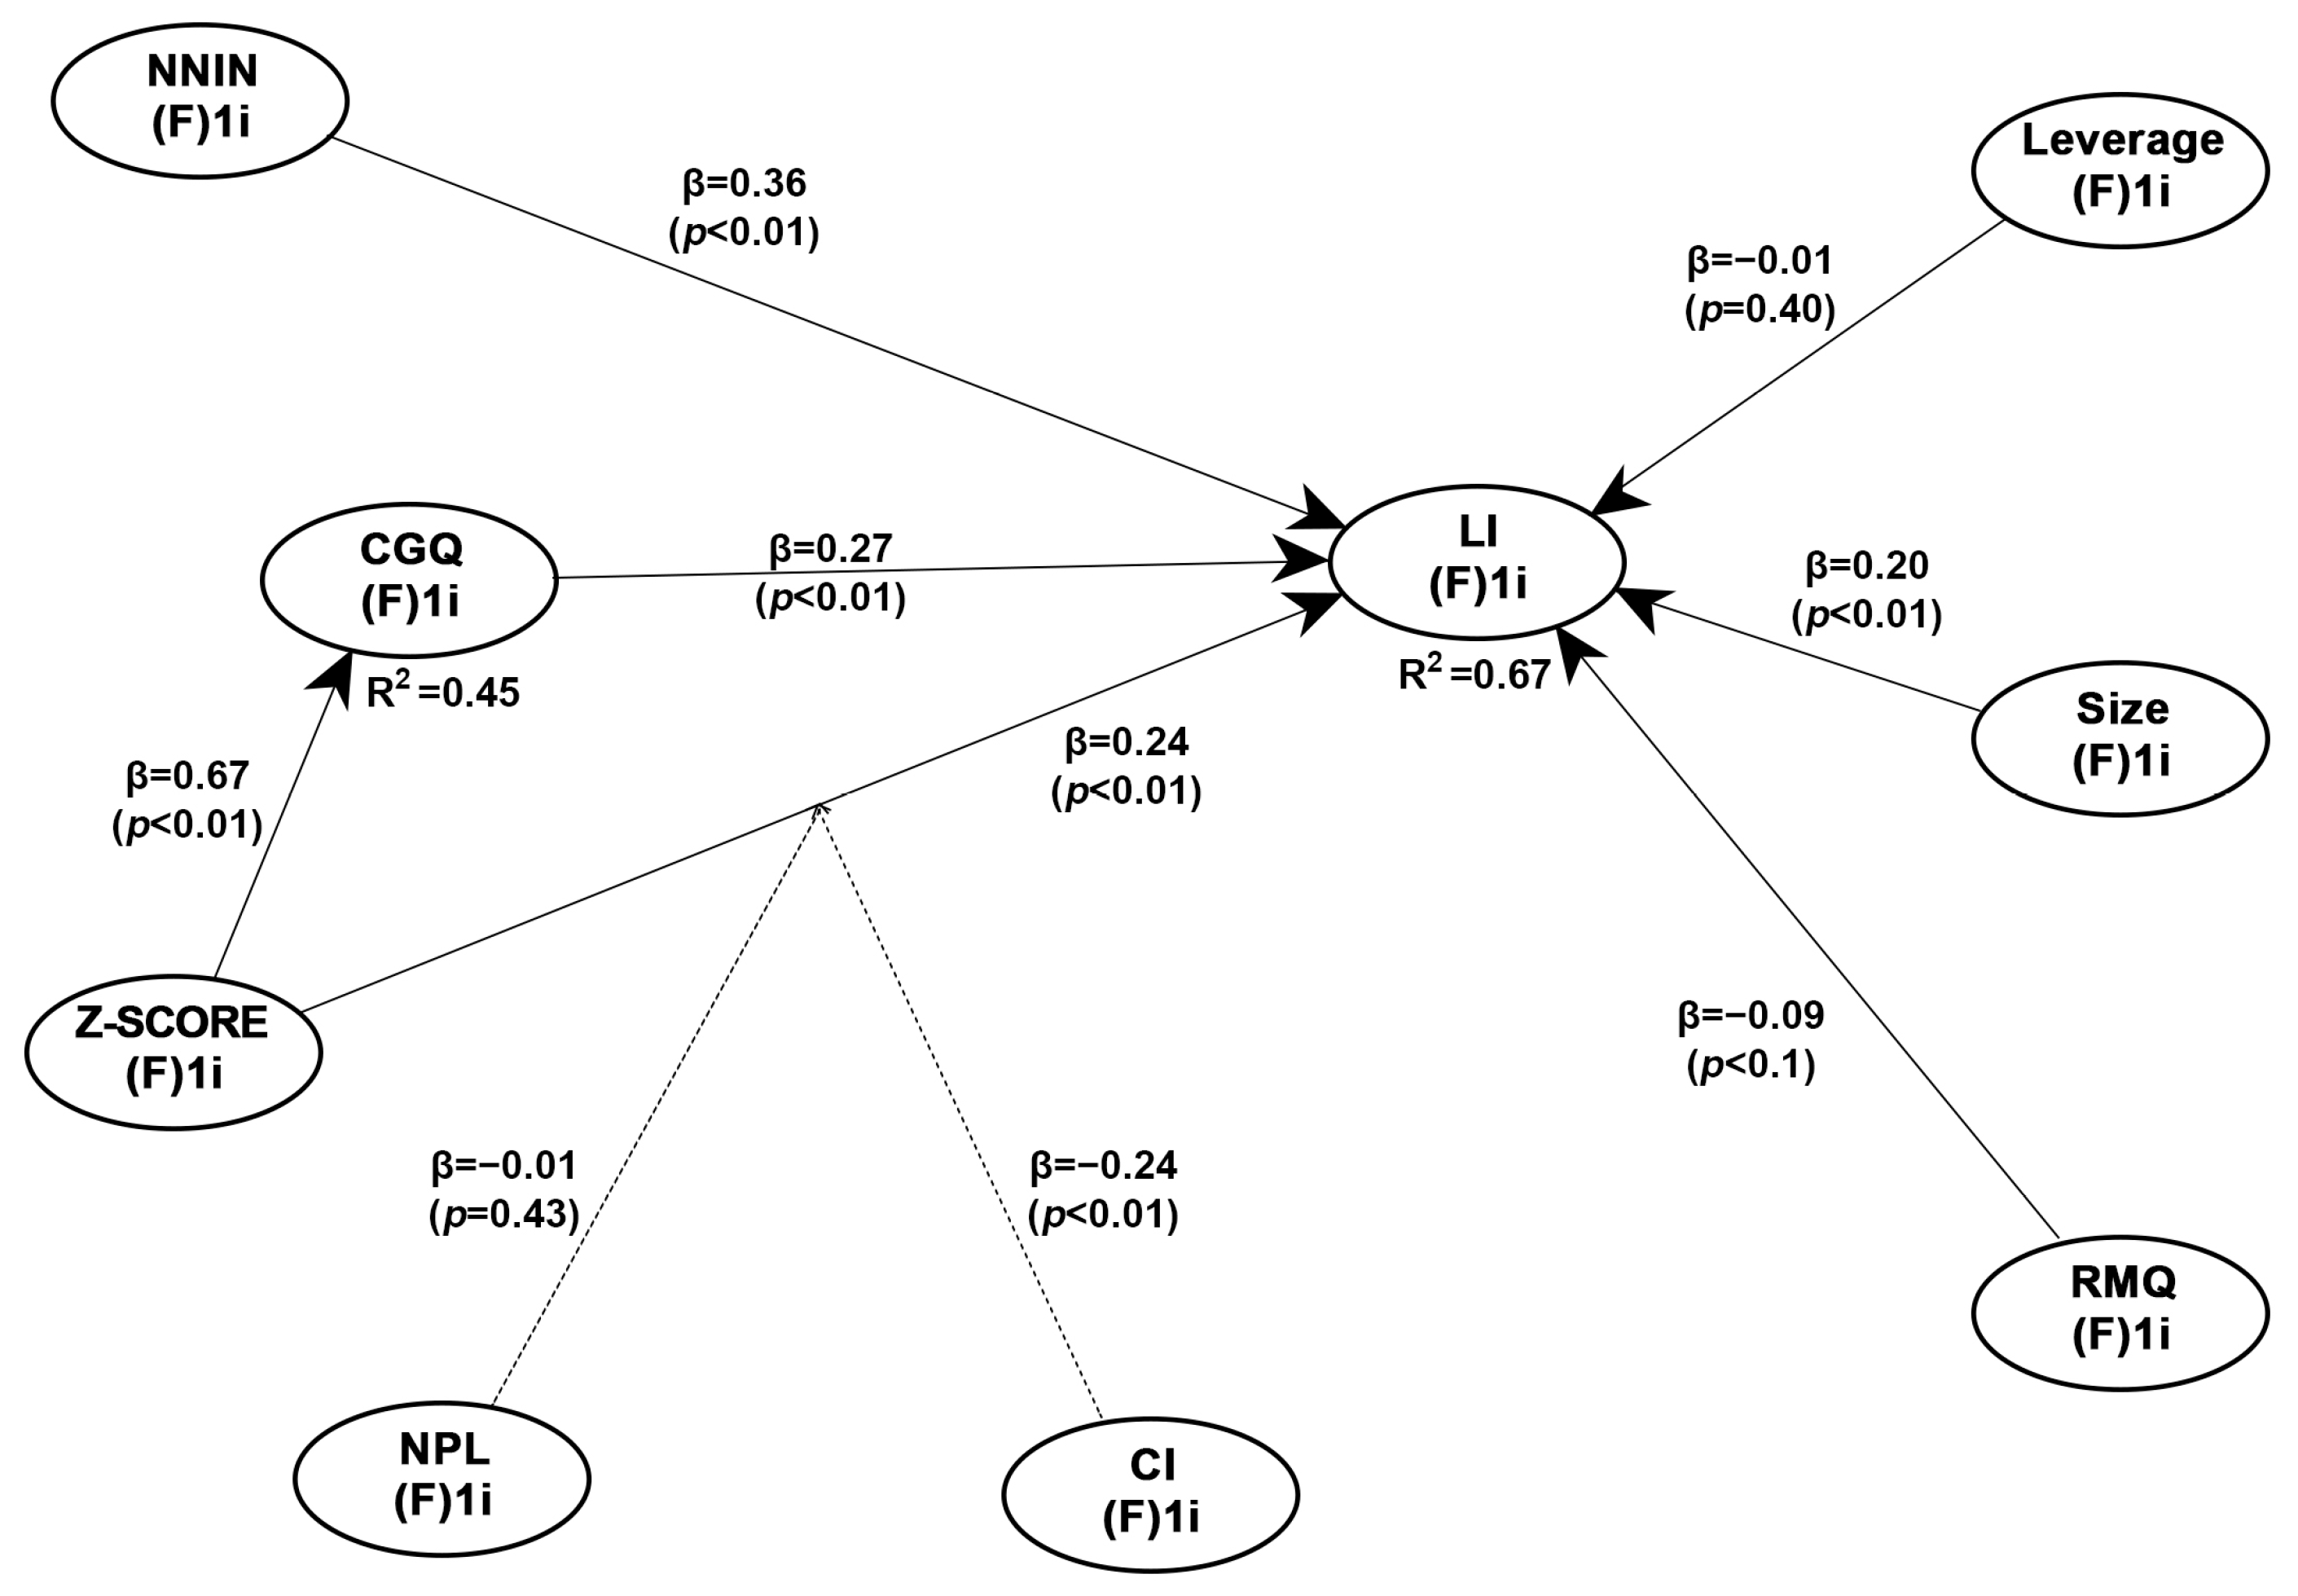
The structural model results for bank market power are presented in
Table 6, while the estimated path coefficients and interaction effects are visually summarized in
Figure 2. Overall, the findings provide strong empirical support for the proposed direct and mediated relationships, with selective evidence for moderation effects. In addition to path coefficients, Cohen’s
f2 effect sizes are reported to evaluate the substantive impact of each predictor, where values of 0.02, 0.15, and 0.35 represent small, medium, and large effects, respectively.
Regarding the direct effects, business model diversification (NNIN), shows a positive and statistically significant relationship with market power (β = 0.356, p < 0.001). This confirms H1 and suggests that as banks shift toward non-traditional income streams, they enhance their competitive positioning, evidenced by a medium-to-large effect size (f2 = 0.192). Financial stability (Z-score) also exhibits a positive and significant effect on market power (β = 0.243, p < 0.001), supporting H2 with a medium effect size (f2 = 0.154). This indicates that stable banks possess the strategic “buffers” necessary to exert greater pricing power in the market.
The mediation analysis further reveals a significant indirect effect of financial stability (Z-score) on market power (LI) through the quality of corporate governance (CGQ). As reported in
Table 6, the indirect path from Z-score to CGQ and subsequently to market power is positive and statistically significant (β = 0.179,
p < 0.001), indicating partial mediation and supporting H5. This suggests that the impact of stability on market power is partially explained by improved governance mechanisms (
f2 = 0.113), which facilitate more disciplined strategic expansion.
In terms of moderation effects, the interaction between NPL and financial stability is statistically insignificant (β = −0.007, p = 0.425), thus failing to support H6 and yielding a negligible effect size (f2 = 0.002). Conversely, the interaction between the complexity index (CI) and financial stability (Z-Score) is negative and significant (β = −0.243, p < 0.001), providing strong support for H7 with a moderate substantive impact (f2 = 0.115). This implies that high institutional complexity acts as a structural friction, diminishing the positive influence of stability on market power.
Regarding the control variables, bank size exhibits a positive and statistically significant effect on market power (β = 0.195, p < 0.001). Financial leverage does not show a significant relationship with market power (β = −0.010, p = 0.399). Risk management quality (RMQ) exhibits a statistically significant negative effect on market power (β = −0.091, p = 0.008). This suggests that rigorous risk monitoring may constrain aggressive pricing strategies associated with high market power.
4.5. Determinants of Bank Efficiency: Structural Model Analysis
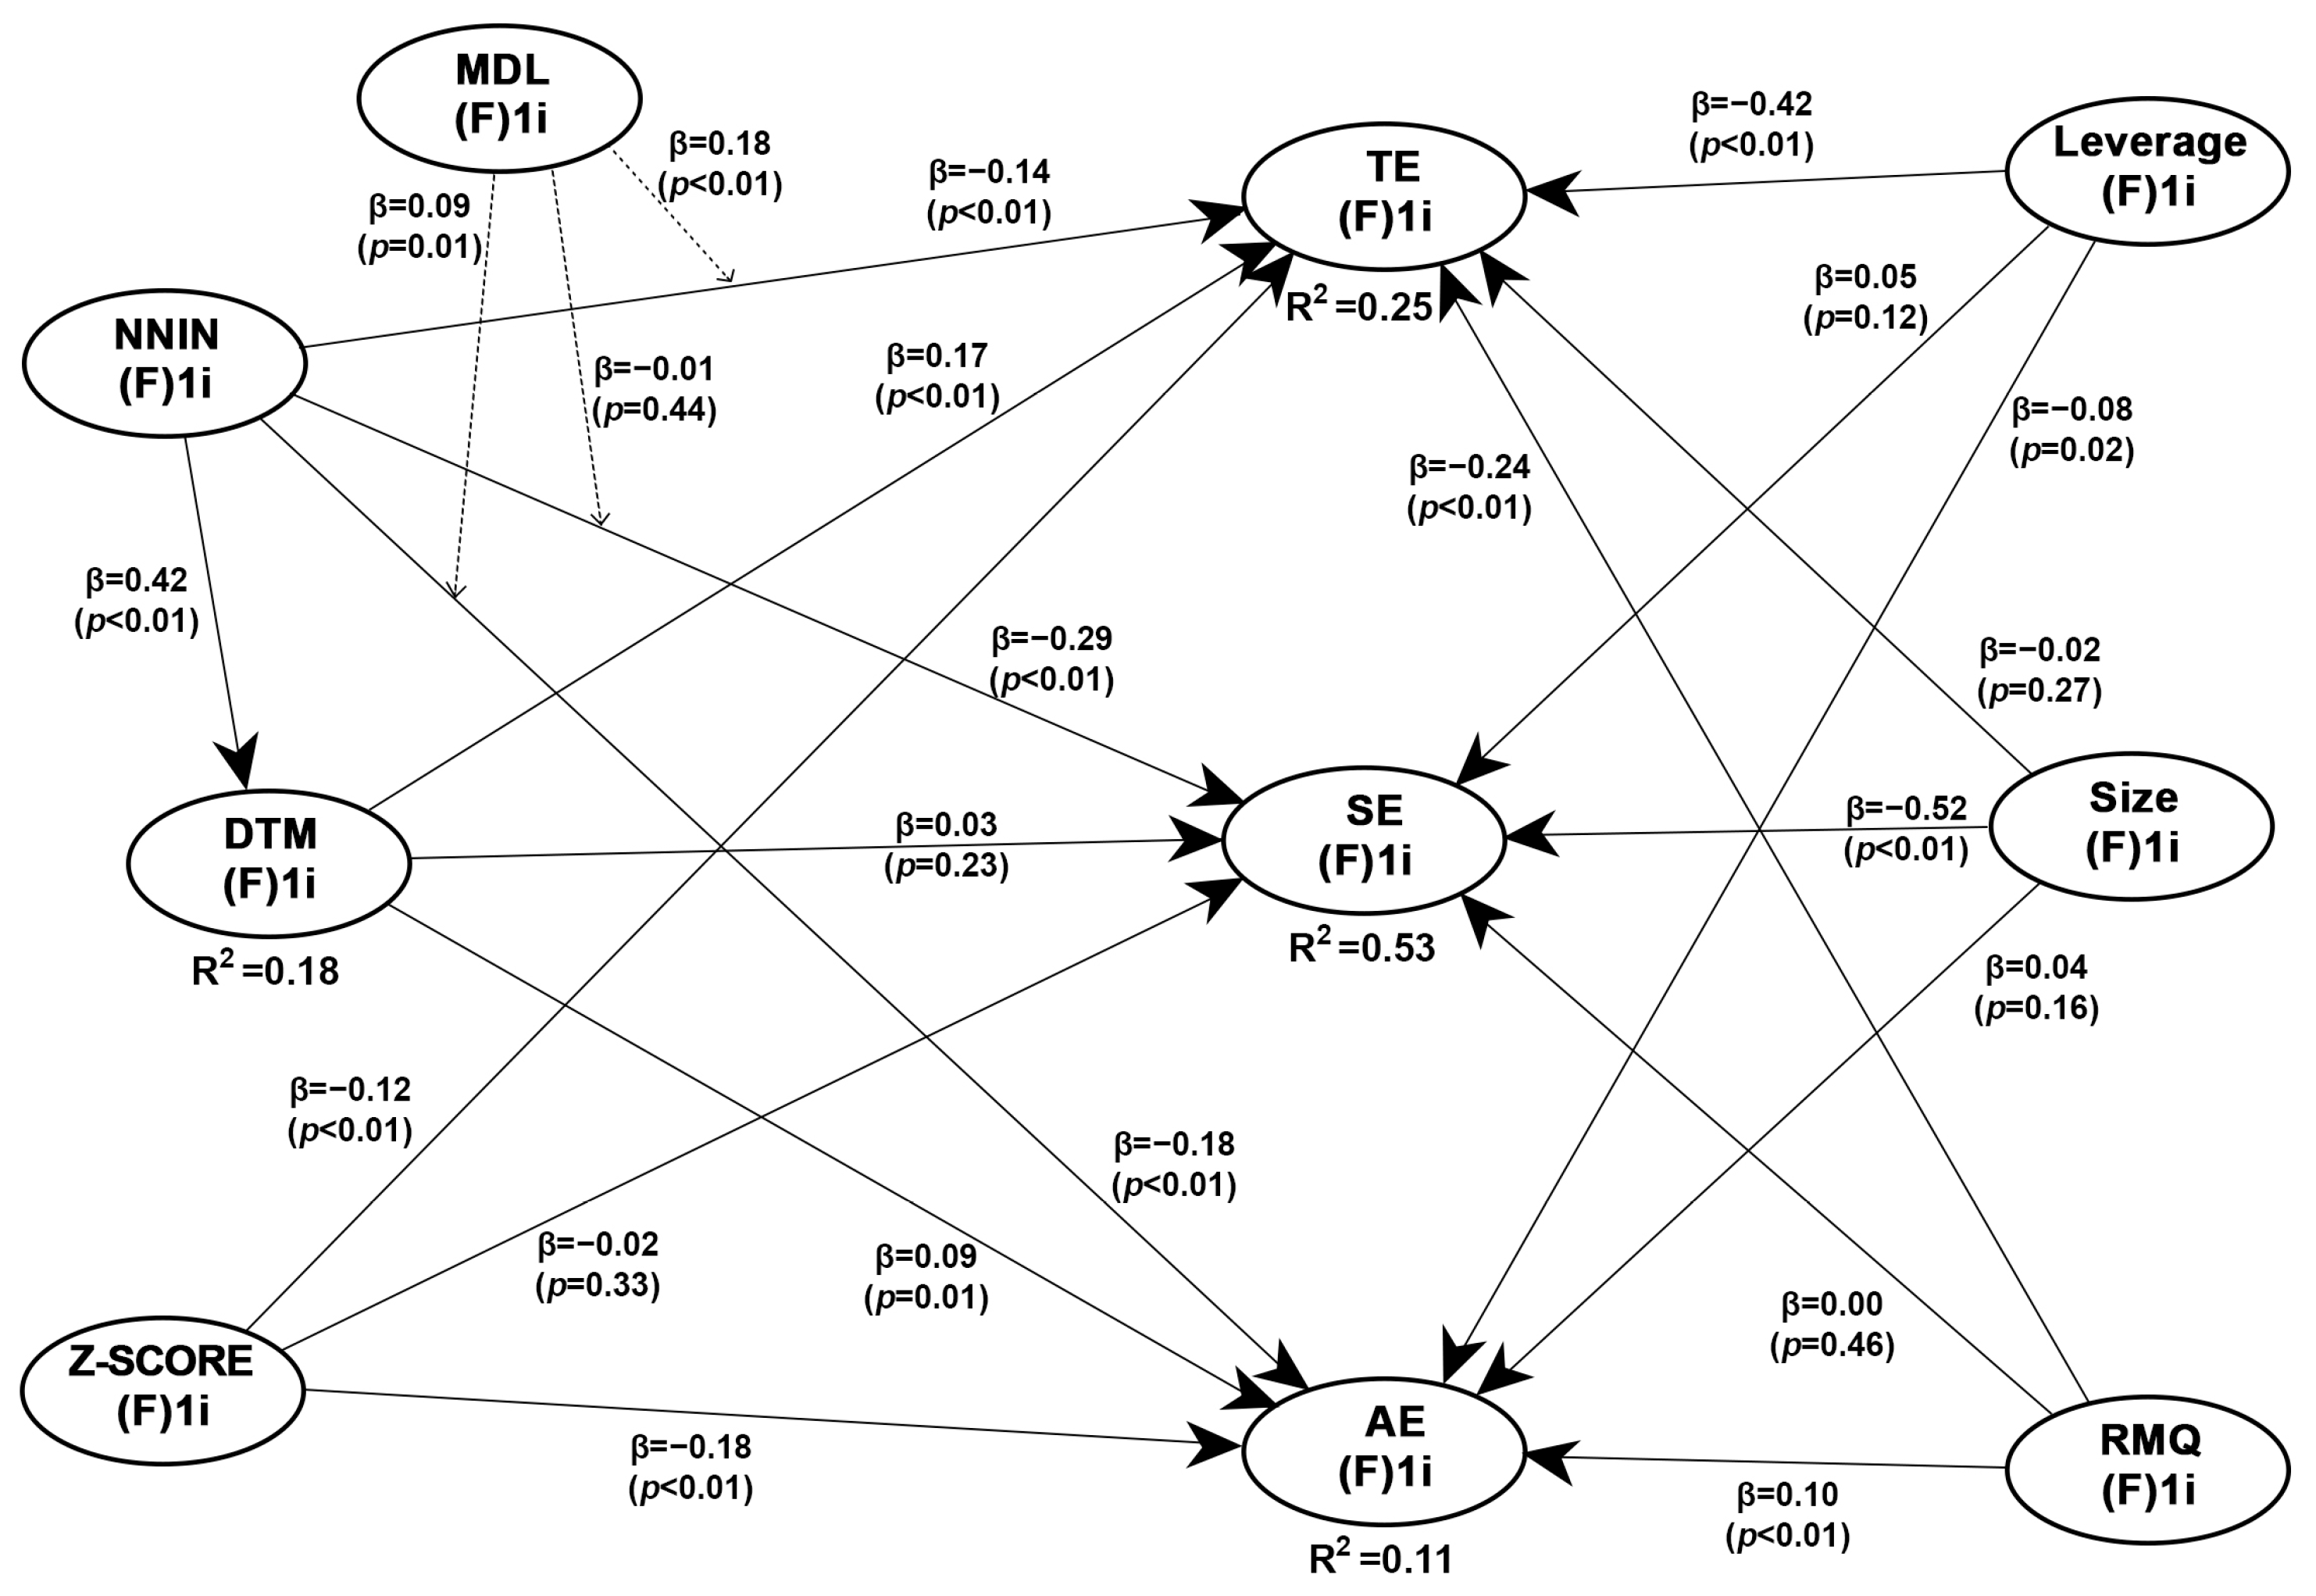
The structural model results for bank efficiency are presented in
Table 7, with the estimated path relationships visualized in
Figure 3. Bank efficiency is assessed using three dimensions, namely technical efficiency (TE), scale efficiency (SE), and allocative efficiency (AE), allowing for a comprehensive evaluation of efficiency determinants.
Regarding the direct effects, business model diversification (NNIN) exhibits negative and statistically significant relationships with all three efficiency measures. Specifically, NNIN has a negative effect on technical efficiency (β = −0.142, p < 0.001), scale efficiency (β = −0.285, p < 0.001), and allocative efficiency (β = −0.181, p < 0.001), indicating that aggressive diversification may lead to resource fragmentation. While the effects on TE and AE are small (f2 < 0.05), the impact on SE is medium-to-large (f2 = 0.171), suggesting significant scale diseconomies; thus, H3a, H3b, and H3c are not supported. Similarly, financial stability (Z-score) has a negative impact on technical efficiency (β = −0.123, p < 0.001) and allocative efficiency (β = −0.176, p < 0.001), while its relationship with scale efficiency is statistically insignificant (β = −0.016, p = 0.333), results in the rejection of H4a, H4b, and H4c, potentially reflecting a “quiet life” effect where higher stability reduces the incentive for cost-minimizing behavior.
The mediation analysis indicates limited support for the role of digital transformation (DTM). DTM partially mediates the relationship between NNIN and technical efficiency with a significant positive indirect effect (β = 0.072, p = 0.004), supporting H8a. This suggests that internal digitalization can mitigate some of the efficiency losses associated with diversification. However, the indirect effects for scale efficiency (β = 0.012, p = 0.330) and allocative efficiency (β = 0.036, p = 0.093) are insignificant, leading to the rejection of H8b and H8c, with negligible substantive impacts (f2 < 0.01).
Regarding moderation effects, market digitalization (MDL) significantly moderates the relationship between NNIN and technical efficiency (β = 0.176, p < 0.001), supporting H9a. Furthermore, the moderating effect on allocative efficiency is positive and significant (β = 0.088, p = 0.011), supporting H9c. These results imply that a mature external digital ecosystem (MDL) can help banks extract better value from diversification, although the substantive effect sizes remain small (f2 ≤ 0.02). The interaction for SE remains insignificant, failing to support H9b.
Regarding control variables, bank size (log of total assets) has a statistically significant negative effect on scale efficiency (β = −0.524, p < 0.001), while its effects on technical efficiency (β = −0.024, p = 0.265) and allocative efficiency (β = 0.039, p = 0.157) are not statistically significant. Financial leverage has a negative impact on technical efficiency (β = −0.422, p < 0.001) and allocative efficiency (β = −0.078, p = 0.020), but does not significantly affect scale efficiency (β = 0.045, p = 0.118). Risk management quality (RMQ) is negatively associated with technical efficiency (β = −0.237, p < 0.001) and allocative efficiency (β = 0.101, p = 0.004), while its relationship with scale efficiency is not statistically significant (β = 0.004, p = 0.462). This reflecting the high operational and monitoring costs inherent in complex, highly leveraged banking environments.
4.6. Multi-Group Analysis Results (ASEAN vs. MENA)
This study further employs Multi-Group Analysis (MGA) to examine whether the structural relationships differ significantly between banks operating in ASEAN and MENA regions. The results of the MGA are reported in
Table 8, with statistically significant group differences identified based on the absolute difference in path coefficients.
For the direct effects on market power, the relationship between business model diversification (NNIN) and market power (LI) is positive in both regions, with a coefficient of 0.227 for ASEAN and 0.304 for MENA, although the difference between the two groups is not statistically significant (Δβ = 0.076). In contrast, the effect of financial stability (Z-score) on market power varies substantially across regions, reflecting differing risk-return trade-offs. The Z-score exhibits a negative coefficient in ASEAN (β = −0.119) but a positive and stronger coefficient in MENA (β = 0.442), with a statistically significant group difference (Δβ = 0.561, p < 0.01), supporting the presence of regional heterogeneity for H2. This suggests that in MENA, financial stability is a prerequisite for competitive dominance, whereas ASEAN banks may sacrifice short-term stability to capture market share in a more fragmented environment.
Regarding efficiency-related direct effects, the relationship between NNIN and technical efficiency is weak in both regions and does not show a statistically significant difference (Δβ = 0.098). However, significant regional differences are observed for scale efficiency and allocative efficiency. The effect of NNIN on scale efficiency is negative in ASEAN (β = −0.243) but positive in MENA (β = 0.174), with a significant difference between the two groups (Δβ = 0.417, p < 0.01). This indicates that MENA banks successfully leverage diversification to achieve economies of scope, while ASEAN banks face scale diseconomies when expanding into non-interest activities. Similarly, NNIN shows a positive coefficient for allocative efficiency in ASEAN (β = 0.037) and a negative coefficient in MENA (β = −0.155), with a statistically significant difference (Δβ = 0.192, p < 0.01).
The effects of financial stability on efficiency also vary across regions. The relationship between the Z-score and technical efficiency is negative in ASEAN (β = −0.114) and positive in MENA (β = 0.035), with a significant group difference (Δβ = 0.149, p < 0.05). A similar pattern is observed for scale efficiency, where the Z-score has a negative coefficient in ASEAN (β = −0.064) and a positive coefficient in MENA (β = 0.087), with the difference being statistically significant (Δβ = 0.152, p < 0.05). In contrast, the effect of the Z-score on allocative efficiency does not differ significantly between the two regions (Δβ = 0.105). These findings highlight that financial stability acts as a driver of operational discipline in the MENA region, whereas it may lead to managerial slack or a “quiet life” effect in ASEAN.
For moderation effects related to market power, the interaction between non-performing loans (NPL) and the Z-score shows opposite signs across regions, with a negative coefficient in ASEAN (β = −0.115) and a positive coefficient in MENA (β = 0.147). The difference between the two groups is statistically significant (Δβ = 0.263, p < 0.01). The moderating effect of the complexity index (CI) on the Z-score–market power relationship is negative in both regions and does not exhibit a significant group difference (Δβ = 0.087). This suggests that high credit risk exacerbates stability-competition trade-offs in ASEAN but may incentivize more aggressive market power preservation in MENA.
Substantial regional heterogeneity is also evident in the moderation effects on efficiency. The interaction between market discipline (MDL) and NNIN on technical efficiency is positive in ASEAN (β = 0.118) but negative in MENA (β = −0.199), with a statistically significant difference (Δβ = 0.317, p < 0.01). Similarly, the moderating effect of MDL on scale efficiency is negative in both regions, although it is stronger in MENA (β = −0.321) than in ASEAN (β = −0.086), with a significant group difference (Δβ = 0.235, p < 0.01). This divergence highlights that the advanced digital maturity of the ASEAN market acts as a catalyst for efficiency gains under diversification, whereas in MENA, rapid digitalization might still represent an operational cost burden for diversifying banks. For allocative efficiency, the MDL × NNIN interaction is strongly positive in ASEAN (β = 0.398) but negative in MENA (β = −0.089), with the largest observed group difference (Δβ = 0.487, p < 0.01).
Regarding control variables, several statistically significant regional differences are observed. Bank size exhibits a positive effect on market power in ASEAN (β = 0.154) but a negative effect in MENA (β = −0.057), with a significant difference (Δβ = 0.211, p < 0.01). Bank size also shows significant group differences across all efficiency measures, with positive effects on technical and allocative efficiency in ASEAN but negative or weaker effects in MENA. Financial leverage exhibits significant regional differences in technical efficiency, with a stronger negative effect in ASEAN (β = −0.524) compared to MENA (β = −0.265). In contrast, no significant differences are observed for scale and allocative efficiency. Finally, risk management quality (RMQ) shows a significant regional difference only for scale efficiency (Δβ = 0.133, p < 0.05). In contrast, its effects on market power, technical efficiency, and allocative efficiency do not differ significantly between the two regions.
4.7. Robustness and Endogeneity Assessment
To ensure the stability of the findings and address potential endogeneity, this study conducted a formal robustness check using Warp3 bivariate causal direction ratios. This test was specifically chosen as it offers a robust mechanism for identifying potential reverse causality without the need for external instrumental variables, which are often difficult to validate in cross-country banking research. The ratios evaluate whether the hypothesized causal flow from the independent and control variables to the dependent variables is statistically stronger than the reverse relationships. The results for the two separate structural models (market power and multidimensional efficiency) are summarized in
Table 9.
The results indicate that the majority of the ratios for the primary strategic variables (NNIN and Z-Score) exceed the threshold of 1.0, particularly in the Market Power and Scale Efficiency (SE) models. This confirms that the hypothesized causal directions are statistically supported over their reverse counterparts. While some dimensions of technical efficiency (TE) and allocative efficiency (AE) show lower ratios, suggesting more complex bidirectional dynamics in resource management, the overall stability of the coefficients remains intact.
Furthermore, the consistency of these findings is bolstered by the multi-group analysis (MGA) conducted across the ASEAN and MENA regions, which confirm that the structural relationships are robust to institutional heterogeneity. Finally, the use of the Warp3 algorithm ensures that the results are stable across both linear and non-linear functional forms, mitigating risks associated with model specification bias.
5. Discussion
The empirical findings of this study offer a nuanced understanding of how business model diversification, financial stability, governance mechanisms, and digital transformation collectively shape bank market power and efficiency. By analyzing conventional banks across the ASEAN and MENA regions, the results reveal distinct pathways for market dominance versus operational efficiency. These findings explain how institutional and digital factors help banks navigate the diversification discount and the quiet life trap, where strategic expansion often conflicts with cost discipline.
The positive and statistically significant effect of business model diversification (NNIN) on market power supports the premise that expanding into non-interest activities strengthens a bank’s competitive positioning. This finding directly addresses the pressure on banks to reconfigure their business models due to compressed net interest margins in low-interest environments. It aligns with the Structure-Conduct-Performance (SCP) paradigm and corroborates evidence from
Setianto et al. (
2025). Diversification enhances market power by stabilizing revenue and enabling favorable pricing strategies. Furthermore, banks generating more revenue from non-interest sources enjoy higher margins because these niche markets face less intense competition (
Das & Pati, 2025). By reducing reliance on interest income, banks can cross-subsidize products and create higher switching costs for customers, thereby consolidating their market dominance.
In parallel, financial stability, proxied by the Z-score, exhibits a strong positive association with market power. This suggests that stability acts as a strategic resource, reinforcing the Resource-Based View (RBV) perspective that internal capabilities drive competitive strength. Higher stability allows for banks to protect their franchise value and signal reliability to the market (
Louhichi et al., 2019). As noted by
Qori’ah et al. (
2025) and
Wu et al. (
2019), stable banks possess the capital buffers necessary to absorb shocks and maintain lending during downturns, effectively “buying” market share when weaker competitors retreat.
However, stability alone is insufficient without effective oversight. The significant mediating role of corporate governance quality (CGQ) indicates that stability requires robust mechanisms to direct financial resources toward value-creating strategies. This finding echoes the governance challenges, where information asymmetry can obscure risk. Board structure remains a significant determinant of financial stability (
Mamatzakis et al., 2023). Furthermore,
Bhatia (
2024) demonstrated that adherence to governance standards, such as effective boards and transparency, is crucial for enhancing profitability and resilience, particularly in low-competition environments.
Crucially, this study identifies structural frictions that limit the benefits of stability. The negative moderation of institutional complexity on the stability–market power nexus supports the “diseconomies of complexity” argument. As banks expand their product portfolios and geographic reach, they develop complex structures that increase monitoring costs (
Laeven et al., 2016). Consequently, even financially stable banks may fail to leverage their capital effectively if their complex structures slow down decision-making or obscure risk signals, a view supported by
Krause et al. (
2017). While the aggregate moderation of non-performing loans (NPLs) was less dominant, the theoretical underpinning suggests that high NPLs can drain managerial attention, as noted by
Berger and DeYoung (
1997), effectively severing the link between stability and aggressive market expansion due to the burden of bad management.
Turning to operational performance, the results reveal a dark side to diversification and stability in terms of efficiency. The negative association between business model diversification and multiple efficiency dimensions strongly supports the diversification discount theory.
Curi et al. (
2015) and
Elyasiani and Wang (
2012) similarly found that diversification often destroys technical efficiency due to increased coordination costs and the complexity of managing disparate business lines. Likewise, the negative impact of financial stability on efficiency aligns with the quiet life hypothesis described by
Ikeda et al. (
2018). This hypothesis suggests that managers of highly stable and dominant banks may feel insulated from market discipline, leading to managerial slack where they avoid difficult cost-cutting decisions or underinvest in necessary innovations. Consequently, excessive stability can breed inefficiency, as managers prioritize safety over optimal resource utilization, a trend also observed by
Miah and Uddin (
2017).
This study’s most novel contribution lies in identifying digital transformation maturity (DTM) as the solution to this efficiency paradox. The positive mediation effect of DTM confirms that digitalization is the missing link that enables banks to manage the complexity of diversification efficiently. This supports
Beccalli (
2007) and
Citterio et al. (
2024), who argue that while IT investment alone may not yield immediate returns, the strategic adoption of digital channels and infrastructure can significantly reduce operating costs and enhance network efficiency. By automating processes, digital maturity allows diversified banks to overcome coordination costs, turning potential inefficiencies into productivity gains, as evidenced by
Liu et al. (
2024).
Moreover, the moderating role of market digitalization level (MDL) underscores the importance of the external environment. Banks in countries with robust digital infrastructure are better positioned to reap the efficiency benefits of their internal strategies (
Cheng et al., 2021;
Vuong et al., 2025). A mature ecosystem reduces transaction friction and facilitates the adoption of fintech innovations. As noted by
Khera et al. (
2022), the widespread adoption of digital financial services acts as a key driver for efficiency, amplifying the positive impact of diversification.
Finally, the Multi-Group Analysis reveals significant regional divergences. The stronger stability–market power link in the MENA region reflects its unique market structure, often characterized by high concentration and a reliance on economic stability tied to oil prices, as noted by
Aliyu et al. (
2023). In contrast, the ASEAN region shows more dynamic efficiency relationships. This is likely driven by its rapidly evolving digital landscape and intense fintech competition mentioned in the introduction. This heterogeneity highlights that “one-size-fits-all” policies are ineffective. MENA banks may benefit more from stability-enhancing governance reforms, while ASEAN banks need to prioritize digital integration to manage the efficiency costs of diversification, aligning with the regional governance insights provided by
D. T. N. Nguyen (
2025).
6. Conclusions
This study examines how banks balance the dual strategic imperatives of securing market power and optimizing multidimensional operational efficiency, as measured by technical, scale, and allocative efficiency, within emerging and transitional banking systems. The findings demonstrate that business model diversification (NNIN) and financial stability play asymmetric roles across these two performance domains. While both factors are significantly associated with stronger market power, they are also linked to efficiency trade-offs across multiple dimensions.
This suggests that strategies aimed at competitive positioning and risk resilience do not automatically correlate with superior operational efficiency. The results further indicate that governance quality and digital transformation act as critical conditioning mechanisms in shaping these relationships. Corporate governance quality partially channels the associated stabilizing effects of financial soundness into market power, reinforcing the role of institutional oversight in transforming stability into strategic advantage.
At the same time, digital transformation maturity is associated with the mitigation of the efficiency losses linked to diversification, particularly regarding technical efficiency, while market digitalization level selectively amplifies or constrains the effectiveness of diversification strategies. The multi-group analysis reveals substantial regional heterogeneity, indicating that the relative importance of stability, diversification, and moderating mechanisms varies between ASEAN and MENA banking systems. These results reflect differences in institutional development and digital readiness, suggesting that the generalizability of the findings to other regions should be interpreted with caution.
Theoretically, this study advances the banking literature by integrating market power and multidimensional efficiency within a unified framework, demonstrating that their determinants operate through distinct, conditional pathways. By accounting for governance, risk, and digitalization, the findings refine views that treat diversification and stability as universally beneficial. From a practical perspective, the results suggest that bank managers should avoid a “one-size-fits-all” approach to strategic expansion. Specifically, managers must balance diversification-driven growth with targeted investments in digital transformation maturity, as internal digital maturity is essential to mitigate the coordination costs and “diversification discount” that often erode operational efficiency. For regulators, the findings imply that fostering financial stability alone is insufficient; they must also prioritize the development of a robust external market digitalization level and digital infrastructure. Such a supportive ecosystem ensures that banks can diversify their income streams and maintain stability without sacrificing efficiency, thereby promoting a more resilient and competitive banking landscape.
Several limitations should be acknowledged. The analysis relies on secondary indicators and a cross-sectional design, which means the observed relationships are reported as significant associations rather than definitive causal claims, in line with the inherent limitations of SEM. Additionally, while providing deep insights into ASEAN and MENA, the specific institutional contexts of these regions may limit the broader generalizability of the results to advanced economies. Future research could extend this framework using longitudinal data, alternative efficiency measures, or broader regional coverage to examine further how banks balance competitive power and operational efficiency under evolving institutional and digital conditions.