
Multifractal Cross-Market Dependence and Dynamic Hedging Under Crisis Regimes: Evidence from Commodity–Equity Interactions


Abstract
1. Introduction
2. Literature Review
2.1. Commodity–Equity Connectedness and Market Spillovers
2.2. Crisis Regimes, Market Instability and Cross-Asset Risk Transmission
2.3. Hedging Role of Commodities Under Market Turbulence
2.4. From Linear Models to Multifractal and Multivariate Volatility Frameworks
2.5. Research Gap
3. Methodology
3.1. Empirical Design and Research Framework
3.2. Multifractal Cross-Correlation Methodology
3.3. Dynamic Hedge Ratio Estimation Using ADCC and GO-GARCH
3.4. Optimal Portfolio Weights and Hedging Effectiveness
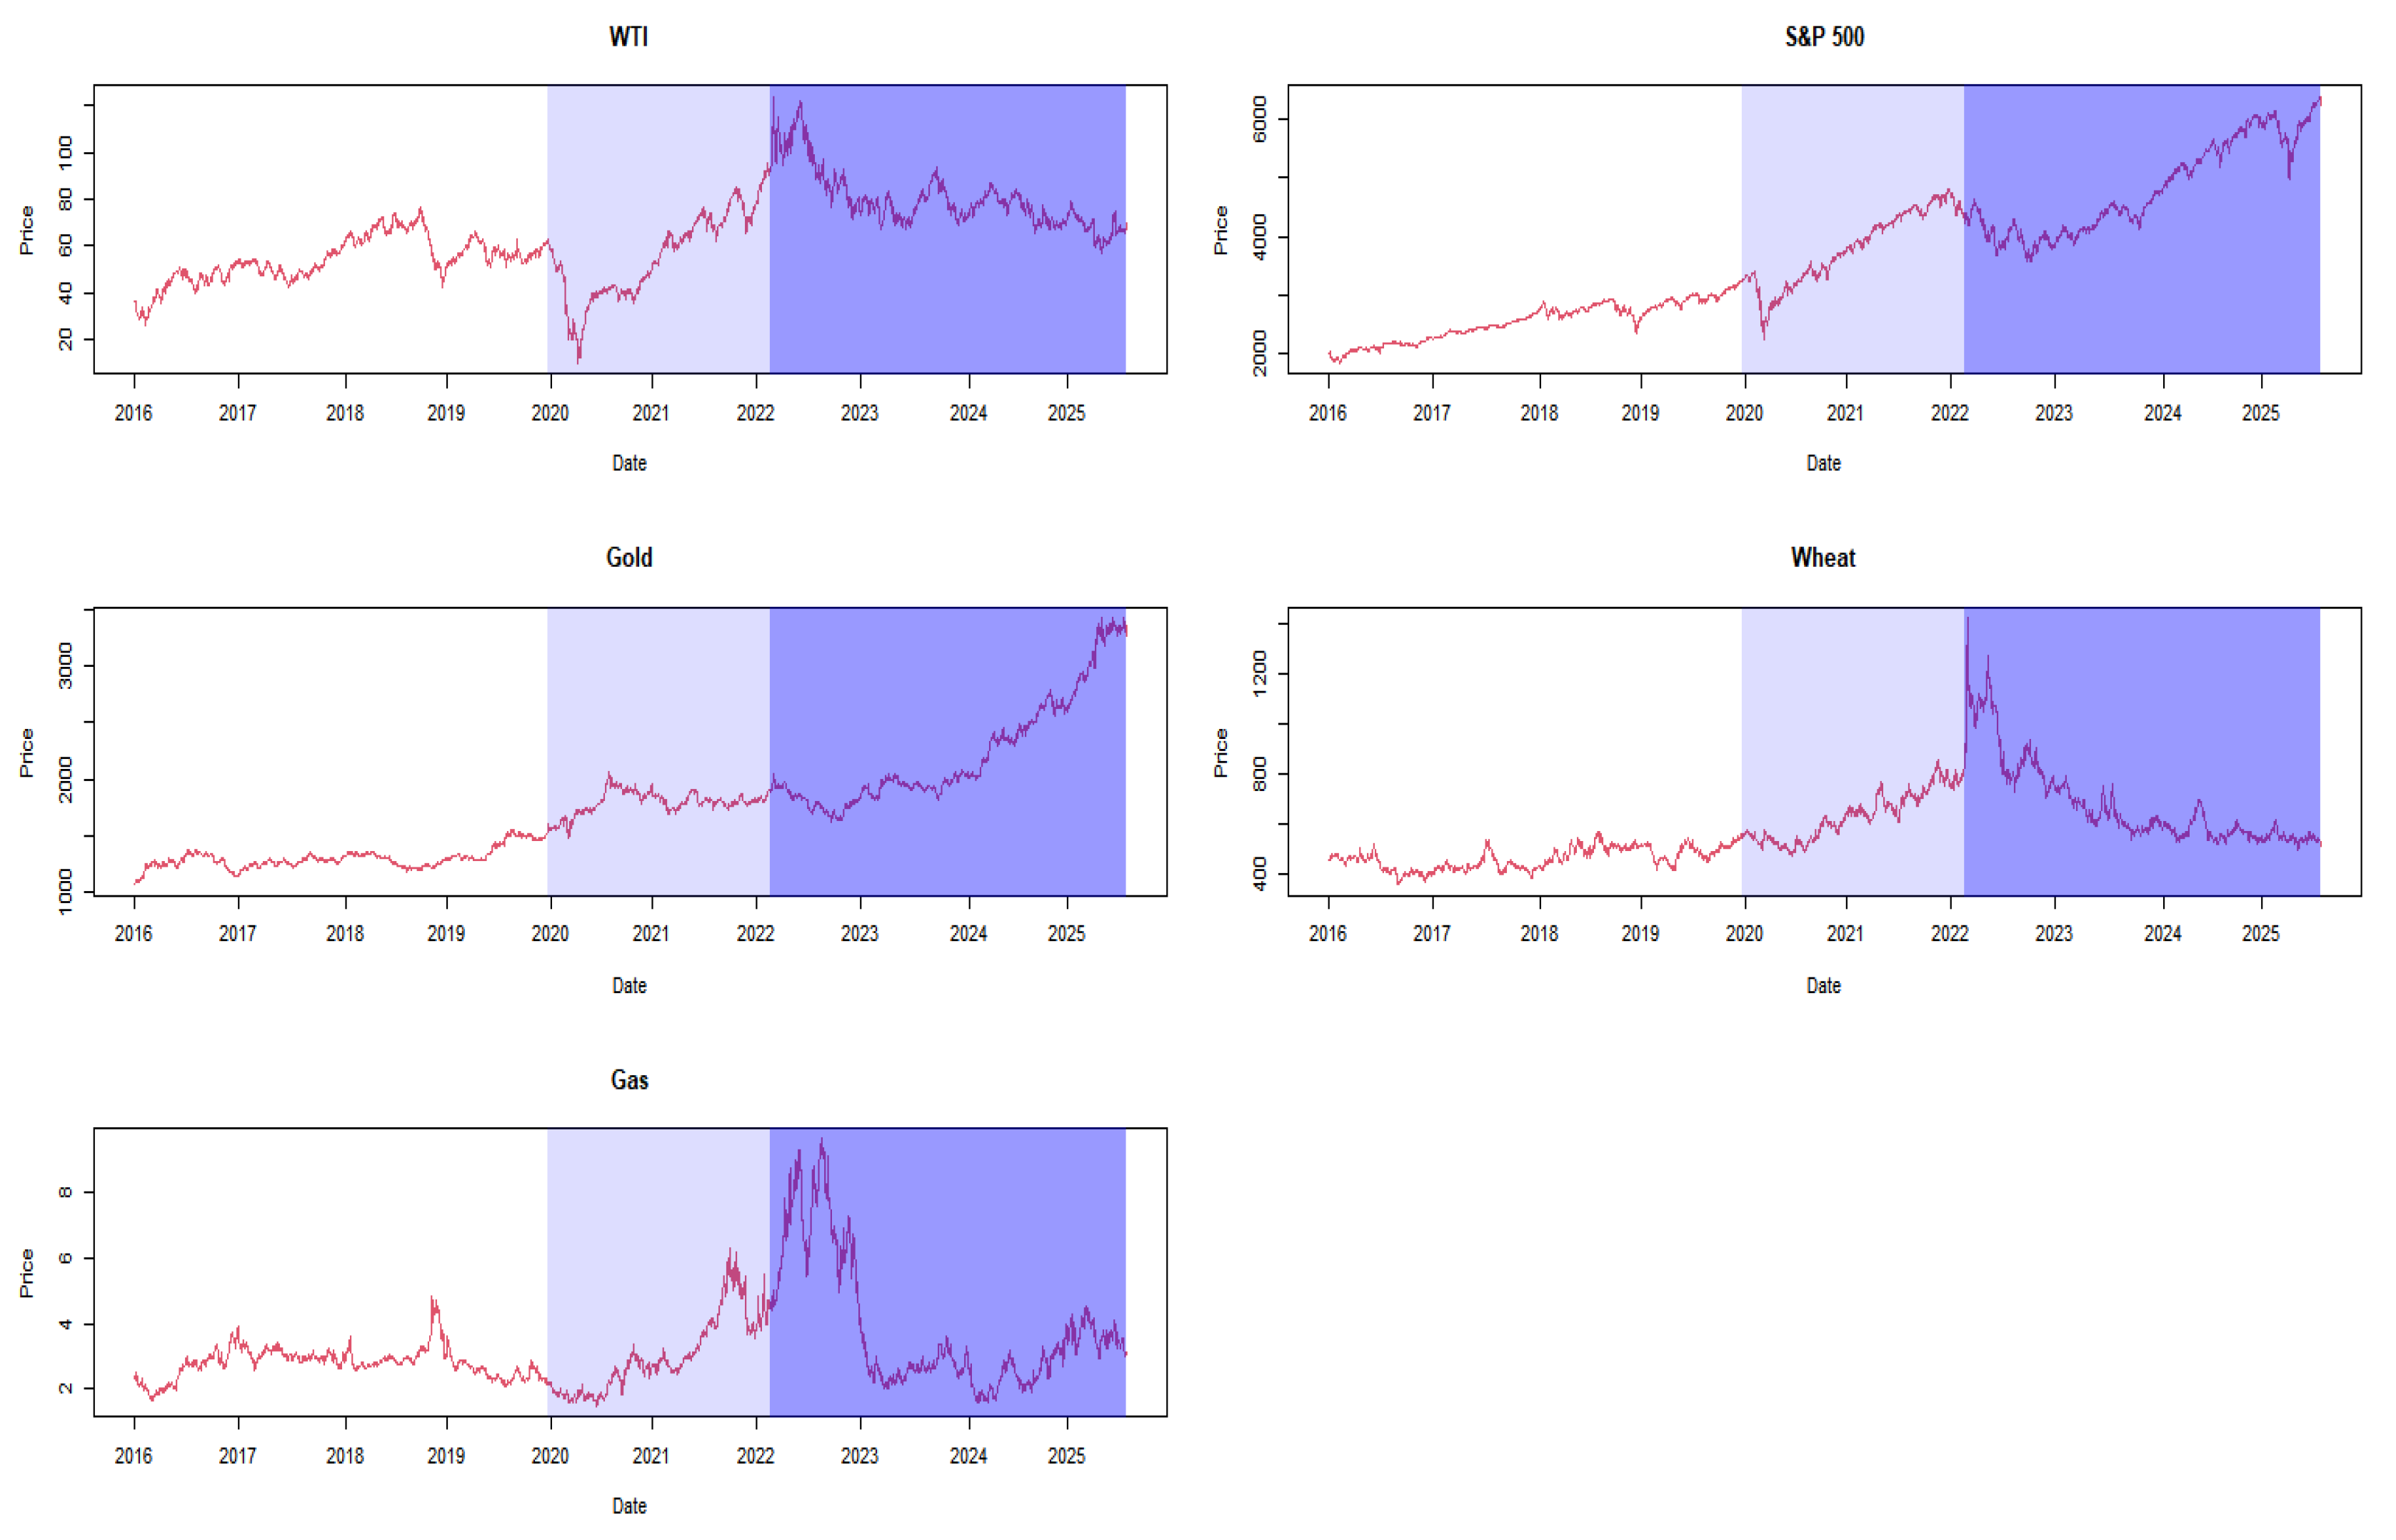
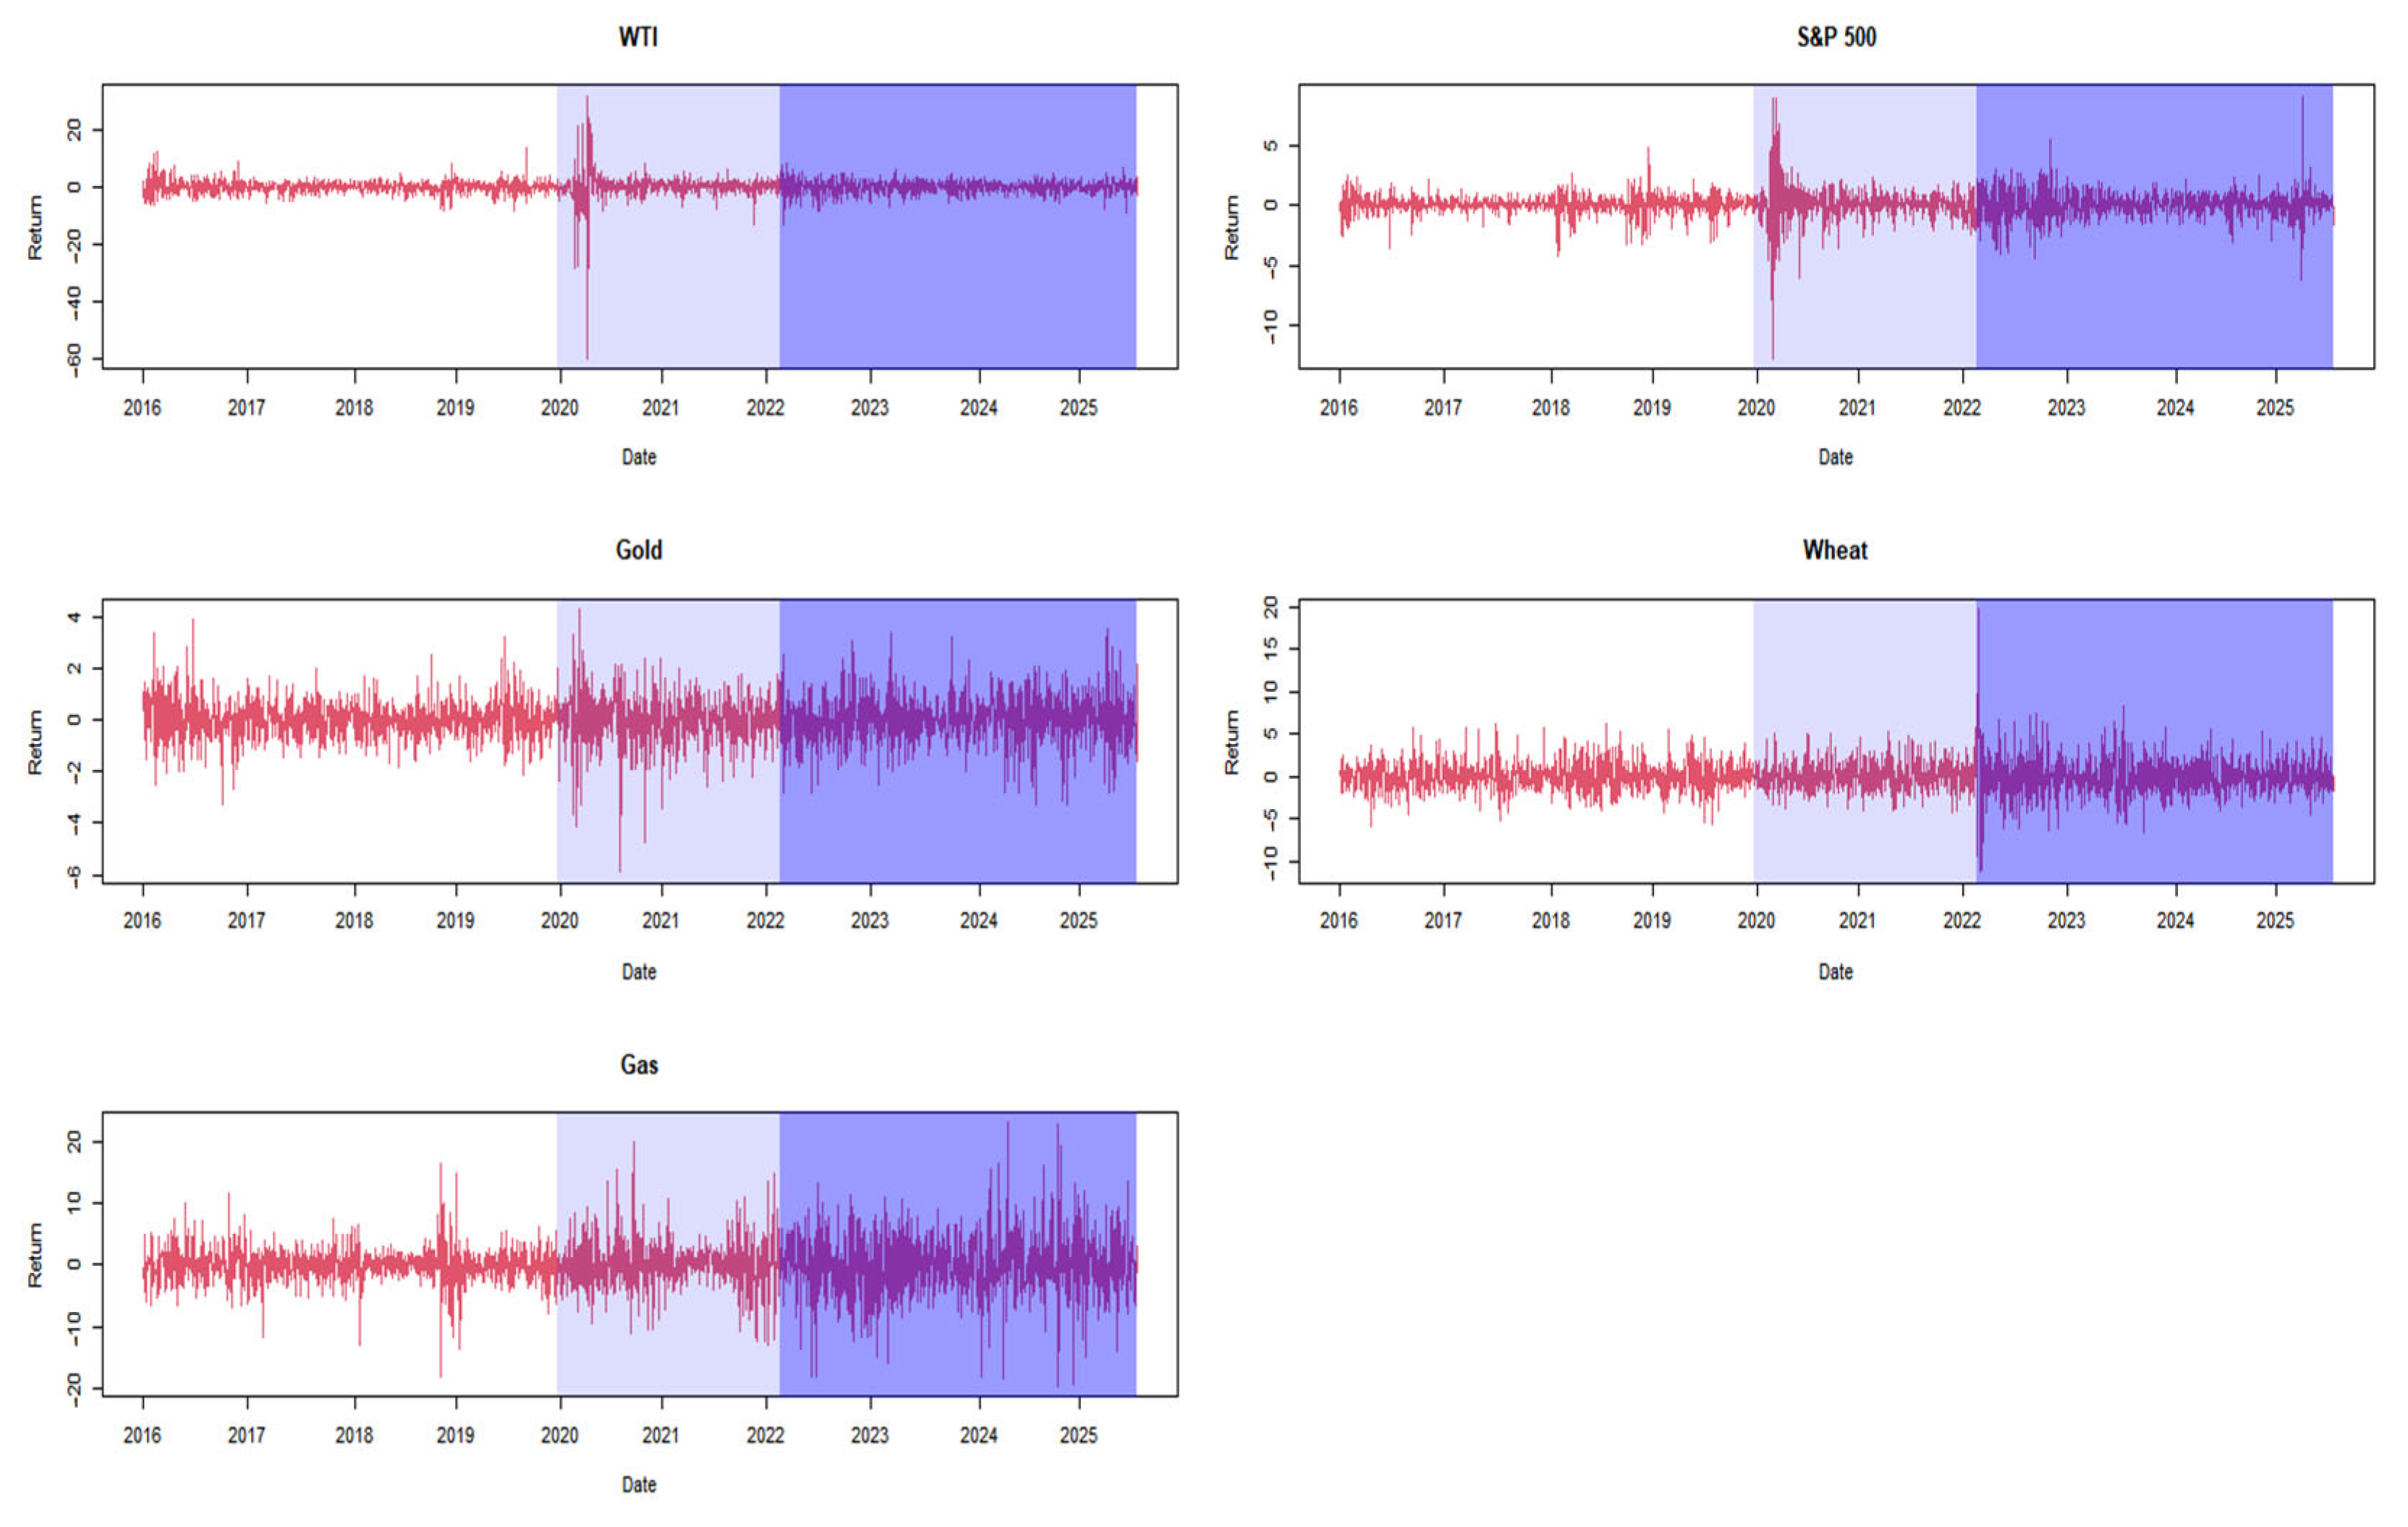
4. Data and Variables
5. Empirical Results and Discussions
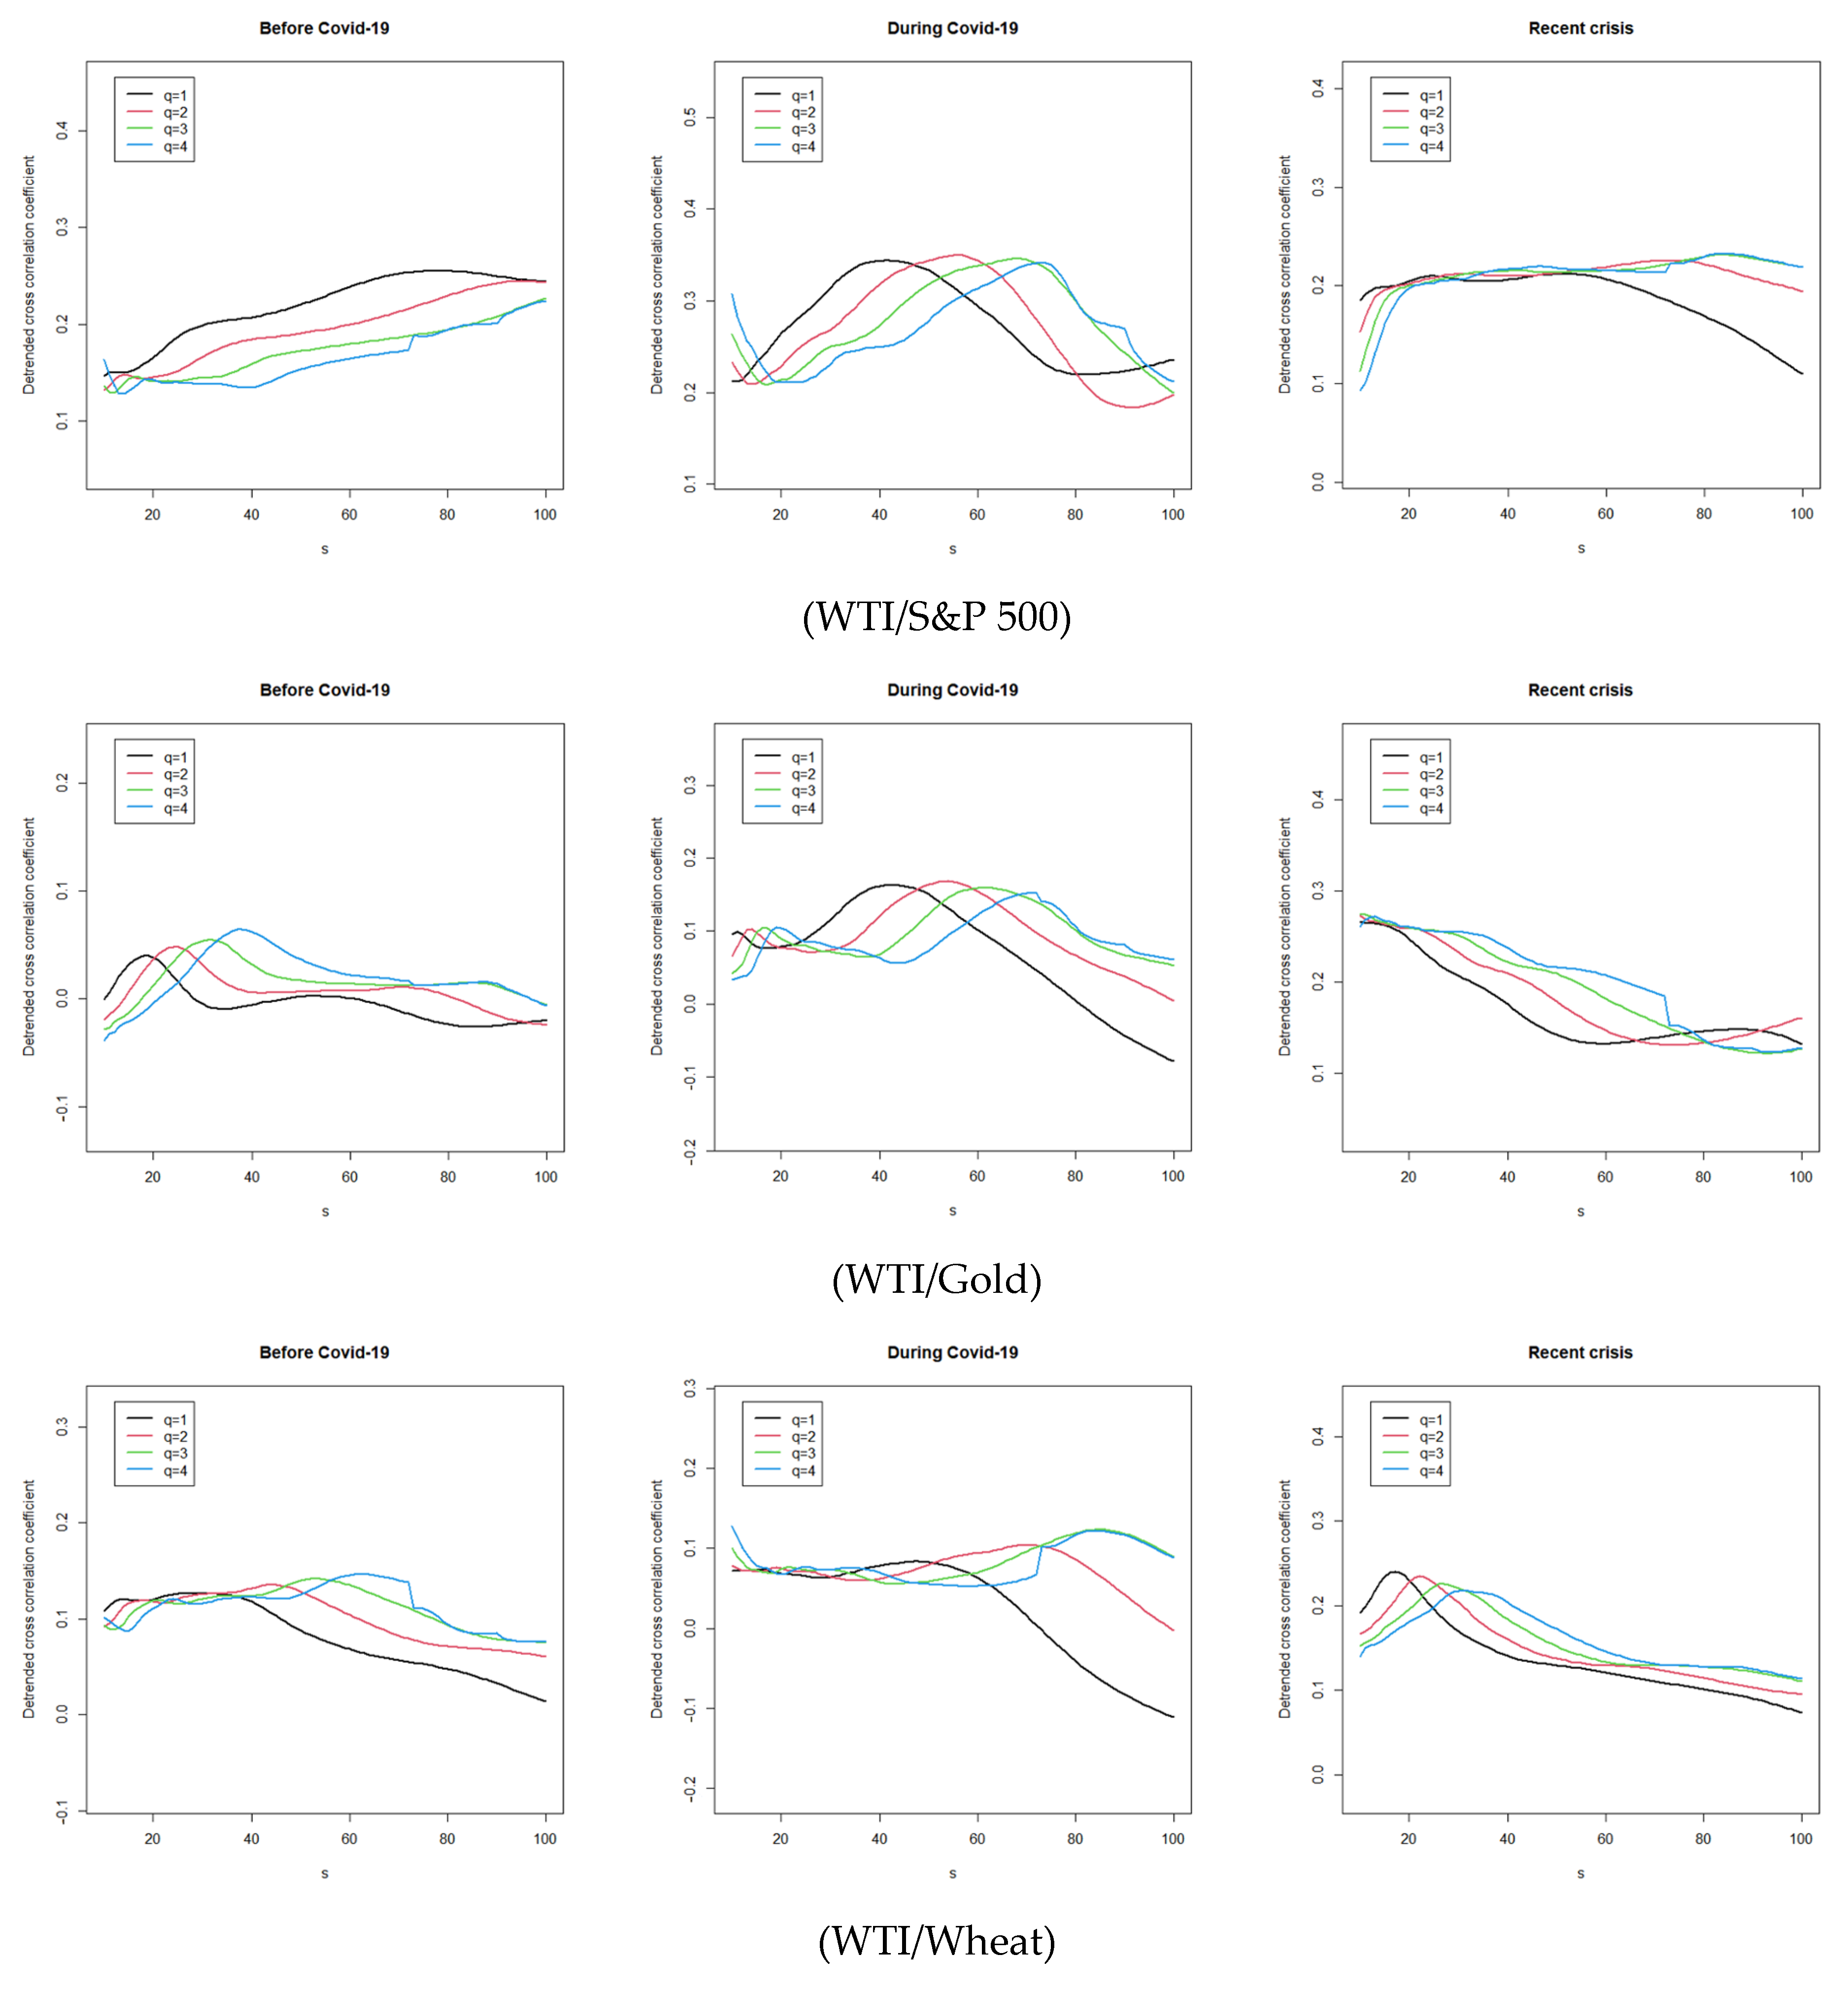
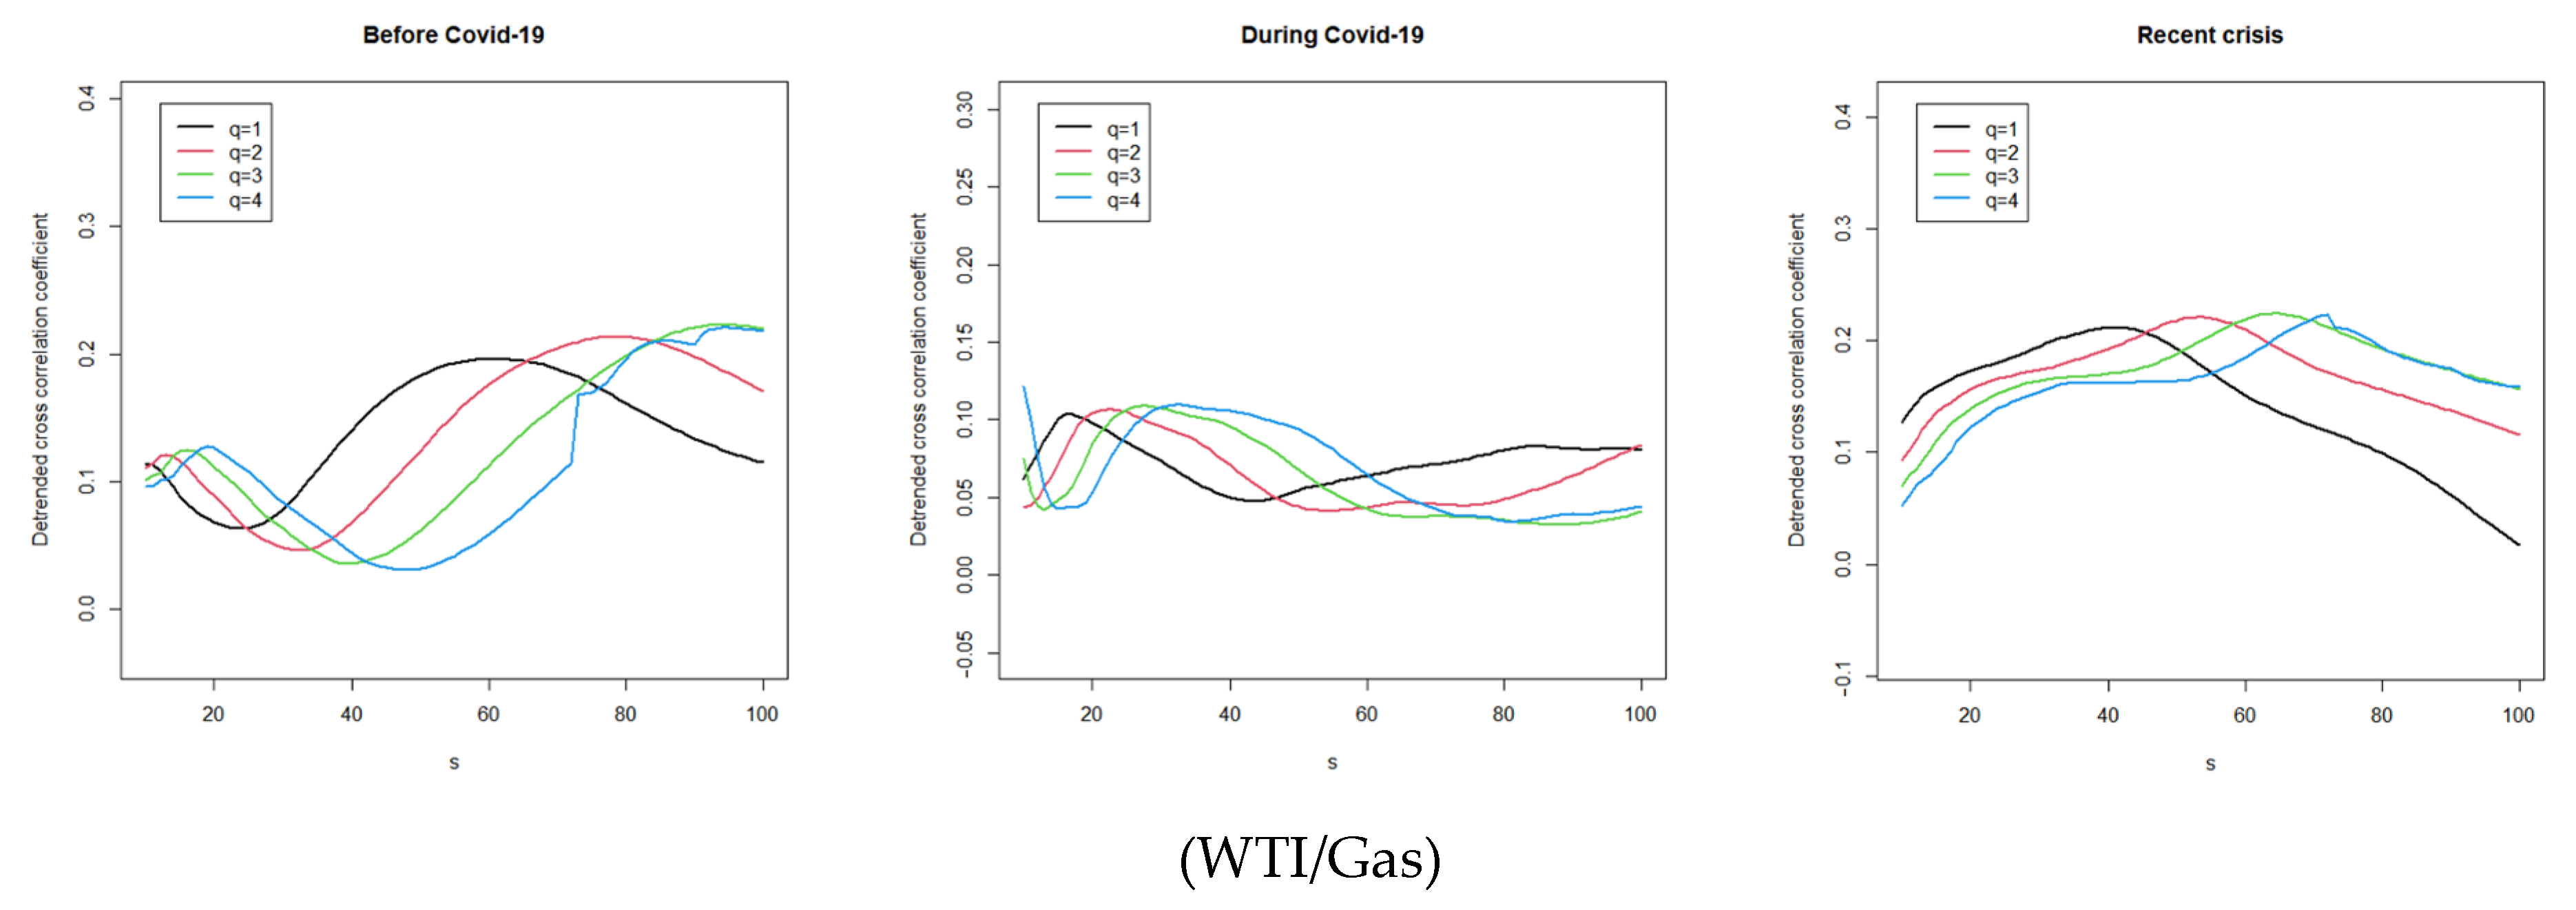
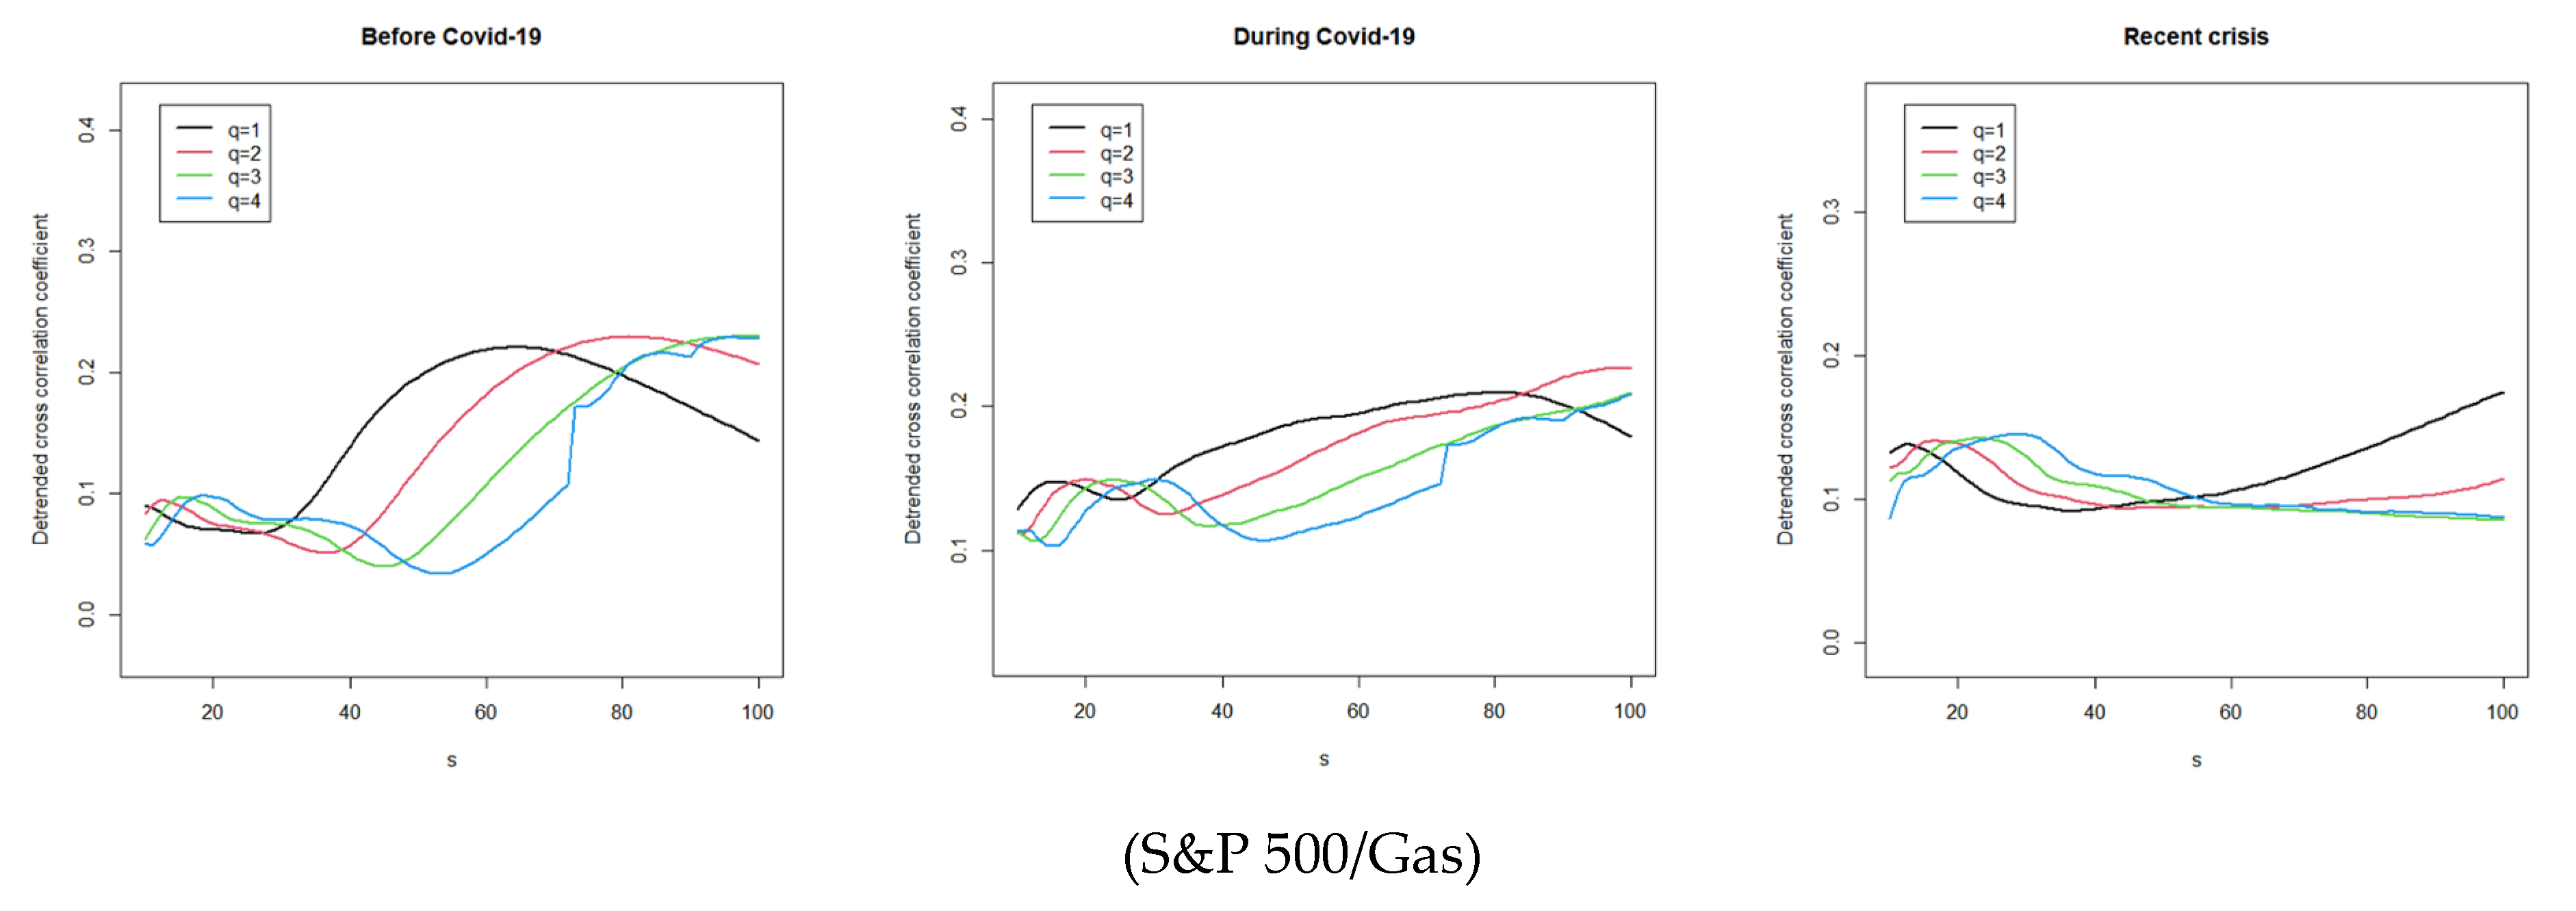
5.1. Cross-Correlation Coefficient
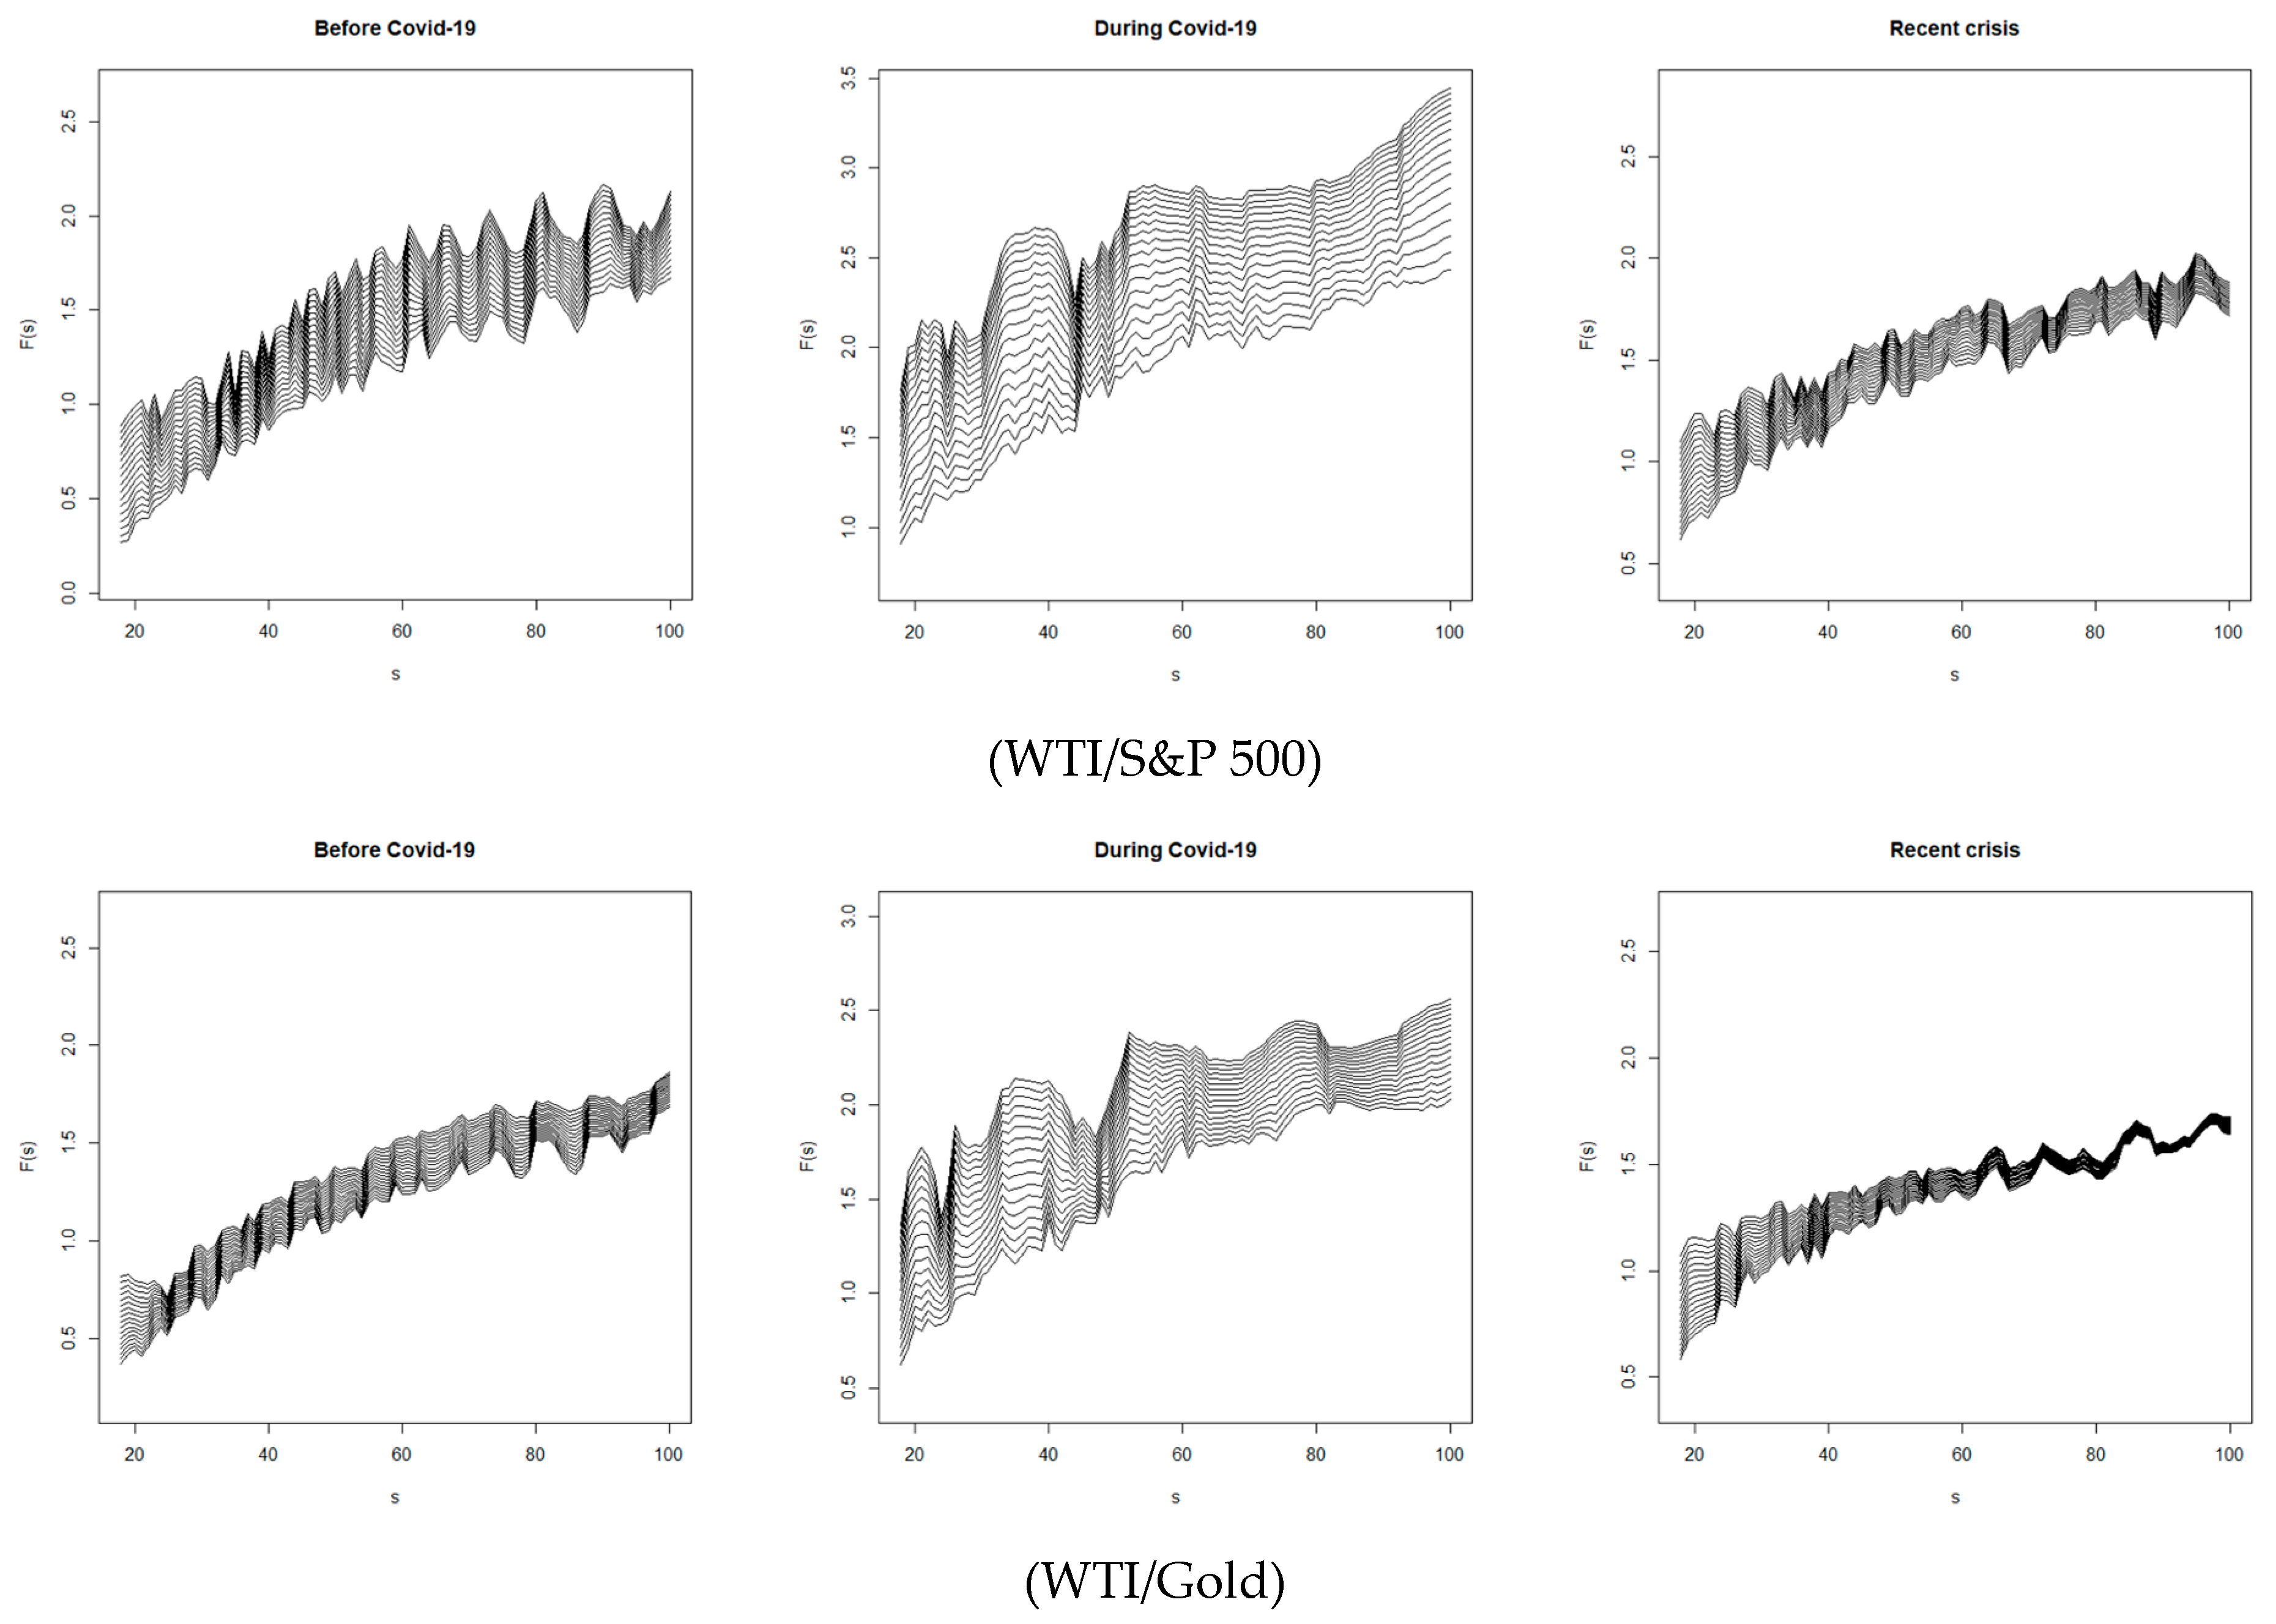
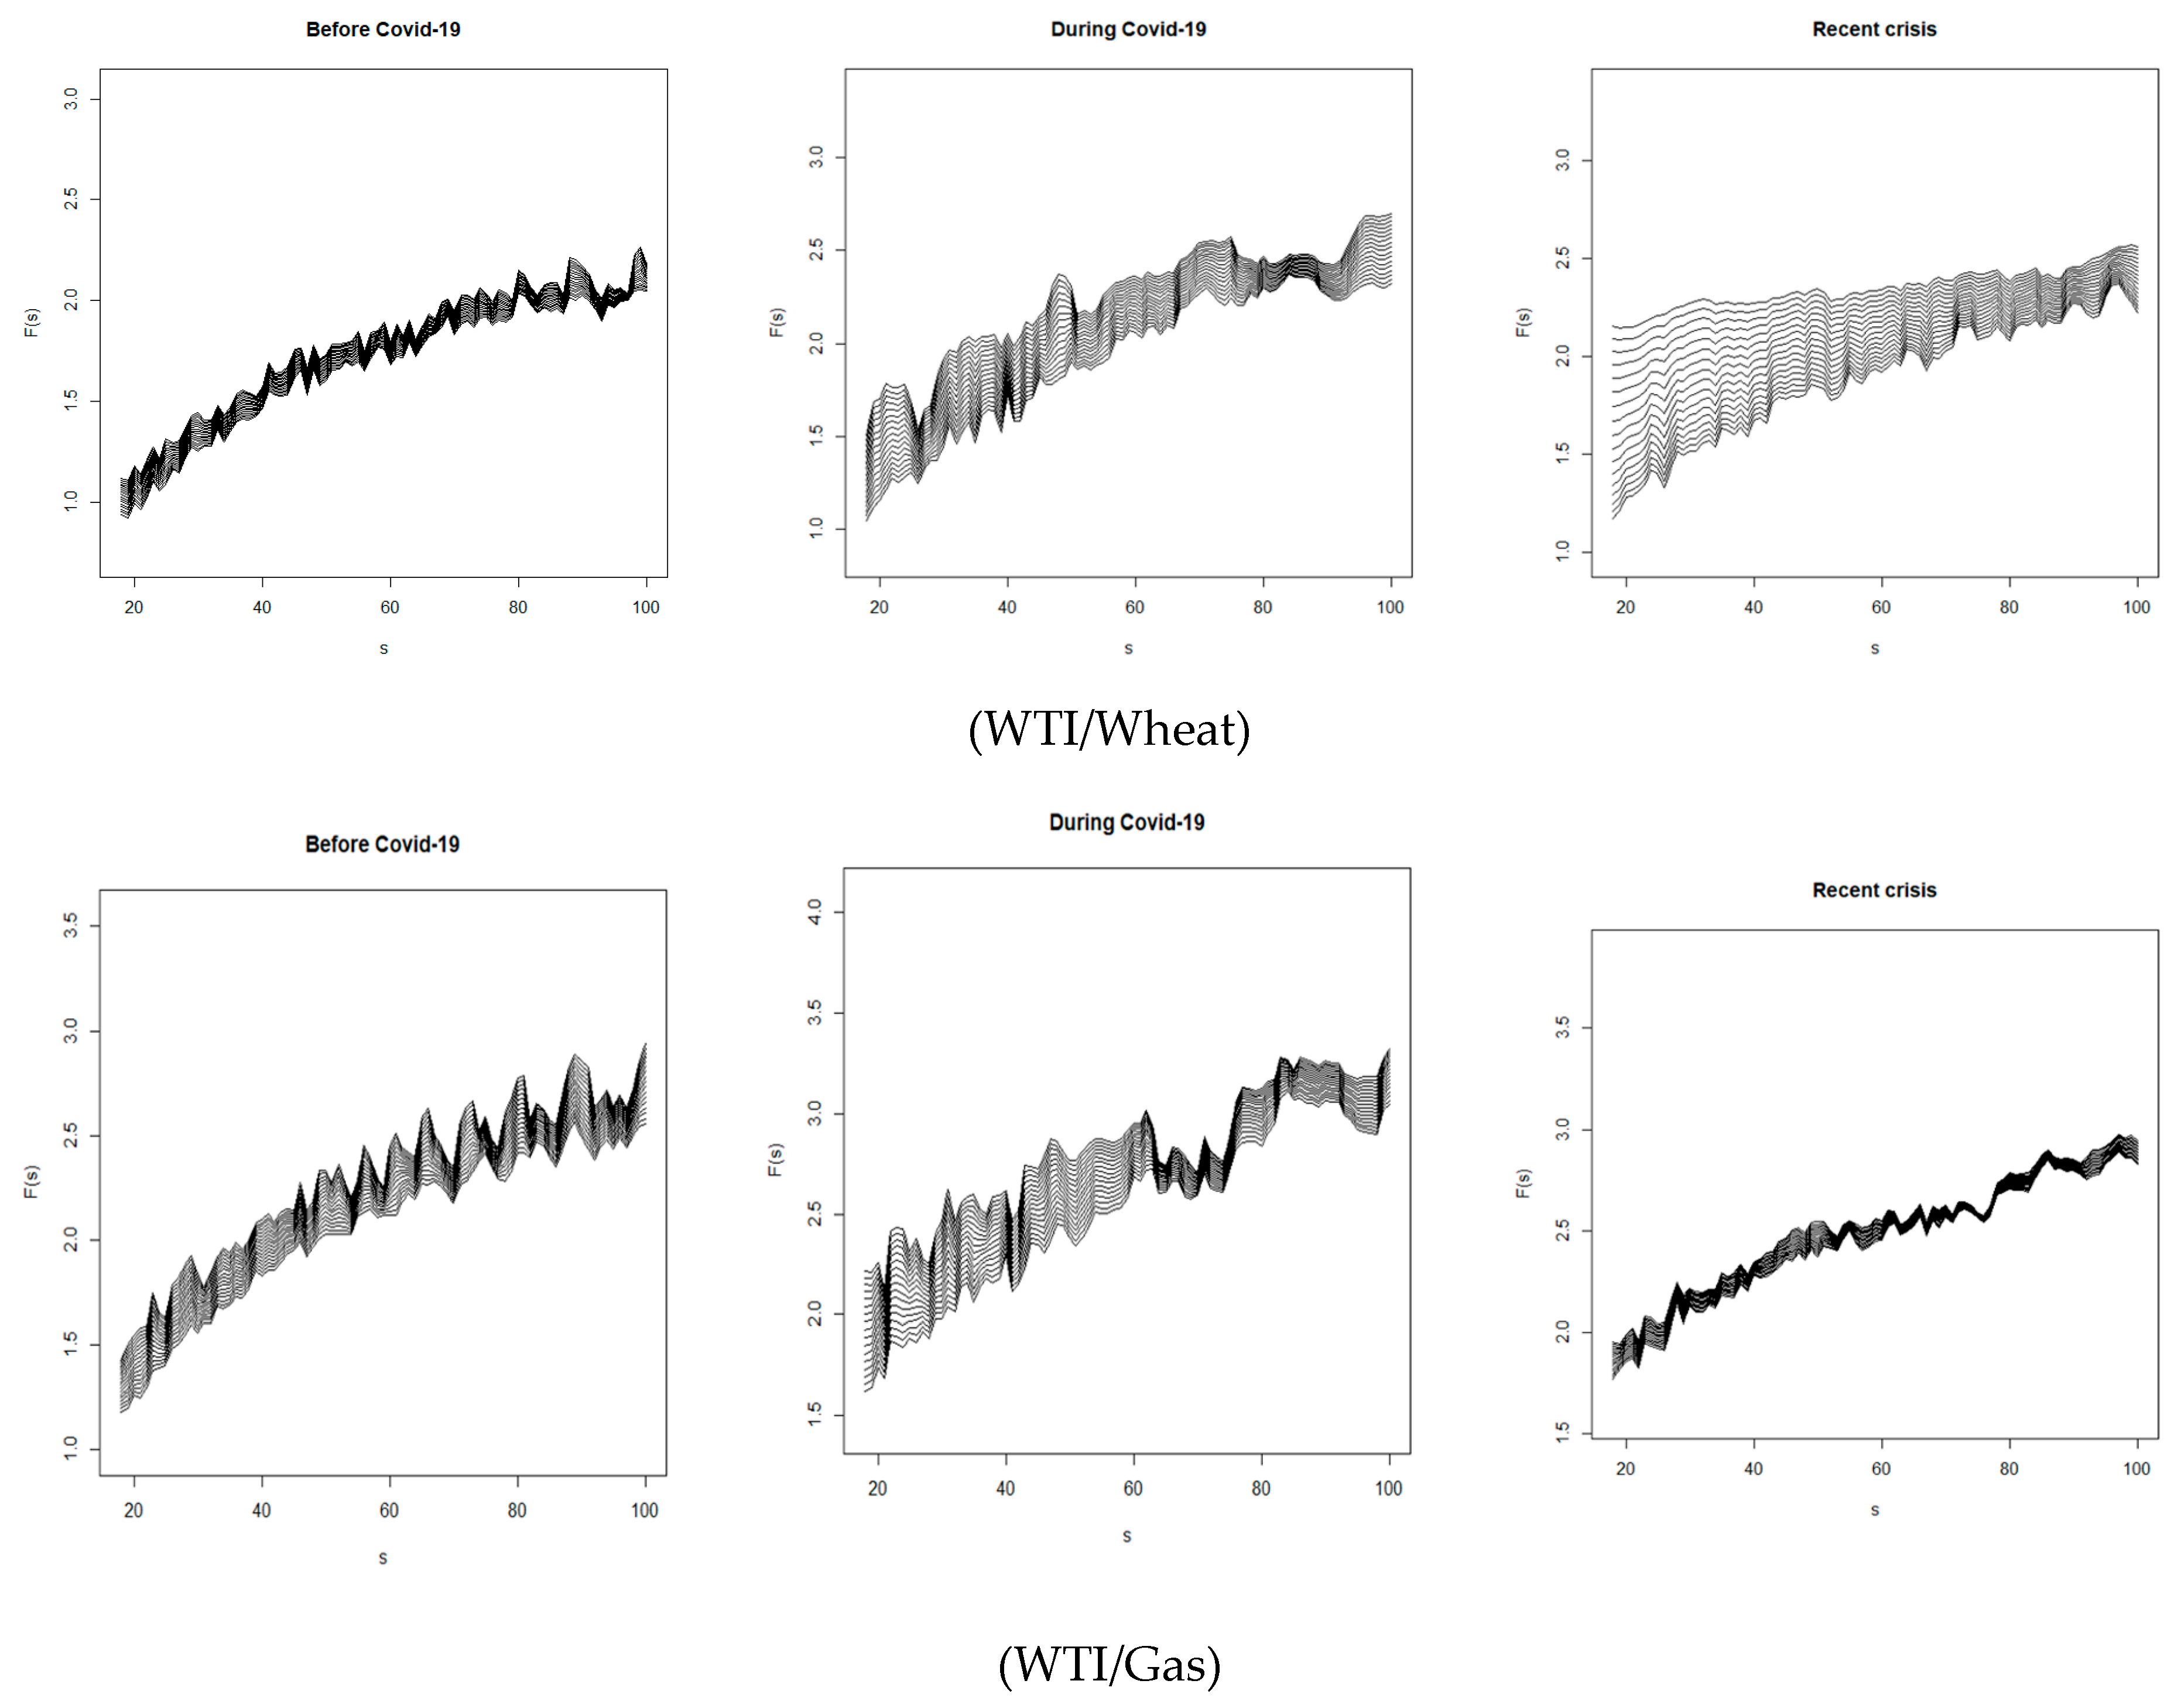
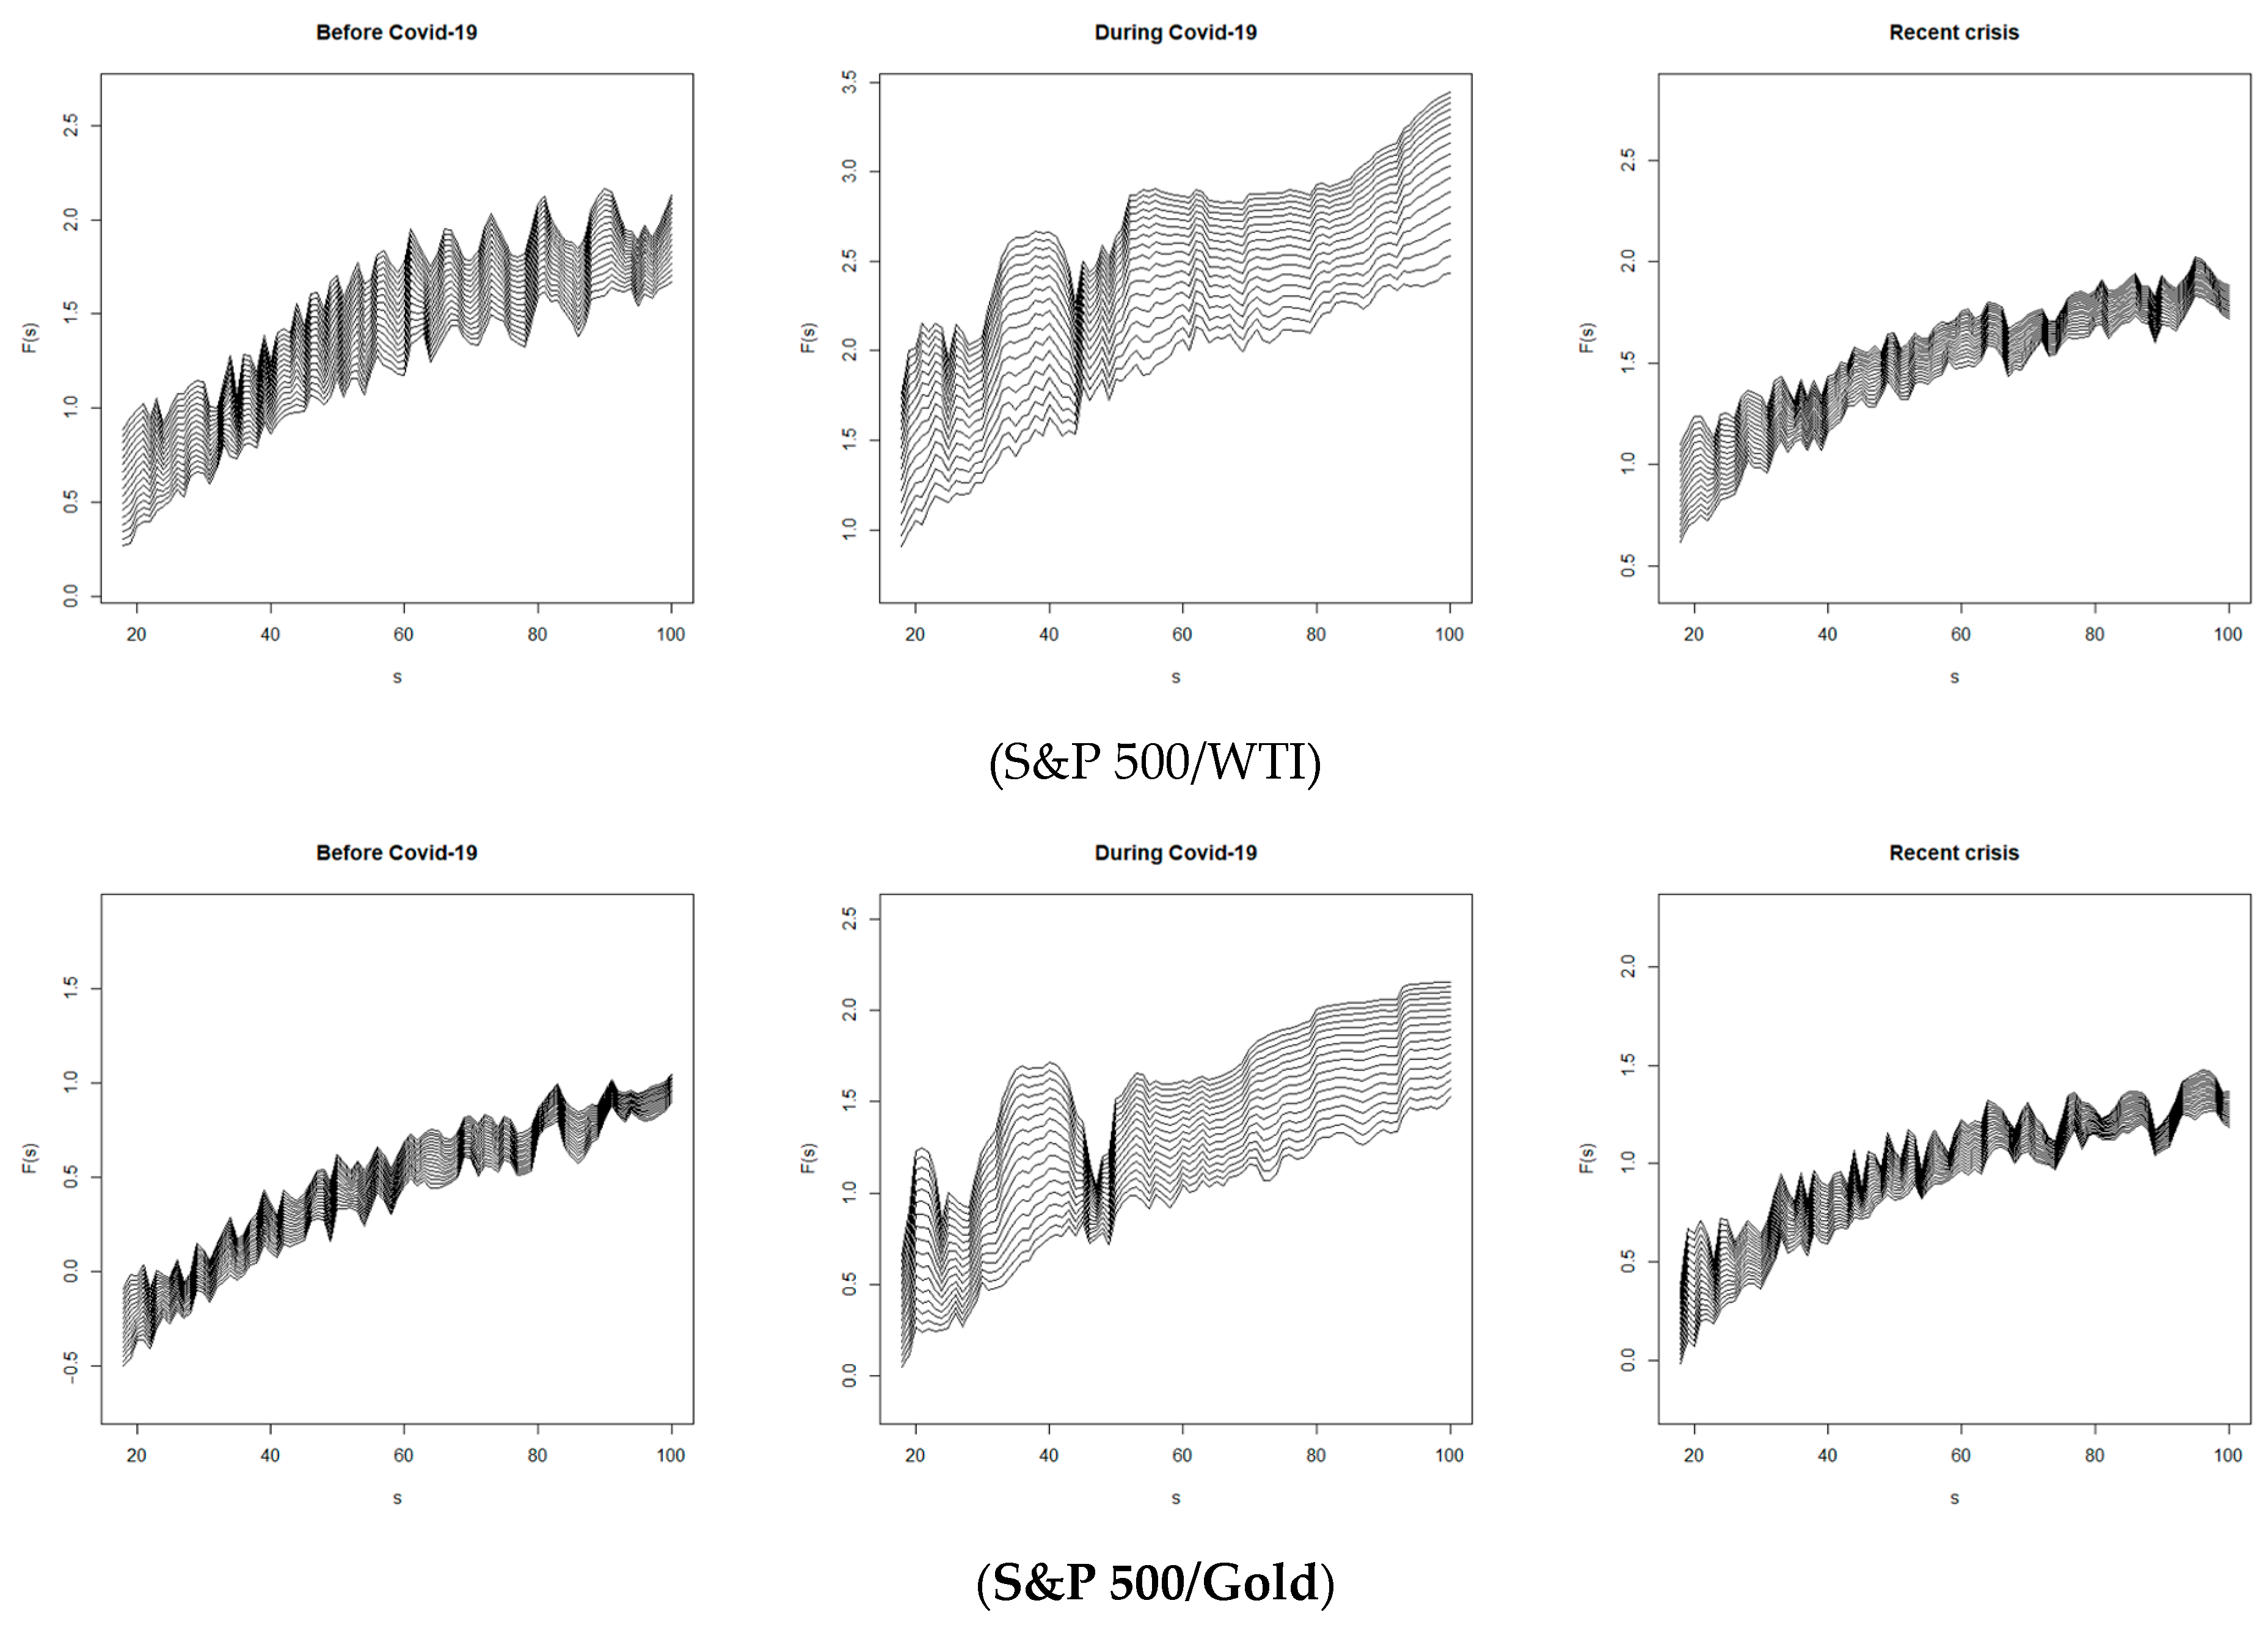
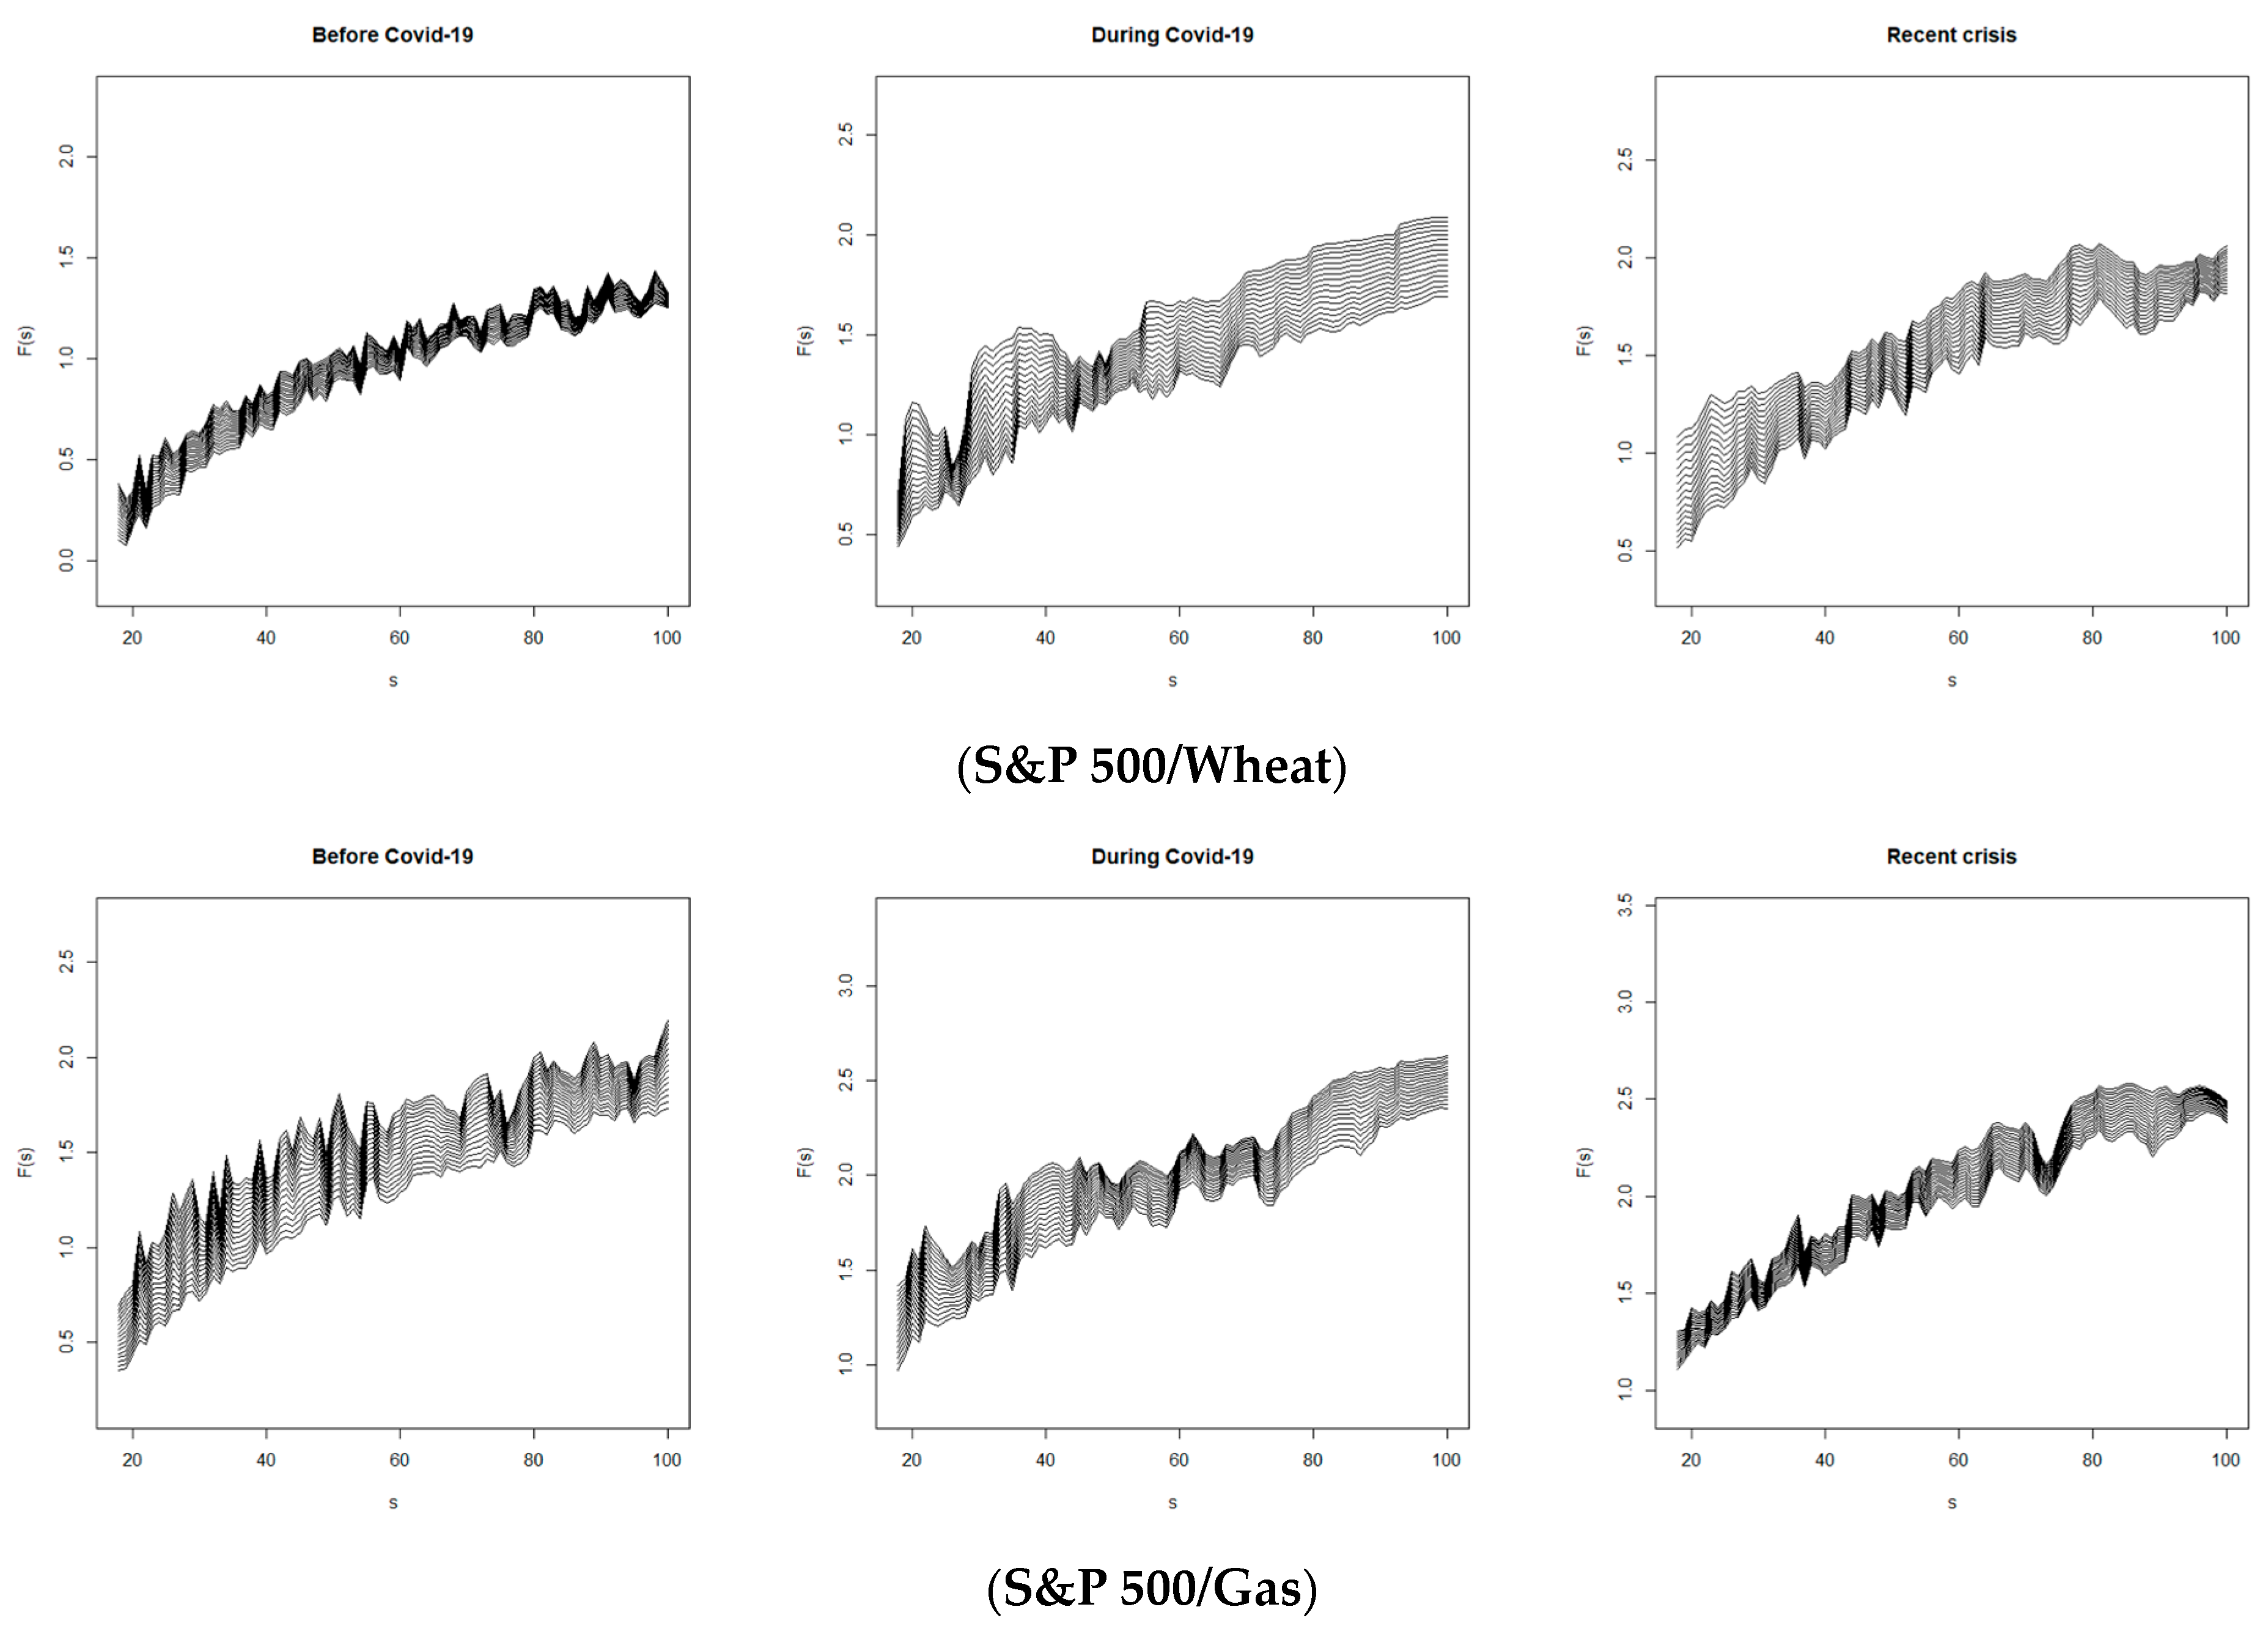
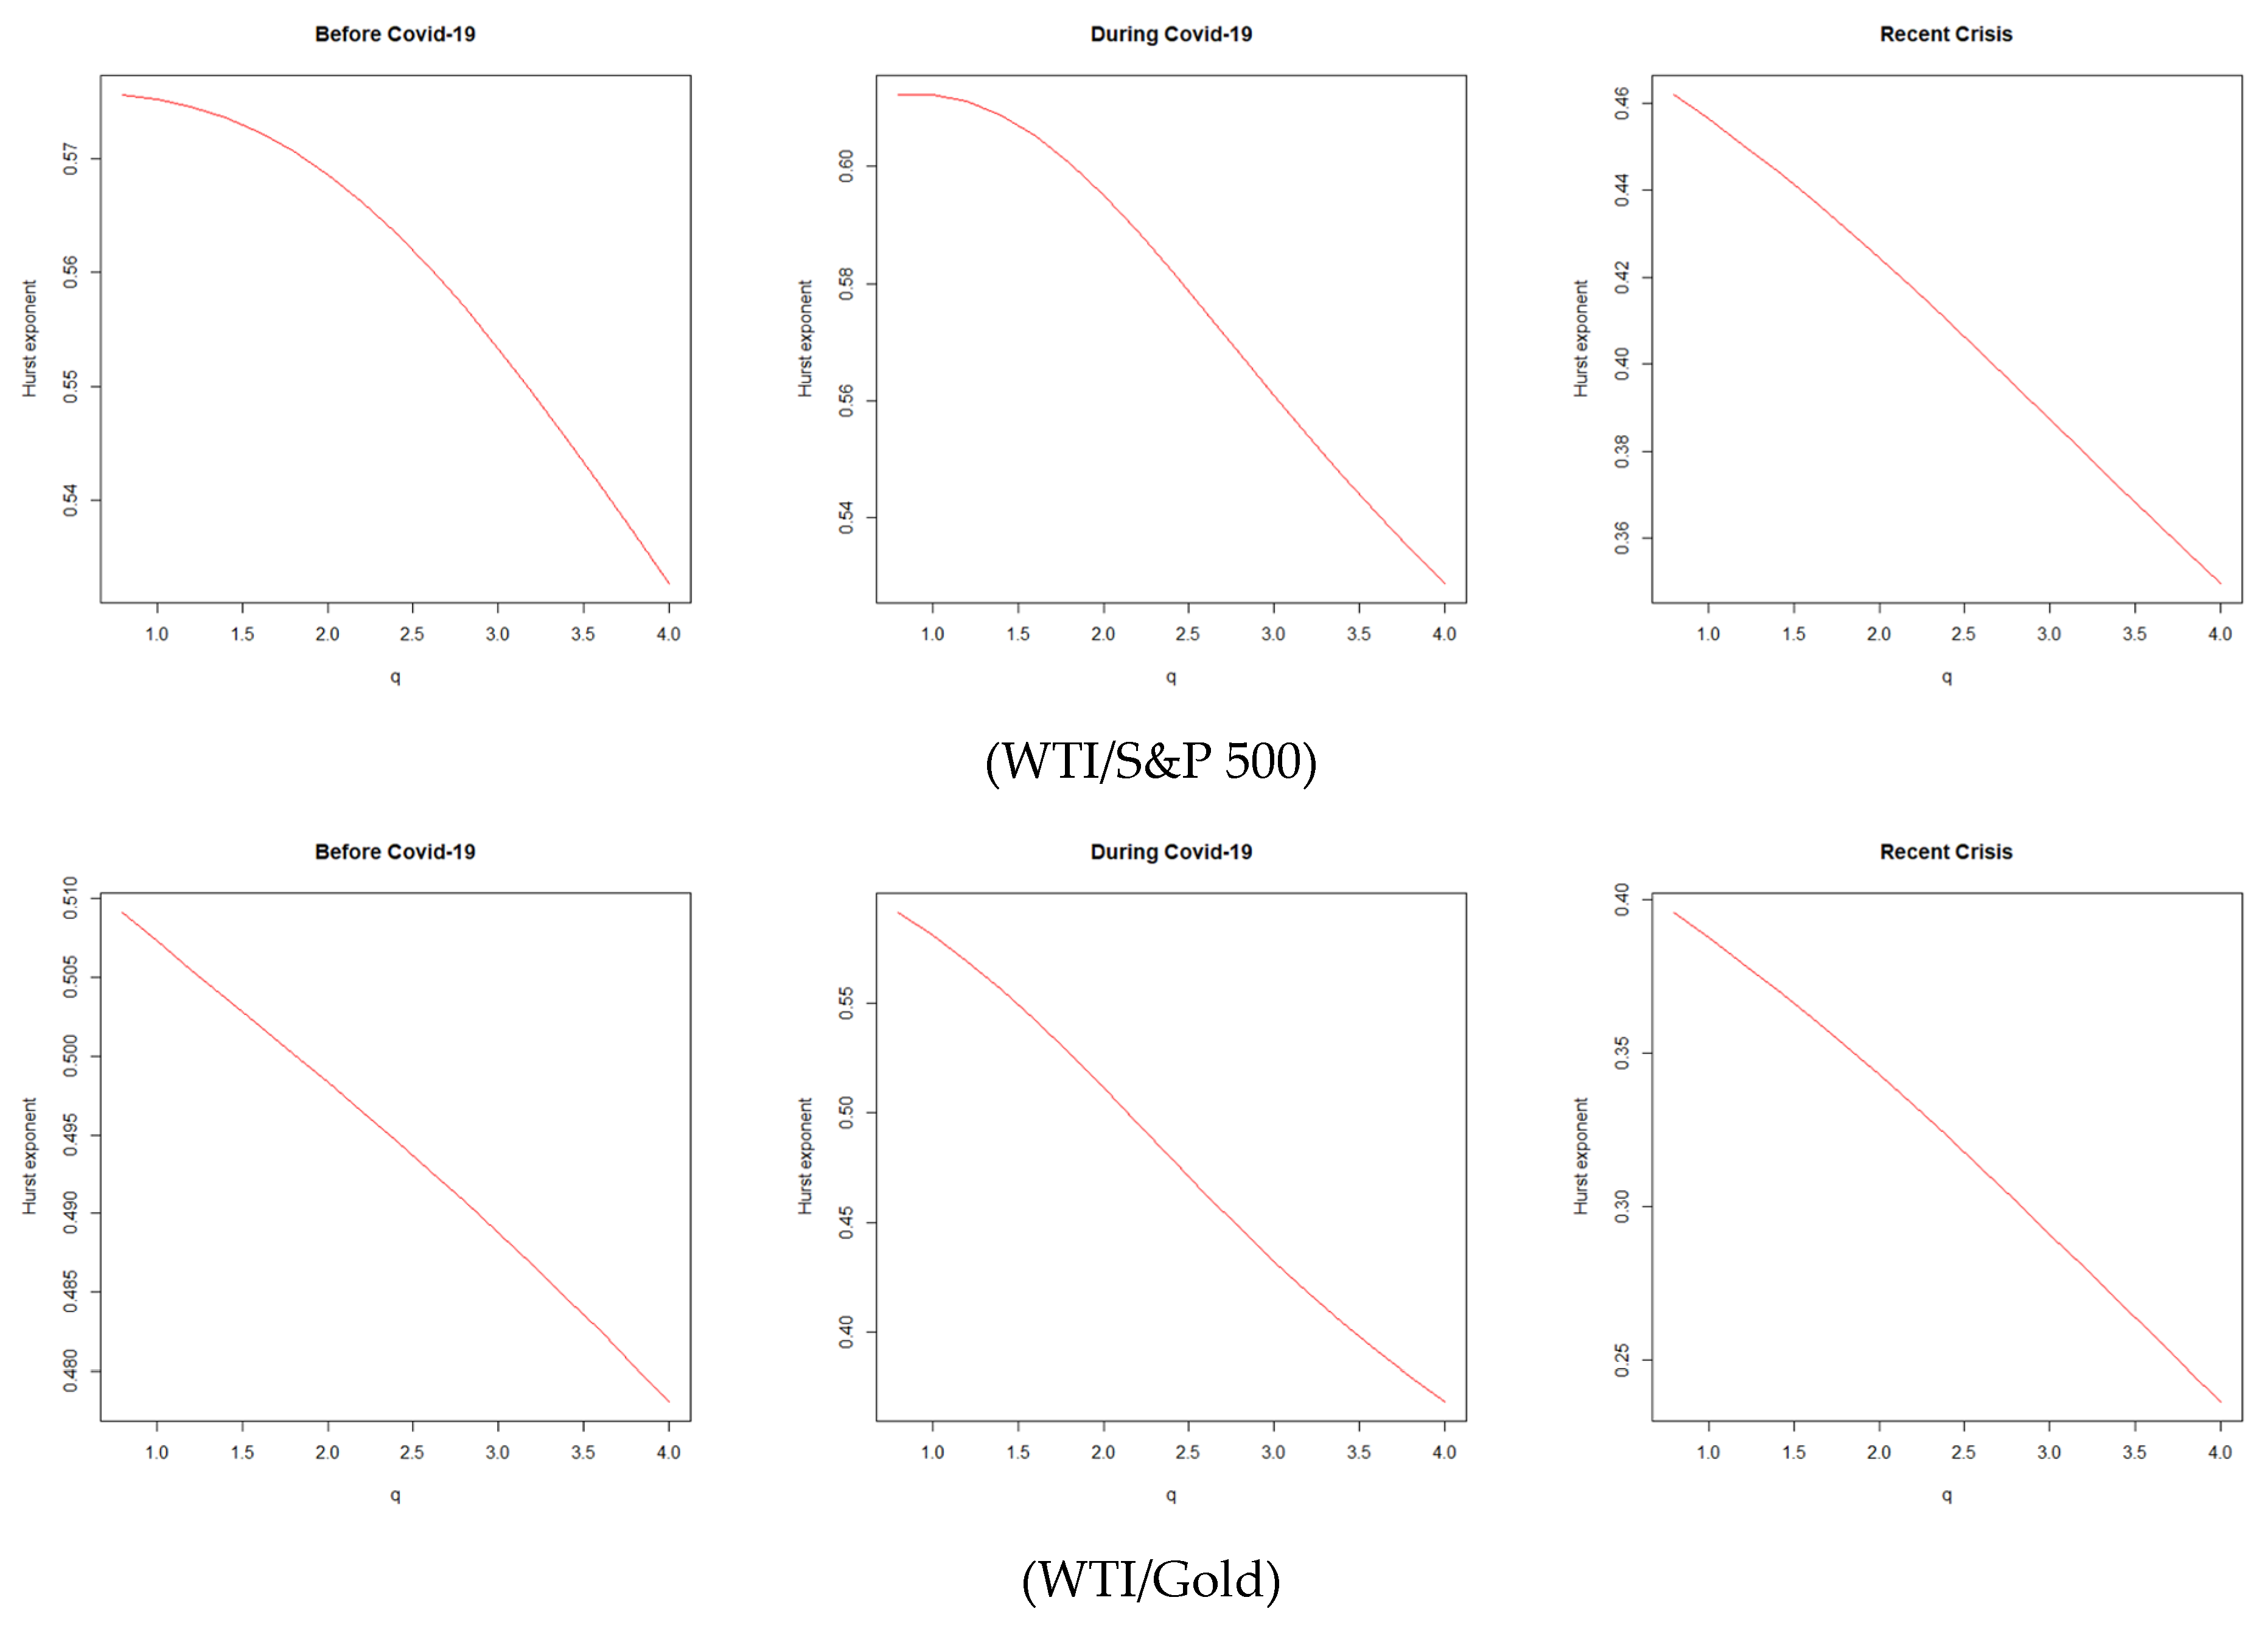
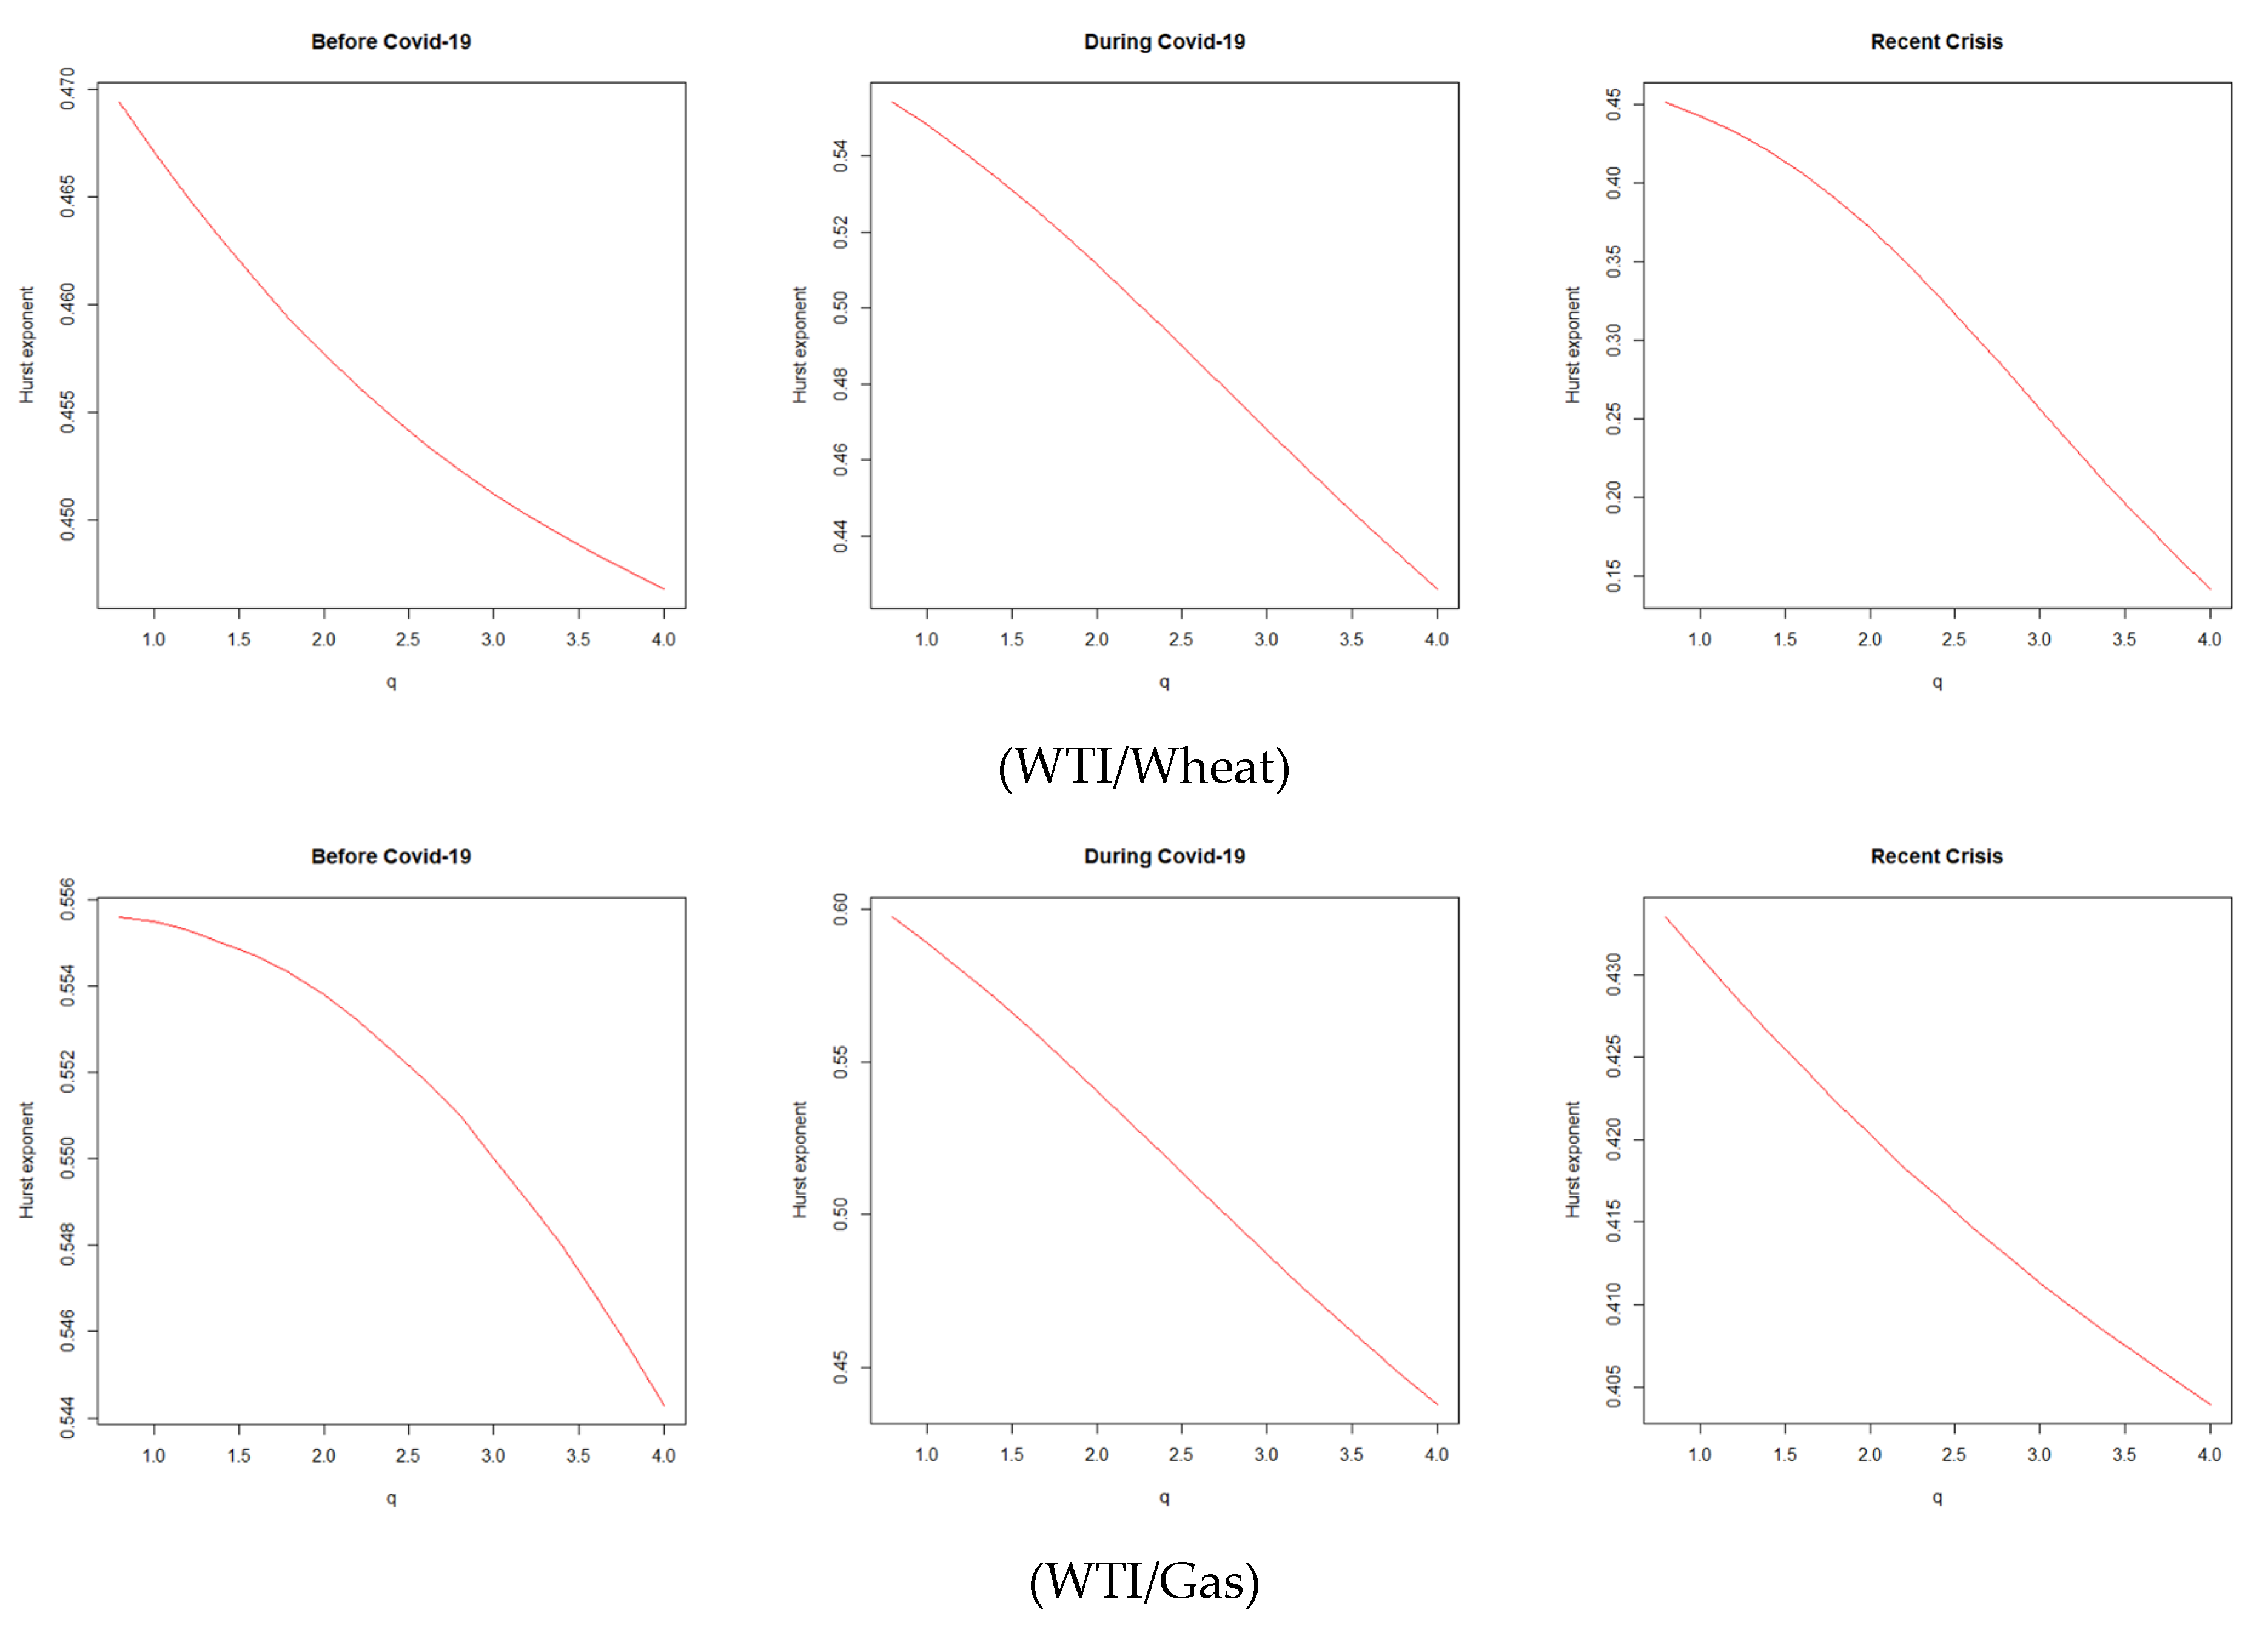
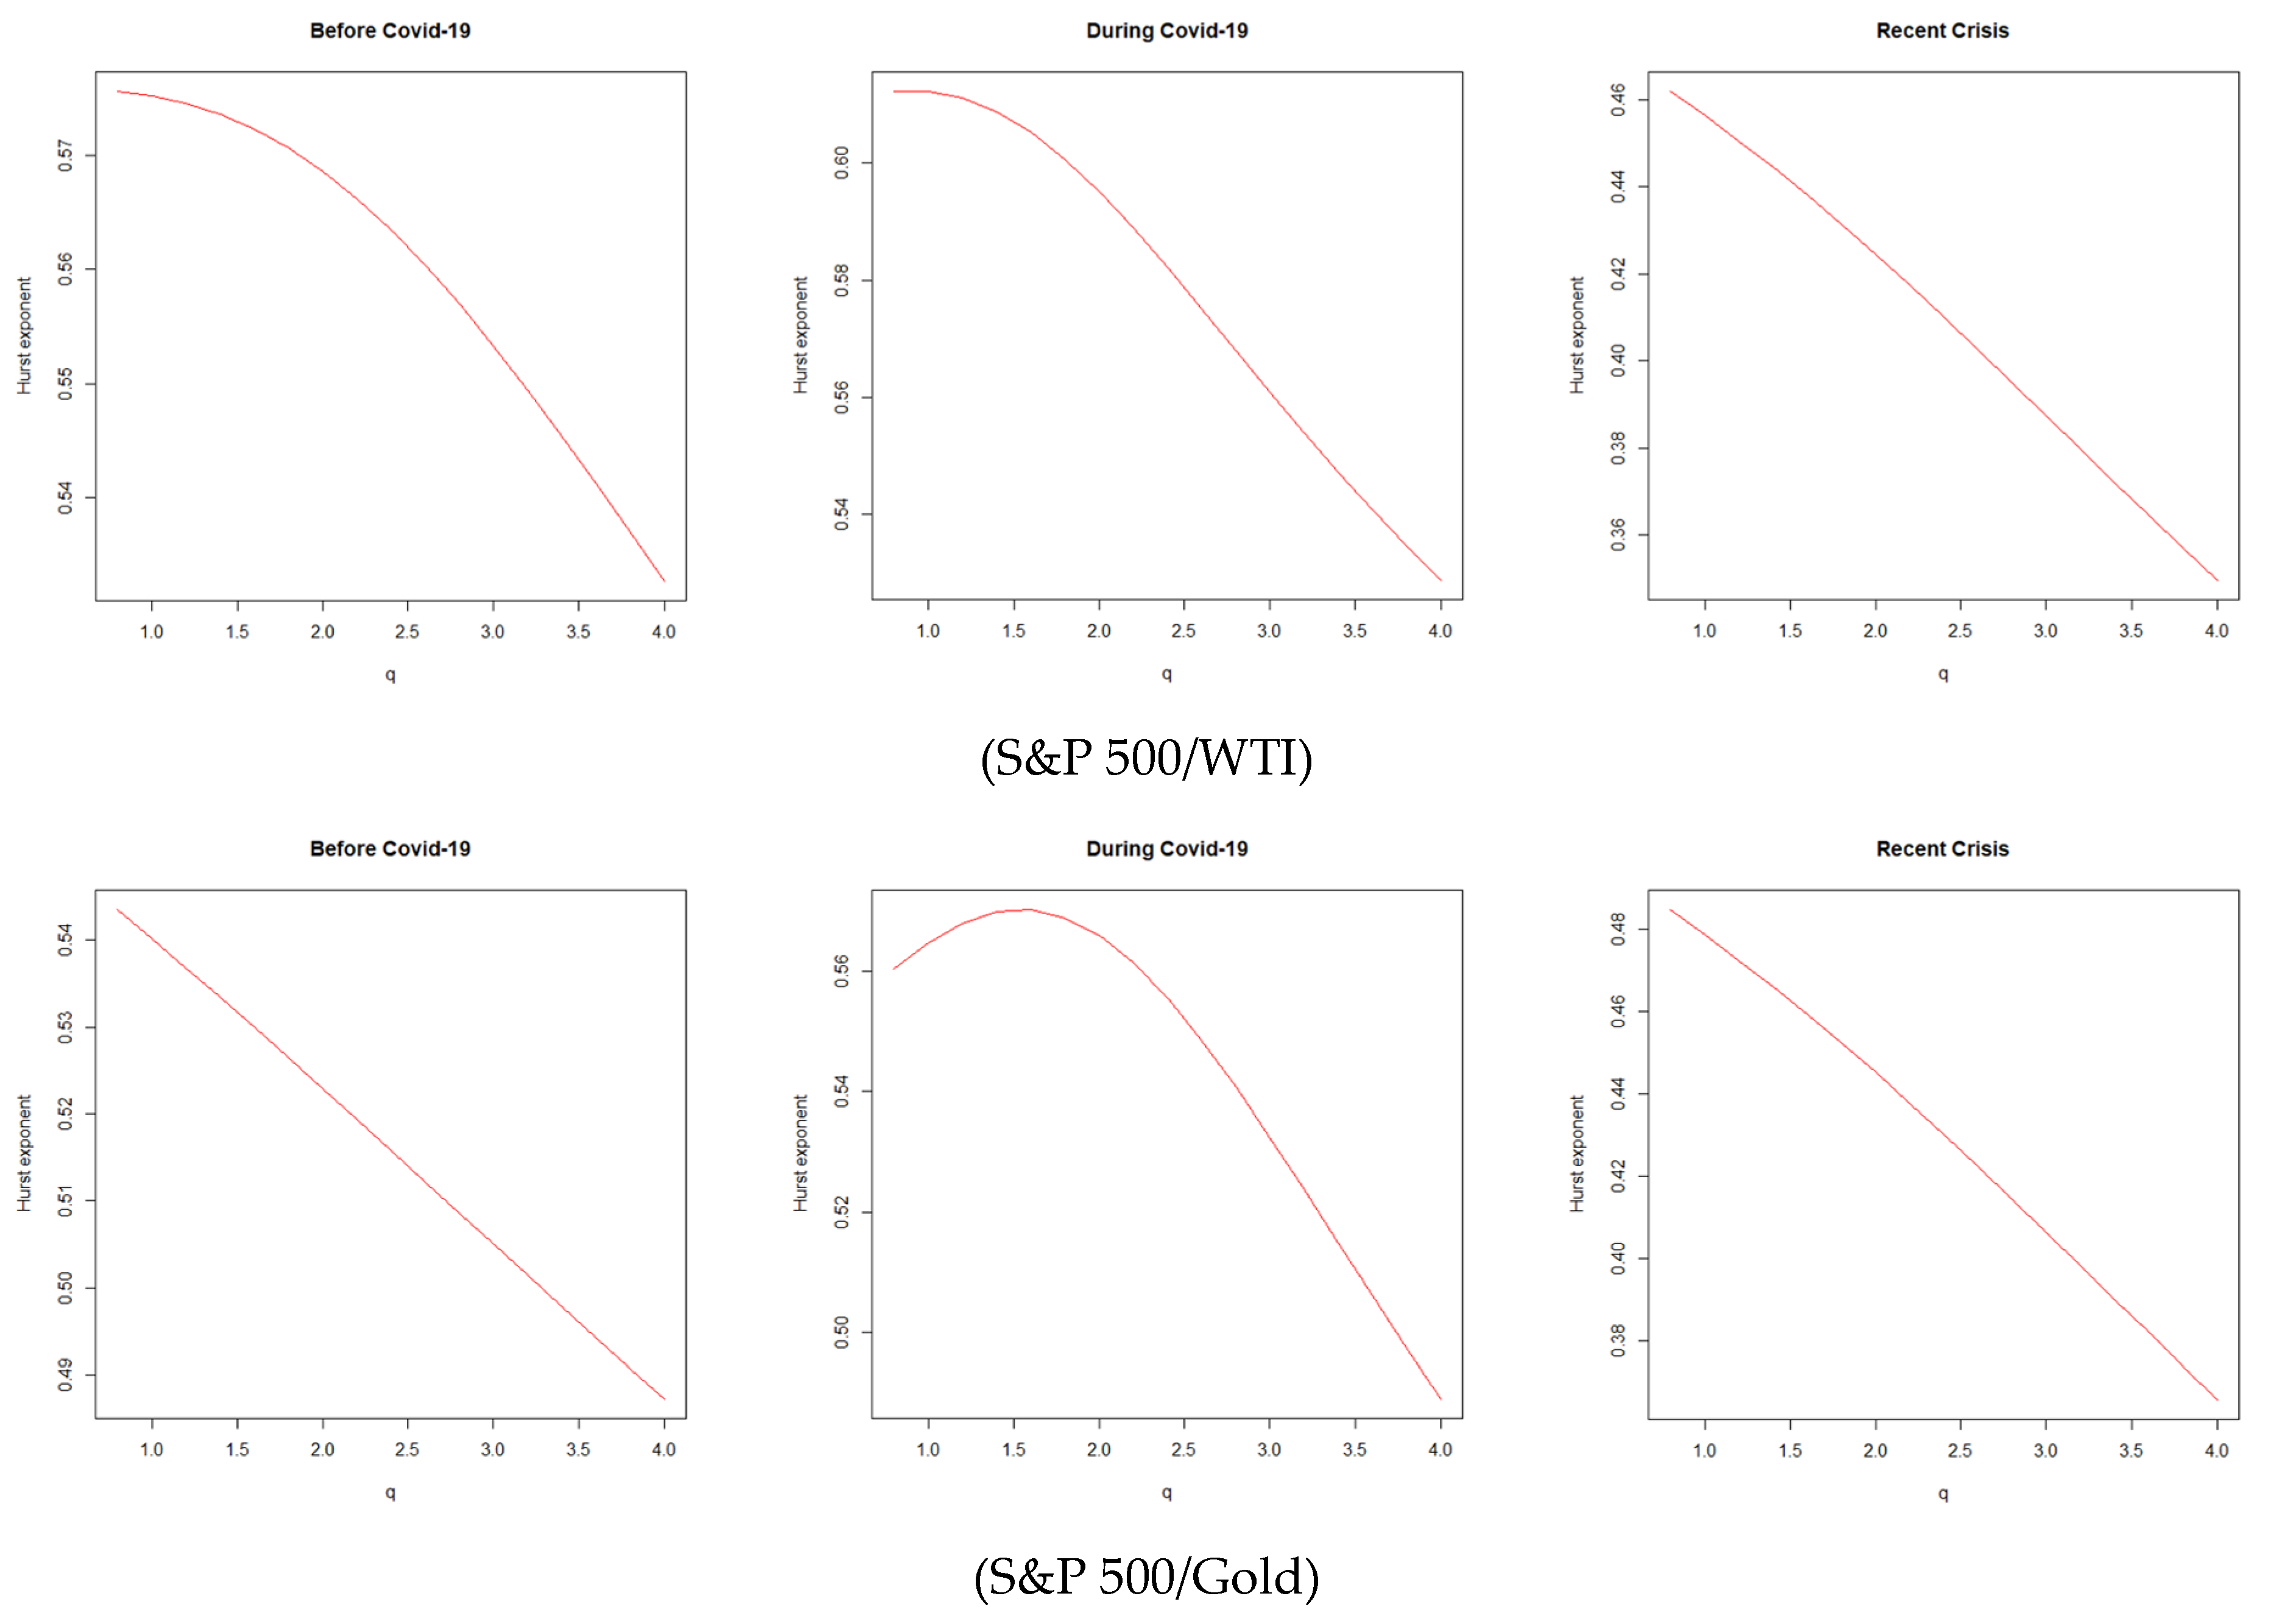
5.2. Multifractal Cross-Correlation Results
5.3. Hedging Effectiveness Analysis
6. Conclusions
Author Contributions
Funding
Data Availability Statement
Conflicts of Interest
Abbreviations
| MFCCA | Multifractal Detrended Cross-Correlation Analysis |
| ADCC-GARCH | Asymmetric Dynamic Conditional Correlation |
| GO-GARCH | Generalized Orthogonal GARCH |
| MGARCH | Multivariate Generalized Autoregressive Conditional Heteroskedasticity |
| GARCH | Generalized Autoregressive Conditional Heteroskedasticity |
| GJR-GARCH | Glosten–Jagannathan–Runkle |
| BEKK-GARCH | Baba–Engle–Kraft–Kroner Generalized Autoregressive Conditional Heteroskedasticity |
References
- Diebold, F.X.; Yilmaz, K. Better to give than to receive: Predictive directional measurement of volatility spillovers. Int. J. Forecast. 2012, 28, 57–66. [Google Scholar] [CrossRef] [Scilit]
- Yiming, W.; Xun, L.; Umair, M.; Aizhan, A. COVID-19 and the transformation of emerging economies: Financialization, green bonds, and stock market volatility. Resour. Policy 2024, 92, 104963. [Google Scholar] [CrossRef] [Scilit]
- Ali, M.; Alam, N.; Rizvi, S.A.R. Coronavirus (COVID-19)—An epidemic or pandemic for financial markets. J. Behav. Exp. Financ. 2020, 27, 100341. [Google Scholar] [CrossRef] [Scilit]
- Mao, Z.; Wang, H.; Bibi, S. Crude oil volatility spillover and stock market returns across the COVID-19 pandemic and post-pandemic periods: An empirical study of China, US, and India. Resour. Policy 2024, 88, 104333. [Google Scholar] [CrossRef] [Scilit]
- Iuga, I.C.; Mudakkar, S.R.; Dragolea, L.L. Agricultural commodities market reaction to COVID-19. Res. Int. Bus. Financ. 2024, 69, 102287. [Google Scholar] [CrossRef] [Scilit]
- Baur, D.G.; Lucey, B.M. Is gold a hedge or a safe haven? An analysis of stocks, bonds and gold. Financ. Rev. 2010, 45, 217–229. [Google Scholar] [CrossRef] [Scilit]
- Lin, F.; Li, X.; Jia, N.; Feng, F.; Huang, H.; Huang, J.; Fan, S.; Ciais, P.; Song, X.P. The impact of Russia–Ukraine conflict on global food security. Glob. Food Secur. 2023, 36, 100661. [Google Scholar] [CrossRef] [Scilit]
- Saad, G. The impact of the Russia–Ukraine war on the United States natural gas futures prices. Kybernetes 2024, 53, 3430–3443. [Google Scholar] [CrossRef] [Scilit]
- Chowdhury, M.A.F.; Hassan, M.K.; Abdullah, M.; Hossain, M.M. Geopolitical risk transmission dynamics to commodity, stock, and energy markets. Quant. Financ. Econ. 2025, 9, 76–99. [Google Scholar] [CrossRef] [Scilit]
- Boungou, W.; Yatié, A. Uncertainty, stock and commodity prices during the Ukraine–Russia war. Policy Stud. 2024, 45, 336–352. [Google Scholar] [CrossRef] [Scilit]
- Parnes, D.; Parnes, S.S. Hedging geopolitical risks with diverse commodities. Int. Rev. Financ. Anal. 2025, 102, 104129. [Google Scholar] [CrossRef] [Scilit]
- Baker, S.R.; Bloom, N.; Davis, S.J.; Terry, S.J. COVID-Induced Economic Uncertainty; Working Paper No. 26983; National Bureau of Economic Research: Cambridge, MA, USA, 2020. [Google Scholar] [CrossRef] [Scilit]
- Díaz, E.M.; Cunado, J.; de Gracia, F.P. Global drivers of inflation: The role of supply chain disruptions and commodity price shocks. Econ. Model. 2024, 140, 106860. [Google Scholar] [CrossRef] [Scilit]
- Manzli, Y.S.; Fakhfekh, M.; Béjaoui, A.; Alnafisah, H.; Jeribi, A. On the hedge and safe-haven abilities of Bitcoin and gold against blue economy and green finance assets during global crises: Evidence from the DCC, ADCC and GO-GARCH models. PLoS ONE 2025, 20, e0317735. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Dogan, B.; Trabelsi, N.; Ghosh, S. Dynamic dependence and causality between crude oil, green bonds, commodities, geopolitical risks, and policy uncertainty. Q. Rev. Econ. Financ. 2023, 89, 36–62. [Google Scholar] [CrossRef] [Scilit]
- Bareith, T.; Fertő, I.; Podruzsik, S. Wheat price dynamics in Hungary: Resilience to shocks. J. Agric. Food Res. 2024, 18, 101511. [Google Scholar] [CrossRef] [Scilit]
- Su, J.; Wang, W.; Bai, Y.; Zhou, P. Measuring the natural gas price features of the Asia-Pacific market from a complex network perspective. Energy 2025, 314, 134133. [Google Scholar] [CrossRef] [Scilit]
- Fry-McKibbin, R.; McKinnon, K. The evolution of commodity market financialization: Implications for portfolio diversification. J. Commod. Mark. 2023, 32, 100360. [Google Scholar] [CrossRef] [Scilit]
- Mukherjee, P.; Bardhan, S. Dynamic Spillovers Among Equity, Gold and Oil Markets During COVID and Russia–Ukraine War: Evidence from India. Asia-Pac. Financ. Mark. 2025, 32, 1099–1127. [Google Scholar] [CrossRef] [Scilit]
- Babar, M.; Ahmad, H.; Yousaf, I. Returns and volatility spillover between agricultural commodities and emerging stock markets: New evidence from COVID-19 and Russian–Ukrainian war. Int. J. Emerg. Mark. 2024, 19, 4049–4072. [Google Scholar] [CrossRef] [Scilit]
- Chowdhury, E.K.; Humaira, U. Transformation of investor attitude towards financial markets: A perspective on the Russia–Ukraine conflict. Int. Soc. Sci. J. 2023, 74, 561–583. [Google Scholar] [CrossRef] [Scilit]
- Cappiello, L.; Engle, R.F.; Sheppard, K. Asymmetric dynamics in the correlations of global equity and bond returns. J. Financ. Econom. 2006, 4, 537–572. [Google Scholar] [CrossRef] [Scilit]
- Mei-jun, L.; Guang-xi, C. Dynamics of asymmetric multifractal cross-correlations between cryptocurrencies and global stock markets: Role of gold and portfolio implications. Chaos Solitons Fractals 2024, 182, 114739. [Google Scholar] [CrossRef] [Scilit]
- Baruník, J.; Kristoufek, L. On Hurst exponent estimation under heavy-tailed distributions. Phys. A 2010, 389, 3844–3855. [Google Scholar] [CrossRef] [Scilit]
- Wen, D.; Wang, Y. Volatility linkages between stock and commodity markets revisited: Industry perspective and portfolio implications. Resour. Policy 2021, 74, 102374. [Google Scholar] [CrossRef] [Scilit]
- Biswas, P.; Jain, P.; Maitra, D. Are shocks in the stock markets driven by commodity markets? Evidence from Russia–Ukraine war. J. Commod. Mark. 2024, 34, 100387. [Google Scholar] [CrossRef] [Scilit]
- Guhathakurta, K.; Dash, S.R.; Maitra, D. Period specific volatility spillover based connectedness between oil and other commodity prices and their portfolio implications. Energy Econ. 2020, 85, 104566. [Google Scholar] [CrossRef] [Scilit]
- Malhotra, G.; Yadav, M.P.; Tandon, P.; Sinha, N. An investigation on dynamic connectedness of commodity market with financial market during the Russia–Ukraine invasion. Benchmarking 2024, 31, 439–465. [Google Scholar] [CrossRef] [Scilit]
- Tu, X.; Leatham, D. From Fields to Finance: Dynamic Connectedness and Optimal Portfolio Strategies Among Agricultural Commodities, Oil, and Stock Markets. Int. J. Financ. Stud. 2025, 13, 143. [Google Scholar] [CrossRef] [Scilit]
- Adekoya, O.B.; Oliyide, J.A. How COVID-19 drives connectedness among commodity and financial markets: Evidence from TVP-VAR and causality-in-quantiles techniques. Resour. Policy 2021, 70, 101898. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Coskun, Y.; Akinsomi, O.; Gil-Alana, L.A.; Yaya, O.S. Stock market responses to COVID-19: The behaviors of mean reversion, dependence and persistence. Heliyon 2023, 9, e15084. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Rubaszek, M.; Szafranek, K. The European energy crisis and the US natural gas market dynamics: A structural VAR investigation. Int. Econ. Econ. Policy 2025, 22, 11. [Google Scholar] [CrossRef] [Scilit]
- Chen, L.; Verousis, T.; Wang, K.; Zhou, Z. Financial stress and commodity price volatility. Energy Econ. 2023, 125, 106874. [Google Scholar] [CrossRef] [Scilit]
- Khan, M.N. Market volatility and crisis dynamics: A comprehensive analysis of U.S., China, India, and Pakistan stock markets with oil and gold interconnections during COVID-19 and Russia–Ukraine war periods. Futur. Bus. J. 2024, 10, 22. [Google Scholar] [CrossRef] [Scilit]
- Huang, W.; Wang, H.; Wei, Y.; Chevalier, J. Complex network analysis of global stock market co-movement during the COVID-19 pandemic based on intraday open-high-low-close data. Financ. Innov. 2024, 10, 7. [Google Scholar] [CrossRef] [Scilit]
- Li, K.; Xie, C.; Ouyang, Y.; Mo, T.; Feng, Y. Tail risk spillovers in the stock and forex markets at the major emergencies: Evidence from the G20 countries. Int. Rev. Financ. Anal. 2024, 96, 103712. [Google Scholar] [CrossRef] [Scilit]
- Reboredo, J.C. Is gold a hedge or safe haven against oil price movements? Energy Econ. 2013, 38, 130–137. [Google Scholar] [CrossRef] [Scilit]
- Belguith, R.; Alnafisah, H.; Snene Manzli, Y.; Jeribi, A. Can Bitcoin and gold have dynamic hedging and safe haven capabilities against the BRICS Plus stock market indices during global crises? Evidence from a time-varying copula approach. Emerg. Mark. Financ. Trade 2025, 61, 3634–3657. [Google Scholar] [CrossRef] [Scilit]
- Said, A.; Ouerfelli, C. Downside risk in Dow Jones equity markets: Hedging and portfolio management during COVID-19 pandemic and the Russia–Ukraine war. J. Risk Financ. 2024, 25, 443–470. [Google Scholar] [CrossRef] [Scilit]
- Moutinho, V.; Almeida, L.; Neves, M.; Monteiro, J. Dynamic cross hedging, conditional co-movements in commodities and financial markets during subprime and sovereign debt crisis: Evidence from China and G7 countries. Rev. Financ. Econ. 2025, 43, 261–285. [Google Scholar] [CrossRef] [Scilit]
- Zeng, H.; Abedin, M.Z.; Ahmed, A.D.; Lucey, B. Quantile and time–frequency risk spillover between climate policy uncertainty and grains commodity markets. J. Futures Mark. 2025, 45, 659–682. [Google Scholar] [CrossRef] [Scilit]
- Nemat, M.; Rahat, B.; Rossi, M.; Salloum, C. Global trade and finance turmoil: The Ukraine–Russia war’s impact. J. Risk Financ. 2025, 26, 516–529. [Google Scholar] [CrossRef] [Scilit]
- Yousfi, M.; Bouzgarrou, H. Quantile time–frequency connectedness between energy and agriculture markets: A study during the COVID-19 crisis and the Russo–Ukrainian conflict. J. Finan. Econ. Policy 2024, 16, 559–579. [Google Scholar] [CrossRef] [Scilit]
- Zhang, Y.; Zhou, L.; Chen, Y.; Liu, F. The contagion effect of jump risk across Asian stock markets during the Covid-19 pandemic. N. Am. Econ. Financ. 2022, 61, 101688. [Google Scholar] [CrossRef] [Scilit]
- Glosten, L.R.; Jagannathan, R.; Runkle, D.E. On the relation between the expected value and the volatility of the nominal excess return on stocks. J. Financ. 1993, 48, 1779–1801. [Google Scholar] [CrossRef]
- Kroner, K.F.; Ng, V.K. Modeling asymmetric comovements of asset returns. Rev. Financ. Stud. 1998, 11, 817–844. [Google Scholar] [CrossRef] [Scilit]
- Gargallo, P.; Lample, L.; Miguel, J.A.; Salvador, M. Sequential management of energy and low-carbon portfolios. Res. Int. Bus. Financ. 2024, 69, 102263. [Google Scholar] [CrossRef] [Scilit]
- Caporin, M.; McAleer, M. Do we really need both BEKK and DCC? A tale of two multivariate GARCH models. J. Econ. Surv. 2012, 26, 736–751. [Google Scholar] [CrossRef] [Scilit]
- Kwapień, J.; Oświęcimka, P.; Drożdż, S. Detrended fluctuation analysis made flexible to detect range of cross-correlated fluctuations. Phys. Rev. E 2015, 92, 052815. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Van der Weide, R. GO-GARCH: A Multivariate Generalized Orthogonal GARCH Model. J. Appl. Econ. 2002, 17, 549–564. Available online: https://www.jstor.org/stable/4129271 (accessed on 5 November 2025). [CrossRef] [Scilit]
- Ku, Y.H.H.; Chen, H.C.; Chen, K.H. On the application of the dynamic conditional correlation model in estimating optimal time-varying hedge ratios. Appl. Econ. Lett. 2007, 14, 503–509. [Google Scholar] [CrossRef] [Scilit]
- Refinitiv Datastream. Database. Refinitiv, London, UK. Available online: https://www.refinitiv.com (accessed on 5 November 2025).
- Shah, W.U.; Missaoui, I.; Younis, I.; Liu, X. Evaluating market downturn connectedness between S&P 500 index funds, gold, and oil markets. J. Futures Mark. 2025, 45, 1278–1297. [Google Scholar] [CrossRef] [Scilit]
- Lee, M.-J.; Choi, S.-Y. Insights into the dynamics of market efficiency spillover of financial assets in different equity markets. Physica A 2024, 641, 129719. [Google Scholar] [CrossRef] [Scilit]
- Gaio, L.E.; Capitani, D.H.D. Multifractal cross-correlation analysis between crude oil and agricultural futures markets: Evidence from the Russia–Ukraine conflict. J. Agribus. Dev. Emerg. Econ. 2025, 15, 19–42. [Google Scholar] [CrossRef] [Scilit]
- Tarigan, J.; Delia, M.; Hatane, S.E. Impact of the Russia–Ukraine war: Evidence from G20 countries. Stud. Econ. Financ. 2025, 42, 135–153. [Google Scholar] [CrossRef] [Scilit]
- Schreiber, T.; Schmitz, A. Surrogate Time Series. Physica D 2000, 142, 346–382. [Google Scholar] [CrossRef] [Scilit]
- Wang, G.J.; Xie, C.; Chen, S.; Han, F. Cross-Correlations between Energy and Emissions Markets: New Evidence from Fractal and Multifractal Analysis. Math. Probl. Eng. 2014, 2014, 197069. [Google Scholar] [CrossRef] [Scilit]
- Mirzaee Ghazani, M.; Khosravi, R.; Caporin, M. Analyzing interconnection among selected commodities in the 2008 global financial crisis and the COVID-19 pandemic. Resour. Policy 2023, 80, 103157. [Google Scholar] [CrossRef] [Scilit]
- Acikgoz, T. The multifractal nature of cross-correlations between emerging market equities and financial assets: An econophysics perspective. Comput. Econ. 2025, 1–28. [Google Scholar] [CrossRef] [Scilit]
- Martins, A.M. How do commodity futures respond to Ukraine–Russia, Taiwan Strait and Hamas–Israel crises? An analysis using event study approach. Stud. Econ. Financ. 2025, 42, 201–217. [Google Scholar] [CrossRef] [Scilit]
- Shao, Y.-H.; Gao, X.-L.; Yang, Y.-H.; Zhou, W.-X. Joint multifractality in cross-correlations between grains & oilseeds indices and external uncertainties. Financ. Innov. 2025, 11, 21. [Google Scholar] [CrossRef] [Scilit]
- Hachicha, N.; Ghorbel, A.; Feki, M.C.; Tahi, S.; Dammak, F.A. Hedging Dow Jones Islamic and conventional emerging market indices with CDS, oil, gold and the VSTOXX: A comparison between DCC, ADCC and GO-GARCH models. Borsa Istanb. Rev. 2022, 22, 209–225. [Google Scholar] [CrossRef] [Scilit]
- Abid, I.; Dhaoui, A.; Goutte, S.; Guesmi, K. Hedging and diversification across commodity assets. Appl. Econ. 2020, 52, 2472–2492. [Google Scholar] [CrossRef] [Scilit]
- Fakhfekh, M.; Jeribi, A.; Ghorbel, A.; Hachicha, N. Hedging stock market prices with WTI, gold, VIX and cryptocurrencies: A comparison between DCC, ADCC and GO-GARCH models. Int. J. Emerg. Mark. 2023, 18, 978–1006. [Google Scholar] [CrossRef] [Scilit]
- Zghal, R.; Melki, A.; Ghorbel, A. Do commodities hedge regional stock markets at the same effectiveness level? Evidence from MGARCH models. Int. J. Emerg. Mark. 2024, 19, 1359–1384. [Google Scholar] [CrossRef] [Scilit]





| Statistic | WTI | S&P 500 | Gold | Wheat | Gas |
|---|---|---|---|---|---|
| Mean | 0.025 (0.683) | 0.046 ** (0.046) | 0.047 *** (0.010) | 0.005 (0.900) | 0.010 (0.898) |
| Variance | 9.483 *** | 1.296 *** | 0.804 *** | 3.836 *** | 16.352 *** |
| Skewness | −2.927 *** (0.000) | −0.690 *** (0.000) | −0.225 *** (0.000) | 0.549 *** (0.000) | 0.032 (0.516) |
| Kurtosis | 76.403 *** (0.000) | 17.253 *** (0.000) | 2.813 *** (0.000) | 5.991 *** (0.000) | 3.400 *** (0.000) |
| Jarque–Bera | 604,777.125 *** (0.000) | 30,856.609 *** (0.000) | 836.027 *** (0.000) | 3821.045 *** (0.000) | 1190.829 *** (0.000) |
| ERS (ADF) | −10.035 *** (0.000) | −22.768 *** (0.000) | −7.504 *** (0.000) | −23.401 *** (0.000) | −14.596 *** (0.000) |
| Q(20) | 69.130 *** (0.000) | 209.921 *** (0.000) | 7.937 (0.732) | 20.354 ** (0.015) | 29.186 *** (0.000) |
| Q2(20) | 465.686 *** (0.000) | 2382.508 *** (0.000) | 262.976 *** (0.000) | 911.592 *** (0.000) | 268.981 *** (0.000) |
| Pair | Δhreal | Δhsurr,mean | Δhsurr,std | p-Value |
|---|---|---|---|---|
| WTI-S&P 500 | 0.055 | 0.265 | 0.142 | 0.92 |
| WTI-Gold | 0.454 | 0.224 | 0.148 | 0.04 |
| WTI-Wheat | 0.654 | 0.254 | 0.118 | 0.01 |
| WTI-Gas | 0.406 | 0.263 | 0.149 | 0.13 |
| S&P 500-Gold | 0.367 | 0.247 | 0.138 | 0.23 |
| S&P 500-Wheat | 0.367 | 0.294 | 0.146 | 0.31 |
| S&P 500-Gas | 0.205 | 0.280 | 0.149 | 0.66 |
| Gold-Wheat | 0.349 | 0.286 | 0.119 | 0.29 |
| Gold-Gas | 0.382 | 0.263 | 0.147 | 0.19 |
| Wheat-Gas | 0.095 | 0.259 | 0.145 | 0.86 |
| Pair | Method | OLS | ADCC-5 | ADCC-20 | ADCC-60 | GO-5 | GO-20 | GO-60 |
|---|---|---|---|---|---|---|---|---|
| WTI-SP500 | HE | 0.049 | 0.052 | 0.058 | 0.051 | 0.035 | 0.052 | 0.042 |
| WTI-Gold | HE | 0.008 | 0.022 | 0.012 | 0.013 | 0.018 | 0.007 | 0.010 |
| WTI-Wheat | HE | 0.013 | 0.016 | 0.014 | 0.014 | 0.014 | 0.013 | 0.014 |
| WTI-Gas | HE | 0.008 | 0.020 | 0.025 | 0.026 | 0.016 | 0.030 | 0.030 |
| SP500-Gold | HE | 0.003 | 0.003 | 0.008 | −0.013 | −0.001 | −0.016 | −0.062 |
| SP500-Wheat | HE | 0.001 | 0.000 | −0.014 | −0.026 | −0.094 | −0.195 | −0.362 |
| SP500-Gas | HE | 0.010 | 0.037 | 0.023 | 0.014 | 0.060 | −0.004 | −0.191 |
| Gold-Gas | HE | 0.000 | 0.000 | 0.001 | 0.000 | 0.000 | 0.000 | 0.000 |
| Wheat-Gas | HE | 0.001 | 0.004 | 0.004 | 0.001 | 0.003 | 0.003 | 0.002 |
| ADCC (Refit = 20) | ||||||||
|---|---|---|---|---|---|---|---|---|
| Period | Optimal Hedge Ratio | Optimal Weight | HE (%) | |||||
| WTI | 1 | Mean | Min | Max | Mean | Min | Max | |
| 2 | 0.071 | 0.010 | 0.244 | 0.893 | 0.321 | 1.000 | 4.277 | |
| 3 | 0.113 | 0.064 | 0.603 | 0.883 | 0.319 | 1.000 | 7.526 | |
| Gold | 1 | 0.080 | 0.086 | 0.711 | 0.867 | 0.132 | 1.000 | 4.248 |
| 2 | 0.098 | 0.483 | 0.932 | 0.471 | 0.009 | 0.843 | 2.505 | |
| 3 | 0.037 | 0.981 | 0.631 | 0.479 | 0.008 | 0.980 | 2.826 | |
| Wheat | 1 | 0.162 | 0.675 | 1.173 | 0.483 | 0.000 | 0.991 | 5.229 |
| 2 | 0.047 | 0.014 | 0.163 | 0.792 | 0.216 | 0.988 | 0.744 | |
| 3 | 0.061 | 0.017 | 0.599 | 0.739 | 0.016 | 0.973 | 0.730 | |
| Natural Gas | 1 | 0.032 | 0.005 | 0.203 | 0.795 | 0.132 | 0.990 | 0.381 |
| 2 | 0.004 | 0.018 | 0.013 | 0.886 | 0.561 | 0.994 | 0.040 | |
| 3 | 0.019 | 0.010 | 0.182 | 0.903 | 0.144 | 0.999 | 0.388 | |
| ADCC (refit = 60) | ||||||||
| WTI | 1 | 0.069 | 0.009 | 0.209 | 0.892 | 0.321 | 1.000 | 3.926 |
| 2 | 0.111 | 0.068 | 0.603 | 0.884 | 0.319 | 1.000 | 7.550 | |
| 3 | 0.080 | 0.086 | 0.711 | 0.867 | 0.132 | 1.000 | 4.273 | |
| Gold | 1 | 0.091 | 0.447 | 0.932 | 0.470 | 0.009 | 0.838 | 2.405 |
| 2 | 0.034 | 0.981 | 0.631 | 0.477 | 0.009 | 0.980 | 2.687 | |
| 3 | 0.161 | 0.678 | 1.173 | 0.483 | 0.000 | 0.991 | 5.158 | |
| Wheat | 1 | 0.047 | 0.014 | 0.163 | 0.797 | 0.216 | 0.988 | 0.751 |
| 2 | 0.058 | 0.017 | 0.400 | 0.742 | 0.024 | 0.973 | 0.728 | |
| 3 | 0.033 | 0.005 | 0.203 | 0.796 | 0.132 | 0.991 | 0.393 | |
| Natural Gas | 1 | 0.005 | 0.006 | 0.014 | 0.885 | 0.561 | 0.994 | 0.031 |
| 2 | 0.017 | 0.001 | 0.079 | 0.904 | 0.144 | 0.999 | 0.356 | |
| 3 | 0.019 | 0.005 | 0.089 | 0.959 | 0.590 | 1.000 | 0.730 | |
| GO-GARCH (Refit = 20) | ||||||||
|---|---|---|---|---|---|---|---|---|
| Period | Optimal Hedge Ratio | Optimal Weight | HE (%) | |||||
| WTI | 1 | Mean | Min | Max | Mean | Min | Max | |
| 2 | 0.217 | 0.020 | 0.848 | 0.501 | 0.041 | 0.910 | 4.091 | |
| 3 | 0.281 | 0.059 | 2.457 | 0.593 | 0.000 | 0.990 | 7.472 | |
| Gold | 1 | 0.181 | 0.078 | 0.367 | 0.660 | 0.291 | 1.000 | 5.349 |
| 2 | 0.163 | 0.632 | 0.107 | 0.544 | 0.260 | 1.000 | 3.329 | |
| 3 | 0.132 | 1.154 | 0.217 | 0.486 | 0.256 | 1.000 | 3.950 | |
| Wheat | 1 | 0.013 | 0.953 | 0.235 | 0.567 | 0.248 | 1.000 | 5.690 |
| 2 | 0.054 | 0.264 | 0.158 | 0.506 | 0.093 | 0.877 | 0.852 | |
| 3 | 0.077 | 3.478 | 4.810 | 0.551 | 0.000 | 0.864 | 1.154 | |
| Natural Gas | 1 | 0.037 | 0.037 | 0.381 | 0.555 | 0.106 | 0.904 | 0.301 |
| 2 | 0.101 | 0.010 | 0.624 | 0.481 | 0.053 | 0.846 | 0.731 | |
| 3 | 0.126 | 0.023 | 3.649 | 0.616 | 0.000 | 0.952 | 1.165 | |
| GO-GARCH (refit = 60) | ||||||||
| WTI | 1 | 0.174 | 0.203 | 0.244 | 0.496 | 0.087 | 0.959 | 4.326 |
| 2 | 0.306 | 0.131 | 0.869 | 0.419 | 0.011 | 1.000 | 6.682 | |
| 3 | 0.335 | 0.193 | 1.846 | 0.338 | 0.000 | 0.710 | 5.357 | |
| Gold | 1 | 0.166 | 0.604 | 0.099 | 0.545 | 0.256 | 1.000 | 2.981 |
| 2 | 0.147 | 1.181 | 0.219 | 0.487 | 0.261 | 0.955 | 3.330 | |
| 3 | 0.015 | 0.967 | 0.231 | 0.567 | 0.247 | 1.000 | 5.606 | |
| Wheat | 1 | 0.046 | 0.279 | 0.096 | 0.505 | 0.094 | 0.881 | 0.807 |
| 2 | 0.044 | 3.481 | 0.717 | 0.553 | 0.036 | 0.867 | 0.825 | |
| 3 | 0.037 | 0.038 | 0.352 | 0.556 | 0.120 | 0.904 | 0.293 | |
| Natural Gas | 1 | 0.112 | 0.028 | 0.625 | 0.476 | 0.053 | 0.849 | 0.906 |
| 2 | 0.151 | 0.026 | 3.620 | 0.612 | 0.000 | 0.957 | 1.319 | |
| 3 | 0.883 | 0.043 | 0.262 | 0.656 | 0.176 | 0.935 | 1.424 | |
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2025 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.
Share and Cite
Jouini, W.; Derbel, M.; Panazan, O.; Gheorghe, C. Multifractal Cross-Market Dependence and Dynamic Hedging Under Crisis Regimes: Evidence from Commodity–Equity Interactions. Fractal Fract. 2026, 10, 5. https://doi.org/10.3390/fractalfract10010005
Jouini W, Derbel M, Panazan O, Gheorghe C. Multifractal Cross-Market Dependence and Dynamic Hedging Under Crisis Regimes: Evidence from Commodity–Equity Interactions. Fractal and Fractional. 2026; 10(1):5. https://doi.org/10.3390/fractalfract10010005
Chicago/Turabian StyleJouini, Wiem, Mouna Derbel, Oana Panazan, and Catalin Gheorghe. 2026. "Multifractal Cross-Market Dependence and Dynamic Hedging Under Crisis Regimes: Evidence from Commodity–Equity Interactions" Fractal and Fractional 10, no. 1: 5. https://doi.org/10.3390/fractalfract10010005
APA StyleJouini, W., Derbel, M., Panazan, O., & Gheorghe, C. (2026). Multifractal Cross-Market Dependence and Dynamic Hedging Under Crisis Regimes: Evidence from Commodity–Equity Interactions. Fractal and Fractional, 10(1), 5. https://doi.org/10.3390/fractalfract10010005