-
Artificial Intelligence Adoption and Ethical Governance in Australian Insurance: Evidence from Web-Based Content Analysis -
Application of Explainable AI and Uncertainty Quantification in Credit Risk Assessment -
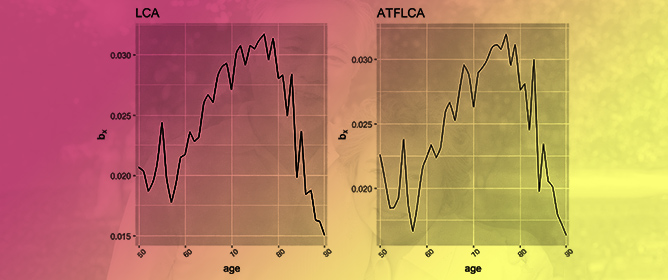
Longevity Option and Longevity Swap De-Risking Strategies Under Frailty-Based Mortality Models -
How Much Risk in U.S. Government Bond Markets Is Transmitted to Their Canadian Counterparts?
Journal Description
Risks
Risks
is an international, scholarly, peer-reviewed, open access journal for research and studies on insurance and financial risk management. Risks is published monthly online by MDPI.
- Open Access— free for readers, with article processing charges (APC) paid by authors or their institutions.
- High visibility: indexed within Scopus, ESCI (Web of Science), EconLit, EconBiz, RePEc, and other databases.
- Journal Rank: CiteScore - Q1 (Economics, Econometrics and Finance (miscellaneous))
- Rapid Publication: manuscripts are peer-reviewed and a first decision is provided to authors approximately 21.8 days after submission; acceptance to publication is undertaken in 7.6 days (median values for papers published in this journal in the first half of 2026).
- Recognition of Reviewers: Reviewers whose reports are timely and of high quality receive an APC discount voucher for a future publication in an MDPI journal. Become a reviewer.
- Journal Cluster of Economics, Finance and Risk Systems: Commodities, Econometrics, Economies, FinTech, Forecasting, Games, International Journal of Financial Studies, Journal of Risk and Financial Management, Platforms and Risks.
Impact Factor:
1.8 (2025);
5-Year Impact Factor:
1.8 (2025)
Latest Articles
Dynamic Equity Performance and Macroeconomic Policy Innovations: Developed vs. Emerging Markets During and After COVID-19
Risks 2026, 14(10), 227; https://doi.org/10.3390/risks14100227 - 28 Sep 2026
Abstract
This paper evaluates whether dynamic abnormal performance acts as a transmission channel for macroeconomic policy innovations during crisis regimes. Applying a daily State-Space Fama–French five-factor framework—extended to heteroscedastic specifications across a majority of test assets—dynamic Jensen’s alphas and market betas are recursively estimated
[...] Read more.
This paper evaluates whether dynamic abnormal performance acts as a transmission channel for macroeconomic policy innovations during crisis regimes. Applying a daily State-Space Fama–French five-factor framework—extended to heteroscedastic specifications across a majority of test assets—dynamic Jensen’s alphas and market betas are recursively estimated via the Kalman filter across 47 international equity markets. Second-stage regressions test policy and orthogonalized exchange rate innovations extracted via OLS detrending. Results confirm broad macroeconomic policy neutrality and market efficiency across 44 markets under extreme stress. However, localized friction-driven departures emerge in specific structural settings, notably the Czech Republic, India, and Mexico.
Full article
(This article belongs to the Special Issue Applied Econometrics and International Finance: Analysis, Modeling, and Development)
Open AccessArticle
Risk Sharing and Shock Propagation in Global Value Chains: A Structural Stress Test in a Multilayer Trade Finance Network
by
Georgios Angelidis
Risks 2026, 14(10), 226; https://doi.org/10.3390/risks14100226 - 28 Sep 2026
Abstract
Global value chains can diversify risk, but they can also transmit production disruptions and financial losses across interconnected economies. This study examines whether trade–finance coupling amplifies systemic loss relative to a trade-only benchmark, how diversification-based risk sharing offsets that amplification, and whether multilayer
[...] Read more.
Global value chains can diversify risk, but they can also transmit production disruptions and financial losses across interconnected economies. This study examines whether trade–finance coupling amplifies systemic loss relative to a trade-only benchmark, how diversification-based risk sharing offsets that amplification, and whether multilayer structure changes systemic rankings. We develop a transparent multilayer stress-testing framework linking trade–value–chain dependence, reconstructed foreign currency portfolio exposures, and cross-layer shock transmission for 20 country-sector nodes. The trade layer is based on 2014 WIOD data, while 2023 CPIS foreign currency asset margins are allocated using relative entropy; 5000 common and idiosyncratic shock simulations are evaluated across alternative propagation and absorption regimes. Mean output-weighted loss increases from 1.009% under trade-only propagation to 1.379% in the baseline multiplex model, while the 95th percentile rises from 5.092% to 6.217%. Eliminating diversification-based absorption raises mean loss to 1.541%, whereas stronger absorption lowers it to 1.251%. Robustness checks using alternative financial scaling and a 12-node aggregation preserve the main qualitative result. These calibrated stress-test outcomes, rather than causal or historical estimates, show that the balance between risk sharing and contagion is benchmark- and state-dependent.
Full article
(This article belongs to the Special Issue Risk-Taking, Risk Sharing, and Systemic Risk in Financial Networks)
Open AccessFeature PaperReview
Climate-Related Credit Risk in Banking: A Critical Review of Empirical Evidence and Methodological Approaches
by
Elena Grinza, Parisa Madhooshiarzanagh and Consuelo Rubina Nava
Risks 2026, 14(10), 225; https://doi.org/10.3390/risks14100225 - 24 Sep 2026
Abstract
This paper provides a critical narrative review of the literature on climate-related credit-risk and its implications for the banking sector. Banks’ exposure to physical and transition climate risks can significantly affect credit quality, lending conditions, and overall financial stability, yet the methods used
[...] Read more.
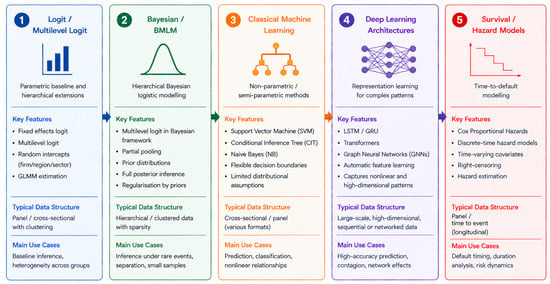
This paper provides a critical narrative review of the literature on climate-related credit-risk and its implications for the banking sector. Banks’ exposure to physical and transition climate risks can significantly affect credit quality, lending conditions, and overall financial stability, yet the methods used to study these effects vary widely, and each faces limitations. This paper systematically assesses the strengths and weaknesses of the main empirical approaches—including regression models, stress testing, and scenario analysis—in the presence of rare default events, unobserved heterogeneity, and quasi-complete separation and highlights unresolved tensions in the evidence base. Building on this assessment, it discusses the Bayesian multilevel logistic model (BMLM) as a conceptual methodological framework for firm-level credit-risk analysis and provides a structured comparison of seven modelling families—including deep learning architectures and survival analysis methods—across eight evaluation dimensions. This paper’s principal contribution is a structured mapping of research objectives, data characteristics, and modelling choices, rather than the advocacy of a single preferred approach.
Full article
(This article belongs to the Special Issue Climate Change and Financial Risks)
►▼
Show Figures

Figure 1
Open AccessArticle
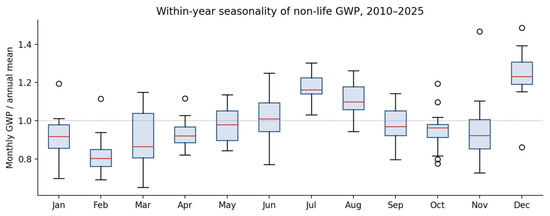
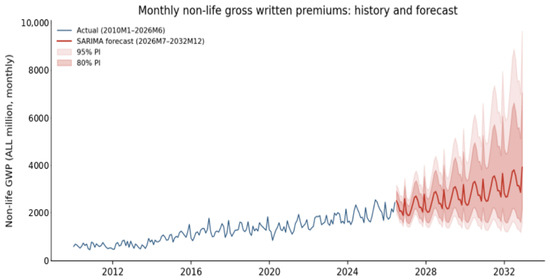
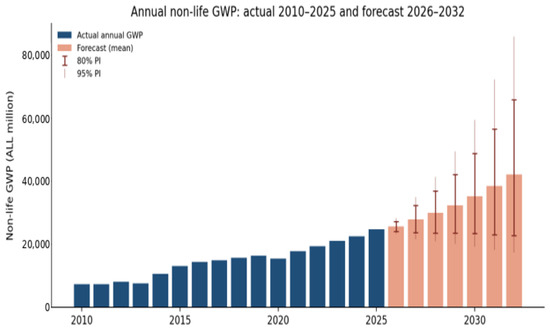
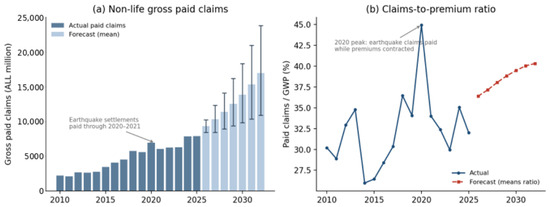
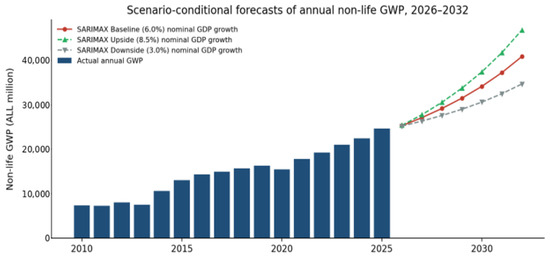
Forecasting Non-Life Insurance Premiums and Emerging Risk Factors in a Developing Market: Evidence from Albania, 2010–2026, with Projections to 2032
by
Albion Kopani and Xhevdet Kopani
Risks 2026, 14(10), 224; https://doi.org/10.3390/risks14100224 - 24 Sep 2026
Abstract
►▼
Show Figures
This paper provides the first monthly frequency analysis and multi-year forecast of the non-life insurance market in Albania. We construct a harmonized monthly dataset of gross written premiums and gross paid claims covering 2010 to mid-2026 from the statistical reports of the Albanian
[...] Read more.
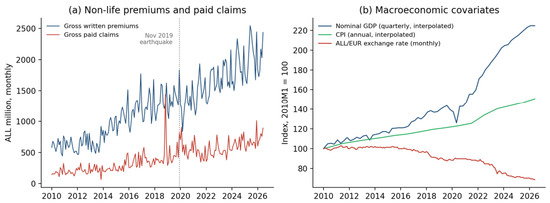
This paper provides the first monthly frequency analysis and multi-year forecast of the non-life insurance market in Albania. We construct a harmonized monthly dataset of gross written premiums and gross paid claims covering 2010 to mid-2026 from the statistical reports of the Albanian Financial Supervisory Authority, following a documented reconstruction protocol that other researchers can reproduce from the public reports. Seasonal time-series models, validated through a hold-out sample and rolling-origin cross-validation, outperform standard benchmarks and yield calendar-year forecasts with simulated prediction intervals through 2032, cross-checked against residual-bootstrap alternatives. The central path indicates continued expansion of premium volume at a gradually moderating pace, while paid claims are projected to grow faster than premiums, implying sustained pressure on underwriting margins. A covariate-augmented extension estimates an income elasticity of premiums close to unity yet does not improve out-of-sample accuracy, supporting the univariate forecasting model and enabling scenario-conditional projections under alternative income growth paths. Structural-break tests date significant shifts to the motor tariff reform, the earthquake, and the pandemic, and cointegration analysis identifies a single long-run premium–claims equilibrium in which claims adjust to premiums while pricing does not respond to claims experience. We draw implications for supervision, pricing conduct, and the EU-accession regulatory transition.
Full article

Figure 1
Open AccessArticle
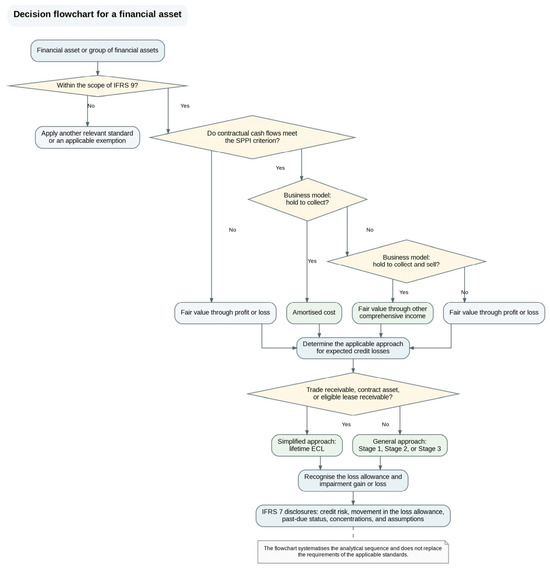
Expected Credit Losses and Risk Disclosure in Financial Asset Reporting by Non-Financial Companies
by
Kiril Luchkov, Nadya Velinova-Sokolova and Vanya Ivanova
Risks 2026, 14(10), 223; https://doi.org/10.3390/risks14100223 - 23 Sep 2026
Abstract
An integrated framework is developed for classifying and measuring financial assets, recognising expected credit losses (ECL), and disclosing financial risk in non-financial entities. Its design is based on the requirements of International Financial Reporting Standard 9 Financial Instruments (IFRS 9) and International Financial
[...] Read more.
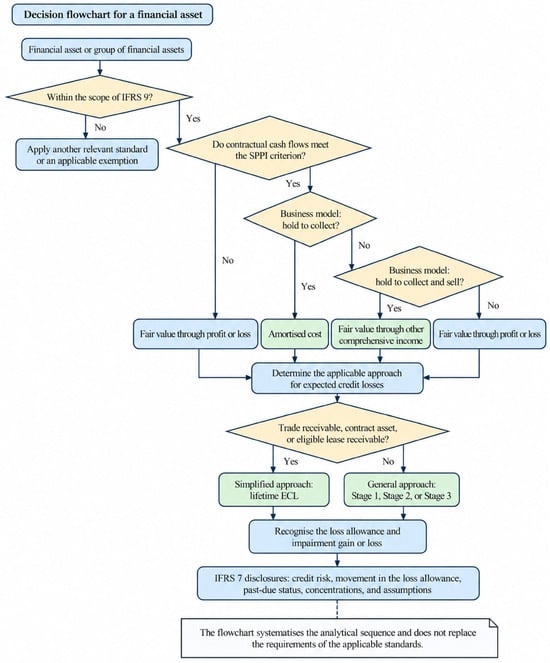
An integrated framework is developed for classifying and measuring financial assets, recognising expected credit losses (ECL), and disclosing financial risk in non-financial entities. Its design is based on the requirements of International Financial Reporting Standard 9 Financial Instruments (IFRS 9) and International Financial Reporting Standard 7 Financial Instruments: Disclosures (IFRS 7). The framework links contractual cash-flow characteristics, business models, measurement categories, impairment approaches, and risk disclosures in a single sequential procedure. Its applicability is examined using publicly available 2024 annual reports of ten large non-financial corporations from multiple sectors. A ten-indicator index is constructed to assess public traceability between accounting policies, loss allowances, trade-receivable information, forward-looking assumptions, and credit-risk disclosures. The application yields an average integration score of 94.00%, with stronger reporting for financial-asset categories, accounting policies, trade receivables, and the general or simplified ECL approach. More limited traceability is observed for the methods used to incorporate forward-looking information and for detailed provision-matrix disclosures. The framework is intended as a structured procedure for analysing public financial statements when internal credit-risk databases and model inputs are unavailable. Its contribution lies in integrating classification, subsequent measurement, impairment, and disclosure rather than treating them as separate compliance tasks. The proposed sequence can support accounting policy design, audit documentation, and comparative disclosure analysis. The index should be interpreted as a measure of reporting traceability rather than the economic accuracy of entities’ internal credit-risk estimates.
Full article
(This article belongs to the Special Issue Financial Accounting and Risk Analysis)
►▼
Show Figures

Figure 1
Open AccessArticle
A Geopolitical Shock, Oil Exposure, and Heterogeneous Equity-Market Responses: Firm-Level Evidence from Saudi Arabia
by
Ibraheem Alaskar, Ibrahim N. Khatatbeh and Ahmad Bash
Risks 2026, 14(10), 222; https://doi.org/10.3390/risks14100222 - 23 Sep 2026
Abstract
►▼
Show Figures
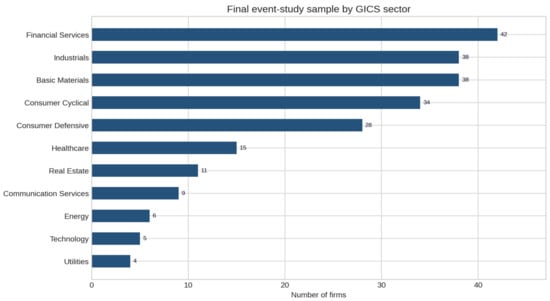
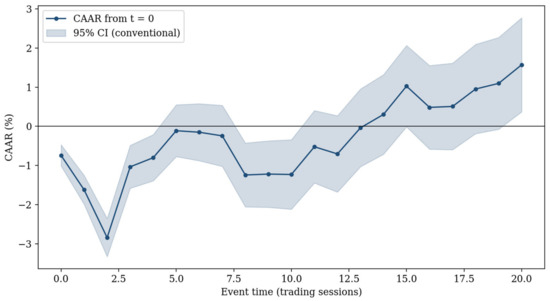
We study the firm-level equity-market response of 230 Tadawul Main Market firms to the outbreak of the U.S.–Israeli military action against Iran on 28 February 2026, using a market-model event study with the domestic TASI benchmark. Because a single geopolitical shock combines a
[...] Read more.
We study the firm-level equity-market response of 230 Tadawul Main Market firms to the outbreak of the U.S.–Israeli military action against Iran on 28 February 2026, using a market-model event study with the domestic TASI benchmark. Because a single geopolitical shock combines a market-wide risk-premium effect with an oil-price effect that accrues to oil-linked firms, the aggregate response is theoretically ambiguous, and we find that its sign in fact depends on how firms are weighted. Equal-weighted abnormal returns are negative around the event, whereas a value-weighted portfolio, dominated by the large oil-linked firms, rises significantly, reaching a cumulative abnormal return of +4.65% at the [0, +2] window (versus −2.84% equal-weighted). In cross-sectional regressions controlling for firm size, leverage, profitability, and sector fixed effects, oil-linked firms earn cumulative abnormal returns approximately 9.0 percentage points higher than non-oil firms over the [0, +5] window, a differential robust to the exclusion of Saudi Aramco, to median (robust) regression, to winsorization, and to leave-one-out estimation. We show that inference in this common-event setting is sensitive to cross-sectional dependence: under a Kolari–Pynnönen adjustment, only the immediate [0, +1] and [0, +2] aggregate windows remain statistically significant, so we treat the cross-sectional differential, rather than the aggregate response, as the paper’s most robust result. Overall, the evidence documents economically large cross-sectional heterogeneity that aggregate index responses conceal; it is consistent with, but does not separately identify, a common risk-premium effect and an oil-related cash-flow effect.
Full article

Figure 1
Open AccessArticle
Blockchain, Artificial Intelligence, and ESG Disclosure Quality: The Moderating Roles of Financial Regulation and Stakeholder Engagement
by
Nashat Ali Almasria, Saleh Al Sinawi, Hassan Aldboush and Ahmad Abu-Dawleh
Risks 2026, 14(10), 221; https://doi.org/10.3390/risks14100221 - 22 Sep 2026
Abstract
►▼
Show Figures
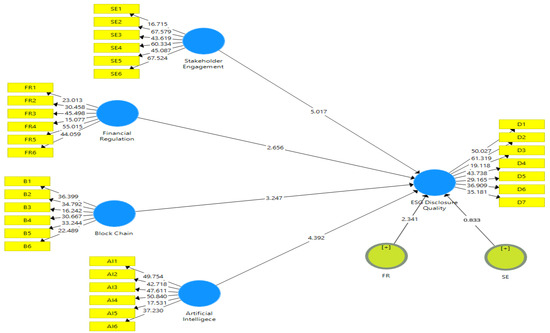
Environmental, social, and governance (ESG) disclosure quality remains constrained by fragmented data, limited verifiability, and inconsistent reporting practices. This study examines whether artificial intelligence and blockchain are associated with perceived ESG disclosure quality and whether financial regulation conditions the artificial intelligence relationship while
[...] Read more.
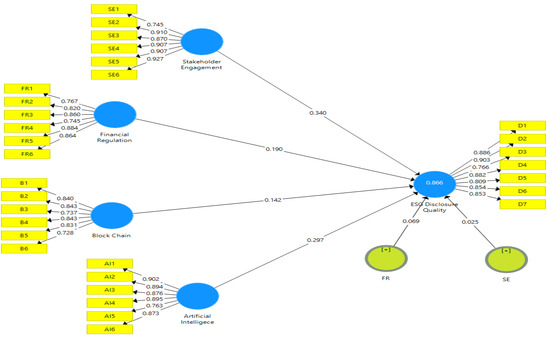
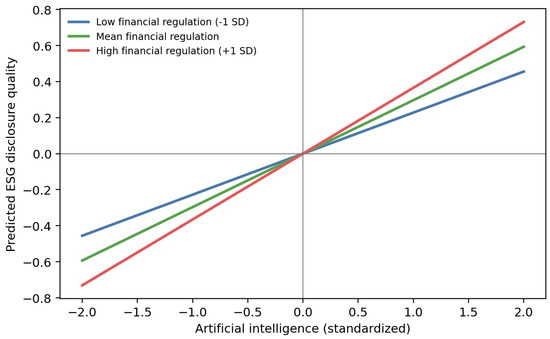
Environmental, social, and governance (ESG) disclosure quality remains constrained by fragmented data, limited verifiability, and inconsistent reporting practices. This study examines whether artificial intelligence and blockchain are associated with perceived ESG disclosure quality and whether financial regulation conditions the artificial intelligence relationship while stakeholder engagement conditions the blockchain relationship. A cross-sectional survey produced 250 usable responses from professionals involved in finance, sustainability reporting, compliance, and corporate governance. Partial least squares structural equation modeling was conducted using SmartPLS 3. Artificial intelligence (β = 0.297, p < 0.001), blockchain (β = 0.142, p = 0.001), financial regulation (β = 0.190, p = 0.008), and stakeholder engagement (β = 0.340, p < 0.001) showed positive direct associations with ESG disclosure quality. Financial regulation positively moderated the relationship between artificial intelligence and ESG disclosure quality (β = 0.069, p = 0.020). The blockchain–stakeholder engagement interaction was not supported because its bias-corrected confidence interval included zero. The model explained 86.6% of the variance in ESG disclosure quality (R2 = 0.866), while blindfolding indicated positive predictive relevance (Q2 = 0.613). However, elevated construct-level collinearity and HTMT values require caution in interpreting the structural effects.
Full article

Figure 1
Open AccessReview
Integrating Geopolitical Risk into Financial Risk Management: Measurement, Transmission Channels, and Risk Governance
by
Pan Han and Manlin Zhang
Risks 2026, 14(9), 220; https://doi.org/10.3390/risks14090220 - 21 Sep 2026
Abstract
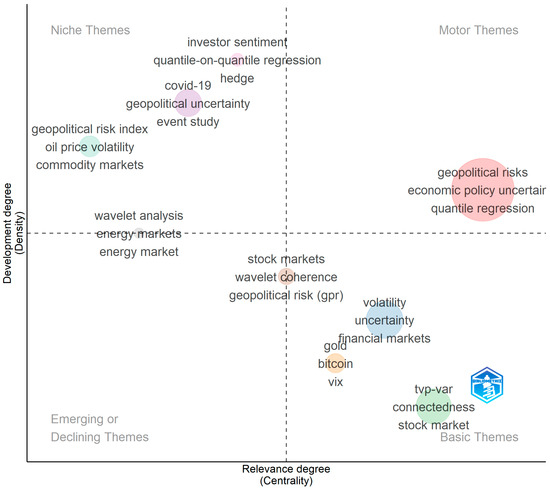
Geopolitical risk has become an increasingly important source of financial uncertainty, with implications for asset prices, financial institutions, capital flows, and financial stability. This review examines how geopolitical risk can be incorporated into financial risk management by synthesizing the literature on measurement, transmission
[...] Read more.
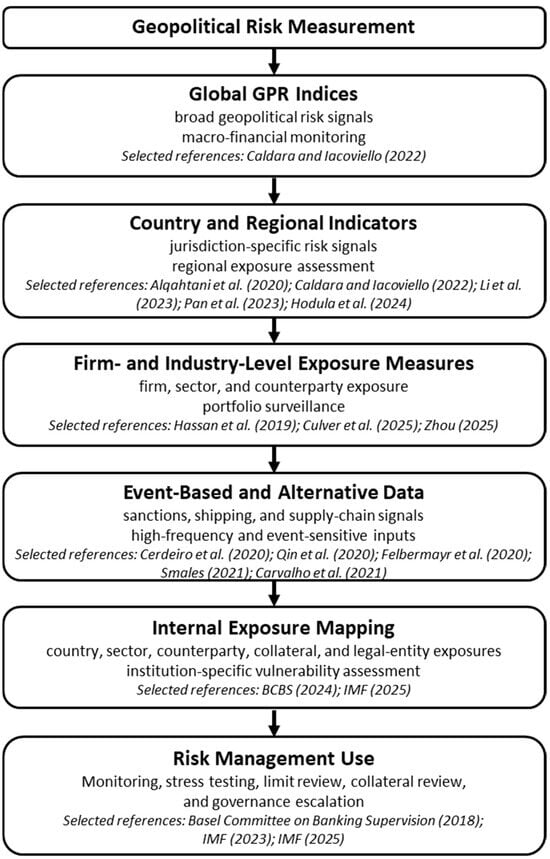
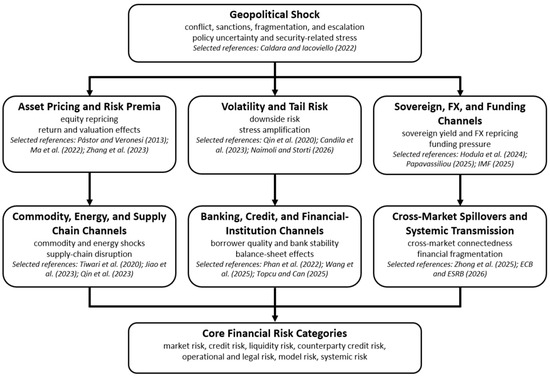
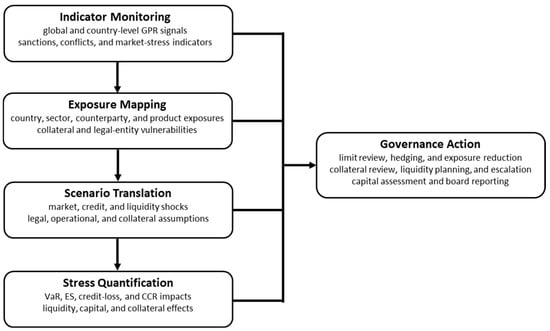
Geopolitical risk has become an increasingly important source of financial uncertainty, with implications for asset prices, financial institutions, capital flows, and financial stability. This review examines how geopolitical risk can be incorporated into financial risk management by synthesizing the literature on measurement, transmission channels, and risk governance. It discusses major approaches to measuring geopolitical risk, including news-based indices, country-specific indicators, broader uncertainty measures, and firm- or industry-level exposure measures. It then reviews how geopolitical risk is transmitted through asset pricing, volatility, tail risk, sovereign and funding channels, commodities, banking stability, and systemic spillovers. A central argument of the review is that geopolitical risk should not be treated as a standalone uncertainty variable. Rather, it is a cross-cutting risk driver that can affect market risk, credit risk, liquidity risk, counterparty credit risk, operational and legal risk, model risk, and systemic risk at the same time. Building on this synthesis, the paper proposes an integrative framework that links geopolitical risk indicators to exposure mapping, scenario translation, stress quantification, and governance action. The review highlights counterparty credit risk, collateral stress, reverse stress testing, and scenario governance as important areas for future research.
Full article
(This article belongs to the Special Issue Emerging Risks in Banking and Finance: Technological Disruption, Climate Change, and Geopolitical Tensions)
►▼
Show Figures

Figure 1
Open AccessFeature PaperArticle
Joint Long-Run Persistence and Cross-Age Dependence in Mortality: A Semiparametric Multivariate Long-Memory Framework
by
Wanying Fu and Barry R. Smith
Risks 2026, 14(9), 219; https://doi.org/10.3390/risks14090219 - 20 Sep 2026
Abstract
►▼
Show Figures
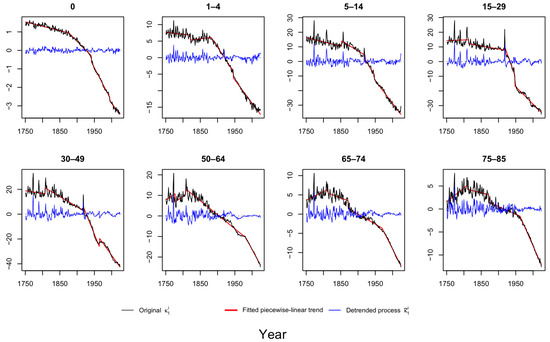
Recent studies have increasingly focused on persistence and long-memory behaviour in mortality data. However, existing research has examined persistence primarily from a marginal perspective, through separate univariate mortality processes, without jointly characterizing long-run persistence and dependence across mortality series. We investigate mortality persistence
[...] Read more.
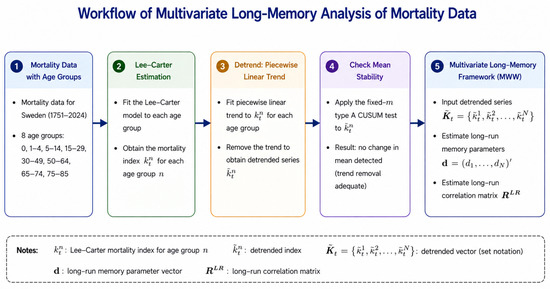
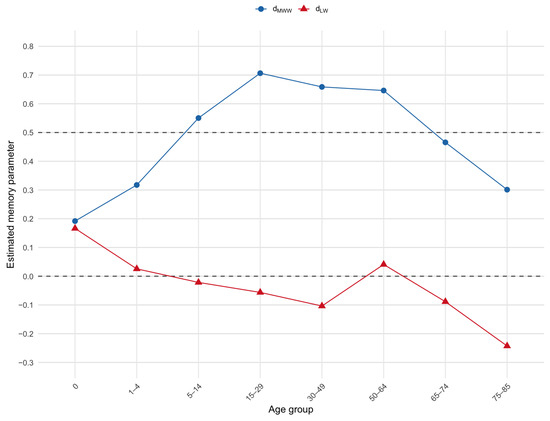
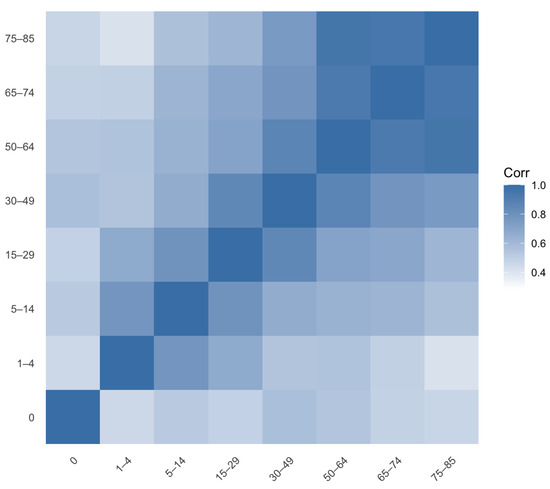
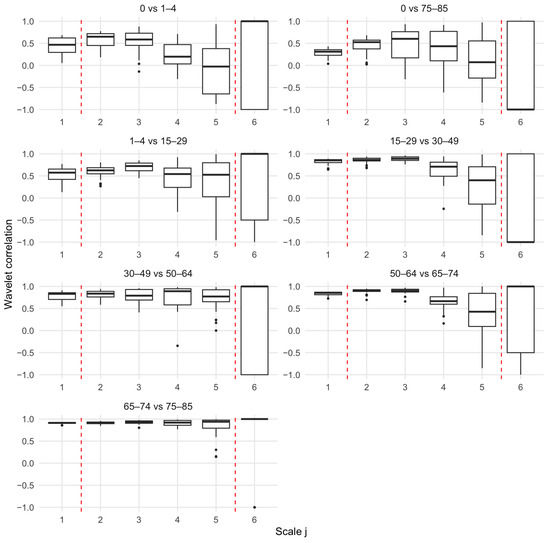
Recent studies have increasingly focused on persistence and long-memory behaviour in mortality data. However, existing research has examined persistence primarily from a marginal perspective, through separate univariate mortality processes, without jointly characterizing long-run persistence and dependence across mortality series. We investigate mortality persistence from a multivariate long-memory perspective by applying, for the first time, a semiparametric multivariate long-memory framework to mortality data. The framework is applied to Swedish mortality data after removing piecewise linear trends from age-group-specific time indices. The results reveal substantial long-run persistence and strong cross-age dependence within the multivariate mortality system, whereas little marginal persistence remains for most individual age groups after detrending. The multivariate long-run memory estimates range from 0.192 to 0.706. Moreover, the average pairwise long-run correlation is 0.655, compared with an average ordinary correlation of 0.526, indicating stronger dependence specifically at low frequencies. These findings suggest that mortality persistence is primarily a cross-age phenomenon rather than a marginal property of individual age-group dynamics. The estimated dependence structure also exhibits clear consecutive-age and age-cluster patterns. The long-run pairwise correlations among the three older age groups (50–64, 65–74, and 75–85) range from 0.927 to 0.952. Overall, the proposed framework provides a new perspective on mortality persistence by demonstrating the importance of analysing persistence jointly across age groups.
Full article

Figure 1
Open AccessArticle
Estimation and Analysis of Trade-Based Money Laundering Using Mirror Trade Data: The Case of South Africa
by
William Gaviyau and Jethro Godi
Risks 2026, 14(9), 218; https://doi.org/10.3390/risks14090218 - 18 Sep 2026
Abstract
Living in a globalised economy, opportunities arise for cross-border trade. As cross-border trading activities increase, they give rise to trade-based money laundering (TBML). Despite trade growth, TBML continues to be prevalent and not widely recognised compared to other traditional forms of money laundering.
[...] Read more.
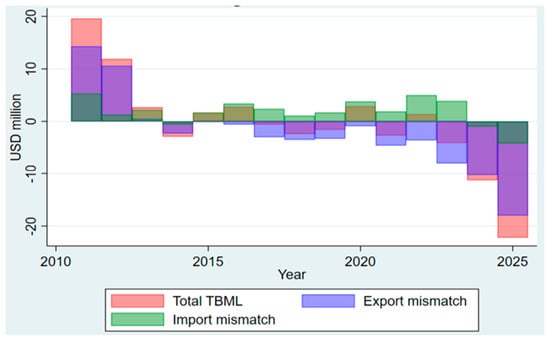
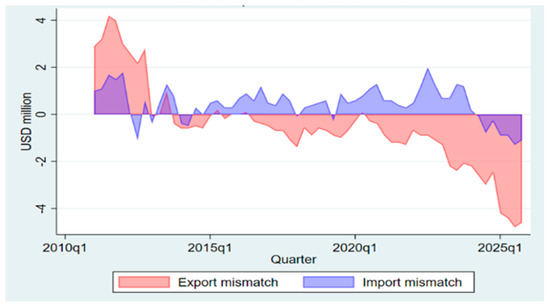
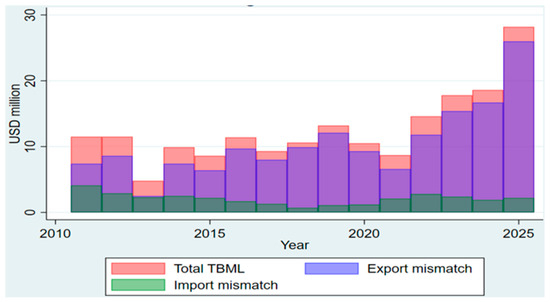
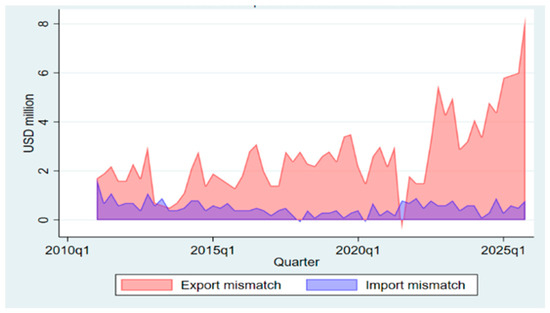
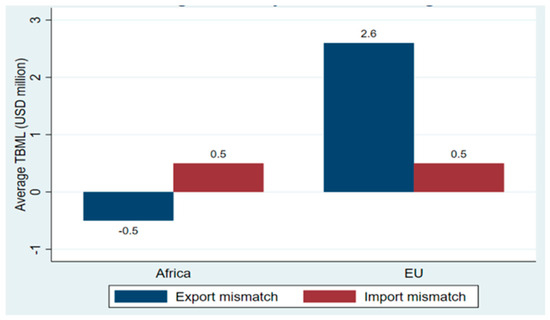
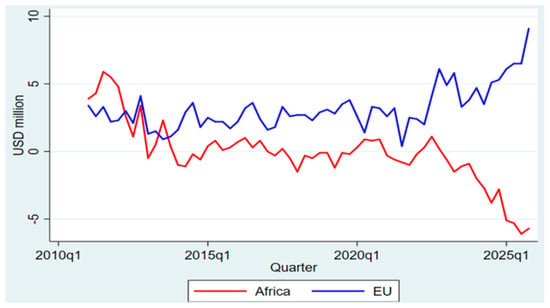
Living in a globalised economy, opportunities arise for cross-border trade. As cross-border trading activities increase, they give rise to trade-based money laundering (TBML). Despite trade growth, TBML continues to be prevalent and not widely recognised compared to other traditional forms of money laundering. Estimation of money laundered globally remains problematic. Therefore, this study estimated and analysed TBML by applying mirror trade data for South Africa (SA) trading with Africa and the European Union (EU). To assist historical quantitative quarterly time series, mirror trade data were gathered covering the period of 2011 to 2025. The findings reveal that the magnitude of SA’s TBML to Africa was highly volatile, while the magnitude of SA’s TBML to the European Union indicated that SA uses EU trade channels for receiving illicit flows into the country. Comparatively, analyses of the structural patterns and trends of SA’s TBML with Africa versus that with the EU over the study period revealed large structural differences, which is a characteristic feature of the two regional economic trading blocs. In conclusion, TBML for SA–Africa was mainly carried out through import over-invoicing, while TBML for SA–EU was carried out through export over-invoicing. The findings contribute to filling the knowledge and practice gaps associated with TBML estimation.
Full article
(This article belongs to the Special Issue AI-Driven Financial Econometrics and Risk Management)
►▼
Show Figures

Figure 1
Open AccessEditorial
Special Issue: “Advancements in Actuarial Mathematics and Insurance Risk Management”
by
Annamaria Olivieri
Risks 2026, 14(9), 217; https://doi.org/10.3390/risks14090217 - 16 Sep 2026
Abstract
Insurance has always relied on the possibility of identifying, modelling, pricing, and managing uncertainty [...]
Full article
(This article belongs to the Special Issue Advancements in Actuarial Mathematics and Insurance Risk Management)
Open AccessFeature PaperArticle
Risk-Adjusted Kelly Investing Under Non-Homogeneous Reward and Risk
by
Sagara Dewasurendra, Pedro Júdice and Qiji Jim Zhu
Risks 2026, 14(9), 216; https://doi.org/10.3390/risks14090216 - 15 Sep 2026
Abstract
In financial applications, the Kelly criterion is a well-known strategy for maximizing long-term growth, but is often criticized for its high-risk approach. To mitigate this effect, previous research proposed two risk-adjusted Kelly criteria in a finite investment horizon: the inflection point, which identifies
[...] Read more.
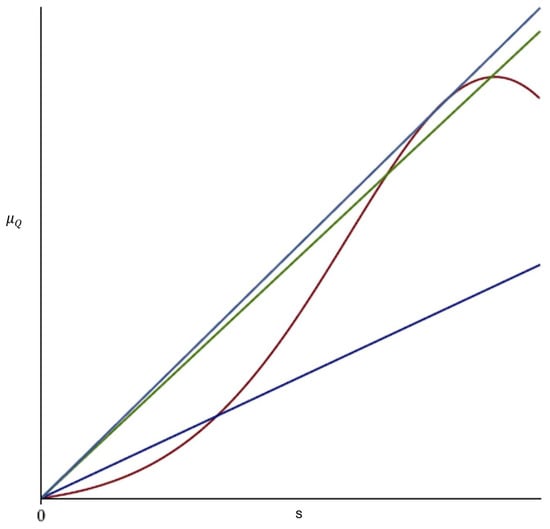
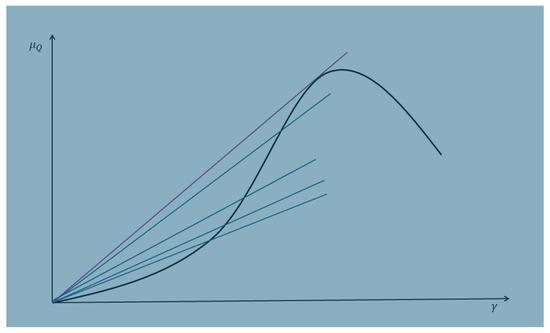
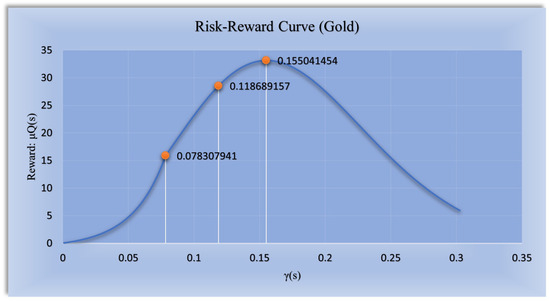
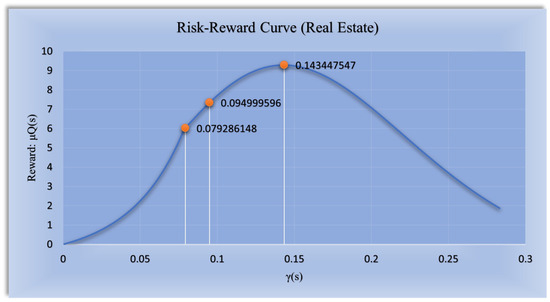
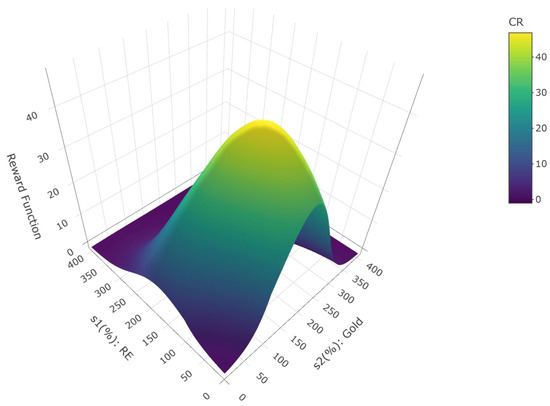
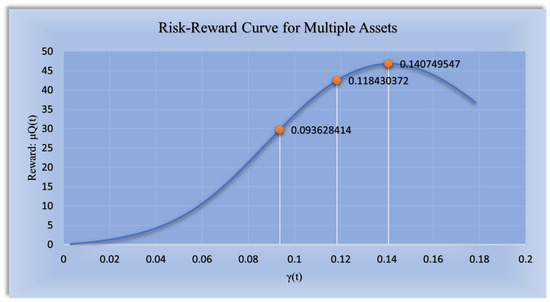
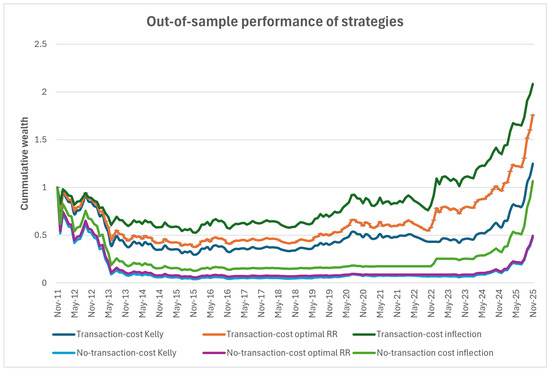
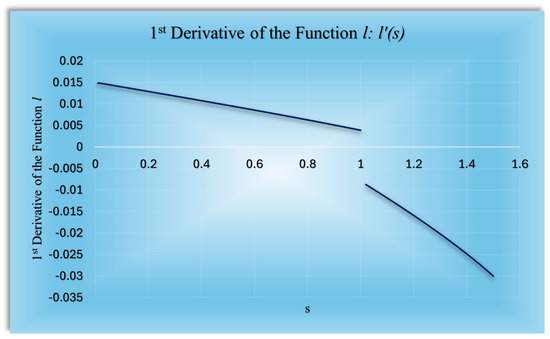
In financial applications, the Kelly criterion is a well-known strategy for maximizing long-term growth, but is often criticized for its high-risk approach. To mitigate this effect, previous research proposed two risk-adjusted Kelly criteria in a finite investment horizon: the inflection point, which identifies optimal marginal return, and the optimal reward-to-risk ratio. These approaches maintain the core benefits of the Kelly criterion while reducing risk. As the investment size is used as a proxy for risk, the theory is developed under a linear and smooth setting. However, in practical cases such as transaction costs, reward and risk become non-homogeneous and non-smooth, thus requiring the development of a novel non-smooth analysis framework for risk-adjusted Kelly strategies, which we conduct in this paper. After developing the theory, we apply it to several practical settings, and extend the framework to multiple assets. The research concludes with an empirical analysis of the risk and reward of the risk-adjusted Kelly strategies applied to transaction costs, confirming the superiority of the proposed strategies to the classical Kelly criterion.
Full article
(This article belongs to the Special Issue Optimization Methods for Financial Risk Management)
►▼
Show Figures

Figure 1
Open AccessArticle
Walk-Forward Evaluation of Early-Warning Models for Large Bitcoin Movements Under Fixed and Train-Only Event Definitions
by
Anupong Sukprasert, Lersak Phothong, Napat Jantarajaturapath, Pongsatorn Tantrabundit and Yanin Tangpinyoputtikhun
Risks 2026, 14(9), 215; https://doi.org/10.3390/risks14090215 - 15 Sep 2026
Abstract
►▼
Show Figures
Evaluations of financial early-warning models can appear stronger when temporal separation is incomplete or when the event definition uses information unavailable at the forecast origin. This study examines one-day-ahead risk ranking of large absolute Bitcoin returns using 334 daily observations from 31 August
[...] Read more.
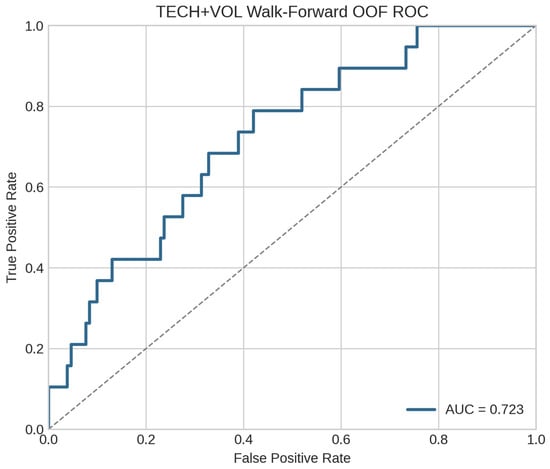
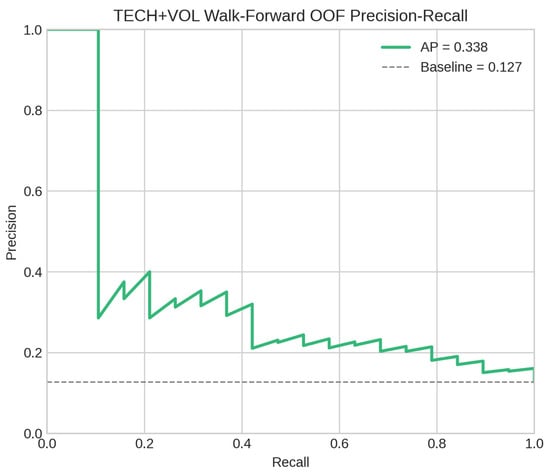
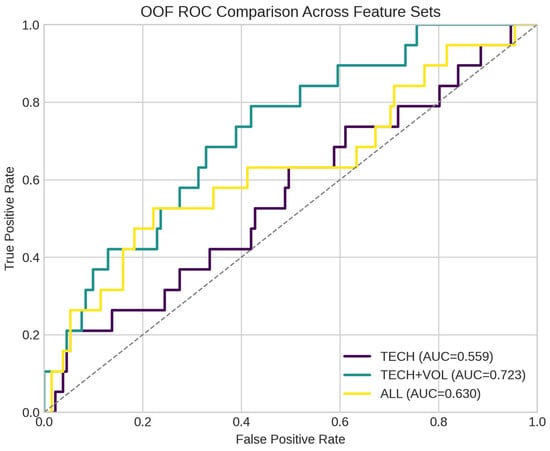
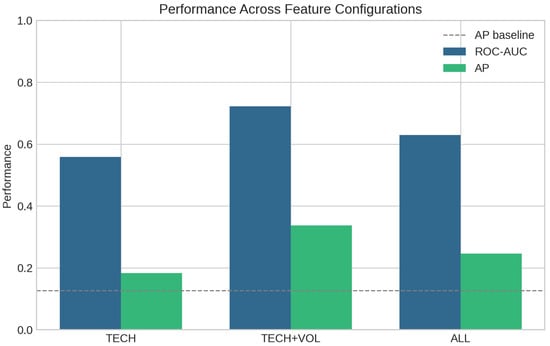
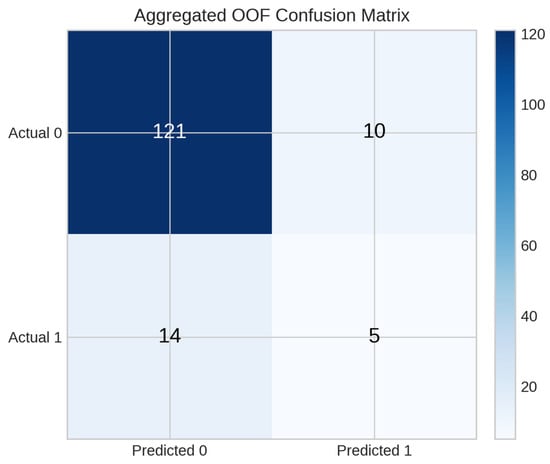
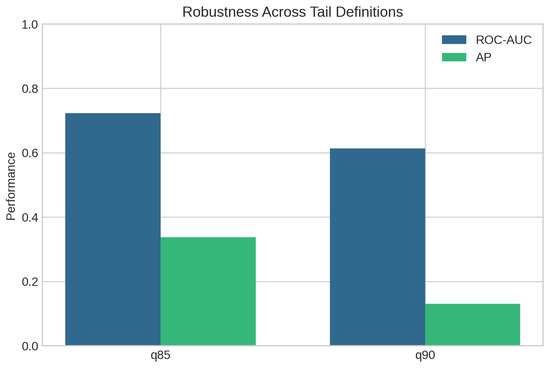
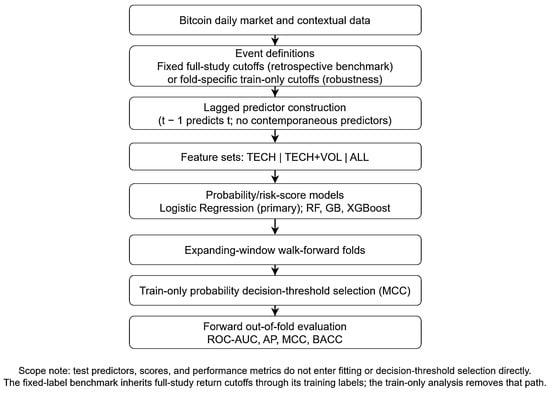
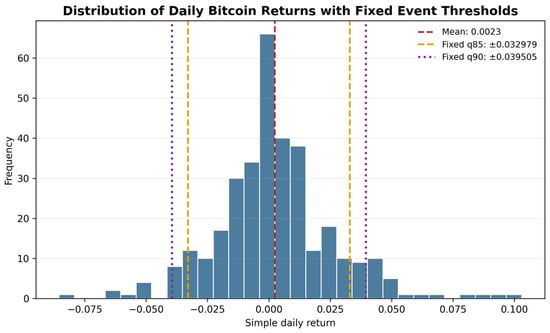
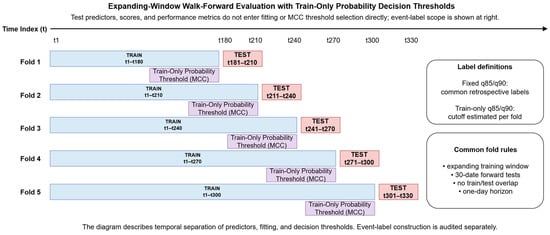
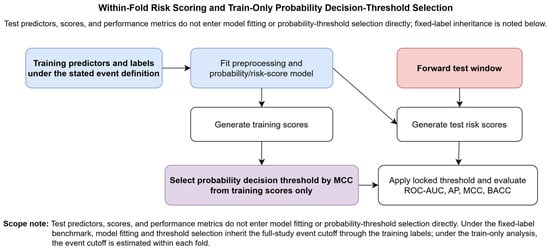
Evaluations of financial early-warning models can appear stronger when temporal separation is incomplete or when the event definition uses information unavailable at the forecast origin. This study examines one-day-ahead risk ranking of large absolute Bitcoin returns using 334 daily observations from 31 August 2024 to 30 July 2025, five expanding-window folds, lagged predictors, training-fold preprocessing, and train-only classification-threshold selection. The original q85 and q90 cutoffs, estimated from the full study-period return distribution, are retained as retrospective fixed-label benchmarks and are complemented by fold-specific train-only cutoffs. Under fixed q85 labels, class-weighted Logistic Regression with technical and market-activity variables achieved pooled ROC-AUC = 0.723 (moving-block 95% CI [0.556, 0.822]) and Average Precision = 0.338 ([0.103, 0.565]); Random Forest yielded 0.739 and 0.352. Pooled MCC was 0.207, but the primary model issued no positive warnings in three of the five fixed-q85 test folds. Under train-only q85 labels, ROC-AUC was 0.674 and Average Precision was 0.174, but the retained MCC threshold-selection rule produced no true positives. Conventional GARCH(1,1), EWMA, and 14-day historical-volatility scores did not exceed the primary model on both ranking metrics. Adding the complete six-variable sentiment and attention block lowered point estimates, although one-variable ablations and a matched-dimension control do not isolate sentiment content from dimensionality and small-sample overfitting. The results provide limited, sample-specific evidence for risk ranking, not evidence of deployment readiness, economic profitability, or cross-asset generalizability.
Full article

Figure 1
Open AccessArticle
A Geometric Vector Framework for High-Dimensional Interaction Modeling Applications to Systemic Risk Using Dot and Cross Product Invariants
by
Guy Burstein
Risks 2026, 14(9), 214; https://doi.org/10.3390/risks14090214 - 15 Sep 2026
Abstract
►▼
Show Figures
The quantification of structural resilience and sub-percentile tail risk represents a major challenge across both corporate financial engineering and modern industrial logistics. Traditional aggregation architectures, such as linear risk matrices and parametric copulas, can exhibit computational and sensitivity challenges when modeling extreme tail-risk
[...] Read more.
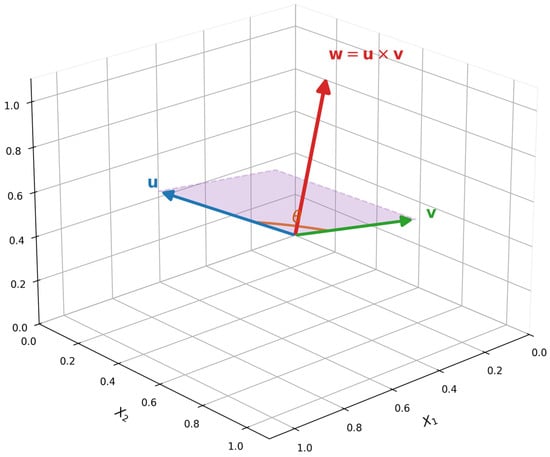
The quantification of structural resilience and sub-percentile tail risk represents a major challenge across both corporate financial engineering and modern industrial logistics. Traditional aggregation architectures, such as linear risk matrices and parametric copulas, can exhibit computational and sensitivity challenges when modeling extreme tail-risk dependencies under sparse data regimes. While parametric copulas are highly effective under standard conditions, they can be sensitive to parameter specifications and sample size limitations in deep-tail regions. This paper highlights a numerical limitation of the Gumbel extreme-value copula in deep-tail regions (F ≥ 0.999). Analytical results indicate that the logarithmic structure of the tail generator produces progressively higher sensitivity near the distribution boundary, yielding an empirical condition number greater than 1220 at the regulatory 99.9% Value-at-Risk (VaR) threshold. This numerical conditioning issue increases sensitivity to sample noise and data scarcity, resulting in a 36.5% underestimation of systemic tail damage. The proposed model formalizes risk scenarios by mapping multi-node threats as normalized directional unit vectors within a compact 3D vector space. Interactions are then calculated algebraically using geometric invariants—the Dot Product for root-cause convergence and the Cross Product Norm for dynamic, second-order risk resonance—effectively contracting high-dimensional combinations into a stable framework. Rather than treating risks as frame-dependent scalar probabilities, this generalized High-Dimensional Geometric Invariant Operational Risk Framework extends legacy structures with domain-agnostic invariants capturing dynamic risk resonance and multi-trigger cascades. Simulation results across rugged operational environments, acute data scarcity (Ntrain = 100), and high-dimensional scaling (50 risk factors) demonstrate that the proposed model outperforms standard alternatives by a factor of approximately 13 in out-of-sample predictive accuracy (MSE = 0.08193) while maintaining absolute parametric stability. Furthermore, a Taylor-series tensor contraction successfully collapses 1275 second-order interactions into just 2 free parameters. This framework bypasses iterative Maximum Likelihood Estimation (MLE) bottlenecks, unlocking real-time, low-latency Monte Carlo stress testing for systemic banking compliance and global supply chain risk governance.
Full article

Figure A1
Open AccessArticle
The Kerper–Bowron Method: Additional Notes on Manufacturer’s Warranties and Collateralization Applications
by
Lee Bowron, John Kerper, Alice Lightfoot and Wheeler Bowron
Risks 2026, 14(9), 213; https://doi.org/10.3390/risks14090213 - 14 Sep 2026
Abstract
The Kerper–Bowron (KB) Method (patent pending) projects expected claims at the individual contract level. This paper extends that cash-flow engine to manufacturer-warranty accruals and to three proposed uses: collateralized risk transfer, lending against service-contract equity, and risk-adjusted customer lifetime value (CLV). Manufacturer warranties
[...] Read more.
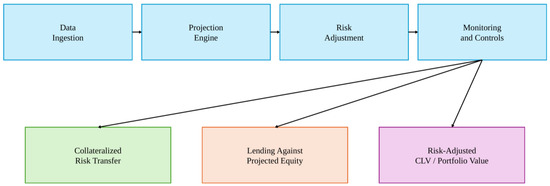
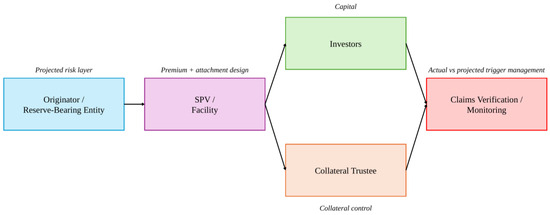
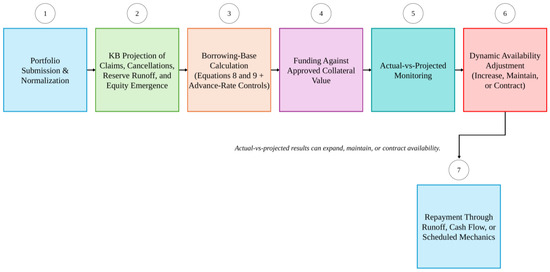
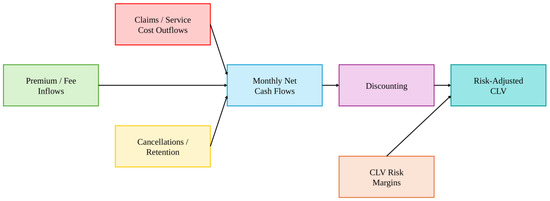
The Kerper–Bowron (KB) Method (patent pending) projects expected claims at the individual contract level. This paper extends that cash-flow engine to manufacturer-warranty accruals and to three proposed uses: collateralized risk transfer, lending against service-contract equity, and risk-adjusted customer lifetime value (CLV). Manufacturer warranties and separately priced service contracts are treated as related but distinct products under ASC 460, ASC 450, and IAS 37. Expected cost per unit of exposure is formed with a generalized linear model; a Tweedie mean–variance function is used as a working choice, not as a tested warranty distribution. Accident-month estimates are allocated to payment months, incurred-but-not-reported cost on pre-valuation months is isolated, and remaining paid cash flow is split into pre-valuation runoff and post-valuation occurrence. One present-value risk margin is taken from the predictive distribution as the present value of the gap between a stated percentile and the mean; a constant loading on the discounted mean is an illustrative substitute when simulation is not run. The contribution is contract-level granularity and a single paid path that can be refreshed as experience and assumptions change. The same paid path can be used as a financial-monitoring tool: expected claims, equity, and risk-adjusted values can be refreshed as time passes, actual results emerge, and model or economic assumptions change. Accuracy, balance sheet derecognition, investor diversification, and lendable capacity would be the subject of further research.
Full article
(This article belongs to the Special Issue Advances in Risk Models and Actuarial Science)
►▼
Show Figures

Figure 1
Open AccessArticle
Financial Risk Valuation of Green Hydrogen Hub Investment Under Techno-Economic Uncertainty: A Real Options Approach in Indonesia
by
Christian Priatmoko and Dzikri Firmansyah Hakam
Risks 2026, 14(9), 212; https://doi.org/10.3390/risks14090212 - 14 Sep 2026
Abstract
►▼
Show Figures
Green hydrogen is increasingly viewed as a strategic energy carrier for industrial decarbonization, regional energy trade, and the transition to low-carbon energy systems. In Southeast Asia, Sumatra is well positioned to develop as a green hydrogen hub because of its abundant renewable energy
[...] Read more.
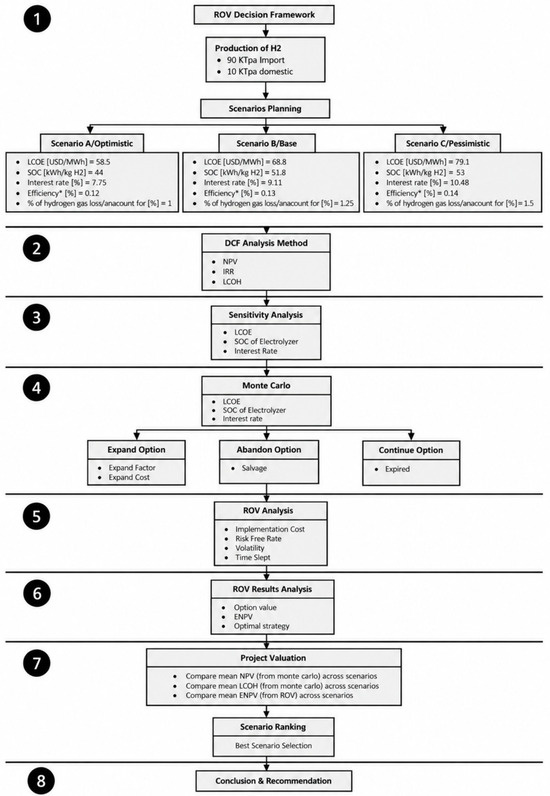
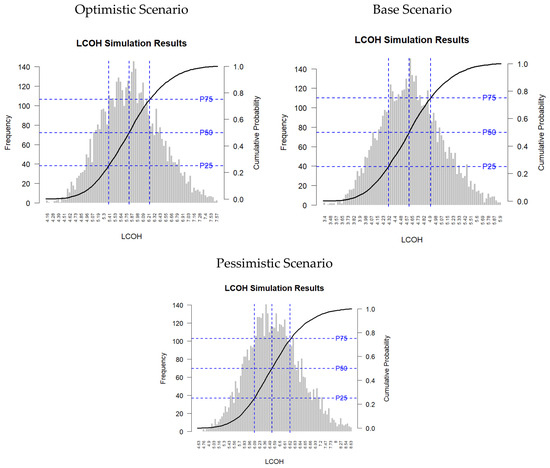
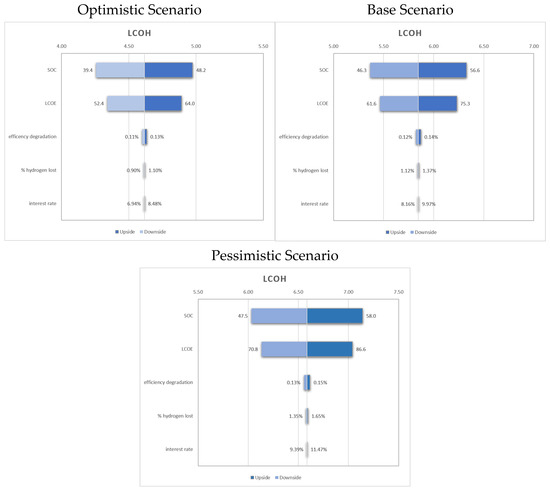
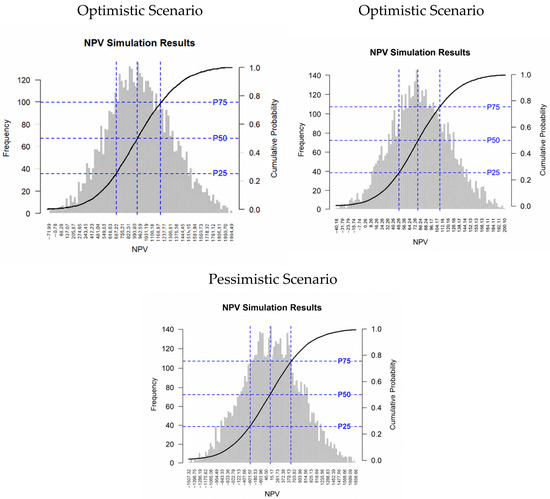
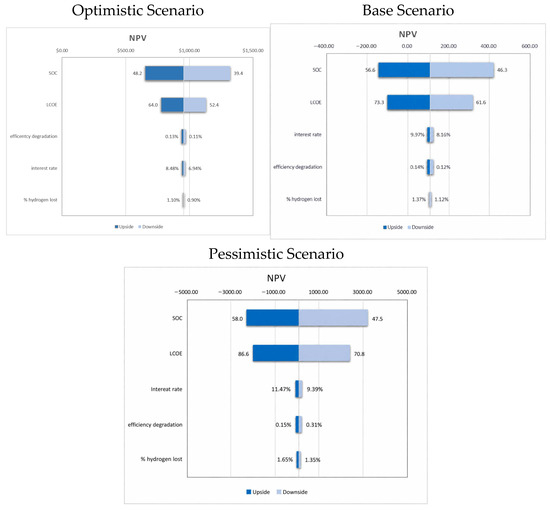
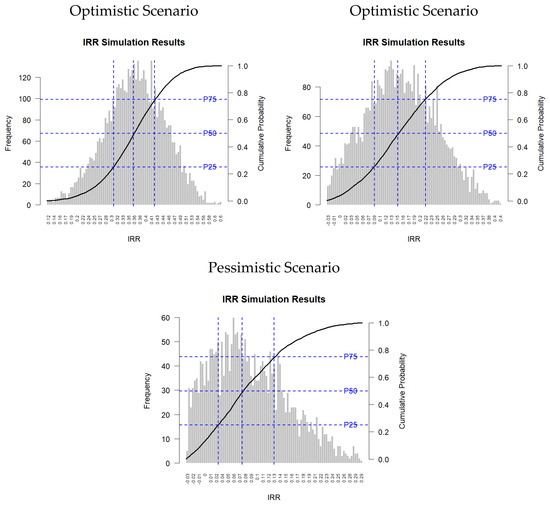
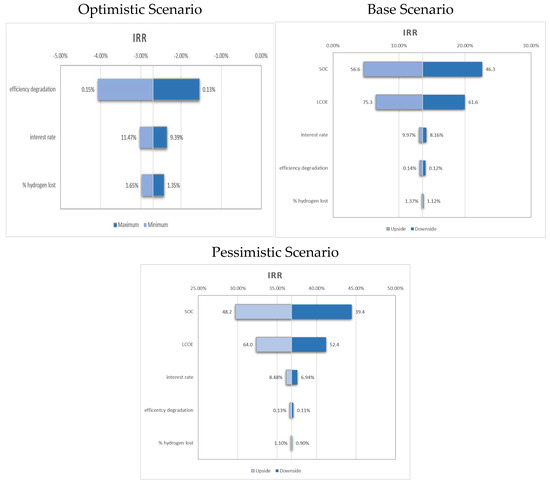
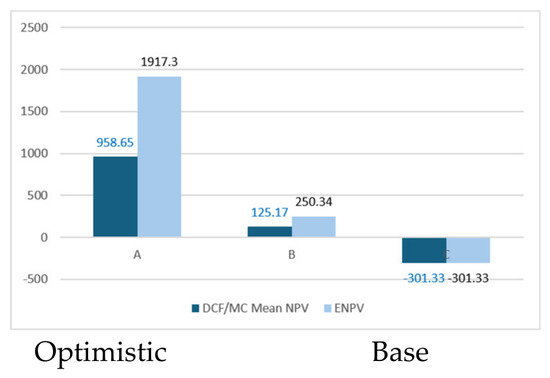
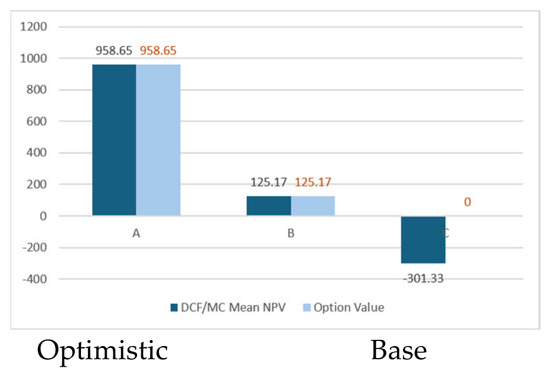
Green hydrogen is increasingly viewed as a strategic energy carrier for industrial decarbonization, regional energy trade, and the transition to low-carbon energy systems. In Southeast Asia, Sumatra is well positioned to develop as a green hydrogen hub because of its abundant renewable energy resources and proximity to Singapore as a prospective import market. This study evaluates the economic feasibility and strategic investment value of a proposed green hydrogen hub in Sumatra under techno-economic uncertainty and identifies the most robust development scenario. An integrated valuation framework was applied, combining Discounted Cash Flow (DCF), sensitivity analysis, Monte Carlo Simulation (MCS), and Real Options Valuation (ROV) across three scenarios: an optimistic hydropower-dominant case, a base hybrid case, and a pessimistic solar-dominant case. The results show that project performance is primarily driven by electricity cost, electrolyzer efficiency, and financing conditions. Scenario A is the most attractive, delivering the lowest mean Levelized Cost of Hydrogen (LCOH) at USD 4.65/kg H2, the highest mean Net Present Value (NPV) at USD 958.65 million, and an Expanded Net Present Value (ENPV) of USD 1917.30 million. Scenario B remains feasible but more sensitive to uncertainty, while Scenario C is economically unattractive. These findings indicate that ROV provides a more realistic decision framework than static DCF by capturing the value of managerial flexibility under uncertainty.
Full article

Figure 1
Open AccessArticle
From Historical Performance to Scenario-Based Forecasting: Assessing Fiscal Gains from GovTech Maturity in Saudi Arabia
by
Mudathir Ahmed Abuelgasim
Risks 2026, 14(9), 211; https://doi.org/10.3390/risks14090211 - 13 Sep 2026
Abstract
This study examines the relationship between GovTech maturity and non-oil revenue in Saudi Arabia over 2016–2024 and assesses the potential fiscal implications of continued digital government development through 2030. Using annual data on the United Nations E-Government Development Index (EGDI), the World Bank
[...] Read more.
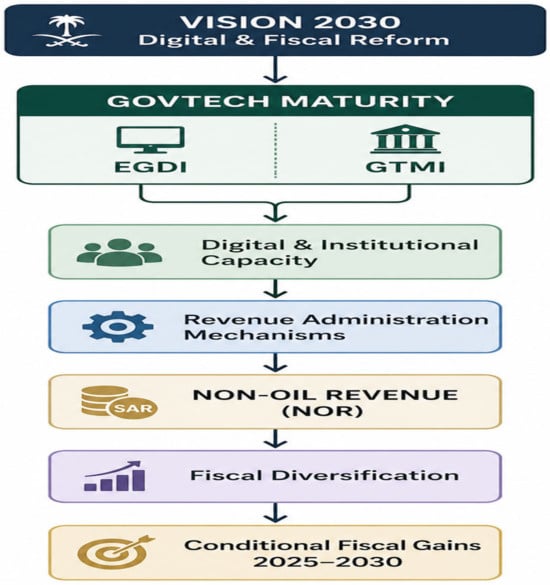
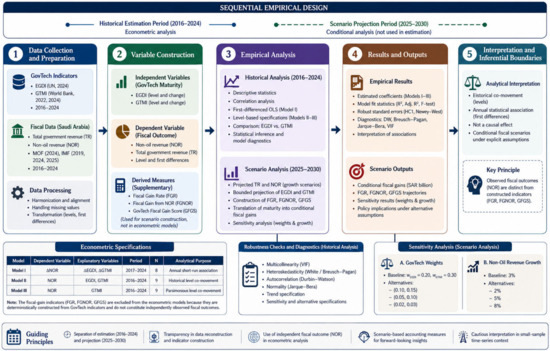
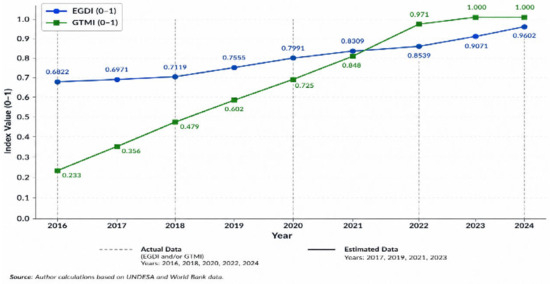
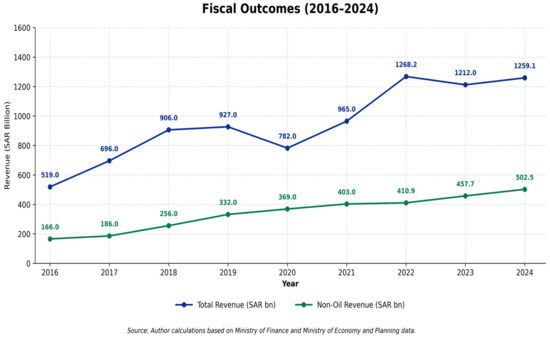
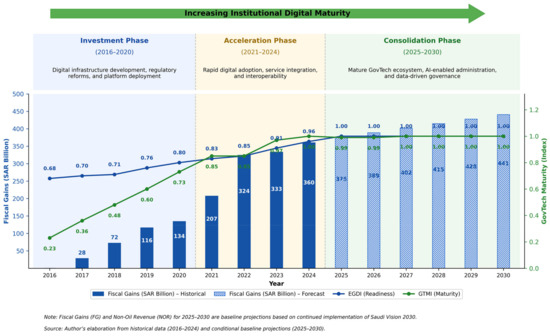
This study examines the relationship between GovTech maturity and non-oil revenue in Saudi Arabia over 2016–2024 and assesses the potential fiscal implications of continued digital government development through 2030. Using annual data on the United Nations E-Government Development Index (EGDI), the World Bank GovTech Maturity Index (GTMI), and government revenue, the analysis combines descriptive and correlation evidence with complementary level-based and first-differenced OLS specifications, supported by diagnostic and robustness checks. The results reveal a positive structural association between GovTech maturity and non-oil revenue in level specifications, particularly for GTMI. Importantly, this relationship does not translate into a statistically significant contemporaneous annual association when the variables are examined in first differences, suggesting that the fiscal relevance of GovTech may operate through cumulative, institutional, and longer-horizon channels rather than through immediate year-to-year revenue effects. Building on this distinction, the study develops conditional scenario projections for 2025–2030, showing that model-implied fiscal gains increase as GovTech maturity advances toward its measurement frontier, although the corresponding monetary outcomes remain sensitive to alternative GovTech weights and fiscal-growth assumptions. The study therefore contributes evidence that distinguishes historical structural co-movement from short-run fiscal transmission and provides a transparent scenario-based framework for assessing the potential fiscal value of digital government maturity. The findings suggest that future fiscal returns will depend increasingly on the effective utilization, integration, and institutional embedding of existing digital government capabilities rather than on further expansion of digital infrastructure alone.
Full article
(This article belongs to the Special Issue AI for Financial Risk Perception)
►▼
Show Figures

Figure 1
Open AccessArticle
Climate Transition Risk and Financial Development in a Resource-Dependent Economy: Evidence from Kazakhstan
by
Lyazzat Kudabayeva, Aizhan Omarova, Saule Kaltayeva, Aktolkin Abubakirova, Aigul Kurmanalina, Mehriban Imanova and Gulimai Amaniyazova
Risks 2026, 14(9), 210; https://doi.org/10.3390/risks14090210 - 11 Sep 2026
Abstract
►▼
Show Figures
Climate transition risks are increasingly relevant to financial development, particularly in resource-dependent economies. However, the existing literature has largely examined how financial development affects environmental outcomes, while the reverse relationship remains comparatively understudied. This study investigates whether carbon emissions and renewable energy consumption
[...] Read more.
Climate transition risks are increasingly relevant to financial development, particularly in resource-dependent economies. However, the existing literature has largely examined how financial development affects environmental outcomes, while the reverse relationship remains comparatively understudied. This study investigates whether carbon emissions and renewable energy consumption influence financial development in Kazakhstan over 1996–2024, controlling for economic growth, inflation, and foreign direct investment. Financial development is measured by domestic credit to the private sector provided by banks (% of GDP). Using the Autoregressive Distributed Lag (ARDL) bounds testing approach and accounting for structural breaks, the study examines short-run and long-run dynamics. The results confirm a long-run equilibrium relationship among the variables, but none of the individual long-run coefficients is statistically significant. This finding does not imply that climate-transition factors are economically irrelevant; rather, it suggests that their effects have not yet translated into persistent, statistically identifiable changes in aggregate bank-based financial development. In the short run, economic growth has a positive effect, while inflation has a negative effect, with renewable energy consumption and foreign direct investment showing lagged effects. The study contributes new evidence on the climate–finance nexus from a resource-dependent transition economy and highlights the evolving, but still limited, transmission of climate-transition dynamics through Kazakhstan’s banking system.
Full article

Figure 1
Open AccessArticle
Iraqi Public Debt Dynamics and Its Fiscal Sustainability in the Context of SVAR and Shock Assessment
by
Hashim Jabbar Hussein and Mahmoud Mousavi Shiri
Risks 2026, 14(9), 209; https://doi.org/10.3390/risks14090209 - 11 Sep 2026
Abstract
►▼
Show Figures
This study examines the dynamic interactions among gross domestic product (GDP), external public debt, and domestic public debt in Iraq and discusses their implications for fiscal sustainability. The observed annual data cover the period 2005–2024, while the values for 2025 are based on
[...] Read more.
This study examines the dynamic interactions among gross domestic product (GDP), external public debt, and domestic public debt in Iraq and discusses their implications for fiscal sustainability. The observed annual data cover the period 2005–2024, while the values for 2025 are based on IMF projections. Because continuous official monthly observations were unavailable, the annual series were temporally disaggregated using cubic-spline interpolation to construct an analytical monthly series. These interpolated values do not represent additional independent observations; therefore, the empirical findings are interpreted as exploratory. A recursive Structural Vector Autoregression (SVAR) model was estimated using Cholesky identification with the ordering GDP, external debt, and domestic debt. The variables were transformed into second differences in their natural logarithms, and a three-lag specification was employed. Impulse-response functions and forecast-error variance decomposition were used to examine the transmission and relative importance of the identified innovations. At the 24-month forecast horizon, GDP shocks explained 93.3% of GDP variation, while external debt was predominantly explained by its own shocks (86.3%). Domestic-debt variation was explained by its own shocks (47.3%), GDP shocks (44.1%), and external-debt shocks (8.6%). These results suggest that domestic debt is more closely associated with changes in domestic economic activity, whereas external debt follows a comparatively persistent path. The findings emphasize the importance of debt composition, non-oil revenue diversification, expenditure management, and coordination between domestic and external borrowing. Because oil revenues and government expenditure are not included as separate endogenous variables, the model does not directly identify oil-revenue or government-spending shocks. Future research should employ genuinely observed quarterly or monthly data and incorporate these fiscal variables explicitly.
Full article

Figure 1
Open AccessFeature PaperArticle
Dynamic Non-Life Insurance Pricing Under Delayed Claim Reporting: A Partially Observed Risk-Sensitive Control Framework
by
Desmond Marozva, Selah Tanaka Marozva and Ştefan Cristian Gherghina
Risks 2026, 14(9), 208; https://doi.org/10.3390/risks14090208 - 10 Sep 2026
Abstract
Non-life insurance pricing is forward-looking, yet its principal cost signal, reported claims, is delayed by the occurrence-to-reporting process. The rating cell is treated as a stylised, homogeneous unit without renewal, lapse, expiry, or cohort dynamics; a fully annual-contract formulation would require these dynamics
[...] Read more.
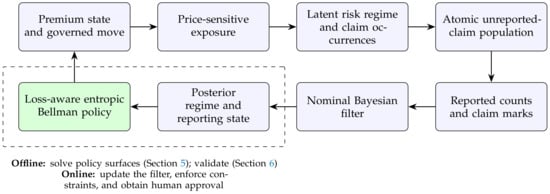
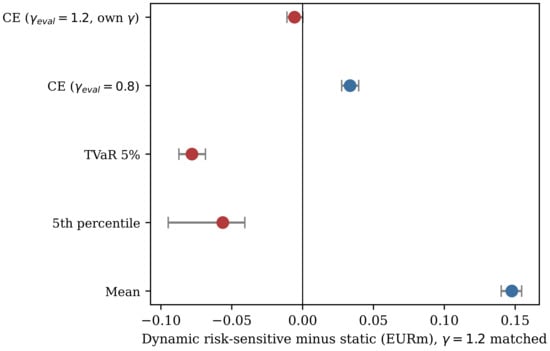
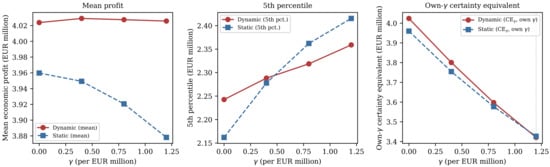
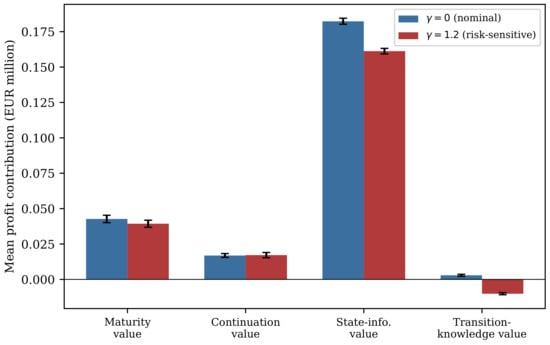
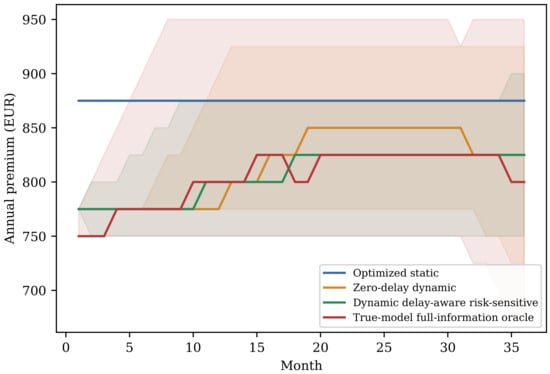
Non-life insurance pricing is forward-looking, yet its principal cost signal, reported claims, is delayed by the occurrence-to-reporting process. The rating cell is treated as a stylised, homogeneous unit without renewal, lapse, expiry, or cohort dynamics; a fully annual-contract formulation would require these dynamics to be modelled jointly with the risk and claims processes. This paper develops a partially observed risk-sensitive control framework in which premium-sensitive exposure generates claims in a latent risk regime, while unreported claims form an atomic population governed by an age-structured transport equation. The numerical instance solved and validated in this research restricts the general model to a memoryless (one-phase) reporting process for tractability. It is best matched to lines with predominantly short-to-medium reporting tails, rather than to the most extreme long-tailed liability or cyber exposures the general model is designed to eventually accommodate. A finite-state reporting reservoir and nominal Bayesian filter provide the decision state, and compound Poisson–Gamma loss enters an entropic Bellman recursion through a closed-form exponential-tilting identity, checked against an independently coded Bellman-residual test. Every dynamic policy is benchmarked against alternatives matched at the same risk-sensitivity parameter and evaluated using common random numbers. This is a general feature of the results, not a single statistic: is a standardised yardstick applied uniformly across strategies, while at the policy’s own is what that policy actually optimises, and the two need not agree. In 3000 out-of-model paths at = 1.2, the delay-aware dynamic policy increases mean profit by EUR 0.148 million and a standardised = 0.8 certainty equivalent by EUR 0.034 million relative to a matched static price. Its fifth percentile and TVaR 5%, by contrast, are lower by EUR 0.056 and 0.078 million. At the policy’s own optimisation level, however, the = 1.2 certainty-equivalent difference is EUR −0.006 million, with a 95% interval reaching zero. The dynamic policy, therefore, does not clearly outperform the matched static price on the exact objective it was optimised to maximise. Matched comparisons attribute EUR 0.039–0.043 million of mean profit to reporting-delay modelling and EUR 0.017 million to dynamic continuation. Separating state observation from transition-law knowledge attributes EUR 0.161–0.182 million to observing the regime exactly, and a small, sign-changing EUR −0.010 to +0.003 million to knowing the true transition law itself. Across an eight-scenario misspecification stress suite, the dynamic policy’s mean-profit advantage over the matched static price is directionally robust in seven of eight scenarios, but it reverses sign under a +30% true-severity shock, indicating that this advantage is sensitive to substantial severity misspecification specifically. Grid, Bellman-residual, and out-of-model filter diagnostics indicate that state reconstruction is economically primary, while entropy risk sensitivity is a secondary overlay whose apparent benefit depends materially on which certainty-equivalent level and evaluation model are used to judge it.
Full article
(This article belongs to the Special Issue Advances in Risk Models and Actuarial Science)
►▼
Show Figures

Figure 1
Highly Accessed Articles
Latest Books
E-Mail Alert
News
Topics
Topic in
Businesses, Economies, IJFS, JRFM, Risks
The Future of Banking and Financial Risk Management
Topic Editors: Eliana Angelini, Elisa Di Febo, Tu DQ LeDeadline: 31 October 2026
Topic in
Economies, JRFM, Risks, Sustainability
The Future of Global Finance and Business: Trends, Policies and Market Evolution
Topic Editors: John Malindretos, Giuliana Andreopoulos, Eleftherios Thalassinos, Ana Cristina SiqueiraDeadline: 31 December 2026
Topic in
IJFS, JRFM, Risks, Sustainability, FinTech, Platforms
Innovations of Digital Finance, Green Finance, Climate Finance and Financial Risk in the AI Era
Topic Editors: Qian Li, Canzhong YaoDeadline: 1 February 2027
Topic in
AI, BDCC, FinTech, IJFS, JTAER, Risks
Artificial Intelligence Applications in Financial Technology, 2nd Edition
Topic Editors: Albert Y.S. Lam, Andy ChunDeadline: 28 February 2027
Conferences
2–4 November 2026
The 2nd International Online Conference on Risk and Financial Management: Revisiting AI and Machine Learning Techniques in Finance and Economics (IOCRF2026)

Special Issues
Special Issue in
Risks
Financial Derivatives and Their Applications
Guest Editor: Stylianos PerrakisDeadline: 30 September 2026
Special Issue in
Risks
Advances in Risk Models and Actuarial Science
Guest Editor: Rui Manuel Rodrigues CardosoDeadline: 30 September 2026
Special Issue in
Risks
Mathematical and Computational Approaches for Financial and Insurance Risk Forecasting
Guest Editors: Kuang-Hsun Shih, Shu-Ping Lin, Yi-Hsien WangDeadline: 15 October 2026
Special Issue in
Risks
Risk Management for Capital Markets
Guest Editors: Yung Ming Shiu, Ching-Yuan HsiaoDeadline: 31 October 2026