Article

Ex-Ante Impact Assessment of Sustainability Information–The Directive 2014/95


1
Department of Law, University of Brescia, Contrada Santa Chiara, 50, 25122 Brescia, Italy
2
Department of Economics and Management, University of Brescia, Contrada Santa Chiara, 50, 25122 Brescia, Italy
*
Author to whom correspondence should be addressed.
Sustainability 2018, 10(2), 560; https://doi.org/10.3390/su10020560
Submission received: 29 December 2017 / Revised: 14 February 2018 / Accepted: 18 February 2018 / Published: 23 February 2018
(This article belongs to the Section Economic and Business Aspects of Sustainability)

Abstract

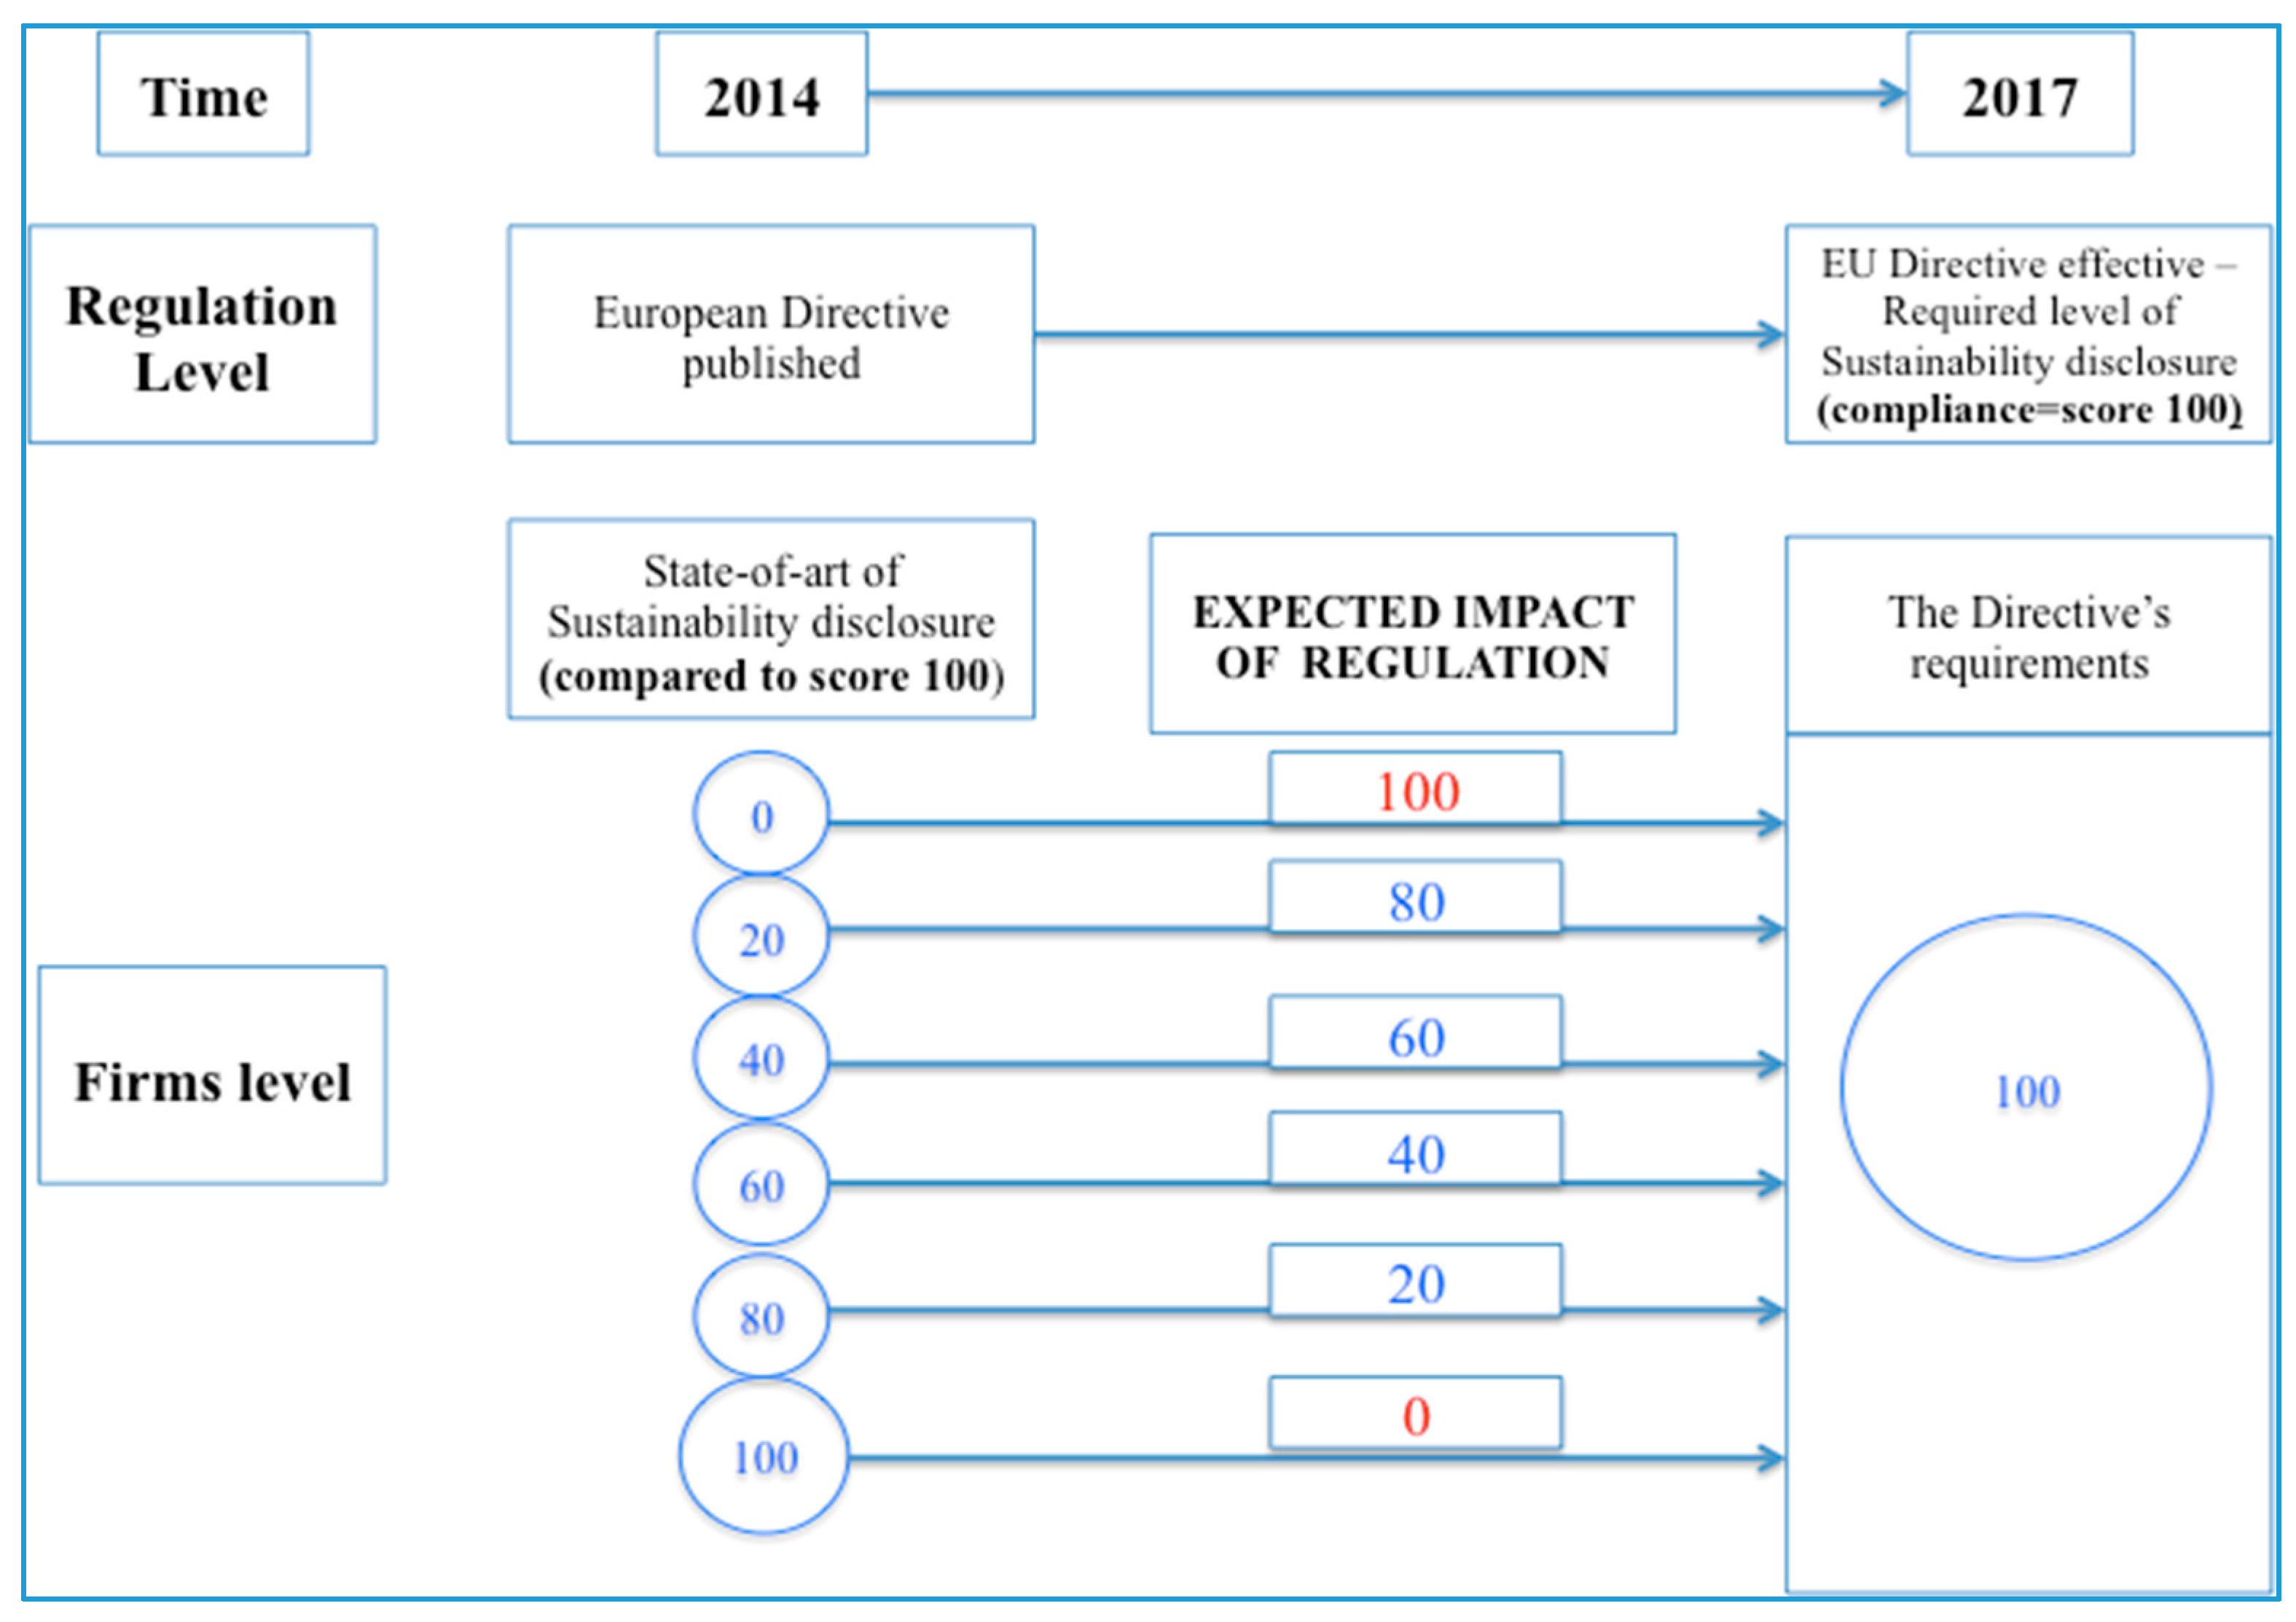
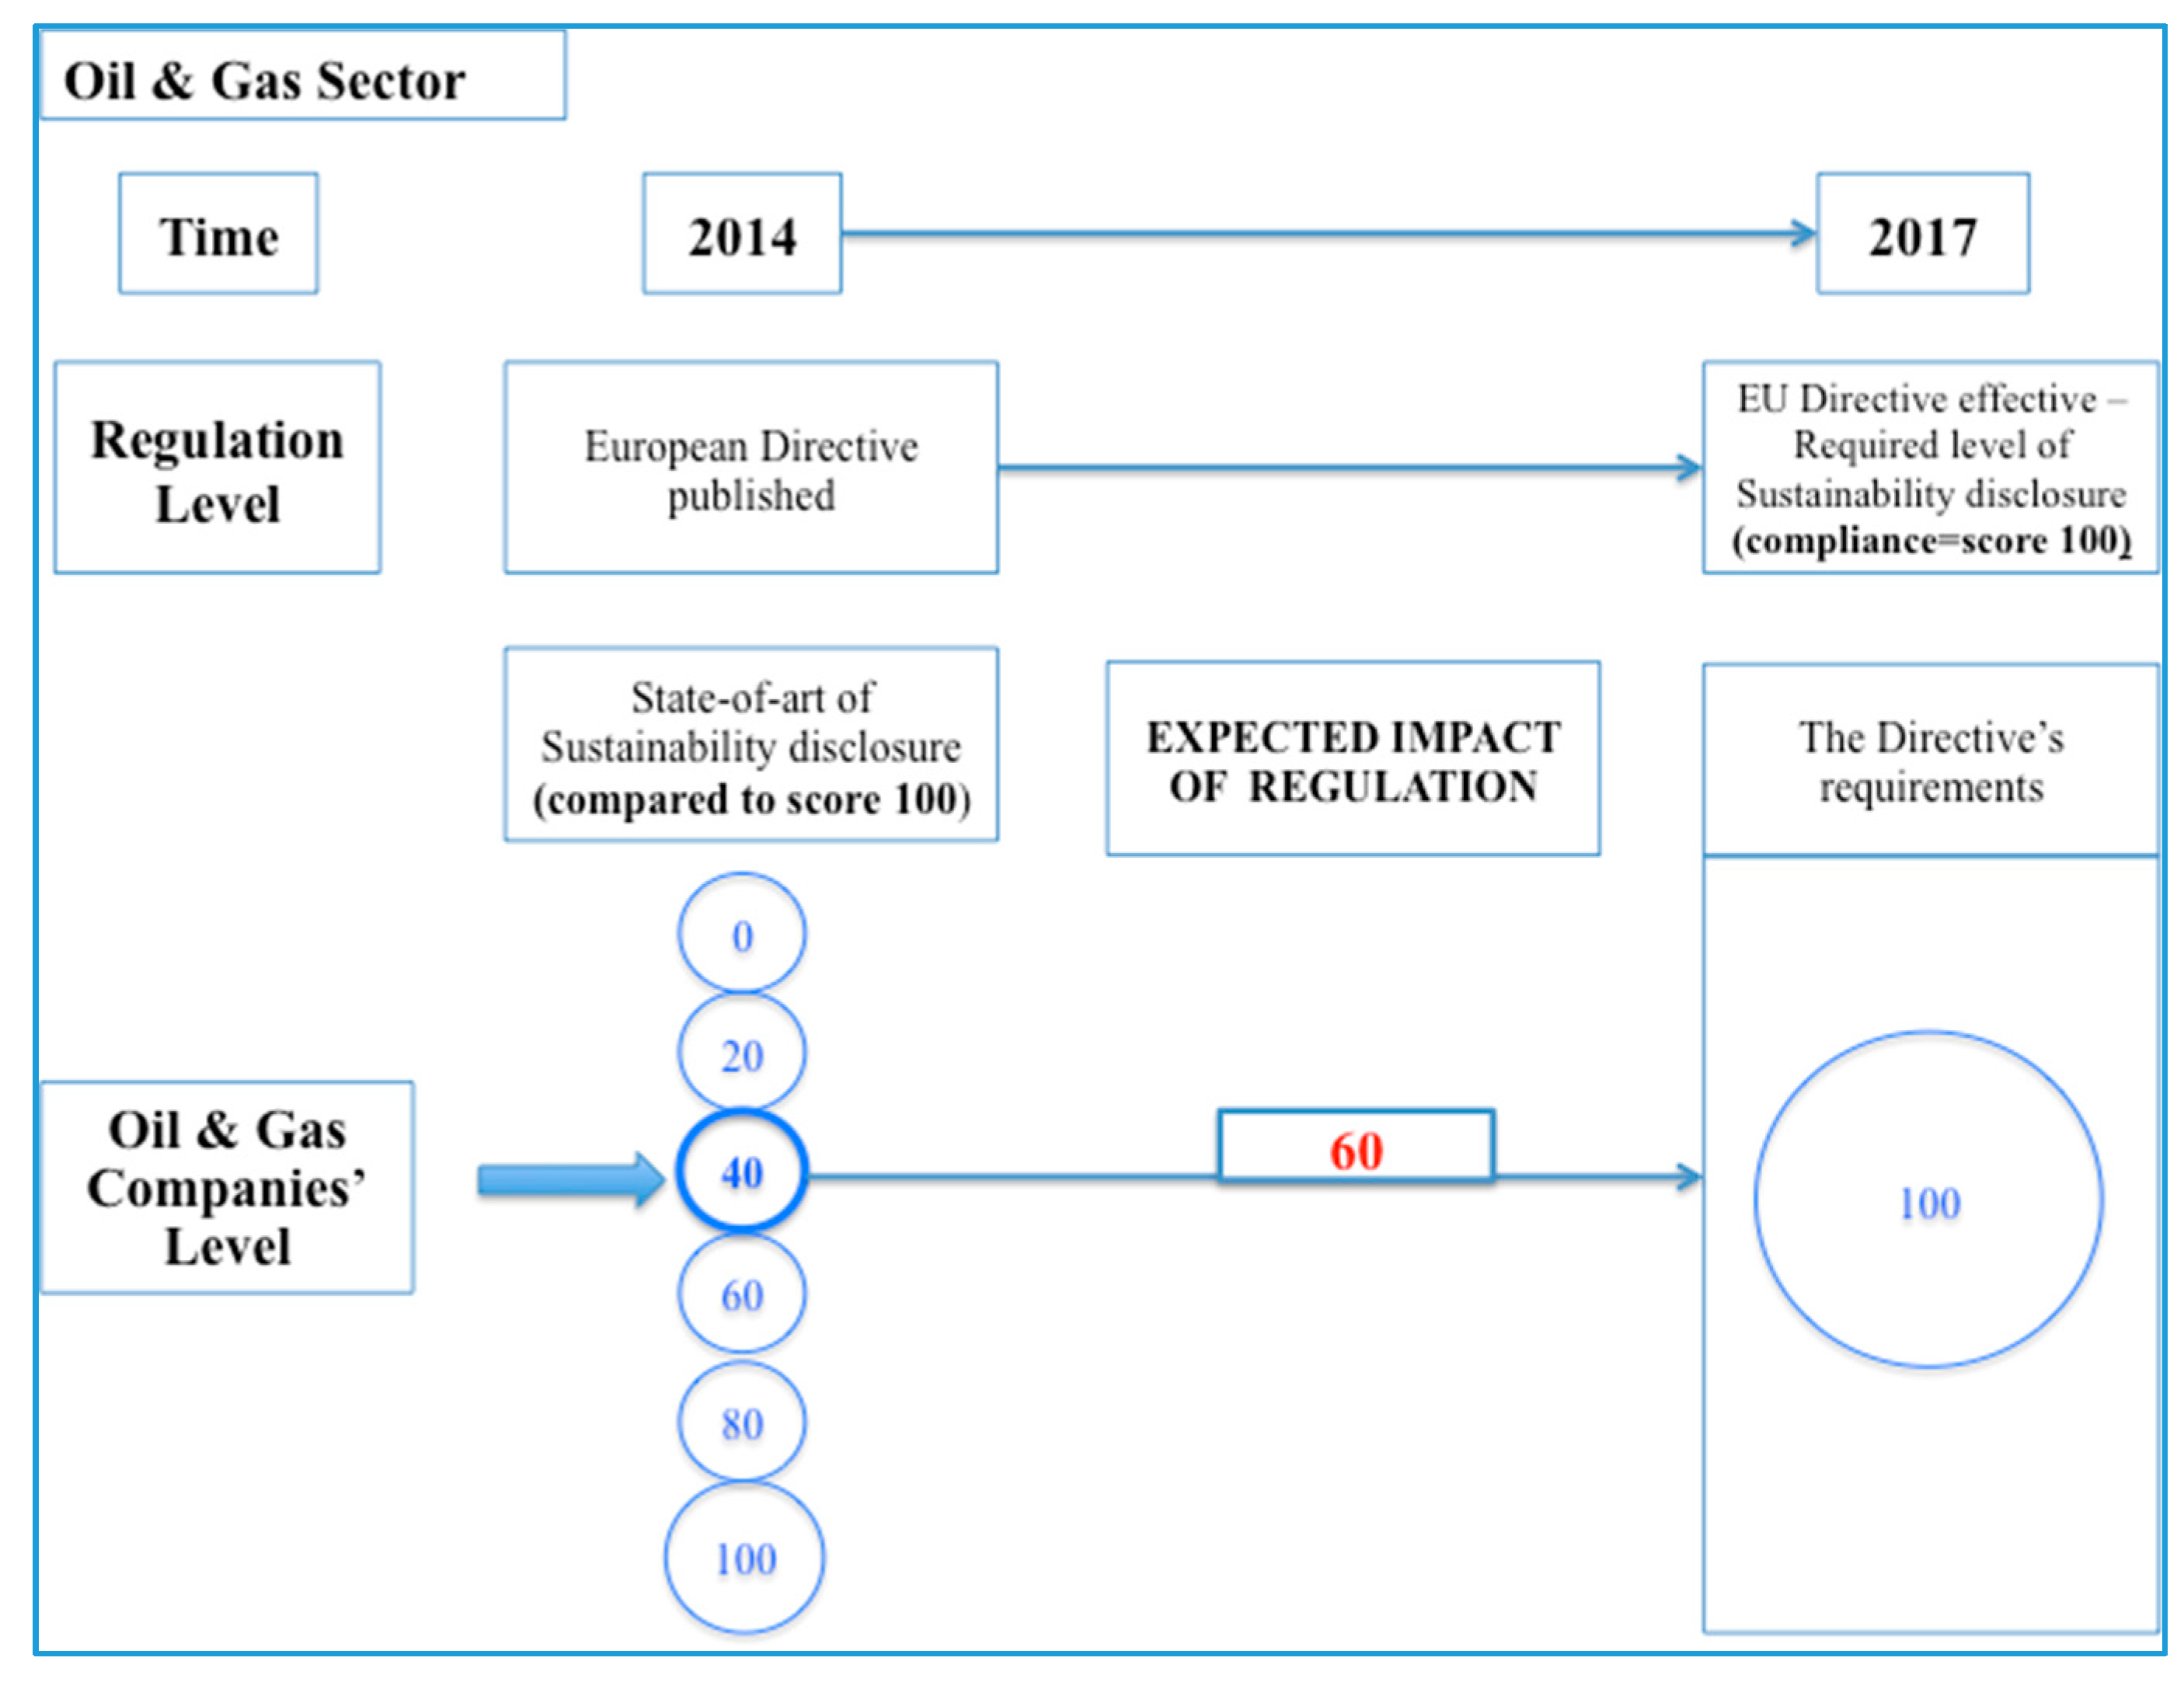
Directive 2014/95, in force since 2017, is the first European step that requires undertakings to provide mandatory non-financial information. The regulation concerns sustainability information, such as environmental, social, and employee information, human rights, and anti-corruption and bribery matters, and the disclosure of diversity policies for board members. According to the theoretical framework of Integrated Assessment (IA), the study aims to examine the expected impact of the Directive within the analysis of empirical evidence before the mandatory approach. This allows, on the regulatory side, evaluation of the quality of the regulation, therefore, whether the law achieves its policy objectives (i.e., if it fills the gap in the sustainability disclosure) and, on the firms’ side, to identify where companies have to invest to meet the legal requirements. The oil and gas sector is chosen as a sample for the study, because it is one of the most advanced sectors in sustainability disclosure, and if the regulation could impact on this sector, it would be the same for less-informed ones. The findings reveal a fair level of completeness of non-financial information, however, there are some areas that have to be improved to achieve the requirements of the Directive. The results also show the presence of overlap between financial and sustainability reports. In conclusion, the quality of regulation is good because it will also increase sustainability disclosure in an advanced sector, such as oil and gas, even if there is an open point on the location of information; companies in this sector will have to invest more in environmental and employee information in future years to comply with the Directive.
Keywords: sustainability reporting; non-financial information; corporate social responsibility; accounting regulation; Directive 2014/95; oil and gas sustainability reporting; non-financial information; corporate social responsibility; accounting regulation; Directive 2014/95; oil and gas