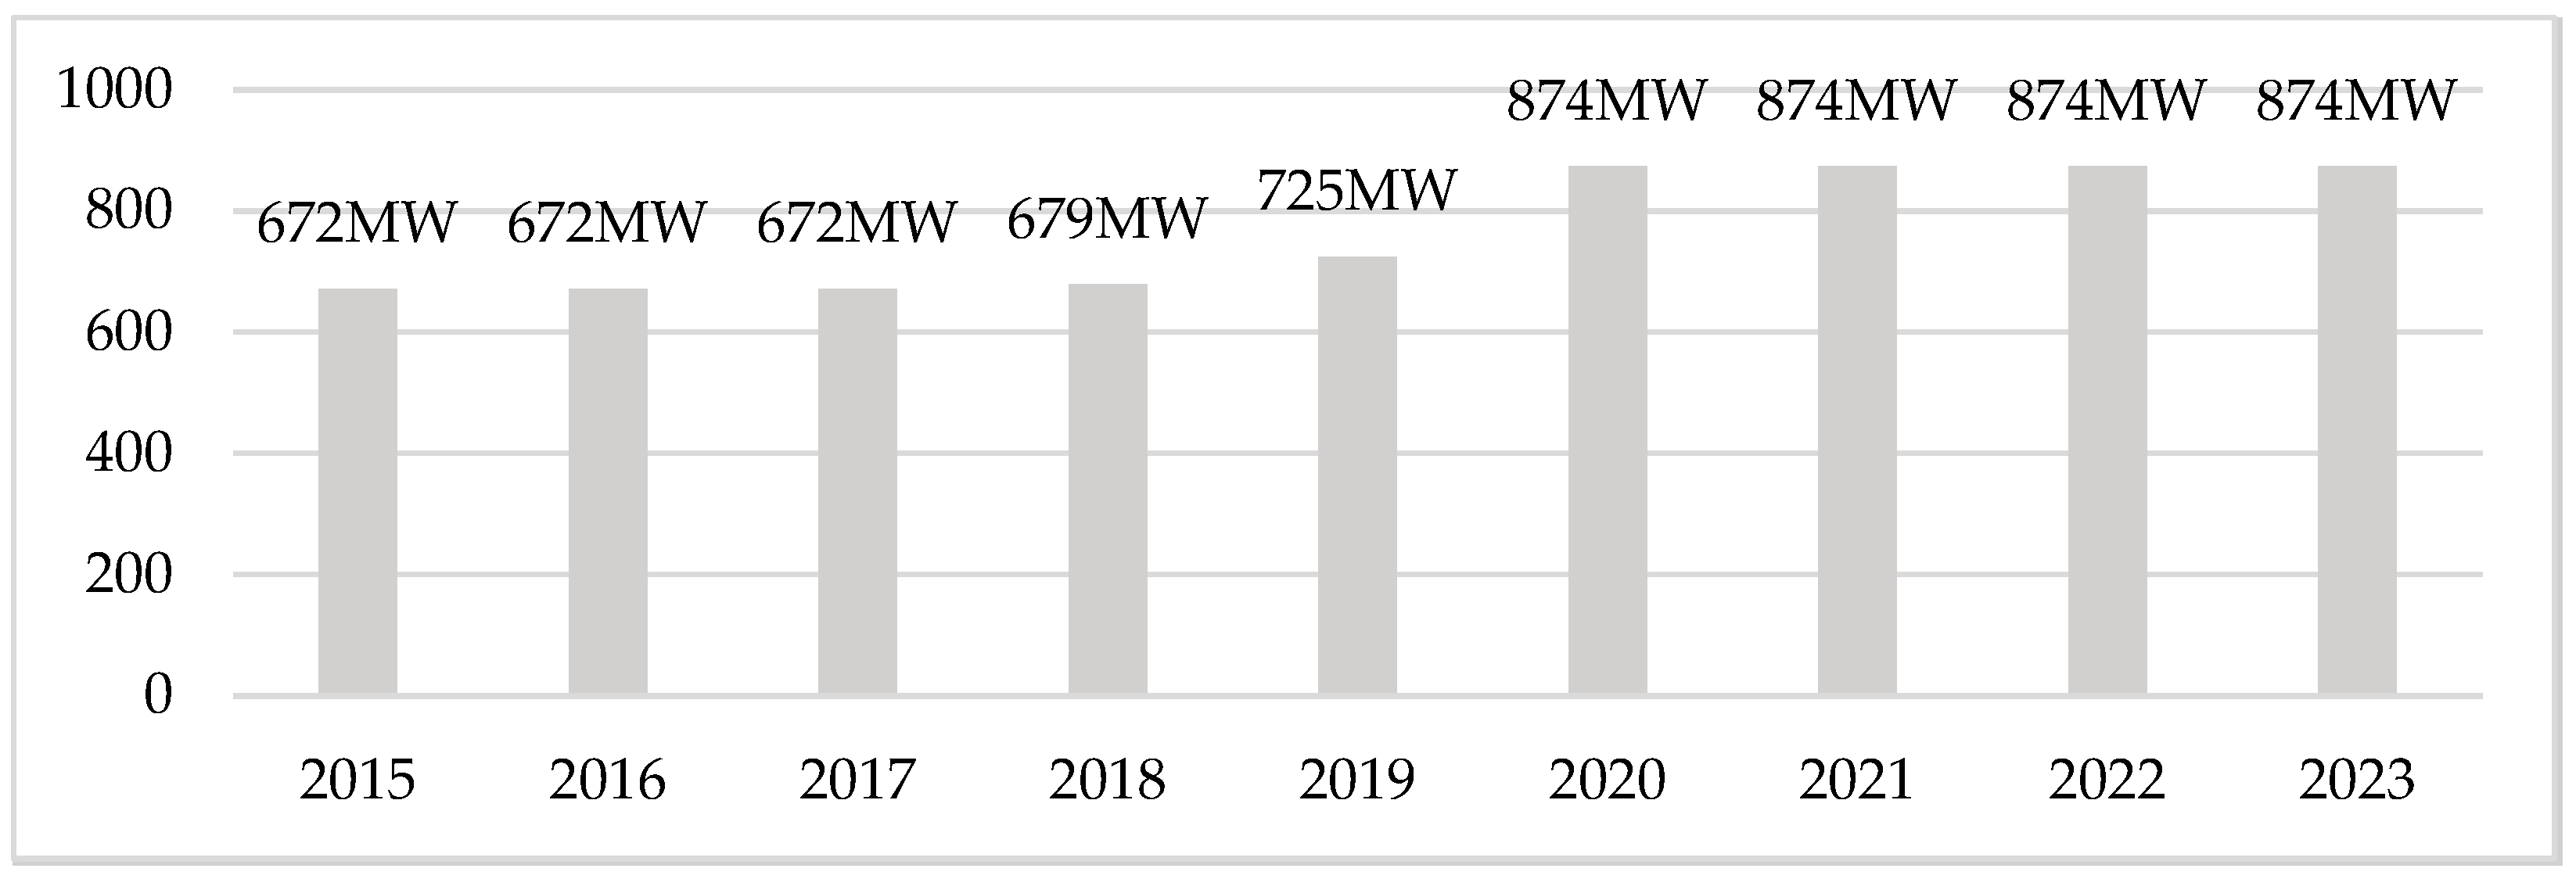Article

The Economics of Sustainable Aviation Fuels: Market Trends and Policy Challenges in Selected EU Countries


by
Laima Okunevičiūtė Neverauskienė
1,
Eglė Sikorskaitė-Narkun
2 and
Manuela Tvaronavičienė
3,4,5,*
1
Department of Economics Engineering, Faculty of Business Management, Vilnius Gediminas Technical University, LT-10223 Vilnius, Lithuania
2
Lithuanian Centre for Social Sciences, Institute of Economics and Rural Development, LT-03220 Vilnius, Lithuania
3
Department of Business Technologies and Entrepreneurship, Faculty of Business Management, Vilnius Gediminas Technical University, LT-10223 Vilnius, Lithuania
4
General Jonas Žemaits Military Academy of Lithuania, LT-10322 Vilnius, Lithuania
5
Institute Humanities & Social Science, Daugavpils University, LV-5401 Daugavpils, Latvia
*
Author to whom correspondence should be addressed.
Sustainability 2026, 18(1), 127; https://doi.org/10.3390/su18010127
Submission received: 15 October 2025 / Revised: 16 November 2025 / Accepted: 3 December 2025 / Published: 22 December 2025
(This article belongs to the Special Issue Energy and Environment: Policy, Economics and Modeling)

Abstract

The aviation sector is one of the largest sources of greenhouse gas emissions, and the European Union (EU) is calling for a rapid transition to sustainable aviation fuels (SAFs). This study aims to assess market dynamics and regulatory challenges of sustainable aviation fuels (SAFs) in the European Union, with emphasis on economic feasibility and the role of policy frameworks. Using econometric methods: Autoregressive Integrated Moving Average (ARIMA) and Vector Autoregression (VAR) models, forecasts of SAF infrastructure development trajectories were produced, while regression analysis was applied to assess the relationship between national GDP and the scale of SAF deployment. The results revealed a statistically significant positive link between higher economic development and faster expansion of SAF infrastructure, highlighting the policy-driven nature of market dynamics. Germany and France demonstrate the greatest growth potential, while countries such as Italy and Denmark show slower progress. The findings confirm that clear regulatory frameworks and targeted economic incentives are essential to stimulate SAF uptake; however, additional investment and stronger policy harmonization across Member States are required to achieve large-scale commercialization and long-term sustainability. The empirical analysis utilizes data from 2015 to 2023 to estimate SAF infrastructure trajectories and policy effects, ensuring sufficient temporal coverage for robust econometric modeling and forecasting.

1. Introduction

1.1. Context and Problem Definition

Since the beginning of the 21st century, the global economy has grown significantly [1], leading to an increasing preference for air travel as a convenient mode of transportation [2,3].
The aviation sector is one of the largest global markets. In 2019, approximately 4.5 billion passengers were transported by air, and the sector employed 87.7 million people worldwide [4]. The aviation industry contributes approximately 3.5 trillion USD to the global economy, which corresponds to 4.1% of Gross Domestic Product (GDP) and accounts for about 2.5% of global CO2 emissions. It is estimated that global demand for air transport increases by 4.5% annually. This demonstrates the rapid growth of the aviation sector, which not only generates jobs but also stimulates various industries such as global trade and tourism. Moreover, air transport enables access to educational opportunities, cultural exchanges, and provides a means to respond swiftly to emergencies. Despite its significant economic and social benefits, the aviation industry is responsible for 5% of global anthropogenic greenhouse gas emissions [5]. Climate change consequences have led to intense weather patterns, rising sea levels, severe droughts, loss of biodiversity, and adverse impacts on ecosystems and human well-being [6,7].
With greenhouse gas emissions rising year on year, the challenges of mitigating and adapting to climate change are increasing [8]. Unless all sectors work together, there will be little chance of preventing “dangerous climate change”, and aviation has a key role to play. Current and future technologies, operational processes and behavioural changes offer many opportunities for other sectors to make clear reductions in CO2 emissions [9].
Energy resilience in today’s context is an important aspect in assessing the market trends for alternative fuels. The energy system is subject to uncertainty due to external factors including energy price fluctuations, climatic conditions, supply and demand characteristics and political instability [10,11,12].
For example, the “Russia-Ukraine conflict” has caused energy shortages in European countries since February 2022, significantly increasing the cost of social activities in Europe. In light of such events and their negative impacts, countries have developed policies to address climate change. In this respect, recent trends include strengthening the protection of the energy system against external challenges, ensuring energy security and continuing the energy transition process [13]. Achieving resilience enhancement and carbon neutrality is a pressing global goal to meet the growing energy demands of diverse users sustainably and economically [14].
In the Paris Agreement, global leaders emphasized the importance of limiting the global temperature rise to 1.5 °C by the end of this century. To achieve this goal, it is necessary to reduce greenhouse gas emissions (GHG) by 43% by 2030. While aviation accounts for about 2.5% of global CO2 emissions, its overall contribution to climate change is greater. In addition to CO2 emissions from fuel combustion, aircraft also affect the concentration of other atmospheric gases and pollutants [15].
After -COVID pandemic, as international travel demand recovered, the aviation sector’s emissions in 2023 reached nearly 950 Mt CO2, which is more than 90% of the pre-pandemic levels. In order to begin reducing emissions within this decade, in line with the 2050 net-zero emissions scenario, concerned countries must increase the share of low-carbon fuels, improve aircraft fuselage and engine designs, optimize operations, and implement demand-reduction solutions [16]. The replacement of petroleum-based aviation fuels with sustainable aviation fuels (SAFs) is a promising step towards transitioning to low-carbon aviation operations. The International Air Transport Association (IATA) predicts that by 2028, global renewable fuel volumes will reach 69 billion liters, and by 2030, 100 billion liters; it is expected that the use of SAFs will reduce aviation industry CO2 emissions by 65% by 2050 [17]. Aviation has a significant positive impact globally in reducing CO2 emissions, but this depends not only on the aviation sector itself but also on the economic level of individual countries. Despite significant progress in improving aircraft efficiency, achieving further substantial results is challenging due to diminishing returns [18].
While external shocks such as the COVID- pandemic, geopolitical conflicts, and energy price volatility are recognized as critical factors shaping the aviation sector and the SAF market, these dynamics were not explicitly incorporated into the present modeling framework. The rationale for this decision lies in the study’s focus on long-term structural trends in biofuel infrastructure development rather than short-term disruptions. Incorporating crisis-related volatility into ARIMA or VAR models would introduce additional uncertainty and risk conflating cyclical shocks with underlying technological and policy-driven dynamics.
Therefore, the assumption of stability with respect to external shocks ensures methodological clarity and isolates the structural drivers of SAF deployment. Nevertheless, the importance of these factors is acknowledged, and their detailed assessment—particularly regarding crisis-induced demand shocks, policy responses, and price fluctuations—represents an essential avenue for future research dedicated specifically to resilience and shock-response dynamics in the SAF market.
Although new aircraft designs and technologies have the potential to reduce the aviation carbon footprint, their widespread implementation requires considerable time, investment, research, development, and certification. Currently, futuristic electric and hydrogen-powered aircraft are being developed, primarily suitable for short-haul routes. It is expected that hydrogen-powered aircraft will be used for commercial purposes no earlier than 2035, replacing the existing fleet of aircraft entirely will take even more time. Given these limitations, SAF has become an important short- and medium-term solution to reduce carbon dioxide emissions in the aviation sector [19,20]. Therefore, to achieve decarbonization in the aviation sector and contribute to a sustainable future, the use of SAF becomes a crucial step in the short- and medium-term perspectives. Current clean aviation energy sources primarily include biomass fuel, electricity, hydrogen, and hybrid solutions. Among them, sustainable aviation fuel (SAF) has garnered significant attention due to its technological, economic, and political advantages, and has been favorably evaluated by many researchers. SAF is produced from renewable biological materials and, compared to fossil fuels, has a significantly lower CO2 emission footprint [21]. However, despite its environmental benefits, the production costs of SAF remain high, making it economically uncompetitive at present [22]. The continuous increase in global aviation emissions has highlighted the urgent need to rapidly switch to sustainable aviation fuels instead of traditional aviation fuels to reduce emissions. The use of SAF can reduce greenhouse gas emissions by 50–90% compared to conventional jet fuels [23].
The aviation sector is experiencing rapid development, including the adoption of sustainable aviation fuels. However, at present, only economically strong countries, along with their airports, airlines, ground services, and other sector participants, are actively engaging in the transition to the use of sustainable aviation fuels, as this process requires significant investments and supportive political backing.

1.2. Research Questions and Objectives

Although the environmental and technological aspects of SAF have been widely discussed in the literature, there is still a lack of comprehensive economic assessments that link market dynamics with policy frameworks in the European Union. Previous studies have largely focused on technological efficiency or global projections, while limited attention has been paid to the economic viability and regulatory challenges faced by individual EU countries. This study addresses this gap by examining the interplay between SAF market development, policy instruments, and economic feasibility within a European context.
The aim of this study is to assess market dynamics and regulatory challenges of sustainable aviation fuels (SAFs) in the European Union, with emphasis on economic feasibility and the role of policy frameworks.
To achieve this aim, the study seeks to address the following research questions:
What are the main growth trends of the SAF market in the European Union, and which countries demonstrate the highest potential?
How do EU regulatory initiatives, such as RefuelEU Aviation, influence SAF supply strategies, tariff policies, and market expansion?
Which economic factors—such as production costs, GDP, and infrastructure development—most significantly affect the economic viability and deployment of SAF across EU member states?

1.3. Contribution and Structure of the Paper

The remainder of this paper is structured as follows. Section 2 presents a review of the relevant literature on SAF development and policy frameworks. Section 3 outlines the materials, data sources, and methods employed. Section 4 reports the empirical results of the analysis. Section 5 discusses these findings in light of existing research and policy debates. Finally, Section 6 provides the main conclusions, policy implications, and directions for future research.

2. Literature Review

2.1. Sustainable Aviation Fuels: Definition, Benefits and Technological Context

As the global aviation industry increasingly demands a reduction in carbon dioxide emissions, the need for sustainable aviation fuels (SAFs) is growing [24]. SAF is like conventional jet fuels derived from kerosene, but it emits significantly less carbon dioxide. This reduction is achieved through various methods, including carbon capture technologies and the use of biogenic carbon feedstocks such as biomass, which help lower the overall number of emitted pollutants. However, the adoption of SAF as an alternative fuel is limited due to insufficient awareness among countries and the lack of corresponding regulations [25]. Therefore, to achieve significant growth in the use of sustainable aviation fuels, it is essential to raise awareness among countries and establish clear legal and regulatory frameworks that encourage the development and implementation of SAF in the aviation sector. Greener aviation is a crucial objective for policymakers aiming to reduce greenhouse gas emissions in the transport sector. Research by scholars indicates that by 2050, the use of sustainable fuels will increase significantly, leading to a reduction in pollution [26]. To reduce the carbon footprint of the aviation industry, it is essential to utilize sustainable aviation fuel. The development and implementation of sustainable aviation fuel are critical steps toward minimizing the carbon footprint of the aviation sector. Various case studies highlight technological innovations and production methods, offering insights into the effectiveness of different approaches. Energy resilience is a very important aspect of SAF research to protect against potential energy disruptions, both from a changing climate and from technological threats. The more efficiently the air transport sector can switch to sustainable aviation fuels, the more the energy resilience of the sector will increase [27,28].

2.2. Policy and Regulatory Frameworks in the EU and International Context

Aviation is one of the fastest-growing sources of greenhouse gas (GHG) emissions. The European Union is taking steps to reduce aviation-related GHG emissions in Europe and is collaborating with the international community to develop global measures [29]. In 2023, the European Union adopted the “ReFuelEU Aviation” program, which mandates the blending of minimum SAF shares by 2050, with additional targets set for synthetic fuels [16].
In the aviation sector, reducing CO2 emissions is highly dependent on international collaboration and agreements, both between business entities and at the high political level. The EU climate policy in the transport sector is a combination of measures, integrating taxes, subsidies, tradable emissions systems, and various types of regulations [30]. The aviation sector accounts for approximately 14% of all transport-related emissions in the European Union, considering only flights within the European Economic Area (EEA). Additionally, the international CORSIA scheme is implemented, covering flights to and from the EEA, aiming to compensate for and reduce carbon dioxide emissions. The mandatory blending of sustainable aviation fuel is gradually increased, starting from 2%, to reduce CO2 emissions, while being supported by subsidies for investments, research, and a partnership worth 1.7 billion euros [30]. The European Union, aiming to reduce greenhouse gas emissions in the aviation sector, has implemented measures that not only regulate pollution but also directly impact on the sector’s economy. The main instrument is the EU Emissions Trading System (ETS), under which, starting in 2026, airlines will no longer receive free allowances and will be required to fully cover their emissions through auctions. This significantly increases operational costs and encourages investment in less polluting technologies. To alleviate the financial burden and promote the transition to SAF, the EU provides additional economic incentives—approximately 1.6 billion euros from ETS revenues are allocated to compensate for the SAF price difference. The level of support depends on the fuel type and the airport’s location, and in some cases, it may reach up to 100% of the price difference. These subsidies are a direct economic tool to make SAF more competitive in the market. Furthermore, 5 million additional allowances are allocated through the Innovation Fund for modern technologies—electrification, synthetic fuel development, and emissions reduction solutions. These measures create a long-term market signal and shape investment directions. A monitoring system for non-CO2 emissions is also planned, which would allow for the assessment of the true impact of flights on the climate and potentially include additional costs. Finally, if the international emissions compensation scheme (CORSIA) proves insufficient, from 2027, departing flights to third countries could be included in ETS, thus increasing their economic responsibility. All these economic and regulatory measures are reshaping the sector’s financial structure—pollution costs are becoming increasingly internalized, and the implementation of sustainable solutions is becoming more economically viable [29]. Policymakers aim to implement regulatory measures that encourage a rapid transition to a broader use of sustainable aviation fuels. However, these measures must be tailored to account for the specificities of different regions, making it essential to differentiate their application based on local challenges and needs.
Existing research on SAF adoption highlights that policy effectiveness depends not only on targets and stated commitments, but also on institutional design, regulatory coherence, and the ability to overcome market and technological barriers [31,32].
For instance, while the RefuelEU Aviation initiative sets ambitious SAF blending mandates, its practical impact is mediated by several factors: infrastructure readiness at airports, the cost differential between SAF and conventional jet fuel, and the willingness of airlines to pass costs on to consumers. Without a structured analysis of such implementation dynamics, policy evaluations risk overestimating their real-world effectiveness.
Moreover, the interaction between overlapping policy instruments requires systematic assessment. The coexistence ETS and direct subsidy schemes for SAF creates potential synergies—such as reinforcing carbon pricing signals with financial support for low-carbon alternatives—but also risks unintended conflicts, such as double counting of emission reductions or distortions in competitive market conditions.
SAF is still not economically viable for airlines, as it is approximately 3.5 times more expensive than conventional aviation fuel. This price gap widens further in the absence of a carbon trading market. However, efforts are being made to ensure that SAF becomes economically sustainable [19]. In 2023, the average price of conventional jet fuel was approximately €816 per ton. When evaluating SAF prices that meet the “ReFuelEU Aviation” requirements, a distinction was made between the SAF currently available in the market and those whose production costs can only be estimated, as the market is still underdeveloped. Currently, only those aviation biofuels produced from raw materials listed in Annex IX, Part B of the Renewable Energy Directive, are available on the market. The average price of these SAF in 2023 was approximately €2768 per ton. [33]. Researchers in their studies are exploring various solutions to reduce the cost of SAF and make the deployment of sustainable fuels more attractive. Another global problem with the use of SAF is public scepticism. In the various research studies on green energy, scientists see this as a major problem [34].
The spectrum of policy measures for sustainable aviation fuels (SAFs) includes both direct and indirect financial incentives, which create a complex and multi-layered regulatory environment that promotes SAF development. Direct financial policy measures can be classified into four main types of incentives: production-based incentives, feedstock subsidies, capital subsidies, and price subsidies. These measures directly impact market actors by reducing financial risks and encouraging investments in the development and deployment of SAF [35]. Price, both in absolute and relative terms, plays a crucial role in determining the allocation of capital and the behavior of economic agents such as producers and consumers. In a free-market economy, prices are shaped by supply and demand, as well as other market conditions that are not directly controlled. All regulatory measures can influence price dynamics and the behavior of market participants. For instance, direct financial incentives, such as subsidies or tax reductions, encourage desired activities, while deterrent incentives, such as higher taxes, may suppress certain activities. Additionally, indirect financial policies encompass regulatory mechanisms that, although not direct financial incentives, influence the behavior of market participants through mandatory requirements or market signals [36,37].
According to the analysis, the size of the sustainable aviation fuel (SAF) market in 2023 was $4.09 billion. It is expected that the SAF market will grow to $4.89 billion by 2035. The Compound Annual Growth Rate (CAGR) for the SAF market during the forecast period (2025–2035) is expected to be around 19.59% [38].
Evidence shows that several leading EU countries have an active SAF policy, which requires not only the right policies and favourable market conditions, but also a good economic situation, a strong aviation sector and the ability to adapt technologically [39], as, for example, conventional aircraft need larger and heavier fuel tanks to achieve a range equivalent to kerosene and SAF [40].

3. Materials and Method

To enhance methodological transparency, the following diagram (Table 1) presents the main stages of the research process, outlining the sequence from literature review to data collection, econometric analysis, and interpretation of results.

3.1. Sampling and Data Collection

The study uses secondary data obtained from publicly available and reliable sources, including Eurostat, the European Aviation Safety Agency (EASA), the International Air Transport Association (IATA), and various industry reports. These sources provide comprehensive information on the production volumes of sustainable aviation fuels, consumption trends, regulatory changes, and emissions in the aviation sector across EU member states.
The following data were collected for the study: SAF market data, including bioenergy capacity in key EU countries that are most focused on SAF market development (France, Germany, Denmark, Spain, Italy). The data were collected from 2015 to 2023. Political data includes mandatory SAF blending requirements. Economic indicators include the number of passengers per year, the number of flights per year, and the GDP of the countries, also covering the period from 2015 to 2023.
The data scope of this study (2015–2023) and the focus on selected EU countries reflect both the historical development trajectory of SAF and the availability of reliable statistical sources. The significance of SAF as a policy and market priority has emerged predominantly over the past decade, with substantial technological progress and regulatory frameworks—such as RefuelEU Aviation—only gaining momentum in recent years. Earlier periods provide limited analytical value, as SAF production and policy adoption were negligible and lacked consistent data.
Furthermore, the emphasis on countries with stronger economies (e.g., Germany, France, Denmark, Italy, Spain) is methodologically justified, since these states have been the primary drivers of SAF deployment in the EU, accounting for the majority of production capacity, infrastructure investment, and policy experimentation. While emerging SAF markets in smaller economies are acknowledged, their contributions remain marginal during the study period and insufficiently documented for robust quantitative modeling.
By concentrating on the past decade and on countries with substantive SAF activity, the study captures the most relevant structural and policy-driven dynamics shaping the European SAF market. At the same time, the limitation is recognized, and future research should extend coverage as more consistent data on emerging markets become available, allowing for a broader comparative assessment.

3.2. Measurement Model

In analyzing historical trends in the SAF market and forecasting future market dynamics, autoregressive integrated moving average (ARIMA) and vector autoregression (VAR) models were used. These models help identify key patterns, seasonal effects, and potential structural changes over time. The ARIMA model is commonly used by researchers in similar studies. It is a traditional time series forecasting method widely applied due to its ability to process various types of time series data and the requirement to use only endogenous variables, without the need for additional exogenous factors [41]. ARIMA is a widely used statistical tool for forecasting time series, particularly well-suited for data characterized by long-term trends and patterns [42].
The ARIMA model is suitable for this study as air transport data are often non-stationery and time dependent. The ARIMA model can capture seasonal trends and irregular shocks, such as those caused by COVID [43].
ARIMA formula:
Y t = 1 Y t 1 + 2 Y t 2 + + p Y t p + θ 1 e t 1 + θ 2 e t 2 + + θ q e t q e t
  • Yt—The time series value at a specific time (for example, biofuel infrastructure capacity),
  • 1, 2,…, p—autoregressive coefficients (AR component),
  • et—error or balance at the time,
  • θ1, θ2,—moving average coefficients (MA component),
  • p ir q—model lag degrees indicating how many previous values and errors should be included in the model.
The VAR model is chosen as a logical alternative to factor-based models. It is popular due to its effectiveness in modeling complex structures and making forecasts [44]
VAR model formula:
Y t = c + A 1 Y t 1 + A 2 Y t 2 + + A k Y t k + e t
  • Yt—a vector of all the values of the variables in period t, that is [Y1,t,Y2,t,…,Yp,t],
  • C—constant vector (each variable can be assigned a constant),
  • A1,A2,…,Ak—autoregression coefficients, which define how previous periods Yt − 1,Yt − 2,…,Yt − kY affects existing values Yt. Each A is an element of a matrix representing the interdependence of different variables, k—the number of lags (for example, k = 1 would mean that only first-degree values are used),
  • et—an error vector containing residuals, i.e., inaccuracies that cannot be explained by past data.
Regression is a data-driven method widely used in a variety of scientific applications. Regression models perform linear or non-linear analysis to show the relationship between dependent and independent variables [45,46].
Regression analysis formula:
Y = β 0 + β 1 X 1 + β 2 X 2 + + β n X n + e
  • Y—biofuel infrastructure capacity,
  • X1,X2,…,Xn—independent variables (number of flights, number of passengers, GDP),
  • β0—constant,
  • β1, β2,…, βn—regression coefficients showing the extent to which each variable influences the dependent variable,
  • e\epsilon—error.
The regression analysis aggregates data for all countries selected for this study: passenger flows, number of flights, biofuel obligations for manufacturers. The independent variable is biofuel infrastructure capacity, while other data such as passenger flows, number of flights, biofuel obligations to producers and GDP are considered as independent variables.
To ensure the robustness and reliability of the econometric results, the statistical validity of the estimated models was verified using standard diagnostic procedures.

3.3. Research Structure and Organization

The study is organized into the following stages:
  • Introduction—Definition of the research problem, formulation of research objectives, and justification of the study’s relevance in the context of the EU aviation sector.
  • Literature Review—Critical overview of existing scientific works, policy documents, and statistical reports. This section provides the contextual foundation by summarizing prior findings and outlining existing regulatory and economic challenges associated with sustainable aviation fuels (SAFs).
  • Materials and Methods—Description of data sources, econometric techniques (ARIMA, VAR, regression analysis), and analytical framework applied. This section also specifies the criteria for selecting indicators and the procedures used for data harmonization.
  • Results—Presentation of the econometric outputs, including forecasts of SAF development trajectories and the statistical relationship between national GDP and SAF deployment.
  • Discussion—Comparative interpretation of the findings in light of previous studies and regulatory frameworks. This section emphasizes the implications of policy design, institutional coherence, and economic feasibility for SAF market development.
  • Conclusions—Synthesis of the study’s key insights. The section addresses research questions, highlights the theoretical and practical contributions, and formulates recommendations for policymakers, with directions for future research.

4. Results

4.1. Descriptive Part

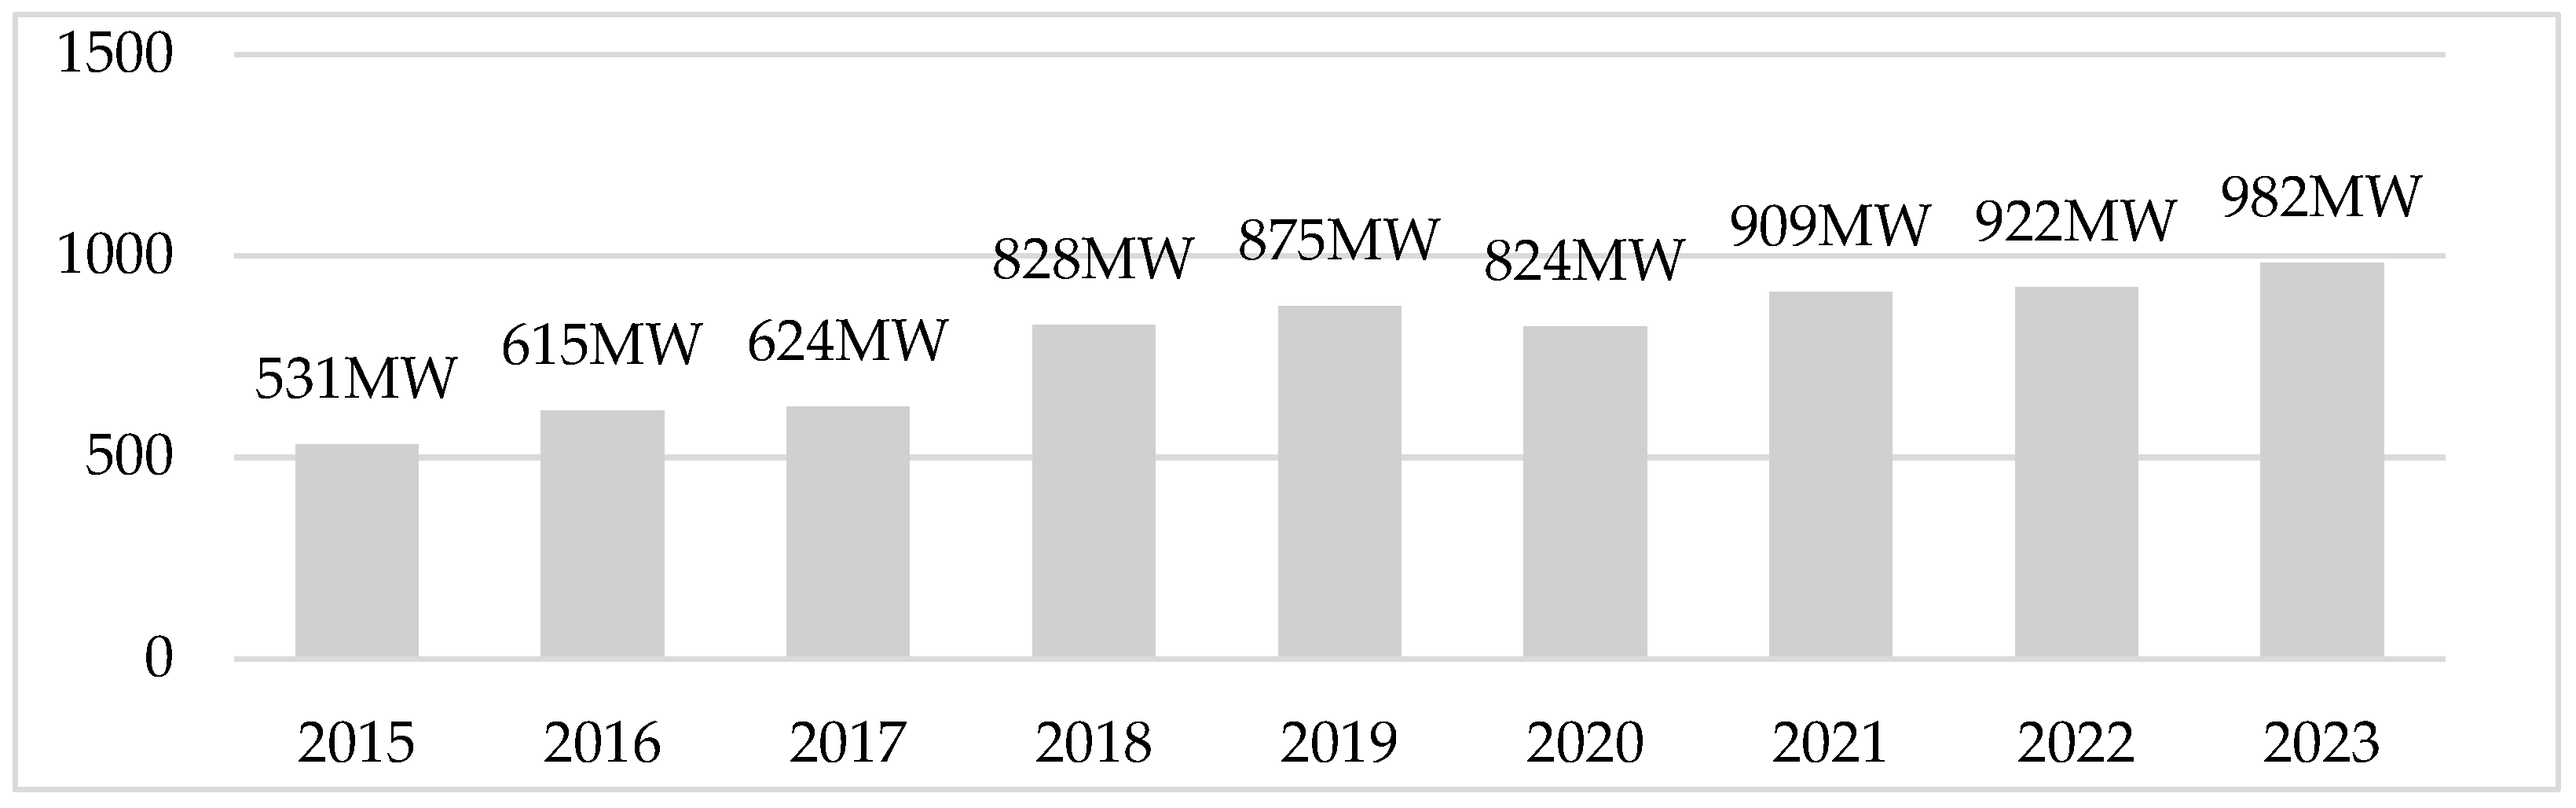
France is becoming a global leader in the SAF market, as it is committed to reducing carbon dioxide emissions from aviation and achieving ambitious climate goals. The French government has set gradual SAF usage targets: 1.5% by 2024, 2.0% by 2025, and 5.0% by 2030 across all flights. Additionally, the target includes a mandate to incorporate synthetic fuels as part of the fuel mix (1.2% by 2030, 2.0% by 2032, and 5.0% by 2035, gradually reaching 35% by 2050) (“Air France-KLM Group”, “Scaling Up Sustainable Aviation Fuel Supply”, 2024). To further support these targets, France has implemented policies and incentives promoting the development and adoption of SAF. Among these are €500 million investments in low-carbon aviation, the expansion of the French incentive tax system (TIRUERT) to encourage SAF use, and funding for research into new SAF production technologies. Additionally, leading French aviation companies, such as Air France and Transavia, are actively involved in SAF projects and collaborate with fuel manufacturers to optimize SAF usage in commercial flights. In 2023, the French government committed to investing a total of €500 million in the development of low-carbon aviation. This investment consists of €300 million for research into low-carbon aircraft and engines, €200 million for the modernization of industrial SAF production, and a goal to create the first low-carbon aircraft by 2030 [47].
Subsequently, the figure displays the biofuel installed capacity in France (Figure 1).
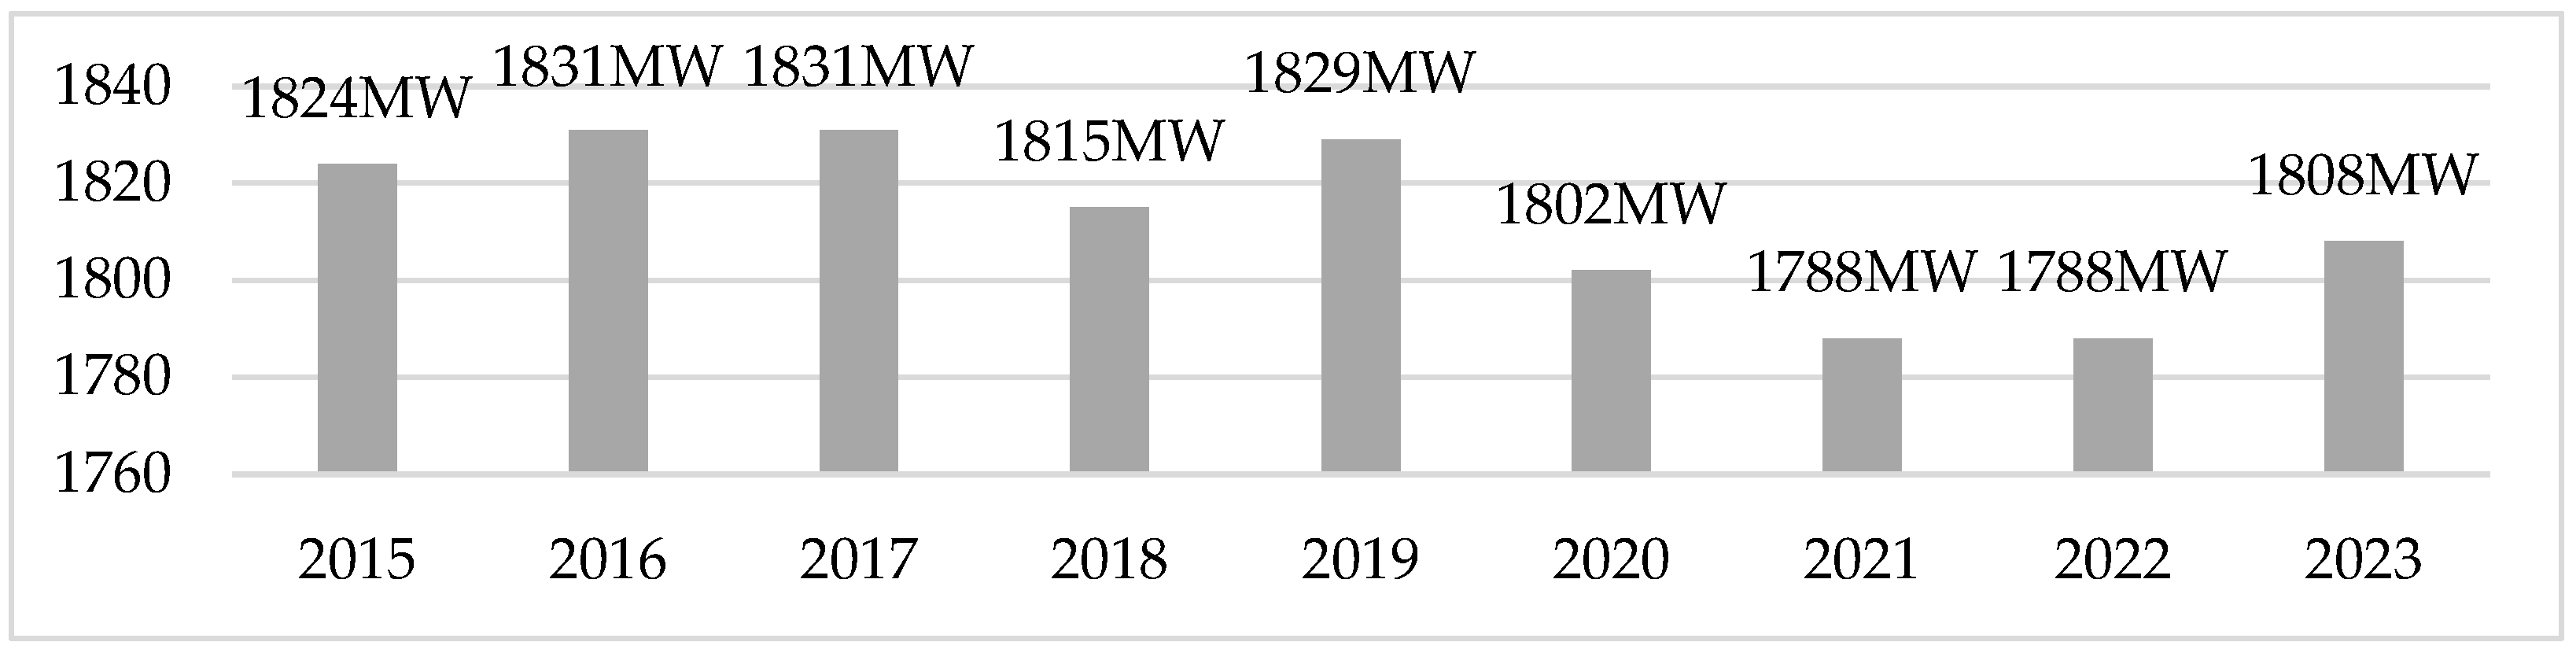
Germany also provides an excellent example for other EU countries in pursuing sustainable aviation sector growth. Germany’s advanced SAF policy and regulations are closely aligned with broader EU initiatives, such as “ReFuelEU,” demonstrating the country’s commitment to sustainable aviation. The German national strategy, which is part of the country’s goal to achieve net-zero emissions by 2045, stipulates that by 2030, aviation fuel suppliers will be required to meet a 2% PtL (Power-to-Liquid) quota. In May 2021, the German government and industry representatives reached an agreement on the “PtL Action Plan,” which includes €1 billion in investments to develop PtL production in Germany, optimize technologies, define sustainability criteria, and establish mandatory renewable jet fuel purchasing and selling targets. The German Aerospace Center (DLR), in collaboration with industry and academic partners, will lead the development of the concept, aiming to produce at least 200,000 metric tons of sustainable jet fuel annually for German air traffic by 2030, reducing the emissions of one-third of all domestic flights. This active policy and strategic investments highlight Germany as a key player in transitioning to sustainable aviation, reinforcing its leadership in moving towards a greener sky. Currently, several initiatives are being implemented to create commercial-scale PtL plants for SAF production. In June 2024, a working group of government and industry leaders urged the adoption of political and industrial commitments to support the development of the SAF market (Figure 2) [48].
Germany is one of the leading markets for SAF. With a well-developed research network and large oil refining capacities for fuel supply, Germany offers a strong infrastructure that will support the further development of SAF [49].
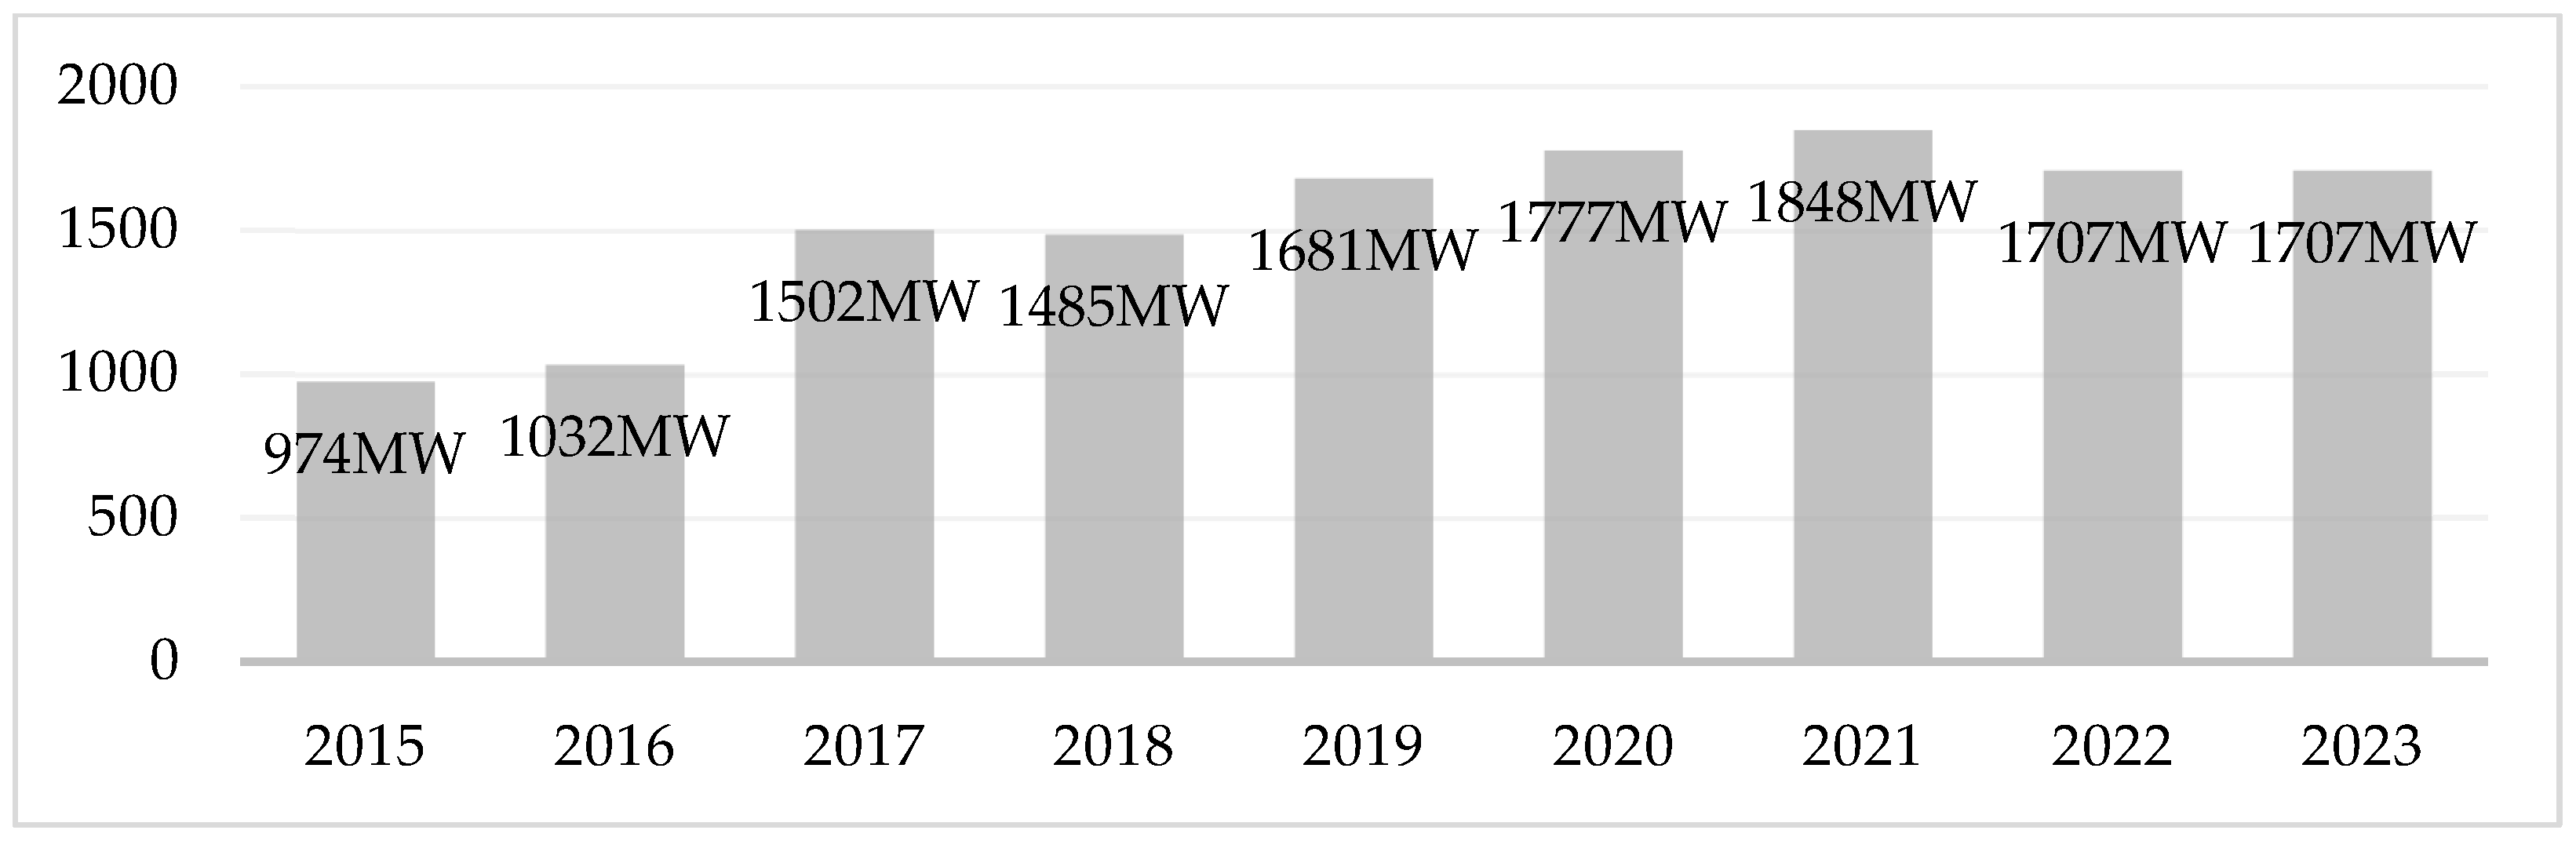
Another EU country, Denmark, is also taking active steps towards gradually transitioning to a sustainable aviation sector. Denmark’s industry is not immune to the challenges faced globally, including high production costs compared to traditional jet fuels, the increasing need for technological advancements to improve the economics of SAF, and the globally coordinated agreements on SAF adoption to encourage necessary investments. However, due to the abundance of renewable energy resources in the country, particularly offshore wind power, and its long history of developing biofuels technologies, Denmark has unique opportunities to capitalize on the market possibilities presented by SAF. The Danish government has allocated funds to encourage commercial-scale SAF production, as part of its ambitious carbon dioxide emission reduction goals. This political support has driven investment activities, and as a result, many local SAF development projects will begin this year, with SAF production already underway [50].
Subsequently, the figure displays the biofuel installed capacity in Denmark (Figure 3).
It is expected that biofuels will play an increasingly important role in decarbonizing Denmark’s aviation sector. Given the aviation sector, voluntary commitments by airlines, and the growing investments in research and development, SAF is poised to take a much more significant position within Denmark’s biofuel sector [50].
Spain plays a significant role in the EU’s efforts towards a sustainable aviation sector. It is expected that by 2050, Spain’s aviation sector will require approximately 5 million tons of SAF annually for decarbonization. To achieve this, Spain would need to establish 30 to 40 plants across the country to meet the national demand. According to an Iberia Airlines report, Spain’s production capacity by 2050 may far exceed domestic needs, and with additional plants, the country could export large quantities of SAF to the international market [51]. The following data presents the installed biofuel production capacity in Spain (Figure 4).
Spain is becoming a key player in the European SAF market, with the potential to make a significant global contribution. Due to regulatory support, strategic funding, and investments in new technologies, Spain’s SAF market is well-positioned for rapid growth [51].
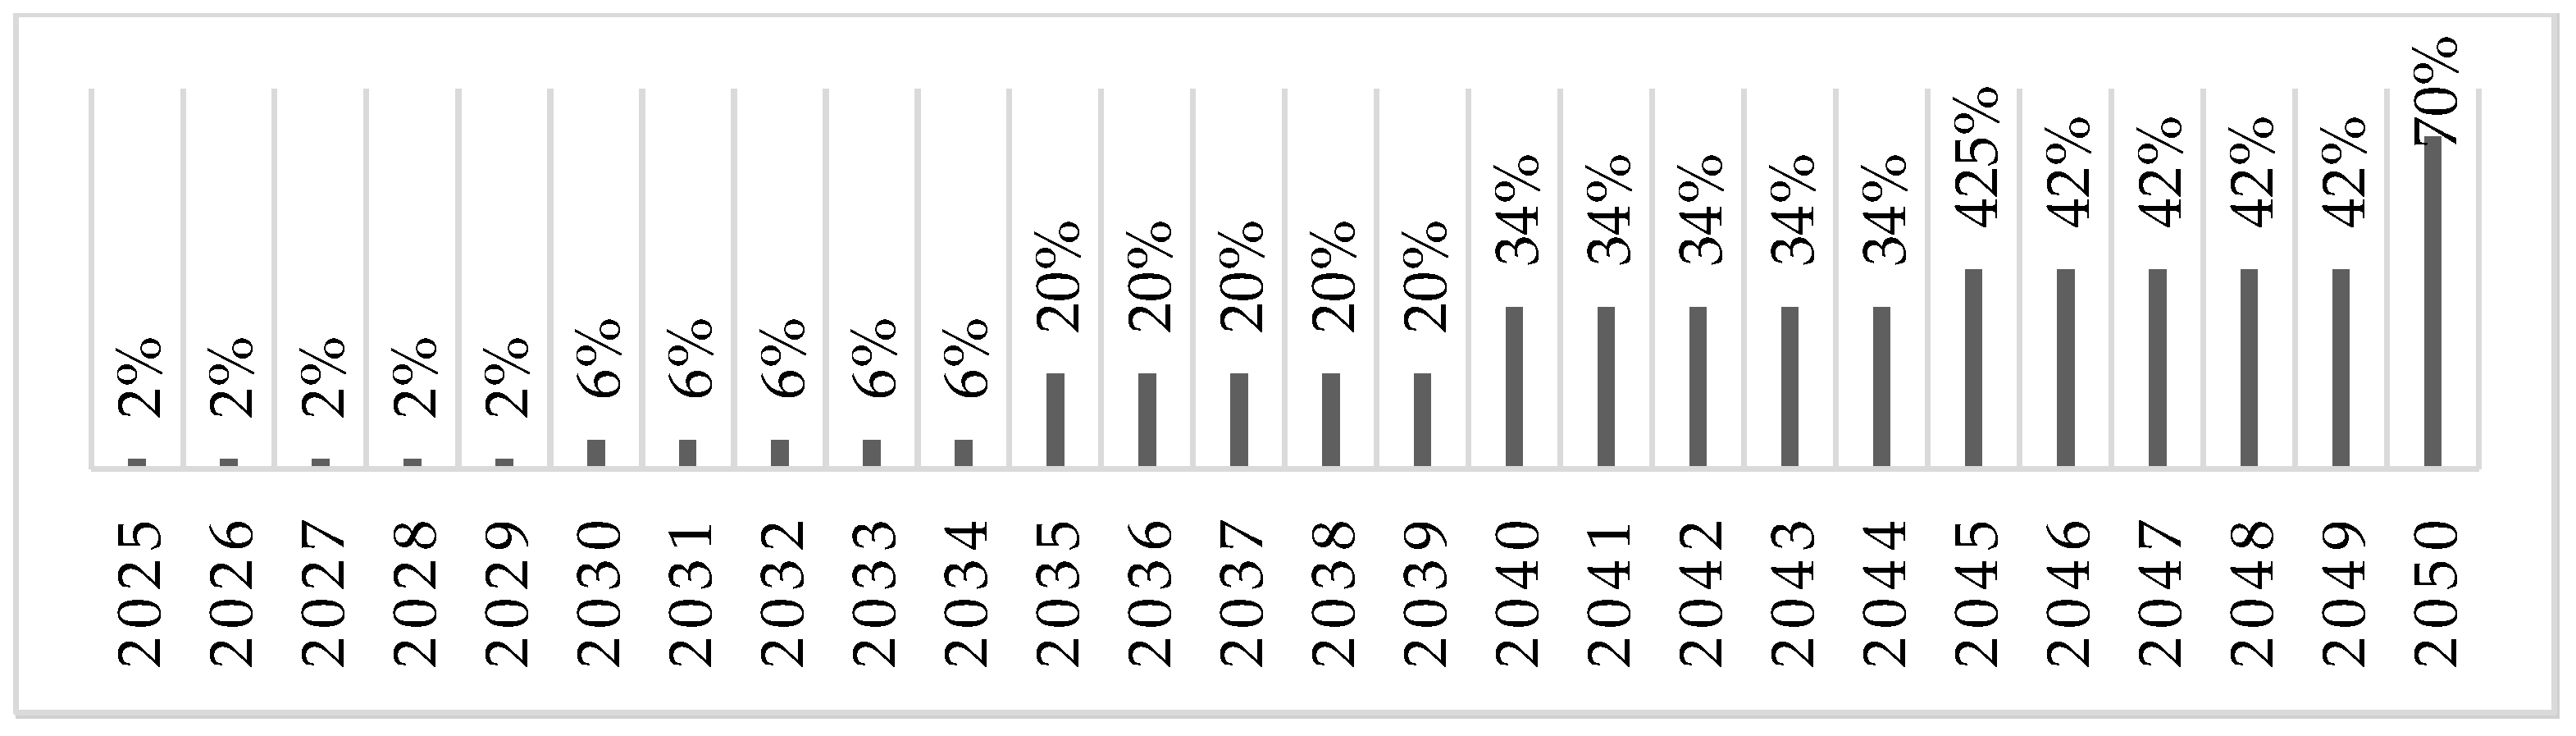
Italy’s SAF market is still in its early stages of development but is rapidly growing due to the aviation sector’s need to decarbonize, driven by the country’s high air traffic volume. This emphasizes the importance of using SAF to reduce aviation’s environmental impact. Italy aims to achieve an ambitious SAF production capacity of 150,000 tons by 2024, demonstrating its commitment to promoting a robust SAF industry. Italy’s national legislation on SAF is closely aligned with EU regulations aimed at reducing emissions in the transport sector. The country is also working to become more actively involved in international initiatives promoting SAF development. One of these initiatives is the Turin Joint Statement on Sustainable Biofuels, in which the G7 countries committed to accelerating SAF development towards reaching net-zero targets by mid-century. In Italy, SAF blending targets are aligned with the ReFuelEU Aviation initiative: starting at 2.0% for the period 2025–2029 and increasing to 6.0% by 2030 [52]. Italy’s growing aviation sector and existing biofuel production capacities provide favorable conditions for the development of SAF. However, to achieve this, it is essential to strengthen national policies, encourage investments in advanced fuels (especially synthetic SAFs), and ensure that the biofuel sector is directed towards aviation decarbonization. Only by integrating both technological and regulatory solutions can Italy position itself as a leader in the transition to climate-neutral aviation [41].
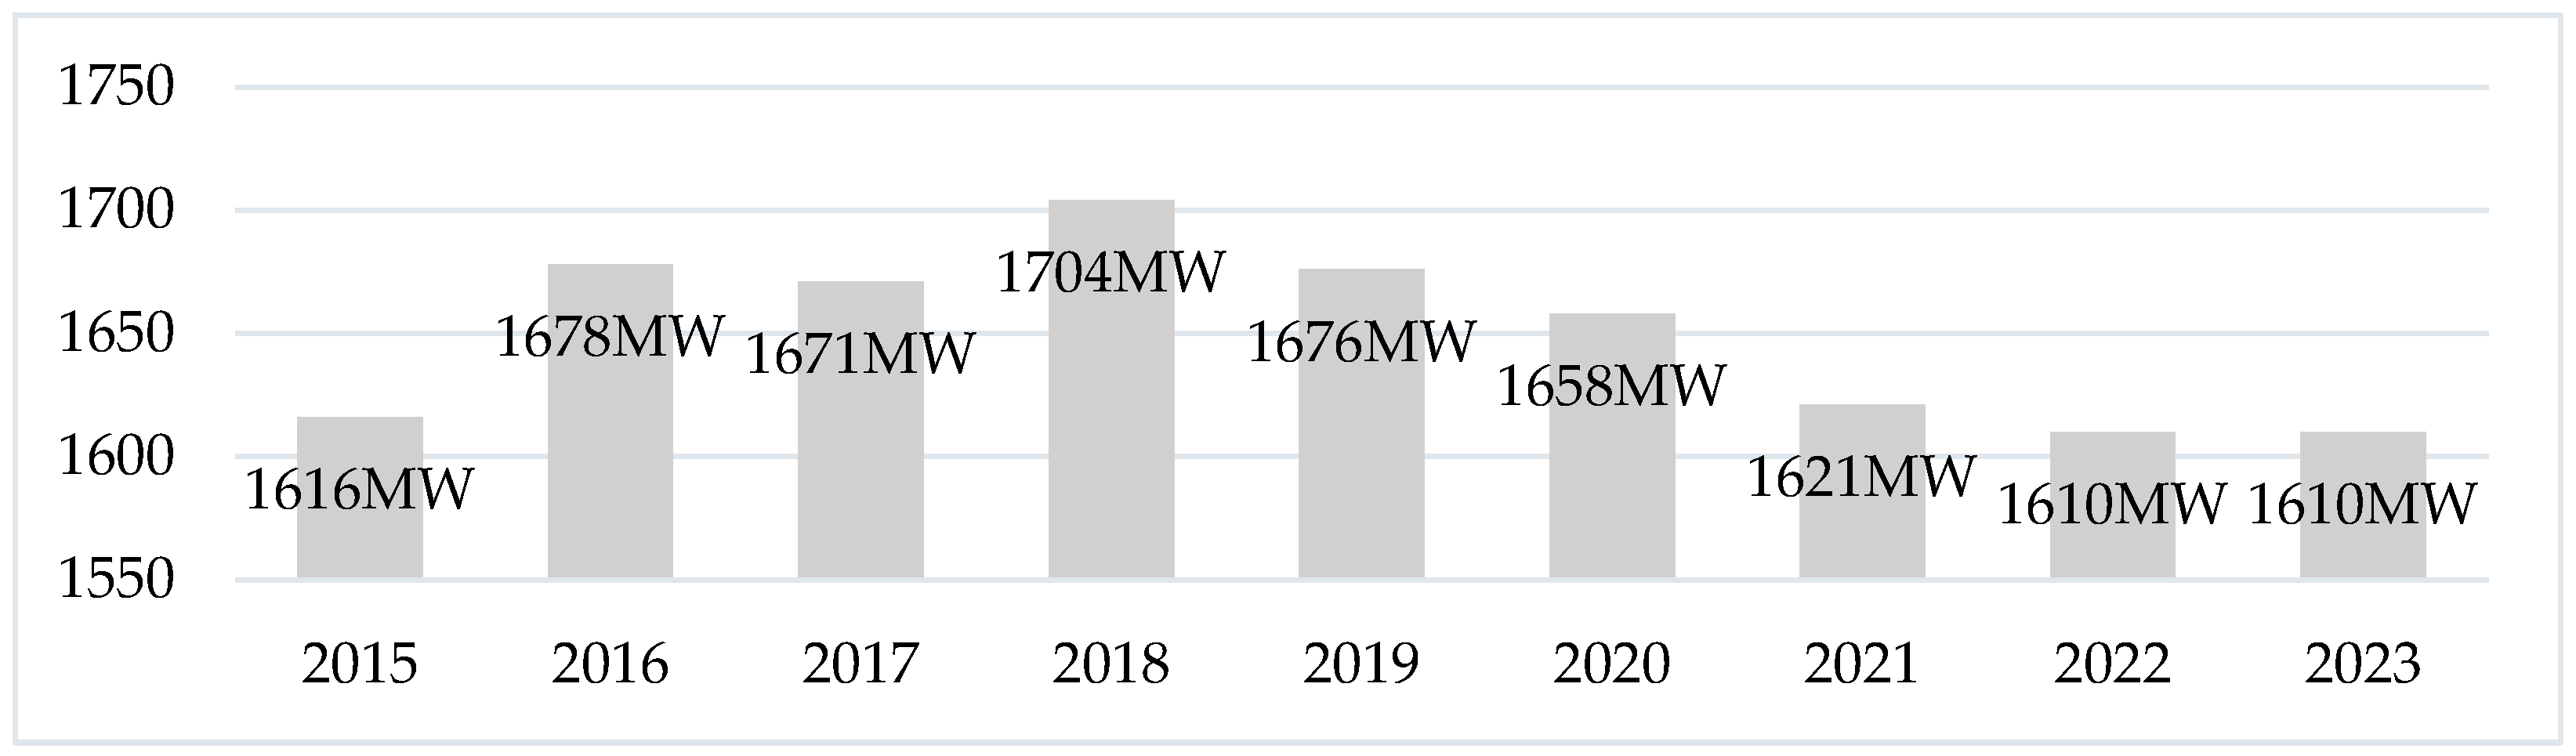
The figure that follows illustrates the installed biofuel capacity in Italy (Figure 5).
The chart provided shows that Italy’s biofuel production capacity remained relatively stable at around 1600 MW between 2015 and 2023, with minor fluctuations. Despite the fact that overall biofuel production did not grow rapidly, Italy ranks 5th in Europe for biofuel production, thus holding potential to leverage these resources for SAF development.
The figures on installed biofuel production capacity in selected EU member states (France, Germany, Denmark, Spain, and Italy) highlight divergent trajectories in the development of sustainable aviation fuels (SAFs). France and Germany demonstrate the most dynamic growth, driven by ambitious national targets, substantial state investments, and strong policy support. Denmark and Spain are leveraging their renewable energy potential, yet the transition to large-scale commercial production remains a critical challenge for achieving meaningful decarbonization in aviation. Italy’s relatively stable but limited capacity indicates underutilized potential for SAF development, despite its significant biofuel sector. These disparities underscore that SAF market expansion is primarily conditioned by the consistency of policy frameworks, the pace of technological innovation, and the scale of economic incentives. Hence, coherent EU-wide strategies, coupled with targeted national policies, are essential to ensure more balanced progress and broader SAF availability across the Union.
Biofuels, biomass and bioenergy are key to transitioning to sustainable energy systems, meeting global energy needs and supporting the UN Sustainable Development Goals [54]. The implementation of ReFuelEU implies commitments for fuel suppliers, EU airports, and aircraft operators. Aviation fuel suppliers are required to ensure that all aviation fuel supplied to aircraft operators at each EU airport contains a minimum percentage of SAF (Figure 6).
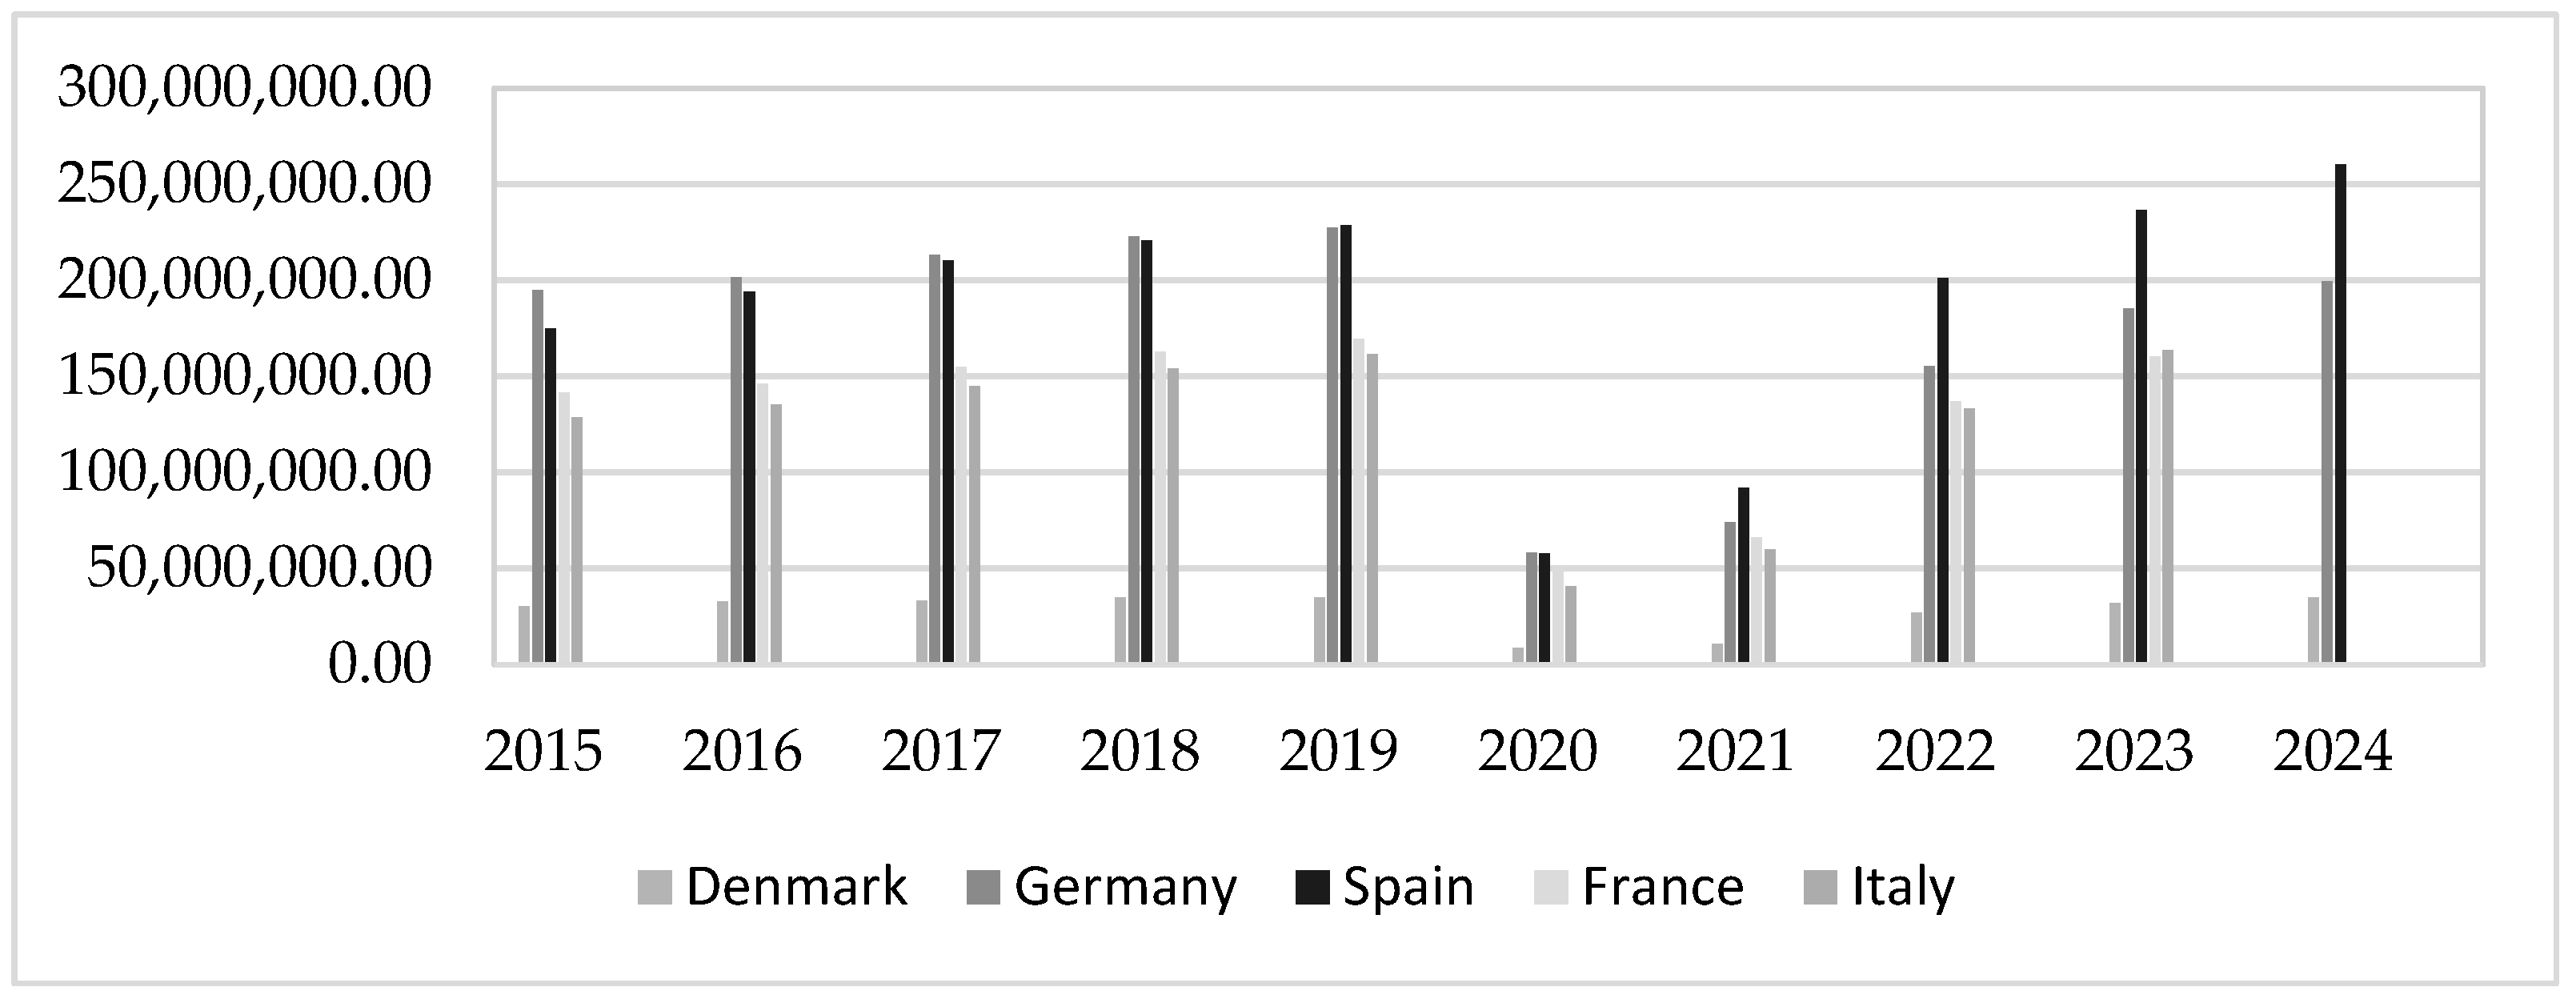
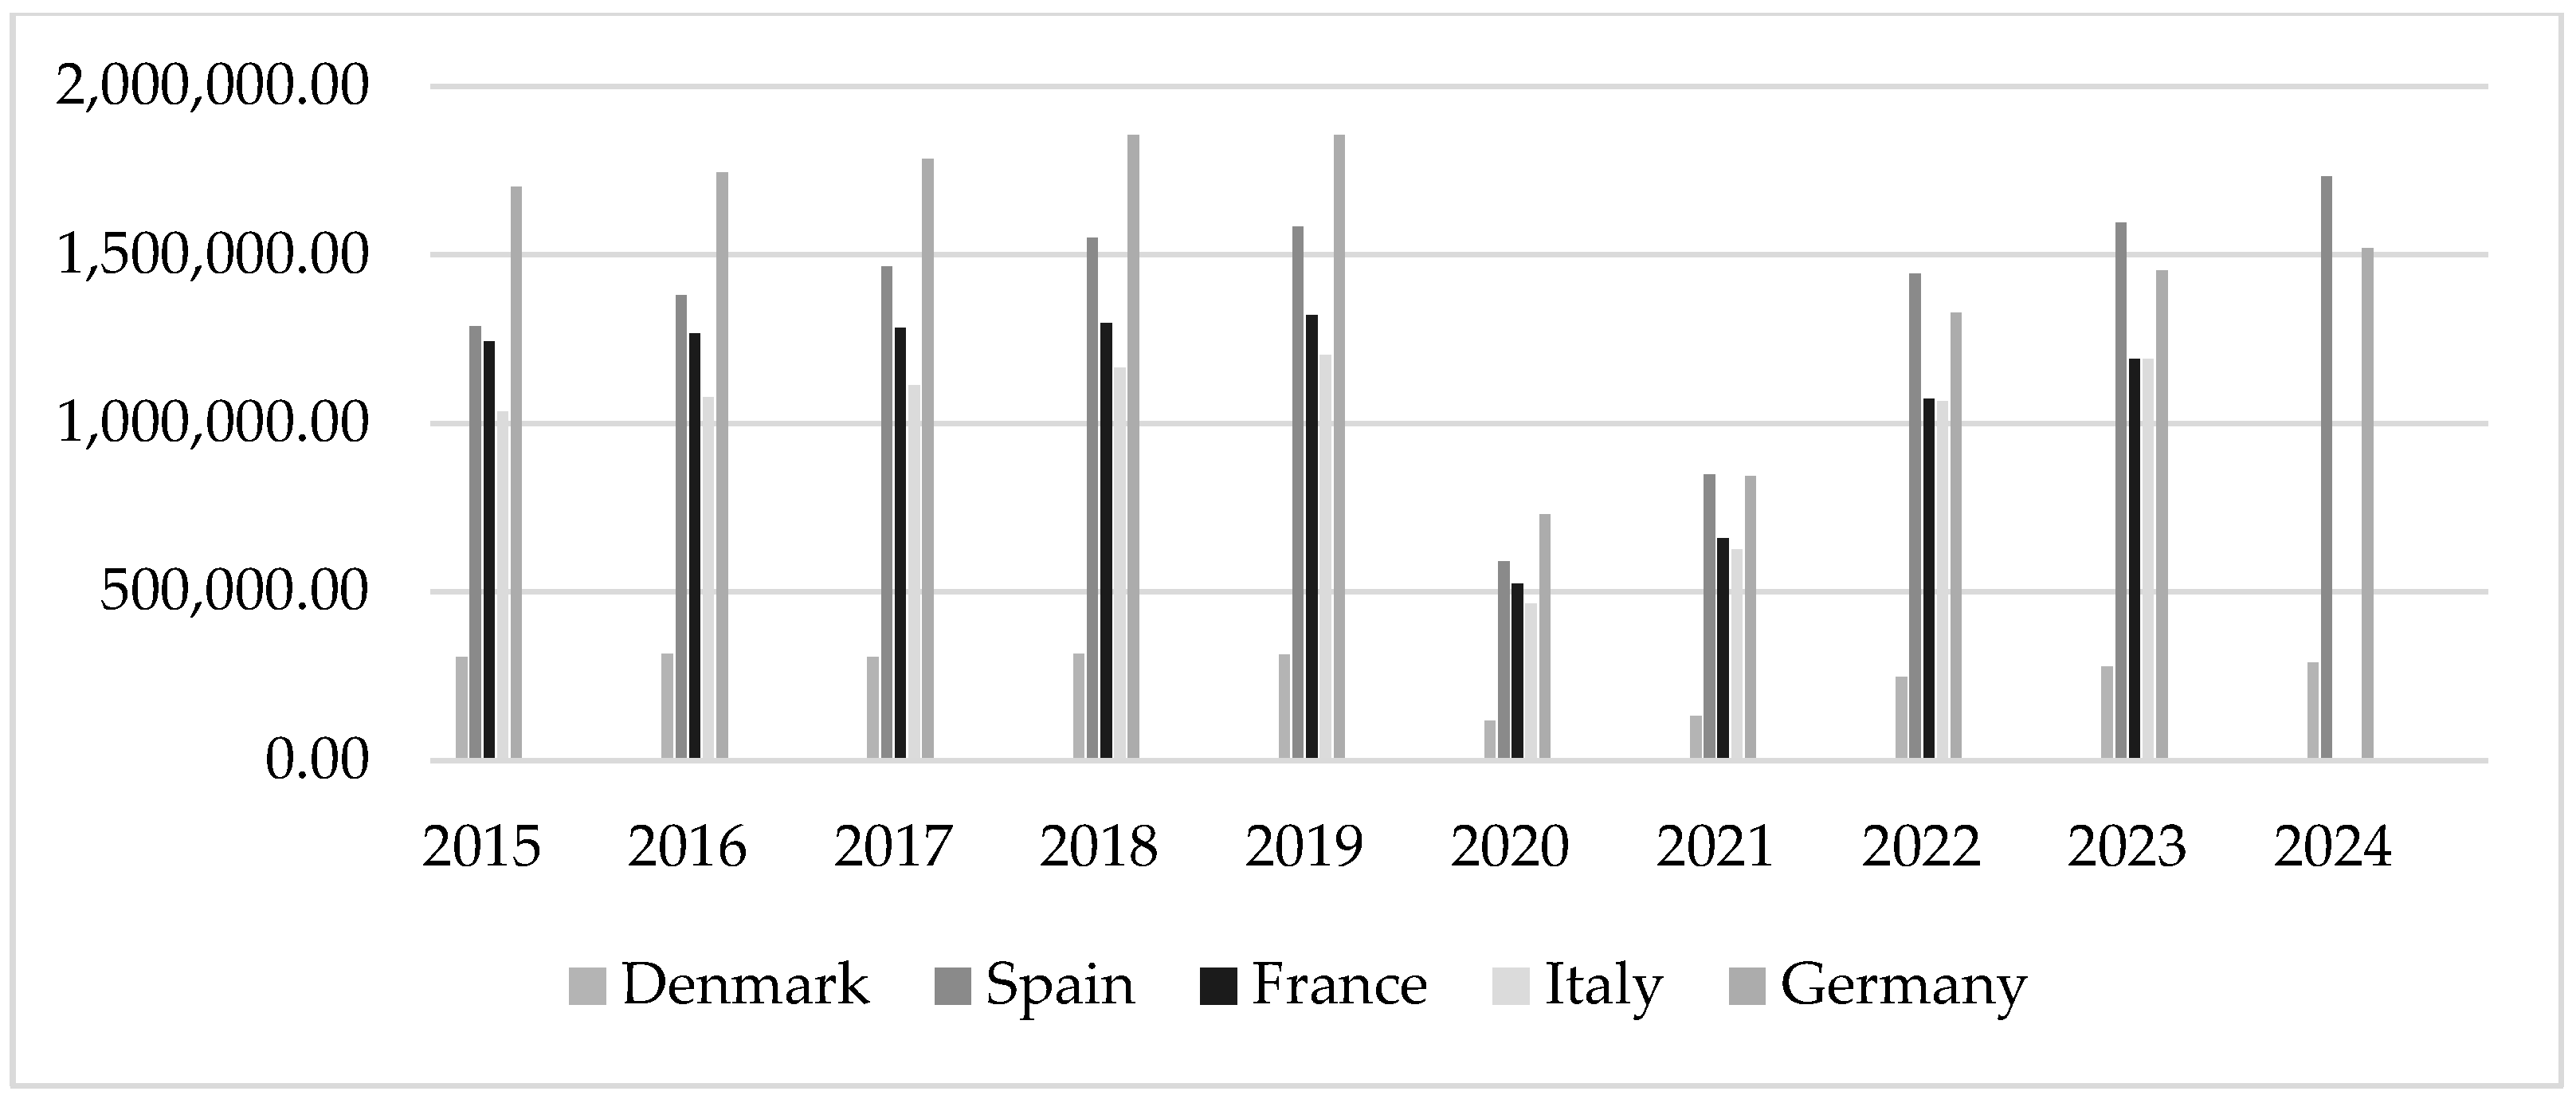
The number of passengers and numbers of flights per year in the selected countries is an important indicator for this study, as it is directly related to fuel demand, and thus SAF must align with changes in demand [56]. The graphs depicts passenger flows and numbers of flights and numbers of flights in Germany, France, Denmark, Spain, and Italy for the period from 2015 to 2024 (Figure 7 and Figure 8).
Sustainable aviation fuels are expected to be one of the most important fuel alternatives for decarbonising aviation. Many companies have already started to work with manufacturers to expand the SAF economy. SAF is produced from different types of fuels, such as biomass, biomethane and flue gases, in different ways [59].
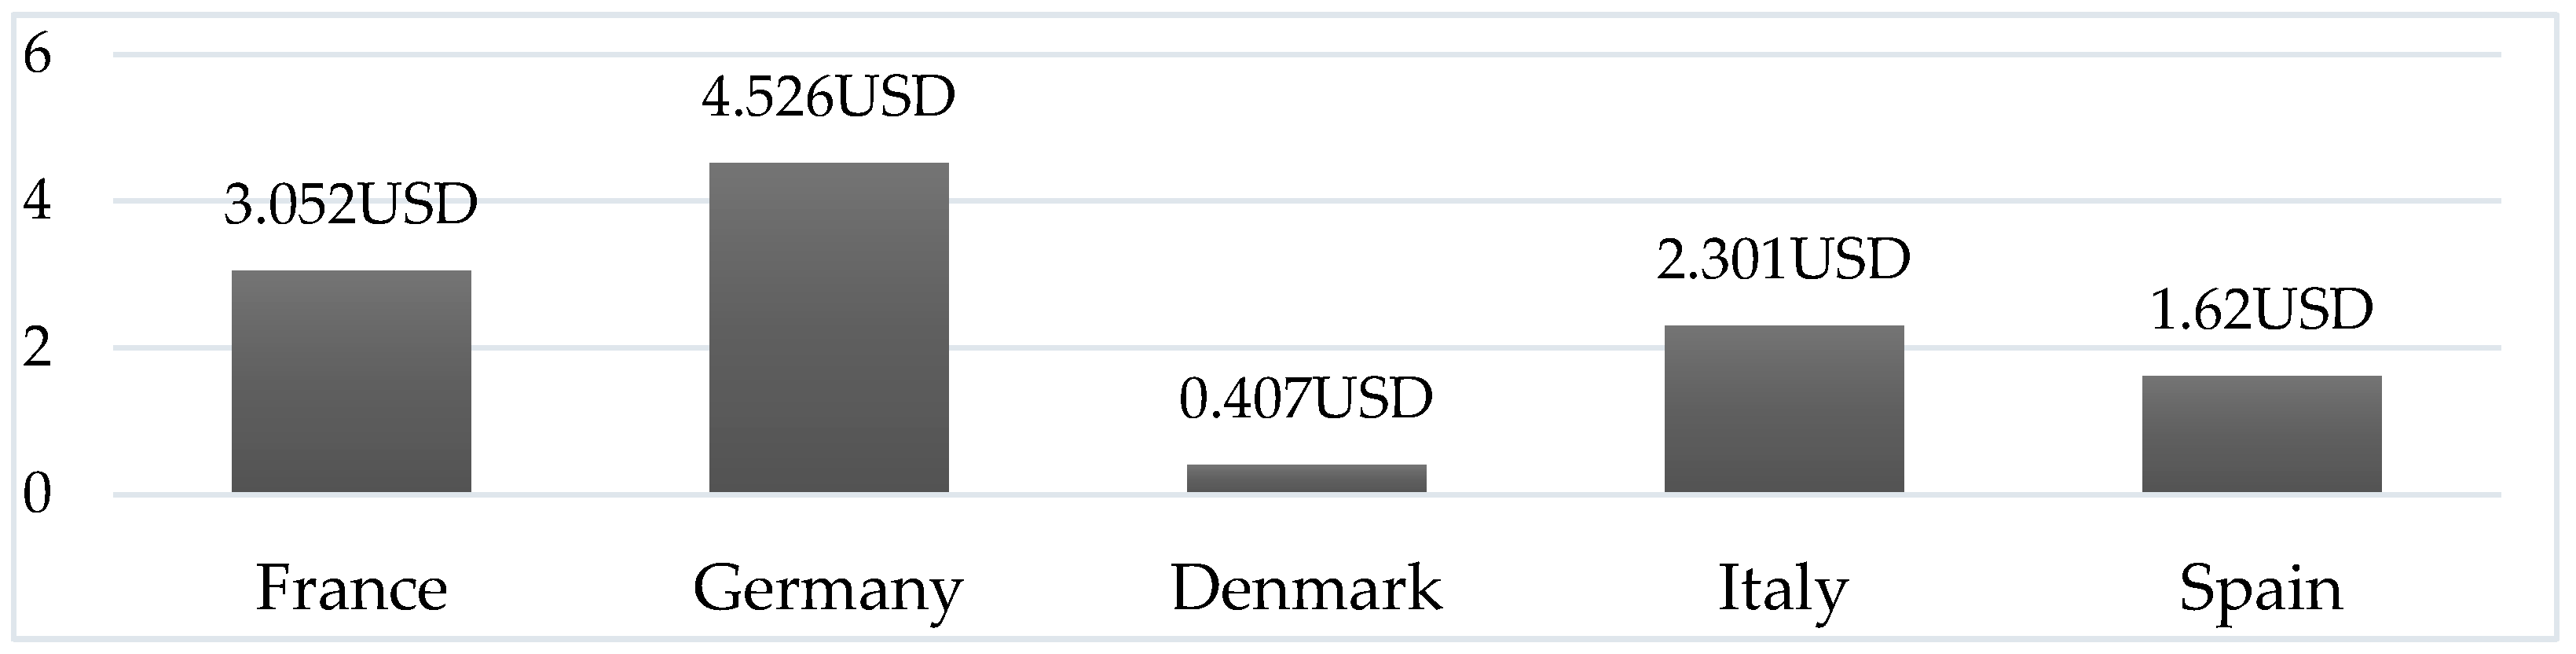
The GDP of member states is a crucial indicator when analysing the development of SAF and its economic and political context [60]. GDP reflects a country’s capacity to invest in SAF research, production infrastructure, and subsidies; the higher the GDP, the greater the ability to finance PtL plants and develop national strategies for SAF expansion. For instance, Germany, with a high GDP, can fund PtL facilities and create national strategies for SAF growth. This indicator also reflects the extent to which SAF is utilized or supported relative to a country’s economy. GDP is included in the regression model as a control variable to avoid distortions (Figure 9).
While macro-level policies and market frameworks are essential for understanding SAF development, the microeconomic strategies of airlines, suppliers, and airports are equally critical, as they directly influence adoption rates, competition, and consumer responses.
Recent literature highlights that market participants’ behavior plays a decisive role in the diffusion of SAF. Studies show that airlines adopt mixed-fleet fuel strategies (partially blending SAF with conventional jet fuel) to hedge against cost volatility [62]. Fuel suppliers often rely on long-term offtake agreements to mitigate investment risks [63], while airports act as facilitators of fuel infrastructure development, creating coordination platforms between suppliers and carriers. This body of research suggests that the success of SAF integration depends not only on macro-level policy frameworks but also on the strategic decisions and adaptive capabilities of individual actors [64].
SAF production faces major uncertainties and challenges. High production costs, specific distribution and storage requirements, and technical constraints such as energy storage and infrastructure retrofitting further complicate the production of SAF. The production costs of most of the SAF production pathways are higher than fossil jet fuels due to the high raw material and/or capital costs, which reduces the market competitiveness of SAF compared to fossil jet fuels.
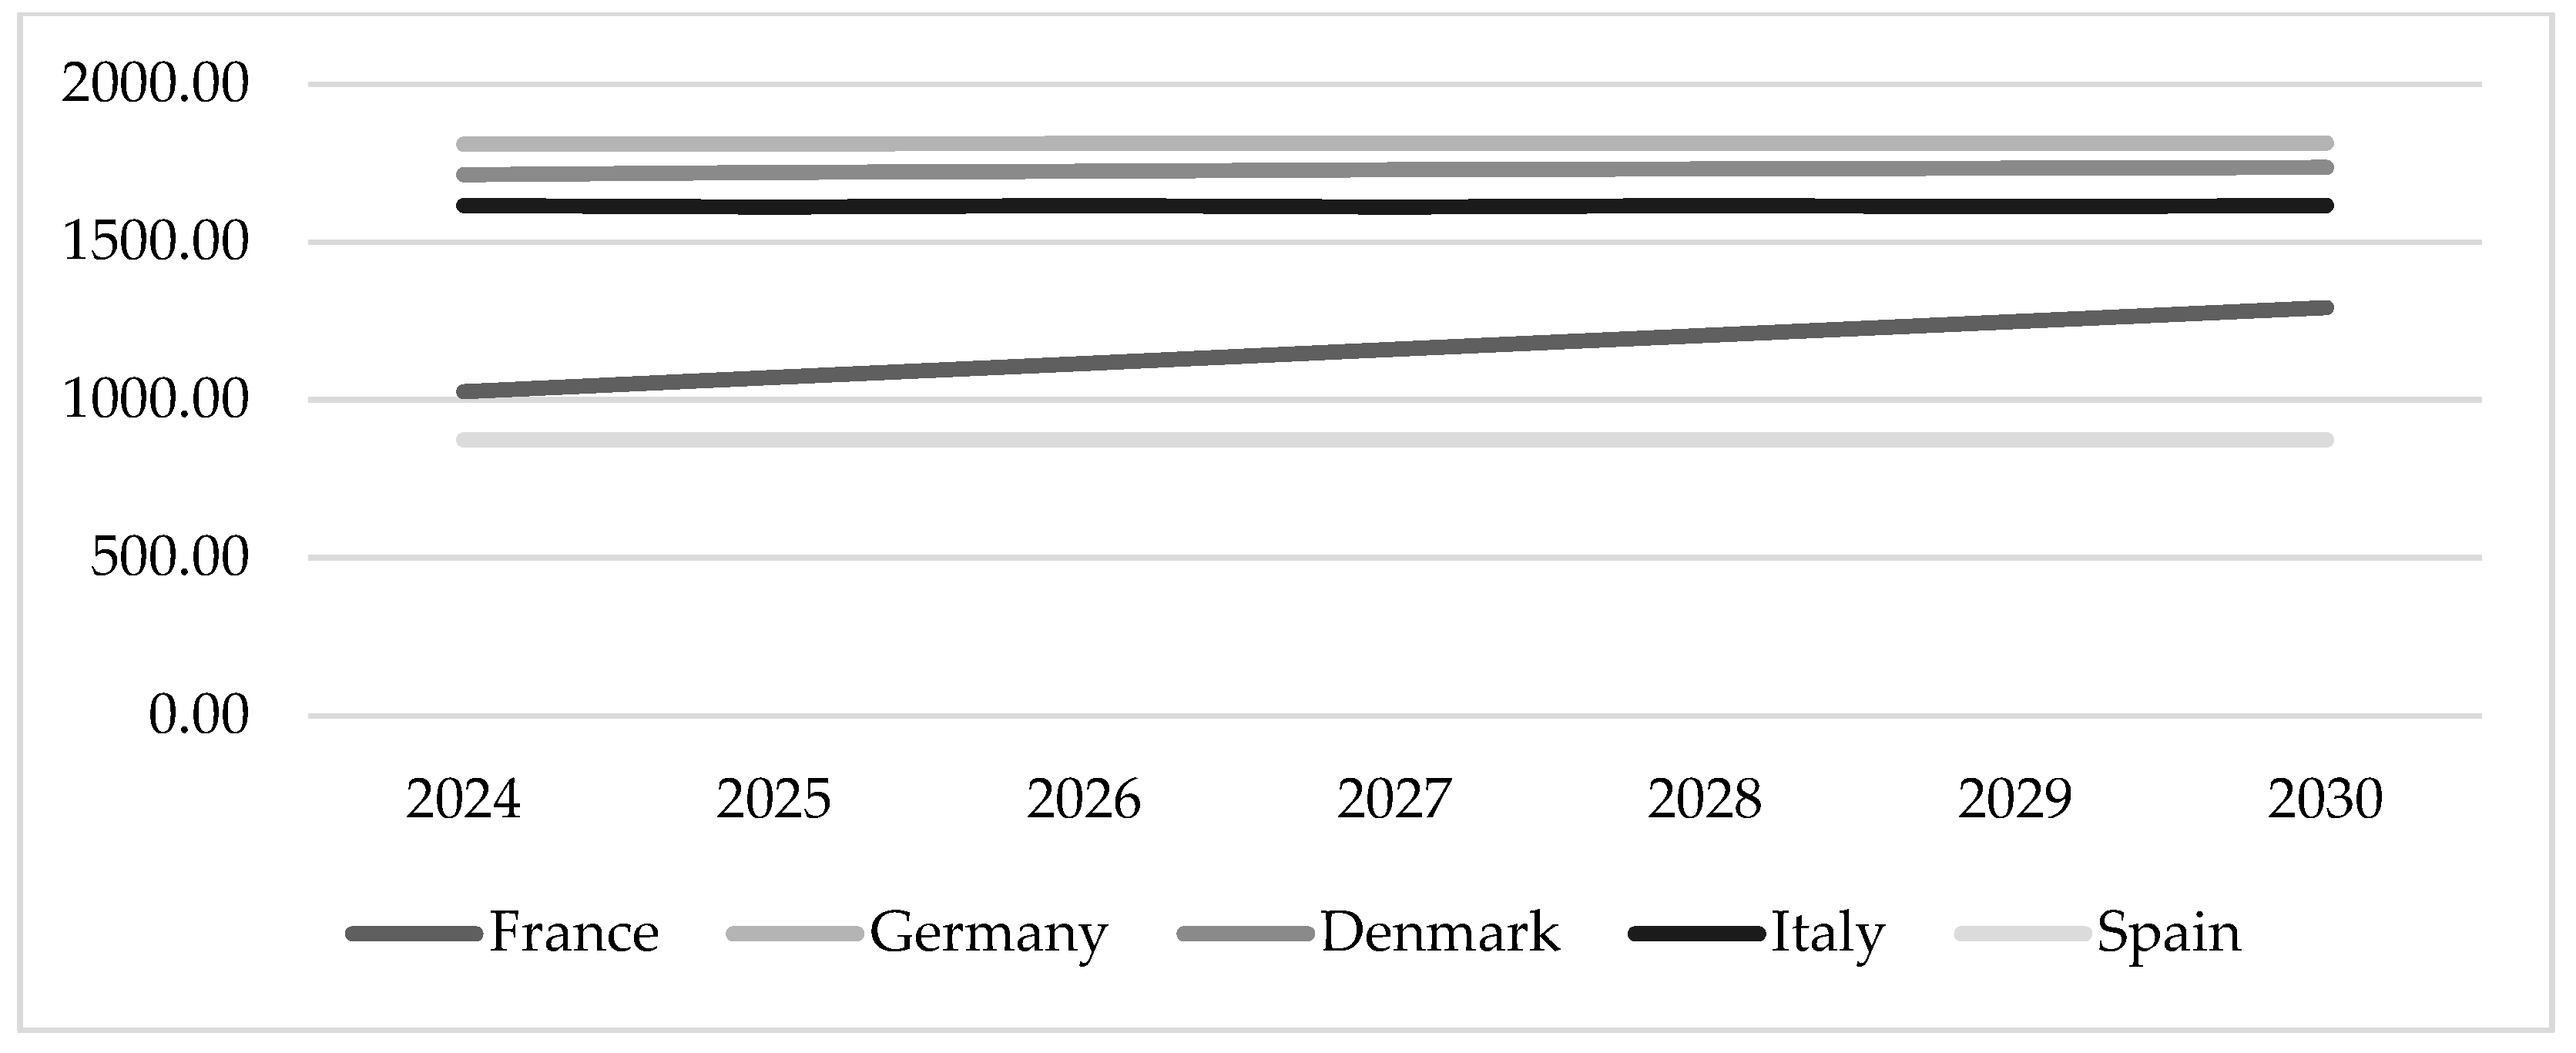
The study estimated the biofuel infrastructure development forecasts for each country considered in this paper using ARIMA and VAR models. It is important to estimate the future biofuel infrastructure capacity of countries, as this allows us to assess the feasibility of achieving the sustainability goals and to plan the necessary investments to ensure a green energy transition. Forecasts also help to identify the necessary policy assumptions and accurately predict fuel demand to effectively meet decarbonization targets. For the purposes of the calculations, national GDP is assumed to remain constant. The study assumes constant GDP to avoid the influence of macroeconomic fluctuations and to more clearly isolate the dynamics of biofuel infrastructure and the aviation sector; potential GDP variations can be addressed in future scenario analyses (Figure 10).

4.2. ARIMA Model Results

Germany and Denmark demonstrate the strongest growth potential, while France and Italy show steady growth. Spain forecasts stability rather than significant growth, which may reflect national economic and political challenges in implementing biofuel technologies.
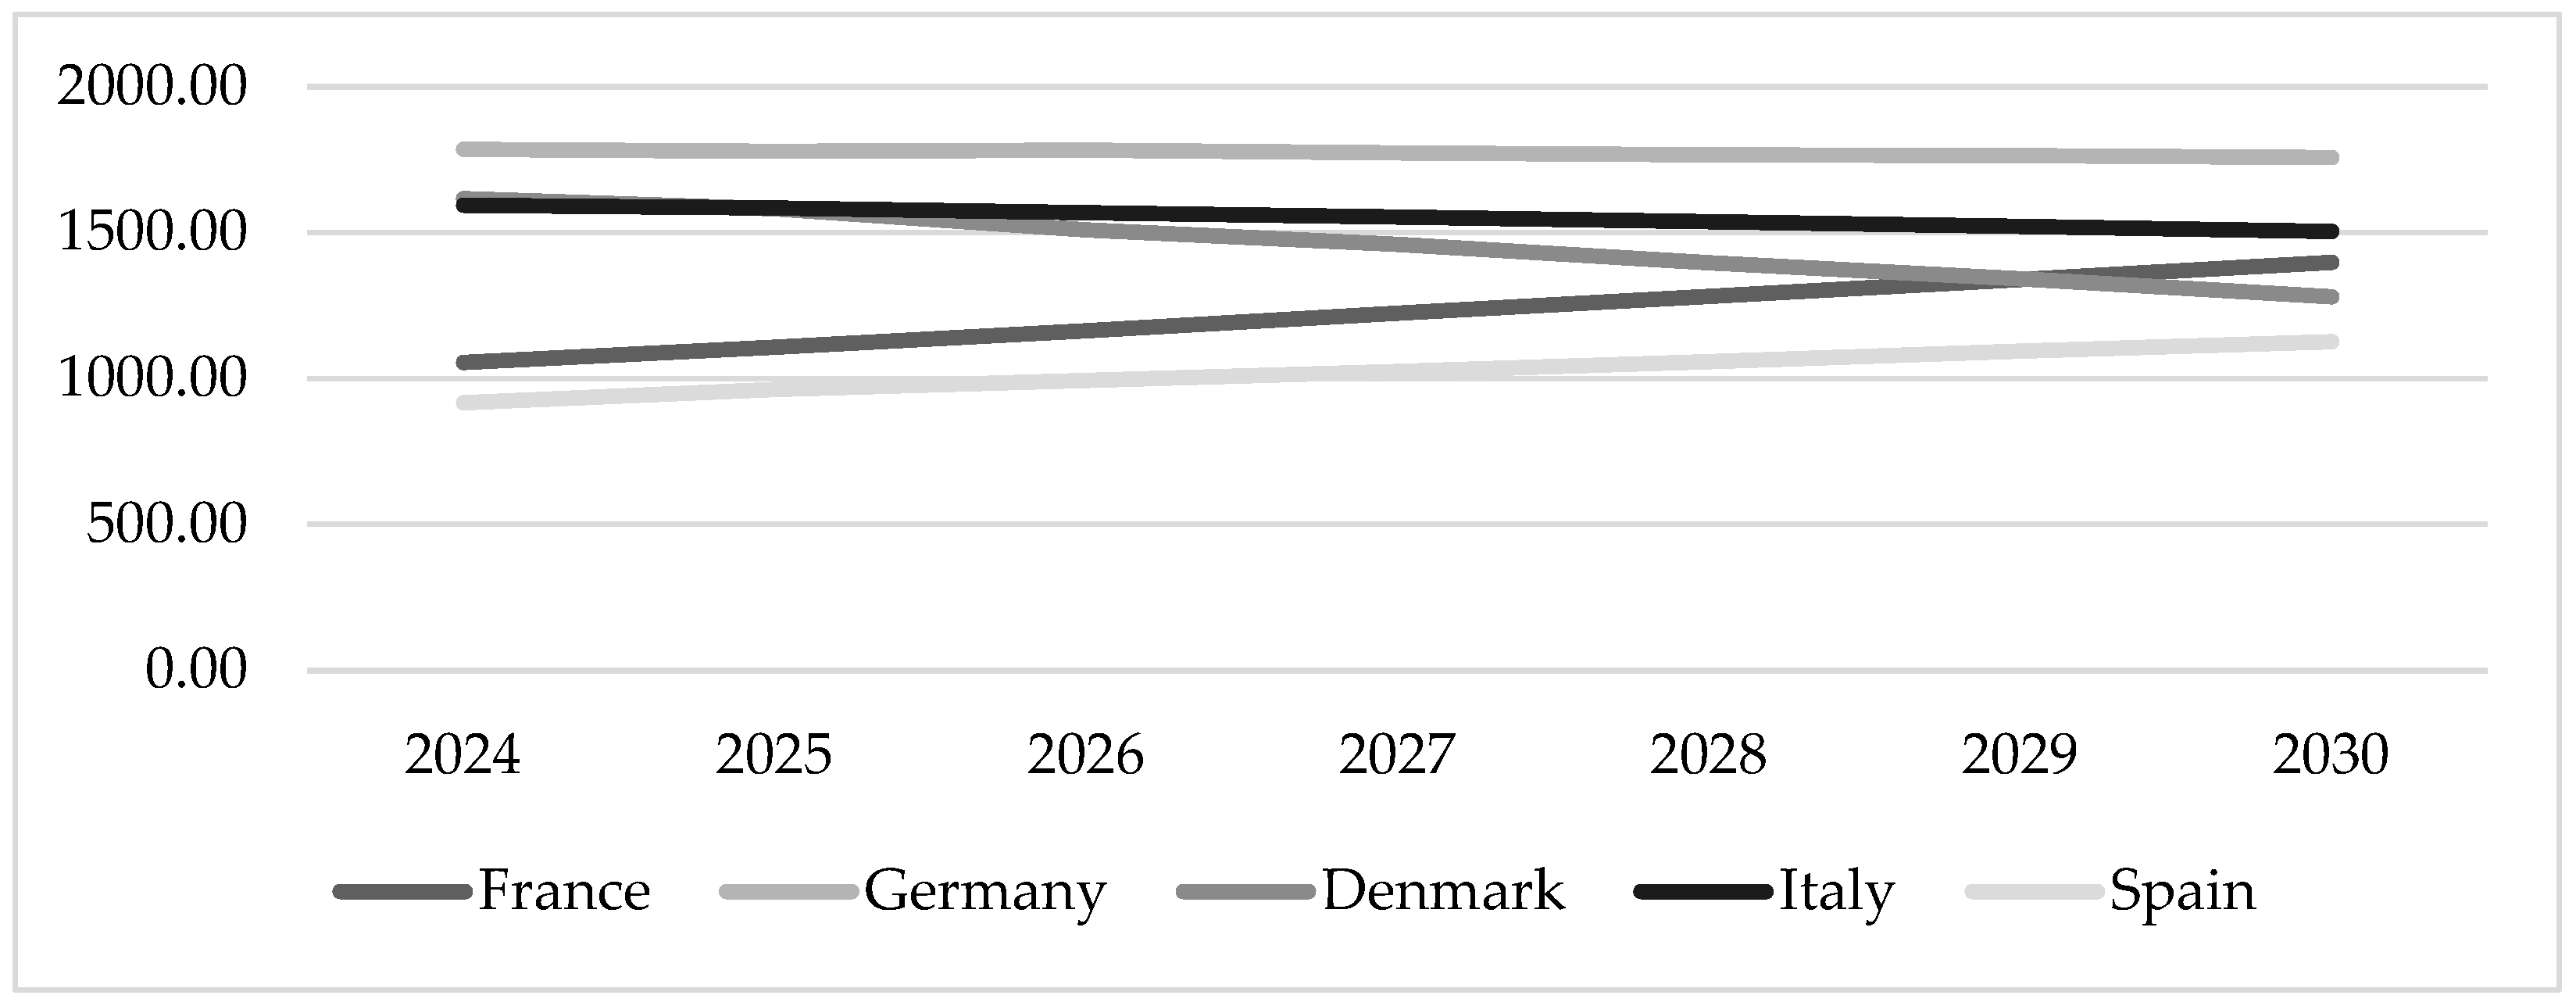
The next step, based on the same data, is the calculation using the VAR method (Figure 11).

4.3. VAR Model Results

Germany and France show higher growth potential, while Denmark and Italy display slower growth. Spain is expected to experience stability, which may reflect the country’s national economic and political challenges in implementing biofuel technologies. This demonstrates the different strategies and potential challenges of each country in developing biofuel infrastructure.
The ARIMA model mostly predicted slower growth or stability, while the VAR model forecasted higher growth in many countries, particularly in Germany and France, due to its ability to assess the impact of economic factors. In Spain, the growth forecast was higher according to the VAR method, which may consider the country’s efforts to develop biofuel infrastructure, while the ARIMA model showed stability. This suggests that the VAR model is more responsive to external economic factors and national policies, while the ARIMA model typically relies on historical data, thus predicting less change in the future.
These findings also highlight the heterogeneity among EU member states in terms of economic capacity, aviation sector scale, and resource endowment. For example, countries such as Germany and France, with larger economies and stronger policy frameworks, demonstrate higher growth potential in SAF infrastructure, while Spain shows relative stability, reflecting both political and economic constraints. This heterogeneity suggests that SAF market development in the EU cannot be understood as a uniform process, but rather as a set of differentiated national trajectories shaped by structural conditions and policy choices. Recognizing these differences is essential for interpreting overall EU market trends, as aggregated results may obscure important country-specific dynamics that influence the effectiveness of common EU-wide policies such as RefuelEU Aviation.

4.4. Regression Analysis

After performing regression analysis, where biofuel infrastructure capacity was considered the independent variable, and passenger numbers, flight counts, and GDP were considered dependent variables, the following results were obtained (see Table 2 and Table 3 below):
Passenger numbers and flight counts have less impact, but their influence is not statistically significant in this regression. The model explains 93.99% of the changes (according to R2), indicating that the model fits the data well.
The regression results confirm GDP as the only statistically significant driver of SAF infrastructure capacity, indicating that economic strength is the key enabling factor for large-scale investments and policy support mechanisms. This suggests that SAF development in the EU is shaped primarily by macroeconomic capacity and government intervention rather than by immediate aviation demand, as reflected in the weak effects of passenger numbers and flight counts. The high explanatory power of the model (R2 = 93.99%) reinforces this conclusion, showing that SAF market expansion follows structural, policy- and investment-driven dynamics rather than short-term fluctuations in aviation activity.

5. Discussion

The study showed that EU countries are striving to implement sustainable aviation fuel (SAVE) targets at different speeds and with varying strategies. Germany and France stand out with their ambitious policy measures and economic incentives, which could drive rapid growth in SAF adoption. For example, Germany is implementing national initiatives aimed at increasing SAF production and ensuring fuel supply through international partnerships, while France has set strict fuel blending quotas and planned significant investments in decarbonization technologies [16]. On the other hand, Spain and Italy are showing slower progress due to both technical and economic challenges. These countries will need to take additional steps to catch up with the leading nations, including increased investments in technology development and stronger regulatory support. This indicates that to accelerate the adoption of sustainable fuel, collaboration and additional economic and political incentives are essential.
The results of the study also highlight that while the ARIMA model predicted higher growth in many countries, the VAR model placed greater emphasis on the impact of economic factors, particularly GDP, and demonstrated that this factor can significantly contribute to the development of the biofuels sector. A higher GDP may be closely linked to greater opportunities for investing in sustainable technologies and creating more favorable conditions for sustainable energy policies [19]. This confirms that higher economic development often provides a greater incentive for investment in new technologies and ensures stronger support for sustainable energy policies.
The study showed that EU countries pursue different speeds and strategies in implementing sustainable aviation fuel (SAF) targets. Germany and France stand out with their ambitious policy measures and economic incentives, which could drive rapid growth in SAF usage [47,49]. On the other hand, Spain and Italy demonstrate slower progress, requiring additional efforts to catch up with the leading nations [51,53].
The findings suggest that the current SAF market in the EU is shaped not only by policy incentives but also by the strategic responses of airlines and suppliers. Airlines face a trade-off between sustainability commitments and cost competitiveness: some carriers pass increased SAF costs onto ticket prices, potentially shifting consumer demand towards lower-cost competitors. Others seek to differentiate themselves by emphasizing their environmental branding, despite higher operational costs. Similarly, suppliers and airports engage in collaborative investment models, spreading the risks of SAF infrastructure deployment. These behaviors reshape the competitive landscape, suggesting that micro-level dynamics may significantly influence the effectiveness of macro-level policies.
Our results show that the transition to sustainable aviation fuels has the potential not only to significantly reduce emissions of greenhouse gases and other pollutants, but also to strengthen the energy resilience of the air transport sector. Given that diversifies fuel supply sources, it reduces dependence on fossil fuel imports and reduces the risks associated with geopolitical events and supply chain disruptions. However, our analysis and previous studies [11,12] reveal that in many countries there is still a lack of engagement and awareness of the vulnerability of energy dependence by both the public and public and private stakeholders. Energy dependency—especially when fuel supply is concentrated in narrow channels—creates weak links in the sector, limits the ability to react quickly to market fluctuations, and increases fuel price volatility [6]. Successful integration of SAF therefore recommends the formulation of comprehensive policy measures, strengthening public–private partnerships, targeting investments in advanced decarbonization technologies and digital supply chain management solutions, while enhancing public involvement through education and awareness initiatives. This would build sustainable fuels infrastructure, enhance energy security and facilitate climate-friendly air transport.
Furthermore, it is important to emphasize that the observed market behavior is closely linked to the implementation of the EU SAF mandate under the ReFuelEU Aviation regulation. This mandate serves as a demand-creation mechanism, ensuring that fuel suppliers and airlines face a predictable and steadily increasing requirement to blend SAF into conventional aviation fuel. As a result, SAF deployment in the EU is no longer driven solely by voluntary environmental commitments but is structurally embedded in the regulatory framework. The mandate reduces investment uncertainty for producers, stabilizes expectations regarding future demand, and strengthens the economic rationale for scaling production capacity. Therefore, the effectiveness of SAF market expansion is directly dependent on the consistency and credibility of long-term policy commitments at the EU level.

6. Conclusions

The economy of sustainable aviation fuel (SAF), market trends, and related policies are still in a developing stage, with only a few EU countries taking significant steps toward transitioning to SAF. As a result, the importance of research examining the economy of sustainable aviation fuels will continue to grow in the future, to assess the progress of countries in transitioning to sustainable aviation fuels and identify effective measures to accelerate this process.
First, SAF Market Growth Potential: The market is expected to expand, driven by technology and policy support. Germany and France show the strongest growth, while Italy and Denmark progress more slowly.
Second, Regulatory Impact: EU initiatives, especially RefuelEU Aviation, significantly influence SAF deployment, fuel supply strategies, and market development.
Third, Economic Viability: Although SAF offers major environmental benefits, high production costs limit competitiveness, emphasizing the need for stronger financial and policy support.
Fourth, GDP and Biofuel Infrastructure Development: The results of the study show that the GDP of countries has a significant positive impact on the growth of biofuel infrastructure. This confirms that higher economic development creates favorable conditions for investment in SAF technologies and their implementation.
Fifth, the literature analysis has shown that the development of sustainable aviation fuels is strongly linked to the energy resilience of the air transport sector. On the one hand, this means more choice and less dependence on fossil fuels, but on the other hand, there are risks in terms of managing demand for sustainable aviation fuels and the stability of supply chains. There is also the important aspect of technological progress to ensure safety and proper operation.
The findings of this study extend beyond the economic dimension, aligning closely with broader sustainable development objectives. The expansion of sustainable aviation fuels directly contributes to SDG 7 (Affordable and Clean Energy) by diversifying the energy base of aviation, SDG 9 (Industry, Innovation and Infrastructure) by fostering technological progress and new investment in energy infrastructure, and SDG 13 (Climate Action) through the reduction in greenhouse gas emissions in a hard-to-abate sector. Furthermore, the harmonization of EU policies and the stimulation of SAF markets also support SDG 12 (Responsible Consumption and Production) by encouraging a transition toward more sustainable energy use patterns. By linking SAF deployment to these goals, the study underlines not only the economic and regulatory importance of SAF but also its broader role in achieving long-term environmental and social sustainability.
In addition, the findings highlight that the EU SAF mandate plays a key structuring role in market development, shifting SAF deployment from voluntary initiatives toward a regulation-driven model of stable demand. The trajectory and pace of SAF scale-up therefore depend not only on technological and economic factors, but also on maintaining coherent and predictable long-term policy commitments.
Future studies should focus on the long-term development of SAF, with particular.
Future research should focus on the long-term development of sustainable aviation fuels (SAFs), emphasizing the effectiveness of policy measures and their link to economic factors. Comparative studies between the EU and other regions are needed to assess how different regulatory models affect SAF adoption. In addition, micro-level analyses of airline strategies, consumer behavior, and supply chain resilience would provide valuable insights into the practical challenges of implementing SAF and its role in achieving climate neutrality.

7. Limitations and Future Research

This study focuses on structural, long-term market and policy dynamics shaping the deployment of sustainable aviation fuels (SAFs) in the European Union. As such, several limitations should be acknowledged. First, the analysis relies on secondary data covering the period 2015–2023, during which SAF markets were still emerging and available capacity data may not fully capture small-scale or pilot production activities. Second, while ARIMA, VAR, and regression models provide insight into market trajectories and key economic drivers, the effects of short-term shocks—such as pandemic-related travel disruptions, fuel price volatility, and geopolitical events—were not explicitly modelled. Their influence was acknowledged conceptually but excluded to preserve analytical clarity and isolate structural determinants. Third, the study primarily focused on major EU economies; future research could incorporate a broader set of member states to examine convergence or divergence patterns in SAF deployment.
Future research could expand on this work by integrating scenario-based modeling of external shocks, conducting comparative analyses across regulatory regimes beyond the EU, and examining micro-level decision-making by airlines, airports, and fuel suppliers. Additionally, a more detailed assessment of cost pass-through mechanisms and consumer willingness-to-pay would contribute to a deeper understanding of the economic viability of SAF in commercial aviation.

Author Contributions

Conceptualization, L.O.N.; methodology, L.O.N. and E.S.-N.; experiment and data analysis, L.O.N., E.S.-N. and M.T.; conclusions, L.O.N. and M.T.; discussion, L.O.N. and E.S.-N.; writing—original draft preparation, L.O.N., E.S.-N. and M.T.; writing—review and editing, L.O.N. and M.T. All authors have read and agreed to the published version of the manuscript.

Funding

This research received no external funding.

Institutional Review Board Statement

Not applicable.

Informed Consent Statement

Not applicable.

Data Availability Statement

The original contributions presented in the study are included in the article.

Conflicts of Interest

The authors declare no conflicts of interest.

References

  1. Komarova, V.; Čižo, E.; Balodis, J.; Kokarēviča, A.; Ruža, O.; Kudiņš, J. Development of transport infrastructure and its impact on territorial production. Entrep. Sustain. Issues 2023, 10, 338–356. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  2. Raman, R.; Gunasekar, S.; Dávid, L.D.; Rahmat, A.F.; Nedungadi, P. Aligning sustainable aviation fuel research with sustainable development goals: Trends and thematic analysis. Energy Rep. 2024, 12, 2642–2652. [Google Scholar] [CrossRef] [Scilit]
  3. Kirmizi, M.; Aygun, H.; Turan, O. Energetic and exergetic metrics of a cargo aircraft turboprop propulsion system by using regression method for dynamic flight. Energy 2024, 296, 131153. [Google Scholar] [CrossRef] [Scilit]
  4. Champeecharoensuk, A.; Dhakal, S.; Chollacoop, N.; Phdungsilp, A. Greenhouse gas emissions trends and drivers insights from the domestic aviation in Thailand. Heliyon 2024, 10, e24206. [Google Scholar] [CrossRef] [Scilit]
  5. Lau, J.I.C.; Wang, Y.S.; Ang, T.; Seo, J.C.F.; Khadaroo, S.N.B.A.; Chew, J.J.; Lup, A.N.K.; Sunarso, J. Emerging technologies, policies and challenges toward implementing sustainable aviation fuel (SAF). Biomass Bioenergy 2024, 186, 107277. [Google Scholar] [CrossRef] [Scilit]
  6. Bag, S.; Routray, S.; Rahman, M.S.; Shrivastav, S.K. Investigate the effect of green hydrogen supply chain integration on supply chain resilience: Organization information processing theory perspective. Int. J. Prod. Econ. 2025, 284, 109613. [Google Scholar] [CrossRef] [Scilit]
  7. Okunevičiūtė Neverauskienė, L.; Dirma, V.; Tvaronavičienė, M.; Danilevičienė, I. Assessing the Role of Renewable Energy in the Sustainable Economic Growth of the European Union. Energies 2025, 18, 760. [Google Scholar] [CrossRef] [Scilit]
  8. Sabauri, L.; Kvatashidze, N. Sustainability reporting issues. Entrep. Sustain. Issues 2023, 11, 282–289. [Google Scholar] [CrossRef] [Scilit]
  9. Thummala, V.; Hiremath, R.B. Green aviation in India: Airline’s implementation for achieving sustainability. Clean. Responsible Consum. 2022, 7, 100082. [Google Scholar] [CrossRef] [Scilit]
  10. Okunevičiūtė Neverauskienė, L.; Tvaronavičienė, M.; Linkevičius, D. Energy Efficiency, CO2 Emission Reduction, and Real Estate Investment in Northern Europe: Trends and Impact on Sustainability. Buildings 2025, 15, 1195. [Google Scholar] [CrossRef] [Scilit]
  11. Wan, K.; Fan, Y.; Liu, B.-Y. Energy supply resilience under low-carbon transition: Long-term multi-national assessment. Energy 2025, 326, 136311. [Google Scholar] [CrossRef] [Scilit]
  12. Chen, H.; Yan, H.; Gong, K.; Geng, H.; Yuan, X.C. Assessing the business interruption costs from power outages in China. Energy Econ. 2022, 105, 105757. [Google Scholar] [CrossRef] [Scilit]
  13. Han, S.; Bin Kamaruddin, B.H.; Shi, X.; Zhu, J. Achieving energy resilience: Studying renewable and fossil fuel energy generation drivers and COPE-28 pathways of China. Energy Strategy Rev. 2025, 58, 101669. [Google Scholar] [CrossRef] [Scilit]
  14. Shafiei, K.; Seifi, A.; Hagh, M.T. A novel multi-objective optimization approach for resilience enhancement considering integrated energy systems with renewable energy, energy storage, energy sharing, and demand-side management. J. Energy Storage 2025, 115, 115966. [Google Scholar] [CrossRef] [Scilit]
  15. Richie, H. What Share of Global CO2 Emissions come from Aviation?—Our World in Data 2024. Available online: https://ourworldindata.org/global-aviation-emissions (accessed on 1 April 2025).
  16. Gössling, S.; Humpe, A. The global scale, distribution and growth of aviation: Implications for climate change. Glob. Environ. Change 2020, 65, 102194. [Google Scholar] [CrossRef] [Scilit]
  17. Lv, X.; Zhao, C.; Yan, N.; Ma, X.; Feng, S.; Shuai, L. Sustainable aviation fuel (SAF) from lignin: Pathways, catalysts, and challenges. Bioresour. Technol. 2025, 419, 132039. [Google Scholar] [CrossRef] [Scilit]
  18. Yu, L.; Huang, M.M.; Jiang, S.; Wang, C.; Wu, M. Unmanned aircraft path planning for construction safety inspections. Autom. Constr. 2023, 154, 105005. [Google Scholar] [CrossRef] [Scilit]
  19. Xu, Y.; Zhang, Y.; Deng, X.; Lee, S.Y.; Wang, K.; Li, L. Bibliometric analysis and literature review on sustainable aviation fuel (SAF): Economic and management perspective. Transp. Policy 2025, 162, 296–312. [Google Scholar] [CrossRef] [Scilit]
  20. Zhang, R.; Cao, J.; Wang, W.; Tan, E.; Zhu, R.; Chen, W.; Zhang, Y. Research on design strategies and sensing applications of energy storage system based on renewable methanol fuel. Results Eng. 2023, 20, 101439. [Google Scholar] [CrossRef] [Scilit]
  21. Li, Y.; Guan, B.; Guo, J.; Chen, Y.; Ma, Z.; Zhuang, Z.; Zhu, C.; Dang, H.; Chen, L.; Shu, K.; et al. Renewable synthetic fuels: Research progress and development trends. J. Clean. Prod. 2024, 450, 141849. [Google Scholar] [CrossRef] [Scilit]
  22. Cui, Q.; Jia, Z.; Li, Y. Path analysis of using hydrogen energy to reduce greenhouse gas emissions in global aviation. Cell Rep. Sustain. 2024, 1, 100133. [Google Scholar] [CrossRef] [Scilit]
  23. Cui, Q.; Chen, B. Cost-benefit analysis of using sustainable aviation fuels in South America. J. Clean. Prod. 2024, 435, 140556. [Google Scholar] [CrossRef] [Scilit]
  24. Aksoy, H.; Domene, M.G.; Loganathan, P.; Blakey, S.; Zea, E.; Vinuesa, R.; Otero, E. Case study on SAF emissions from air travel considering emissions modeling impact. Transp. Res. Interdiscip. Perspect. 2025, 29, 101341. [Google Scholar] [CrossRef] [Scilit]
  25. Wang, B.; Ting, Z.J.; Zhao, M. Sustainable aviation fuels: Key opportunities and challenges in lowering carbon emissions for aviation industry. Carbon Capture Sci. Technol. 2024, 13, 100263. [Google Scholar] [CrossRef] [Scilit]
  26. Bardon, P.; Massol, O.; Thomas, A. Greening aviation with sustainable aviation fuels: Insights from decarbonization scenarios. J. Environ. Manag. 2025, 374, 123943. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  27. Wei, M.; Jiang, Z.; Pandey, P.; Liu, M.; Li, R.; O’Neill, Z.; Dong, B.; Hamdy, M. Energy resilience in the built environment: A comprehensive review of concepts, metrics, and strategies. Renew. Sustain. Energy Rev. 2025, 210, 115258. [Google Scholar] [CrossRef] [Scilit]
  28. Zubi, G.; Kuhn, M.; Makridis, S.; Coutinho, S.; Dorasamy, S. Aviation sector decarbonization within the hydrogen economy—A UAE case study. Energy Policy 2025, 198, 114520. [Google Scholar] [CrossRef] [Scilit]
  29. European Commission. Reducing Emissions from Aviation—European Commission 2025. Available online: https://climate.ec.europa.eu/eu-action/transport/reducing-emissions-aviation_en (accessed on 1 April 2025).
  30. Ovaere, M.; Proost, S. Cost-effective reduction of fossil energy use in the European transport sector: An assessment of the Fit for 55 Package. Energy Policy 2022, 168, 113085. [Google Scholar] [CrossRef] [Scilit]
  31. Gnadt, A.R.; Speth, R.L.; Sabnis, J.S.; Barrett, S.R.H. Technical and environmental assessment of all-electric 180-passenger commercial aircraft. Prog. Aerosp. Sci. 2019, 105, 1–30. [Google Scholar] [CrossRef] [Scilit]
  32. Sgouridis, S.; Kimmich, C.; Solé, J.; Černý, M.; Ehlers, M.H.; Kerschner, C. Visions before models: The ethos of energy modeling in an era of transition. Energy Res. Soc. Sci. 2022, 88, 102497. [Google Scholar] [CrossRef] [Scilit]
  33. EASA SAF Market|EASA. 2025. Available online: https://www.easa.europa.eu/en/domains/environment/eaer/sustainable-aviation-fuels/saf-market#current-and-future-saf-production-capacity (accessed on 15 April 2025).
  34. Gupta, S.; Kumar, R.; Kumar, A. Green hydrogen in India: Prioritization of its potential and viable renewable source. Int. J. Hydrog. Energy 2024, 50, 226–238. [Google Scholar] [CrossRef] [Scilit]
  35. Watson, M.J.; Machado, P.G.; da Silva, A.V.; Saltar, Y.; Ribeiro, C.O.; Nascimento, C.A.O.; Dowling, A.W. Sustainable aviation fuel technologies, costs, emissions, policies, and markets: A critical review. J. Clean. Prod. 2024, 449, 141472. [Google Scholar] [CrossRef] [Scilit]
  36. IATA IATA—Sustainable Aviation Fuel (SAF). 2025. Available online: https://www.iata.org/en/programs/sustainability/sustainable-aviation-fuels/ (accessed on 8 April 2025).
  37. Okuneviciute Neverauskiene, L.; Klepone, D. Empirical evidence on the startup growth in the Baltic Region high tech land-scape. Transform. Bus. Econ. 2024, 23, 1164–1191. [Google Scholar]
  38. Nagralel, P. Global Sustainable Aviation Fuel Market Overview. 2025. Available online: https://www.marketresearchfuture.com/reports/sustainable-aviation-fuel-market-11965?utm_term=&utm_campaign=&utm_source=adwords&utm_medium=ppc&hsa_acc=2893753364&hsa_cam=20817078453&hsa_grp=156383738099&hsa_ad=683078494771&hsa_src=g&hsa_tgt=dsa-21894277868 (accessed on 14 April 2025).
  39. Bazienė, K.; Gargasas, J. Sustainable innovative technology solutions for the energy sector. Entrep. Sustain. Issues 2023, 11, 215–226. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  40. Igielski, M. Project management in the renewable energy sources industry in Poland—Identification of conditions and barriers. Entrep. Sustain. Issues 2023, 10, 135–151. [Google Scholar] [CrossRef] [Scilit]
  41. Zhong, W.; Zhai, D.; Xu, W.; Gong, W.; Yan, C.; Zhang, Y.; Qi, L. Accurate and efficient daily carbon emission forecasting based on improved ARIMA. Appl. Energy 2024, 376, 124232. [Google Scholar] [CrossRef] [Scilit]
  42. Al-lami, A.; Török, Á. Regional forecasting of driving forces of CO2 emissions of transportation in Central Europe: An ARIMA-based approach. Energy Rep. 2025, 13, 1215–1224. [Google Scholar] [CrossRef] [Scilit]
  43. İnan, T.T. Post-Covid air transport recovery: A multidimensional analysis of European airports under eurocontrol. Case Stud. Transp. Policy 2025, 20, 101444. [Google Scholar] [CrossRef] [Scilit]
  44. Boonen, T.J.; Chen, Y. VAR Model with Sparse Group LASSO for Multi-population Mortality Forecasting. Int. J. Forecast. 2025, 42, 259–280. [Google Scholar] [CrossRef] [Scilit]
  45. Akyuz, E.; Tezer, T. Techno-economic feasibility and regression analysis of green hydrogen production from solar and wind energy in Türkiye. Int. J. Hydrog. Energy 2025, 142, 1184–1195. [Google Scholar] [CrossRef] [Scilit]
  46. Singh, R.; Umrao, R.K.; Ahmad, M.; Ansari, M.K.; Sharma, L.K.; Singh, T.N. Prediction of geomechanical parameters using soft computing and multiple regression approach. Measurement 2017, 99, 108–119. [Google Scholar] [CrossRef] [Scilit]
  47. Pan American Finance. Global Sustainable Aviation Fuel Report. 2025. Available online: https://panamericanfinance.com/insights/energy-transition/global-saf-report-2024/regional-markets-overview-saf24/france-saf24/ (accessed on 15 April 2025).
  48. Pan American Finance. Germany SAF24|Pan American Finance. 2025. Available online: https://panamericanfinance.com/insights/energy-transition/global-saf-report-2024/regional-markets-overview-saf24/germany-saf24/ (accessed on 15 April 2025).
  49. International Trade Administration. Germany Sustainable Aviation Industry. 2024. Available online: https://www.trade.gov/market-intelligence/germany-sustainable-aviation-industry (accessed on 15 April 2025).
  50. Pan American Finance. Denmark SAF24|Pan American Finance. 2025. Available online: https://panamericanfinance.com/insights/energy-transition/global-saf-report-2024/regional-markets-overview-saf24/denmark-saf24/ (accessed on 15 April 2025).
  51. Pan American Finance. Spain SAF24|Pan American Finance. 2025. Available online: https://panamericanfinance.com/insights/energy-transition/global-saf-report-2024/regional-markets-overview-saf24/spain-saf24/ (accessed on 15 April 2025).
  52. Italian Civil Aviation Authority. A Roadmap for Sustainable Aviation Fuels in Italy. Enac Path for the Definition of SAF Policy; ENAC: Roma, Italy, 2024. [Google Scholar]
  53. Pan American Finance. Italy SAF24|Pan American Finance. 2025. Available online: https://panamericanfinance.com/insights/energy-transition/global-saf-report-2024/regional-markets-overview-saf24/italy-saf24/ (accessed on 16 April 2025).
  54. Raman, R.; Sreenivasan, A.; Kulkarni, N.V.; Suresh, M.; Nedungadi, P. Analyzing the contributions of biofuels, biomass, and bioenergy to sustainable development goals. iScience 2025, 28, 112157. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  55. McCausland, R. ReFuelEU Aviation Handbook; IATA: Montreal, QC, Canada, 2024. [Google Scholar]
  56. Dobruszkes, F.; Decroly, J.M.; Suau-Sanchez, P. The monthly rhythms of aviation: A global analysis of passenger air service seasonality. Transp. Res. Interdiscip. Perspect. 2022, 14, 100582. [Google Scholar] [CrossRef] [Scilit]
  57. Eurostat. [avia_paoc] Air Passenger Transport by Type of Schedule, Transport Coverage and Country. 2025. Available online: https://ec.europa.eu/eurostat/databrowser/view/avia_paoc__custom_16310774/default/table?lang=en (accessed on 18 April 2025).
  58. Eurostat. [avia_tf_acc] Aircraft Traffic Data by Reporting Country. 2025. Available online: https://ec.europa.eu/eurostat/databrowser/view/avia_tf_acc__custom_16297747/default/table?lang=en (accessed on 18 April 2025).
  59. Midilli, A.; Aluç, A.E.; Şengüler, F.; Köse, A. Sustainable aviation fuel production. Ref. Modul. Earth Syst. Environ. Sci. 2025, 6, 660–689. [Google Scholar] [CrossRef] [Scilit]
  60. Wei, M.; Xiong, Y.; Sun, B. Spatial effects of urban economic activities on airports’ passenger throughputs: A case study of thirteen cities and nine airports in the Beijing-Tianjin-Hebei region, China. J. Air Transp. Manag. 2025, 125, 102765. [Google Scholar] [CrossRef] [Scilit]
  61. World Bank Group. GDP (Current US$)—Spain, France, Italy, Denmark, Germany|Data. 2025.
  62. Cai, Y.; Zhang, Y.; Zhang, A. Oil price shocks and airlines stock return and volatility—A GFEVD analysis. Econ. Transp. 2025, 41, 100396. [Google Scholar] [CrossRef] [Scilit]
  63. Liang, Y.Y.; Shahabuddin, M.; Ahmed, S.F.; Tan, J.X.; Ali, S.M. Optimizing sustainable aviation fuel supply chains: Challenges, mitigation strategies and modeling advances. Fuel 2025, 402, 135972. [Google Scholar] [CrossRef] [Scilit]
  64. Churikanova, O.; Pilova, D.; Giordano, B.; Piccinetti, L.; Amoruso, M. Circular economy and smart specialisation business strategies: The Dnipropetrovsk region case. Insights Into Reg. Dev. 2025, 7, 109–130. [Google Scholar] [CrossRef] [Scilit]
Figure 1. Biofuel Installed Capacity in France (MW) [47]. Source: Authors’ elaboration.
Sustainability 18 00127 g001
Figure 2. Biofuel Installed Capacity in Germany (MW) [48]. Source: Authors’ elaboration.
Sustainability 18 00127 g002
Figure 3. Biofuel Installed Capacity in Denmark (MW) (Pan American Finance, 2025a). Source: Authors’ elaboration.
Sustainability 18 00127 g003
Figure 4. Biofuel Installed Capacity in Spain (MW) [51]. Source: Authors’ elaboration.
Sustainability 18 00127 g004
Figure 5. Biofuel Installed Capacity in Italy (MW) [53]. Source: Authors’ elaboration.
Sustainability 18 00127 g005
Figure 6. The minimum percentage obligation for fuel suppliers [55]. Source: Authors’ elaboration.
Sustainability 18 00127 g006
Figure 7. Passenger traffic during the period from 2015 to 2024 [57]. Source: Authors’ elaboration.
Sustainability 18 00127 g007
Figure 8. Number of flights during the period from 2015 to 2024 [58]. Source: Authors’ elaboration.
Sustainability 18 00127 g008
Figure 9. GDP of states in 2023 (USD) [61]. Source: Authors’ elaboration.
Sustainability 18 00127 g009
Figure 10. ARIMA projections of biofuel infrastructure development. Source: Authors’ elaboration.
Sustainability 18 00127 g010
Figure 11. VAR projections of biofuel infrastructure development. Source: Authors’ elaboration.
Sustainability 18 00127 g011
Table 1. The main stages of the research process.
1. Identification of the problem and definition of the context.
Objective: to define the research problem and indicate the need to assess the economic and political aspects of SAF in selected EU countries.
2. Literature review.
Objective: to review existing research on SAF, regulatory frameworks, and economic flexibility.
3. Data collection and preparation.
Objective: to collect secondary data.
4. Econometric modeling.
Objective: to apply ARIMA and VAR models for forecasting SAF infrastructure trajectories and regression analysis for determining economic relationships.
5. Results interpretation and discussion.
Objective: Interpret model outcomes in the context of EU policy frameworks and economic literature.
6. Conclusions and policy recommendations.
Objective: to summarize conclusions, identify limitations, and suggest directions for future research.
Source: Authors’ elaboration.
Table 2. Statistical Summary of the Regression Model Explaining SAF Infrastructure Development.
MetricValuep-ValueInterpretation
Multiple R0.969Very strong positive correlation between the independent and dependent variables
R20.939 (93.99%)Model explains 93.99% of the variation in biofuel infrastructure capacity
Adjusted R20.904Adjusted for number of predictors—still shows very good explanatory power
Standard Error162.95 MWTypical deviation of observed values from the model’s predictions
F-statistic26.06Model is significant (F > 1 and low p for overall fit)
Significance F (p)0.0018Since p < 0.05, the overall model fit is statistically significant
Intercept (constant)1638.34 MW0.607Not statistically significant (p > 0.05); intercept could be omitted in a refined model
Source: Authors’ elaboration.
Table 3. Effects of Key Factors on SAF Infrastructure Development.
PredictorCoefficientp-ValueInterpretation
Passenger Numbers5.80589 × 10−6 MW0.135Each additional passenger adds ~0.0000058 MW; not statistically significant (p > 0.05)
Flight Counts–0.001149 MW0.071Each additional flight reduces capacity by ~0.001149 MW; marginal effect, not fully significant
GDP (trillion units)1341.24 MW0.011Each extra trillion in GDP adds ~1341 MW; statistically significant (p < 0.05), strongest effect
Source: Authors’ elaboration.
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content.