
Article

Comparative Analysis of Second- and Fourth-Order Runge–Kutta Methods for Solving Chaotic Dynamical Systems

Department of Mathematical and Computational Sciences, University of Venda, Private Bag X5050, Thohoyandou 0950, South Africa
AppliedMath 2026, 6(7), 112; https://doi.org/10.3390/appliedmath6070112
Submission received: 28 May 2026 / Revised: 1 July 2026 / Accepted: 2 July 2026 / Published: 14 July 2026

Abstract

This study presents a comparative numerical investigation of second-order and fourth-order Runge–Kutta methods for solving chaotic dynamical systems. The Lorenz, Genesio–Tesi, and Rössler systems are considered because of their nonlinear behavior and high sensitivity to initial conditions. The numerical schemes investigated include the Midpoint, Improved Euler, Ralston, and fourth-order Runge–Kutta (RK4) methods. The performance of the methods is evaluated in terms of convergence behavior, numerical accuracy, stability characteristics, and computational cost. A stability analysis of each chaotic system is carried out through equilibrium point determination and Jacobian eigenvalue analysis. Numerical simulations are implemented in MATLAB 2023 version, and comparisons are performed using different step sizes. The results indicate that all numerical methods converge as the step size decreases; however, the RK4 method consistently provides significantly smaller errors and improved stability properties compared with the second-order schemes. The findings further demonstrate that higher-order numerical integration methods provide superior performance for highly sensitive chaotic systems where accuracy and reliability are essential.

1. Introduction

The study focuses on investigating the efficiency and effectiveness of solving the Lorenz, Genesio–Tesi and Rössler systems of equations by using the Midpoint, Improved Euler’s, Ralson methods and Runge–Kutta method of order four. The Lorenz equations is a system of ordinary differential equations that were first studied by a mathematician and meteorologist Edward Lorenz. This system is used to model the unpredictable behavior of weather. They represent the convective motion of a fluid cell that is warmed from below and cooled from above [1]. The Genesio–Tesi system is a system of ordinary differential equations which were implemented by Roberto Genesio and Alberto Tesi in 1992 as an electronic circuit. They are made of three-dimensional differential equations, with one of them being quadratic. The Rössler system is a system of three nonlinear ordinary differential equations that were studied by Otto Rössler in the 1970s [2]. The ordinary differential equations in the system define a continuous-time dynamical system that exhibits chaotic dynamics associated with fractal properties of the system.
The chaotic system of equations will be solved using the numerical methods, which are mathematical tools that are designed to solve numerical problems in the study of numerical analysis. In numerical analysis, these numerical methods attempt to find approximate solutions of problems than exact solutions [3,4,5,6,7,8,9,10]. In theory, a numerical method begins with an initial point and then moves forward in time to find the next solution point. The procedure is repeated in order to map out the solution. To determine the current value, single-step methods refer to only one previous point and its derivative. Runge–Kutta methods, for example, take some intermediate steps to obtain a higher-order method but then discard all previous information before proceeding to the next step, which is contrary to the Multi-step methods that improve efficiency by retaining and using information from previous steps rather than discarding it. In this project, the selected numerical methods, the fourth-order Runge–Kutta and second-order Runge–Kutta methods, are used to solve the mathematical problems that are chaotic in nature in order to investigate the accuracy and efficiency of the methods.
The Runge–Kutta methods were developed around the 1990s by two German mathematicians, Carl Runge and Wilhelm Kutta [11]. They are a family of implicit and explicit iterative single-step methods including Euler’s method. Runge–Kutta methods are effective and widely used family of numerical methods for solving the initial-value problems of differential equations. The primary disadvantage of these methods is that they require significantly more computational time than multi-step methods, whereas their main advantages are that they are easy to implement and stable [12,13,14,15]. We have single-step methods, such as the Euler, Heun’s, Midpoint and the Ralston methods, which are used to find approximate solutions of Initial Value Problems (IVPs). The main advantage of these other single-step methods is that they are simple and direct. They mostly require fewer evaluations at a point than the Runge–Kutta methods, which require more than just one evaluation at a point to obtain a solution. These methods require less computational time than the Runge–Kutta methods. Although this is the case, the Runge–Kutta methods are more stable than these other single-step methods. For instance, Euler’s methods are conditionally stable. They are only stable when the step size is significantly small [16].
The theory of chaos dates back to 1963, when it was first reported by Lorenz for a system of ordinary differential equations modeling weather phenomena [17]. Since then, a large number of chaotic phenomena and chaotic behavior have been observed and reported in a wide range of systems, including electrical circuits, lasers, fluid dynamics, mechanical devices, population growth, and many other scientific applications [18]. Chaos theory is a study of random or unpredictable behavior in systems [19]. Such behavior is mostly studied in natural systems, such as the weather, biological and physical processes, and electromagnetic processes. Chaos theory states that a system is chaotic if ordered regular patterns can be seen to arise out of random, under certain conditions [20,21,22,23,24].
The selected chaotic systems are considered to be highly sensitive to their initial conditions; that is, a small change in their initial conditions results in a significant change in the solution. This motivates the investigation and applicability of the second and fourth-orders Runge. This study presents a novel comparisons of solutions obtained by the Midpoint, improved Eulers, Ralston and Runge–Kutta methods of order four when solving the Lorenz, Genesio–Tesi and Rössler systems of chaotic equations.
The existing literature contains numerous studies on numerical approximations of chaotic systems using Runge–Kutta methods. However, limited studies provide a systematic comparison of multiple second-order Runge–Kutta variants against the fourth-order Runge–Kutta method across different chaotic systems while simultaneously assessing convergence properties, stability characteristics, and computational efficiency. This study addresses this gap through a unified comparative framework using the Lorenz, Genesio–Tesi, and Rössler systems. Specifically, the manuscript highlights that, unlike many previous studies focusing on a single chaotic system or one numerical method, this work presents a unified comparative investigation of multiple second-order Runge–Kutta variants, and the classical RK4 method across three benchmark chaotic systems while simultaneously analyzing convergence behavior, stability characteristics, numerical accuracy, and computational efficiency within the same computational framework.
Section 2 presents the problems addressed in this study. Section 3 outlines the theoretical results. Section 4 provides the stability analysis of the chaotic systems, while Section 5 describes the numerical solution procedure. Section 6 presents and discusses the numerical results, and Section 7 concludes the study.

2. Problem Formulation

The problems of interest in this research are the Lorenz, Genesio–Tesi, and Rössler chaotic systems. In this chapter, a stability analysis of these systems is performed using the Lyapunov stability analysis in the first approximation [25]. The second- and fourth-order Runge–Kutta methods are derived and applied to the problems.

3. Theoretical Results

3.1. Theorem 1: Existence and Uniqueness of Solution [26]

Theorem 1.
Consider the initial value problem,
d y d t = f ( t , y ) , y ( t 0 ) = y 0 ,
where ( f ( t , y ) ) is continuous in a region,
R = ( t , y ) : | t t 0 | a , | y y 0 | b ,
and satisfies a Lipschitz condition in (y), that is,
| f ( t , y 1 ) f ( t , y 2 ) | L | y 1 y 2 | ,
for some positive constant, ( L ) .
Then, there exists a unique solution ( y ( t ) ) of the initial value problem in some interval containing ( t 0 ) .
Proof. 
The proof follows directly from the Picard–Lindelöf theorem. Since ( f ) is continuous and satisfies the Lipschitz condition, successive approximations generated through Picard iteration converge uniformly to a unique solution.    □

3.2. Theorem 2: Consistency of the Runge–Kutta Methods

Theorem 2.
The Midpoint, Improved Euler, Ralston, and RK4 methods are consistent numerical methods.
Proof. 
A numerical method is consistent if its local truncation error satisfies
lim h 0 τ ( h ) h = 0 .
For RK2 methods, τ ( h ) = O ( h 3 ) , while for RK4, τ ( h ) = O ( h 5 ) . Thus,
lim h 0 τ ( h ) = 0 ,
showing that the methods are consistent.    □

3.3. Theorem 3: Order of Accuracy of RK2 and RK4

Theorem 3.
The Midpoint, Improved Euler, and Ralston methods possess second-order accuracy, while RK4 possesses fourth-order accuracy.
Proof. 
Expanding the exact solution using Taylor series gives
y ( t + h ) = y ( t ) + h y + h 2 2 y + h 3 6 y +
Comparing the Taylor expansion with the RK2 approximations shows agreement through terms of order O ( h 2 ) , producing local truncation error O ( h 3 ) and global error O ( h 2 ) . Similarly, RK4 matches terms up to O ( h 4 ) , resulting in O ( h 5 ) local truncation error and O ( h 4 ) global error. Hence, the RK2 methods are second-order accurate, and RK4 is fourth-order accurate.    □

3.4. Theorem 4: Convergence of the Runge–Kutta Methods

Theorem 4.
If a numerical method is both consistent and stable, then it is convergent.
Proof. 
By the Lax Equivalence principle,
Consistency + Stability Convergence .
Since the considered Runge–Kutta methods are consistent and stable for sufficiently small step sizes, they are convergent.    □

3.5. Theorem 5: Global Error Bound

Theorem 5.
Assume that (f(t,y)) satisfies the Lipschitz condition with a constant (L). Then, the global error satisfies
| y ( t n ) y n | e L ( t n t 0 ) 1 L τ ( h ) ,
where ( τ ( h ) ) denotes the local truncation error.
Proof. 
Using Gronwall’s inequality together with the local truncation error estimate gives the stated bound.    □

4. Chaotic Systems and Stability Analysis

4.1. Lorenz System

Edward Lorenz derived the system [27], given by the following system of ordinary differential equations
d u d t = a 1 ( v u ) , d v d t = u s + a 2 u v , d s d t = u v a 3 s ,
where a 1 , a 2 , and a 3 are greater than zero. These Equations, (1) were derived by Lorenz to model a two-dimensional fluid cell between two parallel plates at different temperatures [28]. In this project, we study the case where a 1 = 10 , a 2 = 28 , and a 3 = 8 3 with initial conditions u ( 0 ) = 1 , v ( 0 ) = 5 , and s ( 0 ) = 10 , which is the case study that Lorenz conducted [29].

Stability Analysis of the Lorenz System

Given the Lorenz system (1), we set d u d t = 0 , d v d t = 0 , and d s d t = 0 to determine the equilibrium points of the system [30]. In setting the Lorenz system equations to zero, we obtain the following equations:
a 1 ( v u ) = 0 ,
u s + a 2 u v = 0 ,
u v a 3 s = 0 .
Solving Equations (2), (3) and (4) simultaneously, we learn that
v = u .
From Equation (5) v = u , using this in Equation (3), we obtain the following:
s = a 2 1 .
From Equation (6), we learn that u = 0 . Using this in Equation (5) gives the following:
v = u = 0 .
By substituting v = 0 and u = 0 as determined in Equation (7) into Equation (4), we obtain the following:
s = 0 .
From Equations (7) and (8), we learn that the origin is one of the equilibrium points of the system, that is
x 1 = 0 0 0 .
By substituting Equation (6), s = a 2 1 , and Equation (5), v = u , into Equation (4), we obtain the following equation:
u 2 = a 3 a 2 1 , u = ± a 3 a 2 1 .
It follows from Equation (10) that, when s = a 2 1 , u = ± a 3 a 2 1 , and from Equation (5), v = u = ± a 3 a 2 1 . From this, we learn that the Lorenz system has two more equilibrium points, which are
x 2 = a 3 a 2 1 a 3 a 2 1 a 2 1 ,
and
x 3 = a 3 a 2 1 a 3 a 2 1 a 2 1 .
By substituting the parameters a 1 = 10 , a 2 = 28 , and a 3 = 8 3 , the equilibrium points of the system are
x 1 = 0 0 0 ,
x 2 = 6 2 6 2 27 ,
x 3 = 6 2 6 2 27 .
To analyze the stability of the system, a Jacobian matrix [30] of the form J ( x ) = f ( x ) x is constructed, where
f 1 ( t , u , v , s ) = a 1 ( v u ) ,
f 2 ( t , u , v , s ) = u s + a 2 u v ,
f 3 ( t , u , v , s ) = u v a 3 s .
such that
J ( x ) = f 1 u f 1 v f 1 s f 2 u f 2 v f 2 s f 3 u f 3 v f 3 s ,
is the Jacobian matrix corresponding to the system.
By finding the first partial derivatives of Equations (14)–(16) with respect to u, v and s, and substituting them into the Jacobian matrix (17), we obtain the following Jacobian matrix:
J ( x ) = a 1 a 1 0 s + a 2 1 u v u a 3 .
Using the given parameters of a 1 , a 2 and a 3 for the Lorenz system (1), the Jacobian matrix becomes
J ( x ) = 10 10 0 s + 28 1 u v u 8 3 .
To draw conclusions about the stability of the system, the eigenvalues of the Jacobian matrix (19) are determined with respect to each equilibrium point [30], that is
det J ( x ) λ I = 0 .
For the equilibrium point x 1 ( 11 )
J ( x 1 ) = 10 10 0 28 1 0 0 0 8 3 ,
det J ( x 1 ) λ I = 0 , λ + 8 3 λ 2 + 11 λ 270 = 0 .
By solving Equation (21), we learn that the eigenvalues are
λ 1 = 8 3 ,
λ 2 = 1201 11 2 ,
λ 3 = 1201 11 2 .
λ 3 is greater than zero; this implies that the equilibrium point x 1 is unstable.
Subsequently, the same procedure is followed to determine the eigenvalues for the other equilibrium points, x 2 and x 3 .
For the equilibrium point x 2 (12), we obtain the following Jacobian matrix and eigenvalues.
J ( x 2 ) = 10 10 0 1 1 6 2 6 2 6 2 8 3 ,
det J ( x 2 ) λ I = 0 , 10 λ 10 0 , 1 1 λ 6 2 , 6 2 6 2 8 3 λ = 0 , λ 3 41 3 λ 2 304 3 λ 1440 = 0 .
Solving Equation (25) using a numerical root-finding method for the cubic characteristic polynomial, we find the following eigenvalues:
λ 1 = 13.8546 ,
λ 2 = 0.09396 + 10.1945 i ,
λ 3 = 0.09396 10.1945 i .
The real parts of λ 2 and λ 3 are all greater than zero; this suggests that x 2 is an unstable equilibrium point.
For the equilibrium point x 3 (13), we obtain
J ( x 3 ) = 10 10 0 1 1 6 2 6 2 6 2 8 3 ,
det J ( x 3 ) λ I = 0 , λ 3 41 3 λ 2 304 3 λ 1440 = 0 ,
Solving Equation (29) using a numerical root-finding method for the cubic characteristic polynomial, we find the following eigenvalues:
λ 1 = 13.8546 ,
λ 2 = 0.09396 + 10.1945 i ,
λ 3 = 0.09396 10.1945 i .
The real parts of λ 2 and λ 3 are all greater than zero; this suggests that x 3 is an unstable equilibrium point.
For the given values of the parameters of a 1 , a 2 and a 3 , none of the equilibrium points of the Lorenz system are stable. This implies that the system is unstable at all its equilibrium points.
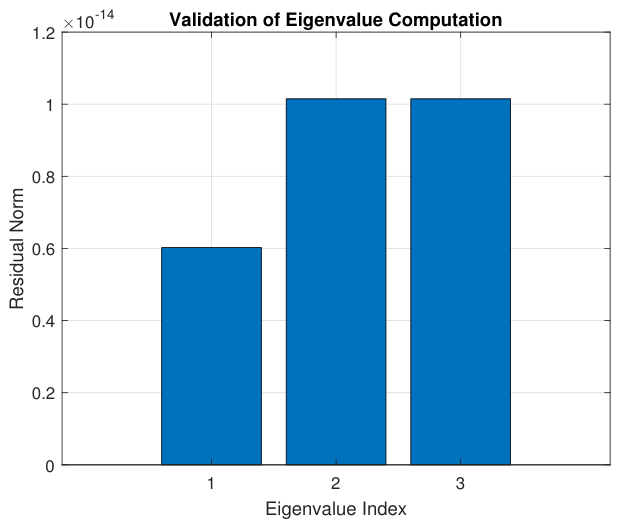
The residual norms of all the computed eigenvalues are of order 10 14 , which show that the eigenvalue computations are highly accurate and numerically stable.

4.2. Genesio–Tesi System

This system was proposed by Roberto Genesio and Alberto Tesi [31]. It is given by the following differential equations:
d u d t = v , d v d t = s , d s d t = a 1 s + a 2 v + a 3 u + u 2 ,
with the parameters a 1 = 1.2 , a 2 = 2.92 , and a 3 = 6 with initial conditions u ( 0 ) = 0.2 , v ( 0 ) = 0.3 and s ( 0 ) = 0.1 . It is said that the three ordinary differential equations of this system depend on real negative parameters of a 1 , a 2 , and a 3 [32].

Stability Analysis of the Genesio–Tesi System

Given the Genesio–Tesi System (33), we set d u d t = 0 , d v d t = 0 , and d s d t = 0 to determine the equilibrium points of the system. This leads to the following equations:
v = 0 ,
s = 0 ,
a 1 s + a 2 v + a 3 u + u 2 = 0 .
We learn from Equations (34) and (35) that v = 0 and s = 0; using this in Equation (36), we obtain
u = a 3 .
From Equations (36) and (37), it follows that the system (33) has two equilibrium points, which are
x 1 = 0 0 0 ,
x 2 = 0 0 a 3 ,
For the stated parameters of a 1 , a 2 , and a 3 of the system (33), we learn that the equilibrium point (39) is
x 2 = 0 0 6 ,
By setting
f 1 ( t , u , v , s ) = v ,
f 2 ( t , u , v , s ) = s ,
f 3 ( t , u , v , s ) = a 1 s + a 2 v + a 3 u + u 2 ,
and finding the first partial derivatives with respect to u, v, s of Equations (41)–(43) to construct a Jacobian matrix (17) corresponding to the system, we obtain
J ( x ) = 0 1 0 0 0 1 a 3 + 2 u a 2 a 1 .
For the chosen parameters of a 1 = 1.2 , a 2 = 2.92 , and a 3 = 6 for the system (33), the Jacobian matrix (44) becomes
J ( x ) = 0 1 0 0 0 1 6 + 2 u 2.92 1.2 .
The eigenvalues of the Jacobian matrix (45) with respect to the equilibrium point (38) are given by
det ( J ( x 1 ) λ I ) = 0 ,
which leads to the following equation.
λ 1 0 0 λ 1 6 2.92 1.2 λ = 0 , λ 3 1.2 λ 2 2.92 λ 6 = 0 .
Solving Equation (46) using a numerical root-finding method for the cubic characteristic polynomial, we find the following eigenvalues
λ 1 = 0.22197 + 1.8975 i ,
λ 2 = 0.22197 1.8975 i ,
λ 3 = 1.64393 .
The real parts of λ 1 and λ 2 are both greater than zero; this means that the equilibrium point x 1 (38) is unstable.
The eigenvalues corresponding to the Jacobian matrix (45) with respect to the equilibrium point x 2 (40) are given by
det ( J ( x 2 ) λ I ) = 0 .
Determining the eigenvalues from Equation (50), we obtain
λ 1 0 0 λ 1 6 2.92 1.2 λ = 0 , λ 3 1.2 λ 2 2.92 λ + 6 = 0 .
Solving Equation (51) using a numerical root-finding method for the cubic characteristic polynomial, we find the following eigenvalues:
λ 1 = 1.15027 + 2.03193 i ,
λ 2 = 1.15027 2.03193 i ,
λ 3 = 1.10054 .
We learn that λ 3 is greater than zero; this implies that the equilibrium point x 2 of the system is also unstable.
The Genesio–Tesi system (33) is unstable at both of its equilibrium points. This means that, for the stated parameters of a 1 , a 2 and a 3 , the system is unstable.
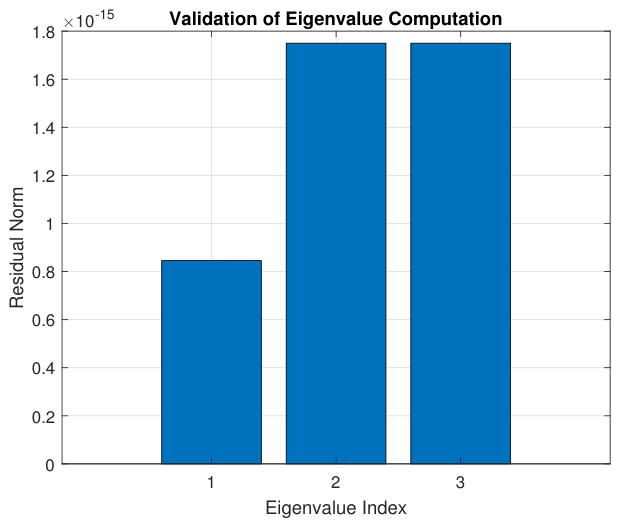
The residual norms of all the computed eigenvalues are of order 10 15 , which show that the eigenvalue computations are highly accurate and numerically stable.

4.3. Rössler System

The system was studied by Otto Rössler [2]. It is represented by the following set of ordinary differential equations:
d u d t = ( v + s ) , d v d t = u + a 1 v , d s d t = a 2 + u s a 3 s ,
where the parameters a 1 , a 2 , and a 3 are greater than zero. The system (55) defines a continuous-time dynamical system that exhibits chaotic dynamics with the fractal properties of the attractor for selected values of a 1 , a 2 and a 3 [33]. Rössler observed chaotic behavior when conducting the study [34] with a 1 = 0.2 , a 2 = 0.2 , and a 3 = 5.7 subject to the initial conditions u ( 0 ) = 0 , v ( 0 ) = 0 , and s ( 0 ) = 0 .

Stability Analysis of the Rössler System

Given the Rössler system (55), by setting d u d t = 0 , d v d t = 0 , and d s d t = 0 to find the equilibrium points of the system, we obtain the following equations:
( v + s ) = 0 ,
u + a 1 v = 0 ,
a 2 + u s a 3 s = 0 .
Solving the Equations (56)–(58) simultaneously, we find that
v = s .
from Equation (56).
By substituting v = s from Equation (59) into Equation (57), we obtain
u = a 1 s .
From Equation (60) u = a 1 s , using this in Equation (58), it follows that
a 1 s 2 a 3 s + a 2 = 0 , s = a 3 ± a 3 2 4 a 1 a 2 2 a 1 ,
By substituting s = a 3 ± a 3 2 4 a 1 a 2 2 a 1 from Equation (61) into Equation (60) and (61), we obtain
u = a 1 a 3 ± a 3 2 4 a 1 a 2 2 a 1 .
v = a 3 ± a 3 2 4 a 1 a 2 2 a 1 .
Equations (61)–(63) suggest that the system has two equilibrium points, which are
x 1 = a 1 a 3 + a 3 2 4 a 1 a 2 2 a 1 a 3 + a 3 2 4 a 1 a 2 2 a 1 a 3 + a 3 2 4 a 1 a 2 2 a 1 .
x 2 = a 1 a 3 a 3 2 4 a 1 a 2 2 a 1 a 3 a 3 2 4 a 1 a 2 2 a 1 a 3 a 3 2 4 a 1 a 2 2 a 1 .
For the stated parameters of a 1 , a 2 , and a 3 of the system (55), the equilibrium points x 1 (64) and x 2 (65) of the system are
x 1 = 5.69297 28.46487 28.46487 .
x 2 = 0.00703 0.03513 0.03513 .
By letting
f 1 ( t , u , v , s ) = ( v + s ) ,
f 2 ( t , u , v , s ) = u + a 1 v ,
f 3 ( t , u , v , s ) = a 2 + u s a 3 s ,
and finding the first partial derivatives of (68)–(70) with respect to u , v , s to construct a Jacobian matrix, (17), corresponding to the system, we obtain
J ( x ) = 0 1 1 1 0.2 0 s 0 u 5.7 .
The eigenvalues of the Jacobian matrix with respect to the equilibrium point x 1 (66) are determined by evaluating
det J ( x 1 ) λ I = 0 .
Evaluating Equation (72) gives
λ 1 1 1 0.2 λ 0 28.46487 0 0.00703 λ = 0 , λ 3 + 0.19297 λ 2 29.4635 λ + 5.6894 = 0 .
Solving Equation (73) using a numerical root-finding method for the cubic characteristic polynomial, we find the following eigenvalues
λ 1 = 6.42954 × 10 6 + 5.42803 i ,
λ 2 = 6.42954 × 10 6 5.42803 i ,
λ 3 = 0.19298 .
The real parts of λ 1 and λ 3 are greater than zero; this indicates that the equilibrium point x 1 is unstable.
The eigenvalues of the Jacobian matrix (71) with respect to the equilibrium point x 2 (67) are determined by evaluating
det J ( x 2 ) λ I = 0 .
Evaluating (77) gives
λ 1 1 1 0.2 λ 0 0.03513 0 5.69297 λ = 0 , λ 3 5.49297 λ 2 + 0.103464 λ + 5.68594 = 0 .
Solving Equation (78) using a numerical root-finding method for the cubic characteristic polynomial, we find the following eigenvalues
λ 1 = 5.68697 ,
λ 2 = 0.09700 + 0.99519 i ,
λ 3 = 0.09700 0.99519 i .
The real parts of λ 2 and λ 3 are greater than zero; this indicates that the equilibrium point x 2 is also unstable.
The Rössler system (55) is unstable at all its equilibrium points for the stated parameters of a 1 , a 2 , and a 3 .
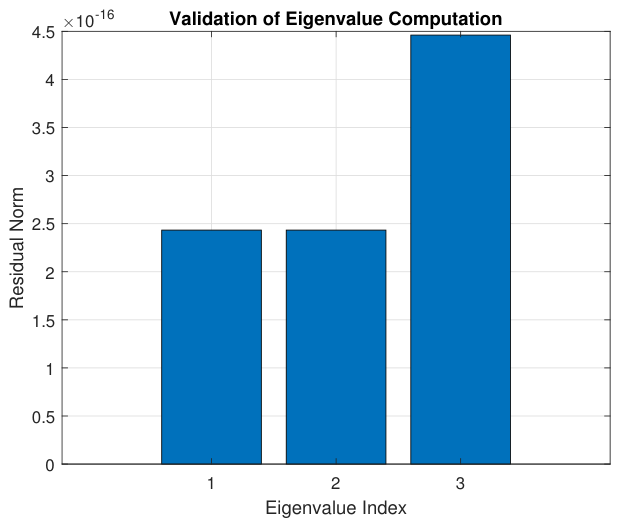
The residual norms of all the computed eigenvalues are of order 10 15 , which show that the eigenvalue computations are highly accurate and numerically stable.

4.4. Derivation of the Runge–Kutta Methods of Order Two and Four

The second-order Runge–Kutta method forms part of the family of explicit iterative Runge–Kutta methods. It is used to solve ordinary differential equations of the form d u d t = f ( t , u ) , given an initial condition, u ( a ) = α . It provides the approximate value of u for a given point, t. The classical RK4 method provides higher-order accuracy than the second-order Runge–Kutta methods, as its local truncation error is of order 2 (i.e., O ( h 2 ) ) and global truncation error is of order 1 (i.e., O ( h ) ) [35,36,37].
The general s-stage Runge–Kutta recurrence formula is
u n + 1 = u n + h i = 1 s a i k i ,
where the stage values k i are defined by
k i = f t n + p i h , u n + h j = 1 s q i j k j , i = 1 , 2 , , s .
The coefficients a i , q i j , and p i define the specific Runge–Kutta method.
u i + 1 = u i + h ( a 1 k 1 + a 2 k 2 ) ,
with
k 1 = f ( t i , u i ) , k 2 = f ( t i + p 1 h , u i + q 11 h k 1 ) .
The Taylor series expansion of u ( t i + h ) about t i is given as follows:
u ( t i + h ) = u ( t i ) + h u ( t i ) + h 2 2 u ( t i ) + h 3 3 ! u ( t i ) + O ( h 4 ) .
where
u = f ( t i , u i ) , u = f t + f u f .
By substituting Equation (87) into (86), we get the following
u ( t i + h ) = u ( t i ) + h f + h 2 2 f t + f u f + O ( h 3 ) .
By substituting Equation (85) into (84) with the use of Taylor expansion, we obtain the following equation:
u i + 1 = u i + h ( a 1 + a 2 ) f + h 2 2 ! a 2 ( p 1 f t + q 11 f u f ) .
By comparing the coefficients on Equations (88) and (89), the following system of equations is obtained:
a 1 + a 2 = 1 , p 1 a 2 = 1 2 , q 11 a 2 = 1 2 .
Since we have three equations and four unknowns, we can assume the value of one of the unknowns. The other three will then be determined from the three equations. Generally, the value of a 2 is chosen to evaluate the other three constants. The three values generally used for a 2 are 1 2 , 1 and 2 3 , and they are known as Heun’s Method, the midpoint method and Ralston’s method, respectively. The Improved Euler’s (Heun’s method) is given as follows:
u i + 1 = u i + h 2 k 1 + k 2 ,
where
k 1 = f ( t i , u i ) , k 2 = f ( t i + h , u i + h k 1 ) .
The Midpoint is given as follows:
y i + 1 = y i + h k 2 ,
where
k 1 = f ( t i , u i ) , k 2 = f t i + 1 2 h , u i + 1 2 h k 1 .
The Ralston’s method is given as follows:
u i + 1 = u i + h 1 3 k 1 + 2 3 k 2 ,
where
k 1 = f ( t i , u i ) , k 2 = f t i + 3 4 h , u i + 3 4 h k 1 .

4.5. Derivation of Runge–Kutta Method of Order Four

The fourth-order Runge–Kutta method forms part of the family of explicit iterative Runge–Kutta methods. It is used to solve ordinary differential equations of the form d u d x = f ( t , u ) , given an initial condition u ( a ) = α . It provides the approximate value of u for a given point, t. It is considered to be more effective than the other explicit Runge–Kutta methods, as its local truncation error is of order 5 (i.e., O ( h 5 ) ), and its global truncation error is of order 4 (i.e., O ( h 4 ) ) [35]. In general, the Runge–Kutta method of order is given by
u t + h = u t + h i = 1 s b i k i ,
where
k i = f t n + c i h , u n + h j = 1 s a i j k j , for i = 1 , . . , s & n = 0 , , N
where the fixed scalars a i j , b i and c i are the coefficients of the Runge–Kutta formula.
In order to derive the fourth-order Runge–Kutta method, we obtain the following recurrence equation for the fourth-order Runge–Kutta method from (97)
u i + 1 = u i + h ( a 1 k 1 + a 2 k 2 + a 3 k 3 + a 4 k 4 ) ,
where
k 1 = f t i , u i , k 2 = f t ( i ) + h 2 , u i + h 2 k 1 , k 3 = f t ( i ) + h 2 , u i + h 2 k 2 , k 4 = f t ( i ) + h , u i + h k 3 .
Therefore, by using the Taylor method to expand the terms (100) of the Runge–Kutta method (99), we obtain the following:
k 1 = f ( t , u ) , k 2 = f t + h 2 , u + h 2 , = f + 1 2 h f t , k 3 = f t + h 2 , u + h 2 , = f t + h 2 , u + h 2 f ( u + h 2 k 1 ) , = f + h 2 f t + h 2 f t t k 4 = f ( t + h , u + h k 3 ) , = f + h f t + 1 2 h 2 f t t + 1 4 h 3 f t t t .
Substituting (101) into Equation (99) gives the following equation:
u i + 1 = u i + h a 1 f + a 2 ( f + h 2 f t ) + a 3 f + h 2 ( f t + h 2 f t t ) + a 4 f + h f t + h 2 2 f t t + h 3 2 f t t t ) , = y i + h f a 1 + a 2 + a 3 + a 4 + h 2 1 2 a 3 f t + 1 2 a 3 f t + a f t + h 3 1 4 a 3 f t t t + 1 2 a 4 f t t + h 4 1 4 a 4 f t t .
Using the Taylor method to expand Equation (102) on the right gives
u i + 1 = u i + h y + h 2 2 ! u + h 3 3 ! u + h 4 4 ! u + O ( h 5 ) , = u i + h f + h 2 2 f t + f f u + h 3 6 f t t + 2 f f t u + f 2 f u u + f u f t + f ( f u ) 2 + h 4 24 f t t t + 3 f t u f t + 2 f t u .
Comparing the coefficients of Equation (103) and Equation (102), we obtain the following system of equations:
1 = a 1 + a 2 + a 3 + a 4 , 1 2 = 1 2 a 2 + 1 2 a 3 + a 4 , 1 6 = 1 4 a 3 + 1 4 a 4 , 1 24 = 1 4 a 4 .
Solving the above system of equations gives a 1 = 1 6 , a 2 = 1 3 , a 3 = 1 3 , and a 4 = 1 6 . It then follows that Equation (99), which is the Runge–Kutta method of order 4, is
u i + 1 = u i + h 6 ( k 1 + 2 k 2 + 2 k 3 + k 4 ) .

5. Algorithm Addition

Algorithm 1: Numerical Solution Procedure

Algorithm 1: Numerical Solution Procedure
1.
Define chaotic system parameters
2.
Specify initial conditions
3.
Select step size h
4.
Implement Midpoint method
5.
Implement Improved Euler method
6.
Implement Ralston method
7.
Implement RK4 method
8.
Compute numerical solutions
9.
Determine infinity norm errors
10.
Evaluate convergence rates
11.
Compute computational time
12.
Compare numerical results
13.
Plot trajectories and phase portraits

6. Results and Discussion

This section presents the comparative results of the numerical solutions obtained for Runge–Kutta methods of orders two and four. The comparisons focus on accuracy, error distribution, and the computational cost. The infinity norm is calculated using the formula L = max 0 n N | | y n y ( t n ) | | . MATLAB was used for the computations. The reference solution was generated using MATLAB’s adaptive solver ode45.
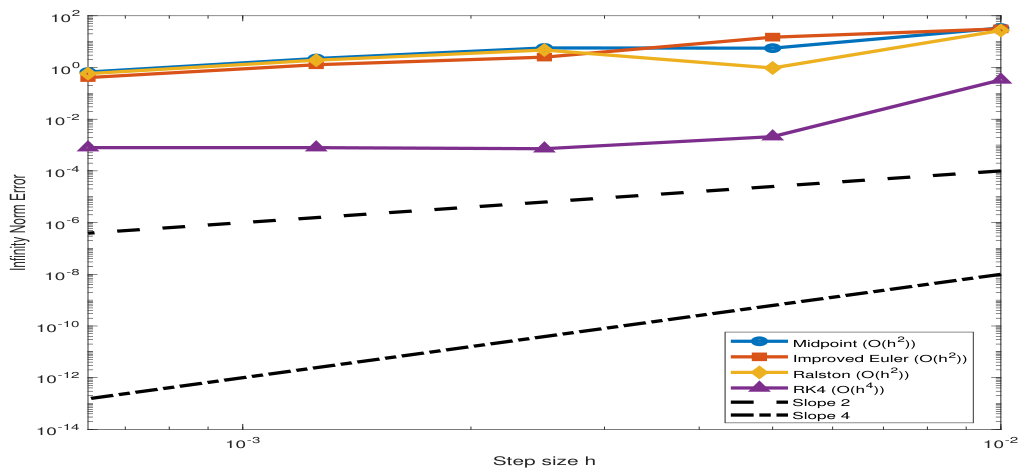
For the Lorenz system in Table 1, all second-order methods (Midpoint, Improved Euler, and Ralston) exhibit relatively large errors for coarse step sizes. As the step size decreases from h = 0.01000 to h = 0.00063 , the errors reduce significantly, confirming the convergence of the methods. Among the second-order schemes, the Improved Euler method initially produces slightly smaller errors than the Midpoint and Ralston methods, while the Ralston method shows competitive performance for smaller step sizes. However, the RK4 method clearly outperforms all second-order methods, producing errors several orders of magnitude smaller across all step sizes. For example, at h = 0.00500, RK4 attains an error of 2.12 × 10 3 , whereas the second-order methods still produce errors of order 10 0 to 10 1 . This behavior confirms the superior accuracy and stability of the fourth-order Runge–Kutta scheme for highly sensitive chaotic systems such as the Lorenz equations.
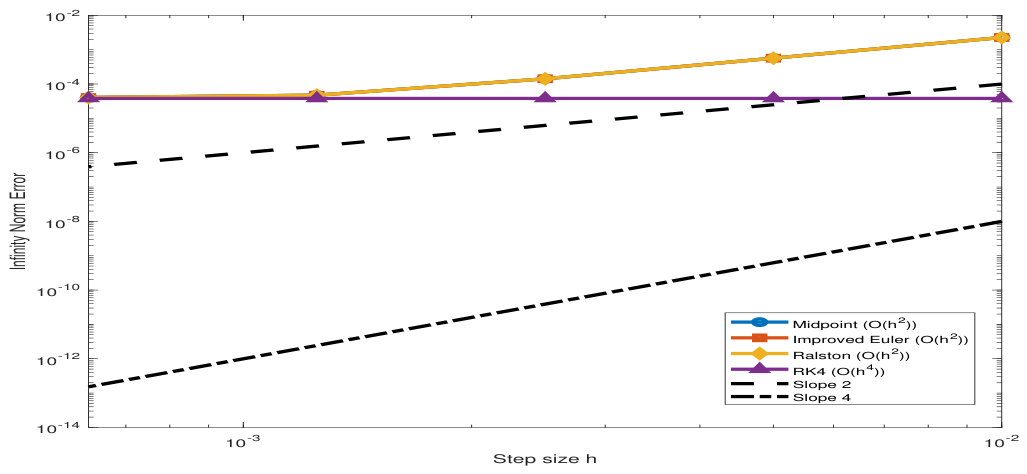
Table 2 presents the convergence results for the Genesio system. The Midpoint, Improved Euler, and Ralston methods display nearly identical error values for all step sizes, indicating that these second-order methods possess comparable numerical behavior for this problem. The errors decrease consistently as the step size is refined, which verifies the expected convergence property of the methods. The RK4 method again provides substantially smaller errors than the second-order methods. Interestingly, the RK4 error remains almost constant around 3.80 × 10 5 even as the step size decreases. This is due to the fact that, once the discretization error becomes sufficiently small, further reduction in the step size provides only marginal improvement because round-off errors, floating-point arithmetic, and the accuracy of the benchmark solution begin to dominate the total numerical error.
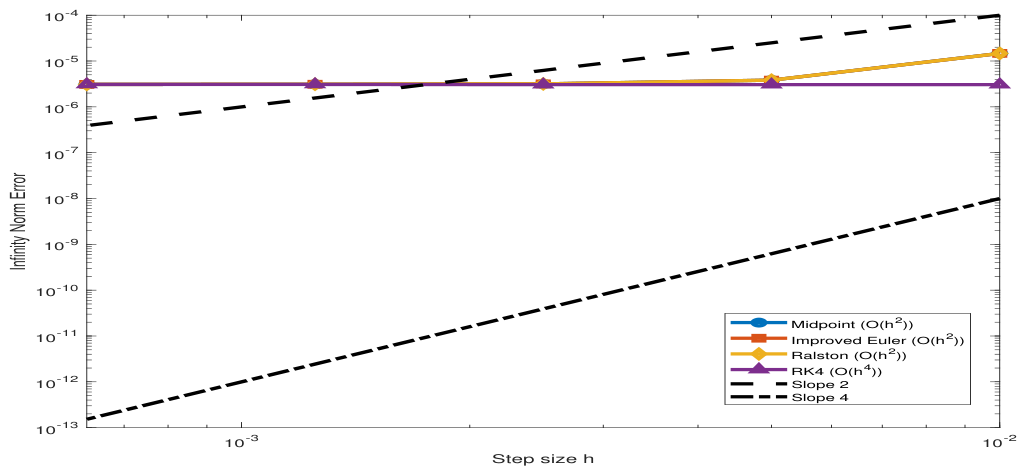
Similarly, the results for the Rössler system in Table 3 indicate strong convergence properties for all methods. The Midpoint, Improved Euler, and Ralston methods again produce identical numerical errors, with the error decreasing rapidly when the step size is reduced from 0.01000 to 0.00500 . However, beyond this point, the reduction becomes less pronounced, indicating that the solutions are approaching a limiting numerical accuracy. The RK4 method consistently achieves the smallest errors, approximately 3.05 × 10 6 , and remains highly stable for all step sizes considered. The near-constant RK4 error for smaller step sizes further demonstrates the robustness and efficiency of the fourth-order method for solving chaotic dynamical systems.
The numerical results presented in Table 1, Table 2 and Table 3 illustrate the convergence behavior of the Midpoint, Improved Euler, Ralston, and RK4 methods when applied to the Lorenz, Genesio, and Rössler chaotic systems. In general, the results demonstrate that decreasing the step size h improves the numerical accuracy of all methods, although the rate of improvement differs among the schemes and dynamical systems considered. The numerical experiments confirm that all methods converge as the step size decreases, but the RK4 method provides the highest accuracy and best stability characteristics among the methods investigated. The second-order methods are computationally simpler and still produce acceptable approximations for sufficiently small step sizes, but their errors remain significantly larger than those of RK4, particularly for strongly nonlinear and chaotic systems, such as the Lorenz model. These findings demonstrate the advantage of higher-order numerical integration techniques when solving sensitive dynamical systems where accuracy is critical.
The results presented in Table 4 illustrate that the computational results show that the performance of the numerical methods varies, depending on the chaotic system being solved. RK4 achieved the best computational efficiency for the Lorenz system, while the Ralston method performed best for the Genesio–Tesi system, and the Midpoint method was most efficient for the Rössler system. Although RK4 is a higher-order method, it did not consistently produce the lowest computational cost across all systems. Overall, the findings indicate that computational efficiency is problem-dependent, and lower-order methods can sometimes outperform higher-order methods for certain chaotic systems.
The infinity norm plots shown in Figure 1, Figure 2 and Figure 3 further validate the theoretical orders of convergence of the methods. The slopes corresponding to the second-order methods align closely with O ( h 2 ) , while the RK4 method follows the expected O ( h 4 ) convergence trend. This agreement between theoretical and numerical convergence confirms the correctness of the implementation of the methods.
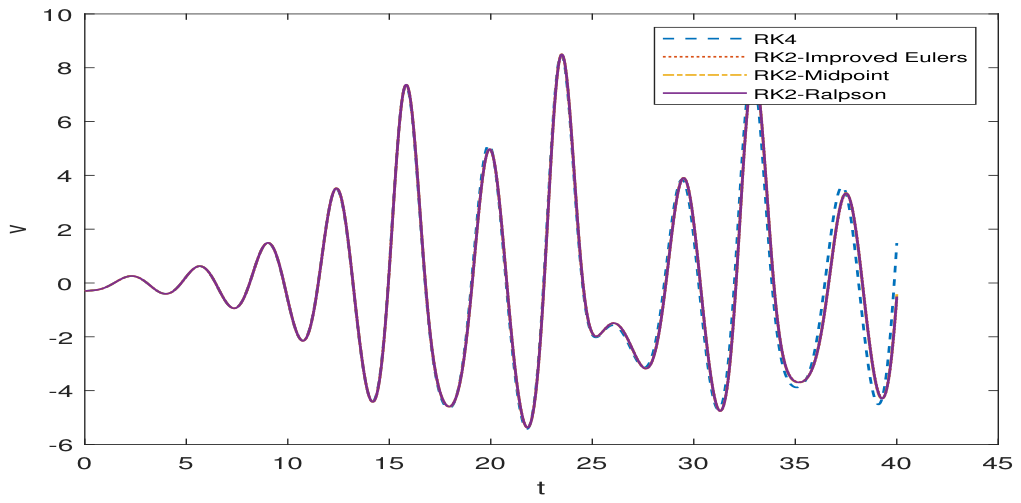
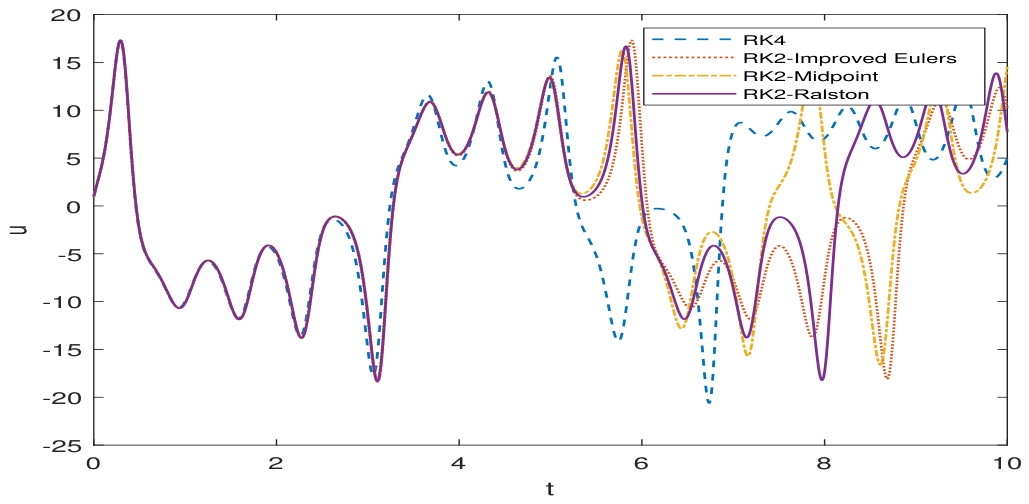
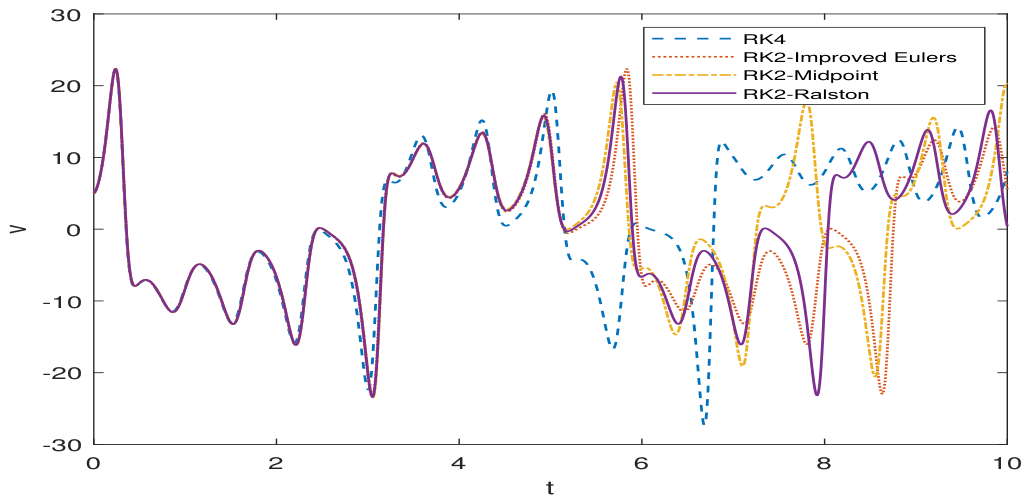
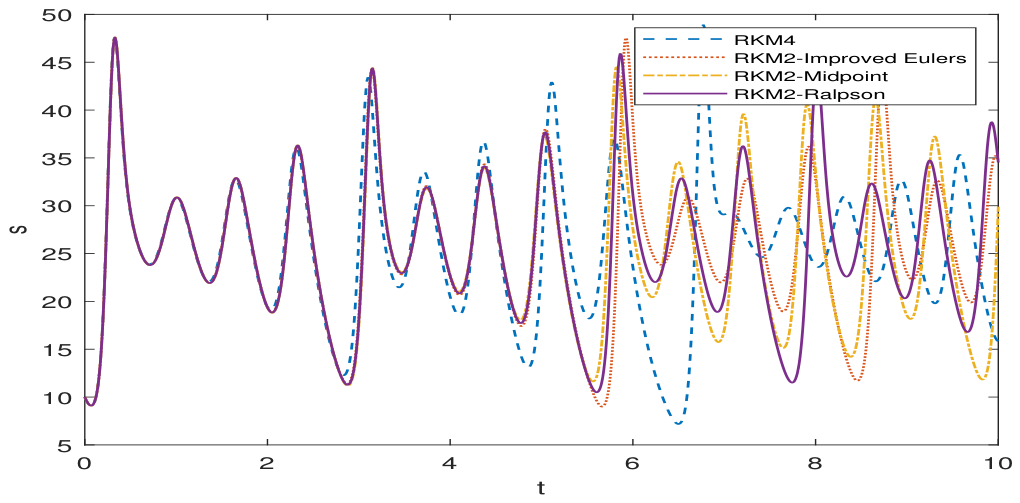
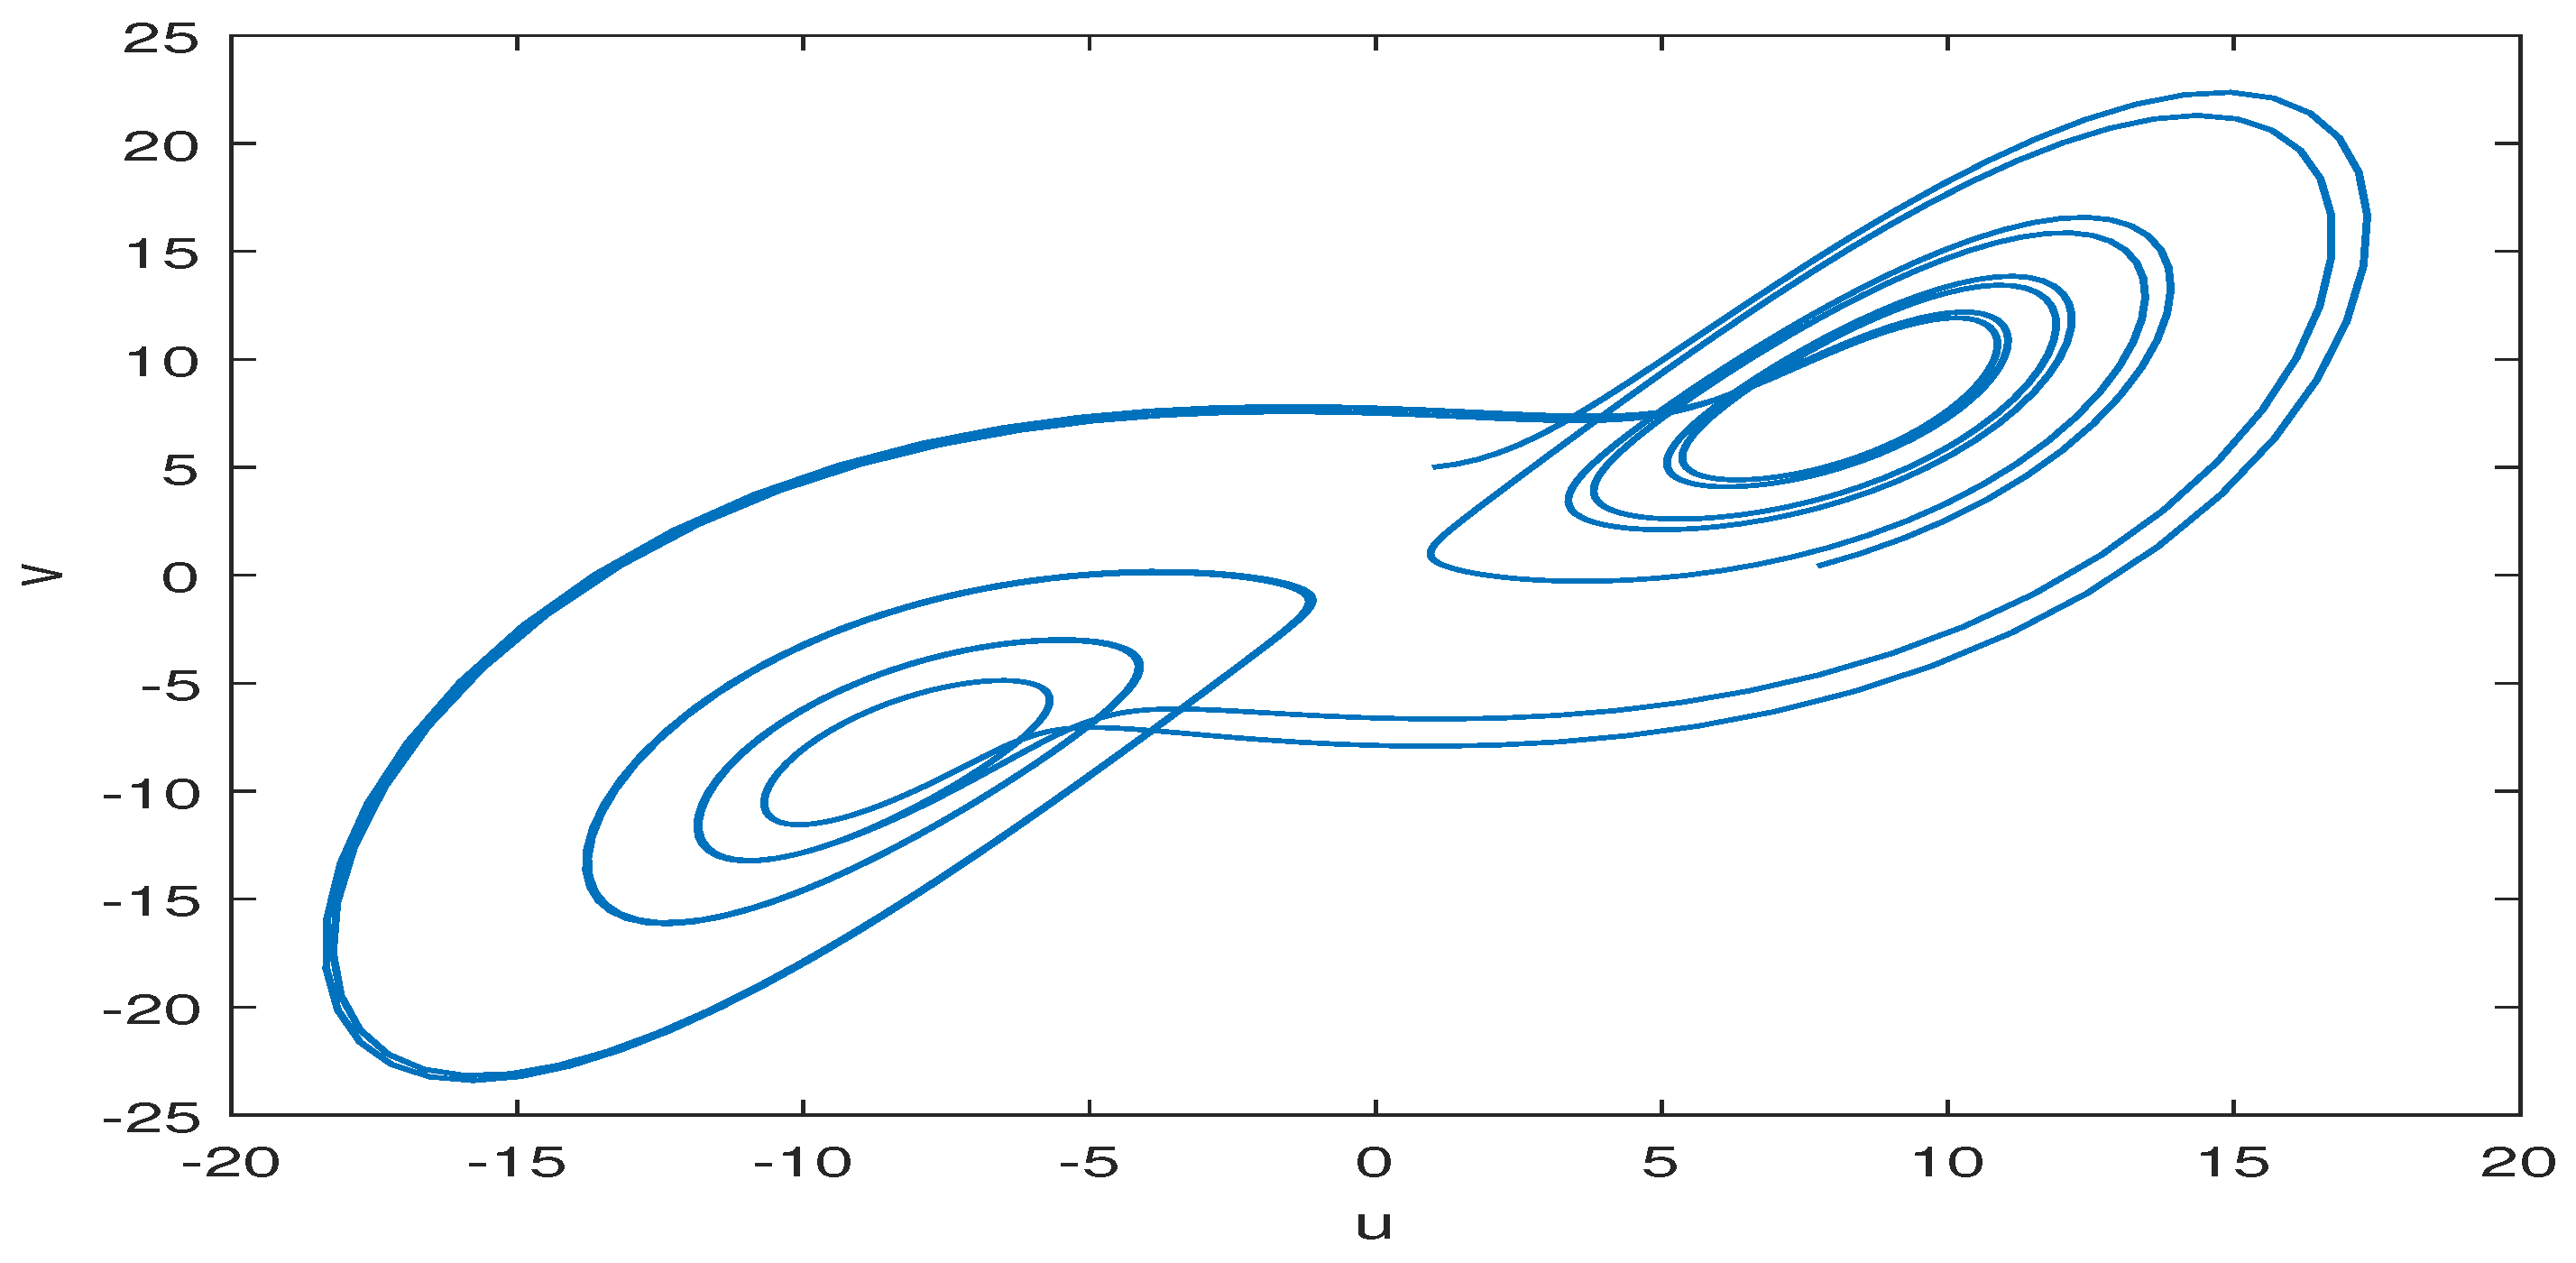
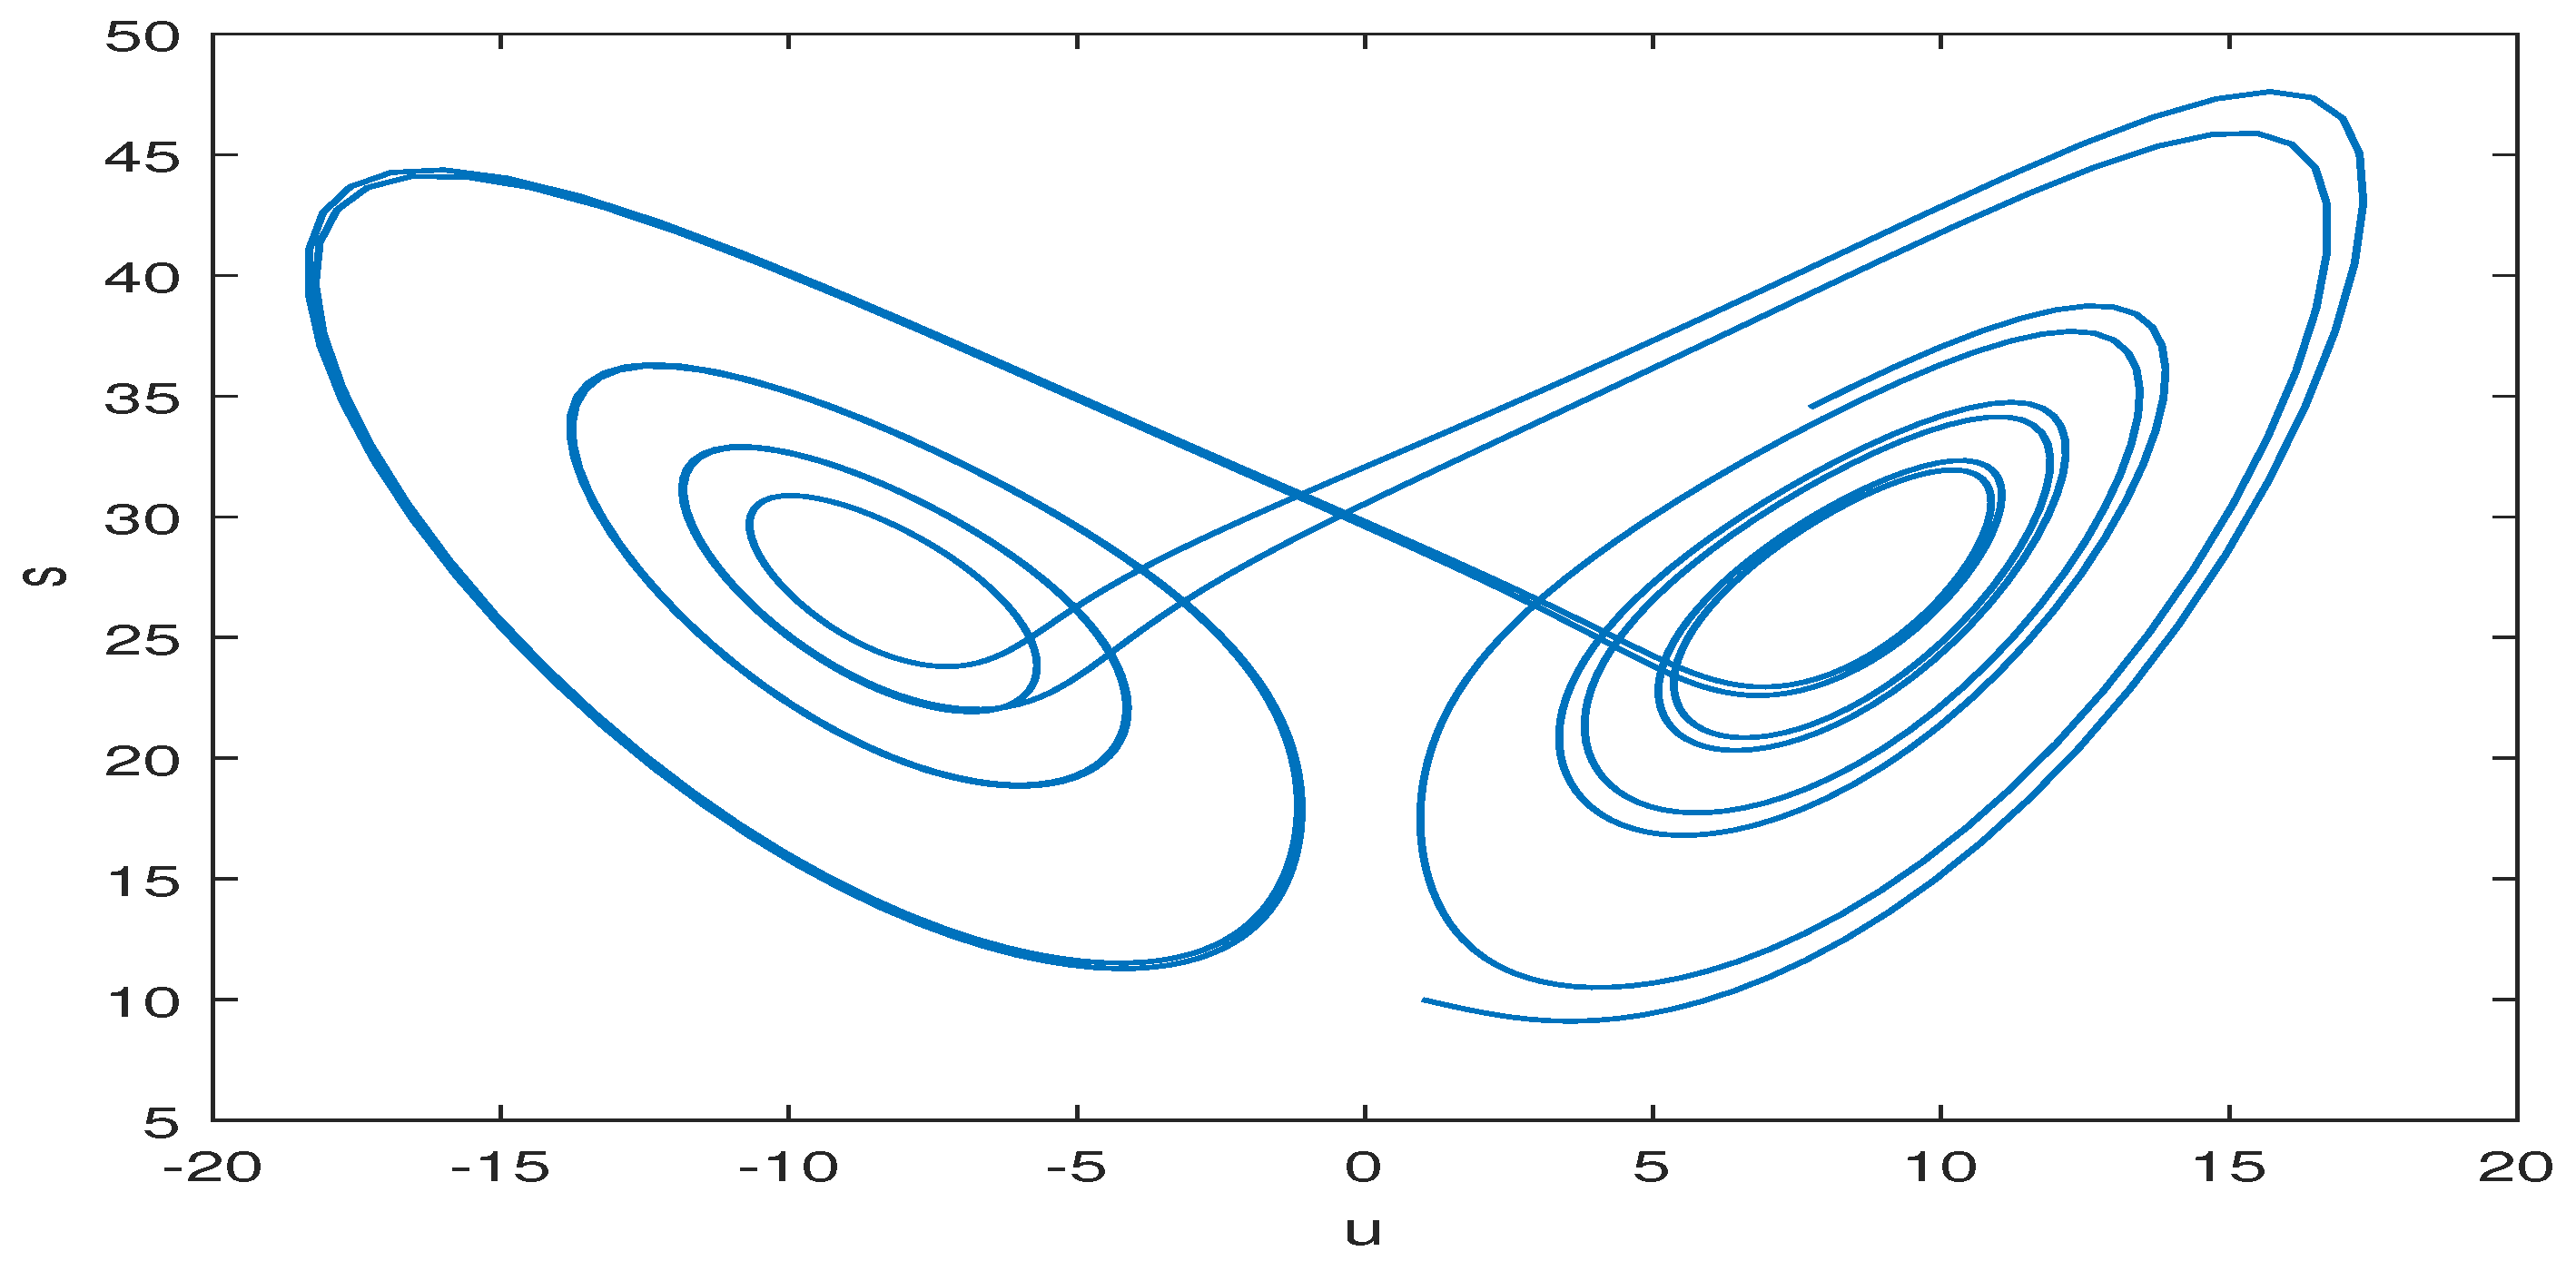
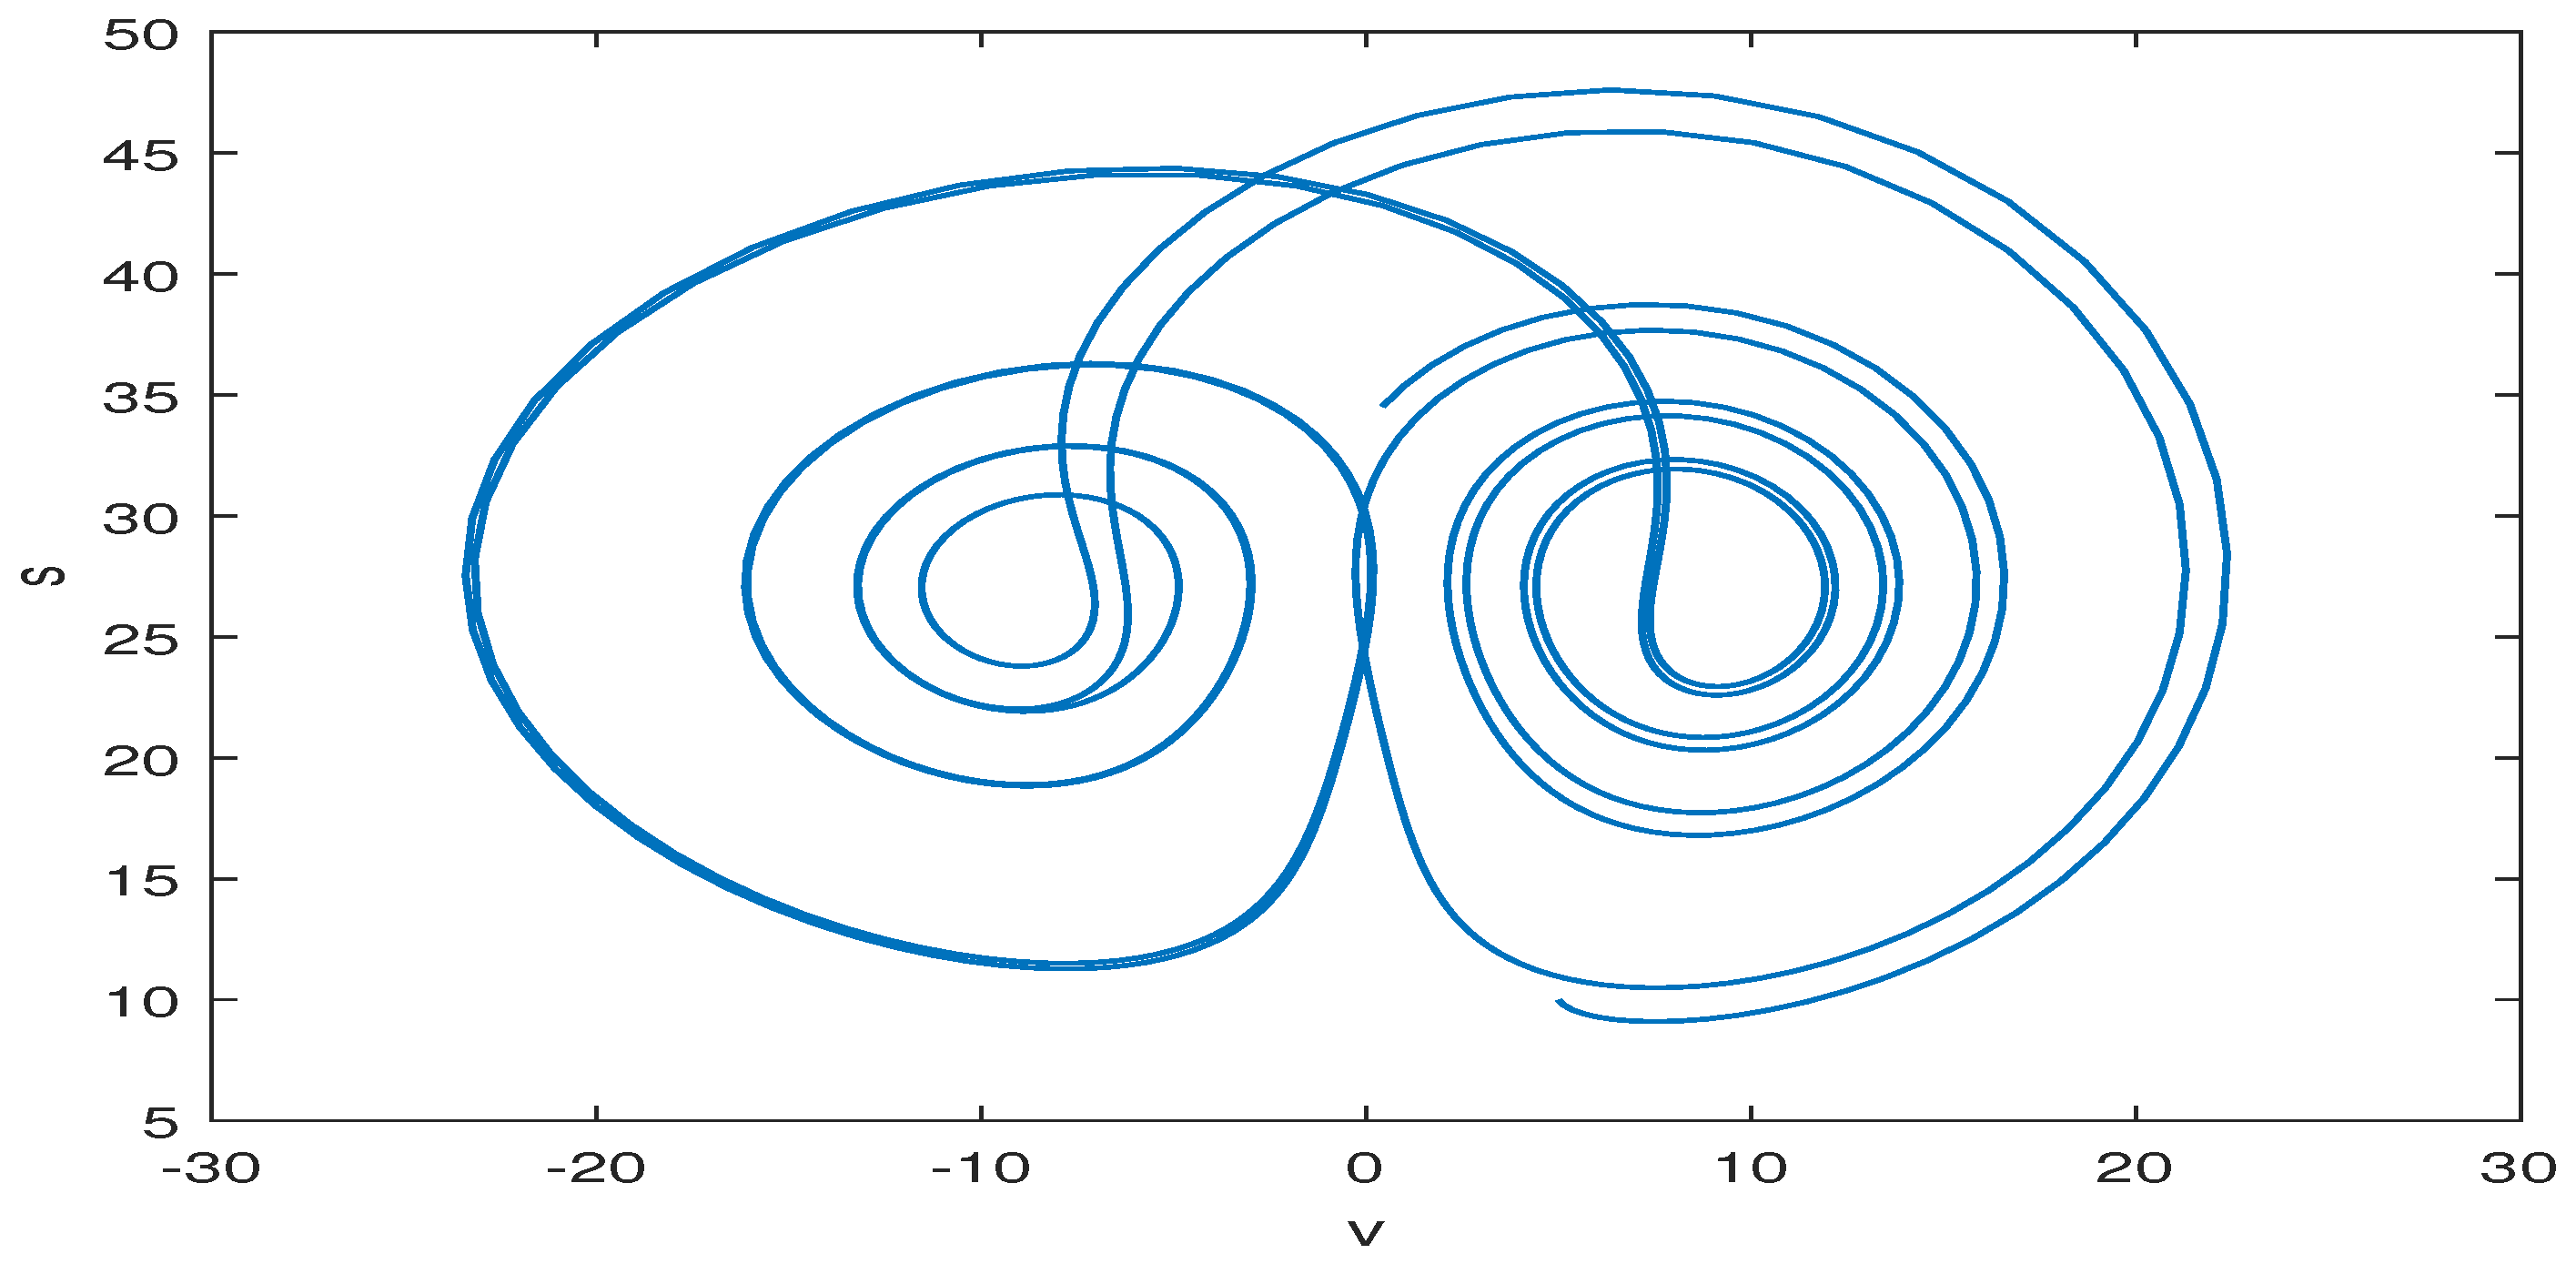
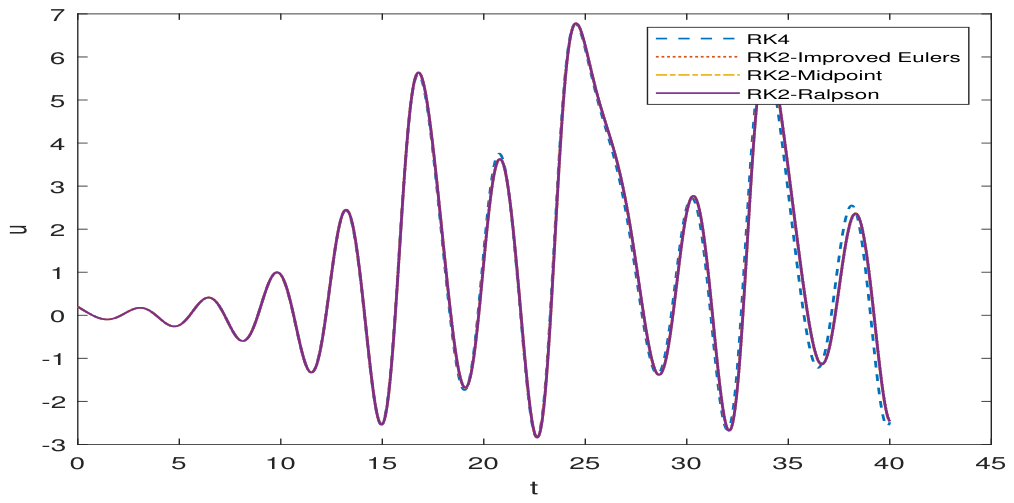
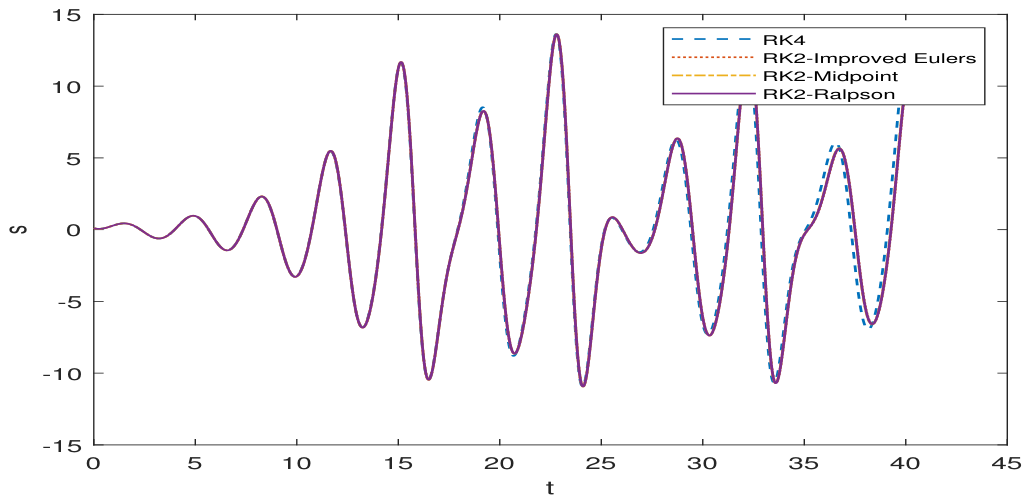
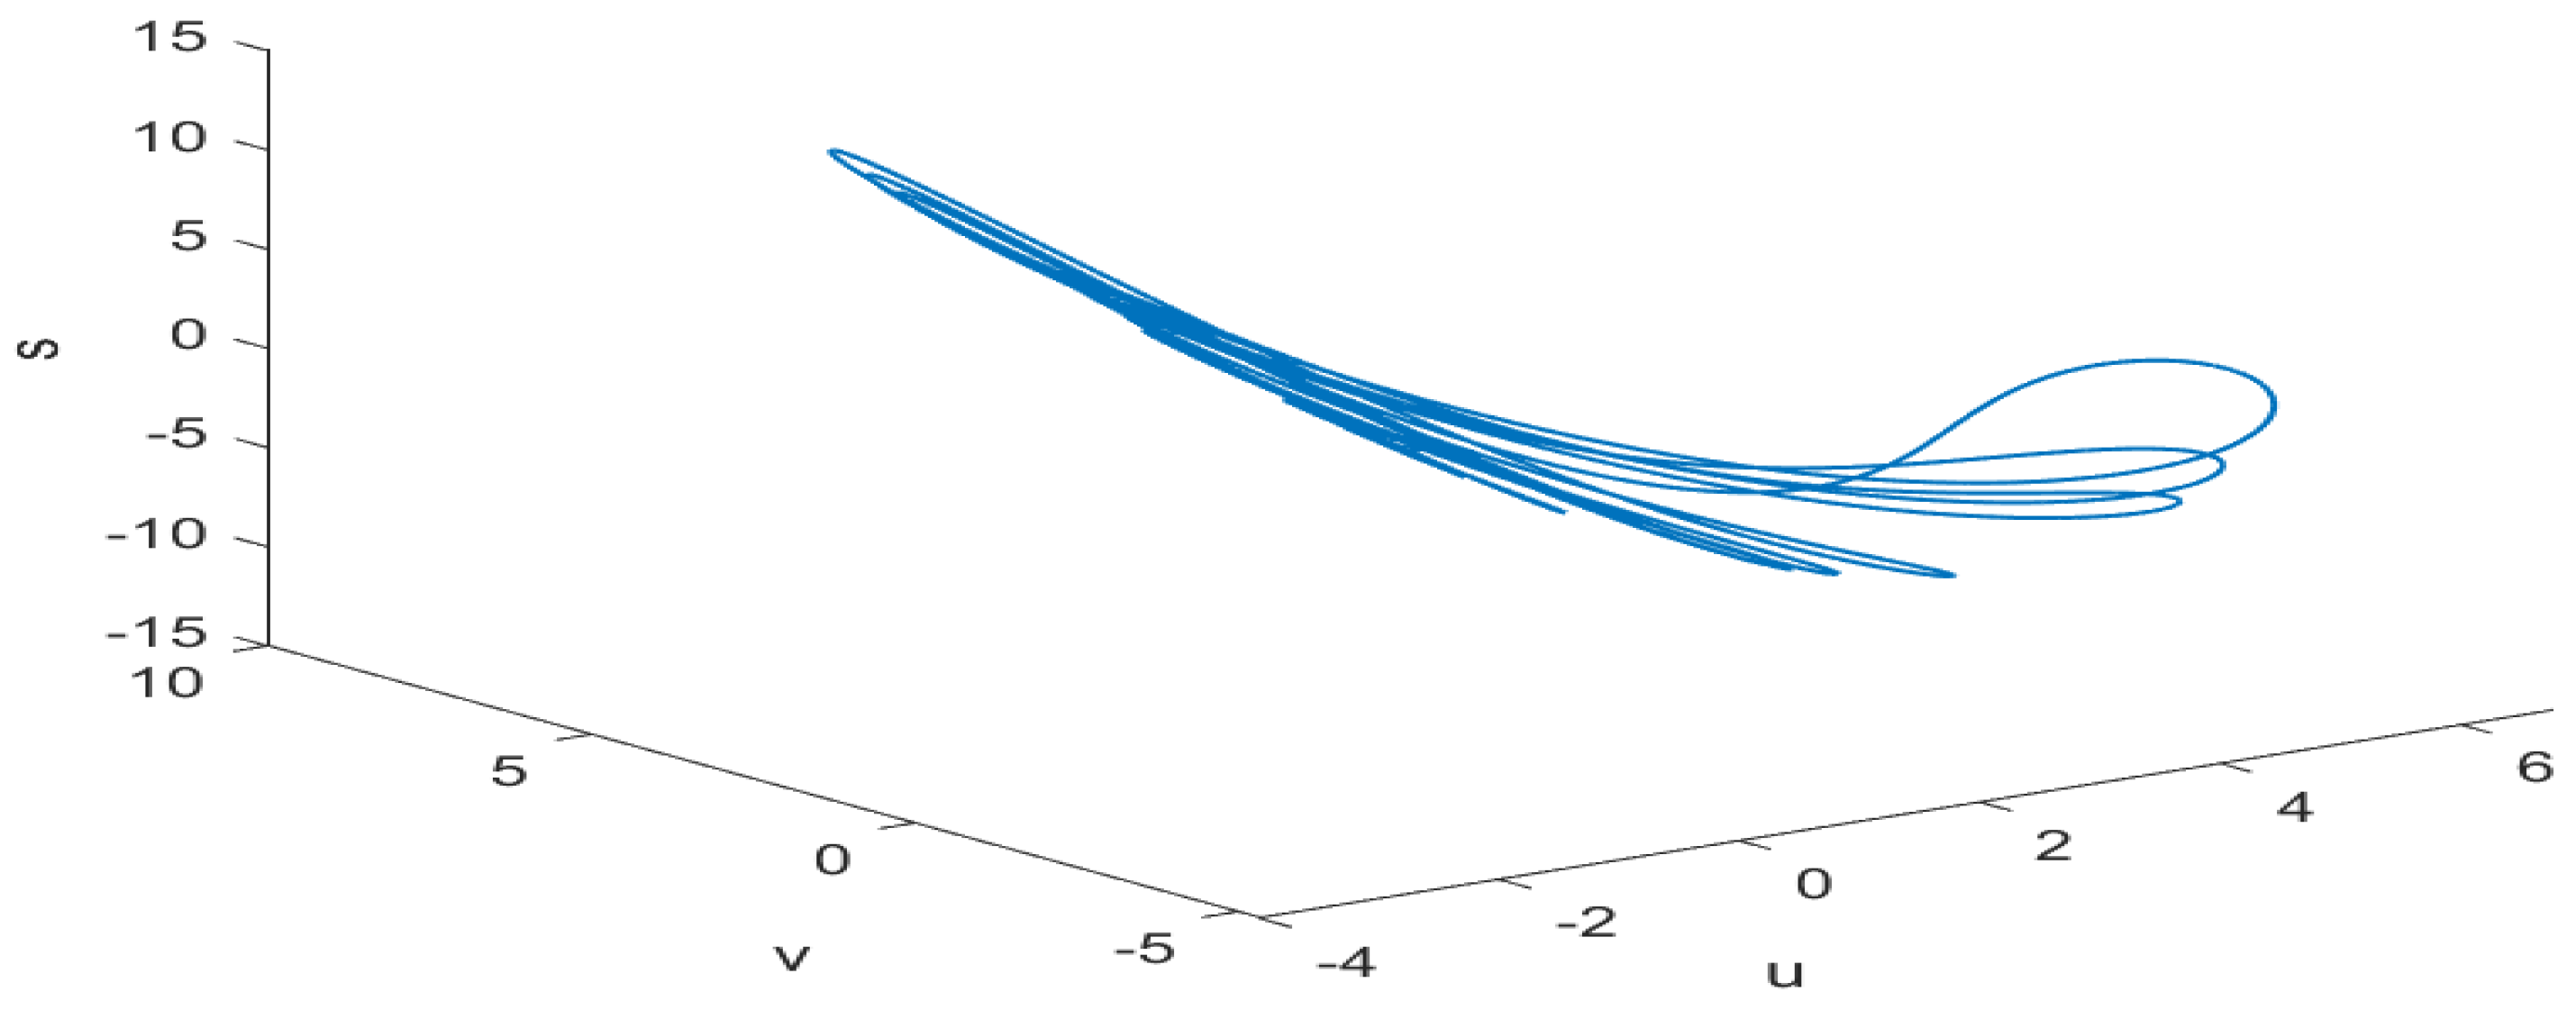
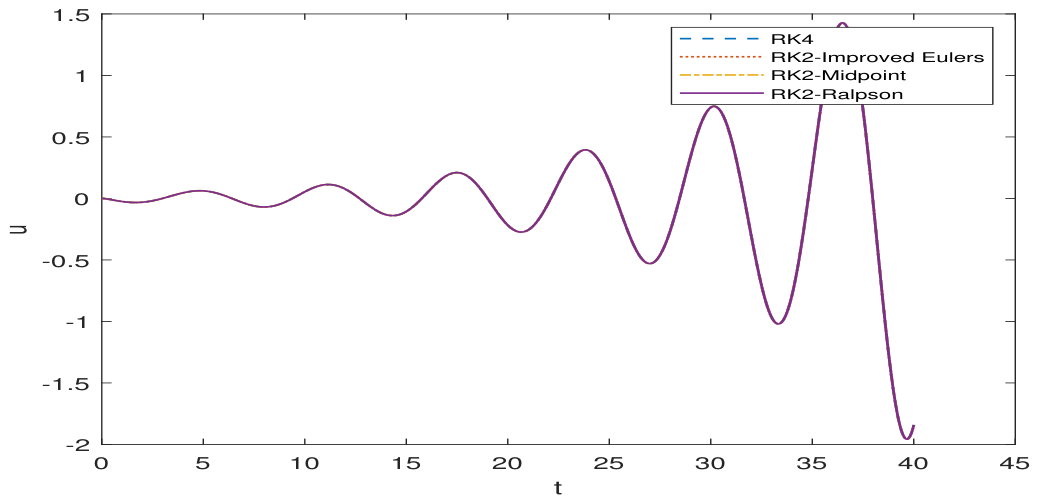
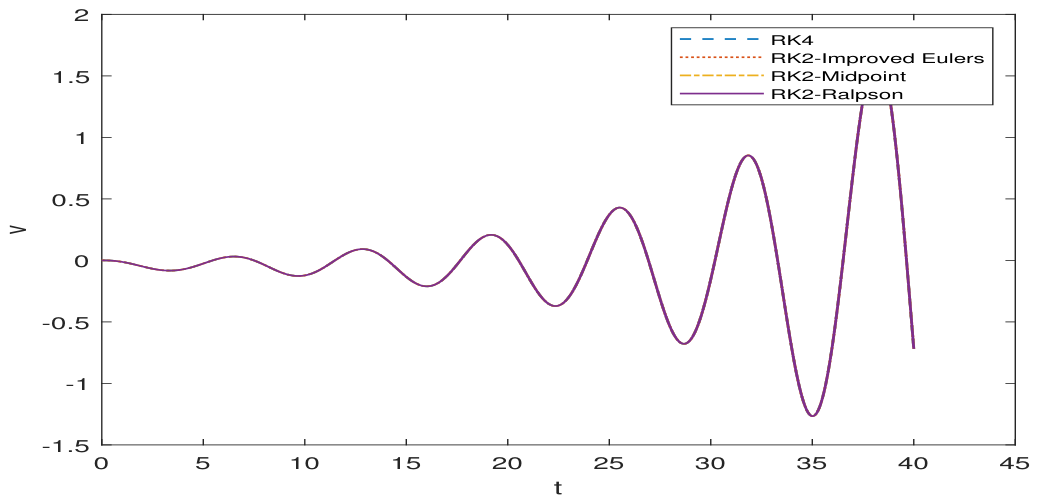
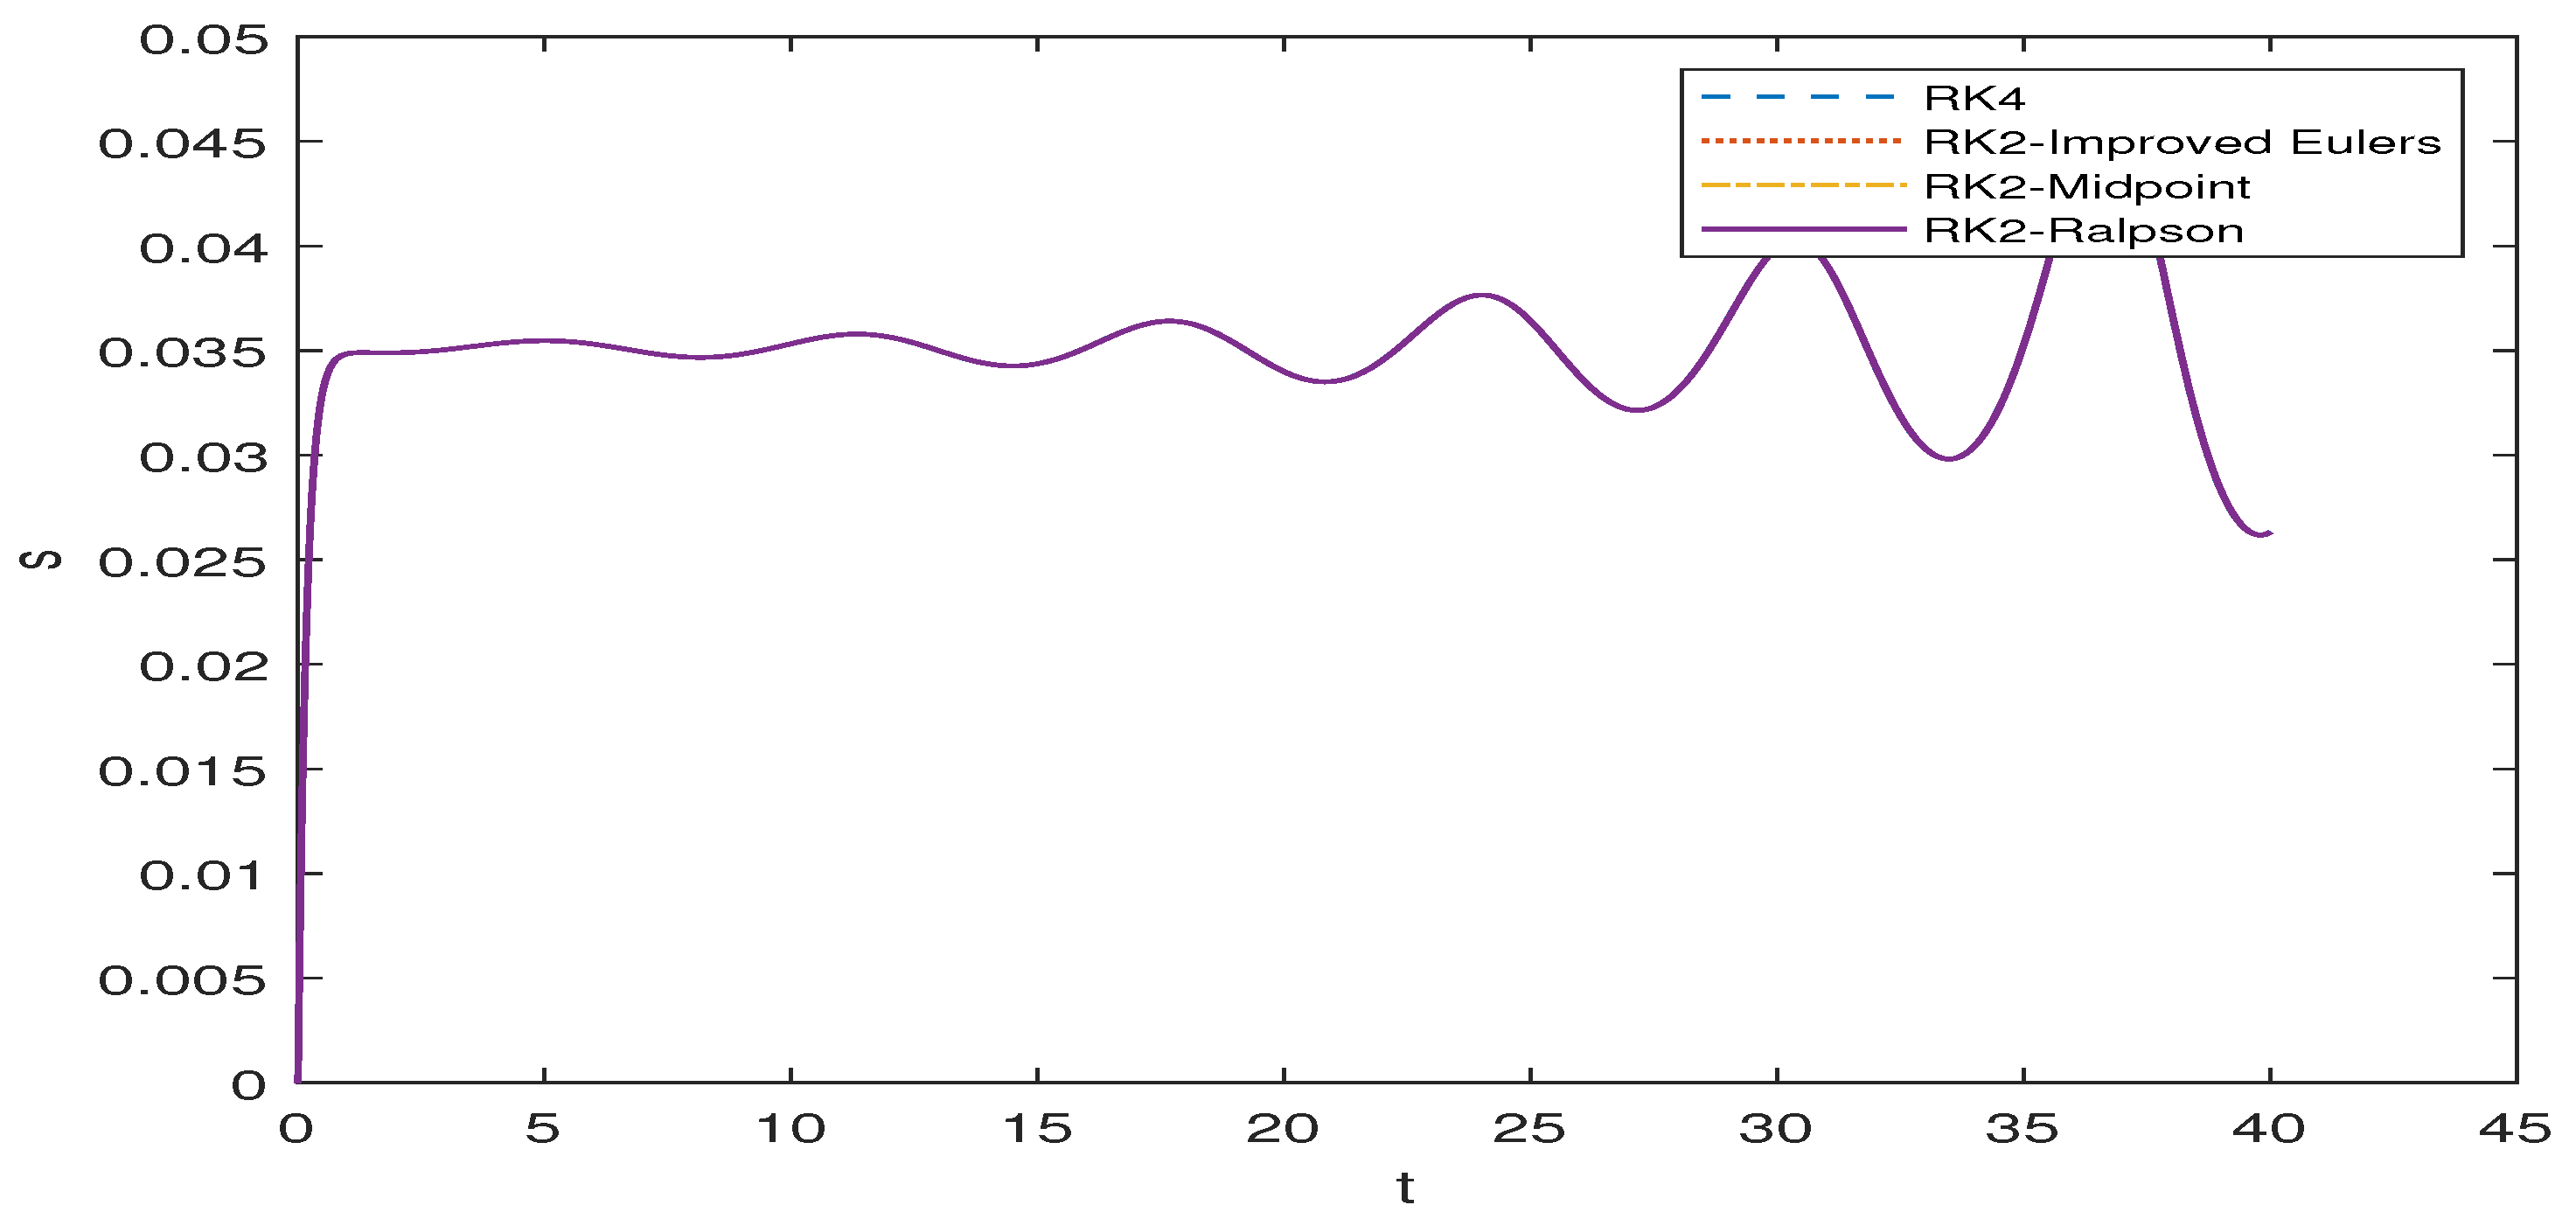
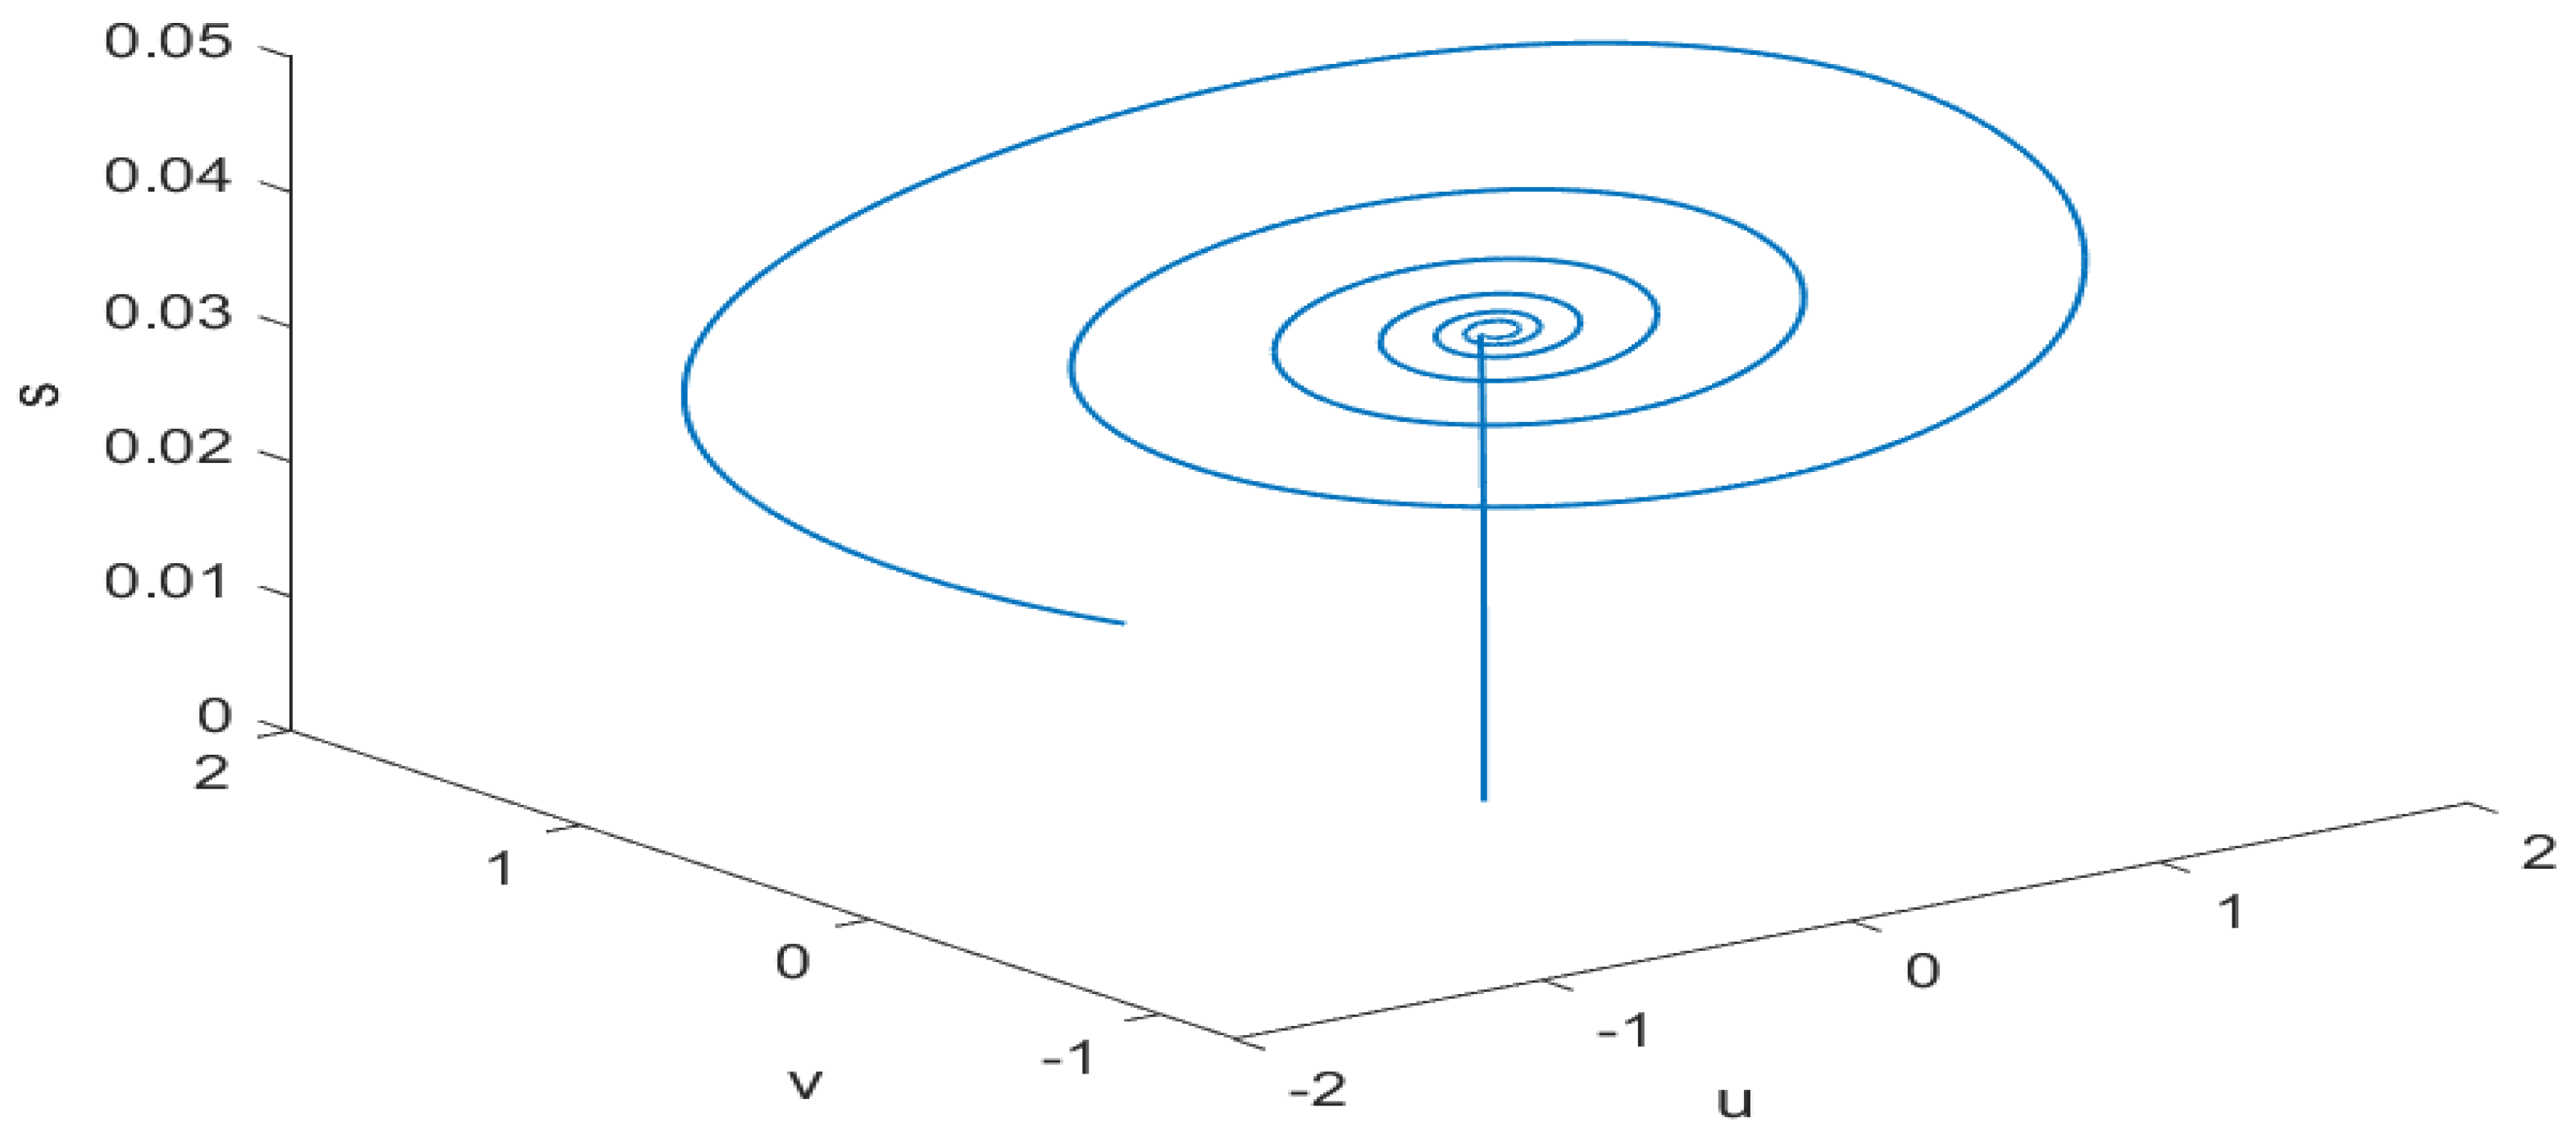
The time evolution plots and phase portraits presented in Figure 4, Figure 5, Figure 6, Figure 7, Figure 8, Figure 9, Figure 10, Figure 11, Figure 12, Figure 13, Figure 14, Figure 15, Figure 16, Figure 17, Figure 18, Figure 19 and Figure 20 illustrate the qualitative behavior of the chaotic systems. The numerical solutions generated by all methods generally followed similar trajectories, especially for smaller step sizes. However, the RK4 solutions remained smoother and more stable over longer integration intervals, whereas slight deviations became visible in the second-order methods due to accumulated truncation errors. The phase portraits also successfully captured the chaotic attractors associated with the Lorenz, Genesio–Tesi, and Rössler systems, demonstrating that the numerical schemes were capable of reproducing the essential dynamics of the systems.
The results indicate that, while the Midpoint, Improved Euler, and Ralston methods are computationally simpler and easier to implement, they are less accurate for highly sensitive chaotic systems. In contrast, the RK4 method provides significantly better numerical accuracy, stronger stability properties, and more reliable long-term approximations. These findings highlight the importance of using higher-order numerical integration techniques when solving nonlinear chaotic differential equations where precision and stability are critical. The superior performance of RK4 can be attributed to its higher-order truncation accuracy and multiple intermediate evaluations within each time step. Chaotic systems are highly sensitive to small perturbations, and numerical errors propagate rapidly over time. The RK4 method effectively reduces the accumulation of these local errors, thereby providing more stable long-term approximations than second-order methods.

7. Conclusions

This study investigated the efficiency and effectiveness of the Midpoint, Improved Euler, Ralston, and fourth-order Runge–Kutta numerical methods when solving the Lorenz, Genesio–Tesi, and Rössler chaotic systems. The stability analysis showed that all selected systems are unstable at their equilibrium points, confirming their chaotic nature and sensitivity to initial conditions. The numerical experiments demonstrated that all methods converge as the step size decreases. However, the RK4 method consistently produced the smallest errors and exhibited superior stability and convergence properties compared to the second-order methods. The Midpoint, Improved Euler, and Ralston methods produced acceptable approximations for sufficiently small step sizes, but their errors remained considerably larger than those of RK4, especially for the Lorenz system, where chaotic effects are more pronounced.
The infinity norm analysis and graphical comparisons confirmed the theoretical convergence orders of the methods, with the second-order schemes following O ( h 2 ) convergence and RK4 following O ( h 4 ) . Furthermore, the phase portraits and solution trajectories successfully reproduced the chaotic dynamics of the systems under consideration. Based on the obtained results, it can be concluded that the RK4 provides the highest numerical accuracy and robustness among the investigated methods, whereas computational efficiency depends on the particular chaotic system considered. Future studies may extend this work by investigating adaptive step-size Runge–Kutta methods, implicit schemes, or machine learning-based numerical approaches for solving more complex chaotic and hyperchaotic systems.

Funding

This work was funded by the University of Venda, grant number P750.

Data Availability Statement

The original contributions presented in this study are included in the article. Further inquiries can be directed to the corresponding author.

Acknowledgments

The The author would like to thank the Department of Mathematical and Computational Sciences at the University of Venda for their academic support and constructive research environment during the preparation of this work.

Conflicts of Interest

The authors declare that there is no conflict of interest regarding the publication of this paper.

Abbreviations

The following abbreviations are used in this manuscript:
Abbreviations:
RK2Runge-Kutta Methods of order two
RK4Runge Kutta Method of order four
CPU timeComputational time
Nomenclature:
xSpatial variable
tTime variable
Δ x Change in spatial variable
Δ t Change in time variable

References

  1. Buscarino, A.; Fortuna, L.; Frasca, M.; Sciuto, G. A Concise Guide to Chaotic Electronic Circuits; Springer International Publishing: Berlin/Heidelberg, Germany, 2014. [Google Scholar]
  2. Letellier, C.; Roulin, E.; Rössler, O.E. Inequivalent topologies of chaos in simple equations. Chaos Solitons Fractals 2006, 28, 337–360. [Google Scholar] [CrossRef] [Scilit]
  3. Suli, E.; Mayers, D.F. Solution of Equations by iteration. In An Introduction to Numerical Analysis; University of Oxford: Oxford, UK, 2003; pp. 2–35. [Google Scholar]
  4. Peinado, J.; Ibáñez, J.; Arias, E.; Hernández, V. Adams–Bashforth and Adams–Moulton methods for solving differential Riccati equations. Comput. Math. Appl. 2010, 60, 3032–3045. [Google Scholar] [CrossRef] [Scilit]
  5. Lorenz, E.N.; Haman, K. The essence of chaos. Pure Appl. Geophys. 1996, 147, 598–599. [Google Scholar]
  6. Gleick, J. Chaos: Making a New Science; Penguin: New York, NY, USA, 2008. [Google Scholar]
  7. Dogan, N. Numerical solution of chaotic Genesio system with multi-step Laplace Adomian decomposition method. Kuwait J. Sci. 2013, 40, 109–121. [Google Scholar] [CrossRef] [Scilit]
  8. Eftekhari, S.A.; Jafari, A.A. Numerical simulation of chaotic dynamical systems by the method of differential quadrature. Sci. Iran. 2012, 219, 1299–1315. [Google Scholar] [CrossRef] [Scilit]
  9. Li, J.M.; Wang, Y.L.; Zhang, W. Numerical Simulation of the Lorenz-Type Chaotic System Using Barycentric Lagrange Interpolation Collocation Method. Adv. Math. Phys. 2019, 2019, 1030318. [Google Scholar] [CrossRef] [Scilit]
  10. Ghorbani, A.; Saberi-Nadjafi, J. A piecewise-spectral parametric iteration method for solving the nonlinear chaotic Genesio system. Math. Comput. Model. 2011, 54, 131–139. [Google Scholar] [CrossRef] [Scilit]
  11. Butcher, J.C. A history of Runge-Kutta methods. Appl. Numer. Math. 1996, 20, 247–260. [Google Scholar] [CrossRef] [Scilit]
  12. Ahamad, N.; Charan, S. Study of numerical solution of fourth order ordinary differential equations by fifth order runge-kutta method. Int. J. Sci. Res. Sci. Eng. Technol. 2019, 6, 230–238. [Google Scholar] [CrossRef] [Scilit]
  13. Roman, P. Application of the Adams-Bashfort-Mowlton method to the numerical study of linear fractional oscillators models. In AIP Conference Proceedings; AIP Publishing LLC: Melville, NY, USA, 2021; Volume 2365, p. 020007. [Google Scholar]
  14. Galeone, L.; Garrappa, R. Fractional adams–moulton methods. Math. Comput. Simul. 2008, 79, 1358–1367. [Google Scholar] [CrossRef] [Scilit]
  15. Dattani, N.S. Linear multistep numerical methods for ordinary differential equations. arXiv 2008, arXiv:0810.4965. [Google Scholar]
  16. Hahn, G.D. A modified Euler method for dynamic analyses. Int. J. Numer. Methods Eng. 1991, 32, 943–955. [Google Scholar] [CrossRef] [Scilit]
  17. Kapitaniak, T. Chaotic Oscillations in Mechanical Systems; Manchester University Press: Mancherster, UK, 1991. [Google Scholar]
  18. Oestreicher, C. A history of chaos theory. Dialogues Clin. Neurosci. 2022, 9, 279–289. [Google Scholar]
  19. Marion, R. Complexity theory for organizations and organizational leadership. Complex. Leadersh. 2008, 1, 1–15. [Google Scholar]
  20. Mann, S.R. Chaos Theory and Strategic Thought; Army War Coll Carlisle Barracks PA: Carlisle, PA, USA, 1992. [Google Scholar]
  21. Moaddy, K.; Hashim, I.; Momani, S. Non-standard finite difference schemes for solving fractional-order Rössler chaotic and hyperchaotic systems. Comput. Math. Appl. 2011, 62, 1068–1074. [Google Scholar] [CrossRef] [Scilit]
  22. Park, J.H. Synchronization of Genesio chaotic system via backstepping approach. Chaos Solitons Fractals 2006, 27, 1369–1375. [Google Scholar] [CrossRef] [Scilit]
  23. Ogata, S.; Iwayama, T.; Terachi, S. Effect of system noise on chaotic behavior in Roessler type nonlinear system. Int. J. Bifurc. Chaos Appl. Sci. Eng. 1997, 7, 2871–2879. [Google Scholar] [CrossRef] [Scilit]
  24. Yu, Y.; Li, H.X.; Wang, S.; Yu, J. Dynamic analysis of a fractional-order Lorenz chaotic system. Chaos Solitons Fractals 2009, 42, 1181–1189. [Google Scholar] [CrossRef] [Scilit]
  25. Unbehauen, H. (Ed.) Control systems, robotics and automation-volume III. In System Analysis and Control: Classical Approaches-III; EOLSS Publications: Abu Dhabi, United Arab Emirates, 2009. [Google Scholar]
  26. Heinonen, J. Lectures on Lipschitz Analysis; University of Jyvaskyla: Jyvaskyla, Finland, 2005. [Google Scholar]
  27. Leonov, G.A.; Kuznetsov, N.V. On differences and similarities in the analysis of Lorenz, Chen, and Lu systems. Appl. Math. Comput. 2015, 256, 334–343. [Google Scholar] [CrossRef] [Scilit]
  28. Mathale, D.; Dlamini, P.G.; Khumalo, M. Compact finite difference relaxation method for chaotic and hyperchaotic initial value systems. Comput. Appl. Math. 2018, 37, 5187–5202. [Google Scholar] [CrossRef] [Scilit]
  29. Lorenz, E.N. Predictability: A problem partly solved. Proc. Semin. Predict. 1996, 1, 1–18. [Google Scholar]
  30. DeJesus, E.X.; Kaufman, C. Routh-Hurwitz criterion in the examination of eigenvalues of a system of nonlinear ordinary differential equations. Phys. Rev. A 1987, 35, 5288. [Google Scholar] [CrossRef] [Scilit]
  31. Faieghi, M.R.; Delavari, H. Chaos in fractional-order Genesio–Tesi system and its synchronization. Commun. Nonlinear Sci. Numer. Simul. 2012, 17, 731–741. [Google Scholar] [CrossRef] [Scilit]
  32. Wu, X.; Wu, H.; Yan, Z.; Huang, Y. Chaos Anti-Synchronization between Chen System and Genesio System. Open Access Libr. J. 2016, 3, 1. [Google Scholar] [CrossRef]
  33. Dlamini, P.G. On Spectral Relaxation and Compact Finite Difference Schemes for Ordinary and Partial Differential Equations; University of Johannesburg: Johannensburg, South Africa, 2015. [Google Scholar]
  34. Li, C.; Hu, W.; Sprott, J.C.; Wang, X. Multistability in symmetric chaotic systems. Eur. Phys. J. Spec. Top. 2015, 224, 1493–1506. [Google Scholar] [CrossRef] [Scilit]
  35. Carpenter, M.H.; Kennedy, C.A. Fourth -order 2N-storage Runge-Kutta schemes (No. NASA-TM-109112). 1994. Available online: https://ntrs.nasa.gov/citations/19940028444 (accessed on 1 July 2026).
  36. Amma, B.B.; Melliani, S.; Chadli, L.S. Numerical solution of intuitionistic fuzzy differential equations by Runge-Kutta Method of order four. Notes Int. Fuzzy Sets 2016, 22, 42–52. [Google Scholar]
  37. Kaps, P.; Rentrop, P. Generalized Runge-Kutta methods of order four with stepsize control for stiff ordinary differential equations. Numer. Math. 1979, 33, 55–68. [Google Scholar] [CrossRef] [Scilit]
Figure 1. The figure shows the residual norm of the three eigenvalues with the overall residual norm is 1.36 × 10 14 .
Appliedmath 06 00112 g001
Figure 2. The figure shows the residual norm of the three eigenvalues with the overall residual norm is 2.264 × 10 15 .
Appliedmath 06 00112 g002
Figure 3. The figure shows the residual norm of the three eigenvalues with the overall residual norm is 4.744 × 10 16 .
Appliedmath 06 00112 g003
Figure 4. Comparison Infinity norm error when solving the Lorenz System by the Midpoint, Improved Eulers, Ralston and RK4 Methods.
Appliedmath 06 00112 g004
Figure 5. Comparison Infinity norm error when solving the Genesio–Tesi System by Midpoint, Improved Eulers, Ralston and RK4 Methods.
Appliedmath 06 00112 g005
Figure 6. Comparison Infinity norm error when solving the Rössler System by Midpoint, Improved Eulers, Ralston and RK4 Methods.
Appliedmath 06 00112 g006
Figure 7. Comparison of solution u when solving the Lorenz System by the Midpoint, Improved Eulers, Ralston and RK4 Methods with h = 0.01 .
Appliedmath 06 00112 g007
Figure 8. Comparison of solution v when solving the Lorenz System by the Midpoint, Improved Eulers, Ralston and RK4 Methods with h = 0.01 .
Appliedmath 06 00112 g008
Figure 9. Comparison of solution s when solving the Lorenz System by the Midpoint, Improved Eulers, Ralston and RK4 Methods with h = 0.01 .
Appliedmath 06 00112 g009
Figure 10. Solution u versus v when solving the Lorenz System with h = 0.01 .
Appliedmath 06 00112 g010
Figure 11. Solution u versus s when solving the Lorenz System with h = 0.01 .
Appliedmath 06 00112 g011
Figure 12. Solution v versus s when solving the Lorenz System with h = 0.01 .
Appliedmath 06 00112 g012
Figure 13. Comparison of solution u when solving the Genesio System by the Midpoint, Improved Eulers, Ralston and RK4 Methods with h = 0.01 .
Appliedmath 06 00112 g013
Figure 14. Comparison of solution v when solving the Genesio System by the Midpoint, Improved Eulers, Ralston and RK4 Methods with h = 0.01 .
Appliedmath 06 00112 g014
Figure 15. Comparison of solution s when solving the Genesio System by the Midpoint, Improved Eulers, Ralston and RK4 Methods with h = 0.01 .
Appliedmath 06 00112 g015
Figure 16. Solution u and v versus s when solving the Genesio System with h = 0.01 .
Appliedmath 06 00112 g016
Figure 17. Comparison of solution u when solving the Rössler System by the Midpoint, Improved Eulers, Ralston and RK4 Methods with h = 0.01 .
Appliedmath 06 00112 g017
Figure 18. Comparison of solution v when solving the Rössler System by the Midpoint, Improved Eulers, Ralston and RK4 Methods with h = 0.01 .
Appliedmath 06 00112 g018
Figure 19. Comparison of solution s when solving the Rössler System by the Midpoint, Improved Eulers, Ralston and RK4 Methods with h = 0.01 .
Appliedmath 06 00112 g019
Figure 20. Solution u and v versus s when solving the Rössler System with h = 0.01 .
Appliedmath 06 00112 g020
Table 1. Convergence rate for the Lorenz system.
hMidpointImproved EulerRalstonRK4
0.01000 3.37 × 10 1 3.13 × 10 1 2.71 × 10 1 3.32 × 10 1
0.00500 5.61 × 10 0 1.49 × 10 1 9.59 × 10 1 2.12 × 10 3
0.00250 5.74 × 10 0 2.52 × 10 0 4.75 × 10 0 7.23 × 10 4
0.00125 2.23 × 10 0 1.28 × 10 0 1.92 × 10 0 7.95 × 10 4
0.00063 6.67 × 10 1 4.09 × 10 1 5.81 × 10 1 7.95 × 10 4
Table 2. Convergence rate for the Genesio system.
hMidpointImproved EulerRalstonRK4
0.01000 2.27 × 10 3 2.26 × 10 3 2.27 × 10 3 3.80 × 10 5
0.00500 5.68 × 10 4 5.66 × 10 4 5.67 × 10 4 3.80 × 10 5
0.00250 1.42 × 10 4 1.42 × 10 4 1.42 × 10 4 3.80 × 10 5
0.00125 4.74 × 10 5 4.74 × 10 5 4.74 × 10 5 3.80 × 10 5
0.00063 4.06 × 10 5 4.06 × 10 5 4.06 × 10 5 3.82 × 10 5
Table 3. Convergence rate for the Rössler system.
hMidpointImproved EulerRalstonRK4
0.01000 1.47 × 10 5 1.47 × 10 5 1.47 × 10 5 3.05 × 10 6
0.00500 3.83 × 10 6 3.83 × 10 6 3.83 × 10 6 3.05 × 10 6
0.00250 3.17 × 10 6 3.17 × 10 6 3.17 × 10 6 3.05 × 10 6
0.00125 3.11 × 10 6 3.11 × 10 6 3.11 × 10 6 3.08 × 10 6
0.00063 3.09 × 10 6 3.09 × 10 6 3.09 × 10 6 3.08 × 10 6
Table 4. Computational characteristics of numerical methods when solving Lorenz, Genesio–Tesi and Rössler Systems.
MethodOrderLorenzGenesio–TesiRössler
Midpoint2 0.036065 0.031676 0.003814
Improved Euler2 0.019508 0.007808 0.015813
Ralston2 0.013770 0.006137 0.011535
RK44 0.011759 0.011025 0.019439
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content.