


Abstract
Digital money has transformed from a technological experiment into a central concern of monetary economics, financial regulation, and public policy. Despite rapid growth in cryptocurrencies, stablecoins, central bank digital currencies (CBDCs), and tokenized deposits, the literature remains fragmented across disciplines, with limited cross-cutting synthesis. This article adopts a scoping–integrative review methodology, combining systematic database (Scopus and Web of Science) searches with targeted retrieval of policy and institutional sources (BIS, IMF, Financial Stability Board (FSB), ECB, and national central bank repositories), covering the period 2008–2025, with integrative synthesis of academic, policy, and regulatory sources following PRISMA-ScR reporting principles. The review identifies four competing trust mechanisms underpinning digital money: algorithmic trust associated primarily with cryptocurrencies, private reserve backing trust (stablecoins), sovereign trust underpinning CBDCs, and regulated institutional intermediation supporting tokenized deposits. The proposed digital money ecosystem taxonomy (DMET) classifies digital money instruments across fourteen institutional, governance, technological, monetary, and regulatory dimensions, enabling systematic comparison of cryptocurrencies, stablecoins, CBDCs, and tokenized deposits. Future monetary systems will be hybrid, combining public and private digital money within layered governance arrangements. Interoperability, privacy, programmability, and cross-border governance represent the most critical unresolved policy and research challenges.
1. Introduction
Money is simultaneously a technological artefact and an institutional arrangement. Commodity money depended on the material scarcity of physical objects, fiat money depends on state authority, legal tender legislation, and public confidence, commercial bank deposits depend on regulated financial intermediation, and contemporary digital money increasingly depends on software architectures, data governance, cryptographic protocols, and platform infrastructures. The ongoing transformation of money, therefore, cannot be reduced to mere digitization. It represents a deeper reconfiguration of the institutions and technologies through which value is issued, transferred, stored, and governed across economies [1].
The global debate on digital money was catalyzed by the publication of the Bitcoin white paper in 2008 and the subsequent launch of the Bitcoin network in 2009 [2]. Bitcoin introduced a novel monetary architecture, which is a decentralized, peer-to-peer electronic cash system operating without central intermediaries, relying instead on cryptographic proof and distributed consensus. This innovation challenged foundational assumptions in monetary economics, particularly the necessity of centralized issuance, the role of trusted intermediaries, and the relationship between money and state sovereignty [3,4].
The subsequent decade witnessed an explosion of cryptocurrency experimentation, including alternative consensus mechanisms (proof-of-stake (PoS) and delegated proof-of-stake (PoS)), smart contract platforms (Ethereum, Solana, and Cardano), privacy-focused protocols (Monero and Zcash), and decentralized finance (DeFi) applications that replicate traditional financial services, including lending, borrowing, trading, and derivatives on blockchain infrastructure without traditional intermediaries [5,6]. As of May 2026, cryptocurrency market capitalization stood at approximately USD 2.56 trillion per CoinMarketCap [7], with thousands of digital assets in circulation and millions of users globally [8]. But the extreme price volatility of cryptocurrencies, such as Bitcoin, whose price fluctuated between USD 3000 and USD 69,000 between 2018 and 2021, has limited their utility as media of exchange or stable stores of value [9]. This volatility problem catalyzed the emergence of stablecoins: digital tokens designed to maintain stable value by pegging to fiat currencies (typically the US dollar), commodities, or algorithmic mechanisms [10]. Stablecoins, such as Tether (USDT), USD Coin (USDC), and Binance USD (BUSD), rapidly gained adoption in cryptocurrency trading, cross-border remittances, and DeFi protocols, with aggregate market capitalization exceeding USD 150 billion by 2024 [11], more than doubling to more than USD 300 billion as of May 2026, per DefiLlama [12]. However, BUSD circulation subsequently declined after Paxos ceased issuing new BUSD in February 2023.
The rise of cryptocurrencies and stablecoins, particularly Facebook’s 2019 announcement of the Libra project (later rebranded as Diem before abandonment in 2022), prompted central banks worldwide to accelerate research and development of central bank digital currencies (CBDCs) [13]. CBDCs represent sovereign digital money: direct liabilities of central banks, issued in digital form, potentially accessible to the general public (retail CBDC) or restricted to financial institutions (wholesale CBDC) [14]. By May 2026, 146 countries/currency unions representing 98% of global GDP were exploring CBDCs [15], with more than 20 countries having launched pilot programs or full implementations, including the Bahamas (Sand Dollar, 2020), Nigeria (eNaira, 2021), Jamaica (JAM-DEX, 2022), and China (e-CNY, ongoing pilot since 2020) [15].
More recently, tokenized deposits have emerged as a fourth pillar of the digital money ecosystem. Tokenized deposits represent commercial bank deposits issued on distributed ledger technology (DLT), combining the regulatory protections and deposit insurance of traditional banking with the programmability and composability of blockchain-based assets [16]. Major financial institutions, including JPMorgan, Citibank, HSBC, and Standard Chartered, have launched tokenized deposit pilots, and the Bank for International Settlements (BIS) has explored tokenized deposits through Project Agorá (2024), examining unified ledgers that integrate wholesale CBDC, tokenized deposits, and tokenized securities [17].
Despite exponential growth in academic research, policy analysis, and industry experimentation, the digital money literature remains fragmented across disciplinary boundaries. Economists focus on monetary policy transmission, financial stability, and macroeconomic implications [18,19]. Computer scientists emphasize cryptographic protocols, consensus mechanisms, scalability, and security. Legal scholars examine regulatory classification, jurisdictional challenges, and compliance frameworks [20,21]. Information systems researchers investigate adoption drivers, user behavior, and platform governance. Public policy analysts address financial inclusion, cross-border payments, and geopolitical implications [22,23]. This disciplinary fragmentation limits holistic understanding of the digital money ecosystem and its systemic implications.
This article addresses this gap through a scoping–integrative review that synthesizes multidisciplinary scholarship on cryptocurrencies, stablecoins, CBDCs, and tokenized deposits. The review is guided by three research objectives. (1) Synthesis: to provide a structured synthesis of the evolution of digital money across all four categories, mapping their conceptual foundations, design architectures, economic implications, governance models, and regulatory challenges. (2) Comparison: to develop a comparative framework examining trust mechanisms, governance architectures, liability structures, and regulatory exposures across cryptocurrencies, stablecoins, CBDCs, and tokenized deposits. (3) Taxonomy: to advance the digital money ecosystem taxonomy (DMET), a structured classification framework that categorizes digital money instruments across fourteen institutional, governance, technological, monetary, and regulatory dimensions, including issuer type, liability structure, governance arrangements, trust mechanisms, monetary control, settlement roles, regulatory exposure, primary use cases, degree of decentralization, privacy level, programmability, scalability, energy efficiency, and interoperability.
The paper makes three principal contributions. First, building on established classification frameworks, including the BIS money flower [24] and its extensions, it provides a multidisciplinary synthesis that is, to the author’s knowledge, the first to jointly integrate cryptocurrencies, stablecoins, CBDCs, and tokenized deposits within a unified analytical framework. Second, it advances a comparative analysis that reveals the trade-offs, complementarities, and tensions among different digital money architectures. Third, it introduces DMET, a multidimensional classification framework that evaluates cryptocurrencies, stablecoins, CBDCs, and tokenized deposits across fourteen institutional, governance, technological, monetary, and regulatory dimensions. The taxonomy provides a structured tool for researchers, policymakers, and practitioners to systematically compare and evaluate emerging forms of digital money. The overall conceptual structure of the digital money ecosystem examined in this review is illustrated in Figure 1.
Figure 1.
Conceptual overview of the evolution, classification, governance, and future trajectories of digital money.
The remainder of this paper is organized as follows. Section 2 presents the conceptual foundations and methodological approach adopted in this review. Section 3 examines the evolution of digital money across four major pillars: cryptocurrencies, stablecoins, CBDCs, and tokenized deposits. Section 4 provides a comparative analysis of trust mechanisms, governance structures, and regulatory dimensions across these forms of digital money. Section 5 introduces DMET as a multidimensional classification framework. Section 6 discusses governance, regulatory, and economic implications associated with emerging digital money systems. Section 7 examines the global digital money landscape, practical implications, future research directions, and key limitations. Section 8 concludes the paper.
2. Conceptual Foundations and Methodology
2.1. From Money to Digital Money
Money is conventionally defined by three core functions: medium of exchange, unit of account, and store of value [25]. As a medium of exchange, money facilitates transactions by eliminating the double coincidence of wants problem inherent in barter systems. As a unit of account, money provides a common measure for pricing goods, services, and financial assets, enabling economic calculation and comparison. As a store of value, money allows economic agents to transfer purchasing power across time, though this function requires relative price stability [25].
Historically, money has taken multiple forms: commodity money (gold, silver, and shells), representative money (banknotes backed by precious metals), fiat money (government-issued currency without intrinsic value), and commercial bank money (deposit liabilities of regulated financial institutions) [26]. Each form embodies different trust mechanisms. Commodity money derives value from intrinsic material properties, representative money from convertibility guarantees, fiat money from state authority, legal tender laws, and public confidence, and commercial bank money from regulatory oversight, deposit insurance, and central bank liquidity support [27].
Contemporary monetary systems are characterized by a two-tier structure: central banks issue base money (currency and reserves), while commercial banks create broad money through credit intermediation, issuing deposit liabilities backed by loan assets [28]. This fractional reserve banking system enables credit expansion but introduces maturity transformation risks, liquidity risks, and systemic fragility, necessitating prudential regulation, deposit insurance, and lender-of-last-resort facilities [29].
2.2. Digitization and Tokenization
The distinction between digitization and tokenization is critical for understanding contemporary digital money. Digitization refers to the representation of information in electronic form. Traditional bank deposits are digitized money, recorded in centralized databases maintained by financial institutions [30]. Tokenization, by contrast, refers to the representation of assets or liabilities as programmable digital tokens on distributed ledgers, enabling peer-to-peer transfer, smart contract integration, and composability with other tokenized assets [31].
Tokenization introduces several novel properties. First, programmability allows tokens to embed conditional logic, enabling automated compliance, programmable payments, and integration with smart contracts [32]. Second, composability enables tokens to interact with other tokens and decentralized applications, enabling complex financial operations without intermediaries. Third, atomic settlement allows delivery-versus-payment and payment-versus-payment to occur simultaneously on-chain, eliminating settlement risk. Fourth, transparency and auditability allow transactions on public blockchains to be transparent and immutable, enabling real-time auditing and regulatory oversight (though privacy-preserving techniques can limit transparency) [33].
These properties distinguish tokenized digital money from traditional digitized money and underpin many of the claimed advantages of blockchain-based monetary systems.
2.3. Trust Mechanisms in Monetary Systems
Trust is the foundational element of any monetary system. Economic agents must trust that money will be accepted by others, will retain value over time, and will be protected from counterfeiting, theft, and arbitrary confiscation. Different monetary architectures embody different trust mechanisms. First, algorithmic trust describes cryptocurrencies that rely on cryptographic protocols and distributed consensus mechanisms (proof-of-work (PoW) and PoS to ensure transaction validity, prevent double-spending, and maintain ledger integrity without trusted intermediaries [2,34]. Second, reserve-backed trust explains that stablecoins rely on reserve assets (fiat currency, government bonds, and commodities) held by issuers, with trust depending on reserve adequacy, transparency, auditability, and legal enforceability of redemption rights [35]. Third, sovereign trust describes how CBDCs rely on central bank credibility, legal tender status, and state authority, backed by the full faith and credit of the issuing government [36]. Fourth, intermediated trust can explain how tokenized deposits rely on regulated commercial banks, prudential supervision, deposit insurance, and central bank liquidity support, combining traditional banking trust mechanisms with blockchain infrastructure [17].
The evolution of digital money (Figure 2) can be understood as a contest among these competing trust mechanisms, each offering different trade-offs in terms of decentralization, stability, scalability, privacy, and regulatory compliance.
Figure 2.
Evolution of monetary forms of money, from commodity and fiat money to cryptocurrencies, stablecoins, tokenized deposits, and CBDCs, illustrating shifting trust mechanisms and governance architectures.
2.4. Scoping–Integrative Review Approach
This article employs a scoping–integrative review methodology, combining elements of scoping reviews and integrative reviews to synthesize multidisciplinary literature on digital money [37,38]. Scoping reviews are designed to map the breadth of literature across a research area, identify key concepts, and clarify working definitions, making them particularly suitable for emerging, multidisciplinary fields [39]. Integrative reviews synthesize diverse methodologies (quantitative, qualitative, and theoretical) and generate new frameworks or theoretical models [40].
The scoping–integrative approach is justified by three characteristics of the digital money literature. First, the literature is multidisciplinary and spans economics, finance, computer science, law, public policy, and information systems, requiring synthesis across disciplinary boundaries. Second, the field is evolving rapidly due to technological innovation, regulatory developments, and market dynamics, necessitating an approach that may accommodate emerging concepts and evolving definitions. Third, the literature is conceptually fragmented, where terminology, definitions, and classification schemes vary across disciplines and jurisdictions, requiring conceptual clarification and taxonomic development. The reviewed literature can be broadly classified into four major research streams, as summarized in Table 1. The review protocol was retrospectively registered with the Open Science Framework (OSF Registries) and is publicly available at: https://doi.org/10.17605/OSF.IO/QYCA9 (accessed on 7 September 2026). As registration occurred after completion of the principal search, screening, and synthesis stages, it represents retrospective protocol registration rather than prospective preregistration.
Table 1.
Literature streams by research category, dominant focus, common methods, representative issues, and identified research gaps.
2.5. Research Questions
The primary research question guiding this review is “How has digital money evolved from cryptocurrencies to stablecoins, CBDCs, and tokenized deposits, and what does this evolution reveal about changing sources of trust, governance arrangements, monetary control, and policy risk?”
Five sub-questions structure the inquiry: (1) What design features distinguish cryptocurrencies, stablecoins, CBDCs, and tokenized deposits? (2) How do their governance architectures and liability structures differ? (3) What economic implications are associated with each form across monetary policy, financial stability, and financial inclusion? (4) How are regulators and central banks responding to the rise of private and decentralized digital money? (5) What taxonomy can organize future research and policy analysis on digital money ecosystems?
These questions reflect the need for cross-category synthesis rather than instrument-specific analysis. They are deliberately broad to accommodate the multidisciplinary literature and to enable the development of a comparative framework applicable across jurisdictions and instrument types.
2.6. Search Strategy and Inclusion Criteria
A systematic literature search was conducted across two databases, Scopus and Web of Science, using logically equivalent Boolean queries adapted to each platform’s syntax, as provided in Appendix A. Both queries were bounded through 2025 at the time of the search. The Scopus search returned 11,229 records and the Web of Science search returned 7745 records (18,974 combined) (see Supplementary Material section). After deduplication by DOI and normalized title matching, 12,949 unique records remained. Of these, 540 records focused on non-monetary blockchain applications outside the scope of the DMET framework, including IoT, healthcare, supply chain, construction, and energy applications, and were removed before title-and-abstract screening, leaving 12,409 records to be screened. Given the disproportionately rapid pace of development in this field, since the majority of substantive academic literature on stablecoins, CBDCs, and DeFi has been published since 2021, a two-tier temporal strategy was applied, consistent with recommended practice for reviewing rapidly evolving research areas. First, full systematic screening (2021–2025): every record published between 2021 and 2025 was individually screened at the title-and-abstract level against the inclusion and exclusion criteria below. Second, targeted foundational search (2008–2020): Records published before 2021 were not exhaustively screened; instead, this period was searched for landmark and foundational works, meaning publications establishing core theoretical or technical concepts still in active use (e.g., the original Bitcoin and Ethereum protocol descriptions, seminal CBDC design papers, and early treatments of private versus public digital money), identified through targeted keyword and author-based search. Records now bearing a 2026 publication date were treated as falling within the 2021–2025 full-screening tier, since they were retrieved and screened as part of that same window at the time of search.
This database-driven process was applied in addition to a separate, parallel targeted search of gray literature and institutional sources, including publications from BIS, the International Monetary Fund (IMF), FSB, the European Central Bank (ECB), and the Financial Action Task Force. This additional search was necessary because these repositories are not comprehensively indexed by Scopus or Web of Science and do not support equivalent standardized search syntax. This purposive search identified 48 institutional publications, of which 37 met inclusion criteria.
Inclusion criteria specified the temporal scope described above, together with three further conditions. Eligible publication types included peer-reviewed journal articles, working papers from central banks and international financial institutions, such as the BIS, the IMF, and the World Bank, policy reports, and selected conference proceedings. Publications were limited to those written in English. Relevance was defined as addressing conceptual foundations, design architectures, economic implications, governance models, regulatory frameworks, or empirical evidence related to cryptocurrencies, stablecoins, CBDCs, or tokenized deposits.
Exclusion criteria comprised purely technical cryptographic papers without monetary or economic analysis, opinion pieces without empirical or theoretical grounding, and publications focused exclusively on non-monetary blockchain applications, such as supply chain, healthcare, or general IoT applications.
The complete search, screening, and selection process, including the number of sources of evidence identified, screened, assessed for eligibility, and included, together with reasons for exclusion at each stage, is reported in the PRISMA-ScR flow diagram [41] (Figure 3).
Figure 3.
PRISMA ScR flow diagram of source identification, screening, inclusion, and exclusion criteria.
2.7. Quality Assessment
Quality assessment in a scoping–integrative review differs from appraisal in systematic reviews of clinical interventions, where standardized risk-of-bias tools are applied. In this review, quality screening operates across three source categories.
Peer-reviewed academic articles are assessed on four criteria: (1) relevance to the research questions, (2) methodological rigor, including transparency of data, analytical approach, and replicability, (3) citation contribution, reflecting the influence of the work within the field, and (4) conceptual value, particularly where empirical data are limited and theoretical contributions are primary.
Policy and institutional reports (BIS, IMF, FSB, ECB, Federal Reserve, World Bank, and national central banks) are assessed for (1) the credibility and mandate of the issuing institution, (2) recency and alignment with the 2008–2025 search window, (3) jurisdictional scope (global, regional, or national), and (4) analytical depth, distinguishing substantive policy analysis from purely descriptive or promotional content.
Industry and market sources are used sparingly and only where they provide descriptive or quantitative data not available through academic or institutional channels (e.g., stablecoin market capitalization data and CBDC tracker statistics). Such sources are clearly identified and not used as primary evidence for conceptual or causal claims.
This tiered quality-screening approach addresses a common critique of scoping reviews that they aggregate documents without evaluating their epistemic reliability while preserving the breadth necessary to map a rapidly evolving, multidisciplinary field. Sources that did not meet minimum quality thresholds (e.g., undifferentiated popular media, anonymous commentary, and documents without institutional provenance) were excluded at the screening stage.
2.8. Data Extraction and Synthesis
Data extraction mainly focused on five key questions. First, how are cryptocurrencies, stablecoins, CBDCs, and tokenized deposits defined and classified in the existing literature? Second, what technical, governance, and operational design architectures characterize these forms of digital money? Third, what are their implications for monetary policy, financial stability, payment systems, and financial inclusion? Fourth, what regulatory frameworks and policy approaches have been proposed or implemented to govern their development and use? Finally, what empirical evidence exists regarding adoption, usage patterns, performance outcomes, and broader economic and societal impacts? These questions provided the analytical framework for organizing, comparing, and synthesizing the findings of the reviewed studies.
Synthesis followed a thematic analysis approach, identifying recurring themes, tensions, and gaps across the literature. The DMET Framework is developed iteratively through comparative analysis of classification schemes proposed in the literature and refinement based on conceptual coherence and practical applicability.
2.9. Limitations of the Methodology
The scoping–integrative review methodology has inherent limitations. First, the rapid evolution of the field means that some recent developments may not yet be reflected in peer-reviewed literature. Second, the multidisciplinary nature of the field introduces terminological inconsistencies and conceptual ambiguities that complicate synthesis. Third, the review prioritizes breadth over depth, providing comprehensive coverage at the cost of detailed analysis of specific sub-topics. Fourth, the inclusion of gray literature (central bank reports and policy papers) introduces potential publication bias, as these sources may reflect institutional perspectives rather than independent analysis. These limitations are addressed through triangulation across multiple sources, explicit acknowledgment of conceptual ambiguities, and transparent reporting of inclusion criteria and synthesis methods.
3. The Evolution of Digital Money: Four Pillars
The contemporary digital money ecosystem rests on four pillars: cryptocurrencies, stablecoins, CBDCs, and tokenized deposits. Each represents a distinct approach to digital money, embodying different trust mechanisms, governance architectures, and regulatory exposures.
3.1. Cryptocurrencies: Decentralized Algorithmic Money
3.1.1. Conceptual Foundations and Design
Cryptocurrencies are digital assets that rely on cryptographic protocols and distributed consensus mechanisms to facilitate transactions and control the issuance of new units without central intermediaries [2]. Bitcoin, introduced in 2008, established the first decentralized monetary architecture through blockchain technology, PoW consensus, a fixed supply schedule of 21 million coins, and a peer-to-peer network [2].
Bitcoin’s design is based on four core features: a distributed ledger maintained across network nodes, PoW consensus for transaction validation, public-key cryptography for transaction security, and pseudonymous user identities represented by cryptographic addresses [42,43]. Together, these innovations enable value transfer without reliance on a central authority, while ensuring transparency, security, and network resilience.
Following Bitcoin, thousands of alternative cryptocurrencies (altcoins) emerged with varying governance structures, consensus mechanisms, and functionalities [44]. Among them, Ethereum significantly expanded the scope of digital assets by introducing smart contracts and decentralized applications (dApps), enabling programmable financial services and digital asset ecosystems [45]. Ethereum’s transition to PoS in 2022 further demonstrated efforts to improve scalability and reduce energy consumption while maintaining network security [46].
3.1.2. Decentralized Finance (DeFi)
DeFi extends the functionality of cryptocurrencies beyond payments by replicating traditional financial services, such as lending, borrowing, trading, derivatives, and asset management, through blockchain-based smart contracts rather than conventional intermediaries [47]. DeFi ecosystems rely on a combination of decentralized exchanges, lending protocols, stablecoins, and programmable applications that enable users to interact directly with financial infrastructure [48].
The rapid growth of DeFi demonstrated the feasibility of automated and permissionless financial services, with total value locked (TVL) exceeding USD 100 billion during peak market periods before moderating to approximately USD 80 billion by May 2026 per DefiLlama [12,49]. At the same time, DeFi has exposed important challenges, including smart contract vulnerabilities, governance failures, oracle manipulation, liquidity risks, and regulatory uncertainty [50,51,52]. Consequently, DeFi has emerged as both a major innovation in digital finance and a key testing ground for the opportunities and risks associated with blockchain-based financial systems.
3.1.3. Economic Characteristics and Limitations
Cryptocurrencies exhibit several distinctive economic characteristics that differentiate them from conventional forms of money and financial assets. Most notably, they are characterized by high price volatility, which limits their effectiveness as stable stores of value and reliable media of exchange [53]. Scalability also remains a challenge, as major blockchain networks process significantly fewer transactions than conventional payment systems, although Layer-2 solutions have sought to improve transaction capacity and efficiency [54].
Environmental concerns have been particularly pronounced for PoW cryptocurrencies, such as Bitcoin, whose energy consumption has attracted significant criticism and has been quantified in carbon footprint terms at the level of individual mining operations [55]. The adoption of PoS mechanisms has substantially reduced energy requirements in some networks, most notably Ethereum [56]. This variation in energy intensity is consistent with the broader ESG-in-finance literature, which treats environmental performance as a design-dependent characteristic of FinTech instruments rather than a fixed property of any single technology category [57]. Energy consumption, in the case of cryptocurrencies, varies by consensus mechanism and, within PoW networks specifically, by algorithm and mining hardware profile.
In addition, cryptocurrencies have been associated with illicit activities, including money laundering, ransomware payments, and sanctions evasion, although empirical evidence suggests that such activities represent only a small proportion of overall transaction volumes [58,59]. Consequently, despite their technological innovation, cryptocurrencies continue to function primarily as speculative assets, stores of value, and infrastructure for decentralized financial applications rather than as widely adopted general-purpose payment instruments [60].
3.1.4. Regulatory Challenges
Cryptocurrencies present significant regulatory challenges due to their decentralized architecture, cross-border nature, and evolving legal status. A central issue concerns their classification as commodities, securities, currencies, or a distinct asset class, with important implications for taxation, investor protection, and regulatory oversight [61]. Regulators have also focused on anti-money laundering (AML) and counter-terrorist financing (CTF) requirements, particularly for cryptocurrency exchanges and wallet providers, although decentralized platforms remain difficult to supervise effectively [21]. Additional concerns include consumer protection, market manipulation, cybercrime, taxation compliance, and the growing interconnectedness between cryptocurrency markets and traditional finance, which has intensified discussions regarding systemic risk and financial stability [62,63]. Regulatory responses vary considerably across jurisdictions, ranging from restrictive approaches, such as China’s cryptocurrency ban, to comprehensive frameworks, such as the European Union’s Markets in Crypto-Assets (MiCA) Regulation, while other countries continue to adopt more innovation-oriented regulatory strategies [64]. Collectively, these developments illustrate the ongoing challenge of balancing technological innovation with financial stability, market integrity, and consumer protection. The major characteristics of cryptocurrencies across key analytical dimensions are summarized in Table 2.
Table 2.
Cryptocurrency characteristics across key analytical dimensions.
3.2. Stablecoins: Bridging Volatility and Transferability
3.2.1. Conceptual Foundations and Typology
Stablecoins are digital tokens designed to maintain a relatively stable value by linking their price to a reference asset, typically a fiat currency, commodity, or basket of assets. By combining the transferability and programmability of cryptocurrencies with greater price stability, stablecoins seek to overcome one of the principal limitations of traditional cryptocurrencies and facilitate broader use in payments, trading, and digital finance [10].
Stablecoins can be broadly classified into four categories based on their stabilization mechanisms: fiat-collateralized, crypto-collateralized, algorithmic, and commodity-collateralized stablecoins [10]. Fiat-collateralized stablecoins, such as USDT and USDC, dominate the market and rely on reserve assets and redemption arrangements to maintain stability [65]. Crypto-collateralized stablecoins, exemplified by DAI, use over-collateralized crypto-assets managed through smart contracts. Algorithmic stablecoins attempt to maintain price stability through automated supply adjustments but have demonstrated significant fragility, most notably in the collapse of TerraUSD (UST) [66]. Commodity-backed stablecoins derive their value from underlying physical assets, such as gold [11]. By 2024, fiat-collateralized stablecoins accounted for the vast majority of global stablecoins market capitalization [67].
3.2.2. Use Cases and Adoption
Stablecoins have emerged as a critical component of the digital asset ecosystem, serving a wide range of financial and payment functions. They are widely used as trading pairs and units of account on cryptocurrency exchanges, enabling users to move between volatile crypto-assets and more stable digital representations of fiat currency [68]. Stablecoins also play a central role in DeFi, where they facilitate lending, borrowing, liquidity provision, and other financial activities [69].
Beyond cryptocurrency markets, stablecoins have gained attention for their potential to improve cross-border payments and remittances by offering faster and lower-cost transfers than many traditional payment channels [70]. In economies experiencing high inflation or currency instability, stablecoins have also been used as alternative stores of value and as a means of accessing dollar-denominated assets [71]. In addition, their programmability enables automated and conditional payment arrangements that support a variety of digital financial applications [72]. Reflecting these expanding use cases, stablecoins transaction volumes exceeded USD 10 trillion annually by 2024, highlighting their growing significance within the global digital money ecosystem [11].
3.2.3. Risks and Regulatory Concerns
Despite their growing adoption, stablecoins pose several important financial and regulatory risks. A primary concern is reserve risk, as the stability of fiat-collateralized stablecoins depends on the adequacy, liquidity, and transparency of the assets backing them [35,65,73]. Stablecoins are also vulnerable to run risk, whereby a loss of confidence in an issuer’s ability to honor redemptions may trigger large-scale withdrawals, particularly in the absence of deposit insurance or lender-of-last-resort support [10,74]. Their cross-border nature further creates opportunities for regulatory arbitrage and inconsistent supervisory oversight across jurisdictions [75].
As stablecoins become increasingly integrated with both traditional finance and DeFi, concerns regarding systemic risk and financial contagion have intensified [76]. In addition, widespread adoption of foreign-currency-denominated stablecoins may weaken monetary sovereignty and complicate domestic monetary policy implementation in some economies [77]. These vulnerabilities were highlighted by the collapse of TerraUSD (UST) in 2022, which demonstrated the fragility of certain stablecoin designs and accelerated global regulatory scrutiny of the sector [66].
3.2.4. Regulatory Developments
The rapid growth of stablecoins has prompted regulatory authorities worldwide to develop dedicated oversight frameworks. The European Union’s MiCA Regulation represents one of the most comprehensive approaches, establishing requirements relating to reserve backing, redemption rights, transparency, and prudential safeguards [64]. Other major jurisdictions, including the United States, the United Kingdom, Hong Kong, and Singapore, have similarly proposed or implemented regulatory frameworks aimed at enhancing consumer protection, financial stability, and issuer accountability, although regulatory approaches continue to vary considerably across countries [78,79]. At the international level, FSB has emphasized the importance of comprehensive supervision, cross-border coordination, and consistency with existing financial regulatory standards in the governance of global stablecoins arrangement [76]. Table 3 summarizes the major characteristics and policy implications associated with different stablecoin architectures.
Table 3.
Stablecoin characteristics across key analytical dimensions.
3.3. Central Bank Digital Currencies: Sovereign Digital Money
3.3.1. Conceptual Foundations and Design Choices
CBDCs are digital forms of central bank money that represent direct liabilities of the monetary authority and are denominated in the national unit of account [14]. Unlike physical cash, CBDCs operate in digital form and may be accessible either to the general public (retail CBDCs) or to financial institutions (wholesale CBDCs). As sovereign digital money, CBDCs seek to combine the safety and credibility of central bank liabilities with the efficiency, programmability, and accessibility of modern digital payment systems.
CBDC design involves several interrelated choices concerning user access, distribution architecture, technology, and functionality [4]. These include retail versus wholesale access, account-based versus token-based structures, direct versus intermediated distribution models, interest-bearing versus non-interest-bearing features, and the use of either DLT or conventional centralized infrastructures [80]. In addition, some CBDC initiatives focus primarily on domestic payment systems, while others aim to enhance cross-border payments through interoperability arrangements and multi-CBDC platforms [81]. These design choices involve important trade-offs relating to privacy, financial inclusion, scalability, operational resilience, monetary policy transmission, and financial stability, leading central banks to adopt different approaches based on their institutional objectives and economic conditions [36].
3.3.2. Motivations and Objectives
Central banks are exploring CBDCs for a range of economic, technological, and strategic reasons [82,83]. A primary motivation is the declining use of cash in many economies, which has raised concerns about maintaining public access to central bank money in an increasingly digital environment [84]. CBDCs are also viewed as a means of improving payment efficiency, promoting financial inclusion, strengthening monetary policy transmission, and enhancing the resilience of payment systems [18,85]. In addition, they have attracted interest as a potential solution for improving cross-border payments and preserving monetary sovereignty in the face of growing competition from private digital currencies, stablecoins, and foreign CBDCs [77,86]. Many central banks further regard CBDCs as a catalyst for innovation and competition within the financial sector by providing a secure and interoperable public digital payment infrastructure [87]. The relative importance of these objectives varies across jurisdictions, with advanced economies often emphasizing payment efficiency and monetary sovereignty, while emerging economies tend to prioritize financial inclusion and cross-border payment improvements [23].
3.3.3. Pilot Projects and Implementations
By May 2026, 146 countries/currency unions [15] representing approximately 98% of global GDP were exploring CBDCs, with over 20 jurisdictions having launched pilot programs or operational systems [88]. Early implementations, including the Bahamas’ Sand Dollar, Nigeria’s eNaira, China’s e-CNY, and Jamaica’s JAM-DEX, illustrate diverse policy objectives ranging from financial inclusion and payment efficiency to monetary innovation and digital transformation [15,89,90,91]. At the same time, major economies, such as the Eurozone, the United Kingdom, and the United States, have continued to evaluate CBDC issuance through research, consultation, and pilot initiatives [92]. Internationally, projects led by the BIS Innovation Hub, including Project Dunbar, Project Jura, Project mBridge, and Project Agorá, have demonstrated growing interest in cross-border interoperability, wholesale settlement, and the integration of CBDCs with tokenized financial assets [17,86]. Collectively, these initiatives highlight the transition of CBDCs from theoretical concepts to practical policy experiments within the evolving digital money ecosystem. The principal design characteristics and policy implications of CBDCs are presented in Table 4.
Table 4.
CBDC characteristics across key analytical dimensions.
3.3.4. Risks and Challenges
Despite their potential benefits, CBDCs present important economic, operational, and governance challenges. A key concern is bank disintermediation, as the migration of deposits from commercial banks to CBDCs could affect bank funding and credit creation [93]. CBDCs may also increase financial stability risks during periods of stress by facilitating rapid digital bank runs [85,94]. Privacy remains a central challenge, particularly for account-based systems that require identity verification while balancing AML/CTF requirements and user confidentiality [22,23]. In addition, CBDCs require highly resilient technological infrastructures capable of withstanding cyberattacks, operational failures, and service disruptions [4]. Cross-border adoption may create spillover effects, including currency substitution and pressures on monetary sovereignty in smaller economies [77,95], while implementation requires substantial investments in technology, regulation, and public awareness. Consequently, successful CBDC deployment depends on careful design, robust governance arrangements, and continuous risk monitoring.
3.4. Tokenized Deposits: Programmable Commercial Bank Money
3.4.1. Conceptual Foundations
Tokenized deposits represent a fourth pillar of the digital money ecosystem, distinct from cryptocurrencies, stablecoins, and CBDCs. Tokenized deposits are commercial bank deposits issued on DLT, representing liabilities of regulated banks, and benefiting from deposit insurance, prudential regulation, and central bank liquidity support [8].
Tokenized deposits occupy an intermediate position between stablecoins and CBDCs. Compared with stablecoins, they benefit from stronger regulatory oversight, deposit protection mechanisms, and closer integration with the traditional banking system, although they may offer less flexibility and scope for innovation. Compared with CBDCs, tokenized deposits preserve the role of commercial banks in credit intermediation and customer relationships, thereby reducing concerns about bank disintermediation. However, they do not possess the risk-free status of central bank money and offer fewer opportunities for direct monetary policy transmission. As a result, tokenized deposits are increasingly viewed as a complementary component of the emerging digital money ecosystem, bridging the gap between private digital assets and sovereign digital currencies [17].
3.4.2. Use Cases and Pilot Projects
Tokenized deposits enable a range of innovative financial applications, including programmable payments, atomic settlement, interoperability with tokenized assets, and more efficient cross-border transactions [72]. By combining commercial bank money with DLT, they support automated payment execution, delivery-versus-payment (DvP) settlement, and integration with broader tokenized financial ecosystems.
Interest in tokenized deposits has grown rapidly among major financial institutions. Initiatives such as JPM Coin and Citi Token Services have demonstrated the feasibility of tokenized deposits for wholesale payments, treasury management, and smart-contract-enabled transactions [96]. Other banks, including HSBC and Standard Chartered, have explored their use in trade finance and cross-border payments [97,98]. At the international level, BIS Project Agorá has examined the integration of wholesale CBDCs, tokenized deposits, and tokenized securities within unified ledger architectures, highlighting their potential to support programmable finance and atomic settlement [17]. Collectively, these initiatives illustrate the growing role of tokenized deposits as a bridge between traditional banking systems and emerging digital asset infrastructures [99].
3.4.3. Regulatory Considerations
Although tokenized deposits benefit from existing banking regulation, their implementation on DLT raises several regulatory and operational challenges. Key issues include their legal recognition as equivalent to traditional bank deposits, the applicability of deposit insurance protections, and the development of interoperability standards that enable seamless transfers across different platforms and institutions [76,100]. Additional concerns relate to custody arrangements, control of digital assets, cybersecurity, and compliance with AML and CTF requirements in increasingly programmable and interconnected financial environments [21,76]. In response, several jurisdictions, including Switzerland, Singapore, and the United Kingdom, have begun adapting legal and regulatory frameworks to accommodate tokenized deposits and related forms of digital financial infrastructure [101]. As digital finance evolves, regulatory clarity will play a critical role in supporting the safe and scalable adoption of tokenized deposits within the broader digital money ecosystem. The major milestones in the evolution of digital money between 2008 and 2025 are summarized in Figure 4.
Figure 4.
Timeline of digital money evolution: key milestones from Bitcoin (2008) to CBDC pilots and tokenized deposit platforms (2020–May 2026).
4. Comparative Analysis: Trust, Governance, and Regulation
4.1. Trust Mechanisms
The four pillars of digital money embody fundamentally different trust mechanisms. Cryptocurrencies rely on algorithmic trust, stablecoins on reserve-backed trust, CBDCs on sovereign trust, and tokenized deposits on institutional trust embedded within regulated banking systems. These mechanisms reflect different trade-offs between decentralization and stability, privacy and compliance, innovation, and regulation, consistent with the absence of a single dominant trust mechanism across the four instruments compared in Table 5 [102].
Table 5.
Comparative trust mechanisms across digital money instruments.
4.2. Governance Architectures
Governance architectures vary significantly across digital money instruments (Table 6). Decentralized governance (cryptocurrencies and some stablecoins) offers censorship resistance and community participation but suffers from slow decision-making, coordination challenges, and vulnerability to capture by concentrated stakeholders [51,103]. Centralized governance (CBDCs, tokenized deposits, and most stablecoins) enables rapid adaptation and clear accountability but concentrates power and may limit innovation [23].
Table 6.
Comparative governance architectures across digital money instruments.
4.3. Regulatory Exposures
Regulatory exposures vary across digital money instruments, reflecting their different trust mechanisms, governance architectures, and systemic importance (Table 7). Regulatory approaches are converging toward a principle of “same activity, same risk, same regulation,” with increasing emphasis on comprehensive regulation of stablecoins and cryptocurrency service providers, while preserving space for innovation [104].
Table 7.
Comparative regulatory exposures across digital money instruments.
5. The Digital Money Ecosystem Taxonomy (DMET)
While Table 5, Table 6 and Table 7 compare digital money across trust, governance, and regulatory dimensions, a broader classification framework is needed to systematically organize the growing diversity of digital money instruments. To address this need, DMET is proposed as an integrative framework that captures the key structural dimensions underlying cryptocurrencies, stablecoins, CBDCs, and tokenized deposits. Before detailing the DMET’s structure, it is useful to situate it against the classification frameworks it builds on.
Classification frameworks for digital money have a substantial prior literature. The most widely cited is the BIS “money flower” [24], which sorts instruments by issuer (central bank vs. other), form (digital vs. physical), accessibility (widely available vs. restricted), and transfer mechanism (centralized vs. peer-to-peer). Later frameworks build on it. The IMF “money tree” [77] adds claim-based attributes, and R3′s 2021 CBDC taxonomy [105] extends both to cover CBDC design choices.
These frameworks share two gaps that DMET addresses. First, tokenized deposits emerged as a distinct category only after 2019 to 2023 pilots by JPMorgan, Citibank, HSBC, and others, and no prior taxonomy, including the money flower and R3′s extension, treats them as a structurally distinct fourth category alongside cryptocurrencies, stablecoins, and CBDCs. Second, none of these frameworks combine operational and technological dimensions, such as programmability, scalability, energy efficiency, and interoperability, with the institutional, governance, and trust dimensions they already cover. DMET is not the first multidimensional taxonomy of digital money. To the author’s knowledge, it is the first to jointly classify all four instrument types across both institutional and technological dimensions within a single framework. With this positioning established, the following paragraph sets out DMET’s structure in full.
DMET provides a multidimensional framework for classifying digital money instruments across fourteen institutional, governance, technological, monetary, and regulatory dimensions (Table 8).
Table 8.
Proposed digital money ecosystem taxonomy (DMET).
These dimensions include issuer type, liability structure, governance arrangements, trust mechanisms, monetary control, settlement roles, regulatory exposure, primary use cases, degree of decentralization, privacy level, programmability, scalability, energy efficiency, and interoperability. Together, these dimensions capture both the structural foundations and functional characteristics of cryptocurrencies, stablecoins, CBDCs, and tokenized deposits, enabling systematic comparison across diverse forms of digital money. The taxonomy provides a practical tool for researchers, policymakers, and practitioners to analyze, compare, and evaluate digital money instruments while supporting evidence-based policy development and strategic decision-making [4].
The evolution of digital money can also be understood through a comparative institutional framework that reflects changing trust mechanisms, governance structures, monetary control, and regulatory exposure across different forms of digital money, as illustrated in Figure 5.
Figure 5.
Evolutionary continuums of the digital money ecosystem.
Unlike the money flower [24] and its direct extensions, the IMF money tree [77] and R3′s CBDC taxonomy [105], all of which classify instruments along institutional and legal attributes but omit operational-technological dimensions, the DMET adopts a multidimensional perspective that captures the institutional, technological, and governance characteristics of digital money simultaneously. The framework recognizes that digital money instruments cannot be adequately understood through binary distinctions, such as public versus private money or centralized versus decentralized systems. Instead, they exist along multiple continuums reflecting varying degrees of trust, governance, monetary control, programmability, and regulatory oversight. By integrating these dimensions within a single framework, the DMET facilitates systematic comparison across heterogeneous digital money instruments and provides a foundation for future empirical, policy, and theoretical research.
The DMET taxonomy reveals several key insights:
- No single instrument dominates across all fourteen DMET dimensions. Each digital money instrument offers distinct advantages and disadvantages across different use cases.
- Trade-offs are fundamental, and decentralization, privacy, scalability, regulatory compliance, and stability involve inherent trade-offs. Instruments that excel in one dimension often underperform in others.
- Complementarity: The four pillars are complementary rather than mutually exclusive. Cryptocurrencies provide censorship-resistant infrastructure, stablecoins provide price stability, CBDCs provide risk-free public money, and tokenized deposits provide regulated programmable money. A layered ecosystem incorporating all four may be optimal.
- Evolution and convergence: The boundaries among categories are blurring. Some stablecoins are seeking banking licenses, some banks are issuing tokenized deposits, and some CBDCs are exploring DLT architectures. Convergence and hybridization are likely.
6. Governance, Economic, and Global Implications
6.1. Regulatory Governance Frameworks
6.1.1. International Regulatory Coordination
The cross-border nature of digital money has intensified the need for international regulatory coordination. Major international organizations have issued guidance covering financial stability, prudential regulation, AML compliance, and CBDC development. FSB has proposed recommendations for stablecoin arrangements and broader crypto-asset regulation, emphasizing regulatory consistency and cross-border cooperation [75,76,104]. The Financial Action Task Force (FATF) has established AML/CTF standards for virtual asset service providers, including customer due diligence requirements and the travel rule [21]. BIS has supported international collaboration through CBDC research and Innovation Hub projects [100], while IMF has highlighted the importance of macroeconomic coordination and managing cross-border spillovers [106]. In addition, the Basel Committee has introduced prudential standards governing banks’ exposures to crypto-assets. Despite these efforts, regulatory fragmentation and opportunities for regulatory arbitrage remain significant challenges [107].
6.1.2. Jurisdictional Approaches
Jurisdictions have adopted diverse regulatory approaches to digital money:
- European Union’s MiCA: The Markets in Crypto-Assets Regulation, which entered into force in 2023 and became fully applicable in December 2024, establishes a comprehensive regulatory framework for crypto-assets, including cryptocurrencies, stablecoins, and crypto-asset service providers. MiCA requires authorization, prudential safeguards, transparency, and consumer protection, with additional requirements for significant stablecoins [108].
- United States: The US regulatory approach is fragmented across multiple agencies (SEC, CFTC, OCC, Federal Reserve, FinCEN, and state regulators), with ongoing debates about the appropriate regulatory classification of crypto-assets and the division of regulatory authority. However, legislative proposals have sought to establish a comprehensive federal framework, and as of May 2026, comprehensive legislation has not been enacted [109,110].
- United Kingdom: The UK has brought certain crypto-asset activities within the regulatory perimeter, including AML/CTF regulation of crypto-asset exchanges and wallet providers. The UK government has proposed bringing stablecoins used as payment instruments within the regulatory perimeter, subjecting them to requirements similar to those for electronic money institutions [111].
- Singapore: A comprehensive regulatory framework has been established for digital payment tokens and stablecoin issuers, requiring licensing, AML/CTF compliance, and prudential safeguards in Singapore. This country has positioned itself as a hub for digital asset innovation while maintaining robust regulatory oversight [112].
- Hong Kong: A licensing regime for virtual asset service providers and stablecoin issuers was introduced in 2023 and 2024, respectively, in Hong Kong. Stablecoin regime requires reserve backing, redemption guarantees, and regulatory oversight by the Hong Kong Monetary Authority [113].
- China: China has banned cryptocurrency trading and mining, while simultaneously advancing the e-CNY CBDC pilot. China’s approach reflects a preference for state-controlled digital money over private cryptocurrencies [114].
- Switzerland: A comprehensive legal framework for digital assets, including amendments to banking, securities, and insolvency laws to accommodate tokenized assets and DLT-based financial market infrastructures, has also been established by Switzerland [115].
These diverse approaches reflect different policy priorities, institutional structures, and risk assessments, creating challenges for cross-border digital money activities [104].
6.1.3. Regulatory Challenges and Future Directions
Several regulatory challenges remain unresolved:
- Regulatory classification: The appropriate classification of crypto-assets (commodities, securities, currencies, or sui generis) remains contested, with implications for regulatory authority, investor protection, and taxation [61].
- Decentralized finance: DeFi protocols operate without traditional intermediaries, raising questions about how to apply existing regulatory frameworks designed for intermediated finance. Potential approaches include regulating DeFi protocol developers, front-end interfaces, or DAO governance token holders, but each approach faces conceptual and practical challenges [47].
- Cross-border coordination: Effective regulation of global digital money requires cross-border coordination, but achieving consensus among jurisdictions with different legal systems, policy priorities, and risk assessments is challenging [104].
- Innovation and regulation balance: Regulators face the challenge of mitigating risks without stifling innovation. Regulatory sandboxes, innovation hubs, and principles-based regulation are potential approaches, but their effectiveness remains debated [116].
- Privacy and surveillance: Balancing privacy rights with AML/CTF compliance and law enforcement needs is a central challenge, particularly for CBDCs and account-based digital money systems [22].
- Quantum computing threats: The emergence of quantum computing poses long-term threats to current cryptographic protocols, requiring the development and deployment of quantum-resistant cryptography for digital money systems [117].
Future regulatory frameworks are likely to emphasize comprehensive regulation, cross-border coordination, technology-neutral principles, and adaptive governance that can evolve with technological and market developments [104].
The governance and regulatory challenges identified in this section reinforce the multidimensional nature of digital money highlighted by the DMET framework. Differences in issuer structures, liability arrangements, trust mechanisms, and governance models require regulatory approaches that extend beyond traditional distinctions between public and private money. Future regulatory frameworks are, therefore, likely to combine international coordination, technology-neutral principles, and adaptive governance mechanisms that accommodate continued convergence among cryptocurrencies, stablecoins, tokenized deposits, and CBDCs. This layered governance structure, spanning protocol, institutional, legal, and international dimensions, is depicted in Figure 6.
Figure 6.
Layered governance framework for digital money: protocol, institutional, legal, and international dimensions across cryptocurrencies, stablecoins, CBDCs, and tokenized deposits.
6.2. Economic Implications
6.2.1. Monetary Policy Transmission
Digital money has important implications for monetary policy transmission and monetary sovereignty. CBDCs may strengthen policy transmission by enabling direct access to central bank money and facilitating mechanisms such as targeted transfers, programmable payments, or, in theory, negative interest rate policies [19]. However, large-scale migration of deposits from commercial banks to CBDCs could weaken traditional bank-based transmission channels and increase disintermediation risks [18].
Stablecoins introduce additional challenges, particularly when denominated in foreign currencies. Widespread adoption of dollar-backed stablecoins could reduce the effectiveness of domestic monetary policy in smaller economies and increase exposure to external monetary shocks [77]. Cryptocurrencies may also limit monetary policy effectiveness by providing alternative stores of value and payment mechanisms outside central bank control, although their high volatility and limited use in everyday transactions have so far constrained this impact [65].
6.2.2. Fiscal Policy and Taxation
CBDCs may also affect fiscal administration by facilitating person-to-government payments, including taxes and public levies, and by reducing payment-processing and collection costs [118]. Subject to explicit legal authorization, programmable features could support automated tax withholding or settlement, while the same infrastructure could facilitate tax refunds, subsidies, and social transfers. As a digital form of sovereign currency, CBDC would not necessarily constitute a separately taxable asset—taxation would generally apply to the underlying income, transaction, transfer, or interest earned. These potential efficiencies must nevertheless be balanced against privacy, data protection, cybersecurity, and due-process concerns [19].
6.2.3. Payment System Efficiency
Digital money has the potential to improve payment system efficiency by reducing transaction costs, accelerating settlement processes, and expanding access to digital financial services. By reducing reliance on intermediaries and enabling peer-to-peer transactions, digital money can lower payment costs and streamline financial operations [119]. In addition, near-instantaneous settlement capabilities may offer significant advantages over traditional payment systems, particularly for cross-border transactions that often involve multiple intermediaries and lengthy processing times [86].
Digital money may also promote financial inclusion by expanding access to payment services for unbanked and underbanked populations, especially in emerging economies [120]. These benefits are particularly relevant for cross-border payments, where digital money could improve speed, transparency, and cost efficiency while addressing longstanding limitations of correspondent banking networks [81]. However, realizing these gains will depend on overcoming challenges related to interoperability, regulatory compliance, technological infrastructure, and user adoption [23].
6.2.4. Credit Intermediation
Digital money is reshaping traditional credit intermediation by enabling new forms of lending, borrowing, and asset financing. DeFi protocols facilitate peer-to-peer lending without conventional financial intermediaries, potentially expanding access to credit and increasing market efficiency. However, these arrangements introduce new risks, including smart contract vulnerabilities, over-collateralization requirements, governance weaknesses, and pro-cyclical liquidation mechanisms during periods of market stress [54].
In parallel, the tokenization of loans and other credit instruments may improve liquidity, transparency, and secondary market trading by enabling fractional ownership and more efficient transfer of financial assets. While tokenized credit markets could enhance capital allocation and broaden investment opportunities, they also raise important questions regarding regulatory treatment, investor protection, legal enforceability, and risk management frameworks [72]. As digital credit ecosystems continue to evolve, balancing innovation with financial stability and consumer protection will remain a key policy challenge.
6.2.5. International Monetary System
Digital money has the potential to reshape the international monetary system by influencing currency usage, cross-border payments, and geopolitical dynamics. The growing adoption of dollar-denominated stablecoins may reinforce the international role of the US dollar by extending its use in global payments, savings, and digital asset markets, thereby strengthening existing patterns of monetary influence [77]. At the same time, multi-CBDC platforms and interoperable digital payment infrastructures could reduce reliance on correspondent banking networks and improve the efficiency of cross-border transactions, potentially altering the architecture of international payments [81].
Digital money may also intensify currency competition by lowering switching costs between domestic and foreign currencies, increasing the ability of households and businesses to hold and transact in alternative forms of money. Such developments could amplify exchange rate volatility and complicate domestic monetary management, particularly in smaller and more open economies [102]. Beyond economic considerations, digital money carries significant geopolitical implications, as CBDCs, stablecoins, and digital payment infrastructures may become instruments of strategic competition, influencing sanctions enforcement, financial surveillance, technological standards, and monetary sovereignty [77,121]. Consequently, the future international monetary system is likely to be shaped by the interaction between technological innovation, regulatory coordination, and evolving geopolitical interests.
Collectively, these developments suggest that digital money is reshaping monetary policy transmission, financial stability, payment systems, credit intermediation, and the international monetary order. While CBDCs and tokenized deposits largely extend existing institutional structures into digital environments, cryptocurrencies and stablecoins introduce alternative monetary and payment infrastructures that challenge traditional models of monetary governance. The ultimate economic impact of digital money will depend on the interaction between technological innovation, regulatory frameworks, market adoption, and international cooperation.
6.3. Financial Stability Issues
Digital money presents both opportunities and risks for financial stability. Stablecoins remain vulnerable to confidence shocks, as concerns regarding reserve adequacy or redemption mechanisms may trigger runs, fire sales of reserve assets, and contagion effects that extend into traditional financial markets [10]. Similarly, retail CBDCs could accelerate deposit migration from commercial banks, particularly during periods of financial stress, potentially weakening banks’ funding bases and increasing the risk of rapid digital bank runs. Proposed mitigation measures include holding limits, tiered remuneration structures, and transfer restrictions during crisis periods [93].
In addition, crypto-asset markets continue to exhibit high levels of volatility, leverage, and interconnectedness, raising concerns about systemic risk as links with traditional financial institutions expand [104]. DeFi ecosystems introduce further vulnerabilities, including smart contract failures, oracle manipulation, governance attacks, and liquidity shocks, that may spread across interconnected protocols [50]. Consequently, maintaining financial stability in an increasingly digital monetary environment will require robust regulatory oversight, effective risk management frameworks, and mechanisms to contain contagion across both traditional and digital financial systems.
6.4. Global Digital Money Landscape
6.4.1. Regional Variations
Digital money development exhibits substantial regional variation, reflecting differences in regulatory priorities, financial infrastructure, and monetary policy objectives. The Asia–Pacific region remains at the forefront of CBDC experimentation, led by China’s e-CNY and supported by active initiatives in Singapore, Hong Kong, Thailand, Australia, and India. The region also records some of the highest levels of cryptocurrency adoption, driven by remittances, investment activity, and financial inclusion objectives [23].
Europe and North America have adopted more cautious approaches. The European Union has established one of the world’s most comprehensive regulatory frameworks through MiCA while continuing preparations for a potential digital euro. In contrast, the United States combines high cryptocurrency and stablecoin adoption with a fragmented regulatory landscape, while Canada has prioritized research and experimentation over deployment [118,122].
Emerging markets across Latin America, Africa, and Asia have adopted different combinations of sovereign and private digital money in response to financial inclusion gaps, remittance costs, inflation, currency instability, and monetary sovereignty concerns. Nigeria represents a relatively state-centered approach through the eNaira and cautious treatment of private cryptocurrencies. Brazil follows a more coexistence-oriented model in which DREX is developing alongside substantial cryptocurrency and stablecoin use. India similarly combines a retail CBDC pilot with high private cryptocurrency adoption, although the latter is subject to restrictive taxation. These cases demonstrate that regional variation reflects differences in domestic economic conditions and policy objectives rather than a single emerging-market regulatory model [92,123]. Table 9 summarizes regional patterns in CBDC development, stablecoin regulation, and cryptocurrency adoption.
Table 9.
Regional comparison of the global digital money landscape (May 2026).
6.4.2. Adoption Drivers and Barriers
Digital money adoption is influenced by both enabling and constraining factors. Key drivers include payment efficiency, financial inclusion, cross-border remittances, inflation hedging, technological innovation, investment opportunities, and regulatory clarity [23,124]. Conversely, adoption may be hindered by cryptocurrency volatility, regulatory uncertainty, security concerns, limited merchant acceptance, interoperability challenges, and competition from established payment systems [82]. Adoption patterns also vary across demographic and institutional contexts, with younger and more technologically sophisticated users, as well as populations facing weak financial infrastructure or currency instability, generally exhibiting higher adoption rates.
6.4.3. Future Scenarios
Future scenarios for the global digital money landscape include the following:
- Pluralistic coexistence: Cryptocurrencies, stablecoins, CBDCs, and tokenized deposits coexist within a layered, interoperable ecosystem, each serving different use cases and user segments [100].
- CBDC dominance: CBDCs become the dominant form of digital money, with stablecoins and cryptocurrencies relegated to niche use cases or heavily regulated [26].
- Private digital money dominance: Stablecoins and tokenized deposits become the dominant forms of digital money, with CBDCs playing a limited role or not being issued [10].
- Fragmentation: The global digital money landscape fragments along geopolitical lines, with competing regional blocs (US-led, China-led, and EU-led) developing incompatible digital money systems [102].
- Hybrid systems: Future monetary systems combine public money (cash, reserves, and CBDCs), regulated private money (bank deposits, tokenized deposits, and regulated stablecoins), and selected crypto-asset infrastructures within layered governance arrangements [100].
A hybrid system appears most consistent with current regulatory and market trends, although its configuration is likely to vary across the jurisdictions discussed in Section 6.4.1 [23].
7. Practical Implications, Discussion, and Future Research
7.1. Implications for Policymakers
The evolution of digital money presents policymakers with complex challenges involving monetary sovereignty, financial stability, innovation, and consumer protection. Key policy decisions include the potential issuance and design of CBDCs, the regulatory treatment of stablecoins and cryptocurrencies, and the development of frameworks that balance innovation with risk mitigation [36,75,76]. Given the inherently cross-border nature of digital money, strengthening international regulatory coordination remains essential to address regulatory arbitrage, systemic risks, and interoperability challenges. Policymakers must also consider how digital money can support broader public policy objectives, including financial inclusion, payment system modernization, and economic resilience, while balancing privacy rights with AML/CTF compliance and law enforcement requirements [22].
7.2. Implications for Financial Institutions
Financial institutions must adapt their strategies, technologies, and business models to remain competitive in an increasingly digital monetary environment. Banks and other financial intermediaries face strategic decisions regarding participation in CBDC ecosystems, issuance of tokenized deposits, and the provision of cryptocurrency-related services [100]. At the same time, digital money requires substantial investment in technological infrastructure, including distributed ledger technologies, smart contract capabilities, and interoperability solutions [125]. These developments introduce new operational, cybersecurity, regulatory, and reputational risks that require enhanced risk management frameworks [76]. More broadly, digital money is likely to reshape traditional banking activities, creating both competitive pressures and new opportunities in payments, custody, settlement, and digital asset services while increasing the importance of regulatory compliance across multiple jurisdictions [21].
7.3. Implications for Technology Providers
Technology providers play a central role in enabling the digital money ecosystem through the development of secure, scalable, and interoperable infrastructure. This includes blockchain platforms, payment networks, custody solutions, and technical standards that facilitate interoperability across diverse digital money systems [4,100]. As privacy, security, and regulatory compliance become increasingly important, technology firms are also expected to advance privacy-enhancing technologies, including zero-knowledge proofs, secure multi-party computation, and confidential transaction frameworks [22]. In addition, the emergence of quantum computing highlights the need for quantum-resistant cryptographic solutions capable of protecting future digital money infrastructures [126]. Beyond technical performance, widespread adoption will depend on improving user experience through intuitive interfaces, seamless integration with existing financial systems, and accessible digital wallet solutions [82].
7.4. Implications for Users
Digital money expands the range of financial services available to households and businesses by enabling faster, potentially lower-cost payments, broader access to financial services, and new investment opportunities [23,60]. These benefits may be particularly significant for underserved and underbanked populations. However, users must also navigate important challenges, including trade-offs between privacy and regulatory compliance, exposure to financial surveillance, and increased responsibility for safeguarding digital assets and personal credentials [22,54]. As digital money becomes more widely adopted, financial literacy, digital skills, and user awareness will play an increasingly important role in ensuring safe and effective participation in digital financial ecosystems.
7.5. Future Research Directions
The rapid evolution of digital money continues to generate important technical, economic, regulatory, and societal questions that remain insufficiently understood. Future research should move beyond conceptual discussions and focus increasingly on empirical evaluation, comparative analysis, and interdisciplinary inquiry to support evidence-based policy and institutional decision-making.
7.5.1. Technical Research
Future technical research should focus on enhancing the scalability, interoperability, security, and privacy of digital money systems. Key priorities include the development of scalable blockchain architectures and Layer-2 solutions capable of supporting mainstream transaction volumes, interoperable infrastructures that facilitate seamless interaction across digital money platforms, and privacy-enhancing technologies that balance confidentiality with regulatory compliance [81]. In addition, the emergence of quantum computing highlights the need for quantum-resistant cryptographic standards and more robust approaches to smart contract security, verification, and auditing [126].
7.5.2. Economic Research
Future economic research should move from general conceptual analysis toward testable causal and comparative designs. Priority questions include whether CBDC launches alter bank deposits and credit creation, whether stablecoin de-pegging generates contagion in traditional markets, and whether private digital money adoption weakens monetary policy transmission [18,85]. These questions could be examined through event studies, cross-country panels, difference-in-differences designs, and household- or firm-level adoption data. Research should also estimate effects on payment costs, financial inclusion, currency substitution, and cross-border transactions while distinguishing announced projects, limited pilots, and operational systems [82,102]. Such distinctions are necessary to avoid treating heterogeneous stages of CBDC development as equivalent empirical interventions.
7.5.3. Regulatory and Legal Research
The continued expansion of digital money requires further research on regulatory design, governance, and legal frameworks. Important priorities include the classification and regulation of crypto-assets, prudential requirements for stablecoin issuers, governance arrangements for DeFi, and mechanisms for improving international regulatory coordination [75,76]. Future studies should also examine legal questions related to privacy, surveillance, property rights, insolvency treatment, conflict of laws, and emerging governance models involving public–private partnerships, multi-stakeholder structures, and decentralized autonomous organizations [22,47].
7.5.4. Interdisciplinary Research
Digital money should increasingly be studied as a socio-technical phenomenon shaped by interactions among technology, institutions, markets, and users. Future interdisciplinary research should translate these questions into testable empirical designs. Behavioral surveys and experiments, combined with transaction and adoption data, could examine the drivers of trust and adoption [4,102]. Comparative institutional analysis could investigate how financial inclusion, capital control, and monetary sovereignty priorities shape digital money governance across jurisdictions. Additional work is needed to evaluate the ethical and societal implications of digital money, including issues of privacy, surveillance, financial inclusion, algorithmic governance, and environmental sustainability [22,127]. These approaches connect economics, behavioral science, political science, law, computer science, and sustainability research within an empirically actionable agenda.
7.6. Discussion
The evolution of digital money represents a fundamental transformation in the institutions and technologies through which value is issued, transferred, stored, and governed. This transformation is not a linear technological progression but rather a contest among competing sources of trust, algorithmic consensus, private reserve backing, and sovereign monetary authority, each embodying different trade-offs in terms of decentralization, stability, scalability, privacy, and regulatory compliance. Several key themes emerge from this review. (1) Pluralism and complementarity: The digital money ecosystem is characterized by pluralism rather than winner-take-all dynamics. Cryptocurrencies, stablecoins, CBDCs, and tokenized deposits each offer distinct advantages and disadvantages, serving different use cases and user segments. Cryptocurrencies provide censorship-resistant infrastructure and DeFi applications, stablecoins provide price stability and programmability, CBDCs provide risk-free public money and monetary policy integration, and tokenized deposits provide regulated programmable money with deposit insurance. The DMET framework further demonstrates that these instruments differ across institutional, technological, monetary, and regulatory dimensions, reinforcing the complementarity argument developed throughout Section 4, Section 5 and Section 6 [100]. (2) Trade-offs and tensions: Digital money involves fundamental trade-offs among policy objectives. Decentralization enhances censorship resistance but complicates governance and regulatory compliance. Privacy protects individual autonomy but raises AML/CTF concerns. Scalability enables mainstream adoption but may require centralization or complexity. Stability requires reserve backing or central bank issuance but limits decentralization. Consistent with the DMET framework, no single digital money instrument dominates across all institutional, technological, monetary, and regulatory dimensions, requiring policymakers and market participants to make explicit choices regarding the trade-offs they prioritize [36]. (3) Institutional and technological co-evolution: Digital money is not purely a technological phenomenon but rather a co-evolution of technology and institutions. Technological innovations (blockchain, smart contracts, and cryptographic protocols) enable new monetary architectures, but their adoption and impact depend on institutional factors (regulation, governance, trust, and social norms). Conversely, institutional innovations (new regulatory frameworks, multi-stakeholder governance, and international coordination) shape the trajectory of technological development. Understanding digital money requires integrating technological and institutional analysis [4]. (4) Regulatory divergence in emerging economies: Nigeria and China illustrate how similar commitments to sovereign digital currency can produce different regulatory configurations. Nigeria has linked the eNaira to financial inclusion and payment efficiency while moving from restrictive banking measures toward cautious accommodation of private crypto-assets [90]. China has combined extensive e-CNY experimentation with continuing restrictions on cryptocurrency trading and mining, reflecting stronger priorities concerning state oversight, capital controls, and monetary sovereignty [114]. Under DMET, both CBDCs share sovereign trust and centralized issuance, but their governance arrangement and regulatory exposure differ because digital money policy is conditioned by domestic institutional capacity, inclusion objectives, and attitudes toward private monetary innovation. This comparison explains why regulatory convergence on common risks can coexist with substantial national divergence [104].
7.7. Unresolved Questions
Several critical questions remain unresolved.
Will CBDCs be widely adopted? The success of CBDCs depends on design choices, user experience, merchant acceptance, and competition from private digital money. Early evidence from pilot projects is mixed [82]. Will stablecoins be regulated as banks? Regulatory approaches to stablecoins are evolving, with increasing convergence toward banking-like regulation, but significant variation remains across jurisdictions [76]. Will DeFi be integrated with traditional finance or remain a parallel system? DeFi’s future depends on regulatory developments, scalability improvements, and the resolution of security and governance challenges [47]. Will digital money enhance or undermine financial inclusion? Digital money offers potential benefits for financial inclusion but also risks exacerbating digital divides and excluding populations without digital literacy or infrastructure. Will digital money reshape the international monetary system? The geopolitical implications of digital money, including currency competition, dollar dominance, and monetary sovereignty, remain uncertain and contested [102].
Although these questions remain unresolved, the literature identifies several proportionate policy responses. These include phased and user-centered CBDC pilots, holding limits and tiered remuneration to reduce deposit migration, reserve transparency, and enforceable redemption requirements for stablecoins, and risk-based oversight of DeFi governance and user-facing interfaces. Offline access and digital literacy measures can support financial inclusion, while interoperability standards and coordinated supervision can mitigate cross-border risks.
7.8. Limitations
Several limitations should be acknowledged when interpreting the findings of this review. First, the digital money ecosystem is evolving rapidly, and recent technological, regulatory, and market developments may not yet be fully reflected in the peer-reviewed literature. Although this review incorporates authoritative gray literature, including central bank and international institutional reports, some emerging industry developments may remain underrepresented.
Second, while the review adopts a multidisciplinary perspective, it necessarily emphasizes economics, finance, and public policy. Consequently, more detailed technical discussions of cryptographic protocols, consensus mechanisms, and smart contract architectures fall outside the scope of the analysis. Similarly, the review focuses primarily on developments in major economies and international institutions, providing less detailed coverage of smaller economies and regional experiences.
Third, empirical evidence remains limited for several areas of the digital money ecosystem, particularly CBDCs and tokenized deposits, which remain in relatively early stages of development and deployment. As a result, many proposed benefits, risks, and policy implications continue to rely on theoretical arguments, simulations, or pilot-project evidence rather than extensive real-world observations.
Finally, the review aims to provide a balanced and analytical synthesis; however, the selection and interpretation of evidence inevitably reflect certain assumptions and perspectives. In addition, the DMET framework represents a heuristic classification tool designed to simplify a complex and rapidly evolving ecosystem. As boundaries among cryptocurrencies, stablecoins, CBDCs, and tokenized deposits continue to blur, future refinements may be required to accommodate emerging hybrid forms of digital money.
Despite these limitations, the review provides a multidisciplinary synthesis of the evolving digital money ecosystem that extends existing classification frameworks (such as the money flower taxonomy) and offers a structured framework for future research, policy analysis, and institutional decision-making.
8. Conclusions
Digital money has evolved from a peripheral technological experiment to a central concern of monetary economics, financial regulation, and public policy. The contemporary digital money ecosystem rests on four pillars, which are cryptocurrencies, stablecoins, CBDCs, and tokenized deposits, each embodying different trust mechanisms, governance architectures, and regulatory exposures.
This scoping–integrative review has synthesized multidisciplinary scholarship on digital money, mapping conceptual foundations, design architectures, economic implications, governance models, and regulatory challenges. The review advances three principal contributions: (1) Synthesis: a structured synthesis of the evolution of digital money across all four pillars, integrating insights from economics, finance, computer science, law, and public policy. (2) Comparison: a comparative framework examining trust mechanisms, governance architectures, and regulatory exposures, revealing fundamental trade-offs among decentralization, stability, scalability, privacy, and regulatory compliance. (3) Taxonomy: DMET, a structured classification framework that categorizes digital money instruments according to issuer type, liability structure, governance arrangement, trust mechanism, monetary control, settlement role, regulatory exposure, primary use cases, degree of decentralization, privacy level, programmability, scalability, energy efficiency, and interoperability.
The evolution of digital money is not a linear technological progression but rather a contest among competing sources of trust, algorithmic consensus, private reserve backing, and sovereign monetary authority. No single trust mechanism dominates across all dimensions, suggesting that future monetary systems will be pluralistic and increasingly interoperable, combining public money, regulated private money, tokenized deposits, stablecoins, and selected crypto-asset infrastructures within layered governance arrangements. The emerging digital money ecosystem is, therefore, likely to be characterized by coexistence and complementarity rather than replacement by any single monetary instrument.
The digital money transformation poses profound questions for monetary policy, financial stability, payment systems, financial inclusion, privacy, and the international monetary system. Policymakers must navigate fundamental trade-offs, balancing innovation with risk mitigation, privacy with regulatory compliance, and decentralization with stability. Effective governance of the digital money ecosystem requires comprehensive regulation, international coordination, adaptive frameworks, and ongoing research to inform evidence-based policy.
Future research should address critical gaps in empirical evidence, particularly regarding CBDC impacts, stablecoin run dynamics, DeFi systemic risks, and digital money adoption patterns. Interdisciplinary research integrating technological, economic, legal, and socio-political perspectives is essential to understand digital money as a complex socio-technical system.
The digital money revolution is still in its early stages. The coming decade will determine whether digital money fulfils its promise of more efficient, inclusive, and resilient monetary systems or whether it introduces new risks and instabilities that undermine financial stability and monetary sovereignty. The choices made by policymakers, financial institutions, technology providers, and users will shape the future of money and, with it, the future of economic organization and governance.
Supplementary Materials
The following supporting information can be downloaded at: https://www.mdpi.com/article/10.3390/encyclopedia6090196/s1, File S1: Scopus File; File S2: WoS all 8 files total 7745 records+consolidated.
Funding
This research received no external funding.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
No new data were created or analyzed in this study. Data sharing is not applicable to this article.
Conflicts of Interest
The author declares no conflicts of interest.
Abbreviations
The following abbreviations are used in this manuscript:
| AML | Anti-Money Laundering |
| BIS | Bank for International Settlements |
| BUSD | Binance USD |
| CBDC | Central Bank Digital Currency |
| CBDCs | Central Bank Digital Currencies |
| CTF | Counter-Terrorist Financing |
| DAO | Decentralized Autonomous Organization |
| DeFi | Decentralized Finance |
| DLT | Distributed Ledger Technology |
| DMET | Digital Money Ecosystem Taxonomy |
| DvP | Delivery versus Payment |
| ECB | European Central Bank |
| e-CNY | Digital Yuan (China Central Bank Digital Currency) |
| eNaira | Nigeria Central Bank Digital Currency |
| FSB | Financial Stability Board |
| GDP | Gross Domestic Product |
| ICO | Initial Coin Offering |
| IMF | International Monetary Fund |
| JAM-DEX | Jamaica Digital Exchange |
| KYC | Know Your Customer |
| MiCA | Markets in Crypto-Assets Regulation |
| PoS | Proof-of-Stake |
| PoW | Proof-of-Work |
| PSP | Payment Service Provider |
| PvP | Payment versus Payment |
| TVL | Total Value Locked |
| UST | TerraUSD |
| USDC | USD Coin |
| USDT | Tether USD |
Appendix A
- Scopus final query( TITLE ( “digital money” OR “digital currency” OR stablecoin OR “central bank digital currency” OR cbdc OR “tokenized deposits” OR “tokenized money” OR defi OR “decentralized finance” ) OR ( TITLE ( bitcoin OR ethereum OR cryptocurrency OR blockchain OR “distributed ledger technology” ) AND TITLE-ABS-KEY ( money OR currency OR payment* OR monetary OR banking OR financ* OR regulat* OR polic* ) ) )AND PUBYEAR > 2007 AND PUBYEAR < 2026AND ( LIMIT-TO ( LANGUAGE , “English” ) )AND ( LIMIT-TO ( DOCTYPE , “ar” ) OR LIMIT-TO ( DOCTYPE , “re” ) )
- For Web of Science( TS=(“digital money” OR “digital currency” OR stablecoin OR “central bank digital currency” OR cbdc OR “tokenized deposits” OR “tokenized money” OR defi OR “decentralized finance”) OR ( TI=(bitcoin OR ethereum OR cryptocurrency OR blockchain OR “distributed ledger technology”) AND TS=(money OR currency OR payment* OR monetary OR banking OR financ* OR regulat* OR polic*) ) ) AND DT=(Article OR Review) AND LA=(English) AND PY=(2008–2025)
References
- Prasad, E.S. The Future of Money: How the Digital Revolution Is Transforming Currencies and Finance; Harvard University Press: Cambridge, MA, USA, 2021. [Google Scholar]
- Nakamoto, S. Bitcoin: A Peer-to-Peer Electronic Cash System. 2008, pp. 1–9. Available online: https://papers.ssrn.com/sol3/papers.cfm?abstract_id=3440802 (accessed on 14 August 2026).
- Yermack, D. Is Bitcoin a Real Currency? An Economic Appraisal. In Handbook of Digital Currency; Chuen, D.L.K., Ed.; Academic Press: San Diego, CA, USA, 2015; pp. 31–43. [Google Scholar]
- Auer, R.; Böhme, R. The Technology of Retail Central Bank Digital Currency. BIS Q. Rev. 2020, 85–100. Available online: https://www.bis.org/publications/technology-retail-central-bank-digital-currency (accessed on 14 August 2026).
- Aramonte, S.; Huang, W.; Schrimpf, A. DeFi Risks and the Decentralisation Illusion. BIS Q. Rev. 2021, 21–36. Available online: https://www.bis.org/publications/defi-risks-and-decentralisation-illusion (accessed on 14 August 2026).
- Abdallah-Ou-Moussa, S.; Wynn, M.; Kharbouch, O. Blockchain, Cryptocurrencies, and Decentralized Finance: A Case Study of Financial Inclusion in Morocco. Int. J. Financ. Stud. 2025, 13, 124. [Google Scholar] [CrossRef] [Scilit]
- CoinMarketCap. Cryptocurrency Prices, Charts and Market Capitalizations. Available online: https://coinmarketcap.com/historical/20260517/ (accessed on 14 August 2026).
- Papazian, A.V. The Logic of Money: Crypto Mechanics and the Limits of Tokenisation. J. Risk Financ. Manag. 2026, 19, 196. [Google Scholar] [CrossRef] [Scilit]
- Martínez Raya, A.; Segura-de-la-Cal, A.; Espina Hellín, J. Assessing the Question of Whether Bitcoin Is a Currency or an Asset in Terms of Its Monetary Role. Economies 2025, 13, 357. [Google Scholar] [CrossRef] [Scilit]
- Gorton, G.B.; Zhang, J.Y. Taming Wildcat Stablecoins. Univ. Chic. Law Rev. 2023, 90, 909–972. [Google Scholar]
- Li, D.; Han, D.; Weng, T.-H.; Zheng, Z.; Li, H.; Li, K.-C. On Stablecoin: Ecosystem, Architecture, Mechanism and Applicability as Payment Method. Comput. Stand. Interfaces 2024, 87, 103747. [Google Scholar] [CrossRef] [Scilit]
- DefiLlama. Stablecoin Market Cap Chart, Supply & Peg Data. Available online: https://defillama.com/stablecoins (accessed on 14 August 2026).
- Arner, D.; Auer, R.; Frost, J. Stablecoins: Risks, Potential and Regulation; BIS Working Paper; Bank for International Settlements: Basel, Switzerland, 2020; pp. 1–31. [Google Scholar]
- Cœuré, B.; Cunliffe, J. Central Bank Digital Currencies: Foundational Principles and Core Features: Report No. 1 in a Series of Collaborations from a Group of Central Banks; Series of Collaborations from a Group of Central Banks; Bank for International Settlements: Basel, Switzerland, 2020. [Google Scholar]
- Atlantic Council Central Bank Digital Currency Tracker. Available online: https://www.atlanticcouncil.org/cbdctracker/ (accessed on 19 August 2026).
- Proskurovska, A.; Birch, K. Tokenization of Everything? Exploring the Limits of Blockchain Technologies in the Governance of Financial Markets and Assets. Financ. Soc. 2025, 1–21. [Google Scholar] [CrossRef] [Scilit]
- BIS Innovation Hub. Project Agorá: A Shared Programmable Platform for Wholesale Cross-Border Payments; BIS Innovation Hub Report; Bank for International Settlements: Basel, Switzerland, 2026; pp. 1–97. [Google Scholar]
- Davoodalhosseini, S.M. Central Bank Digital Currency and Monetary Policy. J. Econ. Dyn. Control 2022, 142, 104150. [Google Scholar] [CrossRef] [Scilit]
- Barrdear, J.; Kumhof, M. The Macroeconomics of Central Bank Digital Currencies. J. Econ. Dyn. Control 2022, 142, 104148. [Google Scholar] [CrossRef] [Scilit]
- Zetzsche, D.A.; Buckley, R.P.; Arner, D.W. Regulating Libra. Oxf. J. Leg. Stud. 2021, 41, 80–113. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- FATF. Updated Guidance for a Risk-Based Approach to Virtual Assets and Virtual Asset Service Providers; Financial Action Task Force: Paris, France, 2021; pp. 1–111. [Google Scholar]
- Allen, S.; Čapkun, S.; Eyal, I.; Fanti, G.; Ford, B.; Grimmelmann, J.; Juels, A.; Kostiainen, K.; Meiklejohn, S.; Miller, A.; et al. Design Choices for Central Bank Digital Currency: Policy and Technical Considerations; NBER Working Paper 27634; National Bureau of Economic Research: Cambridge, MA, USA, 2020; pp. 1–110. [Google Scholar]
- Auer, R.; Cornelli, G.; Frost, J. Rise of the Central Bank Digital Currencies: Drivers, Approaches and Technologies; BIS Working Papers; Monetary and Economic Department—BIS: Basel, Switzerland, 2020. [Google Scholar]
- Bech, M.L.; Garratt, R. Central Bank Cryptocurrencies. BIS Q. Rev. 2017, 55–70. Available online: https://www.bis.org/publications/central-bank-cryptocurrencies (accessed on 14 August 2026).
- Mishkin, F.S. The Economics of Money, Banking, and Financial Markets, 13th ed.; Pearson: Hoboken, NJ, USA, 2022. [Google Scholar]
- Bordo, M.; Levin, A. Central Bank Digital Currency and the Future of Monetary Policy; National Bureau of Economic Research: Cambridge, MA, USA, 2017; pp. 1–32. [Google Scholar]
- Viñuela, C.; Sapena, J.; Wandosell, G. The Future of Money and the Central Bank Digital Currency Dilemma. Sustainability 2020, 12, 9697. [Google Scholar] [CrossRef] [Scilit]
- Bibi, S.; Canelli, R. The Interpretation of CBDC within an Endogenous Money Framework. Res. Int. Bus. Financ. 2023, 65, 101970. [Google Scholar] [CrossRef] [Scilit]
- Diamond, D.W.; Dybvig, P.H. Bank Runs, Deposit Insurance, and Liquidity. J. Polit. Econ. 1983, 91, 401–419. [Google Scholar] [CrossRef] [Scilit]
- Huberman, G.; Leshno, J.D.; Moallemi, C. Monopoly without a Monopolist: An Economic Analysis of the Bitcoin Payment System. Rev. Econ. Stud. 2021, 88, 3011–3040. [Google Scholar] [CrossRef] [Scilit]
- Pinna, A.; Ruttenberg, W. European Central Bank Distributed Ledger Technologies in Securities Post-Trading: Revolution or Evolution? N°172, April 2016; European Central Bank: Frankfurt, Germany, 2016; pp. 1–35. [Google Scholar] [CrossRef] [PubMed]
- Mostovenko, O.; Tsap, V.; Borkovych, V.; Rudyk, N.; Nykonenko, V. Assessment of the Risks of Using Smart Contracts in Cryptocurrency Transactions on Domestic Capital Markets. J. Theor. Appl. Inf. Technol. 2025, 103, 8581–8593. [Google Scholar]
- Auer, R. Beyond the Doomsday Economics of “Proof-of-Work” in Cryptocurrencies; BIS Working Papers; Bank for International Settlements: Basel, Switzerland, 2019. [Google Scholar]
- Narayanan, A.; Felten, E.W.; Goldfeder, S.; Clark, J. Bitcoin and Cryptocurrency Technologies: A Comprehensive Introduction; Princeton University Press: Princeton, NJ, USA, 2016. [Google Scholar]
- Lyons, R.K.; Viswanath-Natraj, G. What Keeps Stablecoins Stable? J. Int. Money Financ. 2023, 131, 102777. [Google Scholar] [CrossRef] [Scilit]
- Agur, I.; Ari, A.; Dell’Ariccia, G. Designing Central Bank Digital Currencies. J. Monet. Econ. 2022, 125, 62–79. [Google Scholar] [CrossRef] [Scilit]
- Arksey, H.; O’Malley, L. Scoping Studies: Towards a Methodological Framework. Int. J. Soc. Res. Methodol. 2005, 8, 19–32. [Google Scholar] [CrossRef] [Scilit]
- Whittemore, R.; Knafl, K. The Integrative Review: Updated Methodology. J. Adv. Nurs. 2005, 52, 546–553. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Levac, D.; Colquhoun, H.; O’Brien, K.K. Scoping Studies: Advancing the Methodology. Implement. Sci. 2010, 5, 69. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Torraco, R.J. Writing Integrative Literature Reviews: Guidelines and Examples. Hum. Resour. Dev. Rev. 2005, 4, 356–367. [Google Scholar] [CrossRef] [Scilit]
- Tricco, A.C.; Lillie, E.; Zarin, W.; O’Brien, K.K.; Colquhoun, H.; Levac, D.; Moher, D.; Peters, M.D.J.; Horsley, T.; Weeks, L.; et al. PRISMA Extension for Scoping Reviews (PRISMA-ScR): Checklist and Explanation. Ann. Intern. Med. 2018, 169, 467–473. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Böhme, R.; Christin, N.; Edelman, B.; Moore, T. Bitcoin: Economics, Technology, and Governance. J. Econ. Perspect. 2015, 29, 213–238. [Google Scholar] [CrossRef] [Scilit]
- Reid, F.; Harrigan, M. An Analysis of Anonymity in the Bitcoin System. In Security and Privacy in Social Networks; Altshuler, Y., Elovici, Y., Cremers, A.B., Aharony, N., Pentland, A., Eds.; Springer: New York, NY, USA, 2013; pp. 197–223. [Google Scholar]
- Murugappan, M.; Nair, R.; Krishnan, S. Global Market Perceptions of Cryptocurrency and the Use of Cryptocurrency by Consumers: A Pilot Study. J. Theor. Appl. Electron. Commer. Res. 2023, 18, 1955–1970. [Google Scholar] [CrossRef] [Scilit]
- Buterin, V. A Next Generation Smart Contract & Decentralized Application Platform 2014. Available online: https://ethereum.org/content/whitepaper/whitepaper-pdf/Ethereum_Whitepaper_-_Buterin_2014.pdf (accessed on 25 June 2026).
- Dhillon, V.; Metcalf, D.; Hooper, M. Unpacking Ethereum. In AI Frameworks Enabled by Blockchain; Apress: Berkeley, CA, USA, 2025; pp. 201–256. [Google Scholar]
- Zetzsche, D.A.; Arner, D.W.; Buckley, R.P. Decentralized Finance. J. Financ. Regul. 2020, 6, 172–203. [Google Scholar] [CrossRef] [Scilit]
- Ghaemi Asl, M.; Ben Jabeur, S. Tail Connectedness of DeFi and CeFi with Accessible Banking Pillars: Unveiling Novel Insights through Wavelet and Quantile Cross-Spectral Coherence Analyses. Int. Rev. Financ. Anal. 2024, 95, 103424. [Google Scholar] [CrossRef] [Scilit]
- Staley, I. Blockchain and Decentralized Finance in Fintech Startups in Emerging Markets: A Systematic Literature Review of Opportunities and Challenges. J. Appl. Financ. Bank. 2026, 16, 81–108. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Perez, D.; Werner, S.M.; Xu, J.; Livshits, B. Liquidations: DeFi on a Knife-Edge. In Financial Cryptography and Data Security; Borisov, N., Diaz, C., Eds.; Lecture Notes in Computer Science; Springer: Berlin/Heidelberg, Germany, 2021; Volume 12675, pp. 457–476. [Google Scholar]
- Eisermann, T.; Campajola, C.; Tessone, C.J.; Teixeira, A.S. Concentration in Governance Control across Decentralised Finance Protocols. EPJ Data Sci. 2025, 14, 85. [Google Scholar] [CrossRef] [Scilit]
- Wang, B.; Yuan, X.; Duan, L.; Ma, H.; Wang, B.; Su, C.; Wang, W. DeFiScanner: Spotting DeFi Attacks Exploiting Logic Vulnerabilities on Blockchain. IEEE Trans. Comput. Soc. Syst. 2024, 11, 1577–1588. [Google Scholar] [CrossRef] [Scilit]
- Kakinaka, S.; Umeno, K. Asymmetric Volatility Dynamics in Cryptocurrency Markets on Multi-Time Scales. Res. Int. Bus. Financ. 2022, 62, 101754. [Google Scholar] [CrossRef] [Scilit]
- Gudgeon, L.; Moreno-Sanchez, P.; Roos, S.; McCorry, P.; Gervais, A. SoK: Layer-Two Blockchain Protocols. In Financial Cryptography and Data Security; Bonneau, J., Heninger, N., Eds.; Lecture Notes in Computer Science; Springer International Publishing: Cham, Switzerland, 2020; Volume 12059, pp. 201–226. [Google Scholar]
- Sarkodie, S.A.; Ahmed, M.Y.; Leirvik, T. Trade Volume Affects Bitcoin Energy Consumption and Carbon Footprint. Financ. Res. Lett. 2022, 48, 102977. [Google Scholar] [CrossRef] [Scilit]
- Gnanaprasuna, E.; Kumar, B.A.; Sreenivasulu, A.; Navaneetha, T. Exploring Financial Innovation Through Cryptocurrency: A Global Systematic and Bibliometric Analysis. Int. J. Account. Econ. Stud. 2025, 12, 767–774. [Google Scholar] [CrossRef] [Scilit]
- Sedghiani, N.; Doğan, B. A Survey on Comparative Analysis of ESG Performance: FinTech vs. Traditional Financial Institutions. Ind. Policy 2026, 6, 15–25. [Google Scholar]
- Foley, S.; Karlsen, J.R.; Putniņš, T.J. Sex, Drugs, and Bitcoin: How Much Illegal Activity Is Financed through Cryptocurrencies? Rev. Financ. Stud. 2019, 32, 1798–1853. [Google Scholar] [CrossRef] [Scilit]
- Putranti, I.R.; Windiani, R.; Wen, Q.G.; Zuliyan, M.A. Navigating the Regulatory Landscape: Combating Corruption, Cryptocurrency Crime, and Illicit Finance through Global Coordination. J. Huk. Nov. 2025, 16, 324–345. [Google Scholar] [CrossRef] [Scilit]
- Baur, D.G.; Hong, K.; Lee, A.D. Bitcoin: Medium of Exchange or Speculative Assets? J. Int. Financ. Mark. Inst. Money 2018, 54, 177–189. [Google Scholar] [CrossRef] [Scilit]
- Hacker, P.; Thomale, C. Crypto-Securities Regulation: ICOs, Token Sales and Cryptocurrencies under EU Financial Law. Eur. Co. Financ. Law Rev. 2018, 15, 645–696. [Google Scholar] [CrossRef] [Scilit]
- Gandal, N.; Hamrick, J.; Moore, T.; Oberman, T. Price Manipulation in the Bitcoin Ecosystem. J. Monet. Econ. 2018, 95, 86–96. [Google Scholar] [CrossRef] [Scilit]
- Vidal-Tomás, D.; Aste, T. Integration or Separation? Examining the Dynamic Relationship between Crypto and Traditional Finance. Financ. Res. Lett. 2025, 86, 108927. [Google Scholar] [CrossRef] [Scilit]
- Zetzsche, D.A.; Annunziata, F.; Arner, D.W.; Buckley, R.P. The Markets in Crypto-Assets Regulation (MiCA) and the EU Digital Finance Strategy. Cap. Mark. Law J. 2021, 16, 203–225. [Google Scholar] [CrossRef] [Scilit]
- Griffin, J.M.; Shams, A. Is Bitcoin Really Untethered? J. Financ. 2020, 75, 1913–1964. [Google Scholar] [CrossRef] [Scilit]
- Briola, A.; Vidal-Tomás, D.; Wang, Y.; Aste, T. Anatomy of a Stablecoin’s Failure: The Terra-Luna Case. Financ. Res. Lett. 2023, 51, 103358. [Google Scholar] [CrossRef] [Scilit]
- Adrian, T.; Bains, P.; Bechara, M.; Cerutti, E.; Forte, S.; Grinberg, F.; Gullo, A. Understanding Stablecoins; Departmental Papers; International Monetary Fund: Washington, DC, USA, 2025. [Google Scholar]
- Makarov, I.; Schoar, A. Trading and Arbitrage in Cryptocurrency Markets. J. Financ. Econ. 2020, 135, 293–319. [Google Scholar] [CrossRef] [Scilit]
- Schär, F. Decentralized Finance: On Blockchain- and Smart Contract-Based Financial Markets. Review 2021, 103, 153–174. [Google Scholar] [CrossRef] [Scilit]
- Auer, R.; Haslhofer, B.; Kitzler, S.; Saggese, P.; Victor, F. The Technology of Decentralized Finance (DeFi). Digit. Financ. 2024, 6, 55–95. [Google Scholar] [CrossRef] [Scilit]
- Das, S.R. The Future of Fintech. Financ. Manag. 2019, 48, 981–1007. [Google Scholar] [CrossRef] [Scilit]
- Cong, L.W.; He, Z. Blockchain Disruption and Smart Contracts. Rev. Financ. Stud. 2019, 32, 1754–1797. [Google Scholar] [CrossRef] [Scilit]
- Maex, S.A.; Slavov, S. Initial Evidence on the Content and Market Implications of Stablecoin Reserve Reporting. J. Account. Public Policy 2025, 51, 107309. [Google Scholar] [CrossRef] [Scilit]
- Lee, Y.-H.; Chiu, Y.-F.; Hsieh, M.-H. Stablecoin Depegging Risk Prediction. Pac.-Basin Financ. J. 2025, 90, 102640. [Google Scholar] [CrossRef] [Scilit]
- FSB. Regulation, Supervision and Oversight of “Global Stablecoin” Arrangements: Final Report and High-Level Recommendations; Financial Stability Board: Basel, Switzerland, 2020; pp. 1–73. [Google Scholar]
- Financial Stability Board. High-Level Recommendations for the Regulation, Supervision and Oversight of Global Stablecoin Arrangements; Financial Stability Board: Basel, Switzerland, 2023; pp. 1–24. [Google Scholar]
- Adrian, T.; Mancini-Griffoli, T. The Rise of Digital Money. Annu. Rev. Financ. Econ. 2021, 13, 57–77. [Google Scholar] [CrossRef] [Scilit]
- Tierno, P. The Stablecoin Transparency and Accountability for a Better Ledger Economy (STABLE) Act of 2025: An Overview; Congressional Research Service: Washington, DC, USA, 2025.
- Eichengreen, B.; Viswanath-Natraj, G. Stablecoins and Central Bank Digital Currencies: Policy and Regulatory Challenges. Asian Econ. Pap. 2022, 21, 29–46. [Google Scholar] [CrossRef] [Scilit]
- Kahn, C.M.; Rivadeneyra, F.; Wong, T.-N. Should the Central Bank Issue E-Money? Bank of Canada: Ottawa, ON, Canada, 2018. [Google Scholar] [CrossRef] [Scilit]
- Auer, R.; Haene, P.; Holden, H. Multi-CBDC Arrangements and the Future of Cross-Border Payments; Monetary and Economic Department, Bank for International Settlements: Basel, Switzerland, 2021. [Google Scholar]
- Soderberg, G.; Bechara, M.M.; Bossu, W.; Che, M.N.X.; Davidovic, S.; Kiff, M.J.; Lukonga, M.I.; Griffoli, M.T.M.; Sun, T.; Yoshinaga, A. Behind the Scenes of Central Bank Digital Currency: Emerging Trends, Insights, and Policy Lessons; Fintech Notes; International Monetary Fund: Washington, DC, USA, 2022; Volume 4. [Google Scholar]
- Boar, C.; Wehrli, A. Ready, Steady, Go?—Results of the Third BIS Survey on Central Bank Digital Currency; BIS Papers; Bank for International Settlements: Basel, Switzerland, 2021; pp. 1–23. [Google Scholar]
- Khiaonarong, T.; Humphrey, D. Falling Use of Cash and Demand for Retail Central Bank Digital Currency; IMF Working Paper; International Monetary Fund: Washington, DC, USA, 2022; pp. 1–25. [Google Scholar]
- Keister, T.; Sanches, D. Should Central Banks Issue Digital Currency? Rev. Econ. Stud. 2023, 90, 404–431. [Google Scholar] [CrossRef] [Scilit]
- BIS Innovation Hub. Project Dunbar: International Settlements Using Multi-CBDCs; Bank for International Settlements: Basel, Switzerland, 2022. [Google Scholar]
- Singh, S.; Gupta, S.; Kaur, S.; Sapra, S.; Kumar, V.; Sharma, M. The Quest for CBDC: Indentifying and Prioritising the Motivations for Launching Central Bank Digital Currencies in Emerging Countries. Qual. Quant. 2023, 57, 4493–4508. [Google Scholar] [CrossRef] [Scilit]
- Said, J.E.; Lánský, J. Designing Retail Central Bank Digital Currencies: A Systematic Literature Review of Trade-Offs Between Security, Privacy, and Financial Stability. Int. J. Financ. Stud. 2026, 14, 122. [Google Scholar] [CrossRef] [Scilit]
- Chu, J. Monetary Statecraft and the Bahamian SandDollar. Singap. J. Trop. Geogr. 2026, 47, 131–150. [Google Scholar] [CrossRef] [Scilit]
- Omotubora, A. Same Naira, More Possibilities! Assessing the Legal Status of the eNaira and Its Potential for Privacy and Inclusion. J. Afr. Law 2024, 68, 245–262. [Google Scholar] [CrossRef] [Scilit]
- Singh, G.; Singh, A.; Walia, J.S. Implementing the Digital Yuan in Global Trade Payments: A Strategic Framework for Central Bank Digital Currency Integration. J. Paym. Strategy Syst. 2025, 19, 345. [Google Scholar] [CrossRef] [Scilit]
- Bapat, D.; Sharma, S. Central Bank Digital Currency: A Literature Review and Future Research Agenda Using Bibliometric Analysis and TCCM Framework. China Account. Financ. Rev. 2026, 28, 1–26. [Google Scholar] [CrossRef] [Scilit]
- Bindseil, U. Tiered CBDC and the Financial System; ECB Working Paper Series No 2351; European Central Bank: Frankfurt am Main, German, 2020; pp. 1–42. [Google Scholar]
- Sanchez-Roger, M.; Puyol-Antón, E. Digital Bank Runs: A Deep Neural Network Approach. Sustainability 2021, 13, 1513. [Google Scholar] [CrossRef] [Scilit]
- Chu, Y.; Rathbun, N.S. Monetary Sovereignty and Central Bank Digital Currencies: Competing Models for Future Cross-Border Payment Platforms. Glob. Policy 2025, 16, 329–340. [Google Scholar] [CrossRef] [Scilit]
- Klein, M.; Behzad, S.; Ciaran, B.; Ulbrich, M. Digital Money—A Perspective on Stablecoins, Tokenised Deposits, and CBDCs; Deutsche Bank: Frankfurt am Main, Germany, 2026. [Google Scholar]
- Lee, Z.K.; Wong, J.Y.; Roch, R.; Tan, X.Y. Reinventing Asset Servicing with Distributed Ledger Technology. J. Secur. Oper. Custody 2024, 16, 146. [Google Scholar] [CrossRef] [Scilit]
- Yamaoka, H. Digital Currency and Monetary System. Account. Econ. Law Conviv. 2025. [Google Scholar] [CrossRef] [Scilit]
- Cucculelli, M.; Recanatini, M. Distributed Ledger Technology Systems in Securities Post-Trading Services. Evidence from European Global Systemic Banks. Eur. J. Financ. 2022, 28, 195–218. [Google Scholar] [CrossRef] [Scilit]
- Bank for International Settlements. III Blueprint for the Future Monetary System: Improving the Old, Enabling the New; BIS: Basel, Switzerland, 2023; pp. 85–118.
- Adrian, T. Tokenized Finance; International Monetary Fund: Washington, DC, USA, 2026. [Google Scholar]
- Brunnermeier, M.; James, H.; Landau, J.-P. The Digitalization of Money; National Bureau of Economic Research: Cambridge, MA, USA, 2019; pp. 1–33. [Google Scholar]
- De Filippi, P.; Loveluck, B. The Invisible Politics of Bitcoin: Governance Crisis of a Decentralised Infrastructure. Internet Policy Rev. 2016, 5, 1–28. [Google Scholar] [CrossRef] [Scilit]
- Financial Stability Board. FSB Global Regulatory Framework for Crypto-Asset Activities: Umbrella Public Note to Accompany Final Framework; Financial Stability Board: Basel, Switzerland, 2023; pp. 1–17. [Google Scholar]
- R3 CBDC Working Group. CBDC Research Center Overview and Conceptual Model; R3: New York, NY, USA, 2021; pp. 1–11. [Google Scholar]
- International Monetary Fund. Elements of Effective Policies for Crypto Assets; Policy Paper; International Monetary Fund: Washington, DC, USA, 2023; p. 1. [Google Scholar] [CrossRef] [Scilit]
- Basel Committee. Prudential Treatment of Cryptoasset Exposures; Basel Committee on Banking Supervision; Bank for International Settlements: Basel, Switzerland, 2022. [Google Scholar]
- Kozieł, M. New Regulation of Crypto-Assets in the European Union as an Opportunity and a Threat for Entrepreneurs. In New Challenges of the Global Economy for Business Management; Kot, S., Khalid, B., Ul Haque, A., Eds.; Springer Proceedings in Business and Economics; Springer Nature: Singapore, 2025; pp. 791–805. [Google Scholar]
- Daly, C.; Teager, K.S.; Teitebaum, D.E.; Tessler, L.; Ward, T.G.; Kane, K.E. The GENIUS Act: A Framework for U.S. Stablecoin Issuance. Bank. Law J. 2025, 142, 482–488. [Google Scholar]
- Roy, D.; Dubey, A.; Tiwary, D. Conceptualizing an Institutional Framework to Mitigate Crypto-Assets’ Operational Risk. J. Risk Financ. Manag. 2024, 17, 550. [Google Scholar] [CrossRef] [Scilit]
- Shiva Sankari, V.; Kavitha, R. Bitcoin Adoption and Price Elasticity of Demand: Cross-Country Insights. Humanit. Soc. Sci. Commun. 2025, 12, 930. [Google Scholar] [CrossRef] [Scilit]
- Phang, R. Singapore’s Emerging Regulatory Approach to Stablecoins. Bank. Financ. Law Rev. 2024, 40, 67–104. [Google Scholar]
- Monetary Management Department. Regulatory Regime for Stablecoin Issuers in Hong Kong; Hong Kong Monetary Authority: Hong Kong, China, 2024; pp. 1–7.
- Zeng, L.; Young, M.R.; Hao, W. Currency Digitalization: The Supply, Demand, and Infrastructure Aspects of China’s Central Bank Digital Currency. Financ. Res. Lett. 2025, 85, 108001. [Google Scholar] [CrossRef] [Scilit]
- Swiss Federal Council. Legal Framework for Distributed Ledger Technology and Blockchain in Switzerland; An Overview with a Focus on the Financial Sector; Federal Council Report; Swiss Confederation: Bern, Switzerland, 2018; pp. 1–162. [Google Scholar]
- Zetzsche, D.; Buckley, R.; Barberis, J.; Arner, D. Regulating a Revolution: From Regulatory Sandboxes to Smart Regulation. Fordham J. Corp. Financ. Law 2017, 23, 31. [Google Scholar]
- Almuhammadi, S.; Alghamdi, S. A Novel Transition Protocol to Post-Quantum Cryptocurrency Blockchains. Front. Comput. Sci. 2025, 7, 1457000. [Google Scholar] [CrossRef] [Scilit]
- Board of Governors of the Federal Reserve System. Money and Payments: The U.S. Dollar in the Age of Digital Transformation; Board of Governors of the Federal Reserve System: Washington, DC, USA, 2022; pp. 1–40.
- Auer, R.; Frost, J.; Pastor, J.M.V. Miners as Intermediaries: Extractable Value and Market Manipulation in Crypto and DeFi; Bank for International Settlements: Basel, Switzerland, 2022. [Google Scholar]
- Lee, D.K.C.; Yan, L.; Wang, Y. A Global Perspective on Central Bank Digital Currency. China Econ. J. 2021, 14, 52–66. [Google Scholar] [CrossRef] [Scilit]
- Zhang, F.; Cui, Y.; Campbell-Verduyn, M. Digital RMB vs. Dollar Hegemony? Friendly Foes in China-US Currency Competition. J. Chin. Polit. Sci. 2024, 29, 483–508. [Google Scholar] [CrossRef] [Scilit]
- Tsouris, I.; Thanasas, G.L.; Rigou, M. Assessing the European Central Bank’s Institutional Capacity and Readiness for the Introduction of the Digital Euro. J. Risk Financ. Manag. 2026, 19, 148. [Google Scholar] [CrossRef] [Scilit]
- Alvarez, F.; Argente, D.; Van Patten, D. Are Cryptocurrencies Currencies? Bitcoin as Legal Tender in El Salvador. Science 2023, 382, eadd2844. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Emmanuel, J.T.; Onwe, J.C.; Nweke, C.J.; Dhayal, K.S. Understanding the Drivers of Cryptocurrency Adoption: Insights from the Push-Pull-Mooring Theory Framework. Qual. Quant. 2025, 60, 1491–1513. [Google Scholar] [CrossRef] [Scilit]
- Carstens, A.; Frost, J.; Shin, H.S. A Foundation of Trust Central Banks Should Harness Crypto’s Technical Wizardry to Enable a Rich Monetary Ecosystem. Financ. Dev. 2022, 59, 10–13. [Google Scholar]
- Aggarwal, D.; Brennen, G.; Lee, T.; Santha, M.; Tomamichel, M. Quantum Attacks on Bitcoin, and How to Protect Against Them. Ledger 2018, 3, 68–90. [Google Scholar] [CrossRef] [Scilit]
- van Egmond, N.D.; de Vries, B.J.M. Reforming the Eurozone Financial System: A System-Dynamics Approach. Int. Rev. Financ. Anal. 2024, 93, 103192. [Google Scholar] [CrossRef] [Scilit]
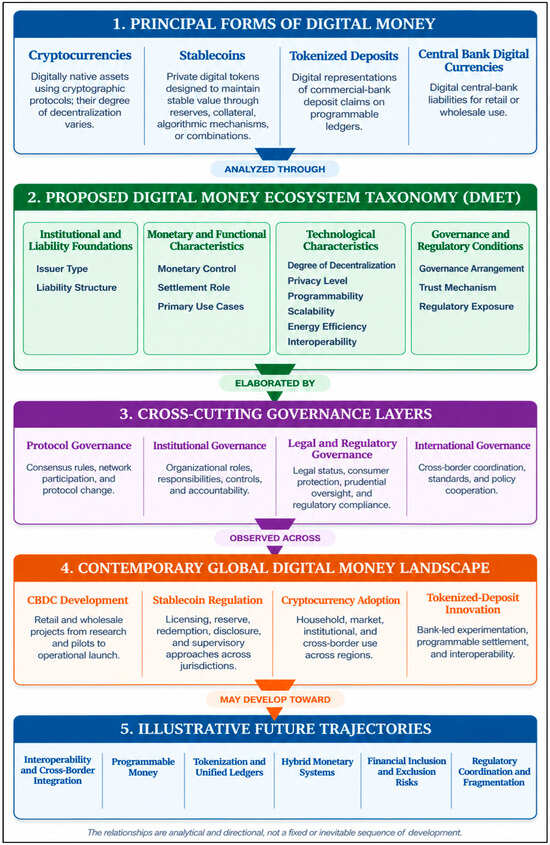
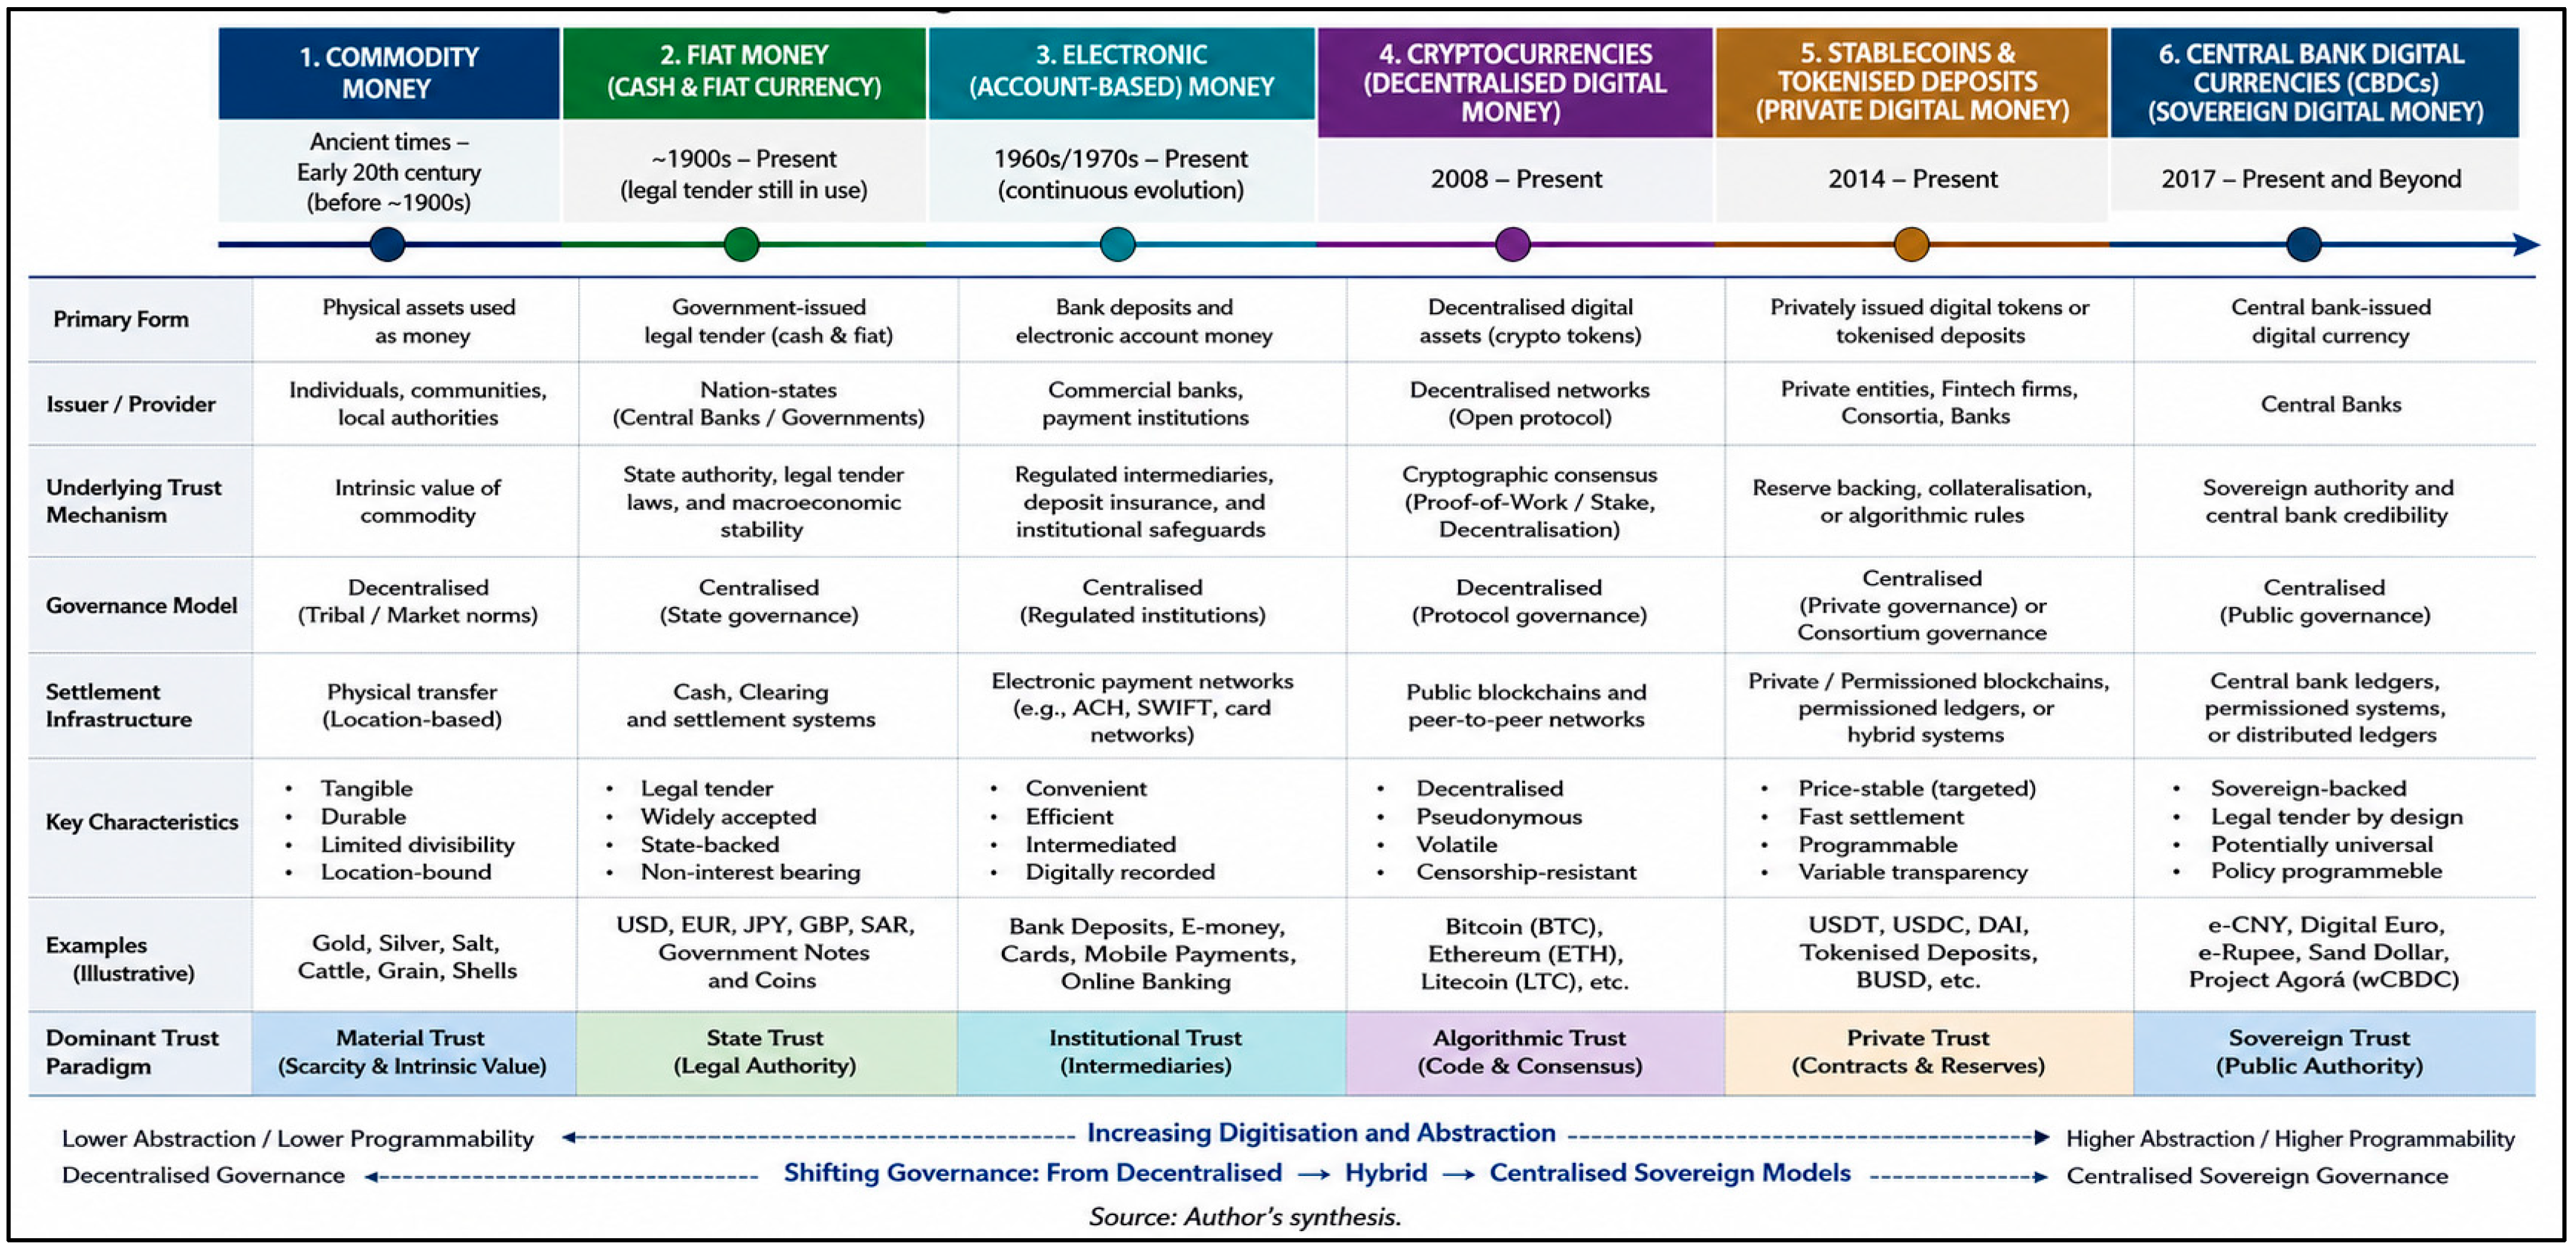
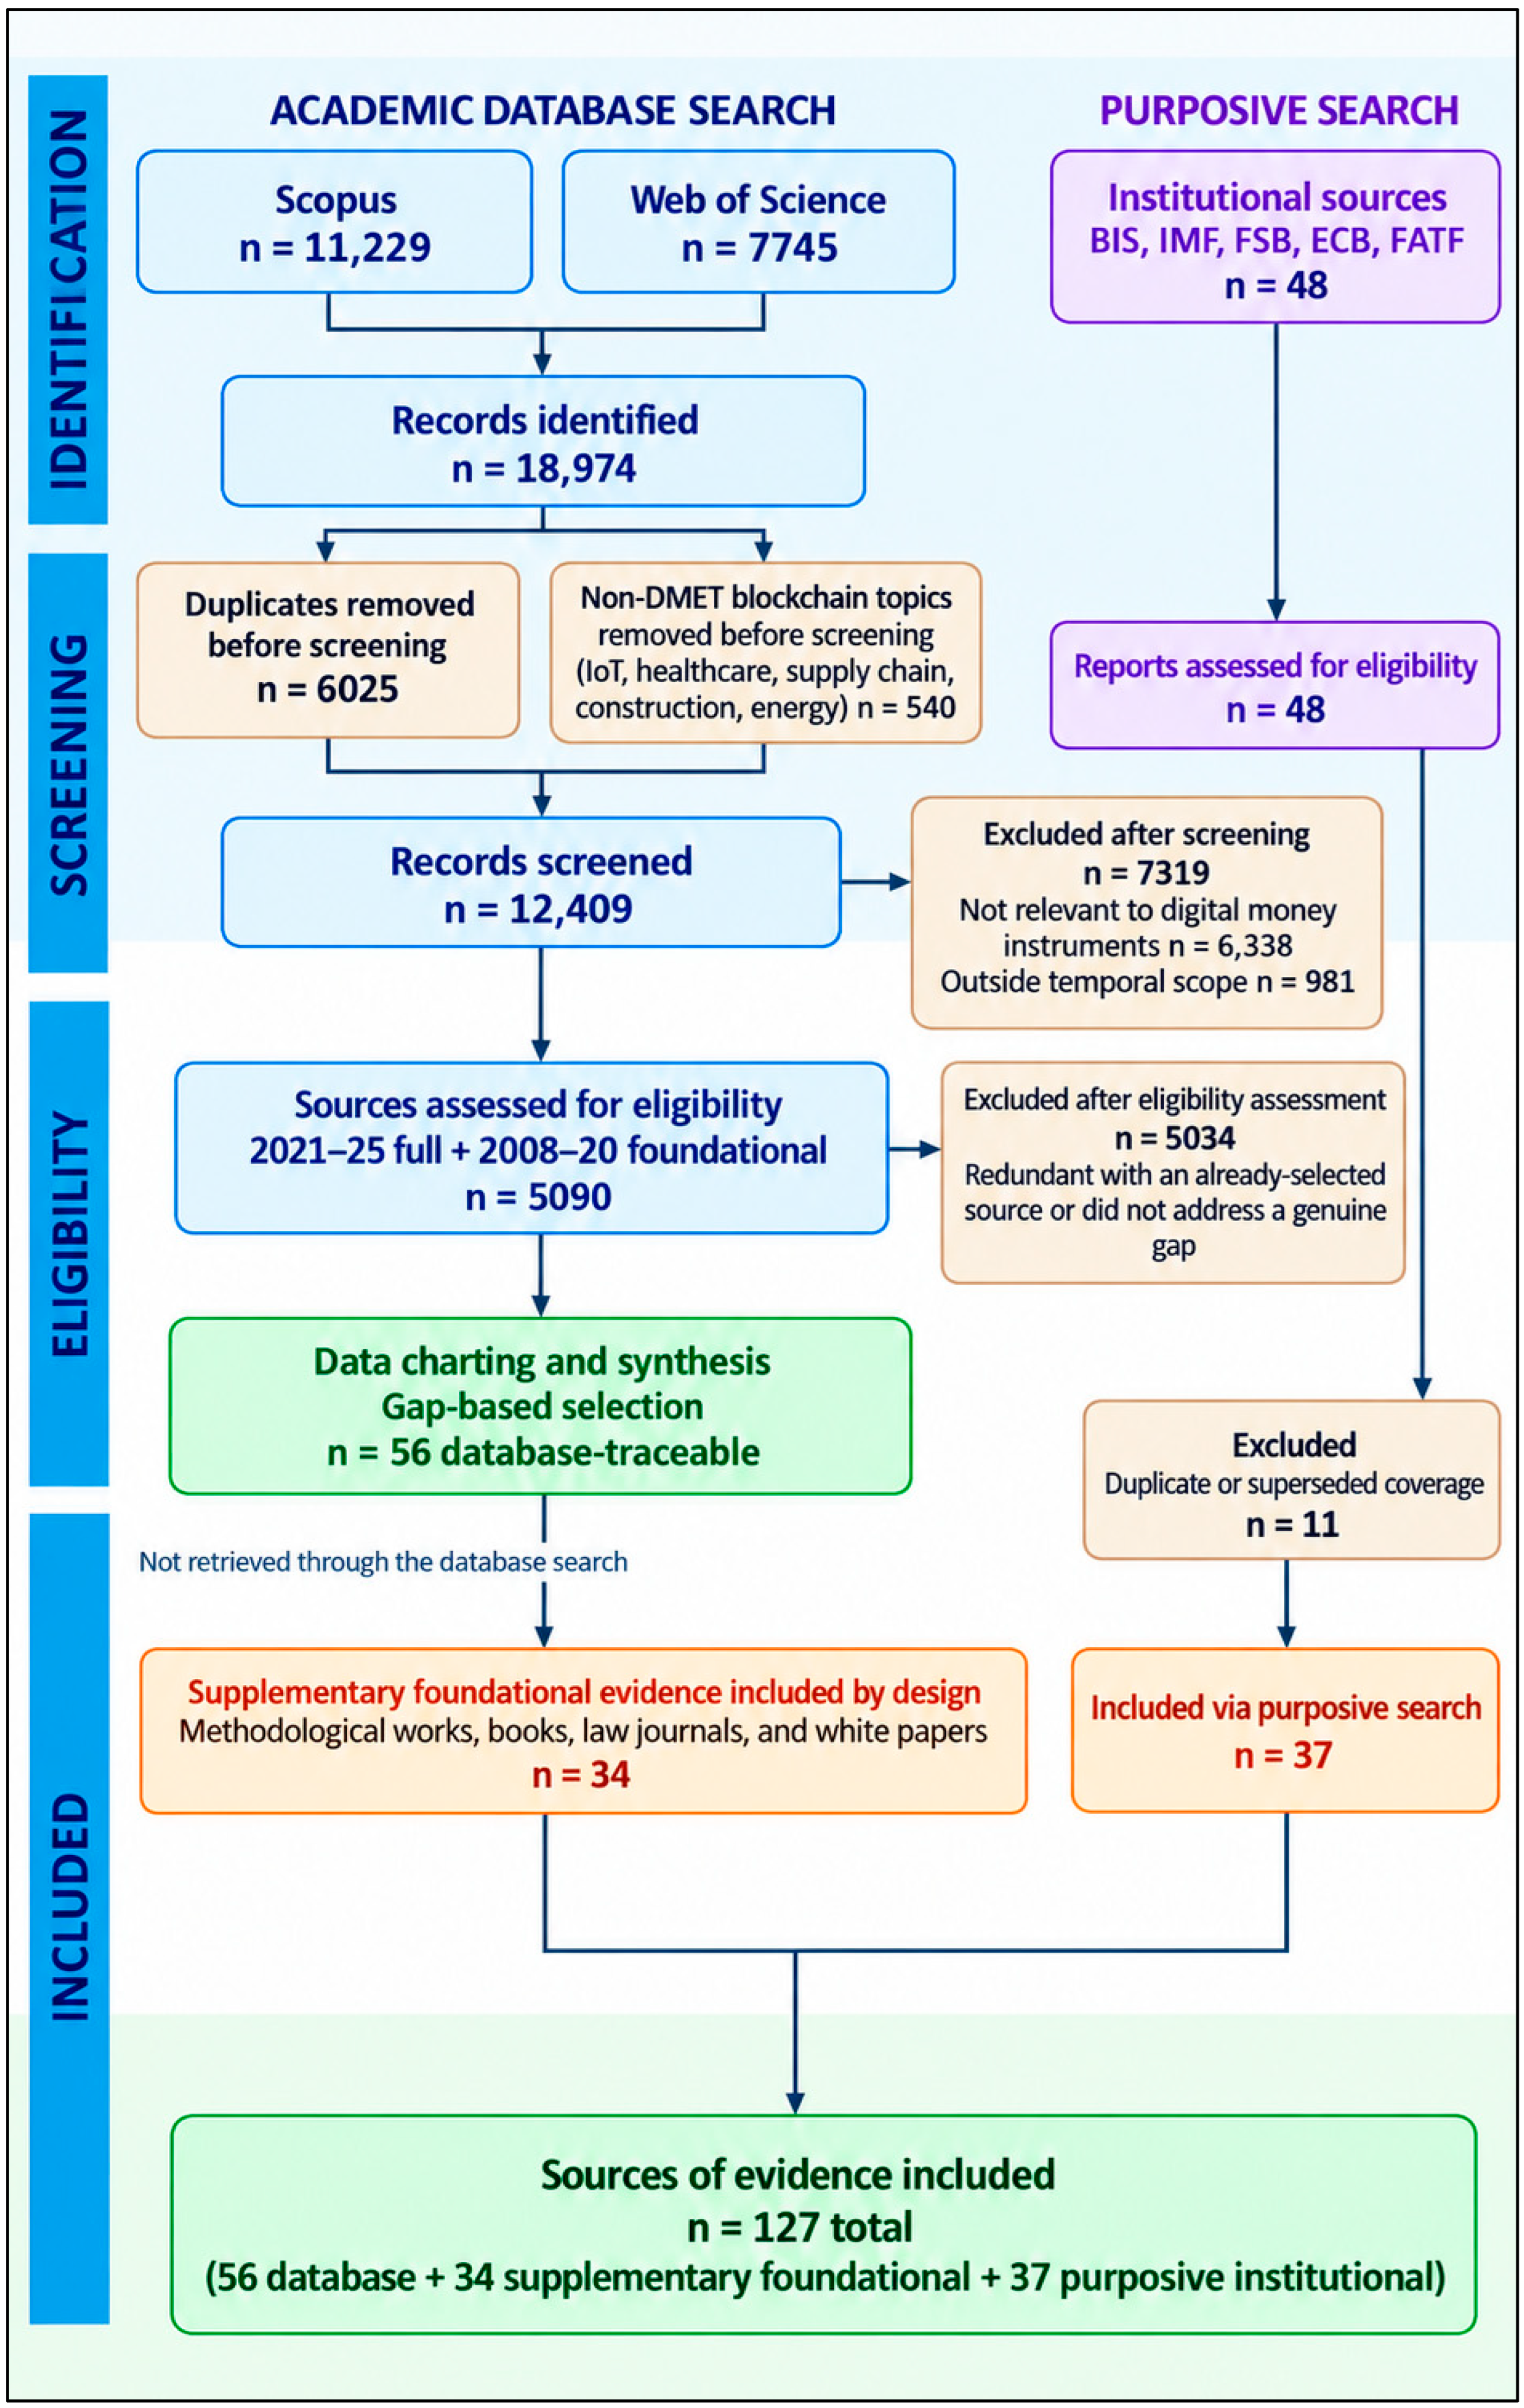
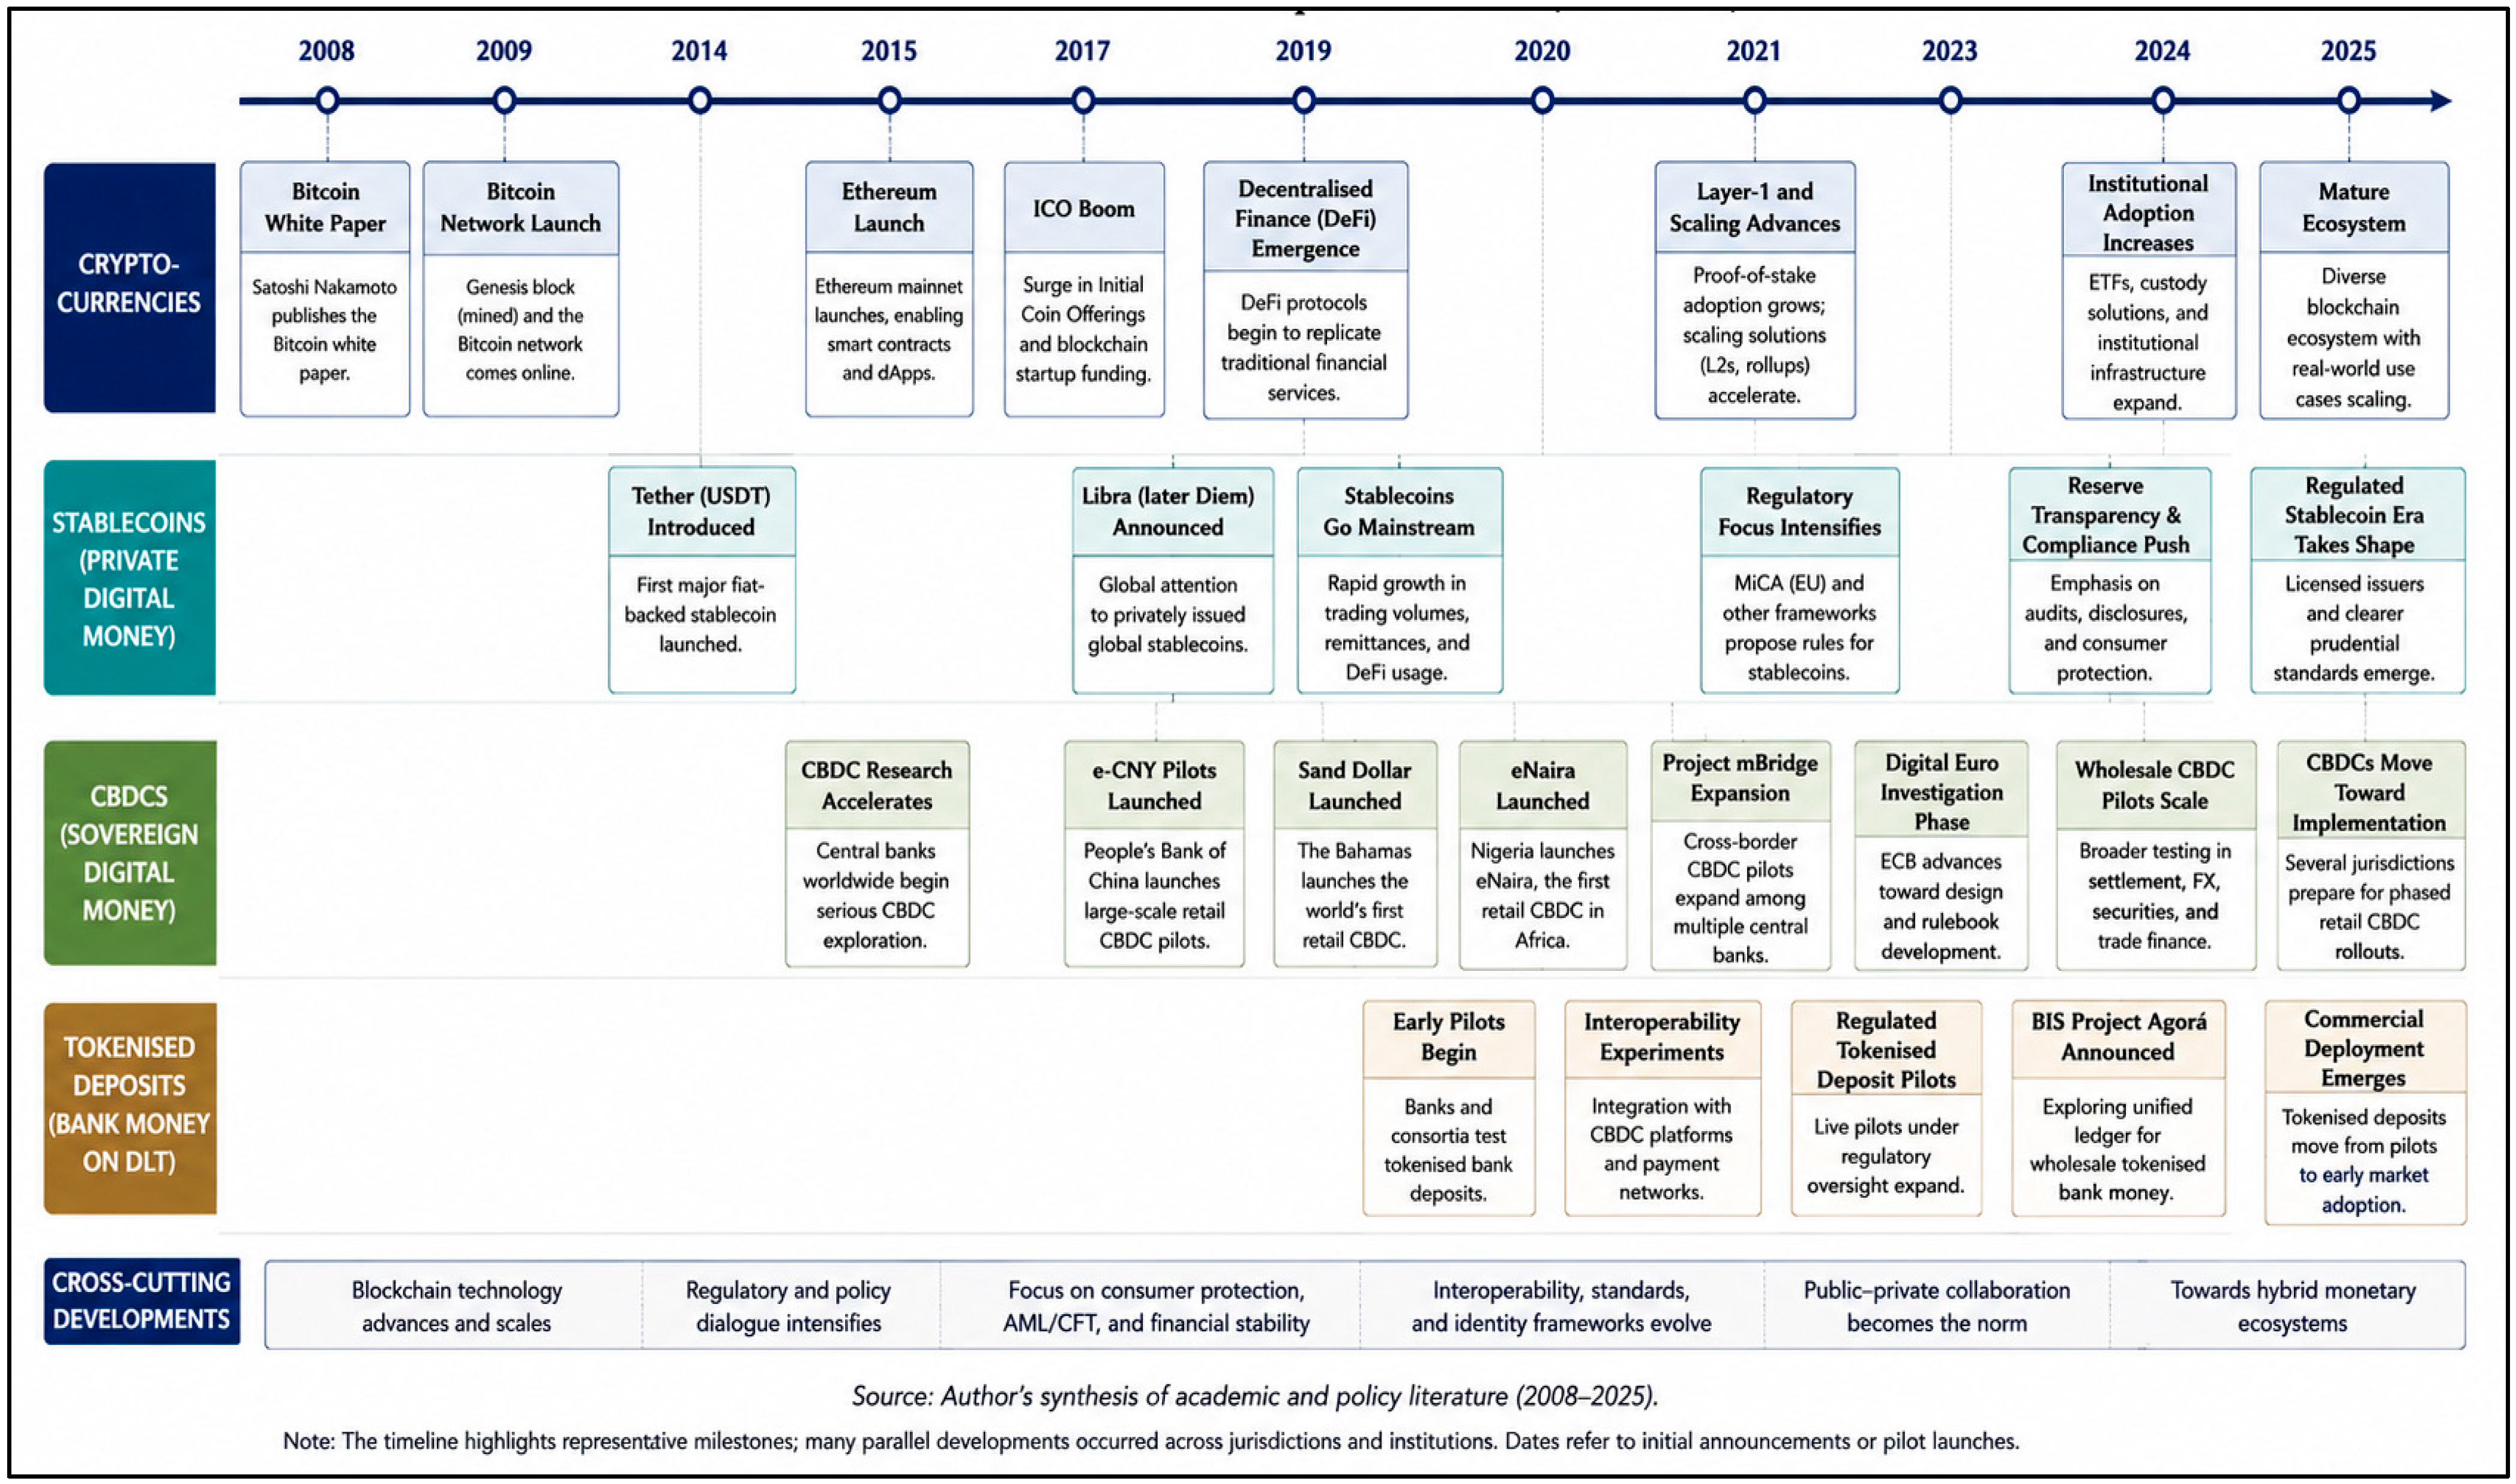
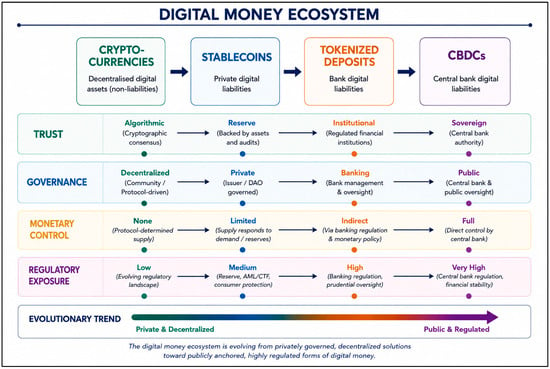
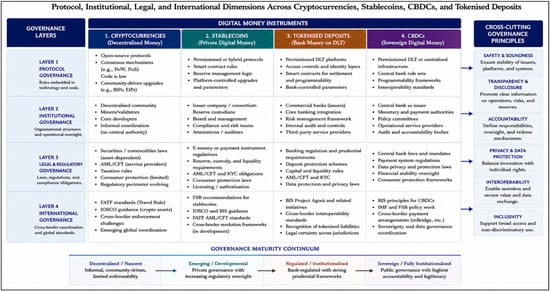
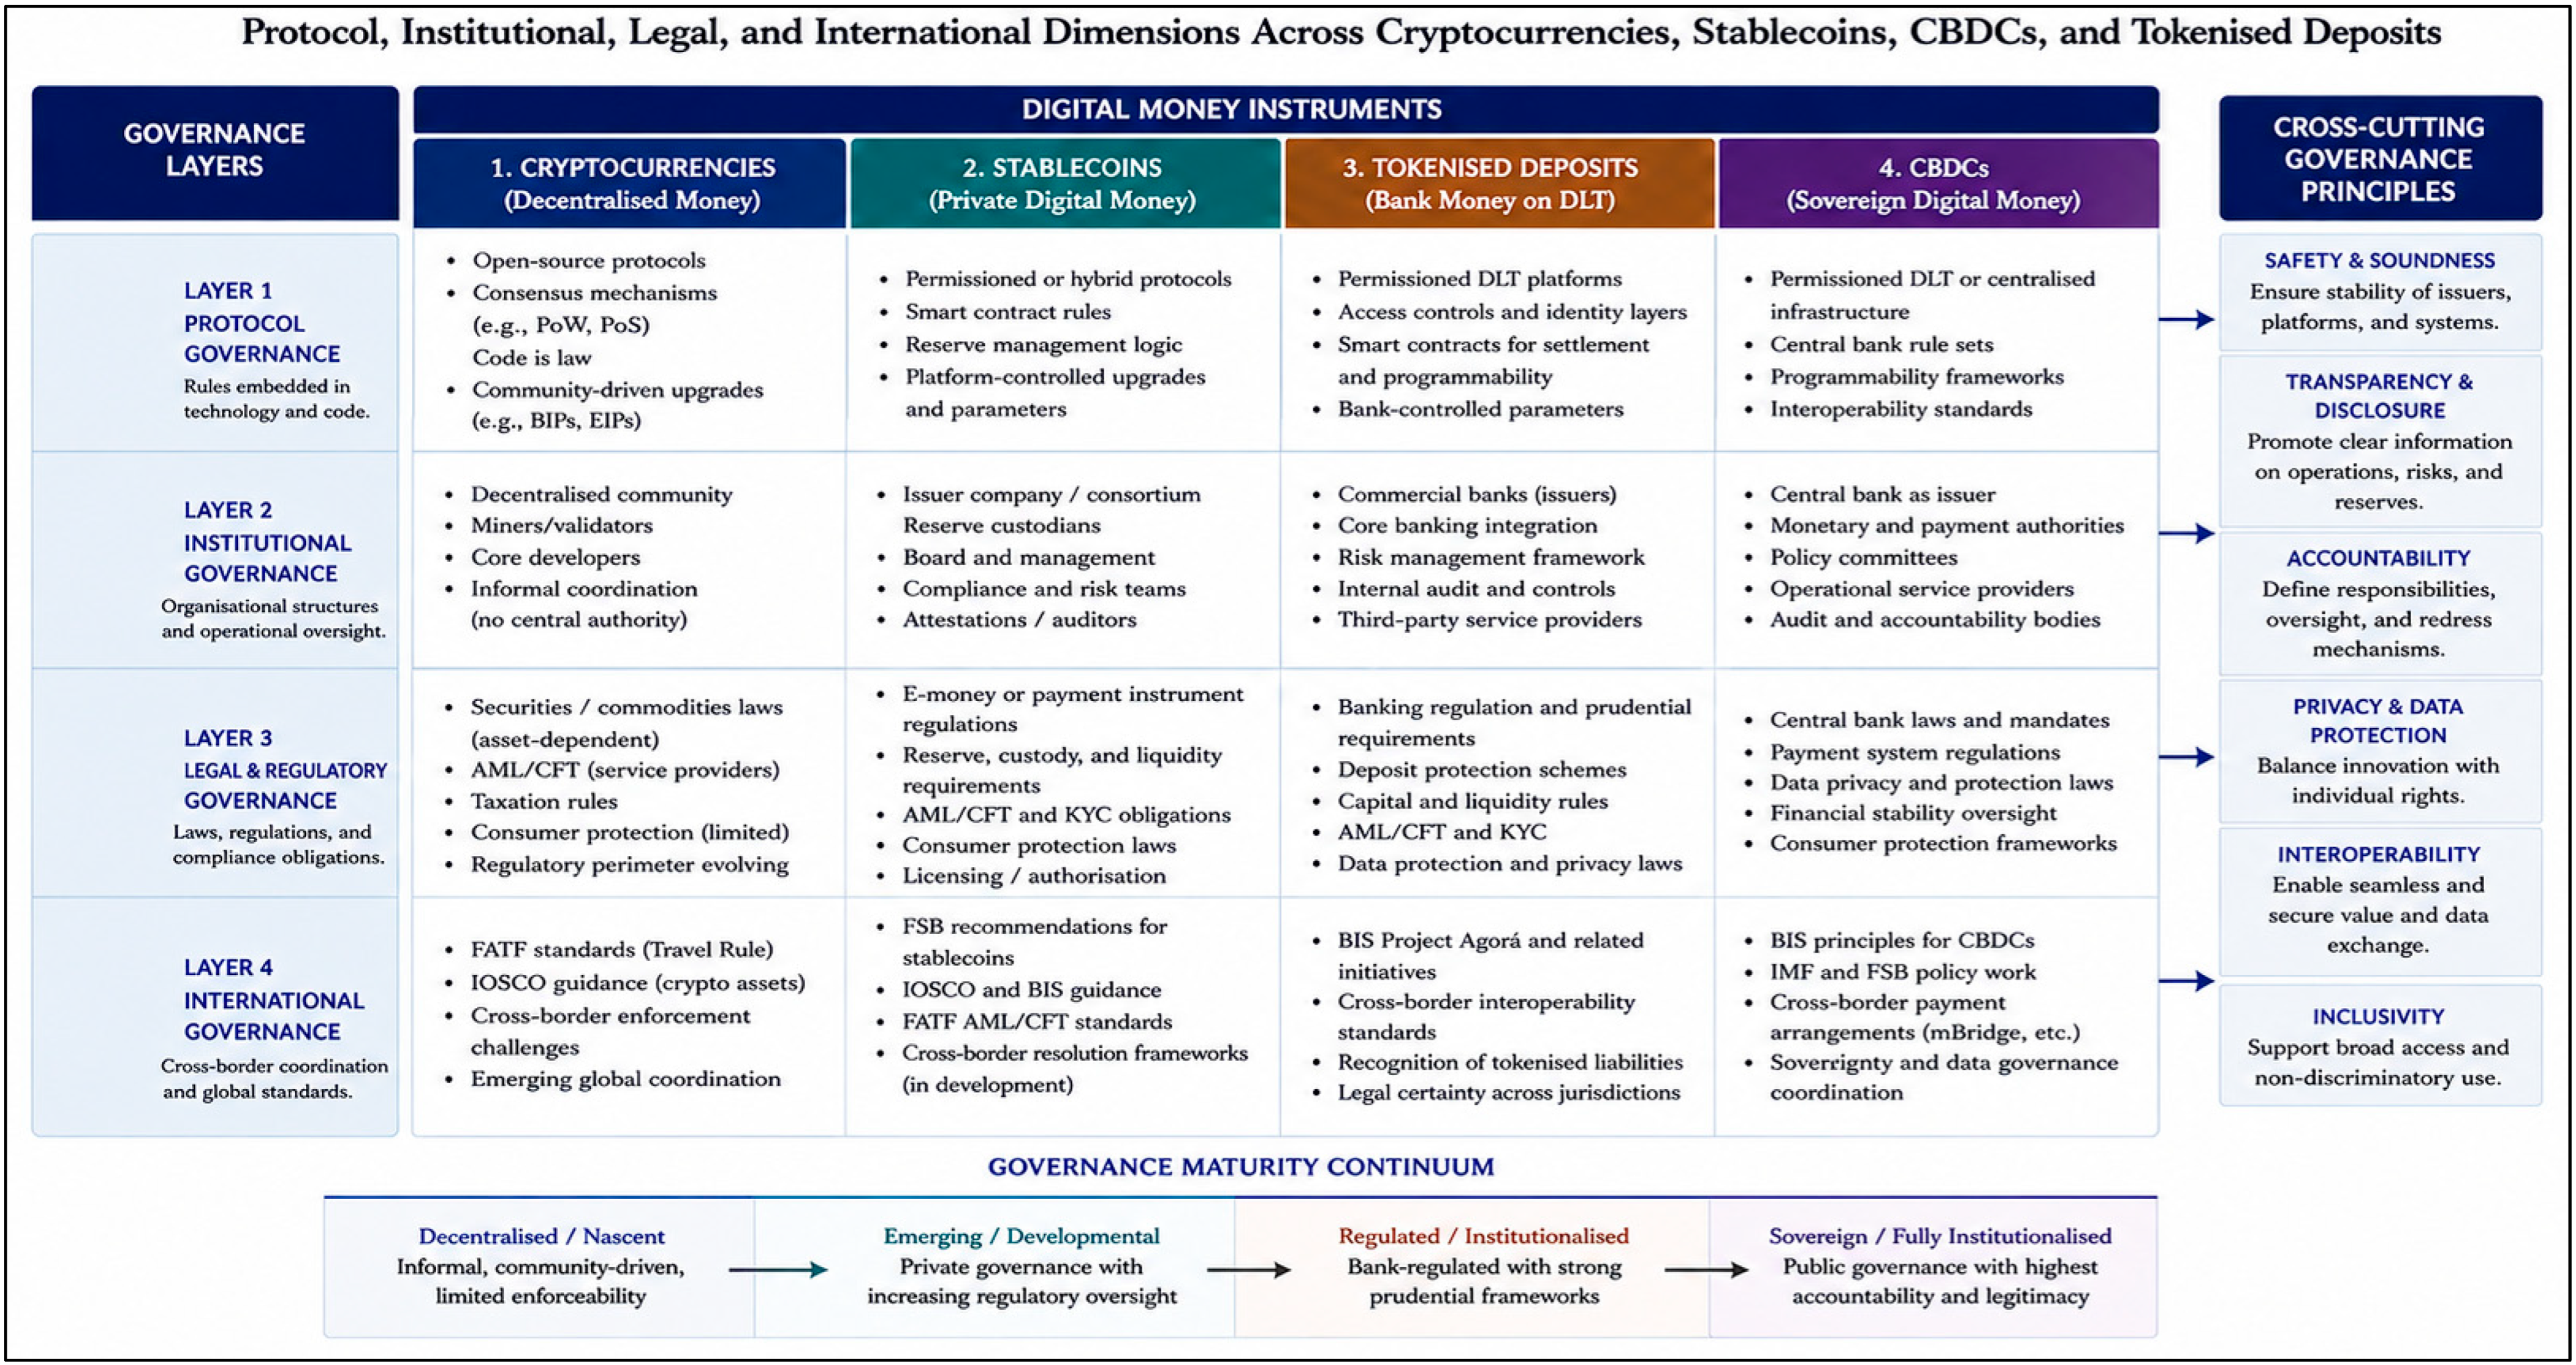

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the author. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.