A Collocation Method Using Diagonal Polynomials for Pricing Geometric Asian Options Under the Mixed Fractional Heston Model


Abstract
1. Introduction
Mixed Fractional Heston Model
2. Diagonal Polynomials
3. Numerical Procedure
3.1. Operational Matrices of Partial Derivatives
- 1.
- Termwhere is the sparse matrix
- 2.
- Termwhere is the sparse matrix
- 3.
- Termwhere is the sparse matrix
- 4.
- Termwhere is the sparse matrix
- 5.
- Termwhere is the sparse matrix
- 6.
- Termwhere is the sparse matrix
- 7.
- Term
3.2. Constructing Algebraic System of Equations
| Algorithm 1 Outlines essential steps for implementing the suggested approach. |
Input: , p, q, r, , and H. Step 1: Define collocation points as Step 2: Define diagonal polynomials. Step 3: Define operational matrices . Step 4: Compute matrices Step 5: Define the equations . Step 6: Collocating the equations in Step 5. Step 7: Solve the linear system arises from Step 6 to obtain . Output: Approximate the solution of the main problem using . |
4. Convergence Analysis
5. Test Problems
6. Conclusions
Author Contributions
Funding
Data Availability Statement
Conflicts of Interest
References
- Abdi, N.; Aminikhah, H.; Sheikhani, A.R. High-order compact finite difference schemes for the time-fractional Black-Scholes model governing European options. Chaos Solitons Fractals 2022, 162, 112423. [Google Scholar] [CrossRef] [Scilit]
- Tian, Z.; Zhai, S.; Weng, Z. Compact finite difference schemes of the time fractional Black-Scholes model. J. Appl. Anal. Comput. 2020, 10, 904–919. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Mehrdoust, F. A new hybrid Monte Carlo simulation for Asian options pricing. J. Stat. Comput. Simul. 2015, 85, 507–516. [Google Scholar] [CrossRef] [Scilit]
- Najafi, A.; Mehrdoust, F. Conditional expectation strategy under the long memory Heston stochastic volatility model. Commun. Stat. Simul. Comput. 2024, 53, 5453–5473. [Google Scholar] [CrossRef] [Scilit]
- Golbabai, A.; Nikan, O.; Nikazad, T. Numerical analysis of time fractional Black–Scholes European option pricing model arising in financial market. Comput. Appl. Math. 2019, 38, 173. [Google Scholar] [CrossRef] [Scilit]
- Sawangtong, P.; Taghipour, M.; Najafi, A. An efficient computational method for solving the fractional form of the European option price PDE with transaction cost under the fractional Heston model. Eng. Anal. Bound. Elem. 2024, 169, 105972. [Google Scholar] [CrossRef] [Scilit]
- Taghipour, M.; Aminikhah, H. A spectral collocation method based on fractional Pell functions for solving time–fractional Black–Scholes option pricing model. Chaos Solitons Fractals 2022, 163, 112571. [Google Scholar] [CrossRef] [Scilit]
- Mesgarani, H.; Beiranvand, A.; Esmaeelzade Aghdam, Y. The impact of the Chebyshev collocation method on solutions of the time-fractional Black–Scholes. Math. Sci. 2021, 15, 137–143. [Google Scholar] [CrossRef] [Scilit]
- Badawi, H.; Arqub, O.A.; Shawagfeh, N. Theoretical study and numerical analysis using step spectral collocation method for stochastic M-fractional differential models of simplified Brownian motion within constant delays process. J. Appl. Math. Comput. 2025, 71, 6773–6805. [Google Scholar] [CrossRef] [Scilit]
- Sawangtong, P.; Najafi, A. Collocation method with Morgan-Voyce polynomials to solve the time fractional long memory Black-Scholes model with jump process. J. Appl. Math. Comput. 2025, 71, 8123–8161. [Google Scholar] [CrossRef] [Scilit]
- Mangal, S.; Gupta, V. Exponential B-spline collocation method with Richardson extrapolation for generalized Black-Scholes equation. J. Appl. Math. Comput. 2025, 71, 3965–3995. [Google Scholar] [CrossRef] [Scilit]
- Ma, P.; Taghipour, M.; Cattani, C. Option pricing in the illiquid markets under the mixed fractional Brownian motion model. Chaos Solitons Fractals 2024, 182, 114806. [Google Scholar] [CrossRef] [Scilit]
- Mehrdoust, F.; Najafi, A.R.; Fallah, S.; Samimi, O. Mixed fractional Heston model and the pricing of American options. J. Comput. Appl. Math. 2018, 330, 141–154. [Google Scholar] [CrossRef] [Scilit]
- Alazemi, F.; Douissi, S.; Es-Sebaiy, K. Berry–Esseen Bounds and ASCLTs for Drift Parameter Estimator of Mixed Fractional Ornstein–Uhlenbeck Process with Discrete Observations. Theory Probab. Its Appl. 2019, 64, 401–420. [Google Scholar] [CrossRef] [Scilit]
- Shi, Q.; Yang, X. Pricing Asian options in a stochastic volatility model with jumps. Appl. Math. Comput. 2014, 228, 411–422. [Google Scholar] [CrossRef] [Scilit]
- Wang, W.; Cai, G.; Tao, X. Pricing geometric asian power options in the sub-fractional brownian motion environment. Chaos Solitons Fractals 2021, 145, 110754. [Google Scholar] [CrossRef] [Scilit]
- Alsenafi, A.; Alazemi, F.; Najafi, A. Geometric Asian power option pricing with transaction cost under the geometric fractional Brownian motion with w sources of risk in fuzzy environment. J. Comput. Appl. Math. 2025, 453, 116165. [Google Scholar] [CrossRef] [Scilit]
- Abdelhakem, M.; Abdelhamied, D.; El-Kady, M.; Youssri, Y.H. Two modified shifted Chebyshev–Galerkin operational matrix methods for even-order partial boundary value problems. Bound. Value Probl. 2025, 2025, 34. [Google Scholar] [CrossRef] [Scilit]
- Abd-Elhameed, W.M.; Youssri, Y.H.; Atta, A.G. Adopted spectral tau approach for the time-fractional diffusion equation via seventh-kind Chebyshev polynomials. Bound. Value Probl. 2024, 2024, 102. [Google Scholar] [CrossRef] [Scilit]
- Horadam, A.F. Extensions of a paper on diagonal functions. Fibonacci Q. 1980, 18, 3–6. [Google Scholar] [CrossRef] [Scilit]







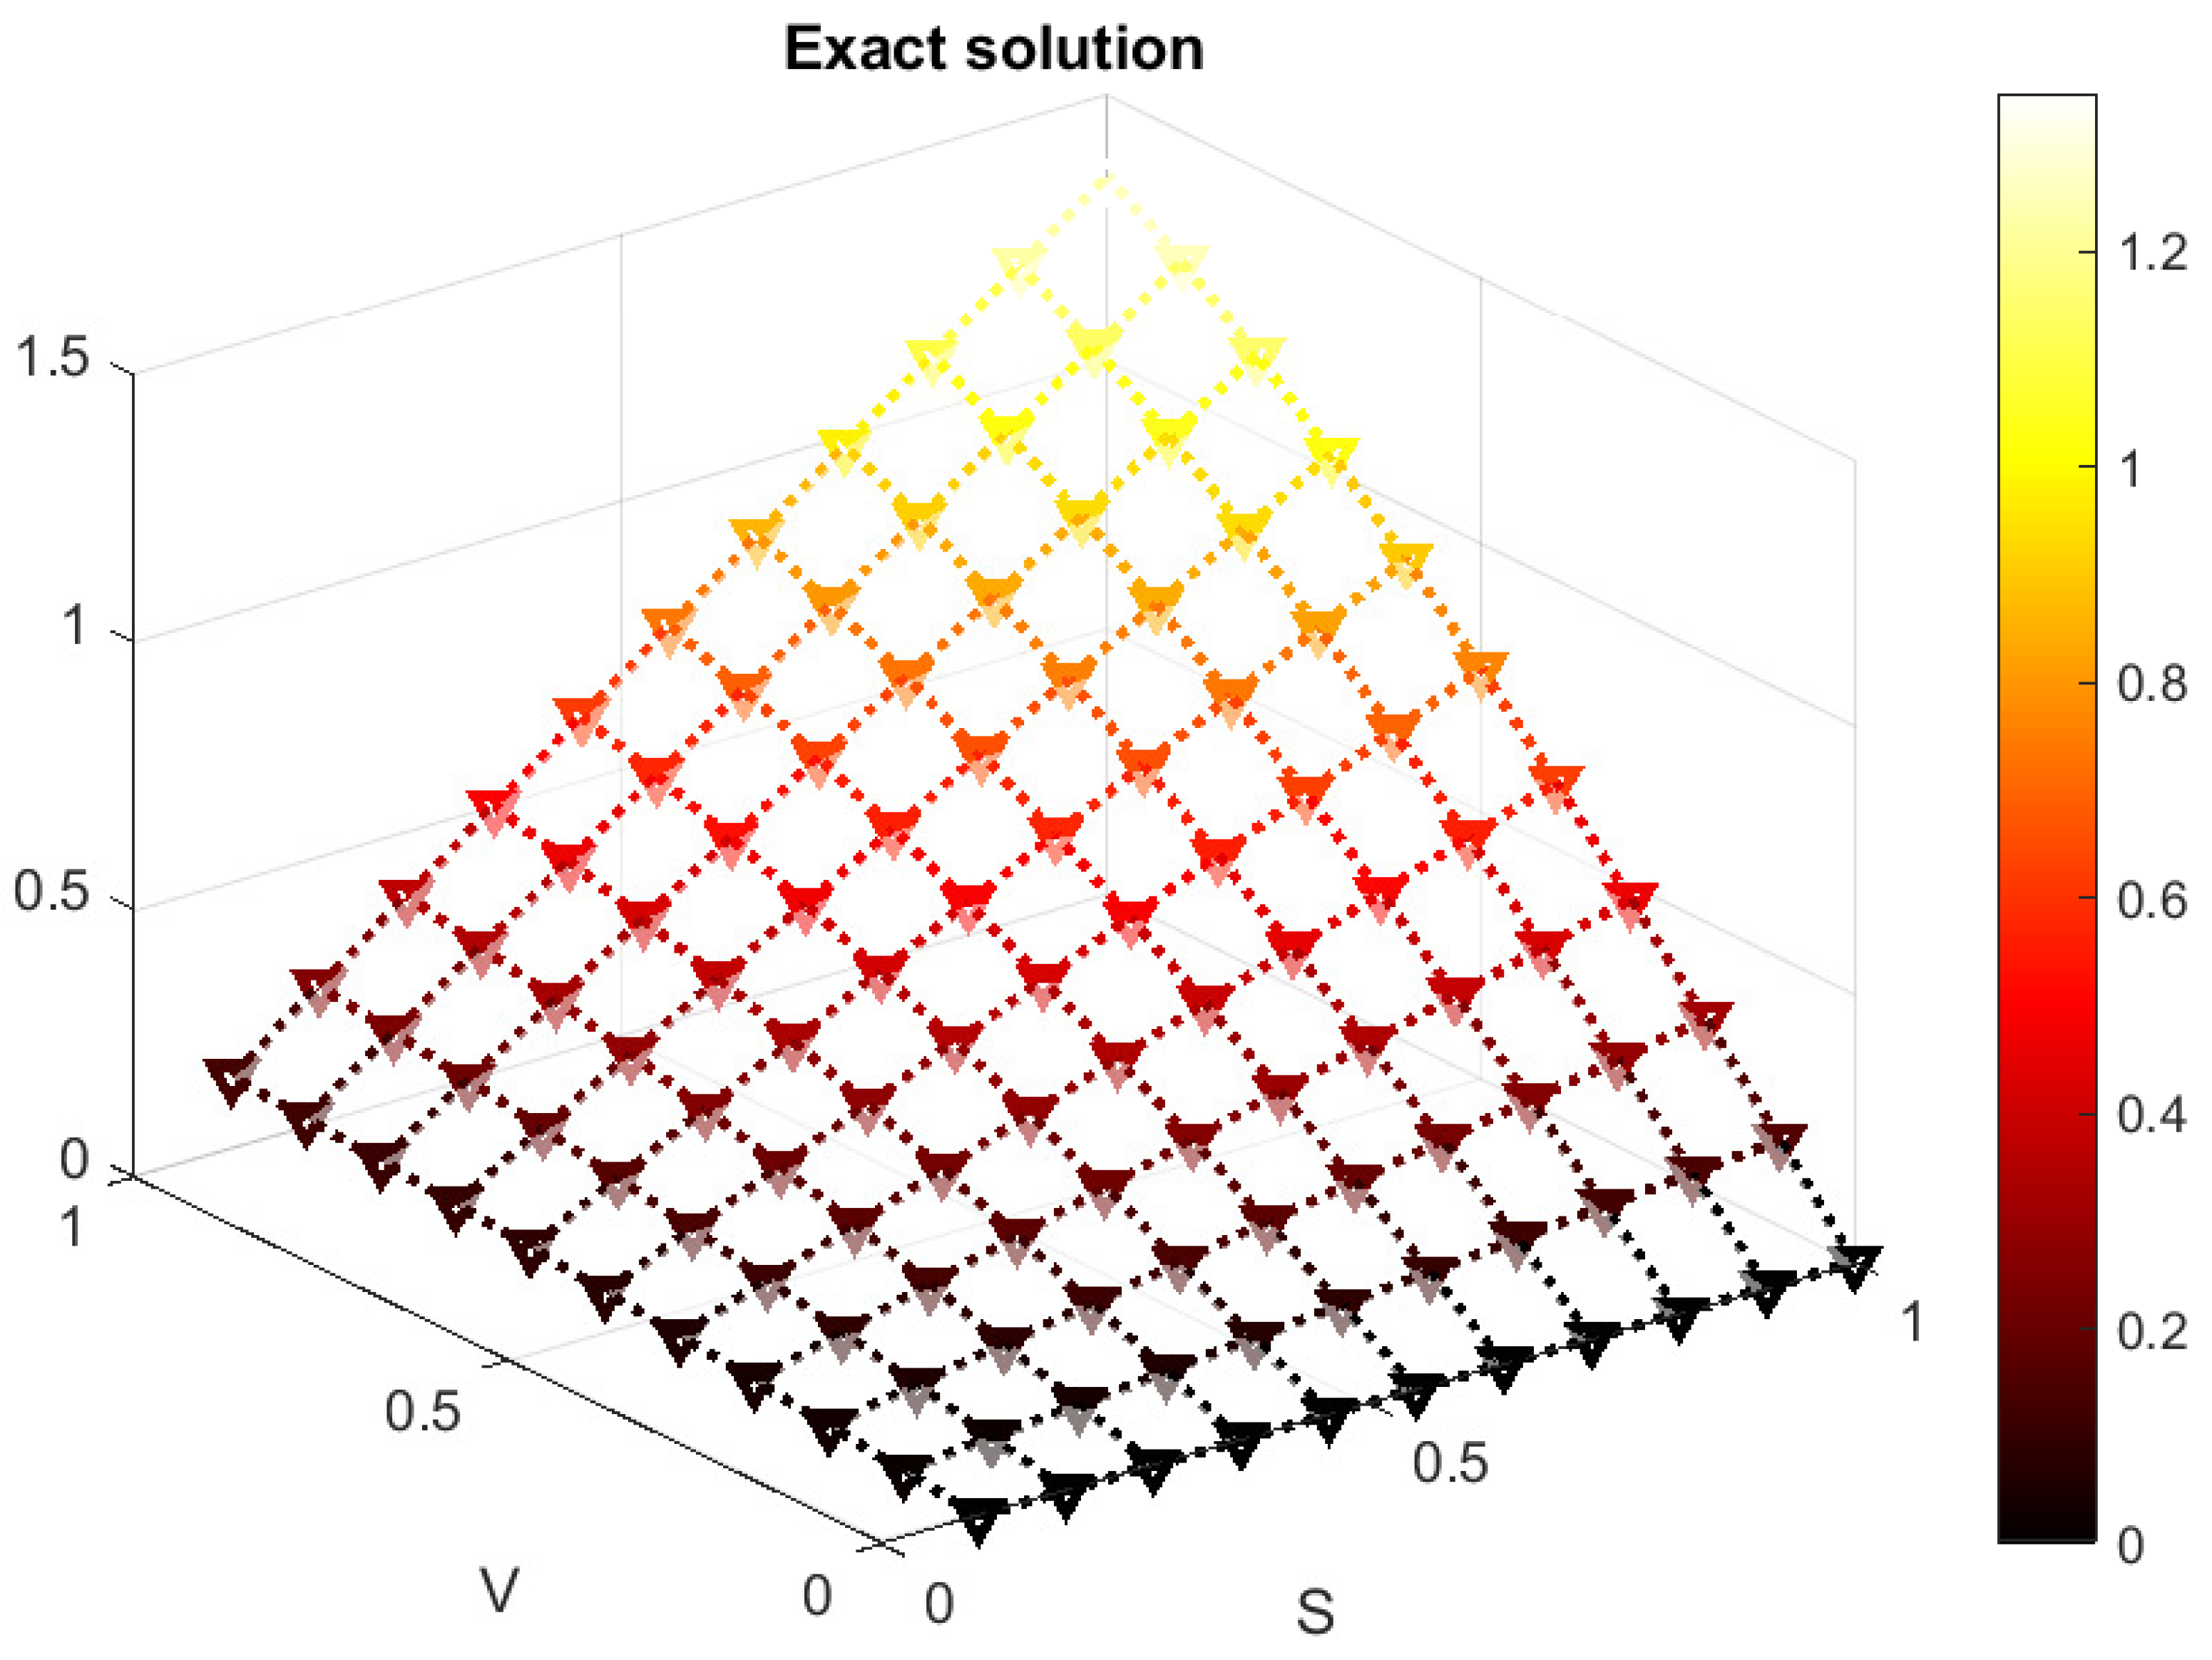

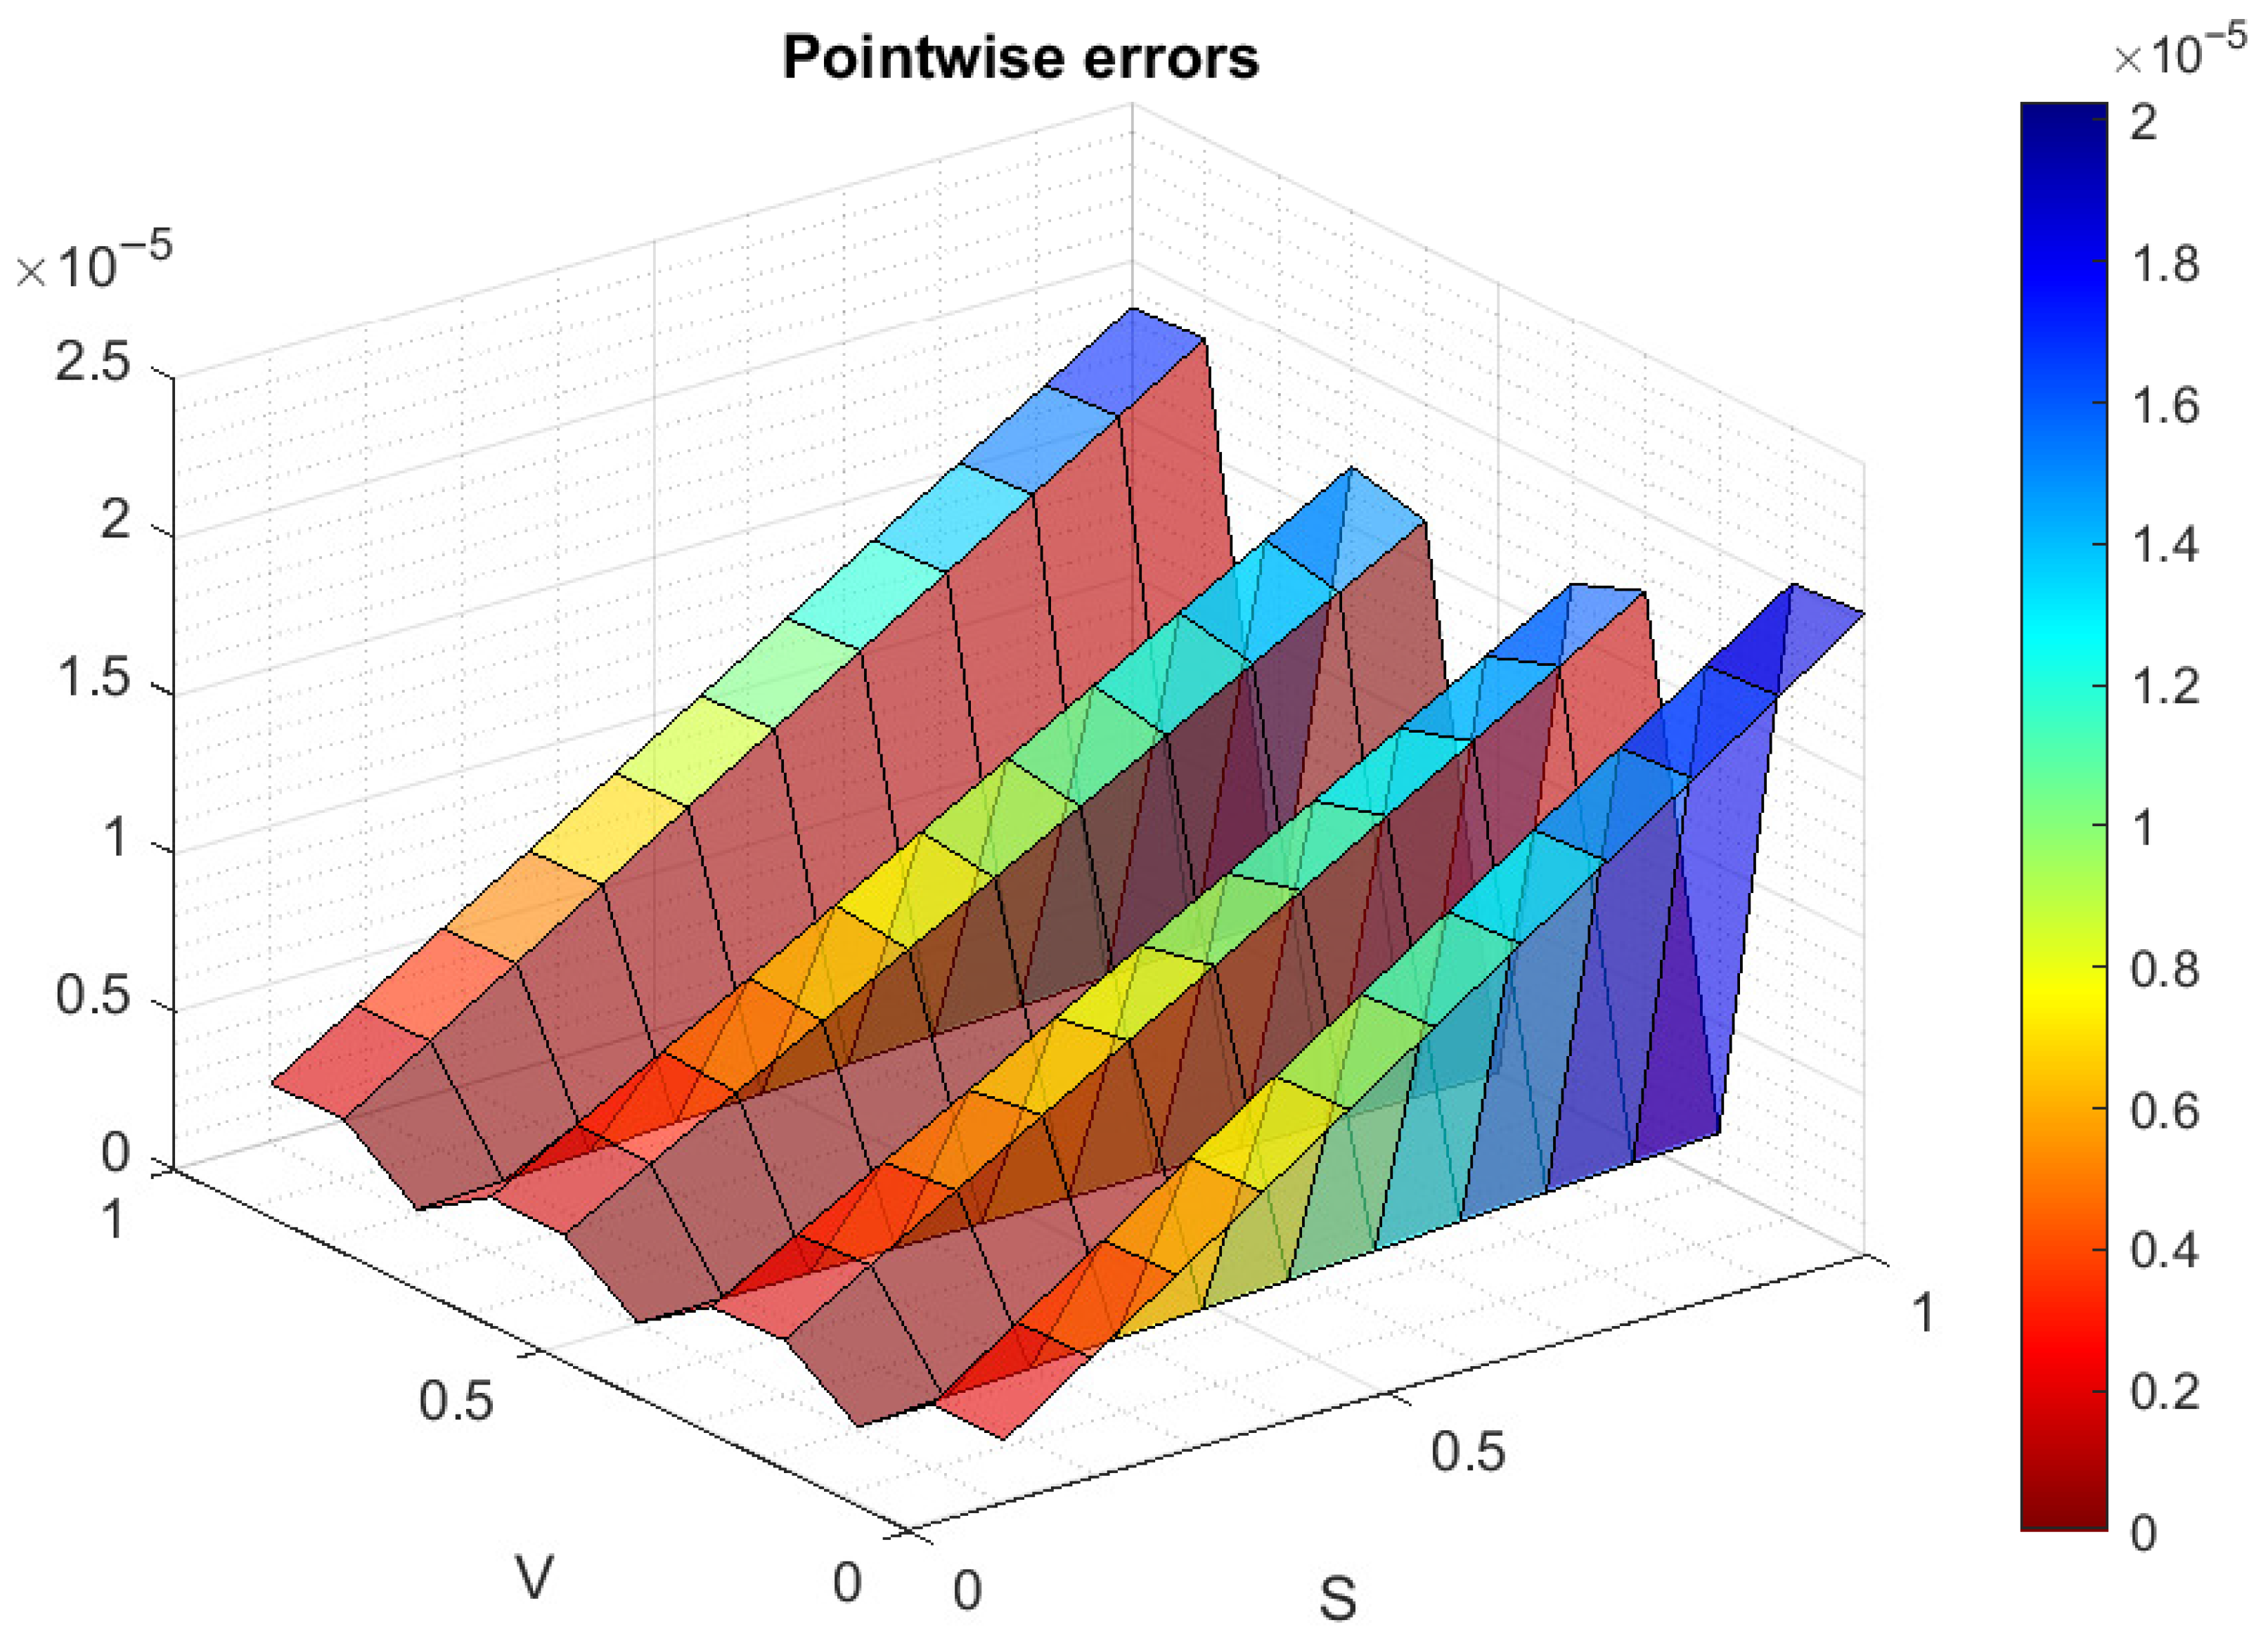
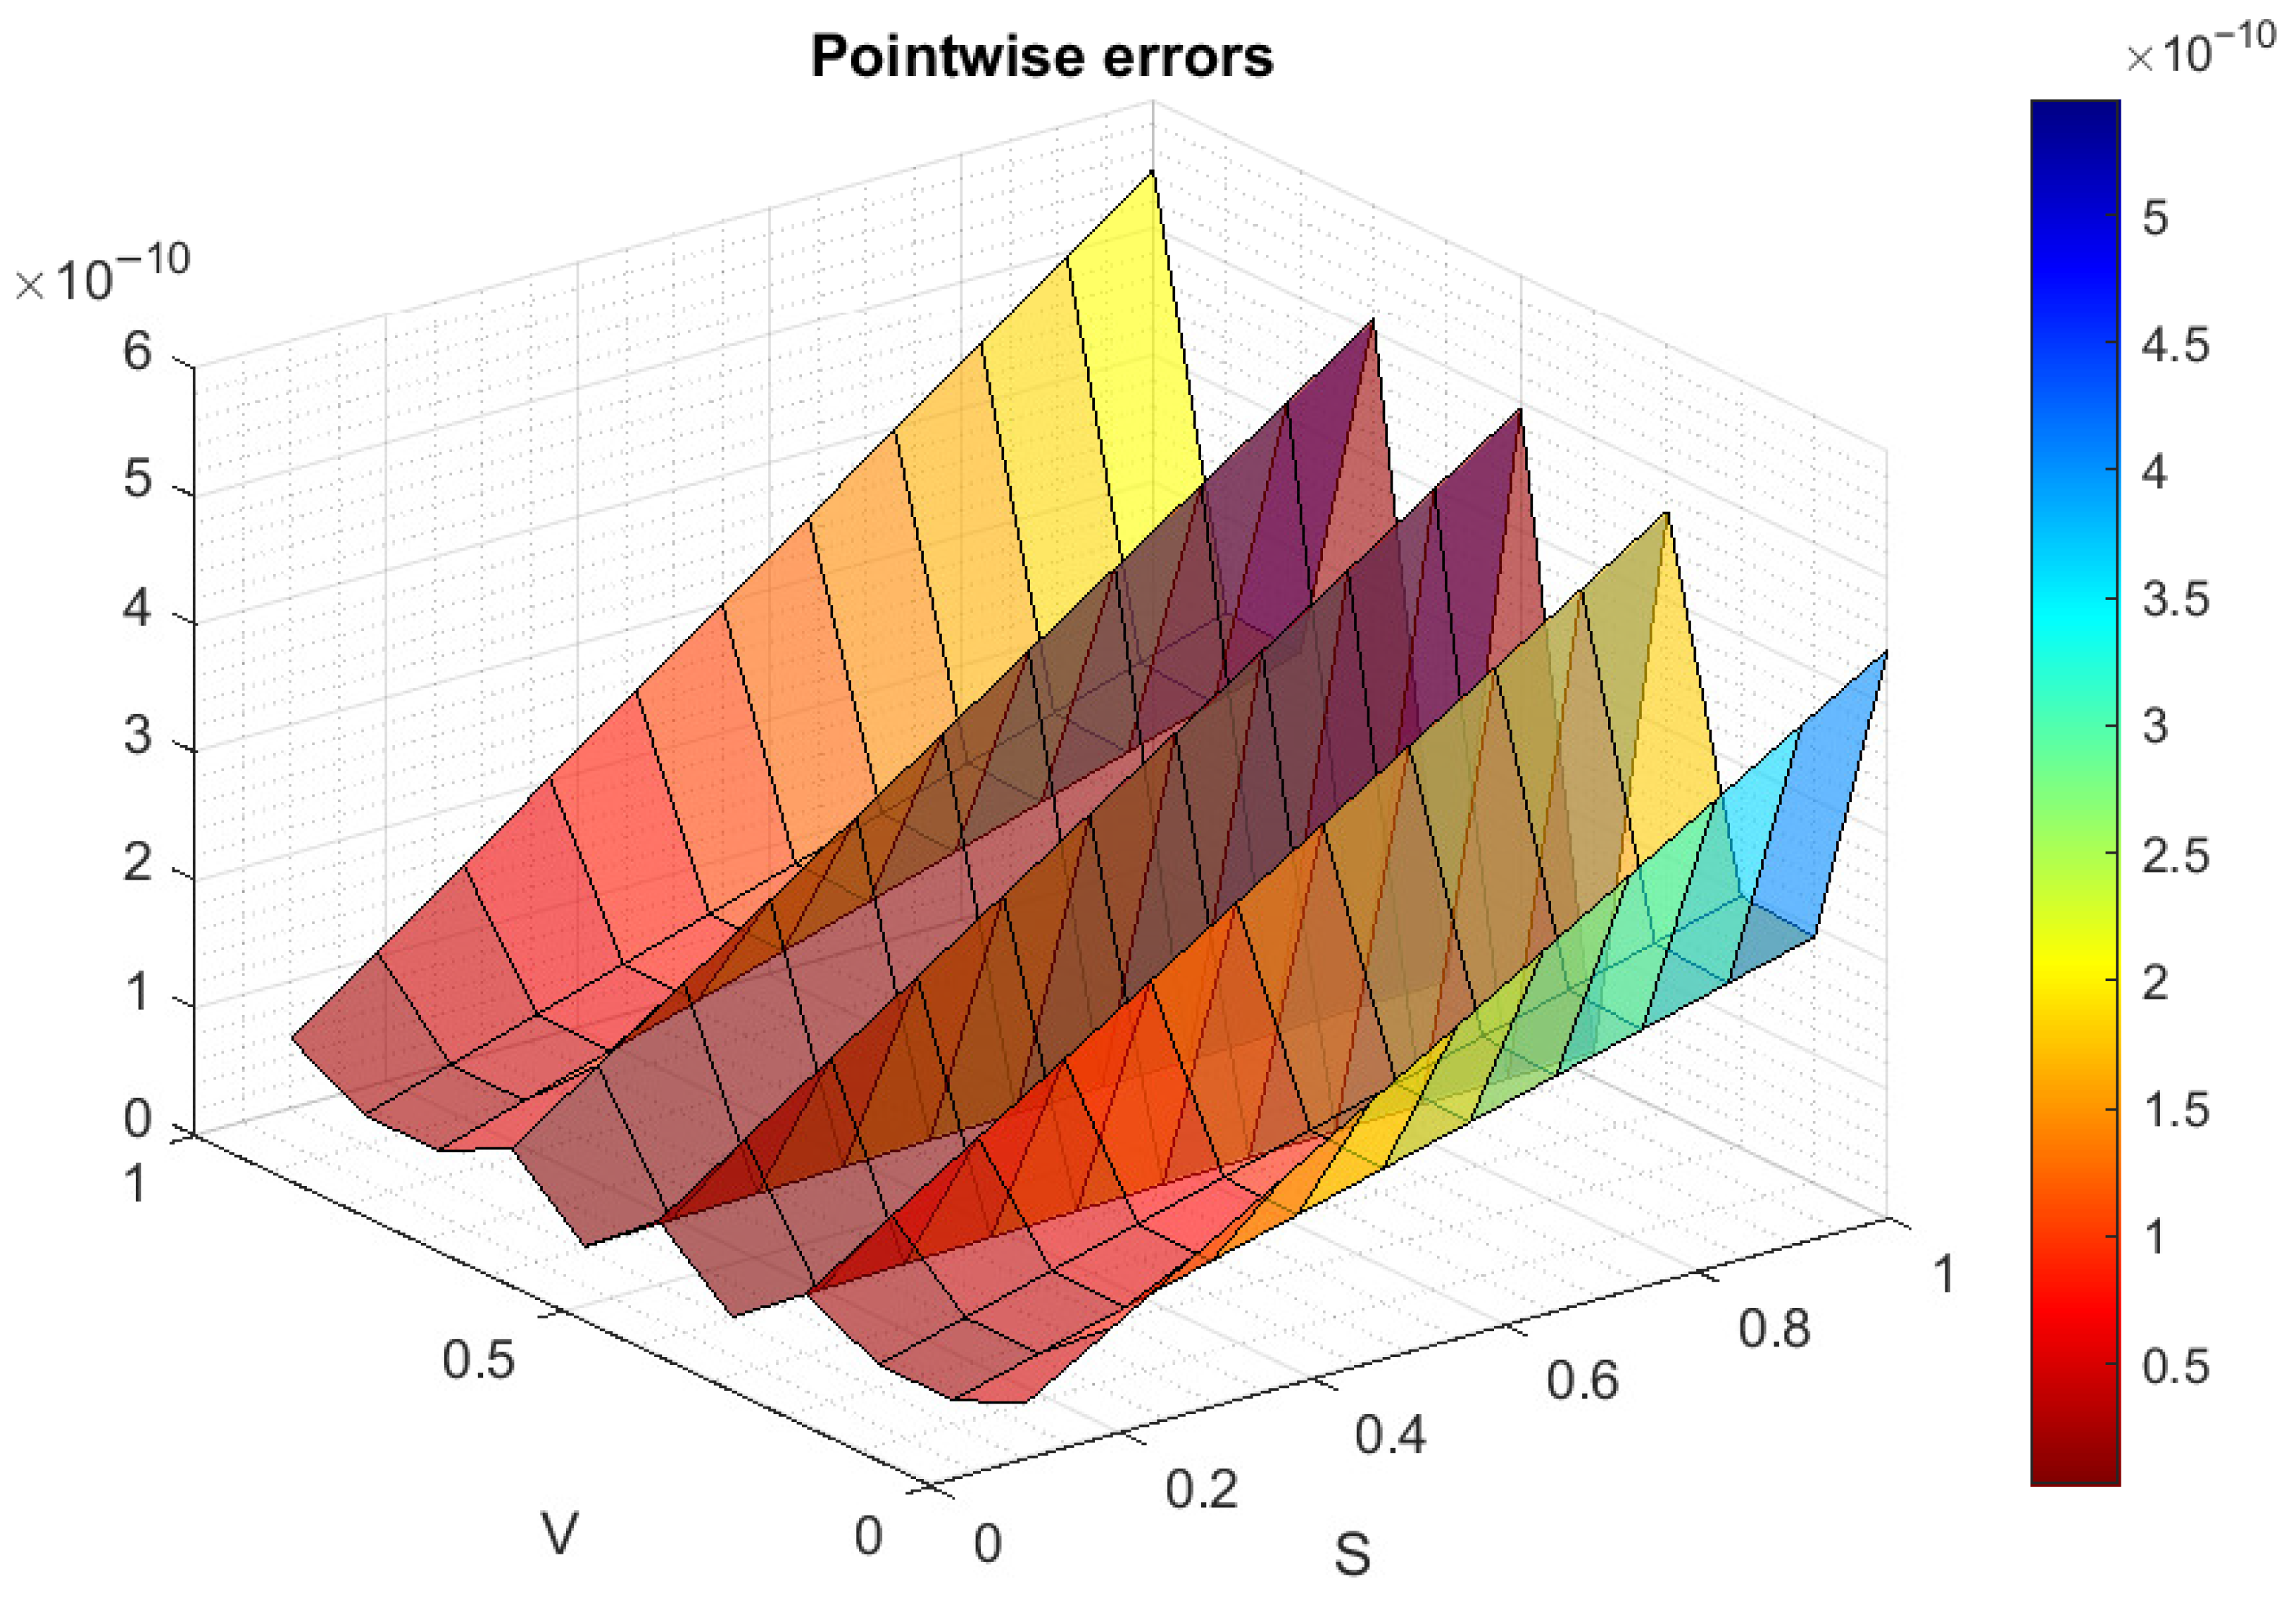



| O = 2 | O = 4 | O = 6 | O = 8 | |
|---|---|---|---|---|
| Monte-Carlo Method (K = 0.6) | 0.3915 | 0.3869 | 0.3843 | 0.3832 |
| Present Method | 0.3821 | 0.3821 | 0.3821 | 0.3821 |
| Monte-Carlo Method (K = 0.7) | 0.2709 | 0.2693 | 0.2689 | 0.2687 |
| Present Method | 0.2684 | 0.2684 | 0.2684 | 0.2684 |
| Monte-Carlo Method (K = 0.8) | 0.0.1762 | 0.1750 | 0.1741 | 0.1737 |
| Present Method | 0.1730 | 0.1730 | 0.1730 | 0.1730 |
| Monte-Carlo Method (K = 0.9) | 0.0907 | 0.0881 | 0.0859 | 0.08503 |
| Present Method | 0.0844 | 0.0844 | 0.0844 | 0.0844 |
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.
Share and Cite
Alsenafi, A.; Alazemi, F. A Collocation Method Using Diagonal Polynomials for Pricing Geometric Asian Options Under the Mixed Fractional Heston Model. Mathematics 2026, 14, 1439. https://doi.org/10.3390/math14091439
Alsenafi A, Alazemi F. A Collocation Method Using Diagonal Polynomials for Pricing Geometric Asian Options Under the Mixed Fractional Heston Model. Mathematics. 2026; 14(9):1439. https://doi.org/10.3390/math14091439
Chicago/Turabian StyleAlsenafi, Abdulaziz, and Fares Alazemi. 2026. "A Collocation Method Using Diagonal Polynomials for Pricing Geometric Asian Options Under the Mixed Fractional Heston Model" Mathematics 14, no. 9: 1439. https://doi.org/10.3390/math14091439
APA StyleAlsenafi, A., & Alazemi, F. (2026). A Collocation Method Using Diagonal Polynomials for Pricing Geometric Asian Options Under the Mixed Fractional Heston Model. Mathematics, 14(9), 1439. https://doi.org/10.3390/math14091439