Article

Reinforcement Learning for Enhancing Bitcoin Risk-Aware Trading with Predictive Signals

Department of Economic Informatics and Cybernetics, Bucharest University of Economic Studies, 010374 Bucharest, Romania
*
Author to whom correspondence should be addressed.
Electronics 2026, 15(4), 793; https://doi.org/10.3390/electronics15040793

Submission received: 22 January 2026 / Revised: 6 February 2026 / Accepted: 10 February 2026 / Published: 12 February 2026

Abstract

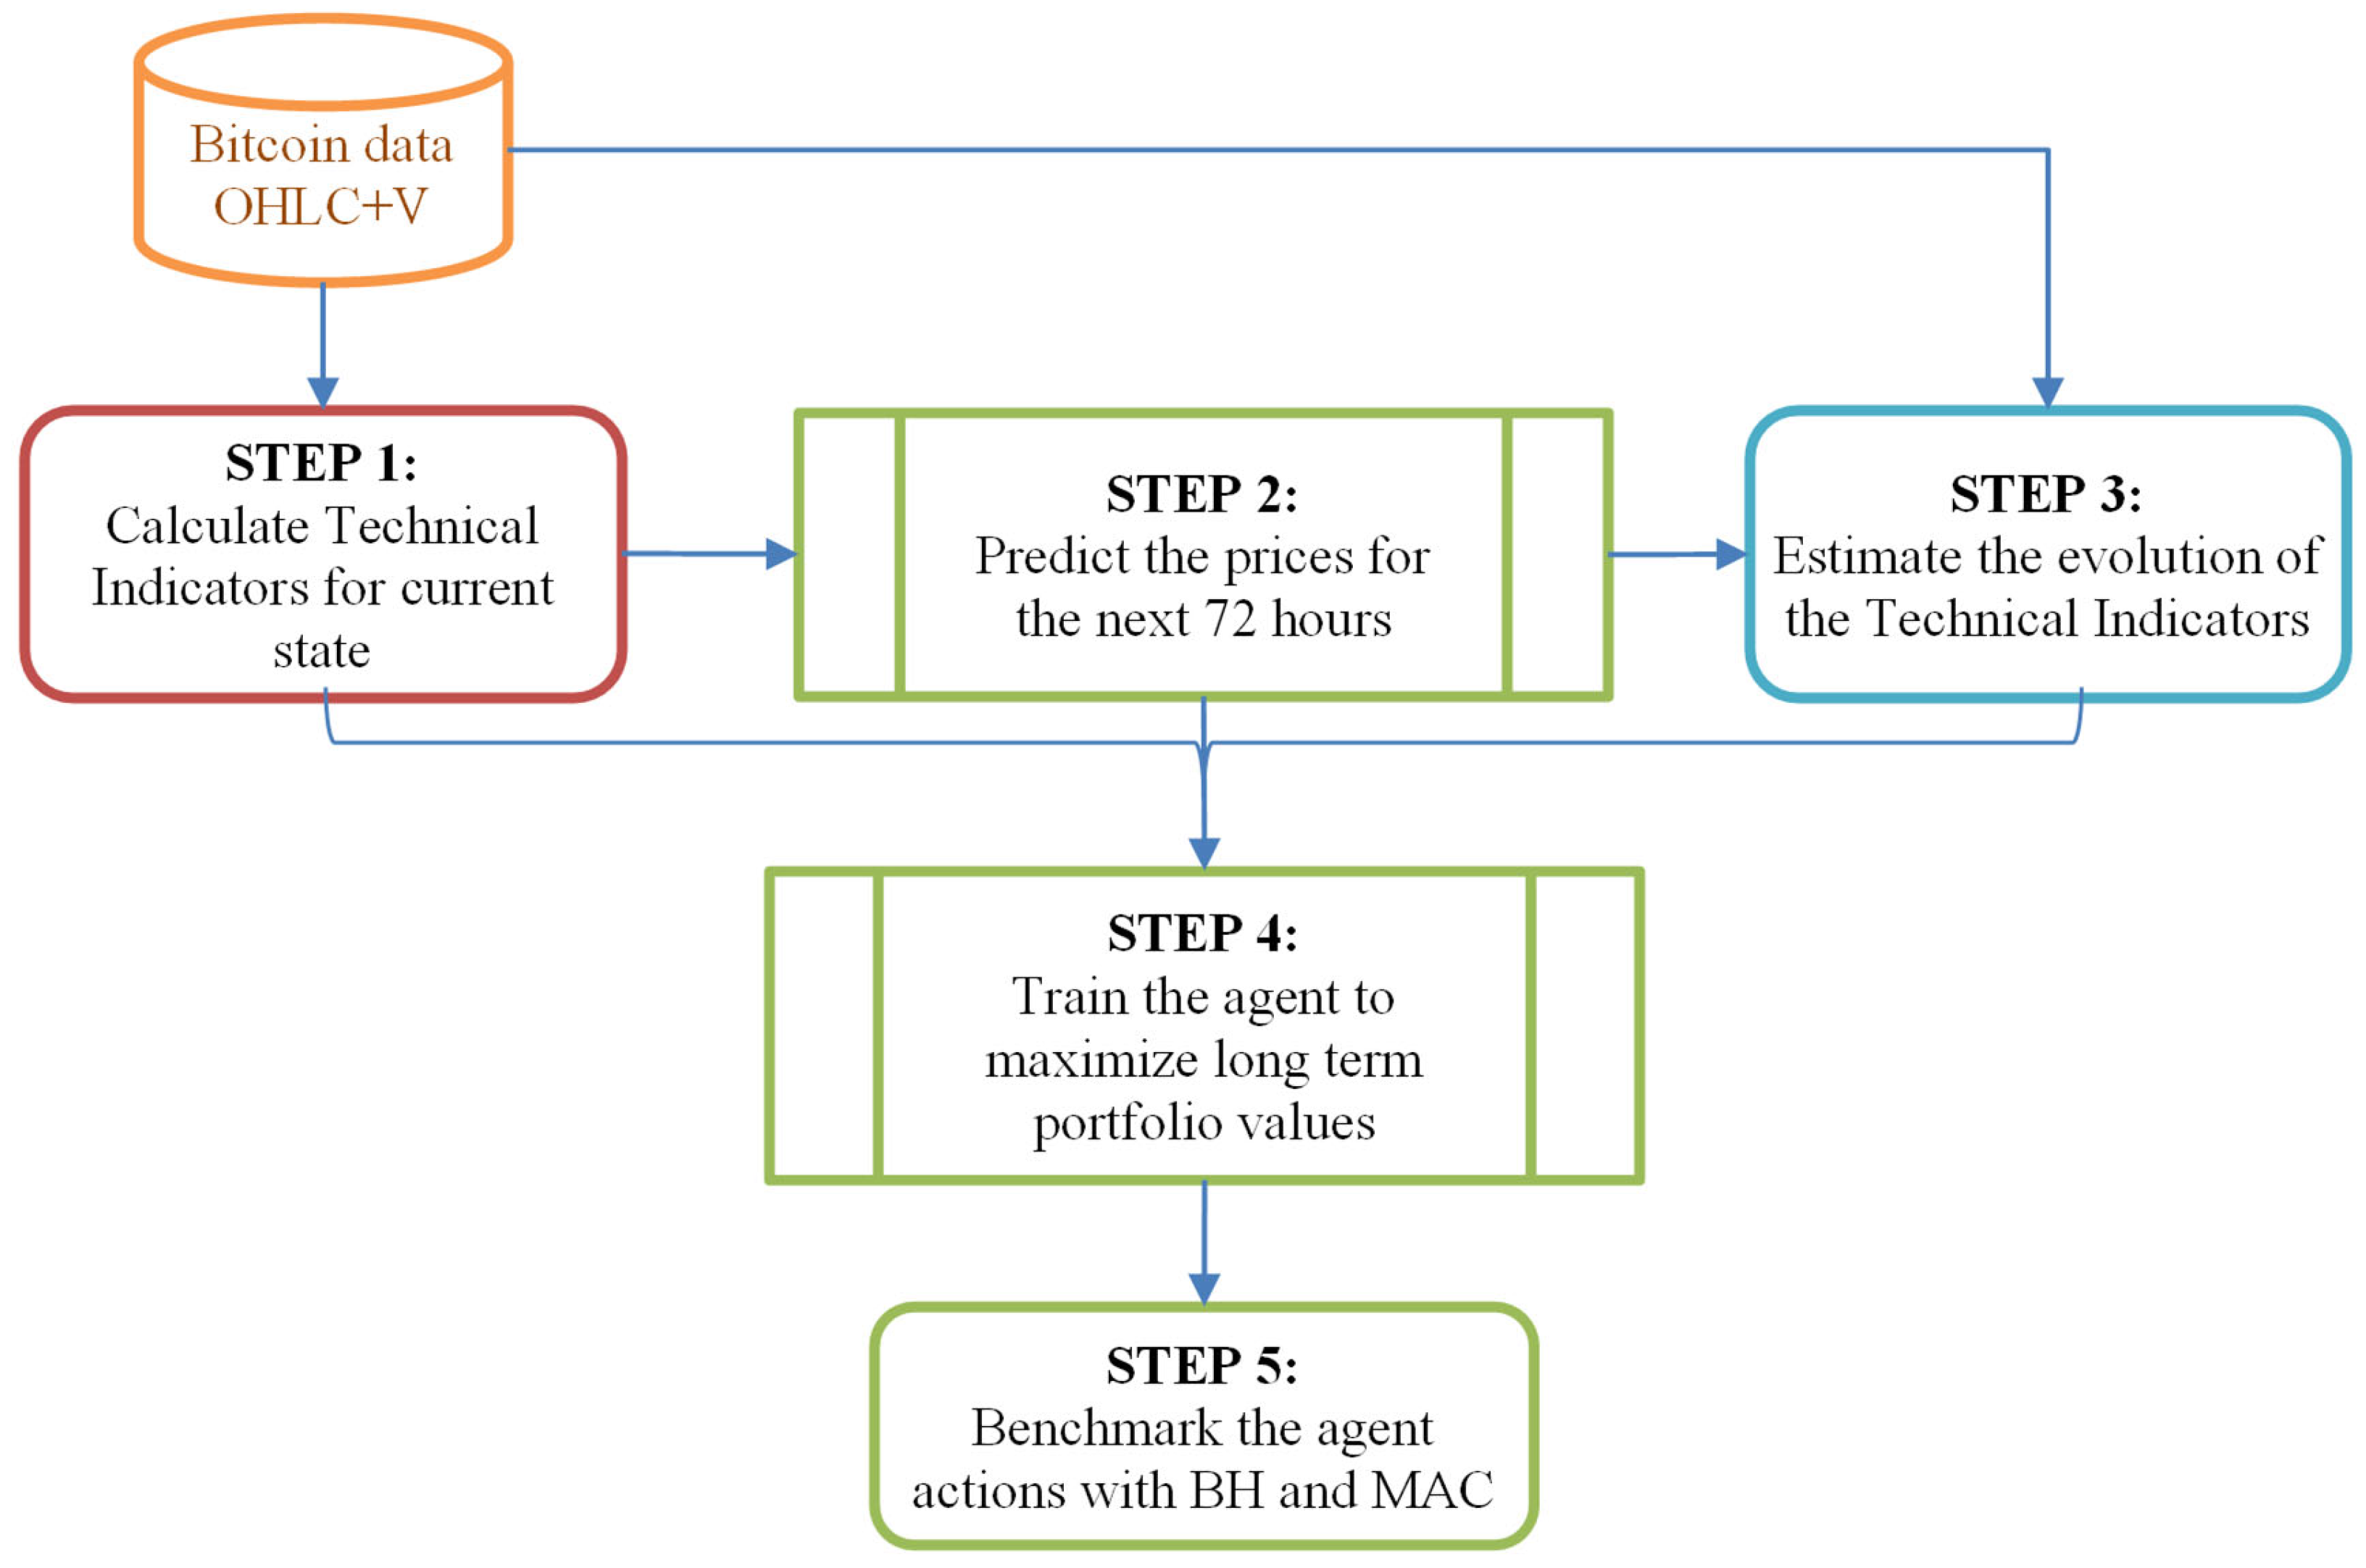
This paper proposes an AI-based trading framework that integrates supervised price forecasting with reinforcement learning (RL)-based decision-making. The objective is to enhance both profitability and risk management in cryptocurrency trading by equipping RL agents with forward-looking market information and risk-aware incentives. The proposed methodology follows a two-stage design. First, a univariate long short-term memory (LSTM) model generates 72 bitcoin price forecasts. These predictions are used to compute future technical indicators, which are combined with current market indicators to construct an enriched, forward-looking state representation. Second, an RL agent is trained in this environment using a novel long-term reward function that incorporates transaction costs, drawdown penalties, volatility penalties, and delayed rewards to promote stable and sustainable trading behavior. Four state-of-the-art RL algorithms (PPO, SAC, TD3, and A2C) are systematically evaluated over randomized 180-day episodes using hourly bitcoin data. The results demonstrate that the proposed agent consistently outperforms conventional buy-and-hold and moving average crossover strategies, achieving an average profit ratio of 32% and a Sharpe ratio of 1.34. These findings highlight the novelty and effectiveness of combining mid-term price forecasts, enriched technical states, and risk-aware RL training for robust cryptocurrency trading.
Keywords: reinforcement learning; forecast; bitcoin trading strategy; technical indicators; recurrent neural networks reinforcement learning; forecast; bitcoin trading strategy; technical indicators; recurrent neural networks