Systematic Review

Automatic Extraction of Suppliers’ ESG Compliance Information from Textual Sources: A Literature Review


Department of Mechanical and Industrial Engineering, University of Brescia, via Branze 38, 25123 Brescia, Italy
*
Author to whom correspondence should be addressed.
Appl. Sci. 2026, 16(8), 4024; https://doi.org/10.3390/app16084024
Submission received: 17 February 2026 / Revised: 10 April 2026 / Accepted: 15 April 2026 / Published: 21 April 2026
(This article belongs to the Special Issue Sustainability and Green Supply Chain Management in Industrial Fields)

Abstract

This paper presents a literature review regarding the automatic extraction of meaningful information regarding suppliers’ ESG and sustainability compliance from textual sources. Assessing suppliers’ ESG compliance has become a key challenge for procurement managers. Given the large number of suppliers and required data points, traditional approaches such as questionnaires and audits are inefficient, ineffective and difficult to scale. To solve this problem, we investigate whether the required information can be automatically harvested from suppliers’ textual sources. Our structured literature review identified 82 papers on which we performed a descriptive analysis, finding a rich and flourishing body of literature produced by a heterogeneous scientific community. We further reduced our sample to 73 full-text articles that supported a more in-depth content-based analysis. We investigated which data sources can be used in particular, which technologies can be leveraged, and which types of outputs can be generated. Even though they could provide much of the required information, corporate websites are rarely utilized as data sources, partly due to the limited adoption of large language models (LLMs). LLMs are less diffused than traditional Natural Language Processing (NLP) techniques due to their recent introduction and some gaps that still limit their performance. This represents both a constraint and an opportunity for future research.

1. Introduction

A supply chain (SC) can be defined as an ecosystem of actors interacting through networked processes to fulfil customers’ needs [1]. Supply Chain Management (SCM) is the coordination of the flows of goods, information, and cash within the SC. Ref. [2] described four fundamental types of SCs, the goals they pursue, and the coordination strategies they employ.
The de-verticalization of international SCs has led many manufacturers to focus on those production phases where they could be distinctive, outsourcing other phases to third parties that are more specialized, more competitive, or that can just count on greater economies of scale [3,4,5]. This significantly increased suppliers’ weight and importance within companies’ offerings [6,7].
ESG evaluates an organization’s commitment to pursue objectives that transcend the mere maximization of shareholders’ profits, including the achievement of specific environmental targets; the consistent integration of principles of diversity, equity, and inclusion; and the systematic adoption of honest and transparent business management practices [8]. A variety of governmental organizations and financial institutions have devised ways to measure how well a specific corporation is aligned with ESG goals. The most significant global movement in this regard was the adoption of the 17 Sustainable Development Goals (SDGs) by the United Nations in 2015 [9]. This sustainability report is a document aimed at reporting firms’ ESG performances [10] and communicating the company’s commitment to ESG goals. It focuses on the company’s commitment to promoting sustainable development [11], describing the initiatives undertaken in the environmental, social and governance fields, and including such aspects as carbon footprint, corporate governance, diversity, equity and inclusion, environmental impact, social impact and sustainable finance practices [12].
If we cross ESG reporting regulatory requirements and standards with the fact that a large chunk of the value generated by any given manufacturing company is in fact produced by its suppliers, we conclude that in the majority of cases it is not sufficient to assess how compliant to ESG principles are a given firm’s internal processes: quite the contrary, firms must extend their sustainability assessment to their upstream supply chain as well [13]. This principle is well represented by the need to compute scope 3 emissions [14,15] on top of scope 1 and 2. Scope 3 refers to indirect greenhouse gas emissions throughout a company’s value chain (upstream and downstream) that are not under its direct control, such as those from suppliers, transportation, use of products sold, and disposal. It represents the vast majority of a company’s carbon footprint and is crucial for effective sustainability strategies and regulatory compliance, although it is the most complex emission category to measure and manage.
Considering the average number of suppliers with which a firm can collaborate (in the hundreds) and the typical amount of data points to collect from each to map suppliers’ ESG compliance (also in the hundreds), the data collection required to deliver an effective sustainability report that encompasses scope 3 emissions and assesses suppliers’ sustainability sets a serious challenge [16]. There are two main ways through which companies collect data regarding their vendors’ ESG compliance: questionnaires and audits. However, these data-collection policies’ efficiency and effectiveness is far from satisfactory; moreover, they do not ensure full control on data completeness and correctness, and—by the same token—frequently require long times to be executed. For this reason, we set out to investigate whether technology can offer a better alternative, and we identified several promising candidates among artificial intelligence techniques applied to textual sources [17], such as automated text-interpretation technologies.
This paper’s two goals are thus to identify: (i) whether the required information is available within freely available textual sources, either as plain text or as embedded documents, and (ii) whether appropriate digital technologies can be leveraged to identify and capture this information. To do so, we performed a literature review of the most recent scientific and technological progress in the collection of suppliers’ ESG compliance information by automatically reading plain text documents.
For this purpose, the remainder of this paper is organized as follows. Section Background reports a structured view on this research’s background literature, mainly regarding ESG reporting, its relevance in the supply chain management realm, how technology can profoundly innovate the way information is achieved, and the current state of the art of text reading technologies as one of the main levers to do so. Section 2 describes the specific methodology adopted to achieve this paper’s goals by first setting the research questions and then detailing how the literature base needed by our literature review was searched for and selected. Section 3.1 contains our descriptive analysis, performed on 82 papers, while Section 3.2 presents the main results of our more in-depth content-based analysis on a restricted sample of 73 papers. Section 4 presents a critical discussion of the main evidence collected, while Section 5 provides the main concluding remarks.

Background

ESG practices have become fundamental in contemporary managerial theory due to their ability to promote accountability, transparency, and resilience within organizations. Research shows that firms integrating ESG into their strategic processes benefit from improved financial performance, risk mitigation, cost efficiencies, and stronger stakeholder legitimacy [18,19]. ESG initiatives also reduce the cost of capital by fostering trust among investors who increasingly prioritize sustainability in decision-making. Regulatory evolution, particularly within the European Union, with frameworks such as the Corporate Sustainability Reporting Directive (CSRD), has institutionalized ESG disclosure as a mandatory governance requirement, shifting sustainability from a communicative tool to a measurable determinant of corporate performance [20]. In this context, ESG reporting enables firms to align sustainability actions with long-term strategic goals, while supporting benchmarking and continuous improvement. Thus, the literature consistently highlights the transition of ESG from peripheral communications to a central component of value creation, shaping competitive dynamics in global markets.
Progress in corporate-level sustainability has shown that most environmental and social risks originate upstream in multi-tier supply chains, where reporting maturity is uneven and suppliers, particularly SMEs, often lack the resources and competencies to disclose ESG performance effectively [21]. These structural asymmetries undermine traceability and create blind spots that may conceal severe misconduct. The Rana Plaza catastrophe in Bangladesh remains the most striking example: apparel suppliers formally certified as compliant failed to ensure even minimal work safety conditions, leading to the death of more than 1100 garment workers [22]. By the same token, more recently, investigations into the Italian luxury industry revealed persistent labor exploitation and illegal subcontracting in the production networks of renowned high-end brands, despite multiple passed audits and public sustainability commitments [23]. Similar controversies have affected global retailers, including Nike and Walmart, in previous decades, where labor abuses and unsafe workplaces in offshore manufacturing facilities resurfaced despite the adoption of tight monitoring protocols [24]. These recurring failures highlight the fragility of current SC ESG assurance systems and show how reputational and legal risks extend well beyond organizational boundaries. Academic research stresses that firms can only achieve credible ESG reporting by integrating sustainability governance into procurement, supplier development and corporate risk management processes [18,19]. SC transparency is increasingly linked to corporate legitimacy, investor confidence and business continuity, especially in regulatory environments with mandatory due-diligence obligations. Hence, ESG reporting has evolved into a holistic SC governance function, where performance depends not only on a firm’s internal actions but also on its ability to monitor, influence and support responsible practices across its entire network of suppliers.
Supplier questionnaires and self-assessment tools remain one of the most widely adopted approaches for collecting ESG information across global supply chains because they are cost-effective, scalable, and easily integrated into procurement processes. However, research shows that this mechanism is intrinsically affected by self-reporting bias from suppliers, who may overstate their sustainability efforts to maintain business relationships or comply with customer expectations [20,25]. The absence of standardized reporting frameworks also generates inconsistencies in the quality and comparability of the collected information, limiting its usability for strategic or regulatory decision-making [21]. Furthermore, questionnaires provide only periodic and static insights into supplier performance, which is problematic in complex and fast-evolving supply networks where ESG conditions can deteriorate rapidly [18]. Scholars argue that for core sustainability issues, such as labor rights protection, occupational safety, human rights, and scope 3 emissions, self-assessment alone is insufficient to ensure compliance and guarantee credible ESG reporting, as suppliers can selectively disclose information without external verification [24]. Therefore, while questionnaires are a foundational component of supplier engagement, the literature increasingly views them as inadequate when adopted as the primary ESG monitoring instrument in global SC governance.
To address the reliability issues of questionnaires, sustainability audits have been widely adopted as an independent verification mechanism. However, theoretical analyses and field investigations reveal persistent structural barriers. Audits are resource-intensive, infrequent, and often limited to first-tier suppliers, leaving opaque information gaps in lower tiers, where risk concentration is higher [21,26]. The literature further highlights the risk of performative compliance, where suppliers adapt to inspection routines without transforming underlying practices [27]. Ref. [24] critiques the audit regime as fundamentally reactive, oriented more toward mitigating brand exposure than addressing systemic labor exploitation. Scholars therefore argue that while audits can contribute to oversight, they must be complemented by more continuous, scalable and data-driven approaches to ensure credible ESG reporting and protect vulnerable workers across global supply networks.
The limitations of traditional ESG data collection have accelerated the integration of digital technologies into sustainability governance. Artificial Intelligence (AI) and Machine Learning (ML) provide the analytical capacity to manage complex and dispersed supplier networks by processing large volumes of heterogeneous data, detecting anomalies and enabling predictive ESG risk assessment [18,19,28]. The literature emphasizes that digital transformation strengthens internal control systems and enhances transparency, enabling firms to monitor sustainability conditions with greater depth and frequency while overcoming the static nature of traditional compliance tools. AI-enabled risk models also support dynamic decision-making by identifying emerging patterns of misconduct before they escalate into crises. Increasingly, scholars argue that ESG performance is shaped not only by compliance outcomes but also by the technological maturity of corporate monitoring systems [21]. Digital solutions empower firms to scale oversight across multiple SC tiers, reducing the fragmentation of information that traditionally characterizes global sourcing. This shift contributes to the institutionalization of sustainability within organizational routines, extending governance responsibilities to procurement, operations, and supplier engagement processes. Regulators and international investors now encourage the integration of digital technologies into ESG governance frameworks, considering them instrumental for ensuring credibility, timeliness, and auditability of disclosed information. Theoretical contributions also highlight the role of digital innovation in reducing power asymmetries within supply chains, strengthening accountability mechanisms and supporting more equal participation by smaller suppliers in sustainability transitions [20]. As a result, AI and ML are increasingly viewed not only as operational enhancers but as structural enablers of a more explicit, objective, resilient, transparent, and future-oriented SC governance. In this emerging paradigm, ESG assurance shifts from a periodic and reactive evaluation toward a continuous monitoring regime, in which sustainability information becomes part of real-time managerial intelligence. This evolution marks a significant theoretical change in how organizations conceptualize accountability and performance measurement, positioning digital data-driven governance as essential for meeting expanding sustainability expectations in global markets.
Within the broader AI landscape, such technologies used to interpret plain readable text as NLP are proving increasingly relevant for improving the quality and availability of ESG information. The literature demonstrates how these technologies can transform large volumes of textual data, ranging from corporate disclosures to regulatory filings, from media sources to social media, and from legal rulings to civil society reports, into comparable ESG indicators, enabling more objective and scalable assessments of ESG practices across supply networks [29,30,31]. This expands access to credible sustainability data beyond self-reporting, supporting early identification of compliance deviations and emerging risks. Scholars increasingly highlight how automated text analysis can enrich governance processes by supporting near real-time scope 3 monitoring and strengthening responsible procurement strategies. The literature therefore identifies automatic textual information extraction as a key enabler of next-generation ESG assurance systems, forming the conceptual basis for the methodology explored in this research.
This paper examines the above-described issues, adopting a supply-chain and operations management perspective. Thus, rather than focusing on the technical development of automated text-interpretation technologies per se, we analyze and discuss how emerging text-analysis technologies can support ESG monitoring across supplier networks.

2. Materials and Methods

The purpose of this study is to examine whether and to what extent automated text-analysis techniques can support the extraction of ESG-related information from freely available textual sources, offering an automatic, scalable, and reliable alternative to traditional data-collection mechanisms such as questionnaires and audits. As noted in the Background Section, these methods suffer from limitations including self-reporting bias, infrequent updates, and high resource demands, while text-reading technologies could—in principle—convert large volumes of unstructured text into actionable sustainability information, and even objective indicators. What remains unclear is whether and how extant research has addressed this intersection and whether current technological solutions can meet firms’ information needs for supplier evaluation.

2.1. Research Questions

To explore this gap, we conducted a systematic literature review by mapping and assessing the works at the convergence of ESG reporting, SC governance, and artificial intelligence technologies capable of extracting information from text. Three guiding questions framed our review: our first research question examines which textual source(s) proves most effective to gather corporate ESG data. In fact, extant research draws on diverse materials, such as sustainability reports, financial reports, regulatory documents, websites, news, judicial filings, and social media. Comparing these sources helps assess which different textual sources constitute a viable and sufficiently informative channel for ESG evaluation, considering factors such as accessibility, frequency of updates, and alignment with due diligence requirements. The second research question concerns the technological dimension and investigates which technique(s) emerges as most suitable to extract ESG content from textual sources, whose heterogeneous and semi-structured nature may require capabilities such as domain adaptation and robust information extraction. The third question investigated by this study concerns which types of ESG information can be extracted from the investigated sources, ranging from environmental to social and governance indicators, and in some cases, aggregated ESG scores or risk metrics. Understanding which dimensions are most frequently targeted, and how well they correspond to compliance-oriented supplier assessments, clarifies the degree to which existing research meets practical needs in procurement and sustainability management. Together, these questions form the conceptual backbone of our review, guiding our analysis of a fragmented body of literature and supporting our evaluation of both the maturity of current NLP solutions and their potential applicability to supplier-focused ESG monitoring.

2.2. Methodology

The methodological approach adopted in this study follows the principles of a systematic literature review (SLR) described by [32] and was conducted and reported in accordance with the Preferred Reporting Items for Systematic Reviews and Meta-Analyses (PRISMA 2020) guidelines [33]. The PRISMA framework was applied to ensure transparency, replicability, and methodological rigor throughout the identification, screening, eligibility, and inclusion phases of study selection. No review protocol was formally registered prior to conducting this study; however, the methodological approach, including research questions, eligibility criteria, and search strategy, was defined ex ante to reduce selection bias and ensure consistency throughout the review process.
We performed all our searches in SCOPUS, one of the most widely used academic literature databases. The choice of the SCOPUS database was motivated by its broad coverage and the homogeneous quality control ensured by its indexing criteria. Other sources, such as the Web of Science, Google Scholar, conference proceedings, and preprint repositories, might include additional contributions or anticipate SCOPUS in indexing new works. However, we considered that relying on a single database ensures a more homogeneous inclusion criterion. By the same token, we decided to restrict our search to only peer-reviewed international journal articles, excluding other contributions that do not ensure the same level of quality and are not subject to a fully double-blind review process. Therefore, while this choice might occasionally exclude some very recent contributions, it was adopted deliberately to ensure consistency in peer-review standards and comparability across the included studies. To mitigate potential limitations, backward and forward snowballing procedures were also conducted.
By integrating a broad search with a rigorous multi-stage selection procedure, the SLR ensures both comprehensiveness and conceptual alignment with the goal of this research: assessing the maturity, methodological diversity and applicability of text-reading techniques for extracting suppliers’ ESG-related information.

2.3. Papers’ Search

The process began with a preliminary scoping exercise aimed at exploring the literature positioned at the intersection of the three domains central to our research questions: the use of AI text-reading technologies, the automatic extraction of actionable ESG-related information, and the focus on suppliers and supply chains. However, although this triple intersection represents the ideal conceptual target of our review, the number of studies simultaneously addressing all three dimensions proved extremely limited. Only 32 papers fulfilled all search criteria, showing that such a narrow specification would not allow for a meaningful systematic assessment of methods and technological trends.
This evidence motivated a refinement of our search policy. Given the limited number of studies explicitly addressing supplier-related ESG information, our final search approach broadened the scope to include studies investigating automatic ESG information extraction from textual sources generically regarding firms, instead of focusing on just a customer’s search for suppliers’ information. The role of supplier-related contexts was then examined in the analysis of the reviewed literature, particularly in the discussion of data source characteristics.
This shift made it possible to capture the broader methodological landscape of ESG information extraction while still identifying, during later phases, those contributions applicable to supplier evaluation through the analysis of freely available textual sources. This refinement also required clarifying the inclusion criteria guiding the selection of studies. A broad criterion was adopted for the use of automated text-interpretation techniques, irrespective of methodological specificities. In contrast, ESG was treated more narrowly, retaining only studies that explicitly address sustainability reporting or assessments within the supplier-related contexts considered during the screening and eligibility stages.
The final search string was therefore constructed by combining ESG-related keywords with a wide set of terms reflecting NLP, automated text extraction and AI-driven text-interpretation techniques. Applied in Scopus, the query searched for the title, abstract and keyword fields, as expressed by Table 1.
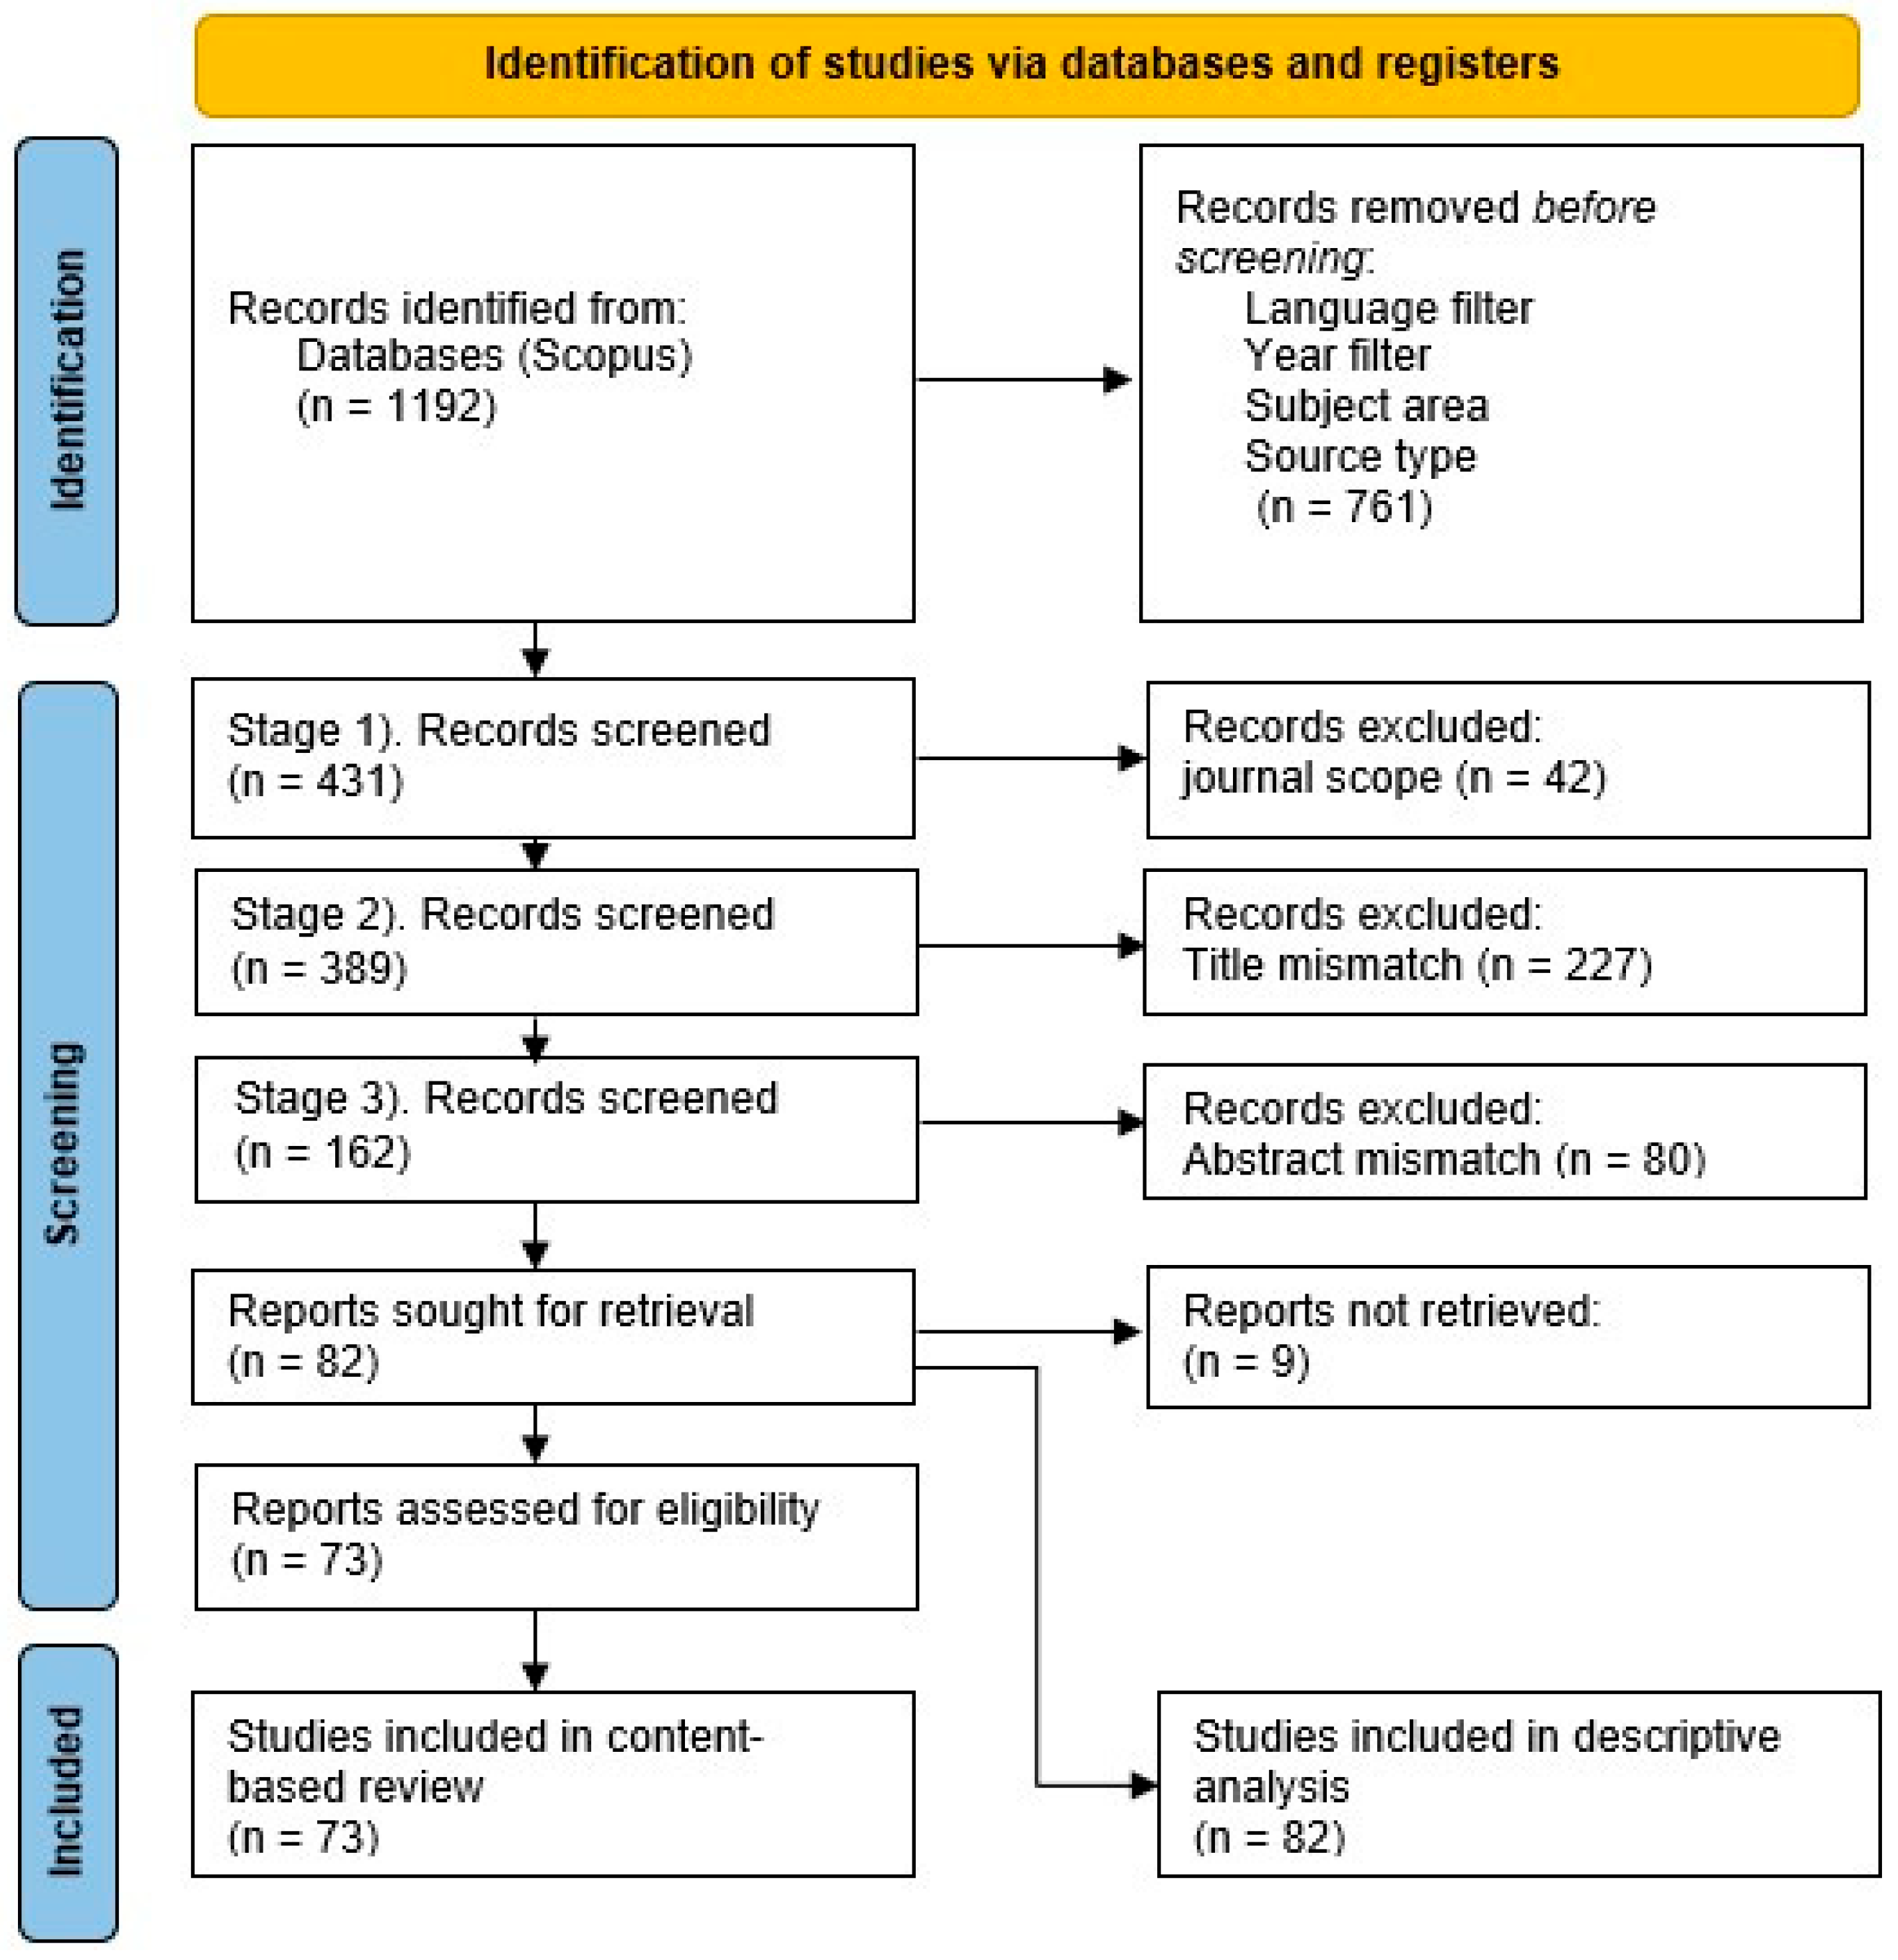
The PRISMA process unfolded through successive stages reflecting the standard SLR protocol (Figure 1). The literature search was initially conducted in October 2025 and subsequently updated in December 2025 to ensure the inclusion of the most recent publications available at the time of review. The final search month was December 2025. The screening process was conducted independently by the two authors. Discrepancies in study selection were resolved through discussion until consensus was reached. No automation tools were employed during the screening process. Inter-reviewer agreement was assessed informally during pilot screening to ensure consistency in the application of inclusion and exclusion criteria.
In the identification phase, as many as 1192 papers were retrieved from the database: before screening, 761 records were removed because they did not meet the inclusion criteria related to language, source, period or subject area. To this extent, the search was restricted only to English-language scientific journal articles published between 2000 and 2025 within such disciplinary areas as: engineering, computer science, business and management, social sciences, environmental sciences, and decision sciences. However, no publications issued before 2010 matched the search criteria in the SCOPUS database. This result was further verified through backward and forward snowballing procedures. This inclusion process resulted in 431 records entering the screening stage.
The screening phase was performed in three stages in sequence. Stage 1 involved discarding all papers that were published in a journal considered unsuitable to meet our objectives, especially due to the peculiar field of knowledge they explored. We excluded papers published in journals whose scope was highly specialized and evidently misaligned with the objectives of this study, such as: Ocean and Coastal Management, Journal of Hospitality and Tourism Research, or Nuclear and Radiation Safety. This led to the exclusion of 42 papers, leaving 389 papers for further examination.
The second screening stage was performed by reading the papers’ titles: each author performed an independent check of how well the papers’ titles matched the selection criteria adopted, namely, to use automated text-interpretation techniques and to focus on firms’ ESG or sustainability information. We decided to keep only those papers whose titles were independently rated by both authors as compliant to both the above-specified selection criteria. After applying the inclusion criteria to the papers’ titles, 227 papers were excluded, leaving 162 studies for abstract assessment.
Screening stage 3 involved applying the same inclusion criteria to the papers’ abstracts rather than their titles. Papers mentioning ESG only marginally, lacking any implementation of text-interpretation techniques, or otherwise misaligned with the objectives of this review, were excluded. Again, we repeated the same double-blind procedure seen above, this time on the papers’ abstracts. This additional stage led to the exclusion of 80 papers, leaving 82 studies deemed eligible for inclusion in the review. Of these 82 studies, 9 reports could not be retrieved due to the unavailability of the full text, resulting in a final sample of 73 studies for qualitative examination. A backward and forward snowballing procedure was also conducted on the eligible studies to identify potentially relevant contributions not captured by the initial search strategy. This analysis was supported by the Biblioshiny interface of the Bibliometrix package; however, it did not lead to the inclusion of additional studies, as the records identified were either already included in the dataset or did not meet the established selection criteria. Accordingly, the full set of 82 studies was retained for the descriptive analysis, while the 73 studies with available full texts constitute the final evidence base for the content-based analysis presented in the subsequent sections.
In order to ensure consistency with PRISMA 2020 recommendations, a simplified methodological reliability assessment of the 73 included studies was conducted. Given the exploratory and mapping-oriented nature of this review, the objective of this assessment was not to exclude further studies on the grounds of their data samples, methodologies or results but to provide transparency regarding the robustness of the underlying evidences. The assessment was performed based on three criteria derived from the methodological information reported in each study: (i) dataset adequacy, referring to the size, diversity, and representativeness of the textual data used; (ii) methodological rigor, referring to the structure and sophistication of the adopted analytical approach; and (iii) validation and evaluation, referring to the presence of explicit validation procedures or performance metrics. Each study was evaluated using a three-point ordinal scale (1–3) for each criterion (1 = low, 2 = medium, 3 = high), based solely on the information explicitly reported in the original articles, without introducing additional assumptions or reinterpretations. The detailed assessment’s results are reported in Appendix A. This quality assessment, however, was not used as a further exclusion criterion but rather to contextualize the robustness of the evidence base supporting our analysis.

3. Results

3.1. Descriptive Analysis

Our descriptive analysis is conducted on a sample of 82 papers, corresponding to all papers that met the eligibility criteria prior to full-text availability screening. This broader set is used to provide an overall mapping of publication trends, outlets, disciplinary distribution and authors’ geographical affiliation before the subsequent content-based analysis, which focuses exclusively on the 73 papers available in full text.

3.1.1. Paper Distribution by Time

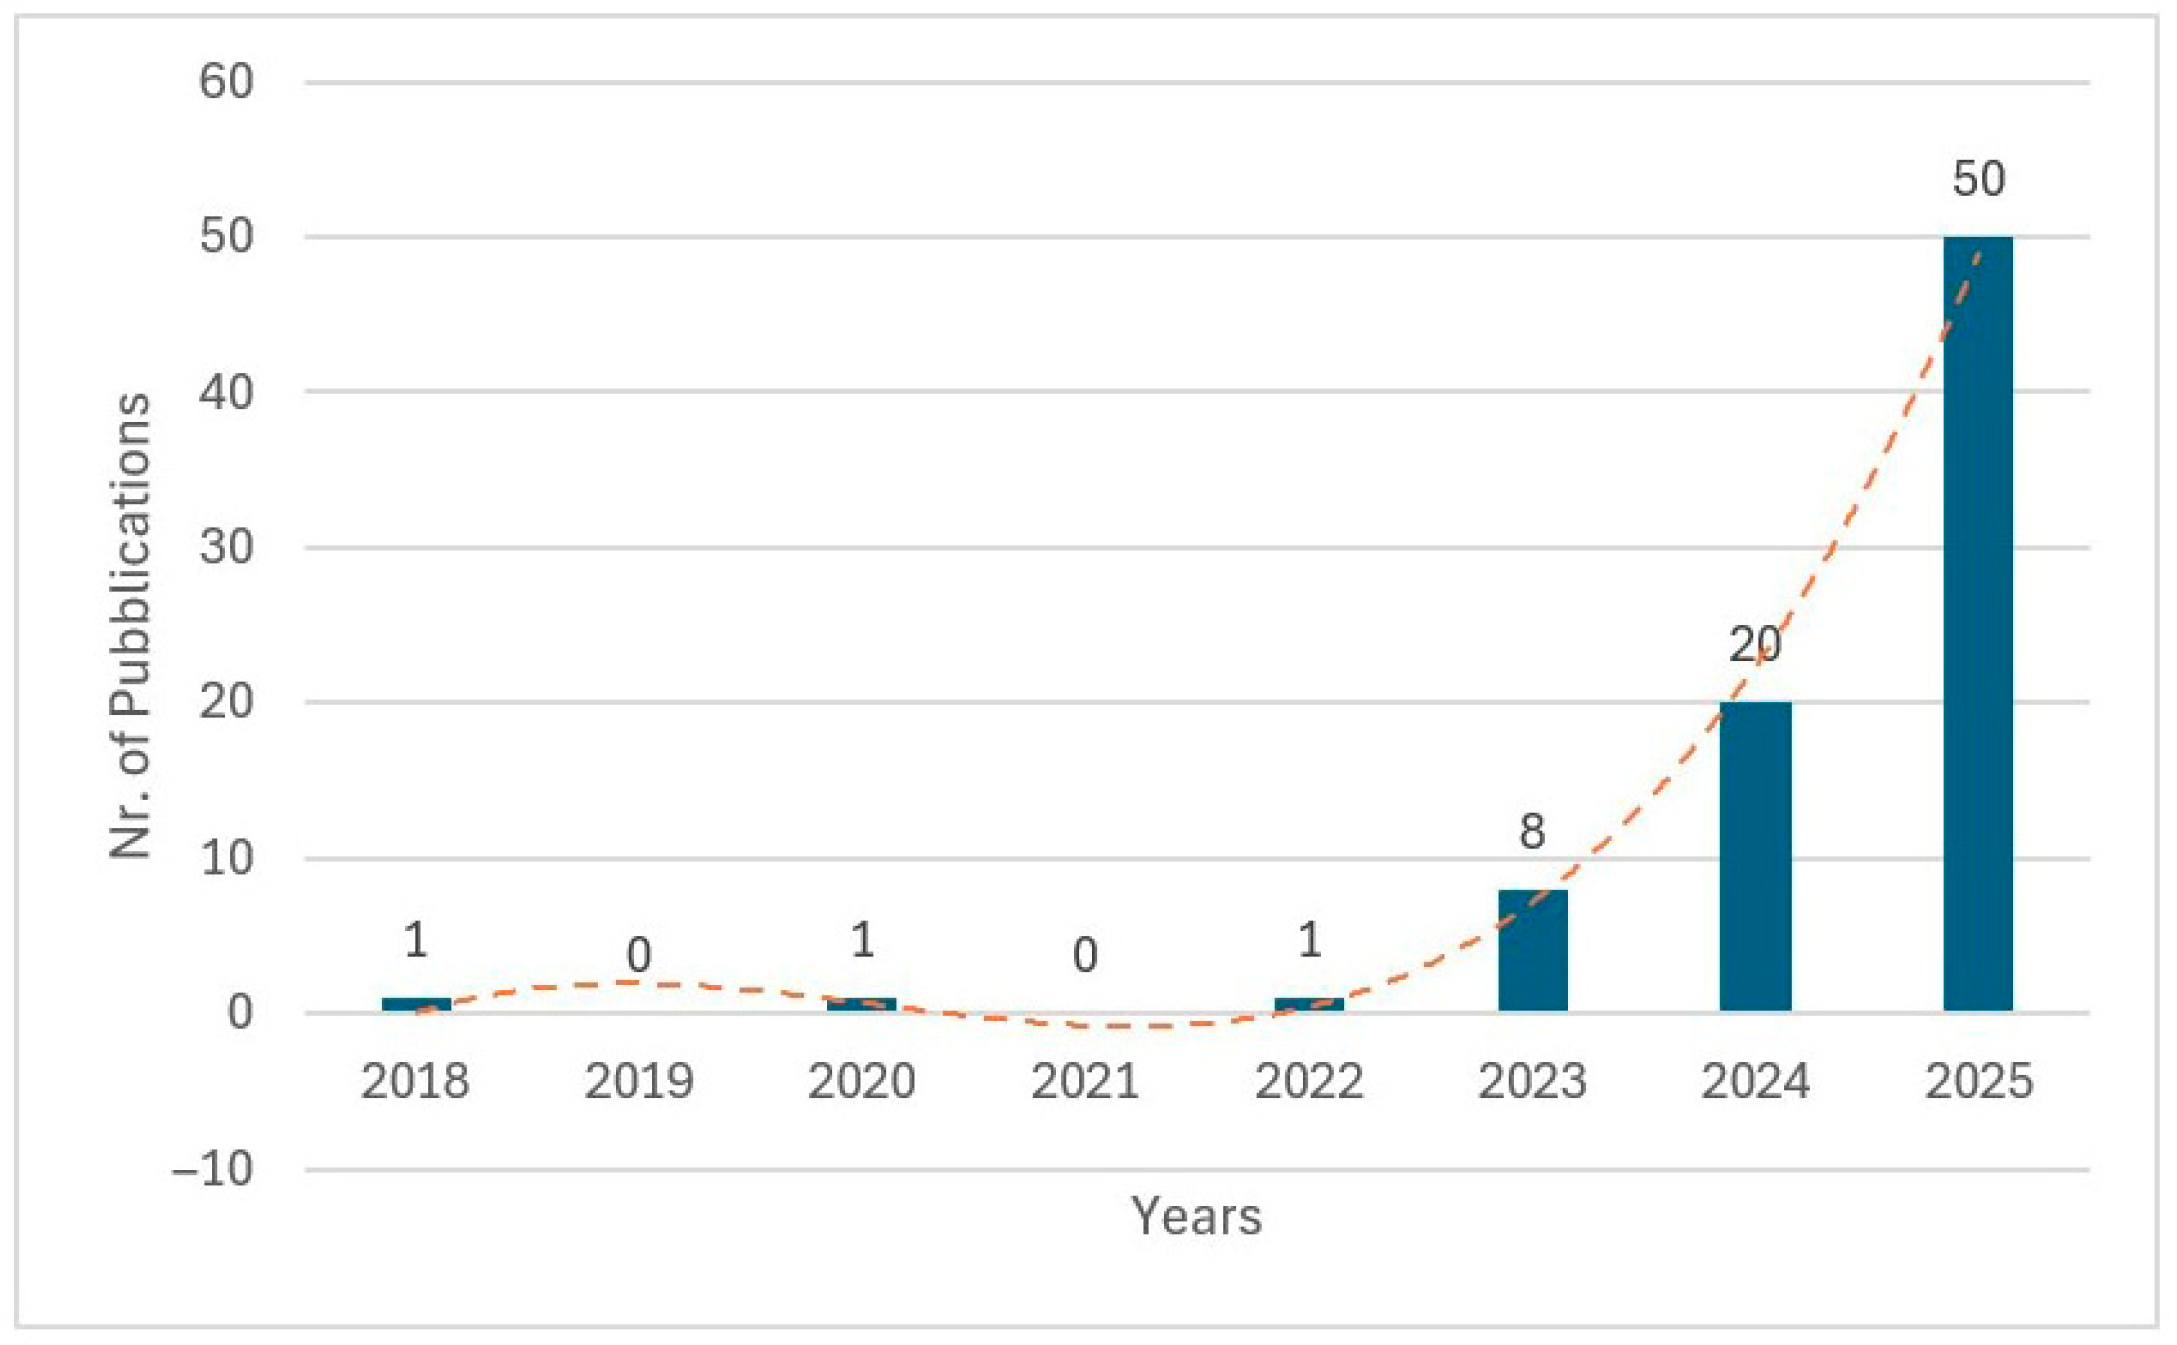
Figure 2 illustrates the annual distribution of the publications. The evidence shows that research on ESG information extraction through automated text-analysis techniques is highly concentrated in recent years and began to skyrocket in 2023, while it attracted only sporadic attention with isolated contributions published between 2018 and 2022. A sharp increase emerges from 2023 onwards, when the number of publications rises markedly (8 papers in 2023) and accelerates further in the following years, reaching a peak in 2025 with 50 published papers. This rapid growth suggests a structural shift in academic interest, driven by the convergence of two factors: the increasing centrality of ESG reporting in regulatory frameworks and corporate governance, and the growing maturity and accessibility of machine-learning and AI techniques capable of processing large volumes of textual data.

3.1.2. Paper Distribution by Journal

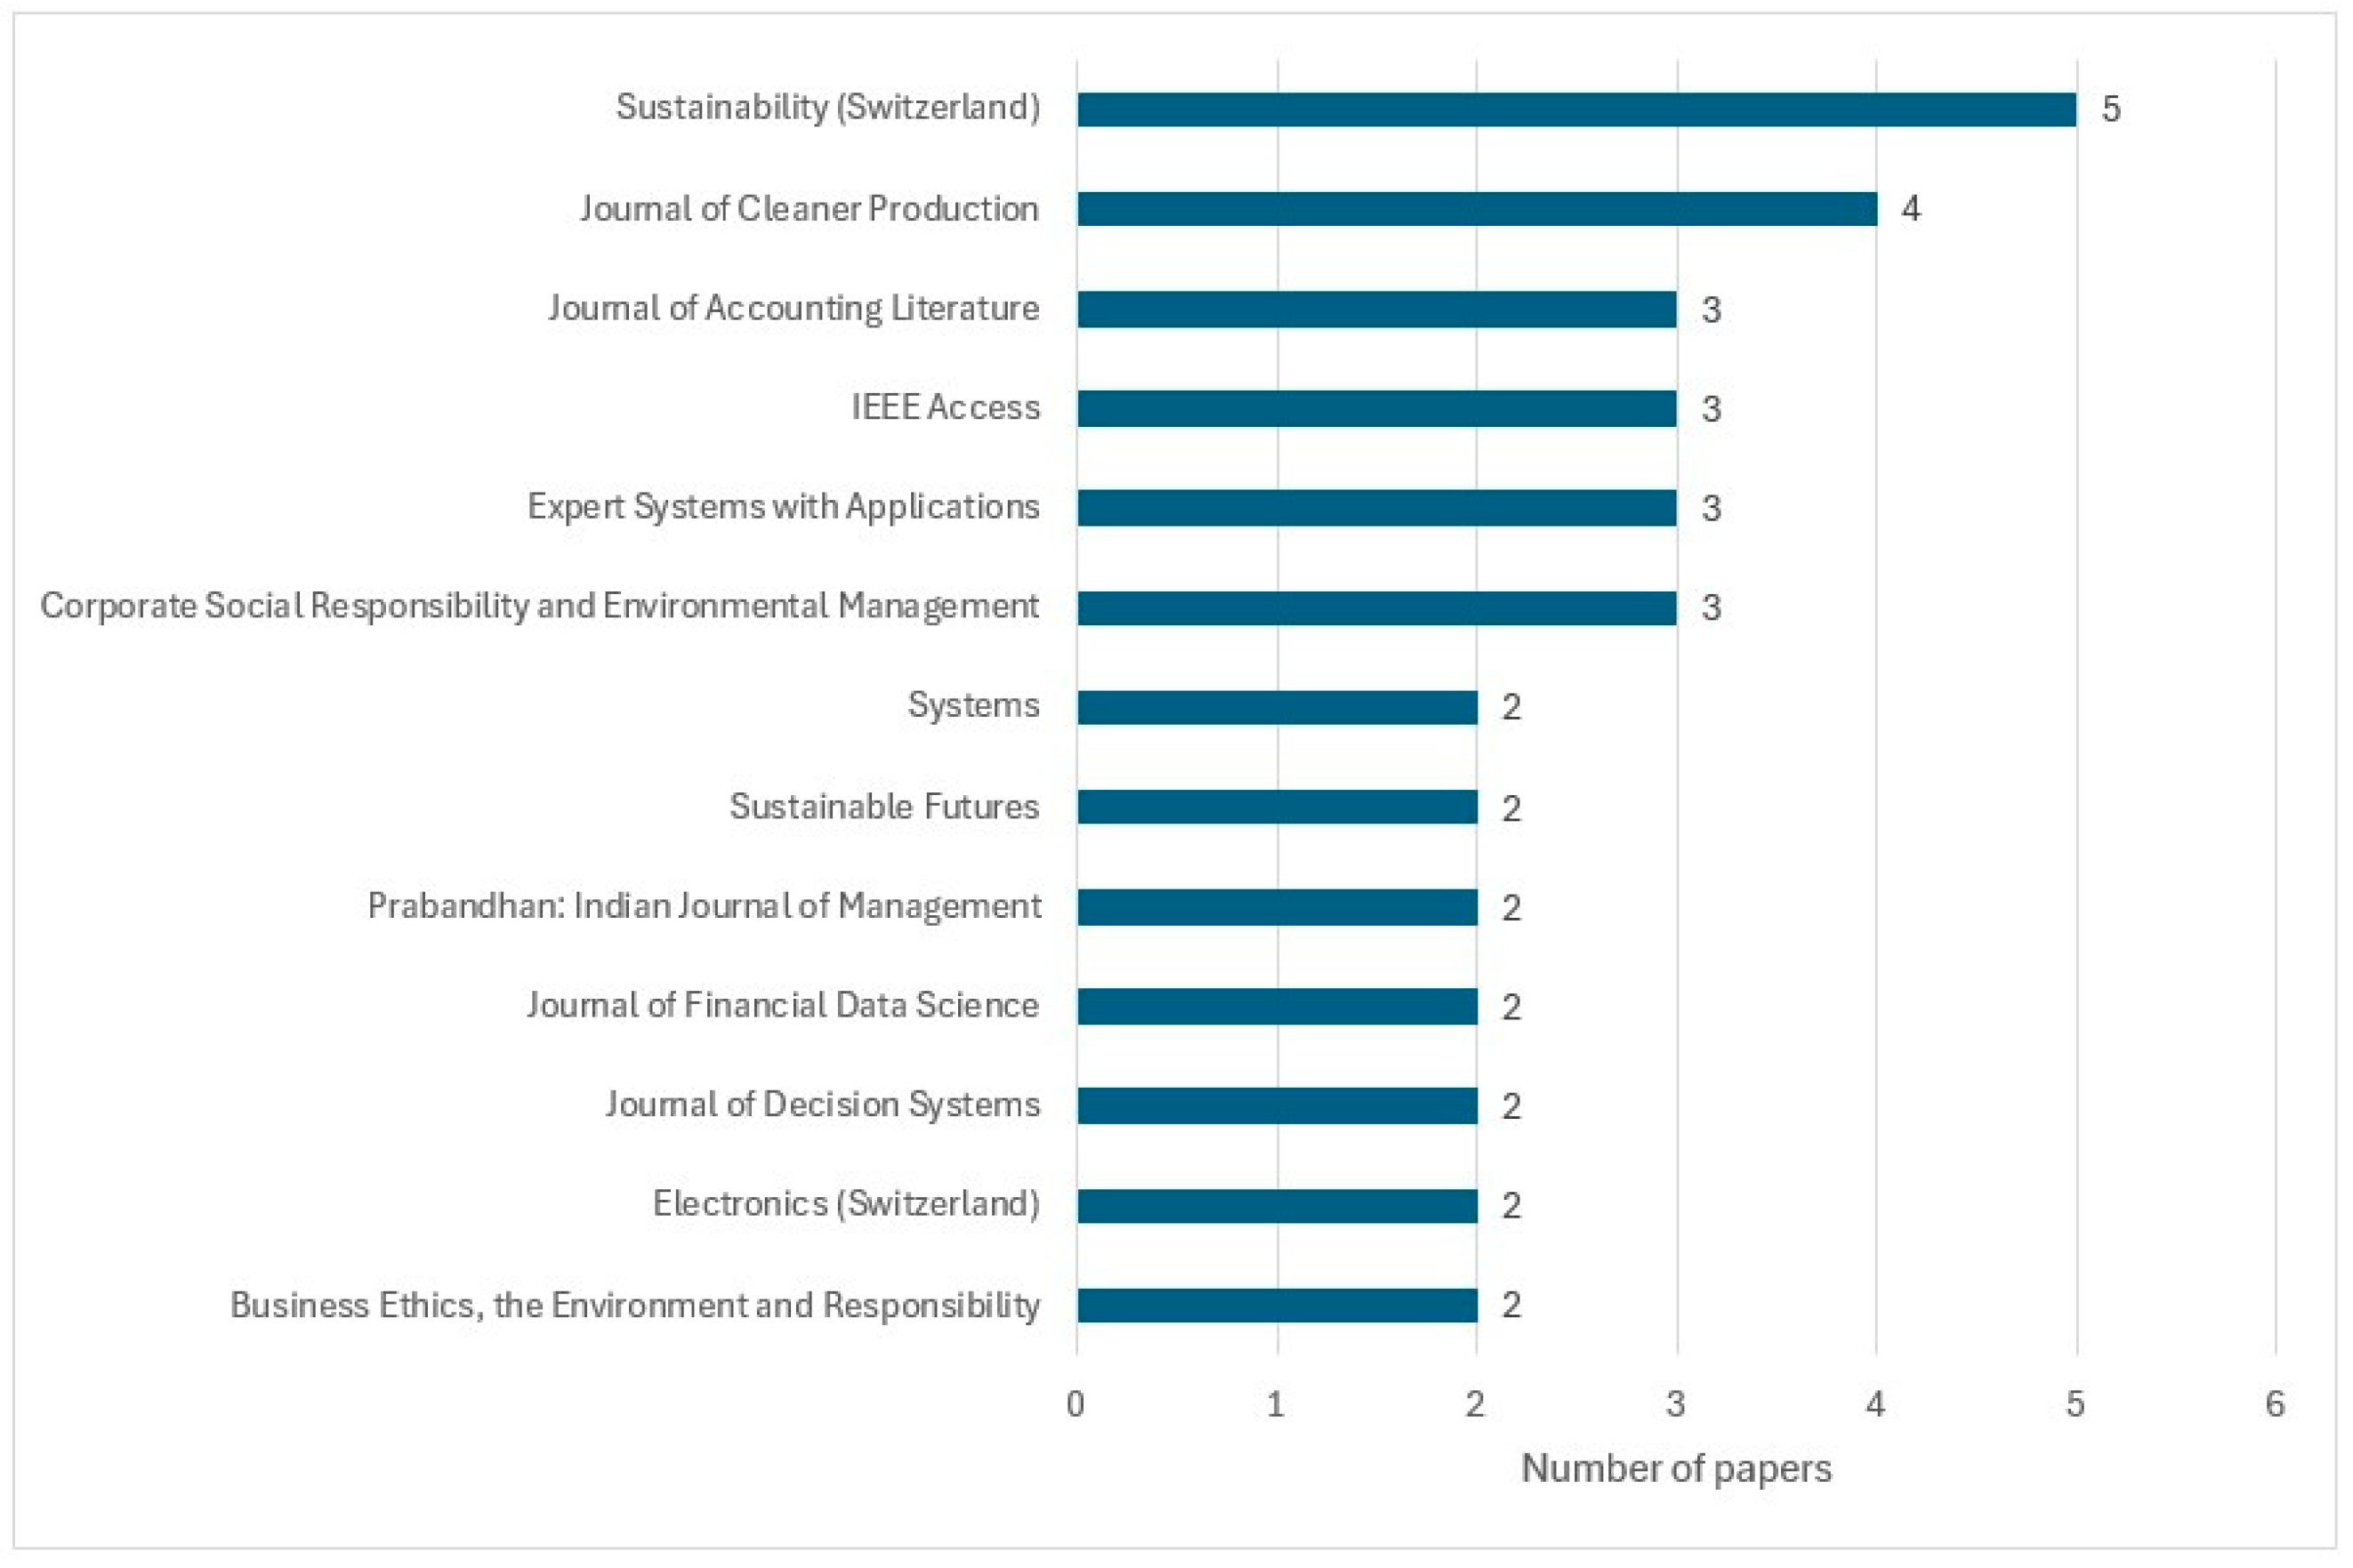
The distribution of the selected papers across scientific journals reveals a highly fragmented landscape: the 82 considered papers were published in 60 different journals, 47 of which contribute only a single article, while a relatively smaller subset of journals accounts for a larger share of the published studies. Specifically, journals publishing at least two articles collectively account for approximately 25% of the journals and 43% of the total papers considered. The presence of this limited core of recurring publication venues is highlighted in Figure 3, which reports only journals with two or more contributions: within this group, no single outlet clearly dominates the field, with even the most prolific journal publishing no more than 5 papers. Overall, this pattern suggests that research on automatic extraction of ESG information from textual sources is still in a formative stage, characterized by cross-disciplinary diffusion rather than consolidation within a small number of specialized journals.
To assess whether this topic’s publication activity is evolving toward greater journal concentration, we computed a yearly journal dispersion index, defined as the ratio between the number of journals and the number of articles published each year (J/A). As reported in Table 2, the index equals 0.875 in 2023 (7 journals out of 8 articles), slightly increases to 0.900 in 2024 (18 out of 20), and then decreases to 0.800 in 2025 (40 out of 50). Overall, the indicator’s rather flat trend suggests that the rapid growth in publications in the most recent year is not yet accompanied by a reduction in dispersion, nor is it pointing to any tendency toward concentration, leaving the publication landscape broadly distributed across many outlets.

3.1.3. Paper Distribution by Discipline

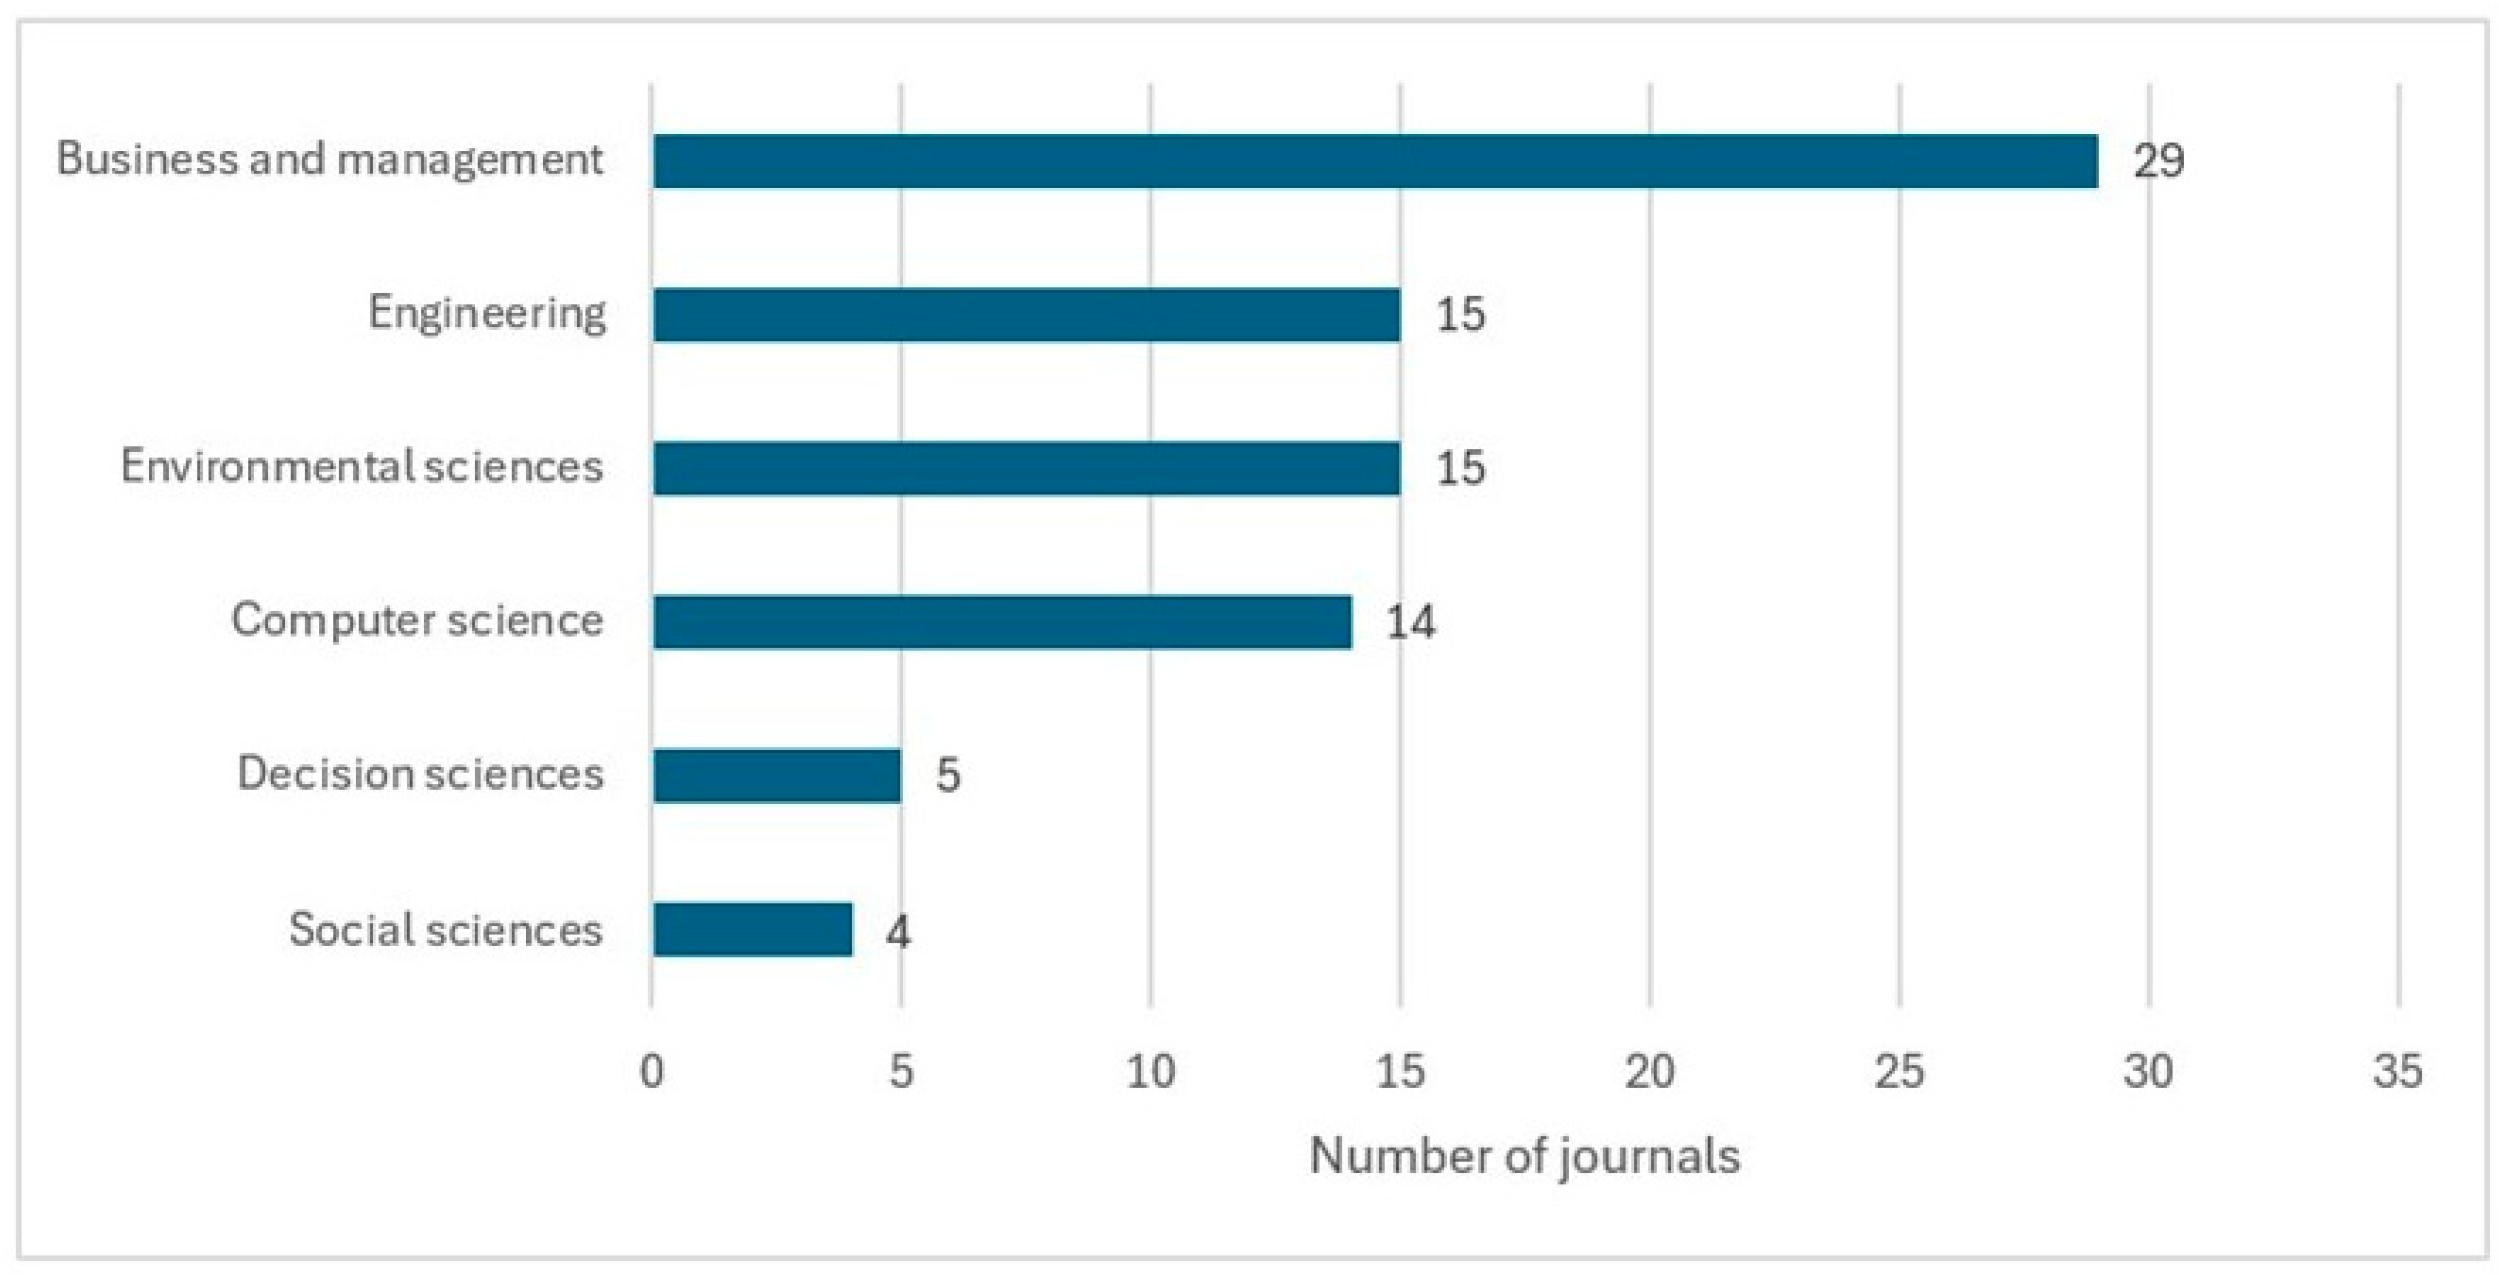
This dispersion across journals is mirrored by a similarly heterogeneous disciplinary composition of the literature. As shown in Figure 4, the analyzed papers are distributed across multiple scientific domains. Journals were grouped according to their primary subject area classification as provided by Scopus. When journals were associated with multiple subject areas, the dominant category indicated by Scopus was adopted for classification purposes. This approach allowed for a standardized and reproducible aggregation of publication outlets into broader disciplinary domains. Business and management is the most prominent disciplinary area, accounting for 29 papers overall (35% of the sample). It is followed by environmental sciences and engineering, with 15 papers each (18%), and by computer science, which contributes 14 papers (17%). Decision sciences and social sciences account for a more limited number of studies. This distribution confirms the intrinsically interdisciplinary nature of this branch of research, which lies at the intersection of managerial, technical and sustainability-oriented perspectives.
Focusing on the most recent years (2023 onwards), the literature shows a clear expansion both in volume and in disciplinary breadth. Publication output increases substantially from 8 papers in 2023 to 20 in 2024, reaching 50 in 2025. Throughout this period, business and management remains the leading domain, rising from 2 publications in 2023 to 6 in 2024, and peaking at 20 in 2025. At the same time, technical and sustainability-oriented areas become increasingly visible: engineering and computer science grow markedly from 2024 onwards, while environmental sciences maintains a consistent presence across the period and contributes strongly in 2025. Overall, the evidence suggests that recent growth has been accompanied by a broader participation of multiple disciplines, reinforcing the interdisciplinary character of the field rather than a consolidation around a single dominant perspective.

3.1.4. Authors’ Geographical Distribution

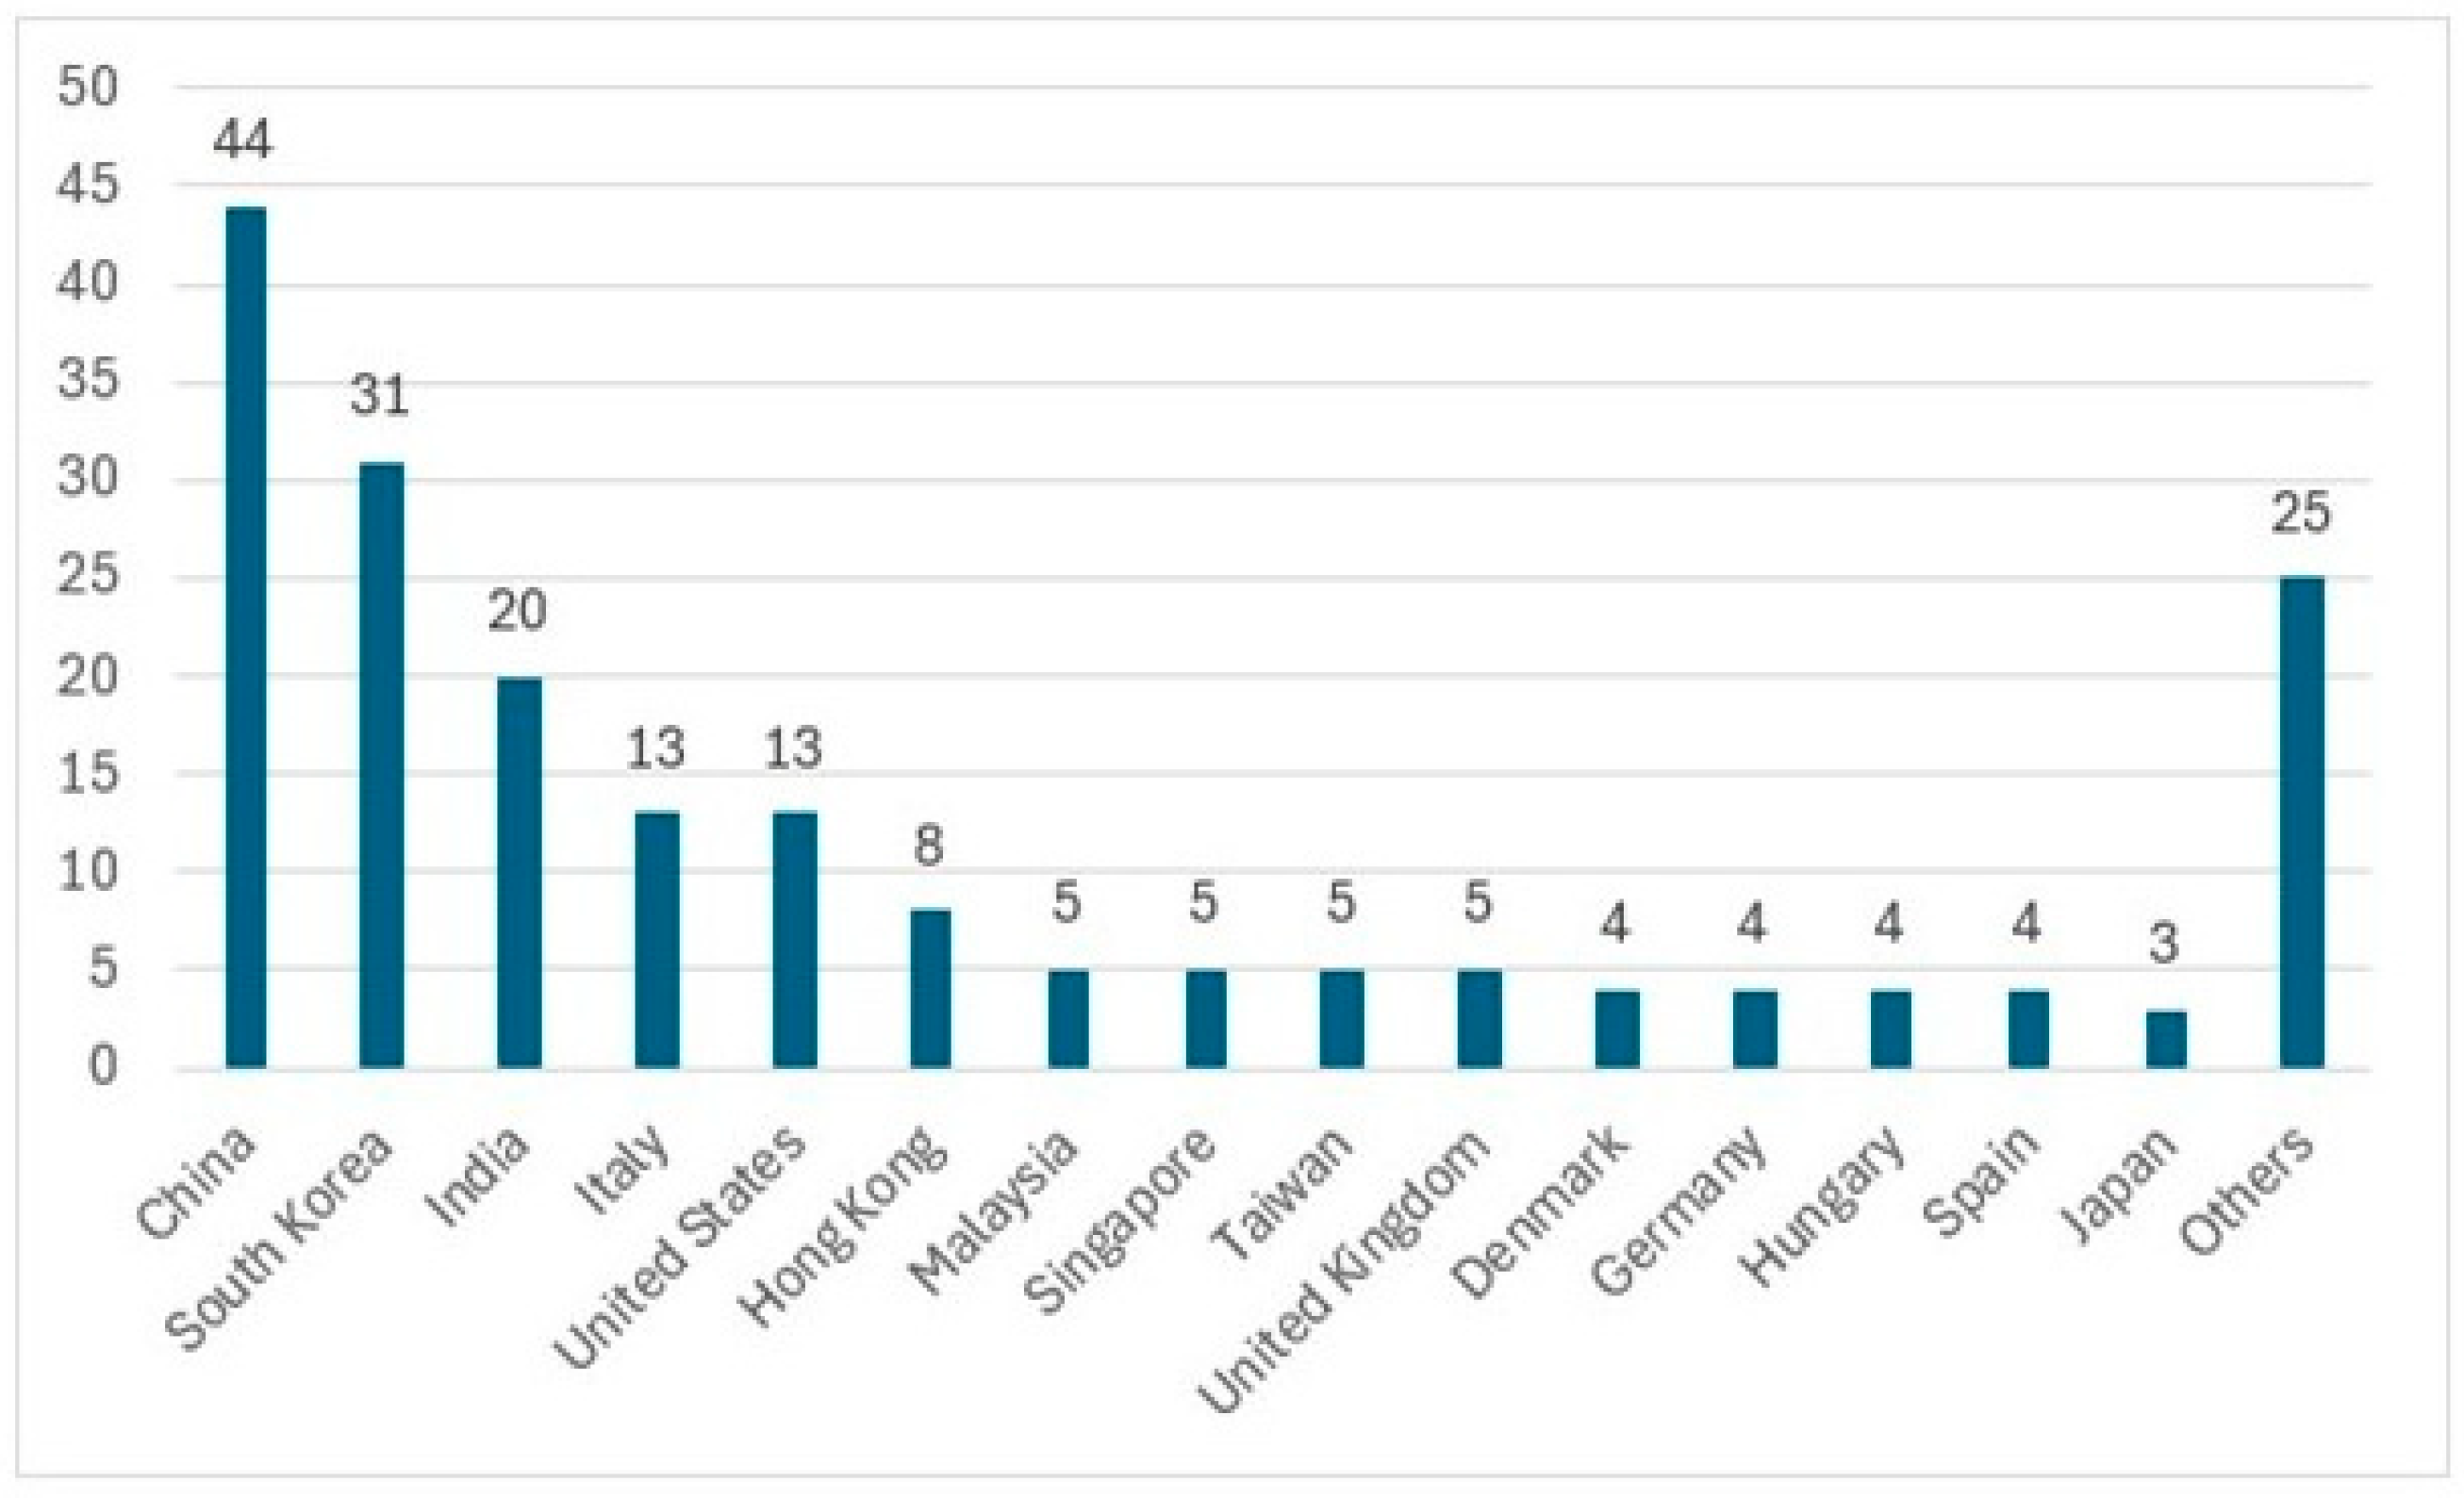
The geographical distribution of the research contributions (Figure 5) provides further insights into the spatial structure of the literature. Given that individual papers often involve multiple authors affiliated with institutions located in different countries, the analysis is based on authors’ affiliations rather than on the country of publication of each paper. Overall, in our 82-paper-strong sample we counted 193 authors affiliated with 184 institutions, sitting in 33 countries worldwide. We found 25 papers with 1 author, 24 with 2 authors, 15 papers with 3 authors and 18 papers with 4 or more authors.
While the literature exhibits contributions originating from a wide range of countries, the evidence here reveals a pronounced geographical concentration of research activities. Just 6 out of 36 countries (namely: China, South Korea, India, Italy, the USA and Hong Kong) account for approximately two-thirds of the authors (129 out of 193). Most intriguingly, 121 contributing authors (about 63%) are affiliated with South or East Asian institutions (especially in China, South Korea and India), confirming the strong regional concentration highlighted in Figure 5, while just 34 belong to European organizations (particularly located in Italy) and 13 to North American ones (specifically in the United States). The remaining affiliations are scattered across other geographical areas, each contributing only marginally to the total count. Overall, this pattern indicates that the core of the extant literature is strongly clustered within the South and East Asian regional context, contradicting our expectation of seeing a greater representation of especially Northern European countries.

3.2. Content-Based Analysis

Overall, the descriptive evidence discussed in the previous section outlines a rapidly expanding and highly interdisciplinary research field, characterized by a fragmented yet increasingly structured publication landscape, a heterogeneous disciplinary composition, and a geographically distributed community of contributors. These patterns provide the contextual foundation for the content-based analysis developed in this section. While the descriptive analysis encompassed 82 papers, this more in-depth examination was conducted on a subset of 73 studies, as the full text was not available for the remaining 9 contributions. The exclusion of these papers was necessary to ensure consistency and reliability in the qualitative coding process, which requires a complete and homogeneous assessment of methodological choices, data sources, and analytical outputs.

3.2.1. Analytical Dimensions and Mapping Criteria

The content-based analysis is structured around the three analytical dimensions that are central to understanding how ESG-related information is extracted from textual data:
  • The data sources that are fed to the content analysis: Our analysis’ starting point is the examination of textual data sources, as the primary goals of this paper are to assess whether ESG-related information can be systematically extracted from heterogeneous and publicly available textual sources and to what extent this process is scalable.
  • The technologies used to extract actionable information from the ingested text, examining how different computational approaches are employed to process the identified textual sources: Analyzing technology in relation to data sources clarifies how methodological choices are shaped by the structure, heterogeneity, and accessibility of the underlying textual material, and to what extent current technological solutions can cope with the challenges posed by supplier-oriented textual ESG information.
  • The outputs generated by the data-extraction process, representing the result produced by the reviewed approaches and determining its practical usability for ESG assessment: Examining outputs as the final step of our analysis enables an assessment of whether the combination of data sources and technologies leads to results that can be effectively integrated into automated ESG monitoring systems, supplier evaluation processes, or compliance-oriented decision-making frameworks.
Although these dimensions are inherently interdependent, they were examined following a deliberate data source → technology → output sequence, reflecting the underlying rationale of this study and its specific research objective.
The 73 full-text articles were systematically mapped according to these three analytical dimensions and their respective subcategories, as summarized in Table 3, which lists the 73 reviewed papers in strict chronological order, according to their month and year of publication, to facilitate the identification of time-related trends. This temporal ordering supports a longitudinal reading of the literature and allows us to examine whether, and to what extent, the data sources, technologies, and outputs adopted by the studies exhibit systematic trends or evolutionary patterns over time. Given that publications from 2025 constitute the largest share of the sample, temporal patterns are interpreted by comparing papers issued in this year with those published in earlier years. The results of this temporal analysis are discussed within each dedicated analytical category.

3.2.2. Data Sources

The first analytical dimension examined in this study concerns the textual data sources used to extract ESG-related information. We considered 6 different data sources, introduced here below:
  • News and media, wherein the textual data examined to extract ESG information is selected from online news content reported by the press.
  • Social and web-based, wherein the textual data examined to extract ESG information belongs to user-generated content in social media and other web-based sources.
  • Data repositories, wherein the ESG material is extracted from independent on-line structured databases and data platforms.
  • ESG disclosures, wherein the input data source consists of the official documents used by corporations to disclose their ESG and sustainability information.
  • Financial disclosures, wherein, by contrast, the input text derives from the corporate official documents reporting their financial statements.
  • Corporate websites, wherein the textual data that is ingested consists of texts from investigated firms’ official websites.
Table 4 summarizes the mapping of the 73 reviewed papers by reporting the frequency with which each data source is used (in the right-most total column) and their pairwise co-occurrence patterns across studies (in off-diagonal cells). The gray diagonal cells report the frequency with which the corresponding data source is used alone, without coupling it with one or more other sources.
A first result emerging from the empirical findings summarized in Table 4 is that textual data sources are rarely used in isolation. Only 16 studies (22% of the sample) rely on a single data source—half of which regard the usage of external data repositories—whereas the large majority adopt multi-source configurations. Dual-source approaches are the most common (35 studies, 48%), followed by triple-source configurations (21 studies, 29%), while more complex combinations remain marginal. And this need to cross-check between different data sources is strengthening in real time, since the average number of sources considered sharply increases from 1.89 before 2025 to 2.22 in 2025.
When considering the total frequency with which each data source appears in the extant literature (singled-out in the right-most column in Table 4), no single data source exhibits clear dominance, although such sources external to the firm as news and media, social and web-based, and data repositories show slightly higher adoption frequencies than internal ones (ESG and financial disclosure, and websites). And this feeble evidence is further moderated by the decreasing time trend of external sources, while by the same token corporate sources—and especially corporate financial disclosures—achieve a sharply increasing time trend, confirming their central role in disclosure-oriented and governance-focused studies that analyze formal commitments, policies, and narratives within controlled corporate communication frameworks [53,76]. Structured external data repositories occupy an intermediate position: while their overall frequency is lower than that of other external and independent sources, they show a comparatively high proportion of single-source usage, accounting for half of all single-source studies and almost one third of all papers that use this data source. This suggests that such databases are often treated as substitutes rather than complements to primary textual sources, particularly in benchmarking, scoring, and large-scale comparative analyses where scalability and standardization are prioritized [81,87]. When combined with other sources, external data repositories typically function as aggregation layers that complement richer textual evidence rather than replacing them.
The co-occurrence patterns reported in Table 4 reveal a limited number of clearly structured associations. Strong linkages emerge between news and media, and social and web-based user-generated content, forming a cluster of external, perception-oriented sources frequently used to capture ESG-related discourse, stakeholder reactions, and reputational signals. A similarly strong association is observed between corporate websites and social media, suggesting that when corporate websites are included, they are often complemented with external discursive sources rather than paired with other corporate disclosures. By contrast, several associations appear consistently weak. Corporate ESG disclosures show limited direct co-occurrence with social media sources, indicating that disclosure-based studies tend to remain largely focused on internally generated content and only rarely integrate stakeholder-generated perspectives.
Taken together, the patterns documented in Table 4 indicate a clear prevalence of mixed corporate-independent source configurations, while studies relying exclusively on corporate-generated or on external sources remain comparatively rare [39,52]. Researchers tend to combine sources with aligned informational roles, such as internal disclosures, with external validation, or media content with social discourse, to balance self-disclosed information with externally generated signals, while avoiding highly complex configurations that would substantially increase methodological complexity [40,86].

3.2.3. Technology

The second analytical dimension examines the computational techniques adopted to automatically process the textual data sources identified in the previous section and to extract ESG-related information. While data sources determine where ESG evidence can potentially be observed, technology determines how such evidence is collected, interpreted, and transformed into usable outputs. In this sense, technology acts as the operational link between the availability of textual material and the feasibility of scalable ESG information extraction.
Building on the content-based coding, the technological landscape can be organized into two conceptually distinct but complementary groups: technologies for text preparation and technologies for data extraction. This distinction reflects a functional separation between approaches whose primary role is to convert textual material into machine-readable form and those that operate on the acquired text to perform ESG interpretation, classification, or synthesis.
The first group includes such consolidated text-elaboration technologies as web scraping and crawling, together with optical character recognition (OCR) and document information extraction. These technologies’ usage is directly shaped by the nature of the data sources discussed in the previous section. Studies relying on corporate websites and online repositories necessarily depend on web-scraping techniques to transform http-coded content into practically usable text [41,87]. By the same token, passing through an OCR technique becomes inevitable every time a document coded in graphical, instead of text format, is processed as the information source of the data-extraction process. Although rarely presented as the main methodological contribution, data-acquisition technologies constitute an indispensable upstream layer, especially in those supplier-oriented contexts, where ESG information is not disclosed through standardized reporting channels. Their main strength lies in scalability and source coverage; however, their limitations are structural, as scraped and OCR-derived text can be noisy, heterogeneous, and error-prone, increasing the complexity of downstream ESG extraction tasks [35,41,91]. Consistently with these references, we found that these technologies are considered overall in 41% of the scrutinized papers, with a sharply decreasing time trend, reflecting the increasing recourse to natively fully machine-readable textual data sources, such as digitally available annual reports, ESG disclosures, news, and structured databases, which enable scalable automated analysis [38,46,52].
The second group encloses technologies able to identify, extract, structure, and synthesize ESG-related information starting from a full-readable-text document. Within this group, three main technology families emerge:
  • Traditional NLP and text mining (NLP) approaches analyze text by counting or matching predefined terms and patterns to identify ESG-related content [40,53].
  • Transformer-based models (TBMs) are more sophisticated techniques that can interpret the meaning of text in context, allowing ESG claims and topics to be identified even when they are expressed implicitly or through narrative language [39,52]. These architectures are typically based on pretrained language models such as Bidirectional Encoder Representations from Transformers (BERT) and its domain-adapted variants (e.g., FinBERT), which leverage attention mechanisms to capture semantic relationships across sentences rather than relying on keyword matching [13,39,70].
  • Finally, large language models (LLMs) further build on TBMs’ capability by generating and synthesizing ESG-related information through prompt-based interaction, enabling flexible interpretation across diverse and weakly structured textual sources [41,94].
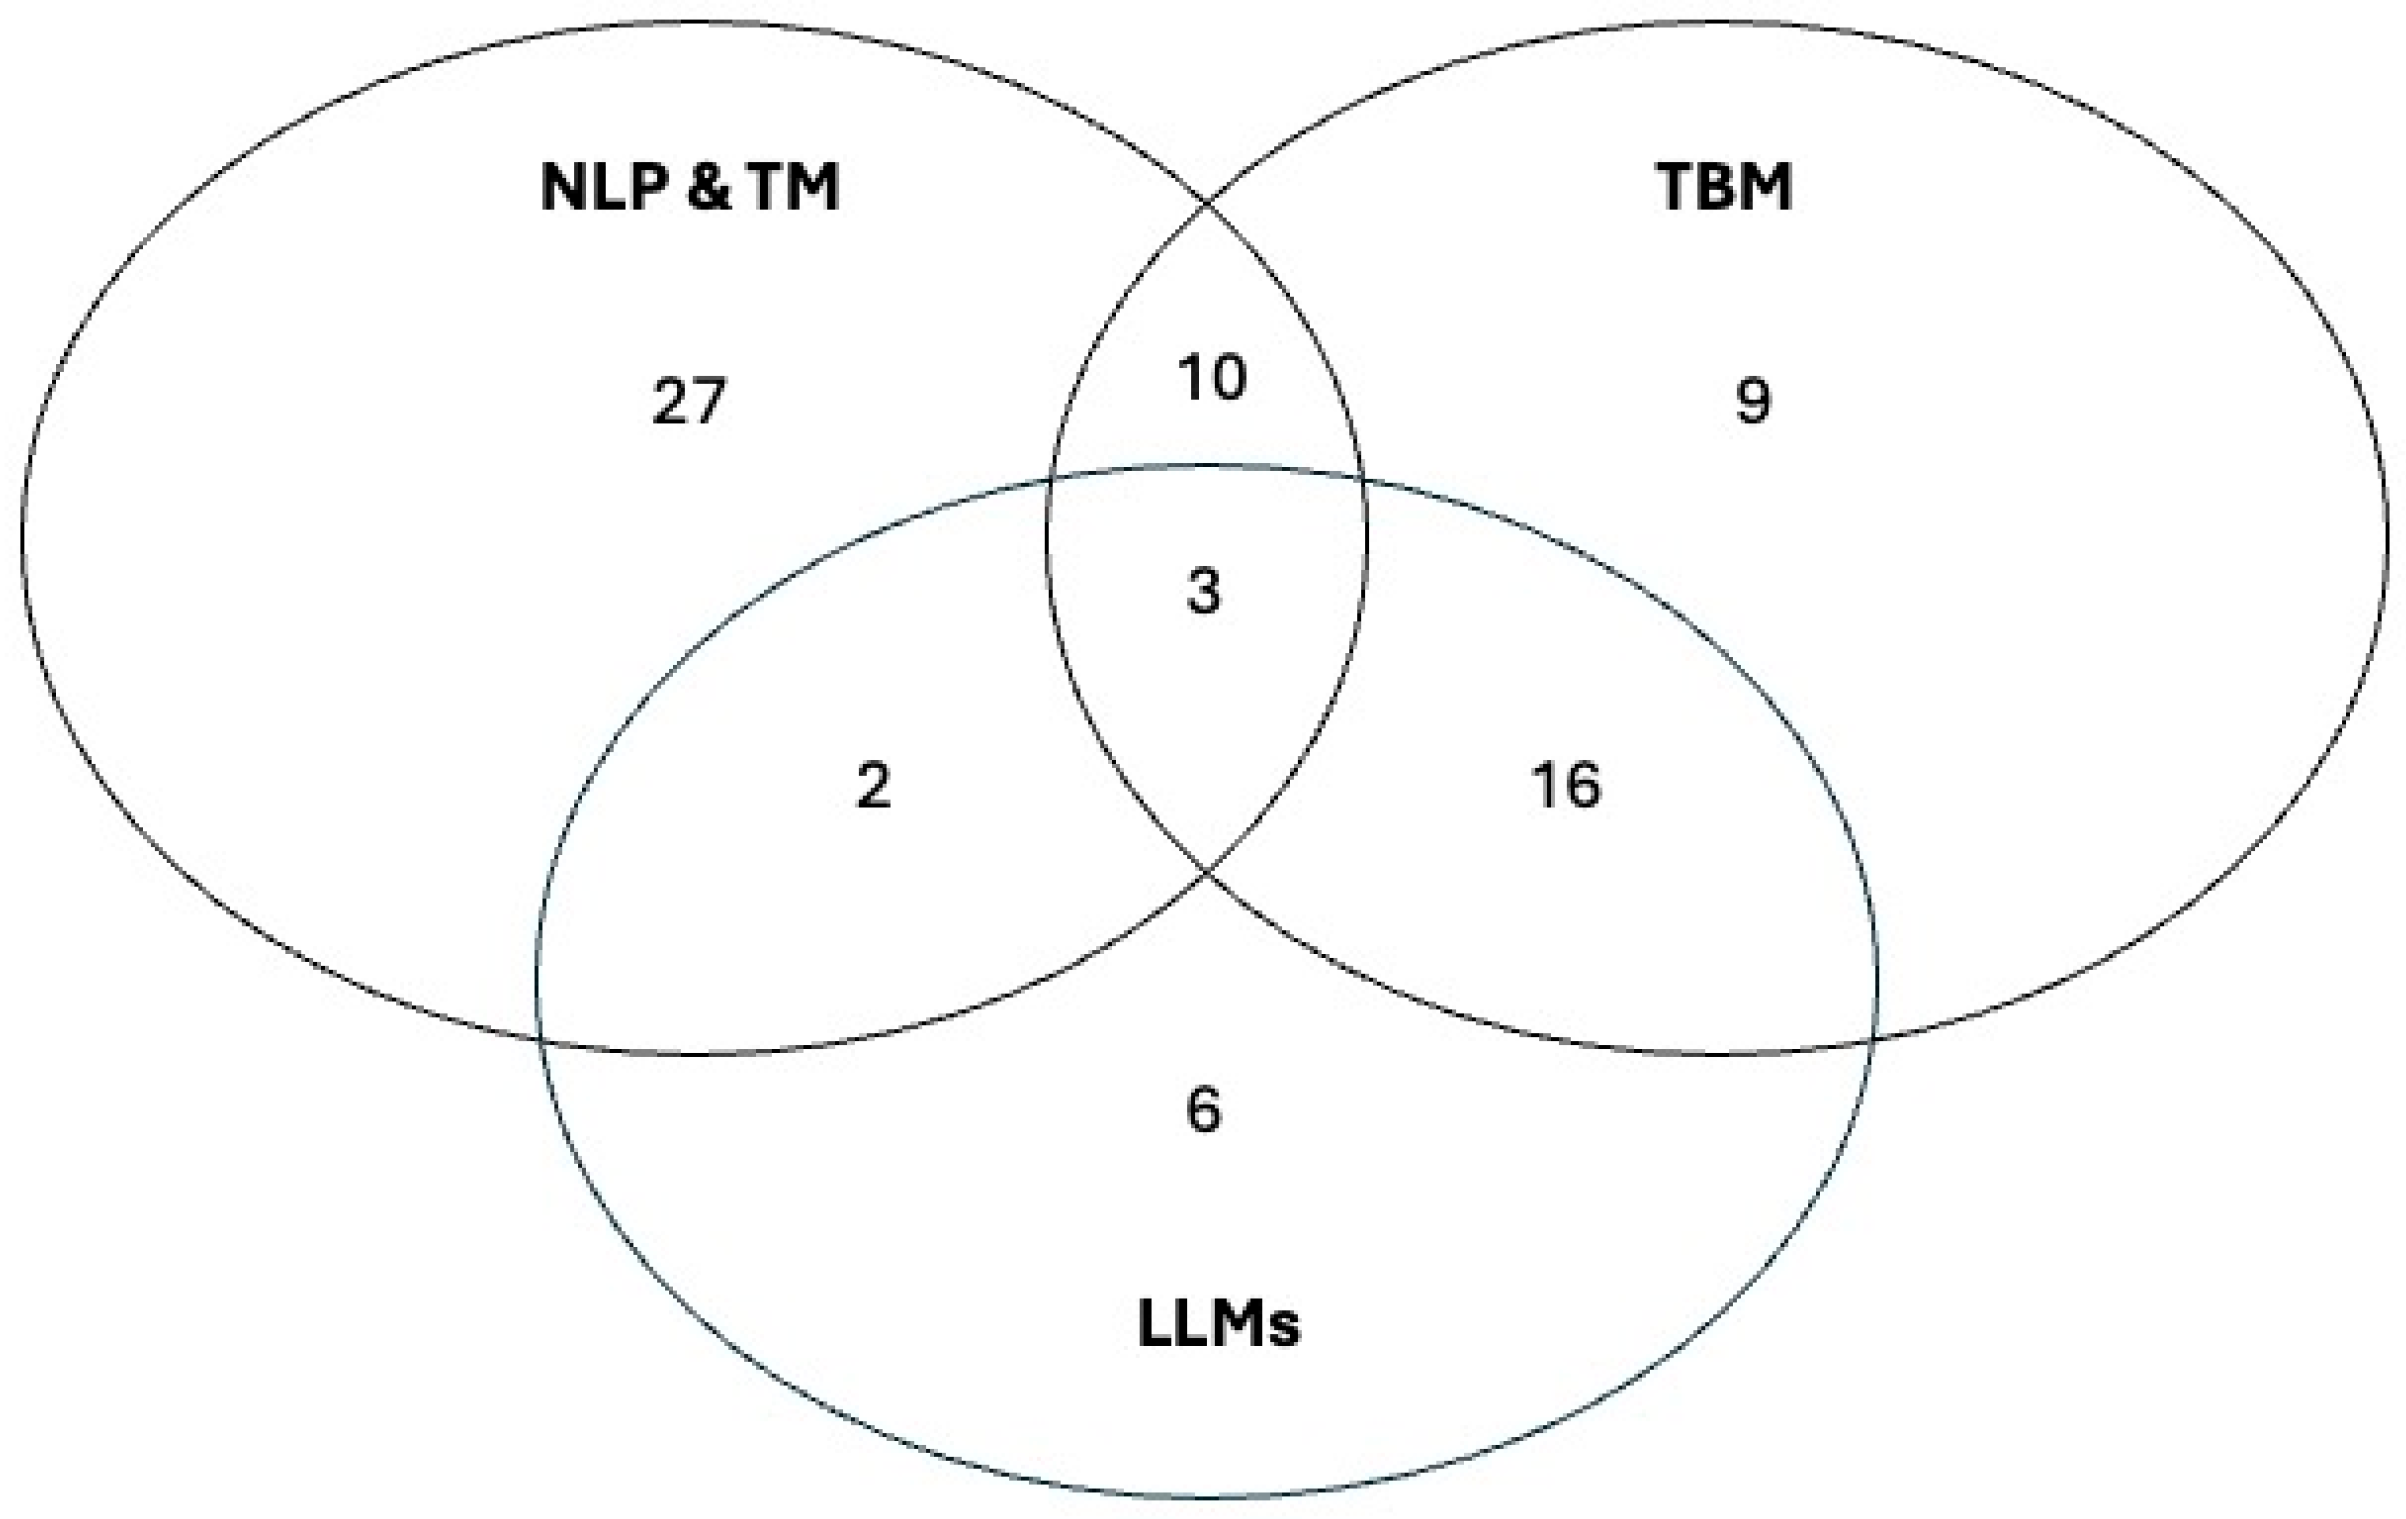
As illustrated in Figure 6, 27 papers rely on just traditional NLP techniques, 9 on just TBMs, and 6 on LLMs. In total, 42 studies (58% of the total sample) rely on a single technological family, while the remaining ones adopt hybrid solutions combining two or three of them. Quite evidently, the bulk of the considered studies prefer to invest in just one technique, choosing the most adapted one for the specific use and result pursued. This tendency does not show any temporal trend, in the sense that it stays stable in the years covered by the 73 papers considered, further underlining this message.
Traditional NLP techniques remain the most widely adopted family across the reviewed literature. This is true for at least three reasons: First, the overall recourse to techniques included in this family accounts for 42 studies, while transformer NLP models are adopted by 38 studies, and LLMs by just 27. Second, the NLP adoption rate stays stable over time, while that of TBMs is sharply dropping, and that of LLMs is rapidly mounting. Third, and most importantly, NLPs are the only category of models that shows a very relevant single utilization: as a matter of fact, 27 of the analyzed studies rely exclusively on traditional NLP and TM approaches, without integrating more recent deep learning architectures, while the same is only true for 9 TBMs and 6 LLMs. However, these traditional approaches might present limits in grasping less formal and more nuanced and implicit elements, which are common in ESG communication.
TBMs represent a more recent technological response to NLPs’ limitations, enabling context-aware semantic processing of ESG-related text. However, TBMs show a rather clear time decline, with a frequency of 56% of papers published before 2025 but only 50% of those published in 2025 or later. Moreover, a mere 9 studies rely exclusively on TBM architectures, while an additional 13 combine TBMs with traditional NLP techniques, and an even larger and increasing chunk of 19 papers considers a hybrid solution encompassing TBMs with LLMs, illustrating that NLPs are rarely used alone and are mostly considered either as a technique to complement more traditional NLP approaches or to be completed by means of more sophisticated LLMs. TBM architectures have represented a breakthrough in automated language processing, enabling the contextual representation of textual information and significantly improving performance in classification, information extraction, and question-answering tasks [39,40]. However, the application of such models to ESG information extraction from publicly available textual content presents several practical challenges. In fact, several of the possible data sources could contain highly heterogeneous structures, multilingual content, and weakly standardized sustainability disclosures, which complicate the development of domain-specific training datasets [39,40,52].
LLMs constitute the most recent and still comparatively limited family of data-extraction technologies, with an adoption rate of just 27 studies (37%) among the scrutinized papers. Moreover, only 6 studies rely exclusively on LLM-based approaches, while 16 of them combine LLMs with TBMs, 2 with NLP models, and 3 with both. This distribution indicates that LLMs are predominantly used as an extension of existing semantic models rather than as standalone solutions, maybe owing to their very new nature, evidenced by the sharply uprising temporal trend of this technology family, which accounts for just 30% of the papers before 2025 and 41% in 2025. In the recent literature, large language models (LLMs) have emerged as promising alternatives to TBMs due to their improved ability to generalize across diverse textual sources and perform zero-shot or few-shot inference [52,94]. Nevertheless, the large-scale deployment of such systems for automated supplier monitoring remains constrained by issues related to data availability, model reliability, and computational cost. It is important to note that many recent large language models (LLMs) are themselves built upon transformer-based architectures. On these grounds we can affirm that TBMs have not disappeared but rather represent the architectural foundation upon which many recent LLM systems are built. The apparent shift observed in the literature therefore does not reflect a decline in TBM architectures per se but rather a transition toward more flexible and general-purpose language models capable of handling more heterogeneous and weakly structured textual sources, such as corporate websites.
Overall, the technological configurations observed across the reviewed studies point to a layered and hybrid landscape: NLP techniques with their large single usage and stable utilization rate over time form the technological base for extracting valuable ESG-related information from textual sources, while the other technological families are typically used either in conjunction with it or between themselves, reflecting attempts to balance interpretability, semantic richness, and scalability.

3.2.4. Output

The third analytical dimension examined in this study concerns the outputs generated by the reviewed approaches, namely, the form in which ESG-related information is ultimately produced once textual data has been collected and processed. Outputs were coded based on the actual deliverables produced by each study, rather than on the stated research objectives or intended results: this distinction is crucial, as different output types correspond to different levels of operational usability.
Five main output categories were identified:
  • Categorical classification—when a textual description is assigned to one or more predefined ESG-related category, such as: ESG pillars, sustainability topics, risk types, etc.
  • Binary attributes—these produce a Boolean yes–no output indicating the presence or absence of specific ESG-related attributes, such as the adoption of a policy, the existence of a certification, or the compliance to a governance practice.
  • Narrative information—this returns extracted passages, summaries, explanations, or free-form textual answers related to the various ESG topics investigated.
  • Numerical KPIs—when quantitative variables, such as emission-related numerical figures or risk indicators, are extracted from textual data.
  • Scores and ratings—when extracted textual evidence is aggregated into synthetic ESG indicators, rankings, maturity assessments or composite indices, such as an aggregate ESG scores.
These categories, along with their co-occurrence patterns, are summarized in Table 5, which reports the extent to which different outputs are combined pairwise within the same study, by analogy with Table 4.
Beyond individual output categories, the analysis reveals that outcomes are rarely generated in isolation, with just 15 papers out of 73 pursuing one single type of output, while more than half of the sample (39 studies) was found to provide two different types of outputs, and 20 of them (27%) three output types. The strongest couples are binary attributes with categorical classification and with narrative information, and categorical classification with scores and ratings, indicating that classification often functions as an intermediate step toward more structured or aggregated results. By contrast, weaker links are observed between narrative information and such quantitative approaches as numerical KPIs, and scores and ratings, reflecting persistent difficulties in translating rich textual interpretations into standardized numerical indicators.
To better understand these configurations, outputs were further aggregated into qualitative (narrative information and categorical classification) and quantitative (numerical indicators, binary attributes, and scores and ratings) groups. Purely qualitative approaches are relatively limited (14 studies), as are purely quantitative ones (13 studies), while most of the literature (46 studies) adopts mixed outputs, combining qualitative and quantitative elements within the same pipeline. Moreover, researchers are getting less interested in qualitative approaches, while increasing their interest in quantitative ones, matching the increasing need to objectively measure firms’ compliance to ESG regulations and a sustainable managerial style [56,57,76]. Indeed, qualitative approaches were dominant with 93% of occurrences in studies published until 2024, as compared to quantitative with 74%; meanwhile, if we look at studies published in 2025, qualitative outputs slow down to a 74% frequency, while quantitative ones hit 85% of the scrutinized papers.
Looking at single outputs, categorical classification is the most frequently observed one, with 42 occurrences (58%). Binary attributes comes next with 33 occurrences. The third most considered category is narrative outputs with 29 occurrences (40%). These patterns indicate that the literature has traditionally focused on structuring and organizing ESG-related textual information, rather than directly producing fully operational indicators. All these three forms of outputs experience a decrease in popularity over time: categorical classification plummets from 67% to 52%, binary attributes has a more moderate shrink from 48% to 43%, while narrative outputs drops sharply from 52% to 33% of studies, suggesting a gradual shift away from purely interpretative approaches toward more operational and decision-oriented outputs. With just 26 occurrences (36%), the extraction of numerical indicators comes fourth [53,95], and only 25 studies (34%) produced scores and ratings outputs [56,57,73]. Although less frequent, these outputs are particularly relevant from a managerial and regulatory perspective, as they enable benchmarking, comparability, and integration into automated ESG assessment systems. However, both of these two types of (quantitative) outputs experienced an increase over time: numerical indicators enact a slight increase, from 33% of studies before 2025 to 37% in 2025, while scores and ratings almost doubled its frequency in the time span covered by this study, passing from 22% to 41% of studies. This trend highlights an ongoing transition in the literature from exploratory text analysis toward the generation of standardized and scalable ESG metrics, which are essential for supporting supplier evaluation and compliance-oriented decision-making.

4. Discussion

Extracting usable ESG and sustainability information from publicly available textual sources can be defined as the intersection of three wider research streams: the first one is managerial and deals with supply chain management and vendors’ ratings; the second is regulatory and is about firms’ compliance to sustainability criteria and ESG regulations; and the third one is technological, concerning the digital techniques that can be harnessed to extract usable data from textual data inputs.
The descriptive analysis performed on our 82-paper-strong sample has highlighted a vibrant research domain currently in full development. We highlighted a very sharp numerical rise over time, with contributions from a wide set of disciplines and countries, published in a particularly large set of very diverse journals belonging to many different research domains. In our view this very strong quantitative evidence proves that the need to automatically extract valuable, trustable and meaningful ESG and sustainability information on selected firms from textual sources is real and relevant, at least in the perception of a widespread research community. Adding to this relevance, we uncovered that not only are numbers rapidly increasing over time, but also the spectrum and diversity of contributions remain very wide and do not seem to aim at a consolidation of this research stream. This in turn could be a good predictor of future business utilization.
Our 73 paper-strong in-depth content-based analysis has developed a more nuanced and detailed investigation of three main aspects: the data source employed; the specific technology leveraged to extract meaningful information from it, and the specific type of output generated. Grounded in the results of this analysis, in the following sections we first provide a general overview of our empirical results, then a detailed discussion of our three research questions.
The results of the quality assessment indicate an overall satisfactory level of methodological robustness across the reviewed studies. The average scores (dataset adequacy = 2.28; methodological rigor = 2.82; validation and evaluation = 2.35) suggest that the literature is generally supported by well-structured methodological approaches, particularly regarding the design and implementation of analytical techniques. At the same time, some variability emerges across the evaluated dimensions, with slightly lower scores observed for dataset adequacy and validation practices. This reflects the heterogeneity of the field and the diversity of research designs, rather than a systematic weakness of the evidence base. Overall, these results support the reliability of the reviewed literature, while also indicating opportunities for further consolidation through the adoption of more standardized datasets and validation procedures in future studies.

4.1. Configurational Insights into ESG Knowledge Extraction

Taken together, the three analytical dimensions examined in this review (data sources, technology, and outputs) can be interpreted as an integrated configurational framework for corporate ESG information extraction from textual sources, rather than as independent analytical categories. Choices made at the three levels are interdependent, to the point that the data source(s) chosen can influence the range of usable technologies, and, in turn, the specific technology adopted may determine the types of outputs that can be reliably generated, and vice versa. From this perspective, ESG information extraction pipelines can be conceptualized as the combination of: (i) one or more specific textual source(s) from which sustainability-related information is retrieved, (ii) one or more computational technique(s) used to process and interpret such information, and (iii) the resulting form(s) of output generated by the analytical process. This configurational view enables the literature to be interpreted not simply as a collection of individual studies but as a set of recurring analytical patterns within a broader framework for automated ESG monitoring.
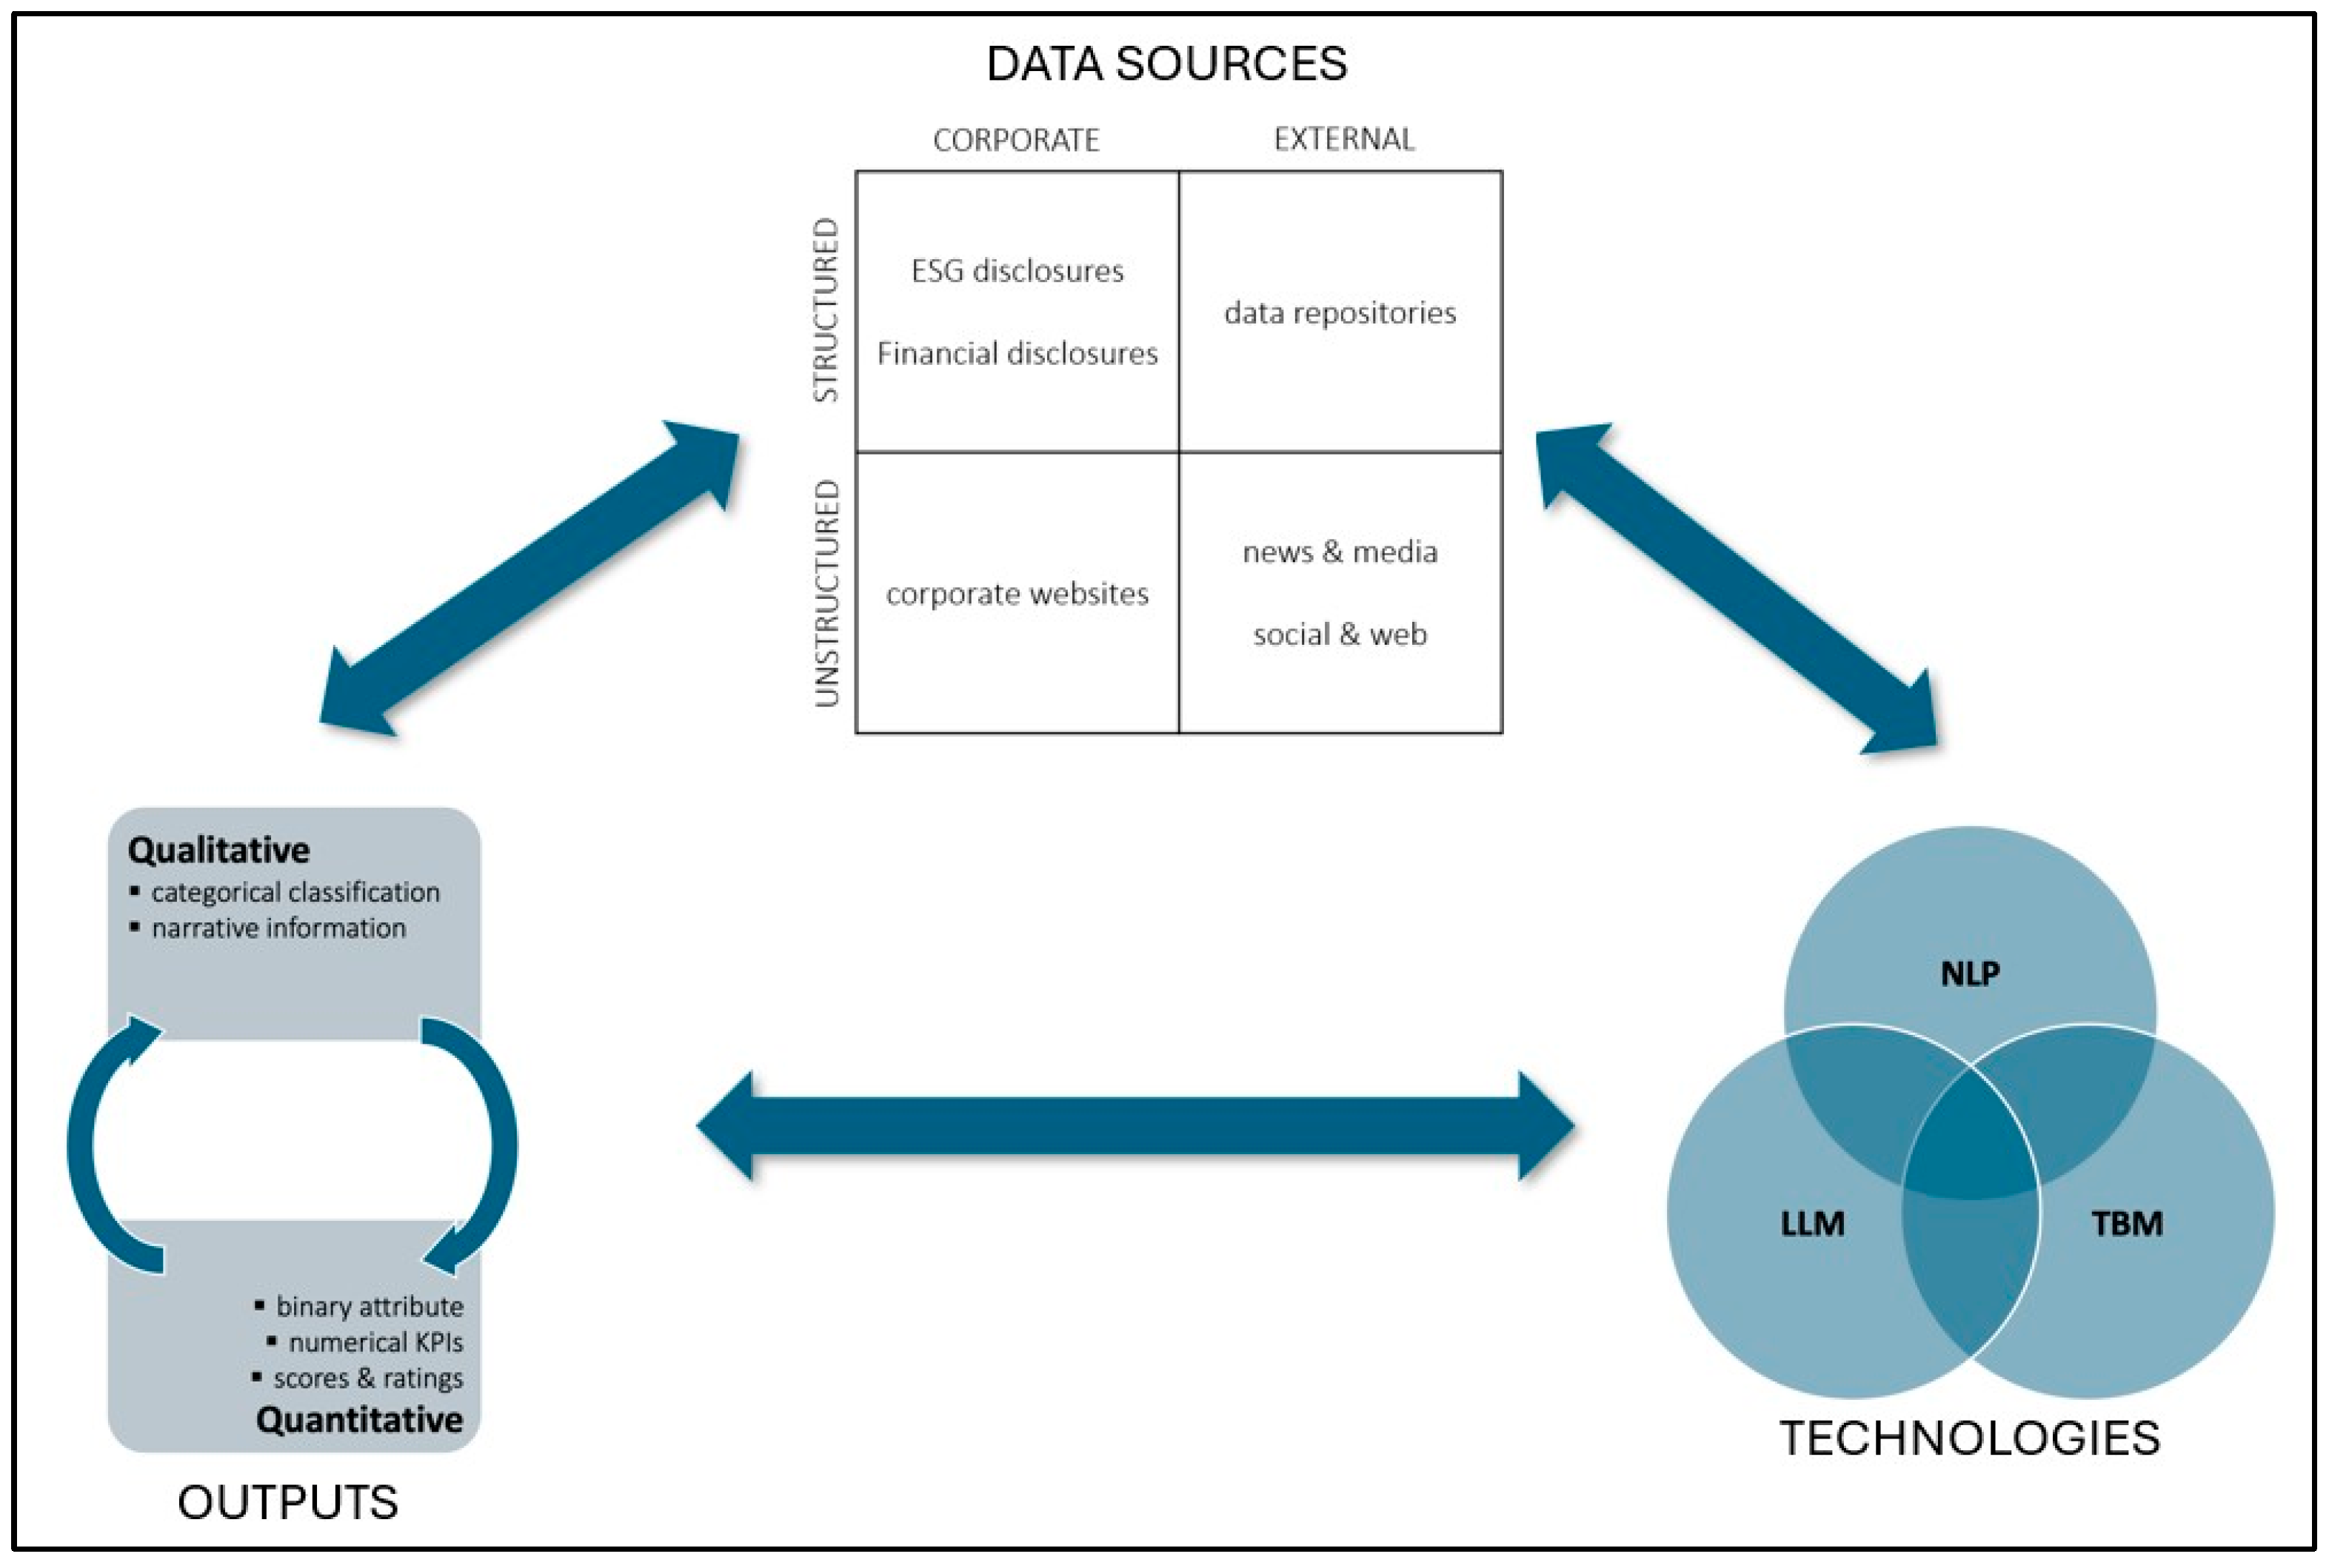
Figure 7 synthesizes the main configurations emerging from the literature by linking data sources, computational technologies, and output types into a unified analytical framework for ESG information extraction from textual sources.
Data sources are organized according to their origin (corporate vs. external) and their degree of structure (structured vs. unstructured). Corporate disclosures and data repositories represent the most structured sources, while corporate websites, news and media, and social and web-based content are inherently unstructured and heterogeneous, with corporate websites emerging as a relatively underutilized and methodologically challenging source within the literature. In the technological landscape, NLP techniques, transformer-based models (TBMs), and large language models (LLMs) coexist and often overlap. Traditional NLP approaches are typically associated with structured sources, whereas TBMs and LLMs are more suitable for processing unstructured and narrative-rich content, although the literature shows a significant prevalence of hybrid configurations combining multiple techniques rather than relying on a single technological approach. Outputs are grouped into qualitative and quantitative categories, reflecting different levels of standardization and operational usability. The circular relationship represented within the two output types within this layer reflects the empirical evidence that ESG extraction processes rarely generate purely qualitative or purely quantitative results, but rather combinations of both. Most studies adopt hybrid output configurations, in which qualitative interpretation and quantitative indicators are jointly produced, often within the same analytical pipeline, where interpretative outputs support the construction of structured indicators and aggregated metrics, enabling a balance between contextual understanding and operational usability.
Overall, the framework highlights a circular configurational logic, in which each of the three layers represented is connected to the other two. For instance, the structure of the data source(s) employed influences the choice of technology, which in turn determines the type of output that can be generated. However, we can read the framework backwards as well, starting from the required or desired output type, which might imply the usage of a certain technology, or set of technologies, in combination with one or more specific textual data types. This circular framework thus emphasizes the need to align these three dimensions within a coherent and integrated analytical configuration.
Data source characteristics, particularly the degree of structure and the origin of the content, play a decisive role in determining technological feasibility. Studies relying on highly structured corporate disclosures and external databases predominantly adopt traditional NLP or hybrid approaches [31,40]. In contrast, approaches operating on unstructured and externally generated sources show a stronger association with TBMs and LLMs, which are better suited to handle narrative variability, implicit claims, and contextual ambiguity [39,52]. By the same token, technological choices act as a mediating layer between data sources and outputs. Traditional NLP techniques are primarily associated with categorical classification and binary attribute outputs [40,42,53], while TBM architectures enable richer semantic interpretation [41,64]. Finally, output types reflect both upstream data constraints and downstream usability requirements since structured corporate disclosures tend to support quantitative ESG proxy construction, while narrative sources favor interpretative or exploratory outputs [41,53]. Quantitative outputs are more frequently associated with structured sources, while qualitative outputs prevail when unstructured data is analyzed [56,57,94].
Overall, the interplay between the three dimensions highlights a persistent trade-off between contextual richness and operational scalability. While recent advances in language modeling have expanded the possibility of processing heterogeneous and weakly structured text, the literature remains polarized between analytically rich yet operationally limited approaches and scalable yet semantically constrained ones. This misalignment is particularly evident in supplier-oriented ESG contexts, where data sources can be inherently unstructured, but outputs must nonetheless support automated and comparable decision-making. Addressing this tension requires aligning data sources, technologies, and outputs within coherent analytical configurations.

4.2. Multi-Source Knowledge Integration for ESG Assessment

Our first research question examines which textual source(s) proves most effective to gather corporate ESG data. We did not find any clearly predominant source, reflecting a shared assumption in the literature that ESG-related information cannot be reliably captured through a single perspective and instead requires triangulation across different types of evidence [18,39,52]. News and media, social and web-based, together with data repositories share a slight leadership as data sources, highlighting the importance attributed to external, event-driven information for capturing ESG-related controversies, reputational dynamics, and public scrutiny that may not be fully observable through corporate self-disclosure alone [34,70]. However, we found that most of the papers resort to two or more data sources as a means to cross-check references and collect both qualitative and quantitative information regarding the considered firm.
Therefore, rather than dealing with one specific data source, we found it more meaningful to investigate the data source characteristics described in Section 4.1 within our taxonomy. The empirical results show a strong prevalence of corporate structured (ESG and financial disclosures) and external unstructured (news and media, and social and web-based) sources. While the prior literature has documented the complementary role of media-based ESG signals in improving corporate risk assessment [30,34], our findings extend this view by showing that these sources are not merely supplementary but frequently combined with corporate structured disclosures within operational ESG extraction pipelines.
This of course leaves corporate websites, as the only corporate unstructured source we found in our sample, out of the mainstream. To the best of our knowledge, the marginal standalone use of corporate websites as primary ESG evidence has not been explicitly documented in previous ESG text mining reviews, which have predominantly focused on formal sustainability disclosures or external reputational signals [18]. Indeed, matching our expectations, we found that corporate websites are currently the least investigated of the data sources considered, and the scientific community’s interest in them is not growing over time at all; meanwhile, we found a strongly positive time trend for other corporate (but structured) sources, which accounted for just 41% of studies until 2024 and skyrocketed to 59% in 2025. Corporate websites also exhibit weak standalone usage and relatively fragmented connections with other corporate sources, reinforcing the view that they are seldom treated as a sufficient primary source of ESG evidence. This finding does not appear to be either supported or contradicted by the extant literature, as previous studies have largely overlooked supplier corporate websites as an independent ESG information source, focusing instead on ESG reports [39], financial disclosures [53], or external media [30]. Indeed, their inclusion appears opportunistic or supplementary, rather than embedded within stable and replicable multi-source extraction pipelines. In other words, when corporate websites are consulted, they are often complemented with external discursive sources rather than paired with other corporate disclosures. This pattern may reflect concerns about the credibility of voluntary ESG communication, as textual similarity analyses have shown that disclosure content may be strategically imitated across firms [95], thus limiting its reliability as standalone compliance evidence. These combinations are particularly prevalent in studies focusing on public perception, controversy detection, and reputational risk analysis [34,86]. This pattern is consistent with prior studies highlighting the methodological challenges associated with corporate websites, including content heterogeneity, lack of standardization, and extraction complexity [35,91].
Therefore, we can answer our first research question by concluding that multi-source designs are prevalent, and that a recurring configuration combines corporate structured sources (e.g., ESG/financial disclosures) with external unstructured sources (e.g., news and social/web-based content), while as of today corporate websites remain a marginal and complementary data source.

4.3. Technological Trajectories in ESG Text Analytics

Our second research question investigates which technique(s) emerges as most suitable to extract ESG content from supplier-oriented textual sources. The landscape we exposed with our literature review is in full transition.
NLP models are mainstream, frequently adopted alone, and show stable frequency over time, consistently with large-scale disclosure analytics relying on dictionary-based or lexicon-expanded approaches [53,76]. Their continued dominance reflects advantages in interpretability, transparency, and computational efficiency, which are often prioritized when ESG signals must be traceable and auditable. However, at the same time, several studies explicitly recognize that these approaches struggle to capture implicit claims, narrative framing, and contextual nuances, which are common in ESG communication [39,40,52]. These limitations have also been highlighted in studies addressing symbolic compliance and ESG-related information asymmetry [30].
Due to these limitations, they are increasingly combined with TBMs: this hybrid configuration reflects an incremental adoption pattern in which transformer models are embedded within existing pipelines rather than replacing them entirely. Overall, their ability to model contextual meaning makes them particularly suitable for capturing implicit and context-dependent ESG information. However, their application remains predominantly analytical rather than fully operationalized for automated compliance extraction at scale [39,52,94].
On the grounds of these drawbacks, their standalone use shows a declining trend and is increasingly complemented by LLM-based approaches, whose adoption is rapidly increasing. LLMs are typically employed in interpretative and flexible extraction tasks, particularly in compliance-support contexts [41,64]. While these models offer flexibility in dealing with heterogeneous and weakly structured textual sources, their use is constrained by unresolved challenges related to reproducibility, prompt sensitivity, computational cost, and regulatory acceptance, particularly in compliance-critical ESG applications [41,64,94].
In addition, the recent literature highlights further critical limitations of LLM-based systems that are particularly relevant in ESG contexts. These include the risk of model hallucinations (i.e., the generation of plausible but factually incorrect outputs), which may compromise the reliability of extracted ESG indicators [41,64]. Furthermore, LLMs are often characterized by limited transparency and explainability, giving rise to “black box” concerns that hinder the traceability and auditability of their outputs in compliance-oriented applications [64,94]. These aspects are particularly critical in ESG audit contexts, where the reliability, reproducibility, and verifiability of extracted information are essential. As a result, current LLM-based approaches cannot yet be considered fully reliable for autonomous compliance verification and should instead be interpreted as decision-support tools requiring human oversight and additional validation mechanisms.
Moreover, these limitations translate into concrete barriers to scalability in supplier monitoring contexts, as LLM-based systems entail substantial computational and integration costs and require validation mechanisms to support stable and auditable decision-support pipelines [41,86], while TBM-based approaches require large labeled datasets that are difficult to obtain for heterogeneous supplier data [34,39].
The increasing attention devoted to LLMs in recent studies should not be interpreted as a replacement of TBM architectures but rather as an evolution of the technological landscape. This characteristic is particularly relevant in the context of supplier-oriented ESG data extraction, where corporate websites often differ substantially in structure, language, and disclosure practices [39,40,52]. Nevertheless, the literature still highlights important barriers to the large-scale deployment of such technologies in supplier monitoring contexts, including heterogeneous website structures, multilingual content, limited standardization of ESG disclosures, and the scarcity of domain-specific training datasets [39,41,52,94].
Therefore, we can answer our second research question by concluding that, as of now, the most suitable technology family to extract suppliers’ ESG and sustainability content from textual sources remains that of traditional NLP models. This result is consistent with the operational requirements of supplier-oriented ESG assessment, which typically relies on structured and standardized outputs (e.g., binary compliance indicators) for scalable supplier screening and evaluation. In this context, NLP-based approaches remain particularly effective, while a gradual transition towards the joint usage of TBMs and LLMs is emerging to address more complex and less structured extraction tasks but will require overcoming the limitations exposed above.

4.4. From Interpretative Signals to Operational ESG Knowledge

The third research question investigated by this study concerns which types of ESG information the considered techniques can extract from the investigated input textual data. Our content-based analysis uncovered multiple categories of outputs, often combined within the same analytical pipeline. While qualitative outputs are shrinking over time, quantitative ones are on the rise, owing to the increasing need to practically map and assess suppliers’ compliance with sustainability criteria and ESG regulations.
Overall, the analysis highlights a fundamental trade-off between interpretability and operationalization: while qualitative outputs reflect a strong emphasis on understanding and structuring ESG-related textual content, quantitative outputs aim to generate standardized indicators that can be directly integrated into automated ESG assessment and supplier evaluation systems. Although prior work has identified similar tensions in ESG reporting analytics [18], this study shows that such outputs are frequently combined within the same pipelines. This gap is particularly salient in supplier-oriented contexts, where scalable and comparable outputs are required despite highly heterogeneous and weakly structured textual sources.
Qualitative outputs (e.g., narrative interpretations or categorical classifications) enable a rich and nuanced representation of ESG-related content, preserving contextual meaning and supporting exploratory or interpretative analyses. However, their limited standardization constrains their direct use in automated decision-making and large-scale supplier evaluation systems. Conversely, quantitative outputs (e.g., binary attributes, numerical indicators, and scores) provide higher comparability, scalability, and operational usability, making them particularly suitable for compliance-oriented applications and automated screening processes. At the same time, these outputs often rely on simplified representations of complex ESG phenomena and may obscure important contextual nuances embedded in textual data.
The literature also suggests that extracting reliable binary compliance indicators (e.g., yes/no signals regarding the presence of specific ESG practices) from suppliers’ textual sources remains a challenging task. Textual sources, especially in supplier contexts, often present heterogeneous, incomplete, or weakly structured information, which complicates the reliable identification of standardized compliance signals [39,40,52]. While some studies demonstrate that computational approaches can derive structured indicators from textual ESG disclosures, the empirical validation of such approaches remains relatively limited and is often conducted on relatively controlled datasets or structured disclosure sources rather than on heterogeneous textual sources [39,52]. Consequently, further research is needed to test the robustness and scalability of methods capable of extracting binary ESG compliance indicators from supplier-oriented textual sources.
A critical issue emerging from the literature concerns the reliability of quantitative ESG indicators extracted from textual data. While such indicators are essential for regulatory compliance and benchmarking purposes, their validity is often affected by data availability, heterogeneity of sources, and the need to rely on proxy constructions that may not fully capture the underlying ESG phenomena. This raises concerns regarding transparency, traceability, and the potential loss of semantic richness in the transition from text to numerical representation.
Recent European regulatory frameworks, such as the Corporate Sustainability Reporting Directive (CSRD) [96] and the Corporate Sustainability Due Diligence Directive (CSDDD) [97], significantly increased the amount of sustainability-related information that firms are expected to collect and monitor across their supply chains. These requirements further reinforce the need for reliable and scalable quantitative ESG indicators. However, the practical extraction of such indicators from suppliers’ textual sources remains challenging. Consequently, while recent advances in NLP, TBMs and LLMs suggest promising opportunities for automated ESG data extraction, further empirical validation is required to demonstrate the scalability and robustness of these approaches in real-world supplier ecosystems.
On the grounds of previous considerations, we can thus conclude that the analyzed technologies, combined with the considered data sources, are able to produce various types of qualitative and quantitative outputs, which are most effectively leveraged when combined to balance interpretability and operational usability.

5. Conclusions

5.1. Technological Implications

Looking at our empirical results from a technological perspective, our analysis highlights a persistent misalignment between technological capabilities and empirical focus. While the results achieved show that LLMs are increasingly capable of handling complex and weakly structured textual content and are frequently presented as a promising direction for future ESG text analytics [52,94], as of today, they are predominantly adopted in combination with other approaches, most notably TBMs, rather than as standalone solutions, reflecting the empirical distribution of technological configurations observed in the literature [41,64].
This pattern suggests that, despite their rapid development, LLMs are not yet fully mature as independent solutions but are instead embedded within hybrid pipelines, where TBMs and traditional NLP techniques still play a stabilizing role [41,64].
Moreover, their application remains largely concentrated on standardized disclosures and mediated sources, such as sustainability reports, financial filings, and news media, while genuinely supplier-oriented sources receive comparatively limited attention [91]. By contrast, the systematic and scalable extraction of compliance-relevant ESG information from supplier-oriented textual sources, including corporate websites, where textual content is inherently fragmented, heterogeneous, and weakly standardized, remains only partially addressed, reinforcing the need for future research that explicitly integrates data-acquisition and data-utilization technologies within supplier-oriented ESG information extraction pipelines [94].
While LLM-based systems show significant potential for extracting sustainability-related information from heterogeneous textual sources, their application raises several critical technical and operational challenges. First, reproducibility represents a major limitation: LLMs’ outputs may vary depending on prompt formulation, model version, and inference conditions, making it difficult to ensure consistent and auditable results [41,64,94]. Second, prompt sensitivity introduces methodological instability, as small variations in input queries may lead to different outputs, particularly when extracting binary compliance indicators. Third, LLMs are affected by hallucination phenomena, meaning they may generate plausible but factually incorrect information, potentially leading to the attribution of ESG practices not supported by actual evidence [41,64]. Fourth, the computational and economic cost of large-scale deployment is non-negligible, especially when analyzing large supplier bases [41,64]. And, finally, LLMs suffer from limited transparency and explainability (the black-box problem), which poses significant challenges in audit and regulatory contexts where traceability is required [41,52,94].
For these reasons, LLMs remain relatively underrepresented in the reviewed literature, and the current evidence suggests that LLM-based ESG extraction systems cannot yet be considered fully reliable as standalone solutions in audit-sensitive environments and should be complemented with validation mechanisms, hybrid architectures, and human oversight [41,52,64,94]. This in turn is currently one major limitation of this research stream, given the significant flexibility in processing heterogeneous and weakly structured textual sources that are typical of LLM technologies as especially compared to the mainstream NLP models. This outcome reinforces one main conclusion of this review: despite significant technological advances, the transformation of text-based ESG and sustainability information into fully operational, scalable, and compliance-relevant outputs remains an open challenge, and the main direction to face this challenge is to develop new technologies in the LLM family that overcome the technological problems that still limit their utilization today.

5.2. Managerial Implications

From a managerial point of view, this paper’s central issue is the quest to achieve ESG and sustainability information regarding a focal firm’s suppliers from publicly available textual sources. Suppliers can be in the several hundreds or even in the thousands; therefore, it is mandatory to achieve substantial automation in the data-extraction process. Moreover, various suppliers could be SMEs, posing doubts on their ability to supply ESG and financial disclosures. Of course, SMEs are also less likely than large multinationals to be covered by news and media, social and web-based, and on-line data repositories; thus, in supplier-oriented contexts, corporate websites often represent the most accessible and sometimes the only publicly available channel of ESG communication, especially for small and medium-sized firms [35,94].
We previously recognized that the distribution and combination of output types highlight a trade-off between interpretability and operationalization: while qualitative outputs reflect a strong emphasis on understanding and structuring ESG-related textual content, more quantitative studies can produce outputs that can be directly integrated into automated ESG assessment and supplier evaluation systems. This gap is particularly salient in supplier-oriented contexts, where scalable and comparable outputs are required despite highly heterogeneous and weakly structured textual sources. The typical information a focal firm is bound to collect in order to map its supplier base ESG compliance is of the quantitative, rather than qualitative, category, and it belongs either to the binary type (for instance, whether a certain supplier issues, or not, a sustainability report or has achieved, or not, the ISO 27001 [98] certification in cybersecurity) or to the numerical type (e.g., the supplier’s CO2 footprint or energy consumption), if not to the scores and ratings type (es. an aggregate ESC score). Boolean yes/no answers in particular can respond to typical questions asked by chief procurement officers when they want to assess their suppliers’ ESG or sustainability compliance. Consistently with these requirements, the reviewed literature shows that textual sources, and in particular corporate websites, can support the extraction of binary (yes/no) indicators by identifying whether firms disclose specific ESG-related elements, such as voluntary certifications, sustainability policies, or governance practices. These outputs are particularly relevant for supplier screening purposes, as they can be directly operationalized within procurement decision-making processes.
As a conclusion, we can build on the evidence discussed above, deriving that the perspective development of suitable LLM technologies proposed in Section 5.1 would support a wider utilization of textual sources, including corporate websites, as input data to harvest ESG and sustainability information and that this—in turn—would enable a more automated, affordable and dependable collection of suppliers’ ESG and sustainability compliance data, which could be used in turn by chief procurement officers to comply with the Corporate Sustainability Reporting Regulation (CSSR) [96] and Corporate Sustainability Due Diligence Directive (CSDDD) [97].
However, to confirm corporate websites as a source of suppliers’ ESG and sustainability compliance information that can be automatically harvested in practice by companies, a further step should be accomplished in this research path by considering factors such as websites’ content accessibility, their frequency of updates, and the actual alignment of their content with due diligence requirements [35,91,94]. In fact, corporate websites are frequently used as marketing and public-relations tools, which means that ESG-related statements may reflect symbolic disclosure or reputational positioning rather than fully verified sustainability performance [30,34,57]. Several studies in the ESG disclosure literature highlight the risk of greenwashing and information asymmetry in self-reported sustainability communication [30,39]. Moreover, the reviewed literature rarely provides systematic verification of the factual accuracy of ESG claims extracted from corporate websites, as most studies focus on information extraction rather than validation. These limitations affect particularly qualitative outputs (e.g., narrative and categorical interpretations), which are more exposed to ambiguity and subjectivity. By contrast, binary and quantitative outputs may offer a higher degree of robustness, as they rely on the identification of explicit statements within the text. As a result, especially qualitative ESG information extracted from corporate websites cannot be assumed to be fully verified but should require triangulation with other sources or additional validation mechanisms.
And even when the viability of the information contained in suppliers’ corporate websites as a base to automatically map suppliers ESG compliance is proven, their cost-effectiveness should be further assessed. In this respect, organizations face a trade-off between developing internal text-analytics capabilities and relying on commercial ESG data providers. Automated LLM-based systems may allow firms to collect ESG information directly from publicly available textual sources [35,91]; however, the development and maintenance of such systems require technical expertise, computational infrastructure, and continuous model updating. Moreover, the adoption of LLM-based solutions also raises concerns related to scalability, computational cost, and governance, particularly when applied to large supplier bases and compliance-critical contexts.
On the other hand, specialized ESG data providers or commercial sustainability databases could supply timely and cheaper data, but of course they are more likely to offer good coverage of large corporations, and crucially they could fall short of supplying SME data. Consequently, the adoption of automated LLM-based ESG monitoring solutions based on suppliers’ corporate websites should be interpreted as a potentially complementary approach rather than a direct substitute for existing ESG data services [35,94]. Automated text-analysis tools based on text contained in suppliers’ corporate websites both could provide data on smaller suppliers that are not covered at all by commercial services and may complement these external sources by monitoring additional ESG-related signals that may not yet be captured in standardized databases [91,94].
As a conclusion, on top of the development of suitable technologies that overcome the current constraints of LLM models advocated in Section 5.1, another currently empty space emerges in the practical exploitation of corporate websites as a particularly suitable textual source of ESG and sustainability information regarding a focal firm’s suppliers. Our literature review highlighted that the usage of corporate websites as data sources in the automated ESG and sustainability compliance data extraction is still not fully proven. To achieve a full proof of viability of corporate websites we need more empirical research where existing LLM models are systematically applied to (especially SMEs) suppliers’ corporate websites and extracted results are systematically cross-checked for completeness and correctness.

5.3. Research Implications

To the best of our knowledge, this is the first scientific review that concentrates explicitly on publicly available textual data sources from which to automatically extract valuable ESG and sustainability information regarding a focal firm’s suppliers. We previously discussed, in Section 5.1, how data-extraction technologies are still ripe and to date lack the potential to fully achieve this result. And in Section 5.2 we have discussed how corporate websites are, on the one hand, the most likely data source to always be publicly available, especially for small suppliers, while on the other hand they might raise some questions regarding their ability to automatically provide the required information in a trustable way. Both these conclusions expose serious limitations of extant research on this topic, while at the same time they show the directions for new and fruitful research.
This said, the empirical evidence demonstrating the large-scale applicability of automated supplier-oriented ESG data monitoring from suppliers’ textual sources remains limited for other reasons as well. Several challenges highlighted in the literature include multilingual content, heterogeneous disclosure practices across different national or regional jurisdictions, and the lack of standardized ESG taxonomies, particularly among smaller firms [39,52]. Future research should therefore focus not only on methodological development but also on empirical validation, testing the scalability of these approaches across multilingual textual sources, heterogeneous regulatory environments, and supplier ecosystems dominated by SMEs.
On top of this, the methodological quality of the studies included in our analysis is also debatable. The reviewed papers differ substantially in terms of dataset size, validation procedures, and evaluation metrics used to assess the performance of text-analysis models. Therefore, the synthesis presented in this study should be interpreted primarily as a mapping of technological approaches and research trajectories rather than as a comparative evaluation of algorithmic effectiveness. This approach is fully consistent with the very preliminary stage of this branch of research. Once the feasibility of this technology and data source has been more rigorously established, further space will open up for more systematic benchmarking studies aimed at assessing the performance of different computational techniques in ESG information extraction tasks.
Moreover, the reviewed literature shows a significant bias in the geographical origin of papers and in the type of firms considered. In fact, a substantial share of the analyzed studies originates from East and South Asia, while relatively fewer contributions address other geographic contexts. In addition, many of the reviewed papers focus primarily on large publicly traded companies rather than on small and medium-sized enterprises (SMEs), even though corporate supply chains typically consist mainly of SMEs. These patterns may limit the generalizability of our findings across different geographical and organizational contexts. However, far from being motivated by any particular choice made at the level of our literature review search criteria, these aspects reflect the current orientation of the literature identified through our systematic review process and point to an important gap in existing research. In particular, the limited focus on SMEs and underrepresented regions highlights the need for future studies to explore more diverse empirical settings and to better capture the heterogeneity of real-world supply chains.

Author Contributions

This paper has been written jointly by the two authors. However, we can specify the following main roles of contributors: M.P. was mainly responsible for conceptualization, methodology and supervision; L.S. was mainly responsible for data curation, formal analysis, investigation, validation and visualization. The writing of the original draft, as well as the review and editing of the final version, was done jointly by the two authors. However, M.P. mainly focused on Section 1, Section 4 and Section 5, while L.S. made a major contribution regarding the Background Section, as well as Section 2.2, Section 3.1 and Section 3.2. All authors have read and agreed to the published version of the manuscript.

Funding

This research received no external funding.

Institutional Review Board Statement

Not applicable.

Informed Consent Statement

Not applicable.

Data Availability Statement

No new data were created or analyzed in this study. Data sharing is not applicable to this article.

Conflicts of Interest

The authors declare no conflicts of interest.

Appendix A

Table A1. Methodological reliability assessment of the included studies, based on three criteria (dataset adequacy, methodological rigor, and validation and evaluation). Scores are assigned on a three-point ordinal scale (1 = low, 2 = medium, 3 = high) using only the information explicitly reported in the original articles.
ReferenceDataset AdequacyMethodological RigorValidation & EvaluationTOT
Gkatziaki et al. (2018) [29]3328
Lee et al. (2022) [34]2226
Saxena et al. (2023) [35]1214
Park et al. (2023) [36]2327
Lee et al. (2023) [37]3328
Jiang et al. (2023) [38]2327
Lee & Kim (2023) [39]3339
Heichl & Hirsch (2023) [40]3328
Yoon et al. (2023) [31]3328
Parikh & Penfield (2024) [41]2327
Gupta et al. (2024) [42]2338
Lim (2024) [43]2327
Gerber (2024) [44]2226
Farkas & Matolay (2024) [45]1214
Minkkinen et al. (2022) [46]1214
Trotta et al. (2024) [47]2316
Lee et al. (2024) [48]3339
Biju et al. (2023) [49]2327
Gatzert & Reichel (2024) [50]2327
Bronzini et al. (2024) [51]3339
Angioni et al. (2024) [52]3339
Li et al. (2024) [19]3339
Lin et al. (2024) [53]3328
Van der Heever et al. (2024) [54]2327
Kim et al. (2024) [55]3328
Mohapatra et al. (2024) [56]3227
Park et al. (2024) [57]3339
Wei & Zeng (2025) [58]2338
Hsu et al. (2025) [59]2338
O’Leary (2024) [60]1214
Banerjee et al. (2025) [61]3339
Zou et al. (2025) [62]3339
Li (2025) [63]2338
Tsang et al. (2025) [64]2327
Blazkova et al. (2025) [65]3339
Martin-Melero et al. (2025) [66]3339
Li et al. (2025) [67]3339
Tan et al. (2025a) [68]3339
Zhang et al. (2025) [69]2338
Lee et al. (2025b) [70]3339
Shuheng (2025) [20]1225
Naveed et al. (2025) [71]3339
Gao & Ju (2025) [72]2237
Lee et al. (2025a) [73]3328
Zhao (2025) [74]1225
Hammad et al. (2025) [26]1315
Huang & Yao (2025) [75]1315
Sun et al. (2025) [76]3328
Tan et al. (2025b) [77]3339
Lee et al. (2025b) [78]3339
Lou et al. (2025) [79]2338
Hąbek (2025) [80]1214
Fan et al. (2025) [13]3339
Mustafa et al. (2025) [18]2316
Kim & Lee (2025) [81]3339
Han et al. (2025) [82]3339
Lukács et al. (2025) [83]3339
Ferraro et al. (2025) [21]2338
Cai et al. (2025) [84]2338
Wang et al. (2025) [85]2327
Lin et al. (2025) [86]2338
Sun & Qiu (2025) [87]3339
Alshareef (2025) [88]3339
Zhou et al. (2025) [89]2338
Park (2025) [30]2338
Feng et al. (2025) [90]3339
Cerchiaro et al. (2021) [91]1315
Kharuddin et al. (2024) [25] 2226
Mohamed & Jamaludin (2025) [92]1214
Nevi et al. (2025) [93]1326
Fildisi et al. (2025) [94]2338
AVERAGE2.282.822.357.45

References

  1. Cooper, M.C.; Ellram, L.M. Characteristics of Supply Chain Management and the Implications for Purchasing and Logistics Strategy. Int. J. Logist. Manag. 1993, 4, 13–24. [Google Scholar] [CrossRef] [Scilit]
  2. Cigolini, R.; Cozzi, M.; Perona, M. A new framework for supply chain management. Int. J. Oper. Prod. Manag. 2004, 24, 7–41. [Google Scholar] [CrossRef] [Scilit]
  3. Buckley, P.J.; Casson, M. Future of the Multinational Enterprise; Palgrave Macmillan: London, UK, 1976. [Google Scholar]
  4. Buckley, P.J. Internalisation thinking: From the multinational enterprise to the global factory. Int. Bus. Rev. 2009, 18, 224–235. [Google Scholar] [CrossRef] [Scilit]
  5. Buckley, P.J.; Strange, R. The governance of the global factory: Location and control of world economic activity. Acad. Manag. Perspect. 2015, 29, 237–249. [Google Scholar] [CrossRef] [Scilit]
  6. Buckley, P.J.; Ghauri, P.N. Globalisation, economic geography and the strategy of multinational enterprises. J. Int. Bus. Stud. 2004, 35, 81–98. [Google Scholar] [CrossRef] [Scilit]
  7. McCann, P.; Mudambi, R. Analytical differences in the economics of geography: The case of the multinational firm. Environ. Plan. A 2005, 37, 1857–1876. [Google Scholar] [CrossRef] [Scilit]
  8. Li, T.-T.; Wang, K.; Sueyoshi, T.; Wang, D.D. ESG: Research progress and future prospects. Sustainability 2021, 13, 11663. [Google Scholar] [CrossRef] [Scilit]
  9. Carlsen, L.; Bruggemann, R. The 17 United Nations’ sustainable development goals: A status by 2020. Int. J. Sustain. Dev. World Ecol. 2022, 29, 219–229. [Google Scholar] [CrossRef] [Scilit]
  10. Benvenuto, M.; Cafiero, C.; Carmine, V. A systematic literature review on the determinants of sustainability reporting systems. Helyion 2023, 9, e14893. [Google Scholar] [CrossRef] [Scilit]
  11. Abeysekera, I. A framework for sustainability reporting. Sustain. Account. Manag. Policy J. 2022, 13, 1386–1409. [Google Scholar] [CrossRef] [Scilit]
  12. Baumüller, J.; Sopp, K. Double materiality and the shift from non-financial to European sustainability reporting: Review, outlook and implications. J. Appl. Account. Res. 2022, 23, 8–28. [Google Scholar] [CrossRef] [Scilit]
  13. Fan, J.; Wang, D.; Zheng, Y. Smart Money, Greener Future: AI-Enhanced English Financial Text Processing for ESG Investment Decisions. Sustainability 2025, 17, 6971. [Google Scholar] [CrossRef] [Scilit]
  14. Hertwich, E.G.; Wood, R. The growing importance of scope 3 greenhouse gas emissions from industry. Environ. Res. Lett. 2018, 13, 104013. [Google Scholar] [CrossRef] [Scilit]
  15. Stenzel, A.; Waichman, I. SC data sharing for scope 3 emissions. npj Clim. Action 2023, 2, 7. [Google Scholar] [CrossRef] [Scilit]
  16. Kotsantonis, S.; Serafeim, G. Four Things No One Will Tell You About ESG Data. J. Appl. Corp. Financ. 2019, 31, 50–58. [Google Scholar] [CrossRef] [Scilit]
  17. Sawicki, J.; Ganzha, M.; Paprzycki, M. The state of the art of natural language processing—A systematic automated review of NLP literature using NLP techniques. Data Intell. 2023, 5, 707–749. [Google Scholar] [CrossRef] [Scilit]
  18. Mustafa, F.; Smolarski, J.; Elamer, A.A. The convergence of artificial intelligence and sustainability reporting: A systematic review of applications, challenges and future directions. Bus. Strategy Environ. 2025, 34, 9761–9784. [Google Scholar] [CrossRef] [Scilit]
  19. Li, S.; Younas, M.W.; Maqsood, U.S.; Zahid, R.A. Impact of AI adoption on ESG performance: Evidence from Chinese firms. Energy Environ. 2024. [Google Scholar] [CrossRef] [Scilit]
  20. Shuheng, Q. ESG Information Disclosure and Path Selection of New Energy Enterprises in the Context of Digital Economy. Management 2025, 3, 30. [Google Scholar] [CrossRef] [Scilit]
  21. Ferraro, G.; Quinto, I.; Scandurra, G.; Thomas, A. The Impact of Artificial Intelligence and Sustainability Management on Fostering ESG Practices and Competitive Perspectives Among SMEs. Corp. Soc. Responsib. Environ. Manag. 2025, 32, 6641–6657. [Google Scholar] [CrossRef] [Scilit]
  22. Clean Clothes Campaign. BSCI 10th Anniversary Shame over Rana Plaza; Clean Clothes Campaign: Amsterdam, The Netherlands, 2013. [Google Scholar]
  23. Remake. Remake Fashion Accountability Report 2022; Remake: San Francisco, CA, USA, 2022. [Google Scholar]
  24. Human Rights Watch. “Obsessed with Audit Tools, Missing the Goal”: Why Social Audits Can’t Fix Labor-Rights Abuses; Human Rights Watch: New York, NY, USA, 2022. [Google Scholar]
  25. Kharuddin, S.; Chen, Y.; Shah, S.M. Sustainable development project management: How esg performance affects corporate value through investment efficiency. Int. J. Ebusiness Egovernment Stud. 2025, 17, 164–190. [Google Scholar]
  26. Hammad, M.Y.; Rahamaddulla, S.R.; Fauzi, M.A. Environmental and governance strategies in ESG for industry 4.0: A systematic review. AIMS Environ. Sci. 2025, 12, 557–575. [Google Scholar] [CrossRef] [Scilit]
  27. LeBaron, G.; Lister, J. Ethical audits and the supply chains of global corporations. Political Leg. Anthropol. Rev. 2016, 39, 281–297. Available online: https://eprints.whiterose.ac.uk/id/eprint/96303/ (accessed on 14 April 2026).
  28. Das, S.; Perona, M. Supply chain risk management automation: A literature review. Electron. Mark. Int. J. Networked Bus. 2025, 35, 104. [Google Scholar] [CrossRef] [Scilit]
  29. Gkatziaki, V.; Papadopoulos, S.; Mills, R.; Diplaris, S.; Tsampoulatidis, I.; Kompatsiaris, I. easIE: Easy-to-use information extraction for constructing CSR databases from the web. ACM Trans. Internet Technol. TOIT 2018, 18, 1–21. [Google Scholar] [CrossRef] [Scilit]
  30. Park, M. Enhancing ESG Risk Assessment with Litigation Signals: A Legal-AI Hybrid Approach for Detecting Latent Risks. Systems 2025, 13, 783. [Google Scholar] [CrossRef] [Scilit]
  31. Yoon, J.; Han, S.; Lee, Y.; Hwang, H. Text mining analysis of ESG management reports in South Korea: Comparison with sustainable development goals. Sage Open 2023, 13, 21582440231202896. [Google Scholar] [CrossRef] [Scilit]
  32. Thomé, A.M.T.; Scavarda, L.F.; Scavarda, A.J. Conducting systematic literature review in operations management. Prod. Plan. Control 2016, 27, 408–420. [Google Scholar] [CrossRef] [Scilit]
  33. Page, M.J.; McKenzie, J.E.; Bossuyt, P.M.; Boutron, I.; Hoffmann, T.C.; Mulrow, C.D.; Shamseer, L.; Tetzlaff, J.M.; Akl, E.A.; Brennan, S.E.; et al. The PRISMA 2020 statement: An updated guideline for reporting systematic reviews. BMJ 2021, 372. [Google Scholar] [CrossRef] [Scilit]
  34. Lee, O.; Joo, H.; Choi, H.; Cheon, M. Proposing an integrated approach to analyzing ESG data via machine learning and deep learning algorithms. Sustainability 2022, 14, 8745. [Google Scholar] [CrossRef] [Scilit]
  35. Saxena, A.; Singh, R.; Gehlot, A.; Akram, S.V.; Twala, B.; Singh, A.; Montero, E.C.; Priyadarshi, N. Technologies empowered environmental, social, and governance (ESG): An industry 4.0 landscape. Sustainability 2022, 15, 309. [Google Scholar] [CrossRef] [Scilit]
  36. Park, J.G.; Park, K.; Noh, H.; Kim, Y.G. Characterization of CSR, ESG, and corporate citizenship through a text mining-based review of literature. Sustainability 2023, 15, 3892. [Google Scholar] [CrossRef] [Scilit]
  37. Lee, H.; Lee, S.H.; Lee, K.R.; Kim, J.H. ESG discourse analysis through BERTopic: Comparing news articles and academic papers. Comput. Mater. Contin. 2023, 75, 6023–6037. [Google Scholar] [CrossRef] [Scilit]
  38. Jiang, L.; Gu, Y.; Dai, J. Environmental, social, and governance taxonomy simplification: A hybrid text mining approach. J. Emerg. Technol. Account. 2023, 20, 305–325. [Google Scholar] [CrossRef] [Scilit]
  39. Lee, J.; Kim, M. ESG information extraction with cross-sectoral and multi-source adaptation based on domain-tuned language models. Expert Syst. Appl. 2023, 221, 119726. [Google Scholar] [CrossRef] [Scilit]
  40. Heichl, V.; Hirsch, S. Sustainable fingerprint—Using textual analysis to detect how listed EU firms report about ESG topics. J. Clean. Prod. 2023, 426, 138960. [Google Scholar] [CrossRef] [Scilit]
  41. Parikh, P.; Penfield, J. Automatic Question Answering from Large ESG Reports. Int. J. Data Warehous. Min. (IJDWM) 2024, 20, 1–21. [Google Scholar] [CrossRef] [Scilit]
  42. Gupta, A.; Chadha, A.; Tewari, V. A NLP model on bert and yake technique for keyword extraction on sustainability reports. IEEE Access 2024, 12, 7942–7951. [Google Scholar] [CrossRef] [Scilit]
  43. Lim, T. Environmental, social, and governance (ESG) and artificial intelligence in finance: State-of-the-art and research takeaways. Artif. Intell. Rev. 2024, 57, 76. [Google Scholar] [CrossRef] [Scilit]
  44. Gerber, A. A content analysis: Analyzing topics of conversation under the# sustainability hashtag on Twitter. Environ. Data Sci. 2024, 3, e5. [Google Scholar] [CrossRef] [Scilit]
  45. Farkas, M.; Matolay, R. Designing the CSRD system: Insights from management systems to advance a strategic approach. J. Decis. Syst. 2024, 33, 200–209. [Google Scholar] [CrossRef] [Scilit]
  46. Minkkinen, M.; Niukkanen, A.; Mäntymäki, M. What about investors? ESG analyses as tools for ethics-based AI auditing. AI Soc. 2024, 39, 329–343. [Google Scholar] [CrossRef] [Scilit]
  47. Trotta, A.; Rania, F.; Strano, E. Exploring the linkages between FinTech and ESG: A bibliometric perspective. Res. Int. Bus. Financ. 2024, 69, 102200. [Google Scholar] [CrossRef] [Scilit]
  48. Lee, H.; Jung, H.S.; Park, H.; Kim, J.H. CORRECT? CORECT!: Classification of ESG Ratings with Earnings Call Transcript. KSII Trans. Internet Inf. Syst. 2024, 18, 1090–1100. [Google Scholar] [CrossRef] [Scilit]
  49. Biju, A.K.V.N.; Thomas, A.S.; Thasneem, J. Examining the research taxonomy of artificial intelligence, deep learning & machine learning in the financial sphere—A bibliometric analysis: AKVN Biju. Qual. Quant. 2024, 58, 849–878. [Google Scholar] [CrossRef] [Scilit]
  50. Gatzert, N.; Reichel, P. Sustainable investing in the US and European insurance industry: A text mining analysis. Geneva Pap. Risk Insur.-Issues Pract. 2024, 49, 26–62. [Google Scholar] [CrossRef] [Scilit]
  51. Bronzini, M.; Nicolini, C.; Lepri, B.; Passerini, A.; Staiano, J. Glitter or gold? Deriving structured insights from sustainability reports via large language models. EPJ Data Sci. 2024, 13, 41. [Google Scholar] [CrossRef] [Scilit]
  52. Angioni, S.; Consoli, S.; Dessì, D.; Osborne, F.; Recupero, D.R.; Salatino, A. Exploring environmental, social, and governance (esg) discourse in news: An ai-powered investigation through knowledge graph analysis. IEEE Access 2024, 12, 77269–77283. [Google Scholar] [CrossRef] [Scilit]
  53. Lin, Y.; Shen, R.; Wang, J.; Julia Yu, Y. Global evolution of environmental and social disclosure in annual reports. J. Account. Res. 2024, 62, 1941–1988. [Google Scholar] [CrossRef] [Scilit]
  54. Van der Heever, W.; Satapathy, R.; Park, J.M.; Cambria, E. Understanding public opinion towards ESG and green finance with the use of explainable artificial intelligence. Mathematics 2024, 12, 3119. [Google Scholar] [CrossRef] [Scilit]
  55. Kim, M.; Kang, J.; Jeon, I.; Lee, J.; Park, J.; Youm, S.; Jeong, J.; Woo, J.; Moon, J. Differential impacts of environmental, social, and governance news sentiment on corporate financial performance in the global market: An analysis of dynamic industries using advanced NLP models. Electronics 2024, 13, 4507. [Google Scholar] [CrossRef] [Scilit]
  56. Mohapatra, A.K.; Matta, R.; Soni, R.; Hiremath, N.V. Evaluating the role of artificial intelligence on ESG reporting: Evidence from India. Prabandhan Indian J. Manag. 2024, 17, 8–22. [Google Scholar] [CrossRef] [Scilit]
  57. Park, J.; Na, H.J.; Kim, H. Development of a Success Prediction Model for Crowdfunding Based on Machine Learning Reflecting ESG Information. IEEE Access 2024, 12, 197275–197289. [Google Scholar] [CrossRef] [Scilit]
  58. Wei, D.; Zeng, Y. Enhancing risk management in inclusive ESG investment portfolios in financial markets through big data analysis. J. Comput. Methods Sci. Eng. 2025, 25, 2275–2287. [Google Scholar] [CrossRef] [Scilit]
  59. Hsu, W.L.; Lin, Y.L.; Lai, J.P.; Liu, Y.H.; Pai, P.F. Forecasting Corporate Financial Performance Using Deep Learning with Environmental, Social, and Governance Data. Electronics 2025, 14, 417. [Google Scholar] [CrossRef] [Scilit]
  60. O’Leary, D. AI for Good: History, Open Data and Some ESG-based Applications. J. Decis. Syst. 2025, 34, 2443182. [Google Scholar] [CrossRef] [Scilit]
  61. Banerjee, S.; Aggarwal, D.; Sengupta, P. Do stock markets care about ESG and sentiments? Impact of ESG and investors’ sentiment on share price prediction using machine learning. Ann. Oper. Res. 2025, 1–40. [Google Scholar] [CrossRef] [Scilit]
  62. Zou, Y.; Shi, M.; Chen, Z.; Deng, Z.; Lei, Z.; Zeng, Z.; Yang, S.; Tong, H.; Xiao, L.; Zhou, W. ESGReveal: An LLM-based approach for extracting structured data from ESG reports. J. Clean. Prod. 2025, 489, 144572. [Google Scholar] [CrossRef] [Scilit]
  63. Li, Y. Collecting Financial Data from Online Sources: Enhancing Large Language Models with Real-Time Search. J. Organ. End User Comput. (JOEUC) 2025, 37, 1–23. [Google Scholar] [CrossRef] [Scilit]
  64. Tsang, Y.P.; Wu, C.H.; Wang, Y.; Ip, W.H. Semantic-driven internet of behaviours for enhancing supply chain ESG capabilities through generative AI. Int. J. Semant. Web Inf. Syst. (IJSWIS) 2025, 21, 1–33. [Google Scholar] [CrossRef] [Scilit]
  65. Blazkova, T.; Pedersen, E.R.G.; Andersen, K.R.R. Sentiments and sustainability: Stakeholder perceptions of sustainable fashion on social media. J. Fash. Mark. Manag. Int. J. 2025, 29, 585–604. [Google Scholar] [CrossRef] [Scilit]
  66. Martin-Melero, I.; Gomez-Martinez, R.; Medrano-Garcia, M.L.; Hernandez-Perlines, F. Comparison of sectorial and financial data for ESG scoring of mutual funds with machine learning. Financ. Innov. 2025, 11, 84. [Google Scholar] [CrossRef] [Scilit]
  67. Li, C.; Keeley, A.R.; Takeda, S.; Seki, D.; Managi, S. Investor’s ESG tendency probed by pre-trained transformers. Corp. Soc. Responsib. Environ. Manag. 2025, 32, 2051–2071. [Google Scholar] [CrossRef] [Scilit]
  68. Tan, C.; Yin, K.; Wu, H.; Zhou, P. Analysts’ ESG attention and stock pricing efficiency: Evidence from machine learning and text analysis. J. Account. Lit. 2025. [Google Scholar] [CrossRef] [Scilit]
  69. Zhang, M.; Shen, Q.; Zhao, Z.; Wang, S.; Huang, G.Q. Optimizing ESG reporting: Innovating with E-BERT models in nature language processing. Expert Syst. Appl. 2025, 265, 125931. [Google Scholar] [CrossRef] [Scilit]
  70. Lee, H.; Kim, J.H.; Jung, H.S. ESG-KIBERT: A new paradigm in ESG evaluation using NLP and industry-specific customization. Decis. Support Syst. 2025, 193, 114440. [Google Scholar] [CrossRef] [Scilit]
  71. Naveed, K.; Farooq, M.B.; Zahir-Ul-Hassan, M.K.; Rauf, F. AI adoption, ESG disclosure quality and sustainability committee heterogeneity: Evidence from Chinese companies. Meditari Account. Res. 2025, 33, 708–732. [Google Scholar] [CrossRef] [Scilit]
  72. Gao, W.; Ju, M. A preliminary test of ChatGPT’s ESG literacy. Manag. Financ. 2025, 51, 857–875. [Google Scholar] [CrossRef] [Scilit]
  73. Lee, H.; Kim, J.H.; Jung, H.S. From corporate earnings calls to social impact: Exploring ESG signals in S&P 500 ESG index companies through transformer-based models. J. Clean. Prod. 2025, 501, 145320. [Google Scholar] [CrossRef] [Scilit]
  74. Zhao, M. Performance Analysis of Japanese Electric Vehicle Manufacturers in Environmental, Social, and Governance Using Text Mining and Predictive Methods. Eng. Proc. 2025, 92, 35. [Google Scholar] [CrossRef] [Scilit]
  75. Huang, C.; Yao, X. Synergies Among Responsible Artificial Intelligence (RAI), Environmental, Social and Governance (ESG), and Sustainable Development Goals (SDGs). IEEE Comput. Intell. Mag. 2025, 20, 20–41. [Google Scholar] [CrossRef] [Scilit]
  76. Sun, Y.; San, Z.; Xu, C.; Davey, H. The Nexus of Managerial Myopia and Transparency in ESG Information: Evidence from the Textual Analysis of ESG Disclosures. Corp. Soc. Responsib. Environ. Manag. 2025, 32, 5469–5489. [Google Scholar] [CrossRef] [Scilit]
  77. Tan, W.; Dong, Q.; Xu, C.; Sun, Y. Navigating the ESG seascape: Media sentiment toward ESG and corporate strategies. J. Account. Lit. 2025. [Google Scholar] [CrossRef] [Scilit]
  78. Lee, H.L.; Hwang, J.H.; Ryu, D.Y.; Kim, J.W. Open-Source Data-Driven Prediction of Environmental, Social, and Governance (ESG) Ratings Using Deep Learning Techniques. Intell. Syst. Account. Financ. Manag. Int. J. 2025, 32, e70003. [Google Scholar] [CrossRef] [Scilit]
  79. Luo, Y.; Cui, X.; Liu, Q.; Zhou, Q.; Zhang, Y. Identifying exaggeration in ESG reports using machine learning techniques. Data Inf. Manag. 2025, 9, 100084. [Google Scholar] [CrossRef] [Scilit]
  80. Hąbek, P. Evaluating ESG Software Solutions for Sustainability Reporting in the Manufacturing Sector. Manag. Syst. Prod. Eng. 2025, 33, 420–432. [Google Scholar] [CrossRef] [Scilit]
  81. Kim, H.; Lee, M. Unraveling the Drivers of ESG Performance in Chinese Firms: An Explainable Machine-Learning Approach. Systems 2025, 13, 578. [Google Scholar] [CrossRef] [Scilit]
  82. Han, J.J.; Jun, S.; Kim, J.W. Examining the Impact of ESG News Sentiment on Corporate Performance: A Comprehensive Analysis by News Topic and Industry. Bus. Ethics Environ. Responsib. 2025. Early view. [Google Scholar] [CrossRef] [Scilit]
  83. Lukács, B.; Rickards, R.C.; Molnár, P.; Suta, A.; Tóth, Á. ESG disclosure topics and reporting frameworks: Exploratory research across automotive, construction, and energy industries. Discov. Sustain. 2025, 6, 649. [Google Scholar] [CrossRef] [Scilit]
  84. Cai, B.; Ye, Z.; Chen, S. Intelligent ESG Evaluation for Construction Enterprises in China: An LLM-Based Model. Buildings 2025, 15, 2710. [Google Scholar] [CrossRef] [Scilit]
  85. Wang, J.F.; Zhang, W.Y.; Tseng, S.P. An innovative ESGH-RAG module with ChatGPT-4o for automatic ESG-report generation. J. Supercomput. 2025, 81, 1103. [Google Scholar] [CrossRef] [Scilit]
  86. Lin, C.Y.; Tseng, T.L.; Xu, H. GPT-Augmented Bayesian Reinforcement Learning Framework for Multi-Objective Supplier Selection. IEEE Trans. Eng. Manag. 2025, 72, 3779–3804. [Google Scholar] [CrossRef] [Scilit]
  87. Sun, Q.; Qiu, X. How does green product certification affect ESG performance? Evidence from dual machine learning. J. Clean. Prod. 2025, 521, 146201. [Google Scholar] [CrossRef] [Scilit]
  88. Alshareef, M.N. Artificial intelligence-enhanced environmental, social, and governance disclosure quality and financial performance nexus in Saudi listed companies under vision 2030. Sustainability 2025, 17, 7421. [Google Scholar] [CrossRef] [Scilit]
  89. Zhou, X.; Peng, Y.; Sun, X.; Cao, X.; Wang, Z.; Zhang, J. Advancing new energy industry quality via artificial intelligence-driven integration of ESG principles. Humanit. Soc. Sci. Commun. 2025, 12, 1491. [Google Scholar] [CrossRef] [Scilit]
  90. Feng, X.; von Mettenheim, H.J.; Sermpinis, G.; Stasinakis, C. Sustainable portfolio construction via machine learning: ESG, SDG and sentiment. Eur. Financ. Manag. 2025, 31, 1148–1169. [Google Scholar] [CrossRef] [Scilit]
  91. Cerchiaro, D.; Leo, S.; Landriault, E.; De Vega, P. DLT to boost efficiency for financial intermediaries. An application in ESG reporting activities. Technol. Anal. Strateg. Manag. 2025, 37, 373–386. [Google Scholar] [CrossRef] [Scilit]
  92. Mohamed, O.Y.; Jamaludin, N.F. Development of an integrated ESG and climate risk assessment framework for semiconductors industries in Malaysia. Sustain. Futures 2025, 10, 101052. [Google Scholar] [CrossRef] [Scilit]
  93. Nevi, G.; Montera, R.; Cucari, N.; Laviola, F. Integrating AI and ESG in digital platforms: New profiles of platform-based business models. J. Eng. Technol. Manag. 2025, 78, 101913. [Google Scholar] [CrossRef] [Scilit]
  94. Fildisi, B.; Vakaj, E.; Dridi, A.; Imran, A.S.; Azad, R.M.A. Integrating AI-driven analytics for enhanced ESG mapping: Aligning local and global perspectives. Sustain. Futures 2025, 10, 101231. [Google Scholar] [CrossRef] [Scilit]
  95. Huang, Q.; Zhang, Y.; Li, X.; Wang, F. Imitation behavior in environmental, social, and governance disclosure: Textual analysis evidence from Chinese listed enterprises. Bus. Ethics Environ. Responsib. 2025, 34, 771–793. [Google Scholar] [CrossRef] [Scilit]
  96. European Commission. Directive (EU) 2022/2464 of the European Parliament and of the Council of 14 December 2022 amending Regulation (EU) No 537/2014, Directive 2004/109/EC, Directive 2006/43/EC and Directive 2013/34/EU as regards corporate sustainability reporting. In Official Journal of the European Union; European Commission: Bruxelles/Brussel, Belgium, 2022. [Google Scholar]
  97. European Parliament and Council. Directive (EU) 2024/1760 on Corporate Sustainability Due Diligence and amending Directive (EU) 2019/1937 and Regulation (EU) 2023/2859. In Official Journal of the European Union; European Parliament and Council: Bruxelles/Brussel, Belgium, 2024. [Google Scholar]
  98. ISO/IEC 27001:2022; Information Security, Cybersecurity and Privacy Protection—Information Security Management Systems—Requirements. International Organization for Standardization: Geneva, Switzerland, 2022.
Figure 1. PRISMA 2020 flow diagram of the study selection process.
Applsci 16 04024 g001
Figure 2. N° of papers per year and time trend of research on the topic.
Applsci 16 04024 g002
Figure 3. Scientific journals publishing at least two papers.
Applsci 16 04024 g003
Figure 4. Number of papers by scientific domain.
Applsci 16 04024 g004
Figure 5. Number of authors by country.
Applsci 16 04024 g005
Figure 6. Adopted data-utilization techniques in our sample of 73 papers. Numbers indicate the number of studies using each technique, while overlapping areas represent studies combining multiple approaches.
Applsci 16 04024 g006
Figure 7. Configurational framework of ESG information extraction from textual sources.
Applsci 16 04024 g007
Table 1. Keyword and inclusion criteria for PRISMA.
CriteriaDescription
Search stringTITLE-ABS-KEY: (“ESG” OR “esg”) AND (“web scraping” OR “data scraping” OR “web crawler” OR “data extraction”
OR
“text mining” OR “data mining” OR “information extraction” OR “NLP” OR “natural language processing” OR “machine learning” OR “artificial intelligence” OR “automated data collection”)
Filters appliedLanguage: English.
Document type: Articles.
Source type: Journal.
Publication years: 2000–2025.
Subject area: Engineering, computer science, business and management, social sciences, environmental sciences, and decision sciences.
Selection criteriaTechnique: Text mining, NLP or automated text interpretation.
Focus: ESG or sustainability reporting.
Table 2. Yearly journal dispersion index (number of journals per article) in the 2023–2025 period.
YearNr. of ArticlesNr. of
Journals
Dispersion Index (J/A)
2023870.875
202420180.900
202550400.800
Table 3. A list of the 73 papers considered, sorted by date of publication and categorized by data source employed, technology adopted and output generated.
ArticlesData SourcesTechnologyOutput Generated
ESG DisclosuresFinancial DisclosuresCorporate WebsitesNews & MediaSocial & Web-Based Data RepositoriesN° of Data Sources Web Scraping & Crawling OCR NLP & TMTBMLLMsN° of Technologies Numerical KPIsNarrative InformationBinary AttributesCategorical ClassificationScores & RatingsN° of Outputs
Gkatziaki et al., 2018 [29] x xx x4xxx 3xxxx 4
Lee et al., 2022 [34] x x2 x 1x xx3
Saxena et al., 2023 [35] xx 2x xx 3 xx 2
Park et al., 2023 [36] x1x x 2 x x 2
Lee et al., 2023 [37] xx 2 xx2 xx 2
Jiang et al., 2023 [38] x x x3xxx 3x x 2
Lee & Kim, 2023 [39] x x 2 x 1 x 1
Heichl & Hirsch, 2023 [40] x x 2x x 2 xx 2
Yoon et al., 2023 [31] x x 2 xx2 xx 2
Parikh & Penfield, 2024 [41] x 1 xxxx4xxx 3
Gupta et al., 2024 [42] x x 2 xx2 xx 2
Lim, 2024 [43] x1x x 2 x x 2
Gerber, 2024 [44] x 1x x 2 x x 2
Farkas & Matolay, 2024 [45] xx 2x x 2 xx 2
Minkkinen et al., 2024 [46] x x 2x x 2 xx 2
Trotta et al., 2024 [47] x1 x 1 x 1
Lee et al., 2024 [48] x x2 x 1 xx2
Biju et al., 2024 [49] x1x xxx4 x x 2
Gatzert & Reichel, 2024 [50] x x x3xxx 3x xx3
Bronzini et al., 2024 [51] x x2 x x2 x xx3
Angioni et al., 2024 [52] xx 2 xx2 xx 2
Li et al., 2024 [19] x x2x xx 3x x x3
Lin et al., 2024 [53] xx 2 x 1x 1
Van der Heever et al., 2024 [54] x 1 x 1 x x 2
Kim et al., 2024 [55] x x2 x 1 xx2
Mohapatra et al., 2024 [56] x x 2 xx 2xxx 3
Park et al., 2024 [57] xx 2 xx2x xx 3
Wei & Zeng, 2025 [58] x x x3 x 1x xx3
Hsu et al., 2025 [59] x1 x1 x x2
O’Leary, 2025 [60] x x x3 x x2 x x 2
Banerjee et al., 2025 [61] xx x3 x 1x 1
Zou et al., 2025 [62] xxx 3 x xx3 xx x3
Li, 2025 [63] xxx 3 x xx3x xx 3
Tsang et al., 2025 [64] xx x 3 x xx3 xxx3
Blažková et al., 2025 [65] xx 2 xx2 xx 2
Martin-Melero et al., 2025 [66] x x 2 x 1 xx2
Li et al., 2025 [67] x 1 xx 2 x1
Tan et al., 2025a [68] x x2 x 1x 1
Zhang et al., 2025 [69] xxx 3 x xx3 xx x3
Lee et al., 2025b [70] x x2 x 1 x xx3
Shuheng, 2025 [20] xx 2 xx 2 xx 2
Naveed et al., 2025 [71] xx 2x x2 x x 2
Gao & Ju, 2025 [72] xx x3 x x2 x 1
Lee et al., 2025 [73] x x 2 xx 2 xx2
Zhao, 2025 [74] x 1 x 1xx 2
Hammad et al., 2025 [26] xx 2x x 2 xx 2
Huang & Yao, 2025 [75] xx 2x x 2 xx 2
Sun et al., 2025 [76] xx 2 x 1x x2
Tan et al., 2025b [77] x x x3x x 2 xx2
Lee et al., 2025c [78] xxx 3 xx2xxx 3
Luo et al., 2025 [79] x x 2 xx2 xx 2
Hąbek, 2025 [80] x 1 x 1 x 1
Fan et al., 2025 [13] xx 2 x 1 x 1
Mustafa et al., 2025 [18] x 1 xxx3 x 1
Kim & Lee, 2025 [81] xx x3 x 1 x1
Han et al., 2025 [82] x x x3 xx 2 xx2
Lukács et al., 2025 [83] x x x 3 x x2 xxx 3
Ferraro et al., 2025 [21] xx 2 xx 2x x 2
Cai et al., 2025 [84] xxx 3 x xx3 xxx3
Wang et al., 2025 [85] xx x 3 x xx3 xxx3
Lin et al., 2025 [86] xx 2 x1x x2
Sun & Qiu, 2025 [87] x1x x 2x x 2
Alshareef, 2025 [88] xx x 3 x xx3xxx 3
Zhou et al., 2025 [89] xx 2 xx 2 xx2
Park, 2025 [30] x1 xx 2x x 2
Feng et al., 2025 [90] x x2 x 1x x2
Cerchiaro et al., 2025 [91] xx 2x x 2 xx 2
Kharuddin et al., 2025 [25] x1 x 1x 1
Mohamed & Jamaludin, 2025 [92] x x x3 x 1x xx3
Nevi et al., 2025 [93] x xx 3 xx x3x xx 2
Fildisi et al., 2025 [94] xx 2 xx2 xx 2
TOTAL n° OF PAPERS242222292727 1815423727 2628334125
Table 4. Pairwise combination of data sources considered in the analyzed literature.
News & MediaSocial & Web-BasedData RepositoriesESG DisclosuresFinancial DisclosuresCorporate WebsitesTotal Frequency
news & media0151064830
social & web-based1520161227
data repositories1008106527
ESG disclosures611049725
financial disclosures46691522
corporate websites812575122
Table 5. Pairwise combination of outputs considered in the analyzed literature.
Categorical ClassificationBinary AttributesNarrative InformationNumerical KPIsScores & RatingsTOT
categorical classification31612101642
binary attributes1601511733
narrative information 121556429
numerical KPIs101165826
scores & ratings16748225
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content.