Article

A Markov Regime Switching Approach towards Assessing Resilience of Romanian Collective Investment Undertakings

by
Leonardo Badea
1,
Daniel Ştefan Armeanu
2,
Iulian Panait
3 and
Ştefan Cristian Gherghina
2,*
1
Department of Finances-Accountancy, Valahia University of Târgovişte, 2 Carol I Boulevard, Târgovişte 130024, Romania
2
Department of Finance, The Bucharest University of Economic Studies, 6 Piata Romana, Bucharest 010374, Romania
3
Faculty of Economics, Hyperion University of Bucharest, 169 Calea Călăraşilor, Bucharest 030615, Romania
*
Author to whom correspondence should be addressed.
Sustainability 2019, 11(5), 1325; https://doi.org/10.3390/su11051325
Submission received: 3 February 2019 / Revised: 13 February 2019 / Accepted: 22 February 2019 / Published: 3 March 2019
(This article belongs to the Special Issue Resilient Infrastructure Systems and Sustainable Economic Growth)

Abstract

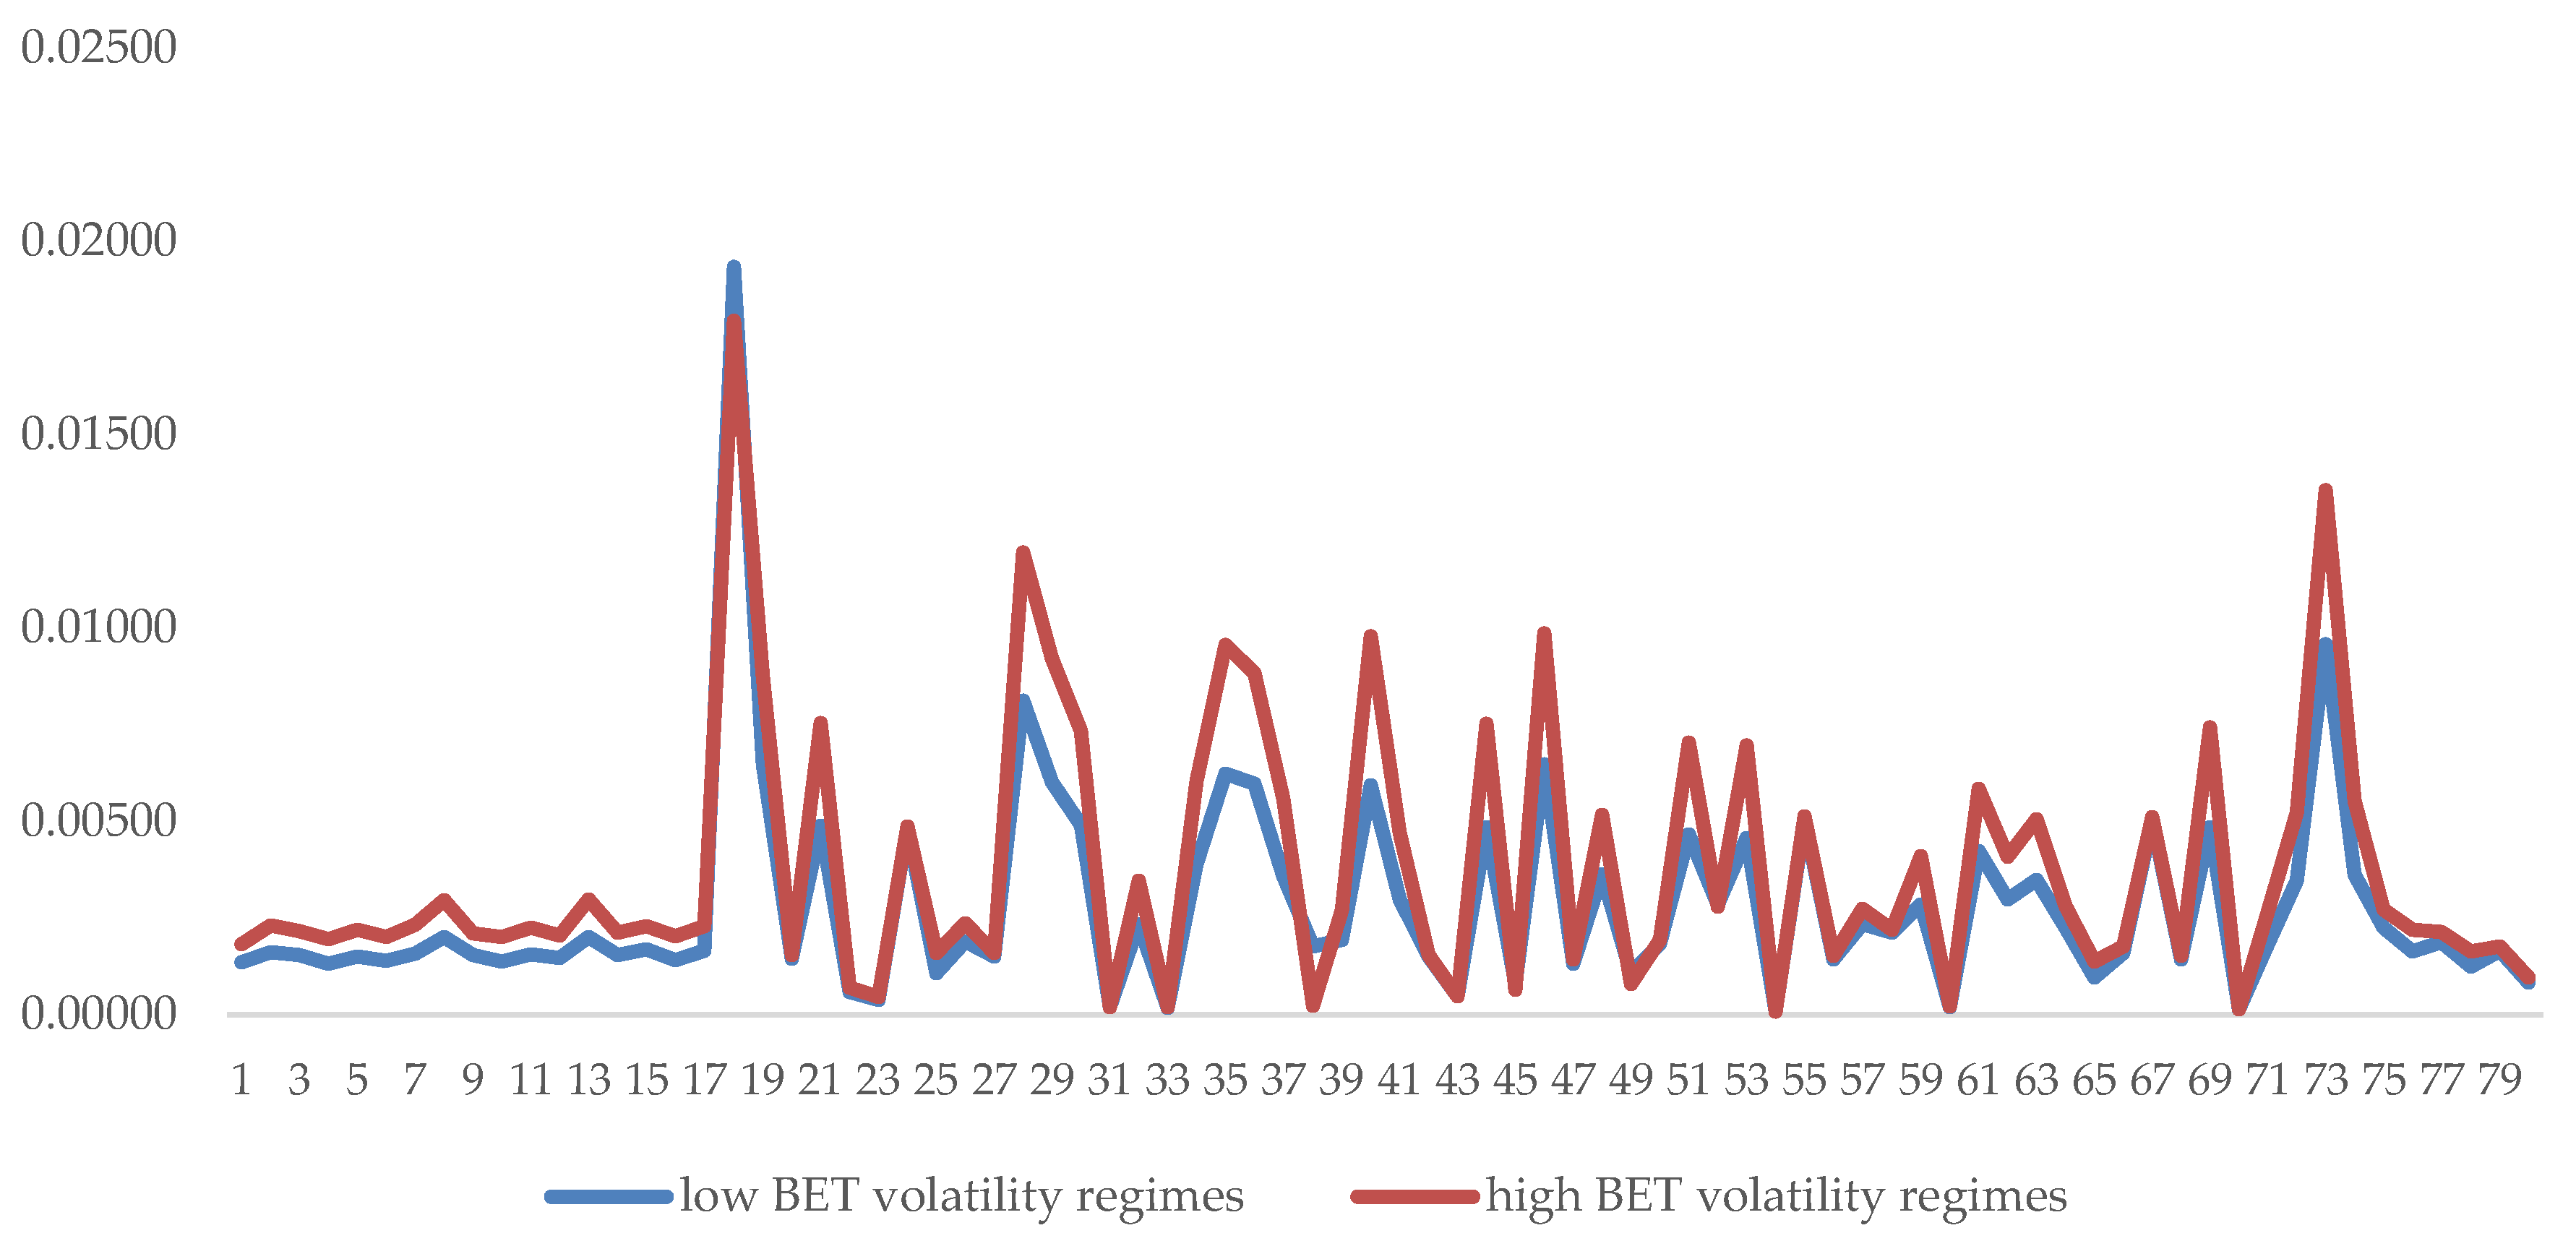
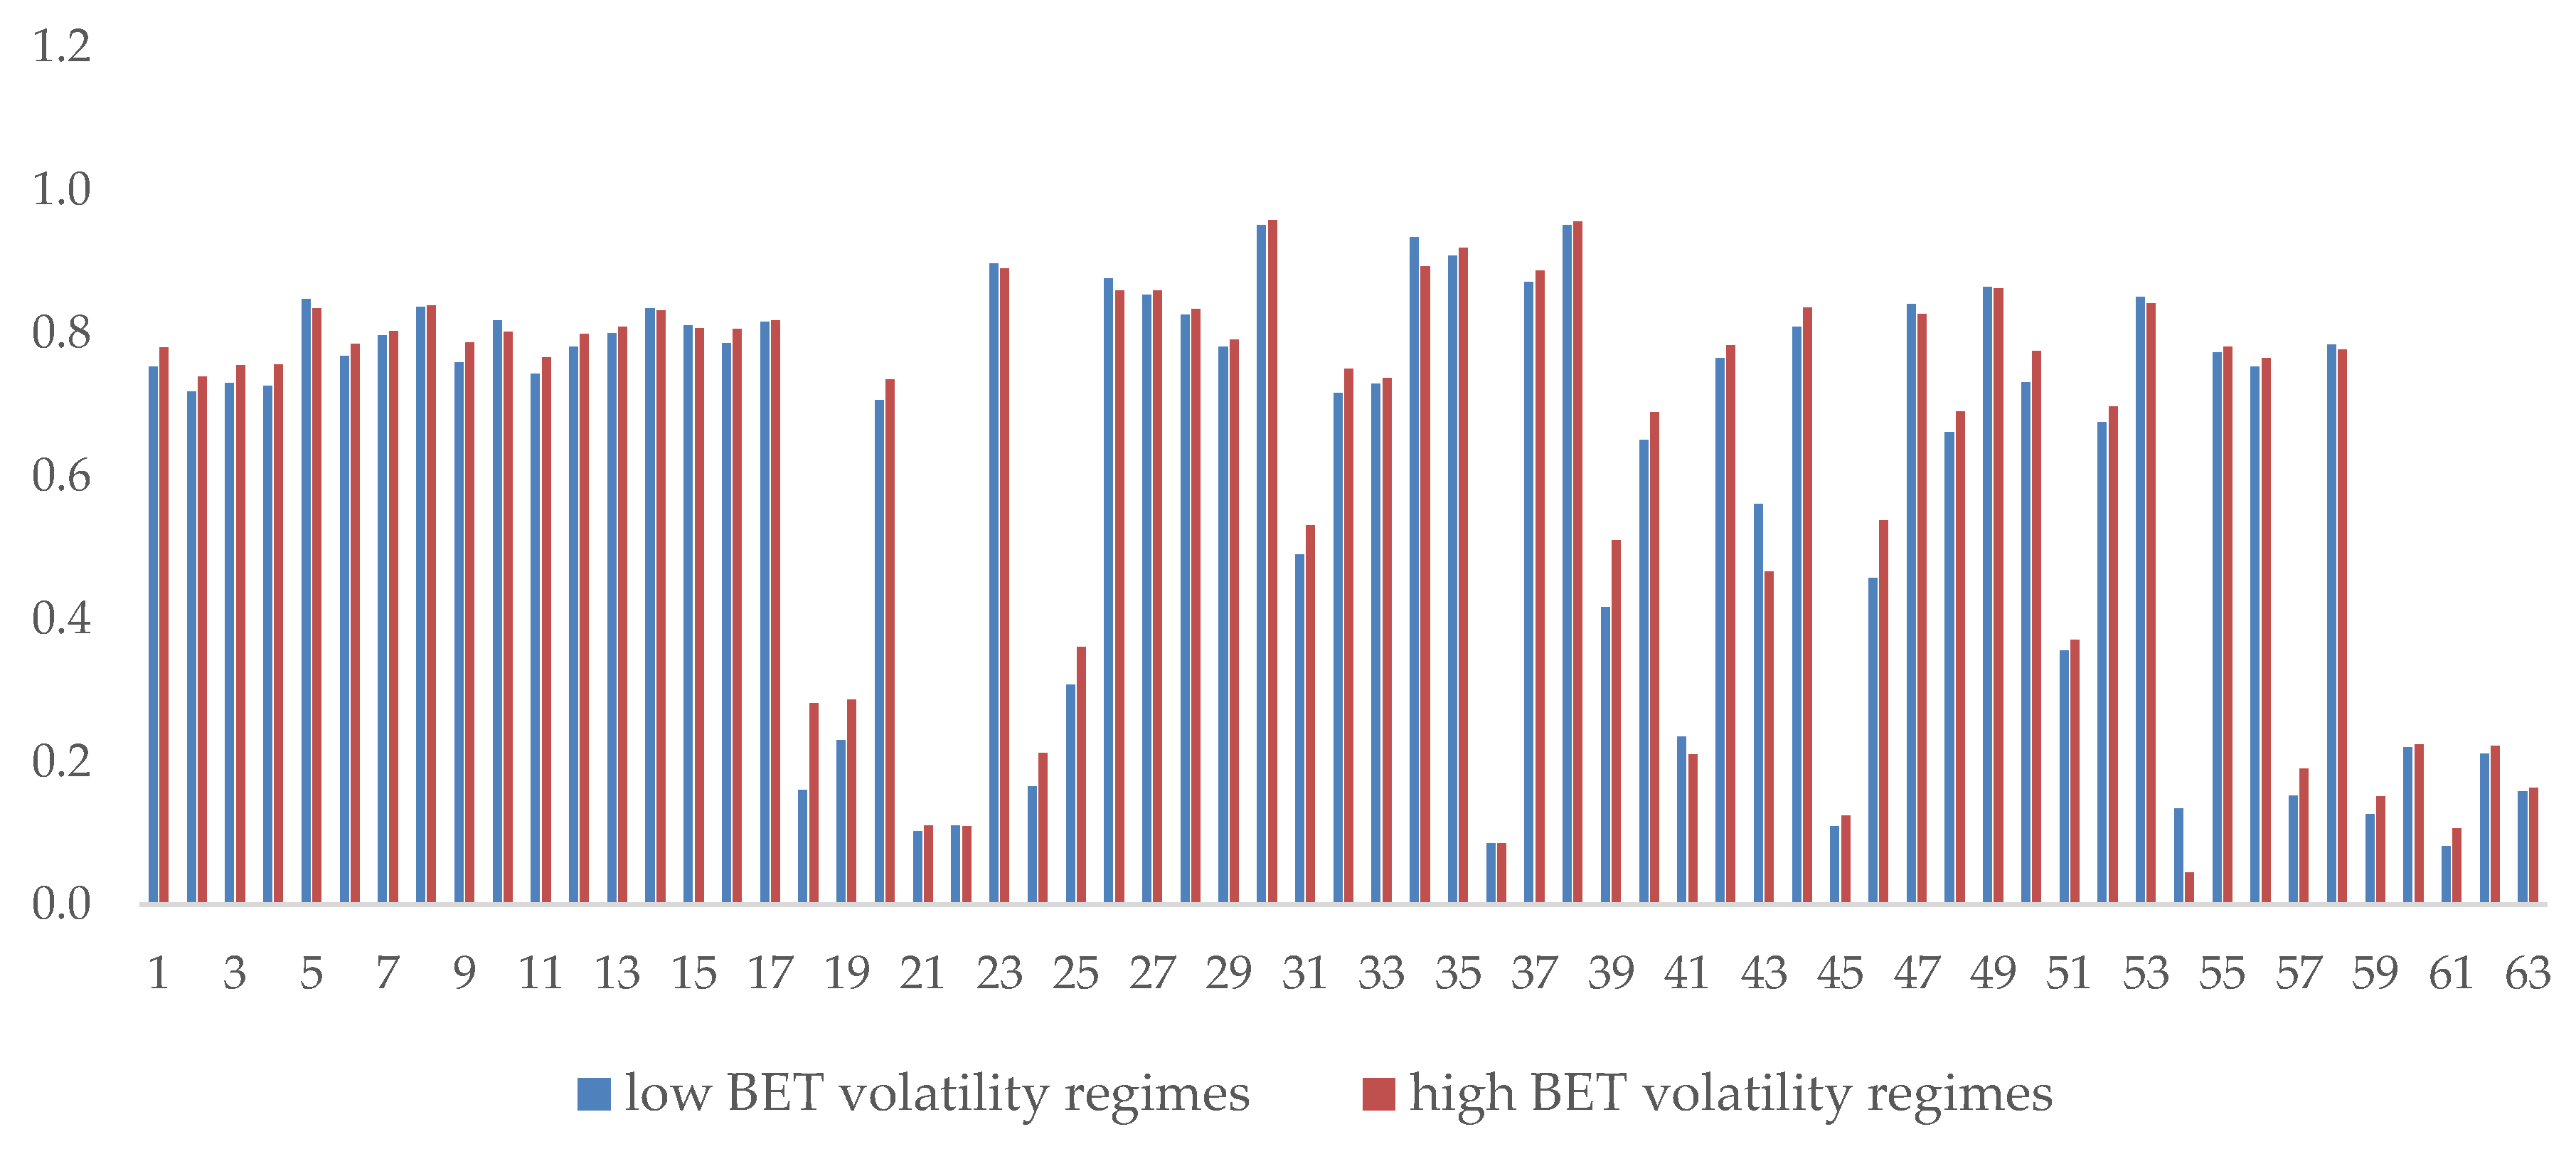
This paper explores the sensitivity of Romanian collective investment undertakings’ returns to changes in equity, fixed income and foreign exchange market returns. We use a sample of 80 open-end investment funds and pension funds with daily returns between 2016 and 2018. Our methodology consists of measuring changes in the daily conditional volatility for the fund returns (EGARCH) and changes in their conditional correlation with selected market risk factors (DCC MV-GARCH) throughout different volatility regimes identified using a Markov Regime Switching model. We argue that, on average, the level of conditional correlations between funds and market risk factors remained stable and unconcerned by the volatility regimes. In addition, for only less than half of the funds in the sample, their volatility regimes were synchronized with those of the selected market risk factors. We found that, on average, fund returns are more correlated with equity returns and less correlated with changes in local bond yields, while not being significantly influenced by changes in foreign bond yields or changes in foreign exchange. During the period investigated equity returns were the most volatile while the funds returns volatility were, on average, much more reduced. Overall, our results show the resilience of the Romanian collective investment sector to the selected market risk factors, during the investigated period.
Keywords: Markov switching; conditional volatility; conditional correlation; market risk; investment and pension funds Markov switching; conditional volatility; conditional correlation; market risk; investment and pension funds