


Abstract
Decarbonization of the Greek economy requires significant investments in clean technologies. This will boost demand for goods and services and will create multiplier effects on output value added and employment, though reliance on imported technologies might increase the trade deficit. This study employs input–output analysis to estimate the direct, indirect, and multiplier effects of green transition investments on Greek output, value added, employment, and imports across five-year intervals from 2025 to 2050. Two scenarios are considered: the former is based on the National Energy and Climate Plan (NECP), driven by a large-scale exploitation of RES and technologies promoting electrification of final demand, while the latter (developed in the context of the CLEVER project) prioritizes energy sufficiency and efficiency interventions to reduce final energy demand. In the NECP scenario, GDP increases by 3–10% (relative to 2023), and employment increases by 4–11%. The CLEVER scenario yields smaller direct effects—owing to lower investment levels—but larger induced impacts, since energy savings boost household disposable income. The consideration of three sub-scenarios adopting different levels of import-substitution rates in key manufacturing sectors exhibits pronounced divergence, indicating that targeted industrial policies can significantly amplify the domestic economic benefits of the green transition.
1. Introduction
Greece, as an EU member state committed to the European Green Deal, is obliged to align its policies with the long-term European goal of climate neutrality by 2050. At the core of the European environmental protection policy is the increase in the penetration of renewable energy sources (RES), the increase in energy efficiency, and the change in energy consumption behavior. More specifically, the European Council under the Green Deal and the Fit for 55 Package has adopted key policy initiatives, which include the following: (i) the strengthening and expanding of the Emissions Trading System (EU-ETS); (ii) the adoption of the Social Climate Fund (SCF) to address the social and distributional impact of the new emissions trading system for buildings and road transport; (iii) the adoption of the Carbon Border Adjustment Mechanism (CBAM) to ensure that the emissions reduction efforts of the EU are not offset by increasing emissions outside of its borders (carbon leakage); (iv) the adoption of binding annual GHG emissions targets in sectors not covered by EU-ETS (road and domestic maritime transport, buildings, agriculture, waste, and small industries); (v) a binding commitment to reduce emissions and increase removals in the land use and forestry sectors; (vi) the adoption of progressive EU-wide emissions reduction targets for cars and vans for 2030 and beyond; (vii) an increase in the share of renewables in the EU’s overall energy consumption to 42.5% by 2030, with an additional 2.5% indicative top up that would allow the overall share to reach 45%; (viii) a reduction in the final energy consumption at EU level by 11.7% in 2030 compared to projections made in 2020, etc. [1].
While the Fit for 55 package establishes a clear and comprehensive framework for reducing GHG emissions in the European Union by 55% in 2030 compared to 1990 levels and for ultimately achieving a climate-neutral economy in 2050, it provides flexibility for member states to shape the most appropriate policy mix to achieve the above-mentioned targets. In this context, the questions that decision makers have to answer are related to the following: (i) the level of ambition of the energy saving policies in the final demand sectors, which is strongly related to the new capacity of RES and other clean technologies as well storage systems that should be integrated into the energy supply system, (ii) the appropriate mix of RES technologies that should be installed in the power generation sector, (iii) the intensity of policies to reduce energy demand and improve energy efficiency per final demand sector (i.e., buildings, transport, industry, etc.), and (iv) the appropriate mix of policies and measures per final demand sector.
Decision makers in Greece are also facing similar questions. The final version of the National Energy and Climate Plan (NECP) adopts the electrification of end-uses mainly through technological changes (heat pumps, electric vehicles, etc.) and the coverage of energy needs through the large-scale development of RES [2]. On the other hand, the NECP is characterized by relatively low ambition regarding interventions aiming to reduce final energy demand through energy renovations of buildings, the promotion of soft mobility and public transport, the promotion of the circular economy in industry, etc. At the same time, the research community has developed scenarios that prioritize the promotion of energy sufficiency and efficiency, while the development of RES and other clean technologies is adopted on a smaller scale, with a view to covering the substantially lower energy needs at national/regional level resulting from the implementation of ambitious policies in the final demand sectors [3,4,5].
Regardless of the policy mix that is ultimately adopted, decarbonization and climate neutrality of the Greek economy require large-scale investments in clean technologies; an increase in the penetration of RES, green hydrogen, and synthetic fuels in the country’s energy system; increasing the strength of energy security through increased energy storage capacity; an improvement in energy efficiency in residential, tertiary, and industrial sectors; and the electrification of transportation as well. The level of investment required for the adoption and implementation of clean technologies directly affects the economy by increasing the demand for goods and services. While initially affecting specific sectors, this impact eventually spreads indirectly throughout the economy due to intersectoral linkages, creating significant multiplier effects on both production and employment. On the other hand, as many of these technologies are developed outside the Greek economy, their application increases the country’s trade deficit over time [6].
In this context, the purpose of this study is to estimate the impact of green transition policies on the Greek economy. By employing input–output analysis, the direct, indirect, and multiplier effects of the investments for the green transition on production, value added, employment, and imports are estimated for every five-year span in the period 2020–2050. The analysis is based on two different transition scenarios. The former is aligned with the Greek NECP and envisages the large-scale exploitation of RES and clean technologies promoting the electrification of final demand, while other energy-saving interventions are implemented at a rather conservative scale. The latter (CLEVER scenario) prioritizes energy sufficiency and efficiency interventions to ensure energy security and reduced energy demand, while the RES and other clean energy resources are utilized at a lower scale, aiming to cover the reduced demand. For both scenarios, three substitution sub-scenarios are developed regarding the volume of imports of the required technologies.
Recent macroeconomic research on the economic effects of green transition interventions, using input–output analysis (IOA), confirms that large-scale green investments can deliver measurable benefits for growth and employment (Table 1). Studies published from 2021 onwards for the EU [7,8], Croatia [9], Turkey [10,11,12], Saudi Arabia [13], China [14,15], Japan [16], and Korea [17] report increases in gross domestic product and labor demand when capital is channeled toward RES, energy efficiency upgrading, and related manufacturing. Previous research in Europe and the United States [6,18,19] confirms these patterns while highlighting the mitigating role of leakages from imports and the importance of the domestic supply chain. In addition, a recent cross-country analysis [20] shows that RES projects create approximately 15 jobs per USD 1 million, which is three times the employment effect of fossil fuel investments (approximately 5 jobs). Furthermore, building energy upgrades create about 22 jobs per USD 1 million, a 46% increase over RES investments, highlighting the labor-intensive nature of efficiency interventions.
Table 1.
Previous research on the economic effects of green transition interventions.
The present study offers a comparison at the economy-wide level of two alternative green transition paths for Greece: the NECP scenario, which allocates most of the spending to large-scale renewable energy technologies and end-use electrification while only conservatively implementing energy saving measures, and the CLEVER scenario, which reverses these priorities, focusing on energy sufficiency and efficiency, as well as scaling up renewables and other clean resources to meet reduced load. By contrasting the macroeconomic impact of these different strategies—one prioritizing electrification and the other, the energy demand reduction—our analysis provides a new comparative perspective on the debate over the optimal investment mixes for a just and efficient green transition, in relation to most previous studies, which focus on the macroeconomic effects of distinct technologies. In addition, this study analyses quantitatively the effects of different scenarios of import substitution in selected industrial sectors, thus highlighting in quantitative terms the importance of enhancing domestic industry during the green transition, an issue often ignored in relevant studies.
The reminder of this paper is organized as follows: Section 2 describes the analytical framework employed and the main assumptions adopted. Section 3 presents the results from the application of the model. Finally, in Section 4 the main findings of the study are discussed, and conclusions are drawn.
2. Materials and Methods
2.1. Methodological Framework
Investment impact assessment methodologies can be grouped into two main types. Top-down approaches trace cross-sectoral flows of goods and services to capture economy-wide effects, and bottom-up approaches use micro-level data of investment to estimate direct economic impacts. Top-down models offer advantages in capturing the broader systemic implications of the green transition. These models, such as IOA, consider the entire economy as an interconnected structure and are suitable for identifying how an investment in the context of the green transition diffuses through the different stages of the product value chain. This perspective is essential for understanding how a specific investment can boost activity in various domestic or international sectors, including manufacturing, construction, and service. In addition, top-down models can account for the induced effects whereby increased income due to energy savings generates additional consumer spending in various sectors, further boosting economic output and employment [21]. Unlike bottom-up studies that stop at the project boundary—estimating only direct impact—IOA captures economy-wide spillovers.
For the Greek green transition, with its diverse interventions and substantial financial commitments, a top-down evaluation is essential to capture the full macroeconomics and cross-sectoral impacts of the green transition. IOA is suitable for quantifying these dynamics because it systematically integrates inter-sectoral linkages and the interactions between intermediate and final demand, thereby illustrating how variations in investment influence aggregate output, value added, and employment across the entire economy [22]. An increasing number of studies worldwide focus on examining the broader macroeconomic impacts of measures promoting the transition to clean energy at international, national, and regional levels by applying IOA [20,23,24,25]. These studies quantify benefits such as job creation and GDP growth and identify possible challenges, including the necessary reallocation of resources away from traditional energy industries, the effect on foreign trade and the balance of payments, and unequal distribution of benefits. Recent studies examine how green investments affect jobs and value added, showing that investments in renewables, energy efficiency, and sustainable agriculture generate significant job gains, both directly within green sectors and indirectly across machinery and equipment suppliers [26,27,28]. A top-down approach such as IOA provides comprehensive accounting of all multiplier effects, facilitating policies that maximize economic and environmental returns.
The basic analytical tool of the IOA is the double-entrance input–output matrix (Table 2), which displays the intersectoral commodity flows in the economy and the sectoral structure of final demand. As analytically described in [29], in an economy divided into sectors of economic activity, the matrix represents the domestically produced intermediate demand, and the matrix represents the imported intermediate demand. The final demand, denoted by the vector , is also expressed as , where the vector represents the final demand satisfied by domestic production, and the vector indicates the final demand satisfied by imports. The total output of the economy is denoted by the vector . Then, the matrix , known as the matrix of domestic technical coefficients, is defined as , where is a diagonal matrix whose diagonal elements are the elements of vector .
Table 2.
Input–output matrix for an economy with sectors.
The total output of the economy is expressed by Equation (1):
where is the identity matrix. The matrix is the well-known Leontief inverse matrix.
Following a similar approach, the matrix of technological coefficients for imported inputs is defined as and the demand for imports , is used to satisfy the final demand expressed in Equation (2):
The vertical linkages (or output multipliers) of the economy are given by the row-vector , according to Equation (3). The element of captures the direct and indirect output generated in the economy because of a one-unit increase in final demand in sector ; in other words, it quantifies sector ’s dependence on all other sectors of the economy.
Similarly, the row vector gives the employment multipliers of the economy, and the row vector gives the value-added multipliers, according to Equations (4) and (5), respectively:
where is the vector of value-added intensity (value added per unit of sectoral output), and is the employment intensity vector (employment per sectoral output unit). The typical element of shows the change in total (direct plus indirect) employment in the economy caused by a change in final demand for sector , while the typical element of shows the change in total (direct plus indirect) value added in the economy caused by a change in final demand for sector .
Finally, the row vector of intermediate-input multipliers is defined by Equation (6):
The typical element of shows the change in the economy’s intermediate imports caused by a change in final demand for sector .
These multipliers are then applied to estimate the impacts of an investment vector on output (), employment (), value added (), and imports (), as follows:
Moreover, the induced effects of the investment sector, i.e., the additional economic activity generated by the resulting increase in household income, are estimated as follows: first, household wage income is estimated based on the change in employment induced by the examined investments. Next, the household saving rate is applied to the additional income to isolate the portion allocated to consumption. Finally, the sectoral distribution of domestic consumption is obtained by applying the input–output table’s shares of total consumption between domestic production and imports [30]. Following the analysis described above, this additional consumption generates induced impacts on output, value added, and employment. Accordingly, IOA provides the quantitative foundation for measuring the economy-wide transmission effects of green-transition investments in Greece. Moreover, it enables the identification of sectoral interdependencies and the estimation of direct, indirect, and induced impacts arising from these investments.
2.2. Construction of the Investment Vectors—Main Assumptions
2.2.1. The Main Transition Interventions
Following the priorities of the two alternative scenarios, the main measures and technologies for the country’s green transition are selected with a horizon of 2050 (Table 3). The first scenario is based on the assumptions and the projections of the NECP [2], which is the country’s official strategic document outlining the goals and the path for transitioning toward climate neutrality by 2050. The second scenario is based on the assumptions and forecasts of the CLEVER scenario, which was developed under the coordination and supervision of the négaWatt organization in France. A bottom-up approach was followed for its formulation, based on consultation between 25 different partners from 20 European countries, including Greece, research institutions, civil society organizations, etc., with the aim of synthesizing the different national objectives into a common European plan [31]. The two alternative scenarios differ in the way in which the intended transition will be achieved. The NECP assumes that the transition will be achieved without any considerable differentiation in energy consumption patterns. Given that the NECP predicts positive growth rates until 2050, energy consumption is expected to increase exponentially in the future because of the increasing economic activity. Therefore, in the NECP scenario, ever-increasing investments in RES technologies are required for energy supply to meet increasing future demand, as well as spending on clean technologies to mitigate the environmental effects of energy-intensive and polluting uses. In contrast, CLEVER proposes a different path for the green transition, with a key feature of reducing energy demand, as well as the demand for energy-intensive and polluting uses. Therefore, in the CLEVER scenario, investments in clean technologies for energy production are contained compared to those of the NECP scenario.
Table 3.
Main decarbonization technologies by intervention sector.
The intervention areas on which the transition measures focus are the following:
- Electricity generation;
- The production of synthetic fuels;
- The promotion of energy efficiency in buildings;
- An enhancement in energy efficiency in industry;
- Intervention in the transportation sector.
2.2.2. The Cost of Transition Measures and Technologies
The cost of each intervention related to the green transition is presented in Table 3 and in detail in Table A1 and Table A2 (Appendix A).
The costs of power generation and green hydrogen and synthetic fuel production interventions are broken down into capital expenditures (CapEx) and operational expenditures (OpEx). It is assumed that both CapEx and OpEx per unit of installed capacity for all RES technologies decline over time due to the economies of scale achieved during their implementation, as the technologies mature and experience with them increases [32,33,34].
Regarding the cost of the electricity transmission and distribution network, the respective cost estimates of the NECP [2] are adopted in this study, excluding the corresponding CapEx of energy storage stations (batteries and pumped storage), since they are calculated separately below.
The total cost for the energy upgrade of residential and non-residential buildings includes the costs of upgrading their external envelope, replacing traditional heating systems with heat pumps, and installing low-energy light bulbs and electric appliances. It is assumed that only 15% of the total average purchase or purchase and installation cost of air conditioners, lamps, and electrical appliances is attributable to the green transition objective (in essence, 15% of the total average purchase or purchase and installation cost attributable to the green transition corresponds to the additional (differential) cost of purchasing a low-energy-consumption electrical appliance instead of a conventional one).
The cost of reducing the carbon footprint of the vehicle fleet corresponds to the differential cost of replacing conventional internal combustion engine vehicles (petrol or diesel) with mainly electric vehicles or with hydrogen/synthetic fuel engine vehicles (the CLEVER scenario provides predictions for more vehicle types than the NECP. Specifically, in addition to the forecasts of future penetration of electric and gas passenger cars and light-duty trucks provided in the NECP, in the CLEVER scenario, the forecasts also involve the number of electric and gas synthetic fuel passenger cars, motorcycles, heavy trucks, and buses for each five-year horizon until 2050). As for the cost of electric charging stations, this is broken down into CapEx and OpΕx, the unitary prices of which (in EUR/kW and EUR/kW/y, respectively) were derived from the literature [35].
In the NECP [2], there is specific reference to the projects that are scheduled to be completed to achieve the goal of reducing greenhouse gas emissions in the railway transport sector. The cost of electrifying the railway network corresponds to the cost of these projects. Regarding the cost of interventions for the decarbonization of the transport sector (except the rail network), this also comes from the NECP [2] (the NECP [2] provides estimates for the average annual investment expenditures (in billion EUR2020), aiming to reduce GHG emissions in the transport sector for every five-year period until 2050).
Finally, the cost of interventions for the green transition includes the reduction in expenditures entailed by the shift from traditional forms of energy production (natural gas, solid fuels, and oil) to clean energy sources.
2.2.3. The Penetration of Transition Measures and Technologies
The penetration of the green transition interventions in the two scenarios is determined based on the predictions of energy requirements overall and by sector and use [2] (see Table 4, and more analytically Table A1 and Table A2, Appendix A).
Table 4.
Penetration, investment costs, and operation and maintenance (O&M) costs of the green interventions included in the scenarios examined.
The penetration of RES technologies for power generation and green hydrogen production is derived directly from the two scenarios under consideration. The NECP [2] projects that by 2050, about 90% of electricity will come from utility-scale photovoltaic parks and offshore wind farms. In the CLEVER scenario, the installed capacities of the RES technologies are significantly lower than in the NECP scenario because of the increased energy efficiency rates adopted in the final demand sectors.
In this context, a greater number of residential buildings are upgraded in the CLEVER scenario compared to the NECP scenario by 2050, focusing on deep renovations instead of shallow upgrades. Moreover, in the NECP [2], 91% of residences are expected to cover their thermal needs with heat pumps by 2050. The respective penetration of heat pumps in the case of tertiary sector buildings is expected to approach 90%. The CLEVER scenario has a goal that from 2030 onwards, the thermal needs of residences will be covered exclusively by heat pumps.
Regarding the penetration of electric plug-in hybrids and synthetic fuel vehicles, the CLEVER scenario extends NECP forecasts by including projections for electric and gas synthetic fuel vehicles—passenger cars, motorcycles, heavy trucks, and buses—for every five-year horizon through 2050.
As for the installed capacity of electric charging stations, it is calculated in both scenarios from the number of electric and hybrid vehicles, assuming that, on an annual basis, the installed output power of publicly accessible charging stations amounts to at least 1.3 kW for each pure electric vehicle in circulation (passenger or van) and 0.8 kW for each plug-in hybrid vehicle in circulation.
2.2.4. Sectoral Distribution Matrix
After analyzing the main measures, technologies, and works involved in the decarbonization of the Greek economy, the sectoral distribution matrix was constructed, which matches these technologies/works with the sectors in which they occur, to construct the corresponding investment vectors for future analysis horizons (Table A3, Appendix B). The elements of each row of the matrix sums to unity, while the ratio of the sum of the elements of each column (which corresponds to a sector of the Greek economy) to the total sum of the elements of the matrix corresponds to the percentage of total expenditures that occurs in this sector.
Most of the expenditures related to green transition technologies and measures correspond to the manufacturing sectors of electrical equipment manufacturing (D27), machinery and equipment manufacturing nec, and repair and installation of machinery and equipment (D31T33). Also, an equally large percentage of the expenditure corresponds to the construction sector and involves the cost of constructing the infrastructure of power plants, green hydrogen, synthetic fuels, and carbon dioxide production units, as well as the remaining civil engineering works required for the implementation and realization of the green transition measures in the final demand sectors. A significant percentage of the expenditure also corresponds to the sector of professional, scientific, and technical activities (D69T75).
2.2.5. Substitution Sub-Scenarios
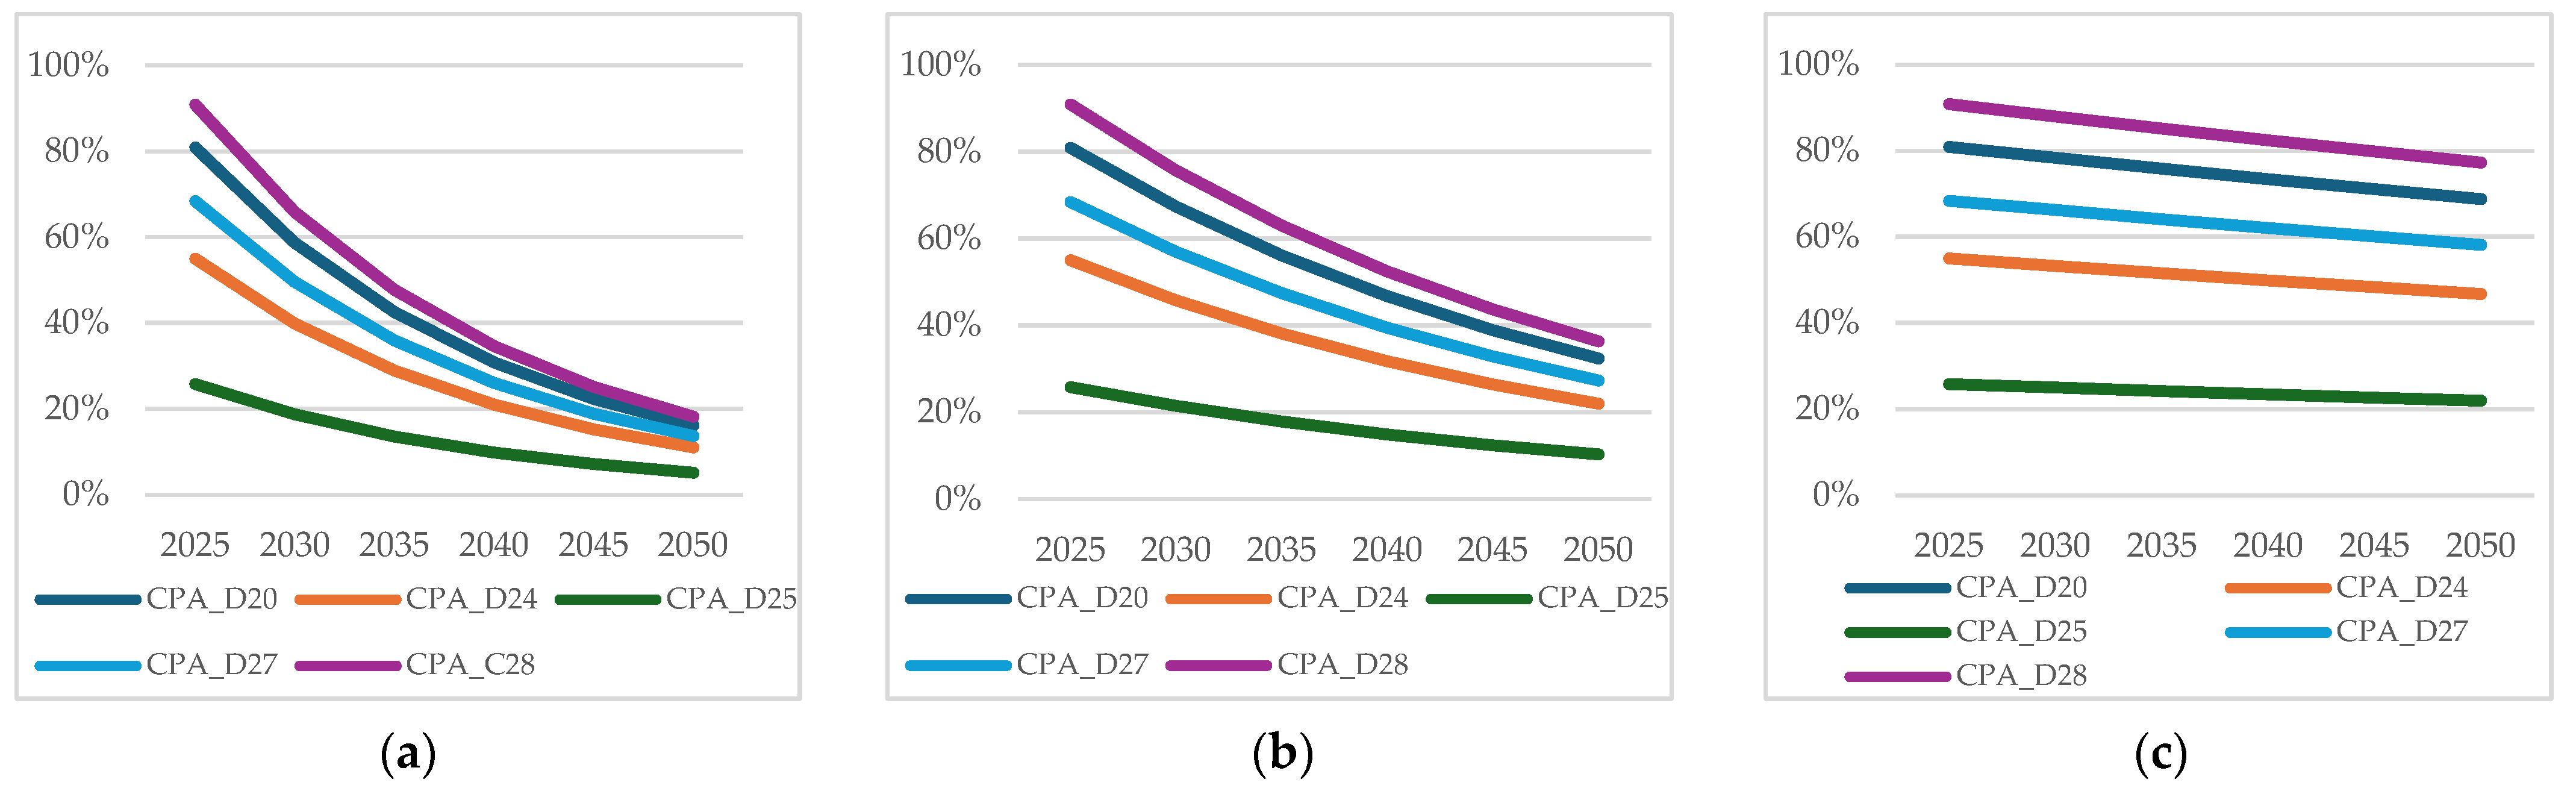
To investigate the extent to which the level of imports of the required technologies affects the economic effects of investments for the green transition, for each of the two main scenarios, three substitution sub-scenarios were developed (i.e., an optimistic, a moderate, and a pessimistic one), assuming different future import rates of the sectors of manufacture of chemicals and products (D20), manufacture of basic metals (D24), manufacture of fabricated metal products, except machinery and equipment (D25), manufacture of electrical equipment (D27), and manufacture of machinery and equipment nec (D28). In the optimistic sub-scenario, imports to satisfy final demand in each of these sectors are assumed to decrease by 80% throughout the period 2020–2050. The corresponding reductions in the moderate and pessimistic sub-scenarios are 60% and 15%, respectively. For the intermediate time horizons, import substitutions in each sector are modeled as an exponential decay, implying constant percentage reductions in imports every five years, equal to 27.52% in the optimistic sub-scenario, 16.74% in the moderate sub-scenario, and 3.20% in the pessimistic one (Figure 1).
Figure 1.
Future import rates for (a) optimistic sub-scenario, (b) moderate sub-scenario, and (c) pessimistic sub-scenario.
3. Results
To estimate the direct and indirect economic effects in both scenarios, and specifically the effects on production, value added, and employment, Equations (7)–(10) were applied, respectively. The effects were estimated for all three sub-scenarios (optimistic, moderate, and pessimistic) and for all five-year horizons of analysis. The input–output table for the Greek economy and the year 2018 were adopted.
3.1. Direct and Indirect Effects
The direct and indirect effects of the green transition interventions for both the NECP and the CLEVER scenarios, and specifically their effects on production, value added, intermediate, final and total imports, and employment are presented in absolute figures in Appendix C (Table A4). It is noted that final imports are derived directly from the investment vectors. However, their analysis is necessary, as the sum of final and intermediate imports constitutes the burden on the country’s trade balance, and in relation to the country’s corresponding macroeconomic data of the year 2023, as shown in Table 5. The effects on the net export of goods express the additional trade balance deficit that is expected to be created, taking into account both imports required to meet the final and intermediate demand, and the newly generated value added as well.
Table 5.
Direct and indirect effects in value added, imports, and employment compared to 2023—both scenarios.
As can be seen in Table A4 and Table 5, the investment spending for the green transition in the NECP scenario is expected to increase both GDP and employment in the Greek economy. The impact on GDP and employment increases over time, following the increase in investment spending. Similar results are obtained in the CLEVER scenario. In the latter, the impacts of investment spending on GDP and employment are moderate compared to the NECP scenario, as the CLEVER scenario places emphasis on increasing future energy efficiency and, consequently, investments in clean technologies for energy production and expenditures to cover ancillary uses and activities are limited compared to those of the NECP scenario. At the same time, however, in both scenarios, the imports required to meet the intermediate and final demand will eventually lead to a deterioration in the country’s trade balance, as expressed by the net exports as a percentage of GDP.
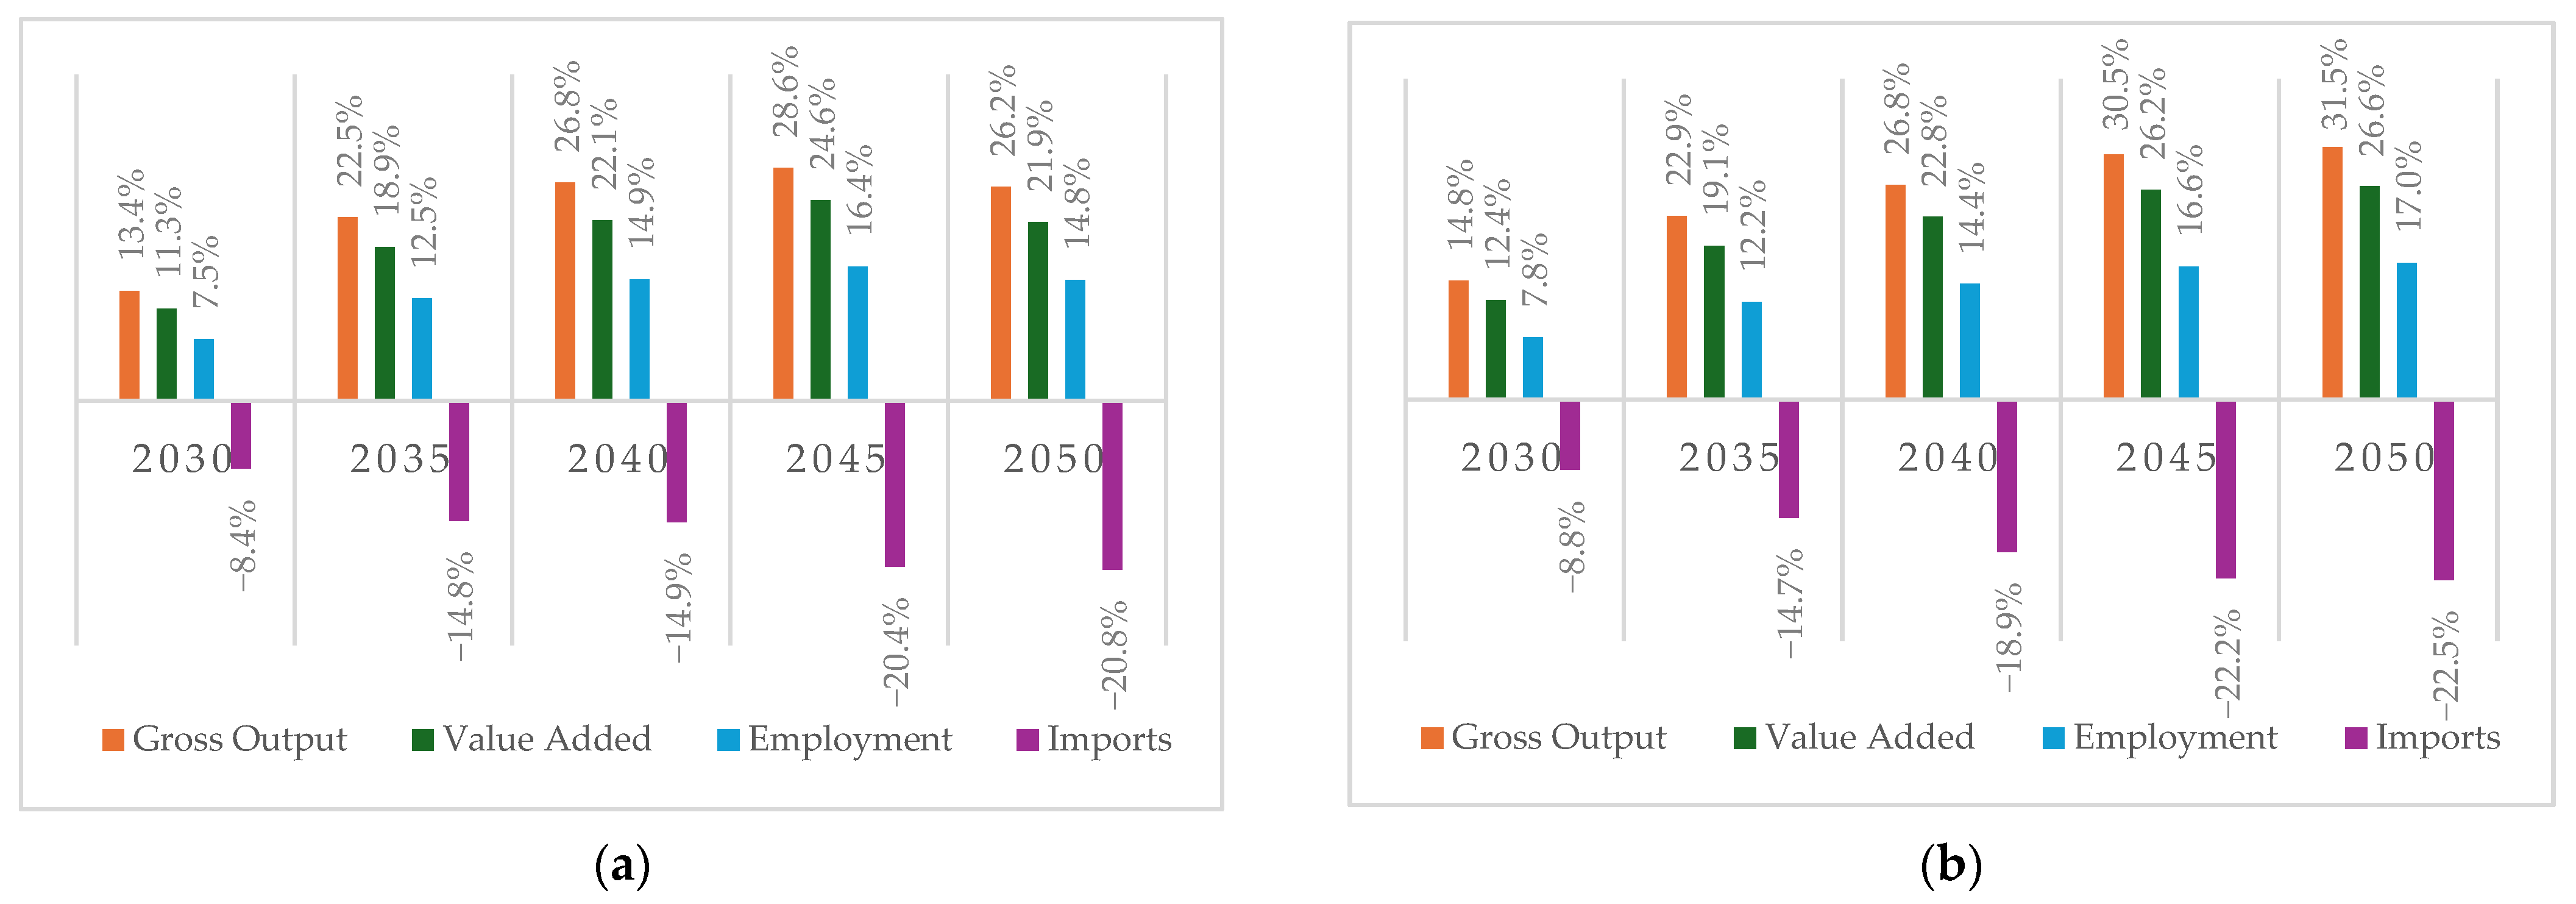
Moreover, according to the results, in both scenarios, there is a high differentiation between the optimistic and the pessimistic sub-scenarios in terms of their outcomes, indicating that policies aiming to support the sectors involved in the investments for the green transition can be particularly effective in strengthening the effects on the examined macroeconomic variables (Figure 2). Especially in the CLEVER scenario, this differentiation is increased, compared to the NECP scenario, as we approach the year 2050, a finding that demonstrates the necessity for the implementation of effective policies to support domestic industrial sectors involved in the green transition.
Figure 2.
Percentage difference between optimistic and pessimistic sub-scenario in (a) NECP scenario and (b) CLEVER scenario.
3.2. Sectoral Analysis
The sectoral distribution of the effects on output, value added, and employment do not vary significantly over time and per sub-scenario in both scenarios (see Table A7, Table A8, Table A9, Table A10, Table A11, Table A12, Table A13, Table A14, Table A15 and Table A16, Appendix D). For convenience, in this section, the results for the moderate sub-scenario for the year 2030 are discussed (Table 6).
Table 6.
Sectors with the highest direct and indirect effects for the moderate sub-scenario in 2030—both scenarios.
Starting with the sectoral total effects on output, in both scenarios, these occur almost in the same limited number of sectors, a reasonable finding, since in both scenarios, the initial investment vectors were constructed from the same sectoral distribution matrix. Specifically, in both scenarios, half or more of the total effects on output are concentrated in the sectors of construction (D41T43); manufacturing nec; repair and installation of machinery and equipment (D31T33); and professional, scientific, and technical activities (D69T75). A significant share of the total effects on output also occurs in the sectors of electrical equipment (D27), wholesale and retail trade (D45T47), fabricated metal products (D25), real estate activities (D68), and machinery and equipment nec (D28). Overall, the total effects that occur in the above sectors account for nearly 87% of the total effects on output.
Similarly, in both scenarios, almost 50% of the total effects on value added is concentrated in the sectors of construction (D41T43); manufacturing nec; repair and installation of machinery and equipment (D31T33); and professional, scientific, and technical activities (D69T75). Another 35% of the total value added generated occurs in the sectors of real estate activities (D68), wholesale and retail trade (D45T47), electrical equipment (D27), fabricated metal products (D25), and financial and insurance activities (D64T66).
Moreover, in both scenarios, nearly 70% of the total effects on employment are concentrated again in the sectors of construction (D41T43); manufacturing nec; repair and installation of machinery and equipment (D31T33); and professional, scientific, and technical activities (D69T75).
The indirect effects of the investments on output, value added, and employment reflect the additional output, value added, and employment generated in the economy because of the additional intermediate demand created by direct investments. In the NECP scenario and the moderate sub-scenario for the year 2030, the indirect effects on output, value added, and employment account for 37.2%, 41.6%, and 27.7% of the total generated output, value added, and employment, respectively. In the CLEVER scenario, the corresponding effects contribute 38.2%, 42.5%, and 27.8% to the generated output, value added, and employment, respectively.
An important aspect of an economy’s investment plans is their impact on the country’s trade deficit. Investments directed in the manufacturing sectors, as is the case with investments toward the green transition, may affect the country’s dependence on imported goods and services, as they are related to the use of specialized equipment and high-tech products, which, in the Greek economy, are mainly covered by imports [43]. Regarding the NECP scenario, over 30% of the leakages are directed to the sector of basic metals (D24) and are followed by percentages of less than 10% in several other sectors.
The implementation of the investment spending in the CLEVER scenario will also result in an increase in imports due to the increased demand for imported intermediate inputs. According to the results of the moderate sub-scenario for 2030, the ratio of imported intermediate inputs to planned domestic investment expenditure is 0.19, meaning that for every EUR 1 million of domestic investment expenditure, approximately EUR 0.19 million is directed to imports. More than 30% of the leakages occur again in the sector of basic metals (D24) and are followed by percentages of less than 10% by several other sectors.
Overall, these findings suggest that investments in the green transition, while boosting growth, imply a non-negligible and heterogeneous import cost, with most imports being capital or intermediate goods, and a significant share of final imports consists of electric vehicles.
3.3. Effects by Occupation
Rapid technological developments and socioeconomic changes are bringing about significant restructuring in the characteristics of employment, creating new needs in knowledge and skills. This process leads to radical changes in occupations and the required skills over time. These changes occur on both the supply and demand sides of the labor market, with intensity in sectors that integrate technological innovations more quickly. For this reason, it is important to identify occupations and skills with high potential in an economy, as well as their linkages to the sectors of economic activity in which they are most concentrated.
In both scenarios, the occupations with the greatest contribution to employment are those of building and related trades workers, excluding electricians (71); food processing, woodworking, garment, and other craft and related trades workers (75); science and engineering professionals (21); electrical and electronics trades workers (74); metal, machinery, and related trades workers (72); business and administration professionals (24); and general and keyboard clerks (41). Most occupations with high expected demand increase belong to the general category of craft and related trades workers, which accounts for 41% of the generated demand in the NECP scenario and 39.2% in the CLEVER scenario.
3.4. The Induced Effects of the Green Transition
To estimate the induced effects, the additional income generated in households due to both direct and indirect effects is determined for each examined scenario. This income is then distributed across the sectors of economic activity of the Greek economy based on the sectoral distribution of households’ domestic consumption. In this way, a new final demand vector emerges, which, due to the additional income, causes a disturbance in the economy and leads to an increase in output, value added, and income as well. It turns out that the induced effects are significant for all macroeconomic measures, as, if added to the direct and indirect effects, they would increase the total output by approximately 20%, increase the total value added by approximately 33%, and increase the total employment by approximately 15% (the induced effects for both scenarios in absolute figures are presented in Appendix C, Table A5).
Table 7 presents the induced value added and employment as a percentage of GDP and total employment, respectively, for the year 2023. It follows that the estimation of the induced effects is particularly important and should not be underestimated during the economic evaluation of the investments. Finally, it should be noted that the sectoral distribution of the induced effects differs from the sectoral effects of the green investments, as it is determined by the structure of domestic consumption. The sectors with the highest induced effects for all the examined macroeconomic measures are these of wholesale and retail trade (D45T47); real estate activities (68); accommodation and food service activities (D55T56); financial and insurance activities (D64T66); food products, beverages, and tobacco (D10T12); crop and animal production, hunting, and related service activities (A1T3); electricity, gas, steam, and air conditioning supply (D35); telecommunications (D61); human health and social work activities (D86T88); and education (D85).
Table 7.
Induced effects of the NECP and CLEVER scenarios examined, expressed as a percentage of GDP and employment of the Greek economy in 2023.
3.5. Additional Socioeconomic Impacts of Energy Savings in Households
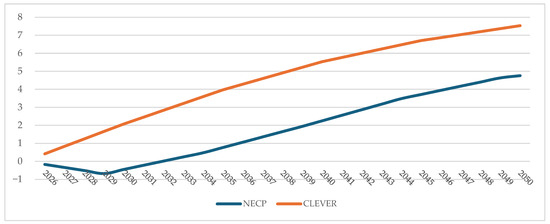
In both the NECP and CLEVEL scenarios, a series of interventions aims to reduce future energy demand and improve energy efficiency. After the amortization of the respective investments, mainly households but also private companies will have additional resources available that can be reinvested in the economy (Figure 3).
Figure 3.
Additional available resources of households due to the green transition (in billions of EUR).
In this section, the impact on the economy of the additional disposable income of households is examined after the amortization (for which a five-year period is assumed) of the investments for energy efficiency improvements. The cost savings are expected to result in an increase in consumption, which will have a multiplier effect on the economy by creating additional output, value added, and employment as well. The sectoral vector of new consumption is constructed based on household consumption data from the input–output table of 2018, which takes into account the distinction between domestically produced and imported consumer goods. Namely, household consumption includes 83% domestic products and 17% imported products (the sectors of electricity generation and petroleum are not included in the vector of new household consumption expenditures, as these are the sectors from which the savings arise). The results for both scenarios are presented in Appendix C, Table A6, for the time horizons under analysis with positive savings, while Table 8 presents the results in value added and employment as a percentage of GDP and total employment in Greece in 2023. The impacts of household energy savings on the economy are significant, and their importance increases over time with the increase in the penetration of clean energy technologies in production and consumption. The sectoral distribution of these effects follows the distribution of the induced effects; that is, the effects are concentrated on the sectors where household consumption is directed.
Table 8.
Effects of energy saving spending as a percentage of GDP and employment of the Greek economy in 2023.
3.6. Multipliers per Type of Intervention and by Sub-Scenario
Finally, the unit multipliers per type of intervention of the two scenarios under analysis are presented, which reflect the additional economic activity and employment created in the economy per EUR one million directed at a specific measure or technology (unit multipliers by investment category are a particularly useful tool for analyzing the performance and economic impact of various investments, as they offer a means of assessing the socioeconomic benefit of an investment and can ensure that decision makers allocate their investment resources more effectively). The unit multipliers of the individual interventions are equal in both scenarios, since they express investments that are made in a similar economic environment, while the unit multipliers of different interventions may differ significantly, as they depend on their degree of dependence on imports, the size and interconnections of the sectors to which the interventions are directed, and the level of technology and labor specialization of the sectors associated with them.
The unit multipliers are estimated for the period 2020–2040; therefore, they express the expected average impact of the corresponding investment expenditures. In the cases of interventions whose cost is broken down into CapEx and OpEx, the unit multipliers for the specific intervention are calculated for both types of costs as well.
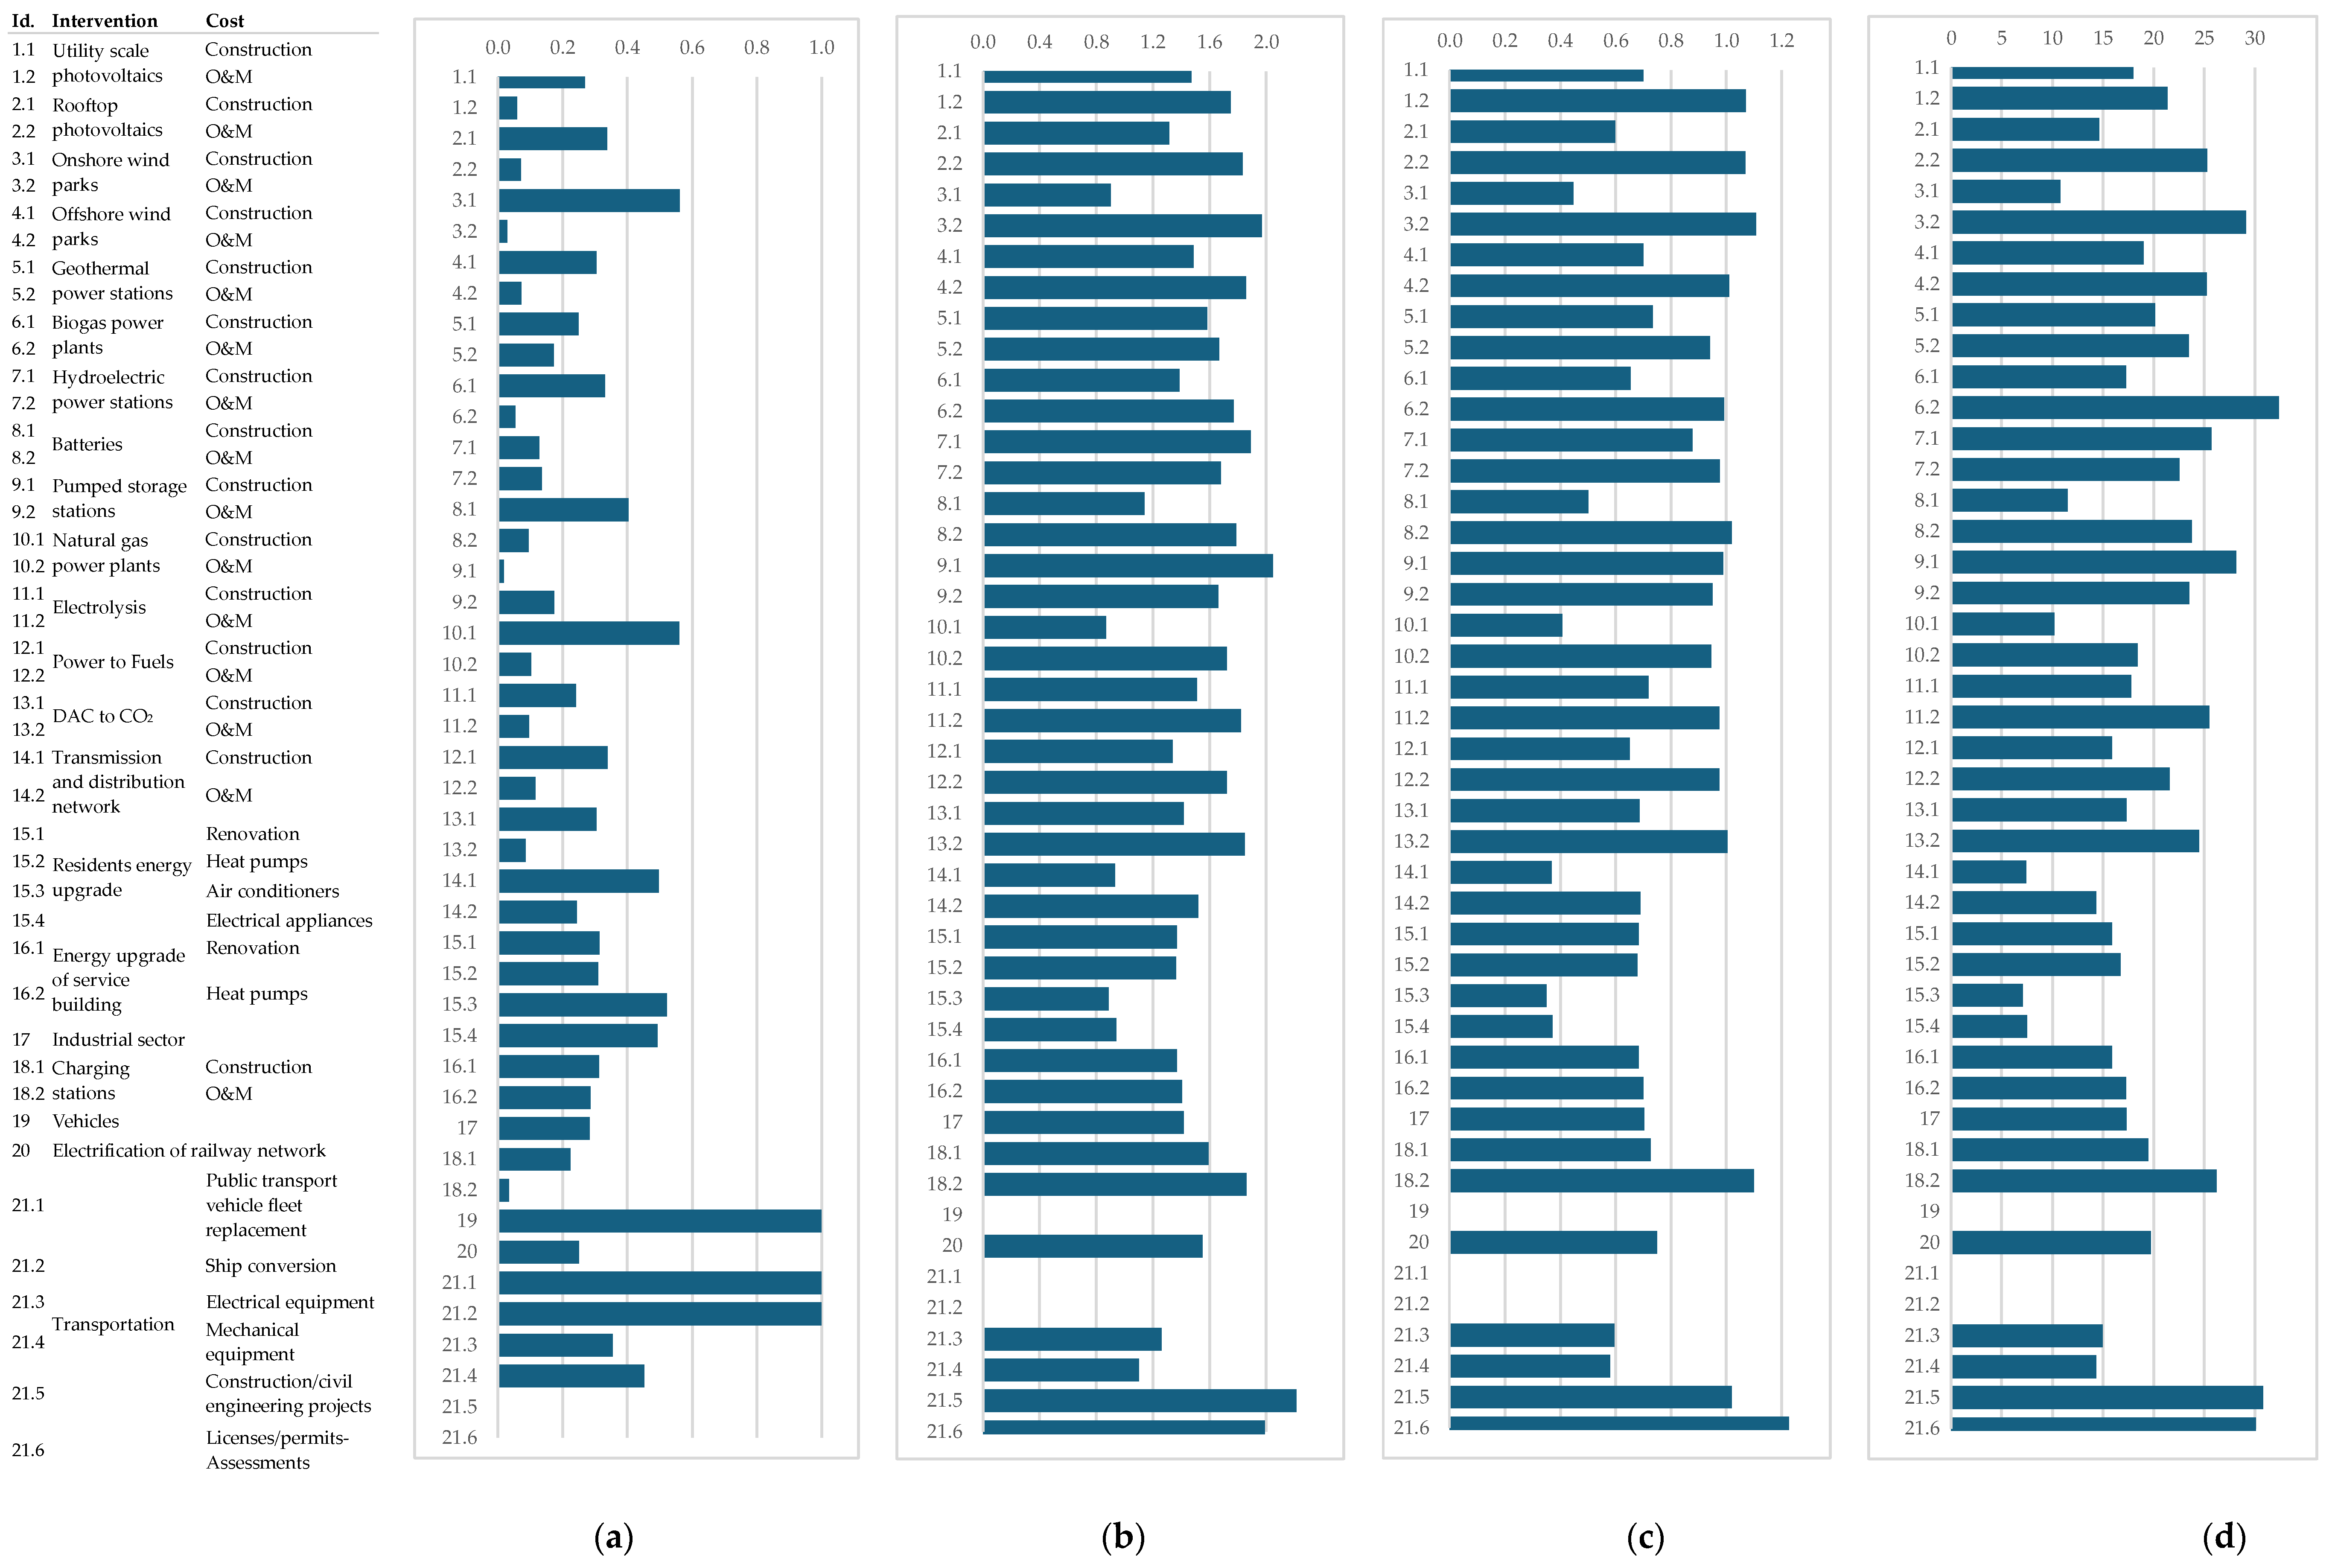
Figure 4a–d present the unit multipliers for all interventions for the moderate sub-scenario in the period 2020–2040. The figures show that the impacts of individual interventions differ significantly, while the scope of their impact on the examined macroeconomic characteristics varies.
Figure 4.
Unitary impacts by type of intervention and per year, as an average estimate for the period 2020–2040, regarding: (a) share of investment per EUR one million directed to imports, (b) production multiplier, per EUR one million, (c) value-added multiplier, per EUR one million, (d) employment multiplier of value in workers per EUR one million.
As can be seen in Figure 4a, the dependence of individual interventions on imports, i.e., the share of imports per unit of investment, ranges from 0% (in construction, permits/studies) to 100% (in vehicle replacement), with an average value of 28.6%. That is, for every EUR 1 million of expenditure, for some of the interventions included in the scenarios under analysis, an average of EUR 286,000 will be channeled into exports. In fact, in all cases, the operation of the interventions creates smaller demand for imports than their construction, a fact that demonstrates the high dependence of the Greek economy on imported industrial products.
Figure 4b shows that the production multipliers, i.e., the value of gross product created per unit of investment, range from 0 (for the replacement of public transport fleet vehicles, which includes imports only) to 2.786 (for the renovation of homes), with an average value of 1.521, meaning that for every EUR 1 million of expenditure, a gross product of EUR 1521 million is produced per year. In the case of production multipliers, the operation of interventions creates greater multiplier effects on production than construction, because of the high degree of dependence of construction on imports.
In Figure 4c, the value-added multipliers, i.e., the value added created per unit of investment, are presented, which range from 0 (for the replacement of a public transport fleet that includes only imports) to 1.525 (for the renovation of homes), with an average value of 0.788. Value-added multipliers are particularly critical, as they capture the impact of investment on GDP. The results show that for every EUR 1 million of expenditure, a gross product of EUR 788,000 per year is generated on average for some of the interventions. In the case of value-added multipliers, it appears that the operation of the interventions creates higher multiplier effects on value added than construction, because of the latter’s high degree of dependence on imports.
As shown in Figure 4d, the employment multipliers, i.e., the new employment created per EUR 1 million of investment in the action, range from 0 people (in the replacement of vehicles, which includes only imports) to 30.8 people (for the operation of biogas plants), with an average value of 19 people. This means that per EUR one million of expenditure, 19 new jobs are created annually. In the case of employment multipliers, it appears that the operation of the interventions creates higher multiplier effects on employment than construction.
Finally, Table 9 reports the value-added and employment multipliers for each sub-scenario. The value-added multiplier indicates the total EUR of gross value added generated per EUR 1 of investment, while the employment multiplier shows the total jobs supported per EUR 1 million of investment, accounting for direct, indirect, induced, and energy-saving effects. Concerning value-added multipliers, the CLEVER scenario clearly outranks the NECP scenario across all time horizons. Specifically, in 2025, the overall multiplier under CLEVER is EUR 1.213 of value added per EUR 1 of investment, compared to 0.956 under NECP; by 2050, it rises to 1.572 versus 1.209, respectively. A similar pattern holds for employment multipliers. Whereas NECP achieves roughly 25 jobs per EUR 1 million of investment, CLEVER exceeds 30 jobs per EUR 1 million. This gap reflects higher induced-contribution multipliers and the impact of energy savings under CLEVER. Thus, CLEVER achieves higher value added per euro invested while significantly enhancing job creation relative to NECP.
Table 9.
Value-added and employment multipliers (impact per EUR1 million of investment) for the scenarios and sub-scenarios examined.
4. Conclusions and Discussion
In recent years, it has been widely recognized that the promotion of clean technologies (i.e., RES, energy-saving technologies, etc.) contributes not only to addressing climate change but also to achieving other broader sustainable development goals. The purpose of this study is to estimate the effects of green transition interventions on the Greek economy. By employing input–output analysis, the direct, indirect, and multiplier effects of the investments for the green transition on output, value added, employment, and imports are estimated for every five-year span until 2050.
The analysis is based on two different transition scenarios: in the former, aligned with the National Energy and Climate Plan (NECP), the transition is pursued through increased investments in clean technologies for promoting the electrification of the final demand and the large-scale development of RES, primarily in power generation, but also in the final demand sectors. The latter (scenario CLEVER) proposes a different approach for the green transition, prioritizing the increased penetration of energy sufficiency and efficiency options to ensure energy security and reduce energy demand, which is then covered by RES. In general, the NECP scenario causes greater direct and indirect impacts on the economy, increasing GDP by 2.4–6.7% in the various horizons of the analysis compared to 2023. Correspondingly, employment increases by 3.5–9.4% during the evolution of investments. The direct and indirect effects of the CLEVER scenario are also significant, but smaller than the NECP, given that the investments of CLEVER are also smaller. Specifically, they increase GDP by 1.8–4.8% and employment by 2.8–6.4% compared to 2023 levels in the various time horizons under analysis. In terms of their total induced effects, the CLEVER scenario generates greater impacts on the economy, as it places greater emphasis on energy saving, and therefore, households, after the amortization of the implemented investments, have additional disposable income for consumption. Specifically, the induced impact of the NECP scenario increases GDP and employment compared to 2023 levels by 0.8–3.6% and 0.4–2.3%, respectively, while the corresponding figures for the CLEVER scenario are 0.8–4.5% and 0.4–2.8%. These results demonstrate that the CLEVER scenario generates greater value added per EUR invested and significantly increases employment outcomes relative to NECP, thereby emphasizing the importance of induced multipliers and energy-saving measures in optimizing the socioeconomic impact of green-transition investments. In other words, even though the NECP scenario requires greater investments compared to CLEVER, the total macroeconomic impacts of the two scenarios in question do not differ significantly due to the structure of the Greek economy (i.e., the increased role of services and construction activities and relatively limited contribution of the industrial sectors) and the CLEVER orientation to prioritize actions that can be implemented to a greater extent by domestic companies.
For each of the scenarios of analysis, three alternative sub-scenarios are examined that assume different degrees of import substitution in selected industrial sectors. The results of the analysis show significant differentiations among the scenarios/sub-scenarios, which indicate that policies aiming to support domestic industrial sectors involved in investments for the green transition are important and may contribute significantly to maximizing the social benefits of green transition, thus facilitating the acceptance of the associated investments by civil society.
Mainly, the NECP scenario, and to a lesser extent the CLEVER scenario, requires the commitment of significant funds for their implementation. These investments lead to a deterioration of the country’s trade balance, as expressed by net exports as a percentage of GDP. That is, both the final and intermediate imports required lead to a significant deterioration in the trade balance in both scenarios, but primarily in the NECP one.
Of paramount importance are the results of the analysis made individually for each intervention considered in the two scenarios. Specifically, among the main RES technologies included in the two scenarios under consideration, the installation of photovoltaics has a greater impact on the economy than wind energy, as a larger part of the required investments is made by domestic companies. The economic footprint of residential photovoltaics is even greater as their operation contributes to energy savings in households and therefore to the creation of additional income for consumption. Other RES technologies, as well as new and synthetic fuels, are characterized by relatively greater macroeconomic impacts per monetary unit of investment. However, their overall footprint in the economy is relatively small due to their limited penetration.
The interventions aimed at the energy upgrade of residential buildings (i.e., insulation of the building shell and installation of heat pumps) create relatively greater impacts on the economy than the main RES technologies. This is partly attributed to the resulting energy savings and to the additional income available to households for consumption after the amortization of these interventions. It is also worth mentioning that these impacts are underestimated in the context of our analysis, as they extend over the entire life of the interventions, which, in some cases, exceeds the time horizon of the analysis. The macroeconomic implications of the interventions examined for the non-residential buildings have a significant but smaller economic footprint compared to the corresponding measures in residential buildings, as the secondary impacts on the economy from increased energy savings are not taken into account.
Regarding interventions in the transport sector, the promotion of electromobility has a very small footprint on the economy per unit of investment for countries like Greece, as a significant portion of the invested capital is directed abroad. On the contrary, the contribution of measures aimed at developing and strengthening transport infrastructure, such as the electrification of railways, the strengthening of public transport systems, the installation of electric chargers, etc., is particularly important. From this perspective, it is of paramount importance that future revisions of the national energy and climate plan place greater emphasis on promoting public transport and railways, increasing their share in the overall transport work.
Finally, in industry, the economic impact of the interventions under consideration is relatively modest and depends on the type of interventions required in each industrial sector.
These results are consistent with the findings of other studies (see, for example, the review paper [20]) that shows that the macroeconomic impacts of interventions aiming to improve energy efficiency are relatively greater than those aimed at promoting cleaner technologies in the energy production sector. However, this may not be the case in economies with a strong industrial base (see, for example, ref. [19] for an analysis in the US).
European climate policies set quite strict and clear targets for reducing GHG emissions and building a carbon-neutral economy by 2050. However, member states have some flexibility in choosing the mix of policies and measures they will adopt in order to achieve these targets For economies like Greece that rely to a significant extent on imports of technological equipment, the green transition should prioritize actions to improve energy sufficiency and efficiency, limiting to some extent the required investments for new RES units and energy storage installations. Upgrading the existing building stock through energy renovation programs contributes not only to significant reductions in energy-related GHG emissions but also to economic growth through increased GDP, creation of new jobs, etc. In the transport sector, electromobility needs to be combined with other measures promoting soft mobility, railways, and public transport, with the aim of covering a significant portion of the transport work that is now satisfied by private vehicles.
Of course, the results are subject to the limitations of the applied methodology. IOA is characterized by certain assumptions that limit its results. In particular, it assumes homogeneity (firms in each sector have identical production technologies, neglecting technological differentiation within sectors), linearity (implying stable technological coefficients, according to the Leontief production function, and ignoring the presence of economies of scale or possible input substitution), and stable prices and wages (therefore not capturing market adjustments caused by price adjustments, constraints on factor supply or wage elasticities, and cost dynamics) [22].
A significant innovation of this study is its treatment of the green transition scenarios for the Greek economy. The large-scale increase in demand for imports is assumed to lead to the development of specific domestic sectors that will substitute for part of these imports, with the extent of substitution detailed in the three sub-scenarios developed. Accordingly, the improvement in terms of trade for the country has been considered, at least in sectors with high participation in the planned investments. However, for all other sectors, the import propensities are considered exogenous, and in the context of the IOA, the applied methodology cannot endogenously capture the exchange rate fluctuations or other changes in the terms of trade.
Consequently, while the results of the IOA provide important insights into the overall and sectoral impacts of the green transition, they may overlook dynamic impacts, such as structural changes, technological developments, price fluctuations, and external trade effects, which are particularly important for large-scale or long-term investments, as shown in this research. Dynamic or computational general equilibrium models could be utilized in future studies to better represent these complexities and produce more reliable findings.
Author Contributions
Conceptualization, S.M., Y.S. and E.G.; methodology, T.M., M.M. and S.M.; software, M.M.; validation, S.M. and Y.S.; formal analysis, M.M. and T.M.; investigation, T.M. and M.M.; resources, T.M., M.M. and S.M.; data curation, Μ.Μ.; writing—original draft preparation, T.M., M.M. and S.M.; writing—review and editing, S.M., Y.S. and M.M.; visualization, T.M. and M.M.; supervision, S.M.; project administration, S.M.; funding acquisition, S.M., Y.S. and E.G. All authors have read and agreed to the published version of the manuscript.
Funding
Part of this research was co-funded by the Greek Ministry of Development under the project JustReDI (Action TAEDR-0537352).
Data Availability Statement
Data are contained within the article. All data included in the National Input–Output Table for the year 2018 are publicly available on the OECD database (https://www.oecd.org/en/data/datasets/input-output-tables.html, accessed on 24 June 2025). Data on employment come from the Labour Force Survey, which is publicly available through the Hellenic Statistical Authority (https://www.statistics.gr/el/statistics/-/publication/SJO03/-, accessed on 24 June 2025).
Conflicts of Interest
The authors declare no conflicts of interest. The funders had no role in the design of the study; in the collection, analyses, or interpretation of data; in the writing of the manuscript; or in the decision to publish the results.
Abbreviations
The following abbreviations are used in this manuscript:
| AFIR | Alternative Fuels Infrastructure Regulation. |
| CapEx | Capital Expenditure. |
| CBAM | Carbon Border Adjustment Mechanism. |
| CLEVER | A Decarbonization Pathway for Europe. |
| DAC | Direct air capture. |
| EU | European Union. |
| EU-ETS | Emissions Trading System. |
| GDP | Gross Domestic Product. |
| GHG | Greenhouse Gas. |
| IOA | Input–Output Analysis. |
| NECP | National Environment and Climate Plan. |
| O&M | Operation and Maintenance. |
| OpEx | Operational Expenditures. |
| REPowerEU | EU Plan Aimed at Reducing Europe’s Dependence on Fossil Fuels and Accelerating the Transition to Green Energy. |
| PtF | Power to Fuels. |
| RES | Renewable Energy Sources. |
| RNFBOs | Renewable Fuels of Non-Biological Origin. |
| SCF | Social Climate Fund. |
Appendix A. Penetrations and Costs of the Green Transition Interventions
Table A1.
Penetration and total investment in green transition interventions per five-year period—NECP scenario.
Table A2.
Penetration and total investment in green transition interventions per five-year period—CLEVER scenario.
Appendix B. Sectoral Distribution Matrix
Table A3.
Sectoral distribution matrix (%).
Appendix C. Total Effects of the Scenarios Examined
Table A4.
Direct and indirect effects on output, value added, imports, and employment—both scenarios.
Table A5.
Induced effects of the scenarios examined.
Table A6.
Effects on the economy from the increase in household consumption spending attributed to the reduction in household energy costs.
Appendix D. Sectoral Distribution of Total Effects
Table A7.
Total effects on output (in millions of EUR per year over every five-year horizon)—NECP scenario.
Table A8.
Total effects on value added (in millions of EUR per year over every five-year horizon)—NECP scenario.
Table A9.
Total effects on employment (in employees per year over every five-year horizon)—NECP scenario.
Table A10.
Total effects on intermediate imports (in millions of EUR per year over every five-year horizon)—NECP scenario.
Table A11.
Total effects on employment by occupation (employees per year over every five-year horizon)—NECP scenario.
Table A12.
Total effects on output (in millions of EUR per year over every five-year horizon)—CLEVER scenario.
Table A13.
Total effects on value added (in millions of EUR per year over every five-year horizon)—CLEVER scenario.
Table A14.
Total effects on employment (in decades per year over every five-year horizon)—CLEVER scenario.
Table A15.
Total effects on intermediate imports (in millions of EUR per year over every five-year horizon)—CLEVER scenario.
Table A16.
Total effects on employment by occupation (employees per year over every five-year horizon)—CLEVER scenario.
References
- European Commission. “Fit for 55”: Delivering the EU’s 2030 Climate Target on the Way to Climate Neutrality. COM(2021) 550 Final. European Union. 2021. Available online: https://eur-lex.europa.eu/legal-content/EN/TXT/?uri=CELEX:52021DC0550 (accessed on 24 June 2025).
- Ministry of Enviroment and Energy. National Energy and Climate Plan; Draft revised version; Ministry of Environment and Energy: Athens, Greece, 2023.
- Creutzig, F.; Roy, J.; Lamb, W.F.; Azevedo, I.M.; De Bruin, W.B.; Dalkmann, H.; Edelenbosch, O.Y.; Geels, F.W.; Grubler, A.; Hepburn, C.; et al. Towards demand-side solutions for mitigating climate change. Nat. Clim. Change 2018, 8, 260–263. [Google Scholar] [CrossRef] [Scilit]
- Zell-Ziegler, C.; Thema, J.; Best, B.; Wiese, F.; Lage, J.; Schmidt, A.; Toulouse, E.; Stagl, S. Enough? The role of sufficiency in European energy and climate plans. Energy Policy 2021, 157, 112483. [Google Scholar] [CrossRef] [Scilit]
- Wiese, F.; Thema, J.; Cordroch, L. Strategies for climate neutrality. Lessons from a meta-analysis of German energy scenarios. Renew. Sustain. Energy Transit. 2022, 2, 100015. [Google Scholar] [CrossRef] [Scilit]
- Markaki, M.; Belegri-Roboli, A.; Michaelides, P.; Mirasgedis, S.; Lalas, D.P. The impact of clean energy investments on the Greek economy: An input–output analysis (2010–2020). Energy Policy 2013, 57, 263–275. [Google Scholar] [CrossRef] [Scilit]
- Guadagno, F.; Reiter, O.; Stehrer, R. The Impact of Green Technologies on GDP and Employment in the EU; wiiw Policy Notes 80; The Vienna Institute for International Economic Studies, wiiw: Vienna, Austria, 2024. [Google Scholar]
- Černý, M.; Bruckner, M.; Weinzettel, J.; Wiebe, K.; Kimmich, C.; Kerschner, C.; Hubacek, K. Employment effects of the renewable energy transition in the electricity sector: An input-output approach. ETUI Res. Pap.-Work. Pap. 2021, 2022, 14. [Google Scholar] [CrossRef] [Scilit]
- Gelo, T.; Šimurina, N.; Šimurina, J. The economic impact of investment in renewables in Croatia by 2030. Energies 2021, 14, 8215. [Google Scholar] [CrossRef] [Scilit]
- Gözkün, K.A.; Orhangazi, Ö. Green transition for Turkey: Growth, employment, and trade deficit effects. Energy Policy 2025, 202, 114577. [Google Scholar] [CrossRef] [Scilit]
- Güler, İ. The Transition of CO2 Emission and Employment Multipliers from Brown to Green Under a Renewable Energy-Based Economic Growth Scenario in Türkiye: 2053 Vision. Int. J. Smart Grid 2025, 9, 43–58. [Google Scholar] [CrossRef] [Scilit]
- Acar, S.; Kat, B.; Rogner, M.; Saygin, D.; Taranto, Y.; Yeldan, A.E. Transforming Türkiye’s power system: An assessment of economic, social, and external impacts of an energy transition by 2030. Clean. Energy Syst. 2023, 4, 100064. [Google Scholar] [CrossRef] [Scilit]
- Alyousif, M.; Belaid, F.; Almubarak, N.; Almulhim, T. Mapping Saudi Arabia’s low emissions transition path by 2060: An input-output analysis. Technol. Forecast. Soc. Change 2025, 211, 123920. [Google Scholar] [CrossRef] [Scilit]
- Ji, J.; Cao, L.; Bi, Y.; Zeng, Y.; Wang, D. Low-Carbon Transformation in Megacities: Benefits for Climate Change Mitigation and Socioeconomic Development—A Case Study of Shenzhen, China. Sustainability 2024, 16, 6062. [Google Scholar] [CrossRef] [Scilit]
- Luo, P.; Tang, X.; Dou, X.; Liu, S.; Ren, K.; Jiang, Y.; Yang, Z.; Ding, Y.; Li, M. Uncovering the socioeconomic impacts of China’s power system decarbonization. Environ. Impact Assess. Rev. 2022, 99, 107015. [Google Scholar] [CrossRef] [Scilit]
- Mulumba, A.N.; Hooman, F. Economic Contributions and Green Job Implications of Japan’s Energy Transition: An Integrated Assessment of Decarbonization Scenarios in Kyushu Region. In Proceedings of the International Exchange and Innovation Conference on Engineering & Sciences (IEICES), Fukuoka, Japan, 17 October 2024; Volume 10, pp. 1246–1254. [Google Scholar] [CrossRef] [Scilit]
- Kim, J.H.; Yoo, S.H. Comparison of the economic effects of nuclear power and renewable energy deployment in South Korea. Renew. Sustain. Energy Rev. 2021, 135, 110236. [Google Scholar] [CrossRef] [Scilit]
- Cai, M.; Cusumano, N.; Lorenzoni, A.; Pontoni, F. A comprehensive ex-post assessment of RES deployment in Italy: Jobs, value added and import leakages. Energy Policy 2017, 110, 234–245. [Google Scholar] [CrossRef] [Scilit]
- Garrett-Peltier, H. Green versus brown: Comparing the employment impacts of energy efficiency, renewable energy, and fossil fuels using an input-output model. Econ. Model. 2017, 61, 439–447. [Google Scholar] [CrossRef] [Scilit]
- Hanna, R.; Heptonstall, P.; Gross, R. Job creation in a low carbon transition to renewables and energy efficiency: A review of international evidence. Sustain. Sci. 2024, 19, 125–150. [Google Scholar] [CrossRef] [Scilit]
- Henriques, C.O.; Sousa, S. A review on economic input-output analysis in the environmental assessment of electricity generation. Energies 2023, 16, 2930. [Google Scholar] [CrossRef] [Scilit]
- Miller, R.E.; Blair, P.D. Input-Output Analysis: Foundations and Extensions; Cambridge University Press: Cambridge, UK, 2009. [Google Scholar]
- Cameron, L.; Van Der Zwaan, B. Employment factors for wind and solar energy technologies: A literature review. Renew. Sustain. Energy Rev. 2015, 45, 160–172. [Google Scholar] [CrossRef] [Scilit]
- Dvořák, P.; Martinát, S.; Van der Horst, D.; Frantál, B.; Turečková, K. Renewable energy investment and job creation; a cross-sectoral assessment for the Czech Republic with reference to EU benchmarks. Renew. Sustain. Energy Rev. 2017, 69, 360–368. [Google Scholar] [CrossRef] [Scilit]
- Mardones, C. Economic, environmental, and social assessment of the replacement of coal-fired thermoelectric plants for solar and wind energy in Chile. J. Clean. Prod. 2023, 411, 137343. [Google Scholar] [CrossRef] [Scilit]
- Bradley, P.; Whittard, D.; Green, L.; Brooks, I.; Hanna, R. Empirical research of green jobs: A review and reflection with practitioners. Sustain. Futures 2025, 9, 100527. [Google Scholar] [CrossRef] [Scilit]
- Mirasgedis, S.; Tourkolias, C.; Pavlakis, E.; Diakoulaki, D. A methodological framework for assessing the employment effects associated with energy efficiency interventions in buildings. Energy Build. 2014, 82, 275–286. [Google Scholar] [CrossRef] [Scilit]
- Perrier, Q.; Quirion, P. How shifting investment towards low-carbon sectors impacts employment: Three determinants under scrutiny. Energy Econ. 2018, 75, 464–483. [Google Scholar] [CrossRef] [Scilit]
- Markaki, M.; Papadakis, S.; Putnová, A.A. Modern Industrial Policy for the Czech Republic: Optimizing the Structure of Production. Mathematics 2021, 9, 3095. [Google Scholar] [CrossRef] [Scilit]
- Jenniches, S. Assessing the regional economic impacts of renewable energy sources–A literature review. Renew. Sustain. Energy Rev. 2018, 93, 35–51. [Google Scholar] [CrossRef] [Scilit]
- Nega Watt Association. Available online: https://negawatt.org/clever-energy-scenario (accessed on 24 June 2025).
- IRENA. Renewable Power Generation Costs in 2021; International Renewable Energy Agency: Abu Dhabi, United Arab Emirates, 2022; ISBN 978-92-9260-452-3. [Google Scholar]
- NRER. Electricity ATB Technologies and Data Overview. 2023. Available online: https://atb.nrel.gov/electricity/2023/technologies (accessed on 24 June 2025).
- Thunder Said Energy. Available online: https://thundersaidenergy.com (accessed on 24 June 2025).
- PWC Electric Vehicles and the Charging Infrastructure: A New Mindset? Available online: https://www.pwc.com/us/en/industrial-products/publications/assets/pwc-electric-vehicles-charging-infrastructure-mindset.pdf (accessed on 24 June 2025).
- Stefanakos, I.P. Possibilities for constructing pumped storage projects in areas of Mainland Greece. In Proceedings of the 17th National Conference of Institute of Energy for South-East Europe: Energy and Development 2012, Athens, Greece, 30–31 October 2012. (In Greek) [Google Scholar]
- Hydrogen Europe. Clean Hydrogen Monitor 2022. Available online: https://hydrogeneurope.eu/clean-hydrogen-monitor-2022/ (accessed on 24 June 2025).
- Sulewski, P.; Ignaciuk, W.; Szymańska, M.; Wąs, A. Development of the Biomethane Market in Europe. Energies 2023, 16, 2001. [Google Scholar] [CrossRef] [Scilit]
- Fasihi, M.; Bogdanov, D.; Breyer, C. Techno-Economic Assessment of Power-to-Liquids (PtL) Fuels Production and Global Trading Based on Hybrid PV-Wind Power Plants. In Proceedings of the 10th International Renewable Energy Storage Conference, Düsseldorf, Germany, 15–17 March 2016. [Google Scholar]
- International Energy Agency. The Future of Hydrogen: Seizing Today’s Opportunities. Report Prepared by the IEA for the G20, Japan. 2019. Available online: https://iea.blob.core.windows.net/assets/9e3a3493-b9a6-4b7d-b499-7ca48e357561/The_Future_of_Hydrogen.pdf (accessed on 24 June 2025).
- Slowik, P.; Isenstadt, A.; Pierce, L.; Searle, S. Assessment of Light-Duty Electric Vehicle Costs and Consumer Benefits in the United States in the 2022–2035 Time Frame. ICCT White Paper. 2022. Available online: https://theicct.org/wp-content/uploads/2022/10/ev-cost-benefits-2035-oct22.pdf (accessed on 24 June 2025).
- ERGOSE. Available online: https://www.ergose.gr/projects/ (accessed on 24 June 2025).
- Markaki, M.; Economakis, G. International Structural Competitiveness and the Hierarchy in the World Economy. World Rev. Political Econ. 2021, 12, 195–219. [Google Scholar] [CrossRef] [Scilit]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2025 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).