Article

Multidimensional Risk-Based Real Options Valuation for Low-Carbon Cogeneration Pathways

Division of Sustainable Development, College of Science and Engineering, Hamad Bin Khalifa University, Qatar Foundation, Doha P.O. Box 5825, Qatar
*
Author to whom correspondence should be addressed.
Energies 2023, 16(3), 1250; https://doi.org/10.3390/en16031250
Submission received: 6 November 2022 / Revised: 19 January 2023 / Accepted: 20 January 2023 / Published: 24 January 2023
(This article belongs to the Special Issue Renewable Based Energy Distributed Generation)

Abstract

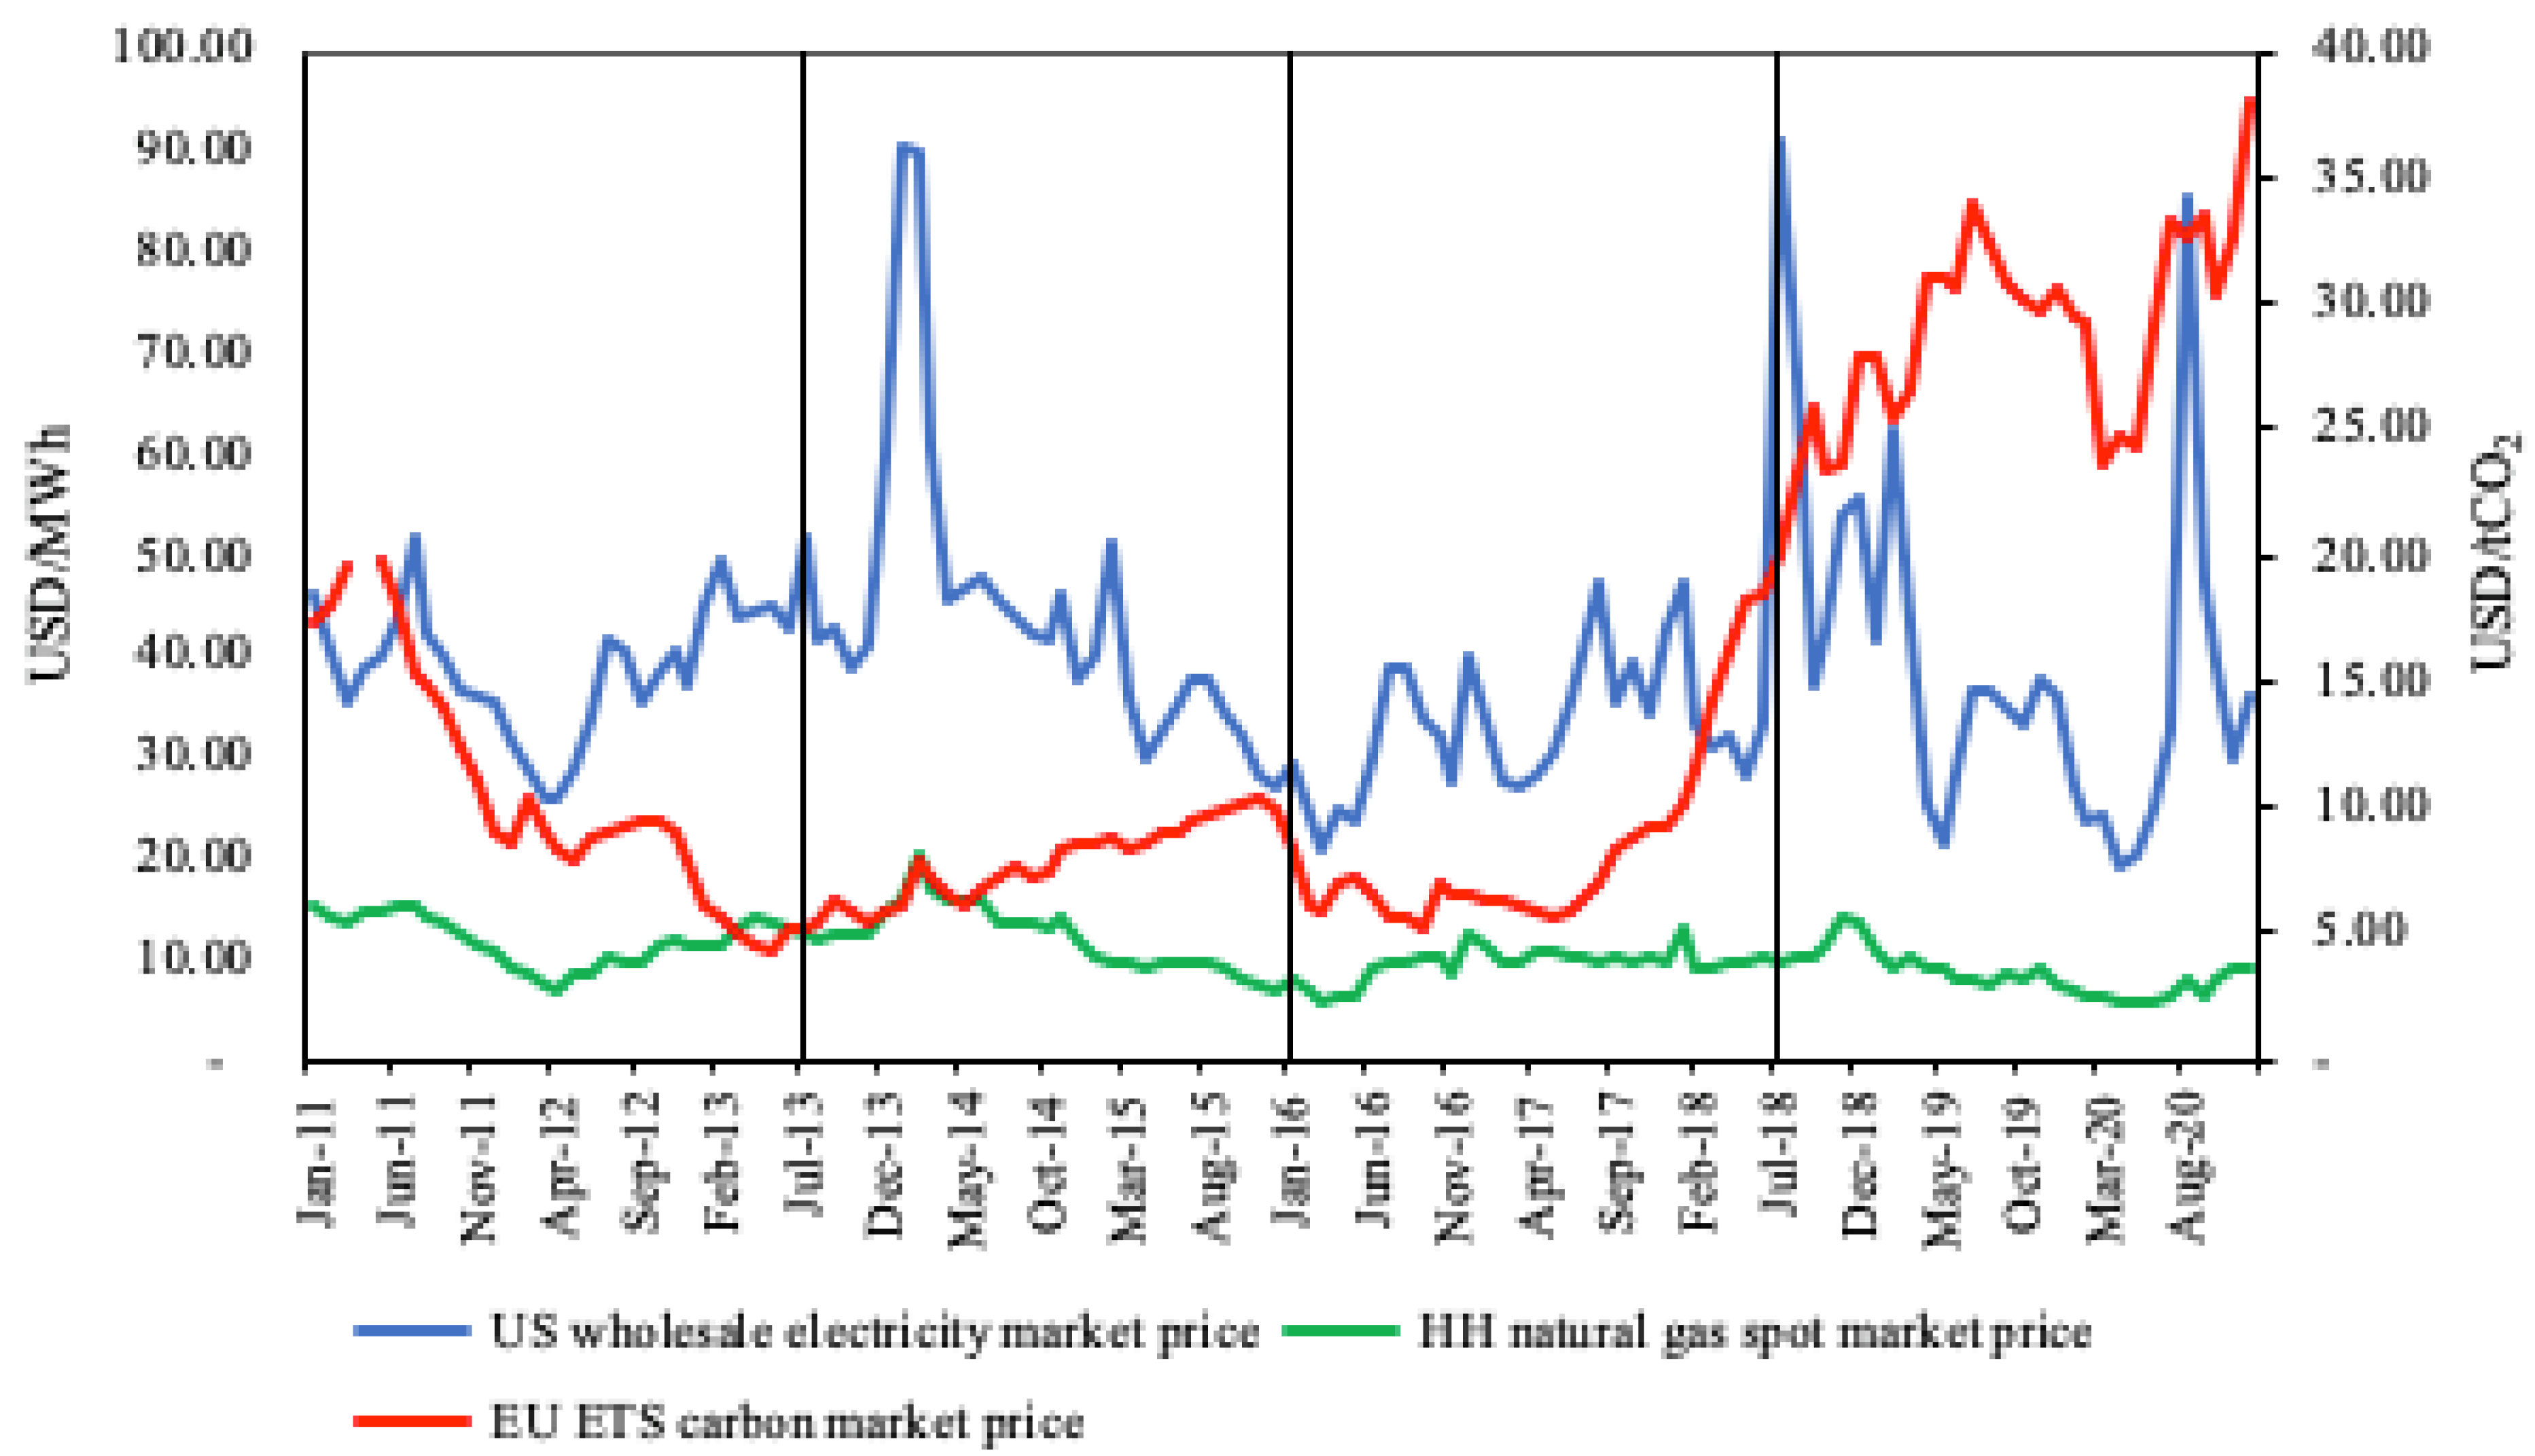
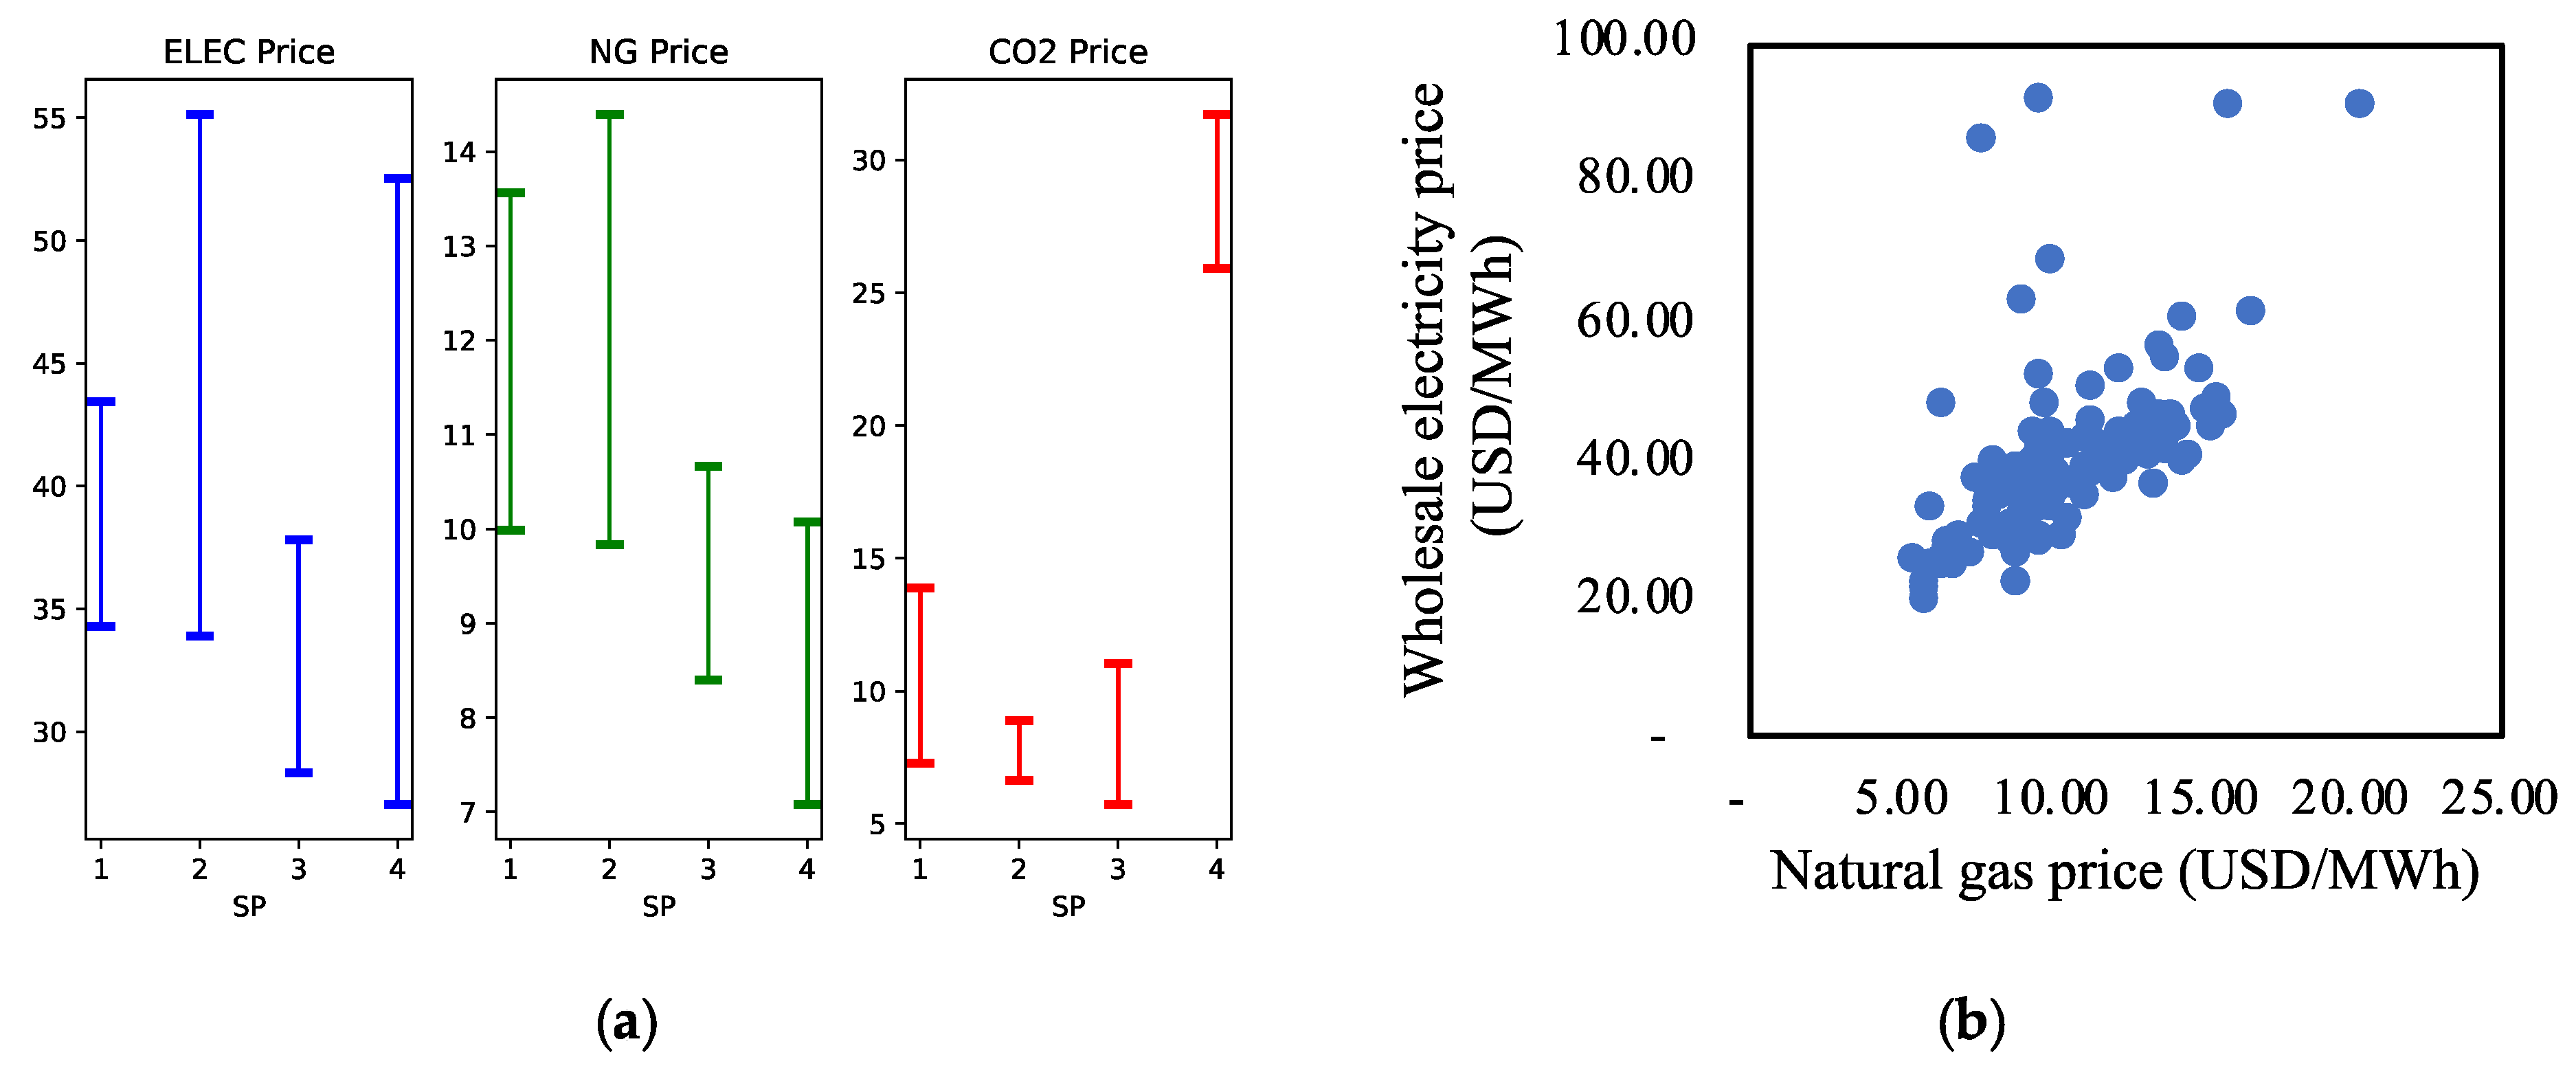
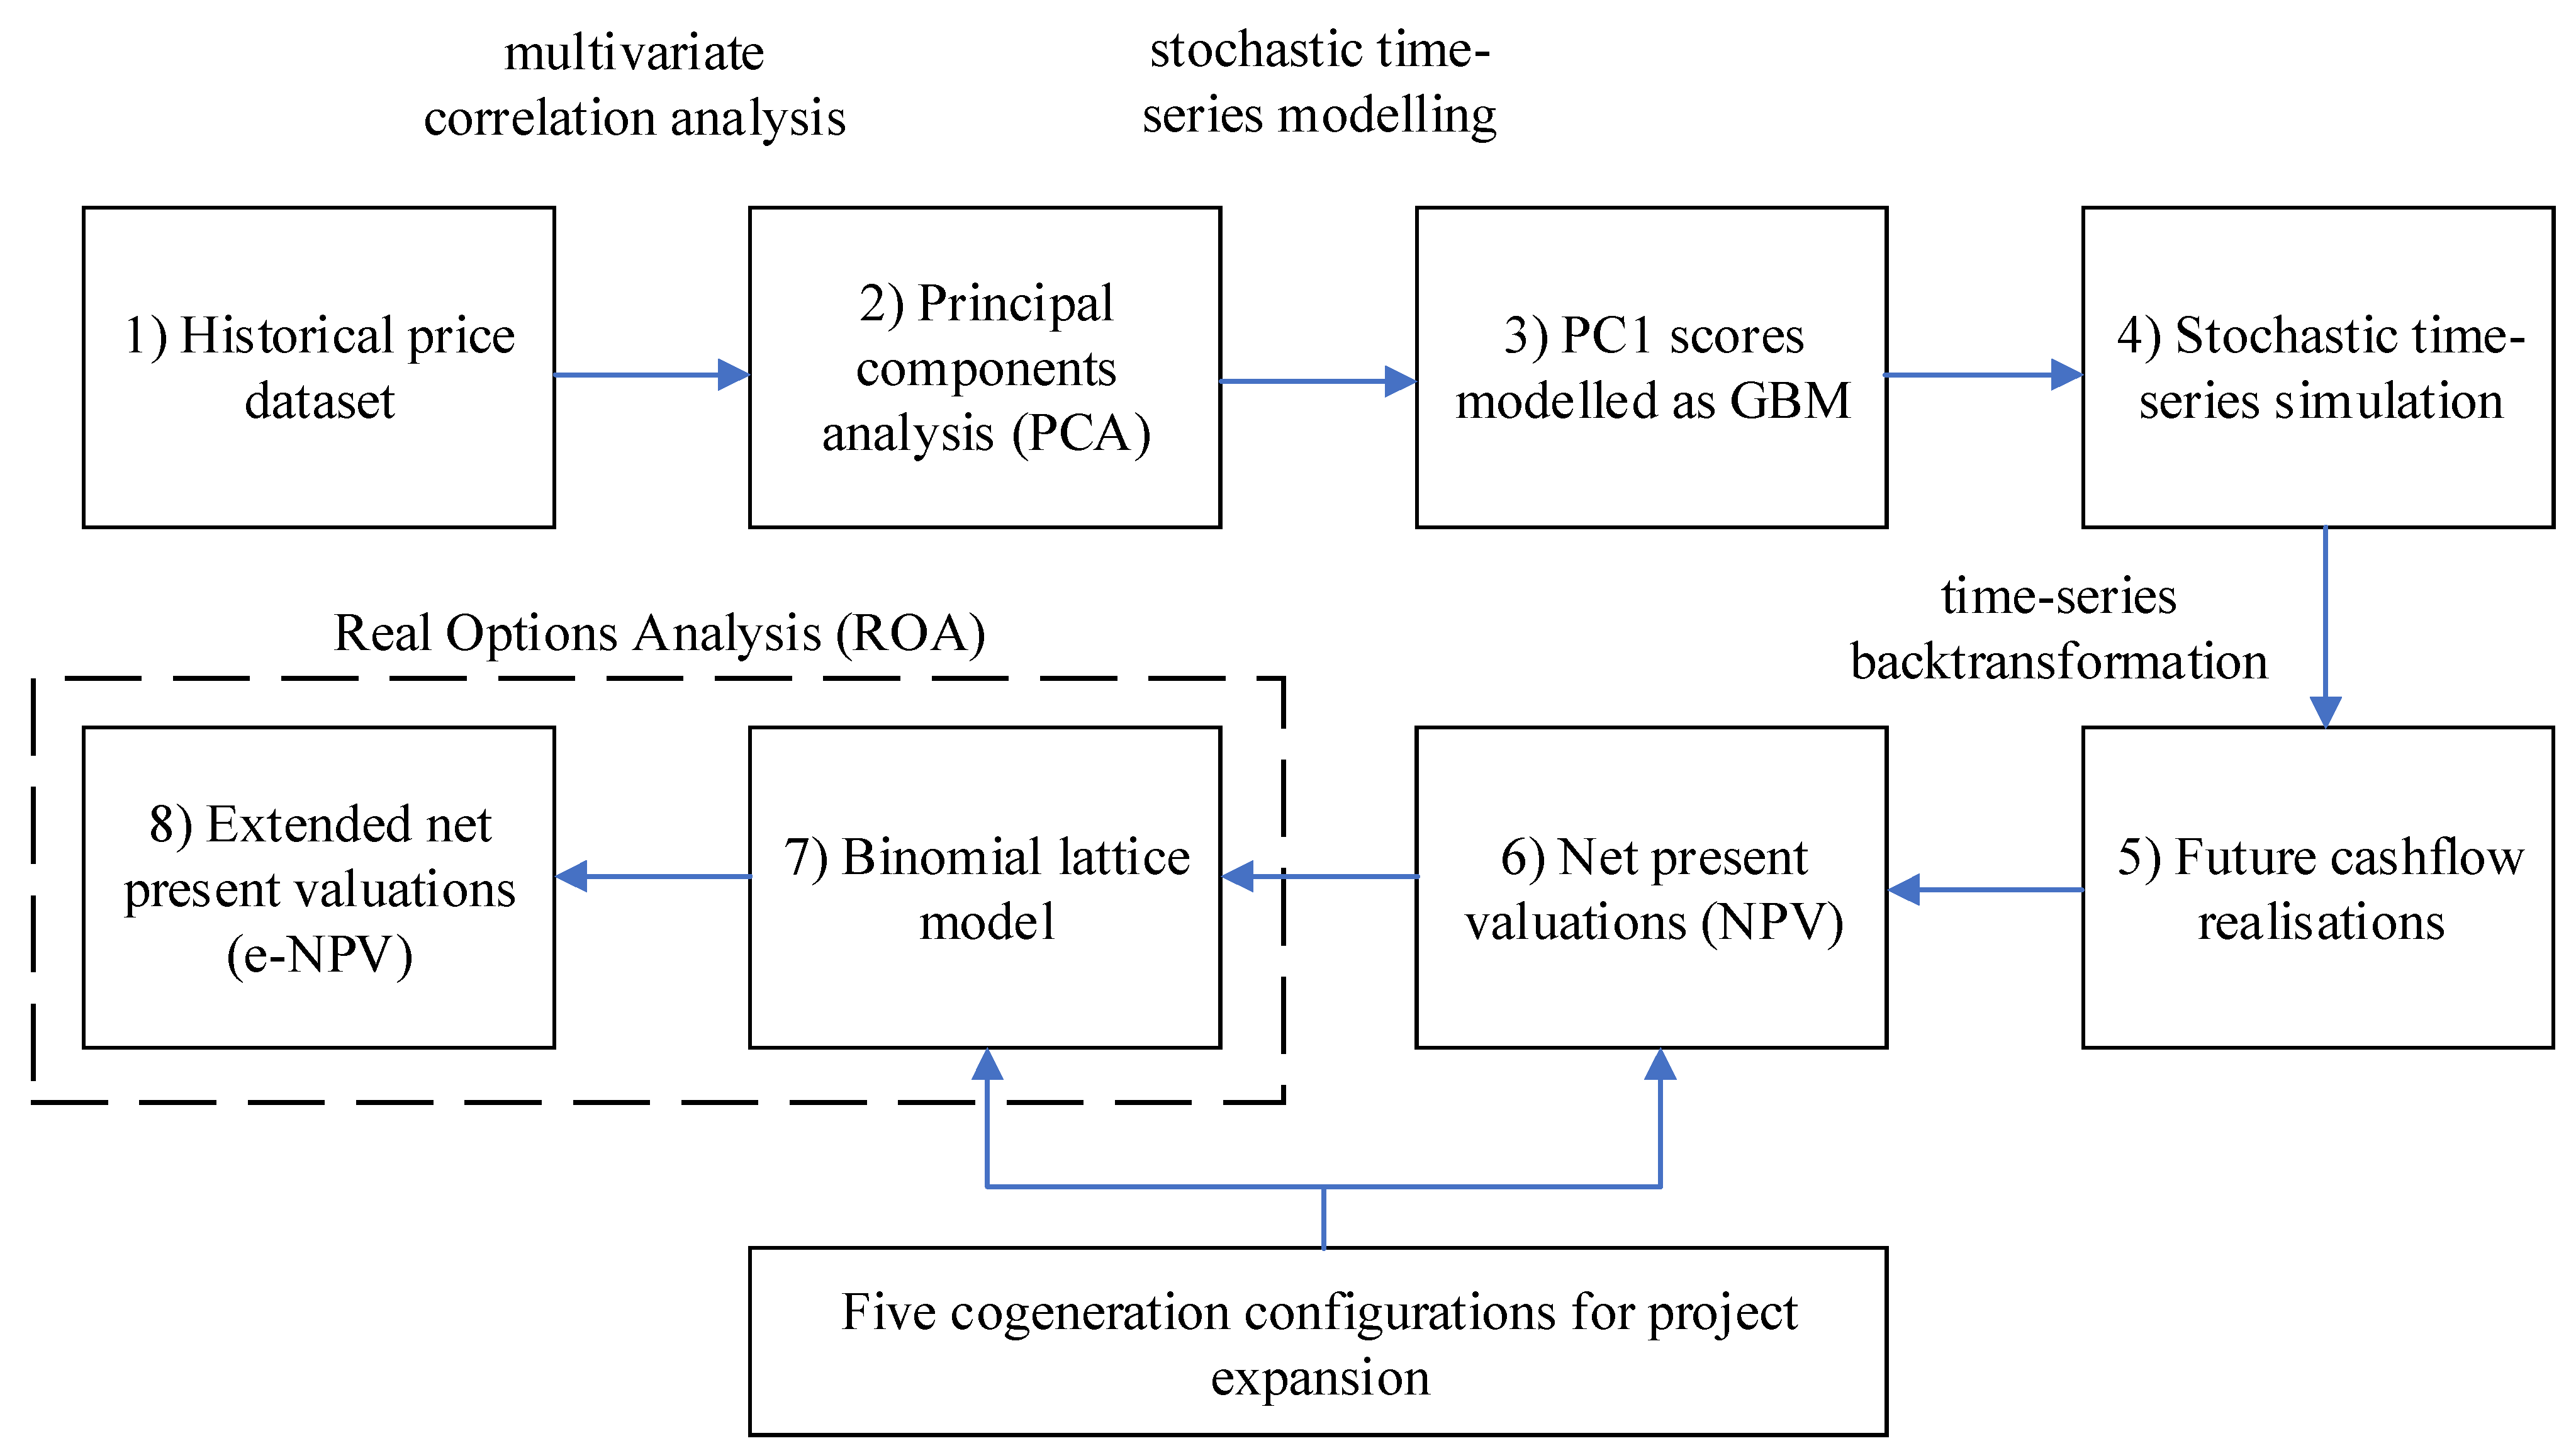
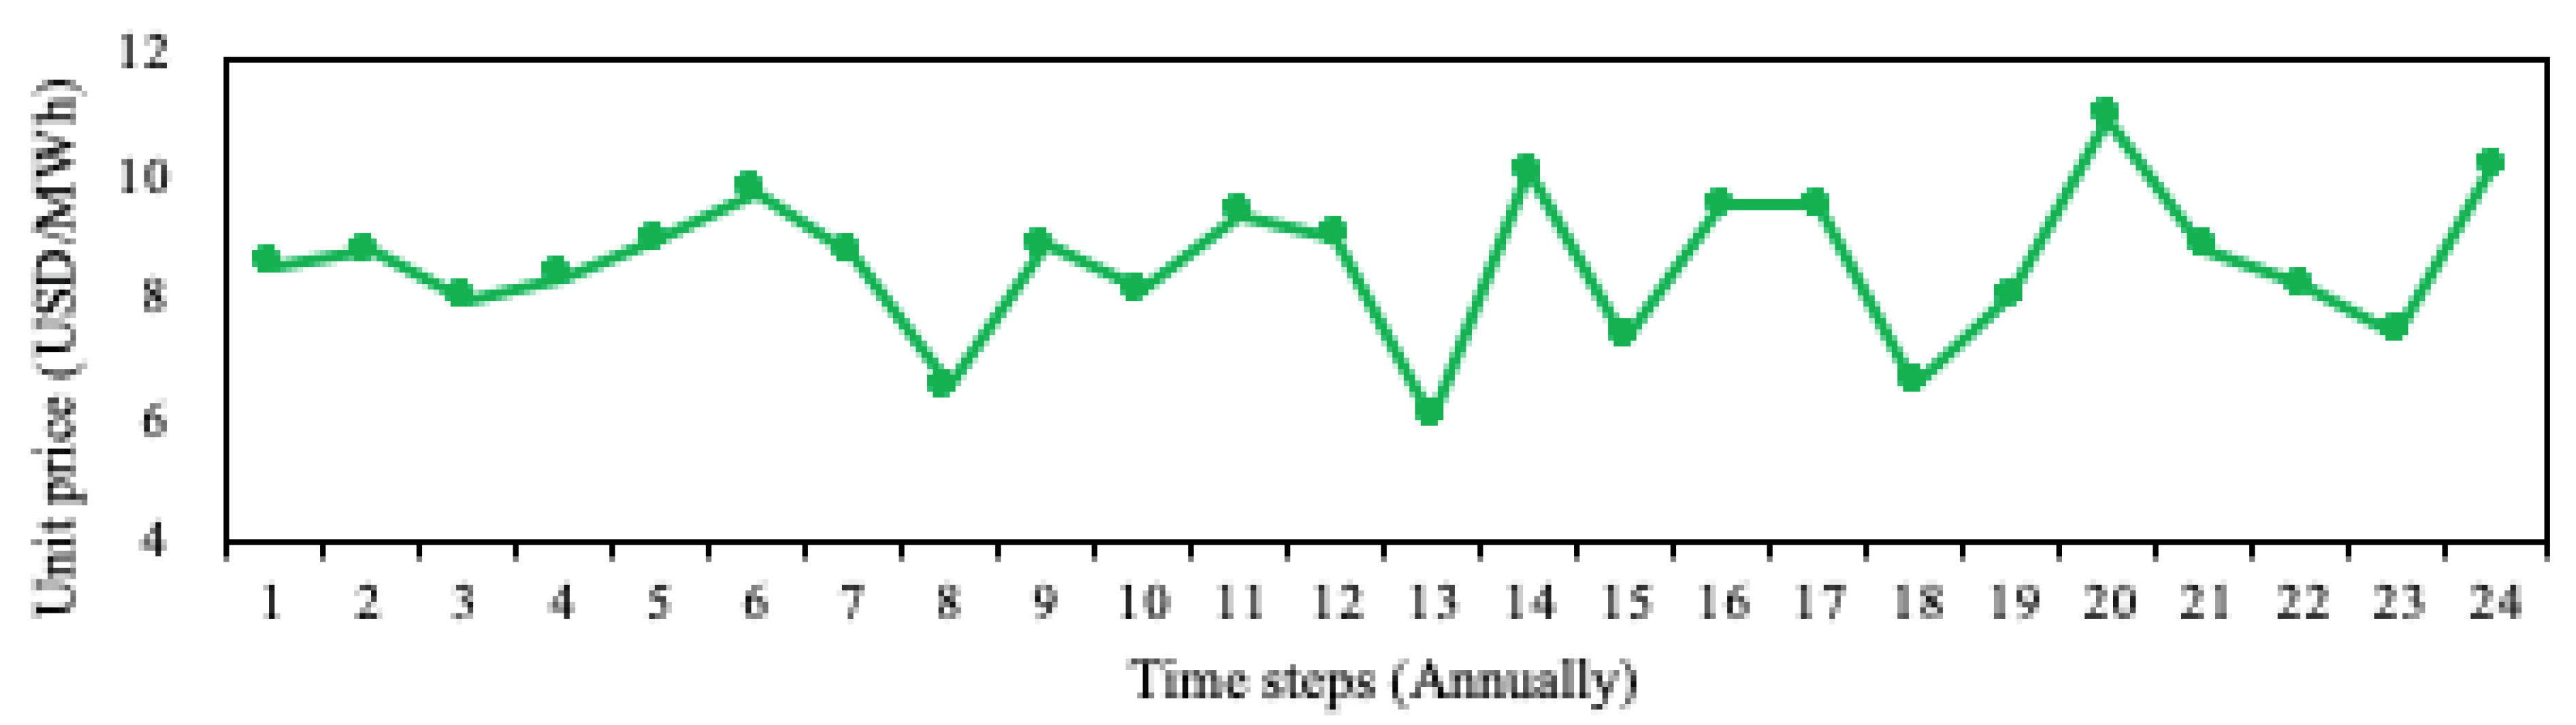
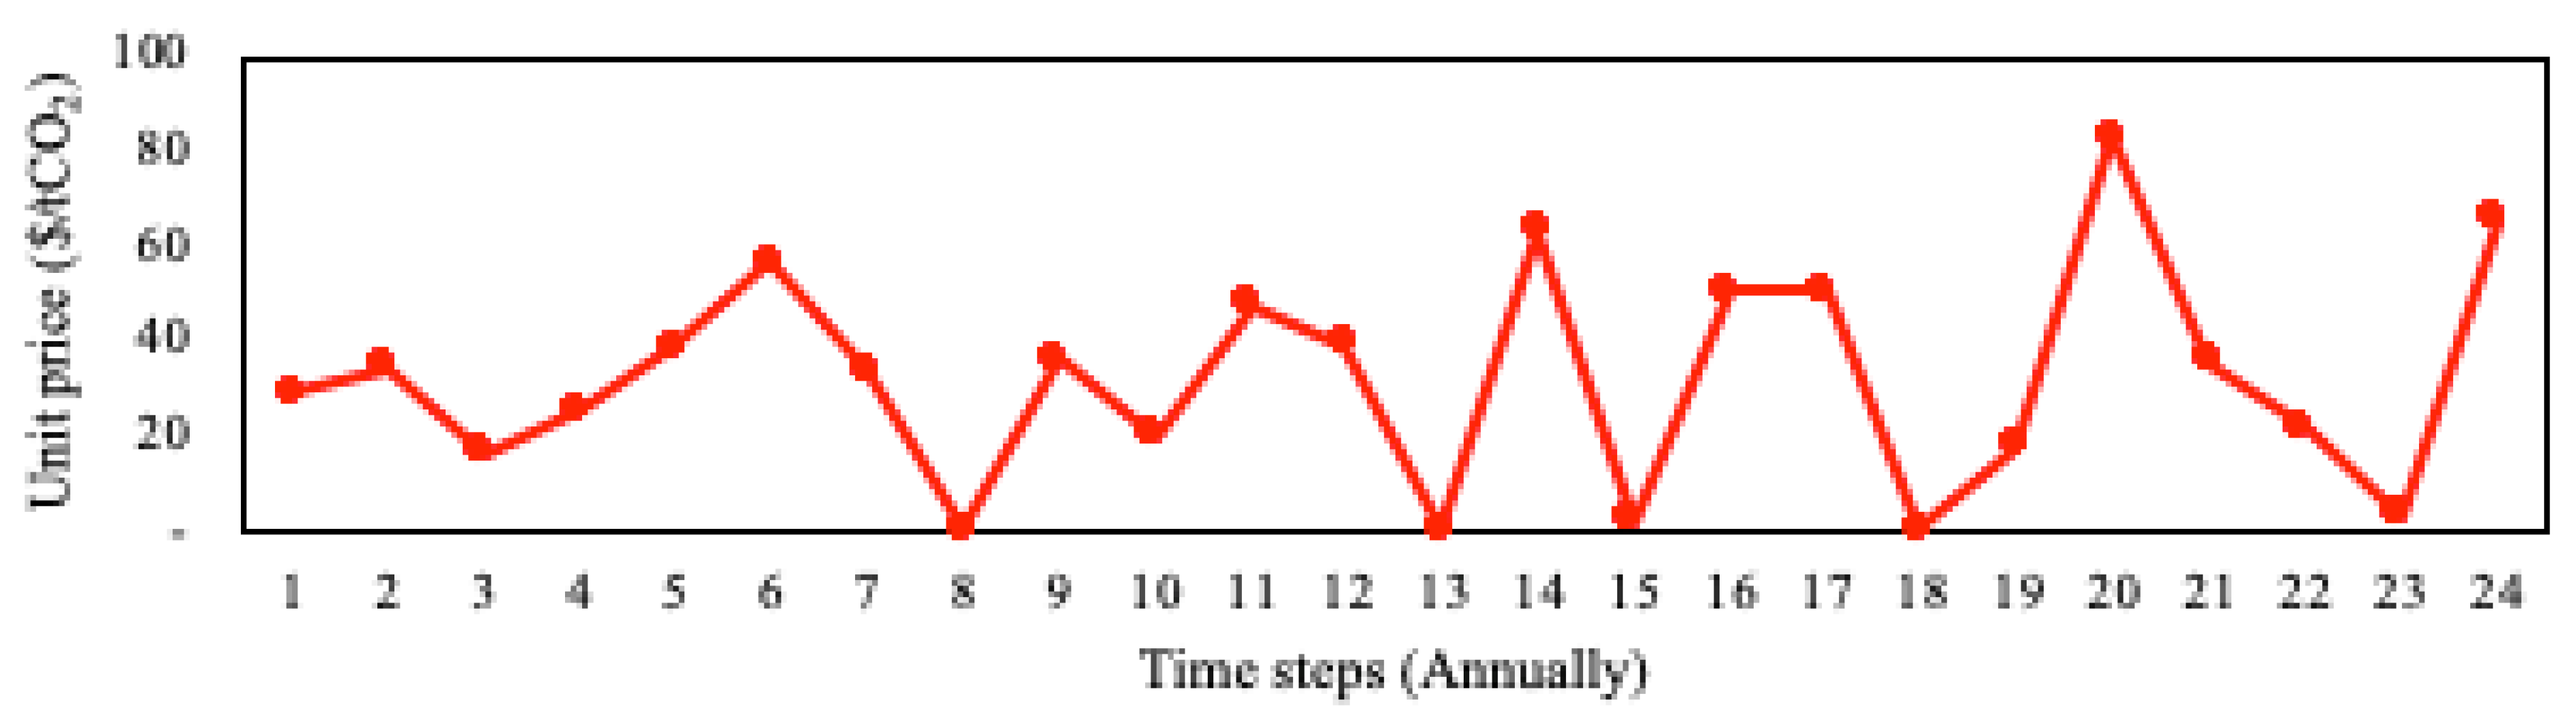
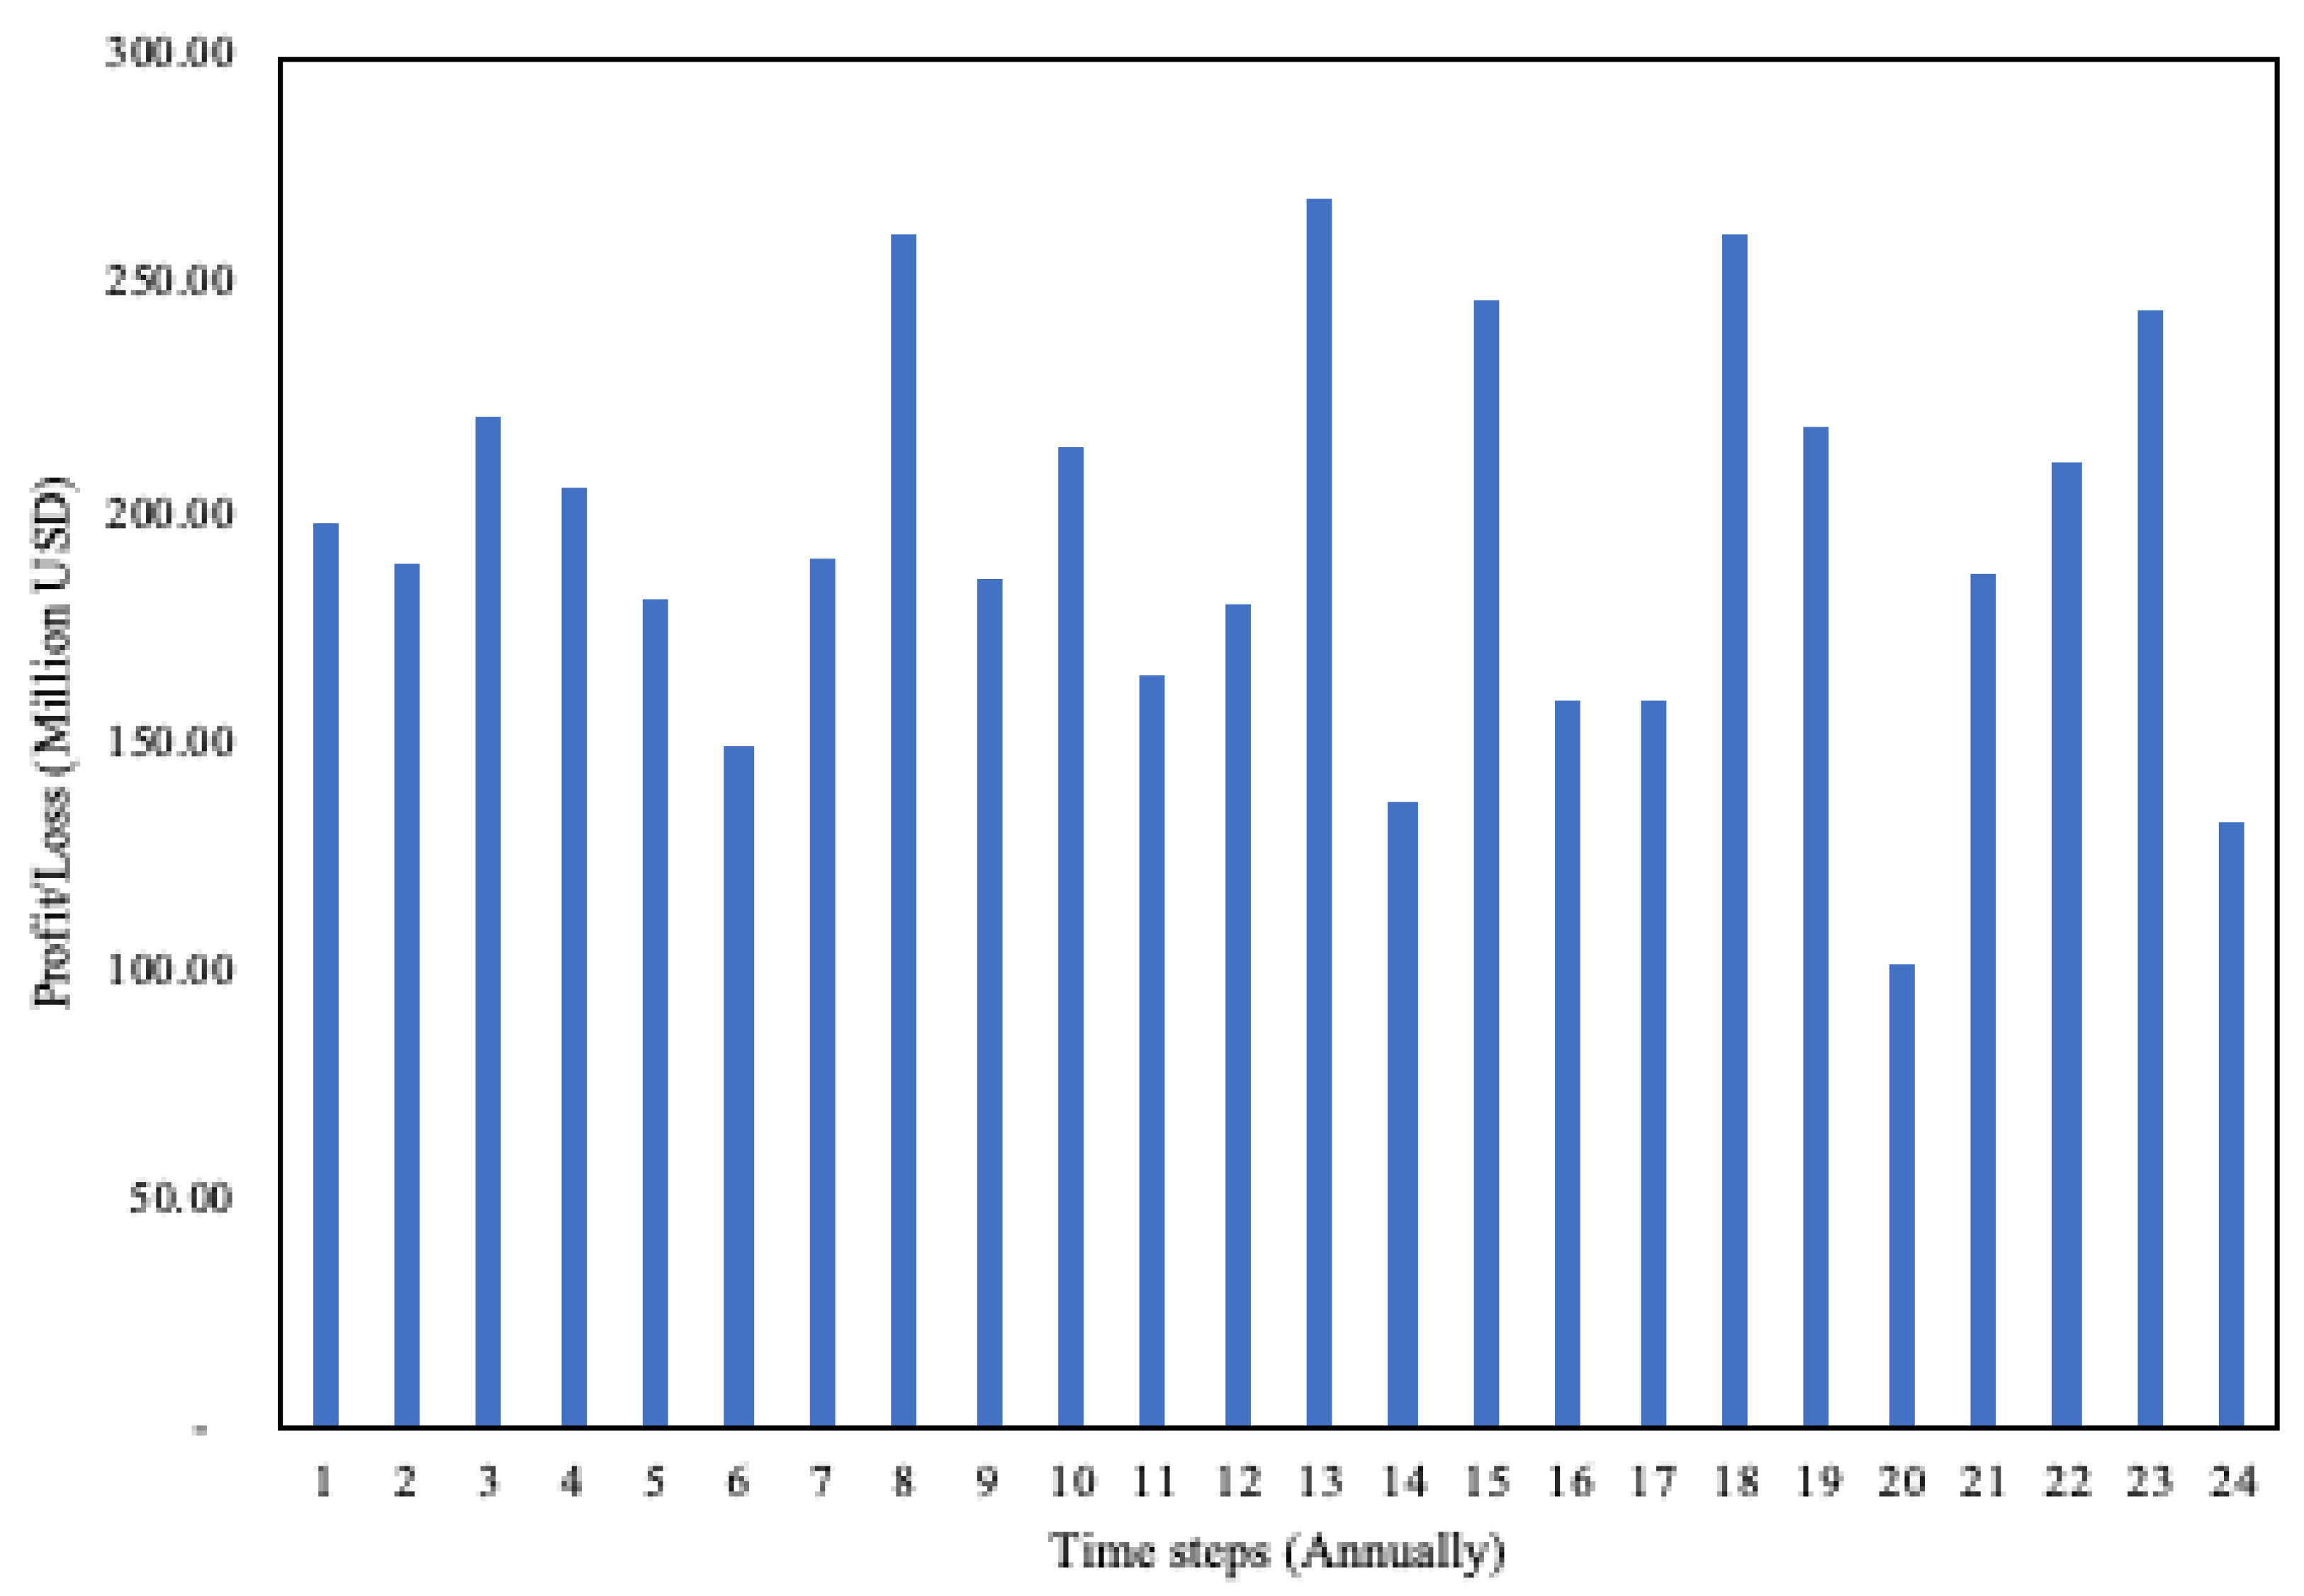
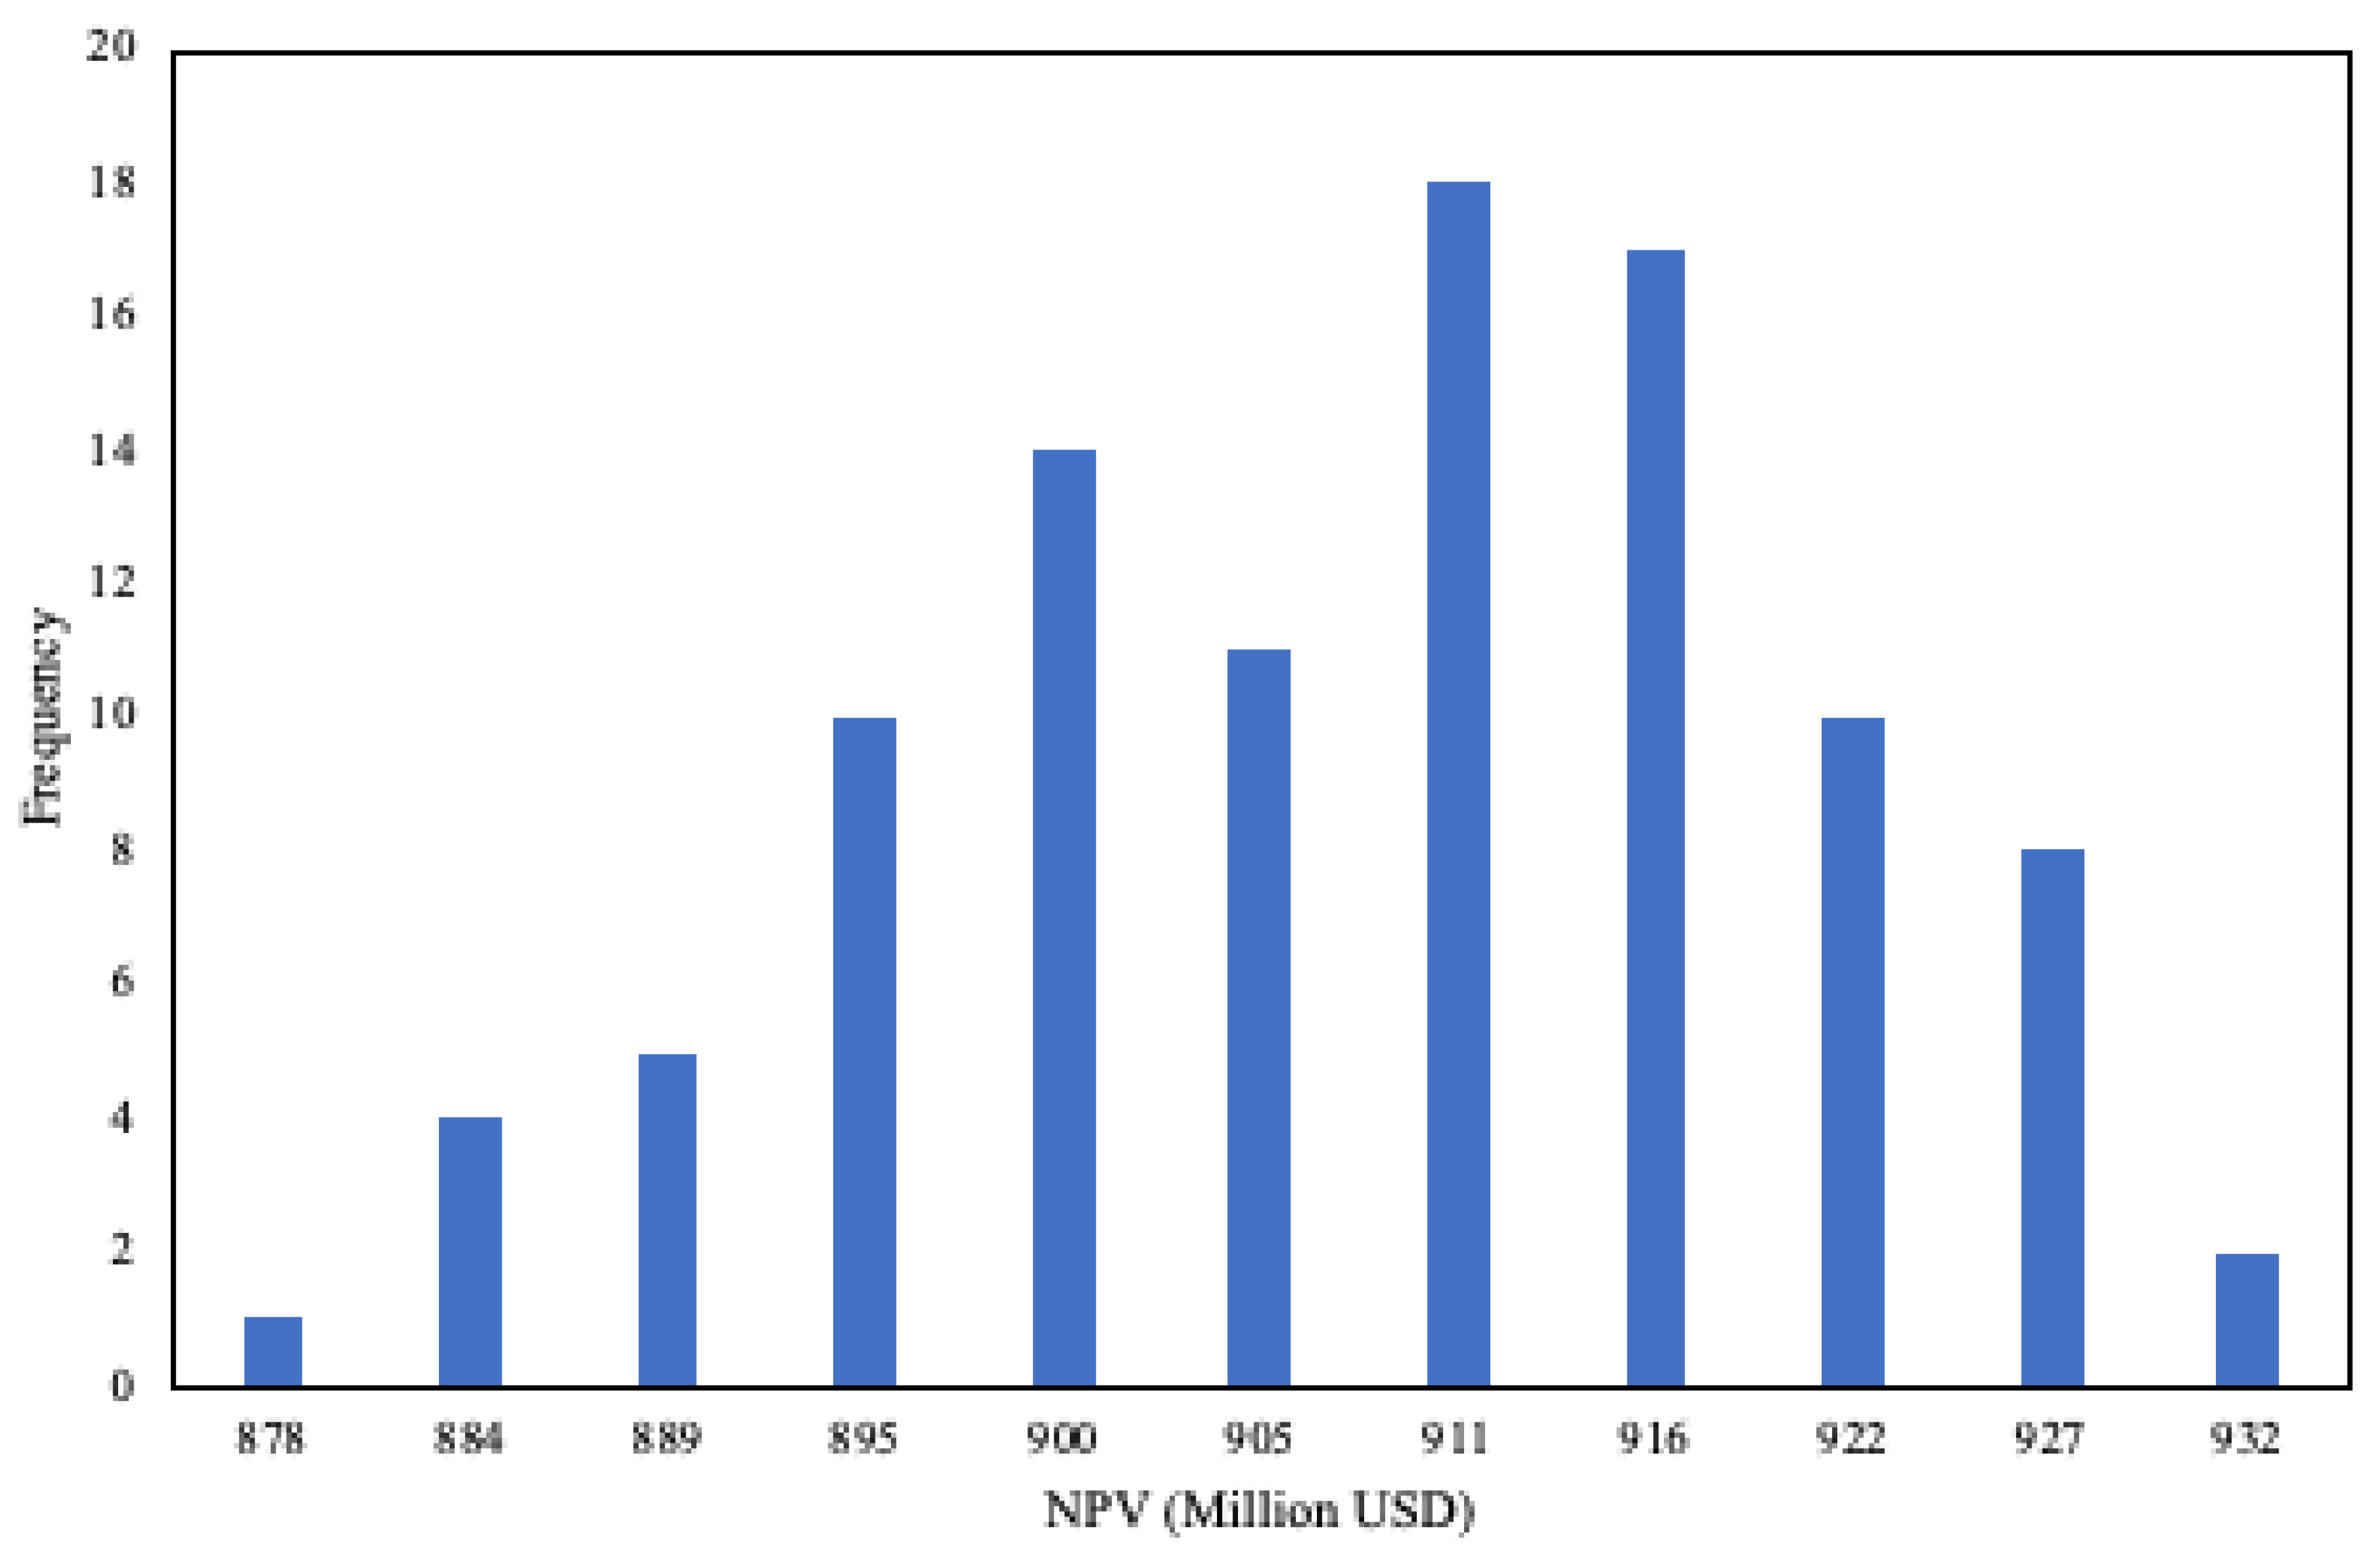
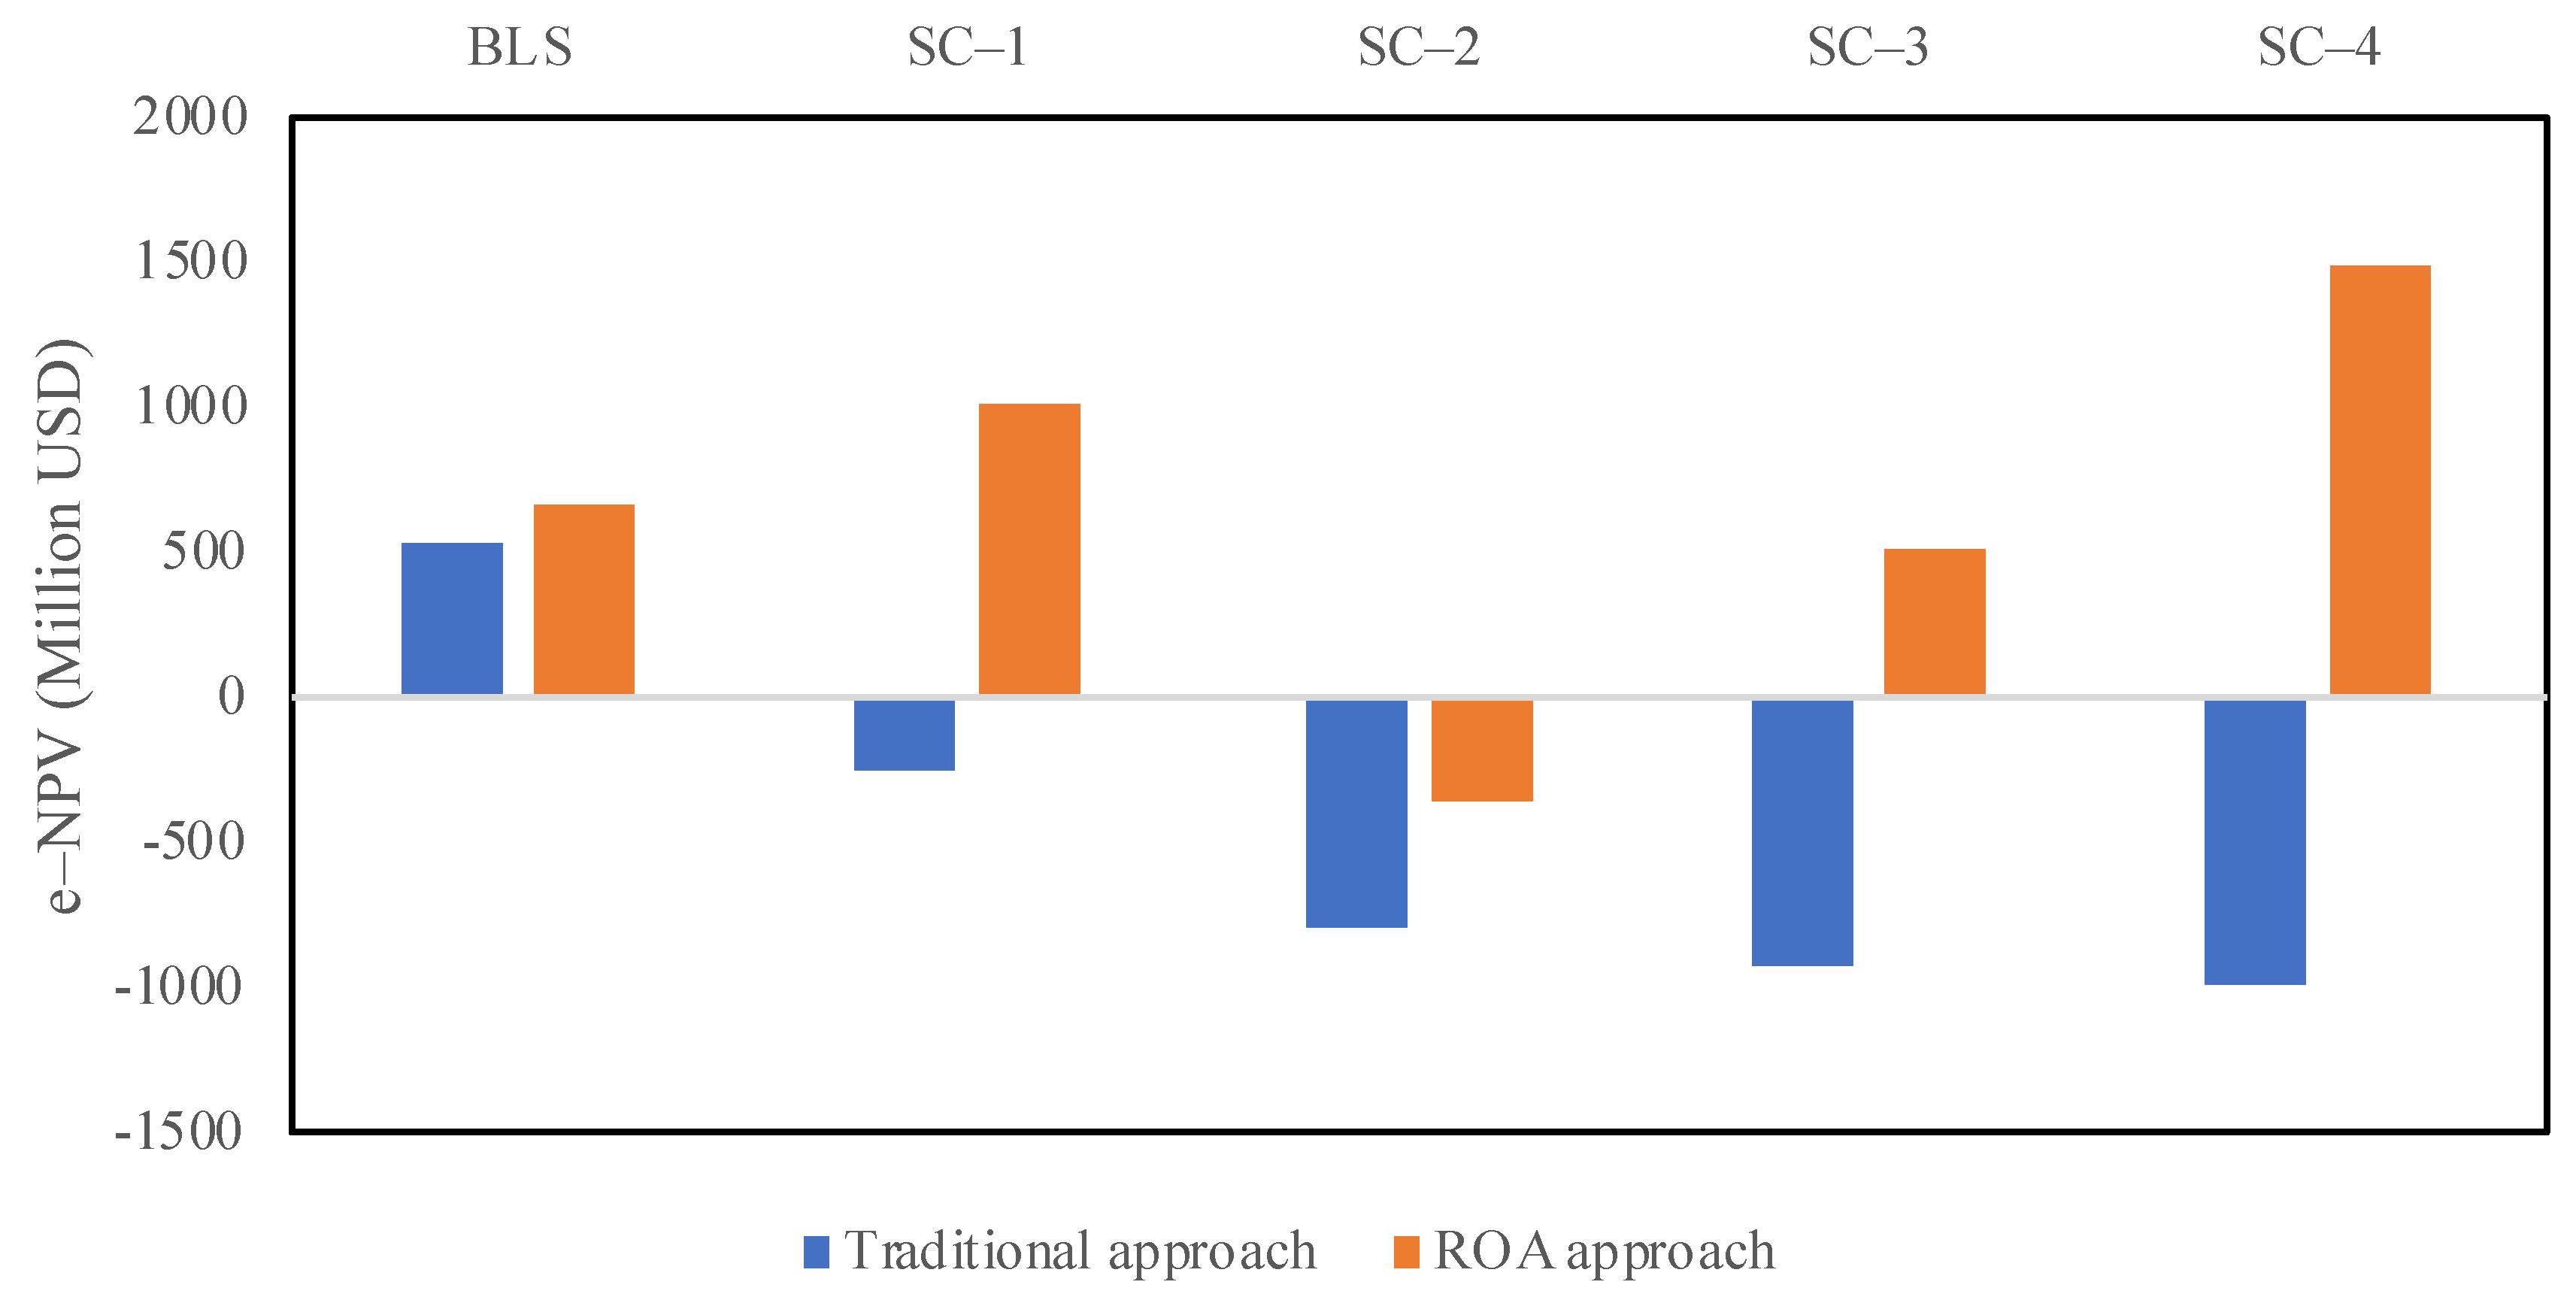
Energy price fluctuations pose a significant risk and uncertainty to financial investments for new developments in conventional power and freshwater cogeneration facilities. This study attempts to address the problem of making robust valuation for low-carbon energy project investments subject to multi-dimensional price risk, particularly looking at some key research questions: (a) how does the correlation structure, or independence, between the price risks affect the project value; and (b) does adding flexibility in investment enhance or worsen the project valuation, given (a). This study identified three price factors with significant fluctuations that impact conventional power generation, namely: wholesale electricity spot price, natural gas spot price, and CO2 market price. The price factors were used to construct a multidimensional risk model and evaluate investment decisions for cogeneration project expansion in the future based on a low-carbon energy mix. To this end, five cogeneration configurations using combined-cycle gas turbine (CCGT) integrated with solar photovoltaics (PV) and carbon capture and storage (CCS) technologies were assessed. A combined price risk was initially estimated by transforming the given price factors representing maximum covariance using principal component analysis (PCA). The trend and volatilities in the major principal component scores (the combined price risk indicator) were modelled using the geometric Brownian motion stochastic process, whose parameters were determined and then used to perform time-series simulation and generate multiple realisations of the principal component. A back transformation was then applied to obtain the simulated values representing future uncertainties in the price factors. The effect of price risk and uncertainties were subsequently evaluated using a recombining binomial lattice model for real options analysis (ROA). There were financial gains when PV was mixed with conventional natural gas-fired technology. Investment in cogeneration configurations with (a) 25% PV share provided a 53% gain in the extended net present value (e–NPV); and (b) 50% PV share provided a 124% e–NPV gain when compared to the baseline cogeneration system with no PV shares. The analyses demonstrate that PV technology is a better hedging option than CCS against future market uncertainty and price volatility.
Keywords: cogeneration; renewable energy; principal component analysis; real options analysis; uncertainty cogeneration; renewable energy; principal component analysis; real options analysis; uncertainty