Article

Financial Time Series Forecasting with the Deep Learning Ensemble Model

1
College of Tourism, Hunan Normal University, Changsha 410081, China
2
Shanghai Kaiyu Information Technology Co., Ltd., Shanghai 202179, China
3
School of Business, Hunan University of Science and Technology, Xiangtan 411201, China
*
Author to whom correspondence should be addressed.
Mathematics 2023, 11(4), 1054; https://doi.org/10.3390/math11041054
Submission received: 31 December 2022 / Revised: 7 February 2023 / Accepted: 8 February 2023 / Published: 20 February 2023

Abstract

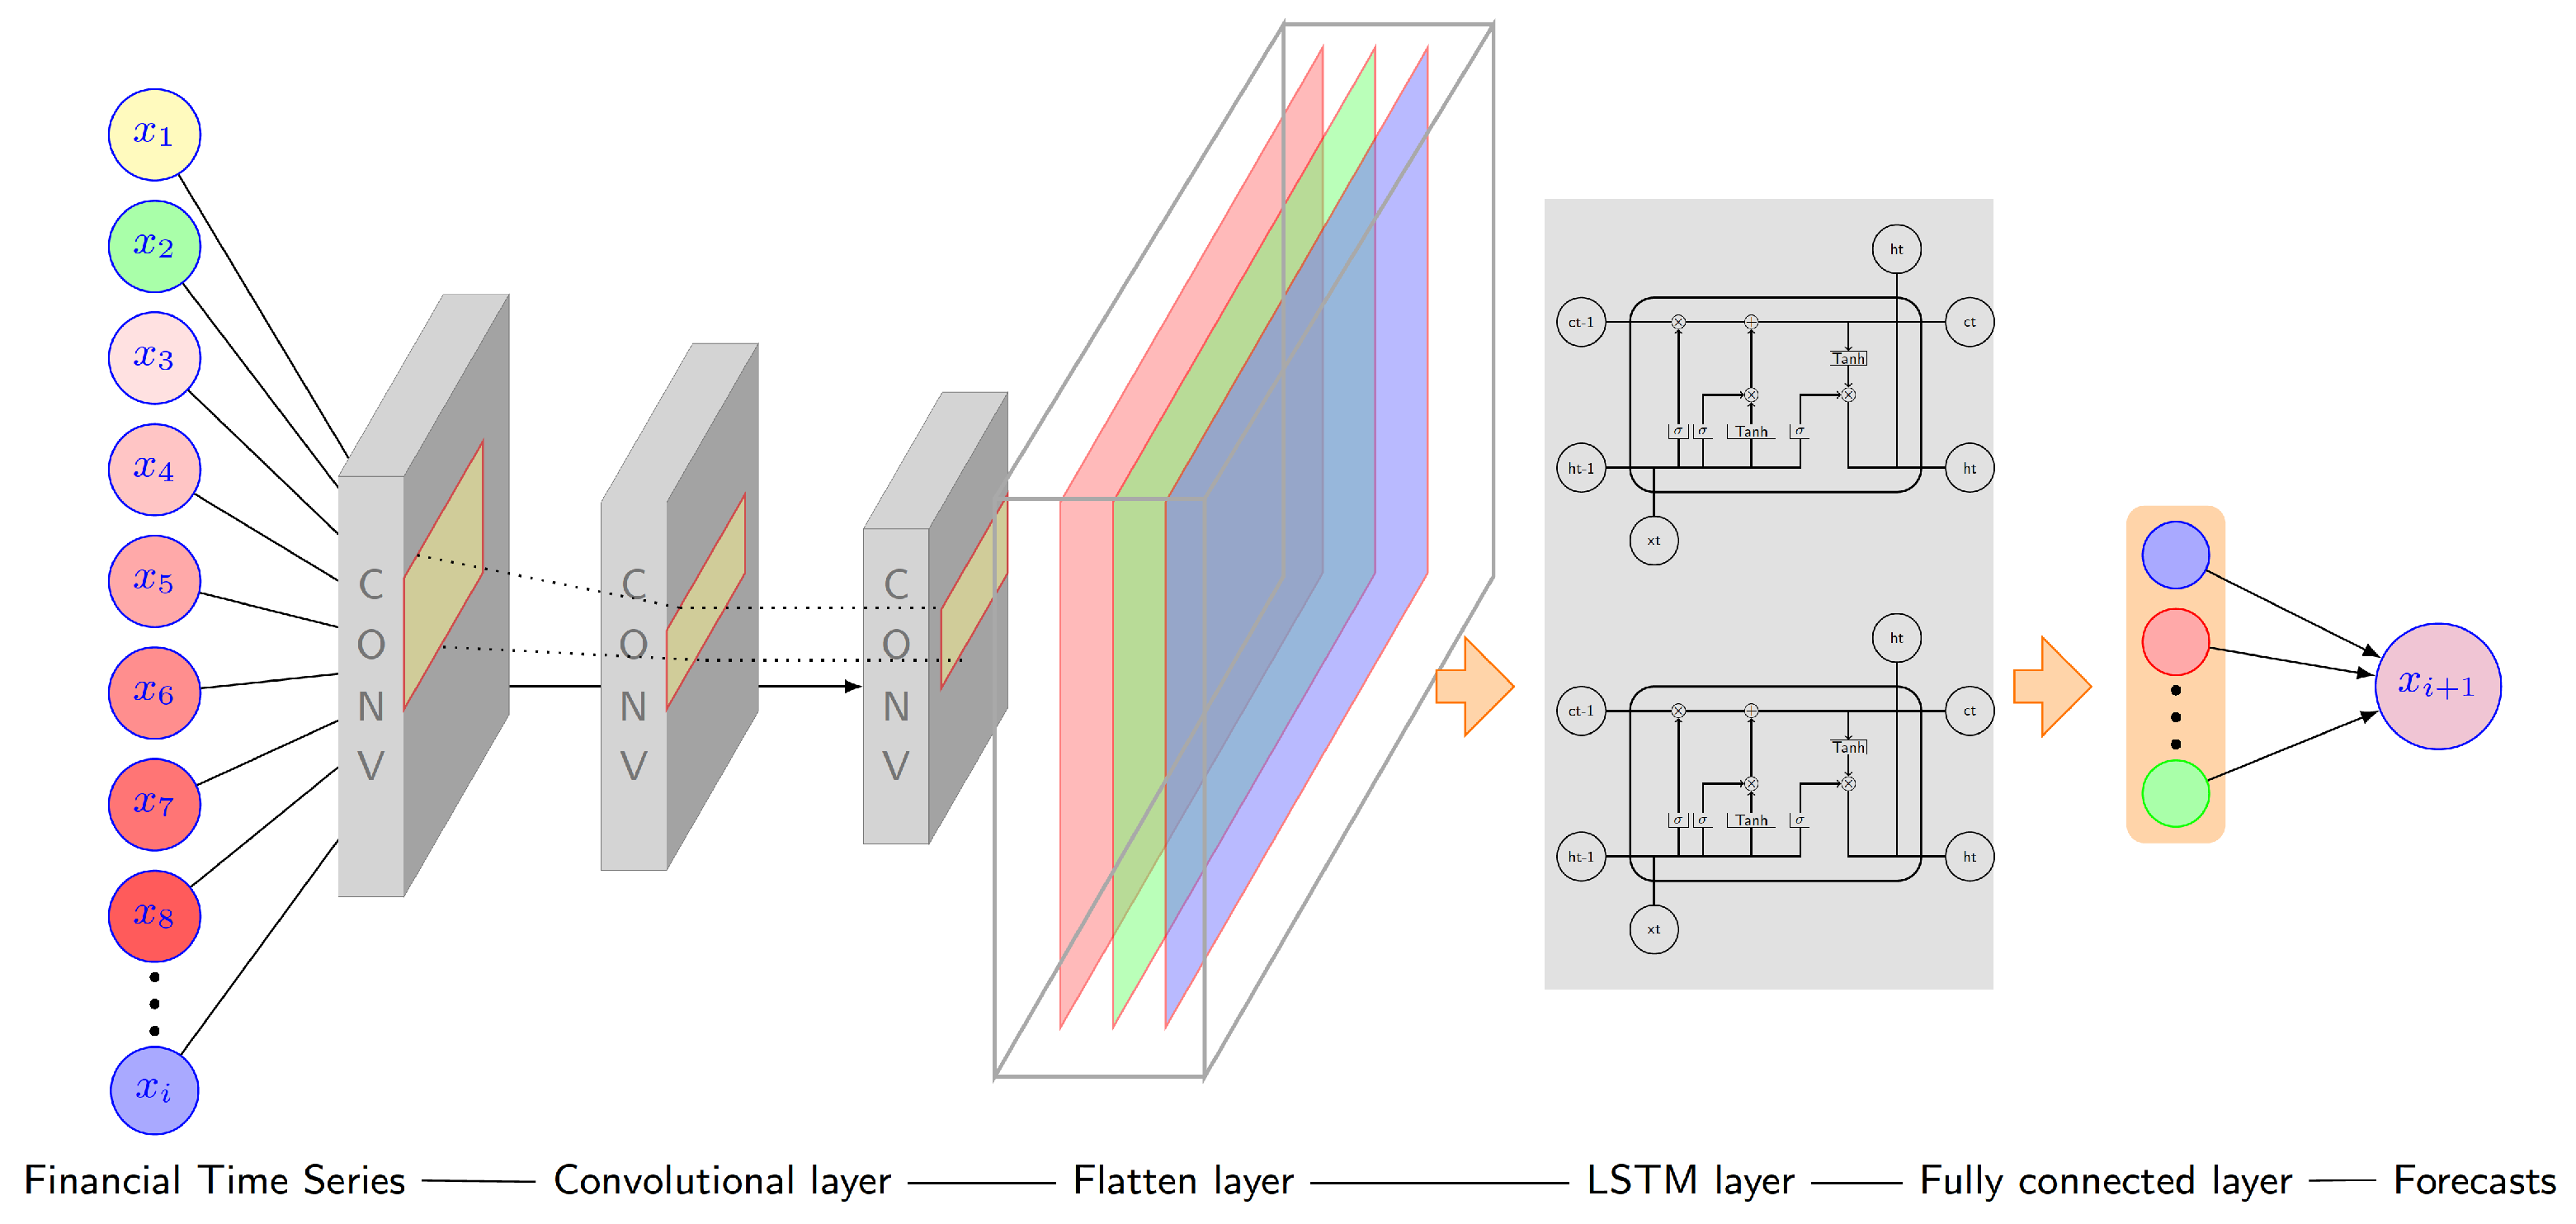
With the continuous development of financial markets worldwide to tackle rapid changes such as climate change and global warming, there has been increasing recognition of the importance of financial time series forecasting in financial market operation and management. In this paper, we propose a new financial time series forecasting model based on the deep learning ensemble model. The model is constructed by taking advantage of a convolutional neural network (CNN), long short-term memory (LSTM) network, and the autoregressive moving average (ARMA) model. The CNN-LSTM model is introduced to model the spatiotemporal data feature, while the ARMA model is used to model the autocorrelation data feature. These models are combined in the ensemble framework to model the mixture of linear and nonlinear data features in the financial time series. The empirical results using financial time series data show that the proposed deep learning ensemble-based financial time series forecasting model achieved superior performance in terms of forecasting accuracy and robustness compared with the benchmark individual models.
Keywords: financial time series; convolutional neural network; long short-term memory; ensemble forecasting model financial time series; convolutional neural network; long short-term memory; ensemble forecasting model