1. Introduction
Accounting conservatism, defined as the timely recognition of losses relative to gains, constrains managerial opportunism and reduces information asymmetry between insiders and investors (
Basu, 1997;
Ball & Shivakumar, 2005). Companies with a high risk of financial anomaly face a more conservative reporting stance when confronted with the risk of litigation (
Adam et al., 2025;
Widhiastuti et al., 2023). Cases in Thailand have shown these real-world consequences. Energy Absolute Plc was penalized because it used fraud in the procurement of equipment. This led to the resignations of company executives and government sanctions (
Reuters, 2024). JKN Global Group was accused of financial fraud. This led to restatements and even delisting (
ContentAsia, 2023;
Orton, 2025). ThaiBMA showed that there were many Thai companies that defaulted on their bond payments between 2023 and 2025. In 2023, five companies defaulted on various series, amounting to around 489.6 million USD (
ThaiBMA, 2023). A total of three companies defaulted in 2024, but the total payment was only around 32.84 million USD (
ThaiBMA, 2024). By 2025, the number continued to rise, with four companies, amounting to around 69.85 million USD. Notably, this is not inclusive of the 14 more companies that postponed the repayment of their bonds in 2025 (
Bangkok Post, 2025). Additionally, the issue of using insider information by officers involved in stock transactions (
Polkuamdee & Online Reporters, 2025) should also be considered. The above issues bring to light the importance of understanding how fraud risk affects reporting behavior within the Thai setting.
Environmental, social, and governance (ESG) performance has arisen as a new nonfinancial aspect playing a significant role in managerial agency (
He et al., 2022;
Cai et al., 2024) and external oversight (
Lu et al., 2025). ESG engagement could improve internal governance, transparency, and reputation signals to external stakeholders. Notably, financially anomalous risk and ESG performance demonstrate theoretically and practically important interactions. Companies with strong ESG engagement could change their conservative reporting differently under financially anomalous risk conditions (
Ferdous et al., 2024). Also, investors demand enhanced conservative reporting by companies with non-financial misbehavior (
Yang & Liu, 2024). Multiplicative financial anomalies and ESG performance enable this research to examine whether ESG weakens and moderates financially anomalous conservative financial reporting.
Understanding this theoretical underpinning and assumption of this study has important implications, especially within emerging economies, such as Thai companies, which are still in the process of development with regard to the enforcement of regulations and adoption of ESG considerations, respectively. Also, the manipulation of ESG reputations could be a managerial means of mitigating anomalous opportunistic behavior by firms.
This research examines the simultaneous effects of financial anomaly risk and ESG performance on the level of accounting conservatism among listed Thai firms. Various proxies of conservatism and different unsupervised machine learning models of financial anomalies are used to analyze how ESG engagement affects incentives associated with financial anomalies for conservative reporting. Specifically, our research question is: How does financial anomaly risk influence firms’ accounting conservatism, and to what extent does ESG engagement condition or moderate this relationship?
The contributions of this study are threefold. Theoretically, the research extends the literature on conditional conservatism by showing that ESG serves as an interactive governance mechanism that adjusts management’s response to risks represented by financial anomalies. Investors, auditors, and regulators will benefit practically from information about the role ESG engagement plays in increasing transparency and reducing opportunistic reporting in companies with high intrinsic risks. The relevance of the findings is strengthened by the use of different indicators of financial anomalies and conditional conservatism. This study shows that the economic consequences of ESG and financial anomalies are significant and that their main effects hold across a range of different alternative empirical models.
The remainder of the paper is organized as follows.
Section 2 reviews the literature and develops hypotheses;
Section 3 describes the data and methodology;
Section 4 presents the results; and
Section 5 concludes.
Literature review and hypothesis development
Accounting conservatism, ESG engagement, and financial anomalies are interconnected through several complementary theories. Accounting conservatism is grounded in contracting theory, information asymmetry theory, and litigation theory. The accounting conservatism emphasizes that timely recognition of losses and delayed recognition of gains mitigates agency conflicts, reduces investor uncertainty, and limits legal liability (
Basu, 1997;
Watts, 2003;
Ball & Shivakumar, 2005;
LaFond & Watts, 2008). Conservatism is thus a state-contingent mechanism that strengthens under heightened uncertainty or external scrutiny.
ESG engagement is primarily informed by stakeholder theory (
Freeman, 1984), legitimacy theory (
Suchman, 1995), and the reputational capital-insurance approach (
Godfrey, 2005). ESG activities build firm legitimacy and enhance reputational capital and trust among investors and regulators. It is more likely to allow managers greater flexibility in reporting and reduce information asymmetry. Depending on the firm’s environment, ESG may substitute or complement conservatism, further reinforcing timely loss recognition under risk when reputational safeguards diminish the need for strict conservative reporting (
Yang & Liu, 2024).
Financial anomalies denote a deviation from fundamental performance and represent information risk. Thus, according to the agency theory and contingent governance theory, companies with high information risk anomalies are subject to extreme scrutiny and reputation pressure. This should motivate companies to take a keen interest in conservative accounting as proposed by
Jensen and Meckling (
1976). It must be emphasized that it is the relationship between ESG and financial anomalies that determines the conservativeness level. They increase conservativeness when anomalies reveal high accounting risks, and reduce conservativeness when external reputation credibility, through reputation capital, is adequate.
The integration of contracting theory, information asymmetry theory, stakeholder theory, legitimacy theory, agency theory, and the contingent governance logic establishes a cohesive theoretical chain of support to explain the interactive relationships between financial anomaly risk, ESG, and accounting conservatism. Financial anomalies reflect elevated levels of information risk and agency conflicts. Under the frameworks of contracting and agency theories, these anomalies increase the demand for conservative financial reporting as a governance mechanism to mitigate opportunistic behavior and litigation risks. Consequently, accounting conservatism functions as a situational internal risk control mechanism that intensifies as information asymmetry and external pressures rise. Based on this theoretical reasoning, we propose the following:
H1: Financial anomaly risk is associated with accounting conservatism.
Simultaneously, ESG performance—rooted in stakeholder and legitimacy theories—helps build reputational capital and strengthens external governance mechanisms, thereby reducing perceived information risk and enhancing the confidence of investors and regulators. Within this framework, ESG acts as an external governance mechanism that may either complement or substitute for accounting conservatism, depending on the severity of the financial anomalies. Specifically, when financial anomalies signal severe accounting risks, ESG credibility further encourages firms to adopt conservative reporting to protect corporate reputation. Conversely, when the legitimacy and credibility derived from ESG are sufficient to alleviate external skepticism, the necessity for stringent conservatism may diminish.
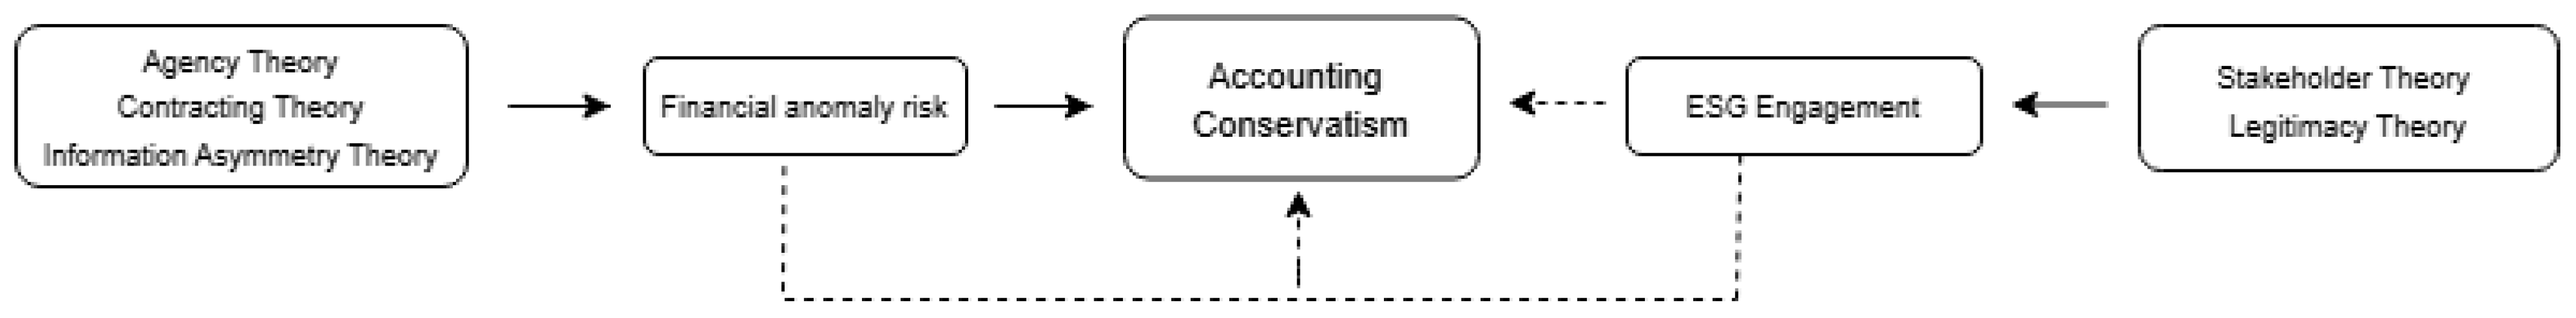
Therefore, financial anomaly risk serves as a ‘situational trigger,’ ESG acts as a ‘reputational governance mechanism that moderates the relationship,’ and accounting conservatism is the ‘observable reporting outcome.’ Together, these three components constitute a contingent governance system wherein internal risks and external legitimacy collectively determine a firm’s level of accounting conservatism in any given context.
Figure 1 presents the conceptual diagram.
The Relationship between financial anomaly and ESG
Recent studies provide evidence that the performance of ESG factors and risk exposures is interrelated (
Nian & Said, 2025). However, the results of the study are not definitive, as they depend on the context (
Khorilov & Kim, 2024). Studies on the correlation of ESG factors and risks in general reveal that enhanced operations of ESG factors positively correlate to decreased idiosyncratic risks or enhanced risk robustness. This could indicate the role of ESG factors as a shock-absorbing tool against corporate risks. Further, the emerging market evidence suggests that ownership structure (
Wahome & Kinuthia, 2025) and financial risks (
Mukti et al., 2025) also influence the disclosure activities of the ESG factors.
Explanations from a theoretical perspective are grounded in theories of legitimacy and stakeholder theory, with firms using ESG as a means of mitigating external risk perception and expectations from stakeholders, especially when faced with economic constraints. Although literature on this topic is emerging, the relationship between anomalies and ESG performance has not been verified. Neither has the process of anomaly disclosure impacted ESG participation.
The effect of financial anomaly and ESG on accounting conservatism
Accounting conservatism is linked to information asymmetry and agency theories, where loss recognition asymmetry serves to shield stakeholders in situations of uncertainty. The current literature considers sustainability context settings, which have shown that corporate-level climatic risks intensify conservative financial reporting, especially when a company’s governance environment is of high quality, implying that corporate governance moderates the relationship between risks and conservatism (
Ferdous et al., 2024)
ESG performance as a holistic measure of sustainability is assumed to interact with financial anomalies and information risk. Good ESG practices may act as a substitute for rigorous conservatism by mitigating perceived risk through reputational capital. Or, they may enhance conservatism in highly anomaly-prone environments by reinforcing external scrutiny and stakeholder expectations. This aligns with recent research on the role of ESG in transparency (
Qin & Lee, 2024) and reporting quality (
Colak & Sarioglu, 2025). However, evidence to date remains varied. Some studies have found increased conservatism associated with ESG in high-risk environments, while others suggest a weakening of the impact when risk is measured through market indicators or governance distortions (
Nian & Said, 2025). Based on these arguments, we propose the following:
H2: ESG engagement moderates the financial anomaly–accounting conservatism relationship.
Because accounting conservatism is a multidimensional construct and may be measured through different approaches, the moderating role of ESG may not be uniform across alternative measurement models. Therefore, we further propose the following:
H3: The moderating effect of ESG on conservatism varies across measurement approaches.
Unsupervised Machine Learning in Anomaly Detection
Unsupervised machine learning is recognized as an effective method of anomaly detection, even without the aid of labeled examples, which makes it very valuable in the context of the rarity of labeled examples of fraud or anomalies in financial or accounting datasets. Unsupervised machine learning helps to find the concealed pattern or patterns in the data, which can be well applied in the context of financial anomaly detection or risk assessment (
Simonian, 2025).
Unsupervised methods in this study include Isolation Forest, Autoencoders, and One-class Support Vector Machine. Isolation Forest isolates anomalous observations by exploiting their rarity and distinctiveness relative to normal data points. Autoencoders learn to reconstruct normal data and flag deviations via high reconstruction errors. The One-class Support Vector Machine learns the boundary of normal data in feature space, and flags points outside this boundary as anomalies.
Recent domain-specific applications have demonstrated that unsupervised machine learning algorithms are effective in risk pattern identification of financial anomalies among corporate financial data (
Nugroho, 2025) and in anomalous transaction identification for auditing purposes (
Li et al., 2025). More advanced models have expanded from unsupervised machine learning to self-supervised or deep learning models to better take advantage of temporal and multi-variable relationships, as are typical for the complexities and high-dimensional datasets that exist for financial data, where anomalies can be subjected to minute variations from normal activity (
Rezapour, 2019;
Simonian, 2025). Such improvements have thus been conducive to the deployment of unsupervised machine learning models in accounting for irregular reporting identification and risk monitoring.
2. Data and Methodology
2.1. Data
The data used in this analysis consist of financial information for firms listed on the Stock Exchange of Thailand (SET), obtained from the SETSMART database over the period 2017–2023. Firms in the financial, banking, and insurance sectors, as well as firms undergoing rehabilitation or restructuring, are excluded from the sample. Variable description is presented in
Table 1.
2.2. Methodology
We construct the financial anomaly (FA) score using ten firm-level accounting and performance ratios that capture different aspects of financial behavior: Accounts receivable turnover (AR), asset turnover (AST), current ratio (CR), debt-to-equity ratio (DE), taxable income over total revenue (ETX), gross profit margin (GP), inventory turnover (INV), net profit margin (NP), quick ratio (QR), and return on assets (ROA). These ratios are then combined using unsupervised learning algorithms to derive a composite score, which captures irregularities in industry-specific firm performance, so as to detect abnormal patterns of finances.
Table 2 below shows the Variance Inflation Factors (VIF) of the ten accounting and performance ratios adopted to derive the financial anomaly (FA). The VIFs suggest low multicollinearity of most of the ratios (ranging between VIF = 1.0 and VIF = 1.4), and relatively higher correlation of liquidity ratios (CR and QR), with a VIF of approximately 9, representing their close resemblance to each other. However, with a VIF of 2.75, generally, multicollinearity appears not to be a concern, thereby permitting all ten ratios to be used in forming the composite score of FA.
To investigate the relationship between financial anomaly, ESG performance, and accounting conservatism, the study operationalizes financial anomaly using a composite financial anomaly score derived from three complementary machine learning techniques: Isolation Forest, Autoencoder, and One-class Support Vector Machine. Each method captures distinct aspects of abnormal financial reporting.
Isolation Forest (ISF)
ISF is employed to detect financial anomalies across Thai listed firms by industry-year. ISF isolates observations by recursively partitioning the feature space, exploiting the fact that anomalies are few and structurally distinct, requiring fewer splits to separate from the bulk of the data (
Liu et al., 2008). The input feature vector for firm
i at time t is:
Financial anomaly on ISF is defined as: .
Following the standard ISF procedure, an ensemble of 100 isolation trees is constructed for each industry-year subgroup, and the average path length of each observation is used to compute its anomaly score . Observations with the shortest average path lengths—indicating easier isolation—receive higher anomaly scores, reflecting potential fraudulent or abnormal reporting. The top 10% of scores within each industry-year are flagged as anomalies.
Industry-year granularity helps ensure that the anomalies discovered are compared within the given industry and year, making the detection relative to others with similar operational and market circumstances. The pooling also avoids the issue of working with sample sizes < 2, and optimizing error treatment helps ensure that all possible sizes are considered. The ISF will include a normalized measure for the level of anomalies discovered. This is to capture patterns that are not directly observable through traditional accounting metrics.
Autoencoders (AE)
We employ an AE to detect firm-level financial anomalies indicative of potential financial anomalies. AE is a neural network trained to reconstruct financial input ratios for each firm
i in year
t.
is the learning of the typical structure of normal reporting patterns (
Hinton & Salakhutdinov, 2006).
For each industry-year group, the AE is trained on standardized inputs to minimize the mean squared error:
The reconstruction function is:
is the autoencoder function parameterized by θ.
is the reconstructed vector (or FI).
The model is trained by minimizing the mean squared reconstruction error (MSE), defined as:
is the squared Euclidean distance between the original and reconstructed feature vectors.
The observations that tend to have higher reconstruction errors, given by the average squared distance of original and reconstructed feature values, are identified as potential anomalies. Thus, this method enables the system to identify the companies whose financial ratios tend to be very different from the usual patterns of similar firms in their industry and year.
One-Class Support Vector Machine (SVM)
SVM is applied to detect financial anomalies by modeling the boundary that encloses the majority of “normal” firm observations in a high-dimensional feature space (
Schölkopf et al., 2001). Observations lying outside this boundary are considered anomalous. The input feature vector for firm
i at time
t is:
The One-Class SVM solves the following optimization problem:
where
is the normal vector to the separating hyperplane;
is a mapping of the input into a high-dimensional kernel space;
controls the fraction of anomalies, and
are slack variables allowing for violations;
defines the offset of the decision boundary and
denotes the number of observations in the industry-year subgroup (
Schölkopf et al., 2001). In practice, we implement a radial basis function (RBF) kernel to capture non-linear patterns of normal financial behavior.
One-Class SVM is applied separately to each industry-year subgroup, standardizing the input features and computing decision values for each observation. Industry-year segmentation ensures contextual detection relative to similar firms, and a minimum group size of five observations is enforced for algorithmic stability.
The resulting SVM score forms one component of the composite financial anomaly score, which integrates the outputs of ISF, AE, and SVM outputs, enhancing robustness by leveraging multiple complementary detection approaches.
To capture a robust measure of financial anomalies, we construct a composite financial anomaly score that integrates all three complementary machine learning-based indicators. Each method captures distinct patterns of atypical financial behavior.
Financial anomaly
The composite score is used as a proxy for financial anomaly (FA). The composite score is calculated by normalizing and averaging the anomaly scores from each method within industry-year groups. Formally, for firm
i at time
t, the financial anomaly is:
where
are the raw Isolation Forest, Autoencoder, and One-Class SVM scores, respectively.
Theoretically, the composite measure is superior to any individual method because it combines the strengths of distance-based, reconstruction-based, and boundary-based anomaly detection. This integration reduces method-specific biases, mitigates false positives, and provides a more comprehensive signal of financial misreporting risk. Empirically, the composite score enhances predictive power and robustness in subsequent analyses of accounting conservatism, as it captures anomalies that might be missed when relying on a single algorithm.
4. Results
The descriptive statistics are presented in
Table 3. Fraud (FA) and R are highly dispersed, whereas E is relatively close to zero but slightly left-skewed. The ESG scores are relatively low (median = 0) with moderate right-skewing due to the diversity in ESG practices that the companies may adopt. All observations are retained. Robust standard errors are used in the regression analysis to ensure valid inference despite skewed distributions.
In
Table 4, accrual-based conservatism is captured using the asymmetric response of earnings to negative operating cash flows. To make the interpretation clearer, we multiply AC by −1 to reverse its sign. After this transformation, a positive coefficient directly represents greater conservatism, whereas conservatism was originally indicated by a negative sign. The coefficient of CF × D is positive and significant (0.915), indicating that, in total, loss is recognized in a timely manner. The result is consistent with existing research (
Ball & Shivakumar, 2005). The coefficient of the negative cash flows and financial anomalies is −0.40 and is significant, indicating that higher financial anomalies are associated with lower levels of accounting conservatism. The findings reveal that there is no uniform impact of ESG on earnings conservatism. The result for negative cash flows and ESG is not significant. This result implies that in situations where financial anomaly risk is not high, management takes less of an account of accounting conservatism due to external credibility resulting from involvement in ESG matters, thereby decreasing information asymmetry. It also implies that there is no statistical significance for the joint impact of negative cash flows, financial anomalies, and ESG on earnings conservatism. Finding statistical insignificance implies that in situations where financial anomaly risk is high, involvement in ESG matters results in less earnings conservatism among organizations, thereby resulting in a delay in recognizing losses in a risky reporting environment.
Overall, the evidence indicates that ESG engagement substitutes for accounting conservatism in low-risk settings. However, ESG does not significantly strengthen conservatism when financial anomaly, litigation, and reputational risks are elevated, suggesting that the role of ESG is state-dependent but asymmetric across risk environments.
Table 5 presents the estimates of market-based conditional conservatism following
Basu (
1997). Conditional conservatism is captured by the interaction between returns and a negative-return indicator (R × D), allowing asymmetric earnings responses to bad versus good news. The model extends the baseline by including FA, ESG, and higher-order interactions to examine whether ESG moderates anomaly-related conservatism. The coefficient of bad news (R × D) is positive and statistically significant, which is consistent with
Basu (
1997). The interaction of bad news, returns, and financial anomalies (R × FA × D) is not significant. This suggests that asymmetric loss recognition is weaker in firms with higher financial anomaly risk. All ESG-related interactions are statistically insignificant, indicating that ESG engagement does not meaningfully moderate market-based conditional conservatism in this context.
Overall, the results imply that financial anomalies attenuate the strength of market-based conditional conservatism, while ESG effects appear limited. This pattern highlights the context-dependent governance role of ESG and aligns directionally with findings from accrual-based measures.
Table 6 presents results from the earnings time-series model. Control variables include LTD, SPR, and SIZE. It should be noted that the main ESG term (ESG main effect) is dropped from this model due to collinearity. The baseline coefficient of E
it−1 × D is expected to be positive and significant, indicating that firms recognize losses in a timely manner and exhibit conditional conservatism. This model extends the baseline by incorporating FA and ESG performance to examine their moderating effects. The coefficient of E
it−1 × D (0.679) is positive and marginally significant, suggesting that overall, firms absorb losses more quickly. The interaction of negative earnings and financial anomaly (E
it−1 × FA × D) is negative and statistically significant, indicating that loss recognition is reduced in firms with higher financial anomaly risk. Notably, E
it−1 × FA × D × ESG is positive and marginally significant. This suggests that ESG engagement partially offsets the reduction in conditional conservatism associated with financial anomalies.
Overall, the results suggest that financial anomalies diminish asymmetric loss recognition. However, ESG performance can mitigate this effect. This highlights the context-dependent role of ESG in reinforcing conservative financial reporting.
5. Discussion
The results across
Table 4,
Table 5 and
Table 6 collectively highlight that accounting conservatism is sensitive to financial anomaly risk and moderated by ESG engagement in a context-dependent manner. Consistent with the prior study (
Alam & Petruska, 2012;
Jones et al., 2008), financial anomalies consistently weaken both accrual-based and market-based measures of conservatism. This reflects delayed or reduced loss recognition in high-risk firms. ESG engagement, however, does not exert a uniform effect. It can partially substitute for conservative reporting in low-risk environments and mitigate the negative impact of anomalies in earnings time-series models, but its influence is limited in accrual- and market-based measures. Our findings on the effect of ESG on accounting conservatism are consistent with evidence from the Turkish context (
Altın, 2025) and those documented in the Malaysian environment (
Abdul Manaf et al., 2024). These patterns suggest that ESG functions as a state-dependent governance mechanism. This should reinforce conservative accounting, primarily when internal practices, rather than market signals, are the main channel for loss recognition. Overall, the evidence underscores that conservatism is shaped by the interaction of firm risk characteristics and governance engagement, rather than ESG or anomalies alone.
It should be noted that the non-uniform ESG effects across accrual-based, market-based, and earnings-based models reflect the multidimensional nature of accounting conservatism. Accrual-based measures capture managerial reporting discretion, market-based measures reflect investor recognition of bad news, and earnings-based models capture intertemporal earnings dynamics. Because ESG primarily operates through reputational capital and reductions in perceived information risk, its influence is more closely aligned with discretionary reporting incentives than with market-level pricing mechanisms or structural earnings persistence. Consequently, ESG does not exert a uniform effect across alternative conservatism proxies, consistent with a state-dependent governance framework in which different economic channels operate simultaneously.
From a theoretical perspective, these findings can be used to elaborate on ESG’s governance function, ranging from the substitutes and/or complements ESG provides for traditional reporting and monitoring mechanisms. ESG engagement can be used alternatively for internal monitoring to reduce the misreporting of earnings, and to mitigate the reduction in conditional conservatism under financial anomaly risk, rather than unconditionally promoting it, or to supply reputational support mainly in accrual-based settings rather than as a uniform substitute for market-imposed accounting rigidity. It is clear, therefore, that ESG assessments must be placed within a multi-faceted analytical context, rather than treating ESG as a direct proxy for reporting quality.
For investors and analysts, ESG scores should not be interpreted as a direct signal of stronger conservative reporting. For companies with high financial anomaly risk or operating stress, high ESG engagement might act to further defer loss recognition. Thus, investors need to consider ESG performance together with financial anomaly indicators to examine earnings quality, especially when the market turns down or during negative cash flows. Anomaly-based risk measures can be embedded into pricing and credit valuation models to enhance the accuracy of risk premiums. For regulators and standard setters, the findings indicate that ESG disclosure frameworks and financial reporting oversight should not be addressed separately. In high-risk settings, reputational capital accumulated from ESG activities may serve as a partial substitute for conservative reporting incentives. This implies the need for joint monitoring systems that take into account both sustainability reporting and financial reporting quality, particularly in sectors with high earnings management or litigation risk. From a corporate management perspective, ESG investments can create reputational cushions that lower the costs of external monitoring and capital. But this flexibility should not be seen as an alternative to transparent reporting in high-risk environments. Corporate managers should understand that overdependence on reputational capital in high-anomaly risk environments could damage reputation and increase future litigation or capital market sanctions. In conclusion, the evidence suggests that accounting decisions are conditional and non-linear in their relationship with ESG engagement and financial anomaly risk. Good governance, therefore, involves integrating sustainability strategies with financial reporting integrity, especially during times of economic stress.
In summary, ESG engagement functions as a state-dependent governance mechanism that can partially substitute for conservative accounting practices under financial anomaly risk, particularly in accrual-based settings. Its effect is less pronounced in market-based measures, highlighting that ESG’s influence on accounting conservatism is conditional, context-dependent, and interacts with firm-specific risk characteristics. These findings have implications for investors, regulators, and management, emphasizing caution in interpreting ESG scores as a direct indicator of reporting quality.
Additional tests
In order to isolate and clarify the role of ESG in our research, we perform another test, utilizing only corporate governance (CG) scores because of their important role in the combined ESG metric. As presented in
Table 7, we repeat analyses in
Table 4,
Table 5 and
Table 6 above, replacing the ESG measure with a dummy for CG. We analyze in what way the governance element, in particular, is responsible for creating empirical findings on accounting conservatism independent of environmental and social elements. It is also necessary to determine whether internal company governance is a reason for the mitigation of reduced conservatism in companies facing a higher risk of financial anomalies.
These findings are strengthened and extended by the earnings time-series model, which models earnings persistence (Eit−1). Lagged earnings positively interact with negative shocks, suggesting that companies adjust earnings in response to negative news. Most importantly, governance partially accelerates losing recognition for negative shocks, especially after controlling for financial anomalies (Eit−1 × FA × CG × D), thereby supporting the fact that good governance discipline adheres to conservative reporting under conditions of risk.
In total, there is evidence that accrual-based methods perform the task of conditional loss recognition most effectively and earnings-based methods represent a robust alternative, while market-based methods are noticeably less responsive. For all model specifications, negative shocks, financial anomalies, and corporate governance have been shown to jointly influence the intensity as well as the speed of loss recognition, which indicates that characteristics as well as control procedures play an important role in conservative accounting.
Our study analyzes the conditional loss recognition, and the approaches considered are accrual-based, market-based, and earnings time-series approaches. For all the approaches, the negative shock (D) is the key factor that indicates the adjustment in the reporting highlighted by the companies in response to the negative events. The accrual-based approach includes CF, which has a highly positive association with accruals in the normal setting. However, the CF and the negative shocks (CF × D) have a statistically significant effect that exaggerates the accruals. The effect is further modified by FA. CF × FA increases the sensitivity of accruals. CF × FA × D has a role in reducing the accruals, and the effect is to indicate that, in the case of negative shocks, companies with anomalies follow a more conservative approach. The effect is further strengthened by the association with CG, which reduces the accruals. The association with CF and FA in the case of negative shocks has a statistical effect that moderates the loss recognition.
The market-based model shows weaker but noticeable patterns. While the main effects of returns (R) and their interactions with shocks (R × D) are less pronounced, interactions with FA and CG suggest that markets partially reflect conditional loss recognition, though these effects are smaller and noisier compared to accruals. This indicates that market prices are less direct or slower in capturing accounting-based conservatism, especially when anomalies and governance structures interact.
The earnings time-series model complements these findings by capturing the persistence of prior earnings (Eit−1). Lagged earnings interact positively with negative shocks, indicating that firms adjust earnings following adverse events. Importantly, governance significantly accelerates loss recognition under negative shocks, particularly when combined with financial anomalies (Eit−1 × FA × CG × D), reinforcing the idea that strong governance enforces conservative reporting in response to risk signals.
Taken together, the results indicate that the accrual-based measures capture conditional loss recognition best, earnings-based measures come in a clear second, and market-based measures are considerably less sensitive. In all model variations, negative shocks, financial anomalies, and corporate governance jointly determine the degree and timing of loss recognition, pointing to the importance of firm-specific characteristics as well as oversight mechanisms for shaping conservative accounting practices.
6. Conclusions
This study examines how financial anomaly risk relates to accounting conservatism and whether ESG engagement moderates this relationship across different empirical measures of conditional conservatism. Using accrual-based, market-based, and earnings time-series approaches, we provide a comprehensive assessment of how firms recognize losses under adverse conditions and how governance-related mechanisms interact with risk. By integrating financial anomaly exposure and ESG performance into established conservatism models, the analysis sheds light on the state-dependent role of ESG in financial reporting behavior.
Overall, the findings provide partial support for H1. Specifically, higher financial anomaly risk is associated with weaker accounting conservatism in two of the three empirical specifications, as reflected in delayed or attenuated loss recognition. However, the market-based model does not yield statistically significant results, suggesting that the effect is not uniformly robust across alternative measurement approaches. Taken together, the evidence indicates that the negative association between financial anomaly risk and accounting conservatism is present but model-dependent. Firms facing elevated anomaly risk appear less timely in incorporating negative information into earnings, which is consistent with reduced reporting discipline in riskier environments. Evidence for H2 is mixed but informative. ESG engagement does moderate the relationship between anomaly risk and conservatism, though the direction and strength of this effect depend on the reporting context. In particular, ESG substitutes for accounting conservatism in low-risk settings, while its mitigating role becomes limited or asymmetric when anomaly-related risks are high. Regarding H3, the results confirm that the moderating role of ESG varies across measurement approaches. Accrual-based models capture the strongest effects, earnings-based models show partial mitigation through ESG or governance mechanisms, and market-based measures exhibit relatively weak sensitivity. This variation underscores the importance of measurement choice when assessing conservatism and governance effects.
However, there are some limitations that should be taken into consideration. Fraud risk is proxied by an equally weighted composite anomaly score derived from three models capturing distinct structural characteristics—tree-based isolation, non-linear reconstruction error, and boundary-based deviation. Given their comparable predictive performance, this ensemble approach enhances robustness and mitigates model-specific bias; however, the equal-weighting assumption may overlook potential differences in model performance, which could affect the precision of the fraud risk measure. The composite ESG measure prevents disaggregated analysis of environmental, social, and governance dimensions. In addition, there might be some endogeneity left unaddressed by both fixed effect models and instrumental variable techniques. Moreover, as the analysis is conducted within a single institutional setting (Thailand), the generalizability of the findings to other regulatory or market environments may be limited. Therefore, their generalizability applies best to contexts with a broadly similar business environment, regulatory framework, enforcement intensity, investor protection, and standards of ESG disclosure.
Future studies might investigate disaggregated ESG performance. They might use dynamic panel models to model ESG or anomaly risk-related time-series changes in conservatism. Cross-country studies also represent a promising avenue for future research. Incorporating qualitative disclosures, audit quality, or internal control measures might explain how ESG risk conditions the risk of financial anomalies to affect conservative reporting.