1. Introduction
Threshold functionals appear throughout the theory of stochastic processes. Given a real-valued process , one may ask when it first crosses a level, how long it remains below a boundary, how often it returns to a prescribed band, or what is the longest interval during which it stays in a sub-threshold regime.
Fix a finite horizon
. For a threshold
, define the sub-threshold time set
This set contains more information than its Lebesgue measure. The cumulative occupation time
records how much time the path spends below
a, but it does not describe how this time is organized. The path may spend one long interval below the threshold, or it may return below the threshold many times for short durations. To capture this temporal organization, one may study the connected components of
, which we call sub-threshold bursts. The longest such burst is
More generally, if
denotes the collection of lengths of the sub-threshold components, arranged in nonincreasing order, then
whenever the level set
has zero Lebesgue measure, whereas
Thus cumulative occupation is additive, while longest-burst duration is extremal and connectivity-sensitive.
This additive/extremal distinction is also the probabilistic counterpart of a distinction from the theory of Parisian-type barrier contracts. A continuous Parisian barrier monitors uninterrupted excursions beyond a barrier: the clock is reset whenever the underlying crosses back to the safe side. In the present threshold notation, the corresponding clock is the longest-burst or longest-excursion functional . By contrast, a cumulative Parisian barrier, often called a Parasian barrier, uses a non-resetting clock and records total time spent beyond the barrier. In the present notation, the corresponding clock is precisely the additive occupation functional . The Parasian trigger is of the form , while the continuous Parisian trigger is of the form . The central theme of the paper is that these two clocks have radically different threshold sensitivities.
The additive clock belongs to the classical theory of occupation times and local times. If
X is a regular one-dimensional diffusion satisfying
then the occupation density formula yields
where
is the semimartingale local time of
X at level
y. Consequently,
at every level where the local-time density is continuous. In the Brownian case, this reduces to
This formula is a direct form of the occupation density formula for continuous semimartingales and diffusions; see, for example, Revuz–Yor [
1], Karatzas–Shreve [
2], and the collection of Brownian formulae in Borodin–Salminen [
3]. Its role in the present paper is not to provide a new local-time identity. Rather, it serves as a benchmark: cumulative Parasian occupation has a local differential structure.
The non-additive clock belongs to a different lineage, governed by excursion lengths rather than by occupation density. The duration of the longest excursion was studied directly by Knight [
4], and ranked excursion lengths, together with penalizations by long excursions, were developed by Pitman–Yor [
5] and Roynette–Vallois–Yor [
6]. The same excursion-age structure underlies the Parisian stopping times introduced into option pricing by Chesney, Jeanblanc-Picqué, and Yor [
7], who obtained the law of the first excursion to reach a prescribed length through Brownian excursions, the Brownian meander, and the Azéma martingale. Schröder [
8] later recast this transform for valuation at an intermediate date. Related excursion-length and Parisian stopping-time formulae have been developed by Gauthier [
9] for height- and length-related stopping times, Dassios–Wu [
10] for perturbed and jump-diffusion models, Dassios–Lim [
11,
12] for one-sided, two-sided and double-barrier Parisian windows, Dassios–Zhang [
13] for the joint law with the hitting time, and Zhang–Li [
14] and Liu–Yang–Zhang [
15] for general Markov and time-inhomogeneous Markov models.
The cumulative, non-resetting side has its own valuation literature. Occupation-time derivatives and cumulative Parisian, or Parasian, options were developed by Hugonnier [
16] and Moraux [
17]. The explicit comparison between Parisian and Parasian structures is emphasized in Zhu–Chen [
18] and Ai–Zhu [
19]. These works primarily fix a barrier and a window and compute or approximate the law of a stopping time for pricing purposes. The present paper is not concerned with valuation. Instead, it fixes the finite horizon and studies the entire threshold-indexed profile of the two clocks: the Parasian profile
and the continuous Parisian profile
.
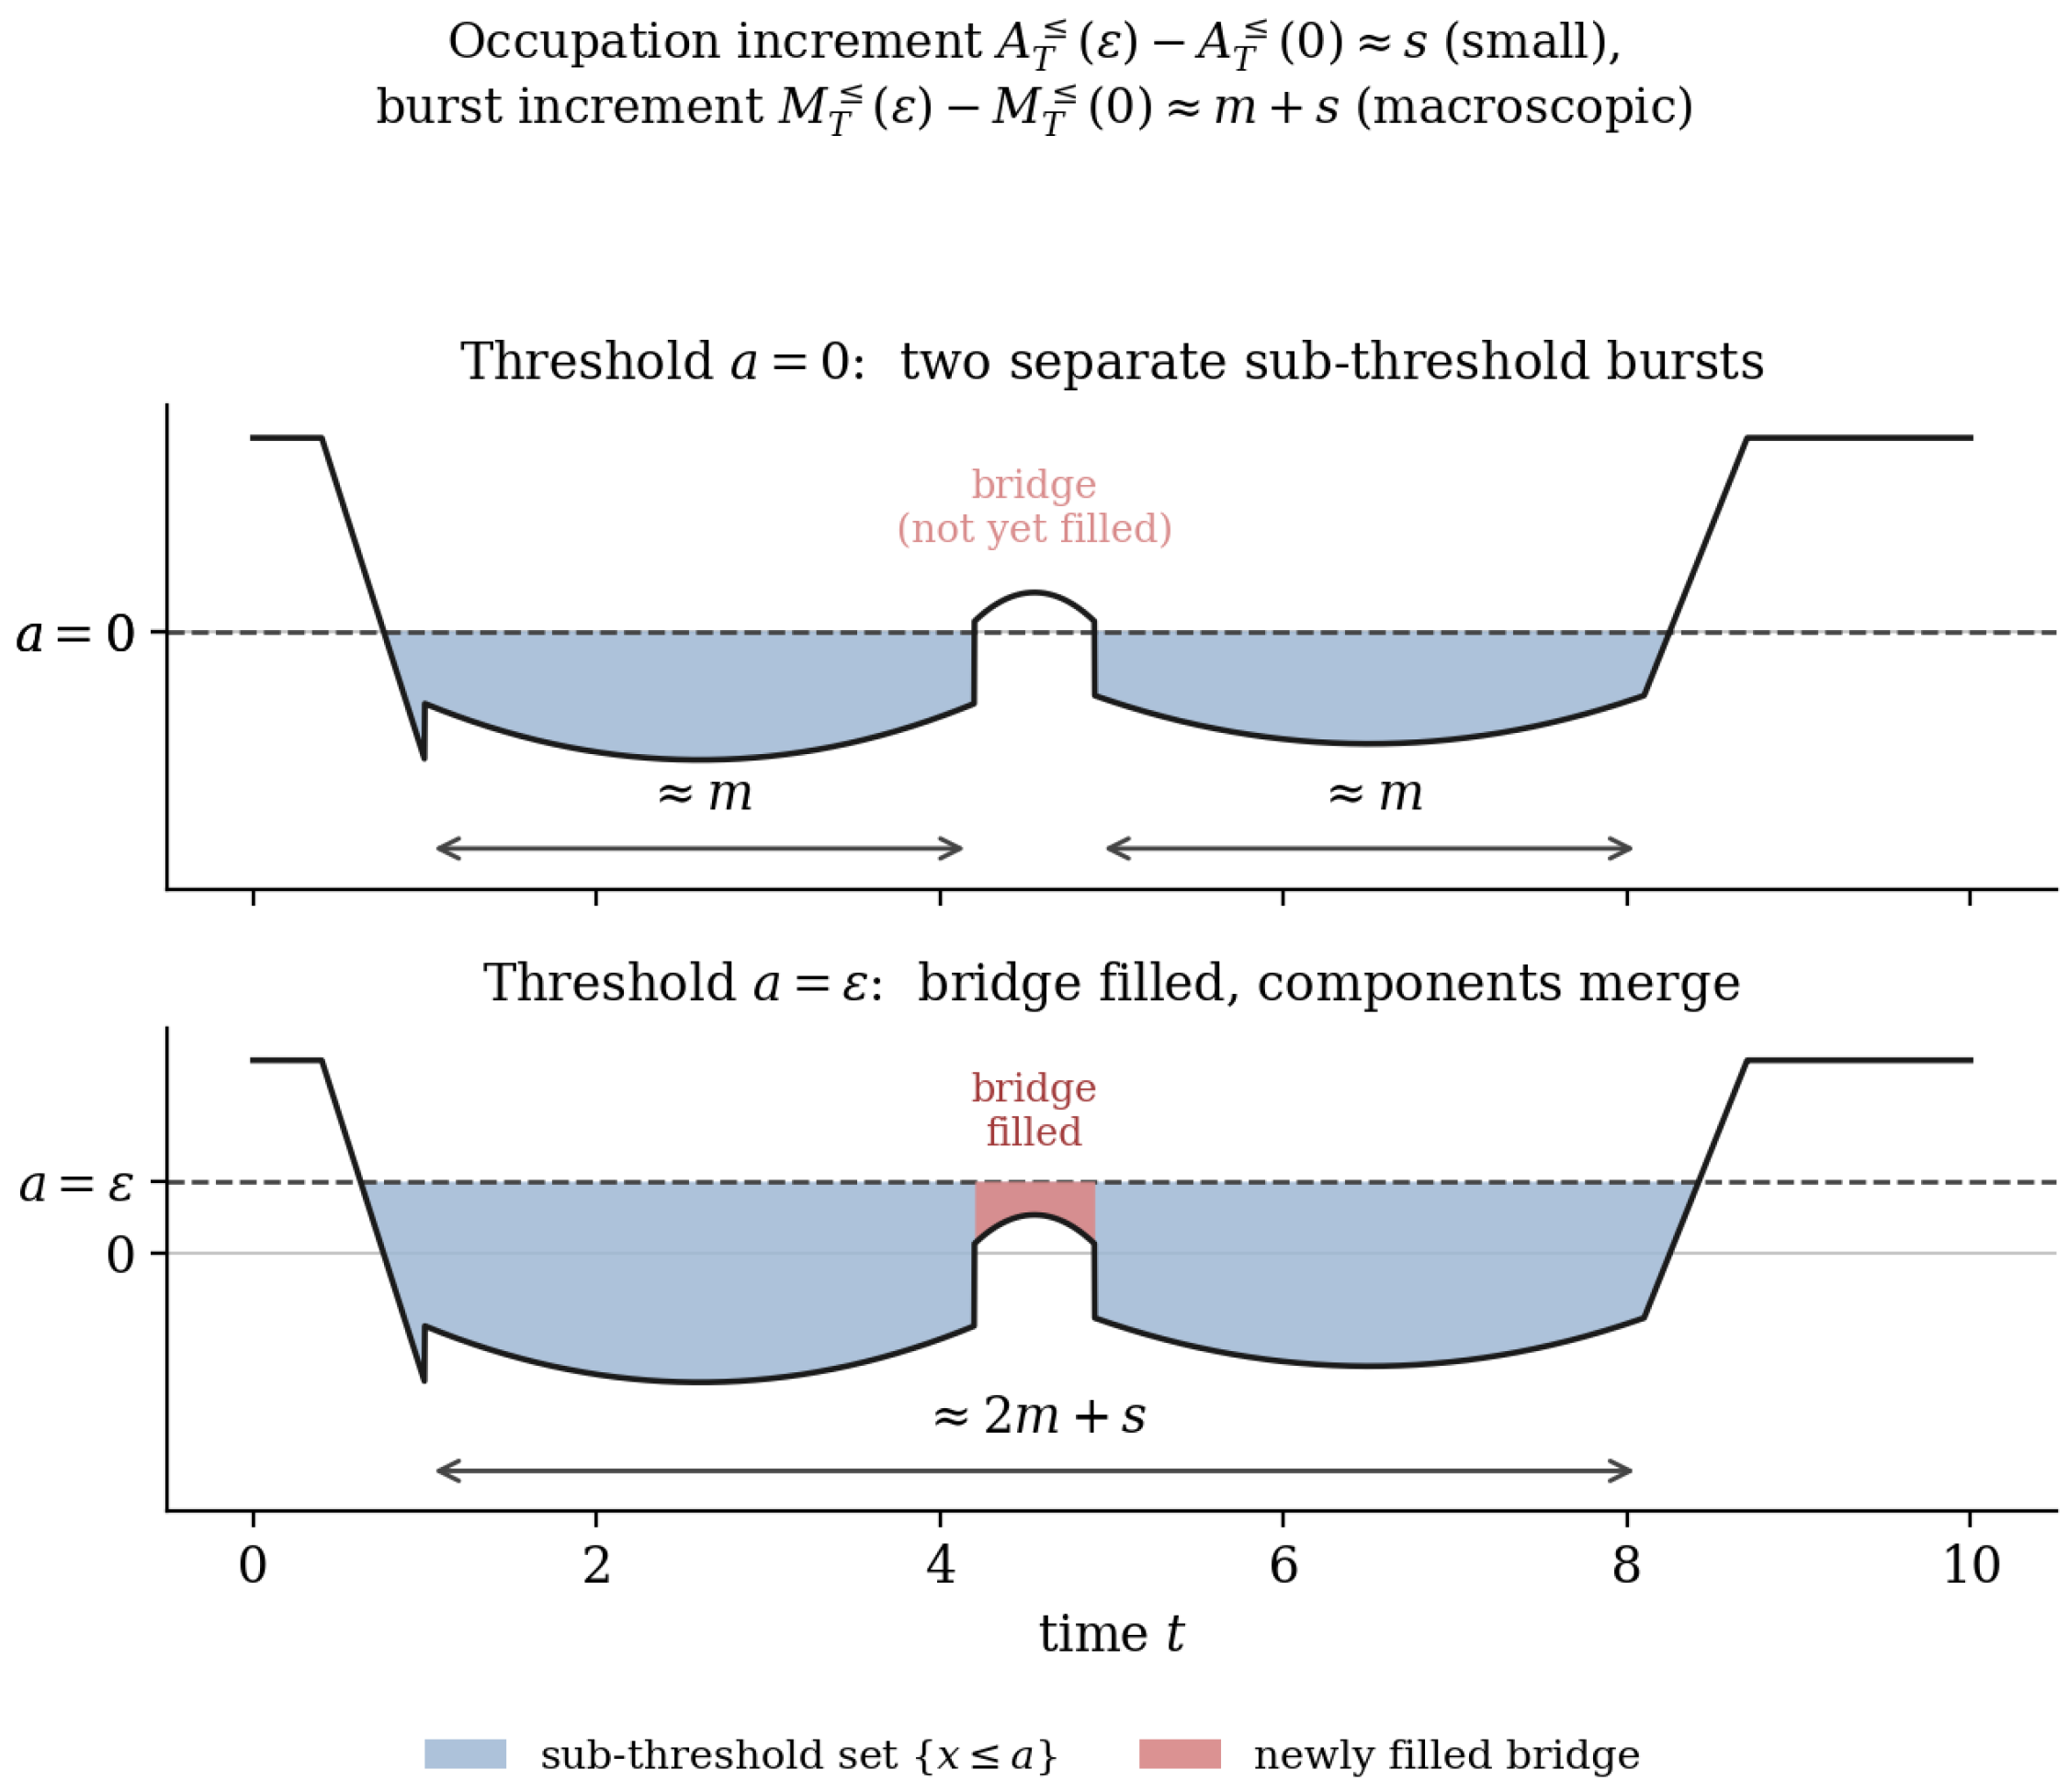
The distinction isolated here is structural. Additive threshold occupation is local-time sensitive. Resetting burst duration is connectivity-sensitive. A small increase in the threshold may add very little occupation time while connecting two large sub-threshold intervals through a short temporal bridge; the occupation increment is then negligible, yet the longest burst may increase by a macroscopic amount.
This gives the central contrast:
cumulative Parasian occupation is additive and local-time sensitive;
continuous Parisian burst duration is extremal, resetting, and merger-sensitive.
The specific contributions of the paper are the following.
- 1.
Foundational threshold-clock decomposition. We formulate the deterministic decomposition of weak and strict sublevel time sets for continuous paths and place it side by side with the additive occupation formula. This provides a common notation for the cumulative Parasian clock and the resetting Parisian clock .
- 2.
One-sided regularity of the longest burst. We prove that the weak longest-burst functional is nondecreasing, that its defining supremum is attained, and that it is right-continuous with left limits. Its strict-sublevel counterpart is the left-continuous regularization of the same monotone object. The jump at a level equals the increase in maximal component length produced by adjoining the level set.
- 3.
Diffusion-level contrast. For regular one-dimensional diffusions, the additive/Parasian occupation profile is locally absolutely continuous with local-time density. By contrast, the continuous Parisian longest-burst profile has merger-driven regularity. At deterministic levels which are almost surely not local-extreme values, weak and strict longest bursts agree almost surely. Whenever the path has a unique interior maximum, the threshold-indexed profile has a positive jump at the maximum level and is therefore not absolutely continuous. Brownian motion satisfies this criterion almost surely.
- 4.
Distributional identity via Parisian times. We show that the longest burst is exactly a one-sided continuous Parisian functional. This yields the Brownian Laplace-transform law through the Chesney–Jeanblanc-Picqué–Yor Parisian transform [
7]. For Brownian motion started below the barrier, we give an explicit decomposition using the hitting time of the barrier, rather than appealing to the different intermediate-valuation problem treated by Schröder [
8]. We also give an excursion-measure formulation in which local time enters only as the Itô excursion intensity.
- 5.
Extensions and model consequences. We discuss smoothed burst statistics, moving thresholds, and standard diffusion examples. In the moving-threshold case, additive occupation is governed by local time on curves, in the sense of Peskir [
20], while burst duration remains merger-sensitive.
To delineate the novelty precisely, we separate what is used from what is new. The excursion-theoretic results on ranked and longest excursions (Knight [
4], Pitman–Yor [
5], Roynette–Vallois–Yor [
6]) and the Parisian stopping-time transforms (Chesney–Jeanblanc-Picqué–Yor [
7] and its extensions [
8,
10,
11,
12,
13,
14,
15]) are invoked as tools and are not re-derived here. What is new is the treatment of the entire threshold-indexed profile
as a deterministic pathwise object: its one-sided (càdlàg/càglàd) regularity together with the exact jump formula, the bridge-merger mechanism that generates the jumps and the consequent failure of absolute continuity, and the pathwise identification of the longest burst with a one-sided Parisian functional. This last point turns the classical Parisian transform into a statement about the profile
itself, rather than about a fixed pricing problem. In short, the excursion and Parisian machinery supplies the marginal Brownian law, whereas the threshold-profile regularity theory, the merger instability, and the additive-versus-extremal (Parasian-versus-Parisian) sensitivity dichotomy are the contribution of the paper.
The paper is organized as follows.
Section 2 introduces the common threshold-clock framework: sublevel time sets, weak and strict burst decompositions, the cumulative Parasian occupation clock, and the local-time sensitivity formula.
Section 3 proves the deterministic one-sided regularity theorem for longest bursts and isolates the bridge-merger mechanism, including a schematic illustration.
Section 4 identifies the longest burst with a one-sided continuous Parisian functional and derives the Brownian Laplace-transform and excursion-intensity forms.
Section 5 develops diffusion consequences and examples, including Brownian motion, Ornstein–Uhlenbeck processes, reflected Brownian motion, and sticky behavior.
Section 6 treats two extensions, smoothed burst statistics and moving thresholds.
Section 7 concludes with open directions.
2. Threshold Clocks: Additive Occupation and Burst Decomposition
This section introduces the common deterministic notation used throughout the paper and places the two threshold clocks side by side. The first clock is the cumulative, non-resetting clock
which is the probabilistic analogue of a Parasian clock. The second clock is the resetting, connected-component clock
which is the finite-horizon version of a continuous Parisian clock.
Let
. For
, define the weak sublevel time set
and the strict sublevel time set
Since x is continuous, is compact and is relatively open in .
The strict sublevel set
decomposes into a countable disjoint union of open intervals, with the convention that intervals may touch the endpoints 0 and
T. We write
where the intervals
are the connected components of
. These intervals are the strict sub-threshold bursts of
x below
a.
For an interval
I, write
for its length. The strict occupation time is
The weak occupation time is
The difference between the weak and strict profiles is exactly the amount of time spent at level
a:
Thus, whenever
the strict and weak occupation times coincide. This is the deterministic expression of the fact that a non-sticky path spends no positive amount of calendar time exactly at one level.
For burst duration, it is often useful to keep both versions. Let be the family of connected components of , and let be the family of connected components of . Components of the weak sublevel set are compact intervals or singletons; components of the strict sublevel set are relatively open intervals.
Define the weak longest burst by
with the convention
if
. Define the strict longest burst by
with the convention
if
.
For
, define the number of macroscopic weak bursts longer than
by
Because disjoint intervals of length greater than
have total length at most
T,
The contrast between and is the deterministic version of the Parasian/Parisian distinction. The functional is cumulative: it adds the lengths of all sub-threshold components. The functional is resetting and extremal: it keeps only the longest single sub-threshold component.
Proposition 1 (Sublevel burst decomposition). Let . Then, for every :
- 1.
is a countable disjoint union of relatively open intervals, and - 2.
is compact, and its connected components are compact intervals or singletons.
- 3.
The weak and strict longest bursts and are well defined and belong to .
- 4.
Proof. The set is open in the relative topology of , hence a countable union of disjoint open intervals; its Lebesgue measure is the sum of their lengths. The set is closed in , hence compact. Connected subsets of the real line are intervals, so its connected components are compact intervals or points. The longest component length is therefore well defined and bounded by T. Finally, any collection of disjoint intervals of length greater than inside has at most members.
We now recall the local-time sensitivity of the cumulative Parasian clock. The point is to isolate the differentiable benchmark against which resetting Parisian burst instability will be compared.
Let
X be a one-dimensional diffusion satisfying
where
is continuous and locally bounded away from zero.
We record the standing hypotheses used for the diffusion-level statements of the paper—the static occupation sensitivity below, the diffusion-level contrast of
Section 3, and the diffusion examples of
Section 5.
H1. X is a regular one-dimensional diffusion with continuous paths.
H2. is continuous and locally bounded away from zero.
H3. The local-time field is continuous.
Hypotheses (H1)–(H3) are precisely those under which the occupation-density formula and its differential consequence below hold almost surely, and they are satisfied by the non-degenerate regular diffusions treated in
Section 5.
Let
denote the semimartingale local time of
X at level
a. Define
The occupation density formula states that, for suitable nonnegative Borel functions
f,
Taking
recovers the cumulative occupation profile (
7).
Thus the local-time field is the threshold density of cumulative occupation. In the terminology of the Introduction, it is the sensitivity density of the Parasian clock. □
Proposition 2 (Static occupation sensitivity).
Assume that is continuous and that σ is continuous and locally bounded away from zero. Then, almost surely, the map is locally absolutely continuous andMoreover, for every sufficiently small ε,and consequentlywhere Proof. The representation (
7) follows directly from the occupation density formula. Under the stated continuity assumptions, the fundamental theorem of calculus gives (
28).
The finite-difference identity follows by subtracting the values at
and
a. Subtracting the first-order term yields
and the displayed bound is immediate.
Proposition 2 gives the differentiable benchmark: the infinitesimal occupation gained by raising a is local time at a. The rest of the paper shows that this principle breaks down for the resetting Parisian clock . □
3. One-Sided Regularity and the Bridge-Merger Mechanism
Let
. Recall the closed and open sublevel sets (
12) and (
13) and the weak and strict longest-burst functionals (
19) and (
20).
We first record that “longest” is literal.
Lemma 1 (The supremum is attained). For every and every , if , then there is a connected component of of length exactly . The same holds for whenever .
Proof. We prove the weak-sublevel statement first; the strict-sublevel statement is treated at the end.
Assume
. Take components
of
with
Since
is compact, pass to a subsequence such that
For any , one has for all sufficiently large n. Hence . By continuity, for every . Therefore . This interval is contained in a connected component of , whose length is at least . By definition of the supremum, the length is exactly .
For the strict-sublevel statement, let . Choose strict components whose lengths tend to m. For all sufficiently large indices, these lengths are larger than . Since disjoint intervals of length greater than inside are finite in number, the supremum over those components is a maximum. Hence one strict component has length . □
Theorem 1 (One-sided regularity and jump structure). Let . Then:
- 1.
Both and are nondecreasing.
- 2.
Consequently is right-continuous with left limits, while is left-continuous with right limits. The two functions are the càdlàg and càglàd regularizations of the same monotone object.
- 3.
The jump of the weak longest-burst profile at a is It is the increase in maximal connected-component length produced by adjoining the level set to the strict sublevel set In particular, is continuous at a if and only if adjoining the level set creates no weak sublevel component whose length is larger than the previous strict longest burst.
- 4.
The set of discontinuities of is at most countable.
- 5.
If, moreover, has finitely many critical points, all strict and with pairwise distinct critical values, then is continuous away from the local-maximum values. At an interior local-maximum value, a two-sided component-merger event occurs. This event produces a positive jump of if and only if the welded component exceeds the previous maximal component length. Endpoint extrema produce only one-sided endpoint changes and are not part of the two-sided merger mechanism. Between consecutive critical values, varies continuously.
Proof. Monotonicity is immediate: if
, then
Every component of the smaller sublevel set lies in a component of the larger one, so the maximal component length cannot decrease.
We use the pointwise set identities
and
For right-continuity, suppose by contradiction that
Then there exist
and components
of
such that
Passing to a subsequence,
For any
, one has
for all sufficiently large
n, hence
Letting
, we obtain
. By continuity,
. Thus
contains a connected subset of length
ℓ, contradicting
. Therefore
Next we prove the left-limit identity. Since
we have
Here implies , which gives the displayed inclusion for every . By monotonicity of the left limit equals the supremum, ; and since any connected component of is an interval contained in , hence in one of its components, its length is at most . Passing to the supremum over yields the stated bound.
Conversely, let
be a strict component of
. For every compact subinterval
, continuity gives
The supremum of the continuous function x over the compact interval is attained and, since throughout I, is strictly below a. Setting gives for all , which is exactly the inclusion recorded next.
Hence there exists
such that
For the just chosen, monotonicity gives . As increases to I we have , so for every strict component I; taking the supremum over such components gives the reverse inequality.
Letting
exhaust
I, and then taking the supremum over strict components
I, yields
The càdlàg and càglàd conclusions follow from monotonicity and these one-sided identities. The jump formula follows immediately.
A nondecreasing real function has at most countably many discontinuities, proving the fourth assertion.
For the finite-critical-points statement, suppose
a is not a critical value of
x. Then every solution of
is transversal, meaning
. By the implicit function theorem, the crossing times vary continuously under small perturbations of the level. Hence the number and ordering of sublevel components remain locally unchanged, and their endpoint locations vary continuously. Therefore
is continuous at
a. At an interior strict local minimum, a new component is born with zero length, so no positive jump of the maximum can occur at the instant of birth. At an interior strict local maximum, two adjacent components merge. Such a merger produces a positive jump precisely when the newly welded component has length larger than the previous strict longest component. Endpoint extrema may change one endpoint of a component, but they do not create the two-sided welding mechanism described above. This proves the final assertion. □
Corollary 1 (Diffusion-level contrast). Let X be a regular one-dimensional diffusion with continuous paths and nondegenerate diffusion coefficient σ. Fix .
- 1.
The additive occupation profile is almost surely locally absolutely continuous, with at every level at which the local-time density is continuous.
- 2.
At any deterministic level a such that almost surely, and the weak longest-burst profile is almost surely continuous at a.
- 3.
If a continuous path x attains its maximum on at a unique point , then has a positive jump at the maximum level Consequently is not absolutely continuous.
- 4.
In particular, for standard Brownian motion on , is almost surely not absolutely continuous.
Proof. The first assertion is Proposition 2.
For the second assertion, Theorem 1 gives
A positive jump can occur only if adjoining the level set at
a welds strict sublevel components into a longer weak component. Such a weld requires
a to be a local-maximum value of the path. If
a is almost surely not a local-maximum value, then the jump vanishes almost surely, and
For the third assertion, suppose
x has a unique interior maximizer
. At the maximum level
m, the weak sublevel set is all of
, hence
The strict sublevel set is
which has two connected components of lengths
and
. Therefore
Any monotone function with a positive jump is not absolutely continuous.
For Brownian motion, the maximum on a compact interval is almost surely attained at a unique time; see, for instance, the standard treatment of Brownian extrema in Karatzas–Shreve ([
2] Section 2.9). The arcsine law for the time of the maximum gives no mass to the endpoints 0 and
T. Therefore the Brownian maximum is attained at a unique interior time almost surely. The preceding deterministic criterion applies, and
is almost surely not absolutely continuous. □
Theorem 2 (Bridge-merger jump).
Let and . Suppose that a two-sided merger occurs at level a: the weak sublevel set has a connected component J whose intersection with the strict sublevel set has exactly two connected components and , with lengths ; writing for the bridge, is a disjoint decomposition. Assume moreover that J realizes the weak longest burst and the strict longest burst, i.e., and . Then
In particular, if the level set has zero Lebesgue measure, then and the jump equals the length of the shorter merged component,
Proof. By the jump formula of Theorem 1, . By hypothesis and . Each point of J satisfies either , and then lies in or , or , and then lies in B; hence is a disjoint union, and additivity of Lebesgue measure gives . Therefore . If then , so and the jump reduces to .□
Thus a two-sided merger raises the longest burst by exactly the shorter of the two flanking components (plus the bridge length, in the sticky case), a quantity unrelated to the occupation gained across the merger. The explicit family of Remark 1 makes the resulting sensitivity ratio unbounded.
Remark 1 (The explicit bridge example). This is the explicit family behind Theorem 2: it realizes a two-sided merger in which the occupation increment can be made arbitrarily small while the burst jump stays macroscopic, so that the sensitivity ratio is unbounded. The preceding corollary gives a robust pathwise mechanism for non-absolute-continuity. A simpler deterministic bridge construction illustrates the same phenomenon at a prescribed level.
Fix , , and a scale with . Choose . Take and consider three time intervals Choose a continuous path x such that on most of , such that on the bridge J, such that outside , and such that all smoothing transitions have total length less than .
At threshold 0, the two long pieces are separate sub-threshold components. At threshold ε, the bridge J is filled and the two pieces merge. Thuswhileafter choosing the smoothing intervals sufficiently short. In particular, there is no universal constant C such thatfor all continuous paths, all a, and all . The construction is illustrated in
Figure 1. At the lower threshold, the two long sub-threshold blocks are separated by a short bridge lying just above the threshold. After the threshold is raised, the bridge is filled and the two components are welded into one component. The newly captured occupation is only of order
s, while the longest-burst increment is of order
.
Remark 2 (Mechanisms of singularity).
Corollary 1 obtained non-absolute-continuity from one sufficient condition, a unique interior global maximum. Theorem 2 identifies the general source of the jumps, and several distinct mechanisms produce them. (a) Non-global local maxima. A two-sided merger at an interior local-maximum value a that is not the global maximum still produces a positive jump as soon as the welded component J becomes the longest burst; the global maximum is not required. (b) Level sets of positive measure. At a sticky level (Section 5.5) the bridge has , contributing the extra term to the jump; there the additive profile itself jumps, so both clocks are discontinuous. (c) Accumulation of merger levels. A path may possess infinitely many interior local maxima, so that the jump set of is countable but possibly dense; the profile is then a monotone function with a nontrivial jump part, and a single positive jump already precludes absolute continuity. The unique-maximizer argument of Corollary 1 is therefore only the simplest instance of the merger mechanism. Example 1 (Weak and strict longest bursts differ).
Take and the symmetric tent , , so that and the unique maximum is attained at . For , has two components each of length ; since has zero length, the strict set agrees up to endpoints, and
At the maximum level , however, is connected, so , whereas has two components of length 1, giving . Hence
This is a two-sided merger in the sense of Theorem 2, with , , and jump . The gap is macroscopic—half the horizon—so the two formulations genuinely differ: the càdlàg profile records the merged burst at the maximum level, while its càglàd regularization retains the longer arm just below it. Both are therefore needed.
4. The Longest Burst as a Continuous Parisian Functional
Throughout this section we fix one normalization of local time and carry it consistently. We use the semimartingale (Tanaka) local time
, normalized so that the occupation density formula of
Section 2 holds in the form
, and so that the inverse local time
is the stable subordinator with
. The one-sided Parisian transform
of Chesney, Jeanblanc-Picqué, and Yor [
7] is expressed below in this same normalization, so that the excursion-intensity computation of Proposition 3 and the transform of Theorem 3 refer to the identical local-time clock. With this convention the negative-excursion Itô measure
used in Proposition 3 is the one induced by the inverse local time above; any other normalization rescales
and the transform by the same factor, leaving every displayed identity invariant.
The preceding section described the longest-burst profile as a deterministic connected-component functional. We now identify the same object with the continuous Parisian, or resetting, clock. This is the exact counterpart of the cumulative Parasian clock
studied in
Section 2. The Parasian event
depends on total time below the threshold; the continuous Parisian event
depends on one uninterrupted below-threshold episode.
The longest-burst functional admits an exact probabilistic description: it is a one-sided Parisian functional. This section records the pathwise identity and then specializes to Brownian motion.
Fix
and
. For a continuous path
x, define the strict below-
a age at time
t by
Thus
is the time already spent in the current strict below-
a excursion. Define the one-sided Parisian time with window
D by
This is the first time at which the current below-threshold episode has lasted at least D.
Lemma 2 (Pathwise Parisian identity).
For every continuous path x,If, in addition,then the same identity holds with in place of . Proof. The event
means that the strict sublevel set
contains a connected component of length strictly larger than
D. Equivalently, there exists a time
at which the path has completed a full below-
a window of length
D since its most recent visit to
a, or since time 0 if the path started below
a and has not yet returned to
a. This is exactly
The final assertion follows immediately from the equality . In particular, for regular diffusions at deterministic levels satisfying the no-local-maximum condition of Corollary 1, strict and weak burst durations coincide almost surely.
The preceding identity is the bridge between threshold-burst profiles and Parisian stopping times. □
Theorem 3 (Brownian longest-burst law through the Parisian transform).
Let B be standard Brownian motion started at x, and fix a barrier , a window , and a Laplace parameter . LetLetdenote the one-sided below-zero Parisian time for Brownian motion started at the barrier 0, with window D. Define the Chesney–Jeanblanc-Picqué–Yor [7] one-sided Parisian transform bywith the standard normalization used in the Parisian-excursion literature [7]. The tail is written with the strict inequality , which is the exact pathwise counterpart of in Lemma 2. Replacing strict by weak inequalities is harmless at continuity points of the corresponding tail distribution.
If , the hitting factor is absent and If , the process starts inside a below-a excursion whose age at time 0 is zero. In this casewhereas, on ,where the second term is independent of and has the at-the-barrier Parisian law. Consequently, The two quantities involving are the standard one-sided Brownian hitting-time terms.
We stress which parts of this statement are new. The transform
is not derived here: it is the at-the-barrier one-sided Parisian Laplace transform obtained by Chesney, Jeanblanc-Picqué and Yor [
7] through Brownian excursions, the Brownian meander and the Azéma martingale, and it is used as a known input. The contribution of the theorem is the reduction of the longest-burst tail
to
via the pathwise identity of Lemma 2, together with the explicit hitting-time decomposition in the case
, where calendar time begins inside a below-barrier excursion of zero age. This last case lies outside the at-the-barrier framework and is distinct from the intermediate-valuation problem of Schröder [
8].
Proof. For any nonnegative stopping time
,
Taking expectations gives
Assume first that
. The Brownian path must hit
a before it can begin a below-
a excursion. By the strong Markov property at
,
where the second term is independent of
and has the one-sided Parisian law for Brownian motion started at the barrier. Hence
The Brownian hitting-time transform is
and the second factor is
. This proves the case
. The case
follows by setting
.
Assume now that
. The process starts below the barrier. If
, then Brownian motion stays below
a throughout
, so the Parisian time is exactly
D. If
, the initial below-
a episode ends before the strict Parisian event has occurred. At
the process is at the barrier, and the strong Markov property gives a fresh independent at-the-barrier Parisian time. Therefore
and
Taking Laplace transforms gives the announced decomposition. □
Remark 3 (Normalization, starting inside an excursion, and drift).
The transform in Theorem 3 is deliberately expressed in the notation of the Parisian-excursion literature. Chesney, Jeanblanc-Picqué, and Yor compute the Brownian one-sided Parisian Laplace transform using Brownian excursions, the Brownian meander, and the Azéma martingale [7]. Schröder’s note [8] concerns a related but distinct issue: valuation during the lifetime of the contract, when the observation time is intermediate and the currently observed excursion age may already be positive. This is different from the case of Theorem 3, where calendar time starts at 0 and the initial below-barrier age is 0. The latter case is handled by the explicit hitting-time decomposition above.For Brownian motion with drift, the structural identity of Lemma 2 remains unchanged, because it is pathwise. Its Brownian law reduces to the driftless one by a Cameron–Martin change of measure: writing for Brownian motion with drift under , the process Y is a standard Brownian motion W started at x under the tilted measure with , so that for every bounded path functional G on , Choosing
and applying Lemma 2 expresses the drifted longest-burst law as an exponentially tilted driftless Parisian functional,
The drift therefore enters only through the exponential weight, and the reduction itself needs no new excursion theory. The explicit transform is modified by the drifted excursion and meander terms; see the Parisian option literature [7,10,11,12,13]. Proposition 3 (Local time as intensity; excursion tail as global object).
Throughout this proposition, denotes the right-sided Tanaka local time at zero,so that the negative-excursion Itô measure satisfiesLet B be standard Brownian motion at level 0, and let denote the Itô excursion measure of negative Brownian excursions under this normalization. If ζ denotes the excursion lifetime and is the longest negative excursion completed before local time ℓ, then Proof. In the local-time clock, Brownian excursions away from zero form a Poisson point process with characteristic measure
n. Negative excursions form one side of this excursion process, with intensity measure
. The number of negative excursions with lifetime greater than
D completed before local time
ℓ is therefore Poisson with parameter
Hence the probability that no such excursion has occurred is
Under the right-sided Tanaka normalization specified above,
This proves the formula.
The value
is tied to the right-sided Tanaka normalization of
fixed above. Under any other admissible normalization
with
, the local-time horizon rescales as
and the excursion intensity as
, so the product
that governs the law of
is invariant. The distribution in the proposition is therefore independent of the chosen normalization, provided the horizon and the intensity are read in the same clock; this is the excursion-level counterpart of the invariance noted for
at the start of
Section 4.
Proposition 3 should be compared with the additive, Parasian benchmark (
28). The same local time enters the additive functional as a pointwise differential density, whereas for the extremal burst functional it appears as the clock intensity of a Poisson process of excursions. The relevant quantity is no longer a local density at level
a, but the global excursion-lifetime tail
Passing from a local-time horizon
ℓ to a deterministic time horizon
T requires accounting for the inverse local-time process and the terminal excursion straddling
T. This is precisely the meander correction encoded in the Chesney–Jeanblanc-Picqué–Yor transform and related Parisian-transform formulae [
7,
8]. □
5. Diffusion Consequences and Examples
Let X be a regular one-dimensional diffusion. For fixed T, the path is continuous almost surely, so all pathwise burst results apply almost surely.
The point of this section is not to derive complete model-specific laws for . Even for classical diffusions, longest-burst laws are generally Parisian or excursion-length laws, rather than local formulas. Instead, the goal is to show how the additive/extremal dichotomy manifests itself in standard diffusion examples.
The additive profile
is controlled by local time. For a regular diffusion satisfying
the occupation-density formula gives the cumulative occupation profile (
7), and hence the local-time sensitivity (
28) at levels where the local-time density is continuous.
The continuous Parisian burst profile
, by contrast, is controlled by the component structure of the random sublevel time set
A threshold increase may add only a small amount of occupation time, but if the newly captured time lies between two pre-existing sub-threshold components, it may weld them into a much longer burst. Thus has local-time sensitivity, while has merger sensitivity.
5.1. Non-Sticky Regular Diffusions
For nondegenerate regular diffusions, the level set
has zero Lebesgue measure almost surely for each fixed
a. Consequently,
almost surely at fixed
a, and
is locally absolutely continuous with derivative (
28).
At the same time, by Theorem 1, the weak longest-burst profile is monotone and càdlàg, while the strict profile is its càglàd regularization. Its jumps are caused by component mergers at local-maximum levels.
This distinction is not merely qualitative. The additive Parasian functional can be recovered by integrating a local density over levels. The longest-burst functional cannot. A short interval of newly captured time may weld two large existing components. Therefore the size of the burst increment depends not only on the amount of newly captured occupation, but also on the location of that occupation within the time axis.
5.2. Brownian Motion
For Brownian motion
the occupation derivative becomes
The expectation-level derivative is
Thus the expected local-time profile is the time-integrated heat kernel.
The longest-burst profile has no analogous local formula. It is a monotone càdlàg level-indexed functional, and by Corollary 1 it is almost surely not absolutely continuous, because Brownian motion attains its maximum at a unique interior time almost surely.
The jump at the maximum level can be described explicitly. Let
which is almost surely unique. At the maximum level
Hence the jump size at the global maximum is
Since
has the arcsine distribution on [0,1], a result going back to Lévy [
21] (see also Karatzas-Shreve ([
2] Section 2.8) for a modern derivation through the reflection principle), one obtains, for
,
This elementary formula is a useful diagnostic. The additive profile is locally described by , but the burst profile has a macroscopic jump whose size is governed by the location of the global maximum.
The law of the event
is the one-sided Parisian tail described in Theorem 3. Thus the Brownian example displays both sides of the theory: a local-time density for additive occupation and a Parisian excursion law for the extremal burst.
5.3. Ornstein–Uhlenbeck Process
Proposition 4 (Ornstein–Uhlenbeck occupation sensitivity).
Let X be the stationary Ornstein–Uhlenbeck process solvingwith invariant density . Then, for every fixed level a, the expected first-order occupation increment satisfiesIn particular, the first-order density of newly captured occupation is , while the first-order increment is . This density is maximal at the long-run mean and decays away from it with the stated Gaussian factor.
Proof. For the Ornstein–Uhlenbeck process defined in Proposition 4, one has
The transition law is Gaussian; the mean, variance and invariant density recalled below are standard for the Ornstein-Uhlenbeck process and may be found, for example, in Karatzas-Shreve ([
2]
Section 5.6) or in the explicit tabulation of Borodin-Salminen [
3]. If
, then
has mean
and variance
Thus the transition density is
Taking expectations in the occupation-density formula yields
Consequently, for small
,
and therefore
In stationarity, the invariant density is
If
has this invariant distribution, then
has density
for every
t, and hence
The first-order expected amount of newly captured time is therefore maximal at the long-run mean 0, and decays away from 0 with Gaussian factor
This gives a quantitative version of the qualitative statement that levels near the long-run mean are revisited frequently. Under stationarity, the expected temporal material captured by raising the threshold from a to has first-order density . Hence the density of possible bridge-filling opportunities is largest near the mean-reversion level 0.
This statement should not be interpreted as a formula for the jump sizes of . The local-time density measures how much time is added when the threshold is raised. A jump of , however, depends on where the newly added time lies in . A very small amount of newly captured occupation may produce no change in the longest burst, or it may connect two long pre-existing components and produce a macroscopic jump.
Thus the mean-reverting drift makes the qualitative burst picture different from Brownian motion. Near the long-run mean, the sub-threshold time set tends to be highly fragmented, and threshold increases may progressively fill small bridges between adjacent visits. Far above or far below the mean, the expected amount of near-level occupation is smaller, and the burst structure is typically less fragmented.
Although an explicit Parisian transform for the Ornstein–Uhlenbeck process is not as elementary as in the Brownian case, the pathwise identity of Lemma 2 still holds. Therefore
is the event that the Ornstein-Uhlenbeck process has a below-
a excursion of duration strictly greater than
D. This is the natural diffusion analogue of the Brownian Parisian event. □
5.4. Reflected Brownian Motion
Let
X be reflected Brownian motion on
:
where
is the reflection term. Thus
K is nondecreasing,
, and
K increases only when
. Equivalently,
For
, the cumulative load below
a is just the usual additive occupation functional
Since the diffusion coefficient is 1 away from the boundary, the occupation-density formula gives
Near
, the behavior is influenced by the boundary local time generated by reflection. With the local-time normalization used in the occupation-density formula,
In the Skorokhod construction of reflected Brownian motion [
22], where the reflection term is the minimal nondecreasing process keeping the path nonnegative, this boundary local time satisfies
Thus the cumulative time spent in a vanishing boundary layer is asymptotically proportional to the boundary local time generated by reflection.
A closed expectation-level statement is available in the canonical case
started from zero. In that case,
and hence
Since
, the symmetry of the centred Gaussian law about the origin gives
, where
denotes the standard normal cumulative distribution function. So,
This is consistent with
because, in this normalization,
The continuous Parisian burst profile below a small threshold , however, does not admit a corresponding first-order local-time formula. It describes episodes during which the reflected process remains close to the boundary. Such episodes may merge when a threshold increase fills a brief upward excursion away from the boundary. Hence the near-boundary longest burst is a connectivity statistic, not a local-time density.
This is relevant in applications where one distinguishes cumulative time spent near a constraint from the longest uninterrupted time spent near that constraint. The first quantity is asymptotically governed by boundary local time. The second is governed by the organization of near-boundary visits into connected temporal components.
5.5. Sticky Behavior
If
X is a sticky diffusion at level
, then
may be positive with positive probability. More precisely, a sticky point arises when the scale function and speed measure of the diffusion assign a positive atom of the speed measure to the single point
. Equivalently, in the stochastic-differential-equation description of sticky Brownian motion of Engelbert-Peskir [
23], the dynamics at the sticky point are governed by a stickiness parameter that forces the local time at
to grow on a set of positive Lebesgue time, so that the occupation indicator
has strictly positive expected integral. In that case the additive occupation profile has a genuine jump at
.
More generally, for every
,
Letting , the second term vanishes under the usual non-sticky behavior away from , while the first term remains. Thus the sticky level contributes an atom in the threshold variable.
In schematic Stieltjes form, the threshold measure associated with
contains a term of the form
Sticky behavior therefore marks a different regime. For non-sticky diffusions, additive occupation is locally absolutely continuous, while burst duration may be unstable because of component mergers. For sticky diffusions, even additive occupation may fail to be continuous at the sticky level.
This example clarifies the role of the non-sticky assumption. In the non-sticky case, the additive functional is regular and the burst functional is singular. In the sticky case, the additive functional itself acquires a discontinuity because the process spends positive Lebesgue time at a single level. Thus the additive/extremal contrast is sharpest in the non-sticky diffusion setting.
5.6. Numerical Validation
We record the numerical experiments that produce the figures and validate the analytic predictions of this section. Throughout, sample paths are generated on with by an Euler–Maruyama scheme on a uniform grid of n steps of size ; the occupation profile is evaluated as times the number of grid points below a, computed from the same simulated ensemble across all levels (common random numbers), and the longest burst as times the longest run of consecutive sub-threshold grid points.
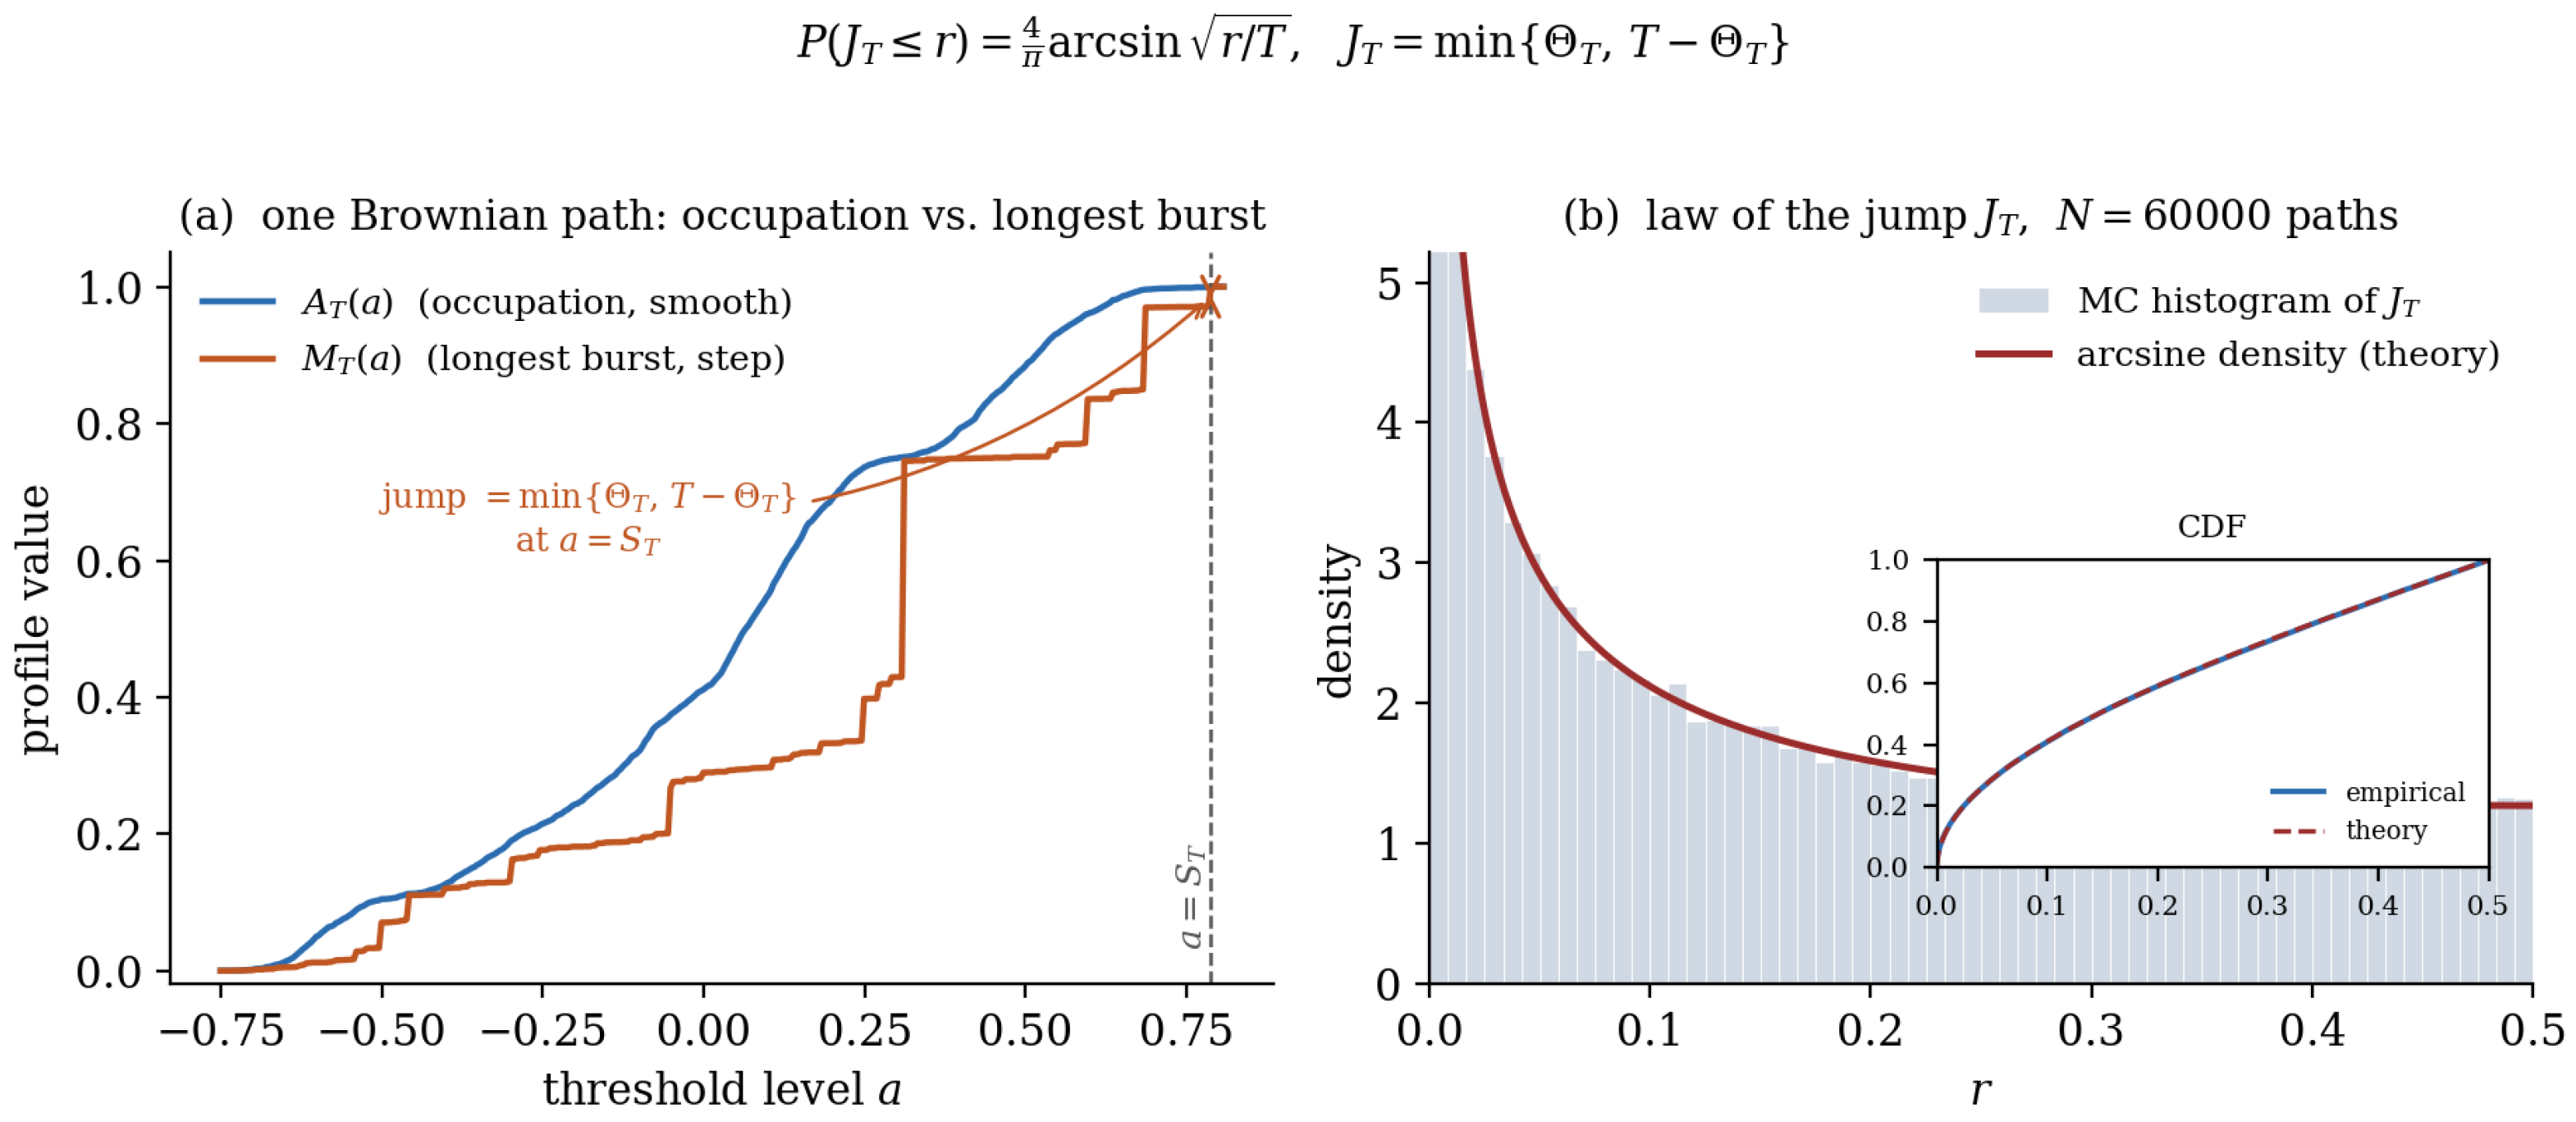
Construction of Figure 2. Panel (a) uses a single Brownian path: the profiles
and
are read off that path over a grid of levels, giving the continuous occupation profile and the step-like longest-burst profile with its jump to
T at the maximum level
. Panel (b) is a Monte-Carlo histogram of the jump
over
N = 60,000 independent paths, with
, overlaid with the arcsine density, the inset comparing the empirical and theoretical CDFs. An independent run of
N = 48,000 paths reproduces the arcsine law
to within
uniformly over
.
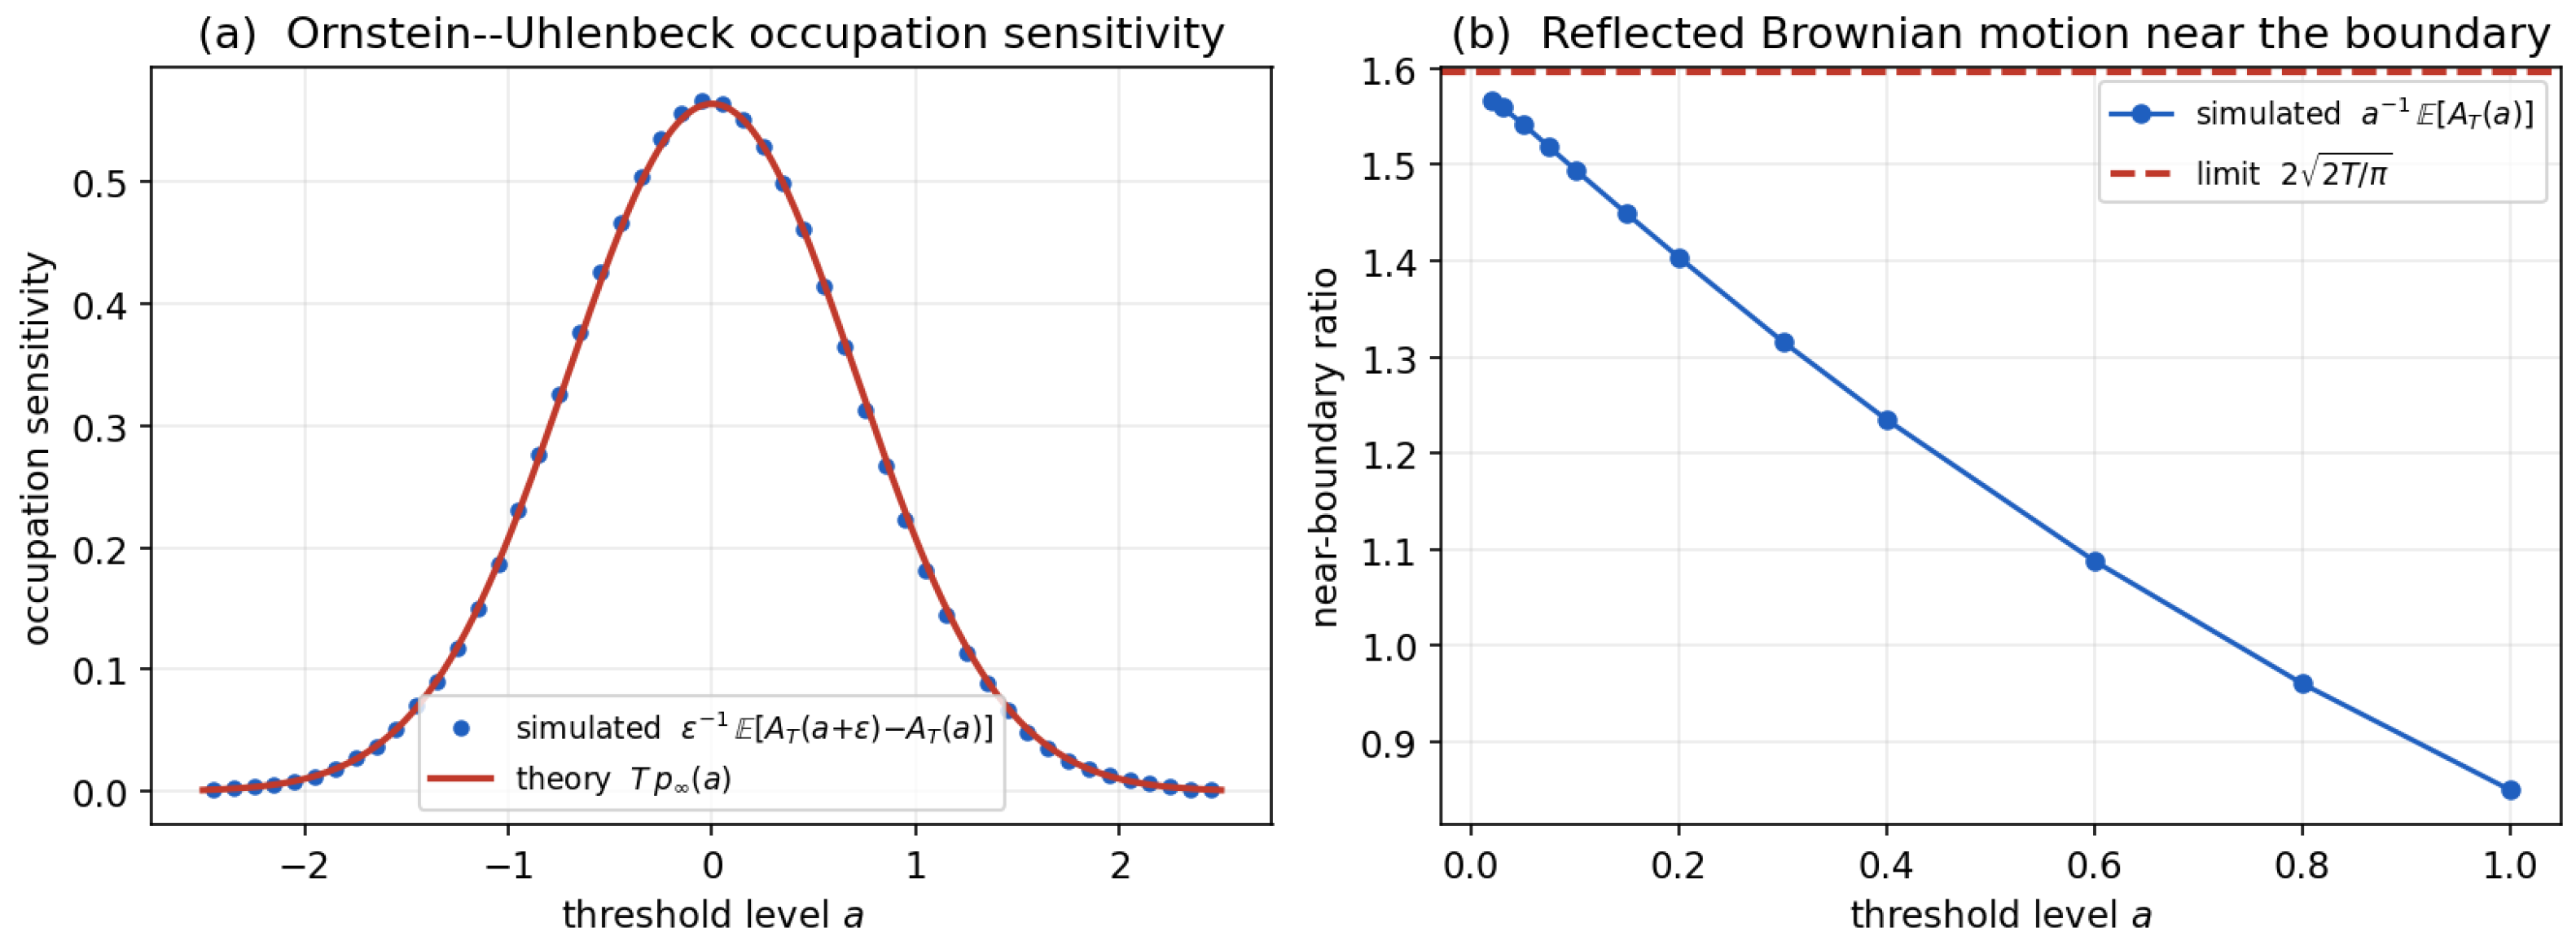
Validation of the diffusion predictions (
Figure 3). Panel (a) tests the Ornstein–Uhlenbeck occupation sensitivity of Proposition 4: for the stationary process with
, the finite-difference sensitivity
over 16,000 paths matches the predicted density
across the level range, peaking at the long-run mean
(simulated
versus
, and
versus
at
). Panel (b) tests the reflected-Brownian near-boundary asymptotics of
Section 5.4: for
the ratio
over 40,000 paths rises toward the predicted limit
as
(for instance
at
and
at
). Together with the arcsine jump law of
Figure 2, these experiments confirm the local-time prediction for the additive clock and the excursion/merger prediction for the burst clock.
7. Conclusions
This paper compared two classes of threshold functionals attached to the sub-threshold time set
: the additive, cumulative
Parasian occupation time
, which for regular one-dimensional diffusions obeys the local-time sensitivity Formula (
28), and the resetting
Parisian longest-burst functional
, the longest connected sub-threshold episode.
We proved that the weak longest-burst profile is monotone, that its supremum is attained, and that it is right-continuous with left limits; the strict-sublevel functional is the corresponding left-continuous regularization. The jump at a level is the increase in maximal component length produced by adjoining the level set. Theorem 2 makes this jump explicit: at a two-sided merger it equals the length of the shorter flanking component (plus the bridge, in the sticky case). This gives a deterministic one-sided regularity theory for burst profiles.
We then showed that this burst profile is not an additive local-time functional. At deterministic levels which are almost surely not local-extreme values, weak and strict longest bursts agree. But a path with a unique interior maximum has a positive jump in its longest-burst profile at the maximum level, and, more generally, so does any two-sided merger (Remark 2). Brownian motion satisfies this condition almost surely. Thus, while additive occupation is locally governed by local time, extreme burst duration is globally governed by connectivity.
Finally, we identified the longest burst with a one-sided Parisian functional. For Brownian motion this gives a Laplace-transform representation through the Chesney–Jeanblanc-Picqué–Yor Parisian transform, extended to the drifted case by a Cameron–Martin tilt; in the local-time clock the law is governed by the Itô excursion-lifetime tail
. The same local time that appears as a density for additive occupation therefore appears, for burst extremes, only as the clock intensity of a Poisson process of excursions. These analytic predictions were confirmed numerically in
Section 5.6.
The extensions preserve the same distinction: additive occupation below a moving boundary is governed by local time on the boundary curve, while burst duration remains sensitive to bridge filling and component mergers.
These two clocks also have a direct reading for monitoring problems in finance and risk management. In barrier-contract terms, the Parasian trigger fires on the total time spent beyond a level and has a local-time-smooth threshold sensitivity, whereas the continuous Parisian trigger fires on a single uninterrupted spell beyond the level and has a discontinuous threshold sensitivity. The merger instability shows that these two monitors react very differently to a small change in the level: raising the barrier slightly can leave the cumulative exposure essentially unchanged while abruptly increasing the longest continuous breach by a macroscopic amount, as soon as a short bridge is filled. A duration-based risk limit on the longest uninterrupted time spent in a stressed region is therefore far more sensitive to the precise placement of the threshold than a cumulative-time limit, and may jump even when average exposure is stable. The same contrast underlies occupation-time versus continuous-Parisian barrier options, drawdown-duration constraints, and any covenant phrased through the longest continuous, rather than the total, time a process spends beyond a level.
Several directions remain open. The Brownian marginal law of
is described by the Parisian and excursion-measure forms of
Section 4, but the joint law of the jump levels and jump sizes of
remains to be characterized. For general regular diffusions, explicit Parisian transforms are typically unavailable and the corresponding marginal laws remain model-dependent. Other natural problems include multidimensional and rough-path analogues, the behavior of burst profiles under discrete observation, and statistical estimation of bridge-merger levels from sampled trajectories. These questions lie beyond the local-time calculus of additive occupation and require a genuinely component-based theory of threshold episodes.