Article

Digital Transformation Disclosure and Green Technological Innovation Toward Sustainable Manufacturing: Evidence from Chinese Listed Firms


1
School of Management, Fudan University, Shanghai 200433, China
2
School of Economics & Management, Shanghai Maritime University, Shanghai 201306, China
3
Business School, Shanghai Jian Qiao University, Shanghai 201306, China
*
Author to whom correspondence should be addressed.
Sustainability 2026, 18(20), 10254; https://doi.org/10.3390/su182010254
Submission received: 28 August 2026 / Revised: 4 October 2026 / Accepted: 6 October 2026 / Published: 9 October 2026
(This article belongs to the Section Sustainable Management)

Abstract

Green technological innovation is important to the sustainable development of manufacturing. As a core driver of transition toward sustainable production patterns, green innovation helps firms reduce environmental externalities while maintaining economic competitiveness. Drawing on the Resource-Based View and the Knowledge-Based View, this study examines the association between digital-transformation disclosure and green technological innovation using 16,231 firm-year observations for Chinese A-share listed manufacturing firms from 2015 to 2022. Green technological innovation is measured by green patent applications, and the baseline specifications use negative binomial models with year and industry fixed effects, province-clustered standard errors, and a full control set that includes firm size. Digital-transformation disclosure is positively associated with green patent applications. Parallel-mediation estimates and province-clustered Bootstrap confidence intervals identify significant indirect effects through inter-organizational knowledge flow, R&D expenditure intensity, and the R&D personnel share. In terms of point estimates, the R&D personnel indirect effect is the largest of the three, followed by knowledge flow and R&D expenditure; however, only the R&D personnel versus R&D expenditure difference is statistically significant, and the three channels are better characterized as complementary. The difference between the knowledge-flow and R&D-expenditure effects is marginally significant. The hypothesized inverted-U moderating pattern of market competition is not statistically significant in the preferred specification with industry and year fixed effects. Split-sample estimates show directional heterogeneity across region, ownership, and firm size, but formal interaction tests do not reject equality of the digital transformation disclosure coefficients across groups. These results document robust associations rather than definitive causal effects and highlight the complementary roles of knowledge recombination, R&D expenditure, and technical personnel in green patenting. These findings carry implications for sustainability-oriented research and management practice by documenting channels through which digital-transformation disclosure is associated with green patent activity in the manufacturing sector.

1. Introduction

Achieving environmentally sustainable industrial development requires fundamental changes in how firms generate, adopt, and diffuse new technologies. Green technological innovation is central to China’s pursuit of high-quality development and its Dual Carbon goals. Green technological innovation is shaped by external conditions—including environmental regulation and market competition—and by firm-level capabilities, including digital infrastructure, knowledge integration, R&D commitment, and human capital [1,2,3,4]. Digital technologies may improve firms’ ability to acquire, process, and recombine information, but the mechanisms linking digital orientation to green innovation remain empirically contested. These studies suggest that digital technologies can optimize resource allocation and lower innovation costs.
However, three gaps motivate the analysis. First, existing studies rarely distinguish the resource-augmentation logic of the Resource-Based View from the knowledge-recombination logic of the Knowledge-Based View [5]. Second, mediation studies often examine R&D, human capital, or knowledge transfer separately, leaving their joint contribution and relative indirect effects unclear [6]. Third, firm-level evidence remains limited on whether market competition nonlinearly conditions the digital–green association and whether the estimated association differs across firm contexts [7].
To address these gaps, we conceptualize digital transformation as an organizational capability that supports green innovation by facilitating knowledge recombination and strengthening R&D and human-capital inputs. We jointly estimate three parallel mediating channels, compare their indirect effects, and test whether market competition nonlinearly conditions the digital–green association. By identifying the channels through which digital capabilities translate into green innovation, this study contributes to the sustainability literature on how firm-level technological transformation can advance environmentally sustainable manufacturing.
We focus on Chinese A-share listed manufacturing firms because manufacturing is environmentally consequential and because firm-level annual reports, financial accounts, and patent records permit the consistent alignment of disclosed digital orientation, organizational resources, and innovation output. The unbalanced panel contains 16,231 firm-year observations from 2015 to 2022. Using negative binomial regressions and a control-function endogeneity check, we evaluate the baseline association, three parallel mediating channels, nonlinear moderation by market competition, and heterogeneity across firm groups.
The study jointly estimates three theoretically distinct mediating channels, compares their indirect effects using province-clustered Bootstrap inference, and evaluates nonlinear moderation by market competition. The empirical design evaluates forward associations and does not identify reciprocal feedback or definitive causal effects.

2. Theoretical Foundations and Literature Review

The Resource-Based View (RBV) explains persistent performance differences through valuable, scarce, and difficult-to-imitate firm resources [8]. In the present setting, digital capabilities can improve the allocation and use of two innovation inputs; R&D expenditure and skilled personnel. The Knowledge-Based View (KBV) treats the acquisition, transfer, and recombination of knowledge as the central source of innovation [9]. It therefore directs attention to the knowledge obtained across organizational boundaries rather than to resource volume alone. The two perspectives imply distinct mechanisms that can be estimated jointly: resource augmentation through R&D investment and R&D personnel, and knowledge recombination through inter-organizational knowledge flow.
Prior research generally reports a positive digital–green association, but its magnitude and mechanisms vary with absorptive capacity, resource constraints, governance, market structure, and the timing and quality of innovation measures [10,11,12,13]. Existing mediation studies often examine R&D, human capital, or knowledge transfer separately and therefore do not establish whether the channels remain relevant when estimated jointly. Recent studies show that environmental regulation can promote green technological innovation by strengthening firms’ endogenous capabilities [14], ESG performance is associated with green technology innovation through financial and managerial channels [15], and green credit can influence green technology innovation through financing and investment mechanisms [16]. Together, these studies reinforce the need to distinguish external institutional conditions from firm-level resources and knowledge mechanisms. Zhou et al. [17] identify knowledge base breadth and knowledge base depth as parallel mediators through which digital technology adoption improves innovation performance. The present analysis extends that framework by distinguishing one knowledge-based channel from two resource-based channels, estimating all three in a parallel model, comparing Bootstrap indirect effects, and testing market competition as a nonlinear boundary condition. This integrated framework also advances the sustainability discourse by clarifying how digital capabilities contribute to green innovation, not only through resource augmentation, but also through knowledge recombination—both of which are central to the transition toward sustainable industrial systems.
Market competition can both encourage and constrain innovation. Competition may increase innovation pressure at low-to-moderate levels, whereas intense competition may compress the slack and time horizon needed for uncertain green projects [18,19]. Because lower HHI indicates stronger competition, this trade-off implies a nonlinear moderating pattern rather than a uniformly positive or negative interaction. This tension motivates an inverted-U boundary condition rather than a monotonic moderation hypothesis.

3. Hypothesis Development

Digital technologies can improve information processing, coordination, and resource allocation across organizational functions and external partners [20,21]. These capabilities reduce search and transaction costs and help firms identify and combine technical knowledge relevant to green patenting. Accordingly:
Hypothesis 1.
A higher level of corporate digital-transformation disclosure is positively associated with green technological innovation.
Under the KBV, external knowledge becomes productive when firms can identify, absorb, and recombine it. Digital tools can lower search and coordination costs and facilitate the acquisition and recombination of knowledge from external organizational sources [22,23]. Accordingly, we posit that:
Hypothesis 2.
Inter-organizational knowledge flow mediates the positive association between digital-transformation disclosure and green technological innovation.
Under the RBV, R&D expenditure is a committed firm-specific resource that supports experimentation and green-technology development. Digital capabilities can improve project screening, monitoring, and resource allocation, thereby increasing R&D expenditure intensity [21,24]. Hence,
Hypothesis 3.
R&D expenditure intensity mediates the positive association between digital transformation disclosure and green technological innovation.
R&D personnel are a strategic resource and carriers of tacit knowledge. Digital transformation increases demand for employees who can combine digital and environmental knowledge and may raise the share of R&D personnel [25,26]. Accordingly,
Hypothesis 4.
The R&D personnel share mediates the positive association between digital-transformation disclosure and green technological innovation.
Competition creates opposing incentives. When competition is weak, limited external pressure reduces firms’ incentive to deploy digital capabilities for green innovation. When competition is intense, compressed margins and shorter planning horizons restrict the resources available for uncertain green projects [18,19]. The association is therefore expected to be strongest at an intermediate level of competition. Therefore,
Hypothesis 5.
Market competition has an inverted-U moderating effect on the relationship between digital-transformation and green technological innovation.
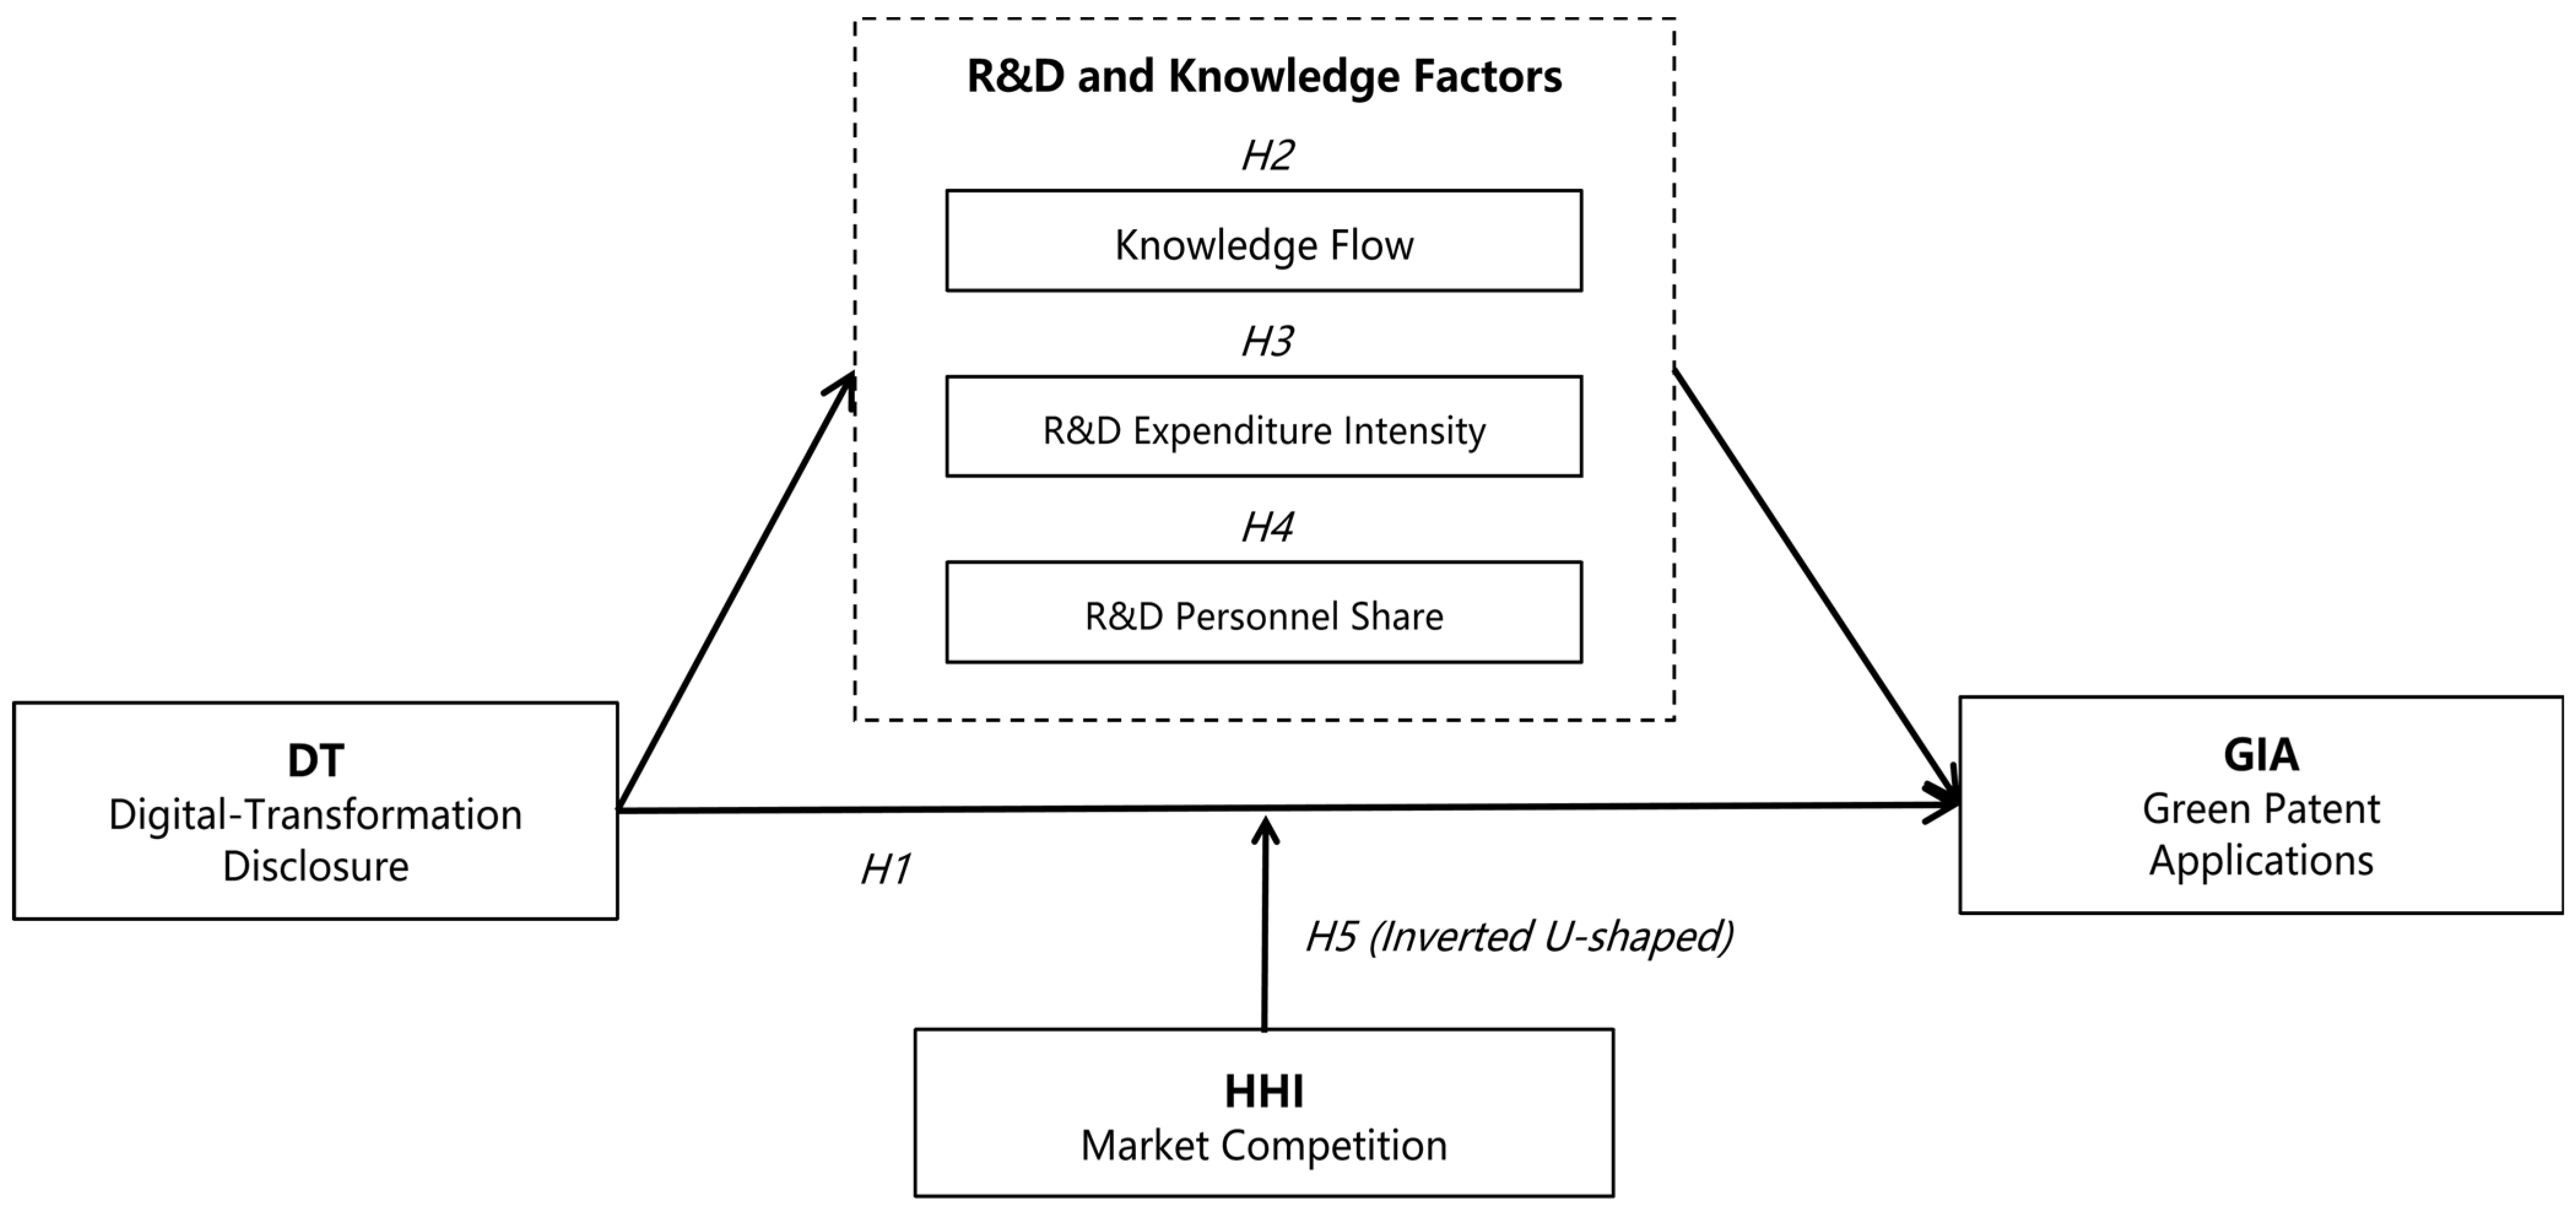
Digital-transformation disclosure is linked in parallel to inter-organizational knowledge flow, R&D expenditure intensity, and the R&D personnel share; each mediator is linked to green patent applications. Market competition moderates the DT–GIA association through DT × HHI and DT × HHI2 (see Figure 1).

4. Research Design

The sample is an unbalanced panel of Chinese A-share listed manufacturing firms from 2015 to 2022. We exclude ST-designated firms and firm-years with missing values required for the baseline specification. The resulting unbalanced panel contains 16,231 firm-year observations. Each subsequent table reports its effective sample size, and subgroup totals are reconciled with the baseline sample. Continuous accounting variables are winsorized at the 1st and 99th percentiles to limit the influence of extreme observations while retaining firm-year records. Binary indicators and count outcomes are not winsorized. This timeframe coincides with the intensification of China’s national policies promoting digital transformation and green development. Manufacturing is among the most resource-intensive sectors and therefore occupies a central position in sustainability transitions.
To improve temporal alignment with annual-report information, the baseline outcome is the number of green patent applications filed in year t; lagged DT is examined separately. Green technological innovation is measured by the number of green patent applications filed by firm i in year t, identified using the WIPO IPC Green Inventory. The count includes both invention patents and utility-model applications. Green patent citations are used as a quality-oriented alternative outcome. Application-year counts provide a closer temporal match to the innovation activity reflected in contemporaneous annual reports [27,28]. As a quality-oriented robustness check, we use the number of citations received by the firm’s green patents. Citation-based output captures the technological influence of green innovation beyond patent quantity.
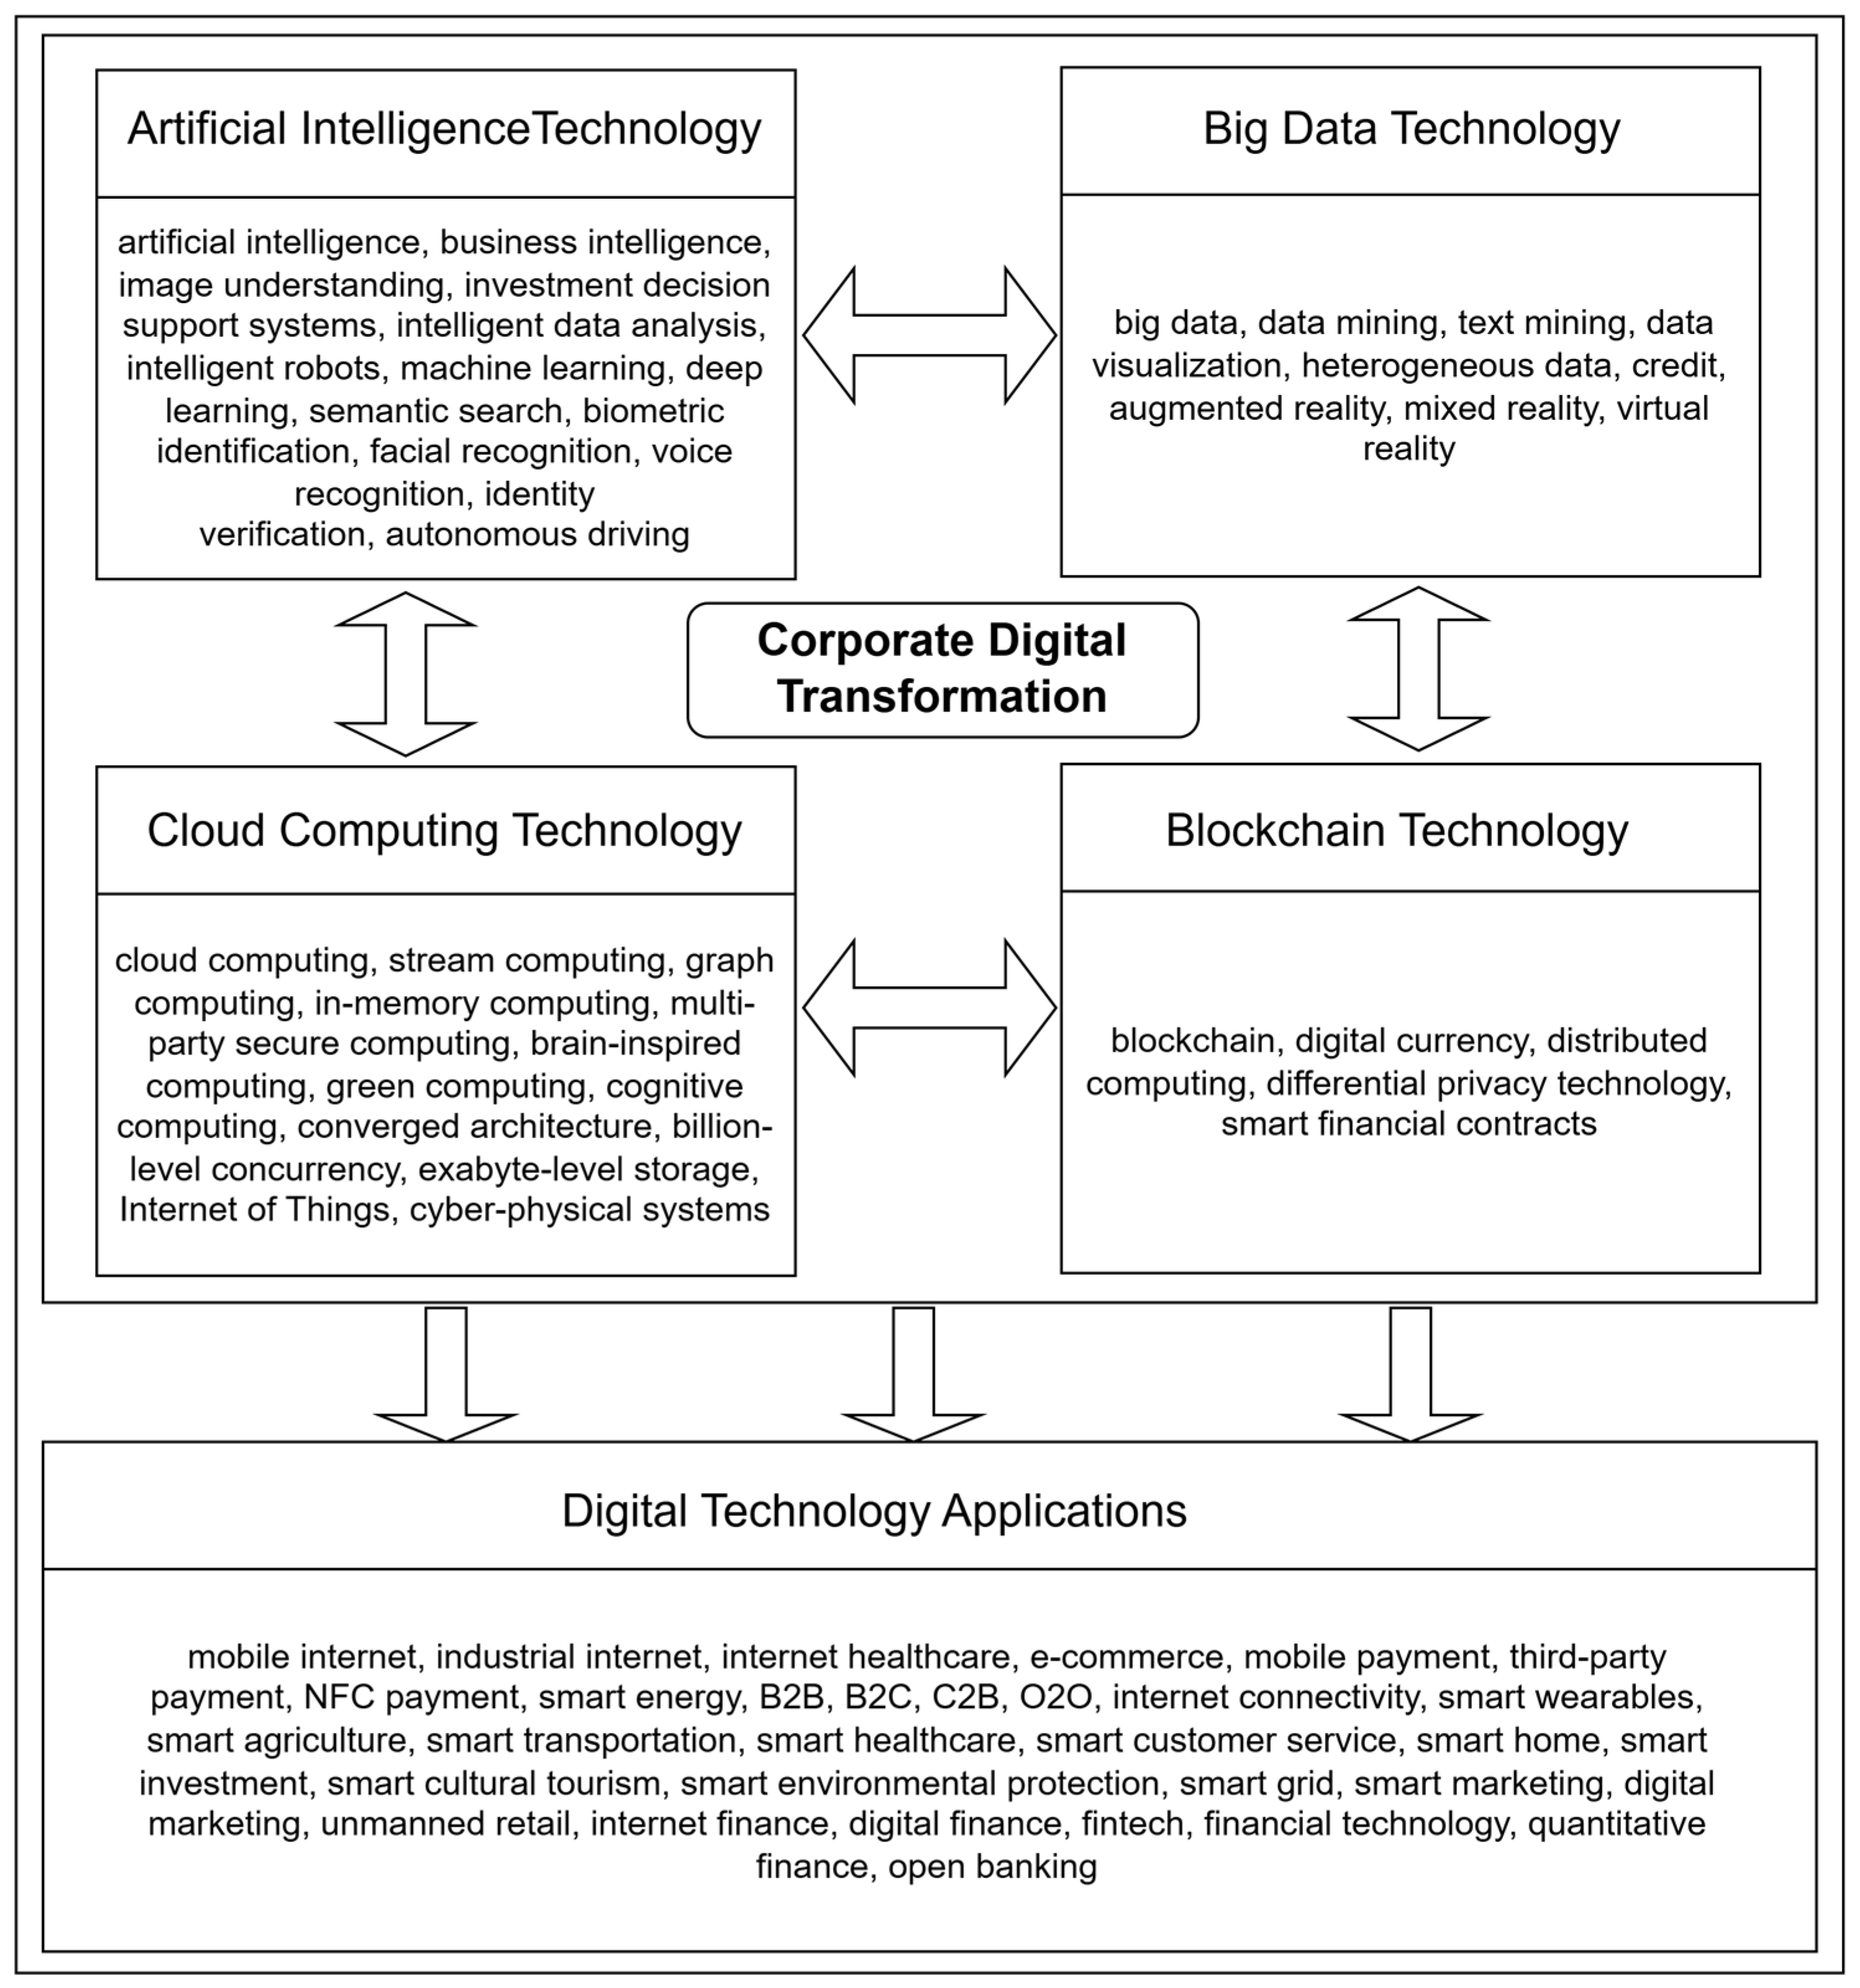
As shown in Figure 2, corporate digital-transformation disclosure (DT) equals ln(1 + the total frequency of validated digital-transformation keywords in the full annual report), following Wu et al. [29]. The index captures disclosed digital orientation rather than the physical stock of digital assets or actual digital expenditure. Underlying digital technology (DTT) equals ln(1 + the frequency of keywords related to artificial intelligence, blockchain, big data, and cloud computing). Digital application (DTU) equals ln(1 + the frequency of keywords describing digital applications in production, operations, and business processes).
Three mediating variables are operationalized as follows: Inter-organizational knowledge flow (KF) is the total number of backward patent citations, which are the firm’s own patents make to prior patented art, aggregated over the firm’s entire patent portfolio (not limited to green patents) in year t and divided by the corresponding two-digit-industry average [30]. The measure is not normalized by the number of the firm’s own patents and therefore captures citation volume relative to the industry average rather than per-patent citation intensity. R&D expenditure intensity (RDS) is R&D expenditure divided by operating revenue [31]. The R&D personnel share (RDP) is the number of R&D employees divided by total employment [32].
Market competition is measured by the Herfindahl–Hirschman Index (HHI) at the 2-digit industry level, where lower HHI denotes fiercer competition, consistent with industrial organization theory [33]. Following the approach of Ma et al. (2023) [34], the HHI is calculated as the squared revenue shares of listed firms within each two-digit industry. A lower HHI indicates greater revenue dispersion among listed firms. Because unlisted firms are excluded, the measure approximates listed-firm concentration rather than the complete product-market structure.
The control set includes firm size, firm age, leverage, return on assets, operating cash flow, revenue growth, board size, board independence, ownership concentration and balance, Tobin’s Q, state ownership, and CEO–chair duality (see Table 1). Board structure and ownership variables are included because corporate governance affects risk tolerance, resource allocation, and the planning horizon for long-term innovation decisions [35,36]. Firm size is directly controlled through the natural logarithm of total assets. Board size is closely associated with organizational scale, Tobin’s Q captures market valuation relative to the firm’s asset base, and leverage and return on assets absorb important differences in capital structure and asset utilization. We retain this parsimonious and consistently available control set while omitting a separate measure of fixed-asset intensity because board, Tobin’s Q, Lev, and ROA capture related dimensions of organizational scale, asset valuation, capital structure, and asset utilization.
All financial data are obtained from CSMAR, patent and citation data from CNIPA via the China Research Data Service Platform, and keyword frequencies from WIND. All estimation and statistical testing are conducted in Stata 18.0.
The baseline specification includes industry and year fixed effects to absorb unobserved sectoral heterogeneity and common macroeconomic shocks, respectively. Standard errors are clustered at the provincial level throughout to allow arbitrary within-province dependence across firms.

5. Empirical Analysis

5.1. Model Specification

Descriptive statistics for the main variables are reported in Table 2. The dependent variable, green patent applications (GIA), exhibits substantial dispersion (mean = 3.03, SD = 18.13) and a right-skewed distribution, with a maximum value of 978 and a median of zero. Its variance substantially exceeds its mean, supporting a count-data specification. Digital-transformation disclosure (DT) has a mean of 1.46, a standard deviation of 1.28, a median of 1.39, a minimum of 0, and a maximum of 4.77, indicating substantial variation across firms. Firm size (Size) has a mean of 22.11 and a standard deviation of 1.15. Mediating variables, knowledge flow (KF), R&D expenditure intensity (RDS), and R&D personnel share (RDP), also display wide ranges, reflecting uneven allocation of innovation resources across the sample. For each negative binomial specification, we report the log likelihood, pseudo R2 when available, the Wald χ2 statistic and its p-value, the number of observations, the fixed-effects structure, and the covariance estimator. For each OLS specification, we report adjusted R2, the model F statistic and its p-value, the number of observations, and the fixed-effects structure. Parentheses report t statistics calculated from province-clustered standard errors unless otherwise stated.
Because GIA is a non-negative count variable and its variance exceeds its mean, we use negative binomial regressions as the baseline specification. The Vuong test yields z = 1.56 and p = 0.0589, marginally favoring the zero-inflated negative binomial model at the 10% level. However, the inflation equation’s constant is −17.276 (p = 0.968), providing no evidence of a distinct structural-zero process. We therefore retain the standard negative binomial model as the baseline specification.
Equations (1)–(4) define the baseline negative binomial model, the mediator equation estimated for each mediator, the parallel-mediation outcome equation, and the nonlinear moderation equation, respectively. The indirect effects and their pairwise differences are evaluated using Bootstrap confidence intervals. Let i index firms, t years, and j two-digit industries. DT denotes digital-transformation disclosure, X is the common control vector, μj denotes industry fixed effects, and λt denotes year fixed effects. Unless otherwise stated, inference uses province-clustered standard errors. The baseline conditional-mean specification is
E(GIAit | ·) = exp(α + βDTit + γ′Xit + μj + λt)
For mediator m in {KF, RDS, RDP}, we estimate the following OLS mediator equation:
M it m   =   α m   +   a m DT it   +   γ m ′ X it   +   μ j   +   λ t   +   ε it m
The three mediators are then entered jointly in the negative binomial outcome equation:
E(GIAit | ·) = exp(α + c′DTit + b1KFit + b2RDSit + b3RDPit + γ′Xit + μj + λt)
For mediator m, am denotes the coefficient of DT in the mediator equation and bm denotes the coefficient of that mediator in the joint outcome equation. The product ambm is reported as the corresponding indirect effect and evaluated using Bootstrap confidence intervals. The nonlinear moderation specification is
E ( GIA it   |   · ) = exp ( α + β 1 c DT it + β 2 c HHI jt + β 2 c HHI jt 2 + β 4 ( c DT it × c HHI jt ) + β 5 ( c DT it × c HHI jt 2 ) + γ ′ X it + μ j + λ t )
Here, cDT and cHHI are mean-centered variables. All moderation specifications include industry and year fixed effects, and the preferred supplementary specification additionally includes industry-specific linear time trends. Standard errors are clustered at the provincial level in all main regressions. Equation (1) is the baseline negative binomial model, Equation (2) is estimated separately for each mediator, Equation (3) is the parallel-mediation outcome model, and Equation (4) is the nonlinear moderation model.

5.2. Results of Benchmark Regression

Table 3 reports three negative binomial specifications. Column (1) reports a random-effects negative binomial model with controls but without year or industry fixed effects; Column (2) adds industry and year fixed effects but no controls; and Column (3) adds the full control set together with year and industry fixed effects. The DT coefficient is 0.168 (t = 11.095) without fixed effects, 0.298 (t = 5.843) with year and industry fixed effects but without controls, and 0.134 (t = 3.403) in the fully controlled specification. All three coefficients are significant at the 1% level. Firm size is positive and highly significant (0.794, t = 14.900), confirming that scale is now directly controlled. The preferred estimate supports H1 as a positive conditional association rather than a causal effect.

5.3. Mediating Effect Analysis

Table 4 reports three OLS mediator equations and a joint negative binomial outcome equation. DT is positively associated with KF (β = 0.109, t = 3.924), RDS (β = 0.323, t = 5.260), and RDP (β = 1.555, t = 5.922), with all three coefficients significant at the 1% level. In the joint negative binomial outcome equation, KF (0.199, t = 9.650), RDS (0.028, t = 2.687), and RDP (0.024, t = 3.557) are positively associated with GIA, while the direct DT coefficient remains significant (0.072, t = 2.223, p < 0.05), indicating partial mediation.
Table 5 reports the Bootstrap indirect effects and their pairwise differences. The R&D personnel indirect effect (0.0377) is the largest, followed by knowledge flow (0.0218) and R&D expenditure (0.0089). All three indirect effects are individually significant. The R&D personnel effect significantly exceeds the R&D-expenditure effect. The knowledge-flow versus R&D-expenditure difference is marginally significant (95% CI: [−0.0002, 0.0259]). The knowledge-flow versus R&D-personnel difference is not statistically significant. The evidence supports complementary rather than hierarchical mechanisms. Because KF is normalized by the industry average rather than by firm portfolio size, the comparison between the knowledge-flow and R&D-expenditure channels should be interpreted alongside this measurement difference.

5.4. Moderating Effect

Table 6 reports the moderation results after restoring both industry and year fixed effects in every specification. The linear interaction between DT and HHI is not statistically significant in Column (1) (0.462, t = 0.850). After the quadratic interaction is introduced, the coefficient on DT × HHI2 is negative and statistically insignificant in Column (2) (−5.381, t = −1.130) and remains insignificant when industry-specific linear time trends are added in Column (3) (−5.567, t = −1.156). Accordingly, H5 is not supported. The implied turning point is HHI ≈ 0.156, calculated as −(cDT × HHI)/(2 × cDT × HHI2) + mean HHI. This value lies well above the sample median of 0.04 and the 75th percentile, implying that most firm-year observations lie on the ascending arm of the estimated curve. The sample may therefore lack sufficient variation in the low-competition range to identify the hypothesized downturn precisely.

5.5. Robustness Tests

Robustness is assessed along three dimensions in Table 7. Using green patent citations as the dependent variable, DT remains positive and significant (0.173, t = 7.467, p < 0.01), indicating that the baseline association extends to a quality-oriented measure of green innovation. When DTT and DTU are entered jointly, DTT is positive and significant (0.134, t = 5.064, p < 0.01), whereas DTU is not statistically significant (0.060, t = 1.531). The equality test yields p = 0.103, which does not reject equal coefficients at conventional levels. In an auxiliary OLS specification with ln(GIA + 1), industry fixed effects, and year fixed effects, DT remains positive and significant (0.072, t = 5.741, p < 0.01). The component results therefore do not support claims that one dimension of digital transformation has a larger association with green innovation than the other.
Table 8 evaluates the stability of the DT coefficient across nested specifications estimated with the same negative binomial estimator used in Table 3. Column (1) includes DT alone, Column (2) adds year fixed effects, Column (3) further adds industry fixed effects, and Column (4) adds the full control set, including Size. The DT coefficient is 0.423 (t = 9.080) in Column (1), 0.426 (t = 8.627) in Column (2), 0.298 (t = 5.843) in Column (3), and 0.134 (t = 3.403) in Column (4); all four estimates are significant at the 1% level. The final estimate matches the preferred specification in Table 3. The decline after industry fixed effects and controls are introduced indicates that sectoral heterogeneity and observed firm characteristics explain part of the unconditional association, while the positive association remains statistically significant across all specifications.
We next assess cross-sectional dependence in the residuals of the baseline model. The residual diagnostics reject the null of cross-sectional independence, motivating tests that absorb richer common shocks or use a more conservative covariance estimator. Table 9 shows that the DT coefficient is 0.134 (t = 3.403) in the preferred baseline, 0.129 (t = 3.629) with year-by-industry fixed effects, and 0.325 (t = 6.681) with year-by-province fixed effects. With province-year two-way clustered standard errors, the coefficient remains 0.134 and its t statistic is 2.768. All four estimates are positive and significant at the 1% level. Thus, cross-sectional dependence is present, but the positive DT–GIA association remains under richer common-shock controls and two-way clustering.
Taken together, the alternative outcome, alternative DT components, OLS specification, nested coefficient-stability checks, richer fixed effects, and two-way clustering yield a consistently positive DT coefficient. These exercises strengthen the robustness of the reported association but do not convert it into a causal estimate.

5.6. Endogeneity Test

Endogeneity checks are reported in Table 10. Using one-period-lagged DT, the coefficient remains positive and significant (0.133, t = 3.377, p < 0.01), with 13,130 observations because the first observation for each firm lacks a lag. The control-function analysis uses the leave-one-out mean DT of other firms in the same province and year. The first-stage coefficient is 0.309 (t = 4.084, p < 0.01). In the second-stage negative binomial model, DT is positive (1.193, t = 2.293, p < 0.05), while the first-stage residual is negative (−1.062, t = −2.042, p < 0.05). These checks reduce concerns about simultaneity and observable forms of endogeneity but do not establish a definitive causal effect because the exclusion restriction cannot be tested directly.

5.7. Heterogeneity Analysis

Table 11 reports split-sample estimates as descriptive results. The eastern group comprises firms registered in Beijing, Tianjin, Hebei, Liaoning, Shanghai, Jiangsu, Zhejiang, Fujian, Shandong, Guangdong, and Hainan; all other provinces are coded as central and western. The two regional subsamples contain 11,790 and 4441 observations, respectively. Table 12 reports pooled negative binomial models with DT × group interactions and province-clustered standard errors. None of the three interaction terms is statistically significant (region p = 0.106, ownership p = 0.239, firm size p = 0.534). After controlling for firm size, the point estimates for state-owned firms (0.119) and large firms (0.112) are smaller than for their respective comparison groups (0.139 and 0.163), reversing the pattern observed in the first-round estimates that omitted the size control. The reversal indicates that the earlier apparent group differences were sensitive to the inclusion of the firm-size control and does not constitute reliable evidence of heterogeneity in the DT–GIA association. The regional split also remains descriptive: the point estimate is 0.156 for eastern firms and 0.124 for central and western firms, but the formal interaction test does not reject equality.

6. Conclusions and Future Research

6.1. Conclusions

Using 16,231 firm-year observations for Chinese A-share listed manufacturing firms from 2015 to 2022, this study applies negative binomial models with firm size and other controls, industry and year fixed effects, and province-clustered standard errors. Digital-transformation disclosure is positively associated with green patent applications: the preferred fully controlled estimate is 0.134 (t = 3.403, p < 0.01). This positive association remains across alternative outcomes, alternative measures of digital transformation, richer fixed-effects structures, two-way clustering, lagged specifications, and a control-function analysis, although these designs do not establish a definitive causal effect. Taken together, these results indicate a robust conditional association between digital-transformation disclosure and green patent activity, with knowledge-based and resource-based channels each contributing a significant indirect effect.
Knowledge flow, R&D expenditure intensity, and the R&D personnel share each exhibit a significant indirect effect. The R&D personnel indirect effect is the largest (0.0377), followed by knowledge flow (0.0218) and R&D expenditure (0.0089). The R&D personnel effect significantly exceeds the R&D-expenditure effect, the knowledge-flow versus R&D-expenditure difference is marginally significant, and the knowledge-flow versus R&D personnel difference is not statistically significant. The evidence therefore supports complementary rather than hierarchical mechanisms. The hypothesized inverted-U moderation by market competition was not statistically significant under the preferred specification with industry and year fixed effects. Formal interaction tests do not reject the equality of the DT coefficients across regional, ownership, and firm-size groups; split-sample point estimates are descriptive. Together, the results support a robust conditional association between digital-transformation disclosure and green patenting while defining clear limits on causal, moderating, and subgroup interpretations.

6.2. Management Implications

Firms seeking to translate digital orientation into green patenting can combine digital investment with knowledge-integration routines, sustained R&D expenditure, and technical personnel development. Because the DTT and DTU coefficients are not statistically different in the joint model, managers should evaluate underlying digital technologies and operational digital applications according to their complementary fit with firm-specific innovation needs rather than presume that one dimension is uniformly superior. Public support can emphasize verifiable digital capabilities and green-innovation outputs without favoring a particular digital component, while recognizing that the estimates do not identify the effects of specific subsidies, carbon policies, or region-specific regulatory instruments. From a sustainability perspective, the documented association between digital-transformation disclosure and green patent activity suggests that digital orientation and knowledge-sharing routines merit further investigation as potential complements to conventional approaches to promoting green innovation in manufacturing.

6.3. Limitations and Future Research

Several limitations suggest directions for future research. First, DT is a full-annual-report keyword measure that captures disclosed digital orientation rather than physical transformation, and the dictionary may contain terms that overlap with green-technology discourse. Future studies could preserve keyword-level source data and construct refined indices that separate digital orientation from green-technology disclosure. Second, the industry-average normalization of KF does not fully remove its dependence on the size of the firm’s patent portfolio; firms with more patents mechanically produce higher citation counts even at constant per-patent rates. The indirect-effect comparisons involving KF should therefore be interpreted with this measurement property in mind, and alternative knowledge-flow proxies that are independent of portfolio scale merit exploration in future work. Third, the models directly control for firm size using the natural logarithm of total assets but do not include fixed-asset intensity, although Board, Tobin’s Q, Lev, and ROA capture related dimensions of organizational scale, asset valuation, capital structure, and asset utilization, residual confounding associated with asset structure may remain. Fourth, HHI is constructed from listed-firm revenues and may not represent the complete product market, so future research could employ competition measures that also reflect unlisted firms. The hypothesized inverted-U moderating effect of market competition was not statistically supported; the HHI distribution in the sample is concentrated at low values, which may limit the statistical power to detect nonlinear moderation. Fifth, the mediation estimates may be affected by unobserved innovation orientation, and the control-function instrument cannot establish the exclusion restriction; credible policy shocks or dynamic identification designs would allow stronger causal inference. Finally, patent applications and citations do not capture all dimensions of environmental performance, and results for Chinese listed manufacturers may not generalize to unlisted firms, other sectors, or other countries; future studies could examine direct environmental outcomes across a broader range of firms and institutional settings. More broadly, future research could situate the digital–green innovation nexus within a wider sustainability framework, incorporating social sustainability dimensions such as employment quality and community welfare alongside environmental outcomes to provide a more comprehensive assessment of digital transformation’s contribution to sustainable development.

Author Contributions

Conceptualization, H.C. and Y.Z.; methodology, H.C. and S.L.; software, H.C. and S.L.; validation, H.C., Y.Z. and B.L.; formal analysis, H.C. and B.L.; investigation, H.C.; resources, Y.Z.; data curation, H.C., S.L. and B.L.; writing—original draft preparation, H.C., Y.Z., S.L. and B.L.; writing—review and editing, H.C., Y.Z., S.L. and B.L.; visualization, B.L. and S.L.; supervision, B.L.; project administration, Y.Z. All authors have read and agreed to the published version of the manuscript.

Funding

This research received no external funding.

Institutional Review Board Statement

Not applicable.

Informed Consent Statement

Not applicable.

Data Availability Statement

No data was generated by this study. The following existing data sources were used: Financial data of listed manufacturing companies from the China Stock Market & Accounting Research Database (CSMAR), available via https://www.csmar.com (accessed on 23 September 2026). Patent application and citation data from the China National Intellectual Property Administration (CNIPA), accessed through the China Research Data Service Platform (CNRDS), available via https://www.cnrds.com (accessed on 23 September 2026). Textual data for measuring corporate digital transformation, including keyword frequencies from annual reports, sourced from the Wind Information Database (WIND), available via https://www.wind.com.cn (accessed on 23 September 2026). All data used in this study are publicly accessible through the above platforms, and the authors confirm that they did not have any special access privileges that others would not have. The analysis code and detailed data processing procedures are available from the corresponding author upon reasonable request.

Conflicts of Interest

The authors declare no conflicts of interest.

Abbreviations

The following abbreviations are used in this manuscript:
RBVResource-Based View
KBVKnowledge-Based View
HHIHerfindahl–Hirschman Index
GIAGreen Patent Applications
DTDigital Transformation Disclosure
DTTUnderlying Digital Technology
DTUDigital Application
KFInter-organizational Knowledge Flow
RDSR&D Expenditure Intensity
RDPR&D Personnel Share
SizeFirm Size
FirmAgeFirm Age
LevLeverage Ratio
ROAReturn on Assets
CashflowCash Flow Ratio
GrowthRevenue Growth Rate
BoardBoard Size
IndepProportion of Independent Directors
ShareShareholding Concentration
InpShareholding Balance
TobinqTobin’s Q Ratio
SOEState-owned Enterprise Indicator
DualDual Roles
NBNegative Binomial

References

  1. Porter, M.E.; Linde, C.V.D. Toward a new conception of the environment-competitiveness relationship. J. Econ. Perspect. 1995, 9, 97–118. [Google Scholar] [CrossRef] [Scilit]
  2. Jaffe, A.B.; Palmer, K. Environmental regulation and innovation: A panel data study. Rev. Econ. Stat. 1997, 79, 610–619. [Google Scholar] [CrossRef] [Scilit]
  3. Verhoef, P.C.; Broekhuizen, T.; Bart, Y.; Bhattacharya, A.; Dong, J.Q.; Fabian, N.; Haenlein, M. Digital transformation: A multidisciplinary reflection and research agenda. J. Bus. Res. 2021, 122, 889–901. [Google Scholar] [CrossRef] [Scilit]
  4. Zhang, J.; Li, S. The Impact of Human Capital on Green Technology Innovation—Moderating Role of Environmental Regulations. Int. J. Environ. Res. Public Health 2023, 20, 4803. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  5. Bergh, D.D.; Doria, L.; Crook, T.R.; Roccapriore, A.Y. Is knowledge really the most important strategic resource? A meta-analytic review. Strateg. Manag. J. 2024, 46, 3–18. [Google Scholar] [CrossRef] [Scilit]
  6. Martínez-Sánchez, Á.; Vicente-Oliva, S.; Pérez-Pérez, M. The relationship between R&D, the absorptive capacity of knowledge, human resource flexibility and innovation: Mediator effects on industrial firms. J. Bus. Res. 2020, 118, 431–440. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  7. Mu, R.; Ma, D.; Zhang, J.; Liu, S.; Zhang, L. Impact of Enterprise Digital Transformation on Green Innovation Dynamics—Empirical Evidence from Growth Enterprise Market-Listed Companies. Sustainability 2026, 18, 2539. [Google Scholar] [CrossRef] [Scilit]
  8. Barney, J. Firm resources and sustained competitive advantage. J. Manag. 1991, 17, 99–120. [Google Scholar] [CrossRef] [Scilit]
  9. Grant, R.M. Toward a knowledge-based theory of the firm. Strateg. Manag. J. 1996, 17, 109–122. [Google Scholar] [CrossRef] [Scilit]
  10. Xu, J.; Yu, Y.; Zhang, M.; Zhang, J. Impacts of digital transformation on eco-innovation and sustainable performance: Evidence from Chinese manufacturing companies. J. Clean. Prod. 2023, 393, 136278. [Google Scholar] [CrossRef] [Scilit]
  11. Zhou, J.; Peng, Y.; Zhang, S.; Tan, Y. The impact of digital transformation on corporate green technology innovation. J. Inf. Knowl. Manag. 2025, 24, 2550013. [Google Scholar] [CrossRef] [Scilit]
  12. Feng, H.; Wang, F.; Song, G.; Liu, L. Digital Transformation on Enterprise Green Innovation: Effect and Transmission Mechanism. Int. J. Environ. Res. Public Health 2022, 19, 10614. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  13. Xue, L.; Zhang, Q.; Zhang, X.; Li, C. Can Digital Transformation Promote Green Technology Innovation? Sustainability 2022, 14, 7497. [Google Scholar] [CrossRef] [Scilit]
  14. Li, S. Environmental regulation policy, firm endogenous capability, and green technological innovation: Evidence from a multi-period DID study in heavily polluting industries. J. Environ. Manag. 2025, 391, 126436. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  15. Gao, X.; He, X.; Sun, C.; Wu, D.; Zhang, J. Innovation in shouldering green responsibility: ESG performance and green technology innovation. Energy Econ. 2025, 142, 108197. [Google Scholar] [CrossRef] [Scilit]
  16. Xu, B.; Lin, B. How does green credit effectively promote green technology innovation? Int. Rev. Financ. Anal. 2025, 102, 104089. [Google Scholar] [CrossRef] [Scilit]
  17. Zhou, Y.; Yang, C.; Liu, Z.; Gong, L. Digital technology adoption and innovation performance: A moderated mediation model. Technol. Anal. Strateg. Manag. 2023, 36, 3341–3356. [Google Scholar] [CrossRef] [Scilit]
  18. Xing, M.Q.; Xu, L. Digital transformation, dynamic capabilities, and green innovation in manufacturing enterprises. Stat. Decis. Mak. 2024, 40, 184–188. [Google Scholar] [CrossRef]
  19. Beneito, P.; Rochina-Barrachina, M.E.; Sanchis, A. Competition and innovation with selective exit: An inverted-U shape relationship? Oxf. Econ. Pap. 2017, 69, 1032–1053. [Google Scholar] [CrossRef] [Scilit]
  20. Xiao, H.J.; Yang, Z.; Liu, M.Y. The social responsibility promotion effect of enterprise digitalization: Testing dual internal and external pathways. Bus. Manag. J. 2021, 43, 52–69. Available online: https://wap.cnki.net/touch/web/Journal/Article/JJGU202111004.html (accessed on 5 October 2026).
  21. Jiang, Y.B.; Xu, C.X.; Ban, X. Digital Transformation and Dual Innovation in Enterprises. Reform Econ. Syst. 2022, 3, 187–193. Available online: http://sass.cn/123003/68954.aspx (accessed on 5 October 2026). [CrossRef] [Scilit]
  22. Song, M. Digital Economy, Knowledge Flow, and Corporate Innovation Performance. J. Tech. Econ. Manag. 2023, 8, 39–44. [Google Scholar] [CrossRef]
  23. Guo, J.J.; Xie, F.J. The Impact of Knowledge Flow on Corporate Innovation: A Case Study of the ICT Industry. China Sci. Technol. Manag. Res. 2022, 42, 137–144. [Google Scholar]
  24. Wang, M.Y.; Li, Y.M.; Wang, Z.T. Research on the transmission of green technological innovation performance in industrial enterprises and the regulatory role of government market regulation. Chin. J. Manag. 2022, 19, 1026–1037+1091. [Google Scholar]
  25. Fu, G.L. A Study on the Impact of Inter-firm R&D Collaboration and R&D Human Capital on Corporate Innovation Performance. Forecasting 2020, 39, 43–50. Available online: https://kns.cnki.net/kcms2/article/abstract?v=xiNUFhx2xxaArZ47OkTM1gLiFSIKhWpu4h0Hwl6r0lD4Tn9ANyBB2kayVJtHLbXR5hWyEl3d3Il1kHxrTM58zso4gannZe_ebQeHZblhBYm1PXJ-L8HdK649OLJzSqNfkt1ojPz6bDNCe-Dmzp3vPoY8q2ejOnCV2klw13_5ydk=&uniplatform=NZKPT (accessed on 5 October 2026).
  26. Guo, J.H.; Zhu, C.L. Digital Transformation, Human Capital Structure Adjustment, and Value Chain Upgrading in Manufacturing Enterprises. China Econ. Manag. 2024, 46, 47–67. [Google Scholar] [CrossRef]
  27. Yang, Z.; Chen, J.; Ling, H.C. Media attention, environmental policy uncertainty, and corporate green technology innovation: Empirical evidence from Chinese A-share listed companies. J. Manag. Eng. 2023, 37, 1–15. [Google Scholar] [CrossRef]
  28. Yin, C.; Salmador, M.P.; Li, D.; Lloria, M.B. Green entrepreneurship and SME performance: The moderating effect of firm age. Int. Entrep. Manag. J. 2022, 18, 255–275. [Google Scholar] [CrossRef] [Scilit]
  29. Wu, F.; Hu, H.Z.; Lin, H.Y.; Ren, X.Y. Corporate Digital Transformation and Capital Market Performance: Empirical Evidence from Stock Liquidity. Manag. World 2021, 37, 130–144+10. [Google Scholar] [CrossRef]
  30. Appio, F.; De Luca, L.D.; Morgan, R.E.; Martini, A. Patent portfolio diversity and firm profitability: A question of specialization or diversification? J. Bus. Res. 2019, 101, 255–267. [Google Scholar] [CrossRef] [Scilit]
  31. Kim, T.H.; Kim, B. Firm’s environmental expenditure, R&D intensity, and profitability. Sustainability 2018, 10, 2071. [Google Scholar] [CrossRef] [Scilit]
  32. Song, J.; Zhang, J.C.; Pan, Y. The Impact of ESG Development on Corporate New Productivity: Empirical Evidence from Chinese A-Share Listed Companies. Contemp. Econ. Manag. 2024, 46, 1–11. [Google Scholar] [CrossRef]
  33. Bain, J.S. Advantages of the large firm: Production, distribution, and sales promotion. J. Mark. 1956, 20, 336–346. [Google Scholar] [CrossRef] [Scilit]
  34. Ma, W.J.; Zhang, H.Z.; Chen, J. The Impact of Corporate Digital Transformation on the Selection of Green Innovation Models. Sci. Res. Manag. 2023, 44, 61–70. [Google Scholar] [CrossRef]
  35. Gao, Z.L.; Tan, W.H. Does Corporate Digital Transformation Promote Green Technology Innovation? Empirical Evidence Based on Text Analysis Methods. Collect. Essays Finance Econ. 2024, 1, 79–91. Available online: https://cjlc.zufe.edu.cn/CN/abstract/abstract2151.shtml (accessed on 5 October 2026).
  36. Li, Q.; Li, D.X.; He, Z.C. Institutional Investor Exit Threats and Corporate Green Innovation. J. Beijing Inst. Technol. (Soc. Sci. Ed.) 2024, 26, 74–88. [Google Scholar] [CrossRef]
Figure 1. Conceptual framework.
Sustainability 18 10254 g001
Figure 2. Keyword spectrum for digital transformation.
Sustainability 18 10254 g002
Table 1. Variable definitions and measurement.
The Variable TypeVariablesSymbolThe Variable Description
Dependent variableGreen Technological InnovationGIANumber of WIPO-classified green patent applications filed by firm
Explanatory variableCorporate Digital TransformationDTLn(1 + total frequency of the validated digital-transformation keywords in the full annual report)
Mediating VariablesKnowledge FlowKFNumber of patent citations/corresponding two-digit-industry average
R&D expenditure IntensityRDSR&D expenditure/operating revenue
R&D personnel shareRDPR&D employees divided by total employment
Moderating VariableMarket CompetitionHHISum of squared revenue shares of listed firms within each two-digit industry
Control VariablesFirm AgeFirmAgeNatural logarithm of the difference between the observation year and the year of establishment + 1
Leverage RatioLevTotal liabilities/total assets at year-end
Return on AssetsROANet profit divided by average total assets
Cash Flow RatioCashflowCash generated from operating activities/total assets
Revenue Growth RateGrowth(Current year’s revenue/Previous year’s revenue) − 1
Board SizeBoardNatural logarithm of the number of board members
Proportion of Independent DirectorsIndepNumber of independent directors/the total number of board members
Shareholding ConcentrationShareNumber of shares held by the largest shareholder/total number of shares
Shareholding BalanceInpSum of the shareholding ratios of the second to tenth largest shareholders divided by the shareholding ratio of the largest shareholder
Tobin’s Q RatioTobinqSum of the company’s current market value of circulating shares, non-circulating shares, and liabilities/total assets
State-owned Enterprise IndicatorSOEOne for state-owned enterprises and zero otherwise
Dual RolesDualOne if the chairperson and general manager are the same person and zero otherwise
Firm SizeSizeNatural logarithm of total assets
Table 2. Descriptive statistics.
VariablesObservations Mean Standard Deviation Minimum Median Maximum
GIA16,2313.0318.130.000.00978
DT16,2311.461.280.001.394.77
KF16,2310.782.050.000.0914.14
RDS16,2315.194.240.104.1426.28
RDP16,23115.4410.180.7513.2155.99
HHI16,2310.060.050.010.040.27
Size16,23122.111.1520.1121.9525.66
FirmAge16,2311.950.920.002.083.33
Lev16,2310.380.180.060.370.83
ROA16,2310.050.07−0.200.050.24
Cashflow16,2310.050.07−0.120.050.25
Growth16,2310.170.36−0.530.112.03
Board16,2312.090.191.612.202.56
Indep16,23137.795.3633.3336.3657.14
Share16,23133.0913.669.5630.8870.11
Inp16,2311.020.790.070.814.06
Tobinq16,2312.151.310.871.738.43
SOE16,2310.230.420.000.001.00
Dual16,2310.340.480.000.001.00
Table 3. Baseline negative binomial results.
(1)(2)(3)
GIAGIAGIA
DT0.168 ***0.298 ***0.134 ***
(11.095)(5.843)(3.403)
Size0.287 ***—0.794 ***
(11.382)—(14.900)
FirmAge−0.202 ***—−0.402 ***
(−6.370)—(−6.285)
Lev0.639 ***—0.814 **
(4.527)—(2.529)
ROA0.826 **—1.181 **
(2.571)—(1.985)
Cashflow0.099—−0.679
(0.409)—(−1.538)
Growth−0.077 *—−0.219 **
(−1.834)—(−2.290)
Board0.050—0.089
(0.399)—(0.446)
Indep0.006—0.001
(1.440)—(0.235)
Share−0.002—−0.009
(−0.941)—(−1.455)
Inp−0.027—−0.152 **
(−0.680)—(−2.271)
Tobinq0.020—0.035
(1.404)—(0.990)
SOE0.233 ***—0.346 ***
(3.839)—(3.355)
Dual−0.077 *—0.022
(−1.880)—(0.235)
_cons−6.839 ***−0.860−18.511 ***
(−11.551)(−1.328)(−14.314)
Observations16,23116,23116,231
Pseudo R2—0.0520.092
Log likelihood−19,976.743−23,341.701−22,360.542
Wald χ2447.731141,660.222121,266.566
Prob > χ20.0000.0000.000
Year FENoYesYes
Industry FENoYesYes
ControlsYesNoYes
ModelRE NBFE NBFE NB
SE clustered by provinceYesYesYes
Note: Column (1) is a random-effects negative binomial model with the full control set, without year or industry fixed effects, and with standard errors clustered by province. Column (2) is a fixed-effects negative binomial model with year and industry fixed effects but without controls. Column (3) is a fixed-effects negative binomial model with the full control set and year and industry fixed effects. Parentheses report t statistics calculated from province-clustered standard errors. *, **, and *** denote statistical significance at the 10%, 5%, and 1% levels, respectively.
Table 4. Parallel mediation result.
(1)(2)(3)(4)
KFRDSRDPGIA
DT0.109 ***0.323 ***1.555 ***0.072 **
(3.924)(5.260)(5.922)(2.223)
KF———0.199 ***
———(9.650)
RDS———0.028 ***
———(2.687)
RDP———0.024 ***
———(3.557)
Size0.687 ***0.335 ***−0.0240.559 ***
(6.860)(6.275)(−0.139)(10.911)
FirmAge0.103 ***−0.832 ***−1.146 ***−0.366 ***
(2.971)(−6.021)(−4.447)(−6.287)
Lev−0.347−4.841 ***−6.278 ***1.348 ***
(−1.419)(−8.604)(−4.085)(5.617)
ROA−0.012−11.479 ***−0.9182.217 ***
(−0.027)(−7.473)(−0.342)(3.672)
Cashflow0.936 **−4.245 ***−15.155 ***−0.152
(2.675)(−5.893)(−6.221)(−0.321)
Growth−0.202 ***−0.0460.599 ***−0.187 **
(−4.315)(−0.483)(3.040)(−2.262)
Board0.428 *0.339−1.4400.112
(1.879)(1.120)(−1.293)(0.822)
Indep0.0170.020−0.009−0.000
(1.634)(1.578)(−0.326)(−0.035)
Share−0.007 *−0.024 ***−0.047 **−0.008
(−1.925)(−3.792)(−2.580)(−1.370)
Inp−0.076−0.1040.184−0.151 **
(−1.103)(−1.075)(0.769)(−2.370)
Tobinq0.097 ***0.613 ***1.078 ***−0.054 *
(5.299)(13.643)(8.232)(−1.890)
SOE0.1160.1241.419 ***0.253 **
(1.001)(0.942)(3.795)(2.510)
Dual0.0060.296 **0.607 **−0.057
(0.123)(2.638)(2.495)(−0.619)
Constant−16.102 ***−5.344 ***9.848 *−13.988 ***
(−8.505)(−3.495)(2.011)(−9.751)
Observations16,23116,23116,23116,231
Adjusted R20.1670.3280.299—
Pseudo R2———0.107
Log Likelihood−33,220.702−43,210.409−57,789.443−21,989.267
F statistic748.62450,118.5784060.853—
Wald χ2———76,415.040
Model p-value0.0000.0000.0000.000
Year FEYesYesYesYes
Industry FEYesYesYesYes
ControlsYesYesYesYes
SE clustered by provinceYesYesYesYes
Note: Columns (1)–(3) are OLS mediator equations and report adjusted R2 and F statistics. Column (4) is the joint negative binomial outcome equation and reports pseudo R2 and Wald χ2. All columns include the full control set, including Size, together with year and industry fixed effects. Parentheses report t statistics calculated from province-clustered standard errors. *, **, and *** denote statistical significance at the 10%, 5%, and 1% levels, respectively.
Table 5. Bootstrap indirect effects and pairwise differences. Panel (A): Bootstrap indirect effects. Panel (B): pairwise differences in indirect effects.
(A)
Mediating ChannelIndirect EffectBootstrap Standard ErrorNormal-Based [95% Conf. Interval]Significance
KF0.02180.0057[0.0106, 0.0330]Significant
RDS0.00890.0043[0.0005, 0.0174]Significant
RDP0.03770.0087[0.0207, 0.0547]Significant
total0.06840.0095[0.0498, 0.0871]Significant
(B)
ComparisonPoint EstimateNormal-Based 95% Confidence IntervalSignificance
KF_RDS0.0128[−0.0002, 0.0259]Marginally Significant
KF_RDP−0.0159[−0.0379, 0.0061]Not Significant
RDS_RDP−0.0287[−0.0501, −0.0074]Significant
Note: Indirect effects are calculated as ambm from three OLS mediator equations and a joint negative binomial outcome equation. Estimates are based on 5000 province-clustered Bootstrap replications with seed 12,345. The table reports Bootstrap standard errors and normal-based 95% confidence intervals. The KF–RDS difference is described as marginally significant because its confidence interval narrowly includes zero.
Table 6. Nonlinear moderation results.
(1)(2)(3)
Variable/StatisticLinear ModerationInverted-U ModerationInverted-U + Industry Trends
cDT0.137 ***0.154 ***0.154 ***
(3.517)(4.118)(4.121)
cHHI−5.055 ***−8.565 **−8.403 **
(−3.106)(−2.336)(−2.378)
cHHI2—20.70620.460
—(1.270)(1.275)
cDT × HHI0.4621.0381.072
(0.850)(1.324)(1.330)
cDT × HHI2—−5.381−5.567
—(−1.130)(−1.156)
Size0.793 ***0.791 ***0.791 ***
(14.951)(14.993)(15.072)
FirmAge−0.400 ***−0.400 ***−0.400 ***
(−6.364)(−6.366)(−6.426)
Lev0.830 **0.830 ***0.830 ***
(2.573)(2.589)(2.598)
ROA1.272 **1.279 **1.287 **
(2.136)(2.137)(2.177)
Cashflow−0.719−0.723 *−0.727 *
(−1.635)(−1.649)(−1.670)
Growth−0.223 **−0.217 **−0.216 **
(−2.342)(−2.259)(−2.244)
Board0.1150.1030.102
(0.592)(0.524)(0.523)
Indep0.0030.0020.002
(0.472)(0.395)(0.399)
Share−0.009−0.009−0.009
(−1.484)(−1.456)(−1.453)
Inp−0.151 **−0.149 **−0.149 **
(−2.286)(−2.285)(−2.287)
Tobinq0.0340.0320.032
(0.960)(0.901)(0.904)
SOE0.346 ***0.345 ***0.345 ***
(3.410)(3.416)(3.410)
Dual0.0320.0300.029
(0.352)(0.333)(0.319)
Constant−18.155 ***−17.964 ***−17.916 ***
(−14.391)(−14.166)(−14.111)
Observations16,23116,23116,231
Pseudo R20.0920.0930.093
Log likelihood−22,348.843−22,345.708−22,345.484
Wald χ2354,725.841113,364.8872,609,034.383
Prob > χ20.0000.0000.000
Year FEYesYesYes
Industry FEYesYesYes
Industry Time TrendNoNoYes
ControlsYesYesYes
SE clustered by provinceYesYesYes
Note: All specifications are negative binomial models and include the full control set, including Size, together with industry and year fixed effects. Column (3) additionally includes industry-specific linear time trends. Parentheses report t statistics calculated from province-clustered standard errors. *, **, and *** denote statistical significance at the 10%, 5%, and 1% levels, respectively.
Table 7. Robustness checks.
Variable/Statistic(1)(2)(3)(4)(5)
CitationsGIA:DTTGIA:DTUGIA:DTT + DTUln(GIA + 1)
DT0.173 ***———0.072 ***
(7.467)———(5.741)
DTT—0.161 ***—0.134 ***—
—(4.828)—(5.064)—
DTU——0.127 ***0.060—
——(2.930)(1.531)—
Size0.796 ***0.787 ***0.810 ***0.788 ***0.281 ***
(15.411)(15.010)(15.376)(15.083)(13.091)
FirmAge0.840 ***−0.392 ***−0.407 ***−0.399 ***−0.156 ***
(17.408)(−6.083)(−6.468)(−6.247)(−8.725)
Lev−0.1650.836 ***0.795 **0.827 ***0.285 ***
(−0.716)(2.644)(2.506)(2.615)(3.523)
ROA−0.1121.228 **1.213 **1.196 **0.371 **
(−0.233)(2.022)(2.043)(1.978)(2.533)
Cashflow1.285 ***−0.698−0.698−0.7000.237
(3.607)(−1.606)(−1.578)(−1.602)(1.641)
Growth−0.234 ***−0.218 **−0.224 **−0.214 **−0.114 ***
(−4.048)(−2.236)(−2.411)(−2.217)(−4.222)
Board0.529 ***0.1010.0720.1080.142 **
(3.666)(0.463)(0.392)(0.523)(2.110)
Indep0.018 **0.0020.0020.0020.005 *
(2.001)(0.243)(0.280)(0.310)(1.706)
Share−0.008 **−0.009−0.009−0.009−0.004 *
(−2.117)(−1.379)(−1.509)(−1.453)(−1.742)
Inp−0.040−0.147 **−0.159 **−0.150 **−0.071 ***
(−0.559)(−2.228)(−2.402)(−2.254)(−2.867)
Tobinq0.137 ***0.0310.0370.0330.027 ***
(5.960)(0.866)(1.066)(0.917)(3.162)
SOE−0.2100.335 ***0.342 ***0.343 ***0.134 ***
(−1.526)(3.351)(3.343)(3.329)(3.782)
Dual−0.0770.0150.0350.0150.006
(−1.252)(0.152)(0.383)(0.161)(0.157)
Constant−18.690 ***−18.326 ***−18.801 ***−18.408 ***−6.401 ***
(−15.276)(−14.174)(−14.315)(−14.275)(−12.939)
Observations16,23116,23116,23116,23116,231
Adjusted R2————0.227
Pseudo R20.1530.0920.0920.092—
Log likelihood−47,654.449−22,354.556−22,369.765−22,351.166−19,621.040
Wald χ21,394,143.63866,097.388101,726.399136,927.624—
F statistic————1154.026
Model p value0.0000.0000.0000.0000.000
Year FEYesYesYesYesYes
Industry FEYesYesYesYesYes
ControlsYesYesYesYesYes
ModelNB citationsNBNBNBOLS ln(GIA + 1)
p-value for DTT = DTU———0.103—
SE clustered by provinceYesYesYesYesYes
Note: Columns (1)–(4) are negative binomial models and report pseudo R2 and Wald χ2 statistics. Column (5) is an OLS model and reports adjusted R2 and an F statistic. All columns include the full control set, including Size, together with year and industry fixed effects. Parentheses report t statistics calculated from province-clustered standard errors. *, **, and *** denote statistical significance at the 10%, 5%, and 1% levels, respectively.
Table 8. Stepwise coefficient-stability checks.
Variable/Statistic(1)
DT only
(2)
+ Year FE
(3)
+ Industry FE
(4)
+ Controls
DT0.423 ***0.426 ***0.298 ***0.134 ***
(9.080)(8.627)(5.843)(3.403)
Size———0.794 ***
———(14.900)
FirmAge———−0.402 ***
———(−6.285)
Lev———0.814 **
———(2.529)
ROA———1.181 **
———(1.985)
Cashflow———−0.679
———(−1.538)
Growth———−0.219 **
———(−2.290)
Board———0.089
———(0.446)
Indep———0.001
———(0.235)
Share———−0.009
———(−1.455)
Inp———−0.152 **
———(−2.271)
Tobinq———0.035
———(0.990)
SOE———0.346 ***
———(3.355)
Dual———0.022
———(0.235)
Observations16,23116,23116,23116,231
Log Likelihood−24,353.882−24,339.259−23,341.701−22,360.542
Wald χ282.442435.388141,660.222121,266.566
Prob > χ20.0000.0000.0000.000
ControlsNoNoNoYes
Year FENoYesYesYes
Industry FENoNoYesYes
ModelNBNBNBNB
SE clustered by provinceYesYesYesYes
Note: All specifications use the same negative binomial estimator as Table 3. Column (4) includes the full control set, including Size. Parentheses report t statistics calculated from province-clustered standard errors. ** and *** denote statistical significance at the 5% and 1% levels, respectively.
Table 9. Cross-sectional dependence robustness.
Variable/Statistic(1)
Baseline
(2)
Year × Industry FE
(3)
Year × Province FE
(4)
Two-Way Clustering
DT0.134 ***0.129 ***0.325 ***0.134 ***
(3.403)(3.629)(6.681)(2.768)
Observations16,23116,23116,23116,231
Log Likelihood−22,360.542−22,212.596−22,864.350−22,360.542
Wald χ2121,266.5663918.2931890.902121,266.566
Prob > χ20.0000.0000.0000.000
Fixed-effects structureYear + IndustryYear × IndustryYear × ProvinceYear + Industry
Full controls including SizeYesYesYesYes
Covariance estimatorProvince clusterProvince clusterProvince clusterProvince + Year two-way cluster
Note: Parentheses report t statistics. All columns include the full control set, including Size. Column (4) replaces the covariance matrix with province-year two-way clustered standard errors; its Wald χ2 is based on the joint test of the baseline-model coefficients. *** denote statistical significance at the 1% level.
Table 10. Endogeneity test.
Variable/Statistic(1)(2)(3)
Lagged DT: GIAFirst Stage: DTControl Function: GIA
LDT0.133 ***——
(3.377)——
DT——1.193 **
——(2.293)
DT_mean_prov—0.309 ***—
—(4.084)—
vhat_prov——−1.062 **
——(−2.042)
Size0.794 ***0.199 ***0.577 ***
(13.646)(10.725)(5.427)
FirmAge−0.495 ***0.037−0.435 ***
(−5.915)(1.461)(−6.975)
Lev0.802 **−0.0770.902 ***
(2.424)(−0.635)(3.098)
ROA1.503 **−0.2711.579 ***
(2.515)(−1.187)(2.881)
Cashflow−0.278−0.439 **−0.301
(−0.579)(−2.717)(−0.640)
Growth−0.265 ***−0.031−0.189 *
(−2.760)(−1.399)(−1.784)
Board0.1090.1190.002
(0.504)(0.992)(0.012)
Indep0.0040.003−0.002
(0.654)(1.295)(−0.277)
Share−0.011−0.000−0.008
(−1.603)(−0.179)(−1.290)
Inp−0.177 **−0.017−0.142 **
(−2.525)(−0.429)(−2.140)
Tobinq0.0250.0170.014
(0.547)(1.500)(0.406)
SOE0.385 ***−0.201 ***0.568 ***
(3.701)(−4.263)(3.973)
Dual0.0400.050−0.056
(0.483)(1.058)(−0.479)
Constant−18.332 ***−3.942 ***−14.619 ***
(−11.408)(−8.001)(−7.745)
Observations13,13016,23116,231
Adjusted R2—0.305—
Pseudo R20.093—0.093
Log likelihood−18,600.906−24,005.749−22,348.284
Wald χ2299,658.878—455,040.875
F statistic—1905.386—
Model p-value0.0000.0000.000
Year FEYesYesYes
Industry FEYesYesYes
ControlsYesYesYes
ModelNB: GIA on LDTFirst-stage OLS: DTSecond-stage control-function NB
SE clustered by provinceYesYesYes
Note: All columns include the full control set, including Size, together with year and industry fixed effects. Parentheses report t statistics calculated from province-clustered standard errors. *, **, and *** denote statistical significance at the 10%, 5%, and 1% levels, respectively.
Table 11. Heterogeneity analysis.
Variable/Statistic(1)(2)(3)(4)(5)(6)
EasternCentral and WesternSOENon-SOELargeSME
DT0.156 ***0.124 **0.119 **0.139 ***0.112 ***0.163 ***
(3.482)(2.371)(2.039)(2.871)(2.664)(3.472)
Size0.849 ***0.720 ***0.701 ***0.848 ***0.802 ***0.927 ***
(12.579)(11.110)(11.172)(12.859)(11.782)(6.919)
FirmAge−0.417 ***−0.510 ***−0.329 ***−0.423 ***−0.491 ***−0.385 ***
(−5.530)(−7.896)(−2.916)(−6.532)(−7.005)(−5.155)
Lev0.571 *0.821 **0.4490.751 **1.140 **0.423
(1.698)(2.025)(0.916)(2.271)(1.981)(1.202)
ROA0.7761.9632.071 *0.9322.742 **0.065
(1.148)(1.644)(1.739)(1.483)(2.422)(0.073)
Cashflow−0.872 ***−0.0331.231−1.187 **0.718−1.564 **
(−3.301)(−0.028)(1.051)(−2.344)(1.386)(−2.451)
Growth−0.131−0.356 **−0.290 **−0.234 **−0.406 ***−0.059
(−1.246)(−2.160)(−2.267)(−2.390)(−4.156)(−0.441)
Board−0.0520.0250.5530.1260.3070.089
(−0.470)(0.051)(1.597)(0.521)(1.026)(0.308)
Indep0.009−0.006−0.0110.011−0.0050.013
(1.391)(−0.680)(−1.108)(1.367)(−0.675)(1.121)
Share−0.015 **0.003−0.015−0.006−0.015−0.006
(−2.082)(0.438)(−1.511)(−0.904)(−1.591)(−1.485)
Inp−0.151 *−0.138 *−0.299−0.090−0.389 ***0.038
(−1.721)(−1.798)(−1.439)(−1.384)(−3.569)(0.454)
Tobinq0.0580.004−0.0040.0540.066 *0.009
(1.390)(0.202)(−0.071)(1.137)(1.783)(0.163)
SOE0.371 ***0.346 **0.0000.0000.336 ***0.395 **
(3.377)(2.045)(.)(.)(3.239)(2.555)
Dual0.071−0.245 **−0.1370.0260.0070.029
(0.681)(−2.028)(−0.725)(0.281)(0.049)(0.279)
Constant−19.788 ***−16.322 ***−16.818 ***−20.249 ***−18.497 ***−22.409 ***
(−14.012)(−8.158)(−11.006)(−11.827)(−12.898)(−7.603)
Observations11,7904441380712,42481158116
pseudo R20.0990.0890.0900.0940.0880.061
Log likelihood−16,316.616−5929.418−6599.141−15,645.759−13,941.795−8253.015
Wald χ23129.57115,324.249307,485.916248,505.092114,767.94571,579.718
Prob > χ20.0000.0000.0000.0000.0000.000
Year FEYesYesYesYesYesYes
Industry FEYesYesYesYesYesYes
ControlsYesYesYesYesYesYes
SE clustered by provinceYesYesYesYesYesYes
Note: Split-sample regressions are descriptive. Formal between-group tests use DT × group interaction terms in a pooled negative binomial model; see Table 12. All specifications include the full control set, including Size, together with year and industry fixed effects. Parentheses report t statistics calculated from province-clustered standard errors. *, **, and *** denote statistical significance at the 10%, 5%, and 1% levels, respectively.
Table 12. Formal between-group tests: DT × group interactions.
(1)(2)(3)
RegionOwnershipFirm Size
DT0.0550.151 ***0.150 ***
(0.986)(3.289)(2.780)
Group dummy: East−0.233——
(−1.310)——
Group dummy: SOE—0.455 ***—
—(3.000)—
Group dummy: Large——−0.109
——(−0.597)
DT_east0.104——
(1.617)——
DT_SOE—−0.077—
—(−1.177)—
DT_large——−0.033
——(−0.622)
SOE control0.342 ***—0.342 ***
(3.419)—(3.335)
Observations16,23116,23116,231
Pseudo R20.0920.0920.092
Log likelihood−22,354.601−22,358.177−22,356.861
Interaction Wald χ22.6131.3860.387
Interaction p-value0.1060.2390.534
Year FEYesYesYes
Industry FEYesYesYes
Full controls including SizeYesYesYes
ModelPooled NBPooled NBPooled NB
SE clustered by provinceYesYesYes
Note: The table reports full-sample pooled negative binomial models with DT × group interaction terms and province-clustered standard errors. Each specification includes the full control set, including Size, together with year and industry fixed effects. The interaction coefficient is the formal test of the between-group difference. None of the three interaction terms is statistically significant at conventional levels. *** denote statistical significance at the 1% level.
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content.