1. Introduction
The green transition has become an increasingly important organizational context, as firms must simultaneously address climate-related risks, sustainability disclosure expectations, carbon management requirements, and rising cross-border regulatory pressures [
1,
2,
3]. In Taiwan, these pressures are particularly salient because many firms are embedded in export-oriented supply chains and must respond to both domestic sustainability policies and international regulatory developments. Under these conditions, environmental, social, and governance (ESG) requirements are not treated as a separate agenda from green transformation; rather, they serve as an institutional and managerial framework through which firms interpret, disclose, and implement green transformation practices. Sustainability-related demands are therefore increasingly linked to organizational legitimacy, competitiveness, and long-term survival [
4,
5,
6].
As sustainability issues grow more complex, firms increasingly rely on external professional actors to address internal capability gaps and support institutional responses. Prior research suggests that amid uncertainty and growing institutionalization, organizations often seek external expertise to interpret evolving requirements, coordinate cross-functional responses, and build new capabilities [
7,
8]. In this context, management consultants are no longer viewed solely as efficiency-focused problem solvers. Instead, they are increasingly expected to serve as intermediaries linking organizational capability-building needs with institutional response demands in ESG-oriented green transformation contexts [
9,
10,
11,
12].
Despite the growing importance of sustainability advisory work, the competency requirements for management consultants in ESG-oriented green transformation contexts remain insufficiently defined. Existing research has examined green transformation, sustainability governance, dynamic capabilities, and institutional pressures; however, relatively little research has systematically explained which consultant competencies are required, how they should be prioritized, and how those priorities reflect organizations’ combined needs for capability development and institutional response. This gap is important from both academic and practical perspectives. For human resource development and organizational behavior research, competency prioritization can clarify the structure of emerging professional roles. For firms and consulting providers, it can support consultant selection, capability assessment, training program design, and professional development [
13,
14,
15].
This study addresses the following scientific question: which competencies should be prioritized for management consultants supporting ESG-oriented green transformation in Taiwan, and how can these priorities be interpreted through the combined lenses of capability development and institutional response? To answer this question, the study adopts dynamic capability theory and institutional theory as complementary perspectives. Dynamic capability theory explains why organizations facing sustainability-related uncertainty may require external support to sense, adapt, and reconfigure their actions [
7,
16]. Institutional theory clarifies why organizations under regulatory and stakeholder pressures may value consulting competencies related to interpretation, legitimacy, compliance, and response [
8,
17]. From these perspectives, consultant competencies are not treated merely as a list of desirable traits but as a structured priority system that reflects how organizations evaluate professional support during green transformation. This view also aligns with research on sustainability-related professional capabilities, which emphasizes not only domain knowledge but also communication, interpretation, contextualization, and practical application [
11,
12,
18].
Accordingly, this study aims to identify and prioritize the competencies required of management consultants engaged in ESG-oriented green transformation. Specifically, it seeks to: (1) develop a structured competency framework through literature-based item generation and expert content validation; (2) prioritize the validated competencies using the best–worst method (BWM) and the technique for order preference by similarity to ideal solution (TOPSIS); and (3) derive implications for consultant selection, capability assessment, training design, and professional development. By integrating expert validation with BWM–TOPSIS-based prioritization, this study contributes to sustainability management, human resource development, and management consulting research by offering a structured, empirically supported framework for understanding consultants’ competency priorities in Taiwan’s ESG-oriented green transformation context.
3. Research Methodology
3.1. Research Design and Taiwan-Based Study Setting
This study adopted an exploratory sequential mixed-methods design to identify, validate, and prioritize the competencies required of management consultants involved in environmental, social, and governance (ESG)-oriented green transformation in Taiwan. This design was selected because the target professional role remains emerging, multidimensional, and situated at the intersection of sustainability management, management consulting, human resource development, and organizational capability building. In this context, the competency requirements of consultants cannot be adequately captured by a single quantitative ranking procedure. Following the logic of exploratory sequential research, this study first developed an initial competency pool through a structured literature-based process, then refined the pool through expert content validation, and finally used survey-based data to generate a structured prioritization of the validated competencies [
35,
36].
The empirical setting of this study is Taiwan. Taiwan offers a relevant context for examining ESG-oriented green transformation because many firms are embedded in export-oriented supply chains and must respond simultaneously to domestic sustainability policies, sustainability reporting expectations, carbon management requirements, and international regulatory pressures. In this setting, green transformation is not treated as a purely voluntary corporate initiative. Rather, it is understood as a managerial and institutional challenge that requires firms to integrate sustainability knowledge, regulatory interpretation, organizational coordination, stakeholder communication, and professional advisory support. Accordingly, management consultants are positioned in this study as external professional actors who may help firms interpret complex requirements, fill internal capability gaps, and translate sustainability-related expectations into actionable organizational practices.
The overall research design consisted of three sequential stages. In the first stage, an initial pool of 150 competency items was developed through a structured, literature-based item-generation process. This stage was intended to ensure that the competency framework was grounded in prior research and in relevant sources on sustainability, consulting, and human resource development. In the second stage, six Taiwan-based experts reviewed the initial competency pool and applied a strict one-strike rule to remove items deemed inappropriate, unclear, unnecessary, or inconsistent with the intended construct. This stage resulted in 48 validated competencies. In the third stage, a formal survey was conducted with 54 respondents relevant to the profession, including individuals involved in ESG or sustainability management, management consulting, human resource decision-making, organizational management, public-sector sustainability work, or related professional roles. Their responses served as the empirical input for the subsequent best–worst method (BWM) and technique for order preference by similarity to ideal solution (TOPSIS) analyses.
The study therefore emphasizes analytical rather than statistical generalization. Its purpose was not to infer competency priorities for all management consultants globally, but to develop and examine a structured competency-prioritization framework in a Taiwan-based, ESG-oriented green transformation context. Accordingly, the results should be interpreted as an empirically grounded, contextually situated priority structure, rather than as a universal ranking applicable across consulting fields or national settings. This positioning also clarifies the role of the 54 respondents: they were not treated as a statistically representative sample of a national population, but as professionally relevant respondents whose work experience, decision-making roles, or advisory involvement enabled them to provide informed judgments on consultant competency priorities.
Table 1 summarizes the three-stage research design and clarifies the role of each stage in the overall process of competency development and prioritization.
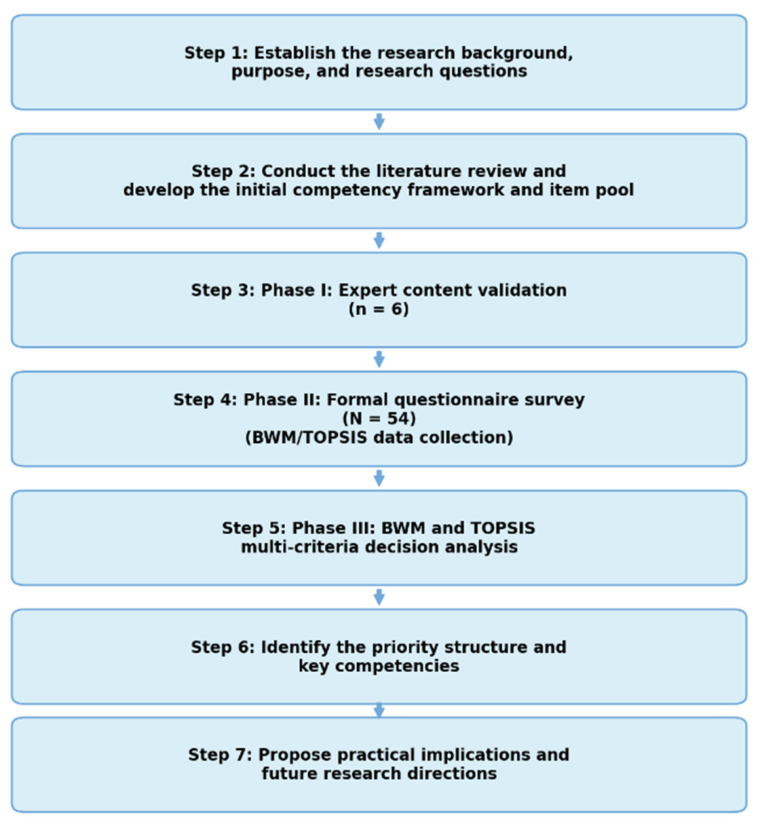
The overall research flow is shown in
Figure 1, linking the research questions, the expert validation procedure, the formal survey, and the BWM–TOPSIS competency prioritization process.
3.2. Literature-Based Competency Development and Expert Content Validation
The first methodological stage focused on developing and validating the competency items used in this study. Because ESG-oriented green transformation consulting is an emerging professional field, no single established competency framework was sufficient to capture the full range of knowledge, skills, and professional judgments required in this context. Therefore, this study adopted a structured, literature-based item development process rather than a full PRISMA-based systematic review. The purpose was not to conduct an exhaustive synthesis of evidence but to construct a theoretically informed and practically relevant initial competency pool for subsequent expert validation.
In this study, the structured, literature-based item development process is a staged procedure that translates prior conceptual, empirical, and professional sources into an initial pool of measurable competency items. The procedure involved identifying relevant knowledge domains, reviewing the literature and professional sources, extracting competency-related concepts, grouping them into theoretically meaningful dimensions, converting them into questionnaire items, and preparing the item pool for expert content validation. This process was intended to support construct-domain coverage and item relevance rather than to provide a PRISMA-based systematic evidence synthesis. This approach aligns with methodological recommendations for literature-based item generation, construct-domain specification, and scale development in organizational and social science research [
37,
38].
The initial competency pool was developed by integrating the literature and professional sources on sustainability management, management consulting, human resource development, ESG disclosure, environmental management standards, carbon management, stakeholder communication, and professional ethics. Based on this process, 150 initial competency items were organized into five major dimensions: green knowledge and skills, organizational change capability, communication and advocacy capability, data analysis and technical application, and ethics and professional responsibility. These dimensions were designed to reflect the multidimensional nature of ESG-oriented green transformation consulting, in which consultants are expected not only to possess technical knowledge but also to support organizational coordination, institutional interpretation, stakeholder communication, and credible professional practice.
Table 2 summarizes the five major competency dimensions used to organize the initial item pool.
After the 150-item pool was developed, six Taiwan-based experts were invited to conduct content validation. The expert panel was intentionally designed to include diverse professional perspectives relevant to ESG-oriented green transformation and competency development. The experts were selected because their experience in sustainability practice, management consulting, organizational management, human resource development, public governance, or academic research enabled them to evaluate whether the proposed items were relevant, clear, necessary, consistent with the intended construct, and practically applicable. In this study, expert validation served as a content-validity procedure rather than a broad stakeholder consultation. Therefore, the panel was limited to experts capable of assessing construct relevance and item quality. Other stakeholders, such as regulators, professional consultant associations, and investors, may also influence the consulting profession; however, they were not included in this validation stage because the purpose was not to represent all stakeholder interests but to refine the competency-item pool before the formal survey. This boundary was adopted to maintain the methodological focus of the content-validation stage while preserving the transparency of the item-screening procedure. The use of expert review to evaluate item relevance and content validity is consistent with established recommendations for content-validation procedures [
39].
Table 3 summarizes the expert panel’s role in the content-validation process.
A strict one-strike rule was applied during the content-validation stage. Under this rule, any item identified by at least one expert as inappropriate, unclear, unnecessary, redundant, or inconsistent with the intended construct was removed from the item pool. This rule was intentionally conservative to prevent ambiguous or weakly relevant items from entering the formal survey and the subsequent BWM–TOPSIS analysis. In other words, the one-strike rule was used to improve the conceptual purity and practical relevance of the competency framework before quantitative prioritization.
This validation logic differs from majority-based item-retention procedures. A majority-based approach may retain an item if most experts consider it acceptable, even when a single expert raises a serious conceptual or practical concern. In contrast, the one-strike rule adopted in this study treated expert objections as signals of potential item weakness. Because the subsequent BWM and TOPSIS analyses depended on the quality of the retained items, this stricter screening procedure was considered appropriate for reducing measurement ambiguity and improving the interpretability of the prioritization results.
The expert validation process reduced the initial pool of 150 items to 48 validated competencies. The retained competencies were not treated as a simple shortened list; rather, they formed a content-validated framework that had passed a conservative screening process. These 48 competencies served as the basis for the formal survey and the subsequent multi-criteria decision-making analysis. The complete list of retained competencies is reported in the
Section 4 and in
Supplementary Table S4, while the detailed basis for item development is provided in the
Supplementary Materials.
3.3. Formal Survey, Respondent Definition, and Data Input Basis
After the expert content validation stage, the 48 validated competencies were incorporated into a formal questionnaire. The complete list of the 48 validated competencies is provided in
Supplementary Table S4. This stage aimed to collect professionally informed evaluations of the relative importance of the validated competencies and to provide empirical input for the subsequent BWM and TOPSIS analyses. The formal survey was not designed as a random population survey. Instead, it used a purposive, professionally relevant sampling strategy, consistent with the study’s aim of developing an analytically meaningful competency-prioritization framework within a Taiwan-based ESG-oriented green transformation context [
35,
36].
In this study, the 54 valid respondents were treated as professionally relevant rather than as a statistically representative population sample. This distinction is important. Respondents were included because their work roles, decision-making responsibilities, advisory experience, or organizational involvement enabled them to provide informed judgments on consultant competency priorities. The respondent group included individuals from corporate sustainability or senior management roles, management or sustainability consulting services, academia or research institutes, government or public-sector organizations, and other related professional contexts. This cross-role composition was intended to capture perspectives from both consultant users and providers, as well as from organizational actors involved in sustainability-related capability development and decision-making.
Table 4 provides the operational definition used to determine whether respondents were professionally relevant to the study.
The final dataset comprised 54 valid responses. This sample size was appropriate for the study’s purpose because the analysis focused on structured professional judgment and multi-criteria prioritization rather than population-level statistical inference. Accordingly, the findings should not be interpreted as representing the views of all consultants or firms in Taiwan. Rather, they reflect an empirically grounded priority structure derived from respondents with professional experience in ESG-oriented green transformation, consulting work, sustainability management, or organizational capability development.
The survey asked respondents to evaluate the importance of the 48 validated competencies. The resulting Likert-scale ratings served as the empirical input for the analytical procedures. Specifically, group-level ratings informed the construction of BWM comparison inputs and TOPSIS ranking calculations. This procedure ensured that the prioritization results were based on a consistent empirical foundation derived from the same respondent dataset. Using a single formal survey dataset also supported transparency and traceability among the validated competency framework, respondent evaluations, and the final prioritization outcomes [
35,
36].
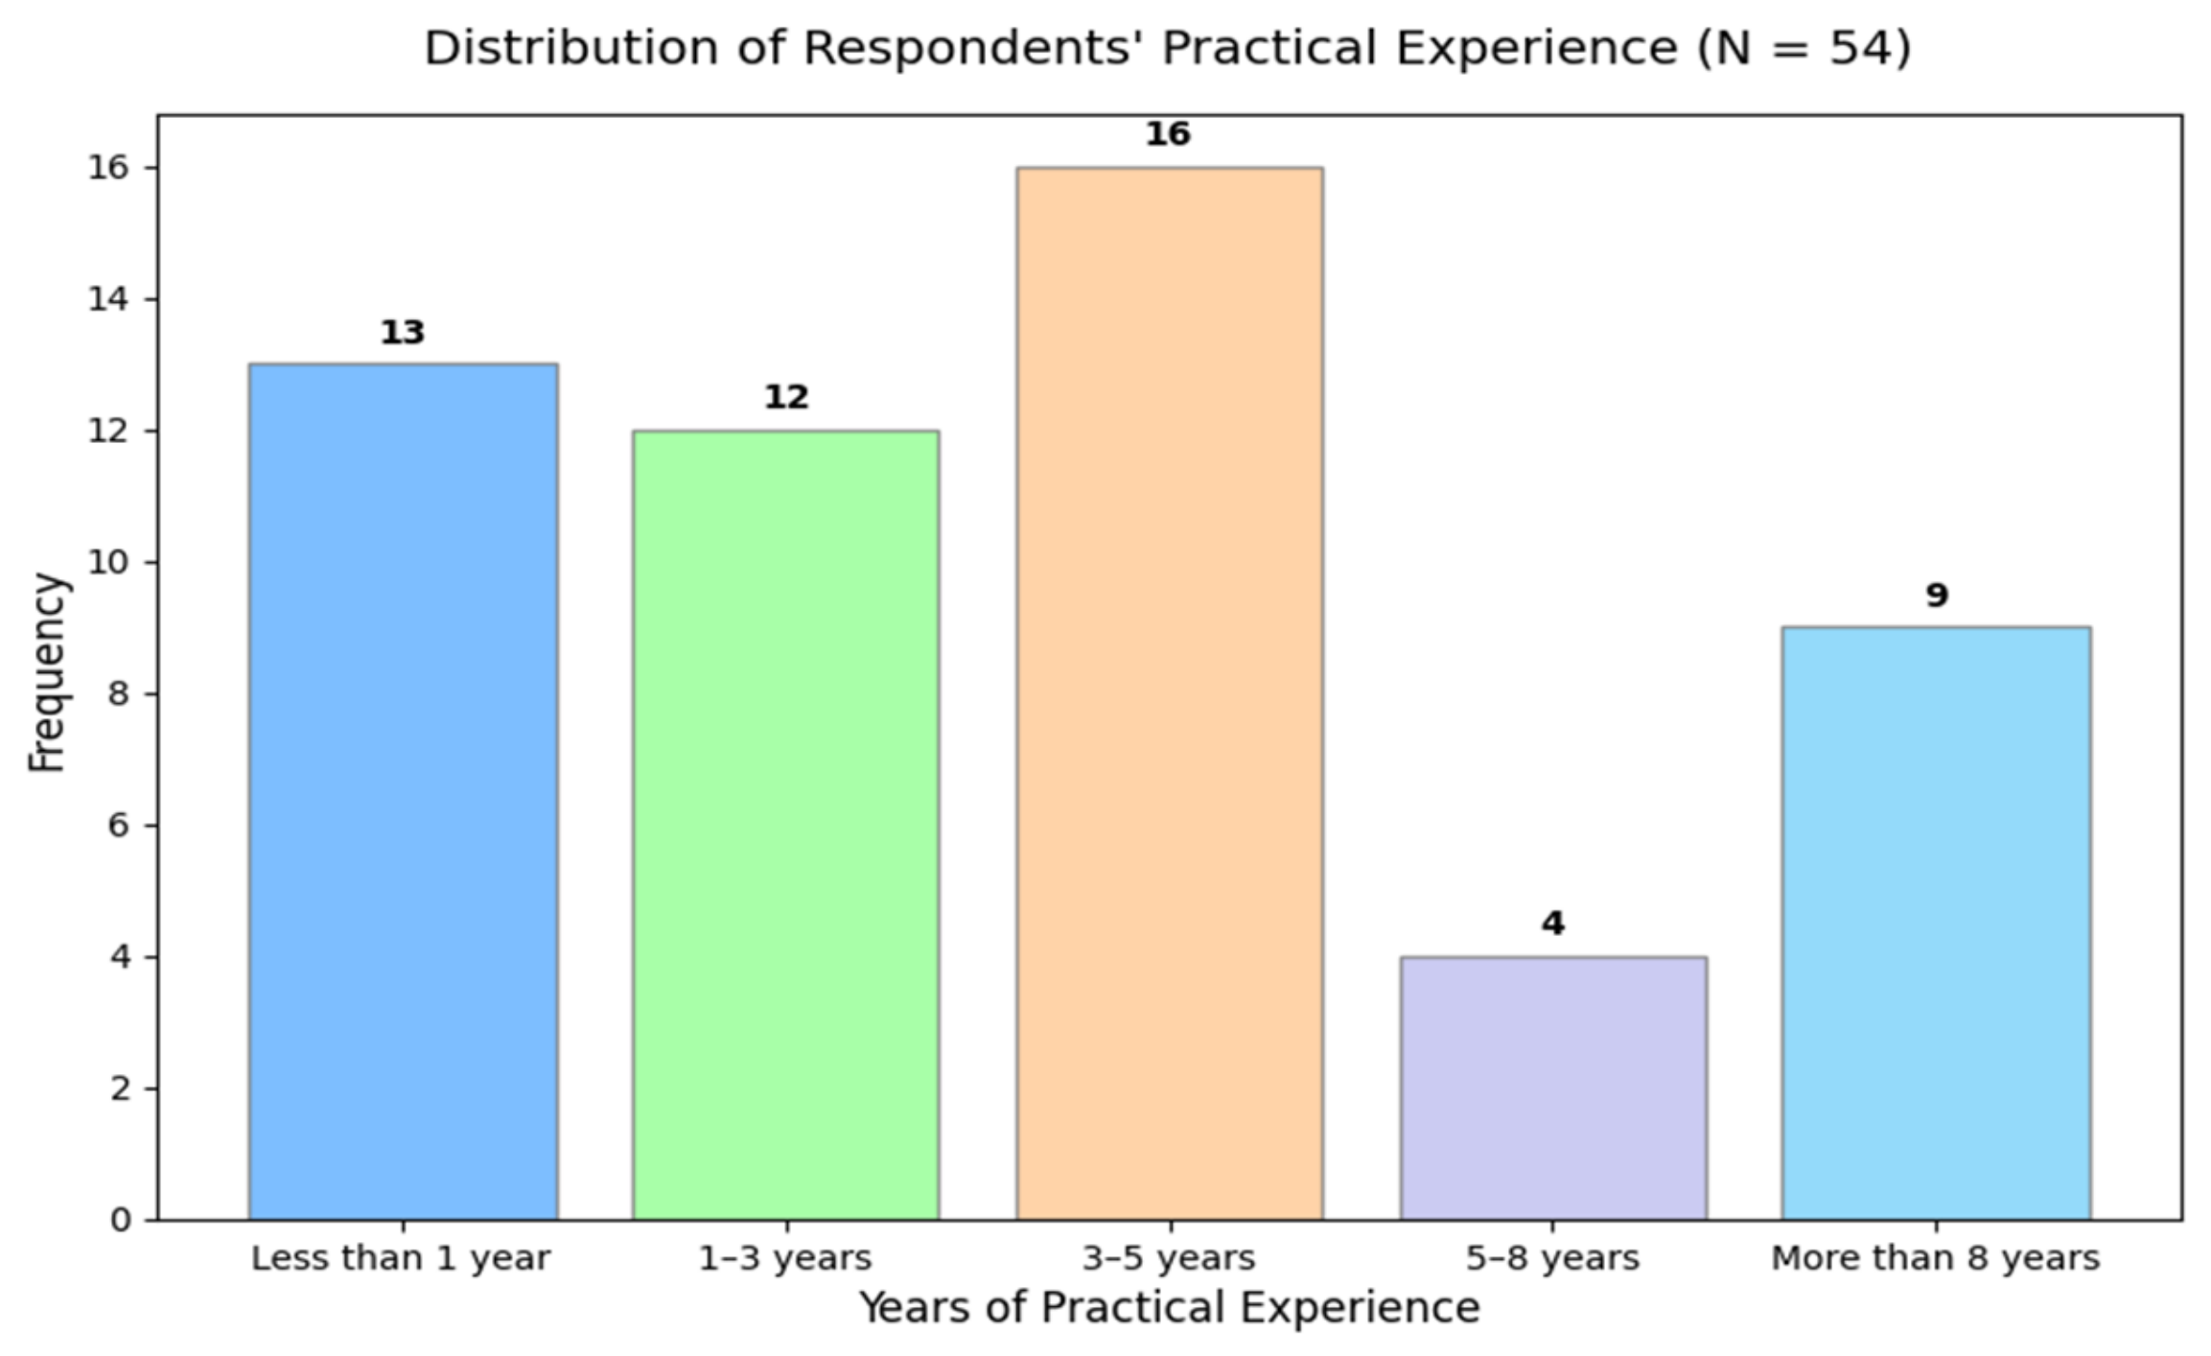
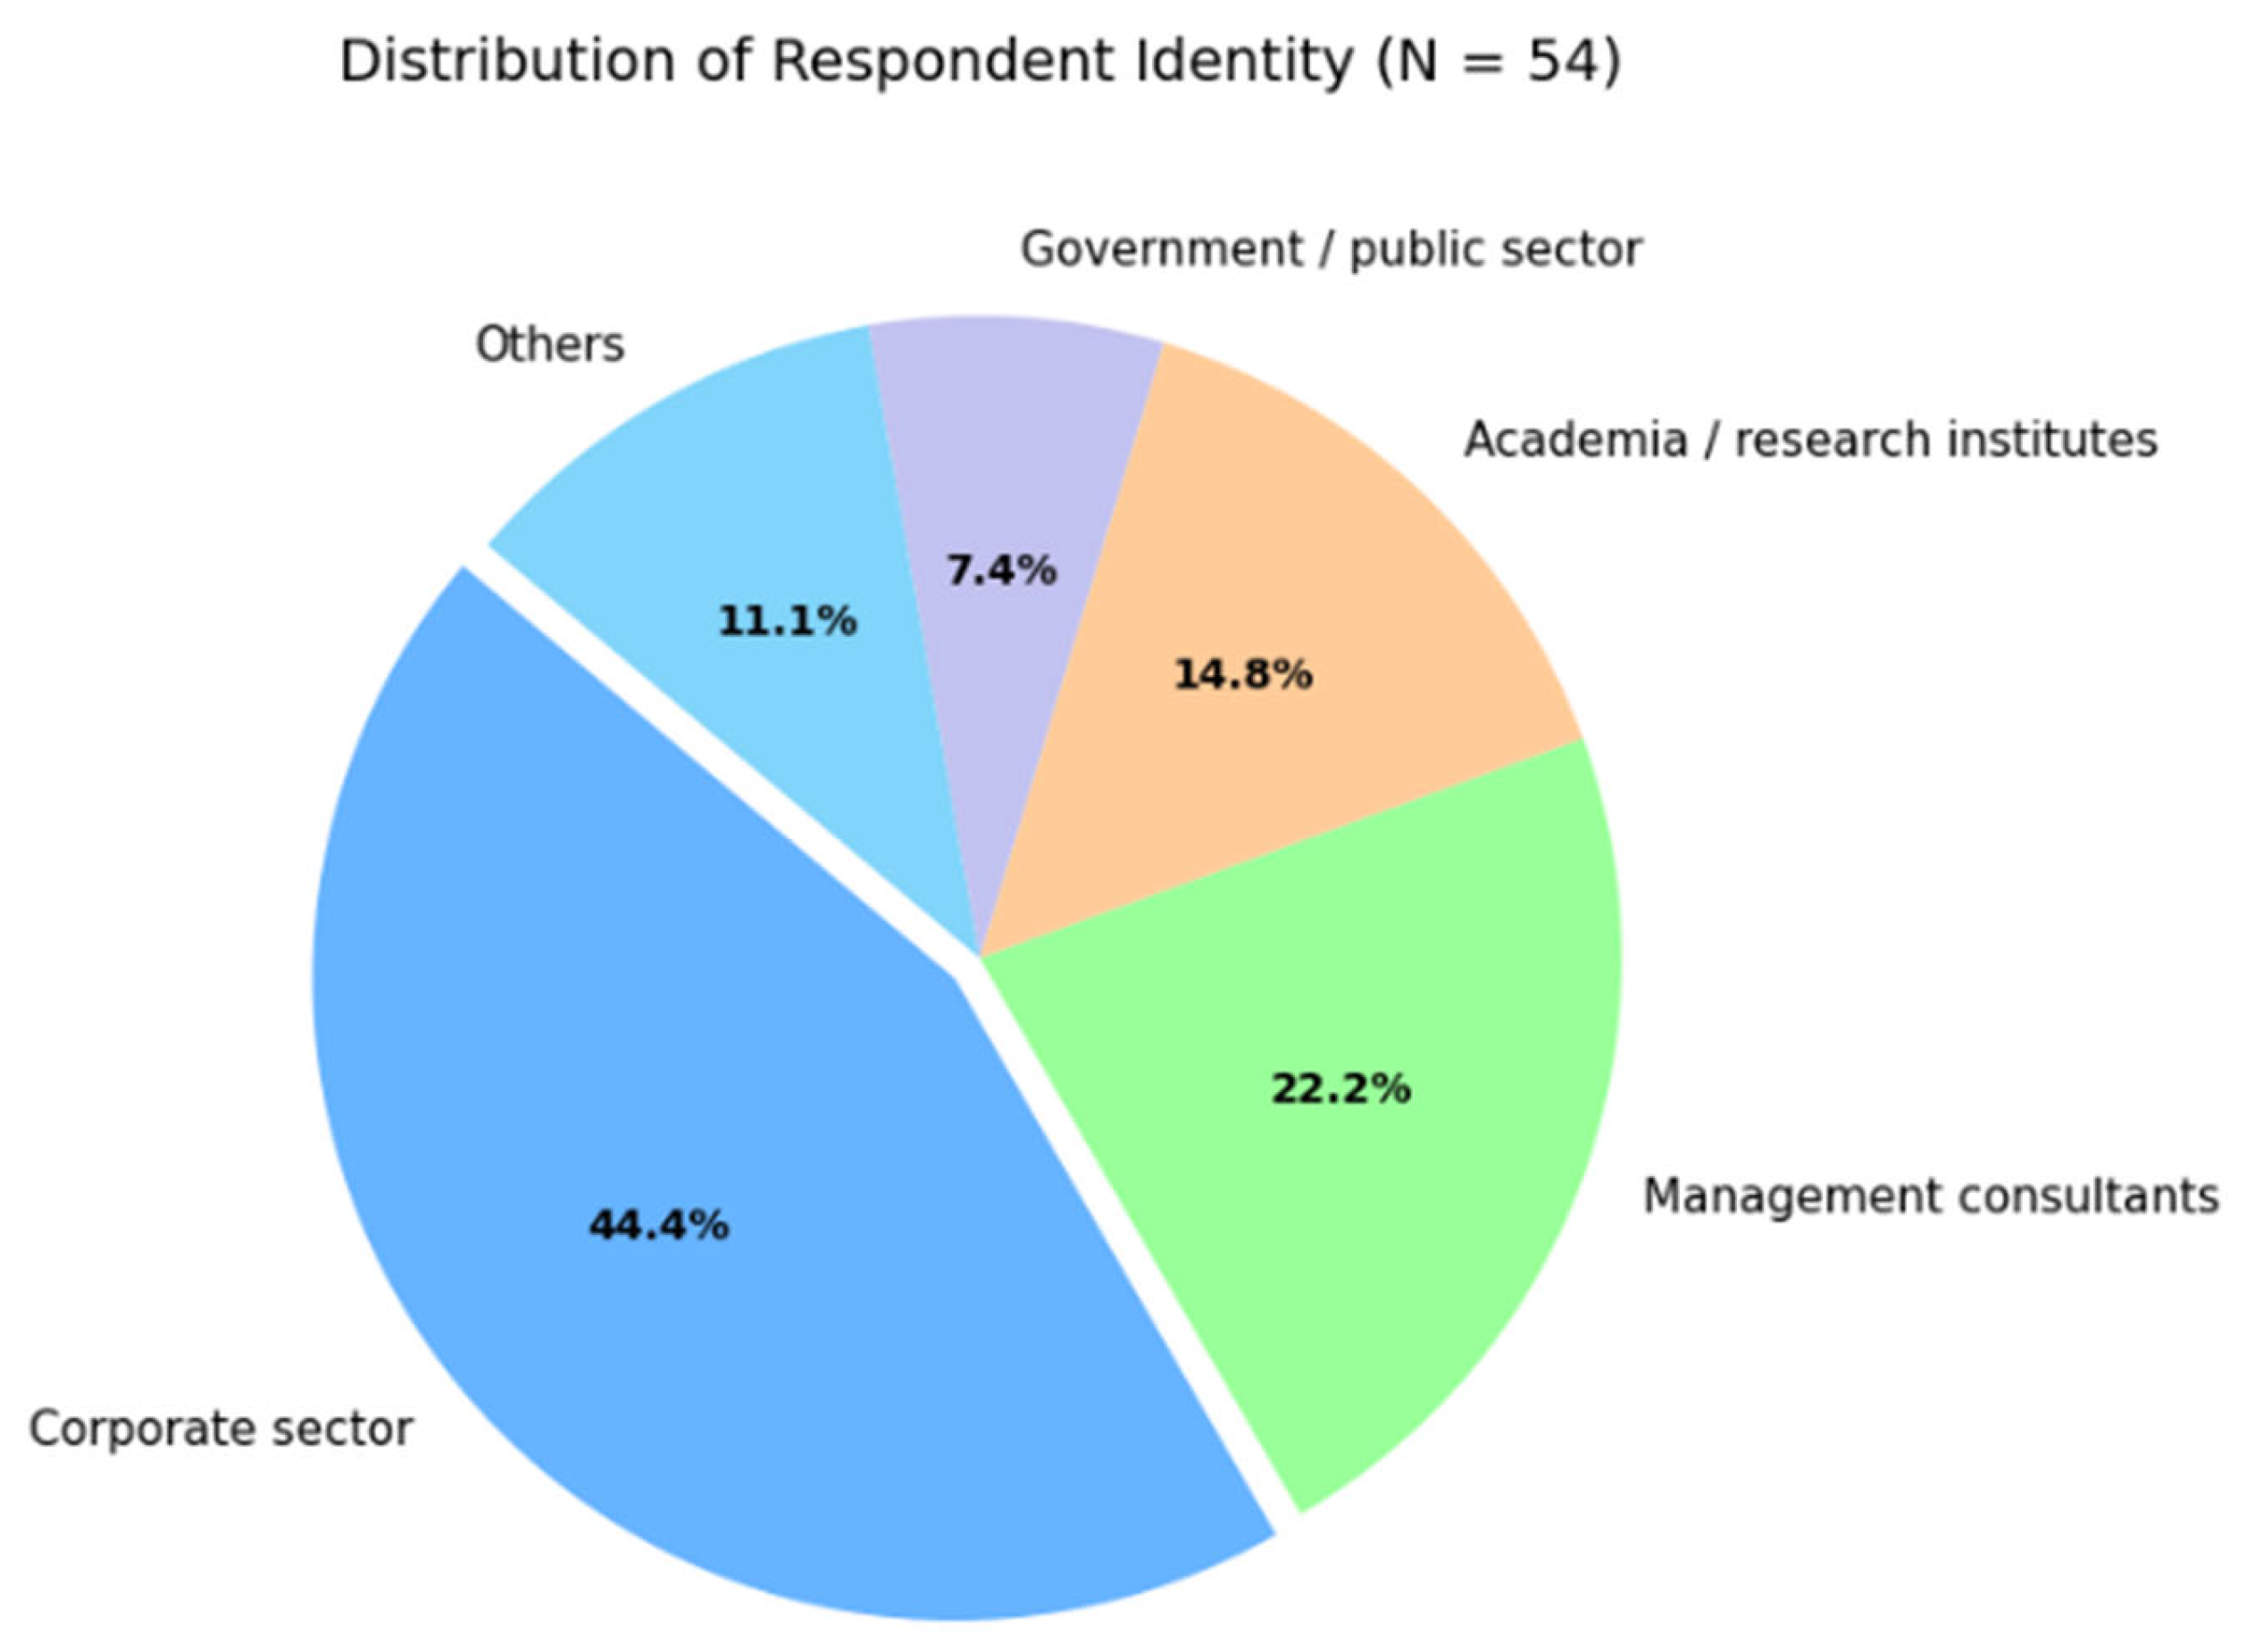
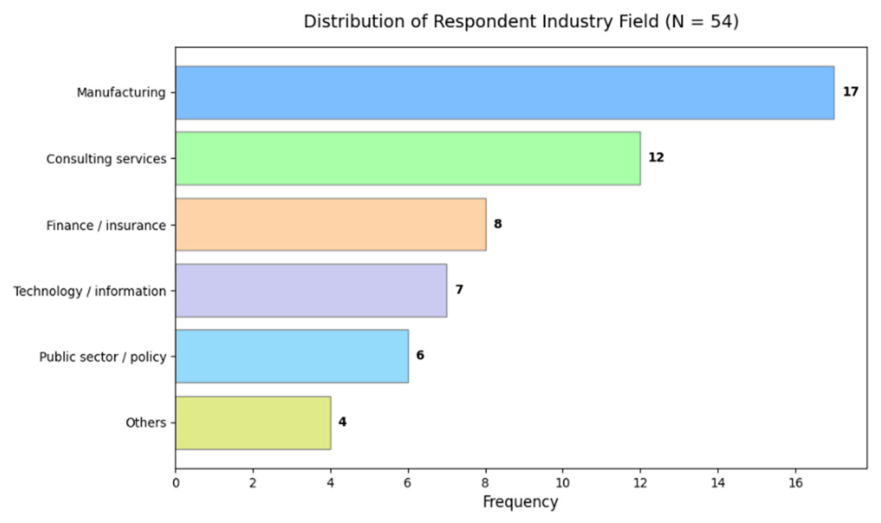
Table 5 presents the statistical profile of the formal respondents, while
Figure 2,
Figure 3 and
Figure 4 show the distributions of the respondents’ identities, practical experience, and industry sectors. These materials appear in
Section 3 because they describe the empirical basis of the formal survey rather than the substantive priority-ranking results.
Methodological Rationale for the BWM–TOPSIS Integration
The use of BWM and TOPSIS in this study followed a sequential rather than redundant logic. BWM was used to estimate the relative weights of the competency dimensions and indicators because it provides a parsimonious comparison structure and a consistency-checking mechanism for weight estimation [
40,
41,
42]. TOPSIS was then used to rank the validated competencies because it evaluates alternatives by their relative closeness to the positive ideal solution and their distance from the negative ideal solution [
34,
43,
44]. Therefore, the two methods served different analytical purposes: BWM established the weighting structure, whereas TOPSIS transformed the weighted information into a priority ranking. The methodological contribution of this study does not lie in proposing a new MCDM algorithm but in applying an integrated framework that combines content validation, BWM-based weighting, and TOPSIS-based prioritization to the competency analysis of management consultants in ESG-oriented green transformation.
3.4. BWM-Based Weight Estimation
After data standardization, this study employed the best–worst method (BWM) to determine the relative weights of competency dimensions and indicators. In this study, group mean scores were transformed into the comparison vectors needed for BWM, thus maintaining the method’s comparative logic while reducing the burden of extensive pairwise comparisons [
40,
41,
42].
The BWM linear programming model is defined as follows:
subject to
where
denotes the consistency deviation,
denotes the weight of criterion
, and
and
denote the mapped comparison elements for the best-to-others and others-to-worst vectors, respectively.
3.5. TOPSIS-Based Priority Ranking
After obtaining the BWM weights, this study employed the technique for order preference by similarity to ideal solution (TOPSIS) to calculate the relative closeness coefficient and determine the final ranking of competencies. The TOPSIS formulation in the main text is presented in a one-dimensional isomorphic form to ensure consistency between the conceptual process and the reported ranking results [
34,
43,
44].
The decision vector is:
The vector-normalized score is:
The weighted normalized score is:
The positive and negative ideal solutions are:
The distance to the positive ideal solution is:
The distance to the negative ideal solution is:
The closeness coefficient is:
A larger indicates that competency is closer to the ideal solution and therefore receives a higher priority ranking.
Linear Mapping from Group Ratings to BWM Comparison Vectors
Since BWM requires a 1–9 comparison scale while this study used five-point Likert-scale group mean scores, a linear mapping procedure was applied to convert the group means into the comparison vectors required for BWM [
40,
41].
If
, then:
This boundary rule prevents division by zero and indicates equal importance within the same comparison set. Detailed variable definitions for Equations (1)–(16) are provided in the equation descriptions above and in the supplementary verification materials where applicable (
Appendix A).
3.6. Reliability, Validity, and Data Quality Checks
Before conducting the BWM and TOPSIS analyses, this study assessed the reliability, validity, and data quality of the formal survey data. These checks were not intended to serve as independent hypothesis tests or prerequisites for parametric inference. Instead, they were used to evaluate whether the validated competency framework and the formal survey responses provided a sufficiently stable, interpretable, and transparent empirical basis for the subsequent multi-criteria decision-making analysis.
Reliability was assessed using internal consistency. Cronbach’s alpha was used to assess whether the retained competency items and their nested item sets demonstrated acceptable internal consistency in the formal survey data. In this study, reliability was examined at multiple levels, including the overall item structure, the secondary indicator sets, and the third-level competency items. This procedure helped determine whether the formal survey responses were sufficiently consistent to support subsequent weighting and ranking procedures.
Validity was addressed through content validity and construct relevance. Content validity was established during the expert-validation stage, in which six Taiwan-based experts reviewed the initial 150 competency items and applied the one-strike rule to remove items deemed inappropriate, unclear, unnecessary, or inconsistent with the intended construct. Construct validity was further supported by the alignment among the 48 retained competencies, the five major dimensions, and the theoretical framing of ESG-oriented green transformation consulting. In this sense, validity was treated not as a single statistical result but as a cumulative judgment based on literature-based item development, expert content validation, and the coherence of the final competency structure.
The Lilliefors-corrected Kolmogorov–Smirnov test was used to assess the distributional characteristics of the formal survey data when the population parameters were unknown and estimated from the sample [
45]. The results indicated non-normality across the item sets tested. This finding does not invalidate the subsequent BWM and TOPSIS procedures, because the main analytical purpose of this study was not to conduct parametric mean comparisons or regression-based inference. Rather, the study used group-level rating information to construct a structured weighting and ranking framework. Therefore, the normality test was interpreted as a diagnostic tool for describing the data distribution and supporting transparency, and not as a condition for determining whether the multi-criteria analysis could be performed.
Kendall’s W was used to assess the degree of agreement among respondents across the competency sets. In this study, the agreement results were interpreted cautiously. A statistically significant agreement pattern does not necessarily indicate strong consensus among all respondents, especially given that the respondent group included consultant users, consultant providers, organizational managers, HR-related decision-makers, academic or research participants, and public-sector actors. Such variation is consistent with the study’s cross-role design and should be understood as part of the professional diversity embedded in ESG-oriented green transformation contexts.
Overall, the reliability, validity, and data quality checks supported the use of the formal survey data as an empirical basis for BWM and TOPSIS analysis. Cronbach’s alpha provided evidence of internal consistency; the expert-validation process supported content validity; the Lilliefors-corrected Kolmogorov–Smirnov test clarified the non-normal distributional characteristics of the data; and Kendall’s W provided information on respondent agreement patterns. Taken together, these procedures strengthened the transparency and interpretability of the competency-prioritization results.
3.7. Summary of the Analytical Procedure
Taken together, the methodology followed a sequential logic linking competency development, expert validation, formal survey evaluation, and multi-criteria prioritization. The initial 150 competency items were generated through a structured literature-based process and then reviewed by six Taiwan-based experts using the one-strike rule. This process produced 48 validated competencies, which were subsequently evaluated by 54 respondents deemed professionally relevant. The formal survey data were then used as the empirical basis for BWM-based weight estimation and TOPSIS-based priority ranking.
This analytical procedure was designed to ensure that the final competency hierarchy was not derived from a single judgment source or an unvalidated item list. Instead, the results were based on a staged process that integrated literature-based item development, expert content validation, survey-based professional judgment, and MCDM-based prioritization. The following section presents the empirical results, including the validated competency set, data quality checks, dimension-level priority structure, indicator-level priority structure, and competency-item-level ranking.
4. Results
This section presents the study’s empirical findings. The results are organized into four parts: the validated competency set, data quality checks, dimension-level priority structure, and indicator- and item-level priority rankings. The respondent profile is reported in the
Section 3 because it describes the empirical basis of the formal survey rather than the substantive ranking results. Accordingly, this section focuses on the validated competencies and the priority structures derived from the formal survey data.
Overall, the results indicate that the competencies required of management consultants in environmental, social, and governance (ESG)-oriented green transformation contexts are not a set of equally weighted professional attributes but a structured hierarchy of priorities. This finding aligns with prior research suggesting that sustainability-related professional roles require not only specialized knowledge but also the ability to interpret institutional pressures, communicate across organizational boundaries, and support capability development [
5,
7,
11,
12,
18].
4.1. Validated Competency Set
The expert content-validation process yielded a final set of 48 validated competencies from an initial pool of 150 competency items. These retained competencies served as the analytical basis for the formal survey and the subsequent BWM–TOPSIS prioritization procedure. The reduction from 150 items to 48 competencies indicates that the final competency set was not treated as a broad inventory of possible consultant skills but as a screened and content-validated framework for ESG-oriented green transformation consulting. This approach aligns with competency-based HRD and scale development perspectives, which emphasize conceptual relevance, item clarity, and content validity when developing professional competency frameworks [
13,
14,
22,
23].
The 48 validated competencies were grouped into five major dimensions: Green Knowledge and Skills, Organizational Change Capability, Communication and Advocacy Capability, Data Analysis and Technical Application, and Ethics and Professional Responsibility. Among these dimensions, Green Knowledge and Skills contained the most retained competencies, followed by Organizational Change Capability. Communication and Advocacy Capability, Data Analysis and Technical Application, and Ethics and Professional Responsibility contained fewer retained items but remained central to the overall competency framework. This structure indicates that ESG-oriented green transformation consulting requires a combination of domain knowledge, organizational coordination, communication and interpretation, data-related capabilities, and professional accountability.
Table 6 summarizes the distribution of the 48 validated competencies across the five major dimensions. The complete list of retained competency items is presented in
Supplementary Table S4 to reduce redundancy in the main text and improve readability.
4.2. Descriptive Statistics, Normality, Reliability, and Agreement
Before analyzing the priority structure, the descriptive and statistical features of the formal survey data were examined. Descriptive statistics were calculated at three levels: the five main dimensions (M1–M5), the 25 secondary indicators (S1–S25), and the 48 third-level competency items (T1–T48). Across these levels, mean scores were generally high, indicating that the respondents regarded the retained competencies as important. At the same time, the standard deviations, interquartile ranges, and coefficients of variation showed sufficient variation in the responses, suggesting that the data were not merely concentrated in a uniformly high-score pattern. Detailed descriptive statistics are reported in
Supplementary Table S2, including
Table S2-1 for the main dimensions,
Table S2-2 for the secondary indicators, and
Table S2-3 for the third-level competency items.
The Lilliefors-corrected Kolmogorov–Smirnov test was used to assess the distributional characteristics of the survey data [
45]. As shown in
Table 7, all tested item sets exhibited non-normal distributions. This result is reported as a distributional diagnostic rather than as a basis for excluding the data from subsequent analysis. Cronbach’s alpha was used to assess internal consistency, and Kendall’s W was used to assess respondent agreement patterns. The results are presented in
Table 7,
Table 8,
Table 9 and
Table 10. These checks provided supporting evidence for the dataset’s stability, reliability, and interpretability before the BWM–TOPSIS prioritization analysis was conducted [
20,
21].
The reliability results indicate that the retained competency structure demonstrated acceptable to excellent internal consistency across the overall scale and the nested item sets. As shown in
Table 8, Cronbach’s alpha was 0.7265 for the five main dimensions, 0.9519 for the 25 secondary indicators, and 0.9795 for the 48 third-level competency items.
Table 9 further shows that the alpha values for the five dimension-level S-item sets ranged from 0.7675 to 0.8943, indicating stable internal consistency across the major competency dimensions.
The Kendall’s W results in
Table 10 indicate varying levels of respondent agreement across the three item sets. Agreement at the main-dimension level was not statistically significant, whereas the secondary-indicator and third-level competency-item sets showed statistically significant but weak agreement. These findings suggest that the priority structure should be interpreted as a statistically identifiable pattern of professional judgment rather than as evidence of strong consensus across all respondents. This interpretation is consistent with the cross-role composition of the respondent group, which included consultant providers, consultant users, organizational managers, and other actors involved in ESG-oriented green transformation.
4.3. Dimension-Level Priority Structure
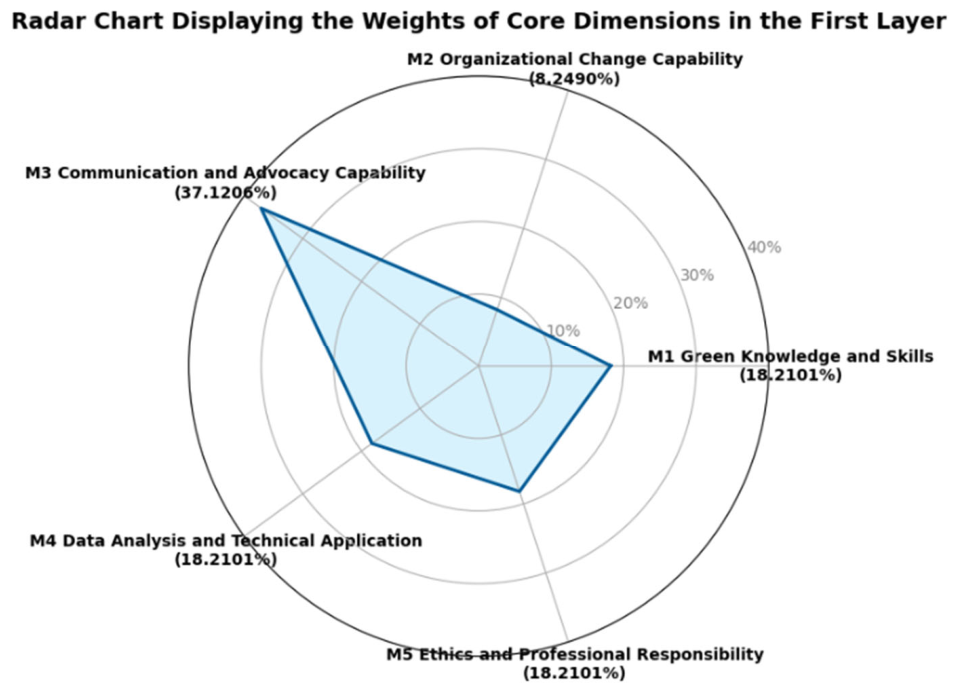
At the major-dimension level, the results reveal a differentiated priority structure. As shown in
Table 11 and
Figure 5, Communication and Advocacy Capability (M3) had the highest overall weight at 37.1206%. Green Knowledge and Skills (M1), Data Analysis and Technical Application (M4), and Ethics and Professional Responsibility (M5) each had a weight of 18.2101%, forming a secondary group. Organizational Change Capability (M2) had the lowest weight at 8.2490%.
The Kendall’s W results in
Table 10 indicate that agreement at the major-dimension level was not statistically significant (W = 0.0272, χ
2 = 5.8824, df = 4,
p = 0.2081). Therefore, the dimension-level weights should be interpreted as reproducible relative-priority outcomes generated by the BWM process, rather than as evidence of strong group consensus. This interpretation is important because the respondent group included professionals from diverse roles and institutional positions, which may reasonably lead to variation in how consultant competencies are prioritized.
Overall, the dimension-level results indicate that Communication and Advocacy Capability occupied the leading position in the competency structure, supported by green knowledge, data-related capability, and professional responsibility. Organizational Change Capability remained part of the framework but received the lowest relative weight at this level. The dimension weights and rankings are shown in
Table 11, and the overall distribution of dimension weights is visualized in
Figure 5. To support the traceability of the BWM solution, the detailed verification of the consistency deviation
at the major-dimension level is provided in
Supplementary Table S5.
4.4. Indicator-Level Priority Structure
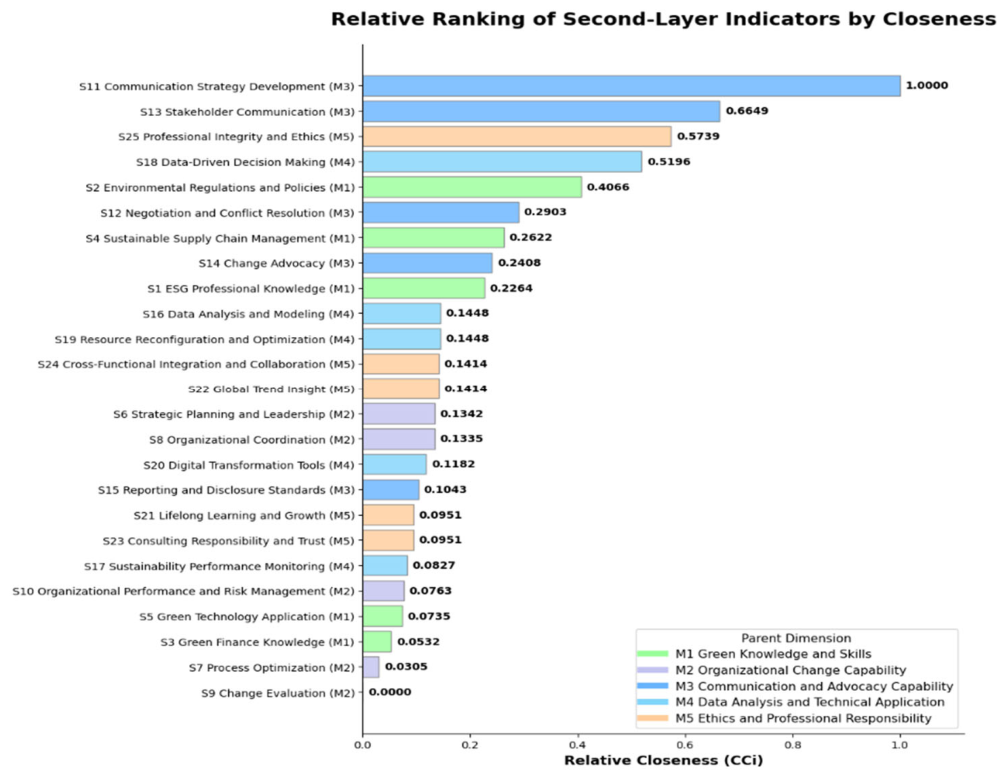
At the second-layer indicator level, the TOPSIS results indicate that the validated competencies were not evenly weighted. As shown in
Table 12 and
Figure 6, the highest-ranked indicator was Internal and External Communication (S11), with a relative closeness coefficient of 1.0000 and a global weight of 15.2806%. This was followed by Training and Education (S13), with a relative closeness coefficient of 0.6649 and a global weight of 10.2978%; Client Trust (S25), with a relative closeness coefficient of 0.5739 and a global weight of 8.9257%; Performance Monitoring (S18), with a relative closeness coefficient of 0.5196 and a global weight of 8.3740%; and Environmental Regulations and Policies (S2), with a relative closeness coefficient of 0.4066 and a global weight of 6.5340%.
These results indicate that the indicator-level priority structure was led by communication- and capability-development-related indicators, with professional credibility, data monitoring, and regulatory knowledge also ranking highly. The inclusion of indicators from multiple parent dimensions in the top five suggests that the priority structure was not dominated by a single competency domain. Instead, it reflected a combination of communication capability, professional trust, technical monitoring, and green regulatory knowledge.
The full TOPSIS results for the 25 secondary indicators are presented in
Table 12.
Figure 6 shows the relative ranking of the secondary indicators by closeness coefficient.
4.5. Item-Level Ranking and Key Competencies
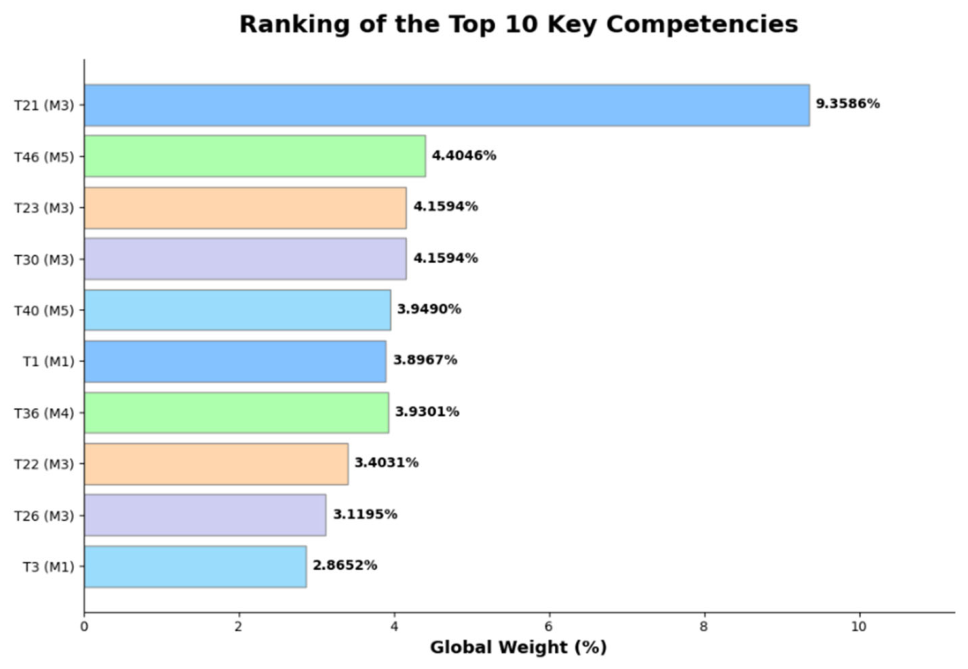
At the third-layer competency-item level, the TOPSIS results further identify the specific competencies that ranked highest within the overall framework. As shown in
Table 13, the highest-ranked competency was the ability to negotiate with stakeholders and build consensus on sustainability initiatives (T21), with a relative closeness coefficient of 1.0000 and a global weight of 9.3586%. This result indicates that stakeholder negotiation and consensus-building were the most prominent item-level competencies in the final ranking.
The next-highest-ranked items included the commitment to promoting pollution-prevention practices to ensure corporate compliance (T46), the ability to design ESG training programs to promote green knowledge (T23), the understanding of international ESG requirements to support cross-border compliance (T30), and the commitment to ESG ethical principles to promote transparency in decision-making (T40). These results show that the highest-ranking competencies were not limited to a single dimension but were distributed across communication and advocacy, ethics and professional responsibility, green knowledge, and data-related support.
Overall, the item-level ranking shows that the most prominent competencies were concentrated in stakeholder communication, consensus building, ESG training, interpretation of international requirements, ethical transparency, knowledge of carbon inventory, KPI design, internal communication, and alignment of sustainability strategy.
Figure 7 visualizes the top 10 key competencies, while
Table 13 presents the full ranking of all 48 third-layer competency items.
5. Discussion
5.1. The Central Role of Communication and Advocacy Capability
One of the clearest findings of this study is that Communication and Advocacy Capability emerged as the leading competency dimension within the overall framework. At the major-dimension level, Communication and Advocacy Capability (M3) received the highest weight, whereas Organizational Change Capability (M2) received the lowest. This result should not be interpreted as indicating that organizational change is unimportant. Rather, it suggests that under current environmental, social, and governance (ESG)-oriented green transformation conditions, respondents placed greater priority on competencies related to interpretation, communication, governance alignment, stakeholder coordination, and consensus-building than on competencies primarily associated with deeper internal restructuring.
This finding is theoretically meaningful because ESG-oriented green transformation often begins amid uncertainty, ambiguity, and institutional pressure. Before firms can implement large-scale internal restructuring, they must first understand external requirements, interpret sustainability-related expectations, communicate across functions, and establish shared meanings among stakeholders. From the perspective of dynamic capability theory, communication and advocacy capabilities support the sensing and interpretation processes that precede organizational reconfiguration [
7,
16]. From the perspective of institutional theory, these competencies also help organizations translate regulatory, normative, and stakeholder pressures into legitimate and understandable organizational responses [
8,
17].
The priority given to communication and advocacy therefore highlights the intermediary role of management consultants in ESG-oriented green transformation. Consultants are valued not only for their technical knowledge; they are also valued for helping organizations interpret complex sustainability demands, coordinate internal and external actors, and translate abstract ESG requirements into actionable decisions. This finding is consistent with prior research suggesting that sustainability-related professional capabilities depend not only on domain expertise, but also on communication, contextualization, interpretation, and practical application [
11,
12,
18].
5.2. Benchmark Competencies and the Significance of Knowledge Translation
At the item level, the highest-ranked competency was the ability to negotiate with stakeholders and build consensus on sustainability initiatives (T21). This result indicates that in environmental, social, and governance (ESG)-oriented green transformation advisory work, the most valued consultant competency extends beyond technical expertise. Rather, it lies in translating sustainability-related knowledge, regulatory requirements, and stakeholder expectations into forms that organizations can understand, discuss, and act upon.
This finding underscores the central role of knowledge translation, stakeholder negotiation, and regulatory interpretation in contemporary sustainability consulting. ESG-oriented green transformation often entails complex standards, reporting expectations, cross-functional coordination, and external legitimacy pressures. Under these conditions, consultants create value not only by providing expert knowledge but also by helping organizations clarify priorities, build internal consensus, and translate abstract sustainability requirements into actionable organizational decisions.
The importance of T21 also aligns with the broader pattern in the empirical results, in which communication, interpretation, professional credibility, and actionable translation ranked highly. In this context, T21 can be understood as a benchmark competency because it reflects the consultant’s role as both a knowledge provider and a boundary-spanning mediator. This interpretation is consistent with prior studies indicating that sustainability professionals contribute not only through domain expertise but also through communication, contextualization, interpretation, and practical application to support organizational response and action [
11,
12,
18].
5.3. Interpreting the Value of Consultants in ESG-Oriented Green Transformation Contexts
Taken together, the findings indicate that the value of management consultants in environmental, social, and governance (ESG)-oriented green transformation extends beyond their technical expertise. Rather, their value also depends on their ability to foster organizational understanding, interpret external demands, support internal alignment, and translate sustainability-related pressures into actionable steps. This role becomes particularly important when organizations face institutional pressure, uncertainty, reporting expectations, and multiple stakeholder demands.
Although the present study does not test a complete causal mechanism, the observed priority structure aligns with prior research indicating that organizations rely on external professionals to interpret environmental changes, coordinate internal responses, and strengthen organizational capabilities under uncertain conditions [
7,
9,
10,
16]. In this context, the identified competency structure should not be viewed merely as a list of individual professional skills. Instead, it can be understood as an empirical priority pattern that reflects how organizations evaluate the competencies required of external advisory support in ESG-oriented green transformation.
This interpretation also helps explain why communication, interpretation, and actionable translation emerged as central elements in the results. In sustainability advisory work, consultants often serve as boundary spanners between external institutional requirements and internal organizational action. Their contribution therefore depends not only on what they know but also on how effectively they translate that knowledge into shared understanding, coordinated decisions, and implementable practices.
5.4. Practical and Developmental Implications
From a practical perspective, the findings suggest that organizations should not select consultants for environmental, social, and governance (ESG)-oriented green transformation solely on technical expertise or regulatory familiarity. Although these capabilities remain important, the results indicate that greater attention should be given to communication, interpretation, stakeholder negotiation, knowledge translation, and problem clarification. These competencies are essential because consultants add value not only by providing specialized knowledge but also by helping organizations understand sustainability-related requirements and translate them into feasible actions.
For client organizations, the competency priority structure can serve as a reference for consultant selection, project team formation, and capability assessment. In particular, organizations may benefit from evaluating whether consultants can clearly explain complex ESG requirements, build consensus among stakeholders, facilitate cross-functional communication, and translate sustainability objectives into actionable implementation steps. This is especially important for firms facing external regulatory pressure yet still needing to build internal understanding and coordination capacity.
For consulting firms and training providers, the findings offer a clearer basis for recruitment, training design, and professional development. Rather than assuming that all competencies should be developed equally, the results support a more targeted approach to capability development. Higher-priority competencies, especially those related to communication, interpretation, stakeholder coordination, and actionable translation, can be treated as core developmental goals, while lower-priority competencies may serve as supporting capabilities. This implication aligns with competency-based perspectives in human resource development, which emphasize aligning selection, training, and professional growth with role-relevant competency structures [
13,
14].
6. Conclusions
This study identified and prioritized the competencies required for management consultants engaged in environmental, social, and governance (ESG)-oriented green transformation in Taiwan. Using an exploratory sequential mixed-methods design, the study first generated 150 competency items through a structured, literature-based process and then refined them through expert content validation, yielding 48 validated competencies. Survey data from 54 professionally relevant respondents were subsequently analyzed using the best–worst method (BWM) and the technique for order preference by similarity to ideal solution (TOPSIS), producing an empirically supported competency framework and priority hierarchy for an emerging sustainability advisory role.
The findings show that consultant competencies in ESG-oriented green transformation are not equally weighted but form a structured hierarchy of priorities. At the major-dimension level, Communication and Advocacy Capability received the highest weight, while Green Knowledge and Skills, Data Analysis and Technical Application, and Ethics and Professional Responsibility formed a secondary tier. Organizational Change Capability received the lowest relative weight, suggesting that respondents placed greater priority on interpretation, communication, stakeholder coordination, professional credibility, data support, and actionable translation than on deeper internal restructuring alone. At the item level, the highest-ranked competency was the ability to negotiate with stakeholders and build consensus on sustainability initiatives. This result indicates that the value of consultants in ESG-oriented green transformation depends not only on technical knowledge or regulatory familiarity but also on their ability to translate complex sustainability requirements into organizationally meaningful, actionable responses.
This study contributes to sustainability management, human resource development, and management consulting research by offering an empirically grounded framework for understanding the competency structure of an emerging professional role. Rather than proposing a new theory, the study clarifies how ESG-oriented advisory competence can be identified, validated, and prioritized through a structured analytical procedure. Methodologically, it demonstrates how expert content validation, BWM-based weighting, and TOPSIS-based prioritization can be integrated to support transparent competency analysis. In practice, the findings provide guidance for client organizations selecting ESG-oriented green transformation consultants, for consulting firms developing recruitment and training programs, and for educators or training providers designing pathways to develop sustainability-related competencies.
Several limitations should be acknowledged. First, the study was conducted in Taiwan and should therefore be interpreted within this institutional and regional context. Second, the respondent group consisted of professionals rather than a statistically representative population sample; accordingly, the findings support analytical rather than statistical generalization. Third, the competency structure reflects the current stage of ESG-oriented green transformation and may evolve as sustainability regulations, reporting practices, digital tools, and organizational capabilities continue to develop. Future research may extend this framework across countries, industries, and advisory contexts, examine how consultant competency priorities change over time, or compare whether similar priority structures emerge under different institutional and sustainability conditions.