


Non-Traditional Systemic Risk Contagion within the Chinese Banking Industry



Abstract
1. Introduction
2. Data and Sample
2.1. Distance to Default
2.2. Distance to Insolvency
2.3. Distance to Capital
3. Methodology
Model Specifications
4. Results
4.1. Distance-to-Default Contagion
4.2. Distance-to-Insolvency Contagion
4.3. Distance-to-Capital Contagion
5. Conclusions
Author Contributions
Funding
Institutional Review Board Statement
Informed Consent Statement
Data Availability Statement
Acknowledgments
Conflicts of Interest
References
- Huang, Q.; De Haan, J.; Scholtens, B. Analysing Systemic Risk in the Chinese Banking System. Pac. Econ. Rev. 2017, 24, 348–372. [Google Scholar] [CrossRef] [Scilit]
- Ho, K.-Y.; Shi, Y.; Zhang, Z. News and return volatility of Chinese bank stocks. Int. Rev. Econ. Financ. 2020, 69, 1095–1105. [Google Scholar] [CrossRef] [Scilit]
- World Bank. China Overview. 2019. Available online: https://www.worldbank.org/en/country/china/overview (accessed on 13 July 2021).
- Huang, Y. Understanding China’s Belt & Road initiative: Motivation, framework and assessment. China Econ. Rev. 2016, 40, 314–321. [Google Scholar]
- Rolland, N. China’s “Belt and Road Initiative”: Underwhelming or game-changer? Wash. Q. 2017, 40, 127–142. [Google Scholar] [CrossRef] [Scilit]
- Liu, Y.; Brahma, S.; Boateng, A. Impact of ownership structure and ownership concentration on credit risk of Chinese com-mercial banks. Int. J. Manag. Financ. 2019, 16, 253–272. [Google Scholar]
- Zhu, N.; Wang, B.; Yu, Z.; Wu, Y. Technical Efficiency Measurement Incorporating Risk Preferences: An Empirical Analysis of Chinese Commercial Banks. Emerg. Mark. Financ. Trade 2015, 52, 610–624. [Google Scholar] [CrossRef] [Scilit]
- Daly, K.; Batten, J.A.; Mishra, A.V.; Choudhury, T. Contagion risk in global banking sector. J. Int. Financ. Mark. Inst. Money 2019, 63, 101136. [Google Scholar] [CrossRef] [Scilit]
- Weber, O. Corporate sustainability and financial performance of Chinese banks. Sustain. Account. Manag. Policy J. 2017, 8, 358–385. [Google Scholar] [CrossRef] [Scilit]
- Witt, M.A. China’s Challenge: Geopolitics, De-Globalization, and the Future of Chinese Business. Manag. Organ. Rev. 2019, 15, 1–18. [Google Scholar] [CrossRef] [Scilit]
- Wang, G.-J.; Jiang, Z.-Q.; Lin, M.; Xie, C.; Stanley, H.E. Interconnectedness and systemic risk of China’s financial institutions. Emerg. Mark. Rev. 2018, 35, 1–18. [Google Scholar] [CrossRef] [Scilit]
- Tobias, A.; Brunnermeier, M.K. CoVaR. Am. Econ. Rev. 2016, 106, 1705. [Google Scholar]
- Acharya, V.V.; Pedersen, L.H.; Philippon, T.; Richardson, M. Measuring Systemic Risk. Rev. Financ. Stud. 2017, 30, 2–47. [Google Scholar] [CrossRef] [Scilit]
- Billio, M.; Getmansky, M.; Lo, A.W.; Pelizzon, L. Econometric measures of connectedness and systemic risk in the finance and insurance sectors. J. Financ. Econ. 2012, 104, 535–559. [Google Scholar] [CrossRef] [Scilit]
- Zhang, W.; Zhuang, X.; Wang, J.; Lu, Y. Connectedness and systemic risk spillovers analysis of Chinese sectors based on tail risk network. N. Am. J. Econ. Financ. 2020, 54, 101248. [Google Scholar] [CrossRef] [Scilit]
- Xu, Q.; Chen, L.; Jiang, C.; Yuan, J. Measuring systemic risk of the banking industry in China: A DCC-MIDAS-t approach. Pac. Basin Financ. J. 2018, 51, 13–31. [Google Scholar] [CrossRef] [Scilit]
- Zhang, Z.; Zhang, D.; Wu, F.; Ji, Q. Systemic risk in the Chinese financial system: A copula-based network approach. Int. J. Financ. Econ. 2021, 26, 2044–2063. [Google Scholar] [CrossRef] [Scilit]
- Blundell-Wignall, A.; Roulet, C. Business models of banks, leverage and the distance-to-default. OECD J. Financ. Mark. Trends 2013, 2012, 7–34. [Google Scholar] [CrossRef] [Scilit]
- Chan-Lau, J.A.; Sy, A.N.R. Distance-to-default in banking: A bridge too far? J. Bank. Regul. 2007, 9, 14–24. [Google Scholar] [CrossRef] [Scilit]
- Nagel, S.; Purnanandam, A. Bank Risk Dynamics and Distance to Default. Available online: https://www.nber.org/system/files/working_papers/w25807/w25807.pdf (accessed on 13 July 2021).
- Merton, R.C. An Intertemporal Capital Asset Pricing Model. Econometrica 1973, 41, 867. [Google Scholar] [CrossRef] [Scilit]
- Saldías, M. Systemic risk analysis using forward-looking Distance-to-Default series. J. Financ. Stab. 2013, 9, 498–517. [Google Scholar] [CrossRef] [Scilit]
- Chan-Lau, M.J.A.; Mitra, M.S.; Ong, M.L.L. Contagion Risk in the International Banking System and Implications for London as a Global Financial Center. IMF Working Paper No. 07/74. 2007. Available online: https://papers.ssrn.com/sol3/papers.cfm?abstract_id=979028 (accessed on 13 July 2021).
- Merton, R.C. On the pricing of corporate debt: The risk structure of interest rates. J. Financ. 1974, 29, 449–470. [Google Scholar]
- Akhter, S.; Daly, K. Contagion risk for Australian banks from global systemically important banks: Evidence from extreme events. Econ. Model. 2017, 63, 191–205. [Google Scholar] [CrossRef] [Scilit]
- Wang, G.-J.; Yi, S.; Xie, C.; Stanley, H.E. Multilayer information spillover networks: Measuring interconnectedness of financial institutions. Quant. Financ. 2020, 1–23. [Google Scholar] [CrossRef] [Scilit]
- Yang, L.; Yang, L.; Ho, K.-C.; Hamori, S. Dependence structures and risk spillover in China’s credit bond market: A copula and CoVaR approach. J. Asian Econ. 2020, 68, 101200. [Google Scholar] [CrossRef] [Scilit]
- Correia, M.; Kang, J.; Richardson, S. Asset volatility. Rev. Account. Stud. 2017, 23, 37–94. [Google Scholar] [CrossRef] [Scilit]
- Leland, H.E. Corporate debt value, bond covenants, and optimal capital structure. J. Financ. 1994, 49, 1213–1252. [Google Scholar] [CrossRef]
- Atkeson, A.G.; Eisfeldt, A.L.; Weill, P.-O. Measuring the financial soundness of U.S. firms, 1926–2012. Res. Econ. 2017, 71, 613–635. [Google Scholar] [CrossRef] [Scilit]
- Salike, N.; Ao, B. Determinants of bank’s profitability: Role of poor asset quality in Asia. China Financ. Rev. Int. 2018, 8, 216–231. [Google Scholar] [CrossRef] [Scilit]
- Zhang, D.; Cai, J.; Dickinson, D.G.; Kutan, A.M. Non-performing loans, moral hazard and regulation of the Chinese commercial banking system. J. Bank. Financ. 2016, 63, 48–60. [Google Scholar] [CrossRef] [Scilit]
- Yao, J.Y.; Chan-Lau, J.A.; Mathieson, D.J. Extreme Contagion in Equity Markets. IMF Work. Pap. 2002, 2, 1. [Google Scholar] [CrossRef] [Scilit]
- Gropp, R.; Gruendl, C.; Guettler, A. The impact of public guarantees on bank risk-taking: Evidence from a natural experiment. Rev. Financ. 2013, 18, 457–488. [Google Scholar] [CrossRef] [Scilit]
- Kocherlakota, N.; Shim, I. Forbearance and Prompt Corrective Action. J. Money Credit. Bank. 2007, 39, 1107–1129. [Google Scholar] [CrossRef] [Scilit]
- Mayes, D.G.; Nieto, M.J.; Wall, L. Multiple safety net regulators and agency problems in the EU: Is Prompt Corrective Action partly the solution? J. Financ. Stab. 2008, 4, 232–257. [Google Scholar] [CrossRef] [Scilit]
- Basel III: A Global Regulatory Framework for More Resilient Banks and Banking Systems; Basel Committee on Banking Supervision: Basel, Switzerland, 2010.
- Black, F.; Scholes, M. The effects of dividend yield and dividend policy on common stock prices and returns. J. Financ. Econ. 1974, 1, 1–22. [Google Scholar] [CrossRef] [Scilit]
- Aggarwal, R.; Jacques, K.T. The impact of FDICIA and prompt corrective action on bank capital and risk: Estimates using a simultaneous equations model. J. Bank. Financ. 2001, 25, 1139–1160. [Google Scholar] [CrossRef] [Scilit]
- Harada, K.; Ito, T. Did mergers help Japanese mega-banks avoid failure? Analysis of the distance to default of banks. J. Jpn. Int. Econ. 2011, 25, 1–22. [Google Scholar] [CrossRef] [Scilit]
- Engle, R.; Sheppard, K. Theoretical and Empirical properties of Dynamic Conditional Correlation Multivariate GARCH. Theor. Empir. Prop. Dyn. Cond. Correl. Multivar. GARCH 2001. [Google Scholar] [CrossRef] [Scilit]
- Engle, R. Dynamic conditional correlation: A simple class of multivariate generalized autoregressive conditional heteroske-dasticity models. J. Bus. Econ. Stat. 2002, 20, 339–350. [Google Scholar] [CrossRef] [Scilit]
- Chang, C.-L.; McAleer, M.; Wang, Y.-A. Modelling volatility spillovers for bio-ethanol, sugarcane and corn spot and futures prices. Renew. Sustain. Energy Rev. 2018, 81, 1002–1018. [Google Scholar] [CrossRef] [Scilit]
- McAleer, M.; Hafner, C.M. A One Line Derivation of EGARCH. Econometrics 2014, 2, 92–97. [Google Scholar] [CrossRef] [Scilit]
- Theissen, E. Price discovery in spot and futures markets: A reconsideration. High Freq. Trading Limit Order Book Dyn. 2016, 18, 249–268. [Google Scholar] [CrossRef] [Scilit]
- Zhang, K.; Chan, L. Efficient factor GARCH models and factor-DCC models. Quant. Financ. 2009, 9, 71–91. [Google Scholar] [CrossRef] [Scilit]
- Basher, S.A.; Sadorsky, P. Hedging emerging market stock prices with oil, gold, VIX, and bonds: A comparison between DCC, ADCC and GO-GARCH. Energy Econ. 2016, 54, 235–247. [Google Scholar] [CrossRef] [Scilit]
- Fang, L.; Sun, B.; Li, H.; Yu, H. Systemic risk network of Chinese financial institutions. Emerg. Mark. Rev. 2018, 35, 190–206. [Google Scholar] [CrossRef] [Scilit]
- Hassan, M.K.; Djajadikerta, H.G.; Choudhury, T.; Kamran, M. Safe havens in Islamic financial markets: COVID-19 versus GFC. Glob. Financ. J. 2021, 21, 100643. [Google Scholar] [CrossRef] [Scilit]
- Kinateder, H.; Campbell, R.; Choudhury, T. Safe haven in GFC versus COVID-19: 100 turbulent days in the financial markets. Finance Res. Lett. 2021, 101951. [Google Scholar] [CrossRef] [Scilit]
- Choudhury, T.T.; Paul, S.K.; Rahman, H.F.; Jia, Z.; Shukla, N. A systematic literature review on the service supply chain: Research agenda and future research directions. Prod. Plan. Control 2020, 31, 1363–1384. [Google Scholar] [CrossRef] [Scilit]
- Choudhury, T.; Daly, K. Systemic risk contagi on within US states. Stud. Econ. Financ. 2021. [Google Scholar] [CrossRef] [Scilit]
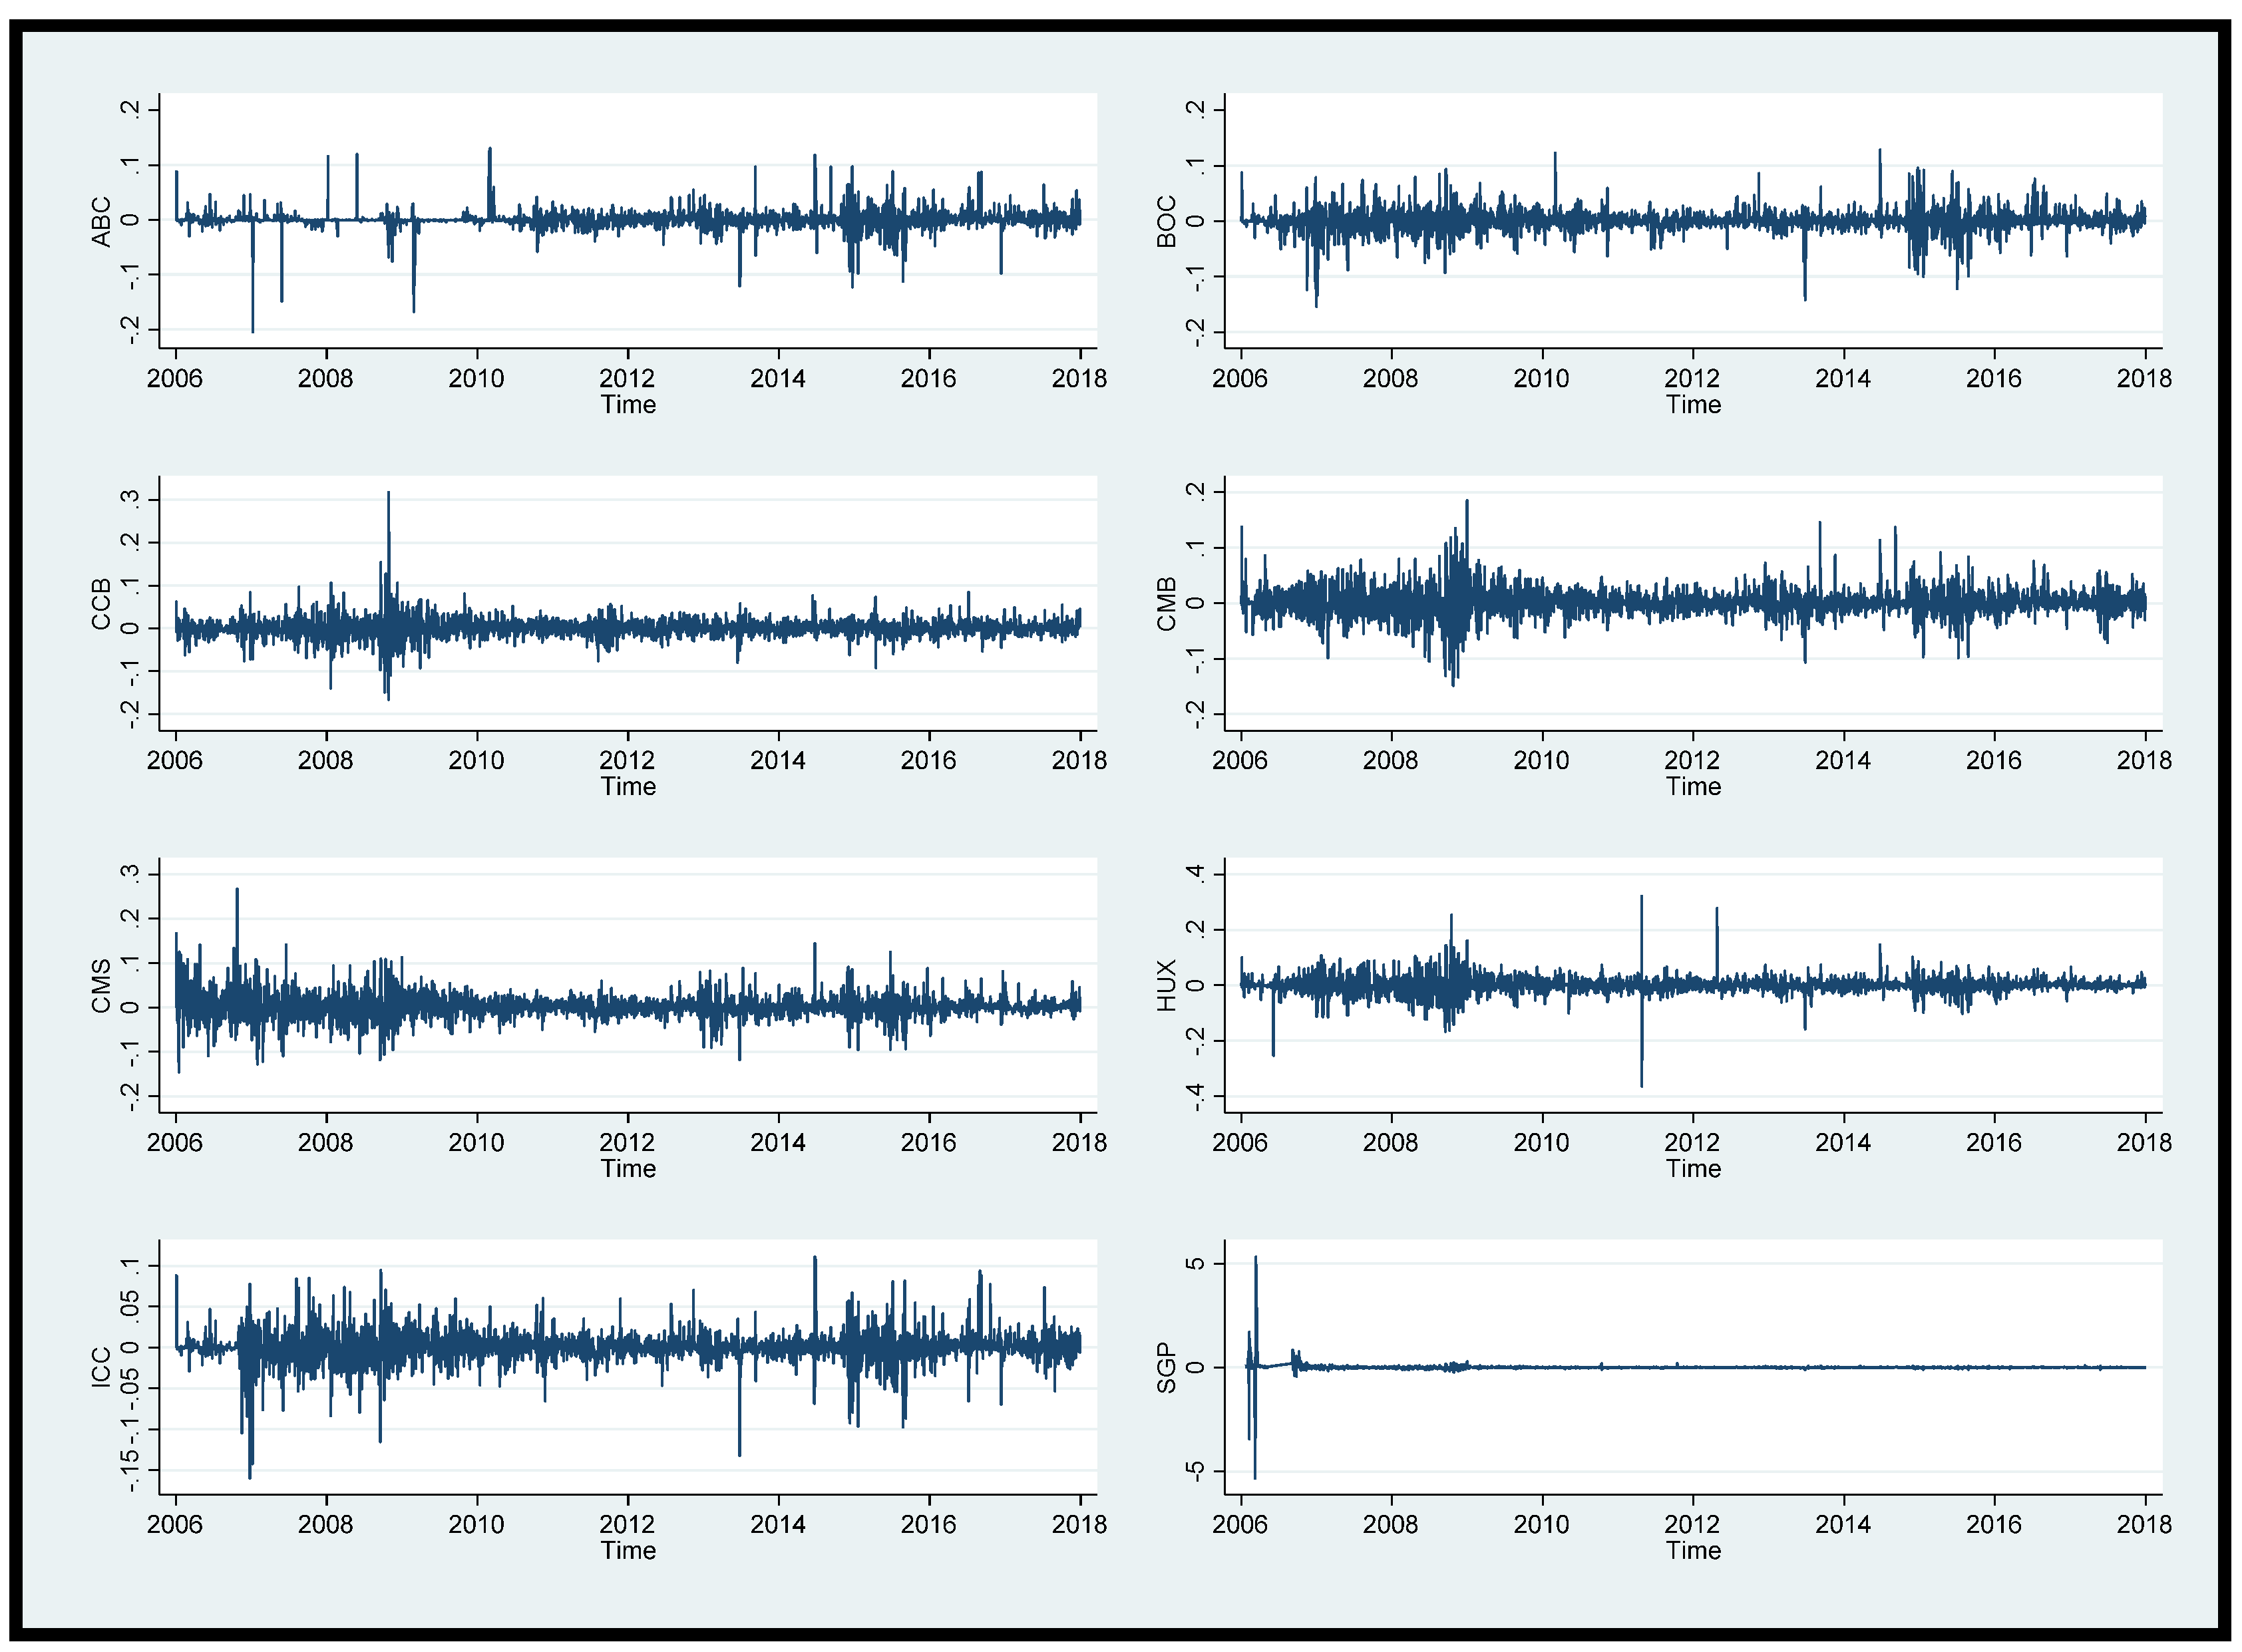
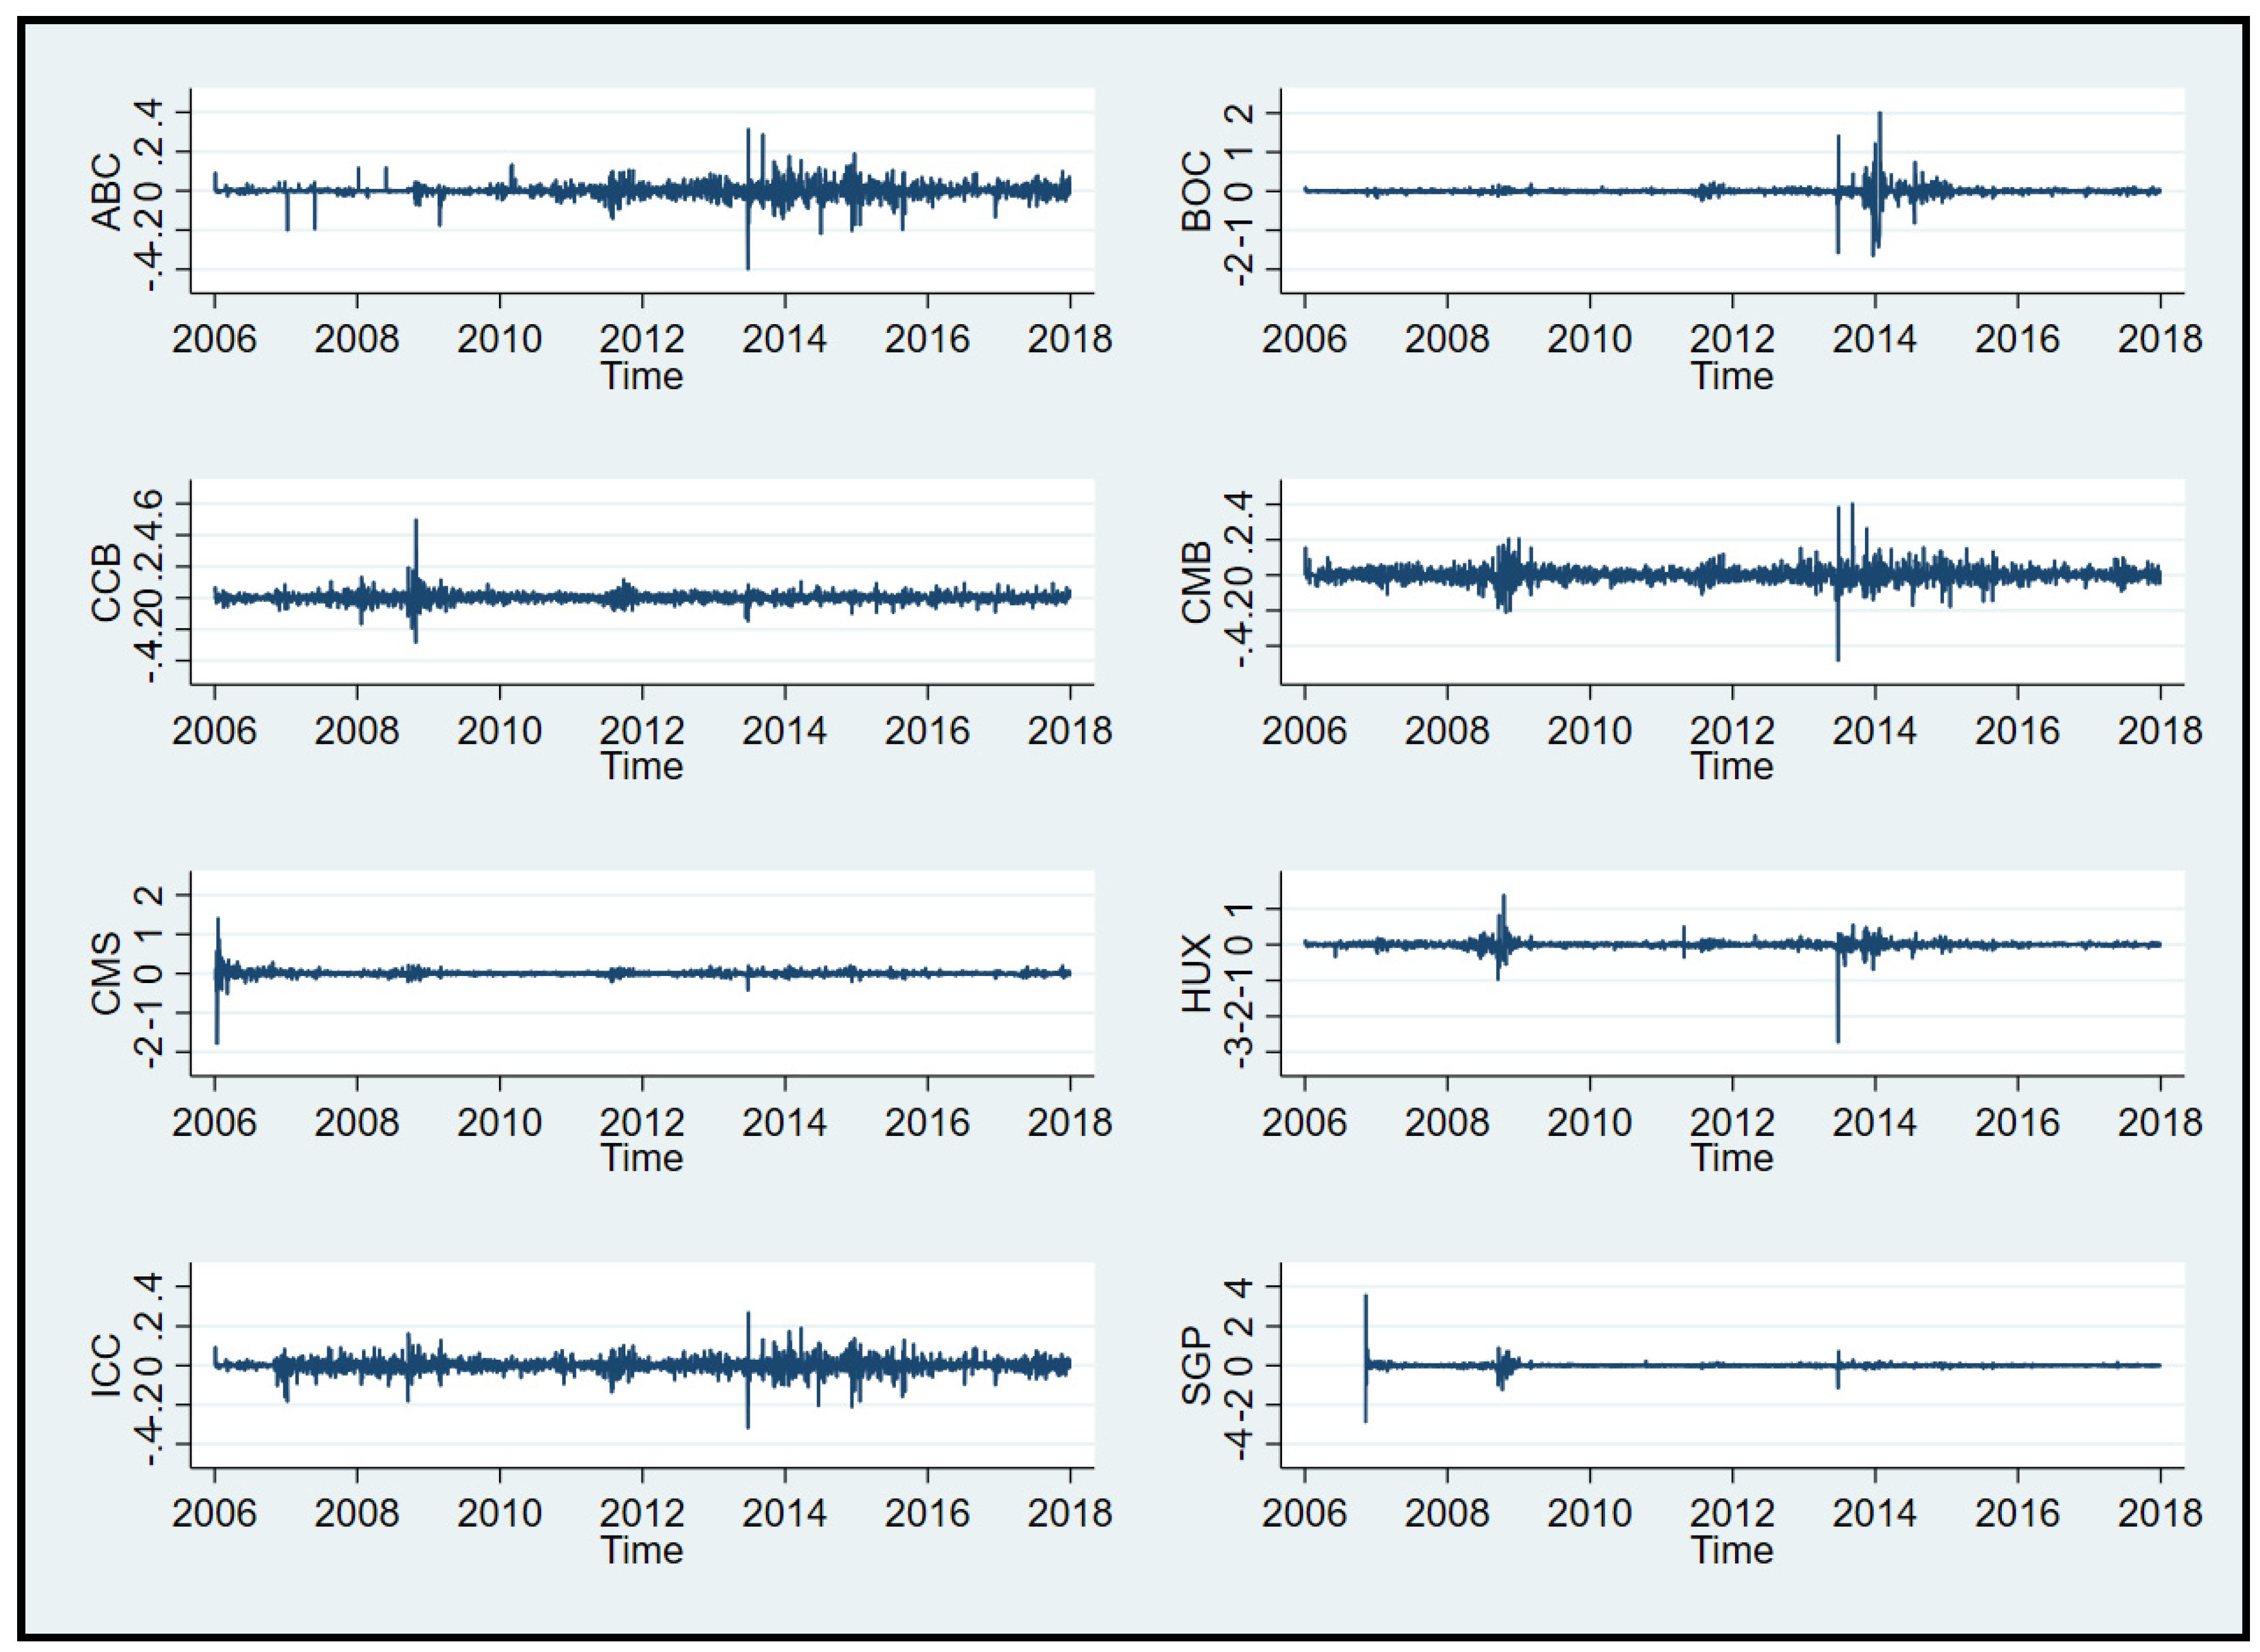
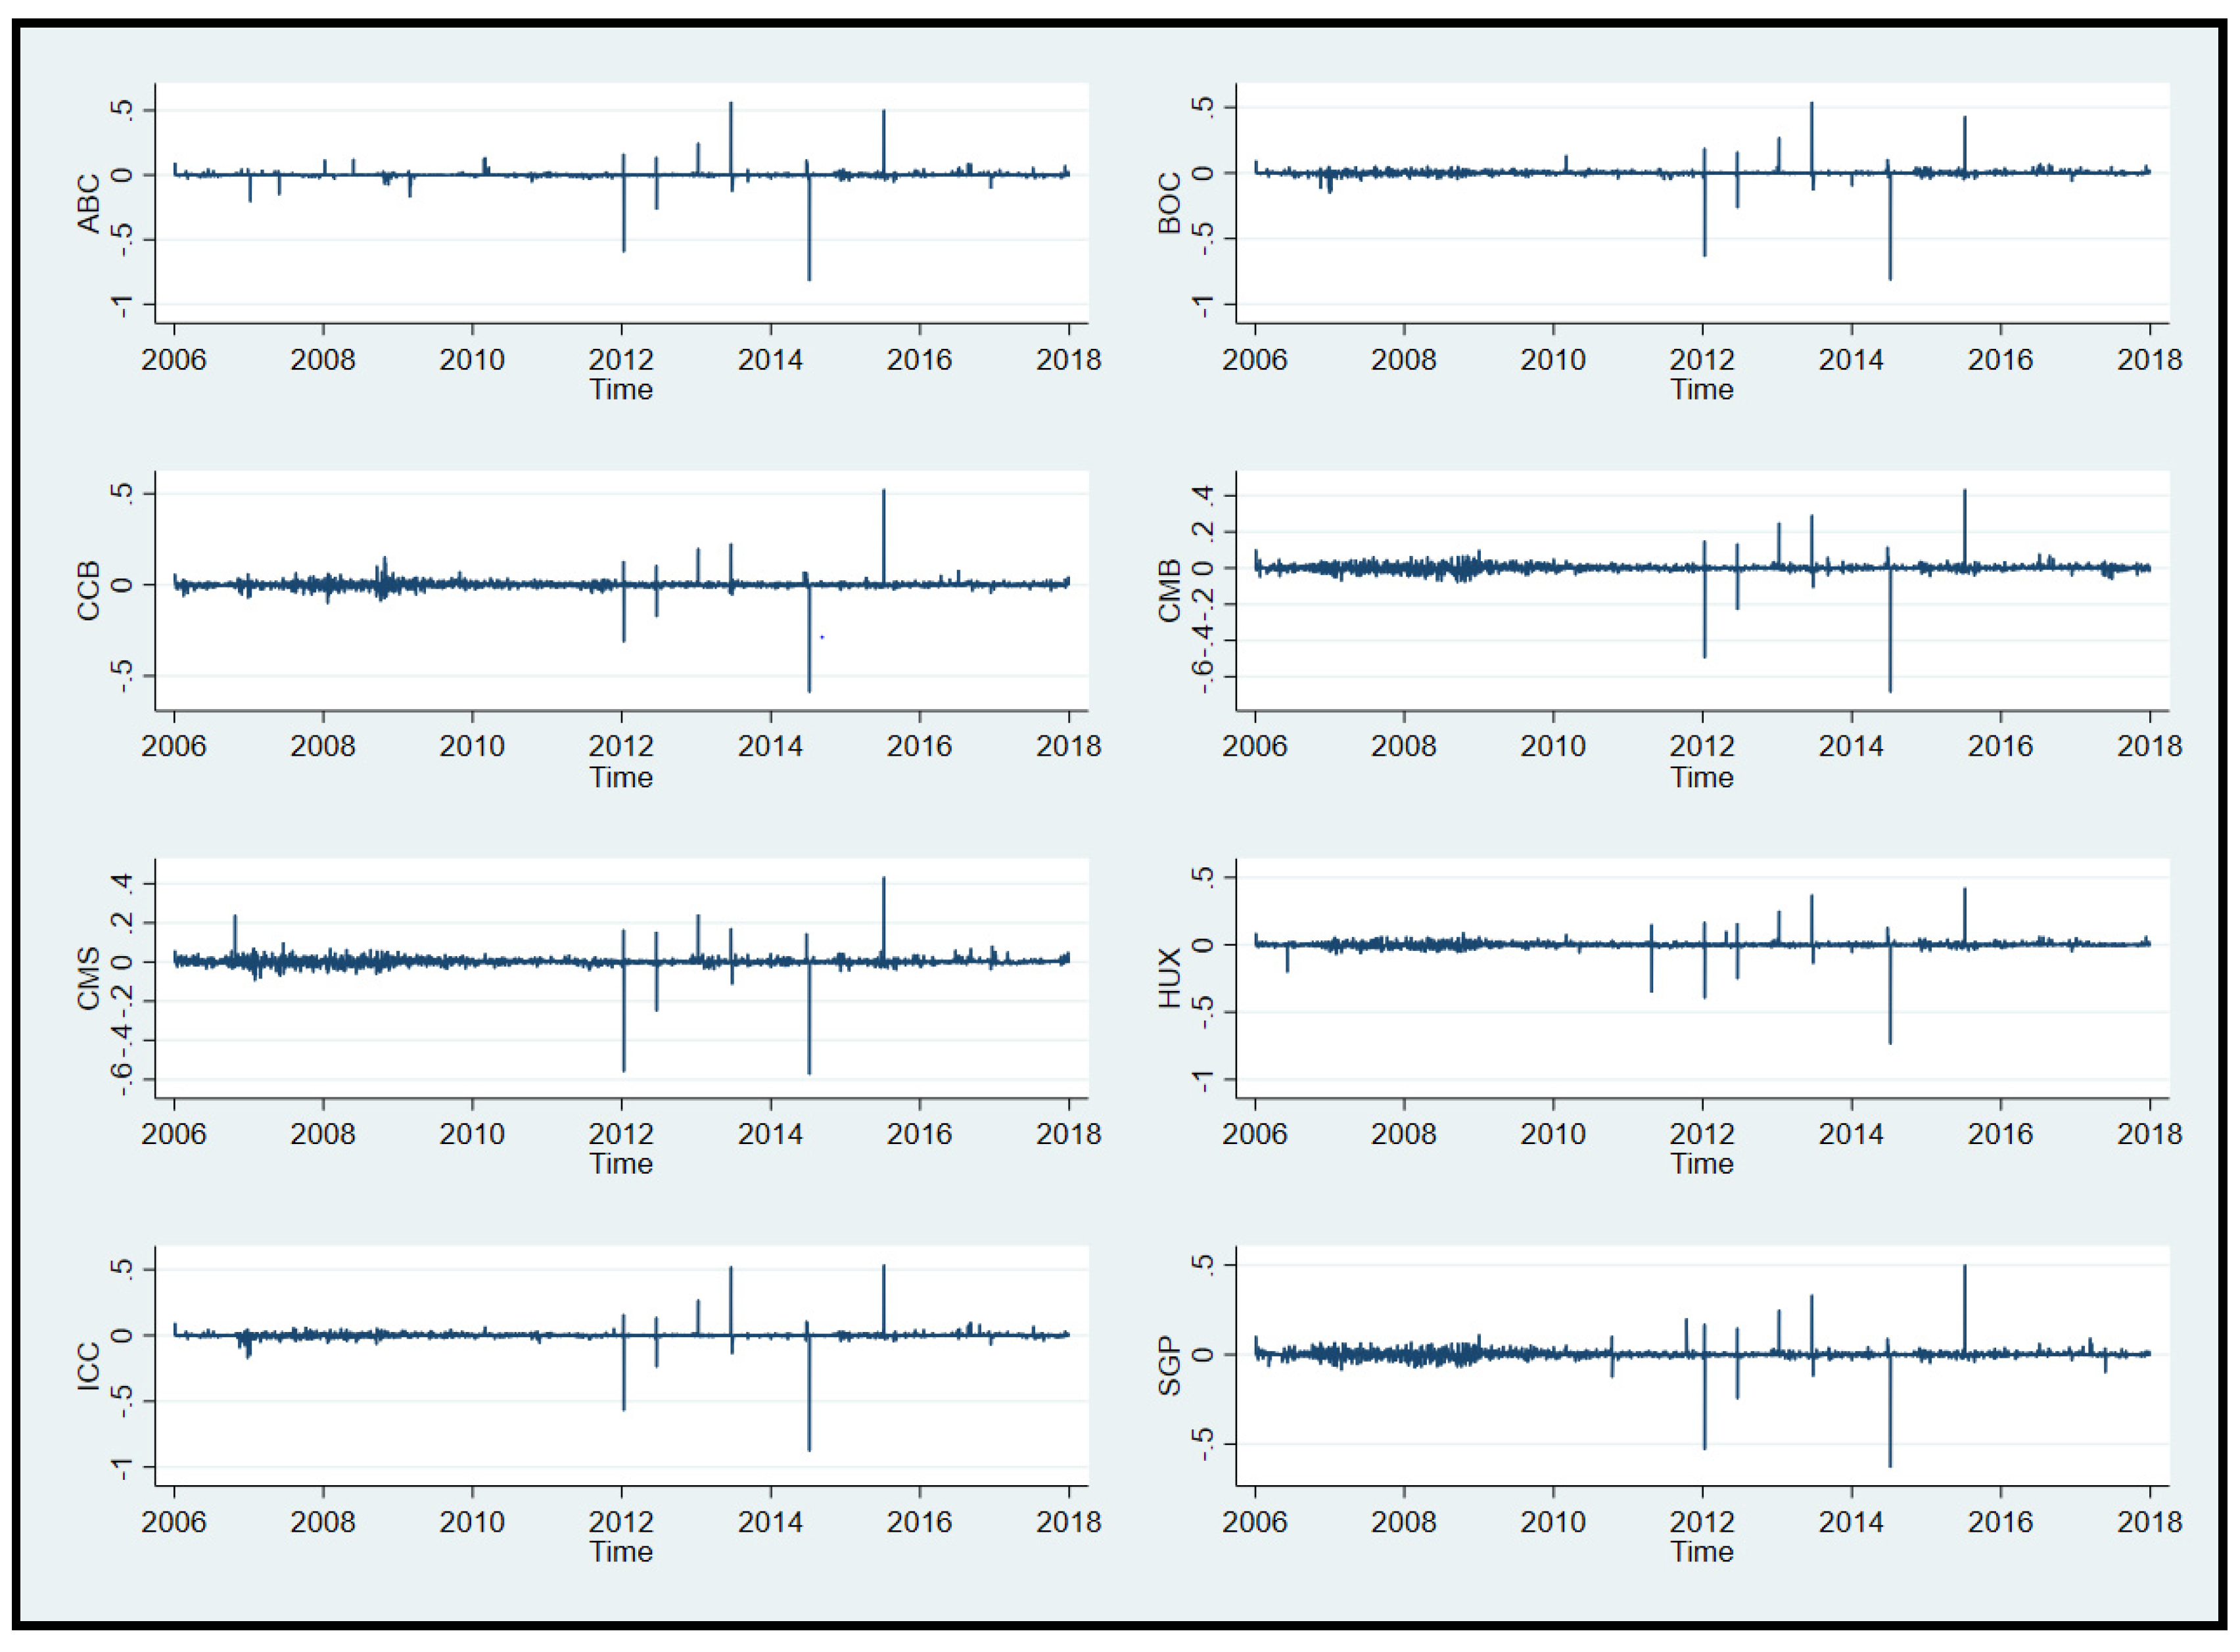
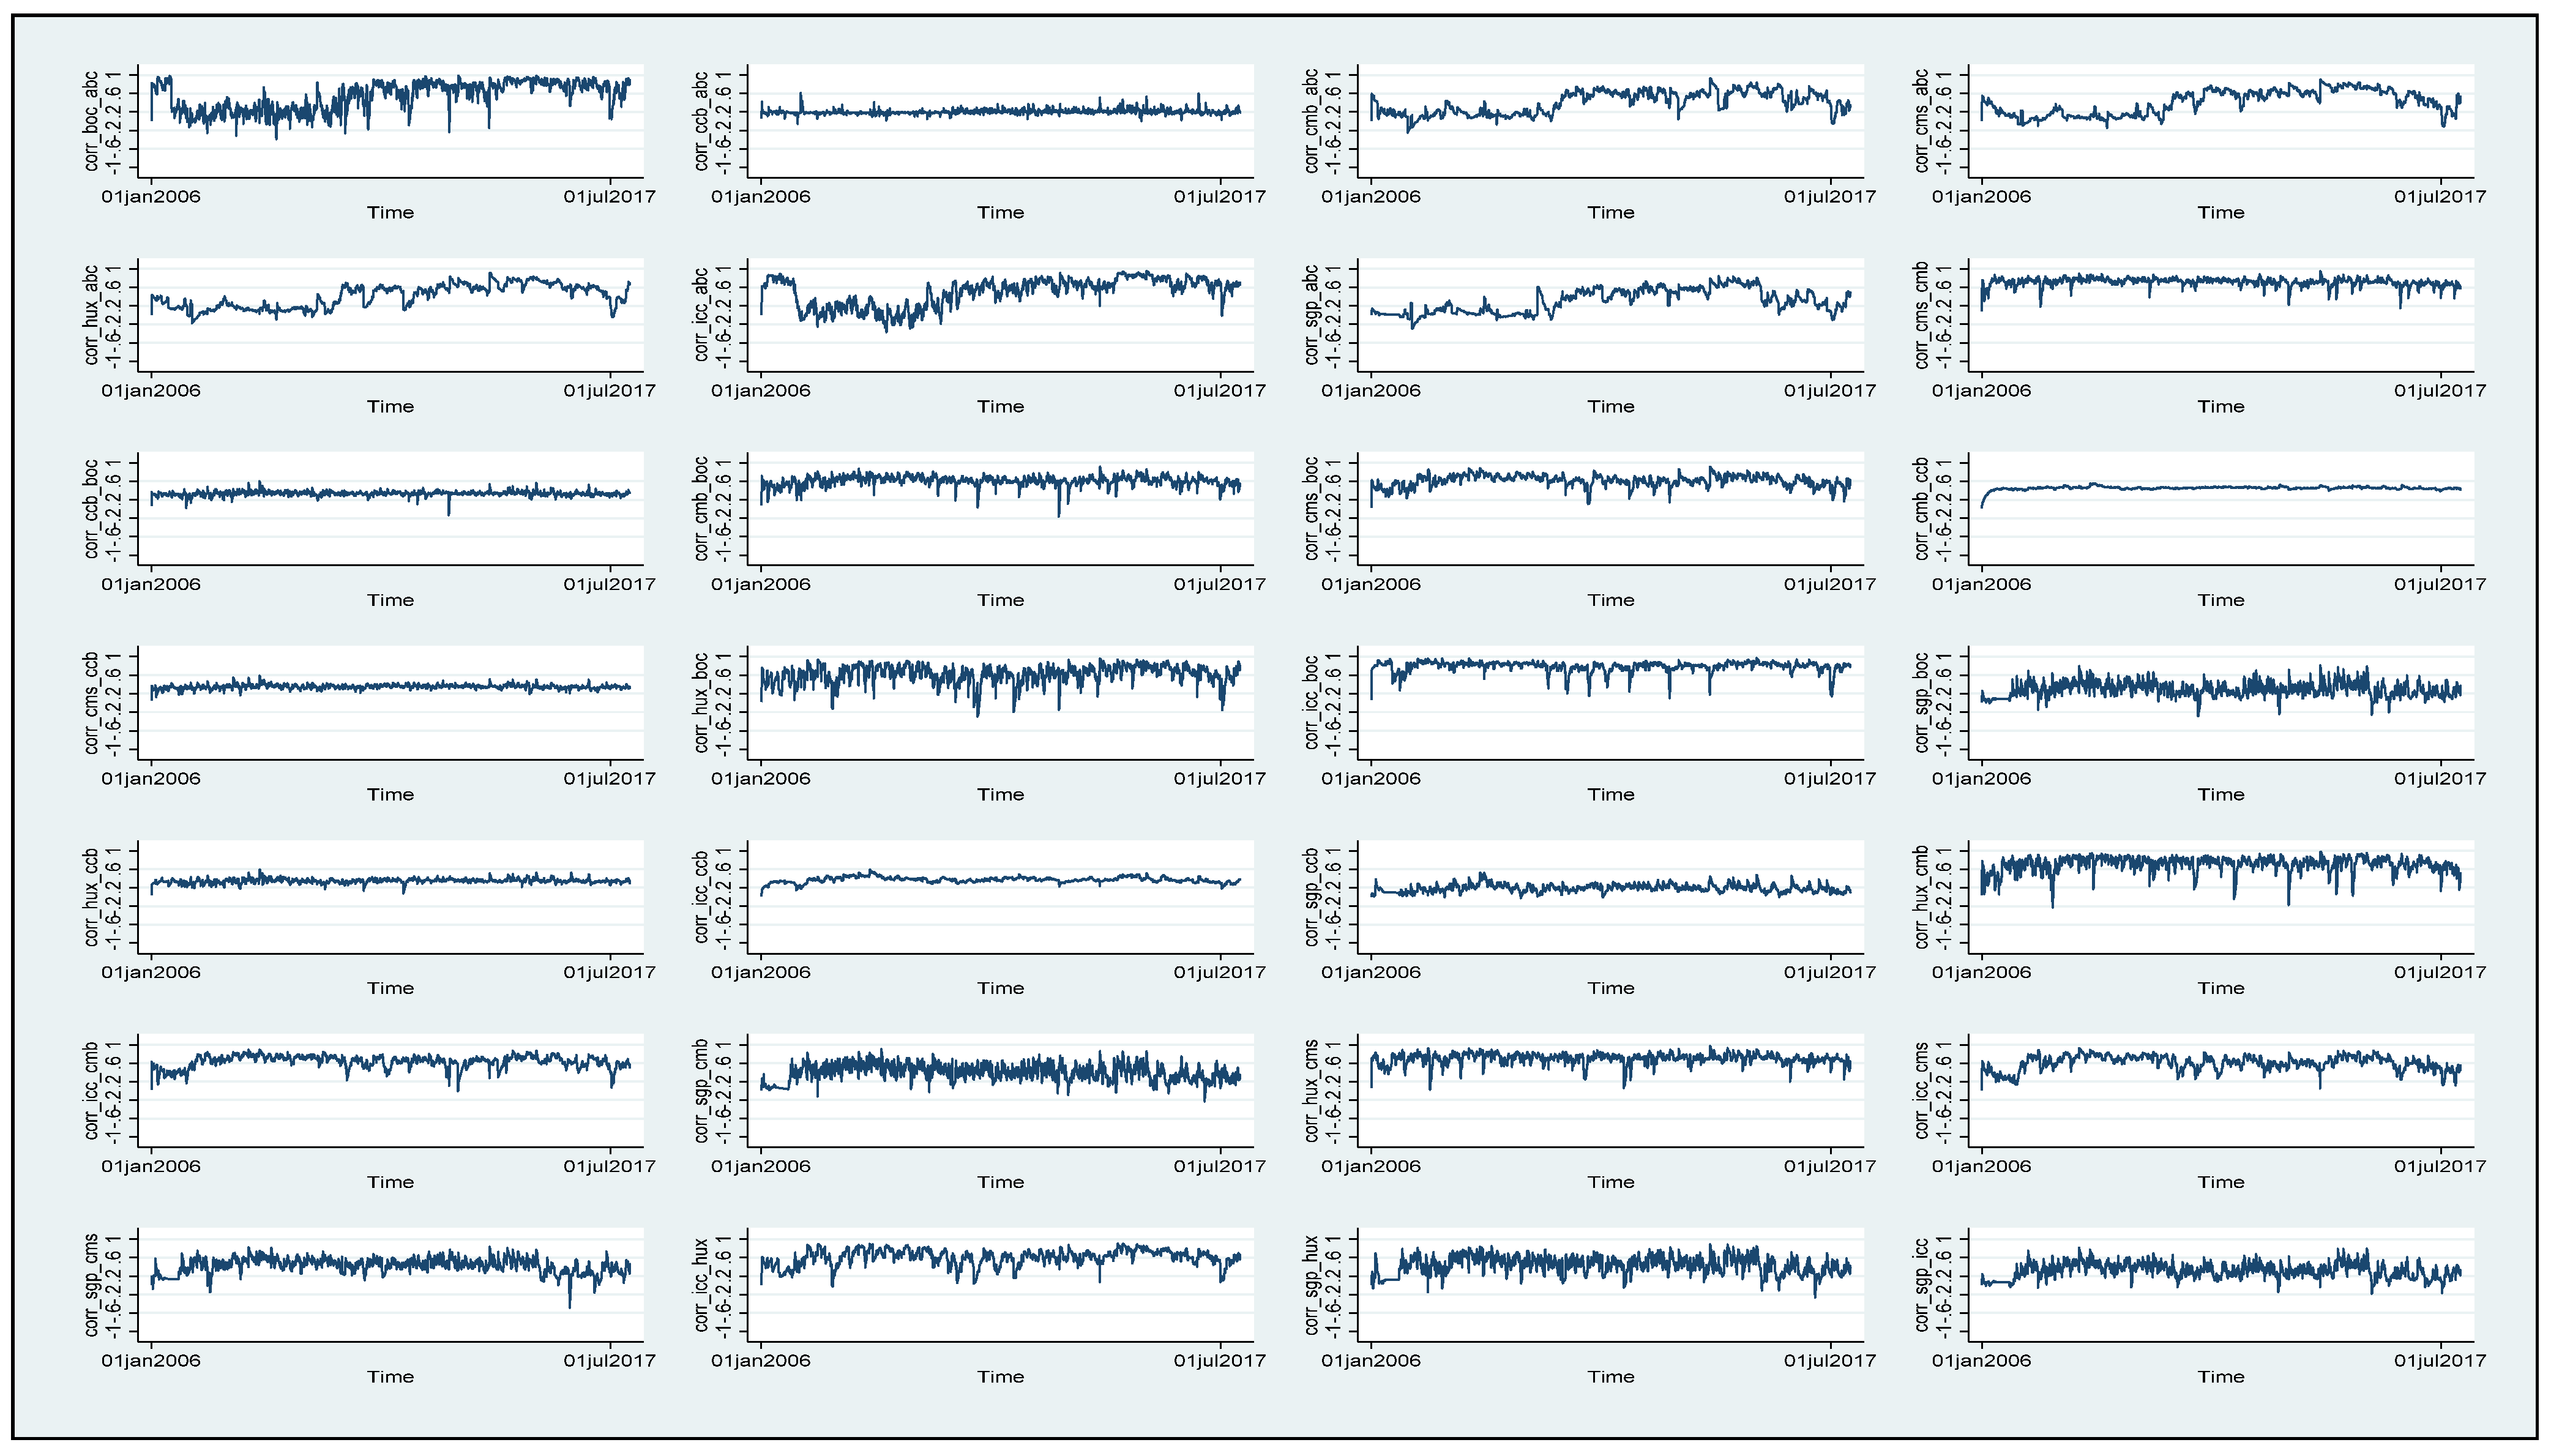
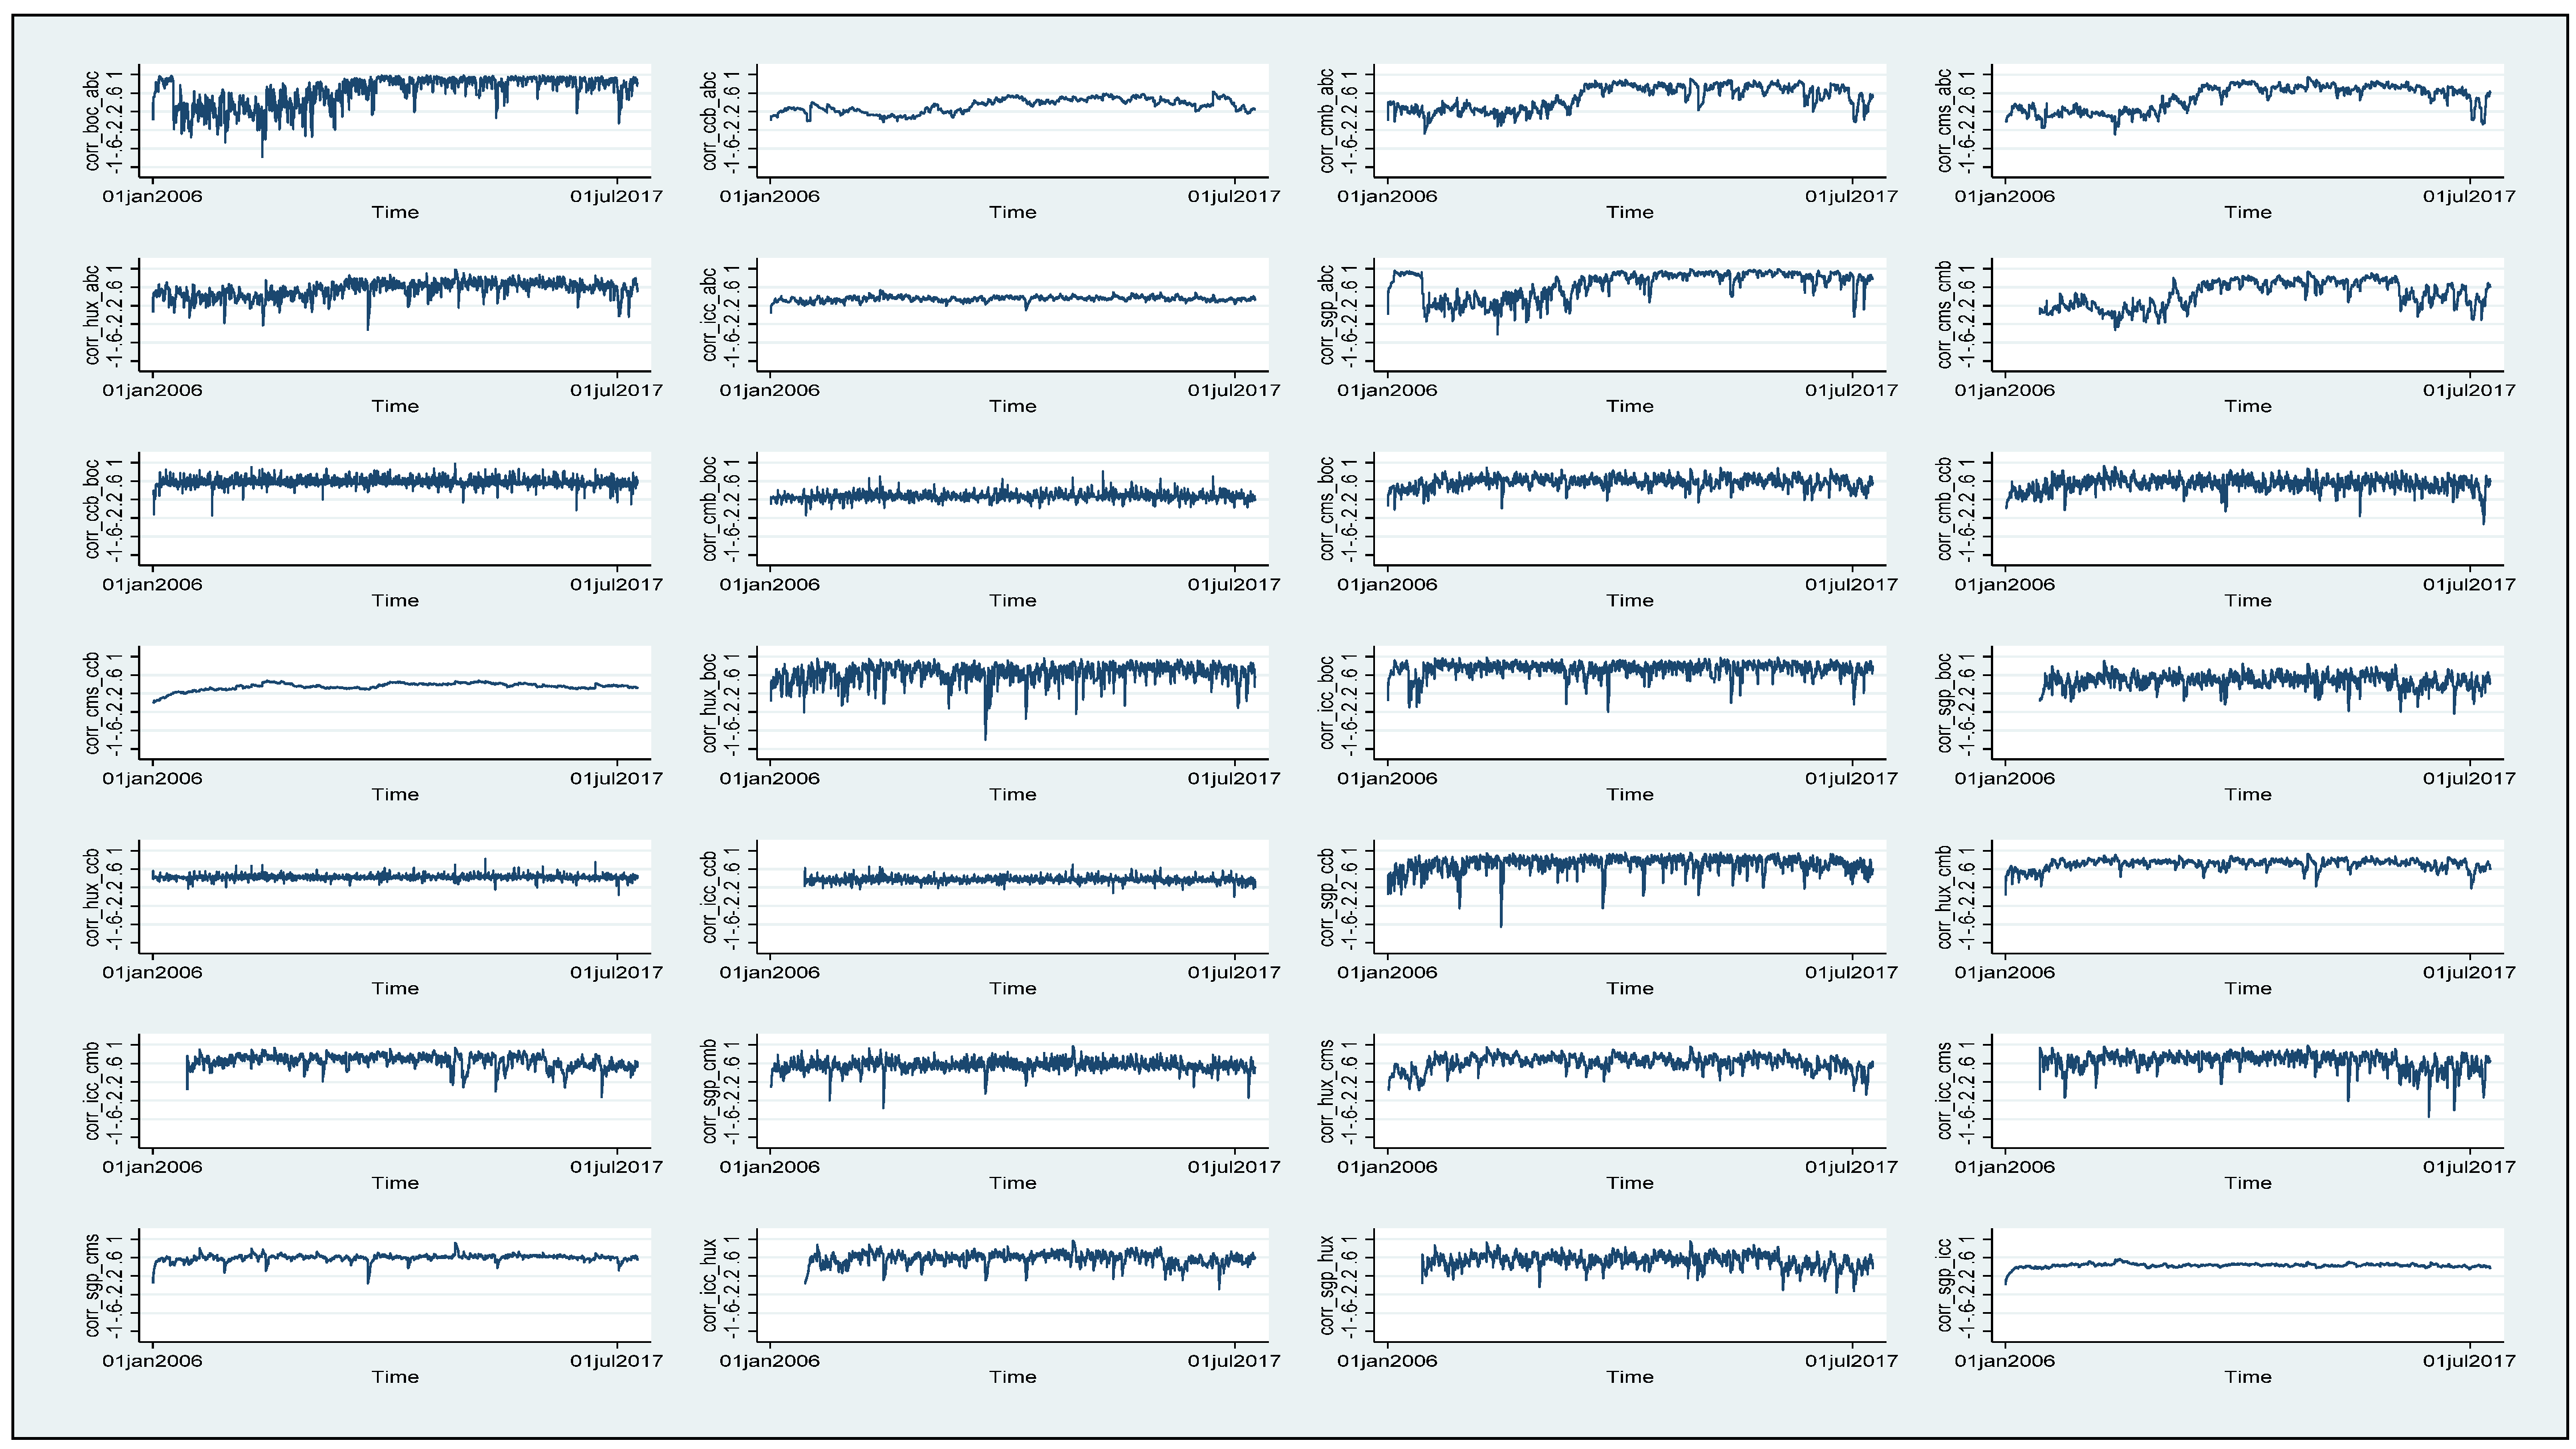
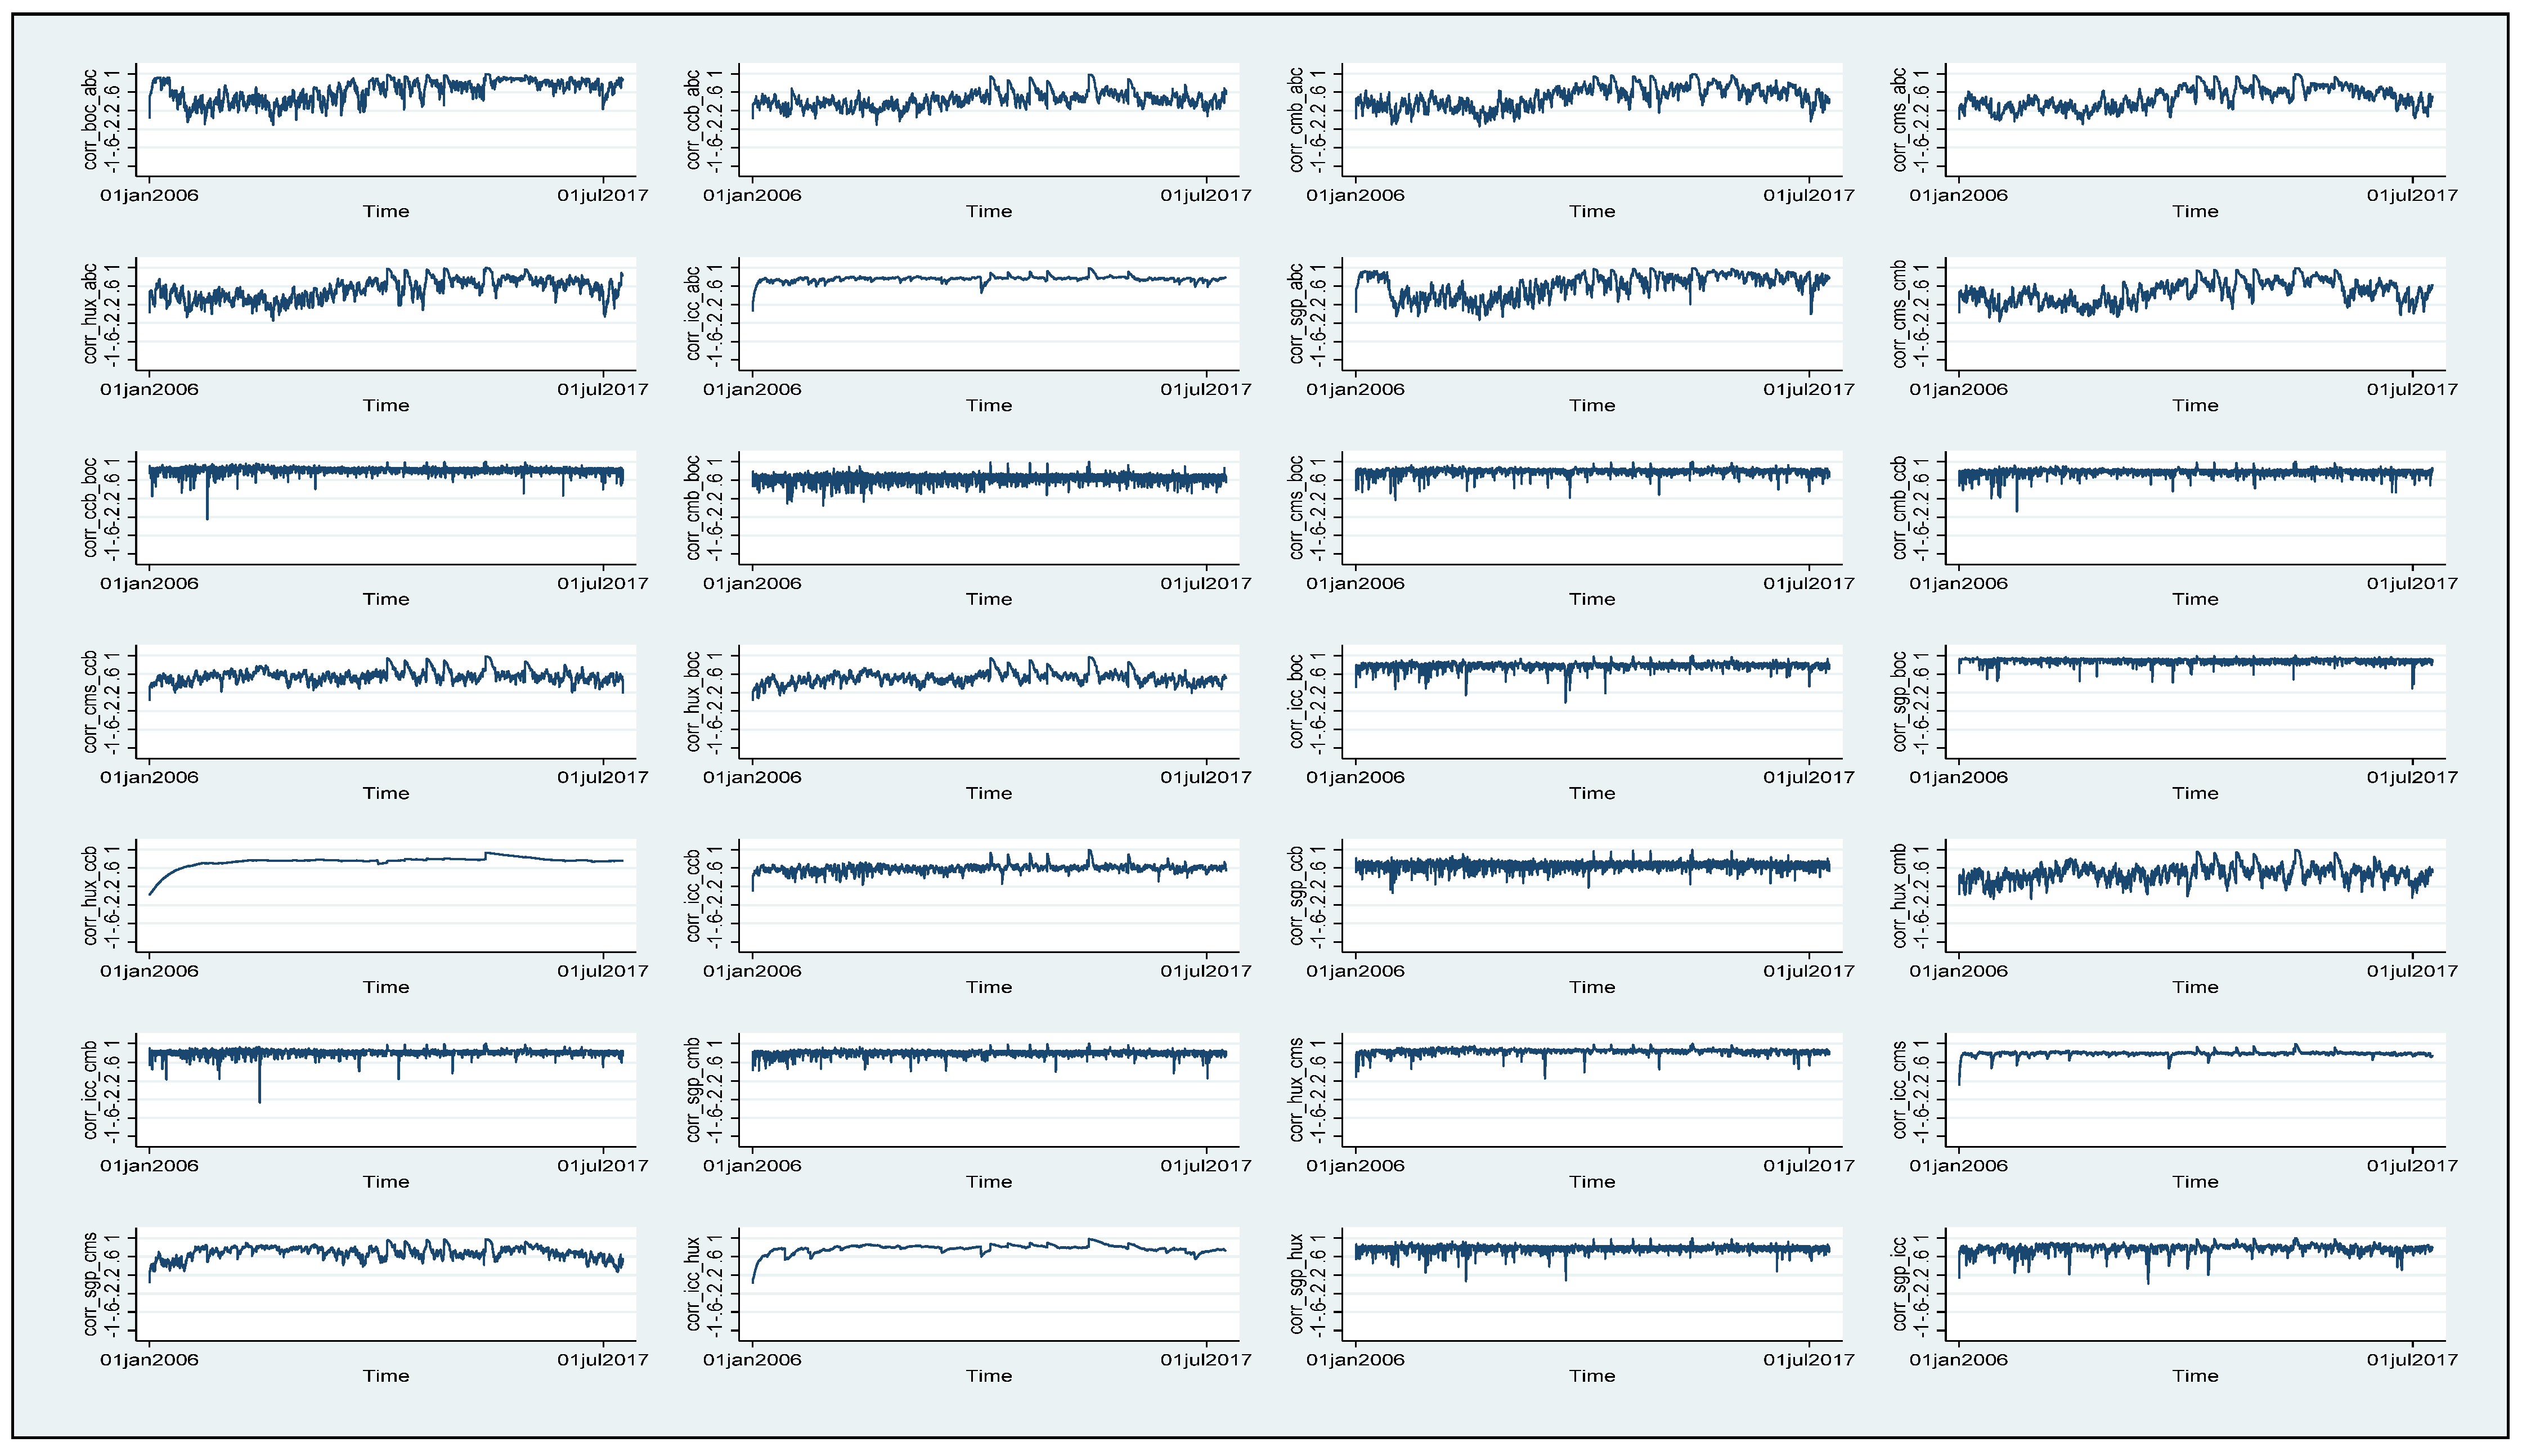

| S. No. | Banks | Short Name | Net Asset Value—Actual | Beta Up 5-Yr Mthly | Sharpe Ratio 5-Yr Mthly | Stock Reports + Risk Score by Data Stream |
|---|---|---|---|---|---|---|
| 1. | Agricultural Bank of China Ltd. | ABC | 249,551,048,992.73 | 0.87 | 0.04 | 10 |
| 2. | Bank of China Ltd. | BOC | 257,092,174,275.84 | 0.86 | 0.02 | 10 |
| 3. | China Construction Bank Corp. | CCB | 296,094,971,900.93 | 1.02 | 0.12 | 10 |
| 4. | China Merchants Bank Co, Ltd. | CMB | 80,063,183,940.38 | 0.99 | 0.30 | 9 |
| 5. | China Minsheng Banking Corp, Ltd. | CMS | 64,218,282,053.19 | 1.18 | −0.01 | 10 |
| 6. | Hua Xia Bank Co, Ltd. | HUX | 32,312,167,973.69 | 1.22 | 0.03 | 10 |
| 7. | Industrial and Commercial Bank of China Ltd. | ICC | 348,003,591,516.90 | 0.62 | 0.08 | 10 |
| 8. | Shanghai Pudong Development Bank Co, Ltd. | SGP | 69,625,080,048.90 | 0.89 | 0.10 | 10 |
| ABC | BOC | CCB | CMB | CMS | HUX | ICC | SGP | |
|---|---|---|---|---|---|---|---|---|
| Mean | −0.01 | −0.01 | −0.01 | 0.01 | 0.01 | 0.01 | −0.01 | 0.01 |
| Standard Error | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 |
| Dickey-Fuller p-Value | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| Standard Deviation | 0.02 | 0.02 | 0.03 | 0.03 | 0.03 | 0.03 | 0.02 | 0.17 |
| Sample Variance | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.03 |
| Kurtosis | 29.53 | 9.64 | 22.30 | 6.52 | 8.38 | 21.50 | 9.55 | 730.30 |
| Skewness | −0.89 | −0.46 | 0.94 | 0.25 | 0.63 | −0.17 | −0.44 | −2.85 |
| Minimum | −0.21 | −0.16 | −0.17 | −0.15 | −0.15 | −0.37 | −0.16 | −5.34 |
| Maximum | 0.14 | 0.13 | 0.32 | 0.19 | 0.27 | 0.33 | 0.12 | 5.35 |
| Count | 3129.00 | 3129.00 | 3129.00 | 3129.00 | 3129.00 | 3129.00 | 3129.00 | 3129.00 |
| ABC | BOC | CCB | CMB | CMS | HUX | ICC | SGP | |
|---|---|---|---|---|---|---|---|---|
| Mean | −0.01 | −0.01 | −0.01 | 0.01 | 0.01 | −0.01 | −0.01 | 0.01 |
| Standard Error | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 |
| Dickey-Fuller p-Value | −0.01 | −0.01 | −0.01 | −0.01 | −0.01 | −0.01 | −0.01 | −0.01 |
| Standard Deviation | 0.04 | 0.11 | 0.03 | 0.04 | 0.07 | 0.10 | 0.04 | 0.13 |
| Sample Variance | 0.01 | 0.02 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.02 |
| Kurtosis | 21.40 | 129.12 | 39.52 | 19.67 | 208.47 | 251.10 | 10.89 | 408.52 |
| Skewness | −0.46 | −0.71 | 1.61 | 0.26 | −1.96 | −7.15 | −0.40 | 3.33 |
| Minimum | −0.40 | −1.66 | −0.29 | −0.49 | −1.79 | −2.73 | −0.32 | −2.95 |
| Maximum | 0.32 | 2.02 | 0.50 | 0.41 | 1.41 | 1.39 | 0.27 | 3.58 |
| Count | 3129.00 | 3129.00 | 3129.00 | 3129.00 | 3129.00 | 3129.00 | 3129.00 | 3129.00 |
| ABC | BOC | CCB | CMB | CMS | HUX | ICC | SGP | |
|---|---|---|---|---|---|---|---|---|
| Mean | −0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 |
| Standard Error | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 |
| Dickey-Fuller p-Value | −0.01 | −0.01 | −0.01 | −0.01 | −0.01 | −0.01 | −0.01 | 0.01 |
| Standard Deviation | 0.03 | 0.03 | 0.03 | 0.03 | 0.03 | 0.03 | 0.03 | 0.03 |
| Sample Variance | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 |
| Kurtosis | 367.97 | 351.15 | 247.76 | 253.10 | 218.59 | 257.42 | 392.18 | 199.94 |
| Skewness | −6.59 | −7.68 | −2.00 | −6.55 | −5.65 | −6.64 | −7.40 | −3.86 |
| Minimum | −0.82 | −0.82 | −0.59 | −0.69 | −0.58 | −0.74 | −0.88 | −0.63 |
| Maximum | 0.57 | 0.54 | 0.53 | 0.44 | 0.44 | 0.42 | 0.54 | 0.50 |
| Count | 3129.00 | 3129.00 | 3129.00 | 3129.00 | 3129.00 | 3129.00 | 3129.00 | 3129.00 |
| Panel A: Mean Equation | ||||||||
| ABC | BOC | CCB | CMB | CMS | HUX | ICC | SGP | |
| ABC | ||||||||
| BOC | −0.01 | |||||||
| CCB | 0.01 | 0.01 * | ||||||
| CMB | 0.01 * | 0.01 ** | 0.01 *** | |||||
| CMS | 0.01 ** | 0.01 ** | 0.01*** | 0.01 *** | ||||
| HUX | 0.01 | 0.01 ** | 0.01 ** | 0.01 *** | 0.01* | |||
| ICC | −0.01 *** | 0.01 ** | 0.01 *** | 0.01 *** | 0.01 *** | 0.01 *** | ||
| SGP | 0.01 | 0.01 | 0.01 *** | 0.01 * | 0.01 | 0.01 ** | 0.01 ** | |
| Panel B: Variance Equation | ||||||||
| ABC | ||||||||
| BOC | 0.01 *** | |||||||
| CCB | 0.01 ** | 0.01 * | ||||||
| CMB | 0.01 * | 0.01 | 0.01 | |||||
| CMS | 0.01 *** | 0.01 *** | 0.01 ** | 0.01 * | ||||
| HUX | 0.01 ** | 0.01 ** | 0.01 ** | 0.01 ** | 0.01 ** | |||
| ICC | 0.01 *** | 0.01 *** | 0.01 ** | 0.01 ** | 0.01 *** | 0.01 *** | ||
| SGP | 0.01 ** | 0.01 *** | 0.01 ** | 0.01 *** | 0.01 *** | 0.01 *** | 0.01 *** | |
| Panel C: Correlation Equation | ||||||||
| ABC | ||||||||
| BOC | 0.73 *** | |||||||
| CCB | 0.26 *** | 0.36 *** | ||||||
| CMB | 0.39 *** | 0.63 *** | 0.42 *** | |||||
| CMS | 0.42 *** | 0.66 *** | 0.37 *** | 0.73 *** | ||||
| HUX | 0.21 | 0.49 ** | 0.33 *** | 0.56 *** | 0.67 *** | |||
| ICC | 0.59 *** | 0.82 *** | 0.38 *** | 0.63 *** | 0.63 *** | 0.47 *** | ||
| SGP | 0.31 * | 0.60 *** | 0.38 *** | 0.70 *** | 0.70 *** | 0.57 *** | 0.58 *** | |
| Panel A: Mean Equation | ||||||||
| ABC | BOC | CCB | CMB | CMS | HUX | ICC | SGP | |
| ABC | ||||||||
| BOC | −0.01 | |||||||
| CCB | 0.01 | 0.01 * | ||||||
| CMB | 0.01 * | 0.01 | 0.01 * | |||||
| CMS | 0.01 | −0.01 | 0.01 * | 0.01 | ||||
| HUX | 0.01 * | 0.01 | 0.01 | 0.01 ** | 0.01 ** | |||
| ICC | 0.01 | 0.01 | 0.01 * | 0.01 ** | 0.01 ** | 0.01 *** | ||
| SGP | 0.01 | 0.01* | 0.01 *** | 0.01 | 0.01 | 0.01 | 0.01 | |
| Panel B: Variance Equation | ||||||||
| ABC | ||||||||
| BOC | 0.01 *** | |||||||
| CCB | 0.01 *** | 0.01 *** | ||||||
| CMB | 0.01 | 0.01 | 0.01 * | |||||
| CMS | 0.01 *** | 0.01 ** | 0.01 ** | 0.01 *** | ||||
| HUX | 0.01 ** | 0.01 ** | 0.01 | 0.01 ** | 0.01 ** | |||
| ICC | 0.01 ** | 0.01 * | 0.01 ** | 0.01 | 0.01 | 0.01 | ||
| SGP | 0.01 ** | 0.01 ** | 0.01 * | 0.01 * | 0.01 *** | 0.01 ** | 0.01 ** | |
| Panel C: Correlation Equation | ||||||||
| ABC | ||||||||
| BOC | 0.52 *** | |||||||
| CCB | 0.30 *** | 0.39 *** | ||||||
| CMB | 0.37 *** | 0.65 *** | 0.40 *** | |||||
| CMS | 0.42 ** | 0.67 *** | 0.48 *** | 0.79 *** | ||||
| HUX | 0.44 *** | 0.58 *** | 0.33 *** | 0.66 *** | 0.73 *** | |||
| ICC | 0.61 *** | 0.81 *** | 0.46 *** | 0.73 *** | 0.73 *** | 0.63 *** | ||
| SGP | 0.40 ** | 0.65 *** | 0.42 *** | 0.77 *** | 0.77 *** | 0.69 *** | 0.70 *** | |
| Panel A: Mean Equation | ||||||||
| ABC | BOC | CCB | CMB | CMS | HUX | ICC | SGP | |
| ABC | ||||||||
| BOC | −0.01 | |||||||
| CCB | −0.01 | 0.01 * | ||||||
| CMB | 0.01 | 0.01 | 0.01 *** | |||||
| CMS | 0.01 | 0.01 | 0.01 *** | 0.01 ** | ||||
| HUX | −0.01 | 0.01 | 0.01 * | 0.01 * | 0.01 ** | |||
| ICC | −0.01 ** | 0.01 * | 0.01 * | 0.01 ** | −0.01 | 0.01 ** | ||
| SGP | −0.01 | 0.01 | 0.01 | 0.01 *** | 0.01 * | 0.01 | 0.01 | |
| Panel B: Variance Equation | ||||||||
| ABC | ||||||||
| BOC | 0.01 | |||||||
| CCB | 0.01 | 0.01 * | ||||||
| CMB | 0.01 | 0.01 ** | 0.01 | |||||
| CMS | 0.01 | 0.01 | 0.01 | 0.01 | ||||
| HUX | 0.01 | 0.01 *** | 0.01 * | 0.01 ** | 0.01 * | |||
| ICC | 0.01 | 0.01 *** | 0.01 *** | 0.01 *** | 0.01 | 0.01 *** | ||
| SGP | 0.01 | 0.01 | 0.01 | 0.01 *** | 0.01 | 0.01 | 0.01 | |
| Panel C: Correlation Equation | ||||||||
| ABC | ||||||||
| BOC | 0.84 *** | |||||||
| CCB | 0.58 *** | 0.63 *** | ||||||
| CMB | 0.72 *** | 0.79 *** | 0.65 *** | |||||
| CMS | 0.66 *** | 0.76 *** | 0.62 *** | 0.80 *** | ||||
| HUX | 0.73 *** | 0.81 *** | 0.66 *** | 0.83 *** | 0.79 *** | |||
| ICC | 0.82 *** | 0.87 *** | 0.64 *** | 0.80 *** | 0.77 *** | 0.79 *** | ||
| SGP | 0.65 *** | 0.78 *** | 0.68 *** | 0.83 *** | 0.82 *** | 0.83 *** | 0.74 *** | |
Publisher’s Note: MDPI stays neutral with regard to jurisdictional claims in published maps and institutional affiliations. |
© 2021 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).
Share and Cite
Choudhury, T.; Scagnelli, S.; Yong, J.; Zhang, Z. Non-Traditional Systemic Risk Contagion within the Chinese Banking Industry. Sustainability 2021, 13, 7954. https://doi.org/10.3390/su13147954
Choudhury T, Scagnelli S, Yong J, Zhang Z. Non-Traditional Systemic Risk Contagion within the Chinese Banking Industry. Sustainability. 2021; 13(14):7954. https://doi.org/10.3390/su13147954
Chicago/Turabian StyleChoudhury, Tonmoy, Simone Scagnelli, Jaime Yong, and Zhaoyong Zhang. 2021. "Non-Traditional Systemic Risk Contagion within the Chinese Banking Industry" Sustainability 13, no. 14: 7954. https://doi.org/10.3390/su13147954
APA StyleChoudhury, T., Scagnelli, S., Yong, J., & Zhang, Z. (2021). Non-Traditional Systemic Risk Contagion within the Chinese Banking Industry. Sustainability, 13(14), 7954. https://doi.org/10.3390/su13147954

