Article

A Carbon Price Prediction Model Based on the Secondary Decomposition Algorithm and Influencing Factors
Department of Economics and Management, North China Electric Power University, 689 Huadian Road, Baoding 071000, China
*
Author to whom correspondence should be addressed.
Energies 2021, 14(5), 1328; https://doi.org/10.3390/en14051328
Submission received: 4 February 2021 / Revised: 22 February 2021 / Accepted: 23 February 2021 / Published: 1 March 2021
(This article belongs to the Section C: Energy Economics and Policy)

Abstract

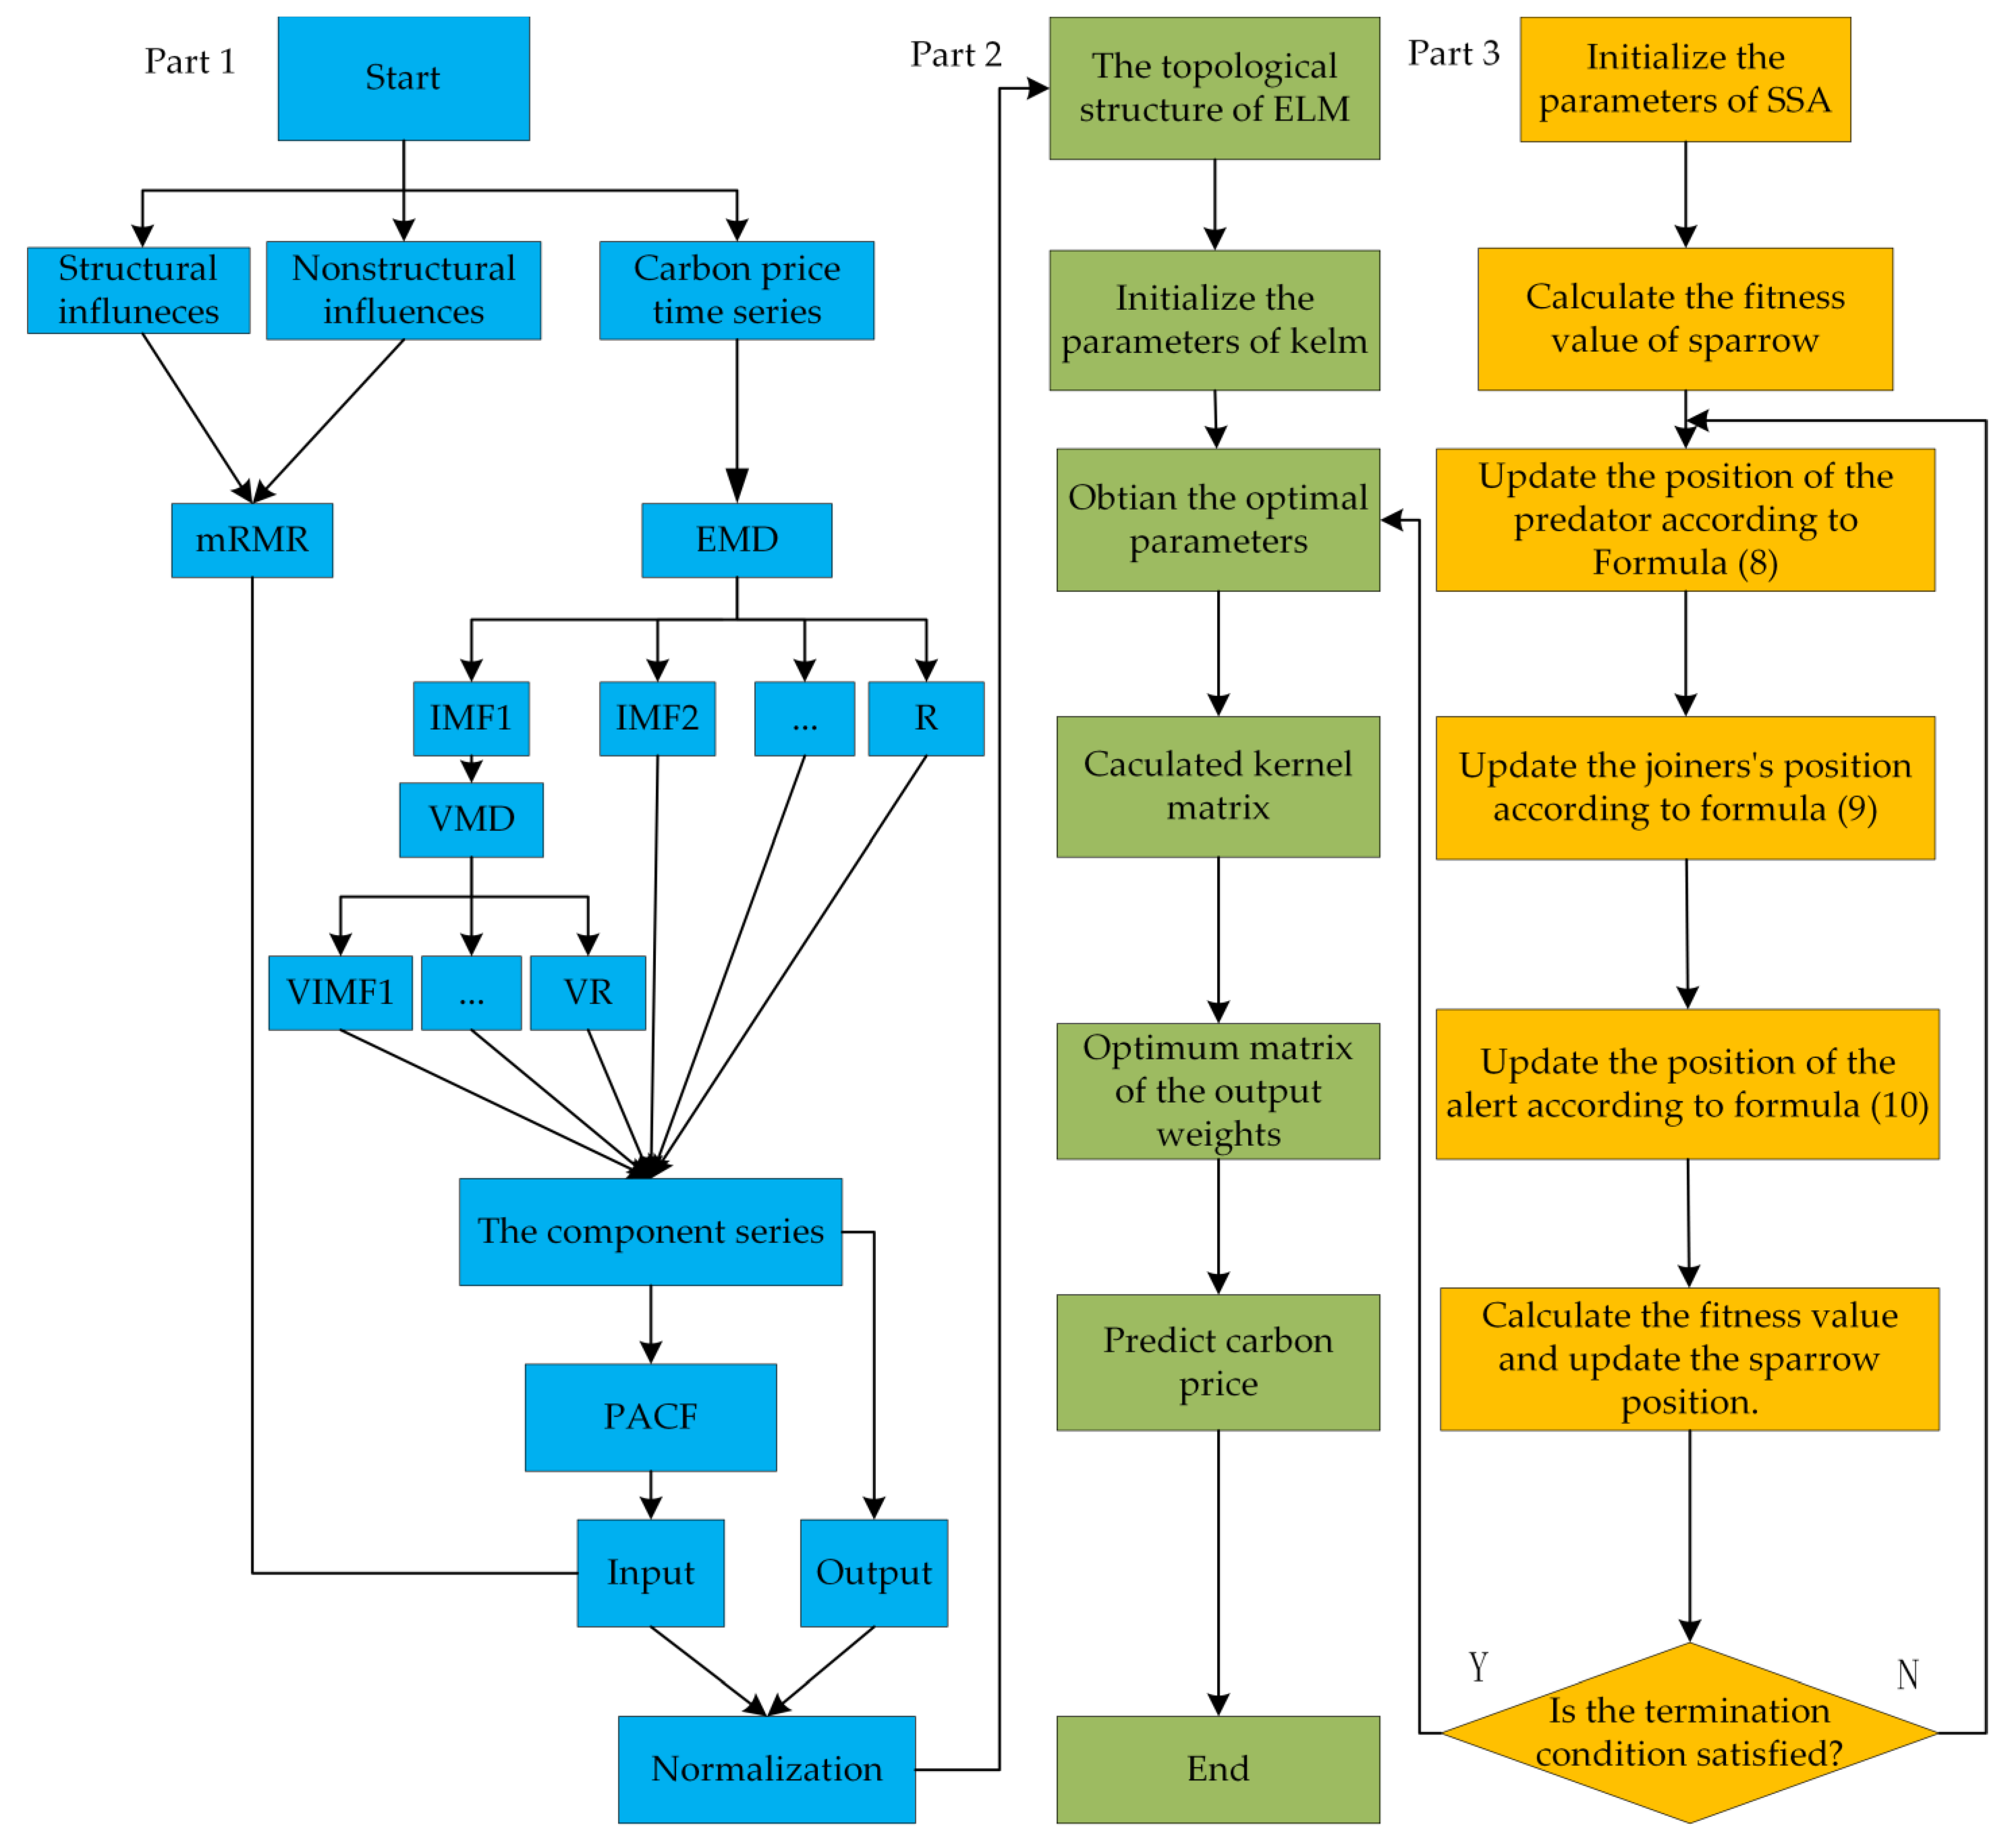
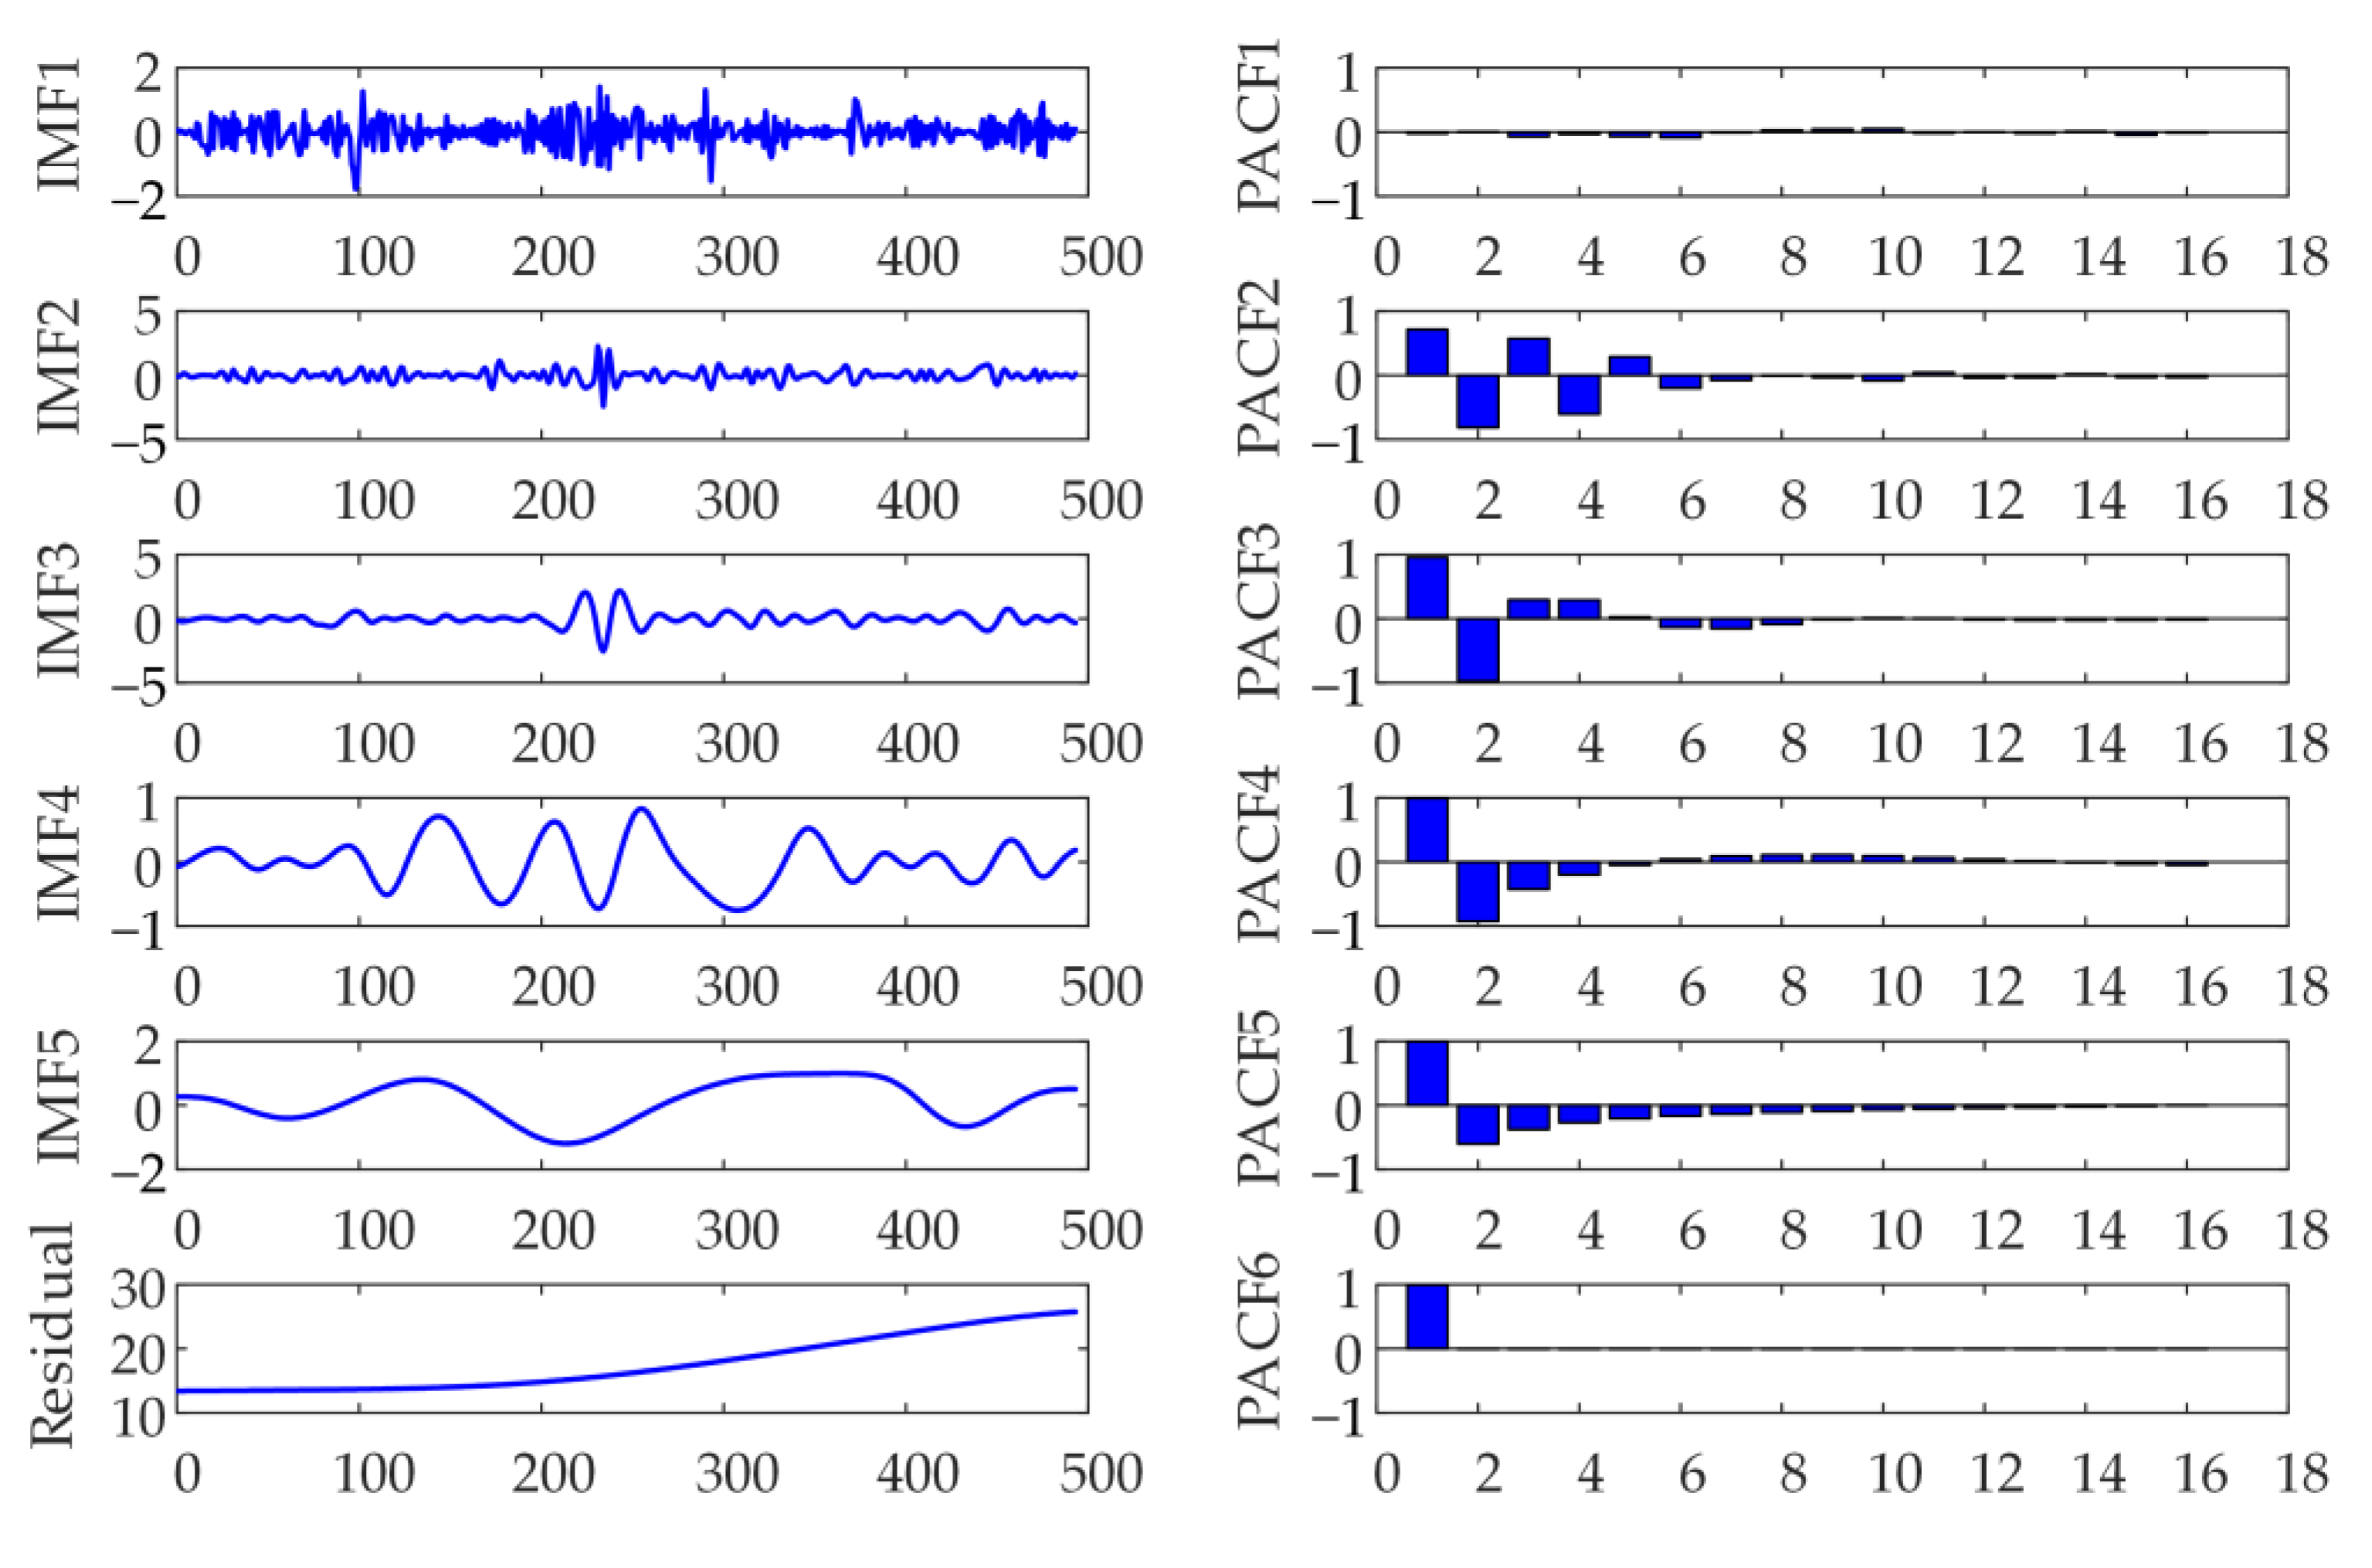
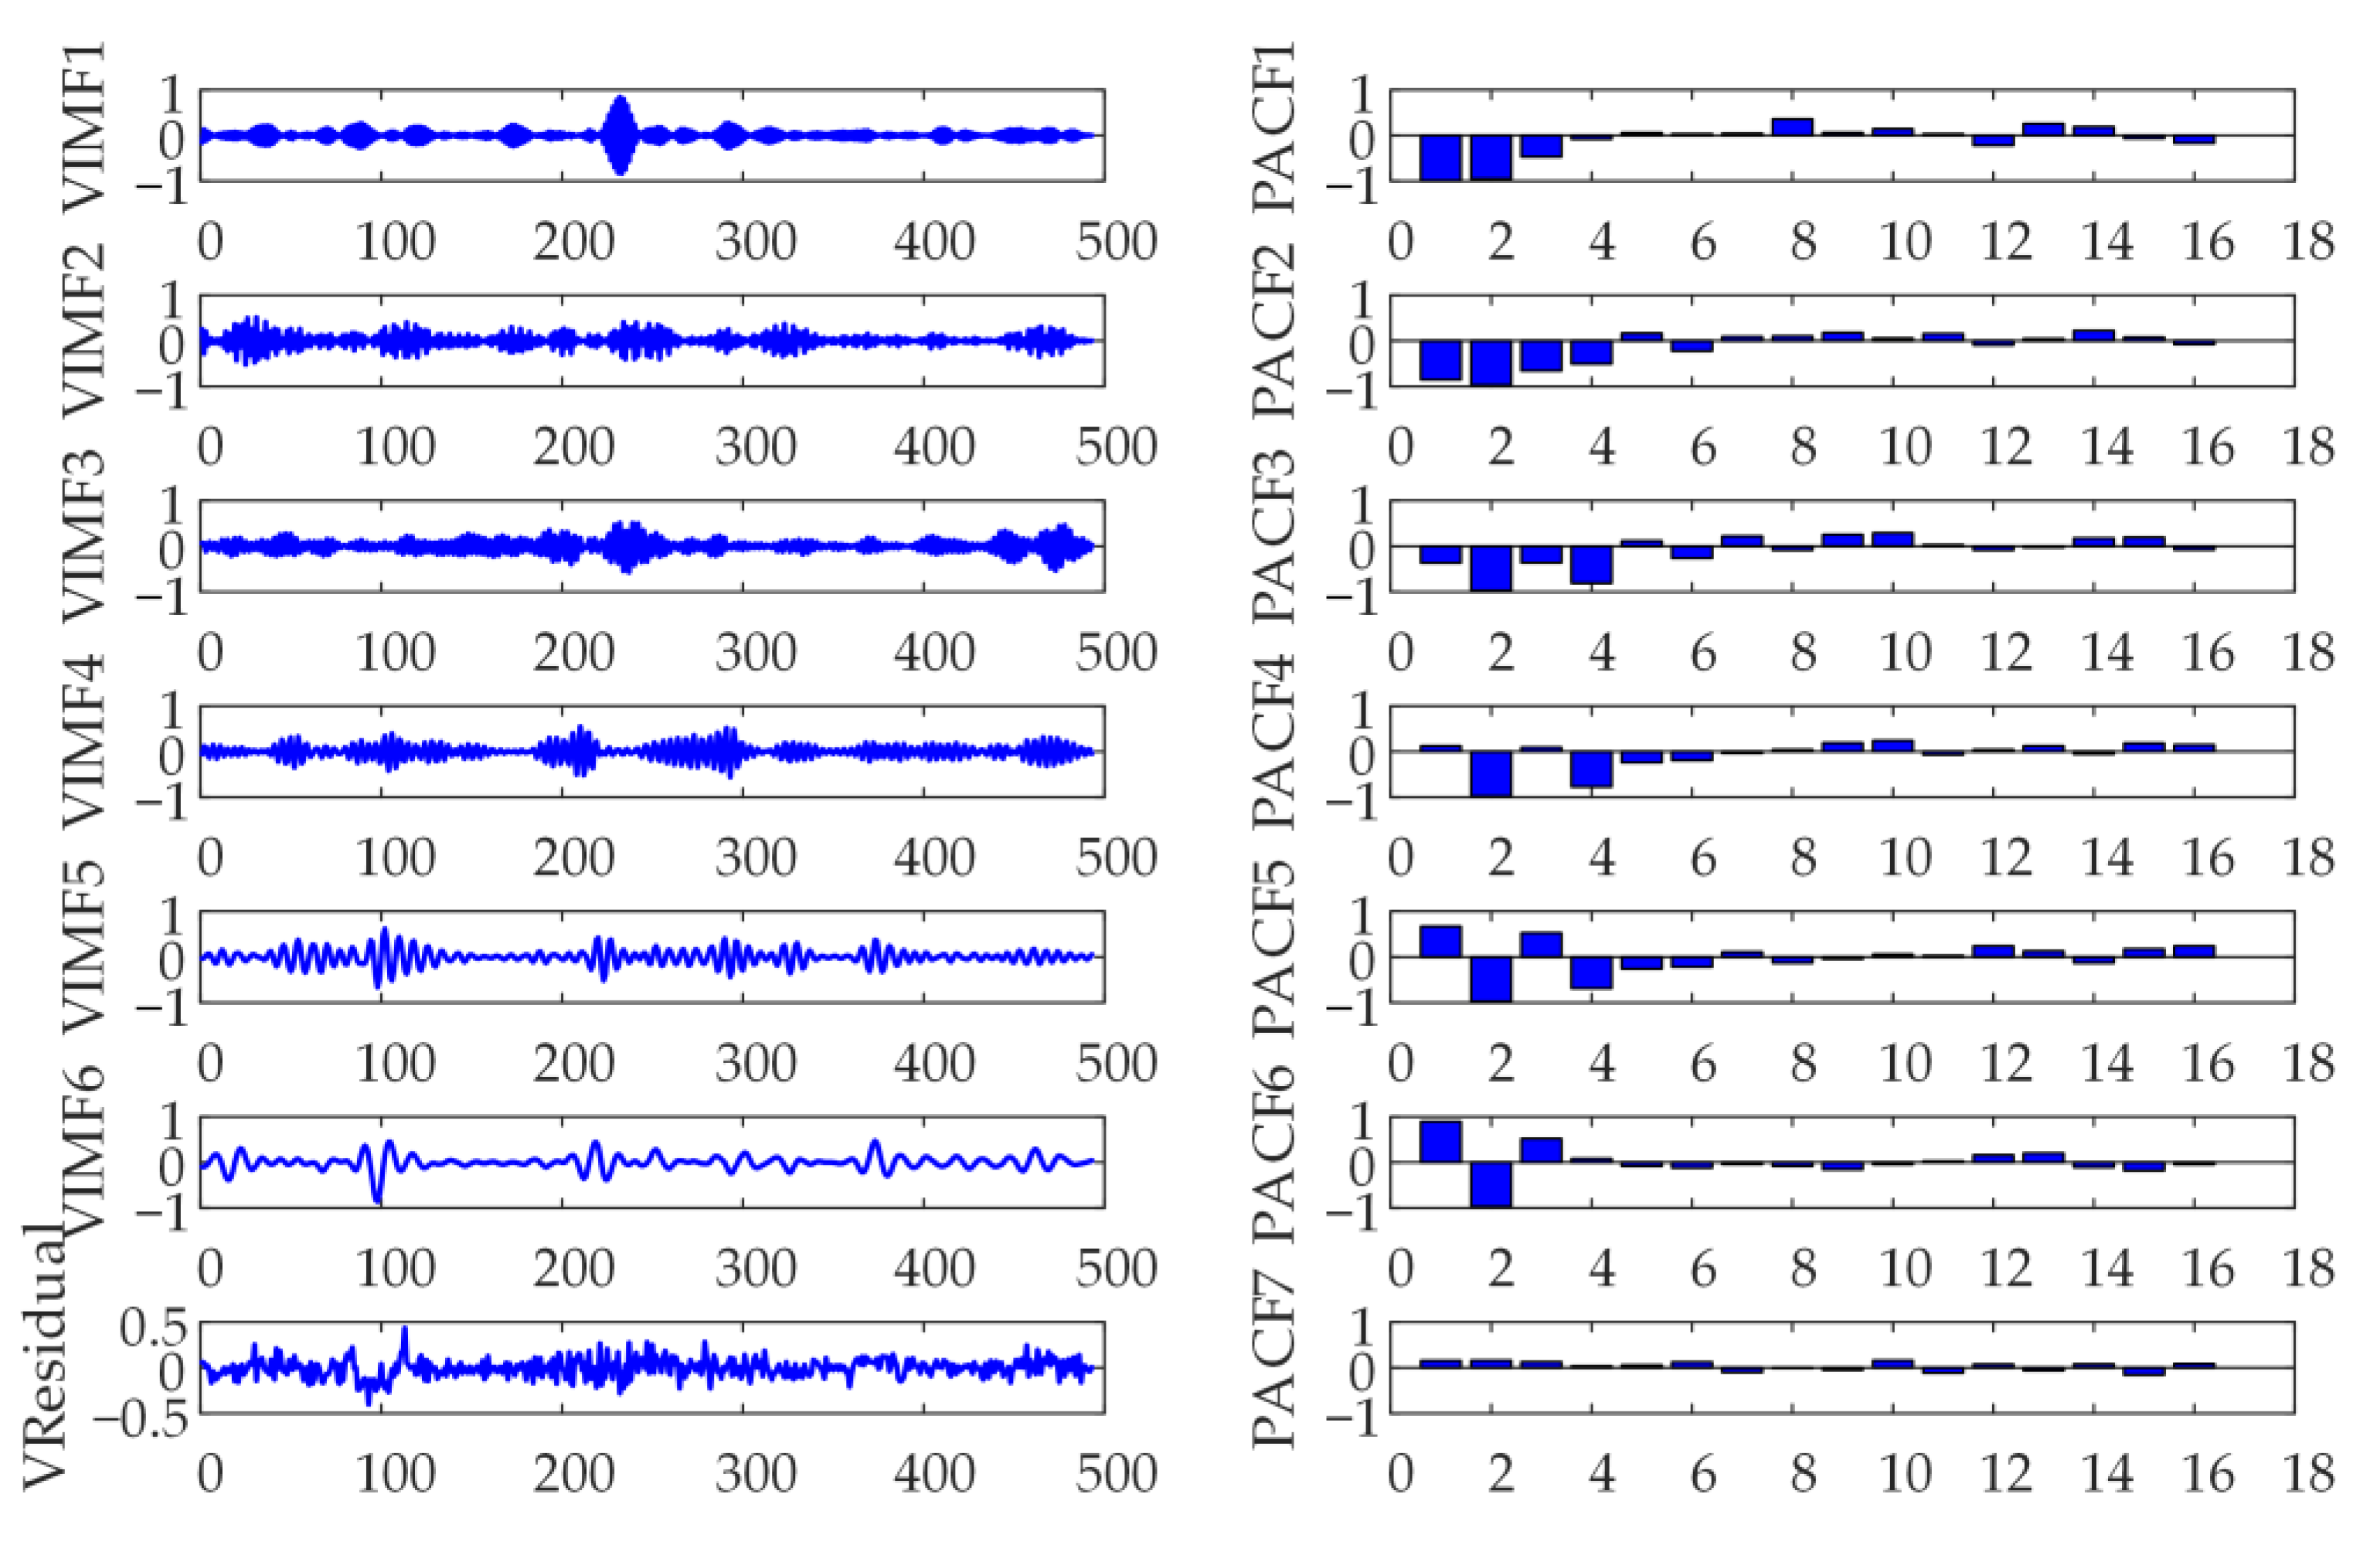
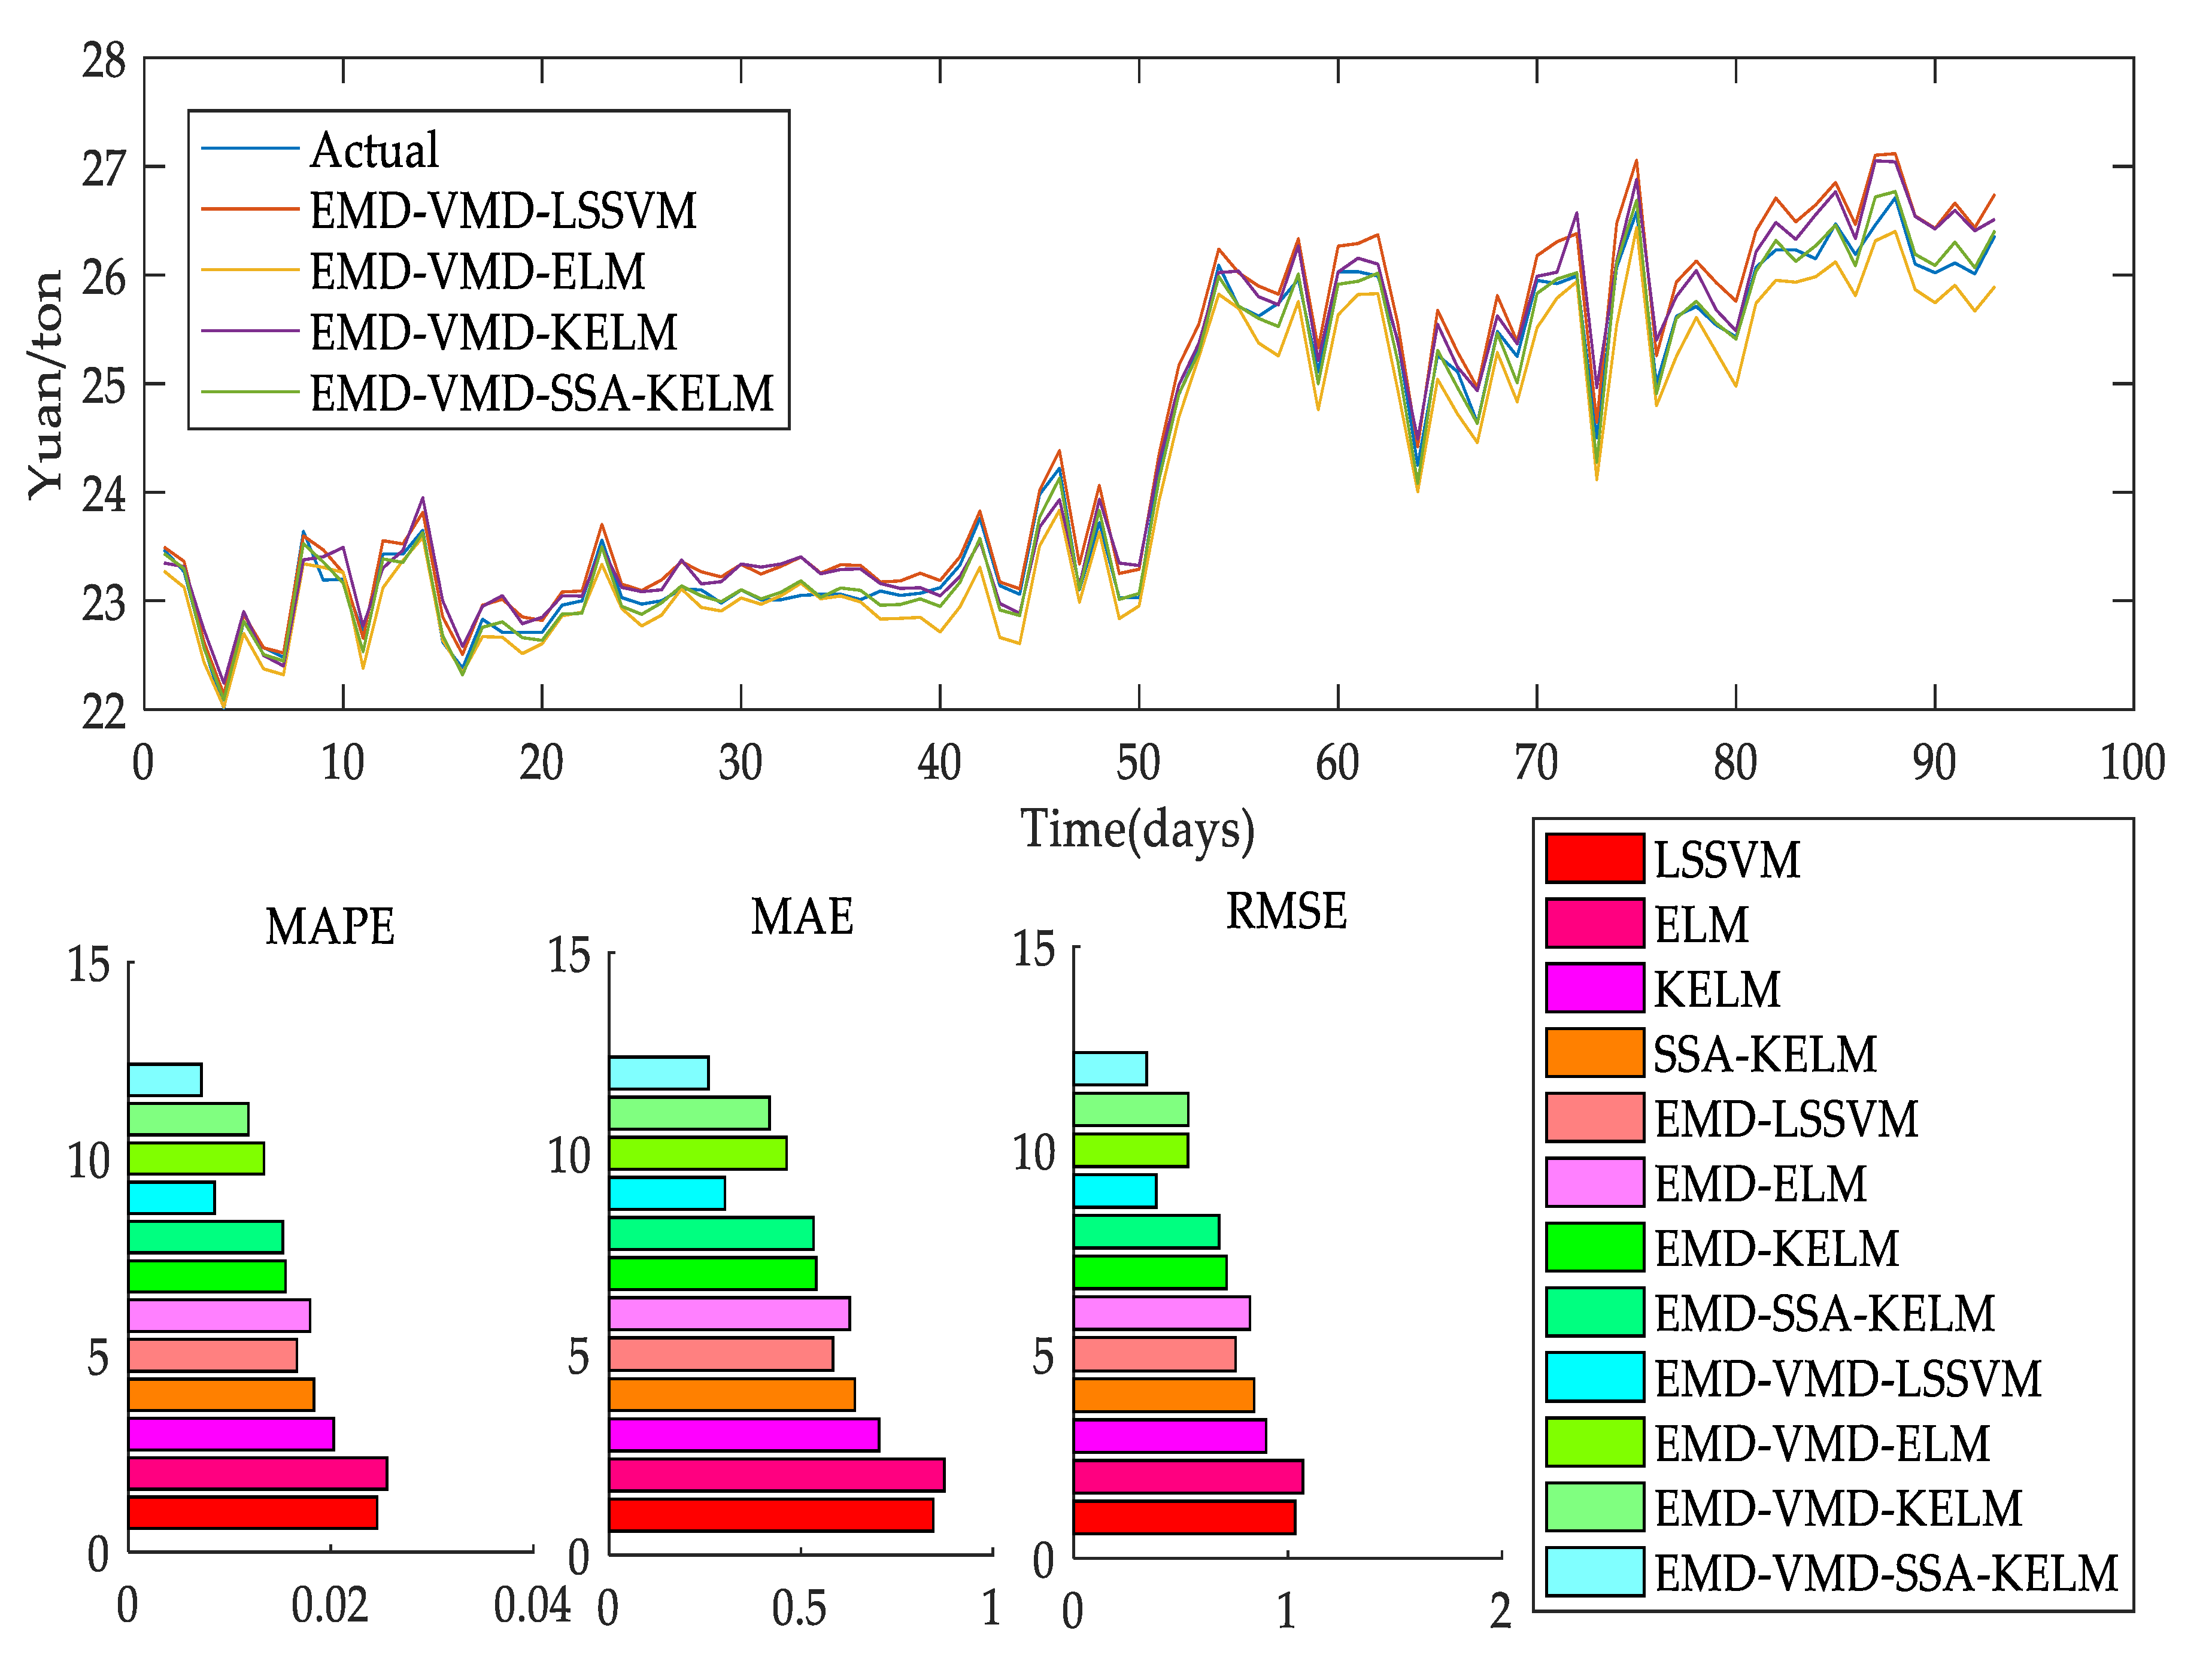
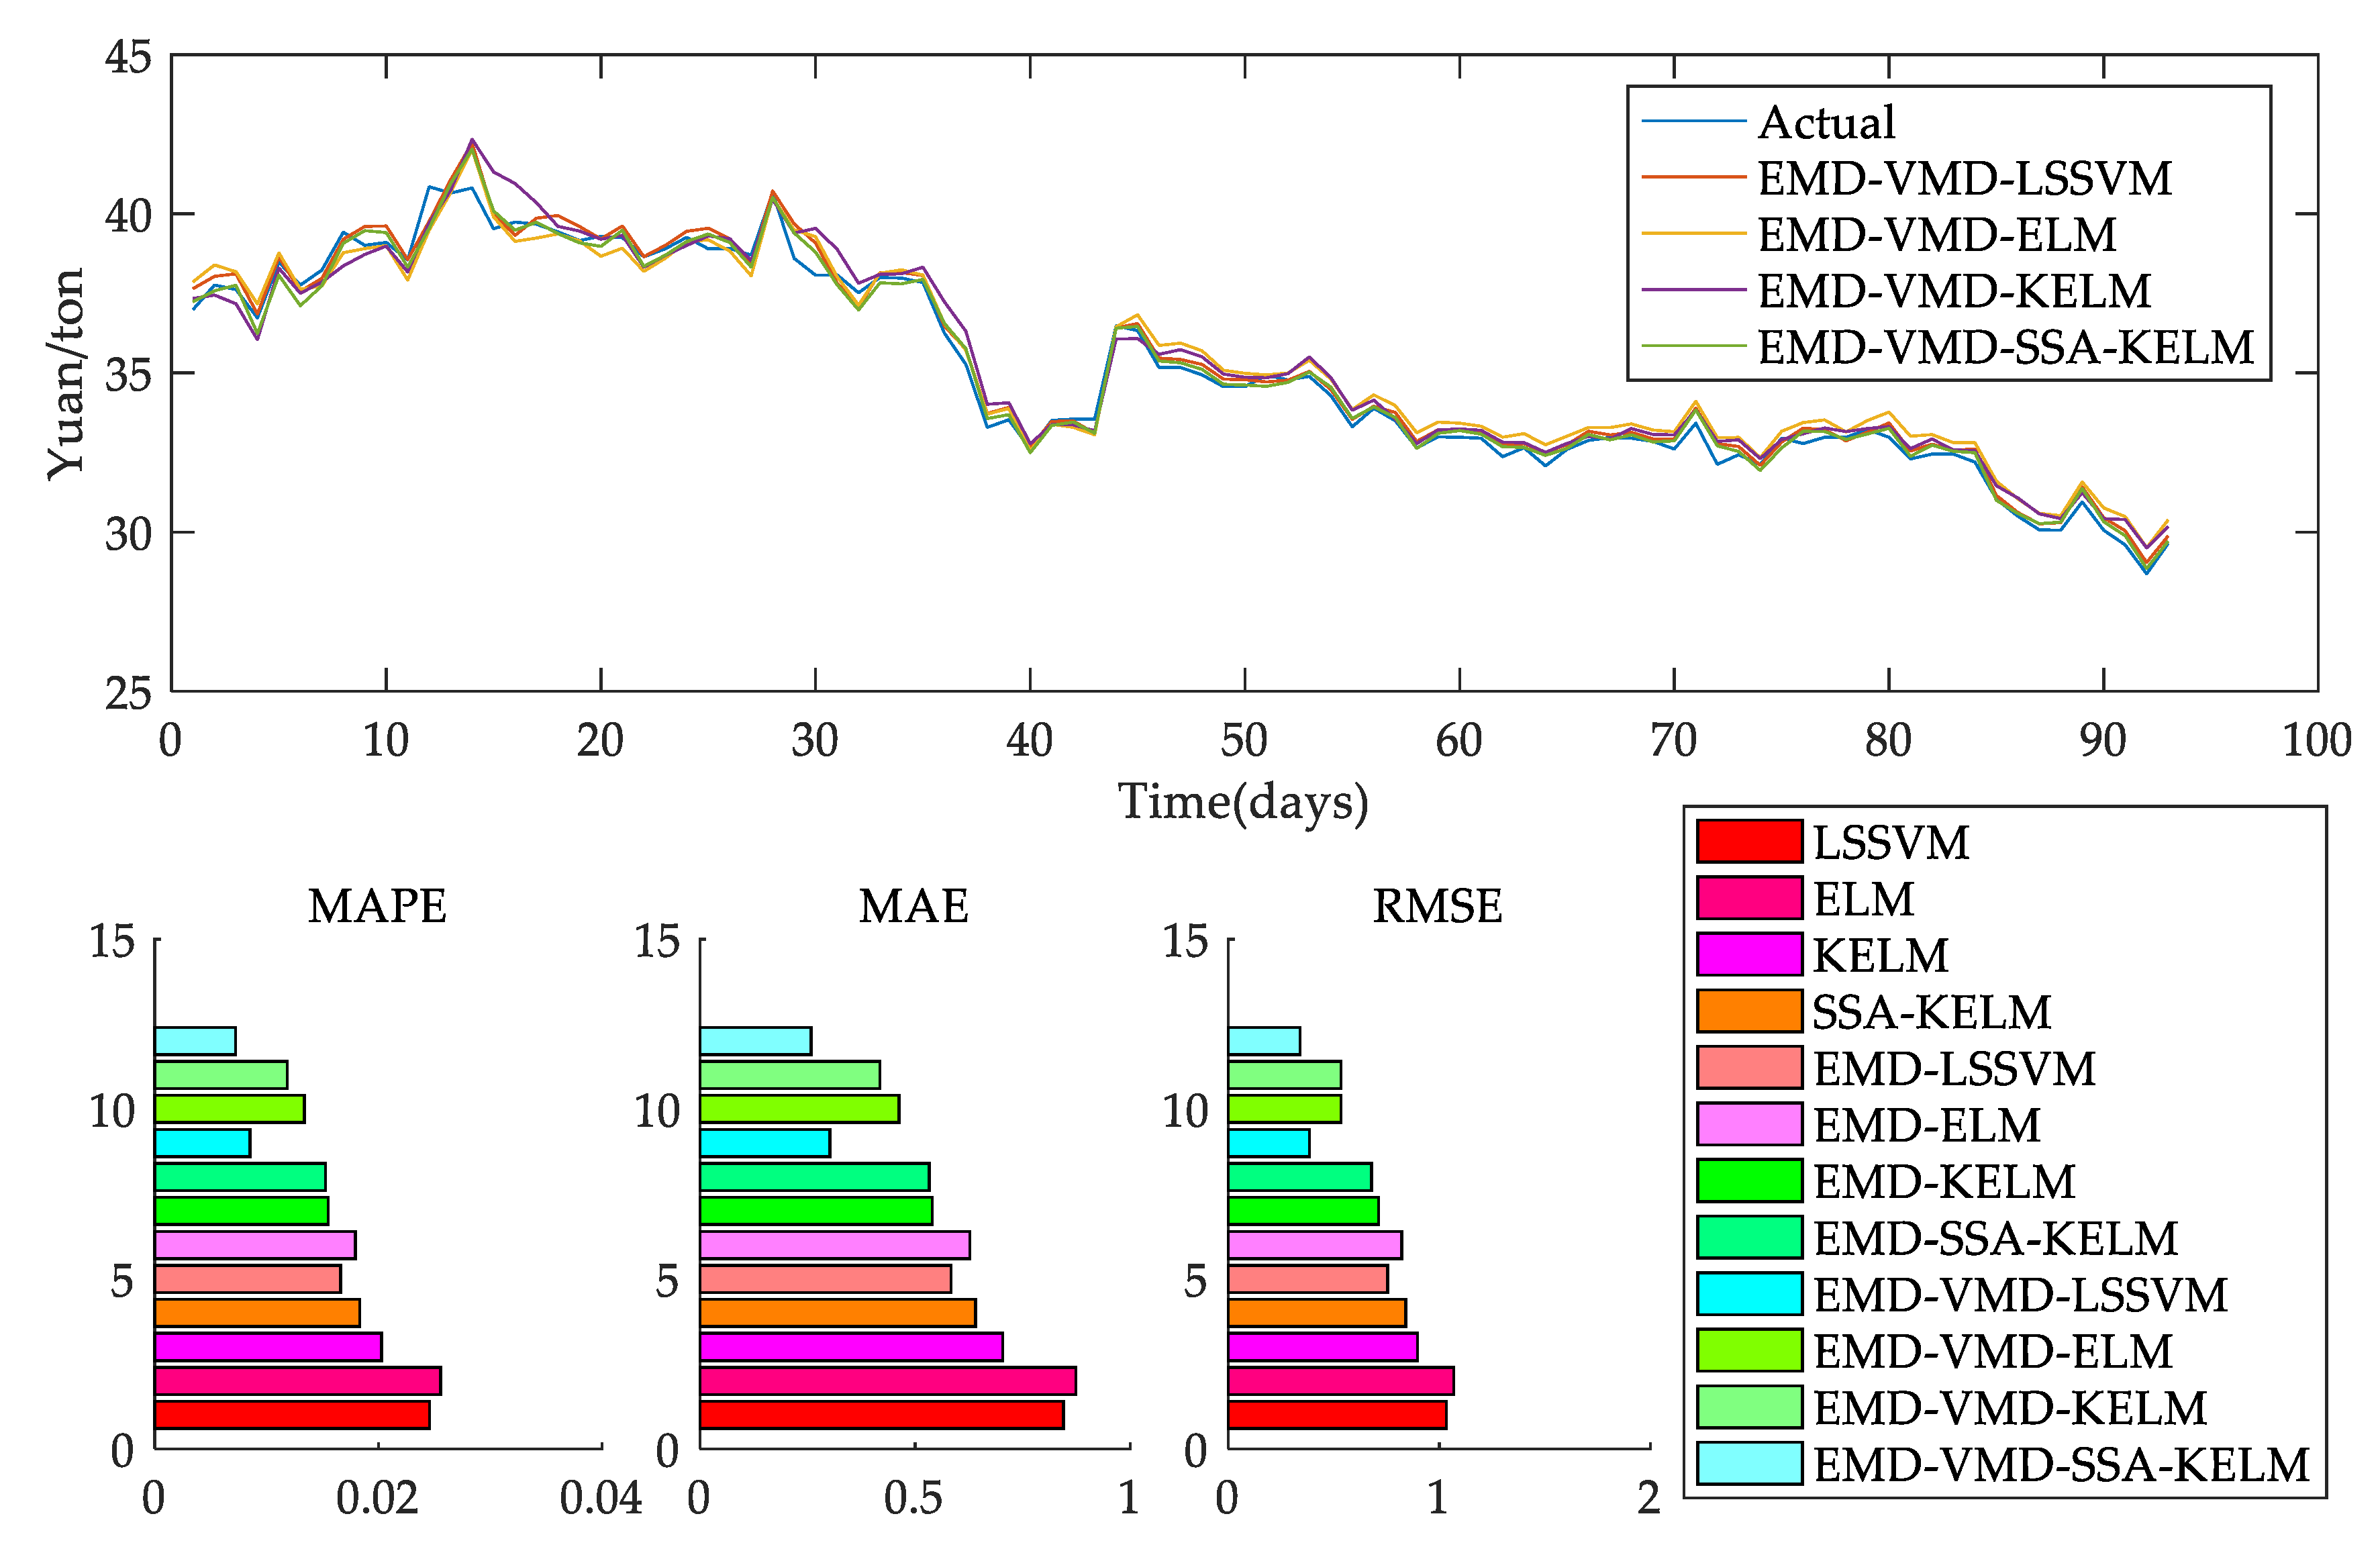
Carbon emission reduction is now a global issue, and the prediction of carbon trading market prices is an important means of reducing emissions. This paper innovatively proposes a second decomposition carbon price prediction model based on the nuclear extreme learning machine optimized by the Sparrow search algorithm and considers the structural and nonstructural influencing factors in the model. Firstly, empirical mode decomposition (EMD) is used to decompose the carbon price data and variational mode decomposition (VMD) is used to decompose Intrinsic Mode Function 1 (IMF1), and the decomposition of carbon prices is used as part of the input of the prediction model. Then, a maximum correlation minimum redundancy algorithm (mRMR) is used to preprocess the structural and nonstructural factors as another part of the input of the prediction model. After the Sparrow search algorithm (SSA) optimizes the relevant parameters of Extreme Learning Machine with Kernel (KELM), the model is used for prediction. Finally, in the empirical study, this paper selects two typical carbon trading markets in China for analysis. In the Guangdong and Hubei markets, the EMD-VMD-SSA-KELM model is superior to other models. It shows that this model has good robustness and validity.
Keywords: carbon price; empirical mode decomposition; variational mode decomposition; sparrow search algorithm; kernel extreme learning machine; secondary decomposition; partial autocorrelation analysis; maximum correlation minimum redundancy algorithm carbon price; empirical mode decomposition; variational mode decomposition; sparrow search algorithm; kernel extreme learning machine; secondary decomposition; partial autocorrelation analysis; maximum correlation minimum redundancy algorithm
Graphical Abstract