Article

Detecting Chaos from Agricultural Product Price Time Series

1
Shandong University of Finance and Economics, Jinan 250014, China
2
Dongfang College, Shandong University of Finance and Economics, Tai'an 271000, China
3
Management School of Tianjin University, Tianjin 300072, China
*
Author to whom correspondence should be addressed.
Entropy 2014, 16(12), 6415-6433; https://doi.org/10.3390/e16126415
Submission received: 13 July 2014 / Revised: 28 September 2014 / Accepted: 20 November 2014 / Published: 5 December 2014
(This article belongs to the Special Issue Complex Systems and Nonlinear Dynamics)

Abstract

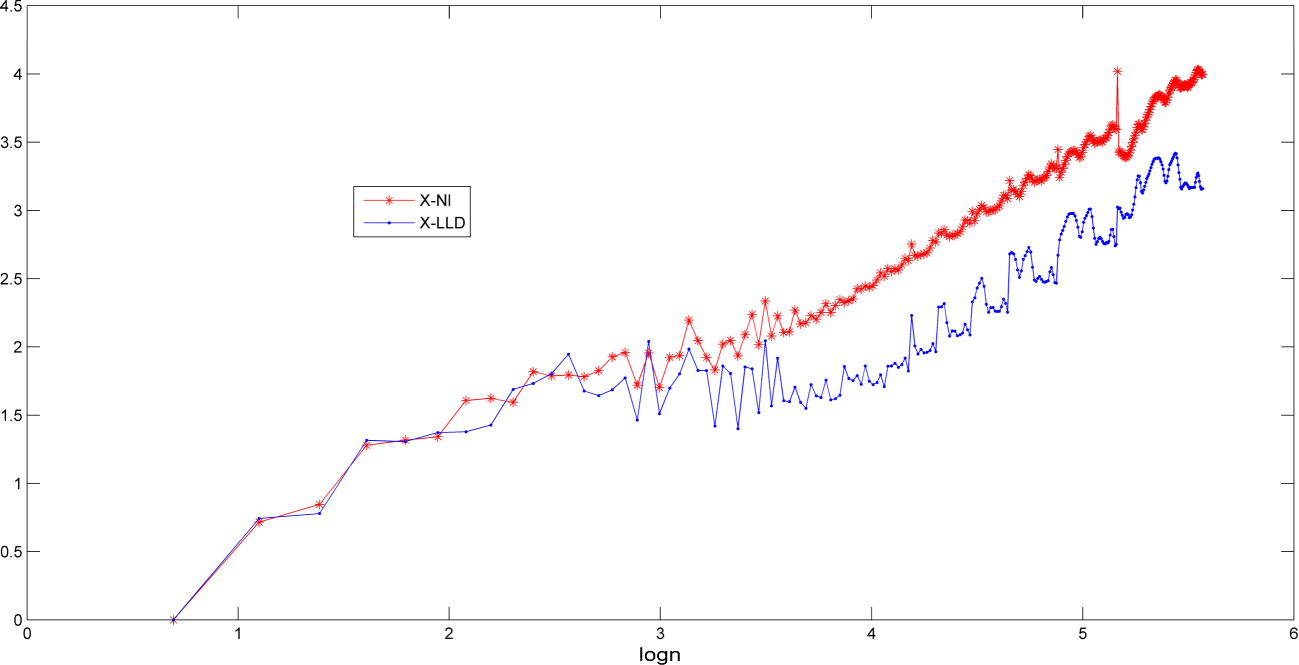
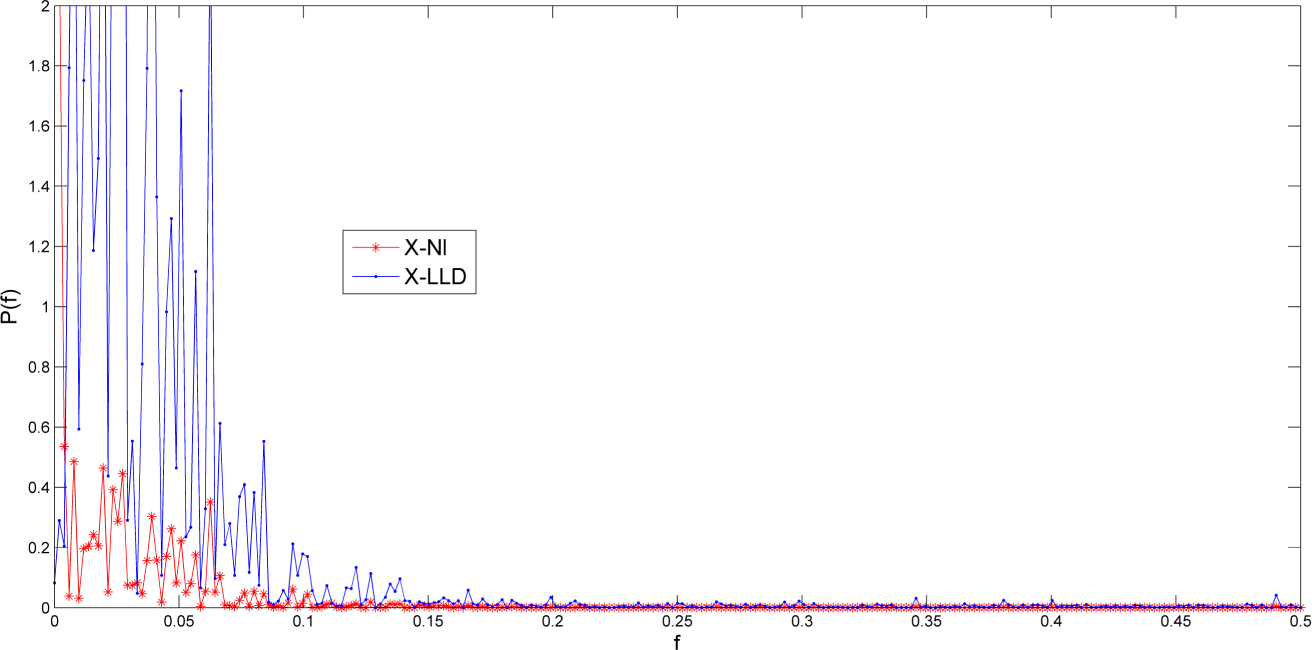
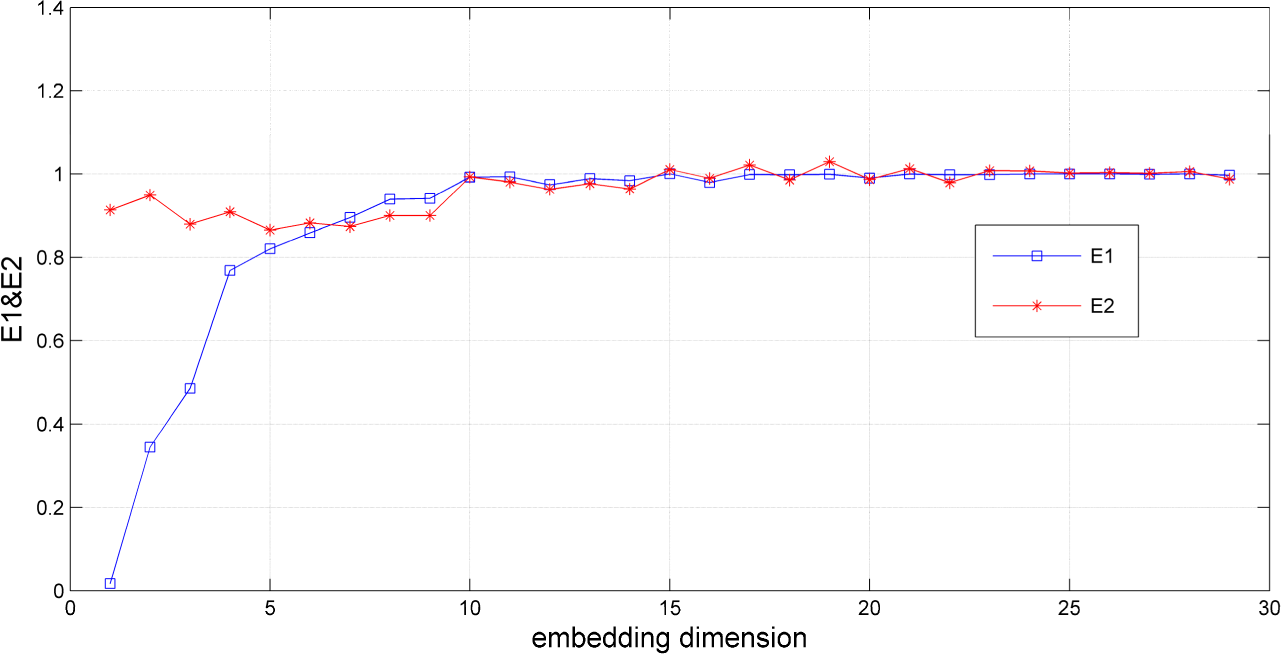
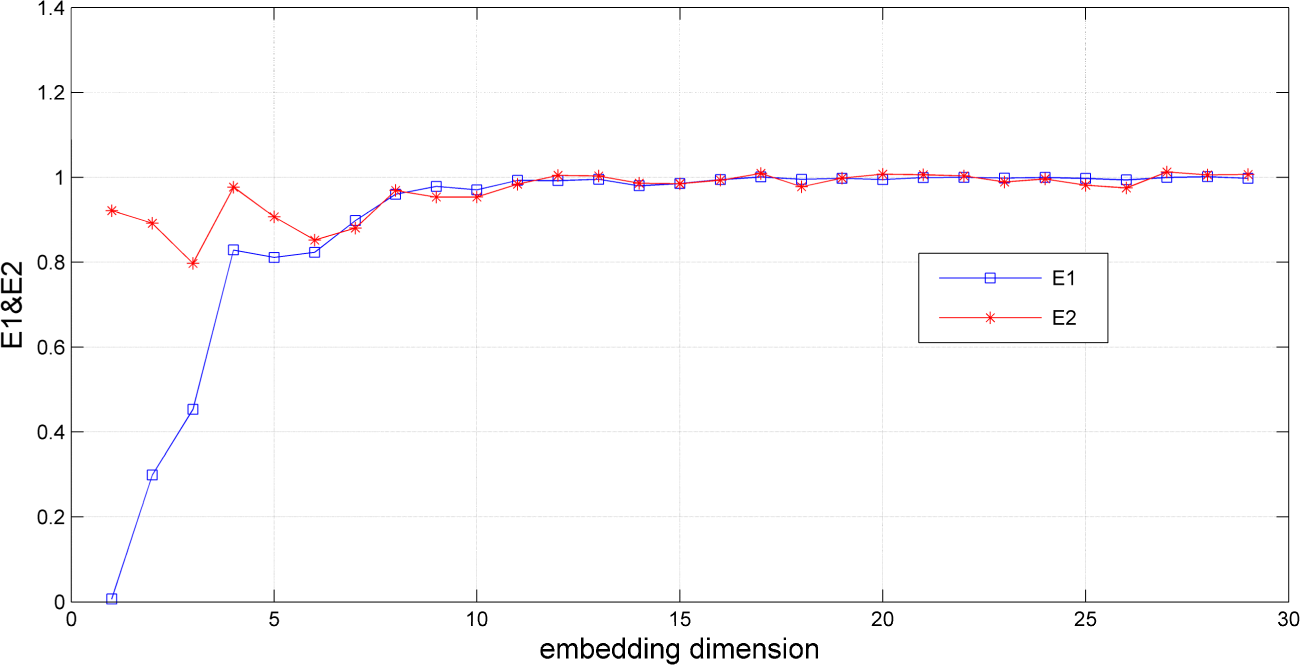
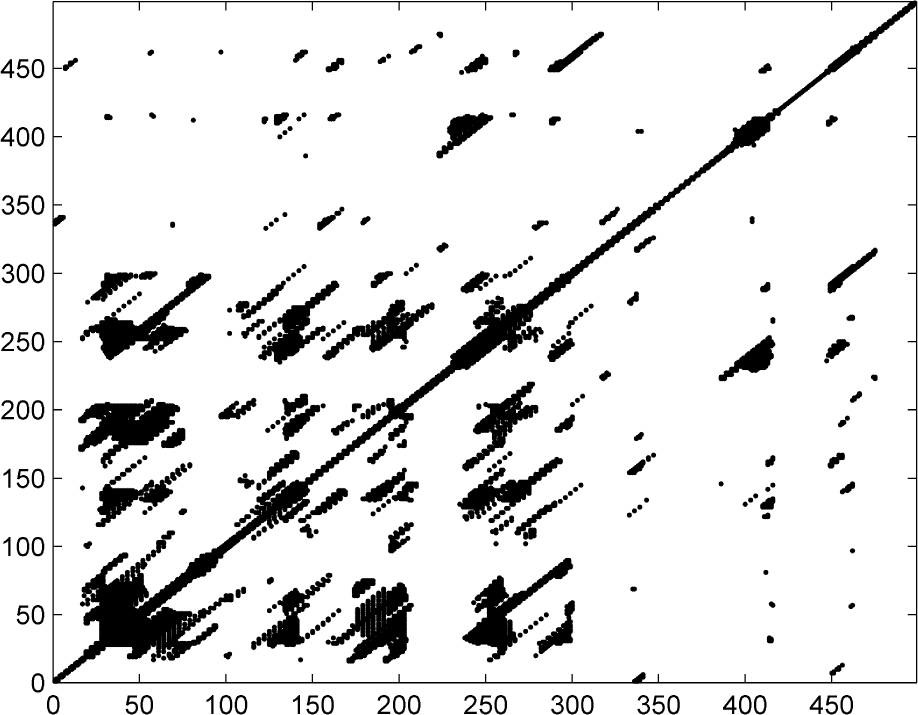
Analysis of the characteristics of agricultural product price volatility and trend forecasting are necessary to formulate and implement agricultural price control policies. Taking wholesale cabbage prices as an example, a multiple test methodology has been adopted to identify the nonlinearity, fractality, and chaos of the data. The approaches used include the R/S analysis, the BDS test, the power spectra, the recurrence plot, the largest Lyapunov exponent, the Kolmogorov entropy, and the correlation dimension. The results show that there is chaos in agricultural wholesale price data, which provides a good theoretical basis for selecting reasonable forecasting models as prediction techniques based on chaos theory can be applied to forecasting agricultural prices.
Keywords: agricultural product wholesale price; time series; chaos; multiple test methodology; selection of forecasting model agricultural product wholesale price; time series; chaos; multiple test methodology; selection of forecasting model