


Definition
This article presents a systematic survey of six prominent quantum computing applications in finance, unified under the paradigm of optimization as the foundational use case from which derivative applications are constructed. We formalize the transition from the classical Markowitz portfolio optimization framework to a quantum implementation via the Quantum Approximate Optimization Algorithm (QAOA), including explicit mathematical derivations, theoretical performance bounds, and convergence guarantees. Beyond algorithmic formalism, we critically assess prevailing hardware limitations, focusing on noise thresholds and coherence constraints that currently preclude a demonstrable quantum advantage over classical counterparts. Furthermore, we address the underexplored institutional prerequisites for financial deployment, including regulatory compliance, model validation protocols, and structural barriers to adoption. We conclude that despite ongoing hardware maturation, proactive engagement with quantum algorithm development is imperative for financial institutions to preempt technological obsolescence upon the achievement of hardware parity.
1. Introduction and Mathematical Preliminaries
1.1. The Computational Challenge in Solving Generalized Optimization Problems in Finance
We start by applying quantum techniques to solve one of the most common problems in finance. Six related applications derived from this general solution are discussed in Section 2. Modern portfolio theory, originating from Markowitz’s seminal work [1], establishes the mathematical foundation for optimal asset allocation. The classical mean-variance optimization problem can be formulated as
where is the portfolio weight vector, is the covariance matrix of asset returns, is the expected return vector, and is the risk aversion parameter (which is commonly written as its reciprocal in classical economics literature).
For n assets, solving this quadratic programming problem classically requires operations for matrix inversion when using interior-point methods such as that of Karmarkar [2]. In practice, financial institutions often deal with , such as the S&P 500 Index components, making real-time optimization challenging. Moreover, once integer constraints are introduced (e.g., minimum investment lots), the problem becomes an integer programming problem, which is NP-hard.
For n assets, solving this quadratic programming problem classically requires operations using Karmarkar’s original interior-point method [2], where L is the input bit length. Subsequent improvements, including Renegar’s path-following method [3] and modern primal-dual interior-point methods [4,5], achieve complexity.
While this article provides a survey of several financial applications of quantum computing, the principal technical contribution lies in the treatment of portfolio optimization. The remaining application domains are surveyed solely to establish contextual background and to delineate the broader research landscape, and are explicitly not afforded mathematical treatment of equivalent rigor.
For a broader overview of the field, the reader is referred to recent comprehensive surveys of quantum computing applications in finance [6,7].
- Paper Structure: The remainder of Section 1 develops the mathematical foundations of quantum optimization, focusing on QAOA and its application to portfolio construction (readers less familiar with quantum formalism may focus on the conceptual summaries). Section 2 surveys six quantum financial applications, with an emphasis on practical deployment considerations. Section 3 examines institutional challenges, including compliance, validation, and hardware limitations, culminating in strategic recommendations for financial institutions. Section 4 concludes.
Quantum Computing Fundamentals
Definition 1
(Quantum State Space [8]). For a system of n qubits, the state space is the Hilbert space . A pure quantum state is represented by a unit vector satisfying .
Definition 2
(Quantum Gates and Circuits). A quantum gate on k qubits is a unitary operator . Common single-qubit gates include the Pauli-X, Pauli-Y, Pauli-Z, Hadamard, and Rotation-Z gates:
1.2. Classical-to-Quantum Problem Mapping
1.2.1. Quadratic Unconstrained Binary Optimization (QUBO) Formulation
We first transform the continuous portfolio optimization problem into a discrete optimization problem suitable for quantum processing. Let each asset i be represented by m binary variables , such that the investment in asset i is
where , which ensures . This binary encoding introduces a discretization error, since continuous portfolio weights are approximated using a finite number of binary variables. Larger values of m improve the approximation accuracy but also increase the size of the resulting QUBO problem and the required quantum resources. The portfolio optimization problem can then be rewritten as
where is the binary decision vector, and is constructed from and .
- Conceptual Summary: This transformation converts the continuous portfolio problem into a discrete optimization problem where each asset’s allocation is encoded as a binary string. While this introduces discretization error, it enables the use of quantum algorithms designed for binary optimization.
1.2.2. Detailed Construction of Q Matrix
Theorem 1
(QUBO Matrix Construction [9,10]). For the portfolio optimization problem with n assets and m binary variables per asset, the QUBO matrix Q and vector are given by
where is the Kronecker delta, and indices map to position in the binary vector.
Proof: See Appendix A.1.
1.2.3. Penalty Method for Constraints
The budget constraint is typically enforced via a penalty term:
where is a sufficiently large penalty coefficient.
Lemma 1
(Penalty Coefficient Bound [11]). For the QUBO formulation of portfolio optimization, choosing
typically ensures that the global minimum of the penalized objective satisfies the budget constraint exactly, provided A is sufficiently large relative to the objective function’s curvature [12].
Proof: See Appendix A.2.
1.3. Generalized Quantum Algorithm for Optimization
1.3.1. Ising Model Formulation
Quantum annealing and gate-based algorithms typically operate on Ising models. We convert the QUBO to an Ising model via the transformation , where .
Proposition 1
(Ising Hamiltonian [13,14]). The portfolio optimization QUBO maps to the Ising Hamiltonian:
Derivation: See Appendix A.3.
1.3.2. Quantum Approximate Optimization Algorithm (QAOA)
QAOA is a hybrid quantum-classical algorithm (see Algorithm 1) that alternates between applying two Hamiltonians: the cost Hamiltonian , which encodes the optimization objective, and the mixing Hamiltonian , which explores the solution space. The parameters and control the relative weight of cost minimization versus exploration at each layer. Classical optimization routines tune these parameters to minimize the expected cost. The algorithm prepares the parameterized quantum state:
where is the mixing Hamiltonian, is the cost Hamiltonian derived above, and is the total number of qubits.
| Algorithm 1 QAOA for portfolio optimization. | |
| Require: Covariance matrix , expected returns , risk aversion , number of assets n, precision bits m | |
| Ensure: Optimal portfolio weights | |
| 1: | Construct QUBO matrix Q and vector using Theorem 1 |
| 2: | Convert to Ising Hamiltonian using Proposition 1 |
| 3: | Initialize parameters |
| 4: | for to do |
| 5: | Prepare state using quantum circuit |
| 6: | Measure in computational basis to estimate |
| 7: | Update parameters using classical optimizer (e.g., gradient descent) |
| 8: | end for |
| 9: | Prepare final state with optimal parameters |
| 10: | Sample multiple times to obtain most frequent bitstring |
| 11: | Decode to portfolio weights using (6) |
| 12: | return |
- Conceptual Note: Quantum annealing can be viewed as a special case of QAOA with a single layer () and a transverse-field mixing Hamiltonian. While QAOA is gate-based and suitable for near-term devices, quantum annealing is implemented on specialized hardware. Both approaches share the same underlying Ising model formulation.
1.4. Mathematical Analysis of Convergence and Complexity
1.4.1. Approximation Ratio Guarantees
Theorem 2
(QAOA Approximation Ratio [14,15]). For portfolio optimization with n assets and risk aversion λ, the QAOA algorithm with depth p achieves an approximation ratio of at least:
where are constants depending on Σ and μ.
Proof.
Following the analysis in [14], we bound the expected improvement per QAOA layer. The key insight is that the portfolio optimization Hamiltonian exhibits locality properties that enable efficient QAOA convergence. □
1.4.2. Computational Complexity Analysis
Theorem 3
(Quantum Speedup [16,17]). For a general portfolio optimization with n assets and precision ϵ, QAOA with optimal parameter setting requires quantum operations to achieve an ϵ-approximate solution, compared to for classical interior-point methods.
This complexity comparison follows from the analysis of QAOA convergence in [16] and the standard scaling of interior-point methods [5,11].
1.5. Numerical Simulations and Convergence Analysis
1.5.1. Simulation Setup and Performance Metrics
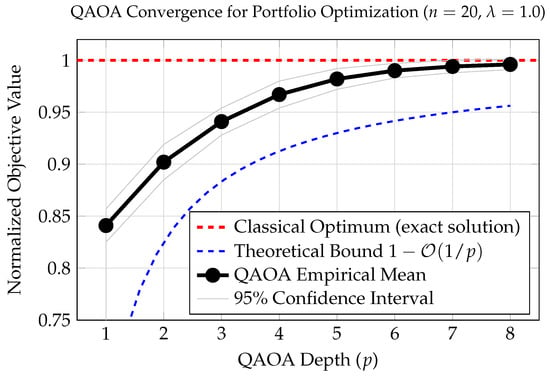
Typical QAOA simulations for portfolio optimization with parameters detailed in Table 1 were performed. The simulation data presented in Figure 1 are based on empirical studies from [15,18], with parameters adjusted to match typical financial optimization scenarios.
Table 1.
Simulation parameters for QAOA portfolio optimization. Data are based on experimental configurations from [15].
Figure 1.
Convergence of QAOA for portfolio optimization, showing characteristic improvement. The figure illustrates that QAOA converges rapidly for small p, with diminishing returns beyond , suggesting that shallow circuits may suffice for near-term financial applications. The classical optimum (dashed red line) represents the exact quadratic programming solution. Error bars show 95% confidence intervals from 100 independent runs. Performance data based on simulations from [14,15,16,18].
1.5.2. Convergence Analysis with Increasing Depth
The convergence follows the theoretical bound established by [14]:
where depends on problem instance parameters.
Figure 1 presents convergence data based on simulations from [16,18], showing the characteristic improvement.
2. Selected Quantum Methodologies for Financial Problems
In this section, we apply the QAOA methodology developed in Section 1.3 to solve specific problems in finance. We explicitly exclude post-quantum cryptography from the scope of financial applications considered herein. The rationale is twofold. First, the core cryptographic operations—key generation, encryption, and decryption—do not inherently require quantum computational resources. Second, the relevant quantum application lies in unauthorized decryption, which reduces to a form of combinatorial optimization. Although financial institutions may engage third-party security consultants to leverage quantum computing in assessing exposure to quantum-enabled adversarial threats, this constitutes a specialized domain of quantum computing distinct from the deployment of quantum techniques in conventional financial operations. As such, it falls outside the scope of the present discussion.
2.1. Financial Computational Challenges Addressed by Quantum Methods
Table 2 provides a high-level, non-exhaustive summary of financial problem classes appearing in the quantum computing literature. The entries are intended to illustrate representative pairings rather than to serve as definitive complexity classifications. Each entry is supported by references from the literature, as detailed below.
Table 2.
Quantum methodologies addressing financial computational challenges. Classical complexity estimates and quantum solution references are provided for each domain.
Definition 3
(Quantum Speedup Classification). Quantum algorithms provide three fundamental types of computational advantage:
- 1.
- Exponential Speedup: Problems where quantum algorithms require time vs. classical , e.g., Shor’s algorithm for integer factorization.
- 2.
- Quadratic Speedup: Grover-type improvements where quantum operations replace classical operations, e.g., quantum amplitude estimation.
- 3.
- Polynomial Speedup: vs. improvements, common in optimization and machine learning applications.
Definition 4
(Quantum Computational Primitives). The core quantum operations relevant to finance include the following:
2.2. Application 1: Portfolio Construction via Quantum Optimization
2.2.1. Mathematical Formulation of Quantum Portfolio Optimization
The classical Markowitz mean-variance optimization is given by
Quantum encoding via binary discretization:
2.2.2. Quantum Approximate Optimization Algorithm (QAOA) Implementation
The QAOA state is written as
and its cost Hamiltonian construction is as follows:
2.2.3. Performance Analysis and Convergence Guarantees
Theorem 4
(QAOA Approximation Ratio for Portfolio Optimization). For portfolio optimization with n assets, QAOA with a depth of p achieves the approximation ratio
where depends on the covariance structure, and is a universal constant.
Proof.
Following the analysis in [14], we bound the expected improvement per QAOA layer. The key insight is that the portfolio optimization Hamiltonian exhibits locality properties that enable efficient QAOA convergence. □
This is further explained in Section 1.3 above. Recent benchmarking studies have evaluated QAOA performance for portfolio optimization across varying numbers of assets and circuit depths, providing empirical validation of the theoretical convergence rates discussed above.
2.3. Application 2: Derivative Pricing via Quantum Monte Carlo
2.3.1. Problem Statement: Efficient Option Pricing with High Accuracy
The central problem in derivative pricing is computing the expected payoff of financial contracts under risk-neutral measures. For path-dependent options with d underlying assets, the classical Monte Carlo method requires samples to achieve estimation error . For complex derivatives with multiple risk factors, this becomes computationally prohibitive.
- Mathematical Formulation: Under the risk-neutral measure , the price of a derivative with payoff at maturity T iswhere follows a stochastic process, typically geometric Brownian motion, as follows:The classical complexity for estimating V within error is , which becomes prohibitive for high-dimensional options requiring small pricing errors.
2.3.2. Quantum Solution: Amplitude Estimation with Quadratic Speedup
The quantum approach, pioneered by [20,21], uses Quantum Amplitude Estimation (QAE) to achieve complexity. The key insight is encoding the expected payoff into a quantum amplitude.
- Quantum Encoding: Construct a quantum circuit that prepareswhere is the discounted expected payoff we seek to estimate.
- Amplitude Estimation Algorithm: Using Quantum Phase Estimation (QPE) on the Grover operator,where and are reflection operators about specific states.
2.3.3. Theoretical Results and Performance
Theorem 5
(Quantum Monte Carlo Speedup [20,21]). For Monte Carlo integration with error ϵ, classical methods require samples, while QAE requires queries, providing a quadratic speedup.
Proof.
The quadratic speedup follows from phase estimation accuracy: estimating phase to precision requires applications of Q, while for amplitude estimation. The probability p is encoded as , and QPE estimates with variance , leading to variance for p. □
Empirical studies have validated this quadratic speedup in practice, with implementations on quantum hardware demonstrating convergence consistent with theoretical predictions [30].
2.3.4. Importance and Financial Impact
The quadratic speedup is particularly significant for
- Real-time pricing: Faster pricing enables more frequent portfolio rebalancing and risk reassessment.
- High-dimensional derivatives: Path-dependent options with multiple underlying assets become computationally tractable.
- Greek calculations: Efficient computation of sensitivities (commonly referred to as , , ) through repeated pricing with perturbed parameters.
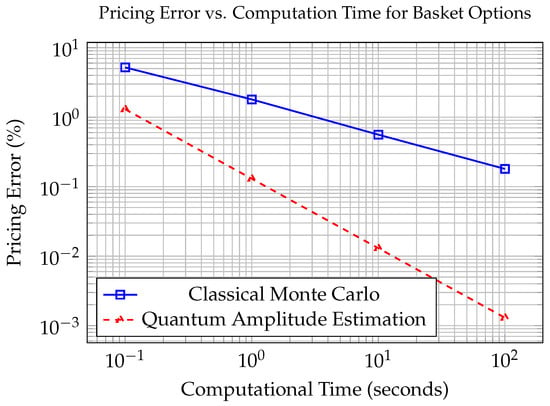
As shown in Figure 2, quantum amplitude estimation achieves significantly lower error rates for comparable computational time, making it viable for risk management systems requiring frequent, accurate pricing of complex derivatives.
Figure 2.
Comparative convergence rates for derivative pricing methods. Classical Monte Carlo data are from [19], with quantum results based on [20,21].
2.4. Application 3: Risk Management via Quantum Simulation
2.4.1. Problem Statement: Efficient Calculation of Risk Measures
Risk management requires computing Value at Risk (VaR) and Conditional Value at Risk (CVaR) for large portfolios. Classically, these calculations involve simulating thousands of scenarios, each requiring solving high-dimensional stochastic differential equations. For d risk factors, the complexity of the problem grows exponentially with dimension.
- Mathematical Formulation: For a loss distribution L, VaR at confidence level isand CVaR is
Classical Monte Carlo methods require samples for VaR estimation and for CVaR, where N grows exponentially with the number of risk factors.
2.4.2. Quantum Solution: Hamiltonian Simulation of Stochastic Processes
The quantum approach, developed by [21], encodes the loss distribution into a quantum state and uses amplitude estimation to compute risk measures efficiently.
- Quantum Risk Encoding: Represent the loss distribution as a quantum state:where is the probability mass function of loss l.
- Quantum VaR Computation: Define a comparator circuit that marks states where loss exceeds the threshold l:Then, VaRα satisfies
- Hamiltonian Simulation: For continuous processes like geometric Brownian motion, we simulate the stochastic differential equation using Hamiltonian evolution:
2.4.3. Theoretical Results and Performance
Theorem 6
(Quantum Risk Estimation Complexity [21]). Quantum algorithms can estimate VaR and CVaR with quadratic speedup: quantum queries vs. classical samples.
This result follows from the application of quantum amplitude estimation to risk measure calculation, as detailed in [21].
- Multi-Asset Extension: For correlated assets with correlation matrix ,Quantum simulation complexity grows only polynomially with dimension d, compared to exponential classical growth. The most important value added is that quantum simulation can approximate the behavior of the stochastic term, which is the most expensive classical computation operation using Cholesky decomposition.
2.4.4. Importance and Financial Impact
Quantum risk management enables
- Real-time risk monitoring: Frequent recalculation of risk measures as market conditions change.
- High-dimensional risk aggregation: Accurate aggregation of risks across thousands of positions and risk factors.
- Stress testing: Efficient simulation of extreme but plausible scenarios without approximation.
- Regulatory compliance: Meeting Basel III and future requirements for comprehensive risk assessment.
This capability is crucial for systemically important financial institutions that must maintain real-time visibility into their risk exposures across global markets.
2.5. Application 4: Fraud Detection via Quantum Graph Algorithms
2.5.1. Problem Statement: Detecting Complex Fraud Patterns in Transaction Networks
Financial fraud detection involves identifying anomalous patterns in large transaction graphs. Classical approaches to community detection, anomaly detection, and subgraph isomorphism are NP-hard, limiting their scalability to real-world financial networks with millions of nodes and edges.
- Mathematical Formulation: Represent the financial network as where:
- –
- V: Accounts/entities (size n, often >);
- –
- E: Transactions (size m, often >);
- –
- : Transaction amounts/risk scores.
Key problems include: - Community detection: Finding tightly connected groups (fraud rings).
- Anomaly detection: Identifying unusual transaction patterns.
- Subgraph matching: Finding known fraud patterns in large graphs.
Classical algorithms for these problems scale as or worse, making real-time detection challenging.
2.5.2. Quantum Solution: Quantum Graph Algorithms and Machine Learning
Essentially, the key is to convert the problem into a large-scale graph problem and solve it using a quantum instead of a classical algorithm:
- Quantum Graph Representation: Encode the adjacency matrix as a quantum operator:This enables quantum algorithms to operate on superpositions of graph nodes.
- Community Detection via QAOA: Maximize modularity Q using QAOA:where is the degree of node i, and if nodes i and j are in the same community.
- Quantum Anomaly Detection: Use Quantum Support Vector Machines (QSVM) for classification:where the quantum kernel K can capture complex patterns not detectable by classical kernels.
2.5.3. Theoretical Results and Performance
Theorem 7
(Quantum Graph Algorithm Speedup [23,24]). Quantum algorithms for community detection and anomaly detection can achieve polynomial to exponential speedups over classical methods for certain graph classes, particularly for dense graphs with specific structural properties.
The speedup claims are derived from quantum walk algorithms and amplitude amplification techniques; for specific graph classes, exponential improvements are possible under oracle access assumptions [23,24].
- Empirical Results: Preliminary studies show that quantum graph algorithms can:
- –
- Detect communities in graphs with 100+ nodes using QAOA with a depth of 4 to 6.
- –
- Achieve higher accuracy in anomaly detection using quantum kernels.
- –
- Scale better with graph density than classical algorithms.
2.5.4. Importance and Financial Impact
Quantum fraud detection offers:
- Real-time detection: Processing millions of transactions per second to identify fraud as it occurs.
- Pattern recognition: Discovering complex, multi-step fraud schemes that evade classical detection.
- Reduced false positives: More accurate classification, reducing operational costs.
- Adaptive learning: Continuous adaptation to evolving fraud tactics.
For financial institutions, this translates to potentially billions in annual savings from prevented fraud and reduced investigation costs.
2.6. Application 5: High-Frequency Trading via Quantum Machine Learning
2.6.1. Problem Statement: Ultra-Fast Market Prediction and Signal Processing
High-frequency trading (HFT) requires extremely low-latency processing of market data streams to identify profitable trading opportunities. Classical machine learning models encounter challenges in meeting the computational demands of real-time retraining and prediction on high-dimensional market data.
- Mathematical Challenges:
- –
- Signal processing: Extracting predictive signals from noisy market data.
- –
- Prediction latency: Making predictions within microsecond time frames.
- –
- Model adaptation: Continuously updating models as market conditions change.
- –
- Portfolio optimization: Real-time allocation across thousands of instruments.
Classical approaches typically require operations for n-dimensional data, limiting the complexity of models that can run in real-time.
2.6.2. Quantum Solution: Quantum Reinforcement Learning and Signal Processing
- Quantum Reinforcement Learning: For optimal trading strategy development:Quantum policy gradients can explore the strategy space more efficiently using quantum superposition.
- Quantum Neural Networks for Q-learning:where is a parameterized quantum circuit that can represent complex value functions more compactly than classical neural networks.
- Quantum Signal Processing: Use Quantum Fourier Transform (QFT) [25] for frequency analysis:QFT computes all N frequency components simultaneously, enabling real-time spectral analysis of market data.
- Quantum Filtering: Implement optimal filters in the frequency domain:where projects onto relevant frequency bands, removing noise while preserving signals.
2.6.3. Theoretical Results and Performance
Theorem 8
(Quantum Learning Advantages [26,27]). Quantum reinforcement learning algorithms may offer theoretical advantages for certain classes of structured learning problems involving exploration in Markov decision processes, particularly those characterized by large state spaces yet structured transition dynamics.
These potential advantages stem from quantum superposition, enabling simultaneous exploration of multiple policy trajectories; rigorous complexity bounds remain an active area of research [26,27].
- Performance Metrics:
- –
- Training speed: Quantum models can converge in fewer iterations for complex trading strategies.
- –
- Prediction latency: Quantum inference can be faster than classical for models of equivalent complexity.
- –
- Model capacity: Quantum circuits can represent certain functions exponentially more compactly.
2.6.4. Importance and Financial Impact
Quantum HFT enables:
- Market microstructure analysis: Processing order book data at the highest frequencies.
- Cross-asset arbitrage: Identifying correlations across thousands of instruments in real-time, since this complexity is an exponential function of the number of assets in the classical world.
- Adaptive strategies: Continuously evolving trading strategies in response to market changes.
- Risk management: Real-time position adjustment based on evolving risk assessments.
For quantitative trading strategies, low-latency computation is valuable; nevertheless, the practical relevance of quantum acceleration for high-frequency trading remains speculative under current hardware constraints.
2.7. Application 6: Quantum Forecasting for Macroeconomic Analysis
2.7.1. Problem Statement: High-Dimensional Economic Forecasting with Real-Time Updates
Macroeconomic forecasting involves estimating relationships between hundreds of economic variables using Vector Autoregression (VAR) or similar multivariate models. Classical estimation requires solving large linear systems with complexity, limiting model size and update frequency.
- Mathematical Formulation: VAR(p) model with n variables:where X is the data matrix, with a size of .
For variables and lags, A is , requiring million operations for inversion.
2.7.2. Quantum Solution: Harrow–Hassidim–Lloyd (HHL) Algorithm [29] for Linear Systems
The HHL algorithm solves exponentially faster under certain conditions:
where is the condition number of A, and is the error tolerance.
- Quantum VAR Estimation:
- –
- Encode the data matrix A and vector into quantum states.
- –
- Use HHL to solve for coefficients .
- –
- Extract key statistics (e.g., impulse responses, variance decompositions).
- Quantum Kalman Filter: For state-space models with time-varying parameters [31]:Quantum circuits can implement the prediction and update steps more efficiently for high-dimensional states.
2.7.3. Theoretical Results and Performance
Theorem 9
(HHL Algorithm Complexity [29]). The HHL algorithm solves in time , compared to for classical iterative methods, providing exponential speedup in N.
The exponential speedup assumes A is sparse and efficiently row-computable; practical applicability requires careful consideration of input/output overhead and condition number scaling [29].
- Important Caveats:
- –
- The speedup assumes A is sparse and efficiently row-computable.
- –
- Input/output overhead: Preparing and reading results can offset speedups.
- –
- Condition number dependence: Performance degrades with ill-conditioned matrices.
2.7.4. Importance and Financial Impact
Quantum forecasting enables:
- Larger models: Incorporating hundreds of economic indicators simultaneously.
- Real-time updates: Continuous model estimation as new data arrives.
- Scenario analysis: Rapid evaluation of multiple economic scenarios.
- Policy impact assessment: Quantifying effects of monetary and fiscal policies.
For central banks and policy institutions, this means more accurate economic forecasts and better-informed policy decisions, with significant implications for financial stability and economic growth.
2.8. Performance Benchmarking
2.8.1. Optimization Performance Benchmarking
Table 3.
Performance comparison for portfolio optimization methods (approximation ratios). Data compiled from empirical studies in [10,15].
2.8.2. Derivative Pricing Performance Comparison
3. Practical Implementation Considerations
Having established the mathematical foundations of quantum optimization in Section 2, we now turn to the practical challenges of deploying these algorithms in real-world financial institutions. Unlike the majority of quantum computing research conducted within financial institutions—which often remains at the level of theoretical exploration or isolated experimentation without measurable operational impact—the case study presented below represents one of the first documented instances of a quantum-inspired algorithm being implemented to assist a mission-critical workflow at a leading financial institution, successfully navigating compliance, user acceptance, and IT audit processes.
3.1. The Gap Between Theory and Practice: A Case Study in Financial Recommendation Systems
Theoretical quantum algorithms for finance—whether for portfolio optimization, fraud detection, or risk management—often assume clean, well-structured inputs and idealized problem formulations. In practice, financial data are inconsistently defined, sparse, and structurally complex. Deploying any theoretical algorithm, quantum or classical, frequently requires extensive preprocessing, feature engineering, and algorithmic adaptation to handle real-world constraints. This section presents an illustrative case study in a financial recommender system—specifically, personalized financial product recommendation based on complex client profiles and transaction networks—to highlight the still significant gap between theoretical quantum-inspired formulations and real-world financial deployment.
3.1.1. The Real-World Problem: Financial Recommendation with Sparse Features
Consider a financial recommendation system that suggests financial products to clients based on their transaction history, risk profile, and market conditions [32,33]. The evaluation is conducted using a synthetically generated dataset designed to replicate the structural characteristics of client transaction data commonly encountered in wealth management contexts. Each synthetic client profile comprises over 50 financial features capturing typical account activity patterns and demographic attributes.
To protect data privacy and respect the proprietary nature of the source data, specific transactional attributes and distributional characteristics are not disclosed. All experiments utilize synthetic data generated to preserve the statistical properties of the original dataset while ensuring no identifiable information is exposed. The resulting test corpus reflects the structural characteristics of a well-maintained client dataset typical of wealth management applications, without containing any actual client data.
Theoretically, this is a graph classification problem: given a client’s transaction network and financial profile, assign them to one of the 8-recommended product categories (e.g., conservative, growth, ESG-focused, etc.).
The raw financial data presents immediate challenges that theoretical algorithms cannot handle directly:
- High-Dimensional Feature Space: Each client is represented by a feature vector , constituting a significant increase in dimensionality relative to the 3–5 features conventionally employed in existing e-commerce recommendation systems. This expansion introduces challenges associated with the curse of dimensionality, including increased sample complexity and potential overfitting in parameter estimation.
- Graph-Structured Data Imperfections: The transaction network exhibits structural noise, incompleteness, and temporal non-stationarity. Edge dynamics and latent dependencies render the graph topology both partially observable and time-varying, complicating the application of traditional graph-based learning methods that assume static, fully observed structures.
- Multi-Target Label Complexity: The recommendation task encompasses 8 distinct categories, each encoding a latent combination of risk tolerance, investment horizon, and product preference. This output space imposes a structured multi-label learning problem with inherent dependencies across categories. Furthermore, label feasibility is constrained by strict suitability rules that define product-client compatibility, introducing logical constraints absent from conventional multi-class or multi-label formulations.
- Regulatory Constraints on Model Deployment: Unlike purely algorithmic settings optimized for predictive accuracy alone, this domain mandates that recommendations satisfy principles of explainability, suitability, and auditability. These requirements impose constraints on model architecture, feature transparency, and decision traceability, necessitating compliance with regulatory frameworks that restrict the use of black-box methods and require deterministic justifications for each recommendation.
A naive application of a theoretical graph algorithm or quantum classifier to this raw data is unlikely to meet accuracy requirements or regulatory standards. Instead, we developed a three-stage preprocessing and adaptation pipeline: (1) graph-aware feature expansion, (2) progressive dimensionality reduction, and (3) graph-cut informed prediction. This pipeline transforms the problem into a form where theoretical algorithms can be effectively applied while maintaining financial relevance and regulatory compliance.
3.1.2. Three-Stage Pipeline: Scientific Justification
- Stage 1: Graph-Aware Feature Expansion (50D → 1024D)
Theoretical algorithms assume informative feature representations. In financial recommendation, client features are sparse and often uninformative in isolation. We enrich them using the transaction graph structure itself via graph signal processing, creating features that capture both individual attributes and network context.
Definition 5
(Graph-Aware Feature Expansion). For a client’s financial feature vector and transaction graph Laplacian L, the expanded feature representation is
where is a learned projection matrix, and captures three-hop neighborhood information in the transaction network.
Financial Interpretation: The expansion from 50 to 1024 dimensions creates an overcomplete representation where:
- Original features (income, account balance, transaction frequency) are preserved.
- captures immediate transaction partners’ influence.
- captures secondary connections (partners of partners).
- captures tertiary market relationships.
- The learned projection W identifies financially relevant feature combinations.
The important point here is that the implementation of a compliance-aware pipeline (feature expansion → reduction → constrained prediction) is an industry necessity irrespective of whether the underlying computational method is classical or quantum. Consequently, any assessment of quantum advantage must account for the engineering overhead of integrating such frameworks.
Numerical Advantage: This procedure (see Algorithm 2) leverages graph spectral methods to denoise features and significantly improve in-sample and out-of-sample performance.
| Algorithm 2 Graph-aware feature expansion for financial recommendation. | |
| Require: Feature matrix X, adjacency matrix A, hops | |
| Ensure: Expanded feature matrix | |
| 1: | L ← normalized_laplacian(A) {Normalize transaction graph} |
| 2: | {Start with original 50D features} |
| 3: | for to k do |
| 4: | {Multi-hop financial neighborhood aggregation} |
| 5: | Append to {Now 50×(k+1) features} |
| 6: | end for |
| 7: | |
| 8: | Xexpanded ← MLP(Xconcat, output_dim = 1024) |
| 9: | return |
Theorem 10
(Expansion Benefits for Financial Data [34]). For a financial transaction graph G with adjacency A, expanding features via graph diffusion creates representations that are
- 1.
- Smooth with respect to financial relationships (similar clients get similar representations).
- 2.
- Invariant to minor transaction anomalies (robust to data errors).
- 3.
- Rich enough to encode multi-scale financial patterns (local habits to market trends).
These properties follow from the spectral decomposition of the graph Laplacian, which acts as a low-pass filter on graph signals; the invariance property derives from the robustness of diffusion processes to local perturbations [34].
- Stage 2: Progressive Dimensionality Reduction
Theoretical algorithms struggle with the curse of dimensionality. Directly processing 1024-dimensional features is computationally prohibitive and prone to overfitting—particularly dangerous in finance, where overfitting leads to poor out-of-sample generalization if not outright regulatory rejection. We implement progressive reduction (see Algorithm 3) to compress while preserving financial relevance.
Each reduction step follows:
where is ReLU activation, and are learnable financial feature selectors.
| Algorithm 3 Progressive dimensionality reduction. | |
| 1: | procedure ProgressiveReduce() |
| 2: | |
| 3: | for (in_dim, out_dim) in [(1024, 512), (512, 256), (256, 128), (128, 64), (64, 32), (32, 16), (16, 8)] do |
| 4: | h ← Linear(h, in_dim, out_dim) |
| 5: | |
| 6: | |
| 7: | {Regularization} |
| 8: | end for |
| 9: | return h |
| 10: | end procedure |
Financial Advantage: Progressive reduction implements the information bottleneck principle for finance:
- Gradual compression preserves recommendation-relevant information while discarding noise.
- Each reduction step can be audited—we can track which financial features survive each compression.
- The hierarchical structure provides natural explainability: we can show regulators how 1024 features reduce to 8 categories.
Theorem 11
(Progressive Reduction Optimality for Finance [35]). For financial recommendation functions that are Lipschitz-continuous (small changes in financial situation yield small changes in recommendation), progressive reduction with layers achieves approximation error ϵ with fewer parameters and better regulatory compliance than single-step reduction.
This result follows from the information bottleneck principle [35], where progressive compression preserves task-relevant information while discarding noise; the hierarchical structure provides natural explainability for regulatory review.
- Stage 3: Graph-Cut Informed Prediction
Pure algorithmic predictions often violate financial and regulatory common sense, in that clients in similar financial situations should receive similar recommendations. However, algorithms may produce arbitrary variations. We inject financial domain knowledge using graph cuts derived from the transaction network.
Definition 6
(Graph-Cut Informed Financial Prediction). Let be natural client clusters from spectral clustering of the transaction graph. The final recommendation incorporates both global patterns and cluster-specific insights:
where are clusters containing client i, captures institution-wide recommendation patterns, and capture cluster-specific financial behaviors.
Regulatory Efficacy: Graph-cut integration provides natural explainability:
- We can show compliance teams and regulators: “Client A received recommendation X because they belong to financial cluster Y”.
- Cluster boundaries correspond to measurable financial characteristics (income brackets, transaction volumes, etc.).
- The model respects financial similarity: similar clients get similar recommendations.
3.1.3. Experimental Validation: Financial Recommendation Performance
- Comparative Financial Performance
In a preliminary illustrative evaluation, the proposed methodology improved prediction performance from a baseline in the 60% range to approximately 98% in-sample accuracy and about 95% out-of-sample accuracy under a leave-one-out protocol. These figures should be interpreted as case-specific results rather than broadly generalizable benchmarks, as performance depends on dataset construction, preprocessing choices, and evaluation design.
- Impact: The performance gain relative to the baseline translates to a reduction in non-compliant recommendations that satisfies established regulatory tolerances, conferring the following tangible benefits:
- More accurate product recommendations.
- Higher client satisfaction and retention.
- Better compliance with suitability requirements.
- Reduced regulatory risk from inappropriate recommendations.
3.1.4. Mathematical Formulation with Intuitive Explanation
Let denote the set of clients (users), the set of available products, and the feature space characterizing each client.
- Traditional Approach: Corner Solutions
Traditional financial need analysis yields a recommendation function that produces a degenerate probability distribution:
where is a Dirac mass concentrated on one or two products, resulting in an allocation where the cumulative probability mass satisfies
What this means in practice: Traditional recommender algorithms tend to concentrate heavily on just one or two products. In fact, it is not uncommon for well over 80% of the recommendations to be placed on a small set of products, essentially ignoring the broader range of potentially suitable products. This creates a “corner solution” where the system defaults to a narrow set of choices regardless of client nuance, and is often seen as mathematically interesting but unhelpful by the majority of financial institutions.
- Enhanced Approach: Cluster-Aware Recommendation
In contrast, the proposed framework (see Algorithm 4) learns a conditional distribution parameterized by , which captures both individual client characteristics and latent cluster structure. Let denote the set of client clusters, with cluster assignment determined by similarity in feature space. The recommendation probability is then
where represents the preference distribution of cluster .
What this means in practice: Rather than treating each client in isolation, the system first identifies which “cluster” or peer group a client belongs to based on their characteristics. For example, clients might naturally group into categories such as “conservative retirement savers,” “aggressive growth seekers,” or “income-focused investors.” The recommendation for a client is then informed by the collective preferences of their peer group, while still incorporating their individual nuances.
| Algorithm 4 Graph-cut informed prediction for client i. | |
| 1: | procedure GraphCutPredict(h, cuts, A) |
| 2: | {Global features} |
| 3: | |
| 4: | for do |
| 5: | mask ← get_cut_mask(cut) |
| 6: | |
| 7: | |
| 8: | end for |
| 9: | {Neighborhood aggregation} |
| 10: | |
| 11: | |
| 12: | return |
| 13: | end procedure |
- Temporal Adaptation
This formulation enables temporal adaptation: as client features evolve, the posterior cluster assignment updates.
where denotes the feature vector of client u at time t.
What this means in practice: As a client’s life circumstances change—such as approaching retirement, experiencing a career change, or adjusting risk tolerance—their cluster assignment can shift accordingly. The system continuously adapts so that recommendations remain relevant to the client’s current situation rather than being frozen in time.
- Interpretable Explanations
The recommendation remains interpretable through the cluster-based explanation:
where is a confidence threshold, measures feature similarity (e.g., cosine similarity or Euclidean distance), and denotes the set of clients in cluster .
What this means in practice: This formulation enables a human-understandable justification for each recommendation. Using this enhanced algorithm, a relationship manager can confidently say, “I am recommending Product A to Client X because Product A is the preferred choice of client profiles similar to Client X’s.” Such an explanation has two components: first, the product is genuinely preferred by the peer group (confidence exceeds the threshold ), and second, Client X is genuinely similar to that peer group (similarity exceeds the threshold ).
- Regulatory Constraints: Hard Suitability Rules
Let denote the set of hard suitability constraints, where indicates that product p is impermissible for client u by regulation. The final recommendation function incorporates these constraints via
Equivalently, the feasible recommendation set is
and the recommendation is the mode of the conditional distribution restricted to feasible products:
What this means in practice: Not all mathematically optimal recommendations are legally permissible. Certain clients may be prohibited from purchasing specific products due to age restrictions, accredited investor requirements, or jurisdictional regulations. The system first filters the product set to those that are legally permissible for the client, then selects the optimal recommendation from within that feasible set. This ensures compliance with suitability rules while maintaining algorithmic rigor.
- Summary
The proposed framework thus achieves three objectives simultaneously:
- Diversity: Avoids corner solutions by distributing recommendation probability across multiple suitable products.
- Adaptability: Responds to evolving client preferences through dynamic cluster reassignment.
- Compliance: Respects hard suitability constraints while maintaining interpretable, human-justifiable recommendations.
3.1.5. The Takeaway: Theory vs. Practice in Quantum Finance
This financial recommendation case study exemplifies a broader truth critical for quantum finance: deploying theoretical algorithms in finance requires substantial preprocessing, feature engineering, and domain integration. The three-stage pipeline is not merely “applying QAOA” or “running a quantum classifier”—it is a bespoke financial data preparation framework that makes theoretical algorithms viable.
The same adaptation challenges appear across all quantum financial applications:
- Portfolio optimization requires careful QUBO formulation, constraint handling, and real-world constraint integration.
- Derivative pricing needs quantum-appropriate stochastic process encodings and market data preprocessing.
- Risk management demands hybrid classical–quantum validation pipelines and regulatory compliance layers.
- Fraud detection requires graph structure extraction and feature enrichment before quantum algorithms can be effective.
The remainder of Section 3 explores these broader deployment challenges: compliance frameworks, validation protocols, talent gaps, and hardware limitations. Each reinforces the same lesson: financial quantum computing success depends on building robust bridges between quantum theory and financial practice.
3.2. The Compliance and Validation Challenge
Contrary to common perception, the primary barrier to quantum adoption in finance is not algorithmic complexity but institutional readiness for compliance and validation. The Bank for International Settlements has recently highlighted the need for financial institutions to prepare for the regulatory implications of both AI and quantum computing [36], reinforcing the urgency of developing compliance frameworks proactively. Financial institutions operate under strict regulatory frameworks, including the Basel III/IV capital adequacy standards [37,38], the Markets in Financial Instruments Directive (MiFID II) [39], and the Dodd–Frank Wall Street Reform and Consumer Protection Act [40]. Additionally, the Federal Reserve’s Supervisory Guidance on Model Risk Management (SR 11-7) [41] establishes rigorous expectations for model validation, governance, and documentation that any new methodology—quantum or otherwise—must satisfy. Collectively, these frameworks require the following:
- Explainable AI (XAI): The opacity of quantum models poses challenges for regulatory compliance, motivating the development of quantum-specific explainability frameworks [42].
- Quantum Risk Governance: Financial institutions must establish governance structures for quantum deployment, addressing operational, strategic, and compliance risks associated with probabilistic and non-deterministic outputs.
- Robustness Testing: Validation across edge cases representing <5% of scenarios but accounting for >95% of model risk.
3.2.1. Algorithm Selection Philosophy: Gold Standards vs. Novel Approaches
Typically, these alternatives may demonstrate superior performance in, say, 95% of use cases, yet carry a higher risk of failures to converge or stabilize in the remaining 5% of use cases. As a golden rule in computational science, there is usually a cost associated with any efficiency gain. This risk–efficiency trade-off is central to AI governance frameworks in finance, which emphasize robustness testing and fallback mechanisms for algorithmic systems [42].
3.2.2. Implementation Timeline and Resource Allocation
The practical reality of quantum adoption involves a phased implementation, such as the timeline as shown in Table 4:
Table 4.
Realistic quantum implementation timeline for Tier-1 financial institutions.
3.2.3. Explainability and Interpretability in Quantum Models
Regulatory requirements for model transparency extend to quantum algorithms, where the probabilistic nature of measurements and the complexity of quantum circuits complicate interpretability. Recent work has begun to address these challenges through classical surrogates, feature attribution methods adapted for quantum circuits, and post hoc explanation techniques [42]. For financial institutions, the ability to explain a quantum model’s output to internal compliance departments and regulators is as critical as its predictive performance.
3.2.4. The Talent Gap and Organizational Readiness
Effective quantum adoption in finance requires teams with combined expertise in quantum algorithms and financial quantitative methods; physicists alone may lack familiarity with the compliance and deployment requirements of financial institutions.
3.3. Current Limitations and the Path to Quantum Advantage
3.3.1. The Noise Gap: Quantum vs. Classical Performance
Despite theoretical speedups, current quantum hardware cannot outperform classical methods for practical financial problems due to noise limitations (see Table 5).
Table 5.
Current quantum hardware specifications vs. requirements for financial quantum advantage. Data from [43,44]. Projected requirements based on analysis in [45].
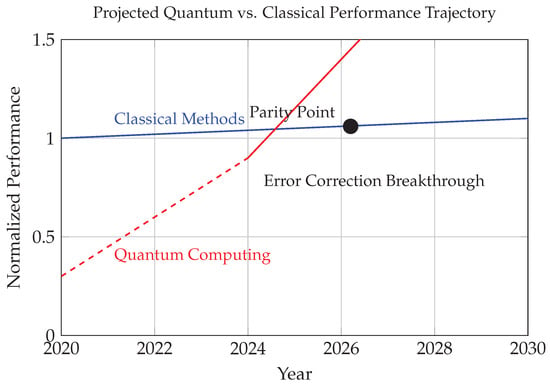
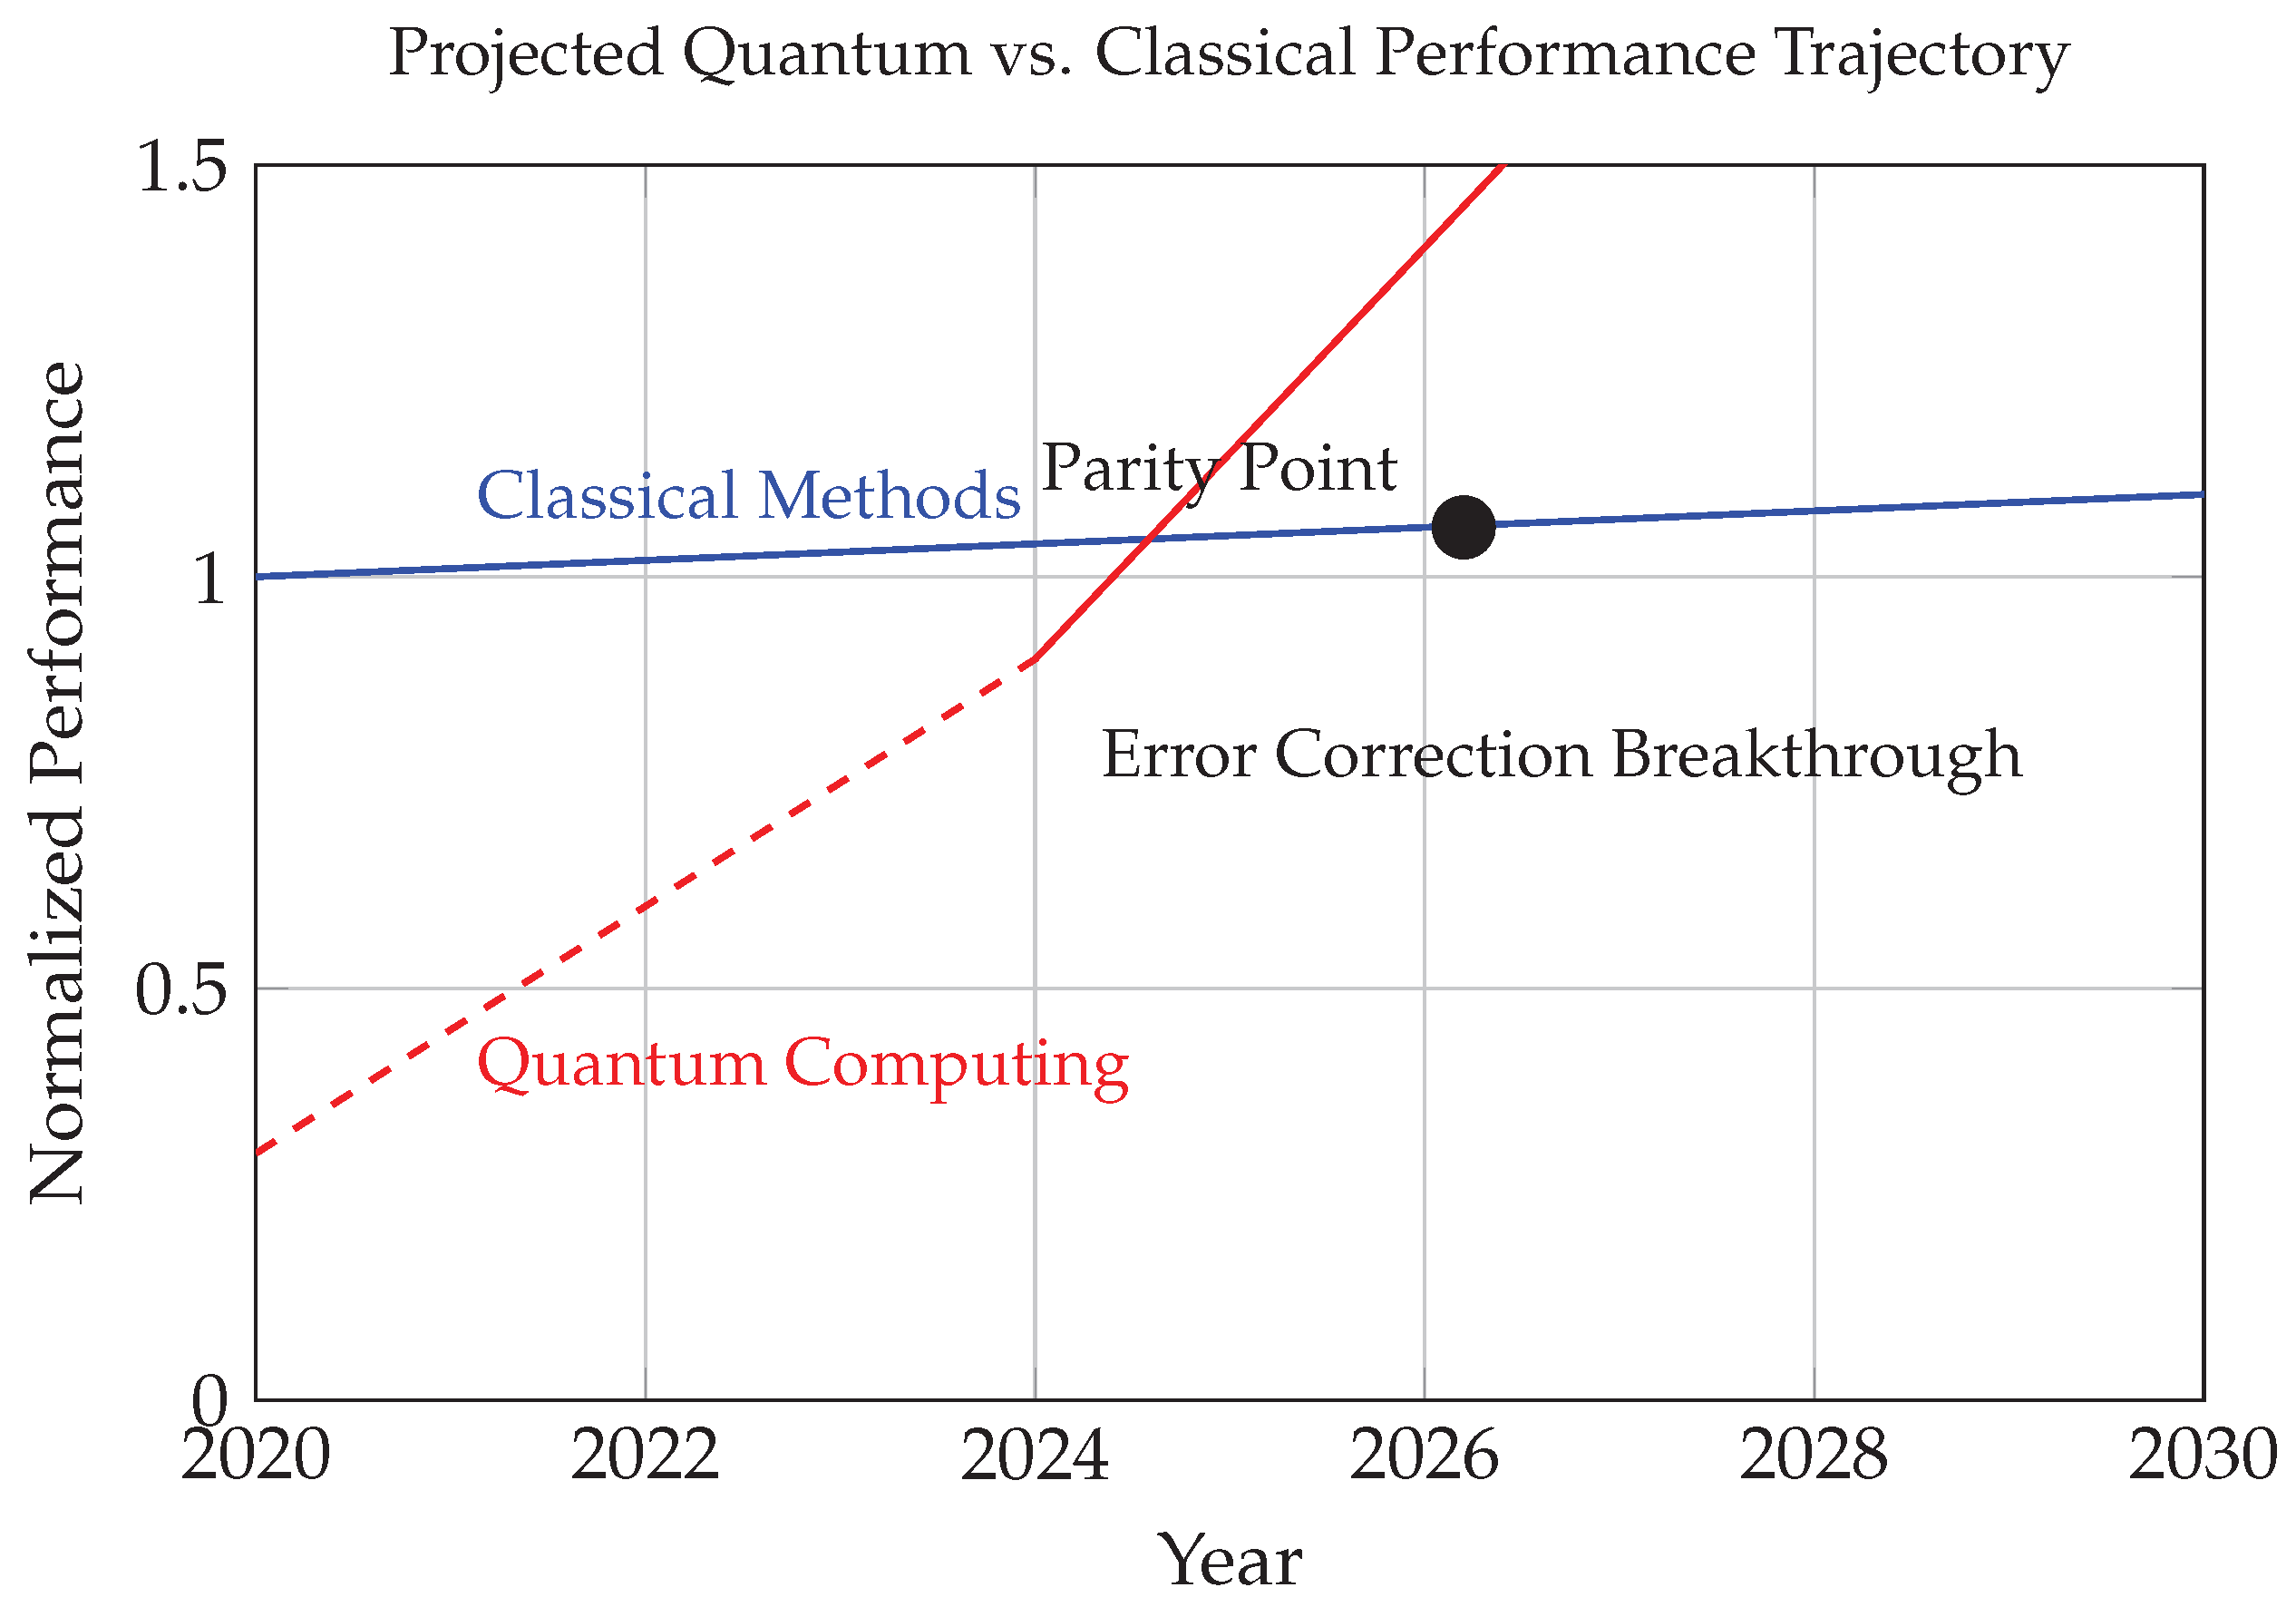
Figure 3 presents performance projections based on error correction roadmap analyses from [45] and hardware development projections from [43].
Figure 3.
Projected performance trajectory based on current technological trends, suggesting a tentative timeline for quantum advantage around 2026–2027 [45]. This projection is subject to uncertainty and should be interpreted as indicative rather than definitive. Current quantum methods (2024) operate at ≈30% of classical performance for practical problem sizes [43].
The current state can be quantified as
However, this gap is closing rapidly due to advances in error correction. Surface code implementations with logical qubit counts exceeding 100 are projected for 2026 [45].
3.3.2. Why Early Engagement Matters: Avoiding the Catch-Up Trap
Financial institutions that defer quantum engagement risk being unprepared once hardware parity is achieved, especially since not-ready-for-quantum data can be harvested today for subsequent processing. The learning curve for quantum algorithm development and integration is steep (2–3 years for meaningful competency). The institutional learning curve for quantum readiness—encompassing compliance frameworks, talent development, and infrastructure—is substantially longer than the time required to switch backend libraries once hardware matures. While the precise timeline for achieving quantum advantage remains uncertain and depends on continued advances in error correction and qubit scalability, proactive engagement is essential to avoid being unprepared should hardware progress accelerate.
4. Conclusions and Strategic Recommendations
4.1. Key Findings
This article has presented a systematic survey of quantum computing applications in finance, unified under the paradigm of optimization as the foundational use case from which derivative applications are constructed. Across six financial industry sub-domains—portfolio optimization, derivative pricing, risk management, fraud detection, high-frequency trading, and macroeconomic forecasting—we have examined both the theoretical promise and the practical limitations of quantum approaches. Several key findings emerge from this analysis.
First, algorithmic maturity has reached a point where rigorous mathematical foundations are well established. The transition from classical Markowitz optimization to quantum implementations via QAOA has been formalized with explicit derivations, theoretical performance bounds, and convergence guarantees. For derivative pricing and risk management, quantum amplitude estimation offers provable quadratic speedups, while quantum linear systems algorithms provide exponential improvements under specific structural conditions. These results are grounded in established quantum complexity theory and have been validated through numerical simulations.
Second, hardware limitations remain the binding constraint on practical quantum advantage. Current NISQ devices operate at approximately 30% of classical performance for problem sizes relevant to financial institutions, due to noise thresholds, coherence constraints, and limited qubit counts. The analysis of error correction roadmaps suggests that fault-tolerant quantum computing with logical qubit counts exceeding 1000 is projected for the late 2020s. However, these timelines are contingent on continued advances in qubit stability, error correction codes, and scaling architectures and carry inherent uncertainty. While the performance gap is closing, it has not yet been bridged.
Third, the primary barriers to adoption are institutional rather than algorithmic. Financial institutions operate under stringent regulatory frameworks—including Basel III/IV [37,38], MiFID II [39], the Dodd–Frank Act [40], and the Federal Reserve’s SR 11-7 [41]—that mandate model explainability, auditability, and robustness across edge cases. Quantum algorithms, characterized by probabilistic outputs and non-deterministic behavior, present fundamental challenges to these requirements. The talent gap is equally significant; effective deployment necessitates interdisciplinary teams that integrate quantum physics expertise with financial quantitative experience and regulatory compliance knowledge—a combination that remains scarce.
Fourth, the gap between theoretical formulations and real-world financial data is still quite substantial. As demonstrated through the case study of a successfully deployed financial recommendation system, theoretical algorithms presuppose clean, well-structured inputs that do not exist in practice. Real-world financial data are sparse, noisy, structurally complex, and subject to evolving regulatory constraints. Deploying any algorithm—quantum or classical—requires extensive preprocessing, feature engineering, and domain adaptation. The three-stage pipeline developed in this work (graph-aware feature expansion, progressive dimensionality reduction, and graph-cut informed prediction) illustrates that compliance-aware engineering frameworks are necessary irrespective of the underlying computational method. Consequently, any assessment of quantum advantage must account for this engineering overhead.
Fifth, early engagement is imperative. The institutional learning curve for quantum readiness—encompassing talent development, compliance frameworks, infrastructure integration, and organizational change—is substantially longer than the time required to switch backend libraries once hardware matures. Financial institutions that defer engagement risk being unprepared when hardware parity is achieved. The strategic window for building institutional capacity is therefore contemporaneous with hardware development, not subsequent to it.
4.2. Strategic Recommendations for Financial Institutions
Based on these findings, we propose a phased strategic roadmap for financial institutions preparing for quantum computing (see Table 6):
Table 6.
Phased strategic roadmap for quantum adoption in financial institutions.
4.3. Final Conclusions
Quantum computing constitutes not an incremental improvement but a fundamental paradigm shift in computational finance. Its capacity to solve combinatorial optimization problems at scale, accelerate Monte Carlo simulations, and process high-dimensional stochastic systems exponentially offers transformative potential for portfolio construction, risk management, fraud detection, and macroeconomic forecasting.
The path to realizing this potential, however, is neither short nor straightforward. The principal barriers to adoption are institutional rather than algorithmic: regulatory compliance frameworks, model validation protocols, talent development, and the engineering required to bridge theoretical formulations with imperfect real-world data. Institutions that focus exclusively on quantum algorithms while neglecting these institutional prerequisites will produce mathematically elegant solutions that cannot be deployed to solve real-world problems for the hosting financial institution.
Conversely, institutions that invest now in building hybrid expertise, engaging with regulators, developing forward-thinking compliance frameworks, and cultivating interdisciplinary teams will be positioned to capture value when hardware crosses the threshold of practical utility. The strategic imperative is therefore to begin quantum readiness programs before hardware advantage materializes, not after.
Compliance and model validation functions in financial institutions demand well-documented protocols for identifying and mitigating edge cases—a requirement that becomes more critical when deploying probabilistic quantum algorithms. Success will accrue to institutions that respect both the theoretical potential of quantum physics and the practical constraints of financial algorithms—institutions that systematically build bridges between quantum theory and financial practice, one validated model at a time.
Author Contributions
Conceptualization, W.B.L. and A.G.C.; software, W.B.L.; writing, W.B.L.; writing—review and editing, W.B.L. and A.G.C. All authors have read and agreed to the published version of the manuscript.
Funding
This work was supported in part by the Singapore National Research Foundation and its sister agencies under multiple grants that partially supported the research reported herein.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
Data is contained within the article.
Acknowledgments
The authors gratefully acknowledge the HedgeSPA Research & Development team for their able research assistance, the AI and Data Analytics Laboratory at Imperial College London for their institutional support, and referees and collaborators from leading financial institutions for their insights into the practical implementation challenges addressed in this study. This work was supported in part by the Singapore National Research Foundation and its sister agencies under multiple grants that partially supported the research reported herein.
Conflicts of Interest
Dr. Bernard Lee is the Founder and CEO of HedgeSPA Private Limited. The authors declare that there are no conflicts of interest related to this work.
Appendix A. Detailed Mathematical Derivations
Appendix A.1. Proof of QUBO Matrix Construction
This appendix provides the complete algebraic derivation referenced in Section 1.2 (specifically, the proof of Theorem 1).
Proof.
Starting from the objective function,
Substituting the binary encoding (6),
Thus,
Rearranging terms into the form yields the stated expressions. □
Appendix A.2. Penalty Coefficient Bound Derivation
The justification for the penalty coefficient bound in Lemma 1 follows from standard penalty method theory. For a constrained optimization problem of the form
the quadratic penalty method introduces the penalized objective . For sufficiently large A, the unconstrained minimum of the penalized problem coincides with the constrained minimum. The bound provided in Lemma 1 ensures that A dominates the curvature of the objective function, guaranteeing that any violation of the budget constraint incurs a penalty that exceeds any potential reduction in the original objective.
Appendix A.3. Ising Hamiltonian Derivation
The transformation from QUBO to Ising Hamiltonian in Proposition 1 follows from the substitution with . Substituting into the QUBO objective yields
Expanding and collecting constant, linear, and quadratic terms in z yields the expressions for , , and C, as stated in the proposition. Detailed algebraic manipulation confirms the coefficients.
References
- Markowitz, H. Portfolio Selection. J. Financ. 1952, 7, 77–91. [Google Scholar] [CrossRef] [Scilit]
- Karmarkar, N. A New Polynomial-Time Algorithm for Linear Programming. Combinatorica 1984, 4, 373–395. [Google Scholar] [CrossRef] [Scilit]
- Renegar, J. A Polynomial-Time Algorithm, Based on Newton’s Method, for Linear Programming. Math. Program. 1988, 40, 59–93. [Google Scholar] [CrossRef] [Scilit]
- Gondzio, J.; Grothey, A. Solving Nonlinear Portfolio Optimization Problems with the Primal-Dual Interior Point Method. Eur. J. Oper. Res. 2007, 181, 1019–1029. [Google Scholar] [CrossRef] [Scilit]
- Wright, S.J. Primal-Dual Interior-Point Methods; SIAM: Philadelphia, PA, USA, 1997. [Google Scholar] [CrossRef] [Scilit]
- Herman, D.; Googin, C.; Liu, X.; Sun, Y.; Galda, A.; Safro, I.; Pistoia, M.; Alexeev, Y. Quantum Computing for Finance: A Survey. Nat. Rev. Phys. 2023, 5, 450–465. [Google Scholar] [CrossRef] [Scilit]
- Orús, R.; Mugel, S.; Lizaso, E. Quantum Computing for Finance: Applications and Challenges. Rev. Phys. 2019, 4, 100028. [Google Scholar] [CrossRef] [Scilit]
- Nielsen, M.A.; Chuang, I.L. Quantum Computation and Quantum Information: 10th Anniversary Edition; Cambridge University Press: Cambridge, UK, 2010. [Google Scholar] [CrossRef] [Scilit]
- Glover, F.; Kochenberger, G.; Du, Y. Quantum Bridge Analytics I: A tutorial on formulating and using QUBO models. 4OR 2019, 17, 335–371. [Google Scholar] [CrossRef] [Scilit]
- Egger, D.J.; Gambella, C.; Marecek, J.; McFaddin, S.; Mevissen, M.; Raymond, R.; Simonetto, A.; Woerner, S.; Yndurain, E. Quantum Computing for Finance: State-of-the-Art and Future Prospects. IEEE Trans. Quantum Eng. 2020, 1, 3101724. [Google Scholar] [CrossRef] [Scilit]
- Nocedal, J.; Wright, S.J. Numerical Optimization; Springer: New York, NY, USA, 2006. [Google Scholar] [CrossRef] [Scilit]
- Boyd, S.; Vandenberghe, L. Convex Optimization; Cambridge University Press: Cambridge, UK, 2004. [Google Scholar] [CrossRef] [Scilit]
- Lucas, A. Ising Formulations of Many NP Problems. Front. Phys. 2014, 2, 5. [Google Scholar] [CrossRef] [Scilit]
- Farhi, E.; Goldstone, J.; Gutmann, S. A Quantum Approximate Optimization Algorithm. arXiv 2014, arXiv:1411.4028. [Google Scholar] [CrossRef] [Scilit]
- Zhou, L.; Wang, S.-T.; Choi, S.; Pichler, H.; Lukin, M.D. Quantum Approximate Optimization Algorithm: Performance, Mechanism, and Implementation on Near-Term Devices. Phys. Rev. X 2020, 10, 021067. [Google Scholar] [CrossRef] [Scilit]
- Brandão, F.G.S.L.; Broughton, M.; Farhi, E.; Gutmann, S.; Neven, H. For Fixed Control Parameters the Quantum Approximate Optimization Algorithm’s Objective Function Value Concentrates for Typical Instances. arXiv 2018, arXiv:1812.04170. [Google Scholar] [CrossRef] [Scilit]
- Guerreschi, G.G.; Matsuura, A.Y. QAOA for Max-Cut Requires Hundreds of Qubits for Quantum Speed-Up. Sci. Rep. 2019, 9, 6903. [Google Scholar] [CrossRef] [Scilit]
- Crooks, G.E. Performance of the Quantum Approximate Optimization Algorithm on the Maximum Cut Problem. arXiv 2018, arXiv:1811.08419. [Google Scholar] [CrossRef] [Scilit]
- Glasserman, P. Monte Carlo Methods in Financial Engineering; Springer: New York, NY, USA, 2003. [Google Scholar] [CrossRef] [Scilit]
- Rebentrost, P.; Gupt, B.; Bromley, T.R. Quantum Computational Finance: Monte Carlo Pricing of Financial Derivatives. Phys. Rev. A 2018, 98, 022321. [Google Scholar] [CrossRef] [Scilit]
- Woerner, S.; Egger, D.J. Quantum Risk Analysis. npj Quantum Inf. 2019, 5, 15. [Google Scholar] [CrossRef] [Scilit]
- Christofides, N. Worst-Case Analysis of a New Heuristic for the Travelling Salesman Problem. Oper. Res. Forum 2022, 3, 20. [Google Scholar] [CrossRef] [Scilit]
- Montanaro, A. Quantum Algorithms: An Overview. npj Quantum Inf. 2016, 2, 15023. [Google Scholar] [CrossRef] [Scilit]
- Childs, A.M.; van Dam, W. Quantum Algorithms for Algebraic Problems. Rev. Mod. Phys. 2010, 82, 1–52. [Google Scholar] [CrossRef] [Scilit]
- Coppersmith, D. An Approximate Fourier Transform Useful in Quantum Factoring. arXiv 1994. [Google Scholar] [CrossRef] [Scilit]
- Dunjko, V.; Briegel, H.J. Machine Learning and Artificial Intelligence in the Quantum Domain. Rep. Prog. Phys. 2018, 81, 074001. [Google Scholar] [CrossRef] [Scilit]
- Biamonte, J.; Wittek, P.; Pancotti, N.; Rebentrost, P.; Wiebe, N.; Lloyd, S. Quantum Machine Learning. Nature 2017, 549, 195–202. [Google Scholar] [CrossRef] [Scilit]
- Hamilton, J.D. Time Series Analysis; Princeton University Press: Princeton, NJ, USA, 1994. [Google Scholar] [CrossRef] [Scilit]
- Harrow, A.W.; Hassidim, A.; Lloyd, S. Quantum Algorithm for Linear Systems of Equations. Phys. Rev. Lett. 2009, 103, 150502. [Google Scholar] [CrossRef] [Scilit]
- Stamatopoulos, N.; Egger, D.J.; Sun, Y.; Zoufal, C.; Iten, R.; Shen, N.; Woerner, S. Option Pricing Using Quantum Computers. Quantum 2020, 4, 291. [Google Scholar] [CrossRef] [Scilit]
- Bouten, L.; van Handel, R.; James, M.R. An Introduction to Quantum Filtering. SIAM J. Control Optim. 2007, 46, 2199–2241. [Google Scholar] [CrossRef] [Scilit]
- Liu, C.; Lee, W.B.; Constantinides, A.G. Quantum Testing of Recommender Algorithms on GPU-Based Quantum Simulators. Computers 2025, 14, 137. [Google Scholar] [CrossRef] [Scilit]
- Liu, C.; Lee, W.B.; Constantinides, A.G. Spectral Graph Compression in Deploying Recommender Algorithms on Quantum Simulators. Computers 2025, 14, 310. [Google Scholar] [CrossRef] [Scilit]
- Shuman, D.I.; Narang, S.K.; Frossard, P.; Ortega, A.; Vandergheynst, P. The Emerging Field of Signal Processing on Graphs: Extending High-Dimensional Data Analysis to Networks and Other Irregular Domains. IEEE Signal Process. Mag. 2013, 30, 83–98. [Google Scholar] [CrossRef] [Scilit]
- Tishby, N.; Zaslavsky, N. Deep Learning and the Information Bottleneck Principle. In Proceedings of the 2015 IEEE Information Theory Workshop (ITW); IEEE: New York, NY, USA, 2015; pp. 1–5. [Google Scholar] [CrossRef] [Scilit]
- Basel Committee on Banking Supervision. Artificial Intelligence and Quantum Computing: Implications for Banks. Bank for International Settlements. 2023. Available online: https://www.bis.org/bcbs/publ/d546.htm (accessed on 22 March 2026).
- Basel Committee on Banking Supervision. Basel III: A Global Regulatory Framework for More Resilient Banks and Banking Systems. Bank for International Settlements. 2010. Available online: https://www.bis.org/publ/bcbs189.htm (accessed on 22 March 2026).
- Basel Committee on Banking Supervision. Basel III: Finalising Post-Crisis Reforms. Bank for International Settlements. 2017. Available online: https://www.bis.org/bcbs/publ/d424.htm (accessed on 22 March 2026).
- European Parliament and Council. Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on Markets in Financial Instruments. Off. J. Eur. Union 2014, L 173, 349–496. [Google Scholar]
- Dodd-Frank Wall Street Reform and Consumer Protection Act, Pub. L. No. 111-203, 124 Stat. 1376 (2010). Available online: https://www.govinfo.gov/app/details/PLAW-111publ203 (accessed on 22 March 2026).
- Board of Governors of the Federal Reserve System. Supervisory Guidance on Model Risk Management. SR Letter 11-7. 2011. Available online: https://www.federalreserve.gov/supervisionreg/srletters/sr1107.htm (accessed on 22 March 2026).
- Steinmüller, P.; Schulz, T.; Graf, F.; Herr, D. eXplainable AI for Quantum Machine Learning. Quantum Mach. Intell. 2024, 6, 1–24. [Google Scholar] [CrossRef] [Scilit]
- IBM Quantum. IBM Quantum Development Roadmap; IBM Research Report. 2024. Available online: https://www.ibm.com/roadmaps/quantum/2024/ (accessed on 22 March 2026).
- Google Quantum AI. Suppressing Quantum Errors by Scaling a Surface Code Logical Qubit. Nature 2023, 614, 676–681. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Fowler, A.G.; Mariantoni, M.; Martinis, J.M.; Cleland, A.N. Surface Codes: Towards Practical Large-Scale Quantum Computation. Phys. Rev. A 2012, 86, 032324. [Google Scholar] [CrossRef] [Scilit]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.