Article

Generalized Market Uncertainty Measurement in European Stock Markets in Real Time


by
Jorge M. Uribe
1,* and
Montserrat Guillen
2
1
Faculty of Economics and Business, Universitat Oberta de Catalunya, 08035 Barcelona, Spain
2
Riskcenter-IREA, Department of Econometrics, Universitat de Barcelona, 08034 Barcelona, Spain
*
Author to whom correspondence should be addressed.
Mathematics 2020, 8(12), 2148; https://doi.org/10.3390/math8122148
Submission received: 29 October 2020 / Revised: 24 November 2020 / Accepted: 26 November 2020 / Published: 2 December 2020

Abstract

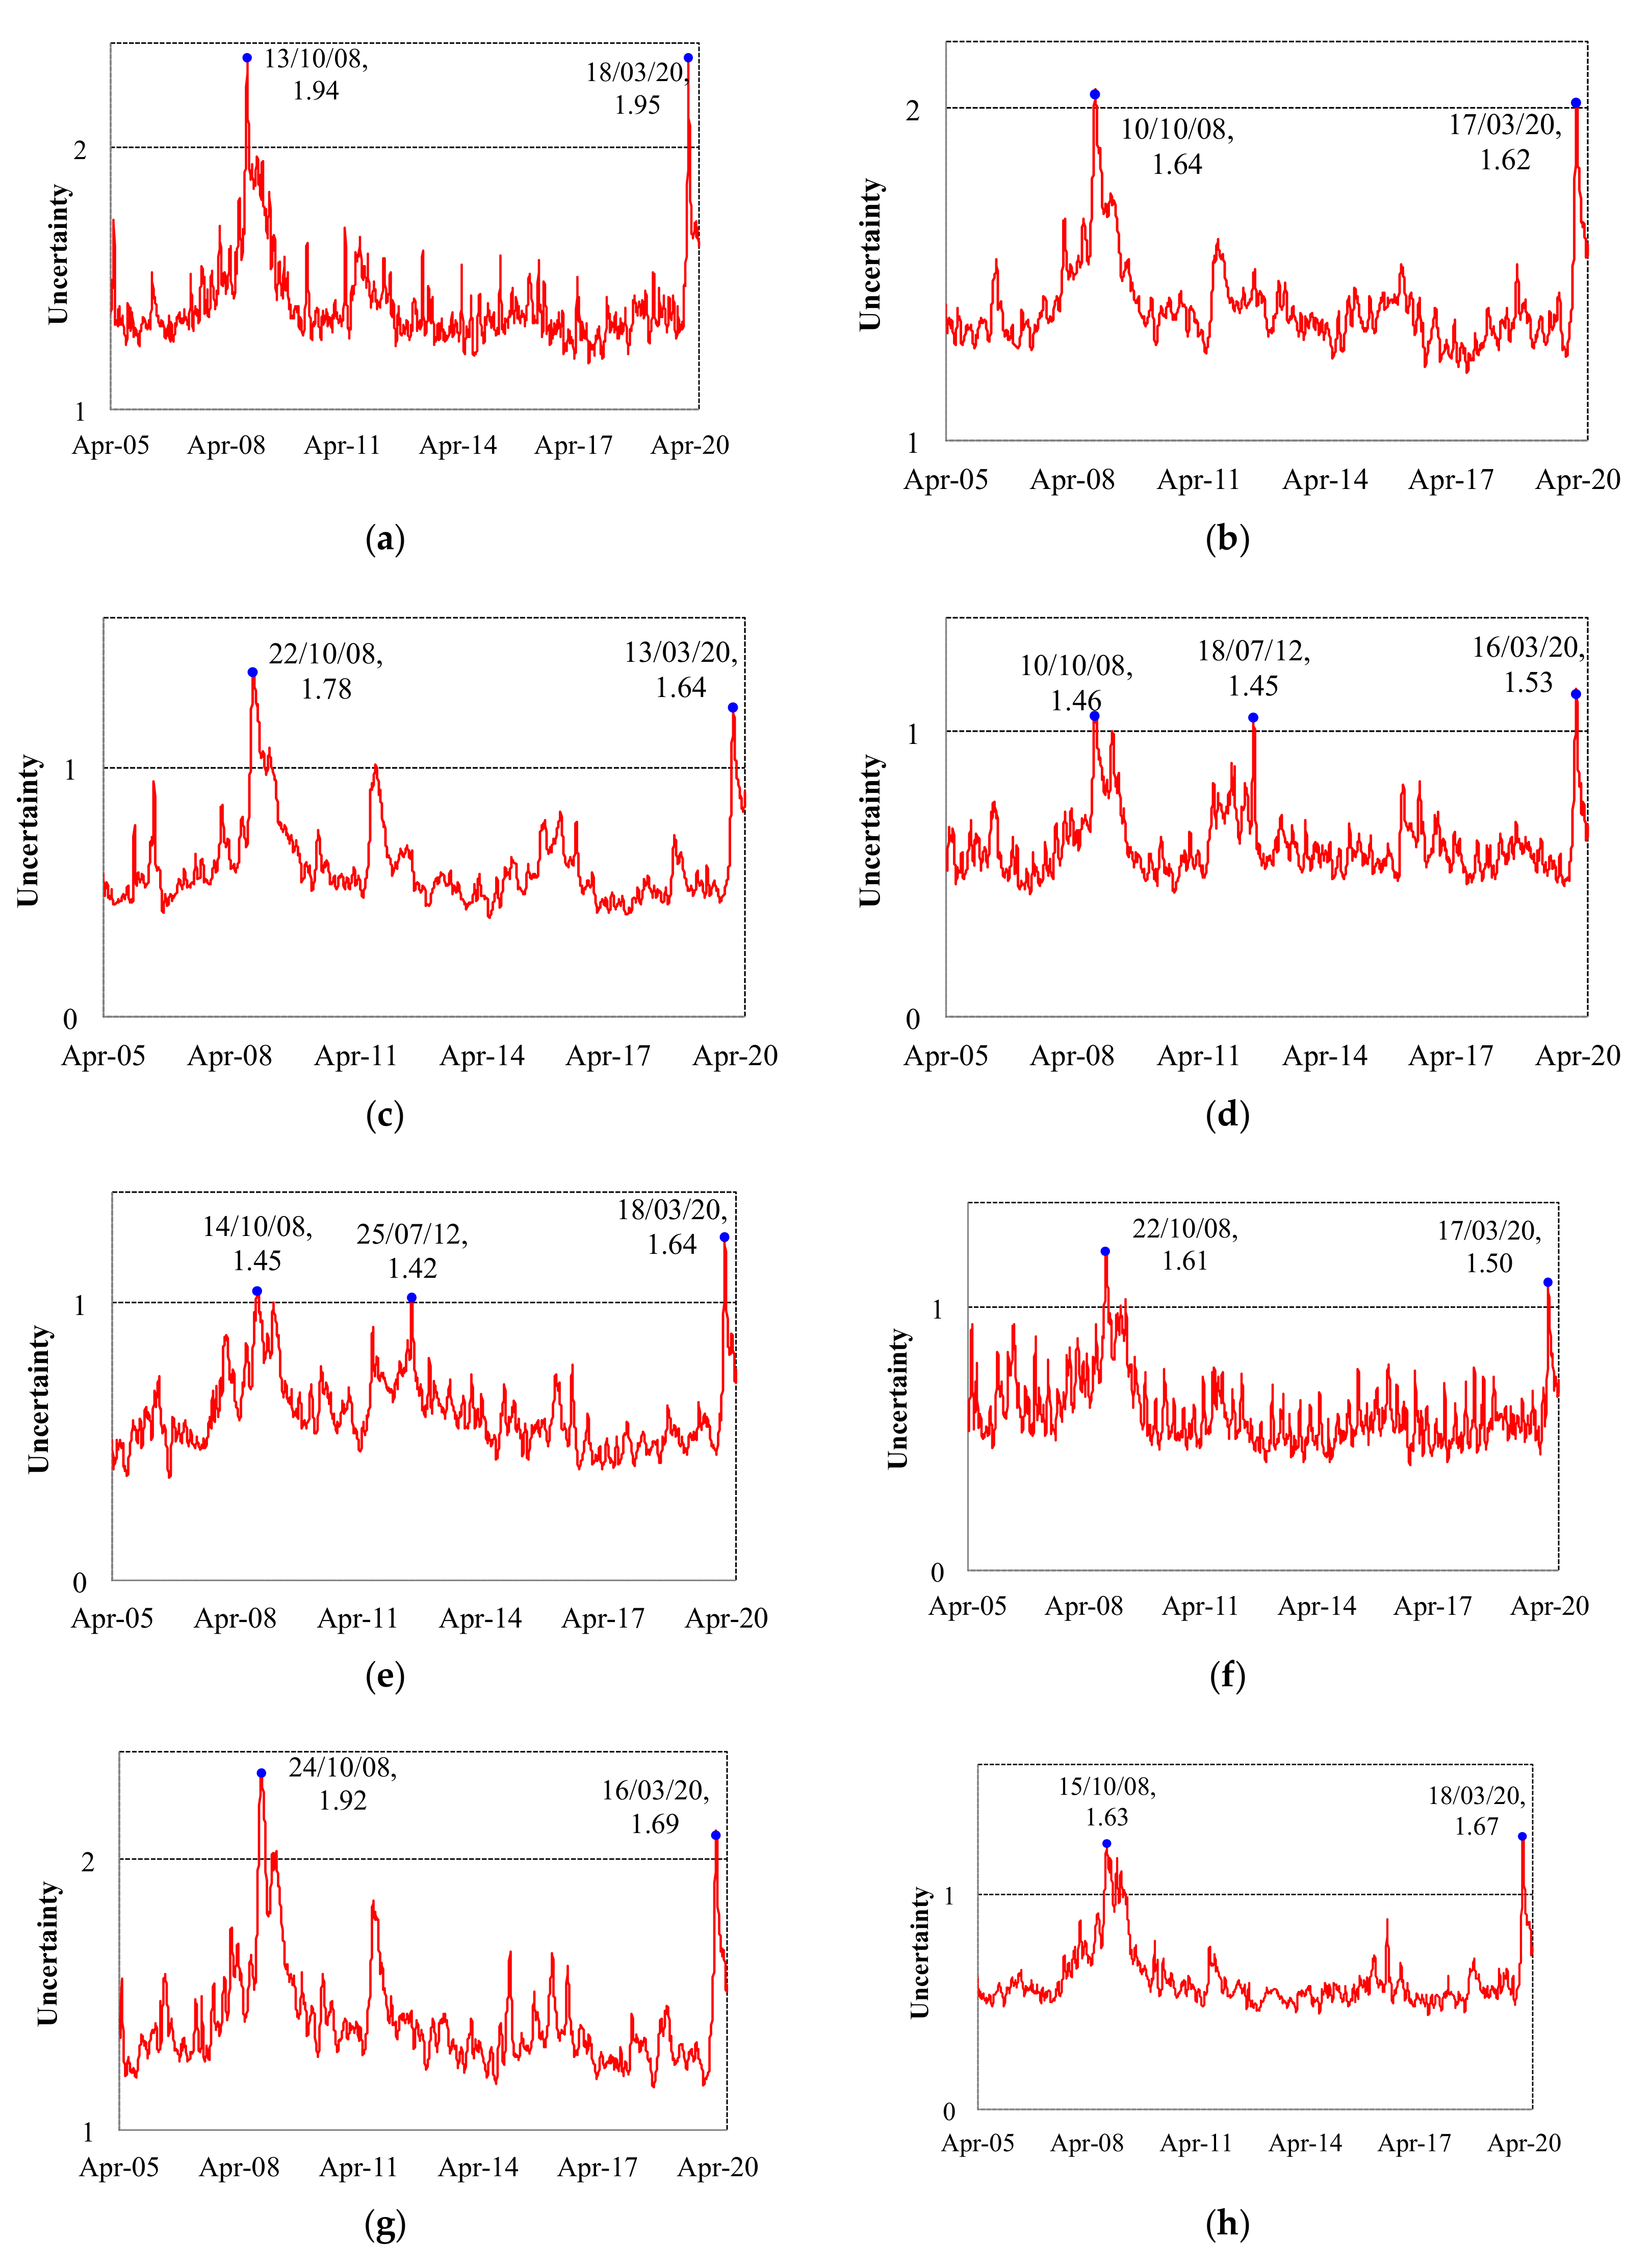
We estimate generalized market uncertainty indicators for the stock markets of eight European countries greatly affected by the recent Covid-19 crisis and the economic measures implemented for its containment and mitigation. Our statistics emphasize the difference between risk and uncertainty, in the aggregate, and provide readily and easily interpretable estimates, in real time, which are relevant for market participants and regulators. We show that generalized uncertainty in Europe was, indeed, at historically high levels in the wake of the recent public health crisis before the large interventions by the European Central Bank, the Fed, and the Bank of England, but also that, for some markets, recently recorded uncertainty levels were still lower than those recorded during the Global Financial Crisis, which puts things into perspective. We also show that uncertainty shocks are extremely persistent, but such persistence varies greatly across countries. The period needed for the markets to absorb half of the shock lies between less than a year and two and a half years.
Keywords: generalized uncertainty; market ambiguity; coronavirus; Covid-19 generalized uncertainty; market ambiguity; coronavirus; Covid-19