
Article

The Mediating Role of Financial Decisions and the Moderating Role of Digital Transformation in the Relationship Between Managerial Characteristics and Financial Performance: Evidence from Vietnamese SMEs
by
Minh Nguyen Ngoc
1,
Cuong Nguyen Thanh
2,* and
Ngoc Nguyen Van
3
1
Department of Business Administration, School of Economics and Business, Nha Trang University, Nha Trang 650000, Vietnam
2
Department of Finance and Banking, School of Economics and Business, Nha Trang University, Nha Trang 650000, Vietnam
3
Department of Economics, School of Economics and Business, Nha Trang University, Nha Trang 650000, Vietnam
*
Author to whom correspondence should be addressed.
Int. J. Financ. Stud. 2026, 14(7), 194; https://doi.org/10.3390/ijfs14070194
Submission received: 20 May 2026 / Revised: 7 July 2026 / Accepted: 16 July 2026 / Published: 21 July 2026

Abstract

This study examines the mediating role of financial decisions and the moderating role of digital transformation in the relationship between managerial characteristics and financial performance among small and medium-sized enterprises (SMEs) in Vietnam. Grounded in Upper Echelons Theory, Behavioral Theory of the Firm, Resource-Based View, and corporate finance theories, the study conceptualizes financial decisions as a formative higher-order construct comprising capital structure, investment, and working capital management decisions. The empirical analysis is based on survey data collected from 510 SMEs in Khanh Hoa Province, Vietnam. The data were analyzed using partial least squares structural equation modeling (PLS-SEM), including mediation and moderation tests. The results show that managerial characteristics have a significant positive effect on financial decisions, which in turn positively affect financial performance. Financial decisions are found to partially mediate the relationship between managerial characteristics and firm performance. In addition, digital transformation positively moderates the relationship between financial decisions and financial performance, indicating that firms with higher levels of digital capability derive greater performance benefits from their financial decisions. Overall, the findings highlight the importance of managerial attributes and digital transformation in shaping financial outcomes through effective financial decision-making in SMEs.

1. Introduction

Small and medium-sized enterprises are widely regarded as a key driver of economic development worldwide through their contributions to employment generation, competitiveness enhancement, and innovation promotion (Ayandibu & Houghton, 2017; Savlovschi & Robu, 2011). In developed economies, SMEs constitute the majority of business entities and contribute substantially to economic growth and job creation (FSB, 2013; Ngek & van Aardt Smit, 2013). In developing and emerging economies, SMEs play an important role in entrepreneurship, local economic development, and unemployment reduction (Reynolds, 2011; Walker & Brown, 2004), while also supporting inclusive growth and poverty alleviation (Ayyagari et al., 2011; Beck et al., 2005; Gbandi & Amissah, 2014). Nevertheless, SMEs in developing countries continue to face considerable challenges related to limited access to finance, resource constraints, and managerial capability, all of which may adversely affect firm performance (Ayyagari et al., 2011; Beck & Demirguc-Kunt, 2006). In the context of Vietnam, SMEs play a pivotal role in the national economy. According to the Ministry of Planning and Investment (2023), SMEs account for more than 97% of all enterprises, contribute approximately 45% of gross domestic product (GDP), and generate over 60% of total employment (Ministry of Planning and Investment, 2023). Despite their important role in the national economy, Vietnamese SMEs continue to encounter significant challenges associated with financial constraints, managerial limitations, and increasing competitive pressure, which may hinder their long-term sustainability and performance.
In an increasingly dynamic and competitive business environment, financial performance has become a critical determinant of firms’ survival and sustainable growth. This issue is particularly important for SMEs because they typically operate with limited financial resources and lower resilience to external shocks compared with large corporations (Beck & Demirguc-Kunt, 2006). Financial performance reflects not only profitability but also the efficient utilization of financial resources to achieve long-term growth and sustainability objectives (Brigham et al., 2004; Ross et al., 2022). Consequently, improving financial performance remains a strategic priority for SMEs in the context of globalization and economic integration.
Within the corporate finance literature, financial decisions are widely regarded as fundamental drivers of firm financial performance. These decisions generally involve capital structure decisions, investment decisions, and working capital management decisions (Brigham et al., 2004; Ross et al., 2022). Extensive empirical evidence suggests that appropriate financing choices, efficient investment allocation, and effective cash flow management can substantially improve firm profitability and operational performance (Abor, 2007; Afrifa & Tingbani, 2018; Deloof, 2003; Frank & Goyal, 2009; Juan García-Teruel & Martínez-Solano, 2007). For SMEs, financial decisions are even more critical because limited access to external financing increases firms’ vulnerability to inefficient managerial decisions. In the Vietnamese context, prior studies have also confirmed the significant influence of capital structure, investment, and working capital management decisions on firms’ financial performance (Hung & Thanh, 2022; Le et al., 2018; A. H. Nguyen et al., 2020; B. Nguyen, 2021).
Beyond financial decisions, managerial characteristics are also considered an important determinant of firm performance, particularly in the context of SMEs, where organizational structures are typically lean and decision-making authority is concentrated in the hands of business owners or top managers. According to Upper Echelons Theory proposed by Hambrick and Mason (1984), strategic decisions and organizational outcomes are substantially shaped by managers’ personal characteristics, cognitive orientations, and professional experiences. Attributes such as financial knowledge, managerial experience, risk-taking propensity, strategic vision, and leadership style may directly influence the quality of managerial decisions and, consequently, firm performance (Finkelstein et al., 2009). Prior studies have shown that managers with stronger financial capability and managerial expertise tend to make more effective decisions, thereby improving firms’ financial performance (Blackburn et al., 2013; Custódio & Metzger, 2014; Nielsen & Nielsen, 2013). In the Vietnamese context, empirical evidence has also highlighted the positive role of managerial capability, intellectual capital, and financial skills in enhancing firm financial performance (Do et al., 2023; Kim & Tran, 2024).
In addition, the rapid development of digital technologies has transformed the way firms manage financial activities and strategic operations. Digital transformation enables firms to improve information processing capability, enhance operational efficiency, reduce information asymmetry, and support more effective financial decision-making (Bharadwaj et al., 2013; Verhoef et al., 2021). From the perspective of dynamic capability theory, digital transformation represents an important strategic capability that enhances firms’ ability to utilize organizational resources more effectively in dynamic business environments (Teece et al., 1997). For SMEs, digital transformation may strengthen the effectiveness of financial decisions and improve firms’ financial performance. However, empirical evidence regarding the moderating role of digital transformation in the relationship between financial decisions and firm performance remains limited, particularly in emerging economies.
Although prior studies have extensively examined the relationships between managerial characteristics, financial decisions, and firm performance, the existing literature remains fragmented. Previous research has largely focused on individual managerial attributes, such as financial knowledge, experience, or risk attitudes, without providing an integrated perspective on how multiple managerial characteristics collectively influence financial decision-making processes. Similarly, studies on corporate finance have examined the importance of financial decisions for firm outcomes; however, limited attention has been given to financial decisions as a mechanism through which managerial capabilities are translated into financial performance, particularly in the SME context. Furthermore, while digital transformation has increasingly been recognized as an important organizational capability, its role in strengthening the relationship between financial decisions and performance remains insufficiently explored. These limitations suggest the need for a more comprehensive framework that integrates managerial characteristics, financial decisions, and digital transformation to explain SME financial performance.
Despite extensive research on managerial characteristics and financial performance, several important research gaps remain. First, prior studies have largely examined financial decisions independently rather than conceptualizing them as an integrated multidimensional construct. Second, limited studies have modeled financial decisions as a formative higher-order construct comprising capital structure decisions, investment decisions, and working capital management decisions. Third, although managerial characteristics are widely acknowledged as important determinants of firm performance, the mediating role of financial decisions remains underexplored, especially in the context of SMEs in emerging economies. Finally, the moderating role of digital transformation in strengthening the effectiveness of financial decisions has received limited empirical attention.
In Vietnam, SMEs continue to face substantial challenges related to access to finance, financial management capability, digital adaptation, and increasing competitive pressure. Given their relatively small scale, limited resources, and centralized governance structures, the quality and effectiveness of financial decisions in SMEs largely depend on managerial characteristics and capabilities. At the same time, the growing importance of digital transformation has created new opportunities for SMEs to improve financial management efficiency, information processing capability, and strategic responsiveness. In this context, examining the mediating role of financial decisions and the moderating role of digital transformation in the relationship between managerial characteristics and financial performance is essential for clarifying how managerial capabilities are translated into organizational financial outcomes under increasingly dynamic business environments.
Motivated by these research gaps, this study examines the mediating role of financial decisions and the moderating role of digital transformation in the relationship between managerial characteristics and financial performance among Vietnamese SMEs. Specifically, the study investigates how managerial characteristics, including risk-taking propensity, managerial experience, financial knowledge, leadership style, and strategic vision, influence firm financial performance through financial decisions. In this study, financial decisions are conceptualized as a formative higher-order construct comprising capital structure decisions, investment decisions, and working capital management decisions.
This study contributes to literature in several ways. First, the study extends Upper Echelons Theory, the Behavioral Theory of the Firm, and the Resource-Based View by explaining how managerial characteristics influence financial performance through financial decision-making processes. Second, the study contributes to SME finance literature by conceptualizing financial decisions as a multidimensional formative higher-order construct comprising capital structure, investment, and working capital management decisions. Third, the study enriches the digital transformation and dynamic capability literature by examining the moderating role of digital transformation in the relationship between financial decisions and financial performance. From a practical perspective, the findings provide implications for SME managers and policymakers in improving financial management capability, accelerating digital transformation, and enhancing firm financial performance.
The remainder of this paper is organized as follows. Section 2 presents the theoretical background and hypothesis development. Section 3 describes the research methodology and data analysis procedures. Section 4 presents the empirical results of the study. Section 5 discusses the research findings based on empirical evidence. Section 6 presents the conclusions along with the theoretical and practical implications of the study. Finally, Section 7 outlines the limitations of the study and provides directions for future research.

2. Literature Review and Hypothesis Development

2.1. Theoretical Background

2.1.1. Upper Echelons Theory

Upper Echelons Theory, proposed by Hambrick and Mason (1984), suggests that strategic decisions and organizational outcomes reflect the characteristics, values, cognitive orientations, and experiences of top managers. Under conditions of environmental uncertainty and incomplete information, managerial decisions are often shaped by individual knowledge, experience, and personal judgment. In the context of SMEs, where decision-making authority is highly centralized, managerial characteristics become particularly influential in determining organizational strategies and performance outcomes. Therefore, this theory provides an important foundation for explaining how managerial attributes such as risk-taking propensity, managerial experience, financial knowledge, leadership style, and strategic vision may influence financial decisions and financial performance.

2.1.2. Behavioral Theory of the Firm

The Behavioral Theory of the Firm was developed by Cyert and March (1963) and argues that organizational decisions are influenced by bounded rationality, managerial cognition, experience, and risk preferences under conditions of imperfect information. In addition, Prospect Theory proposed by Kahneman and Tversky (1979) suggests that financial decision-making is strongly affected by psychological perceptions of risk and uncertainty. These theoretical perspectives help explain why managers with different behavioral and cognitive characteristics may adopt different approaches to financing, investment, and working capital management decisions, thereby affecting firm performance.

2.1.3. Resource-Based View (RBV)

The Resource-Based View introduced by Barney (1991) emphasizes that valuable, rare, inimitable, and non-substitutable resources are essential sources of sustainable competitive advantage. Intangible managerial resources, including financial knowledge, managerial experience, and strategic vision, are considered critical capabilities that can enhance organizational effectiveness and long-term performance. In SMEs, where financial and operational resources are often limited, managerial capabilities become particularly important for improving financial performance and maintaining competitiveness. Accordingly, RBV provides a theoretical basis for examining the relationship between managerial characteristics and firm financial performance.

2.1.4. Corporate Finance Theories

Corporate finance theories provide important explanations regarding how firms make financing, investment, and liquidity management decisions to maximize firm value and financial performance. Trade-off Theory (A. Kraus & Litzenberger, 1973) suggests that firms seek an optimal capital structure by balancing the benefits and costs of debt financing, whereas Pecking Order Theory (Myers & Majluf, 1984) explains firms’ financing preferences under information asymmetry conditions. In addition, investment and working capital management theories emphasize that efficient capital allocation, cash flow management, and short-term asset optimization play significant roles in improving profitability and operational efficiency (Gitman, 1974; Jensen, 1986; Smith, 1980).
This study integrates multiple theoretical perspectives to explain how managerial attributes are transformed into firm financial outcomes. Specifically, Upper Echelons Theory and Behavioral Theory of the Firm explain why managerial characteristics influence financial decision-making processes. The Resource-Based View further suggests that managerial capabilities represent valuable intangible resources that contribute to competitive advantage. Meanwhile, Dynamic Capability Theory explains how digital transformation enables firms to effectively deploy these resources by improving information processing and organizational adaptability. Finally, Corporate Finance Theory supports the role of financial decisions as a critical mechanism through which managerial capabilities are translated into financial performance. Together, these theoretical perspectives provide an integrated framework explaining the relationships among managerial characteristics, financial decisions, digital transformation, and SME financial performance.

2.2. Research Hypothesis Development

2.2.1. Managerial Characteristics and Financial Decisions

In SMEs, managers often play a central role in capital structure selection, investment decisions, and working capital management due to resource constraints and the high concentration of decision-making authority. Rather than representing a homogeneous psychological trait, managerial characteristics in this study are viewed as a multidimensional set of managerial attributes that collectively influence financial decision-making processes. Specifically, risk tolerance reflects managers’ behavioral orientation toward uncertainty, managerial experience represents accumulated practical knowledge developed through prior decision-making, financial knowledge captures analytical capability in evaluating financial information, leadership style reflects managerial approaches toward organizational coordination and resource mobilization, and strategic vision represents a long-term orientation toward organizational development. Together, these characteristics capture key managerial capabilities that shape SME financial decisions.
According to Upper Echelons Theory, firms’ strategic and financial decisions reflect managers’ cognition, experience, and values (Hambrick & Mason, 1984). In addition, the Behavioral Theory of the Firm suggests that financial decisions are substantially influenced by managerial cognition and risk attitudes under conditions of incomplete information (Cyert & March, 1963; Kahneman & Tversky, 1979).
Risk-taking propensity reflects managers’ willingness to pursue financial alternatives characterized by higher uncertainty in exchange for greater expected returns. In SMEs, managers with an appropriate level of risk tolerance are generally more proactive in raising capital, expanding investments, and utilizing financial leverage to exploit market opportunities (Lumpkin & Dess, 1996). Previous studies by Carter and Van Auken (2005) and Buchdadi et al. (2020) also indicate that risk-taking propensity positively affects firms’ financial decisions. Accordingly, this study proposed that:
H1a. 
Risk-taking propensity positively affects the financial decisions of SMEs.
Managerial experience is considered an important intangible resource that enhances managers’ ability to analyze, forecast, and address complex financial situations. Experiential learning theory suggests that knowledge accumulated through practical managerial experience improves decision-making quality over time (Kolb, 1984). In SMEs, where financial decisions largely depend on individual managers, managerial experience facilitates more effective capital structure selection and cash flow management. Empirical studies by Gibson and Van der Vaart (2008) and Gupta and Gregoriou (2018) reported a positive relationship between managerial experience and financial decision quality. Based on the above arguments, the following hypothesis is proposed:
H1b. 
Managerial experience positively affects the financial decisions of SMEs.
Financial knowledge provides managers with a better understanding of investment, financing, and short-term asset management decisions. From the Resource-Based View perspective, financial knowledge represents a strategic resource that enhances financial management capability and improves risk control efficiency (Barney, 1991). Prior studies by Abor (2007), Lusardi and Mitchell (2014), and Santos-Jaén et al. (2021) suggest that managers with stronger financial knowledge tend to make more effective financial decisions. Accordingly, the following hypothesis is developed:
H1c. 
Financial knowledge positively affects the financial decisions of SMEs.
Leadership style is widely recognized as a multidimensional construct comprising different approaches to organizational management and decision-making. Among these, authoritarian leadership and democratic/flexible leadership represent two theoretically distinct dimensions with contrasting characteristics and managerial behaviors (Lewin et al., 1939). Leadership style directly influences how managers organize business operations and make financial decisions. Leadership effectiveness theory suggests that managerial effectiveness depends on the alignment between leadership style and organizational context (Fiedler, 1967). Authoritarian leadership tends to emphasize centralized control and limited employee participation in decision-making, potentially reducing flexibility in long-term financial decisions (Lewin et al., 1939). In contrast, democratic and flexible leadership styles facilitate information exchange, encourage innovation, and improve the quality of financial decision-making (Bass & Avolio, 1994; Yukl, 2020). Thus, based on the above theoretical arguments, the two leadership dimensions are expected to have different effects on SMEs’ financial decisions. Based on the theoretical foundations and previous studies, the following hypothesis is advanced:
H1d. 
Authoritarian leadership negatively affects the financial decisions of SMEs.
H1e. 
Democratic and flexible leadership positively affects the financial decisions of SMEs.
Strategic vision reflects managers’ ability to define long-term organizational direction and allocate resources in alignment with growth objectives. According to (Porter, 2008), firms with a clear strategic orientation are more likely to establish appropriate financial decisions that sustain competitive advantage. In SMEs, managers with strong strategic vision tend to be more proactive in capital structure selection, expansion investment, and cash flow management to support long-term development goals. Gupta and Gregoriou (2018) emphasized the important role of strategic vision in improving financial decision quality. Accordingly, the study puts forward the following hypothesis:
H1f. 
Strategic vision positively affects the financial decisions of SMEs.

2.2.2. Managerial Characteristics and Financial Performance

According to Upper Echelons Theory, managerial characteristics influence not only firms’ decision-making processes but also organizational outcomes (Hambrick & Mason, 1984). Likewise, the Behavioral Theory of the Firm suggests that managers’ cognition and behavioral responses under uncertainty directly affect firms’ financial performance (Cyert & March, 1963; Kahneman & Tversky, 1979). From the perspective of the Resource-Based View (RBV), managerial knowledge, experience, leadership capability, and strategic vision constitute valuable intangible resources that enhance firms’ competitive advantage and financial performance (Barney, 1991).
Managers with an appropriate level of risk tolerance are more likely to pursue investment opportunities and respond proactively to environmental changes, thereby improving financial performance (Lumpkin & Dess, 1996). Empirical evidence from Blackburn et al. (2013), Pratono (2018), Jeje (2020), Rahaman et al. (2021), and Gakure and Karugu (2025) consistently supports this positive relationship. Therefore, the following hypothesis is proposed:
H2a. 
Risk-taking propensity positively affects the financial performance of SMEs.
Managerial experience enhances judgment, improves resource allocation, and enables managers to respond more effectively to complex business situations. Previous studies by Mcmahon (2001), Sadler–Smith et al. (2003), and Karadag (2017) consistently demonstrate that managerial experience contributes to superior financial performance. Accordingly, the following hypothesis is proposed:
H2b. 
Managerial experience positively affects the financial performance of SMEs.
Financial knowledge enables managers to make more effective investment, financing, and financial management decisions, thereby improving firm performance. This relationship has been supported by prior studies, including Mcmahon (2001), Janssen (2006), and Lusardi and Mitchell (2014). Therefore, the following hypothesis is proposed:
H2c. 
Financial knowledge positively affects the financial performance of SMEs.
Leadership style influences how managers mobilize organizational resources and implement business strategies. While authoritarian leadership may reduce organizational flexibility and innovation, democratic and flexible leadership encourages employee participation and enhances organizational performance (Bass & Avolio, 1994). Empirical studies by Nielsen and Nielsen (2013), Antoncic et al. (2018), and Phuoc et al. (2022) provide further support for these relationships. Consistent with the theoretical distinction between these two leadership styles, they are also expected to exert different effects on SMEs’ financial performance. Accordingly, the following hypotheses are proposed:
H2d. 
Authoritarian leadership negatively affects the financial performance of SMEs.
H2e. 
Democratic and flexible leadership positively affects the financial performance of SMEs.
Strategic vision enables managers to establish long-term organizational direction, identify market opportunities, and allocate resources effectively to sustain competitive advantage. Previous studies by Nielsen and Nielsen (2013), Blackburn et al. (2013), and Kaplan and Norton (1996) consistently report a positive relationship between strategic vision and firms’ financial performance. Therefore, the following hypothesis is proposed:
H2f. 
Strategic vision positively affects the financial performance of SMEs.

2.2.3. Relationship Between Financial Decisions and Financial Performance

Financial decisions are considered a critical strategic mechanism influencing firms’ financial performance, particularly in SMEs, which often face resource constraints, limited access to finance, and pressure to maintain liquidity. According to corporate finance theories, financial performance largely depends on firms’ ability to formulate and implement appropriate financial decisions that optimize capital costs, improve resource utilization efficiency, and control financial risks (Brigham et al., 2004; Ross et al., 2022).
In this study, financial decisions are conceptualized as a formative higher-order construct reflecting the strategic integration of multiple financial decision dimensions within the firm. This construct comprises capital structure decisions, investment decisions, and working capital management decisions. Through these decisions, firms can improve investment efficiency, manage debt effectively, optimize working capital, and allocate cash flows more efficiently to enhance profitability and overall organizational performance.
For SMEs, selecting an appropriate capital structure may reduce financing costs and financial risks, while effective investment decisions contribute to competitiveness and growth opportunities. At the same time, efficient working capital management helps firms maintain liquidity, optimize cash flows, and ensure operational stability. Previous empirical studies consistently indicate that effective financial decisions positively influence firms’ financial performance (Abor, 2007; Afrifa & Tingbani, 2018; Deloof, 2003; A. H. Nguyen et al., 2020).
Based on these arguments, the following hypothesis is proposed:
H3. 
Financial decisions positively affect the financial performance of SMEs.

2.2.4. Financial Decisions as a Mediating Mechanism

Previous studies suggest that managerial characteristics do not directly generate financial performance; rather, their effects are primarily transmitted through the quality of firms’ financial decisions. According to Upper Echelons Theory, managers’ cognition, experience, and orientations influence how firms formulate and implement strategic decisions, thereby affecting organizational outcomes (Hambrick & Mason, 1984). Similarly, the Behavioral Theory of the Firm argues that financial decisions are shaped by managerial cognition, risk assessment capability, and experience under conditions of imperfect information (Cyert & March, 1963; Kahneman & Tversky, 1979).
In SMEs, where decision-making authority is often concentrated in the hands of business owners or senior managers, managerial characteristics such as risk-taking propensity, managerial experience, financial knowledge, leadership style, and strategic vision play important roles in shaping firms’ financial decisions. However, these characteristics are translated into financial performance only when reflected through decisions related to capital structure, investment, and working capital management (Abor, 2007; Buchdadi et al., 2020; Gupta & Gregoriou, 2018). Therefore, financial decisions represent the behavioral and strategic mechanism through which managerial characteristics are converted into firm financial performance. Managers with stronger financial capabilities and more effective managerial orientations are expected to make more appropriate capital structure choices, investment decisions, and working capital management practices, which can enhance resource allocation efficiency, financial stability, and overall performance. In this sense, financial decisions do not merely represent outcomes of managerial characteristics but function as an intermediate pathway that explains how managerial attributes influence SME financial performance.
In this study, financial decisions (FD) represent a multidimensional construct encompassing capital structure, investment, and working capital management decisions. Accordingly, FD serves as a strategic mechanism through which managerial characteristics are translated into firm financial performance. Based on the theoretical arguments and prior empirical evidence, the following hypotheses are proposed:
H4a. 
Financial decisions mediate the relationship between risk-taking propensity and the financial performance of SMEs.
H4b. 
Financial decisions mediate the relationship between managerial experience and the financial performance of SMEs.
H4c. 
Financial decisions mediate the relationship between financial knowledge and the financial performance of SMEs.
H4d. 
Financial decisions mediate the relationship between authoritarian leadership and the financial performance of SMEs.
H4e. 
Financial decisions mediate the relationship between democratic and flexible leadership and the financial performance of SMEs.
H4f. 
Financial decisions mediate the relationship between strategic vision and the financial performance of SMEs.

2.2.5. Digital Transformation as a Moderating Mechanism

In the digital economy, digital transformation has increasingly become a critical capability that enhances firms’ operational efficiency and competitive advantage. The adoption of digital technologies enables firms to improve the speed, accuracy, and integration of information processing, thereby reducing information asymmetry and supporting timelier and evidence-based financial decision-making.
From the perspective of Dynamic Capability Theory (Teece et al., 1997), digital transformation is conceptualized not merely as a technological resource, but as an organizational capability that enhances firms’ ability to sense, seize, and reconfigure resources in response to environmental changes. In particular, digital tools such as enterprise resource planning (ERP) systems, digital accounting platforms, and data analytics systems improve firms’ sensing capability by facilitating real-time financial information access and monitoring. This, in turn, enhances the quality of financial decisions related to investment allocation, capital structure optimization, and working capital management.
Moreover, digital transformation strengthens firms’ seizing capability by enabling more accurate evaluation of financial alternatives and more efficient allocation of financial resources. It also enhances reconfiguring capability by allowing firms to rapidly adjust financial structures and operational strategies in response to market volatility and uncertainty. As a result, financial decisions are more effectively translated into operational outcomes, ultimately improving firm financial performance, particularly in SMEs (Bharadwaj et al., 2013; S. Kraus et al., 2021; Verhoef et al., 2021; Zhong et al., 2026).
Accordingly, digital transformation acts as a contextual dynamic capability that strengthens the effectiveness of financial decisions rather than directly generating performance outcomes. Firms with higher levels of digital transformation are therefore better able to convert the quality of financial decisions into superior financial performance. Based on the above arguments, the following hypothesis is proposed:
H5. 
Digital transformation positively moderates the relationship between financial decisions and the financial performance of SMEs.
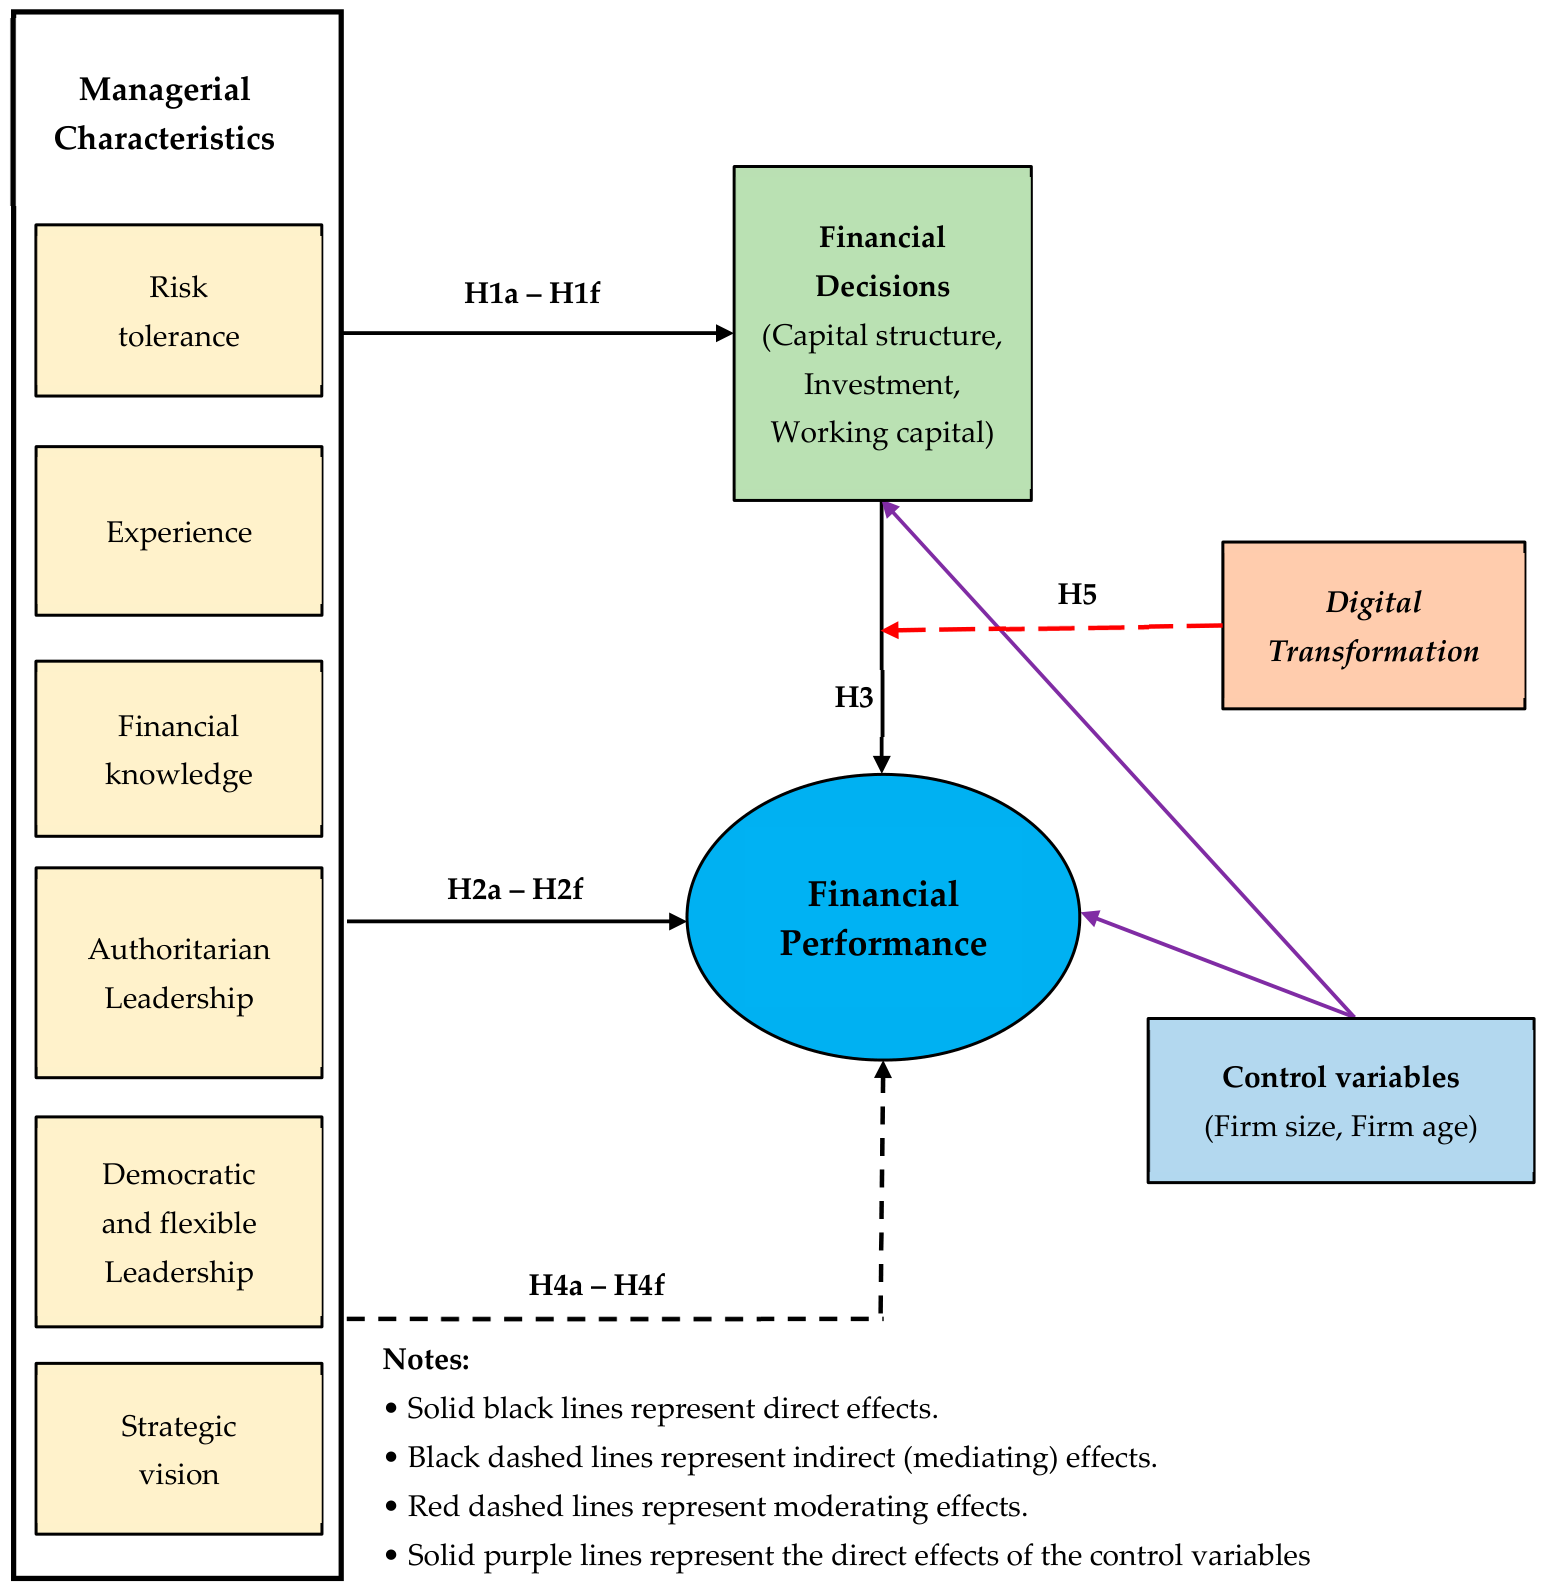
The proposed research model and hypotheses are presented in Figure 1. Hypotheses H1a–H1f examine the effects of managerial characteristics, including risk-taking propensity, managerial experience, financial knowledge, authoritarian leadership, democratic and flexible leadership, and strategic vision, on SMEs’ financial decisions. Hypotheses H2a–H2f examine the direct effects of these managerial characteristics on SMEs’ financial performance. Hypothesis H3 examines the effect of financial decisions on SMEs’ financial performance. Hypotheses H4a–H4f examine the mediating role of financial decisions in the relationships between managerial characteristics and SMEs’ financial performance. Finally, Hypothesis H5 examines the moderating role of digital transformation in the relationship between financial decisions and SMEs’ financial performance. The control variables, namely firm size and firm age, are also included in the research model.

3. Research Methodology

3.1. Sample and Data Collection

This study was conducted on SMEs operating in Khanh Hoa Province, Vietnam. Khanh Hoa was selected because it is one of the most dynamic economic regions in South Central Vietnam, with strong development in trade, services, tourism, manufacturing, and construction. SMEs in Khanh Hoa play an important role in economic growth, employment creation, and business development in Vietnam. In addition, the industrial structure, operational scale, and managerial characteristics of SMEs in Khanh Hoa are relatively similar to those of SMEs across Vietnam, making the sample reasonably representative of the broader Vietnamese SME sector.
The surveyed firms were invited to participate in a study examining the role of managerial characteristics and financial decisions in SMEs’ financial performance. Respondents included business owners, chief executive officers, financial managers, and senior executives directly involved in managerial and financial decision-making processes. A total of 600 questionnaires were distributed using a combination of convenience and purposive sampling methods. After screening and removing incomplete or invalid responses, 510 valid questionnaires were retained for data analysis, representing a valid response rate of 85.0%.
The primary data used in this study were collected through a structured questionnaire survey administered directly to SME owners/managers and senior executives who were involved in managerial and financial decision-making processes. The questionnaire covered information related to managerial characteristics, financial decisions, and firm financial performance. The detailed measurement items and questionnaire contents are provided in Appendix A.
Table 1 presents the profiles of the managers and firms participating in the survey. The results indicate that most respondents were male (74.1%), aged between 41 and 50 years old (38.0%), and held a bachelor’s degree (76.3%). Notably, the majority of respondents occupied positions as business owners or chief executive officers (63.5%), suggesting that the collected responses mainly came from individuals directly involved in corporate management and financial decision-making. Regarding firm characteristics, the sampled firms operated across various sectors, with trade, manufacturing, and construction representing the largest proportions. Most enterprises employed fewer than 10 employees (74.3%), had capital ranging from VND 3 to 20 billion (48.4%), and had operated for 6–20 years, reflecting the common characteristics of the Vietnamese SME sector.

3.2. Variables

The dependent variable is firm financial performance (FP), which is reflected through profitability, liquidity, asset growth, and revenue growth (Dess & Robinson, 1984; Venkatraman & Ramanujam, 1986; Wiklund & Shepherd, 2003). FP was conceptualized as a multidimensional latent construct capturing complementary aspects of SMEs’ financial outcomes, including their ability to generate profits, maintain liquidity, expand their asset base, and achieve revenue growth. Accordingly, FP was operationalized using four indicators and evaluated within the PLS-SEM measurement model, which accounts for the contribution of each indicator and potential measurement error.
In this study, FP was operationalized as a latent construct measured through multiple indicators rather than calculated as a single composite financial index. The four indicators capture different dimensions of SME financial performance and were evaluated within the PLS-SEM measurement model, which considers the contribution of each indicator and potential measurement error. Although objective financial indicators, such as return on assets (ROA) and return on equity (ROE), provide valuable information, obtaining reliable financial statements from SMEs is often difficult because many firms are reluctant to disclose financial information due to confidentiality concerns, limited reporting practices, and the informal nature of SME operations. Consequently, subjective financial performance measures have been widely adopted in SME research as a practical and appropriate alternative (Dess & Robinson, 1984; Venkatraman & Ramanujam, 1986; Wiklund & Shepherd, 2003). Moreover, previous studies have demonstrated that managers’ subjective assessments are strongly correlated with objective financial indicators, supporting the validity of perceptual performance measures when objective financial data are unavailable (Wall et al., 2004). Given that SME owners and managers generally possess comprehensive knowledge of their firms’ financial conditions and performance, profitability, liquidity, asset growth, and revenue growth were assessed through structured questionnaires completed by these respondents. Nevertheless, the use of perceptual measures may introduce respondent bias, which is acknowledged as a limitation of this study.
Five independent variables are included in the model, reflecting managerial characteristics, including experience (EXP), financial knowledge (FIK), risk tolerance (AR), strategic vision (STV), and leadership style (LES). EXP is measured through financial management experience, confidence in handling complex financial issues, and ability to avoid financial mistakes (Bertrand & Schoar, 2003; Hambrick & Mason, 1984). FIK reflects the ability to analyze financial statements, manage cash flow, and assess financial risk (Lusardi & Mitchell, 2014). AR captures the tendency to invest in uncertain but high-return projects, adopt new financial strategies, and allocate substantial resources to large-scale projects (Covin & Slevin, 1989; March & Shapira, 1987; Miller, 1983). STV is measured through long-term planning, market trend anticipation, long-term financial orientation, and growth-oriented thinking (Day & Schoemaker, 2005; Prahalad & Hamel, 1994; Rohrbeck & Gemünden, 2011). LES reflects both authoritarian and democratic leadership tendencies, including decision centralization, employee involvement, control orientation, and encouragement of innovation (Lewin et al., 1939; Vroom & Yetton, 1973; Yukl, 2020). These managerial characteristic variables were operationalized as latent constructs measured through multiple Likert-scale items. The observed responses were not converted into single composite scores through manual calculations; instead, construct scores were estimated using the PLS-SEM algorithm based on indicator contributions and measurement errors. For reflective first-order constructs, reliability and validity were assessed through indicator loadings, Cronbach’s alpha, composite reliability (CR), average variance extracted (AVE), HTMT ratio, and the Fornell–Larcker criterion.
The mediating variable is financial decisions (FD), conceptualized as a second-order formative construct comprising three first-order dimensions: capital structure decisions (CSD), investment decisions (IVD), and working capital management decisions (WCD). These dimensions represent the core areas of corporate financial management, including financing, capital allocation, and liquidity management (Brigham et al., 2004; Ross et al., 2022). This formative specification is theoretically justified because CSD, IVD, and WCD represent distinct and complementary domains of financial management that collectively constitute a firm’s overall financial decision capability. Unlike reflective indicators, these dimensions are not manifestations of an underlying FD construct; rather, they function as formative components that contribute to the formation of FD. Therefore, these dimensions are not expected to be interchangeable or necessarily highly correlated. Following the formative measurement logic, these dimensions are not necessarily required to covary but jointly form the overall FD construct (Diamantopoulos & Winklhofer, 2001; Jarvis et al., 2003; Petter et al., 2007). Building on A. T. L. Nguyen et al. (2022) and Sulistianingsih and Santi (2023), this study conceptualizes FD as an integrated financial decision-making capability. Specifically, CSD reflects managerial choices regarding financing sources and capital structure, including decisions concerning debt financing and retained earnings (A. Kraus & Litzenberger, 1973; Myers & Majluf, 1984). IVD represents decisions related to resource allocation and long-term investment opportunities, reflecting firms’ ability to select and implement value-enhancing investment projects (Biddle et al., 2009; Richardson, 2006). WCD captures short-term liquidity and operational financial management through practices related to receivables, inventories, payables, and cash flow management (Deloof, 2003; Juan García-Teruel & Martínez-Solano, 2007). Accordingly, FD is modeled as a second-order formative construct because each dimension contributes uniquely to overall financial decision capability. A firm may demonstrate strong investment decisions while adopting different approaches to capital structure or working capital management. Thus, changes in any of these dimensions can influence the overall level of FD, while changes in one dimension do not necessarily imply proportional changes in the others. This conceptualization supports the treatment of CSD, IVD, and WCD as formative causes rather than reflective consequences of financial decisions.
The moderating variable is digital transformation (DT), which reflects the extent to which firms integrate and apply digital technologies in managerial activities, decision-making, and operations to enhance efficiency and competitiveness (Bharadwaj et al., 2013; S. Kraus et al., 2021; Verhoef et al., 2021).
Control variables were included in the structural model to account for potential firm-level heterogeneity and reduce concerns regarding omitted variable bias. Following prior SME research, this study controls firm size (SIZE) and firm age (FAGE). Firm size is measured by the number of employees, while firm age is measured by the actual number of years since establishment. These control variables were specified with direct paths to both Financial Decisions (FD) and Financial Performance (FP) to examine whether firm characteristics influence the endogenous constructs.
All measurement scales were adapted from established studies and refined to ensure their suitability for the Vietnamese SME context. The adaptation process included reviewing previously validated scales, assessing their theoretical relevance, refining item wording for contextual clarity, and conducting a preliminary evaluation prior to the formal survey. All observed variables were measured using a seven-point Likert scale ranging from 1 (strongly disagree) to 7 (strongly agree).
To enhance transparency and facilitate replication, complete measurement items, construct descriptions, and sources are provided in Appendix A.

3.3. Method and Data Analysis

This study employed Partial Least Squares Structural Equation Modeling (PLS-SEM) to examine the relationships among managerial characteristics, financial decisions, and SME financial performance. PLS-SEM was selected due to its suitability for complex models involving multiple latent constructs, mediating relationships, and a higher-order formative construct. Compared with covariance-based SEM (CB-SEM), PLS-SEM is particularly appropriate for studies focusing on prediction and variance explanation, especially when the research model includes complex relationships among latent constructs. In this study, PLS-SEM is suitable because the proposed model examines direct effects, mediation effects, moderation effects, and a second-order formative construct of financial decisions. Therefore, PLS-SEM provides an appropriate analytical approach for evaluating the proposed theoretical framework and explaining the factors influencing SME financial performance.
Managerial characteristics, including risk acceptance, managerial experience, financial knowledge, leadership style, and strategic vision, were specified as exogenous constructs. Financial decision (FD) was modeled as a second-order formative construct comprising capital structure, investment, and working capital management decisions, while financial performance was treated as the endogenous construct.
Data analysis was conducted using a two-stage procedure combining exploratory and confirmatory approaches. In the first stage, Exploratory Factor Analysis (EFA) was conducted using SPSS 20 (Principal Component Analysis with Promax rotation) to examine the underlying factor structure, assess dimensionality, and ensure that measurement items loaded appropriately on their intended constructs. This step also allowed for initial item purification and assessment of construct validity. In the second stage, PLS-SEM was applied to validate the measurement model and test the structural relationships among constructs. This sequential EFA–PLS approach enhances the robustness of construct validation by combining exploratory and confirmatory techniques. Given that the data were collected from the same respondents using a single questionnaire, potential common method bias (CMB) was assessed using Harman’s single-factor test.
The measurement model was assessed through indicator reliability (outer loadings), internal consistency reliability (Cronbach’s alpha and composite reliability), convergent validity (AVE), and discriminant validity using the Fornell–Larcker criterion and HTMT. For the higher-order formative construct, multicollinearity was evaluated using VIF values, while indicator contribution was examined through outer weights. The structural model was assessed using path coefficients, coefficient of determination (R2), effect size (f2), predictive relevance (Q2), and model fit (SRMR). Hypotheses were tested using the bootstrapping procedure. All analyses were performed using SmartPLS 4 and SPSS 20, following established PLS-SEM methodological guidelines (Hair et al., 2021a, 2021b, 2021c, 2021d).

4. Empirical Results

4.1. Preliminary Data Screening and Assessment of Common Method Bias

Following data cleaning, 510 valid responses were retained for subsequent analysis. Preliminary data screening indicated that the observed variables exhibited adequate variability, with item means ranging from 3.41 to 3.64 and standard deviations between 0.899 and 1.193, suggesting no evidence of abnormal data distributions.
Given that the data were collected using a cross-sectional self-administered questionnaire, the potential influence of common method bias (CMB) was assessed using two complementary statistical approaches. First, Harman’s single-factor test was conducted using exploratory factor analysis (EFA) with principal component analysis and no rotation in SPSS 20. The first unrotated factor accounted for 27.799% of the total variance, which is below the 50% threshold suggested by Podsakoff et al. (2003), providing initial evidence that common method bias is unlikely to be a serious concern.
To further strengthen this assessment, the full collinearity approach proposed by Kock (2015) was employed. Full collinearity variance inflation factor (VIF) values were estimated for all latent constructs. As shown in Table 2, the full collinearity VIF values ranged from 1.051 to 2.870, all of which were below the recommended threshold of 3.3. These findings provide additional evidence that common method bias is unlikely to materially affect the study’s results.
Overall, the results support the suitability of the dataset for subsequent measurement and structural model analyses.

4.2. Exploratory Factor Analysis

Although the measurement scales were adapted from established studies, they were integrated from multiple sources and applied in the context of Vietnamese SMEs. Therefore, an exploratory factor analysis (EFA) was conducted as a preliminary assessment to examine whether the adapted measurement items retained their expected factor structure in the present dataset before evaluating the measurement model using PLS-SEM.
An exploratory factor analysis was conducted using principal axis factoring with Promax rotation to examine the underlying structure of the measurement scales. The adequacy of the data was confirmed by the KMO statistics and Bartlett’s test of sphericity. The results demonstrated a clear factor structure, with no significant cross-loadings exceeding 0.40. Consistent with the theoretical conceptualization of leadership as comprising two distinct dimensions, the leadership items are loaded onto two separate factors. Specifically, items LES1–LES3 loaded on the authoritarian leadership construct (LES_A), whereas items LES4–LES9 loaded on the democratic and flexible leadership construct (LES_D). These results provide empirical support for the proposed two-dimensional conceptualization of leadership adopted in this study.
Following the EFA procedure, the results confirmed the underlying factor structure of the measurement scales and provided empirical support for the theoretically proposed two-dimensional conceptualization of the leadership construct. Subsequently, the reliability and validity of the first-order constructs were assessed using outer loadings, Cronbach’s alpha, composite reliability (CR), and average variance extracted (AVE) within the PLS-SEM measurement model. The EFA results, including KMO values, Bartlett’s test of sphericity, and total variance explained, are presented in Table 3, while the detailed measurement model assessment results are reported in Table 4. The detailed factor loadings are reported in Appendix B.

4.3. Measurement Model

Following data screening and exploratory factor analysis, the measurement model was assessed using SmartPLS 4.0 to evaluate the reliability and validity of the constructs. The model consists of first-order constructs representing financial performance (FP), financial decision dimensions (CSD, IVD, and WCD), managerial characteristics (EXP, FIK, AR, STV, LES_A, and LES_D), and digital transformation (DT).

4.3.1. Reliability and Convergent Validity

The assessment results indicate that all first-order constructs meet the recommended criteria for reliability and convergent validity (Hair et al., 2021c). Outer loadings exceed the threshold of 0.70, ranging from 0.797 to 0.923. Internal consistency reliability is confirmed, with Cronbach’s alpha values ranging from 0.855 to 0.937 and composite reliability (CR) values ranging from 0.912 to 0.955. In addition, convergent validity is established, as all average variance extracted (AVE) values exceed the recommended threshold of 0.50, ranging from 0.712 to 0.841. Among the constructs, financial performance (FP) demonstrates particularly strong measurement quality (α = 0.937; CR = 0.955; AVE = 0.841), while the remaining constructs also satisfy the required thresholds, confirming the adequacy of the measurement model. The detailed results of reliability and convergent validity for the first-order constructs are presented in Table 4.

4.3.2. Discriminant Validity

Before assessing the structural model, this study evaluated the discriminant validity of the first-order constructs (FOCs) to ensure that the latent variables in the measurement model represented distinct concepts without substantial overlap. Following the recommendations of Henseler et al. (2015), the discriminant validity of the first-order constructs was assessed using the Heterotrait–Monotrait ratio (HTMT) and the Fornell–Larcker criterion (Fornell & Larcker, 1981). The assessment results are presented in Table 5 and Table 6.
Following Henseler et al. (2015), HTMT values should remain below the recommended threshold of 0.85, while values below 0.90 are considered acceptable under less stringent conditions. As reported in Table 4, all HTMT values ranged from 0.021 to 0.783, remaining well below the threshold values. The highest HTMT values were observed between WCD–CSD (0.783), FP–CSD (0.775), and FP–WCD (0.770), but these values were still within the acceptable range. In addition, the Fornell–Larcker results presented in Table 6 show that the square root of the AVE for each construct exceeded its correlations with other constructs. These findings provide further evidence that the constructs are empirically distinct from one another. Overall, the results confirm satisfactory discriminant validity and support the adequacy of the measurement model for subsequent structural model analysis.

4.3.3. Assessment of the Formative Second-Order Construct (Financial Decisions)

Financial Decisions (FD) was modeled as a formative second-order construct comprising three first-order dimensions: capital structure decisions (CSD), investment decisions (IVD), and working capital decisions (WCD). This formative specification is appropriate because these dimensions represent distinct and complementary areas of financial management that jointly form overall financial decision capability. Unlike reflective constructs, these dimensions are not manifestations of an underlying FD concept; rather, each dimension contributes uniquely to the formation of FD. Following the recommended procedures for assessing formative measurement models, the evaluation of FD focused on two main criteria: (1) the absence of multicollinearity among formative dimensions through variance inflation factor (VIF) values, and (2) the significance and relevance of outer weights (Hair et al., 2021b). The results are presented in Table 7.
Table 6 shows that all VIF values range from 2.512 to 2.695, which are below the recommended threshold, indicating that multicollinearity is not a concern among the formative dimensions of FD. Furthermore, all outer weights are positive and statistically significant at the 1% level (p < 0.001), confirming that CSD, IVD, and WCD each make significant contributions to the formation of Financial Decisions. Among the three dimensions, WCD demonstrates the highest outer weight (β = 0.379), followed closely by CSD (β = 0.378) and IVD (β = 0.374). Although the differences are relatively small, the results indicate that all three dimensions play important and complementary roles in forming overall financial decision capability. Therefore, the assessment results support the appropriateness of modeling FD as a second-order formative construct and justify its inclusion in the subsequent structural model analysis.
Furthermore, the discriminant validity between the higher-order Financial Decisions (FD) construct and Financial Performance (FP) was further examined. The HTMT value between FD and FP was 0.883, which remains below the acceptable threshold of 0.90 recommended by Henseler et al. (2015). In addition, the Fornell–Larcker criterion confirms that the square root of AVE for FD (0.884) and FP (0.917) exceeds their inter-construct correlation (0.793), indicating adequate discriminant validity (Fornell & Larcker, 1981). These results indicate that although financial decisions are theoretically related to financial performance, the two constructs represent empirically distinct concepts.

4.4. Structural Model

After confirming the reliability and validity of the measurement model, the structural model was evaluated to examine the proposed relationships among the constructs. The assessment included collinearity diagnostics, explanatory power, effect size, predictive relevance, and hypothesis testing.

4.4.1. Collinearity Assessment

Prior to hypothesis testing, collinearity among predictor constructs was assessed using the inner variance inflation factor (VIF). According to Hair et al. (2021d), VIF values below 5 indicate the absence of critical multicollinearity issues in the structural model. As shown in Table 8, all inner VIF values ranged from 1.005 to 3.975, remaining below the recommended threshold. The highest VIF value was observed for the relationship between FD and FP (3.975); however, it was still within the acceptable range. These findings confirm that multicollinearity does not pose a concern in the structural model and that the model is appropriate for subsequent hypothesis testing.

4.4.2. Coefficient of Determination (R2)

The coefficient of determination (R2) was examined to assess the explanatory power of the structural model, as suggested by Hair et al. (2021d). According to Hair et al. (2021d), R2 values of 0.75, 0.50, and 0.25 can be interpreted as substantial, moderate, and weak explanatory power, respectively.
As shown in Table 9, the model explained 71.4% of the variance in FD and 70.9% of the variance in FP, indicating substantial explanatory power according to the criteria suggested by Hair et al. (2021d). These findings suggest that the proposed model demonstrates strong explanatory capability for both financial decisions and firm financial performance.

4.4.3. Effect Size (f2)

Effect size (f2) was examined to assess the contribution of each exogenous construct to the endogenous constructs. Small, medium, and large effect sizes are commonly represented by f2 values of 0.02, 0.15, and 0.35, respectively (Cohen, 1992; Hair et al., 2021d).
The results in Table 10 reveal that AR, EXP, FIK, LES_A, and STV exerted large effects on FD, whereas LES_D demonstrated a medium effect. Regarding FP, FD and the interaction term DT × FD showed medium effect sizes, while most direct effects on FP were relatively small. Overall, the findings indicate that financial decisions and digital transformation play important roles in explaining SME financial performance.

4.4.4. Predictive Relevance (Q2)

Predictive relevance was assessed using the blindfolding procedure and PLSpredict analysis. Q2 values greater than zero indicate that the model has predictive relevance (Hair et al., 2021d; Shmueli et al., 2016). As shown in Table 11, the Q2 values for FD (0.707) and FP (0.592) were substantially above zero, confirming the predictive relevance of the structural model. The findings indicate that the model possesses satisfactory predictive capability for the endogenous constructs.
Predictive performance was further evaluated using PLSpredict. As shown in Table 12, positive Q2 predict values and lower PLS-SEM RMSE than LM RMSE indicate satisfactory out-of-sample predictive performance.

4.4.5. Goodness-of-Fit

The overall model fit was evaluated using the standardized root mean square residual (SRMR), normed fit index (NFI), and other discrepancy measures. Based on the widely accepted cutoff criteria suggested by Hu and Bentler (1999), SRMR values lower than 0.08 indicate an acceptable model fit. These criteria are commonly employed in structural equation modeling to assess the overall adequacy of model specification.
As presented in Table 13, the SRMR values for both the saturated and estimated models were below the recommended threshold of 0.08, indicating acceptable model fit. In addition, the NFI value of 0.886 suggests satisfactory overall model fit for the PLS-SEM analysis. Overall, the findings confirm that the proposed model achieved an acceptable level of goodness-of-fit.
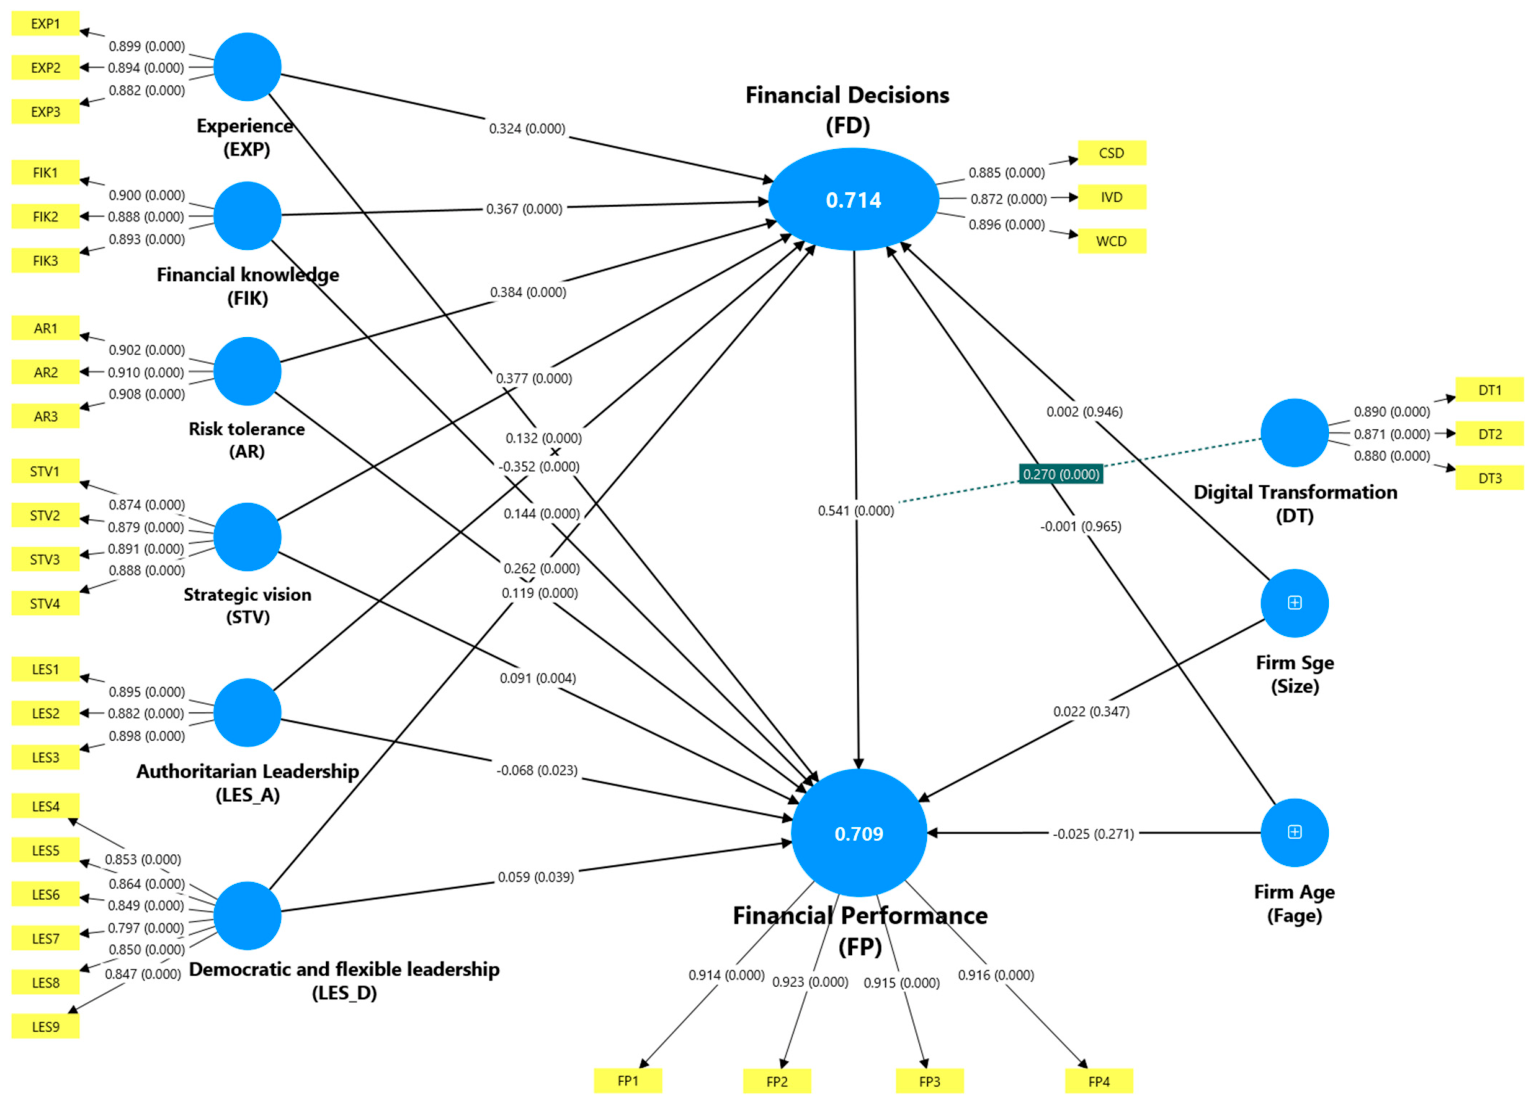
Figure 2 presents the results of the PLS-SEM structural model, including the standardized path coefficients and the explanatory power (R2) of the endogenous constructs.

4.4.6. Hypothesis Testing

Direct Effects
Before testing the proposed hypotheses, bootstrapping with 10,000 resamples was performed to assess the significance of structural relationships following Hair et al. (2021d). The direct effects were evaluated in the full mediation model, including both the paths from managerial characteristics to FD and the direct paths from managerial characteristics to FP. The results are presented in Table 14.
The results presented in Table 14 indicate that all proposed direct relationships were statistically significant. Specifically, AR, EXP, FIK, LES_D, and STV positively influenced FD, whereas LES_A negatively affected FD. In addition, FD demonstrated a strong positive effect on FP (β = 0.541, p < 0.001). Importantly, after including FD in the structural model, all direct effects from managerial characteristics to FP remained statistically significant, providing initial evidence of partial mediation.
In addition to the hypothesized relationships, firm size and firm age were included as control variables to examine whether firm characteristics influenced financial decisions and financial performance. The results show that firm size does not have a significant effect on financial decisions (β = 0.002, p = 0.946) or financial performance (β = 0.022, p = 0.347). Similarly, firm age has no significant effect on financial decisions (β = −0.001, p = 0.965) or financial performance (β = −0.025, p = 0.271). These findings suggest that the observed relationships among managerial characteristics, financial decisions, and financial performance remain robust after controlling for firm-level characteristics.
Indirect Effects and the Mediating Role of Financial Decisions
The mediating role of FD in the relationships between managerial characteristics and FP was assessed through bootstrapping of indirect effects, following the structural model evaluation procedures proposed by Hair et al. (2021d). The results are presented in Table 15.
As shown in Table 15, all indirect effects through FD were statistically significant at the 1% significance level. Furthermore, the direct effects from managerial characteristics to FP remained significant after including FD in the model (Table 14). Therefore, FD partially mediates the relationships between managerial characteristics and financial performance. The VAF values ranged from 57.14% to 73.36% and are reported as supplementary information. These values further indicate the substantial mediating contribution of FD; however, the classification of mediation is primarily based on the significance of direct effects after introducing the mediator.
These findings suggest that managerial characteristics influence SME financial performance through two mechanisms: directly through managerial capabilities and indirectly through financial decision-making processes.
Moderating Effect of Digital Transformation
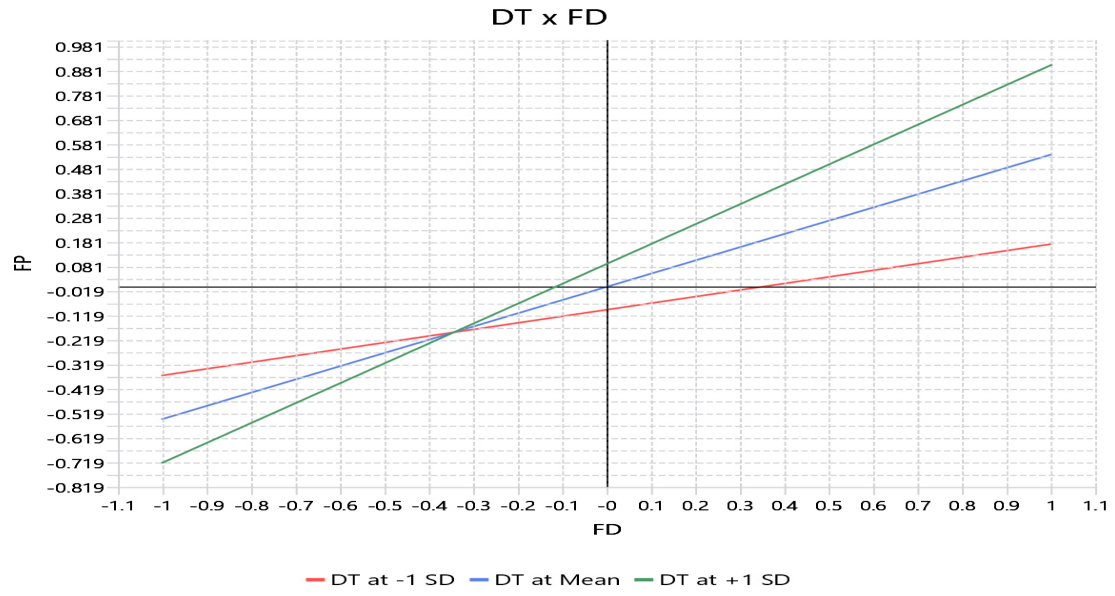
The moderating effect of digital transformation (DT) on the relationship between financial decisions (FD) and financial performance (FP) was examined using the interaction term approach proposed by Hair et al. (2021d). The results, presented in Table 16, show that the interaction term DT × FD has a positive and statistically significant effect on FP (β = 0.270, p < 0.001). The result indicates that digital transformation strengthens the positive relationship between financial decisions and firm financial performance.
To further clarify the nature of this interaction, the simple slope analysis presented in Figure 3 was conducted. The results indicate that the positive effect of FD on FP is stronger when DT is high (+1 SD), as evidenced by a steeper slope, whereas this relationship weakens when DT is low (−1 SD), reflected by a flatter slope.
Overall, these findings confirm that digital transformation plays a significant strengthening moderating role in the FD–FP relationship. Accordingly, higher levels of DT enhance the effectiveness of financial decisions in improving financial performance. This can be explained by the role of digital transformation in improving information quality, accelerating data processing, and supporting more accurate and timely managerial decision-making.

5. Discussion of Findings

The findings provide strong empirical support for the proposed framework and reinforce the explanatory relevance of Upper Echelons Theory, Behavioral Theory of the Firm, Resource-Based View, and corporate finance theories in the SME context. Rather than simply confirming prior empirical evidence, the findings are interpreted in terms of underlying behavioral and capability-based mechanisms, highlighting how managerial cognition and organizational capabilities jointly shape financial decision effectiveness and firm performance. Overall, managerial characteristics significantly influence financial decisions, which subsequently improve financial performance. In addition, financial decisions partially mediate the relationship between managerial characteristics and firm performance, while digital transformation strengthens the effectiveness of financial decisions in enhancing SME outcomes.

5.1. Effects of Managerial Characteristics on Financial Decisions and Financial Performance

The findings indicate that all managerial characteristics significantly influence both financial decisions and financial performance, thereby providing support for hypotheses H1a–H1f and H2a–H2f. However, managerial characteristics exert considerably stronger effects on financial decisions than on financial performance. Specifically, the standardized coefficients for financial decisions range from 0.262 to 0.384 in absolute value, whereas those for financial performance range only from 0.059 to 0.144. This pattern suggests that managerial characteristics contribute to firm performance not only through direct effects but, more importantly, by improving the quality of financial decision-making.
Risk-taking propensity positively affects financial decisions (β = 0.384, p < 0.001) and financial performance (β = 0.119, p < 0.001). Managers with an appropriate level of risk tolerance are more willing to pursue profitable investment opportunities, adopt proactive financing strategies, and respond effectively to environmental uncertainty. Consequently, they achieve superior financial outcomes through both more effective financial decisions and improved organizational performance. These findings support the behavioral perspective that managerial cognition and risk attitudes shape organizational outcomes under uncertainty (Cyert & March, 1963; Kahneman & Tversky, 1979) and are consistent with previous studies by Carter and Van Auken (2005), Blackburn et al. (2013), Pratono (2018), and Rahaman et al. (2021).
Managerial experience also positively influences both financial decisions (β = 0.324, p < 0.001) and financial performance (β = 0.132, p < 0.001). Experienced managers possess greater analytical capability, accumulated knowledge, and practical judgment, enabling them to evaluate financial alternatives more effectively and allocate organizational resources more efficiently. The findings support experiential learning theory (Kolb, 1984) and are consistent with Gibson and Van der Vaart (2008), Gupta and Gregoriou (2018), Mcmahon (2001), Sadler–Smith et al. (2003), and Karadag (2017), all of whom emphasized the important role of managerial experience in improving decision quality and organizational performance.
Financial knowledge exhibits significant positive effects on financial decisions (β = 0.367, p < 0.001) and financial performance (β = 0.144, p < 0.001), indicating that financially knowledgeable managers are more capable of evaluating investment opportunities, selecting appropriate financing sources, managing financial risks, and allocating resources efficiently. These results reinforce the Resource-Based View, which considers managerial knowledge a valuable intangible resource that strengthens organizational capabilities (Barney, 1991). The findings are consistent with Abor (2007), Lusardi and Mitchell (2014), Santos-Jaén et al. (2021), Janssen (2006).
Regarding leadership style, authoritarian leadership negatively affects financial decisions (β = −0.352, p < 0.001) and financial performance (β = −0.068, p = 0.023), whereas democratic and flexible leadership positively influences financial decisions (β = 0.262, p < 0.001) and financial performance (β = 0.059, p = 0.035). These findings indicate that participative leadership promotes communication, knowledge sharing, and organizational adaptability, thereby improving both financial decision quality and firm performance. Conversely, excessive centralization may restrict organizational flexibility and reduce long-term effectiveness. The results are consistent with Lewin et al. (1939), Bass and Avolio (1994), Yukl (2020), Nielsen and Nielsen (2013), Antoncic et al. (2018), and Phuoc et al. (2022).
Strategic vision positively affects financial decisions (β = 0.377, p < 0.001) and financial performance (β = 0.091, p = 0.004). Managers with a strong long-term orientation are more likely to formulate proactive financing, investment, and working capital strategies while effectively identifying market opportunities and allocating organizational resources to sustain competitive advantage. These findings support Porter (2008), Gupta and Gregoriou (2018), Ireland and Hitt (1999), Prahalad and Hamel (1994), and Kaplan and Norton (1996), all of whom emphasized the strategic importance of long-term managerial orientation for organizational success.
A comparison of the standardized coefficients reveals that the direct effects of managerial characteristics on financial performance are consistently much weaker than their effects on financial decisions. For example, the effect of risk-taking propensity decreases from β = 0.384 on financial decisions to β = 0.119 on financial performance, while the corresponding coefficients decline from 0.324 to 0.132 for managerial experience, from 0.367 to 0.144 for financial knowledge, from −0.352 to −0.068 for authoritarian leadership, from 0.262 to 0.059 for democratic and flexible leadership, and from 0.377 to 0.091 for strategic vision. Combined with the strong positive relationship between financial decisions and financial performance (β = 0.541, p < 0.001), these findings suggest that financial decisions constitute the primary mechanism through which managerial characteristics are translated into superior financial performance. This evidence provides strong support for Upper Echelons Theory, which argues that managerial attributes influence organizational outcomes largely through strategic choices, and reinforces the Behavioral Theory of the Firm by demonstrating that managers’ cognitive and behavioral characteristics shape firm performance through financial decision-making processes.

5.2. Financial Decisions and Financial Performance

The study confirms that financial decisions positively affect SME financial performance (β = 0.541, p < 0.001), reinforcing the arguments of corporate finance theories that effective financing, investment, and liquidity management decisions are critical determinants of organizational profitability and operational efficiency. From a theoretical perspective, this implies that financial decisions serve as a key transformation mechanism that converts managerial capabilities into firm-level outcomes. In other words, similar managerial resources may lead to different performance outcomes depending on the quality of financial decision-making processes. Trade-off Theory suggests that firms seek optimal capital structures by balancing the benefits and costs of debt financing (A. Kraus & Litzenberger, 1973) while Pecking Order Theory explains financing preferences under information asymmetry conditions (Myers & Majluf, 1984). The findings are also consistent with previous studies demonstrating that effective financial management practices improve firm profitability and operational performance (Afrifa & Tingbani, 2018; Deloof, 2003; A. H. Nguyen et al., 2020). Similarly, Fama and French (1998) emphasized that financing and investment decisions are important determinants of firm value and long-term performance. Furthermore, the result supports Basu (2024), who found that capital structure plays a significant role in determining SME financial performance. Therefore, financial decisions can be considered a strategic mechanism through which firms transform managerial capabilities and organizational resources into financial outcomes.
In addition, the non-significant effects of firm size and firm age indicate that the influence of managerial characteristics and financial decisions on SME performance is not merely driven by differences in firm scale or maturity. This provides additional confidence that the proposed theoretical mechanism remains valid after accounting for important firm-level characteristics.

5.3. Mediating Role of Financial Decisions

The mediation analysis reveals that financial decisions partially mediate the relationship between managerial characteristics and financial performance. Specifically, all indirect effects through financial decisions were statistically significant (p < 0.001), suggesting that managerial characteristics primarily influence organizational outcomes through strategic and financial decision-making processes. This finding strongly supports Upper Echelons Theory, which argues that organizational outcomes reflect managerial characteristics through strategic choices and decision behavior (Hambrick & Mason, 1984). The result is also consistent with Basu (2024), who reported that leverage exerts a significant but partial mediating effect on SME financial performance. This mediation pattern indicates that managerial characteristics do not automatically translate into superior financial performance but must first be converted into effective financial decision-making outcomes, which act as an intermediate behavioral mechanism.
Compared with previous studies, the current research extends the literature by conceptualizing financial decisions as a multidimensional construct comprising capital structure, investment, and working capital management decisions. This multidimensional view highlights that financial decision-making is not a single operational act, but a coordinated set of strategic choices that collectively determine how managerial capabilities are transformed into firm-level outcomes. Accordingly, the findings provide additional evidence that financial decisions represent a comprehensive strategic mechanism linking managerial capabilities to firm performance in SMEs.

5.4. Moderating Role of Digital Transformation

The findings indicate that digital transformation positively moderates the relationship between financial decisions and financial performance (β = 0.270, p < 0.001). This suggests that SMEs with higher levels of digital transformation are more capable of utilizing financial decisions effectively to improve profitability and operational performance.
Digital transformation enhances the effectiveness of financial decisions by improving information accessibility, analytical capability, and operational coordination. By adopting digital technologies, SMEs can obtain more timely and accurate financial information, monitor cash flows, evaluate investment opportunities, and optimize resource allocation. Therefore, digital transformation does not replace financial decision-making capability but strengthens the extent to which high-quality financial decisions are translated into improved financial performance. The result supports previous studies suggesting that digital transformation enhances information processing capability, organizational flexibility, and strategic responsiveness (Bharadwaj et al., 2013; S. Kraus et al., 2021; Verhoef et al., 2021). Similarly, Vial (2021) argued that digital transformation improves organizational processes and firms’ ability to generate superior performance outcomes. From the perspective of dynamic capability theory, digital transformation represents a strategic capability that enables firms to integrate and reconfigure organizational resources more effectively in dynamic business environments (Teece et al., 1997). This implies that digital transformation does not directly create superior performance but instead enhances the effectiveness of existing managerial financial decisions by improving the speed, accuracy, and adaptability of decision implementation. Accordingly, the same level of financial decision quality may lead to different performance outcomes depending on the firm’s digital capability, highlighting the contingent nature of value creation in digitally transformed SMEs. Therefore, SMEs should simultaneously improve financial decision quality and strengthen digital transformation capabilities to sustain competitiveness in the digital economy.

6. Conclusions and Implications

6.1. Conclusions

This study examined the relationships among managerial characteristics, financial decisions, digital transformation, and financial performance in SMEs based on Upper Echelons Theory, Behavioral Theory of the Firm, Resource-Based View, and corporate finance theories. The findings reveal that risk-taking propensity, managerial experience, financial knowledge, democratic and flexible leadership, and strategic vision positively influence financial decisions, whereas authoritarian leadership negatively affects financial decisions. In addition, financial decisions significantly improve SME financial performance. The results also confirm the partial mediating role of financial decisions in the relationship between managerial characteristics and financial performance, suggesting that managerial capabilities are translated into organizational outcomes primarily through firms’ financial decision-making processes. This highlights that financial decisions function as an essential behavioral transmission mechanism that converts managerial cognition and capabilities into firm-level outcomes. Furthermore, digital transformation positively moderates the relationship between financial decisions and financial performance, indicating that SMEs with stronger digital capability are more likely to utilize financial decisions effectively to improve performance and competitiveness. This also implies that the value of financial decisions is context-dependent and varies according to the firm’s digital capability level. Overall, the study contributes to the SME finance and strategic management literature by integrating managerial characteristics, multidimensional financial decisions, and digital transformation into a unified framework, while providing additional empirical evidence from an emerging economy context.

6.2. Theoretical and Practical Implications

6.2.1. Theoretical Implications

This study contributes to literature in three important ways. First, unlike prior studies that often examine individual financial decisions separately, this research conceptualizes financial decisions as a multidimensional higher-order construct comprising capital structure decisions, investment decisions, and working capital management decisions. This integrated perspective provides a more comprehensive explanation of how SMEs strategically manage financial resources and strengthens the explanatory power of corporate finance theory in SME contexts.
Second, this study extends Upper Echelons Theory by demonstrating that managerial characteristics influence firm financial performance primarily through financial decision-making processes. Rather than assuming a direct relationship between managerial attributes and organizational outcomes, the findings reveal financial decisions as an important behavioral mechanism through which managerial capabilities are transformed into performance outcomes. The study also enriches the Behavioral Theory of the Firm and Resource-Based View by showing that managerial capabilities, including risk-taking propensity, financial knowledge, managerial experience, and strategic vision, enhance financial decision quality and firm performance.
Third, this study extends the digital transformation literature by demonstrating its moderating role in the relationship between financial decisions and financial performance. By positioning digital transformation as a dynamic capability, this study explains why similar financial decisions may generate different performance outcomes depending on firms’ digital capability levels. This finding provides a more nuanced understanding of how SMEs can leverage digital capabilities to enhance the effectiveness of financial resource utilization in dynamic business environments.
Overall, this study moves beyond direct-effect explanations by integrating managerial characteristics, financial decisions, and digital transformation into a unified framework, thereby providing new insights into SME financial management in emerging economy contexts.

6.2.2. Practical Implications

The findings provide several practical implications for SME managers, policymakers, and business support organizations, particularly in emerging-economy contexts where firms often face resource constraints and uncertainty.
First, SME managers should focus on developing managerial competencies that directly improve financial decision quality. Rather than relying only on financial experience, SMEs should strengthen managers’ financial knowledge through targeted training in financial analysis, capital structure planning, investment evaluation, and risk management. In addition, firms should encourage strategic thinking and participative leadership practices to improve information sharing, adaptability, and decision effectiveness.
Second, SMEs should adopt a more integrated approach to financial management practices. Instead of treating financing, investment, and working capital decisions separately, managers should establish coordinated financial planning processes. For example, SMEs should regularly evaluate financing alternatives, align investment decisions with long-term strategic objectives, and implement effective cash flow monitoring systems to improve financial stability and resource utilization.
Third, digital transformation initiatives should be designed according to SME capabilities and business needs. Rather than pursuing complex technologies immediately, SMEs should gradually adopt practical digital solutions such as digital accounting systems, financial management software, cloud-based platforms, and data analytics tools. These technologies can improve financial information accuracy, monitoring capability, and the speed of managerial decision-making.
For policymakers and business support organizations, the findings suggest that SME development programs should move beyond providing financing support alone. Effective support should combine managerial capability development, financial management training, and digital transformation assistance to help SMEs build sustainable competitive advantages in emerging economies.

7. Limitations and Recommendations for Future Research

Despite its contributions, this study has several limitations. First, the cross-sectional design limits the ability to examine causal relationships over time. Although the proposed model is theoretically grounded, potential endogeneity concerns, including reverse causality and omitted-variable bias, cannot be completely excluded. For example, while managerial characteristics and financial decisions may influence firm performance, firms with stronger performance outcomes may also affect managerial decision-making processes and financial practices. Future studies may employ longitudinal approaches, instrumental variable techniques, or other advanced econometric methods to further examine causal relationships among managerial characteristics, financial decisions, digital transformation, and firm performance.
Second, the study relied primarily on self-reported survey data, which may increase the risk of subjective bias. Future research should combine survey data with secondary financial data or objective performance indicators to improve robustness.
Third, the study focuses on SMEs in a specific emerging economy context (Khanh Hoa Province, Vietnam), and the data were collected using convenience and purposive sampling methods. Therefore, the external validity of the findings may be limited, and the results should be interpreted within this contextual boundary rather than generalized to all SMEs in Vietnam or other countries. Future studies may conduct comparative analyses across countries, industries, or institutional environments and employ probability-based sampling techniques to further validate and generalize the proposed relationships.
Fourth, although firm size and firm age were controlled for in this study, industry-specific effects were not examined in the structural model. Future research could incorporate industry dummy variables or conduct multi-group analysis to further investigate whether the proposed relationships vary across different industry contexts.
Finally, future research may extend the model by incorporating additional organizational and environmental factors such as innovation capability, entrepreneurial orientation, corporate governance, or environmental uncertainty. Further studies may also explore the mediating role of digital capability and examine specific dimensions of digital transformation in SME performance.

Author Contributions

Conceptualization, C.N.T. and N.N.V.; methodology, M.N.N., C.N.T. and N.N.V.; formal analysis, M.N.N. and C.N.T.; resources, M.N.N.; writing—original draft preparation, M.N.N. and C.N.T.; writing—review and editing, M.N.N., C.N.T. and N.N.V.; supervision, C.N.T. and N.N.V. All authors have read and agreed to the published version of the manuscript.

Funding

This research received no external funding.

Institutional Review Board Statement

Ethical review and approval were waived for this study because it did not involve any sensitive personal data and/or invasive procedures. This research was conducted in accordance with the regulations of the Department of Business Administration, School of Economics and Business, Nha Trang University. The specific approval details are maintained by the department.

Informed Consent Statement

Informed consent was obtained from all subjects involved in the study. Participation in the survey was voluntary, and the information provided by participants was used solely for research purposes.

Data Availability Statement

The data used in this study were collected through a survey of SMEs in Khanh Hoa Province, Vietnam. The dataset supporting the findings of this study is available from the corresponding author upon reasonable request.

Acknowledgments

The authors would like to thank all managers and representatives of SMEs in Khanh Hoa Province who voluntarily participated in the survey and provided valuable information for this research.

Conflicts of Interest

The authors declare no conflicts of interest.

Appendix A. Measurement Items and Questionnaire Contents

VariablesCodeItemsSource
Financial
Performance
(FP)
FP1My firm achieves a strong level of profitability.Venkatraman and Ramanujam (1986); Dess and Robinson (1984); Shin and Soenen (1998); Deloof (2003); Wiklund and Shepherd (2003); Juan García-Teruel and Martínez-Solano (2007); Richard et al. (2009); Storey (2016); Mendoza-Velázquez et al. (2022).
FP2My firm is able to meet its debt obligations on time.
FP3My firm’s assets have increased significantly in recent years.
FP4My firm’s revenue has grown steadily over the years.
Capital
Structure
Decision
(CSD)
CSD1My firm prefers using retained earnings rather than debt financing to reduce financial risk.Modigliani and Miller (1963); A. Kraus and Litzenberger (1973); DeAngelo and Masulis (1980); Myers (1984); Myers and Majluf (1984); Titman and Wessels (1988); Berger and Udell (1998); Frank and Goyal (2009).
CSD2My firm is confident in maintaining an appropriate debt ratio to optimize financial performance.
CSD3My firm is willing to use debt financing to exploit business opportunities when the benefits outweigh the costs.
Investment
Decision
(IVD)
IVD1My firm invests in new technology or equipment to improve operational efficiency.Richardson (2006); Biddle et al. (2009); Sureka et al. (2022); Erda and Walstrum (2024); Cimini and Kalantzis (2024); Bianchini and Sancho (2025).
IVD2My firm avoids overinvestment to protect the business from financial risk.
IVD3My firm regularly reviews investment decisions to adjust strategies.
Working
Capital
Management Decision
(WCD)
WCD1My firm closely controls accounts receivable to accelerate cash collection.Petersen and Rajan (1997); Shin and Soenen (1998); Deloof (2003); Juan García-Teruel and Martínez-Solano (2007); Gul et al. (2013); Aktas et al. (2015); Kayani et al. (2025).
WCD2My firm manages inventories carefully to avoid excess stock or shortages.
WCD3My firm regularly evaluates accounts payable to optimize cash flow.
WCD4My firm regularly plans and forecasts cash flows to ensure short-term liquidity.
Managerial
Experience
(EXP)
EXP1I have extensive experience in corporate financial management.Hambrick and Mason (1984); Bandura (1997); Bertrand and Schoar (2003); Hambrick (2007); Lown (2011); Farrell et al. (2016); Custódio and Metzger (2014); Kubick and Li (2023).
EXP2I am confident in handling complex financial issues due to my accumulated experience.
EXP3My experience helps the firm avoid major financial mistakes.
Financial Knowledge
(FIK)
FIK1I can analyze financial statements to evaluate the firm’s condition.Brealey et al. (2011); Lusardi and Mitchell (2014); Brigham and Houston (2019); OECD/INFE (2020); CFA Institute (2025).
FIK2I understand how to manage cash flow to ensure business liquidity.
FIK3I am confident in evaluating the financial risks of investment decisions.
Risk tolerance
(AR)
AR1I often invest in projects with uncertain returns but high potential.Miller (1983); Covin and Slevin (1989); Lumpkin and Dess (1996); Weber et al. (2002); Blais and Weber (2006); March and Shapira (1987); Sitkin and Weingart (1995); Meertens and Lion (2008).
AR2I am willing to try new financial strategies even when information is limited.
AR3I am willing to allocate a large proportion of the firm’s resources to a major project.
Strategic
Vision
(STV)
STV1I have a clear plan for developing the business over the next five years.Prahalad and Hamel (1994); Kantabutra and Avery (2010); Tyler (2018); Shea-Van Fossen et al. (2006); Day and Schoemaker (2005); Rohrbeck and Gemünden (2011); Rohrbeck and Schwarz (2013); Sneader et al. (2020).
STV2I frequently anticipate market trends to guide the firm’s financial direction.
STV3I set long-term financial goals rather than focusing solely on short-term profits.
STV4I orient the business toward future growth opportunities.
Leadership Style
(LES)
LES1I usually make decisions without consulting employees.Lewin et al. (1939); Vroom and Yetton (1973); House and Aditya (1997); Farh and Cheng (2000); Bass and Bass Bernard (1985); Brownell and McInnes (1986); Podsakoff et al. (1990); Avolio and Bass (2004); Yukl (2020); Jung et al. (2003).
LES2I require employees to strictly follow my instructions.
LES3I closely supervise the firm’s financial activities.
LES4I encourage employees to participate in financial decision-making.
LES5I usually listen to my team’s opinions before making major decisions.
LES6I believe collaboration with employees improves financial performance.
LES7I encourage employees to take responsibility when participating in financial decisions.
LES8I inspire employees to achieve major financial goals.
LES9I encourage experimentation with innovative financial ideas within the firm.

Appendix B. Exploratory Factor Analysis Results and Rotated Factor Loading Matrix

The exploratory factor analysis (EFA) results and rotated factor loading matrices are presented in Table A1, Table A2 and Table A3.
Table A1. Exploratory Factor Analysis Results for Financial Performance (FP).
Component Matrix a
Component
1
FP20.922
FP40.917
FP30.915
FP10.914
a 1 component extracted.
Table A2. Pattern Matrix for Financial Decision Dimensions.
Pattern Matrix a
Factor
123
WCD30.850
WCD20.801
WCD10.776
WCD40.731
IVD3 0.873
IVD1 0.790
IVD2 0.761
CSD3 0.857
CSD2 0.827
CSD1 0.755
a Rotation converged in 5 iterations.
Table A3. Pattern Matrix for Managerial Characteristics.
Pattern Matrix a
Factor
123456
LES50.831
LES40.814
LES90.814
LES80.811
LES60.806
LES70.789
STV3 0.850
STV2 0.841
STV4 0.841
STV1 0.833
AR3 0.874
AR2 0.855
AR1 0.841
FIK2 0.854
FIK1 0.837
FIK3 0.819
EXP1 0.863
EXP2 0.843
EXP3 0.794
LES1 0.843
LES3 0.840
LES2 0.815
a Rotation converged in 5 iterations.

References

  1. Abor, J. (2007). Debt policy and performance of SMEs: Evidence from Ghanaian and South African firms. The Journal of Risk Finance, 8(4), 364–379. [Google Scholar] [CrossRef] [Scilit]
  2. Afrifa, G. A., & Tingbani, I. (2018). Working capital management, cash flow and SMEs’ performance. International Journal of Banking, Accounting Finance, 9(1), 19–43. [Google Scholar] [CrossRef] [Scilit]
  3. Aktas, N., Croci, E., & Petmezas, D. (2015). Is working capital management value-enhancing? Evidence from firm performance and investments. Journal of Corporate Finance, 30, 98–113. [Google Scholar] [CrossRef] [Scilit]
  4. Antoncic, J. A., Antoncic, B., Grum, D. K., & Ruzzier, M. (2018). The big five personality of the SME manager and their company’s performance. Journal of Developmental Entrepreneurship, 23(4), 1850021. [Google Scholar] [CrossRef] [Scilit]
  5. Avolio, B. J., & Bass, B. M. (2004). Multifactor leadership questionnaire (TM) (pp. 1–10). Mind Garden, Inc. [Google Scholar]
  6. Ayandibu, A. O., & Houghton, J. (2017). The role of small and medium scale enterprise in local economic development (LED). Journal of Business Retail Management Research, 11(2), 133–139. [Google Scholar]
  7. Ayyagari, M., Demirgüç-Kunt, A., & Maksimovic, V. (2011). Small vs. young firms across the world: Contribution to employment, job creation, and growth. World Bank policy research working paper No. 5631. The World Bank. [Google Scholar]
  8. Bandura, A. (1997). Self-efficacy: The exercise of control (Vol. 11). Freeman. [Google Scholar]
  9. Barney, J. (1991). Firm resources and sustained competitive advantage. Journal of Management, 17(1), 99–120. [Google Scholar] [CrossRef] [Scilit]
  10. Bass, B. M., & Avolio, B. J. (1994). Transformational leadership and organizational culture. The International Journal of Public Administration, 17(3–4), 541–554. [Google Scholar] [CrossRef] [Scilit]
  11. Bass, B. M., & Bass Bernard, M. (1985). Leadership and performance beyond expectations (Vol. 25). Free Press. [Google Scholar]
  12. Basu, M. (2024). Mediating effect of capital structure in determining firms’ financial performances of Indian SMEs: A structural equation modelling approach. International Journal of Accounting Finance, 12(1–2), 26–46. [Google Scholar] [CrossRef] [Scilit]
  13. Beck, T., & Demirguc-Kunt, A. (2006). Small and medium-size enterprises: Access to finance as a growth constraint. Journal of Banking Finance, 30(11), 2931–2943. [Google Scholar] [CrossRef] [Scilit]
  14. Beck, T., Demirguc-Kunt, A., & Levine, R. (2005). SMEs, growth, and poverty: Cross-country evidence. Journal of Economic Growth, 10(3), 199–229. [Google Scholar] [CrossRef] [Scilit]
  15. Berger, A. N., & Udell, G. F. (1998). The economics of small business finance: The roles of private equity and debt markets in the financial growth cycle. Journal of Banking Finance, 22(6–8), 613–673. [Google Scholar] [CrossRef] [Scilit]
  16. Bertrand, M., & Schoar, A. (2003). Managing with style: The effect of managers on firm policies. The Quarterly Journal of Economics, 118(4), 1169–1208. [Google Scholar] [CrossRef] [Scilit]
  17. Bharadwaj, A., El Sawy, O. A., Pavlou, P. A., & Venkatraman, N. V. (2013). Digital business strategy: Toward a next generation of insights. In MIS quarterly (Vol. 37, pp. 471–482). Management Information Systems Research Center, University of Minnesota. [Google Scholar]
  18. Bianchini, M., & Sancho, M. L. (2025). SME digitalisation for competitiveness: The 2025 OECD D4SME survey. OECD SME entrepreneurship papers. OECD. [Google Scholar]
  19. Biddle, G. C., Hilary, G., & Verdi, R. S. (2009). How does financial reporting quality relate to investment efficiency? Journal of Accounting Economics of Transition, 48(2–3), 112–131. [Google Scholar] [CrossRef] [Scilit]
  20. Blackburn, R. A., Hart, M., & Wainwright, T. (2013). Small business performance: Business, strategy and owner-manager characteristics. Journal of Small Business Enterprise Development, 20(1), 8–27. [Google Scholar] [CrossRef] [Scilit]
  21. Blais, A.-R., & Weber, E. U. (2006). A domain-specific risk-taking (DOSPERT) scale for adultpopulations. Judgment Decision Making, 1(1), 33–47. [Google Scholar] [CrossRef] [Scilit]
  22. Brealey, R. A., Myers, S. C., & Allen, F. (2011). Principles of corporate finance. McGraw-Hill Education. [Google Scholar]
  23. Brigham, E. F., & Houston, J. F. (2019). Fundamentals of financial management: Concise by cengage (pp. 1–7). Cengage Learning. [Google Scholar]
  24. Brigham, E. F., Houston, J. F., & Clark, D. A. (2004). Fundamentals of financial management. Thomson South-Western. [Google Scholar]
  25. Brownell, P., & McInnes, M. (1986). Budgetary participation, motivation, and managerial performance. Accounting Review, 61, 587–600. [Google Scholar] [CrossRef] [Scilit]
  26. Buchdadi, A. D., Sholeha, A., & Ahmad, G. N. (2020). The influence of financial literacy on SMEs performance through access to finance and financial risk attitude as mediation variables. Academy of Accounting Financial Studies Journal, 24(5), 1–15. [Google Scholar]
  27. Carter, R. B., & Van Auken, H. (2005). Bootstrap financing and owners’ perceptions of their business constraints and opportunities. Entrepreneurship Regional Development, 17(2), 129–144. [Google Scholar] [CrossRef] [Scilit]
  28. CFA Institute. (2025). Introduction to financial statement analysis (Refresher reading). CFA Institute. [Google Scholar]
  29. Cimini, F., & Kalantzis, F. (2024). The impact of the digital and green transitions on investment inefficiency (EIB Working Papers). European Investment Bank. [Google Scholar]
  30. Cohen, J. (1992). A power primer. Psychological Bulletin, 112(1), 155–159. [Google Scholar] [CrossRef] [PubMed]
  31. Covin, J. G., & Slevin, D. P. (1989). Strategic management of small firms in hostile and benign environments. Strategic Management Journal, 10(1), 75–87. [Google Scholar] [CrossRef] [Scilit]
  32. Custódio, C., & Metzger, D. (2014). Financial expert CEOs: CE’s work experience and firm’ s financial policies. Journal of Financial Economics, 114(1), 125–154. [Google Scholar] [CrossRef] [Scilit]
  33. Cyert, R. M., & March, J. G. (1963). A behavioral theory of the firm (1st ed.). Prentice Hall. [Google Scholar]
  34. Day, G. S., & Schoemaker, P. J. (2005). Scanning the periphery. Harvard Business Review, 83(11), 135. [Google Scholar] [PubMed]
  35. DeAngelo, H., & Masulis, R. W. (1980). Optimal capital structure under corporate and personal taxation. Journal of Financial Economics, 8(1), 3–29. [Google Scholar] [CrossRef] [Scilit]
  36. Deloof, M. (2003). Does working capital management affect profitability of Belgian firms? Journal of Business Finance Accounting, 30(3–4), 573–588. [Google Scholar] [CrossRef] [Scilit]
  37. Dess, G. G., & Robinson, R. B., Jr. (1984). Measuring organizational performance in the absence of objective measures: The case of the privately-held firm and conglomerate business unit. Strategic Management Journal, 5(3), 265–273. [Google Scholar] [CrossRef] [Scilit]
  38. Diamantopoulos, A., & Winklhofer, H. M. (2001). Index construction with formative indicators: An alternative to scale development. Journal of Marketing Research, 38(2), 269–277. [Google Scholar] [CrossRef] [Scilit]
  39. Do, H. T. T., Nguyen, P.-H., Tsai, J.-F., Hoang, O. T. N., Bui, T. A., Trinh, T. X., & Nguyen, T. T. (2023). Financing source, investment decision and firm performance of small and medium enterprises (SMEs): Evidence from Vietnam. Available online: https://ssrn.com/abstract=4325614 (accessed on 17 January 2023). [CrossRef] [Scilit]
  40. Erda, T., & Walstrum, T. (2024). How do manufacturers decide when to invest in new equipment? Federal Reserve Bank of Chicago. [Google Scholar]
  41. Fama, E. F., & French, K. R. (1998). Taxes, financing decisions, and firm value. The Journal of Finance, 53(3), 819–843. [Google Scholar] [CrossRef] [Scilit]
  42. Farh, J., & Cheng, B. (2000). Paternalistic leadership: Some further consideration. Indigenous Psychological Research in Chinese Societies, 13, 219–227. [Google Scholar]
  43. Farrell, L., Fry, T. R., & Risse, L. (2016). The significance of financial self-efficacy in explaining women’s personal finance behaviour. Journal of Economic Psychology, 54, 85–99. [Google Scholar] [CrossRef] [Scilit]
  44. Fiedler, F. E. (1967). A theory of leadership effectiveness. Mcgraw-hill series in management. McGraw-Hill. [Google Scholar]
  45. Finkelstein, S., Hambrick, D. C., & Cannella, A. A. (2009). Strategic leadership: Theory and research on executives, top management teams, and boards. Oxford University Press. [Google Scholar]
  46. Fornell, C., & Larcker, D. F. (1981). Evaluating structural equation models with unobservable variables and measurement error. Journal of Marketing Research, 18(1), 39–50. [Google Scholar] [CrossRef] [Scilit]
  47. Frank, M. Z., & Goyal, V. K. (2009). Capital structure decisions: Which factors are reliably important? Financial Management, 38(1), 1–37. [Google Scholar] [CrossRef] [Scilit]
  48. FSB. (2013). Small business statistics. Federation of Small Businesses. [Google Scholar]
  49. Gakure, S. K., & Karugu, J. (2025). Influence of risk taking on performance of small and medium scale enterprises in githurai market, Kenya. Journal of Entrepreneurship Project Management, 9(1), 67–77. [Google Scholar] [CrossRef] [Scilit]
  50. Gbandi, E., & Amissah, G. (2014). Financing options for small and medium enterprises (SMEs) in Nigeria. European Scientific Journal, 10, 327–340. [Google Scholar]
  51. Gibson, T., & Van der Vaart, H. (2008). Defining SMEs: A less imperfect way of defining small and medium enterprises in developing countries (Vol. 11). Brookings Global Economy Development. [Google Scholar]
  52. Gitman, L. J. (1974). Estimating corporate liquidity requirements: A simplified approach. Financial Review, 9(1), 79–88. [Google Scholar] [CrossRef] [Scilit]
  53. Gul, S., Khan, M. B., Raheman, S., Khan, M. T., Khan, M., & Khan, W. (2013). Working capital management and performance of SME sector. European Journal of Business Management Accounting Research, 5(1), 60–68. [Google Scholar]
  54. Gupta, J., & Gregoriou, A. (2018). Impact of market-based finance on SMEs failure. Economic Modelling, 69, 13–25. [Google Scholar] [CrossRef] [Scilit]
  55. Hair, J. F., Hult, G. T. M., Ringle, C. M., Sarstedt, M., Danks, N. P., & Ray, S. (2021a). An introduction to structural equation modeling. In Partial least squares structural equation modeling (PLS-SEM) using R: A workbook (pp. 1–29). Springer. [Google Scholar]
  56. Hair, J. F., Hult, G. T. M., Ringle, C. M., Sarstedt, M., Danks, N. P., & Ray, S. (2021b). Evaluation of formative measurement models. In Partial least squares structural equation modeling (PLS-SEM) using R: A workbook (pp. 91–113). Springer. [Google Scholar]
  57. Hair, J. F., Hult, G. T. M., Ringle, C. M., Sarstedt, M., Danks, N. P., & Ray, S. (2021c). Evaluation of reflective measurement models. In Partial least squares structural equation modeling (PLS-SEM) using R: A workbook (pp. 75–90). Springer. [Google Scholar]
  58. Hair, J. F., Hult, G. T. M., Ringle, C. M., Sarstedt, M., Danks, N. P., & Ray, S. (2021d). Evaluation of the structural model. In Partial least squares structural equation modeling (PLS-SEM) using R: A workbook (pp. 115–138). Springer. [Google Scholar]
  59. Hambrick, D. C. (2007). Upper echelons theory: An update. Academy of Management Review, 32, 334–343. [Google Scholar] [CrossRef] [Scilit]
  60. Hambrick, D. C., & Mason, P. A. (1984). Upper echelons: The organization as a reflection of its top managers. Academy of Management Review, 9(2), 193–206. [Google Scholar] [CrossRef] [Scilit]
  61. Henseler, J., Ringle, C. M., & Sarstedt, M. (2015). A new criterion for assessing discriminant validity in variance-based structural equation modeling. Journal of the Academy of Marketing Science, 43(1), 115–135. [Google Scholar]
  62. House, R. J., & Aditya, R. N. (1997). The social scientific study of leadership: Quo vadis? Journal of Management, 23(3), 409–473. [Google Scholar] [CrossRef]
  63. Hu, L. T., & Bentler, P. M. (1999). Cutoff criteria for fit indexes in covariance structure analysis: Conventional criteria versus new alternatives. Structural Equation Modeling: A Multidisciplinary Journal, 6(1), 1–55. [Google Scholar] [CrossRef] [Scilit]
  64. Hung, N. T., & Thanh, S. D. (2022). Threshold effect of working capital management on firm profitability: Evidence from Vietnam. Cogent Business & Management, 9(1), 2141090. [Google Scholar] [CrossRef] [Scilit]
  65. Ireland, R. D., & Hitt, M. A. (1999). Achieving and maintaining strategic competitiveness in the 21st century: The role of strategic leadership. Academy of Management Perspectives, 13(1), 43–57. [Google Scholar] [CrossRef] [Scilit]
  66. Janssen, F. (2006). Do managers’ characteristics influence the employment growth of SMEs? Journal of Small Business & Entrepreneurship, 19(3), 293–315. [Google Scholar] [CrossRef] [Scilit]
  67. Jarvis, C. B., MacKenzie, S. B., & Podsakoff, P. M. (2003). A critical review of construct indicators and measurement model misspecification in marketing and consumer research. Journal of Consumer Research, 30(2), 199–218. [Google Scholar] [CrossRef] [Scilit]
  68. Jeje, K. (2020). Risk-taking and performance of small and medium-sized enterprises: Lessons from Tanzanian bakeries. Journal of Economics Behavioral Studies, 12(3), 1–22. [Google Scholar] [CrossRef] [Scilit]
  69. Jensen, M. C. (1986). Agency costs of free cash flow, corporate finance, and takeovers. The American Economic Review, 76(2), 323–329. [Google Scholar]
  70. Juan García-Teruel, P., & Martínez-Solano, P. (2007). Effects of working capital management on SME profitability. International Journal of Managerial Finance, 3(2), 164–177. [Google Scholar] [CrossRef] [Scilit]
  71. Jung, D. I., Chow, C., & Wu, A. (2003). The role of transformational leadership in enhancing organizational innovation: Hypotheses and some preliminary findings. The Leadership Quarterly, 14(4–5), 525–544. [Google Scholar] [CrossRef] [Scilit]
  72. Kahneman, D., & Tversky, A. (1979). Prospect theory: An analysis of decision making under risk. Econometrica: Journal of the Econometric Society, 47, 263–291. [Google Scholar] [CrossRef] [Scilit]
  73. Kantabutra, S., & Avery, G. C. (2010). The power of vision: Statements that resonate. Journal of Business Strategy, 31(1), 37–45. [Google Scholar] [CrossRef] [Scilit]
  74. Kaplan, R. S., & Norton, D. P. (1996). Using the balanced scorecard as a strategic management system. Harvard Business Review, 74, 75–85. [Google Scholar]
  75. Karadag, H. (2017). The impact of industry, firm age and education level on financial management performance in small and medium-sized enterprises (SMEs) evidence from Turkey. Journal of Entrepreneurship in Emerging Economies, 9(3), 300–314. [Google Scholar] [CrossRef] [Scilit]
  76. Kayani, U. N., Gan, C., Choudhury, T., & Arslan, A. (2025). Working capital management and firm performance: Evidence from emerging African markets. International Journal of Emerging Markets, 20(4), 1530–1547. [Google Scholar] [CrossRef] [Scilit]
  77. Kim, S. Y., & Tran, D. B. (2024). Intellectual capital and performance: Evidence from SMEs in Vietnam. Asia-Pacific Journal of Business Administration, 16(4), 860–875. [Google Scholar]
  78. Kock, N. (2015). Common method bias in PLS-SEM: A full collinearity assessment approach. International Journal of e-Collaboration, 11(4), 1–10. [Google Scholar] [CrossRef] [Scilit]
  79. Kolb, D. A. (1984). Experiential learning: Experience as the source of learning and development (Vol. 41). Prentice. [Google Scholar]
  80. Kraus, A., & Litzenberger, R. H. (1973). A state-preference model of optimal financial leverage. The Journal of Finance, 28(4), 911–922. [Google Scholar] [CrossRef] [Scilit]
  81. Kraus, S., Jones, P., Kailer, N., Weinmann, A., Chaparro-Banegas, N., & Roig-Tierno, N. (2021). Digital transformation: An overview of the current state of the art of research. Sage Open, 11(3), 21582440211047576. [Google Scholar] [CrossRef] [Scilit]
  82. Kubick, T. R., & Li, Y. (2023). The Effect of Managerial adverse experience on financial reporting. The Accounting Review, 98(3), 307–333. [Google Scholar] [CrossRef] [Scilit]
  83. Le, H.-L., Vu, K.-T., Du, N.-K., & Tran, M. D. (2018). Impact of working capital management on financial performance: The case of Vietnam. International Journal of Applied Economics, Finance Accounting, 3(1), 15–20. [Google Scholar] [CrossRef] [Scilit]
  84. Lewin, K., Lippitt, R., & White, R. K. (1939). Patterns of aggressive behavior in experimentally created “social climates”. The Journal of Social Psychology, 10(2), 269–299. [Google Scholar] [CrossRef] [Scilit]
  85. Lown, J. M. (2011). Development and validation of a financial self-efficacy scale. Journal of Financial Counseling Planning, 22(2), 54. [Google Scholar]
  86. Lumpkin, G. T., & Dess, G. G. (1996). Clarifying the entrepreneurial orientation construct and linking it to performance. Academy of Management Review, 21(1), 135–172. [Google Scholar] [CrossRef] [Scilit]
  87. Lusardi, A., & Mitchell, O. S. (2014). The economic importance of financial literacy: Theory and evidence. Journal of Economic Literature, 52(1), 5–44. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  88. March, J. G., & Shapira, Z. (1987). Managerial perspectives on risk and risk taking. Management Science, 33(11), 1404–1418. [Google Scholar] [CrossRef] [Scilit]
  89. Mcmahon, R. G. (2001). Growth and performance of manufacturing SMEs: The influence of financial management characteristics. International Small Business Journal, 19(3), 10–28. [Google Scholar] [CrossRef] [Scilit]
  90. Meertens, R. M., & Lion, R. (2008). Measuring an individual’s tendency to take risks: The risk propensity scale 1. Journal of Applied Social Psychology, 38(6), 1506–1520. [Google Scholar] [CrossRef] [Scilit]
  91. Mendoza-Velázquez, A., Ortuño-Barba, L. C., Conde-Cortés, L. D., & Finance. (2022). Corporate governance and firm performance in hybrid model countries. Review of Accounting, 21(1), 32–58. [Google Scholar] [CrossRef] [Scilit]
  92. Miller, D. (1983). The correlates of entrepreneurship in three types of firms. Management Science, 29(7), 770–791. [Google Scholar] [CrossRef] [Scilit]
  93. Ministry of Planning and Investment. (2023). Vietnam enterprise white book 2023. Statistical Publishing House.
  94. Modigliani, F., & Miller, M. H. (1963). Corporate income taxes and the cost of capital: A correction. The American Economic Review, 53(3), 433–443. [Google Scholar]
  95. Myers, S. C. (1984). The capital structure puzzle. Journal of Finance, 39, 575–592. [Google Scholar] [CrossRef] [Scilit]
  96. Myers, S. C., & Majluf, N. S. (1984). Corporate financing and investment decisions when firms have information that investors do not have. Journal of Financial Economics, 13(2), 187–221. [Google Scholar] [CrossRef] [Scilit]
  97. Ngek, N. B., & van Aardt Smit, A. (2013). Will promoting more typical SME start-ups increase job creation in South Africa? African Journal of Business Management, 7(31), 3043. [Google Scholar] [CrossRef] [Scilit]
  98. Nguyen, A. H., Pham, H. T., & Nguyen, H. T. (2020). Impact of working capital management on firm’s profitability: Empirical evidence from Vietnam. Journal of Asian Finance, Economics Business Horizons, 7(3), 115–125. [Google Scholar] [CrossRef] [Scilit]
  99. Nguyen, A. T. L., Van Nguyen, D., & Nguyen, N. H. (2022). The relationship between financial decisions and equity risk. Heliyon, 8(8), e10036. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  100. Nguyen, B. (2021). Local institutions, external finance and investment decisions of small businesses in Vietnam. Economic Systems, 45(3), 100880. [Google Scholar] [CrossRef] [Scilit]
  101. Nielsen, B. B., & Nielsen, S. (2013). Top management team nationality diversity and firm performance: A multilevel study. Strategic Management Journal, 34(3), 373–382. [Google Scholar]
  102. OECD/INFE. (2020). International survey of adult financial literacy (Report Paper). OECD/INFE. [Google Scholar]
  103. Petersen, M. A., & Rajan, R. G. (1997). Trade credit: Theories and evidence. The Review of Financial Studies, 10(3), 661–691. [Google Scholar] [CrossRef] [Scilit]
  104. Petter, S., Straub, D., & Rai, A. (2007). Specifying formative constructs in information systems research. MIS Quarterly, 31(4), 623–656. [Google Scholar] [CrossRef] [Scilit]
  105. Phuoc, V. H., Thuan, N. D., Vu, N. P. H., & Tuyen, L. T. (2022). The impact of corporate social and environmental responsibilities and management characteristics on SMES’performance in Vietnam. International Journal of Economics Finance Studies, 14(2), 12445. [Google Scholar] [CrossRef] [Scilit]
  106. Podsakoff, P. M., MacKenzie, S. B., Lee, J.-Y., & Podsakoff, N. P. (2003). Common method biases in behavioral research: A critical review of the literature and recommended remedies. Journal of Applied Psychology, 88(5), 879. [Google Scholar] [CrossRef] [Scilit] [PubMed]
  107. Podsakoff, P. M., MacKenzie, S. B., Moorman, R. H., & Fetter, R. (1990). Transformational leader behaviors and their effects on followers’ trust in leader, satisfaction, and organizational citizenship behaviors. The Leadership Quarterly, 1(2), 107–142. [Google Scholar] [CrossRef] [Scilit]
  108. Porter, M. E. (2008). Competitive advantage: Creating and sustaining superior performance. Simon and Schuster. [Google Scholar]
  109. Prahalad, C. K., & Hamel, G. (1994). Strategy as a field of study: Why search for a new paradigm? Strategic Management Journal, 15(S2), 5–16. [Google Scholar] [CrossRef] [Scilit]
  110. Pratono, A. H. (2018). Does firm performance increase with risk-taking behavior under information technological turbulence? Empirical evidence from Indonesian SMEs. The Journal of Risk Finance, 19(4), 361–378. [Google Scholar] [CrossRef] [Scilit]
  111. Rahaman, M. A., Luna, K. F., Ping, Z. L., Islam, M. S., & Karim, M. M. (2021). Do risk-taking, innovativeness, and proactivity affect business performance of SMEs? A case study in Bangladesh. The Journal of Asian Finance, Economics Business Horizons, 8(5), 689–695. [Google Scholar] [CrossRef] [Scilit]
  112. Reynolds, P. D. (2011). New firm creation: A global assessment of national, contextual, and individual factors. Foundations Trends in Entrepreneurship, 6(5–6), 315–496. [Google Scholar] [CrossRef] [Scilit]
  113. Richard, P. J., Devinney, T. M., Yip, G. S., & Johnson, G. (2009). Measuring organizational performance: Towards methodological best practice. Journal of Management, 35(3), 718–804. [Google Scholar] [CrossRef] [Scilit]
  114. Richardson, S. (2006). Over-investment of free cash flow. Review of Accounting Studies, 11(2), 159–189. [Google Scholar] [CrossRef] [Scilit]
  115. Rohrbeck, R., & Gemünden, H. G. (2011). Corporate foresight: Its three roles in enhancing the innovation capacity of a firm. Technological Forecasting Social Change, 78(2), 231–243. [Google Scholar] [CrossRef] [Scilit]
  116. Rohrbeck, R., & Schwarz, J. O. (2013). The value contribution of strategic foresight: Insights from an empirical study of large European companies. Technological Forecasting Social Change, 80(8), 1593–1606. [Google Scholar] [CrossRef] [Scilit]
  117. Ross, S. A., Westerfield, R. J. J., & Jordan, B. (2022). Corporate finance (13th ed.). McGraw Hill. [Google Scholar]
  118. Sadler–Smith, E., Hampson, Y., Chaston, I., & Badger, B. (2003). Managerial behavior, entrepreneurial style, and small firm performance. Journal of Small Business Management, 41(1), 47–67. [Google Scholar] [CrossRef] [Scilit]
  119. Santos-Jaén, J. M., Madrid-Guijarro, A., & García-Pérez-de-Lema, D. (2021). The impact of corporate social responsibility on innovation in small and medium-sized enterprises: The mediating role of debt terms and human capital. Corporate Social Responsibility Environmental Management, 28(4), 1200–1215. [Google Scholar] [CrossRef] [Scilit]
  120. Savlovschi, L. I., & Robu, N. R. (2011). The role of SMEs in modern economy. Economia, Seria Management, 14(1), 277–281. [Google Scholar]
  121. Shea-Van Fossen, R. J., Rothstein, H. R., & Korn, H. J. (2006). Thirty-five years of strategic planning and firm performance research: A meta-analysis. In Academy of management proceedings. Academy of Management. [Google Scholar]
  122. Shin, H.-H., & Soenen, H. L. (1998). Efficiency of working capital and corporate profitability. Financial Practice and Education, 8, 37–45. [Google Scholar]
  123. Shmueli, G., Ray, S., Estrada, J. M. V., & Chatla, S. B. (2016). The elephant in the room: Predictive performance of PLS models. Journal of Business Research, 69(10), 4552–4564. [Google Scholar] [CrossRef] [Scilit]
  124. Sitkin, S. B., & Weingart, L. R. (1995). Determinants of risky decision-making behavior: A test of the mediating role of risk perceptions and propensity. Academy of Management Journal, 38(6), 1573–1592. [Google Scholar] [CrossRef] [Scilit]
  125. Smith, K. (1980). Profitability versus liquidity tradeoffs in working capital management. Readings on the Management of Working Capital, 42(1), 549–562. [Google Scholar]
  126. Sneader, K., Williamson, S. K., Koller, T., Potter, V., & Babcock, A. (2020). Corporate long-term behaviors: How CEOs and boards drive sustained value creation. McKinsey Company. [Google Scholar]
  127. Storey, D. J. (2016). Understanding the small business sector. Routledge. [Google Scholar]
  128. Sulistianingsih, H., & Santi, F. (2023). Does SME’s financing decisions follow pecking order pattern? The role of financial literacy, risk preference, and home bias in SME financing decisions. Cogent Business Management Science, 10(1), 2174477. [Google Scholar] [CrossRef] [Scilit]
  129. Sureka, R., Kumar, S., Colombage, S., & Abedin, M. Z. (2022). Five decades of research on capital budgeting—A systematic review and future research agenda. Research in International Business Finance, 60, 101609. [Google Scholar] [CrossRef] [Scilit]
  130. Teece, D. J., Pisano, G., & Shuen, A. (1997). Dynamic capabilities and strategic management. Strategic Management Journal, 18(7), 509–533. [Google Scholar] [CrossRef] [Scilit]
  131. Titman, S., & Wessels, R. (1988). The determinants of capital structure choice. The Journal of Finance, 43(1), 1–19. [Google Scholar] [CrossRef]
  132. Tyler, B. (2018). Strategic intent. In The palgrave encyclopedia of strategic management (pp. 1621–1623). Springer. [Google Scholar]
  133. Venkatraman, N., & Ramanujam, V. (1986). Measurement of business performance in strategy research: A comparison of approaches. Academy of Management Review, 11(4), 801–814. [Google Scholar] [CrossRef] [Scilit]
  134. Verhoef, P. C., Broekhuizen, T., Bart, Y., Bhattacharya, A., Dong, J. Q., Fabian, N., & Haenlein, M. (2021). Digital transformation: A multidisciplinary reflection and research agenda. Journal of Business Research, 122, 889–901. [Google Scholar] [CrossRef] [Scilit]
  135. Vial, G. (2021). Understanding digital transformation: A review and a research agenda. In Managing digital transformation (pp. 13–66). Routledge. [Google Scholar] [CrossRef] [Scilit]
  136. Vroom, V., & Yetton, P. W. (1973). Leadership and decision-making (Vol. 110). University of Pittsburgh Press. [Google Scholar]
  137. Walker, E., & Brown, A. (2004). What success factors are important to small business owners? International Small Business Journal, 22(6), 577–594. [Google Scholar] [CrossRef] [Scilit]
  138. Wall, T. D., Michie, J., Patterson, M., Wood, S. J., Sheehan, M., Clegg, C. W., & West, M. (2004). On the validity of subjective measures of company performance. Personnel Psychology, 57(1), 95–118. [Google Scholar] [CrossRef] [Scilit]
  139. Weber, E. U., Blais, A. R., & Betz, N. E. (2002). A domain-specific risk-attitude scale: Measuring risk perceptions and risk behaviors. Journal of Behavioral Decision Making, 15(4), 263–290. [Google Scholar] [CrossRef] [Scilit]
  140. Wiklund, J., & Shepherd, D. (2003). Knowledge-based resources, entrepreneurial orientation, and the performance of small and medium-sized businesses. Strategic Management Journal, 24(13), 1307–1314. [Google Scholar] [CrossRef] [Scilit]
  141. Yukl, G. (2020). Leadership in organizations (9th ed.). Pearson Education India. [Google Scholar]
  142. Zhong, S., Li, S., & Han, C. (2026). The impact of technology finance policy on entrepreneurial activities—An empirical study based on a spatial DID model. Managerial Decision Economics, 47(3), 623–646. [Google Scholar]
Figure 1. Research model.
Ijfs 14 00194 g001
Figure 2. Structural Model Results.
Ijfs 14 00194 g002
Figure 3. The moderating role of digital transformation (DT) in the FD–FP relationship.
Ijfs 14 00194 g003
Table 1. Profile of Respondents and Firms.
CategoriesFrequencyPercent
Gender
  Female13225.9%
  Male37874.1%
Age
  Below 30234.5%
  31–40 7614.9%
  41–50 19438.0%
  51–60 13426.3%
  Above 608316.3%
Educational level
  Bachelor’s degree38976.3%
  College/Vocational/High school12123.7%
Position
  Owners/CEOs32463.5%
  Functional managers18636.5%
Sector of Business
  Manufacturing12825.1%
  Trade13125.7%
  Services9218.0%
  Construction10420.4%
  Agriculture5510.8%
Number of employees
  Below 10 37974.3%
  10–50 10921.4%
  51–200163.1%
  Above 200 61.2%
Capital Size
  Below VND 3 billion18736.7%
  VND 3–20 billion24748.4%
  Above VND 20 billion7614.9%
Firm age
  Below 5 12524.5%
  6–10 17634.5%
  11–20 16231.8%
  Above 20479.2%
Source(s): Authors’ own work.
Table 2. Full Collinearity VIF Assessment for Common Method Bias.
ConstructCodeFull Collinearity VIF
Risk toleranceAR1.330
Work experienceEXP1.051
Financial decisionFD2.870
Financial knowledgeFIK1.342
Financial performanceFP2.374
Authoritarian leadershipLES_A1.146
Democratic and flexible leadershipLES_D1.111
Strategic visionSTV1.247
Source(s): Authors’ own work.
Table 3. Results of Exploratory Factor Analysis (EFA).
ConstructDimensionsNo. of ItemsKMOBartlett’s Test
(p-Value)
Total Variance Explained (%)
Financial performanceFP40.8670.00084.077
Financial decision (FD) *CSD30.9320.00059.753
IVD3
WCD4
Digital transformationDT30.7330.00077.518
Managerial characteristicsAR30.8180.00069.576
FIK3
EXP3
STV4
LES_A3
LES_D6
Note. * Financial Decision (FD) is a second-order construct composed of three first-order dimensions (CSD, IVD, WCD). Source(s): Authors’ own work.
Table 4. Reliability and convergent validity of first-order constructs.
ConstructCodeNo. of ItemsOuter LoadingsCronbach’s AlphaComposite
Reliability (CR)
AVE
Financial performanceFP40.914–0.9230.9370.9550.841
Capital structure decisionCSD30.902–0.9070.8900.9310.819
Investment decisionIVD30.888–0.9080.8800.9260.806
Working capital decisionWCD40.873–0.8860.9030.9320.774
Digital transformationDT30.871–0.8900.8550.9120.775
Work experienceEXP30.882–0.8990.8710.9210.795
Financial knowledgeFIK30.888–0.9000.8740.9220.799
Risk toleranceAR30.902–0.9090.8920.9330.822
Strategic visionSTV40.874–0.8910.9060.9340.780
Authoritarian leadershipLES_A30.882–0.8980.8710.9210.795
Democratic and flexible leadershipLES_D60.797–0.8640.9200.9370.712
Source(s): Authors’ own work.
Table 5. Heterotrait–Monotrait Ratio (HTMT).
ConstructARCSDDTEXPFIKFPIVDLES_ALES_DSTVWCD
AR
CSD0.405
DT0.0300.168
EXP0.0520.3320.021
FIK0.0320.3720.0420.056
FP0.3810.7750.2010.3700.367
IVD0.3940.7290.1500.3570.3050.758
LES_A0.0460.3630.1300.0450.0470.3050.386
LES_D0.0370.2010.0470.0580.0320.1750.2230.032
STV0.0270.3430.0400.0290.0520.2990.3840.0600.075
WCD0.3640.7830.2250.3370.4110.7700.7540.3430.2180.347
Source(s): Authors’ own work.
Table 6. Discriminant validity (Fornell–Larcker Criterion).
ConstructARCSDDTEXPFIKFPIVDLES_ALES_DSTVWCD
AR0.907
CSD0.3600.905
DT−0.0240.1470.880
EXP0.0460.2930.0100.892
FIK−0.0180.330−0.0360.0400.894
FP0.3480.7080.1800.3340.3340.917
IVD0.3490.6450.1310.3130.2690.6880.898
LES_A0.012−0.320−0.1110.039−0.026−0.276−0.3380.892
LES_D0.0150.188−0.039−0.019−0.0140.1690.2050.0110.844
STV−0.0040.3090.0270.009−0.0390.2770.344−0.054−0.0700.883
WCD0.3270.7020.1980.2990.3670.7090.672−0.3040.2040.3150.880
Source(s): Authors’ own work.
Table 7. VIF and Outer Weights of the Second-Order Construct (FD).
RelationshipVIFOuter WeightsT-Valuep-Value
CSD → FD2.5660.37859.1410.000
IVD → FD2.5130.37459.5790.000
WCD → FD2.6950.37960.5900.000
Source(s): Authors’ own work.
Table 8. Collinearity Assessment (Inner VIF Values).
Predictor ConstructsVIFPredictor ConstructsVIF
AR → FD1.005FIK → FD1.015
AR → FP1.593FIK → FP1.575
DT → FP1.128LES_A → FD1.006
DT × FD → FP1.033LES_A → FP1.461
EXP → FD1.008LES_D → FD1.007
EXP → FP1.416LES_D → FP1.292
FD → FP3.975STV → FD1.012
STV → FP1.578
Source(s): Authors’ own work.
Table 9. Coefficient of Determination (R2).
Endogenous ConstructsAdj R2t-Valuep-ValueInterpretation
FD0.71434.4890.000Substantial
FP0.70930.4540.000Substantial
Source(s): Authors’ own work.
Table 10. Effect Size (f2).
Relationshipsf2InterpretationRelationshipsf2Interpretation
AR → FD0.520LargeFIK → FP0.046Small
AR → FP0.031SmallLES_A → FD0.438Large
DT → FP0.027SmallLES_A → FP0.011Negligible
DT × FD → FP0.232MediumLES_D → FD0.241Medium
EXP → FD0.370LargeLES_D → FP0.009Negligible
EXP → FP0.043SmallSTV → FD0.497Large
FD → FP0.259MediumSTV → FP0.018Negligible
FIK → FD0.472Large
Source(s): Authors’ own work.
Table 11. Predictive Relevance (Q2).
Endogenous ConstructsQ2RMSEMAE
FD0.7070.5430.434
FP0.5920.6420.489
Source(s): Authors’ own work.
Table 12. PLSpredict Assessment.
IndicatorsQ2 PredictPLS-SEM RMSELM RMSEIA RMSE
CSD0.5480.6740.6701.002
IVD0.5540.6690.6811.002
WCD0.5550.6690.6681.002
FP10.4720.8360.8841.151
FP20.5120.8270.8941.184
FP30.5120.8340.8891.194
FP40.4890.8330.8911.165
Source(s): Authors’ own work.
Table 13. Model Fit Assessment.
Fit IndicesSaturated ModelEstimated Model
SRMR0.0330.037
d_ULS0.6290.821
d_G0.4210.430
Chi-square1298.0331295.499
NFI0.8860.886
Source(s): Authors’ own work.
Table 14. Direct Effects, Hypothesis Testing, and Control Variables.
HypothesesDirect PathsDirect Effect (β)STDEVt-Valuep-ValueResult
H1aAR → FD0.3840.02415.8690.000Supported
H1bEXP → FD0.3240.02612.2540.000Supported
H1cFIK → FD0.3670.02614.3960.000Supported
H1dLES_A → FD−0.3520.02514.0360.000Supported
H1eLES_D → FD0.2620.02610.1340.000Supported
H1fSTV → FD0.3770.02415.4670.000Supported
H2aAR → FP0.1190.0303.9050.000Supported
H2bEXP → FP0.1320.0304.3480.000Supported
H2cFIK → FP0.1440.0294.9190.000Supported
H2dLES_A → FP−0.0680.0302.2760.023Supported
H2eLES_D → FP0.0590.0292.0690.039Supported
H2fSTV → FP0.0910.0322.8450.004Supported
H3FD → FP0.5410.04611.7000.000Supported
Control Variables
Firm SizeSIZE → FD0.0020.0250.0680.946Not significant
SIZE → FP0.0220.0230.9410.347Not significant
Firm AgeFAGE → FD−0.0010.0260.0430.965Not significant
FAGE → FP−0.0250.0231.1020.271Not significant
Source(s): Authors’ own work.
Table 15. Indirect Effects and Mediation Analysis.
HypothesesIndirect PathsIndirect Effect (β)t-Valuep-ValueVAFMediation Type
H4aAR → FD → FP0.2079.5500.00063.50%Partial mediation
H4bEXP → FD → FP0.1758.4510.00057.14%Partial mediation
H4cFIK → FD → FP0.1999.1310.00058.02%Partial mediation
H4dLES_A → FD → FP−0.1918.5500.00073.36%Partial mediation
H4eLES_D → FD → FP0.1417.7640.00070.50%Partial mediation
H4fSTV → FD → FP0.2049.4350.00069.15%Partial mediation
Note: VAF is calculated as the ratio of the indirect effect to the total effect: VAF = β(Indirect Effect)/[β(Direct Effect) + β(Indirect Effect)]. VAF values between 20% and 80% indicate partial mediation (Hair et al., 2021d). Source(s): Authors’ own work.
Table 16. Results of the Moderating Effect.
HypothesesModerating EffectβSTDEVt-Valuep-ValueResult
H5DT × FD → FP0.2700.0289.7630.000Supported
Source(s): Authors’ own work.
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content.