1. Introduction
In recent years, against the backdrop of China’s continuous economic development and expanding market potential, enterprises have emerged as the primary entities within the market economy. Their governance structures [
1] and market behaviors [
2] have garnered significant attention. Particularly within the manufacturing sector, statistics indicate that the number of manufacturing enterprises in China has surpassed 6 million. Both the scale and quality of these enterprises are steadily improving, playing a crucial role in driving high-quality economic development and facilitating industrial transformation and upgrading. This underscores that focusing research on manufacturing enterprises has become a top priority. According to the Outline of the 14th Five-Year Plan for National Economic and Social Development of the People’s Republic of China and the Long-Range Objectives Through the Year 2035, “China will deepen the implementation of its strategy to build a manufacturing powerhouse and promote the transformation and upgrading of the manufacturing sector.” Concurrently, efforts to “improve the modern enterprise system with Chinese characteristics” continue, emphasizing the optimization of ownership structures and the enhancement of corporate governance effectiveness to strengthen enterprises’ core competitiveness. Under these policy orientations, ownership concentration—as a core element of manufacturing enterprise governance—significantly impacts firms’ bargaining power, resource allocation capabilities, and market positions, making it a crucial topic in academic discourse.
From an industry dynamics perspective, enterprises do not exist in isolation but are embedded within complex supply chain networks, inextricably linked with upstream and downstream businesses to form intricate dynamic competitive relationships. Based on Porter’s Five Forces model, suppliers serve as critical external stakeholders [
3] for enterprises. Their bargaining power directly impacts procurement costs, supply stability, and even profitability. For instance, reasonable bargaining power plays a vital role in achieving corporate performance, enabling enterprises to maintain high profitability levels [
4]. Therefore, exploring the factors influencing supplier bargaining power is crucial for promoting enterprise transformation and upgrading, as well as enhancing market resilience.
Existing research has primarily examined the relationship between supplier bargaining power and factors such as external financing constraints [
5], capacity allocation and channel selection [
6], trade credit supply [
7], and financial leverage [
8]. However, studies focusing on internal corporate governance, particularly ownership concentration, remain scarce. As a key indicator of corporate ownership structure, equity concentration may enhance suppliers’ bargaining power by improving decision-making efficiency [
9], yet simultaneously weaken it by affecting R&D innovation [
10]. This contradictory perspective prevents a unified conclusion on the relationship between ownership concentration and supplier bargaining power, necessitating further clarification and validation. Therefore, grounded in the governance practices and supply chain environment of Chinese manufacturing enterprises, this study focuses on the mechanism through which ownership concentration affects supplier bargaining power. It seeks to answer the following questions: Does ownership concentration significantly impact supplier bargaining power? Does it enhance or weaken supplier bargaining power? What is the underlying mechanism?
Through examining these issues, this paper aims to make the following marginal contributions: (1) From the perspective of ownership concentration in the manufacturing sector, it explores its crucial role in supplier bargaining power, addressing the current literature gap in analyzing the deep-seated interaction between ownership concentration and supplier bargaining power. Grounded in agency theory, property rights theory, and other frameworks, and considering China’s ongoing efforts to optimize corporate governance structures and advance supply chain transformation, the study constructs a complementary theoretical framework. (2) This study examines the underlying mechanism through which ownership concentration influences supplier bargaining power by analyzing R&D investment and industry competition levels, filling gaps in existing domestic and international research. (3) Focusing on manufacturing enterprises, this research holds significant implications for optimizing corporate governance effectiveness, refining ownership structures, and enhancing supply chain efficiency.
3. Research Design
3.1. Research Samples and Data Sources
We employed Stata 17.0 for data processing and analysis. This study employs a sample of manufacturing firms listed on the Shanghai and Shenzhen A-share markets from 2008 to 2022. Industry classifications follow the guidelines issued by the China Association of Industry and Commerce (CAIC). To ensure data reliability, we excluded firms that received Special Treatment (ST) or Particular Transfer (PT) status during the sample period. Entities with substantial missing data or only a single annual observation were also removed. For a limited number of companies with isolated data gaps, linear interpolation was applied to complete the missing values. After these screening procedures, the final dataset comprised 12,261 firm-year observations. The primary data source was the China Stock Market & Accounting Research (CSMAR) database. Additionally, all continuous variables were winsorized at the 1st and 99th percentiles to reduce the influence of outliers.
3.2. Key Variable Definitions
3.2.1. Dependent Variable: Supplier Bargaining Power
Supplier bargaining power refers to a supplier’s ability to influence a company’s procurement costs by adjusting factors such as price and transaction terms, forming a core dimension of the supplier power structure. According to research by Banerjee et al. [
27], when a company’s procurement from a specific supplier accounts for a high proportion of its total procurement costs, the supplier—possessing critical resources or technology—can exert pressure by reducing supply or raising prices. For instance, if the top five suppliers account for over 50% of procurement, switching costs for the company rise significantly, allowing suppliers to leverage this dependency to enhance their bargaining power. Additionally, research by Titman et al. [
28] indicates that supplier bargaining power is closely linked to their investments in relationship-specific assets (e.g., customized production equipment) for the customer. Companies with high reliance on their top five suppliers often require greater dedicated investments from them. To protect their investment returns, suppliers leverage their bargaining power to secure more favorable transaction terms (such as extended payment terms or higher profit margins). Therefore, this paper adopts the supplier bargaining power measurement method proposed by Peng Xiaojia et al. [
29], using the proportion of the top five suppliers’ procurement expenditures to the company’s total procurement expenditures, as disclosed in the China Stock Market & Accounting Research database, as a measure of supplier bargaining power.
3.2.2. Independent Variable: Ownership Concentration
Ownership concentration is a key concept in fields such as corporate governance and finance, primarily measuring the degree to which a company’s ownership is concentrated among its shareholders. Following Nguyen et al. [
30], ownership concentration is measured by the ratio of the number of shares held by the largest shareholder to the total number of outstanding shares. The ownership stake of the largest shareholder is a direct measure of ownership concentration.
3.2.3. Mediating Variable: R&D Investment
Drawing on research by Ghazi H. Sulimany et al. [
31] and considering the current situation of Chinese enterprises, the ratio of corporate R&D expenditure to operating revenue is employed to measure R&D investment.
3.2.4. Adjustment Variable: Industry Competitiveness
Referencing the research by Qing Wang et al. [
32], the Herfindahl index is employed to measure industry competitiveness. Specifically, it is calculated by summing the squares of the ratios of each company’s total assets to the industry’s total assets.
This index serves as a classic metric for assessing industry competitiveness in relevant research. A lower value indicates lower market concentration, meaning more firms within the industry with similar scales, resulting in more intense competition. Conversely, a higher value signifies greater market concentration, stronger monopolistic or oligopolistic tendencies, and weaker competition.
3.2.5. Control Variables
Drawing on existing literature [
33,
34] and considering the current state of Chinese enterprises, the following control variables were selected: firm size (ln_Size), dual-role positions (Dual), firm age (Age), return on assets (ROA), debt-to-asset ratio (Lev), Tobin’s Q (TobinQ), revenue growth rate (Growth), and ownership structure (soe). Additionally, this study controlled for year (year) and firm id (id) (
Table 1).
3.3. Model Selection and Construction
All data used in this paper are panel data sourced from the China Securities Market Research (CSMAR) database. To determine whether a fixed-effects or random-effects model should be adopted for regression, a Hausman test was first conducted. The resulting p-value was 0.0151, which is less than 0.05. strongly rejecting the null hypothesis that “the individual effects in the random effects model are uncorrelated with the explanatory variables.” This indicates that individual effects within the model (such as firm heterogeneity) are correlated with the explanatory variables. Therefore, to accurately estimate the impact of equity concentration (Top1) on firm performance (PC1) while controlling for unobservable heterogeneity and common time trends, this study employs a two-way fixed effects model.
To examine the impact of ownership concentration on suppliers’ bargaining power, Model (1) is constructed.
To deepen understanding of the relationship between ownership concentration and supplier bargaining power, we examine the mediating effect from the perspective of R&D investment and construct Model (2).
Finally, to further examine the impact of equity concentration on firms’ bargaining power, we construct Model (3) to investigate its moderating effect from the perspective of industry competition intensity.
represents supplier bargaining power; represents ownership concentration; denotes R&D investment; indicates industry competition intensity; represents the set of control variables including firm size (ln_Size) and firm age (Age), etc., , , denote the model’s intercept terms, they represent the constant term in the regression model; , , represent the regression coefficients for independent variables or interaction terms. These coefficients are estimated through a panel fixed-effects model, with their magnitude and significance reflecting the direction of the marginal effect of the independent variables on the dependent variable and the statistical reliability of this effect. represents individual fixed effects, denotes time fixed effects, and , , constitute random error terms.
4. Empirical Findings and Analysis
4.1. Descriptive Statistics
Table 2 reports the descriptive statistics for key variables. The minimum value for ownership concentration (Top1) is 13.470, with a maximum of 57.740, indicating significant variation in equity concentration among manufacturing firms. Additionally, the minimum value for supplier bargaining power (PC) is 11.460, and the maximum is 69.490, suggesting substantial differences in bargaining power across manufacturing enterprises. The average value for market competition intensity (Competition) is 0.065, indicating that competition within the manufacturing sector fluctuates within a relatively concentrated range. Meanwhile, the median of 0.050 is lower than the mean, suggesting that a small number of firms with low competition levels have elevated the overall mean. The standard deviation for R&D investment is 3.162, revealing moderate variation in R&D expenditure among the sample firms.
4.2. Baseline Regression
The regression results of this model are presented in
Table 3. Column (1) shows the basic regression results for the Independent variables and the dependent variable. Column (2) presents the regression results with two-way fixed effects after controlling for time and individual effects. Column (3) presents the regression results with time fixed effects, incorporating control variables such as firm size (Size), dual roles (Dual), and firm age (Age). Column (4) displays the regression results with two-way fixed effects, incorporating the control variables while fixing both time and individual effects. Across all four regression columns, the coefficients for ownership concentration (Top1) and supplier bargaining power (PC) are positive and statistically significant at the 0.05 or 0.01 level. This may occur because when corporate ownership is highly concentrated, shareholders can directly or indirectly participate in supplier operations, thereby gaining a more advantageous position in negotiations with customers and enhancing their bargaining power. Thus, Hypothesis H1 is supported.
4.3. Robustness Tests
4.3.1. Replace Independent Variables
Using the shareholding ratio of the top ten shareholders (Top10) as a proxy variable to re-measure equity concentration, the results are shown in Column (1) of
Table 4. The coefficient for Top10 is 0.0282 and is statistically significant at the 0.05 level, indicating that the test results remain robust.
4.3.2. Replace Dependent Variable
This study employs the Herfindahl Index as a proxy variable to remeasure supplier bargaining power. The Herfindahl Index is calculated as the sum of the squares of the ratios of the top five suppliers’ procurement amounts to total procurement amounts. The results are shown in Column (2) of
Table 4. After replacing the dependent variable, the coefficient for Top1 is 0.0102 and remains statistically significant at the 0.1 level, indicating that the test results remain robust.
4.3.3. Exclude Specific Dates
Given the escalation of Sino-US trade friction in 2018, which significantly impacted China’s manufacturing sector—factors such as imposition of additional tariffs, supply chain volatility, and rising raw material import prices may directly affect supplier relationships and bargaining power rather than being driven by ownership concentration—thereby interfering with the relationship between core variables. Therefore, data from 2018 was excluded for robustness testing. The results are shown in Column (3) of
Table 4. The coefficient for Top1 is 0.0560 and remains statistically significant at the 0.01 level, indicating that the test results remain robust.
4.3.4. Constructing the Interaction Effect Between Province and Year
To further mitigate the impact of macro-level factors on estimation results, this study incorporates province-by-year interaction fixed effects into the model to capture the differentiated policy shocks or macroeconomic fluctuations that manufacturing enterprises in various provinces may encounter across different years. As shown in Column (4) of
Table 4, Top1 is statistically significant at the 0.01 level, and its coefficient direction aligns with the benchmark regression results, indicating the robustness of the test results.
4.3.5. Exclude Certain Control Variables
After conducting the above robustness tests, certain control variables in the model may be endogenous to supplier bargaining power, potentially introducing bias in the model estimates. To further ensure model robustness, this study conducted robustness tests by excluding certain control variables (such as TobinQ, Growth, and ROA). The results indicate that after removing these variables, the Top1 variable remains statistically significant at the 0.01 level, and its coefficient direction aligns with the benchmark regression results. This confirms that control variables like TobinQ and Growth do not compromise the model’s robustness, which remains valid.
4.4. Endogeneity Test
To address the endogeneity issue between ownership concentration and supplier bargaining power, the industry-average ownership concentration within the province (prov_ind_mean) is selected as an instrumental variable for endogeneity testing. Regarding instrumental variable selection: First, based on institutional isomorphism theory and information cascade theory, suppliers’ ownership decisions are influenced by other major or successful suppliers within their industry, manifesting in the following scenarios:
- (1)
Manufacturing suppliers within the same province tend to collaborate and share supply chain facilities (components, logistics, labor, etc.) to reduce supply chain costs [
35].
- (2)
Facing a common customer pool, firms may adopt similar ownership structures to maintain equivalent bargaining positions or cost structures.
- (3)
To mitigate operational risks and uncertainties, firms may imitate the business models of successful industry peers.
Thus, the instrumental variable selection satisfies the correlation requirement.
Second, supplier bargaining power depends on firm-level micro factors (order size, switching costs, supplier substitutability, etc.). Provincial-industry averages, as macro factors, cannot directly influence supplier bargaining power. In constructing the instrumental variable, we calculate the arithmetic mean of the ownership concentration (Top1) of all other supplier firms within each unit, excluding the firm itself. It denoted as prov_ind_mean, to serve as the instrumental variable for the supplier firm. Logically, the ownership concentration of other suppliers should not affect the supplier bargaining power of the firm in question. Based on this analysis, the instrumental variable selection largely satisfies the exogeneity principle.
Therefore, the instrumental variable selection in this study is reasonably justified.
Table 4 presents the regression results estimated using the 2SLS method with instrumental variables. The instrumental variable selection passed the under-identification test (Anderson LM test), weak instrumental variable test (Gragg-Donald F), and over-identification test (Sargan-Hansen J test), further corroborating the validity of the instrumental variable choice. Additionally, based on the second-stage regression results, the coefficient for ownership concentration (Top1) is positive and statistically significant at the 0.05 level. This indicates that ownership concentration effectively enhances suppliers’ bargaining power, further validating the robustness of the aforementioned conclusion (
Table 5).
4.5. Heterogeneity Analysis
We perform a heterogeneity analysis by categorizing the sample according to ownership type (state-owned vs. non-state-owned), geographic region, and firm size. The detailed results of these subgroup analyses are reported in
Table 6.
4.5.1. Geographically Based Grouping Test
To examine regional heterogeneity, the sample was divided into eastern and central-western regions for regression analysis. The results, presented in columns (1) and (2) of
Table 6, indicate that Top1 exerts a significantly positive effect in the central-western region, whereas it is statistically insignificant in the eastern region. The specific reason may be that compared to China’s eastern regions with higher marketization levels, market protectionism is likely more pronounced in the central and western regions. In these areas, higher ownership concentration—particularly among enterprises with close government ties—enables companies to embed themselves more effectively within local policy-industry networks. Concentrated ownership structures facilitate the establishment of long-term, favorable relationships between enterprises and local governments, enabling access to non-market resources such as credit support, franchise rights, and local procurement preferences. These resources serve as crucial bargaining chips for supplier enterprises when negotiating with clients. In contrast, supplier enterprises in eastern regions rely more heavily on innovative technologies for their bargaining power, where the impact of ownership concentration is relatively weaker.
4.5.2. Property Rights-Based Grouping Test
To explore ownership heterogeneity, we partition the sample into state-owned enterprises (SOEs) and non-SOEs based on ownership structure and perform subgroup regressions. Columns (3) and (4) of
Table 6 report the results. Top1 shows a significantly positive coefficient in SOEs but an insignificant one in non-SOEs, indicating that ownership concentration enhances supplier bargaining power only in the state-owned sector. This may stem from the unique institutional advantages inherent in the ownership structure of state-owned enterprises (SOEs). First, SOEs typically benefit from stronger government credit endorsements and implicit guarantees, enhancing their credibility and stability within supply chains and reducing perceived default risks for downstream customers. Second, SOEs often face weaker budget constraints, enabling greater capacity for long-term investments in R&D or relationship-specific capital. When this institutional advantage combines with high ownership concentration (often dominated by state-owned major shareholders), internal decision-making can more swiftly convert administrative resources into market bargaining power. Conversely, non-state-owned enterprises lack this institutional safety net; resources concentrated through ownership are more likely directed toward addressing survival issues like financing constraints rather than enhancing supply chain influence. This may stem from the unique institutional advantages inherent in the property rights structure of state-owned enterprises. First, SOEs typically enjoy higher government credit endorsements and implicit guarantees, bolstering their credibility and stability within supply chains and reducing downstream customers’ perceived default risk. Second, SOEs may face weaker budget constraints, granting them greater capacity for long-term planning in R&D investments or relationship-specific investments. When this institutional advantage combines with high ownership concentration (often dominated by state-owned major shareholders), internal decision-making can more swiftly convert administrative resources into market bargaining power. Conversely, non-state-owned enterprises lack this institutional safety net, and the resources generated by their concentrated ownership are more likely to be directed toward addressing survival issues like financing constraints rather than enhancing supply chain bargaining power.
4.5.3. Grouped Test Based on Enterprise Size
To examine firm size heterogeneity, we split the sample at the median of firm size into large enterprises and small-to-medium enterprises (SMEs). The regression results, presented in columns (5) and (6) of
Table 6, show that Top1 exerts a significantly positive effect on bargaining power in large enterprises but remains insignificant in SMEs. This may be because enterprise scale itself constitutes a significant institutional and resource characteristic. Large enterprises possess more robust resource bases, more sophisticated organizational structures, and higher market visibility. High ownership concentration enables the strategic intentions of major shareholders to be executed more efficiently within the enterprise. Simultaneously, large enterprises possess greater capacity to undertake relationship-specific investments and bear their potential risks (such as R&D for specific clients), while concentrated ownership ensures these long-term investments remain uninterrupted by management’s short-termism. This combination of scale resources and centralized decision-making renders large enterprises more irreplaceable in client interactions. Small and medium-sized enterprises, constrained by limited resources, may prioritize survival through concentrated ownership, as their resources remain insufficient to secure dominant positions within supply chains.
4.6. Mechanism Analysis
4.6.1. Mechanism Analysis of R&D Investment
Regarding the discussion on the mechanism linking equity concentration, R&D investment, and supplier bargaining power, this study employs a three-step approach for mediation effect analysis. The results are presented in
Table 7 (1) and (2). Ownership concentration (Top1) significantly positively correlates with R&D investment (RDS) at the 0.01 level, with a coefficient of 0.00486. Conversely, corporate R&D investment significantly negatively correlates with supplier bargaining power at the 0.01 level, with a coefficient of −0.492. Empirical findings confirm the validity of Hypothesis H2. Specifically, as ownership concentration increases, supplier managers, driven by self-interest and long-term corporate development, will enhance the supplier’s R&D investment. Consequently, boosting the supplier firm’s R&D expenditure. However, the enhanced R&D capabilities resulting from increased investment may lead to the absorption of the supplier’s innovative technologies and knowledge during deep technical collaborations with buyers. Particularly when buyers possess strong R&D capabilities, they may leverage absorbed knowledge to cultivate substitute suppliers, thereby weakening the original supplier’s bargaining power. The second scenario involves suppliers undertaking costly R&D investments to meet buyer demands. Buyers, aware of these investments, repeatedly pressure suppliers to lower prices during negotiations, thereby weakening the suppliers’ bargaining power. This aligns with the findings of İbrahim E. Dağdeviren et al. [
35].
4.6.2. Mechanism Analysis of Industry Competitiveness
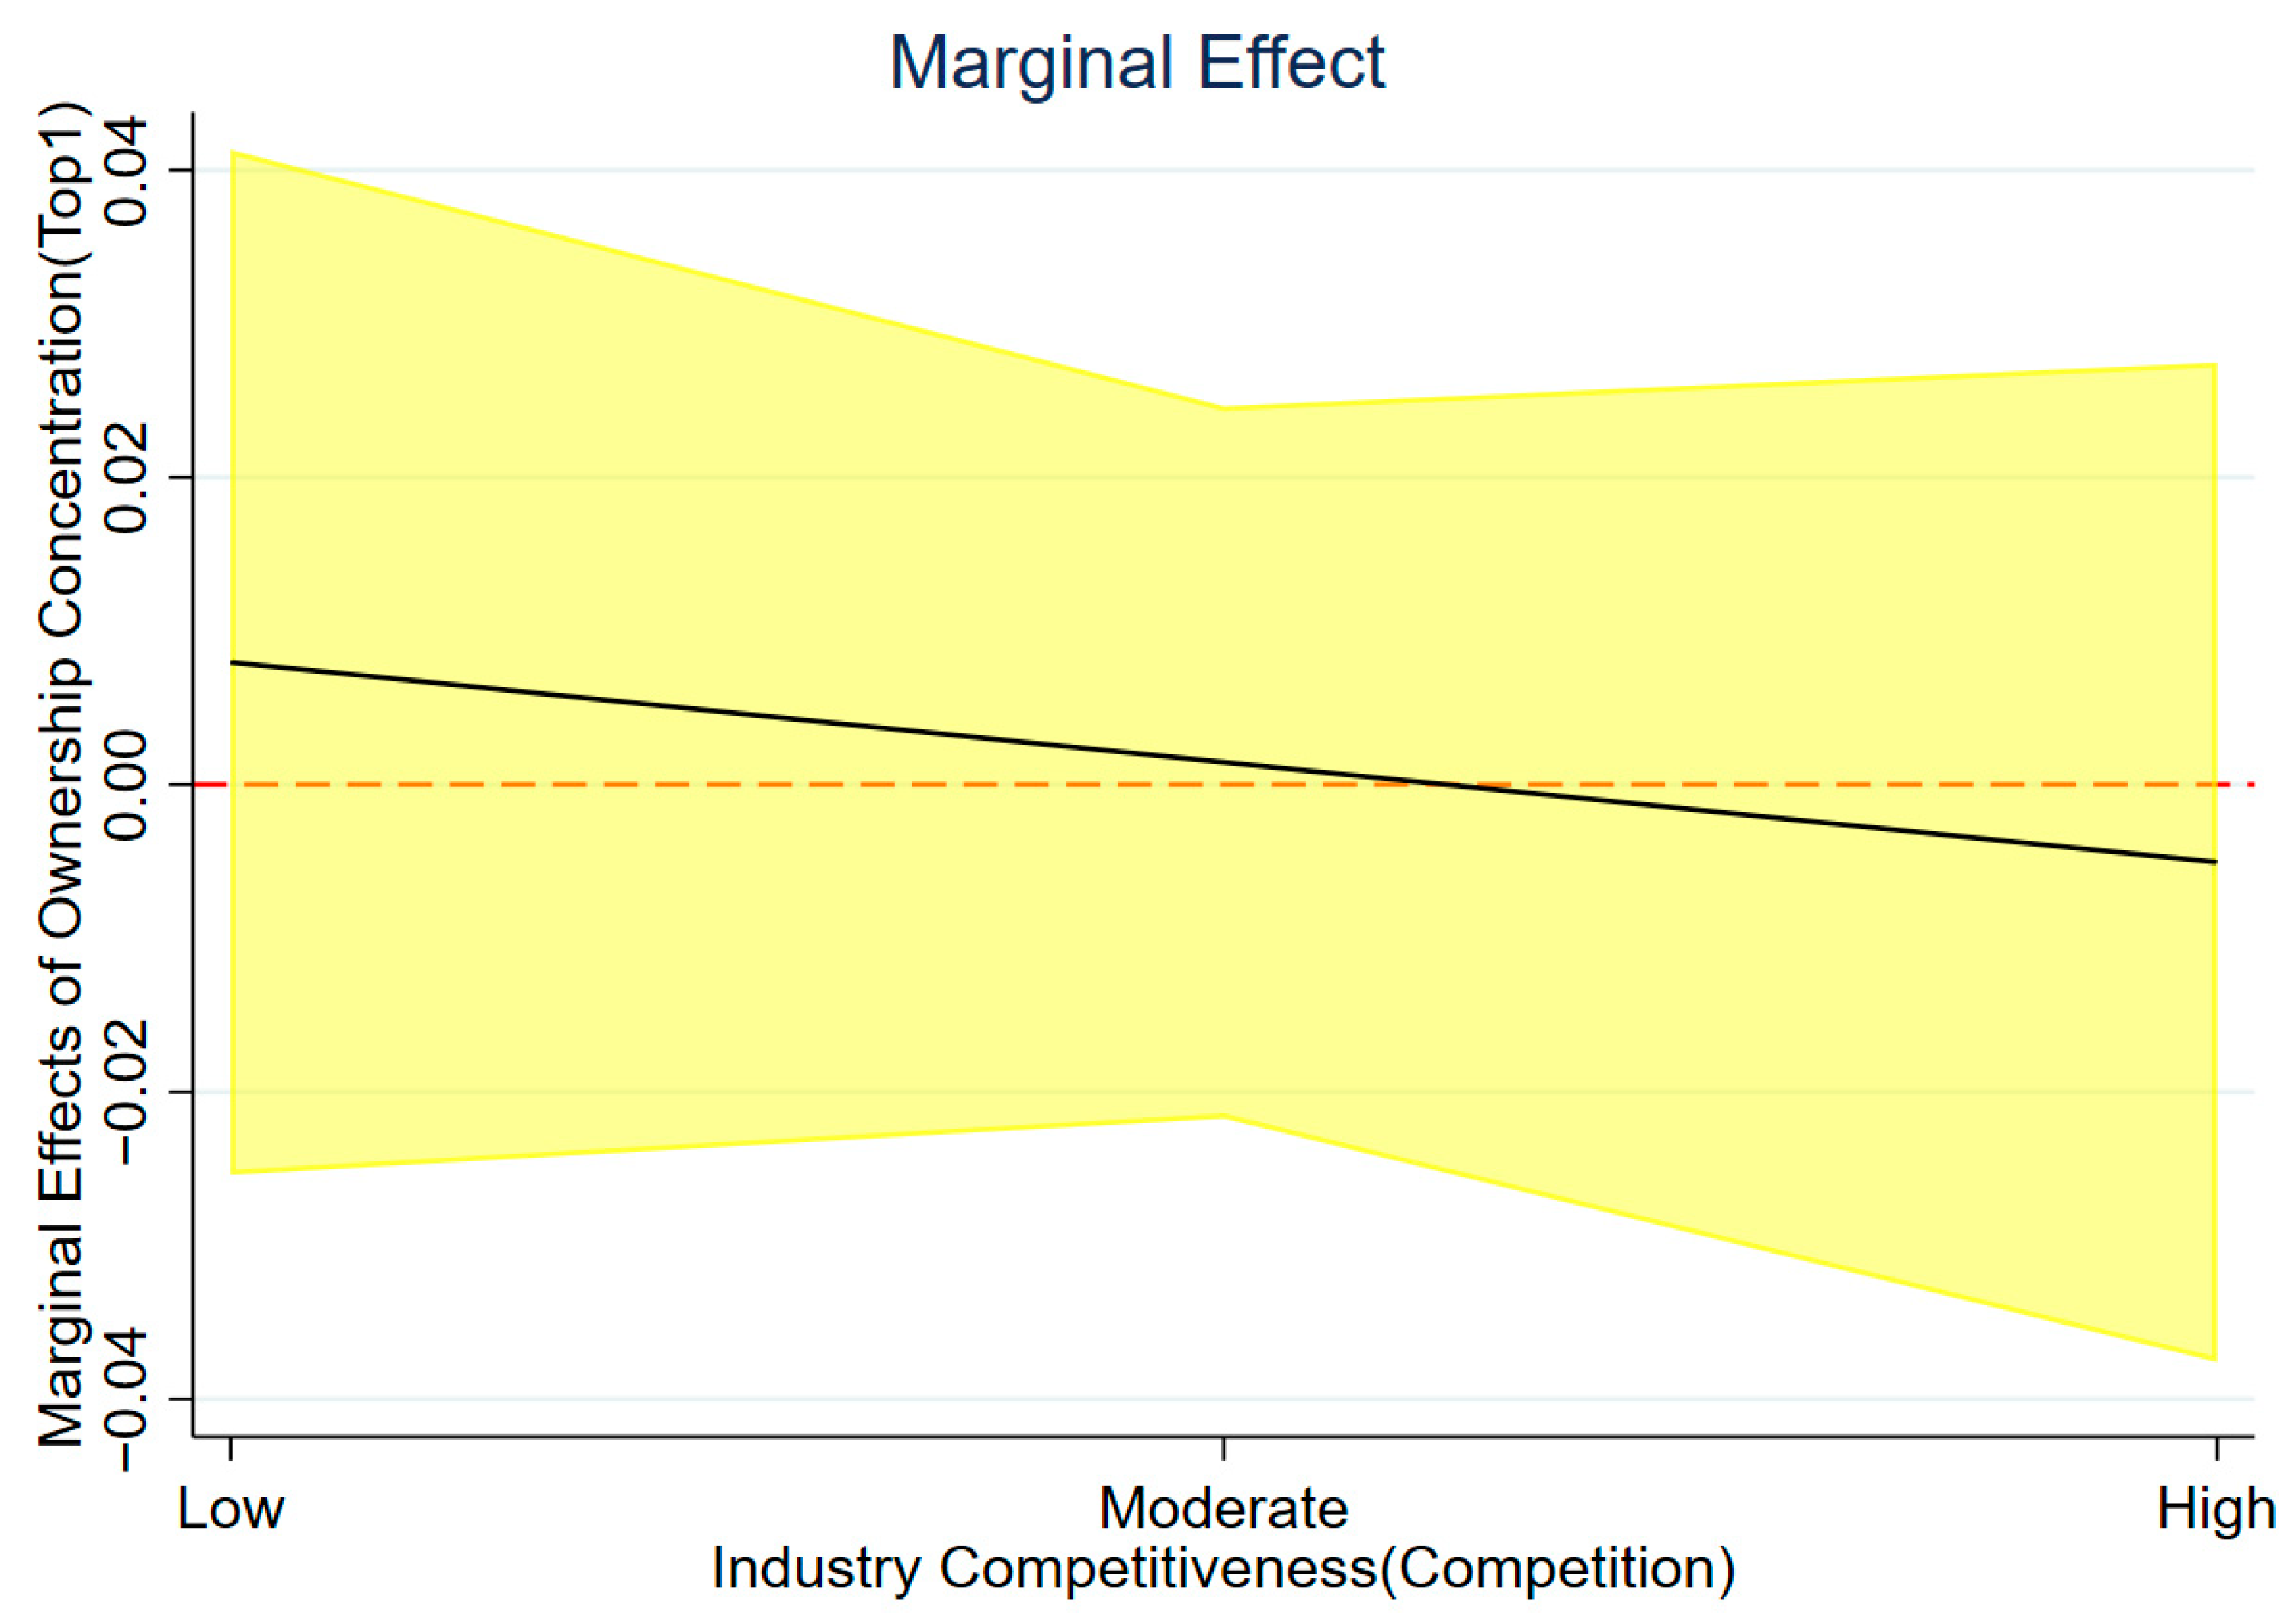
The moderating effect of industry competitiveness and its marginal effects are shown in
Table 8 (1), (2) and
Figure 1. The table results indicate that the interaction term between ownership concentration (Top1) and industry competitiveness (Competition) is significantly negative. That is, as industry competition intensifies, the positive impact of ownership concentration on supplier bargaining power is weakened. Simultaneously,
Figure 1 reveals that the marginal effect is positive under low industry competition. As competition intensifies, the marginal effect gradually turns negative. This indicates that under low-competition conditions, the positive impact of ownership concentration on supplier bargaining power is more pronounced. Therefore, Hypothesis H3 is substantiated.
6. Conclusions
6.1. Research Conclusions
This study examines the impact of ownership concentration on suppliers’ bargaining power using data from the CSMAR database covering Shanghai and Shenzhen A-share manufacturing listed companies from 2008 to 2022. It introduces R&D investment and industry competitiveness as mediating and moderating variables to explore the underlying mechanisms linking ownership concentration and supplier bargaining power. The findings reveal that: (1) Higher ownership concentration significantly enhances suppliers’ bargaining power. (2) Mechanism analysis indicates that R&D investment mediates the relationship between ownership concentration and supplier bargaining power. Specifically, as ownership concentration increases, firms’ R&D expenditure rises, but this increased investment subsequently weakens suppliers’ bargaining power. (3) Heterogeneity analysis reveals that the positive effect of ownership concentration on supplier bargaining power is more pronounced in the central and western regions with higher market barriers, among state-owned enterprises, and among larger supplier firms.
The findings above indicate that concentrated ownership serves not only as a crucial mechanism for optimizing corporate governance structures and mitigating principal-agent conflicts, but also indirectly empowers supply chain relationship management by enhancing internal governance efficiency. This, in turn, strengthens suppliers’ bargaining power and stability within the supply chain. This study expands the research on factors influencing supplier bargaining power from a governance structure perspective, verifying the synergistic effects between internal corporate governance and external supply chain coordination. It also reveals that R&D investment and industry competitiveness play crucial roles in the dynamic interplay between corporate governance and supply chain management. This provides new theoretical perspectives and empirical evidence for understanding the complex interactions between corporate governance and supply chain dynamics.
6.2. Policy Recommendations
Based on the empirical findings of this study, the following policy recommendations are proposed.
First, baseline regression and heterogeneity analysis demonstrate that ownership concentration significantly enhances suppliers’ bargaining power, an effect that is particularly pronounced in state-owned enterprises and large firms. Accordingly, enterprises should optimize their ownership structures to improve governance efficacy. Policymakers are advised to encourage strategic investments that introduce governance checks and balances, while tailoring support mechanisms according to firm ownership type and scale.
Second, mediation analysis reveals that although ownership concentration promotes R&D investment, higher R&D expenditure paradoxically weakens bargaining power—highlighting the risk of innovation lock-in. Firms should emphasize modular design and the development of general-purpose technologies in their innovation strategies, and pursue contractual safeguards in buyer–supplier agreements. Governments can facilitate this shift by establishing industry–academia–research platforms to accelerate the diffusion of generic technologies, thereby reducing suppliers’ dependency on specific clients.
Finally, moderation and heterogeneity analyses indicate that industry competitiveness attenuates the positive effect of ownership concentration, with this weakening effect being more salient in central and western regions, state-owned enterprises, and large firms. It is recommended that firms in highly competitive industries focus on differentiation and cultivate long-term collaborative partnerships. Policies should be region-sensitive: fostering innovation ecosystems in eastern China, while enhancing logistical and institutional support in central and western regions. Furthermore, deepening mixed-ownership reforms can help state-owned enterprises retain their institutional advantages while incorporating market-driven vitality.
6.3. Limitations and Future Directions
- (1)
This paper employs the ratio of procurement expenditures from the top five suppliers to total corporate procurement expenditures as a metric for supplier bargaining power, which has inherent limitations. In reality, factors influencing supplier bargaining power may also include the degree of competition among suppliers, the availability of substitutes, and other variables. Future research may adopt alternative indicators to measure supplier bargaining power, thereby more accurately capturing the causal mechanisms between equity concentration and supplier dynamics.
- (2)
Although we have endeavored to demonstrate the validity of the instrumental variables employed in this paper through both theoretical and empirical analysis, any instrumental variable design inevitably carries certain limitations. For instance, the exogeneity of instrumental variables cannot be directly proven statistically; it can only be argued through theoretical logic and indirect tests. Despite conducting tests for overidentification and placebo effects, we cannot entirely rule out the possibility that this instrumental variable exerts influence through unobserved channels simultaneously related to the bargaining power of supplier firms. Future research may select more exogenous instrumental variables for more refined testing.
- (3)
At the level of studying mechanisms, although R&D investment and industry competitiveness have been introduced as mediating and moderating variables, the impact on internal structural characteristics within supply chains has not been thoroughly explored. These factors may exert significant moderating effects on the relationship between equity concentration and bargaining power.
- (4)
Regarding sample selection, this study primarily relies on publicly available data from manufacturing companies listed on the Shanghai and Shenzhen A-share markets. It does not encompass a large number of non-listed companies or non-manufacturing enterprises, which to some extent limits the generalizability of the research conclusions and their extrapolation across industries.