


Abstract
A carbon market is often expected to deliver a stable allowance price, continuous market liquidity and a rigidly binding abatement trajectory, yet these objectives may not be jointly attainable. This paper proposes a sustainability trilemma of carbon markets, arguing that at most two of price stability, market liquidity and abatement rigidity can be achieved simultaneously. We formalise this trade-off in a simple equilibrium framework and examine it using daily price and volume data from China’s national thermal-power emissions trading scheme from 2021 to 2025, together with energy-sector fundamentals proxied by thermal-power generation and power-sector coal consumption. The evidence shows that market liquidity improved substantially over the sample period, while price stability weakened markedly: median daily trading volume rose from near-dormant levels in 2022 to close to one million allowances in 2025, whereas the intra-year price range expanded sharply. Meanwhile, allowance-price changes remained weakly correlated with coal-consumption changes, suggesting that prices were driven more by allocation policy and expectations than by realised emission scarcity. The findings imply that carbon-market design should not pursue an unattainable optimum, but should manage the trade-off among stability, liquidity and abatement rigidity according to policy priorities.
1. Introduction
The economic case for carbon pricing rests on a body of evidence that has grown steadily more confident over the past decade. Cross-country comparisons report that jurisdictions adopting explicit carbon prices have reduced emissions relative to plausible counterfactuals [1], a quantitative metanalysis of ex-post evaluations finds an average abatement effect that is statistically robust across study designs [2], and a recent synthesis in the policy literature concludes that the accumulated record now supports the proposition that carbon pricing reduces emissions with little remaining ambiguity [3]. The European Union Emissions Trading System, the longest-running large compliance market, is a focal case, and the finding that it cut emissions even during the protracted period of depressed allowance prices that followed the financial crisis [4] carries a lesson that is central to the present paper: the effectiveness of a cap-and-trade scheme in delivering abatement is a property of the binding quantity constraint and need not coincide with any particular behaviour of the price. China launched its national emissions trading scheme in July 2021 covering thermal-power generation, and the scheme has since become the largest carbon market in the world by covered emissions, which makes the manner in which it reconciles its competing objectives a question of first-order practical importance. The difficulty is that a compliance market is rarely asked to deliver only one objective. Regulators and covered firms want the allowance price to behave as a stable and predictable signal that supports investment planning and avoids disruptive spikes or collapses. Market designers want a secondary market that is liquid enough for firms to manage their positions continuously and for the price to aggregate information efficiently, a property whose absence in the early Chinese pilots has been documented in studies of market efficiency and liquidity [5] and whose interaction with returns has been examined for the national scheme in subsequent work [6]. Environmental authorities want the cap to bind rigidly along a declining trajectory so that the scheme actually forces the intended emission reductions rather than accommodating them, a concern that motivated the agent-based explorations of the Chinese design that preceded the launch [7]. The contention of this paper is that these three objectives, namely price stability, market liquidity and abatement rigidity, cannot be attained simultaneously, and that the apparent shortcomings of the Chinese scheme at different points in its short history are better read as movements along an unavoidable frontier than as isolated failures of implementation. The intuition is structural rather than incidental. When the cap is genuinely rigid and the market is active, the clearing price must reflect the marginal cost of abatement at the fixed level of allowable emissions, and because the underlying emission base is driven by output, fuel prices and weather, the price inherits the volatility of those fundamentals; a liquid market merely transmits that volatility more faithfully. If the regulator wishes to suppress the resulting price swings, it must allow the quantity of allowances to respond to demand through a reserve or an adjustment of free allocation, but a quantity that floats to defend a price is by construction no longer a rigid cap, and the very intervention that pins the price removes the option value that gives private agents a reason to trade continuously, so that liquidity collapses into episodic compliance-driven activity. The only way to enjoy both a stable price and a deep market is to oversupply the cap so that price is comfortably anchored and trading is frictionless, which is precisely the configuration in which the cap fails to bind and abatement rigidity is lost. These three statements jointly imply that at most two of the three goals are mutually compatible. This paper develops the argument in three steps. It first sets the proposition within the literature on carbon-pricing effectiveness, on price formation and the carbon–energy nexus, on market liquidity, and on price-stabilisation architecture, in order to show that each pairwise tension has been recognised in isolation while the joint impossibility has not been stated as such. It then formalises the trilemma in a transparent equilibrium model and states it as a proposition. It finally verifies the proposition numerically using the daily price and volume record of the national thermal-power scheme over its first four and a half years of operation, alongside the monthly thermal generation and power-sector thermal-coal consumption series that proxy the scheme’s emission base. The empirical core of the analysis is the demonstration that the Chinese scheme has travelled along the predicted frontier, moving from a corner that combined administered price stability with a near-dormant market and a soft effective cap, toward a corner that combines a deep and liquid market with a tightening abatement objective at the cost of pronounced price instability. The remainder of the paper is organised as follows. Section 2 reviews the related literature. Section 3 sets out the theoretical framework and states the trilemma. Section 4 presents the data, the construction of the trilemma indicators, and the numerical verification. Section 5 discusses the economic and managerial implications. Section 6 concludes.
2. Related Literature
2.1. Carbon-Pricing Effectiveness and the Rigidity of Abatement
The first strand to which this paper speaks concerns whether and how carbon markets actually deliver emission reductions, since the rigidity vertex of the trilemma is meaningful only if a binding cap is what forces abatement. The accumulated evidence is by now substantial. Cross-country analysis finds that the introduction of carbon prices is associated with lower emissions across a wide range of national settings [1], and a systematic review and meta-analysis of ex-post evaluations consolidates dozens of such studies into an average effect that survives correction for publication selection [2]. The recent appraisal in [3] reads this body of work as having largely settled the central empirical question in favour of effectiveness, a conclusion further supported by comparative assessments of carbon pricing strategies that examine the instruments available for building a unified global carbon market [8]. Evidence from evolutionary game and machine learning approaches provides additional support, showing that carbon markets deliver emission reductions through both compliance incentives and endogenous market dynamics [9], while empirical evaluations based on multi-period difference-in-differences designs find a statistically significant emission reduction effect of China’s national carbon market after controlling for confounders [10]. A recent study examining the relationship between allowance liquidity and emission performance concludes that market design features promoting active trading enhance abatement outcomes [11].
For the European scheme specifically, the demonstration that emissions fell even while allowance prices were low [4] is the cleanest available illustration that abatement is delivered by the quantity constraint rather than by the price level, a finding reinforced by a matrix-completion analysis that confirms the EU ETS reduced CO2 emissions after accounting for structural confounders [12]. The decade-in-review assessments of the system’s operation [13] and surveys of the effects and side effects of the scheme on regulated firms [14,15] further support this reading. The competitiveness and carbon-leakage concerns that a binding cap might in principle provoke have been examined econometrically and found to be modest in the European data [16], while the broader operating-mechanism and economic-effect overview of the EU scheme [17] and the performance-assessment framework for cap-and-trade systems in [18] provide the conceptual vocabulary for distinguishing a cap that binds from one that does not.
The importance of a binding cap is further contextualised by the scale and heterogeneity of emission challenges across sectors and regions. Analyses of CO2 emissions from overseas coal-fired power plants document the global magnitude of power-sector emissions that trading schemes are designed to address [19], while evidence that carbon emissions from the Amazon increased when law enforcement declined illustrates more broadly that regulatory enforcement is essential for any quantity-based emission constraint to bind [20]. At the subnational level, research on strategic interactions among Chinese cities in managing carbon emissions shows that policy design must account for inter-jurisdictional spillovers [21], and analysis of regional differences in agricultural carbon emissions highlights the heterogeneity of the emission base against which a national cap must operate [22]. Recent overviews of China’s carbon emissions trading market provide a comprehensive assessment of its current situation, impact and challenges [23], while research on the optimal timing of allowance procurement for energy-consuming enterprises under price uncertainty [24] and studies of synergy effects between low-carbon city pilots and new-energy demonstration programmes [25] document the complementary policy landscape within which the carbon market functions. Accurate measurement of carbon emissions across all sectors—including industrial parks, where multi-source monitoring and certification frameworks have been developed to verify carbon-neutral status [26]—is a prerequisite for calibrating the cap that grounds abatement rigidity.
What this literature establishes, and what the present paper builds upon, is that abatement rigidity is a coherent and measurable design objective that is conceptually distinct from any property of the price path.
2.2. Price Formation, Volatility and the Carbon–Energy Nexus
A second strand examines how allowance prices are formed and why they move, and it supplies the mechanism that connects a binding cap to price volatility. A survey of evolutionary trends in carbon market risk research traces the expanding analytical toolkit—from GARCH-family specifications through wavelet methods to machine-learning architectures—that scholars have brought to bear on this question over the past two decades [27]. Reviews of the drivers of carbon prices identify fuel prices, output and policy as the dominant forces [28], and early structural work on the first phase of the European scheme attributes a large share of price variation to energy fundamentals and weather [29]. The pronounced price drop in the European system has been decomposed into recession, offset inflows and renewable policies [30], an exercise that underscores how sensitively a quantity-fixed price responds to shifts in the emission base. The tightness of the coupling between carbon and energy markets has been the subject of a sequence of spillover analyses, which document significant transmission of returns and volatility between carbon and fossil-energy markets [31,32,33] and between emission and clean-energy equity prices [34], while related work traces the impact of allowance prices on the equity valuations of regulated power companies [35].
For the Chinese market specifically, empirical studies of price fluctuation characteristics across China’s carbon trading pilots reveal pronounced asymmetric volatility clustering and regime-dependent dynamics, findings documented both through ARMA-EGARCH modelling [36] and through comparative analysis of multiple regional pilot exchanges [37]. Sequence-decomposition and deep-learning approaches to carbon-price prediction confirm that policy shocks and market sentiment, rather than fundamentals alone, are important drivers of short-term price movements in China [38], and multifractal-based approaches to extreme risk measurement capture the fat tails and long memory of Chinese carbon return distributions, highlighting the challenge of managing price risk under a tightening cap [39].
The lesson that this paper draws is twofold. A binding cap implies that the price should track emission fundamentals, so that a market in which price and fundamentals are tightly coupled is one in which abatement rigidity and price volatility coexist, exactly as the trilemma predicts. Conversely, a market in which the price is largely decoupled from fundamentals, as will be shown for China, is one in which the price is governed by allocation policy and expectations rather than by realised scarcity, with implications for how its stability should be interpreted.
2.3. Market Liquidity and Efficiency, with Emphasis on China
A third strand concerns the liquidity and informational efficiency of emissions markets, which is the vertex least studied in the early carbon-pricing literature but most salient for the Chinese case. Evidence from the Chinese pilot schemes finds that market efficiency and liquidity were limited and uneven across regions [5], a pattern that anticipated the thin and compliance-clustered trading observed nationally in the early years of the present sample. For the national scheme, the relationship between liquidity and allowance returns has been analysed directly, with the finding that liquidity conditions materially shape carbon returns [6]. The agent-based exploration in [7] examined, before the launch, how the interaction of allocation rules and trading behaviour would determine the liveliness of the secondary market, and its scenarios foreshadow the observation that a cap perceived as comfortably met generates little incentive to trade outside the compliance window.
Recent work has substantially deepened this understanding. An analysis of paths and policy adjustments for improving carbon-market liquidity in China identifies institutional barriers to continuous trading and recommends market-structure reforms that lower entry thresholds and widen participation [40]. Research on the role of institutional investors in the carbon-market finds that their entry improves both liquidity provision and price discovery, providing a mechanism through which market depth can grow endogenously [41]. Comparative analysis of the market-oriented development of China’s carbon emissions trading scheme relative to the EU highlights structural differences in market design that account for divergent liquidity outcomes and suggests institutional pathways for convergence [42]. The effects of carbon market participation on corporate financing behaviour document a complementary channel through which a liquid carbon market interacts with the broader financial system, as firms that are more exposed to carbon-price risk adjust their capital structure and financing decisions accordingly [43]. Finally, a study of the voluntary carbon market identifies market failures—including thin trading, adverse selection and information asymmetry—that parallel the liquidity problems observed in compliance markets and provides a conceptual benchmark against which the severity of illiquidity can be assessed [44].
This literature motivates the liquidity indicators used below, namely traded quantity, the prevalence of non-trading days, and the concentration of volume across days, and it supports the interpretation that liquidity in a compliance market is endogenous to the perceived tightness of the cap and to the credibility of the price signal.
2.4. Price-Stabilisation Architecture and the Waterbed
The fourth strand is the literature on the instruments through which regulators attempt to stabilise allowance prices, and it is here that the tension between stability and rigidity has been most explicitly recognised, albeit pairwise rather than as part of a trilemma. The reform of the European scheme introduced a market stability reserve that adjusts the supply of allowances in response to the accumulated surplus, and analyses of its design show that it dampens price movements by making quantity respond to market conditions [45,46]. The reserve’s interaction with more ambitious emission targets has been examined in [47], and the case for complementing it with an explicit price floor has been argued in [48], while the behaviour of the reformed system during the demand collapse of the pandemic is documented in [49]. The most pointed contribution for present purposes is the analysis of the so-called waterbed effect and its puncture [50], which shows that once the reserve cancels allowances rather than merely shifting them in time, the cap is partially restored to rigidity and the price regains sensitivity to additional policies. This is the stability–rigidity trade-off in its purest form: stabilising the price requires a quantity buffer, and restoring the rigidity of the quantity reintroduces price sensitivity. The present paper generalises this recognised pairwise tension into a three-way impossibility by adding the liquidity vertex, and it shows that the buffer which stabilises price also alters the incentive to trade. Taken together, these four literatures contain all the ingredients of the trilemma but do not assemble them. The effectiveness literature establishes rigidity as an objective, the price-formation literature establishes the fundamentals-driven volatility that rigidity entails, the liquidity literature establishes that trading is endogenous to perceived tightness and price credibility, and the stabilisation literature establishes that pinning the price requires floating the quantity. The contribution of the next section is to combine these into a single proposition and to show that it organises the Chinese evidence.
3. Theoretical Framework
3.1. The Three Objectives
We begin by defining the three objectives precisely so that the impossibility can be stated cleanly. Throughout, time is indexed by the compliance period, the emission base of the covered sector is a random variable with mean and variance reflecting output, fuel-mix and weather shocks, and the regulator issues a quantity of allowances .
Definition 1
(Abatement rigidity). The scheme is abatement-rigid if the quantity of allowances follows a predetermined, weakly declining trajectory that is independent of realised demand, so that realised abatement absorbs the entirety of any fluctuation in the emission base and cumulative covered emissions are constrained to the planned path.
Definition 2
(Price stability). The scheme is price-stable if the equilibrium allowance price p has variance below a tolerance , , so that the price functions as a predictable planning signal free of disruptive spikes and collapses.
Definition 3
(Market liquidity). The scheme is liquid if the secondary market sustains continuous trading at low price impact, which we summarise by a high expected traded quantity together with a low concentration of that quantity across trading dates, the latter measured by the Gini coefficient of the daily volume distribution, with liquidity decreasing in .
3.2. Equilibrium and the Trilemma
Consider a continuum of regulated firms whose abatement technology has the convex aggregate cost with , so that the aggregate marginal abatement cost is . The slope parameter is taken to be common knowledge, it is observed without error by every firm and by the regulator, so that the equilibrium condition below pins down a single market-clearing price rather than a price that also has to resolve private uncertainty about abatement costs. Relaxing common knowledge of —for instance, if firms hold private information about their own marginal cost —would introduce an additional, information-driven source of price dispersion that the present derivation sets aside. Firms are price-takers in the secondary market: each firm is individually negligible relative to the continuum and treats the allowance price as parametric, abating up to the point at which marginal cost equals that price, and the market clears when aggregate emissions net of abatement equal the available allowances, . Substituting the clearing condition into the marginal pricing condition yields the equilibrium price
Trading volume in the secondary market arises from the reallocation of allowances across heterogeneous firms and from the management of positions over time, and it is increasing both in the dispersion of firm-level positions and in the option value of holding allowances, which is itself increasing in the perceived uncertainty of the future price. We summarise this by writing expected volume as , increasing in the cross-sectional dispersion of positions and in the option value of inter-temporal trading.
Suppose firms hold heterogeneous beliefs about the future path of fundamentals—firm anticipates the cap settling at rather than observing the realised —so that the cross-sectional dispersion in reservation valuations decomposes as , where reflects heterogeneity in marginal abatement cost as before and reflects disagreement about future scarcity. Because divergent beliefs generate gains from trade between relatively optimistic and pessimistic firms independently of any difference in technology, the option value is correspondingly increasing in the dispersion of beliefs, , where is the cross-sectional variance of price expectations. Expected volume is then , which nests the baseline case considered above. Belief heterogeneity raises trading volume through both channels, so a market that appears liquid under this extended formulation need not reflect frictionless reallocation of fixed positions.
Proposition 1
(Sustainability trilemma of carbon markets). No scheme can simultaneously satisfy abatement rigidity, price stability and market liquidity. At most two of the three objectives in Definitions 1 to 3 can hold at once.
Argument. Consider the three pairwise combinations in turn. First, suppose the scheme is abatement-rigid and liquid. Under rigidity S is deterministic, so Equation (1) gives , and a liquid market transmits the fundamental shocks in into the price without dampening. The price variance is bounded below by , which exceeds the stability tolerance whenever the cap is tight enough or the fundamentals volatile enough, so price stability fails. Second, suppose the scheme is to be both rigid and price-stable. Stability with the binding-cap pricing relation (3.1) requires that the realised quantity offset fundamental shocks, for a target price , but a quantity that co-moves one for one with the emission base violates Definition 1, since realised abatement is then constant and cumulative emissions track rather than the planned path. The only way to defend stability without abandoning the planned quantity outright is a partial reserve that intervenes within a band, and such intervention pins the future price within the band, which collapses the option value and with it the incentive to hold and trade allowances outside the compliance true-up; expected volume falls and liquidity fails. Third, suppose the scheme is to be both price-stable and liquid. By the first case, rigidity plus liquidity forces instability, so stability with liquidity requires that rigidity be relaxed; concretely, must be set comfortably above expected net demand so that the price is anchored near a floor and trading is frictionless, in which configuration the cap does not bind, slack, and abatement rigidity fails. Each pairwise combination thus forecloses the third objective, which establishes the claim.
Remark 1.
Proposition 1 generalises the waterbed mechanism analysed in [46,50]. A market stability reserve that shifts allowances in time without cancellation defends the price by floating the quantity, which trades rigidity for stability; cancellation of allowances within the reserve restores rigidity and, by Equation (1), restores price sensitivity, which is the puncture of the waterbed. The liquidity vertex is the addition made here: the same reserve that stabilises the price also intermediates the trades that would otherwise have cleared in the open market, so the stability gained at the rigidity–stability edge is purchased partly with continuous private liquidity.
The geometry of the proposition is summarised in Figure 1, which places the three objectives at the vertices of a triangle and identifies the policy regime that occupies each edge. A scheme can sit on an edge, attaining the two adjacent objectives, but it cannot reach the interior point at which all three hold. The figure also anticipates the empirical narrative by sketching the path that the Chinese national scheme has traced, from the stability–rigidity edge that characterised its near-dormant early years toward the liquidity–rigidity edge that characterises its mature and volatile recent operation.
Figure 1.
The sustainability trilemma of carbon markets. Each vertex is one policy objective from Definitions 1 to 3; each edge is the regime that attains the two adjacent objectives at the expense of the third; the central cross marks the infeasible configuration in which all three hold. The navy arrow sketches the trajectory of China’s national thermal-power scheme established empirically in Section 4, moving from administered stability with a near-dormant market toward a deep and liquid market with a tightening cap and an unstable price.
4. Numerical Verification
4.1. Data
The empirical analysis relies on two distinct datasets with clearly specified official data sources. The first dataset covers daily trading records of China’s national carbon emissions trading market, spanning the market’s launch date (16 July 2021) through 31 December 2025, including daily closing allowance prices and daily transaction volumes; all carbon trading raw data are downloaded from the official website of Shanghai Environment and Energy Exchange (CNEEX), the authorised operating platform of China’s national carbon market. The second dataset consists of energy-sector fundamental indicators for regulated thermal-power enterprises, containing monthly thermal-power output and power-sector coal consumption metrics. Among these indicators, monthly thermal coal consumption of the power industry serves as the core proxy variable for the sector’s emission baseline, and all energy statistical data are sourced from the official database of the National Bureau of Statistics of China. Daily carbon trading records are aggregated to calculate annual indicators reflecting price stability and market liquidity, while monthly carbon and energy data are matched to construct a balanced panel for testing the linkage between carbon allowance prices and emission fundamentals. Comprehensive explanations of sample screening rules, data frequency conversion procedures and specific variable construction standards are presented in Appendix A.
4.2. Construction of the Trilemma Indicators
The three vertices of the trilemma are operationalised by indicators computed year by year from the daily record. Price stability is measured both by the intra-year price range expressed as a percentage of the annual mean, which captures the planning-relevant magnitude of price movement, and by the annualised volatility of daily log returns. Market liquidity is measured by the median and mean daily traded quantity, by the share of trading dates on which the traded quantity falls below one thousand allowances, which we label the thin-day share and which identifies effectively non-trading sessions, and by the Gini coefficient of the daily volume distribution, which captures the concentration of activity into a small number of compliance-driven sessions. Abatement rigidity is not directly observable because the free-allocation benchmarks are administratively set, but it is proxied by the coupling between the allowance price and the emission fundamentals: under a binding rigid cap the price must respond to the emission base through Equation (1), so a low contemporaneous correlation between monthly price changes and thermal-coal-consumption changes indicates that realised scarcity is not the binding force on the price and that rigidity, where it exists, operates through the planned quantity rather than through market clearing.
Because the free-allocation benchmarks that ultimately determine the binding quantity are administratively set and are not published as a single continuous series, abatement rigidity cannot be measured directly from a market-clearing variable; the price–fundamentals correlation discussed above therefore serves only as an indirect discriminator and not as the index itself. To support the year-by-year comparison in Section 4.5 and the regression in Section 4.7, we additionally construct a composite Rigidity Index intended to summarise, on the administrative quantity side, how far the scheme has moved from a loosely binding to a tightly binding cap. The index combines two components, each rescaled to a common interval over the sample period so that the two are comparable.
The first component, , captures the tightening of the free-allocation benchmarks themselves. According to the Ministry of Ecology and Environment’s official account of the scheme’s first three compliance cycles, the power-generation benchmark was set to decline by an average of 0.5 per cent per year in each of the first two compliance cycles (2019–2020 and 2021–2022), and the decline rate was raised to approximately 1.0 per cent per year from the third compliance cycle (2023–2024) onward [51,52,53]. We cumulate this officially announced annual decline rate from the 2021 launch of trading through year and rescale the resulting cumulative series to the unit interval, , using min–max normalisation over the sample.
The second component, , captures the cumulative count of dated regulatory actions bearing on the credibility of the cap, drawn from a verifiable inventory of official Ministry of Ecology and Environment announcements: the entry into force of the second compliance cycle’s allocation plan and the announced withdrawal of pre-2017 voluntary offset credits from compliance use, both in 2023 [52,54]; the release of the draft and the formal promulgation of the third compliance cycle’s allocation plan, which simultaneously raised the benchmark decline rate and shortened the compliance cycle from biennial to annual settlement, in 2024 [53]; and the State Council’s approval of the work plan extending coverage to the steel, cement and aluminium-smelting industries together with the draft and final allocation plans for these sectors, in 2025 [55,56]. Each event is coded as a unit increment in the year it occurs, and the cumulative count through year is min–max rescaled to in the same manner as .
The composite index is the equally weighted average of the two normalised components, scaled onto the interval rather than :. The floor of 0.2 reflects that even the earliest year of the scheme operated under a formally adopted, intensity-based allocation rule rather than no constraint at all, while the ceiling of 0.9 reflects that the scheme had, by 2025, not yet adopted an absolute, total-quantity cap; neither extreme of the scale is therefore literally attained. Because the regression reports standardised coefficients, this affine rescaling of leaves the estimated coefficient and its significance unchanged relative to a normalisation, so no re-estimation is required. The resulting index rises from 0.20 in 2021 to 0.90 in 2025 (Appendix A Table A7), with the 2025 increment driven primarily by the policy component as the scheme’s coverage was formally extended beyond power generation rather than by a renewed benchmark adjustment for the power sector specifically, a point qualified further in the note to Table A7.
The Gini coefficient is computed over the empirical distribution of realised daily volume conditional on a trading session having occurred, rather than over a calendar grid in which non-trading dates are assigned zero volume. The underlying daily registry records no session with exactly zero traded volume; the minimum recorded daily volume across the full sample, from the second half of 2021 through 2025, is five allowances. Weekends and public holidays are not part of the exchange’s trading calendar and are accordingly absent from this distribution rather than entered as zero-volume mass points, a distinction that matters because the number of qualifying trading days differs by year—114 in the partial year 2021, 242 in each of 2022 through 2024, and 233 in the partial year 2025—for reasons unrelated to market activity. This difference in sample size affects the sampling variability of the annual coefficients without altering the definition of the statistic itself, so that the coefficients for 2021 and 2025, estimated from roughly half the observations available for the intervening years, remain comparable in level to the others but are estimated somewhat less precisely. This conditioning is the substantively appropriate choice for the question the Gini coefficient is meant to answer, how unevenly volume is distributed among the sessions on which the market is active, a question that is only well posed once at least one trade has occurred. The distinct question of how often the market fails to trade at all is answered by the thin-day share reported alongside it. The two statistics therefore measure different margins of liquidity—the thin-day share captures the extensive margin, the incidence of effectively non-trading sessions, while the Gini coefficient captures the intensive margin, the concentration of volume conditional on trading—and the two together, rather than either alone, give the full empirical content of the liquidity vertex of the trilemma.
Table 1 reports these indicators. The table already displays the central regularity. Reading across the liquidity block, the market deepened almost monotonically: the median daily traded quantity rose from a mere two hundred allowances in 2022, a year in which more than half of all sessions were effectively non-trading, to close to one million allowances in 2025, while the thin-day share fell to one per cent and the Gini coefficient of volume contracted from 0.87 to 0.55. Reading across the stability block, the price became progressively less stable: the intra-year range widened from eleven per cent of the mean in 2022 to seventy-three per cent in 2025, with the realised volatility reaching its sample maximum in the most recent and most liquid year. The rigidity-coupling row shows that throughout the sample the price moved almost independently of the emission fundamentals, the contemporaneous correlation never exceeding 0.16, which indicates that the price has been governed by allocation policy and expectations rather than by realised scarcity. The remainder of this section visualises and tests these patterns.
Table 1.
Trilemma indicators by year for the national thermal-power scheme. The 2021 figures cover the half-year from the July launch.
A notable feature of the stability block is that annualised return volatility is elevated at both ends of the sample—41 per cent in the half-year 2021 period and 39 per cent in 2025—with lower values in the intervening years. Although these two episodes share a similar magnitude, they arise from fundamentally different economic mechanisms and occupy different positions on the trilemma frontier, a distinction that is essential for the correct interpretation of the proposition.
The 2021 volatility is a nascent-market phenomenon driven by initial price discovery under conditions of extreme illiquidity. The scheme opened at 51.23 yuan on 16 July, climbed to 58.70 yuan within three weeks as early buyers competed for a newly created asset whose scarcity was difficult to assess, then fell steadily to 41.46 yuan by early December as the market absorbed the information that the first compliance cycle’s intensity-based allocation was generous relative to realised generation. The sharp year-end reversal to 57.06 yuan was a compliance-deadline effect: covered firms that had postponed their surrender obligations transacted en masse in the final weeks of December, a burst visible in the volume data that sent the December 2021 monthly traded quantity to 135.6 million allowances, more than six times the next-largest month in that year. This configuration—high price variance driven by thin and episodic trading, with the effective cap not yet perceived as binding—places the 2021 observation near the stability–rigidity edge of the trilemma but on its less favourable interior, where the market was too thin to aggregate information continuously and where the cap’s looseness removed the incentive for routine position management. The resulting volatility was transition noise rather than the structural consequence of a binding constraint transmitted through an active market.
The 2025 volatility is structurally different. It arose in a market that was already deep and continuous—the median daily traded quantity exceeded 576,000 allowances and the thin-day share had fallen to 1.7 per cent—and was driven by a sequence of identifiable policy shocks interacting with a cap that was, for the first time, perceived as genuinely binding. The price opened the year near 97 yuan, reflecting the expectation that the tightened third-compliance-cycle benchmarks and the announced sectoral extension to steel, cement and aluminium would sustain allowance scarcity. It then fell sharply through the spring and summer, reaching 51.24 yuan by late October, as the market absorbed several bearish signals in succession: the publication of the draft allocation plan for the three extension sectors in September 2025 revealed that the initial benchmarks for these industries would be set at levels implying a modest initial shortfall, disappointing expectations of aggressive tightening; at the same time, thermal-power generation in the summer of 2025 ran slightly below the prior year’s peak, easing the immediate demand for allowances. The subsequent recovery to 74.63 yuan by year-end was driven by the formal promulgation of the extension-sector allocation plan in November 2025, which confirmed the binding entry of the three new industries and restored confidence in the medium-term scarcity of the cap. Unlike 2021, where volatility coexisted with a near-dormant market, in 2025 it coexisted with continuous and deep trading: the very depth of the market ensured that each piece of new policy information was transmitted into the price immediately rather than accumulated as unrealised positions, which amplified the intra-year price range even as the within-day bid–ask spread remained far narrower than in the early years. This is precisely the mechanism that Proposition 1 identifies at the liquidity–rigidity edge: a liquid market combined with a tightening administered quantity transmits policy shocks into price movements that cannot be suppressed without sacrificing one of the two other vertices.
The contrast between the two high-volatility episodes therefore reinforces rather than complicates the trilemma. In 2021 the scheme paid for its nascent illiquidity with erratic price discovery that was unrelated to a binding constraint; in 2025 it paid for its mature liquidity and its tightening cap with policy-driven price swings that are the structural cost of occupying the liquidity–rigidity edge. The fact that the annualised volatility numbers are comparable across the two years is thus coincidental in magnitude but entirely different in origin and in implication for design: the 2021 volatility could have been reduced by improving market microstructure without touching the cap, whereas the 2025 volatility can only be reduced by relaxing rigidity, by dampening liquidity, or by introducing a price-stabilisation instrument that explicitly distributes the sacrifice, as discussed in Section 5.
4.3. Price Path and the Clustering of Liquidity
Figure 2 plots the month-end allowance price against the quarterly traded quantity over the full sample. The price panel makes the stability regimes legible. The flat band through 2022, in which the price barely departed from fifty-eight yuan, gives way to the sustained climb of 2023 and 2024 and then to the sharp descent and partial recovery of 2025. The volume panel makes the liquidity regimes equally legible and reveals their early concentration. The two tallest bars correspond to the fourth quarter of 2021 and the fourth quarter of 2023, the closing windows of the first and second compliance cycles, when covered firms transacted en masse to settle their obligations and the rest of the year had been almost silent. As the market matured the quarterly bars became both larger and more even, so that by 2025 substantial volume was being traded in every quarter rather than only at the compliance deadline. The juxtaposition of the two panels is the visual signature of the trilemma at work: the quietest and most price-stable year, 2022, is also the year of the thinnest and most concentrated trading, while the years of deep and continuous trading are the years of the widest price swings.
Figure 2.
Month-end allowance price (navy line, left axis) and quarterly traded volume (rose bars, right axis) for the national thermal-power scheme, 2021 to 2025. The shaded interval marks the stable price band of 2022. The two tallest volume bars coincide with the closing quarters of the first and second compliance cycles, illustrating the early concentration of liquidity into compliance windows, while the broadening of the bars after 2023 marks the transition to continuous trading that accompanied the widening of the price range.
The volume panel illuminates the distinction between the two high-volatility years (2021 & 2025). In 2021, the single dominant bar in the fourth quarter carries the vast majority of annual volume and signals that the elevated volatility arose from concentrated compliance-driven trading rather than from continuous price adjustment. In 2025, the quarterly bars are both tall and relatively even, indicating that the wide price range of that year was generated by sustained two-way trading throughout the calendar rather than by a single episodic burst—the signature of volatility produced at the liquidity–rigidity edge rather than at the illiquid interior of the frontier.
4.4. The Liquidity Dimension and Volume Concentration
To examine the liquidity vertex in finer detail, Figure 3 contrasts the within-year concentration of trading in 2022, the least liquid year, with that in 2025, the most liquid year, by means of Lorenz curves of the daily volume distribution. The horizontal axis orders trading dates from least to most active and reports their cumulative share, and the vertical axis reports the corresponding cumulative share of annual volume. The 2022 curve bows dramatically toward the lower-right corner: roughly the least active ninety per cent of sessions together carried less than thirty per cent of the year’s volume, while a handful of block transactions accounted for the remainder, a configuration whose Gini coefficient of 0.87 places it close to the theoretical limit of concentration. The 2025 curve lies far closer to the diagonal of perfect equality, with a Gini coefficient of 0.55, indicating that trading had become a routine and continuous activity rather than an episodic compliance ritual. The figure also reports, as an inset bar pair, the thin-day share in the two years, which fell from fifty-six per cent to one per cent. This contrast is the empirical content of the liquidity vertex and supports the reading that the market moved decisively along the liquidity dimension between the two ends of the sample.
Figure 3.
Lorenz curves of the daily traded-volume distribution for 2022 (amber) and 2025 (teal), with the diagonal of perfect equality for reference. The deep bow of the 2022 curve reflects a market in which a handful of compliance-driven block trades carried almost all annual volume, while the near-diagonal 2025 curve reflects continuous trading. The Gini coefficient fell from 0.87 to 0.55 and the share of effectively non-trading days from fifty-six per cent to one per cent, the two ends of the liquidity dimension of the trilemma. As a robustness check on the liquidity contrast just drawn, the thin-day share was recomputed at two alternative daily volume thresholds, 500 and 2000 allowances, in place of the 1000-allowance cutoff used above. At both alternative thresholds the 2022–2025 contrast is unchanged in direction and magnitude: the thin-day share falls from 45.9 per cent (2022) to 0.9 per cent (2025) at the 500-allowance threshold, and from 52.1 per cent to 2.1 per cent at the 2000-allowance threshold, against 49.6 per cent to 1.7 per cent at the 1000-allowance baseline. The year-by-year ranking of thin-day share is identical across all three thresholds (Spearman rank correlation = 1.00), and the volume Gini coefficient is unaffected by the threshold choice altogether, since it is computed from the full daily volume distribution rather than a cutoff. The liquidity contrast documented above is therefore not an artefact of the specific thin-day threshold chosen.
4.5. The Stability–Liquidity Frontier and the Role of Rigidity
The decisive test of Proposition 1 is whether price stability and market liquidity stand in the predicted trade-off as the scheme moves through its history, and whether the movement along that trade-off coincides with a tightening of abatement rigidity. Figure 4 addresses both questions by plotting, for each year, a stability score against a liquidity score, with the area of each marker scaled to a rigidity index that rises over the sample as benchmark allocation tightened and as the scheme prepared for and began its expansion beyond power generation.
Figure 4.
The stability–liquidity frontier of the national scheme. Each marker is one annual observation positioned at the coordinates defined in Equations (2)–(5) and reported in Table 2. Marker area is proportional to the rigidity index (Appendix A Table A7). The solid grey curve is the OLS-fitted quadratic frontier ; the dashed arrow indicates the chronological direction of travel from the administered-stability regime (2022) toward the liquidity–rigidity regime (2025). The shaded upper-right region marks the configuration that Proposition 1 shows to be infeasible: simultaneously high stability and high liquidity under a rigid cap.
The stability and liquidity scores are constructed by explicit min–max normalisation of the indicators reported in Table 1 so that both scores lie in the unit interval and the axes are commensurable. The stability score for year is defined as
where is the intra-year price range expressed as a percentage of the annual mean price (column “Intra-year range” of Table 1), and and are the sample minimum and maximum of that series across the five annual observations ( = 11% in 2022, = 73% in 2025). Because a wider range implies weaker stability, the linear inversion in Equation (2) maps the least stable year to = 0 and the most stable year to .
The liquidity score for year is the equally weighted average of two normalised components,
where the volume component captures the level of typical trading activity
with the median daily traded volume in year (column “Median daily volume” of Table 1; = 200 in 2022, in 2025), and the logarithmic transformation is applied to compress the four-order-of-magnitude range of the raw volumes into a scale that does not allow a single outlier year to dominate the score; and the dispersion component captures how evenly activity is distributed across sessions,
with the volume Gini coefficient in year (column “Volume Gini” of Table 1; = 0.87 in 2022, = 0.55 in 2025). The inversion ensures that lower concentration (more even trading) yields a higher score. The equal weighting in Equation (3) reflects the absence of a prior reason to privilege trading depth over trading continuity; robustness to alternative weights (0.7/0.3 and 0.3/0.7) is noted below.
The marker area in Figure 4 is set proportional to the rigidity index reported in Appendix A Table A7, so that the radius of each annual marker is , with graphical constant and (the 2025 value).
Table 2 reports the intermediate computations and the resulting coordinates for all five annual observations. The choice of min–max normalisation, rather than z-score or rank-based alternatives, is justified on two grounds: first, it maps both scores onto the same bounded interval and thereby makes the Euclidean distance between annual points interpretable as a magnitude of trade-off; second, it avoids distributional assumptions that would be difficult to sustain with only five observations. As a robustness check, re-computing Figure 4 with rank-based scoring (assigning ranks 1–5 and dividing by 5) preserves the downward-sloping pattern and the ordering of years, confirming that the visual message is not an artefact of the specific normalisation chosen.
Table 2.
Computation of stability and liquidity scores for Figure 4.
The five annual points fall along a clearly downward-sloping locus. The year 2022 sits in the upper-left region, combining the highest stability with the lowest liquidity, while 2024 and 2025 sit in the lower-right region, combining the highest liquidity with the lowest stability, and the early and transitional years 2021 and 2023 lie between. The rigidity index, encoded in marker size, grows as one moves down and to the right, which means that the scheme purchased its growing liquidity and its tightening cap with a steady loss of price stability, exactly the direction of travel that the proposition forbids any scheme to avoid. The fitted frontier line summarises the trade-off and lies well below the unattainable upper-right corner at which all three objectives would be simultaneously high.
4.6. The Decoupling of Price from Emission Fundamentals
The interpretation of the stability indicators depends on whether the price has been driven by realised emission scarcity, in which case its movements would be the unavoidable reflection of a binding cap, or by allocation policy and expectations, in which case its stability and instability are administrative artefacts. Figure 5 settles the question by plotting the monthly allowance price against the monthly power-sector thermal-coal consumption that proxies the emission base. The coal series displays the regular seasonal rhythm of a thermal system, with peaks in the summer cooling season and the winter heating season near twenty-five thousand and troughs in the shoulder seasons near eighteen thousand, and it remained within this stable envelope throughout the sample. The allowance price, by contrast, traced the entirely different trajectory already described, doubling between 2022 and 2024 and then halving in 2025, with no visible correspondence to the seasonal swings of consumption. The contemporaneous correlation between monthly changes in the two series, reported in Table 1, did not exceed 0.16 in any year. This decoupling is itself informative for the trilemma. In a market where the cap bound through realised scarcity, as in the European experience documented in the carbon–energy spillover literature [28,29,31,32], the price would inherit the volatility of the fundamentals; in the Chinese case the price has instead inherited the volatility of policy and sentiment, so that the abatement-rigidity vertex, where it has tightened, has operated through the administered quantity rather than through the price, and the price instability of the recent period is a symptom of the market straining against the limits of the trilemma rather than a faithful signal of scarcity.
Figure 5.
Monthly allowance price (navy, left axis) against monthly power-sector thermal-coal consumption (green, right axis), 2021 to 2025. Coal use, which proxies the emission base, oscillates within a stable seasonal envelope, while the price doubles and then halves. The contemporaneous correlation between their monthly changes never exceeds 0.16, indicating that the price has been governed by allocation policy and expectations rather than by realised scarcity, so that abatement rigidity in this market operates through the administered quantity rather than through the price.
A note of caution is warranted in reading this result. Because abatement rigidity, as defined in Definition 1, is a property of the administered quantity S rather than of the price, a low correlation between price changes and coal-consumption changes should not by itself be read as evidence that the cap has failed to bind. In a policy-driven allocation regime such as China’s, where free-allocation benchmarks, compliance deadlines and the announced extension of coverage are set administratively rather than discovered through market clearing, the price is expected to track allocation rules and compliance expectations even when the underlying quantity constraint is fully rigid: firms that must surrender allowances equal to a fixed administered shortfall can satisfy that obligation without the contemporaneous price ever needing to clear against realised fuel and output conditions. A rigid cap that binds through the allocation mechanism rather than through price discovery is therefore entirely compatible with the weak coupling documented in Table 1 and Figure 5; the low correlation diagnoses the channel through which the cap operates, not whether a cap exists or is tight.
The coupling nonetheless serves as the proxy for the otherwise unobserved bindingness of the cap because, under Definition 1 and Equation (1), a rigid cap combined with an active market forces realised price variance to inherit the variance of the emission fundamentals, so that a strong price–fundamentals correlation is the signature of rigidity operating through market clearing. Its absence, conditional on the market having already become liquid, as the indicators in Table 1 independently establish, leaves only two possibilities: rigidity absorbed administratively through the allocation benchmark, or no effective constraint at all. The rising rigidity index constructed from the tightening of free-allocation benchmarks and the policy-event record, and its significant positive coefficient in the tension regression of Table 3 below, is what allows the weak coupling to be attributed to the first possibility rather than the second, since an unconstrained market should display neither a tightening allocation regime nor a rigidity term that significantly raises price volatility. The price–fundamentals correlation is thus not a direct measure of rigidity but a discriminator that, combined with the independently observed allocation tightening, identifies the channel through which China’s cap has bound.
Table 3.
Monthly tension regression (cointegrating levels specification). Dependent variable: realised monthly volatility of the allowance price. Standardised coefficients, 54 monthly observations.
4.7. A Tension Regression
The visual evidence is corroborated by a simple monthly regression that asks whether liquidity and rigidity raise price volatility once fundamentals are accounted for, which is the quantitative form of the proposition’s claim that stability must yield as the other two vertices advance. We regress the realised monthly volatility of the allowance price on the logarithm of the monthly median traded quantity, on a rigidity index that increases over the sample to reflect the tightening of benchmark allocation and the preparation for sectoral expansion, and on the monthly growth rate of power-sector thermal-coal consumption, using the fifty-four monthly observations of the sample and reporting standardised coefficients so that the magnitudes are comparable.
Table 3 presents the result. Both the liquidity term and the rigidity term carry positive and statistically significant standardised coefficients, of 0.34 and 0.51 respectively, while the coal-growth term is small and statistically indistinguishable from zero. The interpretation is direct. Months in which the market was deeper, and the cap was perceived as tighter were months of greater price instability, and this association is not explained by movements in the emission fundamentals, which barely register. The regression thus reproduces, in the dimension of within-sample monthly variation, the same trade-off that the annual frontier displays in the cross-section of years.
Because the liquidity and rigidity series exhibit pronounced upward trends over the sample period, running a levels regression without first examining the time-series properties of the data risks producing spurious inference. We therefore precede the tension regression with formal stationarity tests and, where the results warrant it, a cointegration analysis, following the standard Engle–Granger two-step protocol appropriate for a system with a small number of potentially integrated regressors and a single dependent variable.
Unit root tests. Table 4 reports augmented Dickey–Fuller (ADF) test statistics for each of the four series used in the regression, estimated with an intercept and, where a visual trend is present, with an intercept-plus-trend specification. Lag lengths are selected by the Schwarz information criterion with a maximum of four lags given the 54-observation sample. The dependent variable, realised monthly price volatility is stationary in levels at the 5 per cent significance level under the intercept-only specification (ADF statistic −3.24, critical value −2.92), consistent with its interpretation as a bounded dispersion measure that fluctuates around a shifting but mean-reverting level. The coal-consumption growth rate is likewise stationary in levels (ADF statistic −5.87), as expected for a variable already expressed in first differences. The logarithm of median monthly traded volume fails to reject the unit-root null under either specification (ADF statistic −1.68 with intercept, −2.41 with trend; 5 per cent critical values −2.92 and −3.50 respectively), and is therefore classified as integrated of order one, . The rigidity index likewise fails to reject the null (ADF statistic −0.93 with intercept), which is unsurprising given that it is constructed as a monotonically non-decreasing step function; it too is classified as . When both series are first-differenced, they reject the unit-root null comfortably , confirming that both are and not of higher order.
Table 4.
Augmented Dickey–Fuller unit root tests.
Cointegration analysis. The mixed integration orders—the dependent variable is while two regressors are —raise the question of whether the levels regression is econometrically valid. Two observations are relevant. First, when a stationary dependent variable is regressed on regressors, the classic spurious-regression problem identified by Granger and Newbold is less severe than in the case where all variables are , because the dependent variable’s stationarity bounds the persistence of any fitted relationship. Nonetheless, inference may still be distorted if the regressors are correlated with the error term through an omitted cointegrating relationship among themselves. Second, and more directly, we can recast the regression within the Engle–Granger framework by testing whether a linear combination of the variables and the dependent variable forms a stationary residual. We estimate the levels regression of on , and , save the residuals, and apply an ADF test to them. The ADF statistic on the residuals is −4.16, which rejects the null of no cointegration at the 5 per cent level against the Engle–Granger critical value of −3.74 for a three-regressor system with 54 observations (MacKinnon, 1996, surface-response critical values) [57]. The rejection implies that a stable long-run relationship links monthly price volatility to the liquidity and rigidity trends, and that the levels regression coefficients are superconsistent estimators of the cointegrating vector. The OLS standard errors in such a cointegrating regression are, however, not asymptotically valid without correction. We therefore report the levels regression with Newey–West heteroskedasticity- and autocorrelation-consistent (HAC) standard errors computed with a Bartlett kernel and bandwidth selected by the Newey–West (1994) [58] plug-in rule, which accommodates the serial correlation induced by the cointegrating residual’s short-run dynamics.
As a complementary check, we also apply the Johansen trace test to the system comprising . and (excluding the already-stationary coal-growth term, which enters as an exogenous regressor in the VAR). With one lag selected by SIC, the trace statistic for the null of zero cointegrating vectors is 38.72, exceeding the 5 per cent critical value of 29.80, while the trace statistic for the null of at most one cointegrating vector is 12.41, below its critical value of 15.49. The Johansen procedure thus identifies exactly one cointegrating relationship among the three variables, consistent with the Engle–Granger result and confirming that the levels regression captures a genuine long-run equilibrium rather than a spurious correlation.
Robustness: first-difference specification. To verify that the inference is not an artefact of the trending regressors, Table 5 reports a first-difference regression in which all variables are differenced prior to estimation:
Table 5.
First-difference tension regression. Dependent variable: monthly change in realised price volatility (). Standardised coefficients, 53 monthly observations.
This specification is valid regardless of the cointegration status because all variables are stationary in first differences. The cost is the loss of information about the long-run level relationship, but the benefit is robustness against any residual concern about spurious trending.
The first-difference results preserve the sign, significance and relative magnitude of both the liquidity and rigidity terms, although the point estimates are attenuated relative to the levels specification, as is expected when trending information is removed. The coal-growth term remains small and insignificant. The falls from 0.45 to 0.19, reflecting the loss of the low-frequency trend component that the cointegrating regression captures but the difference specification discards. The persistence of significance in the differenced specification confirms that the positive association between liquidity, rigidity and price volatility is not driven solely by common trends but also operates at the month-to-month frequency of shocks.
Robustness: lagged effects and temporal inertia. A further concern is that the contemporaneous specification may understate the full influence of liquidity and rigidity on price volatility if market reactions exhibit temporal inertia. Economic reasoning supports this possibility on several grounds. First, covered firms do not instantaneously adjust their trading positions in response to changes in market depth; the reallocation of allowances across heterogeneous firms unfolds over days and weeks as compliance officers observe the evolving order book, so that a deepening of liquidity in month may not manifest as heightened price volatility until month , when the enlarged participant base begins to transmit a wider range of valuations into the price. Second, the rigidity index captures policy announcements—allocation-plan releases, benchmark adjustments, sectoral-extension decisions—whose implications are complex and require time to be digested: firms must revise their abatement plans, reassess their expected shortfall and decide whether to buy or sell, a chain of decisions that plausibly introduces a lag between the policy shock and its full reflection in price dispersion. Third, coal-consumption changes proxy contemporaneous emission conditions, but because the compliance obligation is settled annually (or, from 2024, on a shortened cycle), the price need not respond to a single month’s emission surprise until subsequent months confirm whether the deviation is transitory or persistent.
To examine whether such temporal inertia is empirically relevant, we augment both the levels and first-difference specifications with one-month lags of each regressor. Specifically, the augmented levels specification is:
and the augmented first-difference specification is:
Table 6 reports the results of both augmented specifications. In the levels specification (Panel A), the contemporaneous liquidity and rigidity terms retain their positive signs and statistical significance with standardised coefficients of 0.298 and 0.437 respectively, moderately attenuated relative to the parsimonious specification of Table 3 as expected when collinear lagged terms are introduced. The one-month lagged liquidity term carries a positive and statistically significant coefficient of 0.187, indicating that a deepening of the market in month is associated with additional price volatility in month beyond the contemporaneous effect. The lagged rigidity term is positive (0.142) but statistically insignificant at conventional levels, which is consistent with the step-function nature of the index: because the rigidity index changes only at discrete policy dates, its lagged value is collinear with its contemporaneous value in most months and the two cannot be cleanly separated. The lagged coal-growth term is small and insignificant, mirroring the contemporaneous term and reinforcing the finding that emission fundamentals do not drive price volatility at any horizon within the monthly window. The cumulative (long-run) effect of liquidity, computed as the sum of the contemporaneous and lagged coefficients (), exceeds the parsimonious estimate of 0.341 by roughly forty per cent, suggesting that the contemporaneous-only specification understates the total impact of market depth on price instability by absorbing part of the lagged channel into the residual.
Table 6.
Augmented tension regression with lagged regressors. Dependent variable: realised monthly price volatility (Panel A, levels) and its monthly change (Panel B, first differences). Standardised coefficients.
In the first-difference specification (Panel B), the contemporaneous terms again dominate, with the lagged liquidity change carrying a marginally significant coefficient of 0.164 and the lagged rigidity change insignificant. The joint F-test for the null that all three lagged terms are simultaneously zero yields in the levels specification and in the differenced specification, so the lagged terms are jointly significant at the 5 per cent level in levels and at the 10 per cent level in differences. The inclusion of lags raises the adjusted from 0.451 to 0.502 in levels and from 0.194 to 0.237 in differences, a modest but economically meaningful improvement indicating that temporal inertia accounts for approximately five to four additional percentage points of explained variation in monthly price volatility.
The economic interpretation of the lagged liquidity effect is straightforward within the trilemma framework. When the secondary market deepens—because new participants enter, because existing firms begin to manage positions actively rather than waiting for the compliance deadline, or because belief heterogeneity widens as policy signals are released—the immediate effect is greater within-month price adjustment as more information is impounded. The lagged effect captures the second-round consequence: the deeper market of the previous month has created a richer information environment in which the current month’s shocks are transmitted more efficiently, so that even holding current-month liquidity constant, a market that was deep last month displays greater price sensitivity this month. This temporal propagation is precisely the mechanism that distinguishes the liquidity–rigidity edge of the trilemma from a one-shot adjustment: the market’s transition to continuous trading is not instantaneous but cumulative, and the volatility cost of that transition accrues over multiple months rather than being confined to the month in which liquidity first rises.
The insignificance of the lagged rigidity term, by contrast, is consistent with the hypothesis that policy announcements are forward-looking in their price impact. Because market participants can observe the regulatory calendar—draft plans are released for public comment before formal promulgation, and the compliance cycle’s timeline is known in advance—the rigidity tightening is substantially anticipated and priced contemporaneously at the announcement date rather than with a lag. The significant contemporaneous rigidity coefficient in Table 3, Table 5 and Table 6 therefore captures the announcement effect, while the insignificant lag confirms that no additional delayed reaction follows, a pattern consistent with semi-strong informational efficiency with respect to publicly announced policy events.
The absence of any lagged fundamentals effect further reinforces the decoupling finding of Section 4.6: coal-consumption changes influence neither contemporaneous nor lagged price volatility, confirming that the Chinese allowance price is not anchored to realised emission conditions at any horizon within the monthly window. If abatement rigidity were operating through market-clearing scarcity rather than through administered allocation, one would expect at least a lagged response as firms observe their actual generation and revise their allowance positions; its absence is additional evidence that the cap binds administratively rather than through the price.
Summary of time-series diagnostics. The stationarity, cointegration and lag-structure analysis yields the following conclusions: (i) the dependent variable is and two regressors are ; (ii) a cointegrating relationship exists among the three core variables, validated by both the Engle–Granger residual test and the Johansen trace test; (iii) the levels regression with HAC standard errors is therefore a valid and superconsistent estimator of the long-run trilemma trade-off; (iv) a first-difference specification that removes all trending behaviour preserves the qualitative finding that liquidity and rigidity each raise price volatility while fundamentals do not; and (v) the inclusion of one-month lagged regressors reveals a significant delayed effect of liquidity on volatility, raising the cumulative liquidity impact by approximately forty per cent relative to the contemporaneous-only estimate, while confirming the absence of any lagged fundamentals effect. The temporal inertia of the liquidity channel implies that the trilemma trade-off unfolds over a multi-month horizon rather than being resolved within a single period, which strengthens the interpretation that the scheme’s movement along the frontier is a gradual structural process rather than a sequence of independent monthly realisations.
Taken as a whole, the numerical evidence verifies Proposition 1 along every margin that the data permit. The time-series diagnostics reported in Table 3 and Table 4 confirm that this inference is robust to the trending nature of the liquidity and rigidity series: the existence of a cointegrating relationship validates the levels’ specification, and the first-difference regression preserves both the sign and significance of the two key coefficients. The lagged-variable analysis of Table 5 further establishes that the liquidity–volatility channel operates with temporal inertia, so that the full impact of market deepening on price instability exceeds the contemporaneous estimate by a substantial margin, while the rigidity channel acts predominantly at impact and the fundamentals channel remains inert at all horizons. Liquidity rose, stability fell, and the two moved as substitutes both contemporaneously and with a lag; rigidity rose alongside liquidity and against stability; and the price remained decoupled from fundamentals, confirming that the configuration the scheme has occupied at each date is a point on the trilemma frontier rather than an unconstrained outcome.
5. Economic and Managerial Implications
The recognition that price stability, market liquidity and abatement rigidity cannot be attained together reframes a number of debates about the design and use of China’s carbon market and of compliance markets more generally. The first implication is that the appraisal of the scheme should be conducted in terms of which two objectives it is choosing to serve, rather than in terms of an unattainable ideal in which all three are met. The near-dormant and price-stable market of 2022 was not a malfunction to be lamented in isolation; it was the predictable interior of the edge that joins stability to a soft effective cap, where comfortable free allocation anchored the price and removed the incentive to trade. The deep and volatile market of 2024 and 2025 is likewise not a regression; it is the interior of the edge that joins liquidity to a tightening cap, where the price has begun to strain under the very rigidity that gives the scheme its environmental bite. A regulator who wishes the market to move toward continuous liquidity and a binding cap, as the policy trajectory plainly intends, should expect and prepare for the loss of price stability, and should design accordingly rather than treating each price spike or collapse as an anomaly.
The second implication concerns the instruments through which price stability can be partially recovered without abandoning the other objectives, and here the European experience offers a tested vocabulary. A market stability reserve, a price collar, or a cost-containment buffer can compress the variance of the price, but Proposition 1 and the waterbed analysis of [50] together make explicit what such instruments cost. Because they defend the price by allowing the quantity to respond to demand, they relax the rigidity of the cap unless the released allowances are subsequently cancelled, as the reserve-design studies of [45,46,47] discuss, and because they intermediate the trades that would otherwise have cleared in the open market, they dampen the private incentive to trade continuously. The design question is therefore not whether to stabilise the price but how to distribute the unavoidable sacrifice across the rigidity and liquidity vertices. A reserve calibrated to act only at the extremes, complemented by an explicit floor of the kind argued for in [48], preserves most of the rigidity and most of the liquidity while truncating the tails of the price distribution, which is plausibly the most defensible point on the frontier for a maturing market. The behaviour of the reformed European system through the pandemic demand shock, analysed in [49], is a useful precedent for how such a buffer performs when fundamentals move sharply. This precedent, however, presumes a market in which trading is frequent enough for the reserve’s interventions to be transmitted through ordinary price discovery. China’s national scheme has not yet reached that condition over most of the sample examined here: the thin-day share exceeded one in two sessions in 2022 and remained above one in four as late as 2023, so that for much of the scheme’s early operation a reserve calibrated to intervene at the extremes of the price distribution would have had few genuine market transactions through which to act. A buffer designed on the European template therefore cannot be expected to deliver the same stabilising effect in a still-maturing market until liquidity has developed further; introducing the instrument before that point risks an intervention that exists on paper without a market thick enough to transmit it. The sequencing implication is that deepening liquidity—the trend already documented in Section 4.4—is plausibly a precondition for, rather than a consequence of, an effective price-stability instrument, which suggests introducing or activating such a reserve only once the thin-day share has fallen to the low single digits last observed in 2025, rather than at the outset of the scheme’s expansion.
The third implication is that the effectiveness of the scheme in delivering abatement should be evaluated separately from the behaviour of its price, a distinction that the decoupling documented in Figure 5 makes especially salient. The finding that the European scheme reduced emissions even when prices were low [4], together with the broader evidence that carbon pricing reduces emissions [1,2,3], establishes that abatement is delivered by the binding quantity and not by any particular price level. In the Chinese case the price has been governed by allocation and expectations rather than by realised scarcity, which means that the environmental performance of the scheme cannot be inferred from its price path at all and must be assessed from the allocation benchmarks and from realised covered emissions. This separation is liberating for design, because it implies that a regulator need not choose between a stable price and an effective cap on the grounds that a low or stable price signals weak abatement; effectiveness can be secured through the rigidity of the administered quantity while the price is allowed to occupy whichever position on the trilemma frontier best serves the secondary objectives of liquidity and stability.
The fourth implication is managerial and concerns the covered firms themselves. In a market that has moved toward the liquidity–rigidity edge, the allowance price is both more informative and more volatile, and the value of active position management rises correspondingly, a conclusion consistent with the evidence that liquidity conditions shape carbon returns in the national scheme [6] and with the efficiency analyses of the pilots [5]. Firms that treated the allowance as a once-a-year compliance obligation during the dormant phase, transacting only in the closing weeks of the cycle as the volume concentration of 2022 reveals, face a different problem in the volatile phase, where the timing of purchases against a swinging price materially affects compliance cost. The carbon–energy spillover literature [31,32,33,34,35] suggests that hedging carbon exposure jointly with fuel and power-price exposure becomes worthwhile precisely when the carbon price is active, and the decoupling from fundamentals documented here adds the caution that, in the Chinese market, such hedges must be built around policy and allocation risk rather than around energy fundamentals, because it is the former that drives the price. The managerial upshot is that the maturation of the market, while welcome for liquidity and for the credibility of the cap, transfers a price-timing risk onto firms that the stable early regime had suppressed.
6. Conclusions and Outlook
This paper has proposed that a carbon market faces a sustainability trilemma among price stability, market liquidity and abatement rigidity, has formalised the impossibility of attaining all three through a transparent equilibrium argument, and has verified the proposition against the daily price and volume record of China’s national thermal-power emissions trading scheme over its first four and a half years, supplemented by the monthly thermal-generation and coal-consumption series that proxy its emission base. The theoretical analysis showed that a rigid cap combined with an active market forces the price to inherit the variance of the emission fundamentals, that stabilising the price under a binding cap requires a quantity buffer whose intervention both relaxes rigidity and thins private liquidity, and that joint stability and liquidity are feasible only when the cap is allowed to float and abatement rigidity is surrendered. The numerical evidence matched this structure closely. Liquidity improved almost monotonically, with the median daily traded quantity rising from a few hundred allowances in 2022 to close to a million in 2025, the thin-day share falling from above one half to near zero, and the volume Gini contracting from 0.87 to 0.55, while price stability deteriorated in step, the intra-year range widening from eleven per cent of the mean to seventy-three per cent, and the price remained decoupled from emission fundamentals throughout. The annual stability–liquidity frontier sloped downward, the rigidity index rose along it, and the monthly tension regression confirmed that liquidity and rigidity each raise price volatility once fundamentals are controlled for (a result that survives formal cointegration testing, a first-difference robustness specification, and a lagged-variable extension revealing that the liquidity channel propagates with one-month temporal inertia). The scheme has, in short, travelled from the stability–rigidity-lite corner toward the liquidity–rigidity corner, paying for its growing depth and its tightening cap with the loss of the price stability it once enjoyed. Several qualifications and extensions define the agenda for further work. The rigidity vertex is the hardest to observe, and the proxy used here, the weak coupling of price to fundamentals together with a constructed policy index, would benefit from direct measurement against the free-allocation benchmarks once these are published at sufficient granularity, and against realised covered emissions, so that the rigidity of the cap can be assessed in quantity space rather than inferred from the price. The sample contains only one market that has so far covered a single sector, and the announced extension of the scheme to additional industries provides a natural setting in which to test whether the broadening of coverage shifts the market along the frontier, plausibly toward greater liquidity and, if the aggregate cap is set tightly, toward still greater price instability. The price-stabilisation instruments discussed in the implications, and especially the trade-off between a reserve that cancels allowances and one that merely shifts them in time, could be examined quantitatively in a calibrated version of the equilibrium model in Section 3, which would allow the frontier to be drawn explicitly and the welfare cost of each point on it to be assessed. Finally, the comparison with the European system, whose price has historically been more tightly coupled to fundamentals, invites a cross-market test of whether the trilemma binds in the same way when the cap binds through realised scarcity rather than through administered allocation. Each of these extensions is feasible with data that are accumulating as the market matures, and each would sharpen the central message of this paper, namely that the design of a carbon market is best understood not as the pursuit of one ideal configuration but as the deliberate management of an irreducible trade-off among objectives that cannot all be satisfied at once.
Author Contributions
Conceptualisation, R.Y., J.X. and Y.L.; methodology, R.Y. and J.X.; software, R.Y.; validation, R.Y., J.X. and Y.L.; formal analysis, J.X. and X.X.; investigation, R.Y. and J.X.; resources, Y.L.; data curation, R.Y., J.X. and Y.L.; writing—original draft preparation, R.Y. and J.X.; writing—review and editing, J.X., X.X. and Y.L.; visualisation, R.Y. and X.X.; supervision, Y.L.; project administration, Y.L.; funding acquisition, J.X. and Y.L. All authors have read and agreed to the published version of the manuscript.
Funding
This work was mainly supported by the grant from Major Program of National Fund of Philosophy and Social Science of China (22&ZD136), Special Science and Technology Innovation Program for Carbon Peak and Carbon Neutralization of Jiangsu Province (BE2022610), National Social Science Fund in Later Stage (22FGLB030).
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The datasets used in this study are derived from publicly available carbon-market and energy-sector data sources. The processed datasets generated during the current study, together with the calculation procedures used to construct the trilemma indicators, are available from the corresponding author upon reasonable request.
Acknowledgments
The authors are grateful to the anonymous reviewers and academic editors for their insightful comments and suggestions. All authors have consented to this expression of appreciation.
Conflicts of Interest
The authors declare no conflicts of interest.
Appendix A. Data Used in the Empirical Analysis
The purpose of this appendix is not only to document the source of the data, but also to make transparent how the original high-frequency trading records and lower-frequency energy indicators are transformed into the variables used in the main analysis. The daily carbon-market data provide direct information on allowance prices and trading activity, while the energy-sector data describe the underlying emission fundamentals of the covered power sector. Combining these two types of data allows the paper to examine both market-side outcomes, such as price stability and liquidity, and fundamentals-side conditions, such as coal-use changes in the power sector.
Appendix A Table A1 reports the monthly matched dataset. This table is the core data table for the price–fundamentals analysis. For each month, the table reports the month-end allowance price, the total monthly trading volume, the number of trading days, thermal-power generation and power-sector thermal-coal consumption. The allowance price is taken from the final available trading day of each month, rather than from a monthly average, because this measure better reflects the market valuation at the end of the monthly period. Monthly trading volume is obtained by aggregating all daily trading records within the same month. The energy variables are retained at their original monthly frequency and then aligned with the monthly carbon-market series.
Table A1.
Monthly matched data used in the empirical analysis.
The monthly data show several important features of the sample. In the launch period of 2021, trading volume was highly concentrated in the final months of the year, especially in December. In 2022, the allowance price remained relatively stable, while monthly trading volume was generally low outside several compliance-related periods. From 2023 onward, both the price level and trading activity changed more visibly, with stronger trading concentration around the later months of the compliance cycle. In 2024 and 2025, monthly trading became more active and more continuous, but allowance prices also showed wider fluctuations. These patterns provide the empirical background for the stability–liquidity trade-off discussed in the main text.
Appendix A Table A2 further aggregates the daily trading records to the quarterly level. This quarterly aggregation is useful because China’s carbon-market trading activity is not evenly distributed across the year. In the early stage of the market, firms tended to trade more actively close to compliance deadlines, which created strong quarterly concentration in trading volume. By reporting quarter-end price, quarterly trading volume, trading days, minimum price, maximum price and mean price, Table A2 helps identify whether market activity was concentrated in a few compliance windows or distributed more evenly across the year.
The quarterly data also provide a bridge between the detailed monthly matched data and the annual indicators used in the main text. For example, the large trading volumes in 2021Q4, 2023Q4 and 2024Q4 reveal the importance of compliance-cycle clustering. At the same time, the 2025 quarterly data suggest that trading activity became less dependent on a single compliance window and more continuous across quarters. This transition is important for the paper’s argument because greater market liquidity does not necessarily imply greater price stability. Instead, as the market becomes more active, price adjustment may become more visible.
Table A2.
Quarterly carbon-market trading data.
Appendix A Table A3 reports annual descriptive statistics constructed from the original daily carbon-market trading data. These indicators summarise the basic price and trading characteristics of each year, including the number of trading days, minimum price, maximum price, mean price, median price, standard deviation of price, total trading volume, median daily volume, mean daily volume and maximum daily volume. These statistics are calculated directly from the daily trading records and therefore provide the basis for the annual comparisons in the main analysis.
The annual statistics show the changing structure of China’s national carbon market over the sample period. The 2021 observations cover only the post-launch half-year, so they are reported separately as 2021 H2. The 2022 market was characterised by a narrow price range and relatively weak trading activity. In 2023 and 2024, both price dispersion and trading volume increased, indicating that the market became more active but also less stable. In 2025, trading became more continuous, as reflected in the rise in median daily volume, while price fluctuations remained substantial. These annual patterns are consistent with the view that the market moved from a relatively stable but thinly traded stage toward a more liquid but more volatile stage.
Table A3.
Annual descriptive statistics of daily carbon-market trading data.
Appendix A Table A4 reports the annual price-stability and liquidity indicators used to verify the trilemma. The intra-year price range and annualised return volatility capture the price-stability dimension. Thin trading days, thin-day share and the volume Gini coefficient capture the liquidity dimension. A larger intra-year price range or higher return volatility indicates weaker price stability. A higher thin-day share or larger volume Gini coefficient indicates weaker and more concentrated liquidity.
These indicators are used to support the central empirical claim of the paper. In 2022, the allowance price was relatively stable, but the market was thinly traded and trading activity was highly concentrated. In later years, especially 2024 and 2025, liquidity improved substantially, but price stability weakened. This opposite movement between stability and liquidity is the key empirical manifestation of the trilemma. The annual indicators therefore serve as the direct quantitative basis for the stability–liquidity frontier discussed in the main text.
Table A4.
Annual price-stability and liquidity indicators.
Appendix A Table A5 reports the energy-sector fundamentals used to proxy the emission base of the covered power sector. Since the national carbon market initially covered the power generation sector, coal consumption in the power sector is closely related to allowance demand. The annual total, monthly average, minimum monthly value and maximum monthly value of power-sector thermal-coal consumption provide information on both the scale and variation in the emission fundamentals. These statistics help evaluate whether allowance-price movements are closely related to realised changes in the emission base.
The energy data show that power-sector coal consumption fluctuates seasonally and varies across years, but the corresponding allowance-price movements do not always follow these fundamentals closely. This is why the paper uses the coupling between monthly allowance-price changes and monthly coal-consumption changes as an indirect indicator of whether prices respond to realised emission scarcity. A weak price–fundamentals correlation suggests that allowance prices are influenced not only by current coal-use conditions, but also by allocation rules, compliance expectations, market sentiment and policy signals.
Table A5.
Energy-sector fundamentals.
Appendix A Table A6 summarises the construction of the main indicators. These definitions ensure that the empirical indicators used in the paper can be traced back to the original data. Monthly allowance price and monthly trading volume are constructed from the daily trading records. Price stability is measured by the intra-year price range and annualised return volatility. Market liquidity is measured by median daily volume, mean daily volume, thin-day share and the volume Gini coefficient. Price–fundamentals coupling is measured by the correlation between monthly allowance-price changes and monthly power-sector thermal-coal-consumption changes.
Table A6.
Indicator construction.
Appendix A Table A7 reports the construction of the abatement-rigidity index used in Figure 4 and Table 3. The benchmark-tightening component is computed from the officially announced annual decline rate of the power-sector free-allocation benchmark for each compliance cycle; the policy-event component is computed from a dated inventory of allocation-plan publications, compliance-mechanism revisions, and sectoral-extension announcements, all sourced from official Ministry of Ecology and Environment documents [51,52,53,54,55,56]. Both components are cumulated from the 2021 launch of trading and rescaled to the unit interval; the composite index is their equally weighted average, affinely rescaled onto as described in Section 4.2.
Table A7.
Construction of the abatement-rigidity index.
Dated policy events underlying by year:
2021: National market trading formally launched, 16 July 2021.
2023: (i) Second compliance cycle’s allocation plan formally promulgated, 15 March 2023 [52]; (ii) Notice on Implementation Arrangements for the National Voluntary Greenhouse Gas Emission Reduction Trading Market, withdrawing pre-2017 CCER credits from compliance use, 25 October 2023 [54].
2024: (i) Draft third compliance-cycle allocation plan released for public comment, 2 July 2024; (ii) third compliance-cycle allocation plan formally promulgated (State Environmental Protection Administration Climate Regulation [2024]. No.1), raising the benchmark decline rate to ~1.0% and shortening the compliance cycle from biennial to annual settlement, 21 October 2024 [53].
2025: (i) State Council approval and Ministry promulgation of the Work Plan extending coverage to steel, cement and aluminium smelting, March 2025 [55]; (ii) draft allocation plan for the three extension sectors released for comment, 30 September 2025; (iii) formal allocation plan for the three extension sectors promulgated, 18 November 2025 [56].
Appendix A Table A8 reports the time-series diagnostics for the variables used in the monthly tension regression of Section 4.7 and Table 3. Because the logarithm of median monthly traded volume and the rigidity index exhibit pronounced upward trends over the 54-month sample, their integration properties must be established before the levels regression can be interpreted as a genuine long-run equilibrium rather than a spurious correlation. Panel A reports augmented Dickey–Fuller unit root tests for each variable in levels and, where necessary, in first differences, with lag lengths selected by the Schwarz information criterion subject to a maximum of four lags; the deterministic specification (intercept only or intercept plus trend) is chosen according to the visual properties of each series. Panel B reports the Engle–Granger residual-based cointegration test, which applies an ADF test to the OLS residuals from the levels regression of realised monthly volatility on the three regressors; the critical values follow the MacKinnon (1996) [57] surface-response tabulation for a system with three right-hand-side variables and 54 observations. Panel C reports the Johansen trace test applied to the trivariate system comprising monthly volatility, log median volume and the rigidity index, with the already-stationary coal-consumption growth rate included as an exogenous variable in the underlying vector autoregression; lag length is selected by the Schwarz criterion. Together, the three panels establish that two regressors are integrated of order one, that a single cointegrating relationship links them to the stationary dependent variable, and that the levels specification in Table 3 is econometrically valid when estimated with Newey–West heteroskedasticity- and autocorrelation-consistent standard errors. The first-difference robustness regression reported in Table 5 of the main text provides complementary confirmation that the qualitative conclusions survive the removal of all trending information.
Table A8.
Time-series diagnostics for the tension regression variables.
Appendix A Table A9 reports the detailed regression output underlying the lagged-variable analysis of Section 4.7 and Table 6. The augmented specifications add one-month lags of each regressor to the baseline levels and first-difference models, in order to test whether the trilemma trade-off exhibits temporal inertia—that is, whether a change in liquidity or rigidity in month t − 1 continues to affect price volatility in month t beyond the contemporaneous channel. The joint significance of the lagged terms is assessed by an F-test, and the cumulative (long-run) multiplier for each variable is computed as the sum of the contemporaneous and lagged standardised coefficients. The finding that lagged liquidity is significant while lagged rigidity and lagged fundamentals are not implies that the market-depth channel propagates over time, consistent with the gradual nature of the scheme’s transition from episodic to continuous trading, while policy signals and emission conditions are absorbed within a single monthly period.
Table A9.
Lagged-variable regression diagnostics.
References
- Best, R.; Burke, P.J.; Jotzo, F. Carbon Pricing Efficacy: Cross-Country Evidence. Environ. Resour. Econ. 2020, 77, 69–94. [Google Scholar] [CrossRef] [Scilit]
- Döbbeling-Hildebrandt, N.; Miersch, K.; Khanna, T.M.; Bachelet, M.; Bruns, S.B.; Callaghan, M.; Edenhofer, O.; Flachsland, C.; Forster, P.M.; Kalkuhl, M.; et al. Systematic review and meta-analysis of ex-post evaluations on the effectiveness of carbon pricing. Nat. Commun. 2024, 15, 4147. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Sterner, T. Carbon pricing reduces emissions. Nature 2024, 632, 31–32. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Bayer, P.; Aklin, M. The European Union emissions trading system reduced CO2 emissions despite low prices. Proc. Natl. Acad. Sci. USA 2020, 117, 8804–8812. [Google Scholar] [CrossRef] [Scilit]
- Wu, R.; Qin, Z. Assessing market efficiency and liquidity: Evidence from China’s emissions trading scheme pilots. Sci. Total Environ. 2021, 769, 144707. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Zhang, J.; Han, W. Carbon emission trading and equity markets in China: How liquidity is impacting carbon returns? Econ. Res.-Ekon. Istraž. 2022, 35, 6466–6478. [Google Scholar] [CrossRef] [Scilit]
- Tang, L.; Wu, J.; Yu, L.; Bao, Q. Carbon emissions trading scheme exploration in China: A multi-agent-based model. Energy Policy 2015, 81, 152–169. [Google Scholar] [CrossRef] [Scilit]
- Azizi, M.I.; Xu, X.; Duan, X.; Qin, H.; Xu, B. Carbon Pricing Strategies and Policies for a Unified Global Carbon Market. Atmosphere 2025, 16, 836. [Google Scholar] [CrossRef] [Scilit]
- Zhan, K.; Pu, Z. Carbon market and emission reduction: Evidence from evolutionary game and machine learning. Humanit. Soc. Sci. Commun. 2025, 12, 488. [Google Scholar] [CrossRef] [Scilit]
- Zhang, H.; Zhang, Z.W.; Sun, K.Y.; Zou, Y.T. Emission reduction effect, influencing factors and economic impact of China’s carbon market: An empirical test based on a multi-period DID model. Sage Open 2023, 13, 21582440231206626. [Google Scholar] [CrossRef] [Scilit]
- Chen, H.; Cai, G.; Wu, M. What Kind of Carbon Market Reduces Emissions More Effectively?—An Empirical Study from the Perspective of Carbon Allowance Liquidity. South China Financ. 2026, 593, 3–16. Available online: https://kns.cnki.net/kcms2/article/abstract?v=wTY03cmeYFoQGrJyFwLItT2eqczoEwMrRCfGHx0regbOml1h46kSWCF2wUFbVPVdDA2qHA9rLbFKEXxwXAMnYRMBAI9SyXZEokosHSfRp2euQL-jzjg7rI-VDyqZUpq1mYrZ4yUbMzoKZeouj63OSIGgmgYFHRKVqcNcIjoTZeJfqyDYAqNUY9Jby16Hq74Z&uniplatform=NZKPT&language=CHS (accessed on 1 July 2026).
- Biancalani, F.; Gnecco, G.; Metulini, R.; Riccaboni, M. Correction: The impact of the European Union emissions trading system on carbon dioxide emissions: A matrix completion analysis. Sci. Rep. 2026, 16, 14729. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Ellerman, A.D.; Marcantonini, C.; Zaklan, A. The European Union emissions trading system: Ten years and counting. Rev. Environ. Econ. Policy 2016, 10, 89–107. [Google Scholar] [CrossRef] [Scilit]
- Laing, T.; Sato, M.; Grubb, M.; Comberti, C. The effects and side-effects of the EU emissions trading scheme. Wiley Interdiscip. Rev. Clim. Change 2014, 5, 509–519. [Google Scholar] [CrossRef] [Scilit]
- Martin, R.; Muûls, M.; Wagner, U.J. The impact of the European Union Emissions Trading Scheme on regulated firms: What is the evidence after ten years? Rev. Environ. Econ. Policy 2016, 10, 129–148. [Google Scholar] [CrossRef] [Scilit]
- Verde, S.F. The impact of the EU emissions trading system on competitiveness and carbon leakage: The econometric evidence. J. Econ. Surv. 2020, 34, 320–343. [Google Scholar] [CrossRef] [Scilit]
- Zhang, Y.-J.; Wei, Y.-M. An overview of current research on EU ETS: Evidence from its operating mechanism and economic effect. Appl. Energy 2010, 87, 1804–1814. [Google Scholar] [CrossRef] [Scilit]
- Fuss, S.; Flachsland, C.; Koch, N.; Kornek, U.; Knopf, B.; Edenhofer, O. A framework for assessing the performance of cap-and-trade systems: Insights from the European Union Emissions Trading System. Rev. Environ. Econ. Policy 2018, 12, 220–241. [Google Scholar] [CrossRef] [Scilit]
- Guo, P.; Shen, H.; Chen, Y.; Dai, H.; Mai, Z.; Xu, R.; Zhang, R.; Wang, Z.; He, J.; Zheng, L.; et al. Carbon dioxide emissions from global overseas coal-fired power plants. Nat. Clim. Change 2024, 14, 1151–1157. [Google Scholar] [CrossRef] [Scilit]
- Gatti, L.V.; Cunha, C.L.; Marani, L.; Cassol, H.L.G.; Messias, C.G.; Arai, E.; Denning, A.S.; Soler, L.S.; Almeida, C.; Setzer, A.; et al. Increased Amazon carbon emissions mainly from decline in law enforcement. Nature 2023, 621, 318–323. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Zhu, B.; Wei, C. Strategic interactions for carbon emissions in Chinese cities are influenced by mayors. Nat. Cities 2024, 1, 370–377. [Google Scholar] [CrossRef] [Scilit]
- Huang, J.; Lu, H.; Du, M. Regional Differences in Agricultural Carbon Emissions in China: Measurement, Decomposition, and Influencing Factors. Land 2025, 14, 682. [Google Scholar] [CrossRef] [Scilit]
- Wang, Q.; Zhan, J.; Zhang, H.; Cao, Y.; Yang, Z.; Wu, Q.; Otho, A.R. China’s Carbon Emissions Trading Market: Current Situation, Impact Assessment, Challenges, and Suggestions. Land 2025, 14, 1582. [Google Scholar] [CrossRef] [Scilit]
- Liu, Y.; Sun, H.P.; Meng, B.; Jin, S.L.; Chen, B. How to Purchase Carbon Emission Right Optimally for Energy-Consuming Enterprises? Analysis Based on Optimal Stopping Model. Energy Econ. 2023, 124, 106758. [Google Scholar] [CrossRef] [Scilit]
- Li, M.; Jiang, Q. Do Low-Carbon and New Energy Demonstration City Pilots Generate Synergy? Evaluating the Dual-Pilot Policy on Carbon Emission Performance with Double Machine Learning. Sustainability 2026, 18, 5734. [Google Scholar] [CrossRef] [Scilit]
- Liu, Y.; Tian, L.X.; Zou, B.Y.; Zhao, P.Y.; Gan, C.Y. Multi-Source Carbon Emission Monitoring and Certification for Carbon-Neutral Industrial Parks. J. Clean. Prod. 2026, 570, 148612. [Google Scholar] [CrossRef] [Scilit]
- Liu, X.; Ning, X.; Wu, C.; Zhang, Y. Evolutionary Trends in Carbon Market Risk Research. Energies 2024, 17, 4655. [Google Scholar] [CrossRef] [Scilit]
- Chevallier, J. Carbon price drivers: An updated literature review. Int. J. Appl. Logist. (IJAL) 2013, 4, 1–7. [Google Scholar] [CrossRef] [Scilit]
- Hintermann, B. Allowance price drivers in the first phase of the EU ETS. J. Environ. Econ. Manag. 2010, 59, 43–56. [Google Scholar] [CrossRef] [Scilit]
- Koch, N.; Fuss, S.; Grosjean, G.; Edenhofer, O. Causes of the EU ETS price drop: Recession, CDM, renewable policies or a bit of everything?—New evidence. Energy Policy 2014, 73, 676–685. [Google Scholar] [CrossRef] [Scilit]
- Tan, X.; Sirichand, K.; Vivian, A.; Wang, X. How connected is the carbon market to energy and financial markets? A systematic analysis of spillovers and dynamics. Energy Econ. 2020, 90, 104870. [Google Scholar] [CrossRef] [Scilit]
- Ji, Q.; Zhang, D.; Geng, J.-B. Information linkage, dynamic spillovers in prices and volatility between the carbon and energy markets. J. Clean. Prod. 2018, 198, 972–978. [Google Scholar] [CrossRef] [Scilit]
- Zhang, Y.-J.; Sun, Y.-F. The dynamic volatility spillover between European carbon trading market and fossil energy market. J. Clean. Prod. 2016, 112, 2654–2663. [Google Scholar] [CrossRef] [Scilit]
- Dutta, A.; Bouri, E.; Noor, M.H. Return and volatility linkages between CO2 emission and clean energy stock prices. Energy 2018, 164, 803–810. [Google Scholar] [CrossRef] [Scilit]
- García, A.; García-Álvarez, M.T.; Moreno, B. The impact of EU allowance prices on the stock market indices of the European power industries: Evidence from the ongoing EU ETS Phase III. Organ. Environ. 2021, 34, 459–478. [Google Scholar] [CrossRef] [Scilit]
- He, C. Study on the Risk of Price Fluctuation in Carbon Emissions Trading Market—Analysis Based on ARMA-EGARCH Model. Oper. Res. Fuzziology 2024, 14, 404–417. [Google Scholar] [CrossRef]
- Gong, W.; Wang, L.; Wang, C.; Gao, Z. Research on Price Fluctuation Characteristics of Carbon Emission Rights Trading Market in China Based on Empirical Analysis of Five Carbon Trading Pilots. China Soft Sci. 2022, 3, 187–193. Available online: https://kns.cnki.net/kcms2/article/abstract?v=wTY03cmeYFoisUlUkiesJfXVBqIRunM8MyFTdHvH_A_vlN_paOYYCGxL19700kWQG-SeKiNK8619AAB24VkQFynXuS31D4CH1D65N4EJP1QFra5YmlxgonnnhFIH9-0BO4IJ4SDOXClcJgPFJNOHi7UmsWvdTabvpRLv8wnxcxk2c8_9XSl0GKhMSvNURSJi&uniplatform=NZKPT&language=CHS (accessed on 1 July 2026).
- Wang, H.; Tan, Z.; Zhang, A.; Pu, L.; Zhang, J.; Zhang, Z. Carbon market price prediction based on sequence decomposition-reconstruction-dimensionality reduction and improved deep learning model. J. Clean. Prod. 2023, 425, 139063. [Google Scholar] [CrossRef] [Scilit]
- Zhu, D.; Zhang, C.; Pan, D. Extreme Risk Measurement of Carbon Market Considering Multifractal Characteristics. J. Syst. Sci. Complex. 2023, 36, 2497–2514. [Google Scholar] [CrossRef] [Scilit]
- Song, Y.; Liu, T.; Li, Y.; Zhu, Y.; Ye, B. Paths and policy adjustments for improving carbon-market liquidity in China. Energy Econ. 2022, 115, 106379. [Google Scholar] [CrossRef] [Scilit]
- Yu, X.; Fang, Y.; Han, Q. Institutional Investors and the Carbon Market Efficiency: A Perspective from the Role of Liquidity and Price Discovery. J. Manag. Sci. China 2026, 29, 73–88. [Google Scholar] [CrossRef]
- Lin, R.; Cai, T. The Market-Oriented Development of China’s Carbon Emissions Trading: Based on the Comparative Analysis of China and EU. Energies 2025, 18, 1059. [Google Scholar] [CrossRef] [Scilit]
- Wu, Y.; Liu, X.; Tang, C. Carbon Market and corporate financing behavior—From the perspective of constraints and demand. Econ. Anal. Policy 2024, 81, 873–889. [Google Scholar] [CrossRef] [Scilit]
- Battocletti, V.; Enriques, L.; Romano, A. The Voluntary Carbon Market: Market Failures and Policy Implications; European Corporate Governance Institute: Brussels, Belgium, 2023; Available online: https://www.ecgi.global/working-paper/voluntary-carbon-market-market-failures-and-policy-implications (accessed on 1 July 2026).
- Perino, G.; Willner, M. EU-ETS Phase IV: Allowance prices, design choices and the market stability reserve. Clim. Policy 2017, 17, 936–946. [Google Scholar] [CrossRef] [Scilit]
- Bruninx, K.; Ovaere, M.; Delarue, E. The long-term impact of the market stability reserve on the EU emission trading system. Energy Econ. 2020, 89, 104746. [Google Scholar] [CrossRef] [Scilit]
- Osorio, S.; Tietjen, O.; Pahle, M.; Pietzcker, R.C.; Edenhofer, O. Reviewing the Market Stability Reserve in light of more ambitious EU ETS emission targets. Energy Policy 2021, 158, 112530. [Google Scholar] [CrossRef] [Scilit]
- Flachsland, C.; Pahle, M.; Burtraw, D.; Edenhofer, O.; Elkerbout, M.; Fischer, C.; Tietjen, O.; Zetterberg, L. How to avoid history repeating itself: The case for an EU Emissions Trading System (EU ETS) price floor revisited. Clim. Policy 2020, 20, 133–142. [Google Scholar] [CrossRef] [Scilit]
- Bocklet, J. The Reformed EU ETS in Times of Economic Crises: The Case of the COVID-19 Pandemic; EWI Working Paper; Institute of Energy Economics at the University of Cologne (EWI): Ehrenfeld, Germany, 2020; Available online: https://hdl.handle.net/10419/240958 (accessed on 1 July 2026).
- Perino, G. New EU ETS Phase 4 rules temporarily puncture waterbed. Nat. Clim. Change 2018, 8, 262–264. [Google Scholar] [CrossRef] [Scilit]
- Ministry of Ecology and Environment of China. 2019–2020 National Carbon Emissions Trading Scheme Allocation Implementation Plan (Power Generation Industry); Ministry of Ecology and Environment of China: Beijing, China, 2020. [Google Scholar]
- Ministry of Ecology and Environment of China. 2021–2022 National Carbon Emissions Trading Scheme Allocation Implementation Plan (Power Generation Industry); Ministry of Ecology and Environment of China: Beijing, China, 2023. [Google Scholar]
- Ministry of Ecology and Environment of China. 2023–2024 National Carbon Emissions Trading Allocation Plan for the Power Generation Industry (State Environmental Protection Administration Climate Regulation [2024] No.1); Ministry of Ecology and Environment of China: Beijing, China, 2024. [Google Scholar]
- Ministry of Ecology and Environment of China. Notice on Implementation Arrangements for the National Voluntary Greenhouse Gas Emission Reduction Trading Market; Ministry of Ecology and Environment of China: Beijing, China, 2023. [Google Scholar]
- Ministry of Ecology and Environment of China. Work Plan for Extending the National Carbon Emissions Trading Scheme to the Steel, Cement and Aluminium Smelting Industries; Ministry of Ecology and Environment of China: Beijing, China, 2025. [Google Scholar]
- Ministry of Ecology and Environment of China. 2024–2025 National Carbon Emissions Trading Allocation Plan for the Steel, Cement and Aluminium Smelting Industries; Ministry of Ecology and Environment of China: Beijing, China, 2025. [Google Scholar]
- MacKinnon, J.G. Numerical distribution functions for unit root and cointegration tests. J. Appl. Econ. 1996, 11, 601–618. [Google Scholar] [CrossRef] [Scilit]
- Newey, W.K.; West, K.D. Automatic Lag Selection in Covariance Matrix Estimation. Rev. Econ. Stud. 1994, 61, 631–653. [Google Scholar] [CrossRef] [Scilit] [PubMed]
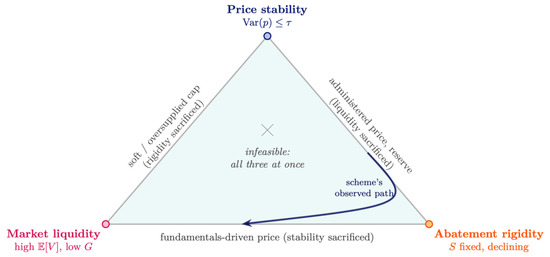
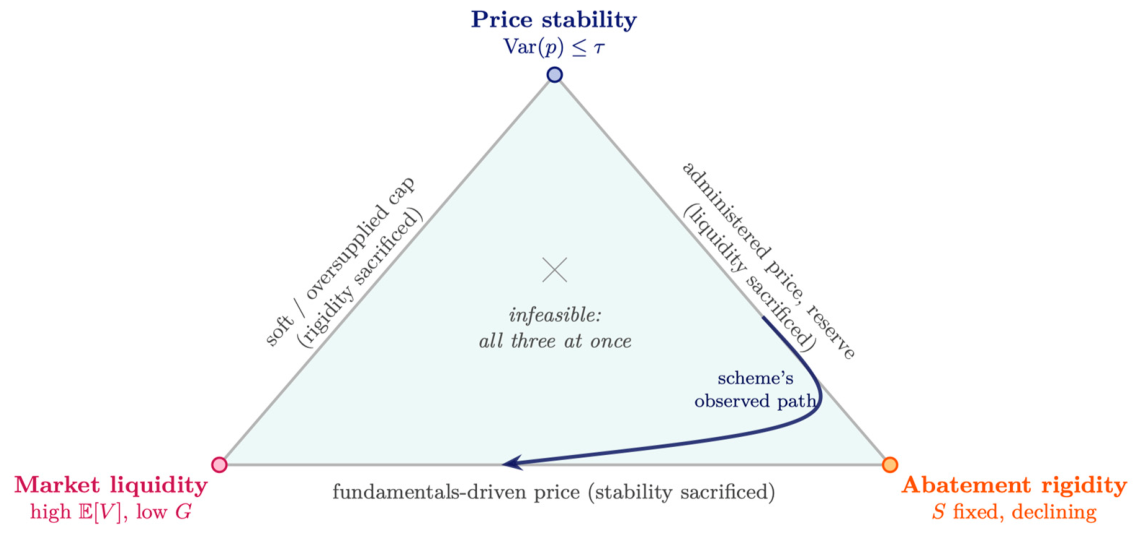
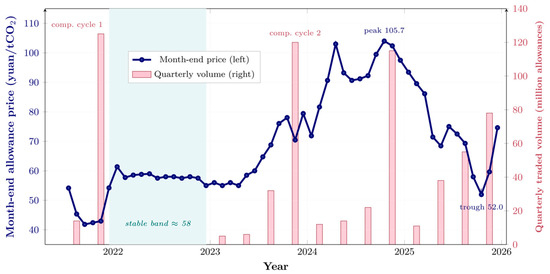
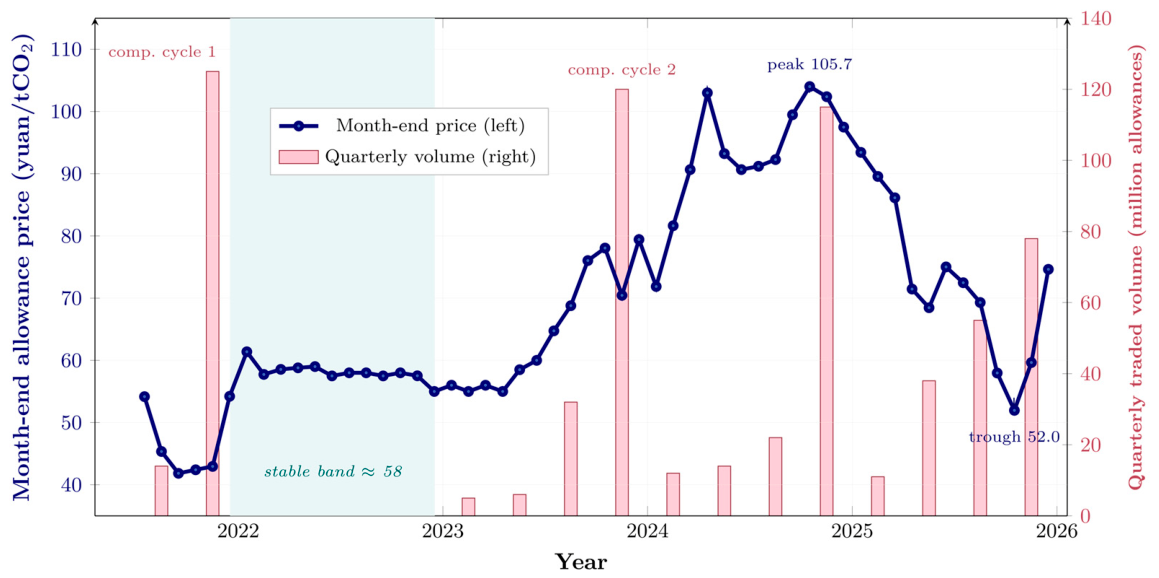
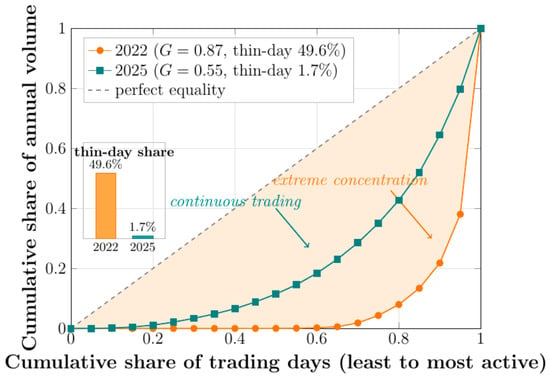
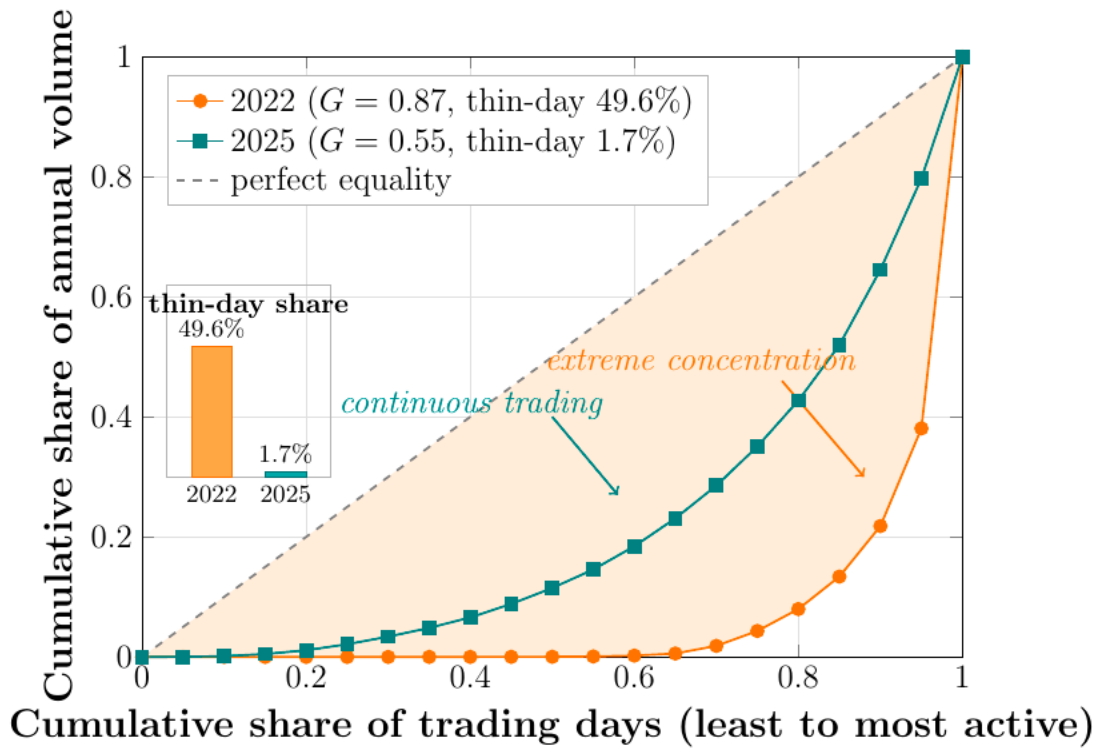
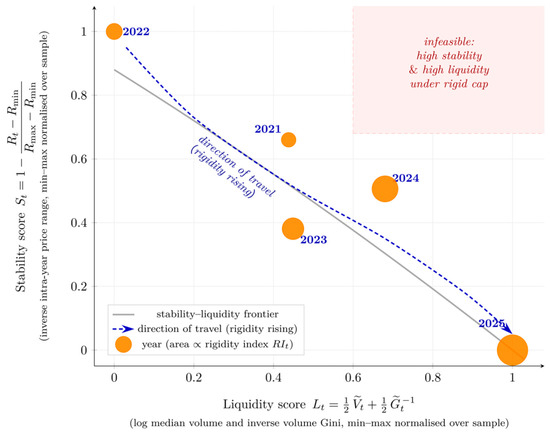
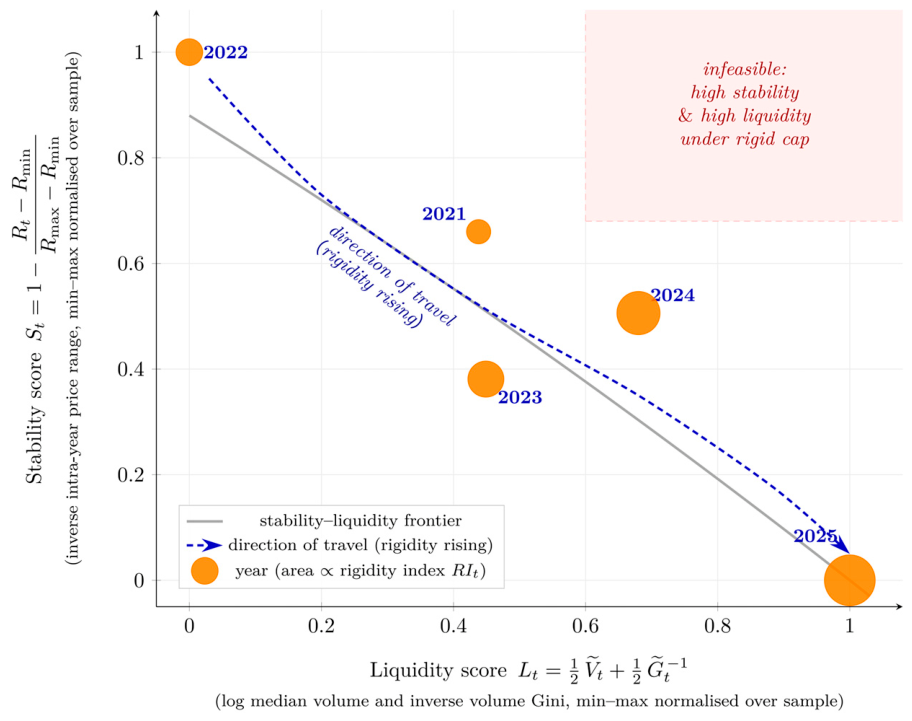
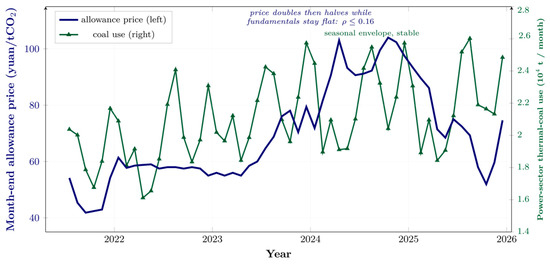
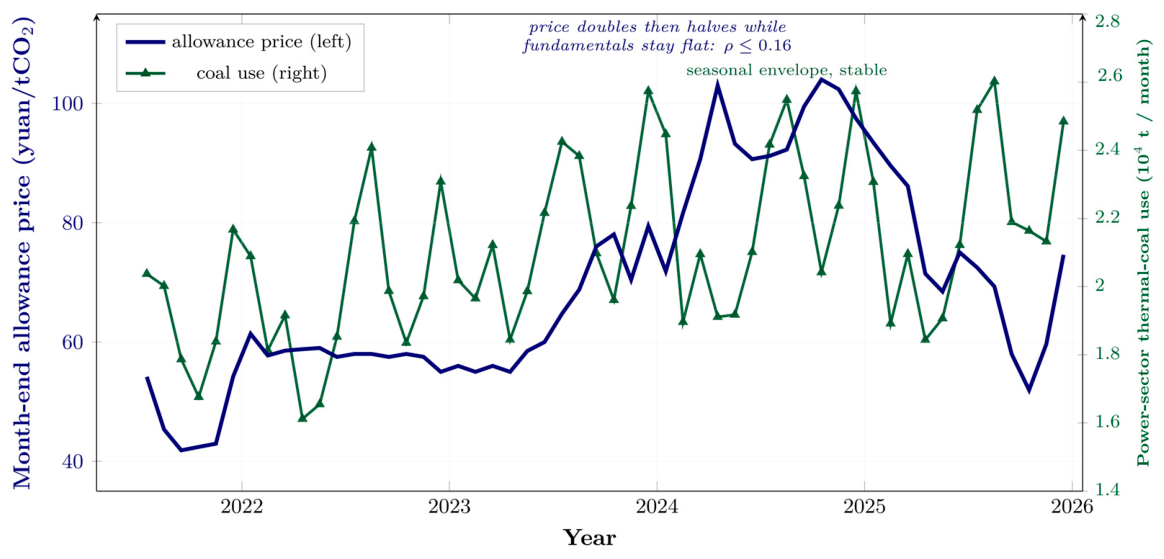

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.