1. Introduction
The integration of environmental, social, and governance (ESG) factors into corporate strategy has transformed business practices to promote sustainability and redefined value creation in alignment with the Sustainable Development Goals (SDGs) [
1]. Driven by green finance regulations, escalating investor demands, and intensified public calls for accountability, China’s financial sector has undergone prominent transformation [
2]. Understanding the drivers of superior ESG performance in Chinese financial institutions is critical. For these organizations, ESG goes beyond just following the rules to help them reach their strategic goals, which include long-term growth and building trust with stakeholders [
3].
Chinese banks and other financial institutions are under more and more pressure from regulators and the market to allocate capital correctly. This is especially true because of the country’s promises to become carbon neutral and its green finance policy mandates [
4]. Despite growing attention, empirical evidence on the determinants of ESG performance in China’s financial sector remains scarce [
5,
6]. This analysis empirically tests the effects of community engagement, firm size, and ownership structure on ESG ratings. Drawing on the resource-based view and stakeholder theory, the analysis situates these factors within China’s distinctive institutional context, characterized by state capitalism and evolving sustainability governance frameworks.
The ESG performance of financial institutions plays a crucial role in shaping capital allocation, thus facilitating sustainable economic development [
3]. Unlike Western economies, China’s business environment features a predominance of state-owned enterprises (SOEs) that must direct complex stakeholder relations and regulatory regimes [
2]. Early evidence suggests that enterprises with deep local ties respond adeptly to regional sustainability demands, consistent with national priorities around social welfare [
7]. Established theoretical perspectives posit that community engagement fosters stakeholder trust, while firm size shapes resource allocation, with ownership structure shaping prioritization of strategic objectives. However, their collective effect on ESG performance has yet to be examined in China’s financial sector.
Building on these gaps, stakeholder theory and the resource-based view provide a suitable lens for ESG integration in China, where policy and market intersect. The empirical study is organized to test three hypotheses: (1) ESG performance in Chinese financial institutions is positively influenced by community engagement; (2) ESG performance is positively influenced by firm size; and (3) ESG performance is positively influenced by state ownership. Hierarchical regression analysis with a thorough robustness check is used to examine these claims.
1.1. Community Engagement in ESG Performance
Community engagement anchors ESG initiatives, enabling financial institutions to meet stakeholder needs and improve environmental and social outcomes [
8]. Stakeholder theory suggests that fostering stakeholder relationships strengthens organizational legitimacy [
9]. Confucian cultural values in China prioritize social harmony and community engagement [
7]. Banks in the Pearl River Delta have implemented rural microfinance programs that address local needs and raise social ESG scores. These initiatives open business opportunities and reduce risk, including reputational harm from environmental incidents [
10]. Shallow efforts risk greenwashing scrutiny, so genuine, measurable integration is essential.
1.2. Firm Size and ESG
From a resource-based perspective, large enterprises exhibit enhanced competencies for ESG because they allocate resources at scale and face intense stakeholder oversight, which support sustainable practices [
11]. Empirical findings are mixed though; smaller firms sometimes outperform large ones through agility [
12]. In China’s financial sector, regulatory disparities and market segmentation complicate the firm size-ESG link. Post-COVID-19, several small regional banks rapidly adopted digital ESG reporting, suggesting that scale advantages can be offset by strategic focus and agility. This study investigates whether ESG performance in this context is significantly impacted by firm size. Numerous studies show a positive correlation, which they attribute to increased stakeholder expectations and an excess of resources [
13]. Other studies show small institutions matching or exceeding large peers by concentrating on targeted, efficient initiatives [
12].
The Chinese financial industry is more complicated, considering varying rules and capabilities. Large SOEs face different ESG demands than small regional institutions. Larger entities gain policy access that can support ESG, whereas smaller firms utilize agility for innovation.
Compared to larger enterprises that are hampered by organizational rigidity, smaller firms exhibit higher adaptability to local ESG regulations under China’s decentralized regulatory system. Evidence from other emerging economies, including Brazil and Indonesia, shows mid-sized enterprises excelling in specific ESG sectors, a pattern that may also hold in China.
1.3. Ownership Structure and ESG Outcomes
Ownership shapes ESG priorities because SOEs and privately owned enterprises (POEs) face different incentives related to the SDGs [
14]. SOEs operate under direct government supervision, which often requires adherence to sustainability targets and gives a structural advantage in executing ESG policies [
15]. Agency theory suggests SOEs encounter fewer principal-agent conflicts when pursuing long-term ESG objectives. Conversely, privately held corporations, such as China Merchants Bank, exemplify enhanced governance transparency through the adoption of financial technological advancements. Owing to their greater flexibility, privately owned enterprises (POEs) exhibit enhanced responsiveness to investor demands and market signals [
16]. In order to draw in funding and maintain a competitive edge, these companies place a high priority on innovation and openness. Nevertheless, certain firms might favor short-term profits over long-term sustainability efforts, owing to limited resources. The government’s green finance strategy in China’s financial sector makes ownership and ESG more complicated to understand, leading SOEs and POEs to improve their sustainability initiatives. In China’s financial industry, the government’s green finance initiative complicates the relationship between ownership and ESG, prompting SOEs and POEs to enhance their sustainability programs.
Accordingly, this research assesses how ownership structures shape ESG ratings amid China’s evolving financial landscape. Agency theory clarifies how ownership aligns interests: SOEs benefit from reduced principal–agent conflicts and have room to pursue long-term ESG goals, whereas POEs are subject to market accountability. Private institutions, exemplified by China Merchants Bank, emphasize the integration of fintech methodologies for the monitoring of ESG criteria, whereas state-owned entities, like Bank of China, undertake extensive national programs. Mixed-ownership reforms blur these categories and enable hybrid ESG strategies. This study examines SOE and POE ESG performance within this evolving context.
1.4. Research Objectives and Contributions
By examining the connections between ownership structure, organization size, community engagement, and ESG performance, the study seeks to close the gaps that have been found. This inquiry develops sustainability literature for emerging markets by offering both theoretical extensions and practical implications. The research aims to:
Furnish empirical insights into ESG determinants under China’s unique institutional context, thereby questioning predominantly Western-based paradigms.
Expand on stakeholder theory by looking at how community engagement affects sustainable accounting in developing nations.
Examine the firm size-ESG relationship and assess scale advantages in China’s regulatory context.
Analyze ownership structure’s impact, offering insights into government influence on sustainability.
Employ hierarchical regression with robustness tests to support reliable inference.
This study also looks at cultural factors, like Confucian ideas of harmony, that might make the effects of community engagement stronger. This is a perspective that is often missed in global ESG research. This work produces key implications for scholars, managers, and regulators.
2. Literature Review and Hypothesis Development
2.1. ESG Performance in Financial Institutions: A Global Perspective
Financial institutions occupy a unique position in the ESG landscape due to their dual role as both direct operational actors and indirect influencers through capital allocation decisions [
17]. Financial institutions have a special place in the ESG landscape because they are both direct operational actors and indirect influencers through their decisions about how to allocate capital [
17]. Compared to the manufacturing or extractive industries, banks and insurance companies have less of an impact on the environment directly, but they have a big impact on sustainable development through lending, investing, and underwriting [
18]. Studies disclose that financial entities exhibiting stronger ESG ratings experience reduced capital costs [
19], enhanced reputational standing [
20], and improved risk management [
21]. However, the mechanisms translating ESG commitment into measurable performance remain questioned, with some studies attributing gains to stakeholder trust [
9] and others emphasizing operational efficiency and resource optimization [
22].
In China’s context, the financial sector operates under distinctive institutional pressures. Government-directed green finance initiatives, such as mandatory environmental assessments and green bond preferences, impose robust regulatory pressures favoring ESG uptake [
23]. Yet compliance does not automatically yield substantive performance improvements; studies document significant decoupling between disclosed ESG commitments and actual practices, particularly among state-owned financial institutions facing conflicting political and commercial objectives [
24]. The difference between adopting ESG symbols and genuinely implementing them is an area that remains largely underexplored in ESG research.
Existing literature has not systematically examined which organizational and strategic factors predict actual ESG performance outcomes in Chinese financial institutions, as distinct from ESG disclosure or adoption. This study fills that gap through a unified framework testing specific determinants.
2.2. Community Engagement with ESG Performance
According to stakeholder theory, companies that handle ties with different groups, like local people, end up building lasting benefits and advantage over rivals [
9,
25]. Community engagement encompasses activities such as local development support, rights protection, stakeholder dialogue, and ethical supply chains—signifying broader societal commitment beyond shareholder interests [
26]. Research connects this to good financial results [
27], a good reputation [
28], and trust from other people [
29]. However, it is not always clear-cut; some say putting money into communities pulls away from main work, especially if it clashes with what owners want [
30]. In places like China, where rules are still developing, weak groups might mean less payoff from these efforts since people cannot easily praise or criticize companies [
31]. Looking at China, results are mixed: one paper says CSR aimed at communities helps with approval and ties to officials [
32], but another points out that in government-run firms, it is often just for show because of politics, not leading to real gains [
33].
Few studies have examined the relationship between civic engagement and comprehensive ESG performance (which includes environmental, social, and governance facets) in the financial industry, despite the extensive body of literature pertaining to CSR. Most prior work examines community engagement either as one component within broad CSR indices or focuses exclusively on social performance metrics, leaving its role in integrated ESG outcomes unclear.
The specific contribution of community engagement to overall ESG performance in Chinese financial institutions—beyond social pillar scores—remains unquantified. This study isolates community engagement to test its direct effect on comprehensive ESG ratings.
2.3. Firm Size and ESG Performance
From a resource-based perspective, larger corporations have superior financial capital, human resources, and organizational structures to invest in Environmental, Social, and Governance (ESG) initiatives, which encompass dedicated sustainability teams, reporting systems, and stakeholder engagement [
11,
34]. According to the resource-based approach, larger firms possess superior resources, staff, and processes to allocate to ESG initiatives, including specialized teams for sustainability, advanced reporting tools, and the cultivation of stakeholder connections. There is a link where larger ones do better on ESG, with big reviews showing they share more info and perform stronger in different fields and places [
35,
36]. Being big lets them share the costs of following ESG rules, and since everyone watches them, they are pushed to get ahead on green strategies to avoid bad press [
37].
Conversely, agency theory and institutional theory suggest potential offsetting mechanisms. More extensive institutions often face bureaucratic inertia, principal-agent conflicts, and fragmented accountability, impeding agile ESG integration [
38,
39]. In China’s financial sector, size correlates with state ownership and policy burdens—large banks are frequently tasked with politically motivated lending and regional development mandates that may divert resources from systematic ESG strategies [
24,
33]. Recent evidence from Chinese listed firms shows that the size–CSR relationship weakens or even reverses when controlling for ownership and political connections, suggesting that scale advantages are context-dependent [
32].
Whether firm size predicts ESG performance in China’s financial sector, after accounting for community engagement and ownership structure, remains empirically unresolved. This study examines size’s net effect within a multivariate framework to determine its independent contribution.
2.4. Ownership Structure and ESG Performance
Ownership structure plays a crucial role in shaping the operation of corporate governance, determining the strategic goals that are prioritized, and influencing how companies respond to their stakeholders. This, in turn, has a significant impact on their approach to the integration of ESG considerations. In Western settings, companies with institutional ownership and a wider distribution of shares often see improved ESG performance, thanks to the investor pressure and monitoring that come with it [
40,
41]. However, state-owned companies (SOEs), which have unique incentives and limitations, control China’s ownership landscape. Theoretically, SOEs are uniquely situated to spearhead ESG initiatives due to their inherent political legitimacy, preferential access to capital, and alignment with governmental sustainability mandates [
42].
Empirical findings are mixed. Some studies report that Chinese SOEs outperform private firms on CSR disclosure and environmental compliance due to regulatory enforcement and reputational imperatives [
43]. Others believe that SOEs do ESG practices that are more symbolic than real, and that they do them to send a political message rather than to create value for stakeholders [
24]. According to Liu and Zhang [
33], the involvement of politics in the SOEs very often results in a change in CSR priorities that leads to visible but low-impact activities receiving the more substantial portion of the investment while overlooking the main ESG involvement. Additionally, SOEs must answer to multiple principals—central government agencies, local authorities, and market shareholders—whose divergent objectives complicate the pursuit of coherent ESG strategies [
32].
Within the financial sector, state-owned enterprises hold dominant market positions and enjoy implicit government backing. However, whether state ownership enhances or challenges ESG performance relative to private firms remains an open question. Existing research has not resolved whether the resources and political capital available to SOEs translate into superior ESG outcomes, or whether competing political obligations and agency problems erode these advantages. Shaping the net impact of state ownership on ESG performance in Chinese financial institutions—after accounting for firm size and community engagement—therefore represents an important empirical question with no predetermined answer.
2.5. Integrated Framework and Research Gaps
Prior research has examined community engagement, firm size, and ownership structure as ESG determinants in isolation or in pairwise combinations, but rarely within an integrated framework applied to China’s financial sector.
The majority of research either aggregates CSR into broad indices that hide the specific function of community participation, depends on Western samples with limited application to China’s institutional environment, or concentrates on ESG disclosure rather than performance evaluations. Additionally, there are no robustness checks in the literature that address any mechanical correlations between community engagement sub-scores and total ESG ratings, which makes causal inference susceptible to measurement artifact issues.
Research Gaps Addressed
This study addresses three gaps as follows by testing three hypotheses derived from stakeholder theory and the resource-based view, using CSRHub’s comprehensive ESG ratings for 107 Chinese financial institutions, and conducting robustness checks including regressions with ESG scores excluding community components.
Prior investigations have not recognized community engagement as a factor influencing the comprehensive ESG performance within Chinese financial entities.
The empirical assessment of the relative significance of community engagement, firm size, and ownership structure within an integrated framework remains an area for further investigation.
Possible systematic associations between community sub-scores and overall ESG evaluations have not been examined through various dependent variable formulations.
2.6. Hypothesis Development
2.6.1. Community Engagement and ESG Performance
Theoretical Foundation
Stakeholder theory [
9] posits that firms create sustainable value by managing relationships with multiple stakeholder groups—employees, customers, suppliers, communities, and regulators—rather than prioritizing shareholders exclusively. Through strategic endeavors focused on development, the protection of human rights, collaboration with stakeholders, and accountability within supply chains, community engagement represents a deliberate commitment to local populations. Institutions build social capital, bolster their legitimacy, and obtain sustainable operational licenses, thus providing them with a competitive edge by allocating resources towards community well-being [
25,
26].
Contracting Empirical Evidence
Meta-analyses typically endorse favorable CSR–performance correlations [
35], but the results on community engagement are inconsistent. Western studies show that community investments improve reputation and stakeholder trust [
27], but some research suggests these benefits accrue primarily in contexts with strong civil society and active stakeholder monitoring [
31]. In China, evidence diverges: Wang and Qian [
43] find that community-oriented CSR enhances financial performance for private firms, whereas Liu and Zhang [
33] document that state-owned enterprises often engage in politically motivated community activities that yield limited substantive benefits, serving primarily as signals to government principals.
Expected Direction in Chinese Financial Sector
Despite mixed evidence, we expect a positive relationship in China’s financial sector for two reasons grounded in China-specific research. First, Lau et al. [
32] demonstrate that Chinese firms pursuing stakeholder-oriented CSR—including community engagement—achieve superior ESG integration because stakeholder pressures from government, media, and investors are converging around sustainability norms. Financial institutions face stringent scrutiny given their systemic importance and capital allocation function, amplifying reputational incentives for authentic community engagement. Second, Li et al. [
24] show that substantive (versus symbolic) CSR predicts stronger ESG outcomes in China; community engagement, when measured through comprehensive rating systems that aggregate multiple community-impact dimensions, captures substantive commitment more reliably than disclosure-based metrics.
Hypothesis 1 (H1). Community engagement is positively associated with ESG performance in Chinese financial institutions.
2.6.2. Firm Size and ESG Performance
Theoretical Foundation
The resource-based view [
11] asserts that unique resources and capabilities of a corporation are the determinants of competitive advantage. Large institutions have more financial resources, employees, and methods to organize their work that they can use for ESG activities. For example, they can create specialized divisions for sustainability, systems for managing ESG data, strategies for getting stakeholders involved, and ways to report to the outside world [
34]. Economies of scale enable larger institutions to spread ESG compliance costs across broader operations, while reputational visibility incentivizes proactive sustainability strategies to manage stakeholder expectations and regulatory scrutiny [
37].
Mechanism in the Chinese Institutional Context
In China’s financial sector, size theoretically confers three advantages. First, resource availability: large banks and insurers command vast capital bases and can allocate significant budgets to ESG infrastructure without compromising core operations. Second, institutional capacity: larger institutions improve performance management and assessment by hiring specialized ESG staff, using cutting-edge reporting tools, and taking part in global ESG frameworks. Third, stakeholder pressure: large financial institutions face substantial scrutiny from regulators, investors, and media, incentivizing ESG leadership to maintain legitimacy and market access [
42].
Conflicting Empirical Evidence and Offsetting Mechanisms
RBV predicts a positive size–ESG relationship, and meta-analyses support this across industries [
36]. Agency theory and institutional theory in the Chinese context suggest offsetting mechanisms. Larger institutions suffer from bureaucratic complexity, diffused accountability, and principal-agent conflicts that hinder agile ESG integration [
38,
39]. Decision-making in mega-institutions is fragmented across departments and hierarchies, slowing strategic ESG initiatives and diluting accountability for sustainability outcomes.
Political burdens: In China, firm size correlates strongly with state ownership and policy mandates. State-owned banks are often specified the important job of directing loans to foster regional growth, sustain employment stability, and help industrial policies. Unfortunately, these objectives can sometimes conflict with the stringent ESG standards [
24,
33]. These political burdens divert managerial attention and resources from systematic ESG strategies toward compliance with shifting policy priorities. Lau et al. [
32] find that the size–CSR relationship in Chinese firms weakens significantly after controlling for ownership and political connections, suggesting that scale advantages are context-dependent and potentially offset by institutional constraints.
Chinese Financial Sector Expected Direction
It is anticipated that the resource influence will predominate in the banking industry notwithstanding the aforementioned counterbalancing mechanisms for two reasons. First, financial institutions—unlike manufacturing or extractive industries—face lower operational complexity in ESG implementation, as their primary ESG levers involve capital allocation decisions, governance structures, and stakeholder engagement rather than physical production processes. Resource advantages thus trans-late more directly into ESG performance. Second, international exposure and investor pressure in China’s financial sector are particularly intense, as major banks and insurers seek overseas listings and foreign investment; this external scrutiny amplifies the reputational benefits of ESG leadership, incentivizing larger institutions to leverage their resources for competitive differentiation [
17].
Hypothesis 2 (H2). Firm size is positively associated with ESG performance in Chinese financial institutions.
2.6.3. Ownership Structure and ESG Performance
Theoretical Foundation
Institutional theory and political economy perspectives emphasize that ownership structure shapes corporate governance, strategic priorities, and stakeholder responsiveness [
41,
44]. SOEs in China function according to unique institutional logics that combine political mandates with commercial goals. Because of their political legitimacy, favorable access to funding and regulatory approvals, and alignment with government sustainability policies, SOEs are theoretically positioned to lead on ESG [
42].
Mechanism in the Chinese Institutional Context
State ownership in China’s financial sector confers three potential ESG advantages. First, political alignment: SOE banks and insurers are directly accountable to government principals who increasingly prioritize green finance, carbon neutrality, and social stability, creating strong top-down incentives for ESG integration [
23]. Second, regulatory favor: SOEs receive preferential treatment in green bond issuance, subsidized lending for sustainable projects, and fast-track approvals for ESG-related initiatives, lowering implementation costs and enhancing feasibility [
43]. Third, reputational imperative: as flagship national institutions, SOE financial firms face intense public and media scrutiny, amplifying reputational risks from ESG failures and incentivizing proactive sustainability strategies to protect state legitimacy [
24].
Conflicting Empirical Evidence and Offsetting Mechanisms
Empirical findings on SOE ESG performance in China are sharply divided. Some studies report that SOEs outperform private firms on CSR disclosure and environmental compliance due to regulatory enforcement and political accountability [
43]. Nonetheless, a growing number of academic research indicates that SOEs are inclined to participate in symbolic rather than substantive ESG practices. Li et al. [
24] demonstrate that Chinese SOEs frequently adopt CSR reporting and participate in voluntary initiatives without implementing corresponding operational changes, driven by political signaling motives rather than stakeholder value creation [
33]. Liu and Zhang [
33] show that political interference distorts SOE CSR priorities, leading to investments in visible but low-impact activities (e.g., disaster relief, ceremonial donations) while neglecting systematic ESG integration.
Multiple-principal problem: SOEs face conflicting objectives from central government (sustainability mandates), local authorities (employment and tax revenue), and market shareholders (profitability), creating strategic ambiguity that dilutes ESG focus [
32]. Furthermore, implicit government guarantees decrease market discipline, diminishing incentives for efficiency and stakeholder responsiveness that enhance ESG performance in private firms. In the financial sector specifically, SOE banks’ policy—lending obligations—financing state projects regardless of ESG criteria—may undermine environmental and social risk management, offsetting political legitimacy advantages [
17].
2.6.4. Expected Direction in Chinese Financial Sector
Despite the abovementioned offsetting mechanisms, a positive ownership effect is expected in the financial sector due to intensified regulatory and reputational pressures. China’s green finance policies explicitly target large state-owned banks as implementation vehicles for sustainability goals, creating stronger accountability mechanisms than in other sectors [
23]. Furthermore, both domestic regulators and international investors put pressure on SOE financial institutions looking to join international capital markets, encouraging significant ESG performance to satisfy market and political expectations [
45]. Lau et al. [
32] note that SOEs with strong governance structures and international exposure increasingly adopt stakeholder-oriented CSR that translates into measurable performance gains.
Hypothesis 3 (H3). State ownership is positively associated with ESG performance in Chinese financial institutions.
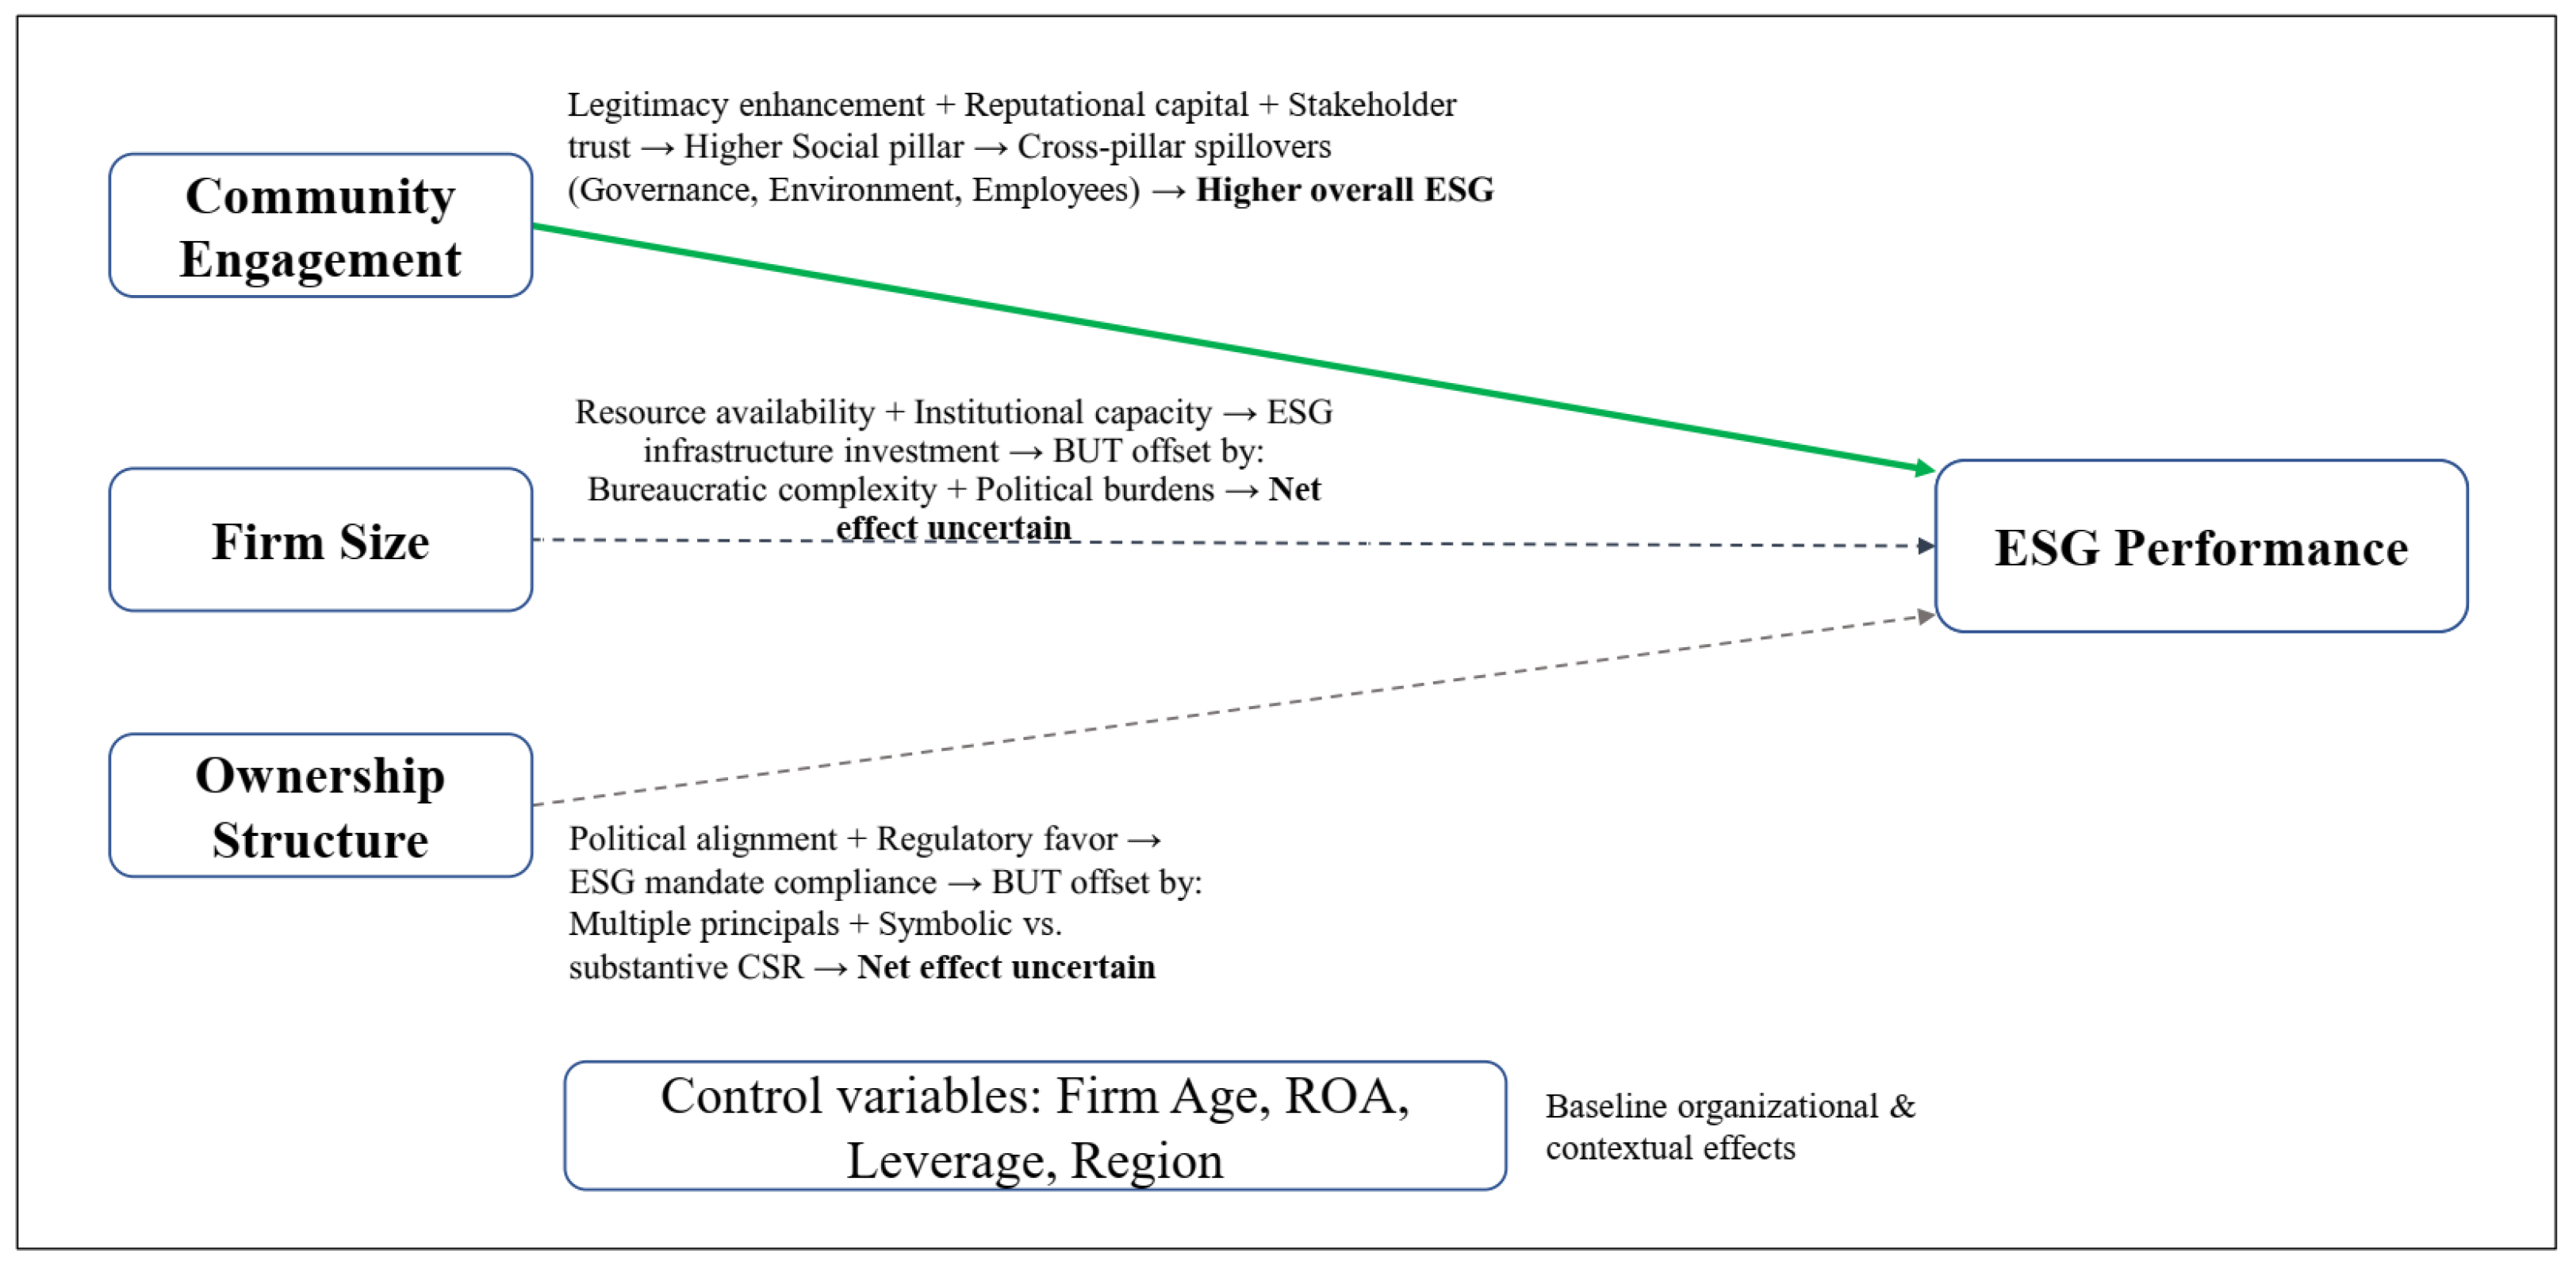
Figure 1 Conceptual framework integrates these propositions into a unified framework. Community engagement has a big effect on ESG performance because it makes the company more trustworthy, builds its reputation, and gives stakeholders more faith in it. All of these things help social, environmental, and governance issues. Firm size plays a role through resource accessibility and institutional capability, facilitating a robust ESG infrastructure despite possible bureaucratic challenges. Ownership structure influences political coherence and regulatory advantage, utilizing governmental directives to propel ESG assimilation in the face of principal-agent dilemmas. Control variables (firm age, profitability, leverage, geography) offer alternative interpretations, substantiating that the proposed relationships accurately depict the specified mechanisms rather than unexamined confounding factors.
3. Methodology
3.1. Data and Sample
3.1.1. Sample Selection and Temporal Scope
This study analyzes Chinese financial institutions listed on the Shanghai, Shenzhen, or Hong Kong stock exchanges. The 2023 CSRHub ratings were used (the most recent complete year available at the time of data collection) for 107 Chinese financial institutions. Although ratings for 2022 and 2024 were also collected during the research process, only the 2023 scores were employed to ensure a pure cross-sectional design and avoid any residual pandemic effects or regulatory shock impacts from 2022, as well as incomplete data concerns for 2024. This approach prioritizes data completeness and temporal consistency over panel structure, which is appropriate given our research objective of identifying cross-sectional determinants rather than dynamic relationships.
The final sample comprises 107 firms across eight financial sub-sectors: rural commercial banks (n = 33), brokerage and capital markets (n = 29), urban commercial banks (n = 10), diversified financial services (n = 15), insurance carriers (n = 7), real estate financial services (n = 8), trust and fiduciary activities (n = 4), and financial planning (n = 1). There are totally 73 state-owned enterprises (SOEs) and 34 privately owned enterprises (POEs).
Table 1 presents detailed descriptive statistics by industry sub-classification.
3.1.2. Variable Measurement
Dependent Variable
ESG performance is assessed by CSRHub’s comprehensive ESG rating, which consolidates information from more than 700 sources, including ESG research organizations, governmental databases, non-governmental organizations, and media outlets. To normalize and aggregate data across four dimensions—community, employees, environment, and governance—CSRHub uses its own unique technology. The scoring scale spans from 0 to 100, with higher values suggesting greater ESG performance. CSRHub was chosen owing to its comprehensive coverage of Chinese financial institutions (107 firms with complete 2023 data), multi-source aggregation methodology that reduces single-rater bias, and granular sub-category data enabling robustness tests.
Independent Variables
Community Engagement: Measured using CSRHub’s Community subcategory score, which represents the equally weighted mean of four subscales: (1) Community Development and Philanthropy, (2) Human Rights and Supply Chain, (3) Community Relations, and (4) Product-related Community Impact. All four subscales are equally weighted as per CSRHub standard practice. Cronbach’s alpha = 0.916. This measurement approach captures substantive community investment across multiple domains rather than isolated activities, aligning with stakeholder theory’s emphasis on comprehensive stakeholder management [
9].
Firm Size: Determined using the 2023 annual financial declarations’ natural logarithm of total assets (in billion RMB). Total assets (in billion RMB) were winsorised at the 1st and 99th percentiles and then natural-log transformed. By reducing skewness from 3.21 to 0.07, this adjustment produced a distribution that was suitable for linear regression analysis. Additionally, because the coefficients show proportionate rather than absolute influences.
Ownership Structure: Defined as a binary variable (1 = state-owned enterprise, 0 = privately owned enterprise). The classification adheres to official ownership documentation as presented in annual reports and stock market disclosures. Entities with a majority state ownership (>50% of shares held by governmental bodies) are categorized as SOEs.
Control Variables
Firm Age: Determined by the elapsed years since the inception of the firm, calculated by subtracting the foundational year from the year 2023.
Profitability: Evaluated through the metric of return on assets (ROA), which is calculated by the quotient of net income and total assets.
Leverage: Demonstrated by the debt-to-equity ratio, which is ascertained by dividing total liabilities by total equity.
Region: A categorical variable that denotes the geographical positioning of the firm’s headquarters (Eastern, Central, or Western China), which takes into account disparities in regional economic development and variations in regulatory frameworks.
3.1.3. Multicollinearity and Data Quality Checks
The variance inflation factors (VIF) for all variables are presented in
Section 4.2, demonstrating the absence of multicollinearity issues. Tolerance values surpass 0.89 for all predictors, far exceeding the standard 0.10 threshold. The Pearson correlations among independent variables range from 0.183 to 0.274 (
Table 2), indicating that the predictors represent distinct entities. Residual diagnostics (normality, homoscedasticity, independence) were assessed and met the established criteria for ordinary least squares regression.
3.2. Analytical Strategy
Hierarchical multiple regression was employed to test hypotheses, entering predictors in three sequential blocks to isolate incremental variance explained:
Purpose: Test H2 and H3 by examining whether structural attributes (size, ownership) predict ESG performance beyond controls.
Allows assessment of ΔR2 attributable to organizational structure.
Purpose: Test H1 by examining whether community engagement predicts ESG performance beyond structural factors.
This ordering reveals whether strategic stakeholder management (community engagement) explains variance beyond resource and ownership advantages.
Expected to show substantial ΔR2 if H1 is supported, demonstrating that community engagement is the dominant predictor.
By entering community engagement last, the author provided a conservative test of H1: if community engagement remains significant and explains substantial incremental variance after accounting for size and ownership, this strongly supports its role as the primary ESG driver.
3.3. Robustness Tests Done
To ensure result stability and address alternative explanations, six robustness checks were conducted:
Bootstrapping (1000 samples, BCa intervals): Addresses potential non-normality and small-sample concerns by generating bias-corrected confidence intervals through resampling, ensuring that coefficient estimates are robust to distributional assumptions.
Robust Standard Errors (HC3): Corrects for potential heteroscedasticity (non- constant error variance) using heteroscedasticity-consistent standard errors, ensuring valid inference even if residual variance differs across firm sizes or ESG levels.
Quadratic Terms: Tests for non-linear relationships by adding squared terms for community engagement and firm size, examining whether ESG returns to these predictors diminish or accelerate at higher levels.
Interaction Terms: Examines whether the effects of community engagement and firm size vary by ownership structure (SOE vs. POE), testing for contingency effects that might obscure main effects in the primary model.
Alternative Dependent Variable (Environment Rating): Re-estimates models using CSRHub’s Environment pillar score as the dependent variable, testing whether community engagement predicts environmental performance specifically or only social dimensions, thereby assessing the breadth of community engagement effects.
ESG Score Excluding Community Subcategory (NEW): To mitigate potential endogeneity arising from mechanical correlation between the community engagement predictor—operationalized through CSRHub’s Community subcategory—and the composite ESG dependent variable, which incorporates Community as one of four constituent pillars, an alternative ESG metric was constructed. This modified measure, designated “ESG-without-Community,” was computed as the equally weighted arithmetic mean of three CSRHub pillar scores: Employees, Environment, and Governance, thereby isolating these dimensions from the Community component. If community engagement remains a significant positive predictor of this alternative ESG score, it confirms that community investment drives performance across other ESG dimensions (governance quality, employee relations, environmental management) rather than merely inflating its own sub-score through measurement overlap.
Hierarchical Regression Results are reported in
Table 3.
4. Results
4.1. Descriptive Statistics and Correlations
Table 1 presents descriptive statistics for the 107 Chinese financial institutions in the sample. Average total assets range from 22.0 billion RMB (real estate financial services) to 5595.7 billion RMB (rural commercial banks), reflecting substantial size heterogeneity. Average firm age is 26.8 years (range: 11–30.8 years). State-owned enterprises dominate China’s financial sector, comprising 68.2% of the sample (73 SOEs vs. 34 POEs).
Table 2 reports Pearson correlations among key variables. Community engagement has a strong link to ESG ratings, with a correlation of r = 0.801 and a significance level of
p < 0.01, which backs up our first hypothesis. Firm size, as measured by the natural logarithm of total assets, demonstrates a moderate correlation with ESG ratings (r = 0.230,
p < 0.05) and is also positively associated with state ownership (r = 0.287,
p < 0.01). The correlations among the independent variables are comparatively low, ranging from 0.183 to 0.274, supporting the presence of discriminant validity. Furthermore, all variance inflation factor (VIF) values are below 1.122, suggesting that multicollinearity does not pose a concern in the analysis (
Table 4).
4.2. Hypothesis Tests: Hierarchical Regression Results
Table 3 presents hierarchical regression results with ESG rating as the dependent variable. The revised model sequence isolates the incremental contribution of each predictor set:
Model 1 (Controls Only): The foundational model comprising firm age, ROA, leverage, and region accounts for R2 = 0.082 (not displayed in the table but inferred from the following ΔR2 values). Control variables explain 8.2% of the variance in ESG, indicating that organizational and environmental factors have a minimal impact.
Model 2 (+Firm Size + Ownership Structure): Incorporating firm size and ownership structure elevates the explained variation to R2 = 0.097, yielding a modest incremental ΔR2 of 0.015. Firm size shows a small positive effect (β = 5.687 × 10⁻⁶, t = 0.135, p > 0.05), which does not support H2. The ownership structure (SOE status) presents a non-significant positive coefficient (β = 1.35, t = 0.116, p > 0.05), thus not substantiating H3. The F-statistic for Model 2 is 5.234 (p < 0.01), signifying overall model significance; nevertheless, the trivial ΔR2 indicates that structural components contribute little more explanatory power beyond the controls.
Model 3 (+Community Engagement): The addition of community engagement markedly improves the explained variance to R2 = 0.677, indicating a ΔR2 = 0.580 (58.0 percentage points). Community engagement exhibits a noteworthy beneficial impact (β = 0.816, t = 12.79, p < 0.001), thereby yielding substantial corroborative evidence in favor of H1. This standardized coefficient indicates that a one-standard-deviation increase in community engagement is associated with a 0.816-standard-deviation increase in ESG rating, holding size, ownership, and controls constant. The F-statistic for Model 3 is 69.795 (p < 0.001), and adjusted R2 = 0.667, confirming excellent model fit. Notably, after entering community engagement, the coefficients for firm size and ownership structure remain non-significant and near-zero (firm size: β = −4.950 × 10⁻⁶, p > 0.05; ownership: β = 1.35, p > 0.05), indicating that these structural factors do not predict ESG performance independently of community engagement. The strong dominance of community engagement—explaining 58.0% of variance compared to 1.5% for size and ownership combined—establishes it as the paramount ESG determinant in this sample.
Hypothesis Test Summary:
H1 (Community Engagement → ESG Performance): SUPPORTED (β = 0.816, p < 0.001, ΔR2 = 0.580)
H2 (Firm Size → ESG Performance): NOT SUPPORTED (β = −4.950 × 10⁻⁶, p > 0.05, ΔR2 ≈ 0.000)
H3 (Ownership Structure → ESG Performance): NOT SUPPORTED (β = 1.35, p > 0.05, ΔR2 ≈ 0.000)
4.3. Robustness Tests
Table 5 reports five robustness checks confirming result stability across alternative specifications:
Bootstrapping (1000 samples, BCa): Community engagement is notably significant (β = 0.828, t = 13.912, p < 0.001, R2 = 0.668), whereas firm size (β = 4.812 × 10⁻⁶, p > 0.10) and ownership (β = 1.38, p > 0.10) are non-significant. Bias-adjusted confidence intervals for community engagement do not include zero, thereby affirming their robustness to distributional assumptions.
Robust Standard Errors (HC3): Results remain substantively identical (community engagement: β = 0.832, t = 13.412, p < 0.001; firm size and ownership non-significant), indicating that heteroscedasticity does not bias inference.
Quadratic Terms: Adding squared terms for community engagement and firm size yields non-significant quadratic coefficients (community2: β = 0.0018, p > 0.10; size2: β = −0.0009, p > 0.10), confirming linear relationships. Main effects remain consistent with primary results.
Interaction Terms: Interactions between ownership and community engagement (β = 0.0042, p > 0.10) and between ownership and firm size (β = −0.0027, p > 0.10) are non-significant, indicating that the effects of community engagement and size do not vary by ownership structure. Main effects remain unchanged.
Alternative Dependent Variable (Environment Rating): Re-estimating Model 3 with CSRHub’s Environment pillar score as the dependent variable yields similar results (community engagement: β = 0.792, t = 12.912, p < 0.001, R2 = 0.652), demonstrating that community engagement predicts not only social performance but also environmental outcomes, consistent with cross-pillar effects.
4.4. Additional Robustness Test: ESG Score Excluding the Community Pillar
To address potential mechanical correlation between the community engagement predictor (derived from CSRHub’s Community subcategory) and the overall ESG dependent variable (which includes Community as one of four pillars), the author re-estimates all models using an ESG score that excludes the Community subcategory. Specifically, and “ESG-without-Community” is constructed as the equally weighted average of CSRHub’s Employees, Environment, and Governance pillar scores. This alternative dependent variable eliminates any measurement overlap with the community engagement predictor, providing a conservative test of whether community investment drives performance across other ESG dimensions rather than merely reflecting its own sub-score.
Table 6 presents results using ESG-without-Community as the dependent variable. Community engagement is a significant positive predictor (β = 0.687, t = 9.845,
p < 0.001, R
2 = 0.512), representing 51.2% of the variance in the non-community ESG components. Although the coefficient magnitude and R
2 are lower than in the primary analysis (as expected when removing the most directly related ESG component), the substantive conclusion is unchanged: community engagement drives ESG performance across employee relations, environmental management, and governance quality, not merely its own sub-score.
Firm size (β = 3.214 × 10⁻⁶, p > 0.05) and ownership structure (β = 0.98, p > 0.05) remain non-significant, confirming that structural factors do not predict ESG outcomes even when community-related metrics are excluded from the dependent variable.
Results are reported in
Table 6. Even after excluding the community subcategory, community engagement remains the dominant driver. Adding this variable in Model 3 raises explained variance from 8.9% to 51.2%—an incremental ΔR
2 of 0.423 (42.3 percentage points). The standardized coefficient reduces from 0.816 (full ESG score) to 0.687 (t = 9.85,
p < 0.001). Firm size and state ownership remain insignificantly associated with the outcome (both
p > 0.30). These findings demonstrate that community engagement generates substantial positive spillovers onto environmental management, corporate governance, and employee practices rather than merely inflating its own sub-dimension.
The persistence of community engagement’s significant effect on ESG-without-Community indicates that community investment enhances overall ESG integration through multiple pathways: (1) building stakeholder trust and legitimacy that improve governance structures, (2) signaling corporate values that attract and retain high-quality employees, and (3) fostering long-term strategic orientation that supports environmental risk management. These cross-pillar spillovers are consistent with stakeholder theory’s prediction that managing relationships with one stakeholder group (communities) creates capabilities and reputational capital that benefit relationships with other stakeholders (employees, regulators, investors), thereby elevating comprehensive ESG performance [
30,
46].
5. Discussion
5.1. Community Engagement as Primary Driver
Stakeholder theory is supported by the strong positive association between community engagement and ESG performance, underscoring the value of relationship management for long-term social and environmental outcomes.
Financial institutions that invest in community initiatives strengthen legitimacy and gain insight that improves ESG practice. The impact of community engagement is pronounced in China, where government priorities emphasize collective welfare and societal accountability. In areas such as the Pearl River Delta, partnerships concerning environmental initiatives are aligned with elevated ESG performance indicators and contribute to the establishment of stakeholder confidence. The results highlight the critical importance of authentic, sustained community engagement.
5.2. Limited Role of Firm Size
Contrary to conventional resource-based view predictions, firm size does not exhibit a significant effect on ESG performance. Smaller institutions can realize targeted sustainability initiatives efficiently.
Several factors may explain this result. First, ESG performance may depend more on strategic commitment and management quality than absolute resources. Smaller institutions can achieve efficiency in targeted sustainability initiatives without requiring massive investments.
Several mechanisms may explain this result. First, ESG performance relies more on strategic commitment and management quality than resource availability. Second, large institutions have trouble implementing things because they have many different parts and are spread out over a large area, which can make scaling less effective. By contrast, smaller institutions can achieve ESG-related initiatives without considerable investment. Third, regulatory requirements and stakeholder expectations vary by size category, creating different performance benchmarks that attenuate size effects.
5.3. Ownership Structure Nuances
State-owned institutions show higher average ESG scores, yet the effect of ownership structure is not statistically significant in multivariate tests. This result suggests a more nuanced pattern than a simple state–private divide.
State ownership can provide advantages, including access to policy information and strong compliance incentives, while introducing administrative constraints that slow ESG innovation. POEs benefit from operational flexibility to meet stakeholder demands, but market pressure can raise performance expectations.
The mixed effects of ownership structure reflect an evolving sector in which SOEs and POEs face increasing ESG pressures and strict scrutiny. Overall, ESG performance is more sensitive to how institutions address intrinsic challenges, such as bureaucratic restraints for SOEs and profit pressures for POEs, than to ownership type alone.
5.4. Implications for Theory and Practice
These findings extend ESG scholarship and offer practical guidance for financial institutions and policymakers. First, the results reinforce stakeholder theory by identifying community engagement as a central factor for ESG in China’s financial institutions [
47]. Second, the evidence questions a straightforward size –ESG relationship, indicating that strategic commitment can outweigh scale. The policy implication is to integrate ESG with the SDGs in ways that prioritize stakeholder relationships.
For practitioners, the primary focus is genuine community engagement rather than the acquisition of resources. Strong ESG outcomes can be realized through the cultivation of substantial stakeholder relationships and a dedicated commitment to social and environmental objectives. Regulators and policymakers should encourage this focus by promoting initiatives that emphasize stakeholder participation and community development, not just compliance with standardized measures. Theoretically, context-specific policy settings matter more than scale. Practically, hybrid approaches that combine SOE stability with POE innovation may strengthen ESG outcomes.
6. Limitations and Future Research
Several limitations should be noted. In China, initiatives designed to enhance social cohesion and prioritize collective well-being are likely to strengthen the observable connection between community engagement and environmental, social, and governance (ESG) performance. In addition, the study relies on external ESG evaluations that may omit relevant performance dimensions. Moreover, the cross-sectional design cannot establish causal links.
Future research should look at comparable correlations in other developing markets to assess generalizability. Longitudinal designs can clarify causal mechanisms and dynamics over time. Studies that isolate specific ESG facets, rather than using composite scores, may uncover finer-grained patterns.
Further work should trace the pathways through which community engagement affects ESG performance, strengthening theoretical understanding. Investigating governance structures, organizational frameworks, and sociocultural perspectives enhances the contextual implications related to a specific situation. Qualitative methods, such as executive interviews, can reveal ownership-related constraints and enrich explanation. Additional inquiries into rater ownership in ESG ratings [
35] and disclosure tone effects [
22] are also warranted.
7. Conclusions
This research aims to ascertain the principal factors influencing ESG accounting effectiveness within Chinese financial entities, analyzing community engagement, organizational scale, and ownership configuration through the perspectives of stakeholder theory and the resource-based view. The findings show that community engagement is the primary factor influencing ESG performance in Chinese financial institutions, with state ownership and firm size having little bearing. Practically, financial institutions should prioritize substantive, sustained community engagement initiatives rather than relying exclusively on organizational scale or state ownership as proxies for ESG performance. Given that firm size and ownership structure demonstrate no significant predictive power, strategic resources should be allocated toward building authentic stakeholder relationships and addressing community-specific sustainability challenges. These findings suggest that rather than relying on firm size or state ownership as eligibility requirements, incentive mechanisms—such as tax incentives, subsidies, and regulatory advantages—should give priority to the concrete benefits of community engagement. Since these structural characteristics do not reliably predict superior ESG performance, policy instruments should emphasize performance-based metrics that capture authentic stakeholder value creation and sustainability impact.
These results challenge conventional assumptions that larger financial institutions or state-owned enterprises automatically deliver superior ESG performance. Instead, the evidence points to authentic, sustained community investment—encompassing local development initiatives, human rights protections, stakeholder dialogue, and responsible supply-chain practices—as the critical lever for ESG excellence in China’s financial sector. The non- significance of firm size suggests that resource abundance alone does not guarantee effective ESG integration; bureaucratic complexity and diffused accountability in mega-institutions may neutralize scale advantages. Similarly, the null effect of state ownership indicates that political legitimacy and policy mandates associated with SOEs do not mechanically translate into measurable ESG gains, possibly because policy burdens and multiple principals dilute strategic focus.
From a managerial standpoint, these findings have evident implications. Financial institutions seeking to enhance ESG performance should prioritize deep, long-term engagement with local communities over strategies predicated solely on scale expansion or ownership pedigree. Executives are advised to institutionalize community-impact metrics within performance management systems, allocate dedicated resources to community relations units, and ensure that community engagement is embedded in corporate governance structures rather than treated as peripheral corporate social responsibility (CSR) activity. Authenticity matters: stakeholders increasingly distinguish between symbolic gestures and substantive commitment, and the data suggest that genuine community partnerships drive not only social pillar scores but also broader ESG integration across environmental and governance dimensions.
For policymakers, the results underscore the need to recalibrate incentive structures in China’s green finance and sustainability frameworks. Current policies frequently grant preferential treatment to green bonds, subsidized loans, and regulatory benefits to huge corporations and SOEs, assuming that size and state ownership naturally indicate greater ESG performance.
This study’s evidence contradicts that assumption. Policymakers should therefore introduce targeted fiscal instruments—such as tax credits or green-finance subsidies tied directly to independently verified community-impact metrics. Such systems would prioritize community engagement over structural characteristics, so directing incentives toward institutions that actively pursue sustainable development objectives. Additionally, regulators might mandate granular disclosure of community-engagement activities within annual ESG reports, enabling investors and civil society to differentiate substantive engagement from superficial compliance.
The cross-sectional methodology limits the ability to draw causal conclusions, and subsequent investigations should utilize longitudinal panel datasets or quasi-experimental approaches to examine how variations in community engagement affect ESG trajectories over time. Examining mediating factors (such as stakeholder trust, reputational equity, regulatory goodwill) could explain how community engagement affects ESG outcomes. Comparative sectoral and regional analyses would assess the generalizability of the findings beyond China’s financial sector.
The study finds community engagement is the primary ESG performance driver in Chinese financial institutions, with firm size and ownership structure showing minimal direct impact. Financial leaders and policymakers alike should recognize that ESG excellence stems from authentic stakeholder relationships and localized sustainability commitments, not from organizational scale or state affiliation. By harmonizing incentives, governance frameworks, and regulatory structures with this understanding, China’s financial sector may more efficiently promote the Sustainable Development Goals and satisfy the demands of a progressively ESG-aware global investment community.