Exploring the Trend of Commodity Prices: A Review and Bibliometric Analysis

Abstract
1. Introduction
2. Methods and Data
3. Statistical Analysis of Commodity Prices
3.1. Research on the Overall Growth Trend
3.2. Publication Sources
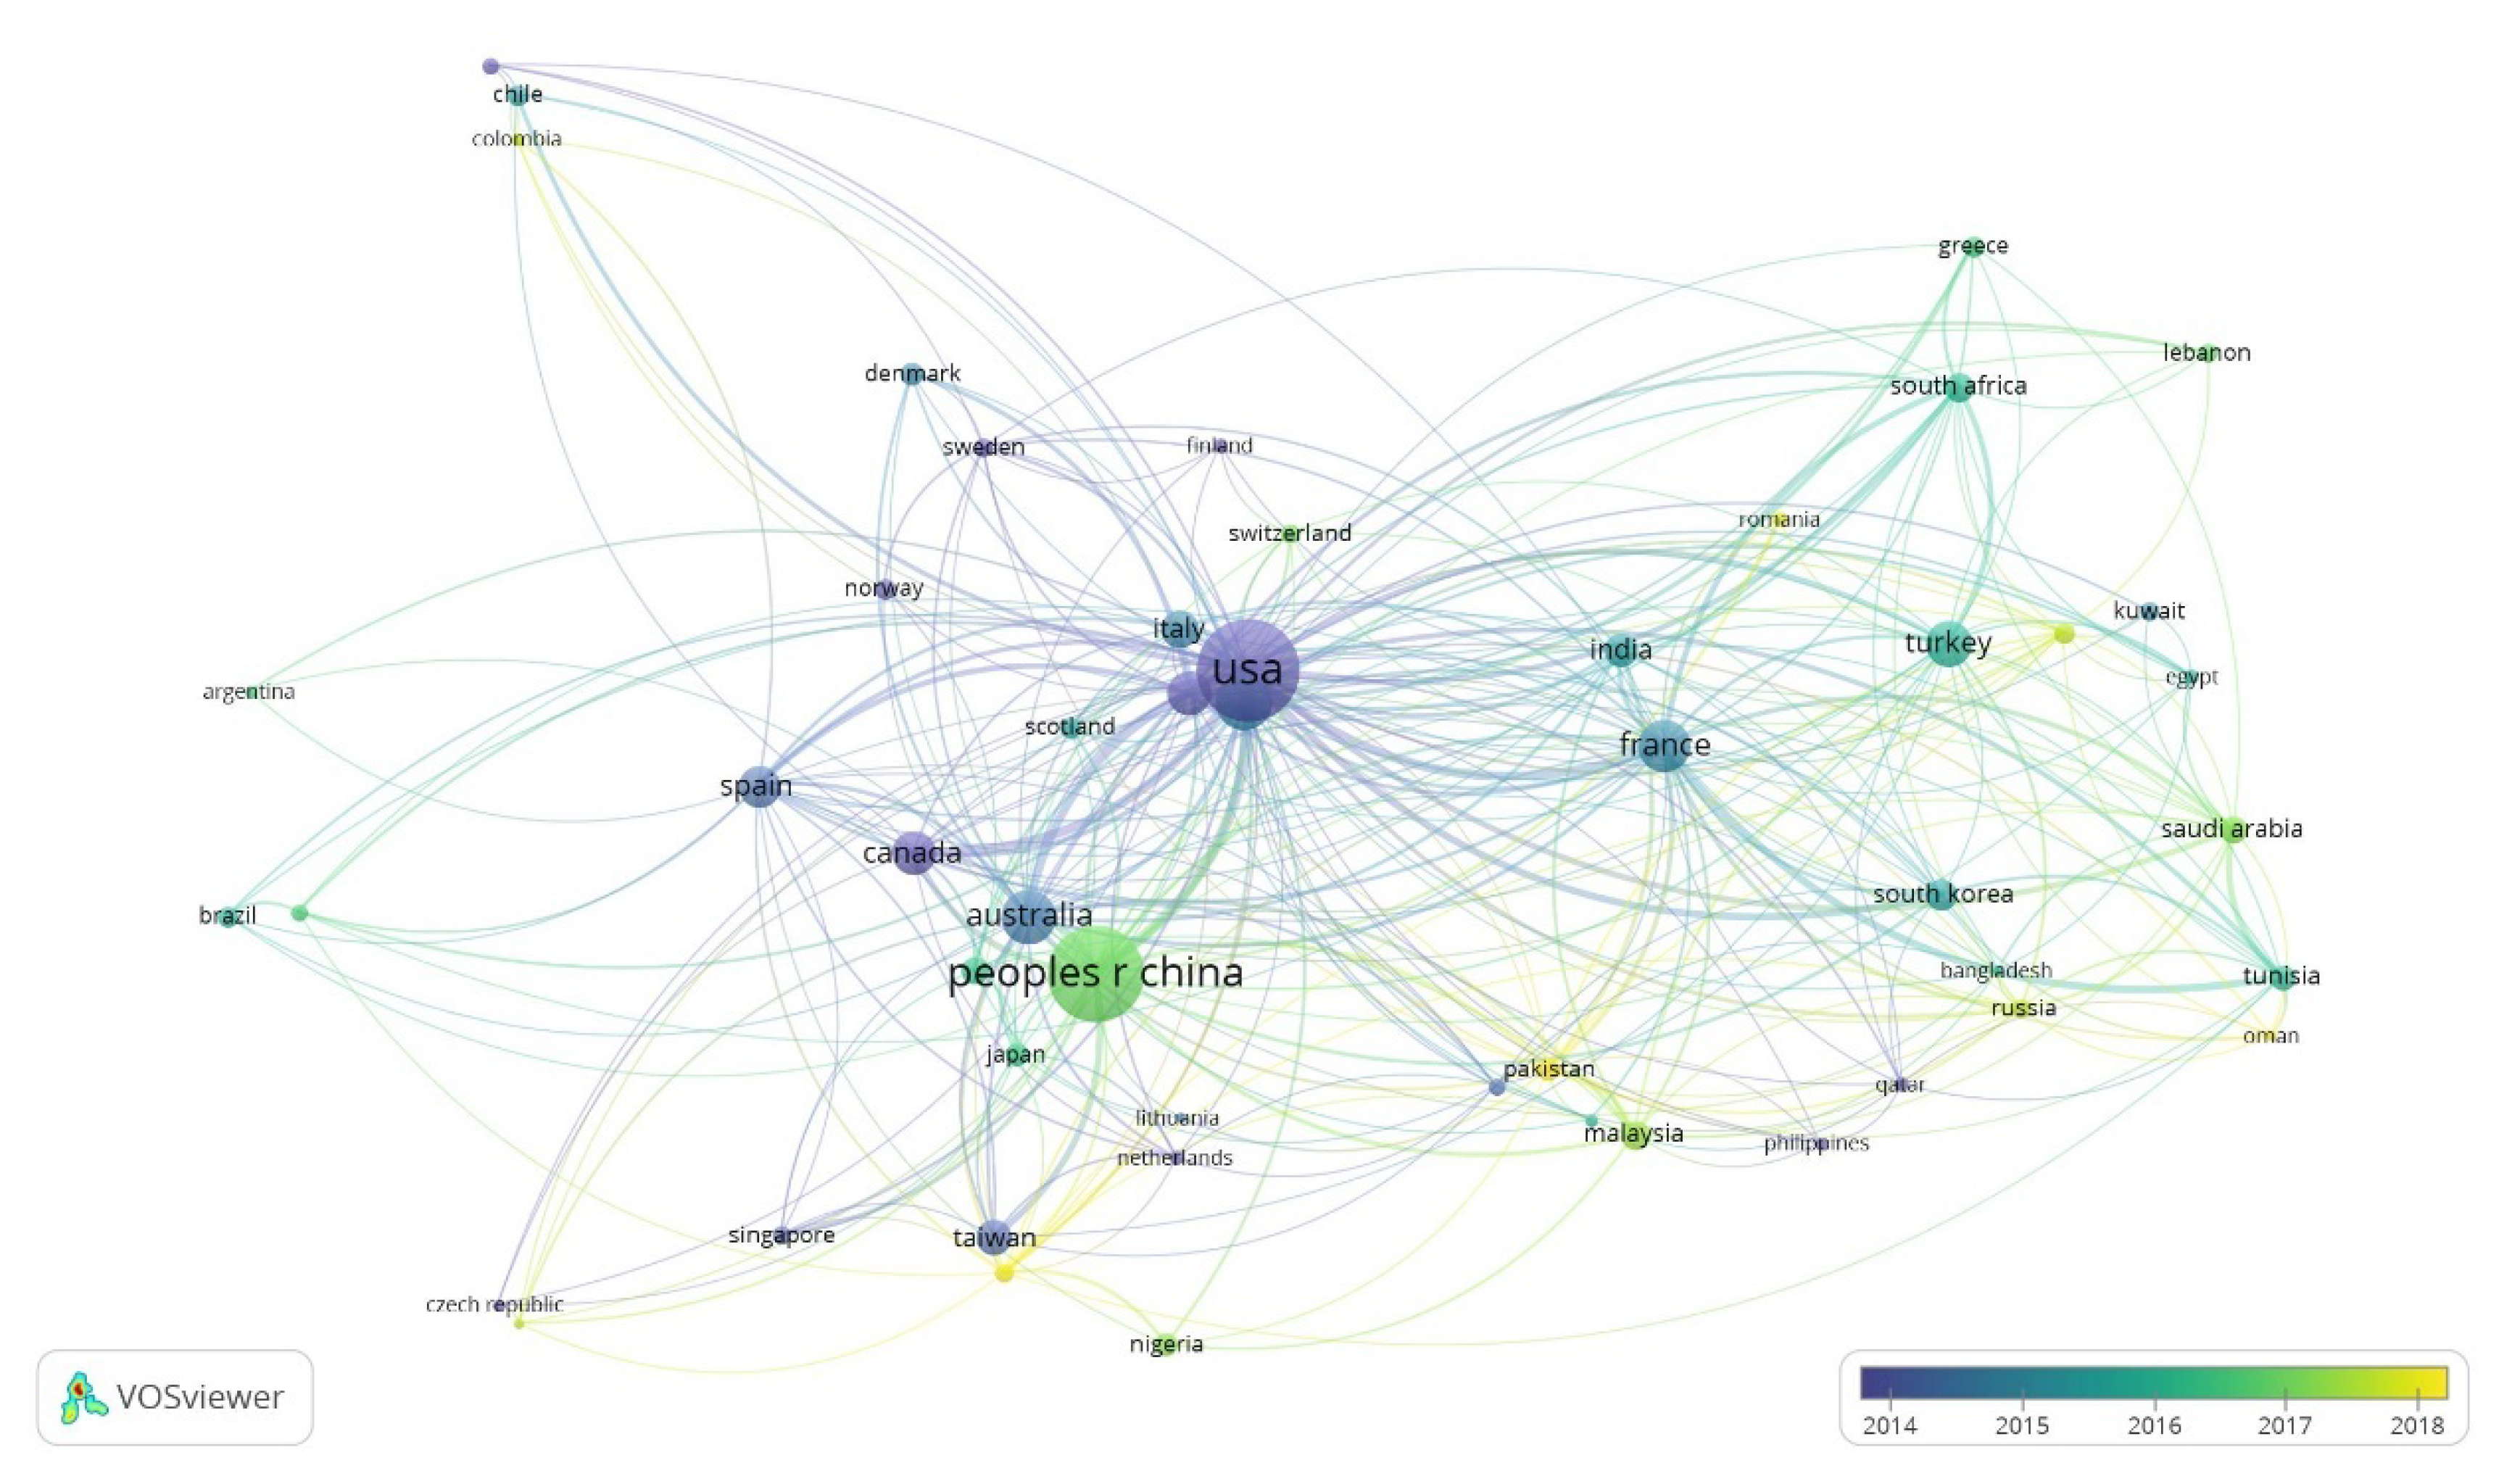
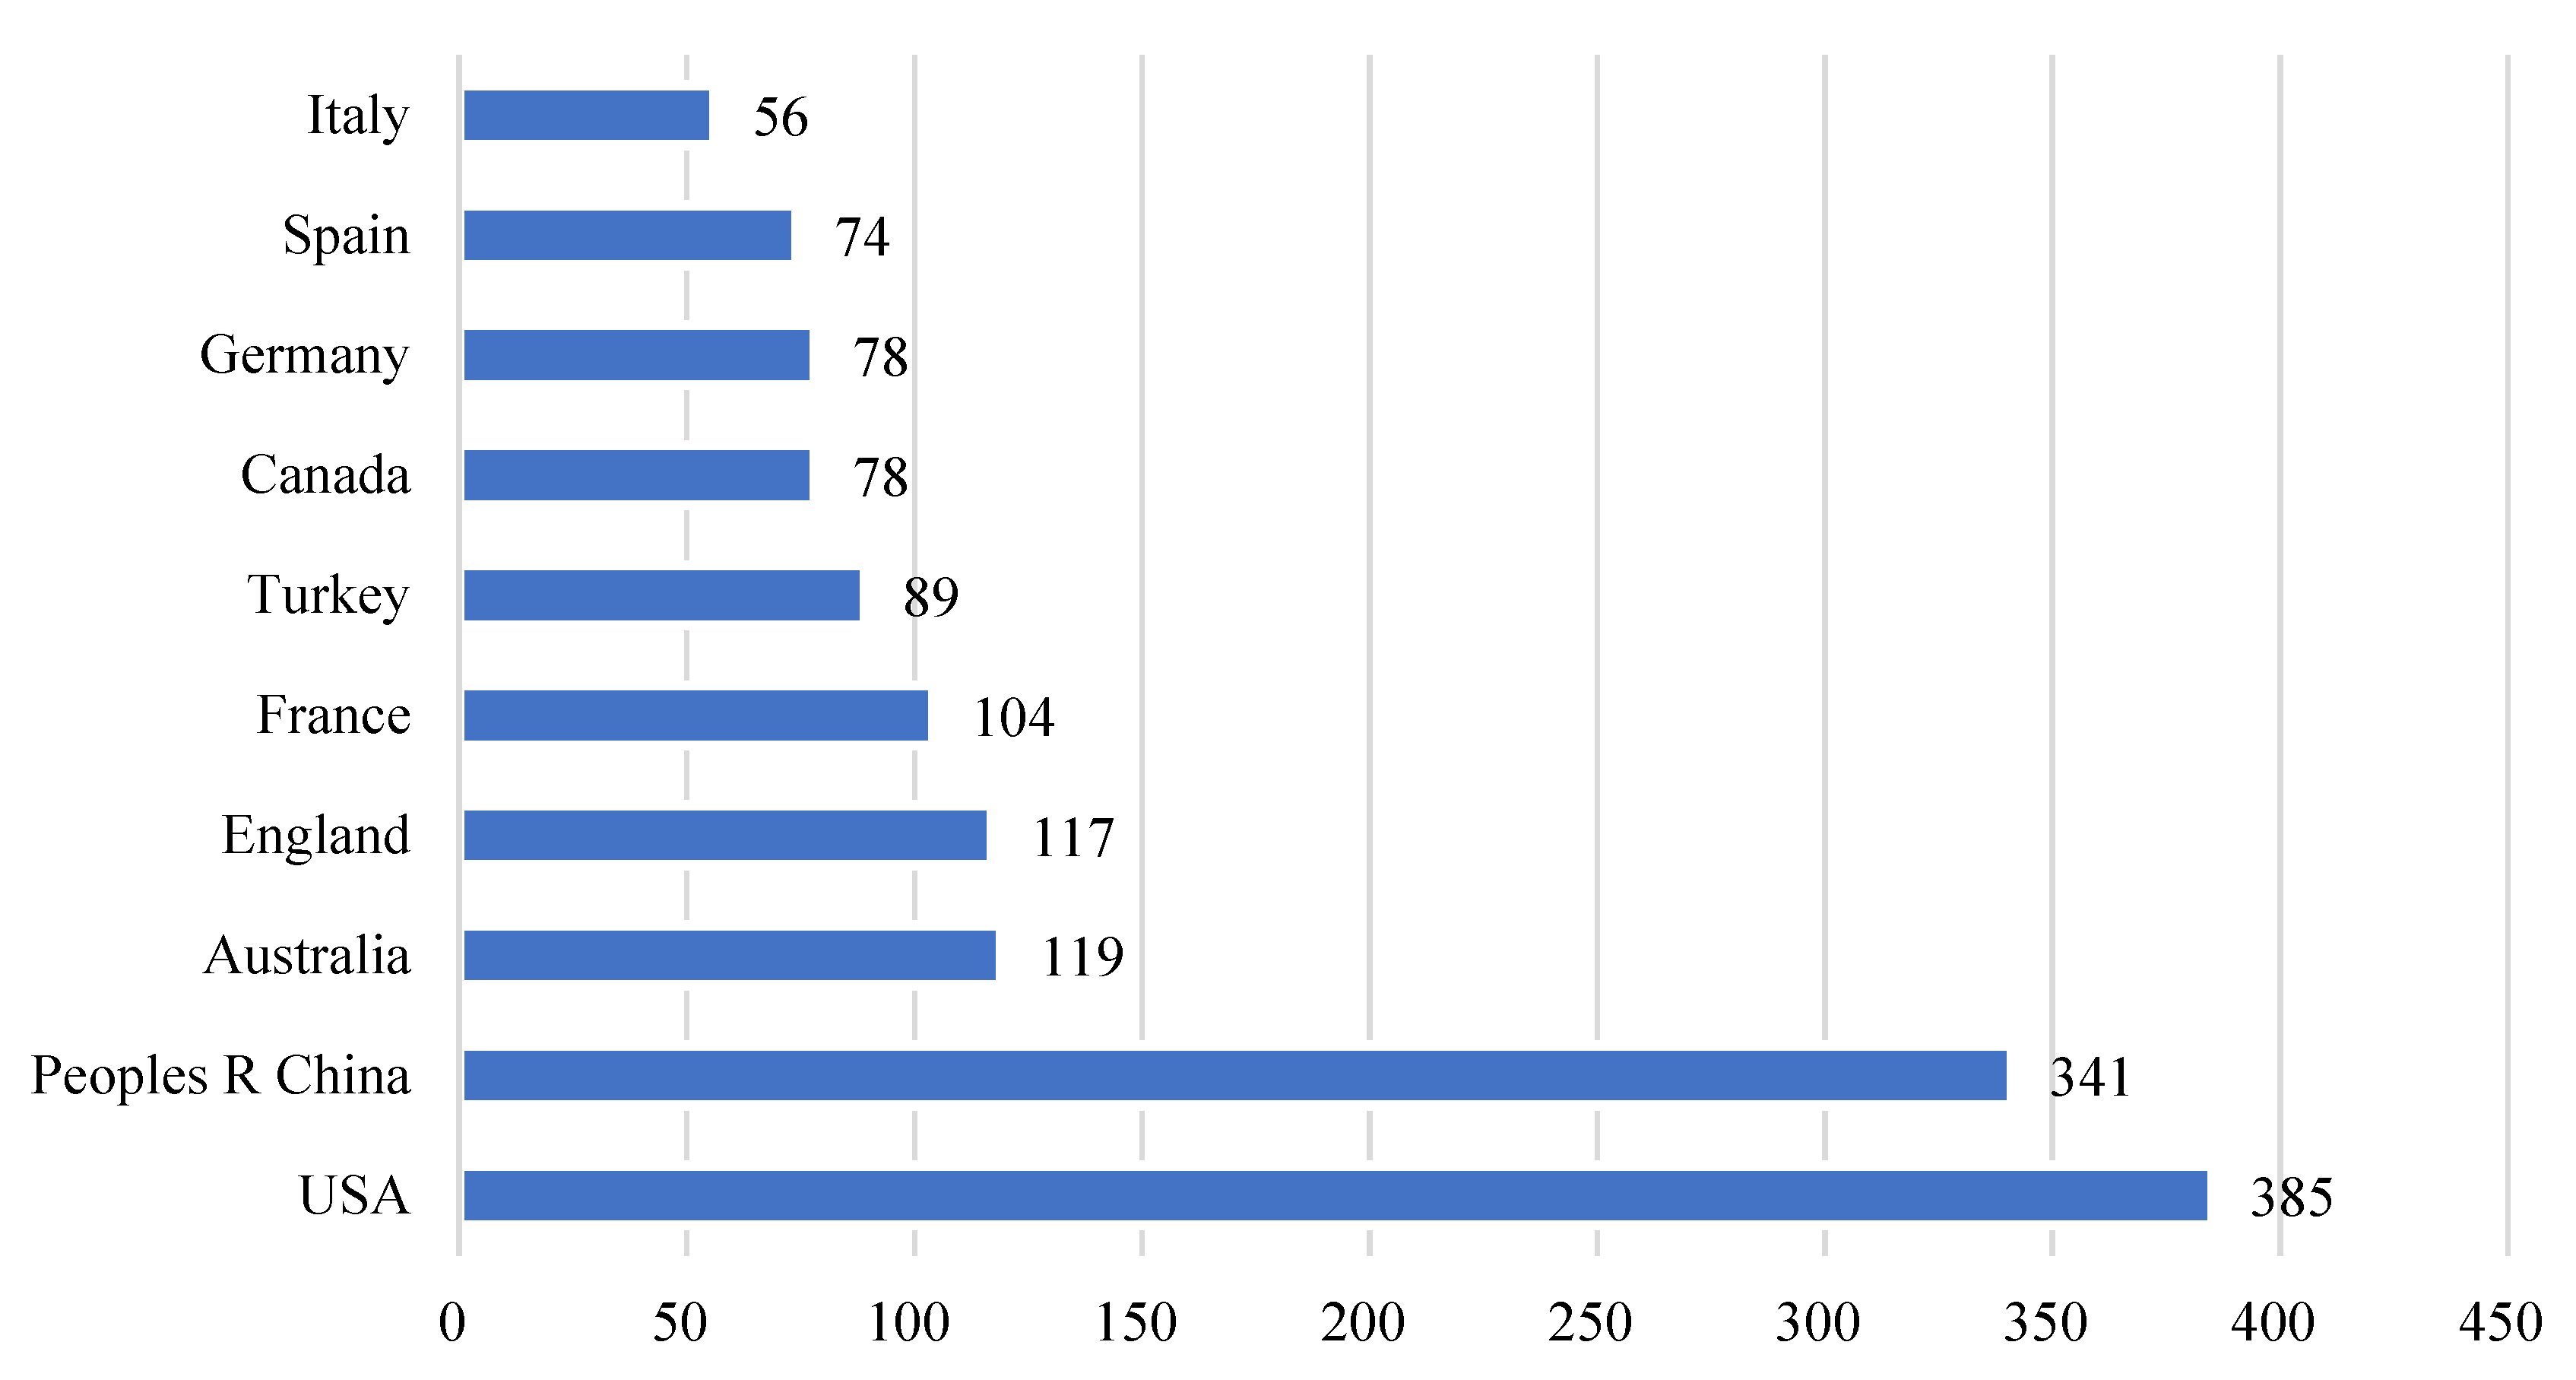
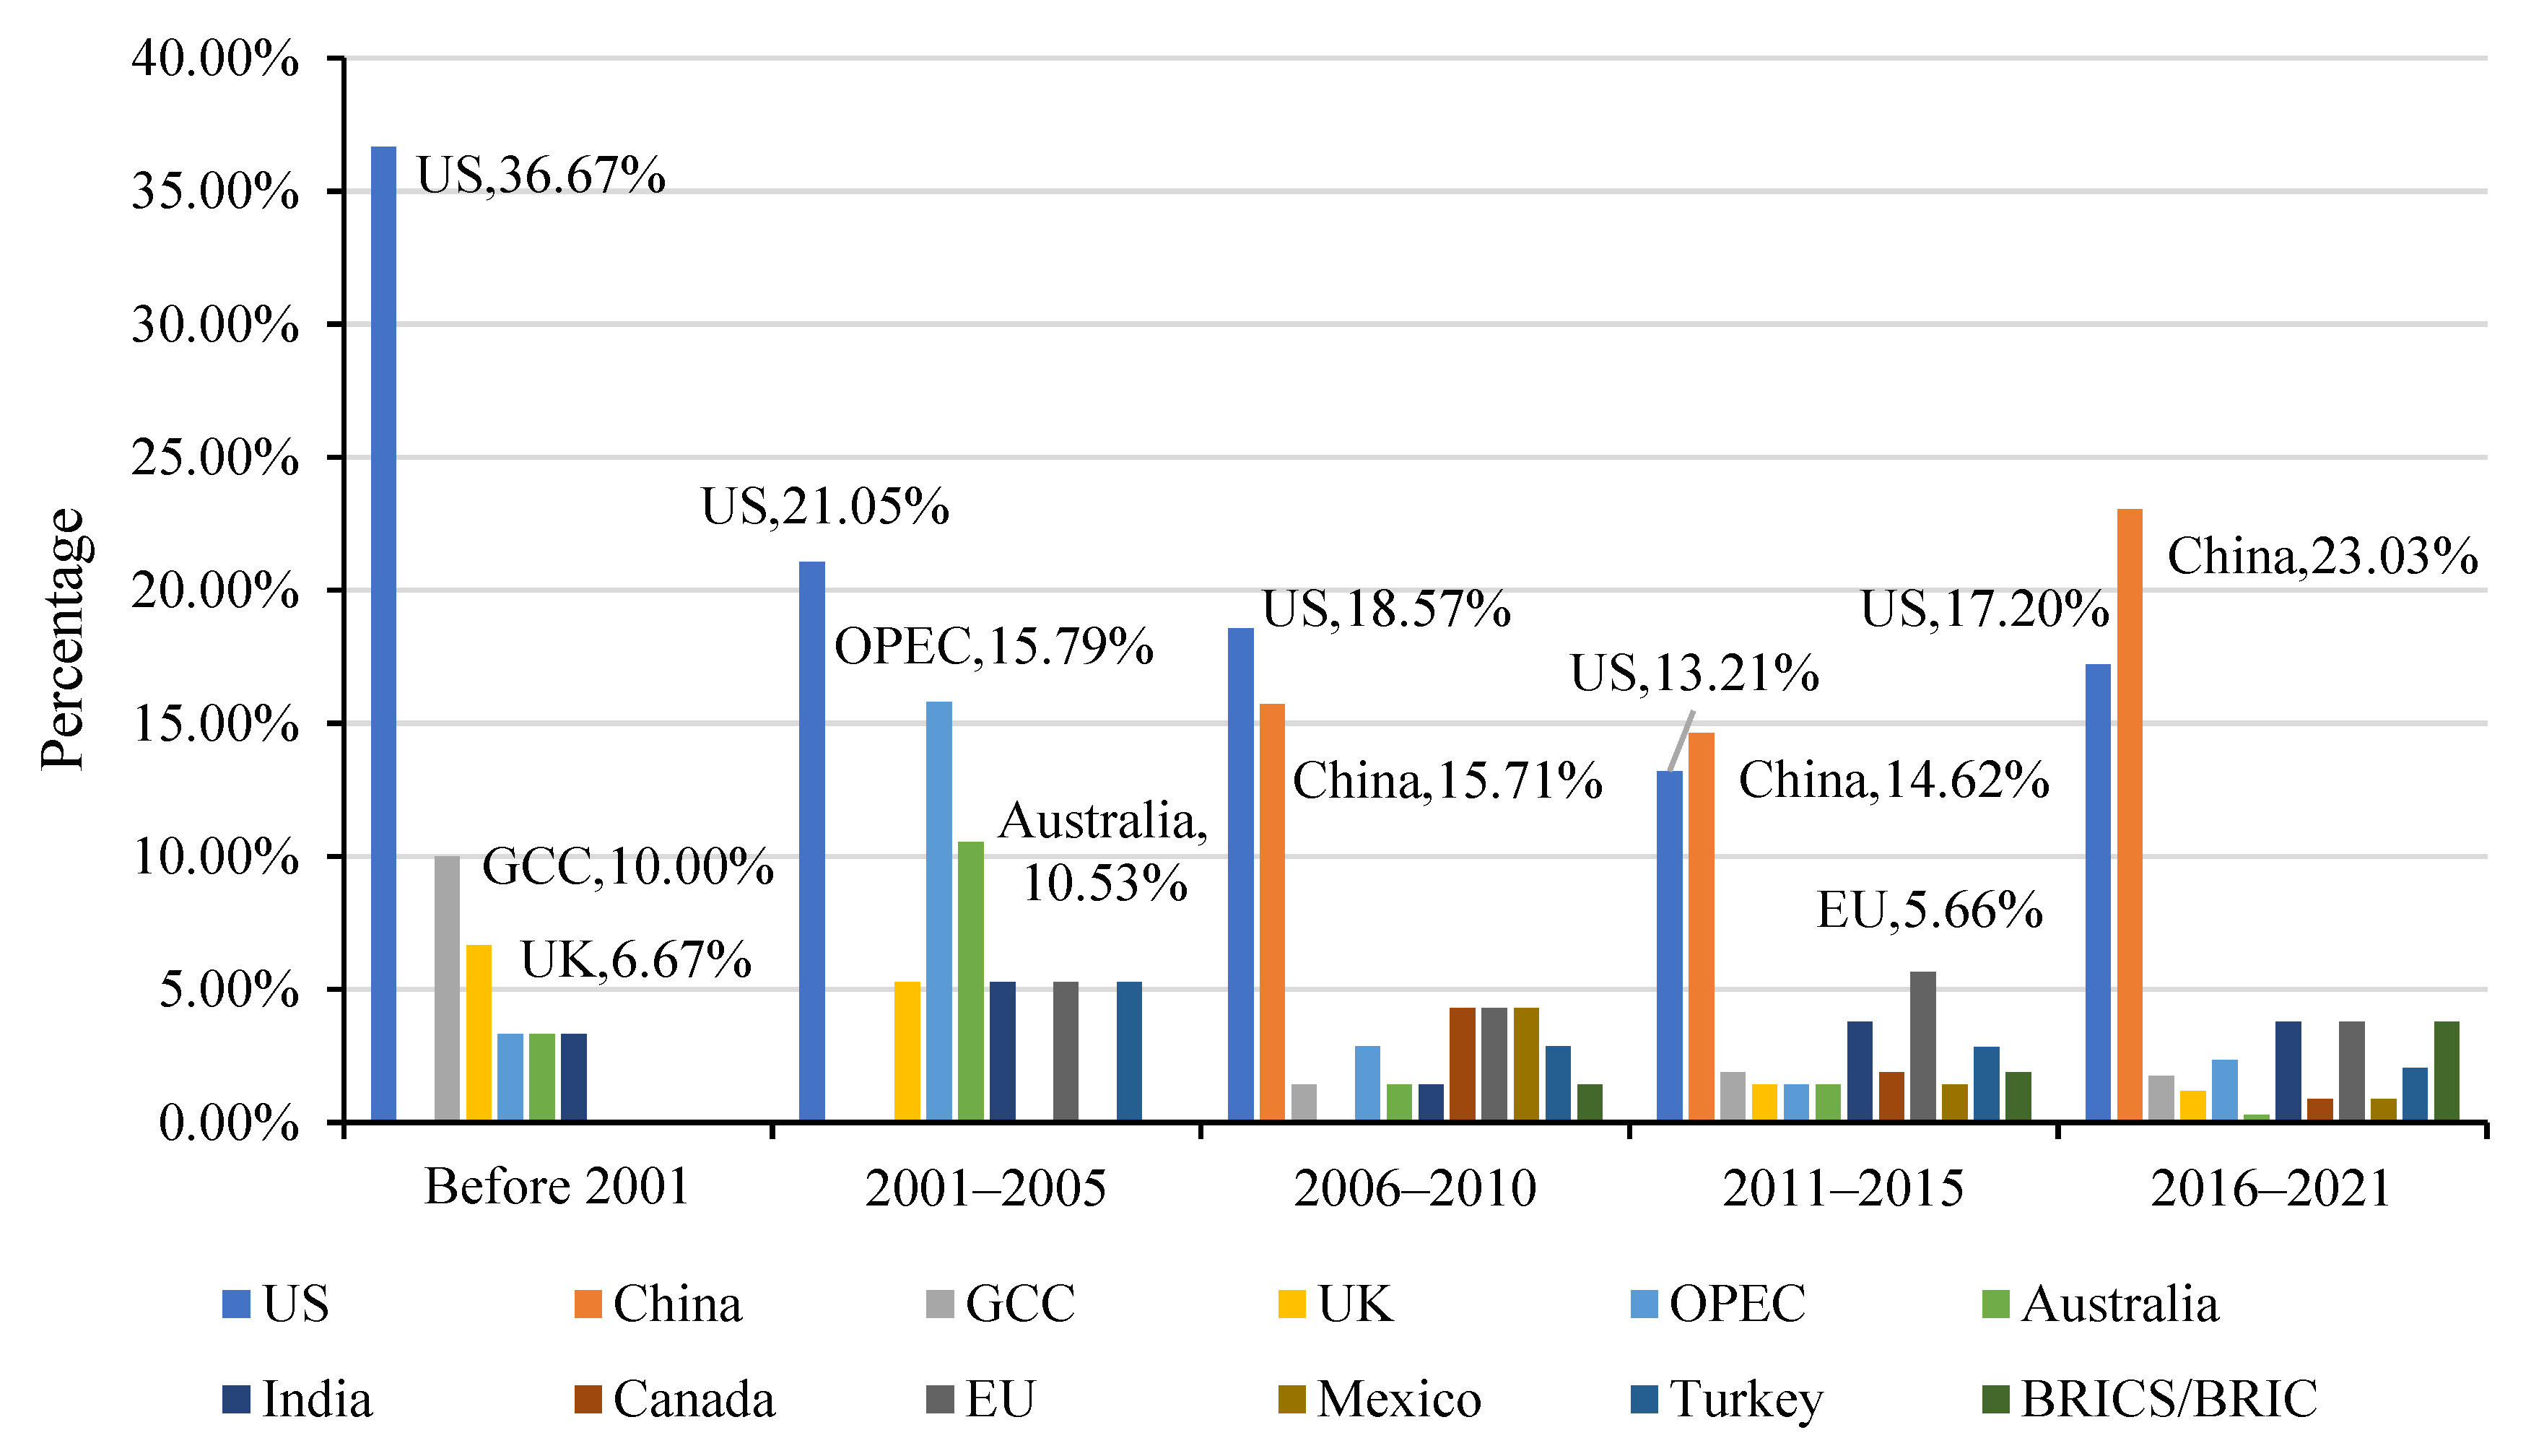
3.3. Research Countries
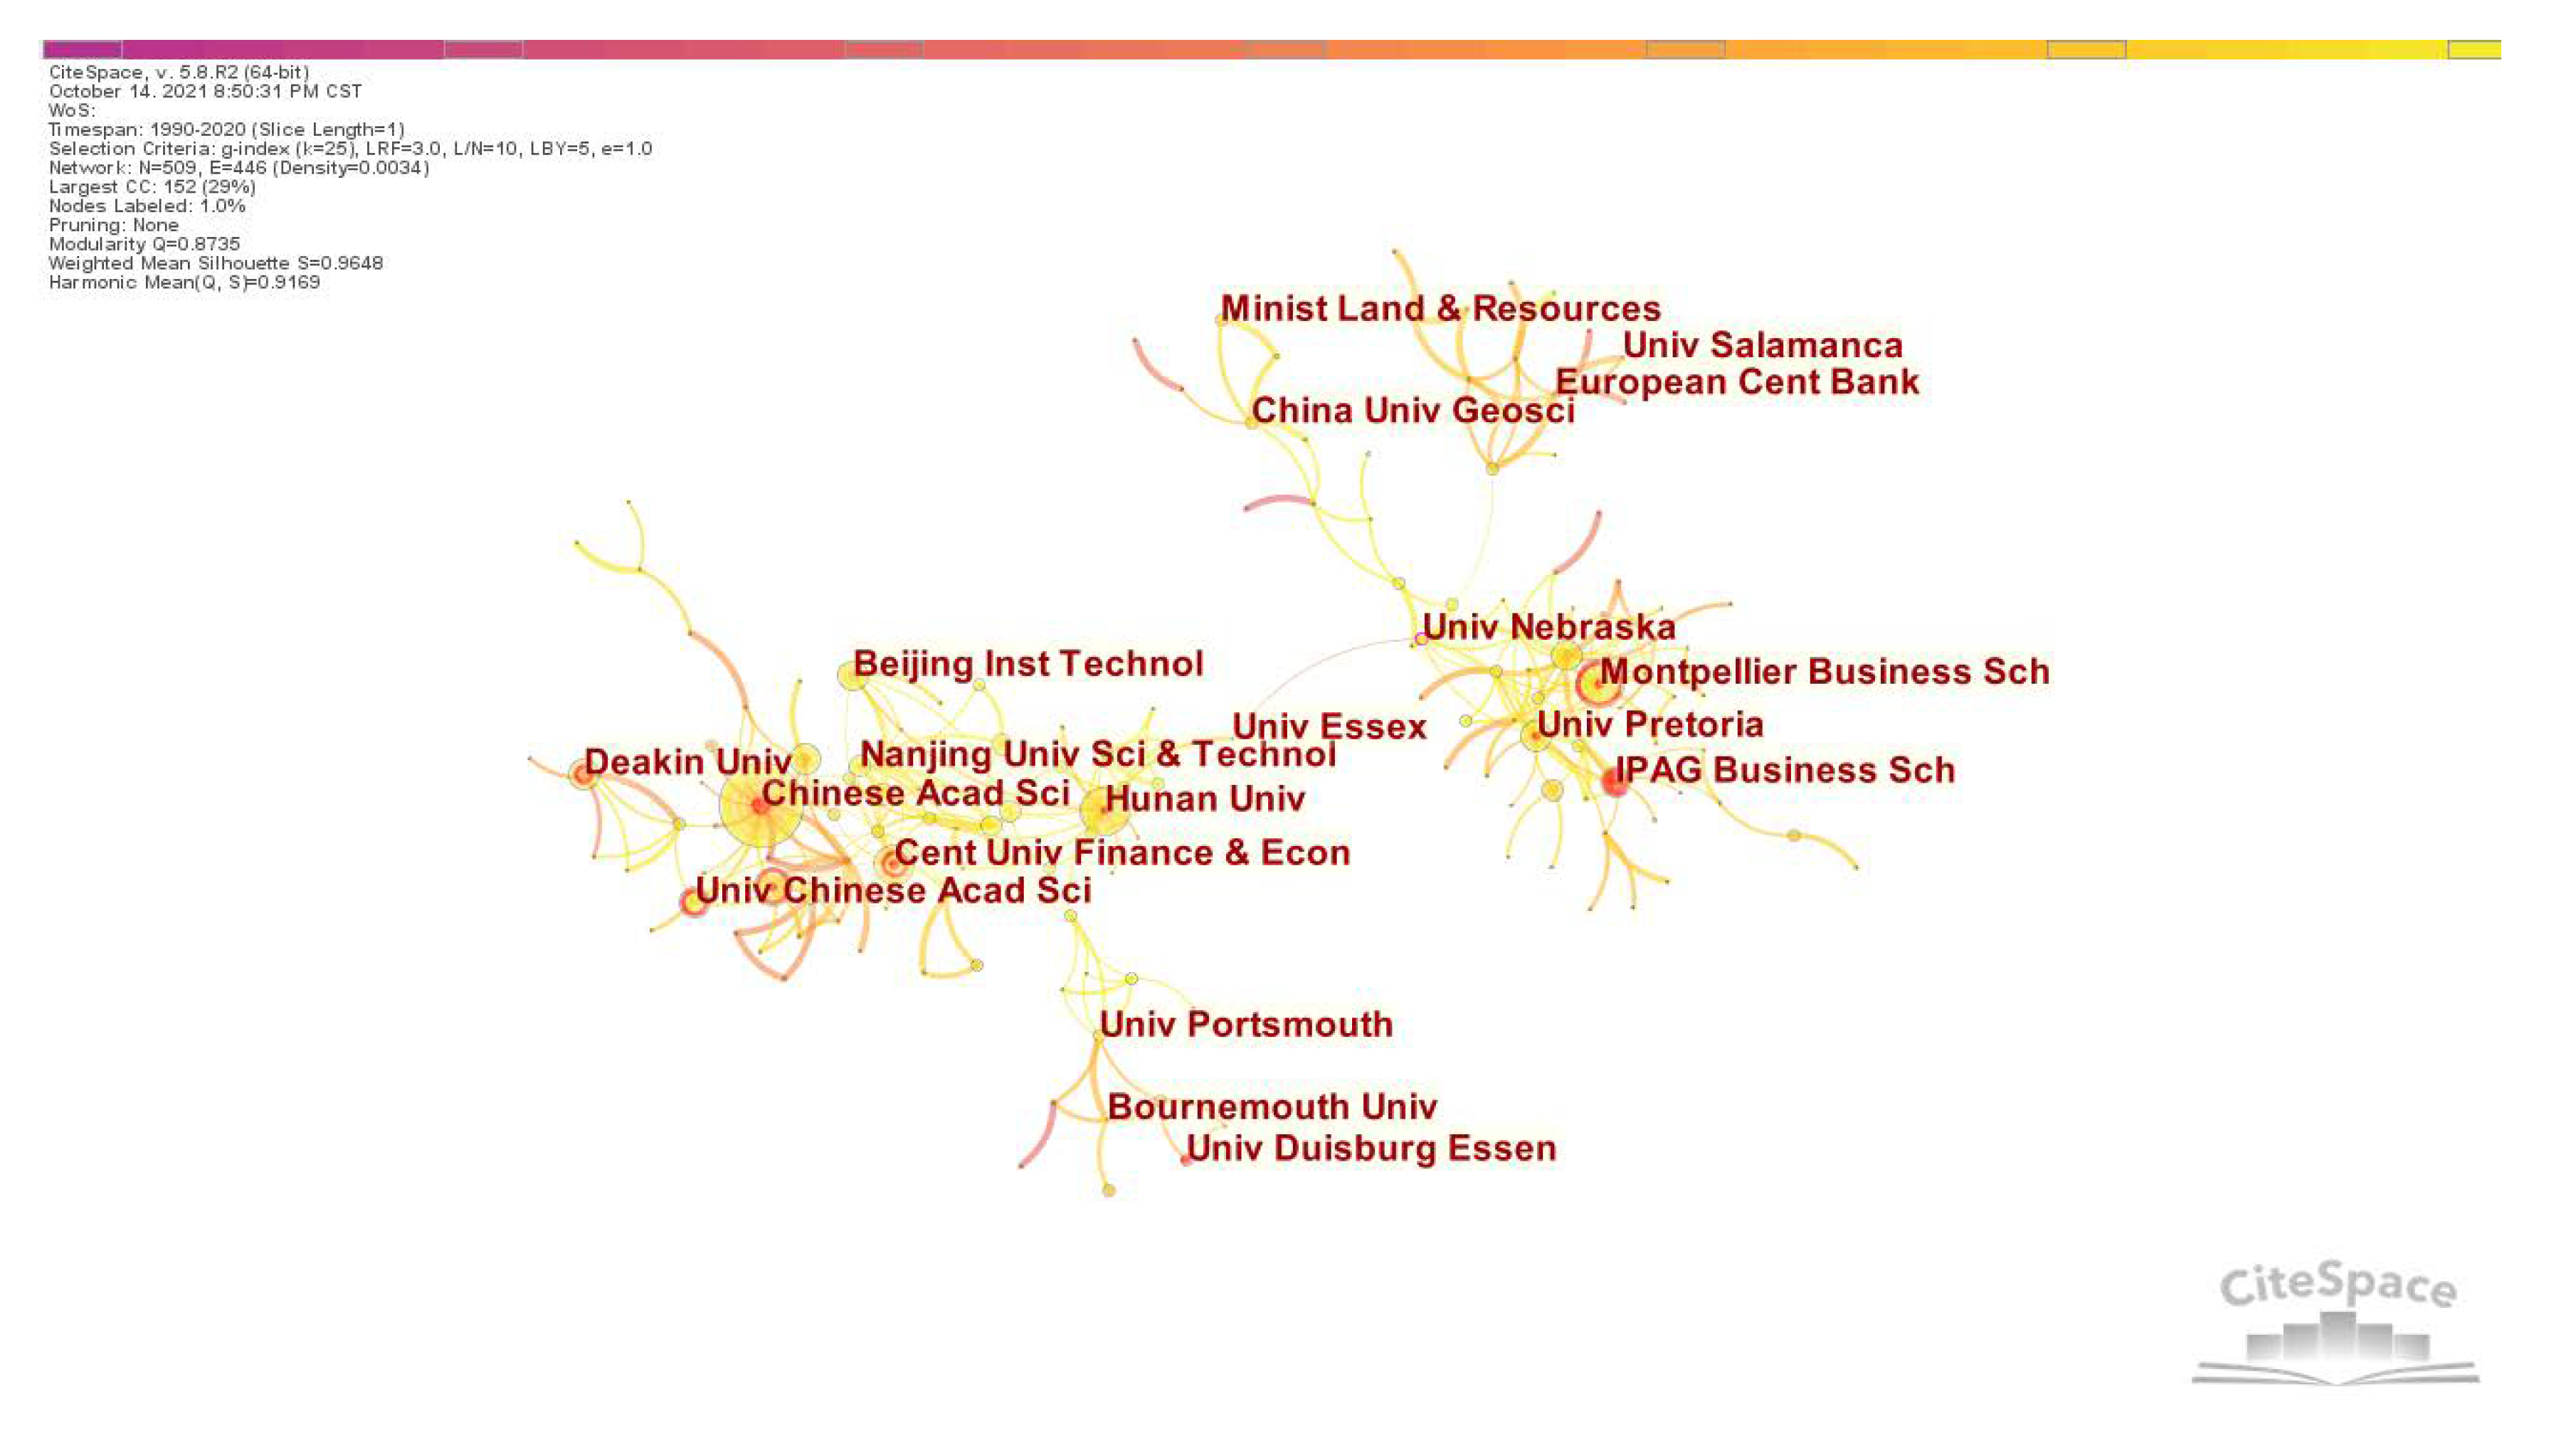
3.4. Analysis of High-Level Scientific Research Institutions
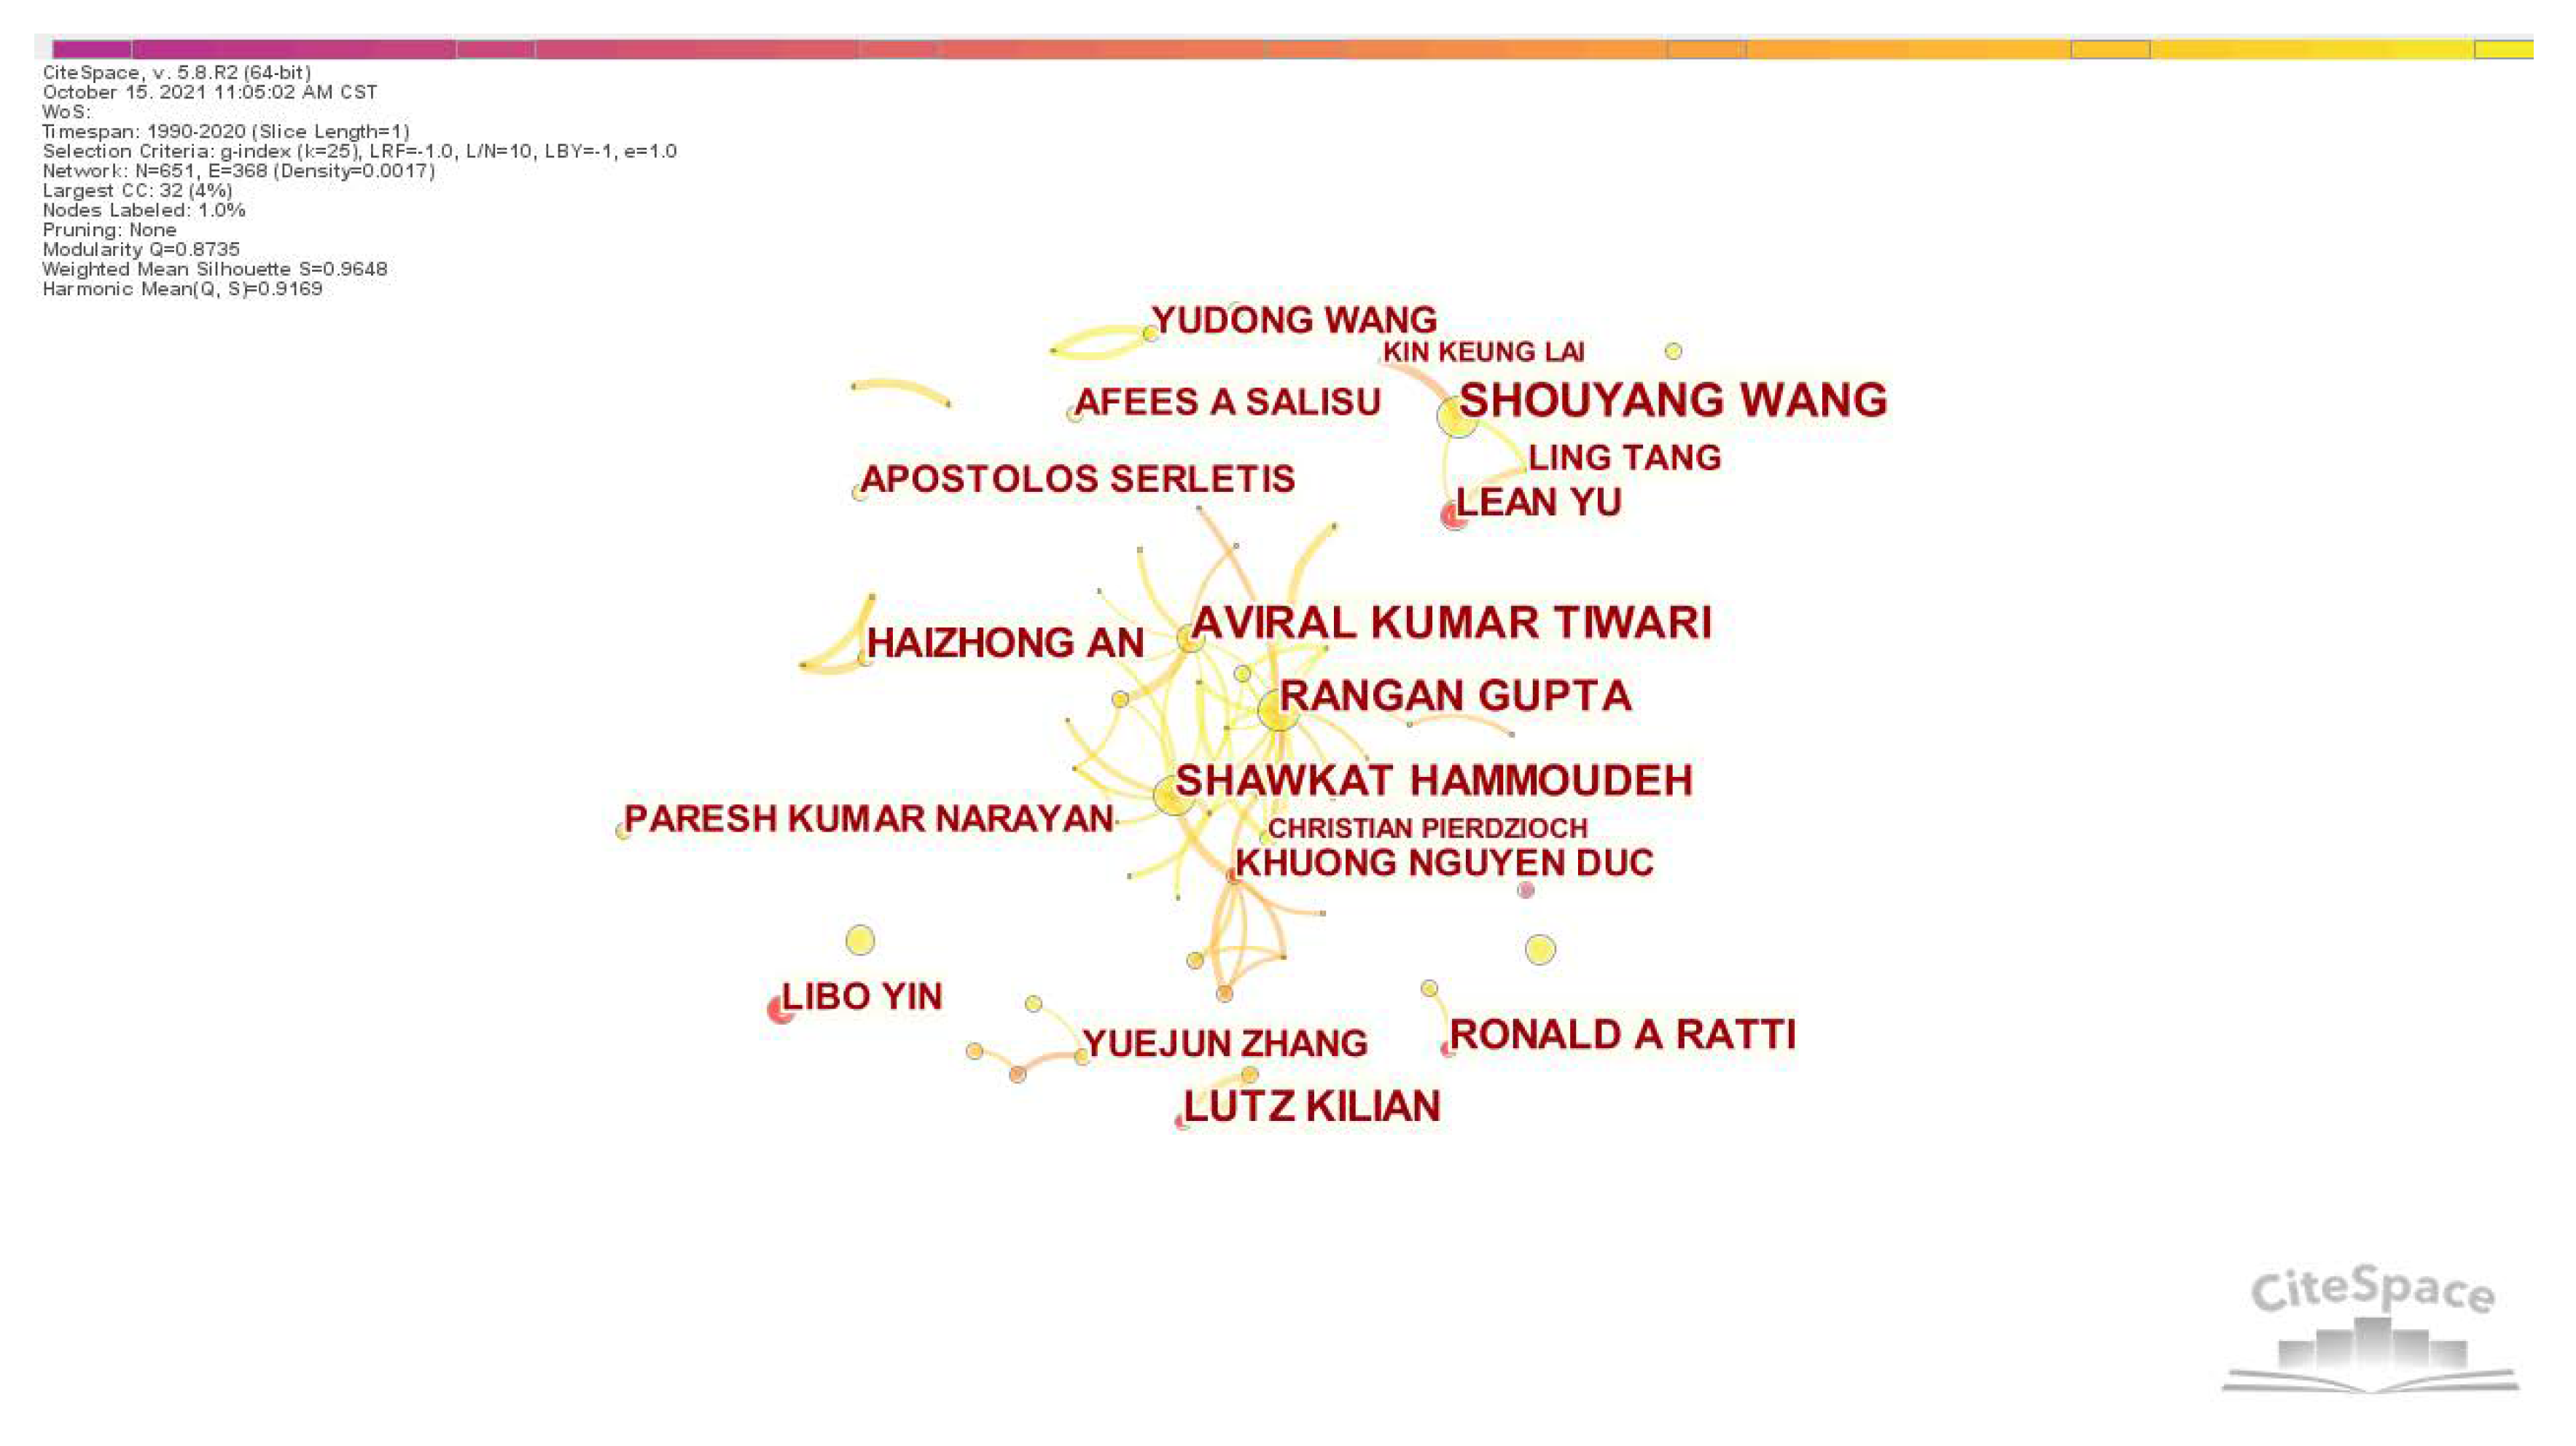
3.5. Analysis of Core Authors
4. Co-Citation Analysis of Commodity Prices
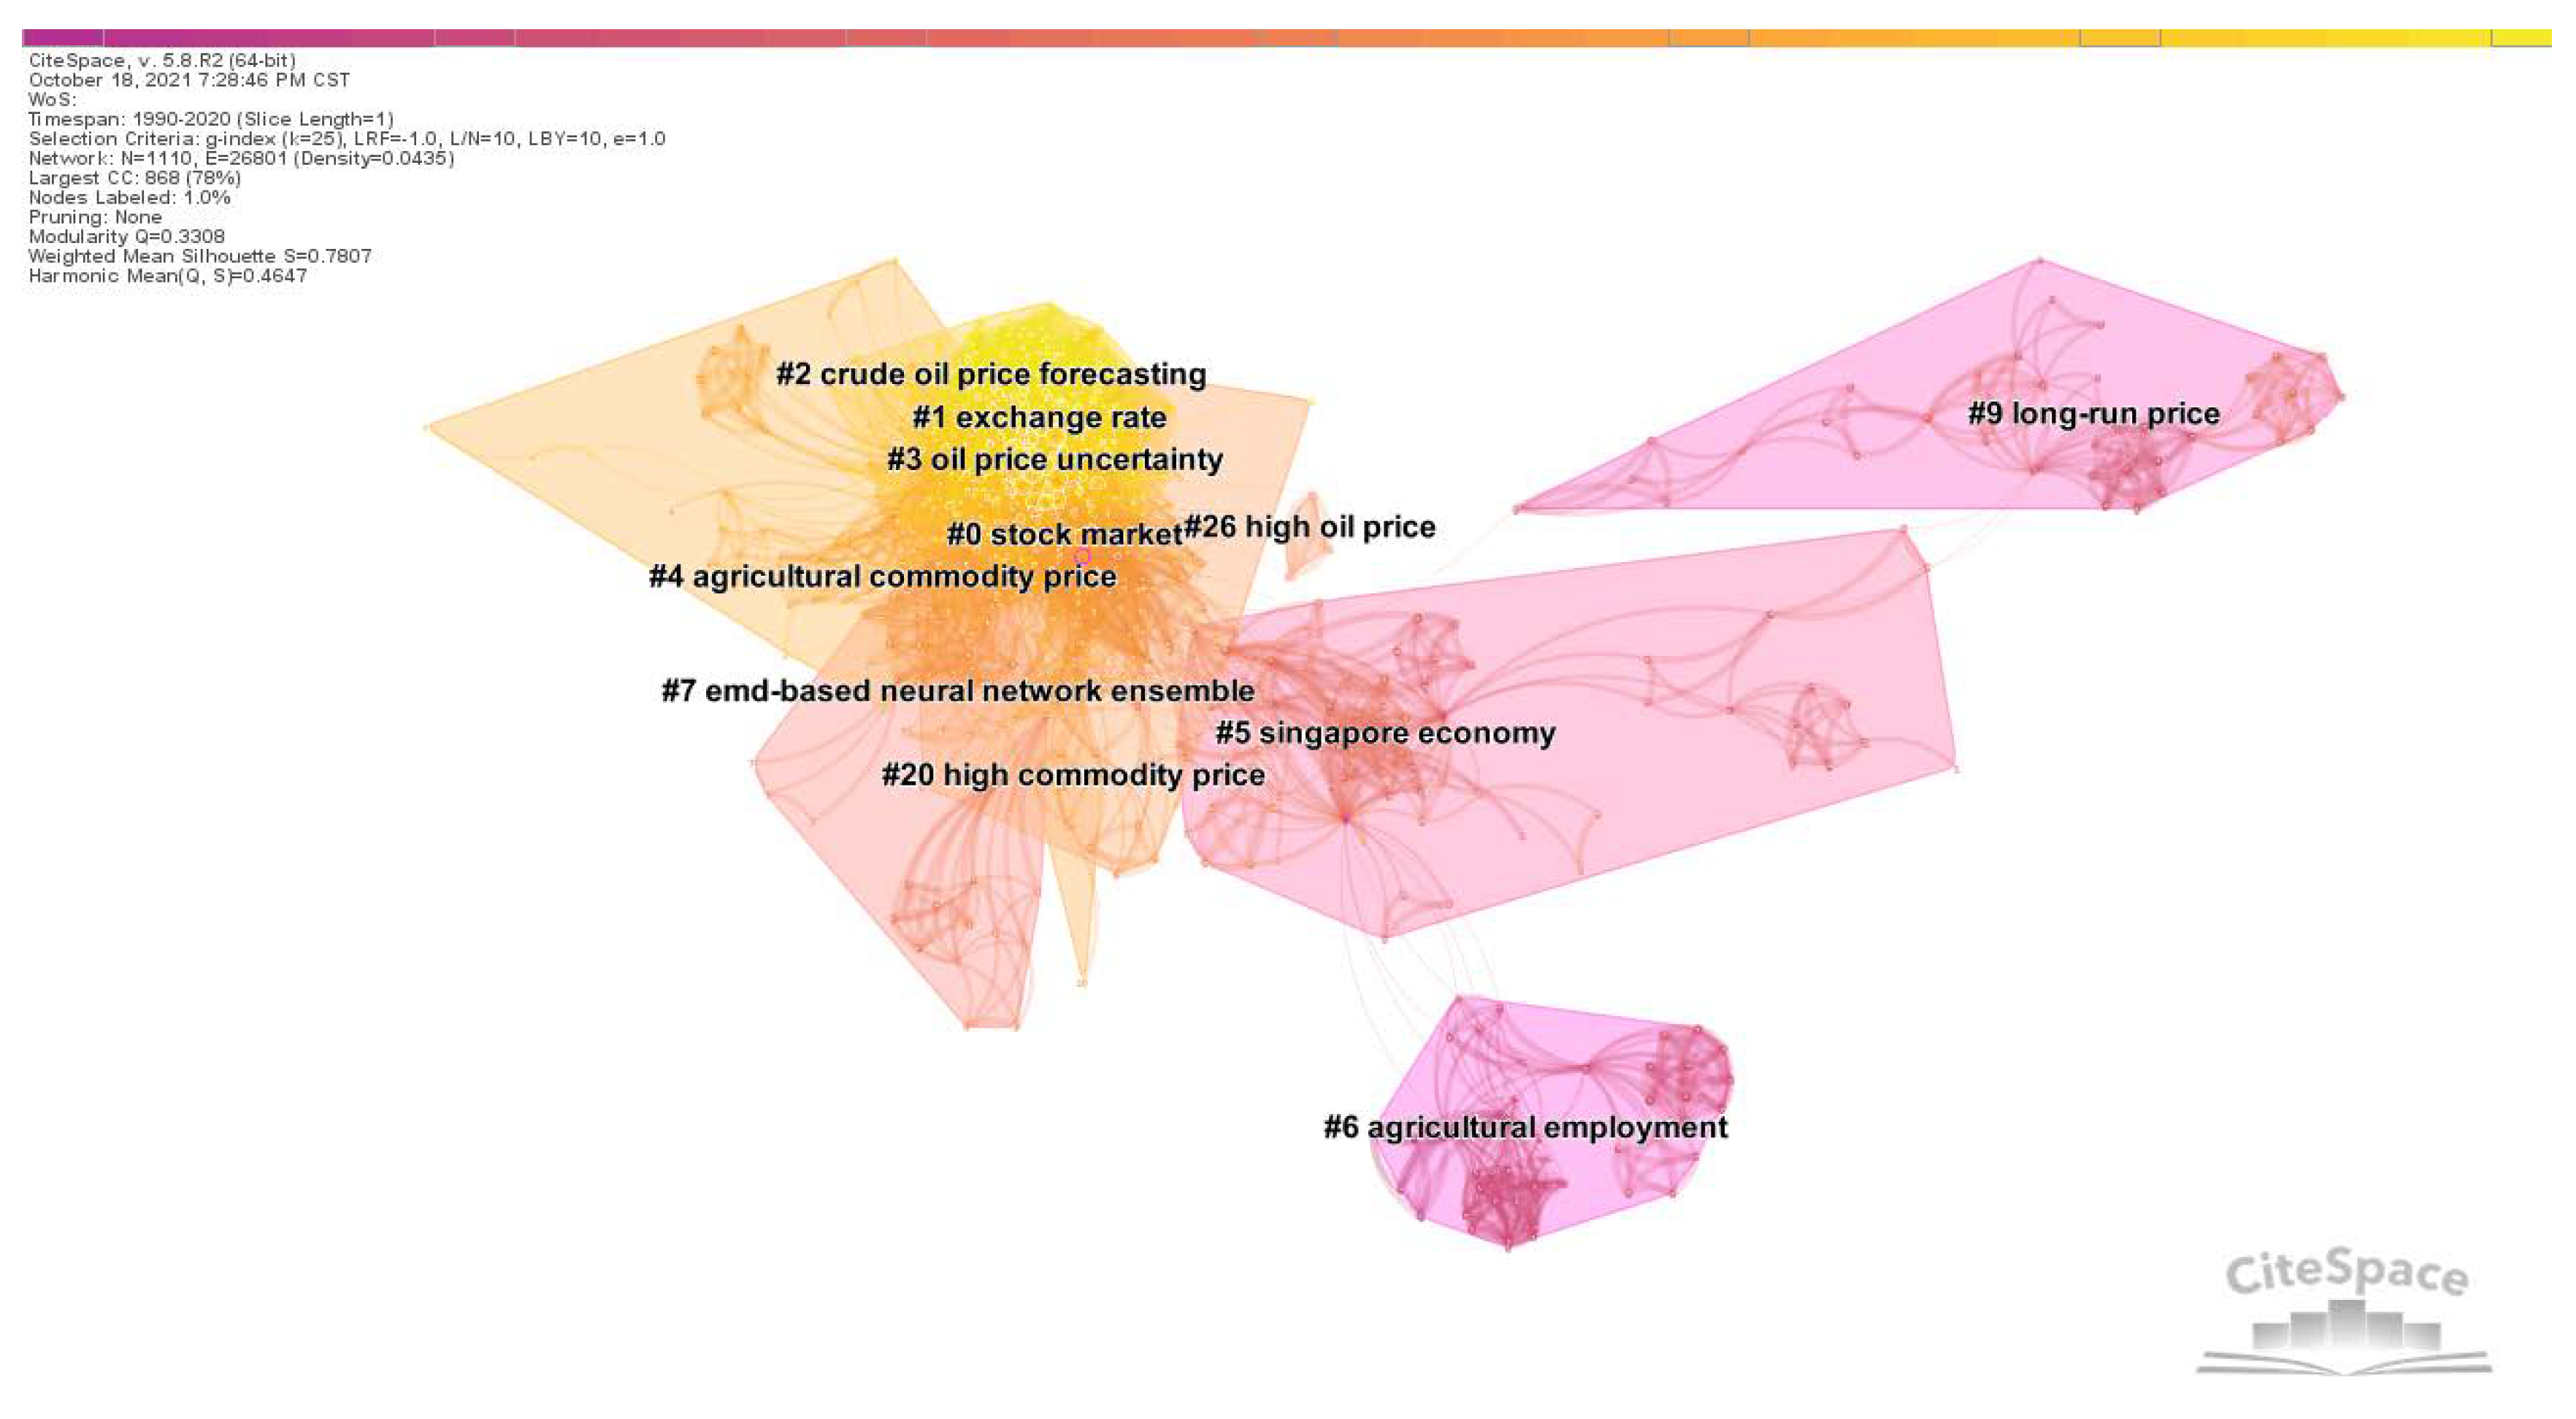
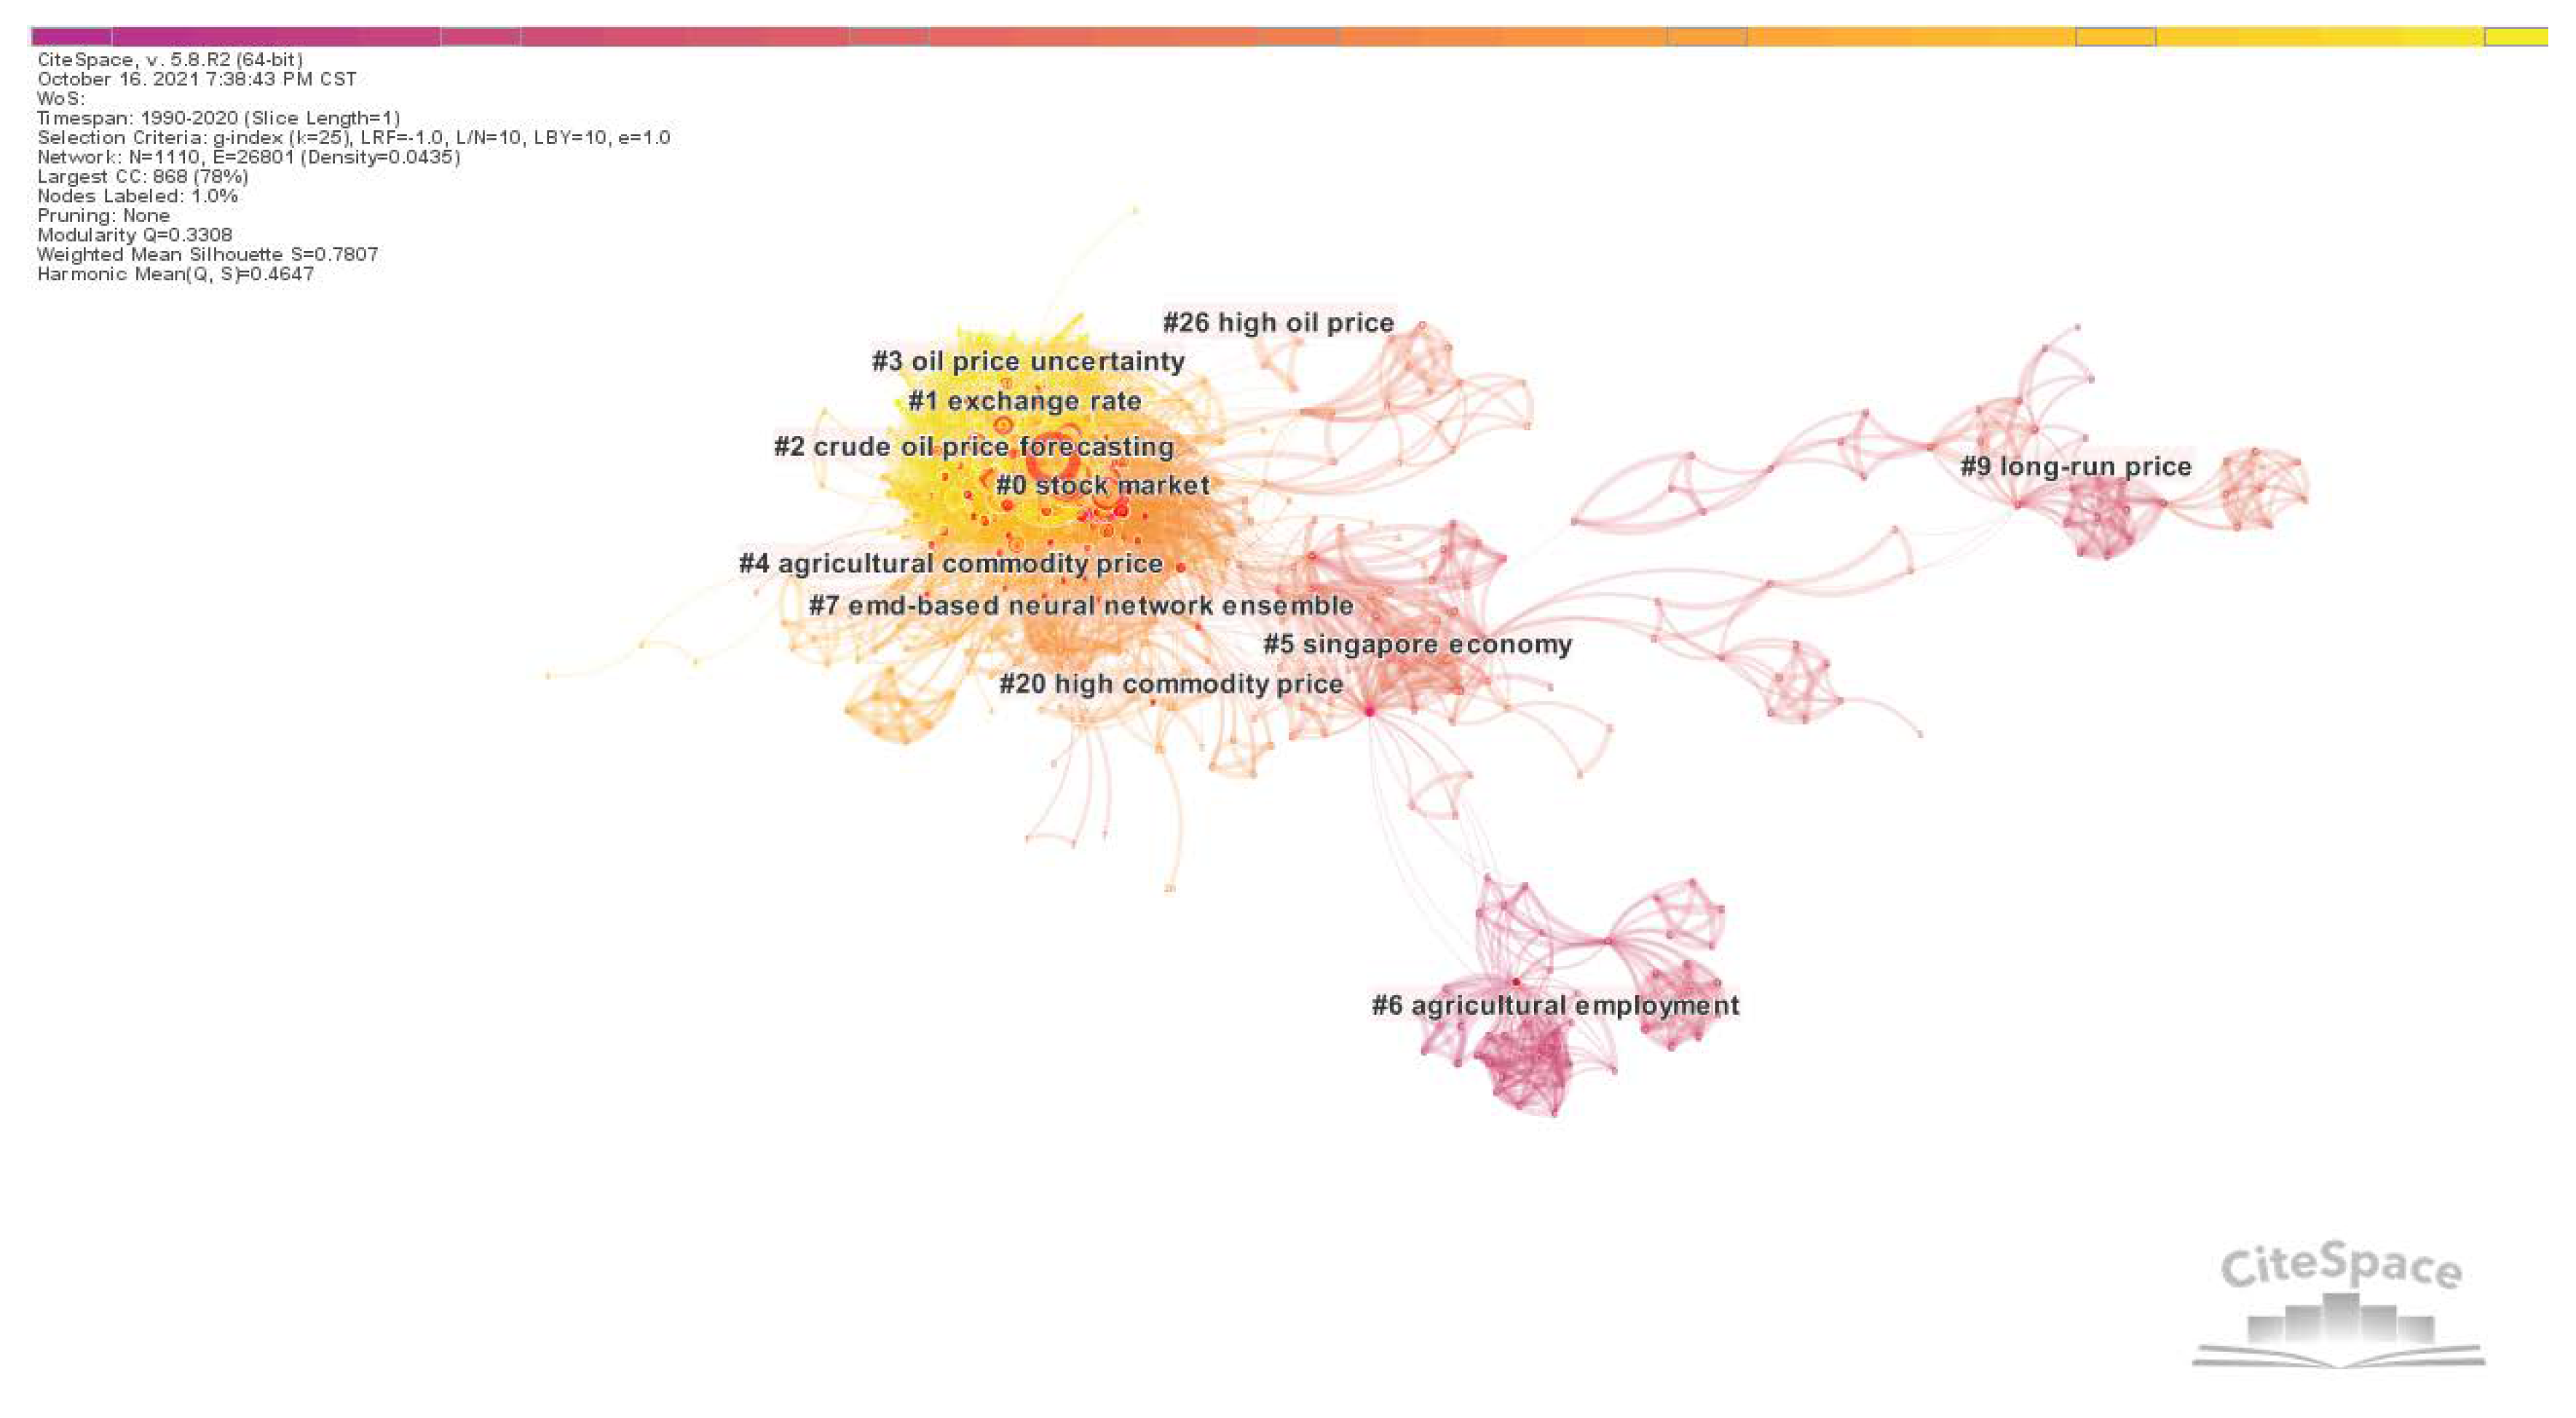
4.1. Cluster Analysis of Co-Cited Articles
- (1)
- Influencing factors of commodity prices (Cluster #1, #9, #20, #26)
- (2)
- The impact of commodity price fluctuations on macro economy (Cluster #3, #4, #5, #6)
- (3)
- Commodity price forecast (Cluster #2, #7)
- (4)
- Financialization of commodities (Cluster #0)

| Research Hotspots | Representative Articles | Main Research Content |
|---|---|---|
| Influencing factors of commodity prices | Hamilton (2009) [20] Dube and Vargas (2013) [25] Zhang et al. (2009) [29] |
|
| The impact of commodity price fluctuations on macroeconomy | Hamilton (1983) [30] Jiménez-Rodríguez (2005) [33] Lardic and Mignon (2006) [34] Ji et al. (2019) [42] Wu et al. (2012) [46] |
|
| Commodity price forecast | Yu et al. (2008) [65] Zhang et al. (2015) [68] Jammazi and Aloui (2012) [82] Zhao et al. (2017) [83] |
|
| Financialization of commodities | Sadorsky (1999) [70] Kilian and Park (2009) [74] Filis et al. (2011) [84] Sim and Zhou (2015) [85] |
|
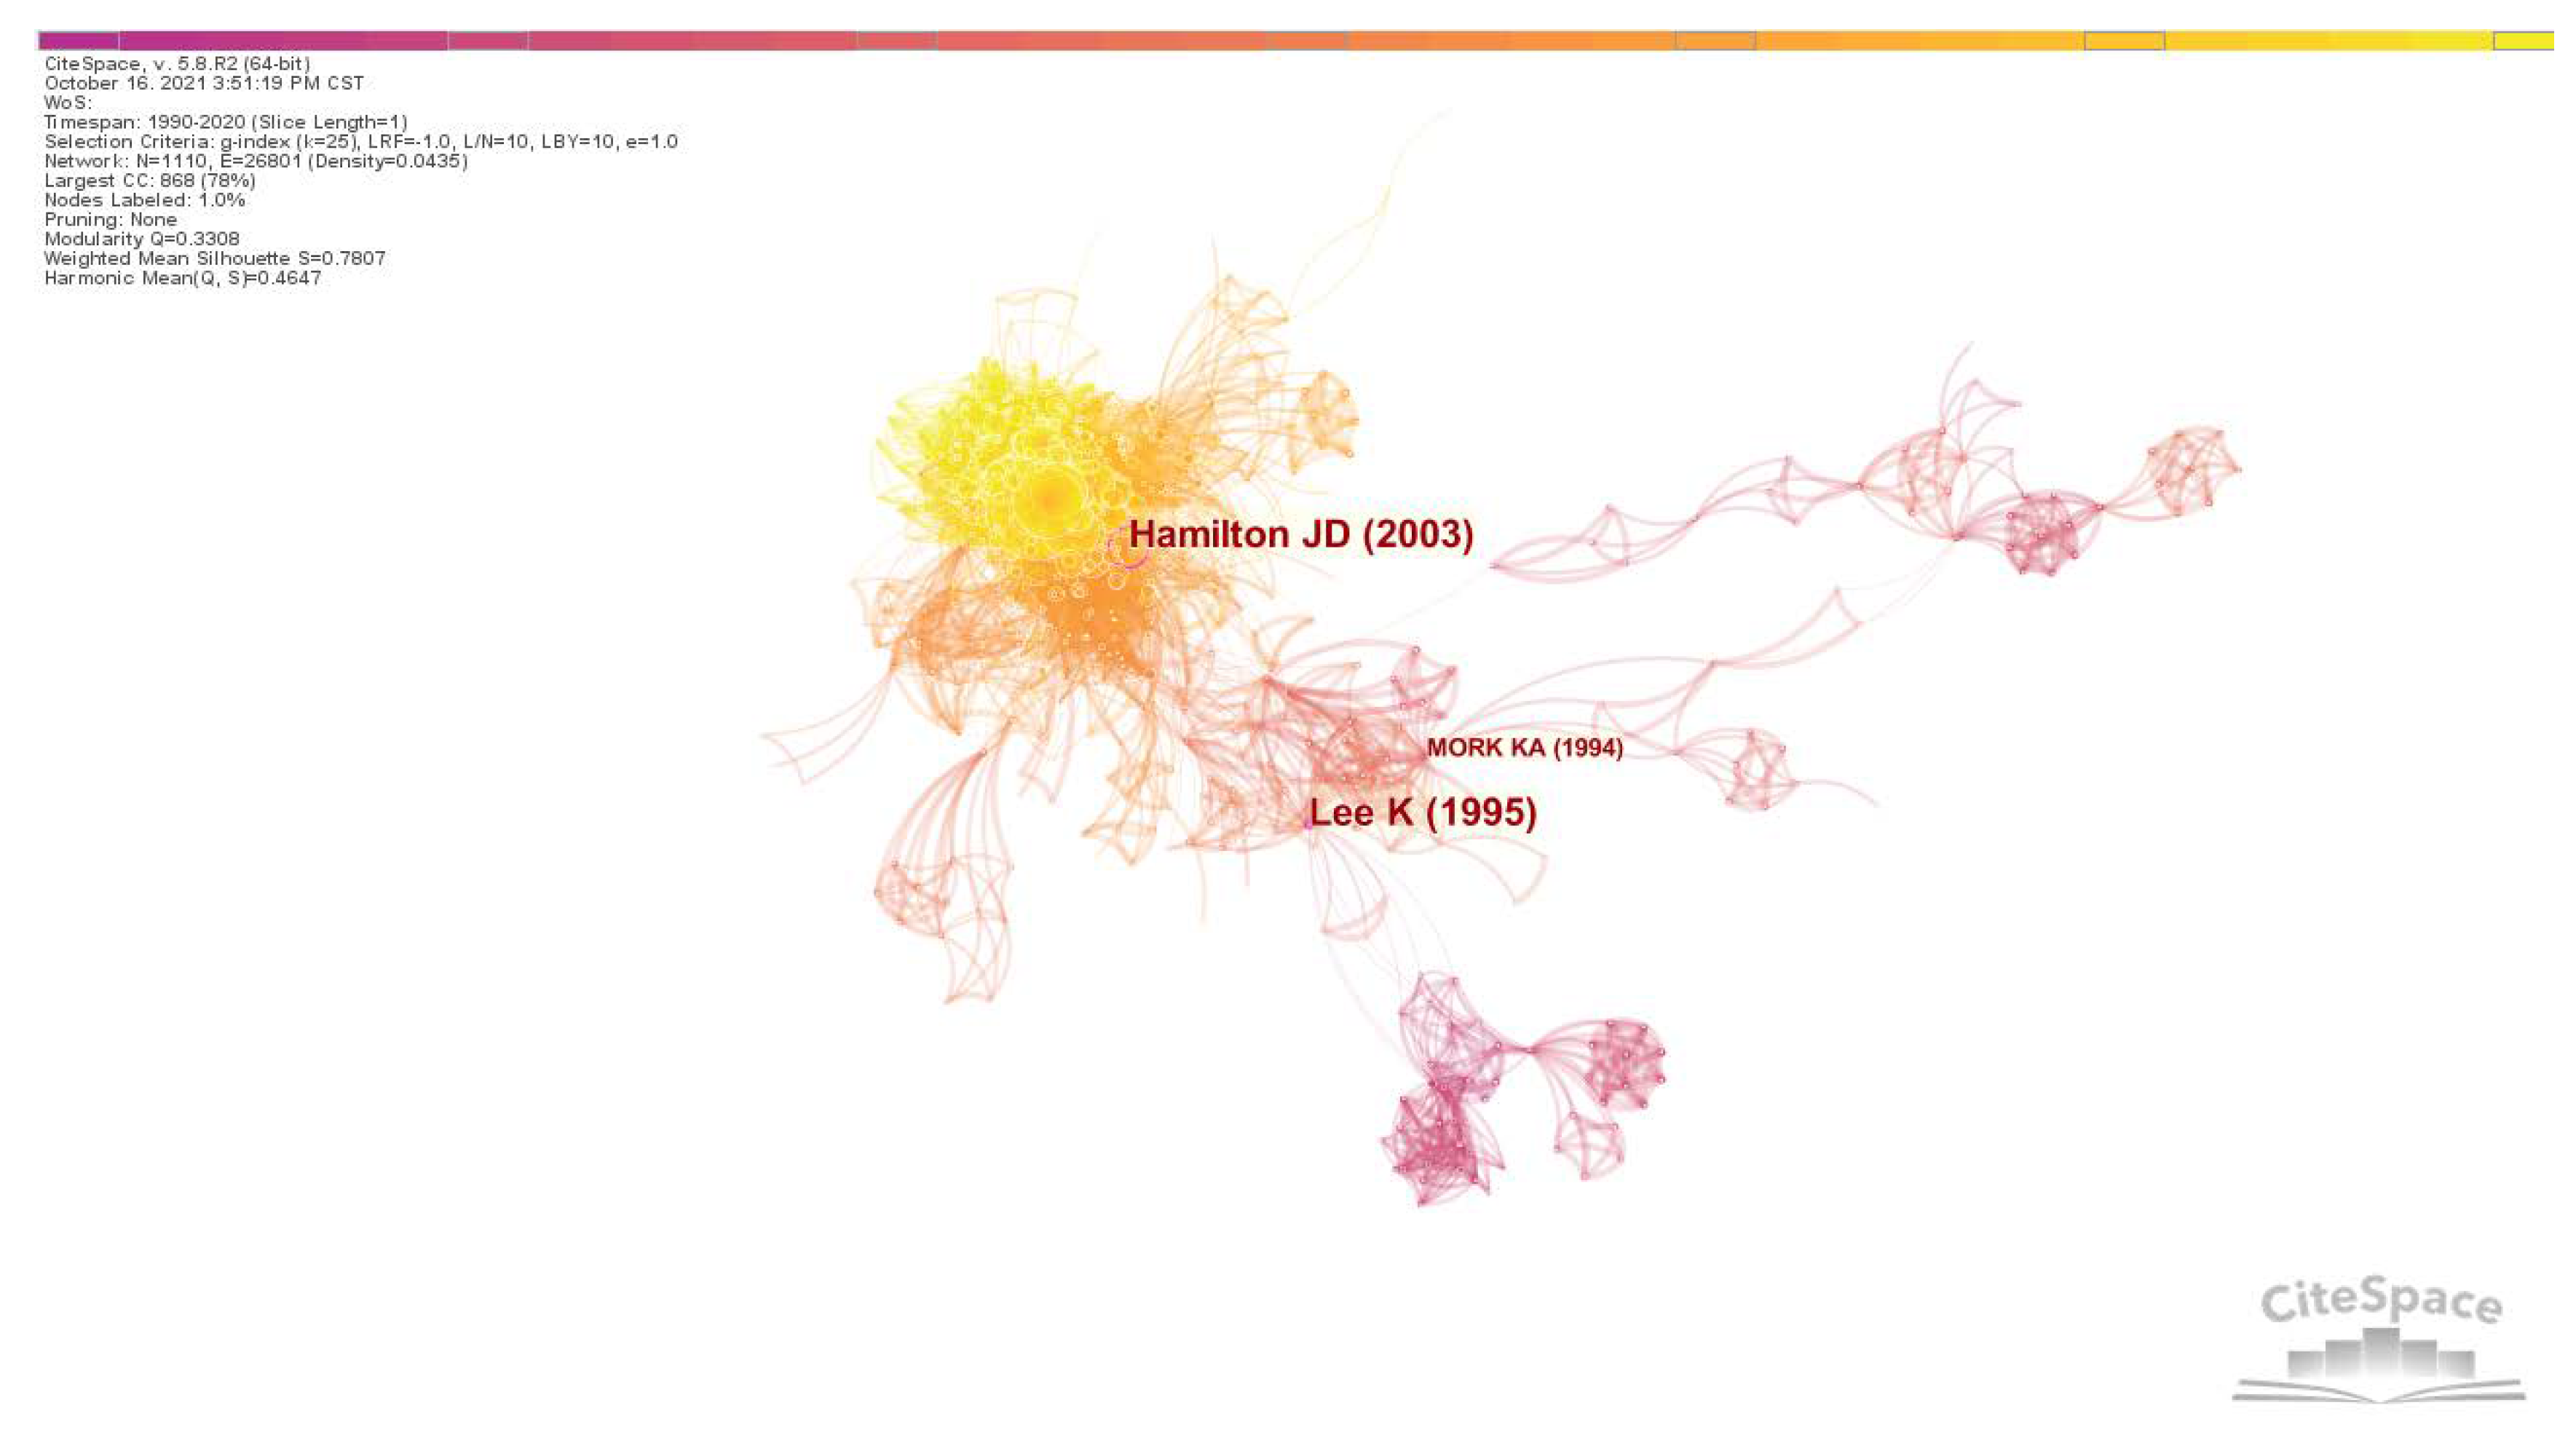
4.2. Analysis of Landmark and Pivot Nodes
| Author | Title | Journal | Cited Frequency | Cluster ID |
|---|---|---|---|---|
| Pivot node | ||||
| Lee et al. (1995) [86] | Oil shocks and the macroeconomy: The role of price variability | The Energy Journal | 24 | #5 |
| Mork et al. (1994) [87] | Macroeconomic responses to oil price increases and decreases in seven OECD countries | The Energy Journal | 23 | #5 |
| Landmark node | ||||
| Hamilton (2003) [88] | What is an oil shock? | Journal of Econometrics | 78 | #0 |
| Highly cited articles | ||||
| Kilian (2009) [74] | Not all oil price shocks are alike: Disentangling demand and supply shocks in the crude oil market | American Economic Review | 295 | #0 |
| Kilian and Park (2009) [90] | The impact of oil price shocks on the US stock market | International Economic Review | 158 | #1 |
| Park and Ratti (2008) [76] | Oil price shocks and stock markets in the US and 13 European countries | Energy Economics | 115 | #0 |
| Kilian and Murphy (2014) [91] | The role of inventories and speculative trading in the global market for crude oil | Journal of Applied Econometrics | 113 | #2 |
| Basher et al. (2012) [89] | Oil prices, stock returns and emerging stock markets | Energy Economics | 89 | #1 |
4.3. Analysis of References with Citation Bursts
5. Conclusions and Future New Research Direction
- (1)
- Increased attention to the impact of major events
- (2)
- Method innovation and selection of commodity price forecasting
Author Contributions
Funding
Institutional Review Board Statement
Informed Consent Statement
Data Availability Statement
Conflicts of Interest
References
- Jacks, D.S.; Stuermer, M. What drives commodity price booms and busts? Energy Econ. 2020, 85, 104035. [Google Scholar] [CrossRef] [Scilit]
- Ghoshray, A. Do international primary commodity prices exhibit asymmetric adjustment? J. Commod. Mark. 2019, 14, 40–50. [Google Scholar] [CrossRef] [Scilit]
- Carter, C.A.; Rausser, G.C.; Smith, A. Commodity booms and busts. Annu. Rev. Resour. Econ. 2011, 3, 87–118. [Google Scholar] [CrossRef] [Scilit]
- Paolantonio, A. OECD-FAO, Agricultural Outlook 2008–2017; Firenze University Press: Firenze, Italy, 2008; pp. 119–123. Available online: http://digital.casalini.it/10.1400/185067 (accessed on 4 October 2021).
- Knez, S.; Šimić, G.; Milovanović, A.; Starikova, S.; Županič, F.Ž. Prices of conventional and renewable energy as determinants of sustainable and secure energy development: Regression model analysis. Energy Sustain. Soc. 2022, 12, 6. [Google Scholar] [CrossRef] [Scilit]
- Wang, G.; Sharma, P.; Jain, V.; Shukla, A.; Shahzad Shabbir, M.; Tabash, M.I.; Chawla, C. The relationship among oil prices volatility, inflation rate, and sustainable economic growth: Evidence from top oil importer and exporter countries. Resour. Policy 2022, 77, 102674. [Google Scholar] [CrossRef] [Scilit]
- Sajid, M.J.; Yu, Z.; Rehman, S.A. The coal, petroleum, and gas embedded in the sectoral demand-and-supply chain: Evidence from China. Sustainability 2022, 14, 1888. [Google Scholar] [CrossRef] [Scilit]
- Borzuei, D.; Moosavian, S.F.; Ahmadi, A. Investigating the dependence of energy prices and economic growth rates with emphasis on the development of renewable energy for sustainable development in Iran. Sustain. Dev. 2022, 1–7. [Google Scholar] [CrossRef] [Scilit]
- Gracia, A.; Gómez, M.I. Food sustainability and waste reduction in Spain: Consumer preferences for local, suboptimal, and/or unwashed fresh food products. Sustainability 2020, 12, 4148. [Google Scholar] [CrossRef] [Scilit]
- Khan, M.M.; Akram, M.T.; Janke, R.; Qadri, R.W.K.; Al-Sadi, A.M.; Farooque, A.A. Urban horticulture for food secure cities through and beyond COVID-19. Sustainability 2020, 12, 9592. [Google Scholar] [CrossRef] [Scilit]
- Yang, M.X.; Chen, W.S.; Zhou, Q.Y.; Yang, B.Y. Visualizing the landscape and trend of Chinese leadership research: 1949–2018. Nankai Bus. Rev. 2019, 22, 80–94. [Google Scholar]
- Chiroma, H.; Abdul-kareem, S.; Shukri Mohd Noor, A.; Abubakar, A.I.; Sohrabi Safa, N.; Shuib, L.; Fatihu Hamza, M.; Ya’u Gital, A.; Herawan, T. A review on artificial intelligence methodologies for the forecasting of crude oil price. Intell. Autom. Soft Comput. 2016, 22, 449–462. [Google Scholar] [CrossRef] [Scilit]
- Ederington, L.H.; Fernando, C.S.; Hoelscher, S.A.; Lee, T.K.; Linn, S.C. A review of the evidence on the relation between crude oil prices and petroleum product prices. J. Commod. Mark. 2019, 13, 1–15. [Google Scholar] [CrossRef] [Scilit]
- Ben Abdallah, M.; Fekete-Farkas, M.; Lakner, Z. Exploring the link between food security and food price dynamics: A bibliometric analysis. Agriculture 2021, 11, 263. [Google Scholar] [CrossRef] [Scilit]
- Leung, X.Y.; Sun, J.; Bai, B. Bibliometrics of social media research: A co-citation and co-word analysis. Int. J. Hosp. Manag. 2017, 66, 35–45. [Google Scholar] [CrossRef] [Scilit]
- Van Eck, N.J.; Waltman, L. Visualizing Bibliometric Networks; Springer: Cham, Switzerland, 2014; pp. 285–320. [Google Scholar] [CrossRef] [Scilit]
- Liu, H.; Li, X.; Wang, S. A bibliometric analysis of 30 years of platform research: Developing the research agenda for platforms, the associated technologies and social impacts. Technol. Forecast. Soc. Chang. 2021, 169, 682–689. [Google Scholar] [CrossRef] [Scilit]
- Li, X.R.; Zhang, X.X.; Li, Z.Y. A bibliometric analysis on business models. Syst. Eng. Theory Pract. 2016, 36, 273–287. [Google Scholar]
- Li, J.; Chen, C.M. Text Mining and Visualization in Scientific Literature, 2nd ed.; Capital University of Economics and Business Press: Beijing, China, 2017. [Google Scholar]
- Hamilton, J.D. Understanding crude oil prices. Energy J. 2009, 30, 179–206. [Google Scholar] [CrossRef] [Scilit]
- Mueller, S.A.; Anderson, J.E.; Wallington, T.J. Impact of biofuel production and other supply and demand factors on food price increases in 2008. Biomass Bioenergy 2011, 35, 1623–1632. [Google Scholar] [CrossRef] [Scilit]
- Awan, O.A. Price discovery or noise: The role of arbitrage and speculation in explaining crude oil price behaviour. J. Commod. Mark. 2019, 16, 100086. [Google Scholar] [CrossRef] [Scilit]
- Baumeister, C.; Kilian, L. Forty years of oil price fluctuations: Why the price of oil may still surprise us. J. Econ. Perspect. 2016, 30, 139–160. [Google Scholar] [CrossRef] [Scilit]
- Chen, S.-T.; Kuo, H.-I.; Chen, C.-C. Modeling the relationship between the oil price and global food prices. Appl. Energy 2010, 87, 2517–2525. [Google Scholar] [CrossRef] [Scilit]
- Dube, O.; Vargas, J.F. Commodity price shocks and civil conflict: Evidence from Colombia. Rev. Econ. Stud. 2013, 80, 1384–1421. [Google Scholar] [CrossRef] [Scilit]
- Gilbert, C.L.; Morgan, C.W. Food price volatility. Philos. Trans. R. Soc. B. Biol. Sci. 2010, 365, 3023–3034. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Ji, Q.; Guo, J.-F. Oil price volatility and oil-related events: An Internet concern study perspective. Appl. Energy 2015, 137, 256–264. [Google Scholar] [CrossRef] [Scilit]
- Nazlioglu, S. World oil and agricultural commodity prices: Evidence from nonlinear causality. Energy Policy 2011, 39, 2935–2943. [Google Scholar] [CrossRef] [Scilit]
- Zhang, X.; Yu, L.; Wang, S.; Lai, K.K. Estimating the impact of extreme events on crude oil price: An EMD-based event analysis method. Energy Econ. 2009, 31, 768–778. [Google Scholar] [CrossRef] [Scilit]
- Hamilton, J.D. Oil and the macroeconomy since World War II. J. Political Econ. 1983, 91, 228–248. [Google Scholar] [CrossRef] [Scilit]
- Balcilar, M.; Van Eyden, R.; Uwilingiye, J.; Gupta, R. The impact of oil price on South African GDP growth: A Bayesian Markov switching-VAR analysis. Afr. Dev. Rev. 2017, 29, 319–336. [Google Scholar] [CrossRef] [Scilit]
- Benhmad, F. Dynamic cyclical comovements between oil prices and US GDP: A wavelet perspective. Energy Policy 2013, 57, 141–151. [Google Scholar] [CrossRef] [Scilit]
- Jiménez-Rodríguez, R.; Sánchez, M. Oil price shocks and real GDP growth: Empirical evidence for some OECD countries. Appl. Econ. 2005, 37, 201–228. [Google Scholar] [CrossRef] [Scilit]
- Lardic, S.; Mignon, V. The impact of oil prices on GDP in European countries: An empirical investigation based on asymmetric cointegration. Energy Policy 2006, 34, 3910–3915. [Google Scholar] [CrossRef] [Scilit]
- Jiménez-Rodríguez, R. Oil price shocks and real GDP growth: Testing for non-linearity. Energy J. 2009, 30, 1–23. [Google Scholar] [CrossRef] [Scilit]
- Khan, M.A.; Husnain, M.I.U.; Abbas, Q.; Shah, S.Z.A. Asymmetric effects of oil price shocks on Asian economies: A nonlinear analysis. Empir. Econ. 2018, 57, 1319–1350. [Google Scholar] [CrossRef] [Scilit]
- Kilian, L.; Vigfusson, R.J. Do oil prices help forecast U.S. real GDP? The role of nonlinearities and asymmetries. J. Bus. Econ. Stat. 2013, 31, 78–93. [Google Scholar] [CrossRef] [Scilit]
- Chen, S.S.; Chen, H.C. Oil prices and real exchange rates. Energy Econ. 2007, 29, 390–404. [Google Scholar] [CrossRef] [Scilit]
- Aloui, R.; Ben Aïssa, M.S.; Nguyen, D.K. Conditional dependence structure between oil prices and exchange rates: A copula-GARCH approach. J. Int. Money Financ. 2013, 32, 719–738. [Google Scholar] [CrossRef] [Scilit]
- Ghosh, S. Examining crude oil price—Exchange rate nexus for India during the period of extreme oil price volatility. Appl. Energy 2011, 88, 1886–1889. [Google Scholar] [CrossRef] [Scilit]
- Huang, Y.; Guo, F. The role of oil price shocks on China’s real exchange rate. China Econ. Rev. 2007, 18, 403–416. [Google Scholar] [CrossRef] [Scilit]
- Ji, Q.; Liu, B.-Y.; Fan, Y. Risk dependence of CoVaR and structural change between oil prices and exchange rates: A time-varying copula model. Energy Econ. 2019, 77, 80–92. [Google Scholar] [CrossRef] [Scilit]
- Reboredo, J.C.; Rivera-Castro, M.A. A wavelet decomposition approach to crude oil price and exchange rate dependence. Econ. Model. 2013, 32, 42–57. [Google Scholar] [CrossRef] [Scilit]
- Sari, R.; Hammoudeh, S.; Soytas, U. Dynamics of oil price, precious metal prices, and exchange rate. Energy Econ. 2010, 32, 351–362. [Google Scholar] [CrossRef] [Scilit]
- Tule, M.K.; Salisu, A.A.; Chiemeke, C.C. Can agricultural commodity prices predict Nigeria’s inflation? J. Commod. Mark. 2019, 16, 100087. [Google Scholar] [CrossRef] [Scilit]
- Wu, C.-C.; Chung, H.; Chang, Y.-H. The economic value of co-movement between oil price and exchange rate using copula-based GARCH models. Energy Econ. 2012, 34, 270–282. [Google Scholar] [CrossRef] [Scilit]
- Papapetrou, E. Oil price shocks, stock market, economic activity and employment in Greece. Energy Econ. 2001, 23, 511–532. [Google Scholar] [CrossRef] [Scilit]
- Ewing, B.T.; Thompson, M.A. Dynamic cyclical comovements of oil prices with industrial production, consumer prices, unemployment, and stock prices. Energy Policy 2007, 35, 5535–5540. [Google Scholar] [CrossRef] [Scilit]
- Guerrero-Escobar, S.; Hernandez-del-Valle, G.; Hernandez-Vega, M. Do heterogeneous countries respond differently to oil price shocks? J. Commod. Mark. 2019, 16, 100084. [Google Scholar] [CrossRef] [Scilit]
- Li, R.; Leung, G.C.K. The relationship between energy prices, economic growth and renewable energy consumption: Evidence from Europe. Energy Rep. 2021, 7, 1712–1719. [Google Scholar] [CrossRef] [Scilit]
- Mukhtarov, S.; Mikayilov, J.I.; Humbatova, S.; Muradov, V. Do high oil prices obstruct the transition to renewable energy consumption? Sustainability 2020, 12, 4689. [Google Scholar] [CrossRef] [Scilit]
- Karacan, R.; Mukhtarov, S.; Barış, İ.; İşleyen, A.; Yardımcı, M.E. The impact of oil price on transition toward renewable energy consumption? Evidence from Russia. Energies 2021, 14, 2947. [Google Scholar] [CrossRef] [Scilit]
- Mukhtarov, S.; Mikayilov, J.I.; Maharramov, S.; Aliyev, J.; Suleymanov, E. Higher oil prices, are they good or bad for renewable energy consumption: The case of Iran? Renew. Energy 2022, 186, 411–419. [Google Scholar] [CrossRef] [Scilit]
- Umar, B.; Alam, M.M.; Al-Amin, A.Q. Exploring the contribution of energy price to carbon emissions in African countries. Environ. Sci. Pollut. Res. Int. 2021, 28, 1973–1982. [Google Scholar] [CrossRef] [Scilit]
- Ma, Y.; Zhang, L.; Song, S.; Yu, S. Impacts of energy price on agricultural production, energy consumption, and carbon emission in China: A Price Endogenous Partial Equilibrium Model Analysis. Sustainability 2022, 14, 3002. [Google Scholar] [CrossRef] [Scilit]
- Sha, R.; Ge, T.; Li, J. How Energy price distortions affect China’s economic growth and carbon emissions. Sustainability 2022, 14, 7312. [Google Scholar] [CrossRef] [Scilit]
- Lee, S.; Chong, W.O. Causal relationships of energy consumption, price, and CO2 emissions in the U.S. building sector. Resour. Conserv. Recycl. 2016, 107, 220–226. [Google Scholar] [CrossRef] [Scilit]
- Guo, Z.; Zhang, X.; Wang, D.; Zhao, X. The impacts of an energy price decline associated with a carbon tax on the energy-economy-environment system in China. Emerg. Mark. Financ. Trade 2019, 55, 2689–2702. [Google Scholar] [CrossRef] [Scilit]
- Malik, M.Y.; Latif, K.; Khan, Z.; Butt, H.D.; Hussain, M.; Nadeem, M.A. Symmetric and asymmetric impact of oil price, FDI and economic growth on carbon emission in Pakistan: Evidence from ARDL and non-linear ARDL approach. Sci. Total Environ. 2020, 726, 138421. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Ike, G.N.; Usman, O.; Alola, A.A.; Sarkodie, S.A. Environmental quality effects of income, energy prices and trade: The role of renewable energy consumption in G-7 countries. Sci. Total Environ. 2020, 721, 137813. [Google Scholar] [CrossRef] [Scilit]
- Huang, S.-C.; Wu, C.-F. Energy commodity price forecasting with deep multiple kernel learning. Energies 2018, 11, 3029. [Google Scholar] [CrossRef] [Scilit]
- Herrera, A.M.; Hu, L.; Pastor, D. Forecasting crude oil price volatility. Int. J. Forecast. 2018, 34, 3029. [Google Scholar] [CrossRef] [Scilit]
- Gupta, R.; Wohar, M. Forecasting oil and stock returns with a Qual VAR using over 150 years off data. Energy Econ. 2017, 62, 181–186. [Google Scholar] [CrossRef] [Scilit]
- Gavriilidis, K.; Kambouroudis, D.S.; Tsakou, K.; Tsouknidis, D.A. Volatility forecasting across tanker freight rates: The role of oil price shocks. Transp. Res. Part E Logist. Transp. Rev. 2018, 118, 376–391. [Google Scholar] [CrossRef] [Scilit]
- Yu, L.; Wang, S.; Lai, K.K. Forecasting crude oil price with an EMD-based neural network ensemble learning paradigm. Energy Econ. 2008, 30, 2623–2635. [Google Scholar] [CrossRef] [Scilit]
- Wang, J.; Li, X. A combined neural network model for commodity price forecasting with SSA. Soft Comput. 2018, 22, 5323–5333. [Google Scholar] [CrossRef] [Scilit]
- Zhang, Y.; Na, S. A Novel agricultural commodity price forecasting model based on fuzzy information granulation and MEA-SVM model. Math. Probl. Eng. 2018, 2018, 2540681. [Google Scholar] [CrossRef] [Scilit]
- Zhang, J.-L.; Zhang, Y.-J.; Zhang, L. A novel hybrid method for crude oil price forecasting. Energy Econ. 2015, 49, 649–659. [Google Scholar] [CrossRef] [Scilit]
- Kristjanpoller, W.; Minutolo, M.C. Forecasting volatility of oil price using an artificial neural network-GARCH model. Expert Sys. Appl. 2016, 65, 233–241. [Google Scholar] [CrossRef] [Scilit]
- Sadorsky, P. Oil price shocks and stock market activity. Energy Econ. 1999, 21, 449–469. [Google Scholar] [CrossRef] [Scilit]
- Hedi Arouri, M.E.; Khuong Nguyen, D. Oil prices, stock markets and portfolio investment: Evidence from sector analysis in Europe over the last decade. Energy Policy 2010, 38, 4528–4539. [Google Scholar] [CrossRef] [Scilit]
- Hedi Arouri, M.E.; Jouini, J.; Nguyen, D.K. Volatility spillovers between oil prices and stock sector returns: Implications for portfolio management. J. Int. Money Financ. 2011, 30, 1387–1405. [Google Scholar] [CrossRef] [Scilit]
- Cong, R.-G.; Wei, Y.-M.; Jiao, J.-L.; Fan, Y. Relationships between oil price shocks and stock market: An empirical analysis from China. Energy Policy 2008, 36, 3544–3553. [Google Scholar] [CrossRef] [Scilit]
- Kilian, L. Not all oil price shocks are alike: Disentangling demand and supply shocks in the crude oil market. Am. Econ. Rev. 2009, 99, 1053–1069. [Google Scholar] [CrossRef] [Scilit]
- Narayan, P.K.; Narayan, S. Modelling the impact of oil prices on Vietnam’s stock prices. Appl. Energy 2010, 87, 356–361. [Google Scholar] [CrossRef] [Scilit]
- Park, J.; Ratti, R.A. Oil price shocks and stock markets in the U.S. and 13 European countries. Energy Econ. 2008, 30, 2587–2608. [Google Scholar] [CrossRef] [Scilit]
- Salisu, A.A.; Oloko, T.F. Modeling oil price–US stock nexus: A VARMA–BEKK–AGARCH approach. Energy Econ. 2015, 50, 1–12. [Google Scholar] [CrossRef] [Scilit]
- Morana, C. Oil price dynamics, macro-finance interactions and the role of financial speculation. J. Bank. Financ. 2013, 37, 206–226. [Google Scholar] [CrossRef] [Scilit]
- Tilton, J.E.; Humphreys, D.; Radetzki, M. Investor demand and spot commodity prices. Resour. Policy 2011, 36, 187–195. [Google Scholar] [CrossRef] [Scilit]
- Ohashi, K.; Okimoto, T. Increasing trends in the excess comovement of commodity prices. J. Commod. Mark. 2016, 1, 48–64. [Google Scholar] [CrossRef] [Scilit]
- Hong, Y.; Wang, S. Big data, machine learning and statistics: Challenges and opportunities. China J. Econom. 2021, 1, 17–35. [Google Scholar]
- Jammazi, R.; Aloui, C. Crude oil price forecasting: Experimental evidence from wavelet decomposition and neural network modeling. Energy Econ. 2012, 34, 828–841. [Google Scholar] [CrossRef] [Scilit]
- Zhao, Y.; Li, J.; Yu, L. A deep learning ensemble approach for crude oil price forecasting. Energy Econ. 2017, 66, 9–16. [Google Scholar] [CrossRef] [Scilit]
- Filis, G.; Degiannakis, S.; Floros, C. Dynamic correlation between stock market and oil prices: The case of oil-importing and oil-exporting countries. Int. Rev. Financ. Anal. 2011, 20, 152–164. [Google Scholar] [CrossRef] [Scilit]
- Sim, N.; Zhou, H. Oil prices, US stock return, and the dependence between their quantiles. J. Bank. Financ. 2015, 55, 1–8. [Google Scholar] [CrossRef] [Scilit]
- Lee, K.; Ni, S.; Ratti, R.A. Oil shocks and the macroeconomy: The role of price variability. Energy J. 1995, 16, 39–56. [Google Scholar] [CrossRef] [Scilit]
- Mork, K.A.; Olsen, O.; Mysen, H.T. Macroeconomic responses to oil price increases and decreases in seven OECD countries. Energy J. 1994, 15, 19–35. [Google Scholar] [CrossRef] [Scilit]
- Hamilton, J.D. What is an oil shock? J. Econom. 2003, 113, 363–398. [Google Scholar] [CrossRef] [Scilit]
- Basher, S.A.; Haug, A.A.; Sadorsky, P. Oil prices, stock returns and emerging stock markets. Energy Econ. 2012, 34, 227–240. [Google Scholar] [CrossRef] [Scilit]
- Kilian, L.; Park, C. The impact of oil price shocks on the US stock market. Int. Econ. Rev. 2009, 50, 1267–1287. [Google Scholar] [CrossRef] [Scilit]
- Kilian, L.; Murphy, D.P. The role of inventories and speculative trading in the global market for crude oil. J. Appl. Econom. 2014, 29, 454–478. [Google Scholar] [CrossRef] [Scilit]
- Davis, S.J.; Haltiwanger, J. Sectoral job creation and destruction responses to oil price changes. J. Monet. Econ. 2001, 48, 465–512. [Google Scholar] [CrossRef] [Scilit]
- Hooker, M.A. Are oil shocks inflationary? Asymmetric and nonlinear specifications versus changes in regime. J. Money Credit. Bank. 2002, 34, 540–561. Available online: https://www.jstor.org/stable/3270701 (accessed on 6 October 2021). [CrossRef] [Scilit]
- Jones, D.W.; Leiby, P.N.; Paik, I.K. Oil price shocks and the macroeconomy: What has been learned since 1996. Energy J. 2004, 25, 1–32. [Google Scholar] [CrossRef] [Scilit]
- Barsky, R.B.; Kilian, L. Oil and the macroeconomy since the 1970s. J. Econ. Perspect. 2004, 18, 115–134. [Google Scholar] [CrossRef] [Scilit]
- Bernanke, B.; Gertler, M.; Watson, M.W. Oil shocks and aggregate macroeconomic behavior: The role of monetary policy: A Reply. J. Money Credit. Bank. 2004, 36, 287–291. [Google Scholar] [CrossRef] [Scilit]
- Cunado, J.; Perez de Gracia, F. Oil prices, economic activity and inflation: Evidence for some Asian countries. Q. Rev. Econ. Financ. 2005, 45, 65–83. [Google Scholar] [CrossRef] [Scilit]
- Wang, Q.; Yang, X.; Li, R. The impact of the COVID-19 pandemic on the energy market—A comparative relationship between oil and coal. Energy Strategy Rev. 2022, 39, 100761. [Google Scholar] [CrossRef] [Scilit]
- Chai, J.; Lu, Q.; Hu, Y.; Wang, S.; Lai, K.K.; Liu, H. Analysis and Bayes statistical probability inference of crude oil price change point. Technol. Forecast. Soc. Chang. 2018, 126, 271–283. [Google Scholar] [CrossRef] [Scilit]
- Zhang, J.; Yuan, X. COVID-19 risk assessment: Contributing to maintaining urban public health security and achieving sustainable urban development. Sustainability 2021, 13, 4208. [Google Scholar] [CrossRef] [Scilit]

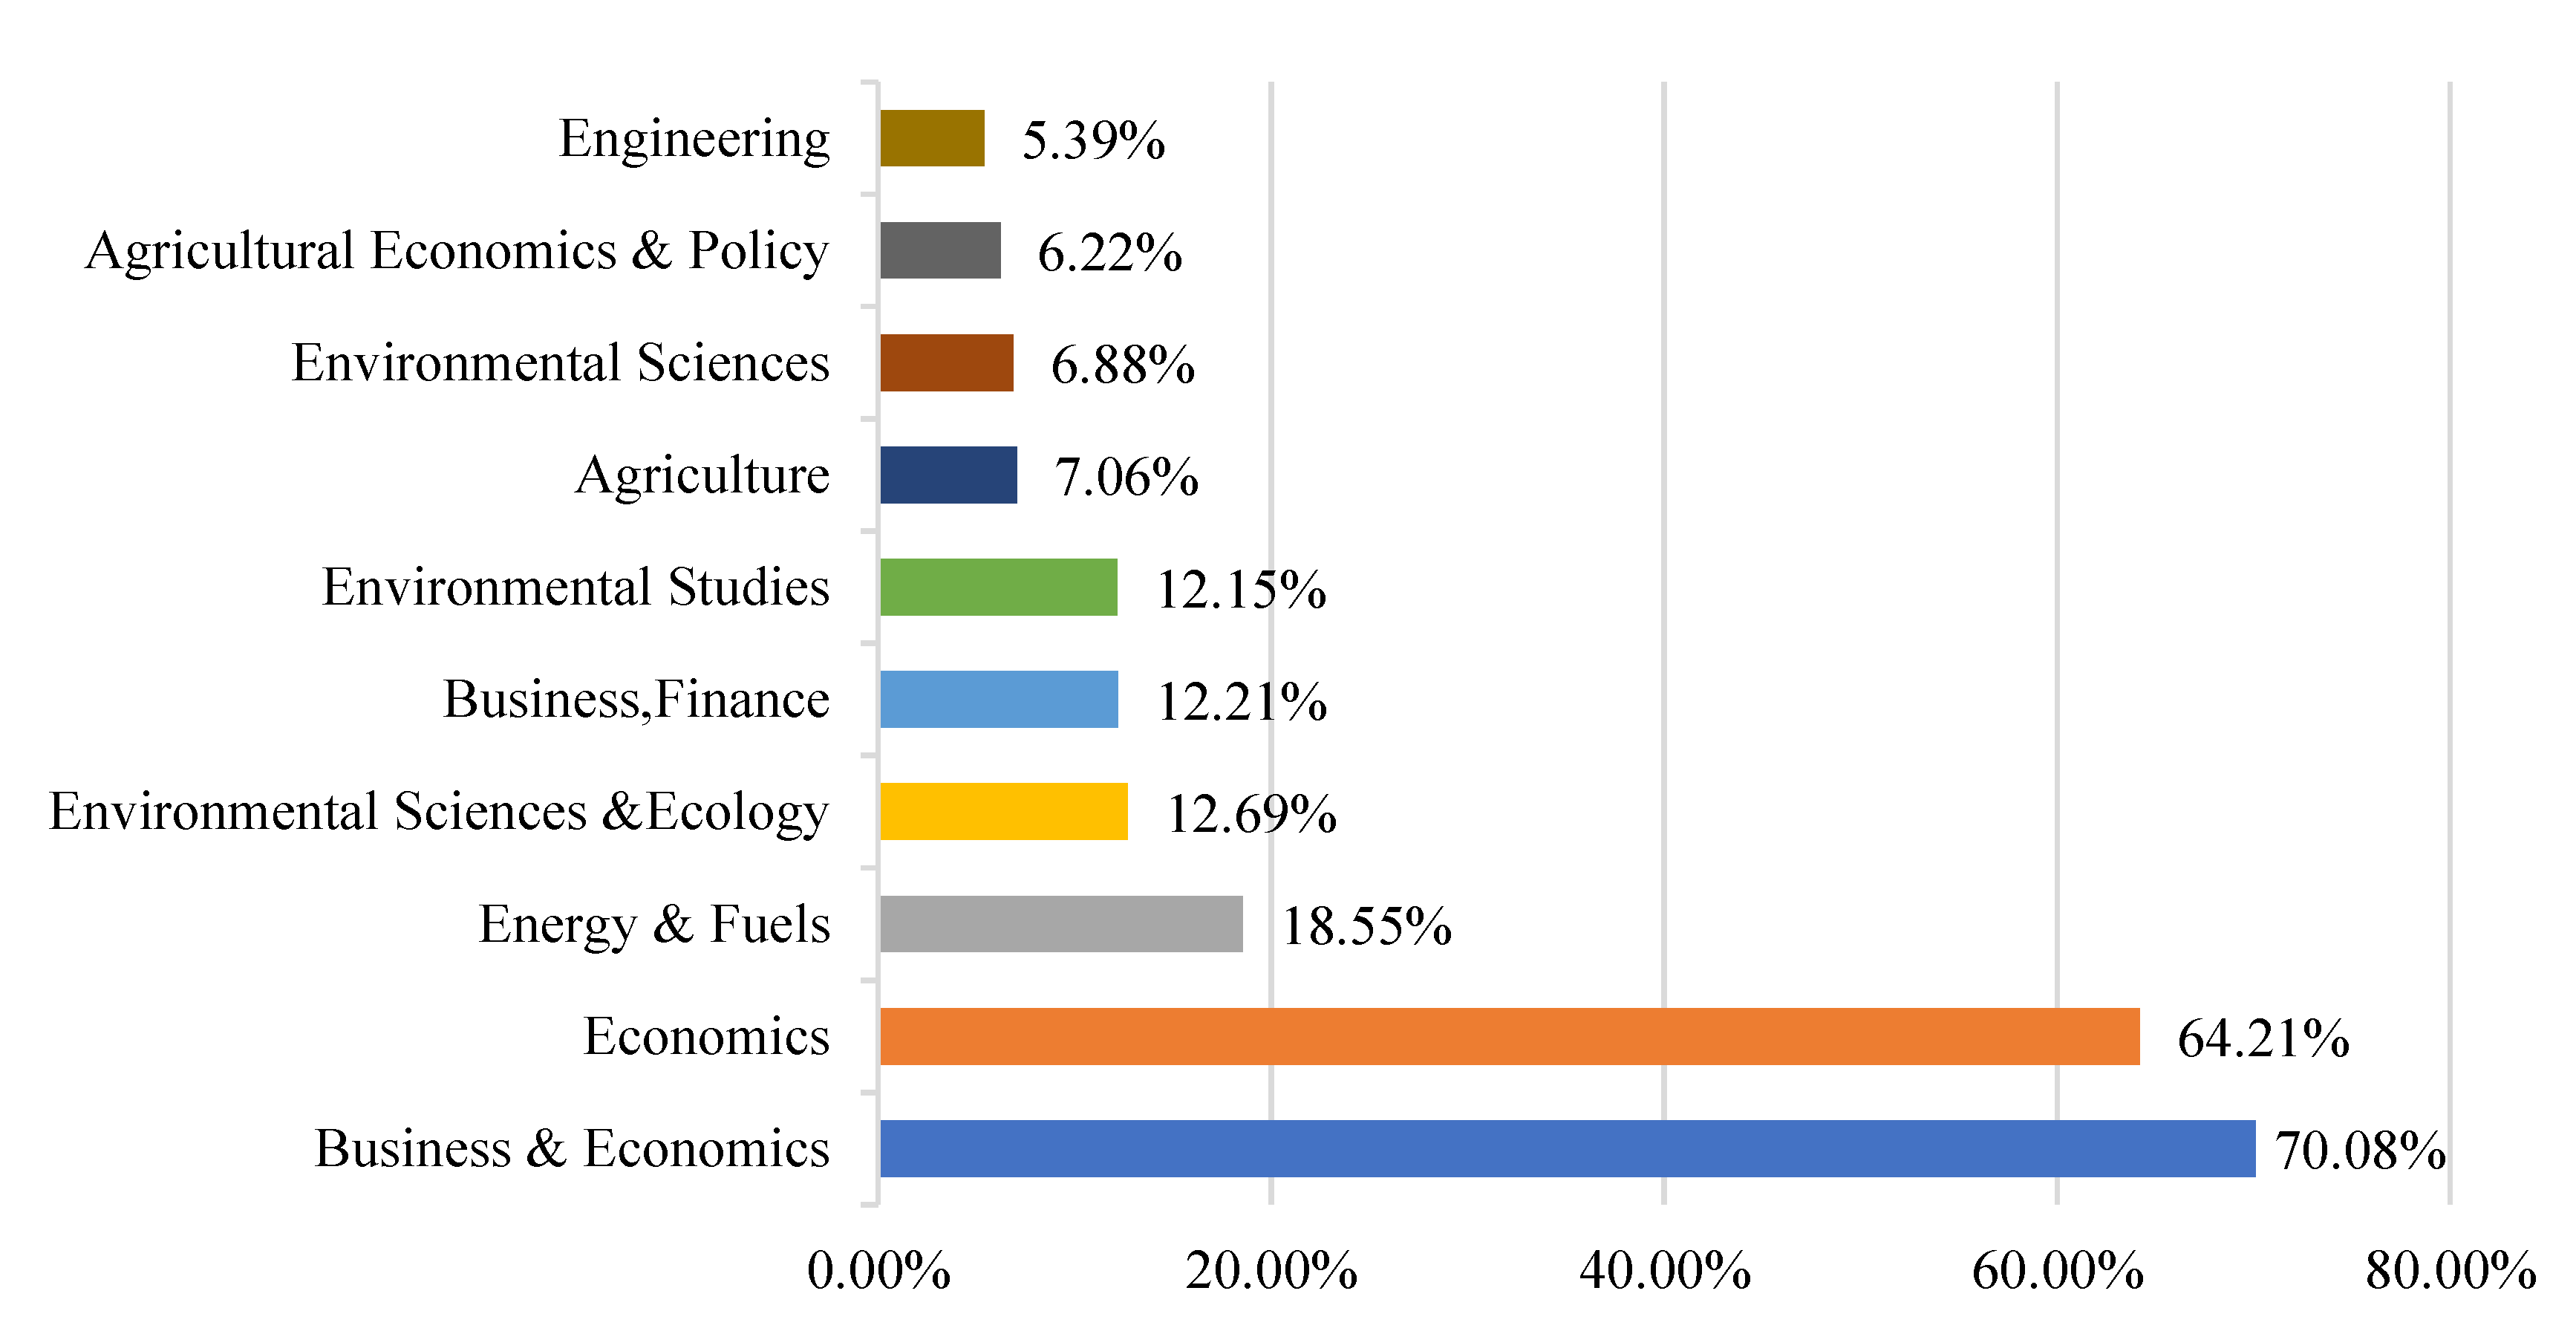
| Citations | Number of Articles Published | Journal | 5 Year Impact Factor |
|---|---|---|---|
| 1051 | 269 | Energy Economics | 7.571 |
| 687 | 79 | Energy Policy | 6.581 |
| 324 | 54 | Energy | 6.845 |
| 466 | 44 | Economic Modelling | 3.412 |
| 433 | 41 | Energy Journal | 2.786 |
| 333 | 38 | Applied Economics | 1.88 |
| 227 | 38 | Resources Policy | 5.654 |
| 299 | 31 | Applied Energy | 9.953 |
| 119 | 30 | Applied Economics Letters | 1.2 |
| 207 | 27 | American Journal of Agricultural Economics | 4.461 |
| Institution | Field | Publications | Regions |
|---|---|---|---|
| Chinese Academy of Sciences | Crude oil price forecasting; factors influencing crude oil prices; crude oil prices and the stock market | 48 | China |
| Hunan University | Crude oil prices and the stock market return; crude oil price forecasting | 26 | China |
| Montpellier Business School | Oil price and precious metal prices; oil price and economy | 21 | France |
| University of Pretoria | The impact of oil price fluctuations on macroeconomy | 20 | South Africa |
| World Bank | Causes and effects of food price crisis; food security; linkage between commodity prices | 18 | |
| Central University of Finance and Economics | Co-movement of commodity prices; crude oil prices and the stock market return; macroeconomic uncertainty and commodity prices | 18 | China |
| Beijing Institute of Technology | Oil price forecasting; oil price and stock return | 18 | China |
| Drexel University | Influencing factors of commodity prices; the impact of commodity price shocks on other factors | 18 | USA |
| University of Chinese Academy of Sciences | Crude oil price forecasting | 16 | China |
| IPAG Business School | Commodity prices and their determinant | 15 | France |
| Rank | Author | Number of People | Number of Articles Published | Proportion of Total/% |
|---|---|---|---|---|
| 1 | Wang S | 1 | 18 | 1.49% |
| 2 | Tiwari A K | 1 | 16 | 1.32% |
| 3 | Hammoudeh S, Gupta R | 2 | 15 | 2.48% |
| 4 | Kilian L | 1 | 14 | 1.16% |
| 5 | Ratti R A, An H | 2 | 11 | 1.82% |
| 6 | Yu L | 1 | 10 | 0.83% |
| 7 | Narayan P K, Wang Y, Zhang Y J, Yin L, Serletis A, Salisu A A, Nguyen D K | 7 | 9 | 5.20% |
| 8 | Wen F, Balcilar M, Reboredo J C, Tang L | 4 | 8 | 2.64% |
| 9 | Baumeister C, Ji Q, Ghoshray A, Nonejad N, Zhao L | 5 | 7 | 2.89% |
| 10 | Liu L, Yu W, Zhu H, Herrera A M, Soytas U, Jiménez-Rodríguez R, Fan Y | 7 | 6 | 3.47% |
| 11 | Arouri M E H, Shahbaz M, De Gracia F P, Uri N D | 4 | 5 | 1.65% |
| 12 | Castro C, Maghyereh A, Zhang C, Huang X, Lai K K, Wohar M E, Shahzad S J H, Nazlioglu S, Huang S, Karaki M B, Pierdzioch C, Gao X, Wei Y, Tao R, Boyd R, Filis G, Baek J | 17 | 4 | 5.61% |
| Total | 52 | 370 | 30.53% |
| Cluster ID | Cluster Label | Cluster Size | Silhouette | Year (Average) |
|---|---|---|---|---|
| #0 | stock market | 209 | 0.656 | 2006 |
| #1 | exchange rate | 141 | 0.698 | 2013 |
| #2 | crude oil price forecasting | 126 | 0.729 | 2012 |
| #3 | oil price uncertainty | 103 | 0.749 | 2014 |
| #4 | agricultural commodity price | 76 | 0.854 | 2009 |
| #5 | Singapore economy | 70 | 0.954 | 1996 |
| #6 | agricultural employment | 47 | 0.995 | 1991 |
| #7 | EMD-based neural network ensemble | 47 | 0.969 | 2001 |
| #9 | long-run price | 38 | 1 | 1993 |
| #20 | high commodity price | 7 | 0.996 | 2008 |
| #26 | high oil price | 4 | 0.996 | 2003 |
| Author | Title | Journal | Year | Strength | Begin | End | Burst Period: 1990–2020 | Cluster |
|---|---|---|---|---|---|---|---|---|
| Davis and Haltiwanger [92] | Sectoral job creation and destruction responses to oil price changes | Journal of Monetary Economics | 2001 | 14.41 | 2003 | 2011 |  | #0 |
| Hamilton [88] | What is an oil shock? | Journal of Econometrics | 2003 | 37.64 | 2005 | 2013 |  | #0 |
| Sadorsky [70] | Oil price shocks and stock market activity | Energy Economics | 1999 | 10.36 | 2005 | 2009 |  | #0 |
| Jiménez-Rodríguez and Sánchez [33] | Oil price shocks and real GDP growth: empirical evidence for some OECD countries | Applied Economics | 2005 | 17.53 | 2007 | 2015 |  | #0 |
| Hooker [93] | Are oil shocks inflationary? Asymmetric and nonlinear specifications versus changes in regime | Journal of Money, Credit, and Banking | 2002 | 12.44 | 2007 | 2011 |  | #0 |
| Jones et al. [94] | Oil price shocks and the macroeconomy: what has been learned since 1996 | The Energy Journal | 2004 | 11.85 | 2007 | 2014 |  | #0 |
| Papapetrou [47] | Oil price shocks, stock market, economic activity and employment in Greece | Energy Economics | 2001 | 11.25 | 2007 | 2011 |  | #0 |
| Barsky and Kilian [95] | Oil and the macroeconomy since the 1970s | Journal of Economic Perspectives | 2004 | 24.28 | 2008 | 2014 |  | #0 |
| Bernanke et al. [96] | Oil shocks and aggregate macroeconomic behavior: The role of monetary policy: A reply | Journal of Money, Credit, and Banking | 2004 | 19.11 | 2008 | 2014 |  | #4 |
| Cunado et al. [97] | Oil prices, economic activity and inflation: evidence for some Asian countries | The Quarterly Review of Economics and Finance | 2005 | 14.73 | 2008 | 2015 |  | #0 |
Publisher’s Note: MDPI stays neutral with regard to jurisdictional claims in published maps and institutional affiliations. |
© 2022 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).
Share and Cite
Zhang, Q.; Hu, Y.; Jiao, J.; Wang, S. Exploring the Trend of Commodity Prices: A Review and Bibliometric Analysis. Sustainability 2022, 14, 9536. https://doi.org/10.3390/su14159536
Zhang Q, Hu Y, Jiao J, Wang S. Exploring the Trend of Commodity Prices: A Review and Bibliometric Analysis. Sustainability. 2022; 14(15):9536. https://doi.org/10.3390/su14159536
Chicago/Turabian StyleZhang, Qi, Yi Hu, Jianbin Jiao, and Shouyang Wang. 2022. "Exploring the Trend of Commodity Prices: A Review and Bibliometric Analysis" Sustainability 14, no. 15: 9536. https://doi.org/10.3390/su14159536
APA StyleZhang, Q., Hu, Y., Jiao, J., & Wang, S. (2022). Exploring the Trend of Commodity Prices: A Review and Bibliometric Analysis. Sustainability, 14(15), 9536. https://doi.org/10.3390/su14159536