


Abstract
Companies in general and family businesses in particular engage in local collaborations in rather diverse areas through their corporate social responsibility activities. The COVID-19 pandemic has made these contributions to community improvement more apparent, suggesting a paradigm shift. This conceptual paper proposes a reflection about the evolution of the corporate social responsibility activities linked to family businesses in emergencies and from the socioemotional wealth perspective. The contribution of this paper is twofold. Firstly, it provides an in-depth reflection on the evolution of philanthropy, posing the following questions: are we witnessing a reinvention of corporate social responsibility within the framework of family businesses because of the global pandemic; does this new trend deserve support, given the fundamental role that family businesses have played in this situation; and if so, what should such support consist of, and what is the optimal channel for articulating it? Secondly, the paper proposes a theoretical framework from the socioemotional wealth perspective to advance research about corporate social responsibility carried out by family businesses. Business families are more likely to implement strategies that promote ethical behavior and CSR activities in their companies. The pandemic situation has created new possibilities for developing CSR.
1. Introduction
The economic importance of family businesses is unquestionable, due to their enormous specific weight in any economy’s GDP (Gross Domestic Product) and employment [1], as they are the predominant way of doing business worldwide [2]. Historically, business families have also provided important patronage with relevant effects on their surroundings. For example, the architectural richness of present-day Florence would be inconceivable without the patronage of the Medici family during the Renaissance. This role not only has been maintained but also has increased and adapted to new political, economic and social contexts throughout history, evolving from the concept of patronage into the broader idea of philanthropy and, especially in modern times, the concept of corporate social responsibility (CSR) [3].
Companies’ philanthropy is included under the domain of corporate social responsibility (CSR) [4,5]. The European Union definition of CSR states that CSR is “a concept whereby companies integrate social and environmental concerns in their firm operations and in their interaction with their stakeholders on a voluntary basis” [6]. Nevertheless, as there is no globally accepted definition, it is generally accepted that CSR refers to “a company’s activities, processes, and status in connection with its related stakeholder obligations” [7] p. 207.
Currently, successful businesses are beginning to be defined by their integration of concepts such as management quality, environmental management, brand reputation, customer loyalty, corporate ethics and talent retention. These concepts constitute common CSR practices. It can be said that CSR strategies are related to sustainable development. Specifically, the measures derived from adopting ethical codes, better environmental practices or human capital development—measures included in the term CSR—are usually considered a good strategy that should lead to better corporate management and thus performance. Firms and investors recognize that investing in accordance with sustainability principles has the capacity to create long-term value [8].
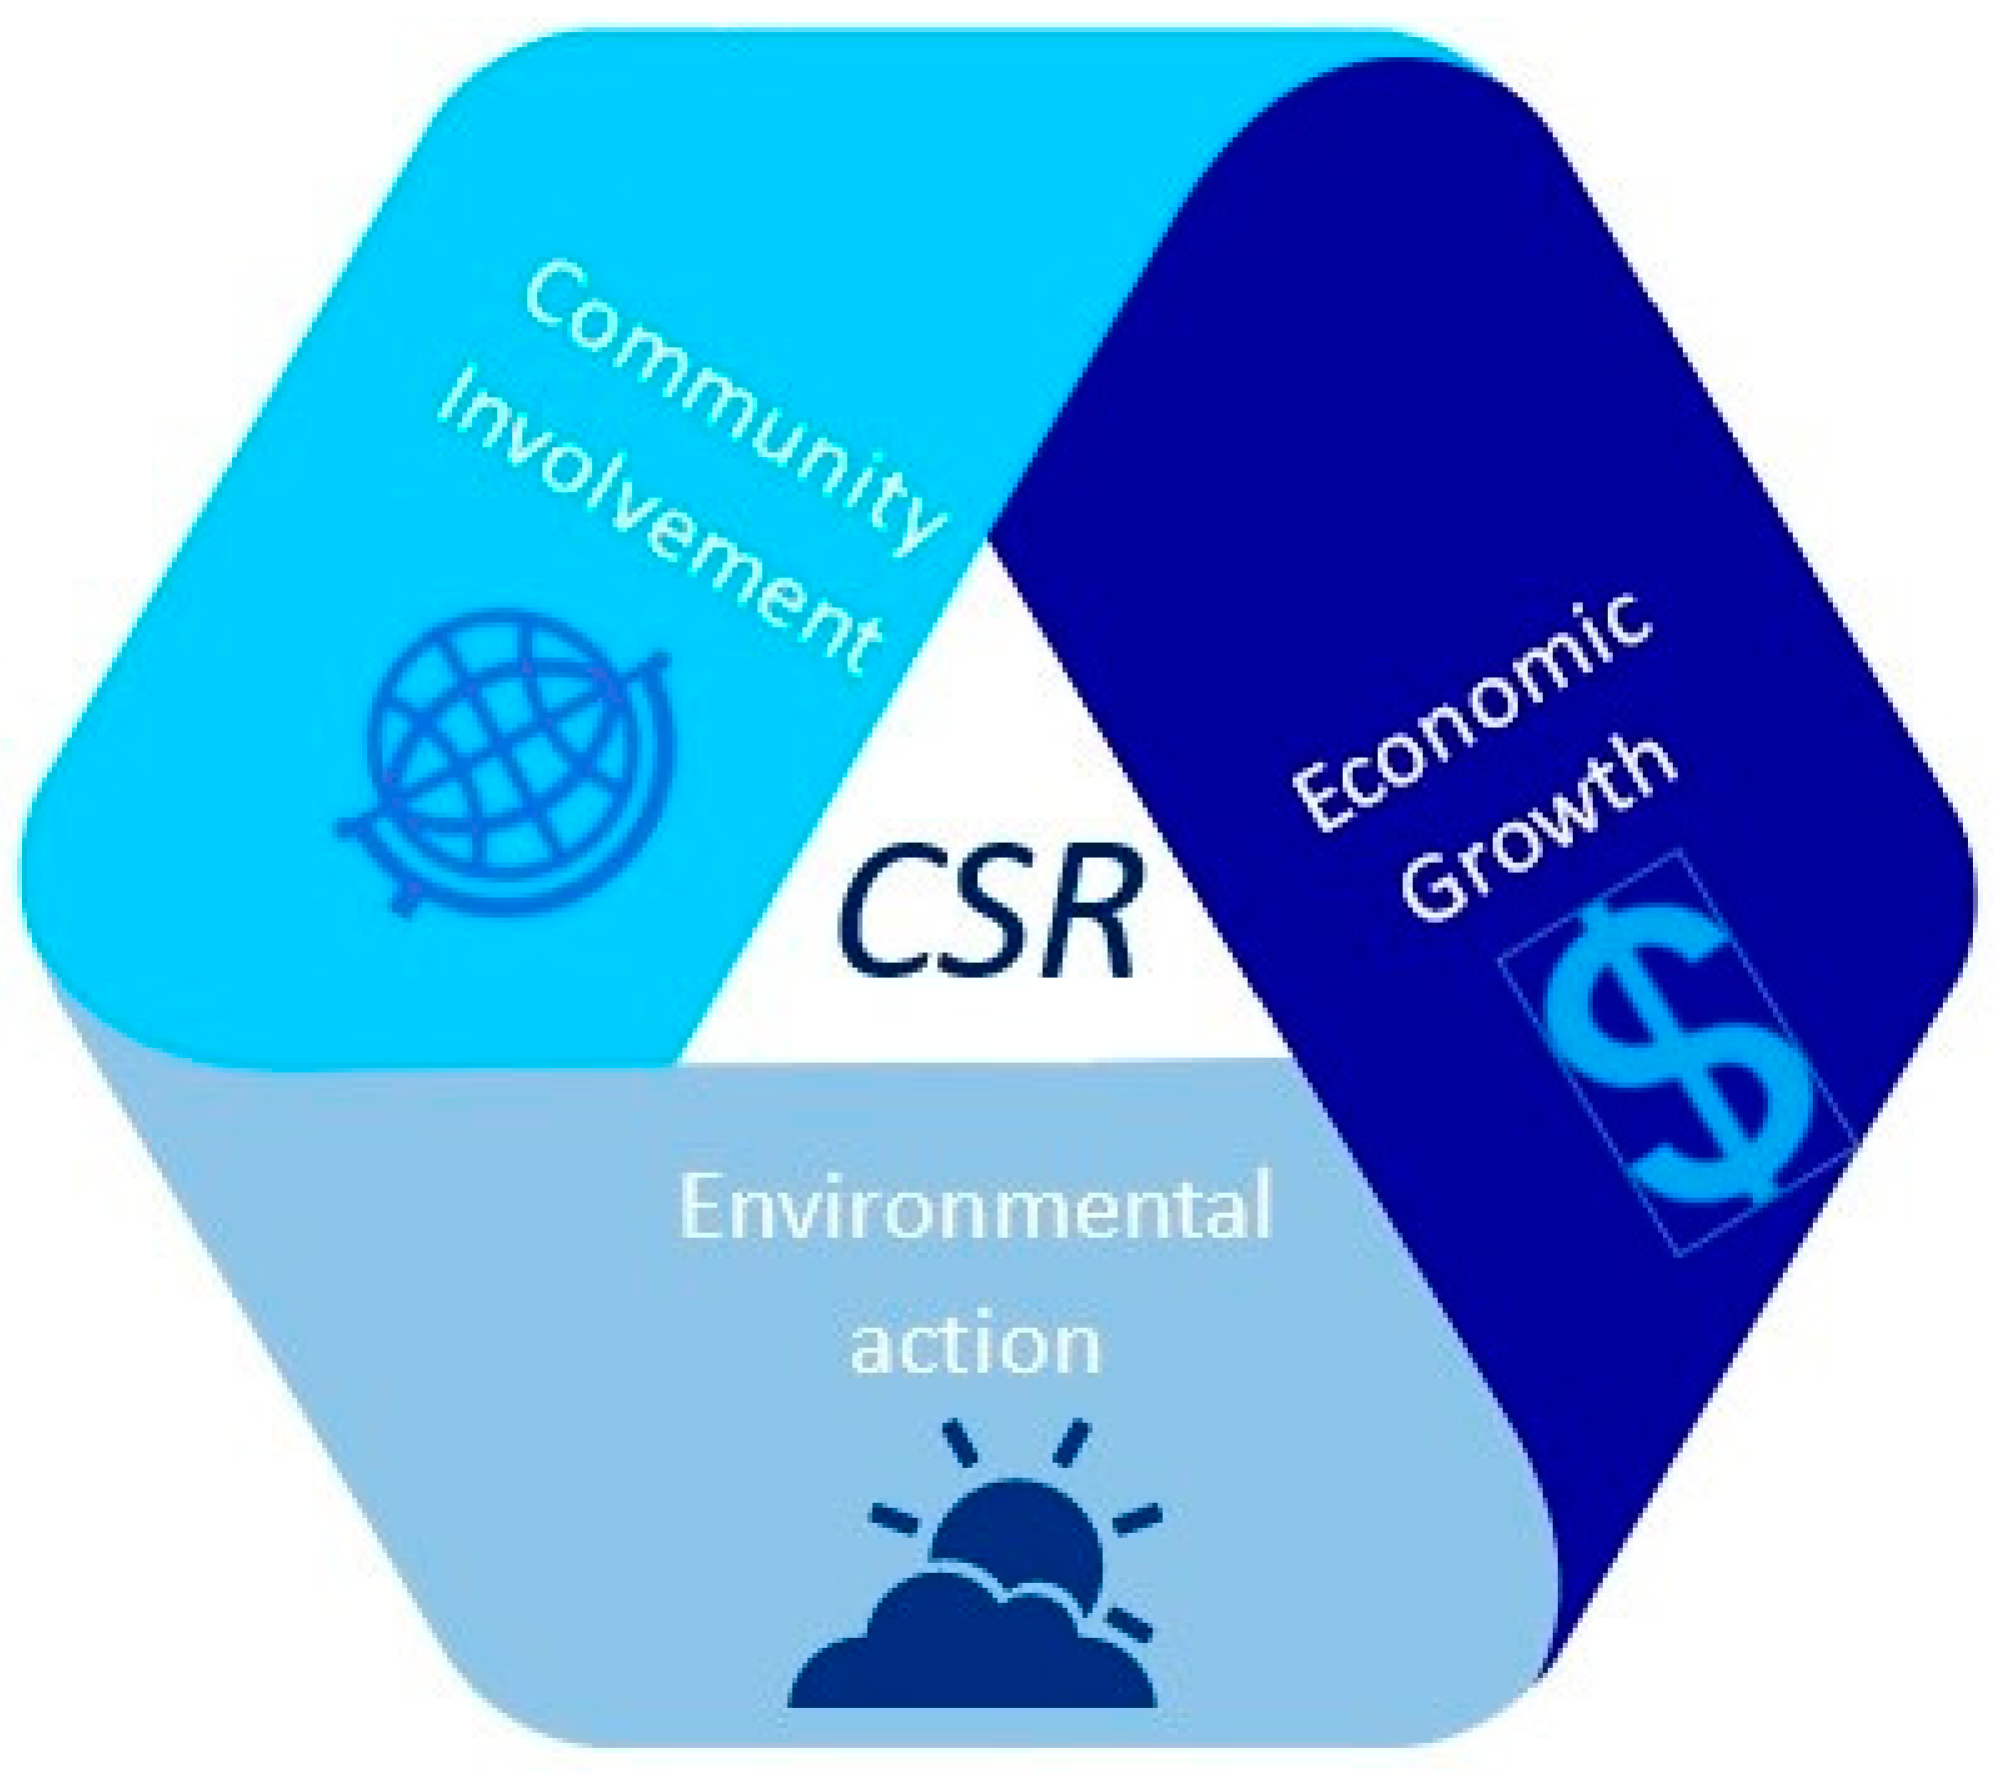
Sustainable development is obtained through the management of environmental, natural, economic, social, cultural and political factors. These issues are interrelated and therefore should not be considered independently. They are part of the concept of CSR and have a voluntary character. They can be grouped into economic, social and environmental areas (the “triple bottom line”) [8] (see Figure 1).
Figure 1.
Activities of Corporate Social Responsibility.
Despite the relevance of family businesses worldwide, to the best of the authors’ knowledge, no previous research has analyzed family businesses and their philanthropic activities during crises or emergencies, such as pandemics. Although business families often collaborate with their local environments in diverse areas (e.g., economic, social, sanitary) through their CSR activities, the COVID-19 pandemic has made these contributions to community improvement efforts clearer, being in most cases appreciated by citizens. However, a certain evolution in the forms leads us to discuss a paradigm shift: philanthropic activities no longer focus solely on traditional economic or material donations but also include knowledge and organizational capacity, which many companies have made available to various governments to help manage and end the pandemic through unprecedented international logistical deployments.
In this paper, we focus on business families that collaborate—whether directly or through their businesses—in activities intended to support and resolve problems during emergencies such as those caused by the COVID-19 pandemic. The following questions must be answered: has CSR been reinvented due to the effects of the global pandemic? Would stronger support for CSR in family businesses be convenient, given its main role in these circumstances? What are the most appropriate mechanisms for this support, and how would they be articulated?
A special feature of business families is their special connection with local environments (in which they conduct business), so they want to return to the society that surrounds them part of what they receive from it. Their long-term vision leads them to think about not only short-term outcomes but also the legacies they will leave to future generations, as they expect that members of the family will continue the business activity. Thus, the motivations that lead business families to carry out philanthropic activities, whether directly or through their companies’ CSR activities, include their desire to pass on their legacies to future generations, their links with the communities in which they develop their activities and their desire to maintain their social reputations. Such philanthropic activity is, in short, a matter of contributing to the maintenance and transmission of a family’s socioemotional wealth (SEW). Therefore, the SEW perspective is the theoretical framework that can best explain business families’ motivations to develop philanthropic activities, especially during emergencies.
This conceptual paper reflects on the evolution of the corporate social responsibility activities linked to family businesses in emergencies from the socioemotional wealth perspective. The contribution of this paper is twofold: firstly, it provides an in-depth reflection on the evolution of philanthropy, posing the following questions: are we witnessing a reinvention of corporate social responsibility within the framework of family businesses because of the global pandemic? Does this new trend deserve support, given the fundamental role that family businesses have played in this situation, and if so, what should such support consist of, and what is the optimal channel for articulating it? Secondly, it proposes a theoretical framework from the socioemotional wealth perspective to advance the research about corporate social responsibility carried out by family businesses. Business families are more likely to implement strategies that promote ethical behavior and CSR activities in their companies. The pandemic situation has created new possibilities for developing CSR.
2. Theoretical Background
2.1. Corporate Social Responsibility in Family Business
Given the important role of family businesses in the world economy, many researchers in areas such as finance, economics and management have studied how family and nonfamily businesses differ in terms of organizational performance and corporate governance [9,10]. However, so far, researchers have overlooked other topics such as CSR [11,12,13,14,15,16,17,18,19,20,21,22,23]. Table 1 summarizes the most-cited works on the topics of “CSR” and “Family business” in WOS. The important family business developments over the last fifteen years seem to have failed to account for business families themselves. Research has instead focused on business-related issues such as objectives, strategies, competitive advantages, leadership, philanthropic practices, professionalization and succession, applying multiple theoretical perspectives. Family influence is implied, and variables related to family involvement (e.g., ownership, generational evolution, participation in management) often serve as proxies for that influence. This indirect approach to business families limits study of the influence of the family and family relations on a company’s evolution, management and objectives, whether economic or noneconomic [24]. Here, we focus on business families because their long-term vision and ideas related to transmitting their legacy to the next generation are essential elements that increase their philanthropic activity. Owner families are able to integrate their decisions to promote this type of CSR activity in their corporate strategies.
Table 1.
Research on CSR and Family Business.
Family businesses are usually characterized by three features: (1) control in the hands of family members, (2) long-term strategic guidelines established by members of the business family and (3) the desire to ensure that control of the company is exercised by successive generations. Thus, according to Chua and Gray [25], this business model is, by definition, governed or led by a dominant coalition controlled by members of the same family. This coalition shapes the vision of the business in a potentially sustainable way for future family generations. According to Cuadrado-Ballesteros et al. [26], a family business is a company in which the founders or their descendants, in addition to majority shareholders, hold senior positions or are present on the board of directors.
Family businesses have financial and nonfinancial objectives. Within the latter, the international literature has highlighted the interest in preserving identity, reputation and longevity as well as safeguarding a positive public image [27,28,29]. A more recent approach addresses SEW [30,31,32], which includes nonmonetary assets (e.g., family unit, community influence, family succession) that have a positive effect on the satisfaction of a business family’s affective needs. This approach recognizes that the objective function of the family business goes beyond simple profit maximization of the neoclassical company and includes pecuniary (earnings) and nonpecuniary objectives (SEW).
However, the major financial scandals of the early twenty-first century and the global economic crisis increased the demand for ethical behavior in the business world [33]. In particular, the crisis affected the welfare of society and showed that things would not go back to the way they used to be [34]. It also indicated the need for new ideas and models to broaden the perspective on the situation. It is thus envisaged that, in addition to the traditional indicators of results (i.e., productivity, competitiveness and the economic growth of the welfare society), it is necessary to account for social indicators, giving rise to the perspective of subjective well-being [35]. In this context, the COVID-19 pandemic has created an unprecedented global crisis on a larger scale than the recent financial crisis. The reaction and collaboration of family companies in the face of this situation represents a new shift in the philosophy of CSR by opening a space for cooperation through not only economic contributions but also collaboration in management and by putting knowledge of companies and family entrepreneurs at the service of the general interest.
2.2. Socioemotional Wealth, Corporate Social Responsibility and Family Business
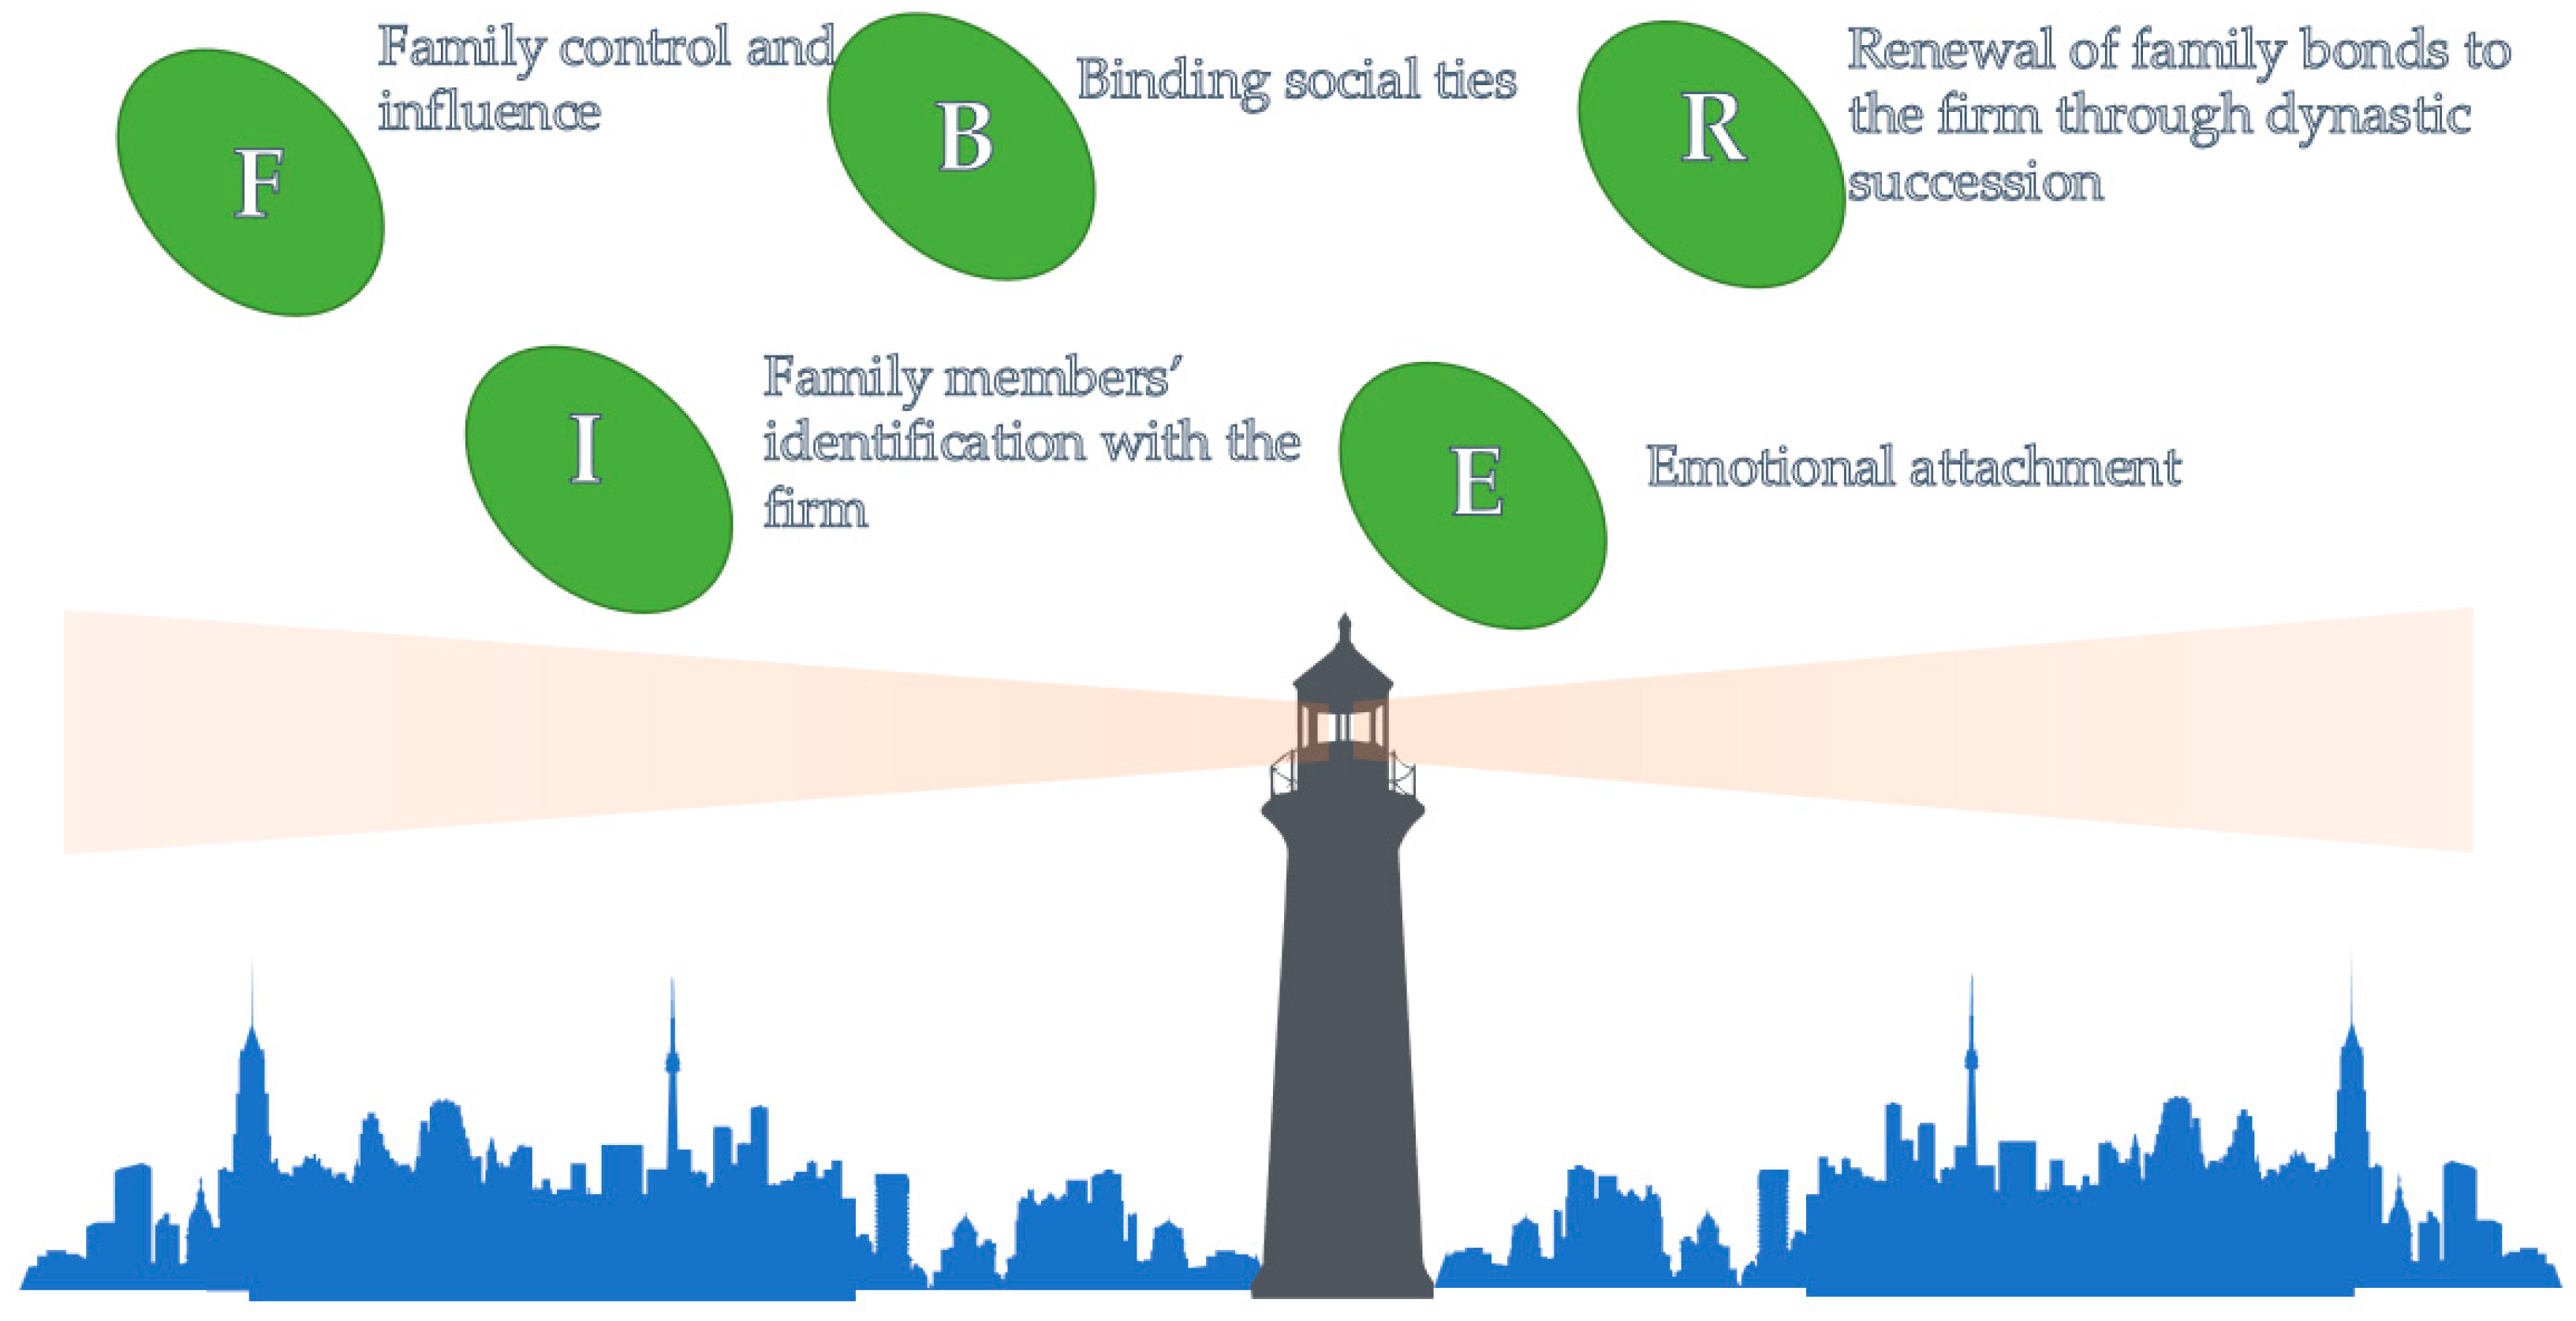
In this paper, we propose using the SEW perspective as a theoretical framework. The perspective involves seeking to preserve the cumulative allocation in a company [36]. Be-rrone et al. [37] p. 258 contended that “SEW is the most important differentiator of the family firm as a single entity and, as such, helps explain why family firms behave distinctively.” SEW refers to “non-financial aspects of the company that meet the affective needs of the family, such as identity, the ability to exert family influence and the perpetuation of the family of the dynasty” [30] p. 106. Therefore, decisions made in the family business field are oriented to the maintenance of the socioemotional legacy even when they may adversely affect performance [38]. Berrone et al. [37] proposed a set of dimensions called FIBER (see Figure 2): family control and influence (F), identification of family members with a company (I), binding social ties (B), emotional attachment of family members (E) and renewal of family ties with a company through dynastic succession (R).
Figure 2.
FIBER (Dimensions of SEW).
We propose using this theoretical framework to understand why business families engage in philanthropic activities or promote CSR in their companies. With regard to the control and influence of family members (F), an owner family controls, directly or indirectly, a family business and its strategic decisions.
Identification of family members with a company (I) is a possible result of the close link between a family and a company. Family ownership of a company provides the family and its members with a sense of identity. Identifying the family with the values and objectives of philanthropy is critical to promoting and enhancing CSR activities.
Identity perceptions are driven not only by the family context but also by a broader social context. Binding social ties (B) refer to companies’ social relations with various stakeholders. Family businesses are often deeply rooted in their local communities. Thus, business families become involved in solving problems in the communities in which they live and develop their businesses with a long-term horizon [3].
Emotional attachment of family members (E) can affect decision-making within a family business. Therefore, decisions can be made on the basis of feelings and relationships among family members.
The renewal of family ties with a company through dynastic succession (R) relates to the long-term vision of maintaining the family’s control of the company in future generations. This transgenerational vision and sense of dynasty are key concerns of family businesses. Business families seek to preserve family wealth for subsequent generations, and that includes not only assets but also family values.
This long-term vision leads the business family to make philanthropic decisions regardless of other economic issues. From this perspective, family companies present greater commitment to CSR or a more favorable focus toward investment in long-term sustainable projects as a mechanism that favors the company’s transfer to future generations [39,40]. In addition, this reinforces the company’s image [36] due to the strong link between the family’s reputation and the company’s success and image [7,41]. Thus, we argue that business families tend to view investments into CSR as leading to increased SEW and therefore allocate a significant volume of their funds to CSR strategies that will make them the most sustainable companies.
Based on the above, SEW preservation appears to be a key factor in the decision-making processes among family businesses, which are more sensitive to social and environmental demands and show greater commitment to CSR [42]. However, it remains unclear whether investments in CSR undertaken by family businesses entail competitive advantages or financial returns due to the prevalence of SEW over the economic-financial criteria in decision-making. The debate surrounding the generation of CSR value in family businesses has delayed its raison d’être in two respects: the questionable returns associated with CSR and aversion to lost SEW as compared to the loss of value creation.
First, despite the many benefits associated with CSR, the literature on this subject maintains that its financial return is dubious, at least in the short-term [43]. Numerous studies have shown that inaccurate results, as well as many other factors such as family ownership, influence this connection. However, most assert that CSR has a positive effect on a company’s performance [44]. Even so, in line with Buchanan et al. [45], overinvestment in CSR generates high cost figures, thus raising concerns about overinvestment. Therefore, based on the agency theory, managers can overinvest in CSR to increase their reputations and preserve their jobs, even at investors’ expense. Overinvesting in such practices can destroy a company’s value [46] for both family and non-family businesses. Oppositely, Porter and Kramer (2011) [47] consider compliance with the law and ethical standards to create shared value. For these authors, creating societal value is “one of the most powerful forces driving growth in the global economy” [47] p.15.
Second, authors such as Gómez-Mejía et al. [48] have argued that families make strategic decisions to ensure the preservation of their SEW, even if they lead to worse financial results. A family business can invest in CSR strategies by visualizing more dangers related to not undertaking such projects than to profits [49]. In particular, Cruz et al. [49] pointed out that the lower financial performance generated by CSR investment will be even lower in family businesses because of the greater attention they pay to ensuring their survival and SEW through CSR practices, despite the potential losses that doing so generates. Thus, business families’ interventions in the face of the crisis generated by the pandemic have highlighted their concerns about long-term sustainability rather than financial returns. Measures by many family employers such as the temporary closure of companies without recourse to dismissals support this assertion.
3. Methodology, Findings and Discussion
Due to the exploratory nature of this study, no pre-defined hypotheses were tested. Rather, the study provides the groundwork for a nuanced understanding of the potential role of business families in helping in emergency situations, such as the one generated by the COVID-19 pandemic [50]. Three research questions related to the CSR activities of family businesses are posed. Information published in the media is used to respond to them. The answers are also justified from the theoretical SEW approach. We propose a reflection about changes in the CSR strategies carried out by family businesses, specifically in emergency situations [51].
3.1. Are We Witnessing a Reinvention of Corporate Social Responsibility within the Framework of Family Businesses Because of the Global Pandemic?
From the SEW perspective, adopted here as a theoretical framework, business families are more likely to implement strategies that promote ethical behavior and CSR activities in their companies [52]. The situation created by the pandemic has created new possibilities for developing CSR, different from traditional donations and collaborations.
CSR strategies have changed. Family businesses, in addition to making financial donations, have collaborated in managing the COVID-19 crsis. Business families have decided to pour their knowledge into developing their philanthropic projects in the five following ways.
- Providing logistical support to the government to purchase and supply essential sanitary equipment.
- The company Inditex (Spain) made its logistical capacity available to the Spanish health authorities for acquiring and transporting sanitary equipment and provided 35 million units of health-protection materials from China. These purchases were made not only by Inditex and the Amancio Ortega Foundation but also by the Government of Spain, autonomous communities and hospitals.
- LVMH (France) secured an order with a Chinese industrial supplier for 7 million surgical masks and 3 million FFP2 masks for France.
- Restructuring production plants and directing lines to the health-care field by manufacturing protective equipment, ventilators and disinfectant gel.
- The LVMH family group remodeled its perfume- and cosmetic-production units to manufacture and distribute hydroalcoholic disinfectant gels for free.
- The L’Oréal group (France) also remodeled its production units to collaborate with European health authorities and manufacture hand-sanitizer gel.
- The Antolín Group (Spain), a Spanish family business specializing in automotive interior components, contributed to fighting the COVID-19 pandemic by manufacturing components for protective screens as well as protective gowns for health personnel.
- Avoiding temporary layoffs as a supportive measure for employees and their communities’ economies, which returns the focus to the owner family that controls the company and has decided to think more about the long-term and its employees than its financial results.
- On 17 March, the Inditex Group temporarily closed 3785 stores in 39 countries, but it decided not to apply temporary employment regulation files (ERTE in Spanish) to its workers and instead continued to pay its workers a full salary.
- Similarly, Hijos de Rivera, the family business owner of Estrella Galicia, decided not to apply ERTE to its staff because, in the words of its CEO Ignacio Rivera, “You have to be supportive in this pandemic, pull out all the stops, and protect this great family that are our workers.”
- Help suppliers by reducing payment periods.
- The L’Oréal group decided to make payments immediately to help its suppliers during the possible economic slowdown resulting from the pandemic.
- Mercadona, a Spanish supermarket chain, also helped its suppliers by injecting liquidity through an extension of its confirming lines worth up to 2.1 billion euros so that these companies could collect their bills on the spot and maintain employment.
- Purely philanthropic activities such as donating millions of dollars or euros in response to the coronavirus, allowing for greater investment into the research and development of treatments and a vaccine for COVID-19, as well as donations in kind (with an example from Big Charitable Gifts, www.philantrophy.com, accessed on 9 December 2020):
- “All In Washington Fund (Seattle): $25 million challenge pledge from Jeff Bezos to match gifts of under $1 million apiece from other donors who give to the fund’s efforts to provide immediate support for people who have been affected by the coronavirus pandemic across Washington State. Bezos founded Amazon.”
- “Covid-19 Therapeutics Accelerator (Seattle) has received a pledge of $20 million from the billionaires Michael and Susan Dell through their foundation. This effort was created in March by the Bill & Melinda Gates Foundation and others to speed up the development of treatments for Covid-19 patients and make it easier for those with the disease to access treatment. Michael Dell founded and leads the technology company Dell, in Austin, TX, USA.”
3.2. Does This New Trend Deserve Support, Given the Fundamental Role That Family Businesses Have Played in This Situation?
As a CSR formula, philanthropy and its paradigmatic instrument, patronage, must be examined in the context of this evolution, the trajectory of which had a strong effect on the emergence of the COVID-19 pandemic. In this context, the measures resulting from the state of alarm have led to a radical transformation of daily life for the time being, which has seriously affected economic activity, given the limitations to which the population has been subjected. However, the family business, with its traditional proximity to its most immediate socio-economic environment, may be at an initial advantage, given an appropriate social responsibility strategy. In this sense, the promotion of patronage, particularly at the local level, can be an opportunity from the perspective of such companies and the public authorities when facing future economic challenges.
In this way, the potential for private collaboration in public interest projects via patronage, as a possible CSR strategy on the part of family companies, stands out. Such businesses’ unique characteristics make such an instrument suitable for meeting immediate future challenges, provided the company meets the public authorities’ guidelines for the promotion of this instrument. Thus, patronage resonates as an ideal instrument for channeling private initiative not only to ensure that action is taken more quickly but also to address a likely situation of social and economic alarm resulting from the coming recession.
3.3. If So, What Should Such Support Consist of, and What Is the Optimal Channel for Articulating It?
In the current pandemic and in the recession to come, it would be appropriate for the public authorities to use all measures at their disposal to increase their available resources. An effective strategy for promoting the patronage activities of family businesses at the local level involves developing an appropriate framework that balances present interests, starting with the limits imposed on regional powers in the exercise of their own competencies. However, according to the Global Philanthropy Index 2018, which was developed by Lilly Family School of Philanthropy at Indiana University, not all countries have environments conducive to philanthropy, so its potential can be strengthened primarily by providing the appropriate legal channels. In addition to specific issues related to legislative technique, at least five crucial aspects must be addressed when designing patronage rules to maximize their potential as a dynamizing instrument for the local economy. First, consideration must be given to competence levels—and therefore the potential for impact on available financial resources—that each administration concerned can enjoy, particularly in strongly decentralized countries.
Second, a matter that can be politically complex is the nature of the sectors in which patronage, traditionally limited to the field of culture, is permitted to operate within that field. Regardless of whether a large number of projects can be incorporated within the framework of such a core in the broadest sense, it is convenient that patronage transcends its usual comfort zone and extends to other areas likely to be addressed through the public–private collaboration that characterizes this mechanism. Thus, in particular, the research (particularly at the level of public universities), health, education, and non-professional sport sectors are capable of integrating the scope of the patronage to facilitate its promotion and increase its impact.
Third, in promoting patronage, the public authorities must not consider it as a completely philanthropic or altruistic activity. This means that a correct balance of interests must allow an adequate combination of economic and non-economic benefits for the patron, in the form of “veiled sponsorship” [53] p. 159. In the first category, tax bonuses stand out, especially deductions on the full share of income tax as well as possible reductions in inheritance tax bases, if applicable. Depending on their intensity, these tax-policy measures may also provide an incentive to prevent family businesses from fleeing to more fiscally attractive territories.
Fourth, the economic measures identified above, which are pointedly tributary, can and should be accompanied by other stimuli in the form of non-economic benefits. These have the advantage of much lower economic and political costs for the public authorities. For instance, recognition of the figure of patronage and the patron for the task can imply an indirect business benefit in the form of social prestige and promotion of the brand, which increases SEW. Other stimuli, such as preferential access to the results of sponsored projects, participation of sponsors in the collegiate advisory bodies of beneficiaries or future beneficiaries, as well public bodies to which relevant competencies can be conferred, may also be included here. All these non-economic benefits, intended in principle to benefit the patron, can also have a positive effect on the image of patronage by facilitating the continuity of the sponsor’s link to the sponsored projects.
Finally, technical aspects related to the modalities of the patronage should not be neglected. As noted above, this is not limited to the mere monetary contributions by the patron. Therefore, its effectiveness can be maximized not only through other means (i.e., not only money but also of any type of goods or services) but also through the various legal tools that can serve this purpose. In this sense, it is not a matter of relying solely on classic donations, accommodations, or cooperation agreements. Rather, it involves expanding the range of possibilities, including civil instruments (e.g., all kinds of transmissions, inter vivos, or mortis causa, as well as condonations or figures present in foreign systems, such as endowments) and fiscal instruments (e.g., the use of tax credits to satisfy the payment of taxes by the patron), that modulate the institution of patronage to increase its efficiency.
4. Conclusions
This study was aimed at understanding how business families can contribute during emergencies through philanthropy or company CSR activities. It analyzes whether the shape and content of philanthropic activities have changed because of the COVID-19 pandemic. This paper contributes to the business-family and CSR literature in several ways. First, it analyzes company CSR activities by focusing on the family, which ultimately influences the strategic decisions driving CSR and ethical behavior in family businesses [54]. Second, it analyzes CSR activities and philanthropy during emergencies by using examples of family business collaborations during the COVID-19 pandemic. Third, from the SEW perspective, this paper discusses why business families are more likely to implement company strategies that drive ethical behavior and CSR activities. Finally, the fundamental role of family businesses in the COVID-19 pandemic is demonstrated by emphasizing that private–public collaborations at the global level are important. Institutions and governments should encourage these new CSR strategies to facilitate business contributions during this new global crisis. They must do so from a normative point of view (e.g., new legal formulas such as a patronage laws, new tax policy measures and reduced bureaucratic complexity) and from one of promoting a new ethical culture of philanthropy in society.
From the SEW perspective, adopted here as a theoretical framework, business families are more likely to implement strategies to promote ethical behavior and CSR activities in their companies [13]. The situation created by the pandemic has created new possibilities for developing CSR, different from traditional donations and collaborations.
Future research should analyze CSR strategies and focus more on the business families than on family businesses to understand the families’ behavior. In this way, we could apply the FIBER scale to measure the SEW that a family business brings to the family nucleus, in terms of CSR. A multi-case study research in line with Bhatnagar et al. [54] could also be considered. The main limitation of this work is derived from its qualitative, non-empirical nature and the difficulty of such a study in terms of access to information. It would be interesting, in light of the above, to conduct a pre- and post-pandemic study that analyzes the CSR strategies of family companies to determine the extent to which these strategies changed during the crisis. These strategies might include not only financial objectives but also those more in line with SEW, to assess their effects on brand image and the families’ reputations.
In general, note that we have discussed the need for and fundamental purpose of CSR. In essence, we have addressed trust, a requirement for all permanent human relationships, as well as long-term vision and interest in sustainability. Neither the most demanding laws nor the best-crafted codes can guarantee good governance by companies without, in addition to professional competence, the ethical commitment of their managers. Their example, along with their behavior patterns, influences the whole organization and its stakeholders. It may seem utopian, but this is the best line of thinking to guarantee the establishment of a new ethical culture in companies in general and in business families in particular.
Author Contributions
Conceptualization, E.R.-L. and M.M.-Á.; methodology, E.R.-L. and M.V.-V.; writing—original draft preparation, E.R.-L. and M.M.-Á.; writing—review and editing, E.R.-L. and M.V.-V.; supervision, M.V.-V. and F.R.-S. All authors have read and agreed to the published version of the manuscript.
Funding
This research received no external funding.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
Not applicable.
Conflicts of Interest
The authors declare no conflict of interest.
References
- Bammens, Y.; Voordeckers, W.; Van Gils, A. Boards of Directors in family businesses: A literature review and research agenda. Int. J. Manag. Rev. 2011, 13, 134–152. [Google Scholar] [CrossRef] [Scilit]
- Rivo-López, E.; Villanueva-Villar, M.; Vaquero-García, A.; Lago-Peñas, S. Do family firms contribute to job stability? Evidence from the great recession. J. Fam. Bus. Manag. 2020. [Google Scholar] [CrossRef] [Scilit]
- Rivo-López, E.; Villanueva-Villar, M.; Suárez-Blázquez, G.; Reyes-Santías, F. How does a business family manage its wealth? A family office perspective. J. Fam. Bus. Manag. 2020. [Google Scholar] [CrossRef] [Scilit]
- Carroll, A.B.; Shabana, K.M. The business case for corporate social responsibility: A review of concepts, research and practice. Int. J. Manag. Rev. 2010, 1, 85–105. [Google Scholar] [CrossRef] [Scilit]
- Hategan, C.D.; Sirghi, N.; Curea-Pitorac, R.I.; Hategan, V.P. Doing well or doing good: The relationship between corporate social responsibility and profit in Romanian companies. Sustainability 2018, 10, 1041. [Google Scholar] [CrossRef] [Scilit]
- European Commission. European Competitiveness Report (2008); European Commission: Luxembourg, 2009. [Google Scholar]
- Marques, P.; Presas, P.; Simon, A. The heterogeneity of family firms in CSR engagement: The role of values. Fam. Bus. Rev. 2014, 27, 206–227. [Google Scholar] [CrossRef] [Scilit]
- López Pérez, M.V.; García Santana, A.; Rodríguez Ariza, L. Sustainable Development and Corporate Efficiency: A Study Based on the Dow Jones Sustainability Index. J. Bus. Ethics 2007, 75, 285–300. [Google Scholar] [CrossRef] [Scilit]
- Kashmiri, S.; Mahajan, V. Beating the recession blues: Exploring the link between family ownership, strategic marketing behavior and firm performance during recessions. Int. J. Res. Mark. 2014, 31, 78–93. [Google Scholar] [CrossRef] [Scilit]
- Villanueva-Villar, M.; Rivo-López, E.; Lago-Peñas, S. On the relationship between corporate governance and value creation in an economic crisis: Empirical evidence for the Spanish case. Bus. Res. Quart. 2016, 19, 233–245. [Google Scholar] [CrossRef] [Scilit]
- Deniz, M.; Suarez, M. Corporate social responsibility and family business in Spain. J. Bus. Ethics 2005, 56, 27–41. [Google Scholar] [CrossRef] [Scilit]
- Fassin, Y.; Van Rossem, A.; Buelens, M. Small-business owner-managers’ perceptions of business ethics and CSR-related concepts. J. Bus. Ethics 2011, 98, 425–453. [Google Scholar] [CrossRef] [Scilit]
- Campopiano, G.; De Massis, A. Corporate social responsibility reporting: A content analysis in family and non-family firms. J. Bus Ethics 2015, 129, 511–534. [Google Scholar] [CrossRef] [Scilit]
- Mitchell, R.K.; Agle, B.R.; Chrisman, J.J.; Spence, L.J. Toward a theory of stakeholder salience in family firms. Bus. Ethics Quart. 2011, 21, 235–255. [Google Scholar] [CrossRef] [Scilit]
- Stavrou, E.; Kassinis, G.; Filotheou, A. Downsizing and stakeholder orientation among the fortune 500: Does family ownership matter? J. Bus. Ethics 2007, 72, 149–162. [Google Scholar] [CrossRef] [Scilit]
- Uhlaner, L.M.; Berent-Braun, M.M.; Jeurissen, R.J.M.; de Wit, G. Beyond size: Predicting engagement in environmental management practices of dutch SMEs. J. Bus. Ethics 2012, 109, 411–429. [Google Scholar] [CrossRef] [Scilit]
- Van Gils, A.; Dibrell, C.; Neubaum, D.O.; Craig, J.B. Social issues in the family enterprise. Fam. Bus. Rev. 2014, 27, 193–205. [Google Scholar] [CrossRef] [Scilit]
- Sageder, M.; Mitter, C.; Feldbauer-Durstmueller, B. Image and reputation of family firms: A systematic literature review of the state of research. Rev. Manag. Sci. 2018, 12, 335–377. [Google Scholar] [CrossRef] [Scilit]
- O’Boyle, E.H., Jr.; Rutherford, M.W.; Pollack, J.M. Examining the relation between ethical focus and financial performance in family firms: An exploratory study. Fam. Bus. Rev. 2010, 23, 310–326. [Google Scholar] [CrossRef] [Scilit]
- Sundarasen, S.D.D.; Je-Yen, T.; Rajangam, N. Board composition and corporate social responsibility in an emerging market. Corp. Gov. Int. J. Bus. Soc. 2016, 16, 35–53. [Google Scholar] [CrossRef] [Scilit]
- Feliu, N.; Botero, I.C. Philanthropy in family enterprises: A review of literature. Fam. Bus. Rev. 2016, 29, 121–141. [Google Scholar] [CrossRef] [Scilit]
- Hou, T.C. The relationship between corporate social responsibility and sustainable financial performance: Firm-level evidence from taiwan. Corp. Soc. Responsib. Environ. Manag. 2019, 26, 19–28. [Google Scholar] [CrossRef] [Scilit]
- Wiklund, J. Commentary: “Family firms and social responsibility: Preliminary evidence from the S&P 500”. Entrep. Theory Pract. 2006, 30, 803–808. [Google Scholar] [CrossRef] [Scilit]
- Madison, K.; Holt, D.T.; Kellermanns, F.W.; Ranft, A.L. Viewing family firm behavior and governance through the lens of agency and stewardship theories. Fam. Bus. Rev. 2016, 29, 65–93. [Google Scholar] [CrossRef] [Scilit]
- Chua, G.; Gray, S.J. Family ownership, board independence and voluntary disclosure: Evidence from Hong Kong. J. Int. Account. Audit. Tax. 2010, 19, 93–109. [Google Scholar] [CrossRef] [Scilit]
- Cuadrado-Ballesteros, B.; Rodríguez-Ariza, L.; García-Sánchez, I.M. The role of independent directors at family firms in relation to corporate social responsibility disclosures. Int. Bus. Rev. 2015, 24, 890–901. [Google Scholar] [CrossRef] [Scilit]
- Sharma, P.; Chrisman, J.J.; Chua, J.H. Strategic management of the family business: Past research and future challenges. Fam. Bus. Rev. 1997, 10, 1–35. [Google Scholar] [CrossRef] [Scilit]
- Anderson, R.C.; Reeb, D.M. Board composition: Balancing family influence in S&P 500 firms. Adm. Sci. Q. 2004, 49, 209–237. [Google Scholar] [CrossRef] [Scilit]
- Berrone, P.; Cruz, C.; Gómez-Mejía, L.R.; Larraza-Kintana, M. Socio-emotional wealth and corporate responses to institutional pressures: Do family-controlled firms pollute less? Adm. Sci. Q. 2010, 55, 82–113. [Google Scholar] [CrossRef] [Scilit]
- Gómez-Mejía, L.R.; Haynes, K.; Núñez-Nickel, M.; Jacobson, K.J.L.; Moyano-Fuentes, J. Socioemotional wealth and business risks in family controlled firms: Evidence from Spanish olive oil mills. Adm. Sci. Q. 2007, 52, 106–137. [Google Scholar] [CrossRef] [Scilit]
- Shepherd, D.A. An emotions perspective for advancing the fields of family business and entrepreneurship: Stocks, flows, reactions, and responses. Fam. Bus. Rev. 2016, 29, 151–158. [Google Scholar] [CrossRef] [Scilit]
- Garcés-Galdeano, L.; Larraza-Kintana, M.; Cruz, C.; Contín-Pilart, I. Just about money? CEO satisfaction and firm performance in small family firms. Small Bus. Econom. 2017, 49, 825–839. [Google Scholar] [CrossRef] [Scilit]
- Burns, D.J. Exploring the effects of using consumer culture as a unifying pedagogical framework on the ethical perceptions of MBA students. Bus. Ethics A Eur. Rev. 2012, 21, 1–14. [Google Scholar] [CrossRef] [Scilit]
- Guardiola, J.; Picazo-Tadeo, A.; Rojas, M. Economic crisis and well-being in Europe: Introduction. Soc. Indic. Res. 2015, 120, 319–322. [Google Scholar] [CrossRef] [Scilit]
- Kahneman, D.; Wakker, P.; Sarin, R. Back to Bentham? Explorations of experienced utility. Q. J. Econom. 1997, 112, 375–406. [Google Scholar] [CrossRef] [Scilit]
- Cennamo, C.; Berrone, P.; Cruz, C.; Gómez-Mejía, L.R. Socioemotional wealth and proactive stakeholder engagement: Why family-controlled firms care more about their stakeholders. Entrep. Theory Pract. 2012, 36, 1153–1173. [Google Scholar] [CrossRef] [Scilit]
- Berrone, P.; Cruz, C.; Gomez-Mejia, L.R. Socioemotional wealth in family firms: Theoretical dimensions, assessment approaches, and agenda for future research. Fam. Bus. Rev. 2012, 25, 258–279. [Google Scholar] [CrossRef] [Scilit]
- Chen, Q.; Hou, W.; Li, W.; Wilson, C.; Wu, Z. Family control, regulatory environment, and the growth of entrepreneurial firms: International evidence. Corp. Gov. An Int. Rev. 2014, 22, 132–144. [Google Scholar] [CrossRef] [Scilit]
- Kim, J.; Fairclough, S.; Dibrell, C. Attention, action, and greenwash in family-influenced firms? Evidence from polluting industries. Organ. Environ. 2017, 30, 304–323. [Google Scholar] [CrossRef] [Scilit]
- Binz, C.A.; Ferguson, K.E.; Pieper, T.M.; Astrachan, J.H. Family business goals, corporate citizenship behaviour and firm performance: Disentangling the connections. Int. J. Manag. Enterp. Dev. 2017, 16, 34–56. [Google Scholar] [CrossRef] [Scilit]
- Sharma, P.; Sharma, S. Drivers of proactive environmental strategy in family firms. Bus. Ethics Q. 2011, 21, 309–334. [Google Scholar] [CrossRef] [Scilit]
- Vardaman, J.M.; Gondo, M.B. Socioemotional wealth conflict in family firms. Entrep. Theory Pract. 2014, 38, 1317–1322. [Google Scholar] [CrossRef] [Scilit]
- Orlitzky, M.; Schmidt, F.L.; Rynes, S.L. Corporate social and financial performance: A meta-analysis. Organ. Stud. 2003, 24, 403–441. [Google Scholar] [CrossRef] [Scilit]
- Harjoto, M.; Laksmana, I. The impact of corporate social responsibility on risk taking and firm value. J. Bus. Ethics 2018, 151, 353–373. [Google Scholar] [CrossRef] [Scilit]
- Buchanan, B.; Cao, C.X.; Chen, C. Corporate social responsibility, firm value, and influential institutional ownership. J. Corp. Financ. 2018, 52, 73–95. [Google Scholar] [CrossRef] [Scilit]
- Barnea, A.; Rubin, A. Corporate Social Responsibility and Conflict between Shareholders. J. Bus. Ethics 2010, 97, 71–86. [Google Scholar] [CrossRef] [Scilit]
- Porter, M.E.; Kramer, M.R. Creating Shared Value. Harvard Bus. Rev. 2011. Available online: http://hbr.org/2011/01/the-big-idea-creatingshared-value (accessed on 12 December 2020).
- Gómez-Mejía, L.R.; Cruz, C.; Berrone, P.; De Castro, J. The bind that ties: Socioemotional wealth preservation in family firms. Acad. Manag. Ann. 2011, 5, 653–707. [Google Scholar] [CrossRef]
- Cruz, C.; Larraza-Kintana, M.; Garcés-Galdeano, L.; Berrone, P. Are family firms really more socially responsible? Entrep. Theory Pract. 2014, 38, 1295–1316. [Google Scholar] [CrossRef] [Scilit]
- Gehringer, T. Corporate Foundations as Partnership Brokers in Supporting the United Nations’ Sustainable Development Goals (SDGs). Sustainability 2020, 12, 7820. [Google Scholar] [CrossRef] [Scilit]
- Rubio-Mozos, E.; García-Muiña, F.E.; Fuentes-Moraleda, L. Application of Ecosophical Perspective to Advance to the SDGs: Theoretical Approach on Values for Sustainability in a 4S Hotel Company. Sustainability 2020, 12, 7713. [Google Scholar] [CrossRef] [Scilit]
- Yu, A.; Ding, H.B.; Chung, H.M. Corporate social responsibility performance in family and non-family firms: The perspective of socio-emotional wealth. Asian Bus. Manag. 2015, 14, 383–412. [Google Scholar] [CrossRef] [Scilit]
- Palencia-Lefler Ors, M. Donación, mecenazgo y patrocinio como técnicas de relaciones públicas al servicio de la responsabilidad social corporativa. Anàlisi 2007, 35, 153–170. [Google Scholar]
- Bhatnagar, N.; Sharma, P.; Ramachandran, K. Spirituality and Corporate Philanthropy in Indian Family Firms: An Exploratory Study. J. Bus. Ethics 2020, 163, 715–728. [Google Scholar] [CrossRef] [Scilit]

Publisher’s Note: MDPI stays neutral with regard to jurisdictional claims in published maps and institutional affiliations. |
© 2021 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (http://creativecommons.org/licenses/by/4.0/).