The Moderating Role of Digital Transformation in the Relationship Between Audit Quality and Aggressive Tax Avoidance: Empirical Evidence from the Jordanian Industrial Firms

 , , , and
Abstract
1. Introduction
2. Literature Review and Hypotheses Development
2.1. Aggressive Tax Avoidance
2.2. Quality Audit and Aggressive Tax Avoidance
2.2.1. Audit Size and Aggressive Tax Avoidance
2.2.2. Audit Fees and Aggressive Tax Avoidance
2.3. Digital Transformation as a Moderator
2.4. Control Variables
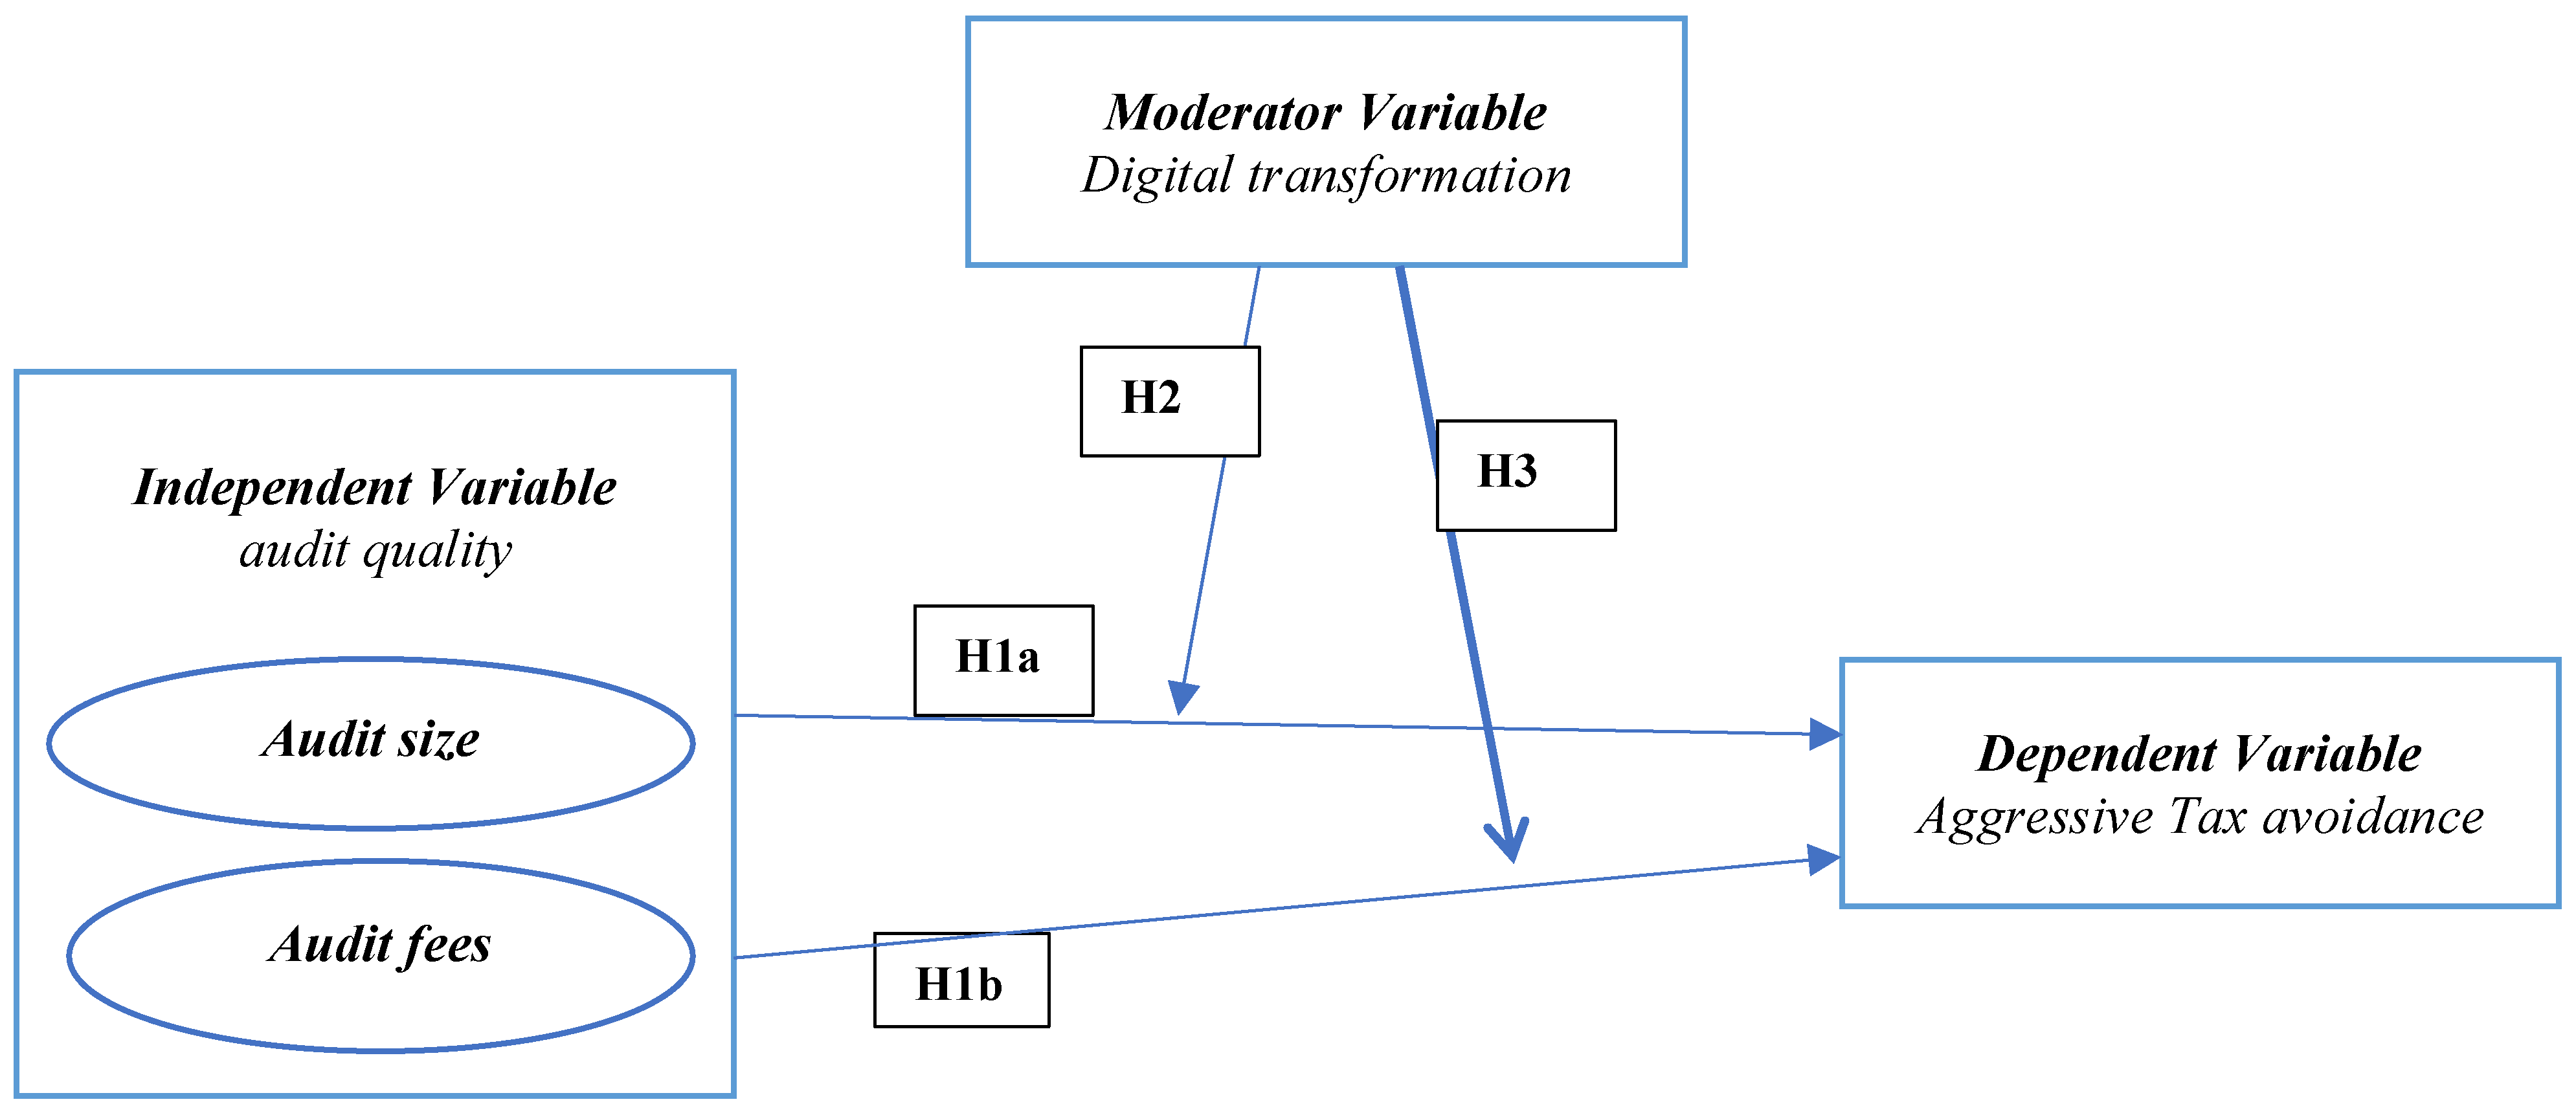
2.5. Conceptual Framework
3. Research Methodology
3.1. Sample Selection and Data Collection
3.2. Variable Measurement
3.3. Empirical Models
- i = firm (1–30)
- t = year (2020–2025)
- α = intercept
- β1 = coefficient of Big Four (BIG4)
- β2 = coefficient of Audit Fee Intensity (LnAUQFEE)
- β3 = coefficient of ROA
- β4 = coefficient of Firm Size (LnFRME)
- β5 = coefficient of Leverage (LEV)
- β6 = coefficient of Firm Age (FAGE)
- β7 = coefficient of Digital Transformation (DT)
- β8 = coefficient of interaction term (LnAUQFEE × DT)
- β9 = coefficient of interaction term (BIG4 × DT)
- ε = error term
4. Empirical Results and Discussion
4.1. Panel Unit Root Tests (Stationarity)
4.2. Descriptive Statistics

| Variable | LLC t-Statistic | p-Value | Order of Integration | Decision |
|---|---|---|---|---|
| TAXAV_w | −10.050 | 0.000 | I(0) | Stationary |
| LnAUQFEE | −10.376 | 0.000 | I(0) | Stationary |
| BIG4 | — | — | Binary | Not applicable |
| DTC | −11.414 | 0.000 | I(0) | Stationary |
| ROA_w | −12.246 | 0.000 | I(0) | Stationary |
| LnFRME | −11.087 | 0.000 | I(0) | Stationary |
| LEV | −12.807 | 0.000 | I(0) | Stationary |
| FAGE | −13.088 | 0.000 | I(0) | Stationary |
| Variables | Obs | Mean | Std. Dev | Min | Max | p1 | p99 | Skew | Kurt |
|---|---|---|---|---|---|---|---|---|---|
| TAXAV | 180 | 0.101 | 0.108 | −0.146 | 0.394 | −0.146 | 0.394 | 0.275 | 2.939 |
| BIG4 | 180 | 0.267 | 0.443 | 0 | 1 | 0 | 1 | 1.055 | 2.114 |
| logfees | 180 | 4.069 | 0.367 | 2.903 | 4.972 | 2.903 | 4.938 | −0.107 | 5.554 |
| DTC | 180 | 3.719 | 0.484 | 2.079 | 4.7 | 2.398 | 4.554 | −0.719 | 3.135 |
| ROA | 180 | 0.045 | 0.14 | −0.751 | 0.585 | −0.751 | 0.585 | −1.59 | 16.285 |
| logfrme | 180 | 7.403 | 0.58 | 6.049 | 9.336 | 6.081 | 9.331 | 0.742 | 4.926 |
| LEV | 180 | 0.456 | 0.118 | 0.251 | 0.65 | 0.251 | 0.648 | −0.108 | 1.745 |
| FAGE | 180 | 37.167 | 11.489 | 20 | 72 | 21 | 71 | 1.035 | 4.14 |
4.3. Matrix of Correlations
4.4. Diagnostic Tests
4.5. Results of Panel Data Models
4.5.1. Random Effects
4.5.2. Fixed Effects
4.5.3. Hausman Test
4.6. Robustness Tests
4.6.1. System-GMM Estimation
4.6.2. Alternative Dependent Variable: Book-Tax Differences (BTD)
4.7. Hypothesis Results and Discussion
4.7.1. Control Variables (FGLS) Regression (Model 1)
4.7.2. Control + Independent Variables) FGLS) Regression (Model 2)
4.7.3. Independent Variables +CDT (FGLS) Regression (Model 3)
4.7.4. Moderator Variables (FGLS) Regression (Model 4)
4.7.5. System-GMM Results
4.7.6. FGLS Robustness: Alternative Dependent Variable—Book-Tax Differences (BTD)
5. Discussion
6. Conclusions
6.1. Theoretical and Policy Implications
6.2. Limitations and Future Research
Author Contributions
Funding
Institutional Review Board Statement
Informed Consent Statement
Data Availability Statement
Conflicts of Interest
Appendix A. Supplementary Figures


References
- Abu Quba, H. Y., Al-Hajaya, K., & Eltweri, A. (2025). Does the interplay between audit committee independence and audit quality mitigate tax avoidance? Evidence from non-financial firms listed on the amman stock exchange. Administrative Sciences, 15(11), 426. [Google Scholar] [CrossRef] [Scilit]
- Ado, A. B., Rashid, N., Mustapha, U. A., & Ademola, L. S. (2020). The impact of audit quality on the financial performance of listed companies nigeria. Journal of Critical Reviews, 7(9), 37–42. [Google Scholar] [CrossRef] [Scilit]
- Al-Ajmi, J. (2009). Audit firm, corporate governance, and audit quality: Evidence from Bahrain. Advances in Accounting, 25(1), 64–74. [Google Scholar] [CrossRef] [Scilit]
- Alawamreh, M. I. S., Latiff, A. R. A., Yusri, Y., Al-Radaideh, I. S., Thaer, A., & Alalawnh, N. A. K. (2026, April). The moderating role of digital transformation on the relationship between board gender diversity and tax avoidance: Evidence from Jordan. In 2026 international conference on artificial intelligence for sustainable engineering and innovation (AISEI) (pp. 1019–1024). IEEE. [Google Scholar]
- Alkurdi, A., & Mardini, G. H. (2020). The impact of ownership structure and the board of directors’ composition on tax avoidance strategies: Empirical evidence from Jordan. Journal of Financial Reporting and Accounting, 18(4), 795–812. [Google Scholar] [CrossRef] [Scilit]
- Alles, M., & Gray, G. L. (2024). The marketing on big 4 websites of big data analytics in the external audit: Evidence and consequences. International Journal of Accounting Information Systems, 54, 100697. [Google Scholar] [CrossRef] [Scilit]
- Allingham, M. G., & Sandmo, A. (1972). Income tax evasion: A theoretical analysis. Journal of Public Economics, 1(3–4), 323–338. [Google Scholar] [CrossRef] [Scilit]
- Alm, J. (2012). Measuring, explaining, and controlling tax evasion: Lessons from theory, experiments, and field studies. International Tax and Public Finance, 19(1), 54–77. [Google Scholar]
- Almaharmeh, M. I., Shehadeh, A., Alkayed, H., Aladwan, M., & Iskandrani, M. (2024). Family ownership, corporate governance quality and tax avoidance: Evidence from an emerging market—The case of Jordan. Journal of Risk and Financial Management, 17(2), 86. [Google Scholar] [CrossRef] [Scilit]
- Almarayeh, T. S., Aibar-Guzmán, B., & Abdullatif, M. (2020). Does audit quality influence earnings management in emerging markets? Evidence from Jordan. Revista de Contabilidad, 23(1), 64–74. [Google Scholar] [CrossRef] [Scilit]
- Almatarneh, Z., Bashatweh, A. D., Alqudah, M. M., & Jarah, B. A. F. (2026). The impact of external audit quality on reducing illegal accounting practices of firm size and corporate governance in Jordan. Humanities and Social Sciences Letters, 14(1), 502–514. [Google Scholar] [CrossRef] [Scilit]
- Al-Qudah, A. M. (2021). The determinants of tax revenues: Empirical evidence from Jordan. International Journal of Financial Research, 12(3), 43. [Google Scholar] [CrossRef] [Scilit]
- Amara, N., Bouzgarrou, H., Bourouis, S., Alshdaifat, S. M., & Al Amosh, H. (2025). The interaction effect of female leadership in audit committees on the relationship between audit quality and corporate tax avoidance. Journal of Risk and Financial Management, 18(1), 27. [Google Scholar] [CrossRef] [Scilit]
- Anjarwi, A. W. (2026). The digital transformation of tax audits: How AI, big data, blockchain, and advanced analytics are reshaping tax evasion detection. Journal of Business Analytics, 1–12. [Google Scholar] [CrossRef] [Scilit]
- Appelbaum, D., Kogan, A., & Vasarhelyi, M. A. (2017). Big data and analytics in the modern audit engagement: Research needs. Auditing: A Journal of Practice & Theory, 36(4), 1–27. [Google Scholar] [CrossRef] [Scilit]
- Arellano, M., & Bond, S. (1991). Some tests of specification for panel data: Monte Carlo evidence and an application to employment equations. The Review of Economic Studies, 58(2), 277–297. [Google Scholar] [CrossRef] [Scilit]
- Athira, A., & Ramesh, V. K. (2023). COVID-19 and corporate tax avoidance: International evidence. International Business Review, 32(4), 102143. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Ayoola, T. J. (2022). Audit fees, audit seasonality and audit quality in Nigeria: A mediation analysis. Journal of Financial Reporting and Accounting, 22, 1152–1175. [Google Scholar] [CrossRef] [Scilit]
- Balakrishnan, K., Blouin, J. L., & Guay, W. R. (2019). Tax aggressiveness and corporate transparency. The Accounting Review, 94(1), 45–69. [Google Scholar] [CrossRef] [Scilit]
- Baltagi, B. H. (2008). Econometric analysis of panel data (4th ed.). Wiley. [Google Scholar]
- Barney, J. (1991). Firm resources and sustained competitive advantage. Journal of Management, 17(1), 99–120. [Google Scholar] [CrossRef] [Scilit]
- Behrend, M. J., Khan, S., Ko, Y. W., & Park, S. (2020). Abnormal audit fees and audit quality: Evidence from the Korean audit market. Journal of International Accounting Research, 19(3), 37–60. [Google Scholar] [CrossRef] [Scilit]
- Belahouaoui, R., & Attak, E. H. (2024). Digitalization of tax administration and tax avoidance. In Impact of digitalization on reporting, tax avoidance, accounting, and green finance (pp. 200–225). IGI Global Scientific Publishing. [Google Scholar] [CrossRef] [Scilit]
- Bilicka, K., Dubinina, E., & Janský, P. (2026). Fiscal consequences of corporate tax avoidance. Journal of Public Economics, 257, 105613. [Google Scholar] [CrossRef] [Scilit]
- Binh, N. T. T. (2025). Transforming auditing in the AI era: A comprehensive review. Information, 16(5), 400. [Google Scholar] [CrossRef] [Scilit]
- Blundell, R., & Bond, S. (1998). Initial conditions and moment restrictions in dynamic panel data models. Journal of Econometrics, 87(1), 115–143. [Google Scholar] [CrossRef] [Scilit]
- Central Bank of Jordan. (2025). Recent monetary & economic developments in Jordan—November 2025; Research department, monthly report; Central Bank of Jordan. Available online: https://www.cbj.gov.jo/ebv4.0/root_storage/en/eb_list_page/november_2025-0.pdf (accessed on 5 July 2026).
- Chen, M., Zhao, K., & Jin, W. (2024). Corporate digital transformation and tax avoidance: Evidence from China. Pacific Basin Finance Journal, 85, 102400. [Google Scholar] [CrossRef] [Scilit]
- Chen, S., Chen, X., Cheng, Q., & Shevlin, T. (2010). Are family firms more tax aggressive than non-family firms? Journal of Financial Economics, 95(1), 41–61. [Google Scholar] [CrossRef] [Scilit]
- Chen, W., & Meng, F. (2024). Is corporate digital transformation a tax haven? International Journal of Managerial Finance, 20(2), 304–333. [Google Scholar] [CrossRef] [Scilit]
- Chiari, A. (2024). Revenue losses from corporate tax avoidance: Estimations from the UNUWIDER government revenue dataset. Review of Development Economics, 28(2), 600–629. [Google Scholar]
- Cohen, J. (1988). Set correlation and contingency tables. Applied Psychological Measurement, 12(4), 425–434. [Google Scholar] [CrossRef] [Scilit]
- DeAngelo, L. E. (1981). Auditor size and audit quality. Journal of Accounting and Economics, 3(3), 183–199. [Google Scholar] [CrossRef] [Scilit]
- DeFond, M., & Zhang, J. (2014). A review of archival auditing research. Journal of Accounting and Economics, 58(2–3), 275–326. [Google Scholar] [CrossRef] [Scilit]
- Desai, M. A., & Dharmapala, D. (2006). Corporate tax avoidance and high-powered incentives. Journal of Financial Economics, 79(1), 145–179. [Google Scholar] [CrossRef] [Scilit]
- Dyreng, S. D., Hanlon, M., & Maydew, E. L. (2008). Long-run corporate tax avoidance. The Accounting Review, 83(1), 61–82. [Google Scholar] [CrossRef] [Scilit]
- Dyreng, S. D., Hanlon, M., & Maydew, E. L. (2019). When does tax avoidance result in tax uncertainty? The Accounting Review, 94(2), 179–203. [Google Scholar]
- Flick Network. (2025). E-invoicing in Jordan: JoFotara compliance requirements. Available online: https://www.flick.network/en-jo/e-invoicing-jordan-jofotara (accessed on 5 July 2026).
- Francis, J. R. (2011). A framework for understanding and researching audit quality. Auditing: Journal of Practice & Theory, 30(2), 125–152. [Google Scholar] [CrossRef] [Scilit]
- Francis, J. R., & Yu, M. D. (2009). Big 4 office size and audit quality. The Accounting Review, 84(5), 1521–1552. [Google Scholar] [CrossRef] [Scilit]
- Garcia-Bernardo, J., & Janský, P. (2024). Profit shifting of multinational corporations worldwide. World Development, 177, 106527. [Google Scholar] [CrossRef] [Scilit]
- Graham, J. R., Hanlon, M., Shevlin, T., & Shroff, N. (2014). Incentives for tax planning and avoidance: Evidence from the field. The Accounting Review, 89(3), 991–1023. [Google Scholar] [CrossRef] [Scilit]
- Graham, J. R., & Tucker, A. L. (2006). Tax shelters and corporate debt policy. Journal of Financial Economics, 81(3), 563–594. [Google Scholar] [CrossRef] [Scilit]
- Green, S. B. (1991). How many subjects does it take to do a regression analysis. Multivariate Behavioral Research, 26(3), 499–510. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Greene, W. H. (2000). Econometric analysis (4th ed., pp. 201–215). International Edition. Prentice Hall. [Google Scholar]
- Gujarati, D. N. (2003). Basic econometrics (4th ed.). McGraw-Hill. Available online: https://www.scirp.org/reference/referencespapers?referenceid=1142287 (accessed on 8 February 2026).
- Gunn, J. L., Kawada, B. S., & Michas, P. N. (2019). Audit market concentration, audit fees, and audit quality: A cross-country analysis of complex audit clients. Journal of Accounting and Public Policy, 38(6), 106693. [Google Scholar] [CrossRef] [Scilit]
- Guo, R., Jia, Y., & Shentu, L. (2025). The effect of audit digital transformation on audit quality: Evidence from digital bank confirmations. China Journal of Accounting Studies, 13, 247–281. [Google Scholar]
- Hair, J. F., Black, W. C., Babin, B. J., & Anderson, R. E. (2014). Multivariate data analysis (7th ed.). Pearson Education Limited. [Google Scholar]
- Hanlon, M., & Heitzman, S. (2010). A review of tax research. Journal of Accounting and Economics, 50(2–3), 127–178. [Google Scholar] [CrossRef] [Scilit]
- Hausman, J. A. (1978). Specification tests in econometrics. Econometrica: Journal of the Econometric Society, 46, 1251–1271. [Google Scholar] [CrossRef] [Scilit]
- Hay, D. C., Knechel, W. R., & Wong, N. (2006). Audit fees: A meta-analysis of the effect of supply and demand attributes. Contemporary Accounting Research, 23(1), 141–191. [Google Scholar] [CrossRef] [Scilit]
- Hogan, B., & Noga, T. (2015). Auditor-provided tax services and long-term tax avoidance. Review of Accounting and Finance, 14(3), 285–305. [Google Scholar] [CrossRef] [Scilit]
- Hossain, M. S., Ali, M. S., Ling, C. C., & Fung, C. Y. (2024). Tax avoidance and tax evasion: Current insights and future research directions from an emerging economy. Asian Journal of Accounting Research, 9(3), 275–292. [Google Scholar] [CrossRef] [Scilit]
- Hsiao, C. (2022). Analysis of panel data. Cambridge University Press. [Google Scholar]
- Ichsani, S., & Susanti, N. (2019). The effect of firm value, leverage, profitability and company size on tax avoidance in companies listed on index LQ45 Period 2012–2016. Global Business and Management Research: An International Journal, 11(1), 307–311. [Google Scholar]
- IMF. (2024). Jordan: 2024 article IV consultation, second review under the extended arrangement under the extended fund facility, and request for modification of performance criteria—Press release; staff report; and statement by the executive director for jord. Available online: https://www.imf.org/en/Publications/CR/Issues/2024/12/17/Jordan-2024-Article-IV-Consultation-Second-Review-Under-the-Extended-Arrangement-Under-the-559656 (accessed on 13 March 2025).
- Jain, S., & Agarwalla, S. K. (2023). Big-4 auditors and audit quality: A novel firm life-cycle approach. Meditari Accountancy Research, 31(5), 1436–1452. [Google Scholar] [CrossRef] [Scilit]
- Jensen, M. C., & Meckling, W. (1976). Theory of the firm: Managerial behavior, agency costs and ownership structure. Journal of Financial Economics, 3(4), 305–360. [Google Scholar] [CrossRef] [Scilit]
- Kaawaase, T. K., Nairuba, C., Akankunda, B., & Bananuka, J. (2021). Corporate governance, internal audit quality and financial reporting quality of financial institutions. Asian Journal of Accounting Research, 6(3), 348–366. [Google Scholar] [CrossRef] [Scilit]
- Kanagaretnam, K., Lee, J., Lim, C. Y., & Lobo, G. J. (2016). Relation between auditor quality and tax aggressiveness: Implications of cross-country institutional differences. Auditing: A Journal of Practice & Theory, 35(4), 105–135. [Google Scholar] [CrossRef] [Scilit]
- Kovermann, J., & Velte, P. (2019). The impact of corporate governance on corporate tax avoidance—A literature review. Journal of International Accounting, Auditing and Taxation, 36, 100270. [Google Scholar] [CrossRef] [Scilit]
- Lanis, R., & Richardson, G. (2012). Corporate social responsibility and tax aggressiveness: A test of legitimacy theory. Accounting, Auditing & Accountability Journal, 26(1), 75–100. [Google Scholar] [CrossRef] [Scilit]
- Larcker, D. F., & Rusticus, T. O. (2010). On the use of instrumental variables in accounting research. Journal of Accounting and Economics, 49(3), 186–205. [Google Scholar] [CrossRef] [Scilit]
- Lennox, C. S. (1999). Audit quality and auditor size: An evaluation of reputation and deep pockets hypotheses. Journal of Business Finance & Accounting, 26(7–8), 779–805. [Google Scholar] [CrossRef] [Scilit]
- Lennox, C. S., Lisowsky, P., & Pittman, J. (2013). Tax aggressiveness and accounting fraud. Journal of Accounting Research, 51(4), 739–778. [Google Scholar] [CrossRef] [Scilit]
- Lennox, C. S., Wang, C., & Wu, X. (2023). Delegated leadership at public accounting firms. Journal of Accounting and Economics, 76(1), 101572. [Google Scholar] [CrossRef] [Scilit]
- Lestari, N., & Nedya, S. (2019). The effect of audit quality on tax avoidance. Cogent Business and Management, 7(1), 329–333. [Google Scholar] [CrossRef] [Scilit]
- Lohapan, N. (2021). Digital accounting implementation and audit performance: An empirical research of tax auditors in Thailand. Journal of Asian Finance, 8(11), 121–131. [Google Scholar] [CrossRef]
- Marzuki, M. M., & Syukur, M. (2021). The effect of audit fees, audit quality and board ownership on tax aggressiveness: Evidence from Thailand. Asian Review of Accounting, 29(5), 617–636. [Google Scholar] [CrossRef] [Scilit]
- Ministry of Finance. (2019). Income tax law No. 34 of 2014 as amended by law No. 38 of 2018. Income and Sales Tax Department. [Google Scholar]
- Modigliani, F., & Miller, M. H. (1958). The cost of capital, corporation finance and the theory of investment. The American Economic Review, 48(3), 261–297. [Google Scholar]
- Pesaran, M. H. (2015). Time series and panel data econometrics. Oxford University Press. [Google Scholar]
- Porter, D. C., & Gujarati, D. N. (2009). Basic econometrics. McGraw-Hill Irwin. [Google Scholar]
- Qawqzeh, H. K., Endut, W. A., Rashid, N., & Dakhlallh, M. M. (2020). Impact of the external auditor’s effectiveness on the financial reporting quality: The mediating effect of audit quality. Journal of Critical Reviews, 7(6), 1197–1208. [Google Scholar]
- Rego, S. O. (2003). Tax-avoidance activities of U.S. multinational corporations. Contemporary Accounting Research, 20(4), 805–833. [Google Scholar] [CrossRef] [Scilit]
- Richardson, G., & Lanis, R. (2007). Determinants of the variability in corporate effective tax rates and tax reform: Evidence from Australia. Journal of Accounting and Public Policy, 26(6), 689–704. [Google Scholar] [CrossRef] [Scilit]
- Riguen, R., Salhi, B., & Jarboui, A. (2020). Do women in board represent less corporate tax avoidance? A moderation analysis. International Journal of Sociology and Social Policy, 40(1–2), 114–132. [Google Scholar] [CrossRef] [Scilit]
- Rizqia, A., & Lastiati, A. (2021). Audit quality and tax avoidance: The role of independent commissioners and audit committee’s financial expertise. Journal of Accounting Auditing and Business, 4(1), 14. [Google Scholar] [CrossRef] [Scilit]
- Roodman, D. (2009). How to do xtabond2: An introduction to difference and system GMM in Stata. The Stata Journal, 9(1), 86–136. [Google Scholar] [CrossRef] [Scilit]
- Simunic, D. A. (1980). The pricing of audit services: Theory and evidence. Journal of Accounting Research, 18, 161–190. [Google Scholar] [CrossRef] [Scilit]
- Tang, M., Hu, Y., Hou, Y. G., Oxley, L., & Goodell, J. W. (2025). Fintech development, corporate tax avoidance and firm value. International Review of Financial Analysis, 97, 103765. [Google Scholar] [CrossRef] [Scilit]
- Tanko, U. M. (2020). The moderating effect of profitability on the relationship between ownership structure and corporate tax avoidance in Nigeria listed consumers goods firms. International Journal of Business and Technopreneurship, 10(2), 153–172. [Google Scholar]
- Tax Justice Network. (2024). State of tax justice 2024. Tax Justice Network. [Google Scholar]
- Vial, G. (2021). Understanding digital transformation: A review and a research agenda. Managing Digital Transformation, 28, 13–66. [Google Scholar] [CrossRef] [Scilit]
- Vitali, S., & Giuliani, M. (2024). Emerging digital technologies and auditing firms: Opportunities and challenges. International Journal of Accounting Information Systems, 53, 100676. [Google Scholar] [CrossRef] [Scilit]
- Wang, X., & Li, Y. (2020). Big 4 audit quality and financial reporting: A binary coding approach. Contemporary Accounting Research, 42(3), 200–215. [Google Scholar]
- Wilde, J. H., & Wilson, R. J. (2018). Perspectives on corporate tax planning: Observations from the past decade. The Journal of the American Taxation Association, 40(2), 63–81. [Google Scholar] [CrossRef] [Scilit]
- Wooldridge, J. M. (2002). Econometric analysis of cross section and panel data (Vol. 108, pp. 245–254). MIT Press. [Google Scholar]
- Wooldridge, J. M. (2010). Econometric analysis of cross section and panel data. MIT Press. [Google Scholar]
- Zhang, L., & Bin Balia, S. S. (2024). Digital transformation and corporate audit risk: Mediating effects of auditor behavior. Finance Research Letters, 67, 105754. [Google Scholar] [CrossRef] [Scilit]
- Zhang, Q., & She, J. (2024). Digital transformation and corporate tax avoidance: An analysis based on multiple perspectives and mechanisms. PLoS ONE, 19(9), e0310241. [Google Scholar] [CrossRef] [Scilit] [PubMed]
- Zhu, F., Zhang, D., & Li, L. (2025). Effects of digital media development on corporate financial behavior: Moderating role of corporate social responsibility. Finance Research Letters, 74, 106718. [Google Scholar] [CrossRef] [Scilit]
- Zimmerman, J. L. (1983). Taxes and firm size. Journal of Accounting and Economics, 5, 119–149. [Google Scholar] [CrossRef] [Scilit]
- Ziniuk, M., Dyeyeva, N., Bogatyrova, K., Melnychenko, S., Fayvishenko, D., & Shevchun, M. (2022). Digital transformation of corporate governance. Financial and Credit Activity Problems of Theory and Practice, 5(46), 300–310. [Google Scholar] [CrossRef] [Scilit]

| Variables | (1) | (2) | (3) | (4) | (5) | (6) | (7) | (8) |
|---|---|---|---|---|---|---|---|---|
| (1) TAXAV | 1.000 | |||||||
| (2) BIG4 | −0.069 | 1.000 | ||||||
| (3) logfees | 0.339 | 0.627 | 1.000 | |||||
| (4) DTC | 0.125 | 0.110 | 0.165 | 1.000 | ||||
| (5) ROA | 0.266 | 0.205 | 0.569 | 0.025 | 1.000 | |||
| (6) logfrme | 0.097 | 0.257 | 0.394 | 0.050 | 0.241 | 1.000 | ||
| (7) LEV | 0.213 | −0.014 | 0.057 | −0.002 | 0.055 | −0.053 | 1.000 | |
| (8) FAGE | 0.159 | 0.195 | 0.297 | 0.115 | 0.113 | −0.015 | 0.087 | 1.000 |
| TAXAV | Coef | Std.Err | t-Value | p-Value | [95% Conf | Interval] | Sig | ||
|---|---|---|---|---|---|---|---|---|---|
| BIG4 | −0.098 | 0.039 | −2.52 | 0.012 | −0.174 | −0.022 | ** | ||
| logfees | 0.14 | 0.05 | 2.80 | 0.005 | 0.042 | 0.238 | *** | ||
| ROA | 0.081 | 0.055 | 1.47 | 0.142 | −0.027 | 0.188 | |||
| longform | 0 | 0.025 | −0.01 | 0.993 | −0.049 | 0.049 | |||
| LEV | 0.138 | 0.047 | 2.94 | 0.003 | 0.046 | 0.229 | *** | ||
| FAGE | 0.001 | 0.001 | 0.60 | 0.548 | −0.002 | 0.003 | |||
| Constant | −0.534 | 0.226 | −2.36 | 0.018 | −0.977 | −0.092 | ** | ||
| Mean dependent var | 0.101 | SD dependent var | 0.108 | ||||||
| Overall r-squared | 0.271 | Number of obs | 180 | ||||||
| Chi-square | 27.464 | Prob > chi2 | 0.000 | ||||||
| R-squared within | 0.077 | R-squared between | 0.378 | ||||||
| TAXAV | Coef | Std.Err | t-Value | p-Value | [95% Conf | Interval] | Sig | ||
|---|---|---|---|---|---|---|---|---|---|
| o | 0 | ||||||||
| logfees | 0.049 | 0.123 | 0.39 | 0.694 | −0.195 | 0.292 | |||
| ROA | 0.092 | 0.059 | 1.56 | 0.121 | −0.025 | 0.208 | |||
| longform | 0.008 | 0.111 | 0.07 | 0.944 | −0.212 | 0.228 | |||
| LEV | 0.138 | 0.048 | 2.87 | 0.005 | 0.043 | 0.233 | *** | ||
| FAGE | 0.001 | 0.004 | 0.37 | 0.709 | −0.006 | 0.008 | |||
| Constant | −0.272 | 0.859 | −0.32 | 0.752 | −1.969 | 1.425 | |||
| Mean dependent var | 0.101 | SD dependent var | 0.108 | ||||||
| R-squared | 0.081 | Number of obs | 180 | ||||||
| F-test | 2.557 | Prob > F | 0.000 | ||||||
| Akaike crit. (AIC) | −481.734 | Bayesian crit. (BIC) | −462.576 | ||||||
| TAXAV_w | Coef | St.Err | t-Value | p-Value | [95% Conf | Interval] | Sig | ||
|---|---|---|---|---|---|---|---|---|---|
| ROA | 0.159 | 0.033 | 4.89 | 0 | 0.095 | 0.223 | *** | ||
| logfrme | 0.022 | 0.009 | 2.30 | 0.022 | 0.003 | 0.04 | ** | ||
| LEV | 0.183 | 0.046 | 3.95 | 0 | 0.092 | 0.273 | *** | ||
| FAGE | 0.002 | 0 | 3.62 | 0 | 0.001 | 0.002 | *** | ||
| Constant | −0.208 | 0.075 | −2.76 | 0.006 | −0.355 | −0.06 | *** | ||
| Mean dependent var | 0.101 | SD dependent var | 0.108 | ||||||
| Number of obs | 180 | Chi-square | 61.135 | ||||||
| TAXAV | Coef. | St.Err | t-Value | p-Value | [95% Conf | Interval] | Sig | ||
|---|---|---|---|---|---|---|---|---|---|
| logfees | 0.139 | 0.022 | 6.23 | 0 | 0.095 | 0.183 | *** | ||
| BIG4 | −0.116 | 0.019 | −6.21 | 0 | −0.152 | −0.079 | *** | ||
| ROA | −0.013 | 0.022 | −0.58 | 0.559 | −0.057 | 0.031 | |||
| logfrme | 0.015 | 0.013 | 1.14 | 0.255 | −0.011 | 0.04 | |||
| LEV | 0.037 | 0.025 | 1.51 | 0.132 | −0.011 | 0.086 | |||
| FAGE | 0.002 | 0.001 | 4.47 | 0 | 0.001 | 0.004 | *** | ||
| Constant | −0.648 | 0.114 | −5.69 | 0 | −0.872 | −0.425 | *** | ||
| Mean dependent var | 0.101 | SD dependent var | 0.108 | ||||||
| Number of obs | 180 | Chi-square | 98.620 | ||||||
| TAXAV_w | Coef. | St.Err | t-Value | p-Value | [95% Conf | Interval] | Sig | ||
|---|---|---|---|---|---|---|---|---|---|
| BIG4 | −0.111 | 0.013 | −8.32 | 0 | −0.137 | −0.085 | *** | ||
| logfees | 0.158 | 0.02 | 7.90 | 0 | 0.119 | 0.197 | *** | ||
| ROA | −0.004 | 0.035 | −0.12 | 0.902 | −0.074 | 0.065 | |||
| logfrme | 0.006 | 0.009 | 0.75 | 0.455 | −0.011 | 0.024 | |||
| LEV | 0.117 | 0.044 | 2.67 | 0.007 | 0.031 | 0.203 | *** | ||
| FAGE | 0.002 | 0 | 4.24 | 0 | 0.001 | 0.003 | *** | ||
| DTC | 0.026 | 0.01 | 2.54 | 0.011 | 0.006 | 0.046 | ** | ||
| Constant | −0.777 | 0.09 | −8.66 | 0 | −0.953 | −0.601 | *** | ||
| Mean dependent var | 0.101 | SD dependent var | 0.108 | ||||||
| Number of obs | 180 | Chi-square | 240.834 | ||||||
| TAXAV | Coef | St.Err | t-Value | p-Value | [95% Conf | Interval] | Sig | ||
|---|---|---|---|---|---|---|---|---|---|
| Big4 | −0.058 | 0.104 | −0.55 | 0.579 | −0.261 | 0.146 | |||
| logfees | −0.168 | 0.17 | −0.99 | 0.324 | −0.501 | 0.165 | |||
| ROA | 0.006 | 0.037 | 0.17 | 0.869 | −0.066 | 0.079 | |||
| logfrme | 0.007 | 0.009 | 0.87 | 0.385 | −0.009 | 0.024 | |||
| LEV | 0.118 | 0.045 | 2.65 | 0.008 | 0.031 | 0.206 | *** | ||
| FAGE | 0.002 | 0 | 3.92 | 0 | 0.001 | 0.003 | *** | ||
| DTC | 0.025 | 0.011 | 2.32 | 0.02 | 0.004 | 0.046 | ** | ||
| cdtbig | −0.007 | 0.013 | −0.51 | 0.607 | −0.032 | 0.018 | |||
| cdtfee | 0.031 | 0.016 | 1.91 | 0.056 | −0.001 | 0.062 | * | ||
| Constant | 0.531 | 0.671 | 0.79 | 0.428 | −0.784 | 1.847 | |||
| Mean dependent var | 0.101 | SD dependent var | 0.108 | ||||||
| Number of obs | 180 | Chi-square | 221.463 | ||||||
| Variable | Coefficient | Std. Err | z-Value | p-Value | Sig |
|---|---|---|---|---|---|
| BIG4 (instrumented) | −0.108 | 0.023 | −4.70 | 0.000 | *** |
| LnAUDFEE | 0.132 | 0.031 | 4.26 | 0.000 | *** |
| ROA | −0.011 | 0.028 | −0.39 | 0.694 | |
| LnFRME | 0.013 | 0.011 | 1.18 | 0.238 | |
| LEV | 0.124 | 0.046 | 2.70 | 0.007 | *** |
| FAGE | 0.002 | 0.001 | 3.45 | 0.001 | *** |
| DTC | 0.023 | 0.012 | 1.92 | 0.055 | * |
| Constant | −0.701 | 0.128 | −5.48 | 0.000 | *** |
| Variable | Coef | Std. Err | t-Value | Sig |
|---|---|---|---|---|
| BIG4 | −0.089 | 0.021 | −4.24 | *** |
| LnAUDFEE | 0.044 | 0.018 | 2.44 | ** |
| ROA | −0.019 | 0.031 | −0.61 | |
| LnFRME | 0.009 | 0.011 | 0.82 | |
| LEV | 0.091 | 0.038 | 2.39 | ** |
| FAGE | 0.001 | 0.000 | 3.11 | *** |
| DTC | 0.017 | 0.009 | 1.89 | * |
| cdtfee | 0.022 | 0.013 | 1.69 | * |
| cdtbig | −0.005 | 0.011 | −0.45 | |
| N = 180 | Chi-square = 198.43 (p < 0.001) |
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.
Share and Cite
Alawamreh, M.I.; Abdul Latiff, A.R.; Yusri, Y.; Al-Radaideh, I.S.; Thaer, A.; Abdelrehim, M.; Almousa, M.M. The Moderating Role of Digital Transformation in the Relationship Between Audit Quality and Aggressive Tax Avoidance: Empirical Evidence from the Jordanian Industrial Firms. J. Risk Financ. Manag. 2026, 19, 527. https://doi.org/10.3390/jrfm19070527
Alawamreh MI, Abdul Latiff AR, Yusri Y, Al-Radaideh IS, Thaer A, Abdelrehim M, Almousa MM. The Moderating Role of Digital Transformation in the Relationship Between Audit Quality and Aggressive Tax Avoidance: Empirical Evidence from the Jordanian Industrial Firms. Journal of Risk and Financial Management. 2026; 19(7):527. https://doi.org/10.3390/jrfm19070527
Chicago/Turabian StyleAlawamreh, Mohammad Ismail, Ahmed Razman Abdul Latiff, Yusniyati Yusri, Ibrahim Saleh Al-Radaideh, Abutaber Thaer, Mahmoud Abdelrehim, and Mohammad Mosleh Almousa. 2026. "The Moderating Role of Digital Transformation in the Relationship Between Audit Quality and Aggressive Tax Avoidance: Empirical Evidence from the Jordanian Industrial Firms" Journal of Risk and Financial Management 19, no. 7: 527. https://doi.org/10.3390/jrfm19070527
APA StyleAlawamreh, M. I., Abdul Latiff, A. R., Yusri, Y., Al-Radaideh, I. S., Thaer, A., Abdelrehim, M., & Almousa, M. M. (2026). The Moderating Role of Digital Transformation in the Relationship Between Audit Quality and Aggressive Tax Avoidance: Empirical Evidence from the Jordanian Industrial Firms. Journal of Risk and Financial Management, 19(7), 527. https://doi.org/10.3390/jrfm19070527