


Abstract
In this study, we consider the problem of testing for a parameter change in general integer-valued time series models whose conditional distribution belongs to the one-parameter exponential family when the data are contaminated by outliers. In particular, we use a robust change point test based on density power divergence (DPD) as the objective function of the minimum density power divergence estimator (MDPDE). The results show that under regularity conditions, the limiting null distribution of the DPD-based test is a function of a Brownian bridge. Monte Carlo simulations are conducted to evaluate the performance of the proposed test and show that the test inherits the robust properties of the MDPDE and DPD. Lastly, we demonstrate the proposed test using a real data analysis of the return times of extreme events related to Goldman Sachs Group stock.
1. Introduction
Integer-valued time series models have received widespread attention from researchers and practitioners in diverse research areas. Since the works of McKenzie [1] as well as Al-Osh and Alzaid [2], integer-valued autoregressive (INAR) models have gained popularity in the analysis of correlated time series of counts. Later, as an alternative, Ferland et al. [3] proposed using Poisson integer-valued generalized autoregressive conditional heteroscedastic (INGARCH) models (see Engle [4] and Bollerslev [5]). Since then, INGARCH models have been studied by many authors, such as Fokianos et al. [6], who developed Poisson autoregressive (Poisson AR) models with nonlinear specifications for their intensity processes. The Poisson assumption on INGARCH models has been extended to include negative binomial INGARCH (NB-INGARCH) models (Davis and Wu [7] and Christou and Fokianos [8]), zero-inflated generalized Poisson INGARCH models (Zhu [9,10] and Lee et al. [11]), and one-parameter exponential distribution AR models (Davis and Liu [12]). The latter are also known as general integer-valued time series models and have been studied by, among others, Diop and Kengne [13] and Lee and Lee [14], who considered change point tests for these models.
The change point problem is a core issue in time series analysis because changes can occur in underlying model parameters owing to critical events or policy changes, and ignoring such changes can result in false conclusions. Numerous studies exist on change point analysis in time series models; refer to Kang and Lee [15] and Lee and Lee [14], and the articles cited therein, for the background and history of change points in integer-valued time series models. Lee and Lee [14] conducted a comparison study of the performance of various cumulative sum (CUSUM) tests using score vectors and residuals through the Monte Carlo simulations. In their work, the conditional maximum likelihood estimator (CMLE) is used for the parameter estimation and also the construction of the CUSUM tests. However, the CMLE is often damaged by outliers, and so is the performance of the CMLE-based CUSUM test. In general, outliers easily mislead the CUSUM test since they can be mistakenly taken for abrupt changes; in the opposite, they can misidentify change points in their presence on time series. Among the robust estimation methods, we adopt the minimum density power divergence estimator (MDPDE) approach—proposed by Basu et al. [16]—as a remedy and propose to use the density power divergence (DPD)-based test as a robust change point test.
The MDPDE method is well known for consistently making robust inferences in various situations, and the trade-off between efficiency and robustness is managed via the tuning parameter. Basu et al. [16] introduced the MDPDE using the independent and identically distributed observations, and later, Ghosh and Basu [17] extended their method to the independent but not identically distributed samples. For earlier works in the context of time series, see Lee and Song [18], Kim and Lee [19], Kang and Lee [20], and Kim and Lee [21], who deal with the MDPDE for GARCH models, multivariate times series, and (zero-inflated) Poisson AR models. Kim and Lee [22] demonstrated that the MDPDE for general integer-valued time series models has strong robust properties, with little loss in asymptotic efficiency relative to the CMLE. This motivates us to use the MDPDE to construct a robust change point test for general integer-valued time series models. More precisely, we anticipate that the robust property of the MDPDE would be inherited to the proposed change point test, so that the influence of outliers should be reduced when performing a parameter change test in the presence of outliers. Although the problem of testing for a parameter change in integer-valued time series models has been investigated by many researchers, the testing procedure for observations with outliers has not been widely studied. This motivates us to develop a MDPDE-based robust change point test for general integer-valued time series models.
Kang and Song [23] proposed an estimate-based robust CUSUM test that uses the MDPDE to detect parameter changes in Poisson AR models. However, this type of test is known to suffer from severe size distortions, especially when the true parameter lies at the boundary of the parameter space. Thus, we use the test deduced based on an empirical version of the DPD, which is the objective function of the MDPDE. Song and Kang [24] and Kang and Song [25] applied DPD-based change point tests in GARCH models and Poisson AR models, respectively. However, the DPD approach basically shares the same spirit as the score-based CUSUM test of Lee and Lee [14] (see Remark 3 in Section 2.2), in that both are based on derivatives of objective functions. Thus, the idea is easily adapted to one-parameter exponential family AR models. As for a parameter change test for independent samples based on divergence measures, see Batsidis et al. [26,27], who consider the -divergence as a measure. We also refer to Martín and Pardo [28], who point out the importance of a Wald-type test based on DPD in dealing with the change point problem.
Monte Carlo simulations are conducted to evaluate the performance of the proposed test. Here, we compare the DPD-based test and the score-based CUSUM test to demonstrate the superiority of the proposed test in the presence of outliers. Then, we provide a real data analysis of the return times of extreme events related to Goldman Sachs Group (GS) stock to illustrate the proposed test. The paper proceeds as follows. Section 2 constructs the DPD-based change point test for general integer-valued time series models, and states its weak convergence theorem. Section 3 presents a simulation study and a real data analysis. Section 4 concludes the paper. All proofs are provided in the Appendix A.
2. Construction of the MDPDE and Change Point Test
2.1. MDPDE for General Integer-Valued Time Series Models
Let be the observations generated from general integer-valued time series models with the conditional distribution of the one-parameter exponential family:
where is a -field generated by and is a non-negative bivariate function defined on , depending on the parameter , and satisfies for some for all . Here, is a probability mass function, given by
where is the natural parameter and and are known functions. This distribution family includes several famous discrete distributions, such as the Poisson, negative binomial, and binomial distributions. If , and become the conditional mean and variance of , and . The derivative of exists for the exponential family; see Lehmann and Casella [29]. Since , is strictly increasing, and since , is also strictly increasing. To emphasize the role of , we also use and to stand for and , respectively.
Davis and Liu [12] showed that the assumption below ensures the strict stationarity and ergodicity of :
- (A0)
- For all and ,where satisfy .
They also demonstrated that there exists a measurable function , such that almost surely (a.s.).
Meanwhile, the DPD between two density functions g and h is defined as
For a parametric family with densities given by and a distribution H with density h, the minimum DPD functional is defined by In particular, if , . Then, given a random sample with unknown density h, the MDPDE is defined by
where and
When and 1, the MDPDE becomes the MLE and the -distance estimator, respectively. Basu et al. [16] revealed that is consistent for and asymptotically normal. Furthermore, the estimator is robust against outliers, but still exhibits high efficiency when the true distribution belongs to a parametric family and is close to zero. The tuning parameter controls the trade-off between robustness and asymptotic efficiency. A large escalates the robustness while a small yields greater efficiency. The conditional version of the MDPDE is defined similarly (cf. Section 2 of Kim and Lee [22]).
For generated from (1), the MDPDE for general integer-valued time series models is defined as
where
and is updated recursively using the following equations:
with an arbitrarily chosen initial value . The MDPDE with becomes the CMLE from (3).
Kim and Lee [22] showed that under the regularity conditions (A0)–(A9) stated below, the MDPDE is strongly consistent and asymptotically normal. Conditions (A10) and (A11) are imposed to derive the limiting null distribution of the DPD-based change point test in Section 2.2. Below, V and represent a generic integrable random variable and a constant, respectively; the symbol denotes the -norm for matrices and vectors; and is taken under , where denotes the true value of .
- (A1)
- is an interior point in the compact parameter space .
- (A2)
- .
- (A3)
- for some .
- (A4)
- .
- (A5)
- If there exists , such that a.s., then .
- (A6)
- for some .
- (A7)
- The mapping is twice continuously differentiable with respect to , and satisfies
- (A8)
- a.s.
- (A9)
- a.s. implies .
- (A10)
- a.s.
- (A11)
- for some .
Proposition 1.
Under(A0)–(A5), a.s. as , and further, under(A0)–(A9),
where
and is defined by substituting for in (3).
Remark 1.
In our empirical study, discussed in Section 3.2, we select an optimal α using the method of Warwick [30] and Warwick and Jones [31]. We choose α that minimizes the trace of the estimated asymptotic mean squared error ():
where is the MDPDE with and is the estimate of the asymptotic variance of , computed as
Remark 2.
Instead of(A6), Kim and Lee [22] assumed
to prove Proposition 1. Note that this condition is satisfied directly if(A3)and(A6)hold. In our study, we alter the above condition to(A6)to prove Lemma A1 in the Appendix A, which is needed to obtain the limiting null distribution of the DPD-based change point test in Section 2.2.
The following INGARCH(1,1) models are typical examples of general integer-valued time series models:
where , with , and is compact. Condition (A0) trivially holds, and the process has a strictly stationary and ergodic solution. Condition (A1) can be replaced with the following:
- (A1)′
- The true parameter lies in a compact neighborhood of , where
Moreover, we can express
where the initial value is taken as for simplicity. Based on the above and (A4), the conditions (A2), (A5), and (A7)–(A10) are all satisfied for INGARCH(1,1) models, as proven by Theorem 3 of Kang and Lee [15]. Kim and Lee [22] showed recently that the following Poisson and negative binomial INGARCH(1,1) models satisfy (A3) and (A4). Furthermore, following the arguments presented in Section 3.2 of their study, (A6) holds for these models as well. Below, we show that (A11) holds for Poisson and negative binomial INGARCH(1,1) models.
• Poisson INGARCH(1,1) model:
In this model, and . Since , (A11) holds owing to (A3).
• NB-INGARCH(1,1) model:
where NB denotes a negative binomial distribution with parameters and . To be more specific, it counts the number of failures before the r-th success occurs in a sequence of Bernoulli trials with success probability p. Here, r is assumed to be known. In this model, and . From the fact that and , we have , which is positive and strictly decreasing on . Moreover, since , it holds that
and also has the same upper bound. Hence, (A11) is satisfied.
In addition to the above models, general integer-valued time series models also include nonlinear models, such as the integer-valued threshold GARCH (INTGARCH) model:
where with , is compact, and l is a non-negative integer value. For more details, see Remark 3 in Kim and Lee [22].
2.2. DPD-Based Change Point Test
As a robust test for parameter changes in general integer-valued time series models, we propose a DPD-based test for the following hypotheses:
To construct the test, we employ the objective function of the MDPDE. That is, our test is constructed using the empirical version of the DPD. Let be that in (2). To implement our test, we employ the following test statistic:
where
is a consistent estimator of . For the consistency of , see Lemma A5 in Appendix A.
Using the mean value theorem (MVT), we have the following, for each ,
where is an intermediate point between and . From , we obtain that, for ,
Furthermore, since is nonsingular (cf. proof of Lemma 7 in Kim and Lee [22]), this can be expressed as
Substituting the above into (4) yields
In Appendix A, we show that the first two terms on the right-hand side of (5) converge weakly to , where is a d-dimensional standard Brownian bridge and the last term is asymptotically negligible. Therefore, we obtain the following theorem.
Theorem 1.
Suppose that conditions(A0)–(A11)hold. Then, under , we have
Therefore,
We reject if is large; see Table 1 of Lee et al. [32] for the critical values. When a change point is detected, its location is estimated as
Remark 3.
The proposed test with is the same as the score-vector-based CUSUM test proposed by Lee and Lee [14], given by
where is defined in (3), is the CMLE, and . In the next section, we compare the performance of with that of in the presence of outliers.
3. Empirical Studies
3.1. Simulation
In this section, we evaluate the performance of the proposed test (with ) through simulations, focusing on the comparison with . First, we consider the Poisson INGARCH models:
where is set to 0 for the data generation and is set as the sample mean of the data. The sample sizes considered are and 1000, with 1000 repetitions for each simulation. For the comparison, we examine the empirical size and power at the nominal level of 0.05, which has a corresponding critical value of 3.004. To calculate the empirical size and power for each test, we consider cases with and those in which changes to at the middle time , respectively.
Table 1 presents the results when the data are not contaminated by outliers, showing that both tests ( and ) exhibit reasonable size, even when is close to 1. When , outperforms in terms of power; however, as the sample size increases to , exhibits similar power to that of , particularly when is small. The power of tends to decrease as increases, confirming that an MDPDE with large results in a loss of efficiency.
Table 1.
Empirical sizes and powers for Poisson integer-valued generalized autoregressive conditional heteroscedastic (INGARCH)(1,1) models when no outliers exist.
To evaluate the robustness of the proposed test, we assume that contaminated data are observed instead of in (6) (cf. Fried et al. [33]):
where are independent and identically distributed (iid) Bernoulli random variables with success probability p and are iid Poisson random variables with mean . We assume that , , and are all independent. In this simulation, we consider the cases and . The results are reported in Table 2, Table 3, Table 4 and Table 5, showing that suffers from size distortions that become more severe as either p or increase. In contrast, compensates for this defect remarkably well, yielding comparable power to that of when . This indicates that as more data are contaminated by outliers, increasingly outperforms .
Table 2.
Empirical sizes and powers for Poisson INGARCH(1,1) models when and .
Table 3.
Empirical sizes and powers for Poisson INGARCH(1,1) models when and .
Table 4.
Empirical sizes and powers for Poisson INGARCH(1,1) models when and .
Table 5.
Empirical sizes and powers for Poisson INGARCH(1,1) models when and .
Next, we consider the following NB-INGARCH(1,1) models:
where and are 0 and the sample mean of the data, respectively. We set , and use the same parameter settings as in the Poisson INGARCH model case. In order to evaluate the robustness of the test, we observe contaminated data , as in (7), where are generated from (8), are iid Bernoulli random variables with success probability p, and are iid NB random variables. We consider the cases and . The results are reported in Table 6, Table 7, Table 8, Table 9 and Table 10, showing similar results to those in Table 1, Table 2, Table 3, Table 4 and Table 5. Our findings show that the DPD-based test performs reasonably well in terms of both size and power, regardless of the existence of outliers. In addition, we confirm that the proposed test outperforms the score-based CUSUM test when the data are contaminated by outliers.
Table 6.
Empirical sizes and powers for negative binomial INGARCH (NB-INGARCH)(1,1) models when no outliers exist.
Table 7.
Empirical sizes and powers for NB-INGARCH(1,1) models when and .
Table 8.
Empirical sizes and powers for NB-INGARCH(1,1) models when and .
Table 9.
Empirical sizes and powers for NB-INGARCH(1,1) models when and .
Table 10.
Empirical sizes and powers for NB-INGARCH(1,1) models when and .
3.2. Real Data Analysis
In this section, we demonstrate the validity of using a real data analysis. To this end, we analyze the return times of extreme events related to GS stock, which are constructed based on the daily log-returns for the period of 5 May 1999 to 15 March 2012. Davis and Liu [12] and Kim and Lee [22] previously investigated this data set in their works on geometric INGARCH(1,1) models (i.e., NB-INGARCH(1,1) models with ).
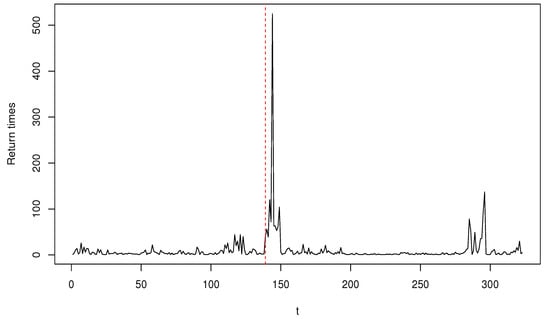
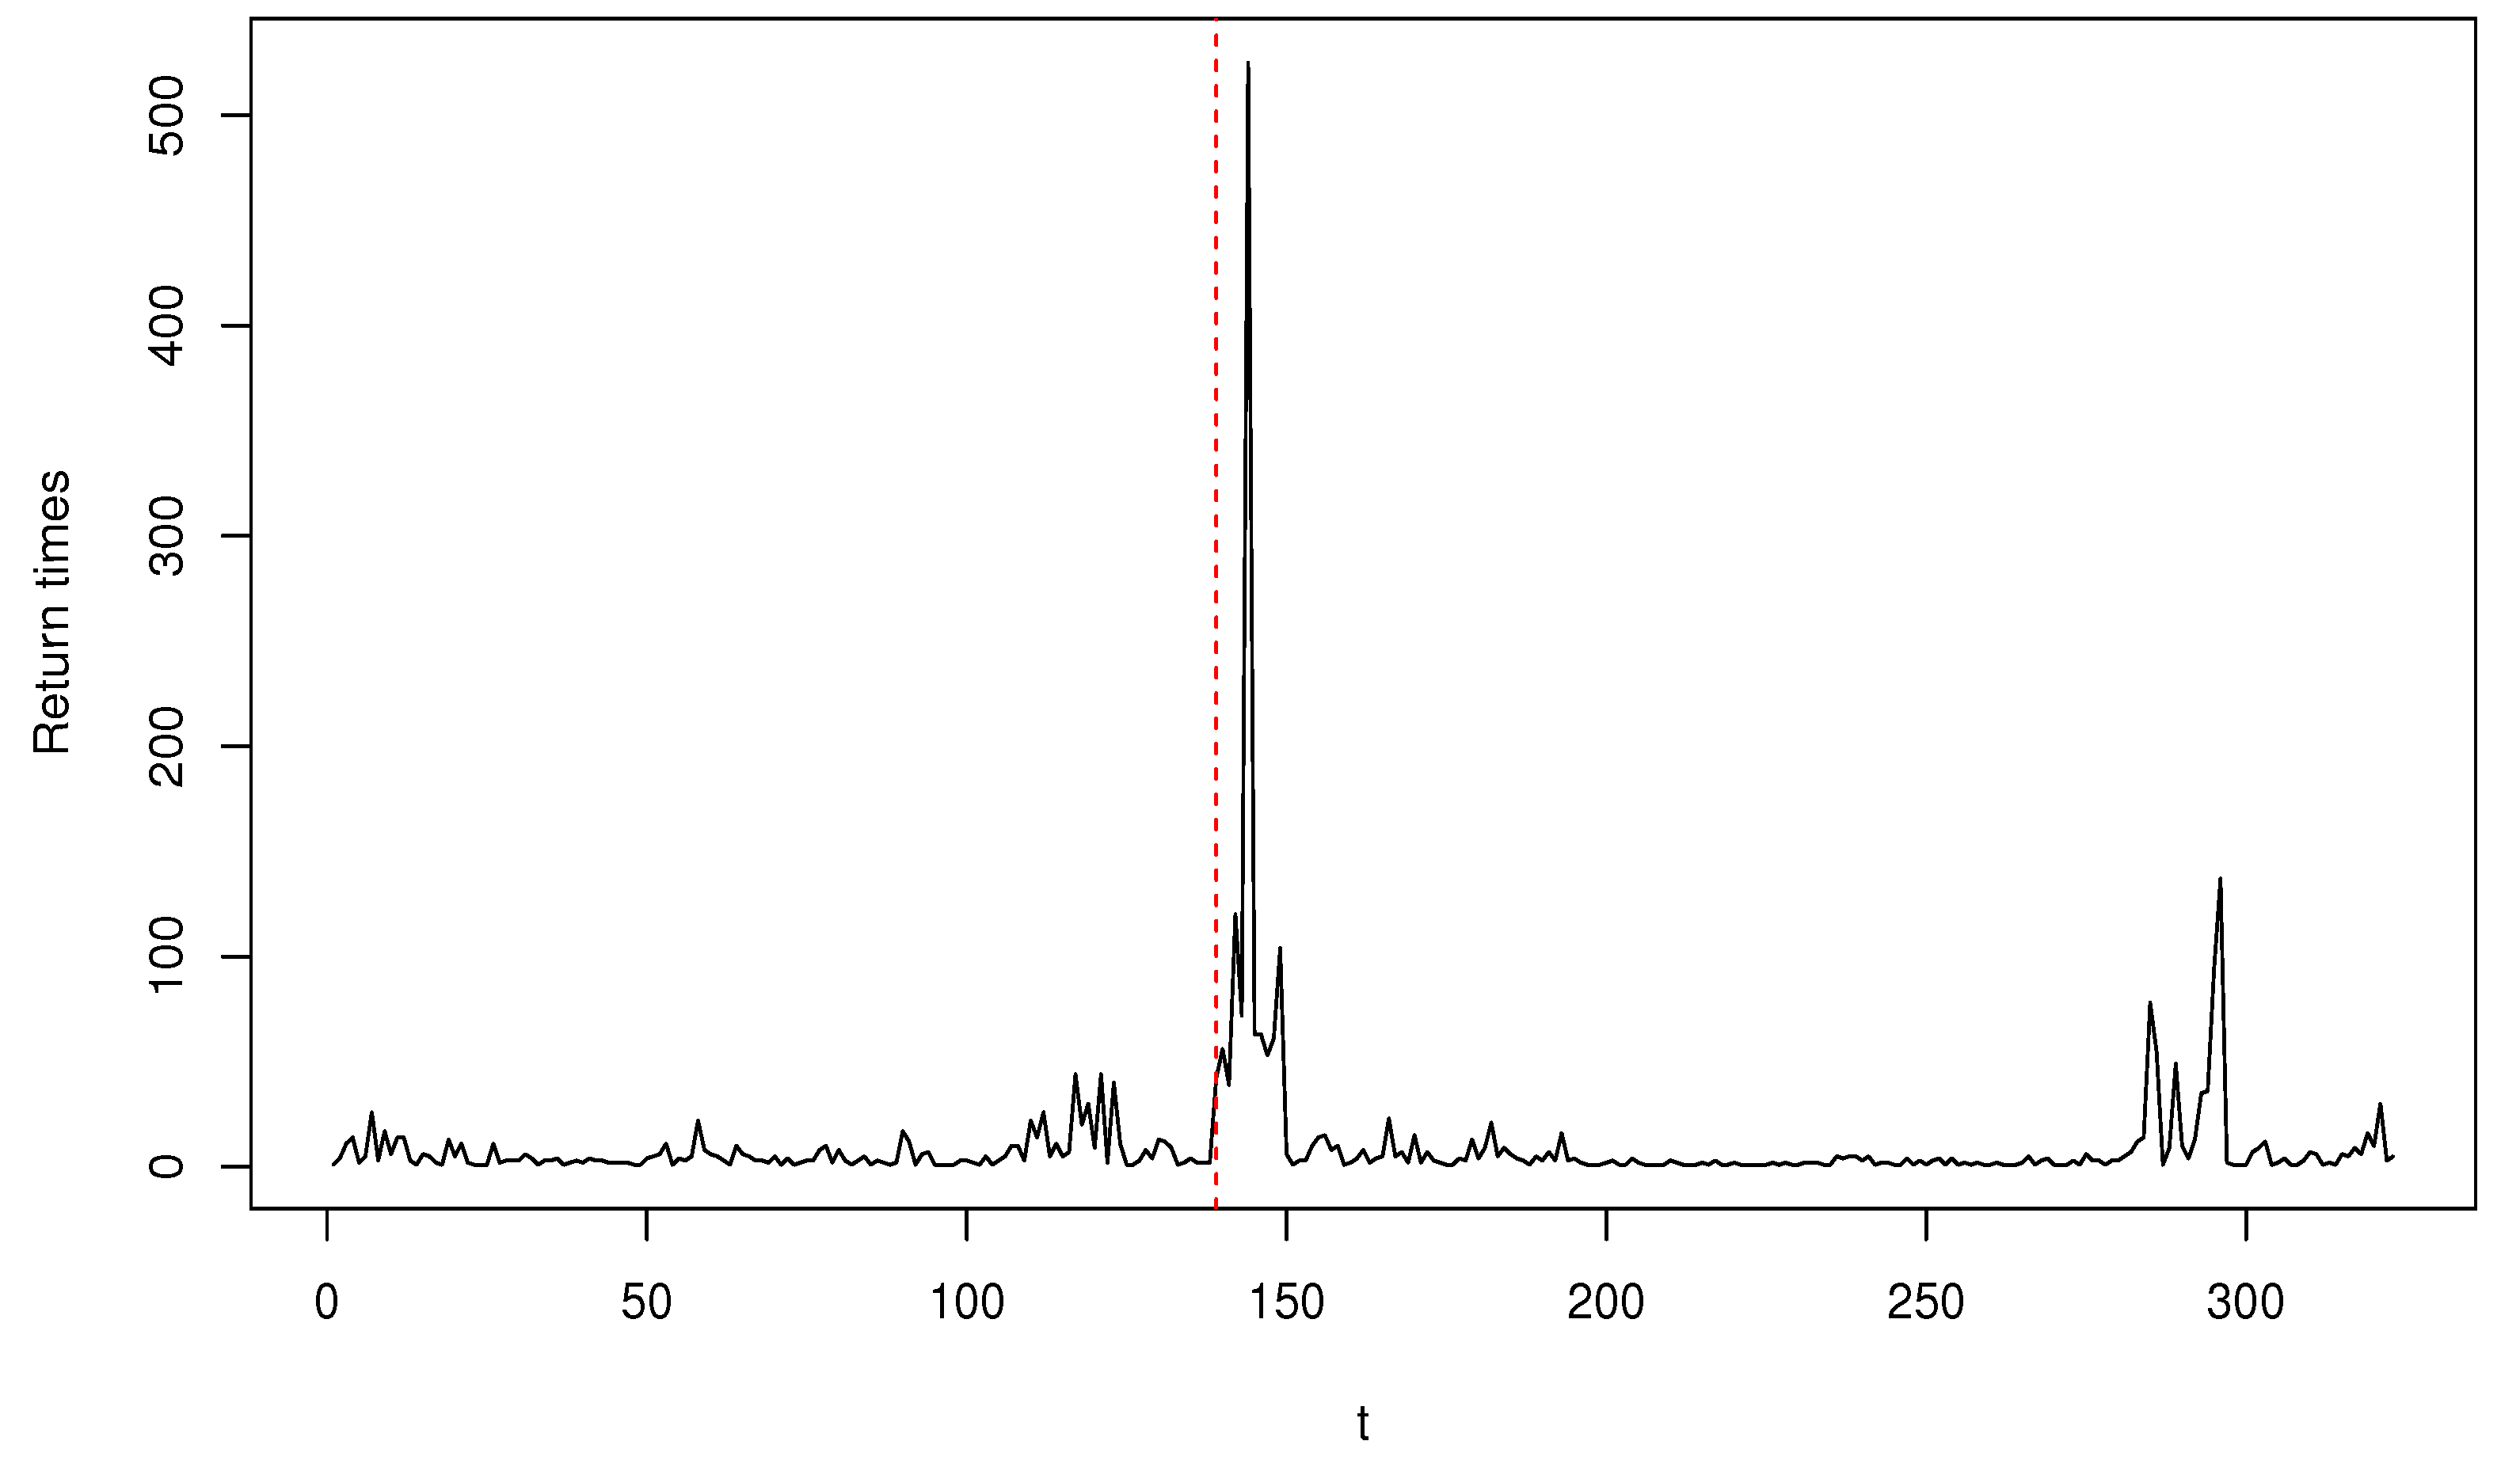
We first compute the hitting times, , for which the log-returns of GS stock fall outside the 0.05 and 0.95 quantiles of the data. The return times of these extreme events are calculated as . Figure 1 plots , . The figure shows that the data include large observations; for example, a sample variance of 1106 with a sample mean of 10.01 indicates the existence of aberrant observations.
Figure 1.
Plot of the return times of extreme events for Goldman Sachs Group (GS) stock.
Since , we consider a geometric distribution that counts the total number of trials, rather than the number of failures, to fit the following geometric INGARCH(1,1) models to the data:
where is set as the sample mean of the data. Kim and Lee [22] showed that the optimal for the MDPDE is 0.25, using the criterion provided in Remark 1. The results for the parameter estimation are summarized in Table 11 for (CMLE) and 0.25 (MDPDE with optimal ); figures in parentheses denote the standard errors of the corresponding estimates. We observe that, compared with the CMLE, the MDPDE with is quite different and has smaller standard errors.
Table 11.
Parameter estimates for geometric INGARCH(1,1) models.
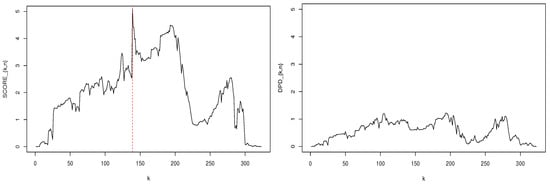
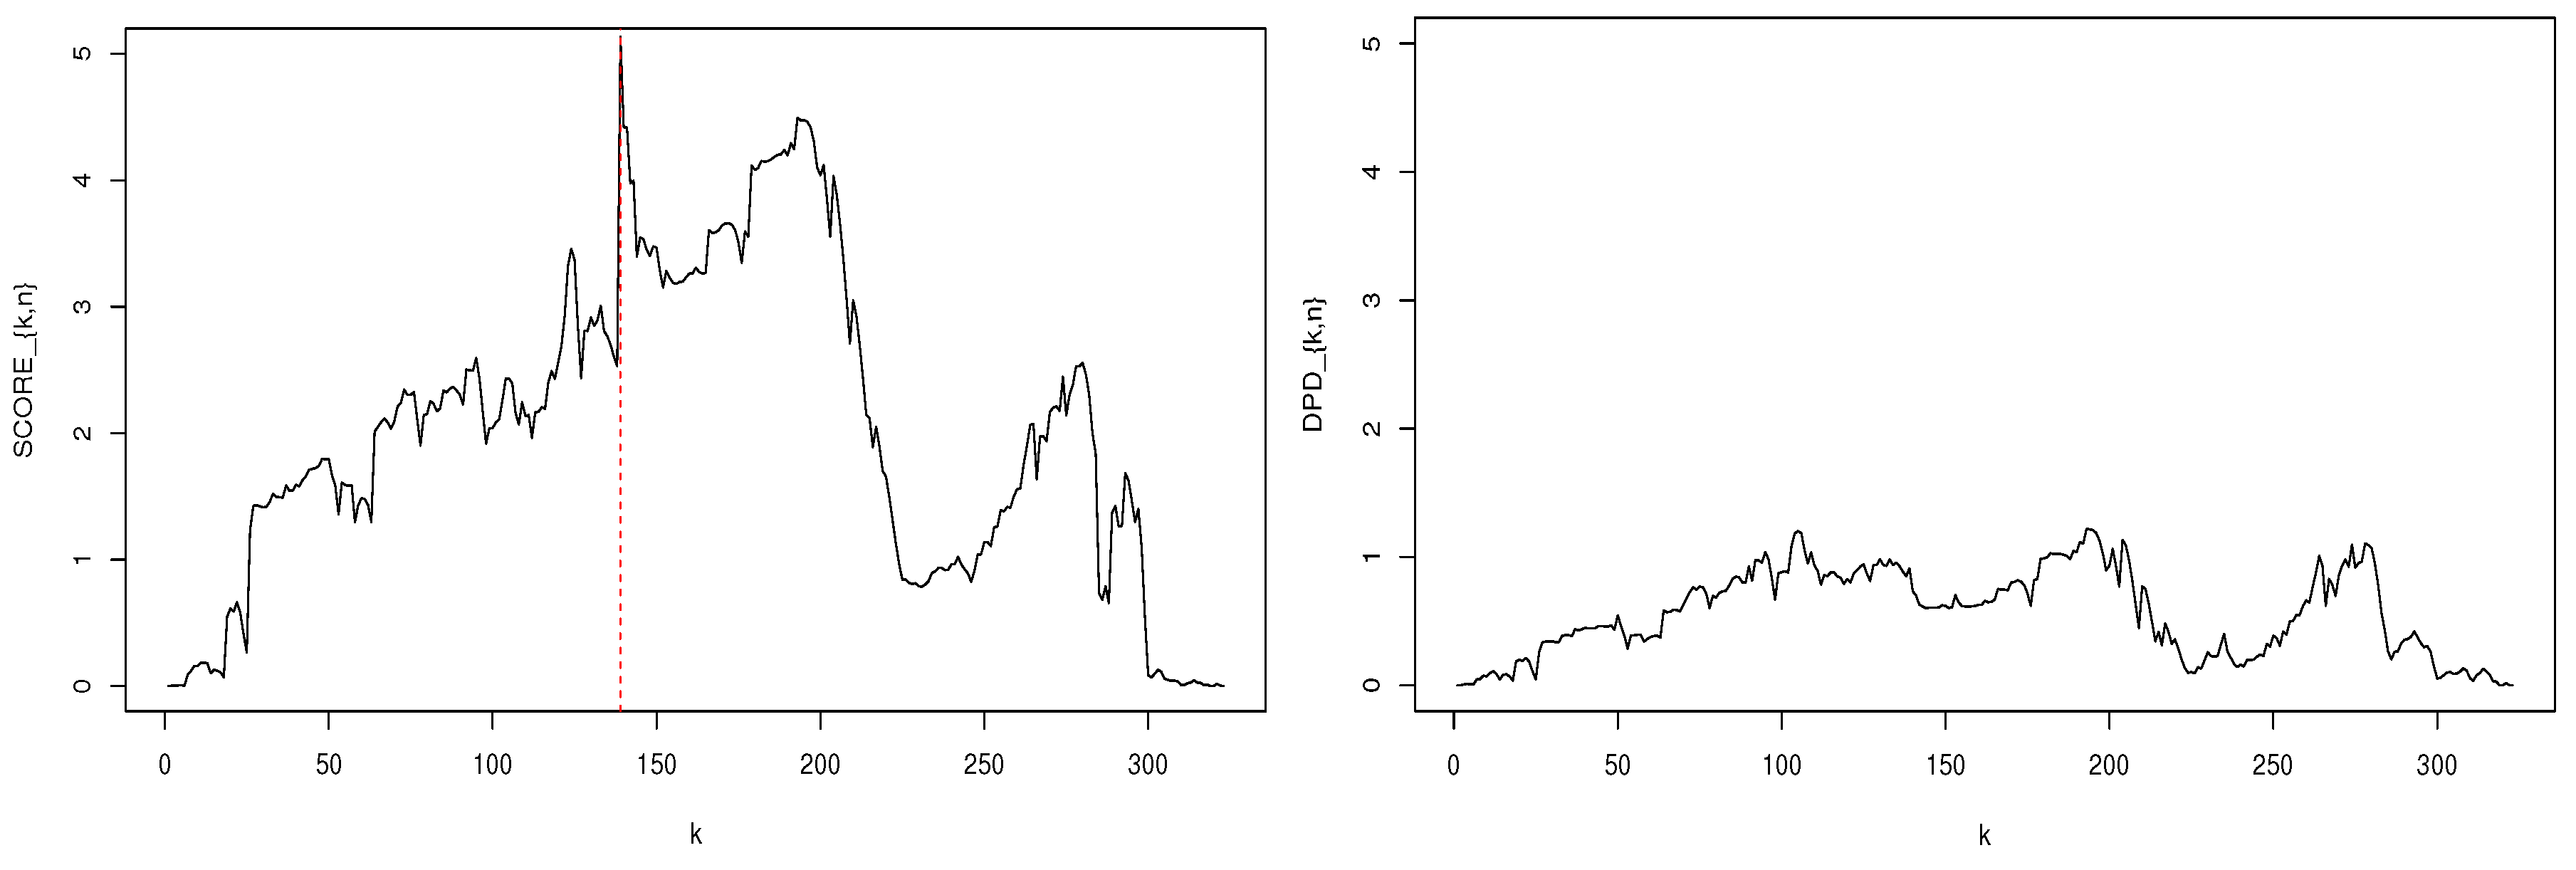
Next, we use and ( with ) to perform a parameter change test at the nominal level of 0.05 (the corresponding critical value is 3.004). Let and . The left and right panels of Figure 2 display and , respectively. For most k, appears to be smaller than , which is definitely attributed to the robustness of the MDPDE and DPD. We obtain , which suggests the existence of a parameter change. In Figure 1 and Figure 2, the red, vertical, dashed line represents the location of a change when is applied. However, this result is not so reliable because can signal a change point affected by outliers as seen in the previous section, and the change point is truly detected at the occurrence time of an outlier in this case. In contrast, yields a value of 1.219, indicating that no change point exists. This result clearly demonstrates that outliers can severely affect parameter estimates and change point tests by mistakenly identifying a change point. Our findings confirm that the DPD-based change point test provides a functional and robust alternative to the score-based CUSUM test in the presence of outliers.
Figure 2.
Plots of and .
4. Conclusions
In this study, we developed a DPD-based robust change point test for general integer-valued time series models with a conditional distribution that belongs to the one-parameter exponential family. We provided regularity conditions under which the proposed test converges weakly to the function of a Brownian bridge. The simulation study showed that the DPD-based test produces reasonable sizes and powers regardless of the existence of outliers, whereas the score-based CUSUM test suffers from severe size distortions when the data are contaminated by outliers. In the real data analysis using the return times of extreme events related to GS stock, the score-based CUSUM test supported the existence a parameter change, due to the influence of outliers, while the DPD-based test did not detect a change point because of its robust property. This result confirms the validity of the proposed test as a robust test in practice. It is noteworthy that the DPD-based test can be feasibly extended to other parametric models as far as the asymptotic properties of the MDPDE for the models are validated. We leave the issue of extension to other models as our future study.
Author Contributions
Conceptualization, B.K. and S.L.; software, B.K.; methodology, B.K. and S.L.; formal analysis, B.K. and S.L.; data curation, B.K.; writing—original draft preparation, B.K. and S.L.; funding acquisition, B.K. and S.L. All authors have read and agreed to the published version of the manuscript.
Funding
This work was supported by the National Research Foundation of Korea (NRF) grant funded by the Korea government (MSIT) (NRF-2019R1C1C1004662) (B. Kim) and (NRF-2018R1A2A2A05019433) (S. Lee).
Conflicts of Interest
The authors declare no conflict of interest.
Appendix A
In this appendix, we prove Theorem 1 for ; refer to Lee and Lee [14] for the case of . The following properties of the probability mass function of the non-negative integer-valued exponential family are useful for proving Lemma A1. For all and :
- (E1)
- ,
- (E2)
- ,
- (E3)
- ,
- (E4)
- ,
- (E5)
- .
Throughout this section, we denote and employ the notation , and for brevity. Furthermore, if we define two functions and as
we obtain
Lemma A1.
Suppose that conditions(A3),(A6), and(A11)hold. Then, we have
Proof.
The proofs for the first four parts of the lemma can be found in Lemma 4 of Kim and Lee [22]. The fifth part is obtained directly from the third part, together with the fact that .
By the MVT, (E1)–(E5), (A3), (A6), and (A11), we have
where is an intermediate point between and , and . Note that since is strictly increasing, lies between and . Then, because , the last part of the lemma is established. □
Lemma A2.
Suppose that conditions(A0)–(A11)hold. Then, under , we have as ,
and
Proof.
It is sufficient to show that as ,
and
Note that we can write
Using Lemma 2.1 of Straumann and Mikosch [34], together with Lemma A1, (A2), (A4), (A7), (A8), (A10), and Lemma 1 of Kim and Lee [22], the right-hand side of the last inequality converges to 0 a.s. as . Hence, the first part of the lemma is verified.
Similarly, we have
and the right-hand side of the last inequality also converges to 0 a.s. from Lemma 2.1 of Straumann and Mikosch [34]. Therefore, the lemma is asserted. □
Lemma A3.
Suppose that conditions(A0)–(A11)hold. Then, under , we have as ,
where is a d-dimensional Brownian motion.
Proof.
First, we show that is nonsingular. Since , we have . Hence, it holds that for ,
from (A9), which implies that is nonsingular.
Note that
and is finite from Lemma 5 of Kim and Lee [22]. Since is stationary and ergodic, it holds from the functional central limit theorem for martingales (cf. Section 18 in Billingsley [35]) that
Furthermore, we can show that
from Lemma 6 of Kim and Lee [22]. Hence, the lemma is verified. □
Lemma A4.
Suppose that conditions(A0)–(A11)hold. Then, under , we have as ,
where is any double array of Θ-valued random vectors satisfying .
Proof.
From Lemma 5 of Kim and Lee [22], it holds that
Since is continuous in , for any , we can take a neighborhood , such that
by decreasing the neighborhood to . Since converges to a.s. by Proposition 1, we can write that for sufficiently large n,
By Lemma A2, a.s. By using (A1) and the stationarity and ergodicity of , we have
Finally, since converges to 0 a.s., we can show that
and
which assert a.s. Therefore, the lemma is established. □
Proof of Theorem 1.
First, we show that
From Lemma A3, we have
Since by Lemma A3 with , using Lemma A4, it holds that
where denotes that corresponding to when . Hence, (A2) is verified.
Lemma A5.
Suppose that conditions(A0)–(A11)hold. Then, under , we have as ,
Proof.
In a similar way to Lemma A4, from Lemma 5 of Kim and Lee [22], we can also take a neighborhood , such that
Note that we can write
By Lemma A2,
Since converges to a.s. by Proposition 1, from (A4), we have
Finally, by the ergodic theorem, a.s. Therefore, the lemma is established. □
References
- McKenzie, E. Some simple models for discrete variate time series. J. Am. Water Resour. Assoc. 1985, 21, 645–650. [Google Scholar] [CrossRef] [Scilit]
- Al-Osh, M.A.; Alzaid, A.A. First order integer-valued autoregressive (INAR(1)) process. J. Time Ser. Anal. 1987, 8, 261–275. [Google Scholar] [CrossRef] [Scilit]
- Ferland, R.; Latour, A.; Oraichi, D. Integer-valued GARCH processes. J. Time Ser. Anal. 2006, 27, 923–942. [Google Scholar] [CrossRef] [Scilit]
- Engle, R.F. Autoregressive conditional heteroskedasticity with estimates of the variance of United Kingdom inflation. Econometrica 1982, 50, 987–1007. [Google Scholar] [CrossRef] [Scilit]
- Bollerslev, T. Generalized autoregressive conditional heteroskedasticity. J. Econom. 1986, 31, 307–327. [Google Scholar] [CrossRef] [Scilit]
- Fokianos, K.; Rahbek, A.; Tjøstheim, D. Poisson autoregression. J. Am. Stat. Assoc. 2009, 104, 1430–1439. [Google Scholar] [CrossRef] [Scilit]
- Davis, R.A.; Wu, R. A negative binomial model for time series of counts. Biometrika 2009, 96, 735–749. [Google Scholar] [CrossRef] [Scilit]
- Christou, V.; Fokianos, K. Quasi-likelihood inference for negative binomial time series models. J. Time Ser. Anal. 2014, 35, 55–78. [Google Scholar] [CrossRef]
- Zhu, F. Modeling overdispersed or underdispersed count data with generalized poisson integer-valued garch models. J. Math. Anal. Appl. 2012, 389, 58–71. [Google Scholar] [CrossRef] [Scilit]
- Zhu, F. Zero-inflated Poisson and negative binomial integer-valued GARCH models. J. Stat. Plan. Infer. 2012, 142, 826–839. [Google Scholar] [CrossRef] [Scilit]
- Lee, S.; Lee, Y.; Chen, C.W.S. Parameter change test for zero-inflated generalized Poisson autoregressive models. Statistics 2016, 50, 540–557. [Google Scholar] [CrossRef] [Scilit]
- Davis, R.A.; Liu, H. Theory and inference for a class of observation-driven models with application to time series of counts. Stat. Sin. 2016, 26, 1673–1707. [Google Scholar]
- Diop, M.L.; Kengne, W. Testing parameter change in general integer-valued time series. J. Time Ser. Anal. 2017, 38, 880–894. [Google Scholar] [CrossRef] [Scilit]
- Lee, Y.; Lee, S. CUSUM test for general nonlinear integer-valued GARCH models: Comparison study. Ann. Inst. Stat. Math. 2019, 71, 1033–1057. [Google Scholar] [CrossRef] [Scilit]
- Kang, J.; Lee, S. Parameter change test for Poisson autoregressive models. Scand. J. Stat. 2014, 41, 1136–1152. [Google Scholar] [CrossRef] [Scilit]
- Basu, A.; Harris, I.R.; Hjort, N.L.; Jones, M.C. Robust and efficient estimation by minimizing a density power divergence. Biometrika 1998, 85, 549–559. [Google Scholar] [CrossRef] [Scilit]
- Ghosh, A.; Basu, A. Robust estimation for independent non-homogeneous observations using density power divergence with applications to linear regression. Electron. J. Stat. 2013, 7, 2420–2456. [Google Scholar] [CrossRef] [Scilit]
- Lee, S.; Song, J. Minimum density power divergence estimator for GARCH models. Test 2009, 18, 316–341. [Google Scholar] [CrossRef] [Scilit]
- Kim, B.; Lee, S. Robust estimation for the covariance matrix of multivariate time series based on normal mixtures. Comput. Stat. Data Anal. 2013, 57, 125–140. [Google Scholar] [CrossRef] [Scilit]
- Kang, J.; Lee, S. Minimum density power divergence estimator for Poisson autoregressive models. Comput. Stat. Data Anal. 2014, 80, 44–56. [Google Scholar] [CrossRef] [Scilit]
- Kim, B.; Lee, S. Robust estimation for zero-inflated Poisson autoregressive models based on density power divergence. J. Stat. Comput. Simul. 2017, 87, 2981–2996. [Google Scholar] [CrossRef] [Scilit]
- Kim, B.; Lee, S. Robust estimation for general integer-valued time series models. Ann. Inst. Stat. Math. 2020, in press. [Google Scholar]
- Kang, J.; Song, J. Robust parameter change test for Poisson autoregressive models. Stat. Probab. Lett. 2015, 104, 14–21. [Google Scholar] [CrossRef] [Scilit]
- Song, J.; Kang, J. Test for parameter change in the presence of outliers: The density power divergence based approach. arXiv 2019, arXiv:1907.00004. [Google Scholar]
- Kang, J.; Song, J. A robust approach for testing parameter change in Poisson autoregressive models. arXiv 2019, arXiv:1908.11466. [Google Scholar]
- Batsidis, A.; Horváth, L.; Martín, N.; Pardo, L.; Zografos, K. Change-point detection in multinomial data using phi-divergence test statistics. J. Multivar. Anal. 2013, 118, 53–66. [Google Scholar] [CrossRef] [Scilit]
- Batsidis, A.; Martín, N.; Pardo, L.; Zografos, K. ϕ-divergence based procedure for parametric change point problems. Methodol. Comput. Appl. Probab. 2016, 18, 21–35. [Google Scholar] [CrossRef] [Scilit]
- Martín, N.; Pardo, L. Comment on: Extensions of some classical methods in change point analysis. Test 2014, 23, 279–282. [Google Scholar] [CrossRef] [Scilit]
- Lehmann, E.; Casella, G. Theory of Point Estimation, 2nd ed.; Springer: New York, NY, USA, 1998. [Google Scholar]
- Warwick, J. A data-based method for selecting tuning parameters in minimum distance estimators. Comput. Stat. Data Anal. 2005, 48, 571–585. [Google Scholar] [CrossRef] [Scilit]
- Warwick, J.; Jones, M.C. Choosing a robustness tuning parameter. J. Stat. Comput. Simul. 2005, 75, 581–588. [Google Scholar] [CrossRef] [Scilit]
- Lee, S.; Ha, J.; Na, O.; Na, S. The cusum test for parameter change in time series models. Scand. J. Stat. 2003, 30, 781–796. [Google Scholar] [CrossRef] [Scilit]
- Fried, R.; Agueusop, I.; Bornkamp, B.; Fokianos, K.; Fruth, J.; Ickstadt, K. Retrospective Bayesian outlier detection in INGARCH series. Stat. Comput. 2015, 25, 365–374. [Google Scholar] [CrossRef] [Scilit]
- Straumann, D.; Mikosch, T. Quasi-maximum-likelihood estimation in conditionally heteroscedastic time series: A stochastic recurrence equations approach. Ann. Stat. 2006, 34, 2449–2495. [Google Scholar] [CrossRef] [Scilit]
- Billingsley, P. Convergence of Probability Measures, 2nd ed.; Wiley: New York, NY, USA, 1999. [Google Scholar]

© 2020 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (http://creativecommons.org/licenses/by/4.0/).