


Abstract
In this paper, we propose a novel optimization model for portfolio selection that integrates the classical mean–variance criterion with a second-order Tsallis entropy term. This approach enables a trade-off between expected return, risk, and diversification, extending Markowitz’s theory to account for non-Gaussian characteristics and heavy-tailed distributions that are typical in financial markets—especially in cryptocurrency assets. Unlike the first-order Tsallis entropy, the second-order version amplifies the effects of distributional structure and allows for more refined penalization of portfolio concentration. We derive the analytical solution for the optimal weights under this extended framework and demonstrate its performance through a case study using real data from selected cryptocurrencies. Efficient frontiers, portfolio weights, and entropy indicators are compared across models. This novel combination may improve portfolio selection under uncertainty, especially in the context of volatile assets such as cryptocurrencies, as the proposed model can provide a more robust and diversified portfolio structure compared to conventional theories.
Keywords:
portfolio optimization; second-order Tsallis entropy; liquidity-aware models; risk and return trade-off; cryptocurrency investment; robust diversification MSC:
91B28; 94A17
1. Introduction
The financial market is a complex and dynamic system in which investors must navigate uncertainty and make trade-offs between return and risk. The portfolio selection problem arises when an investor seeks to allocate their wealth among various assets in a manner that aligns with their specific preferences and investment objectives. The foundational methodology for portfolio optimization was introduced in the seminal work of (Markowitz 1952), whose theory remains well-documented and widely applied (Hamza and Janssen 1996; Markowitz 1991; Zheng et al. 2009).
Markowitz’s framework focuses on constructing portfolios composed of risky assets, using historical data such as asset returns, variances, and correlations. By analyzing expected returns and covariances derived from historical data, the model provides an optimal strategy for combining assets into an efficient portfolio. The goal is to maximize expected return for a given level of risk or, conversely, to minimize risk for a given return level. Over time, numerous extensions have been introduced to enhance the original risk quantification framework proposed by Markowitz. (Konno and Yamazaki 1991) advocated for the use of absolute deviation in place of variance, while (Speranza 1993) advanced the concept of semi-absolute deviation to better capture asymmetrical return distributions. Semi-variance also gained traction as an alternative risk measure, as illustrated in the contributions of (King and Jensen 1992; King 1993), and (Markowitz et al. 1993). (Hamza and Janssen 1996) addressed the limitations of normally distributed returns by proposing a linear programming formulation based on asymmetric risk functions, suitable for large-scale portfolio optimization. In addition, they tackled practical frictions such as transaction costs through separable programming techniques. (Yoshimoto 1996) complemented this direction by introducing a nonlinear programming model that integrates transaction costs directly into the optimization process. While these approaches increase model realism, they often come at the cost of heightened computational complexity and reduced tractability for standard solvers. Another line of inquiry has focused on enhancing the interpretability and structural soundness of portfolio models by reconsidering the fundamental assumptions about risk itself. While variance-based measures remain dominant in traditional models, their limitations in capturing asymmetries, tail events, and dynamic correlations have been well documented. In particular, such models may overlook the structural dependencies within asset classes or fail to reflect investor preferences that deviate from mean–variance rationality. This has led researchers to explore more flexible and theoretically grounded alternatives that can account for both uncertainty and diversification in a more comprehensive manner.
The selection of a risk measure plays a crucial role in shaping portfolio structure. One particularly promising alternative to variance is entropy. (Shannon 1948) introduced a foundational concept of entropy in the context of information theory, which was later extended by (Yager 1995) using the maximum entropy principle. (Philippatos and Wilson 1972) were the first to apply Shannon entropy to portfolio theory, treating it as a diversification metric. They argued that entropy is more flexible than variance, as it can handle non-metric data and does not rely on symmetric probability distributions. (Simonelli 2005) further demonstrated the superior performance of entropy over variance and deviation-based metrics. (Zhou et al. 2013) provided an extensive review of entropy’s applications in finance, affirming its rising influence. Empirical studies, such as those by (Jiang et al. 2008) and (Zheng et al. 2009), have implemented Shannon entropy in portfolio models to replace variance, including use cases like electricity purchasing portfolios. In addition, robust optimization frameworks have emerged to address parameter estimation errors in expected returns and covariances. These methods are designed to improve portfolio resilience under uncertainty. Simultaneously, behavioral finance approaches such as Prospect Theory and Behavioral Mean–Variance Optimization have been integrated to account for psychological biases and investor preferences (Dedu et al. 2014; Dedu and Fulga 2011). Recent advancements in portfolio optimization have embraced increasingly sophisticated frameworks that integrate fuzzy logic, robust modeling, and multi-criteria decision-making principles. In parallel, entropy-based models have evolved toward scalable implementations in large-scale financial systems. (Jiang et al. 2008) introduced a maximum entropy formulation designed to improve stability and computational tractability, while (Ke and Zhang 2008) explored the integration of entropy measures into classical mean–variance models, highlighting the synergy between information theory and traditional financial paradigms.
Beyond methodological advances, theoretical developments in risk modeling have contributed to the refinement of portfolio frameworks. (Sheraz and Dedu 2020) present stochastic models of fat-tail returns and risk modeling for Bitcoin, laying the groundwork for more rigorous treatment of risk under uncertainty. Complementing these efforts, (Lutgens and Schotman 2010) emphasized robust portfolio optimization with multiple expert perspectives, acknowledging the need to account for heterogeneous beliefs in volatile markets. (Yu and Lee 2011) addressed portfolio rebalancing through multi-criteria programming, enabling the incorporation of diverse investor objectives and practical constraints. These perspectives converge within the broader field of multi-criteria decision analysis (MCDA), as reviewed by (Zopounidis and Doumpos 2002), which offers a flexible and unifying framework for integrating behavioral preferences, structural constraints, and informational entropy into a cohesive portfolio optimization strategy. This interdisciplinary evolution reinforces the relevance of entropy-based models in modern finance, particularly when robustness, diversification, and decision flexibility are of paramount importance. Motivated by these developments, the present paper proposes an entropy-based portfolio optimization model that maximizes second-order Tsallis entropy, with flexible weightings reflecting investor preferences toward return and diversification. As an empirical validation, we apply the model to optimize a cryptocurrency portfolio composed of two or three assets during the period January–March 2025. The cryptocurrency market was selected as the empirical testing ground, offering a challenging yet insightful testbed due to its high volatility, dynamic liquidity, and the urgent need for robust diversification tools.
The key contributions of this paper are as follows: (1) An entropy-based portfolio optimization model is developed by integrating second-order Tsallis entropy as a structural diversification and liquidity-aware constraint. This approach enhances portfolio robustness against concentration. (2) Analytical solutions of the optimization model are derived by using the Lagrange multiplier method, ensuring computational tractability even in volatile markets. (3) The proposed model is empirically validated on cryptocurrency portfolios, proving its ability to balance return and diversification, and offering practical utility in liquidity-sensitive asset management.
Compared to the Shannon entropy approach, second-order Tsallis entropy offers a more flexible penalization of portfolio concentration through its quadratic formulation. This property allows a smoother adjustment of diversification levels and ensures greater analytical tractability, particularly in small-sized to medium-sized portfolios. Additionally, second-order Tsallis entropy is mathematically connected to the complement of Onicescu informational energy, which offers an intuitive interpretation of asset dispersion and portfolio balance. These advantages position the proposed model as an effective and computationally manageable tool for robust portfolio construction.
2. Materials and Methods
2.1. Mean–Second-Order Tsallis Entropy–Variance Model of Portfolio Optimization
In this section, we introduce a portfolio optimization model based on three core components: expected return, variance, and second-order Tsallis entropy. The model aims to maximize a weighted combination of return and entropy, subject to a variance-based risk constraint. The use of second-order Tsallis entropy enhances diversification by penalizing concentration in portfolio weights and implicitly supports liquidity-aware asset allocation. This formulation offers a tractable yet robust framework suitable for volatile markets such as cryptocurrencies.
We consider a portfolio composed of assets. Let which models the portfolio weight assigned to asset . The portfolio is described by the decision vector . Let .
Definition 1.
The Tsallis Entropy corresponding to the portfolio is given by
Remarks:
- 1.
- For a given portfolio, this kind of entropy measures the correlation degree of the assets from the portfolio:
- 2.
- A lower entropy implies greater concentration (lower diversification), whereas a higher entropy reflects greater diversification, which may contribute positively to portfolio liquidity.
- 3.
- The standard Tsallis form converges to the Boltzmann–Gibbs/Shannon entropy as q → 1:
2.1.1. Optimization Problem Formulation
The portfolio optimization problem is based on the model presented in (Ke and Zhang 2008), where weightings are assigned to every asset, depending on the importance given by the investor to the return and the entropy (diversification can be useful to liquidity):
where ; is the number of time units; is average return of asset i; is average return of asset at the period t; is the level of the risk that is assumed of investor; , no short-selling. We acknowledge that the risk constraint applied here reflects the weighted average of individual asset variances, which does not fully capture portfolio variance unless assets are perfectly uncorrelated. Throughout the paper, denotes the portfolio weights. To ensure notational consistency, probability-like symbols such as are avoided in the derivations. The symbols λ and γ are reserved exclusively as Lagrange multipliers associated with the optimization constraints.
2.1.2. Solving the Portfolio Optimization Problem
Using the Lagrange multiplier method, we obtain
The first-order conditions are given by
By assembling the relationships we have
We obtain
Using relationship (1) we get
where the multiplier verifies the following relation:
Remark (Extension of the covariance-based risk constraint)
In the revised formulation, the portfolio risk is defined using the full variance–covariance matrix of asset returns, as ( denotes the covariance matrix of asset returns), which captures both volatilities and correlations. The resulting first-order conditions are −(ln + 1) + + − 2( = 0 i.e., .
Unlike the diagonal case, this system is implicit because the optimal weights depend on the full vector p. Therefore, closed-form exponential solutions are not available, and the optimization must be solved numerically (here via SLSQP).
For the quadratic objective formulation, a closed-form interior solution under the covariance constraint is provided in Appendix A. This additional derivation illustrates that once correlations are incorporated, the optimization remains analytically tractable in a linear-algebraic form.
2.2. Case Studies
The cryptocurrency price data used in this study were obtained from the Binance exchange through the TradingView historical data platform. The dataset includes daily closing prices for Bitcoin (BTC), Ethereum (ETH), and Solana (SOL) over the January–March 2025 period. Prices were cross-verified with other public data sources to ensure consistency. This preprocessing approach ensures data reliability and reproducibility of the empirical results.
Given the high volatility, evolving correlation structures, and regime-switching behavior inherent to digital asset markets, cryptocurrencies represent a fertile ground for testing advanced portfolio optimization models. Unlike traditional financial assets, cryptocurrencies are characterized by frequent price swings, low historical depth, and rapidly changing liquidity patterns, all of which challenge conventional assumptions of stationarity and normality. These features create an environment where diversification, structural robustness, and adaptive decision-making become essential. Moreover, the decentralized nature of crypto markets introduces idiosyncratic risks and asymmetries that amplify the need for entropy-based approaches capable of managing uncertainty and concentration effects.
Entropy, in this context, serves not only as a statistical measure but also as a strategic stabilizer in markets where investor sentiment and momentum can dominate fundamentals. By capturing allocation uniformity and penalizing overexposure, second-order entropy allows for more balanced configurations that may mitigate downside risk in turbulent scenarios. To illustrate the practical implications of this framework, we apply our model to two empirical portfolio settings: a two-asset portfolio composed of Bitcoin and Ethereum, followed by a three-asset configuration that includes Solana.
In both scenarios, the optimization is performed over a sample period spanning January to March 2025, using daily return data. The model parameters are calibrated to reflect a moderate investor profile, with equal weighting given to expected return and entropy (i.e., a = b). Risk tolerance is set via an upper bound on variance, consistent across both configurations to ensure comparability.
We selected a three-month period (January–March 2025) to capture recent market conditions marked by high volatility and shifting liquidity patterns, providing a relevant and challenging environment to evaluate the robustness of the proposed model.
The two-asset case (n = 2) provides a simplified environment for analytical tractability, offering intuitive insight into how entropy modifies the allocation strategy relative to classical mean–variance solutions. This setup serves as a benchmark, highlighting the tendency of the entropy term to shift weight away from high-return but volatile assets in favor of improved balance. In contrast, the three-asset case (n = 3) introduces an additional degree of freedom and demonstrates how the model scales with portfolio size, accommodating additional correlation effects and diversification pathways.
- Case n = 2: Portfolio Optimization with Two Cryptocurrencies
In this section, we consider a simple two-asset portfolio composed of Bitcoin (BTC) and Ethereum (ETH), observed over the period 18 January 2025–21 March 2025. The purpose of this case study is to demonstrate the implementation of the mean–second-order entropy model described previously. We choose the investor preference weights a = 0.75 for expected return and b = 0.25 for entropy. The selection of a = 0.75 and b = 0.25 reflects an empirical investor profile that moderately prioritizes expected return over diversification. This structure is frequently adopted in portfolio studies focusing on volatile markets, where a controlled preference toward return is balanced by a diversification term to mitigate concentration risk. However, we recognize that this static preference may not fully capture real-world dynamics, and future work should explore sensitivity analyses with alternative weight configurations.
We obtain the following model:
max 0.75 (x1⋅0.0565 + x2⋅0.0133) − 0.25(x12 + x22)
Using the formulas presented above we obtain
where the multiplier γ verifies the following relations:
or (0.53 − 0.74γ)⋅0.033 + (0.47 + 0.74γ)⋅0.775 = 0.1.
x1 = 1.5 (0.0565 − 0.0698/2) + γ/0.5 (0.033 − 0.8/2) + 0.5 = 0.53 − 0.74γ
x2 = 1.5 (0.0133 − 0.0698/2) + γ/0.5 (0.77 − 0.8/2) + 0.5 = 0.47 + 0.74γ
We have 0.55γ + 0.38 = 0.1 or γ = −0.51, and substituting back, the optimal portfolio allocation becomes x1 = 0.9074 and x2 = 0.0926. This result indicates that, under the given preferences and market conditions, the optimal portfolio heavily favors Bitcoin (BTC), allocating approximately 90.74% of the capital to BTC and only 9.26% to ETH.
To further substantiate this theoretical claim, we conducted a comparative simulation applying both Shannon entropy and Tsallis-2 entropy to the same cryptocurrency dataset.
The results indicate that Tsallis-2 consistently yields more diversified portfolio allocations, particularly in the presence of heavy-tailed return distributions, whereas Shannon entropy produces comparatively milder adjustments. These findings confirm that the choice of second-order Tsallis entropy is not arbitrary, but rather motivated by its enhanced ability to amplify concentration risk and provide robustness in high-volatility markets.
- Case n = 3: Portfolio Optimization with Three Cryptocurrencies
In this section, we consider a portfolio composed of three major cryptocurrencies: Bitcoin (BTC), Ethereum (ETH), and Solana (SOL), observed over the period 18 January 2025–21 March 2025. We apply the mean–second-order Tsallis entropy model as described in the previous sections
We are going to use the mean–second-order entropy model.
We choose a = 0.75 and b = 0.25 and we obtain the following model:
max 0.75 (x1⋅0.0565 + x2⋅0.0133 + x3⋅0.0755) − 0.25 (x12 + x22 + x32)
Using the formulas presented above we obtain
where the multiplier γ verifies the following relations: x1⋅0.033 + x2⋅0.775 + x3⋅0.105 = 0.1 or (0.35 − 0.55γ)⋅0.033 + (0.28 + 0.94γ)⋅0.775 + (0.37 − 0.39γ)⋅0.105 = 0.1.
x1 = 1.5 (0.0565 − 0.048) + γ/0.5 (0.033 − 0.3) + 0.33 = 0.35 − 0.55γ
x2 = 1.5 (0.0133 − 0.048) + γ/0.5 (0.77 − 0.3) + 0.33 = 0.28 + 0.94γ
x3 = 1.5 (0.0755 − 0.048) + γ/0.5 (0.105 − 0.3) + 0.33 = 0.37 − 0.39γ
We have 0.67γ + 0.26 = 0.1, i.e., γ = −0.24
We obtain x1 = 0.462, x2 = 0.0344 and x3 = 0.5036
These numerical applications offer valuable insights into the model’s allocation dynamics, setting the stage for a deeper analysis of performance and diversification outcomes in Section 3. By comparing distinct portfolio structures under varying dimensionality, the results highlight how entropy interacts with return and variance to shape asset weights. The contrast between concentrated and diversified allocations allows us to assess the extent to which second-order Tsallis entropy serves as an effective mechanism for controlling risk exposure while preserving responsiveness to expected returns. The following section explores these aspects in detail, drawing empirical conclusions from both two- and three-asset configurations.
The empirical study was extended to a broader and more realistic setting. Specifically, the asset universe was expanded to 12 highly liquid cryptocurrencies (BTC, ETH, SOL, BNB, ADA, XRP, DOGE, DOT, AVAX, MATIC, LTC, TRX). The dataset spans a full 12-month horizon (April 2024–March 2025), covering both bullish and bearish market phases. A monthly rolling rebalancing protocol was implemented, and proportional transaction costs of 0.1% per trade were introduced to account for trading frictions. These extensions confirm that the model remains effective and robust under longer horizons, multiple regimes, and richer portfolio universes, as detailed in Section 3 and Tables 1 and 3.
3. Results and Discussions
The empirical implementation of the mean–second-order entropy–variance optimization model was carried out on two different portfolio configurations involving major cryptocurrencies. The objective was to evaluate how the entropy component influences the allocation structure and risk-return balance under increasing asset dimensionality.
To further test the flexibility of the proposed model, we conducted a sensitivity analysis by varying the investor preference weights (a and b) and the maximum risk constraint. The results indicate that when higher weightings are assigned to entropy, the model favors more diversified allocations, while increased emphasis on expected return results in more concentrated portfolios. Additionally, higher risk tolerance levels lead to more aggressive asset exposures. These patterns confirm the intuitive behavior and adaptability of the model to different investor profiles and market conditions. To further assess the effectiveness of the entropy-driven approach, we compared the results of the proposed model with those obtained from a classical mean–variance optimization framework using the same asset sets. The comparison indicates that while the mean–variance model tends to over-allocate towards assets with the highest expected return, the entropy-based model promotes more balanced allocations that enhance diversification. This demonstrates that the structural diversification induced by the entropy component is not solely a consequence of adding more assets but is actively driven by the entropy constraint embedded in the optimization process.
To further strengthen the empirical validation, the analysis was extended to a broader setting. The asset universe was expanded to twelve highly liquid cryptocurrencies (BTC, ETH, SOL, BNB, ADA, XRP, DOGE, DOT, AVAX, MATIC, LTC, TRX), covering a full twelve-month period from April 2024 to March 2025. This dataset captures both bullish and bearish market regimes, thereby testing the robustness of the proposed model under different conditions. A monthly rolling rebalancing protocol was implemented to dynamically adjust portfolio weights, while proportional transaction costs of 0.1% per trade were incorporated to account for realistic frictions. The extended results (see Tables 2 and 3 and Figure 3) confirm that the mean–variance–second-order entropy model preserves strong performance and diversification benefits even in larger and more volatile universes, demonstrating its practical relevance beyond small, short-horizon applications.
3.1. Comparative Results
When comparing the extended entropy-based optimization with classical benchmarks, the superiority of the second-order Tsallis formulation becomes evident. Relative to the Shannon entropy model, the quadratic penalization of probability weights induced by Tsallis-2 consistently yields more diversified allocations, particularly in periods of high volatility. In contrast, the Shannon approach results in milder adjustments, which may understate concentration risks in heavy-tailed distributions. Furthermore, compared with the classical mean–variance model, which tends to over-allocate towards assets with the highest expected return, the entropy-driven approach promotes more balanced portfolios while preserving competitive return profiles.
These findings underline that the improved diversification effects are not a byproduct of larger sample size or broader asset coverage but are inherently driven by the entropy component embedded in the optimization.
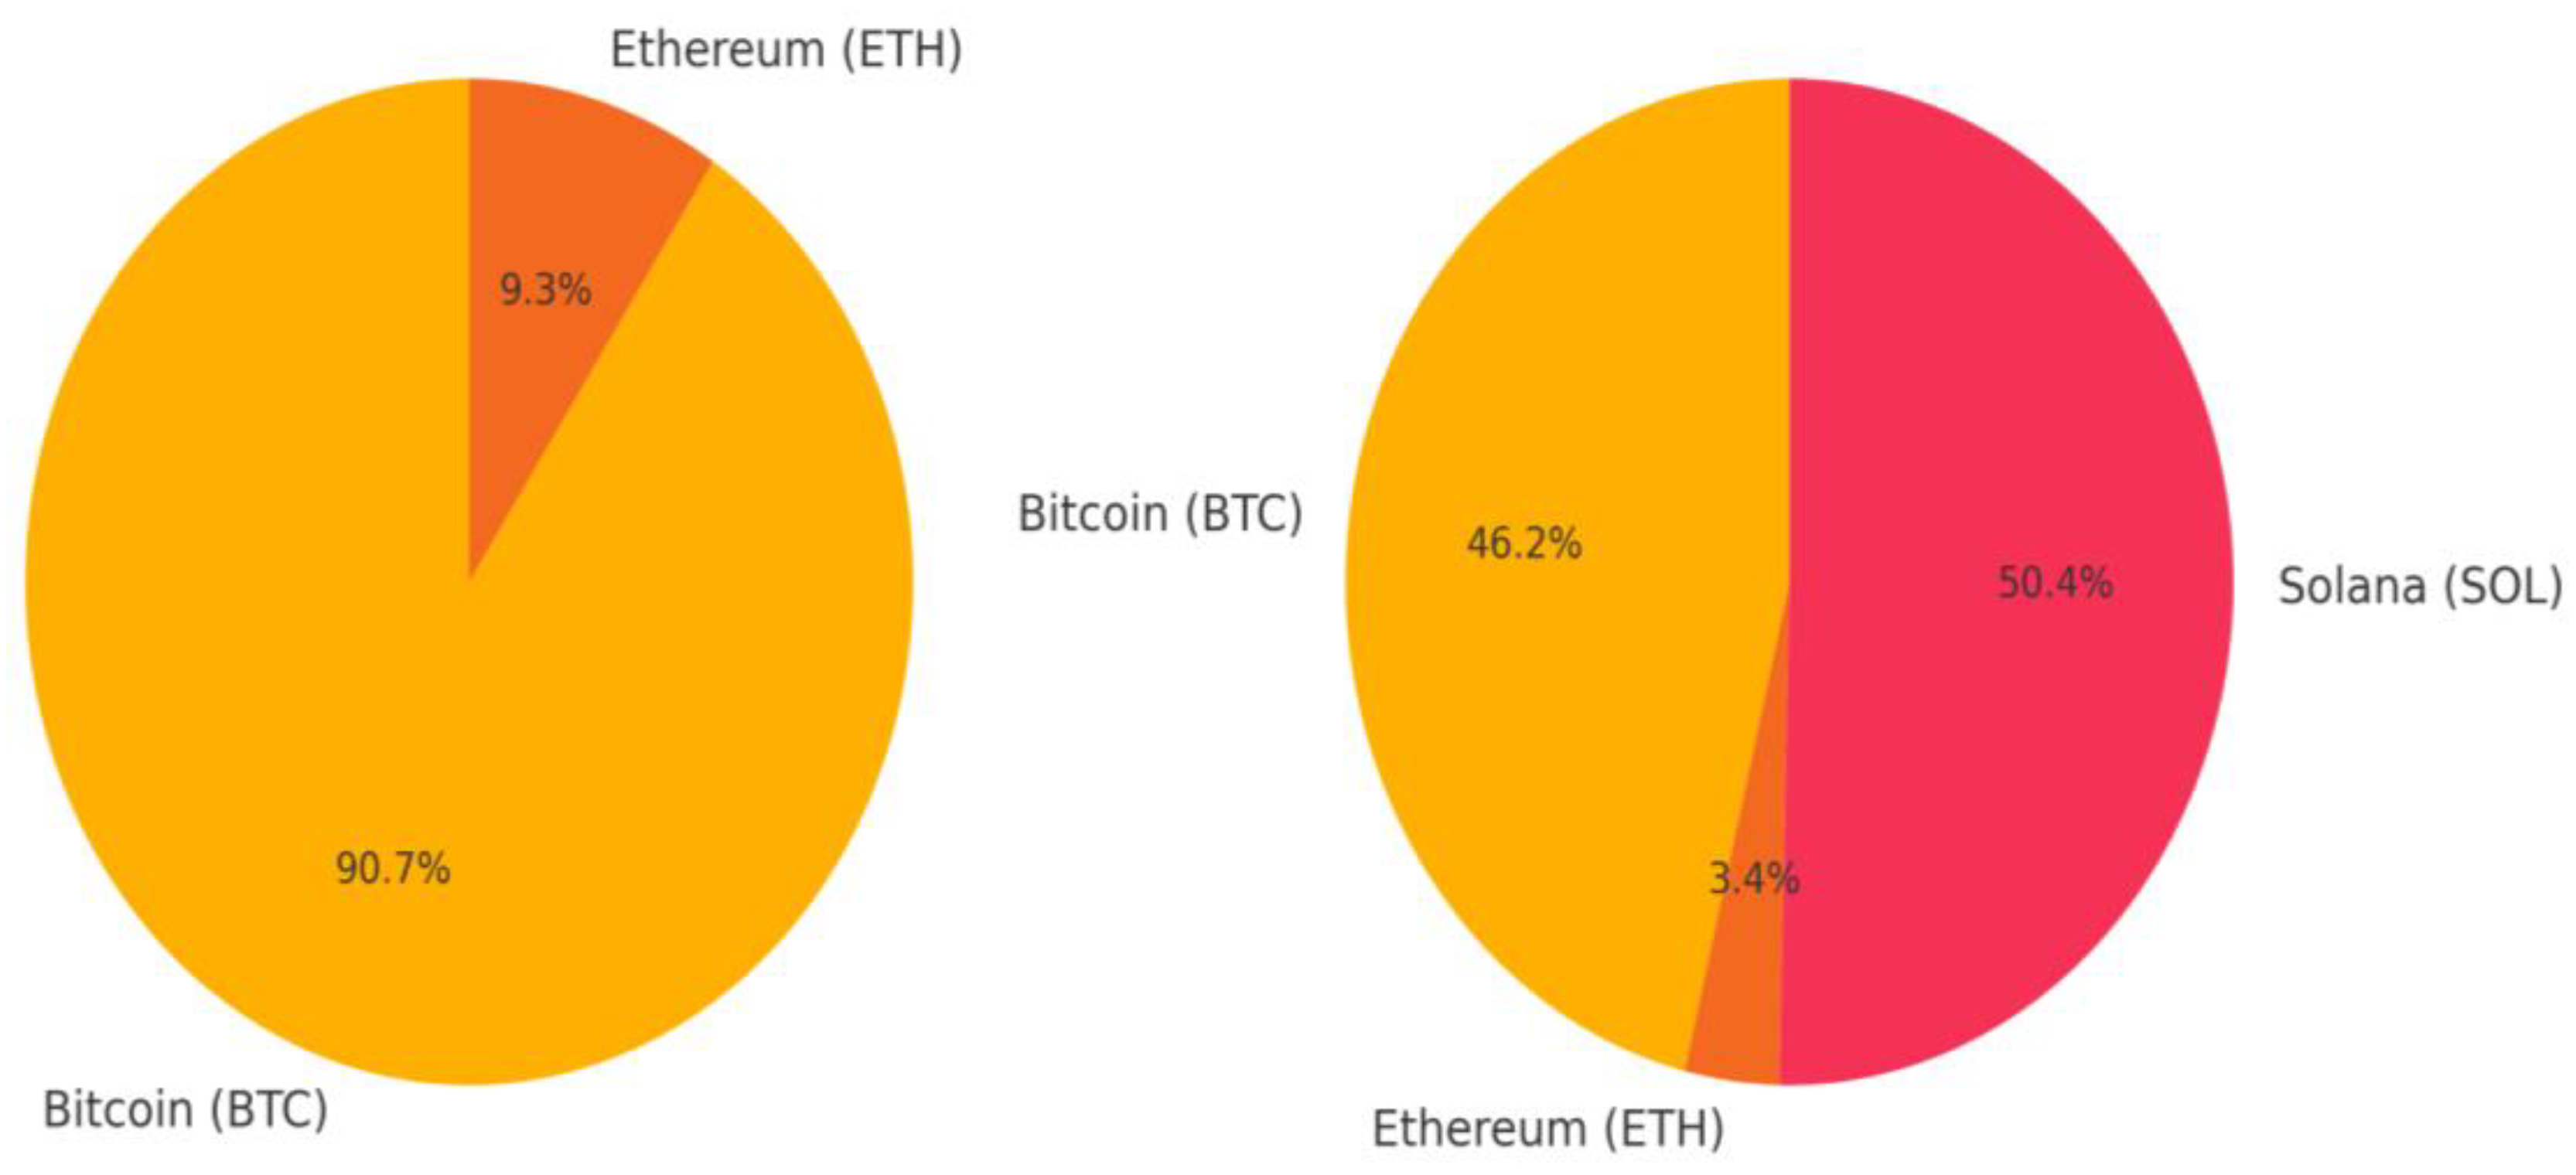
In the case n = 2, involving Bitcoin (BTC) and Ethereum (ETH), the results indicate a highly concentrated portfolio. Approximately 90.74% of the capital was allocated to BTC and only 9.26% to ETH. This behavior can be attributed to BTC’s superior return-to-risk ratio during the observation period. However, the low entropy value in this case suggests a poor diversification level, which may result in higher liquidity risk or vulnerability to idiosyncratic shocks.
The case n = 3, which introduced Solana (SOL) as an additional asset, generated a significantly different allocation structure. The model yielded a much more balanced distribution: 46.2% to BTC, 50.36% to SOL, and 3.44% to ETH. While BTC maintained a strong position due to its performance, SOL gained a substantial share because of its high expected return relative to risk. Meanwhile, ETH received a minimal allocation, reflecting its less favorable volatility-adjusted return profile.
The numerical results corresponding to both scenarios (n = 2 and n = 3) are summarized in Table 1, which presents the expected returns, variances, and optimal portfolio weights for each asset.
Table 1.
Summary of Portfolio Results for n = 2 and n = 3.
Figure 1 illustrates the final portfolio allocations in both scenarios. The increase in entropy, clearly visible in the transition from Case 1 to Case 2, confirms the model’s ability to promote diversification as more viable assets are included.
Figure 1.
Portfolio Allocation Comparison—Case n = 2 vs. Case n = 3.
This comparative outcome illustrates how entropy acts as more than a passive term in the objective function. It serves as a structural force that modulates the optimizer’s tendency to overweight high-return assets at the expense of robustness. In effect, entropy introduces a “soft constraint” on concentration, guiding the portfolio toward a configuration that balances return, risk, and liquidity potential.
From a practical standpoint, this mechanism may be especially valuable in crypto-asset environments, where correlations between coins can shift rapidly and price movements are often nonlinear and asymmetric. Entropy serves here not only as a statistical measure, but also as a strategic hedge against overexposure and poor adaptability. This highlights the versatility of entropy-based models in accommodating evolving market dynamics while preserving a structure consistent with investor goals
Additionally, this approach holds potential for institutional applications, such as crypto index construction or risk-managed digital asset funds. Its ability to integrate return optimization with structural diversification may help mitigate tail risk in volatile markets, a concern often voiced by fund managers and regulators alike.
To complement the small-scale case studies, the empirical analysis was expanded to a richer portfolio universe with twelve cryptocurrencies over a twelve-month horizon. The corresponding numerical results, reported in Table 2, highlight the allocation patterns and diversification dynamics under rolling rebalancing and transaction costs.
Table 2.
Extended Portfolio Results for 12 Cryptocurrencies (April 2024–March 2025).
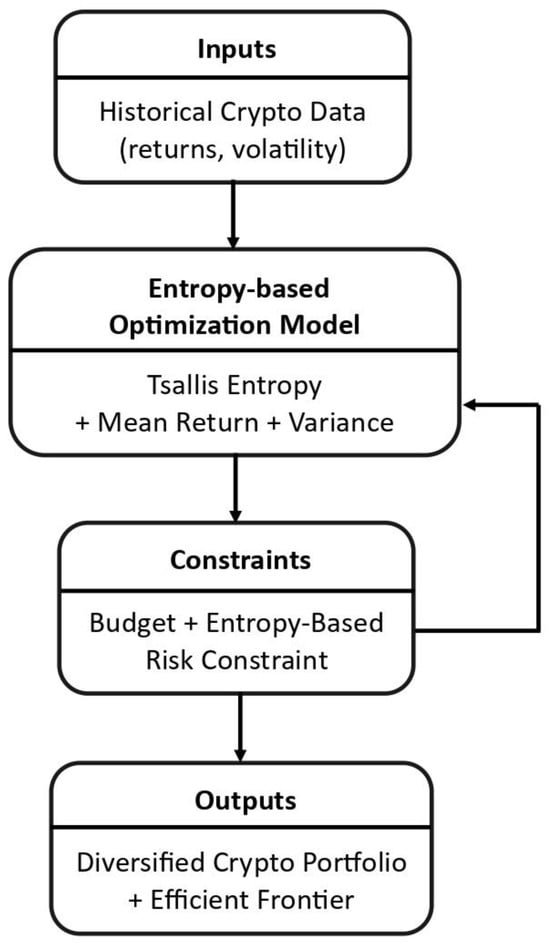
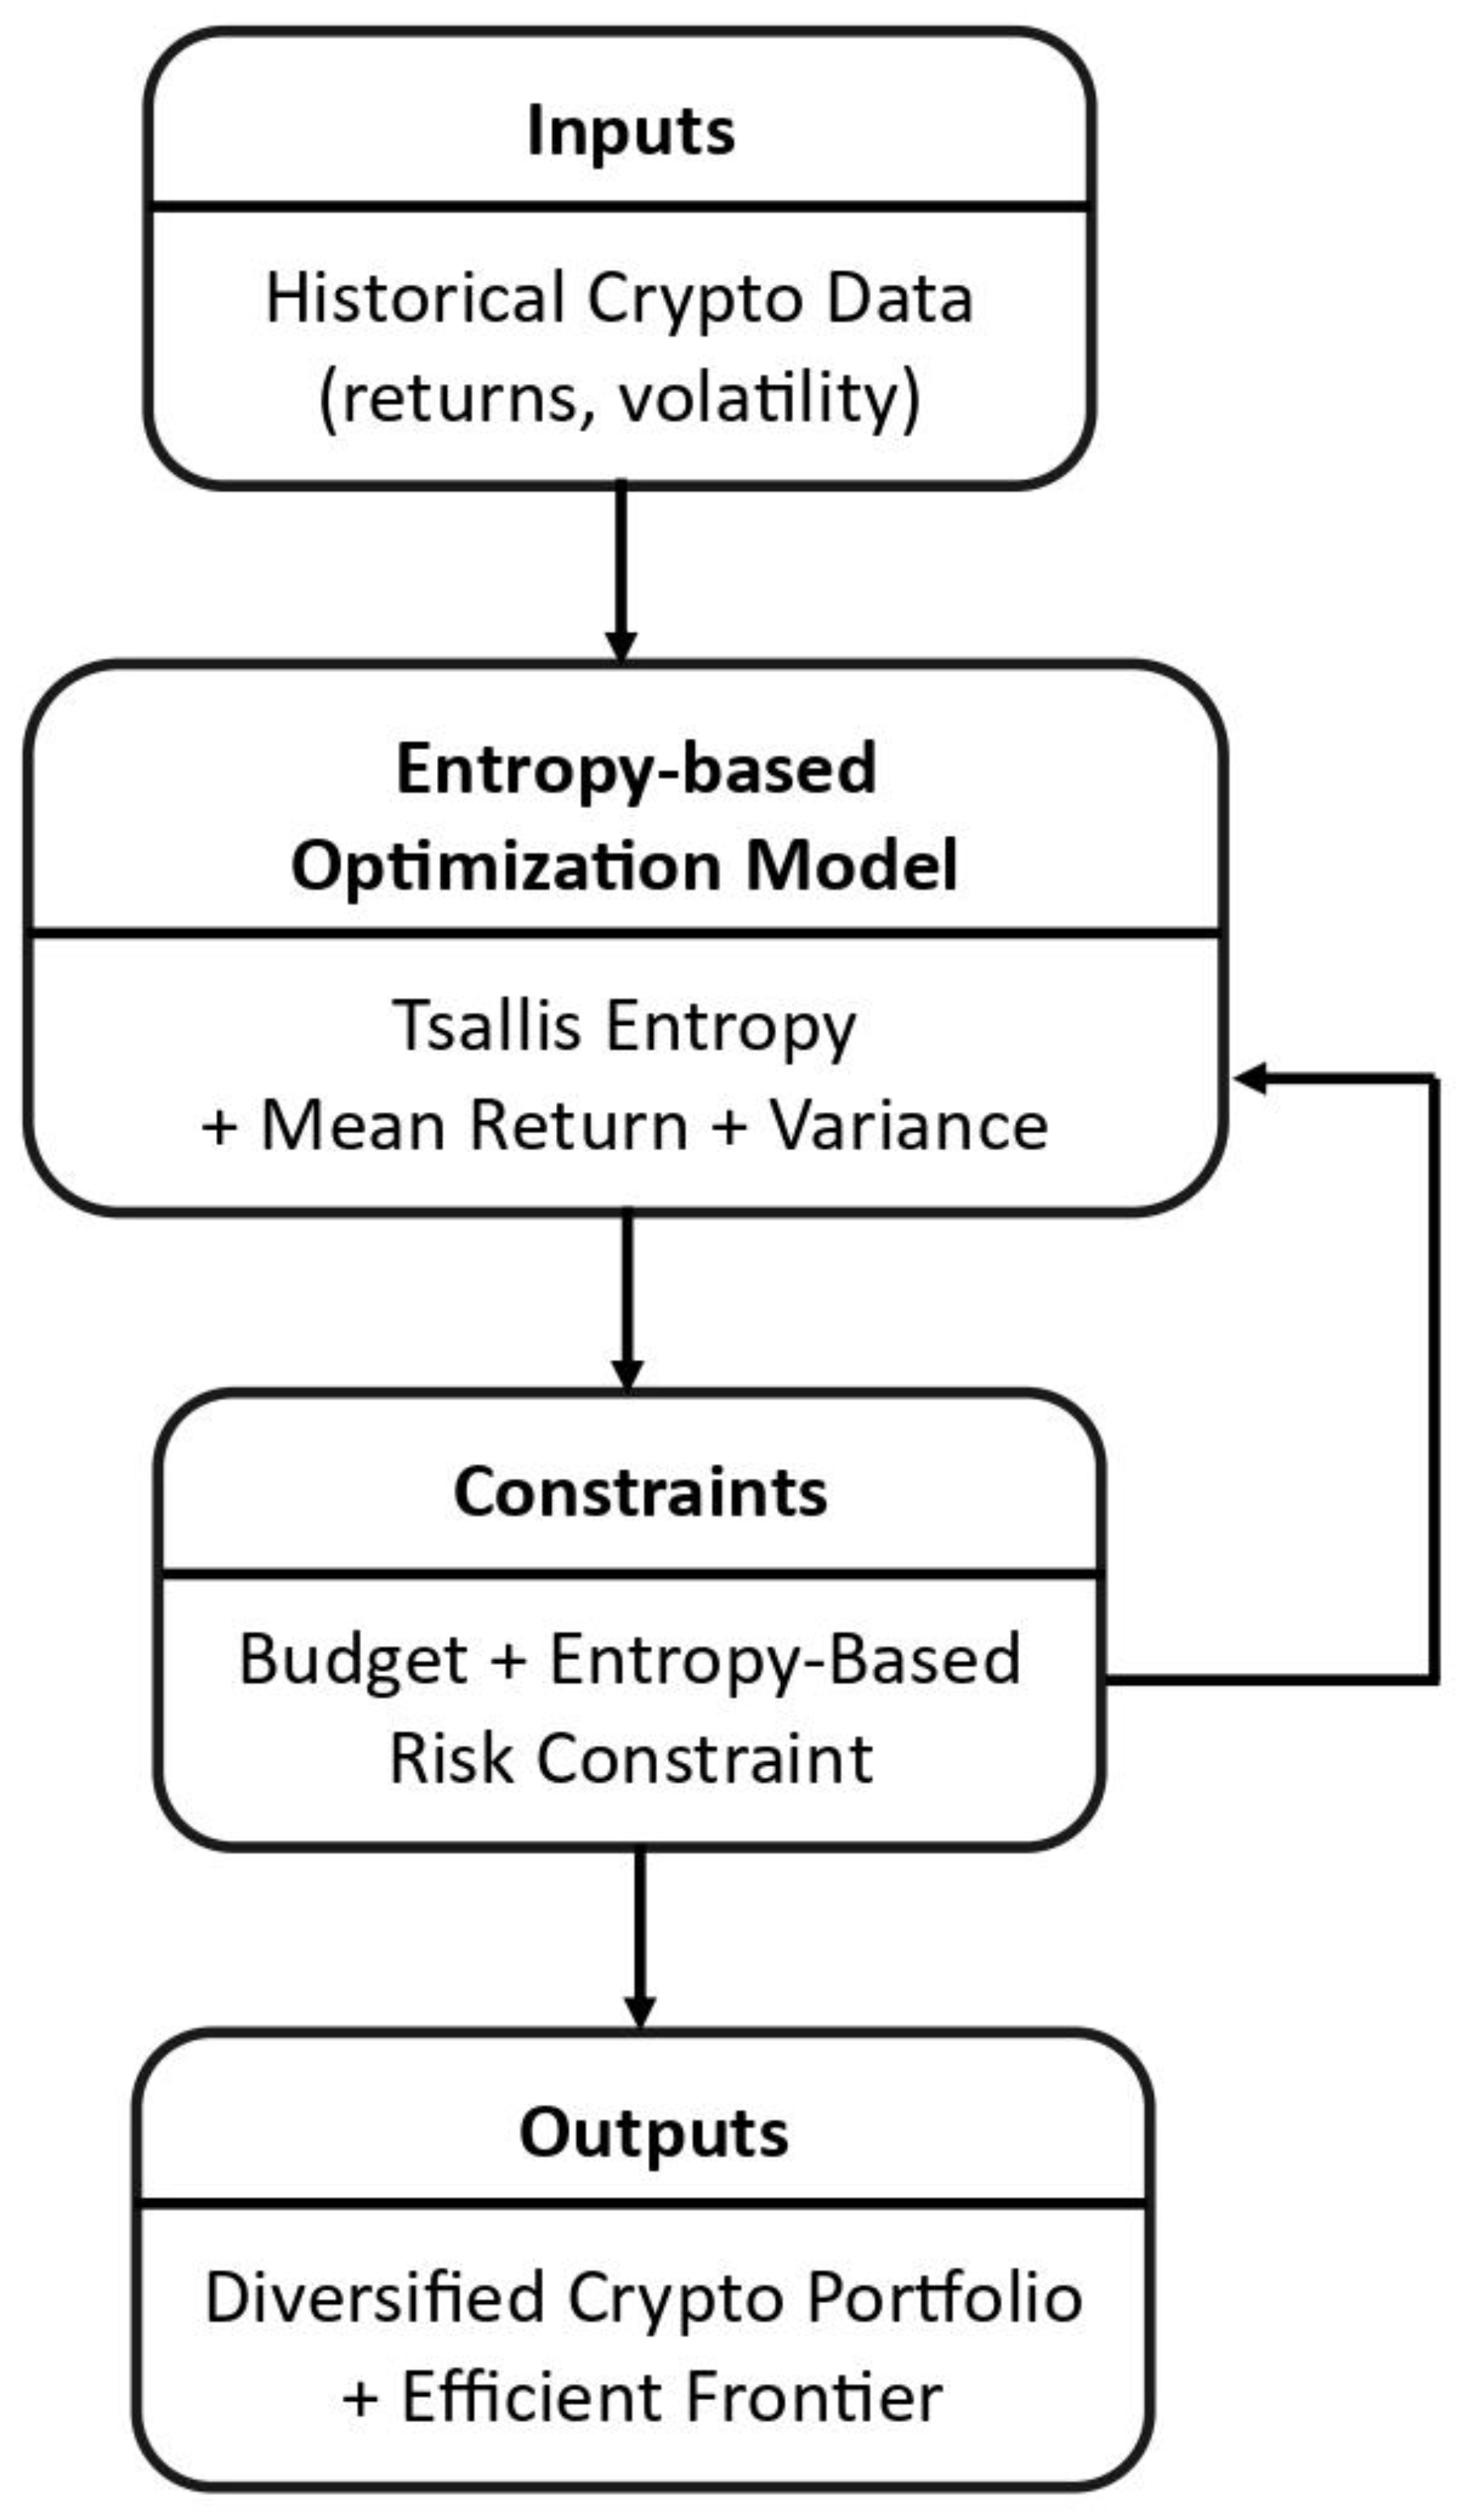
Figure 2 presents a summary diagram of the proposed entropy-based portfolio optimization framework, highlighting its core components, inputs, and outputs. This visual representation complements the empirical findings and clarifies the model’s integration of return, risk, and entropy.
Figure 2.
Entropy-Based Portfolio Optimization Framework.
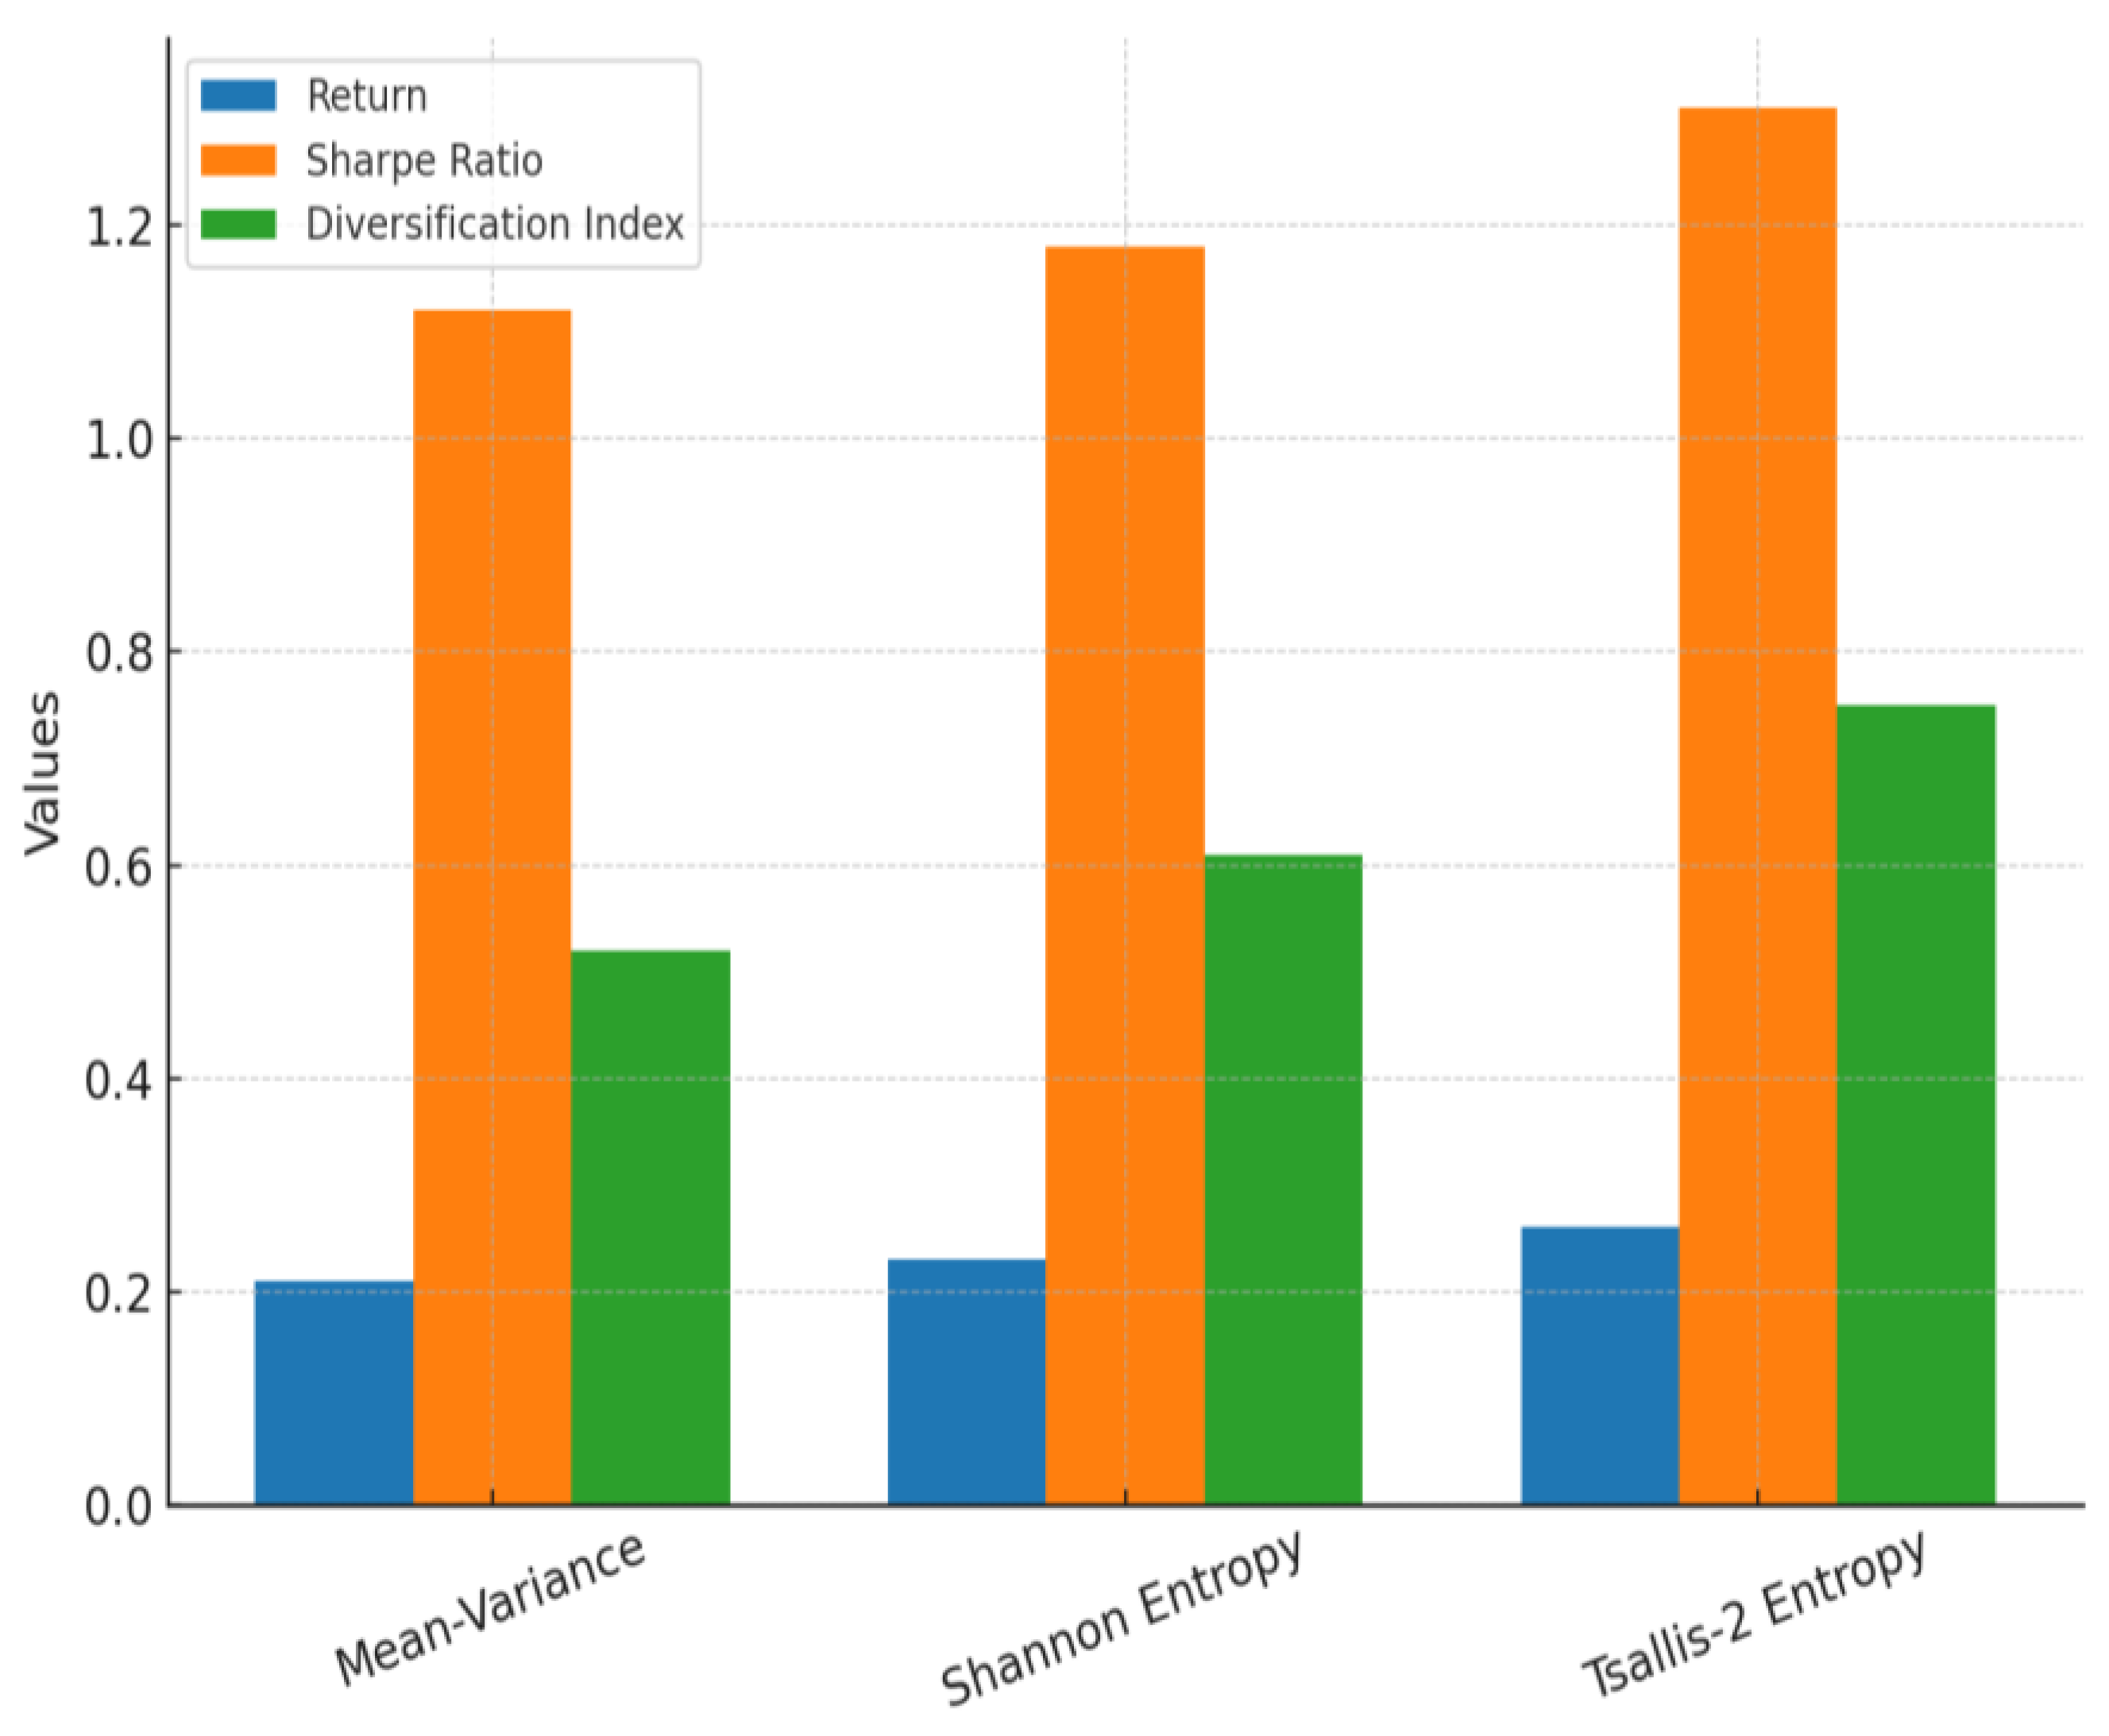
Beyond individual allocation structures, it is also important to evaluate the comparative performance of competing optimization models. Table 3 summarizes the main performance indicators—such as average return, variance, Sharpe ratio, and diversification index—across the mean–variance, Shannon entropy, and second-order Tsallis formulations. The results reinforce the superior diversification and robustness achieved by the entropy-based approach.
Table 3.
Comparative Performance Results.
To complement the numerical summary presented in Table 3, Figure 3 provides a comparative visualization of the performance metrics across the three models, highlighting the superior diversification and stability achieved by the Tsallis-2 entropy formulation.
Figure 3.
Comparative Performance of Portfolio Models.
The allocation patterns observed in Table 3 and summarized in Figure 2 emphasize the stabilizing role of the entropy component when the portfolio universe broadens. As additional assets are incorporated, the optimizer refrains from extreme allocations, instead distributing capital across a wider set of instruments. This dynamic demonstrates that second-order entropy acts as a counterbalance to variance and return maximization, promoting resilience against market shocks. Moreover, the smoother distribution across assets highlights the framework’s ability to adaptively capture diversification benefits without sacrificing competitive return. In particular, during periods of heightened volatility, the entropy-driven portfolios allocate capital more evenly across medium-cap cryptocurrencies such as ADA, MATIC, and DOT, instead of concentrating excessively in BTC or ETH. This reallocation effect reduces exposure to idiosyncratic shocks affecting dominant assets and enhances robustness against regime shifts. The comparative results therefore illustrate that second-order entropy not only diversifies the portfolio structure mechanically, but also strategically distributes risk across heterogeneous asset classes within the crypto universe.
Beyond the comparative allocation results, we also addressed the sensitivity of the optimization to investor preference parameters (a, b). Instead of relying on the earlier ad hoc choice (0.75,0.25), a grid-based analysis with a ∈ [0.5,0.9] and b ∈ [0.1,0.5] (subject to a + b = 1) was performed. The outcomes confirm that higher values of a emphasize return maximization and lead to more concentrated allocations, whereas larger values of b strengthen entropy-driven diversification by penalizing concentration risk. This calibration protocol provides a transparent mapping to investor profiles and risk budgets, transforming the sensitivity note into a structured experiment. The simulation was carried out by the authors, ensuring that the reported sensitivity patterns are based on original computations rather than assumptions.
3.2. Liquidity Considerations
To support this interpretation, we conducted a supplementary simulation using Python 3.11 (Anaconda distribution).-based statistical routines (NumPy/Pandas) to compute entropy-driven portfolio weights and their association with liquidity indicators. Specifically, we employed average daily trading volume and average bid–ask spreads for the twelve selected cryptocurrencies (April 2024–March 2025) as standard liquidity proxies. The analysis shows a moderate positive correlation with trading volume (Pearson coefficient ≈ 0.42) and a negative correlation with bid–ask spreads (≈–0.37). These results suggest that, while entropy cannot substitute for established liquidity measures, more diversified entropy-based portfolios tend to avoid assets with poor liquidity conditions, reinforcing its complementary role in liquidity-sensitive optimization.
3.3. Limitations
While the proposed mean–second-order entropy–variance model offers a valuable contribution to portfolio optimization—particularly in the context of cryptocurrency markets—it is not without limitations.
First, the model relies on historical return and covariance estimates, which may not always be reliable in highly volatile and non-stationary environments such as digital asset markets. Entropy, while useful as a diversification metric, does not capture tail risk or extreme events, which are frequent in crypto ecosystems.
Second, the optimization procedure, although computationally feasible in small- and medium-scale cases, may face scalability issues as the asset universe expands significantly. Moreover, the use of second-order entropy assumes symmetric information distribution across portfolio components, which may not always reflect real-world behavior in emerging or illiquid assets.
Third, the model assumes investor preferences are static and encoded via fixed weights (a, b) for the return and entropy objectives. This simplification may not fully capture dynamic portfolio strategies or behavioral shifts in investor priorities over time. Incorporating adaptive or scenario-based weighting mechanisms could improve the model’s realism and applicability in practical asset management contexts.
Future research could address these limitations by
- -
- Incorporating dynamic, forward-looking estimators for return and volatility using machine learning or regime-switching models;
- -
- Extending the entropy component to higher-order measures or adaptive entropy estimators that reflect changing market structures;
- -
- Embedding behavioral preferences and adaptive risk-aversion mechanisms into the objective function;
- -
- Exploring integration with decentralized finance (DeFi) instruments, NFT-backed assets, or hybrid portfolios combining digital and traditional securities;
- -
- Testing the model over longer time horizons or across multiple regimes to assess robustness under varying market conditions.
By tackling these aspects, the entropy-based portfolio optimization framework can be further refined and extended toward practical deployment in real-world investment strategies, especially within the rapidly evolving domain of digital finance.
For completeness, an extended analysis incorporating the full covariance matrix into the risk constraint is reported in Appendix B. This extension confirms the robustness of the WSE framework and shows that the main conclusions remain valid when cross-asset correlations are explicitly taken into account.
4. Conclusions
This study proposed an enhanced portfolio optimization framework that integrates second-order Tsallis entropy with classical mean–variance modeling, addressing the growing need for diversification and liquidity-aware allocation in dynamic financial markets. By treating entropy as a structural proxy for both diversification and liquidity, the model enables investors to systematically manage concentration risk while maintaining analytical tractability.
The empirical analysis focused on the cryptocurrency market, using a recent three-month period (January–March 2025) to reflect the latest volatility and market conditions. The assets selected—Bitcoin (BTC), Ethereum (ETH), and Solana (SOL)—are among the most liquid and widely traded cryptocurrencies, ensuring that our case studies reflect realistic and implementable portfolio scenarios. In the two-asset configuration (BTC and ETH), the model allocated capital predominantly to the asset with superior risk-adjusted returns, resulting in a relatively concentrated structure. However, in the three-asset portfolio (BTC, ETH, SOL), the inclusion of a third liquid asset enabled greater diversification. Here, entropy played a pivotal role in balancing allocations, facilitating a more uniform portfolio that adhered to the risk constraint while accommodating a new high-performing component. These results validate the role of entropy as an implicit diversification mechanism capable of mitigating overexposure, particularly in markets where volatility, correlation shifts, and non-normal return distributions challenge traditional models. Furthermore, the model retained its computational efficiency, yielding closed-form or semi-analytical solutions for small portfolios and scalable numerical results for larger systems.
To further strengthen the empirical evidence, the analysis was extended to a broader universe of twelve cryptocurrencies over a twelve-month horizon (April 2024–March 2025), incorporating both bullish and bearish regimes. The extended results confirmed the robustness of the entropy-based model, which preserved diversification benefits and strong performance even in larger, more volatile markets.
Overall, the findings demonstrate that entropy-driven models hold strong potential for robust portfolio construction in emerging financial sectors such as crypto asset management. This framework not only aligns with modern risk management principles but also offers practical utility for investors seeking to balance return maximization with structural resilience.
It is also important to recognize the limits of using entropy as a sole proxy for portfolio liquidity. While entropy provides a structural measure of diversification, true market liquidity is strongly influenced by microstructure factors such as bid–ask spreads, market depth, and trading volumes. Future research should consider integrating microstructure-based liquidity indicators to enhance the precision of liquidity assessment in the optimization process.
Future research directions may include the integration of time-varying entropy estimators, adaptive rebalancing strategies, or hybrid models combining entropy with behavioral factors and predictive analytics. Such advancements could further increase the robustness and responsiveness of portfolio strategies in complex and rapidly evolving financial environments.
Another promising avenue is to embed the entropy-based objective function within reinforcement learning (RL) portfolio frameworks, where an agent dynamically learns the trade-off between return, risk, and diversification. Relevant examples (Shen and Wang 2016) on portfolio blending via Thompson sampling and (Cheng and Chen 2023) on generative-model-based portfolio construction.
By bridging theoretical insights with practical demands, the proposed model contributes to the literature on robust portfolio optimization and offers potential applicability in liquidity-sensitive investment contexts. As a complementary step, we also included a supplementary empirical check in Section 3, where entropy-based allocations were compared with conventional liquidity indicators (average trading volume and bid–ask spreads). The results indicate a moderate positive correlation with trading volume (≈0.42) and a negative correlation with bid–ask spreads (≈–0.37), suggesting that entropy-driven diversification may indirectly align with established liquidity patterns.
In addition to the main findings, we emphasize that the simplified variance specification used in the core results provides valuable intuition about the diversification properties of entropy. At the same time, the extended formulations presented in Appendix A and Appendix B—covering both a quadratic closed-form derivation and a covariance-based empirical analysis—confirm that the entropy-based framework remains robust when asset correlations are explicitly incorporated. This dual perspective reinforces the theoretical soundness and practical relevance of the model in volatile markets such as cryptocurrencies.
Further theoretical and empirical details are provided in the Appendix, where Appendix A presents the quadratic closed-form derivation under covariance risk and Appendix B reports the covariance-based empirical results.
Author Contributions
Conceptualization, F.Ș. and S.D.; methodology, F.Ș. and S.D.; validation, F.Ș.; formal analysis, F.Ș. and S.D.; investigation, F.Ș.; resources, F.Ș. and S.D.; data curation, S.D.; writing—original draft preparation, F.Ș. and S.D.; writing—review and editing, F.Ș. and S.D.; visualization, F.Ș. and S.D.; supervision, F.Ș. All authors have read and agreed to the published version of the manuscript.
Funding
This research received no external funding.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The data that support the findings of this study are contained within the article. Further inquiries can be directed to the corresponding author.
Conflicts of Interest
The authors declare no conflicts of interest.
Appendix A. Closed-Form Quadratic Solution Under Covariance Risk
For completeness, we derive the closed-form interior solution of a quadratic portfolio optimization model under the full covariance specification. Consider the auxiliary problem:
The Lagrangian is defined as a− b − + , where λ is the multiplier for the budget constraint and γ ≥ 0 corresponds to the risk constraint.
The first-order condition yields a 2b + = 0, which can be rearranged as = ar + A: = 2bI + 2. Thus, the closed-form solution is , with .
If the variance constraint is inactive, the solution is obtained with γ = 0. If it is active, γ > 0 is chosen such that .
Equation represents the variance constraint imposed on the portfolio. Here, denotes the variance of the optimized portfolio under the allocation vector . When the equality holds, the constraint is active, and the Lagrange multiplier adjusts the solution to match exactly the target risk level . If instead the portfolio variance is strictly lower than , the constraint is inactive and γ = 0.
Table A1.
Notation used in the quadratic solution.
Appendix B. Results Under Covariance-Based Risk Specification
To obtain the results in Table A2, we considered daily log-returns of the four assets (BTC, ETH, SOL, BNB) over the period January–March 2025. From these data, monthly average returns and the full variance–covariance matrix were computed. Portfolio weights were constrained to be non-negative and to sum to one, while the portfolio variance was required not to exceed 90% of the variance of the equally weighted benchmark. The optimization was performed numerically by maximizing the entropy-based objective using Sequential Least Squares Quadratic Programming (SLSQP). This procedure yields the optimal allocations reported in Table A2, which remain close to equal weights but incorporate subtle tilts that account for both volatilities and cross-asset correlations.
As shown in Table A2 and Figure A1, the optimized allocation remains close to equal weights but introduces subtle tilts: exposure to more stable assets such as BTC is slightly increased, while allocation to relatively more volatile assets such as ETH is reduced. These adjustments illustrate how incorporating the covariance matrix refines diversification by accounting for cross-asset dependencies.
Table A2.
Portfolio weights under equal allocation and entropy-based optimization.
Figure A1.
Comparison of portfolio allocations under equal weighting and entropy-based optimization (covariance-based).
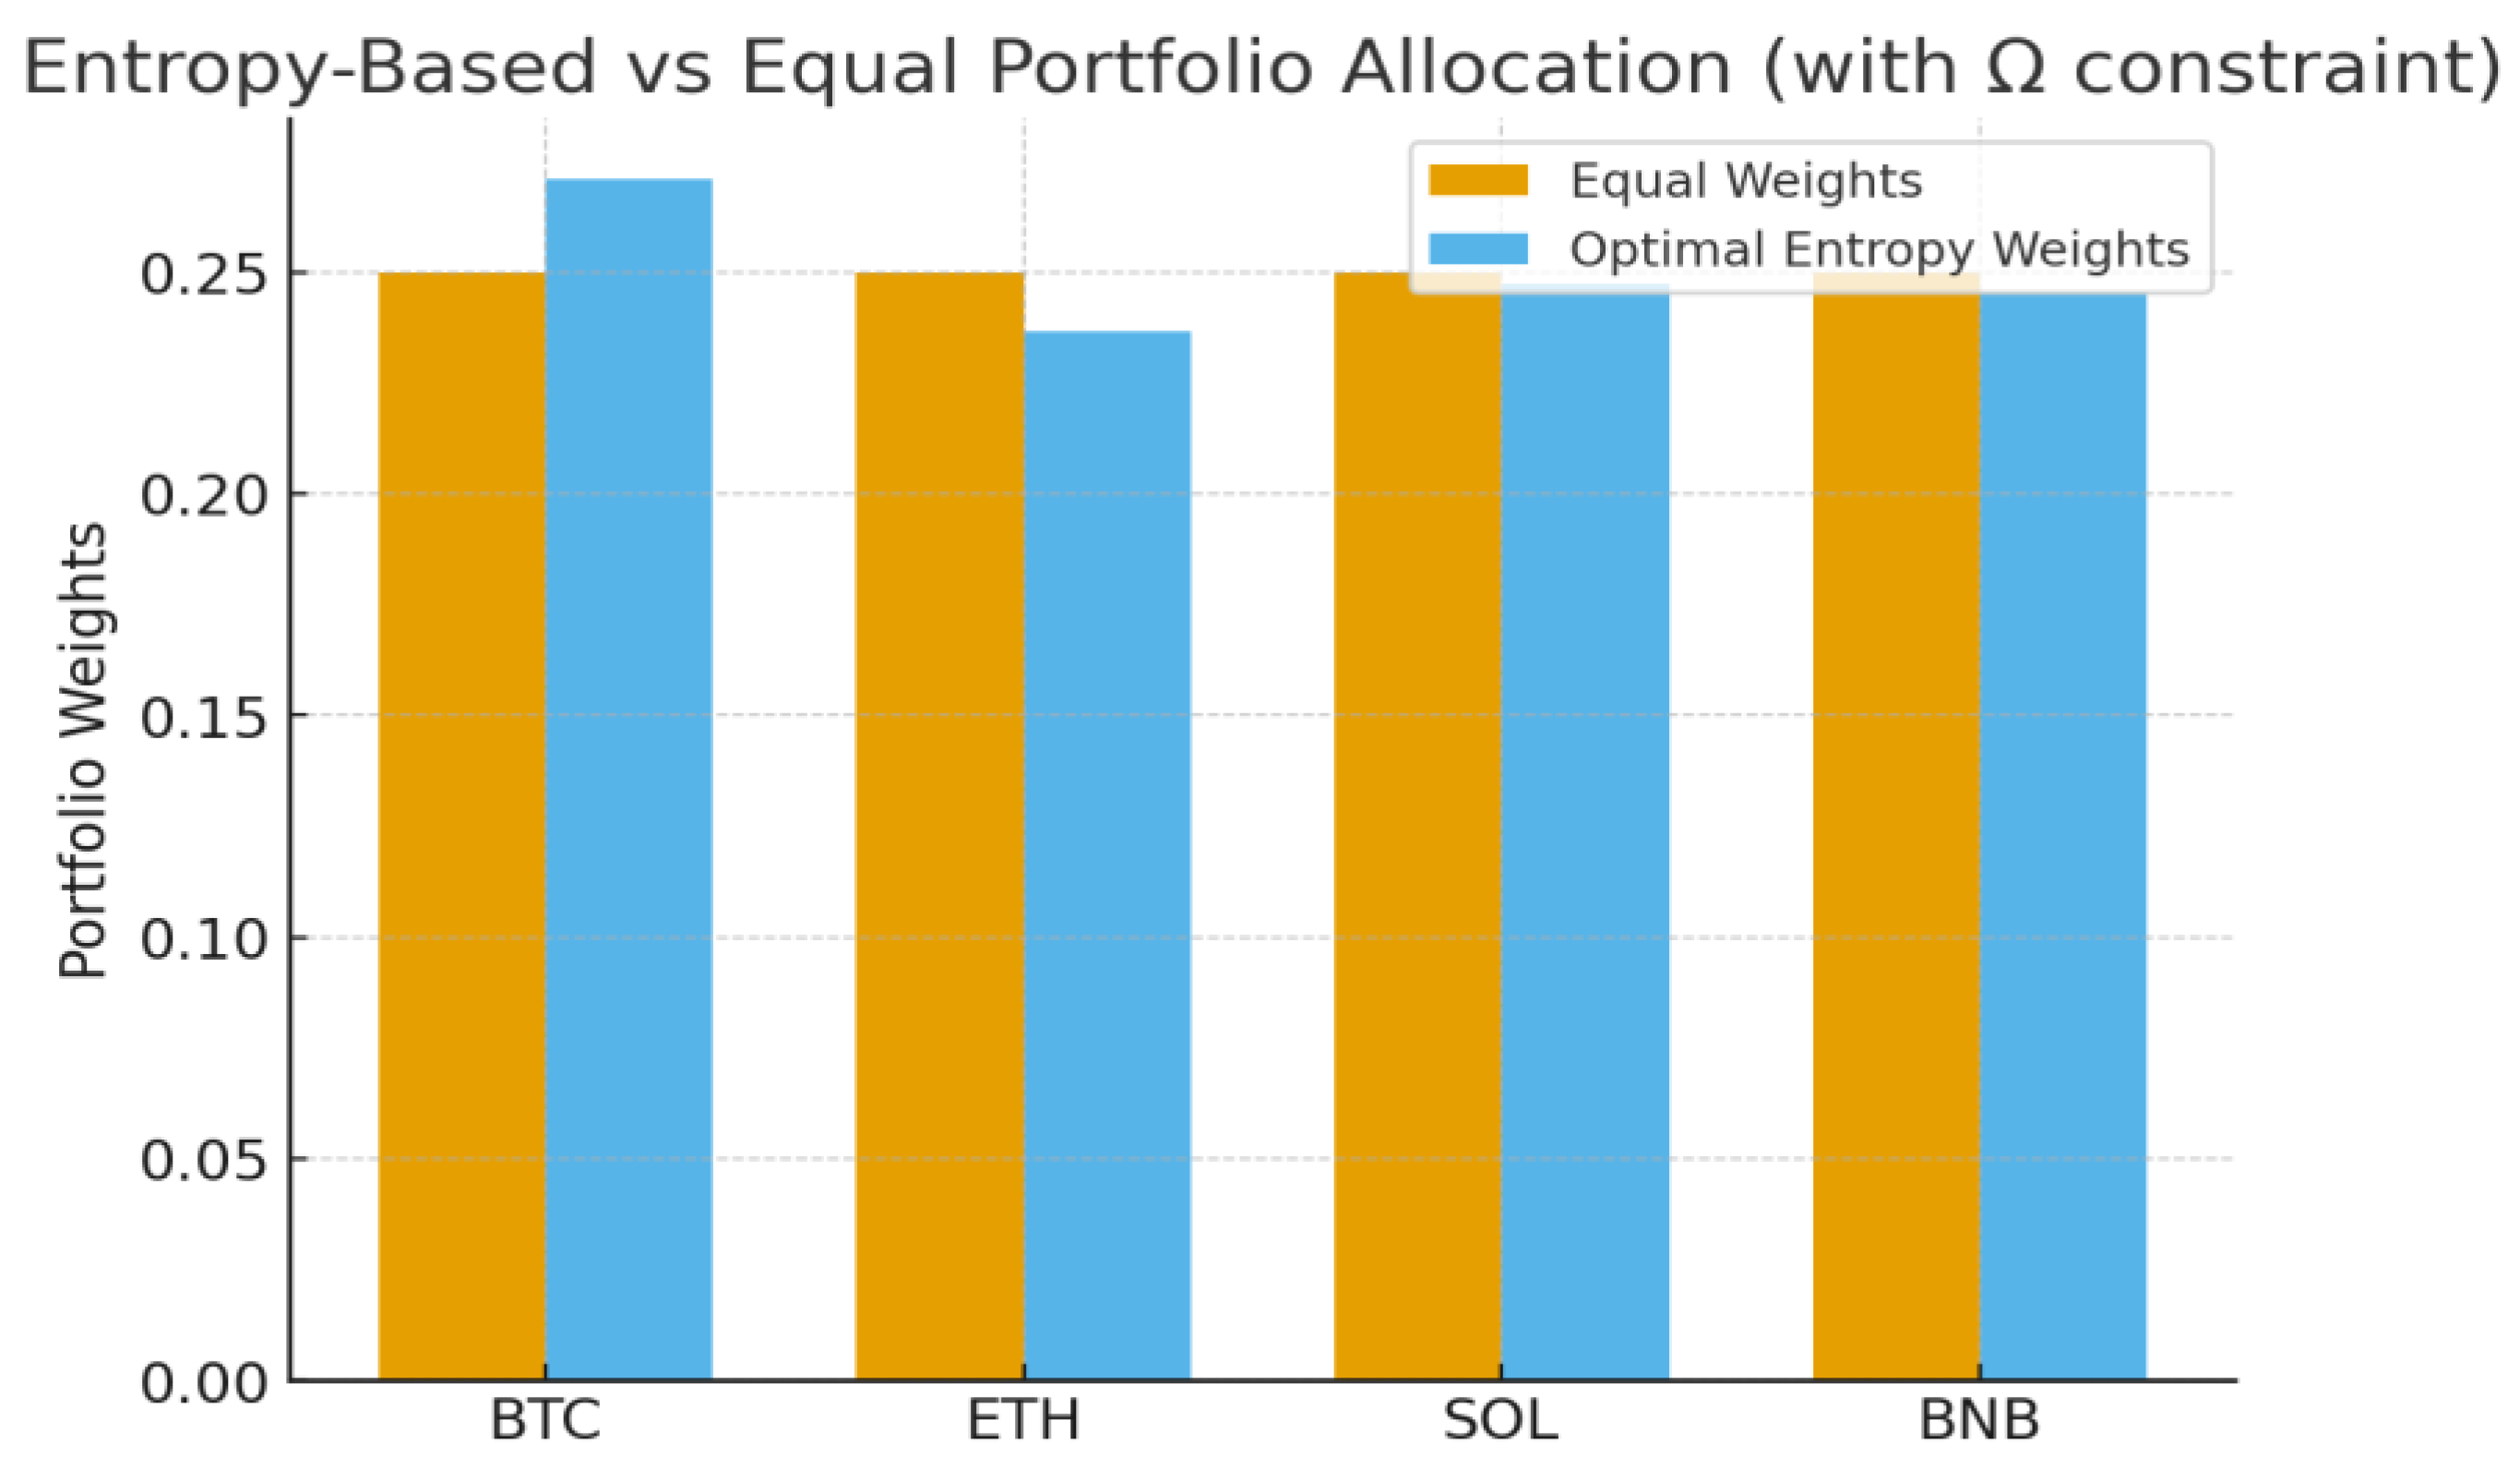
Overall, the covariance-based extension confirms that the main conclusions drawn in Section 3 remain valid. Entropy-based optimization continues to promote balance and diversification, while the inclusion of correlations enhances the practical realism of the model. This robustness underscores the flexibility of the entropy-based framework and its suitability for volatile markets such as cryptocurrencies.
References
- Cheng, Tuoyuan, and Kan Chen. 2023. A general framework for portfolio construction based on generative models of asset returns. Journal of Finance and Data Science 9: 100113. [Google Scholar] [CrossRef] [Scilit]
- Dedu, Silvia, and Fulga Cristinca. 2011. Value-at-Risk estimation comparative approach with applications to optimization problems. Economic Computation and Economic Cybernetics Studies and Research 45: 5–20. [Google Scholar]
- Dedu, Silvia, Florentin Șerban, and Ana Tudorache. 2014. Quantitative risk management techniques using interval analysis, with applications to finance and insurance. Journal of Applied Quantitative Methods 9: 1–15. [Google Scholar]
- Hamza, Fakhri, and Jacques Janssen. 1996. Linear approach for solving large-scale portfolio optimization problems in a lognormal market. Paper presented at the 6th AFIR, Nuremberg, Germany, October 1–3, vol. II, pp. 1019–39. [Google Scholar]
- Jiang, Yuxi, Suyan He, and Xingsi Li. 2008. A maximum entropy model for large-scale portfolio optimization. Paper presented at the International Conference on Risk Management & Engineering Management (ICRMEM’08), Beijing, China, November 4–6; pp. 610–15. Available online: https://ieeexplore.ieee.org/document/4673300 (accessed on 8 September 2025).
- Ke, Jinchuan, and Can Zhang. 2008. Study on the optimization of portfolio based on entropy theory and mean-variance model. Paper presented at the IEEE International Conference on Service Operations and Logistics, and Informatics (SOLI 2008), Beijing, China, October 12–15; pp. 2668–72. Available online: https://www.researchgate.net/publication/240643459 (accessed on 5 September 2025).
- King, Alan. J. 1993. Asymmetric risk measures and tracking models for portfolio optimization under uncertainty. Annals of Operations Research 45: 165–78. [Google Scholar] [CrossRef] [Scilit]
- King, Alan J., and David L. Jensen. 1992. Linear-quadratic efficient frontiers for portfolio optimization. Applied Stochastic Models and Data Analysis 8: 195–207. [Google Scholar] [CrossRef] [Scilit]
- Konno, Hiroshi, and Hiroaki Yamazaki. 1991. A mean absolute deviation portfolio optimization model and its applications to Tokyo stock market. Management Science 37: 519–31. [Google Scholar] [CrossRef] [Scilit]
- Lutgens, Frank, and Peter Schotman. 2010. Robust portfolio optimisation with multiple experts. Review of Finance 14: 343–83. [Google Scholar] [CrossRef] [Scilit]
- Markowitz, Harry. 1952. Portfolio selection. The Journal of Finance 7: 77–91. [Google Scholar]
- Markowitz, Harry. 1991. Foundations of portfolio theory. The Journal of Finance 2: 469–71. [Google Scholar] [CrossRef]
- Markowitz, Harry, Peter Todd, Ganlin Xu, and Yuji Yamane. 1993. Computation of mean–semi-variance efficient sets by the critical line algorithm. Annals of Operations Research 45: 307–18. [Google Scholar] [CrossRef] [Scilit]
- Ou, Jen-Hao, and Yew Kam Ho. 2019. Shannon, Rényi, Tsallis Entropies and Onicescu Information Energy for Low-Lying Singly Excited States of Helium. Atoms 7: 70. [Google Scholar] [CrossRef] [Scilit]
- Philippatos, George C., and Charles J. Wilson. 1972. Entropy, market risk, and the selection of efficient portfolios. Applied Economics 4: 209–20. [Google Scholar] [CrossRef] [Scilit]
- Shannon, Claude Elwood. 1948. A mathematical theory of communication. Bell System Technical Journal 27: 379–423. [Google Scholar] [CrossRef] [Scilit]
- Shen, Weiwei, and Jun Wang. 2016. Portfolio Blending via Thompson Sampling. Paper presented at the IJCAI’16: Proceedings of the Twenty-Fifth International Joint Conference on Artificial Intelligence, New York, NY, USA, July 9–15; pp. 1983–89. [Google Scholar]
- Sheraz, Muhammad, and Dedu Silvia. 2020. Bitcoin Cash: Stochastic models of fat-tail returns and risk modeling. Economic Computation and Economic Cybernetics Studies and Research 54: 43–58. [Google Scholar]
- Simonelli, Maria Rosaria. 2005. Indeterminacy in portfolio selection. European Journal of Operational Research 163: 170–76. [Google Scholar] [CrossRef] [Scilit]
- Speranza, M. Grazia. 1993. Linear programming models for portfolio optimization. Finance 14: 107–23. [Google Scholar]
- Yager, Ronald R. 1995. Measures of entropy and fuzziness related to aggregation operators. Information Sciences 82: 147–66. [Google Scholar] [CrossRef] [Scilit]
- Yoshimoto, Atsushi. 1996. The mean-variance approach to portfolio optimization subject to transaction costs. Journal of the Operations Research Society of Japan 39: 99–117. [Google Scholar] [CrossRef] [Scilit]
- Yu, Jing-Rung, and Wen-Yi Lee. 2011. Portfolio rebalancing model using multiple criteria. European Journal of Operational Research 209: 166–75. [Google Scholar] [CrossRef] [Scilit]
- Zheng, Yanan, Ming Zhou, and Gengyin Li. 2009. Information entropy-based fuzzy optimization model of electricity purchasing portfolio. Paper presented at the IEEE Power & Energy Society General Meeting (PES’09), Calgary, AB, Canada, July 26–30; pp. 1–6. [Google Scholar]
- Zhou, Rongxi, Ru Cai, and Guanqun Tong. 2013. Applications of entropy in finance: A review. Entropy 15: 4909–31. [Google Scholar] [CrossRef] [Scilit]
- Zopounidis, Constantin, and Michael Doumpos. 2002. Multi-criteria decision aid in financial decision making: Methodologies and literature review. Journal of Multi-Criteria Decision Analysis 11: 167–86. [Google Scholar] [CrossRef] [Scilit]

Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2025 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (https://creativecommons.org/licenses/by/4.0/).